

Blogs
Underfill Market to Hit $945M by 2032: 5 Shifts Reshaping the $517M Base
By PW Consulting, 2026-09-21
The Underfill Market: Strategic Trends and Commercial Opportunities Beyond the Numbers
The underfill market has evolved from a niche materials segment into a critical enabler of advanced semiconductor packaging, driven by the relentless scaling of computing performance and the structural vulnerabilities of miniaturized interconnects. As of the base year 2025, the total addressable market for underfill solutions stands at approximately 516.72 million USD, building on a compound annual growth trajectory that has propelled revenue from 335.83 million USD in 2020 to a projected 944.58 million USD by 2032. This expansion reflects a 9.0 percent CAGR across the forecast window, a pace that outstrips broader electronic materials growth and signals a structural shift rather than a cyclical upturn. The market’s maturation is tempered by a moderate concentration profile, with the top three players commanding roughly 45 percent of revenue and the top five reaching about 55 percent, leaving meaningful whitespace for differentiated formulators and regional specialists.
Across the forecast horizon extending through 2032, the revenue curve steepens as advanced packaging adoption accelerates and form factor constraints force more aggressive underfill integration. The growth is not uniformly distributed; it is concentrated where thermal stress, mechanical reliability, and miniaturization intersect—environments that increasingly demand faster flow profiles, rework-compatible chemistries, and selective thermal or optical properties. For executives and capital allocators, the underfill market now operates as a strategic input layer where material choices directly influence yield, board-level reliability, and total cost of ownership in high-value assemblies.
Tube Filler Market
Key Challenges and Inflection Points Shaping the Market
Despite robust demand tailwinds, the underfill sector faces a set of interconnected challenges that will separate resilient players from those caught in margin compression. First, feedstock volatility has moved from an intermittent nuisance to a structural cost pressure. Epichlorohydrin supply disruptions, combined with freight surcharges, have pushed spot epoxy prices to multi-year highs, crimping gross margins for smaller formulators and forcing tougher sourcing and pricing decisions across the value chain. This pressure is especially acute for producers who lack backward integration or long-term offtake agreements, as raw material swings can quickly erase the pricing power that technical differentiation normally provides.
Second, regulatory scrutiny is reshaping formulation roadmaps and trade flows simultaneously. Environmental mandates in key markets are accelerating the phase-down of hazardous constituents in electronic materials, pushing developers toward compliant chemistries that must still meet stringent mechanical and thermal targets. At the same time, trade actions—including anti-dumping investigations and duties on epoxy resins in several jurisdictions—have recalibrated regional supply dynamics, with knock-on effects on availability and pricing for downstream underfill producers. The net effect is a market where compliance and sourcing resilience are now procurement criteria, not afterthoughts.
Third, application requirements are fragmenting faster than traditional product lines can accommodate. The underfill universe spans capillary, no-flow, molded, and specialty variants, each with distinct process windows and property demands. High-performance computing, silicon photonics, and sensor-dense modules increasingly require materials that balance mechanical protection with thermal management or optical clarity, often within tighter tolerances and higher throughput expectations. Suppliers that treat these as variations of a single offering risk falling behind formulators who design for specific application envelopes and reliability profiles.
Core Drivers Reshaping Demand and Competitive Dynamics
Technological innovation continues to be the most visible driver. Advances in advanced packaging architectures have expanded the envelope of where underfills are deployed, from conventional flip-chip assemblies to ball grid array configurations and chip scale packaging approaches that push device density and thermal flux. In parallel, formulation science has progressed toward faster flow characteristics, lower stress profiles, and targeted enhancements such as thermal conductivity or optical transparency. These are not incremental tweaks; they are responses to reliability requirements at the edge of thermal-mechanical limits, where underfill performance directly affects lifecycle durability and rework economics. Recent product introductions illustrate this trajectory: capillary-grade epoxy systems optimized for complex AI and high-performance computing large-body packages, no-flow and molded variants tuned to reduce voids and residual stress, and specialized underfills engineered for silicon photonics, image sensors, and AR/VR modules where optical clarity and low stress are non-negotiable.
Policy and regulatory developments are accelerating formulation shifts even as they introduce trade uncertainty. Environmental directives targeting hazardous substances in electronic components are compelling formulators to develop compliant chemistries without sacrificing flow, adhesion, or thermal performance. Concurrently, trade measures on epoxy resins—investigations, duty impositions, and sharp declines in certain import flows—have reshaped regional availability and pricing. These forces create a bifurcated environment: manufacturers in regions with stable feedstock access and aligned regulatory timelines gain a cost and continuity advantage, while others must invest in supply diversification, alternative chemistries, or localized production footprints to protect delivery and margin.
Demand-side behavior is also changing the growth equation. End-equipment manufacturers are increasingly connecting underfill selection to system-level reliability, rework flexibility, and lifecycle cost rather than treating it as a commodity input. As devices become denser and environments harsher—think edge AI hardware, automotive-grade electronics, and sensor-laden modules—procurement and engineering teams evaluate underfill options through the lens of risk reduction and assembly efficiency. This is evident in the growing emphasis on materials that support faster processing, lower void rates, improved vibration resistance, and thermal-shock endurance, especially in aerospace-grade and MEMS-adjacent applications where failure modes are costly.
Supply chain and cost structure dynamics further amplify these trends. With certain epoxy feedstocks experiencing multi-year price highs and regional trade flows constrained, the cost of underfill is less a function of volume alone and more a function of feedstock strategy, formulation efficiency, and process compatibility. Formulators that can balance performance with throughput, enable rework where needed, and reduce downstream defects gain levers to protect margins even in a higher input-cost environment. Meanwhile, demand for specialty grades—such as thermally conductive, nano-filled, or optically clear formulations—creates pockets of pricing resilience that are less exposed to commodity epoxy swings.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The market’s competitive architecture reflects a blend of established global formulators and specialized specialists, each pursuing distinct routes to defensibility. Henkel has leaned into performance leadership for advanced packaging, offering epoxy underfill systems designed for capillary flow and complex AI/HPC package geometries, with an emphasis on flow behavior and reliability under demanding conditions. NAMICS focuses on flip-chip and capillary underfills with stress-optimized formulations, targeting applications where mechanical robustness and thermal cycling performance are central to field reliability.
In the high-reliability assembly segment, H.B. Fuller positions around epoxy underfills for PCB assembly and flip-chip/BGA/WLCSP applications, emphasizing fast flow, reworkability, and structural reinforcement—an approach that aligns with manufacturers seeking to balance throughput with repair economics. Parker LORD contributes thermoset epoxy options for densely populated flip-chip and advanced encapsulation, with formulations aimed at compatibility and process reliability. Epoxy Technology has carved a niche with optically clear, low-stress underfill formulations suitable for flip-chip, potting, and encapsulation, addressing applications where transparency and stress control are critical. Master Bond extends into thermally conductive and nano-filled epoxy underfills, emphasizing vibration and thermal-shock resilience for electronics and MEMS devices, an angle that maps well to ruggedized assemblies. YINCAE has expanded a product family spanning optical-clear and high-conductivity underfills, including releases targeting large chips, silicon photonics, and advanced packaging with improved thermal dissipation.
The strategic differentiation across these players clusters around three axes: application-centric formulation, processing economics, and reliability tailoring. Application-centric players design chemistries for specific package types and use cases, such as optical modules or heat-dense advanced packages. Process-oriented players optimize for flow speed, void reduction, and rework compatibility to reduce total assembly cost. Reliability-oriented players engineer for stress, thermal-shock, and vibration performance in environments where failure is expensive. The strongest portfolios combine two or more of these axes, but few compete equally across all of them, leaving room for focused specialists to capture value in high-demand niches.
Market structure is evolving along two parallel paths. Consolidation pressure is rising where scale in formulation, sourcing, and global distribution confers cost and continuity advantages, especially in a high-feedstock-cost environment. At the same time, differentiation is intensifying as application requirements bifurcate—advanced packaging, silicon photonics, sensors, and ruggedized electronics each pull material development in different directions. This creates an opening for new entrants and regional specialists who can move quickly on targeted form factors, localized supply relationships, or compliance-forward chemistries, even as larger incumbents defend share through breadth and process integration. Recent product launches—capillary systems for large-body AI packages, optical-clear underfills for photonics and imaging modules, and thermally conductive variants for heat management—underscore how fast the competitive frontier is moving and how product timing increasingly matters as much as technical merit.
Forward Outlook: Three Trends That Will Define the Next 3 to 5 Years
The first trend is the deepening integration of underfill selection into advanced packaging roadmaps. As package architectures become more heterogeneous and thermal-mechanical loads increase, underfill will be specified earlier in design cycles, with property targets tied to specific board-level and system-level reliability goals. This will favor suppliers that can translate application requirements into formulation choices rapidly and can support validation with consistent process performance. Commercial opportunity lies in co-development models, application-specific grades, and technical support that reduces qualification time for OEMs and contract assemblers.
The second trend is the widening value gap between commodity and specialty underfills. Commodity-grade capillary and no-flow products will remain volume drivers, but the fastest margin recovery and stickier customer relationships will accrue to formulations with targeted thermal, optical, or mechanical properties—particularly where reworkability, low void content, and vibration or thermal-shock resilience directly reduce downstream cost. Companies that can protect feedstock costs while delivering these attributes will command pricing resilience even as spot epoxy prices fluctuate. Opportunity resides in building lines that balance throughput with differentiation, and in aligning product portfolios with high-growth applications such as AI/HPC packaging and photonics-enabled modules.
The third trend is the recalibration of regional supply and regulatory alignment. With trade measures and environmental mandates shaping availability and formulation priorities, regional continuity and compliance readiness will become competitive differentiators. Manufacturers that secure feedstock diversity, anticipate regulatory shifts, and localize where trade dynamics warrant will reduce delivery risk and margin volatility. The opportunity is to structure supply and product strategy around regional demand profiles and compliance timelines, while avoiding over-reliance on single-source inputs that are exposed to trade or logistics shocks. The principal risk here is timing: if trade enforcement or feedstock constraints tighten faster than regional alternatives scale, short-term availability and cost pressure could disrupt qualifying processes and delay program ramps.
Strategic Implications by Stakeholder
For packaging manufacturers and device assemblers, the priority is to treat underfill selection as a reliability and cost lever rather than a commodity line item. That means mapping application envelopes—thermal flux, mechanical stress, optical requirements, rework needs—to formulation properties, and qualifying materials that reduce voids, accelerate process flow, and improve field durability. It also means stress-testing feedstock continuity and trade exposure in the supply base, since margin protection increasingly depends on sourcing strategy as much as on volume discounts.
PW Consulting
For investors, the opportunity is concentrated in differentiated formulators and application-focused specialists that can capture margin resilience in specialty grades while managing feedstock and trade risk. Favor companies with clear application alignment, process-efficient chemistries, and the ability to support validation quickly. Caution is warranted where portfolios are overly exposed to commodity epoxy swings without offsetting differentiation, or where regional supply is tightly coupled to trade-sensitive feedstocks. The market’s growth profile supports participation, but returns will accrue to those who combine technical focus with supply resilience.
For procurement and supply chain leaders, the mandate is to expand qualification beyond price-per-kilogram and ensure continuity under shifting trade and regulatory conditions. Diversify qualified sources, build scenario plans for feedstock volatility, and include compliance readiness in sourcing criteria. Where possible, align with suppliers who can provide application-specific support, consistent quality, and transparent feedstock strategies, reducing the chance that a single disruption cascades into qualification delays or cost overruns.
Worldwide Underfill Dispenser Market
The underfill market is entering a phase where technical fit, supply resilience, and application timing determine competitive advantage more than volume alone. For decision-makers seeking deeper segmentation, company-specific benchmarks, and tailored sourcing or investment scenarios, a comprehensive research study can translate these trends into actionable plans for specific product lines, regions, and customer segments.
For detailed analysis of this topic, please visit the official page: Underfill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rubber Conveyor Belt Market: Why the 4.05% CAGR Path from 2026–2032 Redefines Strategy
By PW Consulting, 2026-09-21
Rubber Conveyor Belt Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Snapshot and Core Challenges
The global rubber conveyor belt market has transitioned from a post-pandemic recovery phase into a period of measured, structurally driven growth. Revenue reached approximately 3.38 billion USD in 2025, expanding from 2.80 billion USD in 2020 at a compound annual growth rate of 4.05 percent. The forecast period through 2032 projects the market to approach 4.46 billion USD, with growth trajectories reflecting both steady baseline demand and periodic accelerations tied to heavy industrial capital cycles. This trajectory signals a market that is no longer defined by volatile rebounds but by operational efficiency imperatives, material handling scale-up, and the gradual replacement of aging infrastructure across mature and emerging economies.
Despite this constructive outlook, the industry faces intersecting challenges that will separate agile operators from stagnant incumbents. First, raw material price volatility and supply chain fragmentation continue to compress margins, particularly for manufacturers reliant on synthetic rubber, carbon black, and steel cord inputs. Second, the regulatory and operational push toward energy efficiency and emissions reduction is forcing end-users to reassess belt specifications, favoring longer-life, lower-friction solutions that carry higher upfront costs but deliver measurable total cost of ownership benefits. Third, market concentration remains pronounced, with the top three players holding roughly 45 percent share and the top five approaching 60 percent. This concentration creates a dual dynamic: established leaders benefit from scale, technical credibility, and service networks, while smaller producers face pressure to differentiate through niche applications, regional agility, or cost-optimized manufacturing footprints.
For executives and investors, the implication is clear. The market is not simply growing; it is restructuring around performance metrics, service intensity, and regional demand shifts. Strategy that ignores these structural forces risks exposure to commoditization, whereas strategy that aligns product portfolios, supply chain resilience, and customer-facing value propositions with the new operating reality can capture disproportionate share.
PW Consulting Chemical & Energy Research Center
2. Key Drivers Reshaping the Market
Technological Innovation and Material Performance
The most consequential driver is the ongoing evolution of reinforcement technology and compound engineering. Steel-cord reinforcement, for example, is forecast to post a 6.05 percent CAGR through 2031, outpacing broader market growth. This acceleration is not a statistical artifact; it reflects a practical shift in how operators design material handling systems. Steel-cord belts provide high tensile strength and low elongation, enabling longer single-flight conveyors that lower energy consumption and reduce maintenance frequency. As mining, cement, and bulk logistics operators seek to minimize downtime and energy intensity, the specification conversation is moving from "replace like-for-like" to "optimize system performance." This shift favors manufacturers with advanced carcass design capabilities, consistent quality control, and the technical service infrastructure to support engineered solutions rather than commodity replacement.
Beyond reinforcement, innovation in cover compounds, abrasion resistance, and heat or oil resistance is expanding the addressable use cases for rubber belts in environments previously dominated by alternative materials. The commercial reality is that value is migrating toward performance-justified pricing, where buyers accept higher unit costs in exchange for extended service life, fewer belt related stoppages, and reduced total energy consumption. Manufacturers that can quantify these benefits and supply evidence-backed specifications will command better margins and stronger customer retention.
Regulatory and Operational Pressure on Efficiency and Safety
Policy and regulatory trends are not acting as blunt constraints; they are reshaping procurement logic. Environmental and workplace safety expectations are increasing scrutiny on dust generation, spillage, and maintenance-related exposure in bulk handling facilities. Simultaneously, energy cost awareness is driving procurement teams to evaluate conveyor systems through a lifecycle lens. In this environment, belt selection becomes a strategic variable rather than a tactical purchase. Industry recognition patterns reflect this shift: ContiTech was named Best Conveyor Belt Supplier for the third consecutive time in Chile in October 2025, with additional recognition for belt cleaners. Such recurring validation in demanding operating environments signals that leading suppliers are being rewarded not merely for product availability but for reliability, local operational support, and complementary system solutions that reduce material carryback and maintenance burden.
For decision-makers, the operational takeaway is that compliance and efficiency are converging. Regulations and corporate sustainability goals are increasingly aligned with the same outcome: fewer failures, less energy waste, and lower exposure to operational risk. Suppliers that can position their offerings within this combined narrative gain access to procurement conversations that were previously locked behind price negotiations.
Demand-Side Shifts in Mining, Manufacturing, and Logistics
Demand is being reshaped by the differing growth rhythms of core application sectors. Mining continues to anchor market volume, supported by bulk material movement in extractives and the need to transport ore, coal, and aggregates across increasingly large site layouts. Manufacturing and logistics and warehousing are expanding on the back of throughput optimization, automation compatibility, and the need for dependable internal material movement in high-lot operations. What unites these segments is a declining tolerance for unplanned downtime and a growing willingness to invest in belts that integrate cleanly with broader conveyor system design.
A notable demand-side change is the shift from reactive replacement to planned lifecycle management. Operators are increasingly aligning belt procurement with maintenance scheduling, conveyor redesign, and site expansion plans. This creates opportunities for suppliers that can offer application engineering, installation guidance, and failure analysis as part of the value proposition. It also raises the barrier for pure price-based competition, because buyers are comparing packages rather than unit prices alone.
Supply Chain and Cost Structure Evolution
Cost structures are being recalibrated by input volatility, logistics complexity, and the strategic reorganization of manufacturing footprints. In response, leading companies are pursuing consolidation of production assets, selective localization, and tighter control over critical inputs. Yokohama Rubber’s consolidation of its conveyor belt subsidiary in China illustrates this direction. The move was designed to further stabilize earnings under its Yokohama Transformation 2026 medium-term plan, reflecting a broader tendency to rationalize regional operations where scale, coordination, and margin stability can be improved. Rather than expanding everywhere, mature players are prioritizing operational coherence and earnings predictability.
At the same time, the supply base is being tested by the need to balance cost competitiveness with specification integrity. Lower-cost production can win short-term procurement rounds, but inconsistent quality creates hidden costs in the field. The market is therefore developing a clearer hierarchy: premium engineered belts for demanding applications, cost-competitive belts for less severe service, and a growing expectation that suppliers clearly differentiate these tiers rather than blur them. The companies that manage this tiering transparently will be better positioned to defend margins while retaining volume.
Heavy Duty Conveyor Belts Market
3. Competitive Landscape and Leading Strategies
Structural Positioning of Core Players
The competitive set reflects a blend of specialized European technology suppliers, large international rubber producers, and increasingly capable Asian manufacturers serving both domestic and export markets. SIG S.p.A. operates as a specialized manufacturer of rubber conveyor belts and elevator belts with textile and steel carcass construction for bulk material handling, positioning itself around application specificity and carcass expertise. ContiTech leverages its broader industrial rubber and materials handling heritage to supply energy-efficient and heavy-duty models for industrial, mining, and materials handling applications, with an emphasis on system-level performance and recognized field reliability.
In China, Zhejiang Double Arrow Rubber Co., Ltd. stands out as a leading producer of fabric, steel cord, solid woven, aramid, and specialized rubber conveyor belts, supported by global sales and ISO certifications. Qingdao Rubber Six Conveyor Belt Co., Ltd. similarly manufactures fabric, steel cord, and heavy-duty rubber conveyor belts under the Rubber Six and Zhonghua brands, reflecting the scale and range available within the Chinese supply base. On the Japan-linked side, The Yokohama Rubber Co., Ltd. manufactures rubber conveyor belts through its wholly owned subsidiary Shandong Yokohama Rubber Industrial Products Co., Ltd., while Bando Chemical Industries, Ltd. supplies conveyor belts and related rubber products for industrial power transmission and materials handling. Fenner Dunlop Conveyor Belting rounds out the landscape with durable rubber and PVC conveyor belts for mining, industrial, and heavy-duty applications, distributed across EMEA and the Americas.
These profiles matter because they reveal two competing axes of advantage. One axis is application depth: companies that emphasize carcass technology, cover compound engineering, and technically supported solutions. The other axis is reach and cost orchestration: companies that combine broad product ranges, certifications, and multi-region distribution with disciplined manufacturing. The strongest players increasingly operate along both axes by offering tiered portfolios, credible technical service, and recognizable reliability in demanding markets.
Differentiation and Strategic Themes
Several strategic themes differentiate the leaders from the rest of the field. First, engineered solution selling is becoming a margin defense mechanism. Suppliers that can size belts to conveyor geometry, material characteristics, and throughput targets reduce the likelihood of under-specification and over-specification, both of which create friction in procurement and maintenance. Second, recognition and repeatability in difficult operating environments build a form of credibility that is hard for new entrants to replicate quickly. Recurrent awards or customer validations in high-stress regions indicate that a supplier’s products and support infrastructure perform under real conditions, not just in specification sheets.
Third, organizational consolidation is becoming a strategic lever. Yokohama Rubber’s subsidiary consolidation in China demonstrates how companies can seek earnings stability and operational focus rather than pursuing undifferentiated geographic expansion. This pattern suggests that future competition will not only be about who has the broadest footprint, but about who manages its footprint with the greatest coherence, quality consistency, and capital discipline. Fourth, complementary system components are gaining attention. Belt cleaners and related accessories are increasingly part of the commercial conversation because they reduce carryback, improve cleanliness, and lower maintenance effort. Recognition of belt cleaner performance alongside belt supply signals a market that is progressively valuing integrated material handling outcomes.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market is likely to evolve through selective consolidation among scale players seeking margin stability and operational efficiency, alongside continued fragmentation in regional and niche segments where local service, cost positioning, or specialized applications matter. New entry remains possible, but the barriers are rising in the premium engineered segment, where performance history, testing capability, and customer trust compound over time. In the value segment, entry and competition remain more fluid, though price competition alone is increasingly risky as buyers become more aware of lifecycle costs and specification sensitivity.
For manufacturers and investors, the strategic question is where competitive advantage is being created and preserved. In demanding mining and heavy industrial applications, advantage is being built through technical reliability, long-life designs, and service density. In broader industrial and logistics applications, advantage is increasingly tied to consistent quality, predictable delivery, and clear segmentation between duty levels. The companies that can articulate and deliver these distinctions will be better placed to sustain pricing power and customer loyalty.
4. Future Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape commercial outcomes. The first is the continued shift toward steel-cord and high-performance reinforcement in applications where conveyor length, load intensity, and energy efficiency justify the specification. With steel-cord belts forecast to grow at a 6.05 percent CAGR through 2031, the commercial opportunity lies in application engineering, lifecycle justification, and service support that helps operators realize the intended efficiency gains. The revenue opportunity is not simply in selling more belts; it is in aligning product selection with system-level performance so that higher specification becomes a defensible investment rather than a premium price objection.
The second trend is the growing importance of recognized reliability and localized support in key operating regions. Recurring supplier recognition in challenging environments suggests that buyers increasingly value proof of performance and responsive service over generalized brand claims. This creates commercial opportunities for manufacturers that invest in regional technical presence, failure analysis capability, and fast response to field issues. It also raises the stakes for suppliers that depend on remote selling without sufficient local problem-solving capacity, because trust in demanding applications is difficult to build and easy to lose.
The third trend is the rationalization of manufacturing and service footprints around earnings stability and cost discipline. As seen in recent corporate moves to consolidate subsidiaries and focus on medium-term transformation plans, companies are likely to favor operational clarity over unchecked expansion. For buyers and investors, this can translate into more predictable supply, clearer product segmentation, and potentially stronger supplier commitment to quality and service in core markets. For exporters and smaller regional players, the implication is that scale, certification, and consistent execution will matter more than before, especially where buyers are under pressure to reduce total cost of ownership without sacrificing reliability.
Potential risks and uncertainties should be monitored closely. Raw material swings can undermine margin plans even when demand is healthy. Over-investment in heavy industrial capacity during cyclical upswings can create exposure if mining or cement activity soften. Regulatory and sustainability expectations may accelerate specification upgrades, which is favorable for premium suppliers but challenging for cost-focused operators with limited engineering support. Finally, the line between rubber and alternative belt materials in some applications may narrow if competing technologies improve on cost, weight, or maintenance characteristics. Competitive strategy will therefore require continuous reassessment of where rubber belts hold a durable advantage and where substitution risk is rising.
5. Strategic Actions for Decision-Makers
For Manufacturers and Suppliers
Develop a clearly segmented portfolio that separates engineered high-performance solutions from cost-competitive standard offerings, with transparent differentiation in duty, reinforcement, and expected service life. Build the technical service capability needed to justify higher specifications through application engineering, lifecycle analysis, and field failure insights. Prioritize operational coherence in key regions, focusing on quality consistency, delivery reliability, and recognized performance in demanding environments rather than pursuing growth that dilutes margin or control. Where complementary system components such as belt cleaners are relevant, evaluate whether bundling or coordinated solution selling can strengthen customer retention and differentiate from pure product suppliers.
For Investors
Assess exposure not only to top-line market growth, but to the structural forces that determine margin quality: reinforcement mix, application intensity, regional service density, and the ability to defend price through performance justification. Companies with disciplined manufacturing consolidation, credible field recognition, and a defensible position in steel-cord or other faster-growing reinforcement types are better aligned with the market’s direction than generic volume players. Monitor for cyclical risk in mining-anchored demand and for substitution pressure in less severe applications, and weigh these against the durability of engineering-led differentiation and regional reputation.
For Procurement and Operations Leaders
Shift evaluation criteria from unit price to total cost of ownership, incorporating energy efficiency, expected service life, downtime reduction, and maintenance burden. Use specification as a strategic lever: select belt types that match material characteristics and conveyor geometry, and request evidence-backed performance data rather than accepting generic claims. Strengthen supplier relationships where local support, failure analysis, and rapid response are available, because these capabilities increasingly determine operational resilience. Where possible, align belt procurement with planned maintenance and conveyor optimization programs to capture the full value of higher-specification solutions.
Conveyor Belts Market
For decision-makers seeking a deeper, segment-level view of growth trajectories, regional demand dynamics, duty-level breakdowns, and company-level strategic positioning, the full market research report provides the additional granularity needed to translate these trends into customized action plans. The broader market trajectory is clear; the practical advantage lies in the details that connect product strategy, sourcing decisions, and capital allocation to the operating realities shaping the next phase of demand.
For detailed analysis of this topic, please visit the official page: Rubber Conveyor Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Wire Enamels Market: Strategic Trends and Commercial Opportunities Through 2032
The global Wire Enamels Market has entered a phase of structural expansion, defined by steady revenue growth, technological differentiation, and shifting demand patterns across industrial and transportation sectors. From a baseline of approximately 952.5 million USD in 2020, the market scaled to 1287.75 million USD in 2025, reflecting an annualized growth trajectory that positions the segment for continued uplift. Projections for the forecast period spanning 2026 through 2032 indicate revenue will advance toward 2032.1 million USD by the end of the horizon, underpinned by a compound annual growth rate of 6.8 percent. The 2020 to 2025 historical window captured the market’s recovery from supply chain disruptions, followed by a demand rebound driven by motor manufacturing, transformer replacements, and the accelerating adoption of electric drivetrains. As the industry moves into the mid-to-late 2020s, the growth curve is no longer solely dependent on volume expansion; it is increasingly shaped by formulation performance, regulatory compliance, and regional capacity realignment. For executives and investors evaluating exposure to industrial coatings and electrical insulation materials, the market presents a structurally favorable environment, but one that requires disciplined positioning to navigate raw material volatility, evolving compliance mandates, and intensifying product differentiation.
Despite the positive macro trajectory, the industry is confronting a set of inflection points that will determine which participants capture disproportionate value over the next several years. The first challenge lies in balancing performance requirements with cost control. End-users in motors and automotive components increasingly demand insulation systems that withstand higher operating temperatures, improved thermal dissipation, and extended service life, while simultaneously pressuring suppliers for more predictable pricing. This tension is amplified by the second challenge: raw material cost dynamics. Fluctuations in resin feedstocks, pigment supplies, and specialty chemical intermediates have repeatedly raised production expenses across the value chain, prompting manufacturers to reassess procurement strategies and pricing architectures. The third challenge involves the regulatory environment. Stringent environmental standards on solvent-based formulations are accelerating the transition toward low-VOC and solvent-free solutions, forcing incumbents and new entrants alike to invest in reformulation, testing, and compliance documentation. Together, these forces are reshaping competitive benchmarks. Companies that can integrate advanced polymer chemistry, stabilize input costs through strategic sourcing, and align product portfolios with regulatory and performance expectations are best positioned to convert market growth into durable margin expansion.
Technological Innovation and Formulation Breakthroughs
Product innovation is becoming a primary vector of differentiation in the Wire Enamels Market, with advances centered on hybrid architectures, thermal stability, and application-specific reliability. Organic-inorganic hybrid polyamide-imide formulations have emerged as a notable development, offering enhanced insulation performance for high-demand electrical systems where thermal endurance and mechanical resilience are critical. These hybrid systems are particularly relevant for electric vehicle powertrains, wind turbine generators, and other high-performance electrical applications that push conventional enamel limits. Parallel progress in polyesterimide and polyamide-imide chemistries is enabling manufacturers to deliver tailored solutions for magnet wire coatings, allowing winding producers to optimize balance between dielectric strength, flexibility, and cure characteristics. The shift toward formulation precision is also supported by improved process control and closer collaboration between enamel suppliers and winding wire manufacturers. Rather than treating enamels as commodity coatings, leading participants are positioning them as engineered components within larger motor and transformer designs. This approach creates room for premium positioning, especially where customers seek to reduce failure rates, improve energy efficiency, or extend maintenance intervals. Innovation is therefore not only a technical storyline; it is a commercial strategy that links material performance directly to end-product value.
Policy and Regulatory Pressures Reshaping Formulation Paths
Regulatory momentum is exerting a powerful influence on product design and manufacturing choices. Environmental requirements targeting solvent-based wire enamels are encouraging a broader migration toward sustainable low-VOC solutions and solvent-free systems. This transition is not simply a compliance exercise; it affects formulation stability, application behavior, curing requirements, and downstream processing compatibility. Manufacturers must therefore coordinate changes in chemistry with customer production environments to ensure that new coatings perform reliably under real-world winding and impregnation conditions. In parallel, regulatory scrutiny around emissions, workplace safety, and chemical handling is increasing the importance of documentation, testing protocols, and transparent supply chain practices. Companies that proactively align their portfolios with evolving standards can reduce the risk of retrofit costs, specification changes, and market access delays. Conversely, late adaptation can leave suppliers exposed to customer qualification bottlenecks and regional compliance mismatches. The regulatory trajectory also intersects with customer expectations for sustainability, meaning that environmental performance is increasingly part of the purchasing rationale rather than a separate administrative issue.
Demand-Side Shifts in Motors, Automotive, and Electrical Equipment
Demand behavior is changing as end-use sectors reassess performance, reliability, and electrification goals. Motors remain the dominant demand anchor, reflecting their pervasive role in industrial machinery, HVAC systems, and increasingly efficient electric drives. Automotive components represent another high-growth demand center, where the expansion of electrified powertrains and the need for robust motor windings are elevating the importance of high-performance insulation materials. Beyond these segments, transformers and industrial equipment continue to contribute meaningfully, supported by grid infrastructure upgrades, industrial automation, and replacement cycles for aging equipment. Home appliances and other smaller-scale applications add breadth to the demand base, though they typically place different emphasis on cost and processing convenience versus extreme thermal or mechanical performance. A key demand-side trend is the growing preference for enamel solutions that can support higher efficiency and reliability without compromising manufacturability. This is prompting closer specification alignment between enamel suppliers and winding producers, as well as more rigorous qualification processes for new formulations. The commercial implication is clear: demand growth is increasingly tied to applications where insulation performance directly affects system outcomes, giving advanced products a stronger value proposition than in lower-specification settings.
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost structure dynamics remain a central factor shaping competitiveness. Volatility in raw material inputs, including resin and pigment pricing, has increased production expenses and complicated margin planning for producers. This environment is encouraging more active procurement strategies, such as multi-source sourcing, long-term supply arrangements, and formulation adjustments that reduce exposure to volatile intermediates without sacrificing performance. Capacity decisions are also being revisited in response to regional demand patterns and cost considerations. Investments in production footprint expansion are being directed toward locations where demand growth is strongest and where manufacturers can better serve local winding wire producers and component manufacturers. At the same time, pricing actions are becoming more selective, with increases tied to specific chemical families and market conditions rather than applied uniformly across all products. These adjustments reflect a broader move toward disciplined portfolio management, where profitability depends on aligning cost recovery with value delivered in each application segment. Supply chain resilience is therefore not just a logistics concern; it is a strategic differentiator that affects pricing credibility, delivery reliability, and the ability to scale advanced formulations.
PW Consulting Chemical & Energy Research Center
Competitive Dynamics and Strategic Positioning
The competitive landscape features a mix of specialty coating manufacturers, large materials companies, and integrated wire and coating suppliers, with no single dominance pattern across all regions or application segments. Market concentration remains moderate, with the top three participants holding a combined share in the mid-twenties and the top five only slightly higher, indicating that differentiation, regional presence, and application-specific expertise still matter greatly. This fragmented-but-specialized structure creates opportunities for companies that can combine formulation strength with strong customer proximity and technical service capabilities. Several leading participants are pursuing distinct strategic angles. One established European-focused manufacturer has built a broad portfolio of high-performance enamels for magnet wire coatings, emphasizing global production sites and custom solutions for motors and electric vehicles. This provider has also taken steps to expand capacity in southern China to align supply with rising regional demand, while implementing selective price adjustments across major chemical families to reflect changing market conditions. Another major coatings company has advanced hybrid polyamide-imide solutions, including a recent launch of an organic-inorganic hybrid wire enamel recognized for its relevance to electric vehicles, wind turbines, and high-performance electrical systems. That product momentum signals a deliberate push into segments where insulation reliability is a critical purchasing criterion. A large U.S.-based materials company has supported its polyesterimide offering through capacity-related expansion tied to an acquisition, reinforcing its ability to supply electric vehicle and industrial motor applications. A Japanese specialist has focused on high-efficiency insulation materials developed in collaboration with electric vehicle component producers, illustrating the value of application-side partnerships in refining product fit. In parallel, an integrated wire and coating supplier serves winding wire manufacturers with enameled wire and enamel offerings, while another global materials producer provides resins and coating inputs that support high-temperature and motor applications. These varied strategies highlight a market where value capture depends on combining chemistry, capacity, and customer-facing engineering rather than competing on price alone.
Market Evolution Toward Integration, Differentiation, and Targeted Entry
The market structure is evolving along several directions at once. Consolidation pressure exists in regions where scale, regulatory compliance, and technical service requirements raise the barrier to effective competition, yet the moderate concentration levels suggest that specialization and regional strength remain viable paths. Differentiation is intensifying around performance classes, with high-performance polyesterimide, polyamide-imide, and hybrid formulations attracting greater attention than lower-specification alternatives in demanding applications. This creates a two-layer competitive environment: one where commodity-adjacent products compete on cost and supply reliability, and another where engineered coatings compete on thermal endurance, dielectric robustness, and application fit. New entry and expansion activity is likely to remain selective, favoring participants with existing chemical expertise, production know-how, and customer relationships in motors, transformers, or automotive components. At the same time, capacity additions are being shaped by regional demand centers, especially where electrification and industrial modernization are accelerating. The overall trend is toward a more segmented market in which success depends on matching product architecture to application requirements, maintaining dependable supply, and adapting to regulatory change without losing commercial momentum.
Outlook: Three Structural Trends Shaping 2026 to 2032
The next several years are likely to be defined by three reinforcing trends. First, high-performance and hybrid enamel formulations will continue to gain share in demanding applications as electric vehicle motors, wind power equipment, and advanced industrial drives push insulation requirements higher. This trend favors suppliers that can demonstrate measurable improvements in thermal resistance, reliability, and process compatibility, and it creates opportunities for premium pricing where performance outcomes are clearly valued by customers. Second, sustainability-driven reformulation and regulatory compliance will become standard elements of competitive capability rather than occasional initiatives. Low-VOC and solvent-free directions will increasingly influence specification decisions, procurement criteria, and regional market access, making formulation agility and compliance readiness a durable advantage. Third, regional capacity alignment will grow in importance as manufacturers seek to serve local demand more efficiently and reduce exposure to input cost disruptions and logistics constraints. Together, these trends suggest a market where growth is not uniform across products or geographies, but is concentrated in segments where performance, compliance, and supply reliability converge. The commercial opportunity lies in identifying those convergence points early and building the technical and operational capabilities required to serve them consistently.
Worldwide Retangular Enameled Wire Market
These trends also carry risks that warrant careful monitoring. Raw material volatility can compress margins if pricing mechanisms lag cost movements, especially in periods when resin and pigment inputs fluctuate sharply. Regulatory changes may outpace reformulation timelines, creating qualification gaps or regional mismatches that slow adoption of new products. Demand intensity can also vary by segment, with electrification-related applications potentially experiencing cyclical or project-driven swings that affect planning accuracy. Additionally, capacity expansion in high-growth regions may intensify competition if multiple suppliers pursue the same demand pockets simultaneously, placing pressure on both pricing and customer qualification cycles. Managing these uncertainties will require scenario-aware sourcing, disciplined product roadmaps, and close engagement with downstream customers to anticipate specification shifts before they become disruptive.
Strategic Actions for Different Decision-Maker Profiles
For manufacturers and product leaders, the priority is to sharpen formulation strategy around the applications that most value performance differentiation. This means investing in hybrid and high-temperature systems where insulation reliability translates into customer benefits, while maintaining a cost-competitive baseline for lower-specification segments. Equally important is building technical service capabilities that help winding wire producers and motor manufacturers integrate new enamels efficiently, since adoption often depends on processing compatibility and qualification support as much as on material properties. For investors and corporate development teams, the focal point should be the intersection of electrification-driven demand, regulatory-driven reformulation, and regional capacity shifts. Opportunities are likely to be strongest where suppliers can demonstrate both product leadership and supply resilience, especially in motors and automotive components. Evaluating exposure should therefore go beyond headline growth figures to include portfolio mix, pricing discipline, compliance readiness, and regional manufacturing alignment. For procurement and sourcing leaders, the practical goal is to balance performance, cost, and continuity risk by diversifying supply where possible, aligning specifications with sustainability and reliability requirements, and monitoring input cost trends that may affect pricing stability. Long-term supply agreements and early engagement on reformulation transitions can help reduce disruption risk while preserving access to advanced insulation materials.
The Wire Enamels Market is moving from steady growth toward a more performance-sensitive and regulation-shaped competitive environment. The companies that capture the most value will be those that align product architecture with demand intensity, operate with resilient cost structures, and respond quickly to compliance and application changes. For decision-makers seeking deeper segmentation detail, regional demand patterns, and customized scenario planning, the full PW Consulting research report provides the additional data and structured analysis needed to translate these strategic themes into precise commercial decisions.
Enameled Wire Market
For detailed analysis of this topic, please visit the official page: Wire Enamels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Cabin Air Filter Market: Why 5.8% CAGR and Shifting Segments Change Everything
By PW Consulting, 2026-09-21
The Automotive Cabin Air Filter Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The automotive cabin air filter market has evolved from a commoditized replacement component to a strategic element of vehicle health, passenger safety, and OEM value engineering. Revenue across the global market reached approximately $3.5 billion in 2025, building on a steady expansion from roughly $3.0 billion in 2020. The trajectory reflects both volume growth in vehicle parc and a qualitative shift toward higher-performance filtration media, improved sealing, and integrated cabin health features. Forward estimates point to continued expansion through 2032, with a compound annual growth rate of 5.8 percent, indicating that incremental gains will increasingly come from premiumization and regulatory-driven specification changes rather than baseline replacement demand alone.
Europe and Asia Pacific together account for the largest share of revenue, reflecting dense vehicle populations, stringent emissions and air quality frameworks, and relatively fast fleet turnover in key markets. North America remains a meaningful contributor, supported by a high aftermarket penetration and a consumer base that has grown more attentive to in-cabin air quality. Latin America and the Middle East and Africa represent smaller but gradually expanding opportunities, often shaped by aftermarket service patterns and localized air quality concerns. The revenue distribution underscores a market where regional regulatory intensity, vehicle mix, and consumer awareness intersect to determine end-market appetite for advanced filtration.
Behind the top-line growth, the industry faces several structural challenges. First, the overlap between filtration performance, packaging constraints, and serviceability is becoming more complex. Modern vehicle architectures place cabin air filter housings in tighter spaces, sometimes near sensitive components such as wiring harnesses. This creates a design and service risk: a filter change that is intended to be routine can, if executed improperly, damage adjacent systems. Recent safety actions in the United States highlight this tension. A Part 573 safety recall report and a related service information bulletin addressed potential damage to air conditioning wiring harnesses during cabin air filter replacement on certain vehicles. An engineering investigation was initiated after field incidents involving thermal events in model year 2024 vehicles where the filter housing cover sits close to the air conditioning wiring harness. The follow-up bulletin mandated procedure modifications to avoid harness damage during replacement. For OEMs and service networks, these developments add a layer of process control, training, and design-risk management that did not exist when cabin filters were treated as simple consumables.
Second, the regulatory environment is tightening filtration expectations while simultaneously reshaping adjacent vehicle systems. More stringent ambient air quality standards for particulate matter are raising the bar for what consumers and regulators expect from in-cabin filtration. At the same time, the phase-down of high-global-warming-potential hydrofluorocarbons in model year 2025 has accelerated the adoption of advanced cabin air filtration systems as part of broader climate and refrigerant transitions. In Europe, Euro 7-style expectations are pushing particle filtration performance down to very small sizes, influencing both OEM specifications and aftermarket acceptable performance. The cumulative effect is a market where compliance is no longer a checkbox but a continuous performance requirement that can affect material selection, media layering, and validation cycles.
Third, the combination of rising performance expectations and cost sensitivity is reshaping competitive dynamics. Activated carbon and combination products command stronger positioning in segments where odor, gaseous pollutants, and allergen reduction matter, but they also increase material and manufacturing complexity. Electrostatic and media-engineered solutions offer efficiency gains, yet they must be balanced against airflow, load, noise, and service life. Suppliers and buyers alike are navigating a tension between specification ambition and total cost of ownership, especially in commercial fleets and price-sensitive aftermarket channels. The result is a market in transition: growth is real, but it is unevenly distributed across regions, vehicle types, and product tiers, and the competitive winners will be those who can manage performance, service risk, and cost at the same time.
Key Demand Drivers
The market is being pulled forward by a small number of high-impact forces that are reshaping both product design and commercial positioning.
Technology Innovation and Media Engineering
Media architecture remains the central differentiator. The industry is moving beyond basic particulate capture toward layered solutions that combine mechanical filtration, adsorption, and electrostatic effects. Activated carbon media continues to play a central role for odor and gaseous contaminant control, while nanofiber and electrostatically enhanced materials are increasingly used to raise capture efficiency without excessively restricting airflow. Multi-layer designs are also enabling more compact housings and better balance between filtration efficiency and system load. Recent product guidance from leading suppliers shows how these technologies are being adapted to specific vehicle categories, including motorhomes, where activated carbon protection against odors and harmful gases is being emphasized for prolonged cabin occupancy and varied operating environments.
This technology shift matters because it changes the basis of competition. A filter that was once evaluated primarily on particulate arrestance is now judged on odor management, allergen reduction, durability, and ease of integration. That, in turn, creates room for differentiation in both OEM sourcing and aftermarket branding, especially where consumers associate filtration quality with overall cabin health and comfort.
Automotive Cabin Air Quality Sensor Market
Policy and Regulatory Environment
Regulatory pressure is a growing source of demand for higher-efficiency cabin filtration. Stricter ambient particulate matter standards are reinforcing the value proposition of filters that can remove a very high proportion of fine particles. At the same time, tighter vehicle-level emissions frameworks and refrigerant transitions are indirectly raising the importance of cabin air quality, because they encourage broader system changes and a more holistic view of in-cabin environmental control. Europe’s push toward filtration of extremely small particles and the United States’ refrigerant-related transitions both illustrate how policy is influencing product expectations beyond traditional replacement cycles.
For manufacturers and fleet operators, the regulatory trajectory creates two practical effects. One is a rising floor for acceptable performance, which compresses the lowest end of the market and rewards suppliers with validated media and testing capabilities. The other is an opportunity to position advanced filtration as part of a broader safety, health, and compliance narrative, rather than as a standalone part number.
Demand-Side Shifts in Consumer and Fleet Behavior
Passenger car buyers are increasingly aware of air quality as a component of vehicle livability, particularly in urban environments and regions with seasonal pollutant spikes. That awareness has elevated the appeal of combination and activated carbon solutions in premium and mid-tier segments, and it has also influenced service behavior, where filter replacement is being viewed more proactively rather than purely reactively. In commercial vehicles, fleet operators are weighing cabin filtration alongside driver comfort, retention, and operational reliability, especially where vehicles operate in dusty or high-pollution conditions. In two-wheelers, demand is smaller but still growing in markets where exposure to traffic emissions and particulate matter is uneven and where affordable upgrade paths can improve rider experience.
These behavioral changes are important because they expand the conversation beyond technical specs. The commercial case for better filtration is increasingly tied to perceived health benefits, comfort, and brand positioning, which gives suppliers and automakers a stronger storytelling and value-selling platform.
Supply Chain and Cost Structure Evolution
The cost picture is being shaped by the interplay of media complexity, validation requirements, and the need to maintain serviceability. Higher-performance materials and layered constructions can improve capability, but they also create pressure on sourcing, manufacturing consistency, and quality control. At the same time, the service-side incidents discussed earlier are forcing reconfiguration of replacement procedures and, in some cases, packaging or access design. That adds indirect cost in training, documentation, and warranty-related risk management. Suppliers that can standardize high-quality media, control variability, and design for service-friendly installation are better placed to protect margins while meeting performance expectations.
Competitive Landscape and Leading Strategies
The competitive structure is moderately concentrated, with the top three players holding a notable share and the top five extending that advantage further. Concentration at this level indicates that scale, OEM relationships, media expertise, and brand recognition matter, but it also leaves room for specialized players to compete in niches such as performance filtration, aftermarket branding, or specific application segments.
European suppliers remain particularly prominent, reflecting deep OEM integration, strong engineering heritage, and broad coverage across passenger cars, trucks, and off-highway applications. One global filtration specialist has emphasized nanofiber and activated carbon technologies across OEM and aftermarket lines, with recent recommendations tailored to motorhomes that highlight activated carbon protection against odors and harmful gases. Another major German supplier has focused on both original equipment and retrofit applications, spanning particulate and combination filters. A third large industrial and automotive supplier has built a position around high-efficiency particle and activated carbon options for OEM integration, while a fourth German filtration technology company is known for advanced media aimed at protection against pollutants and allergens. Together, these players illustrate how leading vendors combine media science, broad application coverage, and channel strength to defend share.
In Asia, Japanese manufacturers have carved out strong positions through integration with vehicle programs and specialized media approaches. One major Japanese supplier has highlighted multi-layer media designed for optimal airflow and filtration efficiency, including particulate-electrostatic concepts, while another has developed OEM cabin filters integrated into Toyota and Lexus vehicle models. These examples show how regional strengths in manufacturing discipline and OEM relationships can support consistent volume and specification alignment.
North American participants bring a different set of advantages. Some focus on high-efficiency products for automotive and commercial vehicle applications across OEM and replacement markets, while others emphasize specialized filtration media or performance-oriented and washable solutions. A separate aftermarket-oriented group has expanded consumer visibility through branded variants, illustrating how retail presence and brand recognition can complement product capabilities in the replacement channel.
The strategic patterns among leaders are clear. First, differentiation is increasingly tied to media architecture and validated performance rather than commoditized fitment alone. Second, the most resilient players are those that can serve both OEM and aftermarket channels, because OEM programs provide scale and specification influence while aftermarket channels provide reach and margin flexibility. Third, application breadth matters: suppliers that address passenger cars, commercial vehicles, and select two-wheeler or niche segments can smooth cyclicality and capture cross-segment learning. At the same time, the landscape is evolving. Consolidation pressure persists among smaller players that cannot match validation costs or OEM integration requirements, while new entrants and specialist media companies can still gain ground where they offer distinct efficiency, serviceability, or branding advantages. The recent regulatory and serviceability issues also suggest that design integration, documentation, and field support will become more important competitive factors, not just filter performance on a spec sheet.
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape where value is created in this market.
PW Consulting Automotive & Machinery Research Center
Performance Premiumization with Serviceability as a Design Constraint
Demand for higher-efficiency and odor-controlling products should continue to rise, especially where air quality concerns and consumer expectations overlap. However, the most successful offerings will be those that balance performance with accessible replacement design and clear service instructions. The recent safety and service bulletin activity is a reminder that a filter’s value proposition is not limited to filtration efficiency; it also includes the risk profile of the replacement process. Suppliers and vehicle programs that design for both performance and safe service access will be better positioned to reduce field issues and protect customer trust.
Worldwide Automotive Air Filter Housing Market
The commercial opportunity here is twofold: advanced media can support higher-margin product tiers, and service-friendly design can reduce warranty exposure and strengthen OEM and fleet relationships. The risk is that performance gains are undermined by packaging compromises or by replacement procedures that are too easy to mishandle.
Regulatory-Driven Specification Escalation
As ambient air quality standards tighten and vehicle-level expectations evolve, filtration requirements will continue to move up the performance curve. This will likely compress the lowest tier of the market and increase reliance on validated media, repeatable manufacturing, and testing capability. It also creates an opening for suppliers that can translate regulatory requirements into practical, cost-effective product architectures for both OEM and aftermarket use.
The risk is that compliance pressure becomes fragmented across regions and programs, making it harder to scale a single solution globally. Companies that can maintain a core platform while adapting media and sealing options to local requirements will have an advantage in managing complexity without sacrificing margin.
Channel Blending and Aftermarket Brand Building
The aftermarket will remain a major growth driver, but its composition is changing. Consumer awareness is supporting demand for higher-quality replacement filters, while commercial buyers are looking for consistent performance and reduced operational disruption. At the same time, branded aftermarket offerings and performance-oriented products are expanding visibility and choice. This blending of channels means that competitive success will depend not only on supply reliability but also on consumer communication, fitment clarity, and distribution reach.
A key commercial opportunity is to build recognizable value propositions in the replacement channel around health, comfort, and reliability, rather than competing solely on price. A key risk is channel conflict and margin erosion if premium claims are not backed by visibly differentiated performance or service experience.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat cabin air filtration as a system-level attribute rather than a low-cost replaceable part. That means investing in media architecture that can address particulate, odor, and allergen concerns while maintaining airflow and durability, and validating designs against real-world service scenarios. It also means coordinating packaging, access, and documentation so that replacement does not create avoidable risk. Companies that can demonstrate consistent performance across OEM and aftermarket use, with clear instructions and robust quality control, will be better positioned as performance expectations rise.
For investors, the most interesting signals are the shift toward premiumized media, the growing importance of regulatory-driven specification changes, and the channel dynamics that favor suppliers with both OEM credibility and aftermarket visibility. Evaluation should focus on whether a company has defensible media technology, the ability to serve multiple applications, and the operational discipline to manage serviceability and compliance risk. In a market growing at a mid-single-digit rate, differentiation and execution quality matter more than volume alone.
For procurement and fleet buyers, the strategic question is not whether to buy a better filter, but how to make filtration choices that align with operating conditions, service processes, and total cost goals. That calls for selecting products with validated performance for the relevant environment, ensuring that replacement procedures are clear and compatible with the vehicle, and avoiding low-cost options that may compromise airflow, seal integrity, or service safety. In commercial operations, standardization can reduce complexity, but it should be paired with enough performance headroom to handle variable pollution and dust exposure.
The market’s direction is becoming clearer: growth will continue, but the most valuable opportunities will belong to those who can integrate filtration performance, regulatory readiness, service safety, and channel execution into a coherent offering. For decision-makers who need detailed segmentation data, company-level positioning, and tailored guidance for specific regions or applications, the full research report provides a deeper evidence base and more granular recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dairy Packaging Market 2026: Why 4.89% CAGR and Plastic Dominance Reshape the Industry
By PW Consulting, 2026-09-21
Dairy Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global dairy packaging market has demonstrated steady expansion over the past half-decade, moving from approximately USD 18.48 billion in 2020 to an estimated USD 23.68 billion in 2025. This growth trajectory reflects a compound annual growth rate of 4.89 percent across the historical period, with the market projected to reach USD 33.17 billion by 2032. The expansion is not uniform across geographies or material categories, but rather reflects a complex interplay of regional demand patterns, material preferences, and packaging format adoption. North America and Europe continue to represent the largest revenue pools, while Asia Pacific has emerged as a highly dynamic growth region, driven by rising dairy consumption, developing cold-chain infrastructure, and shifting retail formats.
Despite the positive top-line momentum, the sector is confronting several structural challenges that are reshaping competitive dynamics. First, regulatory pressure around recycled content and packaging waste is accelerating across multiple jurisdictions, forcing manufacturers to redesign portfolios ahead of compliance deadlines. Second, input cost volatility and raw material availability are compressing margins, particularly for plastic-based solutions where resin pricing and circular feedstock access remain uneven. Third, the market is experiencing a functional divergence between traditional aseptic and ambient-stable formats versus fresh and chilled dairy packaging, each requiring distinct material performance, barrier properties, and supply chain capabilities. These overlapping pressures mean that scale alone is no longer a sufficient competitive moat; packaging suppliers must simultaneously manage sustainability compliance, line-speed compatibility, and regional demand nuances.
A further complication lies in market concentration. The top three participants account for roughly 28.5 percent of total market value, while the top five hold approximately 35.2 percent. This fragmentation suggests that while leading suppliers command meaningful share, a substantial portion of revenue is distributed across regional specialists, material providers, and niche format manufacturers. For procurement leaders and investors, this concentration profile signals both competitive optionality and the need for careful supplier evaluation, as performance differences in barrier technology, recyclability, and regional compliance readiness can materially affect total cost of ownership.
Key Demand Drivers
Technology Innovation and Barrier Performance
Material and format innovation remains one of the most consequential drivers of market evolution. Suppliers are increasingly engineering cartons, films, and rigid containers that reduce or eliminate aluminum barriers, integrate higher recycled content, and maintain aseptic or high-barrier performance for sensitive dairy products. Recent commercial deployments illustrate this direction: SIG Combibloc introduced an alu-free aseptic carton system for milk in Slovenia, combining a full-barrier design with reduced material complexity. In parallel, paper-based barrier cartons have been extended to high-speed production lines, with early deployment in Asia for soy milk applications. These developments reflect a broader industry shift toward formats that balance shelf-life requirements with recyclability and material simplification. For dairy processors, the practical implication is a widening set of packaging options that can align with sustainability targets without sacrificing operational efficiency, provided that line compatibility and sealing performance are validated early in the qualification process.
Innovation is also visible in flexible and rigid plastic solutions. High-performance butter wraps and specialized film structures have expanded the functional envelope for dairy subsegments that require moisture, oxygen, and aroma barriers under chilled or ambient conditions. At the resin level, polymer suppliers are increasingly emphasizing recycled and bio-attributed grades for dairy cups, trays, and films, responding to both regulatory mandates and brand-owner commitments. The strategic takeaway is that packaging performance is no longer defined solely by barrier integrity or fill-speed compatibility; it now encompasses material provenance, end-of-life pathways, and compliance with emerging recycled-content thresholds.
Policy and Regulatory Environment
Regulatory momentum is a defining driver of packaging decisions in the dairy sector. In the United States, Washington State has established a stepped recycled-content requirement for plastic dairy milk containers, beginning at 15 percent post-consumer recycled content in 2028, rising to 25 percent by 2031, and reaching 50 percent by 2036. California's SB 54, which entered into force in May 2026, imposes minimum recycled content requirements on single-use dairy packaging and reinforces producer responsibility obligations. At the same time, seven U.S. states have implemented Extended Producer Responsibility programs that include specific mandates tied to dairy containers, adding operational complexity for multi-state processors and packagers.
In Europe, the Packaging and Packaging Waste Regulation entered into force in February 2025, with general application beginning in August 2026, and sets minimum recycled content targets for plastic packaging from 2030 onward. These regulatory layers are not isolated administrative requirements; they are reshaping sourcing strategies, material selection, and supplier qualification criteria. Dairy brands operating across regions must now navigate a patchwork of deadlines, recycled-content thresholds, and reporting obligations. For packaging suppliers, the opportunity lies in offering materials and formats that are pre-aligned with these requirements, reducing the compliance burden for dairy customers while creating defensible differentiation in regulated markets.
Consumer and Buyer Behavior
Demand-side changes are reinforcing the sustainability and functionality agenda. Retailers and foodservice operators are increasingly specifying packaging that supports recycled-content claims, reduces material complexity, and aligns with broader corporate sustainability commitments. Consumers, in turn, are responding favorably to packaging that communicates responsible sourcing and recyclability, particularly in categories such as fluid milk, yogurt, and plant-based dairy alternatives where brand positioning often hinges on health and environmental attributes. This behavior does not automatically translate into premium pricing, but it does influence shelf allocation, private-label specifications, and tender criteria, especially among large retail chains and regional distributors.
Worldwide Dairy Logistics Market
At the same time, dairy consumption patterns are diversifying. Fresh and chilled categories continue to grow in many markets, while ambient and shelf-stable formats remain important for distribution efficiency and export reach. Plant-based dairy alternatives are also expanding the addressable market for cartons, pouches, and bottles designed for liquid foods with varying viscosity and acidity profiles. The combined effect is a more segmented demand environment in which packaging suppliers must demonstrate flexibility across formats, line speeds, and application requirements rather than relying on a single standardized solution.
Supply Chain and Cost Structure
Cost structure and supply chain resilience are increasingly central to packaging strategy. Resin availability, recycled feedstock supply, and energy inputs all influence the economics of dairy packaging, and regional disparities in circular infrastructure can create uneven access to compliant materials. Suppliers with integrated film extrusion, resin production, or regional conversion capacity are better positioned to manage these variables, but even they must contend with line-speed requirements, changeover efficiency, and qualification timelines when introducing new materials or barrier designs. For dairy processors, the cost conversation is shifting from unit price toward total cost of ownership, including compliance risk, line performance, spoilage reduction, and downstream recyclability. This reframing favors suppliers that can provide documented material provenance, consistent quality across batches, and clear roadmaps for meeting future recycled-content thresholds.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global packaging systems providers, flexible and rigid material specialists, and resin suppliers that enable downstream packaging performance. Tetra Pak and SIG Combibloc remain prominent in aseptic carton and pouch systems for liquid dairy, with positioning that emphasizes barrier performance, line compatibility, and increasingly, material reduction and recycled-content roadmaps. Elopak focuses on gable-top cartons for dairy, juice, and plant-based beverages, with recent expansion into U.S. production capacity for sustainable carton formats. Amcor and Berry Global bring broad flexible-film and rigid-plastic capabilities, respectively, with product portfolios that span dairy films, bottles, tubs, and closures. Huhtamaki contributes paperboard cartons and plastic trays for dairy applications, while Winpak and ProAmpac emphasize flexible pouches, films, and high-performance wraps for fluid dairy and cheese products. Alfipa specializes in PET bottles and closures for dairy and yogurt, and INEOS Styrolution supplies recycled and bio-attributed polystyrene for dairy cups and trays, including recent sour cream cup launches with recycled content for German retail.
The strategic differentiation among these players is less about presence in every category and more about depth in specific performance niches. Leading carton and aseptic system providers are investing in aluminum-free and paper-based barrier options that can be deployed on high-speed lines, reducing material complexity while preserving shelf-life performance. Flexible packaging specialists are expanding high-barrier film structures and butter wraps that address moisture, oxygen, and aroma challenges with narrower material footprints. Resin suppliers are positioning recycled and bio-attributed grades as enablers for compliance and brand claims, effectively embedding themselves earlier in the value chain. This pattern suggests a market in which value is increasingly captured by suppliers that can combine technical reliability, documented sustainability attributes, and regional compliance readiness.
Luxury Packaging Market
Market evolution is likely to feature both consolidation and differentiation. Larger multi-material suppliers may pursue bolt-on capabilities that broaden their format coverage or strengthen regional production footprints, while regional specialists can thrive by serving localized compliance requirements, specific dairy subsegments, or niche format needs. New entrants and niche players may find opportunity in recycled-content resins, mono-material designs, and format simplification, particularly where regulatory deadlines create near-term demand for compliant alternatives. For procurement teams, the practical implication is to evaluate suppliers not only on current pricing and capacity, but also on their ability to meet upcoming recycled-content mandates, support line-speed requirements, and provide transparent material documentation across regions.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the mainstreaming of reduced-material and aluminum-free barrier formats for dairy packaging. As high-speed line compatibility improves and commercial deployments expand beyond early adopters, these formats can become viable options for a broader set of fluid milk and liquid dairy applications. The commercial opportunity lies in offering processors a path to simplify material streams, improve recyclability perception, and align with retailer and regulatory expectations without sacrificing operational performance. Suppliers that can demonstrate reliable sealing, barrier durability, and compatibility with existing or upgraded filling lines will be well positioned to capture demand during this transition.
A second trend is the accelerating alignment of packaging portfolios with recycled-content mandates and Extended Producer Responsibility obligations. As deadlines approach in the United States and Europe, dairy brands and packagers will increasingly prioritize materials with documented recycled content, traceable sourcing, and clear compliance roadmaps. This creates opportunities for resin producers, film extruders, and converters that can supply consistent recycled or bio-attributed grades at scale, as well as for packaging systems providers that can integrate these materials into certified formats. The related risk is supply concentration: recycled feedstocks and compliant resins may remain constrained in certain regions, leading to price volatility or qualification bottlenecks if demand surges ahead of infrastructure build-out.
A third trend is the continued segmentation of dairy packaging by consumption channel and product type. Fresh and chilled categories will place greater emphasis on cold-chain compatibility, moisture resistance, and convenience features, while ambient and export-oriented products will continue to value aseptic stability, light protection, and extended shelf life. Plant-based dairy and hybrid beverages will further expand demand for cartons, pouches, and bottles designed for varied rheology and acidity. The commercial opportunity here is format specialization: suppliers that can tailor barrier properties, opening systems, and fill-speed performance to specific subcategories can command stronger positioning than those offering generic solutions. The uncertainty is that channel growth may diverge by region, and regulatory or retail specifications may shift faster than packaging qualification cycles, requiring suppliers and processors to maintain agile development pipelines.
Underlying these trends is the persistent challenge of balancing performance, cost, and compliance. Innovations that reduce material complexity or increase recycled content must still meet barrier, hygiene, and line-speed requirements. Regulatory progress may accelerate demand for compliant materials, but uneven regional infrastructure can create short-term constraints. Consumer and retailer preferences may favor sustainability claims, yet price sensitivity in private-label and commodity dairy segments can limit willingness to pay. Navigating this environment will require disciplined portfolio planning, early supplier engagement, and a clear understanding of which packaging attributes truly influence commercial outcomes in each market.
Strategic Recommendations for Decision Makers
For dairy manufacturers and brand owners, the priority is to align packaging strategy with near-term regulatory deadlines and long-term material goals without disrupting line performance. This means qualifying reduced-barrier, aluminum-free, and higher-recycled-content options early, validating compatibility with existing filling lines, and mapping compliance requirements across the regions where products are sold. Procurement teams should request documented material provenance, recycled-content consistency, and clear roadmaps for meeting future thresholds, treating these attributes as part of total cost of ownership rather than optional enhancements. Where possible, companies should prioritize suppliers that can support multiple formats or provide transitional solutions that bridge current performance needs and future compliance targets.
For packaging manufacturers and material suppliers, the strategic opportunity lies in building defensible differentiation through technical reliability and compliance readiness. Investing in high-speed line compatibility for sustainable formats, expanding recycled and bio-attributed material options, and strengthening regional production or qualification capabilities can create meaningful advantage in a fragmented market. Suppliers should also consider how to communicate performance and compliance clearly to dairy customers, since documentation, repeatability, and transition support are increasingly decisive in tender evaluations. In a market where the top five participants account for just over a third of total value, focused strength in a specific format, material, or region can be a durable positioning strategy.
For investors and strategic planners, the market presents a profile of steady growth with selective pockets of faster value creation. Revenue is expanding at a mid-single-digit pace, but the most attractive opportunities are concentrated in sustainable barrier innovation, recycled-content supply chains, and format specialization aligned with regulatory and retail demand. Due diligence should therefore focus on a supplier's ability to meet upcoming mandates, its exposure to regional compliance risk, its line-speed and barrier performance track record, and its access to compliant feedstocks. Portfolio exposure should be evaluated not only by current revenue share, but by the company's positioning relative to the regulatory and technology shifts that will shape purchase decisions through 2032. For decision makers seeking deeper segmentation data, regional breakdowns, and tailored scenario planning, the full PW Consulting dairy packaging research report provides the detailed granularity needed to translate these trends into precise commercial actions.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nanodiamond Powder Market CAGR 7.62%: Beyond Growth to Strategic Shifts
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Detonation Synthesis Nanodiamond Powder Market
Market Current State and Core Challenges
The detonation synthesis nanodiamond powder market has transitioned from a niche advanced materials segment into a commercially significant industry, underpinned by a consistent revenue trajectory across the historical period through 2025 and a projected expansion phase extending to 2032. The market has demonstrated compound annual growth that reflects steady industrial adoption, with valuation milestones crossing into higher hundred-million-dollar territory in recent years and maintaining momentum across the forecast window. This trajectory signals maturation rather than speculative hype, anchored by recurring demand from precision manufacturing, surface engineering, and industrial lubricant applications.
Commercial scaling, however, encounters structural friction. First, production consistency at the nanoscale remains a persistent bottleneck. Detonation synthesis inherently yields particles with variable size distributions, surface functionalization profiles, and residual impurity levels. Batch-to-batch reproducibility directly influences downstream performance in high-tolerance applications, forcing manufacturers to invest heavily in post-synthesis classification, purification, and surface engineering. Second, regulatory and compliance frameworks are tightening across key end markets. Evolving safety, environmental, and quality standards for nanomaterials are reshaping procurement requirements and documentation expectations. In parallel, stricter characterization mandates in European markets have raised operational complexity for suppliers seeking to maintain access to regulated sectors. Third, geopolitical and security dynamics are constraining the transnational movement of explosive-related materials essential to detonation-based synthesis. This supply-side friction forces regionalization of certain production steps, increases logistics overhead, and compels manufacturers to redesign sourcing and inventory strategies around fragmented regulatory boundaries.
PW Consulting
Together, these forces define the market's current inflection point: demand is broadening, but the path to reliable, compliant, and cost-efficient scaling is narrowing into a more disciplined operating environment where technical quality, documentation rigor, and supply resilience carry as much commercial weight as base material pricing.
CVD Diamond Market
Key Drivers of Market Change
Technological Innovation and Material Engineering
Advancements in surface functionalization, particle classification, and dispersion stabilization are reshaping the commercial value of detonation synthesis nanodiamond powder. As end users demand repeatable performance in polishing slurries, lubricant formulations, and composite matrices, suppliers are moving beyond commodity-grade powders toward engineered variants with tailored surface chemistry and controlled agglomeration behavior. This shift increases the technical barriers to entry but also expands margin potential for producers capable of delivering application-specific material profiles. The emphasis on functional consistency is particularly relevant where nanodiamonds interact with sensitive substrates, advanced coatings, or high-performance mechanical interfaces, making precision and reproducibility key commercial differentiators rather than optional enhancements.
Policy and Regulatory Environment
Regulatory consolidation is simultaneously creating trust and adding operational cost. The establishment of clearer safety, environmental, and quality expectations for nanodiamond materials is fostering broader industrial integration, especially in biomedical and aerospace-adjacent applications where material integrity and traceability are non-negotiable. At the same time, the cost of compliance is rising in certain jurisdictions, particularly where nanomaterial characterization and safety documentation requirements have become more demanding. Manufacturers that proactively align production, testing, and documentation practices with emerging expectations are better positioned to secure long-term supply agreements, while those lagging behind face growing friction in regulated procurement cycles. Potential future restrictions on production processes or workplace exposure limits could further reshape operating economics, making early regulatory readiness a strategic asset rather than a reactive expense.
Alongside domestic regulatory shifts, transnational trade constraints are altering sourcing logic. Security-related controls on explosive-related materials used in detonation synthesis increasingly complicate cross-border movement, forcing companies to evaluate regional production footprints, inventory buffering, and localized processing options. This dynamic favors organizations with flexible supply architectures and discourages over-reliance on single-geography synthesis routes.
Demand-Side Shifts in Industrial and High-Performance Applications
Demand is increasingly driven by performance optimization rather than cost substitution alone. In precision polishing compositions, the push for finer surface finishes, reduced tool wear, and consistent removal rates is reinforcing interest in nanoscale diamond additives that deliver predictable cutting and abrasion behavior. In lubricant and tribological applications, buyers are evaluating nanodiamond additives for potential improvements in friction management, wear reduction, and thermal stability under demanding operating conditions. Composite material developers are also exploring nanodiamond incorporation as a route to enhance mechanical, thermal, or functional properties, though adoption often depends on dispersion quality and compatibility with matrix systems. Across these demand segments, the purchasing criterion is shifting from bulk availability toward verified performance, lot consistency, and technical support capability.
Supply Chain and Cost Structure Evolution
The cost structure of detonation synthesis nanodiamond powder is increasingly shaped by energy intensity, purification requirements, and compliance overhead rather than raw input pricing alone. Energy consumption during synthesis and downstream processing, combined with the need for classification and surface treatment, positions manufacturing as a process-heavy activity where margin protection depends on throughput efficiency and yield control. Supply chain resilience has also become a cost and continuity factor. With certain inputs and intermediate materials subject to trade and security constraints, companies are investing in buffer inventories, multi-source procurement, and regional processing networks to reduce disruption risk. This transition favors suppliers that can demonstrate stable lead times, controlled quality, and transparent documentation, especially for customers operating under strict procurement or qualification timelines.
Competitive Landscape and Leading Strategies
The market remains relatively fragmented at the top, with a limited group of established players holding meaningful but not dominant share. This structure creates room for differentiation through product quality, application engineering, regulatory readiness, and customer intimacy rather than scale alone. Companies that treat nanodiamond powder as an engineered material solution, rather than a standardized commodity, tend to build more durable commercial relationships and defend pricing more effectively in mature application categories.
Adámas Nanotechnologies, based in Virginia, USA, has positioned itself around application-tailored offerings that emphasize controlled particle characteristics and customer-specific material support. Its commercial relevance rests on the ability to translate synthesis output into reproducible material formats suited to precision use cases, where buyers value technical consistency and collaborative problem-solving. Carbodeon Ltd. Oy, operating from Finland, has built recognition around specialized functional materials and surface-engineered nanodiamond products, with a strong orientation toward high-performance industrial and technology-facing applications. Its differentiation often centers on material functionality, purity control, and the ability to meet demanding specification thresholds.
Synthetic Diamond Grit Market
Ray Techniques Ltd., based in Israel, has pursued a focused approach tied to advanced nanodiamond solutions and specialized production know-how. In a market where end-user qualification cycles can be lengthy, companies with clear process expertise and the ability to document material behavior gain an advantage in sectors where performance proof carries substantial weight. PlasmaChem GmbH, from Germany, contributes to the competitive field through a materials science orientation that appeals to buyers seeking reliable functional powders and well-defined product attributes. Its positioning reflects a broader European emphasis on documentation, specification discipline, and application readiness. Advanced Abrasives Corporation, in the USA, represents the industrial-grade side of the landscape, where commercial strength is linked to integration with abrasive and surface-treatment applications, supply reliability, and knowledge of downstream processing requirements.
Strategically, leading players generally differentiate along three axes: material consistency and specification control, application-specific engineering and technical support, and compliance or documentation readiness for regulated customers. The most resilient firms combine these elements rather than relying on a single advantage. As a result, competition is less about absolute price leadership and more about total value delivery across quality, availability, and qualification support.
The market structure is likely to evolve through selective consolidation and functional specialization rather than rapid concentration. Larger industrial material suppliers may pursue acquisitions or partnerships to secure nanodiamond capabilities, while smaller producers may compete by focusing on niche grades, proprietary surface treatments, or regional supply advantages. New entrants face meaningful hurdles in reproducibility, scale-up, and qualification, but can still succeed by targeting underserved application needs or offering distinct material formats. For incumbents, the strategic imperative is to protect reputation for consistency while expanding into higher-value application configurations that reduce exposure to commodity-style price competition.
Future Outlook: Trends and Commercial Implications
From Generic Powders to Application-Engineered Grades
Over the next three to five years, the market is likely to move further toward differentiated product architectures. Purchasers in polishing, lubrication, and composite applications are expected to demand more clearly defined particle characteristics, surface states, and dispersion behavior. Suppliers that standardize quality while offering configurable grades will be better positioned to capture premium demand. The commercial opportunity lies in building modular product platforms that can address multiple end-use requirements without sacrificing reproducibility, enabling customers to standardize on a smaller set of trusted materials while still meeting application-specific targets.
Regulatory Readiness as a Competitive Moat
Compliance and documentation capabilities will increasingly separate suppliers that win regulated procurement cycles from those that face repeated qualification friction. As expectations around safety, characterization, and traceability become more entrenched, manufacturers that invest early in standardized testing, record-keeping, and customer-facing technical documentation will reduce time-to-qualification and lower the risk of procurement disruption. This trend favors organized, process-disciplined producers and creates an opening for buyers to consolidate sourcing around suppliers with demonstrated regulatory maturity. The principal risk is that compliance requirements may continue to escalate unevenly across regions, forcing companies to maintain parallel documentation or operational practices to preserve market access.
Regionalization and Supply-Architecture Adaptation
Trade and security constraints surrounding explosive-related inputs are likely to reinforce regionalization of certain synthesis and processing activities. Over the forecast period, companies may increasingly design supply networks that reduce dependence on cross-border movement of sensitive materials, while still preserving cost efficiency and quality control. This shift creates opportunities for localized processing, regional inventory hubs, and partnerships that distribute risk across jurisdictions. It also introduces uncertainty: companies that fail to adapt sourcing models may face longer lead times, higher logistics costs, or intermittent access constraints. Buyers, in turn, may place greater weight on supply continuity assurances when evaluating vendors, especially for mission-critical or hard-to-qualify applications.
Strategic Recommendations for Decision-Makers
For Manufacturers and Material Suppliers
Prioritize reproducible product quality and surface engineering capability as core commercial assets. Invest in classification, purification, and functionalization processes that allow a single platform to serve multiple application segments without compromising consistency. Align internal documentation, characterization, and safety practices with emerging regulatory expectations before they become binding procurement requirements, since early readiness shortens qualification cycles and reduces market-access risk. Where possible, build supply flexibility around sensitive inputs and intermediate materials to mitigate trade-related disruption and protect continuity for high-value customers.
For Investors and Corporate Development Teams
Evaluate opportunities based on technical differentiation and application attachment rather than volume assumptions alone. Companies with defensible surface-engineering know-how, clear quality control systems, and active engagement in regulated or performance-critical end markets are more likely to sustain pricing power and durable customer relationships. Pay close attention to supply-chain exposure, regional production assumptions, and compliance readiness, as these factors increasingly influence margin stability and scalability. In consolidation scenarios, the most attractive targets are typically those that combine material expertise with operational discipline and the ability to support demanding qualification processes.
For Procurement and Sourcing Leaders
Shift sourcing criteria toward verified lot consistency, technical support capacity, and qualification readiness, especially when nanodiamond powders are used in precision polishing, lubricant enhancement, or composite development. Favoring suppliers with transparent characterization practices and documented quality systems can reduce downstream variability and shorten internal approval timelines. Where supply continuity is critical, diversify across vendors with different production footprints or regional setups, and confirm that documentation and compliance practices align with procurement and regulatory requirements. Treat material specification discussions as strategic conversations rather than transactional price negotiations, since long-term performance reliability often determines total cost more than unit price alone.
As the market continues to mature, the commercial winners will be those that convert technical consistency, regulatory readiness, and supply resilience into dependable customer value. For decision-makers seeking deeper segment-level insight, demand scenarios, competitive benchmarks, and tailored sourcing or investment implications, an expanded analysis is available through the full PW Consulting research report, where detailed data and customized guidance can support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Detonation Synthesis Nanodiamond Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oligosaccharide Market 2026: 6.5% CAGR Trajectory and Strategic Shifts Across Key Segments
By PW Consulting, 2026-09-21
Oligosaccharide Market: Strategic Trends and Commercial Opportunities Through 2032
The global oligosaccharide market has entered a phase of structural expansion, transforming from a niche ingredient category into a mainstream strategic asset for food, nutrition, and pharmaceutical innovators. Valued at approximately USD 170.0 million in 2025, the market is projected to reach USD 261.0 million by 2032, advancing at a compound annual growth rate of 6.5 percent across the forecast horizon. This trajectory reflects more than incremental demand; it signals a fundamental recalibration of how manufacturers, regulators, and end consumers view complex carbohydrates as functional, health-modulating ingredients. For executives navigating long-cycle product portfolios, the window to shape positioning, secure supply resilience, and align with regulatory momentum is narrowing. Understanding where the market is headed, and why, separates reactive pricing plays from durable competitive advantage.
Market Snapshot and Structural Realities
The data points to a market that has consistently added value over the past five years, with revenue climbing from USD 122.0 million in 2020 to the current baseline of USD 170.0 million. Growth is not accelerating chaotically; it is compounding steadily, which suggests that buyer preferences, formulation science, and production economics are converging rather than shifting unpredictably. The market remains moderately fragmented in terms of concentration, with the top three players accounting for roughly 34.2 percent of revenue and the top five reaching 45.8 percent. This distribution matters because it indicates room for specialized entrants and regional champions to compete on formulation expertise, proprietary processing, or localized regulatory navigation, while the largest players leverage scale, integrated supply chains, and broad application portfolios.
The current environment is not characterized by unconstrained expansion. Instead, it is defined by several inflection points that will determine which organizations capture disproportionate value over the next three to five years. First, osmotic tolerance between health claims, formulation functionality, and cost efficiency remains a persistent tension for product developers. Oligosaccharides are no longer evaluated solely on prebiotic efficacy; they must also deliver taste, texture, stability, and dose usability across diverse matrices. Second, regulatory alignment is accelerating in key infant nutrition and functional food categories, effectively converting compliance requirements into competitive moats. Companies that anticipate claim substantiation and ingredient approval timelines will gain shelf and contract advantages, while laggards risk reformulation delays and market entry gaps. Third, feedstock and processing economics are becoming more sensitive to macro variables, making cost-to-serve and process flexibility strategic differentiators rather than back-office concerns. These dynamics do not weaken the market outlook; they clarify where value will be created and defended.
Core Drivers Reshaping the Competitive Equation
Market movement over the forecast period is being pulled by a small number of structural forces that interact across technology, regulation, demand behavior, and supply chain economics. Recognizing how these forces compound is essential for portfolio planning and investment coordination.
Technological innovation and process maturity are reshaping what is commercially viable. Advanced enzymatic synthesis, precision fermentation, and more selective purification methods are reducing the complexity gap between bulk carbohydrate production and high-purity functional ingredients. The practical effect is broader applicability across infant formula, dietary supplements, and pharmaceutical-adjacent formulations, where consistency, purity, and repeatability are non-negotiable. Public disclosures from late 2025 and early 2026 reinforce this direction: a major 2'-fucosyllactose supply initiative is moving into global distribution following collaboration between leading ingredient and chemical companies, while a dedicated short-chain fructo-oligosaccharide producer simultaneously expanded from three to four production lines and completed the full operation of a fourth facility equipped with automated quality control and advanced enzymatic synthesis. These moves indicate that leaders are not simply adding capacity; they are upgrading process capability to meet stricter specification requirements and higher batch-to-batch reliability expectations.
Xylooligosaccharides (XOS) Market
Regulatory and policy dynamics are converting scientific consensus into commercial clarity. In infant nutrition, regulatory frameworks are increasingly permitting oligosaccharide blends that better approximate the functional profile of human milk, creating formulation pathways that were more restrictive in prior cycles. European food safety authorities continue to maintain verification and health claim processes for key oligosaccharide categories in infant nutrition and functional foods, which raises the bar for documentation but also stabilizes demand for ingredients with established dossiers. Meanwhile, major Asian markets have updated infant-formula standards to align with international reference frameworks, coinciding with persistently large birth cohorts that sustain baseline demand for nutritionally complete early-life products. The strategic implication is that regulatory harmonization, when paired with clear claim routes, lowers perceived risk for manufacturers and accelerates adoption in categories that previously required lengthy internal validation.
Demand-side evolution is expanding the addressable use cases beyond traditional gut health narratives. Consumers and institutional buyers are increasingly treating oligosaccharides as multifunctional ingredients that support formulation goals across digestion, metabolic comfort, and product differentiation. This broadening mindset is especially visible in dietary supplements and food and beverage applications, where brands seek ingredients that can carry both functional positioning and label clarity. At the same time, procurement teams are placing greater weight on ingredient provenance, processing transparency, and supply consistency. The result is a buyer environment that rewards credible science, reproducible specification performance, and the ability to integrate into diverse production lines without compromising product stability.
Supply chain and cost structure shifts are introducing both pressure and opportunity. Feedstock pricing remains tied to broader commodity markets, with sucrose-linked inputs affecting enzymatic synthesis economics in regions where industrial energy costs are structurally elevated. This does not make cost management impossible, but it does make it a strategic variable. Organizations that design for feedstock flexibility, regional sourcing redundancy, and energy-efficient processing are better positioned to protect margins when input volatility spikes. Conversely, manufacturers that depend on narrow input channels or inflexible process designs face greater exposure to cost transmission that cannot be fully absorbed by downstream pricing.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of global scale players, specialized ingredient manufacturers, and regional producers with distinct processing strengths. No single archetype dominates every application, and the market’s moderate concentration allows multiple winning strategies to coexist.
Fructooligosaccharide (FOS) Market
Large integrated companies are leveraged around application breadth, process know-how, and global distribution. In infant nutrition and specialized formulations, firms with fermentation and enzymatic capabilities are competing on purity, consistency, and the ability to supply human milk oligosaccharide-related ingredients such as 2'-fucosyllactose at commercial scale. Their advantage lies in the combination of scientific credibility, production repeatability, and the operational capacity to support stringent customer requirements across multiple geographies. These players also benefit from the ability to cross-link ingredient development with broader nutrition portfolios, which can shorten time-to-market for blended or multi-functional offerings.
Specialized manufacturers are competing on product range, application specificity, and responsiveness. Several firms focus on fructo-oligosaccharides, galacto-oligosaccharides, isomalto-oligosaccharides, and xylo-oligosaccharides for food, infant formula, and prebiotic uses, with differentiation rooted in chain-length control, format flexibility, and the ability to supply both powder and syrup forms. This group often wins by aligning closely with formulators’ practical needs, including solubility profiles, sweetness impact, stability under processing conditions, and dosage convenience. Regional players with strong local regulatory familiarity and efficient production layouts can also outperform on total delivered cost, particularly where logistics and import friction would otherwise erode competitiveness.
PW Consulting
Recent operational developments point to a landscape that is expanding in capability while tightening in quality expectations. Capacity additions are being paired with process modernization rather than treated as simple volume plays. The completion of dedicated production lines, implementation of automated quality control, and investment in enzymatic synthesis infrastructure suggest that the next phase of competition will center on reliability, specification control, and the ability to fulfill increasingly specific formulation briefs. At the same time, large dairy-linked and nutrition-oriented operators are expanding adjacent capacities that support broader functional ingredient portfolios. This signals an industry trend toward more integrated ingredient ecosystems, where oligosaccharides are not isolated commodities but components of broader formulation strategies spanning protein, lipid, and carbohydrate functionalities.
The market structure is likely to evolve through selective consolidation and continued differentiation rather than uniform concentration. Larger players may pursue strategic combinations that strengthen geographic coverage, application portfolios, or process technology. Smaller and mid-sized firms will likely continue to defend niches through formulation expertise, specialized molecule profiles, and fast response to customer formulation changes. New entrants will find opportunity primarily where they bring a distinct technical angle, such as novel purification routes, alternative feedstock pathways, or targeted health-claim positioning supported by robust documentation. The enduring competitive advantage will belong to organizations that can combine credible science, scalable and controllable production, and the commercial agility to serve multiple application categories without diluting quality.
Forward Outlook: Trends and Commercial Implications
The next three to five years will likely be shaped by three interlocking trends that translate directly into commercial opportunities and execution risks.
Precision and specification escalation will become the norm rather than the exception. As regulatory frameworks mature and application requirements become more demanding, buyers will increasingly differentiate between generic functional carbohydrate supply and ingredients that meet tightly controlled purity, chain-length, and batch-consistency parameters. The commercial opportunity here is clear: suppliers that can deliver repeatable specifications, transparent documentation, and application-specific formats will be able to command stronger commercial terms and longer-term supply relationships. The risk is equally clear. Organizations that compete primarily on price without corresponding quality and reliability infrastructure will face margin compression and reduced negotiating leverage as customers rationalize supplier bases.
Category convergence will expand the value pool across food, supplements, and infant nutrition. Regulatory alignment and formulation science are making it easier to position oligosaccharides across adjacent use cases without treating each category as entirely separate. This convergence creates opportunities for integrated product strategies, co-development with downstream brands, and portfolio architectures that capture demand across multiple consumption occasions. For manufacturers, the strategic task is to design ingredient platforms that can flex across applications while maintaining the documentation and consistency credentials required in higher-scrutiny categories. For investors, the opportunity lies in identifying operators whose process technology and application roadmap can serve more than one demand channel without sacrificing regulatory credibility.
Supply resilience and input-cost agility will move from operational concerns to strategic differentiators. As feedstock and energy cost sensitivity persists, the ability to source flexibly, manage regional cost structures, and engineer processing efficiency will shape both competitiveness and customer confidence. Companies that can demonstrate supply redundancy, predictable quality under variable input conditions, and transparent cost governance will be better positioned to secure long-term agreements. The uncertainty to monitor includes potential volatility in raw material markets, energy cost fluctuations in key production regions, and changes in trade or import dynamics that can alter delivered economics. Planning that assumes a single stable cost trajectory is likely to underprepare organizations for the range of plausible scenarios.
Actionable Priorities for Decision Makers
The commercial path forward depends on the role an organization plays in the value chain, but several priorities apply broadly.
- For ingredient and product manufacturers: invest in specification control and process modernization before expanding volume alone. The most durable position will come from repeatable purity, format flexibility, and documentation readiness that supports both food and supplement use cases. Align product development with regulatory and claim trajectories in target geographies rather than treating compliance as a late-stage checkpoint. Build feedstock and energy flexibility into sourcing strategies so that cost pressures do not force reactive discounting or inconsistent supply.
- For investors and corporate development teams: evaluate opportunities based on technological defensibility, application breadth, and the ability to meet rising quality expectations. Volume growth is attractive, but the more valuable question is whether a platform can sustain premium positioning as specifications tighten and buyer consolidation accelerates. Pay attention to companies that are upgrading enzymatic synthesis, automated quality control, and multi-format capability, because these capabilities tend to translate into longer-term commercial resilience rather than temporary capacity advantages.
- For procurement and R&D leaders: treat oligosaccharide sourcing as a multi-factor decision involving functionality, stability, documentation, and supply reliability, not just price per unit. Prioritize suppliers that can support application-specific requirements and provide clear evidence trails for regulatory and claim contexts. Diversify where feasible to reduce exposure to single-source risk, especially for formulations that depend on consistent performance across geographies or production lines.
The strategic stakes in this market are rising because the ingredient is becoming more central to product differentiation, regulatory positioning, and consumer-facing health narratives. That makes timely, granular intelligence valuable for anyone deciding where to allocate capital, how to structure supply relationships, or which formulation roadmaps to prioritize. Detailed segment-level demand splits, regional absorption patterns, company-specific capability mapping, and scenario-based volume and pricing assumptions can materially improve the quality of those decisions. For teams that need a sharper operational lens, the full PW Consulting research report provides the deeper segmentation, competitive benchmarking, and forward modeling required to convert these strategic signals into concrete plans.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
WiFi Thermostats Market: Decoding the 21.07% CAGR and $17.35M Growth Roadmap
By PW Consulting, 2026-09-21
The WiFi Thermostats Market: Strategic Trends and Commercial Opportunities Through 2032
The global WiFi thermostats market has entered a phase of accelerated expansion, transforming from a niche smart home accessory into a core component of energy management infrastructure. Driven by escalating energy costs, expanded utility rebate programs, and rapid advances in sensor and connectivity technologies, the sector is reshaping how residential, commercial, and industrial facilities approach heating and cooling control. Understanding the underlying dynamics of this market requires moving beyond headline figures to examine the structural shifts that will define competitive positioning, product roadmaps, and investment allocation over the next several years.
Thermostats Market
Market Landscape and Core Challenges
Scale, Trajectory, and Concentration Dynamics
From a valuation of approximately $1.75 million in 2020, the WiFi thermostats market has climbed steadily to reach $4.55 million in 2025, with forward projections indicating sustained momentum through the end of the decade. The forecast period spanning 2026 to 2032 anticipates a compound annual growth rate of 21.07 percent, reflecting robust adoption curves across multiple end-use segments and geographic regions. Revenue is expected to reach $5.6 million in 2026, escalate to $8.12 million by 2028, and surpass $12 million by 2030, ultimately reaching $17.35 million by 2032. This trajectory underscores the market's transition from incremental consumer adoption to broader infrastructure integration, where smart climate control becomes a baseline expectation rather than a premium differentiator.
Market concentration tells a nuanced story. The top three players collectively account for roughly 45 percent of total revenue, while the top five expand that share to approximately 52 percent. This moderate concentration suggests a landscape that remains accessible to well-positioned challengers, yet increasingly rewards scale advantages in distribution, brand recognition, and platform ecosystem integration. Companies that can harmonize hardware performance, software interoperability, and retail or channel partnerships are capturing disproportionate share, while smaller players face mounting pressure to justify differentiation in a category where core functionality is becoming commoditized.
Key Challenges and Inflection Points
Three structural challenges define the current market environment and will determine which participants thrive over the forecast horizon.
Interoperability and protocol fragmentation remain persistent friction points. Although industry alliances have made meaningful progress toward unified standards, the reality on the ground is a patchwork of proprietary ecosystems, varying degrees of open API support, and inconsistent implementations across HVAC manufacturers. For end users, this creates purchase hesitation and post-installation regret when devices fail to communicate seamlessly with existing smart home or building management platforms. For manufacturers, it necessitates continuous engineering investment to maintain compatibility across an expanding field of third-party integrations, raising development costs and slowing time-to-market for feature upgrades.
Regulatory compliance is reshaping product design and market access. Jurisdictions with aggressive energy efficiency mandates are introducing certification requirements that directly affect which models can be sold, installed, and incentivized. In certain regions, occupant-controlled smart thermostats must meet specific energy savings performance thresholds to qualify for rebate eligibility or even market entry. These requirements compress the margin for low-cost, minimally featured products and push manufacturers toward designs that embed advanced scheduling algorithms, occupancy detection, and usage analytics. Companies that treat compliance as a checkbox exercise risk losing eligibility for utility programs that serve as critical demand catalysts.
Margin compression and supply chain complexity create a third pressure point. The segment below the $150 price threshold remains highly competitive, with retailers and online marketplaces driving down average selling prices through bundling, promotional cycles, and private-label alternatives. Meanwhile, the tier above $150 commands a larger revenue share but demands higher engineering investment, more sophisticated sensor arrays, and stronger software support. Manufacturers must navigate the tension between volume-driven growth and value-driven profitability, all while managing component availability, firmware update lifecycles, and the increasing expectation for continuous post-sale software improvements.
Key Drivers of Market Evolution
Technological Innovation and Sensor Integration
The pace of hardware and software innovation is a primary catalyst for market expansion. Modern WiFi thermostats increasingly incorporate radar-based occupancy detection, advanced air quality monitoring, and onboard diagnostics that provide real-time feedback on HVAC system health. These capabilities transform the device from a simple temperature regulator into an energy intelligence hub, enabling more granular scheduling, proactive maintenance alerts, and adaptive comfort profiles. The integration of widely adopted interoperability frameworks has further reduced barriers to cross-platform compatibility, allowing thermostats to function as coordinated nodes within broader home or building automation networks rather than isolated appliances.
Smart Thermostats Market
Recent product introductions illustrate how manufacturers are translating these technical capabilities into market-facing differentiation. In early 2025, a major incumbent unveiled a new smart thermostat model at a leading consumer technology exhibition, emphasizing interoperability certification and energy efficiency validation, with retail availability scheduled for the spring season. Later in the year, the same company expanded its premium lineup with a high-resolution touchscreen model that introduced live doorbell video streaming, indoor air quality monitoring, and integrated HVAC diagnostics, positioning the device at the upper end of the price spectrum. By early 2026, that premium model had received recognition as the leading smart heating and cooling product in its category, signaling strong market receptivity to feature-rich, multi-function devices. These moves reflect a broader industry pattern: manufacturers are using innovation cycles not merely to update form factors, but to deepen the value proposition around energy management, system health, and ecosystem integration.
Policy and Regulatory Environment
Government efficiency mandates and utility incentive programs are reshaping demand patterns with remarkable speed. In California, occupant-controlled smart thermostats are required to meet specific certification standards tied to energy savings compliance, creating a clear regulatory baseline that filters out non-compliant products and channels demand toward models that demonstrably reduce heating and cooling waste. Beyond this jurisdiction-specific mandate, a broader network of utility and state-level programs has emerged, offering financial incentives that directly lower the effective purchase price for qualified devices.
Multiple programs now provide rebates or cash-back incentives of up to $100 for ENERGY STAR-certified smart thermostats, with eligibility tied to certification status, installation timing, and sometimes mandatory WiFi registration after deployment. Some programs target self-installed units purchased within a defined calendar window, while others pair incentives with specific installation requirements or participation in broader demand-response initiatives. These incentives serve as powerful demand accelerators, particularly in price-sensitive segments where the upfront cost of a smart device has historically been a barrier. For manufacturers and retailers, aligning product portfolios with rebate eligibility criteria is no longer optional; it is a core commercial strategy that directly influences conversion rates and average selling prices in participating markets.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are evolving rapidly on both the residential and commercial fronts. In residential settings, consumers increasingly view smart thermostats as part of a broader home efficiency and comfort strategy rather than standalone gadgets. Rising utility costs, heightened awareness of carbon footprints, and the normalization of app-based home management have made programmable, learning, and remotely accessible thermostats a practical purchase rather than a speculative luxury. The growing preference for devices that can integrate with voice assistants, geofencing routines, and multi-room comfort schedules reflects a desire for seamless, low-friction energy management that operates in the background without requiring constant manual intervention.
Commercial operators face a different but complementary set of drivers. Facility managers and building owners are under increasing pressure to reduce operational energy expenditures while maintaining occupant comfort and meeting sustainability reporting requirements. Smart thermostats in commercial contexts are valued for their ability to centralize scheduling, respond to occupancy patterns, and integrate with broader Building Management Systems that aggregate data across lighting, HVAC, and security functions. The shift toward hybrid work schedules and variable occupancy patterns has further amplified the need for adaptive climate control that can optimize energy use without sacrificing comfort during peak usage periods.
Supply Chain and Cost Structure Dynamics
The cost structure of WiFi thermostats is being reshaped by both component-level advancements and shifting manufacturing footprints. Improvements in low-power wireless modules, embedded processors, and sensor integration have gradually reduced the bill of materials for core functionality, enabling manufacturers to add features without proportionate cost increases. At the same time, the expectation for continuous firmware updates, cloud connectivity, and long-term software support introduces ongoing operational costs that must be factored into product pricing and lifecycle planning. Companies that can balance hardware economies with sustainable software support models are better positioned to maintain margins as the market matures and competition intensifies.
Distribution channel dynamics also play a role in cost and margin outcomes. Retail partnerships, online marketplaces, and direct-to-consumer channels each carry distinct customer acquisition costs, return profiles, and brand exposure benefits. The availability of utility rebates and energy certification programs further influences channel strategy, as products that are explicitly listed for incentive eligibility tend to perform more predictably in markets where consumers are aware of and actively seeking those savings. Aligning supply chain agility with channel-specific demand patterns is becoming a critical capability, particularly as regional incentive programs adjust eligibility windows and certification requirements.
Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The market's leading participants have carved out distinct strategic identities that reflect their heritage, ecosystem leverage, and target customer segments. Resideo Technologies, operating from its Scottsdale headquarters, serves as the primary provider of Honeywell Home WiFi smart thermostats, with a portfolio spanning multiple series models that incorporate interoperability certification, energy monitoring, and HVAC integration. The company's recent product cadence demonstrates a dual-track strategy: expanding accessibility through mainstream models with efficiency certification while simultaneously pushing into the premium tier with high-resolution displays, air quality sensing, and diagnostic capabilities. Recognition from industry award programs in early 2026 underscores how this approach has resonated with evaluators and early adopters who value both energy performance and feature depth.
ecobee, based in Toronto, has built its identity around advanced sensing and environmental awareness. Its thermostat lineup emphasizes radar-based occupancy detection, air quality monitoring, and comprehensive WiFi connectivity, targeting customers who prioritize comfort precision and indoor environmental quality alongside energy savings. By differentiating on sensor sophistication and whole-home awareness, ecobee positions its devices as integrated components of a healthier, more responsive living environment rather than simple temperature controllers.
PW Consulting
Google, through its Alphabet Inc. umbrella, brings a platform-centric approach to the category. Its thermostat offerings are built around AI-driven learning, geofencing capabilities, and interoperability support, leveraging the company's broader ecosystem to deliver seamless integration with mobile devices, voice assistants, and automated routines. The strategic advantage here lies in user familiarity, software continuity, and the ability to bundle climate control into a wider smart home experience that reduces setup complexity and encourages long-term engagement.
Emerson Electric Co., headquartered in St. Louis, has focused on optimized smart home integration, voice control compatibility, and energy-efficient HVAC performance. Its thermostat designs emphasize reliability, straightforward installation, and smooth interoperability with existing home automation setups, appealing to customers and installers who value stability and ease of use alongside measurable energy improvements.
Evolution of the Market Structure
The competitive field is evolving along multiple axes simultaneously. Consolidation pressure exists, particularly as larger platform owners and diversified home technology companies seek to bundle climate control into broader offerings. At the same time, market fragmentation persists in the value-oriented segment, where regional brands, private-label offerings, and online-first competitors compete aggressively on price and feature lists. The result is a market that rewards clear strategic positioning rather than uniform feature escalation.
One emerging trend is the bifurcation between utility-aligned, compliance-focused devices and premium, experience-driven models. The former category benefits directly from incentive programs and regulatory mandates, making certification and rebate eligibility central to go-to-market strategy. The latter category competes on design, sensor capabilities, software experience, and ecosystem integration, appealing to customers willing to pay a premium for advanced functionality and aesthetic integration. Companies that attempt to straddle both segments without clear differentiation risk diluting their brand message and stretching engineering resources across incompatible priorities.
New entrants and ecosystem incumbents are also reshaping competitive dynamics. Platform companies with existing user bases, cloud infrastructure, and software development capabilities can leverage thermostat rollouts as extensions of broader smart home or building management strategies, using hardware as an engagement touchpoint rather than a standalone profit center. Traditional hardware manufacturers, meanwhile, are investing in software maturity, interoperability certifications, and service ecosystems to defend against platform-driven competition and to increase switching costs for end users who value long-term reliability and continuous feature updates.
Future Trends and Commercial Opportunities
Trend One: Energy Intelligence as a Standard Expectation
Over the next three to five years, the defining shift in the WiFi thermostats market will be the transition from basic remote control to proactive energy intelligence. Devices will increasingly be expected to learn occupancy patterns, adjust to utility rate structures, participate in demand-response events, and surface actionable insights about HVAC performance and energy waste. This trend opens commercial opportunities for manufacturers that can package analytics, scheduling optimization, and utility program participation as clear, user-facing value propositions rather than buried technical features. For commercial and industrial buyers, the opportunity lies in integrating thermostat data into broader facility energy management dashboards, turning climate control devices into sources of operational intelligence that support sustainability reporting and cost reduction initiatives.
The risk side of this trend centers on data privacy expectations and software sustainability. As devices collect more usage patterns and environmental data, end users and enterprise purchasers will scrutinize data handling practices, cloud dependency, and long-term update commitments. Manufacturers that fail to communicate transparent data policies or that underinvest in post-sale software support risk losing trust and facing attrition as competitors offer clearer privacy assurances and more predictable update roadmaps.
Trend Two: Incentive-Driven Demand and Compliance as Market Gateways
Regulatory mandates and utility incentives will continue to function as powerful demand gateways, particularly in regions where energy costs are high and efficiency goals are aggressive. The pattern of rebates and certification requirements is likely to expand rather than contract, with more jurisdictions aligning smart thermostat eligibility with broader decarbonization and grid flexibility objectives. Commercial opportunities here include designing product lines that are explicitly optimized for rebate qualification, ensuring that marketing and retail execution clearly communicate incentive availability, and building installer and consumer education programs that reduce friction in the rebate redemption process.
The uncertainty lies in the variability and timing of program availability. Incentives can be capped, paused, or reconfigured based on funding cycles and policy priorities, creating demand volatility if product planning assumes perpetual rebate availability. Companies that treat incentives as accelerators rather than structural revenue foundations, and that maintain product relevance even in the absence of active rebate windows, will be more resilient to program fluctuations.
Trend Three: Ecosystem Integration and Platform Competition
The market's future will increasingly be shaped by how well thermostats integrate into broader smart home and building management ecosystems. Consumers and facility operators alike prefer cohesive experiences where climate control, lighting, security, and air quality operate as coordinated systems rather than disconnected devices. This trend favors participants that can demonstrate reliable cross-platform compatibility, straightforward setup processes, and ongoing software compatibility as third-party ecosystems evolve.
Commercial opportunities include partnerships with platform providers, open API strategies that encourage third-party integrations, and product designs that make the thermostat a visible, intuitive node within a larger automation environment. The associated risk is over-reliance on any single ecosystem partner, which can create vulnerability if platform priorities shift, compatibility standards change, or competitive dynamics alter the value of integration. A balanced approach that maintains multi-platform support while delivering a distinct, reliable user experience offers the most sustainable path.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize certification alignment and interoperability as foundational product requirements rather than optional add-ons. Devices that meet prevailing energy efficiency standards and support widely recognized connectivity frameworks are better positioned to qualify for incentive programs, integrate with third-party ecosystems, and withstand regulatory shifts across multiple jurisdictions. Simultaneously, invest in software maturity and post-sale support as a differentiator. As hardware features become more comparable across competitors, the quality of scheduling algorithms, update reliability, and user-facing energy insights will increasingly determine long-term satisfaction and repeat engagement.
Consider a segmented product strategy that clearly separates compliance-aligned, incentive-friendly models from premium, experience-driven devices. Each segment requires distinct engineering priorities, channel execution, and messaging. Blurring the lines between them can lead to confused positioning, margin erosion, and missed opportunities in both the incentive-sensitive and premium experience markets.
For Investors and Strategic Allocators
Evaluate participants based on their ability to sustain software value and navigate regulatory complexity, not solely on hardware shipment growth. The market's rapid expansion masks divergent underlying quality among competitors, particularly in how well companies manage certification requirements, ecosystem integration, and long-term firmware support. Companies that treat these dimensions as core competencies are better positioned to defend margins and capture share as the market matures and early-adopter enthusiasm gives way to more discerning, value-focused purchasing.
Monitor the trajectory of utility and state-level incentive programs as a leading indicator of regional demand intensity. Shifts in rebate availability, certification thresholds, and installation requirements can rapidly alter which product tiers and features are commercially attractive in specific markets. Portfolio exposure that accounts for geographic and program-level variability is more resilient than strategies that assume uniform, uninterrupted incentive support.
For Procurement and End-User Decision Makers
When evaluating WiFi thermostats, prioritize compatibility with existing HVAC equipment, support for relevant efficiency certifications, and clarity around post-installation software support. The most attractive device on a feature list may not be the best fit if it lacks certification eligibility for local incentive programs or if its software update commitments are unclear. In commercial and industrial settings, assess integration pathways with existing building management systems and verify that data access, scheduling controls, and demand-response participation capabilities align with operational requirements.
Treat the purchase decision as an entry point into an ongoing energy management relationship rather than a one-time hardware transaction. Devices that offer transparent energy insights, reliable scheduling, and sustained software support deliver greater long-term value than those that emphasize a narrow set of launch-time features without a clear roadmap for continued improvement.
Conclusion
The WiFi thermostats market is advancing rapidly, propelled by technology maturation, regulatory pressure, utility incentives, and shifting consumer and enterprise expectations. The growth trajectory through the end of the decade reflects a category that is transitioning from discretionary smart home upgrades to integral components of energy management strategy. Success in this environment will belong to participants that combine clear product segmentation, robust certification and interoperability alignment, and sustained software investment with a disciplined approach to regional incentive dynamics and ecosystem integration.
For leaders who need to move beyond high-level market narratives and into actionable, segment-specific planning, a comprehensive research report is available that provides deeper breakdowns of regional and price-tier dynamics, end-use performance patterns, detailed competitive benchmarking, and customized strategic recommendations aligned with specific business objectives. Accessing that level of detail can shorten decision cycles, sharpen product and investment prioritization, and ensure that market entry or expansion strategies are built on a precise understanding of where demand is forming, which compliance and incentive structures matter most, and how competitive positioning is likely to evolve as the market scales toward its next growth phase.
For detailed analysis of this topic, please visit the official page: WiFi Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Capecitabine Market Value Hits $494M in 2025: Decoding the 6.01% CAGR Growth Path to 2032
By PW Consulting, 2026-09-21
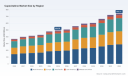
The Capecitabine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The capecitabine market has matured from a niche oncology therapy into a widely deployed oral chemotherapy option with established clinical pathways, global distribution footprints, and a pricing landscape shaped by generics competition and brand stewardship. Recent market data underscore a steady, compounding growth trajectory: global revenue climbed from roughly 369 million in 2020 to 494 million in 2025, with the market projected to expand from about 508 million in 2026 to more than 743 million by 2032, reflecting a compound annual growth rate near 6.0 percent. This pace signals durable demand, but it also masks structural shifts underway across regulatory requirements, product innovation, supply chain resilience, and competitive positioning. For executives and investors, the challenge is no longer whether capecitabine will grow—it is how each stakeholder can navigate a landscape where volume expansion, risk management, and differentiation increasingly determine commercial outcomes.
Understanding the market today requires looking beyond top-line growth to the forces reshaping how capecitabine is prescribed, manufactured, distributed, and reimbursed. The category sits at the intersection of oncology care delivery, regulatory modernization, and generic supply dynamics. That combination creates both opportunity and fragility. Growth is being driven by broad utilization across multiple tumor types and care settings, yet the same breadth makes the market sensitive to therapy substitutions, formulary decisions, and manufacturing disruptions. In the sections that follow, the focus is on what matters most for strategic planning: the core challenges framing the market, the drivers altering pace and margin, the competitive profiles shaping access, the trends likely to unfold over the next three to five years, and the actions different stakeholders can take now.
Market Context and Core Challenges
The capecitabine market has demonstrated consistent expansion, with annual revenues moving from the high 360-million range in 2020 to just under 500 million by 2025 and continuing upward through the forecast horizon. Growth is broad-based, with significant shares concentrated across major oncology indications and distributed through both hospital and retail/online pharmacy channels. Regionally, North America and Asia Pacific represent substantial portions of total value, alongside meaningful European demand and smaller but notable contributions from Latin America and the Middle East and Africa. The competitive structure remains relatively fragmented, with top three players holding roughly 26 percent of market value and the top five near 29 percent, indicating that no single manufacturer dominates the category outright. This environment supports multiple commercial models—branded stewardship, generic scale, and specialty distribution—but also raises questions about pricing discipline, supply reliability, and how brand differentiation will compete as more players enter the space.
Several challenges define the current inflection point. First, the regulatory baseline is tightening around patient safety and treatment personalization. Updated prescribing information and safety labeling have begun to reshape treatment protocols, placing greater emphasis on pre-treatment screening for enzyme deficiencies that affect drug metabolism. These requirements are clinically rational, but they introduce operational complexity for providers, pharmacy networks, and manufacturers who must ensure adherence across varied care settings. Second, supply chain reliability has emerged as a recurring risk. Even for a well-established oral oncology product, demand spikes and manufacturing or logistics disruptions can lead to shortages, as seen in recent episodes affecting specific branded and generic presentations. In a market where continuity of care is paramount, shortages not only create clinical inconvenience but can also shift purchasing behavior and erode trust in supply commitments. Third, the competitive landscape is evolving through both consolidation and fragmentation. Brand rights and distribution agreements have changed hands, while multiple generic manufacturers continue to build volume across regions. The result is a market where access, pricing, and channel relationships matter as much as product formulation.
Key Drivers Shaping the Capecitabine Market
Innovation and Next-Generation Formulations
Product innovation is one of the more consequential drivers in the mid-term outlook. While capecitabine is a long-established agent, a next-generation formulation has entered clinical evaluation with the aim of improving exposure to the active metabolite and refining the safety profile relative to standard monotherapy. Early-phase data have drawn attention because they suggest the possibility of enhanced efficacy or tolerability without abandoning the core therapy paradigm. If later-stage trials confirm these signals, the impact could extend beyond a single product: improved formulations may influence prescribing preferences in oncology settings, support combination strategies, and create a basis for differentiation that is not solely dependent on price. Even where new formulations do not replace existing options, the clinical conversation around optimization can shift expectations and encourage manufacturers to invest in value-added positioning.
Regulatory Modernization and Testing Requirements
Regulation is increasingly a structuring force rather than a compliance afterthought. Recent regulatory actions have included label updates that revise indications, dosage regimens, and safety information, including considerations around dihydropyrimidine dehydrogenase deficiency. In parallel, guidance has moved toward making genetic testing a prerequisite before treatment initiation in relevant contexts. This shift aligns with broader oncology trends emphasizing precision prescribing and risk mitigation, but it also affects workflows and procurement. Providers must integrate testing into care pathways, pharmacies must manage counseling and documentation, and manufacturers need to ensure that product information and support materials reflect new expectations. Where regulatory updates are clear and consistent, they can reduce uncertainty and support adoption; where they vary by region, they create fragmentation that complicates global planning.
PW Consulting
Demand-Side Shifts in Oncology Care Delivery
Demand is being shaped by how cancer care is delivered and accessed. Capecitabine remains attractive in part because of its oral administration, which supports flexible treatment models and can reduce the burden of frequent clinic visits for eligible patients. As oncology services expand in outpatient and community-based settings, oral therapies with established efficacy profiles continue to find use across colorectal, breast, gastric, pancreatic, and other indications. At the same time, payer and formulary dynamics influence which versions are accessed and at what price. Hospitals and retail/online pharmacies both play substantial roles in distribution, meaning that channel strategy and contracting are as important as clinical fit. The net effect is a demand environment that is resilient but sensitive to reimbursement policy, site-of-care preferences, and the availability of reliable supply at the point of care.
Supply Chain, Cost Structure, and Access Reliability
Cost structure and supply reliability are recurring drivers of commercial performance in generic-heavy oncology categories. Manufacturing scale, quality control, logistics, and regional sourcing decisions all influence margin and availability. Episodes of unexpected demand and interruption have demonstrated that even mature products can face shortage risk when supply planning does not keep pace with utilization or when distribution channels encounter disruption. For buyers, this creates a need to diversify sources, monitor inventory buffers, and assess supplier robustness beyond price alone. For manufacturers, it underscores the value of predictable production, responsive distribution, and clear communication during constraints. In market segments where multiple suppliers compete, the ability to maintain continuity can be a more durable advantage than temporary price positioning.
Competitive Landscape and Leading Strategies
Branded Stewardship and Rights Transitions
A defining feature of the competitive landscape is the interaction between branded product stewardship and the broader generic ecosystem. One originator and marketer continues to anchor the branded position for capecitabine tablets in colorectal and breast cancer treatment, maintaining clinical familiarity and long-standing provider relationships. At the same time, another major pharmaceutical company acquired worldwide rights to the branded product in 2023 and now markets it across key regions, including China and Japan. This transition illustrates how brand ownership can shift while still preserving access to a recognized product identity in important markets. For incumbents and new rights holders alike, the strategic priority is to manage formulation consistency, provider education, and region-specific compliance while defending the clinical value proposition against generic substitution where appropriate.
Generic Scale, Distribution Partnerships, and Regional Reach
On the generic side, several manufacturers have built profiles based on tablet production and channel partnerships. Indian-based producers supply U.S. and international markets through arrangements with distributors and pharmaceutical services companies, extending reach across retail and hospital channels. Another group of manufacturers markets generic tablets through established U.S. pharmaceutical partners, while additional producers distribute through other major service networks. Outside the United States, branded and generic positions coexist, with manufacturers in Australia and other regions producing and marketing their own presentations. The pattern suggests that competitive advantage in generic segments depends on three things: reliable manufacturing capacity, efficient distribution agreements, and the ability to meet regional requirements without sacrificing consistency. Companies that can align supply with channel needs and regulatory expectations are better positioned to capture volume when shortages or demand shifts occur.
Competitive Evolution: Consolidation, Differentiation, and Entry Dynamics
The market structure is not static. The concentration metrics indicate a moderately fragmented landscape, leaving room for both consolidation and new entry. Rights acquisitions have already altered the branded side, and similar moves could continue as companies seek to strengthen oncology franchises or acquire established product identities. On the generic side, entry is facilitated by manufacturing capability and distribution relationships, but sustainable positioning increasingly depends on more than low price. Differentiation can come from continuity of supply, consistent quality, responsive customer support, and alignment with testing and safety requirements. Over time, the competitive field is likely to separate into tiers: players with strong regional relationships and dependable supply, and those that remain more vulnerable to channel and regulatory shocks. For decision-makers, the implication is to look beyond brand names and short-term pricing to assess whether a supplier can be relied upon across cycles of demand and disruption.
Forward Outlook: Three to Five-Year Trends
Tighter Integration of Safety, Testing, and Prescribing Workflows
As regulatory expectations around genetic screening and safety information become more embedded, the market is likely to move toward greater integration of testing and prescribing workflows. This trend will affect hospitals, pharmacies, and manufacturers in different ways. Providers will need streamlined processes to confirm eligibility and manage exceptions. Manufacturers and service partners may invest in educational materials, decision support, and communication that reduce friction in implementation. For commercial strategies, the opportunity is not simply compliance; it is the chance to position products and services as easier to use safely and consistently. Suppliers that help institutions manage the operational burden of testing and counseling can strengthen relationships and reduce the likelihood of adoption barriers. The risk is that uneven implementation across regions or institutions creates confusion or slows utilization, particularly where guidance is not fully harmonized.
Formulation and Clinical Optimization as a Differentiator
Clinical optimization is set to become a more visible battleground. If next-generation formulations continue to demonstrate improved exposure and safety signals in later trials, they could influence prescribing in gastrointestinal and other advanced cancers, especially where clinicians are balancing efficacy with tolerability. Even before any new formulation achieves broad adoption, the direction of travel matters: the category is increasingly framed by the question of how to deliver the therapeutic benefit of capecitabine with a better patient experience or a more favorable risk profile. For manufacturers, this opens a pathway to differentiation based on clinical value rather than price alone. For investors, it suggests that early-stage programs with clear mechanistic rationale and well-designed trials may carry strategic optionality, though development risk remains substantial and outcomes are uncertain until pivotal data are available.
Oxaliplatin Market
Supply Resilience as a Commercial Moat
Supply resilience is expected to play a larger role in competitive advantage. Repeated interruptions in specific branded and generic presentations have highlighted that availability can be as decisive as price in oncology procurement. The practical consequence is that procurement teams and hospital networks will increasingly evaluate suppliers on continuity, lead-time reliability, and the ability to manage regional demand fluctuations. For manufacturers, this means that robust production planning, quality systems, and logistics responsiveness will be central to commercial performance. Markets in which demand grows steadily but supply remains vulnerable will reward suppliers that can demonstrate dependable access. The downside risk is that shortage events or quality concerns in specific lots or regions can quickly shift purchasing and reputation, making resilience a strategic necessity rather than an operational detail.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Holders
Manufacturers should treat supply continuity and regulatory readiness as core commercial assets, not back-office functions. That means investing in production reliability, clear lot traceability, and proactive communication during constraints, as well as ensuring that labeling, safety information, and support materials reflect current guidance. Where branded products are involved, stewardship should emphasize clinical consistency, provider education, and region-specific compliance, especially in markets where rights have changed hands. Where generic positions are the focus, competitive advantage will likely come from dependable access, efficient distribution partnerships, and the ability to meet local requirements without sacrificing quality. Companies should also monitor formulation innovation closely, since even partial clinical gains can reshape expectations in the category and create new positioning opportunities.
For Investors and Strategic Planners
Investors should evaluate capecitabine exposure with an emphasis on resilience, channel strength, and regulatory alignment rather than volume growth alone. Growth is likely to continue at a steady pace, but the composition of value will increasingly favor participants that can manage safety requirements, maintain availability, and navigate regional differences. In due diligence, it is worth examining supplier robustness, distribution relationships, and exposure to shortage or quality risk, as well as any pipeline programs that could affect long-term positioning. Close attention to label updates, testing requirements, and regional regulatory variation will help anticipate shifts in demand patterns and procurement behavior. The commercial upside is real, but it is best captured by those who can distinguish durable structural advantages from short-term pricing dynamics.
Worldwide Azacitidine Market
For Procurement, Hospitals, and Pharmacy Networks
Procurement and clinical operations teams should prioritize diversified sourcing and contingency planning for oral oncology products, even where the category is mature. This includes maintaining visibility into multiple suppliers, understanding buffer strategies, and ensuring that testing and safety workflows are aligned with current prescribing expectations. Contracts and service-level expectations should reflect the importance of continuity, with attention to lead times, substitution rules, and communication protocols in the event of disruption. Where possible, institutions can benefit from working with partners that offer clear quality systems, responsive support, and consistent availability. As regulatory and clinical expectations evolve, procurement strategies that incorporate both clinical reliability and supply resilience will be better positioned to sustain patient access without unnecessary cost or interruption.
The capecitabine market is moving through a phase where growth and complexity are advancing together. Demand remains broad, the category spans multiple care settings and indications, and the competitive field includes both established branded stewardship and a vigorous generic ecosystem. At the same time, regulatory modernization, supply fragility, and clinical innovation are reshaping how value is created and captured. For executives, investors, and procurement leaders, the most useful question is not whether the market will expand, but which capabilities will determine who gains share, who protects margins, and who maintains uninterrupted access. Detailed segmentation, regional patterns, supplier profiles, and scenario analysis are available in the full PW Consulting research report, which provides the deeper data and customized guidance needed to translate these trends into specific commercial decisions.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cell Culture Market: Why the 11.2% CAGR and Biopharma Shift Redefine Growth Through 2032
By PW Consulting, 2026-09-21
Cell Culture Market — Strategic Trends and Commercial Opportunities (2025–2032)
The cell culture market has moved well past its experimental phase. Between 2020 and 2025, revenue expanded from 16.32 billion to 27.58 billion, reflecting sustained adoption across biomanufacturing, diagnostics, and emerging therapeutic platforms. The trajectory is expected to continue at a compound annual growth rate of 11.2 percent through 2032, with the overall market projected to reach 58.02 billion. The forecast period from 2026 to 2032 will be shaped not by a single breakthrough, but by converging pressures on technical performance, regulatory clarity, supply chain resilience, and application-specific customization. For executives and investors, the central question is no longer whether demand will persist, but how to position for the structural shifts that will separate prepared players from the rest.
Primary Cell Culture Market
Market Snapshot and Core Challenges
From Steady Expansion to More Demanding Performance Standards
Growth in the sector has been consistent, but the nature of that growth is changing. Early expansion relied heavily on broad adoption of standardized media, basic consumables, and established equipment platforms. The next phase is being driven by higher-value, more complex applications that demand reproducible performance, defined formulations, and compatibility with scale-up workflows. This shift places new expectations on suppliers and users alike. A product that performs well in a research setting is no longer sufficient if it cannot maintain consistency in a manufacturing environment or meet the documentation and quality expectations associated with therapeutic development.
A second challenge lies in the gap between innovation and operational readiness. Many promising technologies and culture formats are introduced as proof-of-concept or early capability. Translating those advances into reliable, cost-effective, routine use often requires additional process development, qualified materials, and tightly controlled handling practices. That transition creates friction. It also creates opportunity for organizations that can bridge the divide between early-stage promise and practical deployment.
Cell Culture Media Market
Regulatory and Quality Expectations Are Reshaping Supplier and User Behavior
Regulatory and quality expectations are becoming more explicit across cell-based workflows. In cell and gene therapy development, flexibility in chemistry, manufacturing, and control requirements has been emphasized to accelerate development for smaller patient populations. At the same time, broader expectations for microbial purity, contamination control, and GMP-aligned practices continue to influence how reagents, media, and consumables are specified and handled. In sterile cell culture operations, contamination control has moved from a technical detail to a business-critical concern, because deviations can affect timelines, validation, and confidence in the process.
This creates a more demanding operating environment. Users are not only evaluating performance and price; they are also considering documentation quality, consistency, traceability, and the ability to align with evolving expectations in their specific application area. Suppliers that treat compliance and quality systems as integral to the product—rather than as a separate administrative layer—are better positioned to support customers navigating this environment.
Supply Continuity and Raw Material Variability Are No Longer Peripheral Issues
Another structural challenge is the sensitivity of cell culture performance to raw material consistency and supply continuity. Culture media components and related inputs remain exposed to variability in sourcing, manufacturing, and logistics. Even when individual products are technically sound, variability across lots or interruptions in availability can reduce manufacturing efficiency and increase process risk. In an environment where reproducibility and timeline discipline matter more than ever, these issues can have outsized consequences.
The implication is clear: cost and performance can no longer be considered in isolation from resilience. Buyers want predictable performance, and suppliers need credible strategies to manage variability, secure critical inputs, and reduce dependence on fragile supply pathways. This is especially important as applications become more specialized and substitution options become more limited.
Key Drivers of Market Change
Technical Innovation Is Moving From Niche Capability to Operational Necessity
One of the most important drivers is the rising sophistication of cell culture requirements across applications. Cultivation formats, media designs, and process-supporting reagents are being refined to improve consistency, reduce undefined components, and support scale-up. The emphasis is increasingly on reproducibility and control, particularly where cell-based processes are expected to support therapeutic development, biologics production, or advanced tissue-related applications. Innovation is no longer limited to creating a product that works; it is increasingly about creating a product that can work reliably across multiple users, workflows, and operational conditions.
This matters commercially because technical differentiation is becoming harder to replicate quickly. Where a supplier can offer a stable formulation, defined composition, or application-tailored support, it gains more than a product advantage; it gains a reduction in the user’s risk and development burden. In that sense, innovation is becoming a commercial multiplier, especially when it is paired with practical support for scale-up, documentation, and process integration.
Policy and Regulatory Dynamics Are Accelerating Certain Applications While Raising the Compliance Bar
Policy and regulatory developments are shaping both the pace and the structure of demand. Regulatory flexibility for cell and gene therapies has helped reduce some of the earlier friction associated with development timelines and small patient populations. This flexibility can encourage investment in areas where rapid iteration and tailored process design are important. At the same time, broader quality expectations for biological medicinal products and sterile operations continue to influence purchasing decisions, process design, and supplier selection.
The strategic effect is twofold. First, more permissive or flexible approaches to certain requirements can unlock activity in high-value areas that might otherwise face prolonged development cycles. Second, even as flexibility increases in some respects, quality and contamination control expectations remain substantial. Companies that anticipate these dual pressures—moving faster where allowed, but maintaining discipline where it matters—will be better equipped to convert opportunity into reliable output.
Demand-Side Shifts Are Expanding Beyond Traditional Research Use
Demand is evolving as end users move from exploratory research toward more applied, production-oriented, and therapy-linked use cases. In biopharmaceutical production, the push toward scalable and reliable manufacturing continues to support demand for consumables and process inputs that can perform consistently at higher volumes. In diagnostics and drug screening, the need for reliable cell-based models contributes to sustained interest in well-characterized reagents and media. In tissue engineering and regenerative medicine, demand is often more specialized, but it is also disproportionately important because it pushes the market toward higher specification products.
This shift in demand is more than a volume story. It changes the value equation. Where use is narrowly research-focused, standardization and price may dominate. Where use moves closer to production or therapeutic application, users increasingly value traceability, defined composition, and support for scale-up and quality expectations. Companies that can align product design and service models with these application-level expectations are more likely to capture and retain demand.
Supply Chain and Cost Structure Pressures Are Reshaping How Products Are Purchased and Managed
Cost structures and supply conditions are increasingly influencing how buyers plan, qualify, and maintain their cell culture inputs. Variability in raw materials and disruption risk in supply chains for culture media components continue to affect manufacturing efficiency. That means procurement decisions are being shaped not only by unit cost, but also by the predictability of supply, the robustness of supplier quality systems, and the ability to manage substitution without compromising process performance.
This environment favors suppliers that can demonstrate breadth of sourcing, controlled manufacturing consistency, and credible continuity planning. It also encourages buyers to think more carefully about qualification lead times, inventory strategy, and multi-supplier risk. In practice, the commercial opportunity lies in reducing uncertainty: for suppliers, by building more resilient and transparent supply propositions; for buyers, by aligning sourcing strategy with process criticality rather than price alone.
Competitive Landscape and Leading Strategies
Window of Differentiation: Specialized Formulations, Application Alignment, and Quality Infrastructure
The market includes a broad set of players spanning media, consumables, equipment, reagents, and specialized application support. Several companies have built strong reputations by emphasizing different parts of the value proposition. Some focus on specialized media formulations, including classical, serum-free, and perfusion-optimized options, alongside custom bioprocessing and cell therapy-related solutions. Others offer broad portfolios that cover mammalian, primary, stem, and three-dimensional culture formats, supported by reagents and transfection tools. A further set of suppliers emphasizes GMP-aligned production sites, animal-component-free options, or custom development of media for specific therapeutic or manufacturing contexts.
The differentiating factor is not simply breadth. Breadth matters, but only when it is connected to a credible technical and quality story in the areas where customers are most sensitive. In this market, the strongest positioning tends to come from combinations of three elements: formulation focus or application specificity, consistency in supply and performance, and the ability to support customers through documentation, customization, or process-aligned service. When those elements are aligned, a supplier can compete on more than price and still retain customers as applications become more demanding.
Recent Activity Reflects the Same Strategic Focus
Recent developments illustrate how companies are trying to strengthen the links between products, applications, and operational reliability. In 2026, one major player launched a commercial platform combining research-use stromal cells with cell culture media, an example of pairing biological material with supporting media to simplify workflow integration. The same company also entered a collaboration focused on advancing adeno-associated virus production enhancers, signaling demand-side interest in process-supporting technologies for viral vector applications. In parallel, a major catalog release in early 2026 highlighted updated cell culture solutions alongside sustainability certifications, pointing to the growing relevance of product updates and externally visible responsibility claims. Another important move came from a company entering GMP-related custom cell culture media services for biomanufacturing, expanding its footprint into more production-oriented, specification-sensitive work.
These moves are not isolated. Together, they suggest a market where companies are investing in combinations of capabilities rather than single-product advantages. The most telling pattern is the increasing emphasis on integration: linking materials, workflows, and service support in ways that reduce friction for users who need consistency, documentation, and application readiness.
Concentration, Consolidation, and the Room for New Entrants
The market remains moderately concentrated, with the top three firms accounting for over half of revenue and the top five approaching nearly seven-tenths. That level of concentration indicates that scale, portfolio breadth, and established customer relationships provide meaningful advantages, especially in higher-volume and more specification-intensive segments. It also suggests that new entrants cannot rely on generic product offerings to break in easily. Differentiation usually needs to be sharper, whether through formulation specialization, target application depth, custom service capability, or quality and compliance readiness.
At the same time, the environment still leaves space for focused players. In areas such as xeno-free, serum-free, chemically defined, or custom media for primary and stem cell cultures, specialized competence can still build durable demand. In biomanufacturing and gene therapy-adjacent workflows, suppliers that can provide GMP-grade options, scalable support, or tailored reagents may find strong positioning even in a concentrated market. The broader trend, therefore, is not simply consolidation. It is selective consolidation, where scale advantages matter in some parts of the market while specialization and application depth continue to matter in others.
PW Consulting Health Care Research Center
Outlook for the Next Three to Five Years
Trend 1: Specification Depth Will Become a Standard Purchasing Criterion, Not a Premium Add-On
Over the next few years, well-defined formulations, documented consistency, and application-relevant performance are likely to become more routine expectations rather than niche differentiators. As cell-based workflows become more production-oriented and more closely connected to therapeutic or quality-sensitive use cases, users will increasingly compare materials on criteria beyond basic performance and price. Suppliers that continue to treat documentation, defined composition, and consistent manufacturing as core features rather than optional support will be better positioned to win and retain business.
The commercial opportunity here lies in making specification depth usable for the buyer. That means not only offering higher-specification products, but also reducing the effort required to qualify them, integrate them into workflows, and justify them internally. In practice, the winning position may combine product quality with practical implementation support.
Trend 2: Process-Adjacent Solutions Will Matter More Than Standalone Products
A second likely trend is the growing importance of solutions that help users move from product selection to process reliability. This includes media and reagent portfolios designed for scale-up, workflow-oriented combinations of materials, and service models that support custom needs in biomanufacturing or specialized cell culture applications. The direction is toward reducing the number of disconnected decisions a buyer must make. Where a supplier can help connect materials with process goals, it can become more embedded in the user’s operation.
For companies, this suggests that the next competitive battles will be fought not only on product specifications, but also on integration, service, and the ability to support higher-stakes use cases. For buyers, the opportunity is to work with suppliers that can reduce process risk rather than merely supply components.
Trend 3: Regional Demand Journeys Will Diverge as Local Ecosystems Mature
Market growth will not unfold uniformly across regions. Some regions will continue to be anchored by established biopharmaceutical and life-science infrastructure, while others will increasingly reflect emerging manufacturing capacity, expanding research activity, and local efforts to build greater self-sufficiency in critical inputs. Over time, this can create different demand rhythms: one region may emphasize advanced applications and premium specification products, while another may prioritize access, cost efficiency, and gradual capability building.
The strategic implication is that regional strategy should be tailored rather than transplanted. A product, service, or quality proposition that works in one market may need adjustment in another to match local maturity, procurement habits, and regulatory context. Companies that recognize these differences early can avoid the common mistake of treating the market as a single homogeneous opportunity.
Risk and Uncertainty to Watch
Several sources of uncertainty remain. Regulatory guidance can continue to evolve, and even flexibility-oriented changes may be accompanied by stricter expectations in specific areas, especially around contamination control and material quality. Supply chain variability and raw material inconsistency can still interrupt manufacturing efficiency, particularly when critical components are concentrated in fragile sourcing pathways. There is also the risk that promising technologies or specialized applications may not scale commercially as quickly as anticipated, which would affect the pace at which high-specification demand converts into broad revenue.
These uncertainties do not negate the growth outlook, but they do argue for scenario-aware planning. Companies that prepare for multiple possible paths—flexible demand patterns, evolving compliance expectations, and intermittent supply disruption—are better placed to respond without overcommitting to a single assumption.
Strategic Actions for Decision Makers
For manufacturing and supplier organizations, the priority is to align product and service strategy with the areas where customers are likely to value consistency, documentation, and application fit most highly. That can mean deepening specialization in defined or animal-component-free formulations, strengthening GMP-aligned production capabilities where relevant, or building clearer support for scale-up and customization. Where a company already has a strong portfolio, the next question is whether its commercial model helps customers reduce process risk or simply adds another product option. The former is more durable than the latter in a market that is becoming more specification-sensitive.
For investors and corporate development teams, the key is to distinguish between market growth and value capture. Revenue expansion is broad, but not every segment or company will capture value equally. Attention should be directed toward suppliers with credible differentiation in high-specification applications, strong quality and continuity capabilities, and a history of moving products into more demanding use cases. Equally important is assessing whether a company’s growth depends on genuinely durable advantages or on temporary pricing and volume conditions.
For procurement and operations leaders, the strategic move is to broaden the evaluation framework. Price and basic performance still matter, but so do lot consistency, documentation quality, qualification effort, and supply continuity. In practice, that means mapping inputs to process criticality, prioritizing resilience where disruption risk is material, and avoiding over-reliance on single sources for components that can affect process reliability. A more deliberate procurement posture can reduce downstream risk and improve long-term operational stability.
The market’s trajectory through 2032 will likely reward organizations that prepare for a more demanding, more application-specific, and more integrated operating environment. The companies and buyers that benefit most will be those that treat cell culture inputs not as interchangeable consumables, but as part of a broader system of performance, quality, and continuity. For readers interested in a more detailed breakdown of segments, regional dynamics, and competitive positioning, the full PW Consulting report provides deeper data and customized guidance for applying these insights to specific strategic decisions.
For detailed analysis of this topic, please visit the official page: Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com