

Blogs
Baby Bottles Market 2025-2032: 5.32% CAGR Growth Drives Regional and Material Shifts
By PW Consulting, 2026-09-21
The Baby Bottles Market: Navigating Growth, Safety, and Innovation Through 2032
The baby bottles market stands at a critical inflection point, shaped by steady demand growth, evolving safety expectations, and a competitive landscape where material science, regulatory scrutiny, and clinical performance increasingly determine market success. With total revenue projected to reach approximately 2,760.0 million USD in 2025 and expand to roughly 3,938.0 million USD by 2032, the sector is positioned for a long-term growth trajectory at a 5.32% CAGR across the 2026-2032 period. The historical record from 2020 through 2025 shows an uneven but ultimately upward path, with 2022 marking a brief plateau before accelerated expansion resumed in 2023-2025. This pattern reflects more than demographic tailwinds; it reveals a category reshaping itself around functionality, safety certification, and brand trust.
PW Consulting Health Care Research Center
For executives, investors, and strategic planners, the strategic question is no longer whether demand will persist. The question is where value will accumulate as safety incidents, material substitution, and formulation-led differentiation raise the bar for entry and retention.
Market Snapshot and Core Challenges
The market's size and trajectory provide a backdrop of resilience, but the underlying dynamics point to structural pressure points. Revenue has moved from 2,271.0 million USD in 2020 to 2,760.0 million USD in 2025, and forward estimates suggest continued expansion into the late 2030s. Growth is broad-based, but concentration remains meaningful: the top three players hold about 47.5% of the market, while the top five account for roughly 52.0%. This level of concentration indicates that leading brands still command significant shelf presence, channel leverage, and consumer recognition, yet it also leaves substantial room for specialized entrants and regional challengers to gain traction through focused value propositions.
Three strategic challenges define the current environment.
- Safety and material credibility have become decisive purchase criteria. Incidents involving lead detection, peeling plastic shells, and decal contamination have heightened scrutiny from regulators, retail buyers, and informed parents. Trust is now earned through testable material specifications, certification transparency, and rapid corrective action, not simply brand heritage.
- Anti-colic functionality and feeding performance are narrowing the gap between commodity and premium offerings. As clinicians, caregivers, and retail recommendations increasingly emphasize reduced spit-up, better airflow, and nipple designs that mimic natural feeding rhythms, products that fail to demonstrate functional benefit face eroding relevance regardless of price position.
- Regulatory divergence across regions is adding complexity to launch planning and production consistency. Different markets apply varying standards for materials, device safety, and labeling, which means global portfolios must balance scale efficiencies with localized compliance and testing. Any lapse can trigger recalls, retail delistings, or reputational damage that takes months to repair.
These challenges are not obstacles to dismiss; they are filters that are reallocating share toward manufacturers that can prove safety, performance, and consistency at scale.
Key Demand and Supply Drivers
Several interlocking forces are shaping the market's direction. Their combined effect is pushing the category toward higher-performing materials, more rigorous certification, and more clinically grounded product claims.
Technology Innovation and Material Advancement
Material choice has moved from a cost decision to a positioning decision. The market is no longer split simply between plastic and glass; silicone, stainless steel, and advanced thermoplastics each carry distinct tradeoffs in durability, weight, thermal behavior, and perceived safety. Recent developments illustrate how material upgrades are becoming a visible brand asset. One notable example is the adoption of high-performance thermoplastic in manufacturing to improve durability and safety consistency, signaling that material sourcing can be used as a competitive differentiator rather than a hidden supply decision. Similarly, hybrid constructions that combine the clarity and feel of glass with the impact resistance of plastic have gained attention by attempting to address the breakage concerns that limit glass adoption in certain channels.
Innovation is also advancing in venting and nipple geometry. Bottom-vent designs, internal vent systems, and gradual-slope nipples aim to reduce air ingestion, manage flow, and support more natural sucking patterns. Where these features are supported by clinical data or documented reduction in colic symptoms and spit-up, they move from marketing claims to product proof points. That proof matters increasingly in a market where caregivers compare options based on observable outcomes and peer recommendations.
Policy and Regulatory Environment
Regulators are tightening expectations around product safety, and the consequences of non-compliance have become highly visible. Voluntary recalls tied to choking hazards, peeling shells, and contamination concerns have underscored the importance of proactive quality control and post-market surveillance. In parallel, some jurisdictions have imposed bans on certain self-feeding devices due to choking, aspiration, and suffocation risks, reflecting a broader willingness to restrict product forms that do not meet safety thresholds.
These regulatory signals have two practical implications. First, they raise the baseline for what qualifies as an acceptable product in major markets, favoring manufacturers with robust testing protocols and traceable production processes. Second, they create reputational ripple effects: a recall in one category or brand can heighten consumer caution across the category, making transparent certification and rapid remediation essential for defending shelf space. Companies that can demonstrate compliance through recognized testing agencies and maintain clear documentation are better positioned to sustain retail relationships and consumer confidence.
Demand-Side Shifts in Consumer Behavior
Caregivers are making decisions with greater information and higher expectations. The modern purchase journey often involves comparing anti-colic performance, material safety, ease of cleaning, compatibility with breast pumps, and brand responsiveness to safety concerns. Parents are also increasingly receptive to products that offer functional benefits beyond basic containment, such as reduced gas, easier temperature control, or designs that support transition between breastfeeding and bottle feeding.
At the same time, brand trust is being re-evaluated. Hospital-trusted positioning, clinical data, and visible certification have gained influence because they help cut through ambiguity. Premiumization is evident in segments where consumers accept higher price points for perceived safety, comfort, or design refinement, but value remains important in price-sensitive channels. This bifurcation means that brands must be explicit about their value proposition rather than relying on generic category demand.
Supply Chain and Cost Structure Dynamics
Material availability, manufacturing consistency, and compliance testing all influence cost structures. As advanced materials and specialized components become more common in premium products, producers must manage the balance between performance gains and input costs. The market's concentration profile suggests that scale players still benefit from procurement leverage and distribution reach, but targeted investment in material quality and testing can allow smaller brands to compete on credibility rather than price alone.
Supply-side resilience is also increasingly tied to safety performance. A single quality failure can disrupt production schedules, retail orders, and brand perception simultaneously. Manufacturers that invest in process control, batch traceability, and pre-market testing reduce the likelihood of costly corrections later. In practice, the cost of prevention is often lower than the cost of a recall, a retailer audit, or a prolonged trust deficit.
Competitive Landscape and Leading Strategies
The market features a mix of established multinational brands, regionally strong players, and newer entrants focused on performance and certification. The strategic positions vary, but several patterns are clear.
Philips Avent has built a strong identity around anti-colic and Natural Response bottles, with AirFree venting technology and orthodontic nipples as core elements of its value proposition. Its positioning leans on functionality and familiarity, reinforced by broad retail availability and a recognizable brand footprint. BIBS represents the premium Danish approach, combining BPA-free polypropylene and borosilicate glass options with anti-colic valves, appealing to consumers who prioritize material clarity and design. Dr. Brown's differentiates through its Original Internal Vent System and clinical colic reduction data, giving it a credibility anchor in a category where caregivers look for demonstrable outcomes.
NUK continues to benefit from hospital-trusted associations and anatomically shaped nipples, with both glass and plastic options that cater to consumers seeking traditional trust signals and material choice. Evenflo, with more than a century of manufacturing history, uses its long track record and balance flow nipples to maintain relevance across classic and anti-colic segments. Tommee Tippee has leaned into eco-conscious positioning with Closer to Nature bottles and plant-based material options, aligning with consumers who weigh environmental considerations alongside feeding performance. Chicco addresses breakage concerns directly through hybrid unbreakable glass-to-plastic constructions using Invinci-glass technology, targeting the segment that wants glass-like aesthetics without the fragility risk.
Pigeon and Lansinoh both emphasize natural-feel feeding experiences through gradual slope nipples, with Lansinoh particularly aligned to breastfeeding-focused users. TOMY has historically offered reusable bottle systems with convenience-oriented features, though recent safety events have shown how quickly product reputation can shift when quality issues emerge. Thyseed's recent activity illustrates the opportunity for newer entrants to compete through clinically oriented design and certification strength, including bottom-vent anti-colic design and multi-test safety validation.
Several strategic themes cut across these profiles.
- Performance validation is becoming a yes-or-no gate. Brands that can connect product design to reduced colic, less spit-up, or improved feeding comfort are better positioned to command attention in both premium and recommendation-driven channels.
- Material strategy is a brand signal. Glass, silicone, advanced plastic, and hybrid constructions each communicate a different promise. The most effective portfolios do not merely offer choices; they explain why each material matters for a specific user need.
- Certification and transparency reduce friction. In an environment where recalls and contamination concerns have raised caution, documented testing and clear compliance positioning help protect both retail relationships and consumer trust.
- Speed of response matters more than before. When quality issues arise, the ability to pause sales, investigate, update designs, and communicate clearly can determine whether a brand recovers quickly or loses momentum for an extended period.
The competitive landscape is evolving through both consolidation and fragmentation. Established brands continue to hold meaningful share, but the presence of specialized entrants with focused certifications and targeted anti-colic claims suggests that fragmentation can persist where differentiation is credible. At the same time, retail consolidation and channel gatekeeping can favor brands that already meet stringent compliance and performance expectations, nudging the market toward a smaller set of trusted suppliers in certain segments. The long-term outcome is likely to be a layered market: dominant brands in broad distribution, specialized leaders in performance- and safety-focused segments, and periodic newcomer success where design and validation create a clear jump in perceived value.
Strategic Outlook: 2026-2032
Looking ahead, three trends are likely to shape where value is created and where risk concentrates.
Trend 1: Safety and certification will increasingly define premium positioning
As caregivers and retail buyers become more attuned to material safety, testing documentation, and post-market performance, certification is moving from a compliance requirement to a commercial asset. Brands that proactively validate materials, communicate test results, and maintain rigorous quality controls will be better equipped to defend price points and shelf placement. This trend also raises the stakes for any product that relies on weaker documentation or outdated materials, particularly as consumer awareness of contamination and choking hazards continues to grow.
The commercial opportunity lies in turning safety into a differentiated narrative. This does not mean overclaiming; it means clearly linking material selection, testing protocols, and design choices to practical outcomes such as durability, chemical stability, and reduced failure risk. In practice, the brands that win here will be the ones that make safety legible to consumers and buyers without relying on fear-based messaging.
Trend 2: Anti-colic and feeding-performance innovation will reshape segment boundaries
Functional innovation is likely to remain one of the strongest drivers of upgrade behavior. Bottom-vent systems, internal venting, nipple geometry, and material combinations that reduce air intake or improve latch feel will continue to influence purchasing decisions, especially where claims are supported by data or strong user feedback. As these features become more common, the market may see a shift in which basic bottles face greater pressure to justify their value, while functionally advanced products gain share among consumers seeking measurable comfort improvements.
The strategic implication is that product roadmaps should prioritize validated performance over feature count. A single well-executed venting or nipple design with credible evidence can outperform a broader set of unexamined features. Companies that can demonstrate clinically meaningful or user-verified reductions in colic symptoms and spit-up are better positioned to capture attention in both premium and recommendation-led channels.
Trend 3: Regional divergence and channel complexity will reward focused portfolios
Because regulatory expectations, material preferences, and channel dynamics differ by region, global one-size-fits-all portfolios will face growing tension. Some markets will emphasize material safety and device restrictions more heavily, while others will prioritize price accessibility or specific design preferences. Retailers and distributors are likely to continue consolidating their supplier base where trust, compliance, and performance are easiest to verify.
This environment creates opportunity for companies that design regionally informed portfolios rather than simply exporting a single product architecture. It also increases the value of local certification, localized consumer insight, and channel-specific packaging or messaging. Brands that can align product specifications with regional expectations while maintaining consistent quality standards will be better placed to scale without triggering compliance or reputation friction.
Potential risks and uncertainties remain significant. Recalls and contamination incidents can quickly reshape consumer perceptions and retailer confidence. Regulatory changes may restrict certain product forms or raise testing requirements, affecting both cost and time-to-market. Material substitution can create new performance benefits but also introduces validation burdens. In addition, competitive intensity may increase as new entrants use certification and functional claims to break into established segments, while larger brands respond with portfolio breadth and distribution strength. Companies that assume category growth alone will protect them risk being overtaken by rivals that convert safety and performance into clearer consumer value.
Implications for Decision Makers
Different stakeholders will extract value from the market in different ways, but the underlying requirements are similar: credible differentiation, verifiable safety, and disciplined execution.
For Manufacturers and Brand Leaders
Treat material and venting design as strategic decisions rather than engineering details. The brands gaining ground are those that can articulate why a specific material, venting system, or nipple shape matters for comfort, safety, or durability, and then back that claim with testing or clinical support. Portfolio design should also reflect the tension between scale and specialization. A broad range of products can capture more usage scenarios, but only if each variant has a clear purpose and consistent quality controls. Finally, post-market responsiveness should be built into operating routines, because the speed and clarity of response to a safety issue can be as important as the product design itself.
Worldwide Baby Glass Bottles Market
For Investors and Strategic Partners
Focus on companies with defensible proof points and operational discipline. Revenue growth is meaningful, but in a market where recalls and contamination concerns can disrupt reputation quickly, the quality of a company's testing infrastructure, certification posture, and corrective-action capability is equally important. Preference should go to brands that combine functional differentiation with documented safety validation and clear compliance processes, especially where they can sustain retail relationships and consumer trust over time. Diversification across materials and price points can be valuable, but only when each segment has a coherent value proposition rather than overlapping, undifferentiated SKUs.
For Procurement, Retail, and Channel Buyers
Use safety documentation and performance claims as part of sourcing criteria, not as optional background information. Asking for material specifications, testing results, and evidence of post-market monitoring can help reduce exposure to product failures and subsequent disruptions. It is also worth weighing portfolio breadth against accountability: a smaller set of well-documented, performance-validated suppliers may offer more predictable shelf performance than a larger group of weakly differentiated options. In channels where consumer caution is high, brands that communicate transparency and respond quickly to issues are likely to generate fewer interruptions and stronger end-consumer confidence.
Feeding Bottle Market
The baby bottles market is not simply expanding; it is being re-sorted by trust, performance, and material credibility. That re-sorting creates clear winners and losers among brands that look similar on the shelf but differ sharply in how they validate safety and demonstrate feeding benefit. The most valuable insights for any stakeholder come from understanding which product attributes, certification standards, and launch strategies will hold up under scrutiny, and where the next wave of differentiation will emerge as regulations, materials, and consumer expectations continue to evolve. Detailed segment data, company-level tracking, and customized scenario analysis can sharpen these priorities further for organizations preparing specific product, investment, or sourcing decisions.
For detailed analysis of this topic, please visit the official page: Baby Bottles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Residential Elevators Market: Why 5.45% CAGR and Region Shifts Redefine Growth
By PW Consulting, 2026-09-21
The Quiet Infrastructure Boom: Strategic Dynamics in the Residential Elevators Market
What was once considered a luxury reserved for ultra-high-net-worth estates has steadily evolved into a mainstream accessibility and lifestyle feature across global housing markets. The residential elevators sector is expanding through a combination of demographic shifts, accessibility awareness, and incremental technological maturation. Valued at approximately 224.17 million USD in 2025, the market has followed a short-term plateauing pattern before resuming steady growth, with a projected compound annual growth rate of 5.45 percent spanning the 2026 through 2032 forecast window. Historical trajectories from 2020 to 2025 reveal an industry that absorbed pandemic-era construction volatility, recalibrated to shifting housing demand, and now operates in a period where growth is increasingly tied to product differentiation and installation agility rather than raw volume expansion alone.
Market concentration remains moderately fragmented, with the top three operators capturing roughly 38.7 percent of total revenue and the top five accounting for approximately 52.1 percent. This distribution signals a sector where incumbents hold meaningful share through regional service networks and brand recognition, yet still leave substantial room for specialized entrants, retrofit-focused innovators, and regional manufacturers that can address localized housing stock and code variations. The structural balance between established players and agile newcomers defines how value is captured across product tiers and end-user segments.
Identifying the Structural Inflection Points
Three overlapping challenges are reshaping how manufacturers, dealers, and end-users approach residential vertical mobility. The first revolves around material cost volatility and tariff exposure. Steel and component pricing pressures have altered margin structures across the value chain, pushing manufacturers to reconsider sourcing strategies, standardize sub-assemblies, and adjust pricing models without sacrificing installation timelines. The second challenge is regulatory alignment. Residential elevator installations increasingly sit at the intersection of safety certification, regional building codes, and insurance expectations. As standards evolve and jurisdictions tighten inspection and maintenance requirements, companies that fail to synchronize design, documentation, and service readiness face longer approval cycles and elevated compliance risk. The third challenge is installation friction in existing housing stock. Many target homes were not designed with vertical circulation in mind, making shaft construction, pit requirements, and spatial reconfiguration a decisive factor in purchase decisions. The market is therefore rewarding solutions that reduce structural intrusion, shorten project timelines, and simplify dealer sequencing.
Worldwide Bucket Elevators Market
These pressures are not purely defensive. They function as filters that separate commoditized pricing competition from value-based differentiation. Players that can balance material resilience, code-ready engineering, and low-disruption installation are increasingly positioned to command premium share and stronger service margins.
Key Drivers Reshaping Demand and Competitive Positioning
Technology Innovation and Product Architecture
Product design is shifting from purely mechanical reliability toward space-efficient, installation-light architectures. Pitless and shaft-free configurations, modular assembly approaches, and low-footprint vertical platforms are gaining traction in retrofit scenarios where homeowners and builders prioritize minimal structural alteration. Alongside hardware evolution, control interfaces, smoother ride calibration, and quieter operation are becoming baseline expectations rather than optional upgrades. These features influence not only purchase decisions but also long-term service contracts and repeat installations across multi-property owners and accessibility-focused housing programs.
Recent product and market activity illustrates how manufacturers are translating engineering improvements into commercial positioning. In early 2026, Garaventa Lift showcased its LUMA home elevator at a major industry trade event and was recognized among the event’s must-see products, reinforcing the commercial relevance of contemporary design alongside functional performance. Savaria expanded North American production capabilities through a new assembly and shipping facility in South Carolina, signaling a deliberate move to reduce lead-time risk and strengthen regional fulfillment. Residential Elevators updated its 2025 catalog to refresh product offerings and configuration drawings, a seemingly routine action that actually reflects how manufacturers use catalog clarity and specification readiness to accelerate dealer quoting and homeowner decision-making.
Regulatory and Standards Environment
Safety standards and installation mandates are becoming more explicit, with significant implications for engineering documentation, service protocols, and regional market access. In the United States, ASME A17.1 remains mandatory for residential elevator installation, alteration, service, repair, testing, and maintenance, creating a unified baseline for compliance and inspection readiness. In Canada, CSA B355 governs residential elevator safety standards and influences design, testing, and ongoing certification requirements. Meanwhile, ISO 8100-1/2 standards are set to launch in March 2026, replacing EN 81-20/50 with a 36-month transition period. This transition introduces both harmonization opportunities and compliance timing risk, especially for companies operating across multiple regions or exporting equipment that must satisfy evolving certification pathways.
From a commercial standpoint, regulatory clarity can be a competitive advantage when paired with proactive documentation and service infrastructure. Manufacturers that invest early in compliance mapping, installer training, and maintenance tracking tend to shorten project approval cycles and reduce post-installation liability exposure. Conversely, delays in aligning product specifications with updated standards can translate into stranded inventory, rework, or regional market hesitation.
Demand-Side Shifts in Housing and Accessibility
Demand is increasingly shaped by two parallel narratives: aging-in-place accessibility and the premiumization of multi-level residential design. For single-family homes, vertical accessibility is no longer viewed exclusively through a medical or mobility-assist lens; it is also framed around universal design, long-term home value, and lifestyle flexibility. Multi-family buildings and other applications represent a smaller but strategically important share of demand, often driven by affordability housing retrofits, accessibility compliance, and property value enhancement in denser residential settings. Across these segments, the decision-making unit is expanding beyond the homeowner to include remodelers, occupational therapists, accessibility consultants, and property managers, all of whom influence specification and procurement timing.
Elevators Market
This broadening stakeholder map is changing how products are sold and specified. Installers and dealers that can articulate total project cost, disruption reduction, code alignment, and after-installation service are gaining stronger positioning than those competing primarily on equipment price. The market is rewarding clarity of scope and predictable installation outcomes.
PW Consulting Automotive & Machinery Research Center
Supply Chain and Cost Structure Realignment
Material costs, logistics, and labor availability continue to influence pricing architecture and project feasibility. Steel cost increases, partly driven by tariff exposure and supply chain disruptions, have raised input expenses for residential elevator manufacturing and impacted broader material expenses across the sector. These pressures are prompting a reevaluation of bill-of-materials strategy, inventory buffering, and regional sourcing. For dealers and installers, the cost structure shift also affects project quoting stability, which makes standardized configurations and modular components more attractive than heavily bespoke builds in price-sensitive segments.
The commercial implication is straightforward: resilience in supply planning is increasingly a margin protection strategy. Companies that strengthen supplier diversification, improve demand forecasting, and align product families to common sub-components are better equipped to manage cost variability while preserving competitive pricing and delivery reliability.
Competitive Landscape and Strategic Differentiation
How Leading Players Are Positioning
The competitive field combines established elevator expertise with specialized residential-focused innovators. Savaria manufactures traditional and panoramic residential elevators for North American homes, using its regional manufacturing scale and product breadth to support broad market coverage. Inclinator specializes in fully customizable residential elevator solutions, positioning around design flexibility and tailored residential applications. Garaventa Lift produces custom home elevators, including the Elvoron series and LUMA models, and has reinforced its market visibility through trade recognition and product-focused outreach. Stiltz Lifts offers modular, shaft-free residential elevators designed for compact home installations, an approach that directly addresses the retrofit and space-constraint demand segment. PVE manufactures pitless vacuum-based residential elevators such as the PVE30, PVE37, and PVE52 series, leveraging a distinctive technology narrative to differentiate from conventional mechanical systems. Residential Elevators operates as a full-service provider manufacturing custom residential elevators in the USA, emphasizing end-to-end execution and domestic production. Cambridge Elevating leads in residential elevator design and installation with models such as Elmira and Heritage, combining design credibility with installation capability. AmeriGlide offers hydraulic and drum-mechanism residential elevators for accessibility-focused homes, targeting a demographic and functional use case where reliability and ease of use are central. Nibav Lifts provides air-driven, pitless residential home elevators for small homes and retrofits, aligning with lightweight installation needs. Otis offers Gen2 residential elevator systems for luxury and high-rise homes, bringing broader elevator heritage and premium positioning into the residential segment.
These profiles reveal a market where differentiation is built on a few recurring axes: installation footprint, customization depth, technology narrative, service reach, and regional production capability. No single formula dominates. Instead, firms are choosing where to compete on convenience, where to compete on engineering prestige, and where to compete on total installed cost and service continuity.
Market Structure Evolution: Consolidation Pressure and Niche Expansion
The moderate concentration levels suggest that consolidation is possible but not inevitable. Larger players with national service networks and multi-product portfolios can capture cross-selling opportunities and standardize installation workflows. At the same time, specialized manufacturers with distinct installation advantages or technology profiles can sustain strong niches by solving specific homeowner pain points, particularly in retrofit scenarios. New entrants and smaller regional firms continue to find openings where installation simplicity, faster delivery, or localized code familiarity create meaningful value. The result is a market that is neither fully consolidated nor highly atomized, but rather stratified by application complexity and installation context.
Over the next several years, this stratification is likely to sharpen. Companies that can deliver consistent installation outcomes, maintain code compliance across regions, and reduce material and labor exposure will be better positioned to expand share. Pure price competition will remain a risk for undifferentiated offerings, especially where material volatility and labor constraints compress margins for all but the most efficient operators.
Forward Outlook: Trends Shaping the Next Three to Five Years
Installation-First Product Strategy as a Growth Lever
Future growth will depend as much on how easily a system can be integrated into existing homes as on the mechanical performance of the elevator itself. Solutions that minimize shaft work, reduce pit requirements, and accelerate commissioning will likely capture disproportionate attention in retrofit-heavy markets. This trend benefits manufacturers that can standardize installation kits, simplify dealer training, and provide predictable project scopes. The commercial opportunity lies in turning installation efficiency into a pricing umbrella: when disruption is lower and timelines are shorter, homeowners and remodelers are more willing to proceed, and dealers can handle higher project throughput with less site risk.
Standards Convergence and Compliance as a Market Filter
As safety and performance standards transition and align across regions, the ability to demonstrate compliance will increasingly influence procurement decisions, especially for multi-region dealers and developers. Companies that proactively map product documentation, service procedures, and maintenance tracking to updated standards will reduce friction in quotation, approval, and ongoing service. This creates a twofold opportunity: tighter compliance posture can shorten sales cycles, and it can also support premium positioning for projects where safety assurance, insurance alignment, and long-term service reliability are decisive. The uncertainty lies in transition timing and regional interpretation, which may create short-term unevenness in demand as dealers and inspectors adapt.
Regional Production and Supply Resilience as Margin Defense
Regional manufacturing expansion and supply chain recalibration are likely to remain strategic priorities as companies seek to contain material cost exposure and improve delivery predictability. Domestic or near-market assembly can reduce logistics complexity and improve responsiveness to local specification requirements. This trend does not automatically guarantee cost leadership, but it can support more stable quoting, faster turnaround, and stronger relationships with regional dealers and installers. The associated risk is capital intensity and execution complexity: facility expansion and sourcing realignment must be matched with demand forecasts and inventory discipline to avoid overcapacity or uneven utilization.
Actionable Implications for Decision Makers
For Manufacturers and Product Leaders
- Prioritize installation-light architectures and modular product families that reduce structural disruption and simplify dealer quoting, especially for retrofit and small-home segments.
- Strengthen standards readiness ahead of regulatory transitions by aligning design documentation, installer training, and service tracking with the evolving certification landscape.
- Diversify sourcing and standardize common sub-components to protect margins against steel and material cost volatility while preserving delivery reliability.
For Investors and Strategic Capital
- Evaluate companies on total installed-solution capability, including service reach, compliance readiness, and regional fulfillment, rather than on equipment specifications alone.
- Watch for acquisition and partnership signals where a strong product profile is paired with weak installation or service infrastructure, as this gap often defines the next value-creation opportunity.
- Monitor regional capacity expansion for evidence of scaled demand durability and margin resilience, not just capacity addition in isolation.
For Procurement, Dealers, and Property Stakeholders
- Compare proposals on total project scope, installation disruption, code alignment, and ongoing service obligations, not solely on equipment price.
- Specify configurations that reduce structural modification requirements where feasible, as this can improve project predictability and homeowner acceptance.
- Include long-term maintenance and inspection readiness in the evaluation criteria, since post-installation compliance and service continuity increasingly shape total cost and risk.
From Market Context to Strategic Clarity
The residential elevators market is moving through a phase where growth is no longer driven by a single macro tailwind but by a combination of product practicality, compliance alignment, and supply resilience. That combination favors organizations that can translate engineering, installation, and regulatory readiness into a coherent commercial offering. For decision makers evaluating product roadmaps, investment targets, or procurement strategy, the most useful next step is to examine how these dynamics interact within specific regions, applications, and competitive positions.
A fuller segmentation view, company-level benchmarking, and scenario-based projections can sharpen those choices by connecting broad market direction to the operational and commercial details that actually determine outcomes. Detailed market maps and custom strategic recommendations are available through the complete PW Consulting residential elevators research report, which expands on the structural trends, competitive positioning, and regional dynamics discussed here.
For detailed analysis of this topic, please visit the official page: Residential Elevators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nursing Bras Market: How 8.1% CAGR and Wireless Surge Redefine Growth Through 2032
By PW Consulting, 2026-09-21
Navigating the Nursing Bras Market: Strategic Trends and Commercial Opportunities Through 2032
The nursing bras market has entered a phase of structurally accelerated growth, reshaping how apparel manufacturers, healthcare-adjacent brands, and retail distributors approach maternal wellness categories. Valued at approximately $1.1 billion in 2020, the market expanded to roughly $1.48 billion by 2025, reflecting a compound annual growth rate of 8.1 percent through the 2026–2032 forecast window. By 2032, total revenue is projected to approach $2.5 billion. This trajectory is not merely a function of population growth; it signals a broader cultural and functional shift in how maternal wear is designed, distributed, and valued. For executives and investors, the category represents a high-velocity niche where comfort, material science, and inclusive sizing converge with rising healthcare awareness and evolving postpartum lifestyles.
Bra Cups Market
1. Market Reality and Core Challenges
A Category Outgrowing Its Traditional Ambitions
The market’s expansion from 2020 through 2025 was steady rather than explosive, but the underlying composition shifted meaningfully. Revenue growth accelerated as wireless designs gained share over traditional underwire constructions, and as lactation-specific demand outpaced pregnancy-only applications. The base-year footprint in 2025 sits at roughly $1.48 billion, with the forecast arc pointing toward consistent mid-to-high single-digit annual gains. Such growth rates place nursing bras among the faster-appreciating segments within the broader intimate apparel and maternal care landscape.
Despite the positive macro picture, the industry faces structural pressure points that will define competitive positioning over the next several years. First, standardization remains elusive. Size inclusivity, fabric elasticity, and closure mechanisms vary widely across price tiers, creating friction for consumers who seek predictable comfort across pregnancy, nursing, and pumping phases. Second, supply chain complexity is rising. Producing nursing bras that accommodate inclusive sizing demands specialized labor for custom fabric cutting and sewing across global networks. This constraint elevates lead times and compresses margins for brands that cannot optimize cut-and-sew workflows or secure reliable material suppliers. Third, regulatory and compliance expectations are tightening. Material safety certifications such as Oeko-TEX® directly influence supplier qualification and product clearance, forcing brands to embed compliance into procurement rather than treating it as a post-production checkbox. These challenges are not insurmountable, but they reward operators who invest early in design standardization, supplier qualification, and demand forecasting.
2. Key Drivers Shaping the Next Phase
Material Innovation and Hands-Free Functionality
The most visible driver is the shift toward wireless, seamless, and hands-free configurations. Consumers increasingly favor wireless nursing bras for convenience, and hands-free pumping styles have seen higher adoption in the United States. This preference is not cosmetic; it reflects a functional demand for garments that support milk expression while minimizing disruption to work, travel, and daily routines. Recent product validations underscore the commercial pull of this trend. In June 2025, the Sublime® Hands-Free Pumping & Nursing Bra was recognized as Nursing Bras and Tanks Product of the Year at the Baby Innovation Awards, signaling that hands-free engineering has moved from niche experimentation to award-recognized category leadership. A year earlier, in July 2024, a maternity and nursing bra launched with ultra-soft fabric designed for versatile pregnancy-to-nursing use, illustrating how brands are compressing multiple life stages into single SKU architectures. These developments show that innovation is no longer confined to closure mechanisms; it now spans fabric hand-feel, stretch recovery, and integrated pumping support.
For businesses, the implication is clear: product roadmaps that treat nursing bras as basic apparel will lose share to designs that combine lactation functionality with everyday wearability. Fabric selection, seam placement, and strap engineering are becoming core differentiators rather than secondary specifications.
Policy, Reimbursement, and Healthcare Alignment
The policy environment is adding a subtle but meaningful layer of demand support. In the United States, breastfeeding support programs may provide partial reimbursement for specialized nursing bras under certain health insurance plans. While reimbursement is not universal and often depends on plan design and documentation, it introduces a pathway that lowers effective out-of-pocket cost for targeted consumers. This dynamic encourages brands to think beyond pure retail velocity and consider how product positioning, documentation, and clinical-adjacent messaging can align with employer and insurer wellness programs.
At the same time, material regulation continues to shape sourcing decisions. Oeko-TEX® safety standards for materials in nursing bras directly influence supplier certifications and product compliance, making textile sourcing a strategic gate rather than a commodity exercise. Brands that pre-qualify compliant fabric mills and maintain transparent traceability will face fewer launch delays and fewer compliance-related setbacks.
Demand-Side Shifts: Inclusive Sizing and Lifestyle Integration
Demand is being reshaped by a consumer base that expects garments to accommodate body changes without forcing trade-offs between support and comfort. Maternity and postpartum wear is no longer treated as a temporary category; it is increasingly integrated into broader lifestyle wardrobes. Women seek bras that transition from pregnancy through lactation, that suit busty fits, and that remain aesthetically neutral enough for everyday use. This expectation is pushing manufacturers to expand size ranges, reinforce support slings, and reduce visible hardware that disrupts the garment’s silhouette.
The price spectrum also reveals how demand is segmenting. Entry-level nursing bras from mass retailers range from roughly $16.99 to $20, while premium offerings from specialist brands exceed $50. This gap is not merely a pricing artifact; it reflects divergent value propositions. Mass-tier products compete on accessibility and basic functionality, whereas premium players compete on fabric softness, seamless edges, inclusive fit, and specialized pumping support. Brands that can articulate and deliver a clear point of difference within the premium tier are capturing willingness to pay that mass offerings cannot easily replicate.
Supply Chain and Cost Structure Pressures
On the supply side, labor and material orchestration are becoming critical cost levers. Nursing bra production requires specialized labor for custom fabric cutting and sewing to meet inclusive sizing demands across global supply chains. This specialization constrains the ability to scale through generic cut-and-sew partners, and it raises the importance of supplier relationships, pattern engineering, and yield optimization. Brands that invest in modular pattern families, fabric standardization where possible, and disciplined inventory planning will be better positioned to manage cost volatility without sacrificing fit or compliance. Conversely, operators that rely on fragmented sourcing and ad hoc sizing expansion will face margin erosion and inconsistent quality.
3. Competitive Landscape and Leading Strategies
Strategic Positioning Across the Value Chain
The competitive set spans specialist maternal brands, broader intimate apparel players, and equipment-centric companies that have extended into wearable support. Several themes emerge from recent activity. Specialist brands are leaning into wireless, seamless, and hands-free designs with inclusive sizing that spans pregnancy and postpartum. One Oceanside-based brand has concentrated on wireless, seamless, hands-free nursing and pumping bras with easy nursing access, stretchy fabrics, and inclusive sizing from pregnancy through postpartum. Its July 2024 launch of a maternity and nursing bra with ultra-soft fabric for versatile pregnancy-to-nursing use, followed by a September 2024 bundle collaboration with a lactation equipment partner for a nursing and wearable pumping bra bundle, illustrates a strategy that blends product versatility with ecosystem partnership.
In Australia, a maternity-focused brand emphasizes full-coverage, seamless nursing bras and maternity lingerie with supportive slings and style for busty and everyday wear. This positioning targets consumers who want coverage and support without sacrificing appearance, a segment that often remains under-served by minimalist designs. In Canada, another brand offers body silk seamless nursing bras, everyday wireless styles, and maternity apparel with emphasis on comfort and size-inclusive fit, reinforcing the broader industry tilt toward seamless construction and fit breadth. In the United States, a New Jersey-based designer creates combo maternity, nursing, and pumping bras with modern, stylish closures and premium fabrics for active and postpartum moms, showing that closure aesthetics and fabric premiumization can coexist with functional versatility.
A Denver-based brand provides ultra-soft, hands-free pumping and nursing bras with innovative designs and wide size ranges for comfort during feeding, a configuration that directly addresses the hands-free adoption trend noted earlier. European players continue to anchor on support and seam engineering. A German brand offers specialized nursing bras in seamless and underwire styles with seamless edges and enhanced support for breastfeeding, while a Swiss company provides maternity and nursing bras with quick-dry technology, breathable zones, and integrated pumping support. These offerings demonstrate that support, moisture management, and pumping integration remain viable differentiators even as wireless designs gain momentum.
How Leaders Differentiate
Across these players, differentiation clusters around a few repeatable advantages. The first is functional integration: hands-free pumping compatibility, quick-dry or breathable zones, and closures that balance accessibility with security. The second is fit architecture: inclusive sizing, supportive slings, and stretch-managed fabrics that accommodate fluctuating bust size without sacrificing shape. The third is aesthetic assimilation: seamless edges, neutral styling, and fabrics that feel more like everyday basics than specialized medical-adjacent garments. Brands that combine two or more of these advantages tend to command stronger positioning and more resilient pricing.
Partnerships are also becoming strategic. The September 2024 collaboration between a lactation equipment maker and a specialist bra brand produced a nursing and wearable pumping bra bundle designed for enhanced feeding convenience. This type of alliance links garment functionality with expression equipment, creating a combined solution that can improve customer retention and cross-category visibility. As the category matures, similar partnerships with employers, insurance-adjacent programs, and retail channels may become more common.
Market Structure and Evolutionary Pressures
Market concentration indicates a moderately consolidated landscape, with the top three firms holding approximately 52 percent of revenue and the top five closer to 78 percent. This structure suggests that scale players have meaningful influence over channel access, sourcing leverage, and brand visibility. At the same time, the presence of strong specialist brands and regional players indicates room for targeted differentiation, especially where fit, fabric, and functionality are executed with precision. The likely trajectory is not a race to pure consolidation but a bifurcated market: scaled brands compete on breadth, distribution, and bundled solutions, while specialists compete on design depth, material comfort, and segment-specific fit. New entrants will find the most traction by solving a specific consumer pain point—hands-free usability, size-inclusive support, or premium fabric hand-feel—rather than by entering as generic alternatives.
4. Future Trajectory: Trends and Commercial Opportunities
Wireless and Hands-Free as Baseline Expectations
Over the next three to five years, wireless and hands-free designs are likely to transition from growth segments to baseline expectations in many markets. Adoption is already strongest where convenience and dual-use functionality matter most, and as more employers normalize flexible lactation routines and more consumers prioritize wardrobe continuity, the demand for bras that support nursing and pumping without compromising daily wear will keep rising. The commercial opportunity lies in product architectures that reduce SKU complexity while expanding use-case coverage. Brands that can deliver a single platform with adjustable support, reversible styling cues, and compatible pumping integration will capture efficiency gains and improve consumer retention across life stages.
Regional Momentum and Channel Reconfiguration
Geographically, the market is broad but uneven. North America anchors a large share of revenue, reflecting strong retail footprint, established maternal care awareness, and reimbursement-adjacent pathways. Europe contributes a substantial base with a focus on support, seam quality, and compliance-driven material sourcing. Asia Pacific represents a meaningful and growing footprint, where expanding maternal care awareness, e-commerce penetration, and urbanization are broadening access to specialized nursing wear. Latin America and the Middle East and Africa together form smaller but developing demand pools, often shaped by retail distribution, cultural acceptance, and channel availability.
For businesses, the strategic implication is that growth will not come from a single region executing identically. North America may reward hands-free innovation and bundle partnerships; Europe may reward compliance-forward sourcing and support engineering; Asia Pacific may reward size-inclusive assortments and digitally native distribution. Companies that align product, channel, and sourcing to regional preferences will extract more value than those that treat the market as uniform.
Premiumization, Fit, and Compliance as Margin Anchors
A second medium-term trend is premiumization anchored in fit and compliance rather than branding alone. As entry-level price points remain anchored in the teens and premium offerings sit above $50, the margin opportunity for specialist brands depends on proving functional and tactile superiority. Consumers are willing to pay for garments that genuinely reduce discomfort, accommodate sizing changes, and integrate lactation needs without feeling specialized in a clinical sense. Simultaneously, compliance-driven material expectations will increasingly act as a margin protector for prepared brands, since certified sourcing reduces the risk of reformulation, delayed launches, and reputational friction. Companies that treat compliance and fit as design inputs—not downstream checks—will be better positioned to sustain premium pricing and lower returns.
The principal uncertainty is consumer volatility across the pregnancy-to-postpartum window. Purchase timing is clustered, body changes are rapid, and satisfaction is highly sensitive to fit and function. Overproduction in the wrong sizes or styles can quickly erode inventory health, while underinvestment in inclusive sizing can limit addressable demand. Brands that pair disciplined demand forecasting with modular pattern families and flexible fabric sourcing will navigate this volatility more effectively.
5. Strategic Guidance for Decision-Makers
For Manufacturers and Brand Operators
First, compress the product architecture. Where possible, design modular platforms that span pregnancy, nursing, and pumping with adjustable support elements, so that development investment yields multiple sellable configurations without fragmenting inventory. Second, treat fabric and closure engineering as core IP. Hands-free compatibility, seamless edges, stretch recovery, and moisture management are no longer nice-to-haves; they are the attributes that justify premium pricing and reduce fit-related returns. Third, embed compliance into sourcing. Pre-qualify material suppliers for relevant safety certifications and maintain traceability that can support faster approvals and fewer redevelopment cycles. Finally, standardize inclusive sizing through disciplined pattern engineering rather than ad hoc expansions, because specialized labor for custom cutting and sewing is a scarce and costly resource that rewards repeatable, yield-optimized workflows.
For Investors
Look for operators that demonstrate functional differentiation with commercial proof, not just design ambition. Award recognition for hands-free pumping and nursing bras, successful product transitions from pregnancy into lactation, and bundled partnerships with lactation equipment providers are indicators that a product strategy is resonating with real usage patterns. Favor businesses that show control over compliant material sourcing, disciplined SKU breadth, and pricing power above the entry tier without relying solely on brand nostalgia. Evaluate channel mix carefully: digitally native reach, selective retail partnerships, and alignment with employer or insurance-supported wellness programs can compound growth more efficiently than broad but shallow distribution.
For Procurement and Channel Leaders
Prioritize assortments that balance accessibility with functional depth. Entry-level price points remain important for volume, but premium-tier SKUs with verifiable comfort, inclusive fit, and pumping compatibility are where basket value and repeat purchase potential increase. For specialty retail and e-commerce, curated bundles that pair nursing bras with compatible pumping accessories can improve conversion and reduce post-purchase support friction. For wholesale and distribution, align regional assortments to local preferences: emphasize hands-free and versatile designs where convenience dominates, and prioritize support engineering and compliance-forward materials where those attributes carry greater weight.
PW Consulting Information & Electronics Research Center
The nursing bras market is moving from a niche maternal category to a functionally sophisticated segment with wider lifestyle relevance. Growth is sustained, but the value is shifting toward operators who can integrate comfort, compliance, inclusive fit, and lactation functionality into coherent product platforms. Detailed segment-level sizing, regional channel dynamics, and company-specific benchmarking can sharpen execution further, and fuller research is available for teams that need granular data and tailored recommendations.
Worldwide Breastfeeding Accessories Market
For detailed analysis of this topic, please visit the official page: Nursing Bras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Bulk Molding Compounds Market: Strategic Shifts and Commercial Opportunities Through 2032
The Bulk Molding Compounds (BMC) market has moved past a period of steady expansion and entered a phase defined by structural reconfiguration, margin pressure, and accelerating material innovation. From 2020 through 2025, the sector recorded consistent revenue growth, culminating in a base-year valuation of approximately $2,622 million in 2025. Forward projections indicate that the market will reach roughly $3,652 million by 2032, supported by a compound annual growth rate of 4.9 percent. This trajectory reflects more than incremental demand; it signals a maturing ecosystem where traditional material advantages are being tested by cost volatility, regulatory shifts, and substitution threats from advanced thermoplastics and engineered thermosets. Decision-makers across manufacturing, procurement, and capital allocation must understand how these dynamics are reshaping competitive positioning and where durable value creation lies.
Market Structure and Core Challenges
A Mature Ecosystem with High Double-Digit Margins Under Pressure
The BMC market remains moderately concentrated, with the top three players capturing roughly 40 percent of global revenue and the top five extending that share to approximately 45 percent. This concentration suggests that scale, formulation expertise, and specialized compounding capabilities continue to matter, but it also indicates that there is meaningful room for specialized suppliers, regional players, and application-focused innovators. The revenue base is split across several material families, with polyester-based compounds representing the largest share, followed by epoxy and vinyl ester formulations, while a diverse group of specialty and blended systems occupies a notable portion of the portfolio. Application-wise, electrical and electronics end-use segments and automotive and transportation applications account for the largest demand pools, with building and construction and other industrial applications forming secondary but stable demand layers. Rather than treating these splits as static categories, it is more useful to view them as competing demand centers where formulation performance, cost, and regulatory compliance determine which material system wins in a given application.
Three Defining Challenges at the Current Inflection Point
First, raw material volatility continues to challenge production economics. Unsaturated polyesters, glass fibers, mineral fillers, and various additives are highly sensitive to crude oil movements, petrochemical supply interruptions, and regional energy pricing. When feedstock costs swing sharply, compounding margins compress quickly unless suppliers have secured long-term agreements, adjusted formulations dynamically, or passed through costs without disrupting volume. This environment rewards manufacturers that can protect cost predictability through formulation flexibility and supply diversification.
Second, environmental and regulatory pressure is reshaping formulation requirements, especially in transportation and electronics. Stricter emission targets, recyclability expectations, and chemical management frameworks are pushing developers toward lower-weight compounds, improved flame performance without brominated or otherwise restricted chemistries, and more recyclable or lower-impact resin systems. Compliance is no longer a peripheral consideration; it is becoming an integral part of qualification cycles and customer specifications, particularly where vehicle lightweighting, energy efficiency, and sustainability reporting intersect.
Sheet Molding Compound (SMC) Market
Third, substitution risk from advanced thermoplastics and hybrid composite strategies is intensifying in certain application areas. Where processing speed, design flexibility, or recyclability is prioritized, engineers increasingly evaluate alternatives to conventional BMC. This does not diminish the role of BMC overall, but it sharpens the requirement for differentiation. Suppliers that only compete on price or generic performance are more exposed, while those that can demonstrate superior electrical insulation, chemical resistance, flame performance, or cost-to-function value in a specific use case retain stronger positioning.
Worldwide Thermoset Molding Compounds Market
Key Drivers Reshaping Demand and Competitive Dynamics
Technical Innovation and Formulation Breakthroughs
The market is being shaped as much by incremental formulation advances as by headline product launches. Improvements in flexural and tensile performance, better dimensional stability, enhanced surface finish, and more consistent processing behavior are expanding the range of parts that can be produced efficiently through compression and transfer molding. At the same time, development efforts are increasingly oriented toward multifunctional compounds that combine flame resistance, electrical insulation, and mechanical durability in a single system, reducing the need for secondary treatments or coatings. Recent operational moves illustrate this shift. IDI Composites International opened a new 120,000-square-foot global headquarters and manufacturing facility in Noblesville, Indiana, dedicated to BMC production and research and development. This type of investment signals a focus on integrated scale, faster formulation iteration, and application-specific development rather than commoditized production alone.
PW Consulting
Policy and Regulatory Direction
Regulatory frameworks are accelerating reformulation priorities across multiple regions. The EU Circular Economy Action Plan and REACH-related chemical management expectations are encouraging more eco-friendly and recyclable compound development, while tighter emission and efficiency standards in the automotive sector are driving demand for lighter, higher-performance molded components. These policies influence not only what can be sold, but how quickly new formulations can be qualified, how suppliers document compliance, and which chemistries remain viable in long-term contracts. In practice, regulatory momentum is converting sustainability from a marketing attribute into a design constraint that shapes resin selection, filler choices, and end-of-life considerations.
Demand-Side Shifts in Electrical, Automotive, and Industrial Applications
On the demand side, electrification and vehicle efficiency goals are expanding the need for lightweight, thermally stable, and electrically insulating components in transportation. In electrical and electronics applications, the push for compact enclosures, reliable insulation, and improved flame performance supports continued use of BMC where dimensional stability and cost-effectiveness matter. Meanwhile, industrial and building applications continue to rely on BMC for corrosion-resistant fittings, utility components, and custom molded parts that benefit from replicable geometry at moderate production volumes. A common thread across these end-use segments is the growing preference for suppliers that can reduce qualification time, offer consistent lot-to-lot performance, and support application engineering rather than simply ship resin systems.
Supply Chain and Cost Structure Realignment
Cost structures remain tied to petroleum-derived feedstocks and fiber supply dynamics, making margin management a strategic discipline rather than an operational afterthought. Volatility in unsaturated polyester resin pricing, fillers, and fibers affects cost predictability across the value chain and encourages suppliers to rethink sourcing models, blend strategies, and inventory planning. Companies that adapt by expanding approved raw material options, adjusting filler ratios without sacrificing performance, or regionalizing supply to reduce freight and tariff exposure are better positioned to maintain stable pricing and service levels. This realignment also favors suppliers that can provide transparent cost narratives and flexible commercial terms, especially in applications where total installed cost and lifecycle reliability matter more than unit price alone.
Competitive Landscape and Leading Strategies
How Leading Players Differentiate
The competitive field includes a mix of application-focused compounders, regionally rooted manufacturers, and larger resin and materials firms that leverage broader chemistry portfolios. IDI Composites International positions itself around dedicated BMC production for automotive, electrical, and industrial applications, with an emphasis on integrated manufacturing and development capacity. Mar-Bal, Inc. concentrates on thermoset compounding for electrical and industrial molded parts, where consistent electrical performance and reliable molding behavior are central to customer selection. Menzolit operates as a global producer spanning BMC and sheet molding compounds, serving automotive, electrical, and transport sectors with a focus on formulation breadth and application engineering. Resonac, formerly known as Showa Denko, brings advanced material engineering capabilities to high-performance BMC applications, supporting customers that require specialized thermal, electrical, or mechanical characteristics. Polynt SpA contributes a general-purpose compound portfolio alongside related thermoset systems, offering a balance of availability, consistency, and formulation range. Hexion Inc. leverages its thermoset resin expertise to supply BMC for industrial and automotive uses, benefiting from resin chemistry depth and downstream application support.
Strategic Positioning and Differentiation Levers
Across these players, the most effective differentiation tends to emerge from three overlapping capabilities. The first is formulation agility: the ability to tailor resin chemistry, fiber architecture, and additive packages to the exact requirements of an application while maintaining consistency. The second is application engineering and qualification support: helping customers reduce time to production through material selection guidance, processing recommendations, and predictable performance data. The third is supply reliability: dependable delivery, inventory availability, and cost transparency that reduce total program risk for OEMs and tier suppliers. Companies that combine these capabilities tend to hold stronger positions even in a market where concentration is moderate and switching costs can appear lower than they actually are once qualification and performance history are factored in.
Structural Trends in Market Configuration
The market structure appears to be moving through a phase of selective consolidation alongside continued niche specialization. Larger investments in integrated facilities, such as dedicated headquarters and manufacturing centers, point toward economies of scale and more centralized development. At the same time, regional suppliers and application specialists remain relevant where local service, rapid response, and custom formulation are valued. New entry is possible but challenging because qualification cycles, performance consistency, and customer confidence create real barriers, even though formulation IP, niche application access, and regional cost advantages can still support targeted entry. The likely outcome is not a simple shakeout but a layered market in which broad-scale suppliers compete on consistency and cost, while specialists compete on performance, application fit, and engineering support.
Forward Outlook: Trends and Commercial Opportunities
Trend 1: Formulation-as-a-Differentiator Becomes Central
Over the next three to five years, BMC suppliers are likely to compete increasingly on tailored performance packages rather than generic compound categories. Expect more emphasis on lightweighting, flame performance within evolving regulatory expectations, improved electrical reliability, and processing stability that lowers scrap and cycle-time variability. The commercial opportunity lies in embedding formulation support earlier in the design process. Suppliers that can influence material selection during component development, rather than responding only after specifications are fixed, will capture stronger value and longer customer relationships.
Trend 2: Regionalization and Supply Resilience Gain Strategic Weight
Sourcing and production footprints are likely to become more deliberately regionalized or multi-nodal to reduce exposure to feedstock shocks, logistics disruption, and tariff uncertainty. For customers, this creates an opportunity to diversify approved suppliers and negotiate contracts that balance cost, availability, and technical support. For manufacturers, the opportunity is to build capability that can serve regional demand with consistent quality, faster lead times, and clearer cost structures. The companies that can demonstrate resilience without sacrificing performance will be better positioned to retain volume during periods of market volatility.
Trend 3: Sustainability Requirements Move Into Spec-Driven Selection
Sustainability expectations are shifting from broad brand messaging toward specification-level criteria, especially in automotive and electrical applications. This creates a need for documented material attributes, clearer pathways for recyclability or end-of-life handling, and chemistry choices aligned with evolving regulatory expectations. The commercial opportunity is for suppliers that can translate sustainability goals into measurable performance and compliance data, enabling customers to justify material decisions in both engineering and procurement reviews. The principal risk is that overly generic sustainability claims will lose credibility if they are not supported by formulation details, testing evidence, and supply-chain traceability.
Actionable Implications for Decision-Makers
For Manufacturers and Compounders
Prioritize formulation flexibility and application engineering as core competitive assets. Build the ability to adjust resin, fiber, and additive combinations without compromising certification or performance consistency, and invest in capability that shortens qualification cycles for customers. Where possible, regionalize key supply and production capacity to improve lead-time reliability and reduce exposure to feedstock and logistics volatility. Differentiate through measurable processing benefits, such as lower scrap rates, predictable cycle times, and stable lot performance, rather than competing primarily on headline price.
For Investors and Capital Allocators
Evaluate exposure based on formulation depth, application mix, and supply-chain resilience rather than scale alone. Favor business models that combine margin protection through diversified raw material sourcing with demand visibility from long-cycle automotive, electrical, or industrial programs. Watch for signs that competitors are moving up the value chain through R&D investment and integrated facilities, because these moves can reshape regional pricing power and share dynamics. Be attentive to substitution risk in applications where thermoplastics or hybrid strategies are gaining traction, and assess whether target companies have credible responses in the form of lighter weight, higher performance, or cost-to-function advantages.
For Procurement and Engineering Leaders
Treat supplier selection as a total-cost and risk decision rather than a unit-price comparison. Evaluate compound performance in the context of processing reliability, qualification speed, flammability or electrical requirements, and long-term availability. Diversify approved suppliers where feasible to reduce exposure to single-source disruption, and seek partners that can provide transparent cost narratives and formulation support during component design. Where regulatory and sustainability expectations are increasing, request documented evidence of material attributes, compliance alignment, and any relevant end-of-life considerations so that sourcing decisions remain defensible across engineering, procurement, and compliance reviews.
Conclusion
The BMC market is entering a period in which growth is no longer enough on its own to secure advantage. The combination of feedstock volatility, evolving regulatory expectations, and increasing demand for application-specific performance is rewarding suppliers that can integrate formulation expertise, supply resilience, and engineering support into a coherent offering. For companies and investors operating in this space, the strategic imperative is to move beyond generic positioning and toward differentiated value that can withstand cost pressure and substitution risk. More granular segmentation detail, regional demand patterns, and customized scenario analysis can help decision-makers translate these trends into specific sourcing, investment, and development choices. For teams that require deeper end-use breakdowns, formulation-level comparisons, or a tailored assessment of regional opportunity, a detailed commercial study can provide the additional structure needed to turn these market signals into precise action.
For detailed analysis of this topic, please visit the official page: Bulk Molding Compounds (BMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Agricultural Inoculants Market: Why 10.41% CAGR Redefines Industry Growth
By PW Consulting, 2026-09-21
The Agricultural Inoculants Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The agricultural inoculants market has moved decisively from a niche biological input category to a structural component of modern crop production. Between 2020 and 2025, global revenue expanded from approximately USD 0.85 billion to USD 1.42 billion, reflecting consistent double-digit momentum even as broader agribusiness cycles faced volatility. Looking ahead through 2032, the trajectory points toward a USD 2.84 billion endpoint, supported by a compound annual growth rate of 10.41 percent. This expansion is not simply a function of incremental adoption; it reflects a deeper recalibration in how producers, policymakers, and input suppliers approach soil biology, nutrient efficiency, and crop protection.
What makes this period distinctive is the convergence of biological efficacy with commercialization scale. Inoculants are no longer evaluated solely as substitutes for conventional inputs. They are increasingly positioned as productivity multipliers that enable reduced synthetic fertilizer use, improved stress resilience, and alignment with sustainability programs. That shift in value proposition is reshaping product architectures, partnership models, and go-to-market strategies across the sector.
For decision-makers, the immediate question is less about whether the market will grow and more about who captures disproportionate value in a space that is simultaneously fragmenting by application specificity and consolidating around integrated biological platforms.
Core Challenges and Market Inflection Points
Despite the favorable growth backdrop, the industry faces structural tensions that will separate durable players from transient entrants.
Biostimulants Market
First, consistency of biological performance remains the defining commercial hurdle. Live microorganisms must survive formulation, storage, application timing, and variable field conditions while delivering measurable yield or nutrient-use improvements. Products that perform reliably in controlled trials can disappoint under real-world heterogeneity. This creates a credibility gap that slows repeat purchases and complicates retailer recommendations. Companies that can demonstrate repeatable performance across geographies and seasons are building a moat that premium positioning and broader adoption increasingly require.
Second, the market is navigating a regulatory environment that is simultaneously enabling and constraining. In some jurisdictions, biologicals are being streamlined into sustainable-input frameworks that encourage substitution away from purely chemical programs. In others, strict product-category definitions limit the organisms, claims, and formulations that can be marketed. The European Union’s Regulation 2019/1009, for example, anchors biofertilizer marketing to a defined set of microbial genera and mycorrhizal fungi. Such rules create clarity for compliant products but also raise barriers for portfolios that depend on broader strain sets or novel delivery claims. Firms must treat regulatory design not as a fixed backdrop but as an active variable in product strategy.
Third, the sector is confronting a commercialization bottleneck. Strong institutional interest and pilot programs do not automatically translate into widespread adoption at scale. Extension services, agronomic support, and dealer education determine whether inoculants are treated as high-potential tools or as optional add-ons. USDA’s Partnerships for Climate-Smart Commodities allocated substantial funding to soil microbiome enhancement projects, and the USDA National Institute of Food and Agriculture has supported extension coverage for microbial inoculant technologies in organic and regenerative farming systems. These initiatives expand awareness and trial, yet they also underscore that adoption depends heavily on local agronomic translation. The market’s next phase will reward players who can convert research momentum into repeatable field-level execution.
What Is Really Driving Growth
The market’s upward path is being shaped by four reinforcing forces rather than a single tailwind.
Technology innovation is the most visible driver. Advances in strain selection, formulation stability, and microbial function are expanding what inoculants can deliver beyond traditional nitrogen fixation. Gene-edited nitrogen-fixing microbial technologies are moving from experimental concepts to commercial realities, with recent large-scale farm trials indicating operational efficiency gains and improved returns in specific crops. This matters commercially because it signals that biologicals can be engineered with greater functional predictability, which in turn supports premium pricing, tighter crop positioning, and stronger farmer confidence.
Policy and sustainability frameworks are second. Organic certification land in North America and Europe expanded at roughly 8.2 percent annually between 2020 and 2025, increasing demand for biological inputs permitted within those systems. At the same time, public programs tied to climate-smart practices are encouraging soil-health investments that favor microbiome-based tools. For manufacturers and distributors, this means the addressable base is widening in two directions: regulated specialty systems that explicitly require biological compatibility and mainstream acreage seeking input efficiency and compliance with sustainability commitments.
Demand-side behavior is changing too. Producers are increasingly managing for total input economics rather than isolated yield gains. With nutrient costs and application complexity under scrutiny, microbial solutions that improve nutrient-use efficiency, support soil function, or reduce reliance on specific chemical programs become more attractive. The buyer mindset is shifting from “Does this product work in ideal conditions?” to “Does this product improve my margin profile across variable conditions?” That reframing creates more room for multi-benefit inoculant platforms, especially those aligned with seed treatment, in-furrow placement, or soil health programs.
Supply chain and cost structures are evolving as well. Biological manufacturing requires refrigeration, stabilization, carrier materials, and stringent quality control. As demand scales, companies are investing in production reliability, shelf-life management, and regional distribution capacity. These investments raise the operational bar but also reinforce differentiation. Players with more robust formulation science and logistics can offer more dependable delivery, which is increasingly important as inoculants move from early adopters to broader mainstream use.
Competitive Landscape and the Battle for Positioning
The leadership group in agricultural inoculants is defined less by a single product and more by how companies integrate biologicals into broader crop portfolios, formulation capabilities, and customer reach. The competitive field includes multinational crop-science organizations, specialized biologicals companies, and region-focused innovators.
Large diversified players are positioning inoculants as an extension of seed treatment and crop protection strategies. Their advantage lies in distribution scale, agronomic networks, and the ability to bundle biological solutions with established seed and crop programs. BASF SE anchors its approach around integrated crop protection with Bacillus biocontrol lines and nitrogen-fixing inoculants such as Nodulator PRO for corn and soybean. Bayer AG emphasizes seed treatment and microbial inoculant solutions within its Crop Science division. Syngenta Group Co., Ltd. integrates microbial inoculants into its wider crop protection and seed portfolio, using biologicals to reinforce broader system offerings rather than stand-alone biological sales alone.
Specialized biologicals companies are competing through functional focus and product depth. Novonesis A/S brings bacterial and fungal inoculants aimed at nutrient uptake and soil health across field crops. Lallemand Inc. and Premier Tech Ltd. extend microbial inoculant offerings into cereals, vegetables, horticulture, and crop nutrition. These companies often compete on formulation know-how, strain expertise, and close relationships with growers and dealers who value biological specificity.
PW Consulting
A newer set of innovators is pushing performance boundaries through advanced strain engineering and precision-oriented application. Corteva, Inc. advances its Utrisha N nitrogen-fixing platform alongside biologicals designed for seed-treatment-first crop solutions. Pivot Bio, Inc. has moved gene-edited nitrogen-fixing microbial technologies into commercial launches for cereals and cotton, following large-scale farm trials that emphasized improved returns and operational efficiency. Groundwork BioAg Ltd. focuses on mycorrhizal inoculants for crop nutrition, Verdesian Life Sciences LLC on nutrient-use-efficiency microbial inoculants and biostimulants, and XiteBio Technologies Inc. on microbial inoculant technologies tied to precision agriculture. Together, these companies illustrate a shift from broad biological categories toward more targeted claims and functional reliability.
Regional and application specialists are also shaping the market. Bioceres Crop Solutions Corp. offers crop solutions that include microbial inoculants for sustainable agriculture, with a footprint that ties biologicals to broader field-crop needs. Valent BioSciences LLC and Koppert Biological Systems B.V. concentrate on biologically oriented pest and crop management, while Koppert’s microbial biologicals fit within integrated pest and crop management programs. This mix of global scale, functional specialization, and regional depth is producing a competitive environment where differentiation is increasingly tied to formulation, compatibility, agronomic support, and claims substantiation.
The market is not consolidating into a single model. Instead, it is evolving in two directions at once. One direction favors integration: larger crop-science organizations embedding biologicals into seed and protection systems to increase attachment rates and cross-selling. The other favors specialization: companies that can make stronger, more defensible claims in specific crops, functions, or farming systems. New entrants continue to appear where there is credible strain science, a clear use case, and a route to distribution. The likely outcome is a layered competitive structure in which a few broad platforms coexist with a growing set of crop- and function-specific solutions.
Three Strategic Trends to Watch Over the Next Three to Five Years
The next phase of market development will likely be shaped by three interlocking trends.
First, biological products will move from generic “microbial input” positioning to more defined functional categories with clearer agronomic claims. As formulation stability improves and strain-level performance is better characterized, companies will increasingly sell around specific outcomes such as nutrient-use efficiency, stress buffering, or compatibility with reduced-input systems. For businesses, this implies greater importance in claim validation, trial design, and agronomic messaging. The winners will be those who can match product capability with credible, repeatable field evidence rather than broad category hype.
Second, distribution models will become more specialized. Seed-applied biologicals, in-furrow systems, and soil-applied formulations each demand different handling, timing, and agronomic advice. This will push manufacturers and distributors to build crop-specific commercial architectures rather than relying on uniform product buckets. Partnerships with seed companies, dealers, and extension networks will matter more because adoption is increasingly determined by how well a biological fits into season-long decision-making. Companies that invest in compatibility testing, application guidance, and localized support will have an advantage in converting trials into repeat purchases.
Third, sustainability-linked programs and regulatory definitions will continue to influence product design and market access. Funding tied to climate-smart commodities, regenerative practices, and organic systems is expanding the incentive to adopt microbiome-based tools, while regulatory frameworks are sharpening the boundary between approved biological categories and broader biostimulant or soil amendment claims. This creates both opportunity and constraint. Firms that design products with regulatory clarity, organic compatibility, and sustainability reporting in mind can unlock access to higher-growth segments. At the same time, companies should expect that market access may vary by region and that product claims will face greater scrutiny as biologicals move from niche to mainstream.
Risks and Uncertainties That Could Reshape the Outlook
The growth path is promising but not guaranteed. Biological performance variability remains the central risk. If field-level inconsistency persists across a meaningful share of products, adoption could plateau at a level below the premium pricing needed to sustain aggressive investment. Price sensitivity is another factor. In periods of compressed farm margins, biologicals that are viewed as additive costs without clear economic payoff may lose ground to lower-cost alternatives.
Regulatory divergence could also create uneven market conditions. Product definitions that favor a narrow set of organisms in one region may limit portfolio flexibility, while other regions may move more quickly toward broader biological-use frameworks. This can privilege companies with adaptable formulation strategies and multi-claim capability while challenging those dependent on a single regulatory interpretation.
Finally, scaling biologicals requires more than scientific promise. Manufacturing reliability, cold-chain or stabilization requirements, carrier availability, and quality control can impose cost structures that erode margins if not managed carefully. Companies that underestimate the operational complexity of commercial-scale biological production may find that early market enthusiasm does not translate into sustained profitability.
Worldwide Biological Silage Inoculants Market
Actionable Implications for Decision-Makers
For manufacturers and product developers, the strategic priority is to strengthen the link between formulation science and commercial reliability. Investments that improve shelf stability, consistency across lots, and compatibility with existing application systems will likely generate more commercial leverage than product breadth alone. Crop-specific claim development, supported by rigorous field validation, can also help differentiate in a category where credibility is a key purchase driver. Where possible, designing products with regulatory clarity and sustainability-program alignment in mind can open access to higher-value segments without relying on generic biological positioning.
For investors, the attractive opportunities are shifting from category-level growth narratives to company-level execution quality. The more durable bets will likely be on firms that can demonstrate repeatable performance, scalable manufacturing, and defensible distribution relationships. Portfolio strategies that distinguish between broad biological platforms and highly targeted functional solutions may outperform undifferentiated exposure to the category. Monitoring commercialization milestones, trial-to-adoption conversion, and regulatory positioning can provide earlier signals than headline revenue alone.
For procurement teams and agribusiness purchasers, the focus should be on total agronomic and economic fit rather than isolated product features. Evaluating inoculants through the lens of application compatibility, season-long performance, dealer support, and compatibility with sustainability or certification requirements will produce better outcomes than short-listing based on label claims alone. Pilots tied to measurable operational metrics, with clear criteria for scale-up, can reduce adoption risk while building internal evidence for repeat purchasing and program design.
The agricultural inoculants market is entering a phase where strategy is less about recognizing momentum and more about aligning product design, commercial execution, and regulatory positioning with how biologicals are actually used in the field. The companies and organizations that make those choices deliberately are best positioned to convert a growing market into durable competitive advantage. For readers seeking a more granular view of segment dynamics, regional demand patterns, competitive benchmarks, and scenario-based sizing across the forecast period, the full PW Consulting study provides the detailed breakdowns and customized frameworks needed to support investment, product, and procurement decisions at a more granular level.
For detailed analysis of this topic, please visit the official page: Agricultural Inoculants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Aluminum Plating Machine Market CAGR Insights: What Fuels the 8.9% Growth
By PW Consulting, 2026-09-21
The Strategic Shift in the Vacuum Aluminum Plating Machine Market: Trends and Commercial Opportunities Through 2032
The vacuum aluminum plating machine market is entering a decisive growth phase, driven by the convergence of environmental mandates, technological maturation, and shifting industrial demand patterns. Valued at approximately 302.9 million USD in 2025, the market has expanded from 180.1 million USD in 2020, reflecting a compound annual growth rate of 8.9 percent through 2032. By the end of the forecast period, total market revenue is projected to reach 547.4 million USD. This trajectory signals more than incremental expansion; it points to a structural realignment in how manufacturers approach surface finishing, metallization, and coating processes. Understanding the forces shaping this landscape is essential for executives, investors, and procurement leaders who must navigate capital allocation, compliance timelines, and competitive positioning.
Market Landscape and Core Challenges
The market's growth narrative is anchored in steady incremental gains across the 2020 to 2025 period, followed by an acceleration in the forecast horizon. Revenue climbed from 180.1 million USD in 2020 to 222.16 million USD in 2022, then to 247.73 million USD in 2023 and 275.44 million USD in 2024. The 2025 baseline of 302.9 million USD sets the stage for a forecast continuum that moves from 320.57 million USD in 2026 to 368.52 million USD in 2027, 397.15 million USD in 2028, 430.25 million USD in 2029, 467.26 million USD in 2030, 501.88 million USD in 2031, and 547.4 million USD in 2032. This progression underscores a market that is expanding beyond early adoption cycles into broader industrial integration. Yet the headline figures mask underlying friction points that decision-makers must address.
Structural Complexity and Process Variability
One of the most persistent challenges in this market lies in the inherent variability of vacuum aluminum plating processes. Aluminum metallizing requires precise handling of metal wire, vacuum chamber fixtures, and controlled deposition environments. The loading and unloading phases remain labor-intensive, introducing moderate unit costs and operational bottlenecks. Facilities that scale production without standardizing workflow design often encounter throughput inconsistencies, yield fluctuations, and maintenance overhead that erode margin expectations. For manufacturers evaluating equipment investments, the challenge is not simply acquiring a plating system but integrating it into a cohesive production architecture that minimizes manual intervention while maintaining coating quality.
Regulatory Pressure and Compliance Timelines
A second critical challenge stems from tightening environmental and emissions regulations. Revisions to the EPA Clean Air Act and amendments to the EU Volatile Organic Compound Directive have intensified the push toward solvent-free coating processes. Vacuum technology has emerged as a preferred pathway to eliminate solvent emissions and reduce hazardous waste generation. Simultaneously, China's National Emission Standards and the California Air Resources Board have accelerated the replacement of wet coating systems with vacuum-based aluminum plating equipment. These regulatory shifts are not abstract; they carry concrete infrastructure implications. Heavy capital investment ranging from 500,000 USD to 5 million USD per facility is required for equipment upgrades to meet environmental compliance deadlines. Organizations that delay planning for these transitions risk operational disruptions, retrofit penalties, and competitive disadvantage as peers capture early compliance benefits.
Market Concentration and Competitive Pressure
The market remains moderately concentrated, with the top three players accounting for 54.2 percent of revenue and the top five holding 67.8 percent. This concentration reflects the technical expertise, capital intensity, and regulatory navigation capabilities required to compete effectively. However, concentration also creates pressure on smaller participants and new entrants to differentiate through niche applications, regional service networks, or specialized 코팅 architectures. Companies that cannot match the process reliability, compliance readiness, or application breadth of leading suppliers face margin compression and customer attrition. The strategic question for mid-tier and emerging players is whether to pursue consolidation, focus on underserved segments, or invest in technological features that command premium positioning.
Key Drivers of Market Evolution
Technology Innovation and Process Optimization
Technological advancement is a primary engine of market growth, particularly in the areas of vacuum deposition precision, automation integration, and coating durability. Next-generation vacuum coating machines are increasingly designed to optimize industrial coatings for both performance and sustainability. Features such as enhanced vacuum pump systems, real-time video monitoring, and upgraded generation architectures enable tighter process control, reduced defect rates, and broader application flexibility. The recent introduction of high vacuum metal deposition machines with forensic-grade monitoring capabilities illustrates how equipment sophistication is expanding beyond traditional industrial use into precision and specialized finishing contexts. These innovations lower the total cost of ownership over time by improving yield consistency and reducing rework, making vacuum aluminum plating more attractive relative to legacy wet coating methods.
PW Consulting Automotive & Machinery Research Center
Policy and Regulatory Tailwinds
Regulatory developments are transforming compliance from a cost center into a market catalyst. Mandates that require the elimination of solvent emissions and the reduction of hazardous waste are directly favoring vacuum-based metallization over conventional electroplating and wet coating. The substitution effect is visible across multiple industrial verticals, where manufacturers are replacing older systems with vacuum aluminum plating equipment to meet emission standards while maintaining surface quality. Policy-driven demand is not uniform across regions, but the directional trend is clear: jurisdictions with stringent air quality and volatile organic compound frameworks are accelerating equipment replacement cycles. This regulatory momentum creates a predictable demand pipeline for manufacturers that can demonstrate compliance-ready configurations and documented emission reductions.
Demand-Side Shifts in Packaging and Electronics
Demand patterns are evolving as downstream industries prioritize lightweighting, aesthetic differentiation, and functional coating performance. Packaging applications continue to represent a substantial share of market activity, driven by the need for barrier properties, visual appeal, and durable surface finishes on plastic and film substrates. Electronics applications also contribute significantly, where aluminum metallization supports reflectivity, conductivity, and protective coating requirements for components and enclosures. Consumer and enterprise expectations for premium finishes, corrosion resistance, and consistent appearance are pushing manufacturers to adopt vacuum plating processes that deliver repeatable results at scale. The shift is not merely about replacing one coating method with another; it is about aligning surface engineering capabilities with product performance targets and brand positioning.
Supply Chain and Cost Structure Dynamics
Cost structures in vacuum aluminum plating are influenced by raw material inputs, equipment intensity, and labor workflow design. Aluminum metallizing requires metal wire and vacuum chamber fixtures, which establish a moderate baseline for unit costs. At the same time, the labor-intensive nature of loading and unloading processes creates opportunities for automation and workflow redesign. Suppliers and end-users alike are scrutinizing the balance between upfront capital expenditure and operational efficiency. Facilities that invest in streamlined material handling, standardized fixture designs, and integrated process controls can reduce per-unit labor exposure and improve throughput. Conversely, organizations that treat equipment acquisition as a standalone purchase without addressing surrounding process architecture often experience cost overruns and productivity gaps. The evolving cost dynamic favors integrated solutions that combine deposition technology with workflow optimization.
Competitive Landscape and Strategic Positioning
The competitive field features a mix of established equipment suppliers and regional specialists, with a notable presence of Chinese manufacturing firms alongside U.S.-based technology providers. This distribution reflects both the global nature of coating demand and the concentration of vacuum equipment production capacity in key industrial corridors. Company strategies differ in emphasis, with some players focusing on broad application coverage across automotive lighting, trim, and decorative functional coatings, while others concentrate on PVD thermal evaporation, multi-arc vacuum coating, and roll-to-roll metallizing for plastics and films. The diversity of product portfolios indicates a market where differentiation is achieved through application expertise, equipment architecture, and service support rather than price alone.
Differentiation Through Application Focus and Process Capability
Leading suppliers distinguish themselves by aligning equipment capabilities with specific end-use requirements. One U.S.-based provider emphasizes sputtering and evaporation metallization systems for high-brightness reflectors, automotive lighting, interior and exterior trim, and decorative functional coatings, positioning its offerings around performance consistency and broad application coverage. Several Chinese manufacturers pursue complementary strategies, with some specializing in magnetron sputtering, resistance evaporation, and cathodic arc ion coating equipment tailored for aluminum metallizing and vacuum metalizing lines. Others focus on web and roll-to-roll metallizing for aluminum evaporation on plastics and films, or on aluminum and silver mirror production lines using vacuum coating equipment. This segmentation of expertise enables suppliers to address distinct customer priorities, from decorative finishes to functional barrier coatings.
Recent Developments and Product Evolution
Recent product activity reinforces the trend toward higher precision, broader finish options, and enhanced process control. In early 2026, a major Chinese supplier released details on decorative PVD chrome and color coating equipment positioned as alternatives to traditional electroplating, signaling continued expansion into premium finish markets. Later that year, the same company highlighted optimization of industrial coatings using next-generation PVD vacuum coating machines focused on durability and sustainability. The launch of a high vacuum metal deposition machine with upgraded generation features, including high vacuum pumps and video monitoring, further demonstrates how equipment portfolios are evolving to serve both industrial and specialized forensic applications. These developments indicate that competitive differentiation is increasingly tied to feature maturity, application versatility, and the ability to support sustainability-oriented coating outcomes.
Plating Equipment Market
Market Structure Dynamics and Entry Pathways
The market structure suggests both consolidation pressure and opportunities for targeted entry. High concentration among leading players raises barriers for general-purpose competitors, but it also creates space for specialists serving niche coating requirements, regional service demands, or cost-sensitive application segments. New entrants that can demonstrate reliable deposition performance, compliance-ready designs, and streamlined integration support may capture share in underserved pockets, particularly where existing suppliers face capacity constraints or where local service responsiveness is valued. At the same time, consolidation remains a plausible trajectory as larger players seek to broaden application coverage, strengthen regional presence, and accumulate process expertise. The evolving landscape rewards companies that clearly define their strategic niche rather than competing broadly on specification sheets alone.
Forward Outlook: Trends and Opportunities to 2032
Accelerated Equipment Replacement Cycles Driven by Compliance
Over the next three to five years, regulatory-driven replacement of wet coating systems is expected to sustain demand for vacuum aluminum plating equipment. As compliance deadlines approach across multiple jurisdictions, facilities will need to coordinate capital planning, installation, and process validation within constrained windows. This creates opportunities for suppliers that can offer structured upgrade pathways, compliance documentation support, and phased deployment models. The commercial implication is clear: organizations that anticipate regulatory timelines and align equipment procurement with facility planning will secure better pricing, smoother integration, and earlier attainment of compliance benefits. The risk lies in underestimating lead times and retrofit complexity, which can compress installation schedules and increase lifecycle costs.
Automation and Workflow Integration as Margin Levers
Automation and workflow integration will become increasingly central to competitive advantage. As labor-intensive loading and unloading processes are identified as cost and variability drivers, manufacturers will look for equipment configurations that reduce manual handling, standardize fixture changeovers, and improve throughput predictability. The trend favors solutions that combine deposition technology with material handling design, process monitoring, and user interface improvements. Companies that proactively redesign workflow architecture around vacuum plating lines can convert moderate unit costs into more stable margin profiles. The uncertainty is that automation investments must be calibrated to production volume and product mix; over-investment in features that do not match actual throughput needs can weaken return profiles.
Expansion of Premium and Functional Finish Applications
A third trend points to growing demand for premium decorative finishes and functional coatings that go beyond basic aluminum metallization. The market is seeing interest in color coating alternatives to electroplating, enhanced durability features, and specialized deposition capabilities that serve precision and forensic contexts. This expansion opens commercial pathways for suppliers that can demonstrate finish quality, repeatability, and application flexibility. For end-users, the opportunity lies in leveraging advanced coating options to differentiate products, meet performance specifications, and respond to consumer expectations for appearance and durability. The risk is that premium finish claims must be supported by consistent process results; without robust quality control, differentiation can quickly erode in competitive bidding environments.
Vacuum Coating Machines Market
Strategic Recommendations for Decision-Makers
For Manufacturers Evaluating Equipment Investments
Manufacturers should approach vacuum aluminum plating equipment decisions as part of a broader process and compliance strategy rather than as isolated capital purchases. Priorities include mapping regulatory timelines to facility upgrade windows, evaluating workflow automation potential, and selecting equipment configurations that align with specific application requirements. It is advisable to compare suppliers not only on deposition specifications but also on integration support, service responsiveness, and demonstrated compliance readiness. Facilities that pilot process changes on a controlled line before full-scale deployment can reduce integration risk and refine throughput expectations.
For Investors Assessing Sector Exposure
Investors should focus on companies with clear application differentiation, credible compliance narratives, and evidence of process innovation that lowers total cost of ownership. Market concentration suggests that leadership positions are defensible, but growth opportunities are not limited to incumbents; specialized suppliers serving niche coating needs or regional service gaps may present attractive exposure. Due diligence should examine the alignment between product roadmaps and regulatory momentum, as well as the extent to which automation and workflow features are translating into customer adoption. Caution is warranted where equipment claims exceed demonstrated process consistency or where upgrade cycles depend on uncertain compliance enforcement timing.
For Procurement and Sourcing Teams
Procurement teams should prioritize total lifecycle value over initial equipment price, incorporating considerations such as compliance documentation, maintenance complexity, material handling efficiency, and service availability. Requesting application-specific performance data and validating it against internal quality targets can reduce the risk of mismatched procurement. Where possible, structuring evaluations around pilot runs and workflow simulations provides a clearer picture of throughput, labor exposure, and defect rates than specification reviews alone. Engaging suppliers early in facility planning also helps align installation schedules with compliance deadlines and production targets.
The vacuum aluminum plating machine market is positioned for sustained expansion, but the distribution of value will depend on how effectively participants navigate regulatory timelines, process complexity, and competitive differentiation. Decision-makers who combine forward planning with detailed segment-level intelligence will be better equipped to identify high-probability opportunities and avoid costly misalignment. For those seeking deeper segmentation data, company-level benchmarks, and tailored strategic recommendations, the full market research report provides a more granular view of the dynamics shaping this sector through 2032.
For detailed analysis of this topic, please visit the official page: Vacuum Aluminum Plating Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Non-PVC IV Bag Market: Tracking the 6.98% CAGR Shift Toward Safer Solutions
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Non-PVC IV Bag Market
The non-PVC intravenous (IV) bag market has moved from a niche alternative to a structural imperative in clinical packaging. Driven by safety concerns, regulatory momentum, and supply chain resilience priorities, the segment is expanding at a compound annual growth rate of approximately 7.0 percent through 2032. From 2020 to 2025, market revenue grew from roughly USD 139 million to USD 184 million, with the trajectory accelerating as healthcare systems consolidate around DEHP-free and PVC-free infrastructure. Forward projections indicate revenue approaching USD 292 million by the end of the forecast period, reflecting sustained demand for infusion packaging that aligns with modern pharmacovigilance standards and procurement policies.
This expansion is not merely a volume story. It represents a shift in materials science, regulatory expectations, and manufacturing strategy that is reshaping competitive positioning across the value chain. For executives, investors, and procurement leaders, the non-PVC IV bag market offers clear signals about where capital, capability, and partnerships will be rewarded over the next several years.
Intravenous Fluid Bags Market
Market Status and Core Challenges
The market has matured rapidly over the past half-decade, but growth is uneven and constrained by structural frictions. While overall revenue is climbing steadily, participants must navigate a landscape where material performance, regulatory compliance, and capacity availability intersect in complex ways. The following challenges define the current inflection point.
Material Performance and Validation Hurdles
Non-PVC formulations must replicate or exceed the barrier properties, durability, and compatibility characteristics historically associated with PVC. Polyolefin and other alternative polymers have advanced significantly, yet scale-up validation remains costly and time-intensive. Clinical stakeholders require documented evidence on extractables, leachables, and drug-container interactions, which slows adoption for newer materials and raises the barrier for smaller entrants. This validation burden is particularly acute in multi-compartment and specialized infusion configurations, where performance requirements are more demanding.
Regional Regulatory Fragmentation
Regulatory and policy climates are diverging across jurisdictions, creating compliance complexity for manufacturers with global footprints. Some regions are moving toward explicit restrictions on phthalate-based plasticizers, while others continue to rely on broader pharmacopoeial standards. This fragmentation forces suppliers to maintain parallel product families and documentation sets, increasing operational overhead and complicating supply planning. At the same time, localized mandates and public tenders are accelerating the shift to DEHP-free and PVC-free options in specific markets, creating pockets of rapid adoption that do not always align with global rollout timelines.
Capacity Concentration and Supply Resilience
The market remains moderately fragmented at the top, with the largest three players holding just under 30 percent share and the top five reaching roughly 35 percent. While concentration is low enough to preserve competition, it also means that capacity additions and validation wins by leading suppliers can materially influence regional availability. Recent supply disruptions and drug shortage episodes have highlighted how container sourcing can become a limiting factor in critical care delivery. Procurement teams are increasingly treating container formats as part of supply resilience strategy rather than a commoditized accessory, which raises the strategic importance of reliable, qualified non-PVC capacity.
PW Consulting
Key Drivers of Market Change
Technology Innovation and Material Science Advances
Material innovation is the central engine of the transition. Polyolefin-based configurations now command the largest share of the product mix, reflecting their balance of safety profile, mechanical performance, and manufacturability. Polyester-based and ethylene vinyl acetate-based variants serve more specialized requirements, including tailored barrier properties and specific drug compatibility needs. Advances in film extrusion, multi-chamber design, and sterilization compatibility have expanded the range of therapies that can be packaged in non-PVC formats, including ready-to-use injectables and combination products. These advancements reduce the historical trade-offs between safety and performance, making non-PVC options viable across a broader set of clinical applications.
Recent product and regulatory milestones illustrate this momentum. A dual-chamber PVC-free and DEHP-free system received FDA clearance for an antibiotic combination, signaling that complex delivery formats are increasingly acceptable in non-PVC designs. In parallel, a major manufacturer coordinated with regulators to temporarily import saline in non-PVC containers to help mitigate shortages, underscoring how container qualification can directly support continuity of care. Another milestone saw an FDA-approved ready-to-use injectable in IV bags, reinforcing the broader shift toward premixed, non-PVC delivery formats that reduce handling risk and streamline clinical workflows.
Policy and Regulatory Environment
Regulatory direction is reinforcing the commercial case for non-PVC packaging. Pharmacovigilance pressures and public health policies are steadily elevating expectations around plasticizer exposure, particularly in vulnerable patient populations. In one notable example, state-level legislation has mandated that manufacturers notify customers of DEHP-free options and restrict DEHP-containing IV bags and tubing within defined timelines, setting a precedent that encourages broader adoption beyond the jurisdiction itself. These requirements are prompting healthcare systems to update procurement guidelines and push suppliers toward standardized DEHP-free portfolios.
Importantly, the regulatory environment is also enabling non-PVC containers to play a role in shortage management. FDA guidance has recognized non-PVC, DEHP-free IV bags as acceptable in drug shortage mitigation programs, including temporary import pathways for saline in non-PVC packaging. This linkage between regulatory clarity and operational resilience is a powerful catalyst: it positions non-PVC packaging not only as a safety choice but also as a contingency asset during supply stress.
Demand-Side Shifts in Clinical and Procurement Behavior
Demand is being reshaped by a combination of clinical preference, procurement policy, and therapeutic portfolio evolution. Blood and blood product transfusion remains the largest application area, reflecting the high sensitivity of these therapies to container interactions and the importance of minimizing extractables and leachables. Nutritional support and medication delivery applications continue to expand as premixed and ready-to-administer formulations gain traction, driven by goals to reduce preparation errors and improve bedside efficiency. Beyond these core uses, additional clinical applications are adding incremental demand as hospitals standardize container formats across service lines.
Procurement behavior is evolving in parallel. Group purchasing organizations and health systems are increasingly specifying DEHP-free and PVC-free options in contracts, while hospital pharmacies are favoring formats that support batch traceability, compatibility, and ease of use. This demand-side pull is amplified by manufacturers seeking to differentiate through safer packaging narratives and robust compatibility data, creating a reinforcing cycle between clinical confidence and commercial uptake.
Supply Chain and Cost Structure Dynamics
Cost structures are shifting as non-PVC materials move from specialized production to higher-volume manufacturing. Economies of scale are improving, particularly where producers have invested in dedicated eco-friendly facilities with multi-chamber capacity. Such scale advantages can compress per-unit costs over time and improve lead-time reliability, both of which matter to buyers seeking predictable supply. At the same time, raw material availability, film grade qualification, and sterilization pathway compatibility remain levers that influence margin and delivery performance.
Partnerships are becoming an important cost and capability strategy. A recent joint venture between an IV solutions manufacturer and a pharmaceutical partner was aimed at strengthening manufacturing and supply of intravenous solutions in North America, reflecting a broader tendency to align container and solution capabilities to reduce coordination risk and improve continuity. As these arrangements deepen, the market may see more integrated offerings that link bag formats, fill-finish processes, and therapeutic portfolios, changing how value is captured across the chain.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field includes global infusion leaders, regional specialists, and material suppliers, each pursuing distinct positioning. Baxter International emphasizes a DEHP-free portfolio that includes non-PVC large-volume bags, leveraging scale and a broad infusion franchise to standardize safer container options across mainstream channels. B. Braun positions itself around a full line of DEHP-free and non-PVC IV bags and containers, differentiating on breadth of format coverage and a stated commitment to PVC- and DEHP-free offerings across drug, solution, and irrigation containers. ICU Medical focuses on an FDA-approved DEHP-free and non-PVC bag portfolio, aligning its container strategy with regulatory readiness and compatibility assurance for U.S. market access.
Regional and specialty players are carving out differentiated niches. A Korean manufacturer operates what is described as the world's largest eco-friendly non-PVC IV fluid plant with multi-chamber bag capacity, using scale and specialized format capability to serve high-volume, sustainability-aligned demand. A Spain-based supplier offers DEHP-free IV bags for pharmaceutical and medical solutions, emphasizing product-grade compatibility for pharma partners. A Germany-based producer supplies PP-based non-PVC films and tubes for IV solution packaging, positioning closer to the material and conversion layer. A Portugal-based company focuses on pharmacopoeia-compliant DEHP-free bags, appealing to buyers seeking documented compliance. A U.S.-based materials company provides high-quality non-PVC materials for infusion bags, enabling downstream converters and fillers. A UK-based materials supplier contributes polyolefin materials for IV and pharmacological bags, reinforcing the material ecosystem. A UAE-based producer operates a facility producing sterile IV bag solutions in non-PVC bags, expanding regional manufacturing optionality and localized supply.
Differentiation Levers and Competitive Dynamics
Leading players are differentiating along several axes: regulatory readiness, format breadth, material innovation, scale, and regional supply presence. Regulatory readiness is especially valuable where customers face tight compliance timelines or require documented DEHP-free options for tenders and policy mandates. Format breadth matters for health systems that want to consolidate container types across therapies and reduce training and handling variability. Scale and dedicated eco-friendly capacity help stabilize lead times and improve cost trajectories, while material and film expertise can shorten qualification cycles for new drug-container combinations. Regional manufacturing presence is increasingly important for supply resilience, local content expectations, and responsiveness to policies that encourage or require domestic sourcing.
Evolution of the Market Structure
The market is likely to evolve through a combination of consolidation among scaled players, deepening specialization among niche suppliers, and selective entry by companies that can bring compliant material platforms and regional capacity. Because concentration at the top remains moderate, there is room for multiple winners, but differentiation will depend on execution in qualification, supply reliability, and partnership ecosystems rather than on scale alone. The ongoing trend toward premixed and ready-to-use formats, together with drug shortage management needs, may encourage more integrated plays that connect bag formats with solution production and fill-finish capabilities. At the same time, suppliers that can offer standardized DEHP-free and non-PVC options with strong compatibility data will be better positioned to capture procurement mandates and public tenders as they expand.
Future Trends and Commercial Opportunities
Accelerated Standardization of DEHP-Free and Non-PVC Formats
Over the next three to five years, DEHP-free and non-PVC container formats are likely to become default expectations in an increasing number of procurement guidelines, especially where regulations and institutional policies are converging. This standardization will reduce the need for parallel inventories, simplify training, and strengthen the bargaining position of suppliers that can provide consistently qualified formats across large-volume and specialized applications. The commercial opportunity lies in offering harmonized portfolios that span blood and blood product transfusion, nutritional support, medication delivery, and other clinical uses, while maintaining documented compatibility and regional compliance. Suppliers that can demonstrate repeatable quality across these applications will be able to capture volume as health systems consolidate container specifications.
Integration of Container, Solution, and Fill-Finish Capabilities
A second trend is the deepening integration of container supply with solution manufacturing and fill-finish operations. Recent partnerships and Joint Ventures point toward closer alignment between bag formats and therapeutic availability, aiming to reduce coordination risk, improve lead times, and support continuity during shortage episodes. For market participants, this suggests value in building or partnering for end-to-end readiness, including sterilization pathways, multi-chamber capability, and validated compatibility with specific drug classes. The opportunity is not only in selling bags, but in enabling reliable, compliant delivery systems that meet hospital and pharmacy requirements for premixed and ready-to-use products. Companies that can connect material selection, format design, and fill-finish compatibility will be better positioned to compete for long-term supply agreements.
Regional Capacity Expansion and Supply Resilience as a Competitive Edge
A third trend is the expansion of regional capacity and localized supply, motivated by regulatory alignment, logistics resilience, and public procurement expectations. The emergence of large-scale eco-friendly non-PVC facilities and regional sterile manufacturing sites indicates that geography is becoming a strategic variable rather than a logistical afterthought. This creates opportunities for suppliers that can offer local content, shorter lead times, and regulatory familiarity, especially in markets where policies are accelerating the shift away from DEHP and PVC. The risk, however, is that capacity additions may outpace qualified demand in some regions or that differing pharmacopoeial standards will require duplicated validation efforts. Participants should plan for flexible capacity models and invest early in the documentation and testing needed to secure multi-market qualification.
Actionable Recommendations for Decision-Makers
For Manufacturers and Suppliers
- Prioritize standardized DEHP-free and non-PVC portfolios with documented compatibility across high-volume applications, especially where procurement mandates and tender language are tightening.
- Invest in multi-chamber and large-volume format capability, as these configurations are increasingly central to premixed and ready-to-use offerings and to shortage mitigation programs.
- Develop regional supply options and partnerships that reduce lead-time risk and align with local regulatory expectations, while maintaining the validation rigor required for multi-market access.
For Investors
- Evaluate exposure to companies with clear non-PVC material platforms, scaled eco-friendly capacity, and regulatory-ready portfolios, as these capabilities are likely to capture disproportionate share in a market that is moving from optional to standard.
- Look for value creation through partnerships that link container formats with solution production and fill-finish readiness, since integration can improve resilience and long-term contract eligibility.
- Consider the timing of regional capacity and policy catalysts, because local mandates and procurement shifts can create step-change demand that rewards companies with qualified supply already in place.
For Procurement and Clinical Operations Leaders
- Specify DEHP-free and non-PVC formats in contracts where possible, aligning container requirements with clinical safety goals and supply resilience planning, and request documented compatibility data to support adoption.
- Assess suppliers on format breadth, validation maturity, and regional availability, not just price, since container reliability and qualification status increasingly influence continuity of care.
- Coordinate across pharmacy, nursing, and supply chain functions to standardize container formats where clinically appropriate, reducing handling variability and strengthening the case for consistent non-PVC adoption.
For executives and investors seeking deeper segmentation, competitive benchmarks, and region-specific procurement dynamics, a detailed market study can translate these strategic signals into prioritization and timing decisions. A comprehensive report with granular segmentation and customized recommendations is available for teams that need to move from directional insight to execution planning.
IV Bags Market
For detailed analysis of this topic, please visit the official page: Non-PVC IV Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Tattoo Ink Market
Market Reality and Core Challenges
The global tattoo ink market has evolved significantly over the past five years, transitioning from a niche artistic sector into a more structured and regulated industry. Market valuation crossed the USD 190 million threshold in 2025 and is projected to reach approximately USD 275 million by 2032. This growth trajectory reflects a compound annual growth rate of 5.36 percent, indicating steady but measured expansion. The market has shown consistent upward movement since 2020, with temporary fluctuations in 2022 giving way to renewed momentum as consumer adoption broadens and manufacturing standards mature. Revenue generation continues to concentrate within a handful of established players, while the broader ecosystem accommodates a mix of regional producers, specialty formulators, and direct-to-consumer brands.
Despite this positive trajectory, the industry faces structural challenges that will shape competitive dynamics in the coming years. Safety and contamination risk remain the most pressing concerns. Historical incidents involving bacterial contamination and inconsistent sterilization practices have drawn regulatory scrutiny and heightened consumer awareness. Manufacturers must now balance artistic formulation with rigorous quality control, a shift that increases operational complexity and raises the barrier to entry for smaller producers. Supply chain volatility adds another layer of pressure. The availability of high-purity pigments, carrier solutions, and packaging materials fluctuates with broader chemical and logistics markets, affecting cost stability and product consistency. These dynamics force companies to decide between absorbing margin pressure or passing costs downstream, a decision that reverberates through pricing strategies and brand positioning.
A third challenge lies in the widening gap between artistic demand and technical standardization. Tattoo artists increasingly expect inks that deliver predictable healing, color retention, and application behavior across skin types and techniques. At the same time, end consumers are more informed, often prioritizing ingredient transparency, vegan formulations, and sterilization certifications. This dual expectation pushes manufacturers to invest in both formulation science and consumer-facing communication, a combination that not all firms can sustain. The market is therefore at a decision point: companies that treat quality and transparency as core competencies will be better positioned to retain professional clients and expand into adjacent applications, while those relying on legacy formulations risk commoditization.
Key Drivers Shaping Market Evolution
Technological Innovation and Formulation Precision
Advancements in pigment dispersion, carrier chemistry, and sterilization technology are redefining what tattoo ink can deliver. Formulators are moving toward pre-dispersed pigments and controlled particle size distributions, which improve color clarity and reduce the risk of uneven application. Sterilization processes have also matured, with manufacturers adopting validated batch-processing methods that minimize contamination risk while preserving formulation stability. These technical improvements translate directly into better healed results, a critical factor for professional artists who prioritize repeatability and client satisfaction. Innovation in this space is not only about aesthetics; it is increasingly about predictability and safety. Brands that can demonstrate consistent batch-to-batch performance and transparent ingredient profiles are gaining traction among studios that treat ink selection as a clinical and artistic decision rather than a commodity purchase.
Regulatory and Health-Safety Dynamics
Regulatory attention is intensifying, reshaping compliance expectations across the value chain. In late 2024, the U.S. Food and Drug Administration issued guidance to help manufacturers and distributors recognize and prevent contamination scenarios, signaling a shift toward proactive risk management rather than reactive recalls. Subsequent public health advisories have highlighted specific contamination concerns, including microbial risks associated with certain products, reinforcing the importance of sterile manufacturing and shelf-life control. On the research front, controlled clinical studies conducted at leading European institutions have provided new insights into how soluble ink ingredients behave in the body, generally indicating that residual levels may be lower than earlier assumptions suggested. These findings do not eliminate safety concerns, but they contribute to a more nuanced scientific dialogue that can inform labeling, formulation choices, and consumer education. For manufacturers, the practical implication is clear: compliance is no longer a checkbox exercise. It requires documented sterilization protocols, traceable ingredient sourcing, and clear communication about product handling and expiration.
Demand-Side Shifts and Application Diversification
Consumer behavior is expanding the use cases for tattoo ink beyond traditional body art. Cosmetic and medical applications continue to grow, driven by demand for semi-permanent aesthetic solutions and specialized clinical procedures. This diversification creates new revenue streams for manufacturers that can adapt formulations to different performance requirements, such as finer pigment grading for cosmetic work or specific handling characteristics for medical contexts. At the same time, mainstream tattooing is increasingly influenced by lifestyle and self-expression trends, with younger demographics and professional artists seeking inks that support complex color work, longevity, and skin-friendly profiles. The demand side is therefore not monolithic; it is splitting into segments with distinct expectations. Companies that understand these nuances can tailor product lines, branding, and education programs to match the priorities of each audience, rather than offering a single formulation strategy across all channels.
Supply Chain and Cost Structure Considerations
Cost structures in the tattoo ink market are influenced by pigment sourcing, carrier formulation, sterilization, packaging, and distribution. High-quality organic and vegan pigments often command premium pricing, while broader chemical market fluctuations can affect raw material costs and lead times. Manufacturers that maintain direct-from-manufacturer models or tightly controlled production environments can sometimes reduce intermediary costs and improve margin resilience. However, scaling these models requires investment in quality assurance, logistics, and batch documentation. The supply chain challenge is not simply about cost reduction; it is about preserving formulation integrity while managing volatility. Brands that build redundancy into sourcing, maintain rigorous in-house testing, and communicate transparently about lead times and batch availability are better equipped to sustain trust with professional buyers who depend on consistent product performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentration of revenue among a relatively small group of established manufacturers, alongside a broader field of regional and specialty brands. The market structure favors companies that combine formulation expertise, sterilization capability, and strong distribution relationships with professional studios. Several U.S.-based manufacturers illustrate different strategic approaches within this landscape. Intenze has built its positioning around professional tattoo and permanent makeup pigments manufactured domestically, emphasizing vegan and sterile formulations engineered for predictable handling, color clarity, and consistent healed results. Its direct-from-manufacturer model supports tighter control over quality and responsiveness to professional clients. Eternal Tattoo Ink and Eternal Tattoo Supply similarly emphasize certified sterilized, vegan, and cruelty-free inks produced in the United States, with a focus on advanced sterilization processes that appeal to safety-conscious buyers.
Other established players pursue differentiated value propositions that hinge on longevity, quality control, and brand trust. Dynamic Color Co. has emphasized premium manufacturing since the early 1990s, relying on pre-dispersed pigments and batch-level quality checks to maintain consistency. World Famous Tattoo Ink leverages decades of experience and a premium vegan formulation narrative to reinforce reliability in a market where artist loyalty is closely tied to performance reputation. Solid Ink focuses on high-quality organic vegan pigments, aligning with the growing demand for cleaner ingredient profiles and ethical sourcing. These strategies reveal a common theme: differentiation is increasingly tied to formulation integrity, sterilization assurance, and the ability to communicate those attributes credibly to professional buyers.
The market structure is evolving along two parallel tracks. On one hand, consolidation pressure is likely to increase as larger manufacturers seek to capture more shelf space, expand into adjacent applications, and leverage scale in quality systems and distribution. On the other hand, niche segmentation is also strengthening, with specialty brands carving out positions around vegan formulations, UV and specialty colors, cosmetic suitability, and region-specific supply relationships. New entrants face a challenging environment because trust and consistency are hard-earned in professional tattoo communities. Success typically requires more than a competitive price; it depends on documented sterilization, reliable batch performance, and strong relationships with artists and distributors who can validate product quality through repeated use. The most resilient brands are those that treat compliance, transparency, and formulation science as strategic assets rather than operational overhead.
Forward-Looking Trends and Commercial Implications
Quality Assurance as a Market Currency
Over the next three to five years, quality assurance is likely to become an even stronger differentiator. As regulatory expectations stabilize and professional buyers become more accustomed to validation practices, brands that can provide clear documentation of sterilization, batch testing, and ingredient transparency will gain an advantage in procurement decisions. This trend creates commercial opportunity for manufacturers that invest in verifiable quality systems and for distributors that prioritize compliant, well-documented products in their portfolios. It also raises the stakes for companies that rely on informal production practices, since procurement teams and studio owners increasingly weigh contamination risk and consistency alongside price and color range. The commercial implication is that reputation in this market will be increasingly tied to demonstrable process control.
Application Expansion and Cross-Use Formulation Strategy
The growth of cosmetic and medical applications suggests that formulation flexibility will be a valuable strategic capability. Inks designed for traditional body art do not always map seamlessly onto semi-permanent cosmetic procedures or clinical use cases, which may require different particle characteristics, viscosity profiles, or handling behavior. Manufacturers that develop modular formulation platforms can serve multiple segments without diluting brand focus, while also capturing higher-margin opportunities in specialized applications. This trend favors companies that can align R&D with end-use requirements and communicate those distinctions clearly to buyers. The opportunity lies in building product families that share core quality standards while meeting segment-specific performance expectations, enabling expansion without sacrificing trust in any one category.
Transparency, Ethics, and Consumer Education
Consumer-facing expectations around vegan formulations, cruelty-free production, and ingredient clarity are likely to keep rising. This is not merely a marketing preference; it influences procurement decisions among artists who want to align their studio practices with client values. Brands that integrate ethical sourcing and clear labeling into their core identity can strengthen loyalty and justify premium positioning. At the same time, consumer education becomes a competitive lever. Studios and distributors that provide accurate information about handling, aftercare, sterilization, and expiration help reduce misuse-related risks and improve outcomes, which in turn reinforces confidence in the products they stock. The broader commercial opportunity is to treat education and transparency as part of the product experience, not as an add-on. A potential risk in this area is overstatement; claims must be supported by verifiable practices, because professional buyers and informed consumers are increasingly able to distinguish between genuine compliance and surface-level branding.
Potential Risks and Uncertainties
Despite the positive outlook, several uncertainties warrant attention. Regulatory trajectories can shift as health authorities refine guidance and respond to new contamination events, which may impose additional documentation or labeling requirements. Supply chain disruptions in pigments or packaging could affect cost stability and availability, particularly for brands with limited sourcing redundancy. Scientific understanding of ink behavior in the body continues to evolve, and while recent controlled studies have provided reassuring data in certain respects, public perception and regulatory focus may still tighten around safety narratives. Finally, competitive intensification could compress margins for brands that cannot differentiate on quality, consistency, or application-specific performance. Companies that monitor these signals and maintain flexibility in formulation, compliance, and sourcing will be better prepared to navigate volatility.
Strategic Actions for Decision Makers
For manufacturers, the priority is to reinforce formulation integrity and verifiable quality as core competitive advantages. Investing in sterilization validation, batch documentation, and ingredient traceability strengthens positioning with professional buyers and prepares the organization for evolving regulatory expectations. It is equally important to develop formulation flexibility that supports adjacent applications without compromising the brand's core reputation. Companies that can align R&D, quality systems, and clear consumer-facing communication will be better equipped to retain artist loyalty and expand into higher-value segments. Pricing and distribution strategies should reflect this emphasis on reliability, since professional clients often prioritize consistent healed results and safety assurance over marginal cost differences.
PW Consulting
For investors, the market offers opportunities in brands that demonstrate defensible quality practices, transparent sourcing, and the ability to serve multiple application segments. Due diligence should focus on manufacturing controls, sterilization capability, regulatory readiness, and the credibility of product claims. Portfolio exposure to companies with direct distribution relationships and strong professional-channel reputations may offer more durable growth than exposure to undifferentiated commodity positioning. Investors should also watch for consolidation dynamics, as established players may seek to acquire specialty brands with strong ethical or technical positioning to broaden their portfolio and strengthen market access.
Ceramic Ink Market
For procurement teams and studio owners, product selection should increasingly weigh documented sterilization, batch consistency, and ingredient transparency alongside color range and price. Building supplier relationships with manufacturers that provide clear quality documentation and reliable lead times can reduce operational risk and improve client outcomes. Procurement decisions should also account for application fit, since inks intended for traditional body art may not be optimal for cosmetic or medical use. Educating staff and clients about proper handling, shelf life, and aftercare reinforces product performance and supports trust in the brand ecosystem. Building a small number of reliable, well-documented supplier relationships often proves more effective than chasing marginal price advantages across a fragmented supplier base.
Detailed segment-level data, regional breakdowns, and customized strategic scenarios can further sharpen these decisions. Readers seeking a deeper look at market sizing, competitive positioning, and application-specific opportunities can access the full research report for more granular analysis and tailored recommendations.
Tattoo Needles Market
For detailed analysis of this topic, please visit the official page: Tattoo Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharmaceutical Grade Sodium Chloride: Asia Pacific’s 67% Share and 5.6% CAGR Reshape Growth
By PW Consulting, 2026-09-21
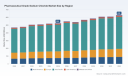
Pharmaceutical Grade Sodium Chloride Market: Strategic Trends and Commercial Opportunities in a Shift-Driven Landscape
Market Snapshot: Growth Trajectory and Structural Realities
The pharmaceutical grade sodium chloride market has settled into a steady expansion phase, with revenue reaching approximately $525 million in 2025 and projected to approach $630 million by 2032. The implied compound annual growth rate of 5.6 percent reflects a market that is growing not through explosive demand surges, but through gradual capacity additions, formulation complexity, and sustained healthcare consumption across mature and emerging regions alike. Historical data from 2020 through 2025 shows a relatively smooth upward trajectory, punctuated by modest step changes rather than sharp inflection points, suggesting that core demand drivers have remained resilient even as feedstock costs, logistics, and regulatory expectations have shifted.
What makes this market structurally interesting is its concentration profile. The top three players account for roughly 28.5 percent of revenue, while the top five capture about 35.2 percent. That level of fragmentation, combined with steady growth, signals a landscape where scale advantages exist but are not insurmountable. Regional and application splits reveal clear concentration patterns: the Asia Pacific region represents the largest revenue pool, while the market is bifurcated by type between active pharmaceutical ingredient grade sodium chloride and hemodialysis grade material. On the application side, injections and hemodialysis dominate the demand base, with oral rehydration salts, osmotic agents, and other uses contributing meaningful but smaller shares. Rather than focusing on individual share percentages, the strategic takeaway is that high-value clinical applications and large-volume therapeutic uses are pulling the market in different directions, each with distinct quality, logistics, and margin expectations.
Several structural challenges and transition points are shaping how participants navigate this growth. First, regulatory scrutiny around impurity profiles, traceability, and batch documentation continues to intensify, especially for materials used in parenteral and dialysis applications where patient safety margins are narrow. Second, cost volatility in energy, purification inputs, and distribution has compressed margins for suppliers that lack integrated quality systems or flexible sourcing models. Third, regional demand growth is uneven, with mature markets facing price discipline and capacity rationalization, while high-growth regions require localized compliance readiness, consistent specification management, and stronger technical support. These dynamics mean that growth alone is not enough; suppliers must convert volume into dependable, specification-grade supply with clear quality differentiation.
Key Drivers Reshaping Demand and Competitive Positioning
Technical Innovation in Purification and Controlled Manufacturing
Advances in purification technology, crystallization control, and analytical verification are redefining what suppliers can reliably deliver at pharmaceutical grade. Improvements in trace metal control, endotoxin management, and particle size consistency have become increasingly important for injection-grade and dialysis-grade applications, where even minor deviations can affect downstream processing or clinical performance. Manufacturers that have invested in closed-loop handling, validated cleaning protocols, and robust quality documentation are better positioned to serve customers who require tight specification adherence across multiple batches. For buyers, this shift means that technical capability is increasingly evaluated not just by certificate compliance, but by the consistency of lot-to-lot performance, the transparency of testing, and the supplier’s ability to support troubleshooting when formulations are adjusted.
Worldwide Pharmaceutical Grade Calcium Hydroxide Market
The innovation curve also extends to packaging, storage, and transport conditions that preserve material integrity. Moisture control, contamination prevention, and shelf-life stability are gaining attention as supply chains become more distributed and inventory strategies more cautious. This matters because pharmaceutical grade sodium chloride is often treated as a commodity input, yet its downstream use can be highly sensitive. Suppliers that align processing improvements with practical logistics and documentation benefits are creating a more defensible value proposition than those competing purely on price.
Regulatory and Policy Environment: Stricter Expectations, Higher Barriers
Policy and regulatory expectations continue to evolve in ways that raise the quality bar and increase the cost of market entry for lower-capability players. Pharmaceutical grade materials sit at the intersection of industrial chemical production and healthcare compliance, which means they are subject to rigorous documentation, quality system expectations, and increasingly detailed impurity surveillance. In practical terms, this environment favors suppliers that can demonstrate controlled manufacturing, reliable audit readiness, and clear traceability from raw source to finished batch. It also reinforces the importance of harmonization across regions, since multinational buyers increasingly seek consistent specifications regardless of sourcing location.
The regulatory backdrop is not solely a constraint; it is also a competitive filter. As compliance expectations rise, suppliers with mature quality infrastructure and experienced regulatory support gain an advantage in securing long-term supply agreements, especially with larger pharmaceutical and dialysis operators that prioritize supply reliability over spot pricing. At the same time, buyers are becoming more discerning about vendor qualification, testing protocols, and change-control management, which raises the stakes for suppliers that treat quality systems as administrative rather than operational capabilities.
Demand-Side Evolution: Clinical Complexity, Volume Growth, and Formulation Strategy
On the demand side, the market is being shaped by a combination of steady clinical consumption and evolving formulation needs. Injections and hemodialysis applications remain central demand pillars because sodium chloride is integral to solution preparation, dilution, and dialysis fluid composition. As healthcare delivery expands and treatment volumes increase, especially in regions scaling hospital infrastructure and outpatient services, demand for dependable pharmaceutical grade material continues to grow. At the same time, formulation strategies are becoming more nuanced, with manufacturers seeking materials that integrate smoothly into multi-component preparations and meet tighter internal quality standards.
Another demand-side development is the growing emphasis on supply assurance. Buyers are less willing to accept variability in lead times, specification consistency, or documentation completeness, particularly when production downtime or batch deviation carries high cost or clinical risk. This is changing purchasing behavior: procurement teams are placing more weight on supplier reliability, technical responsiveness, and continuity planning than on headline price alone. The result is a market where differentiated service and quality assurance can support stronger commercial positioning, especially when tied to long-term supply arrangements.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure: Energy, Sourcing, and Logistics Pressure
Cost structures in this market are influenced by energy usage, purification requirements, source material variability, and distribution complexity. Because pharmaceutical grade sodium chloride requires controlled processing and verification, it is more sensitive than industrial-grade equivalents to fluctuations in operating costs and transport conditions. Suppliers that can manage energy intensity, source consistent inputs, and minimize handling risk gain a margin advantage, while those exposed to fragmented sourcing or less controlled processing face greater volatility.
Logistics further complicates the cost picture. Pharmaceutical-grade materials often require careful storage, contamination control, and documentation handoffs across borders or regions. In markets where import dependence is high or where regulatory clearance adds time and cost, lead-time reliability becomes a commercial differentiator. This environment pushes companies toward either regional sourcing strategies, integrated production and supply models, or stronger partnerships with distributors that can support compliance and traceability requirements. The broader implication is that cost competitiveness in this market is increasingly about operational discipline and supply continuity, not simply unit pricing.
Competitive Landscape: Positioning, Differentiation, and the Shape of Consolidation
Established Players and Differentiated Strategies
The competitive field includes a broad set of global and regional players with distinct strategic orientations. Large diversified chemical and salt producers bring advantages in scale, sourcing breadth, and distribution reach. Their positioning often emphasizes dependable volume supply, multi-region availability, and established quality systems that support pharmaceutical customer qualification. For these companies, the opportunity lies in converting broad salt-production expertise into a controlled pharmaceutical-grade offering that can compete on reliability as well as cost.
Alongside these broader players, specialized producers and regional manufacturers focus on tighter specification control, local compliance readiness, and closer technical engagement with buyers. Their differentiation typically comes from product consistency, responsive documentation, and the ability to serve specific customer segments such as injection preparation, hemodialysis fluids, or regional formulation needs. These companies often compete by demonstrating that they can reduce variability and support tighter integration into customer processes, which is valuable when procurement teams prioritize risk reduction over purely transactional pricing.
A third group of participants operates with a niche or application-specific orientation, serving laboratory, specialty formulation, or highly regulated use cases where documentation, purity thresholds, and batch control are paramount. Their commercial leverage often depends on technical trust, reproducibility, and the ability to maintain stringent handling standards. In a market where the top three and top five players hold only modest combined shares, these specialized positions can remain viable if they deliver clearly differentiated quality and service.
How Leading Companies Are Structuring Advantage
Across the competitive set, several strategic themes recur. One is the focus on controlled processing and quality documentation as a commercial asset. Suppliers that can show consistent impurity control, validated manufacturing practices, and complete traceability are better positioned to win and retain pharmaceutical customers who treat material qualification as a multi-year decision rather than a periodic purchase. Another theme is the alignment of product grades with end-use requirements. Because API-grade and hemodialysis-grade sodium chloride serve different functional and regulatory contexts, companies that clearly articulate grade-specific capabilities and test data can reduce friction in buyer evaluation and strengthen their positioning in targeted segments.
A third recurring strategy is the use of technical service as a differentiator. Suppliers that provide formulation support, specification clarity, troubleshooting assistance, and reliable change-control communication can create stickier customer relationships. This is especially relevant in applications where sodium chloride must integrate with other ingredients or where patient-facing formulations demand high consistency. In practice, competitive advantage is increasingly built on the combination of material quality, documentation reliability, and the supplier’s ability to reduce operational risk for the buyer.
Market Evolution: Fragmentation, Selective Consolidation, and New Entrants
The market’s concentration profile suggests ongoing fragmentation rather than dominance by a small number of incumbents. That structure creates space for both consolidation and new entry, depending on capabilities and regional positioning. Consolidation is likely to occur where scale, quality infrastructure, and regional coverage can be combined to serve multinational buyers more efficiently. In contrast, new entrants may find footholds by addressing specific quality, specification, or service gaps that larger suppliers do not fully cover, particularly in regions where localized compliance and technical support are valued.
A practical evolution to watch is the growing importance of regional supply resilience. Buyers in multiple markets are increasingly attentive to sourcing diversification and continuity risk, which can benefit suppliers that offer dependable local or near-local supply with appropriate quality credentials. At the same time, multinational procurement standards are pushing the market toward greater consistency in documentation and testing expectations, which may pressure smaller players without strong quality systems. The net effect is a landscape where competitive success depends less on claiming general market presence and more on demonstrating reliable performance in the specific grade, application, and region that matters to the customer.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
Trend One: Quality and Traceability Become Commercial Differentiators
Over the next several years, pharmaceutical grade sodium chloride is likely to be evaluated less as a routine chemical input and more as a quality-sensitive component whose consistency, documentation, and traceability directly affect buyer risk. As regulatory and internal quality expectations rise, suppliers with stronger analytical verification, controlled handling, and transparent batch records will be better positioned to secure long-term agreements and command more stable pricing. For manufacturers and procurement teams, this trend means that supplier selection should increasingly weigh quality reliability and documentation completeness alongside cost and lead time.
Trend Two: Regional Demand Growth Will Redefine Sourcing Strategies
Demand growth will remain uneven across regions, with larger revenue pools continuing to attract attention while high-growth areas require more localized readiness. This will encourage suppliers to develop region-specific quality alignment, distribution responsiveness, and technical support capacity. For buyers, the strategic implication is that sourcing decisions may increasingly balance global consistency with regional resilience, especially where supply interruptions or specification mismatches carry high operational risk. Companies that can provide predictable supply in the right region, with appropriate pharmaceutical-grade credentials, will have an advantage in winning disciplined, long-cycle procurement relationships.
Trend Three: Capacity, Cost Discipline, and Margin Pressure Will Separate Operators
As the market grows at a moderate pace, the competitive battleground will shift toward operating efficiency and cost discipline. Energy usage, purification intensity, logistics overhead, and waste control will matter more as buyers become more price-aware and suppliers compete for share in a fragmented market. Operators that can manage cost structures without compromising pharmaceutical-grade consistency will be better positioned to protect margins, while those with weaker process control may face pressure to lower prices or lose qualification status. The risk is that cost-cutting efforts erode the very quality attributes that justify pharmaceutical-grade positioning in the first place, so the winning approach will likely combine efficiency with rigorous quality assurance rather than sacrificing one for the other.
Sodium Chloride Injection Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory expectations may tighten further in ways that raise compliance costs or change documentation requirements, especially for materials used in sensitive clinical applications. Cost volatility in energy and logistics could compress margins and shift sourcing preferences faster than suppliers can adapt. Demand patterns may also evolve if healthcare delivery models change, if formulation strategies shift away from certain uses, or if alternative sourcing models alter how buyers qualify and manage suppliers. Finally, regional supply disruptions or trade friction could expose vulnerabilities in concentrated sourcing strategies, making diversification and continuity planning more important than ever.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to treat pharmaceutical-grade consistency as a growth lever rather than a compliance checkbox. Investing in purification control, analytical verification, and documentation reliability can improve qualification success and support longer contract cycles. Equally important is clarifying grade-specific capabilities so that customers can quickly see which applications a supplier is best equipped to serve. Companies that align product quality, technical support, and regional availability will be better positioned to convert steady market growth into durable share gains.
For investors, the key is to distinguish between suppliers that are scaling volume and those that are building defensible pharmaceutical-grade capability. Growth in this market is real, but value creation will favor operators with strong quality systems, controlled cost structures, and the ability to retain customers through reliability rather than price alone. Investment diligence should therefore focus on manufacturing discipline, regulatory readiness, traceability, and the company’s capacity to serve high-value applications without compromising specification integrity.
For procurement and supply chain leaders, the strategic imperative is to evaluate suppliers on a broader set of criteria than unit price alone. Lead-time reliability, lot-to-lot consistency, documentation completeness, change-control responsiveness, and continuity planning all matter when sodium chloride feeds into injections, dialysis fluids, or other sensitive applications. Diversifying supply where appropriate, qualifying suppliers with strong quality systems, and maintaining clear specification expectations can reduce operational risk while preserving cost discipline.
Given the range of regional, technical, and regulatory variables shaping this market, detailed segment-level data and tailored supply-chain assessment can make a meaningful difference in planning. For decision-makers seeking deeper visibility into volume patterns, application-specific demand, grade-level positioning, and supplier qualification dynamics, a more comprehensive market review can help translate these trends into concrete sourcing, investment, and production decisions.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oligonucleotide Pool Library Market: How 12.35% CAGR & CRISPR Demand Reshape Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Oligonucleotide Pool Library Market
Market State and Core Challenges
The oligonucleotide pool library market has evolved from a specialized research enabler into a strategic infrastructure layer for synthetic biology, functional genomics, and precision therapeutics. Over the past five years, the sector has demonstrated sustained momentum, with market valuation climbing from approximately $880 million in 2020 to $1.875 billion in 2025. Forward projections indicate continued expansion, reaching an estimated $4.2 billion by 2032 and reflecting a compound annual growth rate of 12.35 percent across the 2026–2032 forecast horizon. This trajectory signals a market transitioning from early adoption curves into mainstream scientific and commercial workflows, where oligonucleotide pools are no longer optional research tools but foundational inputs for discovery pipelines and manufacturing processes.
The pace of growth, however, is not uniform across the value chain. Demand is increasingly concentrated around applications that require high complexity, low error rates, and scalable production formats. Target capture workflows, CRISPR/Cas9 design libraries, and gene synthesis programs continue to absorb the largest shares of commercial activity, while library preparation and adjacent use cases are gaining relevance as sequencing and diagnostic platforms become more decentralized. The geographic distribution of activity reflects mature demand centers alongside rapidly expanding research ecosystems, creating a multi-speed environment where supply readiness, regulatory familiarity, and scientific capability vary significantly by region.
At the same time, the industry is navigating several structural challenges that will shape competitive outcomes over the next decade. First, cost volatility in core synthesis inputs remains a persistent pressure point. Phosphoramidite building blocks and related reagents have experienced recurring price fluctuations, introducing uncertainty into unit economics and forcing suppliers to balance margin protection with customer retention. Second, the market is not yet fully consolidated, with competitive intensity spread across established manufacturers and specialized entrants. A moderately fragmented landscape can drive innovation and customization, but it also creates pricing ambiguity and service inconsistency that buyers must navigate carefully. Third, the regulatory trajectory for oligonucleotides is becoming more defined, particularly as synthetic libraries move closer to diagnostic, therapeutic, and commercial applications. Evolving guidance on manufacturing practices, characterization, and quality control is raising the bar for documentation, reproducibility, and compliance, especially for organizations scaling production beyond research-grade environments.
Oligonucleotide Purification Market
These dynamics create a market that is expanding rapidly, but not without friction. The central question for industry participants is no longer whether demand will continue to grow, but how effectively they can manage input risk, align service models with emerging application requirements, and position themselves within a competitive field that is likely to become more structured over time.
Key Drivers of Market Change
Technological Innovation and Synthesis Scaling
The most direct driver of market growth is the continued refinement of oligonucleotide synthesis and library construction technologies. Chip-based and array-based synthesis approaches have expanded the practical limits of pool size, complexity, and turnaround time, enabling researchers and developers to move from small custom batches to large-scale library formats without proportionally increasing cost or lead time. At the same time, improvements in sequence design, error correction, and pool QC workflows have reduced the operational overhead associated with library deployment. This matters because the commercial value of oligonucleotide pools is increasingly tied not just to raw production capacity, but to the reliability and usability of the final product in downstream applications.
Recent industry activity reflects this technological emphasis. Twist Bioscience, for example, has built its market positioning around array-based oligonucleotide pool libraries for gene synthesis, gene editing, and synthetic biology applications, illustrating how synthesis platform differentiation can become a commercial identity. IDT has similarly expanded its relevance by offering custom DNA and RNA oligonucleotide pools tailored to library preparation, CRISPR, and multiplex sequencing workflows. These profiles are not merely product descriptions; they signal a broader shift in which suppliers are competing on application fit, throughput, and integration with customers’ experimental pipelines rather than on price alone.
PW Consulting Health Care Research Center
Regulatory Maturation and Quality Expectations
Regulatory and quality infrastructure is becoming an increasingly important market driver, particularly as oligonucleotide pools move from purely academic contexts into environments where reproducibility, traceability, and consistency carry higher stakes. The EMA’s draft guideline on the development and manufacture of oligonucleotides addressed manufacturing processes, characterization, specifications, and analytical control, signaling a more formal expectation around how oligonucleotides should be produced and documented. Although initially framed around broader development pathways, such guidance has practical implications for pool manufacturers because it raises the baseline for process discipline and quality assurance.
In parallel, regulatory attention in the United States has included focus on generic oligonucleotide challenges, such as quality assessment and immunogenicity considerations for synthetic oligos. These developments do not necessarily slow demand, but they do change the cost of entry and the value of established manufacturing practices. Organizations that can demonstrate robust QC, clear specifications, and dependable documentation are better positioned to serve customers who face increasing internal or external scrutiny. In that sense, regulatory maturation is acting as both a compliance requirement and a competitive filter.
Demand-Side Shifts in Research and Commercial Pipelines
Demand for oligonucleotide pool libraries is increasingly shaped by how scientific and commercial organizations structure their discovery and validation workflows. CRISPR/Cas9 design libraries remain a major demand anchor, reflecting continued investment in gene editing and functional genomics. At the same time, target capture and gene synthesis applications are expanding as researchers and developers seek more efficient routes to screening, validation, and construct generation. The broader trend is toward libraries that can support multiplexed, high-throughput experiments without sacrificing specificity or interpretability.
This demand evolution is also visible in pricing and product structuring. Commercial offerings increasingly reflect tiered or scale-sensitive pricing models, with costs varying substantially depending on pool size and specification. That pattern indicates a market in which buyers are not simply purchasing synthetic material; they are negotiating access to capacity, complexity, and service levels. As a result, demand-side behavior is pushing suppliers to think more carefully about portfolio design, minimum order structures, and the trade-off between flexibility and scale.
Supply Chain and Cost Structure Pressures
No discussion of market drivers is complete without acknowledging the fragile cost structure underlying oligonucleotide production. Phosphoramidite chemistry remains central to synthesis, and ongoing increases in raw material costs have introduced volatility that affects pricing, lead times, and planning assumptions. This is not a transient issue. Raw material dependencies can create exposure to broader supply chain disruptions, which in turn influence how suppliers price risk, manage inventory, and negotiate long-term agreements.
Recent pricing adjustments by service providers illustrate how these pressures translate into commercial decisions. Updates to oligonucleotide synthesis service pricing have been attributed to rising raw material costs and external factors, reinforcing the idea that input economics are actively reshaping market pricing behavior. For buyers, this means procurement strategies need to account for more than unit price; they must consider stability, forecasting alignment, and the durability of supplier relationships under cost pressure. For manufacturers, the challenge lies in balancing pass-through costs with the need to remain competitive, especially when multiple vendors are vying for the same application-driven demand.
Competitive Landscape and Leading Strategies
The competitive environment in this market is defined by a mix of established molecular biology suppliers, synthesis-focused manufacturers, and specialized library providers. Entities such as Twist Bioscience, IDT, Agilent Technologies, CustomArray, LC Sciences, Synbio Technologies, Daicel Arbor Biosciences, GenScript, Dynegene Technologies, General Biosystems, and Creative Biogene each bring distinct positioning to the market, often anchored in specific applications, formats, or workflow advantages.
A few patterns stand out. One is the emphasis on application-specific differentiation. Some suppliers position strongly around gene synthesis and synthetic biology workflows, while others focus on library preparation, CRISPR-related libraries, in-situ hybridization, or targeted sequencing support. This specialization matters because oligonucleotide pools are rarely interchangeable from the customer’s perspective; the value of a pool often depends on how well it fits the experimental design, screening format, or validation pathway.
Another pattern is the importance of scale and synthesis format. Companies leveraging chip-level or array-based synthesis often emphasize throughput and library size as core value propositions, which can be especially attractive for large-scale gene synthesis or functional genomics programs. Others compete by offering custom services, flexible ordering, or strong support for niche applications. In practice, this creates a landscape where some leaders compete on volume and process efficiency, while others compete on customization and service depth.
The market is also characterized by moderate concentration, with leadership shared across multiple firms rather than dominated by a single player. That structure has implications for strategy. For incumbents, the priority is often to deepen application relevance, improve process reliability, and protect margins in the face of input cost volatility. For newer or smaller entrants, the opportunity frequently lies in serving underserved workflows, regional demand, or specialized library formats that larger suppliers may not prioritize. For buyers, the practical takeaway is that supplier selection should be driven by workflow compatibility and service reliability as much as by headline pricing.
Market evolution is likely to proceed along two simultaneous paths: consolidation among players seeking scale, manufacturing efficiency, or broader workflow integration, and differentiation among those targeting specific application segments or technical niches. Recent licensing and technology-sharing activity, such as agreements involving exNA oligonucleotide technology and related reagents for research use, suggest that strategic partnerships and IP-enabled access are becoming more relevant alongside pure manufacturing competition. In a market where performance, quality, and cost are all contested, access to enabling technology can be as important as production capacity.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape the direction of the oligonucleotide pool library market and create distinct commercial opportunities.
One major trend is the continued alignment of library supply with high-value application clusters. Demand will likely remain strongest where oligonucleotide pools directly enable screening throughput, gene editing design, target validation, and construct generation at scale. Suppliers that can package synthesis capability with application-aware design support, QC consistency, and predictable turnaround will be better positioned to capture recurring demand from organizations that rely on libraries as part of standard workflows. The commercial opportunity here is not simply to sell more pools, but to become embedded in the operational rhythm of research and development teams.
A second trend is the growing importance of cost discipline and supply resilience. As raw material volatility persists and pricing becomes more sensitive to external cost pressures, both suppliers and buyers will need stronger planning frameworks. For suppliers, this may mean more structured pricing tiers, improved inventory and feedstock strategy, and clearer communication around cost drivers. For buyers, the opportunity lies in moving from transactional purchasing to more strategic sourcing, including multi-supplier planning, forecast sharing, and evaluation of total workflow cost rather than per-pool price alone. Organizations that handle this transition well can reduce exposure to price shocks while maintaining access to the library formats they need.
A third trend is the broadening of quality and regulatory readiness as commercial differentiators. As guidance continues to develop and applications become more consequential, documentation, reproducibility, and process control will carry increasing weight. Companies that invest early in quality systems, characterization rigor, and transparent specifications may gain access to more demanding customer segments and higher-value projects. Conversely, suppliers that treat quality as a secondary concern may find their addressable market narrowing as customer expectations rise.
These trends carry risk as well. Demand growth could be uneven if certain application areas mature faster than others, or if technology shifts alter the need for specific pool formats. Input cost volatility could compress margins or disrupt planning if supply chains remain vulnerable. Regulatory expectations could increase overhead for smaller operators, potentially accelerating consolidation or raising barriers for new entrants. The net effect is a market with strong upside, but one in which advantage will increasingly belong to players who can manage risk while delivering dependable, application-aligned products.
Oligosaccharide Market
Implications for Decision-Makers
Different stakeholders in this market face distinct strategic priorities, but all can benefit from a clearer view of where demand, cost, and competition are heading.
For manufacturers and service providers, the priority should be to sharpen application alignment and strengthen operational resilience. This includes evaluating which library formats and workflows offer the best combination of demand durability and margin potential, while also reassessing exposure to raw material volatility and lead-time variability. Suppliers that can offer predictable quality, transparent pricing logic, and reliable delivery will have an advantage as customers become more deliberate about vendor selection. It also means paying attention to technology access and partnerships, since differentiation may increasingly come from proprietary synthesis methods, QC capabilities, or specialized library designs rather than from scale alone.
For investors, the useful question is less about whether the market will grow than about where value will accrue within it. The strongest opportunities are likely to be found in companies that can demonstrate durable demand linkages, defensible synthesis or service advantages, and the ability to manage cost volatility without eroding competitiveness. At the same time, it is worth watching for consolidation signals, pricing behavior, and regulatory shifts that could change the relative position of incumbents and entrants. In a market with moderate concentration and strong application specialization, due diligence should focus on workflow relevance, quality infrastructure, and the sustainability of unit economics under cost pressure.
For procurement teams and research organizations, the strategic imperative is to treat oligonucleotide pool sourcing as a workflow decision rather than a commodity purchase. Evaluating suppliers should include attention to application fit, error profiles, turnaround reliability, documentation standards, and the credibility of pricing in the face of raw material volatility. Building a sourcing strategy that balances flexibility with stability can reduce the risk of disruption while improving the consistency of experimental outcomes. Where possible, organizations should also consider forecasting and planning collaboration with suppliers, since cost and capacity dynamics are increasingly intertwined with commercial pricing.
For readers seeking a more detailed view of segmentation dynamics, competitive positioning, pricing structures, and regional demand patterns, the full market research report provides a deeper evidence base and more granular scenario analysis. In a market moving this quickly, the value of detailed intelligence lies in its ability to turn broad trends into specific decisions about suppliers, investment exposure, procurement strategy, and product development priorities.
For detailed analysis of this topic, please visit the official page: Oligonucleotide Pool Library Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com