

Blogs
Natural Astaxanthin Market: Why 9.1% CAGR & Shifting Demand Dynamics Redefine Growth
By PW Consulting, 2026-09-21
The Natural Astaxanthin Market: Strategic Trends and Commercial Opportunities
The natural astaxanthin sector has evolved from a niche antioxidant into a strategically significant ingredient market, driven by converging forces in health and wellness, aquaculture growth, and formulation innovation. Between 2020 and 2025, global revenue expanded from approximately 248.56 million to 372.0 million, reflecting a compound annual growth rate of 9.1 percent. Looking ahead to 2032, the trajectory points toward 686.45 million, with the forecast period (2026-2032) expected to sustain momentum as applications diversify and production systems mature. This growth is not uniform across sources, formats, or end-use categories, and the strategic value for decision-makers lies in understanding where scale, differentiation, and regulatory clarity intersect.
For executives, investors, and procurement teams, the market’s appeal rests on three characteristics: a rich antioxidant profile that commands premium positioning in human nutrition, a biologically active pigment that serves functional roles in animal health, and a supply base that is transitioning from fragmented cultivation to increasingly engineered production environments. Yet the sector is also navigating structural tensions around feedstock economics, regional regulatory divergence, and the balance between batch consistency and cost efficiency. The following analysis maps the current landscape, the forces reshaping it, the competitive postures defining it, and the strategic moves that will separate winners from followers over the next three to five years.
Market Snapshot and Core Tensions
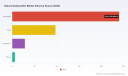
The macro picture is straightforward: demand is expanding, and the revenue curve is steepening as downstream applications broaden. What makes this market strategically interesting is not the headline growth alone, but the way value is distributed across production methods and form factors. Microalgae-derived astaxanthin represents the dominant share of the market, reflecting years of cultivation refinement and the ingredient’s positioning as a clean, plant-based antioxidant. Yeast-based routes account for a meaningful secondary share, offering distinct scalability and cost profiles. Smaller contributions come from krill and shrimp-derived sources, along with other niche inputs. The split matters because each source carries different cost structures, purity expectations, and application fit, which in turn shape pricing power and customer acquisition strategies.
On the formulation side, powder continues to lead in market share, underscoring its versatility across nutraceutical blends, feed premixes, and cosmetic bases. Oil-based formats remain important where bioavailability and sensory performance are priorities, while softgel and other consumer-ready forms occupy a smaller but growing niche as finished-product manufacturers seek convenience and perceived premium quality. Regionally, the market is balanced rather than concentrated in a single hub, with North America, Europe, and Asia Pacific each representing substantial demand centers, and Latin America plus the Middle East and Africa contributing more specialized but increasingly active demand. This geographic spread creates both diversification benefits and complexity in regulatory navigation.
Several structural tensions define the current inflection point. First, feedstock economics remain a persistent pressure point. Natural astaxanthin from Haematococcus pluvialis powder is the primary upstream feedstock for commercial production, with global output estimated at around 800 metric tons annually. This concentration creates sensitivity to cultivation yield, harvest timing, contamination risk, and energy inputs. Companies that can stabilize biomass supply and reduce per-unit production cost gain a durable advantage, but the pathway is capital-intensive and technically demanding.
Second, regulatory divergence is shaping where and how ingredients can be positioned. In the European Union, EFSA concluded in December 2025 that proposed uses of algal meal and oleoresin from Haematococcus pluvialis at levels exceeding the FEEDAP ADI of 0.034 mg/kg body weight per day cannot be established for non-food-supplement applications. At the same time, the powder with 5.0%–5.6% w/w ATX and oleoresin with 10%–12% w/w ATX has been restricted in the EU to food supplements since 1995 under novel food rules. These boundaries create a clear ceiling for certain feed and food uses in Europe, while simultaneously reinforcing the strategic importance of food supplement channels and premium nutraceutical positioning. AstaReal AB also submitted an application in December 2025 for novel food authorization covering algal meal, red viscous oleoresin, and water-dispersible formulations, signaling that the regulatory map is still being redrawn and that clarity, once achieved, can unlock new commercial pathways.
Third, the market is balancing scale against differentiation. With a CR3 of 42.5 percent and CR5 of 56.8 percent, the sector is moderately consolidated, but the room for regional specialists, formulation innovators, and application-specific suppliers remains meaningful. The tension lies in whether growth will be captured by producers who compete primarily on volume and cost, or by those who build defensible positioning through purity claims, traceability, application expertise, and regulatory readiness.
Key Drivers Reshaping the Market
Technology Innovation and Process Maturation
Production technology is moving from artisanal cultivation toward engineered control. Closed-system photobioreactors, improved strain performance, and tighter contamination management are reducing variability in biomass quality and astaxanthin yield. These advances matter because astaxanthin’s value proposition depends heavily on purity, isomer profile, and oxidative stability. Manufacturers that can deliver consistent specifications across batches gain credibility with formulators and finished-product brands, especially in nutraceuticals and cosmetics where claims and consumer trust are tightly linked to ingredient quality. At the same time, open-pond systems continue to play a role where cost efficiency and scale are paramount, particularly for feed-oriented volumes. The strategic question is not which system wins outright, but how each producer aligns technology choice with target applications and margin expectations.
Formulation technology is also advancing the commercial narrative. Water-dispersible and stabilized variants, beadlet integration, and oleoresin refinement expand the ingredient’s usability across matrices that historically posed dispersion or stability challenges. These improvements reduce formulation friction for customers and create opportunities for higher-value, application-tailored offerings rather than commodity-style transactions.
Policy and Regulatory Environment
Regulation is both a constraint and a catalyst. In Europe, the boundaries around feed and broader food uses are being clarified through EFSA opinions, which compresses certain expansion pathways while reinforcing the value of compliance-ready supply. In parallel, novel food authorization efforts signal potential future openings, especially if data packages support broader usage levels or new formulation types. For market participants, the strategic implication is that regulatory readiness is becoming a differentiator. Companies that proactively build dossiers, maintain documentation for traceability and safety, and align labeling and claims with regional requirements can move faster when opportunities open, and avoid disruption when restrictions tighten.
Beyond Europe, regulatory and certification dynamics in destination markets influence purchasing decisions in nutraceuticals, food and beverages, and aquaculture. Organic certification, GRAS status for food use, and contamination control documentation increasingly serve as gatekeeping criteria for buyers who need to defend ingredient choices to regulators, retailers, and end consumers. Regulatory alignment is therefore not simply a compliance exercise; it is a commercial enabler.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, three shifts are particularly relevant. First, the nutraceutical segment continues to anchor demand for natural astaxanthin, supported by consumer interest in antioxidant support, eye health, skin health, and sports recovery formulations. This segment rewards clarity of benefit, clean-label positioning, and brand trust, which in turn favors suppliers that can provide documentation, consistency, and application support. Second, aquaculture and animal feed represent a large and growing demand pool, where astaxanthin’s functional role in pigmentation and health supports adoption in shrimp, salmon, and other species. Here, cost-per-unit performance, batch reliability, and regulatory compliance for feed applications are central, and pricing sensitivity is higher than in premium human nutrition. Third, cosmetics and food and beverage applications, while smaller in share, create high-visibility branding opportunities and can command premium positioning when combined with compelling sensory and stability attributes.
The broader behavioral trend is a move toward ingredients with documented origin, sustainable production stories, and transparency. Buyers are increasingly hesitant to treat natural astaxanthin as a interchangeable input; they want assurance that sourcing, extraction, and final specifications meet the requirements of their specific market and claim structure.
Fucoxanthin (CAS 3351-86-8) Market
Supply Chain and Cost Structure Evolution
Cost structure dynamics are shifting as production volumes scale and operational efficiency improves. Recent developments illustrate this clearly. In June 2025, Cyanotech Corporation reported meaningful improvement in gross margin for fiscal 2025, with increasing production volumes of BioAstin Hawaiian Astaxanthin driving lower per-unit costs. This is a useful signal that scale, when combined with process maturity, can translate into margin expansion rather than merely top-line growth. In May 2025, Beijing Gingko Group announced expansion of astaxanthin manufacturing facilities in Yunnan Province, including a new research laboratory to support its AstaZine natural astaxanthin line. Capacity expansion of this kind indicates confidence in demand durability and a push to strengthen both volume and technical capabilities. Meanwhile, in July 2024, Algatechnologies introduced AstaPure 5% natural astaxanthin for softgels, extending its product line with all-natural extracts. Moves like this show how suppliers are layering formulation-specific offerings onto core production capabilities to capture more value.
The broader supply chain implication is that advantage is increasingly determined by integrated control over cultivation, extraction, and finishing, or by strong partnerships that achieve the same effect. Fragmented, transactional supply chains create exposure to quality variation and price volatility, while integrated or closely coordinated models support specification reliability, margin retention, and faster response to customer needs. Energy costs, water management, and contamination control remain critical cost drivers, especially for microalgae-based systems, and will continue to separate efficient operators from less optimized ones.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market’s competitive core includes a mix of established producers with proprietary cultivation and extraction systems, regional specialists with strong application focus, and larger nutrition and ingredient groups leveraging astaxanthin as part of broader portfolios. The strategic distinction lies less in participation alone and more in how each company constructs defensibility.
AstaReal Inc. operates with a clear brand-centered strategy around natural astaxanthin from Haematococcus pluvialis microalgae, supported by patented cultivation systems and contributions to standards development. Its emphasis on branded extracts, oleoresin, and powder across nutraceutical, cosmetic, and food applications reflects a premium, documentation-rich approach that targets customers seeking reliability and claim support.
Cyanotech Corporation has built a long-standing position around integrated Haematococcus pluvialis cultivation and extraction, with patented open-pond technology and GRAS certification for food use. Its BioAstin Hawaiian Astaxanthin line illustrates how regional identity, certification, and production scale can combine into a recognizable offering. Recent margin improvement tied to higher production volumes reinforces the value of scaling mature processes efficiently.
Algatechnologies Ltd. focuses on high-purity natural astaxanthin from closed-system cultivation, supplying premium extracts and oleoresin with strict contamination control for nutraceuticals, cosmetics, and aquaculture. Its emphasis on purity and controlled environments aligns with buyers who prioritize specification consistency and risk reduction, particularly in sensitive applications.
Beijing Gingko Group stands out as a large-scale producer of natural astaxanthin from Haematococcus pluvialis, offering certified organic biomass, powder, and extracts for global nutraceutical and feed markets. Its scale, ongoing facility expansion, and research investment position it to compete on volume, cost, and broad application coverage, while also building technical depth.
Algalif Iceland operates a large-scale photobioreactor facility and supplies sustainable Haematococcus-derived extracts under its own brand for premium nutraceutical applications. Its strategy highlights how geographic identity, controlled production, and sustainability narratives can support premium positioning in targeted downstream markets.
Fuji Chemical Industry contributes through natural astaxanthin manufacturing via its AstaReal subsidiary, providing high-purity extracts, beadlets, and formulations for human consumption and related applications. This reflects a formulation-oriented model that adds value through finished or semi-finished formats tailored to end-use requirements.
Divis Laboratories Limited participates as a supplier of natural astaxanthin extracts and derivatives, with focus on nutraceutical and cosmetic grades and sustainable sourcing. Its role illustrates the importance of specialty extraction and derivative capabilities in markets where customization and grade differentiation matter.
Astaxanthin (CAS 472-61-7) Market
Differentiation, Consolidation, and New Entry Dynamics
Differentiation is coalescing around several axes: purity and specification control, application-specific formulation support, regulatory readiness, sustainability and traceability claims, and the ability to scale without sacrificing consistency. The most resilient players tend to combine at least two of these strengths rather than competing on a single dimension. For example, a producer may pair controlled cultivation with strong documentation, or combine scale with brand and certification advantages that help customers justify ingredient choices to their own stakeholders.
The market is not moving toward extreme concentration in the near term, but selective integration is likely. Expect more partnerships between cultivation specialists and formulation or distribution networks, more regional capacity investments aligned with local demand and regulatory conditions, and more vertical coordination where producers seek to control feedstock, extraction, and finishing to protect margin and quality. At the same time, new entrants will continue to appear where they can offer a credible technology edge, a defensible sustainability story, or access to an underserved application. The barrier is not simply capital; it is the ability to deliver consistent quality, navigate regulatory complexity, and build buyer trust in a market where claims and contamination risk carry real consequences.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to define the market’s evolution.
-
Application diversification with a premium core. Nutraceuticals will remain the anchor, but growth will increasingly come from better-matched formulations, stabilized variants, and application-specific grades that reduce customer friction and support stronger positioning. Cosmetics and food and beverage uses will remain smaller in share but can deliver outsized brand value when paired with sensory quality and regulatory compliance.
-
Regulatory clarity as a competitive filter. As novel food and feed-related assessments progress, the regulatory map will become clearer in some regions and more constrained in others. Companies that have already invested in documentation, safety data, and compliant positioning will be better placed to expand into newly authorized uses or defend existing channels when restrictions crystallize.
PW Consulting -
Margin improvement through scale and process control. The recent margin improvement reported by established producers suggests that scale, when combined with mature cultivation and extraction processes, can convert volume growth into profitability. Capacity expansions and research investments indicate that leading players are preparing for sustained demand rather than treating growth as a short-cycle opportunity.
-
Sustainability and traceability as purchase criteria. Buyers are increasingly weighing origin, energy and water intensity, and supply transparency. Producers that can substantiate sustainability claims and provide traceable batches will gain advantage in premium segments and in procurement environments where reputational risk matters.
These trends translate into concrete commercial opportunities. For producers, the opportunity lies in aligning capacity and technology with the applications that offer the best combination of margin, growth, and defensibility, rather than chasing all segments equally. For ingredient buyers and formulators, there is an opportunity to secure reliable supply of specification-consistent astaxanthin that supports stronger claims, cleaner labels, and more stable procurement costs. For investors, the appealing thesis centers on operators that combine process maturity, regulatory readiness, and application focus with a credible path to margin expansion as volumes scale.
Potential risks and uncertainties should not be understated. Feedstock availability and cultivation risk can affect supply consistency and pricing, particularly if contamination events or yield variability intensify. Regulatory outcomes may narrow certain applications in key regions, especially where feed and broader food uses face tighter limits. Competitive intensity could compress margins if supply expands faster than demand in specific formats or regions. And claim substantiation expectations may rise, increasing the cost of doing business for suppliers that cannot provide robust documentation and traceability. These risks do not negate the growth outlook, but they do mean that execution quality will determine who captures value.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to match technology and capacity strategy to the applications where differentiation is most defensible. If the target is premium nutraceuticals and cosmetics, investment in controlled cultivation, purity assurance, and documentation is likely to pay off more than pure volume expansion. If the target includes aquaculture and feed, the focus should be on cost efficiency, batch reliability, and compliance with regional feed rules, while preserving enough quality consistency to maintain customer trust. In both cases, formulation-specific offerings and finished or semi-finished formats can help capture more value than commodity supply alone.
For investors, the most compelling opportunities are likely to be found in operators that demonstrate a combination of process maturity, credible regulatory readiness, and a clear application focus. Capacity expansion is meaningful only when paired with the ability to convert volume into margin, and regulatory navigation is increasingly part of the valuation story. Due diligence should examine not just scale and geography, but also contamination control, documentation quality, formulation capability, and the durability of customer relationships in segments where specification consistency matters.
For procurement teams and formulators, the strategic move is to treat natural astaxanthin as a specification-driven ingredient rather than a interchangeable input. Locking in supply partnerships with suppliers that can provide consistent batches, transparent origin, and application support will reduce reformulation risk and strengthen claim confidence. Diversifying across sources and formats where appropriate can also mitigate exposure to regional regulatory shifts or feedstock constraints, especially when planning for longer-term product roadmaps.
The market’s next phase will reward participants who combine technical discipline with commercial clarity. As regulatory boundaries become sharper, production systems become more engineered, and buyers demand stronger documentation and sustainability assurance, the winners will be those who can deliver consistent quality at scale while aligning their offerings to the applications that matter most. For decision-makers seeking to move from broad market awareness to actionable planning, deeper segmentation, supplier benchmarking, and region-specific regulatory mapping will be essential. PW Consulting’s full research report on the natural astaxanthin market provides that level of detail, including segmented demand dynamics, competitive benchmarking, and tailored recommendations designed to support investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Machine Stretch Film Market: Why 5.5% CAGR from 2026 to 2032 Redefines Packaging Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Machine Stretch Film Market
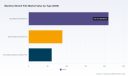
The machine stretch film market has entered a period of structural transformation, moving beyond incremental volume growth to a phase where material science, regulatory pressure, and supply chain resilience redefine competitive advantage. Valued at approximately $360 million in 2025, the market has expanded from roughly $280 million in 2020, reflecting a compound annual growth rate of 5.5 percent through the 2026-2032 forecast horizon. This trajectory is not merely a function of increased pallet wrapping activity; it signals a deeper shift in how logistics operators, manufacturers, and retailers approach load containment, material efficiency, and end-of-life accountability. The market's composition reveals a clear hierarchy in product architecture and application demand, with cast extrusion technologies and logistics-driven use cases commanding the largest revenue shares. Yet the headline figures only scratch the surface. Beneath the growth curve lies a landscape where raw material volatility, extended producer responsibility mandates, and performance differentiation are forcing incumbents and new entrants alike to recalibrate their operating models.
Rebuilding Margins in a Volatile Input Environment
One of the most persistent challenges shaping strategic decision-making is the pricing instability of primary and recycled polyethylene feedstocks. In May 2026, linear low-density polyethylene prices in North America hovered between $1.13 and $1.16 per kilogram, while regional increases of 8.7 to 12.6 percent were reported across Asia and Europe. This input pressure compounds with tighter availability of recycled LLDPE pellets, which traded between 55 and 60 cents per kilogram in 2025 and faced continued upward pressure into 2026 due to supply constraints. For film producers, this environment erodes the traditional cost-pass-through mechanism, particularly in commoditized blown film segments where differentiation is limited. Companies that rely on volume-based pricing without performance or sustainability premiums are seeing margin compression, while those with integrated resin strategies or advanced extrusion capabilities are better positioned to absorb fluctuations without sacrificing competitiveness.
Regulatory Compliance as a Design Constraint, Not an Afterthought
The regulatory landscape has shifted from voluntary sustainability commitments to mandatory material sourcing and reporting requirements. As of August 2025, five U.S. states mandate post-consumer recycled content in plastic packaging, with stretch film falling under flexible packaging targets within extended producer responsibility frameworks. Minnesota's Packaging Waste and Cost Reduction Act, implemented in phases through 2025 and 2026, requires producers to comply with EPR plans that explicitly cover stretch film. Simultaneously, EU and U.S. EPR schemes active in 2026 include mandatory recycled content goals that directly influence production formulations and material procurement. These regulations are no longer peripheral compliance exercises; they are redesigning the economics of film production. Manufacturers must balance recycled content integration with tensile strength, cling, and puncture resistance requirements, while avoiding penalties or market access restrictions in jurisdictions with tightening standards. The operational implication is clear: compliance is becoming a product development parameter, not a post-production adjustment.
Performance Expectations Outpacing Traditional Formulations
A third inflection point lies in the growing disconnect between standardized film specifications and the operational realities of automated wrapping lines. High-throughput distribution centers, robotic palletizers, and precision load containment requirements demand films that maintain stability at high pre-stretch ratios, resist punctures during high-stack storage, and deliver consistent cling without excessive material usage. Traditional blown films often struggle to meet these combined performance thresholds, creating sustained demand for cast and pre-stretched alternatives that offer tighter gauge control, higher elongation, and reduced consumption per pallet. The challenge for producers is to engineer formulations that satisfy these operational demands while navigating recycled content mandates and input cost volatility. Companies that treat performance and sustainability as competing priorities are losing ground to those that integrate both into a single product architecture.
Key Drivers Reshaping Market Dynamics
The market's trajectory is being pulled by four interconnected forces that are redefining how machine stretch films are engineered, sourced, and deployed. Understanding these drivers is essential for executives evaluating capacity investments, procurement strategies, or portfolio positioning.
Advanced Extrusion and Multi-Layer Architecture
Technological progress in nano-layer extrusion and precision gauge control is fundamentally altering the performance ceiling of machine-applied stretch films. Multi-layer coextrusion enables manufacturers to distribute material properties across functional layers, achieving higher stretch ratios and improved load containment without increasing total film weight. Recent product launches demonstrate this shift in action. A major producer commissioned a new 55-layer nano-layer extrusion line in Ohio, delivering machine stretch films with up to 350 percent stretch and approximately 25 percent material reduction. Another specialist introduced pre-stretched film lines incorporating 35 percent post-consumer recycled content while maintaining tensile strength at 22 MPa for machine applications. These developments illustrate a broader industry movement: performance and material efficiency are no longer trade-offs but co-engineered outcomes. For downstream users, this translates into fewer film changes, lower consumption per wrap cycle, and more predictable load stability on automated lines.
Extended Producer Responsibility and Recycled Content Mandates
Policy frameworks are accelerating the integration of recycled polyethylene into machine-grade films, transforming what was once a niche sustainability offering into a compliance-driven baseline. With multiple U.S. states and EU jurisdictions enforcing recycled content targets within EPR schemes, producers are reformulating products to meet minimum thresholds without compromising machine performance. One integrated packaging group launched pre-stretched lines with 35 percent PCR content, while two other major producers introduced stretch film lines featuring 30 percent post-consumer recycled content for high load stability. These milestones reflect a structural shift: recycled content is becoming a spec requirement, not a marketing differentiator. The operational impact extends beyond formulation. Procurement teams must secure consistent recycled resin supply, quality control protocols must adapt to variable feedstock characteristics, and sales teams must articulate performance equivalence to customers transitioning from virgin-only films.
Demand-Side Pressure for Load Containment and Throughput Optimization
End-users are increasingly prioritizing films that reduce waste, minimize changeover downtime, and maintain integrity under high-stack or long-transit conditions. Logistics and distribution operations, which represent the largest application share, are operating with thinner margin buffers and higher throughput expectations, making film consumption a visible cost lever. Food and beverage applications add further complexity, requiring films that balance cling, clarity, and regulatory compliance for perishable or branded goods. Agriculture and industrial packaging sectors demand puncture resistance and weather tolerance, while still seeking material efficiency gains. The common thread across these segments is a preference for films that deliver predictable performance at lower total usage, rather than simply lower price per kilogram. This behavior is reshaping purchasing criteria: total cost per wrapped pallet, line efficiency, and load rejection rates are gaining weight over raw material price alone.
Feedstock Sourcing and Supply Chain Recalibration
The combination of virgin resin price increases and recycled pellet supply constraints is forcing companies to rethink sourcing strategies. Regional price divergence means that producers with geographically diversified resin procurement or localized recycling partnerships can mitigate cost shocks more effectively than those dependent on single-region supply chains. Some manufacturers are integrating recycled polyethylene directly into machine-grade products through new resin blending protocols, while others are investing in closed-loop recovery programs with large logistics customers. The broader implication is that supply chain resilience is becoming a competitive differentiator. Companies that secure predictable access to qualified recycled and virgin feedstocks, while maintaining formulation flexibility, are better equipped to sustain pricing stability and service reliability amid market turbulence.
Worldwide Puncture Resistance Stretch Film Market
Competitive Landscape and Strategic Positioning
The machine stretch film market is characterized by a concentrated core of established producers alongside specialized manufacturers and regional suppliers navigating distinct competitive niches. The top three players collectively account for approximately 55 percent of market revenue, while the top five extend their share to around 70 percent. This concentration reflects the technical barriers to high-performance extrusion, the importance of integrated resin and film production capabilities, and the value of long-term relationships with large logistics and industrial customers. Yet the landscape is not static. Product launches, formulation innovation, and regulatory-driven reformulation are creating pockets of differentiation that allow smaller or regional players to compete on performance specificity rather than sheer scale.
Performance Engineering as the Primary Differentiator
Leading manufacturers are competing on measurable performance attributes rather than generic film availability. One producer emphasizes nano-layer extrusion lines that deliver up to 350 percent stretch with material reduction, targeting automated pallet wrapping operations where film consumption and load stability are critical. Another manufacturer highlights Rite-Gauging technology for consistent pre-stretch and reduced usage, alongside high-cling and high-load containment variants designed for demanding distribution environments. A specialist producer focuses on clarity, stretch performance, and high-strength applications tailored to automated wrapping systems, while a separate player offers series films engineered for pre-stretch levels exceeding 300 percent, high load containment, and puncture resistance. These positioning strategies reflect a shared insight: customers are willing to pay for reliability, reduced consumption, and line compatibility, provided the performance claims are verifiable and consistent.
PLA Biodegradable Stretch Film Market
Sustainability Integration as a Operational Imperative
Sustainability is increasingly embedded into product portfolios rather than marketed as a separate line. Producers are launching films with 30 percent post-consumer recycled content, integrating recycled polyethylene into machine-grade products through new resin protocols, and aligning formulations with EPR and recycled content mandates. One European supplier emphasizes sustainability and performance in its machine-applied stretch films, while a global packaging group positions its machine stretch films within an integrated portfolio focused on performance and cost efficiency. This convergence of sustainability and performance is reshaping competitive dynamics. Companies that treat recycled content integration as a core engineering challenge, supported by consistent feedstock access and robust quality assurance, are building defensible positions. Those that rely on superficial sustainability claims without performance validation risk losing credibility with procurement teams that must meet both cost and compliance targets.
Market Evolution: Consolidation Pressure and Niche Differentiation
The market is experiencing simultaneous forces of consolidation and fragmentation. Scale advantages in resin procurement, extrusion capacity, and distribution networks favor larger producers, particularly in mature regions where automated wrapping infrastructure is widespread. At the same time, regional suppliers and specialists are carving out positions by focusing on specific performance needs, localized service, or regulatory-aligned formulations. New entrants face high technical and compliance barriers, but opportunities exist for companies that can address underserved application requirements, offer verifiable performance improvements, or provide flexible supply arrangements in regions with growing logistics infrastructure. The likely trajectory is a market where a concentrated core sets baseline performance and pricing expectations, while specialized players compete on formulation precision, application-specific engineering, and regional responsiveness.
Forward Outlook: Three Critical Trends for 2026-2032
The next several years will be defined by how quickly producers, investors, and procurement leaders adapt to the intersection of performance demands, regulatory constraints, and input cost dynamics. Three trends are likely to shape strategic outcomes.
Recycled Content as a Baseline, Not a Premium
Mandatory recycled content targets will continue to normalize PCR integration across machine stretch film portfolios. As more jurisdictions enforce minimum thresholds and EPR frameworks tighten, films without qualified recycled content will face procurement disadvantages or market access limitations. This trend creates opportunities for producers with proven formulation stability, consistent recycled resin supply, and transparent compliance documentation. It also introduces risk for companies that overpromise on recycled content without ensuring tensile strength, cling, and puncture resistance remain within specification. The commercial opportunity lies in offering films that meet or exceed regulatory requirements while delivering measurable performance parity or improvement, thereby converting compliance from a cost center into a competitive asset.
PW Consulting
Material Efficiency and Automated Line Optimization
The push toward higher stretch ratios, tighter gauge control, and reduced consumption per pallet will intensify as distribution centers seek to lower total wrapping costs and improve line throughput. Films that enable consistent pre-stretch, minimize changeover variability, and maintain load stability under automated operation will see sustained demand. Producers investing in multi-layer extrusion, precision dispensing compatibility, and application-specific formulations are well positioned to capture this shift. The risk lies in over-engineering films for narrow use cases without ensuring broad compatibility across wrapping equipment and load types. Success will depend on balancing performance specificity with practical deployability across diverse operational environments.
Regional Divergence in Regulatory and Supply Dynamics
Regulatory mandates, recycled resin availability, and virgin resin pricing will continue to diverge across regions, creating uneven competitive conditions. North America and Europe are likely to see faster adoption of EPR-aligned formulations and recycled content integration, while Asia Pacific and emerging markets may experience more gradual regulatory rollout but stronger volume growth driven by expanding logistics infrastructure. LLDPE price increases of 8.7 to 12.6 percent in Asia and Europe, alongside North American price levels around $1.13 to $1.16 per kilogram, illustrate the regional cost landscape that producers must navigate. Companies with flexible sourcing strategies, localized production, or regionally tailored product lines will be better equipped to manage these divergences. The uncertainty centers on the pace and uniformity of regulatory enforcement, the stability of recycled resin supply, and the potential for trade or tariff shifts that could disrupt feedstock flows.
Strategic Actions for Decision Makers
Translating these trends into actionable strategy requires different priorities depending on a company's role in the value chain. The following recommendations highlight where focused effort can yield the strongest returns.
For film manufacturers and producers: Prioritize formulation engineering that treats recycled content and performance as integrated design parameters. Invest in extrusion capabilities that enable higher stretch ratios, consistent gauge control, and material reduction without sacrificing load containment or puncture resistance. Secure diversified resin sourcing to mitigate regional price volatility, and develop transparent compliance documentation that supports procurement teams navigating EPR and recycled content mandates. Differentiate through verifiable performance claims and application-specific solutions rather than volume-based pricing alone.
For investors and portfolio strategists: Evaluate exposure to producers with demonstrated capabilities in advanced extrusion, recycled content integration, and regional supply resilience. Favor companies that can articulate clear performance advantages, maintain formulation flexibility amid input cost fluctuations, and align product portfolios with regulatory trajectories. Monitor consolidation dynamics and niche differentiation opportunities, particularly in regions where logistics infrastructure is expanding and automated wrapping adoption is accelerating. Assess risk around recycled resin supply constraints, virgin resin price divergence, and regulatory enforcement variability.
For procurement leaders and logistics operators: Shift evaluation criteria from price per kilogram to total cost per wrapped pallet, incorporating film consumption, line efficiency, load rejection rates, and compliance readiness. Prioritize suppliers that provide consistent performance at high pre-stretch levels, maintain quality across recycled and virgin blends, and offer documentation that supports EPR and recycled content reporting. Engage early with formulation changes to ensure compatibility with existing wrapping equipment and load profiles, and consider supplier partnerships that provide feedstock transparency and supply stability amid market volatility.
The machine stretch film market is moving into a phase where technical precision, regulatory alignment, and supply chain resilience determine competitive outcomes. The companies that succeed will be those that treat performance, sustainability, and cost efficiency as interconnected objectives rather than competing priorities. For executives seeking granular segmentation data, regional pricing dynamics, competitor benchmarking, and customized strategic scenarios, the full research report provides the detailed framework needed to translate these market-wide insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Machine Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cold Milling Machine Market: 6.26% CAGR and the Strategic Shifts Reshaping 2026–2032 Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Cold Milling Machine Market
The global cold milling machine market has entered a phase of sustained expansion, driven by aging infrastructure, tightening environmental mandates, and a strategic shift toward high-efficiency pavement rehabilitation. Valued at approximately $215 million in 2025, the market has grown at a compound annual growth rate of 6.26 percent over the 2020 to 2025 period and is projected to reach $345 million by 2032. This trajectory reflects more than cyclical road maintenance spending; it signals a structural transformation in how contractors approach surface rehabilitation, material recycling, and emissions compliance. The next seven years will be defined by technological differentiation, regulatory alignment, and regional demand rebalancing.
Reconciliation of Physical Infrastructure Reality and Environmental Mandates
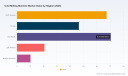
The market's underlying growth is rooted in a pragmatic reality: governments and private developers cannot afford to rebuild entire pavement networks from scratch. Instead, they rely on cold milling as a targeted, cost-effective method to remove deteriorated layers, prepare binding surfaces, and recover reusable aggregates. This operational logic has remained consistent, but the execution environment has changed dramatically. Contractors now face overlapping pressures: tighter municipal budgets, stricter noise and emission limits at urban job sites, and client expectations for project completion times that align with modern logistics windows. Machinery that simply removes asphalt or concrete is no longer sufficient. The winning equipment must integrate precise depth control, consistent output, and verifiable sustainability metrics while maintaining operational flexibility across multiple pavement types.
At the same time, the market confronts fragmentation in adoption readiness. Developed regions with mature road networks are prioritizing fine milling, surface rehabilitation, and emissions-reduced operations. Emerging markets are still scaling basic rehabilitation capacity, often balancing imported high-performance equipment against domestically manufactured alternatives. Navigating this divide requires a clear view of where regulatory pressure converts into procurement behavior, and where cost sensitivity still dictates purchasing decisions.
Key Drivers Shaping Market Dynamics
Technological Innovation and the Automation of Precision Milling
The most consequential shift in the market is the transition from mechanical power to controlled, data-enabled precision. Modern cold milling machines increasingly embed intelligent drum speed regulation, grade and slope tracking, and operator-assist systems that reduce variability in cut depth and material consistency. These capabilities directly affect downstream paving quality and the efficiency of material recycling. When a milling pass produces predictable particle size and uniform surface preparation, contractors spend less time on corrective work and more time maintaining throughput.
Recent product introductions illustrate this trajectory. Wirtgen Group's W 210 XF and W 250 XF models, unveiled in early 2025, emphasize high-output milling combined with advanced automation. The W 250 XF was presented as a high-capacity platform with dual-engine architecture and refined milling technology, targeting large-scale rehabilitation where output and consistency determine project economics. Alongside larger platforms, the same manufacturer introduced the W 50 Re battery-electric small milling machine and an updated generation of recyclers designed for lower specific emissions. This pairing of large-scale high-power machines with compact electrified alternatives reflects a broader industry recognition: different job profiles require different power and control architectures, and electrification is entering the market not as a single solution but as a modular option.
From a commercial standpoint, automation is not merely a feature upgrade. It is becoming a procurement criterion. Contractors evaluating bids increasingly weigh whether a machine can reduce operator fatigue, improve cut consistency across long runs, and provide feedback loops that support maintenance planning. Equipment that integrates these functions into a coherent workflow offers a practical advantage in labor-constrained environments and in projects where site access limits the margin for error.
Worldwide Milling Machine Market
Regulatory Pressure and Emissions Compliance as Procurement Catalysts
Environmental regulation has moved from a compliance backdrop to an active determinant of machine selection. European and global frameworks continue to tighten carbon emission expectations for construction equipment, with enforcement and reporting requirements making real-time emissions visibility more valuable. In this environment, cold milling machines that generate transparent performance data and meet advanced emission standards are better positioned for public tenders and large contractor fleets.
Recent regulatory-aligned developments demonstrate how manufacturers are responding. Wirtgen's latest large milling machines incorporate EU Stage 5 and US EPA Tier 4f emission standards alongside real-time CO2 tracking through performance monitoring systems. Caterpillar's PM Series cold planers are designed around Tier 4 Final and Stage V compliant engines to support sustainable construction and reduce operating cost exposure tied to emissions compliance. Rather than treating emissions as an abstract requirement, leading manufacturers are connecting compliance to operating economics: fuel efficiency, maintenance intervals, and fewer regulatory disruptions on urban or sensitive job sites.
This dynamic matters for strategic planning because it introduces a second layer of value beyond raw capacity. Machines that document emissions performance, reduce specific fuel consumption, and support fleet reporting are easier to justify in tender processes where environmental scoring is part of the evaluation. Over the forecast period, this trend is likely to widen the gap between equipment that meets minimum compliance and equipment that actively supports sustainability reporting and cost control.
Demand-Side Shifts Toward Rehabilitation, Recycling, and Lifecycle Thinking
Demand is increasingly shaped by a lifecycle view of pavement assets rather than a replacement mindset. Municipalities, roadway authorities, and large contractors are focusing on rehabilitation strategies that extend service life, recover aggregates, and reduce the need for virgin material inputs. Cold milling sits at the center of this shift because it enables precise removal of distressed layers and produces milled material that can be reintroduced into recycling streams or base layers.
This demand evolution changes how buyers evaluate machines. Output capacity remains important, but it must be balanced against the ability to handle different materials, switch between coarse and fine milling tasks, and support downstream recycling workflows. Contractors operating in regions with high volumes of asphalt rehabilitation are prioritizing consistent milling quality and rapid setup changes, while concrete rehabilitation users need equipment that manages more abrasive surfaces and maintains drum performance over extended usage. The practical implication is that demand is fragmenting by application logic even as overall market volume rises.
A second demand-side pressure is job-site logistics. Urban rehabilitation projects increasingly require equipment that can operate within constrained access windows, minimize noise impact, and adapt to tighter footprints. This favors machines that combine maneuverability with reliable output and that can integrate into coordinated paving and recycling operations without becoming a bottleneck. In practical terms, the strongest commercial opportunities are emerging where cold milling equipment is sold not as a standalone tool but as part of an integrated rehabilitation process.
Supply Chain Realities and Cost Structure Reframing
Equipment economics are also being reshaped by supply chain considerations and operating cost structures. Engine availability, component sourcing, and the cost of maintaining compliance with evolving emission systems all influence total cost of ownership. High-horsepower platforms, in particular, depend on reliable engine supply and service networks that can support advanced exhaust aftertreatment and diagnostic systems. Any disruption in these areas affects uptime and can alter the attractiveness of certain machine architectures.
At the same time, fuel efficiency has become a direct commercial lever rather than a secondary benefit. Advanced drum speed control and optimized transmission systems can deliver measurable fuel savings, which matters in markets where operating costs are under scrutiny and where contractors run machines for long shifts. Fuel consumption is no longer just an engineering metric; it is a tender differentiator and a fleet budgeting variable. In that sense, cost structure is moving from a static procurement concern to a dynamic performance target.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding approximately 24.6 percent of the market and the top five reaching around 26.2 percent. This level of concentration suggests that scale, brand recognition, and technology leadership are rewarded, but it also leaves meaningful room for differentiated regional participants, application specialists, and new entrants targeting specific job profiles or price-performance segments. Competition is increasingly defined less by raw size and more by the ability to deliver compliant, efficient, and operationally intelligent machines that match local demand patterns.
Wirtgen Group stands out for portfolio breadth and technology integration. Its lineup spans compact models to large platforms, with recent additions emphasizing automation, mill assist controls, and performance tracking for milling operations. The company's 2025 introductions, including the W 210 XF and W 250 XF, reinforce a high-performance large-machine strategy while its battery-electric small milling machine and updated recycler generation indicate a parallel push toward lower specific emissions and electrified compact equipment. The strategic signal is clear: the company is positioning across multiple power and scale points, using automation and emissions visibility as differentiators.
Caterpillar contributes a different kind of strength: large-engine reliability, emissions compliance, and telematics integration. Its PM Series half-lane cold planers, including models such as PM825 and PM620, are built around high-horsepower engines and Tier 4 Final compliance, with telematics support aimed at fleet management and operational efficiency. Caterpillar's positioning benefits from its broader construction equipment ecosystem, where service networks, parts logistics, and machine data integration can extend value beyond the cold planer itself. For contractors managing multiple asset types, that ecosystem appeal can be decisive.
Regional and application-focused players continue to shape competitive dynamics in specialized ways. Bomag, Dynapac, Volvo Construction Equipment, Sakai, Roadtec, and CMI Roadbuilding each maintain cold milling offerings aligned with particular operating profiles or regional expectations. Roadtec's RX Series cold planers, for example, were updated in early 2025 with higher-horsepower Caterpillar Tier 4 Final engines to target higher production and reliability. These participants often compete on feature-fit, service responsiveness, and application alignment rather than attempting to lead on sheer portfolio scale.
In Asia, SANY Group, XCMG Group, LiuGong, and Shantui represent a distinct competitive dynamic. Their SCM, XM, 5100-2/SM, and SM series machines demonstrate strong capability in road construction and infrastructure applications, with a focus on cost-effective high-performance equipment for local and export markets. The strategic implication is that competition is not only about premium features; it is also about whether manufacturers can balance compliance, durability, and price in ways that match the procurement realities of fast-growing infrastructure regions.
Several competitive trends are emerging. First, there is a clear convergence around compliance-driven engineering, with manufacturers treating emission standards and fuel efficiency as baseline expectations rather than optional enhancements. Second, product launches are increasingly paired with digital value propositions, whether through performance tracking, telematics, or operator-assist features. Third, the market is not consolidating into a single winner-takes-most pattern; instead, it is fragmenting by application, power architecture, and region. That means competitive advantage will depend on matching machine characteristics to specific procurement priorities, not simply on offering the largest or most expensive platform.
Future Trends and Commercial Implications
Electrification and Alternative Powertrains Will Expand by Job Profile
Electric and low-emission configurations are entering the market in targeted forms rather than as blanket replacements. Compact milling tasks, urban rehabilitation, and environments with strict site emissions limits are likely to be the earliest adoption zones. Over the next three to five years, expect battery-electric and hybrid-enabled machines to broaden where site constraints, noise restrictions, or localized sustainability requirements make conventional diesel operation less attractive. Commercial opportunity lies not just in selling an alternative powertrain but in defining the applications where it delivers a credible cost and operational case. Manufacturers and distributors that understand which job profiles justify electrified equipment, and how to support charging, deployment, and maintenance, will be better positioned to shape demand rather than react to it.
Cold Planers Market
Automation and Data Feedback Will Become Table Stakes for High-Value Tenders
Real-time milling control, grade support, and performance data capture are moving from premium differentiators to expected features in competitive procurement. As tender evaluation increasingly includes operating efficiency, emissions documentation, and process consistency, machines without meaningful data capabilities risk losing relevance in higher-value contracts. The commercial implication is that equipment value may shift from purchase price toward lifecycle performance and reporting utility. This favors manufacturers and service providers that can package machine performance with fleet diagnostics, maintenance insight, and verifiable operating metrics. It also creates an opening for service-led revenue models, where monitoring, diagnostics, and process optimization become part of the customer relationship.
Regional Demand Divergence Will Deepen Selection Logic
Market growth will not unfold uniformly. Regions with strict emission environments, mature rehabilitation practices, and dense urban projects will favor automated, compliant, and often electrified solutions. Regions focused on capacity expansion and cost efficiency will still reward durable, high-output machines that deliver reliable performance at a competitive total cost of ownership. This divergence means that successful commercial strategies will require regional calibration: product mix, service coverage, financing support, and application messaging all need to align with local procurement priorities. Companies that attempt a single global narrative across all markets will likely leave value on the table.
These trends carry uncertainty. Emissions frameworks may accelerate or shift implementation timelines. Electrification may progress faster in some geographies while remaining limited in others due to infrastructure and cost constraints. Fuel price volatility, component supply conditions, and changes in public infrastructure spending can all reshape the pace of adoption. Commercial planning should therefore treat these trends as directional indicators rather than fixed predictions, and build flexibility into product, service, and market-entry decisions.
Strategic Actions for Decision Makers
For manufacturers and equipment suppliers, the priority is to align product architecture with the real purchasing drivers of the next cycle. That means maintaining a credible path on emissions compliance, treating automation and data capture as core value elements instead of accessories, and explicitly mapping which machine sizes, power options, and features fit which applications and regions. Pricing and service strategies should reflect total cost of ownership, not only upfront specifications. Where feasible, offering bundled diagnostics, maintenance planning support, and emissions reporting capabilities can strengthen customer retention and differentiate offers in competitive bids.
PW Consulting Automotive & Machinery Research Center
For investors and strategic partners, the opportunity is to focus on the segments where regulatory pressure, rehabilitation demand, and technology adoption intersect most strongly. Equipment that combines compliance, fuel efficiency, and operational data is likely to command stronger positioning in tenders and fleet renewals. Vertical relevance matters as much as product specifications: distribution strength, service coverage, parts logistics, and the ability to support electrified or digitally integrated machines are becoming part of the investment thesis. Monitoring the pace of electrification adoption, the stability of emission compliance requirements, and regional procurement behavior will help identify where demand is real and where it is still aspirational.
For procurement leaders and contractors, the practical goal is to evaluate cold milling equipment against operational context rather than headline capacity alone. Project selection should consider cut precision, material recovery needs, site-access constraints, emissions documentation requirements, and the cost implications of fuel efficiency and maintenance intervals. When renewing fleets or entering multi-year rehabilitation programs, buyers benefit from specifying performance expectations that include consistency, reporting, and service support, not just milling width or engine power. Choosing equipment that fits the workflow reduces rework, improves scheduling predictability, and strengthens the business case for rehabilitation-focused projects.
In a market where specifications, compliance, and application fit increasingly determine winning offers, broad market awareness is useful but not enough. Detailed segmentation data, regional procurement patterns, competitive benchmarking, and product-level performance comparisons are what translate strategic direction into practical decisions. For that level of segmentation and actionable recommendation, interested parties can review the complete report.
For detailed analysis of this topic, please visit the official page: Cold Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microgrid Technology Market: Why an 18.5% CAGR to $73.9B Redefines Energy Infrastructure Through 2032
By PW Consulting, 2026-09-21
Beyond Grid Dependency: Strategic Trends and Commercial Opportunities in the Microgrid Technology Market
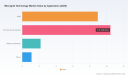
The microgrid technology market is undergoing a structural transformation. Valued at approximately 12.5 billion USD in 2020, the sector expanded to 22.7 billion USD by 2025 and is projected to reach 73.9 billion USD by 2032, reflecting a compound annual growth rate of 18.5 percent over the forecast period. This trajectory signals more than incremental adoption; it indicates a shift from pilot-scale experimentation toward mainstream infrastructure deployment. As distributed energy resources mature and operational priorities evolve, microgrids are transitioning from niche resilience solutions to foundational components of modern energy architecture. For enterprise leaders, the implication is clear: microgrid integration now intersects with capital allocation, regulatory navigation, supply chain strategy, and operational continuity.
The current phase of market development is characterized by accelerated technical validation, yet the pathway from concept to commercial scale remains uneven. Several structural friction points define the present landscape. First, the economics of deployment vary significantly depending on site complexity, load criticality, and regional regulatory frameworks. While standardized configurations benefit from predictable cost curves, customized installations for hospitals, industrial campuses, and critical facilities require substantial engineering investment and multi-stakeholder coordination. Second, the transition toward bidirectional power flows and inverter-based architectures introduces new operational dependencies. Legacy interconnection standards, fragmented approval processes, and evolving cybersecurity expectations create coordination layers that can delay project timelines. Third, the market remains moderately concentrated, indicating that scale advantages, proprietary control systems, and integrated service offerings continue to shape competitive positioning. These dynamics collectively suggest that market growth will increasingly favor organizations capable of aligning technical performance with regulatory clarity, financial structuring, and long-term service reliability.
Key Drivers Shaping Market Trajectory
Technological Innovation and System-Level Integration
The maturation of microgrid technology is being driven less by any single breakthrough and more by the integration of previously siloed capabilities. Advanced energy management systems now coordinate distributed generation, storage, and load-shifting with greater precision, enabling facilities to maintain critical operations during grid disturbances. Controller architectures have improved response times for islanding and reconnection, while hybrid configurations increasingly combine solar, battery storage, and alternative generation pathways to reduce reliance on any single resource. These capabilities are especially relevant in environments where continuity is non-negotiable. Recent projects illustrate this trajectory: one of the largest hospital-based renewable microgrid systems in the United States came online with integrated solar generation, long-duration battery storage, and fuel cell backup designed for emergency power continuity. Within months, the installation transitioned into operational backup mode, demonstrating how integrated microgrid platforms can move from construction to active resilience support while contributing to regional renewable transition objectives. Technological progress is therefore not only enhancing system performance but also expanding the envelope of use cases where microgrids can deliver measurable operational value.
Policy and Regulatory Evolution
Regulatory frameworks are becoming both an enabler and a constraint. On one side, public-sector emphasis on grid resilience, decarbonization, and energy security is encouraging distributed infrastructure investment. On the other, the absence of uniform interconnection standards and the complexity of multi-party approvals can complicate deployment, particularly for single-property installations that must coordinate with internal facilities teams, financial stakeholders, and external authorities including utilities, planning departments, and fire marshals. A recent community guide addressing regulatory barriers highlighted how these coordination requirements can slow project execution for hospitals and other critical facilities, especially when stakeholder alignment and jurisdictional approvals are not mapped early in the development cycle. At the same time, new certification initiatives are beginning to establish baseline expectations for device-level security and interoperability. The introduction of an industry-wide cybersecurity certification program for microgrids, inverter-based devices, and distributed energy resources reflects a broader shift toward standardized safeguards as systems become more digitally managed and networked. For market participants, regulatory developments are no longer background conditions; they are active design parameters that influence architecture choices, procurement timelines, and deployment risk.
Demand-Side Realignment Across Sectors
Demand for microgrid solutions is being reshaped by changing expectations around cost predictability, operational continuity, and sustainability performance. Commercial and industrial operators are increasingly evaluating on-site generation and storage as a means to reduce exposure to grid volatility and support corporate energy objectives. Healthcare institutions, in particular, have emerged as a strategically important segment because their load profiles include mission-critical services that cannot tolerate extended outages. Recent deployments have paired solar arrays with combined heat and power systems to deliver meaningful cost reductions alongside carbon footprint improvements, demonstrating how microgrid installations can serve both financial and operational mandates. In parallel, the growth of remote and constrained infrastructure settings continues to support off-grid and hybrid configurations where grid dependence is impractical or too costly. The common thread across these demand patterns is a move from passive consumption toward active energy management, where facilities treat generation, storage, and control systems as part of a broader continuity and efficiency strategy rather than as standalone capital projects.
Supply Chain and Cost Structure Dynamics
Cost structures across the microgrid value chain are evolving as component maturity, manufacturing scale, and system integration practices improve. Still, cost trajectories are not uniform. Construction expenses can vary substantially by generation mix, storage technology, and site-specific engineering requirements, particularly when advanced energy management optimization is needed to support sensitive loads during outages. Hospital-grade installations, for example, may involve higher per-megawatt investment thresholds because of the need to maintain continuity for intensive care units, operating environments, and other critical functions. At the same time, the long-term financial case for microgrids is increasingly strengthened by their ability to reduce dependency on external supply conditions and provide more predictable generation cost profiles. In certain configurations, operators have realized substantial energy cost reductions by shifting toward fixed generation capabilities and lowering exposure to grid pricing variability. These economic dynamics create a nuanced deployment environment: while upfront capital requirements can be meaningful, lifecycle economics and resilience benefits are becoming more quantifiable, encouraging a longer-range view of return on investment.
Competitive Landscape and Strategic Positioning
Differentiated Value Propositions Among Leading Participants
The competitive environment is shaped by a mix of established industrial players and specialized technology providers, each emphasizing distinct aspects of the microgrid value chain. ABB has positioned itself around integrated microgrid technology solutions that span controllers, energy management systems, and hybrid renewable integration, emphasizing reliable power supply across varied operating conditions. Siemens focuses on microgrid controllers and integrated power solutions designed for seamless islanding and scalability, with particular relevance to critical facilities that require dependable operational transitions. Schneider Electric emphasizes platform-based approaches that combine energy management with renewable integration, targeting commercial and critical infrastructure applications. Eaton differentiates through energy storage systems and DC microgrid solutions aimed at efficient power distribution and backup performance. Honeywell concentrates on energy management and control systems optimized for critical facility resilience, while GE Vernova provides advanced controllers and hybrid solutions oriented toward utility and industrial use cases. S&C Electric Company has built its profile around ultra-fast islanding capabilities that support seamless power continuity, and Bloom Energy offers solid oxide fuel cell technology as an always-on clean generation pathway without combustion. On the project and deployment side, organizations such as Faraday Microgrids and Ameresco have developed focused approaches around hospital-based renewable systems and solar canopy configurations delivered under power purchase arrangements, reflecting the growing importance of tailored deployment models in sensitive institutional environments.
Market Structure and Evolution Patterns
Market concentration suggests that scale, integration depth, and service continuity remain influential in shaping competitive advantage. Organizations with broad component portfolios, established control architectures, and the ability to manage complex interconnection requirements often hold an advantage in higher-stakes deployments. At the same time, the landscape is not consolidating into a single model. Instead, it is evolving along multiple axes: some incumbents are deepening system-level integration and software-driven management capabilities, while specialized entrants continue to compete on niche performance characteristics, such as rapid islanding, fuel cell integration, or sector-specific design expertise. The result is a market in which differentiation increasingly depends on the ability to combine hardware reliability, software intelligence, cybersecurity readiness, and financial structuring flexibility. New entrants and project developers are likely to continue carving out positions where specialized load requirements, regional regulatory knowledge, or novel procurement structures create room for tailored solutions. Over time, the market may see further consolidation among integrated platform providers, alongside continued fragmentation in specialized applications where customization and stakeholder management are central to success.
Microgrid Market
Forward-Looking Trends and Commercial Implications
Scaling of Sector-Specific Microgrid Architectures
Over the next three to five years, one of the most consequential trends is likely to be the expansion of microgrid designs optimized for specific institutional and industrial load profiles rather than generic configurations. Healthcare facilities, data-centric campuses, manufacturing sites, and critical public infrastructure each impose distinct requirements on redundancy, response time, load prioritization, and fuel or storage mix. As deployment experience accumulates, architectures are expected to become more standardized within these segments while retaining the flexibility needed for site-specific constraints. The commercial opportunity lies in developing repeatable design templates, financing structures, and operational service models that reduce project risk and accelerate execution. Organizations that can package proven architectures with predictable performance parameters and clear approval pathways will be better positioned to capture demand in sectors where continuity and compliance are paramount. A related risk is that sector-specific standards and approval expectations may diverge across jurisdictions, increasing complexity for multi-site operators and slowing replication unless coordination frameworks improve.
Integration of Cybersecurity and Interoperability as Core Requirements
As microgrids become more digitally managed and interconnected, cybersecurity and interoperability are expected to move from auxiliary considerations to core procurement criteria. Certification programs and baseline security expectations introduced for inverter-based devices and distributed energy resources indicate that buyers will increasingly evaluate control systems not only on performance but also on vulnerability management, update pathways, and vendor accountability. This shift creates opportunities for suppliers that can demonstrate robust security architectures, transparent certification status, and compatibility with broader facility management and grid-interconnection requirements. It also raises the stakes for system designers, because fragmented device ecosystems or opaque security practices can become integration liabilities. A key uncertainty is the pace at which standards, testing protocols, and procurement specifications will harmonize across regions and customer segments. Until then, cybersecurity readiness may function as both a competitive advantage and a compliance hurdle, depending on the market and project type.
PW Consulting Information & Electronics Research Center
Financial Structuring and Lifecycle Value Optimization
The financial narrative around microgrids is likely to become more sophisticated as operators weigh upfront capital against long-term resilience and cost predictability. In settings where grid dependency carries operational or budgetary risk, microgrids can support fixed-cost generation profiles and reduce exposure to external supply volatility. This makes lifecycle modeling, performance guarantees, and service agreements increasingly important in project evaluation. Financing approaches such as power purchase structures, resilience-based procurement, and shared infrastructure models may broaden access for organizations that prefer operational expenditure frameworks over traditional capital investment. The opportunity for suppliers and developers will lie in aligning technology choices with financial outcomes, including maintenance costs, degradation profiles, storage replacement cycles, and control system longevity. The risk is that unrealistic expectations around savings or performance could undermine project credibility if real-world operating conditions, regulatory constraints, or load complexities are underestimated. Sustainable adoption will depend on transparent modeling and disciplined interpretation of site-specific economics.
Micro Turbine Market
Strategic Implications for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize integration depth over component-only positioning. Architectures that combine control, storage coordination, renewable integration, and cybersecurity readiness will increasingly shape procurement decisions in critical and commercial environments.
- Build repeatable segment playbooks. Tailored design templates for hospitals, industrial facilities, and commercial campuses can reduce sales cycle friction and improve deployment predictability if they account for approval pathways, load prioritization, and local interconnection requirements.
- Treat security and certification as product attributes. Demonstrated compliance with emerging cybersecurity baselines and interoperability expectations can become a differentiator, especially where buyers must justify resilience investments to internal audit, compliance, or governance stakeholders.
For Investors and Capital Allocators
- Evaluate markets through the lens of deployment complexity, not just addressable demand. Segments with high continuity requirements and manageable approval pathways may offer more reliable project conversion than highly fragmented or regulation-constrained environments.
- Watch for consolidation signals among integrated platform providers and specialized deployers. Scale advantages in control software, service networks, and financing partnerships may drive concentration in some segments, while niche expertise remains valuable in others.
- Underwrite lifecycle economics carefully. Savings potential, resilience value, and operational risk reduction can be meaningful, but returns depend on realistic assumptions around engineering costs, storage and component longevity, and ongoing management requirements.
For Procurement Leaders and Facility Operators
- Map regulatory and stakeholder dependencies early. Single-property deployments can face coordination challenges with internal teams and external authorities, so early alignment across facilities, finance, planning, utilities, and safety stakeholders is essential to avoid timeline delays.
- Define critical load priorities before sizing solutions. The value of a microgrid depends heavily on how well its architecture supports the loads that matter most during an outage, making load analysis and redundancy planning central to project design.
- Include cybersecurity and service continuity in evaluation criteria. Procurement decisions should account for device security baselines, management updates, vendor support models, and the operational implications of islanding and reconnection performance.
The microgrid technology market is expanding within a landscape defined by technical integration, regulatory maturation, and increasingly demanding operational expectations. Growth is being shaped not only by the appeal of distributed generation and storage, but also by the need for resilient, secure, and financially defensible energy architectures. For organizations evaluating entry, expansion, or procurement decisions, the most valuable next step is to move beyond headline market sizing and examine the segmentation, cost structures, regulatory pathways, and competitive dynamics that determine project viability in specific contexts. Detailed segmentation data, company-level positioning assessments, and customized strategic analysis can sharpen these decisions and reduce execution risk. PW Consulting offers comprehensive research supporting deeper evaluation of these dimensions for decision-makers seeking a fuller understanding of where value is being created and how to act on it.
For detailed analysis of this topic, please visit the official page: Microgrid Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cloud Gaming Market: Why 28.25% CAGR Redefines Gaming Infrastructure Through 2032
By PW Consulting, 2026-09-21
Cloud Gaming Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The cloud gaming market has transitioned from an experimental concept to a commercially viable sector over the past half-decade. From a base of $1.25 billion in 2020, the sector reached $8.72 billion by 2025, reflecting a compound annual growth rate of 28.25 percent. Forecasts project the market will surpass $11 billion in 2026 and scale to approximately $49.47 billion by 2032. This trajectory signals more than incremental adoption; it indicates a structural shift in how content is delivered, consumed, and monetized across consumer electronics and digital entertainment ecosystems.
Such rapid expansion, however, rests on fragile foundations. The industry currently confronts three critical challenges that will define competitive outcomes over the next several years. First, infrastructure scalability remains uneven. Delivering consistently high-fidelity experiences requires dense edge computing coverage and robust broadband capacity, yet network quality varies dramatically across geographies. Regions with advanced telecommunications infrastructure are experiencing accelerated adoption, while markets dependent on legacy networks face persistent latency and bandwidth constraints that undermine user retention.
Second, content economics and licensing complexity continue to pressure unit profitability. Cloud gaming platforms must negotiate rights agreements with publishers, manage localization requirements, and align game catalogs with regional preferences. These negotiations consume significant operational resources and create friction when attempting to scale service offerings globally. Platforms that rely heavily on licensed third-party titles face margin compression unless they can demonstrate clear value differentiation to rights holders.
Third, user acquisition costs and retention dynamics present a persistent challenge. While initial trial adoption has grown, converting free-tier or trial users into sustained subscribers requires continuous investment in service quality, exclusive content, and ecosystem integration. Churn remains elevated in markets where alternative entertainment options compete for disposable income and screen time. Platforms that fail to build sticky user relationships through hardware integration, social features, or personalized experiences risk cyclical reacquisition cycles that erode lifetime value.
Key Drivers Accelerating Market Growth
Technological Innovation and Streaming Optimization
Advances in encoding algorithms, GPU virtualization, and edge computing have substantially reduced the technical barriers that once limited cloud gaming viability. Modern streaming pipelines now deliver higher resolutions and frame rates with lower latency, widening the addressable device base beyond traditional gaming hardware. The integration of artificial intelligence into streaming optimization, demonstrated by recent platform enhancements from NVIDIA in early 2026, illustrates how algorithmic improvements can dynamically adjust quality parameters based on network conditions and device capabilities. These technical breakthroughs reduce the dependency on high-end local hardware and enable premium experiences on smartphones, tablets, and televisions that previously could not support demanding titles.
Policy and Regulatory Environment
The regulatory landscape is undergoing rapid reconfiguration, with implications for infrastructure investment and market entry strategies. In mid-2025, the Federal Communications Commission moved to eliminate net neutrality rules and remove broadband provider restrictions as part of a broader deregulatory initiative. This shift alters the competitive dynamics for content delivery, potentially reducing compliance burdens for cloud gaming operators while raising questions about long-term network neutrality and prioritization practices. Simultaneously, European policymakers are pursuing digital sovereignty objectives. The European Commission's March 2026 proposal for a Technological Sovereignty Package and the €75 million allocation to the EURO-3C federated telco-edge-cloud project signal a strategic push to strengthen regional cloud infrastructure autonomy. These initiatives create both opportunities for localized infrastructure partnerships and compliance complexity for operators navigating divergent regulatory regimes across continents.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations increasingly favor convenience, cross-device continuity, and instant access over ownership of discrete hardware. Gamers are demonstrating willingness to stream titles across smartphones, tablets, PCs, and connected televisions, reducing the threshold for entry into interactive entertainment. This behavior aligns with broader digital consumption trends where subscription access replaces one-time purchases, and where content libraries are expected to be available anywhere. Enterprise and educational sectors are also exploring cloud-based interactive environments for training, simulation, and collaborative applications, extending demand beyond consumer gaming and creating adjacent revenue streams for platforms that can adapt their streaming infrastructure to non-gaming use cases.
Gaming Market
Supply Chain and Cost Structure Evolution
Data center energy demand is reshaping operating cost calculations for cloud-intensive services. U.S. data centers are projected to nearly double their combined energy consumption from approximately 80 gigawatts in 2025 to 150 gigawatts by 2028. For cloud gaming operators, this trend translates into higher infrastructure costs unless mitigated through efficient cooling technologies, renewable energy sourcing, and workload optimization. Companies that invest in energy-efficient architectures and strategic power procurement will gain cost advantages that compound over time, particularly as scale increases and marginal compute costs become a more significant factor in service profitability.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The market features a mix of platform-scale incumbents, hardware-integrated operators, and specialized streaming providers. Microsoft has expanded Xbox Cloud Gaming access through device optimizations and Azure edge node improvements, broadening reach to existing hardware ecosystems while leveraging its subscription content library. This approach emphasizes ecosystem leverage, using cloud streaming as an extension of a broader gaming and services portfolio rather than a standalone revenue center. NVIDIA differentiates through technical performance, offering RTX-powered virtual GPUs that enable high-fidelity streaming at elevated resolutions and frame rates. Its recent platform enhancements focus on AI-driven quality optimization and broader device compatibility, positioning performance fidelity as a core value proposition for enthusiasts and performance-sensitive users.
Amazon Luna continues to integrate cloud gaming with Fire TV hardware, creating a direct streaming pathway for subscribers within a controlled device environment. This hardware-software alignment reduces friction for users already embedded in Amazon's consumer electronics ecosystem. Sony has pursued a parallel strategy by enabling cloud streaming of PlayStation titles to its Portal handheld device without requiring a console, effectively decoupling premium content access from dedicated gaming hardware. Blacknut has pursued a distribution-focused model, securing pre-installation partnerships on devices such as the Logitech G Cloud handheld, which provides immediate access to a large catalog of premium titles and reduces adoption barriers for hardware partners seeking to differentiate their products. Boosteroid operates as a multi-platform streaming service emphasizing broad device support and session quality, targeting users who prioritize accessibility across heterogeneous device environments rather than deep integration with a single hardware ecosystem.
Market Structure Evolution
Concentration trends indicate a maturing market where leading operators capture a disproportionate share of value. The top three providers account for approximately 57.3 percent of market revenue, while the top five reach 74.2 percent. This concentration reflects the advantages of scale in infrastructure investment, content licensing, and user acquisition. However, the landscape is not static. Hardware integration partnerships are creating niche entry points for specialized platforms, while telecommunications operators are beginning to bundle gaming services with network packages, as seen in recent 5G gaming offerings from European carriers. These developments suggest a trajectory toward both consolidation at the top and fragmentation at the edges, where device manufacturers, network providers, and regional platforms can carve out defensible positions through integration, localization, or niche performance specialization.
New entrants face steep barriers in content rights, infrastructure scale, and brand trust, but opportunities exist for operators that align cloud gaming with adjacent value propositions. Device manufacturers can use pre-installed streaming platforms to enhance hardware appeal. Telecoms can differentiate broadband offerings with optimized gaming pathways. Regional platforms can compete on localization, language support, and publisher relationships that global incumbents may prioritize less aggressively. The strategic question for each participant is whether to compete on scale, on integration depth, or on specialized performance and service quality.
Future Trends and Commercial Opportunities
Edge-Native Infrastructure and Network-Service Bundling
Over the next three to five years, cloud gaming success will increasingly depend on proximity-aware infrastructure and network-level service optimization. As 5G standalone networks expand and edge computing nodes proliferate, operators that coordinate streaming delivery with telecommunications partners will gain latency and reliability advantages. Bundled offerings that pair broadband or mobile plans with gaming subscriptions will lower acquisition costs and increase stickiness, particularly in markets where telecoms hold strong consumer relationships. Commercial opportunities will emerge for platforms that design their service architecture to leverage these partnerships, including co-branded packages, zero-rating arrangements where permissible, and network-aware quality scaling that adapts experience parameters to connection characteristics.
Hardware-Software Convergence and Ecosystem Lock-In
The boundary between cloud gaming services and consumer hardware will continue to blur. Handheld devices, smart televisions, and connected set-top boxes will increasingly ship with streaming platforms pre-integrated, reducing the friction of initial adoption and creating default access pathways. This convergence benefits hardware manufacturers seeking differentiation and service providers seeking scaled distribution. The commercial implication is clear: platforms that secure pre-installation or deep integration agreements with device makers will capture a larger share of incremental users, while those relying solely on app-store discovery or web-based onboarding will face higher acquisition costs and lower conversion rates. Strategic partnerships with hardware OEMs, including co-marketing and joint optimization efforts, will become a decisive competitive lever.
AI-Driven Personalization and Adaptive Streaming Economics
Artificial intelligence will play an expanding role in both user experience and operational efficiency. Adaptive streaming algorithms will optimize bitrate, resolution, and frame delivery in real time based on network conditions, device capabilities, and user preferences. On the content side, AI-assisted curation and recommendation systems will improve discovery, reducing the friction that leads to trial abandonment. These capabilities create opportunities to increase engagement and reduce churn without proportional increases in content licensing spend. However, the same technologies raise expectations for service quality, and platforms that lag in adaptive optimization may experience disproportionate user dissatisfaction as baseline expectations rise across the market.
Risk Factors and Uncertainties
Several uncertainties could alter the trajectory outlined above. Regulatory divergence between regions may complicate global service architectures, particularly as digital sovereignty initiatives encourage localized infrastructure requirements. Energy cost escalation for data centers could compress margins unless offset by efficiency gains or favorable power contracts. Content rights negotiations may become more expensive as publishers recognize the strategic value of cloud distribution and demand higher revenue shares or exclusivity terms. Finally, competitive intensity could trigger price compression in subscription tiers, forcing platforms to differentiate through performance, integration, or exclusive content rather than price alone. Operators that build diversified revenue streams and maintain flexibility in infrastructure and licensing strategies will be better positioned to navigate these variables.
Strategic Recommendations for Decision Makers
For Platform Operators and Device Manufacturers
Prioritize integration depth over standalone reach. Embedding cloud gaming capabilities into hardware product lines, operating system environments, or network service bundles creates inherent distribution advantages that pure software-play strategies struggle to replicate. Invest in adaptive streaming quality and device-specific optimization to ensure that the user experience meets expectations across heterogeneous conditions. Where possible, pursue partnerships with telecommunications providers to align service delivery with network capabilities and to access bundled customer acquisition channels. For hardware manufacturers, treat pre-installed streaming platforms as a product differentiator and negotiate terms that ensure catalog relevance and technical compatibility over the device lifecycle.
For Investors and Strategic Capital Allocators
Evaluate operators based on infrastructure efficiency, content licensing sustainability, and ecosystem integration rather than headline user growth alone. Metrics such as cost per streaming hour, retention curves by acquisition channel, and the proportion of revenue derived from integrated hardware or network partnerships offer clearer signals of durable competitive advantage than top-line subscriber counts. Favor business models that combine recurring subscription revenue with ancillary monetization paths, including hardware margins, network bundling fees, or enterprise and education extensions. Monitor regulatory developments in key regions, as digital sovereignty and infrastructure policies will influence where capital can be deployed most efficiently and which operators gain preferential access to local edge resources.
Gaming Laptop Market
For Procurement and Partnership Decision Makers
When selecting cloud gaming service providers or infrastructure partners, assess streaming reliability under variable network conditions, the flexibility of content catalogs, and the operator's ability to support multiple device form factors. Prioritize partners that demonstrate a clear roadmap for adaptive quality optimization and that maintain transparent performance reporting. For organizations exploring cloud gaming as a component of broader digital entertainment or training strategies, consider the long-term implications of vendor lock-in and negotiate terms that preserve portability and integration flexibility. Track infrastructure energy commitments and sustainability practices as indicators of long-term cost discipline and operational resilience.
PW Consulting
The cloud gaming market is entering a phase where differentiation will be determined less by the mere availability of streaming and more by the quality of integration, the efficiency of delivery, and the durability of user relationships. Decision makers who align their strategies with these structural drivers will be better positioned to capture value as the market scales toward the end of the decade. For organizations requiring detailed segmentation data, regional breakdowns, competitive benchmarking, and customized scenario analysis, comprehensive research resources are available to support deeper evaluation and strategic planning.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Patient Data Management Systems Market 2026: Why 11.2% CAGR And ICU Adoption Redefine Growth
By PW Consulting, 2026-09-21
The Patient Data Management Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The global patient data management systems (PDMS) market has entered a phase of accelerated structural transformation. Valued at approximately 527.36 million USD in 2020, the market has grown to an estimated 888.06 million USD by 2025, reflecting a compound annual growth rate of 11.2 percent through the forecast horizon extending to 2032. By the end of that period, total market revenue is projected to surpass 1.85 billion USD. This trajectory is not merely a reflection of incremental IT spending; it signals a fundamental reorientation of how clinical data is captured, integrated, and operationalized across care settings.
The growth curve reveals distinct inflection points. The period from 2020 to 2023 delivered steady expansion, while the 2024 to 2025 window accelerated as hospitals confronted compounding pressures: staffing constraints, regulatory mandates, and the operational urgency of interoperable data flows. Projections for 2026 through 2032 indicate that revenue will compound at a pace that outpaces many traditional healthcare IT segments, driven by consolidation of clinical workflows, cloud migration, and the formalization of PDMS as regulated medical device infrastructure.
Yet the headline figures obscure a market that is actively reconstituting itself. Growth is uneven across deployment models, clinical environments, and geographic regions. Vendors are navigating a landscape where interoperability expectations, cybersecurity exposure, and regulatory classification requirements are reshaping procurement criteria. For executives and investors, the strategic question is no longer whether PDMS adoption will continue, but how value will be captured amid shifting integration standards, mounting security liabilities, and evolving reimbursement and funding mechanisms.
Market Snapshot: Scale, Trajectory, and Structural Tensions
The market's expansion from roughly 527 million USD in 2020 to nearly 888 million USD in 2025 reflects a compound growth rate of 11.2 percent, with forecasts extending to 2032 indicating a pathway toward 1.85 billion USD. This trajectory is anchored by several structural forces: the normalization of PDMS as a clinical documentation and device integration layer, the formalization of risk management and approval processes under hospital IT regulations, and the simplification of functional requirements within industry standards. Together, these factors have lowered adoption friction while simultaneously raising the baseline expectation for what a compliant, production-grade system must deliver.
PW Consulting
Concentration patterns further clarify the market's maturity. The leading vendors collectively account for approximately half of total revenue, with the top three and top five firms each representing roughly 50 percent of the market. This concentration suggests a landscape where established players hold significant share, yet the remaining half is distributed across regional specialists, niche integrators, and emerging cloud-native entrants. The implication for strategy is clear: scale advantages exist, but they are not insurmountable when differentiated clinical workflows, localized compliance needs, or cloud-first deployment models create openings for targeted positioning.
The current market is also defined by three interlocking challenges that are reshaping vendor and buyer behavior alike.
- Interoperability expectations are outpacing legacy integration architectures. Hospitals increasingly demand seamless connectivity across monitors, ventilators, infusion pumps, and electronic patient records, yet many installed bases were designed around single-function documentation rather than hospital-wide data orchestration.
- Cybersecurity and operational resilience have become procurement determinants. The exposure of cloud-based electronic patient record platforms to ransomware incidents has elevated security architecture, backup readiness, and incident response capabilities from technical considerations to board-level risk management criteria.
- Regulatory classification and funding mechanisms are simultaneously enabling and constraining adoption. PDMS are classified as medical devices requiring risk management and approval processes, while funding instruments such as hospital future acts have catalyzed deployments in specific regions. This dual dynamic accelerates certain rollouts while imposing compliance costs and timeline uncertainties elsewhere.
These tensions do not slow the market; they redistribute value. Vendors that can reconcile interoperability, security, and regulatory compliance within coherent deployment models are gaining negotiating leverage, while those relying on fragmented, point-solution messaging are facing longer evaluation cycles and more stringent proof-of-value requirements.
Key Drivers Shaping the Next Wave of Growth
The market's trajectory is being propelled by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a momentum loop that is likely to sustain double-digit growth through the late 2020s.
Patient Engagement Software Market
Technology innovation and integration maturity. The shift from isolated documentation tools to integrated clinical data layers is the most visible technological driver. PDMS platforms are increasingly expected to connect diverse bedside devices, normalize data streams, and feed structured information into broader hospital information and electronic patient record environments. Recent operational deployments illustrate this consolidation: centralized standardized documentation systems are now being implemented across multiple provincial hospitals, embedding PDMS into anaesthesia and intensive care workflows with the explicit goal of improving data quality and cross-hospital communication. At the same time, integration showcases at major industry events are emphasizing closed-loop processes that link media and documentation solutions directly into PDMS and hospital information systems, reducing manual handoffs and supporting continuity of care.
Policy and regulatory environment. Regulatory dynamics are acting as both a catalyst and a filter. PDMS are classified as medical devices and must undergo approval processes that include risk management under hospital IT regulations, which raises the barrier to entry for immature solutions but strengthens confidence in vetted platforms. At the same time, functional requirements for patient data management systems have been simplified in standards, lowering the implementation burden for baseline compliance. New guidelines, laws, and regulations are being directly integrated into PDMS standard content, meaning that vendors must treat regulatory updates as continuous product obligations rather than periodic certification events. This environment rewards platforms with disciplined change management and penalizes those that treat compliance as a static checklist.
Demand-side behavior and clinical workflow pressure. Hospitals are confronting staff shortages alongside budget constraints, which makes PDMS adoption less about optional digitization and more about workflow survival. Complex clinical environments require documentation, device traceability, medication management, and nutritional or pediatric percentile tracking without adding administrative burden. The demand signal is shifting accordingly: buyers are prioritizing systems that can centralize documentation, improve data quality, and reduce the cognitive load on clinical staff. This demand-side pressure is particularly acute in intensive care and anaesthesia settings, where device density and data volume make manual reconciliation impractical.
Cost structure and deployment model evolution. The cost equation is being reshaped by cloud transformation and the operational economics of platform maintenance. Cloud-based hospital information and electronic patient record systems are moving into production, with major medical centers completing launches and phasing out legacy platforms over multi-year transition windows. This shift alters total cost of ownership calculations, introducing subscription and hosting considerations while reducing on-premises maintenance overhead. However, it also introduces dependency on vendor security posture and continuity planning, as evidenced by incidents where ransomware attacks disrupted electronic patient record portals across a large share of hospital organizations using a specific platform. The cost conversation has therefore expanded from license and implementation to include resilience, data protection, and recovery readiness.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a small group of established vendors with deep clinical integration expertise, complemented by regional specialists and integration-focused entrants. The leaders have built their positioning around distinct clinical use cases, device connectivity breadth, and the ability to embed PDMS within broader hospital information and monitoring environments.
German-based vendors illustrate the depth of specialization emerging in the market. One prominent player focuses on certified PDMS integrated with its hospital information system, emphasizing ICU device connectivity, medication management, nutritional balance, and pediatric percentile features. This configuration targets high-acuity environments where documentation precision and cross-referencing across clinical parameters are essential. Another German firm offers a PDMS suite integrated with acute care monitoring systems for ICU, operating room, and neonatal intensive care settings, with an emphasis on centralized data management, prescription traceability, and optimization of patient care. A third German provider centers its offering on anaesthesia and intensive care departments, delivering centralized documentation, improved data quality, and cross-hospital communication capabilities. These profiles share a common thread: they are designed for environments where device density, regulatory scrutiny, and data continuity requirements are highest.
In the Netherlands, a different integration philosophy is gaining traction. A vendor has advanced a hospital-wide electronic patient record solution with PDMS capabilities that communicate across monitors, ventilators, and infusion pumps throughout the facility. This approach reflects a broader enterprise integration mindset, where PDMS is treated as a connective layer within a unified digital infrastructure rather than a departmental add-on. The emphasis on hospital-wide device communication aligns with buyer expectations for fewer integration silos and more consistent data semantics across care units.
Recent developments illustrate how these positions are being reinforced and tested in practice. One vendor completed a PDMS deployment across anaesthesia and intensive care departments at a state hospital, extending a centralized standardized documentation model to multiple provincial hospitals. Another vendor's cloud-based hospital information and electronic patient record platform reached production at a major medical center, with a phased transition away from legacy systems extending through the following year. Concurrently, a ransomware incident affecting a widely used electronic patient record portal disrupted operations for a substantial portion of hospital organizations, underscoring the operational and reputational stakes tied to platform security. Integration-focused demonstrations have further highlighted the push toward closed-loop processes and point-of-care hardware and monitoring integration, signaling that PDMS is increasingly evaluated as part of a broader clinical technology ecosystem rather than a standalone documentation tool.
Patient Record Management Market
The market is evolving along three overlapping paths. First, consolidation pressure is growing as buyers prefer fewer, more capable platforms that can cover multiple departments and device types, reducing integration overhead and vendor management complexity. Second, differentiation is sharpening around clinical specificity, with vendors competing on anaesthesia, ICU, neonatal, and medication management capabilities rather than generic data capture. Third, new entrants and integration specialists are probing niches where cloud-native architecture, streamlined compliance updates, or specialized device interoperability can offset the incumbency advantages of larger players. The net effect is a market where share is defended through integration depth and compliance readiness, while growth is increasingly contested in segments where deployment model, security posture, and workflow fit matter more than brand recognition alone.
Forward Outlook: Three Trends That Will Define 2026 to 2032
The market's next phase will be shaped by the interaction of integration expectations, security realities, and regulatory continuity. Three trends are likely to dominate strategic planning for the coming years.
- Integration will become the primary value proposition, not a feature. As PDMS is expected to connect devices, documentation, and broader hospital information environments, the competitive advantage will shift from data capture to data orchestration. Platforms that can normalize device outputs, maintain consistent semantics across departments, and support cross-hospital communication will command stronger positioning. The opportunity lies in designing for interoperability as a default architecture, with standardized interfaces and continuous alignment to evolving functional requirements.
- Security and resilience will reprice risk and procurement criteria. High-profile disruptions to electronic patient record platforms have made cybersecurity a central element of vendor evaluation. Buyers will increasingly prioritize architectures with robust access controls, segmented operations, tested recovery processes, and transparent incident readiness. For vendors, the commercial implication is that security maturity may become a differentiator that shortens sales cycles for risk-averse buyers while exposing weaker platforms to prolonged scrutiny. The uncertainty is that threat landscapes and regulatory expectations will continue to evolve, requiring ongoing investment that may pressure margins if not managed efficiently.
- Regulatory integration will shift from periodic certification to continuous compliance. With new guidelines and regulations being embedded directly into PDMS standard content, vendors must treat compliance as an operational discipline. This dynamic favors platforms with structured update mechanisms, clear traceability between regulatory changes and product content, and the ability to demonstrate risk management continuity. The business opportunity is to reduce the lag between regulatory change and product readiness, which can become a decisive factor in public procurement and hospital IT approvals. The risk is that vendors unable to absorb this continuous load will face rework, delays, and competitive disadvantage.
These trends intersect with commercial models in ways that will matter for both suppliers and buyers. Deployment architectures will increasingly blend on-premises device connectivity with cloud-hosted record and documentation layers, creating hybrid environments that demand careful orchestration of data flow, access control, and maintenance responsibilities. Funding and regulatory incentives will continue to influence regional adoption patterns, making some geographies more responsive to near-term expansion while others remain constrained by budget cycles and implementation capacity. The overarching opportunity is to align product roadmaps and commercial narratives with the reality that PDMS is becoming a regulated, integrated, and security-sensitive component of clinical infrastructure rather than a discretionary IT enhancement.
Strategic Recommendations for Decision Makers
The market's trajectory offers distinct implications for manufacturers, investors, and procurement leaders. Each group faces a different set of priorities, but all benefit from treating PDMS as a continuously evolving clinical data and compliance platform rather than a static software purchase.
For manufacturers and platform vendors. Prioritize integration architecture and security readiness as core product investments, not ancillary capabilities. Buyers are evaluating device connectivity breadth, documentation centralization, and the ability to embed regulatory updates into standard content, so differentiation should be built around clinical workflow fit, interoperability reliability, and demonstrable risk management continuity. Where possible, position PDMS as part of a hospital-wide data strategy that reduces silos, supports cross-department documentation, and aligns with evolving electronic patient record environments. Continuous compliance mechanisms and transparent update practices can become meaningful commercial advantages in procurement cycles that increasingly weight regulatory maturity.
For investors and strategic backers. Focus on vendors whose value proposition is tied to integration depth, clinical specificity, and resilience rather than pricing alone. The concentration dynamics suggest that scale incumbents retain advantages, but the distributed share outside the leaders indicates room for differentiated platforms that address cloud migration, security maturity, and specialized workflows in anaesthesia, ICU, and neonatal settings. Monitor deployment milestones, platform transition timelines, and security incident responses as leading indicators of operational credibility. Be mindful that margin profiles can be affected by the ongoing investment required for compliance updates, integration maintenance, and security hardening, making operating discipline as important as growth potential.
For hospital leaders and procurement teams. Treat PDMS selection as a multi-year operational decision that should be evaluated against integration scope, security architecture, compliance continuity, and clinical workflow alignment. Favor platforms that can communicate across monitors, ventilators, infusion pumps, and electronic patient records without creating new documentation silos, and verify that risk management and approval processes are clearly defined and maintained. Weigh the total cost of ownership including hosting, maintenance, resilience, and incident recovery rather than focusing narrowly on initial implementation cost. Demand evidence of how regulatory updates are incorporated into standard content and how the platform supports centralized documentation with improved data quality across departments.
Timely, granular intelligence is essential because the market is changing on multiple fronts at once: integration expectations, security realities, regulatory content, and deployment models are all shifting within the same procurement and planning cycles. Detailed segment data, regional dynamics, and vendor-specific implementation patterns can materially affect go-to-market priorities, investment theses, and purchasing decisions. For decision makers who need deeper segmentation, competitive benchmarking, and customized scenario planning, PW Consulting's full research report provides extended data and tailored guidance to support execution.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Perth has become an increasingly attractive location for households and businesses looking to generate clean electricity and reduce their reliance on conventional energy. With abundant sunshine throughout much of the year, solar technology can be a practical option for properties of different sizes. Choosing the right solar panel Perth WA solution involves more than simply selecting panels. Homeowners need to consider system capacity, roof orientation, inverter technology, battery storage, electricity consumption, installation quality, and available incentives. At the same time, understanding how solar electricity Perth systems operate can help property owners make informed decisions about energy generation, usage, and long-term household electricity management.
Understanding Solar Energy in Perth
Solar power systems convert sunlight into usable electrical energy through photovoltaic panels. During daylight hours, the panels generate direct current electricity, which is converted into usable alternating current by an inverter. The electricity can then supply appliances, lighting, cooling systems, and other household loads.
A well-designed solar panel Perth WA installation considers the property's roof space, shading, energy consumption, and expected generation. Instead of choosing a system based only on its panel count, homeowners should evaluate how much electricity they use throughout the day and evening. This approach can make the system more closely aligned with actual energy requirements.
Solar electricity Perth solutions can also support businesses, rental properties, community facilities, and other buildings. Commercial installations may use larger arrays and more sophisticated energy-management technology to help businesses manage daytime electricity demand.
Choosing the Right Solar Panels
Solar panels are available in different technologies, efficiencies, physical sizes, and warranty structures. Well-known manufacturers such as SunPower, REC, LONGi, JinkoSolar, Trina Solar, and Canadian Solar offer products designed for different applications.
When comparing a solar panel Perth WA system, it is useful to examine panel efficiency, temperature performance, degradation rates, product warranties, and installation requirements. Higher efficiency can be particularly useful where roof space is limited because more electricity can potentially be generated from a smaller area.
However, panel quality is only one part of system performance. The design should also account for roof orientation, tilt, shading from nearby buildings or trees, and local environmental conditions. Professional system design can help ensure that the panels work effectively with the inverter and other components.
The Importance of the Solar Inverter
The inverter is one of the most important components in a solar installation. Panels produce direct current electricity, while most household appliances use alternating current. The inverter performs the conversion and manages the flow of electricity between the solar array, home, grid, and battery where applicable.
Popular inverter brands include Fronius, Sungrow, SolarEdge, and GoodWe. Each manufacturer offers different technologies and monitoring capabilities. Some systems provide detailed performance information through mobile applications, allowing homeowners to monitor electricity generation and consumption.
For solar electricity Perth installations, inverter selection should match the size and configuration of the panel array. It should also accommodate future plans, such as adding a battery or integrating an EV charger.
Solar Battery Storage
A solar battery can store excess electricity generated during the day for use when solar production falls. This can be particularly useful for households that consume significant amounts of electricity during the evening.
For example, a home may generate substantial solar electricity while occupants are working or studying elsewhere. Rather than exporting all excess generation, a battery can store some of that energy for later use. Products such as Tesla Powerwall and other home energy-storage systems are designed to support this type of energy management.
When considering a solar panel Perth WA installation, battery capacity should be matched with household electricity consumption. A larger battery is not automatically necessary for every property. The right capacity depends on factors such as daily energy use, solar generation, evening consumption, electricity tariffs, and future energy requirements.
Solar Power and EV Charging
Electric vehicles are becoming an important consideration for households planning their future energy systems. An EV charger can be integrated with a solar installation to use locally generated electricity for vehicle charging.
During periods of strong solar generation, excess electricity may be directed toward an EV rather than being entirely exported to the grid. Smart charging technology can help coordinate vehicle charging with solar production and household electricity demand.
For homeowners considering solar electricity Perth alongside an EV, it can be useful to plan the solar system, inverter, battery, and charger as a connected energy solution. This approach may provide greater flexibility as household electricity consumption changes over time.
Rebates and Incentives
Government rebates and incentives can influence the overall cost of installing solar technology. Eligibility, program rules, certificate values, and other conditions can change, so homeowners should check the current requirements before making an investment.
The availability of a rebate may reduce the upfront cost of an eligible system, although the final financial outcome depends on the property's electricity usage, system size, installation cost, electricity prices, and energy-generation performance.
Anyone researching solar panel Perth WA options should therefore compare the complete installed cost rather than focusing only on the advertised panel price. A detailed quote should explain equipment, installation, warranties, applicable incentives, and any additional electrical work.
Solar for Perth Homes and Businesses
Solar systems can be designed for a wide range of property types. A small household may require a relatively compact system, while a larger home with air conditioning, pool equipment, an EV, and other high-consumption appliances may require greater generation capacity.
Businesses can also benefit from solar electricity Perth systems because many commercial properties consume electricity during daylight hours, when solar generation is available. Offices, warehouses, workshops, retail buildings, and professional premises can all have different energy profiles, so system design should reflect actual consumption patterns.
Across areas such as Balcatta, Bayswater, Belmont, Bentley, Cannington, Carlisle, Churchlands, Cloverdale, Dalkeith, Dianella, East Perth, Embleton, Floreat, Glendalough, Joondanna, Kewdale, Nedlands, Nollamara, Osborne Park, Queens Park, Redcliffe, Shenton Park, St James, Subiaco, Tuart Hill, Victoria Park, and West Perth, property characteristics can vary considerably. Roof size, orientation, shading, building age, and electricity consumption should therefore be assessed individually.
Comparing Solar System Quotes
Getting multiple quotes can make it easier to compare equipment and installation approaches. However, the cheapest quote is not necessarily the most suitable option. A meaningful comparison should include panel specifications, inverter brand, system capacity, expected generation, installation inclusions, warranties, monitoring equipment, and battery compatibility.
When comparing a solar panel Perth WA proposal, homeowners should also ask whether the quoted system has been designed specifically for their property. A professionally designed system should take roof characteristics and electricity consumption into account rather than relying solely on a standard package.
For solar electricity Perth projects, it is also worth asking about after-sales support and maintenance arrangements. Solar systems can operate for many years, making installation quality and ongoing support important parts of the overall decision.
Long-Term Solar Planning
Solar technology should be viewed as part of a property's broader energy strategy rather than simply a collection of panels on a roof. Electricity consumption may change as households purchase an EV, add air conditioning, install a pool, work from home, or introduce additional appliances.
Planning for these changes can make a solar system more adaptable. A suitable inverter, adequate switchboard capacity, battery compatibility, and intelligent monitoring can provide greater flexibility for future upgrades.
A well-designed solar panel Perth WA system can therefore combine panels, an inverter, battery storage, and EV charging according to the property's current and future needs. This integrated approach can help homeowners understand how electricity is generated, stored, consumed, and exported.
Conclusion
Solar energy has become an important consideration for Perth property owners seeking greater control over electricity generation and consumption. Selecting suitable panels, an efficient inverter, optional battery storage, and compatible EV charging technology can create a more flexible household energy system.
Whether a property is located in Subiaco, Nedlands, Osborne Park, Victoria Park, Belmont, or another Perth neighbourhood, system design should be based on the individual property's roof characteristics and electricity requirements. Understanding rebates, equipment warranties, expected generation, and installation quality can also make the purchasing process clearer.
For anyone researching solar panel Perth WA solutions, comparing complete systems rather than individual components provides a more useful basis for evaluation. Likewise, understanding how solar electricity Perth works can help homeowners and businesses plan an energy system that reflects their present requirements while allowing room for future changes.
Location:- Perth, Western Australia
https://simple.wikipedia.org/wiki/Perth,_Western_Australia
https://sites.google.com/view/perth-solar-power/
https://www.consumerprotection.wa.gov.au/publications/solar-panel-systems-factsheet
https://www.energy.gov.au/solar/financial-benefits-solar/government-rebates-and-loans-solar
The X-Ray Security Scanner Market: Strategic Shifts and Commercial Opportunities in a High-Growth Security Landscape
The global X-ray security scanner market is undergoing a structural transformation. Valued at USD 7.4 billion in 2025, the sector is projected to expand at a compound annual growth rate of 6.5 percent, reaching approximately USD 11.5 billion by 2032. The trajectory from 2020 through 2032 reflects a market that has moved beyond post-9/11 security baseline spending into a phase defined by technological modernization, regulatory recalibration, and shifting threat perceptions across transportation and commercial infrastructure. Market concentration remains moderate, with the top three players collectively accounting for roughly 24.6 percent of global revenue and the top five capturing approximately 26.2 percent. This fragmented yet strategically consolidating landscape creates distinct pathways for differentiated positioning, whether through hardware innovation, software-enabled analytics, or integrated service architectures.
Behind the headline growth figures lies a market navigating several inflection points. Operators are balancing throughput requirements against deeper imaging fidelity, budget-constrained public agencies are weighing capital expenditure against lifecycle costs, and end-user environments are demanding detectors that can distinguish organic from inorganic threats without interrupting passenger or freight flow. At the same time, regulatory mandates are pushing older single-view tunnels toward replacement, privacy considerations are redirecting certain screening applications toward alternative modalities, and supply chain volatility is reshaping procurement timelines and vendor selection logic. Understanding where these pressures converge is essential for manufacturers, investors, and procurement leaders seeking to align their strategies with the next cycle of demand.
Market Landscape and Core Challenges
The revenue distribution across the market in 2025 underscores a clear structural emphasis on body screening and aviation-transformation applications, which together represent the dominant share of installed and deployed systems. Baggage and parcel scanning continues to anchor volume demand, while commercial facilities increasingly integrate X-ray and complementary imaging solutions to address cargo, logistics, and critical infrastructure screening requirements. The regional spread indicates that Asia Pacific, Europe, and North America collectively drive the bulk of procurement activity, with emerging corridors in Latin America and the Middle East and Africa expanding at a pace that reflects both infrastructure investment and heightened border security postures. Rather than treating these splits as static allocations, decision makers should view them as indicators of where modernization budgets, replacement cycles, and capacity upgrades are concentrating.
Three challenges define the current market turning point.
1. The Dual-View to Computed Tomography Transition
Single-view and dual-view X-ray tunnels remain workhorse systems in many checkpoints, but volumetric imaging is increasingly mandated for higher-risk freight and compressed throughput environments. The shift is not merely a hardware upgrade; it changes installation footprints, operator training requirements, power and cooling demands, and maintenance contracts. Procurement teams that underestimate the integration complexity of CT-based checkpoint systems risk deployment delays, while suppliers that fail to offer phased migration paths or retrofit-compatible architectures may lose share to competitors with more flexible transition strategies.
2. Cost Structures and Unit Economics
Checkpoint-grade systems carry significant capital intensity. Advanced CT screening units for checkpoints command unit prices in the range of USD 2.5 million to USD 3.2 million, roughly four times the cost of traditional dual-view tunnels. This pricing differential forces operators to prioritize deployments, negotiate financing structures, and evaluate total cost of ownership rather than sticker price alone. In parallel, tariff adjustments on certain pallet scanning equipment have prompted buyers and suppliers to revisit sourcing strategies, vendor selection criteria, and deployment timelines, adding uncertainty to procurement planning and inventory positioning.
3. Privacy, Public Perception, and Modality Substitution
Public acceptance remains a strategic variable. Privacy objections have slowed the deployment of backscatter-based systems in certain public venues such as stadiums, nudging operators toward millimeter-wave alternatives and other imaging approaches that balance detection performance with user experience. Although this dynamic pertains more directly to walk-through and stand-off modalities than to conventional X-ray tunnels, it influences the broader screening ecosystem by shaping procurement preferences, policy debates, and the willingness of end-users to adopt newer technologies in high-visibility locations.
Key Drivers Shaping the Market
Market momentum is being propelled by a combination of technological breakthroughs, regulatory pressure, evolving end-user behavior, and shifting cost and supply chain dynamics. These drivers interact in ways that create both urgency and selectivity in procurement decisions.
Technological Innovation and Threat Detection Fidelity
The most consequential technology trend is the migration toward computed tomography and multi-view imaging within checkpoint and cargo screening environments. CT-based systems improve material discrimination, reduce false alarms, and allow operators to rotate and slice reconstructed images, thereby increasing detection confidence while supporting faster passenger and baggage flow. Alongside imaging hardware, software-driven analytics, automated threat recognition, and digital twin integration are reshaping how scanning systems deliver value. Suppliers that pair high-fidelity imaging with integrated software layers can differentiate on operational outcomes rather than raw hardware specifications. Recent commercial activity illustrates this emphasis: Rapiscan Systems received a USD 19 million order to support deployment of non-intrusive inspection solutions, followed by a USD 15 million order for cargo and vehicle inspection systems and services. These placements reflect demand for end-to-end inspection capabilities that span baggage, parcel, freight, and vehicle contexts, with mobile threat detection integrated into the operational workflow.
Policy and Regulatory Pressure as a Demand Catalyst
Regulation continues to function as a powerful demand accelerator. EASA rules now require freight above 150 kg to undergo volumetric imaging, a mandate that is accelerating the replacement of single-view tunnels with higher-capability systems. In the United States, the Transportation Security Administration allocated approximately USD 1.3 billion for 469 CT units in 2025, signaling a decisive commitment to modernization at scale. Regulatory certifications also matter for market access and buyer confidence; for example, OSI Systems received ECAC/EU G1 certification for trace detection solutions for airport security in April 2026, reinforcing the importance of recognized approvals when operators evaluate systems for international deployment. These policy signals help de-risk procurement decisions and create multi-year installation pipelines that suppliers can plan around.
Demand-Side Evolution Across Aviation and Commercial Sectors
Demand is increasingly shaped by end-user priorities that extend beyond baseline compliance. Aviation and transportation stakeholders seek solutions that reduce passenger wait times, improve lane throughput, and provide actionable visualization for operators. Commercial entities, including logistics hubs, warehousing environments, and critical infrastructure operators, are expanding screening footprints to address cargo verification, internal theft and contraband detection, and facility-level security layering. This diversification means that manufacturers must tailor value propositions to distinct operating environments: checkpoint speed and ergonomics in aviation, while robustness, scale, and integration with warehouse management or cargo handling systems in commercial contexts. The relative revenue weight of aviation-transportation and commercial applications in 2025 confirms that both segments remain central to growth, but their requirements and purchasing cycles differ meaningfully.
Supply Chain Realities and Cost Architecture
Supply chain conditions continue to influence market behavior. Component availability, semiconductor constraints, and the cost of precision mechanical and sensing elements affect lead times and final system pricing. Tariff adjustments on selected pallet scanning equipment have already compelled buyers and suppliers to revisit vendor selection, sourcing strategies, and deployment timelines. In response, some operators are dual-sourcing critical subassemblies, negotiating longer-term service agreements to stabilize lifecycle costs, and planning deployment schedules with greater flexibility. Suppliers that can demonstrate resilient supply chains, transparent pricing, and modular architecture are better positioned to secure commitments in an environment where procurement teams are risk-aware and timeline-sensitive.
Security Screening Systems Market
Competitive Landscape and Leading Strategies
The competitive field combines established security hardware specialists, diversified defense and aerospace players, and regionally strong manufacturers with growing international reach. Market share is distributed rather than dominated, which rewards clear positioning and executable go-to-market strategies. Several companies illustrate the breadth of strategic approaches currently shaping the market.
Worldwide Security Laser Scanner Market
Rapiscan Systems, based in the United States, emphasizes Orions and Z Portal systems for baggage, parcel, freight, and vehicle inspection, with mobile threat detection integrated into its offering. The company’s recent order flow and certification activity reflect a strategy centered on non-intrusive inspection breadth, regulatory alignment, and service-supported deployments. Smiths Detection, headquartered in the United Kingdom, focuses on HI-SCAN and SDX X-ray systems for checkpoint and cargo screening, positioning around proven checkpoint performance and cargo inspection reliability. L3Harris Technologies, also U.S.-based, highlights ASCT and RSM-7 X-ray screening systems tailored for aviation and defense contexts, leaning into mission-grade robustness and integration with broader security and defense ecosystems.
Nuctech Company Limited, based in China, offers TSA-600 and T2000 X-ray systems for airports and cargo, pursuing scale, cost competitiveness, and expanding international deployments. Gilardoni S.p.A. of Italy concentrates on security X-ray scanners for baggage and parcel inspection, with a focus on precision imaging and specialized inspection workflows. 3DX-Ray, also U.K.-based, targets portable and cabinet X-ray security scanners for threat detection, serving applications where mobility and compact form factors are critical. Analogic Corporation, in the United States, develops advanced X-ray imaging systems for security screening, emphasizing image quality and engineering depth. Leidos, another U.S. player, provides AXM and L-3 X-ray systems for security applications, leveraging large-scale systems integration capabilities. Astrophysics Inc., based in the United States, promotes American-made X-ray security scanning systems for critical infrastructure, aligning with procurement preferences for domestic sourcing in sensitive environments. VOTI Detection, headquartered in Canada, focuses on 3D Perspective X-ray scanners for border and cargo screening, emphasizing volumetric reconstruction suited to border and freight inspection contexts.
Several strategic patterns emerge from this landscape. First, incumbents are expanding beyond hardware into software-assisted interpretation, service contracts, and lifecycle management, because recurring revenue and operational outcomes increasingly determine win rates in competitive tenders. Second, differentiation is shifting from single-dimension specifications to integrated value propositions that combine imaging fidelity, throughput, ergonomics, certification, and support responsiveness. Third, the market is experiencing selective consolidation pressure: larger players with diversified portfolios can cross-sell across aviation, cargo, and commercial segments, while smaller specialists compete by focusing on portable systems, cabin formats, or niche inspection workflows. At the same time, regional sourcing preferences and tariff-related adjustments are prompting buyers to diversify supplier bases and re-evaluate vendor risk, which opens opportunities for manufacturers that can demonstrate reliable delivery, clear compliance posture, and adaptable deployment models.
PW Consulting
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026 through 2032 horizon, several trends are likely to define where value concentrates and how competitive advantage is earned.
Trend 1: CT and Multi-View Adoption Will Move From Exception to Expectation in High-Traffic Checkpoints
As regulatory mandates and throughput requirements compound, volumetric imaging will become standard in major aviation corridors and high-volume cargo nodes. The commercial implication is a multi-year replacement and upgrade cycle that favors suppliers capable of offering migration pathways, site-ready installation packages, and operator training programs. Manufacturers that can reduce integration friction and demonstrate measurable improvements in alarm resolution times will capture disproportionate share in this cycle. Investors should watch for recurring service revenue, spare parts pipelines, and software license structures that accompany hardware deployments, because these elements increasingly determine long-term margin profiles.
Trend 2: Software-Defined Screening and Automated Interpretation Will Redefine Value Capture
Image reconstruction is only part of the value chain. Automated threat recognition, alarm classification, and operator decision support are becoming critical differentiators. Systems that reduce cognitive load, shorten training curves, and integrate with broader security information workflows will be preferred in environments where staffing constraints and consistency requirements are acute. This trend creates opportunities for companies that can bundle analytics, analytics updates, and remote support into their offerings, and it raises the stakes for hardware-only entrants that lack a credible software roadmap. A key uncertainty is the pace at which algorithms and recognition models must be updated to keep pace with evolving threat profiles and regulatory expectations, which can pressure both development cycles and certification timelines.
Trend 3: Procurement Diversification and Sourcing Resilience Will Shape Vendor Selection
Recent tariff adjustments and component supply volatility are pushing procurement teams to diversify vendor lists, dual-source critical subassemblies, and re-evaluate deployment timelines. This environment rewards suppliers with transparent supply chains, predictable lead times, and the ability to offer modular or staged deployments that align with budget cycles. For buyers, the commercial opportunity lies in negotiating total cost of ownership-based contracts that include maintenance, calibration, and software support, rather than optimizing narrowly on initial capital outlay. For manufacturers, the opportunity lies in designing architectures that can be configured flexibly across regions and use cases without fragmenting production too extensively. A persistent risk is that tariff and trade policy shifts may continue to disrupt pricing assumptions and delivery schedules, particularly for pallet scanning equipment and certain cargo inspection platforms, requiring continuous monitoring of policy trajectories and supplier exposure.
Strategic Actions for Decision Makers
The market’s direction rewards proactive positioning. The following actions are most relevant depending on role and objectives.
For Manufacturers and Technology Providers
Prioritize integrated value propositions that combine imaging capability, automated interpretation, and service-led lifecycle support. Develop migration paths that allow operators to transition from dual-view to CT-enabled systems without full rip-and-replace disruptions. Strengthen supply chain visibility and offer modular architectures that can be adapted to regional requirements and procurement constraints. Where relevant, pursue recognized certifications and demonstrate compliance with major regulatory frameworks, because these credentials reduce buyer risk and expand addressable markets. Differentiate on operational outcomes such as alarm resolution speed, operator training time, and throughput under real-world conditions rather than on specifications alone.
For Investors and Strategic Capital Allocators
Assess companies based on their ability to capture recurring revenue through services, software, and maintenance contracts, not only on hardware sales. Favor portfolios with exposure to the aviation-transportation and commercial segments that are benefiting from modernization mandates and expanded screening footprints. Monitor the competitive impact of tariff adjustments and sourcing diversification on margins and market share, particularly in pallet and cargo scanning segments where procurement behavior is being re-evaluated. Track the pace of CT adoption in checkpoint environments as a leading indicator of capital intensity, installation pipelines, and supplier differentiation opportunities. Be mindful of policy-driven demand spikes that can create short-term revenue surges but may also compress margins if supply chains are not scaled appropriately.
For Procurement Leaders and End-User Organizations
Structure acquisitions around total cost of ownership, including installation, training, calibration, software updates, and service response times. Plan for phased deployment where possible to align capital expenditure with budget cycles and operational readiness. Evaluate vendor resilience carefully, including lead time stability, parts availability, and the ability to support multiple sites or modalities from a single integration framework. Where privacy-sensitive environments are involved, consider modality trade-offs and user experience implications alongside detection performance to ensure adoption and public acceptance are not compromised. In cargo and freight contexts, align system selection with regulatory requirements for volumetric imaging above specified weight thresholds to avoid future compliance risk and replacement pressure.
Closing Perspective
The X-ray security scanner market is entering a phase in which growth is increasingly tied to technology modernization, regulatory alignment, and the ability to deliver measurable operational outcomes. Revenue expansion from 2025 toward 2032 will be shaped by the pace of CT adoption, the maturation of software-assisted interpretation, and the resilience of supply chains under tariff and component pressures. Competitive advantage will accrue to organizations that treat screening systems as part of a broader security and operational workflow rather than as isolated hardware purchases.
For executives, planners, and investors seeking granular segmentation data, regional demand trajectories, detailed company benchmarking, and customized procurement scenarios, the full PW Consulting study provides a more comprehensive view of the market’s subsegments, competitive moves, and forward scenarios. The complete report extends the analysis into deeper segmentation detail, deployment pattern trends, and strategic recommendations tailored to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: X-Ray Security Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automatic Tire Inflation System Market: Why 6.98% CAGR Changes Everything
By PW Consulting, 2026-09-21
The Automatic Tire Inflation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global automatic tire inflation system (ATIS) market has entered a phase of steady, structurally driven expansion. Valued at approximately 215 million USD in 2025, the market has grown from roughly 163 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through 2032. This trajectory is not merely a function of incremental demand; it signals a broader transformation in how fleets, manufacturers, and regulators approach tire management. As operational costs rise and sustainability mandates tighten, ATIS has shifted from a niche add-on to a strategic component of vehicle architecture and fleet optimization.
The market's growth pattern reveals distinct inflection points. Revenue expanded modestly through 2022, then accelerated in 2023 and 2024, reaching 207.42 million USD before stabilizing near 215 million USD in 2025. This acceleration aligns with broader industry shifts: heavier emphasis on fuel efficiency, increased scrutiny of tire-related safety incidents, and the gradual integration of tire pressure management into connected vehicle ecosystems. Looking ahead, the forecast period through 2032 projects continued expansion, with revenue crossing 300 million USD by 2030 and approaching 344.8 million USD by 2032. The pace of growth will depend on how quickly adoption cascades from early-adopter segments into mainstream commercial and passenger vehicle applications.
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive dynamics and investment decisions over the next decade.
Core Challenges and Inflection Points
One of the most significant hurdles is the uneven regulatory landscape. In many jurisdictions, ATIS remains an optional feature rather than a mandated requirement. This creates a paradox: the systems deliver measurable safety and efficiency benefits, yet compliance frameworks do not consistently incentivize adoption. Fleet operators weighing capital expenditures must weigh tangible operational savings against the absence of regulatory compulsion. The result is a market where adoption velocity depends heavily on demonstrable return on investment rather than compliance-driven demand.
A second challenge lies in integration complexity. Retrofitting existing fleets with automatic inflation systems requires compatibility with diverse valve assemblies, air supply configurations, and telematics platforms. For new vehicle manufacturers, embedding ATIS into chassis design demands coordination across engineering teams, supply chains, and certification processes. These integration frictions slow deployment cycles and increase upfront costs, particularly for mid-sized operators who lack the scale to negotiate customized solutions or absorb installation downtime.
A third inflection point is the evolving definition of system value. Early generations of ATIS focused primarily on maintaining target pressure levels. Today, the market increasingly expects intelligent monitoring, real-time diagnostics, and data integration with fleet management software. This shift raises the bar for competitors: companies that offer standalone mechanical or pneumatic solutions without connected capabilities risk marginalization as buyers prioritize systems that feed actionable insights into broader operational workflows.
Key Drivers Shaping Market Trajectory
The expansion of the ATIS market is being propelled by a convergence of technological, regulatory, demand-side, and supply chain forces. Understanding how these drivers interact is essential for stakeholders evaluating market entry, product development, or capital allocation.
Technology Innovation and Intelligent Monitoring
Advancements in sensor technology, wireless communication, and edge computing have transformed ATIS from a pressure-maintenance tool into a data-generating asset. Modern systems now incorporate integrated sensors that continuously monitor tire conditions, log performance metrics, and transmit information to centralized dashboards. This evolution matters because tire under-inflation remains a leading cause of premature wear, elevated fuel consumption, and roadside failures. By automating pressure correction and coupling it with visibility into tire health, these systems reduce manual inspection burdens and enable predictive maintenance strategies.
Recent developments illustrate this trajectory. In early 2026, RIX Industries received a 204,500 USD SBIR Phase I contract from the Federal Motor Carrier Safety Administration to prototype a Weight Equalization Smart Automatic Tire Inflation System. The project targets per-tire real-time pressure management, highlighting a growing emphasis on precision control and load-aware inflation logic. Such initiatives signal that innovation is moving beyond generic pressure maintenance toward context-sensitive algorithms that adapt to cargo distribution, terrain, and operating conditions.
Policy and Regulatory Environment
Regulatory signals are subtly reshaping the adoption calculus. While ATIS is not universally mandated, inspection frameworks and electronic compliance standards are creating an environment where properly functioning tire pressure management systems carry indirect advantages. For example, recent inspection guidance clarifies that an ATIS unit is not classified as required equipment on commercial motor vehicles, and a defective or alert-status system does not automatically trigger a violation. This regulatory posture reduces the compliance risk of adoption while preserving the operational case for installation. It also means that manufacturers must ensure their systems meet relevant electromagnetic compatibility and electronic equipment standards to avoid unintended certification hurdles.
PW Consulting Automotive & Machinery Research Center
Parallel compliance milestones reinforce this trend. Systems on the market have been documented as conforming to FCC Part 15 rules and Industry Canada RSS-210 for electronic equipment, while other centralized tire inflation platforms declare conformity to EMC directives, ISOBUS standards, and environmental resistance specifications. These compliance layers are not mere formalities; they reduce integration friction for fleets operating across borders and signal maturity to buyers who prioritize reliability and auditability.
Demand-Side Shifts in Fleet and Consumer Behavior
On the demand side, fleet operators are increasingly treating tire management as a lever for total cost of ownership reduction rather than a maintenance afterthought. Proper inflation directly influences fuel economy, tire lifespan, and unscheduled downtime. As freight margins remain constrained and labor shortages complicate roadside inspection routines, the economic argument for automated pressure management strengthens. Large trailer fleets that have already deployed ATIS on a significant scale report sustained benefits in keeping tires properly inflated and improving fuel efficiency, which reinforces the credibility of the technology among peer operators.
Passenger vehicle applications are also gaining attention, particularly as connected car platforms expand and consumers become more accustomed to vehicles that self-monitor and self-adjust. While commercial vehicles currently represent the larger revenue share, the passenger segment benefits from the same underlying logic: reduced wear, improved safety margins, and alignment with broader vehicle intelligence trends. The challenge for suppliers is to adapt system architectures to the cost, packaging, and user-experience expectations of passenger markets without sacrificing reliability.
Supply Chain and Cost Structure Evolution
Cost dynamics are being reshaped by component innovation and manufacturing scale. Sealing technologies, for instance, have advanced to the point where central tire inflation seals can self-adjust across terrains, reducing CO₂ emissions and extending tire life. Such improvements lower the total cost of ownership for end users while giving system manufacturers a tangible performance differentiator. At the same time, the broader push toward standardized electronic components and modular architectures is helping suppliers reduce integration complexity and accelerate time to market.
However, supply chain resilience remains a consideration. Systems that depend on specialized sensors, control modules, and custom pneumatic assemblies are exposed to component availability fluctuations and lead-time variability. Manufacturers that invest in component standardization, dual-sourcing strategies, and design-for-manufacturing principles will be better positioned to maintain pricing stability and delivery reliability as demand scales.
Competitive Landscape and Leading Strategies
The ATIS market is characterized by a moderately concentrated competitive structure, with the top three players holding approximately 31.4 percent of revenue and the top five accounting for roughly 38.7 percent. This concentration leaves meaningful room for specialized providers, regional players, and new entrants that can address underserved segments or bring differentiated technology. The competitive arena is not defined by a single winner-takes-all dynamic; rather, it rewards companies that combine technical credibility, integration ease, and compelling operational value propositions.
Strategic Positioning of Leading Players
Several established companies illustrate the diversity of successful strategic positioning. Aperia Technologies has focused on intelligent automatic tire inflation with integrated sensors designed for seamless data collection and reporting, targeting heavy-duty trucks and fleets. This approach positions the company at the intersection of pressure management and fleet analytics, appealing to operators who want actionable visibility alongside automated inflation.
Cummins, through its Meritor Tire Inflation System, has built scale by equipping more than one million trailers with technology that maintains proper tire inflation and reduces wear. The breadth of deployment provides a strong reference base and reinforces the system's status as a proven solution in the commercial trailer segment. Hendrickson International offers a tiered portfolio of tire pressure control systems, including CP, PRO, and PRO-LB automatic inflation models tailored for the trailer industry. This product ladder allows the company to address varying performance and budget requirements within a coherent brand framework.
Pressure Systems International has established a long-standing presence in the market, positioning itself as a global leader in automatic tire inflation systems with integrated TPMS capabilities. Its emphasis on decades of experience and combined inflation and monitoring functionality appeals to buyers seeking consolidated solutions. Rotex Automation brings a European footprint with a patented centralized tire inflation system installed on a significant share of trucks across the region, reflecting deep regional integration and familiarity with local operating conditions. Stemco complements this landscape by focusing on installation efficiency, offering toolkits that streamline trailer tire inflation system deployment, which reduces friction for operators and upfitters alike.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape is evolving along three overlapping directions. First, integration is becoming a decisive advantage. Suppliers that connect inflation hardware with telematics, maintenance platforms, and route-optimization software are creating stickier customer relationships and higher perceived value. Second, differentiation is increasingly tied to intelligent features rather than mechanical performance alone. Real-time pressure management, load-aware algorithms, and diagnostic reporting are becoming baseline expectations in commercial segments, pushing legacy-only offerings toward the periphery.
Third, the market is open to strategic new entrants, particularly those with strong funding pathways or specialized technology. The recent SBIR-funded prototype for a weight equalization smart inflation system exemplifies how targeted innovation can introduce novel capabilities that address specific operational pain points. While such projects are early stage, they signal that the barrier to introducing differentiated concepts remains manageable for well-positioned innovators. Over time, the market may see consolidation among larger platform providers acquiring niche technology, alongside continued fragmentation in regional or application-specific niches.
Future Trends and Commercial Opportunities
Looking ahead to the 2027–2032 window, three trends are likely to shape commercial opportunities and strategic priorities.
From Standalone Systems to Integrated Fleet Intelligence
Automatic tire inflation will increasingly be evaluated as part of a broader fleet intelligence stack rather than as an isolated hardware purchase. Buyers will expect systems that not only maintain pressure but also contribute data to maintenance scheduling, fuel reporting, and safety analytics. This trend creates opportunities for suppliers that invest in open APIs, interoperable data formats, and bundled service offerings. It also raises the stakes for companies that rely on closed architectures, as fleets favor solutions that plug into existing operational workflows.
Precision Control and Load-Aware Inflation Logic
A second trend is the move toward per-tire, condition-aware pressure management. As sensing accuracy improves and control algorithms become more sophisticated, systems will adapt inflation levels to cargo distribution, road surface, and dynamic loading conditions. This precision has direct commercial implications: it can extend tire life, reduce uneven wear, and improve fuel economy under variable operating conditions. Suppliers that can demonstrate measurable performance gains from smart inflation logic will have a stronger case in price-sensitive procurement environments.
Aftermarket Tire Pressure Monitoring System (TPMS) Market
Regional Expansion and Application Diversification
A third trend is the gradual expansion of ATIS adoption beyond mature commercial trailer markets into adjacent applications and regions. Centralized and continuous inflation architectures are finding relevance in off-road and specialized vehicle contexts, while passenger vehicle applications may grow as connectivity and self-diagnosis features become standard expectations. Regional growth will be uneven, shaped by local fleet composition, fuel cost sensitivity, and the pace of telematics adoption. Companies that can adapt system designs to regional operating conditions and cost structures will be better positioned to capture incremental demand.
Risks and Uncertainties
These opportunities are accompanied by risks that stakeholders should monitor. Regulatory frameworks could shift in ways that either accelerate adoption through mandates or introduce new compliance burdens that increase system cost. Supply chain disruptions affecting sensors, control modules, or pneumatic components could pressure margins and delay deployments. Additionally, if macroeconomic conditions compress fleet capital spending, the timeline for broader ATIS adoption may extend, particularly in price-sensitive segments where payback periods are closely scrutinized. Competitive pressure could also intensify if large platform providers bundle inflation capabilities with broader vehicle systems, altering the bargaining dynamics for standalone suppliers.
Actionable Guidance for Decision-Makers
The strategic implications of these trends differ by role, but several priorities apply across the board.
For Manufacturers and Technology Providers
Differentiate through intelligent integration rather than pressure maintenance alone. Invest in sensor accuracy, data interoperability, and installation efficiency, as these elements increasingly determine buyer preference. Standardize components where possible to improve supply chain resilience and reduce cost volatility. Consider targeted partnerships or acquisitions that add complementary capabilities, such as telematics interfaces, advanced sealing technologies, or region-specific installation expertise.
For Investors and Capital Allocators
Evaluate opportunities based on total cost of ownership value propositions and the capacity to scale installation and service networks. Companies with proven deployment volumes, clear compliance alignments, and modular architectures are better positioned to weather procurement cycles and supply variability. Watch for early-stage innovations that address load-aware control or terrain-adaptive sealing, as these features can become meaningful differentiators if they translate into measurable operational savings. Assess the pace of regional adoption carefully, as growth will be uneven and dependent on local fleet economics and telematics maturity.
For Fleet Operators and Procurement Teams
Prioritize systems that integrate with existing maintenance and telematics workflows, reducing the operational burden of data reconciliation and manual inspections. Evaluate installation toolkits and service support as part of the procurement decision, since deployment efficiency directly affects downtime and total cost. When comparing solutions, look beyond headline specifications to verify compatibility with valve configurations, air supply arrangements, and electronic compliance requirements relevant to your operating region. Consider pilot deployments in representative routes and load conditions to validate real-world performance before scaling.
Worldwide Automotive Tire Socks Market
The ATIS market is moving from a phase of incremental adoption to one where intelligent control, integration, and regional adaptation determine competitive advantage. Stakeholders who align product strategies, investment theses, and procurement criteria with these shifts will be better positioned to capture value as the market expands toward the mid-2030s. For decision-makers seeking deeper segmentation data, regional breakdowns, and customized scenario analysis, the full research report provides the detailed frameworks needed to translate these trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Automatic Tire Inflation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microwave Oven Market 2032: Why 3.5% CAGR Growth Trajectory Defies Expectations
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Microwave Oven Market (2025–2032)
Market Outlook: A Mature Appliance Sector in Transition
The microwave oven market has evolved from a quintessential convenience appliance into a more strategically nuanced segment within the broader kitchen appliance landscape. Valued at USD 8.5 billion in 2020, the sector reached an estimated USD 13.5 billion by 2025, reflecting steady expansion driven by consistent household demand and incremental product innovation. Projections through 2032 indicate a 3.5% compound annual growth rate, culminating in a market valuation approaching USD 17.21 billion. While these headline figures suggest a predictable growth trajectory, the underlying dynamics reveal a market navigating structural shifts in consumer behavior, regulatory uncertainty, and supply chain reconfiguration.
The growth narrative is not uniform across all dimensions. Regional performance varies significantly, with Asian Pacific markets continuing to anchor volume demand while North American and European segments exhibit more mature, replacement-driven consumption patterns. Product differentiation has also reshaped how manufacturers allocate capital and design roadmaps. Solo units maintain a dominant share, reflecting their affordability and prevalence in price-sensitive markets, while grill and convection variants capture premium positioning and multi-functionality demand. Similarly, residential applications overwhelmingly drive baseline volume, yet commercial installations represent a strategically distinct segment with different procurement cycles, durability requirements, and service expectations.
High Speed Oven Market
Key Challenges and Inflection Points
Despite the steady top-line trajectory, several friction points are reshaping how stakeholders approach the market. First, the recent policy landscape has introduced regulatory volatility. In May 2025, the U.S. Department of Energy proposed rescinding energy conservation standards for microwave ovens, effectively eliminating prior efficiency requirements. This move reduces compliance burdens for manufacturers but simultaneously removes a historical driver that had accelerated the phase-out of less efficient designs and influenced product architecture. While the change may lower near-term engineering costs, it also introduces uncertainty around future regulatory directionality and consumer perceptions of energy-conscious appliances.
Second, trade policy dynamics are creating cost pressure that ripples through pricing strategies and margin structures. Tariff actions on Chinese-origin goods in 2025 contributed to a measurable increase in core goods consumer prices, with continued effects extending through early 2026. For a category with substantial import-dependent component sourcing and finished goods manufacturing footprints in East Asia, these trade shifts are compressing supply chain flexibility and forcing manufacturers to weigh localized production, alternative sourcing, and pricing absorption more carefully.
Third, the market is approaching a functional saturation point in basic microwave cooking. As standalone heating appliances become commoditized in many households, growth increasingly depends on differentiated value propositions rather than volume replacement alone. This creates a strategic crossroads: manufacturers must decide whether to compete on cost efficiency in mature categories or invest in integrated solutions that address evolving kitchen workflows, space constraints, and connected living environments.
Core Drivers Shaping Market Trajectory
Technological Innovation and Design Evolution
Product innovation remains a central competitive lever, though the nature of innovation has shifted from incremental wattage and capacity upgrades toward integrated functionality and form-factor adaptation. Convection capabilities, air-fry combinations, and smart connectivity features are redefining how microwaves fit into modern kitchens. Leading manufacturers are embedding intelligent interfaces, remote diagnostics, and compatibility with broader smart home ecosystems, positioning microwave ovens not merely as heating tools but as nodes within integrated kitchen management. LG Electronics, for example, has continued advancing its Smart ThinQ platform alongside convection technology, reinforcing the trend toward app-enabled control and performance customization. Such developments appeal to consumers willing to pay a premium for convenience, consistency, and multi-cooking versatility.
At the same time, spatial constraints in urban housing and smaller-footprint living environments are driving demand for compact and flexible configurations. Sharp Corporation’s recent introduction of compact kitchen appliances, including new Convection Microwave Drawer™ Oven models, highlights how design innovation is responding to the need for built-in flexibility and space optimization. These developments illustrate that technology leadership in this market is increasingly defined by how well a product adapts to installation environments, culinary workflows, and aesthetic expectations rather than raw heating specifications alone.
Policy and Regulatory Environment
Regulatory shifts are acting as both a constraint and an enabler, depending on the manufacturer’s positioning and geographic exposure. The proposed rescission of energy conservation standards alters the compliance calculus for U.S.-facing products, potentially freeing engineering resources that would otherwise be directed toward efficiency optimization. However, this does not eliminate all regulatory oversight. The FDA continues to enforce radiation safety performance standards under 21 CFR 1030.10, requiring manufacturer certification and labeling. This framework ensures a baseline of product safety and consumer confidence but also imposes ongoing compliance obligations that influence product design, testing, and market entry timelines.
For global manufacturers, the divergence between evolving energy policy in some markets and persistent safety standards in others creates a patchwork of requirements. Companies must manage product configurations that can satisfy multiple regulatory regimes without sacrificing cost competitiveness or feature consistency. In practice, this regulatory complexity favors manufacturers with mature compliance infrastructure and the ability to modularize design platforms across regions.
PW Consulting
Demand-Side Shifts in Consumer and Commercial Behavior
On the demand side, microwave ovens are benefiting from broader lifestyle and housing trends that value convenience, speed, and multifunctional appliances. Urbanization, smaller household sizes, and time-constrained consumption patterns continue to reinforce reliance on fast-preparation appliances. At the premium end, consumers are increasingly looking for appliances that support varied cooking methods within a single footprint, which has helped sustain interest in convection and grill variants. In commercial environments, demand is shaped by operational efficiency, durability, and throughput requirements. Food service operators, institutional kitchens, and hospitality venues evaluate microwave systems through a different lens than residential buyers, prioritizing serviceability, consistent output, and integration with existing workflow equipment.
A notable demand-side development is the growing sensitivity to total cost of ownership rather than sticker price alone. While budget-conscious segments still favor basic solo models, buyers in higher-income and commercial segments increasingly weigh features, energy behavior, service availability, and brand reliability. This bifurcation is reinforcing segmentation strategies and making it more difficult for undifferentiated products to command share in competitive channels.
Supply Chain and Cost Structure Adjustments
Cost structures in the microwave oven market are being reshaped by a combination of input pricing, logistics volatility, and trade policy exposure. Tariffs on Chinese-origin goods have raised the price baseline for imported components and finished goods, affecting everything from magnetron sourcing to assembly and distribution. In response, manufacturers are recalibrating sourcing strategies, evaluating nearshoring or diversified supplier networks, and adjusting product mix to protect margins without alienating price-sensitive buyers. Midea Group’s ongoing catalog updates, including refreshed countertop and Versa Series offerings, reflect the type of portfolio management required to maintain channel relevance while navigating shifting cost dynamics.
Worldwide Combination Microwave Ovens Market
The supply chain imperative is not only about cost containment. It also involves resilience. Manufacturers with the ability to flex production footprints, maintain component buffers, and respond quickly to channel demand fluctuations are better positioned to manage the trade-offs between volume, margin, and lead time. This has elevated the strategic importance of manufacturing planning and logistics coordination as competitive differentiators in a segment where hardware innovation is sometimes incremental.
Competitive Landscape and Strategic Positioning
Incumbent Strength and Differentiation Paths
The market remains moderately concentrated, with the top three players accounting for roughly 45% of share and the top five approaching 60%. This concentration reflects the presence of large, globally active manufacturers capable of sustaining broad product portfolios, competitive pricing, and multi-channel distribution. Midea Group and Galanz function as major OEM and branded manufacturers, producing microwave ovens for multiple labels and retail channels. Their scale and manufacturing breadth enable them to serve both proprietary brand strategies and third-party sourcing relationships. Midea’s portfolio breadth, including countertop and Versa Series models, underscores a strategy built on product range and channel versatility, while Galanz similarly supports a mix of its own brand and retailer-supplied models.
On the branded premium and feature-differentiated side, LG Electronics and Sharp Corporation emphasize integrated technologies and specialized form factors. LG’s focus on built-in, countertop, and convection models with smart connectivity highlights an orientation toward modern kitchen integration and consumer-facing digital experience. Sharp’s emphasis on Convection Microwave Drawer™ ovens and other countertop and over-the-range models reflects a more architecture-oriented approach, appealing to installations where space, aesthetics, and built-in functionality matter. These differentiated paths show that incumbents are not competing solely on volume; they are also cultivating niches where design, functionality, and ecosystem alignment can support margin resilience.
Whirlpool Corporation and GE Appliances illustrate how established Western appliance groups maintain relevance through multi-brand portfolios and domestic manufacturing elements. Whirlpool’s offerings under Whirlpool, KitchenAid, and Amana brands span multiple consumer segments and price tiers, while GE Appliances has continued to emphasize countertop and built-in models with convection and air-fry options. For these players, brand trust, service networks, and retail relationships remain important assets, especially in markets where post-purchase support and consumer familiarity influence purchasing decisions.
Structural Evolution in the Competitive Field
The competitive landscape is likely to continue evolving along several axes. One is consolidation and selective partnership. Larger manufacturers may pursue channel expansion, regional manufacturing footprint adjustments, or targeted acquisitions to strengthen portfolio coverage or technology capabilities. Another is segmentation-driven specialization, where certain players concentrate on high-volume cost-competitive models while others invest in premium, connected, or built-in solutions. This divergence can create opportunities for new entrants or niche specialists that address underserved needs, such as compact urban installations, commercial-grade durability, or region-specific compliance and pricing requirements.
Recent product and catalog activity illustrates how firms are refining their positioning in real time. Sharp Electronics Corporation’s February 2026 launch of compact kitchen appliances, including a new Convection Microwave Drawer™ Oven, signals a continued push toward space-efficient and design-forward solutions. Midea Group’s March 2026 catalog updates, including compact countertop models and revised Versa Series offerings, demonstrate ongoing portfolio tuning to maintain relevance across channel and consumer segments. These moves are not isolated product events; they reflect broader strategic calibration in response to housing trends, channel demands, and cost pressures.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Functional Integration as a Growth Lever
Over the next three to five years, microwave ovens are likely to gain share not by standing alone as simple reheating appliances, but by functioning as integrated cooking and convenience hubs. Convection, air-fry, and smart-control capabilities will increasingly become baseline expectations in higher-tier segments, while basic solo units remain volume drivers in price-sensitive markets. Commercial opportunity lies in product architectures that allow modular feature sets, enabling manufacturers to cover multiple price points without fragmenting engineering resources. For channel partners, this translates into clearer upsell pathways and stronger differentiation in showroom and online environments.
Trend 2: Space-Optimized and Installation-Focused Designs
As housing footprints shrink in many urban markets and renovation projects prioritize integrated cabinetry and flexible layouts, demand for compact, built-in, and drawer-style configurations is expected to grow. This trend favors manufacturers that can align product design with installation ecosystems and offer solutions that fit diverse kitchen architectures. Commercial opportunity extends beyond consumer retail into renovation channels, property development partnerships, and commercial fit-out procurement, where appliance compatibility and space efficiency influence purchasing decisions early in the project lifecycle.
Trend 3: Supply Chain Realignment and Regional Cost Strategy
Given ongoing trade policy exposure and component sourcing complexity, manufacturers are likely to continue diversifying production and sourcing strategies to protect margin and lead-time reliability. Commercial opportunity exists for firms that can demonstrate supply chain resilience, localized assembly options, or flexible sourcing models to buyers who are increasingly sensitive to availability risk and total cost of ownership. Investors and strategic partners should watch for shifts in manufacturing geography, supplier concentration, and channel pricing behavior, as these factors will influence category profitability more directly than headline demand growth alone.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Regulatory directionality remains fluid, particularly where energy standards are being reevaluated, and future reinstatement or recalibration of efficiency requirements could change design priorities. Trade policy volatility can shift cost structures quickly, especially for categories with heavy import dependence. Additionally, competitive intensity in commoditized segments may compress pricing power, while premium differentiation depends on sustained consumer willingness to pay for features that are not yet considered essential. Finally, macroeconomic sensitivity in major residential markets can affect big-ticket appliance purchase cycles, making the category partly dependent on housing activity, remodeling spend, and discretionary income trends.
Strategic Recommendations for Decision-Makers
For Manufacturers and Brand Strategists
- Develop modular product platforms that can support solo, grill, and convection variants without duplicating engineering effort, allowing faster response to regional price and feature expectations.
- Align design roadmaps with space-constrained and built-in installation trends, including compact and drawer-style options, to capture renovation-driven and urban-living demand.
- Stress-test supply chain exposure to trade policy and component sourcing concentration, and evaluate diversified sourcing, regional assembly, or flexible logistics arrangements to protect margin and availability.
For Investors and Strategic Partners
- Evaluate category exposure by segmentation logic rather than aggregate market size alone; premium convection and smart-enabled segments may offer different risk-return profiles than high-volume solo units.
- Monitor regulatory and trade-policy developments closely, as changes can alter cost structures and compliance investment requirements with limited lead time.
- Prioritize companies with credible manufacturing flexibility, brand-channel strength, and the ability to manage multi-tier portfolios across cost-competitive and differentiated segments.
For Procurement and Channel Leaders
- Balance base-volume sourcing with differentiated SKUs that support margin and consumer upgrade paths, particularly where convection, air-fry, and compact configurations can command stronger positioning.
- Incorporate serviceability, warranty infrastructure, and installation compatibility into evaluation criteria, especially for commercial and multi-unit deployment scenarios.
- Track price and availability signals tied to component imports and trade measures, and adjust sourcing plans to reduce exposure to sudden cost shifts.
The microwave oven market is no longer moving solely on basic replacement demand. It is being reshaped by design innovation, regulatory recalibration, trade-linked cost dynamics, and evolving expectations around how appliances fit into modern kitchens and commercial operations. For decision-makers, the most valuable intelligence is not a single aggregate figure but a clear view of where differentiation is gaining traction, where cost pressure is reshaping margins, and how regulatory and supply chain variables may change competitive advantage over the next several years. Readers seeking deeper segmentation detail, regional dynamics, and customized strategic guidance can explore the full PW Consulting report for a more granular view of the market and its emerging opportunities.
For detailed analysis of this topic, please visit the official page: Microwave Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com