

Blogs
Whole-house Ventilation System Market: How 6.52% CAGR Reshapes Residential Growth
By PW Consulting, 2026-09-21
The Whole-house Ventilation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global whole-house ventilation system market has entered a phase of structural expansion, driven by tightening building codes, growing awareness of indoor air quality, and the broader transition toward energy-efficient residential design. Valued at approximately 3.84 billion USD in 2025, the market has grown steadily from 2.8 billion USD in 2020, reflecting a compound annual growth rate that positions it for sustained momentum through the end of the decade. Projections indicate revenue will reach roughly 5.97 billion USD by 2032, underpinned by a CAGR of 6.52 percent across the forecast period. This trajectory is not merely a function of incremental demand growth; it reflects a fundamental shift in how buildings are designed, regulated, and operated. Ventilation is no longer treated as a passive exhaust function but as an integrated component of indoor environmental quality, energy management, and occupant health.
PW Consulting
The market's expansion is geographically uneven, with mature regulatory environments and high construction activity driving adoption in certain regions, while emerging markets are accelerating uptake as building standards converge with international best practices. Product segmentation reveals a clear preference for heat recovery and energy recovery technologies, which together dominate revenue share due to their ability to balance fresh air intake with thermal efficiency. Residential applications account for the largest share of demand, reflecting both new construction requirements and retrofit activity in existing housing stock. Commercial and industrial segments, while smaller in absolute terms, are growing as facility operators prioritize air quality compliance and energy performance in larger building portfolios. Despite this growth, the market remains moderately fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding a similarly limited share. This fragmentation suggests room for consolidation, strategic positioning, and differentiation as the market matures.
Key Challenges and Inflection Points
The industry faces several structural challenges that will shape competitive dynamics over the next forecasting cycle. First, regulatory fragmentation across jurisdictions creates compliance complexity for manufacturers and distributors. While a growing number of U.S. jurisdictions now require whole-house ventilation systems in new single-family and multifamily construction, the specific standards, testing protocols, and enforcement mechanisms vary widely. This patchwork increases product adaptation costs and complicates market entry strategies for firms targeting multiple regions. Second, the market is experiencing a technology transition as builders and homeowners weigh the performance characteristics of heat recovery versus energy recovery systems. Each approach offers distinct advantages in different climate conditions, and the optimal choice depends on local humidity profiles, energy costs, and design priorities. Misalignment between product capabilities and regional requirements can lead to underperformance, warranty claims, and reputational risk. Third, the industry must navigate supply chain and cost pressures that affect both manufacturing economics and end-user affordability. Component availability, material cost volatility, and labor constraints can compress margins and delay project timelines, particularly in high-growth segments where demand outpaces production capacity.
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Advances in heat and energy recovery technologies are reshaping the value proposition of whole-house ventilation systems. Modern units are achieving higher sensible and latent recovery efficiencies while reducing fan power consumption, enabling builders to meet stringent energy codes without sacrificing indoor air quality. Innovations in enthalpy exchange media, modular design, and integrated controls allow systems to adapt to variable operating conditions and maintain performance across seasonal shifts. Cold-climate optimization has become a particular focus, as manufacturers develop units that maintain recovery efficiency and condensate management in low-temperature environments. These technical improvements are not incremental refinements; they are expanding the addressable market by making ventilation systems viable in regions where earlier generations of equipment struggled to deliver consistent performance.
Policy and Regulatory Environment
Regulatory momentum is one of the strongest catalysts for adoption. Building code adoptions across multiple U.S. jurisdictions now require whole-house ventilation in new single-family and multifamily homes, embedding these systems into the baseline design of new construction rather than treating them as optional upgrades. California's 2025 Energy Code exemplifies this shift by prohibiting exhaust-only systems in new multifamily construction and mandating fault indicator displays for HRV and ERV systems, which raises the bar for monitoring and maintenance. Acceptance testing protocols, such as the 2025 NRCA-MCH-23-A standard, verify airflow, sensible recovery, and fan power compliance for multifamily buildings, creating a more rigorous validation framework. At the national level, ASHRAE Standard 62.2 continues to serve as the reference for minimum ventilation rates in residential mechanical systems, providing a consistent technical baseline that manufacturers can align with. Together, these regulatory developments are converting ventilation from a discretionary specification into a code-driven requirement, which stabilizes demand and encourages standardized product architectures.
Demand-Side Shifts in Consumer and Builder Behavior
Demand is being reinforced by changing expectations around indoor environmental quality. Homebuyers and commercial facility operators increasingly view air quality, humidity control, and ventilation performance as integral to health, comfort, and asset value. This perspective is amplified by greater public awareness of airborne contaminants and the role of mechanical ventilation in managing indoor pollutant levels. Builders are responding by specifying ventilation systems earlier in the design process, integrating them with HVAC architectures to simplify installation and improve balanced air exchange. In multifamily projects, developers are recognizing that compliant, efficient ventilation systems can reduce operational liabilities and support certification goals tied to energy performance and occupant well-being. The result is a demand environment that values not just airflow volume but measurable recovery efficiency, reliability, and ease of commissioning.
Residential Ventilation Systems Market
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as manufacturers scale production, optimize component sourcing, and invest in design-for-manufacturability. Economies of scale are beginning to moderate unit costs for high-volume product lines, though premium segments with advanced controls or specialized climate adaptations remain relatively pricey. The supply chain for core components, including heat exchange media, fans, and control electronics, is maturing but remains sensitive to material price fluctuations and logistics constraints. Firms that secure reliable sourcing, standardize subassemblies across product families, and align production capacity with regional demand patterns are better positioned to protect margins. At the same time, installation and commissioning complexity can affect total cost of ownership for end users, making turnkey solutions and dealer support networks increasingly important competitive factors.
Competitive Landscape and Leading Strategies
The competitive field is populated by a mix of established HVAC manufacturers, specialized ventilation brands, and regional players with strong climate-specific engineering. Carrier offers energy-efficient HRV and ERV ventilator systems designed for whole-house indoor air quality and balanced ventilation, leveraging its broader residential portfolio to integrate ventilation with familiar HVAC platforms. Zehnder America focuses on the ComfoAir series of ERV and HRV units engineered for whole-house fresh air supply with high efficiency, emphasizing performance consistency and installer-friendly design. Panasonic contributes WhisperComfort ERV and related heat and energy recovery systems tailored for whole-house residential use, drawing on its reputation for quiet operation and reliability in connected home environments.
Broan-Nutone and RenewAire both target residential applications with integrated ventilation products and balanced ERV systems, respectively, with an emphasis on whole-house indoor air quality and fresh air exchange. Lifebreath has carved out a position around cold-climate ERV and HRV systems optimized for whole-house ventilation performance, addressing markets where temperature extremes demand robust recovery and defrost management. EXINDA provides HVI-certified ERV units for whole-house fresh air solutions that comply with North American standards, appealing to specifiers seeking verified performance and code alignment. Trane integrates whole-house ventilation with its broader HVAC offerings to improve IAQ and balanced air exchange, positioning ventilation as part of a unified climate control strategy rather than a standalone add-on.
In Europe, STIEBEL ELTRON offers the LWZ series of central ventilation systems with enthalpy heat exchangers for whole-house indoor air quality, reflecting a design philosophy that centralizes air handling for larger or more complex residential layouts. Aereco differentiates through hybrid ventilation systems with room-by-room demand control, targeting applications where adaptive airflow can reduce energy use while maintaining air quality in specific zones. These varied approaches illustrate how companies are aligning product architectures with regional climate needs, installation practices, and buyer expectations.
Strategic Positioning and Differentiation
Leading firms are differentiating along several axes. Some emphasize integration with existing HVAC ecosystems, reducing installation friction and enabling unified controls. Others focus on certified performance, climate-specific engineering, or demand-controlled airflow to appeal to performance-driven specifiers and code-conscious developers. Brand trust, warranty support, and dealer network strength also play outsized roles, particularly in residential markets where installers influence equipment selection. Companies that combine high recovery efficiency with low fan power, clear fault indication, and straightforward commissioning are gaining traction in jurisdictions where testing and compliance requirements are becoming more stringent.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration leaves space for both consolidation and targeted fragmentation. Larger HVAC players may pursue acquisitions to fill geographic gaps, expand product lines, or acquire specialized engineering capabilities in cold-climate or demand-control ventilation. At the same time, niche entrants can thrive by serving specific climate zones, certification requirements, or application segments where standardized offerings fall short. New entrants from adjacent industries, including building automation and indoor air quality monitoring, may seek to bundle ventilation with sensing and control platforms, creating integrated solutions that address both air quality and energy performance. The likely outcome is a maturing landscape where scale advantages matter more, yet differentiated technical positioning remains a viable path to growth.
Future Trends and Commercial Opportunities
Trend 1: Code-Driven Standardization and Certification as a Competitive Moat
As more jurisdictions adopt ventilation requirements and acceptance testing protocols, compliance will become a baseline expectation rather than a differentiator. Products that demonstrate verified airflow, sensible recovery, and fan power performance will be preferred in bid processes and inspections. This trend favors manufacturers that invest in third-party certification, clear documentation, and repeatable commissioning procedures. Commercial opportunity lies in designing product families that can be configured to meet multiple regional standards without extensive custom engineering, reducing time-to-market and installation risk.
Trend 2: Integration of Ventilation with Smart Controls and IAQ Monitoring
The next phase of value creation will come from linking ventilation hardware with sensing, controls, and building management platforms. Demand-controlled ventilation, fault detection, and adaptive recovery strategies can optimize energy use while maintaining air quality targets. This convergence creates opportunities for bundled offerings that combine ventilation equipment with monitoring endpoints and control logic, appealing to homeowners who want visibility and to commercial operators who need centralized management. The risk is that integration complexity can raise costs and create dependency on software ecosystems, so interoperability and open communication pathways will be important to sustain adoption.
Trend 3: Climate-Specific Engineering and Regional Product Strategies
Climate diversity will continue to reward specialized engineering. Cold-climate HRV and ERV performance, humid-region latent load management, and mixed-climate flexibility will remain critical purchase criteria. Companies that maintain distinct product variants for key climate bands, rather than offering a one-size-fits-all lineup, are better positioned to capture regional demand without compromising performance. The associated opportunity is to build regional go-to-market strategies that pair the right product architecture with local installer training, warranty support, and code alignment. A potential risk is over-segmentation, which can inflate inventory and manufacturing complexity; disciplined platform design with modular options is the balance point.
Actionable Guidance for Decision Makers
For Manufacturers and Product Leaders
Prioritize platform strategies that allow climate-specific and code-specific variants to be derived from a common core. Invest in certified performance data, fault indication, and commissioning simplicity, as these features are increasingly tied to approval and installers' willingness to specify. Strengthen dealer and installer support, because in residential markets the installation ecosystem often determines repeat business and brand reputation. Evaluate where integration with HVAC platforms or smart controls adds genuine value versus where it introduces unnecessary complexity, and focus differentiation on the attributes that most directly affect compliance, energy performance, and reliability.
For Investors and Strategic Allocators
Look for companies with clear climate adaptation capabilities, credible certification footprints, and distribution relationships that can scale with code-driven demand. Favor business models that can expand revenue through add-on controls, maintenance services, or retrofit solutions, as these can improve lifetime value without requiring constant new construction volume. Monitor consolidation signals, particularly where larger HVAC portfolios seek to absorb specialized ventilation brands to broaden geographic reach or technical coverage. Be mindful of regulatory variability across regions, which can create uneven revenue trajectories even within a single national market.
For Procurement and Specification Teams
Specify ventilation systems with verified performance, clear fault indication, and documented compliance with relevant standards, rather than relying on nominal airflow claims. Evaluate total cost of ownership including installation complexity, commissioning requirements, and ongoing maintenance, since these factors often determine operational outcomes more than equipment price alone. Where possible, align product selection with regional code trajectories and climate conditions to avoid over-engineering in mild climates or under-specifying in extreme ones. Build relationships with installers and service providers early in the specification process to ensure that selected systems can be deployed and maintained effectively.
The whole-house ventilation system market is moving from optional specification to code-embedded infrastructure, with technological improvements, regulatory momentum, and demand-side expectations reinforcing one another. The firms and investors that understand these dynamics, and that align product strategy with regional requirements and performance verification, are best positioned to capture value as the market expands toward 2032 and beyond. For decision makers seeking detailed segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting report provides the granular analysis needed to translate these trends into concrete action plans.
Energy Recovery Ventilation System Market
For detailed analysis of this topic, please visit the official page: Whole-house Ventilation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Metallocene Catalyst Market
1. Market Landscape and Core Challenges
The metallocene catalyst market has entered a phase of structured expansion, characterized by steady revenue growth and broadening commercial adoption across polymer value chains. Valued at approximately 230.45 million USD in 2020, the sector has progressed to an estimated 302.45 million USD by 2025. Forward projections indicate continued momentum, with the market expected to approach 477.3 million USD by 2032, translating to a compound annual growth rate of 6.85 percent over the forecast horizon. This trajectory reflects a maturing technology base transitioning from specialized applications to mainstream polyolefin manufacturing, supported by performance advantages that conventional catalyst systems struggle to replicate.
Beneath the aggregate growth figures, the market exhibits notable structural characteristics. Concentration metrics indicate that the top three participants control roughly 58 percent of total revenue, while the top five firms account for approximately 68 percent. This distribution suggests a landscape where established players command significant commercial leverage, yet sufficient fragmentation remains to allow targeted disruption. The commercialization pathway for metallocene catalysts continues to balance performance differentiation against cost premium positioning, creating a market where technical capability and application engineering increasingly determine commercial success.
Key Challenges and Inflection Points
The first major challenge centers on cost-structure navigation amid raw material volatility. Metallocene catalysts carry an approximate cost premium of 30 to 40 percent relative to conventional Ziegler-Natta systems used in LLDPE production. This premium creates persistent pressure on converters and polymer producers to justify the incremental expense through demonstrable performance gains, such as enhanced film strength, improved processing efficiency, or downgauging potential. When upstream feedstock costs fluctuate or polymer pricing compresses, the economic calculus for catalyst selection becomes more stringent, forcing suppliers to continuously validate value propositions across diverse operating conditions.
The second inflection point involves regulatory-driven application shifts that reshape demand patterns. The European Union's Packaging and Packaging Waste Regulation mandates recyclable and mono-material packaging by 2030, while stricter environmental rules on single-use plastics compel converters to pursue recyclable monomaterial solutions. These policy frameworks directly influence catalyst demand by elevating the importance of precision chemistry capable of producing polyolefins with tailored rheological and mechanical profiles. Manufacturers that can align catalyst formulations with recyclability requirements and mono-material architecture stand to capture disproportionate demand growth, while those dependent on legacy application mixes face structural headwinds.
A third challenge emerges from regional price dynamics and competitive intensity. Recent market data from March 2026 shows that mLLDPE prices in Northeast Asia reached 1.19 USD per kilogram, reflecting a 2.5 percent downward movement driven by declining upstream ethylene and metallocene catalyst feedstock costs at key producing facilities. While lower input costs can improve margin flexibility, they also intensify price competition and compress differentiation opportunities. Suppliers must therefore manage the dual tension of benefiting from favorable cost environments while defending against commoditization pressures that erode the premium positioning historically associated with metallocene technology.
2. Key Drivers Shaping Market Dynamics
Technological Innovation and Performance Breakthroughs
Advancements in catalyst design and activation chemistry continue to expand the functional envelope of metallocene systems. Single-site metallocene catalysts enable tighter molecular weight distribution and controlled comonomer incorporation, which translates into polyethylene and polypropylene grades with superior film performance, higher extrusion rates, and the ability to produce thinner gauge materials without sacrificing mechanical integrity. Suppliers such as Univation Technologies have commercialized catalyst platforms supporting gas-phase single-site PE production that enable thinner films and higher throughput, demonstrating how catalyst innovation directly addresses converter economics. Similarly, W.R. Grace and Company supplies ActivCat® catalysts and custom-synthesized metallocenes tailored for activation in PE and PP platforms, while LyondellBasell Industries provides Avant single-site metallocene catalysts for specialty metallocene PP and PE products. These technology trajectories indicate that performance differentiation remains a primary engine of commercial adoption, particularly in applications where processing efficiency and end-use properties command premium pricing.
The evolution toward dinuclear metallocene architectures and customized ligand structures further broadens application scope. Nouryon custom-manufactures complex organics including ligands and metallocenes for single-site catalysts and other specialty chemicals, illustrating how upstream chemical synthesis capabilities complement catalyst commercialization. As manufacturers pursue grades optimized for specific film structures, packaging formats, and recycling compatibility, catalyst developers that can rapidly iterate formulations and translate laboratory advances into scalable production gain a strategic edge. This dynamic elevates the importance of R&D agility and application engineering support, shifting competitive advantage beyond raw catalyst performance toward integrated solution delivery.
Regulatory Environment and Sustainability Mandates
Policy frameworks are reshaping demand by imposing structural requirements on packaging and polymer end-use markets. The European Union's Packaging and Packaging Waste Regulation requires recyclable and mono-material packaging by 2030, creating a regulatory tailwind for polyolefins produced with metallocene catalysts that enable precise property control and compatibility with recycling streams. Stricter EU environmental regulations on single-use plastics further compel converters to seek recyclable monomaterial packaging solutions requiring metallocene catalyst precision chemistry. These mandates do not merely influence product specifications; they alter the economics of packaging design by rewarding material architectures that simplify recycling, reduce multi-layer complexity, and maintain performance with mono-material constructions. Catalyst suppliers positioned to support such architectures benefit from a regulatory-driven demand shift that is both durable and geographically concentrated in advanced markets, though its influence increasingly spreads as other jurisdictions adopt similar packaging circularity objectives.
Metallocene Polyethylene Market
The regulatory dimension also interacts with cost dynamics. As converters invest in recyclable solutions, they become more willing to absorb catalyst premiums when the resulting polymer grades enable compliance and preserve functionality. However, this willingness is conditional on clear performance validation and total cost-of-ownership analysis. Suppliers must therefore articulate how metallocene-enabled grades reduce downstream processing costs, support downgauging, or enable recycling-friendly structures, linking catalyst selection to broader sustainability and cost objectives rather than presenting it as an isolated material upgrade.
Demand-Side Shifts in Consumer and Industrial Behavior
End-market demand patterns are increasingly shaped by packaging efficiency, film performance expectations, and sustainability commitments. The launch of new metallocene PE grades illustrates how demand-side priorities translate into product commercialization. In October 2024, TotalEnergies SE launched the Advanced Supertough 12AST05 VLLDPE grade for film and packaging applications, targeting performance attributes that align with converter needs for toughness, sealability, and process reliability. Such product introductions reflect broader trends in which film and packaging manufacturers prioritize materials that support thinner gauges, improved mechanical properties, and compatibility with high-speed converting lines. As consumer brands pursue packaging lightweighting and recyclability goals, demand for polyolefins with tailored properties rises, indirectly strengthening the role of metallocene catalysts in grade development.
Industrial behavior also shifts as producers seek to optimize extrusion throughput and reduce energy intensity. Catalysts that support higher extrusion rates and consistent polymer quality help manufacturers increase line efficiency and reduce per-unit processing costs. When these operational benefits align with product performance gains, the adoption case for metallocene catalysts strengthens across both commodity and specialty segments. This dual benefit—processing efficiency plus end-use performance—makes catalyst selection increasingly strategic, as it affects not only material properties but also production economics and capacity utilization.
Supply Chain and Cost Structure Dynamics
Cost structures in the metallocene catalyst market are influenced by feedstock availability, upstream chemical pricing, and regional production economics. The March 2026 observation that Northeast Asia mLLDPE prices declined amid falling upstream ethylene and catalyst feedstock costs highlights how input-cost movements cascade through the value chain. Lower feedstock expenses can ease margin pressure for polymer producers and, by extension, improve the affordability of catalyst-driven grade upgrades. Yet the same environment can also intensify competition, as lower costs reduce the financial barrier to adopting alternative technologies or increasing output with conventional systems.
Supply chain resilience further shapes commercial strategy. Catalyst manufacturers that maintain reliable access to precursor chemicals, ligand synthesis capacity, and activation support services are better positioned to sustain supply continuity and respond to customer-specific grade requirements. Companies such as Chevron Phillips Chemical, which supplies metallocene catalysts for ethylene polymerization, and Asia-based producers including Mitsui Chemicals, Ube Industries, Prime Polymer, Zibo Xinsu Chemical, Daelim Industrial, SK Chemicals, and Mitsubishi Chemical, reflect a diversified production base spanning multiple geographies and application segments. This geographic breadth supports regional supply security and enables manufacturers to tailor offerings to local demand conditions, though it also requires coordinated management of technology transfer, quality consistency, and customer support across markets.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive field combines global specialty chemical firms, integrated polymer producers, and regional catalyst manufacturers, each pursuing distinct positioning strategies. Univation Technologies, headquartered in Houston, Texas, offers the XCAT™ metallocene catalyst portfolio for gas-phase single-site PE production, with a value proposition centered on enabling thinner films and higher extrusion rates. Its selection by Indian Oil Corporation Ltd. in September 2024 for a world-scale PE production line at Paradip, India, underscores how catalyst suppliers can secure landmark deployments that validate technology credibility and expand reference bases in high-growth markets. Such wins are strategically significant because they combine large-scale commercial proof with regional market entry, creating a template for subsequent adoption in adjacent geographies and applications.
W.R. Grace and Company, based in Columbia, Maryland, emphasizes activation chemistry through ActivCat® catalysts and custom-synthesized metallocenes designed to optimize single-site catalyst performance in PE and PP platforms. This approach highlights a strategic focus on the enabling chemistry layer rather than solely on final polymer grades, allowing Grace to serve as a critical partner in catalyst system design and activation optimization. LyondellBasell Industries, headquartered in Rotterdam, Netherlands, provides Avant single-site metallocene catalysts for specialty metallocene PP and PE products, aligning catalyst offerings with high-value specialty applications where property precision commands premium economics. Nouryon, also based in Arnhem, Netherlands, custom-manufactures complex organics including ligands and metallocenes, positioning within the upstream synthesis segment that supports catalyst developers and specialty chemical programs.
In the Asia-Pacific region, several firms have built substantial capabilities. Mitsui Chemicals, Ube Industries, Prime Polymer, and Mitsubishi Chemical each develop and supply metallocene catalysts for olefin polymerization and polyolefin applications, while Zibo Xinsu Chemical manufactures catalysts for industrial polyolefin applications in China. South Korean participants include Daelim Industrial and SK Chemicals, which provide metallocene catalysts for polymer and polyolefin resin production. Chevron Phillips Chemical, headquartered in The Woodlands, Texas, supplies metallocene catalysts for ethylene polymerization, reinforcing the presence of large integrated chemical companies in the catalyst supply chain. This multi-venue competitive structure means that technology leadership, scale, and regional proximity all influence commercial outcomes, and no single positioning dominates across all application segments.
Differentiation Advantages and Commercial Logic
Differentiation in this market typically rests on a combination of performance precision, application support, and scale economics. Leading suppliers distinguish themselves by delivering catalyst systems that produce consistent polymer properties across production scales, reducing variability and supporting customer quality targets. Equally important is the ability to provide grade-specific guidance, processing recommendations, and troubleshooting support, which transforms catalyst sales from a commodity transaction into a solution relationship. Companies that integrate ligand synthesis, catalyst activation, and application engineering can shorten development cycles for new grades and improve customer retention by embedding themselves in the customer's product development workflow.
Scale and supply reliability constitute another differentiation axis. Large-volume producers benefit from manufacturing efficiency and the ability to support world-scale projects, while regional manufacturers can compete on responsiveness, localized technical service, and cost structures aligned with local feedstock conditions. The market's concentration pattern indicates that scale advantages matter, but they do not automatically determine outcomes, because application-specific performance requirements and regulatory-driven grade demands create niches where tailored solutions outperform generic offerings. As a result, competitive success increasingly depends on aligning catalyst capabilities with the precise requirements of target applications rather than competing on broad specification statements alone.
Evolution of Market Structure
The market is evolving through a combination of consolidation pressure, regional capability expansion, and selective new-entry activity. Existing leaders maintain advantage through established customer relationships, proven large-scale deployments, and integrated technical services. At the same time, regional producers continue to strengthen presence in Asia and other growth markets, where expanding polymer capacity and local content preferences create demand for domestic catalyst supply. New entrants and niche specialists can gain traction by targeting specific application segments, such as recyclable packaging grades or specialty film formulations, where precision chemistry and rapid customization deliver disproportionate value. This dynamic suggests a landscape that is neither fully consolidated nor highly fragmented, but rather stratified into tiers defined by scale, application focus, and regional reach.
PW Consulting
Over the forecast period, the structure is likely to tilt toward stronger coordination between catalyst suppliers and polymer producers as grade development becomes more intertwined with regulatory compliance and sustainability targets. Partnerships, technology licensing, and integrated project commitments may become more common, particularly in large-scale capacity expansions where catalyst selection influences both product economics and long-term competitiveness. The result is a market in which strategic alignment and solution orientation matter as much as baseline catalyst performance.
4. Future Trends and Commercial Implications
Trend One: Sustainability-Linked Grade Development as a Growth Catalyst
Over the next three to five years, regulatory mandates and brand owner commitments are expected to accelerate demand for polyolefin grades designed for recyclability and mono-material packaging architectures. Metallocene catalysts that enable precise property control will play a central role in this shift, because they support the rheological and mechanical characteristics required for downgauging, seal performance, and compatibility with recycling streams. Commercial opportunity lies in developing grade families that explicitly address recyclable packaging requirements, supported by documentation and testing that demonstrate compliance and performance. Suppliers that build sustainability-aligned product portfolios can secure longer-term demand visibility and differentiate from competitors reliant on conventional specification competition. The primary risk is regulatory variation across regions, which can create uneven adoption patterns and require flexible product strategies rather than a single global grade architecture.
Trend Two: Processing Efficiency and Throughput Optimization
A second trend centers on the economic appeal of catalysts that improve extrusion throughput, reduce energy intensity, and enable consistent quality at high line speeds. As polymer producers seek to optimize capacity utilization and lower operating costs, catalyst systems that support higher extrusion rates and stable process windows gain strategic relevance. This trend benefits both commodity and specialty segments, but the strongest opportunity emerges where processing gains can be quantified and linked to total cost reduction. Companies that can demonstrate measurable efficiency improvements through catalyst selection are better positioned to justify premium pricing and expand share in cost-sensitive environments. A related uncertainty is that cost compression in upstream feedstocks can shift attention toward short-term price competition, temporarily weakening the emphasis on performance-driven procurement unless suppliers maintain robust efficiency evidence and application support.
Trend Three: Regionalization of Supply and Application Expertise
The third trend involves increasing regionalization of catalyst supply and technical service, driven by expanding production capacity in Asia and other growth markets, as well as by customer preferences for localized support. Regional manufacturers are likely to deepen capabilities in ligand synthesis, catalyst formulation, and application engineering, while global players will continue to leverage scale and broad technology portfolios. This dual structure creates opportunities for suppliers that can combine global technology credibility with regional responsiveness, particularly in large-scale projects and custom grade development. The commercial implication is that proximity to customer operations, rapid iteration on grade requirements, and strong local technical teams become competitive differentiators. The risk is that regional fragmentation can complicate quality consistency and technology transfer, making supply chain governance and standardized development processes essential for maintaining trust across markets.
5. Strategic Actions for Decision-Makers
For Polymer Manufacturers and Catalyst Users
Manufacturers should evaluate catalyst selection through a total value lens that combines product performance, processing efficiency, and compliance alignment rather than focusing solely on unit cost. Quantifying how metallocene-enabled grades support downgauging, line speed increases, or recyclable packaging structures can clarify the economic case and reduce the perceived burden of the catalyst premium. Building internal capability to test and validate new grades against specific application targets will accelerate adoption of performance-advantaged materials. Where large-scale capacity expansions are planned, engaging catalyst suppliers early in process design and grade definition can improve integration and reduce downstream rework. Timely access to detailed segmentation data, regional pricing dynamics, and competitor capability profiles supports more precise sourcing and product planning decisions.
Worldwide Metallocene Based Polyethylene Market
For Investors and Strategic Planners
Investors should monitor demand shifts tied to packaging regulation, recyclability requirements, and regional capacity additions, because these forces shape the pace and location of catalyst demand growth. Evaluating potential investments or partnerships requires attention to technology differentiation, application engineering strength, and the ability to secure landmark deployments that validate scale and reliability. Companies with strong positions in single-site activation chemistry, ligand synthesis, or specialty grade development may present attractive exposure to higher-value segments, while regional producers with growing technical service capabilities can offer growth optionality in expanding markets. Understanding concentration dynamics and recent commercial milestones helps assess which players are gaining momentum versus those facing pressure from cost competition or slower application adoption.
For Procurement and Supply Chain Leaders
Procurement teams should balance cost objectives with supply resilience and technical support quality, recognizing that catalyst performance variability can affect downstream polymer consistency and production efficiency. Diversifying supplier relationships across global and regional sources can mitigate concentration risk while preserving access to specialized grades. Establishing clear performance criteria, qualification protocols, and cost-totalization frameworks enables more disciplined evaluation of premium catalyst options. Tracking upstream feedstock price movements and regional polymer price trends provides early warning of shifts in cost pressure and competitive intensity, helping procurement calibrate negotiation strategy and inventory timing. Access to current market data and forward indicators strengthens the ability to anticipate supply conditions and align procurement plans with evolving demand requirements.
The metallocene catalyst market is moving toward a more performance-and-compliance-driven competitive environment, where technological precision, application alignment, and regional responsiveness determine commercial outcomes. Decision-makers who integrate catalyst strategy into broader product, cost, and sustainability objectives will be better positioned to capture the value created by this transition. For those seeking deeper segmentation detail, regional breakdowns, and customized strategic recommendations, the full research report provides more granular data and tailored analysis to support specific business decisions.
For detailed analysis of this topic, please visit the official page: Metallocene Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Educational Toys Market: Why 8.47% CAGR and STEM Demand Redefine Growth Strategy
By PW Consulting, 2026-09-21
Navigating the Educational Toys Market: Strategic Trends and Opportunities Through 2032
The educational toys market has transitioned from a niche segment within the broader play industry to a strategic battleground where learning outcomes, developmental science, and consumer purchasing behavior intersect. Market sizing data places the sector at approximately 24.85 billion USD in 2024, reaching an estimated 27.24 billion USD in 2025, with a projected trajectory toward 48.23 billion USD by 2032. The compound annual growth rate across the 2026–2032 forecast window sits at 8.47 percent, signaling a steady but accelerating expansion that outpaces many traditional toy categories. This growth is not merely a function of population expansion; it reflects a structural shift in how parents, educators, and institutions define the value of play. Toys are increasingly evaluated through the lens of skill development, cognitive engagement, and alignment with early learning frameworks rather than pure entertainment appeal. For commercial players, this reframing creates both opportunity and complexity, as the market rewards differentiation and penalizes commoditization.
Several structural inflection points are reshaping how the educational toys sector evolves. First, the convergence of digital interactivity and tactile play has blurred category boundaries. Products that once fell neatly into arts, games, or motor skills categories now routinely blend physical manipulation with screen-informed feedback or app-supported scaffolding. This hybridization challenges traditional product segmentation and forces companies to reconsider how they position, bundle, and distribute offerings. Second, regulatory tightening around safety and traceability is introducing new compliance costs and design constraints. Rules targeting material hazards, electronic component certifications, and digital product documentation are reshaping development timelines and increasing the cost of non-compliance. Third, the market is maturing in a way that makes pure price competition less viable for long-term value creation. Retail channels and procurement teams are paying closer attention to learning efficacy, developmental appropriateness, and brand reputation, which elevates the importance of credible educational positioning over generic toy attributes.
Key Drivers Shaping Market Direction
Technology Innovation and the Hybrid Play Opportunity
Technology remains one of the most decisive forces shaping the educational toys landscape. Advances in low-cost sensors, durable electronic components, and interactive software have enabled manufacturers to embed guided learning mechanics into physical products without sacrificing the hands-on engagement that defines high-quality play. The result is a growing class of products that combine construction, movement, music, or puzzle-solving with feedback loops that adapt to a child's pace or learning goals. Recent product activity illustrates this direction. In January 2026, LEGO Education launched new STEM sets for children aged seven and above designed to encourage curiosity, experimentation, and scientific discovery. Earlier, in October 2025, STEMPlay Labs introduced Wonder Briks and PictoMath, patent-pending construction bricks and math tools aimed at embedding STEM learning into tactile play. May 2025 saw LeapFrog showcase updated educational concepts at Toy Fair, including the Strum & Count Wooden Guitar, signaling renewed interest in combining music and early numeracy through physical interaction. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational lines for children ages 1 through 13, reflecting a broader industry push to align product complexity with developmental stages. These moves point toward a market where interactivity and educational scaffolding are increasingly expected, not optional.
Regulatory and Compliance Shifts as Strategic Factors
Regulatory change is no longer a back-office concern for educational toy companies; it is a strategic variable affecting product roadmaps, sourcing decisions, and market entry timing. In December 2025, the U.S. Consumer Product Safety Commission published its final rule on the Safety Standard for Toys, with specific requirements for water beads, effective March 12, 2026. The rule codifies requirements directly into 16 CFR Part 1250 rather than amending ASTM F963, creating a more prescriptive compliance pathway. Around the same time, the European Union published Toy Safety Regulation 2025/2509 on December 12, 2025, entering into force on January 1, 2026 and applying fully on August 1, 2030. Notably, the new EU framework introduces a digital product passport requirement for all toys, enhancing traceability and compliance documentation across the product lifecycle. These developments matter commercially because they raise the bar for product documentation, material disclosure, and hazard testing, especially for electronics, small components, and age-differentiated lines. Companies that treat compliance as a design input rather than a late-stage checkpoint are better positioned to reduce rework, protect brand reputation, and avoid recalls or enforcement actions.
Demand-Side Shifts in Parent and Educator Expectations
Consumer behavior is evolving in ways that increase the value of products perceived as developmentally useful. Parents and caregivers are more aware of early cognitive, motor, and social-emotional milestones, and they often evaluate toys as tools that support those outcomes. At the same time, educators and institutional buyers continue to look for resources that complement classroom objectives, especially in science, mathematics, and problem-solving. This dual pull has expanded the relevance of products that bridge home play and structured learning. It also raises expectations for age differentiation, clear instructional support, and durable design. Demand is less about novelty alone and more about sustained engagement that can justify repeated use and recommendation within parent networks, schools, and care settings. For manufacturers, this means that educational credibility, not just packaging claims, increasingly influences purchase decisions and repurchase behavior.
Supply Chain and Cost Structure Pressures
Cost dynamics continue to shape commercial strategy, particularly for products that combine electronics, plastics, wood, and packaging. Material price variability, component sourcing, and logistics overhead affect margin resilience, especially for companies managing broad SKU portfolios or launching multiple age-specific variants. At the same time, regulatory requirements can increase testing, documentation, and quality assurance expenses. The net effect is that cost efficiency must be pursued without eroding the tactile and learning qualities that distinguish educational toys from generic alternatives. Companies that standardize platforms, modularize features, or streamline compliance documentation can protect margins while still offering differentiated products. This is especially relevant for category leaders with global footprints, where scale advantages must be paired with disciplined product architecture to avoid complexity-driven cost creep.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Differentiating Playbooks
The competitive field in educational toys is broad and varied, including large multinational toy companies, electronics specialists, construction-focused brands, and niche learning tool providers. Several established players define much of the category's direction through scale, brand recognition, and educational positioning. Mattel continues to offer a wide range of educational toys including construction sets, STEM learning products, and interactive play items, leveraging broad brand reach and distribution. LEGO System A/S and The LEGO Group remain closely associated with construction-based educational toys and STEM sets designed for scientific discovery and creativity, with products spanning early builders and older age groups. Hasbro contributes educational games, role-playing sets, and STEM-oriented toys for skill development, often bridging play patterns with learning outcomes. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development, while LeapFrog focuses on interactive electronic learning toys and books that combine technology with early education. Ravensburger offers wooden puzzles, board games, and STEM building sets for cognitive development, and Melissa & Doug specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers. Tomy develops educational construction toys, robotics, and STEM learning products, while Spin Master provides STEM and interactive educational toys, including licensed educational lines. MindWare emphasizes hands-on learning tools and manipulatives for science, math, and critical thinking. JAKKS Pacific manufactures educational electronic toys and interactive STEM products, and Osmo offers interactive tablet-based educational games and learning kits for ages 3 through 11.
These companies are not competing on the same dimension. Some win through brand equity, platform scale, and retail presence. Others differentiate through age-specific developmental framing, hybrid digital-physical experiences, or specialized learning content. The strategic advantage increasingly belongs to players that can connect product design to clear developmental outcomes while maintaining manufacturing discipline and compliance readiness. Recent activity shows how this differentiation is emerging in practice. The January 2026 STEM sets from LEGO Education target scientific curiosity for older children, while the 2026 expansion by Smart Kids Planet shows a deliberate push to cover ages 1 through 13 with age-appropriate STEM and educational lines. Meanwhile, the March 2026 recall by ZMC Group involving multiple light-up toys due to battery ingestion hazards serves as a reminder that safety failures can quickly undermine brand trust and commercial momentum. In a market where confidence in educational claims and product safety both matter, reputation management is inseparable from product strategy.
Educational Furniture Market
The structure of the competitive field appears to be moving along two simultaneous paths. On one hand, consolidation pressure exists where scale players can absorb compliance costs, extend distribution, and cross-sell across categories. On the other hand, fragmentation remains viable for specialists offering targeted age ranges, pedagogical framing, or unique material and play experiences. New entrants and smaller innovators are actively exploring patent-protected mechanisms, tablet-integrated kits, and construction-based math and science tools, suggesting that innovation is not confined to the largest players. For commercial leaders, the key strategic question is whether to compete through breadth and distribution, through deep category specialization, or through hybrid design that combines tactile play with guided learning features. Each path carries different margin profiles, compliance burdens, and go-to-market requirements.
Forward-Looking Trends and Commercial Implications
Looking across current market dynamics and recent product and regulatory activity, a few trends are likely to define the next three to five years. First, hybrid learning play will continue to expand as a mainstream expectation. Products that integrate construction, puzzle-solving, motor skill development, or musical interaction with structured learning feedback will be better positioned to capture demand from both home and school-adjacent buyers. The commercial opportunity lies in designing modular learning experiences that can scale across age groups without becoming overly complex or costly to manufacture and document.
Second, age-tiered product architecture will become more important as parents and educators seek developmentally appropriate options. The move toward lines that span early childhood through pre-teen years, as reflected in recent expansions, indicates that buyers value progression paths rather than one-off products. Companies that can map product complexity, safety requirements, and learning objectives to clear age brackets are likely to gain shelf and channel relevance. The risk is portfolio bloat: too many overlapping SKUs can dilute focus, increase compliance burden, and complicate inventory management.
Third, compliance and traceability will increasingly shape competitive readiness. The digital product passport direction in the EU and the tighter U.S. rules on specific hazards demonstrate that documentation and material control are becoming part of product competitiveness. Firms that invest early in traceability systems, standardized testing protocols, and clear hazard controls will have stronger launch velocity and lower exposure to enforcement or recall risk. The uncertainty here lies in how quickly full compliance timelines are enforced across regions and how retailers and procurement teams integrate these requirements into vendor evaluation.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to treat educational value and compliance as integrated design constraints rather than separate workstreams. Build product platforms that can support multiple learning objectives and age ranges without inflating SKU complexity. Where electronics or small components are involved, design hazard controls and documentation into the development process from the outset. Consider whether the brand should compete through breadth, specialized age segments, or hybrid interactive play, and ensure that product architecture, sourcing, and distribution are aligned with that choice.
For investors, the market's 8.47 percent CAGR and projected scale expansion toward the end of the decade suggest durable growth, but value capture will depend on execution quality. The strongest opportunities are likely in companies that can demonstrate clear developmental positioning, disciplined compliance readiness, and efficient product platforms. Due diligence should evaluate not only revenue momentum but also portfolio complexity, regulation exposure, safety track record, and the credibility of educational claims. Companies with repeated safety or compliance issues may face disproportionate reputational and commercial costs in a market where trust is a differentiating asset.
Education Software Market
For procurement teams and retail buyers, the emphasis should be on differentiating educational toys through learning support, age appropriateness, and safety documentation rather than price alone. Products that offer clear developmental progression and dependable compliance records are better suited to long-term shelf performance and parent trust. Evaluate supplier capabilities for traceability, testing, and post-launch support, since these factors increasingly influence channel and consumer confidence. Align category decisions with the expectation that educational toys are judged on sustained engagement and credible learning benefits, not short-lived novelty.
For leaders seeking to move faster with more granular visibility, detailed segmentation data, regional performance, and company-specific benchmarking can materially improve planning confidence. The broader trends are clear, but the execution advantages often come from subsegment insight: which age ranges are expanding most rapidly, where hybrid-versus-tactile trade-offs are shifting, and how compliance costs vary by product design and region. A complete research report can provide that depth, including detailed market splits, competitive positioning maps, and scenario-ready forecasts to support product, investment, and purchasing decisions.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Lithium-Ion Battery Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The lithium-ion battery sector has transitioned from a cyclical growth story to a structurally transformative market. Over the past half-decade, the industry has compounded at a pace that defies traditional hardware cycles, driven by the simultaneous electrification of transport and the scaling of stationary storage. As the trajectory extends through the late 2020s and into the next decade, the market is no longer defined by a single technology or application vertical. Instead, it is being reshaped by chemistry diversification, geographic manufacturing realignments, and a tightening regulatory and logistics framework. For executives and investors, the central question has shifted from whether demand will grow to where value will accrue, which chemistries will dominate specific use cases, and how supply chains will adapt to new constraints.
Market Snapshot and Core Challenges
The market has expanded from roughly $184 billion in 2020 to an estimated $326 billion in 2025, with a projected compound annual growth rate of approximately 17.5 percent through 2032. This pace places lithium-ion batteries among the fastest-growing industrial segments globally, underpinned by sustained capital allocation across automotive original equipment manufacturers, utility-scale storage developers, and industrial users. The growth trajectory is broad-based, but it is not uniform. Value creation is increasingly concentrated, and the competitive and operational landscape is becoming more complex as the industry matures.
One of the defining structural features of the current market is a high degree of concentration among leading suppliers. The top three participants account for more than 60 percent of industry revenue, and the top five collectively control a clear majority of market share. This concentration reflects the scale economics of cell manufacturing, the capital intensity of gigafactory construction, and the advantage that integrated players hold in securing supply agreements and industrializing new form factors. For downstream buyers and new entrants, the implication is clear: pricing power, technology roadmaps, and long-term contract availability are increasingly shaped by a small group of incumbents with vertically aligned operations and broad manufacturing footprints.
Lithium-Ion Battery Separator Market
At the same time, the market faces a set of interconnected challenges that will determine the shape of the next growth phase:
Chemistry Fragmentation and Application Fit
The market is no longer a single-technology story. High-nickel NMC formats remain central to premium and performance-oriented electric vehicles, while LFP chemistry has gained substantial traction where cost, safety, and cycle life are prioritized. Other chemistries occupy narrower but strategically important niches, including industrial equipment, specialty consumer devices, and applications that demand fast charging or extreme thermal tolerance. The challenge for manufacturers and buyers is that chemistry selection now carries long-term implications for pack design, thermal management, procurement strategy, and end-of-life handling. As form factors such as cylindrical and prismatic cells continue to evolve, the alignment between cell architecture and application requirements has become a critical source of differentiation rather than a commodity decision.
Raw Material Volatility and Supply Discipline
Demand-side strength continues to put pressure on upstream inputs. Global lithium production expanded significantly in 2025, reflecting sustained appetite from battery manufacturing, yet pricing dynamics remain sensitive to regional imbalances, refining capacity, and the pace of new project commissioning. Battery-grade lithium carbonate spot prices in China rose over the course of the year, illustrating how even in a production-up cycle, short-term availability and logistics can create cost uncertainty. The broader lesson for commercial teams is that raw material availability is no longer a binary supply question; it is a portfolio management problem involving long-term offtake, geographic diversification, recycling pathways, and chemistry mix decisions that influence metal intensity.
Regulatory and Logistics Tightening
The operational environment is also becoming more regulated in ways that directly affect product design, transport, and deployment. New air transport requirements now limit the state of charge for lithium-ion batteries packed with equipment or vehicles to no more than 30 percent of rated capacity, a change that affects logistics planning, inventory management, and cross-border supply chains. Meanwhile, formal standards for advanced battery development are taking shape in major markets, including the establishment of a national framework in China aimed at accelerating safety, energy density, and commercialization of next-generation cells. These developments are not peripheral; they shape time-to-market, testing requirements, and the cost of compliance for manufacturers and integrators operating across jurisdictions.
Key Growth Drivers Reshaping the Market
The growth trajectory is being propelled by a combination of technology momentum, policy direction, demand-side behavior, and supply chain restructuring. Understanding how these forces interact is essential for identifying where commercial advantage can be captured.
Technology Innovation and Form Factor Evolution
Battery performance and manufacturability are advancing through both chemistry refinement and physical design. High-nickel cathode formulations continue to support energy density goals for vehicles where range and power remain decisive purchase factors. At the same time, LFP-based solutions have broadened the addressable market by offering compelling cost and safety profiles, especially in mass-market vehicles, commercial fleets, and stationary storage. A parallel shift is the acceleration of cylindrical and prismatic cell development, including next-generation cell formats that enable higher packaging efficiency and improved manufacturing throughput. Recent product and partnership activity reflects this focus on the intersection of chemistry and engineering: a major Korean supplier partnered to develop next-generation pack technologies using 46-series cylindrical cells, signaling that formatting choices are now central to performance, cost, and scaling strategy.
Solid-state and advanced electrolyte technologies are also moving from laboratory promise toward structured commercialization pathways. With formal development standards now in effect in China for solid-state batteries, the industry is entering a phase where pilot production, safety qualification, and manufacturing readiness will matter as much as cell-level performance. For companies across the value chain, the opportunity is not simply to chase headline energy density numbers, but to align development with the application requirements, qualification timelines, and cost structures that determine whether new chemistry can scale.
Policy and Regulatory Tailwinds with New Constraints
Policy support remains a powerful accelerant, especially where electrification targets, emissions mandates, and storage deployment goals are tied to infrastructure investment and industrial strategy. At the same time, the regulatory environment is becoming more detailed and operationally specific. The introduction of stricter transport state-of-charge limits is a concrete example: it influences how inventory is handled, how cross-border shipments are planned, and how products are staged for deployment. In parallel, standards development for next-generation cells introduces both a pathway to market acceptance and a compliance burden that will distinguish companies with mature quality systems from those still building them. The broader takeaway is that policy is no longer only a demand-side catalyst; it increasingly shapes product design, logistics, and certification strategy.
Demand-Side Shifts Across Automotive and Storage
Automotive electrification continues to anchor the market, but the demand story is broadening. Utility-scale and commercial battery energy storage is expanding as grid operators, developers, and industrial users seek flexibility, resilience, and capacity optimization. Recent commercial activity underscores this diversification: a major battery supplier signed an agreement for gigawatt-hour-scale battery energy storage systems, reflecting the growing institutionalization of storage procurement. At the same time, industrial and specialty applications are creating demand for batteries that balance energy density, durability, and safety in environments where consumer-electronics assumptions no longer apply. This fragmentation of demand means that product strategy cannot be one-size-fits-all; value creation increasingly depends on matching cell and pack characteristics to the operating profile of the end use.
Supply Chain Restructuring and Cost Strategy
The manufacturing map is being redrawn. Capacity expansion is accelerating in multiple regions, with new automotive-oriented production lines coming online and aiming for substantial annual output. One notable example is the commencement of mass production at a new North American automotive battery factory targeting a high annual gigawatt-hour capacity. Such expansions illustrate a broader trend: localization of supply, tighter integration with vehicle programs, and a strategic emphasis on securing manufacturing scale in key end markets. At the same time, companies are refining cost structures through vertical integration, material sourcing strategies, and engineering choices that reduce sensitivity to volatile inputs. The interaction between capacity timing, utilization rates, and raw material dynamics will be a defining factor in margin trajectories over the coming years.
Competitive Landscape and Leading Strategies
The competitive field is shaped by a group of large, well-capitalized manufacturers with differentiated positioning across chemistry, form factor, integration depth, and geography. Rather than competing solely on price, leading players are building advantage through combinations of scale, technological focus, and customer integration.
Strategic Positioning of Core Players
CATL remains a central force in lithium-ion cell manufacturing for electric vehicles and energy storage, with an integrated model that spans materials through systems. Its scale and breadth give it leverage in securing demand, industrializing new form factors, and shaping volume pricing dynamics. BYD has built a distinctive position around LFP-focused solutions, emphasizing safety and long lifespan across vehicles, storage, and industrial applications. Its Blade battery approach reflects a strategy that ties cell design to practical deployment benefits, not just performance specifications. LG Energy Solution operates as a global supplier of high-energy cylindrical and pouch cells for automotive and storage, using a broad customer base and multiple form factors to adapt to differing vehicle and system requirements. Samsung SDI develops lithium-ion batteries across EVs, stationary storage, and consumer electronics, and has advanced prototypes that point toward future chemistry pathways, giving it optionality in next-generation segments. Panasonic Energy continues to specialize in cylindrical cells for automotive use, with manufacturing expansion in North America reinforcing its alignment with regional vehicle production. SK On focuses on high-nickel NCM cells for EVs and plug-in hybrids, positioning around energy density for applications where range and performance remain priorities. Envision AESC concentrates on high-performance prismatic cells for vehicles and storage, offering an engineering-led approach to application-specific requirements. EVE Energy and Gotion High-Tech both serve the demand for prismatic and cylindrical LFP and NCM cells, with Gotion also extending into enclosed storage systems that target high energy density for utility and commercial deployments.
PW Consulting Chemical & Energy Research Center
Recent Developments as Strategic Signals
Recent corporate activity provides a window into how these strategies are being executed. A storage contract for gigawatt-hour-scale systems highlights the institutionalization of energy storage procurement and the importance of reliable supply commitments for large projects. The unveiling of a high-capacity enclosed storage system points to the push for higher energy density in stationary applications, where footprint, integration, and system-level performance increasingly matter. A partnership to develop next-generation pack technologies using advanced cylindrical cells signals the growing importance of cell format and pack engineering as sources of differentiation. And the start of mass production at a new North American factory illustrates the strategic priority of localized capacity for automotive customers, reducing logistics exposure and supporting regional supply objectives. Taken together, these moves show an industry that is investing not only in volume, but in product specificity, system integration, and geographic alignment with demand.
Market Evolution: Consolidation, Differentiation, and Selective Entry
The industry is likely to continue evolving along three tracks. First, scale and integration will keep rewarding incumbents with the capital and operational capability to sustain high utilization and broad customer coverage. Second, differentiation will intensify as chemistries and form factors are matched more precisely to end-use requirements, making product strategy and application engineering more valuable than generic volume positioning. Third, selective new entry will remain possible in focused niches, particularly where a company can secure a distinct chemistry advantage, a strong application relationship, or a regional manufacturing advantage. The practical effect for buyers and investors is that competitive advantage is increasingly found in the alignment of technology, application, and supply chain geography rather than in cell production alone.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape where value is created and where exposure needs to be managed.
Broader Chemistry and Form Factor Rationalization
The market will continue to diversify in the near term, but commercial winners will increasingly be those that can operate across chemistries and formats with clear application focus. LFP is expected to maintain strong relevance in cost-sensitive vehicles and storage, while high-nickel and advanced cylindrical formats remain important where energy density and packaging efficiency matter. Commercial opportunities will arise for companies that can offer flexible sourcing, adaptable pack designs, and credible qualification pathways across multiple chemistries without sacrificing cost discipline. The risk is overexposure to any single chemistry or form factor if demand mix shifts faster than expected.
Storage as a Structural Demand Pillar
Energy storage is increasingly becoming a second anchor for demand growth alongside automotive. As project pipelines mature and procurement becomes more institutionalized, suppliers that can deliver reliable capacity, system-level integration, and predictable lead times will have an advantage. Opportunities include long-term supply agreements, storage-optimized product offerings, and partnerships that connect cell supply with project development and deployment. The uncertainty lies in the pace of grid-related policy implementation, financing conditions for large projects, and the timing of capacity additions relative to demand.
Next-Generation Readiness and Standards-Driven Commercialization
Advanced battery development is moving toward structured commercialization, with standards and pilot production creating a clearer path to market acceptance. Companies that can navigate safety qualification, manufacturing readiness, and application-specific validation will be better positioned to capture value when new technologies reach commercial scale. At the same time, the same standards and logistics changes that enable commercialization can raise the bar for entry and operating complexity. The strategic opportunity is to prepare now for qualification, testing, and supply chain adaptation, rather than waiting for technology maturity to create urgency.
Strategic Actions for Decision-Makers
Different roles in the market face different priorities, but several practical actions apply across the board.
Lithium-ion Battery Recycling Market
For Manufacturers and Technology Developers
- Align chemistry and form factor roadmaps to application requirements rather than generic performance targets, and invest in the engineering and qualification capabilities that make multi-chemistry flexibility commercially viable.
- Treat supply chain resilience as a design input, including long-term material agreements, geographic diversification, and recycling or recovery pathways that reduce exposure to input volatility.
- Prepare operational and compliance capabilities for evolving standards and transport rules now, since these factors increasingly influence time-to-market and deployment logistics.
For Investors and Strategic Capital Allocators
- Focus on the intersection of scale, application fit, and supply alignment when evaluating opportunities, since value creation is increasingly tied to execution across these dimensions rather than to volume alone.
- Track capacity timing and utilization as leading indicators of margin risk, especially where new factories and demand growth are not perfectly synchronized.
- Watch for differentiated positioning in storage and advanced cell formats, where system-level integration and application-specific engineering can create stronger moats than generic cell supply.
For Procurement, OEM, and Deployment Teams
- Diversify sourcing strategies across chemistries and suppliers where feasible, and structure agreements to balance cost, availability, and qualification requirements for the intended application.
- Integrate logistics and compliance constraints, including transport state-of-charge requirements, into inventory and deployment planning rather than treating them as afterthoughts.
- Prioritize suppliers with clear application engineering support and proven system-integration capability, since these attributes increasingly affect project outcomes and total cost of ownership.
The lithium-ion battery market is entering a phase where success depends less on riding a single growth wave and more on navigating a complex set of technology, application, supply, and regulatory choices. For decision-makers who need segmented forecasts, competitive benchmarking, and tailored sourcing or investment scenarios, the full PW Consulting research report provides the deeper data and customization required to act with confidence.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Without Interruption: Strategic Trends Reshaping the UPS Market
The uninterruptible power system market has graduated from a commodity infrastructure play to a strategic enabler of digital transformation. As organizations push data center density, electrify healthcare networks, and digitize industrial operations, power protection is no longer a line item of last resort—it is now a foundational dependency. The industry's expansion signals that reliable continuity is becoming inseparable from performance, safety, and grid interactivity.
The market generated approximately $180.25 million in 2025, building on a consistent recovery from the $130.45 million recorded in 2020. Growth has accelerated through 2024 and into 2025, reflecting deployment momentum across digital, healthcare, and manufacturing environments. Projections extend through 2032, with the market positioned to reach $265.95 million by the end of the forecast horizon. This trajectory corresponds to a compound annual growth rate of 5.85 percent, a pace that underscores structural demand rather than a cyclical uptick. Momentum is broad-based but uneven, with opportunities concentrated where uptime criticality, energy efficiency, and connectivity converge.
Beneath the headline figures, the market faces meaningful pressure points. Power architecture expectations are changing faster than legacy products can adapt, forcing suppliers to reconcile reliability with efficiency, footprint, and sustainability targets. Supply-chain volatility for critical components, combined with evolving energy storage safety standards, creates execution risk for product rollouts and project timelines. At the same time, procurement is shifting from discrete unit purchases toward integrated continuity solutions, rewarding players that can deliver lifecycle performance, remote readiness, and compliance assurance.
Technological Innovation as the New Basis of Competition
UPS design is evolving from simple backup conversion to intelligent, adaptive power delivery. Advances in power electronics, thermal management, and battery chemistry are reshaping what customers expect from a single unit. Compact form factors, higher power density, and modular architectures are enabling deployments in space-constrained and distributed environments, from edge computing rooms to on-premises workstations. At the high end, medium-voltage solutions are eliminating the need for multiple conversion stages in large facilities, reducing energy losses and simplifying infrastructure around intensive compute operations.
A recent wave of product introductions illustrates how targeted innovation is aligning with use-case realities. Vertiv expanded its portfolio across the density spectrum, introducing compact systems for connected homes and workspaces while simultaneously announcing industrial-grade options tailored to manufacturing, transportation, oil and gas, pharmaceuticals, food and beverage, packaging, and steel operations. This dual-track approach shows how manufacturers are segmenting by environment rather than treating the market as a single volume game. The emphasis on distributed digital environments and industrial continuity suggests a broader shift: UPS solutions are increasingly designed for specific operating profiles, thermal conditions, and load dynamics rather than generic backup.
Battery technology is another critical axis of differentiation. The move toward lithium-ion and optimized energy storage configurations is enabling faster response, longer service life in selected duty cycles, and easier integration with distributed IT and edge deployments. This evolution matters because battery selection affects lifetime cost, footprint, maintenance cadence, and compliance. As customers weigh total cost of ownership against resilience requirements, the ability to match storage technology to application risk profiles becomes a competitive lever.
Policy, Safety Standards, and the Compliance Opportunity
Regulatory and safety frameworks are becoming more consequential in procurement decisions, particularly where energy storage interfaces with the grid or occupies shared infrastructure. Certification milestones are increasingly used as trust signals, not just technical checkboxes. The industry's first UL 9540 certification for energy storage safety and performance, achieved on a medium-voltage UPS platform, marked a notable shift in what is expected from large-scale power protection systems. Such certifications can reduce integration friction for data center operators seeking to connect directly to higher-voltage grid infrastructure while maintaining documented safety and performance assurance.
The broader implication is that compliance capability is becoming part of the value proposition. Projects that can demonstrate standardized safety certification, interoperability with microgrid-ready architectures, and documented integration with battery storage and renewable inputs are better positioned in bidding processes that emphasize operational risk reduction. For manufacturers, this opens a strategic path: align product roadmaps with certification pathways early, and use compliance achievements as differentiators in segments where procurement teams are increasingly risk-averse around energy storage and electrical safety.
Demand-Side Shifts: Critical Load Growth and Operational Continuity
Demand is being restructured by the expansion of critical digital infrastructure, healthcare digitization, and the modernization of industrial systems. Data centers remain a primary demand engine, but the nature of that demand is changing as operators manage higher rack densities, tighter space constraints, and more complex cooling and power interactions. Telecommunications networks continue to require resilient back-up as they expand coverage, support edge connectivity, and adapt to evolving service-level expectations. Healthcare environments are increasingly dependent on uninterrupted power for clinical systems, imaging, monitoring, and building operations, elevating UPS from facility support to patient-safety-adjacent infrastructure.
Industrial manufacturing represents another growth vector, driven by automation, process control sensitivity, and the cost of downtime. Transportation, pharmaceuticals, food and beverage, packaging, and steel operations all share a common vulnerability: brief interruptions can disrupt quality, throughput, and safety protocols. This reality is encouraging adoption of industrial-grade UPS solutions that can tolerate harsh environments, vibration, and variable loads while maintaining availability. Residential and distributed workspace applications are also gaining attention, particularly as home offices, small server rooms, and connected environments seek compact solutions that balance protection with usability.
Behaviorally, buyers are placing more weight on lifecycle continuity than on lowest upfront price. The conversation is increasingly framed around availability targets, maintenance access, remote monitoring readiness, and the ability to scale as loads evolve. For suppliers, this means product portfolios must support not only the initial deployment but also ongoing operational needs, including diagnostics, serviceability, and compatibility with broader facility or data center ecosystems.
Supply Chain and Cost Structure: Building Resilience Into Delivery
Cost structures in the UPS market are shaped by component availability, manufacturing scale, and the economics of power-dense designs. Semiconductor availability, transformer lead times, and battery cell supply can influence both product launch timing and margin stability. Suppliers that diversify sourcing, standardize modular architectures, and design for manufacturability are better able to absorb volatility without sacrificing delivery performance. The operational implication is straightforward: resilience now applies to the supply chain as much as to the end equipment, and procurement teams are increasingly attuned to supplier continuity when evaluating partners.
Cost pressure is also being counterbalanced by efficiency expectations. In larger deployments, reducing conversion losses and simplifying grid connection can yield meaningful operational savings over the life of the installation. This convergence of supply-chain discipline and efficiency optimization favors organizations that can deliver standardized, certified solutions with predictable lead times and installation complexity. It also pushes mid-tier and regional players to clarify their position: compete on customization and service responsiveness, or focus on volume segments with streamlined product lines and strong distribution partnerships.
Competitive Landscape: Differentiated Positioning in a Concentrated Market
The UPS market is moderately concentrated, with a small group of established players commanding a significant share of revenue. This concentration reflects the advantages of scale, broad application coverage, and deep integration with larger power management and infrastructure ecosystems. Yet concentration does not imply uniformity. Leading companies are carving out distinct positions through technology focus, application specialization, and ecosystem breadth.
Industrial UPS Market
Schneider Electric continues to strengthen its position by expanding its power protection lineup for high-density IT and industrial applications, including the release of one of the most compact 3-phase UPS units in its class. Its approach leans on integration with broader energy and digital infrastructure capabilities, positioning UPS as part of an overall facility or data center strategy rather than an isolated device. Eaton maintains a strong presence through its emphasis on power management and operational continuity across commercial and industrial environments, with a focus on reliability and lifecycle service. Vertiv is executing a notably broad segmentation strategy, covering compact home and workspace systems as well as industrial-grade platforms and standby series for distributed digital environments. This breadth allows Vertiv to address multiple demand profiles simultaneously, from consumer-adjacent protection to heavy process loads.
ABB is differentiating through high-voltage and medium-voltage innovation, including medium-voltage UPS solutions that enable direct grid connection for large AI-related data center loads. Its certification achievement and microgrid-ready architecture signal an intent to compete where power levels, safety certification, and grid integration complexity are highest. Delta Electronics and Riello UPS bring application-specific depth, often emphasizing efficiency, thermal performance, and industrial durability. Huawei and Toshiba contribute to a diverse supplier base with strong regional footprints and technology heritage, while Piller and Kehua Data provide additional depth in specialized power and data-centric environments. Falcon Electric and Active Power round out the landscape with focused offerings that can compete on niche requirements, rapid deployment, and specific operational profiles.
The competitive trend is moving toward both consolidation and segmentation. Consolidation is likely where customers seek single-vendor accountability across power, cooling, monitoring, and service. Segmentation is equally strong, as product families are increasingly tuned to particular environments, voltage levels, and load characteristics. New entrants and regional players can still succeed by targeting underserved niches, offering agile delivery, or combining hardware with differentiated service and monitoring capabilities. The key is clarity: companies that attempt to serve every segment with a generic portfolio often struggle to communicate value against more focused competitors.
Outlook for the Next Three to Five Years
Several trends are likely to define the next phase of market development. The first is the continued expansion of high-power-density and medium-voltage solutions for large digital infrastructure projects. As compute-intensive environments scale, the ability to connect more directly to higher-voltage sources while maintaining safety certification and reducing conversion losses will become more valuable. Suppliers that can combine high-voltage capability with reliable certification and integration support will capture a meaningful share of complex, high-stakes deployments.
The second trend is the growth of distributed and edge-oriented protection, supported by compact form factors and battery technologies optimized for smaller, decentralized deployments. This shift reflects the broader decentralization of digital infrastructure and the need for continuity outside centralized data centers. Expect increased attention to systems that are easy to deploy, quiet, serviceable, and compatible with distributed IT rooms and workspace environments.
The third trend is the increasing blend of power protection with intelligence and energy integration. Monitoring readiness, fault diagnostics, lifecycle service, and compatibility with battery storage or renewable inputs will increasingly influence purchasing decisions. As operators look to reduce operational risk and improve asset visibility, UPS platforms that can participate in broader energy and facility management ecosystems will gain preference.
PW Consulting
These trends carry clear commercial opportunities. Manufacturers that align product roadmaps with high-density compute needs, industrial ruggedness, and distributed deployment realities can capture demand across multiple segments. Investors should assess where portfolio breadth, certification strength, and service capabilities create durable differentiation, rather than assuming growth will accrue evenly across the market. For procurement and operations leaders, the opportunity lies in selecting solutions that balance immediate protection with long-term scalability, compliance confidence, and integration readiness.
Risks and uncertainties remain. Lead-time volatility, component constraints, and certification timelines can delay launches and affect project economics. Regulatory expectations around energy storage safety may evolve, changing the compliance burden for certain solution classes. In addition, rapid load growth in some digital infrastructure segments could outpace supply capacity in specific geographies or form factors, creating delivery challenges even in a favorable demand environment. Companies that rely on narrow product lines or single-source dependencies will be more exposed to these pressures.
Uninterrupted Power Supply (UPS) Market
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to sharpen segmentation without losing operational efficiency. Product architectures should support distinct deployment contexts—compact distributed environments, high-density IT, and harsh industrial settings—while sharing enough platform commonality to keep manufacturing and service scalable. Certification strategy should be treated as a market access tool, not a back-office task, especially where safety and grid-integration requirements are becoming procurement thresholds. Service and monitoring capabilities should be designed in from the start, because availability and lifecycle support increasingly determine competitive outcomes.
For investors, the most compelling opportunities are likely to appear where product differentiation is anchored in real operational value: power density, safety certification, industrial durability, and integration with energy storage or facility ecosystems. Due diligence should examine how well a company's portfolio matches the demand profiles likely to grow fastest, and whether its supply and certification capabilities can sustain delivery in a tightening environment. Companies with focused positioning and credible compliance achievements are better placed to defend margins and capture complex deals.
For procurement and operations leaders, the focus should shift from unit price to total continuity value. Selection criteria should weigh availability requirements, environmental suitability, certification status, serviceability, and compatibility with existing monitoring or energy management systems. Where possible, prefer solutions that can scale with load growth and support future integration needs, reducing the risk of premature replacement or retrofit. In critical environments, standardization around a smaller set of proven, certified platforms can simplify maintenance, training, and risk management.
Detailed segment-level data, regional deployment dynamics, and company-specific positioning can help translate these strategic signals into precise plans. A more granular view of application mixes, product family performance, and competitive moves by region provides the context needed to prioritize investments, refine sourcing strategies, and align product roadmaps with where demand is actually forming. Readers seeking that level of detail can explore the full market research report for deeper segmentation data and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Uninterruptible Power System (UPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Train Bogies Market
The train bogies market has entered a phase of structural transformation, driven by shifting infrastructure priorities, technological modernization, and evolving regulatory demands across rail networks worldwide. Valued at approximately 215.0 million USD in 2025, the market has steadily expanded from 163.15 million USD in 2020, reflecting consistent capital allocation toward rolling stock modernization and new fleet deployments. Looking ahead, the sector is projected to grow at a compound annual growth rate of 4.2 percent through 2032, reaching an estimated 344.8 million USD. This trajectory signals more than incremental demand; it reflects a foundational shift in how rail operators approach reliability, energy efficiency, and lifecycle management. For executives and investors navigating capital-intensive transportation sectors, the bogies market offers a clear lens into broader rail industry dynamics, where component-level innovation increasingly determines fleet performance and total cost of ownership.
Rail Wheels Market
Despite this positive trajectory, the industry faces several structural friction points that will shape competitive positioning over the next decade. First, raw material volatility continues to pressure manufacturing economics. Steel remains the dominant material in conventional bogie frames, and price fluctuations directly affect production margins and aftermarket pricing models. Second, tightening safety and emissions frameworks are accelerating procurement cycles while raising compliance thresholds. Operating environments now demand stricter adherence to interchange standards, and regional policy shifts are actively redirecting investment toward electrified and lower-emission rail architectures. Third, aftermarket service and refurbishment are becoming strategic battlegrounds. As operators extend fleet lifespans to manage capital constraints, the ability to deliver high-quality overhaul programs, predictive maintenance capabilities, and standardized component compatibility is increasingly decisive. These challenges are not isolated headwinds; they are redefining what qualifies as a competitive offering in the bogies space.
Material Choices and Manufacturing Cost Dynamics
Material strategy has become one of the most consequential decisions in bogie design and procurement. Conventional steel-based frames continue to dominate many applications, but their cost profile is increasingly exposed to commodity volatility and weight-related performance trade-offs. In parallel, composite and lightweight material adoption is gaining traction in specific segments where energy efficiency, acceleration performance, and passenger comfort are prioritized. Reducing structural weight can lower energy consumption and improve operational flexibility, which matters most in urban transit and high-speed configurations where lifecycle operating costs outweigh initial capital considerations. However, material transitions also introduce new considerations around production scalability, repair protocols, and supply chain maturity. Manufacturers that can standardize lightweight components without compromising structural integrity or serviceability will be better positioned to capture premium segments while managing cost exposure.
Regulatory Pressure and Fleet Electrification Pathways
Regulatory evolution is actively reshaping demand patterns across regional rail markets. Stricter safety, wheel-set, and interchange compliance requirements are raising the bar for bogie specifications, particularly in markets where interoperability and cross-border operations are expanding. At the same time, emissions-driven policies are accelerating the transition away from diesel-heavy fleets in certain jurisdictions, stimulating demand for bogie systems designed for electric traction and compatible with modern rolling stock architectures. In regions where locomotive operating restrictions have come into force, rail operators are forced to reevaluate fleet composition and component compatibility sooner than planned. This creates both procurement urgency and longer-term design implications, as bogie suppliers must align product roadmaps with electrification timelines and evolving compliance expectations. For market participants, regulatory momentum is no longer a background variable; it is a direct demand driver.
Train Seat Market
Aftermarket, Refurbishment, and Operational Lifecycle Value
The aftermarket dimension of the bogies market is growing in strategic importance as operators balance new orders with existing fleet preservation. Overhaul programs, component regeneration, and condition-based maintenance are becoming essential levers for controlling total cost of ownership. Recent activity in the sector highlights how service-oriented engagements can anchor long-term customer relationships while generating predictable revenue streams. High-volume refurbishment projects, particularly for established regional fleets, demonstrate that performance restoration and extended service life can be commercially viable when executed with standardized processes and skilled labor capacity. As operators seek to defer greenfield capital expenditures, suppliers capable of delivering reliable overhaul solutions, digital health monitoring, and consistent quality assurance will capture disproportionate value in the service layer of the market.
Key Drivers Shaping Market Evolution
The market’s expansion is not uniform across all applications or geographies. Growth is being pulled by a combination of technological capability, policy mandates, shifting procurement behavior, and evolving supply chain economics. Understanding which forces are structural rather than cyclical is essential for anticipating where demand will concentrate and which capabilities will command pricing power.
Technological Innovation and System Integration
Bogie design is increasingly treated as an integrated system rather than a mechanical subassembly. Digital health monitoring, active suspension concepts, and advanced frame engineering are moving from experimental initiatives into operational use. Real-time condition data enables operators to plan maintenance with greater precision, reducing unplanned downtime and optimizing spare parts requirements. At the same time, innovations in frame architecture are improving ride quality and load distribution, especially in applications where speed, passenger comfort, and infrastructure compatibility matter most. These advancements are not merely product upgrades; they are shifting the value proposition from component supply to performance assurance. Suppliers that combine mechanical reliability with digital visibility can differentiate themselves in a market where operators increasingly prioritize availability and lifecycle cost over lowest initial price.
Policy Environment and Compliance Requirements
Rail policy is acting as both a constraint and a catalyst. Compliance with interchange and safety standards is becoming more rigorous, forcing manufacturers and operators to align specifications across fleets and procurement cycles. In parallel, regional emissions policies are indirectly pulling demand toward electric-compatible bogie architectures and modernized fleets. Where diesel operation faces restrictions or phase-down timelines, procurement strategies are adjusted to favor rolling stock and component configurations that support electrification goals. This regulatory environment tends to favor established players with documented certification experience, while also creating entry points for suppliers whose designs are built to meet evolving compliance baselines from the outset. Policy-driven demand is often less price-sensitive and more specification-driven, which can support margin stability for suppliers able to demonstrate conformity and operational reliability.
Demand-Side Shifts Across Application Types
Application demand is reshaping where bogie volume and value are concentrated. High-speed and passenger-oriented rail systems continue to absorb a significant share of market activity, reflecting ongoing commitments to mobility modernization and urban connectivity. Freight applications, while smaller in relative share, remain important where logistics networks depend on durable, heavy-duty bogie assemblies suited to load-bearing and interchange requirements. Urban transit and metro deployments add another layer of demand, characterized by high utilization rates and strong expectations for reliability, low noise, and energy efficiency. These application segments differ not only in volume but in performance priorities. Passenger-focused systems reward comfort, safety, and digital monitoring, while freight configurations emphasize durability, interchange compatibility, and total lifecycle durability. As a result, suppliers are increasingly expected to tailor engineering and service strategies to distinct operating profiles rather than rely on a single standardized offering.
Supply Chain and Cost Structure Realignment
Cost structures across the bogies market are being tested by input volatility, skilled labor availability, and the economics of scale. Steel price fluctuations remain a material consideration for conventional frame production, influencing both manufacturer margins and downstream pricing negotiations. At the same time, the shift toward specialized materials and advanced manufacturing processes can raise upfront investment requirements, even as they improve long-term operating economics. labor intensity in overhaul and precision assembly operations also matters, particularly where facilities must sustain skilled roles over multi-year service programs. Organizations that can secure stable input sourcing, optimize production throughput, and maintain skilled service capacity will be better positioned to manage cost variability while meeting specification demands. In practice, supply chain resilience is becoming a competitive attribute in its own right, not just an operational concern.
Competitive Landscape and Leading Strategies
The bogies market remains relatively fragmented in terms of concentration, with no single group dominating overall share. This fragmentation creates room for differentiation through engineering capability, service depth, and regional execution quality. Leading participants are pursuing different strategic paths, and the most successful will likely be those that align product architecture with the operational realities of their target segments.
Strategic Positioning Among Key Players
Several established manufacturers have built recognizable positions around specific strengths. Alstom has emphasized passenger train bogies with a focus on safety, reliability, and comfort, supported by substantial production and overhaul capacity. Recent contract activity and facility milestones illustrate a strategy centered on long-term fleet support and high-volume service execution, reinforcing customer retention through lifecycle engagement. CRRC has pushed into lightweight structural innovation, introducing carbon fiber composite frame approaches and advanced bogie concepts for metro and high-speed applications. Its trajectory suggests a focus on material modernization and production automation as differentiators in segments where weight reduction and throughput matter. Siemens has leaned into integration and digital monitoring, positioning its bogie systems as part of broader operational health and performance management capabilities. This approach aligns with operators seeking visibility into asset condition and predictive maintenance. Other participants, including Amsted Rail, Stadler Rail, Bombardier Transportation, Wabtec Corporation, Voith GmbH, Kawasaki Heavy Industries, Tatravagónka a.s., Titagarh Rail Systems Limited, Hyundai Rotem, and regional specialists such as Titagarh, contribute to a diverse competitive field by targeting freight, urban transit, and international rail programs with varied product and service emphases. Rather than a single dominant model, the landscape reflects multiple viable strategies: production scale, lightweight innovation, digital integration, freight durability, and regional service strength.
Market Structure Evolution
Over time, the market is likely to see selective consolidation around players that can combine engineering credibility, service reach, and compliance readiness. At the same time, new entry remains possible in niche applications where lightweight materials, specialized urban transit requirements, or regional manufacturing incentives lower traditional barriers. The more probable outcome is differentiation rather than uniform consolidation: incumbents will defend positions through service ecosystems and product reliability, while targeted innovation will open pockets of advantage in specific application or regional contexts. For buyers and investors, this means that competitive advantage will increasingly come from capability depth and execution consistency, not merely from scale or brand recognition.
Future Trends and Commercial Implications
The next three to five years are likely to be defined by three interlocking trends: broader adoption of lightweight and composite frame technologies in targeted applications, deeper integration of digital health and condition monitoring into bogie systems, and continued acceleration of aftermarket and refurbishment as strategic revenue centers. Each trend carries distinct commercial implications and associated risks.
Trend One: Selective Lightweight Material Adoption
Composite and lightweight structural solutions will expand beyond pilot use into operational deployments where energy efficiency, speed, and ride quality justify the investment. This shift offers clear advantages in metro and high-speed contexts, where reduced mass can improve acceleration, lower energy consumption, and support passenger comfort goals. The commercial opportunity lies in building scalable production methods and service protocols that make lightweight components practical over full lifecycle use. The risk is that material transitions remain costly or operationally complex if repair, inspection, and supplier support ecosystems lag behind initial deployment. Executives should therefore evaluate lightweight adoption not only on performance merits, but also on long-term maintainability and supply continuity.
Trend Two: Digital Monitoring as a Standard Capability
Condition monitoring and digital health data are moving from optional features to expected components of modern bogie systems. As operators seek to reduce downtime and optimize maintenance schedules, real-time visibility into component state will increasingly influence procurement decisions. This trend favors suppliers that can integrate sensing, data interpretation, and maintenance planning into their offerings, translating hardware supply into service-led value creation. The commercial upside is stronger customer stickiness and higher-margin service relationships. The uncertainty lies in data interoperability, cybersecurity expectations, and the operational burden of managing digital infrastructure across mixed fleets. Success will depend on delivering monitoring capabilities that are practical, reliable, and compatible with existing operator workflows.
Trend Three: Aftermarket and Refurbishment as Strategic Focus
As capital constraints persist in many rail markets, preserving existing fleets through high-quality overhaul and refurbishment will remain a priority. This creates durable demand for service capacity, standardized component processes, and skilled labor execution. Organizations with established overhaul facilities, proven quality controls, and strong customer relationships can transform aftermarket work into a stable revenue base while reinforcing long-term procurement relevance. The risk is operational scaling: maintaining consistency across large refurbishment programs requires disciplined process management and trained workforces. Entities that can demonstrate repeatable quality and timely delivery will be better placed to capture this demand.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the applications and compliance environments where demand is most durable. Investing in lightweight structural options, digital condition monitoring, and service-ready design will strengthen positioning in passenger and urban transit segments. Equally important is building cost resilience through stable input sourcing and scalable production, particularly where steel and specialized materials remain central to conventional designs. Companies should also treat overhaul and refurbishment capability as a strategic asset, not a secondary activity, because service execution increasingly determines long-term customer retention.
For investors, the market’s 4.2 percent growth trajectory suggests steady expansion, but value creation will likely concentrate among participants with differentiated engineering, service depth, and regional execution strength. Opportunities are most compelling where suppliers can combine product innovation with recurring service revenue and where regulatory momentum supports electrification and modernization spending. Due diligence should focus on capability maturity, aftermarket exposure, and the ability to manage input cost volatility rather than on headline market size alone.
For procurement and rail operators, the emphasis should be on total lifecycle value rather than initial purchase price. Bogies that deliver reliability, maintainability, and compatibility with digital maintenance systems can reduce operational disruption and support fleet planning over longer horizons. Procurement strategies should also account for compliance readiness and service support, especially where emissions policies and interchange standards are reshaping fleet composition. In markets with active modernization programs, establishing clear specifications and long-term service expectations early can reduce downstream integration risk.
The strategic picture is clear: the train bogies market is expanding, but the real competition is shifting toward performance assurance, service capability, and technology integration. Organizations that understand where value is being created across applications, materials, and aftermarket service will be better equipped to make targeted investment and procurement decisions. For a more detailed view of segment-level dynamics, regional demand patterns, application splits, and company-specific positioning, the full PW Consulting research report provides the deeper segmentation data and customized strategic guidance needed to translate these trends into operational plans.
PW Consulting
For detailed analysis of this topic, please visit the official page: Train Bogies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Hexagonal Boron Nitride Market: Strategic Trends and Commercial Opportunities Through 2032
The hexagonal boron nitride market is undergoing a structural shift. Once confined to niche industrial niches, the material is now embedded in the strategic planning of companies operating in electronics, advanced coatings, and thermal management. Market size has expanded from approximately 766 million in 2020 to an estimated 954 million in 2025, representing a compound annual growth rate of 4.71 percent through 2032. The trajectory points toward a market crossing the 1.3 billion mark by 2032, driven by accelerating demand in high-performance applications and a gradually maturing supply base. This article examines the forces shaping the market, the competitive dynamics at play, and the strategic decisions that will separate winners from laggards over the next five years.
For executives and investors, the central question is no longer whether hexagonal boron nitride will see broader adoption, but where the value will concentrate and how to position for it. The answers hinge on understanding the interplay between technological breakthroughs, regulatory tailwinds, shifting demand patterns, and a supply chain that is beginning to reorganize.
PW Consulting Chemical & Energy Research Center
Market Reality and Core Challenges
The market's recent expansion reflects a compounding of steady industrial demand and targeted investment in applications that require thermal conductivity, electrical insulation, and chemical stability. While the overall growth rate is moderate, it masks underlying volatility across customer segments and geographies. Revenue distribution is not uniform, and the structural drivers differ sharply depending on whether the end use is coatings, thermal management, or specialty industrial processes.
Three challenges define the current inflection point.
-
Raw material economics and feedstock volatility. Although import unit values for combined US boron materials have eased, providing temporary relief for producers, the broader cost environment remains sensitive to logistics, regional pricing, and the availability of refined borax and boric acid. Feedstock stability influences margin predictability and limits the speed at which manufacturers can scale without incurring cost risk.
-
Regulatory and supply chain realignment. The designation of boron as a critical mineral has shifted attention toward domestic production incentives and supply chain resilience. This development creates opportunities for onshore capacity but also raises compliance complexity, investment thresholds, and coordination requirements among miners, refiners, and downstream manufacturers.
-
Application fragmentation and qualification hurdles. Demand is distributed across multiple use cases, but each segment carries distinct technical requirements, testing standards, and procurement cycles. This fragmentation slows the conversion of laboratory promise into commercial volume, particularly in electronics-adjacent applications where material consistency, purity, and integration reliability must be demonstrated.
These challenges are interconnected. Feedstock volatility influences cost structures, regulatory shifts affect where capacity is built and how supply is secured, and application fragmentation determines which segments can scale quickly and which remain constrained by qualification timelines. The net effect is a market that is expanding but not uniformly easy to navigate.
Key Drivers Shaping the Market
Technology Innovation and Performance Breakthroughs
The most consequential driver is the continued improvement in material form and integration methods. Hexagonal boron nitride is increasingly valued not just as a powder but as engineered solutions tailored for specific performance profiles. Advances in monolayer films, high-purity powders, and composite formulations are expanding the addressable set of applications, especially where thermal management and electrical insulation must coexist in compact devices.
Suppliers that can deliver controlled particle size, consistent purity, and reproducible performance characteristics are gaining traction in high-value segments. In semiconductor and advanced electronics contexts, the ability to provide films and powders that meet stringent integration requirements is a meaningful differentiator. This focus on performance consistency is shifting the competitive battleground from volume alone to quality and technical support.
Policy and Regulatory Environment
Policy dynamics are becoming a more visible force. The inclusion of boron in the critical minerals list has formalized government attention on supply security, onshore production, and resilience. For hexagonal boron nitride producers, this signals potential support mechanisms, procurement preferences, and incentives that could favor domestic or allied supply chains.
At the same time, the regulatory environment introduces a dual effect. It can accelerate investment in local feedstock and processing capacity, but it can also lengthen planning horizons as companies navigate qualification, permitting, and partnership structures. Firms that anticipate these shifts and align their sourcing and capacity strategies early are better positioned to benefit from policy momentum rather than respond after the fact.
Demand-Side Shifts in End-Use Industries
Demand is being reshaped by two complementary trends. First, thermal management is moving up the priority list in power electronics, LEDs, and related devices, where efficiency, reliability, and compactness are non-negotiable. Second, in coatings and industrial applications, the material's lubrication, non-stick, and high-temperature stability properties continue to support steady adoption, especially where downtime reduction and surface protection deliver clear operational value.
What is changing is not just the volume of demand but the specificity of requirements. Customers increasingly want materials that are not merely available but demonstrably compatible with their processes, test protocols, and performance targets. This is pushing more technical engagement earlier in the buying cycle and rewarding suppliers that can offer application engineering support alongside product supply.
Supply Chain Evolution and Cost Structure
Supply chain dynamics are evolving as producers react to cost pressures, geographic concentration, and the push for resilience. Import data indicates that unit values for combined US boron materials have softened, which provides some margin breathing room. At the same time, volumes of refined borax and boric acid have remained stable, supporting a more predictable flow into downstream processing.
The broader implication is that the cost environment is improving in the near term but remains exposed to longer-cycle risks. Producers that diversify sourcing, invest in processing efficiency, and secure multi-source feedstock arrangements can translate temporary relief into durable cost advantages. Those dependent on single-channel supply or unable to manage quality consistency may find that any temporary cost improvement is quickly eroded by volatility.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three firms accounting for roughly 52 percent of revenue and the top five closer to 64 percent. This structure suggests meaningful scale advantages for established players, while still leaving room for specialists and regional suppliers to compete on performance, service, and niche positioning.
Several strategic archetypes are visible among the leading companies.
CBN Abrasives Market
-
Large diversified producers offer breadth, global reach, and the ability to serve multiple application verticals. Their advantage lies in scale, integrated capabilities, and the capacity to support customers across thermal management, lubrication, insulation, and advanced ceramics.
-
Specialists and technology-focused firms compete on material form, purity, and application fit. Companies working on high-quality films, high-purity powders, and semiconductor-adjacent solutions are building defensibility by aligning closely with demanding end uses and technical qualification cycles.
-
Regional and volume-oriented manufacturers, particularly in Asia Pacific, leverage scale in powder production and industrial composite applications. Their strength is often rooted in domestic market depth, strong production volume, and cost-competitive positioning.
The differentiation is increasingly less about who can produce hexagonal boron nitride and more about how well a supplier can match material properties to application requirements while maintaining supply reliability. Leading players combine consistent quality, application engineering, and supply chain readiness with a clear focus on the segments where they can win on performance rather than price alone.
Market Structure Evolution
The landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Consolidation may continue among players seeking scale advantages and broader application coverage. At the same time, the demand for specialized films, high-purity materials, and application-specific formulations will sustain a role for focused specialists, especially where technical barriers and qualification requirements create moats.
New entrants will face a steep climb unless they bring a clear advantage in material quality, process control, regional supply access, or application alignment. The critical mineral designation and growing attention to supply resilience may also encourage investment in new capacity, particularly where feedstock access and downstream partnerships can be aligned early.
Forward Trends and Commercial Opportunities
Trend 1: Thermal Management Moves from Opportunity to Requirement
As power electronics, LEDs, and compact high-performance devices continue to advance, thermal management becomes less optional and more foundational. Hexagonal boron nitride's combination of thermal conductivity and electrical insulation positions it for continued relevance. The commercial opportunity lies not simply in higher volume but in integrated solutions that reduce design friction, improve reliability, and shorten qualification cycles for end customers.
Producers that pair material performance with application engineering and predictable supply are likely to capture disproportionate value in this trend. The risk is that without consistent quality and clear integration support, thermal management demand may fragment across suppliers or shift toward alternative materials where performance and availability are easier to certify.
Trend 2: Supply Chain Localization and Critical Mineral Momentum
The critical mineral status of boron is likely to reinforce interest in regional supply chains, domestic sourcing incentives, and resilience-focused procurement. Over the next three to five years, this could translate into new investment in feedstock access, processing capacity, and strategic partnerships that reduce exposure to foreign supply shocks.
The opportunity is for companies to align capacity plans, sourcing strategies, and customer commitments with the direction of policy and procurement preferences. The uncertainty lies in timing and execution. Policy support does not automatically convert into demand at scale, and capacity built without corresponding demand visibility or application fit can create overinvestment risk.
Trend 3: Higher Performance Standards and Application Qualification
Demand across coatings, thermal solutions, and industrial uses is increasingly conditional on verified performance. This raises the bar for consistency, documentation, and technical support. Suppliers that can provide traceable quality, reproducible properties, and application-specific validation will face fewer barriers to scale-up in demanding segments.
The upside is stronger pricing power and longer customer relationships in applications where qualification is a barrier to entry. The downside is that any lapse in quality or supply consistency can rapidly erode trust and open the door to competitors or alternative materials, especially in segments where switching costs are moderate and performance differentials must be proven continuously.
Action Implications for Decision-Makers
For Manufacturers and Material Suppliers
-
Invest in application-visible differentiation. Performance consistency, particle and film control, purity, and integration support matter more as demand shifts toward electronics-adjacent and thermal management applications. Competing on volume alone is increasingly insufficient where qualification and reliability drive selection.
-
Strengthen feedstock resilience and cost control. Even with near-term import unit value relief, build multi-source sourcing and processing efficiency to protect margins against future volatility. Align capacity expansion with segments where demand visibility and qualification pathways are clearest.
-
Prepare for policy-driven supply shifts. Anticipate the implications of critical mineral momentum on sourcing, partnerships, and capacity location decisions. Early alignment with regional supply incentives and resilient feedstock strategies can turn policy momentum into a competitive advantage.
For Investors and Strategic Planners
-
Focus on the segments where qualification and performance create durable advantages. Thermal management and high-purity, application-specific materials offer more defensible positioning than commoditized volume plays. Assess companies on their ability to sustain quality, support integration, and navigate supply chain complexity, not just on production capacity.
-
Watch for consolidation signals and regional capacity shifts. Moderately high concentration leaves room for both consolidation and specialization. Evaluate the strategic logic behind moves that expand application breadth, secure feedstock access, or strengthen regional presence, especially where critical mineral policy and demand resilience are converging.
-
Stress-test assumptions around demand timing and supply response. Policy support and technical promise do not automatically equal immediate volume. Build scenarios that separate near-term cost relief and stable feedstock flows from longer-cycle demand conversion, and assess whether companies have the application alignment to scale without overinvesting.
For Procurement and Sourcing Leaders
-
Prioritize suppliers with verified consistency and application support. In thermals, coatings, and industrial uses, the risk of performance variation or supply inconsistency often outweighs marginal cost savings. Evaluate supply partners on quality documentation, technical engagement, and resilience of their feedstock and capacity base.
-
Diversify strategically, not indiscriminately. Multi-source strategies should be paired with clear criteria for performance equivalence and qualification readiness. The goal is resilience without fragmenting the supply base in ways that increase validation burden or dilute performance reliability.
-
Monitor policy and feedstock signals as part of sourcing risk management. Critical mineral designation and import unit value trends can change the attractiveness of regional supply options and the timing of capacity decisions. Incorporating these signals into sourcing plans helps avoid reactive shifts when supply conditions change.
Conclusion
The hexagonal boron nitride market is moving from steady industrial relevance toward a more strategically significant position, especially where thermal management, high-performance coatings, and advanced electronics applications converge. Growth to the 1.3 billion range by 2032 is plausible within the current trajectory, but the real commercial action will depend on how well participants navigate feedstock economics, regulatory momentum, and application qualification. The winners are likely to be those who convert material capability into application-ready solutions, secure resilient supply chains, and align with the demand profiles that value performance consistency as much as availability.
Boron Nitride Nanotubes (BNNT) Market
For organizations making investment, sourcing, or production decisions, the next step is to assess exposure to these dynamics in detail. A fuller evaluation of segment-level demand, regional supply patterns, competitive positioning, and scenario-based risk can clarify where to build advantage now and where to monitor for change. Detailed analysis is available in the complete research report.
For detailed analysis of this topic, please visit the official page: Hexagonal BN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Eddy Current Sensor Market: How $1.86B Scale and 6.5% CAGR Redefine 2026 Growth
By PW Consulting, 2026-09-21
Navigating the Eddy Current Sensor Market: Strategic Trends and Commercial Opportunities Through 2032
The eddy current sensor market has evolved from a niche instrumentation segment into a critical enabler of precision monitoring, non-destructive testing, and automated control across heavy industry, advanced manufacturing, and critical infrastructure. Tracking the revenue trajectory from 2020 through 2032 reveals a market that has consistently expanded, crossing the 1.1 billion threshold by 2025 and moving toward approaching 1.9 billion by the end of the forecast horizon. The compound annual growth rate sits at approximately 6.5 percent, a rate that signals steady, technology-led expansion rather than cyclical volatility. This growth is not uniform across all segments; it reflects a reallocation of capital toward high-reliability displacement and condition monitoring applications, alongside a steady uptake of advanced inspection probes in asset-intensive sectors.
For executives and investors, the headline numbers matter less than the structural shifts underneath them. The market is maturing in ways that reward suppliers who can pair submicron measurement accuracy with ruggedized packaging, certified reliability, and integration-ready interfaces. At the same time, procurement teams and system integrators face a landscape where raw material volatility, certification requirements, and shifting trade policies are reshaping cost structures and lead times. Understanding these dynamics is essential for positioning product portfolios, negotiating supplier relationships, and anticipating where value will accrue over the next several years.
Market Snapshot and Core Challenges
The revenue path from 2020 to 2032 illustrates a market that has grown through steady adoption rather than sudden spurts. After moving from roughly 850 million in 2020 to approximately 1.195 billion in 2025, the trajectory continues upward with incremental but compounding gains each year, reaching an estimated 1.856 billion by 2032. This pattern points to a market where recurring replacement cycles, expanding end-use monitoring requirements, and the gradual penetration of advanced sensor types are driving volume. The consistency of the growth curve also suggests that demand is becoming more predictable, which benefits suppliers that can plan capacity and service networks with greater confidence.
Despite the positive trajectory, the industry faces a set of challenges that will define competitive outcomes. Three stand out as especially consequential for strategy and operations.
Precision-to-Ruggedness Trade-offs in Harsh Environments
As deployment shifts from controlled laboratory and clean manufacturing settings into turbines, petrochemical plants, and outdoor automation cells, the tolerance for environmental stress has increased sharply. Sensors must now deliver submicron accuracy while surviving high temperatures, moisture, chemical exposure, and mechanical shock. The push for ingress-protected designs, such as IP69K-rated housings, is no longer optional for many industrial buyers. This creates a design tension: protecting the sensing element and electronics without compromising thermal stability, signal integrity, or mounting flexibility. Suppliers that solve this engineering puzzle with purpose-built mechanical designs and validated sealing approaches gain a meaningful advantage in bids where reliability is weighted heavily against price.
Certification, Qualification, and Personnel Requirements
Non-destructive testing and condition monitoring applications increasingly require adherence to recognized standards for both equipment and personnel. For eddy current testing, qualification frameworks for inspectors and the alignment of sensor performance with accepted procedures are becoming table stakes in regulated sectors. This raises the barrier to entry for generic instrumentation and favors suppliers that can document traceability, provide application guidance, and support certification workflows. For buyers, the challenge is not only evaluating sensor accuracy but also ensuring that the entire measurement chain—from probe selection to data interpretation—meets auditable standards. This dynamic is shifting purchasing decisions toward bundled solutions that include training, documentation, and service support, rather than standalone hardware.
Cost Structure Pressure from Materials and Trade Policy
The bill of materials for eddy current probes and instruments is increasingly exposed to commodity and trade dynamics. Copper wire coils, essential to many sensor designs, are subject to price swings tied to broader commodity volatility. At the same time, magnet assemblies used in high-frequency sensors depend on materials that face export constraints in key sourcing regions. Layered on top of this are tariffs and trade measures that affect the landed cost of sensors originating in certain countries, particularly for North American manufacturers. These pressures do not invalidate the market's growth but they do compress margins for suppliers that rely on undifferentiated component sourcing and pass through cost shocks without engineering countermeasures. Forward-looking players are responding with material substitution where feasible, dual-sourcing strategies, and design choices that reduce sensitivity to any single input.
Key Drivers Shaping the Market
Growth in this market is being propelled by a combination of technological advancement, regulatory and standards activity, evolving demand-side behavior, and supply-side restructuring. Each driver reinforces the others, creating a multi-year pull that extends beyond simple capacity expansion.
Technology Innovation: Submicron Accuracy Meets Industrial Hardening
Recent product introductions show a clear emphasis on improving measurement fidelity while extending environmental durability. The launch of new eddy current displacement sensor series with submicron accuracy and high ingress protection ratings reflects a deliberate push to serve applications where even minor measurement drift can affect process quality or equipment safety. In turbomachinery and other rotating equipment, updated sensor specifications for radial and axial displacement are enabling more precise vibration and shaft monitoring, which supports predictive maintenance and reduces unplanned downtime. For non-destructive testing, the continued refinement of eddy current array probes and associated instrumentation is expanding inspection coverage and reducing scan time on complex geometries. These innovations matter because they convert sensors from passive measurement devices into integral parts of reliability and quality programs, increasing their value proposition and sticking power in customer operations.
Policy and Standards Environment: Compliance as a Competitive Moat
Regulatory and standards activity is shaping both procurement and product development. Personnel qualification requirements for eddy current testing reinforce the importance of instruments that produce repeatable, interpretable results and that can be supported with documented procedures. In parallel, equipment-level protection standards are becoming reference points in industrial procurement, with IP-rated sensors increasingly specified where washdown, chemical exposure, or outdoor deployment is expected. This environment rewards suppliers that invest in compliance documentation, application notes, and service frameworks that reduce the administrative burden on end users. It also raises the cost of disintermediation: once a sensor family is integrated into a certified maintenance or inspection workflow, switching costs rise, creating longer contract horizons and more predictable revenue for incumbents.
Eddy Current NDT Equipment Market
Demand-Side Shifts: Predictive Maintenance and Automation Integration
On the demand side, the most important behavioral change is the accelerating move from reactive repair to condition-based and predictive maintenance. Industrial operators are deploying displacement, vibration, and proximity monitoring earlier in asset lifecycles and integrating sensor data into broader digital maintenance strategies. In factory automation, the push for more reliable presence detection, positioning, and displacement feedback is driving adoption in high-cycle environments where contactless measurement offers clear advantages in wear reduction and throughput. In energy and heavy process industries, turbines, generators, and rotating shafts are being monitored with greater rigor to protect availability and extend service intervals. This demand shift is significant because it expands the addressable use cases for eddy current sensors beyond inspection alone, pulling them into continuous monitoring and control loops where recurring value is created.
Supply Chain and Cost Structure: Regional Realignment and Collaboration
Supply-side dynamics are being reshaped by both cost pressures and strategic collaboration. Tariffs and trade measures affecting certain sensor origins are prompting North American and European manufacturers to reconsider sourcing and assembly footprints, with some shifting toward regional integration or diversified supplier bases to manage landed cost and lead time risk. At the same time, partnerships aimed at joint development of advanced displacement sensors for factory automation signal a move toward co-engineering and scaled deployment, where shared roadmaps and large installation targets reduce per-unit risk and accelerate field validation. These developments indicate that the market is moving beyond fragmented, transactional sales toward more structured ecosystems in which partners align on performance targets, qualification paths, and deployment scale. For suppliers, this means that supply chain resilience and partnership strategy are now as important as sensor performance in winning multi-year programs.
Competitive Landscape and Leading Strategies
The market is characterized by a meaningful but not immovable concentration, with the top three competitors accounting for roughly 48 percent of revenue and the top five approaching 58 percent. This structure suggests that established players hold strong positions in high-value applications and regional channels, while there is still room for specialized entrants and regional challengers to capture share in focused segments. The competitive game is increasingly defined by application mastery, environmental robustness, certification support, and the ability to embed sensors into broader automation or inspection solutions rather than selling components in isolation.
Magnetic Field Sensors Market
Differentiation Themes Among Leading Players
Several companies illustrate the breadth of strategic positioning in the market. One German manufacturer has built a reputation around high-precision non-contact displacement measurement, with product lines designed for applications that demand stable accuracy and clean signal performance. Its recent introduction of a new displacement sensor series with submicron accuracy and IP69K protection underscores a strategy of pairing measurement precision with ruggedization for harsh industrial settings. A United States-based specialist focuses on linear encoders and displacement sensors that emphasize reliable linear measurement for automation and machine building, positioning itself around repeatable feedback in production environments. A Canadian company has carved out a differentiated role in non-destructive testing through eddy current array probes and instruments, where inspection coverage and data quality are the primary value drivers. A German test equipment maker emphasizes crack detection and material sorting through its eddy current test instruments and probes, serving qualification-heavy environments where procedural reliability matters as much as hardware performance. A major United States industrial player contributes a different dimension with sensors designed for turbomachinery displacement and vibration monitoring, linking sensor performance to rotating equipment reliability programs.
Additional participants broaden the competitive field. A Japanese manufacturer offers eddy current sensors and measuring systems for displacement, rotation, and vibration, reflecting a strategy that spans multiple measurement modalities within a unified portfolio. A Chinese manufacturer targets non-destructive testing applications with eddy current detectors and testing systems, competing on accessibility and application breadth in inspection workflows. A United States precision instruments company supplies eddy current proximity probes for displacement and vibration measurement, reinforcing the importance of established probe families in condition monitoring. A Japanese measurement systems leader integrates eddy current displacement sensors into broader measurement platforms, illustrating a strategy that leverages platform ecosystems and customer relationships to expand sensor attachment rates. Together, these players show that success is not monolithic: some win on precision and ruggedness, others on inspection coverage, some on platform integration, and others on cost-accessible testing solutions.
Strategic Moves and What They Signal
Recent developments provide a window into how competitors are shaping the next phase of the market. The introduction of a new displacement sensor series with submicron accuracy and high ingress protection indicates that incremental performance gains continue to be a viable growth lever, especially where environmental resilience is becoming a procurement requirement. A partnership between a large automation supplier and a sensor specialist to jointly develop advanced displacement sensors for factory automation, with a target of over 18,000 installations, signals the increasing importance of scaled co-development and deployment-oriented roadmaps. This kind of collaboration reduces risk for both sides and creates a pathway to embedded adoption in standardized automation cells, where sensor selection is influenced by integration readiness and service support as much as by raw specification.
On the instrumentation side, an updated specification sheet for a 5mm eddy current sensor for radial and axial shaft displacement in turbomachinery highlights the continued refinement of rotating equipment monitoring products, where small specification improvements can unlock broader acceptance in reliability programs. More dramatically, the acquisition of a leading eddy current array and NDNondestructive Testing solutions provider by a large industrial corporation demonstrates that consolidation is actively reshaping the landscape. This transaction enhances the acquirer's portfolio in eddy current array and inspection solutions, adding capability that can be leveraged across a broader customer base and combined with adjacent technologies. The implication for the market is that capability concentration is increasing at the high end of non-destructive testing, while displacement and proximity sensing remain competitive across a wider set of specialists and platform players.
Market Evolution: Consolidation, Differentiation, and Selective Entry
The competitive trajectory appears to be moving along three parallel paths. Consolidation is strengthening the offerings of larger players in inspection and condition monitoring, particularly where array-based testing and rotating equipment monitoring can be bundled with broader service and platform capabilities. Differentiation is deepening around environmental robustness, submicron accuracy, certification support, and integration readiness, making product selection more application-specific and reducing the relevance of price-only comparisons in high-stakes deployments. Selective entry remains possible in regional or application-focused niches, especially where suppliers can offer cost-effective testing systems, strong local support, or specialized probe geometries for particular inspection challenges. For buyers, this means that the supplier landscape is increasingly stratified: a handful of broad-capability leaders, a set of application-dominant specialists, and a tail of regional or price-competitive providers. Navigating this landscape successfully requires matching the supplier's strengths to the application's criticality, compliance needs, and integration requirements.
Future Outlook: Trends and Commercial Opportunities
Looking ahead three to five years, the market's direction is likely to be shaped by the convergence of measurement performance, environmental hardening, and integration depth. Three trends stand out as particularly consequential for strategy and investment.
Trend One: Embedded Monitoring Becomes the Default in Critical Assets
Edy current sensors are increasingly being specified earlier in asset design and integrated into continuous monitoring architectures for turbines, generators, rotating shafts, and high-cycle automation equipment. This trend is driven by the availability of ruggedized, high-accuracy sensors and by the economic logic of predictive maintenance: avoiding downtime and extending service intervals creates value that justifies higher sensor performance and more thorough installation. The commercial opportunity here lies in moving from component sales to solution-oriented engagement, where suppliers help define mounting, calibration, data paths, and maintenance procedures. Suppliers that can document reliability in service, simplify integration, and support data workflows will capture more of the lifecycle value than those that stop at the point of hardware sale.
Trend Two: Inspection Coverage and Speed Improvements Expand NDT Use
In non-destructive testing, eddy current array probes and associated instrumentation continue to improve inspection coverage and reduce scan time on complex components. As certification and qualification expectations rise, the ability to produce repeatable, well-documented results becomes a stronger differentiator. The opportunity for technology providers is to align probe designs and instrument features with the practical needs of inspectors and quality teams, including intuitive operation, clear data presentation, and support for standardized procedures. For operators, the upside is faster throughput and broader inspection coverage without sacrificing compliance, which can translate into lower inspection cost per unit and better asset availability. The risk is that procurement may treat inspection sensors as commoditized unless suppliers invest in documentation, training, and application engineering that reinforces the link between equipment performance and inspection quality.
Trend Three: Supply Chain Resilience and Regional Strategy Become Pricing and Margin Determinants
Material volatility in copper and constraints on certain magnet materials, combined with tariffs and trade measures affecting specific origins, are making supply chain strategy a direct determinant of competitiveness. Over the next several years, suppliers that diversify sourcing, qualify alternative materials where performance allows, and structure assembly and logistics to reduce landed-cost exposure will be better positioned to hold margin while remaining responsive to customers. There is also an opportunity for partnerships and co-development models that spread risk across larger installation targets and shared roadmaps, particularly in factory automation where standardized deployments can amortize engineering cost. The uncertainty here lies in the trajectory of trade policy and commodity markets; both can shift quickly, and suppliers that have not built flexibility into their cost structures may find themselves reacting rather than shaping commercial terms.
Strategic Guidance for Decision-Makers
The market's trajectory creates different implications for manufacturers, investors, and procurement organizations. In each case, the key is to align strategy with where value is consolidating and where flexibility is most needed.
For Manufacturers and Product Leaders
- Prioritize ruggedized precision as a combined design objective. Submicron accuracy is increasingly expected, but industrial bids are increasingly won by products that pair accuracy with verified ingress protection, thermal stability, and mounting practicality. Treat environmental robustness as a core specification, not a secondary feature.
- Invest in integration readiness and documentation. Suppliers that provide clear mounting guidance, calibration support, and compliance-relevant documentation reduce the friction of adoption in certified maintenance and inspection workflows. This lengthens contract horizons and raises switching costs in the customer's favor.
- Build supply chain optionality. Where copper and magnet dependencies create exposure, explore qualified alternatives, dual sources, and design adjustments that reduce sensitivity to any single input. Pair this with regional sourcing or assembly considerations where trade policy affects landed cost.
For Investors and Corporate Development Teams
- Focus on application depth over broad component exposure. Value is accruing to players with strong positioning in rotating equipment monitoring, factory automation displacement feedback, and advanced array-based inspection, where performance, certification, and integration create defensible positions. Evaluate targets and partners through the lens of application mastery and service attach rates rather than unit volume alone.
- Watch consolidation in non-destructive testing and the co-development model in automation. Acquisitions that add array and inspection capability can create cross-selling and platform leverage, while partnerships aimed at large installation targets can accelerate deployment and reduce per-unit risk. Both structures can improve competitive durability if they are paired with strong field support and qualification alignment.
- Assess exposure to trade and material dynamics in cost models. Investments that assume stable input costs or single-origin supply may face margin pressure if commodity volatility or tariff structures shift. Portfolios with diversified sourcing and regional flexibility are better positioned to preserve returns through cycles.
For Procurement and Operations Leaders
- Evaluate the full measurement chain, not just the sensor. In regulated or high-availability contexts, total value includes qualification support, repeatability documentation, ingress protection, and the supplier's ability to support installation and service. A marginally cheaper sensor that creates compliance friction or integration rework can carry higher total cost than a better-documented alternative.
- Specify environmental and protection requirements explicitly. Where washdown, chemical exposure, temperature extremes, or outdoor deployment are expected, treat ingress protection and ruggedization as primary selection criteria. This reduces the risk of field failures and rework and aligns procurement with the realities of the operating environment.
- Negotiate with supply continuity in mind. Given volatility in key materials and trade-related cost impacts, consider sourcing strategies that include qualified alternatives, regional supply options, and clear lead-time commitments. Contracts that account for material and logistics realities are more resilient than those based on static pricing assumptions.
The eddy current sensor market is moving from a phase defined by incremental specification gains to one shaped by application integration, environmental robustness, compliance alignment, and supply chain strategy. Growth at a steady mid-single-digit pace through the end of the forecast period provides a constructive backdrop, but the commercial winners will be those who convert that growth into durable positions in critical monitoring and inspection applications. For decision-makers who need segment-level sizing, regional deployment patterns, competitive benchmarking, and tailored scenario planning, a detailed research report can provide the deeper data and structured frameworks required to translate these trends into concrete portfolio, sourcing, and investment decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Eddy Current Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Print Quality Inspection System Market: Why 5.8% CAGR and $300M Expansion Reshape Production
By PW Consulting, 2026-09-21
The Print Quality Inspection System Market: Navigating Strategic Shifts and Commercial Opportunities
The global landscape for print quality inspection systems is undergoing a structural transformation. What was once a niche segment focused on routine defect detection has evolved into a critical infrastructure layer for manufacturing industries where visual fidelity, regulatory compliance, and production efficiency intersect. The market has demonstrated steady expansion over the past half-decade, with revenue climbing from approximately USD 148.5 million in 2020 to USD 201.5 million in 2025. Projections through 2032 indicate continued growth, reaching an estimated USD 300.0 million by the end of the forecast period, supported by a compound annual growth rate of 5.8 percent. This trajectory reflects more than incremental demand; it signals a fundamental reassessment of how manufacturers approach quality assurance in an era defined by tighter regulatory frameworks, rising labor costs, and accelerating automation adoption.
Yet the growth narrative is not uniform across all segments or regions. The market remains moderately fragmented, with the top three players capturing roughly 24.6 percent of total revenue and the top five accounting for approximately 26.2 percent. Such concentration levels suggest a competitive environment where established incumbents hold meaningful advantages in brand recognition, installed base, and technical maturity, but where room exists for differentiated newcomers and niche specialists to carve out defensible positions. The following sections dissect the forces shaping this market, the competitive dynamics at play, and the strategic implications for executives navigating procurement decisions, investment allocations, and product development roadmaps.
Market Structure and the Current Growth Trajectory
The print quality inspection system market has expanded consistently since 2020, with each year underscoring a broader industrial shift toward automated visual verification. Revenue growth between 2023 and 2024, for instance, reflected a notable step change as manufacturers accelerated deployment of inspection hardware on high-speed production lines. By 2025, the market had surpassed the USD 200 million threshold, and forward estimates suggest that annual revenue will continue climbing at a pace that outstrips general manufacturing equipment growth rates. This expansion is not merely a function of unit sales; it is increasingly tied to the value of integrated software, cloud-enabled workflows, and AI-driven defect classification, which together elevate the total cost of ownership and lifetime value of each installation.
Geographically, the market exhibits a multi-polar distribution rather than reliance on a single dominant region. North America, Europe, and Asia Pacific each represent substantial revenue pools, reflecting the widespread adoption of inspection systems across packaging, pharmaceutical labeling, and consumer goods manufacturing. Emerging regions such as Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by localized packaging investments and the gradual modernization of legacy production lines. The geographic spread indicates that demand is not confined to mature industrial economies; rather, it is spreading as manufacturing capabilities and regulatory expectations mature across diverse markets.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the market faces several friction points that will determine which participants capture disproportionate value over the next five to seven years.
First, the transition from traditional rule-based inspection to AI-enhanced defect recognition remains uneven. While the technology promise is clear, manufacturers must weigh the upfront integration complexity against incremental yield improvements. Legacy systems often rely on fixed thresholds and manual calibration, which limits adaptability to shifting substrates, ink formulations, or packaging designs. Upgrading to systems capable of learning from production variability requires not only hardware refresh but also data infrastructure, operator training, and sustained model maintenance. This creates a barrier for mid-sized producers who may lack the internal engineering capacity to manage algorithmic lifecycle management.
Second, regulatory pressure is intensifying the stakes for inspection accuracy, particularly in sectors where visual defects carry compliance or safety implications. In pharmaceutical and medical packaging, print quality is not merely a cosmetic concern; it is tied to traceability, dosage clarity, and patient safety. Recent regulatory updates, including the Quality Management System Regulation that took effect in early 2026 and incorporated ISO 13485:2016 principles, have tightened quality management expectations for device manufacturers. These changes increase the value of inspection systems that can provide auditable records, consistent defect classification, and integration with broader quality management workflows. At the same time, they raise the compliance burden for suppliers who must demonstrate that their inspection solutions meet evolving standards across multiple jurisdictions.
Third, capital intensity and infrastructure requirements constrain adoption in certain deployment contexts. High-speed line scan imaging modules, specialized illumination, and integration with existing web or sheet-fed lines represent significant investment. For some producers, the decision to deploy a comprehensive inspection system competes with other capital priorities, especially when labor shortages are not yet acute enough to force automation. Industry data points to rising labor constraints in manufacturing as a broader catalyst for inspection adoption, but the translation of labor pressure into procurement decisions varies by region, sector, and company size. This creates a bifurcated market where large, efficiency-focused operators move quickly while smaller or margin-constrained players lag.
Core Drivers Shaping the Market
The sustained expansion of the print quality inspection system market is propelled by a convergence of technological, regulatory, and operational forces. Understanding these drivers in isolation is useful; understanding their interaction is essential for strategic planning.
Technological Innovation and the AI Transition
The most consequential shift in the market is the integration of machine vision and AI-based defect detection into inspection workflows. Vendors are increasingly offering systems that combine high-resolution imaging with algorithmic classification, enabling real-time identification of misregistration, color deviation, foreign material, and substrate defects. This evolution addresses a long-standing limitation of earlier inspection approaches: the reliance on static defect libraries that struggle to adapt to new packaging formats or variable production conditions. AI-enhanced systems can reduce false rejects, improve line throughput, and provide richer data outputs that feed into downstream quality analytics.
Product launches and software releases over recent years illustrate how vendors are translating this technological trajectory into commercial offerings. One notable example is the introduction of an AI-powered inspection platform designed for high-speed printing and packaging environments, which emphasizes automated visual quality control and defect detection at production speeds. Another significant development is the release of cloud-based prepress inspection software that operates independently of specific hardware configurations, reflecting a broader industry move toward software-centric value addition. These releases signal that competitive differentiation is increasingly determined by software ecosystems, data portability, and the ability to integrate with prepress, production, and quality management systems rather than by imaging hardware alone.
Regulatory and Compliance Pressures
Regulatory expectations are reinforcing demand for inspection systems that deliver consistency, traceability, and audit readiness. Quality management standards such as ISO 9001:2015 serve as foundational references for inspection workflows across global manufacturing, while sector-specific requirements add further layers of complexity. In pharmaceutical and medical packaging, inspection systems must align with standards enforced by regulatory bodies such as the FDA and EMA, ensuring that print quality supports broader compliance obligations. The recent amendment of device current good manufacturing practice requirements through the Quality Management System Regulation exemplifies how regulatory updates can directly influence procurement priorities by raising the bar for documented quality control and process verification.
For manufacturers operating in regulated environments, the commercial case for advanced inspection systems is strengthened by the potential to reduce compliance risk, streamline audit preparation, and standardize defect documentation across lines and sites. This dynamic is particularly relevant for multinational producers who must maintain consistent quality standards across diverse regulatory regimes. Inspection systems that offer configurable rule sets, robust data logging, and integration with quality management platforms are better positioned to meet these demands than standalone defect detection tools.
Demand-Side Shifts in Packaging and Labeling
Consumer expectations and retail dynamics are reshaping the packaging and labeling sector in ways that indirectly elevate the importance of print quality inspection. Brands are increasingly reliant on packaging as a primary engagement channel, which raises the visibility of print defects and the reputational cost of quality failures. At the same time, the proliferation of short-run packaging, variable data printing, and customized labeling increases production variability, making manual inspection less scalable and more error-prone. In food and beverage, consumer goods, and medical packaging, the combination of higher quality expectations and more heterogeneous production runs drives demand for inspection systems that can maintain accuracy across frequent changeovers.
Worldwide Thermal Warpage Inspection System Market
This demand-side evolution also intersects with operational efficiency goals. As manufacturers seek to minimize waste, reduce rework, and improve first-pass yield, inspection systems function as both a quality gate and a productivity enabler. Real-time defect detection allows operators to intervene before defective material proceeds further down the line, reducing material loss and downstream sorting costs. In high-volume environments, even small improvements in defect capture rates can translate into meaningful savings over time, strengthening the return case for inspection investments.
Supply Chain and Cost Structure Considerations
The cost structure surrounding print quality inspection systems is influenced by component availability, integration complexity, and the broader economics of high-speed imaging hardware. Capital equipment costs and infrastructure investments for advanced line scan modules represent a notable deployment barrier, particularly for producers upgrading from legacy systems or introducing inspection on previously unmonitored lines. At the same time, the supply chain for vision components, illumination systems, and processing hardware continues to evolve, with vendors seeking to balance performance with total cost of ownership.
Rising labor costs and workforce constraints in manufacturing are also reshaping the cost-benefit calculus for inspection adoption. In environments where skilled operators are difficult to recruit or retain, automated inspection offers a pathway to stabilize quality output while reducing reliance on manual inspection labor. This dynamic does not uniformly apply across all markets, but it is increasingly relevant in regions and sectors where labor availability is tightening. The interaction between labor economics and inspection investment helps explain why adoption rates can diverge even among producers with similar product portfolios.
Competitive Landscape and Strategic Positioning
The competitive environment in the print quality inspection system market is characterized by a mix of specialized inspection vendors, broader machine vision providers, and prepress solution companies. This diversity reflects the multidisciplinary nature of the market, which draws on expertise in imaging, color measurement, web monitoring, packaging workflows, and quality management software. The presence of both established European and North American players and rapidly evolving Asian manufacturers adds further complexity, as differing regional strengths shape product focus, pricing approaches, and go-to-market strategies.
Differentiation Strategies Among Leading Players
Leading participants are pursuing differentiation along several axes, with the most successful strategies combining technical capability with workflow integration and sector-specific relevance.
- Some vendors position themselves around AI-powered inspection for packaging and printed products, emphasizing defect detection and prepress verification across dedicated hardware and software series. Their approach targets customers who prioritize integrated solutions with established brand recognition in print inspection.
- Other companies focus on label and flexible packaging applications, offering real-time defect detection and color measurement tools designed to reduce waste and support high-speed production environments. This specialization allows them to align closely with the operational priorities of label converters and flexible packaging manufacturers.
- A separate group develops vision-based inspection systems for printing and packaging that emphasize automated visual quality control at high speeds, often leveraging AI to improve defect classification and adaptability across substrates.
- Web monitoring and inspection specialists serve the pulp, paper, and printing industries with surface defect detection solutions, reflecting a distinct application focus that differs from packaging-centric vendors.
- Providers of integrated web inspection and tension control systems combine print quality solutions with broader process control capabilities, appealing to customers who value unified monitoring across multiple production parameters.
- Machine vision and vision system companies offer automated inspection and verification tools for packaging and labeling, drawing on broader portfolio strength in industrial vision to address print quality as part of a larger automation strategy.
- Prepress and artwork verification vendors concentrate on upstream quality control, enabling automated artwork and packaging verification before production, which complements downstream inspection and can reduce defect propagation.
These positioning differences matter because they shape which customers view a given vendor as a natural fit. A label converter prioritizing real-time waste reduction will evaluate vendors differently than a pharmaceutical packaging producer focused on compliance documentation and audit readiness. Similarly, a printing operation seeking to upgrade both prepress and in-line inspection may prefer a vendor with capabilities spanning both domains, while another may value best-of-breed specialization.
Recent Market Movements and Their Strategic Signals
Recent corporate and product developments provide useful signals about where competitive pressure is intensifying and how vendors are attempting to capture value. One significant move involved the acquisition and restructuring of a prominent inspection company into an independent entity, enabling a dedicated focus on print quality inspection solutions. Such a transformation typically reflects a strategic decision to sharpen product focus, reallocate resources, and respond more agilely to market demands without the constraints of a broader corporate structure. For customers, this can translate into more specialized support and roadmap clarity; for competitors, it may intensify pressure in segments where the newly independent company has strong installed bases.
On the product side, the launch of a next-generation AI inspection system at a major industry event highlighted the continuing emphasis on AI-driven visual quality control for printing applications. Concurrently, another vendor introduced cloud-based prepress inspection software designed to operate independently of specific hardware, underscoring a shift toward software-defined inspection workflows that can reduce dependency on proprietary hardware ecosystems. The visibility of these solutions at major trade events further illustrates how vendors are using industry platforms to demonstrate defect detection capabilities and align product messaging with current production challenges.
Taken together, these developments suggest a market in which hardware capability remains important, but software flexibility, AI maturity, and workflow integration are increasingly decisive in competitive battles. Vendors that can offer modular, upgradeable solutions and clear data pathways between prepress, production, and quality management systems are better positioned to retain customers through technology refresh cycles.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The moderate concentration levels in the market indicate that fragmentation persists, but the trajectory points toward gradual consolidation in certain segments. Larger machine vision and industrial automation companies may seek to expand their footprint by leveraging existing customer relationships and broader automation portfolios, while specialized inspection vendors may pursue partnerships, selective acquisitions, or geographic expansion to strengthen their positions. At the same time, new entrants—particularly those bringing novel AI capabilities or cost-competitive imaging architectures—can gain traction in segments where incumbents are slow to adapt or where price sensitivity is elevated.
The evolution of the market will likely be shaped by the relative success of three dynamics. First, consolidation may accelerate where installed base advantages and service networks create meaningful switching costs, allowing larger players to capture share through bundling and cross-selling. Second, specialization may remain attractive in high-value verticals such as pharmaceutical packaging, where compliance expertise and sector-specific workflows command premium positioning. Third, new entrants may disrupt segments where traditional inspection approaches are perceived as overly rigid or too costly relative to emerging AI-based alternatives. The interplay among these dynamics will determine which companies build durable advantages and which face pressure to differentiate more sharply or reposition.
X-ray Inspection Systems Market
Forward Outlook: Three Trends to Watch
Looking ahead, the print quality inspection system market is likely to be shaped by several interconnected trends over the next three to five years.
AI Maturity and the Shift from Detection to Classification and Prediction
The next phase of AI adoption in inspection systems is expected to move beyond basic defect detection toward more sophisticated classification, root-cause suggestion, and predictive quality analytics. As algorithms become more robust and training data more abundant, inspection systems can increasingly distinguish between defect types, prioritize issues by severity, and feed insights back into process control. This evolution enhances the value of inspection not only as a gate but as an intelligence source that supports continuous improvement. Commercial opportunity lies in systems that can integrate defect data with production parameters, enabling operators to correlate visual defects with substrate changes, ink variability, or machine settings. The primary risk is that AI capabilities may outpace customers’ ability to operationalize them, creating a gap between feature availability and practical benefit realization.
Software-Defined Inspection and Interoperability as Competitive Battlegrounds
The introduction of hardware-independent, cloud-enabled inspection software reflects a broader movement toward interoperability and software-centric value. As manufacturers seek to avoid lock-in and integrate inspection data across prepress, production, and enterprise quality systems, the ability to exchange data seamlessly and configure inspection workflows without hardware constraints will become more important. Vendors that invest in open architectures, standardized data outputs, and flexible deployment models are likely to gain an advantage in environments where multi-vendor equipment and evolving IT strategies are the norm. The risk for the market is that interoperability expectations may pressure margins for vendors reliant on proprietary hardware ecosystems, while also raising the bar for software development and integration support.
PW Consulting
Regulatory Tightening and Sector-Specific Premiumization
As regulatory frameworks continue to evolve, particularly in pharmaceutical, medical, and food-related packaging, the premium on inspection systems that support compliance documentation, audit readiness, and consistent defect classification is likely to increase. This creates a segmentation dynamic in which regulated sectors may adopt higher-specification solutions and accept stronger compliance-related value propositions, while less regulated segments may compete more intensely on price and throughput. Commercial opportunity exists for vendors that can clearly articulate compliance benefits, provide configurable rule sets aligned with sector requirements, and offer data integrity features that support audit trails. The uncertainty lies in the pace and variability of regulatory change across jurisdictions, which can complicate product planning and require ongoing adaptation.
Strategic Guidance for Decision Makers
The trajectory of the print quality inspection system market suggests that decision makers should evaluate opportunities and risks through a lens that goes beyond unit pricing and specification sheets. In practice, three strategic considerations stand out.
For manufacturers and producers considering inspection deployment, the priority should be to align system selection with the broader quality and operational roadmap rather than treating inspection as an isolated procurement. This means evaluating how well a solution integrates with prepress workflows, production line control, and quality management systems, and whether it can scale as defect classification, data analytics, and regulatory documentation needs evolve. It also means assessing total cost of ownership in the context of labor constraints, waste reduction potential, and compliance risk, rather than focusing solely on initial capital expenditure. Where possible, manufacturers should favor solutions that offer modular upgrade paths, configurable inspection rules, and clear data portability, reducing the risk of obsolescence as requirements change.
For investors and strategic partners, the market presents a nuanced opportunity set shaped by the balance between hardware-driven deployments and software-defined value creation. Companies that can demonstrate AI capability, interoperability, and sector-specific relevance are better positioned to capture share than those competing primarily on imaging hardware alone. Investment theses should consider the durability of installed base advantages, the potential for consolidation in segments with high switching costs, and the risk that new entrants with novel AI or cost architectures could challenge incumbents in price-sensitive segments. Due diligence should also account for regulatory exposure, particularly in verticals where compliance dynamics directly influence procurement decisions and solution requirements.
For procurement and quality leaders, the immediate focus should be on building an inspection strategy that balances near-term defect reduction with long-term data utilization. This includes defining clear acceptance criteria for defect classification accuracy, false reject rates, and integration requirements; ensuring that inspection data can feed into broader quality analytics; and evaluating vendor support for changeovers, substrate variability, and evolving regulatory expectations. Procurement decisions made without a clear view of data integration, compliance alignment, and upgrade flexibility may deliver short-term savings but create downstream bottlenecks as quality programs mature. Access to detailed segmentation data, vendor benchmarking, and customized deployment scenarios can materially improve the quality of these decisions, particularly when evaluating multi-vendor shortlists or planning multi-site rollouts.
For executives seeking a more granular understanding of regional demand patterns, application-specific growth differentials, and vendor-level positioning across sub-segments, a deeper dive into the full research dataset can provide the scaffolding needed to translate these market-level insights into actionable plans. Detailed breakdowns of segmentation dynamics, competitive benchmarks, and scenario-based procurement considerations can help clarify where to prioritize investment, which vendor profiles warrant closer evaluation, and how to structure quality inspection roadmaps in line with operational and regulatory realities.
For detailed analysis of this topic, please visit the official page: Print Quality Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
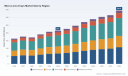
Micro-Lens Arrays Market: Strategic Trends and Commercial Opportunities Beyond 2030
The global micro-lens array (MLA) market has matured into a strategically vital component of modern optical systems, driven by the convergence of photonics innovation, automotive electrification, and high-bandwidth data infrastructure. From 2020 through 2025, the sector expanded from approximately USD 163 million to an estimated USD 215 million, reflecting a compound annual growth rate (CAGR) of 6.49% across the forecast horizon extending to 2032. This trajectory is not merely a function of incremental demand; it signals a structural shift in how precision optics are integrated across telecommunications, advanced driver-assistance systems, medical imaging, and next-generation energy modules. As the market approaches a projected valuation exceeding USD 340 million by 2032, executives and investors must navigate a landscape where technological differentiation, supply chain resilience, and regulatory volatility intersect.
PW Consulting
Market Snapshot: Scale, Structure, and Hidden Pressures
The MLA ecosystem has transitioned from a niche photonics supplier to a foundational enabler of high-value optical architectures. Historical revenue patterns reveal a market that experienced a brief contraction in 2022, followed by a robust rebound and sustained expansion through 2025. This correction was temporary but instructive: it exposed the fragility of highly optimized, geographically concentrated supply chains when confronted with raw material constraints and sudden trade policy shifts. By 2025, the market's recovery and upward momentum underscore a broader reality—demand for micro-optical components is no longer cyclical; it is structurally embedded in multiple high-growth verticals.
Worldwide Microdisplay Spatial Light Modulators Market
Several structural pressures are reshaping how manufacturers, buyers, and capital allocators approach the space. First, precision fabrication requirements have tightened tolerances across pitch accuracy, surface quality, and coupling efficiency, elevating process control costs and extending lead times. Second, raw material dynamics have introduced periodic volatility, particularly for specialty optical glasses doped with rare-earth elements, where sourcing bottlenecks can quickly translate into pricing adjustments. Third, regulatory interventions in major consumer markets have recalibrated procurement strategies, compelling buyers and producers alike to reconsider geographic sourcing, inventory buffering, and localized production pathways. These pressures are not isolated disruptions; they are becoming baseline considerations in strategic planning.
Key Drivers Reshaping the Micro-Lens Arrays Landscape
Technological Innovation and Process Maturation
The acceleration of co-packaged optics (CPO), silicon photonics integration, and high-density fiber coupling has elevated MLAs from passive optical elements to active performance determinants. Fabricators are increasingly deploying wafer-level imprint lithography, two-photon polymerization, and hybrid glass-composite molding to achieve freeform, aspherical, and sub-micron pitch architectures. These process advances enable tighter beam shaping, improved homogenization, and higher coupling efficiency in telecom and datacom environments. At the same time, additive microfabrication techniques are unlocking complex geometries that were previously cost-prohibitive, expanding the design space for machine vision, laser systems, and compact medical optics. The commercial implication is clear: vendors that can translate fabrication agility into repeatable, high-yield production gain a measurable edge in qualification cycles and customer retention.
Policy and Regulatory Realignment
Trade policy adjustments in the United States during 2025 introduced additional duties on imported fused silica substrates and finished microlens arrays, directly altering cost structures and procurement timelines. Rather than treating these measures as transient friction, leading organizations are recalibrating sourcing architectures to reduce exposure to single-point customs risk. This has spurred incremental investments in localized manufacturing, dual-sourcing arrangements, and qualification of alternative substrate materials. Regulatory shifts of this nature typically accelerate supplier consolidation among entities with established compliance infrastructure, while simultaneously opening opportunities for regional producers capable of meeting technical specifications without compromising lead times.
Demand-Side Evolution in End-Use Verticals
Demand momentum is increasingly dictated by application adoption curves rather than broad macroeconomic indicators. In telecommunications and IT infrastructure, the push toward higher bandwidth, lower latency, and integrated optical interconnects continues to drive MLA utilization in fiber coupling and light management. Automotive applications are expanding as advanced lighting architectures, sensing modules, and in-vehicle optical systems require compact, reliable micro-optics that can withstand harsh environmental conditions and meet stringent quality standards. Medical imaging, diagnostic devices, and specialized laser systems contribute a steady, high-value demand stream where precision and repeatability outweigh cost sensitivity. Concurrently, solar module optimization and auxiliary optical applications provide incremental volume that supports capacity utilization. For commercial leaders, the strategic takeaway is to align product roadmaps with the qualification rhythms and technical thresholds of these verticals, rather than competing solely on price in commoditized segments.
Supply Chain and Cost Structure Realities
Precision manufacturing of MLAs remains labor- and process-intensive. High-precision polishing, alignment, and metrology contribute to elevated unit economics, particularly as volumes scale and tolerance requirements tighten. Material supply concentration in select regions for high-grade optical glass introduces vulnerability to geopolitical friction, export control expansions, and localized disruptions. These structural characteristics mean that lead-time reliability, quality consistency, and technical support often carry as much commercial weight as baseline pricing. Organizations that invest in process stabilization, qualification transparency, and resilient material sourcing are better positioned to convert technical capability into sustained contract wins and reduced negotiation friction.
Competitive Landscape: Positioning, Differentiation, and Evolution
The MLA market remains moderately concentrated, with the top three participants collectively accounting for just under a quarter of total revenue and the top five holding a slightly larger share. This fragmentation reflects a market where technical specialization, application-specific qualification, and regional servicing capabilities often matter more than scale alone. Several established players illustrate distinct strategic archetypes that define current competitive dynamics.
Glass-focused fabricators have built reputations around high-precision glass microfabrication, molding, and composite technologies, targeting applications such as CPO, digital imaging, high-brightness LEDs, and OLED architectures. Their differentiation typically hinges on material consistency, yield stability, and deep process know-how in glass-based optics. Custom photonics specialists, by contrast, emphasize design flexibility and rapid iteration, offering dedicated engineering services that help customers translate optical concepts into manufacturable MLA devices. This service-led model supports next-generation photonics development and positions the supplier as a design partner rather than a pure component vendor.
Wafer-scale manufacturers operating on 150mm and 150mm-class platforms serve telecom, datacom, automotive, and consumer segments with a focus on pitch accuracy and coupling efficiency. Their competitive strength lies in standardized substrate handling, repeatable wafer-level processes, and qualification pathways aligned with automotive and semiconductor expectations. Meanwhile, additive microfabrication providers leverage two-photon polymerization to deliver freeform and hybrid micro-optics on fibers and chips, targeting complex geometries and rapid prototyping cycles that conventional lithography cannot easily accommodate. Imprint lithography specialists contribute wafer-level MLAs suited for automotive lighting, fiber coupling, photonic integrated circuits, and semiconductor applications, with quality systems aligned to automotive production standards.
Other participants differentiate through material selection and application focus. Some offer high-grade fused silica arrays with spheric, aspheric, or freeform profiles tailored for fiber coupling, while others emphasize precision polishing and alignment for machine vision, laser systems, and optical sensing. PMMA-based arrays remain relevant for light homogenization and shaping in research, instrumentation, and industrial settings where cost and ease of integration are prioritized. Across these profiles, the common thread is application alignment: vendors that embed their technical strengths within the qualification and performance requirements of specific use cases tend to secure more durable demand.
The competitive trajectory is moving toward selective consolidation and parallel specialization. Larger optical and materials groups are exploring targeted acquisitions or partnerships to broaden substrate capabilities, strengthen regional service coverage, and accelerate qualification in regulated verticals. At the same time, new entrants with advanced fabrication methods or niche design expertise continue to fragment the market at the high-value end, particularly where freeform design, hybrid materials, or custom photonics services create Defensible differentiation. The net effect is a landscape where broad commoditization is limited; value accrues to organizations that can combine technical precision, application understanding, and supply chain reliability.
Optical Lenses Market
Commercial Implications of the Competitive Shift
- Technical service and design engagement are becoming as important as component pricing, especially for customers developing next-generation optical architectures.
- Regional qualification and compliance readiness increasingly influence sourcing decisions, particularly in automotive and telecom environments.
- Substrate availability and material continuity are emerging as deal-critical factors, elevating the strategic importance of diversified sourcing and inventory planning.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Integration-Driven Demand in High-Bandwidth Optical Architectures
As co-packaged optics and photonic integration gain traction in datacom and telecom deployments, MLAs will be evaluated less as standalone components and more as integrated elements within broader optical subsystems. This shift favors suppliers who can support system-level design considerations, including alignment tolerances, thermal stability, and coupling efficiency under realistic operating conditions. The opportunity lies in offering qualified, repeatable MLAs that reduce integration risk for system designers, while the risk is that pricing pressure intensifies if specifications become standardized across multiple vendors.
Trend 2: Regionalization of Sourcing and Manufacturing Capability
tariff measures and raw material concentration risks are accelerating a broader move toward localized production, dual sourcing, and qualification of alternative supply bases. Over the next several years, this is likely to produce a more geographically diversified supplier base for fused silica and specialty glass MLAs, with regional hubs emerging to serve nearby automotive, medical, and industrial customers. The upside is improved lead-time predictability and reduced customs exposure; the downside is that firms without capital to invest in localized capacity or qualification infrastructure may face margin compression or exclusion from preferred supplier lists.
Trend 3: Advanced Fabrication Methods Opening High-Value Niches
Additive microfabrication, imprint lithography, and hybrid molding are expanding the feasible design space for freeform, hybrid, and complex micro-optics. These methods create openings in custom photonics, compact sensing, and specialized imaging applications where performance requirements cannot be met by conventional arrays. The commercial benefit is access to higher-margin, application-specific work; the risk is that process scalability and cost control remain challenging, potentially limiting volume growth if demand stays fragmented across many small programs.
Associated Risks and Uncertainties
- Raw material availability for rare-earth-doped optical glasses may continue to create periodic cost and lead-time volatility during demand spikes.
- Regulatory frameworks can shift quickly, altering the relative attractiveness of different sourcing routes and requiring continuous supply chain reassessment.
- Labor intensity in high-precision polishing and alignment may sustain elevated unit economics, limiting the pace at which cost reductions can be passed through to customers.
- Geopolitical disruptions or export control expansions could disproportionately affect supply chains with concentrated production in a small number of regions.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Prioritize process stabilization and qualification transparency in the segments where you intend to compete. In automotive and telecom environments, documentation, repeatability, and compliance readiness often determine supplier selection as much as baseline performance. Evaluate whether to deepen specialization in a high-value niche—such as custom photonics design, freeform micro-optics, or wafer-level automotive lighting—or to expand substrate and material options to reduce concentration risk. Where feasible, develop dual-sourcing strategies for critical raw materials and consider regional capacity or partnerships that shorten lead times for nearby customer bases.
For Investors and Capital Allocators
Focus diligence on differentiation durability rather than headline growth alone. The most resilient opportunities typically combine technical moats, application-specific qualification, and supply chain resilience. Assess whether target companies have clear pathways to scale without sacrificing quality, whether their customer base is diversified across multiple verticals or overly dependent on a single program cycle, and whether they have responded to recent trade and material dynamics with actionable sourcing or capacity strategies. In a moderately concentrated market, value creation often comes from firms that can convert specialized capability into recurring, qualified demand rather than from broad-based volume plays.
For Procurement and Engineering Leaders
Treat MLA sourcing as a systems-integration decision rather than a commodity purchase. Align specifications with actual performance needs, qualify alternative substrates and suppliers where feasible, and build buffer strategies for materials with known concentration risk. Engage suppliers early on design-for-manufacturability and qualification timelines to reduce downstream rework and schedule risk. Where application requirements permit, balance precision requirements against cost by selecting the simplest architecture that meets system performance targets, reserving high-complexity freeform or hybrid designs for cases where they deliver measurable system-level benefits.
The micro-lens arrays market is entering a phase where technical capability, supply chain resilience, and application alignment determine commercial outcomes more than volume alone. Decision makers who map their strategies to these structural dynamics will be better positioned to capture high-value demand while navigating material, regulatory, and process uncertainties. For organizations seeking detailed segmentation data, regional demand patterns, and tailored recommendations aligned to specific product portfolios or investment theses, the full PW Consulting research report provides the deeper quantitative and qualitative detail needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Micro-Lens Arrays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com