

Blogs
Intelligent Parcel Locker Market: Why 12.5% CAGR and Commercial Buildings Redefine Growth
By PW Consulting, 2026-09-21
The Intelligent Parcel Locker Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The intelligent parcel locker ecosystem has transitioned from a niche convenience to a structural component of modern logistics and urban infrastructure. Between 2020 and 2025, global revenue climbed from approximately $800 million to $1.2 billion, reflecting a compound annual growth rate of 12.5% through the forecast horizon to 2032. By the end of that period, market value is projected to approach $2.74 billion, driven by compounding pressures on last-mile efficiency, the normalization of self-service pickup, and sustained investment in connected physical infrastructure. This trajectory is not merely a function of rising e-commerce volumes; it signals a broader recalibration of how goods move through dense residential, commercial, and transit environments.
For executives, investors, and procurement leaders, the opportunity lies in recognizing where the market is genuinely differentiating versus where it remains commoditized. The sector has entered a phase where deployment speed, carrier-agnostic interoperability, and functional specialization determine competitive advantage. Yet the same forces creating tailwinds also expose operational and regulatory friction that can stall rollouts or compress margins if not addressed early.
Market Snapshot and Structural Constraints
The revenue trajectory across the 2020–2032 window demonstrates steady accumulation rather than cyclical spikes, with the most pronounced inflection occurring between 2023 and 2026. That pattern aligns with the maturation of carrier-agnostic locker networks, the scaling of multi-function units, and the gradual shift from pilot deployments to standardized portfolio strategies. Market concentration remains moderate, with the top three players holding roughly a quarter of total value and the top five capturing just over a third. This fragmented structure indicates room for consolidation but also a landscape where regional specialists, functional innovators, and logistics incumbents can still win through targeted positioning.
PW Consulting
Several constraints are shaping how this growth actually translates into realized deployments. First, the economics of urban footprint acquisition remain uneven. High-density zones offer superior utilization but introduce zoning complexity, property-owner negotiations, and maintenance access challenges that can lengthen sales cycles. Second, the operational reliability of connected lockers depends on a layered stack of hardware durability, secure communications, and software integration with parcel management platforms. Mismatches across those layers create deployment risk, particularly when units must operate continuously in varied weather conditions while maintaining real-time status visibility for both carriers and end users. Third, the shift toward multi-functionality is introducing new performance expectations. Lockers are increasingly expected to accommodate refrigerated freshness, secure laundry exchanges, and modular reconfiguration without sacrificing throughput or simplicity for the end user. Managing that breadth of capability without inflating unit costs or complicating maintenance is a defining engineering and commercial tension.
Core Drivers Reshaping the Market
Technological Innovation and Connected Hardware
The technological evolution of parcel lockers is moving beyond isolated access control toward integrated, sensor-rich systems that support remote diagnostics, flexible carrier routing, and specialized environmental management. Modular architectures now allow operators to scale footprint and functionality as demand patterns shift, while solar-powered and off-grid configurations reduce dependency on site electrification and enable deployment in locations where wiring constraints would otherwise stall installations. Bluetooth- and IoT-enabled notifications have become baseline expectations for contactless, real-time pickup coordination, and secure data handling at the locker level has taken on added importance as tracking and access workflows generate more operational data. These capabilities are not merely feature upgrades; they directly affect utilization, downtime, and the ability of carriers and property operators to manage multiple delivery partners through a single physical footprint.
The commercial implication is clear: hardware differentiation is increasingly tied to how well a locker system integrates into broader operational workflows rather than to standalone metalbox durability. Units that can flexibly accommodate multiple carriers, provide reliable connectivity in densely built environments, and adapt to specialized loads such as perishables or laundry are gaining traction across residential complexes, retail click-and-collect points, and institutional campuses. This is accelerating a shift in procurement criteria from unit price toward total cost of ownership, uptime, and interoperability.
Worldwide Smart Electronic Locker Systems Market
Regulatory and Policy Dynamics
Policy and regulatory conditions are shaping both the pace and the structure of locker adoption. Universal service providers in Europe have expanded parcel locker networks in ways that lower delivery costs and improve consumer convenience, reflecting a strategic alignment between public logistics obligations and private infrastructure deployment. At the same time, data sovereignty frameworks in EU countries require secure, locker-based data handling for parcel tracking and access, which pushes vendors and operators toward more rigorous information governance. Spectrum and wireless regulations further influence deployment by enabling real-time IoT notifications and secure, contactless operations, making regulatory clarity around connectivity an underappreciated enabler of adoption.
These regulatory currents create a dual effect. They raise the compliance burden for cross-border or multi-jurisdiction deployments, but they also provide a structural advantage to operators and vendors that design for secure data handling and standardized connectivity from the outset. In practice, locker networks that treat regulatory alignment as an afterthought face higher integration cost and slower site approval, while those embedding compliance into architecture reduce friction and can scale more predictably across regions.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the normalization of self-service pickup has changed expectations around availability, security, and convenience. Consumers increasingly view round-the-clock access as preferable to constrained delivery windows, especially in urban settings where in-home delivery is less reliable or less desired. For residential and mixed-use properties, parcel lockers address recurring pain points around package theft, concierge burden, and space constraints. In retail environments, click-and-collect lockers help retailers and brands manage foot traffic, reduce missed-handoff friction, and create a more predictable pickup experience. Institutions such as universities and colleges are also deploying lockers to streamline distribution for campus mail, procurement deliveries, and student services.
This demand evolution is broadening the addressable use cases beyond traditional postal and courier handoffs. As a result, locker installations are increasingly evaluated on the strength of the surrounding service model: who operates the unit, how carriers are onboarded, how notifications and access credentials are managed, and how maintenance is handled over the asset life. The market is therefore rewarding operators and vendors that can present a coherent end-to-end story rather than a standalone hardware proposition.
Cost Structure and Last-Mile Labor Economics
Labor economics remain one of the most powerful structural drivers. Intelligent parcel lockers reduce last-mile labor requirements for postal and courier providers by enabling automated self-service access, which helps mitigate the cost and scheduling volatility associated with repeated delivery attempts and individual handoffs. In high-density cities, the deployment of smart lockers also supports more sustainable urban logistics by minimizing physical delivery trips, an outcome that resonates with both cost discipline and sustainability targets. The combined effect is a clearer economic rationale for shared locker infrastructure as a complement to, rather than a replacement for, traditional delivery channels.
This cost dynamic influences both carrier behavior and property-level adoption. Carriers see value in consolidating drop-offs into predictable, self-service points, while building operators and retail managers value the reduced handling burden and improved security profile. The strategic opportunity lies in aligning business models so that these benefits are captured collectively rather than siloed across separate stakeholders, which is often the difference between a one-off installation and a scaled network.
Competitive Landscape and Leading Strategies
The competitive field is diverse, spanning hardware manufacturers, service-oriented networks, and logistics-aligned partnerships that are reshaping how locker infrastructure is deployed and monetized. ZHILAI has emphasized smart locker variants that include solar-powered, Bluetooth-enabled, and refrigerated models, positioning itself around flexible last-mile pickup and self-service use cases. Quadient has built a carrier-agnostic model through Parcel Pending by Quadient, aggregating thousands of locations and pairing locker hardware with management software for residential, retail, and commercial settings. OMNIC has focused on manufacturing indoor and outdoor smart lockers, including solar off-grid options and all-in-one multi-function models suited to logistics and e-commerce operations, with protection specifications that address demanding environments. KEBA has pursued a partnership-led approach, supplying classic parcel lockers and loxmate systems under relationships with bpost and GLS, reinforcing its role in automated delivery infrastructure. Postal Source operates in the United States with intelligent locker solutions oriented toward secure package management and streamlined operations, reflecting demand for dependable hardware and process simplification in local markets.
These profiles illustrate three distinct strategic orientations. One emphasizes hardware versatility and environmental adaptability, appealing to operators with varied site conditions and specialized load needs. Another emphasizes network scale and software-managed interoperability, aiming to become the connective tissue between carriers, property operators, and end users. A third relies on established postal and logistics partnerships to secure volume and deploy standardized locker assets within existing service frameworks.
Strategic Positioning and Differentiation
The companies gaining momentum tend to differentiate along a few consistent dimensions. Carrier-agnostic network design reduces dependency on any single delivery partner and improves asset utilization by accommodating multiple service providers through the same locker footprint. Multi-function hardware, including cooling and laundry-capable configurations, extends the addressable demand beyond standard parcel handoffs and supports higher value-per-site economics where specialized flows exist. Solar and off-grid options broaden deployment feasibility and reduce site preparation costs, which is especially relevant for outdoor installations or properties with limited electrical infrastructure. Secure connectivity and data-handling rigor are becoming differentiators as regulatory expectations rise and as operators rely on remote monitoring, fault detection, and access management across distributed fleets.
Partnership strategies are equally important. Recent activity shows a clear pattern of using rail networks, courier relationships, and technology partnerships to accelerate footprint expansion. In January 2025, Quadient partnered with ScotRail to deploy smart parcel lockers across Scotland’s rail network for 24/7 secure commuter access, illustrating how transit infrastructure can serve as a distributed pickup layer. In February 2025, KEBA was selected as the exclusive supplier of classic parcel lockers for bpost in Belgium for the year, a deal that aligns hardware supply with a universal service provider’s delivery modernization efforts. In April 2025, Expedibox partnered with Virtual.com to deploy 1,700 smart lockers across Canada by 2026, showing how cross-border and multi-operator collaborations can scale regional networks quickly. In July 2025, InPost S.A. acquired a Spanish courier company to expand smart locker network coverage, signaling consolidation and vertical coordination as growth levers. In October 2025, Quadient expanded its strategic partnership with Evri to activate 2,000 additional Parcel Pending by Quadient smart lockers across the UK, reinforcing the carrier-network expansion model.
Market Structure and Evolution Trends
The market’s evolution is trending toward selective consolidation paired with continued specialization. On one hand, acquisitions and deep partnerships are concentrating network assets and carrier relationships in the hands of a smaller number of well-capitalized players. This is most visible in Europe, where locker networks are increasingly tied to postal and courier service strategies and where multi-market rollouts benefit from standardized hardware and software platforms. On the other hand, functional differentiation is creating space for new entrants and regional specialists, particularly in cooling, laundry, solar off-grid, and campus or transit-adjacent deployments. The result is a hybrid structure: a consolidating core network layer, with a more fragmented periphery where specialized use cases, local property relationships, and site-specific regulatory conditions reward tailored solutions.
For the competitive landscape, this means that scale alone is not sufficient. The winners are likely to be those that combine network density with reliable interoperability, functional flexibility where it matters, and a credible operating model for maintenance and software updates across dispersed assets. Vendors and operators that can make locker infrastructure easy to operate for multiple stakeholders will have an advantage in converting individual installations into durable network value.
Forward Trends for the Next Three to Five Years
The next phase of growth will likely be shaped by three reinforcing trends. First, multi-function locker platforms will become more common as operators seek higher utilization from each installation. Refrigerated fresh-food lockers, laundry exchange models, and modular reskinning of standard units will allow sites to serve layered demand without requiring separate infrastructure for each flow. This trend creates opportunity for vendors that can deliver reliable thermal management, sanitary handling, and easy reconfiguration without sacrificing core parcel throughput. It also introduces complexity in service design, since different user workflows and maintenance requirements must be managed under one physical asset.
Worldwide Luggage Storage Locker Market
Second, connectivity and data governance will increasingly determine deployment velocity. As IoT-enabled notifications and remote management become standard, the quality of wireless integration, cybersecurity, and compliance with local data-handling rules will affect how quickly sites can be brought online and how confidently operators can scale. This favors organizations that treat connectivity, access control, and data handling as foundational design choices rather than downstream add-ons. The uncertainty here lies in the unevenness of regulatory requirements across jurisdictions and in the practical burden of maintaining secure, auditable systems across a growing installed base.
Third, network expansion will continue to intersect with public and transit infrastructure, retail real estate, and residential master planning. Rail networks, commuter hubs, grocery-anchored retail, and large residential complexes are natural expansion surfaces because they concentrate foot traffic, improve utilization, and reduce per-delivery friction. This creates commercial opportunity for operators that can negotiate site access, align stakeholder incentives, and sustain uptime across public-facing installations. The risk is that public-sector approval processes, property-owner alignment, and maintenance accessibility can slow rollouts or raise total cost if not managed proactively.
Together, these trends point toward a market where value accrues to entities that can integrate hardware versatility, network interoperability, regulatory readiness, and stakeholder coordination. The commercial opportunity is not simply to sell more lockers, but to build locker ecosystems that produce measurable reductions in delivery friction, operational burden, and missed-handoff losses while remaining adaptable to changing demand.
Strategic Considerations for Decision Makers
For Manufacturers and Technology Providers
Product roadmaps should prioritize modular scalability and interoperability as much as hardware durability. Units that can be reconfigured for cooling, laundry, or standard parcel use, and that support solar or off-grid deployment where site conditions require it, will open more addressable opportunities. Equally important is the software layer: remote diagnostics, secure access workflows, and compatibility with multiple carrier systems reduce the operational friction that often undermines broad adoption. Manufacturers that invest early in these capabilities and document their reliability across varied environments will be better positioned to participate in scaled network deployments rather than one-off sales.
For Investors
The market’s moderate concentration and steady growth trajectory suggest a landscape with both consolidation candidates and specialized innovators. Capital allocation decisions should account for the distinction between asset-heavy network models and hardware-plus-software positions that depend on partnerships for scale. Networks tied to credible carrier relationships, transit or retail footprints, and repeatable site-procurement processes offer more predictable expansion paths, while highly specialized hardware plays may deliver stronger differentiation in narrower segments. Due diligence should emphasize utilization economics, maintenance burden, data-handling compliance, and the durability of partnerships that drive deployment pipelines.
For Procurement and Operations Leaders
Procurement decisions should evaluate locker solutions as long-lived operational assets rather than commoditized endpoints. Key evaluation criteria include carrier-agnostic usability, uptime and remote management capabilities, security and data-handling alignment, and the practicality of installation and maintenance at the intended site types. Where deployments span multiple stakeholders, the operating model matters as much as the hardware: clarity on who manages access, notifications, fault response, and carrier onboarding can determine whether a locker installation becomes a shared efficiency asset or an underused inconvenience. Early alignment among property operators, delivery partners, and technology providers reduces ambiguity and improves the odds of sustained utilization.
Detailed segmentation data, regional deployment economics, and company-level assessments can sharpen these decisions further by showing where functional specialization, partnership structures, and regulatory readiness create the strongest near-term value. Comprehensive research reports can help decision makers compare vendor positions, evaluate site-level viability, and map out differentiated strategies across residential, retail, commercial, and institutional applications with greater precision. For organizations preparing investment, procurement, or expansion choices, deeper intelligence provides the granularity needed to move from broad market confidence to targeted, defensible action.
For detailed analysis of this topic, please visit the official page: Intelligent Parcel Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Methyl Mercaptan Market: Navigating Growth Amid Structural Shifts
The global market for methyl mercaptan (methanethiol) has entered a phase of measured expansion, driven by its indispensable role as an odorant for natural gas and liquefied petroleum gas, alongside a growing footprint as a chemical intermediate in methionine synthesis and specialty applications. From 2020 through 2025, the market grew from approximately USD 118.0 million to a base-year valuation of USD 155.0 million, reflecting recovery trajectories, capacity adjustments, and steady end-use demand. Looking ahead to 2032, the trajectory points toward sustained upward momentum, with forecasts indicating a revenue base that climbs steadily toward USD 225.0 million. This expansion corresponds to a compound annual growth rate of 6.5% across the 2026–2032 forecast period, a figure that signals broad-based acceptance rather than speculative overgrowth. While the headline numbers provide directional clarity, the strategic reality on the ground is more nuanced: growth is uneven across applications, supply chain dynamics are tightening, and regulatory scrutiny is reshaping operational playbooks for producers and downstream users alike.
Market Landscape and Core Challenges
The market's current structure is characterized by a concentration that remains moderately fragmented at the top but increasingly consolidated in terms of strategic capability. The leading three firms account for roughly 35% of revenue, while the top five extend that share to approximately 48%, indicating that scale, integration, and technical differentiation are becoming more important than pure volume dominance. This balance creates room for specialized players while simultaneously raising the bar for competitive resilience. The most consequential shift is not a single disruption but a convergence of constraints that are redefining how value is captured.
One central challenge is the tension between feedstock stability and margin preservation. Methyl mercaptan is predominantly produced through the reaction of hydrogen sulfide with methanol, a route that is technically mature but highly sensitive to methanol pricing, logistics, and regional availability. As methanol markets experience episodic volatility—particularly in major consuming regions where spot prices can spike sharply—producers face a recurring test of whether to pass through costs, absorb them through operational efficiency, or restructure contracts to smooth exposure. The second challenge lies in regulatory complexity. Methyl mercaptan is classified as a toxic substance with a permissible exposure limit of 0.5 ppm under occupational safety standards, and it falls under risk management programs with threshold quantities that require active compliance planning. Its hazardous waste classification further introduces recordkeeping, handling, and transportation obligations that can escalate the cost and risk profile of operations, especially for facilities functioning near urban or environmentally sensitive zones.
A third challenge emerges from application concentration and the reputational sensitivity of odorization. The largest share of demand continues to stem from methane odorant use, which ensures gas leak detection and public safety. While this application is structurally durable, it also subjects producers to scrutiny around consistency, purity, and delivery reliability. Any lapse in quality or continuity can cascade into utility liabilities, regulatory inquiries, and reputational consequences that go beyond price competition. Together, these pressures create a market environment in which operational discipline and technical differentiation matter as much as capacity positioning.
T Dodecyl Mercaptan Market
Key Drivers Shaping Market Dynamics
Technological Innovation and Process Optimization
Innovation in methyl mercaptan production is less about reinventing the core chemistry and more about improving selectivity, purity, energy intensity, and safety. Advances in catalytic formulations, integrated reactor management, and downstream purification have enabled producers to deliver high-purity grades and tailored intermediates that meet the stricter specifications of methionine synthesis and specialty chemical applications. These improvements are strategically significant because they allow manufacturers to move up the value chain rather than compete solely on commodity volume. High-purity offerings can command stronger positioning in animal nutrition and fine chemical synthesis, where consistency and impurity control directly influence downstream performance. At the same time, process improvements that reduce energy consumption and waste generation help offset some of the cost pressure from raw materials, reinforcing margin durability in an environment where feedstock prices can shift quickly.
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for disciplined growth. Occupational exposure limits, risk management requirements, and hazardous waste classification elevate the compliance burden, but they also create a barrier that rewards operators with robust safety systems, documented processes, and strong supply chain traceability. In practice, this dynamic favors producers and distributors that invest in operational maturity, because buyers increasingly view compliance capability as part of overall reliability. Policy signals also influence demand indirectly. As gas networks and industrial consumers prioritize safety and environmental performance, odorization requirements are likely to remain stable or intensify, sustaining volume support for the core application. At the same time, evolving expectations around emissions, handling, and waste management are pushing firms to modernize storage, transport, and reporting practices, which may favor integrated players with the capital and technical resources to adapt quickly.
Demand-Side Shifts in Consumption and End-Use Behavior
Demand growth is being propelled by a combination of energy infrastructure needs and expanding use in animal nutrition and chemical synthesis. Natural gas odorization remains the dominant application, and its durability is reinforced by continued focus on leak detection, network safety, and regulatory expectations around gas quality. Beyond this core, the role of methyl mercaptan as a chemical intermediate is gaining strategic relevance, especially in methionine production and related applications where it supports downstream nutritional and formulation needs. This dual structure is important for commercial strategy because it diversifies exposure: the odorant market provides scale and consistency, while specialty intermediates offer differentiation and higher value capture. Demand-side behavior is also shifting toward buyers who prioritize reliability, specification consistency, and supplier compliance over lowest price, a trend that strengthens the position of suppliers capable of demonstrating technical and operational maturity.
Supply Chain and Cost Structure Evolution
Cost structures are increasingly shaped by regional feedstock dynamics and logistics. Methanol pricing, in particular, has become a critical variable, with spot markets exhibiting periods of sharp movement that can affect production economics and contract stability. For producers, the practical response is to develop more sophisticated procurement strategies, flexible sourcing, and transparent cost pass-through mechanisms where market conditions allow. For downstream users, the implication is that long-term supply relationships, quality assurance, and delivery reliability may increasingly outweigh marginal price differences. The supply chain is also being influenced by geographic diversification. India has emerged as an active production and export base, adding a new layer of capacity and competition that can improve availability but also introduces new expectations around consistency, certification, and compliance. This expansion is constructive for buyers seeking flexibility, while challenging established players to sharpen their value propositions beyond simple volume.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of large-scale integrated producers and focused regional manufacturers, with strategies that diverge based on geographic footprint, product breadth, and technical specialization. Chevron Phillips Chemical Company stands out as a leading-volume producer, positioning methyl mercaptan as a specialty chemical intermediate with strong relevance to methionine synthesis and broader applications. Its scale and integration provide a foundation for consistent supply and broad market reach, and its profile underscores the importance of linking volume leadership with application-specific capability. Arkema S.A. operates through its thiochemicals platform, offering methyl mercaptan and high-purity grades as well as sodium methyl mercaptide alternatives for methionine production. This approach illustrates a strategy of portfolio breadth and application flexibility, enabling customers to select from related chemistries depending on process requirements and formulation goals. Evonik Industries AG incorporates methyl mercaptan within a specialty chemical portfolio tied to animal nutrition and chemical synthesis, emphasizing application alignment and quality differentiation rather than pure commodity competition.
Worldwide Mercaptans Market
A distinct competitive layer is forming among Indian manufacturers such as Vizag Chemical International and Triveni Interchem Private Limited, both active in production and export. Their presence adds capacity and geographic optionality, particularly for international buyers seeking alternative sourcing points and cost-competitive supply. While scale and global integration differ across these companies, the common strategic thread is the ability to meet industrial specifications and export demand with increasing reliability. The competitive trend appears to be evolving along two axes: consolidation of advantage among firms that combine scale, technical quality, and compliance maturity, and differentiation among regional players that can compete on availability, service, and cost while steadily improving process standards.
This landscape is likely to see further selective integration and capability-based competition rather than broad consolidation for its own sake. Buyers are increasingly evaluating suppliers across a wider set of criteria, including purity, delivery consistency, regulatory readiness, and application support. In that environment, firms that invest in technical service, specification control, and transparent sourcing are better positioned than those relying primarily on price leadership. The emergence of new export-oriented capacity also suggests that regional diversification will continue to shape procurement strategies, especially as buyers seek resilience against localized feedstock volatility or logistics disruptions.
Future Outlook: Trends and Commercial Implications
Refined Value Capture Through Application Diversification
Over the next three to five years, the market is expected to tilt further toward value differentiation enabled by application breadth and specification leadership. Odorization will remain the revenue backbone, but the most strategic growth may come from higher-specification grades and intermediate uses that support methionine and specialty synthesis. Businesses that can reliably bridge core odorant supply with specialty-grade capability are likely to capture stronger positioning, because they can serve multiple demand streams while reducing dependence on any single application cycle. For commercial decision-makers, this suggests that product mix strategy and technical service capability will be as important as volume scaling.
Cost Discipline and Feedstock Strategy as Competitive Moats
As feedstock cost volatility remains a defining feature, competitive advantage will increasingly belong to firms that can manage methanol exposure with flexibility and transparency. Long-term procurement agreements, blended sourcing approaches, and operational improvements that reduce energy and waste intensity will help insulate margins. At the same time, buyers are likely to place greater weight on reliability and compliance assurance, meaning that cost leadership alone will be insufficient if it comes at the expense of consistency or risk management. The commercial opportunity here is twofold: producers can differentiate through resilient cost structures and predictable delivery, while buyers can secure supply by prioritizing partners with demonstrated feedstock management and quality control.
Regulatory Maturity as a Structural Advantage
Regulatory expectations around exposure control, risk management, hazardous waste handling, and transportation are likely to remain stringent, and in some contexts may become more operationally demanding. This environment favors organizations that treat compliance not as overhead but as a structural asset. Companies with robust safety systems, documentation discipline, and modern logistics practices will be better positioned to serve customers who face their own audit, ESG, and risk expectations. The commercial takeaway is that regulatory readiness can become a differentiator in supplier selection, especially for large downstream users and utilities where reliability and risk mitigation carry significant operational and reputational weight.
Risks and Uncertainties to Monitor
The principal uncertainties include methanol price volatility, potential regional policy shifts affecting handling and classification, and the possibility of demand softness if gas infrastructure investment or downstream synthesis demand slows. Supply diversification from new export-oriented capacity can improve availability, but it also raises expectations for specification consistency and compliance, which can become a source of friction if standards differ across regions. In addition, any disruption to logistics or distribution networks may disproportionately affect specialty-grade supply, where timing and purity are especially critical. Decision-makers should therefore build flexibility into sourcing and inventory strategies while monitoring regulatory updates that could alter handling requirements or cost structures.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen differentiation beyond volume. Investing in high-purity grades, improving process efficiency, and building transparent feedstock management capabilities can support stronger margins and more resilient customer relationships. Equally important is advancing compliance maturity as a visible capability, since occupational exposure limits, risk management requirements, and hazardous waste obligations are increasingly influential in supplier evaluations. Producers that can demonstrate consistent quality, reliable delivery, and substantive technical support will be better positioned to compete as the market rewards operational discipline alongside scale.
For investors and strategic acquirers, the market's 6.5% growth trajectory through 2032 suggests attractiveness, but value capture will depend on assessing exposure to feedstock volatility and regulatory complexity. Opportunities may be strongest in businesses that combine stable application demand with differentiated product capability or that have clear pathways to improve cost structures through procurement flexibility and process optimization. When evaluating potential investments, attention should extend beyond revenue growth to the durability of margins, the quality of compliance systems, and the alignment between product mix and end-use demand. In this market, the most compelling cases often combine predictable cash flow from core odorant demand with optionality from specialty intermediates and regional sourcing.
For procurement leaders and end-use buyers, the strategic imperative is to balance cost optimization with supply resilience and specification reliability. Price comparisons remain necessary, but they should be weighed against consistency, compliance readiness, and the supplier's ability to support application-specific needs. Diversifying sourcing where appropriate can reduce exposure to regional feedstock volatility or logistics disruption, and building long-term relationships with suppliers that demonstrate strong technical and regulatory capability can reduce the risk of supply interruptions or quality issues. In practice, procurement strategy should treat methyl mercaptan not only as a commodity input but as a component of operational safety and downstream performance.
Conclusion
The methyl mercaptan market is moving through a period in which growth is real but increasingly conditional on operational maturity, application differentiation, and disciplined cost management. The baseline trajectory points to steady expansion, yet the more important strategic question is not whether demand will rise, but how value will be captured as feedstock volatility, regulatory expectations, and competitive diversification reshape the field. Companies that align their product capabilities, compliance systems, and sourcing strategies with these shifts are better positioned to convert market growth into durable advantage. For readers seeking more granular segmentation data, regional detail, and tailored scenario analysis, the full research report offers deeper segmentation and customized guidance to support decisions at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Methyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PhotoMOS Optically Isolated Relay Market: Why 7.5% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Navigating the PhotoMOS Optically Isolated Relay Market: Strategic Trends and Commercial Opportunities
Market Landscape and Defining Challenges
The PhotoMOS optically isolated relay sector has demonstrated consistent expansion over the past five years, with total market revenue climbing from approximately $320 million in 2020 to an estimated $463.5 million by 2025. The forward trajectory points toward sustained growth, with projections indicating a rise to roughly $766 million by 2032, translating to a compound annual growth rate of 7.5 percent. This expansion reflects the technology’s entrenched role in signal and power switching where galvanic isolation, low leakage, and high-frequency performance are non-negotiable. Unlike electromechanical counterparts, optically isolated MOSFET relays eliminate moving parts, reduce contact wear, and enable faster switching cycles, making them increasingly attractive in environments where reliability and footprint constraints dominate design decisions.
Despite the favorable growth trajectory, the industry is navigating a series of structural pressures that are reshaping how value is created and captured. First, raw material dynamics have tightened margins across the supply chain. Substrate costs tied to gallium arsenide and silicon-based components rose sharply in 2024, contributing to a measurable increase in manufacturing complexity. Energy and labor expenses in the sector followed a similar upward path, compounding the challenge for producers operating on thin conversion economics. Second, the competitive field remains moderately concentrated, with the top three players commanding roughly half of total revenue and the top five firms accounting for approximately 65 percent. This concentration provides scale advantages to established players but leaves smaller manufacturers exposed to pricing pressure and input volatility, with nearly 30 percent of smaller producers reporting direct exposure to component cost fluctuations.
A third challenge lies in application-specific qualification and thermal ruggedization. Automotive and high-temperature industrial deployments increasingly demand devices that can operate reliably at elevated temperatures without compromising isolation integrity or switching consistency. Meeting these thresholds requires tighter process control, advanced packaging, and more rigorous validation cycles, which in turn extend time-to-market and raise development costs. Together, these dynamics create a market that is growing steadily but not uniformly; profitability and competitive positioning now depend on how well firms can absorb input cost variability, accelerate qualified product introductions, and align portfolio breadth with high-growth application pockets.
Key Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
The core appeal of PhotoMOS relays continues to be refined through device-level engineering. Recent product iterations emphasize lower on-resistance variability, reduced leakage under idle conditions, and packaging formats that support higher power density without sacrificing isolation margins. Optical semiconductor architectures that combine LED inputs, photodiode detection arrays, and MOSFET outputs have matured to the point where non-contact switching can rival or surpass electromechanical performance in many signal and power routing tasks. These improvements matter commercially because they allow designers to replace multiple discrete components with a single isolated switching element, simplifying board layouts, reducing assembly complexity, and improving long-term reliability in cycling applications.
A concrete example of this trajectory is the introduction of voltage-driven photorelays in compact package formats with elevated temperature ratings. Newly launched devices targeting semiconductor testers, electric vehicles, and high-temperature industrial equipment demonstrate how manufacturers are pushing the envelope on thermal endurance and form factor simultaneously. By shipping voltage-driven models rated for operation at 135°C in small S-VSON4T packages, suppliers are directly addressing the qualification needs of automotive and heavy-duty industrial users who must maintain performance under harsher thermal cycles. The immediate start of volume shipments signals that these enhanced specifications are moving from prototype interest to production demand.
Policy and Regulatory Environment
Regulatory expectations around safety isolation, electromagnetic compatibility, and automotive qualification frameworks continue to shape product roadmaps. Markets that serve medical devices, automotive systems, and telecommunications infrastructure are governed by standards that reward demonstrateable isolation reliability, temperature stability, and long-term drift characteristics. In practice, this means that a relay’s datasheet performance is only part of the commercial equation; documented qualification pathways, traceability, and certifiable manufacturing processes increasingly influence procurement decisions. The regulatory tilt favors suppliers that can provide not only performance metrics but also the documentation and process consistency that downstream integrators require to clear their own validation hurdles.
PW Consulting Information & Electronics Research Center
At the same time, energy efficiency expectations in industrial automation and telecom equipment are nudging designers toward solutions that minimize standby losses and reduce wasted power in switching nodes. Optically isolated relays with stable on-resistance and low leakage align well with these efficiency goals, creating a policy-adjacent tailwind that reinforces demand beyond pure performance considerations.
Demand-Side Shifts Across End Use Segments
Demand patterns are being reshaped by the electrification and automation of core industrial and mobility systems. The push toward smarter factories, responsive motor control, and modular automation architectures is expanding the set of points in a design where isolated switching is useful. Telecommunications infrastructure, particularly where power distribution and signal routing must remain robust under continuous operation, continues to represent a substantial demand base. Medical device developers also rely on isolation for safety-critical circuits, and the trend toward more compact, portable, and battery-aware equipment is reinforcing interest in relay solutions that combine isolation with minimal footprint. Automotive and electric vehicle applications form a faster-growing but more exacting demand pocket, where temperature tolerance, vibration resilience, and high-frequency switching capability determine commercial relevance.
Supply Chain and Cost Structure Evolution
Cost structure remains a pivotal driver of competitive outcomes. The rise in GaAs and silicon substrate costs, coupled with higher energy and labor expenses, has raised the baseline cost of production and increased the importance of yield optimization, packaging efficiency, and supply continuity planning. Smaller manufacturers have been disproportionately affected, with a notable share reporting exposure to component cost volatility and a measurable increase in production energy usage across the sector. This environment rewards firms that can manage bill-of-material variability, secure stable substrate supply, and design around cost-effective package options without compromising qualification readiness.
Strategic sourcing is becoming more important as a differentiator. Producers that build relationships with qualified substrate suppliers, maintain disciplined inventory planning, and design families of parts that share common internal architectures can reduce per-unit complexity and improve margin resilience. In this sense, the cost story is not only about reacting to price increases; it is about engineering the product portfolio and manufacturing flow to tolerate volatility while preserving performance integrity.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of established electronics and components manufacturers with distinct positioning strategies. Panasonic Corporation has built a broad offering around its proprietary PhotoMOS MOSFET-based optically isolated semiconductor relays, with a wide variant range designed to cover automation, automotive, and high-frequency switching needs. Its emphasis on low leakage and stable on-resistance reflects a focus on predictable switching behavior across diverse application conditions. The breadth of variants supports integrators who need multiple specification points within a consistent family, reducing design fragmentation and simplifying substitution decisions.
PhotoMos Relays Market
OMRON Corporation positions its MOSFET relay line around optical semiconductor technology that combines LED input, photodiode array detection, and MOSFET output for non-contact signal and power switching. This framing emphasizes the isolation mechanism and the resulting contactless operation, appealing to applications where switching reliability and isolation clarity are central to the design rationale. OMRON’s strategy appears to lean on integration ease and application breadth, providing engineers with drop-in options that align with established industrial and instrumentation workflows.
Toshiba Electronic Devices & Storage Corporation has focused on photorelays with MOSFET output, including voltage-driven models and high-temperature variants tailored for semiconductor testers, electric vehicles, and high-frequency applications. Its recent push into small packages with elevated temperature ratings illustrates a clear strategic move toward thermally demanding and space-constrained deployments. By targeting automotive and industrial equipment with devices that can withstand higher operating temperatures, Toshiba is positioning itself in segments where qualification durability and package efficiency translate directly into commercial advantage.
Littelfuse, Inc. brings an optically isolated MOSFET power relay portfolio aimed at DC switching in motors, medical systems, robotics, and vehicles, with emphasis on high isolation and current handling. This positioning underscores the power-handling side of the market, where the value proposition extends beyond signal switching to scenarios requiring robust current transfer under isolated conditions. Littelfuse’s focus on power-centric applications complements the broader signal-switching emphasis seen elsewhere, indicating that competition is not monolithic but segmented by performance emphasis and end-use fit.
Strategic Positioning and Differentiation
Across these leaders, differentiation is emerging along three axes: portfolio breadth, application qualification readiness, and packaging efficiency. Broad variant families reduce customer integration effort and create switching costs that favor incumbents. High-temperature and voltage-driven models address the exacting requirements of automotive and industrial users, turning thermal endurance into a competitive moat. Compact packaging that preserves isolation and current capability supports density-sensitive designs, which is increasingly important as equipment footprints shrink and thermal management becomes more constrained.
Commercial success in this environment depends on aligning these attributes with real procurement drivers. Engineers do not select relays on datasheet elegance alone; they choose components that clear qualification gates, fit existing layouts, and can be sourced reliably over the product lifecycle. Suppliers that can demonstrate consistent performance across lot variations, provide clear documentation for safety and isolation requirements, and offer practical mechanical compatibility are better placed to convert technical appeal into sustained design wins.
Market Structure Evolution
The market is likely to see a mix of consolidation and targeted specialization. Incumbents with scale advantages will continue to invest in variant breadth, thermal ruggedization, and qualification support, reinforcing their hold on high-volume application areas. At the same time, smaller manufacturers may find the most viable path through niche focus, such as specialized packaging, custom voltage-driven configurations, or application-specific isolation profiles. New entrants typically face steep qualification and documentation hurdles, but targeted innovation in package form factors or substrate efficiency could create entry points where performance-per-cost improves enough to attract design attention. Overall, the concentration profile suggests that scale matters, yet differentiation in qualified performance and supply stability will determine who captures incremental share in faster-growing application pockets.
Future Trends and Commercial Opportunities
Trend 1: Thermal-Ruggedized, Voltage-Driven Devices in Automotive and Heavy-Duty Industrial Use
The demand for relays that can sustain performance at elevated temperatures is expected to strengthen as automotive and industrial equipment designs push into harsher operating envelopes. Voltage-driven photorelays in compact packages with high temperature ratings are well aligned with this direction, and volume adoption is likely to increase as validation cycles mature and supply stabilizes. The commercial opportunity here lies in securing qualified supply, offering design-in support that shortens customer validation time, and building variant coverage that matches the exact voltage and package needs of target platforms. Firms that can pair thermal robustness with reliable volume availability will be positioned to convert specification leadership into design wins.
The risk side of this trend includes qualification lag. Even when devices are technically capable, automotive and heavy-duty industrial programs require extended validation, and any supply inconsistency or lot variation can slow adoption. Thermal claims must be backed by repeatable manufacturing control; otherwise, the promise of high-temperature operation becomes a marketing point rather than a dependable design advantage.
Trend 2: Consolidation Around Supply Stability and Qualification Support
As input costs and energy expenses remain elevated, buyers will increasingly favor suppliers that reduce risk across the procurement lifecycle. This points toward a trend where the winners are not only those with strong datasheet performance but also those with demonstrated supply continuity, clear qualification documentation, and responsive engineering support. Integrating these capabilities into a coherent value proposition will become a central competitive battleground. The opportunity is to reframe the product offering from a component to a reliability package: part selection assistance, documentation readiness, lot consistency, and lifecycle availability.
The uncertainty here is that consolidation pressure can squeeze smaller players who lack scale in substrate sourcing or packaging efficiency. If smaller manufacturers cannot manage cost volatility or demonstrate qualification readiness, they may lose relevance in volume-driven segments even if their technical performance is competitive. The market may therefore prune the long tail of suppliers, leaving a mix of broad-line incumbents and a smaller set of specialized niche players.
Worldwide Opto-Isolators Market
Trend 3: Higher Switching Density and Application-Leveraged Portfolios
Because optically isolated relays reduce mechanical wear and support faster cycling, they are well suited to designs that need more switching points in less space. As automation, telecom power distribution, and medical equipment continue to increase functional density, demand is likely to grow for relay families that are optimized around specific voltage ranges, isolation requirements, and mechanical footprints. The opportunity is to build application-leveraged portfolios: groups of parts that share internal architecture but cover the voltage, current, and package variations that a given application class requires. This reduces customer integration effort and increases the likelihood of multiple design wins within the same end-use segment.
The risk is that over-broad variant proliferation can dilute manufacturing focus and raise complexity costs. The strategic answer is disciplined portfolio design: cover the most commercially relevant specification points with efficient shared architectures, and avoid spreading resources across low-demand variants that add complexity without proportional revenue potential.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize thermal-ruggedized and voltage-driven variants where automotive and heavy-duty industrial demand is expanding, and align package strategy with the compact form factors that density-sensitive designs require.
- Manage substrate and energy cost exposure through disciplined sourcing, yield improvement, and shared architectures that lower per-unit complexity without sacrificing qualification readiness.
- Invest in qualification documentation and application support as part of the product offering, since selection decisions are increasingly influenced by validation ease and supply reliability as much as by raw performance.
For Investors and Strategic Allocators
- Focus on suppliers that combine variant breadth with credible high-temperature and compact packaging roadmaps, because these attributes are most likely to capture demand in faster-growing automotive, industrial automation, and medical device segments.
- Evaluate exposure to input cost volatility and the company’s ability to sustain margins through sourcing discipline, packaging efficiency, and portfolio concentration on commercially relevant specification points.
- Watch for consolidation signals and niche specialization patterns; the market is likely to reward firms that can demonstrate supply continuity and qualification support, while marginal players without these capabilities may face share erosion.
For Procurement and Design-In Teams
- Evaluate optically isolated relays not only on datasheet metrics but also on qualification pathways, lot consistency, documentation readiness, and lifecycle availability, since these factors influence long-term program risk.
- Assess package and voltage compatibility against existing layouts and future density goals, and favor families that reduce the need for multiple discrete parts across similar switching functions.
- Plan for cost-structure variability by engaging suppliers that can provide transparent sourcing strategies and stable volume commitments, particularly for programs with elevated temperature or high-cycle requirements.
The PhotoMOS optically isolated relay market is expanding along a clear trajectory, but the most important competitive questions are no longer about whether the technology is useful. They are about which suppliers can deliver qualified performance reliably, manage cost volatility without eroding margins, and align portfolio design with the application segments that are growing fastest. For decision-makers navigating this landscape, the edge will come from detailed visibility into segment-level demand patterns, regional intensity, qualification requirements, and the specific product roadmaps that incumbents and specialists are advancing.
To map these dynamics at the granularity required for program planning, vendor selection, and investment allocation, a closer look at segmented demand estimates, regional distribution, and company-by-company positioning is essential. A full research report can provide the detailed breakdown needed to translate these strategic themes into specific sourcing decisions, portfolio priorities, and risk assessments.
For detailed analysis of this topic, please visit the official page: PhotoMOS Optically Isolated Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Biologics and Biosimilars Market: Why 10.42% CAGR and $1T+ Growth Redefine the Industry
By PW Consulting, 2026-09-21
The Biologics and Biosimilars Market: Strategic Trends and Commercial Opportunities Through 2032
Market Trajectory and Structural Challenges
The global market for biologics and biosimilars has entered a sustained expansion phase, with revenue reaching $527.36 billion in 2025 and projected to climb to $1.055 trillion by 2032. This trajectory reflects a compound annual growth rate of approximately 10.42% across the forecast period, signaling robust and compounding demand across therapeutic categories. Historical momentum from 2020 through 2025 demonstrates consistent upward pressure, as the market grew from $321.27 billion to its current level, driven by expanding clinical applications, maturing manufacturing capabilities, and shifting treatment paradigms toward complex biologics. The revenue base is now large enough that even single-digit percentage shifts in adoption or pricing translate into billions of dollars in industry-wide impact.
Despite the headline expansion, the market faces structural friction points that will shape how value is captured over the next several years. First, the disconnect between biosimilar adoption volume and healthcare spending remains pronounced. Regulatory approvals have multiplied, yet biosimilars continue to account for less than 20% of therapeutic market share despite representing over half of total drug expenditure. This gap points to persistent barriers in formulary positioning, interchangeability recognition, and provider confidence rather than a lack of approved alternatives. Second, reimbursement structures are lagging behind product innovation and cost realities. Hospitals and care networks face systemic underfunding, with cumulative underpayments exceeding $100 billion annually, creating margin compression that influences procurement decisions, formulary negotiations, and patient access pathways. These reimbursement constraints can slow the transition from originator biologics to follow-on alternatives even when clinical equivalence is established. Third, the manufacturing and supply base remains geographically concentrated and vulnerable to cost shocks. A significant share of critical inputs, including active pharmaceutical ingredients and sterile injectable capacity, originates from a limited set of international suppliers, while recent trade measures on single-use systems and other process inputs have raised per-batch production costs by 5–10% for mid-scale monoclonal antibody operations. This cost sensitivity matters because biosimilar economics depend on disciplined manufacturing scale and yield optimization to compete against entrenched originator pricing.
Taken together, these conditions define a market where growth is real but uneven, and where competitive advantage will increasingly derive from regulatory strategy, manufacturing resilience, and access-model innovation rather than product approval alone.
Key Drivers Shaping Market Dynamics
The market’s expansion is being propelled by a convergence of scientific, regulatory, demand-side, and supply-side forces that reinforce each other. Understanding these drivers is essential to identifying where commercial opportunity will concentrate.
Technological Innovation and Development Pathways
Developers are benefiting from more efficient pathways to demonstrate biosimilarity and reach the market. Recent regulatory signals have emphasized streamlined approaches to biosimilarity studies, reducing the evidentiary burden for certain follow-on biologics and making interchangeable designations more attainable. These developments matter because interchangeable status can ease pharmacy-level substitution, accelerate formulary inclusion, and support broader utilization without requiring repeated prescriber actions. Alongside regulatory simplification, manufacturing science continues to mature, with process optimization, analytical comparability, and scale-up capabilities improving the economic feasibility of complex molecules. The result is a broader pipeline of candidates targeting high-value therapeutic classes, including monoclonal antibodies and growth-related agents, where originator franchises have historically generated substantial revenue. In this environment, the companies that can compress development timelines while maintaining quality and comparability are best positioned to convert pipeline activity into commercial relevance.
Policy and Regulatory Environment
The regulatory landscape is becoming both more permissive and more operationally complex. Approval activity across 2025 illustrates a steady cadence of decisions across therapeutic categories, including biosimilars in oncology, inflammatory conditions, ophthalmology, and bone metabolism. Interchangeability designations are increasingly recognized as commercially meaningful because they reduce friction in substitution and dispensing. At the same time, regulatory clarity is not uniform across jurisdictions, and developers must navigate divergent expectations for data packages, post-approval commitments, and local market access requirements. For multinational strategies, this means that approval is a necessary but insufficient condition for commercial success; the regulatory win must be paired with launch readiness, health-system engagement, and reimbursement alignment. Companies that anticipate these downstream requirements earlier in development are likely to achieve faster and more durable revenue realization.
Demand-Side Shifts in Clinical and Economic Behavior
On the demand side, payers, providers, and health systems are under sustained pressure to manage biologic expenditure without sacrificing clinical outcomes. This has accelerated interest in alternatives that can preserve efficacy while lowering net cost, especially in high-volume indications such as oncology and autoimmune care. The clinical adoption of biosimilars, however, depends not only on cost but also on confidence in comparability, supply continuity, and therapeutic interchange policies. As health networks consolidate and formulary management becomes more centralized, procurement decisions are increasingly influenced by total-cost-of-care considerations, supply reliability, and contract flexibility. This environment favors developers and distributors that can offer predictable supply, clear pharmacovigilance support, and implementation assistance that reduces the operational burden of switching or introducing new products. In short, demand is moving toward value-supported adoption rather than price-only decision-making.
Cost Structure and Supply Chain Realities
Cost dynamics are reshaping the competitive equation. Biologics manufacturing remains capital and process intensive, and the economics of biosimilars hinge on achieving reliable yields, minimizing batch failures, and controlling input costs. The concentration of critical materials and sterile manufacturing capacity in a limited number of geographies adds exposure to logistics disruption and pricing volatility. Recent trade-related cost increases on process inputs have demonstrated how even moderate cost pressure can affect per-batch economics for mid-scale production. At the same time, reimbursement pressure on providers creates downstream demand for cost predictability. These forces are likely to increase the premium on vertically integrated capabilities, dual-sourcing strategies, and manufacturing footprints that balance scale with resilience. For commercial strategies, it means that supply chain credibility is becoming part of the value proposition, especially in categories where therapeutic continuity is non-negotiable.
Competitive Landscape and Strategic Positioning
The competitive field is shaped by a mix of established multinationals, focused biosimilar specialists, and regional players expanding internationally. Rather than competing solely on molecule count, leading companies are differentiating through portfolio architecture, manufacturing readiness, regulatory cadence, and commercialization execution.
Differentiated Strategic Postures
Several patterns emerge among the companies setting the pace. Amgen has pursued a broad commercial biosimilars footprint, extending across multiple approved products and therapeutic areas, with cumulative portfolio sales exceeding $13 billion since 2018 and continued approvals and launches in 2025. Its strategy emphasizes scale in already-commercialized categories and sustained investment in follow-on biologics that can integrate into existing care pathways. Pfizer has leaned into operational expansion and manufacturing infrastructure as a foundation for growth, with notable operational gains in select categories and a biosimilar portfolio spanning oncology and other areas. This reflects a model in which manufacturing and supply reliability serve as enablers of commercial traction. Sandoz has positioned itself as a dedicated leader in high-quality follow-on biologics, advancing multiple FDA approvals and launches in 2025, with an emphasis on being a specialized partner for health systems seeking established biosimilar options. Celltrion has signaled an aggressive long-term expansion roadmap with a large product target set by the end of the decade, supported by new facility activity and recent launches, indicating a strategy oriented toward volume, geographic reach, and portfolio breadth. Biocon Biologics and Alvotech have each advanced recent approvals and launches, reflecting a focus on executing specific high-value biosimilar opportunities with FDA engagement in 2025. Formycon has concentrated on ophthalmology biosimilars with multiple approved candidates and 2025 launch activity, illustrating the value of indication focus where switching dynamics and specialty distribution can be managed deliberately. Samsung Bioepis has built a multi-product approval base and pursued U.S. commercialization partnerships, showing the importance of partnership structures in markets where launch execution depends on established distribution and accounts access. Fresenius Kabi has continued to expand its biosimilar portfolio in oncology and inflammatory treatment areas with 2025 regulatory activity, underscoring the role of integrated supplier profiles in certain procurement environments.
Across these approaches, a common thread is that approval momentum is increasingly paired with execution readiness. The companies gaining commercial ground are those that combine regulatory progress with manufacturing capacity, switching support, and reimbursement engagement.
Evolving Market Structure
The industry is likely to evolve through a combination of specialization and consolidation pressure. Pure-play biosimilar developers may continue to differentiate by therapeutic focus or by geographic expansion, while larger firms may seek to integrate biosimilars into broader portfolios for bundling, channel access, and risk diversification. The approval pipeline remains active, but fragmentation can create challenges in market access, pricing discipline, and brand recognition unless companies build differentiated commercial models. At the same time, new entrants may find opportunity in underserved indication segments, regional market expansion, and partnership-enabled commercialization rather than in head-to-head competition in saturated categories. Over the next several years, the market will likely reward players that can convert molecule-level activity into durable access, repeat utilization, and reliable supply.
Future Trends and Commercial Implications (2026–2032)
Several forward-looking trends are likely to define how value is created and captured across the forecast period.
Trend One: Interchangeability and Access Design as Commercial Levers
As interchangeable designations and simplified comparability pathways become more accessible, the commercial differentiator will shift toward access design. Products that can be integrated into substitution workflows, supported by clear pharmacist and prescriber guidance, and reinforced by health-system contracting are more likely to convert approval momentum into utilization. The commercial opportunity lies not just in bringing a biosimilar to market, but in shaping the adoption pathway so that it reduces friction for providers and predictability for payers. Companies that invest early in access strategy, including payer engagement, guideline alignment, and implementation support, may secure faster and more defensible market positions.
Worldwide Aflibercept Biosimilars Market
Trend Two: Manufacturing Resilience as a Competitive Asset
Supply concentration and input cost sensitivity will continue to elevate the importance of manufacturing resilience. The companies that can demonstrate dual sourcing, validated scale-up, and consistent batch performance will have a stronger value proposition in categories where continuity is critical. This trend also creates opportunity for partners and suppliers that can support process efficiency, single-use system optimization, and regional capacity strategies. For commercial planning, resilience will increasingly be part of the procurement narrative, especially where health systems are balancing cost control with clinical reliability.
Trend Three: Portfolio and Partnership Strategies to Manage Fragmentation
With a growing number of approved biosimilars and expanding indication coverage, fragmentation will intensify unless managed through portfolio logic and partnership models. There is opportunity in building focused portfolios that span complementary molecules, indications, or geographies, and in using partnerships to accelerate market access in regions where local execution capability is essential. This approach can help companies avoid competing solely on individual molecule price and instead create value through breadth, predictability, and service integration. The strategic implication is that commercial success will increasingly depend on how well companies assemble and execute a portfolio rather than on isolated product launches.
PW Consulting
These trends carry inherent uncertainties. Regulatory expectations may continue to evolve, reimbursement pressure could intensify, and cost shocks related to inputs or trade policy may affect margin profiles. In addition, provider confidence and formulary dynamics may vary by region and therapeutic class, creating uneven adoption even when approval and interchangeability are in place. Businesses should therefore treat growth as an opportunity to be engineered through access, supply, and execution, not as an automatic outcome of pipeline breadth.
Actionable Guidance for Decision-Makers
Different roles in the market face distinct strategic priorities, but all benefit from sharper visibility into pipeline timing, approval cadence, access requirements, and supply resilience.
For Manufacturers and Developers
Prioritize development and launch plans that integrate regulatory strategy with access readiness. Harmonize comparability, interchangeability, and substitution considerations early so that approval translates into smoother adoption. Strengthen manufacturing throughput, input diversification, and quality consistency to protect economics and supply credibility. Consider portfolio design that balances high-volume categories with focused indication plays, and use partnerships where local commercialization capability can accelerate uptake.
For Investors
Evaluate opportunities through a lens that combines pipeline progress with commercial execution capability. Approval announcements are necessary signals, but the durability of value depends on manufacturing readiness, reimbursement positioning, and access design. Pay attention to companies that can demonstrate repeatable launch execution, cost discipline, and credible supply continuity, particularly in categories where switching and utilization depend on health-system confidence. Diversification across therapeutic classes and geographic expansion should be assessed in the context of execution risk rather than treated as automatic growth drivers.
Worldwide Neulasta (Pegfilgrastim) and Biosimilar Market
For Procurement and Health-System Leaders
Use biosimilar adoption as a structured component of total-cost-of-care management rather than a narrow price comparison. Evaluate supply reliability, pharmacovigilance support, implementation assistance, and interchangeability status alongside net cost. Build contracting approaches that reward predictability and continuity, and align formulary decisions with provider workflows to reduce switching friction. A disciplined adoption strategy can support cost management while preserving clinical confidence and therapeutic continuity.
Navigating this market successfully depends on timely, granular intelligence across approvals, access dynamics, manufacturing constraints, and competitive moves. The broader trajectory is clear, but the details that determine commercial outcomes are often segment-specific and time-sensitive. For decision-makers seeking deeper segmentation data, regional nuance, and tailored strategic recommendations, the full PW Consulting research report provides a more detailed view of where to focus resources and how to structure execution for the 2026–2032 period.
For detailed analysis of this topic, please visit the official page: Biologics and Biosimilars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beyond 4.5% CAGR: The Real Drivers Reshaping the Contact Lens Solution Market
By PW Consulting, 2026-09-21
Navigating the Contact Lens Solution Market: Strategic Trends and Commercial Opportunities (2026–2032)
The contact lens solution market is entering a phase of measured but meaningful transformation. Valued at approximately USD 2,200.0 million in 2025, the sector has expanded steadily from USD 1,850.0 million in 2020, reflecting a compound annual growth rate of 4.5% across the 2026–2032 forecast period. By 2032, revenue is projected to reach USD 2,900.0 million. This trajectory signals a market that has moved past early adoption cycles and is now shaped by formulation innovation, regulatory discipline, and shifting consumer expectations around lens care. For executives and investors, the opportunity lies not in chasing volume alone, but in aligning product portfolios, supply chain resilience, and go-to-market strategies with structural shifts that will redefine competitive advantage over the next five years.
Market Landscape and Core Challenges
The market remains concentrated, with the top three players accounting for roughly 65% of revenue and the top five capturing about 75%. This concentration underscores the importance of scale, distribution network strength, and regulatory readiness, but it also masks underlying segmentation dynamics that are reshaping value creation. Multi-purpose solutions continue to anchor the category, while hydrogen peroxide-based systems and specialized formulations carve out meaningful niches for users seeking deeper cleaning, sensitivity management, or compatibility with advanced lens materials. Demand is distributed across rinsing, cleaning, and disinfecting applications, with disinfection representing the largest share of end-use value, reflecting consumer emphasis on eye health and hygiene.
Despite steady growth, the sector faces several structural pressure points that will determine which companies capture disproportionate share:
Worldwide Contact Lenses Cleaner Boxes Market
- Regulatory complexity and formulation change management. Contact lens solutions are classified as Class II medical devices in major markets, requiring 510(k) clearance pathways, sterility validation aligned with recognized pharmacopeial standards, and compliance with tamper-resistant packaging and labeling expectations. Any significant change to formulation, packaging, or manufacturing process can trigger updated submissions, increasing time-to-market and cost for iterative innovation.
- Raw material and preservation trade-offs. Formulations must balance preservatives, wetting agents, disinfectants, and humectants to maintain sterility, lens compatibility, and wearer comfort. Cost volatility in specialty ingredients, combined with sensitivity toward preservative exposure, pushes manufacturers to refine formulations without compromising performance or shelf stability.
- Consumer behavior and reimbursement nuance. Purchasing patterns are increasingly influenced by out-of-pocket convenience, health account eligibility, and the broader shift toward daily disposables. While solutions remain eligible for reimbursement through health flexible spending arrangements in many contexts, the growth of single-use lenses can dampen recurring solution consumption in certain segments, requiring companies to reposition value around comfort, eye health, and lens longevity rather than volume alone.
For decision-makers, the strategic implication is clear: growth will increasingly come from differentiation in formulation, patient experience, and compliance-friendly packaging, rather than from broad-based price competition. Companies that treat regulatory and formulation constraints as design parameters—rather than afterthoughts—will be better positioned to scale new variants and defend margins.
Key Drivers of Market Change
Technological Innovation and Formulation Evolution
Innovation in lens care is moving toward systems that reconcile disinfection efficacy with comfort and material compatibility. Hydrogen peroxide-based platforms have gained traction among users seeking thorough cleaning and reduced preservative exposure, especially for sensitive eyes or extended wear routines. At the same time, multi-purpose solutions continue to evolve with improved wetting agents, protein management, and hydration technologies that support all-day comfort across soft and rigid lens types. The broader lens ecosystem is also influencing solution design: as lens manufacturers introduce advanced optics and material architectures—such as daily disposable lenses incorporating extended depth of focus optics—solution providers must ensure compatibility, stability, and cleaning performance across a widening range of materials and use cases.
The commercial impact is twofold. First, formulation leadership can justify premium positioning when it delivers measurable benefits in comfort, cleanliness, or sensitivity management. Second, compatibility with next-generation lenses creates switching costs and partnership opportunities, as eye care professionals and consumers seek care regimens that preserve lens performance over time.
Contact Lenses Market
Regulatory and Reimbursement Environment
Regulatory discipline remains a central driver of market structure. Because solutions are Class II devices, manufacturers must navigate clearance requirements, sterility testing expectations, and packaging/labeling standards that are designed to protect end users from contamination and misuse. The requirement to discard solution after each use—and the clinical guidance against reusing leftover product—reinforces safety but also shapes consumption patterns and consumer education needs. Any significant design or formulation change can necessitate updated regulatory notifications, which makes portfolio agility dependent on robust quality systems and proactive regulatory planning.
On the demand side, reimbursement mechanics through health flexible spending accounts add a layer of consumer convenience that can influence trial, repeat purchase, and basket size. However, reimbursement is not uniform across jurisdictions or plan types, so commercial teams should treat eligibility as an enabler rather than a baseline assumption. Brands that make safe use, proper disposal, and value articulation explicit in their messaging can convert regulatory and reimbursement realities into trust and repeat usage.
Demand-Side Shifts in Consumer and Professional Behavior
Consumer expectations are increasingly shaped by comfort, eye health, and convenience. Wearers are more informed about lens care hygiene, more sensitive to preservative exposure, and more likely to compare solutions based on feel, compatibility, and ease of use. Professional channels remain influential: eye care practitioners guide recommendations based on lens type, wear schedule, and patient sensitivity, making clinical endorsement a powerful lever for adoption. At the same time, the expansion of daily disposable lenses in certain demographics introduces a strategic counterweight, as some users reduce reliance on reusable lens care products.
This creates a nuanced demand environment. Growth is not simply a function of more wearers; it is a function of which care regimens professionals recommend, which formulations consumers trust, and how effectively brands communicate hygiene and compatibility benefits. Companies that invest in practitioner education, consumer-facing safety messaging, and product experiences that reduce misuse will be better equipped to sustain share even as lens formats evolve.
Supply Chain and Cost Structure Dynamics
The cost structure of contact lens solutions is influenced by specialty ingredients, sterilization and quality control requirements, and packaging integrity. Preservatives, wetting agents, disinfectants, and humectants must be sourced and blended to consistent specifications, while packaging must support tamper resistance and clear labeling. Fluctuations in raw material availability, energy costs, and logistics can pressure margins, particularly for lower-volume or highly specialized variants.
PW Consulting
Resilience is becoming a competitive differentiator. Manufacturers that diversify supplier bases, standardize core formulation platforms to enable efficient scale, and invest in packaging designs that balance safety with cost will be more capable of protecting margins during input cost swings. In addition, businesses that align production flexibility with regional demand patterns can respond more effectively to localized growth without overcommitting capacity.
Competitive Landscape and Leading Strategies
The market is anchored by a mix of large, globally scaled players and specialized manufacturers that compete on formulation depth, material compatibility, and channel relationships. Large incumbents leverage broad distribution, established practitioner trust, and multi-platform portfolios that span multi-purpose and peroxide systems. Their strategic advantage lies in the ability to cross-sell across lens types, sustain brand recognition, and absorb regulatory and quality system investments that smaller entrants may find harder to match.
Specialized firms compete by focusing on underserved needs: preservative-free or peroxide-based options for sensitive eyes, solutions tailored to rigid gas permeable and scleral lenses, and formulations optimized for silicone hydrogel compatibility. These players often win on clinical specificity and practitioner recommendation, building loyalty in niches where fit, comfort, and lens material compatibility matter more than broad brand familiarity. The presence of innovative manufacturers from diverse geographies also introduces fresh formulation ideas and regional go-to-market expertise, intensifying competition in both mature and faster-growing markets.
Several strategic patterns are emerging among leading participants:
- Portfolio architecture that pairs scale with specialization. Leading companies maintain broad multi-purpose franchises while expanding targeted peroxide or sensitivity-focused variants to capture adjacent demand without diluting core brand equity.
- Compatibility and lens ecosystem alignment. As lens materials and optics advance, solution providers that validate performance across silicone hydrogel, rigid, and hybrid formats create practical reasons for professionals to recommend their products, reinforcing repeat usage.
- Safety and compliance as a brand asset. Packaging, labeling, and usage messaging that make proper handling and disposal simple can reduce contamination risk and build trust, turning regulatory requirements into differentiation rather than burden.
- Regional execution with global standards. Companies are balancing standardized quality and formulation platforms with localized distribution and education efforts, allowing them to scale efficiently while adapting to regional prescribing habits and channel dynamics.
The competitive landscape is likely to evolve through a combination of consolidation among scaled players seeking portfolio breadth and incremental entry by specialized firms targeting high-value niches. Merger activity, if it occurs, will probably be driven by the desire to combine distribution reach with formulation expertise or to secure access to specific lens care platforms. At the same time, new entrants will need to clear regulatory hurdles, demonstrate compatibility with contemporary lenses, and establish practitioner trust—barriers that favor disciplined, evidence-led positioning over aggressive price-based launches.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the market’s next phase and create tangible commercial opportunities.
Trend 1: Formulation-led differentiation will increasingly determine share
As volume growth normalizes, competitive wins will come from formulations that deliver clear, perceptible benefits—enhanced comfort, improved protein and deposit management, reduced sensitivity risk, or stronger compatibility with advanced lens materials. Brands that can document performance and communicate it credibly to both practitioners and consumers will be positioned to command better shelf placement, repeat usage, and resilience against private-label pressure.
Commercial opportunity: Invest in variant architectures that extend core platforms into high-value use cases, and build evidence and education programs that translate formulation advantages into recommendation and repurchase.
Trend 2: Integration with the broader lens ecosystem will matter more
The link between lens design and care regimen is tightening. As lens manufacturers introduce new materials and optical designs, solution providers that ensure compatibility and co-develop care protocols can deepen their relevance in professional channels. This ecosystem alignment can also create bundled value propositions, where lens and care choices are optimized together for comfort, hygiene, and lens longevity.
Commercial opportunity: Pursue compatibility validation, practitioner co-education, and channel partnerships that position solution products as integral to lens performance rather than as incidental consumables.
Trend 3: Safety, compliance, and consumer education will become growth levers
Because misuse and reuse can undermine safety and trust, brands that make correct handling, single-use discipline, and disposal easy to understand can reduce risk while reinforcing product credibility. Packaging clarity, labeling precision, and targeted education will increasingly separate reliable performers from commoditized alternatives. Regulatory requirements will continue to raise the floor on quality and safety, but the upside will accrue to brands that treat these requirements as a foundation for consumer confidence.
Commercial opportunity: Design packaging and messaging that reduce misuse, support sterility expectations, and make health-account eligibility or purchase convenience explicit where applicable, thereby improving trial and repeat behavior.
Potential risks and uncertainties should be factored into planning. Input cost volatility and supplier concentration can compress margins if not managed with diversified sourcing and platform efficiency. Regulatory changes or more stringent post-market expectations could lengthen update cycles for formulations and packaging. The continued expansion of daily disposables in select segments may shift consumption patterns away from reusable care products in some geographies, requiring portfolio rebalancing. Finally, reimbursement nuances and regional plan differences mean that demand elasticity will vary, so forecasting should be localized rather than assumed uniform.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities, but all can benefit from a disciplined focus on formulation value, ecosystem alignment, and operational resilience.
For Manufacturers and Brand Leaders
- Prioritize platform-based innovation. Build a small number of robust formulation platforms that can be extended into multi-purpose, peroxide, and sensitivity-focused variants, preserving scale while enabling targeted differentiation.
- Strengthen compatibility and evidence. Validate performance across contemporary lens materials and optics, and equip practitioner channels with clear, credible information that supports recommendation and repeat use.
- Treat compliance as design input. Embed tamper-resistant packaging, clear labeling, and single-use discipline into product experience from the outset, reducing misuse risk and reinforcing trust.
For Investors and Strategic Partners
- Assess differentiation quality, not just scale. Evaluate whether potential targets have defensible formulation advantages, compatibility claims, and practitioner relationships that can sustain pricing power beyond volume growth.
- Watch portfolio fit and regulatory readiness. In consolidation scenarios, prioritize combinations that add genuine platform or niche capability without creating overlapping, low-margin clutter, and confirm that quality systems can support iterative updates efficiently.
- Monitor demand shifts by lens format. Track daily disposable adoption and reusable lens trends at a regional level, since consumption patterns and solution attach rates will diverge across markets and consumer segments.
For Procurement and Channel Decision-Makers
- Evaluate total value, not unit price alone. Consider formulation reliability, compatibility with the lenses you prescribe or stock, packaging integrity, and educational support when selecting care products, since these factors influence patient outcomes and repeat purchase behavior.
- Align sourcing with local demand and compliance expectations. Favor suppliers that can demonstrate consistent quality, clear usage guidance, and responsiveness to regional regulatory and reimbursement conditions.
- Use education to drive correct usage. Provide consumers and patients with straightforward instructions on single-use discipline and safe handling, reducing contamination risk and protecting brand and channel reputation.
The contact lens solution market is not undergoing a sudden disruption; it is evolving through a series of compounding shifts in formulation, regulation, lens technology, and consumer expectations. That evolution rewards companies that can combine scientific rigor with clear value communication, and that treat compliance and compatibility as strategic assets rather than operational constraints. The most resilient strategies will be those that connect product design to real-world use, align with professional recommendation pathways, and remain flexible enough to adapt as lens formats and regional demand patterns continue to change.
For leaders seeking to move from directional understanding to precise execution, a deeper view of segment-level dynamics, regional demand patterns, and company-specific positioning can sharpen prioritization and reduce uncertainty. Detailed segmentation data, competitive benchmarks, and tailored scenario analysis are available in the full PW Consulting report on the contact lens solution market, where the underlying splits and forward-looking assumptions are unpacked for decision-ready use.
For detailed analysis of this topic, please visit the official page: Contact Lens Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
VTS Market Insights: Beyond the 4.9% CAGR with North America Driving $373M by 2032
By PW Consulting, 2026-09-21
The Strategic Evolution of Vessel Traffic Services: Navigating Market Shifts and Commercial Opportunities (2026–2032)
Market Landscape: Growth Trajectory and Structural Challenges
The global Vessel Traffic Services market has entered a phase of measured acceleration, driven by increasing maritime complexity, regulatory modernization, and the integration of digital navigation infrastructure. From 2020 through 2025, the market expanded from approximately $205 million to $267 million in annual revenue. The forecast period from 2026 to 2032 indicates sustained momentum, with projected revenue reaching $373 million by the end of the horizon. The implied compound annual growth rate of 4.9 percent reflects steady demand rather than explosive expansion, suggesting a maturing but still evolving ecosystem where value creation depends on strategic positioning rather than volume alone.
Several structural shifts define the current inflection point. First, legacy VTS deployments are increasingly reaching end-of-life cycles, creating a replacement and upgrade wave that favors providers capable of delivering interoperable, software-defined platforms rather than isolated hardware installations. Second, maritime authorities and port operators are balancing mandatory reporting requirements with budget constraints, making lifecycle cost, operational resilience, and integration with existing shore-side systems decisive purchase factors. Third, the rise of higher-density traffic in confined waterways and environmentally sensitive corridors is intensifying the need for real-time situational awareness, which in turn pushes vendors toward predictive analytics, advanced radar processing, and integrated information services.
These dynamics are not merely operational concerns; they reshape competitive priorities. Suppliers that can align technology roadmaps with procurement realities—modular upgrades, remote monitoring, and standardized training frameworks—are better positioned to convert modernization demand into durable contract relationships. At the same time, the market’s relatively modest concentration indicates room for differentiated plays, particularly for organizations that can combine domain expertise with adaptable architecture.
Core Drivers: Technology, Regulation, Demand, and Cost Realities
The trajectory of VTS adoption is being pulled by four interconnected forces, each reinforcing the others in ways that create both urgency and optionality for maritime stakeholders.
Technology Innovation and the Shift Toward Integrated, Predictive Platforms
The most visible technological driver is the migration from standalone surveillance and tracking tools toward integrated vessel traffic management ecosystems. Modern deployments increasingly combine radar processing, navigation information services, route planning support, and operator workstations into unified environments. This integration reduces operational silos and allows maritime authorities to manage traffic, respond to incidents, and share hydro-meteo and routing guidance through a single operational picture.
Radar technology itself continues to advance, with solid-state architectures and digital processing improving target discrimination in cluttered port environments and coastal zones. Simulation capabilities are also becoming more central to the value proposition, supporting operator training, scenario rehearsals, and system validation before live deployment. These capabilities lower the operational risk of complex upgrades and help organizations maintain readiness during transition periods.
Importantly, the technology conversation is shifting from capability demonstration to integration assurance. Buyers are less interested in isolated features and more focused on whether a solution can connect with existing navigation systems, port community platforms, and communication networks. Providers that can demonstrate interoperability and maintainability are increasingly differentiating themselves from those that compete purely on sensor specifications.
Regulatory and Standardization Pressures as Catalysts for Modernization
Regulatory frameworks are acting as both a baseline requirement and a modernization trigger. Guidance from the International Maritime Organization emphasizes information services for high-traffic and sensitive areas, including hydro-meteo data provision and route planning support. These expectations raise the operational bar for VTS functions and encourage authorities to invest in systems that can deliver consistent, accessible information to vessel traffic.
Standardization initiatives further reinforce this direction. Recommendations from the International Association of Marine Aids to Navigation and Lighthouse Authorities address operator recruitment, qualifications, and training, promoting consistency in how VTS services are staffed and executed across jurisdictions. Harmonized guidance for inland waterways, where applicable, also supports more predictable procurement and deployment patterns for multi-state or cross-border corridors.
In several high-density regions, mandatory reporting and coordinated traffic management have become entrenched operational practices. This regulatory certainty creates a stable demand base for VTS infrastructure, but it also raises expectations around resilience, redundancy, and information quality. Authorities managing these environments are more likely to prioritize solutions that support long-term service continuity and clear upgrade paths.
Demand-Side Shifts: Port Efficiency, Coastal Traffic, and Operational Safety
On the demand side, port operators and coastal authorities are motivated by a combination of throughput efficiency, safety management, and environmental stewardship. Vessel traffic services are increasingly viewed not only as a safety function but also as an operational enabler that supports scheduling, berthing coordination, and incident mitigation. As traffic density rises in congested corridors, the ability to provide structured information services and coordinated traffic oversight becomes more valuable to port economics and operational reliability.
The commercial rhythm of maritime logistics also matters. Fluctuations in trade flows, port call patterns, and coastal routing can create pockets of peak demand that stress existing systems. VTS platforms that can adapt to variable traffic profiles, provide clear operator support, and integrate information services for route and weather awareness help organizations manage volatility without expanding headcount proportionally. This operational flexibility is a meaningful driver for adoption, particularly in environments where labor availability and training pipelines are constrained.
Supply-Side and Cost Considerations: Total Cost of Ownership and Delivery Models
Cost structures are reshaping procurement behavior. Capital expenditure for new installations remains significant, but lifecycle operating costs—maintenance, software updates, training, and spare parts—are increasingly central to procurement decisions. As more systems move toward software-based management and remote support, vendors are being asked to justify total cost of ownership rather than upfront hardware pricing alone.
Delivery models are adapting in response. Organizations are exploring options that reduce on-site integration risk and streamline ongoing support. Simulation-based training, remote diagnostics, and modular upgrade paths can help mitigate long-term operating burdens. At the same time, supply chain considerations for specialized radar components and communication equipment remain relevant, especially where lead times and customization requirements can affect project schedules. Providers that can stabilize delivery and reduce post-deployment friction gain an advantage in competitive tenders.
Competitive Landscape: Strategic Positioning and Emerging Patterns
The competitive environment for VTS reflects a mix of regional specialization, technology breadth, and an emerging tension between integrated platform providers and focused component or capability specialists. Several themes stand out when examining representative participants and recent developments.
A number of established players are anchored in integrated VTS platforms, coastal surveillance, and maritime traffic management systems, often with strong relationships across port authorities and maritime administrations. Their positioning tends to combine domain expertise with broad system scope, allowing them to address multi-element deployments that span surveillance, information services, and operator workstations. For these organizations, differentiation frequently depends on integration maturity, support infrastructure, and the ability to align with local regulatory and operational expectations.
Other participants emphasize specific layers of the value chain. Some focus on radar and coastal surveillance technology, including solid-state radar series designed for reliable detection in challenging environments. Others concentrate on simulation, operator training, and harbor traffic management solutions that complement live VTS operations. This specialization can be advantageous in projects that require proven sensor performance or robust training environments, especially where procurement teams value targeted capabilities alongside broader system compatibility.
Recent developments illustrate how the landscape is being reshaped by corporate strategy as well as technical cooperation. A major maritime instrumentation group announced plans to spin off its maritime unit as an independent company, with a stock exchange listing targeted for the first half of 2026. This move signals a strategic push to position maritime capabilities as a distinct growth entity, potentially sharpening its focus on VTS, coastal surveillance, and related maritime solutions while giving investors a clearer exposure to the sector’s trajectory.
In parallel, technology partnerships and public showcases are reinforcing capability differentiation. Advanced radar technology was presented at a major defense and security exhibition, alongside a partnership intended to strengthen VTS capabilities. Such moves highlight how vendors are combining hardware, software, and partnership channels to expand credibility and reach in contested procurement environments. At the consultancy level, a major professional services firm was appointed to support the modernization of a major city’s Vessel Traffic Services system, underscoring that transformation programs increasingly require integration, governance, and operational redesign—not just equipment replacement.
Taken together, these patterns suggest a market that is neither fully consolidated nor highly fragmented. The relatively balanced concentration among leading participants leaves space for differentiation, but it also means that advantage is increasingly earned through execution quality, integration credibility, and adaptability to local requirements. New entrants and niche specialists can compete by addressing underserved segments, while larger players can leverage breadth and delivery scale. The likely evolution is not a simple consolidation wave, but a selective blending of platform breadth, specialized technology, and professional services expertise.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead to the 2026–2032 horizon, several trends are likely to define where value is created and where execution risk concentrates.
Trend 1: Software-defined, interoperable VTS platforms will become the default procurement expectation. As modernization programs replace aging infrastructure, authorities will favor solutions that can integrate with existing navigation, communication, and port systems rather than requiring isolated stand-alone environments. This shift increases the importance of interface design, data exchange standards, and vendor support for migration and coexistence during transition phases. Commercial opportunity will accrue to providers that can reduce integration risk and demonstrate repeatable deployment patterns across similar port or coastal contexts.
PW Consulting
Trend 2: Operator readiness and training will move from a supporting function to a core buying criterion. Given the emphasis on standardized recruitment, qualification, and training practices, organizations will increasingly evaluate VTS investments through the lens of workforce sustainability. Simulation-based training, scenario rehearsal, and structured competency development will be treated as part of the system’s operational value rather than as optional add-ons. Suppliers that embed training and readiness into their offerings can strengthen retention and reduce the cost of operational discontinuity during upgrades or staffing transitions.
Trend 3: Regional modernization programs will create uneven but significant demand peaks. Large-scale consultancy-led modernization in high-profile ports and coastal systems, combined with ongoing regulatory drivers and replacement cycles, will generate concentrated demand in select geographies and corridors. This creates opportunities for providers with proven delivery capability and local partnership networks. At the same time, demand will not be uniform; some regions may prioritize inland waterways harmonization or smaller-scale upgrades, while others pursue broader coastal surveillance and traffic management transformation. Commercial planning will need to account for this uneven rhythm rather than assuming a linear global expansion path.
These trends carry embedded uncertainties. Procurement timelines can shift with budget cycles and bureaucratic processes. Technology expectations may evolve faster than delivery capacity, particularly where integration complexity is underestimated. Supply constraints for specialized components can affect project schedules, and regulatory interpretations may differ across jurisdictions, influencing requirement definitions and acceptance criteria. Organizations that anticipate these variables and build flexibility into their offerings and project plans are more likely to convert opportunity into durable outcomes.
Strategic Implications for Decision Makers
For executives, investors, and procurement leaders, the VTS market presents a landscape where steady growth is paired with meaningful differentiation potential. The practical question is not whether demand exists, but how to position for the right segments and reduce execution risk.
Voyage Data Recorders (VDR) Market
For manufacturers and solution providers: prioritize integration maturity and lifecycle serviceability over feature volume. Demonstrating interoperability, remote support, simulation-based training, and modular upgrade paths can strengthen competitive positioning, especially where authorities are managing modernization within constrained operating budgets. It is equally important to align product roadmaps with regulatory expectations around information services and operator readiness, since these are increasingly part of procurement rationale. Companies should also consider targeted partnership or consultancy-led engagement models, particularly for large transformation programs where technology is only one component of a broader operational change.
For investors: evaluate exposure through the lens of platform continuity, service revenue potential, and the ability to participate in modernization waves rather than one-time equipment sales. Corporate restructuring moves, such as spin-offs or separate listings targeting maritime units, can indicate where management believes value is most visible, but they also raise questions about delivery scale, customer concentration, and follow-on investment needs. The most resilient opportunities are likely to be tied to recurring support, training, software evolution, and repeated deployment in similar environments, rather than purely project-based revenue.
For procurement and maritime operators: treat VTS selection as an operational continuity decision, not just a technical purchase. Prioritize systems that reduce long-term operating strain through interoperability, maintainable architecture, and training support, and clarify acceptance criteria around integration, information service quality, and redundancy. Where modernization programs are underway, embedding consultancy or integration expertise early can help align technology with governance, staffing, and change-management requirements, lowering the risk of delivery gaps between equipment installation and operational readiness.
The market’s next phase will reward organizations that can connect technology, regulation, and operational practice in practical, repeatable ways. Detailed segmentation analysis, company-level capability mapping, and region-specific procurement dynamics can sharpen planning significantly, especially for teams evaluating entry points, partnership structures, or expansion timing. For decision makers seeking to move from strategic direction to actionable choices, deeper intelligence on submarket size, competitive positioning, and project-level delivery patterns provides a more precise basis for investment and procurement decisions.
Maritime Intercom Market
Readers looking for a fuller view of market size by segment, regional dynamics, and company-level strategy can explore the complete PW Consulting analysis for granular data and tailored recommendations aligned with specific operating contexts.
For detailed analysis of this topic, please visit the official page: Vessel Traffic Services (VTS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Employee Scheduling Software Market 2026: Why 11.2% CAGR Redefines Growth Strategy
By PW Consulting, 2026-09-21
The Employee Scheduling Software Market: Navigating Growth, Fragmentation, and the AI Inflection Point
The employee scheduling software market has transitioned from a tactical admin utility to a strategic operational layer that directly shapes labor costs, compliance exposure, and service continuity. Revenue across the sector expanded from approximately USD 148.5 million in 2020 to an estimated USD 225.0 million by 2025, reflecting a compound annual growth rate of 11.2% over the 2020–2025 period. Forward projections indicate the market will reach roughly USD 250.7 million in 2026 and continue expanding toward USD 367.0 million by 2032, sustained by the same structural tailwinds that drove the earlier acceleration. This trajectory signals more than incremental software adoption; it reflects a fundamental rethinking of how organizations translate demand volatility into shift coverage while controlling overtime, reducing compliance risk, and preserving employee experience.
The growth curve is not uniform. Cloud-based deployment continues to dominate new implementations, while on-premises footprints are shrinking as organizations migrate toward integrated platforms that connect scheduling with payroll, time tracking, and workforce analytics. Mid-size enterprises and small businesses together account for the largest share of adoption volume, driven by the need for affordable, mobile-first tools that can scale without dedicated HRIT teams. Large enterprises are pursuing fewer but deeper deployments, prioritizing forecasting accuracy, multi-site orchestration, and integration with broader HCM ecosystems. Geography also matters: North America remains the largest revenue center, Europe follows with strong compliance-led demand, and Asia Pacific is emerging as the fastest-expanding region as service-sector digitization and flexible staffing models accelerate.
Defining the Current Inflection Points
Despite the expansion, the market sits at a series of crossroads. First, legacy schedulers that rely on static templates and manual overrides are increasingly misaligned with demand patterns characterized by seasonal spikes, last-minute absenteeism, and customer-facing fluctuations. Organizations that continue to manage shifts through spreadsheets or siloed tools face mounting labor mismatches that translate directly into overtime leakage, understaffed service windows, and scheduling friction for employees. Second, compliance complexity is intensifying. Meal-and-rest mandates, overtime thresholds, union rules, and region-specific labor regulations are proliferating, making manual enforcement error-prone and legally risky. Platforms that cannot automate policy enforcement and audit trails are losing relevance in regulated environments. Third, integration expectations are rising. Buyers now assume that a scheduling tool will connect with time and attendance, payroll, demand signals, and workforce analytics without custom middleware. Vendors that remain point solutions risk being bypassed in favor of platforms that can reduce integration debt and administrative fragmentation.
Key Drivers Reshaping the Market
Three to four forces are converging to redefine the value proposition of employee scheduling software, shifting it from convenience to operational leverage.
Technology Innovation and the AI Forecasting Shift
Artificial intelligence has moved from a feature promise to a core differentiator. Modern platforms combine historical attendance, demand signals, seasonality, and employee availability to generate shift forecasts and coverage recommendations that adjust in real time. This matters because scheduling accuracy directly affects labor cost and service quality. Organizations using AI-driven planning and real-time analytics report meaningful reductions in overstaffing and overtime, with customer-reported outcomes pointing to an average 21% decrease in labor costs. At the same time, automated shift planning paired with mobile self-service has been associated with roughly 30% higher shift coverage and 23% lower overtime costs in typical deployments. The strategic implication is clear: scheduling software is increasingly a cost-control and continuity tool, not merely a shift calendar. The vendors winning attention are those that translate forecasting into actionable coverage plans, flag compliance conflicts early, and let employees swap or pick shifts without creating coverage gaps.
Policy and Regulatory Pressure as a Catalyst for Automation
Labor regulation is no longer a static backdrop; it is becoming one of the most powerful adoption drivers. Platforms increasingly embed rules for meal breaks, rest periods, overtime limits, union requirements, and state-specific mandates so that schedule generation and adjustments automatically respect policy boundaries. This reduces legal exposure and administrative burden while giving managers a defensible scheduling process. In parallel, data privacy expectations have hardened, especially for cloud-based tools serving European and regulated markets. Maintaining GDPR and SOC 2 compliance is now table stakes for enterprise buyers, and platforms that can demonstrate consistent controls around data handling, access, and auditability enjoy a shorter sales cycle in sensitive environments. The practical outcome is that compliance automation and privacy assurance are becoming competitive moats, particularly for vendors serving multi-jurisdiction workforces.
Demand-Side Change: Frontline Work Patterns and Employee Expectations
The shape of hourly and frontline work continues to evolve. Service sectors, retail, logistics, healthcare support, and hospitality face demand that fluctuates with weather, seasons, local events, and consumer behavior. Employees, meanwhile, expect greater visibility and control over their schedules, faster shift confirmation, and simpler swap mechanisms. This dual pressure pushes organizations toward scheduling tools that are mobile-first, self-service enabled, and capable of balancing business coverage needs with employee preferences. Mobile clock-in, shift templates, real-time notifications, and team communication features are increasingly expected rather than optional. Companies that ignore the employee experience dimension tend to see higher attrition and last-minute coverage gaps, which in turn inflate labor costs and degrade service consistency.
Worldwide Field Service Software Market
Cost Structure and SaaS Economics Favoring Cloud Deployment
The cost equation favors cloud-based delivery, especially for small and mid-size organizations that lack large internal IT footprints. Subscription economics reduce upfront capital barriers, accelerate deployment, and make it easier to add locations, users, and modules as needs evolve. For larger enterprises, the cloud transition is less about affordability and more about integration and analytics. Centralized data from scheduling, time tracking, and payroll creates visibility into labor cost trends, coverage efficiency, and overtime patterns, enabling more informed workforce planning. This dynamic reinforces the dominance of cloud models in new revenue and explains why on-premises installations are increasingly limited to specialized or legacy environments with strict data residency or operational constraints.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three providers holding roughly 24.6% of revenue and the top five near 26.2%. That leaves substantial room for specialization, regional strength, and segment-focused differentiation. The field spans global HCM-scale platforms, workforce-management specialists, and SMB-oriented mobile tools, each pursuing distinct strategic positions.
Strategic Positioning Among Leading Providers
ADP has built a broad workforce management footprint with ADP Workforce Now, integrating scheduling, time tracking, shift optimization, and compliance tools aimed at hourly and frontline workers. Its strength lies in scale, payroll linkage, and the ability to serve a wide range of organization sizes with a single platform. UKG has pushed enterprise-grade capabilities through UKG Pro and Kronos Workforce Central, emphasizing AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management. The recent expansion of UKG’s integration ecosystem underscores a platform strategy: in March 2026, it introduced 15 Workforce Management APIs to streamline connections with scheduling and time-tracking platforms, reflecting a recognition that interoperability now shapes buying decisions. Ceridian Dayforce positions around a unified platform for global enterprises, combining scheduling, shift assignment, workforce analytics, and automated compliance within a single system, appealing to organizations that want consistency across regions and functions.
Rippling targets growing businesses with an integrated HR and workforce management suite that links scheduling, AI demand forecasting, shift planning, and payroll, reducing the friction of juggling separate tools. Deputy remains focused on shift-based industries with AI labor forecasting, mobile apps, and compliance automation, a model that resonates in retail, hospitality, and light industrial settings. Connecteam and Homebase emphasize SMB usability through app-based scheduling, shift swapping, mobile clock-in, labor cost tracking, and compliance alerts, competing on ease of adoption and day-to-day usability. Paychex Flex and Paycor extend mid-market reach by tying scheduling to payroll and HCM dashboards, providing labor cost visibility and shift management within broader HR processes. When I Work emphasizes employee self-scheduling and real-time reporting, a straightforward value proposition for teams that want flexibility without administrative overhead. Workday brings enterprise HCM depth with advanced scheduling, demand forecasting, and compliance-driven workforce planning for large organizations. Finally, TCP Software and Shiftboard highlight highly operational niches: automated forecasting, mobile management, fatigue management, contingent labor tools, and labor cost reduction for mission-critical environments, where coverage assurance and risk control outweigh convenience alone.
Nurse Scheduling Software Market
How the Landscape Is Evolving
Three trends are reshaping the competitive structure. Integration is becoming a default expectation rather than a differentiator, pushing vendors to offer APIs, prebuilt connectors, and data flows that tie scheduling into payroll, analytics, and demand systems. At the same time, specialization is intensifying in high-stakes segments such as healthcare support, logistics, manufacturing, and other environments where fatigue management, compliance enforcement, and contingent labor coordination carry direct operational and safety implications. A third dynamic is the steady arrival of well-funded new entrants that lean into mobile-first design, AI forecasting, and SMB affordability, expanding choice but also fragmenting attention for buyers. The net result is a market that rewards clear positioning: platforms that can demonstrate measurable coverage improvements, labor cost control, and compliance automation within a buyer’s existing technology stack are gaining traction, while undifferentiated schedulers are facing longer evaluation cycles and stricter comparison criteria.
Forward-Looking Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to determine where value accrues and where new opportunities emerge.
AI-First Scheduling Becomes the Operational Standard
Forecasting and real-time adjustment will become embedded baseline capabilities rather than premium add-ons. As models improve with richer attendance history, demand signals, and policy constraints, organizations will expect scheduling systems to anticipate coverage gaps, recommend shift fills, and flag labor cost risks before shifts are published. The commercial opportunity lies in solutions that connect forecasting with execution: auto-suggested shifts, mobile acceptance flows, and manager dashboards that make actionable decisions fast. Vendors that can show defensible improvements in coverage and overtime—with clear measurement frameworks—will find it easier to justify expansion and renewals.
Compliance Automation as a Core Buying Criterion
The regulatory environment will continue to reward platforms that can encode rules, enforce them at schedule creation, produce audit-ready documentation, and adapt quickly to changing requirements. This is particularly relevant for multi-state, multi-jurisdiction, and unionized workforces. The opportunity for providers is to package policy guidance, rule templates, and document support as part of the workflow rather than as separate services. Organizations that treat compliance automation as a design principle—rather than a retroactive fix—will reduce legal exposure and administrative effort while strengthening employee trust in the scheduling process.
Integration Ecosystems and Workforce Data Platforms
The future value chain is increasingly interoperable. Scheduling will connect more tightly with time and attendance, payroll, labor analytics, and demand planning, creating a more complete view of workforce costs and coverage. Buyers will favor solutions that minimize custom integration work and enable data to move cleanly between functions. This opens opportunities for platforms that act as orchestration layers, standardize data models, and provide APIs that accelerate deployments and reduce total cost of ownership. For enterprises, the prize is workforce visibility that supports planning beyond individual shifts: staffing models, labor budgets, and service-level commitments aligned with realistic demand.
These trends carry uncertainty. AI adoption depends on data quality and change management; inaccurate inputs or poorly governed models can erode trust and limit realized savings. Compliance expectations can shift quickly, requiring vendors and buyers alike to keep pace with new rules and interpretations. Integration depth can also become a double-edged sword: over-engineaging ecosystems may complicate deployments, while under-integrated tools may fail to meet enterprise expectations. Finally, pricing pressure is likely to intensify as more competitors offer AI features at competitive price points, making it essential for providers to differentiate on outcomes, not just feature lists.
Strategic Actions for Decision-Makers
The market’s direction suggests several practical moves, tailored to different roles in the value chain.
PW Consulting Information & Electronics Research Center
-
For enterprise and mid-market buyers evaluating scheduling software: prioritize platforms that link scheduling with payroll and time tracking, enforce compliance rules automatically, and provide measurable coverage and labor-cost outcomes. Run pilots that test forecasting accuracy under real demand variability, not just idealized scenarios. Confirm that the solution supports mobile self-service, shift swaps, and rapid manager overrides without creating policy violations. Assess integration effort early, because hidden middleware and data cleanup can turn a low-cost tool into a high-friction deployment.
-
For investors and strategic partners: focus on providers with credible AI forecasting, strong compliance automation, and clear integration roadmaps, especially those demonstrating repeatable labor-cost reductions and coverage improvements in target verticals. The highest-conviction opportunities are likely in platforms that can serve shift-based and mission-critical environments at scale while maintaining data-privacy assurance for regulated markets. Watch for consolidation signals, since interoperability demands and integration fatigue may drive buyers toward platforms that can unify functions and reduce vendor count.
- For vendors and product leaders: invest in measurable outcome claims, not just feature breadth. Make compliance automation, auditability, and privacy controls visible and easy to validate. Build integration pathways that reduce deployment time and data fragmentation, and design mobile self-service experiences that improve employee adoption while protecting coverage integrity. Differentiation will increasingly come from how well a platform reduces overtime leakage, improves shift coverage, and keeps schedules within policy boundaries without adding manager workload.
The employee scheduling software market is moving from incremental digitization to a more outcome-driven phase in which forecasting accuracy, compliance automation, and integration maturity determine competitive strength. For organizations navigating shifting labor patterns and rising regulatory complexity, the question is no longer whether to adopt scheduling software, but which platform can convert schedule planning into lower labor costs, fewer compliance risks, and more reliable coverage. Detailed segmentation data, vendor-by-vendor benchmarks, and customized adoption roadmaps can sharpen those decisions further; PW Consulting’s full research report provides that deeper breakdown for teams preparing investment, procurement, or product strategy choices in this space.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soy Sauce Market Beyond the 5.4% CAGR: Strategic Shifts Reshaping Asia Pacific Dynamics
By PW Consulting, 2026-09-21
The Strategic Soy Sauce Market: Navigating the Next Wave of Growth
The global condiments sector has long relied on soy sauce as a foundational ingredient, but the current market trajectory suggests a more sophisticated evolution than simple volume expansion. As the industry moves through a period of steady revenue growth and shifting consumption patterns, strategic decision-makers must look beyond headline numbers to understand the structural forces reshaping supply chains, competitive positioning, and consumer expectations. The market has demonstrated consistent momentum over the past half-decade, with revenue figures climbing steadily and a projected compound annual growth rate signaling continued expansion through the early 2030s. Yet this growth masks underlying complexities that demand careful navigation.
From a macro perspective, the industry has transitioned from a mature, regionally concentrated category into a more globally integrated space where premiumization, geographic diversification, and operational scale intersect. Total market revenue has grown from the high twenty-nines billion range in 2020 to surpass the forty-one billion mark by 2025, and forward projections indicate continued upward movement, with the market expected to approach the sixty-billion threshold by 2032. This trajectory reflects more than population growth or basic culinary adoption; it points to a category gaining relevance in modern food preparation, ethnic cuisine globalization, and industrial food formulation. For executives and investors, the headline growth rate of approximately 5.4 percent annually provides a useful baseline, but the real strategic value lies in understanding where growth concentrates, what threatens it, and how incumbents are adapting.
Several structural tensions currently define the industry's inflection point. First, the sector operates within a moderately concentrated environment where a limited number of large producers command meaningful share, yet smaller specialty manufacturers continue to carve out profitable niches through authenticity, craftsmanship, and geographic specificity. This coexistence of scale and specialization creates both competitive friction and partnership opportunities. Second, raw material cost dynamics introduce volatility that can compress margins or force pricing strategies that risk alienating price-sensitive buyers. Third, regulatory divergence across key markets means that compliance requirements, labeling rules, and ingredient transparency expectations differ sharply depending on where a product is manufactured, distributed, or consumed. These three forces, market concentration, input cost variability, and regulatory asymmetry, form the backdrop against which strategic choices must be made.
Understanding the Market Landscape and Its Pressures
The global soy sauce market has matured into a multi-regional industry where cultural familiarity, foodservice integration, and retail convenience collectively drive demand. Asia Pacific remains the dominant revenue contributor, reflecting both deep culinary tradition and large population bases, but growth is increasingly visible in regions where Asian cuisine adoption continues to expand among mainstream consumers. The category is no longer confined to traditional home cooking; it now flows through packaged food manufacturing, restaurant operations, and cross-cultural food experimentation. This broader application footprint has helped stabilize demand even as certain mature markets face slower household penetration growth.
Three challenges stand out as particularly consequential for strategic planning:
Soy Milk Market
- Margin pressure from input cost volatility: Soybeans and fermentation inputs are subject to agricultural cycles, weather disruptions, and commodity trading dynamics. When harvest forecasts shift or trade flows adjust, producers must decide whether to absorb cost increases, renegotiate supplier agreements, or pass changes through to customers, each path carrying commercial risk.
- Regulatory fragmentation: Labeling, nutritional disclosure, and ingredient transparency rules vary across jurisdictions. A product positioned for global distribution must comply with differing standards on GMO disclosure, nutritional labeling, and processing classifications, which can complicate packaging, marketing, and market-entry sequencing.
- Competitive differentiation in a crowded category: Traditional large-scale brewing, accelerated production methods, and artisanal fermentation all compete for shelf space and foodservice contracts. Consumers and professional buyers increasingly evaluate flavor complexity, sodium content, authenticity claims, and sourcing ethics, raising the bar for what constitutes competitive advantage.
These challenges are not insurmountable, but they do require a more deliberate approach to product architecture, supply chain resilience, and geographic prioritization. Companies that treat the category as a single homogeneous proposition risk missing the opportunities hidden in regional taste preferences, application-specific formulations, and regulatory arbitrage where compliant positioning can become a market-access advantage.
Core Drivers Shaping the Next Growth Cycle
The market's forward momentum is not accidental; it is being propelled by a combination of technological advancement, shifting consumer behavior, supply-side restructuring, and evolving regulatory frameworks. Each driver interacts with the others, creating a landscape where advantages compound for organizations that align product strategy with operational readiness.
Innovation in Production and Product Architecture
Fermentation science and process control have progressed beyond the traditional binaries of naturally brewed versus chemically accelerated production. Modern manufacturers are investing in controlled fermentation environments, strain selection, and analytical quality systems that improve consistency while preserving the flavor profiles consumers associate with authenticity. At the same time, product architecture has expanded to include reduced-sodium formulations, cleaner-label variants, and flavor-specialized offerings tailored to specific culinary applications. This innovation is not merely technical; it is commercial. Producers that can deliver consistent taste, adaptable viscosity, and stable shelf performance gain advantages in both retail and industrial food service settings.
Regulatory Divergence as a Strategic Variable
Regulatory environments are not moving in unison, and this divergence has become a meaningful factor in market strategy. In some markets, soy sauce benefits from exemptions or lighter labeling burdens, while in others, GMO disclosure, nutritional labeling, or deeply processed product classification introduces additional compliance steps. These differences shape where companies choose to launch first, how they design packaging, and which ingredient claims they can safely make. For global players, the capability to modularize compliance by region, rather than treating labeling as a single global template, can reduce time-to-market friction and avoid costly reformulation cycles. For smaller brands, understanding regulatory thresholds early can determine whether a product can scale internationally or remains regionally constrained.
Demand-Side Shifts Toward Authenticity and Application Versatility
Consumer and buyer behavior continues to tilt toward products that signal authenticity, craftsmanship, and culinary specificity. This does not mean every segment seeks premium pricing; rather, it means that trust, origin narrative, and flavor reliability increasingly influence purchase decisions. At the same time, foodservice operators and packaged food manufacturers demand ingredients that perform consistently across large batches and varied recipes. The dual demand for artisanal credibility and industrial reliability pushes manufacturers to build portfolios that serve both ends of the spectrum. Brands that can articulate a clear position, whether as a heritage fermented product or a dependable industrial ingredient, are better placed to secure shelf space, contract stability, and repeat procurement.
Pasta Sauce Market
Supply Chain and Cost Structure Realignment
Soy sauce production depends on soybean supply, brewing infrastructure, logistics, and regional labor and energy costs. Agricultural price forecasts for the coming marketing years point to higher season-average soybean prices compared with the prior year, which signals potential cost pressure for upstream inputs. This does not automatically translate into market-wide margin erosion, but it does reward organizations that secure forward contracts, diversify sourcing, and optimize plant utilization. Companies with geographically distributed production footprints can shift volume among facilities, hedge against localized disruptions, and respond more flexibly to currency or logistics shocks. In practical terms, supply chain resilience is becoming a competitive differentiator rather than a back-office function.
Competitive Dynamics and Strategic Positioning
The industry's competitive field is shaped by a mix of long-established brewing specialists, large regional manufacturers, and smaller innovators pursuing distinctive flavor profiles or niche market positions. The largest producers combine scale, export capability, and multi-plant infrastructure, while others compete through premium positioning, regional brand equity, or specialized product development. This structure supports a market where share is contestable but not easily overturned, because scale advantages in brewing capacity, distribution relationships, and ingredient procurement are difficult to replicate quickly.
Several strategic postures are visible across the leading set. One is geographic expansion through local production, which reduces shipping costs, shortens lead times, and signals commitment to a market. A second is premiumization through naturally brewed positioning and taste differentiation, which targets consumers and foodservice buyers willing to pay for perceived quality and culinary authenticity. A third is portfolio breadth across light, dark, and specialty variants, allowing a manufacturer to serve multiple culinary applications and capture demand across different cooking traditions. A fourth is innovation in small-batch, distinctive flavor profiles that can command premium pricing and build loyal following among chefs, specialty retailers, and consumer enthusiasts.
Recent operational developments illustrate how these strategies are playing out in practice. A major Japanese producer with significant U.S. manufacturing presence has been progressing a new American production facility, with first shipments anticipated in the fall of 2026 after groundwork laid in 2024. This kind of investment signals confidence in sustained demand and a desire to deepen local supply capability rather than relying solely on export flows. Meanwhile, in the Chinese market context, leading domestic brands have continued to showcase light, dark, and standard varieties through major trade platforms, reinforcing the importance of category breadth and export visibility for manufacturers seeking broader international reach.
Market structure appears likely to evolve along two parallel paths. Consolidation pressure will persist where scale economics, distribution leverage, and sourcing advantages favor larger operators, especially in price-competitive segments and high-volume foodservice channels. At the same time, fragmentation will remain viable in premium, regional, and specialty segments where authenticity, craft narrative, and differentiated flavor profiles create defensible positions. New entrants that can combine a clear brand story with disciplined production quality, or that can serve an underserved application such as a specific culinary format or a clean-label requirement, can still gain traction without directly challenging the largest incumbents on volume alone.
Forward-Looking Trends for the 2026 to 2032 Window
Looking ahead, several trends are likely to shape how growth is captured and where value accrues. These trends are grounded in current market data, recent operational moves, and the regulatory and demand environment already in motion.
PW Consulting
Local Production and Regional Capacity Expansion
As demand broadens beyond traditional strongholds, the economics of long-distance export versus local manufacturing become more consequential. Additional production capacity in key markets can improve responsiveness, reduce logistics exposure, and support labeling or formulation adaptation to regional requirements. Over the next several years, more manufacturers are likely to evaluate where to place capacity based on demand density, input availability, and regulatory clarity. The strategic implication is that presence in a market will increasingly be judged not just by brand recognition but by supply reliability and local compliance readiness.
Premiumization Paired with Functional Positioning
Premium products will continue to grow in relevance, but premiumization alone will not define success. The most durable growth will likely come from products that combine authentic fermentation or distinctive flavor with practical benefits such as lower sodium, cleaner ingredient lists, or application-specific performance. This pairing allows manufacturers to address both consumer-facing premium demand and buyer-facing formulation needs. Brands that can communicate flavor quality while meeting functional expectations will have a stronger chance of commanding price resilience and repeat usage.
Regulatory Clarity as a Market Access Multiplier
Because regulatory requirements differ across markets, companies that proactively align product design and labeling with local rules can turn compliance into a market-entry advantage. In regions where nutritional labeling is not required, simpler packaging and broader claim flexibility may be available; in regions with stricter disclosure, early adaptation can prevent reformulation delays and protect brand consistency. Over time, the ability to navigate multiple regulatory regimes efficiently will become part of the competitive baseline for companies pursuing international distribution.
These trends carry uncertainty. Cost volatility in soybean supply could compress margins for producers with less flexible sourcing or pricing strategies. Regulatory changes could shift faster than anticipated in some markets, altering labeling obligations or ingredient disclosure expectations. Consumer taste preferences may evolve toward lower-sodium or plant-forward alternatives, requiring manufacturers to innovate without diluting the category's core identity. Each of these risks is manageable with the right data, scenario planning, and operational agility.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with both flavor differentiation and operational resilience. That means evaluating whether portfolio breadth, premium positioning, or local production offers the best return in each target market, and ensuring that sourcing and facility strategy can absorb input cost variability without sacrificing consistency. For investors, the opportunity lies in identifying organizations that combine credible brand equity with scalable production and a clear regional expansion plan, while monitoring where margin exposure to raw material costs and regulatory complexity may create downside risk or require additional capital discipline. For procurement and foodservice buyers, the practical focus should be on supplier reliability, formulation consistency, and compliance alignment, since these factors increasingly determine whether a soy sauce supplier can support large-scale operations across multiple markets without disruption.
Access to detailed segmentation data, regional revenue splits, and granular competitive movement can sharpen each of these decisions. Broad market trajectories provide direction, but precise allocation decisions require clearer visibility into where growth concentrates, how share is shifting among product types, and which operational investments are likely to yield durable advantage. The full research report offers that level of detail, including segmented data, company-level developments, and market-access considerations that support tailored commercial planning.
The soy sauce market is entering a phase where growth is real, but competitive advantage will depend on how well organizations align innovation, compliance, and supply chain readiness with the specific markets and applications they choose to serve. Companies that treat the category as a strategic platform rather than a routine ingredient business are better positioned to convert steady industry expansion into defensible share and healthier margins.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oil Mist Separator Market: Why 5.3% CAGR and Asia Pacific Lead the 2032 Growth
By PW Consulting, 2026-09-21
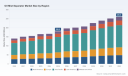
Strategic Trajectories and Commercial Opportunities in the Global Oil Mist Separator Market
The global market for oil mist separators has entered a phase of measured but steady expansion, reflecting broader shifts in industrial air quality standards, manufacturing precision requirements, and energy efficiency mandates. Valued at approximately 140.5 million USD in 2020, the market climbed to 180.8 million USD by 2025, and is projected to reach 259.9 million USD by 2032. This trajectory translates to a compound annual growth rate of 5.3 percent across the forecast horizon, signaling a maturing yet increasingly dynamic sector. Growth is no longer driven solely by incremental equipment replacement; it is being reshaped by tighter emissions controls, smarter filtration architectures, and cross-regional industrial modernization programs. The market remains moderately concentrated, with a handful of established players capturing a dominant share of contract wins, technology patents, and regional distribution networks. This concentration underscores both the barrier to entry for newcomers and the strategic importance of partnerships, licensing, and targeted product modernization for mid-tier manufacturers. As industrial operators balance compliance obligations with productivity targets, the oil mist separator segment is evolving from a commoditized component category into a value-added system integration opportunity.
Mist Eliminator Market
Market Landscape and Core Challenges
Regulatory Pressure and Performance Verification
The industry is navigating a period where compliance and verification requirements are tightening across multiple jurisdictions. Without listing regional revenue splits or application-specific dollar figures, it is clear that manufacturing footprints in both mature and emerging economies are confronting stricter exposure limits for mineral oil aerosols and particulate matter. Occupational safety frameworks now mandate continuous monitoring approaches and defined time-weighted average thresholds for workplace air quality, forcing plant operators to treat filtration not as an optional add-on but as a baseline operational requirement. At the same time, engine and compressor standards are increasingly calling for uniform testing procedures that cover dust collection efficiency, dust capacity, and oil carry-over measurements. These requirements create a dual challenge: manufacturers must demonstrate consistent performance under standardized test conditions, while end users must integrate separator systems that meet verifiable benchmarks rather than nominal specifications.
Technical Complexity Versus Installation Practicality
A second structural challenge lies in balancing filtration performance with physical integration constraints. Oil mist separators are deployed across diverse machine environments, from compact machining centers to large compressor halls, and each deployment presents distinct airflow, space, and maintenance profiles. Mounted configurations dominate volume applications where direct integration with existing equipment is preferred, while standalone units address centralized extraction and facility-wide air cleaning. The challenge for designers is to maintain high capture efficiency without imposing excessive pressure drops, frequent media replacement cycles, or complex ductwork modifications. Operators increasingly favor solutions that can be retrofitted into legacy lines without extensive downtime, yet they also demand filtration performance that aligns with precision tolerances in food-grade, medical, or high-finish machining contexts. Bridging this gap requires material engineering, flow optimization, and service-friendly filter media designs to advance in tandem.
Consolidating Competition and the Cost of Differentiation
A third challenge is the competitive dynamic shaped by market concentration. When a limited group of firms accounts for more than half of total market activity, incumbents benefit from established distribution channels, reference installations, and long-term service contracts. New entrants or smaller regional manufacturers must therefore compete on niche performance attributes, localized support, or total cost of ownership rather than price alone. This environment rewards companies that can articulate measurable operational savings, energy reduction, or maintenance interval extension, while penalizing those that compete purely on hardware cost. As procurement teams become more technical in their evaluation criteria, the burden on suppliers to provide verifiable performance data, installation guidance, and lifecycle cost models grows heavier.
Key Drivers Shaping Market Evolution
Technology Innovation and Energy-Conscious Filtration Design
Innovation in filtration media, airflow control, and system intelligence is a leading catalyst for change. Recent product introductions highlight a clear shift toward energy-aware extraction systems and higher-precision filter units designed for demanding machining environments. Smart energy-saving devices integrated into oil mist extraction systems are gaining traction, reflecting operational priorities around electricity usage, fan load optimization, and variable airflow demand. In parallel, advanced filter units built for high-precision machining environments emphasize finer aerosol capture, stable performance under variable load conditions, and simplified media replacement. These developments matter because they connect directly to two persistent operator concerns: running costs and process consistency. When a separator can reduce parasitic energy consumption while maintaining capture efficiency, the value proposition extends beyond compliance into operational economics. Manufacturers that embed control logic, condition monitoring, or modular media architectures into their offerings are positioning filtration as an active system component rather than a passive accessory.
Regulatory and Standards Evolution
Policy and standardization activity continues to shape purchasing behavior and engineering requirements. Compressed air quality classifications that define strict oil aerosol limits for the highest cleanliness tiers are reinforcing demand in food-grade, pharmaceutical, and precision industrial applications, where even minimal contamination can affect product integrity or process reliability. At the same time, occupational safety expectations for mineral oil mist exposure are pushing facility managers to adopt continuous monitoring and better containment strategies, particularly in environments where multiple machines contribute to cumulative aerosol loads. In parallel, industrial emissions frameworks in major markets are tightening limits on volatile organic compounds and particulate matter from manufacturing facilities, which indirectly accelerates replacement cycles and upgrades for older separator installations. The net effect is a market where regulations do not merely constrain operations; they actively redirect capital toward more capable filtration and air cleaning architectures. Companies that can map their product capabilities to specific regulatory benchmarks, and document compliance through standardized testing, gain a meaningful advantage in specification-driven procurement processes.
Shifts in End-User Behavior and Operational Priorities
Demand-side behavior is changing as plant operators look beyond immediate compliance and evaluate filtration through the lens of productivity, worker comfort, and equipment longevity. Oil mist that escapes containment can affect visibility, housekeeping frequency, coolant loss, and downstream component reliability, all of which influence total operating cost. As a result, purchasing decisions are increasingly influenced by facility managers and engineering teams who weigh filtration performance alongside ease of maintenance, noise reduction, and integration with existing extraction infrastructure. The emphasis on fog-free environments, clearer workstation conditions, and reduced cleaning cycles reflects a broader operational mindset: air quality is not an isolated environmental metric but a contributor to throughput and labor efficiency. This behavioral shift creates opportunities for suppliers who can present separator systems as part of a holistic air management strategy rather than as standalone compliance devices. Case documentation and field references are becoming more influential in this context, since they translate technical specifications into observable operational outcomes.
Supply Chain Structure and Cost Considerations
Cost structures in the filtration sector are being influenced by material availability, manufacturing precision, and the economics of distribution across regions. High-performance filter media, housing materials, and sealing components must meet durability expectations under continuous operation, while suppliers also face pressure to keep lead times predictable and service parts accessible. In a moderately concentrated market, cost leadership is often less about unit price and more about lifecycle economics: how often media must be replaced, how much pressure loss accumulates over time, and how easily a unit can be serviced without specialized labor. These factors are especially relevant as operators reassess capital expenditure against operating expenditure, particularly in facilities facing rising energy costs or tighter maintenance windows. Suppliers that can standardize core assemblies while offering application-specific customizations tend to manage cost and flexibility more effectively than those pursuing fully bespoke designs for every project. This balance between standardization and adaptation is becoming a defining feature of competitive cost positioning.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
Dominant Players and Strategic Positioning
The competitive field features a mix of long-established manufacturers and specialized filtration providers, each leveraging distinct strengths in engineering heritage, application coverage, and service ecosystems. Companies with multi-decade experience in oil mist collectors and workplace air cleaning solutions have built brand recognition around reliability, broad application familiarity, and continued product iteration. Their strategy often centers on maintaining a wide reference base, expanding into adjacent air quality applications, and reinforcing regional service presence. Other firms emphasize industrial mist collection for compressed air and machine tool environments, using application-specific engineering and standardized performance documentation to win specification-driven projects. A further group focuses on advanced oil mist elimination and industrial air purification, differentiating through modular product families, precision filtration architectures, and integration with broader air management systems.
Additional suppliers contribute to the landscape by targeting specific operational niches. Some specialize in oil mist separation for manufacturing plant compressor and turbine systems, where reliability under continuous duty and resistance to oil carry-over are critical. Others concentrate on ecological and application-tailored separator designs for rotating machines and turbines, positioning around sustainability messaging and customized extraction solutions. There is also a cohort of providers that emphasize universal separator coverage across wide engine power ranges or offer industrial mist separators and collectors optimized for machine tool use. Together, these players illustrate a market where differentiation comes from application alignment, engineering documentation, and the ability to support both centralized and distributed installation strategies.
Oil Water Separator Market
Differentiation Levers in a Concentrated Market
In a market where a small group of firms holds a substantial share, differentiation tends to emerge through several recurring levers. First, product intelligence and energy optimization are increasingly central. The introduction of smart energy-saving devices for extraction systems demonstrates how incremental controls can reduce operating burden while preserving capture performance. Second, application specialization matters. Filter units developed for high-precision machining environments reflect an understanding that contamination limits and process tolerances vary significantly by sector, and that generic solutions may not satisfy the strictest cleanliness classifications. Third, ecosystem support and reference building influence procurement confidence. Trade show participation, case study dissemination, and documented installations help translate technical claims into practical credibility. Fourth, standardization of performance verification is becoming a competitive asset. As testing procedures for inlet air cleaning equipment become more uniform and compressor or engine standards increasingly specify measurement approaches for collection efficiency and oil carry-over, suppliers that proactively align with these protocols gain visibility in specification reviews.
Evolution of the Competitive Structure
Looking at recent developments, the market appears to be moving through a phase of selective consolidation in capability rather than purely in corporate structure. Established players are expanding their portfolios through product line extensions, energy-efficiency features, and targeted applications, while also strengthening visibility through exhibitions, case publications, and regional engagement. At the same time, specialized manufacturers continue to compete by focusing on particular machine types, precision cleanliness requirements, or custom extraction configurations. This creates a landscape where scale advantages coexist with niche strength. New entrants face the challenge of overcoming reference inertia, but they can still gain traction by addressing underserved machine configurations, offering more flexible integration options, or providing superior service and documentation. The likely trajectory is not a wholesale shakeout, but a gradual stratification in which broad-line suppliers dominate volume segments and specialized firms secure positions in high-value or technically demanding applications. For decision makers, this means vendor selection is increasingly about matching system architecture to operational profile rather than choosing from a single category of equivalent products.
Forward Trends and Commercial Implications
Smarter, Energy-Optimized Filtration Systems
Over the next three to five years, one of the most consequential trends will be the deepening integration of energy optimization and control logic into oil mist separation systems. As operating cost sensitivity rises and extraction equipment runs for longer periods across multiple shifts, even modest reductions in fan load or airflow waste can create meaningful savings. Systems that adapt output to actual contamination levels, support easier servicing, and provide clearer performance feedback will be better positioned than static, fixed-performance units. Commercial opportunity lies in bundling filtration hardware with controls, service contracts, and documentation that simplify lifecycle management for plant teams. The upside is real, but it depends on manufacturers delivering measurable savings in field conditions, not just in laboratory benchmarks. If promised energy benefits fail to materialize consistently, buyer confidence in smart features may erode.
Stricter Compliance and Cleanliness-Driven Demand
A second trend is the continuing alignment of separator demand with stricter cleanliness and exposure expectations. As occupational exposure limits, compressed air quality classifications, and industrial emissions expectations become more rigorously enforced or more widely adopted in procurement specifications, facilities will face stronger incentives to replace aging equipment and upgrade filtration performance. This creates a sustained upgrade cycle in sectors where product integrity, worker exposure, or emissions reporting carry direct financial or regulatory consequences. The commercial opportunity is in providing verifiable cleanliness performance, standardized test alignment, and documentation that procurement teams can use in specification and audit processes. The uncertainty is that regulatory implementation pace can differ by region and by facility type, which may create uneven demand timing. Suppliers that assume uniform acceleration across all markets risk misjudging where near-term investment will actually appear.
Service-Led Models and Regional Expansion
A third trend is the shift toward service-oriented commercial models and more deliberate regional execution. As installed bases grow and equipment ages, maintenance intervals, media availability, and local technical support will increasingly influence repeat purchasing and system longevity. Companies that build reliable parts supply, clear replacement procedures, and application-specific guidance can convert initial sales into long-term relationships. Regional expansion also remains relevant, especially where industrial modernization, machining capacity growth, and compressor utilization are increasing. Here, success depends on more than product availability; it requires localized engineering support, understandable installation guidance, and a credible service response timeframe. The opportunity is in building trusted regional presence and repeatable deployment models. The risk is that overextension into too many territories without adequate support infrastructure can dilute reliability and weaken the performance reputation that underpins premium positioning.
Actionable Insights for Decision Makers
For Manufacturers and System Suppliers
Differentiation should be anchored in verifiable performance and operational economics rather than product claims alone. Prioritize control features and filtration designs that reduce energy burden and simplify maintenance, then document those benefits in real installation contexts. Align product language with the testing and cleanliness expectations that procurement teams increasingly reference, and build a portfolio that balances standardized assemblies with application-specific adaptations. Invest in reference deployments and case documentation, because credibility in this market is often earned through observable outcomes in actual facilities. Finally, treat service and parts availability as part of the product, since lifecycle reliability frequently determines whether a sale becomes a repeat contract.
For Investors and Corporate Strategists
The market’s moderate concentration and steady growth profile suggest that value creation will come from companies that can combine technical credibility with cost-aware design and strong service execution. Evaluate exposure not only by installed unit volume but by how well a supplier is positioned for the trends shaping the next decade: energy optimization, stricter clean air expectations, and service-led retention. Watch for firms that can demonstrate consistent field performance, clear compliance alignment, and disciplined regional expansion rather than broad but shallow market claims. Be mindful that demand timing may vary by region and by application, so portfolio resilience matters more than betting on a single growth narrative.
For Procurement Teams and End-User Operators
Selection criteria should extend beyond upfront equipment cost to include pressure drop behavior over time, media replacement frequency, service accessibility, and evidence of compliance with relevant exposure or cleanliness expectations. Where precision, food-grade, or auditoried environments are involved, prioritize suppliers that can provide standardized performance documentation and clear installation guidance. Consider total operational impact, including worker visibility, housekeeping burden, coolant retention, and integration with existing extraction infrastructure. When evaluating newer smart or energy-saving features, request field-oriented performance evidence and confirm that control logic will not add complexity without measurable operational benefit. A disciplined evaluation framework reduces the risk of purchasing a nominally compliant system that creates higher maintenance or energy costs downstream.
Conclusion
The oil mist separator market is advancing along a path defined by tighter compliance expectations, smarter filtration design, and a competitive field that rewards both scale and application focus. Steady growth supported by industrial modernization and cleaner air requirements provides a durable backdrop, but the real commercial differentiation will come from how well suppliers translate performance, energy efficiency, and service reliability into measurable operational value. For manufacturers, the opportunity lies in credible innovation and lifecycle economics. For investors, it lies in backing players with disciplined execution and alignment to the compliance and efficiency trends ahead. For operators, it lies in choosing systems that perform under real conditions, not just in specification sheets. Detailed segmentation data, regional demand patterns, and customized scenario analysis can sharpen these decisions further, and organizations seeking that level of granularity are well positioned to explore the full research depth available on PW Consulting for this market.
For detailed analysis of this topic, please visit the official page: Oil Mist Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Clinical Mass Spectrometry Market: Why 9.35% CAGR and LC-MS Dominance Redefine Growth
By PW Consulting, 2026-09-21
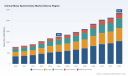
The Clinical Mass Spectrometry Market: Strategic Trends and Commercial Opportunities Through 2032
Market Status and Core Challenges
The clinical mass spectrometry market has transitioned from a specialized scientific instrument segment into a mainstream clinical diagnostic modality over the past half-decade. Market valuation moved from approximately 785.0 million USD in 2020 to 1260.0 million USD in 2025, representing a compound annual growth rate of roughly 8.2 percent across the historical window. Current trajectory models indicate expansion to 1346.99 million USD in 2026 and continued acceleration toward 2360.0 million USD by 2032, with a forecast-period CAGR of 9.35 percent. This growth profile reflects a market that has crossed the chasm from research-grade adoption into routine clinical workflows, driven by the superior specificity and multiplex capability of mass-based quantification compared with traditional immunoassays.
The regional distribution of demand reveals a mature anchor in North America, which accounts for the largest revenue share at 562.22 million USD, followed by Europe at 319.65 million USD and Asia Pacific at 234.95 million USD. Latin America and the Middle East and Africa together represent a combined base of 143.18 million USD, signaling early-stage penetration with substantial room for expansion as healthcare infrastructure and reimbursement frameworks mature. By technology type, liquid chromatography-mass spectrometry dominates installed value at 801.16 million USD, while gas chromatography-mass spectrometry holds 212.76 million USD and matrix-assisted laser desorption/ionization time-of-flight contributes 198.12 million USD, with other modalities rounding out the remainder. Across applications, therapeutic drug monitoring represents the largest clinical use case at 555.11 million USD, newborn screening follows at 315.55 million USD, and hormonal testing, hemoglobin testing, and other indications collectively account for the balance. The market remains moderately concentrated, with the top three players capturing 52.0 percent of revenue and the top five holding 62.0 percent, a structure that preserves room for differentiated entrants while rewarding scale incumbents.
Despite the favorable growth backdrop, the industry faces three structural challenges that will define capital allocation and product strategy in the near term.
Challenge 1: The Complexity-Reimbursement Gap
Mass spectrometry delivers analytical performance that routine immunoassays cannot match, but that performance often carries operational complexity that limits throughput and increases per-test cost. Many clinical laboratories still treat mass spectrometry as a specialized, limited-access service requiring highly trained operators, dedicated sample preparation, and careful method validation. When reimbursement structures do not commensurately reward this complexity, laboratories hesitate to expand mass-based panels, and manufacturers face pressure to simplify platforms without sacrificing analytical rigor. The gap between what the technology can do and what payers and laboratory economics will sustain remains the central friction point in market expansion.
MALDI-TOF Mass Spectrometer Market
Challenge 2: Regulatory Fragmentation Across Indications and Jurisdictions
Clinical mass spectrometry spans diverse indications, each with distinct evidentiary requirements, validation expectations, and regulatory pathways. A system cleared for microorganism identification does not automatically translate into a cleared workflow for therapeutic drug monitoring or hormone quantification. This fragmentation slows portfolio scale-up, increases time-to-market for new assays, and creates uneven competitive advantages across regions. Companies that can navigate a multi-indication, multi-jurisdiction regulatory landscape more efficiently than peers will capture disproportionate share in high-value applications.
Challenge 3: Workflow Integration and Standardization
As clinical mass spectrometry moves from reference laboratories into decentralized hospital and multi-site networks, standardization becomes a binding constraint. Variability in sample handling, chromatography conditions, ionization performance, and data interpretation can undermine comparability across sites and erode confidence in results. The market is increasingly rewarding vendors that offer integrated hardware-software-reagent systems, simplified operator interfaces, and traceable quality controls, while penalizing those that require extensive in-house method development for routine testing.
Key Drivers of Market Change
Technological Innovation and the Push Toward Automation
The most consequential technical shift is the move from manually intensive, laboratory-developed workflows toward automated, integrated platforms that reduce operator dependence and improve reproducibility. Quantitative software suites purpose-built for clinical analysis now accompany single quadrupole and tandem mass spectrometry systems, enabling biomarker verification, precision medicine workflows, and routine quantification with less hands-on intervention. In microorganism identification, software and sample handling innovations are compressing turnaround time and improving the reliability of organism differentiation directly from clinical specimens. These advances directly address the complexity-reimbursement gap by making high-performance mass spectrometry more compatible with high-volume clinical operations.
A concrete illustration of this trajectory is the broad expansion of reagent and assay menus on automated clinical mass spectrometry platforms. Recent milestones include CE Mark approval for an antibiotics drug monitoring reagent pack that broadens an automated mass spectrometry menu to 39 tests covering immunosuppressants, antibiotics, steroids, and vitamin D metabolites. In parallel, regulatory classification progress has lowered operational barriers: steroid assays for mass spectrometry have been classified as moderate complexity under CLIA, which expands the population of laboratories and operators able to run these tests without specialized staffing. Together, these developments demonstrate how regulatory easing and workflow automation can unlock routine clinical access for assays that previously required limited, expert-run environments.
Regulatory and Reimbursement Environment as an Accelerant and a Gatekeeper
Regulatory and coding dynamics are reshaping the commercial landscape for clinical mass spectrometry on two fronts. On the access side, moderate-complexity classification for selected mass spectrometry assays is expanding the addressable laboratory base by removing the requirement for highly specialized operators in routine settings. On the coding side, revisions to CPT codes for mass spectrometry-based testing are influencing reimbursement mechanics. Updated codes such as CPT 82542 for quantitative column chromatography/mass spectrometry reflect ongoing efforts to align coding with current practice, while reimbursement continues to vary by payer and analyte. For manufacturers and laboratory customers alike, the direction of travel matters: clearer, more predictable coding and broader complexity allowances reduce adoption friction, but analyte-specific reimbursement variability still demands careful health-economic justification for each test menu.
These dynamics also create a differentiated advantage for companies that pursue regulatory clearance proactively across multiple indications and regions. A vendor that secures clearance for therapeutic drug monitoring reagents, hormone panels, and microorganism identification systems in sequence can cross-sell across clinical departments, increase installed-base stickiness, and establish reference standards that competitors must match. The regulatory environment is thus not merely a compliance backdrop; it is increasingly a competitive moat.
Demand-Side Shifts in Clinical Practice and Patient Management
Clinical demand is being reshaped by three interrelated forces. First, precision medicine workflows are increasing the need for accurate quantification of biomarkers, drug concentrations, and metabolic markers that mass spectrometry is uniquely suited to measure. Second, the management of complex medication regimens, including antibiotics and immunosuppressants, is driving sustained demand for therapeutic drug monitoring in hospital and specialty settings. Third, early detection programs and screening protocols, including newborn screening, continue to provide a stable and high-volume demand base that rewards throughput, reliability, and standardized workflows.
At the same time, healthcare delivery is shifting toward consolidated networks and standardized testing protocols. Larger laboratory systems are seeking platforms that can support multiple indications on a single instrument footprint, reduce training burden, and provide traceable quality controls across sites. This demand-side consolidation is pushing vendors toward modular, software-centric architectures and multi-test menus, and away from single-application, laboratory-developed approaches that are difficult to scale across a health system.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structure is becoming a more explicit competitive variable as installed bases grow and laboratories compare total cost of ownership across platforms. The economics of clinical mass spectrometry depend not only on instrument price but on reagent costs, consumables durability, calibration frequency, service coverage, and the labor required to maintain compliance. Vendors that can reduce per-test operating cost through automation, longer calibration intervals, integrated reagents, and remote diagnostics are increasingly favored in procurement decisions, particularly in cost-sensitive environments.
Supply chain resilience is also under scrutiny. Platforms that reduce dependence on highly customized sample preparation steps and that offer standardized reagent packs tend to be more resilient to staffing volatility and consumable supply disruptions. As a result, the market is rewarding designs that prioritize workflow robustness and predictable consumable economics over maximal analytical flexibility alone.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Thermo Fisher Scientific continues to anchor its strategy in quantitative clinical analysis and precision medicine workflows. Its LCQUAN quantitative software paired with ISQ EM/EC single quadrupole LC-MS systems is positioned for quantitative clinical analysis, biomarker verification, and precision medicine applications. The strategic emphasis is on software-driven quantification and a platform that supports accurate routine workflows and biomarker work, appealing to laboratories that want a credible quantitative foundation with room to extend into precision medicine use cases.
Waters Corporation leans into therapeutic drug monitoring and biomarker applications with its MassTrak LC-MS/MS platform and related solutions. A distinguishing element is the availability of FDA-cleared systems for TDM and biomarker workflows, which directly addresses the regulatory-access driver in the market. This clearance-centric approach is strategically important because it shortens the path for laboratories seeking validated, regulatorily recognized workflows rather than building laboratory-developed methods from scratch.
Bruker Daltonics differentiates through microorganism identification and differentiation, with MBT Compass HT CA software, MBT FAST Shuttle US IVD, and clinical microorganism mass spectrometry systems. The FDA clearance of its microorganism identification and differentiation system as Class II under special controls formalizes a regulatory pathway and supports adoption in clinical microbiology workflows. Bruker's positioning reflects the value of a focused application with clear clinical identity, which can be expanded within microbiology departments and integrated with broader laboratory information systems.
Roche Diagnostics International AG is pursuing a broad multi-indication IVD strategy on an automated clinical mass spectrometry platform. Its cobas Mass Spec solution with Ionify reagent packs spans therapeutic drug monitoring for antibiotics, steroid hormones, and vitamin D metabolites, supported by the Cobas i601 analyzer and an expanding IVD menu. The strategic signal is clear: Roche is using automation, a wide test menu, and regulatory milestones to position mass spectrometry as a routine clinical workhorse rather than a niche specialty tool.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three vectors. First, consolidation pressure is rising among scale incumbents that can cross-sell across applications and leverage installed bases to lower service and consumable costs. The top-three concentration near 52.0 percent and top-five near 62.0 percent indicates that leading players already hold meaningful share, but the remaining 38.0 percent is large enough to support specialized entrants with differentiated applications or regional strengths.
Second, differentiation is shifting from raw analytical capability toward integrated, regulatory-cleared, workflow-friendly solutions. In this environment, a vendor's ability to deliver cleared assays, simplified operator experience, and multi-test menus on a single platform is becoming as important as instrument performance alone. This favors companies that can orchestrate hardware, software, reagents, and regulatory clearance as a unified clinical solution.
Third, new entrants and regional players are finding openings in specific applications or geographies. Lower-concentration regions such as Latin America and the Middle East and Africa present early-stage demand where localized service, pricing, and workflow simplicity can be decisive. Similarly, application niches with clear clinical identity and regulatory clarity, such as microorganism identification or antibiotic TDM, can support focused entrants who build depth rather than breadth.
Future Trends and Commercial Opportunities
Trend 1: Routine Clinical Access Will Expand as Complexity Barriers Lower
Over the next three to five years, regulatory classification progress and automation will continue to broaden the laboratory base able to run mass spectrometry assays. Moderate-complexity classification for selected steroid and other assays is an early indicator of a broader shift toward routine access. The commercial opportunity lies in panels and platforms that can scale across diverse laboratory types without requiring specialized operators, supported by clear coding pathways and defensible health economics. Vendors and laboratory customers that invest early in these accessible workflows will capture utilization before the market consolidates around a smaller set of standardized platforms.
Trend 2: Multi-Indication, Software-Centric Platforms Will Become the Default Architecture
Healthcare systems increasingly prefer platforms that support multiple indications on one footprint with consistent software, quality controls, and data management. This favors architectures that separate application expansion from hardware replacement, allowing laboratories to add tests through software and reagent updates rather than capital upgrades. The commercial opportunity is for vendors that can package multi-test menus, traceable QC, and integration with laboratory information workflows as a cohesive solution, while laboratory buyers can reduce capital intensity and standardize operations across departments.
Worldwide High Resolution Mass Spectrometry System Market
Trend 3: Therapeutic Drug Monitoring and Steroid/Immunosuppressant Panels Will Remain Central Growth Engines
Therapeutic drug monitoring is already the largest application segment, and the strategic rationale is strong: managing antibiotics, immunosuppressants, and steroid-related markers requires precise quantification with clinical turnaround that mass spectrometry can provide. As automated reagent packs and cleared workflows expand, these panels can move from specialized use into more routine hospital and specialty settings. The commercial opportunity lies in full-panel strategies that bundle antibiotics, steroids, immunosuppressants, and vitamin D metabolites around a single platform, creating cross-department utilization and stronger laboratory retention.
Risks and Uncertainties
Several risks temper the outlook. Reimbursement variability by payer and analyte can slow adoption for specific tests even when analytical performance is strong. Regulatory timelines and classification outcomes remain uncertain across indications and regions, meaning portfolios that depend on a single clearance event face concentration risk. In addition, if automation and software do not deliver the expected reduction in operating cost and training burden, the complexity-reimbursement gap will persist and limit throughput gains. Finally, coding and reimbursement updates can shift the economics of specific assays, requiring continuous health-economic monitoring rather than one-time justification.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
- Prioritize integrated, software-centric architectures that allow multi-test expansion without hardware replacement, and pair them with cleared or clearly regulatory-tracked workflows for high-value indications such as TDM, steroid panels, and microorganism identification.
- Design for operational simplicity and total cost of ownership, not just analytical performance. Reduce training burden, automate sample preparation where feasible, and offer predictable reagent and calibration economics to win procurement decisions in consolidated laboratory networks.
- Build multi-indication, multi-region regulatory strategies in advance. Early and sequential clearances across applications and jurisdictions can become a defensible competitive moat and accelerate cross-sell within health systems.
For Investors and Strategic Partners
- Focus on companies that convert regulatory and workflow advantages into installed-base growth and recurring consumable revenue, particularly where moderate-complexity classification, cleared assays, and broad test menus expand the addressable laboratory base.
- Evaluate exposure to reimbursement and coding risk at the analyte level. Investments tied to panels with clearer coding pathways and stronger health-economic support are less exposed to reimbursement variability than narrow, single-test offerings.
- Watch for consolidation opportunities in regional markets where service capability, pricing, and workflow simplicity matter more than cutting-edge analytical novelty. Localized execution can be a durable advantage in earlier-stage regions.
For Procurement and Laboratory Decision Makers
- Evaluate platforms based on total cost of ownership, regulatory status of assays, and the ability to standardize across multiple indications and sites, rather than instrument specifications alone. A platform that supports several cleared panels with integrated QC and data management can reduce operational risk and capital intensity.
- Assess training burden, staffing resilience, and service coverage as part of the sourcing decision. Workflows that lower dependency on specialized operators and offer predictable maintenance are better suited to high-throughput environments and decentralized networks.
- Monitor coding and reimbursement developments for the specific analytes you plan to run, and align test menu expansion with clear reimbursement pathways and health-economic justification to avoid adoption friction later.
The clinical mass spectrometry market is moving from specialist adoption to routine clinical integration, and the winners will be those who align analytical performance with workflow simplicity, regulatory clarity, and defensible economics. For decision makers who need granular segmentation, region-by-region dynamics, per-application growth drivers, and customized strategic scenarios, a detailed research report can provide the depth required to translate these trends into concrete plans. To access the full segmentation breakdown, competitive benchmarking, and tailored recommendations, request the complete PW Consulting report on the Clinical Mass Spectrometry Market.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com