

Blogs
Worldwide Wireless Communication Systems: The Forces Behind 12.48% CAGR Growth
By PW Consulting, 2026-09-18
Worldwide Wireless Communication Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
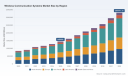
The worldwide wireless communication systems market has evolved from a connectivity utility into a strategic infrastructure layer that underpins digital transformation across industries. Valued at approximately 1.45 billion USD in 2025, the market has demonstrated consistent expansion over the past five years and is projected to accelerate through the 2032 horizon. The compound annual growth rate of 12.48 percent reflects a structural shift rather than a cyclical upturn, driven by the maturation of fifth-generation networks, the gradual retirement of legacy fourth-generation deployments, and the increasing integration of satellite and short-range wireless architectures into unified communication ecosystems.
Despite this robust trajectory, the sector is navigating a set of interconnected challenges that will shape competitive positioning and capital allocation decisions in the near term. The first challenge lies in the physical and economic density of next-generation infrastructure. Deploying advanced radio access networks and backhaul systems requires substantial upfront investment, and operators are under continuous pressure to justify site-level economics while expanding coverage and capacity. This tension is particularly pronounced in regions where population density, terrain complexity, and regulatory approval timelines intersect, forcing vendors and service providers to rethink deployment models and cost-sharing frameworks.
The second challenge centers on fragmentation in standards, interoperability, and vendor ecosystems. The industry is moving toward disaggregated architectures and open interface frameworks, which promise greater flexibility and lower switching costs. At the same time, this transition introduces integration complexity, testing overhead, and the need for new operational competencies. Organizations that cannot manage multi-vendor interoperability or align their hardware and software roadmaps with evolving interface specifications risk higher total cost of ownership and slower time-to-market for new services.
A third challenge is the shifting regulatory and geopolitical landscape. Spectrum allocation decisions, export controls on advanced semiconductors, and platform interoperability mandates are increasingly influencing where and how wireless systems can be designed, manufactured, and deployed. These dynamics are not uniform across regions, which means global players must operate with greater architectural flexibility and regional adaptation. The market's overall concentration, with the top three participants holding roughly 38.45 percent and the top five holding about 52.12 percent, indicates that scale, portfolio breadth, and ecosystem relationships remain decisive, but it also leaves room for specialized players that can deliver differentiated technology or cost advantages in targeted segments.
PW Consulting
Key Drivers Shaping Market Dynamics
Technology Innovation and Architectural Shift
The transition from fourth-generation systems to fifth-generation and emerging fifth-generation advanced capabilities is the most visible driver of market expansion. This is not simply a matter of faster peak speeds; it is an architectural shift that enables network slicing, lower latency, and more granular service differentiation. Recent commercial activity illustrates how quickly these capabilities are being operationalized. In early 2025, Ericsson was selected by Deutsche Telekom to upgrade the 5G standalone core across Germany, signaling a move toward fully independent core architectures that can support diverse enterprise and consumer workloads. Around the same period, Nokia deployed 5G advanced equipment for China Mobile across multiple provinces, reinforcing the industry's push toward higher-throughput radio systems and more efficient resource utilization.
At the device and component level, the innovation curve is extending beyond traditional smartphones and base stations. Qualcomm's introduction of a new 5G modem-RF platform designed to support reduced-capability devices and lightweight wireless standards points to a broader vision in which lower-power, cost-sensitive endpoints can participate in advanced wireless networks. This expands the addressable base beyond high-end mobile devices and creates new pathways for industrial sensors, wearables, and specialized telemetry equipment. Huawei's launch of a 5.5G solution with 10Gbps peak speeds for commercial trials in Asia further underscores the industry's focus on pushing throughput boundaries while preparing networks for denser traffic patterns and more demanding applications.
Policy, Spectrum, and Regulatory Environment
Policy decisions continue to shape both the pace and geography of wireless investment. Spectrum availability remains a foundational enabler, and recent auction activity demonstrates how aggressively operators are securing mid-band and other valuable frequencies. In one notable allocation, the FCC awarded 102 licenses in the 3.45-3.55 GHz band, raising 1.82 billion USD and highlighting the strategic value of mid-band spectrum for balancing coverage and capacity. At the same time, regulatory frameworks are increasingly addressing the broader digital ecosystem rather than wireless infrastructure in isolation. The restoration of net neutrality rules under Title II classification in the United States and the enforcement of interoperability requirements for gatekeeper platforms in the European Union both signal a more interventionist stance on how networks and platforms interact.
These regulatory moves matter because they influence service design, traffic management, and the commercial models that operators and enterprises can build on top of wireless systems. For vendors, regulatory certainty can reduce planning risk, while sudden policy shifts can alter demand forecasts and regional prioritization. For enterprises, clearer rules around interoperability and traffic treatment can lower integration risk and make wireless-dependent solutions more predictable from a compliance standpoint.
Demand-Side Transformation Across Sectors
Demand is no longer concentrated solely in traditional telecommunications services. Industrial operations, consumer devices, and mobility applications are all generating new requirements for reliable, scalable, and often low-latency wireless connectivity. Industrial environments are increasingly adopting private and hybrid network models to support automation, asset tracking, and real-time control, which places a premium on predictable performance and integration with operational technology. Consumer electronics continue to expand the base of connected endpoints, but the more strategically important shift is the growing expectation that devices and services should work seamlessly across cellular, Wi-Fi, and short-range networks depending on context and cost.
In transport and automotive applications, wireless systems are enabling vehicle-to-infrastructure communication, fleet telemetry, and in-cabin connectivity, all of which depend on a combination of coverage, resilience, and spatial reuse. This diversification of end users means that wireless communication systems are becoming multi-purpose platforms rather than single-use networks. The strategic implication is that suppliers must design for flexibility: the same infrastructure should be able to serve mobile operators, enterprises, and vertical industries with different service levels and operational constraints.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by both infrastructure economics and component-level constraints. The average cost of deploying a 5G base station, typically ranging from 100,000 to 300,000 USD per site, remains a meaningful barrier to rapid dense deployment, especially when operators are balancing capital expenditure against uncertain revenue uplift in certain areas. This cost pressure is encouraging experimentation with virtualized radio architectures, centralized processing, and more efficient site designs that can reduce per-location expenditures or improve utilization.
Worldwide Underwater Communication System Market
At the same time, export controls on advanced semiconductors have introduced new uncertainty into the supply of high-performance chips used in both network equipment and end-user devices. Restrictions imposed on semiconductor exports to Huawei in late 2023, for example, illustrate how geopolitical considerations can affect product roadmaps, regional availability, and competitive dynamics. These supply-side factors are pushing companies to diversify sourcing, design for component flexibility, and in some cases re-evaluate where critical manufacturing and integration activities are located.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established infrastructure incumbents, semiconductor and platform specialists, and regional players with strong execution capabilities in specific markets. Ericsson and Nokia remain central to the carrier-grade infrastructure conversation, with portfolios that span radio access, core networks, and cloud-aligned platforms. Ericsson's recent core upgrade work with Deutsche Telekom emphasizes end-to-end control of the standalone architecture, which can be a differentiator for operators seeking to standardize on a single vendor's ecosystem for manageability and service orchestration. Nokia's deployment of 5G advanced equipment for China Mobile highlights a strategy centered on scaling proven radio and baseband technologies across large operator networks while supporting next-generation features such as massive MIMO and advanced antenna systems.
Samsung and Qualcomm illustrate a different but complementary axis of competition. Samsung's expanded Open RAN 5G network work with Verizon in the US Midwest reflects a push toward virtualized and open-interface infrastructure that can reduce dependence on single-vendor stacks and broaden integration options for operators. Qualcomm's modem-RF platforms anchor much of the device-side ecosystem, and its continued investment in reduced-capability and lightweight wireless standards shows a strategy aimed at broadening the range of connectable devices and use cases beyond premium smartphones. This device-to-network alignment is increasingly important because wireless system value is shaped not only by infrastructure performance but also by the diversity and capability of endpoints.
Huawei, ZTE, NEC, Fujitsu, Cisco, and CommScope each occupy distinct strategic positions. Huawei's full-stack 5G approach and emphasis on AI-driven optimization and high-capacity base stations position it as an integrated solution provider, even as export controls and regional restrictions shape where and how its offerings can be deployed. ZTE's focus on macro and small-cell radio systems with carrier aggregation supports operators seeking capacity gains through dense site architectures. NEC's microwave and radio systems serve backhaul and fronthaul needs, which remain critical as traffic grows and fiber availability varies by region. Fujitsu's RIC and O-RAN compliant base stations align with the broader move toward programmable, disaggregated networks. Cisco continues to strengthen its role in enterprise wireless LAN environments by integrating Wi-Fi 6 and 6E access points with SD-WAN and broader networking fabrics, while CommScope provides radio and antenna solutions for small cells and macro sites, addressing the physical-layer realities of densification.
Wireless Communication Intelligent Module Market
What ties these strategies together is a gradual re-balancing between integration and openness. Leading players are investing in platforms that can operate across proprietary and open interfaces, and they are positioning themselves as enablers of hybrid architectures rather than as single-stack vendors. Market concentration remains significant, but the landscape is also becoming more modular, which creates opportunities for specialized suppliers in radios, antennas, control software, device platforms, and integration services. The companies most likely to sustain advantage are those that can combine technical performance with deployment efficiency, multi-vendor compatibility, and the ability to tailor solutions to regional spectrum, cost, and regulatory conditions.
Future Trends and Strategic Implications
Over the next three to five years, one clear trend is the continued convergence of cellular, short-range, and satellite wireless capabilities into more unified service experiences. Networks will increasingly be evaluated not only on peak throughput but on how effectively they can hand off traffic, prioritize critical sessions, and support varied device classes without fragmenting the user or enterprise experience. This creates opportunities for providers that can offer orchestration layers, cross-domain management, and service assurance across heterogeneous environments.
A second trend is the acceleration of virtualized and software-defined radios and cores, which will make networks more adaptable but also increase the importance of integration, automation, and security. As functions become more software-centric, the competitive edge will shift toward operational efficiency, lifecycle management, and the ability to introduce new capabilities without costly hardware replacement cycles. Vendors and operators that invest early in automation, telemetry, and standardized interfaces are likely to gain an advantage in total cost of ownership and service velocity.
A third trend is the widening of use-case diversity across industrial, automotive, and consumer segments, which will increase demand for tailored connectivity profiles rather than one-size-fits-all network designs. This opens commercial opportunities for private network solutions, vertical-specific service bundles, and endpoint platforms optimized for power, cost, and specialized performance. The main uncertainty lies in how quickly standards, spectrum, and regulatory frameworks will align to support these differentiated offerings at scale. Geopolitical constraints, spectrum affordability, and deployment economics could slow adoption in some regions, while more favorable conditions may enable faster commercialization elsewhere. Companies that can model these variables and adapt their architectures accordingly will be better positioned to capture value as the market matures.
Actionable Guidance for Decision Makers
For infrastructure manufacturers and technology suppliers, the priority is to design for flexibility without sacrificing performance. This means investing in architectures that can support both integrated and open interfaces, building portfolios that address a broad range of device classes and deployment scenarios, and reducing the integration cost of multi-vendor environments. Suppliers that can demonstrate lower site-level deployment complexity, efficient spectrum use, and credible interoperability will be better placed to compete in a market where cost pressures and regulatory diversity are both rising.
For investors, the most valuable signal is where capital is flowing across the stack. Interest is likely to remain strong in core modernization, virtualized and open-interface infrastructure, device platforms that expand the addressable endpoint base, and enabling technologies for backhaul, small cells, and enterprise wireless environments. Portfolio decisions should account for regional exposure, since spectrum policy, export controls, and interoperability mandates are creating uneven competitive conditions across geographies. Diversification into integration, orchestration, and specialized vertical solutions may offer more durable returns than betting solely on generic hardware cycles.
For procurement leaders and enterprise adopters, the focus should be on total lifecycle economics and service assurance rather than on headline specifications alone. Selecting wireless systems that can integrate with existing IT and operational technology environments, support evolving interface standards, and provide predictable performance across cellular, Wi-Fi, and short-range networks will reduce risk as use cases expand. Building internal capability for network management, security, and vendor coordination is increasingly as important as the equipment selection itself.
Given the speed at which spectrum decisions, deployment economics, and regulatory frameworks are evolving, decision makers benefit from maintaining a continuous view of segment-level demand, regional policy shifts, and vendor roadmaps. Detailed segmentation data, region-specific deployment economics, and company-level strategic assessments can sharpen capital allocation, product planning, and sourcing decisions in a market that is expanding rapidly but becoming more complex to navigate.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Communication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Waste Collection at 13.5% CAGR: The Real Drivers Behind $6.4B Growth
By PW Consulting, 2026-09-18
The Smart Waste Collection Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
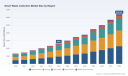
The smart waste collection market has transitioned from a niche urban experimentation space to a mainstream infrastructure priority over the past half-decade. Valued at approximately $2.65 billion in 2025, the sector has expanded from $1.34 billion in 2020, reflecting a compound annual growth rate of 13.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $6.4 billion, signaling a structural shift rather than a cyclical uptick. This trajectory is anchored in the convergence of municipal budget pressures, regulatory mandates for transparent waste tracking, and the maturation of low-power connectivity ecosystems that make sensor-driven logistics economically viable at scale.
The market expansion, however, masks underlying friction points that decision-makers must navigate carefully. First, the cost of deployment remains a persistent barrier for mid-sized cities and commercial operators. Basic smart bin sensor deployments paired with SaaS platforms typically run between €30 and €60 per bin annually, including sensor amortization. While this figure has declined as hardware commoditizes, the total cost of ownership—encompassing installation, network provisioning, platform licensing, and ongoing maintenance—still constrains rapid adoption in budget-constrained environments. Second, data interoperability and integration complexity continue to fragment the value chain. Fleet management systems, route optimization engines, and municipal ERP platforms rarely share common data models, forcing operators to build custom middleware or accept siloed dashboards that limit cross-functional insight. Third, the regulatory landscape is accelerating faster than standardization. Frameworks such as the UK's mandatory Digital Waste Tracking scheme and updated EU Waste Framework Directive requirements are introducing stricter recycling mandates and purity accountability, but compliance pathways vary by jurisdiction, creating uncertainty for multinational operators and technology vendors alike.
These challenges are not deterrents so much as stress tests that will separate durable solutions from short-lived pilots. Organizations that treat smart waste collection as a data infrastructure play—rather than a hardware replacement project—will be better positioned to extract operational leverage and align with evolving compliance expectations.
Key Drivers Behind Market Acceleration
Several interlocking forces are propelling the smart waste collection market toward sustained double-digit growth. Understanding these drivers is essential for anticipating where capital, partnerships, and product development will converge in the coming years.
Technological Breakthroughs in Sensing and Connectivity
Ultrasonic fill-level sensors, solar-powered compaction units, and low-power wide-area network connectivity have matured into reliable, field-tested components. LoRaWAN networks, widely adopted for smart bin monitoring, are undergoing upgrades in 2026 to support hybrid multi-band connectivity, improving coverage in dense urban corridors and reducing reliance on single-network dependencies. This evolution lowers the risk of connectivity gaps that previously undermined route optimization accuracy. On the software side, predictive analytics and route optimization engines are moving beyond static fill-level thresholds toward dynamic models that incorporate historical collection patterns, traffic conditions, and seasonal waste generation profiles. The result is a measurable reduction in unnecessary collection trips, fuel consumption, and labor allocation.
Policy and Regulatory Momentum
Regulation is reshaping waste management from an operational afterthought into a compliance-critical function. The EU Waste Framework Directive updates introduced in early 2026 impose stricter recycling targets and accountability for waste purity, pushing municipalities and industrial operators to demonstrate traceability across collection, sorting, and disposal stages. In parallel, the UK's mandatory Digital Waste Tracking scheme, effective in 2026, is designed to combat waste crime and support circular economy compliance by requiring digital documentation across the waste chain. These mandates create a clear demand signal for platforms that can capture, validate, and report waste movement data with audit-grade reliability. Vendors that embed compliance workflows directly into their analytics and route optimization tools are gaining a structural advantage, as operators seek to avoid fragmented point solutions that increase administrative overhead.
Demand-Side Shifts in Municipal and Commercial Operations
City governments and commercial property managers are increasingly treating waste collection as a service optimization problem rather than a fixed-cost utility. Public space managers, for example, are deploying solar-powered smart waste and recycling stations with compaction and fill-level sensing to reduce collection frequency in high-traffic areas while maintaining cleanliness standards. The deployment of such stations at Emerald Park in partnership with Panda illustrates how public-private arrangements can share deployment risk and align operational incentives. On the commercial side, facility operators face pressure to reduce service disruptions, improve tenant experience, and demonstrate sustainability commitments. Smart collection platforms that provide real-time visibility into bin status and collection scheduling help operators move from reactive pickup schedules to condition-based service models, which in turn supports labor planning and fleet utilization.
Supply Chain and Cost Structure Evolution
The economics of smart waste collection are gradually improving as hardware components become more standardized and software platforms shift toward subscription-based models. Sensor modules and IoT gateways are benefiting from broader industrial IoT supply chain scale, which has helped moderate unit costs and shorten deployment timelines. Meanwhile, the industry context noise around per-bin annual costs of €30–€60 including sensor amortization reflects a broader trend toward unbundled pricing, where hardware, connectivity, and software are priced separately or packaged in tiered service models. This modularity gives operators flexibility to scale incrementally, but it also requires disciplined vendor evaluation to avoid hidden integration and maintenance expenses. Fleet upgrades are another notable shift. The launch of Cart Smart automated garbage and recycling collection using new smart-equipped trucks demonstrates how vehicle-side intelligence—such as onboard scanning, load verification, and route feedback—can complement bin-side sensors, creating a more complete data loop between collection points and hauling operations.
Competitive Landscape and Leading Strategies
The smart waste collection market remains relatively fragmented, with the top three players accounting for roughly 28.5 percent of revenue and the top five reaching approximately 36.2 percent. This concentration leaves substantial room for differentiation, consolidation, and targeted market entry. The competitive field spans solar-powered smart bins, sensor and IoT modules, and software platforms that span route optimization, fleet management, and citizen engagement. Companies are pursuing distinct strategic positions rather than competing on a single dimension.
- Bigbelly has built a recognizable presence in public-space waste management through solar-powered smart waste and recycling stations that combine compaction with fill-level sensing. Its deployments in municipal and commercial public areas emphasize reduced collection frequency and improved space utilization, positioning the brand around visible, self-contained hardware solutions that simplify procurement for parks, campuses, and downtown corridors.
- Ecube Labs operates from a dual hardware-and-platform angle with solar-powered compacting bins and a network management platform that incorporates ultrasonic fill-level sensing and route optimization. Its approach reflects a strategy of tying bin-level intelligence to centralized dispatch, which appeals to operators seeking a single vendor relationship for both field equipment and analytics.
- Sensoneo offers end-to-end smart waste management spanning ultrasonic sensors, data analytics, and route optimization, with a track record in large-scale municipal deployments and deposit return systems. Its recent involvement in Portugal's national Deposit Return System—powering voucher validation and waste tracking—illustrates a strategy of embedding technology into nationally significant compliance and circular economy programs, which can create durable public-sector relationships and reference deployments.
- Evreka focuses on AI-powered digital platforms for waste collection, fleet management, and citizen engagement, with IoT integration tailored to municipalities and operators. Its emphasis on citizen-facing engagement and operational digitization positions it at the intersection of service communication and field execution.
- Rubicon Technologies centers its offering on software for waste and recycling fleet optimization, route planning, and data analytics, serving cities and businesses with a platform-first model. This software-centric positioning allows the company to integrate with existing fleet and municipal systems without necessarily controlling the bin hardware layer.
- Enevo specializes in sensor-based waste monitoring, predictive analytics, and route optimization for haulers and property managers, targeting the operational efficiency layer where fill-level data translates directly into collection scheduling and cost reduction.
- AMCS Group provides an AI-enabled end-to-end waste management and recycling software platform that includes route optimization and smart collection tools, appealing to operators that want a broader enterprise software footprint across recycling, logistics, and customer management.
- Veolia leverages its global environmental services footprint to integrate smart collection technologies, IoT sensors, and data platforms into municipal and industrial operations. Its strategy is less about standalone product sales and more about embedding intelligence into large-scale service contracts, which can accelerate adoption where operators prefer integrated service delivery over fragmented technology procurement.
These companies illustrate a market that is simultaneously differentiating and converging. Hardware-led providers are expanding into software and network management to capture recurring revenue and deepen customer stickiness. Software-centric players are building integrations with sensors and fleet systems to improve data fidelity and route accuracy. Large environmental services firms are layering smart technologies into existing contracts, using scale and service relationships to deploy solutions across multiple sites. The net effect is a landscape where pure-play hardware vendors face pressure to demonstrate platform-level value, while software vendors must prove they can reliably ingest field data and translate it into operational savings.
Market evolution is also being shaped by the pace of standardization and the growing importance of compliance-ready data. As digital waste tracking and recycling accountability requirements tighten, vendors that can offer auditable data flows, transparent reporting, and configurable compliance workflows will likely command stronger positioning in municipal and industrial segments. At the same time, the presence of multiple viable approaches—solar compacting bins, ultrasonic sensors, route optimization platforms, and fleet-side intelligence—suggests continued fragmentation in the near term, with consolidation more likely around integrated data platforms and regional service partnerships than around any single hardware form factor.
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, several trends are likely to define where value is created and where risk accumulates.
From Bin-Level Sensing to End-to-End Data Loops
The next phase of market maturation will increasingly reward solutions that close the loop between bin status, collection execution, and downstream waste handling. Bin-side sensors and compaction units will remain important, but their strategic value will depend on how effectively they feed route optimization, fleet verification, and compliance reporting. Operators that can demonstrate measurable reductions in empty runs, improved container utilization, and traceable waste movement will have stronger grounds for contract renewals and expansion. Commercial opportunity lies in platforms that combine fill-level intelligence with vehicle-side confirmation and analytics that tie collection efficiency to cost and emissions metrics.
Garbage Truck Market
Compliance-Driven Procurement as a Growth Catalyst
Regulatory mandates for digital tracking, recycling purity, and circular economy accountability are converting compliance from a cost center into a procurement driver. Municipalities and industrial operators are more likely to prioritize solutions that can support mandated reporting and reduce the administrative burden of manual documentation. This creates openings for vendors that design data capture and reporting into everyday collection workflows rather than treating compliance as an add-on module. The risk is that divergent national and regional requirements could increase integration complexity, especially for operators running multi-jurisdiction fleets. Standardization efforts and interoperable data models will matter more as compliance scope expands.
Modular Pricing and Fleet-Side Intelligence Will Reshape Adoption Paths
The trend toward modular hardware, connectivity, and software pricing will likely continue, giving operators more flexibility to scale in stages. This modularity lowers initial barriers but also places a premium on disciplined evaluation of total cost of ownership, including network dependencies, data integration effort, and maintenance obligations. At the same time, fleet upgrades that bring intelligence onto collection vehicles—such as automated cart handling, onboard verification, and route feedback—are expected to complement bin-side sensing and improve the reliability of dynamic scheduling. Organizations that align bin-side and vehicle-side data streams will be better positioned to optimize labor, fuel, and container lifecycles. The uncertainty here lies in the pace of fleet renewal and the degree to which smaller operators can fund vehicle-side upgrades alongside sensor deployments.
Strategic Recommendations for Decision-Makers
For manufacturers and technology vendors, the priority is to move beyond standalone hardware specifications and articulate how a solution reduces total operational cost while supporting compliance workflows. Product roadmaps that integrate fill-level sensing, route optimization, and auditable reporting into a coherent data architecture will be easier to position in municipal and industrial procurement processes. Vendors should also anticipate interoperability demands by designing open integration points for fleet systems, municipal platforms, and regional connectivity options rather than locking customers into closed stacks.
For investors, the market's growth trajectory is attractive, but value capture will favor companies with durable recurring revenue, demonstrable operational savings, and exposure to compliance-driven procurement. Due diligence should focus on unit economics across hardware, connectivity, and software components, as well as the strength of municipal and industrial references that validate route optimization and cost reduction claims. Portfolio positioning should account for the likelihood of consolidation around integrated data platforms and regional service relationships, especially where regulatory momentum is strongest.
Worldwide Smart Solar Urban Equipment Market
For procurement teams and operational leaders, the most effective adoption strategy starts with a narrowly defined use case—such as high-traffic public spaces, commercial facilities with irregular waste generation, or municipal corridors with high collection costs—and expands only after measurable savings and data reliability are proven. Evaluation criteria should include total cost of ownership, integration effort with existing fleet and reporting systems, and the vendor's ability to support evolving digital tracking and recycling accountability requirements. Building internal capability to interpret collection data and translate it into scheduling and labor decisions will determine whether smart waste collection delivers its intended operational leverage.
Detailed segmentation data, regional deployment patterns, and customized scenario analysis can help stakeholders narrow where to commit resources and how to sequence investments. Comprehensive research on the smart waste collection market is available for teams that need deeper breakdowns across product types, application segments, and regional dynamics, along with tailored guidance for procurement, partnership, and investment decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Waste Collection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Otolaryngology Endoscopy Market: Why 6.52% CAGR and Shifting Dynamics Redefine Growth
By PW Consulting, 2026-09-18
Navigating the Global Otolaryngology Endoscopy Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
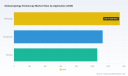
The global otolaryngology endoscopy market has demonstrated consistent expansion, reaching an estimated valuation in 2025 before progressing toward a projected valuation by 2032. This trajectory reflects a compound annual growth rate of approximately 6.52 percent across the forecast horizon. Such growth underscores the procedure's central role in modern ear, nose, and throat care, driven by procedural volume increases and procedural complexity. The market structure reveals notable concentration, with the top three players commanding nearly half of total revenue and the top five entities controlling over sixty percent. This consolidated landscape suggests established incumbents hold significant sway over pricing, distribution channels, and technological standards, while smaller specialized firms navigate limited whitespace without strategic partnerships or niche differentiation.
Several structural headwinds currently shape market dynamics. First, supply chain fragility continues to pressure manufacturers, particularly for precision optics, specialized sensors, and medical-grade polymers. Component shortages and logistics disruptions have historically extended lead times and inflated production costs, forcing companies to reassess inventory strategies and supplier diversification. Second, reimbursement environments remain uneven across regions and procedure codes. While certain automated delivery systems and advanced visualization techniques have secured favorable payment classifications, many health systems face budget constraints that delay capital equipment upgrades. This reimbursement uncertainty directly influences procurement cycles and limits the speed at which newer technologies diffuse into clinical practice. Third, the sector faces a talent and training bottleneck. Advanced endoscopic procedures demand specialized clinical proficiency, yet training infrastructure often lags behind equipment availability. Hospitals and ambulatory surgery centers must invest in simulation programs, credentialing pathways, and continuous education to realize the full value of modern endoscopic platforms, creating an adoption friction point that manufacturers and service providers must address holistically.
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Technological innovation remains the most visible accelerator of market evolution. Visualization quality has improved markedly through enhanced depth-of-field optics, higher-resolution video processors, and integrated imaging workflows. Recent regulatory clearances for systems featuring extended depth of field capabilities and towerless hybrid architectures illustrate how engineering advances translate into procedural efficiency. These platforms reduce setup complexity, improve surgeon ergonomics, and support faster turnover between cases, which matters greatly in high-volume ENT practices. At the same time, single-use flexible endoscopy has matured from a niche concept into a credible alternative for diagnostic procedures. Single-use devices lower cross-contamination risk, streamline reprocessing workflows, and reduce downstream costs associated with sterilization and instrument maintenance. This shift aligns with institutional priorities around infection control and operational simplification, particularly in outpatient settings where throughput and patient turnover are critical metrics.
Regulatory and reimbursement developments are reshaping commercial pathways. Recent clearance activity has expanded the procedural envelope for both diagnostic and therapeutic endoscopy, including indications that support transoral approaches for select oropharyngeal conditions and novel navigation systems designed for cranial and sinus applications. Clearer procedural indications reduce commercial uncertainty and encourage earlier adoption by demonstrating acceptable safety and performance profiles. On the payment side, the assignment of national payment rates to specific procedural codes for automated tube delivery and localized anesthesia techniques signals a broader willingness to recognize technology-enabled efficiency. When reimbursement frameworks explicitly value automation and precision delivery, hospitals gain fiscal justification to invest in compatible capital equipment, creating a virtuous cycle of device uptake and procedural standardization.
Demand-side behavior is shifting as care delivery models evolve. Patients and providers alike increasingly favor minimally invasive diagnostics that can be performed in office-based settings rather than operating rooms. Office-based endoscopy reduces facility fees, shortens wait times, and supports same-day decision-making, making it attractive for both health systems and payers. This preference accelerates demand for portable, high-quality visualization tools and single-use scopes suited to ambulatory workflows. Simultaneously, hospital operators continue to allocate substantial capital toward infrastructure modernization. Large health networks have outlined multi-year capital expenditure programs that explicitly include imaging and endoscopy system upgrades, reflecting a strategic intent to standardize platforms, improve surgical precision, and support expanded service lines. When capital budgets align with clinical priorities, procurement cycles accelerate and multi-year platform agreements become more common.
Laryngoscope Market
Supply chain and cost structures are undergoing parallel transformation. Manufacturers are rebalancing toward regional sourcing, dual-supplier strategies, and modular component designs that allow faster production adjustments when demand shifts. These approaches help mitigate volatility in optical elements, display components, and disposable materials. At the same time, the cost equation for end-users is changing. While advanced visualization platforms require meaningful upfront investment, total cost of ownership arguments increasingly account for reduced reprocessing labor, fewer repair events, and improved case throughput. Buyers are therefore evaluating purchases not solely on sticker price but on workflow integration, service availability, and clinical outcomes. This more sophisticated evaluation framework rewards vendors that can demonstrate measurable operational benefits rather than device features in isolation.
Competitive Landscape and Strategic Positioning
The market is defined by a mix of large diversified conglomerates, focused endoscopy specialists, and emerging innovators targeting specific procedural niches. Established players have built strong positions through broad product portfolios, global distribution networks, and long-standing relationships with surgical teams. Their advantage lies in the ability to offer integrated solutions spanning rigid and flexible scopes, video processors, navigation platforms, and related instruments. This comprehensiveness simplifies purchasing for health systems that prefer fewer vendor interfaces and standardized service contracts. Differentiation among incumbents increasingly depends on workflow integration, image quality, and the degree to which platforms connect with navigation or robotics ecosystems. Companies that can unify planning, visualization, and instrument control within a coherent clinical workflow create meaningful switching costs and support recurring revenue through servicing and consumables.
Several strategic themes distinguish the competitive field. First, single-use and hybrid device strategies are expanding. Some manufacturers have introduced disposable flexible video rhinolaryngoscopes tailored for diagnostic and therapeutic use, while others have brought forward hybrid systems that combine rigid and flexible capabilities within a single platform. These moves address two distinct demands: infection control and reprocessing simplification on one hand, and procedural versatility on the other. Second, navigation and robotics integration is becoming a competitive battleground. Advanced navigation platforms designed for sinus and skull base procedures, along with systems that unify planning and instrument guidance, are gaining regulatory clearances and clinical visibility. These technologies appeal to centers treating complex pathologies where precision and anatomical orientation directly influence outcomes. Third, smaller innovators are carving opportunities through specialized navigation features, steerable flexible platforms for nasal and upper airway applications, and streamlined towerless designs that reduce footprint in crowded procedure rooms. Such entrants often compete on agility, focused clinical claims, and faster iteration cycles.
Market structure appears to be moving along two parallel tracks. Consolidation remains likely as larger organizations seek to expand procedural coverage, geographic reach, and consumables attach rates through acquisitions or partnership arrangements. At the same time, segmentation is intensifying. Different care settings—large academic hospitals, community surgical centers, and office-based practices—have distinct requirements for portability, reprocessing capacity, and capital tolerance. This divergence encourages vendors to develop tiered offerings, where high-end integrated systems serve complex surgical environments while streamlined portable units and single-use options address outpatient and ambulatory demand. New entrants that can demonstrate clear clinical utility, regulatory compliance, and a credible reimbursement pathway stand a realistic chance of gaining footholds, even in a concentrated market, provided they solve a specific workflow pain point rather than competing broadly on general specifications.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
One defining trend is the continued blurring of diagnostic and therapeutic endoscopy. As imaging clarity improves and instrument channels become more capable, clinicians increasingly move from visualization to intervention within the same procedural session. This evolution favors platforms that support smooth transitions from diagnosis to treatment, including compatible instruments, reliable suction and irrigation, and integrated navigation where anatomical complexity warrants it. Companies that design for this continuum—rather than treating diagnosis and therapy as separate product lines—will be better positioned to capture recurring procedural volume and consumables demand.
A second trend is the institutionalization of single-use endoscopy for selected indications. As clinical evidence matures and cost models are refined, single-use flexible scopes are likely to claim a growing share of diagnostic examinations, particularly where turnaround time, sterility assurance, and space constraints matter. The commercial implication is a shift in revenue mix: lower per-unit pricing for disposable devices must be offset by higher volumes, streamlined supply agreements, and reliable distribution. Manufacturers that can standardize specifications, ensure consistent quality, and align with facility procurement cycles will benefit most. At the same time, hybrid strategies that pair durable capital systems with consumable accessories and selected disposables may become the dominant economic model for many providers.
A third trend involves deeper integration of navigation, planning tools, and data-enabled workflow support. Rather than viewing endoscopy as an isolated visualization task, leading centers increasingly treat it as part of a broader procedural ecosystem that includes pre-operative planning, intra-procedural guidance, and post-procedural documentation. This trajectory opens opportunities for software-driven differentiation, interoperable device ecosystems, and analytics that help hospitals benchmark throughput, complication rates, and instrument utilization. The associated risk is that integration requirements raise the barrier to entry and increase dependency on a small number of platform providers. Buyers may consequently demand greater interoperability, transparent data ownership provisions, and flexible service terms to avoid lock-in while still capturing clinical benefits.
Worldwide Respiratory Endoscope Market
Actionable Implications for Decision-Makers
For manufacturers and technology developers, the priority is to build modular yet integrated solutions that serve multiple care settings without sacrificing clinical performance. Portfolio strategy should balance advanced visualization and navigation for complex surgical environments with portable, low-footprint, and single-use options for office-based and ambulatory use. Equally important is aligning product roadmaps with reimbursement realities: devices that help standardize procedures, reduce reprocessing burden, or enable office-based care will find stronger adoption pathways when paired with clear payment logic and clinical evidence. Companies should also invest in training and service ecosystems, since adoption friction often hinges on clinician confidence and operational readiness rather than hardware specifications alone.
For investors, the most promising signals sit at the intersection of workflow simplification and procedural expansion. Capital allocation should favor platforms that demonstrate genuine integration benefits, recurring consumables potential, and credible clearances for expanded indications. It is also prudent to monitor suppliers and sub-systems where supply chain resilience is improving, as component reliability increasingly determines which vendors can scale consistently. Careful attention to reimbursement developments and hospital capital expenditure guidance can provide early indicators of procurement momentum, especially in markets where payment classification changes have recently improved the economics of technology-enabled procedures.
For procurement leaders and health system executives, the strategic question is less about buying a scope than about selecting a platform that fits long-term service lines and operational goals. Evaluations should weigh image quality and instrument compatibility alongside reprocessing demands, training requirements, service coverage, and interoperability with existing navigation or imaging infrastructure. Where possible, pilot programs and structured clinical assessments can reduce uncertainty before multi-year commitments. As the market continues to evolve, organizations that secure detailed, up-to-date intelligence on segment dynamics, pricing structures, and regulatory trajectories will be better equipped to time investments, negotiate terms, and build procurement strategies aligned with both clinical needs and fiscal constraints.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Otolaryngology Endoscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Direct Acting Proportional Reversing Valve With Displacement Feedback Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Overview
The market for the Direct Acting Proportional Reversing Valve With Displacement Feedback is a critical component within hydraulic and automation systems, enabling precise control of fluid flow and direction. These valves are essential for applications requiring smooth, responsive reversing functions, often used in industrial machinery, mobile equipment, and maritime systems. Their core functionalities include proportional control, feedback integration, and reliable reversing capabilities, supporting advanced automation processes.
The Direct Acting Proportional Reversing Valve With Displacement Feedback Market plays a vital role in enhancing operational efficiency and system responsiveness. By providing accurate displacement feedback, these valves improve control accuracy and system stability, ensuring optimal performance across various industries. Their importance is particularly evident in sectors demanding high precision and adaptability, making them indispensable for modern industrial and mobile hydraulic applications.
Market Size and Growth
The current market value of the Direct Acting Proportional Reversing Valve With Displacement Feedback Market is estimated at approximately $1.2 billion. Over the next 7 to 10 years, it is projected to reach around $2.3 billion, representing a compound annual growth rate (CAGR) of about 8%. Growth is driven by increasing automation in manufacturing, rising demand for energy-efficient hydraulic systems, and technological advancements in valve control mechanisms.
The expansion is further supported by the growing adoption of smart hydraulic systems across diverse sectors, including construction, aerospace, and marine industries. As industries seek more precise and reliable control solutions, the demand for these valves is expected to accelerate, reinforcing their strategic importance in modern hydraulic technology.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2282
Key Drivers
- Rising automation in manufacturing processes
- Increasing demand for energy-efficient hydraulic systems
- Technological advancements in valve control and feedback mechanisms
- Expansion of mobile machinery and industrial equipment markets
- Growing emphasis on system precision and control stability
Restraints
- High manufacturing and integration costs
- Technical complexity in feedback system calibration
- Regulatory hurdles related to hydraulic component standards
- Operational challenges in extreme environmental conditions
- Limited aftermarket support in some regions
Segmentation
• By Type
• By Deployment
• By Enterprise Size
• By End User
• By Region
Regional Insights
North America exhibits strong demand driven by automation trends and technological innovation in industrial and mobile machinery sectors. The region’s focus on energy efficiency and system precision further boosts adoption rates.
In Europe, stringent regulatory standards and a mature industrial base foster steady growth. The emphasis on sustainable and smart hydraulic solutions aligns well with the deployment of these valves.
The Asia-Pacific region is experiencing rapid growth, fueled by expanding manufacturing, infrastructure development, and a shift toward automation. Emerging markets are increasingly adopting advanced hydraulic control systems.
Latin America shows moderate growth, primarily driven by construction and mining activities. Adoption is gradually increasing with regional industry modernization efforts.
Middle East & Africa are witnessing rising demand from oil & gas and infrastructure projects. Market expansion is supported by infrastructure investments and industrialization initiatives.
Opportunities
- Expansion into emerging markets with growing industrial bases
- Integration with Industry 4.0 and IoT-enabled hydraulic systems
- Development of smarter, more energy-efficient valve solutions
- Increasing adoption in mobile machinery and autonomous systems
- Innovations in feedback and control technology to enhance reliability
Key Companies
Bosch Rexroth, Parker Hannifin, Eaton Corporation, Danfoss, Moog Inc., Yuken Kogyo, HAWE Hydraulik, Kawasaki, SMC Corporation, MOOG, Rexroth, and Norgren.
Conclusion
The overall outlook for the Direct Acting Proportional Reversing Valve With Displacement Feedback Market remains positive, with long-term growth driven by ongoing industrial automation and technological innovation. As industries prioritize precise, efficient hydraulic control, these valves will continue to gain strategic importance. Their adoption is expected to expand across regions and sectors, underpinning future advancements in hydraulic system performance and control accuracy.
Related Reports
Backscatter X Ray Machines Market , Size Share and Analysis | Report 2033
Backscatter Body Scanner Market , Size Share and Analysis | Report 2033
Multiple Input Multiple Output Synthetic Aperture Radar Mimo Sar Market , Size Share and Analysis | Report 2033
3d Body Holographic Scanner Market , Size Share and Analysis | Report 2033
Pet And Preform Testing Instruments Market , Size Share and Analysis | Report 2033
High Precision Cnc Machining Market , Size Share and Analysis | Report 2033
Wheel Rail Beam Lifting Machine Market , Size Share and Analysis | Report 2033
Wind Proof Pull Rod Of Port Machinery Market , Size Share and Analysis | Report 2033
Large Tonnage Round Section Shackle Market , Size Share and Analysis | Report 2033
Shaped Beam Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Cast Aluminum Cookware Market: Why 5.24% CAGR & Asia Pacific Shift Change Everything
By PW Consulting, 2026-09-18
Global Cast Aluminum Cookware Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide cast aluminum cookware market has demonstrated consistent expansion, with revenue reaching approximately 4.15 billion USD in 2025. The sector has navigated a period of steady growth from 2020 through 2025, transitioning into a forecast period that extends to 2032. Projections indicate the market will approach the 6 billion USD threshold by the end of the forecast window, supported by a compound annual growth rate of 5.24 percent. This trajectory reflects a mature yet evolving industry where volume expansion increasingly depends on value differentiation rather than raw capacity additions.
Several structural shifts are reshaping the competitive baseline. First, regulatory pressure around chemical coatings is accelerating formulation changes across the supply chain. Jurisdictions such as California have moved to restrict cookware containing intentionally added PFAS, effective from early 2025. This creates compliance complexity for manufacturers relying on traditional nonstick chemistries and pushes brands toward alternative surface technologies, reformulated coatings, or uncoated hard-anodized variants. Second, input cost volatility remains a persistent pressure point. Primary aluminum transaction prices have experienced notable swings, and dependence on concentrated production hubs exposes downstream cookware makers to supply disruptions and currency effects. These dynamics compress margins for undifferentiated products while rewarding manufacturers that secure stable sourcing arrangements or pass cost efficiency into premium positioning. Third, channel fragmentation is altering how value is captured. Online commerce has grown its share of distribution, but offline retail still commands substantial volume, particularly in mass-market and regional segments. Companies must balance channel economics, inventory risk, and brand visibility without diluting price discipline.
These challenges are not purely headwinds. They function as filters that reward scale, technical competence, and regulatory readiness. Firms that treat compliance, material sourcing, and channel strategy as integrated design choices are better positioned to convert market growth into durable margin expansion.
Key Demand and Supply Drivers
Technology innovation continues to redefine product value. Advances in nonstick coating formulations, induction-compatible base structures, and multilayer casting methods are enabling lighter cookware with improved heat distribution and durability. Pressure-casting techniques and recycled aluminum integration are also gaining traction, allowing producers to reduce weight, improve consistency, and address sustainability expectations without sacrificing performance. These improvements matter because they expand the addressable use cases for cast aluminum beyond traditional cost-sensitive applications and into premium residential and multi-cooktop environments.
Aluminum Casting Market
Policy and regulatory environments are increasingly shaping product roadmaps. Beyond PFAS-related restrictions, trade policy is affecting landed costs and sourcing decisions. Additional duties on certain aluminum products imported from China have added complexity to cost planning for brands that rely on cross-border supply chains. At the same time, stricter environmental expectations are encouraging material traceability, recycled content, and longer product lifecycles. The combined effect is a market where regulatory and trade dynamics are not external noise but core inputs to product design, supplier selection, and pricing architecture.
On the demand side, consumer behavior is tilting toward convenience, health-conscious messaging, and cookware compatibility with modern kitchens. Households are investing in fewer, higher-quality pieces that work across gas, electric, and induction surfaces. In commercial settings, foodservice operators prioritize dent resistance, consistent heating, and low maintenance, especially in high-volume environments where downtime and replacement frequency directly affect cost control. These divergent requirements create distinct value propositions within the same material category, supporting both premium and value-tier segments simultaneously.
Supply chain and cost structure changes reinforce the importance of flexibility. Primary aluminum production remains geographically concentrated, and regional price disparities can create arbitrage opportunities or exposure depending on sourcing strategy. Manufacturers that combine localized finishing or assembly with disciplined raw material procurement are better equipped to manage tariff exposure, lead times, and working capital. Meanwhile, the shift toward e-commerce and direct-to-consumer models is altering inventory positioning and packaging requirements, making agility in demand forecasting and channel mix a competitive advantage.
Stainless Steel Cookware Market
Competitive Landscape and Leading Strategies
The industry is characterized by a mix of established multinational players, specialized premium brands, and high-volume regional producers. Market concentration remains moderate, indicating that share gains are still achievable through differentiation rather than consolidation alone. Companies are competing on multiple fronts at once: coating performance, induction readiness, aesthetic design, durability claims, and channel reach. The result is a landscape where positioning is increasingly specific rather than generic.
Several strategic archetypes are evident. Premium-focused brands emphasize advanced nonstick surfaces, induction compatibility, and high-temperature oven safety, targeting consumers who value performance and design and are willing to pay for durable, multifunctional products. These players often use trade exhibitions and retail partnerships to reinforce credibility and visibility. Value-oriented manufacturers compete on price, practicality, and broad foodservice suitability, offering standard nonstick lines, woks, saute pans, and steam table components that meet commercial durability expectations without premium pricing. In parallel, brands built around consumer franchises or lifestyle identities use set configuration, hard-anodized exteriors, and accessible price points to capture mainstream retail demand.
Commercial specialists remain critical to the overall market. Suppliers serving foodservice prioritize dent-resistant bottoms, consistent heat transfer, and ease of cleaning, recognizing that total cost of ownership matters more than upfront price in professional kitchens. Their product lines are often optimized for repeated use, high-temperature service, and compatibility with common commercial cooktops and ovens. This commercial segment provides a stable demand base that can offset volatility in consumer discretionary spending.
Recent exhibition activity illustrates how companies are using visible market moments to reinforce product direction. In early 2024, multiple manufacturers showcased cast aluminum skillets, griddles, and nonstick collections at major trade events, highlighting pressure-cast construction, induction readiness, and reformulated surface technologies. These presentations are not merely promotional; they signal where brands are placing bets on future demand, particularly around multifunctionality and compliance-friendly materials.
The competitive trend appears to be moving toward segmentation with overlapping competition. Premium and value tiers are both expanding, but they are not converging quickly because the underlying performance and cost requirements differ. New entrants can succeed by targeting underserved application niches, such as specific induction configurations, commercial durability at mid-range pricing, or region-specific retail preferences. Incumbents, meanwhile, are strengthening moats through coating expertise, sourcing reliability, and brand trust. M&A and partnership activity may increase where scale in sourcing or distribution can convert into margin advantage, but differentiation will remain the primary battleground.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, two to three trends are likely to shape opportunity sets. First, compliance-driven coating innovation will become a standard product requirement rather than a niche advantage. As restrictions on certain chemical additives broaden and consumer sensitivity increases, brands that can deliver durable nonstick performance without relying on restricted chemistries will command stronger shelf positioning and lower regulatory risk. This creates openings for coating specialists, material scientists, and manufacturers that can validate performance claims with consistent test data and transparent sourcing narratives.
PW Consulting
Second, induction compatibility and multifunctionality will increasingly serve as baseline expectations, especially in regions where appliance mix is shifting. Cookware that works reliably across cooktop types and can transition from stovetop to oven expands consumer utility and reduces replacement cycles. The commercial implication is clear: product lines should be designed for interoperability, not just for a single cooking environment. This is especially relevant where kitchen upgrades are accompanied by appliance changes, since cookware compatibility often becomes a purchase criterion at the point of replacement.
Third, supply chain regionalization and cost management will matter more as trade policy and input prices continue to fluctuate. Companies that diversify sourcing, secure longer-term aluminum supply agreements, or adapt product geometry to optimize material use can protect margins more effectively than those dependent on single-channel procurement. There is also opportunity in recycled content and lighter-gauge engineering where performance allows, both to manage cost and to align with sustainability expectations.
These trends carry uncertainty. Regulatory timelines can shift, enforcement intensity may vary by region, and raw material prices can change quickly enough to disrupt planning horizons. Brands that treat these variables as dynamic inputs rather than fixed assumptions will be better prepared to adjust product mixes, pricing, and sourcing without losing market momentum.
Actionable Recommendations for Decision-Makers
Manufacturers should prioritize integrated product design that combines compliance-ready coatings, induction compatibility, and durable base construction. Where possible, investment in coating validation, material traceability, and channel-specific packaging can protect differentiation and reduce exposure to regulatory or trade disruptions. Aligning product roadmaps with both residential convenience and commercial durability requirements can broaden addressable demand without fragmenting brand identity.
Investors should assess exposure to regulatory transitions, input cost sensitivity, and channel mix when evaluating opportunities. Businesses with stable sourcing, clear compliance positioning, and resilient commercial demand tend to offer more predictable operating profiles than those dependent on single-material sourcing or price-led competition. Commercial foodservice-oriented suppliers and brands with strong multifunction performance can provide defensibility even when discretionary consumer spending softens.
Procurement and retail buyers should weigh total cost of ownership, compatibility with existing cooktops, and compliance documentation alongside upfront price. Diversifying across coating technologies and supplier geographies can reduce risk while maintaining product quality. In commercial procurement, prioritizing dent resistance, ease of cleaning, and consistent heating can lower replacement frequency and service interruptions over time.
For organizations seeking a deeper view of segment sizing, regional dynamics, pricing patterns, and competitive benchmarks, the full PW Consulting market study provides detailed segmentation data and tailored scenario analysis to support planning across product, channel, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Aluminum Cookware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Micro Excavator Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global micro excavator market has demonstrated steady expansion over the past five years, evolving from a niche equipment segment into a critical component of urban infrastructure development. Valued at approximately 1,435 million USD in 2025, the market has grown from 1,120 million USD in 2020, reflecting a compound annual growth rate of 5.19 percent projected through 2032. This trajectory indicates a maturation phase where volume growth is increasingly driven by technological differentiation and regulatory compliance rather than purely by population or economic expansion.
Structural shifts within the market reveal diverging growth paths across segments. The zero tail swing category has gained significant ground against traditional tail swing designs, reflecting operator preferences for equipment that maximizes maneuverability in constrained environments. Application-wise, construction and demolition remains the dominant use case, but landscaping and agriculture sectors are exhibiting accelerated adoption rates as property developers and municipal contractors seek compact solutions for precision work. Public utilities represent a stable but slower-growing segment, benefiting from consistent infrastructure maintenance budgets rather than explosive expansion.
Despite positive momentum, the market faces three interconnected challenges that will define competitive battles over the next five years. First, supply chain volatility continues to pressure manufacturing costs. Raw material pricing, particularly for steel components essential to hydraulic systems and chassis construction, has shown variability that complicates long-term pricing strategies. Second, regulatory fragmentation across major markets creates compliance complexity. Emissions standards, safety certifications, and import duties vary significantly between regions, forcing manufacturers to maintain multiple production configurations or absorb compliance costs. Third, labor dynamics are reshaping demand patterns. Persistent skill shortages in construction sectors are accelerating automation requirements, pushing buyers toward equipment with advanced operator aids and telematics capabilities while simultaneously constraining the available workforce to operate even compact machinery.
These challenges do not undermine the market outlook but rather reshape how value is created and captured. Companies that navigate these friction points effectively will secure disproportionate market share, while those relying on legacy product architectures risk margin erosion and customer attrition.
Key Drivers Shaping Market Evolution
Technological Innovation and Equipment Differentiation
Technological advancement stands as the primary catalyst for market growth, transforming micro excavators from simple mechanical tools into connected, precision instruments. Manufacturers are investing heavily in hydraulic system optimization, cab ergonomics, and control interface design. The introduction of joystick controls, improved visibility cabins, and counter-rotation steering mechanisms reflects a broader industry focus on reducing operator fatigue and increasing work efficiency in confined spaces.
Recent product launches illustrate this innovation trajectory. Leading manufacturers have introduced ultra-short tail swing models with enhanced hydraulic responsiveness, enabling tighter turning radii and better access to urban job sites. Updated micro excavator ranges showcased at major industry events have incorporated refined cabin designs that improve operator comfort during extended shifts, directly addressing retention challenges in the construction labor market. New compact excavator models with improved cab comfort have entered the market, targeting contractors who prioritize operator retention alongside equipment performance. Additionally, zero tail swing models compliant with stringent emissions standards have been released, demonstrating how regulatory requirements can coexist with operational efficiency improvements.
Beyond mechanical improvements, digital integration is becoming a competitive differentiator. Telematics platforms that monitor equipment utilization, fuel consumption, and maintenance schedules are increasingly standard features rather than premium add-ons. This connectivity supports fleet management optimization and provides data that contractors use to justify equipment investments through measurable productivity gains.
Policy and Regulatory Environment
Regulatory frameworks are simultaneously constraining and enabling market growth. Emissions standards, particularly in Europe and North America, have compelled manufacturers to redesign engine systems and exhaust treatment components. While compliance adds upfront costs, it also creates barriers to entry that consolidate market positions among established players with sufficient engineering resources and certification infrastructure.
PW Consulting
The European Union Stage V emissions standards, which mandate reduced nitrogen oxide and particulate matter outputs for non-road diesel engines, have been in effect since 2021 and continue to shape product development roadmaps. Manufacturers that achieve compliance efficiently gain access to regulated markets without disruption, while those lagging face shipment delays and potential market exclusion. Similar regulatory pressures exist in other regions through varying mechanisms, creating a complex compliance landscape that rewards manufacturers with global engineering capabilities and diversified production footprints.
Beyond emissions, safety regulations and import policies influence market access. Tariff structures on certain origin countries affect competitive pricing dynamics, with duties on Chinese-origin equipment over specific value thresholds altering the cost advantage that some importers previously enjoyed. These trade policies encourage regional manufacturing investments and supply chain localization strategies among major players seeking to maintain price competitiveness in key markets.
Demand-Side Shifts and Construction Sector Dynamics
Changes in how construction projects are executed and funded are driving sustained equipment demand. Global construction output expanded by 3.5 percent in 2024, supported by infrastructure investments exceeding 10 trillion USD annually. This capital flow into roads, utilities, urban redevelopment, and commercial construction creates consistent demand for compact equipment that can operate in space-constrained environments where larger machinery cannot function effectively.
A critical demand-side dynamic involves labor availability. The construction sector in the United States alone faced a shortage of approximately 500,000 workers in 2024. This labor gap is accelerating demand for compact automation equipment that reduces manual labor requirements and increases individual operator productivity. Contractors are increasingly willing to invest in higher-specification micro excavators with operator aids, improved hydraulics, and telematics because these features help maximize output from smaller crews and reduce reliance on multiple personnel for tasks that compact equipment can handle more efficiently.
Urbanization trends further support demand. As cities expand and existing infrastructure requires renovation, demolition and rebuilding activities increasingly occur in dense neighborhoods where large equipment faces access restrictions, noise limitations, and safety constraints. Micro excavators fit precisely into this operational paradigm, enabling contractors to work in alleys, residential zones, and interior spaces without the logistical burden of larger machines.
Supply Chain and Cost Structure Dynamics
Cost pressures and supply chain stabilization efforts are reshaping manufacturing strategies. Raw material pricing for construction machinery inputs, including hot-rolled steel coils, averaged around 650 USD per metric ton in the fourth quarter of 2024 amid gradual supply chain stabilization. While this represents improvement from earlier volatility, cost management remains a strategic priority as manufacturers balance material expenses with competitive pricing expectations.
Manufacturers are responding through multiple approaches: optimizing component design to reduce material usage, negotiating long-term supplier agreements to lock in pricing, and exploring alternative material specifications where performance requirements allow. Regional production strategies are also gaining traction, with companies establishing or expanding manufacturing footprints closer to end markets to reduce logistics costs, mitigate tariff impacts, and improve supply chain resilience.
The cost structure evolution is not purely defensive. Efficient supply chain management and localized production can become competitive advantages, enabling manufacturers to offer more consistent pricing, faster delivery times, and improved after-sales support. These operational capabilities increasingly factor into procurement decisions alongside equipment specifications.
Competitive Landscape and Leading Strategies
The market features a diverse competitive field spanning established global manufacturers, specialized compact equipment producers, and regional players with strong local presence. Market concentration metrics indicate that the top three companies capture approximately 38.5 percent of revenue, while the top five hold roughly 52.8 percent. This concentration level suggests a moderately consolidated landscape where leading players exert significant influence but substantial share remains available for well-positioned competitors.
Leading manufacturers have adopted distinct strategic positioning approaches. Major equipment companies with broad product portfolios leverage their brand recognition, global service networks, and financial strength to offer micro excavators as part of comprehensive fleet solutions. These players emphasize telematics integration, dealer support infrastructure, and the ability to supply equipment across multiple size classes, appealing to large contractors who value single-source procurement and standardized maintenance processes.
Japanese manufacturers have carved out strong positions through specialization in compact and micro segments. Their product architectures emphasize zero tail swing designs, fuel-efficient engine systems, and refined operator interfaces tailored to precision work. These companies often compete on reliability, maneuverability, and segment-specific engineering rather than broad portfolio breadth. Their focus on micro excavators as a core competency rather than a peripheral offering enables deep optimization of weight, size, and functionality for targeted applications.
European and American players contribute through varied approaches. Some emphasize electrification alongside diesel options, offering zero-emission alternatives for urban environments with noise or air quality restrictions. Others focus on GPS integration and grade control technologies that enhance precision for landscaping and utility work. These technology-forward strategies appeal to contractors operating in regulated urban zones or those seeking to differentiate through higher-precision outputs.
Chinese manufacturers have expanded their presence through competitive pricing and increasingly sophisticated feature sets. Their product ranges target emerging markets and cost-sensitive segments while incorporating intelligent control systems and efficiency improvements that narrow the perceived quality gap with established brands. Trade policy dynamics, including tariff structures on certain origin equipment, influence the competitive balance in specific regions, prompting some Chinese manufacturers to pursue regional assembly strategies or partner with local distributors to navigate trade barriers.
Strategic differentiation is evolving along several dimensions. Electrification represents a growing battleground, with manufacturers offering electric micro excavators under specific weight thresholds for applications where indoor operation, noise sensitivity, or emissions restrictions favor battery-powered alternatives. Telematics and data connectivity are becoming standard expectations rather than differentiators, pushing competition toward deeper integration with contractor fleet management systems and predictive maintenance capabilities.
Excavator Attachments Market
Market evolution trends point toward continued consolidation pressure alongside ongoing fragmentation in niche segments. Larger players may pursue acquisitions to gain specialized technology, regional distribution networks, or product line completeness. At the same time, specialized manufacturers with strong micro excavator expertise can thrive by serving specific applications or geographic markets with focused value propositions. New entrants face high barriers due to engineering complexity, certification requirements, dealer network development costs, and the need to establish reliability reputations, but opportunities exist for companies that bring distinctive technology or serve underserved application niches.
Future Trends and Commercial Implications
Looking toward 2032, several trends will shape market trajectories and create distinct commercial opportunities. The first and most consequential is the acceleration of electrification and alternative powertrain adoption. While diesel micro excavators will remain dominant in the near term, electric models are gaining traction for specific use cases where operational restrictions, urban noise ordinances, or corporate sustainability commitments favor zero-emission equipment. As battery technology improves and charging infrastructure expands, electric micro excavators will capture growing share in landscaping, indoor construction, and municipal applications. Manufacturers that develop robust electric platforms with competitive runtime, fast charging options, and integrated energy management will position themselves advantageously for regulated urban markets and sustainability-focused contractors.
The second trend involves deepening digital integration and data-driven equipment management. Telematics will evolve from basic utilization tracking to predictive maintenance, remote diagnostics, and performance optimization recommendations. Contractors will increasingly expect equipment that integrates seamlessly with their digital workflows, providing data that supports operational decisions, reduces downtime, and improves resource allocation. Companies that offer open data architectures, compatible fleet management software, and responsive remote support will differentiate themselves as the market shifts from evaluating individual machine specifications to assessing total fleet intelligence capabilities.
Excavator Market
The third trend relates to continued urbanization and infrastructure renewal driving sustained demand for compact, maneuverable equipment. As cities densify and renovation activities displace new ground-up construction in many developed markets, the operational niche for micro excavators will expand. Contractors will require equipment that navigates confined spaces, complies with noise and emissions restrictions, and delivers precision work without the logistical complexity of larger machinery. This environment favors manufacturers with strong zero tail swing designs, versatile attachment compatibility, and configurations optimized for urban job site constraints.
These trends carry both opportunities and risks. Electrification promises market expansion but introduces uncertainty around battery costs, charging logistics, and performance parity in demanding applications. Digital integration enhances value but raises expectations for software reliability, cybersecurity, and ongoing technical support that smaller manufacturers may struggle to meet consistently. Urban demand growth is robust but depends on continued infrastructure spending and regulatory environments that sustain construction activity. Economic cycles, interest rate fluctuations, and shifts in government investment priorities could moderate growth rates, particularly in segments dependent on discretionary development rather than essential infrastructure maintenance.
Commercial opportunities will accrue to companies that align product development with these trajectories. Manufacturers can capture growth by expanding electric model ranges, enhancing telematics integration, and optimizing products for urban constraints. Investors can evaluate companies based on their technology roadmaps, regional market access, and ability to navigate regulatory and trade complexity. Procurement professionals can focus on total cost of ownership considerations that include operator efficiency, maintenance predictability, and compliance assurance rather than initial purchase price alone.
Strategic Recommendations for Decision Makers
Manufacturers should prioritize technology roadmaps that balance emissions compliance, electrification capabilities, and digital integration while maintaining cost competitiveness. Investing in zero tail swing architectures, operator comfort improvements, and telematics platforms will address the key purchase drivers identified by contractors. Companies should also evaluate regional production and supply chain strategies to navigate tariff dynamics and raw material cost variability, ensuring that pricing remains attractive while margins are protected through operational efficiency and localized support infrastructure.
Investors evaluating opportunities in this market should focus on companies with clear technological differentiation, strong regional market access, and capabilities to manage regulatory complexity. The moderate market concentration suggests room for growth, but sustained value creation will favor players that can execute on product innovation, service network development, and strategic geographic positioning. Assessing a company's electrification roadmap, data integration maturity, and ability to adapt to trade policy shifts will provide insight into long-term competitive positioning beyond current revenue performance.
Procurement teams and contractors should approach equipment selection with a total cost of ownership mindset that accounts for operator productivity, maintenance predictability, compliance assurance, and fleet integration capabilities. The labor shortage environment makes operator efficiency and retention increasingly valuable, supporting investment in equipment with improved ergonomics, automation aids, and telematics that reduce downtime and simplify fleet management. Evaluating suppliers based on their ability to deliver consistent product availability, responsive service support, and compliance with regional emissions standards will mitigate operational risk and support long-term project execution.
For stakeholders seeking detailed segment-level data, regional analysis, competitive benchmarking, and customized strategic recommendations, comprehensive market research reports provide the depth required for precise planning. Access to granular data across product types, application segments, regional dynamics, and company profiles enables more informed decisions regarding market entry, investment allocation, product development priorities, and procurement strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Diesel Lubricity Improver Market: Why 4.2% CAGR Upsets Old Growth Narratives
By PW Consulting, 2026-09-18
Worldwide Diesel Lubricity Improver Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global diesel lubricity improver market has evolved from a compliance-driven niche into a strategically significant segment within the broader fuel additives landscape. Valued at approximately $475 million in 2020, the sector expanded steadily through the mid-2020s, reaching roughly $585 million by 2025. Forward-looking projections place the market on a trajectory to exceed $780 million by 2032, supported by a compound annual growth rate of around 4.2 percent. This growth reflects a structural shift rather than a cyclical uptick, as refiners, additive formulators, and engine manufacturers navigate the persistent tension between emissions reduction mandates and equipment durability. The consistent upward trajectory underscores how lubricity management has become embedded in fuel specification compliance, supply chain planning, and downstream performance expectations across multiple geographies and end-use sectors.
Behind the headline figures, the industry confronts three interconnected challenges that will shape competitive positioning over the next several years. First, the regulatory baseline continues to tighten. Standards such as EN 590 and GB 19147 mandate a maximum HFRR wear scar diameter of 460 μm at 60°C, which effectively compels the use of lubricity enhancers in ultra-low sulfur diesel formulations. While this creates steady baseline demand, it also compresses the value proposition for basic compliance products, pushing suppliers to differentiate through multi-functional performance rather than single-attribute improvement. Second, feedstock economics introduce volatility into cost structures. The production of diesel lubricity improvers commonly relies on fatty acid derivatives and esters, whose pricing is influenced by upstream vegetable oil markets and crude oil-derived feedstocks. Fluctuations in these input costs ripple through manufacturing economics, squeezing margins for formulators that lack robust hedging strategies or diversified sourcing networks. Third, the transition toward advanced combustion technologies and higher biofuel blending rates is altering the performance envelope. Deposit control, oxidation stability, and cold-flow behavior are increasingly intertwined with lubricity requirements, meaning that legacy stand-alone improvers face pressure to integrate into broader additive packages that deliver synergistic engine protection.
For executives and strategists, these dynamics translate into a market where volume growth is relatively predictable but margin and differentiation trajectories are highly contingent on formulation strategy, supply chain agility, and regulatory interpretation. Companies that treat lubricity improvement as a commodity compliance exercise risk being squeezed by price competition and feedstock exposure, while those that position their offerings as integrated performance solutions capture greater resilience and pricing power. The next section examines the drivers intensifying these shifts.
2. Key Drivers Reshaping the Market
Technological Innovation and Formulation Evolution
Advancements in additive chemistry are redefining what a lubricity improver can deliver beyond baseline wear protection. Formulators are increasingly designing molecules and blends that address HFRR wear scar requirements while simultaneously contributing to deposit mitigation, corrosion resistance, and compatibility with higher biofuel content. This multi-functional approach is particularly relevant as engine manufacturers optimize fuel injection systems for efficiency and emissions control, demanding fuels that protect precision components without compromising combustion cleanliness. Recent product launches illustrate this trajectory. In February 2025, TotalEnergies introduced the RUBIA OPTIMA diesel lubricity improver, tailored for ultra-low sulphur diesel engines in Europe. The launch signals a broader industry pattern: rather than offering narrow lubricity additives, leading suppliers are packaging performance attributes that align with real-world operating conditions and regional fuel specifications. For engine and vehicle manufacturers, this evolution means a growing preference for additive partners that can validate performance across multiple parameters, reducing the burden of multi-supplier qualification and simplifying fuel quality assurance.
Policy and Regulatory Environment
Regulation remains the most reliable demand anchor for diesel lubricity improvers. The widespread adoption of ultra-low sulfur diesel has eliminated naturally occurring sulfur compounds that historically contributed to fuel lubricity, making additives essential for protecting fuel pumps, injectors, and cylinder components. Global fuel standards codify this need through measurable HFRR thresholds, creating a consistent compliance pull across mature and emerging markets. In parallel, environmental agencies maintain oversight of additive formulations to ensure that lubricity enhancements do not undermine emissions performance or air quality objectives. The U.S. EPA, for example, maintains a registered diesel additives list updated as of March 2025 that includes multiple approved lubricity improver formulations for commercial use. This registration framework increases transparency for end-users but also raises the bar for product documentation, testing, and ongoing compliance management. For suppliers, the regulatory environment rewards those with established testing infrastructure, clear homologation pathways, and the ability to adapt formulations as regional standards evolve.
Demand-Side Shifts in Vehicle and Industrial Use
Demand patterns are diverging by application, creating distinct opportunity pockets. Heavy-duty vehicles continue to represent the largest application segment, driven by long-haul logistics, commercial fleet operations, and the durability requirements of high-pressure common-rail injection systems. Passenger vehicles, while smaller in absolute volume, benefit from increasing fuel quality expectations and the persistence of diesel in certain regional markets, particularly where total cost of ownership remains favorable. Industrial and stationary engines constitute another meaningful demand base, especially in power generation, agricultural equipment, and remote-site operations where fuel storage duration and variable operating conditions amplify the need for wear protection. Across these segments, the common thread is that lubricity management is no longer a standalone concern; it is integrated into broader fuel reliability and asset-protection strategies. Fleet operators and industrial buyers are increasingly evaluating total cost of ownership, maintenance intervals, and warranty implications, which broadens the relevance of additive performance beyond immediate wear metrics.
Supply Chain and Cost Structure Dynamics
Cost structures in the lubricity improver market are closely tied to raw material availability and pricing. Fatty acids and ester-based feedstocks form the backbone of many formulations, linking production economics to agricultural commodity cycles and petroleum-derived intermediates. When these input costs fluctuate, manufacturers face pressure on margins unless they can adjust blend architectures, optimize process efficiency, or pass through cost changes without losing volume. The implication is clear: competitive advantage is shifting toward companies with geographically diversified sourcing, long-term supplier agreements, and formulation flexibility that allows substitution among functionally equivalent chemistries. Refineries and terminal operators also influence demand patterns through blending economics and logistics. Additive inclusion decisions at the terminal stage can vary by region, season, and fuel specification, meaning that distribution and partnership models matter as much as molecular performance. Suppliers that can integrate technical service, blending guidance, and inventory alignment into their commercial offerings reduce friction for customers and strengthen retention in a market where switching costs are sometimes lower than the operational risk of inconsistent fuel quality.
PW Consulting
3. Competitive Landscape and Leading Strategies
The competitive map in diesel lubricity improvers is characterized by a blend of global specialty chemical companies, fuel additive specialists, and integrated energy suppliers. Market concentration metrics indicate that a limited number of players command a substantial share of revenues, with the top three holding approximately 45.2 percent and the top five reaching around 62.4 percent. This footprint suggests a market where scale, technical credibility, and customer relationships create meaningful barriers, but it also leaves room for regional specialists and application-focused entrants in underserved niches.
Infineum International Limited, headquartered in the United Kingdom, operates as a major global supplier of diesel fuel additives, with dedicated lubricity improvers formulated for ultra-low sulfur diesel to meet HFRR standards such as EN 590 and equivalent specifications. Its strength lies in broad formulation expertise and a global technical support footprint that helps refiners and distributors align additive programs with regional fuel quality requirements. The Lubrizol Corporation, based in the United States, provides comprehensive diesel performance additive packages with lubricity improvers targeting fuel injection equipment protection in low-sulfur diesel fuels. Lubrizol’s differentiation often comes from packaging lubricity within broader performance solutions, giving customers a streamlined route to multi-attribute fuel improvement. Afton Chemical Corporation, also U.S.-based, offers the HiTEC series lubricity improvers and multi-functional diesel additives designed to restore lubricity in ULSD while meeting global fuel specifications. Afton’s emphasis on brand recognition and application-specific formulations supports a strategy centered on validated performance and customer education.
European chemical majors contribute scale and regional regulatory fluency. BASF SE supplies diesel fuel additives including acidic and non-acidic lubricity improvers for automotive, commercial, and industrial diesel applications, leveraging its broad chemical portfolio to support customized solutions. Evonik Industries AG produces performance additives including lubricity enhancers for low-sulfur diesel fuels used in transportation and industrial sectors, combining specialty chemistry capabilities with application engineering. LANXESS AG and Clariant AG further round out the European field, with LANXESS providing chemical additives for fuels, including lubricity improvement solutions for diesel, and Clariant supplying a fuel additives portfolio containing lubricity improvers compliant with global diesel fuel quality standards. These companies often compete on technical depth, compliance documentation, and the ability to support large-volume programs across multiple jurisdictions.
In the United States, Innospec Inc. develops and markets diesel lubricity improvers such as OLI series products for ULSD and biofuel blends to ensure compliance with wear scar diameter requirements, positioning itself around assurance of specification compliance and compatibility with evolving blending trends. Chevron Oronite Company LLC specializes in fuel additives with lubricity improvers for diesel fuels, supporting refinery and terminal blending to meet international lubricity standards. Its refinery-facing orientation reinforces a strategy built on technical service at the point of fuel production and distribution. Baker Hughes Company delivers fuel additives via its specialty chemicals segment, including lubricity improvers for diesel fuel systems, reflecting the broader trend of large industrial groups using diversified platforms to address fuel performance needs.
Regional and emerging-market players add another dimension to the landscape. Dorf Ketal Chemicals, based in India, offers specialized diesel lubricity improvers and fuel treatment chemicals focused on ULSD applications in emerging markets. Its positioning highlights a growing opportunity set in regions where fuel quality improvement programs are expanding, infrastructure is modernizing, and cost-sensitive formulators seek reliable performance at competitive price points. TotalEnergies SE complements this dynamic from the integrated energy side, marketing diesel additives and lubricity improvers through its additives and special fuels division, including products for ultra-low sulfur diesel. Its February 2025 launch of the RUBIA OPTIMA diesel lubricity improver for ultra-low sulphur diesel engines in Europe demonstrates how integrated energy companies can use product updates to reinforce performance positioning in regulated markets.
Strategically, the leaders differentiate along several axes: multi-functional formulation capability, regulatory compliance infrastructure, technical service depth, and supply chain resilience. Some compete by offering broad additive packages that reduce the number of suppliers a customer must manage. Others emphasize application-specific validation for heavy-duty, passenger, or industrial use. A third group focuses on regional execution, tailoring products and service models to local fuel standards, logistics, and price sensitivity. The market is likely to see continued consolidation among players seeking scale and portfolio breadth, while also witnessing targeted entry or expansion by companies that serve specific geographies or application niches with lean, high-value propositions. For customers, this means more choices but also greater importance in evaluating total value rather than price per kilogram alone.
4. Forward Trends for 2026–2032
Looking ahead, three trends are likely to shape the diesel lubricity improver market over the next several years. The first is the shift from single-attribute lubricity additives to integrated performance packages. As engine equipment becomes more sensitive to deposits, corrosion, and compatibility with renewable blends, customers will increasingly favor formulations that address multiple performance parameters in a single addition step. This favors suppliers that can demonstrate cross-attribute synergy and provide validated testing for real-world operating conditions, opening opportunities for premium positioning and longer-term customer partnerships.
Lubricant Viscosity Index Improvers Market
The second trend is the continued expansion of lubricity improvement demand in regions where fuel quality standards are tightening or where biofuel blending is increasing. Regulatory baselines such as EN 590 and GB 19147 provide a durable anchor in established markets, while emerging economies pursuing fuel quality upgrades and cleaner diesel programs create incremental volume opportunities. Suppliers with strong regional technical presence, flexible formulation options, and credible compliance documentation are best placed to capture this growth. At the same time, the relationship between lubricity enhancers and higher biofuel blends remains an area of active development, as oxygenated components and varying oxidation behaviors can influence both wear performance and storage stability.
The third trend is cost discipline and supply chain adaptability becoming competitive differentiators. With feedstock exposure to fatty acid derivatives and petroleum-linked inputs, companies that can manage input volatility through diversified sourcing, formulation flexibility, and efficient blending operations will protect margins more effectively than those dependent on narrow supply paths. This dynamic may accelerate supplier consolidation in some segments while encouraging niche players to compete on agility, localized service, and rapid response to regional specification changes. A related uncertainty is the pace and shape of fuel transition strategies. If diesel demand in certain passenger segments declines faster than expected, growth may concentrate even more heavily in heavy-duty, industrial, and backup power applications, requiring suppliers to align product roadmaps with where durable diesel use persists. Regulatory interpretations, additive registration updates, and sustainability expectations for feedstocks also introduce variability, making scenario planning essential for both manufacturers and buyers.
5. Strategic Guidance for Decision-Makers
For additive manufacturers and formulators, the priority is to move beyond compliance-only positioning and build demonstrable multi-functional value. Invest in testing that connects lubricity performance with deposit control, engine protection, and compatibility with higher biofuel blends, and align product documentation with the regulatory expectations of key markets. Strengthening supply chain flexibility and feedstock diversification will also be critical to protecting margins amid input cost volatility. Building technical service capabilities that help customers optimize blending and fuel handling can create stickier relationships and reduce exposure to pure price competition.
Fuel Additives Market
For investors, the most compelling opportunities lie in companies with credible formulation differentiation, established compliance infrastructure, and exposure to durable demand in heavy-duty, industrial, and regions undergoing fuel quality upgrades. Evaluate cost structure resilience, sourcing strategy, and the ability to scale multi-functional products as indicators of long-term competitiveness. Monitor how product portfolios evolve relative to biofuel blending trends and regional specification shifts, as these will influence both volume growth and margin profiles. Companies that can balance global reach with regional execution are likely to outperform in a market where local fuel standards and logistics matter.
For procurement and fuel quality stakeholders, the focus should be on total value rather than unit price alone. Compare additive programs on HFRR compliance assurance, compatibility with existing fuel handling practices, storage stability, and the supplier’s ability to support blending optimization and documentation needs. Where possible, consolidate supply around partners that can deliver consistent performance across applications and provide reliable technical support during specification changes or feedstock transitions. Treat supplier selection as a risk-management decision that affects maintenance costs, warranty exposure, and operational reliability over time. For those seeking a more granular view of regional dynamics, application splits, and formulation-level segmentation, the full market research report provides detailed breakdowns and tailored recommendations to support planning and procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Diesel Lubricity Improver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Seam Tracking Laser Sensors: Why 7.5% CAGR Reshapes Market|2026-2032
By PW Consulting, 2026-09-18
The Strategic Evolution of the Smart Seam Tracking Laser Sensors Market
The global market for smart seam tracking laser sensors has entered a phase of structurally accelerating growth, expanding from approximately 490.2 million USD in 2020 to an estimated 685.0 million USD in 2025, with momentum carrying toward more than 1.13 billion USD by 2032. This trajectory translates to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window. The growth is neither cyclical nor narrowly tied to a single industrial cycle; rather, it reflects a foundational shift in how automated fabrication, assembly, and inspection workflows are engineered. Seam tracking has transitioned from a niche alignment aid to a core perception layer that enables closed-loop control in robotic welding, hybrid joining, brazing, and precision inspection. As tolerance stacks tighten and production volumes scale across mobility, marine, and advanced manufacturing sectors, the sensor layer has become the differentiating factor between basic automation and adaptive, high-yield processing.
Despite the clear growth path, manufacturers and system integrators are navigating three overlapping challenges that will define competitive outcomes over the next half decade. First, the industry must reconcile performance expectations with real-world variability. Workshop lighting, surface oxidation, gap deviations, and material heterogeneity consistently degrade the robustness of vision-based tracking if algorithms, optics, and illumination are not co-optimized for production environments rather than controlled lab conditions. Second, supply chain fragility has moved from a logistical nuisance to a strategic cost driver. Concentrated sourcing of high-power semiconductor components, laser optics, and specialty substrates introduces exposure to pricing shocks and lead-time elongation, forcing vendors to redesign bill-of-materials strategies and qualification pipelines. Third, integration complexity remains a persistent adoption barrier. While individual sensor specifications are increasingly impressive, the value is realized only when tracking data is fused seamlessly with robot kinematics, process controllers, and quality management systems, a requirement that demands ecosystem readiness rather than stand-alone hardware superiority. Addressing these friction points is no longer an engineering afterthought; it is the central commercial battleground.
Market Architecture and Concentration Dynamics
The revenue base is distributed across a mix of established sensor specialists and application-focused equipment players, with a meaningful share of total volume concentrated among a small group of incumbents. This concentration does not imply a static hierarchy. Instead, it reveals a market where differentiation is increasingly earned through software maturity, cross-platform compatibility, and lifecycle support rather than pure sensor resolution. The three dimensional profile segment commands the largest revenue share, reflecting the broader industry migration from simple line profiling to volumetric perception that can handle complex joint geometries and variable gaps. Two dimensional profile sensors retain strong adoption in high-speed, lower-complexity tasks where cost and cycle time dominate purchasing decisions, while point laser sensors serve targeted displacement and alignment uses. Geographically, demand is broadest across Asia Pacific, followed by Europe and North America, with Latin America and the Middle East and Africa representing smaller but strategically important footprints tied to localized capacity expansion and export-oriented fabrication. Across application domains, automotive manufacturing leads demand formation, reflecting the impact of electrification on joint designs, material mixes, and throughput requirements. Heavy machinery and infrastructure, shipbuilding, and aerospace and defense each contribute sizable demand blocks shaped by durability requirements, regulatory scrutiny, and the rising use of robotic processes in large-scale structures and precision assemblies.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Sensor Intelligence
The most consequential driver is the maturation of sensor intelligence itself. Modern systems are no longer simply delivering better point clouds; they are increasingly capable of adaptive interpretation under imperfect conditions. Advances in image processing pipelines, real-time filtering, and edge-based inference have improved seam detection reliability in environments where joint preparation varies, weld spatter is present, or surface finish is inconsistent. The practical effect is a reduction in false rejects, fewer manual interventions, and higher first-pass yield, which directly improves the economics of automated joining. In parallel, hybrid approaches that combine laser profile data with displacement and groove detection are reducing the need for multiple stand-alone sensors on the end effector, simplifying payload management and lowering integration risk. Recent product refreshes that emphasize enhanced image processing for precise seam tracking in automated welding illustrate how vendors are shifting from hardware-centric specifications toward application-tuned performance. This shift matters commercially because it expands the addressable envelope from ideal applications into broader, less forgiving production settings where the return on automation is most contested.
Policy, Standards, and Strategic Industrial Directives
Regulatory and policy environments are quietly but decisively reshaping demand patterns. In shipbuilding and advanced marine fabrication, national guidelines promoting smart shipyard development have created explicit tailwinds for robotic welding precision and integrated laser seam tracking. These directives do not merely encourage automation in principle; they support procurement strategies, modernization programs, and supplier qualification paths that make sensor-enabled joining more bankable for yard operators and tier suppliers. Equally important, quality assurance expectations in aerospace, defense, and safety-critical mobility segments are tightening, which elevates the role of inspection-grade tracking as part of a unified process rather than a separate quality gate. When seam tracking becomes part of the process control logic rather than a post-process verification step, the sensor transitions from an optional accessory to a core process enabler. For decision-makers, the strategic implication is that adoption is increasingly influenced by compliance roadmaps, export requirements, and program-level quality targets as much as by unit cost or cycle time.
Demand-Side Transformation in Mobility and Heavy Fabrication
On the demand side, the most visible change is the structural shift in joining requirements across e-mobility, vehicle architecture evolution, and large-scale fabrication. Electric drivetrains, battery enclosures, lightweight structural elements, and mixed-material assemblies introduce new gaps, thicker coatings, and more varied joint geometries than legacy body-in-white production. Robotic laser welding and hybrid joining are responding to these requirements because they can achieve consistent results while preserving productivity, but they also demand higher robustness from the tracking layer. In shipbuilding and infrastructure-adjacent heavy fabrication, similar pressures exist: longer structural runs, complex edge conditions, and a need to reduce rework in high-value assemblies. The common thread is that tolerance control and process repeatability are becoming more valuable than raw speed alone. As a result, end users are more willing to invest in sensors that demonstrably reduce rework, support adaptive path correction, and provide inspection-grade confidence. This demand evolution favors suppliers that can articulate total process value rather than sensor-only performance metrics.
Supply Chain Realities and Cost Structure Pressures
Cost structures are undergoing a simultaneous push and pull. On one side, raw material and component pressures have intensified. Restrictions and export dynamics affecting gallium and germanium, alongside broader concentration in high-power semiconductor and optics supply, have driven notable price increases in critical inputs, with ripple effects across laser-based and optics-intensive sensor designs. On the other side, integration complexity and qualification cycles can inflate total cost of ownership if the sensor is treated as an isolated component rather than part of a coordinated system. The resulting dynamic favors vendors that can stabilize performance despite component volatility, offer modular designs, and deliver predictable field performance with minimal recalibration burden. For buyers, the cost conversation is shifting from sticker price to resilience: supply assurance, multi-source readiness, software support longevity, and integration compatibility now weigh heavily in evaluation. Suppliers that overlook these factors risk margin erosion even when their core technology is competitive.
Worldwide Security Laser Scanner Market
Competitive Landscape and Differentiation in Practice
The competitive field blends specialized sensor manufacturers, welding-equipment integrators, and emerging players with regional cost advantages and application-specific engineering depth. A defining feature of the leaders is that they do not compete solely on resolution or scan speed; they compete on how well the sensing capability is packaged into the target process. Some firms anchor their positioning in high-speed, high-accuracy vision systems explicitly engineered for laser welding, hybrid welding, and brazing, where real-time joint guidance must keep pace with rapid thermal cycles and moving workpieces. Others emphasize optical seam tracking tuned for automated arc and laser welding, with particular attention to e-mobility and automotive use cases where tolerances and material variability are elevated. A further group integrates laser seam tracking sensors directly with robotic welding torches and joint guidance systems, aiming to reduce end-effector complexity and shorten deployment cycles. This diversity in go-to-market posture reflects a market that is still maturing from component competition toward solution-level competition.
Several strategic differentiators are increasingly decisive. First, cross-platform compatibility is becoming a practical necessity. As customers standardize on major robot brands and seek to deploy tracking across multiple cell designs, sensors that demonstrate reliable interoperability with common controllers and robot ecosystems reduce integration friction and expand addressable reuse within a facility. Second, the ability to support both real-time tracking and downstream inspection functions is gaining commercial weight. Systems that can guide the weld and then contribute to bead profile inspection or displacement verification offer a more complete value proposition, especially where quality records and traceability are mandatory. Third, application specialization is creating defensible niches. Vendors with focus on zero-gap detection for sheet metal, aerospace-oriented sensor lines, or specialized weld bead profiling are building domain credibility that generic specifications cannot easily replicate. This does not mean broad platforms are losing relevance; rather, the most resilient players are pairing broad compatibility with application-specific tuning and support.
Laser Displacement Sensor Market
The competitive evolution is also being shaped by a mix of consolidation logic and new-entry pressure. On one hand, established players are likely to deepen vertical integration around software, service, and integration support, because those layers increasingly determine retention and expansion within existing accounts. On the other hand, regional manufacturers and sensor-focused entrants continue to expand, particularly where localized price-performance ratios, faster engineering responsiveness, and strong relationships with domestic robot integrators create a viable path to scale. A notable early signal is the emergence of sensor lines targeting high-stakes verticals such as aerospace, which reflects both demand maturation and the willingness of large customers to qualify specialized offerings for demanding tolerances. The net direction is not simply toward fewer competitors; it is toward clearer segmentation between general-purpose tracking platforms and application-hardened solutions, with the most competitive firms capable of bridging both through modular architectures and adaptable software stacks. For customers, this means the evaluation framework should weigh ecosystem fit and support capability as heavily as raw sensing performance.
Forward-Looking Trends and the Shape of Opportunity
Over the next three to five years, the market is likely to consolidate around three interrelated trends. The first is the expansion of perception from tracking to closed-loop process control. Seam tracking will increasingly feed adaptive path correction, dynamic parameter adjustment, and inspection feedback within a single workflow, reducing dependence on offline quality sampling and shortening response time to process drift. This creates commercial opportunities for vendors that can deliver reliable sensor data in a form that controllers and quality systems can consume without heavy middleware or custom integration work. The second trend is the continued migration from hardware differentiation toward software and algorithm differentiation. As baseline optical and scanning performance becomes more comparable across competent suppliers, the edge will increasingly belong to systems that perform better under variable joint gaps, surface conditions, and production noise, and that can be updated and tuned without extensive re-qualification. The third trend is a growing emphasis on supply resilience and modular design. Given ongoing component volatility, customers will reward suppliers that can articulate risk-mitigated sourcing, maintain performance continuity across revisions, and offer flexible configuration options aligned with different payload, cycle-time, and budget constraints.
These trends translate into concrete opportunity spaces. For system integrators and equipment builders, the opportunity lies in embedding sensor capability earlier in the design of welding cells and large-scale fabrication lines, so that tracking is planned as a process layer rather than retrofitted as an add-on. For end users, the opportunity is to use tracking data not simply to improve alignment but to unlock higher automation rates in applications that were previously considered too variable for unattended operation. At the same time, uncertainty remains. Pricing pressure on critical optical and semiconductor inputs could compress margins or slow product iteration in segments where cost sensitivity is high. Adoption may also fragment if integration standards and data interfaces remain inconsistent, forcing repeated customization across robot platforms and cell architectures. Finally, the competitive mix may shift quickly where regional players gain traction through strong local support and cost positioning. These dynamics do not threaten the broader growth path, but they do reward participants who can balance technological ambition with deployment practicality.
Strategic Actions for Decision-Makers
For manufacturers and equipment integrators, the priority is to treat seam tracking as part of the core process architecture rather than a peripheral feature. Selection criteria should emphasize robust performance under real production variability, compatibility with existing robot ecosystems, and the ability to support both guidance and inspection use cases within a manageable integration footprint. Suppliers that can demonstrate repeatable outcomes across joint variation and surface conditions will increasingly capture preference over those competing only on peak specifications or isolated lab results. This is also the moment to evaluate whether in-house tracking capability, partnership with a sensor specialist, or bundled equipment offerings best fit long-term process roadmaps.
For investors and corporate strategists, the key is to differentiate between sensor hardware exposure and solution-level exposure. Revenue tied to recurring software support, integration services, and application-specific qualification is likely to be more durable than revenue dependent solely on unit volume in commoditizing segments. Watching which companies expand across multiple verticals while maintaining integration simplicity and supply resilience will provide an early signal of which positions are likely to scale. Capital and partnership decisions should account for the possibility that value capture shifts toward players capable of combining perception hardware with the software, support, and ecosystem relationships needed to keep systems operating in demanding environments.
For procurement and operations leaders, the emphasis should move toward total cost of ownership and deployment reliability. Where possible, qualification should include tests that reflect actual gap variation, surface finish, and noise conditions rather than idealized setups. Multi-source readiness, lifecycle support expectations, and compatibility with the dominant robot and controller platforms in the facility should weigh heavily in purchasing decisions. Tracking investments will deliver the strongest returns when they are aligned with broader automation and quality objectives, allowing process teams to reduce rework, increase automation coverage, and build more consistent inspection evidence from the same data stream. For organizations seeking deeper segmentation data, competitive benchmarking, and customized adoption roadmaps, the full research report provides the detailed breakdowns and scenario analysis needed to translate these trends into precise procurement, investment, and product strategy decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Seam Tracking Laser Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Direct Acting Proportional Reversing Valve Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Overview
The Direct Acting Proportional Reversing Valve Market encompasses advanced hydraulic components designed to control directional flow and pressure within fluid power systems. These valves are critical in applications requiring precise control of hydraulic actuators, enabling smooth and responsive operations. Their core functionalities include adjusting flow rates and reversing directions efficiently, making them essential in sectors such as construction, agriculture, and industrial machinery.
The market for these valves is driven by the increasing demand for automation and enhanced control in hydraulic systems. The Direct Acting Proportional Reversing Valve Market plays a vital role in supporting modern industries by improving system responsiveness and operational safety. Its ability to deliver accurate, adjustable control underpins innovations in machinery efficiency and process automation.
Market Size and Growth
The current market value is estimated at approximately USD 2.5 billion. Over the next decade, it is projected to reach around USD 4.8 billion, reflecting a compound annual growth rate (CAGR) of about 7%. Growth is fueled by rising industrial automation, the expansion of mobile machinery, and the adoption of intelligent hydraulic solutions across various sectors.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2280
Key Drivers
• Increasing automation in manufacturing processes
• Rising demand for energy-efficient hydraulic systems
• Growth of mobile machinery and construction equipment
• Technological advancements in valve control mechanisms
• Expansion of industrial infrastructure globally
Restraints
• High initial investment costs for advanced valve systems
• Technical complexity limiting easy integration
• Stringent regulatory standards impacting component design
• Maintenance challenges in harsh operational environments
Segmentation
• By Type: Standard, High-Precision, Customized
• By Deployment: On-Pump, Off-Pump
• By Enterprise Size: Small, Medium, Large
• By End User: Construction, Agriculture, Industrial, Marine
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market benefits from mature industrial sectors and technological innovation, with rising adoption in automation. Europe shows steady growth driven by machinery manufacturing and stringent safety standards. The Asia-Pacific region leads in demand, supported by rapid industrialization and infrastructure development. Latin America is gradually increasing adoption, primarily in agriculture and mining sectors. The Middle East & Africa exhibit growth potential driven by infrastructural projects and industrial expansion.
Opportunities
• Expansion in emerging markets of Asia and Africa
• Integration of IoT and smart hydraulic systems
• Development of energy-efficient, eco-friendly valves
• Adoption in autonomous machinery and robotics
• Industry-specific customized solutions for vertical markets
Key Companies
Bosch Rexroth, Parker Hannifin, Eaton Corporation, Danfoss, Moog Inc., HYDAC, Bosch, Yuken, Hydac, Rexroth, HAWE Hydraulik, Sun Hydraulics
Conclusion
The overall outlook for the Direct Acting Proportional Reversing Valve Market remains positive, with long-term growth driven by industrial automation and technological innovation. Its strategic importance in enhancing hydraulic system control underscores its vital role across numerous sectors. As industries continue to evolve, the market is poised for sustained expansion, offering significant opportunities for established and emerging players alike.
Related Reports
Flat Top Comb Filter Market , Size Share and Analysis | Report 2033
Delay Line Interferometer Market , Size Share and Analysis | Report 2033
Dredge Pump Gearbox Market , Size Share and Analysis | Report 2033
Self Elevating Gearbox Market , Size Share and Analysis | Report 2033
Double Beam Electron Microscope Market , Size Share and Analysis | Report 2033
Steel Aluminum Composite Conductor Rail Market , Size Share and Analysis | Report 2033
Adjustable Insulating Support Market , Size Share and Analysis | Report 2033
Waterproof Board Laying Machine Market , Size Share and Analysis | Report 2033
Spring Insert Type Locknut Market , Size Share and Analysis | Report 2033
Full Face Rock Roadheader Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
HYW Self-Adhesive Tape Market: Why 6.12% CAGR Reshapes Regional Dynamics
By PW Consulting, 2026-09-18
The HYW Self-Adhesive Tape Market: Strategic Trends and Commercial Opportunities Through 2032
The global HYW self-adhesive tape market has entered a phase of steady, structurally supported expansion, with total revenue projected to climb from approximately USD 315.4 million in 2025 to USD 478.02 million by 2032. This trajectory reflects a compound annual growth rate of 6.12 percent over the 2026–2032 forecast horizon, building on a consistent upward path from the 2020 baseline of USD 231.5 million. The growth is not merely cyclical but rooted in enduring shifts in packaging logistics, industrial assembly methods, and material performance expectations. Self-adhesive tapes have transitioned from auxiliary sealing commodities to engineered components that influence supply chain efficiency, product safety, and environmental compliance. As end-user industries recalibrate their material specifications and regulatory frameworks tighten around packaging waste, the tape segment is experiencing both demand acceleration and formulation pressure.
Despite the favorable macro trajectory, three structural challenges are reshaping how participants navigate the market. First, raw material cost volatility, particularly in polymer backings and adhesive resins, is compressing margins and forcing continuous price–performance recalibration. Second, the regulatory environment is shifting from voluntary sustainability commitments to enforceable recycled-content and recyclability mandates, requiring reformulation, supply chain transparency, and compliance verification that many mid-tier producers are still building capacity to absorb. Third, the market is exhibiting moderate concentration, with the top three players collectively accounting for just over 42 percent of revenue and the top five reaching approximately 58 percent, leaving substantial room for specialized, regional, and application-focused entrants but also raising the bar for scale, technical service, and compliance infrastructure. These dynamics mean that growth alone is no longer a sufficient strategic narrative; differentiation in material engineering, regulatory readiness, and value-chain integration is becoming the primary determinant of durable competitiveness.
Key Drivers Reshaping the HYW Self-Adhesive Tape Landscape
Material Innovation and Performance Differentiation
The chemistry mix continues to pivot toward adhesives that balance bonding strength, temperature tolerance, and environmental resistance while meeting downstream recyclability expectations. Acrylic-based formulations remain dominant in value terms, reflecting their broad compatibility with automated dispensing, consistent tack profiles, and suitability for high-speed carton sealing and industrial bonding. Rubber-based adhesives maintain a strong position where cost efficiency and initial tack are prioritized, particularly in medium-weight packaging and general industrial applications. Silicone adhesives, while smaller in absolute terms, are gaining traction in specialized contexts requiring extreme temperature stability, clean removal, or compatibility with sensitive substrates. The strategic implication is that tape performance is increasingly evaluated not just on holding force but on process integration, substrate compatibility, and end-of-life behavior, pushing R&D teams to optimize formulations for both manufacturing throughput and compliance footprints.
Regulatory Pressure as a Catalyst for Product Redesign
Policy frameworks are no longer peripheral considerations; they are actively reshaping formulation roadmaps and procurement specifications. Jurisdictions are moving toward explicit recycled-content minimums, recyclability requirements, and producer responsibility obligations that affect both the adhesive layer and the backing film. In India, regulatory requirements have driven early compliance-oriented product updates, with recycled-content BOPP tapes entering the market to align with national plastic waste management mandates. In Europe, packaging regulations are setting recyclability and recycled-content expectations that cascade into tape specifications used on or as part of packaging systems. The strategic signal is clear: compliance is becoming a design parameter rather than a post-production check, and manufacturers that embed regulatory readiness into their development cycles are better positioned to retain spec-in decisions and avoid reformulation scrambles.
Demand-Side Shifts in Packaging and Industrial Assembly
End-user behavior is changing on two fronts: volume and specification. E-commerce and logistics intensification continue to increase the frequency of carton sealing, reinforcing demand for reliable, high-speed compatible packaging tapes. At the same time, industrial and electronics assembly is placing greater emphasis on tapes that support clean processing, substrate safety, and consistent performance under variable environmental conditions. These use cases favor solutions that reduce line stoppages, minimize waste from misapplication, and align with broader sustainability targets in the purchasing organization. The result is a demand profile that rewards suppliers capable of pairing product performance with application engineering, testing support, and documentation that helps buyers justify material choices internally.
Airtight Tapes Market
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by regional divergence in polymer pricing and by the operational implications of sustainability mandates. Backing materials such as BOPP film exhibit meaningful price differences across major markets, influencing where production is routed and how cost-advantaged formulations are sourced. At the same time, polypropylene-linked cost indicators remain elevated, reinforcing the importance of yield optimization, scrap reduction, and adhesive efficiency. Companies are increasingly evaluating not just per-unit material cost but total cost of compliance, including certification, recycled feedstock availability, and the operational burden of managing multiple formulation grades. This broader cost lens is accelerating consolidation of SKUs around platforms that can serve multiple applications while still meeting regional regulatory thresholds.
Competitive Positioning and Market Evolution
The competitive field is anchored by a mix of global scale players and specialized manufacturers, each pursuing distinct strategic positioning. Large diversified companies leverage broad adhesive science capabilities, integrated film and coating operations, and global distribution networks to serve cross-industry demand. Their advantage lies in 일관된 성능 기준, 응용 엔지니어링 지원, 그리고 규모 기반 공급망 복원력입니다. 유럽 기반의 한 주요 업체는 재활용 PET 캐리어와 친환경 포장 테이프 라인을 강조하며 규제 대응형 제품 아키텍처를 구축하고 있으며, 이는 구매팀이 지속 가능성 목표와 성능 요구사항을 동시에 충족하도록 돕는 포지셔닝입니다. 북미와 아시아 지역의 다른 선도 기업들은 이커머스 포장, 중형·중량 박스 실링, 자동화 라인 호환성에 초점을 맞춘 핫멜트 및 아크릴 기반 솔루션을 강화하며 처리 속도와 공정 안정성을 핵심 차별점으로 삼고 있습니다.
PW Consulting Chemical & Energy Research Center
지역 및 니치 플레이어의 전략은 규모 경쟁보다 규제 적합성, 소재 혁신, 비용 효율적 재활용 함량 활용에 기울어져 있습니다. 예를 들어 인도 시장의 한 제조업체는 현지 EPR 요건에 대응하기 위해 재활용 함량 BOPP 테이프 라인을 확대하며 지역 규정 친화적 포트폴리오를 구축하고 있습니다. 이러한 움직임은 규제 민감도가 높은 시장에서 빠른 대응력과 지역 공급망 접근성이 경쟁 우위로 전환될 수 있음을 보여줍니다. 동시에 일본의 소재 및 테이프 전문 기업들은 BOPP와 특수 필름 기반의 포장·산업 용도를 포괄하며, 기판 호환성과 필름 설계 역량에서 차별화를 모색하고 있습니다.
시장 구조의 진화 방향은 수평적 통합과 수직적 전문화가 동시에 진행되는 양상입니다. 상위권 기업들은 제품 플랫폼을 확장해 여러 응용 분야를 커버하고, 지역별 규제 요건에 맞춰 변형 가능한 공통 기반을 구축하며 포트폴리오 복잡도를 관리하는 경향을 보입니다. 반면 중소형 참여자들은 특정 화학군, 특정 지역 규제 시장, 또는 특정 최종 사용 산업의 기술 요구에 집중해 대체 불가능한 포지셔닝을 확보하려는 움직임을 보입니다. 신규 진입의 문은 여전히 열려 있으나, 성공을 위해서는 단순한 가격 경쟁력이 아니라 시험 데이터, 규제 문서, 일관된 품질 관리, 그리고 구매팀의 내부 검토를 통과할 수 있는 기술 신뢰도가 함께 요구됩니다. 이 환경에서 경쟁 우위는 제품 자체의 성능뿐 아니라 구매 여정 전체를 얼마나 매끄럽게 지원하느냐에 의해 점차 결정되고 있습니다.
Forward Outlook: Trends Shaping the Next Three to Five Years
여러 동인이 겹치면서 향후 3~5년 동안 산업 방향을 규정할 몇 가지 흐름이 뚜렷해지고 있습니다. 첫째, 재활용 함량과 재활용 가능성은 선택적 마케팅 요소가 아니라 제품 설계의 기본 조건으로 자리 잡을 것입니다. 구매 조직은 사양서에 규제 적합 증거를 포함하고, 공급업체는 공통 플랫폼에서 지역 변형을 효율적으로 관리할 수 있는 구조를 갖추게 될 것입니다. 이는 준수형 등급과 고성능 등급 사이의 경계가 더 유연하게 연결되는 제품군으로 이어질 가능성이 높습니다.
Seam Sealer Tape Market
둘째, 응용 공학이 상업적 차별화의 중심축으로 부상할 것입니다. 자동화 라인 호환성, 도포 일관성, 기판 손상 최소화, 환경 조건에서의 접착 신뢰성 같은 요소가 구매 결정의 전면에 나서면서, 단순 가격 비교보다 총 공정 비용과 품질 일관성이 더 큰 비중을 차지하게 됩니다. 이 흐름은 기술 지원, 테스트 데이터, 현장 문제 해결 능력을 갖춘 공급업체에 유리하게 작용할 것입니다.
셋째, 비용 구조와 원료 조달의 지역적 분화가 심화되면서 공급망 설계가 제품 전략과 분리될 수 없게 될 것입니다. 폴리오레핀 계열 재료의 지역별 가격 차이와 재활용 원료의 가용성 변동은 생산 거점, 배합 전략, SKU 관리 방식에 직접 영향을 미칠 것입니다. 기업들은 표준화와 현지화 사이의 균형을 더 정교하게 맞추어야 하며, 그렇지 않을 경우 규제 대응과 원가 경쟁력 사이에서 동시에 압박을 받게 됩니다.
이러한 추세 아래에는 불확실성이 남아 있습니다. 규제 시행 시기와 세부 요건은 지역별로 차이가 있을 수 있고, 재활용 원료의 품질 일관성과 공급 안정성은 조성 전환을늦출 수 있으며, 경기 변동은 포장 및 산업 수요 모두에 영향을 줄 수 있습니다. 그럼에도 기본적인 방향은 명확합니다. 성능, 준수, 공정 통합이 함께 평가되는 시장에서 운영 속도와 데이터 투명성을 갖춘 참여자가 유리한 위치를 점할 가능성이 높습니다.
Strategic Implications for Decision-Makers
제조업체에게는 규제 적합성을 사후 조치가 아니라 제품 플랫폼 설계의 입력 변수로 다루는 것이 중요합니다. 공통 베이스를 중심으로 지역별 변형을 관리할 수 있는 구조를 갖추면 복잡도와 준수 리스크를 동시에 줄일 수 있으며, 응용 지원과 테스트 문서를 강화하면 사양 채택 가능성을 높일 수 있습니다. 또한 원료 가격 변동과 재활용 원료 조달 환경을 고려한 배합 및 재고 전략이 마진 방어에 직접적인 영향을 미칩니다.
투자자에게는 왜곡된 성장 수치보다 플랫폼 확장 능력, 규제 대응 속도, 지역 가격 구조를 흡수할 수 있는 운영 역량이 장기 가치 창출의 핵심이라는 점이 중요합니다. 화학군별 수요 강도, 지역 규제 일정, 원재료 조달의 지역적 차이, 그리고 경쟁사가 제품 플랫폼을 어떻게 단순화하고 있는지는 포트폴리오 판단과 진입 시점 평가에 유용한 기준입니다. 빠른 규제 대응이 가능한 지역 강자와, 글로벌 규모에서 성능 일관성을 확보한 기업 사이의 역할 분리가 심화될 가능성을 주목할 필요가 있습니다.
조달 담당자와 구매 리더에게는 총소유비용 관점으로 전환할 때 더 나은 의사결정이 가능합니다. 도포 효율성, 라인 중단 위험, 규격 변경 시 검증 부담, 그리고 문서화된 준수 증거는 가격표 이상의 가치를 만듭니다. 또한 단일 공급원에 대한 의존도를 낮추면서도 사양 일관성을 유지하려면, 동등한 성능 기준을 충족하는 대체 후보군과 검증된 시험 데이터를 사전에 확보하는 것이 유리합니다.
시장 구조와 규제 환경이 빠르게 재조정되는 상황에서는 세분화된 수요 강도, 지역별 규제 이행 일정, 원재료 가격 경로, 주요 기업의 제품 플랫폼 변화에 대한 최신 정보가 의사결정의 질을 좌우합니다. 이러한 세부 데이터는 단기 조달 전략부터 중장기 포트폴리오 재편까지 연결되므로, 지속적인 모니터링과 적용 가능한 형태의 인사이트 확보가 필수적입니다. 보다 상세한 세분화 데이터, 지역별 규제 이행 타임라인, 기업별 제품 전략과 경쟁 포지셔닝에 대한 심층 분석은 전체 연구 보고서에서 확인할 수 있습니다.
For detailed analysis of this topic, please visit the official page: HYW Self-Adhesive Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com