

Blogs
POE Market CAGR: The 7.6% Growth Story Reshaping Automotive and Packaging Demand
By PW Consulting, 2026-09-21
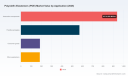
Polyolefin Elastomers (POE) Market: Strategic Shifts and Profitable Pathways Through 2032
The polyolefin elastomers (POE) sector is entering a phase of accelerated transformation, driven by a convergence of material science breakthroughs, shifting end-use requirements, and deliberate capacity strategies. Market size has expanded from 1,200.0 million USD in 2020 to 1,880.0 million USD in 2025, and the trajectory extends through 2032, reaching 3,112.0 million USD. The compound annual growth rate of 7.6 percent over the 2026–2032 forecast period underscores a market that is no longer growing purely on volume expansion, but increasingly on value capture, application migration, and regional realignment.
PW Consulting
A market expanding at this pace does not simply reward incremental improvements. It rewards organizations that can anticipate how performance requirements, regulatory expectations, and supply chain architecture will evolve together. POE has moved from a niche additive and specialty modifier into a core enabler for lightweighting, flexible barrier systems, durable consumer products, and increasingly, advanced electronics and renewable energy components. The question for executives, planners, and investors is not whether the category will grow, but where margin will concentrate and where competition will intensify.
The current landscape is defined by a high degree of concentration, with the top three players accounting for 65.0 percent of market revenue and the top five reaching 80.0 percent. This concentration suggests that leadership positions are already established, but it also signals that the next wave of growth will likely emerge through application-specific differentiation, capacity timing, and strategic consolidation rather than broad-based market sharing.
Market Snapshot and the Structural Crossroads
Over the 2020–2025 period, the category moved from 1,200.0 million USD to 1,880.0 million USD, reflecting a steady step-up in demand across automotive components, flexible packaging, consumer goods, and other applications. By 2025, the regional distribution indicates strong commercial presence across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with the largest revenue pools clustered in the most industrialized and automotive-intensive markets. On a type basis, polyethylene-based POE leads with 1,412.47 million USD, while polypropylene-based POE contributes 467.53 million USD, reflecting differing property profiles and end-use preferences.
This market is now at a structural crossroads. Growth is no longer a simple function of adding capacity; it depends on aligning resin design with application economics, securing feedstock stability, and navigating an increasingly complex sustainability and compliance environment. Three challenges stand out as particularly consequential.
The first is the tension between volume expansion and differentiation. As new capacity comes online and regional supply grows, commodity pressure can compress pricing for undifferentiated grades. The organizations that protect margin will be those that translate technical properties into measurable cost-in-use advantages, not those that compete solely on price per kilogram.
The second challenge is feedstock and input volatility. POE economics remain tightly linked to ethylene, propylene, catalyst systems, and energy costs. Capacity expansions can be undermined if feedstock arrangements, energy exposure, or plant utilization assumptions do not match the operating environment. Pricing power in the category increasingly depends on integrating supply chain resilience with product design.
The third challenge is the evolving regulatory and customer sustainability agenda. Packaging, automotive, and consumer-product buyers are placing greater weight on recyclability, material efficiency, and lower-carbon production pathways. These expectations are reshaping qualification criteria, not only environmental reporting. Materials that cannot support downstream compliance or circularity goals risk losing specification positions, even if they remain technically adequate.
Key Drivers Reshaping the POE Landscape
The market’s direction is being shaped by four reinforcing forces: material innovation, policy and regulatory momentum, demand-side substitution behavior, and supply chain reconfiguration. Each driver is altering where value is created and how quickly it can be captured.
Technological innovation continues to expand the performance ceiling. POE is increasingly chosen not simply for elasticity, but for its ability to improve toughness, sealing behavior, clarity, processability, and integration with other polymer systems. This is enabling adoption in higher-value applications where conventional elastomers or softer plastomers cannot meet combined mechanical and processing requirements. The trend is especially visible where lightweighting and part consolidation reduce total system cost, or where flexible packaging demands better barrier compatibility and strength without sacrificing seal performance.
Policy and regulatory dynamics are changing the qualification bar. In several regions, decarbonization targets, extended producer responsibility frameworks, and packaging redesign expectations are altering the base assumptions for material selection. POE grades that support downgauging, multi-material compatibility, recyclability pathways, or lower embodied carbon profiles gain a practical advantage in specification decisions. In this context, the regulatory environment is not simply a compliance cost; it is becoming a filter through which certain grades become easier to specify and others become harder to defend.
Demand-side behavior is shifting from cost-first selection to performance-in-use economics. Automotive manufacturers continue to push for weight reduction and component simplification. Packaging converters and brand owners are balancing strength, appearance, and process efficiency with sustainability commitments. Consumer goods producers are looking for materials that can improve durability and aesthetic quality while maintaining manufacturability. Across these segments, the buying logic is increasingly tied to total system outcome, including processing speed, rejection rates, downstream recyclability, and end-product performance. That shift creates room for premium and semi-premium POE grades when they solve a real application problem.
Supply chain and cost structure changes are reshaping competitive positioning. New large-scale capacity additions are expanding regional availability, particularly in Asia, while established producers refine global footprints and application portfolios. The market is also seeing targeted moves around feedstock integration, plant location strategy, and consolidation. A recent example is the preliminary merger review initiated in March 2026 by South Korea’s Ministry of Trade, Industry and Resources and the Korea Fair Trade Commission regarding Lotte Chemical’s proposed merger with Yeochun NCC. The business focus of the combined entity is expected to emphasize high value-added LDPE and POE for medical use. Even at the review stage, this development illustrates a broader strategic theme: players are repositioning capacity and product direction toward higher-margin, application-specific grades rather than generic volume.
Worldwide Propylene Based POE Market
Competitive Landscape and the Logic Behind Leading Strategies
The POE market is led by firms that combine scale, application depth, and brand recognition with increasingly targeted technology and regional strategies. The leading ecosystem includes global producers and regional specialists, each pursuing a distinct route to resilience and margin protection.
The Dow Chemical Company remains a central reference point in the market, with the largest POE production footprint and well-known product families such as ENGAGE™ and AFFINITY™ across automotive, packaging, wire and cable, and specialty applications. Its strategic strength lies in breadth of application coverage and the ability to offer multiple performance tiers that fit different buyer requirements.
ExxonMobil Corporation competes through its Vistamaxx™ line, with large-scale operations including facilities such as Baytown, Texas, and a focus on elastomers for adhesives, medical, and packaging segments. Its advantage is rooted in integrated feedstock access and the ability to scale high-performance grades for demanding use cases where consistency and property control matter.
Mitsui Chemicals, Inc. is a key international producer supplying high-performance elastomers for automotive, wire and cable, and industrial applications. Its relevance in the market comes from a clear orientation toward performance-intensive segments where customers are willing to pay for optimized material behavior.
Borealis AG has built a strong position in Europe through its Queo™ platform, with offerings spanning packaging, automotive, and medical applications. Its strength lies in regional proximity to key European converters and end users, combined with a product strategy that emphasizes innovation in polyolefin elastomer design.
LG Chem Ltd. is expanding capacity and targeting automotive and specialty elastomers for high-value applications. In a rapidly growing market, capacity expansion is strategically meaningful only when paired with grade differentiation and customer qualification. LG Chem’s focus reflects that broader logic.
SABIC, through SABIC SK Nexlene Company, produces POE with special relevance in advanced materials, including FORTIFY™ encapsulant grades for solar. This highlights an important evolution in the market: POE applications are moving beyond traditional polymer uses into areas where encapsulation, protection, and high-performance processing are critical.
Wanhua Chemical Group Co., Ltd. has moved aggressively on capacity, with a new 200,000 t/yr unit operational since 2024 and plans to expand toward 600,000 t/yr. This is a signal of how regional dynamics are shifting: large-scale capacity additions can change local supply balances quickly, but sustained advantage will depend on how effectively the producer converts volume into qualified demand.
LyondellBasell Industries N.V. operates POE production across multiple regions and supplies elastomers for wire and cable and industrial uses. Its multi-region presence helps support supply continuity and market access, an increasingly important attribute as buyers prioritize resilience alongside cost and performance.
Taken together, these players reveal a market that is simultaneously concentrated and strategically divergent. The leaders are not all competing in the same way. Some emphasize application breadth and global reach, others emphasize regional proximity and specialized grade design, and a third group is scaling capacity for high-volume markets while trying to lift value through targeted applications. This divergence is one of the most important features of the current landscape.
Consolidation is emerging as a central theme in the next stage of market evolution. Capacity rationalization, feedstock strategy alignment, and the push toward higher-value applications all favor consolidation in select chains. At the same time, differentiation is intensifying at the grade level, meaning that the market is not simply becoming more uniform; it is becoming more segmented by performance need, regional requirement, and application qualification. New entrants and capacity expansions can influence local supply, but winning position will depend on downstream relationships, technical service, and grade-level competitiveness.
PolyOlefin Elastomer (POE) Synthetic Materials Market
Forward-Looking Trends and Where Value Is Likely to Concentrate
Looking ahead across the 2026–2032 horizon, three trends appear especially likely to shape commercial outcomes.
Trend one is application migration toward higher-value specifications. POE demand will increasingly come from applications where the material is selected for system-level benefits rather than simple softness or elasticity. Automotive components will continue to be a major demand pool, but the growth logic will depend on lightweighting, part integration, and improved toughness in more complex assemblies. Flexible packaging will remain significant, with additional emphasis on strength, seal performance, and compatibility with evolving packaging formats. In parallel, specialty uses such as advanced encapsulants and performance-critical industrial applications will gain relative importance, especially where material reliability affects product lifetime or safety performance.
This trend creates commercial opportunity for producers and converters who can translate resin properties into application outcomes. It also raises the stakes for qualification: as applications become more demanding, switching costs increase, but so does the need for robust technical support and consistent supply.
Trend two is the alignment of capacity growth with value capture rather than volume alone. Capacity additions are part of the market’s growth story, but the more strategic question is where new tonnage will be directed. The most attractive positions will likely be in grades tied to higher-margin applications, feedstock-advantaged production, and regions where demand growth outpaces local supply. At the same time, regions or segments with oversupply risk will pressure undifferentiated pricing. That means capacity announcements should be read carefully: scale matters, but application selection, ramp-up quality, and customer qualification determine whether scale becomes profitable.
Trend three is regulatory and sustainability-driven specification change becoming a durable competitive factor. If packaging redesign, circularity expectations, and decarbonization pressures continue to intensify, POE grades that fit into more recyclable or more efficient material systems will have a structural advantage. This is not simply a compliance issue; it influences customer willingness to adopt, brand owner preferences, and downstream converter economics. Producers that can present credible pathways for material efficiency, recyclability compatibility, and lower-carbon production may gain access to specifications that are otherwise difficult to win.
These trends also carry risk. Feedstock volatility can erode the economics of expansion plans. Regulatory frameworks may diverge by region, creating complexity for global product rollouts. Demand shifts can alter qualification priorities faster than capacity can be adapted. And concentration in the market means that competitive reactions from leading players can quickly change pricing dynamics in key grades and regions.
Strategic Implications for Decision-Makers
For manufacturers, the immediate priority is to align grade development with application economics, not merely polymer properties. The market increasingly rewards materials that solve a downstream problem: lighter components, better seals, improved durability, improved process efficiency, or better compatibility with evolving sustainability requirements. Manufacturers should also evaluate where capacity and feedstock assumptions create durable advantage versus where they merely add volume. In a market where the top five players already account for 80.0 percent of revenue, incremental growth will often come from stealing application share through superior solution fit, not from taking broad commodity share.
For investors, the key task is to separate capacity announcements from value creation potential. Large expansions can reshape regional supply, but investment merit depends on application mix, qualification status, feedstock positioning, and the ability to protect pricing in the face of competition. The most defensible opportunities are likely in grades and applications where performance requirements are rising and switching costs are meaningful. Investors should also watch consolidation signals and regulatory developments as indicators of where the supply base is heading, since those changes can reshape competitive dynamics well before financial results fully reflect them.
For procurement and sourcing leaders, the strategic imperative is to manage total cost and qualification risk rather than focusing only on resin price. POE is increasingly specified in applications where performance inconsistency or supply disruption carries a high downstream cost. Sourcing strategies should therefore account for grade suitability, supplier technical capability, regional supply resilience, and the ability of suppliers to support evolving sustainability or compliance expectations. Where possible, long-term supply partnerships should be evaluated against the backdrop of application migration and regulatory change, since today’s qualification decisions can lock in advantages or constraints for several years.
Across all of these perspectives, timing matters. The POE market is large enough, and moving fast enough, that broad narratives can obscure important differences in grade-level demand, regional supply balance, and application qualification momentum. Decision-makers who treat POE as a single market risk missing where margins are actually being created. Those who focus on application-driven performance, feedstock and capacity strategy, and the regulatory direction of end markets are more likely to identify durable opportunities before they become crowded.
For a fuller picture of segment-level dynamics, regional demand patterns, capacity timing, and company-specific positioning, the complete study offers the deeper breakdown required for operational planning and investment decisions. In a market defined by concentrated leadership and simultaneous application divergence, detailed intelligence is often the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Polyolefin Elastomers (POE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Anti-Decubitus Cushions Market: How $738M in 2025 Sparks a 6.05% CAGR Shift
By PW Consulting, 2026-09-21
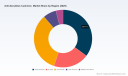
The Anti-Decubitus Cushions Market: Strategic Trends, Competitive Positioning, and Commercial Opportunities Through 2032
Understanding the Current Market Landscape
The global anti-decubitus cushions market has entered a phase of steady expansion, driven by evolving patient care standards, aging demographics, and a growing emphasis on pressure injury prevention across healthcare and home-care settings. From 2020 through 2025, the sector experienced consistent growth, supported by rising institutional procurement of specialized seating solutions and expanding clinical recognition of pressure redistribution technologies. By 2025, the market reached a revenue base that reflects both mature product adoption in established healthcare systems and incremental penetration in emerging care environments. Moving forward, the forecast period through 2032 points toward a sustained mid-single-digit compound annual growth trajectory, indicating that demand is not merely cyclical but structurally anchored in long-term care requirements.
Outdoor Cushions Market
This growth pattern, however, is not uniform. The market continues to navigate a transition from standardized, commoditized cushion designs toward differentiated, risk-stratified solutions that address varying pressure injury severities, patient mobility profiles, and care settings. At the same time, distribution channels, reimbursement pathways, and procurement cycles remain complex, creating barriers to rapid scaling for manufacturers and suppliers alike. Understanding where value is created and where friction persists is essential for executives evaluating market entry, portfolio expansion, or supply chain repositioning.
Core Challenges and Inflection Points
Three structural challenges currently shape the market's trajectory and determine which players can convert volume growth into sustainable margin expansion.
PW Consulting
- Regulatory and compliance fragmentation continues to influence product development cycles and market access. Cushions intended for wheelchair seating and pressure redistribution must satisfy multiple technical and safety expectations, including flammability requirements, washability standards, and performance benchmarks for seating stability and pressure distribution. While certain categories benefit from streamlined premarket pathways, manufacturers still face establishment registration, listing obligations, and the need to maintain documentation that supports clinical procurement and reimbursement eligibility. This layered compliance environment increases time-to-market for new designs and places a premium on regulatory agility.
- Reimbursement architecture and purchasing dynamics create uneven demand visibility. Pressure-reducing support surfaces, including anti-decubitus cushions, are covered under durable medical equipment benefit structures, but actual utilization depends on regional policies, institutional formularies, and cost-containment pressures within healthcare budgets. Buyers often evaluate total cost of ownership, replacement frequency, and clinical outcomes rather than unit price alone, which pushes suppliers to demonstrate value beyond basic pressure relief. This dynamic can slow adoption of premium or specialized designs in cost-sensitive procurement environments, even when clinical rationale is clear.
- Material performance and durability expectations are rising as care settings demand longer service life and consistent skin-contact safety. Products relying on gel inserts, air cells, and foams must balance load distribution, contour adaptation, and resistance to wear while maintaining hygiene and inspection compatibility. As clinical protocols increasingly emphasize proactive pressure injury prevention, the tolerance for inconsistency in cushion performance narrows, forcing manufacturers to refine material selection and quality control rather than compete primarily on price.
Key Demand Drivers Reshaping the Market
Several interconnected forces are expanding the addressable market and altering how suppliers compete. Understanding these drivers helps clarify where growth is likely to concentrate and which capabilities will differentiate future winners.
Technical Innovation and Performance Differentiation
Innovation is shifting from generic cushion construction toward engineered solutions that align with patient risk levels and clinical use cases. Alternating-pressure designs, vertical air-cell architectures, and hybrid foam-and-gel configurations illustrate how manufacturers are tailoring products to specific pressure redistribution goals and positioning needs. These design choices are not cosmetic; they directly affect how effectively a cushion maintains tissue perfusion, reduces shear, and supports prolonged seating without compromising user comfort or caregiver handling.
Material requirements are also becoming more specific. Medical-grade polyurethane, structured foam layers, and air-cell systems must deliver durability, skin-contact safety, and predictable performance over repeated use and cleaning cycles. In parallel, manufacturers are increasingly designing for inspectability and launderability, recognizing that hygiene protocols and routine checks are integral to pressure injury prevention programs. The cumulative effect is a market where engineering rigor and documented performance characteristics increasingly influence purchasing decisions, particularly in higher-acuity or institutional environments.
Policy, Reimbursement, and Standards Alignment
The policy environment plays an outsized role in shaping demand stability. Because pressure-reducing support surfaces are positioned within durable medical equipment coverage frameworks, manufacturers and distributors must continuously align product attributes with coverage logic and procurement criteria. Even when certain device categories are treated with lighter premarket burdens, market access still depends on registration, listing compliance, and the ability to support end-user justification. This creates a structural requirement for transparent product documentation and clear alignment with clinical use cases.
Standards further influence competitive positioning. Performance expectations around seating stability, pressure distribution, and safety characteristics compel suppliers to maintain consistent validation processes. Where standards are well understood and broadly adopted, they can reduce uncertainty and accelerate procurement decisions. Where expectations differ across regions or care settings, they can fragment product roadmaps and increase the operational cost of serving multiple markets. For executives, the practical implication is that regulatory and standards alignment is not a back-office concern; it is a commercial differentiator that affects win rates, channel partnerships, and expansion timing.
Demand-Side Changes in Care Delivery and End-User Behavior
Demand patterns are evolving as care shifts across hospital, rehabilitation, residential, and home environments. Prolonged sitting associated with wheelchair use, supportive seating needs, and positional management requirements create multiple application pathways for anti-decubitus cushions. At the same time, clinical awareness of pressure injury prevention has increased the emphasis on proactive seating solutions rather than reactive treatment. This shift encourages earlier adoption and broader usage across patient populations that may have previously been underserved by standard seating options.
End-user behavior is also changing. Institutions and individual buyers increasingly weigh practical usability, maintenance requirements, and replacement cycles when selecting cushions. A product that performs well in isolation but is difficult to clean, inspect, or fit within existing seating systems may lose out to a moderately less advanced alternative with better workflow compatibility. As a result, manufacturers that integrate ergonomic fit, ease of maintenance, and compatibility with common seating platforms are better positioned to convert clinical desirability into commercial adoption.
Supply Chain Realities and Cost Structure Pressures
The supply side of the market continues to face pressures that influence pricing, product design, and margin management. Raw material selection for air cells, foams, and gel components affects not only performance but also sourcing complexity and production consistency. Manufacturers must manage variability in material availability, processing requirements, and quality assurance while maintaining cost structures that remain acceptable to procurement teams.
At the same time, value migration is occurring toward designs that justify their cost through durability and reduced replacement frequency. In a market where buyers evaluate long-term outcomes and total cost of ownership, suppliers that can demonstrate reliable performance over time may have more room to defend pricing than those competing on short-term unit cost alone. This dynamic is particularly relevant for companies seeking to expand into higher-specification segments or to build trust with institutional buyers who prioritize consistent outcomes over occasional cost savings.
Competitive Landscape and Leading Strategic Postures
The market is characterized by a moderately concentrated competitive structure, with leading players holding meaningful but not dominant shares. This concentration level suggests that scale alone does not guarantee advantage; rather, differentiation through product design, clinical positioning, and channel execution often determines commercial outcomes. Several established companies illustrate distinct strategic approaches within the sector.
Diversified Pressure Care Offering
Some market participants emphasize a broad pressure care portfolio that addresses high-risk patient groups and intelligent pressure management. Companies in this segment often focus on alternating-pressure designs and air-based cushion systems engineered to redistribute load and reduce ulcer risk. By building product lines around specific risk profiles and seating requirements, these suppliers position themselves as solutions providers rather than commodity cushion manufacturers. Their advantage lies in the ability to match product design to clinical need, which can strengthen adoption among care teams seeking targeted pressure redistribution and positioning support.
Specialized Seating and Positioning Expertise
Other players concentrate on seat cushion geometry, vertical air-cell configurations, and positioning-focused designs. These products are developed with an emphasis on reducing pressure injuries in higher-risk scenarios while maintaining stability and pressure redistribution performance. A positioning-oriented approach can resonate in environments where seating alignment, patient stabilization, and injury prevention are equally important. Manufacturers pursuing this path often differentiate by aligning cushion design with practical use requirements, including compatibility with wheelchair systems and ease of inspection or cleaning.
Integrated Mobility and Seating Ecosystems
A further strategic posture involves integrating cushion solutions into broader mobility and seating ecosystems. Companies with strong wheelchair or seating platform presence often leverage their distribution relationships, service networks, and product compatibility to support cushion adoption. Gel and foam insert designs, along with contoured support options, are used to address pressure ulcer prevention and body contour needs within an existing equipment framework. This ecosystem approach can reduce friction for end users, since cushions that fit well with established seating products are easier to specify and deploy.
Air-Cell and Redistribution-Focused Positioning
Certain manufacturers build competitive advantage around air-cell cushion lines designed for optimal pressure redistribution and anti-decubitus protection. Custom and standard configurations allow these suppliers to address varying patient requirements while maintaining a consistent design philosophy centered on load management. This product-centric strategy can be particularly effective in segments where pressure redistribution performance is the primary purchasing criterion and where clinicians or procurement teams seek proven cushion mechanics rather than broader portfolio breadth.
How the Competitive Landscape Is Evolving
The market is likely to continue evolving along several directions. One is gradual consolidation among suppliers seeking to capture broader seating and pressure-care value chains, especially where integrated product compatibility and service coverage can improve customer retention. Another is segmentation, with manufacturers narrowing their focus to particular applications, risk levels, or care settings in order to differentiate on performance rather than price. A third is the ongoing entry of specialized players that bring novel material approaches, ergonomic designs, or digital-adjacent support services into the category. In each case, the central question for executives is whether scale, specialization, or ecosystem integration will create more durable advantage in their target segments.
Forward-Looking Trends and Associated Opportunities
Looking ahead three to five years, the market is expected to be shaped by a small number of high-impact trends that will influence product roadmaps, channel strategy, and investment priorities.
Trend One: Greater Emphasis on Risk-Stratified Seating Solutions
As pressure injury prevention becomes more systematically integrated into care protocols, demand may progressively shift toward solutions matched to specific patient risk profiles rather than one-size-fits-all cushioning. This trend creates opportunity for manufacturers that can document differential performance across use cases and communicate clearly how a given design fits a particular clinical scenario. It also raises the importance of clinical support materials, fit guidance, and application-specific product information in procurement decisions.
Trend Two: Increased Weight on Durability, Hygiene, and Lifecycle Economics
Institutional buyers and home-care users are likely to place greater emphasis on replacement cycles, cleaning compatibility, and long-term performance stability. Products that maintain pressure redistribution characteristics over repeated use, support inspection requirements, and withstand laundering or maintenance routines may gain preference in environments where caregiver time and operational consistency matter. Suppliers that invest in lifecycle design and quality consistency can use these attributes to strengthen value propositions beyond initial purchase price.
Pressure Ulcer Treatment Products Market
Trend Three: Broader Integration with Seating Platforms and Procurement Pathways
The market may increasingly reward cushion designs that align with existing wheelchair and seating ecosystems, as well as with prevailing procurement and coverage logic. Compatibility, fit consistency, and documentation that supports reimbursement or institutional specification can reduce adoption barriers. For suppliers, this suggests value in building partnerships, service support, and product-range coherence that make selection and deployment easier for end users and intermediaries. At the same time, differences in regional reimbursement and standards environments may continue to shape where and how quickly new products scale.
Risks and Uncertainties to Monitor
Several factors could temper or redirect these trends. Changes in coverage interpretation, procurement tightening, or shifts in institutional budgeting could slow adoption of higher-cost designs. Material supply variability and manufacturing consistency challenges may affect product reliability if not managed carefully. In addition, the balance between standardization and specialization will remain contested; too much segmentation can limit economies of scale, while too much standardization can weaken clinical relevance. Executives should track these uncertainties as part of market planning rather than treating growth as automatically linear.
Strategic Implications for Decision Makers
For executives operating in or evaluating this market, the priority is to align product strategy and commercial positioning with the market's actual decision drivers: clinical relevance, durability, compliance support, and integration into care workflows. The following considerations may help structure near-term actions.
- For manufacturers and product developers: Focus engineering and documentation efforts on clearly defined application needs rather than broad, undifferentiated product lines. Where possible, design for inspectability, cleaning compatibility, and seat-platform fit, since these attributes increasingly influence repeat procurement and institutional acceptance. Align validation and material selection with the performance expectations that procurement teams and clinicians use when comparing options.
- For investors and strategic acquirers: Evaluate opportunities based on differentiation quality, reimbursement alignment, and channel leverage rather than headline volume alone. In a market with moderate concentration, value creation often depends on whether a company can maintain pricing power through demonstrable performance, reduce customer switching through compatibility and service, and scale without compromising quality or compliance readiness.
- For procurement leaders and care providers: Evaluate cushions against total use-case performance, including pressure redistribution effectiveness, maintenance burden, replacement expectations, and compatibility with existing equipment. A lower unit cost may be offset by shorter service life or workflow friction. Where possible, standardize selection criteria around clinical outcomes and operational feasibility to simplify sourcing and reduce inconsistent purchasing across sites or departments.
Conclusion
The anti-decubitus cushions market is moving through a period in which growth is supported by structural care needs, but competitive advantage is increasingly determined by how well suppliers translate clinical requirements into usable, durable, and compliant seating solutions. The companies that fare best over the next several years are likely to be those that treat product performance, standards alignment, and procurement reality as interconnected commercial issues rather than separate technical or regulatory matters. As segmentation deepens and end users place greater weight on lifecycle value, the opportunity lies in building offerings that are not only effective in principle but also practical to specify, maintain, and sustain in real care environments.
For detailed analysis of this topic, please visit the official page: Anti-decubitus Cushions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Cords & Extension Cords Market: 6.2% CAGR Trajectory Changes Everything
By PW Consulting, 2026-09-21
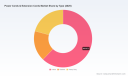
The Power Cords & Extension Cords Market: Strategic Shifts and Commercial Opportunities (2026–2032)
The global market for power cords and extension cords has matured into a sector defined by steady value accumulation, structural segmentation, and incremental but consequential regulatory change. Over the 2020–2025 period, revenue expanded from roughly $3.26 billion to $4.4 billion, establishing a trajectory that carries forward into the 2026–2032 forecast window. The extended outlook points to a compound annual growth rate of 6.2%, lifting projected revenue to approximately $6.68 billion by 2032. This pace is neither explosive nor stagnant; it reflects a market where demand fundamentals are broad-based, yet growth is increasingly tied to differentiation in safety, performance, and application-specific engineering.
Regional activity illustrates a market that is geographically diversified but unevenly developed. North America and Asia Pacific together anchor the largest revenue pools, reflecting mature commercial construction patterns, dense electronics ecosystems, and sustained household demand. Europe remains a substantial contributor, shaped by localized certification regimes and building practices. Latin America and the Middle East/Africa represent smaller but expanding bases, often driven by infrastructure investment, urbanization, and gradual formalization of electrical supply chains. Rather than signaling saturation, the geographic spread highlights where product configuration, voltage standards, and certification pathways must be managed with precision.
The market is structurally split across indoor, outdoor, and heavy-duty product families. Indoor configurations hold the largest share, supported by continuous deployment in homes, offices, and light commercial environments. Outdoor solutions form a smaller but resilient segment tied to construction, outdoor equipment, temporary power setups, and seasonal demand cycles. Heavy-duty cords occupy a distinct position, serving industrial use, medical-adjacent environments, and settings where thermal stress, abrasion resistance, and mechanical durability are non-negotiable. Application-side demand also divides across residential, commercial, and industrial channels. Residential remains the largest demand base, commercial contributes a meaningful mid-tier volume, and industrial represents a specialized segment that rewards higher engineering rigor and compliance confidence.
Key Challenges and Inflection Points
A market growing at a consistent mid-single-digit rate can still feel pressure at the margin. Three challenges stand out as current inflection points. First, raw material volatility is reshaping cost expectations. Price movements in PVC and related polymer inputs have introduced variability in production economics, especially for manufacturers balancing export competitiveness with domestic cost structures. The gap between regional input prices has become more than a procurement issue; it now influences margin planning, inventory strategy, and the timing of price adjustments to downstream customers.
Second, safety and certification requirements are tightening in ways that alter product design and time-to-market. Recent revisions to the UL 817 standard for cord sets and power-supply cords, including new provisions for heater-use power-supply cords, reflect a broader push toward clearer performance expectations in higher-load and thermally sensitive applications. For manufacturers, this is not merely a compliance update. It changes testing protocols, documentation practices, and the engineering margin needed to remain acceptable across North American and internationally harmonized channels.
Third, the market faces an identity challenge around commoditization versus specialization. Many product forms are still viewed as interchangeable, especially in price-sensitive consumer channels. Yet the highest-value opportunities increasingly reside in application-specific performance, traceability, and certification clarity. Companies that compete primarily on generic specifications risk margin compression, while those building defensible positions around medical-grade, industrial-grade, or custom cord sets are better positioned to protect pricing and customer retention.
Key Drivers Reshaping Market Trajectory
The 6.2% CAGR over the forecast horizon is not simply a continuation of past momentum. It reflects structural drivers that interact with one another: technology, regulation, demand-side behavior, and cost architecture. Understanding how these forces converge is essential for deciding where to invest, where to build capability, and where to exercise caution.
Innovation in Materials, Plug Geometry, and Application-Specific Design
One of the more durable drivers is incremental engineering innovation. Power cord and extension cord demand is not only increasing in volume; it is becoming more exacting in specification. This includes better insulation and jacket formulations that balance flexibility, flame resistance, and thermal endurance. It also includes design improvements in connector geometry, strain relief, and cord organization, which matter in both residential convenience and commercial durability. In data center-adjacent and hospital-adjacent settings, where cord integrity is tied to uptime and safety, even modest improvements in strain management, labeling, and configuration consistency can influence procurement decisions.
A second innovation theme is the broadening of purpose-built product families. Heavy-duty and outdoor configurations continue to gain relevance in applications where exposure, repeated flexing, and mechanical stress are routine. Medical-grade and hospital-grade cord sets represent a narrower but higher-stakes segment where performance documentation and certifiable consistency can become competitive differentiators. Custom wiring harnesses and OEM-tailored solutions extend the market beyond standardized retail SKUs into value-added configurations that are less vulnerable to direct price comparison.
Regulatory and Certification Dynamics
Regulatory expectations are becoming a more explicit part of market strategy. Certification is already central to many channels, but recent standard revisions are adding precision around higher-risk use cases. The July 30, 2025 revision of UL 817 introduced new requirements for heater-use power-supply cords, signaling that regulators are paying closer attention to load conditions where thermal management becomes critical. This matters because heater-related applications often operate near the upper bounds of common cord capabilities, where small specification gaps can become safety or reliability concerns.
For companies with North American exposure, UL alignment is a market-access prerequisite in many cases and a competitive trust signal in others. For internationally oriented manufacturers, the challenge is maintaining certification readiness across multiple regulatory regimes while keeping product families efficient enough to avoid over-fragmentation. The practical effect is that compliance is no longer a back-office function; it is increasingly part of product strategy, marketing credibility, and channel access.
Demand-Side Shifts in Residential, Commercial, and Industrial Use
Demand behavior is evolving on both the consumer and enterprise sides. In residential settings, the growth of home offices, entertainment setups, and smart-home devices continues to support accessory demand. Extension cords and power strips are no longer treated solely as temporary utilities; they are being chosen for cord length, barrier compatibility, aesthetic integration, and perceived safety. In commercial environments, demand is shaped by office refurbishment, retail upgrades, hospitality turnover, and the ongoing need for flexible power distribution during fit-outs and reconfigurations.
Industrial demand plays a different role. It is less about volume expansion and more about reliability, specification discipline, and supply assurance. Factories, maintenance operations, and facilities teams often prioritize cords and cord sets that can withstand repeated use, environmental exposure, and inspection regimes. As industrial procurement becomes more selective, the value shifts toward documentation, consistency, and the ability to match cord sets to specific equipment and site conditions.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal driver because it influences both competitiveness and product strategy. Recent pricing movements in PVC illustrate how material economics can diverge by region. In April 2026, China PVC prices were reported near $735.45 per metric ton, while U.S. PVC prices were reported at $822.45 per metric ton. That spread matters for manufacturers operating across export and domestic channels, because it affects landed cost, relative pricing power, and the attractiveness of localization versus import-based supply.
Beyond raw materials, the supply chain is also being shaped by the need for resilience. Procurement teams increasingly value supplier stability, lead-time predictability, and the ability to support custom configurations without excessive turnaround penalty. As a result, some buyers are willing to accept differentiated pricing if it is paired with dependable certification support, batch consistency, and timely delivery. This is gradually shifting the market from pure cost competition toward a more balanced evaluation of cost, risk, and performance assurance.
Competitive Landscape and Leading Strategies
The competitive field is broad, with participants spanning large North American and European manufacturers, Indian electricals players, and specialized Asian cord-set producers. What distinguishes the more successful players is not simply scale, but the ability to align product families with the market’s growing emphasis on safety, application specificity, and configuration flexibility.
Southwire Company LLC occupies a strong position in building wire and cable, including extension cords used in utility, industrial, and commercial applications. Its profile reflects a broad distribution footprint and familiarity with the requirements of installation, infrastructure, and commercial construction markets. For Southwire, the strategic advantage lies in combining product breadth with the credibility needed to serve demanding channel requirements.
Volex plc represents a more globally integrated model, manufacturing power cords, plugs, connectors, and custom wiring harnesses for consumer, industrial, and data center-related uses. Its broad configuration capability supports customers that need standardized solutions and tailored assemblies alike. The strategic implication is that cord-set suppliers with harness and connector expertise can capture additional value by addressing OEM and facility needs beyond simple off-the-shelf cords.
Havells Ltd and Goldmedal Electricals both illustrate the strength of electricals-focused manufacturers in India, with product lines spanning home electricals, extension cords, flexible cables, switches, and power accessories. Their relevance comes from serving both residential and commercial channels with products that balance affordability and practical reliability. In these markets, scale in distribution, brand recognition, and breadth across electrical accessories can be as important as cord-specific engineering.
In China, Ningbo Biaoda Electric Co., Ltd., Jiaxing Hongzhou Cable Co., Ltd., and similar specialized manufacturers reinforce the region’s role as a production base for power cords, power boards, extension cords, and power strips. Their competitive strength typically lies in manufacturing efficiency, configuration variety, and export readiness. The challenge for these players is converting cost and volume advantages into durable positioning, particularly as buyers pay closer attention to certification, traceability, and application suitability.
Taiwan-based YFC-Boneagle Electric Co., Ltd. adds a further dimension through global exports of power cords, cord sets, LAN cables, and networking accessories. Its export-oriented profile underscores how regional manufacturers can compete internationally by aligning with end-market requirements in connectivity and power distribution.
On the U.S. and specialty side, Kord King, Electri-Cord Manufacturing, Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate a different competitive logic. Kord King’s emphasis on premium cords, medical-grade, heavy-duty, and construction-grade cord sets shows how a manufacturer can pursue higher-margin positioning by aligning with demanding use cases. Electri-Cord Manufacturing’s focus on domestic, international, and hospital-grade cords reinforces the same theme: specialty certification and application specificity can create defensible niches. Webber Electronics combines international, North American, hospital-grade, and GFCI power cords across medical, industrial, dental, and commercial markets, reflecting the importance of multi-standard readiness and sector-targeted product lines. Z-Tronix and Quail Electronics extend this pattern with OEM, industrial, commercial, and international configuration capabilities, including custom power cords and cord sets. Their presence suggests that serving both standard and custom requirements can be a practical way to diversify demand while maintaining deeper customer relationships.
PW Consulting Information & Electronics Research Center
Strategic Positioning and Differentiation
Across these companies, several strategic patterns are emerging. One is the move toward application-specific credibility. Manufacturers that can demonstrate consistent performance in medical, industrial, or higher-load contexts are better positioned to escape pure price competition. Another is the blending of standardization with customization. Companies offering both standard cord sets and tailored configurations can capture broader demand while preserving relationships with customers who need tailored specifications. A third pattern is certification readiness as a competitive asset, especially where UL and other standard alignments affect purchasing confidence and channel access.
Market Structure and Evolution
Market concentration remains moderate. A collective concentration reading shows that the top three participants account for roughly 28.5% of the market, while the top five reach about 39.2%. This suggests a field that is not dominated by a small number of incumbents, but still features meaningful leadership positions. The structure leaves room for both consolidation and specialized entry.
Consolidation is plausible in segments where distribution scale, certification infrastructure, and cost discipline matter increasingly. New or expanding entrants can still find openings by focusing on underserved configurations, niche certification needs, or regional demand that is not fully served by larger players. At the same time, the low-concentration structure means that brand trust, product reliability, and compliance documentation can be decisive in purchasing decisions, particularly when buyers compare otherwise similar offerings.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, the market’s direction is unlikely to be driven by a single breakthrough. More likely, it will be shaped by the compounding effect of specification tightening, demand fragmentation, and cost-aware procurement. Three trends are especially relevant for decision-makers.
First, application-specific certification and documentation will become more central to product competitiveness. As revisions such as the UL 817 update for heater-use power-supply cords take effect, buyers in higher-load or higher-risk environments will likely increase scrutiny on whether cords are explicitly appropriate for the intended use. This favors manufacturers that can provide clear guidance, consistent batch quality, and reliable conformity evidence.
Second, cost and material volatility will continue to reward supply chain discipline. With regional PVC pricing divergence and broader input variability, companies that can manage inventory, hedging, sourcing mix, and localized production more effectively will have an advantage in protecting margins without sacrificing service levels. This may also encourage more regionalized production or supplier diversification in response to regional cost differentials.
Wireless Chargers & Power Cords and Portable or Wearable Charging Cable Market
Third, demand will continue to fragment across more specialized use cases, increasing the importance of configuration capability. Residential convenience products will persist at scale, but commercial and industrial buyers will increasingly value solutions tailored to equipment, environment, and installation constraints. That creates opportunities for cord-set suppliers that combine standard SKUs with custom engineering, especially where connectors, cord length, jacket type, and certifying marks must be aligned to specific procurement standards.
Risks and Uncertainties
These opportunities are not risk-free. Regulatory evolution can accelerate and vary by region, imposing additional testing and documentation burdens that disrupt product rollouts if compliance systems are not prepared. Raw material price swings may compress margins more quickly than pricing adjustments can recover them, particularly for manufacturers with limited flexibility in sourcing or product mix. There is also the persistent risk that certain consumer-facing categories remain commoditized for longer than anticipated, making volume growth dependent on distribution strength and promotional intensity rather than value-based differentiation.
Another uncertainty lies in the pace of channel consolidation among buyers. If procurement becomes more centralized and specification-driven, smaller suppliers may face higher barriers to entry unless they can demonstrate clear technical or certification advantages. Conversely, if buyers continue to value flexibility and responsiveness, specialized suppliers may retain a strong position even in a moderately concentrated market.
Actionable Recommendations for Decision-Makers
For manufacturers, the central question is whether product strategy is built around interchangeable volume or defensible specialization. The more durable path is to align at least part of the portfolio with higher-trust applications and clearer certification requirements. That could mean investing in medical-grade or industrial-grade offerings, strengthening documentation for heater-use and other higher-load applications, and ensuring that connector and cord configurations are developed with end-use conditions in mind rather than generic specifications alone. It also means checking whether cost structures can absorb regional material volatility without forcing reactive price moves that erode customer trust.
Appliance Power Cord Market
For investors, the market offers a mix of steady growth and selective upside. Broad exposure may be attractive for its consistency, but the most meaningful value creation is likely to come from companies that demonstrate certification readiness, application specificity, and the ability to serve custom or higher-specification demand. Due diligence should pay attention to whether a company’s product mix is concentrated in price-sensitive commodity segments or balanced with segments that justify stronger pricing and longer customer retention. Supply-chain resilience and regional cost positioning should also be evaluated, given the divergence in raw material pricing and its effects on competitiveness.
For procurement and supply chain leaders, the priority is to treat cord and cord-set purchasing as a specification and risk decision, not solely a unit-cost decision. Evaluations should include suitability for the intended application, certification alignment, traceability, and the supplier’s ability to support standard and custom configurations without unacceptable lead-time penalties. Where operations involve higher loads, medical contexts, or industrial conditions, the cost of qualification errors can exceed the apparent savings from choosing the lowest-priced option. Supplier stability and documentation quality are therefore part of the value equation, not optional extras.
The broader takeaway is that the power cords and extension cords market is changing in ways that reward preparedness. The growth path is solid, but the competitive winners will be those who interpret regulation, cost volatility, and demand fragmentation as strategic signals rather than background noise. For organizations that need detailed segmentation, regional cost dynamics, and application-level demand patterns to refine their plans, deeper commercial intelligence can shorten the gap between high-level strategy and executable action.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cheque Scanner Market: Why the 5.6% CAGR and APAC Shift Change Everything
By PW Consulting, 2026-09-21
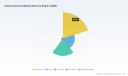
Strategic Trends and Commercial Opportunities in the Cheque Scanner Market
The global cheque scanner market has entered a phase of steady structural expansion, driven by the ongoing digitization of financial back-office operations and the gradual modernization of check processing infrastructure. By 2025, the market has crossed a significant revenue milestone, with industry data placing the total market size at approximately $1 billion. Looking ahead to a forecast period spanning 2026 through 2032, the sector is projected to grow at a compound annual growth rate of 5.6 percent, reaching a multi-billion-dollar valuation by the end of the decade. While this growth trajectory may appear measured in percentage terms, the underlying dynamics reveal a market undergoing meaningful technological maturation, regulatory alignment, and shifting usage patterns across geographic and operational segments.
Document Scanner Market
The historical progression from 2020 through 2025 illustrates a consistent upward curve, reflecting incremental investments by banks and financial institutions to replace legacy handling methods with intelligent imaging solutions. The forecast period suggests that this momentum will continue, albeit with shifting drivers as the market moves from early adoption phases into more mature deployment cycles. As the installed base expands and end-user expectations around speed, image fidelity, and remote processing capabilities evolve, manufacturers and solution providers face an increasingly nuanced landscape where differentiation depends less on basic scanning functionality and more on integration, workflow optimization, and compliance readiness.
Market Maturity and Core Challenges
Operational Scale and Legacy Transition Pressure
One of the defining characteristics of the current market environment is the tension between established processing habits and the operational need to accelerate digitization. Cheque scanners are no longer viewed simply as point hardware; they are components of broader capture ecosystems that must interact with network infrastructure, image quality standards, and downstream processing workflows. Institutions deploying these systems are balancing the need to reduce physical check handling time with the reality that many branches and back-office environments still operate with heterogeneous equipment, varying floor space constraints, and different throughput requirements. This creates a challenge for vendors seeking scalable deployment models and for buyers who must justify standardization across multiple locations.
A second challenge lies in aligning hardware innovation with regulatory expectations. Image quality and data retention requirements have become embedded in the operational fabric of check processing. Systems must not only scan efficiently but also produce images that satisfy established transmission and retention protocols. This regulatory backdrop raises the technical bar for new entrants and reinforces the importance of long-term compatibility, which in turn favors manufacturers with sustained product development roadmaps and robust service networks.
Fragmentation and Coordination Across Use Cases
A third pressure point is the uneven pace of adoption across different operational settings. Some environments prioritize high-volume teller capture and centralized processing, while others require compact desktop solutions that can support distributed branch operations or remote deposit workflows. The coexistence of these divergent needs complicates product strategy, as manufacturers must balance volume-oriented engineering with user-friendly, low-footprint designs. At the same time, end-users are increasingly evaluating scanners as part of broader cost-efficiency and processing-time initiatives, meaning that purchase decisions are increasingly tied to total workflow performance rather than unit-level features alone.
Core Drivers Shaping Market Direction
Technological Innovation and Processing Accuracy
Technological advancement remains one of the most visible catalysts for demand. Modern scanning platforms are being engineered to improve MICR reading accuracy, enhance image capture under varied conditions, and support faster throughput without sacrificing image quality. Recent product introductions illustrate how manufacturers are responding to these expectations. In late 2025, Digital Check Corp. introduced the next-generation TellerScan TS250 UV ultraviolet cheque scanner, succeeding the TS240 model and designed for distribution through its global reseller network. Alongside this, the company emphasized updated CheXpress CX35 and CX35-Network models featuring a zero-footprint design and Smart Button technology. These updates signal a broader industry shift toward compact form factors, simplified operator interaction, and modularity that supports both localized and networked deployment scenarios.
The emphasis on ultraviolet imaging, network-capable configurations, and streamlined physical design reflects a market that is increasingly attentive to space constraints, operator ergonomics, and the ability to integrate scanning into digitally connected branch environments. As imaging specifications become more tightly aligned with downstream processing requirements, scanner performance is evolving from a stand-alone specification into a workflow enabler.
Regulatory Frameworks and Image-Based Clearing Standards
Policy and regulatory frameworks continue to play a central role in shaping procurement behavior and technology requirements. The Check Clearing for the 21st Century Act has provided the legal foundation for image-based clearing, requiring participating institutions to maintain image retention capabilities and implement standardized transmission protocols. This framework has helped accelerate the transition toward digital check processing by giving institutions a clear regulatory basis for moving away from purely physical handling.
Complementing that foundation, Federal Reserve guidelines have established minimum image quality standards for check processing, setting technical specifications that modern scanners must satisfy. These quality mandates have practical commercial consequences: they influence product specifications, encourage consistent image output across different environments, and raise the importance of compliance-grade engineering. For manufacturers, this means that competitive advantage increasingly depends on delivering hardware that reliably meets regulatory image expectations while also reducing operator error and rework.
Demand-Side Behavior and Branch-Level Efficiency Goals
Demand-side dynamics are being reshaped by institutional priorities around processing speed, cost control, and branch-level efficiency. U.S. banks process, analyze, and clear a large volume of checks each day, and many are installing scanners at various branches to shorten the overall clearing cycle. This operational push aligns with broader government guidance that encourages the use of digital checks and image-based workflows. As a result, scanner adoption is increasingly tied to measurable time savings, reduced manual intervention, and faster reconciliation.
At the same time, demand is not limited to large centralized banking operations. Distributed environments that require remote deposit capture and localized image acquisition are also contributing to purchasing activity. This broadening usage profile is encouraging vendors to develop solutions that can serve both high-volume teller environments and smaller-scale branch or back-office settings, creating a more diverse demand base than in earlier phases of market development.
Cost Structures and Deployment Economics
Cost considerations continue to influence how quickly and broadly scanner technology is adopted. Institutions weigh not only upfront hardware expenditure but also installation complexity, maintenance demands, and the ability to standardize devices across sites. The growing availability of network-enabled and space-efficient models is reshaping these economics by reducing some of the physical and operational friction associated with deployment. When a scanner can be integrated into existing branch layouts without extensive floor space requirements, and when it can interface cleanly with capture workflows, the total cost of adoption becomes more attractive relative to the operational benefits it delivers.
PW Consulting Automotive & Machinery Research Center
Supply-side dynamics also matter. Manufacturers with established distribution channels and global reseller networks are better positioned to scale new models efficiently, while those with broader imaging and document capture portfolios can offer complementary capabilities that strengthen the value proposition for end-users seeking integrated solutions.
Competitive Landscape and Leading Strategies
Established Players and Product-Line Differentiation
The competitive field is shaped by a mix of specialized cheque scanner manufacturers and broader imaging and financial systems providers. Digital Check Corp., headquartered in Northbrook, Illinois, continues to emphasize teller capture, remote deposit, and high-volume production imaging through products such as the CheXpress CX35 and TellerScan TS250 series. Its recent product moves highlight an emphasis on refreshed imaging features, network-ready configurations, and reseller-led distribution, reinforcing a strategy centered on product continuity and broad availability.
Panini S.p.A., based in Turin, Italy, positions itself around intelligent cheque scanners such as the EverneXt and Vision X lines, targeting distributed check capture and remote deposit applications. Its approach reflects an orientation toward intelligent capture functionality and flexibility across deployment contexts. Epson America, Inc. offers desktop models like the TM-S1000II and TM-S1000II-NW, combining MICR reading with RDC and back-office capture features, while Canon U.S.A., Inc. supports the imageFORMULA CR-series for desktop and check transport imaging. These players illustrate how established imaging brands leverage document capture expertise to compete in cheque scanning by emphasizing reliability, ergonomic design, and integration with broader office or branch imaging ecosystems.
Currency Count Machine Market
Banking-Centric and Systems-Integrated Approaches
Other competitors bring a stronger systems-integration orientation. ARCA Tech Systems, LLC provides LS40 and LS100 scanners for teller and remote deposit capture, while RDM Corporation supplies network-focused models such as the EC9000i and EC9600i for image capture and MICR applications. NCR Voyix Corporation aligns cheque scanning with broader banking and retail capture systems, positioning scanners as components of integrated financial processing environments rather than standalone devices.
This divergence in positioning matters strategically. Some manufacturers compete primarily on hardware refinement and product-line breadth, while others compete on integration, workflow compatibility, and the ability to match scanner capabilities to institutional capture systems. A market concentration measure indicates that the top three firms account for roughly 24.6 percent of revenue and the top five for about 26.2 percent, suggesting a landscape that remains relatively dispersed while still featuring recognizable leaders with distinct strategic identities.
Evolution of the Competitive Structure
The competitive structure appears to be evolving along several axes. One is the continued refinement of product families to serve both centralized and distributed use cases. Another is the increasing importance of compliance-grade image quality and network readiness as baseline expectations rather than premium differentiators. A third is the role of distribution and integration partnerships in extending reach, especially in environments where branch technology decisions are made in coordination with broader banking technology roadmaps.
New entrants and adjacent imaging brands may find opportunities in niche deployment scenarios or in specific geographic markets where regional service support and localized product features matter. At the same time, established players benefit from product maturity, regulatory familiarity, and existing relationships with financial institutions. The net effect is likely to be a market where competition intensifies not primarily through price alone, but through reliability, integration ease, and the ability to reduce operational friction in real-world branch and back-office settings.
Future Trajectory and Emerging Opportunities
Deeper Integration of Scanning into Digital Capture Workflows
Over the next three to five years, one of the most important trends is likely to be the further integration of cheque scanners into digitally connected capture workflows. As institutions continue to prioritize faster clearing cycles and reduced manual handling, scanners will increasingly be evaluated in relation to how well they support remote deposit capture, networked branch operations, and image-based reconciliation. This creates commercial opportunities for manufacturers that can offer hardware with strong compatibility, straightforward configuration, and predictable service requirements. It also creates opportunities for solution providers that can bundle scanning with workflow software, image quality assurance, and operational support.
Growth in Distributed and Space-Constrained Deployments
A second trend is the continued expansion of distributed capture models, especially in environments where compact, easy-to-deploy devices are preferred. The move toward zero-footprint designs and simplified operator controls suggests that end-users are placing greater value on branch-friendly equipment that can be installed without major layout changes. As a result, there may be growing demand for desktop and low-profile scanners that still meet image quality and MICR reading expectations. For manufacturers, this trend rewards engineering that balances performance with form factor, while for buyers it opens the door to broader standardization across locations with different physical constraints.
Regulatory Alignment as a Stable Demand Anchor
A third trend is the ongoing role of regulatory compliance as a stabilizing force behind procurement. Because image-based clearing frameworks and quality standards are embedded in operational practice, demand for scanners that satisfy these requirements is unlikely to disappear even if overall market growth moderates in certain periods. This creates a degree of structural resilience, but it also means that product roadmaps must keep pace with evolving image expectations and transmission protocols. Companies that treat compliance alignment as a core engineering priority rather than an add-on are better positioned to maintain continuity in purchasing environments where auditability and image retention remain critical.
Risk Factors and Uncertainty
Despite these favorable structural signals, several uncertainties bear watching. If macroeconomic conditions constrain institutional spending, procurement cycles may lengthen, particularly for non-essential hardware upgrades. If imaging standards or clearing protocols shift materially, manufacturers may need to adapt product specifications more quickly than anticipated. In addition, as more functions become digitized and centralized, certain branch-level capture needs could consolidate into fewer device categories, potentially intensifying competition among suppliers seeking to remain relevant across a narrower set of deployment scenarios. Finally, competitive pressure from adjacent imaging technologies and integrated capture platforms could limit standalone scanner growth in segments where end-users prefer bundled solutions.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Product strategy should prioritize three areas. First, keep image quality, MICR reliability, and network compatibility at the center of engineering roadmaps, since these capabilities increasingly function as baseline requirements rather than optional features. Second, invest in deployment-friendly design that reduces installation friction, especially for branch and distributed environments where floor space and setup simplicity matter. Third, strengthen channel and integration partnerships so that new models can reach end-users efficiently and align with broader capture ecosystems. Companies that can demonstrate measurable improvements in throughput, ease of use, and compliance-readiness will be better positioned to justify premium positioning in a market that is maturing but still expanding.
For Investors and Market Observers
From an investment perspective, the market's projected mid-single-digit growth path suggests a sector that is expanding steadily rather than erupting explosively, which makes differentiation and execution quality especially important. Attention should focus on manufacturers with clear product continuity, strong distribution reach, and proven alignment with banking workflow needs. It is also worth monitoring how integration-focused players and broader imaging brands compete for the same procurement budgets, since this can influence share dynamics across both specialized and conglomerate competitors. In this environment, value creation is likely to come from companies that can sustain relevance across multiple deployment models while adapting to regulatory and workflow evolution.
For Procurement and Banking Technology Buyers
For institutions evaluating scanner purchases, the priority should be to assess total workflow impact rather than device specifications in isolation. Key considerations include how well a scanner integrates with existing capture and processing systems, whether it meets applicable image quality expectations, how easily it can be standardized across locations, and what service and support model accompanies the hardware. Given the growing variety of form factors and network-capable options, procurement teams should also weigh whether compact desktop solutions, teller-oriented high-throughput units, or network-integrated devices best match the operational profile of each site. Aligning device selection with branch layout, processing volume, and compliance requirements can reduce implementation friction and improve long-term return on deployment.
As the market continues to evolve from basic scanning toward integrated, compliance-aligned capture environments, the strategic picture becomes more nuanced and more opportunity-rich for organizations that have access to detailed, up-to-date segmentation and competitive data. A deeper review of regional and application-level deployment patterns, product roadmap sequencing, and company-level positioning can help decision-makers translate broad market momentum into concrete procurement, investment, and product decisions. For those seeking a more granular view of these dynamics, the full PW Consulting research report provides expanded segmentation detail, competitive profiling, and customized strategic scenarios tailored to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Cheque Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hole Saw Market: Why 6.98% CAGR and Dry Drilling Shift Redefine Growth to 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Hole Saw Market: A 2026 Outlook
The hole saw market has evolved from a steady, utility-driven niche into a dynamic sector shaped by material science advances, changing construction practices, and selective application expansion. Valued at approximately $335.4 million in 2025 and projected to reach $533.6 million by 2032, the market is on a six-year trajectory that reflects a compound annual growth rate near 7 percent. The historical arc from 2020 through 2025 shows a market that recovered from a mid-cycle correction in 2022 and then accelerated, reaching $328.05 million by 2024 before settling into the current base year. This pattern underscores an industry that is no longer defined by incremental volume growth alone, but by structural shifts in how holes are made, where they are made, and by whom.
The broad-based expansion masks an underlying tension: growth is uneven across material segments, usage modes, and end-user profiles. Bi-metal solutions continue to anchor the market with the largest share, supported by versatility across metal and wood applications and sustained demand from professional trades. Carbide teeth have gained traction in rough-in and composite applications where durability and clean cuts matter, while diamond and carbon steel variants serve more specialized roles. On the application side, dry drilling represents the larger pool, reflecting convenience and speed in field conditions, whereas wet drilling remains essential where heat management and tool longevity are critical. Commercial end users account for the majority of demand, highlighting the importance of rental fleets, contracting workflows, and industrial maintenance, while domestic channels contribute a meaningful second tier driven by repairs, renovations, and DIY-adjacent professional work.
Regionally, North America leads with the strongest revenue concentration, followed by Europe and Asia Pacific, which are close in scale but differ in channel maturity and project mix. Latin America and the Middle East and Africa remain smaller but are not irrelevant; they are shaped by infrastructure cycles, public works programs, and localized procurement practices. The competitive field is highly concentrated, with the top three players holding roughly 78 percent of market share and the top five approaching 88 percent. This concentration points to mature branding, established distribution, and strong ties to professional channels, but it also leaves room for differentiation through product design, service ecosystems, and application-specific solutions.
Saw Wire Market
Market Snapshot and Structural Challenges
The hole saw market today operates in a context where demand is reliable but not uniform. The core revenue base is supported by construction, electrical, plumbing, and maintenance activities, yet the rate of adoption varies by material, use mode, and buyer type. A market moving from $335.4 million in 2025 toward $533.6 million in 2032 implies more than incremental expansion; it implies continued rewiring of how hole-cutting tools are specified, stocked, and used. The historical figures between 2020 and 2025 show resilience after a brief contraction in 2022, with a decisive rebound in 2024 and a stable, slightly higher base in 2025. This trajectory sets up a forecast period from 2026 to 2032 that hinges on continued investment in skilled trades, infrastructure maintenance, and productivity-enhancing tooling.
Beneath the growth headline, three challenges shape the market’s next phase. First, the industry faces a durability-versus-cost dilemma. Higher-performance materials and tooth geometries extend service life, but they also increase unit cost and can complicate trade-off decisions for price-sensitive buyers. Second, specification and compliance complexity is intensifying. Public works and utility projects increasingly require precise diameter control, standards alignment, and documented performance, which favors tools and systems that can meet formal requirements rather than generic substitutes. Third, channel and user behavior are fragmenting by use case. Dry drilling remains the larger operational mode, but wet drilling persists where heat, material hardness, or finish quality demand it. This duality creates a need for flexible product lines and clear guidance rather than one-size-fits-all offerings. These challenges are not barriers so much as filters: they separate products that can travel across applications from those that must earn their place in specific workflows.
Key Demand Drivers Shaping the Next Cycle
Technology and material science remain the most direct levers in this market. High-speed steel and HSS-Co grades underpin cutting performance and durability across metal and wood applications, and their continued refinement supports longer life, cleaner cuts, and better resistance to wear in demanding conditions. On the innovation side, bi-metal platforms are being reinforced with tooth designs that reduce breakage and extend useful life, while carbide and diamond variants are pushed into applications where surface quality and tool longevity justify the premium. The emergence of impact-compatible hole saws with quick-change shanks illustrates a broader push toward compatibility with modern cordless ecosystems and faster changeover on site. These advances are not merely engineering details; they translate into fewer interruptions, less waste, and better predictability for professional users who bill by the job.
Policy and specification environments are also shaping demand in subtle but durable ways. In several jurisdictions, hole saw applications are written into construction specifications for service taps on dip water mains and RCP pipes, for sewer main connections, and for utility work where accurate sizing and avoidance of damage are non-negotiable. ANSI-aligned standards and precise diameter control are increasingly referenced in public contracts for concrete and metal hole cutting, and certain stormwater and utility connection contracts explicitly list hole saw cutting as an approved method. For suppliers, this means that documentation, consistency, and compliance-ready performance can become differentiators. It also means that specifications can lock in demand for particular tool classes in recurring public projects, creating steadier usage patterns than purely discretionary construction spend.
Worldwide Wire Saw Market
On the demand side, buyer behavior is shifting toward systems and reliability rather than isolated consumables. Professional electricians, plumbers, and contractors increasingly evaluate hole saws as part of an end-to-end hole-making setup that includes arbors, ejector mechanisms, and kits sized for common tasks. Educational content and practical demonstrations have gained traction as buyers look for techniques that reduce setup time and improve results without additional jigs. At the same time, the growth of cordless tools continues to reshape expectations around weight, access, and speed, pushing accessory suppliers to optimize tooth geometry and slot designs for faster cutting in battery-powered workflows. The domestic segment adds another layer: while smaller in absolute size than commercial demand, it is responsive to renovation cycles, repair activity, and the availability of clear, application-specific kits that reduce guesswork.
Supply-side dynamics reinforce these demand shifts. The material base for hole saws depends on steel grades, coatings, and tooth technologies that must balance performance with cost and availability. Recent trade activity and product stocking decisions indicate that distributors are expanding assortments to cover a broad size range and to surface top-branded options for professional and industrial use. This breadth matters because buyers in maintenance and renovation contexts value immediate availability across common sizes, while industrial buyers prioritize predictable performance and compatibility. At the same time, raw material considerations and manufacturing complexity can affect lead times and margin structure, making inventory positioning and SKU rationalization important levers for competitiveness.
Competitive Landscape and How Leaders Position
The market is anchored by a concentrated set of U.S.-headquartered manufacturers that compete on application fit, durability claims, and brand trust within professional channels. One leading industrial cutting specialist focuses on complete hole saw system solutions, emphasizing bi-metal platforms with reinforced tooth design aimed at reducing breakage and extending service life. This positioning targets buyers who prioritize uptime and predictable performance in metal-cutting workflows. A second major player specializes in bi-metal hole saws and arbors for professional electricians and industrial use, leaning on a clear identity with trade professionals and a focus on accessories that support efficient hole-making. A third well-known power tool brand offers bi-metal and carbide-tooth hole saws with lifetime tooth break warranties, access slot designs, and claims of faster cutting for cordless tools, aligning its accessory line with the broader cordless productivity narrative. A fourth industrial brand supplies hole cutting tools, arbors, and complete systems for plumbing and construction applications, reinforcing a systems-oriented approach for trade workflows.
A fifth manufacturer emphasizes weld-together bi-metal hole saws with variable tooth design for extended life and improved cutting performance, along with heavy-duty kits, appealing to users who need robust. A sixth developer has pushed into impact compatibility for thin metal cutting, introducing quick-change quarter-inch impact shanks and rapid size changes, a move that responds to the practical need for speed and tool interchangeability on active jobsites. A seventh precision toolmaker contributes hole saw sets within a broader industrial portfolio, supporting applications where accuracy and repeatability are paramount. An eighth brand addresses rough-in and demo scenarios with carbide-tooth sets designed for clean boring through wood and nail-embedded materials, reflecting a focus on finish quality and material complexity in residential and light commercial work.
PW Consulting
These leaders differentiate not just on material or tooth count, but on how well their offerings map to recurring tasks and user expectations. Systems thinking is a recurring theme: arbors, ejectors, kits, and warranty language are used to reduce friction and increase confidence. Brand trust and trade-channel relationships remain powerful assets in a concentrated market. At the same time, the competitive landscape is not static. New product launches and stock expansion decisions show that incumbents continue to refresh assortments and add technical touches, while distributors and content creators explore practical techniques that can change how tools are used. The evolution is less about dramatic market disruption and more about layered differentiation: better compatibility with cordless tools, clearer guidance for specific materials, and stronger alignment with specification-driven public work. Consolidation pressure remains high at the top, but there is ongoing room for specialists to capture niches by solving a narrow, high-friction problem exceptionally well.
Forward-Looking Trends and Where Value Is Likely to Accumulate
Over the next three to five years, one durable trend is the continued synchronization of hole saws with cordless and impact-driven workflows. As battery tools become more prevalent in trade settings, accessories that cut faster, reduce binding, and change over quickly will be favored. This favors tooth geometries, slot designs, and shank configurations that are optimized for modern power sources and for reduced setup time. The commercial implication is that accessory portfolios must be evaluated not in isolation, but as part of the tool-using ecosystem, with speed, compatibility, and breakage resilience becoming core purchasing criteria.
A second trend is the rising importance of specification-driven demand in public works and utility projects. Where standards and precise diameter control are written into contracts, tools that can demonstrate conformance and reliable performance will see more predictable repeat demand. This shifts some competition away from pure price toward documentation, consistency, and the ability to support compliance requirements in sewer, water main, and stormwater applications. Suppliers that can map products to common specifications and provide clear technical backing are better positioned to participate in recurring public project spend.
A third trend is the ongoing segmentation of the market by material and use mode, with bi-metal retaining a broad base, carbide and diamond gaining in targeted applications, and carbon steel serving cost-sensitive roles. The practical takeaway is that growth will likely come from better matching of product attributes to defined tasks, not from a single universal solution. Kits that combine common sizes, complementary arbors, and core-ejection features can reduce friction and expand the addressable set of jobs. In parallel, educational and demonstration content will continue to influence adoption by making advanced techniques accessible without specialized jigs.
These trends carry both opportunities and risks. The opportunity lies in product-line clarity, stronger trade and public-sector alignment, and accessory ecosystems that reduce downtime. The risk is over-indexing on premium materials without clear user value, allowing price pressure and channel fragmentation to erode margins. A related uncertainty is the pace of cordless adoption across different trades and geographies, which can shift the relative attractiveness of specific tooth and shank designs. Finally, specification reliance can be a double-edged sword: it creates steady demand where present, but can also slow switching if new tools must pass formal review before substitution is accepted.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen application fit and reduce friction in the field. That means investing in tooth and slot designs that improve speed and breakage resistance for cordless and impact use, while maintaining clear bi-metal platforms for broad metal and wood coverage. Equally important is the surrounding system: arbors, ejectors, sizing ranges, and warranty language that make the product easier to trust and easier to use. Inventory breadth should be balanced with discipline, focusing on sizes and kits that align with high-frequency tasks in trade and maintenance channels. Where possible, technical documentation and compatibility information should be explicit enough to support specification use and to reduce purchase hesitation.
For investors, the market’s concentration and steady growth create a landscape where execution quality matters more than broad category exposure. Value is likely to accumulate where portfolios are tightly aligned with professional workflows, where durability claims are backed by design and documentation, and where accessory ecosystems increase stickiness within trade channels. The spread between dry and wet use modes, and between commercial and domestic demand, suggests that companies with flexible product strategies and strong channel relationships can sustain more predictable revenue than those dependent on narrow, cyclical segments. Monitoring specification adoption in utility and public works, cordless compatibility trends, and distributor assortment decisions will provide early signals of where demand is heading.
For procurement and operations leaders, the practical mandate is to standardize around tools and systems that reduce changeover time and improve result consistency. Preference should be given to offerings that support common tasks, offer clear diameter control, and come with documentation suitable for specification environments when relevant. Kit-based purchasing can lower error rates and simplify stocking for frequent jobs, while impact-compatible and quick-change designs can improve throughput in battery-powered workflows. In specification-driven projects, confirming that tooling meets referenced standards and diameter requirements should be part of procurement checks, not an afterthought.
For leaders seeking to move faster with segment-level detail, sizing distributions, regional channel dynamics, and supplier-by-supplier positioning, a complete research report is available. It provides granular breakdowns across type, application, end-user, and region, along with company profiles and recent market developments that support scenario planning and market-entry decisions. Accessing that detail enables more precise sizing of opportunities, sharper competitive benchmarking, and customized recommendations aligned with specific product strategies and buyer contexts.
For detailed analysis of this topic, please visit the official page: Hole Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bone Cement Market: 5.8% CAGR Trajectory and 2032 Outlook Beyond the Numbers
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Global Bone Cement Market
The global bone cement market has evolved from a mature, commoditized segment into a dynamically regulated and clinically critical component of orthopedic and spinal care. Valued at approximately $1,226.41 million in 2025, the market has demonstrated consistent expansion over the 2020–2025 period, building on a 2020 baseline of $986.72 million. Forward projections through 2032 place the market at $1,823.54 million, reflecting a compound annual growth rate of 5.8 percent. This trajectory is not merely a function of aging demographics or surgical volume growth; it reflects a structural recalibration driven by clinical outcomes, regulatory tightening, supply chain fragility, and targeted reimbursement shifts. For executives, investors, and procurement leaders, the market presents clear expansion signals but also demands disciplined attention to resilience, differentiation, and compliance readiness.
The current landscape is defined by concentrated market power, wide product divergence, and a sector-wide reckoning with operational vulnerability. Understanding where value will accrue over the next several years requires moving beyond headline market size and examining the underlying forces reshaping procurement, R&D prioritization, and competitive positioning.
Market Landscape and Core Pressures
The bone cement market operates at the intersection of orthopedic reconstruction, trauma fixation, and vertebral augmentation. Historical performance from 2020 through 2025 shows a market that has absorbed inflationary pressures on raw materials, adapted to evolving regulatory expectations, and navigated shifting surgical preferences. The 5.8 percent CAGR projected across 2026–2032 indicates steady, not explosive, expansion. Such growth requires durable clinical adoption, predictable reimbursement pathways, and manufacturing reliability rather than purely volume-driven expansion.
Three structural challenges currently shape strategic decision-making across the value chain:
- Supply concentration and operational fragility: Highly consolidated supply bases create single points of failure. When a major production site experiences packaging faults, sterilization delays, or logistics disruptions, downstream surgical schedules, hospital procurement plans, and regional formularies can be disrupted within weeks. The February 2026 Heraeus Medical production interruption, which temporarily halted pouch bone cement output and delayed first global releases until late June 2026, illustrates how quickly supply reliance can expose procurement vulnerability.
- Regulatory burden and certification timelines: The transition from legacy device frameworks to stricter conformity assessments has raised the bar for market entry and product retention. Manufacturers must align formulation consistency, packaging integrity, traceability, and clinical documentation across jurisdictions. Compliance is no longer a checkbox exercise; it determines which products remain eligible for hospital tenders and which can be marketed across border regions without rework.
- Reimbursement pressure and value-based procurement: Health systems increasingly scrutinize implant and cement selection through total episode-of-care lenses rather than unit price alone. Even where add-on payments or technology-specific coverage exist, procurement teams compare clinical handling characteristics, infection management implications, radiopacity, viscosity profiles, and compatibility with delivery systems. The market rewards products that reduce revision risk, simplify intraoperative workflow, and support predictable supply conditions.
Key Drivers Reshaping the Market
Technological Innovation and Product Differentiation
Innovation in bone cement is increasingly oriented toward clinical reliability and surgical workflow rather than generic material substitution. High- and low-viscosity formulations, radiopaque integration, antibiotic loading strategies, and controlled handling windows are central differentiators. Advances in delivery systems, mixing consistency, and packaging design directly affect intraoperative ease and waste reduction. Products designed to support infection management while maintaining mechanical fixation properties are gaining attention, particularly in arthroplasty and trauma applications where postoperative complications carry high downstream costs.
The February 2026 Biocomposites launch of SYNICEM high- and low-viscosity gentamicin-loaded variants in the UK market demonstrates how targeted product availability can serve both clinical continuity and supply diversification. Similarly, the August 2025 CMS approval of CERAMENT G for New Technology Add-On Payment, providing up to $5,687.50 in additional reimbursement when costs exceed thresholds for open fractures, signals that reimbursement mechanisms can materially influence the commercial pull of differentiated bone cement products. Technology that aligns clinical benefit with reimbursable pathways is better positioned for sustained adoption.
Policy, Regulation, and Compliance-Driven Competition
Regulatory frameworks are reshaping competitive standing. Certification under updated medical device regulations, 510(k) clearances, and re-certifications of legacy product lines affect which companies can scale regionally without interruption. The February 2025 MDR certification for Heraeus Medical’s COPAL G+V Bone Cement and the May 2025 FDA 510(k) clearance for Teknimed F20 bone cement used with the VCFix Spinal System highlight how regulatory achievements act as commercial enablers, not administrative formalities.
For manufacturers, regulatory readiness determines market access windows. For buyers, certifications influence procurement risk and tendering eligibility. The practical implication is that compliance sophistication increasingly separates suppliers that can maintain uninterrupted hospital supply from those dependent on stopgap arrangements.
Demand-Side Shifts in Surgical Practice and Health System Procurement
Surgical demand continues to be shaped by the rising prevalence of osteoarthritis, fragility fractures, and vertebral compression fractures, alongside broader access to joint replacement and spinal augmentation procedures. Yet demand is not uniform across indications. Arthroplasty remains the dominant application, but vertebral augmentation and kyphoplasty continue to draw procedural growth in aging populations, particularly where minimally invasive stabilization is favored.
At the same time, procurement behavior is shifting toward resilience. NHS England’s February 2026 update detailing alternative supply arrangements from Zimmer Biomet and Johnson & Johnson in response to Heraeus constraints illustrates how health systems now treat multi-sourcing, qualification of alternate products, and regional stock buffering as operational necessities. Demand-side behavior is therefore reinforcing supply diversification, qualification readiness, and preference for products with proven handling profiles and delivery system compatibility.
Supply Chain Dynamics and Cost Structure Realities
Bone cement manufacturing relies on resin chemistry, powder-liquid blending precision, sterilization, packaging, and cold-chain or controlled storage considerations where applicable. Cost structures are sensitive to raw material volatility, packaging integrity requirements, and batch consistency. The Heraeus packaging fault demonstrates that even high-quality formulations can be constrained by downstream packaging logistics rather than the cement chemistry itself. For suppliers, the implication is that process control across the full production and packaging chain is a commercial asset, not merely an operational concern.
PW Consulting
For buyers, cost management increasingly involves total cost of procedure rather than cement unit price. Product consistency, reduced waste, reliable delivery, and minimized risk of substitution delays all contribute to cost outcomes that matter to finance and clinical leadership alike.
Synthetic Bone Graft Market
Competitive Landscape and Strategic Positioning
The market is moderately concentrated. The combined share of the top three competitors is approximately 49.5 percent, while the top five reach about 68.2 percent. This concentration reflects the presence of established orthopedic and spinal device leaders, but it also leaves meaningful room for specialized players with strong regional footing, differentiated infection-control offerings, or focused vertebral augmentation solutions.
Leading companies have carved out positions through product families, indication focus, and supply reliability strategies:
- Heraeus Medical has built recognition around high-viscosity antibiotic-loaded PMMA options, including Palacos, COPAL, and Refobacin. Its positioning ties closely to arthroplasty and trauma fixation, and its MDR certification of COPAL G+V in February 2025 reinforced compliance readiness even as the February 2026 packaging disruption exposed supply vulnerability.
- Zimmer Biomet supplies Biomet Bone Cement and Refobacin Bone Cement for joint arthroplasty. Its role as an alternative supplier for NHS England in February 2026 highlights how established portfolios can gain procurement traction during constraint events when alternate products are already qualified or rapidly deployable.
- DePuy Synthes (Johnson & Johnson) offers SMARTSET and DePuy CMW bone cements for hip and knee procedures. As part of a broader orthopedic reconstruction ecosystem, its strength lies in integrated procedure support and the ability to serve as a qualified alternate when supply disruptions affect other vendors.
- Stryker emphasizes KYPHON and Simplex P bone cements for vertebroplasty and orthopedic fixation. Its relevance in spinal augmentation and targeted vertebral applications gives it a differentiated angle within a broader musculoskeletal portfolio.
- Tecres S.p.A. focuses on radiopaque PMMA bone cements and delivery systems for arthroplasty. The September 2025 acquisition of majority assets from Next Science LTD expanded its orthopedic infection control footprint, signaling a strategic move toward portfolio depth and infection-related differentiation.
- Biocomposites has strengthened its profile through SYNICEM high- and low-viscosity antibiotic-loaded cements for orthopedic infection management. Its accelerated UK launch in February 2026 underscores how specialized antibiotic-loaded options can move from long-term product strategy to immediate supply continuity tool during national constraints.
- OsteoRemedies LLC provides SPECTRUM and related PMMA bone cements for orthopedic and joint replacement use, positioning within a competitive arthroplasty-focused segment where reliability and handling matter.
- Medtronic Sofamor Danek supports vertebroplasty and spinal augmentation through KYPHON HV-R and ACTIVOS bone cements, reinforcing a spinal intervention orientation aligned with vertebral augmentation demand.
- Arthrex, Inc. offers G3 40 and G3A 40 radiopaque and gentamicin-loaded PMMA options for joint and shoulder procedures, highlighting niche procedural relevance and antibiotic-loading differentiation.
- Amber Implants combines Teknimed F20 PMMA bone cement with the VCFix Spinal System for vertebral fracture treatment. FDA 510(k) clearance in May 2025 for this combination reflects how system-plus-cement positioning can shape adoption in vertebral fracture workflows.
The competitive evolution is trending toward three overlapping dynamics. First, integration continues as larger portfolios add infection-control assets and cement-plus-delivery combinations, a pattern reinforced by Tecres’ September 2025 acquisition. Second, differentiation is sharpening around viscosity options, radiopacity, antibiotic loading, and intraoperative handling rather than commodity substitution. Third, new entrants and regional specialists remain viable where they can serve localized supply needs, provide niche antibiotic-loaded formulations, or fill qualification gaps during disruption events. The practical lesson is that competitive advantage in this market increasingly depends on the ability to maintain certification continuity, demonstrate handling reliability, and qualify alternative supply pathways before crises occur.
Forward Outlook and Commercial Opportunities
Trend 1: Resilience as a Procurement Criterion
Over the next three to five years, hospital systems and regional procurement groups are likely to treat supply resilience as a primary purchasing criterion alongside clinical performance. The February 2026 disruption and the rapid qualification of alternative products show that buyers are reassessing single-source dependency, stock buffers, and secondary supplier readiness. Commercial opportunity lies in suppliers that can offer dual-source compatibility, predictable batch integrity, packaging reliability, and transparent lead-time communication. Manufacturers that proactively support qualification of alternate SKUs or interoperable delivery systems may gain preferential placement in future tenders.
Trend 2: Differentiation Through Infection Management and Clinical Workflow
Antibiotic-loaded formulations, viscosity options tailored to procedural needs, and cement-plus-delivery system designs are likely to command stronger commercial interest where they reduce complication risk and simplify surgical handling. The accelerated UK launch of gentamicin-loaded SYNICEM variants and CMS coverage support for differentiated open-fracture products indicate that reimbursement and clinical need can reinforce each other when product evidence and handling advantages align. Companies that invest in evidence generation, procedural compatibility, and packaging or mixing consistency are better positioned to capture value beyond base volume growth.
Trend 3: Regulatory Licensing as Strategic Gatekeeping
Certification events are becoming commercial inflection points. MDR certification, FDA 510(k) clearances, and re-certification of legacy lines determine whether products remain on formulary, can be tendered across regions, and can be scaled during disruption. Expected regulatory scrutiny on packaging, traceability, and documentation will likely reward manufacturers with mature quality systems and penalize those with unresolved compliance gaps. For investors and strategists, regulatory readiness is a leading indicator of market access durability.
Potential risks and uncertainties include continued raw material volatility, disruption of packaging or sterilization lines, uneven reimbursement adoption across regions, and the possibility that procedural mix shifts could alter demand intensity for specific cement types. Health systems may also adopt stricter value-based criteria that compress margins unless manufacturers can demonstrate differentiated clinical or workflow benefits.
Strategic Recommendations for Decision Makers
For Manufacturers
- Treat production and packaging control as a competitive asset. Quality systems should extend beyond formulation to include packaging integrity, release consistency, and rapid escalation protocols. Disruption response capability is now part of product value proposition.
- Build multi-indication and multi-viscosity portfolios deliberately. Products that support both arthroplasty and spinal applications, or that offer antibiotic-loaded and standard formulations with compatible delivery systems, can capture broader procurement relevance and improve resilience during regional constraints.
- Align regulatory and reimbursement strategy early. Certification milestones and coverage decisions should inform launch sequencing, indication prioritization, and commercial messaging. Where add-on payment pathways exist, evidence generation and coding readiness can materially improve adoption.
For Investors
- Prioritize companies with certification continuity, diversified supply options, and differentiated infection-control or spinal-augmentation positioning. Market growth will be uneven, and durable value is more likely where regulatory readiness and product differentiation reduce exposure to single-point supply failures.
- Assess supply-chain exposure as part of valuation. Manufacturing concentration, packaging dependency, and regional qualification readiness can materially affect revenue continuity. Disciplined due diligence should include scenario planning around disruption events similar to the February 2026 production halt.
For Procurement and Health System Leaders
- Formalize alternate supplier qualification before constraints emerge. Pre-qualification of compatible products, delivery systems, and antibiotic-loaded variants reduces procedural disruption when primary supply is delayed.
- Evaluate total procedural cost and workflow impact alongside unit price. Cement consistency, intraoperative handling, packaging reliability, and supply predictability influence operating room efficiency and downstream complication risk, which often carry greater financial impact than cement price alone.
For executives and investors seeking segmentation-level revenue splits, regional growth sensitivities, detailed company positioning, and scenario modeling across supply disruption and regulatory timelines, deeper data and customized analysis are essential. PW Consulting’s full research report provides granular market sizing, segmentation detail, competitive benchmarking, and procurement strategy frameworks to support planning beyond the aggregate trends outlined here.
Bone Cement for Spine Market
For detailed analysis of this topic, please visit the official page: Bone Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Travel Insurance Market: How 5.7% CAGR and $32B Demand Reshape Competition
By PW Consulting, 2026-09-21
Mapping the Next Decade of Global Travel Insurance: Strategic Shifts and Commercial Opportunities
The global travel insurance market has moved from a cyclical, trip-specific accessory to a structural component of the broader mobility and risk management ecosystem. Evaluating the historical trajectory from 2020 through 2025 alongside the forecast window extending to 2032 reveals a market that has consistently expanded, with a projected compound annual growth rate of 5.7 percent across the 2026 to 2032 period. Measured in billions of U.S. dollars, the revenue base has climbed steadily, positioning the category at a scale where operational efficiency, distribution innovation, and product differentiation increasingly determine competitive advantage.
This expansion is not occurring in a vacuum. It reflects the convergence of higher travel volumes, elevated consumer expectations around seamless protection, and a industry-wide reckoning with claims processing economics. The market structure is moderately consolidated, with a small group of carriers accounting for the majority of premium volume. That concentration signals both the maturity of core risk underwriting capabilities and the opportunity for agile players to capture share through niche positioning, embedded distribution, and technology-led cost compression.
Business Travel Insurance Market
The State of Play and the Turning Points Shaping Strategy
Several structural tensions define the current market environment. First, claims management remains the dominant cost center across the value chain. A significant share of operational budgets is directed toward adjudication, documentation, and administrative handling, creating a structural drag on margin expansion. Second, regulatory and compliance complexity is intensifying across multiple jurisdictions, with obligations accumulating across authorities and increasing the total cost borne by insurers and, indirectly, by customers. Third, customer acquisition and distribution are shifting from standalone point-of-sale transactions toward embedded, context-aware placements within booking flows, financial platforms, and corporate travel programs. These three dynamics are not isolated; they interact to reshape where value is created and captured.
Pet Insurance Market
For decision-makers, the practical implication is that growth alone no longer guarantees profitability. The market is large enough that incremental premium gains can be offset by claims leakage, compliance overhead, or inefficient distribution. Strategy must therefore combine disciplined underwriting with cost-side optimization and distribution that reduces friction at the moment of need.
Core Drivers Redefining the Market
Technology-Enabled Underwriting and Claims Execution
Digital capabilities are becoming the primary lever for both customer experience and cost structure. Carriers are deploying parametric triggers, automated triage, and API-connected assistance to compress settlement timelines and reduce administrative load. Products that embed directly into airline, agency, or corporate booking processes can issue coverage and, where applicable, trigger rapid refunds or guarantees without the traditional documentation-heavy workflow. This shift is particularly relevant in a category where a substantial portion of spend historically flowed to claims processing and its associated administrative overhead.
The commercial logic is straightforward. When coverage decisions, validations, and assistance interventions are digitized and linked to real-time signals, insurers can improve straight-through processing, lower manual review, and strengthen customer trust through speed. Those gains compound when the same technology stack supports multiple products and channels, allowing carriers to scale without proportionally scaling back-office cost.
Regulatory and Compliance Pressure as a Strategic Variable
Regulation is no longer a peripheral compliance issue; it is a structural input into product design, data handling, and operational governance. Authorities are scrutinizing third-party data feeds, cloud dependencies, and automated decisioning more closely, while accumulated obligations across multiple regulators add measurable cost to the system. In parallel, reimbursement and administrative processes continue to place load on healthcare and support networks, which indirectly raises the importance of streamlined coverage design and clear claims pathways.
For insurers, the strategic response involves more than legal review. It requires data governance architectures that can withstand audit scrutiny, transparent logic for automated decisions, and product structures that minimize unnecessary friction for legitimate claims. Companies that treat compliance as a design constraint—rather than a retroactive fix—can reduce rework, accelerate market entry for new products, and avoid the hidden costs of fragmented data practices.
Demand-Side Behavioral Shifts Across Consumer and Corporate Travel
Travel patterns and protection expectations have evolved. International travel remains a significant share of the category, while single-trip coverage continues to anchor a large portion of demand alongside growing interest in multi-trip and long-stay options for mobile populations. The rise of extended stays, flexible itineraries, and digitally enabled work travel has expanded the relevance of products that can adapt to changing trip structures without forcing customers into rigid plans.
On the corporate side, business travel platforms are increasingly integrating medical, baggage, and disruption coverage directly into the booking and management experience. This reflects a broader expectation: protection should be available at the point of decision, with minimal deviation from the primary workflow. For insurers, this means distribution value is shifting toward partnerships that can deliver context-aware coverage at scale, rather than relying solely on traditional agent or direct-channel purchase journeys.
Cost Structure and the Push for Efficiency
Operational economics remain a defining constraint. The sector continues to allocate heavy resources to claims and its administrative layer, which makes cost discipline a competitive differentiator. Carriers are responding by rethinking process design, automating routine adjudication, and restructuring assistance networks to reduce handoffs. At the same time, pricing transparency is gaining importance, with consumers and corporate buyers alike comparing the daily or trip-level cost of coverage against the breadth of benefits.
The efficiency imperative is shaping portfolio strategy. Products that are over-engineered relative to their risk profile can erode margin, while lean, well-targeted offerings with clear benefit definitions can improve both acquisition and retention. The winners are likely to be those that align product complexity with actual claim patterns and customer usage, rather than building coverage layers that inflate cost without commensurate value.
Competitive Landscape and How Leaders Are Positioning
Incumbent Scale and Portfolio Expansion
Large, diversified carriers continue to anchor the market through broad product suites that span medical coverage, trip cancellation, business travel plans, and global assistance. Their advantage lies in scale, established distribution relationships, and the ability to integrate travel protection into wider enterprise and consumer insurance portfolios. Recent moves to acquire regional portfolios and white-labeled distribution agreements illustrate a strategy of consolidating reach, expanding intermediary access, and capturing established customer flows in key geographies.
This consolidation trend signals that scale players are willing to invest in distribution depth and brand presence where they see durable demand. For competitors, the implication is clear: head-to-head battles on generic coverage are increasingly difficult. Differentiation must come from targeted use cases, superior service models, or distribution advantages that are difficult to replicate.
Specialists and Niche Positioning
A parallel set of players has built strength around specific traveler profiles and coverage priorities. Some focus on high medical limits and group or family structures, others on adventure activities, cruise-specific benefits, or digital nomad itineraries. These specialists often compete on flexibility, clarity of benefits, and alignment with the lifestyle or operational realities of their audiences. Their growth reflects a broader market truth: travelers increasingly evaluate coverage against their actual exposure and usage patterns, not against a one-size framework.
Niche positioning can be durable when it is tied to a genuine risk gap or an underserved travel style. However, it also requires disciplined underwriting and efficient service delivery, because smaller scale can magnify the impact of claims leakage or distribution inefficiency. The most effective specialists combine focused product design with strong operational execution and selective distribution partnerships.
PW Consulting
Embedded Distribution and Parametric Innovation
A notable shift is the move toward coverage that sits inside the transaction flow rather than outside it. Digital parametric products and integrated assistance services are being positioned within airline, agency, and financial institution journeys, enabling immediate benefit triggers such as refunds, weather-related guarantees, and emergency support. Alongside this, business travel platforms are embedding medical and baggage coverage directly for corporate users, reducing the need for separate purchase steps.
This embedded and parametric direction changes the competitive basis. Speed, integration quality, and the reliability of trigger logic become as important as the breadth of coverage. Carriers that can partner effectively with platforms and bookers—while maintaining underwriting integrity and clear customer communication—can secure repeated exposure to high-intent moments. That repeated exposure is valuable because it aligns protection with intent, improving both conversion and relevance.
Concentration, Consolidation, and New Entry Dynamics
The market remains moderately concentrated, with a limited number of carriers commanding a substantial share of premium. That concentration is likely to persist, but it does not imply stagnation. The landscape is evolving through acquisition on one hand and specialized entry on the other. Larger players are expanding portfolios and distribution footprints, while newer and smaller entrants are carving out segments defined by traveler type, coverage philosophy, or distribution model.
This dual dynamic has strategic consequences. For incumbents, the challenge is to absorb new capabilities and geographies without diluting service quality or compliance standards. For entrants, the challenge is to avoid competing purely on price in commoditized segments and instead build defensibility through product clarity, partner ecosystems, or technology that lowers the cost to serve. The market is therefore likely to continue differentiating into broad-scale portfolios and targeted offerings, with the line between them shifting as distribution and technology lower barriers to specific use cases.
Forward Outlook: Three Trends Shaping the 2026 to 2032 Horizon
Embedded, Context-Aware Protection Will Become the Default Entry Point
Over the next several years, a growing share of coverage will be initiated within the booking, corporate travel, or financial services journey rather than through standalone searches. This trend is driven by the alignment of intent and purchase, the demand for speed, and the operational desire to reduce friction. For insurers, the opportunity lies in building APIs, integration standards, and partner relationships that make coverage easy to surface at the right moment. The risk is that poorly integrated offers create noise, reduce trust, or fail to match the traveler’s actual exposure, which can erode the very advantage embedded distribution is meant to create.
Parametric and Automated Benefit Structures Will Expand Where Triggers Are Reliable
Parametric designs and automated assistance are likely to grow in segments where external signals can be used credibly and transparently, such as weather events, delays, and defined disruption scenarios. These structures can reduce documentation burden and accelerate resolution, which is attractive in a cost environment where administrative load is a persistent concern. The limitation is that parametric logic must be carefully designed to avoid misalignment with customer expectations or regulatory scrutiny. Where triggers are ambiguous or perceived as unfair, the model can generate dissatisfaction and reputational risk, so the opportunity is strongest where the basis for payment is clear and verifiable.
Cost Discipline and Portfolio Focus Will Separate Margin Leaders from Volume Chasers
Because a large share of spend continues to flow through claims and its administrative handling, companies that reduce rework, improve triage, and align product complexity with actual usage will gain margin resilience. This favors portfolios with clear benefit definitions, targeted distribution, and a disciplined approach to coverage layers. The uncertainty is that macroeconomic pressure on travel spending, regulatory changes, and data governance requirements can alter the cost base unexpectedly. Organizations that treat efficiency as a continuous capability—rather than a one-time initiative—will be better positioned to protect profitability as the market scales.
Strategic Implications for Decision-Makers
For Carriers and Product Leaders
- Prioritize integration readiness. Build the data, API, and partner capabilities needed to place coverage within booking and corporate travel flows without compromising underwriting quality or customer clarity.
- Reconstruct claims economics. Target the administrative portion of claims spend through automation, standardized documentation, and smarter triage, while maintaining fairness and transparency for legitimate claims.
- Design for real usage. Align benefit structures with how travelers actually move—single trips, repeated short trips, extended stays, and activity-specific exposure—so product complexity supports value rather than inflating cost.
For Investors and Capital Allocators
- Look beyond top-line growth. Evaluate carriers on claims efficiency, distribution quality, and regulatory readiness, since these factors increasingly determine whether premium growth converts into sustainable earnings.
- Favor scalable differentiation. Models that combine niche alignment with technology-led cost compression, or that secure durable embedded distribution, are more likely to defend margins than pure price-based entries.
- Watch consolidation carefully. Acquisitions that expand distribution and regional reach can create value, but integration risk and compliance readiness should be assessed as part of the thesis, not as afterthoughts.
For Corporate Buyers and Distribution Partners
- Treat travel protection as workflow design. The greatest value comes from coverage that fits naturally into booking, travel management, and assistance processes, reducing time and confusion for travelers and administrators alike.
- Clarify exposure before selecting coverage. Match benefit scope to the actual mix of trip types, durations, and traveler profiles, avoiding over-insurance in low-risk segments and under-coverage where exposure is concentrated.
- Demand transparency and reliability. Evaluate partners on the clarity of benefit triggers, speed of assistance, and the robustness of data and compliance practices, since these attributes shape both traveler trust and operational risk.
The market’s scale and growth trajectory create room for multiple winners, but the distribution of value will depend on execution quality. Carriers and partners that combine disciplined underwriting, efficient claims operations, and well-integrated distribution are best positioned to convert expanding demand into durable advantage. For those evaluating entry, expansion, or partnership decisions, the next step is to map the specific segment economics, regional nuances, and competitive moves that will shape outcomes in the coming years. Detailed segmentations, company-level comparisons, and tailored strategic recommendations are available in the full research report, which provides a deeper breakdown of the structures and trade-offs behind these market-level trends.
For detailed analysis of this topic, please visit the official page: Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PC Power Supply Market: Why 4.89% CAGR Growth Redefines the $230.67M Landscape
By PW Consulting, 2026-09-21
The PC Power Supply Market: Strategic Trends and Commercial Opportunities (2026–2032)
The PC power supply market is entering a phase of structured growth defined by efficiency mandates, connector standardization, and shifting workload profiles. Valued at 230.67 million USD in 2025 and projected to reach 322.2 million USD by 2032, the segment will expand at a compound annual growth rate of 4.89 percent between 2026 and 2032. Historical data traces a clear inflection: 163.15 million USD in 2020, a brief contraction to 173.29 million USD in 2022 amid component shortages and demand reallocation, followed by a recovery to 193.0 million USD in 2023 and steady acceleration through 195.33 million USD in 2024. The base-year trajectory to 230.67 million USD reflects a market that has absorbed supply chain volatility and now operates with more predictable capacity. The forecast stretch to 2032 indicates that volume growth will be supported by specification upgrades rather than raw unit proliferation alone.
Market concentration remains moderate. The top three players hold approximately 37.5 percent of revenue, while the top five account for 45.0 percent. This structure leaves meaningful headroom for regional specialists, application-focused entrants, and companies that can align product roadmaps with the evolving requirements of desktop and workstation builds. The industry is not yet dominated by a single architecture or a handful of incumbents; instead, it rewards firms that can translate efficiency targets, connector changes, and power density goals into reliable, cost-competitive offerings.
Core Challenges and Inflection Points
Three tensions shape near-term strategy. First, the transition from legacy ATX specifications to ATX 3.1 reshapes both component requirements and system-level validation. The September 2023 specification introduced the 12V-2x6 connector and mandated a maximum hold-up time of 12 milliseconds to manage GPU power excursions. This change is not cosmetic; it forces revisions in magnetic component selection, control loop tuning, and thermal design. Products that merely meet nominal wattage targets without addressing transient response and connector safety margins face qualification delays and elevated return risk.
Second, raw material and component pricing adds pressure to cost structures. The passive component raw material price index—covering nickel, copper, aluminum, zinc, palladium, ruthenium, tantalum, silver, and oil—stood at 3,399 per index unit in November 2025, an 8 percent increase from April 2012 levels. At the same time, ferrite core prices in the PC PSU supply chain surged 22 percent year-over-year in the first quarter of 2025 due to supply disruptions at Asian producers. These movements compress margins on commodity-oriented lines and reward manufacturers with disciplined bill-of-materials management, dual-source strategies, and design choices that reduce sensitivity to specific magnetic materials.
Third, regulatory pressure is tightening on no-load efficiency and standby consumption. The European Ecodesign Directive and California’s Title 20 are raising the bar for off-load performance, which in turn drives adoption of digital control loops and synchronous rectification. This shift improves efficiency across the operating envelope but raises design complexity and upfront engineering investment. Companies that treat compliance as a checkbox rather than a platform opportunity will find themselves lagging in qualification cycles and total cost of ownership narratives.
Key Drivers Reshaping the Market
The market’s direction is being pulled by a small set of forces that interact with each other more than they operate in isolation. Understanding these drivers helps clarify where value creation is concentrated and where cost and timing risks accumulate.
Technology Innovation and Breakthroughs
ATX 3.1 compatibility and PCIe 5.1 readiness now define what “modern” means in this segment. The 12V-2x6 connector reduces resistance and improves safety during high-current transients, while the 12-millisecond hold-up requirement stabilizes system behavior under sudden GPU load spikes. Manufacturers have responded with fully modular ATX 3.1 designs that pair higher efficiency tiers with cleaner internal layouts. FSP Group, for example, unveiled the FSP2000-57APB 2000W ATX 3.1 flagship power supply for on-premise computing and AI workloads in May 2026, signaling that high-wattage units are moving from enthusiast enclaves into broader workstation and on-prem contexts. Corsair introduced updated HX1500i and RMe series PSUs in February 2026 that are fully compliant with ATX 3.1 and PCIe 5.1, showing that mainstream performance lines are also standardizing on the new specification. These launches illustrate a market where compliance is becoming table stakes and differentiation shifts toward wattage scalability, thermal management, and user-serviceable modularity.
Policy and Regulatory Environment
Efficiency mandates are compressing the lower end of the performance spectrum and encouraging smarter control architectures. Tightened no-load efficiency limits under the European Ecodesign Directive and California’s Title 20 are driving adoption of digital control loops and synchronous rectification in PC PSUs. Digital control improves dynamic response, simplifies calibration across production lots, and supports more granular efficiency mapping. Synchronous rectification lowers conduction losses in the conversion stage, which matters most at partial loads where many systems spend much of their operating time. The regulatory direction is clear: idle and light-load performance will increasingly determine market acceptance, especially in regions where energy cost sensitivity and labeling requirements are strong. This environment benefits firms that can amortize control-platform development across multiple wattages and form factors.
Demand-Side Shifts in Consumer and Enterprise Behavior
Desktop and workstation builds are converging around higher power envelopes, which changes how PSUs are specified and purchased. High-end gaming rigs, content creation workstations, and increasingly capable on-premise computing setups are pushing users toward units that handle transient loads cleanly rather than simply rating high on a steady-state curve. At the same time, the rising popularity of fully modular cables and low-noise operation reflects a consumer base that values serviceability, cable management, and acoustic comfort alongside raw efficiency. Industry activity around trade shows underscores this demand pull. Huntkey showcased innovative high-efficiency PC power supplies at COMPUTEX Taipei 2025 with a focus on AI and gaming applications, while Lite-On Technology demonstrated integrated power solutions for AI data centers and high-performance PCs at COMPUTEX 2026. be quiet! launched the Pure Power 13 M and Titan PLA series ATX 3.1 PSUs in May 2026 with enhanced quiet operation and modular design, aligning product messaging directly with the performance-and-noise trade-off that end users and system integrators now prioritize.
Supply Chain and Cost Structure Dynamics
Cost behavior in magnetics and passive components is reshaping sourcing and design decisions. Ferrite core price increases and the broader passive component index uptick have made it more expensive to rely on generic, high-volume magnetic components without careful design optimization. In response, leading suppliers are pairing efficiency certifications with design choices that reduce material sensitivity, such as tighter integration of digital control, better utilization of synchronous rectification, and more compact thermal paths that allow smaller or fewer heat-stressed elements. The practical implication is that cost leadership now depends on engineering leverage as much as on purchasing scale. Companies that can hold efficiency ratings while reducing bill-of-materials volatility are better positioned to protect margins through cycles of input-price fluctuation.
Competitive Landscape and Leading Strategies
The competitive field includes established premium brands, efficiency-focused specialists, and regional manufacturers expanding their application coverage. The top three firms hold roughly 37.5 percent of revenue, and the top five hold 45.0 percent, indicating that concentration is significant but not prohibitive. This leaves space for differentiation through specification alignment, acoustic performance, modularity, and application-specific features.
PW Consulting Chemical & Energy Research Center
FSP Group operates from Taiwan and has emphasized full modular ATX 3.1 and PCIe 5.1 ready PSUs with 80 Plus Titanium and Cybenetics Titanium efficiency, including flagship models such as the MEGA TI 1650W and VITA GM 1000W. Its May 2026 unveiling of the FSP2000-57APB 2000W ATX 3.1 unit for on-premise computing and AI workloads suggests a strategy that extends high-efficiency modular platforms into higher wattages aimed at heavier workloads. Seasonic, based in Japan, positions around premium fully modular ATX 3.1 compliant PSUs with 80 Plus Platinum and Cybenetics Titanium ratings, including the Prime TX and Vertex series. This profile emphasizes consistency and efficiency credibility in the upper tier of the performance spectrum. be quiet! from Germany focuses on the Dark Power series and Pure Power 13 M PSUs with high-efficiency Gold to Titanium ratings meeting ATX 3.1 standards, with the Pure Power 13 M and Titan PLA series launched in May 2026 highlighting enhanced quiet operation and modular design. For this player, acoustic advantage and user experience are central differentiators. Corsair in the United States offers HX-i, RMx and RMe modular ATX 3.1 PSUs with 80 Plus Platinum and Cybernetics Platinum efficiency for high-end gaming and workstation builds; its February 2026 updates to the HX1500i and RMe series reinforce a strategy centered on specification compliance and the enthusiast-to-workstation bridge.
External AC-DC Power Supply Market
The broader field includes Super Flower from Taiwan, with Leadex Titanium and VII Platinum PRO series offering full modular design, 80 Plus Titanium and Cybenetics Platinum certifications, and PCIe 5.1 support; Lite-On Technology from Taiwan, providing ATX and SFX PC power supply modules with output up to 2200W, Platinum efficiency, and full-range input for desktop and workstation applications; AcBel Polytech Inc. from Taiwan, offering industrial and consumer PC PSUs with CRPS and slim designs up to 3200W, 80 Plus Titanium efficiency, and redundancy features; Delta Electronics from Taiwan, supplying desktop and workstation switching PSUs with high efficiency, 80 Plus ratings, and ATX 3.1 support; ASRock from Taiwan, with Steel Legend SL and Phantom Gaming modular PSUs featuring ATX 3.1 compliance, Gold to Platinum efficiency, and PCIe 5.1 support; Huntkey from China, presenting high-performance PC power supplies showcased at Computex with innovative designs for gaming and workstation applications; Enermax from Taiwan, with Revolution III fully modular ATX 3.1 and PCIe 5.1 PSUs emphasizing high efficiency and low noise operation; and SilverStone from Taiwan, with SX and SX Pro series high-wattage Platinum PSUs featuring modular cables and ATX 3.1 compliance.
Strategically, the leaders are converging on a few common moves while preserving distinct advantages. Full modular ATX 3.1 compliance and PCIe 5.1 readiness are becoming baseline expectations for mid-to-high-end lines. Efficiency credentials spanned by 80 Plus and Cybenetics ratings are used to signal reliability and operational cost savings rather than as isolated badges. Acoustic engineering remains a differentiating lever for brands that can credibly claim low noise under load. At the same time, several players are extending into higher wattages and application-specific features, such as redundancy for industrial contexts or integrated power solutions for AI-oriented setups. This pattern points to gradual consolidation among suppliers that can sustain multi-wattage platforms, while niche entrants continue to compete on form factor, noise, and specialized industrial or workstation requirements. New entry is most viable where a firm can solve a specific pain point—such as transient response, cable serviceability, or acoustic performance—without needing to match the full breadth of a platform leader.
Forward Trends and Commercial Implications
Looking across the 2026–2032 horizon, three trends are likely to shape product roadmaps, sourcing strategies, and channel positioning.
- Higher-wattage modular platforms will move further into workstation and on-premise use. ATX 3.1 and PCIe 5.1 readiness, combined with transient handling requirements, make it easier to justify larger units for systems that must remain stable under variable GPU and compute loads. This expands the addressable use set beyond traditional desktop builds and creates room for products that combine high wattage with clean thermal and acoustic profiles.
- Digital control and synchronous rectification will become standard tools rather than premium features. As efficiency mandates tighten and component costs favor designs that reduce sensitivity to magnetics, control-platform investment will pay back through better performance across load levels and more consistent production calibration. Suppliers that build reusable control architectures can scale more efficiently across wattages and form factors.
- Regional demand will increasingly be served by locally tuned product mixes rather than a single global SKU strategy. Efficiency expectations, cable-management preferences, and acoustic tolerances vary by market. Brands that adapt wattage ranges, modularity options, and noise targets to regional priorities can improve sell-through without sacrificing platform commonality.
Commercial opportunities sit close to these trends. Manufacturers can pursue multi-wattage families that share a control platform while differentiating through airflow, modularity, and transient robustness. Investors can look for suppliers that demonstrate disciplined bill-of-materials management amid fluctuating passive component and ferrite pricing, since margin resilience will increasingly depend on design-led cost control. Channel and procurement teams can evaluate products less on peak wattage alone and more on hold-up performance, connector compliance, and light-load efficiency, which are becoming more relevant to real-world system behavior. Risks remain, including the possibility that input material costs rise faster than design adjustments can offset, that qualification cycles for ATX 3.1 and PCIe 5.1 variants stretch in complex system integrations, and that regulatory changes in key regions alter the cost-performance trade-off for certain efficiency tiers. Firms that monitor these variables continuously and align product timing accordingly will be better placed to capture the 4.89 percent CAGR trajectory expected through 2032.
DIN Rail Power Supply Market
Actionable Guidance for Decision-Makers
For PSU manufacturers, the priority is to convert specification compliance into a platform advantage. Build reusable digital control and synchronous rectification architectures that can span multiple wattages and form factors, then differentiate with noise performance, modularity, and transient response. Treat bill-of-materials volatility as a design problem as well as a sourcing problem, and prioritize component choices that lower sensitivity to ferrite and passive material price swings. Affiliate partnerships and coordinated trade-show presence can help signal readiness for AI-adjacent and high-performance workstation demand without overextending into unrelated categories.
For investors and strategic planners, focus on firms that demonstrate margin resilience through engineering leverage rather than purchasing scale alone. Indicators worth tracking include the breadth of ATX 3.1 and PCIe 5.1 compliant lines, the consistency of efficiency certifications across wattages, evidence of dual-source or design-driven mitigation for passive component and ferrite exposure, and credible acoustic or modularity claims that reduce replacement and return risk. The moderate concentration of the market—top three at 37.5 percent and top five at 45.0 percent—means that targeted alliances, selective acquisitions, and regional product tailoring can shift competitive standing without requiring broad consolidation.
For procurement and system integration teams, evaluation criteria should expand beyond headline wattage. Give weight to 12V-2x6 connector compliance, 12-millisecond hold-up capability, light-load and no-load efficiency behavior, and the real-world noise profile of fully modular designs. These attributes influence system stability, energy cost, and user experience more directly than nominal ratings alone. When selecting suppliers, prioritize those with clear ATX 3.1 alignment and documented support for PCIe 5.1, since these factors reduce integration friction and future-proof builds against connector and transient-performance expectations.
Detailed segment data, pricing sensitivity scenarios, and region-specific product mix recommendations can sharpen these decisions further. Readers seeking granular breakdowns, company-level comparisons, and tailored guidance on sizing, sourcing, and roadmap timing can find the full analysis in the complete PW Consulting market report.
For detailed analysis of this topic, please visit the official page: PC Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Intelligent Parcel Locker Market: Why 12.5% CAGR and Commercial Buildings Redefine Growth
By PW Consulting, 2026-09-21
The Intelligent Parcel Locker Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The intelligent parcel locker ecosystem has transitioned from a niche convenience to a structural component of modern logistics and urban infrastructure. Between 2020 and 2025, global revenue climbed from approximately $800 million to $1.2 billion, reflecting a compound annual growth rate of 12.5% through the forecast horizon to 2032. By the end of that period, market value is projected to approach $2.74 billion, driven by compounding pressures on last-mile efficiency, the normalization of self-service pickup, and sustained investment in connected physical infrastructure. This trajectory is not merely a function of rising e-commerce volumes; it signals a broader recalibration of how goods move through dense residential, commercial, and transit environments.
For executives, investors, and procurement leaders, the opportunity lies in recognizing where the market is genuinely differentiating versus where it remains commoditized. The sector has entered a phase where deployment speed, carrier-agnostic interoperability, and functional specialization determine competitive advantage. Yet the same forces creating tailwinds also expose operational and regulatory friction that can stall rollouts or compress margins if not addressed early.
Market Snapshot and Structural Constraints
The revenue trajectory across the 2020–2032 window demonstrates steady accumulation rather than cyclical spikes, with the most pronounced inflection occurring between 2023 and 2026. That pattern aligns with the maturation of carrier-agnostic locker networks, the scaling of multi-function units, and the gradual shift from pilot deployments to standardized portfolio strategies. Market concentration remains moderate, with the top three players holding roughly a quarter of total value and the top five capturing just over a third. This fragmented structure indicates room for consolidation but also a landscape where regional specialists, functional innovators, and logistics incumbents can still win through targeted positioning.
PW Consulting
Several constraints are shaping how this growth actually translates into realized deployments. First, the economics of urban footprint acquisition remain uneven. High-density zones offer superior utilization but introduce zoning complexity, property-owner negotiations, and maintenance access challenges that can lengthen sales cycles. Second, the operational reliability of connected lockers depends on a layered stack of hardware durability, secure communications, and software integration with parcel management platforms. Mismatches across those layers create deployment risk, particularly when units must operate continuously in varied weather conditions while maintaining real-time status visibility for both carriers and end users. Third, the shift toward multi-functionality is introducing new performance expectations. Lockers are increasingly expected to accommodate refrigerated freshness, secure laundry exchanges, and modular reconfiguration without sacrificing throughput or simplicity for the end user. Managing that breadth of capability without inflating unit costs or complicating maintenance is a defining engineering and commercial tension.
Core Drivers Reshaping the Market
Technological Innovation and Connected Hardware
The technological evolution of parcel lockers is moving beyond isolated access control toward integrated, sensor-rich systems that support remote diagnostics, flexible carrier routing, and specialized environmental management. Modular architectures now allow operators to scale footprint and functionality as demand patterns shift, while solar-powered and off-grid configurations reduce dependency on site electrification and enable deployment in locations where wiring constraints would otherwise stall installations. Bluetooth- and IoT-enabled notifications have become baseline expectations for contactless, real-time pickup coordination, and secure data handling at the locker level has taken on added importance as tracking and access workflows generate more operational data. These capabilities are not merely feature upgrades; they directly affect utilization, downtime, and the ability of carriers and property operators to manage multiple delivery partners through a single physical footprint.
The commercial implication is clear: hardware differentiation is increasingly tied to how well a locker system integrates into broader operational workflows rather than to standalone metalbox durability. Units that can flexibly accommodate multiple carriers, provide reliable connectivity in densely built environments, and adapt to specialized loads such as perishables or laundry are gaining traction across residential complexes, retail click-and-collect points, and institutional campuses. This is accelerating a shift in procurement criteria from unit price toward total cost of ownership, uptime, and interoperability.
Worldwide Smart Electronic Locker Systems Market
Regulatory and Policy Dynamics
Policy and regulatory conditions are shaping both the pace and the structure of locker adoption. Universal service providers in Europe have expanded parcel locker networks in ways that lower delivery costs and improve consumer convenience, reflecting a strategic alignment between public logistics obligations and private infrastructure deployment. At the same time, data sovereignty frameworks in EU countries require secure, locker-based data handling for parcel tracking and access, which pushes vendors and operators toward more rigorous information governance. Spectrum and wireless regulations further influence deployment by enabling real-time IoT notifications and secure, contactless operations, making regulatory clarity around connectivity an underappreciated enabler of adoption.
These regulatory currents create a dual effect. They raise the compliance burden for cross-border or multi-jurisdiction deployments, but they also provide a structural advantage to operators and vendors that design for secure data handling and standardized connectivity from the outset. In practice, locker networks that treat regulatory alignment as an afterthought face higher integration cost and slower site approval, while those embedding compliance into architecture reduce friction and can scale more predictably across regions.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the normalization of self-service pickup has changed expectations around availability, security, and convenience. Consumers increasingly view round-the-clock access as preferable to constrained delivery windows, especially in urban settings where in-home delivery is less reliable or less desired. For residential and mixed-use properties, parcel lockers address recurring pain points around package theft, concierge burden, and space constraints. In retail environments, click-and-collect lockers help retailers and brands manage foot traffic, reduce missed-handoff friction, and create a more predictable pickup experience. Institutions such as universities and colleges are also deploying lockers to streamline distribution for campus mail, procurement deliveries, and student services.
This demand evolution is broadening the addressable use cases beyond traditional postal and courier handoffs. As a result, locker installations are increasingly evaluated on the strength of the surrounding service model: who operates the unit, how carriers are onboarded, how notifications and access credentials are managed, and how maintenance is handled over the asset life. The market is therefore rewarding operators and vendors that can present a coherent end-to-end story rather than a standalone hardware proposition.
Cost Structure and Last-Mile Labor Economics
Labor economics remain one of the most powerful structural drivers. Intelligent parcel lockers reduce last-mile labor requirements for postal and courier providers by enabling automated self-service access, which helps mitigate the cost and scheduling volatility associated with repeated delivery attempts and individual handoffs. In high-density cities, the deployment of smart lockers also supports more sustainable urban logistics by minimizing physical delivery trips, an outcome that resonates with both cost discipline and sustainability targets. The combined effect is a clearer economic rationale for shared locker infrastructure as a complement to, rather than a replacement for, traditional delivery channels.
This cost dynamic influences both carrier behavior and property-level adoption. Carriers see value in consolidating drop-offs into predictable, self-service points, while building operators and retail managers value the reduced handling burden and improved security profile. The strategic opportunity lies in aligning business models so that these benefits are captured collectively rather than siloed across separate stakeholders, which is often the difference between a one-off installation and a scaled network.
Competitive Landscape and Leading Strategies
The competitive field is diverse, spanning hardware manufacturers, service-oriented networks, and logistics-aligned partnerships that are reshaping how locker infrastructure is deployed and monetized. ZHILAI has emphasized smart locker variants that include solar-powered, Bluetooth-enabled, and refrigerated models, positioning itself around flexible last-mile pickup and self-service use cases. Quadient has built a carrier-agnostic model through Parcel Pending by Quadient, aggregating thousands of locations and pairing locker hardware with management software for residential, retail, and commercial settings. OMNIC has focused on manufacturing indoor and outdoor smart lockers, including solar off-grid options and all-in-one multi-function models suited to logistics and e-commerce operations, with protection specifications that address demanding environments. KEBA has pursued a partnership-led approach, supplying classic parcel lockers and loxmate systems under relationships with bpost and GLS, reinforcing its role in automated delivery infrastructure. Postal Source operates in the United States with intelligent locker solutions oriented toward secure package management and streamlined operations, reflecting demand for dependable hardware and process simplification in local markets.
These profiles illustrate three distinct strategic orientations. One emphasizes hardware versatility and environmental adaptability, appealing to operators with varied site conditions and specialized load needs. Another emphasizes network scale and software-managed interoperability, aiming to become the connective tissue between carriers, property operators, and end users. A third relies on established postal and logistics partnerships to secure volume and deploy standardized locker assets within existing service frameworks.
Strategic Positioning and Differentiation
The companies gaining momentum tend to differentiate along a few consistent dimensions. Carrier-agnostic network design reduces dependency on any single delivery partner and improves asset utilization by accommodating multiple service providers through the same locker footprint. Multi-function hardware, including cooling and laundry-capable configurations, extends the addressable demand beyond standard parcel handoffs and supports higher value-per-site economics where specialized flows exist. Solar and off-grid options broaden deployment feasibility and reduce site preparation costs, which is especially relevant for outdoor installations or properties with limited electrical infrastructure. Secure connectivity and data-handling rigor are becoming differentiators as regulatory expectations rise and as operators rely on remote monitoring, fault detection, and access management across distributed fleets.
Partnership strategies are equally important. Recent activity shows a clear pattern of using rail networks, courier relationships, and technology partnerships to accelerate footprint expansion. In January 2025, Quadient partnered with ScotRail to deploy smart parcel lockers across Scotland’s rail network for 24/7 secure commuter access, illustrating how transit infrastructure can serve as a distributed pickup layer. In February 2025, KEBA was selected as the exclusive supplier of classic parcel lockers for bpost in Belgium for the year, a deal that aligns hardware supply with a universal service provider’s delivery modernization efforts. In April 2025, Expedibox partnered with Virtual.com to deploy 1,700 smart lockers across Canada by 2026, showing how cross-border and multi-operator collaborations can scale regional networks quickly. In July 2025, InPost S.A. acquired a Spanish courier company to expand smart locker network coverage, signaling consolidation and vertical coordination as growth levers. In October 2025, Quadient expanded its strategic partnership with Evri to activate 2,000 additional Parcel Pending by Quadient smart lockers across the UK, reinforcing the carrier-network expansion model.
Market Structure and Evolution Trends
The market’s evolution is trending toward selective consolidation paired with continued specialization. On one hand, acquisitions and deep partnerships are concentrating network assets and carrier relationships in the hands of a smaller number of well-capitalized players. This is most visible in Europe, where locker networks are increasingly tied to postal and courier service strategies and where multi-market rollouts benefit from standardized hardware and software platforms. On the other hand, functional differentiation is creating space for new entrants and regional specialists, particularly in cooling, laundry, solar off-grid, and campus or transit-adjacent deployments. The result is a hybrid structure: a consolidating core network layer, with a more fragmented periphery where specialized use cases, local property relationships, and site-specific regulatory conditions reward tailored solutions.
For the competitive landscape, this means that scale alone is not sufficient. The winners are likely to be those that combine network density with reliable interoperability, functional flexibility where it matters, and a credible operating model for maintenance and software updates across dispersed assets. Vendors and operators that can make locker infrastructure easy to operate for multiple stakeholders will have an advantage in converting individual installations into durable network value.
Forward Trends for the Next Three to Five Years
The next phase of growth will likely be shaped by three reinforcing trends. First, multi-function locker platforms will become more common as operators seek higher utilization from each installation. Refrigerated fresh-food lockers, laundry exchange models, and modular reskinning of standard units will allow sites to serve layered demand without requiring separate infrastructure for each flow. This trend creates opportunity for vendors that can deliver reliable thermal management, sanitary handling, and easy reconfiguration without sacrificing core parcel throughput. It also introduces complexity in service design, since different user workflows and maintenance requirements must be managed under one physical asset.
Worldwide Luggage Storage Locker Market
Second, connectivity and data governance will increasingly determine deployment velocity. As IoT-enabled notifications and remote management become standard, the quality of wireless integration, cybersecurity, and compliance with local data-handling rules will affect how quickly sites can be brought online and how confidently operators can scale. This favors organizations that treat connectivity, access control, and data handling as foundational design choices rather than downstream add-ons. The uncertainty here lies in the unevenness of regulatory requirements across jurisdictions and in the practical burden of maintaining secure, auditable systems across a growing installed base.
Third, network expansion will continue to intersect with public and transit infrastructure, retail real estate, and residential master planning. Rail networks, commuter hubs, grocery-anchored retail, and large residential complexes are natural expansion surfaces because they concentrate foot traffic, improve utilization, and reduce per-delivery friction. This creates commercial opportunity for operators that can negotiate site access, align stakeholder incentives, and sustain uptime across public-facing installations. The risk is that public-sector approval processes, property-owner alignment, and maintenance accessibility can slow rollouts or raise total cost if not managed proactively.
Together, these trends point toward a market where value accrues to entities that can integrate hardware versatility, network interoperability, regulatory readiness, and stakeholder coordination. The commercial opportunity is not simply to sell more lockers, but to build locker ecosystems that produce measurable reductions in delivery friction, operational burden, and missed-handoff losses while remaining adaptable to changing demand.
Strategic Considerations for Decision Makers
For Manufacturers and Technology Providers
Product roadmaps should prioritize modular scalability and interoperability as much as hardware durability. Units that can be reconfigured for cooling, laundry, or standard parcel use, and that support solar or off-grid deployment where site conditions require it, will open more addressable opportunities. Equally important is the software layer: remote diagnostics, secure access workflows, and compatibility with multiple carrier systems reduce the operational friction that often undermines broad adoption. Manufacturers that invest early in these capabilities and document their reliability across varied environments will be better positioned to participate in scaled network deployments rather than one-off sales.
For Investors
The market’s moderate concentration and steady growth trajectory suggest a landscape with both consolidation candidates and specialized innovators. Capital allocation decisions should account for the distinction between asset-heavy network models and hardware-plus-software positions that depend on partnerships for scale. Networks tied to credible carrier relationships, transit or retail footprints, and repeatable site-procurement processes offer more predictable expansion paths, while highly specialized hardware plays may deliver stronger differentiation in narrower segments. Due diligence should emphasize utilization economics, maintenance burden, data-handling compliance, and the durability of partnerships that drive deployment pipelines.
For Procurement and Operations Leaders
Procurement decisions should evaluate locker solutions as long-lived operational assets rather than commoditized endpoints. Key evaluation criteria include carrier-agnostic usability, uptime and remote management capabilities, security and data-handling alignment, and the practicality of installation and maintenance at the intended site types. Where deployments span multiple stakeholders, the operating model matters as much as the hardware: clarity on who manages access, notifications, fault response, and carrier onboarding can determine whether a locker installation becomes a shared efficiency asset or an underused inconvenience. Early alignment among property operators, delivery partners, and technology providers reduces ambiguity and improves the odds of sustained utilization.
Detailed segmentation data, regional deployment economics, and company-level assessments can sharpen these decisions further by showing where functional specialization, partnership structures, and regulatory readiness create the strongest near-term value. Comprehensive research reports can help decision makers compare vendor positions, evaluate site-level viability, and map out differentiated strategies across residential, retail, commercial, and institutional applications with greater precision. For organizations preparing investment, procurement, or expansion choices, deeper intelligence provides the granularity needed to move from broad market confidence to targeted, defensible action.
For detailed analysis of this topic, please visit the official page: Intelligent Parcel Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Methyl Mercaptan Market: Navigating Growth Amid Structural Shifts
The global market for methyl mercaptan (methanethiol) has entered a phase of measured expansion, driven by its indispensable role as an odorant for natural gas and liquefied petroleum gas, alongside a growing footprint as a chemical intermediate in methionine synthesis and specialty applications. From 2020 through 2025, the market grew from approximately USD 118.0 million to a base-year valuation of USD 155.0 million, reflecting recovery trajectories, capacity adjustments, and steady end-use demand. Looking ahead to 2032, the trajectory points toward sustained upward momentum, with forecasts indicating a revenue base that climbs steadily toward USD 225.0 million. This expansion corresponds to a compound annual growth rate of 6.5% across the 2026–2032 forecast period, a figure that signals broad-based acceptance rather than speculative overgrowth. While the headline numbers provide directional clarity, the strategic reality on the ground is more nuanced: growth is uneven across applications, supply chain dynamics are tightening, and regulatory scrutiny is reshaping operational playbooks for producers and downstream users alike.
Market Landscape and Core Challenges
The market's current structure is characterized by a concentration that remains moderately fragmented at the top but increasingly consolidated in terms of strategic capability. The leading three firms account for roughly 35% of revenue, while the top five extend that share to approximately 48%, indicating that scale, integration, and technical differentiation are becoming more important than pure volume dominance. This balance creates room for specialized players while simultaneously raising the bar for competitive resilience. The most consequential shift is not a single disruption but a convergence of constraints that are redefining how value is captured.
One central challenge is the tension between feedstock stability and margin preservation. Methyl mercaptan is predominantly produced through the reaction of hydrogen sulfide with methanol, a route that is technically mature but highly sensitive to methanol pricing, logistics, and regional availability. As methanol markets experience episodic volatility—particularly in major consuming regions where spot prices can spike sharply—producers face a recurring test of whether to pass through costs, absorb them through operational efficiency, or restructure contracts to smooth exposure. The second challenge lies in regulatory complexity. Methyl mercaptan is classified as a toxic substance with a permissible exposure limit of 0.5 ppm under occupational safety standards, and it falls under risk management programs with threshold quantities that require active compliance planning. Its hazardous waste classification further introduces recordkeeping, handling, and transportation obligations that can escalate the cost and risk profile of operations, especially for facilities functioning near urban or environmentally sensitive zones.
A third challenge emerges from application concentration and the reputational sensitivity of odorization. The largest share of demand continues to stem from methane odorant use, which ensures gas leak detection and public safety. While this application is structurally durable, it also subjects producers to scrutiny around consistency, purity, and delivery reliability. Any lapse in quality or continuity can cascade into utility liabilities, regulatory inquiries, and reputational consequences that go beyond price competition. Together, these pressures create a market environment in which operational discipline and technical differentiation matter as much as capacity positioning.
T Dodecyl Mercaptan Market
Key Drivers Shaping Market Dynamics
Technological Innovation and Process Optimization
Innovation in methyl mercaptan production is less about reinventing the core chemistry and more about improving selectivity, purity, energy intensity, and safety. Advances in catalytic formulations, integrated reactor management, and downstream purification have enabled producers to deliver high-purity grades and tailored intermediates that meet the stricter specifications of methionine synthesis and specialty chemical applications. These improvements are strategically significant because they allow manufacturers to move up the value chain rather than compete solely on commodity volume. High-purity offerings can command stronger positioning in animal nutrition and fine chemical synthesis, where consistency and impurity control directly influence downstream performance. At the same time, process improvements that reduce energy consumption and waste generation help offset some of the cost pressure from raw materials, reinforcing margin durability in an environment where feedstock prices can shift quickly.
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for disciplined growth. Occupational exposure limits, risk management requirements, and hazardous waste classification elevate the compliance burden, but they also create a barrier that rewards operators with robust safety systems, documented processes, and strong supply chain traceability. In practice, this dynamic favors producers and distributors that invest in operational maturity, because buyers increasingly view compliance capability as part of overall reliability. Policy signals also influence demand indirectly. As gas networks and industrial consumers prioritize safety and environmental performance, odorization requirements are likely to remain stable or intensify, sustaining volume support for the core application. At the same time, evolving expectations around emissions, handling, and waste management are pushing firms to modernize storage, transport, and reporting practices, which may favor integrated players with the capital and technical resources to adapt quickly.
Demand-Side Shifts in Consumption and End-Use Behavior
Demand growth is being propelled by a combination of energy infrastructure needs and expanding use in animal nutrition and chemical synthesis. Natural gas odorization remains the dominant application, and its durability is reinforced by continued focus on leak detection, network safety, and regulatory expectations around gas quality. Beyond this core, the role of methyl mercaptan as a chemical intermediate is gaining strategic relevance, especially in methionine production and related applications where it supports downstream nutritional and formulation needs. This dual structure is important for commercial strategy because it diversifies exposure: the odorant market provides scale and consistency, while specialty intermediates offer differentiation and higher value capture. Demand-side behavior is also shifting toward buyers who prioritize reliability, specification consistency, and supplier compliance over lowest price, a trend that strengthens the position of suppliers capable of demonstrating technical and operational maturity.
Supply Chain and Cost Structure Evolution
Cost structures are increasingly shaped by regional feedstock dynamics and logistics. Methanol pricing, in particular, has become a critical variable, with spot markets exhibiting periods of sharp movement that can affect production economics and contract stability. For producers, the practical response is to develop more sophisticated procurement strategies, flexible sourcing, and transparent cost pass-through mechanisms where market conditions allow. For downstream users, the implication is that long-term supply relationships, quality assurance, and delivery reliability may increasingly outweigh marginal price differences. The supply chain is also being influenced by geographic diversification. India has emerged as an active production and export base, adding a new layer of capacity and competition that can improve availability but also introduces new expectations around consistency, certification, and compliance. This expansion is constructive for buyers seeking flexibility, while challenging established players to sharpen their value propositions beyond simple volume.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of large-scale integrated producers and focused regional manufacturers, with strategies that diverge based on geographic footprint, product breadth, and technical specialization. Chevron Phillips Chemical Company stands out as a leading-volume producer, positioning methyl mercaptan as a specialty chemical intermediate with strong relevance to methionine synthesis and broader applications. Its scale and integration provide a foundation for consistent supply and broad market reach, and its profile underscores the importance of linking volume leadership with application-specific capability. Arkema S.A. operates through its thiochemicals platform, offering methyl mercaptan and high-purity grades as well as sodium methyl mercaptide alternatives for methionine production. This approach illustrates a strategy of portfolio breadth and application flexibility, enabling customers to select from related chemistries depending on process requirements and formulation goals. Evonik Industries AG incorporates methyl mercaptan within a specialty chemical portfolio tied to animal nutrition and chemical synthesis, emphasizing application alignment and quality differentiation rather than pure commodity competition.
Worldwide Mercaptans Market
A distinct competitive layer is forming among Indian manufacturers such as Vizag Chemical International and Triveni Interchem Private Limited, both active in production and export. Their presence adds capacity and geographic optionality, particularly for international buyers seeking alternative sourcing points and cost-competitive supply. While scale and global integration differ across these companies, the common strategic thread is the ability to meet industrial specifications and export demand with increasing reliability. The competitive trend appears to be evolving along two axes: consolidation of advantage among firms that combine scale, technical quality, and compliance maturity, and differentiation among regional players that can compete on availability, service, and cost while steadily improving process standards.
This landscape is likely to see further selective integration and capability-based competition rather than broad consolidation for its own sake. Buyers are increasingly evaluating suppliers across a wider set of criteria, including purity, delivery consistency, regulatory readiness, and application support. In that environment, firms that invest in technical service, specification control, and transparent sourcing are better positioned than those relying primarily on price leadership. The emergence of new export-oriented capacity also suggests that regional diversification will continue to shape procurement strategies, especially as buyers seek resilience against localized feedstock volatility or logistics disruptions.
Future Outlook: Trends and Commercial Implications
Refined Value Capture Through Application Diversification
Over the next three to five years, the market is expected to tilt further toward value differentiation enabled by application breadth and specification leadership. Odorization will remain the revenue backbone, but the most strategic growth may come from higher-specification grades and intermediate uses that support methionine and specialty synthesis. Businesses that can reliably bridge core odorant supply with specialty-grade capability are likely to capture stronger positioning, because they can serve multiple demand streams while reducing dependence on any single application cycle. For commercial decision-makers, this suggests that product mix strategy and technical service capability will be as important as volume scaling.
Cost Discipline and Feedstock Strategy as Competitive Moats
As feedstock cost volatility remains a defining feature, competitive advantage will increasingly belong to firms that can manage methanol exposure with flexibility and transparency. Long-term procurement agreements, blended sourcing approaches, and operational improvements that reduce energy and waste intensity will help insulate margins. At the same time, buyers are likely to place greater weight on reliability and compliance assurance, meaning that cost leadership alone will be insufficient if it comes at the expense of consistency or risk management. The commercial opportunity here is twofold: producers can differentiate through resilient cost structures and predictable delivery, while buyers can secure supply by prioritizing partners with demonstrated feedstock management and quality control.
Regulatory Maturity as a Structural Advantage
Regulatory expectations around exposure control, risk management, hazardous waste handling, and transportation are likely to remain stringent, and in some contexts may become more operationally demanding. This environment favors organizations that treat compliance not as overhead but as a structural asset. Companies with robust safety systems, documentation discipline, and modern logistics practices will be better positioned to serve customers who face their own audit, ESG, and risk expectations. The commercial takeaway is that regulatory readiness can become a differentiator in supplier selection, especially for large downstream users and utilities where reliability and risk mitigation carry significant operational and reputational weight.
Risks and Uncertainties to Monitor
The principal uncertainties include methanol price volatility, potential regional policy shifts affecting handling and classification, and the possibility of demand softness if gas infrastructure investment or downstream synthesis demand slows. Supply diversification from new export-oriented capacity can improve availability, but it also raises expectations for specification consistency and compliance, which can become a source of friction if standards differ across regions. In addition, any disruption to logistics or distribution networks may disproportionately affect specialty-grade supply, where timing and purity are especially critical. Decision-makers should therefore build flexibility into sourcing and inventory strategies while monitoring regulatory updates that could alter handling requirements or cost structures.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen differentiation beyond volume. Investing in high-purity grades, improving process efficiency, and building transparent feedstock management capabilities can support stronger margins and more resilient customer relationships. Equally important is advancing compliance maturity as a visible capability, since occupational exposure limits, risk management requirements, and hazardous waste obligations are increasingly influential in supplier evaluations. Producers that can demonstrate consistent quality, reliable delivery, and substantive technical support will be better positioned to compete as the market rewards operational discipline alongside scale.
For investors and strategic acquirers, the market's 6.5% growth trajectory through 2032 suggests attractiveness, but value capture will depend on assessing exposure to feedstock volatility and regulatory complexity. Opportunities may be strongest in businesses that combine stable application demand with differentiated product capability or that have clear pathways to improve cost structures through procurement flexibility and process optimization. When evaluating potential investments, attention should extend beyond revenue growth to the durability of margins, the quality of compliance systems, and the alignment between product mix and end-use demand. In this market, the most compelling cases often combine predictable cash flow from core odorant demand with optionality from specialty intermediates and regional sourcing.
For procurement leaders and end-use buyers, the strategic imperative is to balance cost optimization with supply resilience and specification reliability. Price comparisons remain necessary, but they should be weighed against consistency, compliance readiness, and the supplier's ability to support application-specific needs. Diversifying sourcing where appropriate can reduce exposure to regional feedstock volatility or logistics disruption, and building long-term relationships with suppliers that demonstrate strong technical and regulatory capability can reduce the risk of supply interruptions or quality issues. In practice, procurement strategy should treat methyl mercaptan not only as a commodity input but as a component of operational safety and downstream performance.
Conclusion
The methyl mercaptan market is moving through a period in which growth is real but increasingly conditional on operational maturity, application differentiation, and disciplined cost management. The baseline trajectory points to steady expansion, yet the more important strategic question is not whether demand will rise, but how value will be captured as feedstock volatility, regulatory expectations, and competitive diversification reshape the field. Companies that align their product capabilities, compliance systems, and sourcing strategies with these shifts are better positioned to convert market growth into durable advantage. For readers seeking more granular segmentation data, regional detail, and tailored scenario analysis, the full research report offers deeper segmentation and customized guidance to support decisions at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Methyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com