

Blogs
Microgrid Technology Market: Why an 18.5% CAGR to $73.9B Redefines Energy Infrastructure Through 2032
By PW Consulting, 2026-09-21
Beyond Grid Dependency: Strategic Trends and Commercial Opportunities in the Microgrid Technology Market
The microgrid technology market is undergoing a structural transformation. Valued at approximately 12.5 billion USD in 2020, the sector expanded to 22.7 billion USD by 2025 and is projected to reach 73.9 billion USD by 2032, reflecting a compound annual growth rate of 18.5 percent over the forecast period. This trajectory signals more than incremental adoption; it indicates a shift from pilot-scale experimentation toward mainstream infrastructure deployment. As distributed energy resources mature and operational priorities evolve, microgrids are transitioning from niche resilience solutions to foundational components of modern energy architecture. For enterprise leaders, the implication is clear: microgrid integration now intersects with capital allocation, regulatory navigation, supply chain strategy, and operational continuity.
The current phase of market development is characterized by accelerated technical validation, yet the pathway from concept to commercial scale remains uneven. Several structural friction points define the present landscape. First, the economics of deployment vary significantly depending on site complexity, load criticality, and regional regulatory frameworks. While standardized configurations benefit from predictable cost curves, customized installations for hospitals, industrial campuses, and critical facilities require substantial engineering investment and multi-stakeholder coordination. Second, the transition toward bidirectional power flows and inverter-based architectures introduces new operational dependencies. Legacy interconnection standards, fragmented approval processes, and evolving cybersecurity expectations create coordination layers that can delay project timelines. Third, the market remains moderately concentrated, indicating that scale advantages, proprietary control systems, and integrated service offerings continue to shape competitive positioning. These dynamics collectively suggest that market growth will increasingly favor organizations capable of aligning technical performance with regulatory clarity, financial structuring, and long-term service reliability.
Key Drivers Shaping Market Trajectory
Technological Innovation and System-Level Integration
The maturation of microgrid technology is being driven less by any single breakthrough and more by the integration of previously siloed capabilities. Advanced energy management systems now coordinate distributed generation, storage, and load-shifting with greater precision, enabling facilities to maintain critical operations during grid disturbances. Controller architectures have improved response times for islanding and reconnection, while hybrid configurations increasingly combine solar, battery storage, and alternative generation pathways to reduce reliance on any single resource. These capabilities are especially relevant in environments where continuity is non-negotiable. Recent projects illustrate this trajectory: one of the largest hospital-based renewable microgrid systems in the United States came online with integrated solar generation, long-duration battery storage, and fuel cell backup designed for emergency power continuity. Within months, the installation transitioned into operational backup mode, demonstrating how integrated microgrid platforms can move from construction to active resilience support while contributing to regional renewable transition objectives. Technological progress is therefore not only enhancing system performance but also expanding the envelope of use cases where microgrids can deliver measurable operational value.
Policy and Regulatory Evolution
Regulatory frameworks are becoming both an enabler and a constraint. On one side, public-sector emphasis on grid resilience, decarbonization, and energy security is encouraging distributed infrastructure investment. On the other, the absence of uniform interconnection standards and the complexity of multi-party approvals can complicate deployment, particularly for single-property installations that must coordinate with internal facilities teams, financial stakeholders, and external authorities including utilities, planning departments, and fire marshals. A recent community guide addressing regulatory barriers highlighted how these coordination requirements can slow project execution for hospitals and other critical facilities, especially when stakeholder alignment and jurisdictional approvals are not mapped early in the development cycle. At the same time, new certification initiatives are beginning to establish baseline expectations for device-level security and interoperability. The introduction of an industry-wide cybersecurity certification program for microgrids, inverter-based devices, and distributed energy resources reflects a broader shift toward standardized safeguards as systems become more digitally managed and networked. For market participants, regulatory developments are no longer background conditions; they are active design parameters that influence architecture choices, procurement timelines, and deployment risk.
Demand-Side Realignment Across Sectors
Demand for microgrid solutions is being reshaped by changing expectations around cost predictability, operational continuity, and sustainability performance. Commercial and industrial operators are increasingly evaluating on-site generation and storage as a means to reduce exposure to grid volatility and support corporate energy objectives. Healthcare institutions, in particular, have emerged as a strategically important segment because their load profiles include mission-critical services that cannot tolerate extended outages. Recent deployments have paired solar arrays with combined heat and power systems to deliver meaningful cost reductions alongside carbon footprint improvements, demonstrating how microgrid installations can serve both financial and operational mandates. In parallel, the growth of remote and constrained infrastructure settings continues to support off-grid and hybrid configurations where grid dependence is impractical or too costly. The common thread across these demand patterns is a move from passive consumption toward active energy management, where facilities treat generation, storage, and control systems as part of a broader continuity and efficiency strategy rather than as standalone capital projects.
Supply Chain and Cost Structure Dynamics
Cost structures across the microgrid value chain are evolving as component maturity, manufacturing scale, and system integration practices improve. Still, cost trajectories are not uniform. Construction expenses can vary substantially by generation mix, storage technology, and site-specific engineering requirements, particularly when advanced energy management optimization is needed to support sensitive loads during outages. Hospital-grade installations, for example, may involve higher per-megawatt investment thresholds because of the need to maintain continuity for intensive care units, operating environments, and other critical functions. At the same time, the long-term financial case for microgrids is increasingly strengthened by their ability to reduce dependency on external supply conditions and provide more predictable generation cost profiles. In certain configurations, operators have realized substantial energy cost reductions by shifting toward fixed generation capabilities and lowering exposure to grid pricing variability. These economic dynamics create a nuanced deployment environment: while upfront capital requirements can be meaningful, lifecycle economics and resilience benefits are becoming more quantifiable, encouraging a longer-range view of return on investment.
Competitive Landscape and Strategic Positioning
Differentiated Value Propositions Among Leading Participants
The competitive environment is shaped by a mix of established industrial players and specialized technology providers, each emphasizing distinct aspects of the microgrid value chain. ABB has positioned itself around integrated microgrid technology solutions that span controllers, energy management systems, and hybrid renewable integration, emphasizing reliable power supply across varied operating conditions. Siemens focuses on microgrid controllers and integrated power solutions designed for seamless islanding and scalability, with particular relevance to critical facilities that require dependable operational transitions. Schneider Electric emphasizes platform-based approaches that combine energy management with renewable integration, targeting commercial and critical infrastructure applications. Eaton differentiates through energy storage systems and DC microgrid solutions aimed at efficient power distribution and backup performance. Honeywell concentrates on energy management and control systems optimized for critical facility resilience, while GE Vernova provides advanced controllers and hybrid solutions oriented toward utility and industrial use cases. S&C Electric Company has built its profile around ultra-fast islanding capabilities that support seamless power continuity, and Bloom Energy offers solid oxide fuel cell technology as an always-on clean generation pathway without combustion. On the project and deployment side, organizations such as Faraday Microgrids and Ameresco have developed focused approaches around hospital-based renewable systems and solar canopy configurations delivered under power purchase arrangements, reflecting the growing importance of tailored deployment models in sensitive institutional environments.
Market Structure and Evolution Patterns
Market concentration suggests that scale, integration depth, and service continuity remain influential in shaping competitive advantage. Organizations with broad component portfolios, established control architectures, and the ability to manage complex interconnection requirements often hold an advantage in higher-stakes deployments. At the same time, the landscape is not consolidating into a single model. Instead, it is evolving along multiple axes: some incumbents are deepening system-level integration and software-driven management capabilities, while specialized entrants continue to compete on niche performance characteristics, such as rapid islanding, fuel cell integration, or sector-specific design expertise. The result is a market in which differentiation increasingly depends on the ability to combine hardware reliability, software intelligence, cybersecurity readiness, and financial structuring flexibility. New entrants and project developers are likely to continue carving out positions where specialized load requirements, regional regulatory knowledge, or novel procurement structures create room for tailored solutions. Over time, the market may see further consolidation among integrated platform providers, alongside continued fragmentation in specialized applications where customization and stakeholder management are central to success.
Microgrid Market
Forward-Looking Trends and Commercial Implications
Scaling of Sector-Specific Microgrid Architectures
Over the next three to five years, one of the most consequential trends is likely to be the expansion of microgrid designs optimized for specific institutional and industrial load profiles rather than generic configurations. Healthcare facilities, data-centric campuses, manufacturing sites, and critical public infrastructure each impose distinct requirements on redundancy, response time, load prioritization, and fuel or storage mix. As deployment experience accumulates, architectures are expected to become more standardized within these segments while retaining the flexibility needed for site-specific constraints. The commercial opportunity lies in developing repeatable design templates, financing structures, and operational service models that reduce project risk and accelerate execution. Organizations that can package proven architectures with predictable performance parameters and clear approval pathways will be better positioned to capture demand in sectors where continuity and compliance are paramount. A related risk is that sector-specific standards and approval expectations may diverge across jurisdictions, increasing complexity for multi-site operators and slowing replication unless coordination frameworks improve.
Integration of Cybersecurity and Interoperability as Core Requirements
As microgrids become more digitally managed and interconnected, cybersecurity and interoperability are expected to move from auxiliary considerations to core procurement criteria. Certification programs and baseline security expectations introduced for inverter-based devices and distributed energy resources indicate that buyers will increasingly evaluate control systems not only on performance but also on vulnerability management, update pathways, and vendor accountability. This shift creates opportunities for suppliers that can demonstrate robust security architectures, transparent certification status, and compatibility with broader facility management and grid-interconnection requirements. It also raises the stakes for system designers, because fragmented device ecosystems or opaque security practices can become integration liabilities. A key uncertainty is the pace at which standards, testing protocols, and procurement specifications will harmonize across regions and customer segments. Until then, cybersecurity readiness may function as both a competitive advantage and a compliance hurdle, depending on the market and project type.
PW Consulting Information & Electronics Research Center
Financial Structuring and Lifecycle Value Optimization
The financial narrative around microgrids is likely to become more sophisticated as operators weigh upfront capital against long-term resilience and cost predictability. In settings where grid dependency carries operational or budgetary risk, microgrids can support fixed-cost generation profiles and reduce exposure to external supply volatility. This makes lifecycle modeling, performance guarantees, and service agreements increasingly important in project evaluation. Financing approaches such as power purchase structures, resilience-based procurement, and shared infrastructure models may broaden access for organizations that prefer operational expenditure frameworks over traditional capital investment. The opportunity for suppliers and developers will lie in aligning technology choices with financial outcomes, including maintenance costs, degradation profiles, storage replacement cycles, and control system longevity. The risk is that unrealistic expectations around savings or performance could undermine project credibility if real-world operating conditions, regulatory constraints, or load complexities are underestimated. Sustainable adoption will depend on transparent modeling and disciplined interpretation of site-specific economics.
Micro Turbine Market
Strategic Implications for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize integration depth over component-only positioning. Architectures that combine control, storage coordination, renewable integration, and cybersecurity readiness will increasingly shape procurement decisions in critical and commercial environments.
- Build repeatable segment playbooks. Tailored design templates for hospitals, industrial facilities, and commercial campuses can reduce sales cycle friction and improve deployment predictability if they account for approval pathways, load prioritization, and local interconnection requirements.
- Treat security and certification as product attributes. Demonstrated compliance with emerging cybersecurity baselines and interoperability expectations can become a differentiator, especially where buyers must justify resilience investments to internal audit, compliance, or governance stakeholders.
For Investors and Capital Allocators
- Evaluate markets through the lens of deployment complexity, not just addressable demand. Segments with high continuity requirements and manageable approval pathways may offer more reliable project conversion than highly fragmented or regulation-constrained environments.
- Watch for consolidation signals among integrated platform providers and specialized deployers. Scale advantages in control software, service networks, and financing partnerships may drive concentration in some segments, while niche expertise remains valuable in others.
- Underwrite lifecycle economics carefully. Savings potential, resilience value, and operational risk reduction can be meaningful, but returns depend on realistic assumptions around engineering costs, storage and component longevity, and ongoing management requirements.
For Procurement Leaders and Facility Operators
- Map regulatory and stakeholder dependencies early. Single-property deployments can face coordination challenges with internal teams and external authorities, so early alignment across facilities, finance, planning, utilities, and safety stakeholders is essential to avoid timeline delays.
- Define critical load priorities before sizing solutions. The value of a microgrid depends heavily on how well its architecture supports the loads that matter most during an outage, making load analysis and redundancy planning central to project design.
- Include cybersecurity and service continuity in evaluation criteria. Procurement decisions should account for device security baselines, management updates, vendor support models, and the operational implications of islanding and reconnection performance.
The microgrid technology market is expanding within a landscape defined by technical integration, regulatory maturation, and increasingly demanding operational expectations. Growth is being shaped not only by the appeal of distributed generation and storage, but also by the need for resilient, secure, and financially defensible energy architectures. For organizations evaluating entry, expansion, or procurement decisions, the most valuable next step is to move beyond headline market sizing and examine the segmentation, cost structures, regulatory pathways, and competitive dynamics that determine project viability in specific contexts. Detailed segmentation data, company-level positioning assessments, and customized strategic analysis can sharpen these decisions and reduce execution risk. PW Consulting offers comprehensive research supporting deeper evaluation of these dimensions for decision-makers seeking a fuller understanding of where value is being created and how to act on it.
For detailed analysis of this topic, please visit the official page: Microgrid Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cloud Gaming Market: Why 28.25% CAGR Redefines Gaming Infrastructure Through 2032
By PW Consulting, 2026-09-21
Cloud Gaming Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The cloud gaming market has transitioned from an experimental concept to a commercially viable sector over the past half-decade. From a base of $1.25 billion in 2020, the sector reached $8.72 billion by 2025, reflecting a compound annual growth rate of 28.25 percent. Forecasts project the market will surpass $11 billion in 2026 and scale to approximately $49.47 billion by 2032. This trajectory signals more than incremental adoption; it indicates a structural shift in how content is delivered, consumed, and monetized across consumer electronics and digital entertainment ecosystems.
Such rapid expansion, however, rests on fragile foundations. The industry currently confronts three critical challenges that will define competitive outcomes over the next several years. First, infrastructure scalability remains uneven. Delivering consistently high-fidelity experiences requires dense edge computing coverage and robust broadband capacity, yet network quality varies dramatically across geographies. Regions with advanced telecommunications infrastructure are experiencing accelerated adoption, while markets dependent on legacy networks face persistent latency and bandwidth constraints that undermine user retention.
Second, content economics and licensing complexity continue to pressure unit profitability. Cloud gaming platforms must negotiate rights agreements with publishers, manage localization requirements, and align game catalogs with regional preferences. These negotiations consume significant operational resources and create friction when attempting to scale service offerings globally. Platforms that rely heavily on licensed third-party titles face margin compression unless they can demonstrate clear value differentiation to rights holders.
Third, user acquisition costs and retention dynamics present a persistent challenge. While initial trial adoption has grown, converting free-tier or trial users into sustained subscribers requires continuous investment in service quality, exclusive content, and ecosystem integration. Churn remains elevated in markets where alternative entertainment options compete for disposable income and screen time. Platforms that fail to build sticky user relationships through hardware integration, social features, or personalized experiences risk cyclical reacquisition cycles that erode lifetime value.
Key Drivers Accelerating Market Growth
Technological Innovation and Streaming Optimization
Advances in encoding algorithms, GPU virtualization, and edge computing have substantially reduced the technical barriers that once limited cloud gaming viability. Modern streaming pipelines now deliver higher resolutions and frame rates with lower latency, widening the addressable device base beyond traditional gaming hardware. The integration of artificial intelligence into streaming optimization, demonstrated by recent platform enhancements from NVIDIA in early 2026, illustrates how algorithmic improvements can dynamically adjust quality parameters based on network conditions and device capabilities. These technical breakthroughs reduce the dependency on high-end local hardware and enable premium experiences on smartphones, tablets, and televisions that previously could not support demanding titles.
Policy and Regulatory Environment
The regulatory landscape is undergoing rapid reconfiguration, with implications for infrastructure investment and market entry strategies. In mid-2025, the Federal Communications Commission moved to eliminate net neutrality rules and remove broadband provider restrictions as part of a broader deregulatory initiative. This shift alters the competitive dynamics for content delivery, potentially reducing compliance burdens for cloud gaming operators while raising questions about long-term network neutrality and prioritization practices. Simultaneously, European policymakers are pursuing digital sovereignty objectives. The European Commission's March 2026 proposal for a Technological Sovereignty Package and the €75 million allocation to the EURO-3C federated telco-edge-cloud project signal a strategic push to strengthen regional cloud infrastructure autonomy. These initiatives create both opportunities for localized infrastructure partnerships and compliance complexity for operators navigating divergent regulatory regimes across continents.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations increasingly favor convenience, cross-device continuity, and instant access over ownership of discrete hardware. Gamers are demonstrating willingness to stream titles across smartphones, tablets, PCs, and connected televisions, reducing the threshold for entry into interactive entertainment. This behavior aligns with broader digital consumption trends where subscription access replaces one-time purchases, and where content libraries are expected to be available anywhere. Enterprise and educational sectors are also exploring cloud-based interactive environments for training, simulation, and collaborative applications, extending demand beyond consumer gaming and creating adjacent revenue streams for platforms that can adapt their streaming infrastructure to non-gaming use cases.
Gaming Market
Supply Chain and Cost Structure Evolution
Data center energy demand is reshaping operating cost calculations for cloud-intensive services. U.S. data centers are projected to nearly double their combined energy consumption from approximately 80 gigawatts in 2025 to 150 gigawatts by 2028. For cloud gaming operators, this trend translates into higher infrastructure costs unless mitigated through efficient cooling technologies, renewable energy sourcing, and workload optimization. Companies that invest in energy-efficient architectures and strategic power procurement will gain cost advantages that compound over time, particularly as scale increases and marginal compute costs become a more significant factor in service profitability.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The market features a mix of platform-scale incumbents, hardware-integrated operators, and specialized streaming providers. Microsoft has expanded Xbox Cloud Gaming access through device optimizations and Azure edge node improvements, broadening reach to existing hardware ecosystems while leveraging its subscription content library. This approach emphasizes ecosystem leverage, using cloud streaming as an extension of a broader gaming and services portfolio rather than a standalone revenue center. NVIDIA differentiates through technical performance, offering RTX-powered virtual GPUs that enable high-fidelity streaming at elevated resolutions and frame rates. Its recent platform enhancements focus on AI-driven quality optimization and broader device compatibility, positioning performance fidelity as a core value proposition for enthusiasts and performance-sensitive users.
Amazon Luna continues to integrate cloud gaming with Fire TV hardware, creating a direct streaming pathway for subscribers within a controlled device environment. This hardware-software alignment reduces friction for users already embedded in Amazon's consumer electronics ecosystem. Sony has pursued a parallel strategy by enabling cloud streaming of PlayStation titles to its Portal handheld device without requiring a console, effectively decoupling premium content access from dedicated gaming hardware. Blacknut has pursued a distribution-focused model, securing pre-installation partnerships on devices such as the Logitech G Cloud handheld, which provides immediate access to a large catalog of premium titles and reduces adoption barriers for hardware partners seeking to differentiate their products. Boosteroid operates as a multi-platform streaming service emphasizing broad device support and session quality, targeting users who prioritize accessibility across heterogeneous device environments rather than deep integration with a single hardware ecosystem.
Market Structure Evolution
Concentration trends indicate a maturing market where leading operators capture a disproportionate share of value. The top three providers account for approximately 57.3 percent of market revenue, while the top five reach 74.2 percent. This concentration reflects the advantages of scale in infrastructure investment, content licensing, and user acquisition. However, the landscape is not static. Hardware integration partnerships are creating niche entry points for specialized platforms, while telecommunications operators are beginning to bundle gaming services with network packages, as seen in recent 5G gaming offerings from European carriers. These developments suggest a trajectory toward both consolidation at the top and fragmentation at the edges, where device manufacturers, network providers, and regional platforms can carve out defensible positions through integration, localization, or niche performance specialization.
New entrants face steep barriers in content rights, infrastructure scale, and brand trust, but opportunities exist for operators that align cloud gaming with adjacent value propositions. Device manufacturers can use pre-installed streaming platforms to enhance hardware appeal. Telecoms can differentiate broadband offerings with optimized gaming pathways. Regional platforms can compete on localization, language support, and publisher relationships that global incumbents may prioritize less aggressively. The strategic question for each participant is whether to compete on scale, on integration depth, or on specialized performance and service quality.
Future Trends and Commercial Opportunities
Edge-Native Infrastructure and Network-Service Bundling
Over the next three to five years, cloud gaming success will increasingly depend on proximity-aware infrastructure and network-level service optimization. As 5G standalone networks expand and edge computing nodes proliferate, operators that coordinate streaming delivery with telecommunications partners will gain latency and reliability advantages. Bundled offerings that pair broadband or mobile plans with gaming subscriptions will lower acquisition costs and increase stickiness, particularly in markets where telecoms hold strong consumer relationships. Commercial opportunities will emerge for platforms that design their service architecture to leverage these partnerships, including co-branded packages, zero-rating arrangements where permissible, and network-aware quality scaling that adapts experience parameters to connection characteristics.
Hardware-Software Convergence and Ecosystem Lock-In
The boundary between cloud gaming services and consumer hardware will continue to blur. Handheld devices, smart televisions, and connected set-top boxes will increasingly ship with streaming platforms pre-integrated, reducing the friction of initial adoption and creating default access pathways. This convergence benefits hardware manufacturers seeking differentiation and service providers seeking scaled distribution. The commercial implication is clear: platforms that secure pre-installation or deep integration agreements with device makers will capture a larger share of incremental users, while those relying solely on app-store discovery or web-based onboarding will face higher acquisition costs and lower conversion rates. Strategic partnerships with hardware OEMs, including co-marketing and joint optimization efforts, will become a decisive competitive lever.
AI-Driven Personalization and Adaptive Streaming Economics
Artificial intelligence will play an expanding role in both user experience and operational efficiency. Adaptive streaming algorithms will optimize bitrate, resolution, and frame delivery in real time based on network conditions, device capabilities, and user preferences. On the content side, AI-assisted curation and recommendation systems will improve discovery, reducing the friction that leads to trial abandonment. These capabilities create opportunities to increase engagement and reduce churn without proportional increases in content licensing spend. However, the same technologies raise expectations for service quality, and platforms that lag in adaptive optimization may experience disproportionate user dissatisfaction as baseline expectations rise across the market.
Risk Factors and Uncertainties
Several uncertainties could alter the trajectory outlined above. Regulatory divergence between regions may complicate global service architectures, particularly as digital sovereignty initiatives encourage localized infrastructure requirements. Energy cost escalation for data centers could compress margins unless offset by efficiency gains or favorable power contracts. Content rights negotiations may become more expensive as publishers recognize the strategic value of cloud distribution and demand higher revenue shares or exclusivity terms. Finally, competitive intensity could trigger price compression in subscription tiers, forcing platforms to differentiate through performance, integration, or exclusive content rather than price alone. Operators that build diversified revenue streams and maintain flexibility in infrastructure and licensing strategies will be better positioned to navigate these variables.
Strategic Recommendations for Decision Makers
For Platform Operators and Device Manufacturers
Prioritize integration depth over standalone reach. Embedding cloud gaming capabilities into hardware product lines, operating system environments, or network service bundles creates inherent distribution advantages that pure software-play strategies struggle to replicate. Invest in adaptive streaming quality and device-specific optimization to ensure that the user experience meets expectations across heterogeneous conditions. Where possible, pursue partnerships with telecommunications providers to align service delivery with network capabilities and to access bundled customer acquisition channels. For hardware manufacturers, treat pre-installed streaming platforms as a product differentiator and negotiate terms that ensure catalog relevance and technical compatibility over the device lifecycle.
For Investors and Strategic Capital Allocators
Evaluate operators based on infrastructure efficiency, content licensing sustainability, and ecosystem integration rather than headline user growth alone. Metrics such as cost per streaming hour, retention curves by acquisition channel, and the proportion of revenue derived from integrated hardware or network partnerships offer clearer signals of durable competitive advantage than top-line subscriber counts. Favor business models that combine recurring subscription revenue with ancillary monetization paths, including hardware margins, network bundling fees, or enterprise and education extensions. Monitor regulatory developments in key regions, as digital sovereignty and infrastructure policies will influence where capital can be deployed most efficiently and which operators gain preferential access to local edge resources.
Gaming Laptop Market
For Procurement and Partnership Decision Makers
When selecting cloud gaming service providers or infrastructure partners, assess streaming reliability under variable network conditions, the flexibility of content catalogs, and the operator's ability to support multiple device form factors. Prioritize partners that demonstrate a clear roadmap for adaptive quality optimization and that maintain transparent performance reporting. For organizations exploring cloud gaming as a component of broader digital entertainment or training strategies, consider the long-term implications of vendor lock-in and negotiate terms that preserve portability and integration flexibility. Track infrastructure energy commitments and sustainability practices as indicators of long-term cost discipline and operational resilience.
PW Consulting
The cloud gaming market is entering a phase where differentiation will be determined less by the mere availability of streaming and more by the quality of integration, the efficiency of delivery, and the durability of user relationships. Decision makers who align their strategies with these structural drivers will be better positioned to capture value as the market scales toward the end of the decade. For organizations requiring detailed segmentation data, regional breakdowns, competitive benchmarking, and customized scenario analysis, comprehensive research resources are available to support deeper evaluation and strategic planning.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Patient Data Management Systems Market 2026: Why 11.2% CAGR And ICU Adoption Redefine Growth
By PW Consulting, 2026-09-21
The Patient Data Management Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The global patient data management systems (PDMS) market has entered a phase of accelerated structural transformation. Valued at approximately 527.36 million USD in 2020, the market has grown to an estimated 888.06 million USD by 2025, reflecting a compound annual growth rate of 11.2 percent through the forecast horizon extending to 2032. By the end of that period, total market revenue is projected to surpass 1.85 billion USD. This trajectory is not merely a reflection of incremental IT spending; it signals a fundamental reorientation of how clinical data is captured, integrated, and operationalized across care settings.
The growth curve reveals distinct inflection points. The period from 2020 to 2023 delivered steady expansion, while the 2024 to 2025 window accelerated as hospitals confronted compounding pressures: staffing constraints, regulatory mandates, and the operational urgency of interoperable data flows. Projections for 2026 through 2032 indicate that revenue will compound at a pace that outpaces many traditional healthcare IT segments, driven by consolidation of clinical workflows, cloud migration, and the formalization of PDMS as regulated medical device infrastructure.
Yet the headline figures obscure a market that is actively reconstituting itself. Growth is uneven across deployment models, clinical environments, and geographic regions. Vendors are navigating a landscape where interoperability expectations, cybersecurity exposure, and regulatory classification requirements are reshaping procurement criteria. For executives and investors, the strategic question is no longer whether PDMS adoption will continue, but how value will be captured amid shifting integration standards, mounting security liabilities, and evolving reimbursement and funding mechanisms.
Market Snapshot: Scale, Trajectory, and Structural Tensions
The market's expansion from roughly 527 million USD in 2020 to nearly 888 million USD in 2025 reflects a compound growth rate of 11.2 percent, with forecasts extending to 2032 indicating a pathway toward 1.85 billion USD. This trajectory is anchored by several structural forces: the normalization of PDMS as a clinical documentation and device integration layer, the formalization of risk management and approval processes under hospital IT regulations, and the simplification of functional requirements within industry standards. Together, these factors have lowered adoption friction while simultaneously raising the baseline expectation for what a compliant, production-grade system must deliver.
PW Consulting
Concentration patterns further clarify the market's maturity. The leading vendors collectively account for approximately half of total revenue, with the top three and top five firms each representing roughly 50 percent of the market. This concentration suggests a landscape where established players hold significant share, yet the remaining half is distributed across regional specialists, niche integrators, and emerging cloud-native entrants. The implication for strategy is clear: scale advantages exist, but they are not insurmountable when differentiated clinical workflows, localized compliance needs, or cloud-first deployment models create openings for targeted positioning.
The current market is also defined by three interlocking challenges that are reshaping vendor and buyer behavior alike.
- Interoperability expectations are outpacing legacy integration architectures. Hospitals increasingly demand seamless connectivity across monitors, ventilators, infusion pumps, and electronic patient records, yet many installed bases were designed around single-function documentation rather than hospital-wide data orchestration.
- Cybersecurity and operational resilience have become procurement determinants. The exposure of cloud-based electronic patient record platforms to ransomware incidents has elevated security architecture, backup readiness, and incident response capabilities from technical considerations to board-level risk management criteria.
- Regulatory classification and funding mechanisms are simultaneously enabling and constraining adoption. PDMS are classified as medical devices requiring risk management and approval processes, while funding instruments such as hospital future acts have catalyzed deployments in specific regions. This dual dynamic accelerates certain rollouts while imposing compliance costs and timeline uncertainties elsewhere.
These tensions do not slow the market; they redistribute value. Vendors that can reconcile interoperability, security, and regulatory compliance within coherent deployment models are gaining negotiating leverage, while those relying on fragmented, point-solution messaging are facing longer evaluation cycles and more stringent proof-of-value requirements.
Key Drivers Shaping the Next Wave of Growth
The market's trajectory is being propelled by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a momentum loop that is likely to sustain double-digit growth through the late 2020s.
Patient Engagement Software Market
Technology innovation and integration maturity. The shift from isolated documentation tools to integrated clinical data layers is the most visible technological driver. PDMS platforms are increasingly expected to connect diverse bedside devices, normalize data streams, and feed structured information into broader hospital information and electronic patient record environments. Recent operational deployments illustrate this consolidation: centralized standardized documentation systems are now being implemented across multiple provincial hospitals, embedding PDMS into anaesthesia and intensive care workflows with the explicit goal of improving data quality and cross-hospital communication. At the same time, integration showcases at major industry events are emphasizing closed-loop processes that link media and documentation solutions directly into PDMS and hospital information systems, reducing manual handoffs and supporting continuity of care.
Policy and regulatory environment. Regulatory dynamics are acting as both a catalyst and a filter. PDMS are classified as medical devices and must undergo approval processes that include risk management under hospital IT regulations, which raises the barrier to entry for immature solutions but strengthens confidence in vetted platforms. At the same time, functional requirements for patient data management systems have been simplified in standards, lowering the implementation burden for baseline compliance. New guidelines, laws, and regulations are being directly integrated into PDMS standard content, meaning that vendors must treat regulatory updates as continuous product obligations rather than periodic certification events. This environment rewards platforms with disciplined change management and penalizes those that treat compliance as a static checklist.
Demand-side behavior and clinical workflow pressure. Hospitals are confronting staff shortages alongside budget constraints, which makes PDMS adoption less about optional digitization and more about workflow survival. Complex clinical environments require documentation, device traceability, medication management, and nutritional or pediatric percentile tracking without adding administrative burden. The demand signal is shifting accordingly: buyers are prioritizing systems that can centralize documentation, improve data quality, and reduce the cognitive load on clinical staff. This demand-side pressure is particularly acute in intensive care and anaesthesia settings, where device density and data volume make manual reconciliation impractical.
Cost structure and deployment model evolution. The cost equation is being reshaped by cloud transformation and the operational economics of platform maintenance. Cloud-based hospital information and electronic patient record systems are moving into production, with major medical centers completing launches and phasing out legacy platforms over multi-year transition windows. This shift alters total cost of ownership calculations, introducing subscription and hosting considerations while reducing on-premises maintenance overhead. However, it also introduces dependency on vendor security posture and continuity planning, as evidenced by incidents where ransomware attacks disrupted electronic patient record portals across a large share of hospital organizations using a specific platform. The cost conversation has therefore expanded from license and implementation to include resilience, data protection, and recovery readiness.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a small group of established vendors with deep clinical integration expertise, complemented by regional specialists and integration-focused entrants. The leaders have built their positioning around distinct clinical use cases, device connectivity breadth, and the ability to embed PDMS within broader hospital information and monitoring environments.
German-based vendors illustrate the depth of specialization emerging in the market. One prominent player focuses on certified PDMS integrated with its hospital information system, emphasizing ICU device connectivity, medication management, nutritional balance, and pediatric percentile features. This configuration targets high-acuity environments where documentation precision and cross-referencing across clinical parameters are essential. Another German firm offers a PDMS suite integrated with acute care monitoring systems for ICU, operating room, and neonatal intensive care settings, with an emphasis on centralized data management, prescription traceability, and optimization of patient care. A third German provider centers its offering on anaesthesia and intensive care departments, delivering centralized documentation, improved data quality, and cross-hospital communication capabilities. These profiles share a common thread: they are designed for environments where device density, regulatory scrutiny, and data continuity requirements are highest.
In the Netherlands, a different integration philosophy is gaining traction. A vendor has advanced a hospital-wide electronic patient record solution with PDMS capabilities that communicate across monitors, ventilators, and infusion pumps throughout the facility. This approach reflects a broader enterprise integration mindset, where PDMS is treated as a connective layer within a unified digital infrastructure rather than a departmental add-on. The emphasis on hospital-wide device communication aligns with buyer expectations for fewer integration silos and more consistent data semantics across care units.
Recent developments illustrate how these positions are being reinforced and tested in practice. One vendor completed a PDMS deployment across anaesthesia and intensive care departments at a state hospital, extending a centralized standardized documentation model to multiple provincial hospitals. Another vendor's cloud-based hospital information and electronic patient record platform reached production at a major medical center, with a phased transition away from legacy systems extending through the following year. Concurrently, a ransomware incident affecting a widely used electronic patient record portal disrupted operations for a substantial portion of hospital organizations, underscoring the operational and reputational stakes tied to platform security. Integration-focused demonstrations have further highlighted the push toward closed-loop processes and point-of-care hardware and monitoring integration, signaling that PDMS is increasingly evaluated as part of a broader clinical technology ecosystem rather than a standalone documentation tool.
Patient Record Management Market
The market is evolving along three overlapping paths. First, consolidation pressure is growing as buyers prefer fewer, more capable platforms that can cover multiple departments and device types, reducing integration overhead and vendor management complexity. Second, differentiation is sharpening around clinical specificity, with vendors competing on anaesthesia, ICU, neonatal, and medication management capabilities rather than generic data capture. Third, new entrants and integration specialists are probing niches where cloud-native architecture, streamlined compliance updates, or specialized device interoperability can offset the incumbency advantages of larger players. The net effect is a market where share is defended through integration depth and compliance readiness, while growth is increasingly contested in segments where deployment model, security posture, and workflow fit matter more than brand recognition alone.
Forward Outlook: Three Trends That Will Define 2026 to 2032
The market's next phase will be shaped by the interaction of integration expectations, security realities, and regulatory continuity. Three trends are likely to dominate strategic planning for the coming years.
- Integration will become the primary value proposition, not a feature. As PDMS is expected to connect devices, documentation, and broader hospital information environments, the competitive advantage will shift from data capture to data orchestration. Platforms that can normalize device outputs, maintain consistent semantics across departments, and support cross-hospital communication will command stronger positioning. The opportunity lies in designing for interoperability as a default architecture, with standardized interfaces and continuous alignment to evolving functional requirements.
- Security and resilience will reprice risk and procurement criteria. High-profile disruptions to electronic patient record platforms have made cybersecurity a central element of vendor evaluation. Buyers will increasingly prioritize architectures with robust access controls, segmented operations, tested recovery processes, and transparent incident readiness. For vendors, the commercial implication is that security maturity may become a differentiator that shortens sales cycles for risk-averse buyers while exposing weaker platforms to prolonged scrutiny. The uncertainty is that threat landscapes and regulatory expectations will continue to evolve, requiring ongoing investment that may pressure margins if not managed efficiently.
- Regulatory integration will shift from periodic certification to continuous compliance. With new guidelines and regulations being embedded directly into PDMS standard content, vendors must treat compliance as an operational discipline. This dynamic favors platforms with structured update mechanisms, clear traceability between regulatory changes and product content, and the ability to demonstrate risk management continuity. The business opportunity is to reduce the lag between regulatory change and product readiness, which can become a decisive factor in public procurement and hospital IT approvals. The risk is that vendors unable to absorb this continuous load will face rework, delays, and competitive disadvantage.
These trends intersect with commercial models in ways that will matter for both suppliers and buyers. Deployment architectures will increasingly blend on-premises device connectivity with cloud-hosted record and documentation layers, creating hybrid environments that demand careful orchestration of data flow, access control, and maintenance responsibilities. Funding and regulatory incentives will continue to influence regional adoption patterns, making some geographies more responsive to near-term expansion while others remain constrained by budget cycles and implementation capacity. The overarching opportunity is to align product roadmaps and commercial narratives with the reality that PDMS is becoming a regulated, integrated, and security-sensitive component of clinical infrastructure rather than a discretionary IT enhancement.
Strategic Recommendations for Decision Makers
The market's trajectory offers distinct implications for manufacturers, investors, and procurement leaders. Each group faces a different set of priorities, but all benefit from treating PDMS as a continuously evolving clinical data and compliance platform rather than a static software purchase.
For manufacturers and platform vendors. Prioritize integration architecture and security readiness as core product investments, not ancillary capabilities. Buyers are evaluating device connectivity breadth, documentation centralization, and the ability to embed regulatory updates into standard content, so differentiation should be built around clinical workflow fit, interoperability reliability, and demonstrable risk management continuity. Where possible, position PDMS as part of a hospital-wide data strategy that reduces silos, supports cross-department documentation, and aligns with evolving electronic patient record environments. Continuous compliance mechanisms and transparent update practices can become meaningful commercial advantages in procurement cycles that increasingly weight regulatory maturity.
For investors and strategic backers. Focus on vendors whose value proposition is tied to integration depth, clinical specificity, and resilience rather than pricing alone. The concentration dynamics suggest that scale incumbents retain advantages, but the distributed share outside the leaders indicates room for differentiated platforms that address cloud migration, security maturity, and specialized workflows in anaesthesia, ICU, and neonatal settings. Monitor deployment milestones, platform transition timelines, and security incident responses as leading indicators of operational credibility. Be mindful that margin profiles can be affected by the ongoing investment required for compliance updates, integration maintenance, and security hardening, making operating discipline as important as growth potential.
For hospital leaders and procurement teams. Treat PDMS selection as a multi-year operational decision that should be evaluated against integration scope, security architecture, compliance continuity, and clinical workflow alignment. Favor platforms that can communicate across monitors, ventilators, infusion pumps, and electronic patient records without creating new documentation silos, and verify that risk management and approval processes are clearly defined and maintained. Weigh the total cost of ownership including hosting, maintenance, resilience, and incident recovery rather than focusing narrowly on initial implementation cost. Demand evidence of how regulatory updates are incorporated into standard content and how the platform supports centralized documentation with improved data quality across departments.
Timely, granular intelligence is essential because the market is changing on multiple fronts at once: integration expectations, security realities, regulatory content, and deployment models are all shifting within the same procurement and planning cycles. Detailed segment data, regional dynamics, and vendor-specific implementation patterns can materially affect go-to-market priorities, investment theses, and purchasing decisions. For decision makers who need deeper segmentation, competitive benchmarking, and customized scenario planning, PW Consulting's full research report provides extended data and tailored guidance to support execution.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
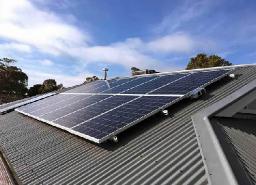
Perth has become an increasingly attractive location for households and businesses looking to generate clean electricity and reduce their reliance on conventional energy. With abundant sunshine throughout much of the year, solar technology can be a practical option for properties of different sizes. Choosing the right solar panel Perth WA solution involves more than simply selecting panels. Homeowners need to consider system capacity, roof orientation, inverter technology, battery storage, electricity consumption, installation quality, and available incentives. At the same time, understanding how solar electricity Perth systems operate can help property owners make informed decisions about energy generation, usage, and long-term household electricity management.
Understanding Solar Energy in Perth
Solar power systems convert sunlight into usable electrical energy through photovoltaic panels. During daylight hours, the panels generate direct current electricity, which is converted into usable alternating current by an inverter. The electricity can then supply appliances, lighting, cooling systems, and other household loads.
A well-designed solar panel Perth WA installation considers the property's roof space, shading, energy consumption, and expected generation. Instead of choosing a system based only on its panel count, homeowners should evaluate how much electricity they use throughout the day and evening. This approach can make the system more closely aligned with actual energy requirements.
Solar electricity Perth solutions can also support businesses, rental properties, community facilities, and other buildings. Commercial installations may use larger arrays and more sophisticated energy-management technology to help businesses manage daytime electricity demand.
Choosing the Right Solar Panels
Solar panels are available in different technologies, efficiencies, physical sizes, and warranty structures. Well-known manufacturers such as SunPower, REC, LONGi, JinkoSolar, Trina Solar, and Canadian Solar offer products designed for different applications.
When comparing a solar panel Perth WA system, it is useful to examine panel efficiency, temperature performance, degradation rates, product warranties, and installation requirements. Higher efficiency can be particularly useful where roof space is limited because more electricity can potentially be generated from a smaller area.
However, panel quality is only one part of system performance. The design should also account for roof orientation, tilt, shading from nearby buildings or trees, and local environmental conditions. Professional system design can help ensure that the panels work effectively with the inverter and other components.
The Importance of the Solar Inverter
The inverter is one of the most important components in a solar installation. Panels produce direct current electricity, while most household appliances use alternating current. The inverter performs the conversion and manages the flow of electricity between the solar array, home, grid, and battery where applicable.
Popular inverter brands include Fronius, Sungrow, SolarEdge, and GoodWe. Each manufacturer offers different technologies and monitoring capabilities. Some systems provide detailed performance information through mobile applications, allowing homeowners to monitor electricity generation and consumption.
For solar electricity Perth installations, inverter selection should match the size and configuration of the panel array. It should also accommodate future plans, such as adding a battery or integrating an EV charger.
Solar Battery Storage
A solar battery can store excess electricity generated during the day for use when solar production falls. This can be particularly useful for households that consume significant amounts of electricity during the evening.
For example, a home may generate substantial solar electricity while occupants are working or studying elsewhere. Rather than exporting all excess generation, a battery can store some of that energy for later use. Products such as Tesla Powerwall and other home energy-storage systems are designed to support this type of energy management.
When considering a solar panel Perth WA installation, battery capacity should be matched with household electricity consumption. A larger battery is not automatically necessary for every property. The right capacity depends on factors such as daily energy use, solar generation, evening consumption, electricity tariffs, and future energy requirements.
Solar Power and EV Charging
Electric vehicles are becoming an important consideration for households planning their future energy systems. An EV charger can be integrated with a solar installation to use locally generated electricity for vehicle charging.
During periods of strong solar generation, excess electricity may be directed toward an EV rather than being entirely exported to the grid. Smart charging technology can help coordinate vehicle charging with solar production and household electricity demand.
For homeowners considering solar electricity Perth alongside an EV, it can be useful to plan the solar system, inverter, battery, and charger as a connected energy solution. This approach may provide greater flexibility as household electricity consumption changes over time.
Rebates and Incentives
Government rebates and incentives can influence the overall cost of installing solar technology. Eligibility, program rules, certificate values, and other conditions can change, so homeowners should check the current requirements before making an investment.
The availability of a rebate may reduce the upfront cost of an eligible system, although the final financial outcome depends on the property's electricity usage, system size, installation cost, electricity prices, and energy-generation performance.
Anyone researching solar panel Perth WA options should therefore compare the complete installed cost rather than focusing only on the advertised panel price. A detailed quote should explain equipment, installation, warranties, applicable incentives, and any additional electrical work.
Solar for Perth Homes and Businesses
Solar systems can be designed for a wide range of property types. A small household may require a relatively compact system, while a larger home with air conditioning, pool equipment, an EV, and other high-consumption appliances may require greater generation capacity.
Businesses can also benefit from solar electricity Perth systems because many commercial properties consume electricity during daylight hours, when solar generation is available. Offices, warehouses, workshops, retail buildings, and professional premises can all have different energy profiles, so system design should reflect actual consumption patterns.
Across areas such as Balcatta, Bayswater, Belmont, Bentley, Cannington, Carlisle, Churchlands, Cloverdale, Dalkeith, Dianella, East Perth, Embleton, Floreat, Glendalough, Joondanna, Kewdale, Nedlands, Nollamara, Osborne Park, Queens Park, Redcliffe, Shenton Park, St James, Subiaco, Tuart Hill, Victoria Park, and West Perth, property characteristics can vary considerably. Roof size, orientation, shading, building age, and electricity consumption should therefore be assessed individually.
Comparing Solar System Quotes
Getting multiple quotes can make it easier to compare equipment and installation approaches. However, the cheapest quote is not necessarily the most suitable option. A meaningful comparison should include panel specifications, inverter brand, system capacity, expected generation, installation inclusions, warranties, monitoring equipment, and battery compatibility.
When comparing a solar panel Perth WA proposal, homeowners should also ask whether the quoted system has been designed specifically for their property. A professionally designed system should take roof characteristics and electricity consumption into account rather than relying solely on a standard package.
For solar electricity Perth projects, it is also worth asking about after-sales support and maintenance arrangements. Solar systems can operate for many years, making installation quality and ongoing support important parts of the overall decision.
Long-Term Solar Planning
Solar technology should be viewed as part of a property's broader energy strategy rather than simply a collection of panels on a roof. Electricity consumption may change as households purchase an EV, add air conditioning, install a pool, work from home, or introduce additional appliances.
Planning for these changes can make a solar system more adaptable. A suitable inverter, adequate switchboard capacity, battery compatibility, and intelligent monitoring can provide greater flexibility for future upgrades.
A well-designed solar panel Perth WA system can therefore combine panels, an inverter, battery storage, and EV charging according to the property's current and future needs. This integrated approach can help homeowners understand how electricity is generated, stored, consumed, and exported.
Conclusion
Solar energy has become an important consideration for Perth property owners seeking greater control over electricity generation and consumption. Selecting suitable panels, an efficient inverter, optional battery storage, and compatible EV charging technology can create a more flexible household energy system.
Whether a property is located in Subiaco, Nedlands, Osborne Park, Victoria Park, Belmont, or another Perth neighbourhood, system design should be based on the individual property's roof characteristics and electricity requirements. Understanding rebates, equipment warranties, expected generation, and installation quality can also make the purchasing process clearer.
For anyone researching solar panel Perth WA solutions, comparing complete systems rather than individual components provides a more useful basis for evaluation. Likewise, understanding how solar electricity Perth works can help homeowners and businesses plan an energy system that reflects their present requirements while allowing room for future changes.
Location:- Perth, Western Australia
https://simple.wikipedia.org/wiki/Perth,_Western_Australia
https://sites.google.com/view/perth-solar-power/
https://www.consumerprotection.wa.gov.au/publications/solar-panel-systems-factsheet
https://www.energy.gov.au/solar/financial-benefits-solar/government-rebates-and-loans-solar
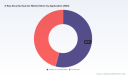
The X-Ray Security Scanner Market: Strategic Shifts and Commercial Opportunities in a High-Growth Security Landscape
The global X-ray security scanner market is undergoing a structural transformation. Valued at USD 7.4 billion in 2025, the sector is projected to expand at a compound annual growth rate of 6.5 percent, reaching approximately USD 11.5 billion by 2032. The trajectory from 2020 through 2032 reflects a market that has moved beyond post-9/11 security baseline spending into a phase defined by technological modernization, regulatory recalibration, and shifting threat perceptions across transportation and commercial infrastructure. Market concentration remains moderate, with the top three players collectively accounting for roughly 24.6 percent of global revenue and the top five capturing approximately 26.2 percent. This fragmented yet strategically consolidating landscape creates distinct pathways for differentiated positioning, whether through hardware innovation, software-enabled analytics, or integrated service architectures.
Behind the headline growth figures lies a market navigating several inflection points. Operators are balancing throughput requirements against deeper imaging fidelity, budget-constrained public agencies are weighing capital expenditure against lifecycle costs, and end-user environments are demanding detectors that can distinguish organic from inorganic threats without interrupting passenger or freight flow. At the same time, regulatory mandates are pushing older single-view tunnels toward replacement, privacy considerations are redirecting certain screening applications toward alternative modalities, and supply chain volatility is reshaping procurement timelines and vendor selection logic. Understanding where these pressures converge is essential for manufacturers, investors, and procurement leaders seeking to align their strategies with the next cycle of demand.
Market Landscape and Core Challenges
The revenue distribution across the market in 2025 underscores a clear structural emphasis on body screening and aviation-transformation applications, which together represent the dominant share of installed and deployed systems. Baggage and parcel scanning continues to anchor volume demand, while commercial facilities increasingly integrate X-ray and complementary imaging solutions to address cargo, logistics, and critical infrastructure screening requirements. The regional spread indicates that Asia Pacific, Europe, and North America collectively drive the bulk of procurement activity, with emerging corridors in Latin America and the Middle East and Africa expanding at a pace that reflects both infrastructure investment and heightened border security postures. Rather than treating these splits as static allocations, decision makers should view them as indicators of where modernization budgets, replacement cycles, and capacity upgrades are concentrating.
Three challenges define the current market turning point.
1. The Dual-View to Computed Tomography Transition
Single-view and dual-view X-ray tunnels remain workhorse systems in many checkpoints, but volumetric imaging is increasingly mandated for higher-risk freight and compressed throughput environments. The shift is not merely a hardware upgrade; it changes installation footprints, operator training requirements, power and cooling demands, and maintenance contracts. Procurement teams that underestimate the integration complexity of CT-based checkpoint systems risk deployment delays, while suppliers that fail to offer phased migration paths or retrofit-compatible architectures may lose share to competitors with more flexible transition strategies.
2. Cost Structures and Unit Economics
Checkpoint-grade systems carry significant capital intensity. Advanced CT screening units for checkpoints command unit prices in the range of USD 2.5 million to USD 3.2 million, roughly four times the cost of traditional dual-view tunnels. This pricing differential forces operators to prioritize deployments, negotiate financing structures, and evaluate total cost of ownership rather than sticker price alone. In parallel, tariff adjustments on certain pallet scanning equipment have prompted buyers and suppliers to revisit sourcing strategies, vendor selection criteria, and deployment timelines, adding uncertainty to procurement planning and inventory positioning.
3. Privacy, Public Perception, and Modality Substitution
Public acceptance remains a strategic variable. Privacy objections have slowed the deployment of backscatter-based systems in certain public venues such as stadiums, nudging operators toward millimeter-wave alternatives and other imaging approaches that balance detection performance with user experience. Although this dynamic pertains more directly to walk-through and stand-off modalities than to conventional X-ray tunnels, it influences the broader screening ecosystem by shaping procurement preferences, policy debates, and the willingness of end-users to adopt newer technologies in high-visibility locations.
Key Drivers Shaping the Market
Market momentum is being propelled by a combination of technological breakthroughs, regulatory pressure, evolving end-user behavior, and shifting cost and supply chain dynamics. These drivers interact in ways that create both urgency and selectivity in procurement decisions.
Technological Innovation and Threat Detection Fidelity
The most consequential technology trend is the migration toward computed tomography and multi-view imaging within checkpoint and cargo screening environments. CT-based systems improve material discrimination, reduce false alarms, and allow operators to rotate and slice reconstructed images, thereby increasing detection confidence while supporting faster passenger and baggage flow. Alongside imaging hardware, software-driven analytics, automated threat recognition, and digital twin integration are reshaping how scanning systems deliver value. Suppliers that pair high-fidelity imaging with integrated software layers can differentiate on operational outcomes rather than raw hardware specifications. Recent commercial activity illustrates this emphasis: Rapiscan Systems received a USD 19 million order to support deployment of non-intrusive inspection solutions, followed by a USD 15 million order for cargo and vehicle inspection systems and services. These placements reflect demand for end-to-end inspection capabilities that span baggage, parcel, freight, and vehicle contexts, with mobile threat detection integrated into the operational workflow.
Policy and Regulatory Pressure as a Demand Catalyst
Regulation continues to function as a powerful demand accelerator. EASA rules now require freight above 150 kg to undergo volumetric imaging, a mandate that is accelerating the replacement of single-view tunnels with higher-capability systems. In the United States, the Transportation Security Administration allocated approximately USD 1.3 billion for 469 CT units in 2025, signaling a decisive commitment to modernization at scale. Regulatory certifications also matter for market access and buyer confidence; for example, OSI Systems received ECAC/EU G1 certification for trace detection solutions for airport security in April 2026, reinforcing the importance of recognized approvals when operators evaluate systems for international deployment. These policy signals help de-risk procurement decisions and create multi-year installation pipelines that suppliers can plan around.
Demand-Side Evolution Across Aviation and Commercial Sectors
Demand is increasingly shaped by end-user priorities that extend beyond baseline compliance. Aviation and transportation stakeholders seek solutions that reduce passenger wait times, improve lane throughput, and provide actionable visualization for operators. Commercial entities, including logistics hubs, warehousing environments, and critical infrastructure operators, are expanding screening footprints to address cargo verification, internal theft and contraband detection, and facility-level security layering. This diversification means that manufacturers must tailor value propositions to distinct operating environments: checkpoint speed and ergonomics in aviation, while robustness, scale, and integration with warehouse management or cargo handling systems in commercial contexts. The relative revenue weight of aviation-transportation and commercial applications in 2025 confirms that both segments remain central to growth, but their requirements and purchasing cycles differ meaningfully.
Supply Chain Realities and Cost Architecture
Supply chain conditions continue to influence market behavior. Component availability, semiconductor constraints, and the cost of precision mechanical and sensing elements affect lead times and final system pricing. Tariff adjustments on selected pallet scanning equipment have already compelled buyers and suppliers to revisit vendor selection, sourcing strategies, and deployment timelines. In response, some operators are dual-sourcing critical subassemblies, negotiating longer-term service agreements to stabilize lifecycle costs, and planning deployment schedules with greater flexibility. Suppliers that can demonstrate resilient supply chains, transparent pricing, and modular architecture are better positioned to secure commitments in an environment where procurement teams are risk-aware and timeline-sensitive.
Security Screening Systems Market
Competitive Landscape and Leading Strategies
The competitive field combines established security hardware specialists, diversified defense and aerospace players, and regionally strong manufacturers with growing international reach. Market share is distributed rather than dominated, which rewards clear positioning and executable go-to-market strategies. Several companies illustrate the breadth of strategic approaches currently shaping the market.
Worldwide Security Laser Scanner Market
Rapiscan Systems, based in the United States, emphasizes Orions and Z Portal systems for baggage, parcel, freight, and vehicle inspection, with mobile threat detection integrated into its offering. The company’s recent order flow and certification activity reflect a strategy centered on non-intrusive inspection breadth, regulatory alignment, and service-supported deployments. Smiths Detection, headquartered in the United Kingdom, focuses on HI-SCAN and SDX X-ray systems for checkpoint and cargo screening, positioning around proven checkpoint performance and cargo inspection reliability. L3Harris Technologies, also U.S.-based, highlights ASCT and RSM-7 X-ray screening systems tailored for aviation and defense contexts, leaning into mission-grade robustness and integration with broader security and defense ecosystems.
Nuctech Company Limited, based in China, offers TSA-600 and T2000 X-ray systems for airports and cargo, pursuing scale, cost competitiveness, and expanding international deployments. Gilardoni S.p.A. of Italy concentrates on security X-ray scanners for baggage and parcel inspection, with a focus on precision imaging and specialized inspection workflows. 3DX-Ray, also U.K.-based, targets portable and cabinet X-ray security scanners for threat detection, serving applications where mobility and compact form factors are critical. Analogic Corporation, in the United States, develops advanced X-ray imaging systems for security screening, emphasizing image quality and engineering depth. Leidos, another U.S. player, provides AXM and L-3 X-ray systems for security applications, leveraging large-scale systems integration capabilities. Astrophysics Inc., based in the United States, promotes American-made X-ray security scanning systems for critical infrastructure, aligning with procurement preferences for domestic sourcing in sensitive environments. VOTI Detection, headquartered in Canada, focuses on 3D Perspective X-ray scanners for border and cargo screening, emphasizing volumetric reconstruction suited to border and freight inspection contexts.
Several strategic patterns emerge from this landscape. First, incumbents are expanding beyond hardware into software-assisted interpretation, service contracts, and lifecycle management, because recurring revenue and operational outcomes increasingly determine win rates in competitive tenders. Second, differentiation is shifting from single-dimension specifications to integrated value propositions that combine imaging fidelity, throughput, ergonomics, certification, and support responsiveness. Third, the market is experiencing selective consolidation pressure: larger players with diversified portfolios can cross-sell across aviation, cargo, and commercial segments, while smaller specialists compete by focusing on portable systems, cabin formats, or niche inspection workflows. At the same time, regional sourcing preferences and tariff-related adjustments are prompting buyers to diversify supplier bases and re-evaluate vendor risk, which opens opportunities for manufacturers that can demonstrate reliable delivery, clear compliance posture, and adaptable deployment models.
PW Consulting
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026 through 2032 horizon, several trends are likely to define where value concentrates and how competitive advantage is earned.
Trend 1: CT and Multi-View Adoption Will Move From Exception to Expectation in High-Traffic Checkpoints
As regulatory mandates and throughput requirements compound, volumetric imaging will become standard in major aviation corridors and high-volume cargo nodes. The commercial implication is a multi-year replacement and upgrade cycle that favors suppliers capable of offering migration pathways, site-ready installation packages, and operator training programs. Manufacturers that can reduce integration friction and demonstrate measurable improvements in alarm resolution times will capture disproportionate share in this cycle. Investors should watch for recurring service revenue, spare parts pipelines, and software license structures that accompany hardware deployments, because these elements increasingly determine long-term margin profiles.
Trend 2: Software-Defined Screening and Automated Interpretation Will Redefine Value Capture
Image reconstruction is only part of the value chain. Automated threat recognition, alarm classification, and operator decision support are becoming critical differentiators. Systems that reduce cognitive load, shorten training curves, and integrate with broader security information workflows will be preferred in environments where staffing constraints and consistency requirements are acute. This trend creates opportunities for companies that can bundle analytics, analytics updates, and remote support into their offerings, and it raises the stakes for hardware-only entrants that lack a credible software roadmap. A key uncertainty is the pace at which algorithms and recognition models must be updated to keep pace with evolving threat profiles and regulatory expectations, which can pressure both development cycles and certification timelines.
Trend 3: Procurement Diversification and Sourcing Resilience Will Shape Vendor Selection
Recent tariff adjustments and component supply volatility are pushing procurement teams to diversify vendor lists, dual-source critical subassemblies, and re-evaluate deployment timelines. This environment rewards suppliers with transparent supply chains, predictable lead times, and the ability to offer modular or staged deployments that align with budget cycles. For buyers, the commercial opportunity lies in negotiating total cost of ownership-based contracts that include maintenance, calibration, and software support, rather than optimizing narrowly on initial capital outlay. For manufacturers, the opportunity lies in designing architectures that can be configured flexibly across regions and use cases without fragmenting production too extensively. A persistent risk is that tariff and trade policy shifts may continue to disrupt pricing assumptions and delivery schedules, particularly for pallet scanning equipment and certain cargo inspection platforms, requiring continuous monitoring of policy trajectories and supplier exposure.
Strategic Actions for Decision Makers
The market’s direction rewards proactive positioning. The following actions are most relevant depending on role and objectives.
For Manufacturers and Technology Providers
Prioritize integrated value propositions that combine imaging capability, automated interpretation, and service-led lifecycle support. Develop migration paths that allow operators to transition from dual-view to CT-enabled systems without full rip-and-replace disruptions. Strengthen supply chain visibility and offer modular architectures that can be adapted to regional requirements and procurement constraints. Where relevant, pursue recognized certifications and demonstrate compliance with major regulatory frameworks, because these credentials reduce buyer risk and expand addressable markets. Differentiate on operational outcomes such as alarm resolution speed, operator training time, and throughput under real-world conditions rather than on specifications alone.
For Investors and Strategic Capital Allocators
Assess companies based on their ability to capture recurring revenue through services, software, and maintenance contracts, not only on hardware sales. Favor portfolios with exposure to the aviation-transportation and commercial segments that are benefiting from modernization mandates and expanded screening footprints. Monitor the competitive impact of tariff adjustments and sourcing diversification on margins and market share, particularly in pallet and cargo scanning segments where procurement behavior is being re-evaluated. Track the pace of CT adoption in checkpoint environments as a leading indicator of capital intensity, installation pipelines, and supplier differentiation opportunities. Be mindful of policy-driven demand spikes that can create short-term revenue surges but may also compress margins if supply chains are not scaled appropriately.
For Procurement Leaders and End-User Organizations
Structure acquisitions around total cost of ownership, including installation, training, calibration, software updates, and service response times. Plan for phased deployment where possible to align capital expenditure with budget cycles and operational readiness. Evaluate vendor resilience carefully, including lead time stability, parts availability, and the ability to support multiple sites or modalities from a single integration framework. Where privacy-sensitive environments are involved, consider modality trade-offs and user experience implications alongside detection performance to ensure adoption and public acceptance are not compromised. In cargo and freight contexts, align system selection with regulatory requirements for volumetric imaging above specified weight thresholds to avoid future compliance risk and replacement pressure.
Closing Perspective
The X-ray security scanner market is entering a phase in which growth is increasingly tied to technology modernization, regulatory alignment, and the ability to deliver measurable operational outcomes. Revenue expansion from 2025 toward 2032 will be shaped by the pace of CT adoption, the maturation of software-assisted interpretation, and the resilience of supply chains under tariff and component pressures. Competitive advantage will accrue to organizations that treat screening systems as part of a broader security and operational workflow rather than as isolated hardware purchases.
For executives, planners, and investors seeking granular segmentation data, regional demand trajectories, detailed company benchmarking, and customized procurement scenarios, the full PW Consulting study provides a more comprehensive view of the market’s subsegments, competitive moves, and forward scenarios. The complete report extends the analysis into deeper segmentation detail, deployment pattern trends, and strategic recommendations tailored to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: X-Ray Security Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automatic Tire Inflation System Market: Why 6.98% CAGR Changes Everything
By PW Consulting, 2026-09-21
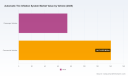
The Automatic Tire Inflation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global automatic tire inflation system (ATIS) market has entered a phase of steady, structurally driven expansion. Valued at approximately 215 million USD in 2025, the market has grown from roughly 163 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through 2032. This trajectory is not merely a function of incremental demand; it signals a broader transformation in how fleets, manufacturers, and regulators approach tire management. As operational costs rise and sustainability mandates tighten, ATIS has shifted from a niche add-on to a strategic component of vehicle architecture and fleet optimization.
The market's growth pattern reveals distinct inflection points. Revenue expanded modestly through 2022, then accelerated in 2023 and 2024, reaching 207.42 million USD before stabilizing near 215 million USD in 2025. This acceleration aligns with broader industry shifts: heavier emphasis on fuel efficiency, increased scrutiny of tire-related safety incidents, and the gradual integration of tire pressure management into connected vehicle ecosystems. Looking ahead, the forecast period through 2032 projects continued expansion, with revenue crossing 300 million USD by 2030 and approaching 344.8 million USD by 2032. The pace of growth will depend on how quickly adoption cascades from early-adopter segments into mainstream commercial and passenger vehicle applications.
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive dynamics and investment decisions over the next decade.
Core Challenges and Inflection Points
One of the most significant hurdles is the uneven regulatory landscape. In many jurisdictions, ATIS remains an optional feature rather than a mandated requirement. This creates a paradox: the systems deliver measurable safety and efficiency benefits, yet compliance frameworks do not consistently incentivize adoption. Fleet operators weighing capital expenditures must weigh tangible operational savings against the absence of regulatory compulsion. The result is a market where adoption velocity depends heavily on demonstrable return on investment rather than compliance-driven demand.
A second challenge lies in integration complexity. Retrofitting existing fleets with automatic inflation systems requires compatibility with diverse valve assemblies, air supply configurations, and telematics platforms. For new vehicle manufacturers, embedding ATIS into chassis design demands coordination across engineering teams, supply chains, and certification processes. These integration frictions slow deployment cycles and increase upfront costs, particularly for mid-sized operators who lack the scale to negotiate customized solutions or absorb installation downtime.
A third inflection point is the evolving definition of system value. Early generations of ATIS focused primarily on maintaining target pressure levels. Today, the market increasingly expects intelligent monitoring, real-time diagnostics, and data integration with fleet management software. This shift raises the bar for competitors: companies that offer standalone mechanical or pneumatic solutions without connected capabilities risk marginalization as buyers prioritize systems that feed actionable insights into broader operational workflows.
Key Drivers Shaping Market Trajectory
The expansion of the ATIS market is being propelled by a convergence of technological, regulatory, demand-side, and supply chain forces. Understanding how these drivers interact is essential for stakeholders evaluating market entry, product development, or capital allocation.
Technology Innovation and Intelligent Monitoring
Advancements in sensor technology, wireless communication, and edge computing have transformed ATIS from a pressure-maintenance tool into a data-generating asset. Modern systems now incorporate integrated sensors that continuously monitor tire conditions, log performance metrics, and transmit information to centralized dashboards. This evolution matters because tire under-inflation remains a leading cause of premature wear, elevated fuel consumption, and roadside failures. By automating pressure correction and coupling it with visibility into tire health, these systems reduce manual inspection burdens and enable predictive maintenance strategies.
Recent developments illustrate this trajectory. In early 2026, RIX Industries received a 204,500 USD SBIR Phase I contract from the Federal Motor Carrier Safety Administration to prototype a Weight Equalization Smart Automatic Tire Inflation System. The project targets per-tire real-time pressure management, highlighting a growing emphasis on precision control and load-aware inflation logic. Such initiatives signal that innovation is moving beyond generic pressure maintenance toward context-sensitive algorithms that adapt to cargo distribution, terrain, and operating conditions.
Policy and Regulatory Environment
Regulatory signals are subtly reshaping the adoption calculus. While ATIS is not universally mandated, inspection frameworks and electronic compliance standards are creating an environment where properly functioning tire pressure management systems carry indirect advantages. For example, recent inspection guidance clarifies that an ATIS unit is not classified as required equipment on commercial motor vehicles, and a defective or alert-status system does not automatically trigger a violation. This regulatory posture reduces the compliance risk of adoption while preserving the operational case for installation. It also means that manufacturers must ensure their systems meet relevant electromagnetic compatibility and electronic equipment standards to avoid unintended certification hurdles.
PW Consulting Automotive & Machinery Research Center
Parallel compliance milestones reinforce this trend. Systems on the market have been documented as conforming to FCC Part 15 rules and Industry Canada RSS-210 for electronic equipment, while other centralized tire inflation platforms declare conformity to EMC directives, ISOBUS standards, and environmental resistance specifications. These compliance layers are not mere formalities; they reduce integration friction for fleets operating across borders and signal maturity to buyers who prioritize reliability and auditability.
Demand-Side Shifts in Fleet and Consumer Behavior
On the demand side, fleet operators are increasingly treating tire management as a lever for total cost of ownership reduction rather than a maintenance afterthought. Proper inflation directly influences fuel economy, tire lifespan, and unscheduled downtime. As freight margins remain constrained and labor shortages complicate roadside inspection routines, the economic argument for automated pressure management strengthens. Large trailer fleets that have already deployed ATIS on a significant scale report sustained benefits in keeping tires properly inflated and improving fuel efficiency, which reinforces the credibility of the technology among peer operators.
Passenger vehicle applications are also gaining attention, particularly as connected car platforms expand and consumers become more accustomed to vehicles that self-monitor and self-adjust. While commercial vehicles currently represent the larger revenue share, the passenger segment benefits from the same underlying logic: reduced wear, improved safety margins, and alignment with broader vehicle intelligence trends. The challenge for suppliers is to adapt system architectures to the cost, packaging, and user-experience expectations of passenger markets without sacrificing reliability.
Supply Chain and Cost Structure Evolution
Cost dynamics are being reshaped by component innovation and manufacturing scale. Sealing technologies, for instance, have advanced to the point where central tire inflation seals can self-adjust across terrains, reducing CO₂ emissions and extending tire life. Such improvements lower the total cost of ownership for end users while giving system manufacturers a tangible performance differentiator. At the same time, the broader push toward standardized electronic components and modular architectures is helping suppliers reduce integration complexity and accelerate time to market.
However, supply chain resilience remains a consideration. Systems that depend on specialized sensors, control modules, and custom pneumatic assemblies are exposed to component availability fluctuations and lead-time variability. Manufacturers that invest in component standardization, dual-sourcing strategies, and design-for-manufacturing principles will be better positioned to maintain pricing stability and delivery reliability as demand scales.
Competitive Landscape and Leading Strategies
The ATIS market is characterized by a moderately concentrated competitive structure, with the top three players holding approximately 31.4 percent of revenue and the top five accounting for roughly 38.7 percent. This concentration leaves meaningful room for specialized providers, regional players, and new entrants that can address underserved segments or bring differentiated technology. The competitive arena is not defined by a single winner-takes-all dynamic; rather, it rewards companies that combine technical credibility, integration ease, and compelling operational value propositions.
Strategic Positioning of Leading Players
Several established companies illustrate the diversity of successful strategic positioning. Aperia Technologies has focused on intelligent automatic tire inflation with integrated sensors designed for seamless data collection and reporting, targeting heavy-duty trucks and fleets. This approach positions the company at the intersection of pressure management and fleet analytics, appealing to operators who want actionable visibility alongside automated inflation.
Cummins, through its Meritor Tire Inflation System, has built scale by equipping more than one million trailers with technology that maintains proper tire inflation and reduces wear. The breadth of deployment provides a strong reference base and reinforces the system's status as a proven solution in the commercial trailer segment. Hendrickson International offers a tiered portfolio of tire pressure control systems, including CP, PRO, and PRO-LB automatic inflation models tailored for the trailer industry. This product ladder allows the company to address varying performance and budget requirements within a coherent brand framework.
Pressure Systems International has established a long-standing presence in the market, positioning itself as a global leader in automatic tire inflation systems with integrated TPMS capabilities. Its emphasis on decades of experience and combined inflation and monitoring functionality appeals to buyers seeking consolidated solutions. Rotex Automation brings a European footprint with a patented centralized tire inflation system installed on a significant share of trucks across the region, reflecting deep regional integration and familiarity with local operating conditions. Stemco complements this landscape by focusing on installation efficiency, offering toolkits that streamline trailer tire inflation system deployment, which reduces friction for operators and upfitters alike.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape is evolving along three overlapping directions. First, integration is becoming a decisive advantage. Suppliers that connect inflation hardware with telematics, maintenance platforms, and route-optimization software are creating stickier customer relationships and higher perceived value. Second, differentiation is increasingly tied to intelligent features rather than mechanical performance alone. Real-time pressure management, load-aware algorithms, and diagnostic reporting are becoming baseline expectations in commercial segments, pushing legacy-only offerings toward the periphery.
Third, the market is open to strategic new entrants, particularly those with strong funding pathways or specialized technology. The recent SBIR-funded prototype for a weight equalization smart inflation system exemplifies how targeted innovation can introduce novel capabilities that address specific operational pain points. While such projects are early stage, they signal that the barrier to introducing differentiated concepts remains manageable for well-positioned innovators. Over time, the market may see consolidation among larger platform providers acquiring niche technology, alongside continued fragmentation in regional or application-specific niches.
Future Trends and Commercial Opportunities
Looking ahead to the 2027–2032 window, three trends are likely to shape commercial opportunities and strategic priorities.
From Standalone Systems to Integrated Fleet Intelligence
Automatic tire inflation will increasingly be evaluated as part of a broader fleet intelligence stack rather than as an isolated hardware purchase. Buyers will expect systems that not only maintain pressure but also contribute data to maintenance scheduling, fuel reporting, and safety analytics. This trend creates opportunities for suppliers that invest in open APIs, interoperable data formats, and bundled service offerings. It also raises the stakes for companies that rely on closed architectures, as fleets favor solutions that plug into existing operational workflows.
Precision Control and Load-Aware Inflation Logic
A second trend is the move toward per-tire, condition-aware pressure management. As sensing accuracy improves and control algorithms become more sophisticated, systems will adapt inflation levels to cargo distribution, road surface, and dynamic loading conditions. This precision has direct commercial implications: it can extend tire life, reduce uneven wear, and improve fuel economy under variable operating conditions. Suppliers that can demonstrate measurable performance gains from smart inflation logic will have a stronger case in price-sensitive procurement environments.
Aftermarket Tire Pressure Monitoring System (TPMS) Market
Regional Expansion and Application Diversification
A third trend is the gradual expansion of ATIS adoption beyond mature commercial trailer markets into adjacent applications and regions. Centralized and continuous inflation architectures are finding relevance in off-road and specialized vehicle contexts, while passenger vehicle applications may grow as connectivity and self-diagnosis features become standard expectations. Regional growth will be uneven, shaped by local fleet composition, fuel cost sensitivity, and the pace of telematics adoption. Companies that can adapt system designs to regional operating conditions and cost structures will be better positioned to capture incremental demand.
Risks and Uncertainties
These opportunities are accompanied by risks that stakeholders should monitor. Regulatory frameworks could shift in ways that either accelerate adoption through mandates or introduce new compliance burdens that increase system cost. Supply chain disruptions affecting sensors, control modules, or pneumatic components could pressure margins and delay deployments. Additionally, if macroeconomic conditions compress fleet capital spending, the timeline for broader ATIS adoption may extend, particularly in price-sensitive segments where payback periods are closely scrutinized. Competitive pressure could also intensify if large platform providers bundle inflation capabilities with broader vehicle systems, altering the bargaining dynamics for standalone suppliers.
Actionable Guidance for Decision-Makers
The strategic implications of these trends differ by role, but several priorities apply across the board.
For Manufacturers and Technology Providers
Differentiate through intelligent integration rather than pressure maintenance alone. Invest in sensor accuracy, data interoperability, and installation efficiency, as these elements increasingly determine buyer preference. Standardize components where possible to improve supply chain resilience and reduce cost volatility. Consider targeted partnerships or acquisitions that add complementary capabilities, such as telematics interfaces, advanced sealing technologies, or region-specific installation expertise.
For Investors and Capital Allocators
Evaluate opportunities based on total cost of ownership value propositions and the capacity to scale installation and service networks. Companies with proven deployment volumes, clear compliance alignments, and modular architectures are better positioned to weather procurement cycles and supply variability. Watch for early-stage innovations that address load-aware control or terrain-adaptive sealing, as these features can become meaningful differentiators if they translate into measurable operational savings. Assess the pace of regional adoption carefully, as growth will be uneven and dependent on local fleet economics and telematics maturity.
For Fleet Operators and Procurement Teams
Prioritize systems that integrate with existing maintenance and telematics workflows, reducing the operational burden of data reconciliation and manual inspections. Evaluate installation toolkits and service support as part of the procurement decision, since deployment efficiency directly affects downtime and total cost. When comparing solutions, look beyond headline specifications to verify compatibility with valve configurations, air supply arrangements, and electronic compliance requirements relevant to your operating region. Consider pilot deployments in representative routes and load conditions to validate real-world performance before scaling.
Worldwide Automotive Tire Socks Market
The ATIS market is moving from a phase of incremental adoption to one where intelligent control, integration, and regional adaptation determine competitive advantage. Stakeholders who align product strategies, investment theses, and procurement criteria with these shifts will be better positioned to capture value as the market expands toward the mid-2030s. For decision-makers seeking deeper segmentation data, regional breakdowns, and customized scenario analysis, the full research report provides the detailed frameworks needed to translate these trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Automatic Tire Inflation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microwave Oven Market 2032: Why 3.5% CAGR Growth Trajectory Defies Expectations
By PW Consulting, 2026-09-21
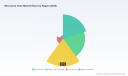
Strategic Trends and Commercial Opportunities in the Microwave Oven Market (2025–2032)
Market Outlook: A Mature Appliance Sector in Transition
The microwave oven market has evolved from a quintessential convenience appliance into a more strategically nuanced segment within the broader kitchen appliance landscape. Valued at USD 8.5 billion in 2020, the sector reached an estimated USD 13.5 billion by 2025, reflecting steady expansion driven by consistent household demand and incremental product innovation. Projections through 2032 indicate a 3.5% compound annual growth rate, culminating in a market valuation approaching USD 17.21 billion. While these headline figures suggest a predictable growth trajectory, the underlying dynamics reveal a market navigating structural shifts in consumer behavior, regulatory uncertainty, and supply chain reconfiguration.
The growth narrative is not uniform across all dimensions. Regional performance varies significantly, with Asian Pacific markets continuing to anchor volume demand while North American and European segments exhibit more mature, replacement-driven consumption patterns. Product differentiation has also reshaped how manufacturers allocate capital and design roadmaps. Solo units maintain a dominant share, reflecting their affordability and prevalence in price-sensitive markets, while grill and convection variants capture premium positioning and multi-functionality demand. Similarly, residential applications overwhelmingly drive baseline volume, yet commercial installations represent a strategically distinct segment with different procurement cycles, durability requirements, and service expectations.
High Speed Oven Market
Key Challenges and Inflection Points
Despite the steady top-line trajectory, several friction points are reshaping how stakeholders approach the market. First, the recent policy landscape has introduced regulatory volatility. In May 2025, the U.S. Department of Energy proposed rescinding energy conservation standards for microwave ovens, effectively eliminating prior efficiency requirements. This move reduces compliance burdens for manufacturers but simultaneously removes a historical driver that had accelerated the phase-out of less efficient designs and influenced product architecture. While the change may lower near-term engineering costs, it also introduces uncertainty around future regulatory directionality and consumer perceptions of energy-conscious appliances.
Second, trade policy dynamics are creating cost pressure that ripples through pricing strategies and margin structures. Tariff actions on Chinese-origin goods in 2025 contributed to a measurable increase in core goods consumer prices, with continued effects extending through early 2026. For a category with substantial import-dependent component sourcing and finished goods manufacturing footprints in East Asia, these trade shifts are compressing supply chain flexibility and forcing manufacturers to weigh localized production, alternative sourcing, and pricing absorption more carefully.
Third, the market is approaching a functional saturation point in basic microwave cooking. As standalone heating appliances become commoditized in many households, growth increasingly depends on differentiated value propositions rather than volume replacement alone. This creates a strategic crossroads: manufacturers must decide whether to compete on cost efficiency in mature categories or invest in integrated solutions that address evolving kitchen workflows, space constraints, and connected living environments.
Core Drivers Shaping Market Trajectory
Technological Innovation and Design Evolution
Product innovation remains a central competitive lever, though the nature of innovation has shifted from incremental wattage and capacity upgrades toward integrated functionality and form-factor adaptation. Convection capabilities, air-fry combinations, and smart connectivity features are redefining how microwaves fit into modern kitchens. Leading manufacturers are embedding intelligent interfaces, remote diagnostics, and compatibility with broader smart home ecosystems, positioning microwave ovens not merely as heating tools but as nodes within integrated kitchen management. LG Electronics, for example, has continued advancing its Smart ThinQ platform alongside convection technology, reinforcing the trend toward app-enabled control and performance customization. Such developments appeal to consumers willing to pay a premium for convenience, consistency, and multi-cooking versatility.
At the same time, spatial constraints in urban housing and smaller-footprint living environments are driving demand for compact and flexible configurations. Sharp Corporation’s recent introduction of compact kitchen appliances, including new Convection Microwave Drawer™ Oven models, highlights how design innovation is responding to the need for built-in flexibility and space optimization. These developments illustrate that technology leadership in this market is increasingly defined by how well a product adapts to installation environments, culinary workflows, and aesthetic expectations rather than raw heating specifications alone.
Policy and Regulatory Environment
Regulatory shifts are acting as both a constraint and an enabler, depending on the manufacturer’s positioning and geographic exposure. The proposed rescission of energy conservation standards alters the compliance calculus for U.S.-facing products, potentially freeing engineering resources that would otherwise be directed toward efficiency optimization. However, this does not eliminate all regulatory oversight. The FDA continues to enforce radiation safety performance standards under 21 CFR 1030.10, requiring manufacturer certification and labeling. This framework ensures a baseline of product safety and consumer confidence but also imposes ongoing compliance obligations that influence product design, testing, and market entry timelines.
For global manufacturers, the divergence between evolving energy policy in some markets and persistent safety standards in others creates a patchwork of requirements. Companies must manage product configurations that can satisfy multiple regulatory regimes without sacrificing cost competitiveness or feature consistency. In practice, this regulatory complexity favors manufacturers with mature compliance infrastructure and the ability to modularize design platforms across regions.
PW Consulting
Demand-Side Shifts in Consumer and Commercial Behavior
On the demand side, microwave ovens are benefiting from broader lifestyle and housing trends that value convenience, speed, and multifunctional appliances. Urbanization, smaller household sizes, and time-constrained consumption patterns continue to reinforce reliance on fast-preparation appliances. At the premium end, consumers are increasingly looking for appliances that support varied cooking methods within a single footprint, which has helped sustain interest in convection and grill variants. In commercial environments, demand is shaped by operational efficiency, durability, and throughput requirements. Food service operators, institutional kitchens, and hospitality venues evaluate microwave systems through a different lens than residential buyers, prioritizing serviceability, consistent output, and integration with existing workflow equipment.
A notable demand-side development is the growing sensitivity to total cost of ownership rather than sticker price alone. While budget-conscious segments still favor basic solo models, buyers in higher-income and commercial segments increasingly weigh features, energy behavior, service availability, and brand reliability. This bifurcation is reinforcing segmentation strategies and making it more difficult for undifferentiated products to command share in competitive channels.
Supply Chain and Cost Structure Adjustments
Cost structures in the microwave oven market are being reshaped by a combination of input pricing, logistics volatility, and trade policy exposure. Tariffs on Chinese-origin goods have raised the price baseline for imported components and finished goods, affecting everything from magnetron sourcing to assembly and distribution. In response, manufacturers are recalibrating sourcing strategies, evaluating nearshoring or diversified supplier networks, and adjusting product mix to protect margins without alienating price-sensitive buyers. Midea Group’s ongoing catalog updates, including refreshed countertop and Versa Series offerings, reflect the type of portfolio management required to maintain channel relevance while navigating shifting cost dynamics.
Worldwide Combination Microwave Ovens Market
The supply chain imperative is not only about cost containment. It also involves resilience. Manufacturers with the ability to flex production footprints, maintain component buffers, and respond quickly to channel demand fluctuations are better positioned to manage the trade-offs between volume, margin, and lead time. This has elevated the strategic importance of manufacturing planning and logistics coordination as competitive differentiators in a segment where hardware innovation is sometimes incremental.
Competitive Landscape and Strategic Positioning
Incumbent Strength and Differentiation Paths
The market remains moderately concentrated, with the top three players accounting for roughly 45% of share and the top five approaching 60%. This concentration reflects the presence of large, globally active manufacturers capable of sustaining broad product portfolios, competitive pricing, and multi-channel distribution. Midea Group and Galanz function as major OEM and branded manufacturers, producing microwave ovens for multiple labels and retail channels. Their scale and manufacturing breadth enable them to serve both proprietary brand strategies and third-party sourcing relationships. Midea’s portfolio breadth, including countertop and Versa Series models, underscores a strategy built on product range and channel versatility, while Galanz similarly supports a mix of its own brand and retailer-supplied models.
On the branded premium and feature-differentiated side, LG Electronics and Sharp Corporation emphasize integrated technologies and specialized form factors. LG’s focus on built-in, countertop, and convection models with smart connectivity highlights an orientation toward modern kitchen integration and consumer-facing digital experience. Sharp’s emphasis on Convection Microwave Drawer™ ovens and other countertop and over-the-range models reflects a more architecture-oriented approach, appealing to installations where space, aesthetics, and built-in functionality matter. These differentiated paths show that incumbents are not competing solely on volume; they are also cultivating niches where design, functionality, and ecosystem alignment can support margin resilience.
Whirlpool Corporation and GE Appliances illustrate how established Western appliance groups maintain relevance through multi-brand portfolios and domestic manufacturing elements. Whirlpool’s offerings under Whirlpool, KitchenAid, and Amana brands span multiple consumer segments and price tiers, while GE Appliances has continued to emphasize countertop and built-in models with convection and air-fry options. For these players, brand trust, service networks, and retail relationships remain important assets, especially in markets where post-purchase support and consumer familiarity influence purchasing decisions.
Structural Evolution in the Competitive Field
The competitive landscape is likely to continue evolving along several axes. One is consolidation and selective partnership. Larger manufacturers may pursue channel expansion, regional manufacturing footprint adjustments, or targeted acquisitions to strengthen portfolio coverage or technology capabilities. Another is segmentation-driven specialization, where certain players concentrate on high-volume cost-competitive models while others invest in premium, connected, or built-in solutions. This divergence can create opportunities for new entrants or niche specialists that address underserved needs, such as compact urban installations, commercial-grade durability, or region-specific compliance and pricing requirements.
Recent product and catalog activity illustrates how firms are refining their positioning in real time. Sharp Electronics Corporation’s February 2026 launch of compact kitchen appliances, including a new Convection Microwave Drawer™ Oven, signals a continued push toward space-efficient and design-forward solutions. Midea Group’s March 2026 catalog updates, including compact countertop models and revised Versa Series offerings, demonstrate ongoing portfolio tuning to maintain relevance across channel and consumer segments. These moves are not isolated product events; they reflect broader strategic calibration in response to housing trends, channel demands, and cost pressures.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Functional Integration as a Growth Lever
Over the next three to five years, microwave ovens are likely to gain share not by standing alone as simple reheating appliances, but by functioning as integrated cooking and convenience hubs. Convection, air-fry, and smart-control capabilities will increasingly become baseline expectations in higher-tier segments, while basic solo units remain volume drivers in price-sensitive markets. Commercial opportunity lies in product architectures that allow modular feature sets, enabling manufacturers to cover multiple price points without fragmenting engineering resources. For channel partners, this translates into clearer upsell pathways and stronger differentiation in showroom and online environments.
Trend 2: Space-Optimized and Installation-Focused Designs
As housing footprints shrink in many urban markets and renovation projects prioritize integrated cabinetry and flexible layouts, demand for compact, built-in, and drawer-style configurations is expected to grow. This trend favors manufacturers that can align product design with installation ecosystems and offer solutions that fit diverse kitchen architectures. Commercial opportunity extends beyond consumer retail into renovation channels, property development partnerships, and commercial fit-out procurement, where appliance compatibility and space efficiency influence purchasing decisions early in the project lifecycle.
Trend 3: Supply Chain Realignment and Regional Cost Strategy
Given ongoing trade policy exposure and component sourcing complexity, manufacturers are likely to continue diversifying production and sourcing strategies to protect margin and lead-time reliability. Commercial opportunity exists for firms that can demonstrate supply chain resilience, localized assembly options, or flexible sourcing models to buyers who are increasingly sensitive to availability risk and total cost of ownership. Investors and strategic partners should watch for shifts in manufacturing geography, supplier concentration, and channel pricing behavior, as these factors will influence category profitability more directly than headline demand growth alone.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Regulatory directionality remains fluid, particularly where energy standards are being reevaluated, and future reinstatement or recalibration of efficiency requirements could change design priorities. Trade policy volatility can shift cost structures quickly, especially for categories with heavy import dependence. Additionally, competitive intensity in commoditized segments may compress pricing power, while premium differentiation depends on sustained consumer willingness to pay for features that are not yet considered essential. Finally, macroeconomic sensitivity in major residential markets can affect big-ticket appliance purchase cycles, making the category partly dependent on housing activity, remodeling spend, and discretionary income trends.
Strategic Recommendations for Decision-Makers
For Manufacturers and Brand Strategists
- Develop modular product platforms that can support solo, grill, and convection variants without duplicating engineering effort, allowing faster response to regional price and feature expectations.
- Align design roadmaps with space-constrained and built-in installation trends, including compact and drawer-style options, to capture renovation-driven and urban-living demand.
- Stress-test supply chain exposure to trade policy and component sourcing concentration, and evaluate diversified sourcing, regional assembly, or flexible logistics arrangements to protect margin and availability.
For Investors and Strategic Partners
- Evaluate category exposure by segmentation logic rather than aggregate market size alone; premium convection and smart-enabled segments may offer different risk-return profiles than high-volume solo units.
- Monitor regulatory and trade-policy developments closely, as changes can alter cost structures and compliance investment requirements with limited lead time.
- Prioritize companies with credible manufacturing flexibility, brand-channel strength, and the ability to manage multi-tier portfolios across cost-competitive and differentiated segments.
For Procurement and Channel Leaders
- Balance base-volume sourcing with differentiated SKUs that support margin and consumer upgrade paths, particularly where convection, air-fry, and compact configurations can command stronger positioning.
- Incorporate serviceability, warranty infrastructure, and installation compatibility into evaluation criteria, especially for commercial and multi-unit deployment scenarios.
- Track price and availability signals tied to component imports and trade measures, and adjust sourcing plans to reduce exposure to sudden cost shifts.
The microwave oven market is no longer moving solely on basic replacement demand. It is being reshaped by design innovation, regulatory recalibration, trade-linked cost dynamics, and evolving expectations around how appliances fit into modern kitchens and commercial operations. For decision-makers, the most valuable intelligence is not a single aggregate figure but a clear view of where differentiation is gaining traction, where cost pressure is reshaping margins, and how regulatory and supply chain variables may change competitive advantage over the next several years. Readers seeking deeper segmentation detail, regional dynamics, and customized strategic guidance can explore the full PW Consulting report for a more granular view of the market and its emerging opportunities.
For detailed analysis of this topic, please visit the official page: Microwave Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strain Gage Market 2026: Unpacking the 4.55% CAGR and $316.6M Growth Path to 2032
By PW Consulting, 2026-09-21
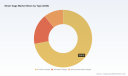
Navigating the Strain Gage Market: Strategic Trends and Commercial Opportunities Through 2032
The global strain gage market has entered a phase of steady, investment-backed expansion. From a base of approximately USD 163.15 million in 2020, the sector climbed to USD 230.12 million by 2025 and is projected to reach USD 316.6 million by 2032. This trajectory reflects a compound annual growth rate of roughly 4.55 percent, a pace that underscores consistent demand across industrial, aerospace, and automotive applications. For executives and strategic planning teams, the market presents a familiar pattern: mature technology platforms coexisting with incremental but meaningful shifts in application requirements, regulatory expectations, and integration models. The real question is no longer whether the market will grow, but where value will concentrate and which capabilities will separate profitable participants from marginal ones.
Market Landscape and Core Challenges
The current market structure reflects a combination of industrial modernization, infrastructure monitoring mandates, and the ongoing digitization of physical systems. Strain gages remain foundational measurement tools for stress analysis, load monitoring, and structural health assessment. Their presence across aerospace testing, automotive validation, and industrial manufacturing means that procurement cycles are tied to broader capital expenditure patterns, engineering program timelines, and compliance-driven testing requirements. Market growth during the historical window from 2020 to 2025 was supported by recovery in industrial production, expanded testing requirements, and renewed attention to structural integrity in critical infrastructure. The forecast period from 2026 to 2032 extends this trajectory, with the market expected to move toward the mid-300 million range as demand becomes more application-specific and more closely integrated with upstream system design.
Despite the clear expansion path, several operational and strategic challenges shape how participants compete. First, standardization and qualification requirements are tightening. Updated measurement standards for strain-based geotechnical and structural monitoring have introduced clearer expectations for installation practices, traceability, and data reliability. These standards reduce ambiguity in high-stakes applications, but they also raise the cost of non-compliance and increase the importance of repeatable installation and calibration procedures. Second, installation complexity and labor expertise continue to constrain throughput. Bonding strain gages to advanced composites, high-temperature substrates, or heterogeneous structures demands trained technicians, controlled environments, and disciplined process documentation. In applications where measurement error carries direct safety, warranty, or certification consequences, labor skill becomes a cost driver rather than a trivial implementation detail. Third, suppliers face pressure to balance product breadth with engineering depth. The market includes producers of foil gauges, wire gauges, semiconductor variants, weldable units, and integrated measurement accessories. Companies that span too many sub-segments risk dilution, while those that specialize too narrowly may miss opportunities in adjacent high-value applications.
For business leaders, the practical implication is that growth in this market is less about raw volume and more about qualification, reliability, and integration readiness. Procurement decisions increasingly weigh total measurement confidence, not just unit price. Engineering teams prefer suppliers that can support application-specific bonding methods, environmental resilience, and documentation that aligns with internal or external audit requirements. Companies that treat strain gages as commodity components may win occasional price-sensitive bids, but they will struggle to retain long-term positions in programs where measurement integrity is a gating factor.
Key Drivers Shaping Demand and competitive dynamics
Technology innovation and application-specific customization
Technology advancement in this market is not dominated by disruptive product resets; it is driven by refinement, reliability, and fit-for-purpose engineering. Foil strain gauges continue to serve as the workhorse category because metallic foil elements offer stable performance, familiar handling, and cost predictability. Alloys such as copper-nickel and nickel-chromium remain common choices for resistive elements, enabling manufacturers to balance sensitivity, durability, and unit economics. At the same time, specialized variants extend the technology into harsher environments. High-temperature bondable gauges, waterproof weldable units, and composite-material-compatible formats address narrowband problems that generic products cannot reliably solve.
Recent industry activity reflects this customization trajectory. Product introductions have increasingly focused on expanding application-ready ranges rather than reinventing core sensing principles. In parallel, technical publications and workshop-based training efforts have reinforced the importance of proper installation, electrical connection practices, and measurement process discipline. These developments matter because the performance of a strain gage system is determined not only by the sensor itself but also by how it is mounted, wired, protected, and interpreted. In markets where customers are acquiring measurement capability for critical assets, suppliers that can deliver both the sensor and the process knowledge around it gain a meaningful advantage.
Policy, standards, and regulatory influence
Regulatory and standards activity is a growing force in how strain gage solutions are specified, validated, and deployed. New measurement standards have been introduced to define precise strain measurement practices for geotechnical monitoring and structural assessment. The adoption of these standards across regional and national bodies creates a clearer compliance path for infrastructure and civil engineering applications, while also raising the baseline expectation for documentation and reproducibility. For manufacturers and system integrators, this environment favors suppliers that already operate with quality management discipline and can demonstrate consistent production and testing practices.
Standardization also has a secondary effect on market structure. As measurement expectations become more explicit, end users are better able to compare offerings on technical merit rather than marketing claims. That tends to reward established performance characteristics, transparent specifications, and support ecosystems that help customers meet audit or certification requirements. In civil infrastructure, mining, and structural monitoring, where long-term data continuity matters, the ability to align with recognized measurement practices can be as important as sensor price.
Demand-side shifts in aerospace, automotive, and industrial manufacturing
Demand behavior across core application areas is evolving around validation intensity, safety assurance, and asset-life management. Aerospace continues to require strain measurement for structural testing, component qualification, and ongoing monitoring. Automotive development and production similarly depend on strain-based data for durability evaluation, load-path analysis, and quality assurance. Industrial manufacturing remains broad-based, with strain gages supporting load cells, process monitoring, machinery condition assessment, and experimental stress analysis.
What is changing is the context in which these measurements are used. Engineering programs increasingly treat strain data as part of a larger evidence chain linked to simulation, digital twin models, and ongoing asset monitoring. That integration raises expectations for sensor consistency, signal quality, and compatibility with broader data acquisition environments. Customers are also paying closer attention to total implementation effort, including mounting preparation, environmental protection, and post-installation calibration. In practice, this means strong demand continues for general-purpose products, but the highest-margin growth often accrues to suppliers that can address specific bonding conditions, environmental ranges, or measurement-system compatibility requirements.
Supply chain considerations and cost structure dynamics
The cost structure of strain gage production is shaped by material inputs, manufacturing precision, quality control, and application support. Foil-based products remain attractive because the core resistive elements rely on established metallic alloys that provide both cost efficiency and stable performance. That said, price competition alone does not determine outcomes in many end markets. Procurement teams in aerospace and infrastructure-related applications often prioritize traceability, environmental robustness, and supplier reliability over marginal unit-cost savings.
Labor and process costs also influence competitiveness. Installation on composites and other non-standard substrates can require specialized training and careful handling to avoid substrate damage or measurement error. When installation quality directly affects test validity or field performance, the cost of labor becomes a structural part of the value proposition rather than an external overhead item. Suppliers that reduce installation friction through product design, clear application guidance, or compatible accessory offerings can lower the total cost of deployment for customers, even if the sensor itself is not the cheapest option. This dynamic encourages differentiation based on ease of use, repeatability, and support documentation.
Competitive Landscape and Leading Strategies
The competitive field includes a blend of specialized sensor manufacturers, broader measurement and sensor groups, and distributors or solution providers that extend reach into end markets. A small number of companies hold a meaningful share of market value, while a long tail of regional and application-focused suppliers competes on specialization, service, and niche technical capability. This structure produces a market where leadership is earned through combination of product breadth, engineering credibility, and the ability to support customers through installation and interpretation challenges.
Worldwide Optical Strain Sensor Market
Several strategic positions are visible among leading participants. Micro-Measurements and Vishay Precision Group operate from a shared sensor heritage that spans general-purpose foil gauges, high-temperature variants, and semiconductor sensor lines. Their relevance in the market stems from the ability to address multiple performance tiers within a single supplier relationship, which is particularly valuable for engineering teams seeking consistent specifications across different test and production environments. Tokyo Measuring Instruments Laboratory has built a differentiated position through an extensive catalog of foil strain gage types, including high-temperature, weldable, and composite-material variants. That breadth allows the company to serve customers with diverse substrate and environmental requirements while maintaining a recognizable product architecture. Hottinger Brüel & Kjær emphasizes electrical foil strain gauges, cylindrical gauges, and integrated measurement systems for load cells, structural testing, and industrial applications, reflecting a strategy that connects the sensor to the broader measurement workflow.
TE Connectivity contributes a transducer- and sensor-oriented perspective, supplying strain gauge-based sensors for automotive, industrial, and general sensing applications. Its position illustrates how strain technology fits into larger electronic sensing portfolios, where integration with downstream signal conditioning and system design can matter as much as the sensing element itself. Omega Engineering and other distributors or solution providers expand market access by bundling sensors, load cells, and accessories into measurement and control systems, lowering the friction for customers who value ready-made configurations over component-level sourcing. Japanese manufacturers such as Kyowa Electronic Instruments add further specialization through foil, wire, weldable waterproof, and protector-type products for industrial and structural use. Similarly, companies like Hitec Products, GEOKON, Sensing Systems Corporation, and ME systeme GmbH focus on specific environment classes or application contexts, from hostile-environment weldable gauges to geotechnical instrumentation and mechanical engineering measurement chains.
The competitive trend is not simply consolidation or fragmentation; it is functional differentiation. Larger groups can leverage scale, multiple brands, and broader application coverage, while smaller specialists compete by solving specific installation, environmental, or documentation challenges that broader portfolios may treat only generically. Recent industry activity reinforces this pattern. New product ranges and technical publications have highlighted the ongoing importance of application-oriented strain gauge solutions, while standards adoption and training events have drawn attention to the operational discipline required for dependable measurements. For entrants and existing players alike, the most durable advantage is likely to come from being the supplier that reduces uncertainty across the full measurement chain, not just at the sensor level.
Future Trends and Commercial Implications
Trend 1: Standards-driven specification and higher qualification barriers
Over the next three to five years, measurement standards and associated qualification expectations are likely to become more embedded in procurement and engineering workflows. As standards for strain measurement are adopted across regional and national contexts, end users will increasingly expect suppliers to demonstrate consistent production quality, clear specification language, and documentation that supports audit and verification activities. This trend favors companies with robust quality management practices and well-defined application support. It also raises the cost of operating in high-compliance segments without the necessary process discipline.
The commercial opportunity here lies in aligning product portfolios with recognized measurement requirements and in offering implementation support that helps customers meet those requirements efficiently. Suppliers that can reduce the time and risk associated with qualification, installation, and reporting will be better positioned in infrastructure, civil engineering, and critical-structure applications.
Trend 2: Broader integration with monitoring systems and data workflows
Strain gages are increasingly part of larger monitoring and testing architectures rather than isolated point sensors. In infrastructure, mining, and structural integrity applications, strain measurement supports real-time observation of ground movement, load behavior, and structural condition. In aerospace and automotive contexts, strain data is used alongside simulation and validation workflows that demand repeatability and traceability. As a result, compatibility with data acquisition environments, signal conditioning, and system-level documentation becomes a more visible purchase criterion.
PW Consulting
This creates opportunities for suppliers that think beyond the sensor and consider how the device fits into installation, wiring, protection, and data interpretation. Product designs that simplify mounting, improve environmental protection, or align with common measurement setups can lower total project risk. The broader implication is that value will increasingly accrue to those who understand the customer’s measurement workflow and can reduce friction at multiple touchpoints.
Trend 3: Application specialization as a margin defense
Because the market is growing at a moderate, sustained pace, pure volume plays will face persistent margin pressure unless supported by scale or distribution advantages. A more reliable path to profitability is application specialization: targeting high-value use cases where measurement accuracy, durability, or certification support justifies a stronger value proposition. High-temperature environments, composite substrates, weldable waterproof configurations, and geotechnical instrumentation are all examples where specialized products can command greater relevance and pricing power than generic alternatives.
At the same time, specialization carries risk if a company overcommits to a narrow niche with volatile demand. The most resilient strategies combine deep capability in selected application areas with enough portfolio flexibility to serve adjacent use cases. For decision-makers, this means evaluating whether a given specialization is durable, whether the target application has structural demand drivers, and whether the supplier can support the customer beyond the sale through training, documentation, and technical service.
Strategic Actions for Decision-Makers
For manufacturers and product leaders
- Prioritize application-ready differentiation over undifferentiated product breadth. Focus engineering effort on the environments, substrates, and installation conditions where measurement reliability matters most.
- Strengthen quality management and specification clarity. As standards adoption increases, the ability to demonstrate consistent production and clear documentation becomes a competitive asset.
- Reduce total deployment friction. Develop accessories, application notes, and training support that help customers install and interpret measurements correctly, especially on composites and in harsh environments.
For investors and strategic backers
- Evaluate exposure to compliance-sensitive and infrastructure-linked applications. Segments where measurement standards and long-term data continuity matter may offer more defensible demand than purely price-driven volume markets.
- Assess portfolio fit rather than sensor count. A company’s value may depend less on how many gauge types it lists and more on how well its products map to durable application needs and integration requirements.
- Watch for consolidation among specialists and solution providers. As end users seek lower implementation risk and broader support, suppliers with strong technical credibility and distribution reach may become attractive acquisition or partnership targets.
For procurement and engineering leaders
- Evaluate total measurement confidence, not just unit price. Consider installation complexity, environmental durability, documentation quality, and compatibility with existing data acquisition workflows.
- Align supplier selection with internal qualification needs. Prefer suppliers that can support traceability, consistent production practices, and application-specific guidance, especially where measurement outcomes affect safety, certification, or long-term asset monitoring.
- Plan for labor and process costs. In applications involving composites or harsh conditions, budget for trained installation and proper process control, since measurement quality depends heavily on how the sensor is applied.
The strain gage market is expanding steadily, but the most important strategic questions are no longer about whether demand will grow. They are about where qualification, integration, and application specialization will concentrate value, and which suppliers can reliably reduce risk across the full measurement chain. For leaders evaluating entry, expansion, or sourcing strategy, detailed segment-level data, application-level demand signals, and company-specific positioning can sharpen those decisions considerably. Comprehensive market research providing deeper segmentation, competitive benchmarking, and scenario-based forecasts is available for teams that need to move from directional insight to actionable planning.
Polariscope Strain Viewer Market
For detailed analysis of this topic, please visit the official page: Strain Gage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LED Strip Market 2032: Why a 9.6% CAGR Redefines the $11B Industry Strategy
By PW Consulting, 2026-09-21
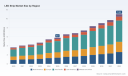
The LED Strip Market: Strategic Trends and Commercial Opportunities Through 2032
The global LED strip market has entered a phase of sustained expansion, with total revenue reaching approximately $5.8 billion in 2025 and projected to approach $11 billion by 2032. The sector is expected to grow at a compound annual growth rate of 9.6 percent across the 2026 to 2032 forecast horizon, reflecting a combination of architectural modernization, smart home adoption, and industrial lighting upgrades. While the headline figures convey momentum, the operational realities behind them matter more to decision makers. Growth is uneven across applications, product architectures, and geographies, and the competitive landscape is shifting from volume-driven commoditization toward specification-driven differentiation. Understanding where value will accrue over the next several years requires a closer look at the forces shaping demand, the strategic moves of leading players, and the structural constraints that will test execution.
Market Snapshot and the Crossroads Ahead
A Market Accelerating but Not Uniformly
The trajectory from 2020 through 2025 shows a steady climb, with revenue moving from roughly $3.67 billion to $5.8 billion. The acceleration reflects post-pandemic construction activity, broader retrofit programs, and the rapid normalization of addressable lighting in both homes and commercial spaces. Projections through 2032 indicate continued upward movement, with the market surpassing $9 billion before the end of the decade and reaching $11.02 billion in 2032. This pace is notable, yet it masks divergent growth paths. Certain application segments, particularly industrial and automotive, are expanding on the back of interior customization, indicator lighting, and electrification-driven design cycles, while residential and commercial demand is shaped by renovation waves, aesthetic expectations, and energy efficiency mandates. The implication is that aggregate growth should not be mistaken for uniform opportunity; specification quality, channel access, and compliance readiness will determine which participants capture disproportionate value.
Three Structural Challenges Shaping Strategy
The first challenge is cost pressure tied to raw materials. Copper input costs rose by more than 36 percent in 2025, a move that directly affects conductor pricing in LED strip circuit boards and has already produced downstream consequences, including increased theft of copper components from installed or warehoused inventory. For manufacturers and distributors, this translates into margin compression and the need to revisit bill-of-materials design, supplier diversification, and inventory hedging. For buyers, it introduces greater price variability and a stronger incentive to lock in specifications early.
The second challenge is regulatory tightening around hazardous substances and safety certification. Three RoHS exemptions for lead in copper alloys, ceramics, and glass glazes are scheduled to expire on July 21, 2026, which will require supply chain adjustments across substrate, solder, and coating choices for LED strip producers. In parallel, UL certification remains a critical requirement for LED strips sold in the United States, and compliance is increasingly a baseline expectation rather than a differentiator. These requirements raise the cost of reformulation and testing, but they also create a moat for companies that can manage conformance at scale and a barrier for those that rely on loosely controlled sourcing.
The third challenge is the rising bar for optical performance in high-end applications. Color rendering index values of 90 or above, combined with a standard deviation of color matching below 3, are becoming standard expectations for specification-grade projects where color accuracy and consistency matter. Meeting these thresholds consistently across batches requires tighter process control, better binning, and more disciplined quality assurance. The market is therefore splitting between low-cost, general-purpose offerings and higher-specification products that command more stable margins and more defensible customer relationships.
Forces Reshaping Demand and Supply
Smart and Aesthetic Lighting as a Demand Catalyst
Consumer and commercial demand is increasingly driven by lighting that does more than illuminate. In residential settings, users want seamless color transitions, music synchronization, and integration into broader home automation ecosystems. In commercial spaces, facility owners and designers are prioritizing uniform appearance, tunable color, and control flexibility that supports both ambiance and energy management. This shift is visible in recent product launches that emphasize gradient effects, outdoor-rated formats, and AI-assisted scene creation, signaling that the value proposition is moving from hardware alone to experience and interoperability. For businesses, this means product roadmaps and channel strategies need to account for software, app ecosystems, and compatibility as core elements of the offering rather than add-ons.
Regulatory and Standards Pressure as a Strategic Variable
Standards and regulations are becoming a more active force in product strategy. The approaching expiration of the RoHS exemptions for lead in specific materials will require reformulation and supplier revalidation for many manufacturers, especially those with narrow supply bases or limited testing capacity. At the same time, safety certification expectations in the U.S. market continue to reinforce UL compliance as a gatekeeper for commercial sales. On the performance side, the expectation that premium applications meet CRI 90+ and SDCM under 3 raises the stakes for color consistency. Companies that invest early in compliant material strategies, robust certification processes, and tighter color control will be better positioned to win specification work and reduce the risk of late-cycle redesigns.
Supply Chain and Cost Dynamics
Beyond raw material volatility, the supply chain for LED strips is being reshaped by the need for higher density, better thermal management, and more consistent output. COB and high-density flexible architectures are gaining attention because they support smoother visual appearance and more controlled luminance, but they also place new demands on component sourcing and assembly precision. The broader effect is a move toward more selective sourcing and greater emphasis on reliability metrics such as energy efficiency, thermal performance, and documented certification. For large-volume buyers, this environment favors suppliers with transparent quality systems and stable lead times, while for smaller buyers it increases the importance of specification clarity to avoid performance drift across projects.
Competitive Landscape and Strategic Positioning
Premium Smart Ecosystems
Philips Hue continues to focus on premium smart LED strips with gradient, outdoor, and integrated home automation capabilities for decorative and architectural use. Its approach emphasizes ecosystem fit, brand trust, and design-sensitive applications where appearance and interoperability matter as much as raw output. Recent activity, including the launch of Flux gradient and Neon outdoor LED strips with staggered availability across Europe and the United States, suggests a continued push into higher-aesthetic and outdoor segments. The strategic value here lies in building recurring engagement through control platforms and use cases that extend beyond initial installation.
LED Display Market
Professional and Modular Systems
LEDVANCE is oriented toward professional and custom LED strip systems, combining drivers, profiles, and modular solutions for commercial, architectural, and industrial projects. Its participation in Light + Building 2026, with a focus on office, education, sports, and industry applications, underscores a strategy centered on specification-driven projects and system-level integration. In this space, differentiation comes from complete installation-ready solutions, predictable performance, and support for complex environments where design intent must be maintained across large surfaces or demanding operational conditions.
PW Consulting
Consumer-Facing Smart Entertainment Lighting
Govee is targeting the home decor and entertainment segment with smart RGBIC and COB LED strips, app-based control, music synchronization, and high-density seamless lighting. Its recent activity, including the introduction of Lumiblend+ color accuracy technology and an AI lighting bot at CES 2026, points to a clear emphasis on user experience, color quality, and software-driven functionality. This model competes on convenience, visual impact, and rapid feature iteration, appealing to users who prioritize immersive effects and easy setup over professional specification workflows.
LED Lighting Market
Performance and Specification-Grade Portfolios
OSRAM concentrates on high-performance LED strips and modules for automotive interior lighting, aftermarket, and entertainment applications, leveraging engineering credibility and application-specific performance. HitLights emphasizes premium high-density COB and linear LED strips with UL listing, energy efficiency, and professional-grade output for commercial and residential projects, aligning closely with specification requirements and safety compliance. Flexfire LEDs focuses on custom high-quality flexible LED strips and accessories for installers and DIY users, with an emphasis on durability and performance, and has recently moved toward strategic price reductions and bulk pricing programs to support project growth. Super Bright LEDs maintains a broad portfolio spanning flexible, color-changing, and COB options for commercial, industrial, and residential use, positioning around breadth and accessibility across multiple end markets.
How the Landscape Is Evolving
The market is showing both consolidation of value and fragmentation of positioning. On one side, leading players are sharpening their identities around ecosystem control, professional system integration, color performance, and compliance readiness. On the other, new entrants and established players alike are experimenting with smart features, COB architectures, and price-oriented programs to capture specific buyer segments. One recent signal is Flexfire LEDs’ announcement of strategic price reductions and a new bulk pricing program in early 2026, which illustrates how competitive intensity can push companies to adjust pricing structures to support project-scale demand. At the same time, the requirement for stronger color accuracy, safety certification, and material compliance is raising the floor for credible participation in higher-value segments. The net effect is a market in which winners are increasingly defined by the ability to combine performance consistency with the right commercial model for each application.
Three Trends Likely to Define the Next 3 to 5 Years
Performance Standards as the New Baseline
The expectation that high-end LED strip applications meet CRI 90+ and SDCM below 3 is likely to become more widespread, extending from premium architectural and retail settings into broader commercial specifications. As this standard diffuses, product portfolios that cannot consistently deliver tight color consistency will face pressure on price and reputation. The commercial opportunity lies in building repeatable binning, quality control, and documentation that allow suppliers to win repeatable specification work and reduce project risk for distributors and installers. The risk is that the performance bar keeps rising faster than process maturity in some segments, creating gaps between marketing claims and field performance.
Smart, Integrated, and Experience-Led Lighting
Over the next several years, LED strip solutions are likely to be judged increasingly on their integration into broader control ecosystems and their ability to deliver programmable, context-aware experiences. Features such as gradient effects, outdoor-rated formats, music or scene synchronization, and AI-assisted lighting control are moving from novelty to expectation in many consumer and light commercial scenarios. This shift opens opportunities for companies that can combine hardware quality with software value, interoperability, and easy post-installation management. The downside is that feature competition can compress margins if differentiation becomes superficial, so sustainable advantage will depend on reliability, compatibility breadth, and genuine use-case fit rather than feature count alone.
Compliance and Material Realignment as a Strategic Filter
The July 2026 expiration of the RoHS exemptions for lead in copper alloys, ceramics, and glass glazes will push manufacturers to adjust material choices and validate alternatives across the supply chain. Combined with the continued importance of UL compliance in the U.S. market and ongoing raw material volatility, this creates a period in which compliance readiness and sourcing resilience will separate scalable operators from more exposed ones. Businesses that proactively recalibrate formulations, certify changes early, and diversify critical inputs will be better placed to protect margins and avoid disruptions. The uncertainty lies in how quickly alternative materials can be qualified without compromising performance or cost, and whether broader commodity swings will intensify pressure on already tight supply chains.
What Decision Makers Should Do Now
For Manufacturers and Brand Builders
Product strategy should be anchored to performance credibility and compliance readiness rather than volume alone. That means prioritizing color consistency, documented safety certification, and material compliance roadmaps that anticipate the 2026 RoHS changes, while also deciding where to compete on ecosystem integration versus specification-grade reliability. Pricing strategy deserves equal attention: recent moves toward bulk pricing and strategic reductions suggest that project-scale demand will reward flexible commercial models, but those models should be built on cost structures that can absorb raw material volatility without eroding trust in specifications.
For Investors and Capital Allocators
The strongest value creation is likely to come from companies that can hold a defensible position in higher-specification segments while managing compliance and material risk efficiently. Look for evidence of tight quality control, certified product lines, and a clear narrative around the application mix, especially exposure to industrial, automotive, and professional commercial segments where performance requirements support more stable pricing. At the same time, monitor smart lighting players for signs that software, interoperability, and user experience are translating into durable engagement rather than one-time hardware sales. Raw material exposure, certification status, and channel strength are all useful filters for separating durable operators from those vulnerable to cost shocks and specification drift.
For Procurement and Channel Leaders
Specification clarity and compliance documentation should be treated as procurement essentials. Demand consistent performance data, certification evidence, and transparent material sourcing, especially when projects require CRI 90+ and tight color matching. Where possible, diversify approved suppliers across regions and product architectures to reduce exposure to single-source risk and copper-driven cost swings. For larger programs, early alignment on compliance timelines and bulk pricing structures can reduce uncertainty and protect project margins.
The LED strip market is expanding at a meaningful pace, but the attractive opportunities are concentrated in segments where performance, compliance, and user experience are becoming non-negotiable. Companies that align product development, sourcing, and commercial models with these shifts will be better positioned to capture durable demand through 2032, while those that rely on undifferentiated volume may face intensifying pressure from both cost dynamics and rising specification expectations. The full landscape is broader than any single product category or competitive move suggests, and the most useful next step is a detailed look at segment-level demand patterns, regional nuances, and the specific compliance and performance thresholds now shaping win conditions across applications.
For detailed analysis of this topic, please visit the official page: LED Strip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Household Dehumidifiers Market: Why Portable Units Drive 4.25% CAGR Growth
By PW Consulting, 2026-09-21
Global Household Dehumidifiers Market: Strategic Trends and Commercial Opportunities Through 2032
The global household dehumidifiers market has reached a defining inflection point. Valued at approximately USD 135.5 million in 2025, the sector has demonstrated consistent expansion over the past five years, with historical revenues climbing from USD 110.0 million in 2020 to USD 135.5 million in 2025. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.25 percent through 2032, reaching an estimated USD 181.0 million by the end of the forecast period. This trajectory reflects structural shifts in how households and commercial properties manage indoor environmental quality, rather than temporary post-pandemic adjustments or cyclical weather patterns.
Beneath these headline figures lies a more nuanced operational reality. Growth is not evenly distributed across product formats, geographic corridors, or use cases. Portable units continue to dominate volume-driven logistics and retail distribution, while integrated whole-home systems command higher margin structures and longer installation cycles. The residential application segment anchors the majority of demand, yet hospitality and specialized facility deployments are steadily expanding as property managers recognize humidity control as a cost-of-ownership and asset-preservation issue. Regional concentration patterns reveal mature markets with high penetration rates alongside emerging corridors where climate volatility, urbanization, and awareness campaigns are accelerating adoption curves.
For executives and investors, the central challenge is no longer whether the market is expanding, but how the structural fractures within it will reshape competitive advantage over the next half decade. Three dynamics will determine who captures value and who faces margin compression.
Regulatory Decarbonization Is Rewriting Product Architecture
Beginning in early 2025, regulatory frameworks in both the United States and Europe have materially altered the refrigerant landscape for dehumidification equipment. U.S. EPA AIM Act provisions have initiated a phasedown of hydrofluorocarbon use across refrigeration, air conditioning, and heat pump equipment, including household dehumidifiers. Simultaneously, EU Regulation (EU) 2024/573 mandates the phase-down of high-GWP refrigerants and prohibits the placement of new equipment using refrigerants above 750 GWP, effective throughout 2025. These rules are not incremental compliance tweaks; they require redesigns of compressors, refrigerant circuits, thermal management systems, and service protocols.
For manufacturers, this translates into higher upfront engineering costs, qualification cycles, and supply chain retooling. For distributors and installers, it introduces potential inventory obsolescence if legacy stock is not aligned with revised specifications. The strategic implication is clear: regulatory alignment is transitioning from a back-office compliance function to a product differentiation lever. Companies that embed low-GWP architectures, transparent lifecycle documentation, and service-friendly component designs early will reduce retrofit risk and position themselves for procurement mandates in climate-conscious regions.
Indoor Air Quality Awareness Is Reshaping Demand Patterns
Consumer expectations around residential environments have shifted permanently. Rising awareness of mold risks, respiratory comfort, and humidity-driven structural deterioration has elevated dehumidification from a seasonal convenience to a baseline indoor air quality consideration. Extreme weather events have repeatedly highlighted how quickly moisture accumulation compromises building integrity, furniture, and occupant health, driving households and property operators to treat environmental control as preventative infrastructure rather than reactive mitigation.
This behavioral shift changes purchasing logic. Buyers are evaluating longevity, serviceability, noise profiles, and integration with broader home automation ecosystems alongside raw moisture removal capacity. The result is a growing premium on products that deliver consistent performance with lower operational friction. Manufacturers that communicate tangible indoor air quality benefits, backed by verifiable efficiency data and straightforward maintenance pathways, are capturing share in segments where trust and repeat usage matter more than short-term promotional pricing.
Desiccant Dehumidifier Market
Trade Policy and Cost Structures Are Introducing Regional Volatility
Tariff evolution and component cost dynamics are adding new layers of complexity to market execution. Recent revisions to the U.S. Harmonized Tariff Schedule apply duties to dehumidifiers with rated water removal capacity below 35 liters per day, altering the economics of entry-level and travel-oriented portable units. At the same time, fluctuating costs for compressors, electronic controls, and insulated housings continue to pressure margin structures, particularly for manufacturers relying on high-volume, low-differentiation product lines.
The commercial implication is a recalibration of where volume and margin can be sustainably captured. Markets with transparent tariff schedules and stable component sourcing are becoming more attractive for scaled production, while regions with fragmented import rules require more localized assortment strategies and pricing discipline. Companies that treat trade exposure as a strategic variable, rather than a periodic finance issue, are better positioned to protect profitability during demand surges and supply disruptions alike.
Key Drivers Shaping the Next Phase of Market Growth
Technology Innovation and the Shift Toward Intelligent, Efficient Operation
Advances in compressor engineering, sensor integration, and adaptive control algorithms are redefining performance expectations. Smart inverter-compressor platforms are enabling more precise humidity modulation, reduced cycling, and smoother energy draw across varying loads. Artificial intelligence-assisted operation is increasingly supporting automatic adjustment to ambient conditions, occupancy patterns, and seasonal transitions, reducing the need for manual intervention and improving user satisfaction in continuous-use scenarios.
PW Consulting
Energy efficiency has become a central battleground. Recent product launches illustrate the industry's direction. The introduction of next-generation whole-home dehumidification systems has emphasized flexible installation configurations, enhanced serviceability, extended lifecycle design, and measurable energy efficiency improvements. In parallel, new dehumidifier series have emerged with reported energy consumption reductions in the fifteen to twenty percent range compared to prior generations, alongside meaningful decreases in associated carbon emissions. These developments signal a broader market move toward products that deliver lower total cost of ownership, not just competitive sticker prices.
Policy and Regulatory Environment as a Competitive Filter
Regulation is functioning as both a constraint and a catalyst. The synchronized push toward lower-GWP refrigerants in the United States and Europe is compelling a rapid transition away from legacy fluid systems. This transition is accelerating innovation in refrigerant selection, heat exchanger design, and leak-detection protocols, while also filtering out manufacturers that lack the engineering resources or supply chain agility to adapt quickly.
For the industry, the policy environment is also shaping procurement behavior. Facility operators, hospitality groups, and property portfolios are increasingly specifying equipment that aligns with internal sustainability targets and regional compliance requirements. As a result, regulatory readiness is becoming a qualifier for larger, multi-unit deployments where replacement cycles are long and reputational or compliance risk is material. Companies that anticipate specification changes and build compliant product lines ahead of mandate deadlines will find themselves in a stronger position during tender processes and channel negotiations.
Demand-Side Behavior and the Normalization of Environmental Control
Consumer and commercial demand is being reshaped by a combination of health awareness, climate variability, and improved product usability. Households are purchasing dehumidifiers with a longer-term perspective, prioritizing quiet operation, straightforward emptying or drainage options, and integration with everyday living spaces. At the same time, commercial operators are expanding deployment in hospitality, storage-adjacent facilities, and specialty environments where moisture control protects assets and supports guest or occupant comfort.
This demand evolution is also changing the adoption pathway. Instead of treating dehumidification as an occasional purchase triggered by a single wet season, buyers are increasingly factoring it into broader home improvement and property management planning. That shift supports steadier repeat demand and creates opportunities for bundled offerings, including complementary air filtration, monitoring, and maintenance services. The businesses that benefit most will be those that align product design and messaging with longer ownership horizons and real-world usage patterns.
Supply Chain Recalibration and Component Cost Dynamics
The cost structure of dehumidifier manufacturing is increasingly influenced by compressor availability, electronic component pricing, and logistics complexity. As product designs grow more sophisticated, the dependence on precision components and integrated control boards rises, making supply continuity and quality consistency more critical. At the same time, regional manufacturing footprints and trade classifications are influencing where cost advantages can be sustained.
Strategic leaders are responding by diversifying component sourcing, standardizing modular architectures where possible, and aligning production schedules with regional demand signals rather than relying solely on centralized volume assumptions. This approach reduces exposure to abrupt cost spikes and improves responsiveness when demand shifts across product types or end-use segments. In practice, supply chain resilience is becoming a margin-protection strategy as much as an operational one.
Competitive Landscape and the Emergence of Differentiated Positioning
The competitive field is consolidating around a blend of large multinational appliance groups, specialized climate technology players, and regional brands with strong channel access. Market concentration remains relatively tight, reflecting the importance of brand trust, distribution reach, and compliance readiness in a market where performance claims and energy credentials directly influence purchase decisions.
Strategic Positioning Across Leading Players
Several manufacturers are pursuing distinct value propositions that illuminate where the market is heading. Midea Group continues to lead in portable and smart Cube-series units, leveraging ENERGY STAR certification and pump options to address the high-volume residential and light commercial segments. Its positioning reflects a focus on accessible feature sets, energy credentials, and retail-friendly product architectures that simplify consumer comparison.
Resideo Technologies has concentrated on whole-home dehumidification through its Honeywell Home line, emphasizing flexible installation, enhanced serviceability, and improved lifecycle performance. The recent launch of a next-generation whole-home dehumidifier highlights the company's emphasis on installation adaptability, service-friendly design, and energy efficiency gains. This approach targets property owners and installers who value long-term maintainability and specification flexibility over short-term unit price alone.
LG Electronics has advanced smart inverter-compressor models for residential indoor air quality control, integrating energy-efficient AI operation into its residential portfolio. The strategic signal here is clear: intelligence and efficiency are being packaged together, positioning the product as part of a connected home environment rather than a standalone utility appliance.
Other participants are carving out defensible niches through compact design, integrated consumer features, and broad retail distribution. Danby Products provides compact and portable units with integrated features tailored to consumer homes. Frigidaire, under Electrolux, manufactures Gallery and other series portable dehumidifiers widely tested for home use, reinforcing a familiar appliance brand presence in mainstream channels. GE Appliances, now part of Haier, supplies portable models integrated with smart controls for household humidity management, aligning convenience with digital connectivity. Whirlpool Corporation produces efficient portable units within its consumer appliance portfolio, relying on distribution breadth and brand familiarity. Honeywell International continues to supply residential and whole-home dehumidifiers with an emphasis on indoor air quality, maintaining a strong association with environmental control credibility. De'Longhi S.p.A. markets compact models for European and global household markets, capitalizing on design-conscious positioning and established regional presence. TCL Technology offers smart portable dehumidifiers through global consumer channels, reflecting the expansion of tech-enabled appliances beyond traditional appliance conglomerates.
Market Structure Evolution: Consolidation, Fragmentation, and New Entry Points
The competitive landscape is evolving along two simultaneous paths. At one end, larger players are strengthening their hold through multi-category portfolios, cross-category brand leverage, and compliance-ready engineering platforms. At the other, specialized and regional entrants are exploiting gaps in compact design, localized service networks, and targeted smart features. The net effect is a market where share gains are increasingly determined by how well a company aligns product architecture with regional regulations, installation ecosystems, and consumer usage expectations.
New entry opportunities are emerging in segments where energy performance, noise reduction, connectivity, and serviceability can be packaged into compelling user experiences. However, the barrier to durable advantage is rising. Low-cost, undifferentiated portable units face intensifying pressure from both tariff adjustments and consumer expectations for efficiency and reliability. In contrast, whole-home and integrated residential solutions reward companies that can demonstrate installation flexibility, component longevity, and verifiable efficiency gains. The market is therefore moving toward a bifurcated structure in which commoditized volume competition coexists with premium, specification-driven differentiation.
Outlook for the Next Three to Five Years
Efficiency and Intelligent Control as Standard Expectations
Over the next several years, energy efficiency and adaptive control will transition from differentiating features to baseline requirements. As regulatory pressure on refrigerants and energy performance continues, and as consumers become more accustomed to automated environmental management, products that cannot deliver measurable efficiency improvements and low-friction operation will face growing displacement risk. The commercial opportunity lies in bundling performance credibility with user experience: intuitive controls, predictable maintenance intervals, and documented energy savings that justify purchase decisions and reduce service burden.
Regulatory Compliance as a Launchpad for Specification Wins
Compliance readiness will increasingly function as an entry ticket for larger residential and commercial deployments. Procurement teams, property operators, and channel partners are likely to prioritize equipment that already aligns with evolving refrigerant rules and energy expectations, especially in regions where sustainability mandates and indoor air quality standards are tightening. Companies that invest early in compliant architectures and transparent documentation will be better positioned to secure multi-unit projects, installer partnerships, and repeat procurement cycles. The risk, for laggards, is a narrowing path to specification lists and a growing reliance on price competition in shrinking legacy segments.
Segmentation Tension Between Volume Portability and Integrated Systems
A persistent tension will shape strategic choices across the market. Portable units will continue to serve mass-market convenience, seasonal needs, and flexible deployment scenarios, but margins in this segment will depend on efficient production, disciplined assortment management, and clear consumer value messaging. Whole-home and integrated residential systems will command stronger value capture where installation complexity, serviceability, and long-term performance can be communicated credibly. Businesses will need to decide whether to compete broadly across both tiers or concentrate on the segment where their engineering, distribution, and service capabilities can sustain defensible economics.
Underlying these trends is a set of uncertainties that decision-makers should monitor closely. Policy implementation details may shift as regulatory agencies refine enforcement approaches. Trade classifications and tariff applications could alter the relative attractiveness of specific capacity thresholds and import routes. Component cost volatility, particularly in compressors and control electronics, may compress margins for manufacturers with limited sourcing flexibility. Finally, consumer adoption could diverge from projections if economic conditions slow discretionary home improvement spending or if competing indoor air quality solutions gain traction in overlapping use cases.
Worldwide Home Use Dehumidifier Market
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
Product roadmaps should treat regulatory alignment, energy efficiency, and serviceability as core design constraints rather than late-stage compliance tasks. Prioritizing low-GWP architectures, modular component designs, and installation-friendly configurations will reduce future retrofit exposure and improve competitiveness in specification-driven deployments. Where portable units remain central to the portfolio, differentiation should come from usability, noise performance, pump or drainage options, and verifiable efficiency credentials rather than capacity claims alone. Where whole-home or integrated systems are emphasized, the value story should center on lifecycle performance, installer-friendly service access, and compatibility with broader residential environmental control ecosystems.
For Investors and Strategic Allocators
Investment attention should focus on companies with credible pathways to compliant product lines, resilient component sourcing, and clear positioning in the segments most likely to command sustainable margins. The market's growth is real, but profitability will increasingly separate along lines of engineering capability, regulatory preparedness, and channel execution. Avoid assuming uniform returns across all product types or regions. Instead, evaluate exposure to tariff-sensitive capacity segments, dependence on single-source components, and the ability to participate in multi-unit or service-supported deployment models where repeat revenue and specification lock-in can strengthen long-term economics.
For Procurement and Channel Decision-Makers
Purchasing strategy should weigh total cost of ownership alongside unit price, particularly where installation complexity, maintenance frequency, and energy draw will influence multi-year operating costs. Specification decisions are increasingly affected by refrigerant compliance, serviceability, and efficiency documentation, especially in properties with sustainability targets or long replacement cycles. Diversifying supplier options, validating lifecycle claims, and aligning assortment choices with regional regulatory timelines will reduce the risk of stranded inventory or premature obsolescence. In channels where consumer education matters, prioritized messaging around quiet operation, intuitive controls, and energy performance is more likely to support repeat satisfaction than emphasis on short-term promotional discounts.
The Household Dehumidifiers Market is entering a phase where growth and differentiation are increasingly intertwined. Regulatory shifts, efficiency expectations, and evolving demand patterns are reshaping the economics of product design, distribution, and procurement. Companies that treat these forces as strategic inputs, rather than isolated operational constraints, will be better equipped to capture value across both volume and premium segments. For decision-makers seeking granular segmentation data, regional margin scenarios, and customized competitive benchmarking, the full PW Consulting research report provides the detailed supporting analysis needed to translate these market-level trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Household Dehumidifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com