

Blogs
Flame Retardant Cable Market: The 4.5% CAGR Shift Reshaping 2032 Demand
By PW Consulting, 2026-09-21
Flame Retardant Cable Market: Strategic Trends and Commercial Opportunities for Forward-Looking Enterprises
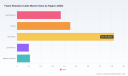
The global market for flame retardant cable solutions has entered a phase of mature, steady expansion characterized by shifting regulatory emphasis and evolving end-user performance requirements. Valued at approximately USD 1.85 billion in 2025, the sector has demonstrated a compound annual growth rate of roughly 4.5 percent through the forecast period extending to 2032, with total revenue projected to approach USD 2.5 billion by the end of the decade. This trajectory reflects a market that is no longer driven primarily by volume growth in traditional construction wiring, but rather by incremental value creation through compliance, safety certification, and application-specific engineering. Growth is increasingly concentrated in segments where fire performance is non-negotiable, where circuit integrity must be preserved under extreme thermal load, and where building codes intersect with operational continuity concerns across transportation, energy, and industrial facilities.
Several structural features define the current landscape. Market concentration remains moderate, with the top three players capturing roughly one-third of total revenue and the top five collectively accounting for close to half. This distribution suggests an environment where scale advantages coexist with meaningful regional and technical differentiation, allowing specialized manufacturers to compete on certification portfolios, insulation chemistry, and application engineering rather than price alone. At the same time, the broader cable industry contends with raw material volatility across copper, plastics, rubber, and aluminum, which directly influences manufacturing economics for flame retardant formulations. These input cost dynamics, combined with rising compliance complexity, have raised the bar for execution and are filtering out operators without strong testing infrastructure or established certification relationships.
Against this backdrop, the market is navigating a series of pivotal challenges that will shape competitive positioning over the next several years. The first is the accelerating pace of regulatory revision across major codes. Ongoing updates to fire safety standards are tightening performance thresholds for emergency circuits, increasing concrete encasement requirements in certain jurisdictions, and aligning fire detection and alarm system expectations with more rigorous cable testing protocols. As building codes evolve toward 2026 and beyond, compliance is shifting from a checkbox exercise to a continuous engineering requirement, pressuring manufacturers to maintain up-to-date certification evidence and technical documentation for each installed base.
A second challenge lies in balancing smoke and toxicity management against mechanical and electrical performance. Low smoke zero halogen formulations and other advanced insulation systems are gaining prominence in enclosed transit environments, high-rise residential buildings, and data-centric facilities where occupant evacuation and equipment survivability are paramount. Yet these materials often require precise compounding, controlled curing, and specialized jacketing to achieve target flame propagation and circuit integrity metrics. The technical trade-offs between halogenated and halogen-free architectures, as well as between cost and fire-rated performance, are forcing suppliers to invest in application-specific validation rather than rely on generic product lines.
A third challenge is the growing alignment of fire safety expectations with operational resilience in mission-critical environments. As facilities such as AI data centers, semiconductor plants, and advanced manufacturing sites demand uninterrupted power under fault conditions, the value proposition of flame retardant cable is expanding beyond life safety toward business continuity. This shift introduces new testing requirements, supply chain rigor, and documentation standards that smaller players struggle to meet consistently, while incumbents leverage their engineering depth to secure long-term specification wins. The result is a market in which differentiation is increasingly earned through demonstrated performance under extreme temperatures, validated circuit survival, and reliable delivery of certified product into complex projects.
Key Drivers Shaping Market Momentum
Innovation in Fire-Resistant Insulation and Circuit Integrity Solutions
Technological progress continues to reshape what flame retardant cable can achieve under real-world fire conditions. Recent product commercialization illustrates how insulation chemistry, conductor shielding, and jacketing design can be integrated to sustain power delivery under severe thermal stress. A notable example is the launch of a medium-voltage fire-resistant cable capable of maintaining circuit function at temperatures up to 830°C, developed specifically for AI data centers and semiconductor plants and aligned with updated IEC 60331-4 standards. This type of capability redefines the performance ceiling for critical infrastructure wiring, where even brief loss of power can translate into significant operational and financial consequences.
Flame Retardant Fabric Market
At the same time, fire-resistant and low smoke zero halogen variants are being refined for high-rise residential, transit, and industrial applications where flame propagation control and circuit integrity are specified as part of project approval. Manufacturers that pair material science expertise with in-house testing and certification workflows are better positioned to convert code changes into specification opportunities. The practical implication for buyers and designers is that performance is no longer determined solely by nominal voltage or conductor size; it increasingly depends on validated behavior under fire exposure, which makes detailed technical comparison and certification evidence central to procurement decisions.
Regulatory Evolution and Compliance as a Specification Driver
Policy and code activity remains a primary force behind demand for compliant fire-resistant solutions. Revisions to widely referenced standards are raising the bar for how emergency circuits are installed and protected, including stronger concrete encasement expectations and enhanced testing alignment for fire detection and alarm systems. In parallel, construction product regulations in major markets require manufacturers to demonstrate compliance through documented testing and certification, adding a layer of traceability that influences both product development and sales cycles.
These regulatory dynamics create a dual effect. On the demand side, they increase the addressable scope for certified flame retardant cables by expanding the range of applications where fire performance must be proven. On the supply side, they raise the cost of entry and ongoing compliance, favoring organizations that can maintain current certifications, support specification teams with technical evidence, and adapt product portfolios quickly when standards are updated. For executives overseeing portfolio strategy, the takeaway is that regulatory tracking should be treated as a core commercial function rather than a back-office compliance task, because the timing and substance of code changes often determine which product variants win in upcoming project cycles.
Demand-Side Shifts Toward Resilience in Critical Facilities
End-user behavior is changing as digital infrastructure and advanced manufacturing become more central to economic activity. Data center operators, semiconductor fabricators, and energy facility managers are placing greater emphasis on continuity of supply under fault conditions, which elevates the importance of cables that can maintain function while resisting flame spread. This demand-side shift is not merely a safety preference; it is increasingly an operational requirement tied to uptime commitments, insurance considerations, and facility certification.
In building and construction, the trend is visible in specification practices that favor documented fire performance for vertical risers, transit interchanges, and enclosed public spaces. In automotive and industrial wiring, fire-resistant insulation options are being evaluated for applications where thermal events could compromise both safety and equipment integrity. Across these segments, the common thread is a growing willingness to pay for verified performance when the cost of failure is high. For suppliers, this creates an opportunity to move beyond commoditized pricing by offering application-engineered solutions with clear certification backing and technical support during the design and approval phases.
Supply Chain and Cost Structure Pressures
The economics of flame retardant cable production are being shaped by input cost volatility and the operational demands of maintaining certified product streams. Fluctuations in copper and polymer markets directly influence manufacturing costs, while the need to produce materials with consistent flame retardant and low smoke characteristics adds complexity to sourcing and compounding. These pressures are encouraging consolidation of production capability in facilities that can achieve scale, control quality tightly, and sustain certification evidence across batches.
Worldwide Flame Retardant Masterbatches Market
Capacity investments in specialized fire-resistant lines reflect this reality. For example, expansion of a fire-resistant LSZH cable production facility has increased annual capacity to better serve demand in high-rise residential and transit sectors, signaling that manufacturers are aligning capacity additions with the applications where compliance and performance requirements are most stringent. Such moves illustrate a broader pattern: investment is flowing toward product lines where specification wins are repeatable and where certification and engineering support can be monetized through long-term contracts and recurring project flow.
Competitive Landscape and the Strategies of Leaders
The market is shaped by a mix of global cable leaders and regionally strong specialists, each pursuing distinct strategic positioning. The leading organizations differentiate not only through scale, but through application focus, certification depth, and the ability to integrate fire safety into broader infrastructure solutions. Their recent actions provide a useful lens on how competitive advantage is being built in this segment.
One global group has concentrated on fire-resistant cables, including low smoke zero halogen variants designed for high-rise, transit, and industrial environments, with particular emphasis on circuit integrity and flame propagation compliance. Its recent capacity expansion in the UK demonstrates a deliberate alignment of production capability with demand in high-specification building and transit projects. This approach positions the company to compete on technical reliability and compliance documentation rather than on price alone, and it signals to specifiers that supply continuity for certified product is a priority.
A major European cable manufacturer has pursued a complementary strategy centered on fire-resistant and fire-retardant solutions for critical infrastructure, with an emphasis on the building and energy sectors. Its recent acquisition of a Spanish low-voltage cable producer specializing in fire-resistant building solutions illustrates a willingness to consolidate regional capability and broaden portfolio coverage where code-driven demand is intensifying. By combining organic standard upgrades with targeted acquisitions, this type of player seeks to secure both technical credibility and local specification relationships, which can translate into more resilient project pipelines.
A South Korean manufacturer has focused on high-performance fire-resistant cables that meet IEC 60331 standards, including medium-voltage and energy storage applications. Its commercialization of a medium-voltage fire-resistant cable designed for AI data centers and semiconductor plants highlights how advanced manufacturing and energy-adjacent demand can pull new performance classes into the market. This trajectory suggests that strategic differentiation can emerge from serving emerging high-value applications where fire safety intersects with power continuity and equipment survivability.
Other active participants extend the competitive picture into automotive and industrial wiring systems, where fire-resistant insulation options are increasingly specified, as well as into high- and low-voltage power cables with fire safety features for energy and infrastructure. An additional industrial and energy-focused player rounds out the landscape by supplying fire-resistant and flame-retardant cables for industrial and energy applications. Collectively, these companies illustrate a market where segmentation is blurring at the edges: players are no longer defined solely by commodity cable volume, but by their ability to deliver certified performance into specific end-use contexts.
The market structure is evolving along several axes. Consolidation is evident where acquirers seek to strengthen regional footprints and expand certified portfolios, particularly in segments tied to building infrastructure and energy. Differentiation is intensifying where manufacturers build technical narratives around circuit integrity, smoke management, and extreme-temperature performance. New entry or re-entry remains challenging because of the certification burden and testing requirements, which tend to favor incumbents with established compliance infrastructure. At the same time, mid-tier specialists can still compete effectively by concentrating on a narrow application set and delivering superior documentation, technical support, and delivery reliability.
Future Outlook: Three Trends to Watch
The next three to five years are likely to be defined by the convergence of stricter compliance expectations, higher performance thresholds, and a more selective allocation of capacity toward high-value applications. One trend to monitor is the continued elevation of certification and documentation as core commercial assets. As codes evolve and specification committees place greater weight on validated fire performance, products with current, well-maintained certification evidence and clear technical narratives will gain an advantage in competitive bids. This trend benefits manufacturers that invest in testing agility and transparent compliance communication, while increasing the risk for those that treat certification as episodic rather than operational.
A second trend is the migration of flame retardant cable requirements into mission-critical digital and energy infrastructure. Data centers, semiconductor facilities, and advanced energy installations are driving demand for solutions that preserve circuit function under severe thermal conditions. This shift expands the strategic relevance of medium-voltage and specialized fire-resistant variants, and it creates opportunities for suppliers that can align product capabilities with the continuity requirements of these facilities. The opportunity is not simply to sell cable, but to participate earlier in the design process and to offer performance data that supports specification and approval.
A third trend is the potential for regional divergence in code intensity and enforcement, which may influence where demand grows fastest and where localized compliance capability becomes a competitive necessity. Areas with accelerating construction of high-rise residential, transit, and critical infrastructure may see stronger pull for certified fire-resistant solutions, while regions with slower code adoption could experience more price-sensitive competition. Organizations operating across multiple markets will need to manage these differences carefully, balancing portfolio standardization with local specification readiness.
These trends carry risk. Raw material volatility can compress margins if pricing mechanisms lag cost movements. Regulatory pace and interpretation can vary by jurisdiction, creating uncertainty for product roadmaps and capacity planning. Supply chain disruptions can affect the availability of certified batches, which in turn can jeopardize project timelines and specification commitments. The commercial implication is that resilience depends on diversified sourcing, disciplined cost management, and the ability to sustain certification continuity even as inputs and standards shift.
Actionable Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to treat certification and application engineering as growth enablers rather than support functions. That means maintaining current alignments with evolving fire safety codes, investing in testing capacity that supports rapid validation of new formulations, and building documentation frameworks that help specification teams justify selection. Companies should also consider targeted capacity and portfolio moves toward applications where circuit integrity and extreme-temperature performance command willingness to pay, especially in data centers, semiconductor facilities, and critical building infrastructure. The guiding question is whether the organization can reliably deliver certified performance into the projects that matter most, and whether its technical narrative is clear enough to win in specification committees.
For investors evaluating exposure to this segment, the key is to distinguish between volume-driven commodity exposure and value-driven compliance exposure. Businesses with strong certification portfolios, application-specific engineering capability, and relationships in high-specification building, transit, and energy markets are better positioned to sustain margins through raw material cycles and code changes. Capacity expansions that target fire-resistant LSZH and medium-voltage fire-resistant lines should be assessed against the durability of demand in the intended end-markets. Due diligence should emphasize the quality of testing and certification processes, the stability of key specification wins, and the company’s ability to adapt product offerings as standards evolve.
For procurement and specification teams, the strategic task is to embed fire performance evidence into early design decisions rather than treating compliance as a last-stage requirement. That includes comparing cable options on validated circuit integrity, smoke and toxicity behavior, and the currency of certification, not just on nominal specifications. Procurement strategies should give weight to suppliers that can demonstrate consistent batch-to-batch compliance, provide timely technical support during approval cycles, and maintain supply continuity for certified product. In environments where downtime costs are high, selecting cable based on documented extreme-temperature performance and circuit survival can reduce operational risk in ways that are not visible on a unit price comparison.
PW Consulting Chemical & Energy Research Center
In a market where regulatory momentum, application criticality, and material economics are reshaping competitive rules, timely access to detailed segmentation data, regional demand signals, and company-level benchmarking becomes a practical necessity. Decision-makers who need granular breakdowns by insulation material, application mix, regional dynamics, and competitor positioning will find that deeper intelligence directly supports portfolio planning, capacity allocation, and specification strategy. For those seeking a more complete view of the Flame Retardant Cable Market—including detailed segmentation data, regional trends, and customized strategic recommendations—PW Consulting’s full research report offers expanded analysis and targeted guidance to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Flame Retardant Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stationery Market Outlook: How Asia Pacific and Education Demand Drive 4.85% CAGR Growth to 2032
By PW Consulting, 2026-09-21
The Stationery Market in 2026: Navigating Growth, Disruption, and Strategic Opportunity
Market Reality Check: Resilient Growth Amid Structural Headwinds
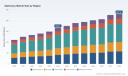
The global stationery market has demonstrated remarkable resilience, expanding from approximately $111 million in 2020 to a projected $166 million by 2025. This trajectory reflects a consistent upward curve, with the sector expected to surpass $230 million by 2032, translating to a compound annual growth rate of 4.85% across the 2025-2032 forecast horizon. Such performance underscores a market that has successfully adapted to shifting consumption patterns, digital disruption, and macroeconomic volatility. Rather than being rendered obsolete by technology, the stationery sector has evolved into a hybrid ecosystem where traditional paper and writing products coexist with specialized, experience-driven offerings. The growth narrative is not merely about volume expansion; it reflects deepening value creation across product tiers, regional dynamics, and end-use applications.
Behind the headline figures lie three structural challenges that are actively reshaping competitive dynamics. First, the tension between digital substitution and tactile utility continues to redefine category relevance. While basic note-taking and administrative documentation have migrated to screens, demand for curated, high-performance, or aesthetically differentiated physical products has intensified. Second, cost pressures and supply chain reconfigurations are forcing manufacturers to recalibrate sourcing strategies, pricing architectures, and inventory positioning. Third, sustainability and circularity expectations are no longer peripheral concerns; they are becoming embedded in procurement criteria, brand positioning, and product design mandates. Companies that treat these forces as isolated issues rather than interconnected strategic vectors risk gradual margin erosion and relevance loss.
Core Growth Drivers Redefining the Stationery Value Chain
Technology innovation in the stationery sector has moved beyond incremental product tweaks into material science, manufacturing efficiency, and intelligent replenishment models. Advances in biodegradable substrates, low-emission inks, and precision molding techniques are enabling brands to reduce environmental footprints while maintaining performance benchmarks. At the same time, digital-to-physical integration is emerging as a differentiator. Brands that link physical products with subscription replenishment, usage tracking, or co-creation platforms are transforming stationery from a transactional commodity into a recurring engagement touchpoint. This shift is particularly visible in segments where consistent quality and supply reliability directly affect user experience, such as educational settings and professional creative workflows.
Regulatory and policy dynamics are simultaneously reshaping input costs and market access. Recent tariff adjustments in major import-dependent markets have elevated effective duty rates, directly affecting manufacturing and retail input costs for office and school supplies. In this environment, companies that previously optimized for low-cost transcontinental sourcing are confronting margin compression unless they rebalance portfolios toward regionalized production, alternative material inputs, or value-added product tiers. The policy signal is clear: cost structures are no longer static, and resilience is increasingly tied to sourcing agility and regulatory foresight rather than sheer volume leverage.
Specialty Paper Market
On the demand side, behavioral shifts in both institutional and professional contexts are rerouting purchasing logic. Educational environments continue to anchor baseline volume, but procurement preferences are increasingly influenced by durability, safety standards, and brand trust. In corporate and residential settings, stationery is being repositioned less as a utilitarian necessity and more as a tool for focus, personalization, and brand expression. The result is uneven category performance: standardized bulk segments face intensifying price competition, while specialized writing instruments, premium paper goods, and creative materials command stronger loyalty and higher perceived value. This bifurcation is a central strategic consideration, because it implies that growth cannot be captured through undifferentiated scale alone.
Supply chain and cost structure evolution completes the driver set. Manufacturing concentration patterns suggest a moderately fragmented landscape, where no small group of players dominates total output. That fragmentation is strategically meaningful: it allows regional specialists and nimble mid-tier manufacturers to compete on responsiveness, customization, and local market intimacy rather than purely on global scale. At the same time, it forces larger multinational operators to differentiate through portfolio breadth, channel strength, and brand architecture. In practice, the most resilient operators are those that combine stable core franchises with agile innovation pipelines and diversified geographic exposure.
Competitive Architecture: Where Leaders Position and How the Map Is Shifting
The global stationery competitive field is defined by a mix of broad-based multinationals, heritage writing brands, and regionally anchored manufacturers. Companies such as BIC, Newell Brands, Faber-Castell, Staedtler, Pilot Corporation, Pentel, Zebra, and Mitsubishi Pencil represent distinct strategic archetypes. Some compete primarily on volume, distribution reach, and school- and office-grade reliability. Others anchor their identity in craftsmanship, premium materials, and professional or creative end-use credibility. This dual structure creates a market where leadership is multidimensional: scale advantage matters, but so does brand trust, product consistency, and the ability to preserve margin in premium subcategories.
Strategic differentiation among leading players increasingly rests on three levers. The first is brand positioning across value tiers. Entrants and incumbents alike must decide whether to defend share in high-frequency, price-sensitive segments or lean into higher-margin creative, executive, and specialty segments where performance and aesthetics justify premium pricing. The second lever is product innovation cadence. In a market where basic functionality is widely available, incremental differentiation in ink flow, grip ergonomics, paper feel, refill systems, and environmental profile can shift purchase preference. The third lever is channel and partnership strategy, especially in education and institutional procurement, where campaign-led engagement, supply reliability, and localized distribution can create durable share advantages.
Recent corporate activity illustrates how leaders are balancing responsibility signaling, demand-side engagement, and product renewal. Sustained sustainability communication and eco-oriented production commitments have become part of the baseline expectation for major manufacturers. Alongside that, school-focused supply campaigns and refreshed product partnerships signal an effort to protect core demand pools while modernizing the assortment. These moves are not isolated public relations actions; they reflect a broader reality that demand retention in education and mass segments requires both reliability and relevance. In parallel, tariff-related cost increases and import volume pressures are pushing companies to scrutinize the economics of cross-border supply, making regional diversification and input substitution increasingly important strategic priorities.
The market structure is evolving along two complementary paths. Consolidation remains plausible in mature categories where scale economics, distribution density, and procurement leverage confer durable advantages. At the same time, fragmentation is gaining ground in creative, premium, and niche segments where smaller players can win through design leadership, specialty materials, and community-driven branding. New entrants are most likely to succeed not by challenging incumbents across the entire aisle, but by capturing underserved demand pockets, leveraging direct-to-consumer engagement, or pairing physical products with digital discovery and replenishment mechanics. For incumbents, the strategic question is whether to absorb these niches through brand architecture and acquisitions or risk gradual erosion in the uppermost value tiers.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The first defining trend is the recalibration of physical and digital stationery roles. Digital tools will continue to absorb routine documentation and collaboration, but physical products will increasingly occupy categories where tangibility, focus, and premium experience matter. This implies sustained demand for well-designed notebooks, specialized writing instruments, and creative materials, while commoditized bulk items face continued substitution pressure. The commercial opportunity lies in building product lines that explicitly serve this hybrid reality: reliable core SKUs for volume stability, paired with curated premium or specialty lines that protect margin and brand equity.
The second trend is the rise of cost-resilient sourcing and product architecture. As input cost volatility and trade policy uncertainty persist, manufacturers and distributors will increasingly weigh total landed cost, lead-time reliability, and repatriation risk alongside unit price. Companies that can flex between sourcing regions, standardize high-volume components, and reserve customization for higher-value subcategories will be better positioned to maintain service levels without sacrificing profitability. The strategic upside is not simply cost reduction; it is the ability to keep product availability stable during periods when competitors face supply bottlenecks or margin-driven assortment cuts.
Greeting Cards Market
The third trend is the embedding of sustainability into procurement and product design as a baseline expectation rather than a differentiator. Recycled content, lower-impact inks, durable refill systems, and packaging optimization are becoming part of competitive parity. In practice, this creates both a risk and an opportunity: brands that lag on credible environmental improvements may face exclusion from increasingly conscious institutional and consumer purchasing criteria, while those that can substantiate performance with verifiable material and process improvements can use sustainability as a trust multiplier. The critical nuance is that sustainability must be paired with product quality and cost realism; otherwise, it becomes a marginal feature rather than a growth enabler.
These trends carry inherent uncertainty. Macroeconomic swings can compress discretionary and institutional spending simultaneously. Trade and tariff dynamics may continue to alter the cost base for import-dependent product lines. Digital substitution could accelerate in specific functional categories faster than suppliers can reposition assortments. Additionally, overinvestment in premiumization without sufficient demand depth can leave companies exposed to inventory imbalances. The most effective forward strategies will therefore combine scenario planning with portfolio discipline, ensuring that core volume is protected while higher-value experiments are sized appropriately.
Strategic Actions for Decision Makers
For manufacturers, the priority is to build a two-speed portfolio architecture. The base of the business should emphasize supply reliability, cost control, and consistent quality in high-frequency segments, while the upper tier should pursue differentiated materials, ergonomics, and brand storytelling that justify premium positioning. Equally important is sourcing flexibility: maintaining redundancy in critical inputs and evaluating regional production options can reduce exposure to tariff shocks and logistics volatility. Innovation cycles should be shortened for refill systems, functional improvements, and sustainability upgrades, because these are the areas where incremental gains can accumulate into durable advantage.
PW Consulting Health Care Research Center
For investors, the opportunity is less about generic sector growth and more about identifying which business models can capture value across the value-tier split. Companies with strong distribution density, credible premium franchises, and the ability to manage input-cost volatility are better placed to convert market expansion into margin expansion. Watch closely for portfolio balance, resilience in education and institutional channels, and evidence that sustainability commitments are being translated into product and process changes rather than communication alone. Valuation and growth potential will increasingly depend on whether a company can defend volume while expanding share of higher-margin subcategories.
For procurement leaders and corporate buyers, the strategic imperative is to treat stationery purchasing as a service continuity decision rather than a simple cost-minimization exercise. Diversification of suppliers, clarity on total cost including duties and lead times, and alignment with sustainability expectations can reduce operational risk while preserving quality. In institutional and corporate contexts, preference should be given to suppliers that combine dependable replenishment with transparent material and production practices, because consistency and trust often outweigh marginal unit-price differences over multi-year contracts.
The stationery market is not standing still, and neither should the organizations depending on it. To map these dynamics to specific subsegments, regional conditions, and customized strategic options, PW Consulting maintains a dedicated stationery market research practice that develops detailed breakdowns and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Stationery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Construction Project Management Software Market: Why 13.82% CAGR & Cloud Shift Redefine Competition
By PW Consulting, 2026-09-21
Construction Project Management Software Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
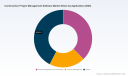
The construction project management software market has evolved from a niche productivity aid into a core infrastructure for operational execution. In 2025, the sector moved past a pivotal inflection point as digital workflows became standard practice rather than a competitive differentiator. The market expanded to USD 1.65 billion, building on a steady trajectory from USD 0.85 billion in 2020. Forward-looking projections point to sustained momentum, with the market expected to reach USD 1.89 billion in 2026, climb to USD 3.12 billion by 2030, and approach USD 4.12 billion by 2032. This equates to a compound annual growth rate of 13.82% across the 2026–2032 forecast window, reflecting both baseline modernization requirements and accelerating adoption among mid-tier contractors seeking scalable, field-ready capabilities.
Despite this expansion, the industry navigates several structural tensions that define where value is created and where stalled adoption erodes returns. First, fragmented project ecosystems continue to complicate interoperability. General contractors, subcontractors, owners, architects, and field crews frequently operate across disconnected data environments. Even as individual platforms mature, the handoffs between bidding, scheduling, field execution, change orders, and financial reconciliation remain vulnerable to manual rework and version control failures. The result is a market where adoption accelerates in pockets but falls short of end-to-end integration at the enterprise level.
Second, the shift toward cloud-native delivery is reshaping operational expectations and procurement norms. Field teams increasingly demand real-time visibility, mobile access, and off-site collaboration, while owners and public agencies expect auditable digital records that support compliance, sustainability reporting, and handover documentation. This creates tension between legacy on-premises deployments that prioritize control and newer cloud models that prioritize accessibility, versioning, and cross-functional coordination. Organizations that lean too heavily on one model risk either losing field agility or creating new data silos.
Third, regulatory and compliance expectations are becoming embedded in project delivery rather than layered on top of it. Digital documentation, safety tracking, change-order transparency, and BIM-aligned collaboration are increasingly treated as baseline requirements for public and large private projects. This elevates the strategic importance of software that can support structured workflows and auditable records, but it also raises the bar for implementation maturity. Firms that procure tools without aligning them to standardized processes often face low utilization, limited data quality, and poor ROI visibility.
Together, these dynamics suggest that market growth will increasingly be driven not merely by tool purchasing, but by the ability to standardize workflows, connect field and office data, and prove measurable improvements in schedule adherence, change management, and risk control.
Key Growth Drivers
Technology Innovation and Workflow Intelligence
The most consequential driver of software demand is the transition from static documentation toward intelligent, connected workflows. Platforms are increasingly expected to support more than task tracking and calendars; they must coordinate RFIs, change orders, submittals, drawings, daily logs, and safety observations within a unified record. Recent platform updates reflect this direction. In June 2026, ProjectHQ released a resource detailing 2026 feature priorities around document control, RFI and change-order workflows, and decision-making support for contractor operations. That same pattern appears across other vendors: Sage Group’s April 2026 release emphasized an enhanced document viewer for PDF handling within construction management workflows, while UDA Technologies’ May 2026 update to ConstructionOnline introduced improved file upload, searchable tabbed selection, a mobile version refresh, and renewed customer satisfaction certifications.
These updates matter because they target the operational friction points that most directly affect project outcomes: document version drift, missed approval cycles, and delayed decisions on scope changes. A platform that shortens the time from issue to decision and preserves a clear audit trail creates value not only for project managers but also for finance, risk, and executive leadership. At the same time, AI-enabled analytics are moving from experimental features into practical decision support. By 2025, roughly 30% of platforms had begun incorporating AI-driven analytics for predicting schedule delays and cost overruns in real time, signaling that predictive insight is starting to become an expected layer of modern project management tools rather than a premium add-on.
Regulatory Pressure and BIM-Driven Collaboration
Policy and procurement requirements are increasingly shaping software selection. In North America and Europe, BIM adoption is being driven by regulatory expectations, with more than 30% of large public infrastructure projects mandating BIM compliance for documentation and sustainability reporting. This is not only an engineering or design concern; it is a project management requirement because BIM-aligned delivery depends on shared models, coordinated clash detection, structured change processing, and consistent handover information. On both sides of the Atlantic, BIM mandates for public sector projects across EU member states and US federal agencies require digital collaboration tools that support clash detection and change order processing, accelerating software integration in project delivery.
PW Consulting Information & Electronics Research Center
Safety and workforce compliance also influence software design. OSHA 30-Hour Construction training and the Site Management Safety Training Scheme certification are mandatory requirements for project compliance in many contexts, directly shaping adoption of integrated software for safety tracking and risk management. As these expectations become routine, construction teams increasingly view software as a mechanism for documenting training status, site safety observations, incident workflows, and corrective actions within the same environment used for scheduling and cost control. A platform that can connect compliance evidence to field operations reduces administrative overhead and supports more consistent audit readiness.
Demand-Side Shifts in Project Delivery
Customer and owner expectations are changing the value proposition of construction software. Owners want earlier visibility into schedule risk, clearer change-order rationales, and better traceability from field events to financial impact. Contractors, in turn, are under pressure to demonstrate predictability and reduce rework. This shifts the buying conversation from feature checklists toward outcomes: Can the system support faster RFI turnaround? Can it reduce disputes around scope changes? Can it give leaders a clearer view of earned progress versus planned progress? These questions favor platforms that combine scheduling discipline, contract visibility, and field execution data in a coherent workflow, rather than siloed tools that only address one function.
There is also a notable change in how firms evaluate data access and collaboration. Cloud-based adoption has grown significantly, with around 60% of firms using cloud platforms for scalable project data access and collaboration across global teams. This trend reflects the need to support geographically dispersed teams, multiple subcontractors, and frequent remote coordination without relying on patchy file-sharing practices. As collaboration becomes a core requirement rather than a convenience, cloud delivery models gain an advantage in scenarios where multi-party visibility, version control, and mobile field use are essential.
Cost Structure and Operational Efficiency
Cost pressures are pushing firms to evaluate software not as an overhead expense but as a lever for reducing loss from poor coordination. Labor shortages, schedule compression, and volatility in materials and subcontractor availability all raise the cost of delays and errors. In this environment, software that improves planning fidelity, streamlines approvals, and supports more accurate forecasting can justify investment by reducing time spent on manual reconciliation and reducing the frequency of expensive rework cycles. The strategic implication is that buyers are increasingly sensitive to total cost of ownership, implementation complexity, and the ability to integrate with existing financial and ERP systems. A platform that requires heavy customization or fails to connect project data to financial outcomes will face harder scrutiny, even if its feature set appears comprehensive.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three players holding roughly half of the market and the top five representing slightly more than half. This concentration suggests that scale, ecosystem reach, and workflow breadth matter, but it also leaves substantial room for specialized players that win on usability, vertical fit, or regional strength. The competitive field is shaped by several distinct strategic postures.
Construction Management Software Market
Procore Technologies continues to position around a construction-native, cloud-based platform covering scheduling, budgeting, document control, RFIs, and mobile field execution. Its strategic advantage lies in workflow depth tailored specifically to construction rather than adapted from generic project management tooling. Autodesk extends its position through construction management capabilities anchored in BIM and design-adjacent workflows, emphasizing integrated collaboration for architectural, engineering, and construction teams. Bentley Systems differentiates through infrastructure-focused solutions, including 4D planning and digital twin-oriented tools suited for civil and large building programs. Trimble combines project execution, resource tracking, and field-to-office integration, aligning software with field data capture and connected construction practices.
On the financial and operations side, Sage Group and CMiC compete by linking project management with accounting, cost control, and profitability tools. Sage’s profile emphasizes full lifecycle handling with financial integration, while CMiC focuses on ERP-grade integration for accounting, workflows, and field communication. Buildertrend has carved out a strong position among residential and commercial builders by bundling AI-informed scheduling, financials, client communication, and all-in-one operations. Jonas Construction Software and other ERP-oriented providers target contractors who want job costing, service management, and integrated project management within a unified system.
The strategic implication is that differentiation is increasingly defined by three axes: construction-native workflow depth, integration with financial and field data, and the ability to serve a specific segment without over-engineering the solution. Large platforms gain advantage by breadth and ecosystem connectivity; mid-market and vertical-focused solutions gain advantage by ease of deployment, faster adoption, and closer fit to the daily routines of smaller project teams.
Market evolution is trending toward selective consolidation and parallel specialization. Consolidation is likely where organizations seek to reduce tool sprawl, standardize data models, and connect project delivery with finance and enterprise reporting. At the same time, specialization will persist because residential builders, civil infrastructure teams, and commercial GCs face materially different workflow requirements, compliance profiles, and field conditions. New entrants and product updates continue to raise the bar on usability, mobile field experience, document handling, and decision support, meaning incumbents must keep improving workflow coherence rather than relying on legacy brand strength alone. Recent release activity from multiple vendors shows a common focus on document control, searchability, mobile access, and workflow-based decision support, suggesting that these are becoming table stakes rather than differentiators on their own.
Future Trends for the Next 3–5 Years
Based on current adoption patterns and product momentum, three trends are likely to shape the market over the next several years.
The first is the shift from retrospective tracking to anticipatory project control. As predictive analytics become more mainstream, platforms will be expected not only to record what happened but to flag emerging schedule risk, cost exposure, and scope drift earlier in the project lifecycle. This will create opportunities for vendors that can translate field activity, schedule status, and financial data into actionable early warnings without overwhelming teams with noise. The commercial upside lies in enabling tighter decision cycles, but the risk is implementation fatigue if predictive features are not embedded into workflows that frontline teams actually use.
Construction Estimating Software Market
The second trend is deeper integration across project delivery, compliance, and financial outcomes. Regulatory expectations around BIM, safety documentation, and public-sector digital collaboration will continue to raise the value of platforms that can connect design coordination, change management, and auditable records. Over time, this should push adoption toward systems that unify contract visibility, schedule performance, safety tracking, and cost control in one operational environment. The opportunity is clearer accountability and fewer handoff failures; the uncertainty is that compliance requirements can differ across jurisdictions and project types, making standardization harder for multi-region contractors.
The third trend is continued segmentation by project type and company size, accompanied by rising expectations for ease of adoption. Cloud-based platforms will remain central for firms that need scalable collaboration and mobile access, but implementation success will increasingly depend on onboarding practicality, training efficiency, and fit with existing systems. Companies that serve specific segments with streamlined workflows may capture strong loyalty even in a concentrated market, provided they can demonstrate measurable improvements in schedule control, change-order handling, and field-office coordination. The downside risk is that over-customization or weak change management can erode the advantages of even well-designed software, especially when organizations buy tools before defining the processes they expect the software to support.
Actionable Guidance for Decision-Makers
For software and platform providers, the priority is to strengthen workflow coherence rather than broaden feature lists indiscriminately. Differentiation is increasingly earned by reducing friction across RFIs, change orders, document control, scheduling, and financial visibility, and by making predictive insights usable in daily operations. Providers should also anticipate that buyers will weigh integration with existing ERP, accounting, and field data systems more heavily than before, especially when procurement decisions must justify operational ROI under tight labor and margin conditions.
For investors, the market presents a compelling growth profile, but selection discipline matters. The strongest opportunities are likely to belong to platforms that can demonstrate retention driven by workflow stickiness, successful integration into financial and field operations, and clear value in segments where project complexity and compliance expectations are rising. It is worth distinguishing between vendors competing on brand and ecosystem scale and those competing on segment-specific usability, implementation speed, and measurable operational impact. Growth narratives should be tested against deployment reality, adoption depth, and the ability to reduce customer friction in document-heavy, multi-party workflows.
For contractors, owners, and procurement teams, the most important step is to link software selection to workflow standards before evaluating vendors. Buying a capable platform without agreed processes for change management, document control, safety tracking, and schedule updates often leads to underutilization and limited return. Organizations should prioritize systems that support field-to-office data continuity, clear audit trails, and integration with financial tracking, while also assessing the practical effort required for onboarding, training, and process change. When evaluating options, request evidence tied to outcomes that matter internally: faster RFI and change-order cycles, fewer rework loops, improved visibility into schedule and cost risk, and more reliable compliance documentation.
Detailed segmentation data, vendor-by-vendor adoption patterns, and customized strategic recommendations can help translate these market dynamics into a concrete action plan for a specific business model, project mix, or investment thesis. For organizations seeking a closer look at the full segmentation landscape and scenario-based guidance, the complete PW Consulting market report provides extended detail and tailored analysis.
For detailed analysis of this topic, please visit the official page: Construction Project Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gas Detectors Market Surges Past $6.2B Why the 6.5% Growth Trajectory Changes Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Gas Detectors Market
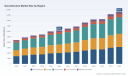
The global gas detectors market has entered a phase of sustained expansion, driven by tightening safety regulations, technological maturation, and a structural shift toward connected, real-time monitoring solutions. Over the historical period from 2020 through 2025, the market advanced from approximately $4.4 billion to $6.2 billion, reflecting steady year-over-year growth as industrial operators, municipal authorities, and energy infrastructure providers increasingly prioritized early detection and continuous environmental monitoring. Looking ahead to the 2026–2032 forecast window, the trajectory points toward a compound annual growth rate of 6.5 percent, with total market value projected to reach nearly $9.6 billion by the close of the period. This growth is not merely a function of incremental replacement cycles; it represents a broader realignment in how organizations conceptualize safety infrastructure, moving from passive, compliance-driven installations toward active, data-integrated monitoring ecosystems.
Market Structure and Concentration Dynamics
The market demonstrates a moderately concentrated structure, with the top three competitors collectively accounting for roughly 58 percent of overall revenue and the top five firms capturing approximately 72 percent. This concentration signals the presence of entrenched incumbents with established distribution channels, mature product portfolios, and significant brand recognition across industrial and municipal verticals. However, the remaining market share is distributed among a diverse set of regional specialists, application-focused manufacturers, and emerging players targeting niche monitoring requirements. The coexistence of dominant global players and agile niche suppliers creates a competitive environment where differentiation increasingly hinges on connectivity capabilities, regulatory compliance readiness, and application-specific engineering rather than raw sensor performance alone.
Key Challenges and Inflection Points
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next five years. First, the regulatory landscape is fragmenting across jurisdictions, with local building codes, pipeline safety mandates, and occupational health standards imposing divergent performance and installation requirements. Organizations operating across multiple regions must navigate inconsistent certification pathways and compliance timelines, which increases integration complexity and raises total cost of ownership for multi-site deployments. Second, the transition from standalone detection hardware to connected, networked monitoring systems introduces cybersecurity, data interoperability, and lifecycle management concerns that many traditional manufacturers are still addressing through product development and service model adaptation. Third, supply chain volatility for specialized sensing components, calibration gases, and semiconductor-based detector elements continues to pressure margins and constrain rapid scale-up for new product lines. These challenges are not insurmountable, but they require strategic foresight and investment in cross-functional capabilities that extend beyond core hardware engineering.
Key Drivers Shaping Market Evolution
Technological Innovation and Sensor Advancement
Advancements in sensor technology are fundamentally reshaping product capabilities and expanding the addressable use cases for gas detection. Infrared-based sensing, enhanced electrochemical cell designs, and improved catalytic bead configurations have increased detection precision, reduced false alarm rates, and extended operational life in harsh environments. Simultaneously, the integration of wireless communication modules, edge computing capabilities, and cloud-anchored fleet management platforms has transformed portable and fixed detectors from isolated warning devices into interconnected nodes within broader safety and asset monitoring networks. Manufacturers that have embedded connectivity into their product architectures are enabling centralized visibility across large facility footprints, real-time alarm escalation, and predictive maintenance workflows that reduce downtime and improve response coordination.
Policy and Regulatory Momentum
Regulatory activity has accelerated across multiple jurisdictions, creating both compliance-driven demand and opportunities for early-adopting solution providers. Recent municipal and federal requirements have mandated natural gas alarms and zoned detection systems in specific residential and commercial building categories, establishing new installation baselines and product specification thresholds. Pipeline safety rules have further emphasized the need for commercially available leak detection equipment that meets defined performance standards, pushing operators to upgrade legacy monitoring approaches with validated, interoperable solutions. Occupational safety guidelines continue to reinforce the requirement for routine air monitoring in hydrogen sulfide and other hazardous gas environments, with renewed emphasis on training, device qualification, and documented compliance. Collectively, these regulatory shifts are converting safety detection from an optional best practice into a codified operational necessity across housing, energy transport, and industrial processing sectors.
Demand-Side Shifts in Operational Behavior
Demand patterns reflect a broader organizational move toward proactive risk management rather than reactive incident response. Facilities managers, safety directors, and operations leaders are increasingly seeking integrated monitoring strategies that combine area-fixed systems with personal and portable units, enabling layered protection across confined spaces, process zones, and perimeter areas. Fleet operators and emergency response organizations are prioritizing devices that support centralized management, automatic reporting, and integration with existing workforce safety platforms. This behavior shift is particularly pronounced in sectors where downtime carries high financial and reputational costs, and where regulatory scrutiny has intensified following high-profile incidents and investigative reports highlighting gaps in residential and commercial fuel-gas detection practices.
Supply Chain and Cost Structure Considerations
Cost structures are being reshaped by the increasing incorporation of digital services, calibration management programs, and extended warranty or lifecycle support offerings. While core sensor and housing costs remain important, the total value proposition now includes software licensing, data subscription models, remote diagnostics, and on-site service networks. Organizations that have built robust service ecosystems are able to smooth revenue streams and deepen customer stickiness, while those that remain purely hardware-focused face margin compression from price competition and component cost variability. Supply chain resilience has therefore become a strategic differentiator, with leading players investing in component sourcing diversification, inventory buffering for critical sensor elements, and regional manufacturing or assembly footprints to reduce exposure to logistical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market's leading companies have built their positions through a combination of broad product portfolios, established industry credibility, and targeted application specialization. Large diversified manufacturers offer comprehensive fixed and portable solutions spanning multi-gas monitoring, flame detection, and hazardous-area certification, allowing them to serve integrated safety programs across industrial, utility, and mining environments. Specialized safety companies have strengthened their standing through reputation for rugged reliability, confined-space expertise, and strong relationships with industrial customers who prioritize worker protection and compliance documentation. European and North American manufacturers alike have advanced their positions by embedding connectivity into flagship portable and fixed product lines, enabling fleet-wide visibility and compliance tracking. Mid-tier and niche players have carved out defensible positions by focusing on specific gas targets, such as hydrogen-specific monitoring for emerging energy applications, or by delivering bespoke fixed detection engineering for demanding process environments.
Strategic Themes Among Leading Players
Several strategic themes are evident across the competitive field. One is the convergence of personal protection and area monitoring into unified safety architectures, with product lines designed to share communication protocols, data standards, and management interfaces. Another is the emphasis on hydrogen-ready and multi-gas flexible detection, reflecting the expansion of new energy infrastructure and the need for equipment that can adapt to shifting gas compositions and operational scenarios. A third theme is the strengthening of aftermarket and service capabilities, including calibration programs, detector refurbishment, and remote health monitoring, which convert one-time capital purchases into recurring engagement models. Trade show participation and product launch cadence have become important signals of market intent, with companies showcasing fire-rescue, civil protection, and industrial detection solutions at major international events, while simultaneously rolling out new portable monitor series and updated product catalogs to refresh portfolios and address emerging application requirements.
Market Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape is evolving along multiple axes. Consolidation pressure remains present among mid-sized suppliers seeking scale in manufacturing, distribution, or service delivery, while larger incumbents continue to evaluate targeted acquisitions or technology partnerships that can accelerate connectivity, sensor diversification, or geographic reach. At the same time, market differentiation is increasingly likely to occur at the application and integration level rather than through generic hardware specifications alone. New entrants and regional specialists can find viable openings by addressing underserved gas targets, tailoring solutions to specific regulatory frameworks, or offering lighter-cost portable options for emerging markets and smaller contractors. However, successful entry typically requires credible certification coverage, reliable supply relationships, and a clear path to either service attachment or channel partnership, given the importance of compliance assurance and lifecycle support in customer purchasing decisions.
Future Trends and Commercial Implications
Trend 1: Connected Safety Ecosystems as the New Baseline
Over the next three to five years, connected detection architectures are expected to become a standard expectation rather than a premium differentiator. Fixed and portable devices will increasingly operate as integrated elements within facility-wide safety and operational technology environments, with data flowing into centralized dashboards, automated alarm escalation workflows, and compliance reporting systems. For manufacturers, this trend creates opportunities to expand software and service attach rates, develop interoperable data standards, and position hardware as entry points to broader subscription-based monitoring programs. For end users, the implication is a shift in procurement criteria toward platform compatibility, data retention policies, integration effort, and total lifecycle cost, rather than sensor price alone.
Trend 2: Regulatory Normalization Across Residential, Pipeline, and Industrial Domains
Regulatory momentum across building codes, pipeline safety mandates, and occupational monitoring requirements is expected to continue normalizing gas detection as a codified infrastructure component. As codes and standards become more explicit about installation zoning, performance thresholds, and maintenance obligations, demand for compliant, certifiable equipment will broaden beyond traditional heavy industrial settings into municipal housing, commercial buildings, and energy transport operations. This opens addressable market expansion for manufacturers with proven certification portfolios and documented compliance support, while raising the bar for competitors that lack established testing records or regional code familiarity. Organizations that invest early in aligning product specifications with emerging code expectations will be better positioned to capture procurement cycles as mandates take effect.
Trend 3: Application Expansion Into New Energy and Specialized Environments
The growing focus on hydrogen-related monitoring, combined with continued demand in oil and gas, chemicals, mining, and emergency response contexts, is broadening the application base for both fixed and portable systems. New energy infrastructure, fleet management requirements, and specialized confined-space operations are driving interest in detectors that can handle evolving gas compositions, support rapid deployment, and integrate with existing safety and logistics workflows. This expansion creates opportunities for companies that can deliver application-engineered solutions, flexible calibration and sensor swap options, and clear guidance on deployment best practices. The corresponding risk is that rapid application diversification can strain product development resources and complicate quality assurance if not managed with disciplined platform architecture and careful validation protocols.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize platform-level design that allows sensor modules, communication interfaces, and management software to evolve without requiring full product line replacements. Invest in certification coverage and compliance documentation that align with the most demanding regional requirements, as these credentials increasingly function as market-access prerequisites rather than optional endorsements. Strengthen aftermarket and service capabilities, including calibration programs, remote diagnostics, and detector lifecycle management, to build recurring revenue and deepen customer retention. Evaluate targeted partnerships or technology acquisitions that can accelerate connectivity, data interoperability, or application-specific detection capabilities, particularly where internal development timelines would lag market expectations.
PW Consulting Automotive & Machinery Research Center
For Investors and Strategic Planners
Focus due diligence on companies that demonstrate a credible transition from hardware-only revenue models to integrated hardware-plus-service portfolios, as this shift often correlates with improved revenue visibility and customer lock-in. Assess exposure to regulatory-driven demand across pipeline safety, residential and commercial building codes, and occupational health mandates, since these drivers can create durable procurement cycles that are less sensitive to short-term industrial cyclicality. Monitor competitive signals such as product launch cadence, trade show positioning, and fleet-management integration capabilities, which often indicate which players are executing effectively on market evolution rather than reacting to it. Be attentive to margin dynamics in sensor supply chains and to the cost implications of connectivity features, as these factors will shape profitability trajectories across the forecast period.
For Procurement and Safety Operations Leaders
When evaluating detection solutions, expand evaluation criteria beyond unit price to include total cost of ownership, interoperability with existing safety platforms, data access and retention terms, calibration and service arrangements, and the supplier's ability to support multi-site compliance documentation. Prioritize architectures that enable layered protection across fixed area monitors, portable units, and personal devices, ensuring coverage continuity as personnel and operations move across zones. Require clear evidence of certification alignment with applicable regional codes and standards, and confirm that the solution provider can deliver training, refresher support, and documented maintenance processes that satisfy both internal safety programs and external audit requirements.
Worldwide Carbon Dioxide Detector Market
Closing Perspective
The gas detectors market is moving through a period of meaningful structural change, where growth is being driven not only by incremental replacement demand but by a broader redefinition of safety detection as a connected, compliance-embedded, and application-diversified capability. Organizations that align product strategy, service design, and regulatory readiness with these shifts will be best positioned to capture value as the market advances toward the end of the decade. The commercial opportunities are substantial, but realizing them requires disciplined investment in platform architecture, certification coverage, and lifecycle support, paired with a clear understanding of where regulatory, technological, and demand-side momentum are converging. For decision-makers seeking deeper granularity on segment dynamics, regional demand patterns, competitive benchmarking, and customized scenario planning, a comprehensive research report provides the detailed data and structured analysis necessary to translate these strategic themes into precise, actionable plans.
Radiation Detector Market
For detailed analysis of this topic, please visit the official page: Gas Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Why Centralised Certificate Management Matters for Modern Organisations
Managing certifications can become increasingly complex as organisations attempt to maintain regulatory compliance while keeping operations running smoothly and protecting workplace safety. As a business expands, important records such as training certificates, licences, competency documentation, inspection reports, and approval records can end up distributed across numerous systems. Some information may sit in email accounts or spreadsheets, while other documents might be stored on shared drives or maintained in physical files. When certification information is dispersed in this way, determining whether employees have current qualifications, equipment holds valid certification, or important approvals are approaching expiry can become unnecessarily time consuming.
Certificate management software provides a centralised way to address these challenges. By bringing certification information together within a structured and secure environment, organisations can reduce the effort involved in searching through separate records. Teams gain a clearer understanding of certification status across employees, contractors, vehicles, equipment, and other assets. When a dependable central record is available whenever it is needed, verifying qualifications, managing compliance responsibilities, and maintaining approval procedures becomes more consistent and straightforward.
Establishing Centralised Certification Control
Certificate management software creates an organised framework for managing certification records throughout their complete lifecycle. Instead of depending on separate spreadsheets, manual reminders, and different procedures across departments, organisations can establish consistent methods for creating, reviewing, approving, storing, and maintaining certification information.
Digital workflows can make approval processes simpler while providing greater visibility into every stage. Certificates can be securely stored alongside records of related activities, including approvals, amendments, and user actions. This makes it easier to understand when a certificate was created or issued, which individual authorised it, and what modifications have occurred afterward. Automated expiry monitoring adds another layer of control by highlighting approaching deadlines and allowing teams to start renewal activities before certifications become invalid.
Dashboards, alerts, secure repositories, and access permissions can operate together to provide a more organised and proactive approach to certification management.
Challenges Associated With Manual Certification Tracking
Spreadsheets and paper based registers are still widely used to manage certification information. Although these methods may work adequately when only a small number of records are involved, maintaining them can become substantially more difficult as certification and compliance requirements expand. During audits, inspections, or operational reviews, manually managed information may result in extended searches, unnecessary delays, uncertainty, and greater exposure to compliance related problems.
The impact of an expired certificate can extend well beyond the document itself. An individual may be unable to enter a worksite, an important activity may be interrupted, a project could be delayed, regulatory concerns may arise, or insurance requirements could become more complicated. What begins as a straightforward administrative mistake can therefore develop into a wider operational challenge.
A digital certificate management solution offers ongoing visibility into certification validity and status. Automated reminders can notify responsible personnel ahead of renewal deadlines, while centralised records make supporting documentation easier to locate when required. Rather than discovering certification deficiencies only after they have caused operational disruption, teams can continuously monitor their responsibilities and resolve potential problems before they become more serious.
Industries Where Certification Management Matters
Organisations operating in sectors with significant certification requirements can benefit from centralised certification management. Construction, utilities, aviation, energy, offshore operations, marine services, and large industrial businesses may all need to manage substantial quantities of certification information relating to employees, equipment, and operational assets.
A single platform can allow compliance teams to oversee employee qualifications, contractor credentials, equipment documentation, vehicle records, service provider certifications, and requirements connected with individual sites. Whether an organisation operates one location or oversees facilities across several regions, centralised management can help maintain consistent certification practices without creating additional unnecessary administrative effort.
Managing the Entire Certification Lifecycle
Effective certificate management should address the complete journey of a certification record, beginning with its creation and continuing through review, approval, storage, monitoring, renewal, or eventual replacement.
Create → Review → Approve → Store → Monitor → Renew
The lifecycle can begin by creating or importing certificate templates based on organisational policies and applicable requirements. Records can then pass through defined approval workflows, giving authorised personnel the ability to examine information and approve documents through secure electronic signatures.
After approval, certificates can remain in a central repository where authorised users can retrieve them without checking several separate systems. Monitoring capabilities provide visibility into current records, approaching expiration dates, and missing documentation. Renewal tasks can be handled individually or across groups of records, helping organisations keep certifications current while reducing repetitive administrative work.
Connections with HR systems, ERP platforms, and workforce management solutions can also help certification information remain aligned across the wider technology environment.
Actions such as approvals, reviews, changes, and decisions can be captured automatically. This creates a traceable audit record that improves accountability while helping organisations prepare regulatory reports more efficiently.
Features That Support Stronger Compliance Management
Modern certificate management platforms can reduce dependence on lengthy manual processes by combining automation, centralised visibility, and controlled access. Common capabilities can include:
- Dashboards providing an overview of certification status across employees, assets, departments, projects, and locations.
- Digital approval workflows supported by secure electronic signatures.
- QR code verification capabilities that allow certificates to be checked efficiently in connected or offline environments.
- Competency management tools that highlight qualification gaps before they affect operational requirements.
- Automated notifications covering renewals, expirations, and other important compliance deadlines.
- Bulk upload and update functions for organisations responsible for managing high volumes of certification records.
- Integration capabilities that connect certification information with HR, ERP, and access control platforms.
- Role based permissions that restrict record access and management activities to authorised personnel.
Together, these capabilities can lower administrative demands, improve transparency, and provide organisations with greater control over certification compliance throughout their operations.
Linking Certifications With Employees and Assets
Certification management often extends far beyond employee qualifications. Vehicles, machinery, specialised tools, and other operational assets may also require inspections, testing, maintenance records, and related approvals.
Certificate management software can connect these documents directly to the appropriate asset, creating a consolidated compliance record for each individual item. Inspection findings, calibration records, maintenance evidence, and approval certificates can be kept together, while future renewal requirements can be monitored through scheduled automation.
This approach can support many different asset categories, including lifting equipment, pressure systems, testing instruments, laboratory equipment, vehicle fleets, and other operational resources. Aviation organisations can bring crew qualifications together with aircraft certification records, marine operators can coordinate vessel approvals with crew documentation, and fleet teams can manage registration, insurance, and roadworthiness records within one controlled environment.
Everyday Operational Benefits
Replacing static spreadsheets with a central certificate management platform can improve efficiency across everyday operations. Audit preparation becomes easier because relevant documentation can be located quickly whenever regulators, customers, insurers, or internal stakeholders request proof of compliance.
Automated workflows can reduce repetitive administrative tasks while encouraging greater consistency and accuracy throughout certification records. Self service functionality can also reduce demands on compliance teams by enabling authorised personnel to access and maintain certification information themselves rather than relying on administrators for every document request or update.
Ultimately, centralised certificate management can create a more organised operational environment. It can minimise avoidable disruption, speed up document retrieval, and help teams respond more effectively whenever evidence of compliance is required.
When reliable certification information needs to remain available whenever required, certificate management software can serve as a dependable central record. Keeping certification data accurate, accessible, and consistently monitored can help organisations fulfil compliance responsibilities while supporting safer operations, stronger governance, and greater confidence across the business.
Book a free demo @ https://toolkitx.com/campaign/certificate-management/
Browse More
https://toolkitx.com/confined-space-permit-template.html
https://toolkitx.com/chemical-work-permit-template.html
Paracetamol Market: Why the 4.5% CAGR Trajectory Changes Everything by 2032
By PW Consulting, 2026-09-21
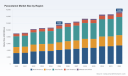
Paracetamol Market: Strategic Trends and Commercial Opportunities Through 2032
The global paracetamol market has reached a significant inflection point, with total revenues climbing to approximately USD 11,500 million in 2025 and a projected trajectory toward USD 15,300 million by 2032. This expansion reflects a compound annual growth rate of 4.5 percent across the 2026 to 2032 forecast window, building on a period of steady recovery and structural reshaping from 2020 through 2025. The market's resilience stems from paracetamol's entrenched position as a first-line analgesic and antipyretic, yet the operating environment is no longer defined by stable demand and predictable margins. Instead, manufacturers, distributors, and investors are navigating a landscape shaped by raw material volatility, evolving regulatory expectations, and shifting consumer preferences that favor differentiated delivery formats. Understanding where value is being created—and where it is being eroded—requires looking beyond headline figures to the underlying dynamics that will dictate competitive outcomes over the next several years.
Market Snapshot and Emerging Challenges
The paracetamol sector has grown from a baseline of roughly USD 9,000 million in 2020 to its current scale, with the pace of expansion accelerating modestly as healthcare systems stabilized and over-the-counter self-medication regained momentum following pandemic-era disruptions. Growth has been broad-based, but regional performance tells a more nuanced story. Asia Pacific and North America together account for the largest revenue shares, reflecting both high population density in the former and strong branded distribution networks in the latter. Europe remains a mature but stable contributor, while Latin America and the Middle East and Africa represent smaller but strategically important markets where access-to-medicine initiatives and pricing reforms continue to shape volume trajectories.
Industry concentration offers another lens on market structure. The top three players command roughly 35 percent of global revenue, while the top five extend that share to approximately 45 percent. Such concentration indicates that scale, supply chain leverage, and regulatory expertise remain meaningful barriers to entry, yet it also signals room for specialization. Smaller and mid-tier manufacturers can compete effectively by focusing on niche formulations, regional regulatory approvals, or value-added delivery systems rather than attempting to match incumbents across every segment.
Several challenges are reshaping how companies approach the market. First, the supply chain for para-aminophenol, the primary precursor for paracetamol synthesis, experienced notable disruption in 2025 when export controls imposed by China constrained global availability. This episode exposed the sector's reliance on a concentrated precursor base and highlighted the vulnerability of cost structures that lack diversification or contractual flexibility. Second, pricing pressures intensified in key markets. In India, the National Pharmaceutical Pricing Authority documented sharp increases in paracetamol prices during 2025, driven by raw material cost escalation and the complex interplay of government production-linked incentive schemes that altered competitive dynamics among domestic manufacturers. Third, the regulatory environment is becoming more demanding. Amendments to US FDA monographs expected in 2026 are projected to raise labeling compliance costs, adding a new layer of expense for both branded and generic producers operating in or exporting to the United States.
For executives, these challenges translate into three immediate priorities: securing more resilient raw material sourcing, preparing for incremental compliance costs that may compress margins on low-differentiation products, and evaluating whether existing portfolio mixes align with markets where pricing power can be defended.
Key Drivers Shaping Market Trajectory
Technological and Formulation Innovation
Innovation in paracetamol has shifted from the molecule itself to the way it is delivered, absorbed, and experienced by patients. Recent developments underscore this focus. In early 2025, Haleon completed a bioequivalence study of an orodispersible paracetamol tablet at a 500 mg dose in healthy adults under fasting conditions. By mid-2025, ClinicalTrials.gov recorded the completion of a Phase 1 bioequivalence study for similar orodispersible tablets. These activities point to a broader industry effort to improve convenience, adherence, and perceived efficacy, particularly in segments where swallowing conventional tablets is a barrier for certain patient populations.
Orodispersible formats are not merely a technical exercise; they represent a pathway to premium positioning in over-the-counter channels where consumer perception and ease of use influence purchase decisions. Companies that can demonstrate consistent bioavailability, stable manufacturing processes, and acceptable taste profiles are better placed to capture share in categories where differentiation has historically been thin. The commercial implication is clear: formulation capability is becoming a competitive lever, and manufacturers that invest in delivery-system expertise can reduce reliance on commodity pricing dynamics.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and cost structures. In India, the National Pharmaceutical Pricing Authority's 2025 findings on paracetamol price increases illustrate how domestic policy can amplify or mitigate the effects of raw material inflation. Production-linked incentive schemes, while intended to strengthen domestic manufacturing capacity, have interacted with cost escalation in ways that produced noticeable price movements and altered competitive positioning among local suppliers.
In the United States, anticipated FDA monograph amendments for 2026 are expected to increase labeling costs for paracetamol products. While these changes do not alter the drug's clinical role, they do affect the economics of product line management. Companies with complex SKU portfolios, multiple packaging configurations, or extensive distribution footprints will need to model the cumulative impact of compliance costs and decide where simplification or consolidation can preserve profitability. Parallel attention to pharmacovigilance expectations remains relevant, as regulatory bodies continue to evaluate the broader safety narrative around widely used analgesics, even when clinical evidence remains reassuring.
Demand-Side Shifts and Consumer Behavior
Consumer behavior continues to evolve in ways that influence both volume and product mix. A growing preference for self-care and accessible over-the-counter options has reinforced demand for paracetamol across multiple indications, including headache, fever, cold and cough, and muscle cramps. The application landscape is broad, and the relative weight of each use case varies by region and demographic profile. What matters strategically is that demand is not monolithic; it is segmented by age, presentation, and purchase context, which creates opportunities for targeted product design and channel strategy.
Recent safety research has also contributed to a more stable demand environment by addressing long-standing public questions. A February 2026 meta-analysis published by UpToDate found no association between prenatal paracetamol use and autism or ADHD risk in low-bias studies with long follow-up. In January 2026, MedicalXpress released findings supporting the safety of paracetamol and ibuprofen in infants under one year of age, with no link to eczema or other measured risks. In April 2026, JAMA Network published a trial comparing acetaminophen versus opioid addition to ibuprofen for pediatric pain relief, contributing to ongoing discussions about optimal analgesia strategies. Collectively, these developments help sustain confidence in paracetamol's role in both adult and pediatric settings, reducing the likelihood that safety concerns will materially disrupt demand in mainstream markets.
Supply Chain and Cost Structure Dynamics
The cost side of the equation has become a strategic focal point. China's dominant position in paracetamol precursor supply has been a defining feature of the market. A May 2026 US State Department report highlighted China's roughly 70 percent share of para-aminophenol supply, with direct US imports at only 17 percent. That concentration became more consequential in 2026, when an Iran-related conflict triggered vessel shortages that restricted API movement from China and drove paracetamol raw material prices up by more than 26 percent in India.
These events are not isolated; they reveal structural dependencies that companies must manage proactively. Firms that depend on single-source precursor procurement or that lack visibility into tiered supplier networks are exposed to both price shocks and availability risk. Conversely, organizations that have built multi-source strategies, maintained strategic inventory buffers for critical inputs, or invested in forward contracting are better positioned to stabilize costs and protect supply continuity. The broader lesson is that supply chain design is now a competitive differentiator in a market where margins on undifferentiated products are already under pressure.
Competitive Landscape and Leading Strategies
The paracetamol market features a mix of large multinationals, established Indian API and formulation producers, and regional specialists. This blend creates a competitive environment in which scale, geographic reach, and formulation capability interact in different ways across segments.
Among the companies shaping the market, several Indian manufacturers stand out for their high-volume production of paracetamol API and finished dosage forms. Granules India Limited, based in Hyderabad, is a major producer of paracetamol API and tablets with extensive global supply relationships. IOL Chemicals and Pharmaceuticals Limited, headquartered in Ludhiana, is an active manufacturer and exporter of paracetamol API and formulations. Farmson Pharmaceutical Gujarat Private Limited, operating from Gujarat, produces paracetamol API and tablets under WHO-GMP and other recognized standards. These firms illustrate the strategic importance of cost-efficient, compliant manufacturing in a market where precursor dynamics and pricing regulation can move quickly.
Larger integrated players bring a different set of advantages. Sun Pharmaceutical Industries Ltd, based in Mumbai, operates as a global pharmaceutical company with paracetamol tablet and API production capabilities. Cipla Ltd, also headquartered in Mumbai, manufactures paracetamol tablets and formulations across multiple markets. Their scale, regulatory infrastructure, and distribution reach allow them to compete across both generic and branded contexts, though they must still navigate the same raw material and compliance pressures affecting the broader industry.
On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. These organizations typically compete on brand equity, patient-facing positioning, and broader portfolio integration rather than price alone.
Acetaminophen Market
The strategic positioning of these players diverges in ways that matter for competitive planning. Indian API and formulation manufacturers often emphasize volume, cost discipline, and export capacity, leveraging regulatory certifications and production efficiency to serve both domestic and international markets. Multinationals and branded players more frequently invest in patient convenience, formulation variety, and trust-based consumer relationships, which can support pricing resilience in categories where differentiation is credible. Companies that combine strong manufacturing fundamentals with formulation-driven differentiation are increasingly well placed to navigate both commodity pressure and premium opportunity.
PW Consulting
Market structure is evolving through selective consolidation and parallel fragmentation. On one hand, larger players continue to seek efficiencies in supply, regulatory management, and distribution, which can lead to tighter integration across API, formulation, and packaging. On the other hand, specialized niche participants are carving out positions around delivery formats, regional approvals, and patient-centric packaging that do not require matching the full scale of the largest competitors. New entrants face meaningful hurdles given existing concentration and regulatory complexity, but targeted entry remains possible where formulation novelty, local market knowledge, or channel access provides a defensible starting point.
Recent industry events reinforce the strategic significance of these divergent paths. Safety and clinical developments have reinforced demand confidence in established use cases, while formulation work on orodispersible tablets indicates where incremental differentiation is being pursued. At the same time, raw material disruptions and pricing actions in key markets show that even well-positioned companies must manage upstream dependencies and regulatory cost exposure with discipline.
Antipyretic and Analgesic Market
Forward Outlook: Trends and Commercial Implications
Trend One: Greater Emphasis on Delivery Format Differentiation
Over the next three to five years, formulation differentiation is likely to become a more visible feature of competition, especially in over-the-counter channels where consumer choice is shaped by convenience, taste, and perceived ease of use. Orodispersible and other patient-friendly formats are attracting clinical and commercial attention, and companies that can bring these formats to market with consistent quality and credible bioequivalence data may gain incremental pricing latitude. The commercial opportunity lies in aligning format innovation with target populations and channel strategies, rather than treating new delivery systems as a generic upgrade. A related risk is that differentiation only pays off when it is supported by manufacturing reliability, taste acceptability, and clear consumer communication; otherwise, premium positioning is difficult to sustain.
Trend Two: Supply Chain Reconfiguration and Sourcing Diversification
The concentration of para-aminophenol supply and the price shocks associated with geopolitical and logistical disruptions point toward a longer-term shift in sourcing strategies. Companies are likely to pursue a combination of multi-source procurement, closer supplier relationships, and regional capacity planning to reduce exposure to single-point failures. For manufacturers with significant exposure to precursor imports, this may mean renegotiating supply terms, qualifying alternative sources, or adjusting production planning to absorb short-term volatility more efficiently. The opportunity here is to convert supply chain resilience into a more stable cost base and more dependable fulfillment, both of which support customer trust and margin protection. The risk is that diversification takes time and capital, and that transitional periods can create their own inefficiencies if supplier qualification and quality assurance are not managed carefully.
Trend Three: Regulatory Cost Management as a Core Competency
As labeling and monograph requirements evolve, particularly in major markets such as the United States, regulatory cost management will become a more central element of portfolio strategy. Companies that proactively rationalize SKU complexity, streamline packaging variations, and align compliance processes with manufacturing workflows are more likely to preserve margins than those that treat regulatory changes as an external cost to be absorbed passively. This trend also intersects with market access and pricing policy in regions such as India, where domestic regulation can interact with raw material economics in ways that drive price outcomes. Businesses that monitor these dynamics closely and incorporate them into planning will be better positioned to anticipate margin shifts and adjust product strategies before pressure becomes acute.
Implications for Decision Makers
For manufacturers, the immediate priority is to strengthen upstream resilience while identifying where formulation or delivery improvements can support differentiation. This means reviewing precursor sourcing strategies, testing alternative supply paths, and assessing whether current portfolio complexity is justified by the margin it generates. Where product lines are commoditized, simplification can reduce compliance burden and improve operating efficiency. Where there is credible potential for a differentiated format, targeted development and evidence generation can create a more defensible position in specific consumer segments.
For investors, the market rewards companies that combine cost discipline with credible differentiation and that demonstrate visibility into supply risk. The most attractive profiles are likely those with diversified sourcing, manageable regulatory exposure, and a clear strategy for where premium positioning is possible. It is equally important to distinguish between growth that comes from volume recovery and growth that is supported by product or process advantages, because the durability of each differs. Raw material volatility and regulatory cost changes should be treated as structural considerations rather than temporary noise, and valuation assumptions should reflect the sensitivity of margins to those factors.
For procurement and supply chain leaders, the priority is to reduce single-point dependencies and increase transparency across tiered suppliers. This includes mapping exposure to precursor concentration, evaluating contractual protections, and planning for periods of elevated cost or constrained availability. Building scenarios that account for geopolitical disruption, vessel availability, and regional pricing actions can improve responsiveness and reduce the likelihood of reactive purchasing at unfavorable terms. Procurement strategy in this market is not only about price; it is about continuity, quality assurance, and the ability to support manufacturing stability when upstream conditions shift.
Bringing the Analysis Together
The paracetamol market is moving through a phase in which growth is real but not uniform, and where competitive advantage will increasingly depend on how well companies manage supply exposure, regulatory cost pressure, and the opportunity to differentiate through formulation and patient-facing value. Demand fundamentals remain strong across core indications, and recent clinical and safety developments have helped sustain confidence in the molecule's role. At the same time, precursor concentration, pricing dynamics in key markets, and evolving compliance expectations mean that the path to profitable growth is narrower than it may appear from headline size alone.
Companies and investors that gain the deepest visibility into these interacting forces will be best positioned to act early—whether that means restructuring sourcing, refining portfolio complexity, investing in format differentiation, or reassessing where pricing power can be defended. The strategic window is open now, before further regulatory changes, supply disruptions, or competitive moves reshape the terms of participation.
For decision makers seeking detailed segmentation data, company-level benchmarks, and scenario-based guidance tailored to specific geographies and product lines, the full PW Consulting research report provides a more granular view of the market and its strategic levers. The broader analysis presented here is intended to frame the most important choices; the complete study is designed to support the next step in planning with deeper segmentation, competitive mapping, and forward-looking scenarios.
For detailed analysis of this topic, please visit the official page: Paracetamol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminate Flooring Market: How the 6.98% CAGR and Residential Demand Redefine Growth
By PW Consulting, 2026-09-21
Navigating the Laminate Flooring Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context: Scale, Growth Trajectory, and Structural Headwinds
The laminate flooring sector has demonstrated resilient expansion over the past half-decade, recovering from a brief contraction in 2024 to reach an estimated USD 1.7 billion in annual revenue by 2025. Over the 2020–2025 historical window, the market expanded at a compound annual rate that reflected both post-pandemic housing activity and a steady shift toward cost-effective, aesthetically versatile flooring alternatives. Looking ahead to the 2026–2032 forecast horizon, the sector is positioned to sustain a robust growth path, with revenues projected to cross the USD 2.6 billion threshold by the end of the period. The annualized growth rate implied by these projections underscores a market that is not merely rebounding but structurally expanding, driven by durable demand signals and incremental product innovation rather than short-lived cyclical spikes.
Despite the favorable top-line trajectory, the industry sits at a inflection point where growth alone no longer guarantees profitability or market share retention. Three structural challenges are reshaping how participants compete and allocate capital. First, raw material volatility—particularly in amino resin inputs—has compressed margins and forced manufacturers to revisit pricing strategies, inventory planning, and formulation alternatives. Second, the regulatory environment has tightened on both sides of the Atlantic, with formaldehyde emission thresholds and performance standards creating a compliance barrier that favors established producers with robust quality systems and penalizes smaller players lacking technical infrastructure. Third, consumer and specifier preferences are shifting faster than traditional product development cycles, placing a premium on waterproof capabilities, realistic wood visuals, and sustainable positioning—attributes that require sustained R&D investment and supply chain coordination.
Cork Flooring Market
Core Drivers Reshaping the Laminate Flooring Landscape
Material Innovation and Performance Upgrades
The most visible driver of market evolution is the transition from traditional laminate as a purely decorative, moisture-sensitive surface to engineered formats that deliver water resistance, enhanced durability, and tighter click mechanisms. Recent product updates emphasizing multi-hour water resistance and spill-defense technologies illustrate how manufacturers are responding to real-life usage scenarios in both homes and light commercial settings. These advances are not cosmetic; they alter the value proposition of laminate relative to rigid core and luxury vinyl alternatives, allowing laminate to retain relevance in moisture-prone spaces such as kitchens, entryways, and some hospitality environments. The integration of advanced locking systems and refined surface treatments also raises installed performance, which matters increasingly to contractors and end-users who weigh total cost of ownership rather than upfront material price alone.
Regulatory Tightening as Both Constraint and Differentiator
Regulatory frameworks governing formaldehyde emissions and product performance have matured from compliance checkboxes into strategic variables. In the United States, emission standards under TSCA Title VI and CARB Phase 2 continue to shape sourcing decisions, while European market access hinges on performance classifications and emission limits that must be demonstrated through consistent testing and documentation. For manufacturers, these requirements raise the cost of entry and reward scale, process control, and transparent supply chains. At the same time, they create a differentiation path for brands that can communicate low-emission credentials and certified performance with credibility. The net effect is a market where regulatory conformance is becoming a competitive asset rather than a simple cost of doing business.
Demand-Side Shifts in Residential and Commercial End Use
Demand patterns reflect evolving lifestyles and asset management priorities. In residential settings, owners are prioritizing flooring that balances visual warmth with practical resilience—especially in households with children and pets, where spill resistance and easy maintenance carry real purchase weight. In commercial applications, facility managers and designers are seeking products that support durability targets, ease of replacement, and sustainability goals without sacrificing design quality. This dual demand profile encourages product line extensions that serve both segments while preserving distinct branding and performance messaging. Trade show activity and industry trend publications reinforce the direction of travel, with recurring emphasis on natural textures, sustainable design narratives, and installation-friendly systems that reduce labor friction.
Supply Chain and Cost Structure Realignment
The laminate value chain remains sensitive to input costs, particularly resin systems and wood fiberboard substrates sourced from sustainably managed forests. Price fluctuations in amino resin inputs during recent periods have rippled through production economics, prompting producers to diversify suppliers, renegotiate contracts, and in some cases reformulate top-layer compositions where feasible. Alongside input volatility, logistics costs and trade dynamics influence landed pricing and geographic availability. Some producers have repositioned local or regional manufacturing as a hedge against tariff-heavy import exposure, using design-forward, PVC-free programs to capture buyers seeking quality and supply security. This reorientation hints at a broader supply chain realignment in which proximity, compliance assurance, and material transparency are gaining strategic weight alongside unit cost.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive set spans large diversified flooring organizations and specialized laminate producers, each pursuing distinct positioning strategies. Several North American-based manufacturers have concentrated on waterproof laminate collections with realistic wood visuals and advanced locking systems, targeting both residential and commercial use cases where moisture performance is a deal driver. Others have built premium lines around integrated technology for durability and low-emission residential options, using certification and performance messaging to justify price premiums and strengthen dealer confidence. In Europe, established panel and flooring groups continue to emphasize high-quality laminate built on wood fibreboard substrates and impregnation papers, aligning product development with on-trend residential and commercial aesthetics. A parallel strand of competition comes from brands advancing sustainable sourcing narratives, including high proportions of sustainably sourced wood and eco-conscious resins, paired with click systems designed to improve installation speed and joint integrity.
Recent activity shows how these strategies are being operationalized. One major European panel and flooring group re-established design-forward, sustainable, PVC-free laminate programs as a high-quality alternative to tariff-heavy imports, signaling a deliberate pivot toward supply resilience and material positioning. Around the same period, another producer showcased new PVC and mineral core flooring technologies alongside laminate offerings at a major trade event, reflecting a broader portfolio approach that treats laminate as part of a wider hard-surface ecosystem rather than a standalone silo. Industry associations and expos continue to function as coordination points for new product catalogs and installation techniques, while trend reports from European producer groups highlight natural textures and sustainable design as recurring themes for upcoming collections. Product-level updates extending water resistance in core collection lines further illustrate the pace of incremental improvement across the market.
PW Consulting Health Care Research Center
Market structure data indicates a moderately fragmented landscape with a consolidated top tier. The combined share of the leading three participants sits below a quarter of total revenue, and the top five collectively account for just over a quarter. This concentration pattern suggests room for both specialized challengers and scaled incumbents, but also implies that share gains are likely to accrue to players that can combine compliance assurance, performance differentiation, and efficient scale rather than to those competing primarily on price. The market is simultaneously consolidating where manufacturing and compliance require capital intensity, while fragmenting in design-led niches where visual differentiation and installation characteristics allow smaller brands to carve out positioning. New entrants tend to succeed when they bring a clear material or performance claim—such as enhanced water resistance, low-emission credentials, or sustainable sourcing—backed by credible documentation and a distribution pathway that reaches specifiers and retailers efficiently.
LVT Flooring Market
Forward Outlook: Three Trends Defining the Next 3–5 Years
Performance-Led Product Convergence
Over the next several years, laminate offerings are likely to converge further toward performance characteristics that were once the domain of rigid core and luxury vinyl products. Water resistance, spill defense, and improved locking systems will become baseline expectations in many residential and light commercial applications, reshaping comparison sets at point of sale. The commercial opportunity lies in packaging these capabilities with credible installation benefits and maintenance narratives that reduce total cost of ownership arguments against competing formats. The risk is a race to the middle if differentiation rests on similar claims without supporting documentation, installation consistency, or durable quality control. Winners will be those who pair performance upgrades with transparent testing, clear warranties, and installer education that converts technical claims into confident purchase decisions.
Sustainability as Specification Currency
Sustainability is transitioning from a marketing accent to a specification factor in both residential and commercial procurement. Sourcing transparency, emission performance, and material choices are increasingly weighed alongside aesthetics and price, particularly in projects with environmental certification targets or corporate sustainability commitments. The commercial opportunity is to build coherent product stories that link sourcing, resin choices, and emission compliance into a verifiable narrative supported by recognized standards and documentation. The uncertainty lies in the pace and harmonization of regulatory expectations across markets, which can shift the relative attractiveness of specific formulations or sourcing models. Participants that maintain flexible input strategies and robust compliance systems will be better positioned to adapt without sacrificing market access.
Regional Rebalancing and Supply Chain Localization
Geographic demand and supply strategies are likely to rebalance as trade dynamics, input cost volatility, and lead-time expectations evolve. Producers with localized manufacturing or diversified sourcing footprints can mitigate exposure to import-related cost shocks and respond more quickly to regional design preferences. The commercial opportunity is to align product portfolios with regional demand signatures—warm natural visuals in some markets, performance-led waterproof lines in others—while maintaining economies of scale in core processes. The risk is over-investment in capacity ahead of demand or under-investment in compliance and quality infrastructure that erodes brand trust. Strategic capacity decisions should be tied to verified regional demand signals and a realistic assessment of input cost trajectories, rather than to short-term promotional cycles.
Decision-Maker Playbook: Actions by Stakeholder Type
For Manufacturers and Brand Owners
- Prioritize performance claims that can be documented and defended, especially water resistance, emission compliance, and installation reliability, because these attributes increasingly determine specification outcomes and reduce returns.
- Diversify resin and substrate sourcing while maintaining formulation integrity, and build scenario plans around input cost volatility so that pricing and margin decisions do not depend on a single supply assumption.
- Align product development with regional demand signatures and installation realities, using design-led and performance-led line extensions where they address real specifier concerns rather than pursuing broad portfolios that dilute focus.
For Investors and Corporate Development Teams
- Evaluate exposure to regulatory and input-cost risk as part of valuation, focusing on producers with credible compliance systems, diversified supply chains, and documented performance advantages that support pricing power.
- Look for consolidation opportunities where scale improves margin stability and market access, but distinguish true operational value from purely financial engineering by examining quality systems, distribution strength, and brand credibility.
- Consider the pace of format convergence carefully, since laminate’s relative attractiveness will depend on its ability to hold performance and aesthetic ground against competing rigid core and vinyl solutions in key demand segments.
For Procurement, Distribution, and Channel Partners
- Assess supplier health and compliance documentation alongside unit pricing, since emission standards and performance consistency affect downstream risk, customer satisfaction, and rework costs over the lifecycle of a project.
- Match portfolio breadth to channel demand, emphasizing product lines with clear installation and maintenance benefits in segments where labor time, durability, and maintenance are decisive for repeat business.
- Track regional trend signals and trade activity to anticipate demand shifts, using design and performance cues to inform range planning and inventory commitments without overcommitting to short-lived style cycles.
Closing Perspective
The laminate flooring market is moving from a phase defined by price competition and basic decorative utility toward one where performance, compliance, and sustainability credentials determine competitive advantage. The mid-term growth path remains attractive, but value capture will favor organizations that convert technical improvements into credible customer benefits, manage input and regulatory risk with discipline, and align portfolios with real regional demand. For leaders seeking to shape strategy rather than react to it, detailed segmentation data, company-level benchmarking, and scenario analysis can sharpen resource allocation and timing decisions. A comprehensive research report offering granular segment splits, competitive profiles, and forward scenarios is available for teams that need to translate these market-level insights into actionable plans with greater precision.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Leave In Meat Thermometers Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Leave In Meat Thermometers Market
Overview
The Leave In Meat Thermometers Market encompasses advanced temperature monitoring devices designed for continuous use during cooking processes. These thermometers are essential tools in professional kitchens and food production facilities, ensuring precise internal meat temperatures for safety and quality. Their core functionalities include real-time temperature tracking, durable sensor integration, and user-friendly interfaces, supporting industries that prioritize food safety and consistency.
The importance of the Leave In Meat Thermometers Market lies in its ability to enhance culinary precision and compliance with health standards. By enabling chefs and food manufacturers to monitor meat temperatures without frequent interruptions, these devices streamline operations. The market’s growth is driven by increasing demand for automation and accuracy in food preparation, making it a vital component of modern food service and processing industries.
Market Size and Growth
The current market value of the Leave In Meat Thermometers Market is estimated at around USD 250 million. Projected growth over the next 7 to 10 years suggests a compound annual growth rate (CAGR) of approximately 8%. This expansion is fueled by rising consumer awareness of food safety, technological advancements, and expanding adoption in commercial kitchens and industrial settings.
Key drivers include the increasing emphasis on health standards, the proliferation of smart kitchen appliances, and the growing trend toward automated cooking solutions. Additionally, rising demand for high-quality, consistent meat products across global markets supports sustained growth.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2070
Key Drivers
• Rising food safety regulations and standards
• Adoption of smart kitchen technologies
• Growing demand for automation in foodservice
• Increasing consumer focus on quality and safety
• Expansion of commercial and industrial food sectors
Restraints
• High costs of advanced sensor technology
• Technical challenges in sensor durability and calibration
• Regulatory hurdles in certain regions
• Operational complexity for small businesses
• Limited awareness in emerging markets
Segmentation
• By Type: Digital, Analog
• By Deployment: Commercial, Residential
• By Enterprise Size: Small, Medium, Large
• By End User: Restaurants, Food Processing, Catering, Household
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits robust demand driven by high food safety standards and technological integration in culinary practices. Europe’s focus on quality standards and regulatory compliance fuels adoption among premium food producers. Asia-Pacific presents significant growth potential due to expanding foodservice markets and rising disposable incomes. Latin America’s increasing industrialization supports market expansion, while the Middle East & Africa show emerging opportunities linked to modernization efforts in food safety practices.
Opportunities
• Expanding adoption in emerging markets
• Integration with IoT and smart kitchen systems
• Development of wireless and portable models
• Industry-specific customizations for food safety compliance
• Adoption in industrial food processing and catering
Key Companies
Johnson Controls, ThermoWorks, Taylor Precision Products, CDN, Maverick, Lavatools, Polder, Inkbird, Kizen, Edlund, iChef, Weber
Conclusion
The overall outlook for the Leave In Meat Thermometers Market remains positive, with long-term growth potential driven by technological innovations and increasing safety standards. As industries continue to prioritize quality and efficiency, the strategic importance of these devices will expand across commercial and industrial sectors. The market’s future growth depends on advancements in sensor technology and broader industry adoption, making it a critical component of modern food safety infrastructure.
Related Reports
Microwave Light Wave Ultrasonic Extractor Market , Size Share and Analysis | Report 2033
Dark Stem Soft Seal Gate Valve Market , Size Share and Analysis | Report 2033
Servo Hydraulic Cylinder Market , Size Share and Analysis | Report 2033
Marine Exhaust Manifolds Market , Size Share and Analysis | Report 2033
Desulphurization And Dust Removal Fan Market , Size Share and Analysis | Report 2033
Dc Tig Welding Machine Market , Size Share and Analysis | Report 2033
Three Phase Tig Welding Machine Market , Size Share and Analysis | Report 2033
Ecm Constant Torque Motor Market , Size Share and Analysis | Report 2033
Single Phase Tig Welding Machine Market , Size Share and Analysis | Report 2033
Cbl Cracking Furnace Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
How Connected Asset Management Can Transform Operational Efficiency
Business assets often do their most important work without attracting much attention. They can continue operating quietly while inefficient practices build beneath the surface. Because problems may not produce immediate alarms, visible damage, or obvious disruption, weaknesses can remain unnoticed for months or longer. Poor asset utilization and limited oversight can steadily raise expenses through reduced productivity, ineffective workforce allocation, increasing maintenance costs, and greater compliance exposure. When these problems finally become visible, the resulting operational and financial impact may already be significant.
For modern organizations, asset management is therefore not simply about preventing equipment breakdowns. It is also about reducing the long-term impact of disconnected systems, limited performance visibility, and decisions made without reliable operational information. This broader view also helps organizations connect day-to-day asset decisions with longer-term operational priorities, making it easier to recognize where resources are being consumed, where attention is required, and where better coordination can prevent avoidable costs from accumulating over time across different teams, sites, and operational processes consistently.
This is why asset management now goes well beyond keeping orderly asset records. A database filled with information does not, by itself, make operations more effective. Organizations need an asset management platform that creates a connected operational foundation, linking asset information with maintenance activities, governance needs, and performance intelligence. When these functions work together, teams can spot early warning signs, make better-informed decisions, and resolve developing problems before they become expensive failures. ToolKitX follows this connected model through a real time environment that unites maintenance, finance, and compliance stakeholders. A dependable shared information base can strengthen consistency, accountability, and operational visibility across the organization.
In ToolKitX, an asset is not simply a fixed record stored inside software. It becomes a digital history that evolves throughout its working life. That journey begins with installation and continues through daily use, inspections, servicing, repairs, upgrades, incidents, and eventual retirement. Each significant activity contributes to the asset's lifecycle record. Teams can therefore see the broader history of an asset instead of reconstructing its story from separate, disconnected sources.
Registration details, inspection findings, maintenance records, service histories, disposal documents, and other essential information can be held within one centralized environment. Teams can quickly determine an asset's location, review its current condition, and understand its operational significance without switching between multiple applications. Visibility can also move beyond the initial purchase cost by incorporating maintenance expenses, downtime risk, repeated failures, and performance patterns. Serial level tracking adds another layer of traceability and accuracy, helping organizations maintain reliable records for audits and accountability.
ToolKitX brings structured maintenance workflows, controlled documentation, and intelligent recommendations together to encourage a more proactive approach. Rather than waiting until equipment stops working, maintenance teams can monitor asset health and respond earlier. As operational information grows, recurring behaviors and performance patterns become easier to recognize. This helps organizations progress from traditional preventive maintenance toward a more predictive, data informed approach to asset management.
Connected asset management becomes especially important when interruptions can have serious operational consequences. Manufacturing, transportation, utilities, and energy organizations all depend on strong reliability, safety, and performance standards. A single equipment problem can affect production schedules, employee safety, and regulatory responsibilities simultaneously. ToolKitX connects asset information, maintenance planning, permit management, and change control within one operational framework. Instead of depending on isolated spreadsheets and separate applications, teams can work from a coordinated environment designed for information sharing and collaboration. Consistent information can support everyday decisions while also simplifying audits, investigations, and management reviews.
From an organization wide view, users can drill down into the details of individual assets. Records may include operating manuals, certifications, calibration documents, approvals, and other supporting files. Keeping these materials together helps management and operational personnel reach important performance information and audit ready documentation faster, without repeatedly collecting records from different places.
Preventive maintenance can be organized around calendar intervals, equipment usage, or condition based events. Tasks can be assigned to technicians, who can capture readings, add photographs, record observations, and complete work orders from the field. These activities can continue when an active internet connection is unavailable. As field data builds over time, organizations gain stronger evidence for assessing reliability, maintenance effectiveness, and changes in asset condition.
Fault information becomes more useful when repeated problems can be analyzed for patterns. ToolKitX turns recurring failures and equipment issues into reliability intelligence that maintenance teams can act upon. Teams can identify assets that repeatedly cause trouble, spot developing concerns sooner, and apply corrective actions before failures lead to costly downtime or serious equipment damage.
Maintenance also relies on having replacement parts available when they are needed. ToolKitX connects inventory information with maintenance requirements by centralizing stock quantities, storage locations, and replenishment needs. Barcode and QR code capabilities can improve inventory accuracy and reduce handling mistakes. Easier access to required components can reduce technician delays, unnecessary searching, and avoidable trips.
Organizational changes can follow defined approval workflows while preserving a complete time stamped history of decisions and activities. This produces a transparent, auditable record for each change, supporting governance and accountability. It can also reduce the manual follow up and continuous monitoring burden placed on teams.
ToolKitX uses an API first microservices architecture that can connect with ERP, MES, SCADA, and other enterprise technologies. Organizations can extend their existing technology environment rather than replacing established systems. By building on current investments, businesses can gain stronger operational visibility, intelligence, and control while continuing to use the technologies already in place.
The platform also supports needs beyond routine maintenance. Real time dashboards bring asset location, condition, and maintenance status together in one interface, helping teams understand current operational conditions more clearly. Asset availability can be supported through threshold monitoring, IoT generated information, and predictive indicators that help reveal potential issues before they become operational disruptions.
Compliance activities can benefit from secure lifecycle records, traceable change histories, and performance information that can be exported when required. Finance teams can gain clearer insight by connecting asset lifecycle costs and performance with ERP processes. This information can support depreciation planning, spare parts forecasting, and future capital investment decisions. Cloud deployment choices and guided implementation services can also help organizations begin realizing value sooner instead of enduring the extended implementation periods often associated with traditional enterprise software.
A mature asset management process can function as a repeatable operating cycle. Assets are registered and identified, maintenance needs are defined, failures are documented with supporting evidence, and dashboards deliver real time visibility into measures such as MTTR and MTBF. As more operational data accumulates, predictive insights can inform future planning and support continuous improvements in asset performance.
When maintenance, inventory, permits, change management, and performance analytics work within one connected environment, organizations can build a clearer picture of how their operations are performing. Frontline teams and leadership can work from the same dependable information, creating a stronger foundation for decisions, greater efficiency, clearer accountability, and more consistent business results.
Book a free demo @ https://toolkitx.com/campaign/asset-management/
Browse More
https://toolkitx.com/electrical-work-permit-template.html
https://toolkitx.com/excavation-work-permit-template.html
https://www.toolkitx.com/blogs.aspx
Solar Encapsulation Materials Market: Why 7.83% CAGR and EVA's Lead Change Strategy
By PW Consulting, 2026-09-21
Global Solar Encapsulation Materials Market: Strategic Trends & Commercial Opportunities
The solar encapsulation materials marketplace has matured from a commodity-driven segment into a strategically critical layer of photovoltaic module performance and longevity. During the 2020-2025 historical period, the sector demonstrated steady expansion, driven by accelerating photovoltaic deployment, material innovation, and shifting module architectures. Current valuations place the overall market at approximately 5.87 billion USD for 2025, with a projected trajectory toward 9.95 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.83 percent across the 2026-2032 forecast window, signaling sustained structural demand rather than cyclical fluctuations.
Behind these headline figures lies a more nuanced transformation. Encapsulation has evolved from a passive protective function to an active enabler of module efficiency, reliability, and warranty economics. This shift is reshaping competitive dynamics, supply network configurations, and investment priorities. Decision-makers evaluating exposure to solar value chains must look beyond volume growth and understand the material, technological, and geographic realignments that are redefining commercial viability in this segment.
Market Snapshot and Structural Realities
The encapsulation sector operates at the intersection of polymer engineering, module architecture, and long-term performance guarantees. Crystalline silicon photovoltaic systems continue to anchor the majority of demand, reflecting their dominant position across utility-scale, commercial, and residential installations. Within the material mix, ethylene vinyl acetate (EVA) retains a leading position, accounting for roughly 55 percent of the market in 2025, while polyolefin elastomer (POE) represents the fastest-growing category, driven by compatibility with advanced cell architectures and improved moisture and potential-induced degradation resistance.
Regional demand is distributed across major solar manufacturing and deployment hubs, with North America holding a notable share, Asia Pacific maintaining strong volume leadership, and Europe sustaining steady consumption supported by local manufacturing incentives and project pipeline development. The market remains moderately concentrated, with the top three suppliers capturing approximately 62.5 percent of revenue and the top five reaching around 75.0 percent. This structure indicates that scale, formulation expertise, and module-maker relationships confer meaningful advantages, even as demand fragmentation across geographies and module types creates room for specialized entrants.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market faces structural frictions that will determine which participants capture value in the next cycle. Three challenges stand out as particularly decisive.
LED Encapsulation Market
Material specification pressure and warranty economics. Twenty-five-year module warranties have become standard expectations rather than premium differentiators. Encapsulants must now demonstrate high gel content, robust moisture barriers, and sustained potential-induced degradation resistance under diverse operating conditions. Failure to meet formulation thresholds increases financial exposure for module makers and complicates downstream bankability. The requirement for gel content above 50-70 percent for POE and EPE formulations, and above 75-80 percent for EVA, illustrates how material performance has become a gatekeeper for commercial acceptance.
Architecture transitions reshaping demand composition. The rise of TOPCon, heterojunction, bifacial, and tandem-oriented concepts is changing encapsulant requirements. Traditional EVA formulations optimized for earlier-generation cell designs require reformulation or replacement when paired with high-efficiency back-contact structures, bifacial light management, or emerging perovskite combinations. Suppliers that can deliver co-extruded solutions tailored to these architectures are gaining strategic relevance, while general-purpose material providers face margin and volume pressure.
Supply network localization and geopolitical realignment. End-users and manufacturers increasingly prioritize supply resilience over lowest-cost sourcing. The expansion of U.S. production capacity for high-performance encapsulants reflects a broader effort to reduce import dependencies and align material availability with domestic module assembly and deployment timelines. At the same time, emerging manufacturing centers in South and Southeast Asia are driving regional demand for cost-competitive yet specification-grade encapsulants. These parallel forces are bifurcating procurement strategies between premium localized supply and volume-driven regional sourcing.
Strategic Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
Encapsulation technology is moving rapidly from commodity film production to engineered material systems that support incremental module efficiency gains and durability requirements. Co-extruded structures are gaining prominence because they enable layered functionality, such as improved UV stabilization, enhanced moisture resistance, or tailored optical properties, without requiring separate processing steps. For bifacial modules, premium anti-reflective and optimized encapsulant films can deliver absolute efficiency improvements in the range of 0.5-1.0 percent, which translates into meaningful energy yield differences over a project lifecycle. This performance link justifies price premiums in the order of 15-25 percent for specification-grade films and reinforces the commercial logic of advanced material investment.
Recent product activity confirms the pace of innovation. Next-generation co-extruded POE and EPE formulations optimized for TOPCon and bifacial modules have advanced toward commercialization, with some offerings demonstrating enhanced potential-induced degradation resistance beyond 300 hours. In parallel, new encapsulant film generations incorporating UV down-conversion technology and ultrafast-cure EVA variants have entered the market alongside capacity expansions designed to support higher-volume deployment. These developments indicate that material innovation is no longer confined to laboratory feasibility; it is being scaled into commercial supply pipelines linked to module-maker qualification cycles.
Policy, Regulation, and Warranty-Driven Standards
Regulatory and financing environments are tightening the performance bar for encapsulants indirectly but powerfully. Long-duration warranties, bankability requirements, and durability expectations are translating into practical formulation thresholds. Advanced encapsulants for bifacial and next-generation modules must meet stringent moisture barrier and potential-induced degradation resistance requirements to support extended warranty commitments. This has elevated the importance of certificate-backed validation, standardized testing, and consistent batch quality.
At the same time, industrial policy and trade dynamics are reshaping where production is located and how supply chains are structured. Domestic capacity expansion in the United States is reducing exposure to cross-border disruptions for high-performance encapsulants used in advanced module types. This localization trend is not merely about cost; it is about securing predictable supply for products where qualification cycles are long and switching costs are high. In parallel, export-oriented manufacturers in Asia are aligning production with regional demand centers and international qualification requirements, creating a more geographically diversified but increasingly specification-sensitive competitive landscape.
Demand-Side Evolution and Module Architecture Shift
Demand growth is being shaped by both volume and value. Solar installation continues to expand across utility, distributed, and commercial segments, but the more strategically important shift is the changing composition of module technology adoption. Crystalline silicon remains the backbone of the market, yet the rising share of high-efficiency variants is altering encapsulant selection criteria. Bifacial modules, TOPCon cells, and back-contact configurations increasingly require materials that preserve optical performance while protecting cell interfaces over decades of operation.
For module manufacturers, this means encapsulant choice is becoming a design decision with direct implications for energy yield, degradation profile, and total cost of ownership. For buyers of finished modules, encapsulant quality is increasingly visible through warranty terms, degradation guarantees, and long-term performance expectations. As a result, encapsulant material is transitioning from a hidden component to a value-differentiating element in product positioning, especially in competitive segments where efficiency and reliability claims are scrutinized during procurement and financing.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being driven by raw material economics, processing complexity, and the premium attached to specification-grade products. Polyolefin-based materials are growing faster than established EVA streams, supported by their compatibility with advanced module designs and improved durability profiles. However, higher-performance films often involve more complex extrusion and formulation requirements, which affect conversion economics and supplier capability thresholds.
The cost dynamic is not simply about raw material price movement; it is about the widening spread between standard and premium encapsulants. Suppliers capable of delivering consistent high gel content, UV stabilization, and co-extrusion performance can capture meaningful margins through specification differentiation, while undifferentiated commodity production faces intensifying competition and pressure from regional capacity additions. This bifurcation is encouraging strategic positioning around either volume reliability or advanced material differentiation, with limited middle ground for players unable to meet either cost or specification targets consistently.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines large multinational polymer and materials companies with specialized regional manufacturers that have built strong relationships with module makers and emerging production hubs. Several patterns define current strategic positioning.
Hangzhou First PV Material Co., Ltd. has established a strong position as a large-scale producer of EVA and POE encapsulation films for crystalline silicon modules, with a product focus that extends to TOPCon, heterojunction, bifacial, and high-efficiency applications. Its scale and breadth allow it to address mainstream and advanced architectures simultaneously, making it a relevant reference point for suppliers seeking to balance volume and specification growth.
Jiangsu Sveck New Material Co., Ltd. has built a profile around EVA, POE, and high-performance co-extruded encapsulant films, with particular emphasis on serving module manufacturers in emerging markets such as Vietnam and India. This geographic orientation reflects an understanding that demand growth is not limited to established hubs and that regional supply proximity can reduce logistics risk and improve responsiveness.
Shanghai HIUV New Materials Co., Ltd. has focused on high-performance polymer materials and UV-resistant encapsulation technologies, emphasizing long-term stabilization and durability. This durability-centered positioning aligns with warranty-driven procurement and suggests a strategy oriented toward performance assurance rather than lowest-cost volume.
Changzhou Betterial Film Technologies Co., Ltd. has moved toward advanced polymer film solutions for photovoltaic encapsulation, including tandem perovskite and back-contact module technologies. This forward-looking product direction illustrates how some suppliers are positioning for next-generation cell concepts before they reach mass deployment, aiming to secure early qualification advantages.
Zhejiang Sinopont Technology Co., Ltd. is expanding its development of high-barrier co-extruded encapsulation films and TOPCon-compatible POE materials, reinforcing the broader industry emphasis on formulation precision for advanced cell architectures. Similarly, Hanwha Solutions, Mitsui Chemicals, Kuraray, SKC, Bridgestone, and Coveme represent established material capabilities and regional strengths, while U.S. and European names such as 3M, STR Holdings, Dow, DuPont, and Eastman contribute advanced polymer chemistry and specialty encapsulant expertise.
RenewSys India and Alishan Green Energy illustrate the growing role of Indian manufacturers in EVA, POE, EPE, and TPO supply. Alishan's recent moves are particularly notable: the company launched a new generation of encapsulant films including low-acid EVA, EPE-NT, and EPE-DC with UV down-conversion technology, expanded capacity to approximately 6.6 GW, and continued toward a 10 GW target by the end of 2026. This scale-up, combined with product differentiation, signals that emerging-market suppliers are not only competing on cost but are also building specification-grade portfolios for advanced applications.
Evolution of Market Structure
The market is simultaneously consolidating at the top and fragmenting in the middle. Concentration among leading suppliers reflects the advantages of scale, formulation depth, qualification track records, and long-standing relationships with module manufacturers. At the same time, technological differentiation is creating niches for specialized players focusing on co-extrusion, UV management, ultrafast curing, or next-generation cell compatibility.
Chip Encapsulation Resin Market
This dual dynamic suggests that the competitive frontier will not be defined purely by price. Instead, it will be shaped by the ability to meet specific module requirements, support qualification timelines, maintain batch consistency, and provide supply continuity in a geopolitically sensitive environment. New entrants with differentiated technology can gain traction in targeted segments, but broad-based competition is intensifying where specifications are relatively standardized and regional capacity is expanding. As manufacturing footprints shift and advanced module adoption accelerates, the landscape is likely to reward suppliers that can combine technical precision with dependable commercial execution.
Forward Outlook: Trends for the Next 3-5 Years
Trend 1: Advanced, Co-Extruded, and Architecture-Specific Encapsulants Will Become the New Baseline for Premium Modules
Over the next several years, co-extruded and architecture-tailored encapsulants will move from differentiated offerings to expected components in high-efficiency and bifacial modules. TOPCon and bifacial adoption will continue to expand, and suppliers that can deliver formulations optimized for moisture resistance, UV behavior, and potential-induced degradation control will be better positioned to secure qualification and repeat procurement. The commercial implication is clear: module manufacturers will increasingly weigh encapsulant performance as part of product design rather than treating it as a generic input.
For suppliers, this trend favors investment in formulation engineering, testing infrastructure, and application-specific product lines. For buyers, it means selection criteria will shift toward proven compatibility with target cell architectures and verifiable long-term stability. The opportunity lies in aligning encapsulant development with module roadmaps early, reducing rework and qualification delays.
Trend 2: Regional Supply Localization Will Deepen Where Premium Modules Are Made and Deployed
Localization of high-performance encapsulant production will continue in regions where advanced module manufacturing and project deployment are concentrated. In the United States, facility expansions for advanced encapsulants are strengthening domestic supply for bifacial, TOPCon, and next-generation high-efficiency modules, mitigating import dependencies from Asia. This pattern is likely to encourage parallel investments in other regions seeking to secure material availability for domestic manufacturing and export-quality production.
PW Consulting
The strategic implication is that supply chain design will become more regionalized and more sensitive to qualification continuity. Suppliers that can build localized capacity or reliable regional partnerships will increase their relevance to customers who prioritize resilience and predictable delivery. At the same time, cost-competitive regional producers in Asia will continue to serve volume demand, creating a market structure where premium localization and efficient regional supply coexist.
Trend 3: Durability-Weighted Procurement Will Redefine Value Comparison Across Materials
Procurement decisions will increasingly incorporate lifetime performance considerations rather than initial material cost alone. Warranty expectations, degradation profiles, and bankability requirements are pushing buyers to evaluate encapsulants through the lens of long-term reliability. Gel content thresholds, moisture barrier performance, and potential-induced degradation resistance are becoming practical decision metrics because they directly affect warranty exposure and asset longevity.
This shift creates opportunity for suppliers that can document durability with consistent quality and credible validation. It also introduces risk for manufacturers that compete primarily on price without robust formulation control. Over time, the market will likely see more explicit differentiation between standard and premium encapsulant tiers, with premiums justified by efficiency, durability, and qualification readiness rather than brand alone.
Risks and Uncertainties
While the outlook is favorable, several uncertainties could alter the pace or direction of value capture. Raw material cost volatility and polymer feedstock dynamics can affect margins, especially for suppliers with limited pricing power. Overcapacity in commodity-grade production could compress returns if demand growth does not absorb new capacity in certain regions. Qualification cycles are lengthy and can delay the commercial payoff of advanced formulations, creating execution risk for companies investing ahead of module adoption curves. Finally, technology transitions in next-generation cells, including tandem and back-contact concepts, remain uneven in timing and scale, which could shift encapsulant demand patterns faster than suppliers anticipate.
Actionable Guidance for Decision-Makers
For Module Manufacturers
Treat encapsulant selection as a product architecture decision rather than a procurement commodity exercise. Align material qualification with your cell technology roadmap, prioritizing suppliers that can demonstrate compatibility with bifacial, TOPCon, and other advanced designs while maintaining batch consistency. Build early-stage testing and qualification into development plans to reduce launch risk and avoid late-stage redesigns. Where warranty and bankability requirements are stringent, prioritize documented durability metrics such as gel content, moisture barrier performance, and potential-induced degradation resistance alongside cost.
For Investors and Strategic Buyers
Evaluate exposure to encapsulant suppliers based on technology differentiation, regional supply positioning, and qualification relationships rather than volume alone. Companies with credible co-extrusion capabilities, UV and durability-focused formulations, and the ability to scale advanced materials for high-efficiency modules are better positioned to capture premium segment growth. At the same time, assess whether capacity expansions are aligned with actual regional demand and whether pricing power is sustainable given regional supply additions. Portfolio value will increasingly depend on a supplier's ability to serve specification-grade demand without being dragged into undifferentiated commodity competition.
For Procurement and Supply Chain Leaders
Diversify sourcing strategies to balance premium localized supply with regional volume options, especially where module assembly, deployment, and warranty exposure create supply continuity requirements. Use qualification lead times to build relationships with suppliers that can support long-term consistency rather than short-term spot pricing. Incorporate performance-based criteria into purchasing decisions, including durability validation and compatibility with target module architectures. This approach reduces switching risk and strengthens resilience against supply disruptions, qualification delays, and regional production shifts.
The strategic significance of encapsulation materials will continue to rise as module architectures become more advanced and warranty expectations more demanding. Market participants that understand the interplay between formulation innovation, regional supply strategy, and procurement-driven durability requirements will be best positioned to manage risk and capture value. For professionals seeking deeper segmentation detail, competitive benchmarking, and tailored scenario analysis across regions and applications, the full PW Consulting research report provides expanded data sets and customized strategic guidance to support immediate planning decisions.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com