



Category: Chemical & Materials
Roasted Pyrite Market 2026: Why 3.86% CAGR and Asia Pacific Growth Signal Repricing
By PW Consulting, 2026-09-18
Roasted Pyrite Market: Strategic Trends and Commercial Opportunities (2025–2032)
The roasted pyrite market has entered a phase of measured expansion, shaped by steady demand from heavy industry and evolving processing standards. Over the past five years, the sector has grown from a base of roughly 402 million USD in 2020 to an estimated 486 million USD in 2025. Looking ahead, the market is projected to reach approximately 633 million USD by 2032, translating to a compound annual growth rate of 3.86 percent across the forecast window. This trajectory reflects a maturing commodity market where volume growth is increasingly tied to efficiency gains, regulatory compliance, and shifting end-use priorities rather than raw demand expansion alone.
For decision-makers evaluating exposure to roasted pyrite, the headline numbers mask a more nuanced reality. Growth is neither uniform nor automatic. The market is navigating a series of structural pressures that will determine which participants capture value and which face margin compression. Understanding these pressures is essential for shaping procurement strategies, capital allocation, and long-term positioning.
Sulphur Bentonite Market
Current Market Profile
The market's footprint is heavily concentrated in a few key application streams, with steel and iron production accounting for the largest share of consumed roasted pyrite, followed by cement manufacturing, paint and pigments, and glass and ceramics. This distribution underscores the material's role as both a chemical input and a functional additive across foundational industrial sectors. Regionally, Asia Pacific dominates consumption, reflecting the scale of metallurgical and cement operations in the area, while Europe, North America, the Middle East and Africa, and Latin America collectively represent more diversified but smaller demand pools. The market structure remains moderately consolidated, with the top three participants holding roughly 42.5 percent of overall share and the top five accounting for 58.3 percent. Such concentration suggests that scale, processing capability, and supply reliability continue to differentiate leading suppliers from smaller or more regionally focused players.
Core Challenges and Inflection Points
Despite the outward growth trajectory, the industry faces several interlocking challenges that will define competitiveness over the next cycle.
Sulphur Recovery Market
- Cost volatility and margin sensitivity. Raw material pricing for pyrite and related sulfur-bearing minerals has shown notable swings, with export benchmarks for roasted iron pyrites from key origins rising sharply in periods of tight supply. For downstream buyers, particularly in sulfur-dependent processes, these fluctuations translate directly into cost unpredictability and pressure on procurement planning.
- Quality standardization and impurity management. As end-use applications demand more consistent performance, the tolerance for variable iron content and residual sulfur has narrowed. Lower-grade material remains commercially relevant in certain segments, but high-purity requirements in specialized applications are pushing producers and buyers alike toward tighter specification control and more advanced beneficiation.
- Regulatory and environmental scrutiny. Roasting processes inherently involve emissions control, heat recovery, and residue management. Continued operational legitimacy depends on demonstrable efficiency in sulfur capture, energy recovery, and cinder utilization. Facilities that cannot meet evolving expectations around residual sulfur levels and process cleanliness face both compliance risk and reputational exposure.
These challenges are not merely operational inconveniences; they are reshaping the logic of market participation. Companies that treat roasted pyrite as a commoditized bulk input may find themselves exposed to price swings and specification gaps, while those that align sourcing and processing with quality, compliance, and reliability are better positioned to secure long-term contracts and steadier margins.
Key Drivers Shaping the Roasted Pyrite Market
The market's trajectory is being pulled forward by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, creating a environment where efficiency, consistency, and supply security carry disproportionate strategic weight.
Technology Innovation and Processing Breakthroughs
Advances in roasting technology are transforming how pyrite is converted into usable industrial materials. Fluid bed roasters capable of high throughput have become a reference point for producers seeking to balance capacity with heat recovery and sulfur capture. Alongside these established systems, flash roasting approaches are drawing attention for their ability to reduce residual sulfur in cinder to very low levels, supporting cleaner downstream acid production and more versatile cinder utilization. Such improvements matter because they directly affect both economics and environmental performance. Lower residual sulfur means less reprocessing, higher product acceptability, and reduced waste handling costs. For buyers, access to roasted pyrite produced through advanced methods can translate into more predictable yields and fewer processing interruptions.
At the product level, recent launches of higher-purity roasted pyrite concentrates illustrate how processing refinements are opening new application pathways. By lowering impurity levels and improving processing efficiency, these grades enable sulfuric acid producers and other users to operate with greater consistency and less downtime. The broader implication is that technology is not only expanding what can be produced but also raising the performance bar that market participants must meet to remain competitive.
Policy and Regulatory Environment
Regulatory dynamics continue to shape the operating context for roasted pyrite. Environmental expectations around emissions, energy recovery, and residue management are becoming more entrenched rather than receding. This is particularly relevant for sulfuric acid-related applications, where roasting remains a niche but active pathway supported by heat recovery systems and low-residual-sulfur cinder outputs. In practical terms, regulatory pressure is acting as both a constraint and a filter: it raises the cost of noncompliant operations while rewarding producers who can demonstrate credible efficiency and environmental controls.
Trade and export patterns also reflect the influence of policy and market structure. Leading export flows of roasted iron pyrites have come from a relatively concentrated set of origins, indicating that trade access, shipping logistics, and origin-specific quality reputations play a meaningful role in how supply reaches end markets. For importers and downstream manufacturers, this means supply diversification strategies must account not only for price but also for origin reliability, quality consistency, and the regulatory posture of source regions.
Demand-Side Shifts in End-Use Industries
Demand for roasted pyrite is closely tied to the operating rhythms of steel, cement, and specialty chemical sectors. In steel and iron production, the material's role as a sulfur and iron source keeps it embedded in core metallurgical workflows. Cement manufacturing represents another significant demand pillar, where pyrite derivatives contribute to process chemistry and product characteristics. Meanwhile, more specialized applications in paints, pigments, glass, and ceramics provide additional demand threads, often with higher specification requirements.
What is changing on the demand side is not necessarily the volume of material consumed in every segment, but the emphasis on quality and predictability. As industrial operators face tighter operating margins and more complex compliance obligations, they increasingly prefer supplied materials that reduce variability in downstream processing. This shift favors suppliers that can offer consistent grades, transparent quality data, and reliable delivery rather than those competing solely on lowest headline price. It also encourages end users to lock in longer-term arrangements with trusted sources, particularly where feedstock security is linked to production continuity.
Supply Chain and Cost Structure Dynamics
The cost structure of roasted pyrite is influenced by a chain of factors that extend from mining and beneficiation through roasting, logistics, and export. Recent periods have shown how quickly raw material economics can shift, with sulfur and pyrite input costs feeding into higher acid price levels in major consumer regions. In one major Asian market, average prices for concentrated sulfuric acid reached elevated levels during the year, reflecting both input cost pressure and regional supply dynamics. Such movements highlight how sensitive downstream industries are to upstream cost changes and why procurement teams monitor pyrite pricing trends as part of broader input cost management.
Supply chain resilience is becoming a strategic priority in its own right. Major restructuring activity, including acquisitions designed to secure roasted pyrite feedstock and expand downstream roasting capacity, signals that market participants are treating feedstock access as a critical asset. Partnerships focused on co-developing roasting capacity and sulfuric acid production further illustrate the trend toward integrated arrangements that reduce exposure to spot-market volatility. At the same time, new plant startups processing pyrite by-products from mining operations demonstrate how feedstock availability can be reshaped by broader mining and metals activity, creating both opportunities and dependencies for roasted pyrite supply.
Competitive Landscape and Leading Strategies
The competitive environment in the roasted pyrite market is defined by a mix of established multinational players, specialized industrial mineral suppliers, and regionally concentrated producers. Rather than competing purely on volume, leading companies are increasingly differentiating through processing capability, application know-how, and supply reliability.
Strategic Positioning of Key Players
Several companies illustrate distinct competitive approaches within the market.
- Equipment and process technology providers. Metso has built a reputation around pyrite roasting plant technology, with offerings that span sulfuric acid production, heat recovery, and metals recovery from roasted material. Its emphasis on high-capacity fluid bed roasters points to a strategy centered on enabling producers to scale efficiently while capturing energy and sulfur value. In a market where processing quality and recovery efficiency are increasingly important, technology-enabled positioning can create stickiness with customers seeking to upgrade or expand capacity.
- Industrial mineral processors and distributors. Washington Mills and Hickman, Williams & Company represent players with strong ties to industrial applications such as abrasives, metallurgy, foundry, and chemical sectors. Their relevance lies in the ability to position roasted pyrite within broader material supply chains, linking product quality to end-use performance. By serving multiple industrial segments, these companies can balance demand variability across applications and maintain relevance even when one sector softens.
- Regional producers with integrated reach. Veneta Mineraria and Chinese manufacturers such as Foshan Pyrite Mineral Materials, Tongling Weight Mineral Products, and UrbanMines reflect the importance of regional production bases with varying degrees of processing depth. UrbanMines, for example, emphasizes high-purity pyrite products delivered in roasted or calcined forms for applications including resulfurization, abrasives, and wastewater treatment. Such positioning shows how product specification and application breadth can serve as differentiation tools in a market where grade consistency and purity are increasingly valued.
Market Consolidation and Evolving Dynamics
The market's moderate concentration suggests room for both consolidation and specialization. Recent corporate activity underscores this direction. A major acquisition valued at approximately 320 million USD brought together a large group and a minerals entity to secure roasted pyrite feedstock and expand downstream roasting capacity. This type of move signals a strategic intent to control more of the value chain, reduce feedstock uncertainty, and strengthen supply credibility with downstream customers.
Partnerships are also reshaping competitive dynamics. A strategic cooperation between a leading tin company and a regional engineering partner to co-develop roasted pyrite roasting capacity and sulfuric acid production highlights how feedstock, processing, and acid output can be aligned to create mutually reinforcing assets. Similarly, the startup of a new pyrite-based plant in Indonesia, processing pyrite ore from a copper mining by-product stream to produce substantial volumes of sulfuric acid, illustrates how by-product utilization can unlock new supply and add scale to the broader ecosystem.
Taken together, these developments point to a market where competitive advantage is increasingly tied to integration, feedstock security, and process quality. New entrants and expanding regional producers can still find space, particularly where they bring specialized grades, reliable logistics, or cost-effective processing. However, long-term positioning will likely favor organizations that can combine supply reliability with verifiable quality and applicable technical support.
Forward Outlook: Trends for the Next Three to Five Years
Based on current market structure and recent developments, several trends are likely to shape the roasted pyrite market through the early part of the next decade.
Trend 1: Purity and Specification Upgrading as a Competitive Baseline
As downstream users seek to reduce variability and improve process efficiency, higher-purity roasted pyrite grades are expected to gain incremental importance, especially in applications where impurity control affects yield, emissions, or product quality. This does not mean lower-grade material will disappear; it will continue to serve cost-sensitive segments. However, the strategic center of gravity is shifting toward grades that offer predictable performance and lower residual sulfur. Companies that can reliably supply such grades, supported by consistent processing and testing, are well placed to capture premium positioning and longer-term contracts.
PW Consulting Chemical & Energy Research Center
Trend 2: Feedstock Security Driving Integration and Partnerships
The combination of raw material cost volatility and the strategic importance of continuous downstream operations is likely to sustain interest in feedstock security. Acquisitions, partnerships, and by-product utilization projects are natural responses to this pressure. Over the next several years, more market participants may pursue integrated arrangements that link sourcing, roasting capacity, and downstream output such as sulfuric acid or specialty iron-rich intermediates. For buyers, this trend could improve supply reliability in some channels while also concentrating supply access among better-integrated players.
Trend 3: Environmental Efficiency as a Commercial Requirement
Roasting technologies that improve heat recovery, reduce residual sulfur, and support cleaner cinder utilization are likely to become more central to commercial discourse. Environmental performance is increasingly intertwined with operational economics, since efficient sulfur capture and energy recovery can lower effective processing costs and improve product acceptability. Firms that invest in demonstrable efficiency gains will be better positioned to meet regulatory expectations and customer preferences, while those that lag may face both cost and market access disadvantages.
Risks and Uncertainties
These trends are not guaranteed paths. Raw material price swings can disrupt procurement plans and compress margins, particularly for buyers with limited flexibility. Regulatory shifts in key regions could alter the cost of compliance or change the attractiveness of certain roasting pathways. Demand conditions in steel, cement, and chemical sectors can also shift with macroeconomic cycles, construction activity, and metals markets. In addition, trade dynamics and export concentration mean that supply disruptions in a few origins can have outsized effects on certain import markets. Anticipating these risks requires active monitoring rather than static assumptions.
Strategic Implications and Actions for Decision-Makers
For executives, planners, and investors weighing exposure to roasted pyrite, the market's evolution suggests several practical priorities.
For Manufacturers and Industrial Buyers
Prioritize specification consistency and supply reliability over short-term price minimization. Where possible, align procurement with suppliers that can demonstrate controlled processing, clear quality parameters, and reliable delivery. Consider longer-term arrangements with credible sources to reduce exposure to spot volatility, especially if roasted pyrite is a critical input to continuous processes. Evaluate how advances in roasting technology and higher-purity grades could improve your own downstream efficiency, and factor those benefits into sourcing decisions.
For Investors and Capital Allocators
Focus on value chain positioning and feedstock security. Companies that combine reliable sourcing with scalable, efficient roasting capacity and clear downstream offtake pathways are more likely to sustain value through cycles. Pay attention to integration signals, such as acquisitions and partnerships that strengthen feedstock control or expand acid and specialty product output. Also assess regional exposure carefully, since demand concentration and export patterns can influence both growth potential and vulnerability to trade or regulatory changes.
For Procurement and Strategy Teams
Build a more dynamic view of the supply base. Track not only pricing but also origin reliability, quality trends, technology upgrades, and corporate activity that may reshape supply access. Develop contingency options for feedstock disruption, including alternative origins and specification adjustments where feasible. In a market where moderate consolidation and integrated moves are becoming more common, early awareness of structural changes can improve negotiating position and reduce surprise.
The roasted pyrite market is moving toward a landscape where quality, efficiency, and supply security matter as much as volume. For organizations that need a sharper view of segment-level dynamics, regional supply patterns, pricing context, and company-specific positioning, the full research report provides deeper segmentation data and tailored analysis to support more precise planning and timing decisions.
For detailed analysis of this topic, please visit the official page: Roasted Pyrite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
RFI Shielded Glasses Market 2026: Why 7.82% CAGR and Healthcare Demand Reshape Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the RFI Shielded Glasses Market: A 2032 Outlook
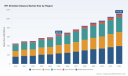
The RFI shielded glasses market has matured into a specialized yet strategically vital segment within the broader electromagnetic compatibility (EMC) and protective infrastructure industry. Over the past five years, the sector has transitioned from niche compliance-driven production to value-added differentiation, driven by tighter electromagnetic standards, expanding imaging and test environments, and a growing recognition that optical clarity cannot be sacrificed for shielding performance. Historical trajectory through the early 2020s established a consistent upward path, with revenue climbing steadily as medical facilities, defense contractors, and electronic testing laboratories upgraded aging shielding infrastructure. The market reached a valuation of approximately $657.39 million in 2025, reflecting sustained investment in controlled electromagnetic environments across critical sectors. Looking ahead, the compound annual growth rate is projected at 7.82 percent, positioning the market to surpass $1.1 billion by 2032.
PW Consulting Chemical & Energy Research Center
This expansion is not uniform. Growth concentrates in applications where visibility, patient or operator safety, and electromagnetic containment intersect, creating structural demand rather than cyclical fluctuations. The market remains moderately consolidated, with a handful of established players capturing a significant share of volume, while regional distribution reflects divergent procurement cycles, regulatory maturity, and industrial base readiness. For decision-makers, this landscape signals both stability and friction: predictable baseline demand exists, but capturing incremental growth requires navigating material constraints, performance trade-offs, and shifting procurement expectations.
Three structural challenges currently define the market's inflection points. First, optical transparency and shielding attenuation remain in persistent tension. Increasing shielding effectiveness across broadband frequencies often requires thicker conductive layers or denser mesh architectures, which can compromise light transmission and introduce visual distortion. Second, supply chain volatility for raw materials and precision coating processes has tightened margins and extended lead times. Float glass substrates, conductive inks, sputtering targets, and specialized wire alloys face price fluctuations and geopolitical sourcing constraints that ripple through manufacturing schedules. Third, certification and compliance complexity continues to raise the barrier for new entrants and mid-tier manufacturers. Medical and defense applications demand reproducible testing, clean room production standards, and documented compatibility with equipment-level standards, which slows product commercialization and elevates development costs. These challenges are not insurmountable, but they reward operators with process discipline, material partnerships, and application-specific engineering capabilities.
Key Drivers Shaping Market Trajectory
Several interdependent forces are accelerating demand and reshaping product expectations across the RFI shielded glasses market. Understanding these drivers clarifies where investment, capacity expansion, and differentiation are most likely to generate durable advantage.
Technological Innovation and Performance Optimization
The most consequential driver is the pursuit of higher shielding effectiveness without degrading optical performance. Conductive film laminates, ultra-fine metal mesh architectures, and improved indium tin oxide coating processes have progressively expanded the performance envelope. Manufacturers are increasingly targeting surface resistance in the sub-ohm to low-ohm range while maintaining light transmission above seventy percent, with some solutions exceeding ninety percent in optimized configurations. This trajectory matters because end-users no longer view shielded glass as a compromise component. Instead, they expect medical visibility standards, display clarity for electronic test setups, and situational awareness in defense enclosures to remain uncompromised while electromagnetic interference is contained.
Worldwide Anti-Interference Shielding Material Market
Recent product development signals reflect this direction. Suppliers are refining micro-replicated conductive grids and woven wire mesh variants that reduce visual artifacts while preserving broadband attenuation. Others are advancing scratch resistance, chemical durability, and clean room compatibility to meet hospital and laboratory environment requirements. The cumulative effect is a shift from generic shielding solutions toward application-tuned optics, where transmission, attenuation bandwidth, mechanical robustness, and durability are engineered together rather than treated as independent specifications.
Regulatory and Standards-Driven Demand
Compliance frameworks continue to shape procurement behavior, particularly in medical and defense settings. Standards addressing electromagnetic compatibility for medical electrical equipment, including requirements for imaging environments such as MRI rooms, create recurring demand for shielding components that must be documented, tested, and installed with predictable performance. In practice, this means shielded glass is not merely a material purchase but a compliance enabler integrated into broader facility and equipment qualification processes.
Regulatory expectations also influence product design choices. RoHS-compatible materials, systematic optical quality control, and clean room manufacturing traceability are increasingly referenced in procurement specifications. For high-stakes environments, these requirements reduce acceptable supplier pools and increase switching costs, reinforcing the value of established compliance documentation and repeatable production processes. The standards environment does not just constrain the market; it filters it, favoring operators who can evidence consistent performance and transparent process control.
Demand-Side Shifts in Critical Infrastructure and Testing
Demand is being reinforced by the expansion and modernization of controlled electromagnetic environments. Medical imaging facilities continue to require visibility and protection in shielded enclosures, where openings, observation windows, and display interfaces must manage stray electromagnetic fields without obstructing clinical workflows. Defense and aerospace programs similarly depend on transparent shielding for enclosures, sensor integration, and sensitive electronics testing, particularly as systems grow more complex and frequency usage intensifies.
Electronic test laboratories represent another structural driver. As device density, wireless functionality, and sensitivity to external interference increase, laboratory environments must maintain repeatable measurement conditions. Shielded windows and display interfaces contribute to isolation without eliminating operator visibility or instrument interaction. This combination of stricter measurement reliability and broader deployment of sensitive electronics sustains demand beyond incremental replacement cycles.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by material availability, coating process efficiency, and customization levels. Float glass remains the dominant substrate, but the value creation occurs in coating uniformity, mesh integration, lamination quality, and finishing tolerances. Manufacturers that can stabilize coating yield, reduce scrap rates, and standardize frame or enclosure integration gain meaningful cost advantages, especially when customization remains a competitive necessity. At the same time, custom sizes, special shapes, and application-specific frame options can create both premium pricing opportunities and operational complexity.
This cost structure incentivizes a strategic balance between standardization and specialization. Operators that over-index on bespoke production may face margin pressure and delivery risk, while those that over-standardize may lose specifications-driven opportunities in medical and defense procurements. The more sustainable path involves modular product architectures, repeatable coating and lamination processes, and selective customization where specifications truly justify the cost.
Competitive Landscape and Leadership Positioning
The competitive environment is characterized by a mix of established shielding specialists, materials-focused manufacturers, and application-oriented integrators. Market concentration is notable, with a core group of companies accounting for a substantial share of revenue, though fragmentation persists at the regional and application-specific level. Leadership in this market is less about scale alone and more about performance consistency, certification readiness, and the ability to match optical and shielding requirements to procurement realities.
Differentiation Through Material and Application Expertise
Leading participants distinguish themselves through clearly defined technical value propositions. Some competitors emphasize high transparency combined with broad frequency coverage, positioning their shielded glass for environments where visibility is paramount, such as medical observation windows and display interfaces. Others focus on metal mesh or ITO-based architectures that deliver strong attenuation while preserving usable light transmission across glass or polycarbonate substrates. A further group leans into mechanical durability and customization, offering laminated float glass, scratch and chemical resistance, and tailored shapes for industrial, medical, or defense installations.
These distinctions matter because procurement decisions in this market are specification-intensive. Buyers often evaluate light transmission, shielding bandwidth, surface resistance ranges, substrate type, and compatibility with enclosure or framing systems. Suppliers that can articulate performance across these dimensions, and back claims with reproducible manufacturing and testing, gain a clearer path to qualification. In contrast, generalist positioning tends to weaken in environments where compliance documentation and environmental durability are equally important as optical performance.
Strategic Positioning by Market Segment
Within the broader competitive field, several players have built reputation advantages aligned with specific application families. Medical-focused suppliers often emphasize compatibility with hospital and imaging environments, referencing standards-aligned design, clean room manufacturing, and the need to protect staff and equipment while maintaining visibility. Defense- and aerospace-oriented participants tend to highlight broadband performance, mechanical robustness, and integration into enclosures or sensitive electronic setups. Test and laboratory suppliers commonly prioritize optical clarity and repeatable shielding behavior for measurement environments. This segmentation is not absolute, but it reflects a practical reality: procurement cycles, testing expectations, and acceptance criteria differ enough that reputation and reference use cases influence shortlisting.
Geographically, the landscape reflects both maturity and growth potential. Established demand centers show deeper qualification pathways and longer replacement cycles, while emerging demand regions often combine infrastructure investment with cost sensitivity. Suppliers with strong regional service, documentation support, and adaptable product configurations tend to navigate these differences more effectively than those relying on one-size procurement models.
Market Evolution: Consolidation, Niches, and New Entries
The market is likely to see continued selective consolidation at the capability level rather than purely through M&A headlines. End-users increasingly favor suppliers who can provide consistent coating quality, shielding performance across target frequency ranges, and reliable delivery of customized dimensions. This dynamic rewards operators with integrated manufacturing and predictable process control. At the same time, niche specialists may thrive by dominating particular application requirements, such as optical-grade shielding for displays, high-transparency observation windows, or cost-optimized solutions for laboratory environments.
New entry opportunities exist, but they are conditional. The barrier is not only technical performance but also qualification burden, repeatability, and the ability to supply with consistent documentation. Entrants that can demonstrate differentiated material approaches, improved transmission-to-attenuation ratios, or streamlined integration with enclosure systems have plausible entry points. However, those entering without clear application focus or compliance readiness face a steep path to shortening procurement cycles and displacing incumbents with established reference use.
Competition is therefore shifting from pure price competition toward performance reliability, traceability, and application fit. Market participants that can balance standardized production efficiency with targeted customization are best positioned to defend margins while expanding into higher-value segments.
Future Trends and Commercial Implications (2026–2032)
Three trends are likely to define the market over the next several years. First, performance expectations will continue to tighten around the transparency-versus-shielding frontier. As imaging systems, electronic test benches, and enclosed defense systems become more sensitive, the tolerance for optical compromise will decrease. Suppliers that can deliver high transmission with effective attenuation across broader frequency ranges will capture preferential positioning, particularly in medical and high-end laboratory applications. This trend creates commercial opportunities for advanced coating processes, refined mesh architectures, and lamination techniques that preserve clarity while improving attenuation consistency.
Second, procurement will increasingly treat shielded glass as part of a system-level compliance and reliability strategy rather than an isolated component. Documentation, standards alignment, clean room production practices, and environmental durability will become stronger differentiators in bidding and qualification processes. Commercial advantage will accrue to manufacturers that can package product performance with reproducible quality control and clear application guidance. This also raises the value of trusted supplier relationships, since replacement windows, display interfaces, and enclosure openings often require long-cycle compatibility with installed infrastructure.
Worldwide Fibers and Electromagnetic Shielding Market
Third, supply and cost pressures will push the market toward smarter portfolio design. Expect greater emphasis on modular product families, reusable frame or enclosure integration approaches, and selective customization only where specifications justify it. Manufacturers that can standardize core coating and lamination processes while offering controlled variation in size, substrate, and finishing will be better equipped to manage margin and delivery risk. Over time, this may also encourage broader adoption of coated film laminate options in applications where glass is not strictly required, expanding the addressable solution set.
Risks and uncertainties remain. Raw material cost volatility, coating yield variability, and freight or sourcing disruptions can compress profitability and extend lead times. Regulatory expectations may become more prescriptive in certain regions or application areas, raising compliance burdens unevenly across suppliers. There is also the possibility of substitution pressure if alternative shielding approaches improve in transparency, cost, or ease of integration. These uncertainties do not undermine the growth trajectory, but they increase the importance of operational resilience and specification agility.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product architecture with specification reality. Build repeatable processes around coating uniformity, optical consistency, and mechanical durability, then reserve customization for applications where performance trade-offs are explicitly justified. Strengthen documentation and testing narratives that support medical, defense, and laboratory procurement requirements, since qualification speed often matters as much as nominal performance. Where possible, structure product families to balance standardization with selective variation in size, substrate, and frame compatibility so that cost and lead time remain controlled.
For investors, the commercial opportunity lies in operators with disciplined manufacturing, defensible compliance readiness, and clear positioning in high-value applications. Preference should lean toward companies that can demonstrate consistent transmission-to-attenuation performance, stable supply relationships, and evidence of repeat qualification in regulated environments. Growth potential is strongest where suppliers can expand beyond replacement demand into system-level shielding upgrades, enclosure integration, and specialized optical shielding for displays or test environments. Due diligence should examine process yield, customization cost exposure, and the ability to scale without eroding optical or shielding performance.
For procurement and engineering leaders, sourcing strategy should prioritize performance reproducibility and integration fit over headline specifications alone. Evaluate suppliers on optical clarity consistency, shielding bandwidth relevance to the operating environment, substrate durability, and the quality of compliance documentation. Where facility or equipment upgrades are planned, consider how shielded windows and display interfaces will interact with enclosure design, maintenance cycles, and future imaging or electronics requirements. Treating RFI shielded glass as a long-cycle system component rather than a commodity purchase reduces rework risk and improves lifecycle value.
Detailed segmentation data, competitive benchmarking, and region-specific procurement dynamics can materially sharpen these decisions. Access to comprehensive upstream, midstream, and downstream analysis helps identify which materials, applications, and geographies offer the most favorable risk-adjusted opportunity in the coming growth cycle.
For detailed analysis of this topic, please visit the official page: RFI Shielded Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Heated Windshield Market Hits $1.2B in 2025, Projected 14.12% CAGR to $3B by 2032
By PW Consulting, 2026-09-17
Strategic Intelligence Brief: Electrically Heated Windshields in the EV Era
The transition to electric mobility has fundamentally altered the thermal management priorities of original equipment manufacturers. Where internal combustion engines offered abundant waste heat for cabin and glass de-icing, battery electric vehicles demand precise, energy-efficient solutions that preserve driving range without compromising safety or driver comfort. Electrically heated windshields have emerged as a critical technology at this intersection, and our latest market research provides a comprehensive, data-driven roadmap for stakeholders navigating this rapidly evolving landscape.
Market Trajectory and Structural Growth Signals
The global market for electrically heated windshields has demonstrated resilient, high-velocity expansion over the past half-decade, scaling from approximately 612.45 million USD in 2020 to a projected 1.207 billion USD by 2025. This trajectory reflects not merely incremental adoption but a structural shift in vehicle architecture, where cabin thermal loads are increasingly decoupled from centralized HVAC systems in favor of localized, intelligent heating elements. Looking ahead, the market is forecast to continue its ascent through 2032, underpinned by a compound annual growth rate of 14.12 percent. By the close of our forecast window, industry revenues are expected to surpass 3 billion USD, signaling a mature but still accelerating commercial phase.
This growth is not uniform across all vehicle segments or technological approaches. The data reveals a clear preference among manufacturers for solutions that minimize parasitic energy drain, accelerate defrost cycles, and integrate seamlessly with advanced driver assistance systems. The shift from conventional 12-volt heating circuits to higher-voltage architectures has further accelerated adoption, enabling manufacturers to deliver rapid thermal performance while preserving the high-voltage battery for propulsion. Understanding where value is being captured, which technological pathways are gaining share, and how regional supply chains are aligning requires a granular view that goes well beyond headline figures. Our report dissects these layers systematically, providing decision-makers with the granularity needed to allocate capital, shape sourcing strategies, and anticipate competitive displacement.
Report Architecture and Operational Content
Our research is structured to bridge strategic oversight with tactical execution. Rather than offering a static snapshot, the analysis maps the interplay between material science, vehicle architecture, regulatory frameworks, and consumer expectations, translating these forces into actionable commercial intelligence. Key deliverable categories include:
- A longitudinal market sizing exercise covering the historical baseline from 2020 through the base year of 2025, alongside a forward-looking forecast extending to 2032, with explicit modeling of demand drivers, adoption curves, and price dynamics.
- A technology segmentation deep-dive comparing conductive coating approaches with fine-wire heating architectures, evaluating performance trade-offs in defrost speed, energy consumption, optical clarity, and integration complexity with ADAS sensor zones.
- A vehicle-type breakdown isolating demand patterns across battery electric and plug-in hybrid platforms, highlighting how chassis electrical architecture, battery capacity, and regional cold-weather usage profiles shape procurement decisions.
- A competitive landscape assessment profiling the strategic positioning, flagship product capabilities, and recent development milestones of leading glass manufacturers and technology specialists.
- A regulatory and compliance overview detailing the safety glazing standards, optical and impact-resistance requirements, and electrical safety mandates that govern heated windshield deployment across major automotive markets.
- A raw material and supply chain lens examining interlayer material dynamics, cost volatility signals, and how material innovation translates into energy savings and acoustic performance for electric vehicles.
Each section is designed to feed directly into product roadmap planning, supplier negotiations, and market-entry evaluations. By anchoring findings in verifiable development trajectories and quantifiable adoption metrics, the report equips strategy, procurement, and engineering leadership with a unified evidence base.
Competitive Landscape and Strategic Positioning
The competitive architecture of the electrically heated windshield market is characterized by a concentrated group of established glass manufacturers alongside specialized technology innovators that are redefining defrost performance benchmarks. Our analysis segments these players by their core technological philosophies, partnership ecosystems, and recent capability demonstrations, revealing distinct strategic postures that will shape procurement dynamics through the forecast period.
Structural Concentration and Incumbent Capabilities
Market concentration remains notable, with the top three participants accounting for a substantial share of total revenue and the top five firms extending that footprint further. This concentration reflects the capital intensity of automotive glass manufacturing, the certification burdens associated with safety glazing standards, and the long qualification cycles inherent in vehicle program development. Within this environment, incumbents have invested heavily in dual-track technology portfolios that address both performance and efficiency imperatives.
AGC Inc. has advanced a HeatControl Windshield built around conductive coating technology for silent electrical de-icing and defogging, while simultaneously offering a Heated Wire Windshield that embeds superfine wires for rapid defrosting. Both product lines are explicitly optimized for electric vehicle thermal management and energy efficiency, positioning AGC to serve automakers seeking either seamless optical integration or high-speed heat delivery depending on vehicle architecture.
Pilkington, operating under the NSG Group, supplies wire-heated windshields engineered for fast defrosting and defogging, with heating elements designed to be compatible with advanced driver assistance systems. Its value proposition emphasizes range extension in cold conditions, directly addressing the winter efficiency penalty that remains a consumer concern for electric vehicle adoption.
Fuyao Glass Industry Group has focused on tungsten-wire heating elements embedded within the polyvinyl butyral interlayer, with wire specifications calibrated for reliable frost, fog, and ice melting. Its offering includes targeted heating zones for wiper, sensor, and camera areas, aligning with the increasing reliance on forward-facing optical systems in electric vehicle platforms.
Saint-Gobain Sekurit has developed the ClimaCoat heated windshield, which employs an invisible conductive coating for de-icing and de-misting while combining heating with heat reflection for all-weather performance. This approach underscores a broader trend among large glass manufacturers to bundle thermal, acoustic, and solar-control functions into integrated glazing solutions that simplify vehicle packaging.
Technology Specialists and Architecture Innovation
Beyond the established glass manufacturers, a set of technology-focused players is reshaping performance expectations through alternative thermal delivery methods. Betterfrost Technologies specializes in pulsed electro-thermal deicing systems that achieve defrost cycles in approximately 60 to 75 seconds while consuming up to 95 percent less energy than conventional HVAC defrosting. This pulsed approach is particularly compelling for electric vehicle winter range preservation, and the company has been actively engaging automakers and Tier 1 suppliers for both electric vehicle and commercial applications, with recent testing activity highlighting the practical readiness of its system.
Hyundai Motor Group, through its Genesis brand, has pursued an architecture-level innovation with 48-volt metal-coated heated glass built on a multi-layer transparent coating. Testing on Electrified GV70 and GV60 platforms demonstrated clearance of 100 percent frost in roughly five minutes, compared with the fifteen-minute timeline of conventional systems, while consuming approximately 10 percent less power. The group has also publicized solar reflection properties as part of the system’s broader efficiency rationale, and the demonstration has drawn attention to the role of 48-volt electrical architectures in reducing energy draw from the high-voltage battery relative to legacy 12-volt systems.
Electrically Heated Windshield for EV Market
These developments illustrate a market where technology differentiation is increasingly tied to energy economics, defrost speed, and ADAS compatibility rather than heating presence alone. Procurement teams evaluating supplier partnerships must therefore weigh not just glass quality and production capacity, but the electrical architecture compatibility, certification status, and integration roadmap of each heating approach.
Industry Dynamics Shaping Demand and Deployment
Several concurrent forces are accelerating the commercial relevance of electrically heated windshields and complicating the decision calculus for manufacturers and suppliers alike. A primary catalyst is the broader migration toward 48-volt electrical architectures in electric vehicles, which enables more efficient powering of heated glazing and reduces the energy penalty traditionally associated with cabin and glass heating. This architectural shift is lowering the barrier for integrating high-performance heated windshields without compromising propulsive range, and it is prompting vehicle programs to revisit thermal management specifications earlier in the design cycle.
On the materials side, the polyvinyl butyral interlayer remains the foundational lamination component for embedding heating wires or conductive coatings. Interlayer pricing dynamics have introduced a volatility variable into supply chain planning, with industry data indicating that export-grade PVB materials experienced year-on-year price movements in the 2025 period. At the same time, advanced interlayer formulations are increasingly marketed for their combined acoustic, thermal, and energy-saving properties, with some product data suggesting that integrated heating functions paired with optimized interlayer characteristics can support meaningful efficiency gains. This dual reality of cost fluctuation and performance optimization requires procurement strategies that balance price risk with specification value.
Regulatory expectations continue to anchor product development. Electrically heated windshields deployed in electric vehicles must comply with automotive safety glazing standards that enforce optical clarity, impact resistance, and electrical safety, while also supporting the integration of ADAS cameras and sensors. Compliance is not merely a minimum threshold; it increasingly functions as a differentiator in program approvals, particularly as heated zones must be coordinated with sensor fields of view and mounting locations. Our report maps these compliance dimensions across key markets, clarifying where certification pathways converge and where regional divergence creates planning complexity.
Strategic Value for 2026 Decision-Making
For organizations making capital allocation, supplier selection, and product planning decisions in 2026, the value of this research lies in its ability to convert macro momentum into operational clarity. The headline growth trajectory and structural drivers establish why the market matters; the segmentation, competitive profiling, and technology comparisons determine where advantage can be captured. Our analysis is designed to answer several decision-critical questions:
Heated Windshields Market
- Which technological pathways are gaining traction among vehicle programs targeting cold-climate markets, and what trade-offs do they present in energy consumption, defrost latency, and ADAS integration?
- How are leading glass manufacturers and technology specialists positioning themselves for the next wave of electric vehicle platforms, and where are the gaps that new entrants or partnership strategies can exploit?
- What supply chain and raw material dynamics should procurement teams monitor to mitigate cost volatility while preserving specification performance?
- How do regulatory and safety glazing requirements shape the commercialization timeline for heated windshield deployments across major automotive regions?
By addressing these questions with rigorously sourced data and forward-looking interpretation, the report enables strategy and engineering leaders to align product roadmaps with market reality, structure supplier negotiations with evidence rather than assumption, and anticipate the competitive implications of technology shifts before they become industry consensus.
Conclusion and Access to the Full Intelligence Package
Electrically heated windshields are no longer a comfort accessory; they are a functional component of electric vehicle energy management, safety compliance, and consumer acceptance in cold-weather markets. The convergence of advanced coating and wire technologies, 48-volt architecture adoption, evolving interlayer materials, and targeted defrost innovations has created a market in which differentiation is accelerating and competitive positioning is being redefined in real time. Our full report provides the complete segmentation data, regional breakdowns, technology comparisons, and company-level profiles required to translate these dynamics into precise strategic action. To access the detailed quantitative models, the full competitive matrix, and the scenario-based forecast supporting these insights, we invite you to review the complete Electrically Heated Windshield for EV Market research on our platform.
For detailed analysis of this topic, please visit the official page: Electrically Heated Windshield for EV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting HDH Titanium Powder Report: Market Hits $524.5M in 2025, Projected 7.2% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Imperatives in the HDH Titanium Powder Market: Navigating Growth and Supply Chain Complexity Through 2032
The global landscape for hydrogenated-dehydrogenated (HDH) titanium powder is undergoing a profound transformation, driven by the simultaneous demands of aerospace defense, medical implant innovation, and the rapid adoption of metal additive manufacturing. For senior leadership and strategic planners, the period between 2026 and 2032 represents a critical window where capacity allocation, supply chain resilience, and purity standardization will dictate market share and profitability. PW Consulting has released a comprehensive market intelligence study designed to equip stakeholders with the actionable foresight required to navigate this high-velocity environment. This analysis serves as an executive overview of the strategic value embedded within our latest HDH Titanium Powder Market research, highlighting the macro-economic trajectories and competitive shifts that will shape decision-making in the coming years.
Macro-Economic Trajectory and Demand Forecasting
Our longitudinal analysis covers historical performance from 2020 through the base year of 2025, with an extensive forecast period extending to 2032. This 13-year view allows us to isolate structural growth trends from short-term volatility. The market demonstrated robust expansion throughout the historical review period, recovering from global logistical disruptions and accelerating as industrial production normalized. By 2025, the total market revenue had firmly established a trajectory that suggests sustained upward momentum.
Looking forward, the forecast model projects a Compound Annual Growth Rate (CAGR) of 7.2 percent across the valuation period. This growth rate is not merely a numerical projection but a reflection of widening application scopes and the substitution of traditional wrought materials in specific high-value sectors. Revenue is expected to climb from approximately 556 million USD in 2026 to over 853 million USD by 2032. For procurement directors and investment committees, this trajectory implies that locking in supply agreements early or investing in capacity expansion before the peak of the growth curve could yield significant competitive advantages. The scale of this expansion suggests that HDH titanium powder is transitioning from a niche material to a strategic commodity essential for advanced manufacturing resilience.
HDH Titanium Powder Market
Segmentation Dynamics and Application Diversification
The demand landscape is fragmented across multiple purity grades and application verticals, each with distinct technical requirements and pricing sensitivities. The market is primarily divided between Commercial Purity (CP) Titanium and Ti-6Al-4V and other alloy grades. While CP titanium continues to hold a substantial share due to its utility in chemical processing and general industrial applications, the alloy segment is witnessing intensified interest from high-performance sectors where mechanical strength and corrosion resistance are paramount.
On the application front, the divergence in usage patterns highlights the versatility of the HDH process. Powder Metallurgy Components remain a traditional stronghold, leveraging the cost-effectiveness of irregular particle shapes. However, Metal Injection Molding (MIM) represents a high-growth vector, driven by the need for complex geometries in medical and consumer goods that traditional machining cannot economically achieve. Industrial additives and chemical applications provide a stable baseline demand, while Surface Coating and Thermal Spray applications offer specialized opportunities for wear resistance and component extension.
It is crucial for strategists to understand that these segments do not grow in isolation. Cross-segment competition for high-purity supplies is intensifying. For instance, the medical sector's requirement for low-oxygen and low-impurity profiles often competes directly with aerospace specifications. Our report details the specific volume flows and value drivers within each segment without exposing the proprietary granularity that would compromise client confidentiality, providing instead the relative weight and growth potential of each vertical to inform portfolio strategy.
Competitive Landscape and Corporate Consolidation
The industry structure is characterized by a moderate concentration, with the top three players controlling approximately 42.5 percent of the market and the top five commanding roughly 58.3 percent. This concentration indicates that while there is room for specialized entrants, scale and integrated supply chains remain powerful moats. The competitive field is globally distributed, with significant hubs in Asia Pacific, North America, and Europe, though Asia dominates in terms of total market revenue contribution.
Key Strategic Players and Operational Focus
Several key enterprises define the current competitive boundaries, each employing distinct strategies to secure market position:
Titanium Powder Market
- Toho Titanium Co., Ltd. and OSAKA Titanium Technologies Co., Ltd. represent the Japanese high-quality heritage, focusing on low impurity levels suitable for sputtering targets, getters, and high-grade powder metallurgy. Toho Titanium's recent corporate integration with JX Advanced Metals Corporation, effective June 2026 following a share exchange agreement, signals a move toward consolidated resource management and potentially expanded R&D capabilities under a larger corporate umbrella.
- Kymera International and ATI Inc. anchor the North American supply chain with a focus on customizable particle size distributions down to 45 microns. ATI Inc.'s expanded long-term agreement with Boeing in July 2025 reinforces the critical link between powder suppliers and major aerospace primes, ensuring steady demand for high-performance grades.
- Chinese manufacturers, including Lasting Titanium Industry Co., Ltd., AEM Metal, Baoji Titanium Industry Co., Ltd., and MTCO, form a significant production bloc. Lasting Titanium, for example, has historically accounted for a vast majority of China's titanium powder exports, leveraging proprietary hydride-dehydride processes to serve global aerospace and medical markets. Their ability to offer wide PSD options and competitive pricing pressures margins across the global supply chain.
- VSMPO-AVISMA Corporation and Höganäs AB round out the global presence, with VSMPO supplying aerospace-grade powders compliant with international standards and Höganäs offering broad application support for additive manufacturing and coatings.
Recent certification updates, such as North Titanium Industry Co., Ltd.'s ISO Quality Management System achievement in January 2025 for high-purity HDH powder, underscore the industry-wide shift toward rigorous quality assurance as a differentiator. Understanding the specific capacity constraints, geographical footprints, and strategic partnerships of these players is essential for supply chain risk assessment.
Supply Chain Vulnerabilities and Regulatory Pressures
Beyond the pure market dynamics, external factors exert substantial pressure on pricing and availability. The HDH production process relies heavily on titanium sponge feedstock, which is converted via hydrogenation to embrittle, crushed, and subsequently dehydrogenated. This technical pathway enables the production of low-cost irregular powders suitable for powder metallurgy and thermal spraying, but it also ties the powder market directly to the volatility of the sponge market.
Geopolitics and Raw Material Security
A critical strategic consideration is the geography of raw material origin. China controls approximately 65 percent of global titanium sponge capacity. This dominance creates inherent supply chain vulnerabilities for HDH powder production, particularly for North American and European manufacturers reliant on imported feedstock. The potential for export controls or tariffs on titanium materials introduces a risk premium that must be factored into long-term budgeting and sourcing strategies.
Furthermore, national security concerns regarding titanium supply have been highlighted in regulatory contexts. The U.S. Department of Commerce Section 232 investigation noted that reliance on foreign titanium sponge imports threatens national security, especially given the lack of domestic commercial production since 2020. These geopolitical undercurrents suggest that future policy interventions could reshape trade flows, incentivizing domestic capacity development or friend-shoring arrangements.
Cost Structures and Regulatory Compliance
Pricing dynamics also play a pivotal role in market adoption. HDH titanium powders typically offer a more cost-competitive alternative compared to gas-atomized spherical powders, with price points varying based on grade, purity, and particle size. This cost advantage drives adoption in powder metallurgy and thermal spray applications where spherical morphology is not strictly required. However, as specifications tighten for medical and aerospace uses, the cost differential may narrow.
Regulatory compliance adds another layer of complexity. For medical implants, HDH titanium powder must comply with standards such as ISO 23301 for sintered titanium materials and products for surgical implants, alongside ASTM specifications for powder metallurgy shapes. Adherence to these standards is not optional but a prerequisite for market entry in high-value segments. Our report analyzes how compliance costs are distributed across the value chain and which regions are most susceptible to regulatory shifts.
Strategic Value of the 2026 Analysis
In an environment defined by volatility and rapid technological iteration, generic market data is insufficient for strategic planning. The PW Consulting HDH Titanium Powder Market report provides the depth required to make informed decisions regarding capacity investment, supplier qualification, and market entry. We have synthesized historical performance, forward-looking forecasts, and competitive intelligence into a cohesive narrative that addresses the specific pain points of procurement, strategy, and R&D leadership.
The analysis avoids superficial aggregation, instead offering a nuanced view of how segmentation splits interact with regional dynamics and regulatory frameworks. We examine how the concentration of market power among key players influences negotiation leverage and how recent corporate developments, such as the integration of major Japanese producers or contract expansions with aerospace primes, signal shifts in supply stability.
Furthermore, the report contextualizes the 7.2 percent CAGR not just as a growth statistic but as a series of milestones that require proactive management. Stakeholders will gain insights into when specific application segments are projected to accelerate, allowing for targeted marketing and production planning. The interplay between raw material costs, geopolitical risks, and technical standards is mapped to help organizations build resilient supply chains that can withstand external shocks.
Conclusion: Positioning for the Next Cycle
The HDH titanium powder market is poised for significant evolution over the next decade. The convergence of aerospace demand, medical innovation, and the cost efficiencies of powder metallurgy creates a fertile ground for growth, but this growth is contingent on navigating complex supply chains and regulatory landscapes. The 2026 baseline represents a pivotal moment where early movers can secure advantages in sourcing and technology partnerships.
PW Consulting's comprehensive study is designed to be the cornerstone of this strategic planning process. By revealing the underlying currents of market concentration, regional dependencies, and application-specific growth vectors, we empower organizations to move beyond reactive decision-making. The full intelligence contained within the report provides the granular detail necessary to refine forecasts and validate assumptions against the latest industry developments.
For leaders committed to securing a competitive position in the titanium value chain, the time to act on these insights is now. We invite you to explore the full depth of our findings to understand how the 2026-2032 trajectory aligns with your specific organizational goals and risk tolerance. The complete market intelligence is available through our secure release portal.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCM Metal Sheet Market to Hit $4.85B in 2025, Grow at 5.15% CAGR Through 2032
By PW Consulting, 2026-09-17
Navigating the 2026 Landscape: A Strategic Introduction to the Pre-Coated Metal (PCM) Sheet Market
The global Pre-Coated Metal (PCM) sheet market stands at a critical inflection point as we move through 2026. For executives, procurement leaders, and strategic planners, the ability to anticipate shifts in substrate pricing, coating technologies, and regional demand trajectories is no longer a luxury—it is a fundamental requirement for maintaining competitive advantage. This article serves as a strategic preview of our newly released comprehensive market research, offering a high-level view of the market forces defining the period from 2026 to 2032. The full report provides the granular intelligence necessary to transform these macro trends into actionable business decisions.
Our analysis is anchored in a robust historical framework spanning 2020 to 2025, which allows us to validate growth patterns and identify structural breaks before projecting forward. The market has demonstrated persistent expansion over this period, evolving from a base valuation of approximately 3,750.25 million USD in 2020 to an estimated 4,850.5 million USD in 2025. This trajectory underscores a resilient demand environment driven by sustained utilization in both household appliance manufacturing and construction sectors, even as the industry navigates fluctuating raw material costs and shifting regulatory expectations.
The 2026-2032 Growth Trajectory and Market Expansion
Looking ahead, the market is projected to follow a steady compound annual growth rate of 5.15 percent throughout the forecast horizon. This growth rate, while moderate, reflects the maturation of core application segments and the increasing sophistication of end-user requirements. The market size is expected to advance from approximately 5,157.81 million USD in 2026 to reach 6,893.69 million USD by 2032. This expansion is not merely a function of volume but is increasingly tied to value addition through advanced coatings, corrosion resistance warranties, and aesthetic customization.
It is important to contextualize this growth within the broader pricing environment. As of March 2026, benchmark pricing for hot-rolled coil steel in the Midwest reached 975 USD per short ton, reflecting a month-over-month increase of 2.1 percent. Furthermore, cold-rolled coil substrates, which are essential inputs for high-quality PCM production, maintain a significant premium of roughly 165 USD per short ton over hot-rolled counterparts. These input cost dynamics directly influence margin structures and pricing strategies for PCM manufacturers. Our research dissects how these cost pressures are being absorbed, passed through to downstream customers, or mitigated through process innovations and substrate substitution, such as the strategic use of aluminum or electro-galvanized steel where appropriate.
Segmentation Dynamics: Substrates, Applications, and Regional Flows
The PCM market is structurally defined by a diverse array of substrates and applications, each with distinct growth drivers and competitive intensities. The substrate landscape is dominated by galvanized steel, which continues to serve as the workhorse material for a wide range of applications due to its balance of cost, formability, and corrosion resistance. Aluminum occupies a significant secondary position, particularly in segments where weight reduction, non-magnetic properties, or specific aesthetic finishes are prioritized. Cold rolled steel also represents a critical substrate category, often selected for premium applications requiring superior surface quality and dimensional precision. The interplay between these material choices is becoming more complex as manufacturers respond to both cost volatility and performance demands.
On the application front, household appliances remain the dominant consumption pillar, absorbing the largest share of PCM sheet utilization. This segment benefits from continuous product refreshes, urbanization trends, and the replacement cycle of major white goods. Construction and infrastructure form the second major pillar, where PCM sheets are used extensively in roofing, cladding, and architectural facades. The long-term corrosion warranties often associated with these products, sometimes extending decades, highlight the critical role of coating integrity and quality assurance. Transportation and furniture represent additional application vectors, each with specific technical requirements regarding formability, surface durability, and environmental exposure.
Regionally, the market exhibits pronounced concentration patterns that reflect underlying industrial capacity and consumption centers. Asia Pacific represents the most substantial market region, reflecting the dense concentration of appliance manufacturing, construction activity, and metal processing infrastructure. Europe and North America constitute significant demand centers with mature markets that emphasize premium finishes, sustainability certifications, and regulatory compliance. Latin America and the Middle East and Africa represent emerging and developing demand pockets where industrialization, infrastructure investment, and appliance penetration rates are gradually expanding the addressable market. Our report provides a detailed, granular breakdown of these regional flows, capacity allocations, and trade dynamics, enabling readers to pinpoint where growth is most likely to materialize and where competitive saturation may be intensifying.
Concentration Dynamics and Competitive Intensity
Market concentration data reveals a landscape that is consolidated yet contested. The top three players collectively account for approximately 42.15 percent of market revenue, while the top five players extend their share to 58.6 percent. This concentration profile indicates a market where scale advantages in coating lines, raw material procurement, and distribution networks are meaningful, but where significant opportunities remain for specialized players, regional champions, and niche technology providers. The presence of a broad competitive field means that differentiation through product performance, service reliability, and supply chain resilience is essential for sustaining market position.
Competitive Landscape: Key Players and Strategic Positioning
The competitive arena for PCM metal sheets spans a global roster of integrated steel producers, specialized coil coaters, and regional manufacturers. Each participant brings a distinct strategic profile, geographic footprint, and technical capability set. Understanding how these companies position themselves is critical for benchmarking, partnership evaluation, and competitive risk assessment.
Global Integrators and Brand Leaders
BlueScope, headquartered in Australia, has established a strong reputation through its COLORBOND prepainted steel portfolio, which targets both construction and industrial applications. The company's emphasis on durability and weather-resistant performance aligns with the long lifecycle expectations of building envelope and structural applications. Similarly, NSSMC (Nippon Steel & Sumitomo Metal Corporation) from Japan operates as a major producer of coated and pre-coated steel sheets, supplying high-performance PCM-grade materials to home appliance and construction markets. Its focus on advanced corrosion resistance and aesthetic finishes positions it as a supplier of choice for applications where surface quality and longevity are paramount.
ArcelorMittal, based in Luxembourg, leverages its global scale to supply pre-painted steel through coil coating processes for building and appliance uses. Its Galvalume and related pre-paint product lines are often backed by long-term corrosion warranties, reinforcing trust in roofing, siding, and fabrication markets where performance guarantees carry substantial commercial weight. POSCO, from South Korea, produces color-coated steel sheets and PCM for both appliances and construction. Notably, the company has advanced into differentiated product development, including PosART and antiviral PCM variants, which illustrate how coating technology innovation can open new value propositions beyond conventional corrosion protection.
Regional Specialists and China-Centric Capacity
A substantial portion of global PCM capacity and production activity is centered in China, where multiple manufacturers have scaled to serve both domestic demand and export channels. Baosteel (China Baowu Steel Group) stands as a large-scale producer of PCM metal sheets for home appliances and construction, offering extensive color-coated portfolios that support high-volume downstream manufacturing. Shanghai Metal Corporation supplies PCM steel with specified thickness ranges and zinc coating parameters, tailored to electric appliance applications such as refrigerators and washing machines, and utilizes imported cold rolling equipment to maintain process quality. Everesteel, also based in China with global export reach including Australia, specializes in PCM pre-coated metal sheets and pre-painted coils for appliances and construction. The company highlights custom color matching with tight tolerances, salt spray resistance performance, and substantial annual capacity, alongside ISO 9001:2015 certification, reflecting a service-oriented approach to quality assurance.
PCM Metal Sheet Market
Other notable participants in the China-centric ecosystem include Yieh Phui (China) Technomaterial, Shandong Guanzhou, HBIS New Material, Zhuhai Speedbird PVC Film Laminated Metal Sheet Co. Ltd., and Zibo Jingtai New Material Co., Ltd. Collectively, these manufacturers contribute to a highly competitive supply environment where production scale, coating line flexibility, and cost efficiency are key differentiators. Their presence reinforces Asia's role as both a production hub and a demand center, while also shaping global pricing dynamics through export availability.
European and Asian Process Specialists
ThyssenKrupp from Germany provides coated and pre-coated steel solutions across various sectors, including appliances, leveraging European engineering standards and process expertise. In Southeast Asia, PCM Processing (Thailand) Ltd., located in Chonburi, operates as a leading Thai manufacturer of pre-painted steel sheets, including PPGI and PPGL grades, meeting international standards. The company supplies high-performance prepainted coils and sheets for household electrical appliances and offers coil center processing and embossing capabilities, which add value through post-coating customization. Dongkuk Steel and JSW Steel further broaden the competitive field, with Dongkuk focusing on pre-coated metal sheets for home appliance and industrial applications, and JSW Steel supplying pre-coated and color-coated steel sheets for appliance and building uses. JFE Steel from Japan rounds out the competitive set with high-performance pre-coated metal sheets that emphasize corrosion resistance for appliance applications.
Recent Developments and Operational Signals
Recent operational activity among key players provides useful signals about capacity utilization, quality emphasis, and market engagement. PCM Processing (Thailand) Ltd. has shared updates during 2025 reflecting ongoing facility activity and community engagement, including events and certification-related attendance, indicating sustained operational momentum and compliance focus. Everesteel has reported a zero rust claims record across more than 3,000 containers shipped in 2024, supported by ongoing lab-verified color matching services, and has released a 2025 pre-coated metal catalog covering a full range of PCM coils and film-coated metals. These developments highlight the growing importance of verifiable quality performance, consistent color matching, and catalog-driven product standardization in securing and retaining downstream contracts.
Industry Context: Compliance, Certification, and Substrates
The commercial viability of PCM products is closely tied to compliance and certification frameworks. Pre-coated metal products typically comply with ISO 9001 quality management standards and environmental directives such as RoHS. Third-party certifications from organizations including SGS, Bureau Veritas, and Intertek are commonly provided to demonstrate quality and compliance for appliance and construction applications. These certifications are not merely procedural; they function as trust mechanisms that reduce procurement risk for downstream manufacturers and construction fabricators. Additionally, environmental product declarations and lifecycle documentation are increasingly relevant, aligning PCM offerings with broader sustainability expectations in building and appliance sectors.
From a technical standpoint, PCM manufacturing generally relies on base substrates that include cold-rolled steel, electro-galvanized steel, and hot-dip galvanized steel with zinc coatings in the range of 40 to 150 grams per square meter, along with aluminum options. These substrate choices influence coating adhesion, formability, corrosion behavior, and final product cost. The availability and pricing of these substrates, combined with coating line capabilities, shape the product mix that manufacturers can offer and the value they can capture. Our research examines how substrate selection strategies are evolving in response to cost pressures, performance requirements, and customer specifications.
Why This Research Matters for 2026 Decision-Making
The strategic value of this market research lies in its ability to connect macro trends with operational implications. For sourcing and procurement teams, understanding the interplay between substrate pricing, coating technology, and regional capacity is essential for mitigating cost volatility and securing reliable supply. For product development and engineering leaders, the report provides context on coating innovations, corrosion performance benchmarks, and aesthetic customization trends that can inform material selection and design-for-manufacturing decisions. For competitive intelligence and corporate strategy functions, the analysis of market concentration, player positioning, and recent operational developments offers a framework for evaluating threats, identifying partnership opportunities, and assessing market entry or expansion feasibility.
Phase Change Material (PCM) Market
Importantly, this research is designed to support decisions that require precision. While this article outlines the broad contours of the market and the strategic themes defining 2026, the full report delivers the detailed segmentation data, regional breakdowns, application splits, and company-level assessments that executives need to quantify opportunity and risk. The complete dataset enables readers to move beyond directional insight and into scenario planning, margin modeling, and prioritization of growth initiatives.
What the Full Report Unlocks
The complete PCM Metal Sheet Market research provides an integrated view across multiple dimensions. It details the segmentation structure across regions, substrates, and applications, allowing readers to identify which segments are driving growth and which are experiencing maturation or intensification. It includes comprehensive profiles of key companies, with headquarters, product focus, and strategic context, enabling benchmarking and targeted competitive analysis. It incorporates recent developments and operational signals that reflect real-time market behavior, supporting a timely and nuanced interpretation of industry dynamics.
In addition, the report embeds industry context around raw material pricing, substrate specifications, and regulatory compliance, ensuring that strategic conclusions are grounded in the operational realities of PCM manufacturing and procurement. By combining historical data validation with a forward-looking forecast through 2032, the research offers a durable reference point for planning cycles that extend beyond the current fiscal year.
Conclusion: Positioning for Informed Action
The Pre-Coated Metal sheet market in 2026 presents a landscape shaped by steady growth, material cost dynamics, evolving substrate strategies, and a competitive field that spans global integrators and specialized regional manufacturers. Success in this environment depends on access to accurate, detailed, and actionable intelligence. This article has outlined the strategic themes and market structure that define the current period, but the depth required for confident decision-making resides in the full research publication. We invite stakeholders to access the complete report to obtain the granular market size data, segmentation breakdowns, competitive profiles, and contextual analysis needed to navigate the PCM market with clarity and precision.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isopropyl Biphenyl Heat Transfer Fluid Market to Hit $346.61M by 2032 at 5.48% CAGR
By PW Consulting, 2026-09-17
Strategic Imperatives in the Isopropyl Biphenyl Heat Transfer Fluid Market: A 2026 Outlook
The industrial landscape of 2026 demands a rigorous recalibration of thermal management strategies. As manufacturing processes push toward higher efficiency thresholds and stricter environmental compliance standards, the selection of heat transfer fluids has evolved from a mere operational detail to a critical strategic decision. The Isopropyl Biphenyl Heat Transfer Fluid Market stands at a pivotal juncture, driven by the dual engines of industrial expansion and regulatory shifts away from legacy chemical compounds.
Isopropyl Biphenyl Heat Transfer Fluid Market
For executives, procurement leaders, and R&D strategists, navigating this landscape requires more than surface-level awareness. It demands a granular understanding of market trajectories, competitive maneuvers, and the underlying dynamics shaping supply chains. Our latest market research publication offers a comprehensive beacon for these decisions, synthesizing historical data with forward-looking projections to illuminate the path forward through 2032.
Market Trajectory and Growth Dynamics
The historical performance of the isopropyl biphenyl sector reveals a consistent upward trend, reflecting the growing reliance on synthetic aromatic fluids in high-temperature applications. Between 2020 and 2025, the market demonstrated resilience and steady expansion, setting a robust foundation for the forecast period. The overall market size, valued in millions of USD, has shown a compound annual growth rate (CAGR) of 5.48 percent from 2026 to 2032.
This growth trajectory is not merely a continuation of past trends but a response to evolving industrial needs. The projection indicates that revenue will continue to accumulate significantly over the next seven years. Such sustained growth suggests a healthy demand environment where replacement cycles and new installations contribute equally to market expansion. For stakeholders, this implies that investing in supply chain resilience and product innovation is not optional but essential to capturing share in a burgeoning market.
Segmentation Strategic Overview
Understanding the market requires dissecting its fundamental components. The research provides a detailed breakdown across three primary dimensions: type, application, and region. However, the strategic value lies not just in the numbers, but in interpreting what these segments mean for capacity planning and market entry strategies.
- Product Type Dynamics: The market is bifurcated into Monomer Grade and Technical Grade isopropyl biphenyl. The distinction between these grades dictates their suitability for specific thermal profiles and purity requirements. High-purity monomer grades often command premium positioning in sensitive applications, while technical grades serve broader industrial needs.
- Application Diversity: Demand is distributed across varied end-use sectors, including chemical processing, polyester and fiber manufacturing, waste heat recovery systems, and electronics cooling. Each application presents unique thermal stability requirements and operating temperature ranges, influencing the specific fluid formulations preferred by end-users.
- Regional Variances: Consumption patterns differ significantly across geographies. Established industrial hubs in North America and Europe maintain substantial demand, while the Asia Pacific region exhibits dynamic growth potential driven by expanding manufacturing infrastructure. Latin America and the Middle East and Africa also contribute to the global footprint, albeit at different scales.
Our report delves deep into these segments without exposing the raw data here. The interplay between grade specifications and application requirements creates niches where competitive advantage can be won or lost. Identifying which segments offer the highest margin potential or the fastest growth is a key outcome of this analysis.
Competitive Landscape and Key Players
The market structure is characterized by a moderately concentrated environment. With a CR3 of 68.45 percent and a CR5 of 84.12 percent, the top players hold significant market power, yet there remains room for specialized manufacturers to carve out positions based on technical differentiation and regional presence. The competitive arena is defined by major chemical corporations and specialized producers who invest heavily in product stability and thermal performance.
Eastman Chemical Company remains a cornerstone of the industry, offering the renowned Therminol 62. This high-purity isopropyl biphenyl mixture is designed for low-pressure liquid phase systems, capable of reaching maximum bulk temperatures of 325°C. Their global availability and reputation for exceptional thermal stability make them a benchmark against which competitors are measured.
Nippon Chemical Texas Inc. (NCTI) provides a robust alternative with their SS-300 product. This mixture of di- and tri-isopropyl biphenyl isomers offers thermal stability up to 330°C. It is particularly noted for its suitability in high-temperature and sub-zero conditions, making it versatile for diverse industrial uses across Texas and beyond.
Dalian Richfortune Chemicals Co., Ltd. has established a strong foothold, particularly in projects involving Concentrated Solar Power (CSP). Their RFCTHERM-IPB is equivalent to Therminol-62, supplying reliable long-term operation for low-pressure liquid phase heat transfer systems. Their experience in large-scale industrial applications adds a layer of operational credibility.
Jiangsu Zhongneng Chemical Technology Co., Ltd. leads in biphenyl derivatives with offerings like SCHULTZ S730. Their fluids cover temperature ranges from -20°C to 330°C, addressing a wide spectrum of thermal requirements. As a leading manufacturer, their production capabilities influence supply dynamics in the region.
Manto Chemistry (Jiangsu Manto Chemistry Co., Ltd.) focuses on high-purity synthetic aromatic heat transfer fluids with their Mantherm IBP, equivalent to Therminol 62. They operate with an annual production capacity of 3,000 tons of isopropylbiphenyl, ensuring dedicated supply for systems between -20°C and 350°C. This capacity commitment signals a strong strategy to secure supply chain stability for their clients.
Rütgers GmbH contributes high-quality synthetic heat transfer fluids based on isopropyl biphenyl mixtures with their Ruetasolv BP series. Designed for high-temperature applications up to 350°C, their German engineering standards reinforce the premium segment of the market.
These players illustrate a market where technical specifications such as maximum bulk temperature, thermal stability, and isomer composition are the primary battlegrounds. Strategic partnerships and capacity expansions are key levers used to maintain competitiveness.
Industry Drivers and Regulatory Context
The growth of the isopropyl biphenyl market is inextricably linked to regulatory and environmental shifts. A critical driver is the phase-out of polychlorinated biphenyls (PCBs). Isopropyl biphenyl mixtures have emerged as viable replacements for PCBs in heat transfer and capacitor fluids following historical regulatory phase-outs. This transition is not merely about compliance; it is about ensuring operational continuity with safer, more sustainable chemical alternatives.
The adoption of isopropyl biphenyl as a dielectric insulating fluid in capacitors after the 1978 U.S. EPA ban on PCB manufacture and distribution underscores the long-term viability of this chemical class. This historical context validates the current market momentum, as industries continue to retrofit and upgrade systems to meet modern safety standards.
Furthermore, raw material dynamics play a crucial role. Dedicated production capacities, such as the 3,000 tons annually maintained by key manufacturers for isopropylbiphenyl, highlight the importance of vertical integration and supply security. Fluctuations in raw material availability or cost can ripple through the value chain, affecting pricing and lead times. Understanding these upstream dependencies is vital for risk management.
Operational Intelligence Within the Report
Our comprehensive study goes beyond high-level summaries. It is designed as a decision-support tool that provides actionable intelligence for various stakeholders.
- Capacity and Supply Analysis: Detailed assessments of manufacturing capabilities, including regional production hubs and capacity expansions, allow readers to gauge supply tightness and potential bottlenecks.
- Technology and Product Roadmaps: Insights into R&D trends help companies anticipate future product specifications, such as improvements in thermal stability limits or eco-friendly formulations.
- Pricing and Cost Structures: While specific price points are reserved for the deep dive, the report analyzes cost drivers, including raw material correlations and regional pricing differentials, enabling better budgeting and negotiation strategies.
- Risk Assessment: Evaluation of regulatory risks, supply chain vulnerabilities, and competitive threats provides a holistic view for strategic planning.
Strategic Value for 2026 Decision Makers
In the context of 2026, the insights provided by this research are instrumental for several strategic objectives.
Market Entry and Expansion: For companies looking to enter the market or expand their footprint, the segmentation data highlights high-growth pockets. Understanding the regional demand intensity and the competitive saturation in specific areas allows for targeted investment rather than scattergun approaches.
procurement and Sourcing: Procurement teams can leverage the competitive landscape analysis to identify alternative suppliers, assess vendor reliability, and negotiate better terms based on a clear understanding of capacity constraints and market concentration.
Product Development: R&D departments can align their innovation pipelines with market needs. Knowing which applications are driving demand—such as waste heat recovery or electronics cooling—guides the prioritization of fluid formulations with specific thermal properties.
Investment Planning: Investors and finance leaders can use the growth projections and market concentration metrics to evaluate the attractiveness of the sector. The steady CAGR and the shift toward safer chemicals suggest a stable long-term investment thesis.
Navigating the Future of Thermal Management
The Isopropyl Biphenyl Heat Transfer Fluid Market is more than a commodity sector; it is a critical enabler of industrial efficiency and safety. As regulations tighten and operational temperatures rise, the choice of fluid becomes a determinant of system longevity and performance.
p.p'-Dibromobiphenyl Market
The data indicates a market that is growing steadily but is also complex. The concentration among top players suggests that collaboration or differentiation is key. The regulatory backdrop ensures that demand for compliant fluids will remain robust. The variation in applications means that a one-size-fits-all strategy is insufficient.
Our full report unpacks these complexities with precision. It offers the granular data and analytical frameworks needed to turn market intelligence into competitive action. From detailed historical tables to forecast models and company profiles, every section is crafted to reduce uncertainty and enhance strategic clarity.
For organizations committed to optimizing their thermal management strategies and capitalizing on the opportunities within this specialized chemical market, deep intelligence is the prerequisite for success. The 2026 horizon offers significant potential for those equipped with the right insights. We invite you to access the complete study to unlock the full spectrum of data and analysis required to navigate this evolving landscape with confidence.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tall Oil Derivative Market Hits $2,650 Million in 2025, Poised to Reach $3,439 Million by 2032
By PW Consulting, 2026-09-16
Strategic Intel for 2026: Navigating Growth and Volatility in the Crude Tall Oil Derivative Market
As industrial demand shifts toward biobased inputs and regulatory frameworks tighten around renewable feedstocks, the crude tall oil derivative market stands at a critical inflection point. For executives, procurement leaders, and strategy teams planning the 2026 cycle, isolated data points will not suffice. Decision-making requires a clear line of sight into structural supply dynamics, competitive realignments, and the pricing mechanisms that will shape margins across the value chain. Our latest research on the Crude Tall Oil Derivative Market delivers that visibility.
Recent headlines have touched on price actions and asset transactions across the sector, but the underlying forces are far more structural. Trade policy adjustments, biofuel mandates, and biomass regulation are simultaneously reshaping feedstock availability and end-use demand. In this environment, a disciplined, evidence-based view of the market is no longer optional. It is the foundation for capital allocation, product portfolio design, and risk management.
Why 2026 Demands a Deeper Read on Tall Oil Derivatives
The market has expanded steadily over the past half-decade, and the trajectory through the end of the decade points to continued, albeit measured, growth. From a base year perspective anchored in 2025, the industry has moved from a 2020 starting point near 2.18 billion USD to an estimated 2.65 billion USD in 2025. Looking ahead, the forecast period from 2026 through 2032 signals a steady climb, with the market projected to exceed 3.4 billion USD by 2032. This path implies a compound annual growth rate of approximately 3.88 percent, a pace that reflects durable demand from adhesives, coatings, and surfactant applications alongside emerging pull from renewable fuel streams.
Crude Tall Oil Derivative Market
Growth at this pace is not uniform. It is being filtered through a set of intersecting pressures: tightening pulp capacity in certain North American corridors due to lumber tariff effects, supply-side yield improvements at mills in Europe driven by biomass restriction rules, and demand-side substitution dynamics created by duties on alternative feedstocks. For firms that depend on tall oil fatty acids, rosin derivatives, or tall oil pitch, these forces translate into a nonlinear pricing and availability environment. The strategic question for 2026 is not whether the market is growing, but where margins will crystallize and how to secure position before structural advantages harden.
Crude Tall Oil (CTO) Market
Our analysis is built to answer that question. Rather than offering surface-level trend statements, the report maps the causal chain from regulation to mill yield, from trade policy to regional supply balance, and from competitive transactions to pricing power. This approach gives leaders a practical framework for scenario planning and for identifying where to invest, where to hedge, and where to reposition.
What the Report Delivers: An Executable View of the Value Chain
The research is designed around operational usefulness. It combines macro market sizing with a structured examination of the segments that matter most to commercial decisions, while preserving enough granularity to support product-level and application-level planning. The report content is organized to help teams move quickly from insight to action.
- Market sizing and forward outlook anchored to a 2025 base year, with a forecast window spanning 2026 through 2032, enabling multi-year budgeting, capacity planning, and long-cycle procurement strategy.
- Product-level decomposition across fatty acids, rosin derivatives, and tall oil pitch, with context on how each stream is positioned relative to demand from industrial formulations and biobased applications.
- Application-driven insights covering adhesives, coatings, and surfactants, including the demand drivers, formulation shifts, and substitution dynamics that are reshaping consumption patterns.
- Regional framing that situates North American, European, Asian Pacific, Latin American, and Middle East and Africa markets within the broader supply and demand architecture, with attention to trade flows, feedstock availability, and regulatory exposure.
- Competitive landscape assessment that profiles the leading producers, refiners, and biorefiners shaping price formation, capacity additions, and market access.
- Event-driven updates that connect recent pricing actions and asset transactions to the broader strategic narrative, helping readers interpret what is signal and what is noise.
Each section is written for application, not just observation. The goal is to give strategy, finance, and commercial teams a shared vocabulary and a consistent evidence base for cross-functional decisions. By integrating market structure with company-level developments and regulatory context, the report supports decisions about vendor selection, long-term supply agreements, product mix adjustments, and regional prioritization.
Competitive Landscape: Consolidation, Capacity, and Pricing Power
The crude tall oil derivative market is characterized by a concentrated set of active producers and refiners, with a meaningful share of revenue held by a relatively small group of companies. This concentration matters because it shapes how quickly pricing adjusts, how capacity constraints propagate, and how new supply enters the system. The leading participants span biorefining, distillation, and downstream formulation, with strong positions in fatty acids and a growing presence in renewable fuel pathways.
Several firms define the strategic center of gravity. In the United States, Kraton Corporation operates a biorefinery focused on converting crude tall oil into tall oil fatty acids and other pine-based derivatives, and it has a visible footprint as a supplier of biobased specialty chemicals and resins. Eastman Chemical Company also contributes to the market through refining and supply of tall oil fatty acids and pine chemicals for coatings, adhesives, and industrial applications. In Europe, UPM-Kymmene Oyj and Stora Enso Oyj both play foundational roles: UPM produces crude tall oil at its Lappeenranta biorefinery for conversion into renewable fuels and tall oil fatty acids, while Stora Enso extracts and supplies crude tall oil from Nordic softwood kraft pulping as a renewable feedstock for pine-based derivatives. Forchem Oyj and Fintoil Oy round out the Nordic processing landscape, with Forchem specializing in distillation and processing of crude tall oil into tall oil fatty acids and other biobased derivatives, and Fintoil operating a large-capacity biorefinery producing tall oil fatty acids and distilled tall oils for industrial use.
Outside this core cluster, the market includes additional regional specialists and integrated players. Ilim Group JSC produces and supplies crude tall oil from its Russian mills and refines it into tall oil fatty acids, adding capacity and supply reach in its operating footprint. Harima Chemicals Group, Inc. distills crude tall oil into tall oil fatty acids, rosin, and other pine-based derivatives, serving paper chemicals and electronics end markets in Japan. SunPine AB extends the value chain into raw tall diesel and other crude tall oil-derived bio-based products, linking the feedstock to renewable diesel and heating oil applications. Together, these participants illustrate the breadth of the market and the variety of routes through which crude tall oil is converted into commercial value.
Recent activity underscores how dynamic this landscape has become. Over the past year, there have been notable pricing actions and asset transactions that signal both supply tightening and portfolio realignment. In late 2025, Kraton Corporation announced a general price increase of 10 percent or higher on tall oil fatty acid products in the EMEA region. That move was followed in early 2026 by a broader global price increase of 10 to 20 percent across its crude tall oil refinery and derivatives portfolio. These adjustments reflect the interplay of demand strength, feedstock conditions, and the pricing latitude that comes with a concentrated supply base.
On the asset side, Ingevity Corporation moved to reshape its portfolio. In September 2025, it signed an agreement to sell its North Charleston crude tall oil refinery and the majority of its industrial specialties product line. The transaction was completed in January 2026, with the assets transferring to Mainstream Pine Products, LLC. This type of transaction matters because it repositions capacity and changes the competitive map, particularly in regions where refinery access and logistical reach influence commercial outcomes. For buyers and competitors alike, such moves alter availability, potential supply routes, and the negotiation dynamics that govern long-term contracts.
These developments are not isolated events. They are symptoms of a market in which access to consistent feedstock, processing capacity, and downstream market access can create durable advantages. Understanding who holds those advantages, and how they are changing, is essential for any firm that depends on tall oil derivatives as a raw material or a growth platform.
Market Dynamics: Regulation, Trade, and Feedstock Realignments
The backdrop for 2026 is defined by regulatory and trade forces that are simultaneously shaping demand and constraining or expanding supply. These dynamics do not operate in isolation; they interact, and their combined effect is what leaders need to anticipate.
On the demand side, the U.S. policy environment has introduced a notable pull factor. An EPA proposal to increase the biodiesel mandate by 56 percent for 2026 would accelerate crude tall oil consumption in U.S. biofuel blends. If implemented, this type of mandate expands the addressable market for tall oil-derived inputs and increases competition for available feedstock. At the same time, trade policy is influencing where demand migrates. EU anti-dumping duties on Chinese biodiesel, set in a range of 23.7 to 36.4 percent, have increased demand for crude tall oil as an alternative feedstock. This substitution effect redirects flows and can raise utilization at producers positioned to serve European buyers.
On the supply side, the picture is equally active. Lumber tariffs of 25 percent applied in U.S.-Canada and U.S.-Mexico trade contexts have reduced North American pulp production capacity in certain corridors, tightening crude tall oil supply where pulp operations are a primary source of the feedstock. This tightening does not simply raise prices; it changes the calculus for long-term supply agreements and for product planning in regions that depend on North American volumes. In parallel, EU RED III biomass restrictions have forced a reduction in pulp industry biomass burning, which has increased crude tall oil yields by an estimated 8 to 12 percent at mills. This yield effect partially offsets supply pressure by improving the amount of tall oil recovered per unit of pulp output, but its benefits are uneven across regions and operating models.
The strategic implication is that 2026 is a year of dual movement: demand is being amplified by biofuel policy and trade-driven substitution, while supply is being reshaped by tariffs and yield changes that are themselves policy-driven. Navigating this environment requires more than a snapshot of current pricing. It requires a forward-looking view of how mandates, duties, and biomass rules will interact with mill economics, refinery throughput, and downstream formulation needs. The report provides that view by connecting each dynamic to likely commercial outcomes and by identifying the regions and product streams where these forces will be felt first and most intensely.
Using This Research to Frame 2026 Decisions
For executives and analysts, the value of the report lies in its ability to convert complex, moving parts into a coherent decision framework. The research supports several practical uses. It can inform sourcing strategy by clarifying where feedstock availability is likely to tighten and where yield improvements or alternative supply routes may provide relief. It can guide portfolio planning by highlighting how demand is shifting across adhesives, coatings, and surfactants, and by indicating where renewable fuel pathways may create additional pull. It can support pricing strategy by contextualizing recent increases within the broader competitive and regulatory environment, helping teams distinguish structural pricing power from temporary adjustments. It can also inform capital and M&A thinking by mapping where capacity is being repositioned and where consolidation may continue.
Importantly, the report is structured to preserve analytical precision without overwhelming the reader with a wall of figures. High-level market size, growth trajectory, and concentration metrics are presented to frame the landscape, while the deeper segmentation detail is reserved for the full study. This design reflects how senior teams actually work: they need the strategic picture first, then the granular data to support specific plans. The complete research delivers that depth, including regional and application-level breakdowns, product-level context, and company profiles that together form a comprehensive intelligence package.
What the Full Study Unlocks
The summary view presented here establishes the strategic terrain, but the complete Crude Tall Oil Derivative Market research goes further. It provides the segmentation detail needed to translate market direction into product and regional plans, the competitive context needed to interpret pricing and capacity moves, and the dynamic analysis needed to anticipate the next shift in policy or trade. For teams preparing for 2026, that combination is what turns uncertainty into a manageable set of choices.
If your organization is evaluating supply commitments, product positioning, regional exposure, or investment in biobased chemical value chains, the full report offers the structured evidence required to move with confidence. The market is expanding, but expansion is being routed through a narrow set of competitive and regulatory choke points. Understanding those choke points is the difference between reacting to change and shaping your position ahead of it.
To access the complete market sizing, segmentation analysis, competitive profiles, and dynamic scenario guidance, explore the full research on the source page. The detailed intelligence there is designed to support concrete 2026 planning across commercial, procurement, and strategy functions.
For detailed analysis of this topic, please visit the official page: Crude Tall Oil Derivative Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PPS Resin Market to Hit $3.47B by 2032, Driven by 7.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Polyphenylene Sulfide Landscape: Strategic Imperatives for 2026 and Beyond
In an era defined by accelerated material innovation, supply chain volatility, and stringent sustainability mandates, the global Polyphenylene Sulfide (PPS) resin market stands at a critical inflection point. For corporate strategists, procurement leaders, and R&D directors across high-performance engineering sectors, the ability to anticipate demand trajectories, identify emerging capacity shifts, and decode competitive positioning is no longer a luxury. It is a prerequisite for sustained market share and margin protection. Our newly released PPS Resin Market Research Report delivers exactly that: a rigorously validated, forward-looking intelligence framework calibrated to guide executive decision-making through 2032 and beyond.
The macro trajectory tells a compelling story. From a baseline of USD 1,450.0 Million in 2020, the market has consistently compounded upward, reaching USD 2,020.0 Million in 2025. Our baseline forecast projects the sector will exceed USD 2,143.6 Million in 2026 and continue its upward march to USD 3,470.0 Million by 2032. Anchored by a robust compound annual growth rate of 7.8 percent, the expansion is neither accidental nor cyclical. It reflects structural demand drivers, evolving material substitution patterns, and deliberate capacity reallocation by Tier-1 producers who are actively reshaping the competitive architecture. Yet, headline figures only scratch the surface. The real strategic value lies in understanding the mechanics beneath the aggregate numbers: how demand is being reallocated across value chains, where production bottlenecks are forming, and which players are positioning themselves to capture disproportionate share in high-margin end-use segments.
This intelligence brief serves as a strategic preview. It outlines the core analytical pillars embedded in our full study, highlights the competitive dynamics currently redrawing the market map, and demonstrates how procurement and product development teams can leverage granular, actionable data to optimize sourcing strategies, de-risk supply chains, and accelerate time-to-market for next-generation engineered components.
Polysulfone Resin Market
Decoding the Report Architecture: What Decision-Makers Will Gain
Our research methodology is built on a multi-layered analytical framework that moves far beyond top-line market sizing. The full report synthesizes historical trajectory data, forward-looking demand modeling, supply-side capacity mapping, and application-specific consumption patterns into a unified decision-support toolkit. Rather than presenting static snapshots, we track momentum. The historical period from 2020 to 2025 establishes the baseline behavior of the market across economic cycles, raw material fluctuations, and regional demand shocks. The forecast window from 2026 through 2032 extends that modeling into scenario-weighted projections that account for macroeconomic variables, technological adoption curves, and regulatory inflection points.
Throughout the document, readers will encounter structured analytical modules designed for direct operational translation. These include demand-side consumption mapping across major end-use verticals, supply-side capacity and utilization tracking by manufacturing geography, and segmentation analysis that isolates growth vectors within resin type categories and application clusters. Each module is cross-referenced with pricing sensitivity indicators, feedstock dependency assessments, and sustainability compliance tracking. The goal is to equip strategists with a complete operational lens: one that connects macroeconomic demand signals to plant-level capacity decisions, and links regulatory developments to formulation and sourcing strategies.
Crucially, the report is structured to support iterative decision-making. Executives can use it to stress-test procurement portfolios, identify long-term supply continuity risks, evaluate joint-venture or contract-manufacturing opportunities, and benchmark internal performance against industry growth curves. R&D and product development teams will find targeted insights into grade differentiation, thermal and chemical resistance requirements, flow characteristics for high-volume injection molding, and the growing importance of recycled-content variants in meeting corporate sustainability targets.
Competitive Recon: Mapping the Architecture of Market Leadership
Market concentration in the global PPS resin sector remains pronounced, with the top three producers collectively accounting for approximately 65 percent of total revenue and the top five controlling roughly 80 percent. This concentration does not imply stagnation. On the contrary, it reflects deliberate capital allocation, technological specialization, and strategic geographic positioning by a tightly aligned group of performance-material manufacturers who are competing on grade formulation, regulatory certification, recycling capability, and application-specific value engineering.
At the heart of this competitive ecosystem sits Celanese Corporation, whose Fortron® PPS resin portfolio has long been associated with high thermal stability, chemical resistance, and consistent performance in automotive and industrial injection molding applications. Operating from Dallas, Texas, Celanese continues to reinforce its position through grade optimization, processing reliability, and deep integration into Tier-1 supply chains. Across the Atlantic, Solvay S.A. has built a formidable presence through its Ryton® PPS brand and Supreme series grades, targeting high-voltage electrical applications, high-flow engineering requirements, and increasingly, sustainability-certified production pathways. The company's ongoing pursuit of mass-balance certification and its footprint across Texas and Belgium underscore a dual focus on performance and compliance-driven market access.
The Asian manufacturing corridor continues to exert structural influence. Toray Industries, Inc. has systematically expanded its Torelina® PPS resin portfolio to serve high-performance automotive and electronics applications, recently completing a second production line expansion at its Gunsan plant in Korea to reinforce regional capacity resilience. DIC Corporation and Kureha Corporation have maintained steady positioning in industrial and automotive segments, with Kureha placing particular emphasis on high-temperature and flame-resistant grades that align with stringent safety specifications in electrical and transport equipment. Tosoh Corporation serves as a specialized supplier across electrical and high-performance engineering applications, while Polyplastics Co., Ltd. has carved a distinct niche through its DURAFIDE® PPS grades, recently advancing into mechanically recycled-content formulations that respond directly to corporate sustainability mandates and circular-economy procurement standards. Rounding out the competitive matrix, Ensinger GmbH provides compounded PPS materials and precision-machining-ready resin solutions for industrial components, reinforcing Europe's role as a hub for specialized, high-value-added formulations.
Recent operational moves by key players confirm that the competitive landscape is actively recalibration. In May 2025, Syensqo announced a capital investment to expand PPS compounding capability at its Augusta, Georgia manufacturing site for Ryton-branded compounds, signaling a strategic push into North American downstream processing and localized supply chain responsiveness. Later in the year, Toray Industries completed the expansion of its second PPS production line at its Gunsan facility in Korea, reinforcing its capacity footprint and regional supply agility. In January 2026, Polyplastics Co., Ltd. launched two new DURAFIDE® PPS grades made from mechanically recycled content, a move that directly intersects with the growing procurement preference for sustainable resin inputs and circular material sourcing.
These developments are not isolated corporate announcements. They are indicators of structural realignment: capacity is being deliberately placed closer to key demand clusters, compounding and formulation capabilities are being expanded to capture higher-margin downstream value, and sustainability certification is transitioning from a compliance checkbox to a competitive differentiator. Understanding who is expanding, where, and why is essential for any organization seeking to optimize long-term sourcing strategy or position new products in high-growth application corridors.
Structural Dynamics Shaping the 2026 Horizon
The trajectory of the PPS resin market is being shaped by an interlocking set of technical, economic, and regulatory forces. At the raw material level, PPS production relies on the polymerization of dichlorobenzene and sodium sulfide as foundational feedstocks. Pricing and supply continuity for these commodity inputs remain highly sensitive to broader chemical market dynamics, and procurement teams must track these dependencies closely as they translate into resin cost structures and margin variability. In the third quarter of 2025, North American PPS prices rose to approximately USD 11,250 per metric ton, driven by intensified demand pull from the automotive and electronics sectors. This price behavior is not an isolated event; it reflects how demand acceleration in high-value applications can rapidly transmit through regional pricing structures, particularly when capacity expansion timelines lag behind consumption growth.
Regulatory and sustainability frameworks are equally influential. The attainment of ISCC PLUS 2 mass-balance certification for PPS production facilities in Texas and Belgium demonstrates how major producers are institutionalizing sustainable manufacturing pathways. As downstream OEMs and Tier-1 suppliers face mounting corporate sustainability targets and customer-facing carbon disclosure requirements, certified sustainable resin inputs are evolving from a niche preference to a qualifying factor in procurement evaluations. The strategic implication is clear: organizations that embed sustainability compliance into sourcing criteria will not only mitigate reputational and regulatory risk but will also gain preferential access to supply from producers who have already navigated the certification pathway.
On the technology and application side, continuous advancements in resin formulation are expanding the boundaries of where PPS can be deployed. Enhancements in thermal stability, chemical resistance, flow characteristics, and flame-retardant performance are enabling deeper penetration into demanding engineering applications where traditional thermoplastics and lower-performance engineering resins fall short. Simultaneously, the rise of recycled-content grades is creating new procurement dynamics. As mechanically recycled PPS formulations gain commercial traction, buyers are confronted with a more complex sourcing landscape that requires evaluation of material consistency, processing compatibility, certification alignment, and total cost of ownership rather than simple price-per-kilogram comparisons.
Strategic Positioning for 2026 and the Road to 2032
As the market moves from baseline recovery and consolidation into an accelerated growth phase, several strategic imperatives are coming into sharp focus for organizations operating in or adjacent to the PPS value chain. First, supply chain resilience must be treated as a structural capability rather than a short-term risk mitigation exercise. The concentration of capacity among a small group of large-scale producers, combined with regional price sensitivity and feedstock dependency, means that diversification of sourcing relationships, forward contracting strategies, and awareness of capacity expansion timelines are essential to maintaining continuity and cost predictability.
Second, application-specific demand mapping should inform both procurement and product development roadmaps. As automotive electrification, high-performance electronics, aerospace component requirements, and industrial precision-machining demand continue to shape consumption patterns, organizations that understand which end-use verticals are accelerating, which are stabilizing, and which are emerging will be better positioned to align capacity acquisition, inventory planning, and new product introductions.
Third, sustainability is becoming a procurement qualifier, not an aspirational add-on. Certified sustainable production pathways, recycled-content grades, and compliance with evolving regulatory expectations are increasingly influencing supplier selection. Organizations that proactively embed these criteria into supplier qualification, technical evaluation, and contract negotiation will reduce exposure to future compliance shocks while strengthening alignment with downstream customer expectations.
Finally, competitive intelligence must be continuous. The recent capacity expansions, grade launches, and certification milestones among leading producers confirm that the market is structurally dynamic. Tracking these moves, understanding the geographic and application logic behind them, and anticipating their downstream impact on pricing, availability, and formulation options will be a decisive factor in maintaining competitive advantage over the next planning cycle and beyond.
PPS Resin Market
Closing the Intelligence Gap
Headline growth rates and aggregate market sizes provide orientation, but they rarely provide direction. Real strategic advantage comes from understanding the mechanics beneath the numbers: how capacity is being reallocated, how grade differentiation is reshaping application eligibility, how sustainability certification is filtering supplier pools, and how pricing behavior reflects demand shifts in high-value end-use sectors. Our full PPS Resin Market Research Report is designed to close that intelligence gap. It translates historical trajectory, forward-looking modeling, competitive mapping, and structural dynamics into a decision-ready framework that procurement, strategy, and engineering teams can apply directly to sourcing plans, capacity negotiations, product roadmaps, and market-entry evaluations.
For organizations preparing for the 2026 decision cycle, the window to build a comprehensive, evidence-backed view of the PPS resin market is open now. The full report provides the granular segmentation detail, regional and application-level consumption trajectories, pricing sensitivity modeling, competitive positioning analysis, and scenario-weighted forecasts needed to move from reactive monitoring to proactive strategy. We invite you to access the complete study on our website, where you will find the full data architecture, detailed segmentation contours, and executive-ready synthesis required to navigate the next phase of market expansion with confidence.
For detailed analysis of this topic, please visit the official page: PPS Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CTBN Market Reaches $70M in 2025, Projected 4.98% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the CTBN Market: Navigating Growth, Competition, and Material Innovation in 2026
The specialty chemicals landscape is undergoing a structural recalibration. Among the most consequential segments for advanced manufacturing, the Carboxyl-Terminated Butadiene-Nitrile (CTBN) market is entering a decisive inflection point. Over the past half-decade, demand trajectories have been shaped by automotive lightweighting mandates, adhesive formulation shifts, and the expanding reliance on polymer-modified epoxy systems across industrial and aerospace applications. As we move through 2026, enterprise decision-makers face a more complex calculus: balancing cost-efficient sourcing against performance-grade material specifications, anticipating regional supply chain realignments, and positioning product pipelines ahead of tightening regulatory and sustainability expectations. Our newly released CTBN Market research report has been designed specifically to convert this complexity into actionable intelligence.
The foundational narrative of this market is one of measured but persistent expansion. Historical consumption patterns from 2020 through 2025 reveal a consistent upward arc, with aggregate revenue climbing from 55.2 million USD to 70.0 million USD. Looking forward across the 2026 to 2032 forecast horizon, the sector is projected to continue its growth path, reaching an estimated 97.86 million USD by the terminal year of the analysis window. This progression translates to a compound annual growth rate of 4.98 percent, a pace that underscores durable industrial demand rather than speculative optimism. The implied trajectory signals steady capacity utilization, incremental formulation upgrades, and sustained procurement activity across mature and emerging applications alike. For procurement leaders and R&D directors, these macro indicators are not merely background statistics; they represent the scaffolding upon which sourcing strategies, capacity planning, and product roadmaps must be constructed.
Why This CTBN Market Research Matters for 2026 Enterprise Decisions
Corporate strategy in specialty chemicals rarely succeeds on intuition alone. It requires a granular understanding of where value is created, where margins compress, and where competitive friction is intensifying. The CTBN Market study is built to address precisely these operational and strategic questions. Rather than offering a static snapshot, the report functions as a decision-support instrument calibrated for the realities of 2026 procurement cycles, technology adoption timelines, and regional market access strategies.
Several structural dynamics make this publication particularly timely:
- The CTBN value chain is no longer driven solely by volume expansion; formulation differentiation, reactive toughening performance, and compatibility with advanced resin systems increasingly determine commercial advantage.
- Supply-side geography is evolving in response to logistics costs, raw material availability, and localized regulatory frameworks, forcing manufacturers to weigh concentration risk against cost efficiency.
- Downstream applications are diverging in their technical requirements. Epoxy modification for adhesives and sealants, composite toughening for automotive and industrial assemblies, and polyurethane precursor performance all impose distinct specification thresholds that influence supplier selection.
- Pricing and contractual frameworks are being reshaped by capacity investments, feedstock variability, and the growing premium attached to consistent batch quality and technical service support.
By mapping these forces into a structured analytical framework, the report enables leaders to test assumptions before they commit capital. Whether the objective is to optimize distributor relationships, evaluate a new plant footprint, refine a product-grade strategy, or identify whitespace in a particular application vertical, the research supplies the evidentiary base needed to reduce uncertainty and accelerate approval cycles.
TCB Bonder Market
What the Report Delivers: Analytical Depth and Actionable Frameworks
To support rigorous planning, the CTBN Market report integrates multiple analytical layers that bridge high-level market sizing with granular commercial insight. The structure is designed to serve both strategic and tactical teams, from executive committees to technical sourcing managers. Core deliverables include:
Market Sizing, Historical Baselines, and Forward Estimates
The analysis begins with a comprehensive historical reconstruction covering the 2020 to 2025 period, establishing a defensible baseline against which growth assumptions can be stress-tested. From that foundation, the forecast window extends through 2032, allowing planners to model revenue trajectories, capacity utilization patterns, and demand timing across multiple planning horizons. Every projection is anchored to observable market behavior rather than abstracted trends, ensuring that downstream decisions rest on plausible, internally consistent assumptions.
Segmentation Architecture for Application and Type Dynamics
Because CTBN chemistry is deployed across distinct end-use environments, the report disaggregates demand by type and application to expose where performance requirements and consumption intensity diverge. This segmentation supports more precise portfolio decisions, including whether to prioritize low-acrylonitrile or high-acrylonitrile grades, how to align formulation capabilities with adhesive and sealant markets versus coatings and composite toughening, and where automotive-linked specifications create durable demand pull.
Regional Market Structure and Access Considerations
Geographic distribution is analyzed to clarify where demand concentration creates scale advantages, where regulatory or logistics conditions influence cost structures, and where localized supply capabilities alter competitive positioning. The regional view does not simply rank territories; it helps organizations evaluate import-export exposure, assess nearshoring and regionalization scenarios, and determine which markets warrant dedicated commercial resources versus selective distribution models.
Competitive Benchmarking and Supplier Intelligence
The report profiles the principal participants shaping the CTBN competitive landscape, with attention to product architecture, application focus, and commercial strategy. Featured companies include:
- Emerald Performance Materials , whose Hypro CTBN carboxyl-terminated butadiene-acrylonitrile copolymer is positioned as a reactive toughener in epoxy resins, adhesives, sealants, and composites for aerospace, automotive, and industrial applications.
- Tanyun Aerospace Materials (Yingkou) Technology Co. , which produces carboxy-terminated butadiene-acrylonitrile rubber as an additive for epoxy resins and thermoset polymers, emphasizing toughness, flexibility, and impact resistance in aerospace composites and structural applications.
- Shandong Qilong Chemical Co., Ltd. , a manufacturer of end-carboxyl-terminated butadiene-nitrile rubber liquid rubber and related functional elastomers for adhesives, sealants, and polymer modification.
- Shanghai Theorem Chemical Technology Co., Ltd. , which exports and supplies CTBN as a high-performance polyurethane precursor and toughener in resins for adhesives, sealants, and advanced composites.
Beyond company-level profiles, the research incorporates concentration metrics that illuminate market structure. With a CR3 of 35.2 percent and a CR5 of 52.8 percent, the landscape reflects a competitive environment in which leading suppliers command meaningful share while still leaving substantial room for specialized players and regional specialists. This structure has direct implications for pricing power, negotiation leverage, and supplier diversification strategy.
Strategic Scenario Tools for 2026 and Beyond
The report closes the gap between descriptive analysis and decision execution by providing scenario-oriented tools. These include demand sensitivity frameworks tied to application growth, type-mix shifts, and regional procurement behavior; competitive response simulations that help anticipate supplier pricing or capacity moves; and sourcing risk assessments that connect material performance requirements to supply continuity considerations. The intent is to enable organizations to model alternative pathways rather than rely on a single forecast.
Competitive Positioning in a Fragmented but Concentrating Landscape
A defining feature of the CTBN market is its blend of technical specialization and commercial contestability. The presence of well-established suppliers with distinct formulation capabilities coexists with regional manufacturers that compete on cost, responsiveness, and application-specific service. For enterprises buying or producing CTBN-based systems, this means supplier evaluation cannot be reduced to unit price alone. Performance consistency, technical assistance, regulatory documentation, and compatibility with downstream processing equipment all influence total cost of ownership.
The competitive analysis in the report is structured to help buyers and producers interpret this environment with precision. Rather than treating market share as a static hierarchy, the study examines how supplier positioning varies by application pressure, type-grade specialization, and geographic access. This approach is particularly relevant in 2026, as firms reassess supplier portfolios in response to changing procurement policies, resilience requirements, and formulation roadmaps. Organizations that understand where concentration creates negotiation constraints and where fragmentation creates alternatives will be better equipped to structure contracts, qualify second sources, and manage supply continuity without overpaying for unnecessary redundancy.
Market Dynamics, Demand Drivers, and the Regulatory-Economic Backdrop
CTBN demand is linked to broader trends in advanced materials, structural performance requirements, and formulation evolution. Automotive programs continue to pursue weight reduction and damage-tolerant composite assemblies. Adhesive and sealant formulators are seeking tougher, more flexible polymer modifications that preserve bond integrity under mechanical stress. Coatings and industrial resin systems increasingly depend on reactive tougheners to balance mechanical performance with processing practicality. These application-level drivers are not uniform; they differ by region, by product class, and by the technical maturity of the end market.
At the same time, market participants are operating within a broader industrial and regulatory environment that continues to reshape infrastructure investment, spectrum access frameworks, and connectivity requirements in adjacent sectors. While these dynamics belong to the wider advanced-technology ecosystem, they indirectly influence the operating context for specialized material supply chains by affecting logistics planning, industrial capacity deployment, and the cadence of capital investment across technology-intensive industries. Regulatory coordination in spectrum and network access, neutrality principles, and efforts to streamline cross-border policy burdens all contribute to the background conditions under which industrial procurement and infrastructure programs advance. Public and private investment in network build-out and shared-access frameworks has expanded materially, with operator spending on spectrum and small-cell deployment reaching substantial levels and annual investment in related radio access and transport infrastructure projected to grow at a double-digit pace through the near term. These conditions do not define CTBN chemistry directly, but they shape the industrial tempo, risk appetite, and capital environment in which specialty chemical suppliers and their customers operate.
For CTBN market participants, the practical implication is clear: demand planning must account for both application-specific technical drivers and the wider industrial environment in which capacity, logistics, and compliance costs evolve. The report integrates these considerations into its forward analysis so that strategic assumptions are grounded in current operating reality rather than historical convenience.
How to Use This Research for 2026 Planning Cycles
The report is constructed for multiple internal audiences and planning workflows. Procurement teams can use the segmentation and supplier profiles to refine grade selection and qualification strategies. Commercial leaders can apply the competitive structure and regional analysis to prioritize market access and partnership models. R&D and product management teams can align formulation direction with the most consequential application and type-grade dynamics. Executive planners can rely on the consolidated market sizing and scenario tools to test growth assumptions and capital allocation priorities.
To support this range of use cases, the study is organized around questions that recur in 2026 decision-making:
- Which demand pools are expanding fastest in specification intensity rather than merely in volume?
- Where do type-grade distinctions create sustainable differentiation versus commoditization risk?
- How should supplier portfolios be structured to balance performance assurance with cost competitiveness?
- Which regional markets warrant closer commercial engagement given concentration, logistics, and regulatory conditions?
- What scenario ranges should be assumed for the 2026 to 2032 period when modeling capacity, sourcing, and product strategy?
Answering these questions requires more than summary data. It requires an evidence base that connects market size, segmentation behavior, supplier positioning, and dynamic operating conditions into a single coherent framework. That is the core function of this publication.
Conclusion: Converting Market Uncertainty into Strategic Advantage
The CTBN market is not defined by abrupt disruption; it is defined by cumulative technical demand, evolving supplier capabilities, and a competitive structure that rewards precision in formulation, sourcing, and market selection. The 2026 to 2032 outlook reinforces the case for disciplined strategic planning. With aggregate revenue projected to advance from 75.38 million USD in 2026 toward nearly 98 million USD by 2032 at a CAGR of 4.98 percent, the opportunity lies not simply in participating in growth, but in shaping how a company captures it. That requires clarity on type-grade positioning, application relevance, geographic exposure, and competitive leverage.
The CTBN Market report is designed to provide that clarity. It offers the analytical depth needed to justify decisions internally, the segmentation discipline required to avoid oversimplification, and the competitive context necessary to anticipate supplier and customer behavior. The full research contains detailed segmentation performance, regional market structures, application-level breakdowns, and extended company profiles that cannot be fully reproduced here. To access the complete dataset, scenario tools, and competitive intelligence, visit the official report page and retrieve the full CTBN Market study.
CTBN Market
For organizations preparing for 2026 sourcing cycles, product commitments, and long-range capacity evaluation, the difference between informed positioning and reactive adjustment will come down to the quality of the underlying intelligence. This research is built to supply precisely that advantage.
For detailed analysis of this topic, please visit the official page: CTBN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zinc Selenide Market Hits $170M in 2025, 4.8% CAGR Outlook to 2032
By PW Consulting, 2026-09-16
Zinc Selenide Market Outlook: Strategic Imperatives for Decision-Makers in 2026 and Beyond
As industrial systems increasingly demand precision infrared optics, zinc selenide (ZnSe) has moved from a niche specialty material to a strategically important component across laser processing, thermal imaging, and spectroscopic instrumentation. The transition is not merely a story of improved device performance. It reflects deeper shifts in supply chain resilience, regulatory scrutiny on critical raw materials, and the competitive dynamics of a concentrated but globally distributed manufacturer base. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the market warrants a structured and evidence-based reading.
Zinc Sulfide Market
This article previews the strategic logic behind our latest Zinc Selenide Market research. It outlines the macro trajectory, the structural forces shaping demand, the competitive landscape, and the operational variables that matter most in planning windows through 2032. The objective is to give leadership teams a credible foundation for decision-making while signaling where deeper, granular intelligence can sharpen execution.
Why the ZnSe Market Matters Now
ZnSe occupies a distinct position in the infrared optics value chain because it combines broad transmissivity in the mid-wave and long-wave infrared with practical manufacturability for components that must withstand high-power laser environments. That combination has made it especially relevant for CO2 laser optics, thermal imaging platforms, and spectroscopy systems used across industrial, medical, and defense-adjacent applications. The material is not a commodity in the traditional sense; it is a performance-critical input where purity, homogeneity, and coatings directly influence end-device reliability.
At the same time, ZnSe markets are shaped by upstream constraints. Seaborne selenium supply, refinery output dynamics, and price volatility in key sourcing regions all feed into production economics for substrates and optical components. Downstream, the growth of infrared-enabled technologies across automation, sensing, and advanced manufacturing continues to expand the addressable space for ZnSe, even as buyers become more selective about quality consistency and supply continuity.
Macro Trajectory: Resilience With Steady Expansion
The market has demonstrated a measured but persistent growth path over the recent historical period, with revenue expanding from 144.0 million USD in 2020 to approximately 170.0 million USD in 2025. That progression reflects more than incremental demand. It indicates a market that is consolidating its role within higher-value optical systems while adapting to fluctuating input costs and shifting regional manufacturing footprints.
Looking forward, the forecast period suggests continued expansion, with the market moving from about 175.5 million USD in 2026 toward roughly 235.0 million USD by 2032. The implied compound annual growth rate of 4.8 percent is not explosive, but it is meaningful in a materials market where scale is often constrained by specialized production capacity, qualified supply chains, and application-specific qualification cycles. For planners, the key takeaway is that ZnSe growth is likely to be durable rather than episodic, with the most significant opportunities accruing to participants who can align product portfolios with higher-growth end-use segments and secure reliable material access.
Because this is a concentrated sector, strategic planning also requires attention to structure. The market is not fragmented in a way that makes pricing or availability purely transactional. Positionality matters, and the firms that can combine material expertise with component-level fabrication, coating capability, and customer-specific qualification support are better placed to capture value beyond base material sales.
Structural Forces Shaping 2026–2032
The forward trajectory is best understood as the interaction of several forces rather than a single demand driver.
Raw material backdrop and cost sensitivity
Selenium availability and pricing remain central to ZnSe production economics. Recent reporting points to reduced domestic output of crude selenium and selenium-bearing copper anode slimes in the United States, alongside price increases in both U.S. and European warehouse markets. Even where percentage changes appear moderate, the practical impact on producers can be outsized because ZnSe manufacturing depends on controlled reaction environments and high-purity precursors. In this context, procurement strategy, inventory design, and supplier qualification are not back-office tasks; they are strategic levers.
Regulatory and safety considerations
ZnSe is treated with caution in handling and environmental compliance. Classifications associated with acute toxicity risks through ingestion and inhalation, as well as toxicity to aquatic life with long-lasting effects, mean that responsible suppliers and end users must manage documentation, containment, and disposal practices with rigor. At the same time, certain regulatory exemptions can be relevant to registration obligations. This dual reality, genuine safety management requirements combined with specific regulatory treatment, makes compliance literacy a differentiator. Companies that can demonstrate controlled handling, transparent documentation, and consistent quality systems may gain an edge in qualified supply chains where auditability matters.
Application pull from infrared-intensive industries
Demand is being reinforced by applications that rely on stable infrared transmission and robust mechanical performance. CO2 laser optics remain a central use case, where ZnSe components are expected to function under sustained power and thermal loading. Thermal imaging and medical or spectroscopy-related systems add further breadth, creating a demand mix that is diversified but still anchored by a few high-impact segments. Organizations planning product investments should treat this as a cue to evaluate where their own roadmaps intersect with infrared optics bottlenecks, particularly in environments where alternative materials may not match ZnSe’s balance of transmission and manufacturability.
Competitive Landscape: Concentrated Expertise, Diverse Footprint
The ZnSe market is best characterized as a specialized arena where competitive advantage stems from material know-how, production consistency, and the ability to deliver finished or semi-finished optics rather than raw crystals alone. The participating firms span multiple geographies and business models, from vertically integrated producers to specialist component suppliers and regional materials experts.
Several firms illustrate the range of strategic positions in the market. Coherent Corp. represents a vertically integrated approach, with capabilities that extend from ZnSe substrates and bulk optical materials through fabrication into lenses, windows, output couplers, beamsplitters, and other infrared optics. This integration can reduce handoff risk between material production and component realization, an important consideration for customers seeking qualified supply for demanding laser and IR systems.
Crystran Ltd. and KORTH Kristalle GmbH reflect deep specialization in polycrystalline ZnSe and high-power laser-grade components. Their emphasis on CVD-based production and controlled homogeneity for 10.6 µm applications underscores how material processing precision directly enables performance in CO2 laser contexts. In practical terms, the ability to supply thicker plates or large-area substrates with consistent optical properties is not a minor detail; it determines whether a component can meet the requirements of high-stress optical assemblies.
Edmund Optics Inc. demonstrates the importance of the distribution and customization layer. By supplying both standard and custom ZnSe components, such firms bridge the gap between material supply and end-application integration, providing optics that are immediately usable in a range of IR setups. For buyers, this model can reduce lead-time risk and simplify procurement for non-custom or lower-volume needs.
Alkor Technologies and Crystaltechno Ltd. illustrate the role of high-purity CVD production and broader II-VI material expertise in the market, including advanced coating capabilities. Meanwhile, Vital Materials Co., Ltd. and R'AIN Group highlight the expanding presence of suppliers aligned to infrared optics, semiconductor lasers, thermal imaging, and advanced detector-related uses. Together, these players point to a landscape where regional presence, material purity, and coating or fabrication support all contribute to market positioning.
Strategic implication: competitive advantage in this market is often cumulative. The strongest positions tend to emerge where suppliers combine material reliability, qualified fabrication, and the ability to support customers through specification, testing, and volume scaling. For buyers and investors alike, understanding these capabilities at the firm level is more useful than treating ZnSe as a uniform commodity.
What the Research Delivers: An Executive-Focused Toolkit
Our Zinc Selenide Market study is designed to support operational and strategic decisions rather than to offer only top-line figures. The report maps the market across type, application, and region, while embedding the macro trajectory within a framing that helps executives interpret risk, opportunity, and timing. It is structured to answer practical questions that arise in sourcing, product planning, and competitive positioning.
The analysis includes:
- A historical and forecast view of market scale and growth dynamics, anchored in a base year of 2025 and extended through the forecast period to 2032, with an emphasis on interpreting trend direction rather than treating numbers in isolation.
- Segmentation that distinguishes among major product types and application contexts, helping teams identify where ZnSe demand is most concentrated and where differentiation is most achievable.
- Regional context that situates demand and supply patterns across key markets, without reducing the story to a single geography, since the material’s supply chain and end-use base are internationally distributed.
- Competitive profiling that goes beyond corporate descriptions to explore the strategic significance of vertical integration, material purity, CVD expertise, component fabrication, and coating capability.
- Regulatory and safety context, including handling considerations and compliance-relevant details that can influence procurement choices, qualification requirements, and supply chain design.
- Upstream factors such as selenium supply and pricing dynamics, integrated into the broader interpretation of cost structure, margin sensitivity, and sourcing resilience.
In short, the report is intended to support decisions about where to participate, how to source, which applications to prioritize, and how to assess competitors not just by scale but by technical and operational credibility.
Decision Themes for 2026 Planning
For leadership teams planning around 2026, several practical themes emerge.
First, treat ZnSe as a performance enabler with supply-chain stickiness. Where end systems depend on dependable infrared transmission and component durability, switching costs and qualification cycles can be significant. That makes supplier reliability and documentation quality strategically valuable, not merely operational.
Zinc Selenide Market
Second, integrate raw-material awareness into procurement and capacity planning. Selenium market conditions, refinery output, and regional price movements can affect cost structures and availability. Even when the market expands steadily, the ability to manage input volatility can determine whether a participant captures margin or merely maintains volume.
Third, evaluate competitive differentiation through capability rather than headline presence. Vertical integration, substrate-to-component control, high-purity CVD production, and coating or customization capacity can matter more than simple product listings. In interviews, sourcing reviews, and partnership decisions, these capabilities should be assessed against the specific requirements of the target application.
Fourth, align product and investment planning with the application mix that most strongly benefits from ZnSe’s properties. CO2 laser optics, thermal imaging, and spectroscopy-related uses are not interchangeable from a materials standpoint. Mapping internal roadmaps to the segments where ZnSe provides the most credible advantage can improve capital efficiency and reduce design risk.
Fifth, incorporate compliance and handling discipline into supplier evaluation. In markets with acute toxicity and environmental sensitivity concerns, robust MSDS practices, auditable handling procedures, and clear regulatory positioning are part of the commercial value proposition. They can influence qualification speed, risk exposure, and long-term partnership stability.
What Is Held Back: Why the Full Intelligence Matters
This preview establishes the strategic frame and the macro logic, but the market’s actionable detail is more granular than any summary can responsibly convey. Segment-level revenue splits, regional breakdowns, application-level allocations, and firm-specific positioning nuances all require careful presentation because they directly affect sourcing choices, investment timing, and competitive benchmarking. Publishing those specifics here would reduce the value of the underlying analysis and, more importantly, could mislead planning if taken out of context.
The full research provides that depth in a structured, decision-ready form, allowing teams to compare opportunities across type, application, and region while interpreting them against the competitive and regulatory environment. It also connects the numbers to the operational realities that determine whether a market trajectory can actually be captured.
How to Use This Insight
The value of this market research is not limited to understanding where the ZnSe market is going. It is most useful when it helps organizations decide what to do next. Procurement teams can use it to refine supplier qualification criteria and scenario planning around input volatility. R&D and product leaders can use it to validate application priorities and material choices. Strategy and corporate development teams can use it to assess where vertical integration, partnerships, or geographic coverage would create durable advantage.
For executives who need to justify resource allocation in 2026, the strongest use of this intelligence is to connect market direction with internal capability gaps and sourcing exposure. That is where the report moves from description to delivery: it is built to support concrete actions, not just narrative awareness.
To access the complete segmentation, competitive assessment, regional interpretation, and operational context, readers are encouraged to explore the full study on the source page. There, the detail is presented in a way that allows teams to integrate it directly into planning workflows, sourcing reviews, and investment discussions.
For detailed analysis of this topic, please visit the official page: Zinc Selenide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


