



Category: Chemical & Materials
PW Consulting: Car Soundproofing Market Hits $277M in 2025, Projected to Reach $406.1M by 2032
By PW Consulting, 2026-09-16
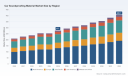
Strategic Silence: Navigating the 2026 Car Soundproofing Material Market
The automotive industry is currently undergoing a profound transformation, shifting from a singular focus on mechanical performance to a holistic emphasis on the passenger experience. At the heart of this evolution lies acoustic comfort. As vehicles become more electrified and connectivity becomes ubiquitous, the cabin has transformed into a mobile office, entertainment hub, and sanctuary. Consequently, the demand for advanced soundproofing materials has surged, creating a complex landscape for manufacturers, suppliers, and investors. PW Consulting's latest market research provides a critical compass for navigating this terrain during the pivotal forecast period extending to 2032.
Market Trajectory and Fundamental Growth Dynamics
Understanding the current market position requires a clear view of the historical performance and future projections. The car soundproofing material sector has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue, recovering swiftly from minor fluctuations experienced in the mid-2020s. This growth trajectory suggests a market that is maturing yet still energized by new technological demands.
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate of 5.65 percent. This figure is not merely a statistic; it represents a significant expansion in total market value over the next seven years. Starting from a base established in 2025, the market is poised to reach substantially higher revenue figures by the end of the decade. For strategic planners, this CAGR signals that the industry is not stagnant. It is expanding at a pace that outpaces inflation and many broader industrial sectors, indicating healthy underlying demand drivers. However, realizing this growth requires understanding the nuances behind the aggregate numbers. The overall revenue pool is expanding, but the distribution of value across different segments and regions varies significantly, a detail thoroughly unpacked in the full report.
Technology Shifts: EV Noise Profiles and Material Innovation
The transition from internal combustion engines to electric powertrains has fundamentally altered the acoustic signature of vehicles. While EVs eliminate engine noise, they introduce new challenges related to road noise, wind noise, and specific high-frequency sounds associated with battery systems and electric motors. This shift has accelerated the adoption of specialized materials designed for superior Noise, Vibration, and Harshness (NVH) management.
Car Soundproofing Material Market
Traditional materials are being re-evaluated against new performance criteria. There is a growing preference for lightweight solutions that do not compromise vehicle efficiency, alongside materials that offer dual functionality such as thermal management. Recent industry developments highlight this trend. For instance, leading manufacturers are showcasing next-generation battery solutions that integrate acoustic and thermal management capabilities. At major industry events in 2026, companies like Autoneum presented advanced battery lid technologies for BEV packs that address both safety and acoustic comfort simultaneously. Similarly, the showcase of battery protection plates with integrated thermal and acoustic features underscores the industry's move toward multifunctional components.
Furthermore, raw material costs remain a critical variable. The pricing of acoustic components, including polypropylene and rubber, fluctuates with global energy and crude oil prices. Strategic procurement and supply chain resilience are therefore essential. Companies must balance the need for high-performance materials with cost efficiency, especially as sustainability targets for carbon reduction in automotive production encourage a transition to recyclable and lightweight acoustic materials. The report delves into how these material shifts impact cost structures and supply chain strategies across different material types.
Regulatory Pressures and Evolving Consumer Expectations
External forces are acting as powerful catalysts for market growth. Government restrictions on motor vehicle noise levels continue to tighten, driving demand for advanced soundproofing materials in new vehicle platforms. These regulations are not uniform globally, creating a patchwork of compliance requirements that OEMs must navigate. The pressure is twofold: meeting legal standards while simultaneously satisfying evolving consumer expectations for quieter cabin environments.
Stricter OEM noise specifications are prompting suppliers to innovate beyond baseline compliance. Consumers now expect premium acoustic environments as a standard feature rather than a luxury add-on. This shift in expectations forces manufacturers to rethink their soundproofing strategies across the entire vehicle architecture. The industry context reflects this dynamic tension between regulation, consumer demand, and technological capability. Our analysis explores how these regulatory and consumer-driven dynamics are reshaping the competitive landscape and influencing product development roadmaps for the forecast period.
Competitive Landscape and Key Player Strategies
The market features a diverse mix of specialized acoustic solution providers and large-scale automotive suppliers. The competitive environment is characterized by moderate concentration, with the top three players holding a significant but not dominant share of the market, while the top five extend this reach further. This structure suggests room for innovation and niche specialization alongside the scale advantages held by major conglomerates.
Key companies such as Dynamat, LLC and ResoNix Sound Solutions represent the specialized end of the spectrum, focusing on visco-elastic sheet sound deadening and premium automotive sound deadening materials respectively. These firms often lead in performance-oriented applications. On the other side, large suppliers like Knauf Automotive, Autoneum, and FORVIA leverage broad manufacturing capabilities and OEM relationships to supply foamed polypropylene plastics, multifunctional acoustic solutions, and soft trim systems. The presence of Japanese manufacturers like Toyota Boshoku Corporation and Sumitomo Riko Company Limited further intensifies the competition, particularly in markets prioritizing integrated acoustic interior solutions.
Strategic movements among these players provide insight into future market directions. Recent developments in 2026 show companies actively investing in product launches and industry engagement. Autoneum celebrated the 15th anniversary of its independent operations while simultaneously releasing its annual report and showcasing new battery protection technologies. Adler Pelzer Group participated in the APG Acoustic Symposium to present acoustic solutions, signaling a focus on knowledge sharing and standard-setting. These activities indicate that competition is not just about price, but about technological leadership and alignment with industry trends such as electrification and sustainability. The full report provides a granular analysis of each key company's product portfolio, market positioning, and recent strategic moves.
Regional Nuances and Application Segments
Geography plays a crucial role in market dynamics. Different regions exhibit varying levels of adoption and demand drivers. While some regions show higher revenue contributions due to established automotive manufacturing hubs, others are emerging as growth areas based on increasing vehicle production and sales. The report breaks down these regional disparities without oversimplifying them, offering a nuanced view of where opportunities lie.
Similarly, the application of soundproofing materials varies across the vehicle. Body soundproofing remains a critical area, but engine soundproofing and other applications also contribute significantly to the total market. The specific valuation and growth rates of these segments are essential for companies deciding where to allocate R&D resources. For example, the increased EV battery noise and vibration management requirements have accelerated adoption of specialized NVH foams in electric vehicle interiors, shifting focus toward specific application areas. Understanding the relative weight and growth potential of each application segment is vital for targeted strategy development.
Automotive Sound Insulation NVH Market
Strategic Value for 2026 Decision-Making
Why does this research matter now? The forecast period beginning in 2026 is a decision-critical window. Companies must finalize supply chain strategies, set R&D priorities, and define market entry or expansion plans based on data that accounts for the electrification shift and regulatory changes. Relying on outdated market assessments risks misalignment with the realities of the EV era and new noise regulations.
This report serves as a strategic tool for several key functions:
- Investment Planning: Identifying high-growth segments and regions to allocate capital efficiently.
- Risk Management: Understanding raw material volatility and regulatory shifts to mitigate supply chain disruptions.
- Competitive Benchmarking: Analyzing the strategies of key players to find gaps and opportunities in the market.
- Product Development: Aligning material innovation with OEM requirements for lightweight, sustainable, and multifunctional solutions.
The content within the report extends beyond high-level summaries. It includes detailed segmentation analysis, competitive profiling, and scenario planning that allows executives to stress-test their strategies. It bridges the gap between raw data and actionable intelligence.
Conclusion: The Path Forward
The car soundproofing material market is at an inflection point. The convergence of electrification, regulatory pressure, and consumer demand for comfort is creating a fertile ground for growth, but also complexity. Success in this environment requires more than just general market awareness; it demands precise, data-backed insights. PW Consulting's comprehensive study offers the depth required to navigate these challenges. By understanding the specific dynamics of regional markets, material types, and application segments, stakeholders can position themselves to capture value in a market projected to grow significantly through 2032. To fully leverage these insights for your strategic planning, we invite you to access the complete report where all segmentation data, regional breakdowns, and competitive analysis are detailed.
For detailed analysis of this topic, please visit the official page: Car Soundproofing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chemical Catalyst Market to Reach $511.9 Million by 2032, Growing at 4.48% CAGR
By PW Consulting, 2026-09-16
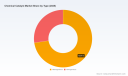
Strategic Imperatives in the Global Chemical Catalyst Market: A 2026 Outlook
The chemical catalyst market stands at a critical inflection point in 2026. As industries navigate the dual pressures of decarbonization mandates and supply chain volatility, catalysts have evolved from mere process enablers to strategic assets that dictate operational efficiency, regulatory compliance, and long-term competitiveness. For executives steering portfolio strategy, capital allocation, and R&D roadmaps, understanding the trajectory of this market is no longer optional—it is foundational.
Precious Metal Catalyst Market
Our latest comprehensive market research report on the chemical catalyst sector provides executives with a rigorous, data-grounded framework to navigate the coming years. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, this analysis captures the structural shifts, competitive maneuvers, and demand-side transformations that will define the industry landscape. Below, we preview the strategic dimensions of this research and articulate why it constitutes an indispensable decision-support tool for 2026 and beyond.
The Macro Trajectory: Sustained Growth Anchored in Industrial Demand
The global chemical catalyst market has demonstrated remarkable resilience and expansion over the past half-decade. Valued at approximately 298.15 million USD in 2020, the sector climbed steadily to reach 375.4 million USD by 2025. This upward trajectory reflects the compounding effect of industrial digitization, expanding petrochemical capacity in emerging economies, and the accelerating deployment of catalysts in environmental and sustainability-driven applications.
Chemical Catalyst Market
Looking ahead, the market is projected to maintain a compound annual growth rate of 4.48 percent through 2032, translating into a valuation of roughly 511.9 million USD by the end of the forecast horizon. This growth is not uniform; it is being shaped by divergent regional industrialization rates, shifting feedstock economics, and deliberate capacity investments by leading manufacturers. For corporate strategists, the implication is clear: the next seven years will reward organizations that align their catalyst procurement, R&D partnerships, and geographic exposure with the underlying demand vectors rather than reacting to short-term price fluctuations.
The report provides a granular breakdown of how these growth dynamics unfold across heterogeneous and homogeneous catalyst categories, as well as across application verticals ranging from petrochemical processing to polymerization, chemical synthesis, and environmental remediation. Rather than presenting static market shares, the analysis maps the interaction between technology readiness, regulatory timelines, and end-user procurement cycles—offering a dynamic view of where value creation is concentrating and where margin compression looms.
Structural Shifts Shaping the 2026 Competitive Landscape
The catalyst industry in 2026 is characterized by a blend of maturity and disruption. On one hand, the market exhibits moderate concentration, with the top three players accounting for approximately 35.5 percent of revenue and the top five commanding 42.0 percent. This concentration reflects the high barriers to entry associated with catalyst development, including proprietary formulation expertise, stringent performance validation, and long qualification cycles in downstream industries. On the other hand, the landscape is being reshaped by technological breakthroughs, evolving environmental regulations, and raw material cost volatility that are altering competitive moats.
Technology and Material Innovation as Differentiators
Recent product launches and capacity expansions underscore how leading firms are leveraging innovation to defend and expand their positions. BASF SE has been particularly active, inaugurating the world's first production facility for 3D-printed sulfuric acid catalysts—a development that signals a broader industry pivot toward advanced manufacturing techniques that enable customized catalyst geometries, improved mass transfer, and reduced waste. Concurrently, the German giant has opened a state-of-the-art R&D center for refinery catalysts co-located with its largest global production site, reinforcing the strategic linkage between research velocity and manufacturing scale. Earlier innovations, such as the SYNSPIRE G1-110 catalyst deployed at Nan Ya Plastics' 2-EH plant, have already demonstrated measurable operational benefits, including annual steam savings and significant CO2 reductions, highlighting how catalyst performance directly translates into sustainability metrics that matter to both regulators and end customers.
Clariant AG has similarly pursued a sustainability-forward product strategy, introducing titanium-based AddWorks catalyst solutions for polyester polymerization as a greener alternative to traditional antimony catalysts. This launch, alongside the earlier deployment of MegaMax 900 methanol synthesis catalysts at European Energy's e-methanol facility in Denmark, illustrates a broader industry trend: catalysts are increasingly being engineered not only for reactivity and selectivity but also for reduced toxicity, lower environmental footprints, and compatibility with renewable feedstock pathways.
Regulatory Pressures and Compliance as Strategic Filters
Regulatory frameworks are exerting an ever-stronger influence on catalyst development, procurement, and market access. Catalyst manufacturers operating in or exporting to European markets must comply with REACH regulations governing substance registration, safety data sheet preparation, and exposure monitoring. For global buyers and suppliers alike, these requirements introduce additional layers of due diligence, documentation, and lifecycle management. Companies that have invested early in compliant formulations, transparent supply chain tracing, and integrated safety protocols are positioned to shorten qualification timelines and reduce regulatory friction. Those lagging behind face the risk of market exclusion or costly remediation. The report examines how REACH compliance and analogous regulatory regimes in other jurisdictions are shaping product portfolios, R&D priorities, and regional market entry strategies.
Feedstock Economics and Raw Material Dynamics
Raw material cost volatility represents another critical variable for 2026 planning. Sulfuric acid, a foundational catalyst precursor and process chemical, has experienced notable price movements driven by shifts in elemental sulfur availability and broader commodity market dynamics. In April 2026, sulfuric acid prices reached approximately 280.80 USD per metric ton in China and 367.80 USD per metric ton in the United States, with upward pressure stemming from reduced byproduct output from copper and zinc smelting operations and volatility in crude oil markets that influence refining activity. For catalyst producers, these feedstock cost fluctuations directly affect margin structures and pricing strategies. For downstream users, they introduce uncertainty into total cost of ownership calculations and underscore the importance of long-term supply agreements, alternative feedstock strategies, and catalyst formulations that optimize material efficiency.
Competitive Intelligence: Navigating a Crowded and Evolving Field
The chemical catalyst market features a diverse set of global players, each with distinct technological competencies, geographic footprints, and strategic priorities. BASF SE, headquartered in Ludwigshafen, Germany, remains a dominant force, particularly in sulfuric acid catalysts, FCC catalysts, and industrial adsorbents. Its recent capacity expansions and R&D investments signal a clear commitment to securing leadership in both traditional and next-generation catalyst applications. Johnson Matthey PLC, based in London, continues to leverage its expertise in precious metal and PGM catalysts to serve chemical and petrochemical end markets, with a particular strength in high-value, performance-critical applications.
Clariant AG, from its Muttenz, Switzerland base, has carved out a strong position in catalysts for propylene, ethylene, and syngas processes, while increasingly differentiating through sustainable formulations. W.R. Grace & Co., operating from Columbia, Maryland, maintains a focused presence in FCC and hydroprocessing catalysts for refining and petrochemical industries, where process reliability and catalyst longevity are paramount. Albemarle Corporation, headquartered in Charlotte, North Carolina, brings its refining and petrochemical catalyst expertise—including its well-known Ketjen brand solutions—to a competitive field where incremental performance gains can yield substantial operational savings.
Haldor Topsoe A/S, based in Lyngby, Denmark, specializes in hydroprocessing and syngas catalysts for chemical synthesis, positioning itself at the intersection of traditional refining and emerging energy transition pathways. Umicore SA, from Brussels, Belgium, brings deep expertise in automotive and industrial precious metal catalysts, leveraging its materials science capabilities across multiple verticals. Evonik Industries AG, headquartered in Essen, Germany, develops specialty catalysts and adsorbents that address niche but high-value chemical applications, often in partnership with downstream innovators. Axens, from Rueil-Malmaison, France, provides catalyst technologies tailored to oil refining and petrochemical processes, with an emphasis on integrated solution delivery. Finally, Sinopec Catalyst Co., Ltd., based in Beijing, China, stands as a major producer of refinery and petrochemical catalysts, reflecting the broader rise of Chinese manufacturers in global supply chains and their increasing capability in both volume production and technology development.
The report provides detailed profiles of these and other key players, analyzing their strategic moves, capacity investments, product launches, and partnership ecosystems. By mapping competitive dynamics against market segmentation and regional demand patterns, the analysis equips executives with the intelligence needed to anticipate competitor behavior, identify partnership opportunities, and assess threats to existing supplier relationships.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Makers
Beyond macro trends and competitive snapshots, this market research report is structured to support concrete business decisions across multiple functional areas. The following elements represent the core operational value provided to subscribers:
- Segmentation Analysis Across Type and Application: The report dissects the market by heterogeneous and homogeneous catalyst types, as well as by application verticals including petrochemicals, polymerization, chemical synthesis, and environmental uses. Each segment is evaluated through the lens of growth drivers, technology maturity, pricing dynamics, and end-user procurement behavior, enabling readers to identify high-opportunity niches and assess the strategic fit of their product or procurement portfolios.
- Regional Demand Mapping and Trade Flow Insights: While the global market is projected to grow steadily, regional trajectories diverge significantly based on industrialization pace, regulatory environment, feedstock availability, and local manufacturing capacity. The analysis provides a nuanced view of demand concentration and growth momentum across key geographies, helping executives calibrate market entry strategies, supply chain configurations, and investment prioritization.
- Competitive Landscape and Strategic Group Mapping: Detailed assessments of leading companies—including their technological capabilities, recent developments, and strategic positioning—allow readers to benchmark their own organizations, identify potential collaborators or acquisition targets, and anticipate shifts in market share and pricing power. The report's coverage of recent capacity expansions, product launches, and R&D investments provides a real-time window into how competitors are shaping the future market structure.
- Regulatory and Compliance Roadmap: With REACH and analogous regulations increasingly influencing catalyst development and market access, the report offers a structured overview of compliance requirements, documentation expectations, and best practices for managing regulatory risk across jurisdictions. This section is designed to support procurement, legal, and R&D teams in aligning their processes with evolving standards.
- Raw Material and Feedstock Risk Assessment: Given the sensitivity of catalyst economics to raw material costs—particularly elemental sulfur, precious metals, and specialty precursors—the report includes an analysis of price trends, supply constraints, and mitigation strategies. This intelligence supports procurement planning, cost modeling, and supplier negotiation strategies in an environment of persistent commodity volatility.
- Forecast Scenarios and Strategic Planning Tools: The 2026–2032 forecast framework is built to support scenario planning, allowing readers to test assumptions around growth rates, segment shifts, and regional demand under different macroeconomic, regulatory, and technology adoption pathways. This flexible structure ensures that the analysis remains relevant even as external conditions evolve.
Strategic Value for 2026 Executive Decision-Making
In an environment where catalyst performance directly influences process efficiency, emissions profiles, and total operating costs, the ability to anticipate market shifts is a decisive competitive advantage. The insights contained in this report are designed to support decision-making across several critical dimensions:
- Portfolio Strategy and R&D Prioritization: By identifying which catalyst types and application segments are experiencing the strongest demand momentum and technological innovation, executives can align R&D budgets, partnership investments, and product development roadmaps with the highest-value opportunities. The analysis of recent product launches and capacity expansions provides a concrete reference point for evaluating where the industry is heading and where white space may exist.
- Procurement and Supply Chain Optimization: For downstream users and industrial buyers, the report's segmentation and regional analysis supports more informed supplier selection, contract structuring, and inventory strategies. Understanding where supply is concentrated, which technologies are gaining traction, and how raw material costs are evolving enables procurement teams to negotiate from a position of knowledge rather than reacting to spot market fluctuations.
- M&A and Partnership Evaluation: The competitive landscape section, combined with the market concentration data and segment growth profiles, provides a structured basis for evaluating potential acquisitions, joint ventures, or technology licensing arrangements. Executives can assess which capabilities are most strategically valuable, which players are strengthening their positions, and where consolidation dynamics may create openings.
- Risk Management and Regulatory Preparedness: With REACH compliance, feedstock volatility, and sustainability expectations all exerting pressure on catalyst markets, the report's coverage of regulatory requirements, raw material trends, and compliance best practices helps organizations anticipate disruptions and build resilience into their operations and supplier relationships.
- Capital Allocation and Geographic Strategy: The regional and segment forecasts support more disciplined capital allocation decisions, whether for new production capacity, R&D facilities, sales and distribution investments, or market entry initiatives. By understanding where demand is growing and which regions present the most favorable regulatory and economic conditions, executives can prioritize investments with greater confidence.
Conclusion: Turning Market Intelligence into Strategic Advantage
The chemical catalyst market is entering a phase where technological innovation, regulatory evolution, and raw material dynamics will increasingly determine which companies capture value and which face margin erosion or strategic obsolescence. The data presented in this research—spanning historical performance, current competitive dynamics, and forward-looking forecasts through 2032—provides a comprehensive foundation for navigating this complexity.
The trajectory from 375.4 million USD in 2025 to an estimated 511.9 million USD by 2032, supported by a 4.48 percent CAGR, reflects more than aggregate growth. It reflects a market being reshaped by deliberate investments in advanced manufacturing, sustainable catalyst formulations, and integrated solution delivery. Companies that understand these shifts at a granular level will be better positioned to optimize procurement, direct R&D investments, manage regulatory risk, and forge strategic partnerships that compound advantage over time.
This report is designed to serve as a strategic reference point for executives across the chemical, petrochemical, refining, environmental, and advanced materials sectors. It combines rigorous quantitative analysis with qualitative insights into competitor behavior, technology trends, and regulatory developments, all structured to support actionable decision-making in 2026 and the years ahead.
To access the full segmentation breakdowns, detailed company profiles, regional demand maps, regulatory compliance frameworks, and scenario-based forecasts, we invite you to visit the source page and explore the complete research deliverables. The depth of intelligence contained in the full report is built to support precise, confident decisions in a market where foresight is the ultimate differentiator.
For detailed analysis of this topic, please visit the official page: Chemical Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Insulating Oil Market Hits $3.41B in 2025, To Reach $5.06B by 2032 at 5.8% CAGR
By PW Consulting, 2026-09-16
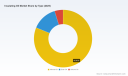
Insulating Oil Market Intelligence Report 2026: Strategic Insights for Power Infrastructure Decision-Makers
The global power transmission and distribution sector stands at a critical inflection point. As aging infrastructure demands modernization and sustainability mandates reshape procurement criteria, insulating oil remains the silent enabler of grid reliability. At PW Consulting, our latest Insulating Oil Market study delivers a comprehensive, data-driven roadmap for corporate strategists, procurement leaders, and engineering executives. This introduction outlines the strategic architecture of the report, highlights the key dynamics that will define the 2026-2032 horizon, and explains why timely, granular market intelligence is no longer optional but essential for competitive positioning.
Executive Overview: Market Trajectory and Strategic Relevance for 2026
Over the historical review window of 2020 through 2025, the insulating oil sector has demonstrated consistent expansion, reflecting steady capital expenditure in electrical infrastructure and a gradual shift toward higher-performance dielectric fluids. The market valuation has progressed from a baseline exceeding two and a half billion USD in 2020 to an estimated base-year valuation approaching three point five billion USD by 2025. This trajectory underscores both the growing electrification footprint across emerging economies and the intensifying maintenance and upgrade cycles in mature grids.
Looking ahead, the 2026-2032 forecast period projects a compound annual growth rate of 5.8 percent. By 2032, the estimated market size is projected to cross the five billion USD threshold. These figures are not merely statistical milestones; they signal structural shifts in fluid chemistry, supply chain diversification, and regulatory compliance pathways. For executives planning capacity investments, supplier negotiations, or product development pipelines, understanding the velocity and direction of this growth is fundamental to mitigating risk and capturing value. The upcoming report translates these macro trends into actionable intelligence, mapping growth pockets, identifying inflection technologies, and quantifying the cost-of-compliance variables that are reshaping procurement economics.
Market Segmentation and Regional Dynamics Decoded
The insulating oil ecosystem is defined by three critical segmentation axes: type, application, and geography. Each dimension carries distinct pricing dynamics, regulatory exposure, and growth profiles that require separate strategic treatment.
By fluid type, the market is anchored by conventional mineral oil formulations, which continue to command the largest share due to legacy infrastructure compatibility and established refining supply chains. Simultaneously, ester-based and silicone-based alternatives are gaining accelerated adoption, driven by heightened fire safety requirements, environmental mandates, and extended equipment lifecycle expectations. The strategic tension between incumbent cost advantages and next-generation performance premiums creates nuanced procurement decisions that demand granular levelized cost analysis.
From an application standpoint, power transformers represent the dominant consumption channel, reflecting their central role in voltage regulation, grid stability, and long-distance transmission. Switchgear, circuit breakers, and reactance assemblies constitute the secondary demand pillar, offering a more specialized but technically demanding application segment where dielectric strength, moisture tolerance, and oxidation stability are non-negotiable performance benchmarks.
Geographically, the market exhibits pronounced divergence. Asia Pacific leads in absolute consumption volume, fueled by rapid grid expansion, industrial electrification, and large-scale infrastructure programs. The North American market reflects a mature but steadily evolving landscape shaped by grid hardening initiatives and aging substation replacements. Europe presents a distinct regulatory-led transition, where sustainability criteria and end-of-life fluid management protocols are accelerating reformulation and recycling investments. Latin American and Middle East and Africa regions operate at lower absolute volumes but exhibit targeted growth pockets tied to specific transmission upgrades and localized industrial demand. The report contains detailed regional demand-to-supply gap analysis, logistics cost modeling, and localized compliance impact assessments that are critical for market entry or capacity allocation decisions.
Insulating Oil Market
Competitive Intelligence: Incumbent Leadership and Strategic Market Maneuvers
The insulating oil sector is characterized by a moderately concentrated competitive landscape. Top-tier players collectively command a substantial share of global production capacity, with the top three and top five firms representing a dominant proportion of the revenue base. This concentration creates a marketplace where scale economies, proprietary refining technologies, and established utility relationships serve as durable moats, while simultaneously leaving space for agile niche players and sustainability-focused innovators to capture differentiated positioning.
The report profiles the core competitive set shaping the market trajectory. Nynas AB, headquartered in Stockholm, continues to reinforce its leadership position in naphthenic transformer oils through the NYTRO brand portfolio, with recent strategic emphasis on bio-based and sustainability-aligned formulations. In May 2025, the company advanced this direction by introducing Nytro Bio 300X, a bio-based ester transformer oil that achieved IEC 62770 vegetable-based fluid classification, delivering dielectric breakdown strength at 800 V/mm and a flash point exceeding 300°C. This launch illustrates how incumbents are leveraging performance credibility to transition legacy customer bases toward eco-compatible alternatives.
APAR Industries Limited, based in Vadodara, India, has built its POWEROIL lineup across naphthenic, iso-paraffinic, and ester-based grades that align with international performance standards. By August 2025, the company secured FM approval for its eco-friendly ester-based natural and synthetic transformer oils, a certification milestone that strengthens its credibility in safety-sensitive procurement environments and opens new addressable segments for sustainable fluid specifications. Savita Oil Technologies Limited, operating from Mumbai with over sixty years of petroleum specialty product experience, remains a recognized producer of TRANSOL transformer oils and insulating fluids, maintaining a strong service orientation for power transmission clients across long operating cycles.
Transformer Oil Market
On the Western hemisphere side, Ergon, Inc. of Jackson, Mississippi, continues to supply dielectric fluids and specialty transformer oils with global distribution reach and rigorous testing infrastructure. In July 2025, the company opened its first Transformer Oil Technology Center in Merak, Indonesia, a strategic facility designed to strengthen quality control, analytical testing, and regional supply responsiveness amid intensifying global energy demand. Aevitas Inc., based in Ayr, Ontario, operates as a specialized supplier and distributor of mineral and silicone insulating oils, complementing its product portfolio with on-site service capabilities and flexible packaging solutions tailored to Canadian and North American transformer operators. Cargill, Incorporated, headquartered in Minneapolis, has intensified its focus on BiO+ FR3 natural ester insulating fluids, emphasizing fire safety and biodegradability. Throughout 2025, the company executed capacity expansion initiatives in the United States to align production capability with rising demand for biodegradable transformer fluid alternatives.
In emerging regional markets, GANELEC of Cape Town delivers IEC-compliant premium transformer oils across Super, High, Standard, and Special grades, supported by filtration services and technical assistance specifically oriented toward African market requirements. The report provides a deeper competitive scoring framework, evaluating each profiled company on manufacturing scale, product breadth, sustainability positioning, certification depth, regional service coverage, and recent strategic capital deployment.
Regulatory Pressures, Environmental Compliance, and Raw Material Volatility
The insulating oil market does not operate in a regulatory vacuum. The 2026 outlook is heavily shaped by overlapping compliance layers that affect formulation choices, supplier qualification, and whole-life cost accounting. In May 2025, the European Union updated its REACH regulation list of Substances of Very High Concern, incorporating certain mineral oil categories used in transformer applications. This update introduces new labeling and reporting obligations with a compliance horizon extending into 2027, compelling distributors, OEMs, and utility operators to reassess inventory strategies, documentation workflows, and substitution pathways.
Beyond Europe, environmental regulations governing the storage, handling, and disposal of used mineral transformer oil are progressively tightening across OECD markets. These evolving standards add compliance overhead and procedural complexity, increasing the relative attractiveness of fluids with reduced environmental persistence and improved end-of-life recoverability. At the same time, crude oil price volatility continues to exert significant influence over the cost structure of petroleum-derived insulating oils. Annual fluctuations approaching thirty percent have been observed, directly affecting pricing predictability for naphthenic and paraffinic variants and reinforcing the case for long-term supply agreements, hedging strategies, and fluid performance optimization that reduces total volume consumption over asset lifecycles.
These dynamics converge to create a decision environment where technical specifications, regulatory foresight, and cost modeling must be integrated rather than evaluated in isolation. The report includes dedicated sections on compliance time horizons, environmental restriction impact mapping, and raw material price sensitivity simulations designed to support scenario planning.
What the Full Report Delivers: Scope, Methodology, and Decision Utility
The PW Consulting Insulating Oil Market study is structured to move beyond surface-level trend description and into operationally actionable intelligence. The full report encompasses historical performance reconstruction for the 2020-2025 period, a forecast model spanning 2026 through 2032, and a multi-layered segmentation framework that enables scenario testing across fluid types, application categories, and regional demand environments.
Key deliverables include:
- A calibrated market size and growth trajectory analysis with sensitivity parameters that reflect regulatory adoption speed, utility capex pacing, and fluid substitution rates.
- Detailed segmentation breakdowns that isolate volume and value dispersion patterns without oversimplifying the strategic differences between mineral, ester, and silicone fluid pathways.
- Competitive landscape assessment covering market share architecture, strategic positioning, product differentiation, certification portfolios, and recent corporate developments across the principal global and regional players.
- Regional market dynamics covering demand drivers, infrastructure investment cycles, import-export logistics considerations, and local compliance burdens that shape opportunity sizing and entry conditions.
- Regulatory and environmental impact analysis that maps impending compliance deadlines, disposal and recycling cost trajectories, and substitution economics for decision-makers evaluating long-term supplier contracts.
- Supply chain and raw material exposure assessment that highlights crude oil linkage, refining margin sensitivity, and logistics cost variability, supporting procurement resilience planning.
- Strategic recommendations tailored for manufacturers, distributors, utility procurement teams, and engineering service providers seeking to align product roadmaps, pricing strategies, and market prioritization with observable demand signals.
The report methodology integrates primary market intelligence, supplier and end-user structural analysis, regulatory tracking, and validated secondary data triangulation. This approach is designed to produce a decision-ready output rather than a passive data collection, ensuring that executive readers can translate findings into investment prioritization, supplier qualification criteria, and regional expansion logic.
Why This Study Matters for 2026 Portfolio and Procurement Strategy
As insulation technologies evolve and environmental expectations harden, organizations that rely on fragmented or outdated market assumptions will face disproportionate exposure to pricing shocks, compliance delays, and specification misalignment. The insulating oil market in 2026 will reward players who can synthesize technical performance, regulatory foresight, and supply chain realism into a coherent commercial strategy. Whether the objective is to secure reliable feedstock access, evaluate entry into ester-based fluid segments, benchmark competitive positioning, or model regional demand growth against infrastructure investment cycles, the underlying data architecture must be robust and current.
The full PW Consulting report provides the analytical depth required to make those decisions with confidence. It connects macro growth signals to segment-specific opportunity sizing, aligns competitive observations with strategic moat analysis, and translates regulatory noise into compliance timelines and cost implications. Most importantly, it preserves the granularity that executive teams need to differentiate viable initiatives from generic assumptions.
To access the complete segmentation models, competitive scoring matrices, regional demand dynamics, and forward-looking scenario frameworks, visit the official PW Consulting Insulating Oil Market research landing page and download the full report. The strategic insights contained within are designed to support informed, timely decision-making throughout the 2026-2032 planning window.
For detailed analysis of this topic, please visit the official page: Insulating Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Para-Cumylphenol Market to Hit $429.87M by 2032 with 5.8% CAGR from $290M in 2025
By PW Consulting, 2026-09-16
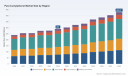
Para-Cumylphenol Market Strategic Outlook 2026: Navigating Growth, Consolidation, and Application Diversification
The global chemical intermediates sector is entering a decisive phase where precision, supply chain resilience, and formulation agility separate market leaders from passive participants. Within this landscape, para-cumylphenol (PCP) has emerged as a foundational building block across multiple high-value downstream industries. Our latest market research delivers a comprehensive, data-driven assessment of the para-cumylphenol market, designed specifically to equip corporate strategists, procurement leaders, and R&D directors with the analytical clarity required for sound 2026 decision-making. This report does not merely track historical volume; it maps the structural forces, competitive pressures, and application shifts that will define commercial trajectories through the end of the decade.
Firms operating in specialty chemicals, advanced materials, and formulation science cannot afford to rely on fragmented supplier briefings or outdated industry snapshots. The para-cumylphenol value chain is experiencing measurable evolution in capacity deployment, grade differentiation, and regional demand pacing. Our analysis integrates verified historical tracking from 2020 through 2025 with a forward-looking projection window spanning 2026 to 2032. The overarching revenue trajectory reflects a compound annual growth rate of 5.8 percent, moving from a baseline valuation of approximately 290.0 million USD in the base year to a projected 429.87 million USD by 2032. These figures are not abstract indicators; they represent the cumulative impact of resin engineering upgrades, adhesive formulation modernization, coating performance mandates, and expanding pharmaceutical intermediate requirements. For executives planning capital allocation, vendor qualification, or geographic footprint adjustments, understanding the pace and composition of this expansion is indispensable.
Why 2026 Demands a Refined Strategic Lens
The current operating environment requires more than top-line forecasting. Companies must evaluate how grade specifications, regional supply dynamics, and end-use substitution patterns interact to shape pricing power, availability, and long-term contract viability. Our research framework is built to surface those linkages without obscuring the operational realities that drive them.
4-Cumylphenol Market
First, the transition from generic chemical sourcing to specification-aligned procurement has intensified. Manufacturers are no longer selecting para-cumylphenol solely on cost; they are evaluating purity thresholds, impurity profiles, batch consistency, and downstream compatibility. Second, the concentration of supply among established producers has created a market structure where relationship management, technical support, and continuity assurance carry substantial commercial weight. Third, application-side innovation is accelerating requirements for tailored intermediate performance, pushing suppliers to align production capabilities with formulation roadmaps rather than treating PCP as a commoditized feedstock. These dynamics converge in 2026, making structured market intelligence a strategic asset rather than an optional reference document.
Report Architecture: What Decision-Makers Will Find Inside
This study is engineered for immediate operational relevance. Rather than presenting isolated statistics, the report constructs a connected analytical narrative that spans market sizing, segmentation logic, competitive positioning, and forward risk mapping. The structure is intended to support multiple decision contexts, from board-level strategic reviews to procurement planning and R&D prioritization.
Readers will encounter a meticulously documented historical reconstruction covering the 2020 to 2025 period, establishing a transparent baseline against which future projections are calibrated. The forecast component extends through 2032 and translates macro-growth signals into actionable directional intelligence. The segmentation architecture dissects the market along multiple commercial dimensions, including product grade classification, application end-use categories, and regional demand distribution. Each segmentation layer is analyzed not as a standalone table, but as an interactive variable that influences pricing behavior, capacity utilization, and supplier selection criteria.
Para-Cumylphenol Market
Beyond sizing and segmentation, the report delivers practical operational content designed to support execution. This includes:
- Detailed assessment of grade differentiation dynamics, with emphasis on how high-purity and low-purity streams serve distinct downstream requirements and pricing environments
- Application-side evaluation that traces how resins, adhesives, coatings, pharmaceutical intermediates, and other industrial uses shape demand stability, substitution risk, and formulation trends
- Regional demand profiling that identifies where consumption momentum is building, which markets are maturing, and how logistical or regulatory factors influence supply routing
- Supply-side structural review that examines capacity deployment patterns, production concentration, and the strategic implications of a consolidated supplier base
- Forward-looking scenario framing that helps organizations stress-test assumptions around volume growth, specification upgrades, and competitive re-alignment through the late 2020s
Every section is cross-referenced to ensure that sizing logic, segmentation behavior, and competitive context reinforce one another. The result is a cohesive intelligence package that allows strategy teams to move from high-level market awareness to targeted commercial action.
Competitive Landscape: Consolidation, Capability, and Commercial Positioning
The para-cumylphenol market is characterized by a notably concentrated supplier environment. Market structure indicators point to a high degree of consolidation, with the top three participants accounting for approximately 80 percent of industry revenue and the top five reaching roughly 82 percent. This concentration is not simply a statistical footnote; it shapes bargaining dynamics, technical service expectations, and supply continuity planning for downstream buyers. In a market where a limited number of producers control the majority of output, relationship durability, specification reliability, and responsiveness to customization requests become central competitive differentiators.
SI Group, Inc., headquartered in Albany, New York, operates as one of the primary large-scale industrial producers of para-cumylphenol. Its commercial relevance extends across multiple downstream pathways, serving as a key intermediate for surfactant production, a monomer for phenolic resins, and a chain terminator in polycarbonate applications. This multi-role positioning gives the company broad exposure to formulation trends and allows it to align production capabilities with diverse end-use requirements.
Dover Chemical, operating through ICC Industries in Findlay, Ohio, manufactures para-cumylphenol as a phenol-based monomer focused on polymer industry applications. Its production orientation reflects the ongoing importance of PCP in polymer engineering, where intermediate quality and consistency directly influence downstream material performance. Suppliers with this profile typically compete on technical reliability, batch control, and the ability to support polymer developers seeking predictable intermediate behavior.
On the Asia Pacific side, Shanghai ShengShan Chemical Technology Co., Ltd. stands out as a major manufacturing presence, recognized as one of China's largest producers of 4-cumylphenol with substantial monthly capacity. Its output supports a wide spectrum of downstream uses, including chemicals, pharmaceuticals, washing products, surfactants, fungicides, preservatives, stabilizers, and electronic-related applications. The breadth of this application base illustrates how a single intermediate supplier can anchor a diversified demand profile, reducing dependence on any single end-use cycle while increasing sensitivity to cross-sector regulatory and formulation shifts.
Beijing Xing Li Gong Mao Co., Ltd. operates as another important supplier within the hydroxybenzene, ketone, aether, and related product spectrum, offering p-cumylphenol as part of a broader intermediates portfolio. Suppliers of this type often compete through portfolio integration, technical documentation support, and supply flexibility, enabling downstream formulators to consolidate vendor relationships while maintaining access to multiple chemical inputs.
Together, these companies illustrate a competitive environment where scale, grade control, application breadth, and geographic positioning intersect. The report examines how such players manage capacity, respond to specification demands, and position themselves relative to regional consumption patterns. Understanding these competitive mechanics is essential for buyers assessing supplier resilience, for investors evaluating market entry or consolidation potential, and for producers benchmarking their strategic posture against established incumbents.
Market Dynamics Shaping Commercial Behavior
The para-cumylphenol market does not evolve in isolation. Its trajectory is influenced by interrelated forces that span raw material economics, downstream formulation priorities, regulatory expectations, and regional industrial development patterns. Our analysis frames these dynamics as actionable considerations rather than abstract trends.
One of the most consequential shifts is the increasing emphasis on performance specification over basic availability. As downstream industries seek improved durability, processing stability, and functional consistency, the value of higher-grade intermediates rises relative to lower-specification alternatives. This does not eliminate demand for standard purity streams, but it reorders commercial priorities and creates a two-tier market environment in which grade alignment, impurity control, and technical support increasingly influence purchasing decisions.
Another defining factor is the concentration of supply and its implications for continuity planning. In a market where a small number of producers command the majority of revenue, procurement teams must look beyond unit pricing and evaluate supplier stability, capacity commitment, and responsiveness to custom grade requests. This environment rewards long-term supplier alignment and makes supplier diversification strategies more complex, since meaningful alternatives may not always be available at comparable specification levels.
Regional demand behavior also plays a central role. Consumption patterns differ by industrial maturity, formulation adoption rates, and local manufacturing footprints. Some markets are driven by established resin and coating production ecosystems, while others are expanding through pharmaceutical intermediate needs, surfactant development, and specialized chemical applications. The report maps these regional variation patterns without reducing them to simplistic rankings, instead highlighting how local industrial structure, logistics, and demand composition influence purchasing rhythm and supply strategy.
How Organizations Can Use This Intelligence in 2026
The strategic value of this report lies in its ability to convert market complexity into structured decision support. For procurement and supply chain leaders, the analysis clarifies where specification requirements are tightening, which supplier relationships merit deeper due diligence, and how regional demand momentum may affect lead times and availability. For R&D and formulation teams, the segmentation and application discussion provides context on how intermediate quality, purity thresholds, and downstream compatibility expectations are evolving across resins, adhesives, coatings, pharmaceutical uses, and other industrial categories.
For executive strategists and corporate planners, the forward projection framework supports scenario planning around volume growth, grade migration, and competitive re-alignment. The report enables organizations to test assumptions about capacity expansion, pricing behavior, and application substitution without relying on unverified industry anecdotes. Investors and market entry teams can use the competitive structure and concentration analysis to evaluate barriers, supplier leverage, and the realistic scope for new capacity or partnership strategies.
Importantly, the study is designed to function as a living reference point for cross-functional alignment. When procurement, technical, and commercial teams share a common evidence base, decisions become faster, risk assessment becomes more disciplined, and supplier negotiations gain strategic context. That is the core purpose of this research: to provide a reliable foundation for 2026 planning and beyond.
What Is Reserved for the Full Report
This overview demonstrates the analytical depth, structural clarity, and commercial relevance of the full study. At the same time, the most operationally sensitive details are intentionally reserved for the complete report. The full version provides the precise segmentation values, regional breakdown figures, application-level revenue distribution, grade-specific sizing, and supplier-level competitive metrics that strategy teams need for concrete planning. Those data points are essential for building procurement models, capacity forecasts, and vendor evaluation matrices, but they are most effective when accessed in full context rather than in isolation.
The complete report also includes the integrated forecasting logic, historical calibration notes, supply-side structural interpretation, and application-side trend mapping that connect high-level market size to practical commercial action. For teams that require defensible numbers, supplier comparisons, and forward-looking scenario support, the full document delivers the granularity needed to move from directional insight to executable strategy.
Para-cumylphenol is no longer a background intermediate; it is a strategically significant input whose market structure, specification demands, and application breadth will increasingly shape downstream competitiveness. Organizations that equip themselves with rigorous, well-structured intelligence will be better positioned to manage supply continuity, align procurement with formulation roadmaps, and anticipate the commercial shifts that define the 2026 to 2032 window. The full report provides the complete evidentiary foundation for that undertaking.
For detailed analysis of this topic, please visit the official page: Para-Cumylphenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Distillation Packings Market to Reach $1,456.41M by 2032 at 6.0% CAGR
By PW Consulting, 2026-09-16
Navigating the Distillation Packings Market: Strategic Intelligence for 2026 Decision-Making
Executive Overview: A Market at an Inflection Point
The global distillation packings market stands at a critical juncture as industrial separation processes demand higher efficiency, lower energy consumption, and stricter compliance with environmental standards. Our latest market research report provides a comprehensive examination of this evolving landscape, offering corporate strategists, procurement leaders, and engineering executives the data-driven foundation needed to make confident decisions in 2026 and beyond.
Building on a historical analysis spanning 2020 through 2025, our forecast model projects sustained growth through 2032, anchored by a compound annual growth rate of 6.0 percent. The market, valued at approximately 965.22 million USD in the 2025 base year, is expected to reach 1,019.74 million USD in 2026 and continue its upward trajectory toward 1,456.41 million USD by 2032. These figures reflect more than incremental expansion; they signal a structural shift in how industries approach mass transfer equipment, driven by technological advancement, regulatory pressure, and regional capacity realignment.
This article serves as a strategic preview of our full Distillation Packings Market report. It highlights the analytical framework, competitive intelligence, and operational dynamics that decision-makers must understand to position their organizations advantageously. Core segmentation data, regional revenue breakdowns, and application-specific valuations are reserved for the complete publication, where they are presented with the granularity required for actionable planning.
Distillation Packings Market
Market Trajectory: From Recovery to Sustained Expansion
The five-year historical window from 2020 to 2025 reveals a market that has consistently outpaced initial projections. Revenue climbed from 750.15 million USD in 2020 to 965.22 million USD by 2025, reflecting a recovery trajectory that accelerated as petrochemical and chemical processing facilities resumed capital expenditure programs following earlier disruptions. The steady year-over-year progression underscores durable demand for distillation internals across multiple processing sectors.
Our forecast period, covering 2026 through 2032, models a continuation of this momentum. The market is projected to surpass the 1 billion USD threshold in 2026 and reach 1,090.35 million USD by 2027. Subsequent years show compounding growth, with valuations of 1,165.98 million USD in 2028, 1,249.42 million USD in 2029, and 1,305.96 million USD in 2030. The latter half of the forecast window reflects moderating but still robust expansion, culminating in a 1,456.41 million USD market size by 2032. This trajectory is supported by ongoing capacity additions in emerging industrial corridors, retrofits of aging distillation columns, and the gradual substitution of conventional trays with advanced packing solutions that deliver superior theoretical stage efficiency.
It is important to note that these aggregate figures provide the macro foundation for our analysis. The complete report dissects the underlying drivers segment by segment, enabling clients to identify which product categories, material specifications, and end-use verticals are contributing most significantly to growth. This layered approach ensures that strategic planners can align procurement timelines, capacity investments, and partnership decisions with the segments that match their operational priorities.
Structural Dynamics: Technology, Regulation, and Operational Realities
Several interconnected forces are reshaping the distillation packings landscape and will continue to influence purchasing behavior throughout the forecast period. First, the technical differentiation between structured and random packing architectures remains a central consideration for process engineers. Structured packings, with their engineered surface area and controlled flow distribution, are increasingly favored in applications where pressure drop minimization and high separation efficiency are paramount. Random packings continue to occupy a significant share of the market, particularly in scenarios where cost-effectiveness, ease of installation, and tolerance for uneven liquid distribution are prioritized. Grid packings and other specialized variants address niche requirements, including high-capacity vacuum operations and temperature-sensitive distillations.
Material selection is another critical determinant of market behavior. Metal packings, typically fabricated from stainless steel or specialty alloys, dominate segments requiring corrosion resistance, mechanical strength, and long operational life. Plastic packings serve applications where chemical compatibility, weight reduction, and lower initial cost are decisive factors. Ceramic packings, while representing a smaller portion of overall demand, remain essential in highly corrosive environments and specific chemical processing contexts. The interplay between material performance, fabrication complexity, and total cost of ownership creates a nuanced decision matrix that our report analyzes in detail.
Regulatory and operational dynamics are equally influential. Environmental regulations targeting volatile organic compound emissions in chemical plants are accelerating the preference for low-emission structured packings in distillation applications. These regulations are not merely compliance checkboxes; they are reshaping engineering specifications and prompting facility operators to reevaluate existing column internals. At the same time, the skilled labor cost differential for precision installation and maintenance of structured packings, which averages 15 percent higher than for random packings, introduces a practical consideration that procurement and operations teams must weigh against long-term efficiency gains.
Supply chain and fabrication considerations further complicate the landscape. Custom corrosion-resistant packings designed for aggressive chemical processes require specialized surface treatments that increase fabrication time by approximately 20 percent compared to standard metal media. Meanwhile, raw material pricing dynamics, such as the current unit price of stainless steel wire gauze for structured packings at approximately 45 USD per cubic foot, directly affect margin structures and pricing strategies. These factors are integrated into our market dynamics analysis to provide a realistic picture of cost pressures, lead time implications, and negotiation leverage.
Competitive Landscape: Key Players and Strategic Positioning
The distillation packings market exhibits moderate concentration, with the top three companies holding a combined market share of 55.5 percent and the top five accounting for 62.3 percent. This concentration reflects the technical barriers to entry, the importance of established engineering relationships, and the value of proprietary packing designs that have been validated across decades of industrial operation. Our report provides a thorough competitive assessment of the organizations shaping this landscape.
Sulzer AG, headquartered in Winterthur, Switzerland, is recognized as a core provider of Mellapak series structured packings and BXPlus gauze packings for distillation columns. The company emphasizes low pressure drop and high efficiency in chemical and petrochemical separations, and its January 2025 introduction of the MellapakEvo structured packing demonstrates a continued commitment to performance enhancement. Koch-Glitsch, based in Wichita, Kansas, USA, offers FLEXIPAC HC structured packings and INTALOX ULTRA random packings, along with the Montz Pak line, optimized for crude vacuum distillation and high-capacity applications. Their portfolio reflects a strong focus on processing conditions that demand robust mechanical design and flexible capacity scaling.
Raschig AG, located in Ludwigshafen, Germany, develops and supplies Raschig Super Ring random packings and metal structured packings for distillation, with a clear emphasis on high-performance mass transfer media. Julius Montz GmbH, also based in Germany, specializes in Montz-Pak wire gauze structured packings tailored for vacuum and temperature-sensitive distillations, delivering low pressure drop per theoretical stage. These European incumbents maintain strong positions through engineering heritage, consistent product innovation, and deep integration with global process design firms.
The competitive field also includes several manufacturers with significant regional presence and growing international reach. Finepac India, headquartered in Pune, manufactures FP series and wiremesh structured packings for distillation columns, prioritizing corrosion resistance and broad application range. Goel Impex, based in New Delhi, supplies high-performance structured packings for distillation, absorption, and stripping, with an emphasis on customized chemical resistance solutions. Ambani Metals, located in Ahmedabad, produces advanced structured packings for efficient separation in distillation and related processes, supported by global export capabilities. These organizations illustrate the expanding influence of manufacturers outside the traditional European and North American core, particularly as cost-competitive engineering and material expertise become increasingly valued.
Chinese suppliers such as Pingxiang Xingfeng Chemical Packing Co., Ltd. and Jiangxi Kelley Chemical Packing Co., Ltd., both based in Pingxiang, Jiangxi, contribute meaningfully to the market. Pingxiang Xingfeng supplies metal random packings including Pall rings for distillation columns, serving petrochemical and chemical industries, while Jiangxi Kelley provides tower packing and structured packings with a focus on high-efficiency random and metal media. In the United States, Mach Engineering, headquartered in Houston, Texas, manufactures X and Y corrugated structured packings for distillation columns, offering both custom and off-the-shelf options. The presence of these diverse players underscores the importance of evaluating suppliers not only by brand recognition but by alignment with specific process requirements, lead time expectations, and regional service capabilities.
Report Contents: Operational Intelligence for Strategic Planning
Our Distillation Packings Market report is structured to deliver practical value at every stage of the decision-making process. Rather than presenting abstract market narratives, the publication focuses on actionable intelligence that can be integrated into capital planning, supplier evaluation, product development, and competitive positioning. The report includes the following core components:
Mass Transfer (Distillation) Market
- Historical and Forecast Revenue Analysis: A detailed examination of market size evolution from 2020 through 2025, followed by a year-by-year forecast extending to 2032. This section provides the quantitative backbone for scenario planning and investment timing.
- Segmentation Framework: A systematic breakdown of the market by type, material, application, and region. Each segmentation dimension is analyzed to reveal growth patterns, share dynamics, and the strategic implications of shifting demand.
- Competitive Profiling: In-depth company assessments covering product portfolios, technological focus, geographic reach, and recent developments. Profiles are designed to support supplier selection, partnership evaluation, and competitive benchmarking.
- Market Dynamics and Cost Drivers: An integrated discussion of raw material pricing, labor cost differentials, fabrication complexity, regulatory influences, and infrastructure considerations that affect total cost of ownership and procurement strategy.
- Strategic Recommendations: Actionable guidance for navigating capacity investments, technology adoption, supplier diversification, and regional market entry, tailored to the needs of engineering firms, processing companies, and equipment manufacturers.
By combining quantitative rigor with qualitative industry context, the report enables clients to move beyond high-level trends and into the specifics that determine project success. Whether the objective is to optimize a distillation column retrofit, evaluate a new supplier relationship, or anticipate demand shifts in a target region, the analysis is organized to support evidence-based decisions.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle presents a unique set of considerations for organizations operating in or adjacent to the distillation packings market. On one hand, the projected growth trajectory suggests expanding opportunity across multiple segments and geographies. On the other hand, the concentration of market share among a limited number of established players, combined with evolving regulatory requirements and cost pressures, demands a disciplined approach to strategy. Our report is designed to help decision-makers navigate this environment with clarity.
For procurement and engineering leaders, the report offers a structured basis for comparing packing types, materials, and supplier capabilities against specific process conditions. The segmentation analysis clarifies where performance advantages are most pronounced and where cost-driven considerations may justify alternative selections. For corporate strategists and investors, the forecast data and competitive profiling provide a foundation for assessing market entry opportunities, partnership potential, and long-term demand visibility. For product development teams, the discussion of operational dynamics, including fabrication time implications and environmental regulation trends, highlights the innovation areas most likely to influence future purchasing criteria.
Importantly, the report does not treat the market as a monolithic entity. It recognizes that the drivers of demand in petrochemical processing differ from those in chemical manufacturing, pharmaceutical applications, and oil and gas operations. Similarly, regional variations in industrial activity, regulatory frameworks, and supplier ecosystems require tailored strategic responses. By preserving the granularity of segmentation data within the full publication, we ensure that clients can extract the precise insights relevant to their operational context without relying on generalized assumptions.
Conclusion: Turning Market Intelligence into Strategic Advantage
The distillation packings market is characterized by steady growth, meaningful technological differentiation, and a competitive structure that rewards organizations capable of aligning product capabilities with process requirements. Our comprehensive report translates this complexity into a clear, data-supported framework that decision-makers can use to reduce uncertainty, prioritize investments, and strengthen their competitive position.
The macro trajectory, from a 965.22 million USD market in 2025 to a projected 1,456.41 million USD by 2032, provides the broad context. The detailed segmentation, competitor analysis, and dynamics assessment provide the precision needed to act confidently. For leaders who require a complete view of the market, including the specific regional, application, and product-level data that underpin our forecasts, the full Distillation Packings Market report is available for immediate review. We invite you to access the complete publication to obtain the full intelligence package and begin integrating these insights into your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Distillation Packings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MIBC Market to Reach $309.17M by 2032, Driven by 4.8% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Methyl Isobutyl Carbinol (MIBC) Market: Navigating Growth and Complexity Through 2032
The global chemical landscape is undergoing a period of structural recalibration, where specialty intermediates like Methyl Isobutyl Carbinol (MIBC) serve as quiet but critical enablers of industrial productivity. From froth flotation in extractive operations to formulation chemistry in coatings and pharmaceutical processes, MIBC occupies a nuanced position in the value chain. Yet, despite its widespread utility, strategic decision-makers often lack a consolidated view of how capacity shifts, regulatory pressures, feedstock volatility, and regional demand patterns converge to shape long-term market trajectories.
This is the explicit purpose behind PW Consulting's latest market research on the Methyl Isobutyl Carbinol (MIBC) Market. Designed as a decision-grade intelligence asset, the report translates years of historical performance, current market architecture, and forward-looking scenario modeling into a coherent strategic narrative. Drawing on a rigorous base year of 2025 and an extensive historical window spanning 2020 through 2025, the study charts a detailed forecast horizon from 2026 to 2032, enabling executives to move beyond reactive planning and toward anticipatory positioning.
The analysis projects the overall MIBC market to expand steadily through the end of the decade, supported by a compound annual growth rate of 4.8 percent measured in U.S. dollars across the forecast window. Historical revenue progression establishes a clear baseline of resilience and incremental expansion, with market valuations building consistently from early-2020s levels and advancing toward a measured trajectory into the late 2020s and early 2030s. This sustained upward path is not merely a function of baseline industrial activity; it reflects the interplay of capacity investments, evolving end-use requirements, and the market's ability to adapt to shifting regulatory and supply-chain conditions. By anchoring the forecast in this historical continuum, the study provides a defensible framework for capital allocation, sourcing strategy, and competitive positioning.
Decoding the Architecture of the MIBC Market
The MIBC market is defined less by a single growth driver than by a mosaic of interdependent demand streams, production grades, and regional dynamics. Understanding how these elements interact is essential for any organization seeking to anticipate shifts in pricing behavior, supply availability, or competitive intensity. The report structures this complexity through a multi-dimensional lens that captures the major demand verticals, the differentiated grade landscape, and the geographic distribution of consumption without reducing the picture to oversimplified aggregates.
On the application side, industry demand spans a broad spectrum of industrial and specialty uses. The analysis explores how flotation-related requirements in mining operations anchor a significant share of consumption, reflecting MIBC's established role as a froth modifier and process aid. At the same time, the study spends considerable attention on the coatings and paints sector, where MIBC functions as a solvent and performance modifier, and on pharmaceuticals and other specialized applications that demand consistent purity and reliability. Each end-use channel carries its own sensitivity to macroeconomic cycles, regulatory scrutiny, and formulation trends. Rather than presenting static allocations, the research examines how these application domains evolve in response to operational demands, substitution pressures, and downstream innovation.
The grade dimension introduces an additional layer of strategic nuance. Technical-grade and industrial-grade MIBC serve distinct customer priorities and market expectations, and their relative positioning shapes pricing behavior, supply-chain requirements, and product development roadmaps. The report maps these grade-level dynamics to help stakeholders understand where value is created, where margin structures diverge, and how quality specifications influence procurement decisions across different buyer segments.
Methyl Isobutyl Carbinol (MIBC) Market
Geographically, the market exhibits a broad but uneven footprint. Demand concentrations reflect long-standing industrial infrastructure, mining activity clusters, coatings and manufacturing ecosystems, and the gradual maturation of regional supply networks. The research provides a structured regional framework that highlights where consumption is most established, where growth momentum is building, and how local production capabilities interact with cross-border trade flows. Importantly, the analysis connects these regional patterns to practical implications for sourcing diversification, market entry timing, and competitive exposure, enabling readers to see geography not as a static map but as a dynamic variable in strategic planning.
Competitive Landscape and Strategic Positioning
The MIBC market is characterized by a relatively concentrated corporate architecture, where a limited set of major producers holds substantial influence over capacity, pricing norms, and innovation directions. This concentration creates both opportunities and constraints for market participants, making competitive intelligence a central pillar of effective strategy. The report delivers a detailed evaluation of the core companies shaping the sector, examining their production footprints, technological capabilities, and recent strategic moves.
European and North American multinationals continue to anchor a significant portion of global capacity. BASF SE, operating from its Ludwigshafen site, has pursued capacity expansions that reinforce its ability to serve downstream demand across flotation frothers, lubricants, and coatings applications. Eastman Chemical Company has taken a distinctly process-oriented approach, integrating real-time monitoring and sustainability enhancements into its MIBC manufacturing to strengthen operational efficiency and support solvent applications in coatings and related fields. Dow Chemical Company maintains MIBC as part of a broader chemical portfolio, leveraging integration pathways that connect production with mining and industrial solvent use cases. Celanese Corporation produces MIBC through established acetone and MIBK routes, supported by a global distribution network that feeds flotation and specialty markets. AkzoNobel N.V. contributes a wide manufacturing footprint focused on coatings, lubricants, and industrial processes, while Solvay S.A. emphasizes high-purity grades for specialty applications spanning mining, pharmaceuticals, and chemical production. Arkema Group and Evonik Industries AG further round out the multinational field, each bringing integrated production capabilities and specialized application focus to their MIBC offerings.
Alongside these established players, regional producers have increasingly asserted themselves through targeted capacity investments and quality-focused supply strategies. In China, Zibo Nalcohol Chemical Co., Ltd. expanded MIBC production capacity by 20 percent with a new production line in early 2024, strengthening its supply position for industrial solvents and frother applications. Shenyang East Chemical Science-Tech Co., Ltd. has built a reputation for consistent-quality MIBC serving mining, coatings, lubricants, and chemical manufacturing, underpinned by stringent quality control practices. These developments illustrate how regional capacity additions can alter supply balances, create new bargaining dynamics, and influence pricing expectations across specific market segments.
The report further contextualizes these company profiles within the broader competitive structure by examining market concentration indicators. With the three largest firms accounting for a substantial share of market revenue and the top five collectively representing an even greater proportion, the industry exhibits a clear hierarchy that shapes competitive behavior. Understanding this concentration is critical for buyers evaluating supplier dependency, for producers assessing the risk of reactive pricing, and for new entrants gauging the barriers associated with scale, integration, and established customer relationships.
Market Dynamics: Feedstock, Regulation, and Geopolitical Pressure
No strategic assessment of the MIBC market is complete without a rigorous examination of the external forces that can accelerate, constrain, or redirect growth. The report devotes substantial attention to the operational and regulatory dynamics that influence both supply-side economics and end-use demand patterns, recognizing that these factors often determine the difference between nominal growth and commercially meaningful expansion.
Feedstock economics form one of the most immediate pressure points. Acetone serves as the primary upstream feedstock for MIBC production, and the trajectory of acetone pricing exerts a direct influence on manufacturing cost structures. The analysis incorporates this relationship into its forward-looking framework, demonstrating how feedstock volatility can compress margins, alter supply-chain behavior, and affect the commercial viability of capacity expansions. By connecting acetone market conditions to MIBC production economics, the study helps stakeholders anticipate cost-driven adjustments in pricing, procurement timing, and inventory strategy.
Regulatory developments introduce an equally important layer of complexity. The European Union's REACH framework, including ECHA's CoRAP evaluation processes, alongside the U.S. EPA's TSCA risk evaluation, has the potential to impose restrictions on MIBC concentrations in solvent applications. These regulatory tracks can reshape formulation requirements, influence product substitution decisions, and alter the competitive balance between grades and applications. Compounding this dynamic, stricter VOC emission standards under the EU Paints Directive and U.S. EPA NESHAP are pressuring coatings formulators to reduce MIBC use in certain contexts. The report examines how these regulatory currents create both compliance demands and innovation incentives, particularly as producers and formulators explore environmentally friendlier alternatives and adjusted formulation architectures.
Geopolitical and supply-chain disruptions further complicate the operating environment. A notable example emerged in April 2026, when U.S. acetone supply tightened sharply due to Middle East shipping disruptions, raising domestic MIBC feedstock costs. Such events underscore the vulnerability of chemical supply chains to logistics bottlenecks, regional instability, and sudden shifts in freight and sourcing conditions. The research integrates these types of disruption scenarios into its strategic analysis, helping organizations assess exposure, evaluate contingency planning, and determine where supply diversification or inventory buffering may deliver tangible resilience benefits.
Taken together, these dynamics illustrate that the MIBC market cannot be evaluated through price and volume alone. Strategic success increasingly depends on anticipating regulatory trajectory, managing feedstock exposure, and building operational flexibility in the face of external shocks.
What the Report Delivers: Operational Depth for Strategic Decisions
The value of this study lies not only in its market sizing and forecasting but in the breadth of operational insight it provides to practitioners. The report is structured to support a wide range of strategic use cases, from executive-level market evaluation to procurement planning, product portfolio assessment, and competitive benchmarking. It combines top-level market architecture with granular analytical modules designed to translate data into action.
Readers gain access to a comprehensive segmentation framework that examines demand by region, type, and application. Rather than simply reporting splits, the analysis interprets what these divisions mean for growth momentum, pricing behavior, and competitive exposure. This approach allows stakeholders to identify which segments are most sensitive to regulatory change, which are best positioned to absorb feedstock cost pressure, and where capacity additions are most likely to alter market balance.
The competitive analysis section delivers company-level profiles that go beyond descriptive summaries. For each major player, the report evaluates production orientation, recent strategic developments, product and application emphasis, and the implications of those moves for broader market dynamics. Recent developments are woven directly into the narrative to show how individual corporate actions—such as capacity expansions, process optimization initiatives, sustainability program launches, and monitoring system deployments—contribute to shifting supply conditions and competitive expectations.
The study also integrates industry-context analysis across feedstock relationships, regulatory trajectories, and geopolitical supply risks. By mapping these themes to specific sections of the market structure, the report helps readers connect external conditions to internal decision points. This includes evaluating the extent to which acetone price movements may affect manufacturing economics, understanding how evolving REACH and TSCA processes could influence solvent-based applications, and assessing the implications of VOC-driven formulation pressure for coatings-related demand.
Throughout, the research maintains a practical orientation. It is designed to answer the questions that matter most to executives and operational leaders: where is demand structurally supported, where is growth more conditional, which competitive moves are likely to reshape supply availability, and what external risks should be priced into planning assumptions. The synthesis of these elements creates a decision-making foundation that can be applied across strategy, sourcing, product development, and risk management functions.
Why the 2026 Outlook Demands a Disciplined Intelligence Edge
As organizations move deeper into the 2026 planning cycle, the MIBC market presents a case study in how specialty chemical sectors reward foresight. The combination of steady long-term growth, concentrated competition, feedstock sensitivity, and regulatory evolution creates an environment where generic assumptions are quickly exposed. Companies that rely on fragmented data sources or outdated market impressions risk misjudging cost trends, overcommitting to vulnerable supply relationships, or overlooking shifts in application-level demand.
This research is built to reduce that uncertainty. By contextualizing historical performance within a disciplined forecast framework and layering in competitive, regulatory, and supply-chain analysis, the report equips decision-makers with a more complete picture of the forces shaping the market through 2032. It highlights not only where growth is likely to materialize but also where strategic caution is warranted, enabling a more balanced approach to investment, procurement, and market positioning.
At the same time, the breadth of this analysis is intentionally supported by detailed segment-level intelligence that goes beyond the scope of this overview. The full report contains the depth of segmentation data, regional demand interpretation, grade-specific dynamics, and company-level strategic evaluation needed to convert high-level insight into precise operational decisions. Accessing the complete study allows readers to move from directional understanding to actionable precision, with the analytical rigor required to support board-level discussion and cross-functional execution.
A Strategic Lens for the Decade Ahead
The Methyl Isobutyl Carbinol (MIBC) Market is not defined by dramatic discontinuities, but by the accumulation of supply-side investments, demand-side pressures, regulatory evolution, and external shocks that gradually reshape competitive conditions. For organizations operating in or adjacent to this market, the strategic imperative is clear: understanding the direction of travel is necessary, but understanding the mechanics behind that direction is what separates reactive participants from proactive strategists.
PW Consulting's market research on MIBC provides that mechanics-focused perspective. It offers a structured, evidence-based view of market size, growth trajectory, segmentation behavior, competitive positioning, and the dynamic forces that will influence outcomes across the 2026 to 2032 horizon. By combining macro-level forecasting with detailed operational analysis, the study is designed to serve as a durable reference point for strategic planning in a market where informed anticipation is a genuine competitive advantage.
Acetyl Tributyl Citrate (ATBC) Market
For detailed analysis of this topic, please visit the official page: Methyl Isobutyl Carbinol (MIBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ferrisil Nickel Market hits $187.5M in 2025, projected 5.15% CAGR to $265.5M by 2032
By PW Consulting, 2026-09-16
Navigating the Ferronickel Market in 2026: Strategic Intelligence for Forward-Looking Enterprises
The global ferronickel industry stands at a critical inflection point. As of the 2025 base year, the total market valuation across the period from 2020 to 2025 reflects a landscape defined by shifting supply chains, evolving regulatory frameworks, and changing demand dynamics driven by stainless steel and alloy manufacturing. Looking ahead, the market is projected to expand from an estimated 197.49 million USD in 2026 to 265.5 million USD by 2032, representing a compound annual growth rate of approximately 5.15 percent. These figures underscore a steady, predictable expansion trajectory, yet beneath the headline numbers lies a complex web of operational decisions, policy interventions, and competitive maneuvers that will determine market winners and laggards over the next seven years.
For procurement leaders, supply chain strategists, and executive decision-makers, understanding these layered dynamics is no longer optional. Early 2026 has already witnessed notable operational catalysts, including the commencement of bulk carrier shipments from newly activated mining operations and the anticipated restart of legacy ferronickel plants following favorable price rallies. At the same time, regulatory shifts such as Indonesia’s differentiated export treatment for ferronickel versus nickel pig iron, coupled with the European Union’s carbon border adjustment data collection mandates, are reshaping trade flows and cost structures. This report has been designed to translate these macro-level signals into actionable, granular intelligence that can be integrated directly into corporate strategy, risk management, and investment planning frameworks.
Unpacking the Ferronickel Market Research: Core Components and Analytical Scope
Our comprehensive Ferronickel Market study is structured to serve as both a diagnostic tool and a forward-looking planning instrument. Drawing on historical data spanning 2020 through 2025, the analysis establishes a robust baseline against which near-term projections and long-range forecasts can be evaluated. The research methodology incorporates multi-source data triangulation, primary industry interviews, and cross-referenced supply-demand modeling to ensure accuracy and relevance for executive audiences.
Key deliverables within the report include:
- Historical Baseline and Trajectory Modeling: A detailed review of market performance from 2020 to 2025, charting revenue movements across multiple operational cycles and identifying the structural drivers behind observed trends.
- Forward-Looking Forecast Framework (2026-2032): A scenario-based projection model that maps expected market evolution under baseline conditions, with explicit consideration of supply-side constraints, demand elasticity, and policy variables.
- Segment-Level Deep Dives: Granular analysis across product classifications and downstream applications, revealing cost structures, substitution dynamics, and demand sensitivity without exposing the proprietary percentage splits and revenue allocations reserved for full-report subscribers.
- Regional Market Architecture: A comparative assessment of geographic demand centers and supply corridors, highlighting infrastructure bottlenecks, trade route efficiencies, and localized regulatory environments that influence pricing and availability.
- Competitive Intelligence dossier: Strategic profiles of leading producers, including operational footprints, capacity investments, partnership networks, and recent corporate developments that signal positioning for the 2026-2032 cycle.
- Regulatory and Raw Material Risk Mapping: An integrated review of export quota adjustments, carbon compliance requirements, ore supply constraints, and pricing transmission mechanisms that directly impact production economics.
The report’s architecture is deliberately designed for operational utility. Each section connects market-level observations to decisions that procurement teams, plant managers, and investment committees face on a weekly basis. Rather than offering abstract market commentary, the analysis prioritizes questions that matter: Where are supply bottlenecks likely to emerge? Which product grades will command premium pricing under tightening ore quotas? How should firms structure procurement contracts to hedge against volatility in raw material delivery and carbon compliance costs?
Structural Dynamics Shaping the 2026 Market Environment
Several interconnected forces are actively reshaping the ferronickel supply-demand equilibrium entering 2026. On the supply side, raw material availability has become a central constraint. Recent industry analysis indicates that major lateritic ore operations in Indonesia have adjusted their 2026 mining quotas significantly below prior-year levels, tightening available feedstock for ferronickel and nickel pig iron production. This quota compression has already translated into elevated delivered pricing for key input materials, with regional nickel pig iron benchmarks reaching levels that reflect both scarcity and logistical delivery costs. Firms that rely on long-term ore supply agreements are now re-evaluating contract terms, while spot-market purchasers face heightened exposure to price volatility.
Simultaneously, operational ramp-ups and restarts are altering the supply narrative. One Philippine-listed producer has initiated bulk carrier shipments from its Surigao operations, targeting multi-million metric ton annual volumes, while a second mine site within the same portfolio began its 2026 mining season with initial shipments directed toward Chinese buyers. In parallel, a European-linked operating group has announced plans to restart both mine and ferronickel plant operations in the first half of 2026, capitalizing on recently improved price conditions. These activity shifts demonstrate that the market is not merely reacting to constraints but actively reconfiguring production capacity in response to price signals and strategic timing.
Regulatory developments add another layer of complexity. Indonesia’s decision to exempt nickel pig iron from a planned centralized export policy while classifying ferronickel differently due to its iron content creates a differentiated export landscape that will influence trade routing and competitive positioning between neighboring producing nations. Meanwhile, downstream importers into the European Union must now navigate data collection and reporting requirements associated with carbon border adjustment mechanisms, applying to both ferronickel and nickel pig iron as of 2025. For companies with significant EU exposure, compliance planning and emissions documentation are transitioning from peripheral concerns to core operational prerequisites.
Ferronickel Market
Worldwide Ferro Titanium Market
Together, these dynamics create a market environment where cost transparency, supply security, and regulatory readiness are decisive competitive advantages. The ability to anticipate quota adjustments, model price transmission through the value chain, and align procurement strategy with evolving compliance obligations will separate agile market participants from those forced into reactive positioning.
Competitive Landscape: Strategic Positioning of Key Industry Players
The ferronickel competitive landscape is characterized by a mix of large-scale diversified miners, regionally focused producers, and specialized alloy manufacturers. Market concentration metrics indicate a moderately consolidated environment, with a handful of leading firms commanding substantial share while a broader tier of regional operators competes on cost efficiency, local integration, and product specialization. Understanding the strategic posture of key competitors is essential for forecasting supply behavior, anticipating pricing pressure, and identifying potential partnership or acquisition opportunities.
Among the most prominent operators, Tsingshan Holding Group has established a significant presence through Indonesian smelter partnerships and integrated laterite ore processing, with a clear strategic emphasis on cost-efficient production for stainless steel applications. Its operational model reflects the broader industry trend toward vertically aligned supply chains that span mining, smelting, and downstream alloy fulfillment. Similarly, Eramet continues to leverage its foothold in New Caledonia and Indonesia, maintaining production of higher nickel-content grades while executing structural balance sheet initiatives designed to preserve operational continuity amid fluctuating commodity cycles.
Vale’s diversified footprint across Indonesia, the Philippines, and New Caledonia underscores the strategic value of geographic diversification in managing ore supply risk and optimizing logistics. PT Antam, as an Indonesian state-owned producer, occupies a distinct position shaped by national industrial policy objectives and domestic downstream processing priorities. Koniambo Nickel’s operations in New Caledonia highlight the continued relevance of lateritic ore processing in established mining jurisdictions, while Anglo American and South32 maintain their own integrated pathways into ferronickel and ferroalloy output through varied asset portfolios.
On the regional manufacturing side, several Chinese and Southeast Asian producers play critical roles in satisfying domestic alloy and stainless steel feedstock demand. Jiangsu Delong Nickel Industry, Shandong Xinhai Technology, Shengyang Group, Linyi Yichen Alloy, SNNC, Pacific Steel Mfg, and Sumitomo Metal Mining each contribute to the broader competitive fabric through specialized production lines, regional distribution networks, and integrated smelting capabilities. European producers such as Larco and Precomprimido further diversify the geographic supply base, catering to regional alloy and foundry requirements while navigating evolving compliance environments.
Recent corporate developments provide tangible signals of how these players are adapting to current conditions. The commencement of mining operations and initial bulk shipments from a Philippine-listed producer illustrates the pace at which new output capacity can enter the market when financing, permitting, and logistical readiness align. Similarly, the operational restart efforts undertaken by a European-linked group in early 2026 demonstrate how price rallies can act as catalysts for reengaging dormant assets. These movements are not isolated events; they reflect a broader industry rhythm in which capacity deployment, quota constraints, and commodity pricing continuously reshape competitive positioning.
What the Full Report Delivers: Decision-Ready Intelligence for 2026 Planning
While the high-level market trajectory and competitive landscape provide essential context, the full Ferronickel Market research report delivers the detailed, decision-ready intelligence that operational leaders require to move from awareness to action. The study goes beyond aggregate sizing to map the specific segments, regional corridors, and application categories that drive revenue concentration and cost variability. Readers seeking complete visibility into how product grade demand intersects with regional supply capacity, or how application-level consumption patterns respond to downstream manufacturing cycles, will find those analyses comprehensively developed within the full report.
The competitive profiling section extends beyond corporate summaries to include strategic capability assessments, investment signals, partnership dynamics, and operational risk exposures that influence each major player’s likely behavior over the forecast horizon. By connecting corporate strategy to market-level outcomes, the report enables readers to anticipate supply responses, evaluate potential disruptions, and model scenarios that factor in competitor decision-making.
Additionally, the regulatory and raw material analysis integrates recent operational disclosures and policy announcements into a structured framework that highlights their direct implications for procurement planning, contract structuring, and cost forecasting. This includes coverage of export quota adjustments, ore supply constraints, carbon compliance data requirements, and pricing transmission trends that affect delivered material costs across multiple jurisdictions. For firms managing cross-border supply chains, these insights provide the foundation for more resilient sourcing strategies and more accurate total cost of ownership calculations.
The report is built for immediate application. Strategic planners can use the segmentation and regional analysis to align inventory targets with anticipated supply availability. Finance and procurement teams can incorporate the cost and pricing dynamics into contract negotiations and hedging frameworks. Executive leadership can leverage the competitive intelligence and regulatory mapping to evaluate market entry, partnership, or capacity investment opportunities with greater confidence.
Conclusion: Act on Intelligence, Not Assumptions
The ferronickel market’s projected expansion over the 2026-2032 period reflects durable demand foundations, but that growth will be distributed unevenly across regions, product types, and applications. Firms that enter this cycle armed only with aggregate market numbers risk missing the structural nuances that determine pricing leverage, supply reliability, and competitive positioning. The strategic value of comprehensive market research lies precisely in its ability to transform broad trends into specific, actionable insights that inform procurement strategy, capacity planning, and risk mitigation.
Our full Ferronickel Market report provides the depth, granularity, and forward-looking analytical frameworks required to make informed decisions in a market defined by quota shifts, operational restarts, carbon compliance demands, and evolving competitive dynamics. For organizations that require complete segmentation data, regional and application-level revenue allocations, detailed competitor capability assessments, and scenario-based forecasting models, the complete study offers a comprehensive intelligence foundation tailored to 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Ferronickel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refractory Metals Market Hits $7.0 Billion in 2025, Projected to Reach $8.39 Billion by 2032
By PW Consulting, 2026-09-16
Securing Critical Edges: Strategic Intelligence for the Refractory Metals Market Through 2032
Refractory metals form the backbone of high-performance engineering, enabling capabilities in aerospace, electronics, and industrial manufacturing that no other material class can match. As geopolitical tensions reshape supply chains and advanced manufacturing drives new demand vectors, understanding the trajectory of this specialized market has become a strategic imperative for executives, investors, and procurement leaders. The latest market research from PW Consulting delivers a comprehensive, data-driven assessment of the global refractory metals landscape, projecting market evolution from the base year of 2025 through the forecast horizon of 2032. This article previews the strategic insights contained within the full report, highlighting the structural dynamics, competitive forces, and regulatory headwinds that will define decision-making in the years ahead.
Market Architecture: Growth Trajectory and Structural Foundations
The global refractory metals market has demonstrated steady expansion over the historical period from 2020 to 2025, progressing from a revenue base of 5.8 billion USD to a projected 7.0 billion USD by 2025. This growth reflects sustained demand from high-value end-use sectors alongside incremental capacity additions and evolving material specifications. Looking forward, the forecast period spanning 2026 to 2032 indicates continued market development, with overall revenue projected to advance toward 8.39 billion USD by the terminal forecast year. The compound annual growth rate across the forecast window registers at 2.7 percent, representing a measured but resilient expansion profile characteristic of a mature, capital-intensive materials sector.
This growth trajectory is neither uniform nor guaranteed. It reflects the interplay of structural demand drivers, supply-side constraints, pricing dynamics, and regional trade policy shifts. The report dissects these layers systematically, providing decision-makers with a framework to evaluate where value will concentrate, which segments will outperform, and how external shocks may alter baseline projections. Rather than offering a static snapshot, the analysis maps the conditional pathways that market participants are likely to navigate, emphasizing the importance of scenario planning and supply chain flexibility.
Refractory Metals Market
Segmentation Dynamics: Where Value Is Created and Competitive Pressure Intensifies
The market segmentation architecture examined in the research reveals several structural characteristics that are critical for strategic positioning. By material type, the market is anchored by tungsten and molybdenum, which together dominate revenue share and underpin the majority of industrial and advanced manufacturing applications. Tantalum and niobium represent smaller but strategically vital subsegments, often serving niche, high-specification roles in electronics, aerospace, and specialty alloys. The report details how these material categories differ not only in absolute scale but in pricing sensitivity, supply concentration, technological substitution risk, and end-market growth profiles.
From an application perspective, aerospace and defense, alongside electronics and semiconductors, constitute the primary demand engines for refractory metals. These sectors demand high purity, consistent quality, and certified supply chains, creating premium positioning for suppliers who can meet stringent qualification requirements. The steel industry remains a meaningful consumption channel, though its growth dynamics are more closely tied to broader industrial cycles and infrastructure investment patterns. The full report breaks down these application profiles with granular attention to demand drivers, material specifications, and the competitive implications of shifting procurement strategies across each vertical.
Regionally, the analysis captures a globally distributed market with meaningful participation across North America, Europe, and Asia Pacific, alongside smaller but strategically relevant activity in Latin America and the Middle East and Africa. The geographic distribution of production capacity, processing infrastructure, and end-market consumption shapes trade flows, tariff exposure, and competitive dynamics in ways that the report examines in depth. Readers of the full publication will find a detailed mapping of regional supply-demand balances, import dependency trends, and the localized effects of trade policy actions that are already altering market behavior.
Competitive Landscape: Concentration, Vertical Integration, and Strategic Maneuvering
Market concentration in the refractory metals sector registers at a CR3 of 38 percent and a CR5 of 45 percent, indicating a moderately consolidated landscape where a handful of large, globally integrated players command significant share, while a broad base of regional specialists, niche processors, and recyclers compete on service, quality, and application expertise. The competitive environment is further shaped by the presence of major primary producers, sophisticated downstream fabricators, and an active secondary processing and recycling ecosystem that is increasingly relevant as supply security and sustainability considerations intensify.
The research provides detailed company profiles and strategic assessments for a comprehensive set of participants spanning North America, Europe, China, Brazil, and Chile. Key North American entities include established producers and fabricators such as Cleveland Tungsten, Inc., Cronimet Specialty Metals USA, Inc., Elmet Technologies LLC, Global Tungsten & Powders LLC, Hyperion Materials & Technologies, Innovative Carbide LLC, Kennametal Inc., Lineage Metallurgical, Molymet Corporation, Niagara Refining LLC, PLANSEE USA LLC, Rhenium Alloys Inc., Thomas & Skinner, Inc., Umicore Canada Inc., and Vista Metals. These organizations represent a cross-section of the industry's capabilities, from primary production and powder metallurgy to specialty alloys, carbide products, and secondary recovery.
On the global stage, the competitive field includes significant primary producers and material specialists such as Jinduicheng Molybdenum Co., Ltd. and Xiamen Tungsten Industry Co., Ltd. in China, CBMM in Brazil as a leading niobium producer, Molymet in Chile, the Plansee Group in Austria, Treibacher Industrie AG, ATI, H.C. Starck Tungsten GmbH in Germany, Ningxia Orient Tantalum Industry, and Climax Molybdenum in the United States. The full report evaluates these players across dimensions including capacity positioning, product breadth, technological capabilities, geographic reach, and strategic responsiveness to supply chain and regulatory shifts.
Recent corporate activity underscores the dynamic nature of this competitive environment. In August 2025, Molymet incorporated Molymet Alloys, LLC in Delaware to advance higher value-added products and related activities, signaling a deliberate move up the value chain. In October 2025, Molymet completed the acquisition of all rights and shares of Rhenium Alloys, Inc., expanding its footprint across molybdenum, tungsten, rhenium, and semiconductor-related product lines. These moves illustrate how established players are consolidating capabilities to capture margin, broaden application coverage, and strengthen supply chain control. The report analyzes such developments not as isolated events but as indicators of broader strategic themes reshaping industry structure.
Market Dynamics: Regulation, Trade Policy, and Supply Chain Realignment
The refractory metals market is operating in an environment where regulatory frameworks, trade policy actions, and raw material pricing dynamics are exerting increasingly direct influence on competitive outcomes. Several developments captured in the research illustrate the nature and pace of these shifts. As of November 2025, the average monthly price for tantalum ore stood at 180 USD per kilogram of Ta2O5 content, reflecting the premium attached to secure, qualified supply in a market with concentrated production and growing demand from electronics and defense applications. In 2025, U.S. tantalum apparent consumption increased 58 percent to 890 tons, accompanied by corresponding rises in imports, highlighting the sensitivity of domestic demand to supply availability and pricing.
Trade policy actions are introducing new volatility and cost structures into the market. In February 2025, China implemented new export controls on selected tungsten items, contributing to sharp price rises for tungsten concentrates and reinforcing concerns about supply concentration for a material that is central to multiple high-value applications. Concurrently, U.S. Section 301 tariffs on tungsten products from China increased to 25 percent effective January 1, 2025, altering the cost calculus for importers and incentivizing efforts to diversify sourcing or develop domestic and allied-supply alternatives. The research also notes that U.S. imports for tungsten concentrates showed increased reliance on China, with data from 2021 to 2024 indicating a 26 percent share amid ongoing supply constraints, underscoring the persistence of dependency even as policy and strategic efforts push toward greater supply autonomy.
These dynamics are not merely background conditions; they are actively reshaping procurement strategies, capacity investment decisions, and competitive positioning. The report integrates these factors into its market assessment, providing a structured evaluation of how regulatory and trade developments influence price formation, supply security, regional competitiveness, and the strategic calculus of major buyers and producers alike. Decision-makers relying on the full publication will find these insights contextualized within scenario frameworks that account for the range of plausible policy and supply outcomes over the forecast period.
Strategic Developments: Capacity, Recycling, and Defense-Driven Demand
Recent activity across the industry points to a clear strategic thrust toward capacity enhancement, supply chain domestication, and the valorization of secondary materials. In November 2025, 6K Additive received a 1.95 million USD Phase II government contract to produce certified tungsten, niobium, and other refractory metal powders from domestic military scrap for defense applications, illustrating the growing intersection of advanced manufacturing, recycling, and national security priorities. Also in November 2025, the U.S. Defense Logistics Agency awarded an 8.6 million USD delivery order for tantalum ingots and secured up to 100 million USD for domestic tantalum processing from ore, reinforcing the strategic importance of tantalum for defense and aerospace applications and signaling sustained government commitment to building resilient domestic supply capabilities.
Further reflecting the push toward supply chain resilience and circular material flows, Plansee Group announced and advanced a U.S. capacity expansion project in February 2026 focused on tungsten recycling and refractory metals production. This development, alongside the broader activity in secondary processing and recycling among firms such as Lineage Metallurgical, Niagara Refining LLC, and Vista Metals, indicates that recycling and material recovery are moving from peripheral considerations to central components of supply strategy. The full report assesses these developments within the context of long-term market evolution, examining how capacity additions, recycling scale-up, and defense-driven procurement intersect with commercial demand growth and competitive dynamics.
Why This Research Matters for 2026 Decision-Making
The refractory metals market presents a distinctive strategic challenge: it is simultaneously a mature, structurally stable materials sector and a rapidly evolving environment shaped by trade policy, supply concentration, technological demand shifts, and heightened attention to supply security. Navigating this landscape requires more than high-level market sizing or generic demand narratives. It demands a precise understanding of segment-level growth drivers, competitive positioning, pricing and cost dynamics, regulatory exposure, and the strategic implications of recent corporate and policy developments.
Refractories Market
The PW Consulting Refractory Metals Market research is designed to meet that need. It combines rigorous historical analysis, a structured forecast framework extending to 2032, detailed segmentation and regional assessment, comprehensive competitive profiling, and integrated analysis of the regulatory and trade dynamics that are actively reshaping the market. The full report goes beyond the macro trajectory to provide actionable intelligence on where value is being created, which competitive moves are reshaping industry structure, and how buyers, producers, and investors can position themselves to manage risk and capture opportunity.
For executives and strategists operating in 2026, the difference between reactive positioning and proactive advantage lies in the quality of intelligence available. The insights previewed here are drawn from a broader body of analysis that drills into the specifics of material-level demand profiles, application-driven pricing dynamics, regional supply-demand balances, competitive capabilities, and the strategic significance of recent contract awards, capacity expansions, acquisitions, and regulatory actions. To access the complete dataset, segmentation detail, competitive assessment, and scenario-based forecasts that underpin these conclusions, we invite you to explore the full report through the source webpage. The comprehensive intelligence contained within is intended to serve as a foundational reference for strategic planning, procurement strategy, investment evaluation, and competitive positioning across the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Refractory Metals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the AMI Inflection Point: Strategic Intelligence for 2026 and Beyond
The Advanced Metering Infrastructure (AMI) landscape is undergoing a structural transformation that demands more than cursory market awareness. As utilities, technology providers, and infrastructure investors calibrate their roadmaps for 2026, the difference between reactive adaptation and proactive market capture hinges on decision-grade intelligence. Our latest market research synthesizes historical trajectories, forward-looking revenue projections, competitive signaling, and regulatory momentum into a single evaluative framework. This article outlines the strategic contours of that research and explains why granular, forward-looking AMI intelligence has become a non-negotiable input for enterprise decision-making in 2026.
The Scale and Trajectory of the AMI Market
Over the historical window from 2020 through 2025, the global AMI market expanded from approximately 11.28 billion USD to 25.06 billion USD. That near-doubling of reported revenue in five years signals more than cyclical upturn; it reflects a foundational re-architecture of how utilities measure, communicate, and manage consumption data across electricity, water, and gas networks. The momentum does not plateau after the base year. Forecasts extending through 2032 project the market climbing to roughly 53.69 billion USD, sustained by a compound annual growth rate of 11.6 percent. This trajectory places AMI squarely among the infrastructure technologies where capital allocation, partner selection, and product positioning carry long-tail consequences.
Several dynamics explain why this expansion is structurally durable. Meter replacement cycles are accelerating in legacy networks where analog or early-generation digital devices can no longer support real-time outage detection, demand response integration, or consumer-facing analytics. At the same time, grid-edge intelligence is shifting metering from a passive billing endpoint to an active node within distribution automation and distributed energy resource management. The revenue trajectory, when read alongside evolving technical standards and cybersecurity expectations, indicates that spending is migrating from hardware-only procurements toward integrated communication layers, data management platforms, and services that sustain network reliability over multi-decade asset lives.
For executives, the strategic implication is straightforward: AMI is no longer a procurement category evaluated solely on unit cost and certification compliance. It is a platform investment whose value compounds through data accessibility, interoperability, and the ability to scale post-deployment. Market-level projections provide context, but the operational questions that determine outcomes—where to deploy first, which communication architectures to standardize, how to sequence software and services spend—are resolved only through segmented analysis that maps growth pools to specific utility requirements and regional regulatory environments. That level of resolution is the core deliverable of our full study, available through the source page, where detailed breakdowns replace headline figures with decision-ready granularity.
Advanced Metering Infrastructure (AMI) Market
Competitive Architecture and Strategic Positioning
The AMI supplier landscape is characterized by a concentrated core of incumbents complemented by specialized players who compete on regional reach, communication technology, or vertical-specific functionality. The market reveals meaningful concentration at the top, with the three largest firms collectively accounting for a substantial share of industry revenue, while the broader top five maintains equivalent aggregate positioning. This concentration signals that scale advantages in manufacturing, network operations, and data platform development continue to matter. Yet concentration at the top does not imply uniformity of strategy. The competitive field is differentiated by how companies sequence hardware, communication infrastructure, software, and services, and by the extent to which they align their portfolios to utility modernization roadmaps.
Itron continues to anchor its AMI positioning around smart residential and commercial metering solutions built for two-way communication, remote upgradeability, interval data storage, and consumer engagement. Its AMI 2.0 orientation and grid-edge intelligence emphasis illustrate a broader industry shift from closed metering appliances to extensible endpoints that can evolve with distribution system needs. Landis+Gyr has focused its offering on next-generation AMI systems that deliver real-time data visibility, edge-level analytics, and intelligent metering across electric, gas, and water applications. That posture reflects the growing utility expectation that meter networks should contribute directly to grid modernization rather than serve as isolated data collectors. Aclara, operating within a broader network technology context, emphasizes smart metering for electric, gas, and water utilities with enhanced grid reliability and customer interaction enabled by two-way AMI networks.
European and globally operating players add distinct value propositions. Sagemcom has expanded its AMI footprint through the SICONIA AMI 2.0 electricity meter family and end-to-end solutions for energy and water, supported by ANSI certification and advanced communication terminals. Honeywell brings its Alpha 4 series into the residential, commercial, and industrial AMI space, emphasizing two-way communication, tamper detection, and integration into smart grid networks. Kamstrup differentiates through advanced metering solutions for water that incorporate embedded acoustic leak detection, flexible RF and AMI networks, and software designed to improve operational efficiency—a clear example of how metering portfolios are extending beyond measurement into loss reduction and asset management.
Asia-linked and internationally active suppliers further broaden the competitive field. Wasion promotes cellular-based AMI solutions and comprehensive smart metering for electricity, water, gas, and heat, leveraging IoT technology and scalable head-end systems that appeal to utilities seeking deployment flexibility and remote scalability. Iskraemeco contributes with residential smart energy meters and eIoT meter series designed for modular communication, smart grid integration, and optimized energy management.
These company-level orientations matter because procurement decisions in AMI are increasingly portfolio decisions. Utilities and large end-users weigh not only device compliance and price but also the resilience of communication pathways, the extensibility of data management capabilities, and the vendor’s ability to support longitudinal service relationships. Recent project activity reinforces this pattern. In December 2025, Itron and the City of Tucson commissioned a new AMI project for water conservation using cellular-based AMI Essentials, deploying 250,000 smart water communication modules alongside a Network-as-a-Service model. In August 2025, Siemens and TRC Companies collaborated with the Salt River Project to upgrade to Gridscale X MDMS, enhancing scalability and data insights for AMI 2.0 readiness. By April 2026, the Jurupa Community Services District reported 50 percent completion of its systemwide AMI project for water meters since September 2025, enabling real-time monitoring through the EyeOnWater application, while the City of Corona Utilities reached 50 percent of installations in its water AMI project that began in summer 2025 using Professional Meters, Inc. as installer.
These developments are not isolated milestones; together, they show how rapidly utilities are moving from planning to partial deployment and how communication architecture, software integration, and service delivery models are becoming integral to project success. Our full report examines the competitive field in greater depth, mapping product and service positioning, recent project activity, and strategic implications for buyers and suppliers. The source page provides the detailed company analyses, cross-referenced developments, and actionable takeaways that headline summaries cannot capture.
Worldwide Distribution Meter Market
Regulatory Signals and Supply Chain Realities
Regulatory developments in 2025 and early 2026 are reshaping how AMI deployments are justified, communicated, and recovered. In the United States, the Colorado governor signed legislation in May 2025 requiring utilities to notify residential customers before installing AMI and to explain their right to refuse installation, a measure that elevates customer transparency and consent into the deployment process. In July 2025, the Kentucky Public Service Commission granted Kentucky Power’s application for a certificate of public convenience and necessity for AMI deployment and regulatory asset recovery of costs, reinforcing the principle that well-structured AMI investments can be recovered when tied to clearly defined public convenience objectives. At the transmission-system level, Texas legislation signed in June 2025 directed ERCOT to develop a demand management service for mandatory curtailment of large loads, effective on or after January 1, 2026, deepening the connection between metering infrastructure and demand-side flexibility.
Outside the United States, the Energy Regulatory Commission of the Philippines approved amended rules to govern AMI implementation by distribution utilities in November 2025, updating 2016 guidelines with technical standards, cybersecurity protocols, and consumer data privacy safeguards. This regulatory evolution illustrates a broader pattern: jurisdictions are moving from permissive AMI frameworks toward more prescriptive expectations around technical performance, data protection, and consumer rights. For utilities and suppliers, that shift means compliance is no longer a static checklist. It is a moving target that must be managed across device certification, communication security, data governance, and customer communication strategies.
On the supply side, AMI hardware relies on widely used semiconductor technologies, including system-on-chip processors and communications chipsets. The supply chain risk profile is therefore aligned with broader electronics and battery supply chains rather than concentrated around rare earth elements. This reality carries two strategic implications. First, component availability and lead-time dynamics can influence deployment pacing and pricing, especially when large municipal or utility-scale procurements coincide with electronics market tightness. Second, product architectures that reduce exposure to single-source dependencies or that emphasize software-defined upgradability can offer more resilient operating economics over the asset life. Our research connects these supply chain considerations to procurement sequencing, vendor selection, and total-cost-of-ownership modeling, issues that require detailed, segment-level evaluation rather than aggregate market figures.
What the Full Study Delivers
The complete market research translates these macro trends and event-level signals into a structured intelligence toolkit designed for 2026 decision-making. Rather than stopping at headline revenue and growth rates, the study builds a practical anatomy of the AMI market across multiple lenses that matter to strategy, procurement, and investment teams. The report is organized to help readers move from awareness to action.
Within the study, readers will find:
- A comprehensive market size and forecast framework that traces revenue trajectories across the historical period and extends through the 2026 to 2032 horizon, with context on the pace and shape of growth.
- Segment-level analysis that disaggregates the market by region, by type, and by application, enabling readers to understand where value is concentrating and how different deployment categories compare in scale and growth behavior.
- Competitive profiling of leading AMI participants, including corporate positioning, offering focus, and the strategic implications of recent projects and technology directions.
- A curated synthesis of recent project milestones, technology integrations, and commissioning activity that shows how AMI initiatives are progressing on the ground and what deployment models are gaining traction.
- Regulatory and reimbursement analysis that connects policy developments, certification expectations, data privacy requirements, and cost recovery mechanisms to planning and procurement risk.
- Supply chain and component considerations that frame semiconductor dependence, communication technology choices, and resilience strategies in the context of multi-year deployment planning.
Crucially, the study maintains a decision-oriented editorial standard. Where aggregate figures establish the strategic stakes, the segmented and company-level analysis provides the resolution needed to evaluate market entry timing, partnership strategy, product roadmap alignment, and procurement prioritization. The detailed regional, type-based, and application-based revenue structures, along with the deeper company and project analyses, are presented in full within the source report so that teams can benchmark assumptions, pressure-test forecasts, and align internal planning with the latest available evidence.
Why This Research Matters for 2026 Decisions
The 2026 planning cycle arrives at a moment when AMI investments intersect directly with grid modernization, customer communication obligations, water loss management, demand flexibility, and data-enabled operational efficiency. Utilities must decide not only whether to deploy AMI but how to sequence technologies, which communication and data architectures to standardize, and how to structure contracts that align vendor incentives with long-term service performance. Suppliers and technology partners must determine where to concentrate product development, which geographies and utility segments to prioritize, and how to differentiate beyond device compliance. Investors and market analysts need to distinguish durable growth drivers from short-term procurement timing effects.
In that environment, strategic advantage comes from information that is both comprehensive and precisely segmented. Aggregate market expansion confirms that the opportunity is large and growing; it does not, by itself, reveal which segments are accelerating fastest, where regulatory frameworks are most supportive or most restrictive, how competitive positioning differs across regions and applications, or how recent project experience is reshaping procurement expectations. Those are the questions that determine execution quality in 2026 and beyond.
Our full AMI market research is designed to answer those questions with the analytical depth and operational relevance that enterprise decisions require. The complete regional, type, and application breakdowns, together with the extended competitive and project-level analyses, are available through the source page. Teams that need to translate market momentum into concrete planning choices will find the detailed intelligence essential for framing scenarios, validating assumptions, and aligning strategy with the most current evidence base.
For detailed analysis of this topic, please visit the official page: Advanced Metering Infrastructure (AMI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biosurfactant Sales Hit $9.02B in 2025, Forecast to $16.93B by 2032 at 9.41% CAGR
By PW Consulting, 2026-09-16
Biosurfactants Market 2026: Strategic Intelligence for the Green Chemistry Transition
The global chemical landscape is undergoing a paradigm shift, driven by stringent environmental regulations, consumer demand for sustainable products, and the urgent need to reduce reliance on petrochemical derivatives. At the forefront of this transition lies the biosurfactant sector. For strategic decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise but a critical component of supply chain resilience and product portfolio optimization. PW Consulting's latest market research provides a comprehensive roadmap for navigating these complexities, offering data-driven insights that extend beyond surface-level trends to uncover underlying structural shifts.
This analysis serves as a strategic overview of the biosurfactant landscape, synthesizing historical performance, growth projections, and competitive dynamics. It is designed to equip industry leaders with the context necessary to make informed capital allocation and product development decisions in a rapidly evolving environment.
Market Trajectory and Growth Momentum
The biosurfactant market has demonstrated consistent resilience and expansion over the past half-decade. Historical data from 2020 through 2025 indicates a steady upward climb in revenue, reflecting the gradual but firm integration of bio-based solutions into mainstream industrial and consumer applications. The market valuation has grown from approximately $5.75 billion in 2020 to an estimated $9.02 billion by 2025. This historical performance lays the groundwork for an aggressive forecast period extending through 2032.
Looking ahead to the 2026-2032 forecast period, the trajectory suggests an acceleration in adoption rates. The market is projected to reach $10.1 billion in 2026, growing to nearly $16.93 billion by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of 9.41 percent. Such growth rates indicate that biosurfactants are moving from niche applications to mainstream commoditization in specific high-value segments. For stakeholders, this implies that the window for establishing early-mover advantages in supply chain partnerships and proprietary formulation technologies is narrowing.
It is crucial to note that this growth is not uniform across all vectors. While the aggregate numbers paint a picture of robust health, the underlying distribution of revenue across regions and applications reveals strategic opportunities that remain partially obscured without granular analysis. The overall market size figures provide a macro foundation, but the real strategic value lies in understanding where the marginal growth dollars are originating and which segments are driving the CAGR.
Industry Dynamics and Regulatory Tailwinds
The acceleration of the biosurfactant market is inextricably linked to a confluence of regulatory pressures and raw material innovations. Several key dynamics are reshaping the cost structures and compliancerequirements for manufacturers, creating both headwinds for traditional petrochemical surfactants and tailwinds for bio-based alternatives.
Regulatory frameworks in major markets have tightened significantly. In Europe, the EU REACH regulations have imposed stricter rules on poorly biodegradable surfactants, prompting a rapid substitution effect. Companies utilizing traditional surfactants face increasing compliance costs and reputational risks, driving them to seek biodegradable alternatives. Furthermore, the EU Industrial Emissions Directive and REACH Annex XVII have introduced new benchmarks requiring biodegradable surfactant alternatives in various industrial processes. These regulatory shifts are not merely compliance checkboxes but are fundamentally altering the addressable market for biosurfactants.
On the policy front, the EU Renewable Energy Directive III has designated glycerol-based biosurfactant products as advanced bio-based chemicals. This designation unlocks carbon credits, improving the economic viability of production and incentivizing investment in glycerol-based pathways. Similarly, in the United States, the EPA Safer Choice program has expanded its listings of green surfactants, enabling biosurfactants like rhamnolipids to serve as compliant alternatives for manufacturers seeking eco-labels.
Raw material dynamics are also playing a pivotal role. A significant development in fermentation economics involves the substitution of crude glycerol from biodiesel production for refined vegetable oils in rhamnolipid fermentation. This shift cuts feed costs substantially, resulting in lower biosurfactant ex-factory prices. This cost optimization enhances the competitiveness of biosurfactants against their synthetic counterparts, removing one of the primary barriers to adoption in price-sensitive applications.
Competitive Landscape and Strategic Positioning
The competitive environment in the biosurfactant market is characterized by a mix of established chemical giants and specialized biotechnology firms. Concentration metrics indicate a consolidated landscape where a small number of players hold significant sway. The CR3 and CR5 concentration ratios both stand at 40.7 percent, suggesting that while the top tier is influential, there is substantial room for mid-tier and niche players to capture value through specialization and regional focus.
Leading incumbents are leveraging their scale and technical expertise to secure market share. Evonik Industries AG, headquartered in Essen, Germany, focuses on producing high-purity rhamnolipids and sophorolipids from renewable corn feedstocks via industrial-scale fermentation at its Slovak plant. This capability allows them to supply consistent, high-quality volumes to demanding sectors. Similarly, Solvay S.A. in Brussels provides biosurfactants and bio-based chemical solutions for both industrial and consumer markets, integrating these products into broader sustainable portfolios. Croda International Plc, based in the UK, produces glycolipid biosurfactants and offers technical support specifically for detergent and personal care uses, highlighting the importance of application-specific know-how.
In personal care and premium applications, Kaneka Corporation and Givaudan SA are prominent. Kaneka manufactures high-purity biosurfactants for premium cosmetic applications, while Givaudan provides biosurfactants for premium personal care and clean-label products, leveraging their fragrance and flavor dominance to cross-sell sustainable ingredients. Stepan Company, operating out of Northfield, Illinois, offers rhamnolipid biosurfactants derived from renewable feedstocks targeted at detergents and personal care, aligning their portfolio with high-volume consumer goods.
Specialized producers are also making significant moves. Jeneil Biotech Inc. and Biotensidon GmbH focus on rhamnolipid and microbial biosurfactants respectively, catering to eco-friendly formulations and eco-labeled detergents. AGAE Technologies, LLC has been particularly active in capacity expansion. In early 2025, they inaugurated the largest retrofitted manufacturing plant in Asia with annual capacity exceeding 1,000 metric tons of rhamnolipid biosurfactants. They subsequently opened a new 3,800 m² plant in Asia with similar capacity and announced US facility plans. Dispersa Inc. in Canada transitioned from pilot reactors to a 50,000 L commercial-scale system targeting 100 metric tons per year of sophorolipids. These capacity expansions signal a shift from R&D curiosity to commercial readiness.
Regional players are also strengthening their positions. Saraya Co., Ltd. and Allied Carbon Solutions Co., Ltd. in Japan specialize in MES and other biosurfactants for industrial cleaning and detergent formulations. Shaanxi Deguan Biotechnology Co., Ltd. in China produces sophorolipid biosurfactants for industrial and personal care markets. Holiferm Ltd. in the UK specializes in sophorolipid production for mass-market eco-friendly surfactants. Locus Fermentation Solutions in the USA develops EPA-approved biosurfactants for personal care and industrial applications. These diverse geographic footprints suggest that supply chain localization is becoming a strategic priority for end-users seeking to mitigate logistics risks.
Report Scope and Methodology
To navigate this complex ecosystem, comprehensive intelligence is required. The PW Consulting Biosurfactant Market research report is structured to provide actionable intelligence across multiple dimensions. The analysis covers a detailed historical review from 2020 to 2025, establishing a baseline for performance evaluation. This historical context is critical for validating growth models and understanding the impact of recent regulatory changes on market uptake.
The forecast period extends from 2026 through 2032, allowing stakeholders to model long-term investment returns and capacity planning. The report dissects the market across key segmentation vectors including region, type, and application. While aggregate growth is positive, understanding the split between Glycolipids, Lipopeptides, and Phospholipids is essential for R&D focus. Similarly, analyzing demand drivers across Detergents, Personal Care, Food Processing, and Oil & Petroleum sectors reveals where margin opportunities are most pronounced. Geographic analysis covers Europe, North America, Asia Pacific, Latin America, and the Mideast and Africa, highlighting regional regulatory nuances and supply chain dynamics.
Microbial Biosurfactants Market
Beyond market sizing, the report includes detailed profiles of key companies, assessing their strategic moves, capacity expansions, and product offerings. Recent developments such as joint ventures, new plant inaugurations, and technology transitions are tracked to provide real-time intelligence on competitive momentum. The analysis also incorporates qualitative dynamics regarding raw material sourcing, regulatory impacts, and technological shifts that quantitative data alone cannot capture.
Biosurfactant Market
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in 2026, the biosurfactant market presents a clear imperative: sustainability is no longer optional, and bio-based chemistry is becoming economically viable. The convergence of regulatory pressure, cost optimization through raw material substitution, and capacity expansion by key players creates a inflection point. Companies that hesitate to integrate biosurfactants risk facing higher compliance costs and supply chain vulnerabilities as petrochemical alternatives face stricter scrutiny.
However, the market is not monolithic. The presence of specialized players alongside giants suggests that partnership strategies will be crucial. A detergent manufacturer may not need to become a fermentation expert but can leverage partnerships with firms like Jeneil Biotech or AGAE Technologies to secure supply. Conversely, ingredient suppliers must navigate the varying requirements of personal care versus industrial cleaning applications, as purity and performance specifications differ significantly.
The data suggests that Asia Pacific and Europe remain critical theaters for growth, driven by both consumption patterns and regulatory leadership. Yet, detailed regional splits and application-specific penetration rates contain the nuanced intelligence required to prioritize specific markets. Access to the full dataset is necessary to identify the specific high-growth pockets within the broader $16.93 billion endpoint.
Investment in capacity, whether through CAPEX or joint ventures, must be timed against the demand curve. The recent capacity expansions by AGAE, Dispersa, and Croda indicate that the supply side is preparing for the forecasted demand. Decision-makers must assess whether their own demand projections align with this incoming supply to avoid market saturation in specific niches or, conversely, to secure offtake agreements before capacity tightens.
Accessing Complete Intelligence
While this overview highlights the macroeconomic trends and competitive dynamics, the full strategic value of the market research lies in the granular data. Detailed segmentation splits, specific regional revenue contributions, and application-level growth rates are essential for building precise financial models and go-to-market strategies. The top-line figures provide confidence in the sector's direction, but the bottom-line details drive allocation decisions.
PW Consulting's comprehensive Biosurfactant Market report offers the depth required to move from general awareness to specific action. It provides the segmentation data, company profiles, and dynamic analysis needed to outperform competitors who rely on aggregate industry knowledge. For organizations seeking to capitalize on the 9.41 percent growth trajectory and navigate the regulatory landscape effectively, acquiring the full intelligence suite is the logical next step. The window to secure strategic positioning in this green chemistry transition is open, but it requires data-backed conviction to act decisively.
For detailed analysis of this topic, please visit the official page: Biosurfactant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


