



Category: Healthy Lifestyle
Strategic Shifts and Commercial Opportunities in the First Aid Kits Market
The first aid kits market has evolved from a commodity-driven safety staple into a strategically differentiated segment where compliance, content innovation, and service models dictate competitive advantage. Valued at approximately $215.0 million in 2025 and projected to reach $284.0 million by 2032, the market reflects a compound annual growth rate of 4.2 percent over the 2026–2032 forecast period. This trajectory is not merely a function of population growth or baseline safety demand; it is being reshaped by regulatory realignment, supply chain pressures, and a structural shift toward specialized, application-specific kits. For executives, investors, and procurement leaders, the current environment presents both operational complexity and clear avenues for margin expansion if positioned correctly.
Understanding where value is created requires looking beyond headline revenue figures. The market's expansion is uneven across types and applications, with common-type kits continuing to anchor volume while special-type kits capture higher unit margins through specialized content and targeted use cases. Application-wise, industrial and commercial environments remain central demand centers, but home care and sports-related deployments are gaining relevance as safety awareness broadens beyond traditional workplaces. Regionally, mature markets continue to set compliance benchmarks, while emerging regions are expanding at a faster pace as regulatory frameworks and workplace safety cultures mature. This fragmentation is not a weakness; it is the structural basis for differentiated go-to-market strategies.
Market Snapshot and Structural Realities
The growth path from 2020 through 2025 demonstrates steady accumulation, with revenue moving from $163.15 million to $215.0 million. The forecast window extends that momentum, reaching $227.94 million in 2026 and climbing toward $284.0 million by 2032. While the overall CAGR of 4.2 percent suggests a mature, predictable market, the underlying pattern reveals inflection points. Growth is not linear; it is being accelerated in segments where regulatory mandates, specialized content, and managed replenishment models intersect. This is why the market's midpoint values matter less than the rate of change within specific applications and kit types.
The industry structure also reflects a moderate degree of concentration. The top three players account for roughly 42.5 percent of market share, while the top five reach approximately 58.7 percent. This concentration indicates that scale, distribution reach, and compliance expertise provide meaningful defensive moats. At the same time, the remaining share distribution leaves room for specialized entrants, private-label partners, and service-led models to compete on differentiation rather than price alone. For decision-makers, the implication is clear: the market rewards players who can align product content, regulatory readiness, and replenishment reliability rather than those who compete purely on kit count or unit cost.
Key Challenges and Inflection Points
The first aid kits market is navigating a set of interdependent challenges that will determine which players gain share and which are squeezed into low-margin commoditization. These challenges are not transient; they are structural and require strategic responses.
- Regulatory and standards realignment is raising the compliance floor. Recent revisions to first-aid kit specifications and quality management expectations are reshaping what qualifies as an acceptable kit in workplace and industrial settings. Compliance is shifting from a static checkmark to an ongoing operational requirement, increasing the importance of documentation, content consistency, and manufacturing discipline.
- Input cost volatility is compressing margins for undifferentiated products. Prices for medical-grade gloves, antiseptic consumables, and trauma care materials rose by nearly 18 percent between 2023 and 2025, driven by supply concentration in Asia and elevated freight costs. Manufacturers and distributors that rely on generic content structures or reactive sourcing are facing margin pressure that cannot be fully passed through to price-sensitive buyers.
- Demand fragmentation is making one-size-fits-all kits less defensible. Buyers increasingly expect kits aligned to specific risk profiles, occupancy types, and operational environments. The broad-volume play is losing differentiation value, while application-tailored kits, replenishment services, and rental or managed stock models are gaining relevance.
Together, these dynamics create a market where compliance readiness, content precision, and service integration are becoming the primary levers of competitive advantage. Companies that treat first aid kits as a simple resell or assembly business will face intensifying pressure, while those that embed quality systems, tailored content, and replenishment reliability into their offering will be better positioned to defend pricing and expand share.
Key Drivers Reshaping the First Aid Kits Market
The market's direction is being shaped by four interlocking drivers: regulatory and standards evolution, input cost and supply chain dynamics, demand-side behavior changes, and product and service innovation. Each driver influences not only volume but also the economics of competition.
Regulatory and Standards Evolution as a Structural Driver
Regulatory developments are no longer peripheral; they are actively redefining product eligibility and manufacturing expectations. The Quality Management System Regulation (QMSR) became effective in February 2026, aligning FDA CGMP requirements with ISO 13485:2016 for medical devices, including first aid kits. This shift matters because it connects first aid kit production more directly to internationally recognized quality management expectations. For manufacturers, the change raises the importance of documented processes, traceability, and consistent quality control. For buyers, it increases confidence in supplier reliability but also raises the bar for supplier qualification.
At the same time, state-level standards activity is pushing kit specifications toward more defined performance expectations. Recent proposals to revise first-aid kit requirements in California have pointed toward alignment with ANSI/ISEA Z308.1-2021 Class A specifications for 2026 compliance. Even where such revisions are still evolving, they signal a broader direction: kit content is being evaluated against more explicit benchmarks rather than generic notions of adequacy. This creates a dual effect. It rewards manufacturers that can demonstrate specification alignment and documented quality systems, while increasing the cost of remaining in the low-compliance segment.
Worldwide Antiseptic First Aid Liquid Market
For commercial strategy, the regulatory driver is best understood as a filter. It does not automatically expand the market, but it accelerates consolidation among suppliers that can meet higher compliance expectations and squeezes out marginal players that cannot sustain the required documentation and process discipline.
Input Cost Dynamics and Supply Chain Realities
Cost structure is becoming a strategic variable rather than a background assumption. The nearly 18 percent increase in prices for medical-grade gloves, antiseptic consumables, and trauma care materials between 2023 and 2025 reflects a combination of supply concentration and freight pressure. This is not simply a purchasing challenge; it influences product architecture, pricing strategies, and the viability of low-differentiation kits.
The most exposed players are those with limited sourcing flexibility and minimal content optimization. When input prices rise, the temptation is to pass costs downstream, but in price-sensitive segments that approach can erode demand or trigger substitution. More resilient players are managing the pressure through a combination of supplier diversification, content rationalization, and value-based packaging. In practice, this means rethinking what goes into a kit, how consumables are replenished, and whether certain items can be sourced or configured in ways that reduce volatility without compromising compliance or functionality.
Supply chain concentration also increases the strategic value of inventory planning and replenishment design. Kits that depend on fragile sourcing paths are vulnerable not only to cost shocks but also to availability disruptions. This is one reason managed replenishment, rental systems, and private-label partnerships are gaining attention: they shift part of the burden of continuity from the end buyer to the supplier, creating a more predictable operating model and a stronger customer relationship.
Demand-Side Shifts in Behavior and Expectations
Demand is changing in ways that favor application specificity and service reliability. Workplace safety expectations are rising, and buyers are increasingly aware that compliance alone is not the same as operational readiness. In industrial and commercial environments, the question is no longer just whether a kit is present, but whether its content matches the actual risk profile of the site, whether it is maintained, and whether replenishment happens without delay.
Home care and sports-related applications are also contributing to broader demand diversification. These segments may not carry the same regulatory weight as industrial settings, but they are expanding the addressable market and encouraging product designs that are easier to use, easier to store, and more intuitive for non-specialist users. The common thread across these demand shifts is that buyers are paying more attention to usability, maintenance, and relevance. Kits that are difficult to restock, poorly matched to real-world use, or opaque in their replenishment process lose credibility quickly.
This demand evolution also affects purchasing behavior. In some contexts, buyers are moving from one-time purchases toward ongoing service relationships. Managed restocking, cabinet solutions, and rental or replenishment programs reduce the administrative burden on buyers and create recurring revenue streams for suppliers. The shift is incremental but meaningful because it changes the economic logic of the market from transactional volume to relationship-based continuity.
Product and Service Innovation as a Competitive Lever
Innovation in this market is less about radical product reinvention and more about precision, usability, and service integration. Special-type kits illustrate this trend by targeting specific scenarios with content designed for higher-acuity needs. Trauma-oriented kits, bleeding control kits, and other specialized configurations are gaining attention because they address use cases where generic kits are insufficient. This does not replace the role of common-type kits, but it creates a higher-value layer in the market where differentiation is easier to sustain.
PW Consulting Health Care Research Center
Service models are also evolving. Wholesale distribution, private-label and contract manufacturing, and managed rental or restocking systems reflect a broader move toward integrated offerings. These models matter because they address multiple buyer pain points at once: compliance, content relevance, replenishment reliability, and administrative burden. Where successful, they create stickier customer relationships and more predictable revenue than standalone kit sales.
Innovation is also visible in how suppliers position themselves for different buyer types. Some players emphasize cost-effective OSHA-compliant workplace kits and refills, which appeal to buyers focused on baseline compliance and operational efficiency. Others prioritize ANSI/OSHA-compliant workplace, industrial, and construction kits, signaling a more specification-driven approach. A further group concentrates on trauma and public-access bleeding control kits, targeting higher-risk environments and first-response needs. Another set of suppliers focuses on premium kits selected by first responders and medical professionals, using clinical credibility as a differentiator. Taken together, these positions show that the market is no longer competing on a single value proposition; it is fragmenting into multiple value pools, each with its own buyer expectations and pricing logic.
Competitive Landscape and Winning Strategies
The competitive field is marked by a mix of scale players, compliance-focused suppliers, specialized trauma-oriented providers, and service-oriented distributors. The presence of established names alongside niche specialists suggests a market where different competitive models can coexist, but only if each is clearly aligned to a defensible position.
Strategic Positioning Among Leading Players
A closer look at leading players shows that competitive advantage is being built through distinct positioning rather than uniform product offerings.
- First Aid Only has leaned into cost-effective, OSHA-compliant workplace kits and refills. This positions the company around baseline compliance, operational simplicity, and replenishment continuity for workplace environments. The strategic value lies in serving buyers who need dependable, specification-aligned kits without unnecessary complexity.
- The American Red Cross emphasizes ANSI/OSHA-compliant workplace, industrial, and construction kits. Its positioning benefits from institutional credibility and a strong association with safety and preparedness. In markets where trust and recognized authority matter, this is a meaningful advantage.
- North American Rescue focuses on trauma and first aid kits, including lumbar first aid kits and public access bleeding control kits. This places the company in a higher-specialization segment where content precision and mission-relevant design can support premium positioning.
- Aero Healthcare operates across wholesale kits, private-label and contract manufacturing, and managed rental or restocking systems. This multi-track model is strategically important because it combines distribution reach with service-based revenue and custom branding opportunities.
- My Medic emphasizes premium first aid kits and supplies selected by first responders and medical professionals. Its differentiation rests on clinical credibility and curated content, appealing to buyers who value expert selection and higher-performance configurations.
- Cintas Corporation offers first aid kits, cabinets, and replenishment services for workplace use. The strength of this model is integration: by combining hardware, kits, and replenishment, it reduces fragmentation for buyers and creates recurring service relationships.
- JumpMedic concentrates on premium first aid kits and supplies designed for emergency needs. Its positioning targets urgent-use scenarios where readiness, usability, and content reliability are especially important.
The pattern across these players is not random. Each is pursuing a distinct value pool: compliance and efficiency, institutional trust, trauma specialization, service integration, clinical credibility, or emergency readiness. The market supports multiple models because buyer needs differ by environment, risk profile, and procurement style. What separates stronger performers from weaker ones is the ability to deliver consistently on the chosen position without diluting it through unrelated expansion.
How the Landscape Is Evolving
The competitive landscape is evolving along three axes: consolidation among scaled players, differentiation among specialists, and new entry through service-led and private-label models.
Consolidation remains plausible where scale, distribution reach, and compliance infrastructure create advantages in procurement, qualification, and ongoing account management. In a market where the top five players already account for a majority share, further consolidation would likely be driven by the need to strengthen replenishment networks, broaden application coverage, and absorb regulatory and quality-system requirements more efficiently.
At the same time, differentiation is intensifying among specialists. Trauma kits, bleeding control kits, premium responder-selected kits, and application-specific configurations are creating spaces where performance and credibility matter more than sheer volume. These segments are smaller in absolute terms but can support stronger margins and more loyal customer bases when executed well.
New entry is also emerging through service-oriented models and private-label partnerships. Buyers that want compliance, replenishment, and brand alignment without building internal complexity are natural candidates for rental, restocking, and contract manufacturing arrangements. This creates opportunities for suppliers that can combine operational reliability with flexible commercial terms, even if they do not lead in raw brand recognition.
The overall trend is toward a market where success depends less on being everywhere and more on being unambiguously strong in a chosen segment. Players that attempt to compete across all applications, all kit types, and all service models without clear prioritization risk being outflanked by more focused competitors.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, the market is likely to be shaped by the interaction of compliance, cost, and demand specificity. Three trends are especially relevant for strategic planning.
Trend 1: Compliance and Quality Systems Will Become Table Stakes, Not Differentiators Alone
As quality management expectations align more closely with recognized international standards and kit specifications continue to be refined, the baseline for market participation will rise. This does not automatically create growth, but it does change the competitive filter. Suppliers that can demonstrate consistent quality, documentation discipline, and specification alignment will face lower qualification friction and stronger buyer confidence. Those that cannot will find it increasingly difficult to remain viable in regulated workplace and industrial channels. The commercial implication is that compliance capability should be treated as core infrastructure, while differentiation will need to come from content relevance, service design, and segment focus.
Worldwide Home Safety Test Kits Market
Trend 2: Application-Tailored Kits and Managed Replenishment Will Capture More Value
Demand is moving toward kits that match real-world risk profiles and toward purchasing models that reduce maintenance burden. This favors suppliers that can design for specific environments, maintain stock reliability, and offer replenishment, rental, or cabinet-plus-service solutions. The opportunity is not only in selling more kits, but in shifting the relationship from transactional purchase to ongoing readiness. For manufacturers and distributors, this trend opens a path to recurring revenue and stronger account retention, provided the operational backbone can support reliable restocking and service execution.
Trend 3: Cost and Sourcing Strategy Will Separate Resilient Players from Marginal Ones
Input cost pressure is unlikely to disappear quickly, especially where supply concentration and freight exposure remain factors. The strategic response will matter more than the headline cost itself. Players that diversify sourcing, optimize content without sacrificing compliance, and build replenishment models that smooth volatility will be better positioned to protect margins. Those that rely on rigid supply paths or undifferentiated kit architectures will be more exposed to price competition and availability risk. Over the next few years, sourcing resilience and content architecture will increasingly determine who can sustain pricing power.
Risks and Uncertainties
These trends are directionally clear, but several uncertainties could alter the pace or shape of market development. Regulatory specifications may evolve unevenly across regions, creating compliance complexity for suppliers operating in multiple jurisdictions. Input cost volatility could intensify if supply concentration persists or if logistics costs rise again. Demand may also shift faster than expected in certain applications, particularly where safety awareness grows or where workplace and public-access preparedness requirements become more stringent. Finally, competitive intensity could increase if new entrants successfully use private-label, rental, or replenishment models to bypass traditional distribution barriers. Each of these risks can be managed, but only if they are anticipated rather than treated as external shocks.
Strategic Actions for Decision-Makers
The first aid kits market rewards clarity of position, operational discipline, and readiness to align product content with real-world use. The following actions are most relevant for different audience types.
For Manufacturers and Brand Owners
- Strengthen quality management and specification alignment as a foundation, not a side initiative. With regulatory expectations moving toward more formalized quality frameworks, the ability to document processes and demonstrate consistent compliance is becoming a market-access requirement.
- Reassess kit content architecture against input cost realities. Where possible, optimize consumables, diversify sourcing, and differentiate through application-specific configurations rather than relying on generic volume plays.
- Choose a defensible value pool and execute against it. Whether the focus is workplace compliance, trauma specialization, responder-selected premium kits, or service-led replenishment, clarity of positioning will matter more than broad but shallow coverage.
For Investors and Strategic Buyers
- Evaluate exposure to compliance-dependent channels and service-based revenue. Businesses with recurring replenishment, rental, or managed stock models may offer more predictable economics than pure transactional kit sales, especially if they can demonstrate reliable execution.
- Look for sourcing and content strategies that signal resilience. Suppliers with diversified supply paths, disciplined cost management, and clear segment focus are better positioned to withstand input price volatility and competitive pressure.
- Assess whether a target's differentiation is real or aspirational. In this market, credibility in specific applications and the ability to maintain specification alignment over time are stronger signals than broad brand claims.
For Procurement and Safety Leaders
- Shift evaluation criteria beyond unit price to include replenishment reliability, compliance documentation, and content relevance. The total cost of an inadequate or poorly maintained kit can exceed the apparent savings from a cheaper purchase.
- Align kit selection to actual site risk profiles and usage patterns. Over-specified kits can waste resources, while under-specified kits can create readiness gaps; the goal is fit, not maximum content.
- Consider service models where administrative burden and restocking risk are significant. Managed replenishment, cabinets, and rental or contract arrangements can improve continuity if the provider demonstrates reliable execution and clear compliance support.
The first aid kits market is entering a phase where strategy matters more than scale alone. Compliance expectations are rising, input costs are reshaping margins, and buyers are increasingly focused on readiness, relevance, and continuity. In that environment, the winners are likely to be those who combine quality discipline with clear segmentation, reliable replenishment, and content designed for real-world use. For organizations seeking a more detailed view of segment dynamics, regional variation, and tailored commercial options, a comprehensive research report can provide the deeper segmentation and scenario detail needed to translate these strategic signals into actionable plans.
For detailed analysis of this topic, please visit the official page: First Aid Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
NB Latex Market 2026-2032: Why 7.45% CAGR and the $215M 2025 Milestone Redefine Growth Dynamics
By PW Consulting, 2026-09-21
Navigating the NB Latex Market: Strategic Trends and Commercial Opportunities Through 2032
The NB Latex Market has matured from a commodity-driven segment into a strategically differentiated landscape where performance specifications, supply chain resilience, and regulatory compliance increasingly determine competitive advantage. Measured in 2025 at approximately USD 215.0 million, the market expanded at a compound annual rate of 7.45% between 2020 and 2025, and forward projections point to sustained momentum through the end of the decade. By 2032, total market size is expected to reach USD 344.8 million, reflecting a trajectory that rewards players capable of aligning product quality, geographic exposure, and operational efficiency with evolving demand patterns.
PW Consulting Health Care Research Center
This growth trajectory is not distributed uniformly. Demand pull comes from multiple end-use channels, while supply-side dynamics remain anchored in a concentrated group of processors and exporters with significant regional footprints. The intersection of tighter environmental regulation, shifting raw material economics, and product specialization is reshaping how value is captured across the chain. For executives and investors, the central question is no longer whether the market will grow, but where differentiation will emerge and how quickly operational models can adapt.
Market Context: Size, Trajectory, and Structural Pressures
A Market Defined by Steady Expansion and Fragmented Value Capture
The overall market has progressed from USD 163.15 million in 2020 to USD 215.0 million in 2025, with the pace of expansion accelerating in recent years as downstream applications broaden and higher-grade latex specifications gain acceptance. The forecast window to 2032 implies continued compounding, though the path will likely be uneven as raw material volatility, regulatory deadlines, and regional demand cycles introduce periodic adjustments. A top-line CAGR of 7.45% signals healthy underlying demand, but it also raises the bar for operational execution, since margin capture increasingly depends on grade consistency, certification readiness, and logistics optimization rather than volume alone.
The value chain remains moderately concentrated. The top three participants account for roughly 23.5% of market revenue, and the top five collectively represent about 28.7%. This structure suggests room for competitive maneuvering, particularly for mid-tier processors that can secure reliable feedstock, differentiate on specialty grades, or embed themselves in customer-specific supply programs. At the same time, the presence of larger, vertically integrated operators indicates that scale advantages in processing capacity, quality control, and export logistics will continue to matter.
Worldwide Latex Binders Market
Key Challenges and Inflection Points
Several structural pressures are redefining the operating environment. First, compliance costs and traceability requirements are rising. The European Union Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. Enforcement timelines have been adjusted, with large and medium operators facing a December 2026 deadline and micro and small operators a June 2027 deadline following changes made in December 2025. This creates a near-term implementation squeeze: companies must build or verify plantation-level traceability, document chain-of-custody processes, and stand ready for customer and regulator scrutiny without derailing existing export flows.
Second, raw material economics are under continuous renegotiation. Price signals in related commodity markets can influence input cost expectations and plantation economics. For example, palm oil prices fell to 4,554 MYR/T on June 5, 2026, down 1.02% from the previous day, while rising 0.60% over the past month and 16.26% compared to the same time last year. Such movements illustrate how agricultural commodity markets can oscillate within short windows, affecting cost planning and hedging strategies for processors that operate around interlinked feedstock ecosystems. In a related policy move, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Although this measure targets palm oil, it reflects a broader pattern of export-duty adjustments in producing countries that can indirectly shape cost structures, trade flows, and regional competitiveness for processors handling multiple agricultural streams.
Third, demand-side expectations are shifting from volume to performance. Buyers increasingly seek latex grades that meet tighter technical specifications, consistent viscosity and purity profiles, and certifications aligned with downstream manufacturing requirements. This creates a divide between suppliers that can reliably deliver standardized, certified products and those that remain dependent on more variable commodity streams. The market is therefore approaching an inflection point where quality assurance and documentation capabilities are becoming as commercially significant as capacity.
Key Drivers Shaping the NB Latex Market
Technical Innovation and Grade Specialization
Innovation in latex processing is increasingly oriented around consistency, contamination control, and specification alignment. For automotive and industrial users, tighter tolerances and dependable lot-to-lot performance reduce downstream processing risk and support broader use in higher-value applications. Suppliers with strong process control, filtration and stabilization capabilities, and quality-certified grades are better positioned to serve customers that require repeatable input characteristics. In practical terms, innovation here is less about radical product reinvention and more about process refinement, analytical rigor, and the ability to package reliability as a commercial differentiator.
This trend benefits processors that can demonstrate controlled parameters and certified output. It also raises the importance of technical service: customers are more likely to commit to suppliers who can support specification matching, troubleshooting, and supply continuity. As a result, the competitive edge is shifting toward organizations that combine operational discipline with application-aware customer engagement.
Policy and Regulatory Environment
Regulatory developments are emerging as a structural driver rather than a peripheral compliance issue. The EU Deforestation Regulation is a prominent example: it requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. The enforcement timeline has been postponed to 30 December 2026 for large and medium operators and to 30 June 2027 for micro and small operators following December 2025 changes. While the postponement provides additional preparation time, the direction of travel is clear: traceability and geolocation documentation are becoming prerequisites for continued access to European channels.
For exporters and processors, the practical implication is that compliance readiness will increasingly influence market access, buyer selection, and contract negotiation dynamics. Companies that invest early in mapping plantation sources, strengthening documentation, and aligning internal processes with geolocation requirements will be better placed to maintain relationships with customers that prioritize regulatory assurance. Those that delay could face higher transaction costs, reduced optionality, or exclusion from certain procurement programs.
Demand-Side Evolution Across End-Use Segments
Demand is broadening beyond traditional channels, and the composition of growth is changing. Automotive applications remain a significant pull, supported by tire and component requirements that favor reliable natural rubber latex inputs. Construction and building materials, consumer goods and personal care, industrial products, and other segments each contribute to aggregate demand in different ways, with varying sensitivity to price, specification, and certification. What matters strategically is that downstream industries are not moving in lockstep. Some channels prioritize cost efficiency, while others place greater weight on performance consistency or compliance documentation.
This segmentation of demand means suppliers need flexible commercial models. A single product strategy is less effective when customers in different verticals evaluate trade-offs differently. Processors that can offer multiple grade options, maintain clear segregation of volumes by specification, and align supply with customer-specific requirements are more likely to retain share as demand patterns shift. The ability to anticipate which segments will expand faster, and to align capacity and certifications accordingly, will be a meaningful source of advantage.
Supply Chain and Cost Structure Dynamics
Cost structures in the NB Latex Market are shaped by feedstock availability, processing efficiency, logistics, and the broader policy environment in producing regions. Price signals from commodity markets can influence planning horizons and risk management decisions. The recent movement in palm oil prices illustrates the kind of volatility that processors may observe in adjacent agricultural markets, with short-term declines coexisting alongside stronger year-on-year comparisons. On the policy side, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Such measures matter because they reflect a recurring theme: producing countries periodically adjust export duties and related fiscal instruments, which can alter cost competitiveness and trade routing over time.
At the same time, supply tightness in major producing countries continues to influence pricing expectations. The World Bank projected Technically Specified Rubber 20 natural rubber prices to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries. This outlook underscores that feedstock economics will remain an important variable for latex processors, particularly where natural rubber is a central input. Companies that can manage procurement risk, secure dependable supply, and optimize processing yields will be better equipped to navigate price fluctuations without sacrificing margin stability.
Competitive Landscape: Positioning, Differentiation, and Evolution
Core Players and Strategic Positioning
The competitive set is anchored by processors and exporters with significant capacity and regional reach, many based in Thailand and neighboring Southeast Asian markets, alongside integrated traders and producers in broader Asian supply chains. Several companies stand out for the way they combine capacity, grade focus, and supply chain positioning.
Latex Powder Market
- Sri Trang Agro-Industry Public Company Limited operates as a leading producer and exporter of natural rubber latex concentrate, with global processing capacity exceeding 1.5 million tonnes per year and about 10% share of global natural rubber consumption. Its scale and market participation give it a strong base for volume reliability and broad customer coverage.
- Von Bundit Co., Ltd. is a major processor and exporter of natural rubber latex with production capacity of approximately 2 million tonnes per annum and emphasis on quality-certified grades. This positions the company around specification reliability and certified output, which aligns with buyers seeking consistent input quality.
- Halcyon Agri Corporation Limited is an integrated producer and processor of natural rubber latex serving tire, glove, and industrial applications with vertical supply chain control. Vertical integration can reduce dependency on external procurement channels and support more controlled feedstock and processing flows.
- Thai Rubber Latex Group Public Company Limited supplies concentrated and creamed natural rubber latex with focus on export volumes to Malaysia, China, and other markets. Its export-oriented profile highlights the importance of logistics, destination-market relationships, and trade routing.
- Southland Rubber Co., Ltd. processes natural rubber latex and solid rubber products with capabilities in specialty grades for healthcare and industrial uses. Specialty-grade capability is a notable differentiator in segments where regulated or performance-sensitive applications matter.
- Thai Hua Rubber Public Company Limited is a major player in concentrated natural rubber latex production and export from Thai plantations. Its positioning reflects the continuing importance of Thailand as a processing and export hub.
- Vietnam Rubber Group is a state-linked producer and exporter of natural rubber latex concentrate with significant share in Southeast Asian supply. Its role illustrates how national-level institutions can influence regional supply dynamics and export availability.
- Sinochem International Corporation is an integrated trader and processor supplying natural rubber latex to global markets. Trade and processing integration can support broad market reach and flexible supply arrangements.
- Num Rubber & Latex Co., Ltd. is an active manufacturer of natural rubber latex products and concentrates for medical and industrial applications. Its focus on medical and industrial segments points to the value of application-specific product development and certification readiness.
- Apcotex Industries Limited is a supplier of natural rubber latex for adhesive, coating, and industrial applications. This specialization highlights demand from industrial formulation uses where latex properties influence end-product performance.
Differentiation Themes Among Leading Players
Across this group, several differentiation themes recur. Scale and processing capacity provide volume reliability and the ability to serve large, multi-site customers. Quality-certified grades and specialty offerings support access to more demanding applications, where specification adherence and documentation are critical. Vertical supply chain control and integration can improve feedstock security and reduce exposure to intermediate market disruptions. Export orientation and destination-market relationships shape commercial reach, especially where logistics, customs coordination, and customer proximity influence service levels. Application-specific focus, whether in healthcare, industrial formulation, tire-related uses, or consumer-adjacent products, allows suppliers to build deeper relationships and more tailored value propositions.
The strategic implication is that no single advantage is sufficient on its own. Capacity without quality control limits access to premium channels. Quality and certification without reliable supply can undermine customer confidence. Export relationships without compliance readiness become riskier as regulatory expectations rise. The strongest positions tend to combine several of these elements in a coherent operating model.
Market Structure Evolution: Consolidation, Diversification, and New Entry
The market is likely to evolve through a combination of consolidation among scaled processors, diversification into higher-value grades and applications, and selective new entry where niche positioning or regional advantages are strong. Moderate concentration leaves space for competitive shifts, but it also encourages larger players to deepen customer commitments, strengthen traceability, and invest in process consistency. Mid-tier participants may pursue specialization, regional partnerships, or certification-driven differentiation to expand their addressable market without competing purely on volume.
New entry is most plausible where companies can demonstrate a clear value proposition: reliable traceability, specialty-grade capability, cost-efficient processing, or access to underserved destination markets. In contrast, entry that relies only on commodity positioning is harder to sustain as buyers increasingly weigh specification reliability and compliance assurance alongside price. Over time, the landscape may become more layered, with premium, certified, and application-specific segments becoming more distinct from standard commodity-grade channels.
Outlook: Three Strategic Trends to 2032
Trend 1: Compliance and Traceability as Commercial Gatekeepers
Traceability and geolocation readiness will increasingly function as commercial gatekeepers for access to regulated markets. The EU Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance, and the adjusted enforcement schedule still places large and medium operators under a December 2026 deadline and smaller operators under a June 2027 deadline. This timeline creates a practical window for preparation, but it also raises the likelihood that compliance maturity will influence buyer decisions and contract eligibility.
The commercial opportunity lies in turning compliance into a differentiator. Suppliers that can present verifiable plantation-level data, robust documentation, and repeatable audit readiness may find it easier to enter or retain relationships with customers that require regulatory assurance. The risk is that companies with weak traceability infrastructure face growing friction, higher transaction costs, or narrowing market access, especially in channels where buyers are especially sensitive to regulatory exposure.
Trend 2: Grade Specialization and Specification-Driven Demand
Demand is expected to place greater weight on specification consistency, certified grades, and application-aligned product attributes. Automotive and industrial channels, in particular, benefit from latex inputs that support stable downstream processing and predictable performance. This favors processors that can maintain tight control over quality parameters and deliver certified output with dependable lot consistency.
For commercial strategy, this trend suggests a shift toward value-based positioning rather than price-only competition. Companies that can match grades to customer requirements, provide technical support, and ensure supply continuity may command stronger relationships and better margin protection. The uncertainty is that specification demands may diverge across segments, requiring suppliers to manage a broader set of product configurations without losing operational efficiency.
Trend 3: Supply-Side Volatility and the Need for Procurement Resilience
Feedstock economics and policy adjustments will continue to shape cost structures and supply planning. With natural rubber prices projected to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries, processors should expect continued pressure on input economics. At the same time, policy actions such as Indonesia raising the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, and short-term commodity price movements like palm oil falling to 4,554 MYR/T on June 5, 2026, illustrate how quickly cost expectations can shift in adjacent agricultural markets.
The strategic response is to build procurement resilience: diversified sourcing where feasible, stronger supplier relationships, improved yield and process efficiency, and disciplined risk management. The opportunity is to reduce vulnerability to price spikes and supply interruptions while maintaining competitive pricing for customers. The risk is that firms with limited flexibility may face margin compression or supply uncertainty when markets tighten or policy changes alter cost dynamics.
Actionable Recommendations for Decision-Makers
For Manufacturers and Processors
Invest early in traceability and documentation infrastructure, especially if European market access is part of the commercial plan. Plantation-level geolocation readiness, chain-of-custody records, and auditable process controls will become more valuable as deadlines approach and buyer expectations firm up. At the same time, review grade architecture and quality systems to ensure the product mix supports specification-driven demand. Where possible, strengthen process consistency and certification readiness so the business can serve higher-value applications without compromising reliability.
For Investors
Look beyond aggregate market size and focus on the structural attributes that determine durable value capture. Scale, vertical integration, certification capability, specialty-grade positioning, and compliance readiness each influence competitive resilience in different ways. Evaluate whether target companies have credible pathways to maintain supply security, meet rising traceability expectations, and serve demand channels that are expanding faster than the average. Pay attention to regional exposure and policy risk, since export-duty changes and commodity price volatility can affect cost structures and trade routing over time.
For Procurement and Supply Chain Leaders
Treat latex sourcing as a multi-factor decision rather than a price-only exercise. Specification consistency, certification status, traceability readiness, and supply continuity should be weighted alongside cost, particularly where downstream manufacturing risk or regulatory exposure is significant. Diversify sourcing where feasible, clarify documentation requirements with suppliers, and establish expectations for geolocation and compliance data if EU-market-bound products are in scope. Building these expectations into procurement criteria early can reduce disruption later and improve negotiating leverage.
The NB Latex Market is entering a phase in which growth is necessary but not sufficient. The companies and investors that fare best will be those that treat compliance readiness, grade specialization, and supply resilience as core strategic capabilities rather than operational afterthoughts. Detailed segmentation data, company-level benchmarks, and scenario-based guidance can help convert these strategic themes into specific investment, sourcing, and product decisions. Readers seeking a more granular view of regional splits, application dynamics, type-level comparisons, and competitive positioning can access the full PW Consulting report for detailed figures and customized recommendations tailored to their commercial objectives.
For detailed analysis of this topic, please visit the official page: NB Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Algae Products Market Surpasses $15B: 8.2% CAGR Trajectory and 3 Strategic Shifts
By PW Consulting, 2026-09-21
Strategic Horizons: Navigating Growth and Complexity in the Algae Products Market
1. Market Trajectory and Core Pressures
The global algae products market has entered a phase of accelerated expansion, driven by converging forces across nutrition, industrial sustainability, and biotechnological innovation. Valued at approximately $9,400 million in 2020, the sector has more than doubled in relative terms, reaching an estimated $15,151 million by 2025. Current projections indicate a steady growth trajectory through 2032, with a compound annual growth rate of 8.2 percent, positioning the market to approach $26.3 billion by the end of the forecast period. This expansion reflects a structural shift rather than a cyclical upturn, as algae-derived ingredients move from niche applications into mainstream dietary supplements, functional foods, animal nutrition, and industrial raw materials.
Worldwide Algal Biofuel Market
Despite the favorable trajectory, the industry stands at a critical juncture where scaling ambitions intersect with operational and regulatory realities. Three interlocking challenges define the current landscape. First, production scalability remains uneven across cultivation methods, with open-pond systems facing climate dependency and contamination risks, while closed photobioreactor and heterotrophic fermentation platforms demand significant capital investment and energy optimization. Second, regulatory scrutiny has intensified in key export markets, particularly around contaminant thresholds, strain-specific safety assessments, and novel-food categorization, raising compliance costs and lengthening time-to-market for new ingredients. Third, the supply chain for high-value fractions such as omega-3 oils, phycocyanin, and specialty proteins continues to experience bottlenecks in downstream processing, drying, and stabilization, which compress margins and limit format flexibility. These pressures are not insurmountable, but they require coordinated investment in process engineering, quality systems, and regional regulatory strategy.
2. Force Multipliers: What Is Driving the Market Forward
Technological Innovation and Strain-Level Breakthroughs
Advancements in cultivation architecture, strain selection, and downstream fractionation are reshaping the economics of algae production. Industry participants are increasingly pairing controlled-environment systems with real-time monitoring, automated feeding, and precision harvesting to improve yield consistency and reduce water and energy intensity. The integration of digital control systems into cultivation facilities has enabled tighter management of growth conditions, which is particularly valuable for high-potency extracts where potency, purity, and batch repeatability command premium pricing. Parallel progress in heterotrophic fermentation and metabolic engineering is expanding the range of commercially viable strains, allowing producers to decouple output from seasonal sunlight and weather variability. These developments are lowering the cost curve for specialized molecules while creating new format options for end users, from stabilized powders to concentrated oils and colorants.
Regulatory Evolution as a Market Catalyst
Regulatory dynamics in major markets are simultaneously tightening and enabling. In 2025, additional chlorella and spirulina strains received Generally Recognized as Safe status in the United States, broadening the formulation toolkit for supplement and food manufacturers. Around the same period, the European Food Safety Authority granted novel-food approvals for algae-derived omega-3 oils and phycocyanin colorants, opening doors for ingredient diversification in European markets. At the same time, both EFSA and the United States Pharmacopeia tightened contaminant thresholds for algae-based ingredients, elevating quality assurance expectations across the value chain. The net effect is a market that rewards disciplined producers with robust analytical capabilities, traceable sourcing, and documented process controls. Regulatory clarity, where it emerges, reduces uncertainty for downstream buyers and accelerates ingredient adoption, while stricter thresholds raise the competitive bar for entrants lacking validated quality infrastructure.
Demand-Side Shifts and Portfolio Reconfiguration
Consumer and corporate behavior is reordering ingredient preferences across multiple categories. Health-conscious consumers are increasingly seeking plant-based, ocean-friendly alternatives to fish-derived omega-3s, a trend that is expanding the addressable market for algal DHA and EPA oils in supplements, functional foods, and maternal nutrition. Beyond personal nutrition, manufacturers in food and beverage are exploring algae-derived proteins, colorants, and texturizing agents to support clean-label and sustainability claims. In animal nutrition, the push for alternative protein and lipid sources in aquaculture and livestock feed is creating incremental demand for algae-based meals and oils, particularly where feed conversion efficiency and disease resistance are priorities. These demand signals are not uniform, but they are broad enough to support diversified product strategies and reduce reliance on any single application vertical.
Supply Chain and Cost Structure Realignment
Cost competitiveness in the algae sector is increasingly determined by downstream efficiency and geographic positioning. Energy consumption, water management, harvesting yield, and drying technology are the primary levers that separate margin-resilient operations from those exposed to commodity volatility. Recent moves to localize cultivation and processing in regions with favorable climate, renewable energy access, and proximity to end markets are helping participants manage freight costs and reduce lead times. At the same time, partnerships between ingredient specialists and technology or agricultural partners are accelerating the commercialization of novel molecules, particularly astaxanthin and high-potency omega-3 fractions. Together, these shifts are turning cost structure from a static constraint into a dynamic design variable, where process choice, location, and collaboration model directly influence market positioning.
3. Competitive Dynamics and Strategic Positioning
The competitive landscape is characterized by a mix of established life-science and ingredients multinationals, specialized algae producers, and emerging technology-driven entrants. Market concentration is significant, with the top three players accounting for approximately 68 percent of revenue and the top five capturing roughly 82 percent, underscoring the advantage of scale, regulatory experience, and integrated supply chains. Yet the ecosystem also includes highly specialized firms that compete on potency, strain uniqueness, geographic sourcing, or application expertise, creating a layered market where leadership is defined as much by differentiation as by volume.
A review of recent corporate activity illustrates how participants are building durable advantage. In mid-2025, a leading algae-based omega-3 and specialty ingredients supplier secured regulatory approval in China for its algae-based omega-3 solutions, extending its commercial footprint into a high-growth market and strengthening its position in nutraceutical and food applications. Shortly thereafter, the same company partnered with an agricultural systems specialist to develop and commercialize natural astaxanthin derived from heterotrophic microalgae, signaling a deliberate expansion into high-value colorant and nutraceutical molecules through collaborative commercialization. In early 2025, a major spirulina producer inaugurated a new cultivation facility equipped with AI-enabled process control, SCADA monitoring, robotics, and zero-discharge systems, demonstrating how operational automation and environmental controls are being embedded into capacity expansion. In the second half of 2025, a prominent life-science and nutrition player launched an ultra-potent algal DHA oil formulation delivering substantially higher DHA and meaningful EPA levels per gram, targeting infant nutrition and premium supplement formats where concentration and dosage efficiency matter. Earlier, in late 2024, a collaborative product launch introduced microalgae-derived cooking oils produced via fermentation from sugarcane sugars, illustrating how alternative feedstock pathways and fermentation platforms are entering the consumer-facing food ingredient space.
Strategic Archetypes in the Market
These activities reveal several distinct strategic archetypes. One is the integrated multinational that leverages regulatory expertise, global distribution, and application support to dominate high-volume categories such as omega-3 oils and nutrition ingredients. Another is the specialist producer that competes on geographic origin, strain heritage, and purity narratives, often building loyalty through quality certification and category-specific formulation knowledge. A third is the technology-forward entrant that uses photobioreactors, fermentation, or advanced downstream processing to access molecules with superior potency, consistency, or cost profiles. Each archetype carries trade-offs: scale and integration support pricing power and market access, while specialization and technology intensity support margin resilience and differentiation but demand disciplined capital allocation and execution.
Evolution of the Competitive Map
Looking ahead, the market is likely to experience both consolidation and fragmentation simultaneously. Larger players will continue to pursue portfolio breadth, regulatory wins, and regional capacity to secure supply reliability for demanding buyers. At the same time, targeted partnerships and licensing arrangements will allow smaller or more specialized firms to commercialize novel molecules without bearing the full burden of standalone scale-up. New entrants with strong fermentation, strain engineering, or process automation capabilities may capture specific formulation niches, particularly where potency, sustainability, or clean-label positioning create meaningful price premiums. The net result is a market in which competitive advantage will increasingly depend on the ability to combine quality assurance, process efficiency, regulatory fluency, and application-specific value propositions rather than on volume alone.
PW Consulting Health Care Research Center
4. Forward Outlook: Trends Shaping the Next 3–5 Years
Three trends are likely to define the market’s evolution over the next several years. The first is the continued migration of algae-derived ingredients from specialty niches into mainstream nutrition and food formats. As regulatory approvals broaden and formulation know-how matures, algae-based omega-3s, proteins, colorants, and functional extracts will appear in more conventional product architectures, supported by consumer preference for plant-based and traceable inputs. The commercial opportunity here lies in format innovation and application engineering: products that deliver dosing convenience, sensory compatibility, and stability will gain shelf preference and retail traction.
The second trend is the growing importance of process intensity and digital control as margin determinants. Facilities that integrate automated cultivation management, precise harvesting, and energy-efficient drying will be better positioned to meet rising quality expectations while managing unit costs. Heterotrophic fermentation and hybrid cultivation models will expand where feedstock availability and process economics align, enabling more predictable output and reducing exposure to climate variability. For commercial teams, the implication is clear: sourcing decisions and partnership strategies should account for process transparency, quality documentation, and scalability pathways, not just current price points.
The third trend is regulatory normalization paired with higher compliance baselines. As more strains and ingredient categories secure approvals and contaminant thresholds become more stringent, the market will reward producers that demonstrate analytical rigor, batch traceability, and consistent documentation. This dynamic will raise barriers for low-cost, low-control operators while creating a more stable environment for established suppliers and well-capitalized newcomers. The associated risk is that compliance costs and approval timelines may compress short-term capacity additions, and that divergence in regional standards could complicate global supply strategies if not managed proactively.
5. Strategic Implications for Decision Makers
For manufacturers and ingredient developers, the priority is to align product roadmaps with where regulatory clarity, demand momentum, and process advantage intersect. This means prioritizing molecules and formats with clear adoption pathways, investing in quality systems and analytical capabilities that satisfy tightening contaminant thresholds, and selecting cultivation or fermentation models that match target margin profiles and volume requirements. Companies should also evaluate partnerships that can accelerate commercialization of high-value fractions, particularly where collaborative models reduce capital exposure while securing supply reliability.
For investors, the key is to distinguish durable advantage from short-term momentum. Favor platforms that combine regulatory track records, process automation, and defensible strain or formulation IP with evidence of scalable unit economics. Evaluate exposure to regional regulatory timelines and contaminant compliance costs, and assess whether a company’s competitive positioning depends on volume, potency, or differentiation. Diversification across applications can reduce concentration risk, but only when each vertical has a credible cost and quality story.
For procurement and formulation teams, the emphasis should be on supply resilience and specification integrity. Build multi-source strategies where feasible, prioritize suppliers with documented quality controls and robust traceability, and validate performance under real formulation conditions rather than relying on potency claims alone. As regulatory expectations rise and demand expands across food, supplement, and feed applications, procurement decisions that embed quality, compliance, and scalability considerations will reduce downstream disruption and support faster time-to-market.
As the market continues to scale, the difference between marginal participation and strategic advantage will increasingly come down to the precision of market intelligence. Detailed segmentation data, regional regulatory tracking, pricing and margin dynamics, and company-level capability assessments are essential inputs for capital allocation, partnership decisions, and formulation planning. Readers seeking deeper segmentation detail, regional demand patterns, and customized strategic recommendations can access the full research report for granular data and tailored guidance.
Microalgae Market
For detailed analysis of this topic, please visit the official page: Algae Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Varicella Attenuated Live Vaccine Market: Why 5.65% CAGR Reshapes Immunization Strategies
By PW Consulting, 2026-09-21
Navigating the Varicella Attenuated Live Vaccine Market: Strategic Trends and Commercial Opportunities Through 2032
The global landscape for varicella attenuated live vaccines is entering a period of structured evolution. After years of steady growth driven by routine immunization mandates and catch-up campaigns, the market is now shaped by a combination of regulatory adjustments, supply chain recalibrations, and the gradual entry of differentiated product profiles. Total market revenue has expanded from approximately $145.3 million in 2020 to an estimated $188.5 million in 2025, with a projected compound annual growth rate of 5.65 percent through 2032. By the end of the forecast period, revenue is expected to approach the $275 million threshold. These figures reflect more than simple volume expansion; they signal a market that is maturing in its geographic reach, refining its application mix, and responding to policy shifts that alter how, when, and for whom vaccines are administered.
For executives and strategic planners, the key takeaway is that growth is no longer uniform. Regional maturation patterns, formulation preferences, and target-age expansions are creating pockets of opportunity that reward early positioning and precise commercial execution. At the same time, concentration among leading manufacturers, evolving dosing recommendations, and intermittent supply disruptions introduce execution risk that must be managed proactively.
Market Snapshot: Size, Trajectory, and Structural Realities
The revenue trajectory from 2020 through 2025 demonstrates a market that has absorbed pandemic-era disruptions and returned to a consistent upward path. The acceleration observed between 2022 and 2025 aligns with the normalization of immunization schedules, continued public funding for childhood programs, and incremental expansion of coverage in emerging economies. Looking ahead, the forecast suggests that annual revenue will surpass $240 million in the late 2020s and continue climbing toward $274.9 million by 2032. This pace indicates a market that is not merely repeating historical patterns but is being reshaped by regional policy adoption, age-group expansion, and formulation competition.
The market remains moderately concentrated, with the top three firms accounting for a significant share of revenue and the top five firms capturing an even larger portion. Such concentration provides scale advantages in manufacturing, regulatory navigation, and tendering, but it also compresses the window for late entrants unless they bring clear differentiation in strain profile, dosing convenience, or regional access. The structural reality is that scale and regulatory familiarity still matter, yet the distribution of growth is widening enough to reward players who can align product attributes with specific country-level priorities.
Key Challenges and Inflection Points
Three interconnected challenges define the current juncture and will influence commercial decision-making over the next several years.
First, regulatory guidance on dosing and combination vaccines is shifting practice patterns. Updated immunization schedules have begun to recommend standalone varicella vaccination for toddlers through early childhood in certain settings, responding to safety considerations associated with combined measles-mumps-rubella-varicella formulations. This guidance alters demand dynamics by reinforcing the role of monovalent attenuated live products in routine schedules and by creating a preference environment that favors vaccines with clearly documented safety profiles and flexible administration routes. For manufacturers, this means that clinical communication, dosing instructions, and real-world evidence become more commercially relevant than in prior years.
Second, supply reliability has emerged as a competitive differentiator. Periodic shortages in specific markets have constrained availability to public programs and government procurement channels, underscoring how manufacturing continuity directly affects market share and program trust. When a product experiences availability gaps, procurement teams and public health authorities reassess sourcing options, sometimes accelerating the evaluation of alternative suppliers or regional manufacturing assets. In this environment, supply chain resilience is not an operational nicety; it is a commercial moat.
Third, the market is navigating a transition in target populations and administration pathways. While routine childhood immunization remains the dominant application, growth is increasingly linked to catch-up initiatives and the gradual consideration of adolescent and adult vaccination in specific regions. Concurrently, product labels and monographs are incorporating updated administration instructions, including options for intramuscular or subcutaneous delivery depending on the market and formulation. These shifts broaden the commercial aperture but also require manufacturers to align clinical messaging, training, and pricing strategies with evolving use cases.
Key Drivers Shaping Market Direction
The forward trajectory of the varicella attenuated live vaccine market is being pulled by a set of complementary forces. Understanding how these drivers interact helps explain why growth is concentrating in certain regions, why formulation preferences matter, and why execution quality increasingly separates leaders from followers.
Technological Innovation and Product Differentiation
Product differentiation is moving beyond brand heritage to include strain selection, cell-line platforms, and administration flexibility. Second-generation attenuated live vaccines built on alternative strains and cell substrates are expanding the field, offering manufacturers new ways to position safety, immunogenicity, and supply adaptability. The availability of products leveraging Vero cell-derived platforms and distinct Oka-lineage or MAV/06-type strains demonstrates that differentiation is increasingly technical and regional. Where a given strain or platform aligns with local regulatory expectations and procurement preferences, it can unlock access even in markets where incumbents have long operated.
Administration flexibility is another subtle but meaningful driver. Updated monographs that clarify dosing and route options for specific products reduce friction in clinical settings and supports adoption by providers who value clear, consistent instructions. In practice, this can influence formulary inclusion, training requirements, and procurement decisions, especially where public programs demand predictable administration protocols.
Policy and Regulatory Environment
Policy signals are actively reshaping demand. Adjustments to national immunization schedules, including recommendations that favor standalone varicella vaccination for younger age groups, reinforce the relevance of monovalent attenuated live vaccines and incentivize manufacturers to maintain strong safety communications and real-world data packages. Regulatory authorizations in new countries also matter because they open revenue streams that were previously inaccessible, particularly when paired with public funding or tender eligibility.
Authorization momentum across multiple regions indicates that the regulatory bar, while rigorous, is navigable when manufacturers present robust clinical and quality documentation. As marketing authorizations accumulate in Latin America and Southeast Asia, and as existing products maintain or extend their labels in established markets, the regulatory environment is functioning as both a gatekeeper and a growth catalyst. For companies, the strategic implication is to treat regulatory engagement as a continuous commercial function rather than a one-time milestone, especially where scheduling changes or reimbursement updates can rapidly alter uptake.
Demand-Side Behavior and Public Program Dynamics
Demand is increasingly influenced by public program design and procurement behavior. Routine childhood immunization continues to anchor volume, but catch-up campaigns and targeted initiatives create episodic surges that can shift short-term ordering patterns and strain supply if not anticipated. In parallel, reimbursement frameworks and price lists for public immunization programs provide transparency that shapes contracting and budgeting. When price visibility is high, procurement teams can compare alternatives more efficiently, which increases the importance of competitive positioning on price, availability, and documented service reliability.
A further demand-side shift is the gradual broadening of age focus. Although the core application remains early childhood, interest in adolescent and adult vaccination is emerging in specific markets, often tied to outbreak response, school entry requirements, or employer health programs. This expansion does not replace the childhood base, but it adds a layer of opportunity for products that can demonstrate appropriate safety, dosing practicality, and acceptability in older populations.
Supply Chain and Cost Structure Considerations
Cost structures in this market are influenced by manufacturing complexity, strain maintenance, quality control, and logistics for temperature-sensitive biologics. Regions with established manufacturing hubs and mature cold-chain infrastructure tend to experience lower friction in distribution, while markets dependent on imports can face higher variability in availability and pricing. Recent episodes of localized shortages have highlighted how production scheduling, fill-finish capacity, and regional demand forecasting interact to determine whether a product remains continuously available.
The commercial lesson is that cost leadership alone is insufficient if it comes at the expense of reliability. Buyers increasingly weigh total cost of ownership, including the risk of stockouts, the administrative burden of re-procurement, and the programmatic impact of interrupted immunization schedules. Suppliers that can demonstrate consistent output, transparent lead times, and contingency planning gain a tangible advantage in both public tenders and private-sector contracting.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a small group of manufacturers with established varicella programs and distinct geographic strengths. Each leader has built a strategic position around a combination of strain profile, regulatory footprint, and market access relationships, and each is adapting to the same structural shifts in different ways.
Merck & Co., Inc. maintains a central position in the United States and several additional markets with its monovalent attenuated live varicella vaccine, leveraging deep familiarity with public immunization programs and established supply programs. Its strategic value lies in the continuity of availability and the breadth of clinical and program-level experience, which supports formulary stability and procurement confidence. In a market where schedule changes and safety discussions influence preference, that institutional familiarity is a meaningful asset.
GlaxoSmithKline plc operates with a globally recognized Oka-strain product and has been extending its footprint through recent authorizations, including a 2026 marketing authorization in Canada. Its strategy reflects a combination of regulatory expansion and ongoing distribution in established markets such as the UK and Australia. The company also illustrates how supply continuity can become a focal point: localized shortages have affected availability for public programs in certain periods, reinforcing the importance of manufacturing resilience and proactive communication with health authorities. Updated dosing and administration instructions in product monographs further support clinical adoption by clarifying route options and reducing uncertainty at the point of care.
GC Biopharma Corp. represents a notable expansion vector, with second-generation attenuated live vaccines that have secured recent marketing authorizations in Guatemala and Vietnam, alongside continued distribution in South Korea. Its approach highlights the commercial potential of differentiated strain profiles and targeted regional entry, particularly where a product can be positioned as the first of its type in a market or where local regulatory acceptance aligns with a specific platform. First clearances in Latin America and Southeast Asia demonstrate that regional first-mover advantages can be achieved when product differentiation and regulatory readiness converge.
SK Bioscience Co., Ltd. continues to build on its commercially available attenuated live varicella vaccine with ongoing distribution in South Korea and additional markets such as Turkey. Its strategy emphasizes regional presence and steady availability, aligning with the broader pattern in which established regional suppliers benefit from familiarity, logistics proximity, and program relationships. In practice, this positions the company to participate in both routine programs and targeted campaigns where local execution matters.
Sinovac Biotech Ltd. brings a Vero cell-derived attenuated live vaccine with WHO prequalification and a sequence of recent authorizations, including approval in Argentina and regulatory clearance in China for adolescents and adults. The company’s trajectory illustrates how a platform-based approach and international prequalification can support cross-market expansion, especially when paired with real-world safety data and age-group extensions. The strategic importance here is the ability to leverage a globally recognized quality marker and then convert it into country-level access through local authorizations and program engagement.
Strategic Positioning and Differentiation
Across these leaders, several differentiating levers are visible.
- Regulatory breadth and continuity: manufacturers that maintain active authorization portfolios and update labels as schedules change are better positioned to remain eligible in public programs.
- Strain and platform differentiation: alternative strains and cell-line platforms provide distinct value propositions that can be matched to regional regulatory expectations and safety discussions.
- Supply reliability and program trust: consistent availability and transparent communication reduce the risk of substitution and strengthen long-term procurement relationships.
- Administration flexibility and clinical clarity: clear instructions on route and dosing support provider adoption and reduce implementation friction.
- Real-world evidence and safety communication: documented post-marketing data and proactive safety messaging strengthen confidence in environments where combination vaccine debates influence preference.
The market is not simply consolidating around incumbents; it is fragmenting by region and application while still rewarding scale where it translates into reliability and access. New entrants and regional champions can gain traction by aligning product attributes with specific policy environments and by securing initial clearances that establish a foothold for broader distribution. At the same time, the presence of multiple differentiated products means that competition is increasingly about fit—how well a product matches a country’s schedule, procurement model, and clinical preferences—rather than about brand alone.
PW Consulting Health Care Research Center
Forward Outlook: Trends and Commercial Implications for 2026–2032
Several trends are likely to define the next several years and create the practical opportunities that decision-makers should monitor.
First, regulatory scheduling shifts will continue to influence product mix and demand patterns. As standalone varicella vaccination gains clearer emphasis in certain age groups, monovalent attenuated live vaccines with strong safety documentation and flexible administration options will remain central to routine programs. The commercial implication is that manufacturers should invest in clinical communication and real-world evidence that support preferred placement in schedules, while procurement teams should anticipate how scheduling updates affect ordering cycles and supply planning.
Second, regional authorization momentum will keep opening incremental revenue pools. Recent clearances in Latin America and Southeast Asia show that country-by-country expansion can compound over time, especially when a product is the first of its kind in a market or when it addresses a specific local preference. The opportunity for manufacturers and investors is to identify sequences of authorizations that create cascading access, where early clearance in one country supports credibility and logistics learning for neighboring markets.
Third, supply resilience will increasingly function as a competitive differentiator. Markets that have experienced shortages are likely to place greater weight on manufacturing continuity, regional production capacity, and transparent supply planning when evaluating suppliers. For providers and public programs, the practical benefit is reduced disruption risk; for manufacturers, the strategic task is to align capacity, forecasting, and contingency mechanisms so that availability becomes a visible and credible advantage.
Worldwide Live Attenuated Varicella Vaccine Market
These trends connect directly to commercial opportunities. Companies that can pair differentiated product attributes with reliable supply and proactive regulatory engagement are well placed to capture share in both routine and catch-up settings. Investors should watch for authorization sequences, pricing transparency in public programs, and the ability of suppliers to maintain continuity during demand surges. Procurement organizations should evaluate not only price but also availability history, administration clarity, and the manufacturer’s capacity to support program-level needs during peak periods.
Potential risks and uncertainties remain. Scheduling guidance can change as safety discussions evolve, which may alter demand tempo for specific formulations. Reimbursement frameworks and price lists can shift contracting dynamics, particularly where transparency increases price sensitivity. Manufacturing and logistics disruptions can create localized shortages that quickly affect program trust and market share. Finally, the entry of additional differentiated products may intensify competition in specific regions, compressing margins unless supported by clear clinical or access advantages. These uncertainties do not undermine the overall growth outlook, but they do elevate the importance of planning for variability rather than assuming a smooth trajectory.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product strategy with the realities of schedule preference, regional authorization, and supply continuity. That means treating regulatory updates and administration instructions as commercial assets, maintaining robust safety communication, and building supply plans that can withstand episodic demand surges from catch-up campaigns. Where a differentiated strain or platform is available, the value is greatest when it is matched to a specific regulatory or procurement context rather than positioned generically. Establishing early clearances in targeted markets can create a platform for broader regional expansion, especially when paired with clear clinical messaging and dependable distribution.
For investors, the most informative signals are authorization sequences, supply reliability records, and the alignment of product attributes with emerging schedule and age-group dynamics. Growth is likely to be uneven across regions, so the opportunity set is less about overall market expansion and more about identifying where differentiation, access, and execution converge. Monitoring public price transparency, tender outcomes, and regional shortage episodes can provide early indications of competitive shifts. It is also prudent to assess whether a company’s manufacturing base and contingency planning are sufficient to support continuity if demand patterns change abruptly.
For procurement organizations and program planners, the decision framework should incorporate total value rather than headline price alone. Availability history, administration clarity, and the manufacturer’s ability to support public programs during peak periods can materially affect programmatic outcomes. As schedules and reimbursement details evolve, maintaining a flexible sourcing strategy and sufficient visibility into contract pricing can help prevent disruption. Where possible, evaluating alternatives before a shortage occurs preserves optionality and reduces the operational cost of reactive procurement.
Timely access to detailed, segment-level intelligence matters because the variables that shape outcomes—authorization timing, regional price dynamics, supply continuity, and schedule-driven demand shifts—can change faster than broad market headlines suggest. A focused view of country-level opportunities, product-specific positioning, and supplier reliability patterns supports more confident decisions on capacity planning, market entry, contracting, and portfolio prioritization. For teams that need granular segmentation, competitive benchmarks, and tailored scenario analysis, the full research report provides the structured detail required to translate these trends into concrete action plans.
BCG Vaccine Market
For detailed analysis of this topic, please visit the official page: Varicella Attenuated Live Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Swab Market: Why 6.98% CAGR to $6.17B by 2032 Changes Everything
By PW Consulting, 2026-09-21
The Medical Swab Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for medical swabs has transitioned from a crisis-driven surge to a more structured, demand-led expansion. Between 2020 and 2025, the market grew from 2.15 billion USD to 3.76 billion USD, reflecting both the lingering effects of heightened diagnostic demand and the normalization of specimen collection as a routine clinical practice. Looking ahead, the market is projected to reach 6.17 billion USD by 2032, expanding at a compound annual growth rate of 6.98 percent. This trajectory suggests that medical swabs are no longer a commoditized afterthought but a strategically relevant component in diagnostics, infection control, and point-of-care workflows.
Yet growth alone does not define strategy. The market is shaped by shifting material preferences, regulatory tightening, supply chain recalibration, and the ongoing consolidation of diagnostic ecosystems. For executives, investors, and procurement leaders, the question is no longer whether demand will continue, but where value will be created and how competitive positions will be defended.
Market Snapshot and Core Challenges
The market's expansion over the past five years has been broad-based, with North America historically accounting for the largest revenue share, followed by Europe and Asia Pacific. This geographic distribution reflects established healthcare infrastructure, higher diagnostic volumes, and stronger procurement formalized through large distributors. At the same time, the product mix has evolved. Foam-tipped and cotton-tipped swabs continue to anchor much of the revenue, while non-woven variants and specialty formats command growing attention in specific diagnostic and wound-care applications. Specimen collection remains the dominant use case, consistent with the market's deep integration into microbiology, respiratory testing, and routine clinical sampling.
Against this backdrop, three challenges stand out as strategic inflection points.
Challenge 1: Quality, Contamination Risk, and Procurement Sensitivity
Quality failures in medical consumables can have outsized consequences because swabs are often used on vulnerable populations and in time-sensitive diagnostic workflows. Regulatory notices and voluntary recalls have highlighted microbial contamination risks in alcohol prep pads and related items, reinforcing scrutiny across the broader category of sterile and semi-sterile medical consumables. For procurement teams, this increases the importance of supplier qualification, lot traceability, and documentation of manufacturing controls. For manufacturers, it raises the cost of compliance and the need for consistent quality systems that can withstand audit cycles and unexpected disruption.
Challenge 2: Regulatory Tightening Around Diagnostics and Specimen Handling
The regulatory environment is becoming more demanding, particularly where swabs intersect with in vitro diagnostics. Proposed and evolving rules on laboratory-developed tests are pushing more diagnostic workflows into formal premarket review and quality system expectations. In parallel, at-home over-the-counter COVID-19 testing frameworks continue to specify self-collection requirements that depend on approved swabs or equivalent sampling media. These changes do not merely alter compliance burdens; they reshape product design requirements, validation pathways, and the speed at which new collection systems can be deployed.
Challenge 3: Material Trade-offs and Supply Chain Exposure
Swab performance is highly dependent on tip material, shaft stiffness, absorption characteristics, and compatibility with transport media. Cotton, foam, flocked, and non-woven formats each present distinct trade-offs in cost, specimen release, and clinical suitability. This material complexity creates supply chain exposure, especially when demand spikes or when specific grades of raw material become constrained. The market has already experienced periods where sterile cotton swabs and gauze-based products faced supply tension during prior surges, and that structural sensitivity remains relevant whenever volume expectations shift quickly.
Key Demand Drivers
The market's continued expansion is not accidental. It reflects a convergence of technology, regulation, demand behavior, and supply-side restructuring that together create durable pull for better sampling tools and more reliable consumable supply.
PW Consulting Health Care Research Center
Technology Innovation in Collection and Preservation
One of the most consequential shifts is the move from simple collection tools to integrated collection-and-preservation systems. Flocked swab formats have become especially relevant because they can improve specimen release and reduce retention compared with traditional fiber mats, making them attractive for microbiology and molecular workflows. More recently, the introduction of FDA-cleared collection and transport systems designed for rapid inactivation and preservation points to a broader trend: swabs are increasingly evaluated not only by how well they collect, but by how well they stabilize specimens, reduce biohazard exposure, and support faster turnaround.
This matters commercially because it changes the basis of competition. In a commoditized price environment, tip material and pack size may dominate purchasing decisions. In a performance-driven environment, validation data, compatibility with diagnostic platforms, and specimen integrity become differentiators. Companies that can demonstrate measurable performance benefits in realistic collection scenarios are better positioned to defend pricing and build preference with laboratory and clinical customers.
Regulatory and Policy Dynamics
Policy and regulatory developments are influencing both product design and market access. Expectations around quality systems, premarket review for certain diagnostic-related products, and clearance pathways for collection systems are encouraging more documented validation and more cautious product claims. At the same time, at-home testing requirements continue to reinforce the role of reliable self-collection materials. The net effect is a market where compliance capacity is increasingly a market-entry barrier, but also a source of trust. Manufacturers with established regulatory competence can convert that competence into preference with risk-averse procurement organizations and integrated diagnostic customers.
Demand-Side Changes in Clinical and Consumer Settings
Demand for medical swabs is being shaped by two overlapping behaviors. In clinical settings, the continued emphasis on rapid diagnostics, respiratory surveillance, and specimen quality keeps sampling materials in steady demand. In consumer-facing settings, the normalization of self-collection for certain tests has expanded the relevance of swabs beyond traditional hospital and laboratory channels. The practical implication is that downstream customers are increasingly sensitive to ease of use, consistency, and clear instructions, especially when the end user is not a trained clinician. Products that reduce variability in collection technique can lower downstream rejection rates and improve overall diagnostic efficiency.
Supply Chain Recalibration and Cost Structure
Cost structures in this market are influenced by raw material availability, manufacturing geography, sterilization and packaging requirements, and logistics for sterile consumables. Companies that can balance quality, lead time, and cost position are gaining advantage, especially as procurement organizations place greater weight on resilience and continuity. There is also a growing premium on transparency: customers want to understand not just unit pricing, but the reliability of supply, documentation supporting sterility and performance, and the ability to scale without compromising control. In that environment, supply chain design becomes a strategic asset rather than a back-office function.
Competitive Landscape and Leading Strategies
The competitive field combines large diversified medical supply companies, specialist swab and collection-system manufacturers, and regional producers with strong cost positions. Market concentration is moderate, with the top three players holding roughly 35 percent of revenue and the top five closer to 47 percent. This level of concentration suggests that scale, brand trust, and channel access matter, but it also leaves room for differentiated specialists and regional challengers to compete on performance, compliance, or cost.
Several companies illustrate the strategic diversity in the market.
Puritan Medical Products has built a strong identity around medical-grade sterile and non-sterile swabs, flocked formats, and collection/transport systems. Its emphasis on U.S.-based manufacturing and FDA-cleared solutions for rapid diagnostics, including SARS-CoV-2-related workflows, reflects a strategy centered on trust, traceability, and regulated performance. The launch of a collection and transport system designed for rapid inactivation and preservation with a fast turnaround illustrates how a focused player can compete on workflow value rather than commodity volume alone.
Copan Diagnostics is widely associated with flocked swab technology for specimen collection in microbiology and diagnostics. Its market position indicates the value of deep application expertise and platform compatibility. Product validation work, such as evaluations of collection formats for enteric pathogen detection on major diagnostic systems, shows how specialists reinforce preference by aligning their sampling tools with the workflows of high-value diagnostic platforms.
BD and Medline Industries represent the broader diversified supplier model. BD provides flocked and cotton swabs across microbiology, diagnostics, and specimen collection, benefiting from scale, distribution breadth, and integration with larger medtech ecosystems. Medline supplies cotton swabs, gauze swabs, and medical disposables to hospitals and healthcare facilities, competing in part on reliability, catalog breadth, and institutional procurement relationships. In this segment, advantage often comes from being easy to specify, easy to procure, and consistent across large-volume contracts.
Dynarex Corporation and Sarstedt AG & Co. KG further illustrate the range of positioning. Dynarex focuses on sterile cotton and medical swabs for clinical, laboratory, and diagnostic use, while Sarstedt provides laboratory and medical sampling swabs, including forensic and diagnostic variants. These players highlight the continued relevance of application-specific offerings, where the value proposition is tied to the needs of particular testing environments rather than to mass-market price competition alone.
Surgical Sponge Market
On the regional side, companies such as GPC Medical Ltd, Hubei Baikang Medical Instrument, Winner Medical, Shenzhen Huachenyang Technology, and Jiangsu Huida Medical Instruments demonstrate the importance of manufacturing capacity, cost efficiency, and export-oriented supply. Several of these manufacturers emphasize compliance with international quality and regulatory standards, which is increasingly necessary for accessing regulated markets and competing beyond purely price-driven channels. Their presence also reflects a broader structural reality: the market is not dominated by a single geography of production, and sourcing strategies are often shaped by the trade-off between cost, lead time, and regulatory acceptability.
Recent market events underscore the operating environment. A voluntary nationwide recall of a large alcohol prep pad product due to potential microbial contamination, affecting more than 170 million units, reminds the industry how quickly quality issues can scale into commercial and reputational exposure. At the same time, product-level progress such as FDA-cleared rapid collection and preservation systems, and validation studies linking swab formats to diagnostic system performance, shows where differentiation is being built.
How the Landscape Is Evolving
Three patterns are shaping competitive evolution.
- Integration around workflows. Swabs are increasingly evaluated as part of a larger collection, transport, and testing workflow. Players that can align their products with diagnostic platforms, specimen stability requirements, and procurement simplification are gaining strategic leverage.
- Differentiation through compliance and evidence. In a market where recalls and regulatory scrutiny heighten risk awareness, documented quality systems, clearance status, and performance validation are becoming powerful trust signals.
- Persistent regional competition. Cost-competitive manufacturers continue to pressure commoditized segments, while regulated and application-specific segments reward specialized capability. The result is a bifurcated environment rather than a uniform race to the bottom.
Future Trends and Commercial Opportunities
Over the next three to five years, the medical swab market is likely to be shaped by a small number of durable trends. Each carries implications for product strategy, sourcing, and investment.
Trend 1: From Collection Tool to Specimen-Integrity Solution
Swabs will increasingly be judged by their contribution to specimen quality, stabilization, and workflow efficiency, not just by tip material or unit cost. This opens opportunities for products that combine superior release performance, compatibility with transport media, and reduced biohazard handling burden. For manufacturers, the opportunity lies in building clinically relevant evidence and making that evidence easy for procurement and laboratory customers to use in decision-making. For buyers, the opportunity is to reduce downstream variability and improve the reliability of diagnostic results.
Trend 2: Greater Regulatory Discipline as a Competitive Filter
As diagnostic-related expectations become more formalized, suppliers with robust quality systems and clear clearance pathways will be better positioned to retain and expand share in regulated channels. This trend favors incumbents and well-prepared specialists, while raising the bar for new entrants that lack documentation, validation capacity, or regulatory experience. Commercially, this means that compliance capability can become a moat, especially in segments where customers are risk-averse or where self-collection and point-of-care use increase the stakes around consistency and safety.
Trend 3: Resilient, Multi-Source Supply as a Procurement Priority
Demand volatility, raw material sensitivity, and the consequences of contamination events are likely to keep supply resilience near the top of procurement agendas. The resulting opportunity is for suppliers that can offer predictable lead times, transparent documentation, and credible contingency plans. For distributors and large healthcare customers, this may mean dual sourcing, stricter qualification criteria, and more emphasis on supplier responsiveness. For manufacturers, it means that operational reliability is a selling point, not merely an operational metric.
Laboratory Swabs Market
Risks and Uncertainties
Despite favorable growth dynamics, several uncertainties warrant caution. Regulatory timelines and requirements can shift, altering validation burdens and market access for certain collection products. Quality events can damage trust quickly, especially when large volumes are involved or when affected products reach vulnerable end users. In addition, raw material cost pressure and capacity constraints can compress margins in commoditized segments, while disease surveillance patterns and testing behavior can influence demand in ways that are difficult to predict far in advance. Companies that assume linear growth without preparing for these variability factors may find their positioning weaker than expected during disruption.
Implications for Decision-Makers
The strategic implications vary by role, but a few priorities cut across the market.
For Manufacturers
Focus on the basis of differentiation. If the product is essentially commoditized, cost discipline, reliable delivery, and strong supplier documentation will be essential. If the product competes on performance, invest in clinically relevant validation, workflow compatibility, and clear evidence that supports preference. In either case, quality systems and traceability are not optional; they are part of the commercial proposition. Manufacturers should also consider whether their portfolio is positioned for the shift toward integrated collection and preservation solutions, where value is created through specimen integrity and process efficiency rather than through the swab alone.
For Investors
Look beyond top-line growth. The market's expansion is encouraging, but value creation will be uneven. Companies with regulatory competence, application-specific expertise, and resilient supply chains are better placed to defend margins and capture preference in regulated segments. Equally important is the risk profile: recall exposure, raw material sensitivity, and dependence on a narrow demand channel can undermine otherwise attractive growth narratives. In this environment, diligence should place substantial weight on quality controls, validation capability, procurement relationships, and geographic or channel concentration.
For Procurement and Supply Chain Leaders
Treat swabs and related consumables as risk-managed inputs rather than interchangeable commodities. Qualification criteria should include not only price and pack configuration, but also documentation supporting sterility, lot control, compatibility with intended workflows, and the supplier's ability to respond to quality events. Where possible, structure sourcing to balance cost with resilience, and maintain visibility into alternative suppliers for critical formats. In regulated environments, procurement decisions increasingly affect downstream diagnostic reliability, so the cost of poor supplier selection can extend well beyond the purchase price.
Getting the Full Picture
This market is moving on multiple axes at once: material performance, regulatory expectations, supply resilience, and workflow integration. For organizations making sourcing, product, or investment decisions, the relevant question is less about whether the market will grow and more about where the next round of differentiation and risk will emerge. Detailed segmentation data, company-level profiles, and scenario-based projections can materially sharpen those decisions, especially when the goal is to align strategy with the specific formats, geographies, and applications most relevant to a given business. For readers seeking a deeper, data-rich view of the medical swab market, a full research report can provide the granular segmentation, competitive benchmarking, and forward-looking detail needed to turn these strategic themes into actionable plans.
For detailed analysis of this topic, please visit the official page: Medical Swab Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Modified Starch Market Outlook: Why 3.5% CAGR and Food Demand Reshape Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Modified Starch Market: A 2025 Perspective
Market Current State and Core Challenges
The modified starch market has established itself as a foundational ingredient segment across multiple industrial and consumer-facing sectors. Over the historical period from 2020 to 2025, the market expanded from approximately 10.5 billion USD to 13.7 billion USD, reflecting steady demand across food processing, paper manufacturing, textiles, and animal feed applications. Forward-looking projections through 2032 indicate continued growth, with revenue expected to reach 17.17 billion USD. The compound annual growth rate over the forecast horizon of 2026 to 2032 stands at 3.5 percent, a trajectory that signals resilience but also underscores the importance of strategic positioning in a maturing landscape.
Market structure reveals a moderately concentrated environment, with the top three players accounting for 35 percent of revenue and the top five capturing 45 percent. This concentration pattern suggests that incumbents enjoy meaningful scale advantages in sourcing, formulation expertise, and distribution networks, yet sufficient fragmentation remains to allow specialized or regional players to compete on functionality, price, or supply reliability. The regional distribution of revenue reflects a globally dispersed supply-demand matrix, with Asia Pacific contributing the largest share, followed by North America and Europe. Such geographic spread creates both opportunities for localized production strategies and vulnerabilities to regional supply disruptions.
Key Challenges and Inflection Points
The current market environment presents several structural challenges that demand strategic attention. First, raw material price volatility has intensified, particularly for tapioca starch, where continuous upward pricing trends and tightening supply were observed toward the end of 2025 and into early 2026, reaching 490 USD per ton. This dynamic pressures cost structures across applications that rely on tapioca-based modification and forces manufacturers to reconsider sourcing diversification and contract structures.
Second, regulatory evolution is reshaping formulation strategies. In the European Union, HS Code 35051090 for modified starches has been subject to CN refinements and duty adjustments effective in 2025, altering trade cost calculations for cross-border transactions. Simultaneously, 2025 updates to FDA labeling guidelines have increased demand for label-friendly modified starches that do not require an E-number or complex chemical name, pushing formulators toward cleaner ingredient narratives. Additionally, 2025 US tariffs on modified starch products have had a direct price impact on imports, creating cost asymmetries that favor domestic production or alternative sourcing corridors.
Corn Starch Market
Third, the market is approaching an inflection point in application mix. While food and beverages remain the dominant end-use category, industrial and non-food applications such as paper, textiles, and adhesives continue to absorb a significant share of modified starch volumes. The strategic question for participants is whether to deepen specialization in high-margin food-grade functionality or to build resilient industrial-grade supply chains that benefit from broader demand diversification.
Key Drivers of Market Change
Technological Innovation and Formulation Breakthroughs
Innovation in modification techniques continues to expand the functional envelope of starch-based ingredients. Physical, chemical, and enzymatic modification pathways each offer distinct performance profiles, with physically modified starch currently commanding the largest share of the type segmentation, followed by chemically modified and enzymatically modified variants. Enzymatic approaches are gaining attention for their ability to produce cleaner ingredient profiles and more tailored functional outcomes, aligning with cleaner-label expectations in food applications.
Recent product-level developments illustrate the pace of innovation. In March 2025, Cargill highlighted a first-of-its-kind dent-corn modified starch designed to improve sauce color and texture, alongside a pectin replacer. This launch underscores a broader trend toward multifunctional ingredients that can replace more expensive or less label-friendly alternatives while preserving or enhancing sensory performance. For manufacturers, such innovations reduce formulation complexity and open opportunities to respond to consumer preferences for simpler ingredient lists without sacrificing product quality.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. The EU CN refinements for modified starches influence duty structures and administrative compliance for exporters and importers, requiring closer attention to classification accuracy and trade documentation. In parallel, FDA labeling updates have elevated the importance of ingredient nomenclature, encouraging suppliers to develop modified starches that can be presented in a label-friendly manner. These regulatory shifts are not merely compliance issues; they affect product positioning, customer education, and the relative attractiveness of modified starches versus alternative thickeners, stabilizers, and texturizers.
Trade policy further complicates the landscape. Tariff actions on modified starch products have impacted import pricing, creating localized cost advantages for domestic producers and prompting re-evaluation of supply chain geography. Companies that can align sourcing, manufacturing, and distribution with the prevailing regulatory and tariff environment will be better positioned to manage margin pressure and maintain competitive pricing.
PW Consulting Health Care Research Center
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, food and beverage manufacturers continue to drive the largest portion of modified starch consumption, reflecting the ingredient's versatility in thickening, stabilizing, and texturizing applications. Consumer preferences for cleaner labels, plant-based formulations, and improved texture have reinforced the relevance of modified starches as functional solutions that can meet multiple objectives simultaneously. In industrial contexts, paper and textile manufacturers rely on modified starches for binding, coating, and finishing functions, where performance consistency and cost efficiency remain decisive.
Trade show activity in late 2025 highlighted the intensity of demand-side engagement. SMS Corporation unveiled high-performance modified starch solutions at Fi Europe 2025 and, in November 2025, presented modified tapioca starch innovations while winning Plant-Based Manufacturing of the Year at Gulfood Manufacturing 2025. These developments indicate that suppliers are actively aligning product portfolios with plant-based and performance-driven demand, while also using industry events to validate innovation and build commercial relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by raw material price movements and regional supply tightness. The tapioca starch price trajectory toward 490 USD per ton illustrates how concentrated supply conditions can rapidly alter input economics for modification producers. In parallel, U.S. potato starch export prices in 2025 ranged from 0.40 USD per kg to 5.74 USD per kg, reflecting wide variability tied to quality, grade, and destination market conditions. Such variability rewards suppliers with diversified feedstock portfolios and flexible formulation capabilities that can shift between corn, wheat, potato, tapioca, and pea sources depending on availability and economics.
The supply chain implications extend beyond raw material procurement. Logistics, trade compliance, and regional production footprints are increasingly important determinants of total delivered cost. Companies that invest in supply chain transparency, multi-source sourcing, and regional manufacturing capacity can mitigate exposure to single-commodity shocks and tariff-driven price distortions, while also improving responsiveness to customer demand cycles.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field includes a mix of global ingredient corporations and specialized regional producers. Cargill, headquartered in Minneapolis, produces and supplies modified starches for personal care, food and beverage, and industrial applications, emphasizing grades with stable viscosity and functional benefits. Ingredion Incorporated, based in Westchester, Illinois, manufactures modified food starches and industrial starches for texturizing, thickening, and stabilizing across food, beverage, and non-food applications. Roquette Frères, located in Lestrem, France, is a global producer of native and modified starches from multiple sources including corn, wheat, potatoes, tapioca, and peas, offering over 300 modified starch variants. Tate & Lyle PLC, headquartered in London, supplies modified starches and starch derivatives for food and beverage, with clean-label and specialty portfolios. These global players derive competitive advantage from broad feedstock access, application laboratories, and established customer relationships across multiple sectors.
Regional and specialized manufacturers add important diversity to the landscape. Premier Starch, based in Bengaluru, India, manufactures modified starches, dextrins, and corrugation adhesives for packaging, paper, paints, abrasives, and mining industries. Angel Starch & Food Pvt. Ltd., also in India, produces modified starches for textile binders, thickeners, emulsifiers, stabilizers, and functional food ingredients. Jay Dinesh Chemicals, with over 50 years of experience in chemical modification processes, manufactures and exports modified starch from India. Vinayak Ingredients provides modified starches derived from maize, cassava, or potato for food additives and industrial use. SMS Corporation Company Limited, headquartered in Thailand, is a global manufacturer and distributor of premium modified tapioca starch for food, pharmaceutical, nutraceutical, paper, adhesive, construction, and textile applications. Grain Processing Corporation, located in Muscatine, Iowa, produces modified starches including acid-modified, oxidized, pregelatinized, and cationic types for industrial and food applications. AEBE U.A., based in the Netherlands, manufactures modified starches for food and industrial sectors. Global Bio-Chem Technology Group Company Limited, a Chinese producer, supplies modified starch products for food and industrial use. SPAC Starch Products India Private Limited manufactures advanced modified starches from maize, corn, and tapioca sources for industrial applications.
Strategic Differentiation and Competitive Evolution
Leading strategies in this market tend to cluster around three pillars: feedstock flexibility, application-specific functionality, and regulatory-aware formulation. Global incumbents leverage multi-source starch portfolios to balance cost and performance across regions, while also maintaining dedicated food-grade and industrial-grade lines. Specialist producers often compete by deepening expertise in particular applications or modification types, offering tailored solutions that address specific processing conditions, label requirements, or regional price dynamics.
The market is simultaneously experiencing consolidation pressures and fragmentation opportunities. Concentration among the largest players reflects the advantages of scale in R&D, quality systems, and global distribution, yet the continued presence of numerous regional manufacturers indicates that local responsiveness, niche functionality, and price competitiveness remain viable differentiation paths. New entrants and expanding regional players can gain traction by focusing on underserved applications, developing cleaner-label modification profiles, or building reliable supply in regions where imported modified starches face tariff or logistics headwinds.
Recent activity among leading companies confirms the emphasis on innovation and market engagement. SMS Corporation's trade show participation in late 2025, including the unveiling of high-performance modified starch solutions at Fi Europe 2025 and the recognition at Gulfood Manufacturing 2025, illustrates how suppliers use visible innovation and industry recognition to strengthen positioning in food and industrial segments. Cargill's March 2025 product innovation further demonstrates the ongoing push toward differentiated functionality that supports label-friendly reformulation and sensory improvement.
Potato Starch Market
Future Trends and Commercial Opportunities
Trend 1: Cleaner-Label and Functionally Efficient Modified Starches
Over the next three to five years, demand for label-friendly modified starches is likely to intensify, driven by labeling guideline updates and consumer expectations for simpler ingredient statements. Commercial opportunities will arise for suppliers that can deliver stable viscosity, thickening, and texturizing performance without relying on nomenclature that complicates label readability. Formulations that can replace pectin, gum, or other more expensive or less desirable ingredients while maintaining sensory quality will be particularly valuable in food and beverage applications. The risk here lies in balancing clean-label positioning with performance consistency; manufacturers must ensure that cleaner ingredient narratives do not erode the functional reliability that customers depend on.
Trend 2: Regional Sourcing and Supply Chain Reconfiguration
Tariff impacts, raw material price volatility, and regional supply tightness are expected to accelerate reconfiguration of supply chains. Companies may increasingly favor regional production footprints, diversified feedstock sourcing, and long-term supply agreements that reduce exposure to single-commodity shocks. Opportunities exist for producers that can offer reliable delivery, transparent cost structures, and flexibility across starch sources such as corn, potato, tapioca, wheat, and peas. The key uncertainty is the trajectory of trade policy and commodity markets; shifts in tariff regimes or unexpected supply disruptions could alter the economics of regional versus cross-border supply strategies.
Trend 3: Industrial and Non-Food Diversification with Performance Focus
While food and beverages remain the largest application segment, industrial uses in paper, textiles, adhesives, and related sectors provide demand diversification and volume stability. Over the forecast period, opportunities will likely emerge for modified starches that deliver consistent binding, coating, and finishing performance at competitive cost, especially where manufacturers seek alternatives to more expensive synthetic additives. The risk is that industrial demand can be sensitive to macroeconomic cycles and substitution pressures; suppliers will need to manage capacity and pricing dynamically to preserve margins during demand fluctuations.
Actionable Guidance for Decision-Makers
For Manufacturers and Ingredient Suppliers
- Strengthen feedstock diversification and formulation flexibility to respond to raw material price volatility and regional supply tightness, particularly for tapioca and potato-based inputs.
- Invest in label-friendly and multifunctional modification profiles that align with evolving FDA and EU expectations, enabling customers to simplify ingredient statements while maintaining performance.
- Use application-level expertise and visible innovation, including trade show engagement and targeted product launches, to differentiate from both global incumbents and regional competitors.
For Investors
- Evaluate exposure to regulatory and tariff dynamics across key regions, recognizing that classification refinements, duty adjustments, and import tariffs can materially affect cost structures and competitive positioning.
- Prioritize companies with diversified feedstock access, application breadth, and the ability to shift between physical, chemical, and enzymatic modification pathways as customer requirements evolve.
- Monitor concentration trends and consolidation potential; while the market remains moderately concentrated, specialized players with strong application niches or regional supply advantages may present attractive value creation pathways.
For Procurement and Supply Chain Leaders
- Build multi-source sourcing strategies that reduce dependence on single starch types or single-origin suppliers, improving resilience against price spikes and supply tightness.
- Align supplier selection with regulatory-aware ingredient profiles, ensuring that modified starch choices support label objectives and trade compliance requirements in target markets.
- Incorporate total delivered cost, including logistics and tariff implications, into sourcing decisions rather than relying solely on ex-works pricing, especially when cross-border trade is involved.
Conclusion
The modified starch market is entering a phase where steady growth coexists with meaningful structural change. Raw material volatility, regulatory updates, and trade policy shifts are reshaping cost and compliance dynamics, while innovation in functionality and cleaner-label formulation is opening new commercial pathways. Companies that combine feedstock flexibility, application-specific expertise, and supply chain resilience are best positioned to convert these dynamics into durable advantage. For decision-makers seeking deeper segmentation data, regional cost modeling, and customized strategic recommendations, the full research report provides the detailed analysis needed to translate these market signals into actionable plans.
For detailed analysis of this topic, please visit the official page: Modified Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Endoscopy Ultrasound Market: Why 7.1% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
The Strategic Horizon of the Endoscopy Ultrasound Market: Growth, Innovation, and Competitive Positioning
The endoscopy ultrasound (EUS) market stands at a compelling inflection point. Valued at approximately $950 million in 2020, the space has grown to an estimated $1,340 million by 2025, reflecting sustained adoption across diagnostic and interventional gastroenterology. With a forecasted compound annual growth rate of 7.1 percent through 2032, the market is projected to surpass $2,170 million within the decade. This trajectory is not merely a function of clinical demand; it reflects structural shifts in how minimally invasive diagnostics are integrated into care pathways, how imaging hardware evolves, and how reimbursement and regulatory frameworks shape commercial viability. For executives, investors, and procurement leaders, the opportunity lies in recognizing which segments, geographies, and product architectures will compound value over the next five years, and which legacy assumptions are already eroding.
Market Landscape and Core Challenges
A Market Defined by Cross-Sectional Innovation and Procedural Convergence
The EUS ecosystem spans a deliberately integrated product set: echoendoscopes, ultrasound processors, biopsy needles, and specialized probes that together enable high-resolution imaging alongside tissue acquisition and therapeutic intervention. Over the historical period from 2020 to 2025, the market crossed the threshold from niche advanced endoscopy to a more mainstream procedural platform. Growth has been propelled by the convergence of diagnostic clarity and minimally invasive biopsy capabilities, particularly in oncology workups and complex gastroenterology cases. The hardware-software integration model has matured, with processors increasingly serving as the computational backbone that interprets signals from scopes and probes, while needles and accessories define the procedural throughput and clinical yield.
The market’s structure also reveals a concentrated competitive field, with a handful of multinational players holding significant share through established distribution channels, clinical training networks, and proprietary imaging pipelines. This concentration creates both stability and friction: incumbents benefit from installed-base economics and procedural familiarity, while smaller entrants must either differentiate on architecture, cost, or workflow simplification to gain traction.
Three Pressing Challenges Shaping the Near-Term Trajectory
Even as the market expands, several structural challenges are redefining how value is created and captured. The first is the tension between imaging fidelity and procedural efficiency. Clinicians are increasingly unwilling to trade scan time, learning curve, or setup complexity for marginal gains in resolution. The next generation of EUS systems is therefore being judged not only on image quality, but on how seamlessly they integrate into existing endoscopy workflows, how quickly specialists can achieve competency, and how reliably devices can be reprocessed between cases.
PW Consulting Health Care Research Center
The second challenge is the reimbursement and coding environment. EUS procedures rely on standard outpatient coding structures, with payments varying across regions and payer mix. While this provides a baseline pathway for utilization, it also means that adoption is sensitive to procedural coding shifts, outpatient site-of-service economics, and the relative cost burden of disposables versus capital equipment. Vendors and providers alike must navigate the operational reality that revenue generation depends on both clinical value and administrative predictability.
The third challenge lies in regulatory clearance and clinical validation cadence. New devices in this space typically require premarket notifications, and the bar for differentiation increasingly includes not just technical performance but infection-prevention compliance, reprocessing validation, and documented procedural support. This regulatory layer is not a barrier per se, but it does reshape time-to-market dynamics and raises the operational burden for companies introducing novel architectures or accessory ecosystems.
Key Drivers Reshaping the Market
Technology Innovation as the Core Value Multiplier
The most visible driver of market momentum is the continued refinement of imaging and procedural tools. Advanced ultrasound platforms are pushing higher resolution and more structured imaging outputs, while echoendoscopes and linear scopes are being engineered to improve navigation, durability, and image consistency across varied patient anatomies. At the same time, biopsy needles and accessories are evolving toward more reliable tissue acquisition, with designs that emphasize secure sampling and compatibility across procedural use cases. The practical implication is that EUS is increasingly positioned as a single procedural environment where diagnosis, sampling, and in certain cases intervention can be coordinated without disjointed device switching.
Recent product announcements illustrate this trajectory. In May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States through a partnership with Canon, signaling a continued push toward advanced imaging integration and cross-company engineering collaboration. The same period saw Olympus expand its visible EUS solution set at Digestive Disease Week 2026, reinforcing the message that the company is competing on platform breadth as much as individual hardware. Earlier, in September 2025, Fujifilm launched the Arietta 850 EUS processor alongside its 700 Series linear scopes, emphasizing enhanced image clarity for EUS applications. These moves are not isolated product launches; they are indicators of a competitive posture in which imaging clarity, processor capability, and scope architecture are being optimized together rather than in isolation.
Regulatory and Reimbursement Context as Commercial Architecture
Regulation and reimbursement form the structural scaffolding within which EUS adoption scales. On the regulatory side, new EUS devices typically move through FDA 510(k) clearance pathways, as exemplified by recent premarket notifications for systems such as Olympus’s EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and EndoSound’s Vision System. This clearance process is a predictable requirement, but it also means that innovation cycles must accommodate not only engineering milestones but documentation, validation, and post-clearance support. The practical effect is that companies with mature regulatory workflows and established quality systems can convert development progress into commercial availability more reliably than those still building compliance infrastructure.
On the reimbursement side, EUS procedures are generally covered under standard outpatient CPT codes, with Medicare national average payments providing a reference point for site-of-service economics. The nuance is that payment variability across payers and settings can influence how aggressively hospitals and ambulatory surgery centers adopt capital-intensive imaging platforms, especially when disposables such as needles add recurring cost. The business implication is that value propositions increasingly need to account for total procedural economics rather than device performance alone.
Demand-Side Shifts Toward Integrated, Minimally Invasive Workflows
Demand is being reshaped by the broader movement toward outpatient, minimally invasive diagnostics and the growing expectation that advanced imaging should support both detection and tissue acquisition. Oncology-related workups and gastroenterology procedures remain central to utilization, and clinicians are looking for platforms that reduce handoffs, shorten setup, and improve reproducibility across operators. This is a subtle but important shift: the purchase decision is increasingly anchored not just by image quality, but by the predictability of the entire procedural flow from insertion to sampling to reprocessing.
Training and on-site application support have become part of the value equation. The availability of certified clinical application specialists who provide EUS training and procedural optimization support is a differentiator for many institutions, especially as new platforms and accessories enter the workflow. In practice, the ability to shorten learning curves and standardize techniques contributes directly to adoption velocity and long-term utilization rates.
Supply Chain and Material Considerations
Behind the clinical narrative, supply chain and material choices are shaping product durability, cost structure, and differentiation. EUS biopsy needles rely on medical-grade materials such as nitinol with multi-layer sheaths to support secure tissue acquisition, and these material decisions influence both performance and unit economics. At the same time, companies that supply ultrasonic components for EUS probes and accessories occupy an important supporting role in the value chain, contributing to imaging consistency and manufacturing scalability. The broader implication is that competitive advantage is not solely defined by brand or platform; it is also shaped by the reliability of component supply, reprocessing compatibility, and the ability to manage recurring accessory economics.
Ultrasound Market
Competitive Landscape and Leading Strategies
Incumbents Competing on Platform Breadth and Ecosystem Integration
The market’s leadership tier is anchored by large, diversified players with the capacity to offer integrated portfolios spanning processors, echoendoscopes, needles, and accessories. Olympus Corporation remains a prominent reference point, with a comprehensive EUS portfolio that includes processors, echoendoscopes, miniature probes, biopsy needles, and advanced imaging systems. Its recent U.S. introduction of the Aplio i800 EUS Premium Ultrasound System in partnership with Canon, along with expanded EUS visibility at Digestive Disease Week 2026, illustrates a strategy centered on strengthening imaging capability while maintaining broad procedural coverage. For institutions already using Olympus ecosystems, this approach reinforces installed-base continuity and clinical training familiarity.
Fujifilm Holdings Corporation has taken a parallel but distinct path, focusing on processor-image clarity improvements and scope architecture. Its launch of the Arietta 850 EUS processor and 700 Series linear scopes at ACG 2025 reflects a design emphasis on high-resolution imaging and procedural consistency. This positions Fujifilm as a strong alternative for sites prioritizing image performance and processor evolution, particularly where imaging clarity is a decisive clinical or purchasing factor.
Boston Scientific Corporation, Medtronic plc, Pentax Medical, and Cook Medical each bring differentiated strengths to the market. Boston Scientific’s emphasis on EUS-guided biopsy systems, needles, and processors aligns with procedural efficiency and tissue acquisition workflows. Medtronic’s offering of EUS endoscopes, needles, and ultrasound-guided interventional tools builds toward a broader interventional orientation. Pentax Medical contributes echoendoscopes and processors for diagnostic and therapeutic applications, while Cook Medical’s portfolio of EUS endoscopes, needles, and stents supports GI intervention. These companies compete not only on product features but on how well their portfolios map to institutional procedure mixes and clinical priorities.
Specialists, Niche Entrants, and the Value of Workflow Disruption
Beyond the broad-portfolio players, the market includes specialists and newer entrants targeting specific friction points. EndoSound, Inc. has developed a Vision System that converts standard upper GI endoscopes into full EUS capability, a concept that directly addresses capital cost and equipment deployment flexibility. This kind of approach appeals to sites seeking to expand EUS access without committing to a fully new scope fleet, and it highlights a competitive dynamic in which software-assisted conversion and modular capability can challenge traditional hardware-centric purchasing.
Worldwide Ultra HD Endoscope Market
Other participants illustrate the breadth of the supporting ecosystem. ConMed Corporation and CONMED Corporation focus on EUS biopsy needles and accessories, where recurring consumable economics and procedural reliability matter. Medi-Globe Corporation, HUACO HEALTHCARE TECHNOLOGIES CO., LTD, and SonoScape Medical Corp. contribute EUS scopes, ultrasound systems, and accessories, expanding regional and value-tier options. B.Braun, Philips, and Smith & Nephew add further depth across needles, systems, and therapeutic products. Steris plc occupies a critical supporting role through endoscope reprocessing and sterilization, reinforcing the operational requirement that EUS devices must be validated for safe reuse. Downstream and upstream component suppliers such as NIHON DEMPA KOGYO CO., LTD also play a meaningful role in enabling probe and transducer performance. Limaca Medical rounds out the landscape with a precision EUS biopsy device concept, reflecting continued experimentation with tissue acquisition optimization.
Market Structure Dynamics: Concentration, Integration, and Selective Entry
With a substantial share concentrated among a limited set of large players, the market’s evolution is likely to be shaped by a mix of integration, selective acquisition, and targeted differentiation rather than uniform fragmentation. Large incumbents will continue to benefit from distribution scale, training infrastructure, and installed-base momentum. At the same time, the presence of companies pursuing modular or conversion-based architectures suggests that differentiation may increasingly come from reducing capital burden, simplifying scope management, or improving accessory economics. The competitive question for the next few years is whether the market rewards broad platform dominance, or whether workflow-specific innovations can carve out durable niches by solving procurement and operational constraints.
Future Trends and Commercial Opportunities
Trend One: Imaging and Procedural Platforms Will Be Judged as Integrated Systems
Over the next three to five years, EUS purchasing is likely to shift further from evaluating discrete components toward assessing how processors, scopes, needles, and support services function as a single procedural system. The practical opportunity for providers and manufacturers is to align product roadmaps with workflow continuity: faster setup, more consistent imaging across operators, and accessories that integrate cleanly into sampling workflows. Companies that can demonstrate measurable improvements in procedural predictability, training efficiency, and reprocessing compliance will have stronger positioning than those competing only on headline image quality.
A related commercial opportunity lies in total-cost and utilization framing. As sites balance capital equipment decisions against recurring disposable costs, vendors that offer transparent economics, reliable accessory supply, and on-site application support will be better positioned to influence long-term procurement. The risk to watch is over-indexing on advanced features without corresponding gains in ease of use or consumable efficiency, which can slow adoption in cost-sensitive outpatient settings.
Trend Two: Reimbursement Logic and Site-of-Service Economics Will Shape Adoption Patterns
Because EUS procedures are embedded in standard outpatient coding and payment structures, adoption will continue to be sensitive to site-of-service economics and payer mix. As more procedures move to ambulatory and outpatient environments, the relative economics of capital equipment, disposables, and procedural throughput will matter more than ever. This creates an opportunity for vendors and providers to develop more explicit value narratives that connect clinical outcomes with operational efficiency and reimbursement predictability.
The uncertainty here is that coding and payment environments are not static. Shifts in outpatient reimbursement practice, regional payment variation, and the cost profile of needles and accessories can influence how quickly new platforms are deployed or refreshed. Companies and buyers that monitor coding and payment dynamics closely will be better prepared to anticipate adoption cycles and plan capacity accordingly.
Trend Three: New Entrants Will Pressure Legacy Assumptions Around Capital and Access
The emergence of systems that convert standard scopes into EUS-capable platforms, alongside continued experimentation in biopsy device design, suggests that the market will see ongoing pressure to reduce capital intensity and broaden access. This does not eliminate the role of full-featured dedicated systems, but it does introduce more choice for institutions that want to expand EUS capability without full fleet replacement. For innovators, the opportunity is to prove that converted or modular approaches can deliver reliable imaging and sampling performance with predictable reprocessing and support requirements.
The associated risk is that performance, durability, and clinical confidence must be demonstrated consistently. New architectures that appear attractive on cost must still meet regulatory clearance expectations, reprocessing validation standards, and the clinical workgroup expectations that drive sustained utilization. The market will likely reward entrants that combine economic appeal with credible validation and visible procedural support.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
Position product roadmaps around integrated procedural value rather than isolated specifications. That means aligning processor imaging, scope design, and needle/accessory performance with training, reprocessing, and support economics. Where possible, differentiate by shortening the learning curve, improving consistency across operators, and demonstrating total procedural efficiency. For companies with broad portfolios, reinforce installed-base continuity through clear upgrade paths and application support. For smaller or more specialized entrants, focus on a defined point of friction—such as capital reduction, modular capability, or accessory reliability—and build a credible evidence and support package around it.
For Investors and Strategic Allocators
Evaluate companies based on their ability to convert innovation into predictable commercial availability and repeat utilization. Regulatory competence, application support infrastructure, and supply chain reliability for consumables are not secondary details; they are part of the execution equation that determines whether a product gains traction. Pay attention to players that are strengthening imaging partnerships, expanding processor capabilities, or pursuing modular approaches, while also assessing the durability of their reimbursement and reprocessing assumptions. Diversification across the ecosystem—including processors, scopes, needles, and reprocessing support—can provide a more complete view of where value is likely to compound.
For Procurement Leaders and Clinical Administrators
Structure evaluation criteria around total procedural workflow, not just image performance or list price. Consider how a platform affects training timelines, reprocessing compliance, accessory availability, and the economics of recurring disposables. Where capital constraints are significant, assess whether modular or conversion-based solutions can deliver the required clinical capability with lower deployment burden, provided they meet clearance and validation requirements. Ensure that procurement decisions are linked to a clear plan for clinical application support and staff competency development, since adoption velocity often depends on these operational factors as much as hardware selection.
Closing Perspective
The endoscopy ultrasound market is expanding on the back of imaging refinement, procedural integration, and sustained demand for minimally invasive diagnostics, but the most valuable insights for decision makers lie in how these forces interact. Future advantage will belong to organizations that treat EUS as a workflow system, manage reimbursement and reprocessing realities with discipline, and differentiate in ways that are both clinically credible and operationally efficient. For executives and investors seeking deeper segmentation detail, competitive profiling, and customized commercial guidance, the full PW Consulting market report provides the granularity needed to translate these trends into precise, actionable strategy.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Car Care Products Market 2032: What Really Fuels the 4.5% CAGR Growth Beyond 15.4×10³ Million
By PW Consulting, 2026-09-21
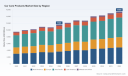
The Car Care Products Market: Strategic Trends and Commercial Opportunities Through 2032
The global car care products market is navigating a period of structural transformation. With total revenue reaching approximately USD 11,500 million in 2025 and projected to expand at a compound annual growth rate of 4.5% through 2032, the sector is moving beyond cyclical demand patterns toward a more innovation-driven and regulation-shaped landscape. The market has demonstrated steady recovery from the volatility of the early decade, with revenue climbing from USD 9,500 million in 2020 to a base of USD 11,500 million in 2025. Forecasts indicate continued growth, with revenue expected to reach USD 15,400 million by 2032, though the trajectory will not be uniform. Mid-period fluctuations, such as the slight contraction projected in 2028 before accelerating again toward 2032, signal that pricing dynamics, regulatory shifts, and innovation cycles will create uneven growth pockets rather than a straight-line expansion.
For executives, strategists, and investors, the size of the market is only the starting point. The strategic question is how value is redistributed across product categories, application channels, and geographic demand centers, and which capabilities will determine market share in the next cycle. The concentration structure of the industry, with the top three players accounting for roughly 42% of revenue and the top five capturing about 55%, indicates a moderately consolidated landscape. This creates room for both competitive pressure from established multinationals and meaningful disruption from specialized entrants that can command premium positioning through performance differentiation or format innovation.
Market Landscape and Core Challenges
The car care products market operates at the intersection of consumer discretionary spending, professional detailing services, and increasingly, regulatory and trade dynamics that reshape cost structures. The sector's revenue base has grown at a moderate but persistent pace, reflecting a combination of vehicle parc expansion, renewed emphasis on vehicle appearance as a value-preservation behavior, and the gradual formalization of care routines among both retail and commercial users. However, the headline growth rate masks underlying tensions that decision-makers must address when positioning product portfolios, pricing strategies, and geographic exposure.
One of the most consequential challenges is the rising impact of trade and tariff policy on input costs and competitive positioning. Recent policy actions have adjusted import conditions for automobiles and automobile parts, with duties that extend indirectly into the broader automotive ecosystem. For car care manufacturers and formulators, these measures matter because they influence the cost of imported raw materials, packaging components, and specialized chemical inputs, as well as the competitive balance between domestically produced and imported finished goods. In a market where ingredient quality, coating performance, and formulation consistency are central to brand trust, even modest cost pressure can compress margins unless companies can pass through changes without eroding volume.
A second challenge lies in the shifting balance between do-it-yourself and do-it-for-me application channels. While both segments remain significant, the relative growth trajectories of each are being reshaped by workforce availability in professional detailing, consumer time constraints, and the growing sophistication of products that are designed to be effective with less user expertise. Companies that rely heavily on one channel face exposure if user behavior or service economics move in an unanticipated direction. The practical implication is that product design, packaging format, and go-to-market strategy must increasingly accommodate hybrid usage models rather than treating consumer and commercial applications as separate silos.
A third challenge is the premiumization paradox. Consumer and commercial buyers are demonstrating willingness to pay more for products that promise longer-lasting protection, easier application, or enhanced aesthetic results. At the same time, inflationary sensitivity and the availability of value-oriented alternatives restrict how much premiumization can be counted on as a standalone growth engine. The result is a market where superior performance must be evidenced not just through claims but through demonstrable results, repeat usage, and integration with broader care routines. Brands that can translate product superiority into clear consumer-facing or service-facing value propositions are better positioned to defend margin, while those competing primarily on price face a narrowing path to sustainable differentiation.
Key Demand Drivers and Structural Forces
Technology Innovation and Formulation Breakthroughs
Product performance is increasingly defined by advances in protective coatings, quick-application finishes, and formulations that reduce the effort required to achieve professional-grade results. The segment focused on glaze and coating products, while smaller in absolute terms than wax and cleaning categories, plays an outsized role in shaping the premium narrative of the market because it directly addresses durability, gloss retention, and surface protection. Innovation in this space is not only about chemistry; it is also about usability. Products that combine protective performance with shorter curing times, reduced sensitivity to application conditions, or compatibility with a broader range of substrates can unlock faster adoption among both retail users and commercial detailers.
Recent product launches illustrate how companies are using new formulations and catalog expansion to reinforce positioning. In early 2025, Luminous introduced a new catalog of premium car care products emphasizing advanced detailing and protection formulas, signaling a continued push toward differentiated performance claims in the higher-end segment. Later in the year, Stinger Chemicals announced plans to launch its Quantum Car Care Line at a major industry event, targeting commercial users with specialized retail products. These moves reflect a broader pattern: innovation is being deployed both to elevate the performance ceiling in premium categories and to create purpose-built offerings for professional and retail channels that demand consistency, throughput, and specialized protection characteristics.
Car Care Cosmetics for Petrol Channel Market
Policy and Regulatory Environment
Regulatory and trade policy is becoming a more prominent force in the market's cost and competitive dynamics. Adjustments to import duties on automobiles and parts have direct and indirect implications for the automotive aftermarket ecosystem, including the suppliers of care products that serve vehicle owners, service providers, and fleet operators. While car care products are not always the primary target of such measures, the broader policy environment influences the cost of inputs, the relative attractiveness of domestic versus imported manufacturing, and the strategic calculus of supply chain design.
Car Wax Market
The practical significance for market participants is that regulatory volatility is no longer a peripheral risk. Companies with flexible sourcing strategies, regional manufacturing footprints, and the ability to reformulate around input availability are better equipped to manage sudden cost shifts. At the same time, the regulatory environment can create opportunity for firms that can demonstrate compliance, consistency, and transparency as competitive advantages. In segments where trust and performance claims matter, the ability to navigate policy shifts without disrupting product availability or quality becomes part of the brand promise itself.
Demand-Side Shifts in Consumer and Commercial Behavior
Demand patterns are being reshaped by evolving attitudes toward vehicle ownership, maintenance, and appearance. Vehicles are increasingly viewed not only as transportation assets but also as personal spaces and, for many owners, as items whose condition has tangible economic and emotional value. This has supported demand for products that preserve interior surfaces, protect exterior finishes, and simplify routine maintenance. At the same time, professional detailing and commercial fleet care continue to drive demand for higher-volume, repeatable, and operationally efficient products.
The interior segment represents a meaningful portion of market value, reflecting sustained attention to surfaces, materials, and cleanliness inside the cabin. Exterior care remains the largest body-part category, consistent with the visibility and protection benefits that drive purchase decisions. In application terms, both DIY and DIFM channels contribute substantially, but their relative importance varies by region, customer segment, and product type. Companies that understand where convenience, performance, and service support matter most can tailor product formats, instruction design, and distribution to the channel in which they compete, rather than treating all demand as interchangeable.
Supply Chain and Cost Structure Dynamics
The cost environment for car care products is influenced by raw material availability, chemical input pricing, packaging costs, and logistics complexity. As with many consumer and industrial goods, the ability to manage these pressures depends on formulation flexibility, supplier diversification, and packaging efficiency. Products that rely heavily on specialized imported inputs may face greater exposure to tariff-related and logistics-related cost fluctuations, while those with more standardized ingredient profiles or regional supply options can adapt more readily.
In addition, the market's moderate concentration means that larger players often have advantages in procurement scale, distribution breadth, and brand investment capacity. Smaller or more specialized firms, however, can compete by focusing on performance niches, channel-specific needs, and faster product iteration. The strategic implication is that cost management and innovation are not separate agendas; they are increasingly intertwined. A formulation decision that reduces sensitivity to volatile inputs, or a packaging change that improves shelf efficiency and user experience, can have a direct impact on competitiveness in a market where differentiation is often subtle and repetition of purchase depends on consistent satisfaction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a group of established manufacturers and specialists, each with a distinct positioning strategy. Turtle Wax operates as a broad-based manufacturer of washes, waxes, coatings, and detailing supplies, giving it a wide touchpoint across consumer and professional needs. Meguiar's maintains a strong identity around high-quality chemicals, polishes, waxes, and interior and exterior appearance products, with an emphasis on performance credibility in appearance care. SONAX positions itself in the premium automotive chemical segment, focusing on vehicle maintenance and detailing products that appeal to users seeking higher-end results. Stinger Chemicals develops both retail and commercial product lines for detailing and protection, giving it a dual-channel orientation that can adapt to different purchasing and usage contexts.
Beyond these specialists, larger diversified manufacturers also participate in the market. 3M contributes abrasives, cleaners, polishes, waxes, and detailing compounds, leveraging its broader materials science capabilities and distribution reach. Calumet's role as a manufacturer of specialty solvents, waxes, and petrolatums used in consumer car care formulation illustrates the importance of upstream ingredient and input suppliers in shaping what is ultimately possible at the finished-product level. Together, these companies reflect a market in which competitive advantage comes from a combination of brand trust, formulation expertise, channel relationships, and the ability to align product claims with real-world performance.
Several strategic patterns are visible among the leaders. One is segmentation discipline: companies are increasingly differentiating not just by brand but by intended user, application context, and performance promise. Another is the use of product-line expansion to capture adjacent demand without diluting core positioning. Catalog launches and specialized line introductions, such as those seen in 2025, are examples of how firms attempt to broaden relevance while maintaining a credible performance narrative. A third pattern is the growing importance of channel-specific product design. Commercial users often prioritize consistency, coverage, and operational efficiency, while retail buyers may weigh ease of use, visible results, and perceived value. Companies that design for these differences rather than offering a uniform portfolio across all channels are better placed to defend share and pricing.
PW Consulting Health Care Research Center
The market structure also suggests ongoing evolution rather than static competition. With a moderately concentrated base, there is room for consolidation among players seeking scale in procurement, distribution, or brand investment. At the same time, new entrants and niche specialists can gain traction by focusing on underserved use cases, premium protection claims, or specific regional demand patterns. The most successful players are likely to be those that can combine a clear positioning with operational flexibility, allowing them to adapt product offerings and supply strategies as demand and policy conditions shift.
Forward Outlook: Three Strategic Trends for 2026 to 2032
The next several years are likely to be defined by a combination of product performance competition, channel rebalancing, and continued sensitivity to cost and regulatory pressures. Three trends stand out as particularly relevant for commercial planning.
The first trend is the continued premiumization of protection and finish products, especially in categories associated with longer-lasting results and easier application. As users become more discerning and more aware of the link between surface care and vehicle appearance, demand for products that deliver durable gloss, resistance to environmental wear, and simplified application is expected to remain strong. The commercial opportunity lies in creating credible, repeatable performance stories that support higher price points without depending solely on marketing claims. Products that can demonstrate measurable differences in durability, ease, or finish quality are more likely to command loyalty and reduce price sensitivity over time.
The second trend is the ongoing realignment between DIY and DIFM demand, influenced by labor availability, consumer time use, and the increasing sophistication of user-friendly formulations. Even within the DIY segment, products that reduce effort and increase consistency can blur the line between consumer and professional outcomes. For commercial users, the opportunity is in products that improve throughput, reduce variability, and support service quality across multiple locations or fleets. For manufacturers and distributors, the strategic priority is to ensure that product design, instructional support, and packaging are aligned with the practical realities of how each channel actually uses the product.
The third trend is the increasing importance of supply-side resilience and regulatory adaptability. Tariff adjustments and import policy shifts can influence input costs, sourcing decisions, and competitive positioning, particularly for products that depend on specialized imported components. Companies that build redundancy into sourcing, maintain formulation flexibility, and can communicate reliability to customers will be better positioned to manage disruption. Conversely, firms that are heavily dependent on a single supply route or a narrow set of inputs may face more volatile margin performance. This creates an opportunity for players to differentiate not only through product performance but also through operational dependability and transparent compliance practices.
These trends are not without risk. Premiumization depends on sustained consumer and commercial willingness to invest in appearance care, which can weaken if macroeconomic pressure intensifies. Channel shifts may not unfold uniformly across regions, making geographic assumptions risky if treated as universal. Regulatory and trade policy can change quickly, altering cost structures and competitive dynamics in ways that are difficult to predict far in advance. The market's growth path also includes intermittent deceleration points, as reflected in the mid-period forecast pattern, which suggests that short-term momentum should not be mistaken for a guaranteed straight-line trajectory. Companies that plan for variability, rather than assuming constant acceleration, will be better prepared to allocate resources and adjust strategies as conditions evolve.
Actionable Priorities for Decision Makers
For manufacturers, the priority is to align product innovation with the performance and usability expectations that actually drive repeat purchase. This means investing in formulations and formats that deliver visible, durable results while reducing the risk of user error or inconsistent outcomes. It also means evaluating where portfolio breadth adds value and where focus sharpens competitive positioning. Companies should assess channel-specific needs carefully, since the same product may need different packaging, instructions, or performance emphasis depending on whether it is sold into retail, professional detailing, or fleet contexts.
For investors, the emphasis should be on identifying companies with credible differentiation, resilient supply strategies, and the ability to convert product superiority into measurable customer retention. Market size and growth rate provide a useful backdrop, but the more important questions are whether a company can defend margin in a moderately concentrated market, whether its innovation pipeline addresses real user pain points, and whether its cost and sourcing structure can withstand regulatory or input-price shocks. Businesses that combine strong positioning with operational flexibility are more likely to sustain advantage through uneven growth cycles.
For procurement and commercial buyers, the priority is to balance performance requirements with total cost of ownership, taking into account not only unit price but also consistency, application efficiency, and the downstream impact on service quality or customer satisfaction. In professional and fleet environments, variability in results can create hidden costs through rework, customer complaints, or inconsistent presentation. Evaluating product options against practical usage conditions, rather than against label claims alone, can help buyers select solutions that support both operational reliability and end-user perception.
Across all these perspectives, one consistent theme is that the market is becoming more demanding in terms of proof, not just promise. As product performance expectations rise and cost and regulatory pressures intensify, the ability to access detailed segment-level intelligence, competitive benchmarks, and scenario-based planning assumptions becomes increasingly valuable. Organizations that can ground strategic choices in granular data on product categories, application channels, regional demand patterns, and supplier dynamics will be better equipped to anticipate shifts and act before they become obvious to the broader market.
The car care products market is moving toward a phase in which durable differentiation will depend on the intersection of formulation quality, channel alignment, and operational resilience. Growth to 2032 is supported by steady demand and continued product innovation, but the value created will accrue disproportionately to companies that can convert broad market momentum into focused, defensible positioning. For executives and investors seeking a deeper, segment-level view of these dynamics, a more detailed research assessment can provide the kind of customized insight needed to sharpen portfolio strategy, evaluate competitive exposure, and prioritize the opportunities most relevant to a specific business context.
For detailed analysis of this topic, please visit the official page: Car Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Home Appliances Market: How 6.98% CAGR and Regional Shifts Redefine Growth Through 2032
By PW Consulting, 2026-09-21
Navigating the Home Appliances Market: Strategic Trends and Commercial Opportunities Through 2032
The global home appliances market has entered a phase of sustained expansion, reflecting deep structural shifts in how households and commercial enterprises consume, manage, and upgrade essential equipment. From 2020 through the base year of 2025, the sector demonstrated consistent upward momentum, with revenues climbing steadily as consumption patterns evolved and product categories matured. Current market size figures sit at 938.5 million USD, and forward projections indicate the base year will be followed by continued compound annual growth averaging 6.98 percent through the 2026 to 2032 forecast horizon. By the close of that period, revenues are expected to reach 1,495.2 million USD. This trajectory is not merely a function of population growth or replacement cycles. It reflects a convergence of technological advancement, regulatory recalibration, supply chain repositioning, and shifting consumer expectations that together reshape competitive dynamics and redefine where value is created.
For executives, strategists, and investors evaluating the home appliances sector, the headline growth rates tell only part of the story. The more consequential questions revolve around which segments will capture disproportionate share, how regulatory and trade environments will alter cost structures and sourcing strategies, and what operational or partnership models will separate resilient operators from those exposed to margin compression. Understanding these dynamics requires moving beyond aggregate figures and examining the forces that are actively redirecting capital, innovation, and market positioning across the industry.
Market Snapshot and Core Challenges
The home appliances market has grown from 743.2 million USD in 2020 to a base year valuation of 938.5 million USD, with the pathway from 2021 through 2024 showing steady annual increases that reflect both recovering post-pandemic demand and gradual upgrades in product portfolios. The forecast period from 2026 onward projects a market expanding to 979.21 million USD, then accelerating through subsequent years to reach 1,495.2 million USD by 2032. This growth cadence suggests that demand is broadening rather than merely rebounding, with new product categories, connectivity features, and commercial applications contributing incremental revenue streams alongside traditional residential replacements.
Beneath these aggregate trends, several structural challenges and inflection points are reshaping how companies plan for the coming years. The first is the intensifying friction between trade policy and manufacturing economics. Recent tariff adjustments on steel and aluminum imports, along with derivative duties affecting certain non-electric domestic cooking appliances, stoves, ranges, and washing machines, have introduced new cost volatility. Import volumes face downward pressure while domestic production costs rise, forcing manufacturers to weigh localized assembly against margin preservation. The second challenge lies in product safety and compliance risk. Regulatory warnings and recalls across categories such as small room tower heaters, steam cleaners, and hair dryers underscore the scrutiny facing manufacturers as appliance functionality becomes more electrified and digitally integrated. Failure to anticipate compliance requirements or to maintain rigorous quality controls can disrupt product pipelines and erode consumer confidence. The third inflection point is the widening divergence between traditional mechanical appliance performance and the expectations set by connected, AI-assisted, and energy-responsive products. Companies that treat smart features as additive accessories rather than core design parameters risk ceding premium positioning to competitors who embed intelligence into user workflows and service ecosystems from the outset.
Key Growth Drivers
Technological innovation continues to be the most visible engine of differentiation. Advances in kitchen automation, personalized guidance features, and cordless cleaning technologies illustrate how manufacturers are translating computational capability into tangible user benefits. Recent product introductions have showcased AI-driven cooking assistance integrated into connected home ecosystems, alongside premium cordless stick vacuums leveraging advanced filtration and micro-cleaning mechanisms. These launches signal a broader shift from standalone appliance functionality toward integrated experiences that reduce friction in daily routines and provide actionable feedback on usage patterns. The commercial implication is clear: differentiation increasingly depends on software architecture, sensor integration, and post-purchase service models as much as on mechanical durability or energy efficiency ratings.
Policy and regulatory environments are simultaneously reshaping cost structures and competitive boundaries. Tariff frameworks targeting steel, aluminum, and derivative articles have introduced meaningful uncertainty into sourcing strategies. The expansion of tariff inclusions to cover additional derivative appliances, portable non-electric cooking devices, and related components means that import-dependent supply chains face both direct duty exposure and indirect cost pass-through effects. At the same time, regulatory bodies are heightening safety expectations across multiple categories, reinforcing the need for proactive compliance management. For manufacturers with significant cross-border component flows, the strategic response involves mapping exposure across the bill of materials, evaluating domestic or near-shore production alternatives, and aligning product design with evolving tariff classifications to avoid unintended duty escalation.
On the demand side, consumer and commercial behavior alike are shifting toward efficiency, convenience, and resilience. Households are prioritizing appliances that reduce energy consumption, simplify maintenance, and integrate smoothly with broader smart home environments. The appetite for connected functionality is no longer confined to premium niches; it is expanding as users become more comfortable with app-based controls and automated scheduling. Commercial buyers, meanwhile, are evaluating appliances through the lens of operational continuity, compliance, and total cost of ownership rather than sticker price alone. This dual pressure pushes manufacturers to design products that perform reliably under varied usage patterns while providing data that supports predictive maintenance, service optimization, and energy management.
Supply chain and cost structure dynamics complete the driver set. Component availability, freight volatility, and regional manufacturing capacity all influence how quickly companies can scale new models or adjust to regulatory shifts. Investments in U.S. manufacturing expansion, including commitments exceeding 3 billion USD over a five-year horizon, highlight the strategic priority of domestic capability for certain product lines, including vertical zoneline air conditioners and demand-response electric water heaters. Such capital deployment does more than mitigate tariff risk; it positions companies to respond faster to localized demand, adapt product specifications to market-specific requirements, and reduce dependency on long, multi-tier logistics networks. The broader implication is that supply chain resilience is increasingly a competitive attribute rather than a back-office operational concern.
Worldwide Energy-efficient Household Appliance Market
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of large incumbents commanding a substantial share of revenues. This concentration creates a landscape where scale advantages in procurement, distribution, and brand recognition coexist with intense competition on product innovation and regional positioning. Leading players span major appliance specialists, diversified consumer electronics groups, and premium brand portfolios, each pursuing a distinct strategic emphasis. Some companies lean on broad brand families and deep installed bases in core categories such as refrigerators, washers, dryers, and ranges. Others differentiate through premium engineering, ecosystem integration, and brand equity in high-end segments. Chinese manufacturers continue to expand their global footprints, combining scale production with increasingly sophisticated feature sets and aggressive geographic diversification.
Recent developments illustrate how these companies are attempting to tilt the competitive balance. A premium appliance group launched an AI-driven kitchen guidance feature within a connected home application and introduced new cordless stick vacuums with advanced cleaning technology for the North American market. These moves reflect a focus on post-purchase engagement and differentiated cleaning performance, areas where incremental improvements can strengthen brand loyalty and support premium pricing. Another major domestic manufacturer announced a collaboration centered on specialty baking equipment, signaling a willingness to target niche usage patterns with tailored solutions and co-branded partnerships that elevate category relevance. The same company also disclosed a large multi-year investment program to expand U.S. manufacturing capacity, explicitly tied to air conditioning and demand-response water heater models that align with energy and grid-interaction trends. A separate strategic partnership between a European appliance group and a large Chinese manufacturer aims to accelerate growth and innovation in North America, illustrating how cross-border alliances are being used to combine engineering capabilities, scale, and regional market access.
These actions point to several evolving dynamics. Consolidation and partnership activity are increasing as companies seek to pool technology, share development costs, and access distribution pathways that would be slower to build organically. At the same time, segmentation is sharpening: premium brands are doubling down on connected experiences and specialized performance, while scale manufacturers are optimizing cost structures and expanding into adjacent categories. New entrants and niche innovators are finding opportunities not by challenging incumbents across the entire product spectrum, but by targeting specific workflows, unmet consumer preferences, or commercial applications where incumbent portfolios are less dense. The strategic question for incumbents is whether they can sustain differentiation as feature sets converge and as tariffs and compliance costs reshape the economics of global sourcing.
Forward-Looking Trends and Commercial Implications
One of the most consequential trends over the next three to five years is the deepening integration of intelligence and connectivity into mainstream appliance portfolios. AI-assisted guidance, usage personalization, and ecosystem interoperability are moving from premium differentiators to expected baseline features in key categories. The commercial opportunity lies in designing products where software and sensors create measurable improvements in cooking precision, laundry efficiency, cleaning performance, or energy management, and in building service models that leverage device data for predictive maintenance and customer retention. The risk is that intelligence becomes a commodity if multiple competitors adopt similar platforms without meaningful differentiation in user experience or service reliability.
Worldwide Domestic Appliances Market
A second trend is the reconfiguration of trade, sourcing, and manufacturing footprints in response to tariff and compliance pressures. As duties on steel, aluminum, and derivative articles affect cost structures, companies will continue to evaluate localized production, supplier diversification, and design adjustments that reduce exposure to tariff classifications. This creates opportunities for manufacturers with flexible production networks and for suppliers positioned in regions that benefit from trade realignment. The uncertainty to monitor is the pace and scope of future policy adjustments; abrupt changes can disrupt sourcing plans, alter margin assumptions, and shift the relative attractiveness of import-based versus domestic assembly models.
A third trend is the expansion of commercial and specialty applications as growth contributors. Demand-response electric water heaters, vertical zoneline air conditioners, and niche baking or cleaning solutions indicate that appliances are increasingly evaluated for their role in broader energy systems, operational efficiency, and targeted consumer experiences. Companies that can align product design with grid-interactive capabilities, commercial compliance requirements, or specific user workflows stand to capture value beyond traditional replacement cycles. The counter-risk is execution complexity: commercial specifications, certification demands, and service expectations can differ sharply from residential models, and misjudging these requirements can lead to costly market-entry setbacks.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to treat connectivity, compliance, and sourcing strategy as integrated design constraints rather than separate workstreams. Product roadmaps should account for tariff exposure across derivative components, embed intelligence that delivers measurable user value, and align manufacturing footprints with the markets where demand and policy dynamics are most volatile. Building post-purchase engagement through data-driven service, personalized guidance, and ecosystem interoperability can strengthen retention and support premium positioning. At the same time, quality and safety controls must be calibrated to heightened regulatory scrutiny, particularly in categories with elevated recall or hazard risk.
For investors, the focus should be on identifying companies with durable differentiation in a market where concentration is high and feature convergence is accelerating. Favor operators that demonstrate credible pathways to margin resilience under shifting tariff regimes, that invest in domestic or near-shore capacity where it aligns with demand and policy trends, and that can translate smart features into service-based revenue or stronger brand loyalty. Pay close attention to partnership structures and cross-border alliances, as these can accelerate access to technology and regional markets but also introduce integration and execution risk. Monitor recall patterns and safety compliance as leading indicators of operational discipline and reputational exposure.
For procurement and commercial buyers, the emphasis should shift from unit cost to total cost of ownership, energy performance, compliance assurance, and service responsiveness. Appliances that support demand-response capabilities, reduce maintenance downtime, and integrate cleanly into existing operational or smart home environments can deliver value that outweighs initial price premiums. Vendor evaluation should include assessments of manufacturing resilience, sourcing transparency, and readiness to adapt to evolving regulatory requirements, particularly where procurement volumes make tariff exposure and recall risk material.
PW Consulting Health Care Research Center
The home appliances market is evolving along multiple fronts simultaneously: technology is reshaping user expectations, policy and trade frameworks are altering cost and sourcing logic, and demand is broadening across residential, commercial, and specialty applications. Navigating this environment requires granular insight into segment dynamics, regional exposures, competitive moves, and the operational implications of regulatory change. Detailed breakdowns of segmentation, regional trajectories, competitive benchmarking, and scenario analysis are available through the full market research report, where deeper data and tailored recommendations can support planning for specific categories, geographies, and strategic objectives.
For detailed analysis of this topic, please visit the official page: Home Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Disposable Gloves Market 2026: Why 8.7% CAGR and Nitrile Demand Reshape Strategy
By PW Consulting, 2026-09-21
Navigating the Disposable Gloves Market: Strategic Trends and Commercial Opportunities Through 2032
The global disposable gloves market has transitioned from a crisis-driven supply story into a structurally expanding category defined by material innovation, regulatory realignment, and persistent capacity dynamics. Valued at approximately $31.7 billion in 2025, the market is projected to reach $56.8 billion by 2032, expanding at a compound annual growth rate of 8.7 percent over the forecast period. This trajectory reflects an industry that has absorbed the shock of pandemic-era demand spikes, recalibrated production footprints, and now operates within a more normalized but still highly competitive environment. For executives, strategists, and investors, the opportunity lies not in chasing volume alone but in understanding where material differentiation, compliance readiness, and regional supply chain positioning create durable advantages.
The market's growth is broad-based, yet uneven across segments. Healthcare continues to anchor demand, reflecting sustained emphasis on infection control, clinical procurement standards, and occupational safety. Industrial and food service applications contribute incremental but structurally important volume, particularly as regulatory scrutiny and consumer expectations elevate baseline protection requirements. Material preferences are shifting as well, with nitrile capturing a larger share of procurement decisions due to its balance of chemical resistance, puncture durability, and latex-allergy avoidance. At the same time, the industry remains moderately concentrated, with the top three players accounting for roughly 40 percent of revenue and the top five approaching 55 percent. This concentration suggests that scale, distribution access, and compliance infrastructure still matter, but it also leaves meaningful room for specialized manufacturers and regional suppliers to compete on performance, sustainability, or localized service.
Market Snapshot and Core Challenges
The disposable gloves industry is now navigating a phase where growth is no longer derived from emergency stockpiling but from underlying expansion in healthcare capacity, industrial safety standards, and food handling compliance. Between 2020 and 2025, the market advanced from roughly $20.9 billion to $31.7 billion, a period that included both pandemic-induced demand surges and subsequent normalization. The forecast period through 2032 points to continued expansion, but the character of that expansion is changing. The market is increasingly shaped by capacity additions, material substitution, and the cost implications of compliance and labor across manufacturing regions.
Three challenges stand out as strategic inflection points. First, the industry is operating in an environment of capacity overhang. Global glove production capacity is expected to exceed 500 billion pieces annually within the next two years, while demand is estimated around 400 billion pieces. This imbalance creates pricing pressure, particularly for standardized commodity gloves, and rewards manufacturers that can differentiate through quality, certification, or specialized material performance rather than volume alone. Second, regulatory and trade dynamics continue to reshape sourcing strategies. Modifications to withhold release orders, FDA-aligned facility requirements, and growing scrutiny of labor and compliance practices in export-oriented markets have introduced new layers of risk and cost into global procurement. Third, the cost structure gap between low-labor-cost export hubs and domestic producers remains a persistent tension. Foreign manufacturers can offer disposable gloves at average prices as low as $0.02 per glove, while U.S. producers face significantly higher wages and operational costs. This divergence does not simply create a price differential; it forces buyers and manufacturers alike to weigh total cost of ownership, supply continuity, and compliance assurance rather than unit price in isolation.
For decision-makers, the practical implication is that the market is bifurcating. Commodity-grade volume competes heavily on price and logistics, while differentiated products—whether defined by chemical resistance, accelerator-free formulations, biodegradability, or regional compliance readiness—command more resilient positioning. The challenge is to determine where a given organization can credibly compete and what capabilities are required to sustain that position.
Key Drivers of Market Change
Several forces are converging to shape the next phase of growth. These drivers are not independent; they interact across technology, regulation, demand behavior, and supply economics, creating a market in which advantage increasingly comes from integrating multiple dimensions rather than optimizing a single variable.
Technological Innovation and Material Performance
Material innovation is moving from incremental improvement to functional differentiation. Nitrile remains the dominant material focus, but within that category, manufacturers are introducing formulations that address long-standing pain points such as chemical exposure, dermatological sensitivity, and environmental footprint. Recent product launches illustrate this shift. One major hygiene and protection company introduced a disposable glove line offering up to 15 minutes of resistance to acetone and aggressive chemicals, directly targeting laboratory, industrial, and clinical use cases where chemical compatibility has traditionally required heavier or more expensive protective options. Another initiative launched accelerator-free nitrile gloves designed to reduce chemical exposure risks for healthcare workers, reflecting a growing emphasis on wearer safety beyond basic barrier protection.
These developments matter because they change the value proposition of disposable gloves from simple contamination control to task-specific performance. In procurement terms, they create room for premiumization in segments where failure costs are high, whether in surgical environments, chemical handling, or food processing hygiene. They also raise the bar for competitors, since performance claims increasingly need to be supported by testing, certification, and consistent manufacturing quality.
Medical Disposable Gloves Market
Policy, Regulatory, and Compliance Realignment
Regulatory and compliance dynamics are becoming a strategic variable rather than a background condition. In the United States, the disposable gloves category intersects with FDA-registered facility expectations, medical device regulations, and trade enforcement actions that can alter import availability overnight. The modification of a withhold release order on certain Malaysian glove producers, for example, demonstrated how compliance status can shift market access for specific suppliers while leaving broader sourcing strategies intact. At the same time, domestic producers have emphasized that their FDA-registered facilities employ local workforces with higher labor costs, framing compliance and supply chain predictability as part of the value they provide.
Beyond the United States, traceability and sustainability disclosure are gaining traction. One rubber and materials traceability company expanded its industrial platform to cover global latex and nitrile disposable gloves, advancing transparency in circular materials and supply chains. This type of initiative signals that buyers may increasingly expect visibility into raw material origins, processing practices, and end-of-life attributes, especially in procurement environments where ESG commitments are tied to supplier selection. For manufacturers, compliance and traceability are becoming part of the product offering, not just operational hygiene.
Demand-Side Shifts in Healthcare, Industrial, and Food Service
Demand behavior is evolving on multiple fronts. In healthcare, the pandemic accelerated a structural awareness of PPE adequacy, stockpile discipline, and infection prevention, but the post-crisis reality is more nuanced. Hospitals and care providers are now balancing cost containment with resilience, which favors suppliers that can offer reliable availability, consistent quality, and documentation supporting clinical and regulatory requirements. In industrial settings, safety standards and chemical handling requirements continue to drive demand for gloves that perform beyond basic barrier protection. In food service, hygiene expectations and regulatory oversight maintain a baseline of recurring demand, though price sensitivity is often more pronounced.
A broader demand-side trend is the normalization of procurement decision-making around total value. Buyers are increasingly weighing factors such as chemical resistance, allergy management, comfort and tactility for repetitive tasks, and sustainability attributes alongside unit cost. This does not eliminate price competition, but it expands the criteria by which suppliers can differentiate. For manufacturers, the implication is that product portfolios need to be aligned with real end-use scenarios rather than generic volume positioning.
Supply Chain Economics and Capacity Realignment
Supply chain economics remain central to the market's trajectory. The projection that global capacity will outpace demand in the near term underscores an environment where excess supply can pressure margins, particularly for undifferentiated products. At the same time, regional production strategies are being reconsidered in light of trade policy, logistics risk, and the desire for closer alignment between manufacturing footprint and end markets. Some manufacturers are expanding domestic or near-customer production to reduce exposure to tariff, detention, or compliance uncertainty, while others continue to rely on scale advantages in lower-cost regions.
Cost structures are therefore not just a pricing issue but a strategic design choice. Companies that can manage the tension between scale efficiency and regulatory readiness, or between low unit cost and performance differentiation, are better positioned to protect margins when commodity pressure intensifies. The market is rewarding those who can articulate why their cost structure is appropriate for the segment they serve.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The competitive field includes large non-latex producers, established multinational protection companies, regional Malaysian manufacturers with global export reach, and distributors that anchor healthcare procurement. The strategic positioning of these players reveals distinct paths to advantage, and the recent activity across the industry highlights how those paths are being reinforced.
One of the most visible strategic moves is scale leadership in non-latex gloves. A Shandong-based manufacturer reported revenue growth of 4.23 percent to RMB 9.93 billion in its 2025 annual results and expanded annualized production capacity to 103 billion non-latex disposable glove pieces, reinforcing its position as the world's largest non-latex glove manufacturer. This type of scale positioning is valuable because it supports cost efficiency, supply continuity, and the ability to serve large global buyers with consistent volume. However, scale alone is increasingly insufficient if procurement criteria shift toward specialized performance or traceability. The strategic question for scale leaders is how to preserve cost advantages while adding credibility in premium or compliance-sensitive segments.
Disposable Medical Gloves Market
In contrast, some competitors are building advantage through product specialization and certification. A U.S.-based manufacturer operating a large FDA-registered facility supplies powder-free nitrile and biodegradable polyurethane disposable gloves for medical, laboratory, industrial, food handling, and janitorial use. Its positioning emphasizes regulated medical gloves and domestic production infrastructure, which can be appealing to buyers prioritizing compliance assurance, supply predictability, and workforce-related messaging. The contrast with lower-cost import alternatives illustrates how domestic producers attempt to compete on reliability and regulatory readiness rather than pure unit price.
Multinational protection companies are leaning into performance innovation and sustainability recognition. One global leader launched a disposable glove with enhanced chemical resistance and received a business sustainability award for product innovation in the disposable gloves category. This dual focus—functional performance plus external validation of sustainability—reflects a strategy aimed at professional buyers who need demonstrable capabilities and increasingly need to justify procurement choices against environmental and safety criteria. Another major manufacturer exhibited its range of nitrile, latex, and biodegradable disposable gloves at a regional medical trade show, signaling continued emphasis on product breadth and compliance documentation as commercial tools.
Malaysian manufacturers continue to play a central role in the global supply network. Several publicly listed companies maintain broad portfolios across nitrile, latex, and biodegradable gloves, with strong documentation practices and export-oriented operations. Their strategic challenge is navigating the combination of capacity expansion, trade compliance variability, and price competition while preserving quality reputation. The presence of multiple large exporters in the same region also means that buyers have alternatives, which increases the importance of service, specification alignment, and consistent fulfillment.
Distributors and healthcare-focused suppliers add another layer to the landscape. Large U.S. distributors provide medical disposable gloves to healthcare institutions and position themselves as procurement partners rather than pure manufacturers. Their value lies in aggregation, logistics, clinical sourcing expertise, and the ability to coordinate supply across multiple product lines. In a market where availability and documentation can be as important as the glove itself, distribution strength can translate into sticky customer relationships.
Taken together, the landscape is evolving through a mix of consolidation pressure and segmentation opportunity. Scale players compete on volume and cost; specialized manufacturers compete on performance, compliance, or sustainability; distributors compete on service and sourcing integration. New entrants and smaller producers can still find room by targeting specific applications, regions, or material preferences, especially where larger players are less motivated to customize. The broader trend is toward clearer strategic identity: companies that try to be everything to everyone are more exposed to commodity pressure, while those with a defined value proposition are better positioned to defend margin and customer loyalty.
Forward Outlook: Trends Shaping the Next 3–5 Years
Looking ahead, several trends are likely to define the market's direction and create distinct commercial opportunities.
One major trend is the continued shift from generic protection to application-specific glove performance. As buyers in healthcare, industrial, and laboratory settings become more sophisticated about chemical resistance, allergen reduction, and wearer comfort, demand for specialized formulations should remain resilient. This creates opportunity for manufacturers that can validate performance claims, align product lines with real workflow requirements, and communicate value in procurement language rather than generic specification sheets. The risk is that performance claims raise expectations and invite scrutiny, so testing, quality control, and documentation become critical assets.
A second trend is the growing importance of sustainability and traceability as procurement criteria. Even if price remains decisive in many segments, sustainability attributes and supply chain transparency are increasingly used to narrow supplier shortlists or support internal ESG commitments. Companies that can provide credible information about material sourcing, manufacturing practices, and end-of-life options may gain preference in categories where buyers must demonstrate progress to stakeholders. The uncertainty here is the pace and consistency of buyer demand across regions and sectors; sustainability premium willingness is not uniform, and green claims will face increasing scrutiny.
A third trend is the ongoing rebalancing of capacity and trade flows. With global production capacity projected to exceed demand in the near term, the market will likely experience periods of intensified price competition, especially in standardized gloves. At the same time, trade policy adjustments, compliance enforcement, and regional supply preferences may create episodic disruptions that benefit suppliers with flexible footprints or strong documentation readiness. The commercial opportunity lies in anticipating where availability risk or compliance risk will matter most to buyers and positioning supply accordingly. The risk is that overcapacity could compress returns for undifferentiated products and make expansion decisions more hazardous unless they are tied to clear demand signals or differentiated positioning.
Implications for Decision-Makers
The market's evolution suggests different priorities depending on a company's role in the value chain.
For manufacturers, the strategic imperative is to clarify where differentiation is credible and economically sustainable. If the goal is to compete on volume, scale, and cost efficiency must be paired with disciplined capacity planning to avoid sinking into undifferentiated oversupply. If the goal is to compete on performance or compliance, product development, testing infrastructure, certification readiness, and documentation quality become the primary investment areas. Manufacturers should also assess whether their portfolios map clearly to end-use scenarios, because procurement teams increasingly select gloves based on task requirements rather than generic category purchases. In practice, the most resilient strategies often combine one strong axis of advantage with sufficient operational discipline to protect it.
For investors, the opportunity is to distinguish between cyclical volume plays and structurally advantaged positions. Capacity expansion can look attractive in a growing market, but the current overhang suggests that returns will depend heavily on segment selection, pricing power, and cost control. Companies with strong compliance positioning, specialized product lines, or durable distribution relationships may offer more predictable exposure than those reliant on commodity-volume assumptions. Investors should also monitor trade and regulatory developments, since market access can shift quickly for specific suppliers or regions, altering competitive dynamics without changing underlying demand.
For procurement leaders and supply chain decision-makers, the priority is to move beyond unit-cost comparisons and evaluate total cost of ownership under realistic risk scenarios. That includes considering availability resilience, compliance documentation, chemical or allergen requirements, and the potential consequences of supply disruption in critical applications. Diversification across suppliers, materials, or regions can reduce exposure to single-point failures, while specification alignment can reduce waste and improve wearer compliance in practice. The most effective procurement strategies treat glove sourcing as a risk-managed input rather than a purely transactional purchase.
For organizations that need a deeper, more granular view of segment dynamics, regional variations, and company-level positioning, a comprehensive research report can provide the level of detail required to translate these strategic themes into operational decisions. Granular data on material splits, application demand patterns, and competitive moves can help clarify where to commit resources, how to structure sourcing, and which indicators to track as the market continues to evolve.
Closing Perspective
The disposable gloves market is no longer defined solely by emergency demand or commodity volume. It is increasingly shaped by material innovation, compliance consciousness, capacity economics, and procurement sophistication. Growth through 2032 is expected to remain robust, but the rewards will accrue to organizations that can align product capabilities, supply chain resilience, and segment focus with the realities of how buyers evaluate value today. For executives and investors, the key is to treat the market as a competitive landscape with distinct strategic niches rather than a single homogeneous opportunity. Those who do are better positioned to capture durable advantage as the industry matures.
For detailed analysis of this topic, please visit the official page: Disposable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


