



Category: IT & Electronics
PW Consulting: Financial Planning Software Market Hits $3.85B in 2025, 15.72% CAGR to $10.66B by 2032
By PW Consulting, 2026-09-16
The Financial Planning Software Market: Strategic Intelligence for 2026 Enterprise Decisions
The financial planning software market has evolved from a niche utility into a central nervous system for wealth management, corporate finance, and advisory practices. As organizations navigate an environment defined by rapid technological adoption, tightening compliance frameworks, and shifting client expectations, the ability to make informed technology investments is no longer optional. This market research report delivers a comprehensive, data-grounded examination of the sector, equipping executives, procurement leaders, and strategic planners with the intelligence required to position their organizations ahead of the curve in 2026 and beyond.
Market Trajectory and the Scale of Opportunity
Understanding where the market stands today requires a clear view of its historical momentum and forward-looking trajectory. Over the past half-decade, the financial planning software sector has demonstrated consistent expansion, reflecting broader digitization trends across financial services and corporate finance functions. The market's valuation has progressed steadily from approximately 2.28 billion USD in 2020 to an estimated 3.85 billion USD in 2025, underscoring a compound annual growth pattern that signals both industrial maturation and sustained demand.
Projecting forward, the sector is positioned to accelerate through the end of the decade. Current forecasts indicate that market revenue will surpass 4.37 billion USD in 2026, climbing progressively to reach roughly 10.66 billion USD by 2032. This growth is anchored by a projected CAGR of 15.72 percent across the forecast horizon, a rate that reflects not merely incremental adoption but a structural shift in how financial planning is executed, delivered, and integrated into broader operational workflows. For enterprise decision-makers, this trajectory carries a clear implication: the window for evaluating, selecting, and deploying next-generation planning platforms is actively open, and delay carries measurable competitive risk.
The scale of this expansion is not uniform across all segments, nor is it driven by a single catalyst. Growth is being distributed across multiple vectors, including platform modernization, service-led implementation and advisory models, and the broadening application of planning tools beyond traditional budgeting into scenario modeling, risk assessment, and advanced analytics. The report maps these vectors in detail, enabling buyers to distinguish between headline growth and the specific demand pockets most relevant to their operational context.
What This Report Delivers: Operational Intelligence for Strategic Planning
Market sizing alone does not inform procurement decisions or product roadmaps. Executives require a granular understanding of how the market is structured, who is competing, what regulatory constraints shape deployment, and where innovation is converging with practical utility. This research report is designed to translate macro-level trends into actionable strategic guidance.
Investment Management Software Market
Comprehensive Segmentation and Use-Case Mapping
The analysis dissects the market across multiple dimensions, providing a structured view of how demand is distributed across platform types, service offerings, and functional applications. Rather than presenting static splits in isolation, the report contextualizes each segment against adoption drivers, pricing dynamics, integration requirements, and implementation complexity. Decision-makers will gain clarity on which planning functionalities are seeing the strongest institutional traction, how platform versus service spending patterns differ across organization sizes, and where complementary capabilities are creating bundling opportunities or competitive differentiation.
Competitive Landscape and Vendor Positioning
The report profiles the dominant and emerging players shaping the market, examining their strategic focus, product philosophies, and recent moves that signal where the industry is heading. Key companies include Envestnet, eMoney Advisor, RightCapital, SS&C Technologies, and Orion Advisor Technology, each bringing distinct approaches to financial planning software. Envestnet's MoneyGuide platform emphasizes goals-based and comprehensive planning integrated with wealth management workflows. eMoney Advisor centers on cash-flow-based and goals-based planning, supported by client portals and collaborative planning tools. RightCapital distinguishes itself through tax-efficient planning, scenario analysis, and advisor productivity enhancements. SS&C Technologies offers Black Diamond wealth solutions, embedding financial planning modules within portfolio management and billing ecosystems. Orion Advisor Technology provides a planning platform tied to practice management and advisor reporting.
These profiles are not merely descriptive. The report evaluates each vendor's positioning relative to market demand, integration depth, compliance readiness, and innovation cadence. By mapping vendor strategies against buyer priorities, the analysis helps organizations shortlist candidates based on fit rather than brand recognition alone.
Recent Developments and Innovation Signals
Speed of iteration is a critical differentiator in software markets, and the financial planning sector is no exception. The report tracks recent product launches, platform enhancements, and ecosystem expansions that reveal where vendors are investing. Notable activity includes Envestnet's March 2026 launch of MoneyGuide Dash, designed to simplify and streamline the planning experience with modernized capabilities, followed by May 2026 announcements around AI-driven data automation and deeper MoneyGuide integration into proposal workflows, client records, and planning processes at the Elevate 2026 conference. Earlier, the R4 2025 release introduced tax management insights integrated into proposal strategy modification workflows.
eMoney Advisor has similarly moved to strengthen collaborative and extensibility features, including the April 2026 introduction of CoPlanner for team-based financial planning and decision-making, and a October 2025 platform enhancement that launched a new developer site for API integrations supporting market extensions. These developments illustrate a broader pattern: vendors are racing to reduce manual friction, embed intelligence into planning workflows, and open their platforms to third-party innovation. The report analyzes what these moves mean for buyers evaluating long-term platform viability and integration roadmaps.
Market Dynamics: Regulation, Security, and the Compliance Imperative
The financial planning software market does not operate in a vacuum. Regulatory expectations, data protection requirements, and fiduciary standards are now integral to platform selection and deployment. The report dedicates substantial attention to the compliance landscape, translating regulatory complexity into practical procurement considerations.
Across the sector, platforms are expected to meet rigorous security and documentation standards. IRS Publication 4557 sets the benchmark for client data handling, requiring SOC 2 Type II certification and Written Information Security Plan documentation for software that manages sensitive financial information. These requirements are not optional add-ons; they are baseline expectations that influence vendor eligibility, implementation timelines, and ongoing operational risk. The report outlines how leading platforms are structuring their compliance postures and what questions buyers should raise during due diligence.
Simultaneously, fiduciary and disclosure obligations continue to shape software design. Regulation Best Interest compliance features are increasingly embedded within planning tools to support fiduciary disclosure standards enforced by the SEC, ensuring that recommendations and planning outputs align with regulatory expectations. U.S. data storage and protection also must comply with SEC and FTC standards for financial data requests and safeguarding, adding another layer of scrutiny to infrastructure decisions.
Beyond U.S. frameworks, data privacy laws are tightening globally, with GDPR and related regimes demanding enhanced guardrails even for North American users whose data may intersect with international systems or multi-jurisdictional operations. The report examines how these regulatory pressures are influencing vendor architectures, data residency options, and the broader risk calculus for organizations selecting planning software. For buyers, the takeaway is clear: compliance capability is now a core component of value, not a peripheral checkbox.
Why This Research Matters for 2026 Decision-Making
Enterprise leaders face a crowded field of vendors, a fast-moving innovation cycle, and a compliance environment that rewards diligence. In this context, comprehensive market intelligence serves as a force multiplier. The report enables decision-makers to triangulate three critical questions: where is the market going, who is best positioned to serve specific organizational needs, and what capabilities must a platform demonstrate to remain viable over the implementation lifecycle?
The strategic value of this research extends across multiple functions. Procurement and technology teams gain a structured framework for evaluating platform types, service models, and functional coverage against internal requirements. Finance and advisory leaders receive insight into which planning applications are gaining institutional traction and how those applications align with evolving workflow priorities. Executive teams benefit from a competitive landscape view that highlights vendor strategy, innovation velocity, and concentration dynamics, supporting more confident investment and partnership decisions.
Financial Planning Software Market
Market concentration data further contextualizes the competitive environment. With the top three providers accounting for approximately 34.5 percent of market share and the top five reaching roughly 48.2 percent, the market exhibits meaningful but not prohibitive concentration. This structure suggests both the presence of established incumbents with scaled capabilities and sufficient room for specialized providers to compete on differentiation, niche functionality, and integration depth. The report explores how this balance shapes vendor negotiations, switching considerations, and the incentives that drive ongoing product development.
Aligning Technology Investment with Operational Reality
Selecting financial planning software is not a purely technical exercise. It intersects with practice management, advisor productivity, client experience, data governance, and long-term scalability. The report emphasizes the importance of aligning platform capabilities with operational realities, including team collaboration models, proposal and workflow integration, tax and scenario analysis needs, and the demand for transparent, client-facing planning experiences.
As platforms incorporate AI-driven automation, enhanced data integration, and richer collaboration features, the definition of an effective planning environment is expanding. Organizations that evaluate vendors against a comprehensive set of criteria, rather than isolated feature lists, are better positioned to realize return on investment and avoid costly rework. The research provides the comparative context needed to make those evaluations systematically.
Conclusion: Positioning for the Next Phase of Market Growth
The financial planning software market is entering a phase defined by accelerating adoption, intensifying competition, and rising expectations for security, compliance, and workflow intelligence. With a robust growth trajectory and a diverse set of vendors pursuing distinct strategic angles, the opportunity for organizations to strengthen their planning capabilities is substantial, but so is the complexity of navigating the landscape.
This market research report offers the depth, structure, and competitive context required to move from uncertainty to informed action. It translates macro growth signals into segment-level insight, maps vendor strategies against buyer priorities, and frames regulatory demands as integral to platform evaluation. For executives and planners preparing for 2026 and the years that follow, the report provides the intelligence foundation necessary to make technology decisions with confidence, precision, and strategic foresight.
To access the complete analysis, including detailed segmentation breakdowns, vendor comparisons, regulatory mapping, and forward-looking scenario context, we invite you to explore the full report. The complete intelligence package is designed to support procurement planning, vendor selection, and strategic roadmap development with the rigor that today's financial planning environment demands.
For detailed analysis of this topic, please visit the official page: Financial Planning Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Last Mile Delivery Market to Hit $353.57M by 2032 at 9.8% CAGR
By PW Consulting, 2026-09-16
Last Mile Delivery Market Outlook 2026: Navigating Growth, Complexity and Strategic Opportunity
The last mile delivery sector stands at a decisive inflection point. As urban commerce accelerates and consumer expectations converge around speed, transparency and reliability, the operational layer that moves goods from local depots to end recipients is no longer a cost center to be minimized. It is a competitive battleground that shapes brand loyalty, margin structures and geographic expansion. Our latest market research on the Last Mile Delivery Market translates this complexity into a structured, decision-ready intelligence framework designed explicitly for leaders planning their 2026 operating and investment strategies.
This research is built for executives who need to move beyond headline market narratives. It maps the trajectory of the sector through a rigorous historical-to-forecast lens, anchors growth assumptions in verifiable market sizing, and then unpacks the operational, competitive and regulatory forces that will separate resilient operators from those forced into reactive positioning. The objective is straightforward: provide a precise enough view of where the market is heading to inform capital allocation, partnership evaluation, technology roadmapping and regional prioritization, while deliberately leaving the most granular breakdowns for the full report.
Market Trajectory and the Strategic Context for 2026
Over the past five years, the last mile delivery market has demonstrated a consistent expansion trajectory thatoutpaces many adjacent logistics segments. Historical market sizing from 2020 through 2025 reflects a compound growth pattern shaped by e-commerce penetration, retail network reconfiguration and the normalization of same-day and next-day fulfillment expectations. From a base of approximately 115.2 million USD in 2020, the market expanded steadily year over year, reaching an estimated 183.76 million USD by 2025. This historical run-rate sets the foundation for the forward-looking period, and the forecast horizon through 2032 signals that the sector is not merely sustaining momentum but accelerating it.
The projected compound annual growth rate of 9.8 percent across the forecast window positions last mile delivery as one of the more structurally attractive segments within the broader logistics and supply chain ecosystem. Growth is not uniform across time or geography, and the report treats that heterogeneity as a strategic variable rather than background noise. By 2026, market sizing moves to an estimated 204.78 million USD, and forward projections extend upward through the early 2030s, with the trajectory reflecting the combined effects of volume expansion, vehicle and technology mix evolution, and service model diversification. The strategic implication for 2026 planning is clear: organizations that treat last mile delivery as a fixed-cost operational function will face a widening gap relative to competitors who design their networks around scalable, data-driven cost-to-serve models.
For decision-makers, the most valuable lens is not the size of the market alone, but the structure of participation within it. The report examines market concentration patterns that illustrate how value is distributed across incumbents, technology-forward platforms and specialized regional operators. This concentration context matters because it informs realistic expectations around vendor leverage, partnership competition, pricing power and the likelihood of consolidation. Rather than presenting a simple leaderboard, the analysis situates concentration within the operational realities of routing optimization, workforce management, regulatory exposure and customer communication expectations that now define competitive parity.
What the Research Delivers: An Executable Intelligence Framework
This market research is structured as a practical instrument for strategy, operations and investing teams, not merely a descriptive overview. The report combines market sizing, forecast modeling and segmentation analysis with a detailed mapping of competitive offerings, recent corporate activity and the operational forces reshaping cost and service economics. The intent is to provide a common factual foundation that can support scenario planning, vendor evaluation, market entry analysis and operational redesign.
The segmentation architecture explores how the market decomposes across vehicle types, service approaches, delivery models and end-use applications. These dimensions are analyzed to surface where operating economics diverge, where technology adoption is driving measurable efficiency gains, and where structural headwinds or regulatory pressure may alter the attractiveness of specific pathways. Regional splits are examined to reflect differences in urban density, infrastructure readiness, labor market dynamics and consumer purchasing behavior. The analysis is deliberately framed to show how each segment influences cost structures and service feasibility, so that leaders can assess where their own operating model is most exposed or most advantaged.
Beyond segmentation, the report delivers a detailed competitive landscape that profiles leading platforms and logistics software providers. These profiles are built around real operating capabilities rather than marketing positioning, covering route optimization logic, real-time visibility, dispatch and courier network management, exception handling, customer communication and integration patterns. The research also tracks recent corporate developments that signal how capital and partnerships are being deployed to reshape competitive positioning. These developments include major acquisition activity, cross-market expansion moves, same-day shipping partnerships and capacity-strengthening transactions. Read together, they reveal where incumbents are reinforcing their networks, where technology platforms are pursuing scale, and where consolidation is likely to alter procurement and partnership options.
The research also integrates the operating conditions that determine whether growth translates into profitable execution. Labor economics remain a central pressure point, with workforce costs representing a substantial share of total last mile expenses and express delivery commanding premium wage structures. At the same time, regulatory attention is intensifying around urban delivery facilities, truck emissions, subcontracted labor models and local traffic management. Cities are expected to impose stronger restrictions on delivery traffic over the coming years, creating a structural tension between rising parcel volumes and sustainability and access constraints. Energy costs, labor availability and the disproportionate operating cost burden associated with the final delivery stage all reinforce a central point: volume growth alone does not guarantee margin expansion. The report uses these dynamics to help leaders identify where operational redesign, automation, route density improvement and network orchestration can materially shift cost-to-serve outcomes.
Importantly, the report maintains a disciplined boundary between public-facing industry context and proprietary analytical depth. High-level market sizing, concentration indicators and segment architecture provide a strong directional foundation, while the finer breakdowns in regional share, application-level value, vehicle-type splits and company-level benchmarking are reserved for the full study. This design allows executive readers to immediately grasp the strategic shape of the market while preserving the report's differentiated data as a reason to engage with the complete intelligence package.
Strategic Decisions the Report Is Built to Inform
The research is organized around several high-stakes decisions that leaders are actively facing for 2026 and adjacent planning cycles. First, it supports market prioritization logic by clarifying how growth patterns, concentration and operating conditions differ across geographies and usage contexts. For organizations evaluating new regional entry, expansion sequencing or capacity investment, the report provides a framework for weighing demand momentum against infrastructure readiness, labor dynamics and regulatory friction.
Second, the analysis is built to support technology and vendor strategy. As last mile operations become more dependent on routing intelligence, real-time visibility and customer-facing communication, the choice of platform or orchestration layer increasingly determines service consistency and operational flexibility. The competitive profiles and operating capability comparisons help teams assess which solution characteristics matter most for their delivery model, fleet composition, courier network structure and exception-management requirements.
Third, the research informs partnership and procurement planning in a period of active consolidation. Recent acquisition activity and partnership announcements in the broader delivery ecosystem signal that the vendor landscape is changing quickly. For operators negotiating routing software, courier networks, fulfillment partnerships or capacity agreements, the report provides context on where capabilities are being combined, where scale is being accumulated, and where competitive tension may create better negotiating positions or, conversely, reduce alternative sourcing options.
Last Mile Delivery Market
Fourth, the study is designed to support cost and service trade-off analysis. Because labor intensity, traffic restrictions, energy expenses and density variability all influence profitability, leaders need a structured way to evaluate where service-level commitments are economically sustainable and where operational redesign is necessary. The report frames these trade-offs without over-simplifying them, allowing executives to identify the levers most relevant to their own network design, vehicle mix and service promises.
Same-day Delivery Market
How to Use This Research for 2026 Planning
The strongest value of this research emerges when it is used as a shared reference point across strategy, operations, procurement and technology teams. Rather than treating market growth as a single metric, leaders can use the report to align on the underlying drivers that make growth achievable or risky in specific contexts. That includes differentiating between demand-led expansion and capacity-led expansion, between technology-enabled efficiency and labor-dependent service models, and between regions where regulatory and infrastructure conditions support rapid scaling versus those where access and cost pressures require more cautious sequencing.
For capital planning, the report supports more disciplined scenario construction by linking historical growth, forecast momentum and concentration patterns to realistic assumptions about vendor selection, partnership availability and operating cost behavior. For operational planning, it helps identify where route optimization, visibility, customer communication and exception management are likely to remain differentiators rather than table stakes. For corporate development and partnership teams, the recent activity tracked in the research offers a practical lens on where consolidation and capability accumulation are reshaping the competitive map.
The analysis also encourages leaders to think in terms of resilience rather than optimization alone. In a market where parcel volumes continue to rise while regulatory, labor and access constraints intensify, the most durable operating models are those that can adapt vehicle mix, dispatch logic, customer communication and network density without sacrificing service reliability. The research provides the factual scaffolding needed to evaluate where that adaptability is already present and where it must be built.
Accessing the Full Intelligence
The overview presented here establishes the strategic shape of the last mile delivery market, surfaces the core operating and competitive dynamics shaping 2026 decisions, and frames the decisions the full research is designed to support. What it does not attempt is to extract the complete segmentation detail, company-level benchmarking, regional value breakdowns or proprietary analytical conclusions that give the study its decision-grade specificity. Those elements are preserved in the full report so that executives, analysts and operating leaders can work from a precise, internally consistent dataset rather than a generalized summary.
For teams that need to allocate budget, select vendors, prioritize markets, assess partnership options or redesign cost-to-serve logic in the current environment, the full research offers the depth required to move from directional awareness to concrete action. The objective of this introduction is to give you enough substantive insight to recognize the analytical rigor behind the study, while maintaining the core data and differentiated findings as a reason to access the complete market research directly.
If your 2026 planning depends on a clear, evidence-based view of where last mile delivery is heading and how leading operators are repositioning around it, the full report provides the structured intelligence necessary to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Last Mile Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts SRAM Market to Reach $684 Million by 2032 with 5.23% CAGR
By PW Consulting, 2026-09-16
Navigating the SRAM Landscape: Strategic Imperatives for 2026 and Beyond
The Static Random Access Memory (SRAM) market stands at a critical inflection point. As foundational infrastructure for high-performance computing, automotive electronics, and industrial automation, SRAM remains a vital component in the global semiconductor value chain. However, the combination of shifting supply dynamics, intensifying competitive pressures, and evolving end-use demands requires stakeholders to look beyond headline figures and understand the structural forces shaping the trajectory through 2032.
This analysis introduces our latest comprehensive market research on the SRAM sector, designed specifically for executive teams, product strategists, and investment committees who require actionable intelligence to navigate an increasingly complex environment. Rather than offering static snapshots, the study maps the interplay between technological evolution, regulatory scrutiny, and regional supply realignment, providing a decision-ready framework for 2026 planning and beyond.
Static Random Access Memory (SRAM) Market
Market Trajectory: Sustained Expansion Amid Structural Shifts
The SRAM market has demonstrated consistent growth over the past half-decade, transitioning from a post-pandemic recovery phase into a more mature expansion cycle. Starting from a baseline of approximately 380.0 million USD in 2020, the sector progressed through a period of accelerated adoption, reaching 444.43 million USD by 2023 and crossing the 460 million USD threshold in 2024. By the 2025 base year, total market valuation settled at 480.0 million USD, reflecting stabilized demand patterns and incremental capacity adjustments across key manufacturing hubs.
Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 5.23 percent. This trajectory suggests a move toward the 684.0 million USD range by the end of the outlook window. Importantly, this growth is not linear or uniformly distributed. The market is experiencing divergent forces: sustained pull from high-speed computing applications coexists with supply-side normalization that is gradually easing earlier bottlenecks. For strategic planners, the key takeaway is that volume expansion will be accompanied by margin recalibrations, pricing oscillations, and shifting value capture across product tiers.
The research isolates these dynamics through scenario-based modeling that accounts for both baseline adoption curves and disruption triggers, such as capacity ramp-ups, component substitution pressures, and evolving procurement cycles. Stakeholders who rely on single-point forecasts risk misaligning capital allocation, production scheduling, and partnership strategies with the actual cadence of market evolution.
Segmentation Architecture: Where Value Is Concentrated
A rigorous examination of the SRAM market requires a multi-dimensional segmentation lens. Our study breaks down the landscape across product architecture, end-use application, and geographic footprint, revealing how specific sub-segments are driving disproportionate share and shaping competitive positioning.
Product Architecture Dynamics
Within the type-based segmentation, distinct performance and cost profiles are redefining buyer preferences. Synchronous SRAM configurations continue to command significant share, driven by their alignment with high-clock-speed architectures and low-latency memory hierarchies. Asynchronous variants maintain relevance in cost-sensitive and latency-tolerant deployments, particularly where design simplicity and power efficiency outweigh raw throughput requirements. A broader category of alternative and specialized SRAM implementations is also gaining traction, reflecting ongoing innovation in peripheral integration, radiation-hardened designs, and application-specific memory subsystems.
The report evaluates how these architectural distinctions influence pricing premiums, qualification timelines, and supply commitments across different buyer profiles. Decision-makers will find explicit guidance on when to prioritize synchronous architectures for performance-critical roadmaps versus when asynchronous or hybrid approaches provide more favorable total cost of ownership.
Application-Driven Demand Patterns
SRAM consumption is not monolithic; it is shaped by the distinct design cycles, qualification standards, and volume profiles of each end market. Automotive applications represent a substantial demand pool, propelled by advanced driver-assistance systems, in-vehicle connectivity, and the proliferation of electronic control units requiring fast, reliable memory buffering. Industrial deployments contribute a meaningful share, supported by factory automation, edge instrumentation, and ruggedized environments where memory endurance and temperature resilience are paramount.
Consumer electronics, IT and telecommunication infrastructure, and aerospace and defense collectively form additional demand pillars. Each vertical presents a unique combination of volume intensity, specification strictness, and procurement behavior. For example, telecommunications and data networking contexts increasingly favor high-speed SRAM solutions that can sustain throughput in AI-adjacent workloads, while aerospace and defense programs emphasize radiation tolerance and long lifecycle availability. The study maps these application-level pressures to procurement strategy recommendations, enabling teams to anticipate qualification timelines, forecast volume ramps, and structure supply agreements accordingly.
Geographic Footprint and Regional Realignment
Regional dynamics are undergoing a subtle but consequential recalibration. North America and Asia Pacific continue to anchor significant portions of market activity, reflecting the concentration of advanced electronics manufacturing, semiconductor design activity, and high-performance computing deployment. Europe and Latin America contribute substantive demand, influenced by regional industrial bases, automotive clusters, and localized supply chain strategies. The Middle East and Africa represent an emerging frontier where infrastructure modernization and defense-related electronics programs are gradually expanding addressable demand.
The report avoids simplistic regional scorecards. Instead, it examines how trade policy considerations, onshore manufacturing incentives, logistics complexity, and local content expectations are reshaping regional sourcing strategies. This regional granularity enables multinational teams to evaluate where to prioritize supplier diversification, where to invest in qualification partnerships, and where pricing differentials offer structural advantages.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The SRAM market exhibits notable concentration, with a small group of established players accounting for the majority of share. The research quantifies this dynamic through concentration metrics that highlight the extent to which top-tier firms dominate supply relationships, qualification pipelines, and volume procurement. Such concentration has practical implications for buyers and suppliers alike: it influences negotiation leverage, roadmap visibility, and the speed at which new entrants can gain traction.
Among the companies profiled, GSI Technology, Inc., based in San Jose, California, exemplifies a focused strategy centered on high-performance and radiation-hardened SRAM products tailored for networking, aerospace, and defense applications. Its market positioning reflects a deliberate emphasis on specialized performance requirements rather than broad commodity volume. The company’s trajectory also illustrates how high-speed SRAM solutions are benefiting from sustained demand pull from AI data center environments, where latency sensitivity and throughput stability are critical design constraints.
The study goes beyond company profiles to assess competitive behavior across several dimensions. It evaluates how incumbents are defending positions through lifecycle management, qualification leverage, and application-specific engineering support. It also examines where differentiation is increasingly tied to reliability certifications, supply assurance commitments, and integration support rather than raw memory specifications alone. For organizations evaluating supplier relationships or assessing potential partnership structures, the report provides a structured view of who holds advantage in which context, and why.
Industry Dynamics: Regulation, Supply Evolution, and Demand Catalysts
The SRAM market does not operate in a vacuum. Several concurrent developments are actively reshaping the operating environment and will influence strategic options throughout the forecast period.
Regulatory and legal scrutiny has emerged as a material consideration. Investigations have been initiated into multiple SRAM manufacturers regarding alleged antitrust violations, signaling heightened attention to competitive conduct within concentrated semiconductor segments. For enterprise buyers, this introduces both risk management requirements and potential opportunities to renegotiate terms as market conduct is examined. For suppliers, compliance posture and documentation rigor are becoming integral to maintaining customer confidence and avoiding disruption.
On the supply side, manufacturing strategies are evolving. Certain players are expanding onshore capacity for related memory technologies under strategic agreements, reflecting a broader push toward supply resilience and localized production capabilities. While these initiatives often target adjacent product lines, they influence the broader memory ecosystem by altering capacity availability, cost structures, and the geographic distribution of manufacturing assets. The report tracks these shifts to help organizations anticipate where supply reassignment may create advantages or constraints for SRAM procurement.
Demand-side catalysts remain powerful. AI data center expansion continues to drive sustained interest in high-speed SRAM solutions, with select suppliers reporting significant year-over-year revenue growth in recent quarters. This growth underscores the strategic importance of SRAM within performance-sensitive compute architectures, even as the market also encounters pricing pressures from improving supply conditions. Sector analysis indicates that price trajectories may face downward adjustment as supply improves, with notable declines projected in specific quarters. For procurement and product planning teams, this underscores the value of timing-aware sourcing strategies rather than static pricing assumptions.
Taken together, these dynamics create a market environment where strategic agility is a competitive necessity. The report integrates each of these forces into a coherent narrative, enabling readers to evaluate how regulatory exposure, supply realignment, and application-driven demand will interact over the planning horizon.
What the Research Delivers: An Executable Intelligence Framework
This market research is structured to move beyond descriptive summaries and toward decision-grade analysis. The study is organized to support a range of strategic use cases, including product roadmap planning, procurement optimization, competitive benchmarking, and investment prioritization.
Content coverage includes a thorough segmentation analysis across type, application, and region, supported by scenario-based projections that account for both baseline adoption and disruption-driven variance. The report also contains a detailed competitive assessment that evaluates positioning, differentiation levers, and concentration implications across the leading players. Beyond structure and sizing, the analysis incorporates macro and regulatory developments, translating them into practical implications for supply strategy, risk management, and go-to-market planning.
Operational tools within the study include procurement timing guidance in the context of projected price movements, supplier evaluation criteria aligned with application-specific requirements, and regional sourcing considerations that factor in trade dynamics and manufacturing geography. For R&D and engineering leadership, the report maps technology trajectory signals to product planning horizons, helping teams determine where performance-oriented SRAM architectures provide durable advantage and where cost-optimized alternatives better match demand profiles.
Magneto Resistive RAM (MRAM) Market
Importantly, the research is designed to be actionable without being prescriptive in a one-size-fits-all manner. Instead, it provides the analytical scaffolding for organizations to test assumptions, compare alternatives, and select strategies that fit their specific exposure to automotive, industrial, computing, telecom, and defense segments.
Strategic Implications for 2026 Decision-Making
The SRAM market in 2026 will reward organizations that treat memory procurement and product integration as strategic levers rather than tactical costs. Several implications emerge clearly from the current trajectory.
First, timing and flexibility matter more than ever. With supply conditions improving and price movements projected in specific periods, rigid long-term commitments may leave value on the table or expose teams to avoidable risk. Scenario-aware sourcing strategies, tiered supplier portfolios, and qualification-ready alternatives can provide resilience while preserving optionality.
Second, application-specific differentiation is increasingly decisive. As automotive, industrial, and high-performance computing segments each impose distinct performance, reliability, and lifecycle requirements, suppliers and buyers alike must align SRAM selections with end-use realities rather than generic specifications. The report provides the mapping needed to make those alignments explicit.
Third, regulatory and supply chain developments should be monitored as strategic variables. Antitrust scrutiny, onshore manufacturing investments, and evolving trade expectations can influence supplier stability, pricing structure, and regional availability. Integrating these factors into planning cycles helps organizations anticipate disruption rather than react to it.
Finally, competitive concentration means that market intelligence must be current and granular. Understanding who holds advantage in which segment, which technologies are gaining traction, and where demand catalysts are intensifying can inform partnership choices, product roadmaps, and investment priorities with greater confidence.
Conclusion: Moving From Context to Competitive Advantage
The SRAM market is undergoing a period of recalibration in which growth remains intact but the path to value capture is becoming more nuanced. Macro expansion is supported by sustained application demand and evolving compute architectures, yet the operating environment is increasingly shaped by supply reassignment, pricing oscillations, regulatory attention, and concentrated competitive dynamics. In this context, high-level market knowledge is necessary but insufficient. Decision-makers need segment-level clarity, scenario-aware projections, and an integrated view of how regulation, supply, and demand interact.
PW Consulting’s SRAM Market Research offers that depth. It is built to support executive planning, procurement strategy, product development alignment, and competitive positioning with a rigorous, forward-looking framework. For teams preparing for 2026 and beyond, the study provides the intelligence required to convert market complexity into informed action.
To explore the full segmentation detail, competitive assessments, regional dynamics, and scenario-based forecasts that underpin this analysis, please access the complete report through our official research portal. The complete intelligence package is available there for organizations ready to integrate SRAM strategy into their broader planning agenda.
For detailed analysis of this topic, please visit the official page: Static Random Access Memory (SRAM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Musical Instrument Market Hits $137.5M in 2025, Projects 6.46% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intel for 2026: Navigating the Musical Instrument Market Landscape
The global musical instrument market stands at a critical inflection point in 2026. Beyond the romanticism of melody and performance, the sector is a complex commercial ecosystem shaped by supply chain friction, shifting consumer demographics, and technological convergence. For executives, investors, and product leaders, understanding the structural forces driving this industry is no longer optional—it is a prerequisite for sustainable growth and risk mitigation.
At PW Consulting, we have just released our comprehensive Musical Instrument Market research report, a definitive intelligence asset designed specifically for enterprise decision-making in the 2026-2032 horizon. This article serves as a strategic preview, outlining the market's foundational mechanics, the competitive architecture, and the pressing operational challenges that define the current landscape. While we invite you to explore the full methodology and granular breakdowns in our complete publication, this overview establishes why this research is a vital compass for your next strategic moves.
Market Trajectory and Growth Architecture
The musical instrument sector has demonstrated remarkable resilience through recent macroeconomic volatility. Drawing on historical performance from 2020 through 2025, the industry has consistently expanded its revenue base, transitioning from a post-pandemic recovery phase into a period of steady, demand-driven growth. Our models project the total market valuation to reach approximately 143.59 million USD in 2026, with a clear upward trajectory continuing through 2032, where the market is anticipated to breach the 212.0 million USD threshold. This expansion is underpinned by a compound annual growth rate of 6.46 percent, a figure that translates into meaningful opportunities for market participants who can correctly position their portfolios against evolving demand centers.
It is crucial to recognize that these macro-level projections are not a uniform tide. Growth is unevenly distributed across product categories, use cases, and geographic territories. The interplay between traditional acoustic craftsmanship and modern electronic integration is reshaping consumption patterns, while infrastructure investment in music education and professional performance ecosystems continues to inject fresh capital into the supply chain. Our research dissects these currents with precision, identifying the specific demand nodes where commercial value is concentrating and where saturation risks are emerging.
The Competitive Ecosystem: Incumbents and Innovation Drivers
The competitive architecture of the musical instrument market is characterized by a blend of heritage manufacturing powerhouses and agile technology innovators. Concentration among the top tier remains significant, with the three largest players commanding a combined market share of approximately fifty percent, while the top five entities collectively account for sixty percent of total revenue. This oligopolistic structure does not stifle innovation; rather, it creates a highly stratified landscape where market leaders defend their positions through technological differentiation, global distribution networks, and deep brand equity, while mid-tier and niche players compete through specialization and targeted consumer engagement.
Yamaha Corporation, headquartered in Japan, continues to set the benchmark for comprehensive portfolio coverage. Its dominance spans guitars, pianos, keyboards, wind instruments, and digital music products, giving it unparalleled leverage across both beginner and professional segments. Roland Corporation, also based in Japan, has carved out a formidable identity in digital synthesizers, electric guitars, pianos, and integrated music technology solutions, positioning itself at the intersection of hardware craftsmanship and software-driven sound design. On the American side, Fender Musical Instruments Corporation remains synonymous with electric guitars, basses, amplifiers, and acoustic instruments, maintaining a cultural relevance that transcends mere product functionality. Steinway & Sons and Kawai Musical Instruments Mfg. Co., Ltd. compete in the premium piano segment, catering to conservatory-level professionals and discerning homeowners who prioritize acoustic fidelity. C.F. Martin & Co., Inc. and Eastman Music Company have built enduring reputations around acoustic guitars, mandolins, and banjos, anchoring the heritage segment with meticulous craftsmanship. In the wind and percussion domains, Conn-Selmer Inc., Buffet Crampon Group, and Meinl percussion reinforce the ecosystem's breadth, while D'Addario & Company, Inc. sustains a critical upstream position through strings, accessories, and maintenance products that support instrument lifecycles across categories.
Recent 움직임을 underscore the intensity of competitive signaling. In January 2026, Epiphone revived the cult-classic Gibson RD guitar as part of its Futura series lineup, introducing fresh designs, new pickups, and varied tonal options to reengage legacy enthusiasts. Ibanez simultaneously debuted updated TOD nylon models featuring new finishes, refined ergonomics, and upgraded Fishman acoustic imaging, explicitly targeting shred-friendly playability. Roland unveiled flagship updates including new digital instruments and music technology solutions at NAMM 2026, reinforcing its technology-forward positioning. Meinl percussion returned to the NAMM Show 2026 to showcase innovations and strengthen global network connections, while the Music China Organizing Committee announced that Music China 2026 would launch an inaugural Music Lifestyle & Creative Products Zone targeting Gen Z audiences with new thematic zones. These developments are not isolated product launches; they are strategic bets that signal where incumbents believe the next wave of consumer attention will originate.
Regulatory Frictions and Supply Chain Realities
While demand dynamics continue to drive top-line expansion, the operational environment in 2026 is heavily complicated by regulatory and trade-policy friction. Tariff exposure has emerged as one of the most consequential variables for market participants. In the first quarter of 2026, the average effective tariff rate on musical instrument imports into the United States reached 16.6 percent, a notable increase from the 15.9 percent recorded in 2025. This upward shift has tangible downstream effects: imports of wind instruments in 2025 fell by 27 percent, while piano imports declined by 20 percent, reflecting both price sensitivity among entry-level buyers and procurement recalibration among distributors.
The tariff landscape is not uniform across product categories. Higher effective tariff rates for pianos, acoustic keyboards, strings, and wind instruments more than tripled in 2026 compared to 2024, creating a highly asymmetric cost environment that disproportionately affects categories reliant on cross-border component sourcing and finished-goods importation. Sector-level analyses indicate that tariff-related price increases accounted for the entire 1.9 percent rise in combined revenues for the one hundred largest U.S.-based suppliers of music products, pushing aggregate revenues to approximately 10.5 billion USD in 2025. Beyond consumer-facing pricing dynamics, Section 232 tariffs on metals have elevated domestic input costs for manufacturers that depend on imported raw materials, compressing profit margins and forcing difficult trade-offs between absorption, pass-through, and product redesign.
For strategic planners, these dynamics introduce a new layer of scenario planning. Cost structures are no longer static, procurement pathways are subject to geopolitical recalibration, and margin preservation requires a more sophisticated understanding of regional sourcing alternatives, tariff engineering, and pricing elasticity across customer segments. Our report provides a structured framework to navigate these uncertainties, mapping the exposure points and identifying the operational levers that can insulate profitability without sacrificing market share.
Structural Shifts in Demand and Application
The demand architecture of the musical instrument market is undergoing a quiet but profound restructuring. Educational use remains the dominant application driver, reflecting sustained institutional investment in music programs, afterschool enrichment, and community-based learning initiatives. Professional use continues to represent a high-value segment, anchored by performance venues, recording studios, touring ecosystems, and institutional conservatories that demand reliable, high-fidelity instruments. Personal use, meanwhile, has expanded beyond casual hobbyism, driven by the democratization of music creation, the proliferation of home studio setups, and the growing cultural emphasis on creative self-expression among younger demographics.
These application streams do not operate in isolation. They intersect with regional consumption patterns, product category preferences, and channel dynamics in ways that create both synergies and trade-offs. A product strategy optimized for educational volume may not translate effectively to professional-grade performance expectations. A distribution model built around direct-to-consumer digital channels may underperform in markets where tactile retail experiences and dealer networks remain the primary purchase drivers. Our research maps these intersections systematically, helping organizations avoid the common pitfall of overgeneralizing demand and instead align product roadmaps, pricing architectures, and channel strategies with the specific realities of each application segment.
What the Full Report Delivers: Translating Intelligence into Execution
The complete PW Consulting Musical Instrument Market report is built for practitioners who require more than high-level trends. It delivers an integrated intelligence platform that connects market sizing, segmentation, competitive profiling, and regulatory scenario analysis into a single, actionable reference. Readers will gain access to historical performance baselines spanning 2020 to 2025, forward-looking projections through 2032, and a detailed dissection of the structural forces that will shape revenue allocation across the forecast window.
Musical Instrument Market
Flutes Instrument Market
The report provides deep operational coverage across multiple dimensions. It examines how demand is distributed across product categories and use cases, identifies the geographic territories where growth momentum is strongest, and unpacks the competitive maneuvers that market leaders are deploying to defend and expand their positions. It also delivers a close reading of the trade-policy environment, translating tariff shifts and input-cost pressures into practical guidance for procurement, pricing, and geographic footprint decisions. Throughout, the analysis is anchored in real-world signals, including recent product launches, trade-show innovations, and event-level strategic announcements that reveal how incumbents are repositioning themselves in response to evolving consumer expectations.
Beyond descriptive analysis, the report is structured to support decision-making. It highlights where concentration risk is building, where white-space opportunities exist for targeted product introductions or regional expansion, and where margin compression is most likely to intensify under current regulatory trajectories. For organizations planning capital allocation, product portfolio adjustments, or market-entry initiatives, the report provides the contextual depth required to move from intuition to evidence-based strategy.
Strategic Imperatives for 2026 Decision-Makers
As the market moves through 2026, several strategic imperatives are coming into focus. First, tariff environment resilience must be embedded into product planning and sourcing architecture. Organizations that rely on single-source cross-border supply chains face heightened vulnerability, while those that have diversified input pathways and built flexible pricing models are better positioned to preserve margins without alienating price-sensitive customers. Second, the convergence of acoustic heritage and digital functionality is accelerating, and product roadmaps that treat these domains as separate silos risk missing the integrated experiences that modern consumers increasingly expect. Third, the generational shift in music consumption is reshaping not only what instruments are purchased, but how they are discovered, evaluated, and integrated into broader lifestyle and creative ecosystems. Engagement strategies that fail to account for this shift will struggle to build durable brand affinity.
Finally, competitive intelligence is no longer a periodic exercise. The cadence of product launches, technology unveilings, and regional event strategies is intensifying, and organizations that monitor these signals systematically will be better equipped to anticipate shifts in consumer attention and competitor positioning. The recent activity at NAMM 2026, the revival of legacy guitar designs, the expansion of creative product zones targeting younger audiences, and the ongoing refinement of digital instrument portfolios all point to a market that is simultaneously honoring its heritage and actively reinventing its value proposition.
Access the Complete Intelligence Package
The musical instrument market in 2026 rewards organizations that combine strategic foresight with operational discipline. Growth is real, but it is unevenly distributed, and the cost environment is increasingly complex. Success will belong to those who can align product portfolios with true demand drivers, manage regulatory exposure proactively, and interpret competitive signals with precision rather than assumption.
This article has outlined the structural contours of the market and the strategic questions that matter most. However, the full resolution of these questions requires deeper data, segmented analysis, and scenario-grade modeling that only the complete PW Consulting Musical Instrument Market report can provide. We invite you to access the full publication to obtain the comprehensive breakdowns, competitive assessments, and forward-looking projections necessary to inform your 2026 decisions with confidence. The detailed intelligence is available at the source page, where the complete research architecture, methodology, and actionable insights await your review.
For detailed analysis of this topic, please visit the official page: Musical Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pressure Sensors Market to Hit $22.88B by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Pressure Sensors Market: Navigating 2026 and Beyond
Executive Overview
The global pressure sensors market stands at a critical inflection point as we move through 2026. Following a trajectory of consistent expansion from 2020 through 2025, the sector has matured into a complex landscape where technological differentiation, supply chain resilience, and regional dynamics converge to shape competitive outcomes. Our latest market research provides decision-makers with a comprehensive, data-backed roadmap to navigate this evolving environment, offering actionable intelligence that extends far beyond superficial market summaries.
Understanding the pressure sensors market requires more than tracking headline numbers. It demands a granular appreciation of how type-specific demand shifts, application-driven procurement cycles, regional adoption patterns, and competitive maneuvers interact to create both risk and opportunity. This report is designed for executives, product strategists, procurement leaders, and investors who require precision intelligence to allocate capital, prioritize R&D pipelines, and position portfolios against structural market shifts.
While broader market indicators provide essential context for strategic planning, the true value of this research lies in its operational depth. We examine the underlying drivers that will determine which organizations capture disproportionate value in the years ahead, and which risk being displaced by more agile, technologically adept competitors.
Medical Pressure Sensors Market
Macro Trajectory and Strategic Context
The pressure sensors market has demonstrated robust growth over the past half-decade, with total market revenue expanding from approximately 10.8 billion USD in 2020 to an estimated 14.75 billion USD by 2025. This expansion reflects sustained demand across industrial automation, automotive electrification, medical device innovation, and infrastructure modernization. Looking forward, the market is projected to continue its upward trajectory through the 2026 to 2032 forecast period, with a compound annual growth rate of 6.5 percent. By 2032, total market revenue is anticipated to reach 22.88 billion USD, underscoring the sector's long-term structural momentum.
Such macroeconomic visibility is valuable, but it is only the starting point for informed strategy. Growth rates mask significant variation in how different sensor categories perform, how regional markets evolve at divergent paces, and how application-specific procurement behaviors reshape purchasing patterns. Executives who rely solely on aggregate forecasts risk misallocating resources or misjudging the timing of market entry and exit decisions. Our research dissects these layers of complexity, enabling leaders to build plans grounded in segment-level reality rather than top-line approximation.
Pressure Sensors Market
The forecast period also coincides with a phase of heightened industry volatility. Supply chain reconfiguration, raw material cost pressures, regulatory certification burdens, and tariff-driven production economics are simultaneously reshaping cost structures and competitive positioning. Organizations that anticipate these dynamics and embed flexibility into their operating models will be better equipped to preserve margins and accelerate time-to-market, even as the broader environment grows more challenging.
Key Industry Dynamics Shaping 2026
-
Reciprocal tariff policies across major economies have introduced new cost pressures and forced supply chain reconfiguration decisions for pressure sensor manufacturers. Producers must now weigh the trade-offs between localized production, diversified sourcing, and inventory strategy in ways that directly affect unit economics and delivery reliability.
-
Silicon wafer availability and broader semiconductor material supply constraints continue to influence production timelines for piezoresistive pressure sensor manufacturing. These disruptions ripple through component lead times, capacity planning, and qualification cycles, particularly for organizations dependent on high-volume MEMS fabrication.
-
Stainless steel and ceramic pressure sensor cells face mounting price erosion and margin compression as elevated material and labor costs intersect with high-volume production demands. This environment rewards manufacturers that can optimize bill-of-materials efficiency, streamline assembly processes, and differentiate through performance rather than commodity cost alone.
-
Hazardous area certifications such as ATEX and IECEx add 20 to 30 percent to product development costs for industrial pressure sensors. For companies targeting process industries, oil and gas, and utility applications, certification strategy and time-to-certification have become critical determinants of commercial viability and competitive reach.
These dynamics do not affect every segment equally. Some categories benefit from resilience in high-precision or specialized applications, while others experience intensified price competition as commoditized solutions encounter cost headwinds. The research unpacks which segments are most exposed, which are insulated by technical barriers, and how leading players are adjusting their portfolios to navigate the new cost and compliance reality.
Competitive Landscape and Strategic Positioning
The pressure sensors market features a diverse field of established multinational manufacturers, specialized engineering firms, and technology-focused innovators. Competitive advantage in this environment is increasingly defined not by scale alone, but by the ability to combine material science expertise, packaging innovation, application-specific calibration, and compliance readiness into solutions that reduce total cost of ownership for end users.
Several core companies illustrate the range of strategic approaches shaping the market. Honeywell International Inc. continues to strengthen its industrial, transportation, and HVAC portfolio through heavy-duty pressure sensors, board-mount solutions such as the ABP series, and high-pressure transducers leveraging piezoresistive technology. Its recent introduction of a 13MM pressure sensor tailored for cleanroom semiconductor environments highlights how targeted product development can open doors in highly specialized, standards-driven applications.
TE Connectivity Ltd. maintains a broad technology footprint spanning board-level devices, media-isolated sensors, and pressure transducers built on piezoresistive MEMS and silicon strain gauge architectures. Its ability to serve medical, industrial, automotive, and aerospace sectors with pressure ranges spanning from ultra-low to extremely high values demonstrates the commercial power of versatile platform technologies. Merit Sensor complements this landscape with surface-mount piezoresistive sensors and modules focused on ultra-low-pressure differential and gage measurement for industrial use, reflecting a strategy centered on precision in demanding control environments.
In the industrial and utility segment, ABB Ltd. has expanded its offering with a new P-Series pressure transmitter portfolio designed for high-precision measurement, reinforcing its emphasis on robust, chemically resistant, and ingress-protected devices. Gems Sensors & Controls, Setra Systems, Ashcroft Inc., and SSI Technologies each contribute ruggedized designs and application-focused engineering, targeting demanding fluid measurement, HVAC, material handling, and high-accuracy industrial environments. These firms illustrate how physical durability, environmental resilience, and tailored form factors remain decisive in sectors where failure costs are high.
High-temperature and extreme-environment capability represents a distinct competitive frontier. Sentek Instrument has advanced its position through the NovaPT-E sapphire pressure sensor, which has demonstrated reliable operation at pulse temperatures up to 1500 degrees Celsius and demodulation at frequencies up to 60 kHz. Its recent contract win to supply high-temperature sensors to a major jet engine manufacturer for applications above 1000 degrees Celsius underscores the growing importance of extreme-environment measurement in aerospace and advanced propulsion systems.
On the component and integration side, Amphenol Corporation, Microsensor Corporation, MPI Melt Pressure, and several semiconductor-centric players contribute specialized capabilities ranging from leadless miniature packages to custom melt-pressure measurement solutions. Meanwhile, Bosch Sensortec, NXP Semiconductors, and STMicroelectronics embed pressure sensing functionality within broader IC and MEMS platforms, particularly for automotive and consumer applications. This segmentation between discrete sensor specialists and integrated semiconductor suppliers creates distinct value chains, each with its own cost structure, innovation cadence, and customer engagement model.
Market concentration remains moderate, with the top three firms and top five firms collectively holding meaningful but not dominant shares of total revenue. This structure suggests that while scale advantages and distribution reach matter, there is substantial room for specialized players to win on performance, certification, customization, and service. The research evaluates how these concentration patterns are likely to evolve as consolidation, partnerships, and technology platform strategies reshape competitive boundaries.
Report Scope and Actionable Intelligence
This market research is built for operational decision-making. It moves beyond descriptive analysis to deliver the kind of structured intelligence that product leaders, strategy teams, and commercial executives can translate directly into planning and execution. The report's content is designed to answer the questions that matter most when allocating resources and defining market strategy in 2026 and beyond.
What the Report Covers
-
Market sizing and forecast architecture across the full 2020 to 2032 timeline, with a focused 2026 to 2032 forecast window that supports near-term budget planning and longer-term portfolio strategy.
-
Detailed segmentation analysis by type, application, and region, enabling readers to identify where demand is strengthening, where saturation risk is rising, and where white space remains for differentiated offerings.
-
Competitive profiling of major participants, including technology positioning, product capabilities, geographic reach, and recent strategic actions that signal where each company is placing its bets.
-
Recent industry developments, including product launches, contract wins, and milestone achievements that illustrate the pace of innovation and the practical direction of market demand.
-
Regulatory, certification, and compliance considerations that affect development timelines, cost structures, and market access in industrial, medical, and hazardous-area applications.
-
Supply chain and input-cost dynamics, with attention to materials, semiconductor dependencies, labor economics, and tariff exposure that influence margin outcomes and sourcing strategy.
-
Strategic frameworks for interpreting segment attractiveness, prioritizing investment, and aligning product roadmaps with the most resilient demand vectors.
Who Should Use This Research
-
Corporate strategy and business development teams seeking to assess market entry, expansion, partnership, or acquisition opportunities.
-
Product managers and R&D leaders responsible for sensor portfolio planning, feature prioritization, and technology roadmapping.
- Procurement and supply chain executives evaluating supplier options, cost risk, and resilience strategies in a shifting materials and tariff environment.
-
Investors and market analysts requiring structured, defensible market intelligence to support valuation, due diligence, and sector monitoring.
-
Engineering and operations leaders in end-user industries who need to understand sensor capability trends, compliance requirements, and integration implications.
Why This Research Matters for 2026 Decisions
The pressure sensors market in 2026 is not simply larger than it was five years ago; it is more structurally complex. Growth persists, but the sources of growth are spreading across different sensor types, applications, and regions at uneven rates. At the same time, cost pressures from materials, labor, tariffs, and certification requirements are compressing the economics of commoditized segments while elevating the strategic importance of performance, reliability, and application-specific engineering.
In this environment, effective decision-making depends on understanding not just where the market is going, but why it is going there and what that implies for competitive positioning. A forecast number can inform revenue targets, but only a detailed segmentation and competitive analysis can reveal which product lines deserve investment, which customer segments warrant deeper engagement, and which supply chain assumptions need to be stress-tested.
Our research is designed to provide exactly that level of clarity. It gives executives the evidence needed to challenge assumptions, prioritize initiatives, and reduce uncertainty in planning cycles. By linking market size and growth trajectories to segment-level mechanics and real-world competitive moves, the report helps organizations align strategy with the realities of demand, cost, and technology development.
The complete analysis contains the detailed segmentation data, company-by-company competitive evaluation, and scenario-sensitive interpretation needed to support high-stakes decisions. Readers who require the full depth of market sizing, segment breakdowns, and strategic benchmarking are encouraged to access the complete report through our source page, where the full intelligence package is available for immediate use in strategic planning.
Conclusion
The pressure sensors market offers substantial opportunity for organizations that can combine technological credibility, supply chain discipline, and segment-focused strategy. With sustained growth projected through 2032 and a competitive landscape that rewards differentiation, the window for proactive positioning is open, but it is not unlimited. Tariff exposure, material constraints, certification costs, and evolving end-user requirements will continue to test companies that rely on generic product strategies or rigid operating models.
This report provides the strategic foundation needed to act with confidence in 2026. By translating market-scale trends into operational insight, it enables leaders to make sharper investment decisions, build more resilient supply strategies, and target the applications and regions where the next wave of value creation will emerge. The full research details are available through our source page for teams ready to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Pressure Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Temperature Controllers Market to Hit $3,132.63M by 2032, 4.6% CAGR
By PW Consulting, 2026-09-16
Navigating Precision: Strategic Insights for the Industrial Temperature Controllers Market in 2026
Executive Summary: The Case for Strategic Foresight
In the complex landscape of industrial automation, temperature control remains a foundational element of operational efficiency, product quality, and safety. As we move beyond the base year of 2025, enterprise leaders face a critical juncture. The trajectory of the Industrial Temperature Controllers Market is not merely a function of technological advancement but a reflection of broader macroeconomic shifts, regulatory pressures, and evolving manufacturing demands. Our latest comprehensive market study is designed to equip stakeholders with the granular intelligence necessary to navigate this evolving terrain.
This article serves as a strategic primer, outlining the scope, methodology, and competitive dynamics analyzed in our full report. While we highlight key market forces and structural trends here, the proprietary segmentation data, detailed revenue forecasts, and specific risk assessments contained within the complete publication remain exclusive to our subscribers. The objective is to demonstrate the depth of our analysis while underscoring the necessity of accessing the full intelligence package for actionable decision-making.
Market Trajectory and Growth Vectors
The historical performance of the industrial temperature control sector indicates a steady expansion, driven by the relentless need for precision in processing industries. Our analysis covers historical data spanning from 2020 through 2025, establishing a robust baseline for forecasting the period from 2026 to 2032. The market has demonstrated resilience and consistent upward momentum, reflecting the integral role of thermal management in modern industrial operations.
Looking forward, the forecast period anticipates continued growth, underpinned by a compound annual growth rate that signals sustained investment in automation technologies. This growth is not uniform across all vectors; it is propelled by specific technological shifts and regional industrialization efforts. Understanding the magnitude of this expansion requires a nuanced view of how different controller types and application sectors contribute to the overall revenue pool. While the aggregate market size figures point to a significant valuation by the end of the forecast period, the strategic value lies in dissecting the drivers behind these numbers.
Key growth vectors include the modernization of legacy manufacturing infrastructure and the adoption of smart control systems in emerging economies. However, capturing these opportunities requires more than top-line figures. It demands an understanding of the interplay between supply chain dynamics, component availability, and the specific thermal requirements of high-growth sectors such as energy and advanced manufacturing.
Irrigation Controllers Market
Competitive Landscape and Key Players
The market structure is characterized by a mixture of established global conglomerates and specialized regional players. Our report provides an in-depth profiling of key companies that are shaping the competitive environment. Understanding the strategic positioning of these entities is vital for companies looking to benchmark their performance or identify potential partnership opportunities.
Among the leaders, Omron Corporation stands out with a strong focus on PID process controllers. Their offerings are deeply integrated into industrial automation and manufacturing workflows, emphasizing precision regulation that aligns with high-standard automation protocols. Headquartered in Kyoto, Japan, Omron continues to leverage its global footprint to deliver solutions that cater to complex industrial requirements.
Similarly, Watlow Electric Manufacturing Company maintains a significant presence, particularly in the realm of precision temperature controllers and thermal management systems. Based in the United States, Watlow's portfolio extends to multi-loop process controllers, addressing applications where multiple thermal zones must be managed simultaneously. Their approach underscores the importance of reliability in harsh industrial environments.
On the other side of the spectrum, Yudian Temperature Control Technology Co., Ltd. represents a pivotal player in the global supply chain, headquartered in Xiamen, China. Yudian has distinguished itself not only through product volume but through regulatory and standards leadership. Notably, Yudian was the first in the instrumentation industry to achieve UL certification as of 2012, a milestone that opened doors to stringent international markets. Furthermore, the company has led the drafting of the core Chinese national standard GB/T 20819.1-2015 for Controllers with Analogue Signals for Industrial Process Control Systems. This involvement in standards setting signals a long-term commitment to compliance and interoperability. Their products are exported to over 150 countries and regions, highlighting their extensive global distribution network.
Additionally, Wuxi Keen Technology Co., Ltd. (Cakeen) is increasingly relevant, particularly for integrated PID temperature controllers and semiconductor-related heating solutions. Based in Wuxi, Jiangsu Province, their growth reflects the broader trend of specialized manufacturers catering to high-tech manufacturing needs where precise thermal control is critical for component integrity.
The competitive dynamics are further influenced by market concentration. Our analysis indicates a moderately concentrated market where top players hold significant share, creating both barriers to entry and opportunities for consolidation. Understanding the strategic moves of these key firms—from product launches to geographic expansion—is essential for anticipating market shifts.
Segmentation and Application Drivers
A core component of our research is the detailed breakdown of the market by type and application. The choice of controller technology often dictates the efficiency and cost-effectiveness of an industrial process. The market is segmented into categories such as On/Off Controllers, Proportional Controllers, and PID Controllers. Each category serves distinct operational needs, from simple heating tasks to complex, variable Process control loops requiring high precision.
In terms of application, the demand is spread across a diverse range of industries. Sectors such as Metals Mining & Metallurgy, Chemicals, and Food & Beverages represent significant consumption hubs due to the critical nature of temperature in material processing and safety compliance. Energy & Power and Oil & Gas also remain steady contributors, driven by infrastructure maintenance and operational safety requirements. General Manufacturing and other sectors provide additional volume, reflecting the ubiquitous need for thermal management across the industrial base.
While aggregate figures provide a view of total market size, the strategic insight lies in recognizing how these segments interact. For instance, the shift towards automation in food processing may drive demand for specific controller types that differ from those preferred in metallurgy. Our full report delves into these nuances, providing the specific revenue breakdowns and growth rates for each segment without the noise often found in generalized industry summaries.
Regional Dynamics and Market Concentration
Geographically, the market exhibits distinct characteristics influenced by local industrial policies, manufacturing capacity, and adoption rates of advanced automation. The analysis covers five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Industrial Temperature Controllers Market
Asia Pacific often emerges as a critical hub due to the density of manufacturing activity and rapid industrialization. However, mature markets in North America and Europe continue to drive demand through upgrades and replacements of existing infrastructure. Latin America and the Middle East and Africa present growth opportunities linked to resource extraction and energy sector developments.
Market concentration metrics suggest that while the market is accessible, scale and distribution networks play a crucial role in securing market share. Companies operating in this space must navigate varying regulatory environments and supply chain complexities unique to each region. Our report analyzes these regional disparities to help stakeholders identify where to focus their commercial efforts.
Regulatory and Compliance Influences
Regulatory frameworks and industry standards significantly impact product development and market access. Compliance is no longer optional; it is a competitive differentiator. As noted in our findings, certain manufacturers have moved early to secure certifications that facilitate international trade. For example, achieving UL certification can be a gateway to North American markets, while adherence to national standards like GB/T in China ensures domestic competitiveness and export compliance.
These regulatory milestones affect not only the manufacturers but also the end-users who require assurance of safety and reliability. In sectors like chemicals and energy, non-compliance can lead to severe operational risks. Therefore, our market study incorporates an analysis of how regulatory trends are shaping product specifications and procurement criteria. This includes tracking standards development and certification achievements that may alter the competitive balance.
Methodological Rigor and Data Integrity
To ensure the reliability of our insights, the report employs a multi-faceted research methodology. This includes extensive primary interviews with industry stakeholders, suppliers, and end-users, supplemented by secondary research from credible industry databases and financial reports. The data is validated through triangulation to minimize bias and ensure accuracy.
Our base year analysis establishes the current market state, while the forecast period utilizes trend analysis and modeling to project future performance. We account for variables such as economic fluctuations, technological disruptions, and supply chain constraints. This rigorous approach ensures that the insights provided are robust enough to support high-stakes strategic planning.
Strategic Value for 2026 Decision Makers
Why does this matter for your organization in 2026? In an environment where capital allocation must be precise, understanding the market trajectory of industrial temperature controllers can inform investment decisions, product development roadmaps, and supply chain strategies.
- Investment Planning: Identify high-growth segments before they become saturated.
- Competitive Benchmarking: Understand where key players are focusing their R&D and sales efforts.
- Risk Mitigation: Anticipate regulatory changes and supply chain disruptions that could impact operations.
- Market Entry Strategy: Evaluate regional potentials based on detailed demand analysis rather than generic assumptions.
The full report provides the specific data points required to execute these strategies. It moves beyond general trends to offer actionable intelligence on revenue potentials, market shares, and specific growth rates across all analyzed dimensions.
Conclusion: Accessing the Full Intelligence
The Industrial Temperature Controllers Market is poised for continued evolution, driven by technological refinement and industrial demand. However, navigating this landscape requires more than surface-level observations. It demands a deep dive into segmentation, competitive moves, and regional specifics.
This article has outlined the scope and strategic relevance of our latest study. To access the complete repository of data—including detailed segmentation revenues, specific CAGR breakdowns by segment, and comprehensive company profiles—we invite you to consult the full report. Equip your team with the precise intelligence needed to lead in 2026 and beyond. The future of industrial precision belongs to those who plan with data-driven confidence.
For detailed analysis of this topic, please visit the official page: Industrial Temperature Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Healthcare Supply Chain Market to Reach $344.8M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Healthcare Supply Chain Management Market: A 2026 Perspective
As the global healthcare ecosystem accelerates its digital transformation, supply chain management has evolved from a backend operational function to a strategic imperative. The convergence of regulatory pressure, demand for clinical resilience, and the rapid adoption of artificial intelligence is reshaping how pharmaceutical companies, medical device manufacturers, distributors, and healthcare providers orchestrate the movement of critical materials. PW Consulting latest market research provides a comprehensive intelligence framework designed to guide enterprise decision-making through 2032. This briefing outlines the structural trajectories, competitive dynamics, and operational realities defining the healthcare supply chain management landscape, while highlighting the analytical depth available in our full report.
Macro Economic Trajectory and Strategic Context
The healthcare supply chain management market has demonstrated consistent expansion over the past half-decade, driven by heightened visibility requirements, inventory optimization mandates, and the integration of cloud-native platforms across regulated environments. From a base valuation of approximately 163.15 million USD in 2020, the market expanded steadily through 2024, reaching 197.3 million USD, before crossing the 215.0 million USD threshold in 2025. Looking ahead, the market is projected to advance to 231.91 million USD in 2026, with sustained growth trajectories that ultimately push the addressable revenue envelope toward 344.8 million USD by 2032.
This expansion reflects a compound annual growth rate of 6.98 percent across the forecast horizon of 2026 through 2032. For enterprise strategists, this sustained upward curve is not merely a numerical indicator. It signals structural shifts in procurement architecture, real-time inventory governance, and the commercialization of AI-enabled orchestration tools that are redefining operational benchmarks. Organizations that align their investment roadmaps with these growth vectors position themselves to capture margin resilience, reduce clinical supply disruptions, and strengthen compliance postures as regulatory frameworks intensify.
Historical data further contextualizes this momentum. The segment demonstrated steady annual increases from 2021 through 2024, with each successive year reinforcing the market compounding baseline. The 2025 valuation of 215.0 million USD established a decisive inflection point, reflecting accelerated enterprise adoption of integrated supply chain platforms, expanded service engagements, and the broader commercialization of cloud-based deployment models. As 2026 progresses, the projected 231.91 million USD market size underscores how healthcare organizations are transitioning from pilot implementations to scaled, enterprise-wide supply chain architectures.
Core Segment Architecture and Operational Priorities
The structural composition of healthcare supply chain management spending reveals where enterprise attention and capital allocation are converging. Software remains the dominant component category, reflecting the industry prioritization of integrated platforms that unify purchasing, inventory, warehouse, and transportation workflows. Alongside software, services command substantial investment, underscoring the continued reliance on implementation expertise, managed operations, and consultative optimization as organizations navigate complex clinical and regulatory environments. Hardware investments, while proportionally smaller, remain essential for facilities that require specialized tracking infrastructure and on-site logistics tooling.
Functionally, purchasing management represents the largest share of operational spend, highlighting the strategic weight placed on supplier relationship orchestration, procurement visibility, and cost-rationalization initiatives. Inventory management follows as a critical operational pillar, driven by the need to balance availability against carrying costs in environments where shortages carry direct clinical consequences. Warehouse operations, transportation coordination, and order management collectively form the execution backbone of healthcare logistics, each addressing distinct pain points ranging from sterile handling requirements to last-mile specimen movement and high-velocity replenishment cycles.
From a product perspective, pharmaceutical and biotechnology supplies dominate managed volumes, reflecting the stringent cold-chain requirements, serialization mandates, and regulatory scrutiny inherent in drug distribution. Medical devices and equipment constitute the next major category, with complex asset tracking, maintenance scheduling, and procurement coordination demanding specialized supply chain capabilities. Additional product categories round out the managed portfolio, ensuring the framework accommodates diverse operational needs across the healthcare value chain.
Deployment architecture further shapes adoption velocity. Cloud-based models lead in deployment preference, driven by scalability, real-time data integration, and the ability to centralize visibility across distributed facilities. On-premise deployments persist where data sovereignty, legacy system integration, or highly controlled environments favor localized infrastructure. Other deployment configurations accommodate hybrid approaches and transitional architectures as organizations modernize at varying paces.
End-user demand is broadly distributed, with manufacturers and healthcare providers each commanding substantial engagement. Manufacturers focus on upstream coordination, demand forecasting, and outbound logistics efficiency, while healthcare providers prioritize internal procurement optimization, clinical inventory control, and supply assurance across departments. Distributors, alongside other end-user categories, complete the ecosystem by enabling intermediary logistics, cross-facility movement, and regional fulfillment capabilities.
Competitive Dynamics and Strategic Positioning
The competitive landscape is defined by a diversified set of specialists and platform-scale vendors, each pursuing distinct value propositions within healthcare supply chain management. Market concentration remains moderate, with the top three competitors collectively accounting for 34.5 percent of market share and the top five reaching 45.2 percent. This fragmentation signals both opportunity and complexity: enterprises can select from a wide spectrum of capabilities, but must also navigate differing integration models, regulatory alignment, and maturity levels across vendor offerings.
Tecsys Inc., headquartered in Toronto, Ontario, anchors its strategy on end-to-end inventory visibility, supplier workflow management, and AI-driven intelligence tailored to regulated healthcare environments. Its Elite Healthcare SCM platform is engineered to reduce costs while preserving continuity of patient care, with recent updates in early 2026 expanding agentic capabilities designed to mitigate shortages, minimize waste, and strengthen compliance risk management. Chooch AI, based in San Mateo, California, pursues a distinctive autonomous vision approach, leveraging agentic AI for automated hospital inventory tracking, real-time replenishment, and ERP integration without reliance on manual counts or traditional barcode workflows. Its recognition with a 2025 AI Breakthrough Award reflects growing enterprise interest in hands-free, vision-based inventory automation.
MedSpeed, operating from Elmhurst, Illinois, emphasizes same-day healthcare logistics and system-wide last-mile movement of specimens, pharmaceuticals, and supplies. Its focus on intra-company supply chain integration addresses the acute operational challenge of moving time-sensitive materials across distributed care networks. Premier Inc., headquartered in Charlotte, North Carolina, combines AI-driven supply chain optimization with group purchasing and real-time insights to strengthen procurement resilience. In February 2026, Premier announced a large-scale, multi-year technology investment program to build an intelligent healthcare supply chain of the future, signaling a long-horizon commitment to platform modernization and network-wide efficiency.
Enterprise-scale platform providers continue to exert structural influence. Oracle Corporation, based in Austin, Texas, integrates clinically aware supply chain capabilities within its Fusion Cloud SCM portfolio, with September 2025 enhancements expanding AI-powered visibility and efficiency tools for healthcare operations. Infor Inc., headquartered in New York, advances CloudSuite healthcare supply chain management with a focus on clinically integrated optimization, targeting shortage reduction and the mitigation of operational friction across provider networks. Manhattan Associates, located in Atlanta, Georgia, positions its AI-native ActivePlatform for unified supply chain orchestration, planning, and execution, with healthcare-specific tailoring for logistics complexity and compliance requirements.
For enterprises evaluating vendor partnerships, the strategic question is not simply which platform offers the broadest feature set, but which combination of intelligence, deployment flexibility, regulatory alignment, and clinical workflow integration best matches an organization operational reality. The report provides a structured comparative lens that goes beyond product descriptions to examine how each competitor approaches integration complexity, change management, and the operational outcomes that matter most in regulated care environments.
Regulatory Architecture and Operating Conditions
Healthcare supply chain management does not operate in a regulatory vacuum. The HIPAA Security Rule requires accurate and thorough assessment of potential risks and vulnerabilities affecting the confidentiality, integrity, and availability of all electronic protected health information. This obligation extends into supply chain software operations, where third-party service providers must be subject to due diligence and ongoing oversight to ensure they do not introduce exposure into the protected data environment.
Recent regulatory developments have further tightened the compliance perimeter. Federal Register proposed modifications to the HIPAA Security Rule in early 2025 sought to strengthen cybersecurity protections for electronic protected health information within healthcare supply chains, signaling heightened expectations for vendor risk management, access controls, and incident readiness. Subsequent guidance from the HHS Office for Civil Rights reinforced that the Security Rule is designed to be scalable and technology neutral, applying across entities ranging from small providers to large cloud service providers engaged in supply chain management. Additional oversight from the New York Department of Financial Services emphasized the necessity of continuous monitoring for third-party providers that access or process nonpublic information.
Healthcare Supply Chain Managements Market
Next Gen Supply Chain Market
These regulatory dynamics create a dual mandate for supply chain leaders. On one hand, digital modernization and AI-enabled automation are essential to achieving the visibility and responsiveness modern healthcare logistics demand. On the other, each technology investment must be evaluated for data governance implications, third-party risk exposure, and alignment with evolving security expectations. The operational consequence is that compliance is no longer a separate initiative from supply chain strategy; it is a design constraint that shapes platform selection, integration architecture, and vendor governance.
What the Full Research Delivers
PW Consulting Healthcare Supply Chain Management Market research is designed to convert macro trends into executable strategy. The report provides a detailed segmentation mapping across region, component, function, product managed, deployment model, and end user, enabling leaders to benchmark their portfolio positioning against the broader market architecture. Rather than presenting data in isolation, the analysis connects each segment to operational implications, investment prioritization, and competitive positioning.
The study includes a thorough competitive profiling framework that evaluates strategic focus areas, technology orientation, and recent development activity across leading vendors. By aligning product capabilities with market demand patterns, the report helps procurement, IT, and supply chain executives distinguish between vendor narratives and measurable operational value. Recent product launches, partnership announcements, and award recognitions are contextualized within broader adoption trends, helping organizations assess which developments represent meaningful capability shifts versus incremental enhancements.
Our research also examines the regulatory environment in depth, translating compliance requirements into practical decision criteria for platform selection, vendor due diligence, and data governance architecture. The analysis addresses how security expectations influence cloud adoption, third-party integration, and the deployment of AI-driven automation in regulated healthcare settings. For organizations planning multi-year modernization roadmaps, this regulatory context is essential for de-risking investment and ensuring that operational efficiency gains do not come at the expense of compliance exposure.
Additionally, the report incorporates scenario-based forecasting that maps growth trajectories across the forecast period, allowing leaders to test strategic assumptions against multiple market pathways. This forward-looking structure supports resource allocation decisions, capacity planning, and vendor negotiation strategies by clarifying where demand is most likely to intensify and which functions will command disproportionate attention as the market matures.
Strategic Takeaways for 2026 Decision-Makers
The healthcare supply chain management market is entering a phase where scale, intelligence, and compliance fuse into a single strategic agenda. Several priorities stand out for executives shaping investment and operating decisions in 2026 and beyond.
- Align technology investments with clinical outcomes. Platforms that connect procurement, inventory, and logistics directly to patient care continuity deliver value that transcends cost reduction, strengthening organizational resilience during supply volatility.
- Treat AI adoption as an orchestration challenge, not a point solution. Autonomous tracking, agentic replenishment, and predictive visibility tools are advancing rapidly, but their impact depends on integration depth, workflow redesign, and governance maturity.
- Embed regulatory readiness into platform selection. As HIPAA-related expectations and third-party oversight requirements intensify, vendors must demonstrate not only functional capability but also defensible data handling, risk management, and compliance alignment.
- Benchmark against segment-weighted demand patterns. Understanding where purchasing management, inventory control, cloud deployment, and pharmaceutical management concentrate spend helps organizations prioritize modernization efforts that reflect actual market momentum.
- Evaluate vendor ecosystems through an outcomes lens. With moderate market concentration and a diverse set of specialists and platform providers, the strategic differentiator lies in measurable improvements to shortage mitigation, waste reduction, and operational friction across care networks.
The full PW Consulting Healthcare Supply Chain Management Market research report provides the detailed segment sizing, competitive benchmarking, regulatory analysis, and strategic scenario frameworks needed to convert these priorities into a structured execution plan. For leaders navigating vendor evaluation, capital allocation, and multi-year supply chain strategy, the complete intelligence package offers the depth required to make decisions with confidence in a market that is expanding steadily and evolving rapidly.
For detailed analysis of this topic, please visit the official page: Healthcare Supply Chain Managements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antivirus Market Hits $4.72B in 2025, Projected to Reach $7.11B by 2032
By PW Consulting, 2026-09-16
Navigating the 2026 Antivirus Software Landscape: Strategic Insights from PW Consulting
Market Trajectory and Growth Dynamics
The global antivirus software market stands at a critical inflection point as organizations navigate an increasingly complex threat environment. Our latest research indicates that the market has evolved significantly from its 2020 baseline of approximately 2.7 billion USD to an estimated 4.72 billion USD in 2025. This growth trajectory reflects not merely expansion but a fundamental transformation in how enterprises and individual users approach endpoint security. The forecast period through 2032 projects the market to reach 7.11 billion USD, representing a compound annual growth rate of 6.0 percent. These figures underscore a market that continues to demonstrate resilience and adaptive capacity despite evolving competitive pressures and regulatory constraints.
Our analysis reveals that this growth is not uniform across all segments or geographies. The historical data from 2020 through 2025 shows periods of acceleration followed by consolidation, suggesting that market participants who understand the underlying drivers will be best positioned to capture value in the forecast period. The transition from traditional signature-based detection to AI-powered behavioral analysis represents one of the most significant shifts in the industry, fundamentally altering how security solutions deliver value to end users and enterprise clients alike.
The Strategic Imperative for Decision Makers
For enterprise leaders and technology procurement teams, understanding the antivirus software market in 2026 requires more than tracking headline figures. It demands a nuanced appreciation of how regulatory frameworks, technological innovation cycles, and competitive dynamics intersect to shape purchasing decisions and deployment strategies. The NIS2 Directive implementation across 22 EU member states with common incident reporting templates adopted by the NIS2 Cooperation Group on 26 May 2026 has created new compliance obligations that directly influence antivirus software selection criteria. Organizations must now evaluate solutions not only for their technical capabilities but also for their ability to support standardized incident reporting and reduce administrative burden.
On 20 January 2026, the European Commission proposed targeted amendments to the NIS2 Directive to simplify compliance for 28,700 companies, including 6,200 micro and small enterprises. This regulatory evolution signals a broader trend toward making cybersecurity requirements more accessible while maintaining meaningful protection standards. Simultaneously, CISA scaled Endpoint Detection and Response Persistent Access Capabilities to more than 60 federal agencies with over 500,000 endpoints visible in 2025, blocking 2.62 billion malicious connections in federal civilian networks. These government-level deployments establish benchmarks that influence private sector expectations and procurement standards.
NIST finalized SP 800-70r5 Revision 5 in 2026, updating the National Checklist Program for IT Products with enhanced mapping to NIST Cybersecurity Framework 2.0 outcomes. This development provides a structured framework for evaluating antivirus solutions against recognized security standards, making it an essential reference point for organizations developing procurement specifications or evaluating existing security investments.
Antivirus Software Market
Worldwide Anti-malware Protection Market
Competitive Landscape and Key Players
The antivirus software market exhibits significant concentration, with the top three players commanding approximately 60 percent of total market share and the top five firms controlling roughly 75 percent. This consolidated structure creates both opportunities and challenges for market participants. Established players leverage extensive customer bases, brand recognition, and integrated ecosystem advantages, while smaller vendors compete through specialization, innovation, and targeted value propositions.
Microsoft, headquartered in Redmond, Washington, maintains a dominant position through Microsoft Defender Antivirus, which offers built-in endpoint protection with real-time threat detection for Windows devices. The integration of security capabilities directly into the operating system provides a competitive moat that standalone vendors must continuously work to overcome. NortonLifeLock, based in Tempe, Arizona, focuses on Norton 360 antivirus and security suites that provide comprehensive malware detection, VPN services, and identity protection for consumers and families. McAfee, located in Santa Clara, California, delivers McAfee Total Protection with unlimited device security, firewall capabilities, and ransomware defense across platforms.
Bitdefender, headquartered in Bucharest, Romania, distinguishes its offering through Bitdefender Total Security, which features AI-powered behavioral analysis and lightweight performance for endpoint protection. Kaspersky, based in Moscow, Russia, provides antivirus and endpoint solutions with advanced threat intelligence and EDR capabilities for both enterprise and consumer use. Trend Micro, from Tokyo, Japan, emphasizes cloud-based threat prevention and security for multi-device environments through its antivirus and XDR solutions. Sophos, operating from Abingdon, Oxfordshire, United Kingdom, offers managed endpoint protection with strong performance in independent tests.
Avast and AVG Technologies, both based in Prague, Czech Republic, serve the consumer and small business markets with security suites featuring scam detection, device cleanup tools, and performance optimization. ESET, from Bratislava, Slovakia, focuses on ESET NOD32 antivirus with advanced UEFI scanning and hardware-level endpoint security. Avira, headquartered in Berlin, Germany, provides lightweight, user-friendly protection with minimal system impact. Malwarebytes, based in Santa Clara, California, delivers targeted remediation and low-resource scanning through its anti-malware suite.
Additional market participants include TotalAV, which offers beginner-friendly protection with strong scam and phishing blocking; Surfshark, based in The Hague, Netherlands, which bundles antivirus with VPN services for all-around digital security; AhnLab, from Seoul, South Korea, which provides certified protection and performance in enterprise tests through its V3 Internet Security product; and G Data, headquartered in Cologne, Germany, which emphasizes multi-layer defense and real-time threat blocking.
Recent Developments Shaping the Market
The competitive dynamics in the antivirus software market continue to evolve through product launches, industry recognition, and research validation. In May 2026, Gen Digital unveiled a revolutionary modular antivirus platform through Avast, featuring industry-leading device protection, scam detection, optional no-log VPN, data breach monitoring, and device cleanup capabilities. This product launch reflects a broader industry trend toward modular, customizable security solutions that allow users to select features aligned with their specific needs and risk profiles.
Also in May 2026, CrowdStrike was named a Leader in the 2026 Gartner Magic Quadrant for Endpoint Protection for the seventh consecutive time, achieving the highest Ability to Execute and Completeness of Vision scores. This recognition reinforces the importance of platform-based approaches that integrate antivirus capabilities with broader endpoint detection and response functionalities. In March 2026, the Info-Tech Research Group recognized endpoint protection solutions in its 2026 Emotional Footprint Report, highlighting their central role in safeguarding devices across distributed environments.
Segmentation Dynamics and Market Structure
Our research provides comprehensive analysis across multiple dimensions of market segmentation. The product landscape spans desktop antivirus solutions, mobile antivirus applications, server antivirus deployments, and emerging cloud-based antivirus offerings. Each segment presents distinct value propositions, deployment considerations, and growth trajectories. Understanding the relative contribution and interaction between these segments is essential for developing effective go-to-market strategies and investment allocation decisions.
Application-based segmentation reveals distinct user groups with varying requirements and purchasing behaviors. Enterprise security deployments represent a significant portion of market activity, driven by organizational risk management priorities and regulatory compliance obligations. Individual user segments reflect consumer demand for personal data protection, privacy enhancement, and device security across increasingly connected home environments. Government sector deployments introduce additional considerations around certification requirements, procurement processes, and mission-critical reliability standards.
Regional dynamics further shape market performance, with established markets demonstrating maturity and saturation tendencies while emerging markets present growth opportunities driven by digital transformation initiatives, increasing internet penetration, and rising cybersecurity awareness. The geographic distribution of market activity reflects differences in regulatory environments, economic development levels, technology adoption patterns, and competitive intensity across regions.
Why This Research Matters for 2026 Strategic Planning
Organizations operating in or adjacent to the antivirus software market face critical strategic questions that demand rigorous, evidence-based analysis. Which product categories will capture disproportionate growth in the forecast period? How will regulatory developments affect competitive positioning and procurement decisions? What capabilities will distinguish market leaders from followers as AI-powered security solutions become increasingly prevalent? Our comprehensive research addresses these questions through detailed market sizing, segmentation analysis, competitive profiling, and scenario-based forecasting.
The report provides actionable intelligence for product strategy development, investment allocation, partnership evaluation, and competitive positioning. decision-makers will gain insights into market concentration patterns, growth driver identification, barrier analysis, and emerging trend assessment. The granular segmentation data enables precise market sizing for specific product categories, application types, and geographic territories, supporting targeted strategic initiatives and resource optimization.
Our analysis of key companies includes detailed profiles covering product portfolios, strategic focus areas, market positioning, and recent developments. This competitive intelligence supports benchmarking exercises, partnership due diligence, and market entry feasibility assessments. The inclusion of recent industry developments, regulatory updates, and recognition events provides context for understanding near-term market dynamics and anticipating future shifts in competitive advantage.
Accessing Complete Market Intelligence
This overview represents a fraction of the comprehensive analysis contained in our full market research report. The complete study includes detailed regional breakdowns, segment-level revenue projections, competitive positioning matrices, regulatory impact assessments, and strategic recommendations tailored to different stakeholder types. Organizations seeking to make informed decisions about market entry, product development, investment allocation, or competitive strategy will find substantial value in the depth and breadth of our analysis.
To access the complete market intelligence, including all segmentation data, regional analyses, competitive profiles, and strategic recommendations, please visit our website to download the full report. Our team of industry analysts remains available to discuss specific research questions, custom analysis requirements, and strategic advisory engagements tailored to your organization's unique needs and objectives.
The antivirus software market in 2026 presents both opportunities and challenges for market participants. Success will depend on the ability to interpret market signals accurately, anticipate competitive moves, align product strategies with evolving customer requirements, and navigate regulatory complexity with agility. PW Consulting's comprehensive research provides the foundation for making these strategic decisions with confidence and precision.
For detailed analysis of this topic, please visit the official page: Antivirus Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ride Sharing Market Hits $47.22B in 2025, Projects 5.85% CAGR to $69.79B by 2032
By PW Consulting, 2026-09-16
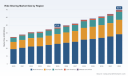
Strategic Horizons in the Ride Sharing Market: A 2026 Decision-Maker’s Guide to Sustainable Mobility Growth
The global ride sharing ecosystem has evolved from a disruptive novelty into a foundational pillar of modern urban and interurban mobility. As enterprises, municipalities, and mobility operators navigate an era defined by regulatory realignment, autonomous technology maturation, and shifting consumer expectations, the need for precise, forward-looking intelligence has never been more acute. PW Consulting’s newly released ride sharing market research delivers exactly that: a comprehensive, data-grounded examination of an industry poised for sustained expansion through the end of the decade. This introduction outlines the strategic architecture of the study, highlights the macro-level trajectory shaping 2026 corporate planning, and demonstrates how decision-makers can translate analytical depth into actionable competitive advantage.
The Macro Trajectory: Mapping an Industry in Deterministic Expansion
Over the past half-decade, the global ride sharing sector has demonstrated remarkable resilience and consistent upward momentum. Historical valuation data from 2020 through 2025 reveals a market that has systematically outpaced pre-pandemic projections, recovering swiftly from operational disruptions and reinvesting in platform sophistication, fleet modernization, and geographic penetration. The baseline valuation has climbed steadily across successive fiscal periods, establishing a robust foundation for the current forecast cycle.
Looking ahead, our modeling frameworks project a compound annual growth rate of approximately 5.85% across the 2026 to 2032 horizon. This trajectory reflects a confluence of structural drivers: urbanization intensification, the normalization of app-based mobility as a primary transit alternative, and the gradual integration of alternative powertrains into commercial fleets. By the close of the forecast window, the sector is positioned to surpass significant valuation thresholds, reshaping how capital is allocated, how partnerships are structured, and how regulatory compliance is priced into operational models. For executives evaluating market entry, portfolio diversification, or technology investments, these macro indicators provide a reliable compass—but they represent only the starting point. The real strategic differentiation lies beneath the headline figures.
Beyond Headline Numbers: What the Report Delivers for 2026 Strategy
PW Consulting’s research framework is engineered for practitioners who require more than aggregate market sizing. The study dissects the ride sharing value chain through multiple analytical lenses, ensuring that strategic, financial, and operational leaders can extract precise insights tailored to their functional mandates. Rather than presenting static snapshots, the report maps intercurrent dynamics—how pricing architectures interact with regional regulatory environments, how service-tier positioning influences customer retention, and how application-specific demand patterns reshape fleet deployment strategies.
The analytical architecture encompasses detailed breakdowns of market structure across geographic territories, service classifications, and utilization contexts. Each segmentation is examined not in isolation, but as part of an interconnected ecosystem where cross-regional demand shifts, tiered pricing elasticity, and destination-driven utilization patterns collectively inform competitive positioning. Additionally, the study evaluates market concentration dynamics, highlighting how dominant platform architectures shape pricing power, network effects, and barriers to entry. For strategy teams, this means moving beyond speculative trend-chasing toward evidence-based scenario planning that accounts for both near-term operational realities and long-term structural shifts.
Competitive Architecture: Navigating a Consolidated but Dynamic Landscape
The ride sharing sector remains characterized by pronounced concentration, with a small cohort of globally scaled platforms commanding the majority of market share. This consolidation has not eliminated competitive friction; rather, it has elevated the complexity of differentiation. Market leaders must balance scale economies with localized service quality, regulatory adaptability, and technological innovation, while emerging and regional players pursue niche positioning, transparent pricing models, and multi-modal service integration.
Carpooling Market
The report provides granular corporate profiling for pivotal industry participants, examining their operational footprints, strategic priorities, and recent market maneuvers. Uber Technologies, Inc. continues to anchor the global landscape through its expansive network architecture and deepening integration with public-sector mobility procurement, including recently formalized government-wide ride procurement frameworks that extend its footprint into federal civilian and defense ecosystems. Lyft, Inc. has reinforced its North American operational base through sustained platform expansion and capital allocation strategies that signal confidence in long-term urban mobility demand.
Ride Sharing Market
In parallel, regional and specialized operators are redefining competitive boundaries. Bolt Technology OÜ maintains aggressive multi-country expansion, leveraging localized driver incentives and streamlined urban routing. Grab Holdings Limited has entrenched itself as a comprehensive Southeast Asian mobility and services ecosystem, blending ride sharing with adjacent consumer platforms to drive retention and cross-utilization. inDriver has carved a distinct positioning around transparent, user-negotiated pricing and driver-centric earnings structures, appealing to cost-sensitive urban demographics. Via Transportation, Inc. continues to pioneer on-demand microtransit and optimized ride-pooling architectures, addressing gaps in scheduled public transit and suburban connectivity.
The study traces how these players are responding to compounding industry catalysts. Autonomous vehicle integration has transitioned from pilot experimentation to commercial deployment, with driverless ride-hailing services launching in key metropolitan corridors and freight-mobility partnerships accelerating the testing of autonomous integration into existing platform architectures. Simultaneously, public-sector engagement is deepening, as government agencies formalize rideshare procurement pathways, extend membership benefits to workforce populations, and integrate mobility solutions into broader transportation procurement portfolios.
Forces Reshaping the Boardroom: Regulation, Electrification, and Labor Frameworks
No strategic assessment of the ride sharing market would be complete without addressing the regulatory and structural transformations currently recalibrating operational economics. Across major jurisdictions, compliance requirements are evolving from peripheral considerations into core architectural constraints. In North America, environmental mandates are accelerating fleet electrification timelines, with regulatory bodies establishing aggressive zero-emission targets for mobility platforms and tying compliance to measurable greenhouse gas reductions. These requirements are not merely sustainability initiatives; they fundamentally alter capital expenditure planning, vehicle procurement cycles, and total cost of ownership calculations.
Europe’s regulatory trajectory introduces parallel complexity. The impending platform worker directive, scheduled for full implementation in late 2026, will standardize employment benefits and worker protections across digital mobility platforms. This framework is expected to reshape cost structures, influence driver acquisition and retention dynamics, and compel platforms to re-evaluate operational models that rely on highly flexible labor arrangements. For market participants with significant European exposure, compliance readiness and workforce model adaptation will become decisive competitive variables.
At the same time, public-sector mobility procurement is maturing into a structured, long-duration revenue stream rather than a sporadic opportunity. Government-wide purchasing frameworks now encompass multi-year performance periods, integrate civilian and defense mobility needs, and extend ancillary benefits that deepen platform loyalty among institutional user bases. These developments signal a broader paradigm shift: ride sharing is increasingly treated as essential infrastructure, subject to procurement standardization, performance accountability, and integration with public transportation planning.
Why 2026 Demands Precision Intelligence
The 2026 decision environment is defined by simultaneity. Companies must concurrently manage autonomous fleet transition timelines, comply with divergent regional labor and emissions mandates, optimize tiered pricing architectures, and respond to demand patterns that vary sharply across urban, airport, and rural mobility contexts. Aggregate market forecasts alone cannot inform the nuanced trade-offs required at the portfolio, operational, or investment level. Decision-makers need segmentation-level clarity, competitive scenario modeling, and regulatory impact mapping that connect high-level growth trajectories to executable strategic choices.
PW Consulting’s ride sharing market research is constructed to meet that requirement. The study provides a structured reference architecture for evaluating expansion timing, service-tier prioritization, geographic weighting, and partnership strategy. It enables boards and executive teams to assess where concentration dynamics create scale advantages, where regulatory inflection points will alter margin profiles, and where emerging platform models may disrupt incumbent positioning. By synthesizing historical performance, forward-looking growth modeling, and real-time industry catalysts, the report equips stakeholders with the analytical rigor necessary to move from reactive adaptation to proactive strategic design.
Accessing the Full Intelligence Architecture
This introduction offers a strategic preview of the analytical frameworks and industry dynamics underpinning our latest ride sharing market research. The complete study expands far beyond this overview, delivering detailed segmentation analysis, competitive maneuver mapping, regulatory scenario evaluation, and structured insights designed for immediate integration into corporate planning processes. For executives, investors, and strategy leaders seeking to align 2026 initiatives with validated market trajectories, the full report provides the granular intelligence required to convert macro growth signals into disciplined, high-conviction action. We invite decision-makers to access the complete research architecture, where comprehensive data models, detailed corporate profiles, and forward-looking scenario analyses are synthesized into a single, actionable reference for navigating the next phase of mobility market evolution.
For detailed analysis of this topic, please visit the official page: Ride Sharing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Bank Information Systems Market to Reach $1,580.8M by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-16
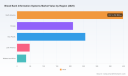
Strategic Intelligence for the Next Wave: Inside the Blood Bank Information Systems Market Outlook 2026
The global blood bank information systems market is entering a phase of structural acceleration, driven by tightening regulatory frameworks, the digital transformation of transfusion workflows, and the financial imperative to convert legacy inventory operations into scalable, interoperable platforms. Our newly published market research report, Blood Bank Information Systems Market: Strategic Intelligence for the Next Wave 2026–2032 , maps this transition with executive-grade precision. Covering the historical baseline from 2020 through 2025 and projecting forward to 2032, the study translates complex operational, technological, and compliance forces into a decision-ready architecture for health systems, blood centers, procurement leaders, and investment teams.
For organizations planning cycles in 2026, the difference between reactive procurement and strategic positioning lies in understanding how macro trajectories intersect with grounded, operational realities. This report is engineered to deliver that clarity. Below is a preview of the analytical rigor, structural breakdowns, and competitive intelligence contained within our full dataset.
A Market Reaching an Inflection Point
The industry has demonstrated sustained, compound growth over the past half-decade. From a historical revenue base of approximately 658.5 million USD in 2020, the market advanced through successive years of expansion, reaching 947.0 million USD in 2025. That progression is not merely a function of incremental digitization; it reflects a fundamental re-architecture of how blood is tracked, allocated, tested, and transfused across institutional and regional networks.
Looking ahead, the forecast trajectory indicates continued momentum, with the overall market projected to surpass the 1.5 billion USD threshold by 2032. The implied compound annual growth rate across the 2026–2032 forecast horizon stands at 7.8 percent. While these headline figures provide essential directional context, the strategic value for executives lies in what sits beneath them: the relative weight of deployment models, the pace of institutional adoption, the shifting cost structures associated with cloud architectures, and the compliance-driven procurement triggers that accelerate upgrade cycles.
Regulatory Acceleration as a Procurement Catalyst
Compliance has evolved from a baseline requirement into a dominant force shaping technology investment. In the United States, FDA regulations mandate that blood bank information systems support complete traceability from donor to recipient, eliminating gaps that previously allowed fragmented record-keeping to persist across standalone modules. Across the Atlantic, the European Union’s Substances of Human Origin (SoHO) Regulation introduces expectations for real-time, audit-ready data trails, placing a premium on systems capable of maintaining unbroken lineage documentation under live operational conditions.
These regulatory expectations are not theoretical. Recent industry data indicates that 72 percent of blood centers identify regulatory compliance as the primary driver for upgrading blood bank information systems. That dynamic reframes the purchasing conversation: organizations are no longer evaluating platforms primarily on incremental feature sets, but on their capacity to future-proof audit workflows, integrate with laboratory and electronic health record ecosystems, and withstand jurisdictional scrutiny without operational friction.
Architecture Shifts: From Capital-Seated Infrastructure to Scalable Deployment
A parallel transformation is underway in how these systems are provisioned. Traditional on-premises deployments, once the default model for institutional blood management platforms, are being re-evaluated against cloud-based architectures that reduce upfront capital expenditure while enabling elastic inventory management. Cloud delivery models allow blood centers and hospital networks to scale allocation logic, donor tracking, and inventory visibility without the rigidity of fixed infrastructure.
The strategic implication is nuanced. Lower capital barriers do not automatically translate into faster adoption; they introduce new considerations around data sovereignty, interoperability with legacy EHR environments, and the total cost of ownership across multi-year contracts. Our report examines these trade-offs explicitly, helping decision-makers align deployment strategies with institutional readiness, staffing capacity, and compliance calendars.
Functional Core: What the Systems Actually Do
At the operational level, blood bank information systems are converging around a shared set of functional imperatives, even as vendors differentiate through workflow design, integration depth, and compliance instrumentation. The core capabilities span several interconnected domains:
- Donation management workflows that coordinate scheduling, donor eligibility, collection tracking, and post-donation documentation across distributed intake sites.
- Transfusion service orchestration that links pre-transfusion testing, crossmatch logic, issue controls, and bedside allocation into a closed-loop process designed to reduce error surfaces.
- Inventory control and traceability that reconcile stock levels, expiration management, component segmentation, and quarantine protocols while maintaining donor-to-recipient lineage.
- Regulatory and standards alignment that hardcodes compliance checks, audit-ready reporting, and documentation practices aligned with accreditation bodies and jurisdictional requirements.
- Interoperability and integration that connect blood bank operations with laboratory information systems, hospital EHRs, and regional sharing networks.
Vendors approach these functions from different strategic angles. Some emphasize modular suites that can be deployed incrementally across inventory and point-of-care allocation workflows. Others position transfusion-centric platforms with embedded safety checks and compliance instrumentation built into daily operations. A further cohort structures their offerings around web-accessible blood bank and transfusion service environments designed to standardize pre-transfusion testing, inventory control, and accreditation alignment. Still others embed blood bank functionality inside broader electronic health record platforms, pursuing integrated donor, inventory, and transfusion workflows within a unified clinical ecosystem.
Evaluating these approaches requires more than feature comparison. It requires understanding which architecture maps to an institution’s existing integration maturity, which compliance obligations are most immediate, and which operational pain points are severe enough to justify migration or expansion. The report provides the structured lens required to make that assessment without defaulting to vendor-led narratives.
Competitive Landscape: Concentration, Differentiation, and Recent Moves
Market concentration in this sector remains relatively distributed. Aggregate data indicates that the top three competitors account for roughly 26.8 percent of total market revenue, while the top five capture approximately 34.5 percent. That structure suggests room for specialized differentiation, regional expansion, and workflow-specific positioning, even as larger platforms leverage scale and integration breadth.
Blood Bank Information Systems Market
Several established players define the current competitive frontier. Haemonetics offers a modular blood bank information system portfolio designed to support inventory control, traceability, point-of-care allocation, and safe transfusion workflows. WellSky has built a transfusion blood bank information system with embedded safety checks, EHR and laboratory integration, and compliance tools oriented toward patient safety and operational continuity. SCC Soft Computer provides a web-based blood bank and transfusion service information management environment that incorporates pre-transfusion testing, inventory control, and alignment with AABB and FDA expectations. Mediware Information Systems delivers blood bank information system modules focused on transfusion service management, inventory control, and regulatory compliance. Cerner Corporation approaches the category from within its broader electronic health record platform, pursuing integrated donor, inventory, and transfusion workflows as part of a connected clinical architecture.
Recent activity among these leaders underscores how the market is evolving in practice. In early 2026, WellSky advanced its transfusion platform with a new kits feature focused on inventory and workflow optimization for blood banks, reflecting a continued emphasis on operational efficiency within compliance-oriented environments. Later in the year, SCC Soft Computer participated in a major regional conference in Australia, showcasing its web-based blood bank system and signaling ongoing attention to international deployment contexts and demonstration-led engagement. These moves are representative of broader patterns: the push toward workflow refinement, the emphasis on modular or web-accessible architectures, and the continued relevance of live demonstration and conference-based engagement in a sector where trust, compliance, and operational fit dominate procurement decisions.
Report Scope: What Decision-Makers Will Find Inside
Our full study is built for executives who need more than directional trends. It is structured to support procurement strategy, portfolio planning, competitive positioning, and investment prioritization across the 2026–2032 horizon. The report includes:
- Historical and forecast market sizing from the 2020 baseline through the 2032 projection, with attention to the pace of growth across the forecast window and the inflection points that shape planning assumptions.
- Functional and adoption-oriented segmentation that breaks down how demand distributes across core system types and major application environments, enabling readers to understand where operational concentration lies and which contexts are expanding most rapidly.
- Regional demand architecture that contextualizes how mature and emerging markets differ in infrastructure readiness, compliance pressure, and procurement cadence, without reducing the analysis to static share rankings.
- Deployment and cost-structure analysis covering the shift toward cloud-based delivery, its implications for capital expenditure, scalability, inventory management, and integration effort.
- Competitive profiling of the leading platforms, including functional positioning, integration strategies, compliance emphasis, and recent product and market activities that signal likely direction.
- Regulatory and reimbursement context that maps FDA traceability expectations, EU SoHO audit-trail requirements, and the compliance-driven upgrade behavior observed across blood centers.
- Strategic implications for 2026 planning that translate the data into procurement timing, vendor evaluation criteria, integration prioritization, and risk management considerations.
Throughout the report, the emphasis remains on usable intelligence rather than abstract sizing. The objective is to help leadership teams determine not only where the market is moving, but how that movement should change operational planning, vendor selection, and compliance readiness in the near term.
Blood Bank Market
Why This Research Matters for 2026 Decisions
The 2026 planning cycle coincides with a convergence of pressures that make blood bank information systems a strategic subject rather than a purely operational one. Regulatory obligations are tightening across major jurisdictions. Cloud delivery is reshaping cost expectations and deployment flexibility. Integration with laboratory and EHR environments is becoming a threshold requirement rather than a differentiator. And compliance-driven upgrade behavior is accelerating procurement conversations that previously unfolded over multi-year horizons.
In that environment, incomplete market intelligence carries real cost. Decision-makers who rely on high-level trends without segment-level clarity may misjudge where adoption is actually concentrated. Teams that evaluate vendors without a structured view of compliance fit, integration debt, and deployment economics may overinvest in features that do not reduce operational risk. Organizations that treat regulatory alignment as an afterthought may find themselves forced into reactive migrations under audit pressure.
Our report is designed to reduce those uncertainties. By combining macro trajectory, functional segmentation, competitive positioning, and compliance context into a single analytical framework, it enables leaders to evaluate architectural choices, procurement timing, and vendor fit with greater confidence. The headline growth trajectory and the 7.8 percent forecast compound rate provide the strategic backdrop; the actionable intelligence lies in the structural breakdowns, adoption patterns, and competitive dynamics that explain how that growth is being generated and where it is likely to concentrate.
Preview, Not Replacement
This article provides a directional lens into the full study, but it cannot substitute for the data depth, comparative tables, and segment-level analysis contained in the complete report. The specific breakdowns that allow procurement teams to map demand concentration, evaluate regional readiness, and benchmark competitive positioning are developed in detail within our published dataset. Those insights are central to building defensible 2026 strategies, and they are best reviewed in the full analytical context.
For executives, analysts, and procurement leaders responsible for blood bank information systems planning, the report offers a structured foundation for evaluating where to invest, what to prioritize, and how to align technology decisions with compliance, interoperability, and operational resilience goals. The market’s next phase will reward organizations that can translate regulatory pressure, deployment flexibility, and integration requirements into disciplined, evidence-based choices. Our research is intended to support exactly that process.
For detailed analysis of this topic, please visit the official page: Blood Bank Information Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


