



Category: market research
The Wedding Dress Market: Navigating Growth, Innovation, and Strategic Positioning
Market Snapshot and Core Challenges
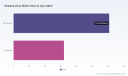
The wedding dress market has entered a phase of steady, structurally driven expansion. Revenue grew from approximately 120.0 million USD in 2020 to 186.0 million USD in 2025, reflecting a compound annual growth rate of 6.08 percent across the historical period. The trajectory is expected to continue, reaching an estimated 280.7 million USD by 2032. This growth is not merely a post-pandemic rebound; it signals a maturing consumer base willing to allocate discretionary spending to wedding apparel, supported by broader economic recovery and shifting social habits around engagement and celebration.
Despite the favorable top-line momentum, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, market concentration remains moderate, with the top three players holding roughly 25 percent of revenue and the top five capturing about 30 percent. This fragmentation means scale advantages are limited, and leadership cannot rely on dominance alone. Instead, differentiation, brand trust, and operational resilience determine share gains. Second, the apparel supply chain continues to navigate cost volatility, material availability, and lead-time uncertainty. Manufacturers and designers must balance premium craftsmanship expectations with the pressure to deliver predictably, especially as wedding calendars become more compressed and customization requests grow. Third, the market is experiencing a shift in how gowns are sourced and used. The relative weight of off-the-rack and customized offerings, alongside usage patterns spanning personal purchase, rental, and photographic studio needs, indicates that consumers are no longer choosing based on category alone. They are evaluating total experience, flexibility, and perceived value. Companies that treat these categories as siloed segments risk missing cross-category demand signals.
Wedding Ring Market
For executives, the practical implication is clear: healthy growth does not automatically translate into profitable growth. The winners will be those who address structural friction in sourcing, inventory, and customer experience while building brand narratives that justify price points and repeat engagement.
Key Drivers Shaping Market Dynamics
Several forces are converging to reshape how value is created in the wedding dress market. Understanding these drivers is essential for anticipating where competitive advantage will emerge.
Technological Innovation and Operational Breakthroughs
Digital design tools, fit simulation, and data-informed inventory planning are reducing the cost of experimentation while improving speed to market. Designers can prototype more variations with fewer physical samples, and retailers can align stock levels more closely with demand patterns. These capabilities matter because the wedding dress category has traditionally relied on intuition and seasonal collections. Technology is now enabling more responsive design cycles, better sizing accuracy, and fewer unsold units. For manufacturers, the same tools support more efficient production scheduling and clearer communication with buyers, which is especially valuable in a market where customization and detail-oriented craftsmanship carry premium expectations.
Party Costumes Market
Policy and Regulatory Environment
Operational transparency, labor standards, and material sourcing requirements are becoming more visible across the apparel sector. While the wedding dress market is not subject to a single defining regulation, broader expectations around responsible sourcing and production practices are influencing procurement decisions. Brands and factories that can document sourcing practices, maintain consistent quality controls, and demonstrate reliable compliance are increasingly preferred by retailers and international buyers. This trend does not fundamentally alter demand, but it raises the barrier for informal or opaque supply chains and rewards operators with disciplined processes and traceable operations.
Demand-Side Shifts in Consumer and Business Behavior
Consumers are approaching wedding apparel with more deliberate criteria. Personal purchase remains a major driver, but the purchase decision is increasingly shaped by fit, style longevity, sustainability considerations, and the overall service experience rather than brand name alone. At the same time, rental and photographic studio applications continue to represent meaningful demand pools, reflecting a broader willingness to treat wedding apparel as part of a flexible celebration ecosystem rather than a single-use asset. This is pushing businesses to think beyond the gown as a standalone product and toward integrated offerings that combine styling, access, and presentation.
On the business side, buyer preferences are also changing. Retailers and distribution partners want predictable replenishment, clearer differentiation, and strong visual identity. The market’s moderate concentration means many brands compete on aesthetics and localization, but the most resilient operators are those that connect product quality with measurable service reliability.
Supply Chain and Cost Structure Evolution
The cost environment remains a central concern. Material prices, labor conditions, shipping variability, and production lead times all influence margin stability. In response, many operators are reassessing make-versus-buy decisions, supplier concentration, and inventory depth. The practical shift is toward greater diversification and more disciplined planning. Rather than relying on a single production model, leading participants are building flexibility into sourcing and capacity, allowing them to respond to regional demand changes and minimize disruption. This flexibility is becoming a strategic asset, particularly for companies that must serve both premium custom work and higher-volume lines without compromising delivery performance.
Competitive Landscape and Leading Strategies
The competitive field is broad and geographically diverse, spanning established American-designed brands, European manufacturing capacity, Asian production capabilities, and specialized luxury or contemporary players. This diversity is one of the market’s defining features. It creates opportunities for niche differentiation, but it also raises the need for clear positioning.
Strategic Positioning Among Key Players
Several themes emerge when looking at how leading companies compete. American-designed brands tend to emphasize design identity, detail, and perceived craftsmanship. Some highlight handmade construction or in-house production, using that narrative to support premium pricing and loyalty. Others focus on contemporary aesthetics or romantic detailing to attract buyers looking for distinctiveness rather than conventional styles. Luxury-oriented brands build their value proposition around exclusivity, fit, and collection storytelling, often reinforced through events and seasonal launches that keep the brand in front of buyers and press.
Meanwhile, manufacturing-centric participants compete on scale, reliability, and customization support. Large production facilities in Europe and Asia serve as critical capacity nodes for broader industry demand, offering wholesale and made-to-order capabilities that allow brands and retailers to access consistent output. Their advantage lies in volume flexibility, repeatable quality, and the ability to support a range of design specifications. In parallel, some brands are leaning into modern, sustainable, or niche aesthetic directions to stand out in a crowded field, recognizing that differentiation often comes from a coherent point of view rather than from broad assortment alone.
PW Consulting
Differentiation as the Core Competitive Lever
Because market concentration is moderate, no single company dominates the category through size alone. That makes positioning especially important. The strongest operators combine a recognizable design language with dependable execution. They do not simply sell a gown; they sell a coherent experience that includes fit, presentation, delivery, and brand trust. Events such as trade show attendance, collection launches, and designer-focused gatherings play a visible role in maintaining that presence. Recent industry activity illustrates this rhythm: Ricca Sposa appeared at Barcelona Bridal Fashion Week in April 2026, Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, Kaya Wedding attended European Bridal Week in April 2026, and Allure Bridals hosted designer events including Once Upon a Dress in May 2026. These moments are not merely calendar items; they are mechanisms for reinforcing brand relevance, testing demand cues, and maintaining relationships with retailers, press, and buyers.
How the Landscape Is Evolving
The market is evolving along multiple paths at once. On one side, there is room for continued fragmentation, as new designers and regional brands enter with targeted aesthetics or direct-to-consumer models. On the other side, consolidation pressure exists for players that need scale in production, distribution, or brand reach. The most likely outcome is not a simple winnowing, but a layered market in which a few broadly recognized names anchor consumer awareness while many specialized players compete in distinct niches. New entrants that can articulate a clear design identity, demonstrate reliable fulfillment, and build digital visibility will have a realistic path to relevance. Established players, meanwhile, will need to protect their positioning by refreshing collections, strengthening supply discipline, and deepening relationships with the channels that matter most to their customers.
Outlook for the Next Three to Five Years
Looking ahead, three trends are likely to define strategic opportunities and risks.
- Design and sourcing will become more integrated. As digital tools and production planning improve, brands that can connect design intent with manufacturing capability more tightly will gain speed and consistency. This integration supports both premium custom work and broader line efficiency, reducing the tension between uniqueness and scalability.
- Consumer expectations will keep moving toward experience-rich purchasing. Fit, personalization, presentation, and post-purchase service will matter as much as the gown itself. Companies that create a smoother journey from discovery to delivery will be better positioned to defend margins and build repeat engagement, including through rental and studio-related demand where appropriate.
- Regional production and supply diversification will remain strategic priorities. The market’s growth will continue to depend on reliable capacity and predictable lead times. Businesses that concentrate all sourcing in one channel or region may face unnecessary exposure, while those that build a balanced supplier base and maintain contingency options will be more resilient to cost and logistics shocks.
These trends open practical opportunities. Design-led brands can deepen loyalty by strengthening fit, service, and collection coherence rather than relying solely on aesthetic novelty. Manufacturers and wholesalers can capture value by becoming more responsive partners, offering clear customization pathways, and demonstrating dependable output. Retail and distribution players can use stronger supplier relationships and better assortment planning to reduce inventory risk while maintaining visual freshness. At the same time, uncertainty remains. Economic fluctuations can affect discretionary spending, costume and accessory demand can shift as celebration habits evolve, and competitive pressure can intensify if too many brands chase the same aesthetic or price point. The market’s growth is durable, but profitability will still depend on disciplined execution.
Strategic Recommendations for Decision-Makers
Different participants will need different priorities, but several actions apply broadly.
For Manufacturers and Brand Operators
Invest in the capabilities that connect design to delivery. That means clearer production planning, flexible sourcing, and fit or sizing improvements that reduce returns and rework. Build a distinctive design position that can be communicated consistently across channels, and treat events and seasonal launches as strategic touchpoints rather than optional marketing activities. Consider where customization, wholesale, and own-brand offerings can coexist without diluting operational focus.
For Investors
Focus on operators with a credible differentiation story and evidence of execution discipline. In a moderately concentrated market, scale alone is less decisive than brand clarity, supply reliability, and channel relationships. Evaluate whether a company’s design identity is sustainable, whether its production model can support demand without compromising quality, and whether its go-to-market approach aligns with changing consumer behavior. Look for signs that the business can manage cost volatility while preserving margin integrity.
For Retailers and Procurement Teams
Prioritize partners that can deliver consistency, transparency, and flexibility. Assortment decisions should balance recognizable style leadership with inventory discipline, and sourcing strategies should not over-concentrate risk in a single supplier or region. Where rental, studio, or multi-use demand is relevant to the customer base, partner selection should reflect the ability to support varied use cases, not just standard retail distribution. Commercial terms and delivery reliability will matter as much as design appeal when planning for seasonal peaks.
Strategic decisions in this market are most effective when informed by detailed segmentation, regional dynamics, and competitive benchmarks. Broad trends indicate direction, but precise choices about product mix, sourcing, pricing architecture, and channel focus require deeper data. Readers seeking a more granular view of segment splits, company positioning, and forward demand scenarios can explore the full PW Consulting Wedding Dress Market research report for expanded analysis and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beyond the 6.09% CAGR: What’s Really Driving the $11.34B Mascara Market Through 2032
By PW Consulting, 2026-09-21
The Mascara Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2026–2032)
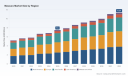
The global mascara market has matured into a high-contrast landscape where volume growth coexists with intensifying structural pressures. Over the historical period from 2020 to 2025, the category expanded from approximately 5.2 billion USD to 7.5 billion USD, reflecting steady consumer demand and repeated product innovation cycles. The trajectory continues into the forecast window through 2032, with the market projected to reach 11.34 billion USD and a compound annual growth rate of 6.09 percent. These figures are not just a measure of incremental sales; they signal a category that is broadening its functional promises, migrating across channels, and being reshaped by sustainability mandates and packaging engineering. For executives and investors, the central question is no longer whether mascara will grow, but which value pools will capture disproportionate share and how fast the cost and compliance curves will move.
Beneath the headline expansion sits a market that is consolidating around a small number of global players while simultaneously fragmenting at the formulation, applicator, and packaging levels. The top three participants command roughly 65 percent of category revenue, and the top five extend that share to nearly 78 percent. This concentration indicates that scale advantages in acquisition, distribution, and brand architecture remain powerful, yet the same concentration also invites targeted disruption from niche formulators, regional manufacturers, and contract partners that can move faster on ingredient innovation, applicator design, and sustainable packaging. The market’s evolution is therefore best understood as a dual dynamic: broad-based growth on the outside, competitive differentiation on the inside.
Market Snapshot: Growth with Consolidation
The category’s growth curve has been supported by multiple reinforcing forces: repeat purchase behavior in daily wear, demand for specialized effects such as lengthening, volume, and curl retention, and a broadening pipeline of prestige and mass-market SKUs. Yet the distribution of revenue concentration also underscores a strategic reality. Scale players benefit from global supply visibility, retail relationships, and cross-brand leverage, but they must continually reinvest in formulation, claims substantiation, and packaging upgrades to defend shelf space and e-commerce visibility. Mid-tier and private-label manufacturers, by contrast, compete on speed, customization, and cost-efficient production, positioning themselves as critical nodes for brands that want to expand their mascara assortments without building in-house capacity.
For decision-makers, this snapshot translates into a clear takeaway: growth is real, but it is not evenly distributed across players, formats, or geographies. The opportunity lies in identifying which sub-segments of the value chain are most exposed to margin expansion, which formats are most likely to command premium pricing, and where entry barriers are low enough to reward agile innovation rather than brute scale.
Current Structural Challenges and Turning Points
The category faces three interconnected challenges that are reshaping how companies plan capacity, R&D, and go-to-market strategy. First, formulation and applicator performance are increasingly scrutinized by consumers who expect lash-care benefits, precise application, and long-lasting wear without smudging or flaking. Achieving these claims simultaneously creates engineering tension: richer formulas can compromise brush glide, while lighter formulas may reduce pigment intensity or curl retention. Companies that can integrate lash-conditioning attributes with high-pigment delivery and ergonomic application will be better positioned to defend premium price points.
Second, sustainability and material compliance are moving from marketing narratives to operational constraints. The packaging and applicator segments are under pressure to reduce fossil-based plastics, lower carbon intensity, and increase recycled content. This transition is not cosmetic; it affects tooling, supplier qualification, quality control, and cost structures. Where sustainable materials were once a differentiation layer, they are now becoming a baseline expectation in many retail and channel environments. Firms that delay material transitions risk facing procurement friction and brand perception gaps, while those that move early can secure supplier relationships and design leadership.
Lipstick Market
Third, competitive intensity is compressing the room for undifferentiated entry. The high concentration at the top means that new claims, packaging novelty, and branded storytelling must be unusually sharp to gain attention. At the same time, contract manufacturers and private-label suppliers are expanding their capabilities, making it easier for brands to launch with credible production backing. The result is a market where speed-to-shelf and formulation distinctiveness matter as much as scale. Pure price competition is increasingly risky because it erodes the investment needed for sustained innovation and compliance.
Key Drivers Reshaping the Mascara Category
The market’s direction is being pulled by a mix of technology, regulation, consumer behavior, and supply economics. Understanding how these forces interact is essential for assessing where durable advantage can be built.
Innovation in Formulation and Applicator Engineering
Performance expectations have expanded beyond basic volume and length. Consumers increasingly look for brush designs that improve precision and product deposition, formulas that support lash condition, and finishes that balance wear time with natural movement. Brush geometry and fiber selection directly influence how mascara coats lashes, how easily it separates clumped product, and how well it holds a curl. Innovation in this area is becoming a tangible source of differentiation rather than a purely aesthetic exercise.
Recent activity in the applicator space reflects this shift. At major industry events, suppliers have showcased packaging and applicator technologies with stronger sustainability profiles and design novelty. One German manufacturer presented a collection built around new brush designs and shadow printing decoration on packaging made from 100 percent post-consumer recycled plastic, an approach that also reduces CO₂ emissions by up to 26 percent. A UK-based packaging supplier introduced a cellulose-derived renewable fiber applicator intended as a renewable alternative to synthetic materials for mascara and brow products. These developments are significant because they combine performance engineering with material transition, showing that sustainability and application quality can be advanced together rather than traded off.
For manufacturers and brand owners, the implication is clear: applicator and packaging innovation is becoming a competitive lever that affects both consumer perception and operational sustainability. Companies that treat brush design and material science as core R&D priorities can create more defensible product architectures and reduce exposure to future material restrictions.
Regulatory and Sustainability Pressure as a Design Constraint
Sustainability commitments are increasingly embedded in brand and supply strategies rather than treated as separate CSR initiatives. In the mascara category, this means greater attention to formulation origin, biodegradability or natural derivation targets, recyclable packaging, and lower-carbon manufacturing outcomes. Public commitments from major groups have set ambitious timelines for making a high share of mascara formulations biodegradable or naturally derived, reinforcing a direction that is likely to influence sourcing standards, ingredient selection, and supplier qualification across the industry.
This regulatory and reputational environment creates both risk and opportunity. On the risk side, companies dependent on legacy synthetic formulations or non-recyclable packaging may face rising compliance costs and potential channel resistance. On the opportunity side, brands that align formulation, packaging, and communications early can build authenticity in a category where consumers are increasingly attentive to material claims. Importantly, credibility depends on consistent execution across the value chain, not on isolated packaging swaps. A sustainable brush paired with an unchanged formula or a vague messaging strategy can undercut the intended effect.
Consumer and Channel Behavior Shifts
Demand patterns are evolving around use context, not just product type. Daily wear remains the dominant usage environment, which sustains high baseline demand and repeated purchase cycles. At the same time, event and professional makeup applications continue to support premium SKUs and specialized finishes. The practical effect is that the category is served by a dual rhythm: a high-frequency core that rewards reliability, ease of use, and value, and a higher-margin periphery that rewards performance claims, packaging prestige, and trend responsiveness.
Channel dynamics reinforce this bifurcation. E-commerce and digitally native brands have lowered the barrier for launches and made it easier for smaller labels to reach niche audiences. Retail environments, however, still reward shelf impact, repeat conversion, and strong claims substantiation. In practice, this means that brands must reconcile two demands: the consumer-facing promise that drives first purchase, and the consistent performance that drives repurchase and recommendation. Mascara is a category where disappointing performance is difficult to hide, so formulation reliability and applicator consistency are not just product attributes; they are commercial safeguards.
Supply Chain and Cost Structure Pressures
Material availability, packaging input costs, and production flexibility are becoming more prominent in strategic planning. As brands shift toward recycled and renewable materials, they also shift their dependency map, which can introduce new qualification cycles and short-term cost variability. At the same time, manufacturers that can offer a broad texture range, multiple packaging options, and scalable private-label production are increasingly valuable partners for brands managing portfolio complexity.
This environment favors companies that can balance cost discipline with innovation readiness. In practical terms, that means maintaining a supplier base capable of meeting sustainability specifications, investing in process stability to reduce rework and waste, and designing product architectures that can be adapted across markets without excessive rework. For procurement and operations leaders, the goal is not only to manage today’s input costs, but to build a supply architecture that can absorb material transitions without compromising quality or delivery.
Competitive Landscape and the Shape of Advantage
Scale Leaders and Their Strategic Postures
The market’s leading participants are pursuing different but overlapping forms of advantage. One global group anchors its mascara portfolio across mass and prestige brands, using strong brand architecture to cover a wide range of performance claims and price points. Another large corporation competes in the premium and clinical-influenced space with an emphasis on wear technology and curl retention across several established labels. A third major consumer goods company focuses on accessible volume and lengthening performance through mass-market brands, leveraging distribution breadth and price accessibility.
These scale players share common strengths: global reach, significant R&D resources, established retail relationships, and the ability to cross-leverage brand equity across regions. Their strategic challenge is to keep portfolios fresh enough to maintain relevance while maintaining the consistency required to defend volume. In a concentrated market, leadership is less about presence and more about continuous renewal of claims, formats, and packaging stories.
Prestige Positioning and Regional Specialists
On the prestige side, luxury houses and regional specialists compete through differentiated application mechanisms, refined aesthetic signatures, and targeted lash-care narratives. Some players emphasize advanced brush technology and long-lasting pigmentation to justify premium positioning; others focus on precise application and conditioning benefits in Asian markets, where preferences for curl, length, and clean formulation can be especially pronounced. There are also K-beauty-aligned developers working on curling and lengthening effects that respond to regional styling expectations.
This segment is less about raw scale and more about design credibility, application elegance, and regional nuance. For premium brands, the opportunity lies in making performance claims feel both sophisticated and demonstrable, while for regional specialists the opportunity lies in translating local preferences into exportable innovation.
The Expanding Role of Contract and Private-Label Manufacturing
A significant portion of category expansion is enabled by manufacturers that provide end-to-end production, custom formulas, and diverse applicator and packaging options. These partners support a wide spectrum of brand strategies, from budget-priced launches to more premium private-label projects. Their value proposition is increasingly tied to speed, flexibility, and the ability to produce multiple texture ranges without requiring the brand to build its own factory footprint.
Several manufacturers in this space operate with long track records in color cosmetics and a strong export orientation, while others offer customizable formulas and packaging support for direct and private-label markets. This layer of the industry is strategically important because it lowers the execution risk for new product development and allows brands to test concepts with less capital intensity. For investors and brands evaluating partnerships, the key is to assess a supplier’s capability not just in volume output, but in claim-ready formulation control, packaging consistency, and sustainable material readiness.
PW Consulting
How the Landscape Is Evolving
The competitive field is not simply consolidating; it is reconfiguring around capability clusters. At one end, global brands seek scale, portfolio coverage, and sustainability credibility. At the other, contract manufacturers and applicator suppliers create the infrastructure that enables more launches, faster iteration, and more material options. Between them, private-label and regional players can win by offering either cost-efficient execution or distinctive formulation and packaging combinations that larger players may not prioritize immediately.
The most likely trajectory is continued concentration among the largest branded players, alongside a vibrant mid-tier and supplier ecosystem that expands the number of viable market entrants. This means the market will keep generating both acquisition targets and partnership opportunities. The brands and investors that benefit most will be those that can distinguish between genuine capability and surface-level novelty when evaluating potential collaborations or acquisitions.
Outlook: Three Trends Shaping 2026–2032
Trend 1: Performance-Material Integration as a New Standard
The most durable opportunity in the category is the convergence of performance engineering and sustainable material design. Brush architecture, fiber selection, formula delivery, and recyclable or renewable packaging are increasingly evaluated together, not in isolation. Products that can combine lash condition, precise application, and credible material transitions will have an advantage in both consumer acceptance and long-term regulatory resilience. The commercial payoff is not just premium pricing; it is reduced exposure to future input constraints and stronger brand trust in a category where performance disappointment is highly visible.
The accompanying risk is execution complexity. Integrating new materials may require tooling changes, supplier requalification, and reformulation work that affects cost and lead time. Brands that underestimate these operational demands may find sustainability positioning difficult to sustain at scale.
Trend 2: Claim Substantiation and Credibility as Commercial Moats
As claims around volume, length, curl hold, and lash care multiply, substantiation becomes a competitive necessity. Consumers and retail partners increasingly expect supported statements rather than aspirational language alone. In practice, this trend elevates the importance of testing, consistency, and formulation discipline. Companies that build robust evidence pipelines can defend price and shelf space more effectively, while those relying on vague promises will face growing pressure as the category becomes more crowded and more scrutinized.
A key risk here is overclaiming relative to actual performance. In mascara, weak substantiation can quickly translate into reviews, repurchase issues, and brand erosion. The upside is similarly strong: credible, well-communicated performance can drive both trial and loyalty, especially in daily-use categories where repetition matters.
Trend 3: Regional Specialization and Exportable Innovation
Preferences for curl, length, conditioning, and finish are not uniform across markets, and the category’s growth will continue to be shaped by regional taste profiles as well as global brand reach. Asian markets, for example, have shown strong interest in precision application and conditioning-oriented benefits, while other regions may prioritize long-wear, waterproof resilience, or volume. This diversity favors companies that can localize formulas and brush designs without losing production efficiency, and it creates export opportunities for regional innovators who can translate local preferences into formats that travel well.
Face Mask Market
The main uncertainty is globalization versus localization balance. Over-standardizing can blunt regional relevance, while over-fragmenting can raise cost and complexity. The winning model is likely to combine a core platform with region-specific adaptations, allowing scale where possible and differentiation where necessary.
Strategic Implications for Decision-Makers
The mascara category is expanding, but the value is being created by companies that align innovation, sustainability, and execution discipline rather than by those that rely on growth alone. The following priorities are most relevant across common stakeholder groups.
- For manufacturers and brand owners, prioritize applicator and packaging innovation as core product strategy, not as a secondary packaging decision. Treat brush design, fiber choice, and material transitions as levers that influence both performance perception and long-term compliance readiness.
- For investors, distinguish between branded scale that is being renewed through credible formulation and packaging programs and scale that is resting on legacy assets. The stronger opportunities are likely in platforms that can demonstrate sustainable material readiness, substantiated performance, and flexible manufacturing partnerships.
- For procurement and supply chain leaders, build resilience into material sourcing by qualifying suppliers capable of meeting recycled and renewable specifications without sacrificing quality consistency. Map the transition risks early so that sustainability targets do not create unexpected production bottlenecks.
Across all three perspectives, timely and detailed market intelligence is valuable because the category is moving on multiple fronts at once: formulation expectations, applicator technology, packaging materials, and concentration dynamics. Decisions made without a clear view of where capacity, differentiation, and regulatory pressure are heading can lead to missed entries, underestimated costs, or weak claim positioning. A more complete picture of segment-level dynamics, regional variation, and supplier capability typically separates reactive planning from proactive positioning.
For teams that need a deeper breakdown of segmentation details, regional patterns, and competitive capability mapping, the full PW Consulting market report provides expanded data and customized analytical context to support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Class 1E Nuclear Instrumentation Cables Market: 3.6% CAGR Trajectory and 2032 Outlook
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Class 1E Nuclear Power Plant Instrumentation Cables Market
Market Overview and Core Challenges
The Class 1E instrumentation cables market for nuclear power plants has demonstrated steady growth over the past half-decade, evolving from a niche specialty segment into a critical infrastructure component with defined long-term trajectory. Between 2020 and 2025, the global market expanded from approximately $31.51 million to $38.25 million, reflecting a compound annual growth rate that positions the sector for continued expansion. Projections through 2032 indicate the market will reach nearly $50 million, with a forecasted CAGR of 3.6 percent. This growth profile is notable in an industry often characterized by long lead times and conservative capital allocation, suggesting that instrumentation cable demand is becoming increasingly decoupled from the traditional cycles of new plant construction and more tightly linked to lifecycle management, digitalization, and regulatory modernization.
Despite the positive trajectory, the market faces several structural challenges that will shape competitive dynamics and investment decisions over the next decade. The first challenge lies in the tension between aging fleet management and new build programs. A significant portion of installed nuclear capacity in North America and Europe operates beyond original design life assumptions, requiring continuous cable replacement, requalification, and system upgrades. Simultaneously, the pipeline of new nuclear projects, particularly small modular reactors and advanced designs, introduces different qualification pathways and interface requirements that legacy cable manufacturers must adapt to without compromising performance or compliance. Balancing these two demand streams creates operational complexity for suppliers and procurement teams alike.
The second challenge centers on qualification rigor and regulatory consistency. Class 1E cables are safety-related components, and their qualification frameworks are deeply embedded in standards such as IEEE 323, IEEE 383, and 10 CFR 50.49. While these frameworks provide necessary assurance for loss-of-coolant accident and high-energy line break environments, they also impose lengthy testing cycles, documentation burdens, and configuration control requirements. Any divergence in how regulators or utilities interpret environmental qualification, field splice approval, or aging management can create delays, cost variability, and supplier risk. This dynamic makes regulatory alignment a strategic variable rather than a static compliance checkbox.
A third challenge involves material evolution and environmental compliance. The push to eliminate certain brominated flame retardants, including DecaBDE, has reshaped wire and cable formulations. Suppliers must maintain nuclear-grade performance while adhering to evolving chemical restrictions, such as those enforced under U.S. EPA regulations. This transition affects insulation integrity, jacket durability, and long-term aging behavior, requiring revalidation of qualifications and potentially altering supply chain sourcing strategies. Companies that manage this transition smoothly gain a credibility advantage, while those that lag face technical and commercial exposure.
Key Drivers Shaping Market Dynamics
Several interconnected forces are driving the growth and transformation of the Class 1E instrumentation cables market. Understanding these drivers provides a foundation for evaluating where commercial opportunities are most likely to materialize.
Mineral Insulated Cables Market
Technological Innovation and Long-Life Design Requirements
Technological progress in cable design is a primary catalyst. The industry trend toward 60-year service life expectations places emphasis on radiation resistance, thermal stability, and mechanical durability under accident conditions. Leading cable solutions now target qualification levels that support operation in loss-of-coolant accident and high-energy line break environments while maintaining signal integrity for monitoring, data recording, and control functions. For example, certain Class 1E instrumentation cables are engineered to endure harsh nuclear environments and support safety-critical circuits for reactor coolant pumps, safety valves, and control rod positioning. This level of performance is not merely a technical specification; it directly influences plant safety case submissions, asset life extension strategies, and the willingness of operators to standardize on fewer qualified suppliers.
Innovation also extends to cable types and application coverage. Instrumentation cables serve distinct roles inside and outside the reactor island, and the requirements differ materially. Cables installed inside the reactor environment must address higher radiation doses, stricter LOCA/HELB exposure scenarios, and tighter integration with safety systems. Cables outside the reactor face different environmental and electrical stressors but remain subject to rigorous qualification because they support safety-related instrumentation. Meanwhile, nuclear island and conventional island cable categories continue to evolve as plant designs integrate more digital I&C architectures and require greater separation between safety and non-safety functions. These design shifts are pushing suppliers to develop qualified product families that can be configured for multiple plant zones without compromising compliance.
Policy and Regulatory Environment
Regulatory frameworks remain a defining driver of market structure and supplier qualification strategies. The alignment of cable qualification with IEEE 323, IEEE 383, and 10 CFR 50.49 creates a common baseline, but the operational interpretation of these standards influences purchasing behavior and project timelines. Regulatory guidance that reinforces environmental qualification expectations and field splice requirements increases the value of suppliers that can demonstrate robust documentation, traceability, and quality systems. In this environment, the presence of a NQA-1 quality program and compliance with 10 CFR Appendix B becomes a commercial differentiator, not just a quality administrative measure.
Policy momentum around nuclear as a low-carbon baseload source is also indirectly strengthening instrumentation cable demand. As governments and utilities reassess energy security and decarbonization pathways, nuclear fleet retention, life extension, and selective new build programs receive greater attention. Even when new construction timelines remain long, the associated engineering, qualification, and supply chain preparations begin early. This means instrumentation cable suppliers that can support both legacy fleet upgrades and emerging reactor designs are better positioned to capture demand across multiple project phases.
Demand-Side Changes and Operational Priorities
Utilities and plant operators are increasingly prioritizing reliability, aging management, and digital integration. As plants pursue license renewals and output optimization, instrumentation systems must maintain accuracy and availability over extended horizons. This drives replacement and retrofit activity for cables that support safety-related monitoring and control functions. At the same time, the shift toward more data-intensive operations increases the importance of instrumentation cabling that can reliably transmit measurement and status information without introducing noise or degradation risks. Demand is therefore not limited to new installations; it is equally shaped by the need to preserve and modernize existing safety systems.
Procurement behavior is also evolving. Operators are placing greater weight on supplier qualification records, installed base references, and demonstrated compliance histories. In safety-critical contexts, the perceived risk of adopting unproven cable solutions often outweighs marginal cost differences. As a result, suppliers with extensive installation footprints and clear qualification narratives gain preference in competitive evaluations. This dynamic reinforces the importance of track record, technical documentation, and long-term service commitments in shaping demand patterns.
Supply Chain and Cost Structure Considerations
Cost structures in this market are influenced by raw material selection, qualification overhead, and manufacturing controls. The move toward DecaBDE-free formulations illustrates how environmental compliance can intersect with material cost and performance validation. Suppliers that proactively adjust formulations and maintain qualification status reduce the risk of project disruption and rework. In parallel, quality program requirements and rigorous testing increase the fixed cost of participation, which tends to favor established manufacturers with scalable processes and documented quality systems. This does not necessarily fragment the market; instead, it raises the barrier to entry and rewards suppliers that can manage both technical and regulatory complexity efficiently.
Supply chain resilience is becoming more relevant as utilities seek to reduce uncertainty in long-lead safety-related components. For instrumentation cables, resilience is not only about volume availability but also about consistency of qualification, traceability of materials, and the ability to support field modifications or replacements without compromising safety cases. Suppliers that can provide transparent documentation and repeatable production controls are better positioned to meet these expectations.
Competitive Landscape and Leading Strategies
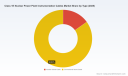
The competitive landscape is characterized by a concentrated group of specialized manufacturers with strong regional footprints and differentiated qualification narratives. Market concentration reflects the high barriers associated with safety-related cable qualification, installed base development, and ongoing compliance maintenance. With the top three competitors holding a combined share around 55 percent and the top five near 57 percent, the market favors incumbents that have invested in long-term qualification programs and accumulated references across multiple plant environments.
Prysmian, based in Italy, has built its positioning around fully environmentally qualified Class 1E instrumentation cables that support monitoring, data recording, and information transmission within safety-critical circuits. Its offering is designed to meet IEEE 323, IEEE 383, and 10 CFR 50.49 requirements for LOCA/HELB environments and is structured around long service life expectations. A notable aspect of its strategy is the emphasis on environmental compliance, including DecaBDE-free formulations aligned with U.S. EPA prohibitions. This combination of nuclear qualification and environmental regulatory alignment gives Prysmian a dual narrative: technical assurance for safety-related applications and forward compatibility with chemical restriction trends.
Marmon IEI, headquartered in the United States, differentiates through radiation-resistant LDVC, control, and instrumentation cables, including its RSCC® product line, with installations reported across more than 130 nuclear plants worldwide. Its strategy emphasizes proven field deployment and quality system rigor, with manufacturing conducted under a 10 CFR Appendix B, NQA-1 quality program. This installed base and quality framework create a strong reference advantage in utility evaluations, particularly where operators value documented performance across diverse plant conditions and long operational horizons.
Shawflex, based in Canada, focuses on EQ/Class 1E nuclear-grade power, control, and instrumentation cables and assemblies tailored for CANDU, LWR, and SMR plants. Its qualification scope includes IEEE 323, IEEE 383, and CSA N290.13, with performance targets up to 250 Mrad/200°C and 60-year life expectations. By spanning multiple reactor types and supporting both traditional and emerging designs, Shawflex positions itself as a flexible supplier for markets where reactor diversity and program-of-record considerations matter. This multi-design capability is especially relevant as SMR interest expands and operators seek suppliers that can adapt to different environmental and qualification contexts.
Habia Cable, headquartered in Sweden, supplies Habiatron™ LOCA and non-LOCA Class 1E instrumentation cables, including thermocouple types, for applications such as reactor coolant pumps, safety valves, and control rod positioning. Its designs are built around a 60-year operational life in nuclear safety systems. Habia's strategic emphasis on safety system-critical applications reinforces its positioning as a specialist in high-consequence instrumentation circuits, where qualification integrity and application specificity are paramount.
Okonite Company, also based in the United States, offers Okoguard and FMR-N Class 1E nuclear power, control, and instrumentation cables qualified per IEEE 383 and 10 CFR 50.49 for safety-related applications in nuclear generating stations. Its approach aligns with the broader U.S. market emphasis on regulatory conformity and safety-related use cases, supporting utilities that prioritize documented compliance and established product families for in-service and new installation contexts.
Across these competitors, several strategic themes emerge. First, qualification depth is a core competitive asset. Suppliers that can demonstrate alignment with multiple standards and provide clear environmental qualification narratives are better positioned to win preference in utility procurements and life-extension projects. Second, installed base and reference installations matter significantly. In a market where safety cases and aging management decisions influence purchasing, demonstrated deployment across many plants reduces perceived risk. Third, product family breadth is increasingly valuable. Suppliers that can serve both nuclear island and conventional island needs, or support multiple reactor technologies, gain flexibility in bid responses and can better align with operator standardization goals.
PW Consulting
The market is likely to evolve through a combination of consolidation among qualified specialists and selective entry by suppliers capable of meeting the qualification and quality system thresholds. Pure price competition is less effective in this context because qualification, documentation, and compliance overhead create natural cost floors. Instead, differentiation will come from technical assurance, application coverage, regulatory readiness, and the ability to support both legacy fleet and new build requirements. New entrants will face steep barriers unless they bring differentiated qualification pathways, strong quality system infrastructure, or unique application expertise.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Class 1E instrumentation cables market and create distinct commercial opportunities.
One key trend is the acceleration of lifecycle management demand for existing fleets. As more assets approach or exceed original design horizons, operators will continue to invest in cable replacement, requalification, and system upgrades to support license renewal and reliability objectives. This trend favors suppliers that can offer qualified replacement solutions, clear aging management guidance, and efficient integration with ongoing plant modifications. Commercial opportunities will arise not only in cable sales but also in technical support services that help operators manage qualification continuity and minimize interruption to safety-related systems.
A second trend is the growing relevance of reactor design diversity, including SMRs and advanced concepts. While new build volumes may remain uneven, the preparatory engineering and qualification work associated with these designs will stimulate demand for instrumentation cables that can meet varied environmental and regulatory expectations. Suppliers that can map their qualification portfolios to multiple reactor types and demonstrate adaptability to different safety system architectures will be better placed to capture early engagement opportunities. Over time, if SMR deployments scale, standardized cable solutions that can be reused across projects may create volume efficiencies and reduce qualification redundancy.
A third trend is the continued intersection of nuclear qualification and environmental material compliance. As chemical restrictions and sustainability expectations evolve, cable formulations will keep adapting. This creates opportunities for suppliers that can maintain nuclear performance while meeting broader environmental goals. It also introduces a strategic consideration for procurement teams: material transitions should be evaluated not only for regulatory compliance but also for qualification implications, long-term aging behavior, and supply continuity. Suppliers that proactively manage these transitions can convert a compliance requirement into a competitive advantage.
These trends carry inherent uncertainties. Regulatory interpretation can shift, project timelines can slip, and material qualification updates can introduce delays if not managed carefully. In addition, the balance between fleet life extension and new build momentum will vary by region, affecting where demand concentrates and how suppliers should allocate development resources. Market participants should therefore treat these trends as directional signals rather than guaranteed outcomes, and build flexibility into their qualification, sourcing, and engagement strategies.
Extra High Voltage Cables Market
Actionable Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen qualification narratives and reduce friction in compliance demonstration. This includes maintaining robust documentation across IEEE 323, IEEE 383, and 10 CFR 50.49 expectations, ensuring quality systems align with NQA-1 and 10 CFR Appendix B expectations where relevant, and preparing clear pathways for material transitions such as DecaBDE-free formulations. Suppliers should also consider expanding application coverage to address both nuclear island and conventional island needs, and evaluate how their product families can support multiple reactor types without fragmenting qualification efforts. Differentiation will increasingly come from the ability to combine technical assurance, regulatory alignment, and practical deployment experience.
For investors, the market offers exposure to a specialized, compliance-driven segment with steady long-term demand characteristics. The most relevant indicators are not short-term volume spikes but the durability of qualification programs, the breadth of installed references, and the capacity to serve both life-extension and new build contexts. Due diligence should focus on whether a company's qualification assets are portable across projects, whether its quality systems can withstand regulatory scrutiny, and whether its material and supply strategies are resilient to evolving environmental requirements. Investments in suppliers that can sustain 60-year service life narratives and maintain compliance efficiency are better positioned to benefit from the market's projected growth path.
For procurement teams and utility decision-makers, the focus should be on reducing long-term risk through supplier selection that emphasizes qualification continuity, documented compliance, and application fit. Given the safety-related nature of Class 1E instrumentation cables, preference should be placed on suppliers with strong reference installations and transparent quality frameworks, especially when cables must support aging management, field modifications, or integration with modernized I&C architectures. Procurement strategies should also account for the potential impact of material transitions on qualification status and service life, ensuring that compliance decisions do not inadvertently create technical or schedule risk. Detailed segment-level intelligence can help clarify which supplier profiles and product families best match specific fleet conditions, reactor types, and project phases.
For readers seeking a deeper breakdown of segment dynamics, regional demand patterns, and tailored strategic scenarios, the full PW Consulting report provides expanded data and decision frameworks beyond the overview presented here.
For detailed analysis of this topic, please visit the official page: Class 1E Nuclear Power Plant Instrumentation Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mining Equipment Market 2026: Why 5.8% CAGR and Surface Mining Shifts Change Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Mining Equipment Market
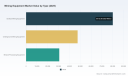
The global mining equipment market is entering a phase of disciplined expansion, characterized by structural shifts in technology, regulatory pressure, and evolving demand patterns across commodity cycles. Between 2020 and 2025, market revenue grew from approximately $122.3 billion to $158.5 billion, reflecting a compound annual growth rate of 5.8% over the period. Forward projections indicate the market will continue expanding through 2032, with revenue expected to approach $235.6 billion by the end of the forecast horizon. This trajectory is not merely a function of commodity price cycles; it reflects a deeper realignment in how mining operations are designed, equipped, and operated. For executives and strategic planners, the opportunity lies in interpreting these structural shifts rather than extrapolating historical growth patterns.
The market remains moderately concentrated, with the top three players capturing roughly 52% of revenue and the top five approaching 65%. This concentration underscores the scale advantages required to compete in original equipment manufacturing, parts distribution, and aftermarket service networks. Yet concentration does not imply stagnation. Competitive dynamics are being reshaped by product differentiation in electrification, automation, and digital integration, as well as by supply chain reconfiguration and regional demand shifts. The following analysis examines the current market landscape, the forces driving change, the evolving competitive architecture, and the strategic implications for manufacturers, investors, and procurement leaders.
Market Landscape and Core Challenges
The mining equipment sector is navigating a transition from volume-driven expansion to value-driven differentiation. Revenue growth over the past five years has been supported by sustained capital expenditure in metal and mineral extraction, alongside replacement cycles for aging fleets. However, the same period has introduced several structural challenges that are reshaping competitive positioning and investment priorities.
First, decarbonization mandates and customer sustainability requirements are forcing a reevaluation of conventional equipment architectures. Mining operators are under increasing pressure to reduce scope 1 and scope 2 emissions, which is accelerating interest in battery-electric, hybrid, and hydrogen-ready platforms. This shift is not uniform across segments. Surface mining operations, which typically operate in open environments with higher payload requirements and longer haul distances, face different electrification constraints than underground operations, where ventilation costs, space limitations, and safety regulations create distinct engineering trade-offs. Equipment manufacturers must balance performance, total cost of ownership, and infrastructure readiness without compromising operational reliability.
Second, supply chain volatility and input cost dynamics are creating new margins pressures and sourcing strategies. In early 2026, steel prices remained near the bottom of the current price cycle, with little meaningful recovery projected for the year. At the same time, U.S. import tariffs of 25% on steel and aluminum have enabled domestic producers to capture greater market share and temporarily higher pricing, while the European Union's carbon border adjustment mechanism and tightened safeguard measures are expected to suppress near-term steel price recovery before stronger growth materializes in 2027. These dynamics are compounded by projections that global steel demand will rise modestly by 0.4% to 1.8 billion metric tonnes in 2026 following a 2.6% contraction in 2025. For equipment manufacturers, this environment requires disciplined procurement, regionalized sourcing where feasible, and pricing strategies that reflect both input cost trajectories and customer tolerance for price adjustments.
Mining Machine Market
Third, labor availability and skill constraints are affecting equipment design and service models. High-quality metallics availability may become a tighter constraint, supporting increased value in scrap grading and blending for mining equipment production. Beyond materials, the broader labor equation is shifting as mines adopt more automated and remotely supervised operations. This transition changes the skill profile required for maintenance, diagnostics, and fleet management, creating both a challenge for traditional service delivery and an opportunity for providers that can integrate training, remote support, and predictive maintenance into their commercial offerings.
These challenges are not isolated. They interact with each other and with regional demand patterns, creating a market environment where the winners are likely to be those that can integrate product innovation, supply chain resilience, and service differentiation rather than competing primarily on hardware specifications alone.
Key Drivers of Market Change
Several interconnected forces are shaping the direction of the mining equipment market. Understanding these drivers is essential for anticipating where demand will intensify, which product categories will gain share, and how competitive advantages will be constructed over the next several years.
Technology Innovation and Operational Integration
Automation and digital connectivity are moving from incremental features to core design principles. Manufacturers are increasingly embedding payload management, load-haul cycle optimization, and near-real-time operational data analysis into equipment platforms. Recent product launches illustrate this trajectory. In March 2026, Caterpillar introduced the Cat 6040 mining shovel integrating standard technologies such as Cat Payload to improve load-haul cycle efficiency. In April 2026, Volvo Construction Equipment launched the world's first serially produced electric articulated haulers for zero-emission quarry and mining operations. In April 2025, Hitachi Construction Machinery announced the LANDCROS Connect Insight solution for near-real-time operational data analysis of mining machinery. These developments point to a broader shift in which equipment is no longer evaluated solely on mechanical performance but also on its ability to generate actionable operational data and reduce energy intensity per ton moved.
Construction Equipment Market
Drilling and underground equipment are experiencing similar evolution. In May 2025, Epiroc introduced the Diamec Automated Rod Magazine for core drilling rigs, enabling 225 meters of automated drilling without manual input. This kind of automation reduces cycle interruptions, improves consistency, and addresses labor constraints in exploration and development drilling. The strategic implication is clear: equipment that reduces manual intervention, improves utilization rates, and integrates with broader site data ecosystems is gaining competitive relevance, particularly in operations where throughput consistency and energy efficiency are prioritized.
Policy and Regulatory Environment
Regulatory frameworks are becoming a decisive factor in equipment selection and regional market dynamics. Carbon-related regulations, import tariffs, and trade safeguards are reshaping cost structures and competitive positioning. The EU's carbon border adjustment mechanism and tightened safeguard measures are expected to influence steel pricing and import patterns, while U.S. tariffs on steel and aluminum have altered the domestic supply landscape. These policies do more than affect input costs; they influence where equipment is sourced, how total cost of ownership is calculated, and which manufacturers can compete effectively in specific regions.
Sustainability mandates are also affecting procurement criteria. Mining companies are increasingly required to demonstrate emissions reductions across their operations, which elevates the importance of equipment that supports lower energy consumption, alternative power sources, and reduced on-site emissions. This regulatory tailwind is not uniform across jurisdictions, but it is persistent enough to shape product roadmaps and commercial priorities, particularly in markets where government procurement, permitting, or community expectations are tied to environmental performance.
Demand-Side Shifts in Mining Operations
Demand for mining equipment is being reshaped by the commodity mix, operational efficiency goals, and the pace of fleet renewal. Metal mining continues to represent a substantial share of equipment demand, reflecting the criticality of copper, lithium, nickel, and other materials for electrification and industrial transition. Mineral mining and coal mining also drive significant equipment needs, though the growth trajectories and investment priorities differ by region and commodity strategy.
Beyond commodity volumes, demand is increasingly influenced by how mining companies conceptualize total cost of ownership. Operators are weighing not only purchase price but also energy consumption, maintenance intervals, parts availability, automation capabilities, and downtime risk. This shift favors suppliers that can offer integrated solutions, predictable service economics, and data-enabled performance guarantees. It also creates openings for differentiated offerings in segments where electrification, automation, or specialized underground configurations can deliver measurable operational improvements.
Supply Chain and Cost Structure Evolution
The cost structure of mining equipment production is undergoing recalibration. Input price cycles, trade policy, and material availability are influencing sourcing strategies and margin management. Steel prices near the bottom of their cycle, combined with tariff-driven regional price divergence, are prompting manufacturers to reconsider procurement timing, supplier diversification, and build-vs-source decisions. At the same time, expectations that global steel demand will stabilize and then grow modestly suggest that input cost volatility may persist rather than normalize quickly.
These dynamics are encouraging greater attention to material efficiency, scrap utilization, and supply chain transparency. The potential tightening of high-quality metallics availability is likely to increase the value of advanced scrap grading and blending practices in equipment production. Manufacturers that can manage material quality, reduce waste, and maintain delivery reliability under input constraints will be better positioned to protect margins and meet customer delivery expectations.
Competitive Landscape and Leading Strategies
The competitive architecture of the mining equipment market is defined by a mix of large, globally scaled manufacturers and specialized players with strong positions in specific equipment categories or operational environments. Scale confers advantages in R&D investment, global service networks, and the ability to standardize platforms across regions. Specialization, by contrast, can create defensible positions in underground equipment, drilling systems, mineral processing, or regional service networks where local knowledge and responsiveness are critical.
Caterpillar maintains a leading position in surface mining equipment, including haul trucks, excavators, loaders, and autonomous haulage systems, supported by a broad portfolio and integrated technology offerings. Komatsu competes across surface and underground equipment such as excavators, dump trucks, and drill rigs, and has been expanding its U.S. distribution footprint through strategic dealership acquisitions, including the acquisition of six Core Machinery dealerships in Arizona and California in June 2025 to strengthen its reach for southwest mining customers. Hitachi Construction Machinery produces hydraulic excavators and electric dump trucks for large-scale surface operations and has advanced its digital analytics capabilities through the LANDCROS Connect Insight solution.
In underground mining, Sandvik and Epiroc hold strong positions in rock drilling tools, excavation systems, and underground machinery, with Epiroc also advancing automation in drilling through products like the Diamec Automated Rod Magazine. Liebherr and Volvo Construction Equipment contribute to surface operations with haul trucks, excavators, and articulated haulers, with Volvo's recent entry into serially produced electric articulated haulers signaling a shift toward zero-emission equipment in quarry and mining settings. Sany Group is expanding its presence with electric and conventional mining excavators and loaders, reflecting broader competitive participation from Chinese manufacturers in both conventional and electrified categories.
Mineral processing and specialized equipment add further differentiation. Metso provides mineral processing equipment and machinery for mining operations, while Boart Longyear specializes in diamond core drilling equipment and services for exploration. Terex manufactures crushers, conveyors, and haul trucks, and J.H. Fletcher & Co. focuses on continuous miners, roof bolters, and underground equipment. MacLean Engineering supplies underground mining vehicles and battery-powered loaders, illustrating the growing relevance of electrified underground platforms. The inclusion of legacy assets such as Bucyrus International within the Caterpillar portfolio also highlights how historical acquisitions continue to shape product breadth and market reach.
Strategic Positioning and Differentiation
Leading manufacturers are differentiating along several axes. One is product electrification and zero-emission capability, as seen in Volvo's electric articulated haulers and Sany's electric excavators and loaders. Another is digital integration and operational analytics, reflected in Caterpillar's payload technologies, Hitachi's Connect Insight, and broader industry movement toward data-enabled fleet management. A third is service and distribution reach, where Komatsu's dealership expansion and established global service networks illustrate the importance of local responsiveness and parts availability. A fourth is specialization in underground or processing equipment, where Sandvik, Epiroc, Metso, and MacLean derive advantage from deep application expertise and targeted product architectures.
Market Evolution: Integration, Fragmentation, and New Entrants
The market is likely to continue evolving through a combination of consolidation, niche specialization, and new competitive pressure. Scale players may pursue selective acquisitions or partnerships to expand digital capabilities, electrified product lines, or regional service coverage. At the same time, specialized manufacturers can maintain or expand share by focusing on performance in constrained environments, such as underground operations or exploration drilling, where application-specific engineering matters more than broad platform standardization.
New entrants and expanding manufacturers are introducing additional competition, particularly in electrified equipment and cost-competitive conventional product lines. This is not necessarily a threat to incumbents if incumbents respond with clear differentiation in reliability, total cost of ownership, service integration, and data-enabled operations. The more significant risk is complacency in product roadmaps or service models in a market where customer expectations are shifting toward lower emissions, higher utilization, and more predictable operating costs.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape market opportunities and strategic priorities.
One key trend is the acceleration of electrification and alternative-power equipment in selected segments. Serial production of electric articulated haulers and continued development of battery-powered underground loaders indicate that electrification is moving from pilot projects to commercial deployment in specific use cases. The opportunity lies in identifying where energy savings, ventilation reductions, regulatory compliance, and total cost of ownership align to make electric or hybrid equipment economically attractive. The risk is that electrification adoption may be uneven, constrained by charging infrastructure, payload requirements, and operational heterogeneity across sites.
A second trend is the deepening integration of automation and data analytics into equipment and fleet operations. Products that improve load-haul efficiency, automate drilling cycles, or provide near-real-time operational insights are becoming more common. The commercial implication is that value creation is shifting partly from hardware alone to the software, services, and performance assurance that surround it. Manufacturers and service providers that can translate operational data into measurable efficiency gains, reduced downtime, and better maintenance planning are likely to strengthen their competitive position. The uncertainty lies in the pace at which mining companies adopt integrated digital workflows and the degree to which data interoperability standards mature across sites and vendors.
PW Consulting
A third trend is the reconfiguration of supply chains and input cost management in response to policy and material availability. Tariff environments, carbon-related regulation, and steel demand projections suggest that regional cost structures will remain divergent and that material quality constraints may increase the importance of advanced scrap handling and blending. For equipment producers, the opportunity is to build more resilient sourcing, improve material efficiency, and communicate total cost of ownership in ways that account for policy-driven price dynamics. The risk is that input volatility and trade policy uncertainty could compress margins or disrupt delivery schedules if not managed proactively.
These trends converge on a common theme: competitive advantage will depend on the ability to combine product innovation with operational relevance, supply chain discipline, and service differentiation. Markets that are growing at a mid-single-digit rate can still generate significant value reallocation if participants position themselves in the right segments, with the right technology mix, and the right commercial model.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product roadmaps with the operational realities of decarbonization, automation, and total cost of ownership expectations. This means advancing electrified and hybrid options where they can deliver measurable benefits, embedding data and payload optimization into mainstream product lines, and strengthening service and distribution capabilities that reduce downtime and improve customer outcomes. It also means treating supply chain resilience and material efficiency as strategic capabilities rather than procurement details, particularly as input cost cycles and policy environments remain fluid.
For investors, the relevant question is where value is likely to accrue across the equipment and services value chain. Opportunities are probably strongest in companies that can combine scale with differentiated technology in electrification, automation, or underground specialization, and in providers that can capture recurring value through service, parts, and data-enabled performance offerings. Caution is warranted where competitive positioning depends primarily on price without corresponding advantages in reliability, service, or total cost of ownership, especially in an environment where input costs and regulatory dynamics can shift regional competitiveness quickly.
For procurement leaders and mining operators, the strategic imperative is to evaluate equipment decisions through a broader operational lens. This includes comparing conventional and electrified options not just on acquisition cost but on energy consumption, ventilation impact, maintenance patterns, automation potential, and service availability over the asset life. It also includes assessing supplier capabilities in digital integration, remote support, and parts logistics, since these factors increasingly influence uptime and operating economics. Where possible, procurement strategies should incorporate flexibility for fleet mixing, phased electrification, and service models that align supplier incentives with performance outcomes.
For all of these audiences, the value of detailed segmentation data, regional demand patterns, and company-level benchmarking is substantial. Nuanced decisions about product mix, market entry, service expansion, and procurement timing depend on granular insight into where growth is concentrated, which segments are gaining or losing share, and how competitive positioning is evolving across regions and applications. The broader trends outlined here provide direction, but the precision required for investment, product strategy, and sourcing decisions comes from deeper segmentation and company-level analysis.
Strategic positioning in the mining equipment market will increasingly be determined by how effectively organizations translate structural shifts into product, service, and supply chain decisions. The companies that act on these trends with discipline, focus, and operational relevance are best placed to capture value as the market continues its path toward $235.6 billion by 2032.
For detailed analysis of this topic, please visit the official page: Mining Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Reprocessed Medical Device Market: Strategic Trends and Commercial Opportunities
The reprocessed medical device market has transitioned from a niche cost-saving measure to a strategic component of healthcare sustainability and supply chain resilience. As of 2025, the sector is valued at approximately 1.55 billion USD, reflecting steady growth from a 2020 baseline of around 0.99 billion USD. The trajectory points toward a compelling expansion phase, with the market projected to exceed 4.6 billion USD by 2032, driven by a compound annual growth rate of nearly 17 percent. This growth is not merely a function of inflationary adjustments or volume expansion; it reflects a fundamental shift in how healthcare systems approach device utilization, waste reduction, and operational efficiency. For executives and investors tracking MedTech dynamics, the reprocessed device space represents a convergence of regulatory maturity, clinical acceptance, and financial pragmatism that is reshaping procurement strategies across hospital networks and ambulatory surgery centers.
However, the market’s momentum is accompanied by structural challenges that demand strategic attention. First, regulatory fragmentation across jurisdictions creates uneven adoption pathways. While certain regions have standardized reprocessing frameworks, others are still formalizing legal and quality-system requirements, leading to inconsistent commercialvelocity. Second, the industry operates with a relatively fragmented competitive landscape, characterized by a low concentration ratio where the top three players collectively account for only around twenty-six percent of market revenue and the top five entities hold less than thirty percent. This dispersion suggests ample room for consolidation, partnership formation, and competitive differentiation, but it also means that no single organization currently dominates the value proposition across all device categories or geographies. Third, the operational economics of reprocessing—spanning cleaning, disinfection, inspection, and functional testing—require disciplined cost control and validation rigor to maintain clinician confidence and procurement ROI. Facilities processing instruments in trays or peel packs face per-unit cost dynamics that must be managed alongside throughput capacity and sterility assurance standards.
Worldwide Medical Device Reprocessing Market
Key Drivers Shaping the Reprocessed Device Ecosystem
Several interlocking forces are accelerating the market’s evolution, each carrying distinct implications for commercial strategy and operational planning.
Used And Refurbished Medical Devices Market
Technological Innovation and Validation Advancements
Progress in reprocessing technology has expanded the scope of devices that can be safely and reliably reprocessed. Modern closed-loop systems, advanced sterilization protocols, and rigorous functional testing frameworks have enabled reprocessors to validate single-use devices for multiple clinical cycles without compromising performance. The ability to secure device-specific regulatory clearances—for example, gaining approval to reprocess steerable introducers and mapping catheters for additional uses—demonstrates how targeted technical validation can unlock new product categories and reinforce a reprocessor’s market position. These innovations reduce the historical skepticism around reprocessed device reliability and create a foundation for broader clinical acceptance across cardiology, laparoscopic, orthopedic, and gastroenterology applications.
Regulatory and Reimbursement Alignment
Policy developments are increasingly supporting the commercial viability of reprocessing. Regulatory frameworks now require that FDA-regulated reprocessing activities be conducted by commercial reprocessors or hospital systems operating under manufacturer-like quality system regulations, with appropriate clearances and compliance documentation. Importantly, reprocessed devices that meet regulatory standards are eligible for reimbursement under standard healthcare payment structures on comparable terms to non-reprocessed devices. This reimbursement parity reduces the financial burden on healthcare providers and aligns reprocessed procurement with existing budgeting cycles. Coupled with recent regulatory initiatives in Europe that have formalized the legalization of medical device reprocessing to advance sustainable healthcare practices, the policy environment is shifting from cautious oversight to active enablement.
Demand-Side Shifts in Healthcare Delivery
Healthcare providers are under sustained pressure to balance clinical quality, cost containment, and environmental stewardship. The expansion of ambulatory surgery centers and outpatient procedural volumes has intensified the need for cost-effective device sourcing without sacrificing operational reliability. Reprocessed devices offer a tangible pathway to reduce per-procedure expenditures while supporting institutional sustainability goals. Clinician and procurement teams are increasingly evaluating reprocessed options not solely as a cost alternative, but as a supply chain diversification strategy that mitigates exposure to single-use device shortages and price volatility. This demand-side evolution is particularly evident in high-utilization specialties where device turnover is frequent and reprocessing can yield measurable cost and waste reductions.
Supply Chain and Cost Structure Dynamics
The economics of reprocessing have matured to the point where per-instrument processing costs are now well-characterized and increasingly predictable. Processing expenses for devices in trays or peel packs have established ranges that allow facilities to model procurement savings with greater precision. At the same time, supply chain efficiency initiatives—such as closed-loop reprocessing workflows and paid donor programs—have streamlined the movement of devices between clinical sites and reprocessing facilities. These operational improvements lower friction in the reverse logistics chain and make reprocessed sourcing more scalable for mid-sized surgical centers and hospital networks seeking to optimize device utilization without compromising sterility or turnaround time.
Competitive Landscape and Leading Strategies
The reprocessed medical device market is shaped by a diverse set of participants ranging from specialized reprocessors to large medtech and healthcare supply enterprises. Despite the low overall market concentration, distinct strategic patterns are emerging among organizations that have built or expanded their reprocessing capabilities.
PW Consulting
Strategic Positioning and Differentiation
Leading players are differentiating themselves along several dimensions. Some specialize in device-specific reprocessing with extensive regulatory clearances, building authority in high-value categories such as electrophysiology and cardiology devices. This clearance-driven approach creates barriers to entry for less validated competitors and reinforces trust with clinical teams that require documented performance consistency. Others have focused on specialty segments such as ENT and orthopedic devices, leveraging closed-loop reprocessing and donor programs to serve ambulatory surgery centers with an emphasis on cost reduction and supply chain efficiency. Large medtech and distribution organizations, meanwhile, have integrated reprocessed offerings into broader sustainability portfolios, pairing reprocessed devices with remanufactured solutions and institutional sustainability programs. Their scale and existing hospital relationships allow them to bundle reprocessing into wider procurement engagements, often positioning it as part of a comprehensive cost and waste reduction strategy.
Recent Dynamics and Market Evolution
Recent industry developments highlight how the competitive landscape is being reshaped by regulatory milestones, partnership activity, and regional policy shifts. One notable advancement is the achievement of multiple FDA clearances by a specialized reprocessor for a steerable introducer, reinforcing its position as the only reprocessor cleared for that device and illustrating how clearance accumulation can create defensible commercial positioning. Alongside this, strategic partnerships between reprocessing organizations and established surgical equipment providers are enhancing workflow integration within sterile processing departments, improving the operational fit of reprocessed devices into existing hospital systems. In parallel, regulatory developments in Europe have formalized reprocessing legality, expanding the addressable market for European-focused reprocessors and signaling a broader institutional commitment to sustainable healthcare practices.
Consolidation, Fragmentation, and New Entrants
The market’s low concentration suggests multiple pathways for evolution. Consolidation through acquisitions or partnerships could accelerate as larger organizations seek to expand reprocessing portfolios or acquire clearance portfolios and operational expertise. At the same time, fragmentation may persist in specialty niches where device-specific validation requirements and regional regulatory differences create natural segmentation. New entrants are likely to emerge where there is clear regulatory clarity, demonstrated reimbursement parity, and measurable cost advantages for high-utilization device categories. Organizations that can combine rigorous quality systems, device-specific validation, and integrated supply chain solutions will be best positioned to capture share as the market scales.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to define the reprocessed medical device market and create distinct commercial opportunities.
Expansion of Reprocessable Device Categories
As validation protocols become more sophisticated and regulatory pathways more familiar, the range of reprocessed devices is expected to broaden beyond current high-volume categories. Cardiovascular and laparoscopic devices have already demonstrated strong adoption, but additional device types in orthopedic, gastroenterology, and general surgery applications are poised for increased reprocessing activity as clinical confidence grows and procurement teams seek wider cost and sustainability benefits. Organizations that invest early in device-specific validation and build clearance portfolios can secure first-mover advantages in emerging categories.
Integration with Sustainable Healthcare and Procurement Strategies
Reprocessing is increasingly embedded within broader institutional sustainability programs and procurement transformation initiatives. Healthcare systems are aligning device sourcing decisions with environmental targets, waste reduction commitments, and total-cost-of-care objectives. This integration creates opportunities for reprocessors and suppliers to position their offerings as part of coordinated sustainability and cost-management programs rather than isolated procurement alternatives. The commercial implication is clear: value propositions that combine clinical reliability, cost savings, and verifiable sustainability outcomes are more likely to gain traction with executive-level procurement decisions.
Regional Policy Harmonization and Market Expansion
As more jurisdictions formalize reprocessing regulations and reimbursement alignment, geographic expansion will become a more predictable growth lever. Recent regulatory developments in Europe and ongoing regulatory clarity in other markets indicate a trend toward greater harmonization, which can reduce entry barriers and support scaled commercial operations. However, regional differences in validation requirements, procurement practices, and clinical workflows will still demand localized strategy design. Organizations that navigate these differences with flexible operational models and region-specific compliance expertise will be better equipped to capture cross-market growth.
Potential Risks and Uncertainties
Despite the positive trajectory, several risks warrant attention. Regulatory changes or divergent standards across regions could introduce compliance complexity and slow adoption in certain markets. Reimbursement policies, while currently supportive, could evolve in ways that affect the financial attractiveness of reprocessed procurement. Additionally, any perception of quality or performance inconsistency—whether driven by isolated operational failures or insufficient validation transparency—could undermine clinician confidence and procurement momentum. Competitive dynamics may also intensify as larger players expand their reprocessing portfolios or pursue partnerships that compress margins for smaller specialists. Managing these risks requires disciplined quality systems, transparent validation practices, and proactive engagement with procurement and clinical stakeholders.
Strategic Action Points for Decision-Makers
For executives, strategists, and investors evaluating the reprocessed medical device market, the following considerations can help translate market dynamics into actionable priorities.
For Manufacturers and MedTech Enterprises
Integrate reprocessing considerations into product lifecycle and sustainability planning. Evaluate which device portfolios are most amenable to reprocessing and assess opportunities to partner with or support qualified reprocessors. Building compatibility with reprocessing workflows—through design-for-reprocessing principles, documentation support, and engagement with regulatory validation processes—can strengthen market positioning and align product strategies with evolving procurement norms.
For Investors and Strategic Allocators
Assess the reprocessed device space through the lens of regulatory clearance accumulation, device-specific validation depth, and supply chain integration capability. Organizations that have secured multiple clearances for high-value device categories and demonstrated operational scalability are positioned to benefit from expanding demand and consolidation trends. Monitor partnership activity and regional policy developments as leading indicators of market acceleration and competitive realignment.
For Procurement Leaders and Healthcare Providers
Evaluate reprocessed device programs as part of a broader cost and sustainability strategy rather than a standalone procurement tactic. Establish internal validation criteria that balance clinical performance requirements, sterility assurance, and financial impact. Engage with reprocessors that provide clear documentation, consistent turnaround, and integration support for sterile processing workflows. Where applicable, design procurement frameworks that capture total-cost benefits, including waste reduction and supply chain resilience, alongside per-unit savings.
The reprocessed medical device market is advancing along a clear growth trajectory, supported by regulatory maturity, reimbursement alignment, and increasing demand for sustainable and cost-effective healthcare delivery. Yet the market’s full potential will be realized by organizations that move beyond broad market awareness to precise segmentation, device-specific validation strategies, and region-tailored commercial execution. Detailed segment-level data, competitive benchmarking, and customized strategic guidance can materially improve decision quality in this evolving landscape. Accessing a comprehensive research report provides the granularity needed to map growth pockets, assess competitive positioning, and build actionable plans aligned with specific organizational objectives. For leaders seeking to act decisively in this space, deeper intelligence is the bridge between recognizing opportunity and capturing it.
For detailed analysis of this topic, please visit the official page: Reprocessed Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Fructooligosaccharide (FOS) Market at a Strategic Inflection Point: Growth Dynamics and Commercial Pathways
The global market for fructooligosaccharides (FOS) has moved beyond experimental nutrition into a phase of structural expansion, where demand signals across food, infant nutrition, dietary supplements, and animal feed increasingly intersect with regulatory clarity and formulation innovation. Valued at approximately USD 252.0 million in 2025, the market has traced a discernible upward trajectory since 2020, when it stood near USD 195.0 million. After modest consolidation in 2022, revenue climbed to USD 207.88 million, then accelerated through 2023–2024 before reaching the current baseline. The forward path reflects a projected compound annual growth rate of 8.25 percent across the 2026–2032 horizon, with revenue expected to move from roughly USD 265.1 million in 2026 toward USD 440.0 million by 2032. This trajectory suggests more than incremental growth; it points to a maturing prebiotic category where FOS is being embedded into mainstream ingredient portfolios rather than treated as a niche additive.
Such scaling does not occur in a vacuum. The market has reached a point where volume expansion, application diversification, and regulatory acceptance are beginning to reinforce one another, yet the same forces also expose bottlenecks in supply, formulation, and competitive positioning. For executives evaluating ingredient strategy, this environment rewards those who can align product readiness with consumer expectations, regulatory pathways, and cost structures that remain under pressure in key raw material chains.
Market Context: A Growing Category With Structural Complexity
The scale and pace of FOS adoption are visible in the way the category now spans multiple end-use environments. Rather than relying on a single growth engine, the market is being carried by simultaneous expansion across food and beverages, infant formula, dietary supplements, pharmaceuticals, and animal feed. Each application brings a different set of performance expectations, regulatory thresholds, and procurement cycles. Food and beverage applications tend to prioritize taste modulation, sugar reduction, and digestive health positioning, while infant nutrition demands rigorous safety documentation and tolerance data. Dietary supplements often depend on functional claims and premium positioning, and animal feed applications are shaped by cost sensitivity and gut-health outcomes. This breadth creates resilient demand, but it also requires suppliers to manage distinct validation requirements and formulation constraints.
At the same time, the market is not operating as a loosely organized field of interchangeable producers. Concentration metrics indicate a moderately consolidated landscape, with three leading firms accounting for a meaningful share of activity and a broader top five reinforcing the structure. This level of concentration signals that scale, technical service capability, and regulatory documentation increasingly matter. New entrants and smaller producers can still find openings in specialized niches or regional channels, but broad-based competition often favors organizations that can combine consistent supply, application support, and a credible safety narrative.
Core Challenges and Inflection Points
Despite the favorable growth profile, several challenges are shaping the near-term trajectory of the FOS market. The first is the tension between demand diversification and raw material constraints. Many FOS streams depend on chicory root or sucrose-based enzymatic conversion, and both pathways face volatility related to crop cycles, sourcing geography, and processing economics. Seasonal fluctuations in chicory root supply continue to challenge scaling, particularly where inulin-derived routes form a major part of production. This creates a structural cost risk that can disrupt margins and complicate long-term capacity planning.
The second challenge lies in regulatory and tolerance validation. As FOS moves into infant formula and broader functional food categories, manufacturers must navigate established concentration limits and evolving safety documentation expectations. For example, FOS maintains GRAS status for infant formula at specific usage levels, and additional safety and gastrointestinal tolerance data are being reviewed as new uses are proposed. The presence of multiple regulatory references across jurisdictions means that formulation teams and commercial leaders cannot rely on a single global playbook. A product well positioned in one region may require different documentation, labeling rationale, or usage thresholds in another.
The third inflection point is competitive differentiation in a category where functional benefits are increasingly expected rather than exceptional. As sugar reduction and gut-health positioning become mainstream, FOS is no longer competing only on prebiotic credentials but also on sensory performance, formulation compatibility, and metabolic health narratives. That shift raises the bar for suppliers. The winners will be those who can deliver reliable functionality while supporting customers with clinical or tolerability evidence, application testing, and clear claims guidance.
Core Drivers Reshaping the FOS Landscape
Several forces are pushing the market beyond baseline growth. The first is technology and formulation innovation. Producers are refining enzymatic processes and product grades to balance prebiotic efficacy, solubility, and organoleptic neutrality. The ability to offer short-chain and other FOS variants tailored to specific applications has become a commercial advantage, especially where formulators need solutions that reduce sugar without compromising texture or mouthfeel. This is visible in recent product activity across major suppliers, where companies have expanded FOS offerings to support sugar reduction, functional foods, and infant nutrition. Capacity investments and new functional ingredient line extensions suggest that suppliers are treating FOS not as a commodity line but as a platform for flexible, application-specific solutions.
The second driver is a regulatory environment that is providing both stability and new openings. In several markets, FOS already enjoys a defined regulatory footing for specific uses, which reduces uncertainty for large-scale adoption. In the United States, GRAS notices continue to support expansion into infant products and conventional food and beverage categories, with safety data under review up to early 2025. In the European Union, FOS has long been permitted in restricted amounts in baby formula and follow-on formula, creating a durable pathway for infant nutrition applications. In Canada, FOS is recognized within natural health product frameworks. These approvals do not guarantee automatic growth, but they lower the regulatory friction that often slows ingredient adoption in sensitive categories.
The third driver is a shift in demand-side behavior. Consumers and brand managers are increasingly treating digestive health and sugar reduction as interrelated priorities rather than separate goals. FOS fits naturally into that convergence, which helps explain its growing presence in functional snacks, beverages, and supplement formats. A notable example is the launch of a functional chocolate line in Japan that used FOS to replace added sugar, offering products with substantially less or no added sugar while emphasizing gut health and calorie reduction. This kind of hybrid value proposition illustrates how FOS can be used as a dual-purpose ingredient: supporting metabolic and digestive positioning while helping formulators meet taste and reformulation targets.
A fourth driver is emerging clinical and metabolic research that broadens the narrative beyond traditional gut-health claims. Certain FOS variants have been associated with stimulation of GLP-1 hormone levels in clinical research, opening interest in metabolic health and weight management applications. While such findings do not automatically translate into commercial claims, they create strategic optionality. If subsequent data and regulatory interpretations continue to support metabolic benefits, the FOS category could gain new relevance in lifestyle nutrition and functional health segments that are currently underserved by conventional prebiotic messaging alone.
Supply-side economics also remain influential. The cost and availability of key raw materials continue to shape competitive dynamics. Where inulin-derived routes dominate, seasonal and supply chain volatility creates challenges for consistent scaling. This reinforces the value of diversified sourcing strategies, flexible production routes, and supplier relationships with demonstrated supply reliability. For procurement and strategy teams, this is a reminder that FOS purchasing decisions cannot be reduced to unit price alone; they must also account for continuity, grade consistency, and the ability to support downstream formulation requirements.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment reflects a group of established ingredient suppliers with distinct regional strengths, formulation capabilities, and application focus areas. Beneo GmbH operates across Europe with FOS grades such as Beneo-scL85 designed for sugar reduction, functional foods, and infant nutrition, and has been strengthening its position through product modernization and investments that support expanding production capacity. Meiji Holdings brings a strong brand and formulation heritage through products such as Actilight and Meioligo, with applications spanning functional foods, supplements, and prebiotic uses worldwide. Cargill and Ingredion contribute broad ingredient portfolios and formulation support, targeting infant formula, dietary supplements, functional beverages, and nutraceutical applications, often with GRAS-supported or multiple-grade offerings that simplify customer adoption. Tate & Lyle remains focused on enzymatic short-chain FOS with production arrangements aligned to infant products, conventional foods, and beverages.
The competitive picture is not limited to large multinational incumbents. Galam Group produces short-chain FOS and inulin-derived variants for prebiotic and sugar-reduction applications, and has highlighted clinical research related to GLP-1 stimulation that may support future metabolic-health positioning. Cosucra produces chicory-derived FOS and inulin for food, infant nutrition, and functional ingredients, reinforcing the importance of European sourcing and application depth. Roquette Frères supplies FOS and resistant starch blends for infant formula and dietary supplements, suggesting an increasing appetite for combination ingredient systems. Quantum Hi-Tech reflects a more Asia-focused production footprint, serving food, feed, and supplement channels and illustrating how regional supply can become strategically important where local demand and sourcing preferences are strong.
Worldwide Short Chain Fructooligosaccharides Market
Several strategic patterns emerge from this landscape. First, differentiation is increasingly built on more than supply availability. Leading players are distinguishing themselves through grade variety, application support, regulatory documentation, and the ability to match specific use cases such as infant formula tolerance requirements or sugar-reduction targets in consumer foods. Second, the category is showing signs of both consolidation and fragmentation. In core ingredient distribution and major applications, scale and technical service favor larger players. In specialized formats, regional markets, or particular value propositions, smaller or regional suppliers can maintain relevance by serving niches that larger portfolios do not address with the same focus. Third, the market is likely to see continued evolutionary pressure from new product launches, regulatory filings, and capacity expansions that reshape competitive priorities over time.
Recent developments underscore how companies are using regulatory actions and product innovation to reinforce positioning. A GRAS notice filed for short-chain FOS for use in infant products and conventional food and beverage categories reflects ongoing efforts to support broader application scope through documented safety review. At the same time, product launches emphasizing reduced sugar, gut health, and functional benefits show how FOS is being integrated into consumer-facing narratives rather than remaining solely an industrial ingredient. Clinical research on metabolic endpoints further illustrates how suppliers and product developers are exploring adjacent opportunities beyond conventional prebiotic positioning.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, a few trends appear especially consequential. The first is deeper integration of FOS into mainstream reformulation strategies, particularly where sugar reduction and digestive-health claims must coexist in the same product. As consumers become more accustomed to functional ingredients in everyday foods and beverages, FOS may be selected less as a specialty additive and more as a standard tool in formulation toolkits. For suppliers and brand owners, this implies greater demand for grades that perform reliably across varied matrices and for documentation that supports both technical adoption and claim substantiation.
The second trend is the widening of application narratives to include metabolic health and weight-management contexts, supported by emerging clinical signals. If GLP-1-related interest continues to gain traction in scientific and commercial discussions, FOS could find new relevance in products targeting satiety, glycemic support, or broader metabolic wellness. This does not eliminate the importance of gut-health positioning, but it suggests that FOS may be positioned in more layered benefit narratives. The commercial implication is that companies should prepare for potentially more complex claim pathways and validation requirements, while also recognizing the upside if regulatory and scientific consensus expands.
The third trend is a continued push toward supply resilience and cost control as the category scales. With raw material seasonality and production economics remaining constraints, the market may reward suppliers that can demonstrate stable output, flexible grade options, and transparent supply planning. Buyers may increasingly weigh continuity and technical reliability alongside price. This creates an opportunity for organizations that invest in supply chain robustness and multi-source strategies, especially if demand accelerates in applications where interruptions are costly or difficult to manage.
PW Consulting
These trends carry uncertainty. Regulatory review processes can slow expansion into sensitive applications, and new clinical narratives may take time to mature into accepted positioning. Raw material volatility can pressure margins and complicate capacity deployment. In addition, competitive intensity could compress differentiation if sugar-reduction and prebiotic benefits become broadly available across ingredient options. Organizations that monitor these variables carefully will be better positioned to adapt their portfolios, claims, and sourcing strategies as conditions evolve.
Galactooligosaccharides (GOS) Market
Strategic Actions for Decision-Makers
The current market environment suggests several practical priorities for different stakeholder groups.
-
For ingredient manufacturers and suppliers, the priority is to align product roadmaps with the converging demands of sugar reduction, digestive health, and emerging metabolic-interest applications. That means investing not only in production capacity but also in the documentation, application testing, and regulatory readiness that help customers adopt FOS with confidence. Differentiation will increasingly depend on whether a supplier can support formulation performance across multiple food and supplement matrices while maintaining credible safety narratives for sensitive uses.
-
For investors and corporate strategy teams, the market signals a category where demand breadth and moderate consolidation create opportunities, but also where cost volatility and regulatory specificity can shape returns. Due diligence should consider application mix, regional exposure, raw material dependency, and the strength of technical service capability in addition to headline growth. In particular, portfolios with diversified end-use use cases may be more resilient than those concentrated in a single channel exposed to seasonal or regulatory shocks.
-
For procurement and brand owners, the strategic task is to treat FOS selection as a multi-factor decision. Beyond unit cost, buyers should evaluate grade suitability for the intended application, tolerance and safety documentation for regulated uses, supply continuity, and the supplier’s ability to support future reformulation or claim strategies. In sugar-reduction programs especially, the interaction between taste, texture, and prebiotic function can determine whether FOS becomes a viable long-term ingredient or a limited trial.
Given the pace of regulatory filings, clinical exploration, and application innovation, detailed segment-level intelligence can materially improve timing and resource allocation. A fuller view of regional demand patterns, application-level pricing and volume dynamics, competitive positioning by grade, and supply chain sensitivities can help decision-makers move from broad market optimism to implementation choices with clearer risk controls. For executives and investors seeking to act on FOS opportunities, that level of granularity is often the difference between a plausible opportunity and a plan that can be executed with confidence.
For detailed analysis of this topic, please visit the official page: Fructooligosaccharide (FOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chitosan Market Insights: Decoding the 19.76% CAGR and Asia Pacific Power Shift
By PW Consulting, 2026-09-21
The Chitosan Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2026–2032)
The chitosan market has transitioned from a niche biopolymer segment into a strategically significant arena for industrial, agricultural, and life sciences applications. Measured in millions of USD, the global market expanded from 7.77 in 2020 to 19.15 in 2025, and the trajectory points toward 67.66 by 2032, reflecting a compound annual growth rate of 19.76 percent across the forecast horizon. This scale of acceleration is atypical for mature chemical segments and signals a convergence of regulatory tailwinds, application diversification, and supply-side restructuring. For executives and investors evaluating biomaterial portfolios, chitosan now represents a cross-disciplinary platform rather than a single-product category, with value creation increasingly tied to grade specificity, regulatory positioning, and source diversification.
Market Snapshot and Structural Realities
The historical progression from 2020 through 2025 shows consistent expansion, with each year building on prior demand adoption and capacity additions. The forward curve from 2026 to 2032 compounds at nearly twenty percent annually, implying that incremental growth will be driven less by baseline industrial consumption and more by new application penetration, regulatory clarity, and substitution dynamics in water treatment, cosmetics, pharmaceutical and biomedical use, food and beverages, and emerging agricultural formulations. At the same time, the market structure remains moderately concentrated, with the top three firms capturing approximately 42 percent of revenue and the top five approaching 48 percent. This concentration level indicates that scale players hold meaningful advantages in purity consistency, regulatory documentation, and cost discipline, yet enough fragmentation persists to allow specialized entrants to compete on molecular weight, source origin, or application-specific formulation.
The industry sits at a genuine inflection point. First, the regulatory conversation around chitosan classification is accelerating in key geographies, particularly in organic agriculture and crop protection. Recent technical reviews and subcommittee proposals have opened a pathway to classify chitosan as nonsynthetic under organic crop production rules, with votes and final determinations expected in the near term. This matters because regulatory status directly shapes allowable use cases, labeling claims, and market access for agricultural and processing applications. Second, raw material dependence on crustacean exoskeletons continues to tie chitosan supply chains to seafood processing volumes, aquaculture dynamics, and regional byproduct availability. That linkage introduces volatility in feedstock consistency, contamination risk, and cost structure, especially when capture fisheries or shellfish processing cycles shift. Third, the segment is witnessing a source diversification push, with insect-derived chitin and chitosan production expanding through black soldier fly feedstock processes. This alternative pathway is still developing, but it is already influencing strategic planning among producers seeking to reduce marine dependency and broaden customer eligibility in markets sensitive to shellfish allergen concerns or sustainability criteria.
Core Drivers Reshaping the Market
Several forces are interacting to sustain the current growth path and reshape competitive priorities.
Technological innovation and grade specialization are moving from general-purpose chitosan to application-tailored molecular architectures. High-purity pharmaceutical, food, and agricultural grades now require distinct deacetylation levels, molecular weight ranges, and contamination controls. In parallel, inhaled drug delivery represents a notable frontier, with first commercially available chitosan formulations for inhalation entering the market and opening doors for pulmonary and respiratory applications. Clean-label and sustainable chitosan ranges are also being introduced, reflecting demand from cosmetics, food, and biomedical customers who prioritize traceability, bio-based sourcing, and reduced processing footprints. For manufacturers, differentiation is increasingly defined by the ability to deliver reproducible specifications at scale, not merely by producing chitosan as a commodity.
Worldwide Chitosan Glycolate Market
Policy and regulatory environment is shaping adoption speeds and permissible use cases. In the European Union, chitosan and chitosan hydrochloride remain approved as basic substances for plant protection, with ongoing review and potential renewal under current implementing regulations and recent scientific statements. In the United States, there has been a series of petitions to the organic standards body for uses spanning wine processing aids and pesticide applications, culminating in technical reports and subcommittee proposals under active review. These developments matter for commercial planning because they influence whether chitosan can be positioned as a nonsynthetic input in organic systems, how quickly new agricultural products can reach market, and what documentation burden suppliers must carry to serve regulated end markets. Companies that invest early in regulatory-grade documentation and application testing are better positioned to capture premium segments once approvals or clarifications land.
Demand-side behavior is shifting among both enterprises and end consumers. In agriculture, regenerative farming practices are encouraging adoption of chitosan-based seed treatments and bio-stimulants that support crop defense and nutrient efficiency, particularly where growers seek reduced reliance on synthetic inputs. In cosmetics and personal care, demand continues to favor biopolymers with perceived sustainability and skin compatibility benefits. In pharmaceutical and biomedical contexts, interest is growing around wound care, drug delivery, and functionalized derivatives that can be engineered for specific biological interactions. Across these channels, purchasing decisions are increasingly influenced by specification reliability, source transparency, and application performance, which rewards suppliers with strong technical service capabilities and validated use-case data.
Supply chain and cost structure dynamics remain central to margin outcomes. Because chitosan is predominantly extracted from marine shellfish exoskeletons as a byproduct of the global seafood processing industry, supply availability is influenced by crustacean aquaculture and capture fisheries volumes. This structure creates a strategic tension: producers benefit from byproduct economics, but they also inherit variability in feedstock quality, regional processing capacity, and season-dependent supply. As a result, cost competitiveness increasingly depends on upstream integration, purification efficiency, and the ability to secure consistent raw material streams. The emerging insect-derived route offers an alternative supply logic that may reduce dependence on marine channels over time, though commercial scale, cost parity, and customer acceptance are still being validated.
Competitive Landscape and Strategic Positioning
The competitive set spans industrial-scale marine-sourced producers, specialized pharmaceutical and biomedical formulators, regional agricultural solution providers, and emerging alternative-source innovators. Leadership patterns suggest three strategic archetypes.
Scale producers with grade breadth have built advantage through high-purity output across pharmaceutical, food, and agricultural grades, supported by industrial-scale processing and established export channels. Firms in this group typically compete on consistency, documentation, and breadth of grade offerings, allowing them to serve multiple application verticals from a shared processing base. Their strategic edge lies in converting byproduct availability into a broad commercial portfolio while maintaining quality systems that meet regulated end markets.
Specialists in purity and application focus concentrate on cosmetic, pharmaceutical, and medical uses with customized formulations. These players often differentiate through tight control of molecular properties, tailored product development, and close engagement with downstream formulators. Their value proposition is less about volume dominance and more about specification precision, technical support, and regulatory readiness for sensitive applications. In a market where performance requirements differ sharply by end use, this focused model can command higher value capture per unit of output.
Application-oriented and regionally anchored players are expanding the commercial frontier through targeted product launches and distribution partnerships. In agriculture, chitosan-based seed treatments and bio-stimulants have been introduced for regenerative farming, supported by regional rollouts that address specific crop systems and farming practices. In parallel, some producers are pursuing distribution partnerships to broaden availability in emerging markets, where access and channel development can be as important as product performance. These moves reflect a market in which application value, local support, and supply reach increasingly determine competitive success.
The landscape is evolving along both consolidation and fragmentation axes. Consolidation pressure exists where scale, regulatory documentation, and cost discipline create advantages for larger processors, especially in marine-sourced commodity grades. At the same time, fragmentation persists in specialized biomedical grades, alternative-source production, and application-specific agricultural formulations, where capital intensity is lower but technical expertise and market access are decisive. New entrants are most likely to succeed by targeting unmet specification needs, sustainable source narratives, or regulated use cases that require dedicated development and compliance support. Recent product introductions in inhaled delivery, clean-label ranges, and agricultural bio-stimulants illustrate how targeted launches can open distinct commercial lanes without requiring dominance across the entire market.
Strategic Outlook for 2026–2032
Looking ahead, several trends are likely to shape value creation opportunities over the next three to five years.
Regulatory clarity will unlock application expansion. As organic classification discussions and plant protection reviews progress, the market is likely to see clearer boundaries for chitosan use in crop production and processing. If classification moves in favor of nonsynthetic status in key jurisdictions, agricultural and organic-market demand could accelerate, and suppliers with compliant documentation and application data will be first in line to capture that expansion. The main uncertainty is timing and final scope, since regulatory outcomes can vary by region and by specific use category.
Source diversification will move from option to strategic necessity. Traditional marine dependency will continue to create feedstock volatility, while insect-derived and other alternative pathways will gain traction where sustainability claims, allergen considerations, or supply resilience are priorities. Over the forecast period, the strategic question is not whether alternative sources will grow, but which applications will adopt them first and at what cost premium. Producers that can offer both marine and non-marine options, or that can secure reliable alternative feedstock streams, will have stronger negotiating positions with customers seeking supply continuity.
High-value applications will increasingly define the growth mix. Water treatment, cosmetics, pharmaceutical and biomedical use, food and beverages, and agriculture each bring different specification requirements and margin profiles. In the coming years, the fastest value accumulation is likely to occur where chitosan is positioned as an engineered input rather than a bulk additive, particularly in biomedical delivery systems, targeted agricultural formulations, and specialty cosmetic ingredients. This shift will reward companies with strong R&D, application testing, and customer co-development capabilities, while pressuring generic producers to compete primarily on cost and availability.
Potential risks and uncertainties should be factored into planning. Feedstock variability can disrupt purity consistency and cost assumptions, especially when seafood processing cycles change. Regulatory processes can move slower than anticipated, or result in narrower approvals than hoped, affecting near-term commercialization plans. Alternative-source technologies may face scaling challenges, cost gaps, or customer acceptance hurdles before reaching meaningful share. Finally, as concentration remains moderate, price competition in commodity-grade segments can compress margins if differentiation is weak.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align grade strategy with application economics. Investing in reproducible specification control, regulatory documentation, and application-specific technical service will create more durable positioning than competing solely on volume. Where possible, building flexibility across source options and purification pathways can reduce exposure to marine feedstock variability and open new customer segments.
For investors, the most attractive exposure is likely to come from companies with clear application anchors, defensible purity or formulation capabilities, and credible routes to regulated markets. Due diligence should focus on feedstock resilience, specification consistency, regulatory readiness, and the credibility of application claims in high-value segments such as biomedical delivery, regenerative agriculture, and specialty cosmetics. It is equally important to assess whether growth expectations rely on generic volume expansion or on differentiated use cases with stronger pricing power.
Worldwide Chitosan for Water and Waste Treatment Market
For procurement and sourcing leaders, specification transparency and supply reliability should be weighted alongside price. Given raw material linkages and the increasing importance of grade specificity, multi-source strategies and supplier qualification based on documented purity, contamination controls, and application support can reduce risk. Where organic certification, allergen sensitivity, or sustainability claims matter for downstream markets, sourcing decisions should account for source origin, processing method, and compliance documentation rather than treating chitosan as a uniform input.
PW Consulting
As the market moves through this phase of regulatory evolution, source diversification, and application specialization, the ability to act on detailed segment-level intelligence becomes a competitive advantage. For teams that need deeper segmentation data, regional dynamics, and customized strategic scenarios, the full research report provides additional detail to support planning and execution.
For detailed analysis of this topic, please visit the official page: Chitosan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind Band Saw Blades Market's 5.5% CAGR Growth to 2032
By PW Consulting, 2026-09-21
Band Saw Blades Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context and Core Challenges
The global band saw blades market has demonstrated steady expansion over the past half-decade, with revenue valued at approximately USD 1.75 billion in 2025 and a projected trajectory toward the USD 2.5 billion range by 2032. This growth reflects a compound annual growth rate of roughly 5.5 percent, signaling a mature yet resilient sector that continues to attract capital and innovation. The market’s size is supported by broad industrial activity, yet its progression is not uniform across all applications or geographies. Instead, the sector is navigating a set of structural inflection points that will determine which participants capture disproportionate value in the coming years.
One of the most pressing challenges lies in raw material volatility. High-carbon strip steel remains the foundational input for the majority of band saw blades, and its pricing is deeply tied to global steel supply dynamics. When alloy availability tightens or energy costs shift, producers face margin compression that can quickly erode pricing power. This vulnerability is compounded by the fact that advanced blade formulations, particularly those incorporating carbide tips or specialized bi-metal constructions, rely on high-speed steel alloys whose supply chains have shown periodic disruption. Manufacturers that fail to secure forward contracting strategies or diversify alloy sourcing risk being forced into reactive pricing models that undermine long-term profitability.
A second challenge centers on regulatory and compliance complexity. Safety and quality standards in North America and Europe increasingly require periodic inspection, tension testing, and documented quality control protocols. ISO 9001 certification has become a baseline expectation for manufacturers operating in precision metal cutting, while European CE marking compliance ensures that blades meet industrial safety requirements for metal processing equipment. These mandates are not merely bureaucratic hurdles; they shape procurement decisions, increase the cost of market entry, and create a barrier that favors established players with robust documentation and testing infrastructure. At the same time, they open a subtle window for suppliers who can position compliance as a value-added service rather than a pure cost.
Circular Saw Blades Market
A third challenge is the tension between consolidation and niche specialization. The market exhibits notable concentration, with the top three participants accounting for a substantial share of revenue and the top five extending that dominance further. This structure suggests that scale, distribution networks, and brand trust remain powerful moats. Yet it also indicates that the competitive center of gravity is shifting toward differentiated product architectures, application-specific blade designs, and service-integrated offerings. Companies that compete solely on price in commoditized segments face margin erosion, while those that engineer blades for particular material hardness, cut speed, or vibration profiles are building defensible positions. The industry is thus at a crossroads where scale alone will not guarantee advantage, and specialization must be executed with operational discipline.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Breakthroughs
Innovation in blade geometry, tooth design, and material composition is reshaping performance expectations across metal fabrication, woodworking, and specialized industrial applications. Bi-metal constructions continue to anchor the largest share of product revenue, benefiting from their balance of toughness and edge retention. However, the most consequential advances are appearing in carbide-tipped formulations and optimized tooth profiles that extend blade life in high-production environments and reduce downtime in continuous cutting operations. Recent product launches and catalog updates from leading manufacturers underscore this trajectory. In early 2026, one of Europe’s largest blade producers presented new sawing solutions at a major industry fair in Hamburg, signaling continued investment in next-generation cutting performance. Shortly afterward, another European specialist released an updated product catalog featuring new carbide-tipped band saw blades, reinforcing the shift toward harder-wearing, application-tailored designs. Earlier in 2025, a notable milestone highlighted the upper limit of blade capability when a premium bi-metal blade was selected for use on the world’s largest band saw, with a workpiece capacity exceeding five meters. This deployment illustrates how blade engineering is extending into extreme-scale industrial settings where reliability and dimensional stability are paramount.
PW Consulting
The practical implication for buyers and manufacturers is that performance differentiation is increasingly measurable. Reduced changeover frequency, consistent cut quality across varying material hardness, and resistance to premature tooth wear translate directly into lower total cost of ownership. Suppliers that can validate these claims through documented field performance and application engineering support are gaining preference in procurement processes that once prioritized unit price alone.
Policy and Regulatory Environment
Regulatory frameworks are influencing both product design and market access. Mandatory periodic inspection and tension testing protocols, alongside ISO 9001 and CE compliance expectations, create a compliance layer that affects how blades are specified, sourced, and maintained. These requirements are not uniform across regions, which means multinational operators must navigate a patchwork of standards while maintaining consistent quality. At the same time, safety-driven procurement criteria are becoming more explicit. Plants that operate high-tension or high-capacity sawing equipment are increasingly tying blade purchases to documented conformity and traceability. This environment rewards manufacturers that have built quality management systems into their production workflows and can provide clear evidence of batch consistency, material traceability, and mechanical performance under standardized testing conditions.
For suppliers, the regulatory landscape is a double-edged sword. It raises the cost of participation but also creates a structural preference for proven providers. The companies that treat compliance as a core capability rather than a back-office function are better positioned to win contracts in regulated environments and to expand into markets where safety documentation is a prerequisite for vendor approval.
Demand-Side Shifts in Industrial and Commercial Applications
Demand is being reshaped by the way manufacturers and fabricators approach throughput, material efficiency, and equipment utilization. In metal working, the push for higher productivity in structural steel, super alloys, and heavy-section cutting continues to favor blades that maintain cutting accuracy over extended runs. In wood working and food-related applications, the emphasis leans toward clean cuts, reduced material waste, and blades that perform reliably under variable conditions. Across these segments, procurement teams are increasingly evaluating blades through the lens of total operating cost rather than sticker price. This shift is reinforced by the reality that blade changes, re-tensioning, and unplanned downtime carry significant indirect costs in high-volume production settings.
Worldwide Welded Band Saw Blades Market
A further demand-side dynamic is the growing preference for suppliers that can offer application-specific guidance. Fabricators handling high-strength steels or composite-heavy workpieces often require blades with tailored tooth geometry and hardness profiles. When manufacturers provide technical support, selection assistance, and documented cut recommendations, they reduce the risk of suboptimal blade choice and create a relationship anchor that extends beyond transactional purchasing. This trend is especially relevant for mid-sized fabricators that lack in-house metallurgy expertise but still need consistent performance from their cutting equipment.
Supply Chain and Cost Structure Pressures
Cost structures in the band saw blades market are being redefined by raw material volatility and the economics of advanced alloy usage. High-carbon strip steel pricing remains sensitive to global supply conditions, and fluctuations in high-speed steel alloys continue to affect production costs for advanced blades. These pressures are prompting producers to revisit procurement timing, inventory buffering, and manufacturing yield. The companies that are managing cost effectively are not simply passing price changes through to customers; they are investing in process optimization, reducing scrap rates, and aligning blade design with material availability in ways that preserve margin without sacrificing performance.
Supply chain resilience is also becoming a competitive consideration. Procurement departments in metal fabrication and industrial machining are increasingly aware that blade availability, consistent batch quality, and predictable delivery schedules matter as much as the blade itself. Suppliers that can demonstrate stable lead times and transparent sourcing for critical inputs are gaining trust in environments where production continuity is a top priority. This dynamic is gradually shifting the basis of competition from purely technical specifications to a broader reliability equation that includes material security and service responsiveness.
Competitive Landscape and Leading Strategies
Differentiating Through Product Architecture and Application Focus
The competitive field is populated by a mix of established European and North American manufacturers, with a growing presence from specialized producers in Central and Eastern Europe and Asia. Several leading companies have built their positioning around distinct product architectures and application expertise. One European leader stands out for its scale, global sales network, and focus on precision metal-cutting blades, consistently showcasing solutions at major industry events and securing high-profile deployments in extreme-capacity sawing environments. Another prominent North American manufacturer emphasizes premium bi-metal construction and optimized tooth geometry across metal, wood, plastics, and composites, appealing to users who value versatility and documented performance. A third U.S.-based producer concentrates on heavy structural steel, super alloys, and high-production applications, pairing American-made manufacturing with carbide-tipped tools designed for demanding metallurgical conditions.
German and Swedish specialists further enrich the landscape by emphasizing carbide-tipped and bi-metal designs for industrial metal and construction materials, as well as trimetal and bi-metal blades for heavy-duty cutting with specialized series engineered for difficult materials. Czech and U.S. manufacturers round out the field with bimetallic and wood-cutting options, plus full-line industrial blades that cover both bi-metal and carbide-tipped variants. Chinese producers focusing on bi-metal blades for high-strength steel are also part of the equation, offering capacity and cost-oriented alternatives for specific industrial applications. Together, these participants illustrate a market where differentiation is achieved not through a single formula but through a combination of material strategy, tooth design, production location, and application storytelling.
Strategic Positioning and Evolving Market Structure
The strategic positioning of leading players reflects a clear split between scale-driven distribution and performance-driven specialization. Larger, globally networked manufacturers leverage broad catalogs, established service channels, and event-based visibility to maintain brand prominence and capture share across multiple industrial segments. Their advantage lies in reach, consistency, and the ability to serve multinational procurement requirements. Smaller or regionally anchored specialists, by contrast, often compete by deepening expertise in particular material classes, cutting conditions, or end-use scenarios. This can include precision-focused metal cutting, heavy structural steel, or niche wood and composite applications where tailored geometry and hardness profiles deliver measurable gains.
The market structure appears to be evolving along two parallel paths. Consolidation pressure remains real, given the concentration of revenue among the top participants and the compliance and scale advantages that favor established players. At the same time, there is room for differentiation and selective fragmentation when suppliers can prove that application-specific engineering reduces total cost of ownership. New entrants and regional producers are most likely to succeed when they bring a clear technical claim, a defensible cost position, or a service model that addresses a gap in the incumbent offering. Pure price competition in undifferentiated segments, however, is increasingly unsustainable as raw material volatility and compliance costs raise the floor for viable operations.
Recent activity reinforces these strategic patterns. Trade fair presentations and catalog updates in 2025 and early 2026 show that leading manufacturers are continuously refreshing their portfolios and using industry events to signal innovation and application breadth. The emphasis on carbide-tipped expansions, bi-metal optimization, and high-capacity deployments suggests that the competitive conversation is moving toward performance validation, material handling capability, and the ability to support demanding cutting environments.
Forward Outlook: Trends and Opportunities for the Next Three to Five Years
Based on current market dynamics and the trajectory of product development, three trends are likely to shape the band saw blades market through the latter half of the decade.
-
Application-specific blade engineering will become a mainstream purchasing criterion. As fabricators and machining operations place greater weight on total cost of ownership, blades that are optimized for particular material hardness, section size, or production rhythm will gain preference. The opportunity lies in pairing technical claims with field-validated performance data, selection guides, and application support that reduce the risk of suboptimal blade choice. Suppliers that institutionalize this capability will be better positioned to command value in segments where cutting efficiency and blade life directly affect throughput.
-
Material security and cost management will separate durable performers from reactive price-takers. Continued volatility in high-carbon strip steel and high-speed steel alloys will keep cost structures under pressure. Companies that strengthen forward sourcing, improve yield, and align product design with material availability will be more resilient. The commercial opportunity is to convert this resilience into reliable delivery and consistent quality, which are increasingly valued by procurement teams focused on production continuity.
-
Compliance and quality documentation will function as both a barrier and a differentiator. Standards related to inspection, tension testing, ISO 9001, and CE conformity are likely to remain salient, especially in regulated industrial environments. Suppliers that embed quality systems into production and can provide clear evidence of batch consistency and safety conformity will find it easier to win vendor approvals and expand into markets where documentation is a prerequisite. The risk is that companies with weaker documentation infrastructure will face slower access to certain procurement channels, even if their base product performance is adequate.
These trends point to a market where opportunity is concentrated in performance validation, material resilience, and application service. At the same time, uncertainty remains in the pace of raw material price swings, the potential for further regulatory tightening, and the risk that overcapacity in commoditized segments could pressure margins if differentiation fails to keep pace. Participants should therefore monitor not only product innovation but also supply chain strategy and compliance readiness as interconnected drivers of long-term competitiveness.
Strategic Actions for Decision-Makers
For manufacturers and brand leaders, the priority is to convert technical differentiation into measurable customer value. This means investing in application-specific blade designs, documenting performance under realistic cutting conditions, and aligning sourcing and manufacturing processes to absorb raw material volatility without compromising quality. Companies that can demonstrate extended blade life, consistent cut quality, and reliable delivery in demanding metal, wood, and food-related applications will strengthen their position against both established rivals and cost-oriented entrants. It is equally important to treat compliance infrastructure as a strategic asset, using quality certification and safety documentation to widen access to regulated procurement channels.
For investors evaluating the sector, the analytical focus should center on companies that combine defensible product architecture with supply chain discipline and a clear application narrative. Scale and distribution matter, but the more durable advantages are likely to accrue to players that can maintain margin through material cost cycles, prove performance in high-production environments, and serve procurement teams that prioritize total operating cost over unit price. Portfolio exposure should also account for the balance between consolidated leaders and specialized contributors, since the market is being shaped by both concentration dynamics and pockets of application-driven differentiation.
For procurement and operations leaders, the most effective approach is to evaluate band saw blades through a broader cost-and-risk lens. Specification decisions should consider blade life, changeover frequency, tension and inspection requirements, and the availability of technical support for material-specific selection. Where cutting operations handle high-strength steels, super alloys, or variable wood and composite conditions, partnering with suppliers that provide application guidance and consistent batch quality can reduce downtime risk and improve predictability. It is also prudent to build sourcing strategies that account for raw material volatility and compliance documentation, ensuring that supplier selection reflects both performance and operational resilience.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, product splits, and company-specific positioning, the full research report provides a more granular foundation for planning. Detailed breakdowns of type, application, and regional revenue, along with expanded competitive profiles and recent development timelines, can support more precise segmentation, pricing strategy, and outlook modeling. In a market where advantage increasingly depends on product specificity, material resilience, and compliance readiness, access to structured, granular intelligence can sharpen decision-making and reduce the risk of acting on incomplete signals.
For detailed analysis of this topic, please visit the official page: Band Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
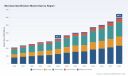
Navigating the Microbial Identification Market: Strategic Trends and Commercial Opportunities Through 2032
The microbial identification market has entered a decisive growth phase, transitioning from a specialized laboratory tool to an essential operational capability across healthcare, pharmaceutical quality control, food safety, and environmental monitoring. Valued at USD 212.0 million in 2020, the market expanded steadily to USD 327.2 million by 2025, reflecting a compound annual growth rate of 9.07 percent projected through 2032. At that trajectory, revenue is expected to surpass the USD 600 million threshold by the end of the forecast window. This expansion is not merely a function of incremental laboratory adoption; it signals a structural shift in how organizations detect, classify, and respond to microbial threats and quality deviations.
The momentum is sustained by converging pressures. Rising antimicrobial resistance, tightening regulatory expectations for contamination control, and the growing economic cost of delayed or inaccurate identification have elevated microbial identification from a discretionary upgrade to a core compliance and risk-mitigation function. At the same time, the market remains relatively fragmented. The top three players account for approximately 24.6 percent of total revenue, while the top five hold 26.2 percent, indicating that scale advantages exist but have not yet produced a consolidated oligopoly. This concentration profile leaves meaningful room for differentiated positioning, regional expansion, and technology-led disruption.
Key Challenges and Inflection Points
Despite the clear growth trajectory, several structural challenges are reshaping how participants compete and how end users evaluate solutions. The first challenge lies in the widening performance gap between centralized reference laboratories and decentralized point-of-need settings. Traditional identification workflows still struggle with turnaround time, sample preparation complexity, and database limitations when confronting rare, fastidious, or rapidly evolving pathogens. Organizations that require same-day decisions in clinical, manufacturing, or field environments are increasingly unwilling to accept multi-day turnaround cycles, forcing vendors to balance analytical depth with operational simplicity.
A second inflection point centers on regulatory and reimbursement alignment. Regulatory clearance, quality management certification, and coding mechanisms for test reimbursement are no longer peripheral compliance issues; they directly shape market access, purchasing confidence, and the economic viability of new systems. As diagnostic and quality-control workflows become more automated and integrated, ambiguous reimbursement pathways or inconsistent certification expectations can slow adoption, even when the underlying technology is mature. Participants that treat regulatory strategy as an afterthought risk losing momentum to competitors who design clearance, documentation, and billing alignment into their product roadmaps from the outset.
A third challenge emerges from data usability and workflow integration. Identification is only valuable when it feeds timely decisions. Laboratories and production environments increasingly expect systems that not only classify organisms but also connect results to downstream actions, such as antibiotic stewardship decisions, batch release judgments, or environmental corrective measures. Vendors that deliver isolated identification outputs without interoperable software, standardized reporting, or scalable database updates are seeing their solutions marginalized in consolidated laboratory ecosystems. The market is therefore moving from a hardware-centric evaluation toward a total-workflow assessment.
Key Drivers of Market Change
Technological Innovation and Analytical Performance
Technology advancement remains the most visible driver of adoption. Modern identification platforms are increasingly judged on speed, accuracy across difficult organism classes, and the ability to scale database coverage without sacrificing reproducibility. In clinical and industrial settings, this means systems must handle gram-positive and gram-negative bacteria, anaerobes, yeasts, mycobacteria, molds, and resistant pathogens with consistent confidence. The competitive edge is shifting toward solutions that combine reliable spectral or molecular discrimination with streamlined sample handling and high-throughput software workflows.
Recent product developments illustrate this direction. In March 2025, bioMérieux received FDA 510(k) clearance for its VITEK COMPACT PRO ID/AST system, designed to support rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. The launch reflects a broader push toward integrated identification and susceptibility workflows that compress turnaround time while preserving interpretive value for treatment and quality decisions. Later in the year, Bruker expanded its FDA-cleared portfolio by securing clearance for additional claims on the MALDI Biotyper CA System, extending the cleared reference library to 549 species and introducing workflow-oriented software and shuttle capabilities intended to improve laboratory throughput. These developments matter because they show two distinct but converging strategies: one emphasizing integrated ID/AST utility for routine lab operations, the other expanding organism coverage and workflow efficiency for high-volume identification environments.
Pathogen Detection Market
Regulatory and Policy Environment
The regulatory landscape is becoming a defining commercial variable. In the United States, FDA 510(k) clearance for microbial identification tests has growing practical significance because it can enable reimbursement pathways through CPT codes, directly affecting the economics of test adoption in clinical settings. This linkage between clearance and reimbursement is changing how laboratories evaluate new systems. A technically capable platform that lacks clear regulatory status or documented quality-system certification may face longer procurement cycles, more conservative pilot decisions, or limited budget allocation.
Beyond clearance, quality management expectations continue to shape procurement in medical-grade applications. ISO 13485 certification has become a baseline expectation for systems intended for medical use, influencing buyer confidence in consistency, risk management, and post-market support. At the same time, regulatory momentum around antimicrobial stewardship is reinforcing demand for faster and more reliable identification in clinical environments, where earlier organism characterization can support more targeted therapy and reduce unnecessary broad-spectrum use. For manufacturers, this means regulatory strategy is no longer a documentation exercise; it is a market-access lever that affects sales cycles, customer confidence, and the speed at which new features can be commercialized.
Demand-Side Shifts Across End-Use Segments
Demand is expanding beyond traditional diagnostic laboratories. Pharmaceutical manufacturing quality control continues to drive consistent adoption, as contamination events carry steep consequences in terms of batch loss, investigation cost, and regulatory exposure. In this environment, identification is not simply a scientific exercise; it is part of a containment and root-cause workflow that must be fast, traceable, and repeatable. Food safety and environmental monitoring represent additional demand centers, where organizations increasingly need to detect and identify contaminants before they escalate into recalls, site closures, or compliance breaches.
Behaviorally, purchasers are shifting from isolated instrument evaluation toward workflow-level purchasing. Laboratories and quality teams want systems that fit existing staffing models, reduce manual touchpoints, and produce results that integrate with laboratory information systems or quality management processes. This is especially relevant in settings where skilled microbiologists are in short supply or where throughput demands exceed the practical capacity of legacy methods. As a result, adoption decisions increasingly weigh database breadth, software usability, and the ability to standardize identification across multiple sites or shifts.
Supply Chain and Cost Structure Dynamics
Cost structures are being reconsidered across the value chain. The operational burden of microbial identification is no longer limited to instrument acquisition; it includes consumables, database access, calibration and maintenance, training, and the hidden cost of delayed results. In many organizations, the true cost comparison between methods depends on total turnaround time, error rates, and the downstream impact of misidentification or inconclusive results. This has increased interest in platforms that reduce hands-on time and minimize repeat testing, even when upfront instrument economics appear less advantageous.
Supply chain resilience is also influencing procurement strategy. Organizations operating across multiple geographies or managing critical production processes are more cautious about dependence on single-source consumables or proprietary workflows that are difficult to scale during disruptions. That caution is encouraging interest in systems with robust support networks, predictable consumables availability, and software architectures that can be updated without repeated hardware replacement. For vendors, this environment rewards transparent total-cost narratives and dependable service models as much as it rewards analytical performance.
Competitive Landscape and Leading Strategies
The competitive landscape reflects a market where performance, regulatory readiness, and workflow design are being used to carve out defensible positions rather than compete solely on price. Bruker Corporation, based in Billerica, Massachusetts, has emphasized the MALDI Biotyper CA System as a focused offering for microbial identification, with FDA-cleared MALDI-TOF mass spectrometry intended to support rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. Its associated MBT Compass HT CA software is positioned to improve workflow efficiency, an increasingly important consideration for laboratories handling high sample volumes or seeking to reduce manual bottlenecks. Bruker’s recent expansion of cleared claims and reference library coverage suggests a strategy centered on broadening organism coverage and strengthening the practical usability of the system in cleared-use settings.
bioMérieux, headquartered in Marcy-l’Étoile, France, has taken a different but complementary approach, emphasizing integrated identification and susceptibility testing through its VITEK MS PRIME and VITEK COMPACT PRO systems. Its FDA 510(k)-cleared MALDI-TOF and automated ID/AST offerings are designed for both clinical and industrial microbial identification, with expanded databases that address mycobacteria, molds, and resistant pathogens. The company’s emphasis on combined ID/AST functionality reflects a strategy aimed at environments where identification is only one step in a broader decision chain, particularly where antibiotic stewardship, infection control, or quality release decisions depend on timely susceptibility information alongside organism identification.
Microbial Air Samplers Market
The strategic differentiation between these leaders is instructive. One approach prioritizes broad organism coverage and workflow efficiency for identification-intensive operations. The other emphasizes integrated clinical and industrial utility, linking identification more tightly to downstream interpretation and action. Both strategies address real buyer priorities, but they appeal to different purchasing rationales. In practice, this means competition is increasingly segment-specific: laboratory types, throughput profiles, organism mix, and regulatory requirements all influence which value proposition is more compelling.
PW Consulting
Market Structure and Evolution
Market concentration remains moderate, leaving the industry in a phase where scale matters but does not yet dictate outcomes. That structure favors companies that can combine credible technology, clear regulatory positioning, and strong application-specific messaging. It also leaves space for regional players and niche entrants that can serve localized demand, specialized organism panels, or specific compliance environments more flexibly than larger platforms. Over time, the market is likely to move toward selective consolidation, but not uniformly. Consolidation will probably be driven by workflow integration, database stewardship, and service-network economics rather than by instrument pricing alone.
New entrants and technology shifts will continue to test incumbents, especially where identification can be embedded into broader diagnostic, quality, or environmental monitoring ecosystems. However, entry barriers remain meaningful because practical adoption depends on more than analytical promise. Buyers look for cleared or certified status where applicable, established database maintenance, predictable consumables supply, and integration with existing laboratory or manufacturing workflows. As a result, the most durable competitive advantage will belong to organizations that treat identification as an end-to-end capability rather than a standalone instrument sale.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends is the continued compression of identification workflows into faster, more decision-ready formats. Laboratories and quality teams are unlikely to accept longer turnaround times simply because a method is familiar. The demand for same-day or near-real-time identification will keep pushing platforms toward higher throughput, simpler sample handling, and software that reduces interpretation burden. Commercially, this trend favors vendors that can demonstrate measurable workflow gains, not just incremental accuracy improvements.
A second trend is the growing importance of database depth and updateability as a competitive asset. As pathogen populations evolve and industrial contamination profiles become more diverse, static identification libraries will become less valuable than actively maintained, expandable databases. Organizations will increasingly evaluate whether a vendor can sustain coverage for emerging or less common organisms, support regional variation in microbial profiles, and deliver updates without disrupting operations. This shifts competitive advantage toward companies with strong bioinformatics, curation processes, and customer-support infrastructure.
A third trend is the alignment of identification solutions with stewardship and risk-management objectives. In clinical settings, faster identification supports antimicrobial stewardship by enabling more informed therapy decisions earlier in the care pathway. In pharmaceutical, food, and environmental contexts, identification increasingly supports contamination response, root-cause analysis, and compliance documentation. Solutions that connect identification results to actionable downstream workflows are likely to gain preferential consideration because they reduce the operational gap between result generation and decision implementation.
These trends create tangible commercial opportunities. Vendors can capture share by packaging identification with workflow software, database services, and support models that reduce total operating burden. Procurement teams can lower risk by prioritizing systems that align with their organism mix, throughput needs, and regulatory context rather than choosing on instrument specifications alone. Investors and strategic partners should pay attention to companies that demonstrate not only technical credibility but also the ability to navigate clearance, certification, reimbursement alignment, and multi-site deployment. At the same time, uncertainty remains. Reimbursement pathways can shift, regulatory expectations can tighten, and adoption can slow if workflow integration proves more difficult than anticipated. Database maintenance costs, training demands, and consumables availability may also influence the realized pace of growth, especially in cost-sensitive or resource-constrained environments.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Product strategy should be built around total workflow value rather than identification performance in isolation. That means prioritizing database curation, software usability, service reliability, and regulatory readiness as core commercial assets. Where applicable, clearance and certification should be treated as enablers of market access and purchasing confidence, not as optional compliance milestones. Companies should also define their positioning by application context, since clinical, pharmaceutical, food safety, and environmental buyers evaluate risk, turnaround, and integration needs differently.
Go-to-market execution should emphasize predictable operating economics and demonstrable time-to-result benefits. In fragmented markets, regionalized support, site-level deployment expertise, and clear documentation can be as influential as product features. Manufacturers that can show how identification reduces repeat testing, shortens investigation cycles, or supports stewardship and quality decisions will have stronger leverage in competitive evaluations.
For Investors and Strategic Partners
Investment theses in this space should account for more than top-line growth rates. Sustainable value creation depends on regulatory positioning, database and software stewardship, service economics, and the ability to serve multiple end-use segments without diluting focus. Because market concentration is moderate, there is room for both scaled incumbents and specialized players, but long-term winners are likely to be those that can convert technological capability into repeatable deployment and customer retention.
Partners should also monitor where identification is becoming embedded into broader workflows. Opportunities may arise not only in instrumentation but also in middleware, data interpretation, quality documentation, and support services that make identification results more actionable. Conversely, exposure to segments with unclear reimbursement, weak service infrastructure, or limited regulatory alignment may carry higher execution risk.
For Procurement, Laboratory, and Quality Leaders
Purchasing decisions should begin with the operational problem rather than the instrument category. Define the required organism coverage, acceptable turnaround time, staffing constraints, and integration needs before evaluating vendors. In many cases, the more relevant comparison is not instrument price but total workflow impact, including hands-on time, repeat testing, database relevance, and the reliability of ongoing support.
Where regulatory compliance and reimbursement affect adoption, confirm clearance status, certification expectations, and coding implications early in the evaluation process. Also assess whether the solution can be deployed consistently across multiple sites or shifts, since standardization often determines whether identification capabilities deliver enterprise value or remain confined to a single high-performing unit.
Conclusion
The microbial identification market is expanding under the influence of clearer regulatory expectations, stronger demand for faster and more actionable results, and a competitive field that is increasingly rewarding workflow-integrated solutions. Growth to the USD 600 million range by 2032 is plausible, but the commercial winners will be determined by how effectively organizations translate analytical capability into reliable, compliant, and decision-ready operations. For executives, investors, and procurement leaders, the strategic priority is to look beyond specifications and evaluate how identification solutions fit into the broader economics of risk reduction, throughput, and stewardship. For those seeking a more detailed view of segment-level demand, regional dynamics, and vendor-specific positioning, the full market research report provides the deeper breakdown needed to shape execution plans with greater confidence.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Strategic Shift Reshaping the PCB Design Software Market
The electronic design automation landscape supporting printed circuit board development has entered a period of accelerated structural change. Between 2020 and 2032, the global market for PCB design software is projected to expand from roughly $2.17 billion to $10.11 billion, reflecting a compound annual growth rate of 13.7 percent. This trajectory rests on more than steady hardware shipment growth. It signals a fundamental recalibration of how electronic systems are conceived, simulated, validated, and handed off to manufacturing. Market participants that treat PCB design tools as generic utility licenses are misreading the market. The value is shifting toward integrated workflows, simulation depth, ecosystem interoperability, and the ability to compress design cycles without sacrificing signal integrity or compliance readiness.
Two inflection points define the current moment. First, design complexity is outrunning legacy toolchains. Modern PCBs routinely combine multi-layer stacks, high-speed serial interfaces, power delivery networks, and embedded sensing functions. Engineers increasingly need a single environment where schematic capture, layout, 3D mechanical clearance, and electromagnetic or thermal simulation can be iterated without file translation loss or versioning friction. Second, the gap between premium enterprise platforms and accessible open-source or entry-tier tools is widening in capability, but narrowing in expectation. Free and community-driven suites have matured enough to influence feature roadmaps and pricing expectations, forcing commercial vendors to justify their cost through workflow efficiency, collaboration, and verification depth rather than basic drafting functions.
The markets leadership structure remains moderately fragmented, with the top five vendors collectively accounting for less than 30 percent of revenue and the top three below a quarter. That fragmentation is both a symptom and an opportunity. It reflects diverse end-market needs, differing regional procurement models, and the persistence of specialized tools for enterprise, mid-market, and hobbyist or startup use cases. It also suggests that consolidation will not arrive through blunt acquisition alone. Value creation will increasingly come from platform breadth, data continuity across design phases, and the capacity to serve regulated industries without forcing every customer into the same deployment model.
Key Drivers Redefining Growth
Technical Innovation Is Moving From Drawing Boards to Verified Systems
The most consequential driver is the migration from drafting-centric workflows to verification-aware design. Tools that bundle schematic, layout, and simulation into integrated suites reduce the rework spiral that historically drained engineering time. In practical terms, earlier signal integrity checks, power distribution analysis, and 3D mechanical co-design shorten feedback loops between electrical, thermal, and mechanical teams. Recent product updates from established vendors have focused on parallel library management, AI-assisted routing aids, and strengthened collaboration features. These improvements are not cosmetic. They address the real bottleneck in modern electronics development: the handoff between design intent and physical realization. When a design team can maintain a synchronized library, run targeted simulations earlier, and resolve clearance or routing conflicts before fabrication, the total engineering cost drops and time-to-market compresses.
At the same time, openness is reshaping expectations. The continued release cadence of mature open-source PCB design suites keeps raising the floor for usability, community libraries, and cross-platform accessibility. That matters commercially because it pressures proprietary vendors to differentiate on integration depth, support, and enterprise-grade assurance rather than on feature availability alone. The presence of capable free or low-cost tools does not eliminate the premium segment; it clarifies it. Buyers who can tolerate more manual coordination may choose accessible suites, while those facing complex signal integrity, large team collaboration, or strict manufacturing data handoffs are willing to invest in environments that reduce coordination risk.
Regulatory And Compliance Pressure Is Becoming A Design Requirement
Regulatory change is no longer a downstream concern. It is influencing how PCB design workflows are configured from the outset. The U.S. Quality Management System Regulation, aligned with ISO 13485:2026, imposes mandatory risk-based design controls, traceability, and documentation requirements on medical device PCB design processes. Effective February 2026, that framework increases the cost of informal or poorly documented design practices in regulated hardware. For software providers, this creates a growing preference for tools that support design traceability, version control, validation records, and audit-ready outputs. The commercial implication is straightforward: electronics entering regulated segments increasingly need design environments that can demonstrate not just what was built, but how decisions were captured and verified.
On the cybersecurity side, the EU Cyber Resilience Act introduces obligations for digital products, including software used in the design and maintenance of connected systems, to address vulnerability handling and security maintenance. Reporting duties for actively exploited vulnerabilities begin in September 2026. For PCB design software vendors and their customers, the practical effect is heightened attention to update cycles, dependency management, and secure handling of proprietary design assets, especially when cloud-linked collaboration or third-party libraries are involved. Compliance is becoming a procurement criterion, not just a legal checkbox.
Demand-Side Shifts Are Accelerating Iteration Cycles
End-market demand is pushing design teams toward faster, more iterative development. In consumer and computing electronics, product refresh cycles and feature differentiation continue to reward designs that can integrate new components while preserving board real estate and thermal margins. In telecommunications, higher bandwidth and denser subsystems raise the stakes for routing discipline and simulation accuracy. Medical devices combine miniaturization with stricter documentation and risk management expectations. Industrial and automotive applications introduce harsh-environment reliability, long product lifecycles, and increasing electronic content per unit. Across these segments, the common thread is the need to reduce late-stage design changes. When design software supports earlier validation and clearer collaboration, engineering teams can absorb more complexity without paying for schedule slip.
Cost Structures And Deployment Preferences Are Shaping Adoption
Cost dynamics are influencing who buys what, and how. Premium enterprise PCB design software subscriptions for leading integrated tools begin at roughly $4,235 per user per year, before training, configuration, and hardware considerations. Advanced design work also depends on capable workstations and experienced engineers, which increases total cost of ownership for smaller organizations and can slow adoption of premium suites. That economic reality reinforces a bifurcated market: enterprise and complex-project users invest in high-capability environments to protect schedule and quality, while smaller teams often blend accessible tools, in-house expertise, and selective simulation or verification services.
PW Consulting
Deployment models remain shaped by data sensitivity. On-premise deployment continues to dominate for PCB design software in aerospace, defense, and automotive sectors because those segments require strict data security and intellectual property protection. This is a durable advantage for vendors that can offer secure, locally controlled workflows with the same feature depth as cloud-enabled alternatives. At the same time, collaboration features and library synchronization are becoming more attractive in less constrained industries, creating a tension that vendors must manage: flexibility versus control, and shared workflow efficiency versus data isolation. The winners will be those that can offer both paths without fragmenting the user experience.
Competitive Positioning And Market Evolution
The competitive landscape is defined less by raw market share than by workflow philosophy and target segment clarity. Altium has maintained a strong identity around an integrated PCB design environment that combines schematic capture, layout, simulation, and collaboration in a single workflow. Its value proposition centers on reducing tool-switching friction and making mid-to-enterprise engineering teams more self-sufficient. Zuken operates with a more tiered platform logic, pairing enterprise-grade solutions for complex subsystem and 3D layout with mainstream PCB design tools and electrical design platforms. That structure lets it serve organizations with varied complexity levels while keeping a hand in both high-end and broader market needs. Siemens EDA brings a portfolio spanning PCB design, layout, simulation, analysis, and verification, aligning naturally with customers who want continuity across design and verification stages and who already value industrial-scale process discipline. Cadence has been advancing AI-enabled PCB design, layout, and analysis through its OrCAD X platform, leaning into the expectation that intelligent assistance can reduce routine load and improve decision quality in complex layouts.
Below the commercial leaders, the market includes open-source and accessible EDA offerings that exert influence through reach, community contributions, and baseline usability. These tools matter strategically because they shape training pipelines, attract new designers, and pressure commercial vendors to justify premium pricing through measurable efficiency gains. They also illustrate that entry barriers in basic PCB design are lower than ever, while barriers in high-performance, high-reliability, and highly regulated design remain substantial. Industry groups are recognizing the skills gap as well. A global electronics association launched an introductory PCB design course in early 2026 focused on layout and schematic skills using EDA tools, signaling that workforce readiness is becoming part of the ecosystem conversation. The practical outcome is a market where capability, training, and certification are increasingly linked, especially for organizations trying to expand design capacity without sacrificing quality.
Electrical Design Software Market
The market structure is evolving along three axes. Integration is deepening where customers face complexity and coordination overhead. Differentiation is sharpening where vendors compete on simulation fidelity, library management, collaboration, and compliance support rather than on feature counts. And new entry pressure persists from open and accessible tools, especially at the lower end of the market and in education and startup segments. Consolidation is possible, but it will likely be selective. Buyers in regulated and high-complexity segments value continuity and support more than brand aggregation. Mid-market and cost-sensitive buyers value flexibility and practical learning curves. The most resilient strategies will be those that align product architecture with actual workflow pain points rather than with headline feature announcements.
Forward Outlook: Three Trends To Watch
The next three to five years are likely to be shaped by three interlocking trends. First, simulation and verification will move earlier and deeper into the design flow. As boards carry more high-speed interfaces, denser power networks, and tighter mechanical constraints, the cost of discovering problems late will keep rising. Tools that enable targeted simulation, earlier signal and power integrity checks, and smoother mechanical co-design will become core purchasing criteria, especially in telecommunications, computing, medical, and automotive-adjacent applications. The commercial opportunity here is not only in selling licenses but in reducing downstream engineering and rework costs. Vendors and service providers that can demonstrate measurable reductions in iteration cycles will have stronger positioning.
Printed Circuit Board Market
Second, compliance readiness will become a more explicit part of tool selection. Regulatory expectations around risk-based design controls, traceability, and documentation in medical devices, along with cybersecurity obligations for digital products and vulnerability reporting, raise the stakes for design environments that support auditable processes and disciplined data handling. Organizations that adopt design workflows with better record-keeping, version discipline, and secure asset handling will be better positioned for regulated market access. Vendors that help customers map tool capabilities to compliance workflows can turn regulatory pressure into a differentiator. The risk, however, is that compliance requirements could slow adoption if tools are perceived as cumbersome or if update and vulnerability management processes are weak.
Third, the market will continue to segment by deployment model and total cost of ownership. On-premise control will remain important in defense, aerospace, and automotive contexts, while cloud-linked collaboration and library synchronization will gain ground where data isolation is less critical and team coordination matters more. At the same time, premium subscription economics will keep challenging smaller firms, reinforcing demand for flexible purchasing, scalable training, and selective use of high-end tools only where complexity justifies them. A third risk lies in the skills pipeline. Advanced tools require capable engineers and adequate hardware. If organizations invest in software but underinvest in training and workstation readiness, adoption will underperform and the perceived value of premium suites will erode.
What Decision-Makers Should Do Now
For hardware manufacturers and design organizations, the strategic priority is to align tool selection with actual complexity and risk rather than with generic feature lists. If a team regularly handles high-speed signals, dense layouts, or regulated documentation, the payoff from integrated design, earlier simulation, and stronger library and collaboration control tends to be higher. If the work is more standard in scope, accessible or mid-tier tools may deliver more efficient use of budget, especially when combined with targeted external verification or training. In either case, it is worth auditing the total cost of ownership: subscription cost, training time, workstation requirements, data security constraints, and the cost of late-stage design changes. Treat software choice as a workflow decision, not a licensing event.
For investors and strategic partners, the opportunity lies in identifying vendors and platform plays that convert workflow friction into measurable efficiency. The most durable value is likely to come from tools and ecosystems that reduce rework, improve traceability, and support both secure and collaborative deployment depending on customer need. Watch for differentiation that is tied to real engineering outcomes: faster convergence, better signal and power integrity handling, smoother handoffs to manufacturing, and clearer compliance support. Be cautious of offerings that compete mainly on price without addressing the coordination and verification gaps that drive cost in complex electronics development. Also monitor the training and workforce dimension, since design tool value is realized only when engineers can use advanced capabilities effectively.
For procurement and technology buyers, the practical move is to evaluate tools against the organization’s regulated exposure, collaboration needs, and internal skill level. Where medical, automotive, or cyber-relevant considerations apply, prioritize environments that can support documentation discipline, traceability, and secure handling of proprietary design data. Where teams are smaller or budget-constrained, test whether a lower-cost toolchain can meet current needs and where its limits will appear as complexity grows. Clarify whether the organization requires on-premise control or can benefit from shared collaboration, and ensure that procurement includes training, deployment configuration, and hardware readiness rather than license cost alone. Detailed segmentation data, vendor-by-vendor capability comparisons, and deployment economics can materially improve these decisions, which is why deeper research and tailored assessments remain valuable for organizations making near-term platform commitments.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


