



Category: market research
PW Consulting: Automated Side Load Trucks to hit USD 3,168.95M by 2032 at 6.42% CAGR
By PW Consulting, 2026-07-13
Automated Side Load Garbage Trucks Market — Strategic Outlook for 2026 Decision-Makers (PW Consulting)
Executive snapshot
PW Consulting’s latest market study on Automated Side Load Garbage Trucks provides a compact, decision-oriented briefing for executives, fleet operators, OEMs, and capital allocators preparing plans for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the analysis shows a market growing at a compound annual growth rate (CAGR) of 6.42%. The industry-wide revenue base reaches approximately USD 2.05 billion in 2025, and our scenarios project material expansion through 2032 as municipalities and private haulers accelerate replacement cycles, electrification pilots, and safety retrofits.
Automated Side Load Garbage Trucks Market
Why this study matters for 2026 strategic choices
- 2026 will be a hinge year: short-term budget cycles collide with longer-term regulatory timetables on emissions and equipment safety. Decisions taken this year will lock in fleet profiles for 7–12 years.
- Capital allocation is shifting from pure vehicle purchases to integrated vehicle-plus-energy and digital-service investments that change total cost of ownership (TCO) profiles.
- Supply-side consolidation has already begun: the top three vendors account for a meaningful plurality of market revenue and the top five approach a clear majority, creating both scale advantages and white-space opportunities for specialist suppliers.
- Operational priorities—route productivity, operator safety, maintenance predictability—are increasingly as important as vehicle acquisition price when evaluating automated side loaders.
Core market dynamics shaping 2026 strategies
Three structural forces dominate near-term strategy:
Automated Side Load Garbage Trucks Market
- Regulatory acceleration: North American and European environmental mandates are tightening emissions and incentivizing low- or zero-emission collection vehicles. At the same time, safety standards require anti-collision sensing, operator presence detection, and emergency override systems—raising the technical bar for next-generation side loaders.
- Technology bifurcation: The market is polarizing between traditional diesel platforms with optimized hydraulics and compaction systems, and electric or gas-adapted platforms that incorporate dedicated energy systems for collection duties. Some manufacturers deploy independent battery systems to power collection functions while remaining chassis-agnostic, which reduces integration risk for municipalities testing electric drive lines.
- Service and retrofit economics: Improved arm design, compaction efficiency, and modular electronics are shifting value to body manufacturers and telematics providers. For many operators, retrofit and aftermarket solutions that extend life and improve safety are becoming higher-return investments than full unit replacement.
Technical realities operators must weigh
Decisions about chassis, body, and control systems are technical decisions with strategic impact. Typical design features to consider in procurement and retrofit planning include:
Automated Side Load Garbage Trucks Market
- Hydraulic systems and lift mechanisms rated for typical residential container ranges and reach envelopes up to industry-standard distances; robustness in compaction (e.g., design compaction loads) is a gating factor for route productivity.
- Independent electric collection systems that allow bodies to function on diesel or electric chassis, simplifying pilots of battery-electric powertrains and reducing vehicle obsolescence risk.
- Mandated safety systems (sensors, operator presence detection, emergency overrides) which alter cab ergonomics and training requirements and can materially change downtime and liability exposure.
Competitive landscape — what the vendor field means for buyers and investors
The automated side loader vendor landscape has a mix of long-established body specialists and nimble niche players. The market exhibits moderate concentration (top three players capture a meaningful plurality; top five approach clear majority), which creates distinct strategic implications:
- Heil Environmental (Chattanooga, TN) — Strengths: full-line automated side loaders with established continuous-pack and electric body variants. Strategic edge in integrated electric body solutions and extended reach arms; ideal partner for fleets seeking turnkey electrified collection bodies while testing chassis electrification. Watch for productization of battery-backed collection modules.
- McNeilus Truck and Manufacturing (Dodge Center, MN) — Strengths: versatile arm designs and modularity across diesel and electric chassis, emphasis on tight-space operation. Competitive posture attractive to large haulers that value route-level flexibility and multiple body-chassis combinations.
- Labrie Enviroquip Group (Quebec) — Strengths: adaptability across manual, semi-automated and fully automated modes. Offers a lower-integration risk path for municipalities wanting staged automation adoption and fallback manual operation during transition windows.
- New Way Trucks (Scottdale, IA) — Strengths: robust lift capacity and under-CDL options; strong appeal to operators focused on payload and compaction performance rather than electrification alone.
- Amrep (California) — Strengths: heavy-gauge wear-plate construction (e.g., Hardox usage) and durability focus; differentiated value proposition where abrasive wear and high cycle applications dominate costs.
- Curbtender Inc. (USA) — Strengths: historical innovator with focused portfolio exclusively on automated side loaders; deep operational know-how and product pedigree dating to the 1970s. Attractive for fleets prioritizing proven designs and field-tested reliability.
- KANN Manufacturing (USA) — Strengths: high-compaction bodies and flexible eject/tip configurations; well positioned where heavy-compaction or specialized disposal workflows are critical.
For suppliers and investors, the market structure favors players who can scale manufacturing efficiencies while adding high-margin services (telematics, maintenance contracts, retrofit kits). For buyers, the vendor set requires a formal scorecard that ranks integration risk, future-proofing (battery compatibility), safety compliance, and aftermarket support.
Strategic playbook for 2026 — recommended actions
Our research translates into a prioritized, actionable playbook for 2026. Below are the top initiatives to operationalize within 90–180 days and the metrics to track.
- Pilot to scale electrification deliberately: Run 12–24 month pilots using body-mounted battery systems before committing to full electric chassis procurements. Track pilot KPIs: route completion rates, duty-cycle energy consumption, and battery availability.
- Adopt a modular procurement standard: Insist on body-chassis decoupling options in RFPs so future chassis swaps are possible without full vehicle replacement. Include clauses for battery interoperability and telematics API access.
- Prioritize safety retrofits: Budget for anti-collision sensors and operator-presence systems as mandatory retrofit items; these reduce liability and are increasingly non-negotiable for compliance.
- Expand aftermarket and retrofit offerings: For OEMs, build higher-margin service contracts around diagnostics, predictive maintenance, and arm-system refresh kits. For investors, target companies offering these recurring revenue streams.
- Use scenarios for CapEx planning: Model TCO under three scenarios (status-quo diesel, hybrid-electric transition, full electrification) to stress-test replacement timing and grant funding impacts.
- Prepare supply continuity playbooks: Given growing demand and moderate concentration at the top, secure long-lead components (hydraulic valves, wear-plate steel, battery modules) via multi-year supply agreements or dual-sourcing strategies.
- Evaluate M&A selectively: Targets that bring telematics, battery-integration IP, or specialized compaction/eject systems offer the fastest path to margin expansion and defensible differentiation.
What the full PW Consulting report delivers (practical contents)
The full study is designed to be immediately actionable for procurement, fleet planning, and corporate strategy teams. Key deliverables include:
- Scenario-based financial models (TCO, CapEx/Opex sensitivity) calibrated to multiple duty cycles and electrification pathways.
- Supplier scorecards and RFP templates that encode safety and interoperability requirements.
- Retrofit economics and break-even analyses for extending vehicle life vs. replacement with electrified units.
- Regulatory compliance checklists tied to OSHA, EU Machinery Directive, and regional emissions rules—mapped to product and retrofit requirements.
- Case studies of pilot deployments and a playbook for scaling from proof-of-concept to fleet-wide rollouts.
- Deal-level guidance on partnerships, JV structures, and M&A targets informed by market concentration and service adjacencies.
In keeping with our “trailer” principle, the full report includes detailed segment-level figures, regional allocation, and proprietary unit economics that are reserved for subscribers and the primary report download. High-level macro metrics (base year, forecast period, CAGR, and consolidated concentration indicators) are summarized above to support immediate strategic planning.
How to use this intelligence in three planning horizons
- 90 days: Finalize pilots with two vendor partners (one legacy body specialist, one electric-capable innovator). Implement mandatory safety retrofit policy for priority routes.
- 6 months: Run consolidated TCO scenarios for FY27 CapEx and adopt a modular procurement template. Begin supplier qualification for battery modules and telematics providers.
- 18 months: Scale successful pilots across high-value routes, execute on aftermarket service rollouts, and consider M&A to acquire technical gaps in battery integration or telematics.
Conclusion — the strategic value for 2026
For 2026 decision-makers, the automated side load garbage truck market presents a clear set of opportunities—and pitfalls. The sector is growing at an annualized pace in the mid-single digits, driven by emissions policy, safety mandates, and a shift to lifecycle-focused procurement. Success will not come from choosing the lowest-cost body or chassis in isolation; it will come from orchestrating chassis, body, energy systems, and services into an interoperable, safety-compliant, and financially defensible fleet strategy.
PW Consulting’s full report supplies the segment-level numbers, supplier comparisons, and executable templates organizations need to move from strategy to execution. Access the full study to obtain the detailed segment breakdowns, regional allocations, and proprietary models that inform precise CapEx budgeting and vendor selection.
For detailed analysis of this topic, please visit the official page: Automated Side Load Garbage Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Recombinant Collagen Market to Reach USD 4,120M by 2025 — PW Consulting
By PW Consulting, 2026-07-13
Recombinant Collagen Market 2026: Strategic Preview for Executive Decision‑Making
As recombinantly produced collagens cross the threshold from laboratory novelty to commercial-grade biomaterials, corporates and investors face an inflection point. PW Consulting’s Recombinant Collagen Market study synthesizes five years of market evolution and a robust seven‑year forecast to 2032, delivering the strategic intelligence required to act decisively in 2026. Our analysis shows the market growing from roughly USD 1.18 billion in 2020 to an estimated USD 4.12 billion in 2025, accelerating into 2026 and beyond with a compound annual growth rate (CAGR) of 28.5% through 2032 — a trajectory that projects the market toward approximately USD 23.8 billion by 2032.
Recombinant Collagen Market
Why 2026 Is a Strategic Pivot Year
Three converging forces make 2026 the year to convert exploratory R&D into commercial commitments:
Recombinant Collagen Market
-
Technology maturation: Fermentation systems (notably E. coli and Pichia pastoris) have reached production yields that materially change cost and scale economics, enabling suppliers to contemplate ton‑scale outputs and fiber spinning at commercial yields.
Recombinant Collagen Market -
Regulatory validation: Breakthroughs in product approvals and device classifications for recombinant human‑sequence collagens are shifting risk profiles for clinical and implantable applications, shortening the timeline from prototype to market.
-
Market pull across adjacent end markets: Demand signals from medical aesthetics, functional skincare, wound care, bioprinting and biomedical research are converging — creating cross‑market opportunities for platform providers and application specialists.
For executives, 2026 is therefore not just another forecast point; it is the year to lock supply, prioritize platform investments, and define partnership and IP strategies that will determine positioning across the next growth cycle.
The Strategic Value of Our Study
PW Consulting’s report has been constructed explicitly to support boardroom decisions and investor diligence. The study delivers:
-
Actionable market sizing and growth scenarios — robust, auditable top‑line demand curves from 2020 through 2032 that integrate historical adoption with forward‑looking inflection points.
-
Supply‑chain and manufacturing economics — technology roadmaps for expression systems, demonstrated yield benchmarks, and facility‑scale considerations that illuminate capital intensity and unit economics at multiple scale points.
-
Regulatory and reimbursement playbooks — mapped pathways for clinical, implantable and cosmetic product categories, including case studies of recent regulatory milestones that materially change approval risk.
-
Commercial strategies and go‑to‑market options — segmentation of plausible routes (direct sales, OEM/ODM, license, partnership, toll‑manufacture) and the tradeoffs for each given market concentration and competitive dynamics.
-
Peer benchmarking and M&A scaffolding — comprehensive competitor profiles and scenario models to test acquisition, joint‑venture, or greenfield expansion returns under conservative and aggressive growth cases.
To honor the “preview” principle and preserve the report’s commercial value, this introduction demonstrates the analytical depth you can expect while intentionally omitting granular segment breakdowns and proprietary model outputs — these are reserved for the full report and dataset available on our website.
Competitive Landscape — Who’s Setting the Pace
The recombinant collagen ecosystem today is a mix of multi‑national chemical/biotech incumbents, venture‑backed platform pioneers, and high‑scale regional manufacturers. Market concentration metrics indicate a moderate but meaningful level of aggregation, with the top three companies representing a sizable share of revenues and the top five accounting for the majority of leading capabilities. This structure favors both scale players that can invest in GMP‑grade capacity and nimble specialists that master platform differentiation.
-
Evonik Industries (Essen, Germany): Evonik’s VECOLLAN® platform — now available in clinical‑grade material — signals a shift by major chemical players toward GMP clinical supply and medical device enablement. Evonik is well‑positioned to serve bioprinting and device integrators requiring clinical‑trial grade inputs and regulatory support.
-
CollPlant Biotechnologies (Rehovot, Israel): CollPlant’s plant‑derived rhCollagen and proprietary bioinks have reported preclinical and comparative study wins that strengthen its position in 3D bioprinting and regenerative aesthetics. Recent milestones demonstrate the platform’s translational progress toward full‑scale clinical and aesthetic applications.
-
Geltor (United States): Geltor’s focus on engineered human‑mimetic polypeptides and ingestible beauty platforms showcases how protein engineering can be monetized across consumer and clinical adjacencies. Their productization approach offers lessons for brand‑oriented entrants seeking consumer pathways into a traditionally clinical space.
-
Jellatech, PlantForm, Giant Biogene and other regional leaders: These firms illustrate two alternative strategic archetypes — high‑tech cellular agriculture platforms (Jellatech, PlantForm) that emphasize sustainability and vegan supply chains, and large‑scale, regionally focused manufacturers (Giant Biogene, Jinbo, Bloomage, Zhuhai Gene‑Biocon, Jland Biotech) that prioritize production scale and cost competitiveness for skincare and dressing markets.
-
Specialist suppliers and commodity OEMs (e.g., Alfa Chemistry): Their role as industrial‑scale raw material suppliers and private‑label partners will be pivotal in commoditizing certain collagen grades while higher‑margin, clinical‑grade niches remain differentiated.
Recent strategic moves illustrate trajectories worth monitoring: Evonik’s clinical‑grade product launch materially lowers the barrier for device manufacturers to adopt recombinant platforms; CollPlant’s positive 3D bioprinting data and preclinical large‑volume implant prints elevate expectations for tissue engineering applications; and regulatory approvals in China for implantable recombinant collagen devices have reduced approval risk in select clinical pathways. Collectively, these developments are shifting the risk/return calculus for investments across the value chain.
Supply & Technology Dynamics
Key technical and capacity signals in our study include improved expression yields and concrete scaling progress. Advanced Pichia strains and optimized E. coli systems now report multi‑gram‑per‑liter yields under production conditions — a threshold that enables industrialization of previously laboratory‑bound constructs. At the same time, manufacturing footprints are expanding: select Asian facilities have demonstrated multi‑ton annual capacities for high‑purity recombinant collagen, a factor that will influence pricing and regional supply security in the near term.
Convergence of spinning technologies and dry‑fiber manufacturing — supported by targeted public funding for co‑development projects — points to an emerging value chain where recombinant collagen fibers can be produced and converted into medical textiles, implantable scaffolds and advanced cosmetic formats at scale.
Implications for 2026 Strategic Choices
Based on our scenario analysis, PW Consulting recommends executives consider the following priority actions in 2026:
-
Secure tiered supply agreements that include options for clinical‑grade material escalation; avoid single‑source exposure for critical clinical programs.
-
Prioritize platform partnerships rather than outright technology bets where time‑to‑market matters; licensing or joint development can accelerate entry while preserving capital.
-
Invest selectively in scalable expression routes and downstream analytics — improving yield and impurity profiles is the fastest lever to improve unit economics.
-
Map regulatory pathways early and build clinical evidence plans aligned to device vs. cosmetic use cases; recent device approvals reduce but do not eliminate regulatory complexity.
-
Explore adjacent monetization models (bioinks, contract manufacturing, OEM formulations) to diversify revenue while core product clinicalization progresses.
What You’ll Find in the Full PW Consulting Study
The full report is designed as an executable toolkit for strategic teams and will include:
-
Detailed, auditable market models (historical 2020–2025 and forecast 2026–2032) and scenario analyses.
-
Segment‑level demand drivers and vendor capabilities (note: detailed split data and proprietary inputs are available in the full dataset).
-
Supplier scorecards, cost curves, and recommended supplier selection matrices tailored to clinical vs. consumer applications.
-
Regulatory roadmaps and best‑practice evidence generation templates for device, implantable and cosmetic pathways.
-
M&A and partnership playbooks with valuation sensitivity analyses under multiple adoption timelines.
Final Note — Why Our Preview Matters
Recombinant collagen occupies a strategic juncture between biological innovation and scalable manufacturing. The market’s high CAGR and accelerating top‑line dynamics create both substantial opportunity and the potential for strategic missteps if timing, supply and regulatory readiness are misaligned. PW Consulting’s study equips leaders with the foresight to choose when to partner, when to build, and how to prioritize investments that will yield competitive advantage by the close of this decade.
For access to the full dataset, segmentation detail, and proprietary models that underpin this preview, please visit the report page on our website or contact your PW Consulting account director. The full intelligence package contains the guarded inputs and split‑level analysis necessary to finalize boardroom decisions in 2026.
For detailed analysis of this topic, please visit the official page: Recombinant Collagen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Multifunctional Scrubber Market to Reach USD 723.35M by 2032 (8.12% CAGR)
By PW Consulting, 2026-07-13
Handheld Multifunctional Scrubber Market — Strategic Preview for 2026 Decisions
As companies plan product launches, channel investments, and M&A in 2026, the handheld multifunctional scrubber market presents a clear growth runway and an operational landscape that rewards decisive product- and supply-chain-led strategies. Our PW Consulting market study synthesizes five years of historical performance (2020–2025) and a multi-scenario forecast through 2032 to produce a single, actionable narrative: the market has moved from a niche, price-driven accessory category into a stable, innovation-led consumer appliance segment. Total market scale reached an elevated base in 2025 and — under our central projection — expands at a compound annual growth rate of roughly 8.12% over the 2026–2032 forecast window. The result: material addressable growth for incumbent brands, new entrants, and adjacent-technology investors alike.
Handheld Multifunctional Scrubber Market
Why this report matters for 2026 strategic choices
-
Timing: 2026 is the window where product feature parity gives way to platform differentiation. Battery performance, waterproofing standards, modularity (interchangeable heads / magnetic quick-connects), and ergonomic reach become decisive purchase triggers rather than discretionary features.
Handheld Multifunctional Scrubber Market -
Investment prioritization: With sustained mid-single-digit-plus CAGR, companies should shift from short-term promotional pushes to three-year roadmaps that lock in supply (batteries, brushless motors) and after-sales revenue (consumables and accessories) streams.
Handheld Multifunctional Scrubber Market -
Channel strategy: E-commerce remains growth-focused, but omnichannel playbooks that integrate retail visibility, bundled consumables, and subscription models can accelerate monetization of installed bases.
-
Regulatory and trade considerations: Tariff classifications and cross-border battery regulations are operational risks that require customs and compliance planning as part of go-to-market launches.
High-level market trajectory (what we disclose — and what we withhold)
Our study provides the full time-series of market size from 2020 through 2025 and a detailed projection through 2032. To summarize the headline: the category expanded meaningfully during the 2020–2025 period and, on our central forecast, continues to grow at around 8.12% CAGR over 2026–2032, reaching materially larger scale by the end of that horizon. We intentionally withhold granular region-by-region and application-by-application breakdowns in this preview to preserve the commercial value of the full report; those detailed splits — essential for regional pricing, inventory staging, and route-to-market decisions — are available in the complete dataset on our site.
What the full report contains (practical, execution-focused deliverables)
-
Market sizing and growth scenarios: baseline, upside, and downside paths with sensitivity to battery raw-material pricing and durability assumptions.
-
Segmentation frameworks: product architecture (corded vs cordless; runtime bands; reach/extension features), consumer use-cases, and channel matrices — all linked to unit economics and margin modeling.
-
Competitive landscaping: detailed profiles, feature-to-price mapping, and capability gap analysis for headline and second-tier competitors (including product specs, IP signals, and distribution footprints).
-
Supply chain heatmap: critical component suppliers (motors, batteries, seals), single-point-of-failure analysis, and supplier diversification scenarios with quantified inventory and lead-time impacts.
-
Commercial playbooks: GTM options for premiumization, subscription consumables, value bundles, private label strategies, and retailer co-investment models.
-
Regulatory and compliance annex: import classification considerations, battery transport rules, recycling obligations, and country-level labeling requirements.
-
Opportunity scans: adjacent acquisitions, licensing plays (connector ecosystems, brush designs), and IoT-enabled service upsell concepts with revenue uplift estimates.
-
Play-testing and implementation checklist: prioritized 100–200 day actions for product, supply chain, marketing, and finance owners.
Competitive landscape — what matters to senior leaders
The category remains commercially fragmented: the top three vendors account for under one-fifth of global market value while the top five approach roughly one-third — a structure that creates space for both niche specialists and cross-category consumer appliance brands. That fragmentation drives aggressive product innovation, pricing pressure in tactical channels, and an attractive environment for roll-up strategies. Below we provide synthesis-level signals on key players and tactical implications.
-
HOTO (Zhuhai/Shanghai) : Known for cordless models emphasizing runtime and IPX waterproofing with magnetic interchangeable heads. The brand’s recent recognition in mainstream testing enhances trust and creates retail pull-through opportunities. Strategic implication: competitors should match validated waterproofing and battery claims, or risk losing shelf credibility.
-
Casabella (USA) : Combines product ergonomics (extendable handles) with established consumer-channel relationships. Their strength is design-led differentiation for household convenience. Strategic implication: invest in accessory ecosystems and ergonomics — features that justify higher ASPs in mainstream channels.
-
Ruby Horsepower (Telebrands/BulbHead) : Leverages direct-response and impulse channels to scale — high RPM claims and a compact product mix. Strategic implication: channel-first players can rapidly grow low-touch SKUs but must defend margin erosion from promotions.
-
IEZFIX & LABIGO (China-based brands) : Focus on high-RPM cordless models and value propositions for global households. These players underscore how price/performance convergence is moving faster in online marketplaces. Strategic implication: incumbents should protect brand equity through warranty, after-sales, and certified accessories.
-
Dirt Devil, Hoover, BLACK+DECKER (US/international incumbents) : Established appliance brands bring distribution breadth and cross-selling capability. Recent product introductions (e.g., new 20V MAX offerings with integrated lighting and high-capacity batteries) signal a move toward platformized cordless ecosystems. Strategic implication: cross-category incumbents can accelerate adoption via bundled offerings linked to existing battery platforms.
Recent product and industry signals to prioritize in 2026
-
Independent endorsements matter: product awards and third-party testing (e.g., Good Housekeeping) materially influence retailer assortments and shopper conversions.
-
Battery performance windows are the new feature wars: runtime claims and quick-charge capabilities drive purchase decisions more than minor brush head differentials.
-
Modularity and ease-of-use (magnetic quick-connects, extendable handles, IPX ratings) are turning points for mainstream adoption; these are design bets that justify price premiums and subscription strategies.
-
Supply resilience is strategic: brands that lock battery and motor capacity, and that implement quality gating on seals and motors, avoid the negative PR and warranty costs that erode brand trust.
Regulatory and consumer-behavior dynamics
Two categories of external forces deserve board-level attention in 2026. First, trade and customs classifications around battery-powered handheld appliances can materially affect landed costs and SKU economics — requiring early engagement with customs counsel. Second, consumer testing and review ecosystems increasingly reward transparent runtime and waterproof claims; inconsistency between marketing and verified performance results in rapid reputational damage in digital channels. Finally, raw-material dynamics for lithium-ion cells continue to dictate battery pricing and availability — an input risk that directly influences both ASPs and promotional cadence planning.
Recommended 2026 playbook (practical actions)
-
Prioritize cordless-platform investment: lock cell supply, standardize on a modular battery architecture, and create migration paths to higher-voltage ecosystems within your brand family.
-
Design for accessories as annuity revenue: magnetic connectors, certified brush heads, and consumable programs are low-capex, high-margin ways to improve customer LTV.
-
Operationalize waterproofing and durability claims: invest in third-party testing to secure retailer listings and to reduce return rates that damage margins.
-
Double-down on omnichannel measurement: coordinate DTC, e-commerce marketplaces, and brick-and-mortar launches to avoid channel cannibalization and to maximize full-price sell-through.
-
Scenario-planning for input shocks: model battery-price pass-throughs and set tiered promotional guardrails tied to margin thresholds.
How PW Consulting’s study accelerates decision-making
Our analysis turns macro trends into executable decisions. For a category growing at mid-single-digit-plus CAGR with an observable shift toward cordless, modular products and a fragmented competitive field, the right moves in 2026 are concrete: prioritize battery partnerships, lock waterproofing and durability claims, and build accessory-led annuities. The full PW Consulting report supplies the spreadsheets, channel-level sizing, and supplier contact maps you need to operationalize those moves — while this preview intentionally leaves the detailed segment tables and granular regional/application splits for clients who download the complete study.
Next steps
-
For product leaders: use our 100–200 day checklist to convert engineering priorities into validated product claims and retailer-ready specs.
-
For commercial teams: request the channel-level demand curves in the full report to design assortment and promotional calendars for 2026.
-
For corporate development: review our M&A target landscape where bolt-on playbooks are matched to topology (manufacturing, battery suppliers, or accessory specialists).
To access the full dataset, detailed regional and application splits, and the complete competitive profiles and supplier heatmaps that underpin these strategic recommendations, consult the PW Consulting Handheld Multifunctional Scrubber Market report. The preview above is designed to establish the strategic context — the report delivers the operational detail you will need to act in 2026 with confidence.
For detailed analysis of this topic, please visit the official page: Handheld Multifunctional Scrubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Press Hardening Machine Market to Reach USD 1,021.32M in 2025; 7.32% CAGR to 2032
By PW Consulting, 2026-07-13
Press Hardening Machine Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As the automotive value chain accelerates its shift toward electrification, stringent safety standards, and heavier integration of ultra-high-strength steels (UHSS), press hardening equipment has moved from a niche production technology to a strategic capital asset. This preview distills the strategic relevance of PW Consulting’s full Press Hardening Machine Market study for 2026 decision-makers. It highlights the macro trajectory, competitive dynamics, operational stress points, and the pragmatic levers executives should consider this year — while deliberately reserving the granular segment and regional tables for subscribers to the full report.
Press Hardening Machine Market
Macro snapshot: a market in growth and industrial transition
The press hardening machine market has demonstrated a resilient recovery and structurally positive outlook. After a cyclical trough in early 2020, the market scaled back to pre-pandemic volumes and has continued to expand, reaching a global market size of approximately USD 1,021.3 Million in the base year (2025). Our forecast model projects continued expansion into the late 2020s, with a compound annual growth rate (CAGR) of around 7.32% through the forecast horizon. By the early 2030s the market is expected to be materially larger than today’s baseline, reflecting persistent demand for lightweight, safety-critical automotive structures, higher throughput automation investments, and energy efficiency-driven retrofits of legacy lines.
Press Hardening Machine Market
Why 2026 is a pivot year for corporate strategy
- Demand signal clarity: OEM specifications for occupant safety and EV platform architectures are cementing the role of press-hardened parts in vehicle bodies. Press hardening enables production of UHSS components with tensile properties up to c. 2000 MPa, and in some modern architectures press-hardened content can account for a material share of the vehicle body measured in double-digit percentages — making the technology a non-negotiable design choice for many platforms.
- CapEx timing and scale: With the market growth trajectory and continuing OEM sourcing commitments, capital allocation decisions made in 2026 will determine equipment vintage for the next decade. Delays or under-investment risk capacity bottlenecks and strategic dependence on third-party suppliers; conversely, oversized early commitments risk underutilization if platform designs evolve.
- Operational transformation: Energy efficiency, inline process monitoring, and automation are no longer optional performance enhancements. Solutions such as servo-driven presses and multi-layer furnace systems can materially lower energy consumption, directly affecting operating margins and environmental footprint.
Dynamics shaping near-term returns and operational risk
- Materials cost volatility: Steel remains the dominant input for press hardening processes. Industry analysis indicates raw-materials represent a dominant share of primary steel production costs, implying that variations in steel pricing and alloy premiums can swing process economics substantially. This underlines the need for procurement flexibility, material-efficiency engineering, and hedging or vertical integration strategies.
- Energy and process efficiency: Field data from leading OEM suppliers shows that servo-driven press solutions can reduce energy consumption of forming operations substantially; combined with multi-layer furnace architectures, firms can realize double-digit reductions in line energy intensity. These gains translate directly to operating cost reductions and improved sustainability metrics — increasingly important for OEMs under regulatory and investor scrutiny.
- Quality and compliance: The adoption of inline process monitoring (pyrometers, IR cameras, closed-loop control) has become a practical necessity for meeting heat-treatment standards and auditability (e.g., CQI-9 equivalents). Process monitoring is also a key enabler for reducing scrap, improving repeatability, and shortening ramp-up cycles for new parts.
- Modularity vs. turnkey trade-offs: Buyers face a choice between highly integrated turnkey lines and modular, upgradable cells. Turnkey suppliers reduce integration risk but can involve longer lead times and higher upfront CAPEX; modular cells can accelerate time-to-market and spread CAPEX over multiple program phases but require stronger in-house systems integration capability.
Competitive landscape — concentration, capability vectors, and tactical moves
The supplier ecosystem is moderately concentrated. The top three vendors account for a clear majority share of the installed base, with the top five capturing a significant portion of global revenues — a structure that favors established turnkey providers but leaves room for niche engineering specialists and custom-equipment manufacturers to capture specialized opportunities.
Press Hardening Machine Market
Key vendor capabilities and implications for buyers:
- AP&T (Ulricehamn, Sweden): A pioneer in the press hardening domain with substantial installed experience. AP&T’s turnkey approach — including servo presses, multi-layer furnaces, SkyLines concepts for large complex components, and embedded inline monitoring — positions it strongly for OEMs seeking integrated, energy-efficient solutions. Their recent SkyLines presentations emphasize multi-part integration and energy optimization for EV manufacturing, a strategic theme for long-cycle platform programs.
- Fagor Arrasate (Arrasate, Spain): Noted for end-to-end automated press hardening systems, including servo-hydraulic hybrid presses and multilevel furnaces. Their strength lies in scale and full-line engineering for high-volume programs where predictable throughput and low-touch operation are priorities.
- Schuler Group (Göppingen, Germany): Focused on high-precision, high-output systems. Technologies that prioritize flexible production (e.g., multi-part per cycle architectures) make them attractive where production mix flexibility and takt variability are required.
- Macrodyne Technologies Inc. (Canada): A vendor for bespoke hydraulic and servo hot stamping presses with deep experience around complex parts. Their approach suits engineering-led OEMs and tier-1 suppliers producing non-standard or evolving part geometries.
- Loire Gestamp (AFM) (Hernani, Spain): Specializes in hydraulic hot stamping and integrated line components. Their practical experience on automotive applications and furnace/transfer systems makes them a choice for projects emphasizing robustness and simplicity.
Recent vendor activity reinforces these themes. AP&T’s mid-2025 SkyLines showcase clarified the energy and sustainability advantages of integrated multi-layer furnace concepts for EV component manufacture, while Macrodyne’s participation at MACH 2026 highlighted continued demand for custom hydraulic press solutions. Buyers should treat vendor roadmaps and demonstrated energy metrics as procurement differentiators, not just price levers.
What PW Consulting’s full study delivers to a decision-maker in 2026
Our full report is built as an operator’s playbook and a board-level briefing in one package. It synthesizes market sizing, supplier benchmarking, economics, operational diagnostics, and executable tactics across a set of deliverables designed for immediate use in 2026 planning cycles:
- Proprietary demand model and sensitivity scenarios that translate vehicle program schedules into equipment demand and utilization profiles across the planning horizon.
- Vendor scoring matrices across technical, delivery, service, energy, and TCO dimensions — with blind-spot checks for retrofit vs new-build economics.
- Practical CAPEX/OPEX models and lifecycle cost calculators to compare technology pathways (hydraulic vs servo-mechanical vs hybrid) and furnace architectures.
- Procurement checklists, sample RFP language, and contractual clauses to mitigate lead-time, warranty, and intellectual property risks.
- Operational playbooks for commissioning, inline process monitoring implementation (pyrometry/IR camera integration), and CQI-equivalent compliance workflows.
- M&A and partnership maps identifying potential tuck-in targets, strategic JV profiles, and integration risk assessments.
- Case studies and plant-layout exemplars that show how to sequence investments to preserve optionality for later platform changes.
To avoid compromising the tactical value of these tools, the preview intentionally omits the granular regional and application splits, vendor revenue tables, and certain price-sensitive unit economics — these are available in the complete report.
Priority moves for 2026 — a practical checklist
- Align CapEx timelines with validated OEM program commitments, using scenario-based gating to preserve optionality.
- Prioritize energy-efficiency investments (servo presses, multi-layer furnaces) where payback matches corporate sustainability targets and regulatory timelines.
- Mandate inline process monitoring for new lines to secure quality, auditability, and reduced ramp-up waste.
- Adopt a layered vendor strategy: partner with turnkey providers for high-volume, mission-critical lines and engage specialist suppliers for complex or low-volume parts.
- Hedge raw-material exposure through procurement contracts, alternative material choices, or process yield improvements that lower material intensity.
- Accelerate workforce upskilling in automation, process control, and furnace metallurgy to reduce reliance on external integrators over time.
- Incorporate supplier energy metrics into procurement scoring to capture life-cycle cost advantages, not only upfront price.
Conclusion — positioning for advantage
For 2026, the press hardening equipment decision is both tactical and strategic. It touches procurement, manufacturing strategy, sustainability targets, and product engineering. The market’s growth profile and the technology-led differentiation across suppliers mean that well-timed decisions will compound into durable competitive advantage. PW Consulting’s full Press Hardening Machine Market study equips executives with models, vendor diagnostics, and executable playbooks to make those decisions with confidence.
For organizations preparing board presentations, supplier negotiations, or industrial transformation roadmaps this year, the complete report contains the underlying tables, vendor scorecards, regional demand splits, and downloadable financial models referenced here. Access to that detailed intelligence will materially shorten decision cycles and sharpen negotiation positions — and it is available on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Press Hardening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Consulting Market to Reach USD 28,417M in 2025 with 13.45% CAGR
By PW Consulting, 2026-07-13
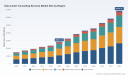
Data Center Consulting Services Market — Strategic Preview for 2026 Decision-Makers
As organizations accelerate digital transformation, artificial intelligence adoption, and hyperscale capacity builds, the global market for data center consulting services has entered a sustained expansion phase. Our new PW Consulting market study — covering historical performance through 2025 and a detailed forecast horizon beginning in 2026 — shows a multi‑year structural growth trajectory with a compound annual growth rate (CAGR) of 13.45% for the forecast period. The market crossed a significant milestone in 2025 and is projected to continue scaling meaningfully into the early 2030s.
Data Center Consulting Services Market
Why this study matters for decisions made in 2026
-
Timing capital allocation: 2026 is a year of discrete windows for committing to new build, modular expansion, or colocation agreements. Our market model translates high-level growth signals into scenario-based demand curves so CFOs and infrastructure owners can align multi-year CAPEX with realistic utilization trajectories and energy cost assumptions.
Data Center Consulting Services Market -
Optimizing operating models: Rapid changes in workload placement and hybrid architectures force choices between managed services, in‑house operations, and co-located models. The report provides TCO frameworks and migration playbooks that surface the critical breakpoints where outsourcing or retaining operations materially alters lifetime cost.
Data Center Consulting Services Market -
Mitigating regulatory and compliance exposure: New privacy laws, sectoral rules for sensitive data handling, and emissions-focused generator regulations are making compliance a design consideration rather than a box checked at the end. The research synthesizes current regulatory developments and models the operational impact on design, staffing, and contingency planning.
-
Sustainability and community license to operate: Environmental, social and governance (ESG) expectations are no longer peripheral. Investors and site hosts increasingly require biodiversity, water management and community engagement strategies embedded in project plans; the report quantifies how these practices affect project timelines and capital needs.
What the PW Consulting report delivers (practical, action-ready content)
-
Integrated market model: A calibrated topline model that links macro demand drivers to near-term capacity needs and consultant service demand across a multi-year forecast horizon. This model is accompanied by transparent assumptions and sensitivity levers for power pricing, server density trends, and utilization efficiency.
-
Decision playbooks: Step-by-step playbooks for build vs buy choices, migration sequencing from brownfield to modernized platforms, and rapid assessment templates for colocation and interconnection strategies.
-
Financial toolkits: TCO calculators, capital planning templates, and scenario-based IRR/NPV illustrations tailored to data center projects under varying energy, labor, and regulatory regimes.
-
Vendor and partner evaluation materials: Due-diligence checklists, contracting red-lines for services and construction management, and a vendor scorecard methodology that balances technical competency, delivery reliability, and sustainability credentials.
-
Operational playbooks: Staffing and skills roadmaps, maintenance and spare-parts optimization, and a practical migration & cutover checklist designed to reduce downtime risk in complex retrofits.
-
Risk register and mitigation matrices: A prioritized enumeration of technical, regulatory, and community risks with recommended mitigation actions and contingency budgets.
Note: the report contains granular segmentation by region, service type and end‑use industry and a comprehensive supplier revenue matrix. To preserve this brief’s role as a strategic preview, those granular splits and company revenue line items are intentionally withheld here — they are available in full in the published study.
Competitive landscape — how the supplier universe is shaping 2026 outcomes
The data center consulting services market remains fragmented: the top three firms account for less than one‑fifth of total market revenue, and the top five remain below 30% concentration. This fragmentation creates divergent strategic options for buyers: engage a wide ecosystem of specialists for best-in-class technical outcomes, or consolidate with a smaller set of large integrators to simplify program management.
-
AECOM and Jacobs (both with major US bases): leaders in site selection, design, and end-to-end project delivery for mission‑critical facilities. Their strengths lie in global program management, heavy civil and MEP engineering, and delivery of complex capital projects at scale.
-
Arup and Ramboll : engineering and sustainability specialists who are frequently engaged on projects where energy efficiency, architectural integration, and biodiversity/ESG outcomes are defining success criteria. Ramboll’s recent partnership to embed biodiversity into a large campus project highlights the growing demand for nature‑positive design approaches.
-
Accenture and IBM Consulting : strategy and IT transformation partners focused on cloud migration, hybrid architectures, and embedding AI into infrastructure operations. Accenture’s recent expansion of capital project delivery capabilities through an acquisition demonstrates the increasing crossover between management consulting, digital tools, and construction management.
-
Deloitte , PwC , and EY : advisory firms that combine risk/compliance, tax, and operational transformation services, and are often selected for program governance, regulatory assurance, and enterprise risk assessments tied to large-scale builds.
-
JLL : a specialist in real estate, site selection, and investment advisory. JLL’s market outlooks and campus-level capacity projections are widely used by corporates and investors to inform site strategy and land acquisition timing.
-
HCL Technologies , TCS , and Kyndryl : providers with strong heritage in managed services and infrastructure operations, positioned for long-term outsourcing contracts and run-books that capture operational knowledge at scale.
-
McKinsey & Company : a strategic advisor for C‑suite decisions around platform strategy, M&A, and large transformation programs where organizational design and future-state operating models are the primary focus.
Recent developments and regulatory dynamics that will shape 2026 playbooks
-
Capital project delivery and digital tools: Significant M&A and capability builds among major consultancies are accelerating the fusion of construction management with AI-driven planning tools. Expect shorter design cycles but greater emphasis on digital twin and construction analytics to manage schedule and cost risk.
-
Workforce and labor: Large-scale training initiatives focused on electrical trades and specialized data center skillsets are beginning to materialize. Organizations that lock in training partnerships now will reduce long-term labor premium risk.
-
Regulatory shifts: New emissions rules for backup generators in some jurisdictions and enhanced federal and state privacy controls have elevated compliance into a core project constraint. Design decisions for redundancy, emissions control, and data handling now have immediate operational and permitting implications.
-
Capacity outlook: Industry forecasts anticipate a step‑up in capacity demand over the next five years, changing the calculus for power procurement, land strategy, and grid interconnection planning. Buyers must integrate capacity scenarios into both short-term resource commitments and long-term siting decisions.
Practical 90‑day action plan for 2026
-
Conduct a regulatory impact scan focused on generator emissions, privacy obligations, and bulk data handling rules; map any near-term project milestones that might be affected.
-
Run an immediate TCO and sensitivity analysis using low/medium/high scenarios for power cost and utilization — prioritize projects where payback is most sensitive to energy price volatility.
-
Initiate or expand workforce partnerships for electrical and critical facilities trades; include apprenticeship metrics and retention KPIs in vendor RFPs.
-
Pilot a modular or prefabricated approach on a single project to compress schedule risk and test vendor integration capabilities.
-
Update procurement templates with ESG and compliance conditions, and issue an RFP to assess market pricing for integrated delivery versus specialist engagements.
Why PW Consulting’s full study is a strategic asset
The full PW Consulting Data Center Consulting Services Market study combines a rigorously validated market model, executive interviews, supplier revenue matrices, and practical implementation toolkits. It is designed to convert market intelligence into executable plans — whether you are an operator sizing next‑generation capacity, an investor evaluating campus plays, or a CISO assessing compliance exposure across a global estate.
This preview intentionally highlights the analytical framework, competitive dynamics, and decision-ready outputs while omitting the report’s granular segmentation and supplier revenue line items. For procurement-ready vendor scorecards, region- and service-level demand curves, and downloadable financial templates, please consult the full report.
PW Consulting stands ready to support your 2026 strategy session with bespoke scenario runs, stress tests of your portfolio under regulatory and energy price shocks, and hands-on workshops to operationalize the report’s playbooks into your capital planning and vendor selection processes.
For detailed analysis of this topic, please visit the official page: Data Center Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
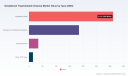
Gestational Trophoblastic Disease Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the Gestational Trophoblastic Disease (GTD) market designed to frame boardroom and commercial-strategy conversations for 2026. This briefing synthesizes market momentum, clinical and regulatory inflection points, competitor positioning, and the practical intelligence our full report delivers — while deliberately withholding detailed segment tables to encourage direct access to the underlying dataset and model.
Gestational Trophoblastic Disease Market
Why GTD deserves a seat at your 2026 strategy table
-
Clinically driven market growth: The GTD market has grown from a narrow specialty niche into a clearly expanding opportunity. The overall market rose from USD 412.3 Million in 2020 to USD 546.04 Million by the 2025 base year and is forecast to continue expanding, reaching USD 810.26 Million by 2032. This trajectory is supported by a forecast CAGR of 5.81% for 2026–2032, which positions GTD among steadily growing rare-oncology subsegments where incremental clinical advances translate rapidly into commercial uptake.
Gestational Trophoblastic Disease Market -
Actionable clinical levers: Recent guideline updates, new clinical data and the emergence of immunotherapy and targeted repurposing studies are shifting treatment algorithms and referral pathways. For executives, this means that late-stage clinical evidence and guideline adoption timelines — not just first-to-market approvals — will determine commercial outcomes.
Gestational Trophoblastic Disease Market -
Manageable competitive density: The market shows moderate concentration among established oncology and generics players, creating a landscape where well-positioned entrants can scale via partnerships, formulary strategies and guideline adoption without confronting extreme fragmentation or monopolistic incumbency.
Market trajectory and what the headline numbers mean for 2026 choices
From a strategic planning standpoint, the market’s compound growth and absolute scale have immediate implications for resource allocation. The mid-single-digit CAGR through 2032 indicates reliable expansion driven by steady incidence, improved diagnosis/monitoring, and the selective adoption of novel therapeutics and combinations. For 2026 planning cycles, leaders should treat the market as a growth platform that rewards:
- Focused clinical development investments that shorten time-to-guideline inclusion.
- Commercial models that prioritize guideline adoption, center-of-excellence penetration, and payer evidence generation.
- Partnerships with established oncology manufacturers and specialty distributors to bridge supply and access gaps in target geographies.
Clinical and regulatory dynamics shaping near-term commercial outcomes
Three dynamics will most strongly influence commercial trajectories in 2026 and beyond:
-
Guideline-driven uptake. The 2025 international consensus guidance from the EOTTD–ESGO–GCIG–ISSTD consortium has formally recognized avelumab as an option in certain low-risk GTN cases to avoid escalation to multi-agent chemotherapy in select settings. Guideline inclusion accelerates payer consideration and clinician adoption; companies should prioritize real-world evidence and economic modeling to convert guideline statements into on-the-ground utilization.
-
Immuno-oncology and rescue strategies. Checkpoint inhibitors (pembrolizumab, avelumab and others) are increasingly used in chemo-resistant GTN or in trials. While most checkpoint inhibitors lack indication-specific regulatory approvals for GTN as of 2026, NHS England-type recommendations and trial signals create a pragmatic pathway for off-label or directed access programs. This trend opens a practical commercial channel for manufacturers with existing immuno-oncology franchises and necessitates lifecycle strategies for label expansion or formal registration.
-
Novel modalities and repurposing. Early-stage work — such as focused ultrasound research and preclinical studies repurposing statins for choriocarcinoma — suggests potential future adjacencies beyond classic cytotoxic agents. These approaches are not yet commercialized at scale but represent strategic optionality for companies exploring platform technologies or combination regimens.
Competitive landscape: pragmatic positioning and rivalry
The GTD therapeutic environment is populated by multinational originators, established generics manufacturers, and oncology specialist players. From a competitive-mapping perspective:
-
Large originators (e.g., longstanding oncology franchises) currently benefit from brand recognition, distribution reach, and existing guideline-relevant product portfolios. Their muscle is especially pronounced where immunotherapy or branded oncology agents intersect with GTD care pathways.
-
Generics and injectable suppliers control critical access levers for cytotoxic backbones and supportive care. Supply reliability, cost management and hospital formulary relationships are decisive in settings where single-agent chemotherapy remains standard of care.
-
Specialist biopharma and academic spin-outs focusing on rare gynecologic tumors can create outsized clinical and commercial impact by delivering compelling efficacy or tolerability improvements that shift first-line practice or permit de-escalation of multi-agent regimens.
Key corporate archetypes represented among active players include: large multinational originators with immuno-oncology capability, established generic injectables manufacturers, and clinical-stage innovators testing novel combinations. Market concentration metrics indicate that a small group of companies capture a meaningful majority of commercial activity, but not enough to preclude new entrants with differentiated clinical evidence or nimble access strategies.
Recent developments that materially affect 2026 decisions
-
Clinical data — A high-profile analysis presented at the 2026 ESMO Sarcoma & Rare Cancers Congress reported an improvement in complete response rates when first-line avelumab was combined with an 8-day methotrexate schedule versus methotrexate alone in low-risk GTN. This kind of head-to-head and external-control-informed evidence will shape clinicians’ risk/benefit calculus and reimbursement conversations.
-
Guideline updates — The 2025 multi-society consensus that incorporated avelumab as a potential option in certain low-risk cases underscores how guideline language can pivot the market without awaiting conventional regulatory label changes.
-
Policy-level access — NHS England-style recommendations for checkpoint inhibitor use in refractory high-risk GTN establish pathways for targeted access programs and influence global payer evaluations, particularly in countries with centralized decision-making.
Commercial playbook for 2026
Executives should prioritize a triaged set of actions to convert the market’s growth into durable revenue streams and competitive advantage:
-
Clinical evidence acceleration: Invest in pragmatic trials and registries that align tightly with guideline committees’ evidence requirements (comparative effectiveness, hCG normalization metrics, safety in fertility-preserving contexts).
-
Guideline-first market access: Coordinate publication, consensus engagement and payer dossiers to translate guideline mentions into reimbursement pathways rapidly.
-
Supply and specialty channel optimization: For injectable and chemotherapy suppliers, secure hospital-level contracts, stock reliability assurances and educational outreach to key referrers (maternity units, gynecologic oncology centers).
-
Label-extension and lifecycle planning: For companies with checkpoint inhibitors or biologics, map out evidence strategies to move from trial/compassionate use into formal indications or strong place-in-therapy positions.
What PW Consulting's full GTD report delivers
Our complete market study translates the strategic implications above into executable deliverables for 2026 action plans. The full report includes:
-
Proprietary market model with historical (2020–2025) and forecast (2026–2032) line items, sensitivity analyses and scenario outputs you can plug into investment and portfolio models.
-
Regulatory and guideline timelines with jurisdiction-by-jurisdiction access risk scoring and payer-impact matrices.
-
Detailed competitor dossiers and capability maps — from branded immunotherapies to generic injectables — with candidate go-to-market scenarios and partner/opportunity heatmaps.
-
Actionable commercial strategies: three prioritized GTD go-to-market playbooks (originator-led, generics optimizer, and innovator entry) with staffing, evidence, and budget estimates for initial 24-month rollouts.
-
Center-of-excellence and referral network analysis identifying clinical nodes where investments in medical-education and access programs yield highest ROI.
Recommended next steps for 2026 corporate planning
-
Sponsor an evidence-acceleration workshop this quarter to align clinical, HEOR and market-access teams around priority trials and registry designs that can convert into payer-friendly endpoints.
-
Complete a short-list of partnership targets across injectables manufacturers, specialty distributors and academic centers to de-risk supply and speed center penetration.
-
Run a rapid payer-scenario simulation using our forecast model to stress-test pricing and reimbursement assumptions under alternative guideline adoption trajectories.
Closing note
The GTD market is at an inflection where focused clinical evidence and smart access strategies will create disproportionate returns for companies that act this year. PW Consulting’s full report provides the granular segmentation, modeled scenarios, and playbooks required to make those moves with confidence. For executives preparing budgets, M&A screens, or late-stage development plans in 2026, this is a market where timing, evidence design, and partnership selection will decisively shape who leads the next phase of growth.
Access the full dataset and executable appendices on our report page to unlock the segment-level detail and downloadable models that enable immediate implementation.
For detailed analysis of this topic, please visit the official page: Gestational Trophoblastic Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Desktop Refractometers Market to reach USD 641.05M by 2032 at 5.18% CAGR
By PW Consulting, 2026-07-13
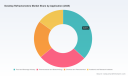
Desktop Refractometers Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As laboratory instrumentation budgets tighten and quality-control expectations rise across food, medical and industrial end markets, desktop refractometers have moved from specialist bench-top tools to mission-critical instruments embedded in routine workflows. PW Consulting’s latest market study finds that the global desktop refractometers market reached approximately USD 450 million in the base year (2025) and is positioned to expand at a steady compound annual growth rate (CAGR) of 5.18% through the 2026–2032 forecast horizon, approaching the mid-hundreds of millions by 2032. This briefing summarizes the strategic takeaways our report delivers for executives planning investments, partnerships, and product roadmaps in 2026 — without disclosing the proprietary segment tables and granular breakdowns reserved for the full report.
Desktop Refractometers Market
Why this study matters for 2026 planning
-
Durable demand drivers: Refractometry remains a low-friction measurement method with enduring relevance in QA/QC, clinical diagnostics (where specific reimbursement and coding regimes apply), and research settings. That persistence creates predictable replacement cycles that underpin recurring service, calibration and consumable revenue streams.
Desktop Refractometers Market -
Technology migration and product differentiation: The market shows continued migration toward digital, automated desktop instruments where usability, multi-scale measurement, and temperature control are competitive differentiators. Winning in 2026 will depend on translating measurement accuracy into workflow value (connectivity, LIMS integration, governed user experiences).
Desktop Refractometers Market -
Profitability levers are shifting: Optical components and precision prisms remain a critical cost driver in unit economics, and choices on materials and sourcing materially affect margin profiles and total cost of ownership offered to customers.
What the full PW Consulting report contains (practical, operational tools)
-
Market sizing and validated forecasts (historical 2020–2025 baseline, forward 2026–2032 scenarios) with an integrated financial model you can adapt for board-level planning.
-
Scenario playbooks: three operational scenarios (defensive, base, growth) that map demand, pricing, and supply constraints to measurable KPIs and P&L impacts — designed for rapid sensitivity testing ahead of capital allocation.
-
Go-to-market blueprints: channel strategies for direct vs. distributor models, service and calibration network economics, and a commercialization checklist to accelerate uptake in clinical and industrial accounts.
-
Technology and product roadmaps: feature-prioritization matrices (e.g., multi-wavelength capability, temperature control, touchscreen UX, connectivity standards), recommended R&D staffing mixes, and a pricing ladder to protect ASPs while capturing add-on service revenue.
-
Supply chain and procurement playbook: critical-component risk heatmaps, sourcing strategies for high-value optical elements, and tactical levers (dual-sourcing, strategic inventory, supplier JIT agreements) to reduce lead-time volatility.
-
M&A and partnership targets: a short-list of niche innovators, calibration-service consolidators, and digital-data players whose integration could accelerate platform value — accompanied by estimated deal-sizing frameworks and integration risks.
-
Regulatory and reimbursement navigation: practical guidance for meeting clinical laboratory quality standards, and for positioning products to be compatible with reimbursable workflows where applicable.
Market structure and competitive posture
The market is best described as moderately consolidated: market-leading suppliers command a meaningful share of global revenue, while a mid-tier of regional specialists and OEM suppliers capture the balance. The top-three suppliers together account for a substantial portion of the market, and the top-five extend that concentration further — a dynamic that favors scale players able to sustain R&D and global service networks, while creating openings for agile specialists that focus on verticalized solutions and service-led differentiation.
Competitive landscape — what to watch in 2026
-
Atago Co., Ltd. (Tokyo, Japan) — Strengths: scale in desktop refractometers, strong product portfolio across clinical and industrial lines, recognized for precise Brix and refractive-index offerings. Watch: Atago’s recent RX-5000α-Plus launch (enhanced touchscreen and expanded clinical scales) signals a continued push on user experience and clinical adjacencies. Strategic implication: incumbents must match UX and scale serviceability to defend clinical lab share.
-
Rudolph Research Analytical (New Jersey, USA) — Strengths: laboratory-grade instruments with strict compliance and temperature control; known for USP/EP-capable models. Watch: Certification updates in 2024 reinforce Rudolph’s positioning for regulated pharmaceutical customers. Strategic implication: compliance-oriented features can justify premium pricing in regulated channels but require focused regulatory support and documentation.
-
Anton Paar GmbH (Graz, Austria) — Strengths: premium research-grade refractometers and multi-wavelength instruments for pharmaceutical and chemical QC. Watch: trade show activity and presentation of the Abbemat family at major medical events underscores a demand-driven R&D cadence. Strategic implication: differentiation through measurement breadth (multi-wavelength) is a viable route to higher ASPs in research applications.
-
Mettler Toledo (Greifensee, Switzerland) — Strengths: broad laboratory equipment footprint and strong channel access in clinical and pharmaceutical markets. Strategic implication: integration into broader lab ecosystems (scales, balances, analytics) is a competitive moat; smaller vendors should pursue API and data-standards compatibility to retain customers.
-
Schmidt + Haensch (Berlin, Germany) — Strengths: specialized optical manufacturing and niche laboratory solutions, particularly for diagnostics and beverages. Strategic implication: niche leaders can leverage domain expertise (e.g., beverage analytics) to sustain higher margins and loyal customer bases.
-
Bellingham + Stanley / Xylem Analytics (Tunbridge Wells, UK) — Strengths: industrial and clinical desktop models with an emphasis on accuracy and robustness. Strategic implication: combining industrial-grade reliability with clinical usability is a narrow but effective band for differentiation.
Regulatory, reimbursement and supply considerations
-
Quality frameworks: Desktop refractometers used in clinical settings must align with contemporary laboratory quality standards (for example, ISO 15189), which affects product documentation, validation packages, and post-market surveillance expectations.
-
Reimbursement touchpoints: specific procedural codes exist that cover refractometry in certain clinical workflows; aligning product positioning to those workflows can improve hospital procurement economics and shorten sales cycles.
-
Component risk: high-precision optical components (e.g., prism assemblies) are a non-trivial portion of bill-of-materials cost and require strategic procurement. Manufacturers should evaluate long-term supply agreements, qualification of alternate materials where appropriate, and the total lifecycle cost to customers (durability, sterilizability, warranty).
-
Regulatory limitation on direct use: desktop models are intended for laboratory research and clinical measurement; they are not typically cleared for direct patient contact without appropriate encapsulation and validation — a restraint that shapes product form-factor and service models.
Strategic plays for 2026 — recommended actions
-
Invest selectively in digital differentiation: Prioritize connectivity (secure LIMS integration, cloud-based calibration logs), advanced UI, and automated temperature compensation — features that buyers are increasingly valuing over raw hardware specs.
-
Lockdown optical supply lines: Negotiate multi-year agreements, consider co-investing in supplier capacity, and validate alternative materials to reduce single-source risk on critical prisms and optical assemblies.
-
Service and consumables as recurring revenue: Expand calibrated service networks, subscription calibration plans, and consumable programs to improve customer stickiness and predictability of revenue.
-
Pursue regulatory-first productization: For players targeting clinical labs, invest in validation documentation and post-market support to shorten procurement cycles and position for higher ASPs.
-
Evaluate tuck-in M&A for capability gaps: Acquire niche measurement-tech startups, calibration networks, or software providers to accelerate platform capability and expand routes to market without a multi-year organic R&D timeline.
How to use PW Consulting’s analysis in your 2026 planning cycle
-
Board-level investment cases: use the report’s integrated financial model and scenario outputs to stress-test capex and R&D requests against three demand scenarios.
-
Commercial planning: adopt the go-to-market playbooks to align sales incentives, distributor coverage, and service capacity ahead of product launches.
-
Procurement and supply security: implement the supplier risk matrix and procurement playbook to mitigate optical-component shortages and reduce lead-time exposure.
-
M&A diligence: leverage our short-listed targets and integration checklists to accelerate deal screening and post-merger integration planning.
Conclusion and next steps
The desktop refractometers market offers predictable growth driven by durable use-cases across clinical, food & beverage, and industrial laboratories. Scale players will continue to leverage breadth and service networks, while specialist vendors that tightly couple measurement capability with workflow integration can capture disproportionate value. For executives planning 2026 resource allocation, the strategic priorities are clear: accelerate digital and compliance-enabled differentiation, harden supply chains for optical components, and convert one-time hardware sales into recurring service revenue.
PW Consulting’s full Desktop Refractometers Market report contains the proprietary segmentation, district- and application-level analytics, and downloadable financial models that operational teams and boards need to execute these strategies. Access the complete study and our scenario models at the report landing page to unlock the data-backed, executable intelligence behind this briefing.
For detailed analysis of this topic, please visit the official page: Desktop Refractometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stabilizer Bars Market to reach USD 8,678 Million by 2032 at 4.8% CAGR
By PW Consulting, 2026-07-13
Stabilizer Bars Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
The stabilizer bars market has demonstrated steady expansion through the recent cyclical period and is poised for continued growth across the coming decade. Our consolidated market model shows the global market rising from approximately USD 5.1 billion in 2020 to USD 6.25 billion in the base year 2025, and—under the central scenario—reaching nearly USD 8.68 billion by 2032. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of 4.8%. These headline figures provide a reliable anchor for capital allocation, product roadmap decisions, and commercial strategies in 2026.
Stabilizer Bars Market
Why this brief matters for 2026 decision-makers
-
Timing capital: With predictable mid-single-digit CAGR, CFOs can size near-term investments (tooling, plant capacity, automation) against a modest but resilient growth backdrop rather than a binary boom-or-bust outlook.
Stabilizer Bars Market -
Product prioritization: OEMs and Tier-1 suppliers face a clear trade-off between legacy solid designs and lightweight hollow or active stabilizer solutions driven by electrification and fuel economy regulations. The market-level growth masks important margin differentials tied to technical complexity — a key input for 2026 R&D budgets.
Stabilizer Bars Market -
Commercial playbooks: Procurement and pricing teams must incorporate raw-material sensitivity and tariff exposure into 2026 agreements. Our analysis illustrates how steel price cycles and policy actions materially affect supplier economics even when end-market demand is steady.
Market dynamics shaping 2026 strategy
Several converging forces will determine winners and losers in the next 12–24 months:
-
Cost-pressure meets technical premium. Volatility in hot-rolled coil pricing (European averages around 650 EUR/mt in late 2023) and enduring trade measures (e.g., US steel tariffs) increase the importance of raw-material hedging, regional sourcing, and design-for-cost. At the same time, lightweight and active stabilizer systems command material and engineering premiums that improve product margins when adopted at scale.
-
Vehicle mix and regulatory drivers. Global passenger car production remains a critical demand lever (roughly 66 million units in 2023), while safety and structural regulations (such as roof-strength standards) continue to reinforce demand for robust, high-quality stabilizer components. OEM platform decisions on electrification and chassis architectures will disproportionately benefit suppliers who can deliver lightweight, integrated modules.
-
Technology substitution and differentiation. Hollow, cold-formed, and active stabilizer architectures offer substantial mass reduction (technical literature cites weight cuts up to ~40% versus traditional solid designs). The adoption curve for these technologies is uneven across vehicle segments and geographies; therefore, strategic bets on tooling and R&D should be calibrated by expected adoption timing rather than purely by headline growth.
-
Supply-chain localization. Geopolitical friction and tariffs are driving OEMs and Tier-1s to accelerate regional sourcing. For 2026, companies with nimble footprint strategies and the ability to reallocate capacity quickly will be best placed to capture near-term share shifts without incurring margin erosion.
Competitive landscape — what to watch in 2026
The sector presents a moderately concentrated topology: the three largest players account for a meaningful but not overwhelming share of global sales, while the top five players approach a plurality. This structure produces a mix of scale-driven competition and technical differentiation.
-
ZF Friedrichshafen AG — Global leader in chassis systems, increasingly positioning active stabilizer technologies (e.g., showcased active systems at industry events). Their scale and OEM relationships make them a strategic partner for OEMs seeking integrated chassis solutions.
-
Magna International Inc. — Offers end-to-end stabilizer systems via multiple divisions, deploying integration capabilities as a competitive moat for body and chassis modules. Their global manufacturing footprint and systems approach are relevant for OEMs consolidating suppliers.
-
Tenneco Inc. — Focused on ride-control components, Tenneco competes on breadth of product portfolio and aftermarket reach. Their exposure to commercial vehicle platforms is a differentiator where product lifecycles and replacement demand matter.
-
Benteler, thyssenkrupp Steel, Mubea — These firms illustrate two complementary strategic vectors: lightweight tubular and hollow-product engineering (Benteler, Mubea) and advanced material supply (thyssenkrupp). Recent product launches targeting electric-vehicle architectures and investments in hollow designs are tactical responses to OEM weight-reduction mandates.
-
Regional specialists (Hyundai WIA, NHK Spring, Chuo Spring, Dura Automotive) — Strong OEM ties and focused manufacturing competence enable them to defend regional share and provide localized design variants; strategic partnerships or M&A could expand their reach into adjacent vehicle segments.
Recent corporate moves underscore the market’s direction: active stabilizer demonstrations by major chassis suppliers signal growing OEM interest in smart chassis control; product launches of lightweight hollow bars targeted at EVs indicate early monetization routes for higher-margin designs; and capacity expansions in North America underscore near-term localization trends. For 2026, these actions foreshadow where competitive pressure and margin opportunities will concentrate.
What the full PW Consulting report provides (practical deliverables)
This research is designed as an operational playbook, not an academic thesis. Key deliverables include:
-
Comprehensive market model (2020–2032): consolidated historicals and forward scenarios with sensitivity to vehicle production, weight-reduction adoption, and raw-material cost trajectories. Headline totals are provided in USD Million; detailed subsegment revenue tables and supplier-level splits are included in the full report.
-
Supplier scorecards: capability maps, capacity footprints, technology investments, and likely OEM affinity. Scorecards enable rapid vendor shortlisting for sourcing and M&A due diligence.
-
Raw-material & tariff impact simulator: pass-through matrix and scenario runs (steel price spikes, tariff changes) to quantify margin pressure and required price adjustments.
-
Product-strategy playbooks: go-to-market approaches for hollow vs. solid vs. active stabilizer offerings, including recommended R&D priorities, localization strategies, and integration opportunities with broader chassis systems.
-
M&A and partnership screening tool: prioritized targets by strategic fit (technology, regional footprint, customer base) with indicative valuation ranges under multiple synergy assumptions.
-
Operational risk heatmap: near-term supply constraints, regulatory exposures, and demand-shock scenarios with mitigation actions and trigger points for senior management.
Note: in keeping with the “preview” purpose of this brief, we intentionally withhold proprietary subsegment tables and supplier revenue splits here. Those detailed datasets are available in the full PW Consulting report and are meant to support direct commercial and investment decisions.
Practical 2026 use cases — how clients are applying these insights
-
Procurement teams create multi-year contracts incorporating steel-price collars and regional escalation clauses to protect margins while ensuring supply continuity.
-
Product planners prioritize hollow/active stabilizer modules on platforms slated for electrification to capture lifecycle cost and efficiency gains.
-
Corporate development groups use our supplier scorecards and M&A screening to fast-track bolt-on acquisitions that add hollow-manufacturing capability or regional capacity.
-
Investors and private-equity sponsors model downside scenarios driven by regulatory or tariff shocks, informed by our raw-material sensitivity simulator and supply-chain localization analysis.
Methodology & data integrity
The analysis is grounded in a triangulation of sources: OEM production and platform roadmaps, supplier financials, industry-standard steel pricing benchmarks, public regulatory texts, targeted interviews with Tier-1 procurement and engineering leads, and event-driven intelligence (product launches, capacity announcements). Our base-year construct uses 2025 as the frame of reference, historical observations cover 2020–2025, and forecasts span 2026–2032 under three bespoke scenarios. Revenue units are presented in USD Million. We perform regular back-testing and sensitivity runs to ensure robustness versus fast-moving inputs such as raw-material cost swings and tariff actions.
Final thought — the strategic inflection point for 2026
For executives planning budgets and strategic moves in 2026, the stabilizer bars market offers a window of opportunity: steady headline growth gives room to pursue structural shifts—lightweighting, active control, and regional manufacturing—without the pressure of hyper-growth competition. The strategic priority is to convert engineering differentiation into sustainable commercial advantage while insulating margins from material and policy volatility.
PW Consulting’s full Stabilizer Bars Market Report delivers the granular, transaction-ready intelligence needed to execute those choices. For access to the complete dataset, supplier revenue splits, and executable playbooks, request the full report via the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Stabilizer Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acute Care Telemedicine Market USD 27,450.5M (2025), 14.82% CAGR
By PW Consulting, 2026-07-13
Acute Care Telemedicine Services Market: Strategic Insights for 2026 Decision-Making
As healthcare systems, payers, and technology vendors confront accelerating demand for remote acute care, the Acute Care Telemedicine Services market is transitioning from a disruptive experiment to an operational imperative. Our latest PW Consulting market research frames this evolution with a clear, investment-grade narrative: the market expanded from roughly USD 20.85 billion in 2023 to an estimated USD 27.45 billion in 2025, and is on a trajectory—driven by clinical adoption, platform maturation, and shifting reimbursement—to exceed USD 72.13 billion by 2032 at a compound annual growth rate (CAGR) of 14.82% (USD, revenue in Million). For executives making 2026 strategy choices, this study is designed to convert that trajectory into near-term advantage while protecting the confidential tactical data that drive competitive differentiation.
Acute Care Telemedicine Services Market
Why 2026 Is a Pivotal Inflection Point
-
Policy and payment clarity will shape capital allocation. Temporary reimbursement policies and state-level licensure reforms are converging toward a new baseline in many markets; decisions made in 2026 will lock in network architectures and contract structures for multiple years.
Acute Care Telemedicine Services Market -
Service model experimentation gives way to scale economics. Early adopters who invested behind proof-of-concept programs in 2022–2024 are now facing operational choices—centralized command centers, hybrid hub-and-spoke architectures, or on-demand staffing—that determine margin capture.
Acute Care Telemedicine Services Market -
Talent and technology constraints are now visible operational risks. Physician shortages and specialist sourcing have already elevated staffing costs and will meaningfully affect unit economics unless mitigated by automation, novel contracting, or cross-state licensing strategies.
Market Trajectory – What the Numbers Tell Us
The reported growth path is not academic: rising from approximately USD 20.85B (2023) to USD 27.45B (2025) signals solid commercial validation across multiple acute-care specialties and hospital settings. The forecast CAGR of 14.82% to 2032 encapsulates sustained demand for tele-ICU, tele-stroke, emergency telemedicine, and other acute modalities as hospitals prioritize throughput, specialist access, and cost avoidance. By 2026 the market is projected to accelerate further—an indicator that 2026 investments will be the fulcrum for capturing scale-related benefits.
Strategic Imperatives for 2026
-
Design for interoperability, not lock-in. Buyers should insist on open APIs, standards-aligned streaming and data exchange, and modular contracting to preserve optionality as clinical workflows adapt.
-
Prioritize clinical ROI over tech novelty. Procurement decisions must be driven by measurable improvements in time-to-treatment, transfer avoidance, and length-of-stay deflection rather than feature checklists alone.
-
Build hybrid operational models. A blend of hub-and-spoke command centers for high-acuity coverage plus localized on-demand services for episodic surges balances cost and responsiveness.
-
Lock down workforce strategies now. Given documented staffing pressures and attendant 15–20% increases in clinician cost in certain settings, organizations should pursue a mix of domestic centralized staffing, locum models, and targeted international partnerships where regulatory and quality frameworks permit.
Competitive Landscape — Who Matters and Why
The sector’s commercial dynamics are shaped by a mix of specialist acute-care providers, digital platform vendors, and integrated health systems. Market concentration is moderate: the top three providers account for a meaningful share of supply while the top five control a majority, indicating room for both scale players and focused specialists.
-
Access TeleCare (Dallas, TX; https://accesstelecare.com) has repositioned itself as a multi-specialty acute telemedicine provider and now emphasizes 24/7 coverage across neurology, psychiatry, critical care and ED support—an approach that favors health systems seeking a single-vendor clinical stack.
-
Eagle Telemedicine (Leawood, KS; https://eagletelemedicine.com) focuses on hospitalist and intensivist services for rural and critical-access hospitals, a profile that aligns with providers prioritizing continuity and local integration over broad platform features.
-
Avera eCare (Sioux Falls, SD; https://www.avera.org/ecare) operates one of the largest acute telemedicine networks, offering command-center models and extensive inpatient coordination—an attractive partner for regional systems scaling clinical oversight.
-
Teladoc Health (Purchase, NY; https://www.teladoc.com) and Amwell (Boston, MA; https://business.amwell.com) have leveraged platform capabilities to serve enterprise hospital customers with tele-stroke, tele-ICU, and ED physician support; their strengths lie in technology depth and integration potential.
-
Sound Physicians (Tacoma, WA; https://soundphysicians.com) integrates tele-hospitalist services into broader acute care management programs, offering a blend of clinical management and on-site services that appeals to system-level purchasers.
Recent moves—rebranding, geographic expansion, and partnerships—signal competitive jockeying for scale and specialty depth. Examples include Access TeleCare’s rebrand to emphasize broader capabilities (Nov 2023), Eagle Telemedicine’s regional expansion (Jan 2024), and Avera eCare’s partnership to bolster rural ED coverage (Jun 2024). These maneuvers are early indicators of the consolidation and alliance strategies likely to intensify through 2026.
What This Report Contains — Actionable Frameworks (Not Just Charts)
-
Commercial models and financial templates calibrated to acute care use cases, enabling CFOs to build 36–60 month P&L scenarios tied to utilization, staffing, and reimbursement sensitivity.
-
Buyer’s playbook for technology selection, including an interoperability checklist, security and latency thresholds, and a vendor scorecard tailored to acute workflows.
-
Regulatory and reimbursement maps that translate federal guidance, state licensure nuances, and accreditation requirements into executable compliance steps for 2026 deployments.
-
Operational blueprints for hub-and-spoke and hybrid delivery models, with staffing templates, escalation protocols, and KPI dashboards designed to shorten time-to-value.
-
Vendor landscape analysis with strategic options (partner, build, acquire) and decision trees for hospital systems, payers and technology vendors.
-
Practical risk matrices covering cybersecurity, clinical governance, and workforce fragility—and mitigation playbooks aligned to senior leadership priorities.
Regulatory, Reimbursement and Standards Dynamics
-
Reimbursement momentum has been supportive—but not permanent. For example, Medicare Part B parity for certain acute telemedicine modalities was extended through the end of 2024; future determinations will influence hospital contracting and capital planning.
-
Cross-state licensure remains a gating factor. Compliance options include state licensure, participation in the Interstate Medical Licensure Compact, and targeted MARs—each with implications for speed to scale.
-
Clinical standards matter. Platforms must meet minimum bandwidth and video-resolution standards as defined by clinical societies to be safe and defensible in high-acuity scenarios.
-
Accreditation expectations are rising: The Joint Commission now expects telehealth programs delivering acute care to adhere to validated safety and quality standards—an operational requirement that influences vendor selection and program governance.
Scenarios and Use Cases—How to Translate Insight into Decisions
-
Scenario A—Rapid Scale: For systems aiming to centralize acute coverage, the study provides phased investment schedules, vendor interoperability requirements, and staffing roadmaps that deliver break-even timelines tied to transfer-avoidance and reduced ICU LOS.
-
Scenario B—Targeted Specialty Rollout: For organizations prioritizing tele-stroke and tele-ICU, the research prescribes technology minimums, partner selection criteria, and outcome-linked contracts for specialty groups.
-
Scenario C—Rural Safety Net: For rural hospitals and health systems, the report identifies partnership archetypes and shared-service models that offset specialist scarcity while preserving local governance.
How Senior Leaders Should Use This Research in 2026
-
C-Suite: Use the strategic options and financial templates to set five-year capital and operating budgets that reflect realistic adoption curves and regulatory scenarios.
-
Procurement & IT: Apply the vendor scorecard and interoperability checklist to upcoming RFPs to avoid costly lock-in and to ensure clinical-grade performance.
-
Clinical Leaders: Leverage the KPI dashboards, accreditation playbook and staffing templates to operationalize quality metrics and control clinical risk.
-
Investors & M&A Teams: Use the competitive landscaping and concentration indicators to prioritize targets and bid strategies that capture consolidation upside or defend against it.
Next Steps and Where to Find the Full Intelligence
This introduction outlines the strategic contours that matter most for 2026 planning—market scale, growth dynamics, competitive moves, and the policy landscape. PW Consulting’s full report contains the proprietary segment models, vendor level scorecards, and executable financial templates that operational teams and boards need to move from intent to execution. To access the complete dataset, scenario models, and implementation-ready tools, please refer to the report landing page linked in our release notes.
In 2026, the winners will be those who convert macro momentum into predictable operations—balancing clinician capacity, regulatory certainty, and interoperable technology while preserving the clinical governance that acute care demands. PW Consulting’s Acute Care Telemedicine Services market research is built to accelerate that transition without exposing the granular segmentation that differentiates proprietary strategies.
For detailed analysis of this topic, please visit the official page: Acute Care Telemedicine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Utility Monitoring System Market to Hit USD 16,155.5M by 2032 (14.33% CAGR)
By PW Consulting, 2026-07-13
Water Utility Monitoring System Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, actionable briefing that frames the strategic choices utilities, vendors, and investors must make in 2026. Our full Water Utility Monitoring System Market study provides the data, vendor scorecards, and executable templates behind these conclusions. This article illustrates the market trajectory, the forces shaping competitive advantage, and the practical actions that deliver measurable ROI — while intentionally omitting the granular segmentation tables and proprietary forecasting matrices that drive procurement and M&A plays (those are available in the full report).
Water Utility Monitoring System Market
Market Trajectory — why 2026 is a pivotal inflection point
The global water utility monitoring systems market has moved from an early-adopter phase into a rapid commercial scaling stage. Our model shows the market expanding from roughly USD 3.45 billion in 2020 to about USD 6.33 billion in 2025, and projecting to exceed USD 16.15 billion by 2032. This translates into a robust compound annual growth rate of approximately 14.33% across the 2026–2032 forecast window. For corporate strategists and utility executives, that means the financial and competitive consequences of decisions made in 2026 will compound materially over the next decade.
Water Utility Monitoring System Market
- Demand is driven by a confluence of regulatory pressure, asset renewal cycles, drought and climate adaptation planning, and the imperative to curb non‑revenue water.
- Technology maturation — particularly cloud platforms, digital twins, and edge-sensor analytics — is lowering the marginal cost of actionable monitoring while raising the value of services layered on top of raw telemetry.
- Cybersecurity, spectrum and telecom policy, and workforce shifts are emerging as strategic constraints — not just implementation details.
Practical contents of the PW Consulting study (what you will actually use)
Our report is designed as a decision-support toolkit, not a theoretical treatment. Key deliverables include:
Water Utility Monitoring System Market
- Proprietary market model and scenario engine (base case, accelerated digital adoption, and constrained-capex scenarios) with downloadable inputs you can re-run for your planning.
- Go-to-market playbooks for vendors (product roadmaps, pricing levers, partnership archetypes) and adoption roadmaps for utilities (pilot design, procurement language, and O&M handoffs).
- Vendor risk and capability scorecards with mapped strengths, blind spots, and likely consolidation targets (highly actionable for sourcing teams and corporate development).
- Regulatory-impact matrix and compliance checklist, covering critical infrastructure guidance, data residency, spectrum allocation, and cybersecurity requirements that shape procurement and operations.
- Sample financial models: CapEx-to‑Opex conversion scenarios, life‑cycle TCO templates, and NPV-based ROI thresholds tailored to water utility budgeting windows.
- Implementation playbooks and change-management checklists covering labor reallocation, training, and vendor-managed services contracting.
Competitive landscape — who matters and why (strategic implications)
The vendor ecosystem blends traditional instrumentation and SCADA leaders with metering specialists and software-first entrants. In broad strategic terms:
- Metering specialists with strong AMI/AMR portfolios are doubling down on communications modules and analytics to move up the value chain from devices to outcome-based services. Expect continued investment in leak detection, automated interval reads, and field-hardened wireless nodes.
- Large industrial automation and energy players are leveraging their SCADA, control systems, and cybersecurity capabilities to capture utility-level monitoring and process-control work, particularly in treatment plants and pumping stations.
- Pure-play digital vendors and cloud platform providers are the catalyst for digital twin and GIS-based monitoring adoption; their advantage is rapid feature rollouts and low marginal deployment costs, but they must demonstrate operational resilience in regulated utility environments.
Representative strategic profiles (non-exhaustive):
- Established metering firms are extending into adjacent sensing (e.g., sewer and manhole monitoring) and analytics through M&A and targeted product extensions — a clear signal that meter-plus-service bundles will be a durable commercial model.
- Automation conglomerates are integrating AI-enabled predictive modules and emphasizing cybersecurity features, positioning themselves for large-scale municipal and industrial deals where integration risk is a key buying criterion.
- Regional vendors and network specialists maintain advantage on last-mile communications and regulatory compliance in territories where spectrum policy or telecom regulation governs IoT deployments.
Recent industry moves underscore these dynamics: acquisitions to broaden sensing portfolios, product launches embedding advanced cybersecurity and AI for predictive operations, and strategic partnerships to deploy AMI modernization projects with finer time-series data granularity. Each action suggests vendors are competing on bundled outcomes — not just meters or SCADA systems — which changes procurement evaluation criteria.
Regulatory and operational constraints shaping 2026 choices
- Cybersecurity for water infrastructure has risen to a national-policy priority. Utilities and vendors must design systems with network segmentation, encrypted telemetry, and continuous monitoring as baseline requirements — not premium options.
- Funding pressures and aging assets create competing priorities: replacing physical infrastructure vs. investing in digital overlays. Many jurisdictions face infrastructure funding gaps running into the high hundreds of billions, which will drive phased deployments and creative financing structures.
- Spectrum allocation and telecom policy — from LoRaWAN and NB‑IoT licensing to local data privacy rules — materially affect communications architecture and recurring connectivity costs. Local regulatory constraints will dictate whether private networks, utility-owned radios, or carrier IoT services are practical.
- Labor economics: digital metering reduces manual reading headcount but reallocates spend to cybersecurity, data operations, and vendor service contracts. Workforce transition plans are a non-trivial part of the ROI calculus.
Strategic recommendations for executives — 90-day to 36-month actions
To convert market growth into sustainable advantage in 2026, PW Consulting recommends a layered, risk-aware approach:
- First 90 days — Prepare: Run the scenario engine using your utility-specific inputs; audit telemetry security posture; shortlist two pilot sites with clear performance KPIs (leak reduction, meter-to-cash improvement, or sampling frequency uplift).
- 3–12 months — Pilot and procure: Deploy a time‑phased AMI/monitoring pilot with an incumbent-neutral tender that evaluates device performance, network economics, and vendor SLAs; include clauses for data ownership and cybersecurity audits.
- 12–36 months — Scale and transform: Move from CAPEX-heavy purchases toward hybrid procurement (meter-as-a-service, managed analytics). Invest in digital twins for high‑risk network segments and operationalize predictive maintenance workflows to shift O&M budgets to pre-emptive interventions.
For vendors and investors, the essential moves are:
- Develop outcome-based contracting capabilities (performance guarantees tied to NRW reduction or meter-read accuracy).
- Invest in hardened, certifiable cybersecurity stacks and background compliance artifacts to shorten procurement cycles with regulated buyers.
- Pursue horizontal partnerships (telecoms, cloud providers, local integrators) rather than attempting to own every layer; the winner will be the one that orchestrates a reliable, low-friction stack.
- Use M&A selectively to fill sensing or software gaps, focusing on assets that enable recurring-service revenue rather than one-time hardware sales.
What the full PW Consulting report will enable you to do
Executives who use our full deliverable will be able to:
- Build a defensible, board-ready digital water investment case with detailed TCO and phased payback scenarios;
- Write procurement specifications and KPIs that avoid common traps (vendor lock-in, insufficient cybersecurity, ambiguous data rights);
- Identify high-probability acquisition targets and partnership archetypes based on capability gaps in device, network, or software layers;
- Quantify upside and downside risks across multiple adoption curves and negotiate SLAs that align incentives for long-term network performance.
Final thought — why 2026 decisions compound value
The market’s projected growth trajectory and accelerating technological maturity mean that near-term choices will determine competitive positioning for at least a decade. Suppliers that move from selling hardware to delivering measurable operational outcomes will capture the most durable value. Utilities that treat monitoring systems as strategic infrastructure — integrating cybersecurity, procurement discipline, and workforce transition plans — will realize the fastest, most defensible improvements in service reliability and financial performance.
PW Consulting’s full Water Utility Monitoring System Market report contains the granular forecasts, vendor ratings, procurement templates, and regulatory mappings necessary to act with confidence in 2026. For teams preparing RFPs, planning pilots, or scoping M&A, the report converts market insight into executable programs. Visit our research portal for access to the full dataset and implementation playbooks.
For detailed analysis of this topic, please visit the official page: Water Utility Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


