



Category: market research
PW Consulting: Beard Shave Formula Market to Hit USD 11,719.4M by 2032 with 4.85% CAGR
By PW Consulting, 2026-07-13
Beard Shave Formula Market — Strategic Briefing for 2026 Decisions
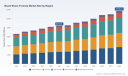
PW Consulting’s Beard Shave Formula Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames a rapidly maturing category that blends legacy mass‑market players, heritage wet‑shaving artisans, and digitally native beard‑care specialists. At the macro level the market demonstrates stable expansion — growing from roughly USD 6.6 billion in 2020 to about USD 8.4 billion in 2025, and projected to reach approximately USD 11.7 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 4.85% over the forecast window. This briefing distils the strategic implications of those trends for corporate decision‑makers in 2026 while intentionally withholding granular regional and application breakdowns to preserve the full report’s role as a primary source for transaction and product planning.
Beard Shave Formula Market
Why this report matters for 2026 strategic choices
- Capital allocation: Budgeting for R&D, supply‑chain resilience, and targeted distribution experiments (DTC, retail, professional channels) should be informed by the market’s mid‑single‑digit growth profile and the premiumization occurring within the category.
- Portfolio strategy: The combination of scale incumbents and agile niche players means incumbents must decide whether to defend mass channels or selectively invest in premium/natural formulations while challengers must prioritize scalability and margin capture.
- M&A and partnerships: The competitive concentration metrics in the study indicate meaningful room for consolidation and bolt‑on acquisitions to secure capabilities (formulation science, DTC fulfillment, barber channel relationships).
- Regulatory & operational risk: Recent changes in grooming policy across military services and ongoing natural‑oil supply volatility require proactive scenario planning for demand shocks and margin pressure.
Market trajectory and what the numbers tell you
The category’s steady expansion through 2025 underscores resilient end‑user demand for beard‑specific shave preparations and ancillary grooming products. From a strategic viewpoint, two macro takeaways are critical: first, growth is consistent but not explosive — the market rewards targeted differentiation over broad heavy CAPEX bets on volume alone. Second, market concentration is meaningful but not prohibitive: the top three firms account for a material share of the market, while the top five accumulate a clear majority, leaving definable pockets of opportunity for focused entrants and incumbents pursuing adjacent premium or natural segments.
Beard Shave Formula Market
For executives, the implication is clear: incremental share gains remain attainable through product innovation, channel optimization, and brand positioning, but these moves must be calibrated against realistic growth expectations and disciplined margin management. The market’s projected climb to the low double‑digit billions by 2032 means long‑term value creation, but it will be unevenly distributed — the premium and specialty niches are likely to expand faster than commoditized segments.
Beard Shave Formula Market
Segmentation shape without the minutiae
The beard shave formula category is usefully decomposed along product form (gels, creams, foams, oils and soaps), end‑use (individual consumers, professional barber services, hospitality/other institutional uses), and regional dynamics. These axes drive very different product requirements — from performance‑centric formulations designed to soften coarse beards and minimize irritation, to botanically driven premium products prioritizing natural sourcing and skin protection.
Rather than publish detailed regional and application shares here, this briefing emphasizes decision‑relevant distinctions: product form factors dictate R&D and packaging choices; channel mix dictates marketing, pricing, and fulfillment models; and regional regulatory environments influence claims, testing, and labeling requirements. The full report contains the granular segmentation matrices and historical series required for rigorous SKU‑level P&L modeling.
Key dynamics and tail risks shaping 2026 strategy
- Regulatory shifts: Changes issued across U.S. military services in 2025–2026 tighten the scope for long‑term medical shaving waivers and reinforce clean‑shave standards in certain duty contexts. These moves create short‑to‑medium‑term demand variability in institutional channels and emphasize the need for manufacturers to diversify channel exposure.
- Raw‑material volatility: Premium formulations increasingly rely on natural oils (e.g., argan, jojoba). Supply chain volatility for these inputs is ongoing and can materially compress margins for products marketed on natural‑ingredient credentials unless procurement and pricing strategies are adjusted.
- Premiumization & consumer behavior: Elevated willingness to pay for natural, performance, and skin‑sensitive products drives faster growth at the premium end. Consumers are also demonstrating loyalty to brand experiences (barber partnerships, subscription replenishment models) more than to commodity price points.
- Retail & DTC dynamics: Traditional retail still moves high volumes, but subscription DTC and curated bundles are proving to be higher margin growth engines for smaller and digitally native brands, forcing incumbents to reconcile channel conflict with margin uplift opportunities.
Competitive landscape—what incumbents and challengers are doing
The market reflects a classic multi‑channel competitive structure: global CPG giants leverage scale and retail reach; premium heritage brands trade on craft and ritual; and indie DTC players capture premium mindshare with authentic storytelling and ingredient claims. Highlighting a cross‑section of players illustrates strategic variety:
- Procter & Gamble (United States) — Leverages household brands and extensive distribution to defend mass and performance segments. Scale R&D and shelf presence remain core advantages, particularly for broad reach and cost management.
- Unilever (U.K./Netherlands) — Combines mainstream strength with digital playbooks (including subscription models via acquired platforms). Their strategic posture emphasizes multi‑brand ownership to cover both value and premium spaces.
- L'Oréal Group (France) — Focused on technical formulations and skin‑centric claims under specialist men’s grooming lines; strength lies in formulation science and professional channel partnerships.
- The Art of Shaving (United States) — A luxury, ritualized approach to shave preparation and in‑store services; competitive moat exists in experiential retail and premium pre‑shave portfolios.
- Beiersdorf AG (Germany) and Edgewell Personal Care (United States) — Represent well‑positioned incumbents balancing mass skin‑comfort claims with targeted innovations for sensitive or coarse beard care.
- Clarins (France) and other premium cosmetic houses — Prioritize botanical and skin‑health narratives, appealing to consumers seeking premium natural credentials backed by established beauty credibility.
- Independents (e.g., Honest Amish, Beardbrand, Proraso, Cremo) — Capture niche audiences via authenticity, heritage, or performance messaging. These brands are natural acquisition targets for scale players seeking premium or DTC capabilities.
Strategically, incumbents must weigh defensive investments (price, placement, private label competition) against offensive plays (acquisitions of indie brands, targeted premium launches). For challengers, the path to scale runs through differentiated formulations, razor‑thin fulfillment economics for subscriptions, and selective retail partnerships that preserve brand premium.
What the full PW Consulting report delivers (operationally focused)
Our comprehensive report is designed to convert insight into action. Highlights include:
- Market sizing and growth scenarios at global, regional, and channel levels (historical series and 2026–2032 projections).
- Product‑level and channel segmentation frameworks with SKU‑level implication maps for R&D and pricing.
- Supply‑chain and raw‑material risk maps, including stress tests for natural‑oil price increases and mitigation playbooks.
- Competitor dossiers with positioning matrices, route‑to‑market strategies, and acquisition target lists (including valuation heuristics for M&A screening).
- Regulatory heat maps and scenario planning templates addressing grooming policy changes and labeling/compliance risks in key markets.
- Actionable go‑to‑market playbooks for incumbents and challengers — DTC subscription pilots, retail assortment optimization, and barber/pro channels monetization.
- Five prioritized strategic imperatives and a 12‑month execution roadmap tailored for management teams evaluating investments or portfolio pivots in 2026.
The body of the report includes the detailed tables, regional splits, and unit economics that are intentionally not reproduced in this brief to preserve analytical value for subscribers and project partners.
Practical recommendations for 2026 — five priority moves
- Lock in strategic raw‑material arrangements: Negotiate multi‑year supply contracts or joint‑ventures for volatile natural oils; consider formula reformulation buffers where feasible to protect margins.
- Segmented product architecture: Build distinct SKUs for performance, skin‑sensitive, and botanical premium buyers — but centralize R&D to reduce duplication and accelerate claim validation.
- Channel‑tailored go‑to‑market: Pilot premium DTC subscription bundles while maintaining defensive retail shelf presence; establish barber partnerships as both revenue and R&D labs for product validation.
- Regulatory & institutional scenario planning: Quantify exposure to military and institutional channels and diversify to consumer channels in regions where grooming policies tighten.
- M&A & partnership focus: Use tuck‑ins to acquire DTC capabilities, artisanal formulations, or sustainable sourcing expertise — prioritize deals that accelerate margin recovery and brand credibility.
Closing — why access the full report
This briefing surfaces the strategic crossroads facing players in the beard shave formula market as they plan for 2026. The category offers predictable aggregate growth and compelling pockets of premium expansion, but value will accrue to organizations that combine supply‑chain foresight, disciplined product architecture, and channel agility. PW Consulting’s full report supplies the granular regional splits, product‑form revenue tables, scenario models, and competitive benchmarks necessary to convert the insights above into executable plans and rigorous investment theses.
For boards and leadership teams preparing 2026 budgets, product roadmaps, or M&A screens, the full dataset and playbooks are essential. Contact PW Consulting to obtain the complete report, download the interactive models, and schedule a strategy session tailored to your firm’s exposure in this evolving category.
For detailed analysis of this topic, please visit the official page: Beard Shave Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Consumer IoT Market 2026: Strategic Imperatives and Actionable Intelligence
Executive snapshot
Between 2020 and 2025 the consumer IoT market more than doubled in scale, reflecting rapid adoption across smart home, wearables, personal electronics and in-vehicle consumer interfaces. Our base-year analysis (2025) places the global market at USD 208.5 Billion. From 2026 the market is forecast to expand at a compound annual growth rate (CAGR) of 14.85% through 2032, driving total market value to roughly USD 550 Billion by the end of the forecast window. This pace is transformational: it converts adjacent consumer electronics markets into platform- and service-led businesses and raises the strategic stakes for product, channel and regulatory positioning in 2026 and beyond.
Consumer Iot Market
Why this research matters for 2026 decisions
-
Timing: 2026 is a pivot year. With a high-growth runway ahead, incumbents and challengers must choose whether to double down on hardware differentiation, migrate to software-and-service models, or pursue hybrid plays that lock consumers into ecosystems.
Consumer Iot Market -
Regulatory inflection: New regulatory requirements—most notably EU-level cyber resilience rules with phased compliance and local US/California laws governing device security—mean product roadmaps and compliance budgets must be reconciled now, not later.
Consumer Iot Market -
Consolidation pressure: Market concentration is meaningful but not prohibitive—top-three vendors control roughly one-third of the market while top-five approach one-half—creating windows for focused challengers and M&A-driven scale plays.
-
Interoperability and standards: Matter and other certification programs have matured rapidly; interoperability is shifting from a convenience play to a baseline market expectation. Device makers who are late to certify will face distribution frictions and higher returns costs.
What leaders need to know — five strategic implications
-
Reframe product portfolios around services and recurring revenue. As unit growth accelerates, lifetime value and retention will increasingly separate winners from losers. Hardware alone no longer delivers defendable margins; subscription and bundled services (cloud features, AI enhancements, extended warranties) are decisive.
-
Design for regulatory-first security. With regional laws mandating baseline security controls and disclosures, security-by-design will be essential to market access. Companies should prioritize secure boot, timely OTA updates, vulnerability disclosure processes, and Supplier Security SLAs to avoid being locked out of major markets or facing reputational and financial risk.
-
Prioritize interoperability and developer enablement. The proliferation of certified Matter devices and the widening ecosystem of thread/low-power connectivity demand a developer-friendly platform strategy. Investing in SDKs, clear developer documentation, and partner certification accelerates channel adoption and reduces customer friction.
-
Optimize BOM and channel economics without sacrificing differentiation. Emerging wireless standards and next-generation silicon create cost-and-performance trade-offs that impact pricing strategy. Product teams must balance advanced connectivity and on-device AI with yield-sensitive component choices and scalable manufacturing partners.
-
Hone go-to-market (GTM) segmentation and partnerships. The effective GTM mix will be a hybrid of DTC, retail alliances, telco-bundling and retail-embedded experiences. Strategic partnerships (CE retailers, telcos, platform vendors) will accelerate reach while reducing customer acquisition costs for software-driven services.
Competitive landscape—positions and near-term moves to watch
The market is populated by strong platform incumbents and a vibrant set of category specialists. Leading players leverage ecosystems, distribution, brand and developer scale—while smaller, focused companies compete on price, niche features and speed-to-market. Key strategic observations on major vendors:
-
Amazon: Deep strengths in voice, retail distribution and cloud services give Amazon a structural advantage for platform-led monetization. Recent wearable and AI upgrades signal intent to expand user touchpoints beyond the living room into daily personal devices.
-
Google: Integration with the broader Android and services stack, plus continued investment in Matter support, positions Google to be the interoperability anchor for many OEM partners. Platform openness remains a double-edged sword—accelerating adoption but diluting direct monetization levers.
-
Apple: A privacy-first positioning and tight hardware-software integration continue to justify premium pricing and loyalty. Expansion of third‑party Thread/HomeKit support creates opportunities for embedded partners but also raises expectations for strict privacy and certification compliance.
-
Samsung: Strength in appliances and a broad device portfolio makes Samsung a natural integrator of multi-category experiences. Investments in next-generation connectivity (Wi‑Fi 7 readiness) are aimed at preserving leadership in high-throughput home applications.
-
Category specialists (Philips/Signify, Sonos, iRobot, Arlo, Wyze, TP‑Link): These firms are bifurcating into two strategic archetypes—(1) product-first premium specialists who monetize via brand and service extensions, and (2) value incumbents who scale through low-cost BOM and distribution. Their agility makes them key M&A targets for platform players seeking category fill.
Macro tailwinds, headwinds and risk matrix for 2026
-
Tailwinds: Strong consumer replacement cycles, rising acceptance of subscription models, and enhancements in on-device AI will drive both unit volumes and ARPU.
-
Headwinds: Compliance costs, escalating support/resolution expectations, and macro-driven component pricing volatility can compress margins—especially for hardware-first models.
-
Regulatory risk: Non-compliance with regional cybersecurity and product safety rules can restrict market access, incur fines and increase return rates; conversely, early compliance can be a commercial differentiator.
-
Concentration risk: While major platforms control significant share, there remains space for vertical specialists and regional champions—timing and partnership selection determine success.
What the PW Consulting report delivers (practical, transaction-ready outputs)
Our full study is built for decision-makers who need executable guidance, not just high-level signals. Deliverables include:
-
Top-down market-sizing and growth scenarios (base, upside, downside) through 2032, with sensitivity analysis on price, penetration and replacement cycles.
-
Vendor landscape and strategic positioning maps, including vendor scorecards that evaluate product breadth, platform strength, developer ecosystem, monetization capability and regulatory readiness.
-
Commercial playbooks: GTM archetypes, channel economics templates, pricing simulations and subscription packaging options tailored to consumer segments.
-
Compliance and security roadmaps aligned with EU, US and subnational regulations—practical checklists for product teams and sample contractual clauses for supplier security obligations.
-
M&A and partnership target screening: criteria-driven shortlists for bolt-on acquisitions, JV structures and OEM co-development frameworks.
-
Technology deep dives: connectivity standards roadmap, edge vs cloud AI trade-offs, lifecycle OTA strategies and cost engineering levers for BOM reduction.
-
Operational playbooks: support and reverse-logistics modeling, warranty and repair economics, and CX design templates to minimize churn.
How to use this intelligence in 90‑, 180‑ and 365‑day plans
-
90 days: Conduct a rapid compliance gap assessment against regional security standards, prioritize Matter/Thread certification paths, and run a topline ARPU sensitivity to subscription price points.
-
180 days: Finalize GTM partner agreements (telco bundles or retail exclusives), pilot bundled subscription offers, and lock component supply agreements to hedge near-term cost volatility.
-
365 days: Scale platform investments, execute targeted M&A or strategic alliances to fill portfolio gaps, and migrate installed base customers to service-led revenue streams.
Why PW Consulting’s analysis is different
We combine rigorous, transparent market modeling with practitioner-grade playbooks and legal/compliance checklists. Our methodology triangulates vendor disclosures, primary interviews, component-level BOM analysis and certification registries—yielding forecast scenarios that are both defensible and operationally actionable. Importantly, while this briefing surfaces critical strategic directions and macro metrics (historic and forecast totals, CAGR, concentration indicators), we intentionally withhold certain granular segmentation metrics and proprietary regional allocations in public summaries to preserve the analytical value of our full dataset.
Next steps — access to the full dataset and custom briefings
If your 2026 strategy depends on precise regional mix, application demand curves, OEM-level unit economics or bespoke scenario runs, our full report and custom consulting engagements provide the detailed segmentation, downloadable datasets and interactive models you need. The full intelligence package includes the complete breakdown across components, applications and regions, plus the vendor-level revenue and share estimates used to build our strategic recommendations.
Visit our report page to download the executive report and request a tailored briefing—PW Consulting will help you convert the market’s growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Consumer Iot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trial Process Management Market to Reach USD 6,880.83M by 2032 (13.18% CAGR)
By PW Consulting, 2026-07-13
Trial Process Management System Market: Strategic Briefing for 2026 Decision-Makers
As organizations recalibrate clinical development strategies in 2026, Trial Process Management (TPM) systems have shifted from “nice-to-have” operational tools to strategic infrastructure that directly impacts time-to-decision, regulatory risk, and trial economics. This briefing—drawn from PW Consulting’s latest market research—summarizes the high-level market trajectory, competitive dynamics, regulatory forces, and the pragmatic decision framework executive teams should use this year. It is designed to demonstrate the report’s analytical depth while preserving the proprietary segmentation and scoring that unlocks tactical plans in the full study.
Trial Process Management System Market
Market Trajectory: Scale and Growth Expectations
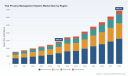
TPM adoption has accelerated through the 2020s. On a macro basis, the global TPM market more than doubled from its early‑decade baseline and reached nearly USD 2.9 billion in 2025 (base year). Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of around 13.2% over the 2026–2032 forecast window, reaching the mid‑single‑digit billions by the end of the period. That growth is being driven by a combination of platform modernization, cloud migration, regulatory tightening around data protection and electronic records, and the emergence of AI-enabled orchestration layers that promise to compress study build and execution cycles.
Trial Process Management System Market
Why This Matters for 2026 Decisions
- Cost-to-Operate vs. Speed-to-Market: With sponsors and CROs under pressure to shorten development timelines, TPM systems are now a lever both for operational cost control and schedule risk mitigation. The right platform choice influences monitoring frequency, query resolution times, and protocol adherence—metrics that materially affect study economics.
- Regulatory & Cyber Requirements: Emerging regulatory expectations (including tighter HIPAA security requirements and evolving GDPR guidance on data protection by design) make platform security and privacy engineering a board-level procurement criterion. Validation, encryption, and auditability are non‑negotiable.
- Vendor Differentiation through AI and Site Enablement: Vendors that combine core CTMS capabilities with AI for study build, risk-based monitoring, and virtual trial orchestration are moving from feature vendors to strategic partners.
- Integration as a Competitive Filter: Interoperability with EDC, EHR, safety databases, and finance systems determines whether a TPM investment delivers expected efficiency gains or becomes another silo that increases integration cost.
What the Full Report Delivers (Actionable Modules)
- Market sizing and a transparent forecast methodology (historical 2020–2025; forecast 2026–2032; base year 2025; USD, revenues in Millions).
- Segmented demand analysis across deployment modes, end‑user types, and regional markets—presented with scenario modelling and sensitivity to regulatory and technology shocks.
- Vendor landscape and comparative benchmarking: capability matrices, go‑to‑market positioning, integration readiness, product roadmaps, and M&A/partnership tracking.
- Implementation playbooks for sponsors, CROs, and sites: procurement checklists, validation timelines, pilot designs, change management templates, and TCO models that incorporate labor and cloud hosting realities.
- Risk register and compliance checklist aligned to current regulatory expectations (e.g., FDA 21 CFR Part 11, GDPR Art.25, HIPAA Privacy and Security Rule updates), plus recommended vendor contract clauses and BAA considerations.
- Commercial intelligence: pricing models, licensing benchmarks, and recommendations for outcome‑based contracting and vendor consolidation strategies.
Competitive Landscape: Strategic Positions and Near‑Term Moves
The TPM market is characterized by a mix of large platform integrators, specialized CTMS vendors, and service-heavy CROs that bundle TPM capabilities into broader offerings. Leading providers are pursuing distinct strategies that matter to buyers:
Trial Process Management System Market
- Veeva Systems —Continuing its enterprise platform focus, Veeva’s site‑oriented product introductions signal a dual approach: maintain strong sponsor/CRO footprint while enabling site adoption and data flow efficiency. Site-centric offerings that lower site burden can materially influence enrollment and source document timelines.
- Medidata (Dassault Systèmes) —An aggressive AI and orchestration strategy positions Medidata as a hub for study simulation, build automation, and real‑time optimization. Recent strategic partnerships and AI ecosystem announcements demonstrate a push to embed predictive and prescriptive intelligence across lifecycle stages.
- Oracle —With established enterprise implementations and recognized integration strengths, Oracle remains a default choice for organizations prioritizing depth of integration across EHR/EDC and regulatory compliance scaffolding.
- Advarra —Focused on academic and site networks, Advarra’s enhancements emphasize financial management, regulatory automation, and reporting—areas with immediate ROI for institutions that run high volumes of investigator‑initiated and academic trials.
- Parexel, IQVIA, Clario, RealTime, ArisGlobal, MasterControl —Each brings differentiated value: Parexel and IQVIA pair TPM with CRO services and broad data platforms; Clario targets endpoint and device-focused workflows; RealTime and Advarra strengthen site workflows; ArisGlobal and MasterControl cater to compliance‑heavy, regulated environments.
Recent vendor moves—strategic AI partnerships, product launches focused on site enablement, and enhanced analytics—signal a competitive phase where platform orchestration, AI augmentation, and site economics will determine leadership. Buyers should treat vendor roadmaps and AI safety guardrails as procurement deal‑breakers.
Regulatory and Operational Dynamics that Shape Vendor Selection
- Data Protection & Security: Proposed HIPAA Security Rule updates introduce mandatory encryption, routine vulnerability scanning, and annual penetration testing for entities processing ePHI—raising validation and continuous compliance costs for both cloud and hybrid implementations.
- Data Protection by Design: GDPR Article 25 increasingly constrains how TPM vendors manage identifiable health data. Buyers must require documented pseudonymization strategies, access minimization, and built‑in privacy controls in vendor due diligence.
- HIPAA Privacy Requirements: Expect more rigorous expectations around BAAs, minimum‑necessary access, and disclosure documentation when TPM vendors handle data on behalf of covered entities.
- Regulatory Records & Auditability: Standards such as FDA 21 CFR Part 11 and EMA guidelines remain central—platforms must support electronic signatures, secure audit trails, and validated system life‑cycle management.
- Operational Cost Drivers: Primary cost contributors are specialized labor for configuration, validation, and compliance monitoring, alongside cloud hosting fees that scale with data volume and integration complexity. These must be fully captured in TCO and ROI models.
Practical Guidance: Procurement & Implementation Priorities for 2026
- Adopt a risk‑based procurement scorecard that weights interoperability, AI maturity (with auditability), site ergonomics, and regulatory evidence over feature checklists.
- Build validation and compliance costs into budget cycles from Day‑1. Plan for continuous validation activities tied to security patching, AI model updates, and integration changes.
- Pilot for impact: run short, instrumented pilots focused on enrollment speed, query cycle time, and monitoring‑efficiency metrics. Use these to derive evidence for scaling and price negotiations.
- Negotiate outcome‑oriented terms where practical (e.g., migration credits tied to user adoption thresholds, service credits for integration SLAs, or shared savings for workflow automation gains).
- Prioritize vendors that publish explainability and monitoring tools for AI components—regulators and auditors increasingly expect governance artifacts for autonomous decision support.
- For site networks and academic centers, seek site‑friendly licensing and deployment models that minimize administrative burden and support multi‑sponsor collaboration.
Strategic Questions PW Consulting Helps Clients Answer
- Which TPM architecture (cloud‑native, hybrid, or on‑premise) minimizes TCO while satisfying near‑term compliance milestones?
- How to structure a phased rollout that delivers measurable operational wins within the first 12 months?
- What vendor partnership model—best‑of‑breed integrations vs. single‑vendor platforms—best aligns with our portfolio strategy and clinical complexity?
- How to score vendor AI propositions for safety, auditability, and real‑world impact on trial timelines?
- Which contract terms and KPIs should be non‑negotiable in an era of tighter data protection rules?
Our full Trial Process Management System Market report provides granular answers to these questions—complete with segmented demand tables, vendor scorecards, pricing benchmarks, implementation timelines, and downloadable procurement templates. The analysis blends quantitative market projection with qualitative vendor due diligence to support actionable 2026 roadmaps.
Next Steps
For executive teams planning TPM investments in 2026, the immediate priority is to align clinical, IT, privacy, and procurement stakeholders around a single, measurable set of objectives—then use that charter to evaluate vendors against the priorities and risks outlined above. PW Consulting’s full report and advisory engagements are designed to convert those objectives into negotiation strategies, validated implementation plans, and measurable KPIs that preserve study timelines while controlling compliance risk and operational cost.
Contact PW Consulting’s Life Sciences practice to access the complete market study, vendor benchmarks, and tailored advisory services that translate the market’s projected growth and vendor dynamics into a practical 12–36 month execution plan.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Satellite Control Market to Hit USD 35,470M by 2032 at 7.45% CAGR
By PW Consulting, 2026-07-13
Satellite Control Service Market: Strategic Preview for 2026 Decision‑Makers
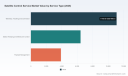
As PW Consulting’s Senior Strategy Advisor and Industry Lead, I present an executive preview of our Satellite Control Service Market study — a pragmatic guide designed to orient corporate strategy, procurement, and investment decisions in 2026. The market for satellite control services has moved from niche operations to a core component of commercial space value chains. Our baseline analysis shows the market expanding from roughly USD 15.2 billion in 2020 to about USD 21.45 billion in 2025, and we forecast continued growth to an estimated USD 35.47 billion by 2032 at a compound annual growth rate (CAGR) of approximately 7.45% across the forecast horizon. For leaders planning capital allocation, partner selection, or M&A activity in 2026, the choices made this year will determine who captures durable operational value as this market doubles in scale.
Satellite Control Service Market
Why 2026 Is a Strategic Inflection Point
Several concurrent forces converge in early 2026 to make this a decisive year for satellite control strategies:
Satellite Control Service Market
- Regulatory recalibration: major jurisdictions are moving to simplify licensing, widen spectrum access, and harmonize approvals for satellite infrastructure — creating windows for faster deployments and cross‑border commercial models.
- Operational economics: capital intensity for ground infrastructure remains high, but shared ground-station and GSaaS (Ground Station as a Service) models are rapidly maturing as a cost mitigation pathway for operators and new entrants.
- Technology and mission diversity: multi-orbit architectures and mixed constellations (LEO/MEO/GEO and beyond) increase complexity for telemetry, tracking and command (TT&C), driving demand for integrated ops platforms and resilient network fabrics.
- Competitive consolidation: market concentration metrics show a meaningful presence of scale incumbents alongside a growing cohort of specialist GSaaS providers and defense primes — creating both partner and competitor dynamics that must be navigated deliberately.
Taken together, these dynamics make 2026 the year to pivot from opportunistic experiments to repeatable operating models and resilient supplier strategies.
Satellite Control Service Market
What PW Consulting’s Study Delivers — Practical, Transaction‑Ready Intelligence
This report is built for operators, infrastructure investors, systems integrators, and advanced users of satellite services who need actionable outputs rather than abstract predictions. Key deliverables include:
- Market sizing and growth drivers: rigorous top‑down and bottom‑up models covering the market from 2020 through our 2026–2032 forecast window, with scenario variants reflecting regulatory, spectrum, and technology outcomes.
- Decision frameworks: procurement scorecards, supplier shortlisting criteria, and risk‑weighted TCO models that let you compare GSaaS versus in‑house station builds under multiple mission profiles.
- Operational blueprints: recommended architectures for multi‑orbit control, resilient TT&C routing, and disaster recovery for mission‑critical operations.
- Commercial playbooks: go‑to‑market templates for service bundling, pricing levers, and partnership structures tailored to commercial, government/military, and civil/scientific use cases.
- Vendor diagnostics: structured vendor scorecards and negotiation playbooks to quantify service coverage, latency, security posture, and escalation SLA tradeoffs.
- M&A and investment toolkit: due‑diligence checklists, synergy quantification models, and three stress‑test scenarios to evaluate targets and alliances.
- Regulatory tracker and spectrum impact map: an integrated view of near‑term regulatory proposals and their operational impact on licensing, spectrum availability, and infrastructure approvals.
The study combines quantitative forecasts with hands‑on tools you can adapt directly to purchasing cycles, board deliberations, and program roadmaps.
Competitive Landscape — Who Matters, and How to Position
The market exhibits a mix of incumbent operators, integrated systems houses, and specialized ground‑network providers. Concentration is material but not prohibitive — the largest three players control a meaningful share of market activity while the top five increase that presence further. This creates both power centers and plenty of tactical openings for niche providers and partnerships.
- Global ground‑network specialists (examples include leading regional GSaaS players): these firms anchor multi‑orbit TT&C and data acquisition through dense ground footprints and are advancing capability for lunar and deep‑space missions. Their strategic advantage is reliable, geographically diversified access and operational experience across mission profiles.
- Integrated satellite operators (major fleet operators and commercial broadcasters): these organizations leverage end‑to‑end control capabilities tied to their fleet economics. They trade some flexibility for strong coordination between flight operations and services monetization.
- Defense and prime systems houses (large aerospace and defense firms): these players bring hardened telemetry, security architectures, and mission assurance — a preferred option for government and military programs where compliance and continuity are decisive.
- New‑wave GSaaS and boutique operators : agile providers focus on API‑first access, developer support, and low‑friction on‑ramping for small satellite constellations. They are winning business where speed and integration matter more than legacy scale.
Recent industry moves underline these patterns: a leading GSaaS operator announced continued network expansion in early 2026 to reinforce multi‑orbit TT&C; an integrated operator released a results update reaffirming its global control capabilities; a major managed connectivity vendor secured a five‑year renewal supporting military network operations; and a constellation operator accelerated gateway deployments in late 2025 — all evidence of active investment on both infrastructure and service fronts.
Strategic Plays for 2026 — Practical Steps
- Adopt hybrid GSaaS/in‑house operating models. For most organizations, blended models deliver the best risk/return: outsource routine coverage and burst capacity, retain mission‑critical control and security domains in‑house.
- Lock-in regulatory and spectrum pathways. Prioritize engagements with regulators and spectrum holders now — policy changes in major markets are time‑sensitive and will materially affect deployment timelines and operating economics.
- Design for resilience and cyber‑assurance. Insist on hardened routing, cross‑provider redundancy, and end‑to‑end encryption and key management as preconditions for supplier selection.
- Use supplier scorecards to avoid lock‑in. Scorecards should quantify service diversity (multi‑orbit, multi‑antenna), restoration SLAs, and interoperability with third‑party mission control systems.
- Be opportunistic on M&A and partnerships. Look for acquisitions that add geographic ground coverage, API integration capability, or spectrum access; pursue commercial alliances to accelerate go‑to‑market while minimizing CAPEX.
How to Use This Study in Your 2026 Planning
Use the report as the single source of truth for three critical activities in 2026:
- CapEx and OpEx planning — use our TCO models to evaluate build vs buy under multiple utilization curves and spectrum scenarios.
- Supplier selection and contract design — apply our procurement templates and SLA matrices during RFQs to capture service continuity and upgrade pathways.
- Portfolio and M&A strategy — leverage our scenario analyses and vendor diagnostics to prioritize targets and quantify post‑merger integration risk.
Beyond the executive summary and trend narrative, the full study includes interactive dashboards, downloadable financial models, and a regulatory timeline you can embed into board materials and investment memoranda.
Closing — Where This Preview Leaves You
2026 is not a year to wait. The satellite control services market is scaling predictably and structurally — supported by policy shifts, GSaaS maturation, and mission diversity. Our study synthesizes these dynamics into decision‑ready outputs: models, scorecards, and roadmaps that help you move from strategy to execution without losing optionality.
This preview deliberately surfaces the analysis framework, headline market scale, and strategic recommendations while reserving the granular sub‑segment and regional split data for the full report. To access the segment‑level allocations, regional and service type breakdowns, vendor scorecards, and the interactive scenario models that underpin our recommendations, please consult the full report materials on the PW Consulting research page.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 24-Hour Emergency Roadside Assistance Market to Grow at 5.12% CAGR (2026–2032)
By PW Consulting, 2026-07-13
24 Hour Emergency Roadside Assistance Market — Strategic Preview for 2026 Decision-Makers
As executives plan capital deployment, partnerships, and operating models for 2026, the 24 Hour Emergency Roadside Assistance market presents a mix of predictable growth and sudden structural shocks. At a macro level the market moved into the mid‑tens of billions (USD) in the early 2020s and—after steady organic expansion—stood at roughly USD 31.9 billion in our 2025 base year. PW Consulting projects a continued upward trajectory into 2026 and beyond, with a near‑term step increase followed by a compound annual growth rate of about 5.12% across our 2026–2032 forecast horizon. That growth masks a market undergoing technological disruption, regulatory realignment and changing partner economics; this preview explains why those dynamics matter to strategic decision-making in 2026 and how our full study operationalizes the intelligence you need.
24 Hour Emergency Roadside Assistance Market
Why 2026 is a Strategic Inflection Point
Three concurrent trends make 2026 particularly consequential:
24 Hour Emergency Roadside Assistance Market
- Service demand is growing, but cost structures are changing. Volume growth is steady, driven by vehicle parc expansion, rising use of pay‑per‑use and subscription bundles, and greater fleet utilization. At the same time, severity and unit costs are shifting—driven by factors such as more complex vehicle systems, increasing EV presence, and localized infrastructure deterioration—creating margin pressure for providers that fail to adapt their operating models.
- Technology is rewriting the operational playbook. AI dispatch, telematics integration, and digital marketplaces are changing how customers summon help and how providers match resources. White‑label platforms and marketplace players are taking share from legacy models by offering faster response and more transparent pricing to insurers, OEMs and fleets.
- Regulatory and liability vectors are fragmenting risk. New state‑level rules and uneven standards for emergency roadside vehicles and EV incident management are creating localized cost and compliance variation. Some jurisdictions are already introducing storage and handling requirements for damaged EVs that materially affect tow and recovery costs; others lack clear vetting and liability frameworks, exposing buyers and providers to operational risk.
These inflection drivers are not theoretical. They are already manifested in recent market activity: new OEM service alignments, platform rollouts, and consolidations of fleet service teams. For decision‑makers, 2026 is the year to translate strategic intent—whether growth, defense, or divestiture—into executable roadmaps.
24 Hour Emergency Roadside Assistance Market
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
Our full 24 Hour Emergency Roadside Assistance Market study is designed as a decision tool for CEOs, heads of strategy, business development and operations leaders. It goes well beyond high‑level slides to provide the playbooks and analytics teams can use in negotiations, investments and pilots. Highlights include:
- Top‑down market sizing and three forward scenarios (conservative, base, accelerated), calibrated to observed demand shocks and supply constraints.
- Unit economics and pricing frameworks tailored to insurers, OEMs, fleet operators and independents, with sensitivity matrices to stress‑test cost inputs.
- Competitive landscaping with strategic profiles of incumbent and emerging players—coverage models, partner strategies, tech stacks and service propositions—mapped to SWOT and capability heatmaps.
- Operational playbooks: network optimization models, right‑sizing patrol footprints, technician productivity benchmarks and real‑time dispatch KPIs.
- Technology adoption roadmap: telematics integration, AI dispatch, digital payment and claims automation, plus implementation budgets and ROI timelines.
- Regulatory and compliance compendium: jurisdictional risk scoring, contract clauses to mitigate liability, and contingency playbooks for evolving EV handling rules.
- M&A and partnership playbook: valuation multipliers by business model, integration pitfalls, and a prioritized target list for roll‑up or capability acquisition strategies.
- Commercial templates and a 90‑/180‑/360‑day implementation checklist for pilots and scale rollouts.
The report includes data tables, modeling workbooks and scenario drivers that allow clients to replace assumptions with their own inputs. (Note: detailed segment tables and regional splits are available only in the full report.)
Competitive Dynamics — Who Matters and Why
The competitive field combines membership‑based giants, white‑label platform specialists, OEM‑aligned partners and digitally native disruptors. Each archetype faces different strategic tradeoffs:
- Membership clubs and large multinationals leverage scale, brand trust and dense patrol networks. Their challenge is modernizing legacy systems and monetizing beyond membership fees without eroding perceived value.
- White‑label dispatch and platform providers sell orchestration and margins to insurers and OEMs. Their value proposition is speed and integration—partners benefit from cost predictability and digital claims workflows—but these players must continuously invest to keep latency and coverage gaps low.
- OEMs and insurers are moving between outsourcing and insourcing. OEMs increasingly seek to control post‑sale customer experience; insurers balance cost control with customer retention. Strategic choices here shape the mid‑term landscape for service providers.
- Digital disruptors and marketplaces focus on consumer convenience and immediate availability, pushing incumbents to raise service levels while compressing margins in commoditized service lines.
Market concentration metrics indicate a moderately consolidated landscape where top players command material share but meaningful room exists for specialist entrants and regional champions. That structure creates attractive windows for targeted M&A, capability buys (e.g., AI dispatch, EV recovery units), and regional partnerships that can deliver scale economics quickly.
Regulatory and Operational Risks: A Practical Assessment
Regulatory fragmentation is one of the most actionable risks firms must manage in 2026. A few concrete dynamics to factor into planning:
- Local rules that increase recovery and storage costs for damaged EVs change margin math for tows and long‑dwell incidents—procurement teams need contingency pricing and contract language to avoid unexpected fees.
- States without clear vetting requirements for roadside providers create legal exposure for buyers who rely on third‑party crews; insurers and corporate fleets should update vendor due diligence and indemnity clauses accordingly.
- Variability in allowable warning‑light configurations and usage conditions for roadside service vehicles creates compliance complexity for national fleets. Standardize the strictest common denominator in fleet specifications to avoid localized fines or interrupted operations.
- Operational demand shocks, such as sudden spikes in pothole‑related calls, require flexible capacity strategies—short‑term surge contracts, mobile repair units, and predictive maintenance partnerships with municipalities can reduce incidence and cost.
Mitigating these risks is not purely legal work: it requires ops redesign (equipment, training), pricing discipline, and targeted investments in EV‑capable recovery assets and technician certification programs.
Concrete Strategic Options for 2026
Based on our analysis, leaders should prioritize a portfolio of actions that balance near‑term defensiveness with medium‑term capability building:
- Quick wins (0–6 months): update vendor contracts to include explicit EV handling and storage responsibilities; pilot AI dispatch modules to reduce response latency; implement surge capacity clauses for seasonal or infrastructure‑driven demand spikes.
- Capability builds (6–18 months): invest in EV recovery assets and battery‑safe storage bays; integrate telematics feeds for predictive service and automated dispatch; formalize OEM and dealership partnerships to capture post‑sale service flows.
- Strategic expansion (12–36 months): evaluate bolt‑on acquisitions for geographic coverage or tech assets; consider a two‑brand strategy—premium branded patrols and a low‑cost digital fulfillment arm—to protect margin across segments.
How to Use This Report to Drive Board‑Level Decisions
For executives, the value of the PW Consulting study is its ability to translate market signals into executable plans. Use it to:
- Inform capital allocation and operational budgets with scenario‑driven P&L impacts;
- Benchmark performance versus peers on core KPIs—time to arrival, first‑time fix rate, cost per incident—and set realistic stretch targets;
- Prioritize tech pilots and vendor negotiations with clear ROI pathways;
- Design compliance playbooks to mitigate jurisdictional variability and EV‑related exposure;
- Drive M&A or partnership decisions with a modeled view of integration economics and synergies.
Closing: Why Access to Full Data Matters
This preview surfaces the strategic takeaways that should influence boardroom decisions in 2026: sustained market growth, rising complexity from vehicle and regulatory change, and a competitive environment where technology and partnerships determine winners. The full PW Consulting report contains the granular segmentation, regional overlays, provider benchmarking tables and downloadable modeling workbooks that executives need to quantify options, stress‑test plans and execute with confidence. For teams preparing investment memos, procurement renegotiations, or operational redesigns, that level of detail is essential—this preview is designed to guide your immediate priorities and compel the deeper analysis available in the full study.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: P Series Glycol Ether Market to Reach USD 4,950M in 2025; 2026–32 CAGR 4.85%
By PW Consulting, 2026-07-13
P Series Glycol Ether Market: Strategic Intelligence for Decision-Makers in 2026
Executive snapshot
In 2025 the global P Series glycol ether market reached an estimated USD 4,950 million (base year 2025). Our analysis projects a steady compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window, driving the market toward roughly USD 6.9 billion by 2032 under the central-case scenario. For leadership teams planning capital allocation, supply-chain adjustments, product portfolio moves, or M&A activity in 2026, these topline dynamics provide a quantitative framework that balances near-term volatility with multi-year structural growth.
P Series Glycol Ether Market
Why this study matters for 2026 decisions
-
Actionable timing: The short-term market environment is increasingly event-driven — operational disruptions, commodity swings and regulatory signals now exert outsized influence on margin, availability and pricing. Executives who align tactical moves (spot procurement, hedging, interim sourcing) with a clear multi-year strategy can preserve margin and optionality without sacrificing long-term growth exposure.
P Series Glycol Ether Market -
Portfolio prioritization: P Series glycol ethers remain essential solvents across coatings, electronics, cleaners and specialty industrial applications. Our study decodes where industrial demand will concentrate and where customers will prioritize performance, low-VOC/safety profiles and supply security — inputs that should govern capex and innovation budgets in 2026.
P Series Glycol Ether Market -
Risk-managed growth: The market’s mid-single-digit CAGR masks episodic supply tightness and feedstock swings. Companies that adopt scenario-driven capacity planning and layered procurement strategies will be best positioned to convert volatility into profitable share gains.
Market dynamics shaping 2026 strategy
-
Supply shocks and short-cycle price signals: Early 2026 saw material industry events that underline operational risk. A major Bayport facility fire prompted a force majeure declaration from a leading producer in March 2026, while at the same time another global producer announced price increases for P Series products. These twin developments illustrate how single-site incidents and coordinated pricing moves can rapidly tighten regional availability and push spot prices upward. Procurement teams must therefore build contingency playbooks to bridge weeks-to-months of disruption without cascading downstream outages.
-
Feedstock volatility: Propylene oxide (PO) is the primary upstream feedstock for P Series glycol ethers, produced by addition of PO to alcohols. Price behaviour in PO markets has been bifurcated; late-2025 indices showed Q4 weakness in some regions, while early-2026 benchmarks reflected a rebound (North American PO was reported near USD 1.14/kg in March 2026, up from December levels). The implication for buyers and producers is clear — margin sensitivity to PO must be modeled across rolling price scenarios, and where feasible, contracts should include transparent cost-pass-through mechanisms.
-
Regulatory inflection: Regulatory scrutiny has intensified. In late 2025 the EPA proposed Significant New Use Rules (SNURs) under TSCA for certain glycol-ether–related substances, signaling potential restrictions or new testing requirements. This creates near-term compliance costs and medium-term formulation risk for product lines that rely on legacy glycols. R&D and regulatory affairs budgets should be calibrated to accelerate safer-substitute development, defensible exposure assessments and expanded compliance monitoring in 2026.
-
Geographic production footprint: Western Europe retains an outsized role both as a producer and consumer region for P Series glycol ethers. That position influences global logistics, export flows and substitution levers; companies with flexible regional hubs will be better able to respond to demand shifts and regional policy changes.
Competitive landscape: implications for industry players
The P Series market remains moderately concentrated at the top, with the three largest producers accounting for a meaningful share and the top five amplifying that concentration further. This structure creates both competitive pressure and cooperative dynamics: leading producers exert price leadership and can mobilize capacity redeployment in response to disruptions, while midsize and regional players win via agility, niche product quality or localized service models.
-
Global majors: Dow, BASF, LyondellBasell, Eastman and Shell represent the classical integrated, scale-oriented competitors. Their advantage is breadth of production capacity, global distribution networks and ability to offer coordinated cost-pass-through or supply guarantees to large customers. The March 2026 price moves and force majeure event demonstrate how these players can influence short-term market mechanics — a strategic reality buyers and smaller suppliers must monitor closely.
-
Regional specialists and niche suppliers: Companies such as INEOS Oxide, KH Neochem, Chang Chun Group, Sasol and Solventis operate with regional depth, formulation know-how, or specialized grades tailored to electronics, inks or high-performance coatings. These players often win in customers’ development cycles where technical compatibility and regulatory compliance trump unit-cost advantages.
-
Strategic playbook by firm type: Scale players should prioritize resilient asset maintenance, forward hedging and selective premiumization of specialty grades. Regional/niche players should double down on technical services, co-development agreements and supply continuity guarantees to displace incumbent suppliers during shocks.
What the full report delivers (practical, non-theoretical)
-
Topline and scenario forecasts: A transparent base-case and two alternate scenarios (tight-supply / policy-constrained) for 2026–2032 with sensitivity tables that map price, feedstock and demand elasticity to revenue outcomes.
-
Supply-chain stress tests: Playbooks for procurement and manufacturing teams that quantify stock buffers, dual-sourcing thresholds and break-even points for spot purchases during capacity outages.
-
Regulatory impact matrix: An actionable roadmap that translates proposed TSCA/SNUR actions and other jurisdictional measures into product-level compliance steps, timelines and potential reformulation costs.
-
Commercial strategies: Segment-targeted go-to-market options (premiumization, reformulation, service/technical partnership models) and tactics to protect margin while chasing growth in targeted end-markets.
-
Competitor dossiers and benchmarking: Summaries of the major producers, their asset footprints, strategic moves, recent public actions and operational risk indicators — designed to support M&A screening and supplier selection without relying on committee-driven anecdotes.
-
Data packages and model templates: Downloadable financial models, procurement calculators and market-sizing workbooks that let internal teams re-run scenarios using client-specific cost structures and sales mixes.
How to convert insight into 2026 decisions
-
Procurement: Immediately stress-test key supplier contracts for force majeure exposure, renegotiate to include clearer cost-pass-through and ramp contingency clauses, and adopt layered sourcing (primary, secondary, emergency) with defined trigger thresholds.
-
Manufacturing and capex: Prioritize reliability investments in critical plants and evaluate modular debottlenecking projects that can be executed in 6–18 months to capture market opportunities created by competitors’ downtime.
-
R&D and compliance: Accelerate screening of low-risk solvent alternatives and invest in toxicology and exposure testing required by evolving regulatory frameworks. Early movers will reduce reformulation friction and retain share among customers who have strict regulatory demands.
-
M&A and portfolio: Use the quantified scenarios in the report to identify targets whose value is asymmetric under supply-constrained cases (e.g., small regional producers whose assets become strategically valuable during tight cycles).
-
Commercial: Implement tiered pricing and service packages that reward long-term contracts and volume commitments, while preserving optionality for spot exposure where margin upside is material.
Risk checklist for 2026 planners
-
Operational risk: Single-site incidents and under-maintained assets can produce outsized market effects; maintain live readiness plans.
-
Commodity risk: Model PO price swings and embed flexible pass-through or hedge instruments where warranted.
-
Regulatory risk: Monitor TSCA/SNUR timelines and prepare rapid-response regulatory dossiers to avoid customer delisting or market access delays.
-
Competitive risk: Track price leadership moves by majors and be ready to defend commercial relationships during supplier-led price adjustments.
Why PW Consulting’s P Series Glycol Ether Market study is a strategic asset
The study combines a disciplined macro-to-micro market-sizing approach with scenario modeling, supplier-risk scoring and executable playbooks geared toward 2026 priorities. We deliberately present high-confidence topline forecasts (base-year and CAGR) while preserving the competitive utility of our proprietary segmentation tables for registered users — the result is a report that gives you enough strategic intelligence to act decisively, but saves the granular tactical levers for the report delivery and client workshops where we can align recommendations to your P&L and operational cadence.
Next steps
For executive teams preparing 2026 budgets or rethinking their supply strategy, the full report and its accompanying data models provide the granular segmentation, supplier-by-supplier profiles, and downloadable templates that turn the scenarios above into executable 90–180 day plans. Contact our P Series practice to arrange a briefing, obtain the complete datasets, or commission a tailored stress-test using your cost and production parameters.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Biomass for Power Generation: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
As the energy transition pivots from proof‑of‑concept projects to large‑scale deployment, biomass for power generation is reasserting itself as a commercially mature, policy‑sensitive segment of the low‑carbon electricity mix. Our latest market model—anchored on 2025 as the base year—shows the global biomass power market expanding at a compound annual growth rate of 6.89% through the 2026–2032 forecast window, moving from a 2025 market size of USD 111.8 Billion toward a materially larger global opportunity by 2032. This growth trajectory reflects persistent policy support, ongoing coal‑to‑biomass conversions, decarbonisation market signals, and incremental technology improvements that together make 2026 a pivotal planning year for developers, utilities, equipment vendors and financiers.
Biomass For Power Generation Market
Why this research matters for 2026 strategic decisions
- Timing capital allocation: With a robust near‑term growth profile, 2026 will be a key year to commit capital to projects that can leverage existing permitting windows, grid access and established supply chains.
- Policy arbitrage and incentives: Recent regulatory developments—especially in the United States—change the calculus for both greenfield projects and retrofits. Qualifying for technology‑neutral clean production credits or investment credits based on lifecycle emissions profiles materially alters project IRRs.
- Supply‑chain and feedstock risk management: Feedstock markets are tightening in some corridors even as densified biomass trade remains global. Buyers and project sponsors must move from spot purchasing to contractual security and blended sourcing strategies to protect margins.
- M&A and consolidation strategy: The sector’s low headline concentration (CR3 ~18.5%; CR5 ~24.2%) signals a fragmented competitive landscape—creating a prime window for scale‑seeking consolidation, vertical integration, or bolt‑on acquisitions to secure offtake and feedstock.
- Technology selection and decarbonisation strategy: With options spanning direct combustion, gasification, anaerobic digestion and CCUS integration, selecting the correct technology stack for a given feedstock and market will be a decisive value driver.
What this PW Consulting report delivers (practical, actionable content)
- Transparent market-sizing and scenario forecasts (2026–2032) with sensitivity runs for price, feedstock availability and permitting delays.
- Project‑level economics templates and LCOE benchmarking tailored to common plant sizes and technology pathways, enabling rapid financial triage of opportunities.
- Feedstock supply‑chain playbooks: procurement strategies, logistics optimisation, densification economics and certification risk maps.
- Regulatory and incentives compendium, including tax credit eligibility criteria and scenario assessments for policy shifts in major markets.
- Competitor intelligence dossiers covering strategic positioning, asset footprints, vertical integration, and likely M&A targets.
- Technology risk matrices and vendor shortlists for EPC, boiler and emissions control equipment, as well as CCUS retrofitting feasibility analyses.
- Deal structuring and financing templates highlighting optimal covenant structures, offtake contracts and sponsor equity profiles for 2026 market realities.
Competitive landscape — reading the tea leaves
The sector’s strategic map is composed of several archetypes that matter for how 2026 plays out:
Biomass For Power Generation Market
- Vertically integrated incumbents: Companies that pair large biopower fleets with captive fuel production or long‑term pellet supply arrangements are positioned to defend margins as feedstock cost volatility increases. Their playbook emphasizes scale, contract discipline and control of densification or pellet logistics.
- Utilities and major energy groups: Large utilities are converging on biomass as a dispatchable renewable to complement intermittent resources, with a focus on coal‑to‑biomass conversions and CHP integrations. These players bring balance‑sheet capacity but face reputational and sustainability scrutiny that requires robust lifecycle accounting.
- EPC and equipment specialists: Technology suppliers and engineering houses are moving up the value chain to offer performance guarantees, emissions compliance packages and retrofit pathways—critical for projects that aim to retrofit coal assets or integrate CCUS.
- Regional developers and integrators: Local champions in Asia, Latin America and Europe are executing projects that reflect local feedstock profiles and permitting realities. Their advantage is speed to market and local stakeholder networks.
- Feedstock specialists: Dedicated pellet and densified fuel producers are strategic partners or acquisition targets for sponsors seeking to secure long‑term feedstock and manage quality variation across supply sources.
Illustrative recent developments accentuate these themes: in 2025–2026 several notable deployments and capacity additions—from large new plant commissionings in Japan and Vietnam to the commissioning of new PKS processing capacity in Malaysia—show developers and equipment suppliers translating strategic commitments into operating assets. These moves underline the sector’s operational momentum and the immediate availability of projects for investors willing to move in 2026.
Biomass For Power Generation Market
Market dynamics to watch in 2026
- Feedstock pricing and logistics: Recent market data shows material spreads between domestic and export densified fuel prices, and localized gate costs for mixed mill and forest residues that should be modelled into project bids. Sponsors must incorporate these real‑world inputs when stress‑testing their fuel procurement strategies.
- Availability of policy credits: In several jurisdictions, qualifying for production or investment tax credits now depends on lifecycle GHG performance or emerging interpretations of carbon‑removal credits—creating a bifurcation in project economics between ‘credit‑qualified’ and ‘market‑only’ assets.
- Carbon policy expansion: Legislative developments proposing broader eligibility for carbon‑capture incentives to include forest residue products change the downstream economics of bioenergy‑with‑carbon‑removal options and wildfire‑mitigation projects.
- Project finance appetite: Appropriations and government support in 2026 are nudging banks and institutional lenders to view biomass as a policy‑aligned, financing‑worthy asset—provided developers can demonstrate robust sustainability credentials and supply‑chain traceability.
- Technology convergence: CCUS readiness, hybridisation with gas or hydrogen, and modular gasification are cross‑cutting trends that will separate near‑term winners from laggards.
How to use the PW Consulting intelligence in 2026 — recommended playbook
- Run rapid portfolio triage against our scenario set: Re‑score opportunities for policy sensitivity, feedstock security and technology fit to prioritise the top 20% of projects for capital allocation in 2026.
- Pursue vertical hedges: Evaluate selective backward integration—either via offtake‑anchored pellet contracts, equity stakes in feedstock processing, or long‑term tolling arrangements—to stabilise input costs.
- Structure incentives capture: Align project designs and lifecycle models to meet eligibility thresholds for production and investment credits where available; treat tax‑credit qualification as a determinant of project staging.
- Design modular and retrofit‑friendly technical approaches: For coal‑to‑biomass conversions and distributed CHP, prefer modularity and CCUS‑compatible layouts that preserve future upside optionality.
- Prepare for consolidation: Use the market’s fragmentation to pursue targeted M&A—accretive acquisitions of regional developers, pellet capacity, or EPC capabilities can accelerate scale and improve negotiating leverage.
- Operationalise sustainability and traceability: Embed third‑party certification, supply‑chain traceability and lifecycle GHG accounting into contracts to preserve access to both public incentives and private corporate offtakers.
Conclusion — the decision horizon for 2026
2026 represents a convergence year where policy windows, feedstock market developments and capital market appetite create asymmetric opportunities for sponsors who come prepared with deep technical, commercial and regulatory playbooks. Our market forecast and scenario analyses quantify a clear growth pathway, but the outcome for individual projects will hinge on policy eligibility, fuel procurement structures, and the ability to deploy scalable technologies that can be financed under tightened sustainability screens.
Next steps
PW Consulting’s full Biomass for Power Generation Market report provides the granular segmentation, regional and technology forecasts, a searchable project database and downloadable financial models you need to execute in 2026. The executive preview above highlights the strategic vantage points; the complete dataset contains the compartmentalised market splits, asset‑level economics and supplier scorecards that operational teams and C‑suite decision‑makers will use to convert strategy into deployed capital.
For detailed analysis of this topic, please visit the official page: Biomass For Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biopharma Autoclaves Market to Reach USD 4,405.14M by 2032 (8.5% CAGR)
By PW Consulting, 2026-07-13
Biopharmaceutical Autoclaves Market 2026: Strategic Intelligence for Executive Decisions
As biopharmaceutical manufacturing accelerates into its next phase of scale-up, autoclaves remain a mission-critical node in sterile processing, terminal sterilization and laboratory operations. PW Consulting’s latest market study—covering historical performance (2020–2025) and a forward-looking forecast horizon (2026–2032)—translates raw market movements into boardroom-ready guidance for procurement, plant expansion, technology adoption and M&A planning in 2026.
Biopharmaceutical Biopharma Autoclaves Market
Why this analysis matters for 2026 decision-makers
-
Defensible capital allocation: The biopharma autoclave market has demonstrated robust expansion through 2025, with the study’s base-year benchmarking and a projected compound annual growth rate of 8.5% underpinning our revenue model. Understanding where this growth is concentrated—by use-case, configuration and supplier capability—is essential to sizing capital and service investments that will deliver compliant throughput in 2026.
Biopharmaceutical Biopharma Autoclaves Market -
Operational continuity and regulatory risk mitigation: Regulatory frameworks and validation expectations (ISO 17665:2024, EN 285, ISO 17665-1, and cGMP/IQ-OQ-PQ protocols aligned with EU GMP Annex 15) are converging on stricter documentation, data integrity and cycle validation. The study maps the implications of these requirements to procurement specifications and operational OPEX to avoid costly re-qualification or non-conformances during scale-up.
Biopharmaceutical Biopharma Autoclaves Market -
Technology and automation roadmap: Edge innovations—including IoT-enabled sensors, AI-driven cycle validation and modular goods-handling—are rapidly moving from pilots into commercial offerings. Our analysis explains how these capabilities materially change total cost of ownership (TCO), qualification burden and floor-space planning for multi-shift production in 2026.
-
Competitive and supply-chain positioning: Market concentration metrics indicate a landscape where a cluster of established engineering and life-science equipment firms retain meaningful share, but mid-tier and regional suppliers continue to influence tender dynamics. For procurement leaders, this means tailoring RFPs to capture lifecycle service clauses and validation IP protections—factors often more impactful than list price.
Market trajectory—macro snapshot (high level)
PW Consulting’s model tracks the market in USD million, drawing from five years of historical data and a seven-year forecast window. The market has expanded steadily from the early 2020s, with an inflection as vaccine production, biologics scale-up and facility modernization projects accelerated. The research quantifies both the near-term market size at the 2025 base and the expected uplift into 2026 and beyond—enabling capital planning that aligns with revenue and capacity forecasts across the sector.
Importantly, the study couples macro figures with scenario analysis: base-case growth tied to current pipeline maturation; upside tied to accelerated adoption of single-use-bioprocessing hybrids and rapid deployment of modular plants; and downside scenarios tied to regulatory slowdowns or capital market pressures. This structure lets CFOs and plant managers stress-test procurement and build decisions against plausible 2026 operating environments.
What the report contains—actionable chapters for 2026
-
Market sizing and forecast methodology: Transparent modeling assumptions, currency (USD, revenue in Million), sensitivity testing and scenario outputs suitable for board-level capital approvals.
-
Commercial segmentation architecture: Multi-dimensional breakouts by configuration, application and region (detailed tables and waterfall analyses are in the full report). Note: this executive preview intentionally withholds line-item segmentation figures—access the full data pack for the granular splits needed for procurement bid-spec formation.
-
Buyer journey and procurement levers: Time-to-delivery, validation burden (IQ/OQ/PQ timelines), spare-parts risk, lifecycle service revenue modelling and negotiation guidance to reduce TCO while maintaining compliance.
-
Technology assessment and integration playbook: Comparative evaluation of IoT, AI-enabled validation, modular goods handling and automated CIP/SIP interfaces—each linked to retrofit vs. greenfield cost and qualification implications.
-
Regulatory and validation implications: Practical templates for aligning supplier contracts with ISO 17665:2024 and Annex 15 expectations, including audit evidence, data retention and electronic signature controls.
-
Supplier scorecards and RFP templates: A standardized vendor evaluation framework scoring performance, validation support, spare-part logistics, software lifecycle management and cybersecurity posture.
-
M&A and partnership intelligence: Mapping recent product launches, strategic partnerships and notable acquisitions to highlight areas of consolidation, capability gaps and potential bolt-on targets for companies seeking to expand sterilization or validation portfolios.
Competitive landscape—what to watch in 2026
The competitive field is dominated by established engineering and life-science equipment companies that combine domain expertise in sterilization processes with global service footprints. Market concentration indicates that leading manufacturers collectively hold a meaningful share of total market revenue, but the landscape is fragmented enough to allow regional specialists and technology-focused challengers to win on tailored solutions and validation support.
-
STERIS plc — Offers high-throughput steam sterilizers and autoclaves designed for cGMP environments. Their strength lies in validated, high-capacity solutions and an established lifecycle service network—attributes that favor large-scale manufacturers and contract operations seeking predictable uptime and documented compliance.
-
Getinge AB — Focused on modular, highly automated sterilization systems. Recent launches introduce IoT-enabled sensors and AI-driven cycle validation, and goods handling systems for continuous operation have been advanced—moves that shift the value proposition from equipment sale to automation-enabled process assurance.
-
Belimed AG — Positions reliability and regulatory compliance at the center of its product messaging. Their solutions appeal to facilities where integration with existing sterile processing lines and predictable validation support are priorities.
-
Fedegari Srl — High-end process equipment vendor with a focus on cGMP steam sterilizers. Recent strategic partnerships targeting cell and gene therapy modularization reflect a pursuit of niche, high-growth subsegments that demand flexible, scalable sterilization platforms.
-
Consolidated Sterilizer Systems, Beta Star, BMT USA, Steelco, Syntegon, Telstar, Astell, Priorclave, Shinva, Tuttnauer, Nicos Group — These suppliers range from laboratory-focused manufacturers to large-scale pharmaceutical equipment specialists. Their competitive advantage often derives from specialization (e.g., media and glassware sterilization, facility-level terminal sterilizers), regional service networks, and the ability to supply validated packages for bespoke process workflows.
Recent market activity underscores accelerating innovation and consolidation. Notably, product launches integrating IoT and AI validation (early 2025), and strategic partnerships to serve cell and gene therapy modalities, point toward a bifurcation: vendors that can bundle automated validation and lifecycle service will capture more value, while those focused strictly on hardware risk margin pressure.
Regulatory and validation tailwinds—practical implications
ISO 17665:2024 and related standards are raising the bar for documentation and validation. For 2026 planning, organizations must budget not only for equipment acquisition but also for the expanded validation workload and supporting software that ensures data integrity and audit readiness. The report includes a compliance checklist and a time-phased qualification plan tailored to common procurement scenarios (retrofit, capacity addition, greenfield), enabling realistic scheduling and CAPEX phasing.
Strategic playbook—recommended next steps for executives in 2026
-
Prioritize suppliers who demonstrate integrated validation capabilities and robust software lifecycles—these reduce latent compliance risk and speed time-to-release.
-
Structure procurement to include performance-based service SLAs, spare-part consignment options and cyber-secure software update pathways to protect production continuity and electronic validation records.
-
Adopt a two-track technology investment approach: short-term retrofits to capture immediate throughput gains, and medium-term modular investments that enable rapid scaling for emerging modalities (e.g., CGT).
-
Use our supplier scorecards and RFP templates to convert qualitative vendor claims into measurable acceptance criteria tied to IQ/OQ/PQ milestones.
-
Monitor M&A signals and partnership announcements—these often presage bundled offering strategies that will influence pricing and service availability in procurement cycles through 2026.
Getting the full picture
This executive preview surfaces the core strategic implications derived from PW Consulting’s full market study but omits detailed segmentation tables and granular regional/application revenue line items that underpin procurement-level decisions. For purchasing teams, plant engineers, and corporate strategists who require the full dataset—detailed TAM/SAM/SOM breakouts, configuration-by-application matrices, supplier scorecards, and downloadable RFP templates—the complete report and dataset provide the necessary inputs to finalize 2026 CAPEX and operations plans.
PW Consulting’s Biopharmaceutical Autoclaves Market study is engineered to turn market intelligence into executable decisions: specifying the right equipment to meet regulatory expectations, optimizing lifecycle costs, and positioning organizations to capture the productivity gains that automation and digital validation deliver. In an environment where sterilization failures are unacceptable and time-to-market is everything, the right data in 2026 is a strategic advantage.
For detailed analysis of this topic, please visit the official page: Biopharmaceutical Biopharma Autoclaves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Helicopter Crash-Resistant Seats Market — USD 1,650.45M in 2025, 5.06% CAGR to 2032
By PW Consulting, 2026-07-13
Helicopter Crash Resistance Seats Market — Strategic Preview for 2026 Decision‑Makers
As governments, OEMs and helicopter operators enter a new procurement and modernization cycle in 2026, the helicopter crash resistance seats market is becoming a strategic locus for safety, certification risk mitigation, and aftermarket revenue capture. PW Consulting’s forthcoming market research frames that debate with a data‑driven forecast and practical playbooks tailored for C‑suite, business unit leaders, and procurement heads. This preview summarizes the study’s strategic value and highlights the high‑impact takeaways you need when making 2026 investment and sourcing decisions — while preserving the granular segmentation and proprietary models that sit behind the full report.
Helicopter Crash Resistance Seats Market
Market trajectory at a glance
- Market momentum: The industry has expanded from an estimated USD 1.28 billion in 2020 to roughly USD 1.65 billion in 2025, reflecting modernization programs, fleet renewals, and retrofit demand.
- Near‑term position: PW Consulting’s base year is 2025; our model projects the market to be about USD 1.72 billion in 2026 as the forecast period begins.
- Outlook: Over the 2026–2032 forecast horizon the market grows at a compound annual growth rate (CAGR) of 5.06%, reaching an estimated USD 2.33 billion by 2032 under the central scenario.
Those headline numbers indicate steady, durable growth — not a speculative spike — and they matter differently to different stakeholders: OEMs and Tier‑1 suppliers see product roadmaps and certification calendars; independent retrofitters and MROs view a growing aftermarket opportunity; defense procurement planners see long‑term sustainment budgets and standards compliance obligations.
Helicopter Crash Resistance Seats Market
Why this report matters for 2026 decisions
- Certification is the gating factor. Regulatory requirements and military crashworthiness standards directly drive specification choices and program timing. Expect certification timelines to define winners and losers in 2026 procurement cycles.
- Material and supply risk is strategic. Energy‑absorbing systems rely on constrained inputs (notably aluminum honeycomb cores and advanced composites). Changes in raw material pricing and availability materially affect total cost of ownership and time to field upgrades.
- Aftermarket monetization is maturing. Retrofit kits and Supplemental Type Certificates (STCs) will be the shortest path to near‑term revenue; operators seek low‑disruption upgrades that preserve aircraft availability.
In short: if your 2026 decisions involve seat procurement, retrofit strategy, or capability investment, you must align technical R&D, certification sequencing, and supply agreements — all of which are covered in the full study.
Helicopter Crash Resistance Seats Market
What the PW Consulting report contains (practical deliverables)
- Proprietary demand forecast (2026–2032) by platform, seat type and channel, with sensitivity scenarios and upside/downside cases tied to defense budgets and commercial helicopter activity.
- Certification and regulatory playbook mapping FAA, EASA and MIL standards to product development and timeline risk (including dynamic crash test requirements and downcrash velocities).
- Supply‑chain heat map and cost drivers: vendor tiering, raw material bottlenecks, and a quantified supplier concentration analysis to support sourcing strategies.
- Competitive benchmarking and scorecards for incumbent and challenger suppliers — product capabilities, certification track record, STC portfolio, and route‑to‑market for aftermarket upgrades.
- Commercial models: TCO templates, pricing decks, and service contract archetypes for operators and OEMs to evaluate lease, retrofit and replacement propositions.
- M&A and partnership screening: prioritized targets by capability gap, geographic footprint and aftermarket presence; modelled synergies and integration risk factors.
- Execution playbooks: procurement RFP language, certification engagement timelines, and go‑to‑market tactics for retrofit programs and OEM supply agreements.
The full report converts these deliverables into actionable steps and Excel models you can use directly in negotiation and investment planning sessions. This preview intentionally omits detailed segmentation outputs — the exact regional, platform and seat‑type splits are available in the full report and underpin the forecasts above.
Core market dynamics shaping 2026 choices
- Standards and dynamics: FAA and EASA dynamic crash requirements are non‑negotiable design constraints. For military platforms, MIL‑STD‑1290(AV) sets more aggressive survivability targets that drive heavier, more complex energy‑absorbing systems and influence platform compatibility decisions.
- Materials and weight trade‑offs: Aluminum honeycomb cores remain a dominant energy‑absorption solution but recent supply constraints pushed their industry price higher. Conversely, carbon fiber composites enable around a 25% weight reduction for equivalent impact protection in many new designs, altering lifecycle fuel and payload economics.
- Technology convergence: Two technological pathways are emerging — modular retrofit kits optimized for rapid STC adoption, and integrated seat systems designed into new build platforms. Cellular composite absorbers (cellular foams / engineered lattice materials) are gaining traction in military validation programs for next‑generation attenuation.
- Concentration and aftermarket leverage: Market concentration is meaningful — a relatively small number of suppliers account for a large share of global certified deployments. That concentration drives supply leverage but also creates opportunity for specialized retrofit players to capture niche share.
Competitive landscape — who matters now
Companies with proved certification track records and integrated engineering capability control the architectural choices operators face. Key players profiled in the report include:
- Martin‑Baker Aircraft Co. Ltd. (Denham, UK) — long established in crashworthy seating, with MIL‑STD and FAA certified energy‑absorbing systems for heavy military platforms.
- Safran Seats (Issoudun, France) — a major supplier across civil and defense markets, with certified solutions meeting EASA CS‑27/29 and FAA Part 27/29 dynamic crash requirements.
- IPECO Holdings Ltd. (Droitwich, UK) — specializes in modular, frangible pan and stroke mechanisms for widely used helicopter types; strong in OEM retrofit interfaces.
- DART Aerospace (Mississauga, Canada) — aftermarket and STC specialist with recent certifications for common light‑platform helicopters; a pragmatic partner for operators seeking rapid upgrade paths.
- SKYDEX Technologies Inc. (Englewood, CO, USA) — innovator in cellular composite energy absorbers with validated programs in U.S. military seat evaluations.
- Gentex Corporation (Carbondale, PA, USA) — delivers integrated crew seat systems designed to meet MIL‑STD‑1290 crash standards for rotary‑wing crews.
Recent public developments underscore the split between aftermarket certifiers and material innovators: aftermarket STC activity has accelerated (notable certifications in 2022–2023) while material and energy‑absorbing technology received military validation contracts. These dual trends create distinct strategies — scale and certification breadth for incumbents; niche innovation and speed‑to‑market for agile players.
Strategic implications and recommended actions for 2026
- Procurement: Lock in multi‑year supply agreements for critical raw materials and absorbers; include price‑escalation clauses tied to material indices and clear acceptance gates for certification milestones.
- Product strategy: Prioritize modularity. Design seats and frames to accept energy‑absorbing inserts or cellular composites so you can refresh protection levels without full seat replacement.
- Certification approach: Invest in pre‑certification testing and early engagement with regulators. For retrofit players, pursue STCs for the highest‑volume platforms first to create cashflow and reference installations.
- R&D and sourcing: Allocate R&D to lightweight composite solutions and validate them for dynamic crash events. Simultaneously secure alternative sources for aluminum honeycomb to de‑risk supply chains.
- M&A and partnerships: Consider acquiring or partnering with STC‑savvy retrofitters and materials innovators to accelerate entry into adjacent platform families and aftermarket channels.
- Aftermarket monetization: Sell seats as a service where viable — combine installation, certification management and lifecycle support to capture recurring revenue.
How to use the full PW Consulting study
The full study contains the detailed, account‑level intelligence that supports the headline forecast and strategic recommendations summarized here: platform‑by‑platform demand curves, regional and application splits, supplier revenue profiles, STC and certification timelines, cost models, and a prioritized action matrix for procurement, R&D and M&A leaders. If you are preparing capital budgets, negotiating supplier contracts, or defining a seat product roadmap in 2026, the proprietary models and negotiation templates in the report will materially reduce execution risk and speed decision cycles.
Methodology and credibility
PW Consulting’s forecast is built from a layered methodology: bottom‑up aircraft fleet and retrofitable seat counts, validated by OEM production schedules and defense procurement plans; material and supplier capacity overlays; and scenario stress tests for raw material shocks and regulatory tightening. The study’s base year is 2025 and the forecast period is 2026–2032, with an explicit central case CAGR of 5.06% — conservative enough to test investment theses yet responsive to accelerated retrofit initiatives.
Next steps
For executives preparing to set 2026 budgets or reconsider supplier relationships, PW Consulting can provide tailored briefings that map the report’s models to your fleet mix, procurement cycle and risk tolerance. The summary above highlights where value is created and where execution fails; the full report contains the granular segmentation, price decks and supplier scorecards you need to act.
To access the complete dataset, granular regional and application splits, and the downloadable Excel models that underpin the forecast, contact PW Consulting or visit our report page. The decisions you make in 2026 about certification sequencing, supplier commitments, and retrofit go‑to‑market will determine whether you capture the asymmetric returns the market now offers.
For detailed analysis of this topic, please visit the official page: Helicopter Crash Resistance Seats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Remote Monitoring for Aquaculture Market to Reach USD 1,884.4M by 2032 at 12% CAGR
By PW Consulting, 2026-07-13
Remote Monitoring Systems for Aquaculture: Strategic Priorities for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused executive preview of our new market research on Remote Monitoring Systems for Aquaculture — a pragmatic “trailer” designed to highlight the strategic value this analysis delivers to corporate leaders preparing decisions in 2026. The full report contains proprietary segment-level datasets, vendor scorecards, purchase‑spec templates, and model spreadsheets; this article demonstrates the depth of our approach while intentionally withholding those core datapoints to guide you to the source for the complete intelligence package.
Remote Monitoring System For Aquaculture Market
Why 2026 Is an Inflection Point
-
Technology convergence: Sensors, low‑power communications, AI-based vision, and edge analytics have reached a level of maturity that enables meaningful automation of routine monitoring tasks and faster, data‑driven interventions on farms.
Remote Monitoring System For Aquaculture Market -
Regulatory pressure and cost of noncompliance: Increasing water‑quality and effluent requirements—backed by regional directives and national permit regimes—are driving demand for continuous, auditable monitoring. In countries with established regulatory frameworks, compliance costs per farm can be material, creating an operational imperative to modernize monitoring systems.
Remote Monitoring System For Aquaculture Market -
Commercialization of precision aquaculture: Leading vendors and research groups have published field trials and product initiatives demonstrating sensor accuracy and integrated solutions, accelerating commercial adoption and investor interest.
Market Size and Growth Dynamics
The remote monitoring systems market for aquaculture has transitioned from niche pilot projects to a robust commercial market. Our base‑year assessment for 2025 places the global market at approximately USD 852.4 Million. Under conservative and consensus assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of roughly 12% over the forecast period (2026–2032), reaching the neighborhood of USD 1.88 Billion by 2032.
That trajectory reflects three parallel forces: accelerating deployment in higher‑value commercial farms; commoditization of basic sensors coupled with monetization of platform & analytics services; and an expanding addressable market as new species, systems (e.g., RAS, offshore cages), and geographies adopt continuous monitoring. Historical growth from 2020 through 2025 shows an accelerating adoption curve, which underpins near‑term investment returns for vendors and operators willing to scale pilots into operational rollouts.
Competitive Landscape — Patterns, Not a Hall of Names
The vendor ecosystem is both diverse and strategically segmented. A small group of established platform and equipment providers captures a meaningful share of the installed base, while a broad long tail of specialized suppliers and regional players serves niche use cases. Market concentration metrics show a moderate level of concentration among the largest firms, leaving material scope for consolidation, alliances, and vertical integration.
From a capabilities perspective, companies tend to compete along five axes:
- Sensor accuracy and robustness: High‑quality dissolved oxygen, ammonia, pH, and conductivity sensing — including calibration and fouling mitigation — remains the baseline requirement.
- Platform and analytics: Cloud and edge platforms that translate raw telemetry into operational actions (alerts, feed optimization, health flags) create recurring revenue potential.
- AI and vision: Computer‑vision systems for biomass estimation and health diagnostics are becoming a differentiator for sea‑based and land‑based farms.
- Connectivity: Satellite, cellular, and proprietary radio solutions target the connectivity gap for offshore and remote inland sites.
- Integration and services: Installation, maintenance, regulatory reporting, and data‑as‑a‑service offerings are where margins and customer stickiness concentrate.
Leading solution providers illustrate these strategic postures: some prioritize end‑to‑end platform integration (hardware + software + services), others specialize in a high‑precision component (eg. hydroacoustic biomass estimation), while a growing cohort focuses on AI-driven software overlays that can be hardware‑agnostic. The result is an ecosystem friendly to partnerships — technology vendors collaborating with connectivity providers and integrators to create turnkey offers for different farm archetypes.
Recent Industry Signals that Matter for 2026
-
Product innovation and farm design: Recent product initiatives that combine advanced remote monitoring with novel farm structures indicate vendors are moving beyond point solutions to platform‑level differentiation.
-
Independent validation: Published field trials reporting high accuracy levels for advanced dissolved oxygen and ammonia sensors reduce technical risk for adopters and shorten procurement cycles.
-
Market intelligence and buyer guidance: Industry guides with technical specifications and budget ranges are standardizing procurement language — lowering barriers for farms to issue RFPs and for vendors to bid at scale.
-
Regulatory tightening: National and supra‑national water quality standards and permit regimes continue to raise the minimum monitoring baseline; this increases the addressable service market for continuous monitoring and compliance reporting solutions.
What Our Report Delivers — Practical, Executable Outputs
This research is intentionally action‑oriented. Core deliverables include:
- Dynamic market model (2020–2032) with scenario simulations to stress‑test go‑to‑market plans and investment cases.
- Vendor profiling and a shortlisting tool that scores suppliers on technology fit, deployment maturity, service footprint, and commercial model.
- Procurement templates and technical specifications for common farm archetypes (offshore cages, RAS, pond systems) to shorten RFP cycles.
- Technology roadmaps and decision trees that link monitoring objectives (compliance, welfare, feed efficiency, biomass estimation) to recommended sensor, connectivity and analytics stacks.
- Case studies that quantify operational outcomes from real deployments, including sensor reliability, downtime impacts, and ROI sensitivities.
- Regulatory matrix mapping monitoring requirements to reporting and system feature sets for major regulatory regimes and guidance documents.
We designed these deliverables for use by corporate strategy teams, CTOs, procurement leads, and business unit heads — enabling them to convert market intelligence into procurement specifications, pilot roadmaps, and M&A target lists. The full report also contains downloadable data tables and vendor scorecards that are deliberately omitted from this preview.
Strategic Recommendations for Executives in 2026
-
Adopt a tiered monitoring strategy: segregate essential compliance monitoring (regulated telemetry) from value‑added analytics (feed optimization, early disease detection), and procure accordingly.
-
Prioritize open, modular platforms: choose systems that enable multi‑vendor sensor ecosystems to avoid supplier lock‑in and accelerate adoption of emerging AI services.
-
Pilot AI/vision paired with robust sensor arrays: combine acoustic/vision-based biomass estimation with water‑quality telemetry to materially improve feeding efficiency and health monitoring.
-
Design connectivity redundancy: for offshore and remote sites, integrate satellite and local radio options to ensure continuous data flows and regulatory audit trails.
-
Embed regulatory reporting into operational dashboards: treat compliance data as a by‑product of operations to reduce audit overhead and liability exposure.
-
Consider strategic partnerships or bolt‑on M&A to fill capability gaps quickly — particularly in AI analytics, satellite connectivity, or regional service networks.
How to Use the Model This Year
Executives should apply our market model to three immediate decision use cases:
-
CapEx allocation: translate adoption curves and ROI sensitivities into phased capital deployments aligned with farm expansion or retrofits.
-
Vendor selection: use the vendor shortlisting tool to create an RFP that distinguishes proven sensor robustness from lab‑grade performance claims.
-
New product and pricing strategy: map competitor positioning and market growth rates into subscription and hardware lease models to optimize recurring revenue while reducing customer entry cost.
Concluding Perspective
Remote monitoring systems are moving from compliance nicety to strategic enabler across aquaculture operations. The market’s robust compound growth and accelerating deployments create windows for both vendors and farm operators to capture disproportionate value — if they align technology choices with regulatory realities and operational priorities. The landscape is neither winner‑takes‑all nor purely fragmented; it is a durable platform market with pockets of consolidation and several distinct routes to scale.
For executives who need to convert market trends into executable programs in 2026 — from procurement and piloting to M&A and product strategy — our full PW Consulting report supplies the granular segment matrices, vendor scorecards, and financial models required to act confidently. This preview surfaces the strategic contours; the complete intelligence, including the segment‑level datasets and supplier evaluations that underpin our recommendations, is available through the report portal.
For detailed analysis of this topic, please visit the official page: Remote Monitoring System For Aquaculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


