



Category: market research
PW Consulting: Extended Warranty Market to Reach USD 295M by 2032 at 9.0% CAGR
By PW Consulting, 2026-07-12
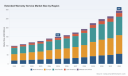
Extended Warranty Service Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking, decision-focused preview of our Extended Warranty Service Market study. Between 2020 and 2025 the market expanded from USD 100 Million to USD 150 Million (base year 2025), driven by rising product complexity, digital distribution, and evolving consumer expectations. Our forecast (2026–2032) projects a continued compound annual growth of 9.0%, taking the market toward roughly USD 295 Million by 2032. This briefing explains why those macro dynamics matter for corporate strategy in 2026 while deliberately withholding granular subsegment tables and exact regional or application shares — a curated invitation to the full report for tactical execution details.
Extended Warranty Service Market
Why the Extended Warranty Market Demands Executive Attention in 2026
-
Structural revenue resilience: Extended warranty services are shifting from a seasonal upsell to a predictable, recurring-revenue line for manufacturers, retailers, and specialist providers. The market’s steady climb from 2020 through 2025 and the forecasted double‑digit tailwinds in several quarters signal a durable monetization path for product lifecycles that were previously revenue-neutral after sale.
Extended Warranty Service Market -
Technology-driven differentiation: Advanced vehicle electronics, connected appliances, and smart devices have increased both failure modes and service complexity. This is attracting insurers and fintech players who can underwrite, price, and manage claims using telematics, diagnostics, and predictive analytics — converting service liability into a managed profit center.
Extended Warranty Service Market -
Distribution evolution: Digital marketplaces, retailer-integrated protection plans, and OEM-embedded offerings are redistributing margin and control across the value chain. Companies that understand channel economics in 2026 will extract higher lifetime value from customers and avoid margin erosion from commoditized third-party resellers.
-
Regulatory and reimbursement pressure: Recent state-level statutes and evolving agency guidance create compliance obligations that affect product design, disclosure, and reimbursement mechanics. Prepared organizations can turn compliance into competitive advantage; unprepared ones face distribution bottlenecks and elevated dispute rates.
Market Dynamics: Drivers, Headwinds, and Strategic Implications
-
Key growth drivers: Increasing product complexity, proliferation of subscription-style ownership, extension of protection to new product categories, and consumer acceptance of paid protection are driving the market’s expansion. Our historical-to-projection trajectory highlights how these drivers compound over time.
-
Operational headwinds: Claims inflation, parts scarcity, and repair labor shortages add pressure to margins. Additionally, reimbursement frameworks and consumer protection rules are introducing greater transparency and potential cost pass-throughs for servicers.
-
Channel and product innovation: The most effective players in 2026 will combine modular coverage design, dynamic pricing linked to telematics or usage, and frictionless claims via digital-first repair ecosystems. This is not hypothetical — product roadmaps and recent launches show incumbents shifting in this direction.
-
Regulatory watchlist: New statutory requirements around plan forms and insurer involvement, coupled with federal guidance on reimbursement limits, mean companies must revalidate contractual terms and claims processes. Regulatory readiness should be a board-level priority for firms with cross-jurisdictional operations.
Competitive Landscape — Positioning and Strategic Moves
The competitive field comprises global insurers, specialist vehicle providers, retailer-aligned digital protectors, and marketplace platforms. The market remains relatively fragmented; leading firms have meaningful scale but do not dominate the market entirely, leaving room for targeted consolidation and new entrants with differentiated capabilities.
-
Assurant, Inc.: A specialist in protection services that is doubling down on integrated product bundles. Recent product launches combining vehicle protection with device repair illustrate how Assurant is packaging vertical expertise with cross-category benefits — a model that raises switching costs and improves retention.
-
Asurion: Strong in retail and carrier channels with deep repair-network capabilities. Asurion’s playbook focuses on rapid claims fulfillment and B2C distribution scale, which is essential for high-volume, low-ticket warranties.
-
Vehicle specialists (Endurance Warranty Services, CarShield, CARCHEX): These providers compete on tailored mechanical coverage, flexible underwriting, and customer financing. Their strength is brand affinity in the automotive aftercare segment and agility in pricing niche risks.
-
Global insurers (AIG, AXA, Allianz Partners, AmTrust): These incumbents leverage balance sheet scale, reinsurance access, and broad distribution to offer white-label programs to OEMs and retailers. Their advantage is capital efficiency for large warranty portfolios and regulatory know‑how for cross-border programs.
-
Digital-first players (SquareTrade under Allstate): They exemplify integration of ecommerce, streamlined claims, and retailer partnerships. Their model highlights the economics of embedding warranty at point-of-sale and servicing via standardized repair channels.
Recent developments underscore these strategic shifts. In 2025, a major consumer electronics OEM expanded its in-country protection program to include broader home appliance coverage — a move that signals OEMs are integrating extended protection into core customer propositions. Also in 2025, a leading protection specialist launched a bundled vehicle and device protection product for advanced vehicle technologies; this hybrid approach is emblematic of product convergence across categories.
What Our Full Report Delivers (Operational Value You Can Act On)
The complete PW Consulting Extended Warranty Service Market report is built for teams that need to move from insight to implementation. Highlights include:
-
Validated market sizing and scenario forecasts (base year 2025; historical window 2020–2025; forecast 2026–2032) with sensitivity tables that let you stress-test pricing, claims inflation, and channel mix assumptions.
-
Actionable go-to-market frameworks for OEMs, insurers, and retailer partners — including distribution economics, partner revenue shares, and GTM playbooks tailored to different ownership and channel models.
-
A competitive playbook covering product design, digital claims orchestration, vendor selection criteria for repair networks, and technology architecture required to scale usage-based and connected warranties.
-
M&A and partnership screeners: a prioritized list of capability adjacencies, criteria for tuck-in versus transformational deals, and financial models that quantify synergies for sample transactions.
-
Regulatory and compliance matrix: jurisdictional obligations, required contract disclosures, and practical remediation steps to align sales, legal, and claims operations with emerging standards.
-
Implementation roadmap with 90/180/360-day milestones, capability sprints (data, underwriting, claims automation), and KPI dashboards to monitor revenue per contract, retention, and claims loss ratio.
Strategic Recommendations: Priorities for 2026
-
Embed product differentiation at the point of sale. Use modular coverage constructs and optionality (e.g., higher-tier tech support, remote diagnosis) to reduce price-driven churn and raise average revenue per user.
-
Invest in claims automation and predictive maintenance. Shortened cycle times and lower service costs materially affect loss ratios; invest now to capture the compounding returns over the forecast horizon.
-
Mobilize regulatory readiness. Conduct a rapid compliance audit focused on contract forms, disclosure requirements, and reimbursement policies. Align legal, underwriting, and product teams on remediations ahead of new enforcement timelines.
-
Diversify distribution and consider white-label offerings. Retailer and OEM partnerships accelerate scale and capture customer lifecycle economics — but require tight SLAs and integrated data flows.
-
Explore targeted M&A to secure repair networks, telematics capabilities, or digital claims platforms. The market’s fragmentation creates attractive tuck-in opportunities to buy capabilities instead of building them.
Conclusion — How to Use This Preview
The Extended Warranty Service Market is moving from an accessory line item to a strategic revenue engine. By 2026, executives must decide whether to lead (invest in product, data, and distribution), follow (partner with best-in-class providers), or exit (de-risk by divesting warranty portfolios). Our research shows that early investments in digital claims, regulatory preparedness, and channel integration pay back across retention and margin metrics as the market grows at a mid‑high single-digit CAGR through 2032.
This preview intentionally omits detailed regional and application splits and other granular tables to preserve the strategic integrity of the research. For the full dataset, detailed segmentation analysis, vendor scorecards, and implementation templates — which translate these strategic implications into executable 90–360 day plans — please consult the complete PW Consulting Extended Warranty Service Market report on our website.
For detailed analysis of this topic, please visit the official page: Extended Warranty Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Elastomeric Infusion Pumps to hit USD 1.38B by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Elastomeric Infusion Pumps Market — Strategic Outlook for 2026 Decision‑Makers
As health systems, payers, and device manufacturers prepare budgets and strategic roadmaps for 2026, the Elastomeric Infusion Pumps Market presents a clear, actionable growth story — but one that requires nuanced interpretation. PW Consulting’s latest industry study (base year 2025; historical series 2020–2025; forecast 2026–2032) quantifies and contextualizes that story: the market reached approximately USD 885.0 Million in 2025 and is projected to expand to roughly USD 975.8 Million in 2026, continuing on a compound annual growth path of 6.98% through the 2026–2032 forecast window, culminating in a market environment materially larger by 2032.
Elastomeric Infusion Pumps Market
Why this study matters for 2026 decisions
-
It converts headline growth into operational choices. The mid-single-digit-plus CAGR translates into concrete implications for manufacturing scale, inventory strategies, and reimbursement negotiations — particularly for players deciding whether to prioritize ambulatory/home infusion versus inpatient channels.
Elastomeric Infusion Pumps Market -
It exposes strategic inflection points. Recent regulatory shifts, reimbursement clarifications, and raw‑material dynamics mean that a “business-as-usual” playbook will underperform. Companies that align product development, quality assurance, and go‑to‑market tactics with these inflection points will capture outsized value.
Elastomeric Infusion Pumps Market -
It equips investors and M&A teams. The market’s structure and growth trajectory are sufficient to support bolt-on acquisitions, contract manufacturing expansions, and niche product entries — but target selection must be informed by clinical use cases, regulatory readiness, and durable reimbursement coding.
Market trajectory — what the numbers imply (not just enumerate)
Across 2020–2025 the market showed resilience through pandemic disruption and shifting care pathways. The 2025 market size (USD 885.0 Million) reflects recovery and adoption of ambulatory infusion paradigms. The forecast baseline (2026) and the 6.98% CAGR through 2032 reflect accelerating demand driven by outpatient surgery, home-administered antibiotic and chemotherapy regimens, and escalating interest in simplified infusion modalities that reduce hospital bed days.
For operators, the implication is straightforward: modest but sustained growth enlarges the economic runway for incremental product investments, while also increasing competitive pressure on manufacturing capacity and component sourcing.
Key dynamics shaping the market
-
Regulatory tightening and device assurance: The FDA’s Infusion Pump Improvement Initiative has raised the bar for documentation, safety assurance cases, and real‑world testing. Manufacturers must now build defensible, traceable risk mitigation dossiers — a nontrivial investment that favors companies with established engineering and quality systems.
-
Reimbursement stability matters more than headline rates: Recent policy actions have reaffirmed separate payment pathways for specific infusion therapies in outpatient settings, preserving access economics for ambulatory devices. The practical effect for manufacturers and hospital purchasing groups is that sustained payer recognition reduces commercialization risk, but success still depends on local coding strategies and contracting execution.
-
Raw‑material and formulation innovation: Advances in medical‑grade elastomers — silicone blends with polyurethane and polyisoprene variants — are materially altering flow stability characteristics and shelf behaviour. These materials choices influence device performance (flow precision, relaxation time), sterilization workflows, and supply‑chain complexity.
-
Cost and capital patterns: Elastomeric devices retain an up‑front cost advantage relative to reusable electronic pumps, particularly for single‑use clinical pathways in ambulatory care. That cost profile makes them attractive in low‑resource and home care settings, but also compresses margins for commodity suppliers.
-
Safety signals and market trust: Isolated malfunction reports and MAUDE entries underscore the reputational sensitivity of infusion devices. Transparent post‑market surveillance and rapid corrective‑action capacity are now a commercial necessity as much as a regulatory one.
Segmentation and what we deliberately withhold here
The full report contains granular segmentation by region, device type (continuous vs. variable vs. patient‑controlled), and clinical application (e.g., pain management, antibiotic therapy, chemotherapy), together with multi‑scenario forecasts. In keeping with the “trailer” principle of this executive summary, we demonstrate analytical depth while intentionally withholding the fine‑grained split figures and regional/application-level revenue tables. This is to ensure clients rely on the complete dataset and methodology inside the paid report before making high‑stakes capital or M&A decisions.
Competitive landscape — profiles and strategic implications
-
Baxter International Inc. — Offers SimplFusor ambulatory systems that emphasize mobility and reduced device weight versus electronic alternatives. Strategic view: Baxter’s strength in hospital procurement and established home infusion channels makes it a natural partner for integrated therapy bundles; its risk is slower iteration on next‑gen elastomer materials versus agile niche players.
-
Avanos Medical, Inc. — Producer of the ON‑Q system focused on post‑surgical pain management and disposable components. Strategic view: Avanos’ continued reimbursement recognition for ON‑Q improves its commercial defensibility; competitors should monitor payer coding stability and consider complementary products that broaden procedural applicability.
-
B. Braun Melsungen AG — Offers continuous and variable‑rate systems; recently an EasyPump device had a reported over‑infusion event in early 2026. Strategic view: Quality governance and transparent post‑market response will determine whether the incident becomes a transient reputational issue or a lasting competitive liability.
-
Fresenius Kabi AG — Supplies integrated home infusion solutions; strategic position strengthened by global home care penetration and product breadth. Strategic view: Large OEMs can leverage scale to absorb regulatory and testing costs, but must avoid commoditization of core disposable components.
-
Nipro Corporation & Terumo Corporation — Japanese OEMs with strong ambulatory and hospital ties. Strategic view: Regional manufacturing agility and supply‑chain integration make these players attractive partners for localized rollouts and regulatory filings.
-
ICU Medical, Smiths Medical, Leventon, First Medical Source (InfuLife) — A mix of component specialists, AI‑enabled product developers, and cost‑focused suppliers. Strategic view: The market’s middle tiers are where consolidation and vertical integration will accelerate; companies with differentiated clinical evidence or lower total cost of ownership will be acquisition targets.
Recent developments — catalytic events to watch
-
Early 2026: A reported over‑infusion event associated with a major OEM’s elastomeric device highlighted the need for robust post‑market surveillance and faster communication channels between manufacturers and clinicians.
-
Early 2026: Reimbursement policy updates reaffirmed separate outpatient payment pathways for certain ambulatory pumps, reducing short‑term commercial uncertainty for established products.
-
March 2026: New product introductions (e.g., disposable smart elastomeric pumps) signal a move toward multifunctional devices that address intermittent and continuous therapy needs — a potential vector for differentiation if paired with clinical evidence and payer engagement.
What’s inside the full PW Consulting study (practical contents)
-
Market sizing and forecasting models (2020–2032) with downloadable datasets and sensitivity scenarios.
-
Segment deep dives: methodology, assumptions, and market drivers for device type, clinical application, and region (granular tables and heat maps available in the report).
-
Supply‑chain analysis: raw material sources, test protocols for elastomer blends, supplier concentration risks, and cost pass‑through sensitivities.
-
Regulatory and reimbursement playbook: mapping of FDA expectations, coding pathways, and payer engagement strategies tailored to outpatient and home infusion rollouts.
-
Competitor benchmarking: strategic profiles, capability matrices, recent M&A and product moves, and a strategic 2x2 for go‑to‑market positioning.
-
Commercialization checklists: clinical evidence requirements, field training templates, and pricing scenarios tied to payer negotiations.
-
M&A and partnership playbook: valuation heuristics, integration risks, and three investment cases (bolt‑on, platform expansion, disruptive entry).
Actionable recommendations for 2026
-
Prioritize regulatory readiness now. Prepare robust safety assurance dossiers aligned to the FDA’s guidance — this reduces time‑to‑market risk and enhances buyer confidence.
-
Lock in supply of medical‑grade elastomer formulations and qualify secondary sources. Material performance now differentiates flow stability and shelf life.
-
Design payer engagement around outpatient coding stability. Preserve economic access by documenting total cost of care benefits (reduced inpatient days, readmission avoidance) rather than only device price.
-
Invest selectively in product features that translate to clinical adoption: simple dosing verification, ease of use for home caregivers, and integration with telehealth follow‑up tools.
-
For investors: target mid‑tier suppliers and specialty technology companies with validated clinical use cases — these are the most likely consolidation candidates.
How to use this research
Use the full PW Consulting report to convert macro growth (USD 885.0 Million in 2025, USD 975.8 Million in 2026, 6.98% CAGR through 2032) into tactical plans: determine manufacturing scale‑up timelines, prioritize R&D investments, and shape payer conversations. The executive summary you are reading is a strategic preview; the full dataset, scenario models, and competitor dossiers are required to execute with confidence.
For procurement teams, product leaders, M&A groups, and private equity investors preparing 2026 plans, this study offers a rigorous, executable roadmap — demonstrated methodology, complete transparency on assumptions, and the specific operational checklists you need to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Elastomeric Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Remote Control Market to Reach USD 344.8 Million by 2032 at a 4.8% CAGR
By PW Consulting, 2026-07-12
Remote Control Market — Strategic Preview for 2026: Positioning, Risks, and Opportunity Playbooks
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present this strategic preview of our new Remote Control Market research. This introduction synthesizes the report’s most consequential insights for executive decision-making in 2026, highlighting market momentum, competitive dynamics, regulatory inflection points, and the practical levers leaders should pull to convert uncertainty into advantage. The full dataset, segmented forecasts, and granular vendor benchmarking are available in the complete report; this piece deliberately omits proprietary subsegment tables to preserve the value of the primary research and to direct readers to the source for transaction-grade detail.
Remote Control Market
Market trajectory in one view
The remote control market is no longer a mature, static appliance market — it is an adjacent infrastructure that bridges consumer devices, industrial teleoperation, and connected ecosystems. Our model (base year 2025, historical window 2020–2025, forecast 2026–2032) shows steady expansion driven by converging trends in connectivity, industrial automation, and human-machine interface (HMI) innovation. The market rose from the early‑2020s baseline and reached approximately USD 215.0 Million in 2025. Under our central scenario the market expands at a compound annual growth rate of 4.8% through 2032, reaching roughly USD 344.8 Million by the end of the forecast horizon.
Remote Control Market
These headline figures reflect an evolution in demand: traditional consumer remotes remain a significant base, while higher‑value nodes such as industrial radio controls, AI‑enhanced automation interfaces, and long‑distance teleoperation platforms are increasing average selling prices and total addressable spend per deployment. For decision makers, this means the growth opportunity is less about volume alone and more about mix and monetization of advanced control capabilities.
Remote Control Market
Why this research matters for 2026 strategy
- Investment prioritization: The report translates headline growth into investment buckets (product R&D, software platforms, certification and spectrum access), enabling CFOs to size near‑term capital needs against forecasted revenue uplift.
- Commercial go‑to‑market: We map the sales motions that win — direct OEM partnerships for embedded controls, channel plays for retrofit consumer devices, and managed services models for industrial teleoperation.
- Risk calibration: Our scenario analyses quantify exposure to regulatory swings, spectrum availability, and broadband infrastructure constraints so executives can hedge technology bets and contractual commitments.
- M&A and partnership scouting: The research surfaces capability gaps and attractive target archetypes — everything from niche industrial radio specialists to software platform firms enabling voice, AI agents, and telemetry integration.
What the report delivers — practical, transaction‑grade outputs
- Integrated market model (historical performance + seven‑year forecast) with sensitivity levers for pricing, adoption rate, and technology substitution.
- Scenarios and playbooks that translate regulatory and infrastructure permutations into concrete strategic actions (e.g., defer, double down, or pivot).
- Competitive intelligence dossiers and supplier scorecards built from primary interviews, patent landscaping, and product roadmaps.
- Commercial frameworks: value propositions, channel economics, and partner fit matrices tailored to consumer, industrial, and emerging teleoperation customers.
- M&A screening toolkit that overlays strategic fit, integration complexity, and short‑term ROI to prioritize targets.
Competitive landscape: capabilities, moves, and what they imply
The market structure remains fragmented by capability and use case rather than dominated by a single business model. Measured concentration is modest (CR3 and CR5 indices indicate a market with space for scale and specialization), signaling opportunities for disciplined consolidation and vertical integration where justified.
- Universal Electronics Inc. (UEI) — UEI’s strengths are platform integration and consumer HMI: voice-enabled universals, RF capable remotes, and embedded control stacks for TVs, set‑top boxes, and smart home devices. Strategically, UEI is positioned to monetize software and cloud‑enabled features layered on top of hardware footprints. For incumbents and new entrants, UEI’s playbook underscores the commercial premium available when device control is coupled with cloud services and extended warranty or subscription revenue.
- URC (Universal Remote Control) — URC’s Total Control® and Complete Control® ecosystems and recent expansion of Automation Engine with AI Agents signal an aggressive push into software‑defined automation and intelligent HMI. Their integration of environmental sensing plugins and voice ecosystems exemplifies the trajectory from remote as a physical input to remote as an orchestration node for home and commercial environments. Partnerships and platform licensing will be the critical battleground here.
- Cattron — With a focused industrial product portfolio and recent launches (notably new radio remote packages and advanced systems for hoists and cranes), Cattron illustrates the premium of domain expertise in safety‑critical, ruggedized control. For industrial customers, reliability, certification, and lifecycle support trump unit price. Cattron’s moves suggest consolidation opportunities in the industrial segment, and highlight the ROI of investing in interoperable control protocols and service agreements.
- Liebherr — Liebherr’s LiReCon teleoperation demonstrations show the frontier potential of long‑distance, low‑latency remote control for heavy machinery. Teleoperation shifts value from single‑device control to systems engineering — integrating connectivity, edge compute, and operator interfaces. Large OEMs demonstrating teleoperation capabilities create new partnership and platform opportunities for software providers and systems integrators.
Together, these players exemplify three strategic axes: consumer HMI/platform monetization, niche industrial reliability and certification, and emergent teleoperation systems. Each axis requires different commercial, regulatory, and engineering playbooks.
Regulation, spectrum, and infrastructure: tailwinds and headwinds
Decision makers must navigate mixed signals in the policy landscape. Recent regulatory moves and court rulings create a complex backdrop: one strand of policy has reclassified broadband services in ways that reinforce open access principles, while other legal developments have shifted regulatory control toward legislative and state implementations, creating patchwork outcomes for access and pricing. Data sovereignty concerns—especially around independent satellite communications and remote region operations—add compliance burdens for cross‑border deployments.
Practically, two infrastructure realities matter for 2026 planning. First, achieving ubiquitous, low‑latency connectivity requires significant fiber and last‑mile investment; national programs and private capex will influence where high‑value teleoperation use cases are feasible. Second, spectrum policy and sharing frameworks will determine how reliably remote control applications (particularly those needing real‑time, high‑bandwidth links) can scale. Our scenarios explicitly model spectrum access constraints and the economic tradeoffs of licensed vs. shared bandwidth strategies.
Technology evolution and product strategy considerations
- Software‑led differentiation: Voice, AI agents, telemetry dashboards, and subscription services are increasingly where margin resides. Hardware remains necessary but commoditizable.
- Interoperability and standards: Vendors that invest in open APIs, common protocols, and modular hardware to enable third‑party integrations will find larger ecosystem opportunities and higher exit multiples.
- Safety, certification, and lifecycle services: Especially in industrial and teleoperation contexts, compliance and guaranteed service levels drive procurement. Product warranties, remote diagnostics, and preventative maintenance offerings become strong differentiators.
Actionable decision framework for 2026
- Map scenarios: Build three investment scenarios (Constrained Connectivity, Platform Consolidation, Teleoperation Acceleration) and stress‑test product roadmaps and cash flows against each.
- Prioritize bets: Allocate R&D across software capabilities, ruggedized industrial products, and teloperation piloting, based on margin profiles and go‑to‑market speed.
- Secure spectrum and connectivity partners: Negotiate early with carriers and satellite providers where long‑distance or low‑latency links are strategic; consider spectrum leasing and sharing strategies.
- Design flexible commercial models: Mix up‑front hardware sales with SaaS subscriptions, managed service fees, and outcome‑based contracts to align incentives with customers.
- Use M&A selectively: Acquire capabilities (software platforms, industrial radio specialists, or teleoperation system integrators) to accelerate time to market; use our M&A screening toolkit to assess integration complexity and payback.
How to use the full PW Consulting report
This preview outlines the strategic contours that matter for 2026. The full Remote Control Market report provides the transaction‑grade inputs you need to operationalize these actions: downloadable forecast models (with scenario toggles), granular regional and application splits, device‑level ASP trends, detailed vendor revenue benchmarks, primary interview excerpts, and a prioritized M&A target list. For boards, corporate strategy teams, and business unit leaders, the report turns the macro outlook and competitive analysis into executable milestones and financial commitments.
PW Consulting’s research deliberately balances openness and exclusivity: we provide the analytical scaffolding and strategic playbooks publicly, while the granular segmentation tables and vendor scorecards — the pieces your commercial and M&A teams will use in negotiations — are accessible in the full report.
For 2026, leaders who treat remote control not as a peripheral accessory but as a strategic interface — one that connects software, networks, and operational outcomes — will capture disproportionate value. This research is designed to get you from insight to action.
For detailed analysis of this topic, please visit the official page: Remote Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Interactive Kiosk Market Set to Grow at 8.05% CAGR Through 2032
By PW Consulting, 2026-07-12
Interactive Kiosk Market — 2026 Strategic Briefing
Executive snapshot
As companies prepare budgets and go-to-market plays for 2026, the interactive kiosk sector presents a renewed window of strategic opportunity and operational complexity. Our latest market model, anchored on the 2025 base year, shows the global marketplace expanding from roughly USD 37.6 billion in 2025 to approximately USD 64.6 billion by 2032 — a trajectory underpinning an 8.05% compound annual growth rate across the 2026–2032 forecast period. That momentum is the product of converging forces: renewed retail automation investments, healthcare and government digitization programs, QSR transformation toward app-less ordering, and public-infrastructure projects pairing information services with mobility and energy use cases.
Interactive Kiosk Market
Why this research matters for 2026 decisions
-
Portfolio prioritization: With a market that has grown markedly since 2020 (our historical series traces expansion from the mid-20s to the high-30s in USD Billion prior to the forecast), every capex allocation must be screened against near-term ROI and multi-year adaptability. 2026 is the year many organizations transition pilots into scaled rollouts — and they need a playbook that balances hardware, software, services, and lifecycle economics.
Interactive Kiosk Market -
Vendor selection and risk management: Consolidation is nascent but material; our concentration metrics show the market’s top-three players account for a meaningful but not overwhelming share of revenue (CR3 ~36%, CR5 ~42%). That market structure favors bespoke solutions and regional specialists as much as global platform vendors, so procurement must be calibrated to risk, support footprint, and integration capability.
Interactive Kiosk Market -
Regulation and civic programs: Local government programs and public-private funding models are reshaping deployment economics and privacy obligations. Case examples — municipal programs that have adopted zero-cost-to-taxpayer supply models and sidewalk kiosk initiatives to support local merchants — are shifting how projects are funded and governed. Companies that can marry compliance, funding creativity, and operational guarantees will win municipal and transportation business in 2026.
Market trajectory — what the top-line tells you
The headline growth rate (8.05% CAGR, 2026–2032) conceals structural nuance. The last half-decade shows robust adoption across enterprise verticals as well as diversified procurement models: outright purchases, managed-service contracts, and outcome-based offerings. Our full model traces that evolution across a five-year historical window and a seven-year forecast horizon, providing scenario-based projections that reflect different adoption curves (conservative, base, and aggressive). For executive planning this means scenario hedging is essential: a mid-range investment program aligned to the base case will preserve optionality while capturing the majority of measurable upside if the market tracks the accelerated path.
What’s inside the report — practical, operational, and decision-ready
This research is designed for executives and practitioners who must translate market signals into executable plans. The report organizes evidence and tools into four operational pillars:
-
Market sizing and scenario models — a reproducible forecasting engine (2026–2032) with sensitivity toggles for adoption, hardware price deflation, and service-margin compression. These models let you stress-test investment returns across deployment scales without exposing the segmented granularities here in the preview.
-
Use-case playbooks — prioritized templates for retail, QSR, healthcare, transportation, and public information deployments. Each playbook includes KPIs, baseline TCO components, staffing and training profiles, and a short-list of high-value integrations (payments, identity, wayfinding, analytics).
-
Procurement & vendor evaluation toolkit — a vendor scorecard, RFP checklist, and contract clause library covering SLAs, maintenance windows, spare-parts logistics, and data privacy obligations. These are crafted to support both centralized procurement and distributed franchise models.
-
Implementation accelerators — deployment sequencing maps, change-management checklists, and a compact ROI calculator tailored for pilots scaling to enterprise programs. The accelerators include templates to quantify labor reallocation, customer throughput gains, and cross-sell uplift attributable to interactive interfaces.
Competitive landscape — who to watch and how to partner
The ecosystem blends specialized kiosk manufacturers, POS and ATM incumbents, industrial hardware vendors, and pure-play software platforms. The market’s CR3 and CR5 metrics indicate a moderately fragmented landscape where mid-sized specialists coexist with established global vendors. Strategic implications for 2026:
-
Tiered partnership strategies: Engage large system integrators and incumbents for enterprise-wide rollouts that require deep payment, security, and legacy-system integration. Examples of organizations operating at scale include established ATM and POS suppliers that bring banking-grade security and entrenched channel relationships.
-
Co-innovation with design-led kiosk specialists: Boutique manufacturers and design firms offer rapid prototyping and ADA-compliant industrial design. Their value is highest in verticals where form-factor and customer experience are differentiators.
-
Software-as-platform plays: Interactive-software vendors and touchscreen-platform providers deliver the orchestration layer that multiplexes hardware, analytics, and third-party integrations. For buyers, platform extensibility and lifecycle licensing terms are as important as upfront feature sets.
Representative firms profiled in our competitive chapter include KIOSK Information Systems, Olea Kiosks, Pyramid Computer, ACRELEC, Diebold Nixdorf, NCR Voyix, Advantech, Fujitsu, and Samsung — each described with a concise capability map (hardware strengths, vertical focus, integration footprint). Also covered are smaller, innovative vendors that provide niche services (wayfinding, creative experience design, or industrial ruggedization). The report’s vendor matrix compares these firms across service breadth, geographic reach, and product modularity without publishing proprietary market-share breakdowns in this summary.
Regulatory and infrastructure dynamics shaping 2026 deployments
Recent municipal programs illustrate shifting procurement architectures: some cities are adopting zero-cost-to-taxpayer concession models with strict privacy safeguards; others are deploying kiosk networks explicitly designed to support local small business activation along pedestrian corridors. Public-private partnerships that couple interactive kiosks with adjacent infrastructure (for example, curbside services and EV charging) demonstrate how kiosks are being bundled into broader urban-service contracts. On the vendor side, incumbents reporting quarter-on-quarter revenue growth tied to self-service upgrades signal that financial institutions and retailers continue to prioritize modernized touchpoints. For planners, the takeaway is straightforward: compliance, privacy-by-design, and multi-service bundling have moved from “nice-to-have” to procurement prerequisites.
Practical moves for 2026
-
Prioritize modularity: Specify hardware and software decoupling to extend lifecycles and reduce refresh costs. Modular kiosks lower upgrade friction when payment rails or security standards evolve.
-
Embed funding flexibility: Explore managed services, revenue-share models, and municipal concession agreements to minimize upfront capital and accelerate rollouts without compromising governance.
-
Run velocity pilots: Short, instrumented pilots with rapid feedback loops validate UI/UX hypotheses, operational costs, and partner performance ahead of enterprise rollouts.
-
Lock in privacy and accessibility early: Build checklists and standardized contract language for data handling and ADA compliance, since these are now central to procurement decisions across public and private sectors.
How to use the full research
This briefing is a directional guide. The full PW Consulting Interactive Kiosk Market report supplies the actionable artifacts buyers and operators need to execute in 2026: downloadable financial models, a complete vendor comparison matrix, prioritized investment scenarios, and templated procurement language. The full report also disaggregates market sizing across geographies, kiosk types, and application verticals — information that purchasing teams and strategic planners will require to finalize budgets and vendor shortlists. (To preserve competitive value in this preview, those segmented tables are available only in the full deliverable.)
Closing — the strategic window for 2026
2026 is a hinge year. Market fundamentals show sustained expansion, with the global market expected to grow meaningfully beyond the 2025 base. The organizations that win will be those that combine disciplined financial modeling, flexible procurement strategies, and partnership architectures that integrate hardware, software, and service layers. Our research equips leaders with both the high-level market context and the operational tools necessary to convert a growing market into measurable business outcomes. For teams preparing 2026 plans, the time to move from exploratory pilots to repeatable deployment engines is now — but do so with the market intelligence and playbooks that mitigate execution risk.
Next step
Access the full report to download the forecasting model, run your custom scenarios, and get the complete vendor matrix and procurement templates that will enable rapid, low-risk scaling in 2026. PW Consulting’s industry desk stands ready to support bespoke scenario workshops and vendor selection sprints.
For detailed analysis of this topic, please visit the official page: Interactive Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydroxyacetic Acid (Glycolic Acid) Market to Reach USD 628.84M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-12
Hydroxyacetic Acid (Glycolic Acid, CAS 79-14-1): Strategic Intelligence for 2026 Decision-Making
Executive snapshot
Glycolic acid (hydroxyacetic acid) has moved from a niche specialty chemical to a strategically relevant input across personal care, specialty industrial cleaners, textiles, and select pharmaceutical and food-processing applications. Our PW Consulting market study, with a 2025 base year and a forecast window through 2032, captures this transition: the global market has expanded from the low‑hundreds of USD Million in 2020 to an estimated USD 415.0 Million in 2025, and our modeled trajectory shows sustained acceleration through the forecast period, underpinned by a compound annual growth rate of 6.8% (2026–2032).
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Why this study matters for 2026 decisions
- Timing of investment and capacity moves: The market’s mid‑single‑digit CAGR masks pockets of faster growth tied to bio‑based supply innovations and higher‑purity grades for pharma and electronics. For corporate boards and investors evaluating brownfield or greenfield capacity in 2026, the study translates market growth into realistic utilization ramp profiles and payback windows under multiple feedstock scenarios.
- Risk calibration in procurement: Recent feedstock volatility—illustrated by upward pressure on oxalic acid and ethylene glycol prices and regional spikes in formaldehyde costs—means procurement strategies calibrated in 2026 must emphasize hedging, supplier diversification, and qualification of alternative chemistries. Our analysis provides actionable procurement stress tests and switching cost matrices.
- Regulatory and ESG alignment: Environmental compliance costs have risen materially for downstream European users; 2025 saw a notable increase in compliance‑related spending. Managers planning 2026 product roadmaps need to prioritize lower‑impact grades and bio‑based sourcing to future‑proof market access and avoid margin erosion from tightening environmental standards.
What the macro picture reveals
At an aggregate level, glycolic acid exhibits steady expansion: the market size climbed from approximately USD 315 Million in 2020 to USD 415 Million in 2025, and our baseline forecast anticipates it continuing to grow to the high hundreds by the end of the decade. That expansion is not uniform—growth in certain high‑purity segments and end‑use niches outpaces the headline number—but the 6.8% CAGR for the forecast window provides a robust planning anchor for capital allocation and product strategy in 2026.
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Market structure and competitive dynamic
The competitive landscape is characterized by a mix of global leaders with advanced manufacturing platforms, national champions focused on cost‑competitive supply, and regional specialists targeting niche applications. Market concentration is moderate: the top three players account for roughly one‑third of the market, while the top five approach half. This structure creates space for both scale players to pursue capacity and innovation plays, and for agile suppliers to carve out specialty niches.
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
- Scale & technology leaders: Producers leveraging continuous manufacturing, high‑purity process control, and bio‑based feedstock technology are positioned to serve pharmaceutical, electronics, and specialty chemicals demand with differentiated pricing power and higher margins.
- Volume & cost players: Fine‑chem manufacturers and chemical intermediates producers remain critical to volume supply for industrial applications. Their strategy centers on operational efficiency and logistics optimization to protect margins when feedstock prices spike.
- Regional specialists and contract manufacturers: Strategic partnerships between high‑purity technology owners and regional contract manufacturers are emerging as a repeatable model to combine technology leadership with local market access and regulatory compliance.
Notable recent developments and what they imply
- Bio‑based pilot capacity comes online: The commissioning of new bio‑based glycolic acid pilots signals a potential inflection point in feedstock sourcing. Producers and buyers should evaluate how bio‑based sourcing affects long‑term cost curves, sustainability claims, and route‑to‑market for premium grades.
- Product portfolio upgrades for high‑purity markets: New technical‑grade offerings targeting electronics etching and pharmaceutical use highlight a bifurcation in the market: standard industrial grades versus value‑added high‑purity products. This bifurcation has strategic implications for plants, QA regimes, and certification investments initiated in 2026.
- Commercial partnerships and co‑development: Recent alliances between high‑purity manufacturers and contract manufacturing organizations reduce time‑to‑market for pharmaceutical suppliers while protecting IP and capital. Corporates pursuing growth should consider partnership roadmaps as an alternative to direct investment.
Raw materials, cost dynamics and supply risk
Feedstock volatility is a real and present driver of margin volatility. Since late‑2024 and into 2026 we have observed pockets of tightness and price migration across oxalic acid, ethylene glycol, and formaldehyde—each of which can transmit to glycolic acid producers depending on their synthetic route. In practice, buyers and sellers must model multiple price paths and plan working capital accordingly. Our full report provides linked price‑path scenarios and margin sensitivities that are essential for 2026 contract negotiation and capex approvals.
Strategic implications by stakeholder
- Producers (large & medium): Reassess the trade‑off between volume and quality: investing in high‑purity process capability or bio‑based feedstock can create differentiated growth, but requires longer lead times and stricter regulatory compliance. Use our scenario models to map investment timing to expected ROI under conservative and aggressive market cases.
- Private equity and strategic investors: Market concentration and predictable growth create attractive roll‑up opportunities, provided integration plans address quality assurance, regulatory exposure, and feedstock risk. Our M&A playbook identifies value levers, typical synergies, and integration pitfalls observed across recent transactions.
- Downstream formulators: For cosmetics and specialty cleaners, there is a near‑term imperative in 2026 to qualify multiple sources and secure long‑term supply agreements with grade‑specific quality metrics. The report offers supplier shortlists and qualification templates tailored to cosmetic and pharmaceutical quality regimes.
- Procurement and risk managers: Adopt a tiered sourcing strategy that blends spot, term, and alliance‑based supply; use hedging where appropriate; and incorporate environmental compliance cost pass‑throughs into supplier contracts. Our standard contract clauses and risk allocation templates can be implemented immediately.
What the PW Consulting report delivers — practical, transaction‑grade content
Beyond strategic narrative, the report is designed for commercial and operational decision‑makers who need executable outputs in 2026. It includes:
- Transparent market sizing methodology and reconciled top‑down/bottom‑up estimates for 2020–2025 and projected 2026–2032 trajectories.
- Scenario models (base, downside, upside) with sensitivity to feedstock price paths, purity mix, and regulatory tightening.
- Price benchmark matrices and contract negotiation playbooks for term and spot purchasing.
- Supply‑chain maps and constraint analyses identifying concentration points and logistical choke points under multiple disruption scenarios.
- Actionable go‑to‑market playbooks for launching high‑purity and bio‑based product lines, including sample QA/QC checklists and regulatory prerequisites by jurisdiction.
- Detailed company profiles and competitive positioning for major players, including technology differentiators, capacity footprints, and recent strategic moves.
- M&A target screens, valuation ranges, and integration checklists tailored to roll‑up and bolt‑on strategies.
- Regulatory and sustainability matrix highlighting compliance cost drivers and mitigations that matter for 2026 procurement and product approvals.
Competitive highlights — what to watch in 2026
We track three strategic playbooks among market participants: (1) technology/quality leadership built around continuous and high‑purity manufacturing platforms; (2) cost‑focused volume producers leveraging scale and regional feedstock advantages; and (3) integrated partnerships pairing technology owners with contract manufacturers to accelerate commercialization while limiting capital exposure.
Key incumbents exemplify these playbooks. Some are market leaders in high‑purity production through proprietary continuous manufacturing; others are established fine‑chemical exporters serving industrial demand. Recent capacity and product launches by leading European and global chemical players, combined with strategic partnerships, are worth monitoring as catalysts that could shift supply dynamics and price realization over the next 18–36 months.
How to use this intelligence in 2026
- Start with a short‑form sensitivity run: model your exposure to a 10–20% feedstock shock using our provided templates to see whether margins compress to unacceptable levels and whether price pass‑through is viable.
- For capex proposals, deploy our scenario models to stress‑test payback periods under conservative demand adoption rates for premium grades.
- Use the supplier shortlists and qualification templates to compress supplier onboarding timelines from months to weeks—critical when negotiating 2026 term contracts.
- If pursuing M&A, apply our target architecture and integration checklist to evaluate targets quickly and prioritize actions that de‑risk quality and regulatory exposures.
Final note — the trailer principle
This article is intentionally selective: it surfaces the strategic contours, competitive dynamics, and prioritized actions that matter for making defensible decisions in 2026. To preserve analytical traction and the commercial integrity of actionable sub‑segment data (region‑by‑region demand curves, grade‑specific pricing, and detailed supplier revenue splits), we reserve those tables, models, and raw datasets for the full report and its downloadable datasets.
For a thorough, transaction‑ready pack—complete with financial models, supplier scorecards, contract clause templates, and the granular segmentation that supports confident 2026 execution—please consult the full PW Consulting Hydroxyacetic Acid (Glycolic Acid) market study. The report delivers the level of detail required to convert strategic intent into measurable outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gaming Market 2026: Strategic Signals from PW Consulting’s Market Research Preview
As organizations prepare their 2026 strategic roadmaps, the global gaming market presents a unique mix of scale, velocity and structural change. PW Consulting’s latest market research — rooted in an audited base year of 2025 — shows the industry expanding from approximately USD 130 billion in 2020 to USD 189 billion in 2025, and poised to approach USD 355 billion by 2032 under our base-case outlook. This trajectory implies a compound annual growth rate of roughly 9.43% across the forecast horizon. For decision-makers, that macro momentum matters — but the critical value lies in understanding where growth, consolidation and disruption will intersect, and how to translate those inflections into executable moves in 2026.
Gaming Market
Why this report matters for 2026 decision-making
-
Orientation in a fast-growing market: With sustained high single-digit CAGR, leaders must choose between doubling down on core franchises, scaling platform plays, or entering adjacencies. The report isolates the strategic trade-offs each path entails.
Gaming Market -
Operational translation, not just forecasts: Beyond top-line projections, the research provides playbooks for product roadmaps, live-ops economics, talent sourcing, and supply-chain resilience — all essential to convert market tailwinds into durable cashflow.
Gaming Market -
Regulatory and macro foresight: The study synthesizes recent regulatory signals and macro shocks (tariffs, shifting consumer protections, and adjacent gambling market dynamics) into risk-adjusted scenarios for product launches and market entry.
-
M&A and competitive positioning: With market concentration that favors large incumbents yet leaves opportunity for focused challengers, the report guides buyers and sellers on valuation levers and integration priorities.
What the research delivers — practical components of the report
-
Robust market sizing and forecasting model: Transparent assumptions link historical performance (2020–2025) to a set of scenarioled forecasts (2026–2032) that can be stress-tested for client-specific use.
-
Segment and channel playbooks: Actionable GTM templates for platform strategies (hardware, console ecosystems, PC, and mobile), developer economies, and third-party distribution without publishing sensitive granular splits in this preview.
-
Competitive benchmarking: Outcome-focused scorecards for major platform owners and leading publishers covering product pipeline, monetization quality, R&D productivity, and partner ecosystems.
-
Monetization and retention toolkit: Standardized live-ops KPIs, cohort analysis templates, and scenario-based LTV/CAC models to prioritize investment across content and user acquisition.
-
Regulatory & supply-chain risk register: Prioritized mitigations for tariffs, import disruptions, and emergent regulatory threats with playbooks for pricing, localization and lobbying posture.
-
M&A playbook and valuation levers: Checklist for target screening, synergies, and integration sequencing tailored to the gaming value chain.
-
Executive workshops and decision dashboards: Ready-to-use board materials and a 90-day implementation roadmap for rapid strategy execution.
Competitive landscape — what executives need to know now
The industry’s structure combines powerful platform owners with influential first- and third-party content creators. Concentration metrics indicate meaningful scale at the top, but the market remains sufficiently fragmented to allow nimble entrants and specialist studios to capture disproportionate returns if they assemble the right assets.
-
Nintendo: The recent hardware cycle — marked by the launch of Nintendo’s next-generation console in 2025 — reshapes platform dynamics. Rapid uptake of new hardware compresses the time window for content monetization and elevates the value of exclusive IP and family-friendly ecosystems.
-
Sony Interactive Entertainment & Microsoft: Both continue to balance hardware innovation with cloud-service and subscription strategies that blur lines between console ownership and service access. Their playbooks highlight bundling economics, first-party exclusives and backwards compatibility as leverage points.
-
Valve: With its Steam ecosystem and handheld hardware initiatives, Valve illustrates the power of distribution platforms to influence PC and handheld lifecycles; distribution governance and developer revenue shares are strategic battlegrounds.
-
SEGA & SEGA SAMMY CREATION: These players showcase diversification — from consoles and IP to arcade and venue-based entertainment — offering lessons in multi-channel monetization and brand extension.
-
Major publishers (Take-Two, EA, Ubisoft, Epic): Content owners remain central. Their investments in live services, proprietary engines, and cross-media IP exploitation underscore the premium on long-term engagement models over one-off title sales.
Recent product launches and collaborations materially affect planning horizons: a fast-selling new console compresses product roadmaps; high-profile content or hardware tie-ins reshape consumer expectations; and cross-industry moves (e.g., branded collaborations or venue-based launches) redefine addressable markets. These developments, coupled with an uneven regulatory backdrop, argue for scenario-driven, flexible strategies rather than deterministic plans.
Five strategic imperatives for 2026
-
Design for cross-platform engagement and modular IP: Prioritize architectures and content design that enable simultaneous monetization across hardware generations, cloud services and mobile touchpoints.
-
Embed live-ops and analytics into product development: Shift investment from episodic releases to continuous engagement, supported by real-time data flows that drive retention and incremental monetization.
-
Hedge supply-chain and price exposure: The report’s analysis correlates import-tariff risk to consumer pricing sensitivity. Sophisticated procurement strategies, localized manufacturing, and dynamic pricing can preserve margins when hardware costs spike.
-
Operationalize regulatory readiness: With a significant portion of executives viewing unregulated prediction markets and regulatory uncertainty as major threats, firms must develop compliance playbooks, lobbying strategies and adaptable product features to mitigate legal and reputational risk.
-
Adopt a disciplined M&A posture: Use buy-versus-build frameworks to capture IP, talent and platform capabilities. Prioritize targets that accelerate live-ops competencies, platform interoperability, or unlock underserved monetization vectors.
Scenario thinking and KPIs — converting outlook into measurable action
Our baseline forecast uses the 9.43% CAGR to map a credible path to 2032. From that baseline, the report provides two alternate scenarios: a policy-constrained downside, and an accelerated-adoption upside tied to cloud, 5G and adjacent-vertical convergence. Each scenario contains tailored KPI sets and budget reallocation templates.
-
Suggested strategic KPIs: retention by cohort (D30/D90), ARPU by monetization stream, CAC payback period, content engagement per DAU, hardware attach rate (where applicable), and partner revenue share.
-
Investment triggers: thresholds for additional spend on live-ops, platform subsidies, or M&A integration based on early funnel conversion and LTV attainment.
Using the full report — next steps
This preview is intended to equip executives with the directional insights needed to prioritize 2026 initiatives. The full PW Consulting report contains the granular segmentations, regional playbooks, proprietary Excel models and annexed data tables that underpin these recommendations. PW’s consulting team also offers customized workshops that translate the report’s scenarios into a tailored 90-day strategic plan and a one-year transformation roadmap.
Immediate, practical next steps we recommend for leadership teams are:
-
Run a one-day executive alignment session using the supplied decision dashboards to pick a primary and secondary strategic axis for 2026.
-
Authorize a 60–90 day pilot to operationalize a live-ops hypothesis or a supply-chain hedging strategy informed by the report’s models.
-
Commission a rapid M&A screen mapping potential tuck-ins that accelerate access to critical capabilities identified in the report.
In a market that is scaling materially — nearly doubling in under a decade under our baseline — the winners will be those who combine rigorous scenario planning with fast execution. PW Consulting’s full research package captures that balance: precise enough to drive confident investment, and practical enough to support immediate action. For the granular segment data, regional breakdowns, and downloadable financial models that you’ll need to finalize 2026 budgets and M&A strategies, please refer to the full report.
For detailed analysis of this topic, please visit the official page: Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aseptic Filling Machine Market to Hit USD 1.99B by 2032 at 7.26% CAGR
By PW Consulting, 2026-07-12
Pharmaceutical Aseptic Filling Machine Market: Strategic Imperatives for 2026
As capital allocation, regulatory enforcement and product pipelines converge in 2026, procurement and strategy teams at pharmaceutical manufacturers, contract development and manufacturing organizations (CDMOs), original equipment manufacturers (OEMs) and private equity investors face one immutable fact: aseptic fill-finish capability is now a strategic bottleneck. Our new PW Consulting market study on the Pharmaceutical Aseptic Filling Machine market provides an actionable playbook for decision-makers who must balance compliance, capacity and cost under accelerating timelines.
Pharmaceutical Aseptic Filling Machine Market
Why this study matters for 2026 decisions
The market for aseptic filling machines is recovering from pandemic-era surges and entering a structurally higher-growth phase driven by biologics, single-dose injectables and global regulatory harmonization. With a base-year market sizing anchored in 2025 and a forecast horizon extending through 2032, the study quantifies how the market expands under realistic regulatory and technology adoption scenarios. The headline: the market, measured in USD Billion, has strengthened materially since 2020 and—at a compounded annual growth rate (CAGR) of 7.26%—is projected to approach USD 2.0 Billion by 2032. That macro trajectory frames investment timing, procurement cadence and service-model design in your capital planning cycles.
Pharmaceutical Aseptic Filling Machine Market
What the market trajectory tells strategic planners
-
Acceleration in capital spend: The market size has grown steadily since 2020 and reached a new structural baseline in 2025. The combination of capacity rebuild, greenfield biomanufacturing and replacement of legacy lines means demand is less cyclical and more driven by strategic capacity additions.
Pharmaceutical Aseptic Filling Machine Market -
Predictable expansion window: With a 7.26% CAGR baked into our base case, organizations that commit to capacity upgrades in 2026–2028 position themselves to capture the mid-cycle demand that peaks later in the decade.
-
Investment scale and ROI timing: Modern isolator-based, gloveless and integrated filling lines require meaningful upfront capex and validation lead times. Planning a 2026 procurement implies production upside in 2028–2029; delaying procurement risks extended qualification windows and lost production opportunities.
Regulatory and operational dynamics that shape tactical choices
-
Annex 1 and global alignment: The revised EU GMP Annex 1 continues to drive adoption of isolator-based or RABS solutions with continuous environmental monitoring. This regulation is a de facto baseline for multinational manufacturers and contract providers serving EU markets.
-
US FDA design expectations: By 2026, FDA guidance and expectations emphasize modern cleanroom design, separative equipment and integrated material transfers—factors that materially affect line architecture and validate effort.
-
Capital intensity and scale constraints: Independent analyses and industry surveys indicate that installation and validation costs for fully automated aseptic lines commonly exceed multimillion‑dollar thresholds, constraining adoption among smaller manufacturers and creating demand for modular, phased deployments.
-
Infrastructure preference: High initial capex has catalyzed demand for modular, scalable designs and for service-driven business models (equipment-as-a-service, managed capacity) that reduce up-front spending while preserving compliance and yield.
Competitive landscape — positioning and implications
The competitive field remains moderately fragmented: the three largest firms account for a meaningful share of installed capacity, and the top five increase that concentration further. This structure creates differentiated opportunities for incumbents and challengers alike.
-
Syntegon Technology (Stuttgart) — Known for integrated liquid filling and isolator-based RTU solutions, Syntegon competes on system integration and global service footprints. Their modular lines appeal to multinational players needing consistent validation packages.
-
Bausch+Ströbel (Ilshofen) — Specialist in aseptic cleaning, filling and stoppering; strength in turnkey lines and complex high-speed vial applications. Their engineering-driven approach suits high-volume manufacturing.
-
Dara Pharma (Spain) — A focused supplier of complete aseptic lines with nimble customization capabilities; attractive to regional producers and CDMOs seeking rapid configuration.
-
Groninger (Crailsheim) — Strong in RTU containers and fully integrated process lines; emphasis on packaging compatibility and downstream automation.
-
IMA Group & Marchesini Group (Italy) — Broad portfolios across liquid and powder processing; Marchesini’s strategic manufacturing stakes and partnerships broaden its access to North American clinical and commercial customers.
-
OPTIMA Pharma (Schwaebisch Hall) and Tofflon (Shanghai) — Deliver turnkey isolator and lyophilization-capable systems. OPTIMA emphasizes turnkey projects and freeze-drying integration; Tofflon competes on cost-competitive, rapidly deployed systems for liquid and lyophilized products.
-
Rommelag — Pioneer of Blow-Fill-Seal technology with differentiated solutions for aseptic bottling and semisolid applications, often selected where BFS offers throughput and sterility advantages.
-
AST (Tacoma) — Known for adaptive, compact filling systems used across clinical and small commercial runs; attractive to organizations that need flexible, high‑quality small-batch capability.
Recent industry developments underscore consolidation and capacity alliances. A notable 2026 strategic move saw Marchesini Group expand its equity and operational integration with AST, creating a stronger combined capability in fill-finish—an instructive example of how manufacturers and suppliers are using equity and partnership strategies to secure downstream manufacturing capacity. Separately, major equipment installations by established OEMs at regional CDMOs demonstrate how rapid automation contracts can materially increase batch capacity and shorten time-to-market for sterile products.
Where the real opportunities — and risks — lie for 2026
-
For manufacturers and CDMOs: Prioritize modular, validated platforms that enable phased capacity adds. Where capital is constrained, negotiate capacity-sharing agreements or outcome-based contracts with OEMs to de‑risk upfront spend.
-
For OEMs and system integrators: Differentiate through lifecycle services, digital monitoring and remote validation tools. Aftermarket revenue and spare-parts optimization materially improve lifetime customer economics.
-
For investors and acquirers: Target assets that combine engineering differentiation with service businesses and recurring revenue—companies that can monetize validation packages, spare parts and remote support are higher-margin and more defensible.
-
For regulators and quality organizations: Expect inspection focus to shift toward integrated monitoring, data integrity across process controls and supply-chain traceability; equipment architects should design with auditability as a first-class requirement.
How our report turns insight into action
PW Consulting’s full study is built as a practical decision-support toolkit for executives who must act in 2026. Key deliverables include:
-
Market-size and demand-models (2020–2025 historical; 2026–2032 forecast) with scenario sensitivity to regulatory change and biologics adoption rates.
-
Procurement playbooks and a capital planning template that translate validation timelines, installation phasing and regulatory milestones into cash‑flow and ROI projections in USD Billion terms.
-
Supplier benchmark matrix combining technical fit, geographic service coverage and lifecycle costs—designed to shorten vendor selection from months to weeks.
-
Technical gap assessment and validation checklist for isolator, RABS and BFS architectures, enabling rapid internal audits prior to vendor engagement.
-
M&A and partnership screens that identify potential bolt-ons (technology or service-oriented) and provide integration roadmaps focused on compliance retention and customer retention.
-
Risk heat maps mapping regulatory, supply-chain and labor-cost scenarios to mitigation actions and financial contingencies.
We intentionally preserve granular segment-level splits, explicit regional percentage shares and line-item market shares for the full report to ensure our clients receive controlled, validated inputs for tender and M&A processes. The analysis presented here is designed to demonstrate the strategic depth and actionable framing we provide—while the full dataset and vendor-specific metrics are available in the report package.
Recommended actions for Q3–Q4 2026
-
Fast-track technical due diligence on any planned isolator or RABS procurement; expect 6–12 month lead times for delivery and a similar window for qualification.
-
Model three procurement scenarios (CAPEX-heavy, hybrid-service and full-service) and compare net-present-value and time-to-volume outcomes for each product line requiring sterile fill.
-
Pursue strategic supplier partnerships that include capacity reservation clauses and service SLAs to hedge against industry backlogs.
-
Prioritize digital retrofit investments for installed lines—real-time monitoring and remote diagnostics reduce downtime and regulatory friction.
-
If pursuing M&A, focus on targets with strong aftermarket revenues and validated client contracts—these assets are more resilient to equipment cycle shifts.
Final note
The aseptic filling equipment market in 2026 is not just a procurement decision; it is a strategic lever that affects product timelines, regulatory risk and unit economics for sterile pharmaceuticals. Our PW Consulting study equips leaders with the foresight, templates and competitive intelligence required to convert market growth—projected at a 7.26% CAGR into 2032 and approaching USD 2.0 Billion—into durable strategic advantage. For the complete dataset, vendor-level benchmarking and the downloadable procurement toolkit, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Aseptic Filling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Instant Noodles Market to Hit USD 98.46B by 2032 at 6.19% CAGR
By PW Consulting, 2026-07-12
Instant Noodles Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking interpretation of our Instant Noodles Market research tailored for executive decision-making in 2026. This briefing synthesizes the study’s most consequential signals — growth trajectory, competitive posture, regulatory inflection points, and tactical options — while reserving the report’s granular segment tables and proprietary models for subscribers and licensed clients. Think of this as the strategic trailer: substantive, directional, and intentionally non-exhaustive to focus boardroom debate and immediate priorities.
Instant Noodles Market
Market Snapshot: growth you can bank on
The instant noodles category re-entered a phase of robust expansion after pandemic-era volatility. On a macro basis, global retail value climbed from roughly USD 49.2 billion in 2020 to about USD 64.7 billion in 2025, reflecting resilient demand across price tiers and formats. With base-year 2025 as our operational anchor, the market is projected to grow through the 2026–2032 forecast window at a compound annual growth rate of 6.19%, reaching an upper-nine-figure industry value by 2032.
Instant Noodles Market
Why does this matter for 2026 planning? A mid-single-digit CAGR in a consumer staples category translates into predictable topline expansion that still accommodates significant product churn, channel disruption, and margin reallocation. In practice that means: stable category demand allows room to invest in premiumization and sustainability, but market share shifts can be rapid where incumbents fail to adapt to new regulatory or health-driven expectations.
Instant Noodles Market
Why 2026 is an inflection year
- Regulatory acceleration: Multiple jurisdictions are moving from voluntary guidance to mandatory front-of-package and recyclability mandates that will materially affect formulation, labeling, and packaging supply chains. Players that pre-empt these changes will shorten time-to-shelf and preserve promotional flexibility.
- Premiumization and health modernization: Demand for fortified, lower-sodium, plant-based, and chef-driven variants is converting value into higher-margin sub-categories. Reformulation and credible health claims will be a gating factor for shelf- and e-commerce assortment.
- Channel bifurcation: Traditional grocery and convenience operations remain important but co-exist with accelerated direct-to-consumer and modern-trade strategies that reward brand storytelling and variant breadth.
- Supply-chain concentration risks: Ingredient sourcing, packaging inputs, and single-source OEM capacity create asymmetric risk. Recent product recalls and quality events underscore the need for tightened traceability and contingency capacity.
What PW Consulting’s full Instant Noodles Study delivers
The report is structured to convert market intelligence into operational action across strategy, commercial, and supply functions. Key deliverables include:
- Validated historical market series (2020–2025) and a detailed 2026–2032 forecast model with scenario toggles for pricing, raw-material shocks, and premium mix shifts.
- SKU-level pricing and elasticity matrices derived from retail scanner and e-commerce datasets, enabling SKU rationalization and promotional optimization.
- Channel-centric playbooks for grocery, convenience, and direct-to-consumer launch plans, including digital microsite templates and trade promotion best-practices.
- Packaging and sustainability impact assessment tied to regulatory milestones and sourcing timelines, plus vendor scorecards for recycled-content suppliers.
- Competitor dossiers and strategic option maps for key global and regional players, accompanied by M&A and JV opportunity heatmaps.
- Operational toolkits: short-term crisis response, recall mitigation checklist, and a 12–18 month execution calendar.
To protect the commercial integrity of the dataset we have omitted granular region/application shares and SKU-by-SKU values from this preview. These are available in the full report and via our interactive subscriber dashboard.
Key market dynamics and strategic implications
- Premiumization opportunity: Consumers are trading up within the category — seeking restaurant-quality, artisanal, and fortified options. Brands that combine authentic flavor narratives with improved nutrition profiles can capture incremental margin and retailer premium space.
- Health and labeling as market shapers: Mandatory front-of-package systems and country-specific nutrient labeling timelines will force reformulation cycles and alter promotional claims. Companies delaying compliance face both market access and reputational risk.
- Sustainability is table-stakes: Upcoming recycled-content and traceability mandates necessitate early supplier development and packaging redesign. Brands that embed circularity claims with transparent QR-driven traceability will win shelf preference without sacrificing speed-to-market.
- Channel sophistication: E-commerce and D2C platforms reward assortment depth and storytelling; in contrast, mass retail prioritizes price/promotional efficiency and SKU rationalization. A hybrid go-to-market that segments SKUs by channel converts assortment complexity into commercial ROI.
- Moderate-to-high branded concentration: The category exhibits a notable branded leadership cluster that controls a large share of value — yet the market remains porous for local champions and agile challengers, particularly in regions with strong regional taste preferences.
Competitive landscape — strategic takeaways
Our competitive analysis synthesizes product strategy, geographic footprint, innovation focus, and vulnerability exposures across major players. Highlights:
- Nissin Foods Holdings (Tokyo): A pioneer with a strong innovation pipeline in convenience and health-forward cup formats. Their experiential sampling tactics signal a continued focus on demand stimulation at point of consumption.
- PT Indofood (Jakarta): A dominant regional brand operator with deep local flavor IP and distribution muscle. Their playbook emphasizes local-market taste leadership and cost-efficient mass production.
- Uni-President (Taiwan): Diverse portfolio management and fortified options position them well in markets prioritizing nutrition claims.
- Nongshim & Samyang (South Korea): Leaders in spicy and premium positioning, with aggressive export strategies targeting global spicy-food demand.
- Toyo Suisan / Maruchan (Japan/US): Strong in seafood and limited-edition flavors; recent retail expansion shows strategic attention to North American mass distribution.
- Regional challengers (Vietnam, Thailand, Russia, etc.): Local producers blend authenticity and cost advantage, making them attractive partners or acquisition targets for global entrants aiming faster market access.
Recent corporate actions underscore two themes: proactive demand activation (e.g., experiential sampling and targeted retail expansion) and operational vulnerability (several high-profile recalls in 2025–2026). These developments amplify the importance of integrated quality-control and crisis communication capabilities in any 2026 plan.
Scenario planning: three operational pathways for 2026 board decisions
- Baseline (Most likely): Continued mid-single-digit growth. Priorities: SKU rationalization, conservative capex for line-extension in premium formats, pilot recycled-content packaging, and strengthened QC for high-volume SKUs.
- Upside (Premium acceleration): If premium/health variants outpace expectations, accelerate NPD pipelines, expand higher-margin cup formats, and allocate incremental distribution funding to modern trade and D2C.
- Downside (Regulatory or quality shock): Prioritize recall readiness, accelerate supplier dual-sourcing, and tighten traceability. Delay non-critical expansion capital and preserve working capital for promotional defense.
12–18 Month Execution Playbook (high-impact tactical moves)
- Quick-win SKU rationalization: eliminate low-velocity SKUs and redeploy spend to hero premium SKUs that span channels.
- Reformulation sprints: prioritize sodium, saturated fat reductions and plant-based noodle options with minimal cost disruption.
- Packaging pivot: pilot recycled-content packaging on top-tier SKUs and roll out QR-based provenance labeling ahead of local mandates.
- Trade-lift programs: negotiate category resets with major retailers and secure premium shelf placements tied to new-product exclusives.
- Digital-first D2C trials: subscription bundles and limited-edition flavor drops to gather consumer data and test price elasticity.
- Supplier resilience: audit highest-risk inputs and establish dual-sourcing contracts with capacity options.
- Quality & recall playbook: implement cross-functional rapid response drills and a consumer-communications template library.
- M&A screen: shortlist regional brands with strong flavor IP and manufacturing footprint for bolt-on acquisition.
- Consumer insight cadence: deploy monthly tracker for flavor trends, health claims, and pack-preference signals in core markets.
- Governance & compliance: assign a cross-border regulatory lead to map labeling and packaging mandates against SKU timelines.
Why PW Consulting’s dataset matters for 2026 decisions
Our study combines a validated historical series (2020–2025), a forward-looking 2026–2032 forecast envelope, and scenario-based financial sensitivities — all calibrated to retail scanner, e-commerce, and manufacturer-sourced inputs. Subscribers gain access to the underlying model so they can: stress-test price promotions, simulate reformulation cost impact, and quantify the ROI for packaging investments over a 3–5 year horizon.
This preview intentionally omits the detailed regional, format, and channel splits that are the commercial core of the dataset. Those segment tables are the decision-grade inputs procurement, commercial, and M&A teams rely on. If your 2026 planning cycle requires actionable slices (SKU by channel by market), our interactive report and consulting workshops convert the intelligence into executable workstreams within 30 days.
Next steps for executives
- Prioritize compliance and quality: assign budget and leadership to packaging compliance and traceability now.
- Run a rapid SKU portfolio audit to free up promotional budget for premium launches.
- Engage PW Consulting for a tailored workshop that maps our forecast scenarios to your P&L and supply chain tolerances.
In an industry characterized by steady macro expansion but high tactical churn, 2026 is the year to align product, channel, and compliance strategies. Treat the category’s predictable growth as permission to invest — but structure investments to survive regulatory shifts and quality shocks. For access to the full dataset, proprietary segmentation, and our interactive forecast model, please consult the complete Instant Noodles Market report or contact PW Consulting’s market team for a licensed briefing.
For detailed analysis of this topic, please visit the official page: Instant Noodles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Chip Handler Market — USD 680M in 2025, 4.7% CAGR (2026–2032)
By PW Consulting, 2026-07-12
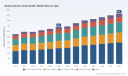
Semiconductor Chip Handler Market — Strategic Briefing for 2026 Decisions
Executive snapshot
The semiconductor chip handler market is maturing into a mission-critical enabler of advanced packaging and high-throughput test flows. From a base of USD 550 Million in 2020 the market expanded to USD 680 Million by the 2025 base year and is forecast to reach approximately USD 928 Million by 2032. The medium-term trajectory implies a compound annual growth rate of 4.7% across the 2026–2032 forecast window. Market concentration is material: the top three firms capture roughly two-thirds of revenue (CR3 ≈ 65%), while the five largest firms approach three quarters (CR5 ≈ 75%).
Semiconductor Chip Handler Market
Why this matters for 2026 corporate decision-making
- Capital planning: a modest, steady expansion at ~4.7% CAGR signals predictable capacity needs rather than explosive replacement cycles—useful for capex phasing and leasing strategies.
- Supplier strategy: high concentration creates both dependency risks and supplier-bargaining asymmetries; buyers should prioritize supplier resilience and flexible contracts.
- Technology roadmap alignment: handler innovation (automation, thermal control, vision systems, AI-driven maintenance) is tightly coupled with packaging trends and test flow automation—decisions on internal development vs. third-party integration will materially affect time-to-volume for new products.
- Regulatory & geopolitical risk: export controls and incentive programs change the calculus for regional sourcing and capacity expansion—2026 is a pivot year for aligning commercial plans with policy constraints and funding opportunities.
What PW Consulting’s Semiconductor Chip Handler Study delivers (practical, decision-ready content)
This research is structured as a working toolkit for 2026 strategy execution rather than a purely descriptive market paper. Core deliverables include:
Semiconductor Chip Handler Market
- Robust market-sizing and trend narrative from 2020–2025 (historical) and a seven-year forecast (2026–2032) with scenario analysis (base, upside, downside) to stress-test capex plans.
- Buy-side decision frameworks: a supplier selection scorecard, total cost of ownership (TCO) template, and retrofit vs. greenfield decision trees for handler investments.
- Vendor diagnostics and competitive playbooks: strategic profiles, capability maps, and partner-fit matrices that translate vendor capabilities into procurement requirements by test-type and packaging architecture.
- Supply-chain mapping: critical upstream inputs, single-point-of-failure analysis, and mitigations for raw-material and labor constraints relevant to handler OEMs and subsystem suppliers.
- Operational KPIs and deployment playbooks: throughput modeling, thermal-management validation steps, and an AI-enabled predictive-maintenance pilot plan that can be executed in 90–180 days.
- M&A and partnership roadmaps: valuation heuristics, capability-acquisition checkpoints, and integration milestones for buyers seeking rapid access to advanced handler technologies or regional service networks.
- Primary intelligence: interviews with OEMs, OSATs, IDMs, and service providers; field-validated case studies showing real-world TCO outcomes and yield impacts post-handler upgrades.
Note: the full report contains gated, granular segmentation tables (by handler type, function, application, and region) and proprietary quantitative splits—these are intentionally withheld here to direct readers to the full dataset and vendor scorecards.
Semiconductor Chip Handler Market
Competitive landscape — how to read vendor behavior in 2026
The handler market is dominated by a small set of specialists and systems integrators. Understanding each player’s strategic vectors is essential when shaping supplier portfolios or evaluating partner investments.
- Advantest Corporation (Tokyo) — Strengths: high-throughput platforms and a clear focus on AI/HPC test stacks. Strategic implications: best partner for buyers prioritizing scale and front-line test automation for logic and memory at advanced nodes. Recent visibility at SEMICON events underscores continued product and ecosystem investments.
- Cohu, Inc. (San Diego) — Strengths: modular handler architectures and thermal-control subsystems. Strategic implications: candidates for integration when thermal management and flexible reconfiguration across device families are priority objectives.
- ASMPT (Singapore) — Strengths: breadth across assembly and test automation; tight fit to advanced packaging flows. Strategic implications: attractive for OSATs and IDMs seeking turnkey assembly-to-test solutions and tighter interface engineering across process stages.
- TESEC Corporation (Tokyo) — Strengths: niche capabilities in discrete, MEMS, and power IC handlers. Strategic implications: strong fit for specialized high-reliability device lines where test mechanics differ from commodity ICs.
- Boston Semi Equipment (USA) — Strengths: agile product development in pick-and-place and SLT lines; recent product-line expansions broaden the addressable final-test portfolio. Strategic implications: potential supplier for mid-volume lines and custom automation projects.
- SRM Integration (Penang) — Strengths: high-speed IC handlers and custom automation for final test. Strategic implications: regional advantage in Southeast Asia for buyers co-locating with back-end assembly clusters.
- HON. PRECISION (Taichung) — Strengths: Taiwan-based engineering depth for flash/memory and MEMS test handlers. Strategic implications: logical partner for memory-oriented test lines and nearshore support to Taiwanese fabs and OSATs.
- Pentamaster (Penang) — Strengths: integration of vision systems and pick-and-place automation for final test and power modules. Strategic implications: good fit where vision-enabled inspection and automation yield are prioritized.
- NS Technologies (Kanematsu Group, Japan) — Strengths: throughput-oriented handlers supporting logic, memory, and automotive chips. Strategic implications: a viable partner for scale-out initiatives where global service and high throughput are required.
Recent vendor moves—exhibitions, product launches, and demo roadmaps—confirm the market’s focus on AI-enabled optimization, thermal precision, and modular architectures suitable for mixed-technology lines. These tactical shifts are summarized in the full report alongside vendor scorecards and risk matrices.
Industry dynamics and risk factors shaping 2026 outcomes
- Regulatory overlays: U.S. export controls on advanced compute chips and related equipment introduce conditionality for some sales channels and OEMs. Buyers and suppliers must embed compliance checkpoints into procurement and partnership agreements.
- Policy tailwinds: CHIPS Act funding and allied programs materially influence capital availability for domestic expansion in the U.S.—this creates windows for co-investment and subsidy-aligned capacity planning in 2026.
- Raw-material dependencies: substrates and mechanical components rely on epoxy resins, metal alloys, and ceramics; volatility or quality constraints in these inputs directly affect handler lead times and retrofit feasibility.
- Labor and automation: handler adoption continues to accelerate as firms mitigate labor scarcity and raise throughput. Investments in semi- and fully-automatic handlers should be benchmarked against labor cost curves and expected yield improvements.
- Energy and operational efficiency: leading handlers are embedding AI-driven predictive maintenance and software-defined optimization to reduce energy consumption and operating expense—key for sustainability targets and OPEX reduction in 2026.
Recommended 90–180 day actions for decision-makers
- Execute a supplier resilience stress test: map single-source dependencies, validate alternate vendors, and negotiate short-term capacity options tied to clear service-level metrics.
- Initiate a pilot for AI-enabled predictive maintenance: select one high-volume line, instrument key handler assets, and run a 90–day trial to quantify downtime reduction and energy savings.
- Align CAPEX with scenario outputs: reserve growth-capex tranches tied to the forecast scenarios in this report so that expansion is triggered by measurable demand or incentive milestones.
- Embed export-control and subsidy compliance into contracts: add clauses that account for licensing regimes and CHIPS program commitments to de-risk cross-border procurement and co-investments.
- Prioritize retrofitability in specs: when issuing RFPs, score vendors not only on throughput but on modular retrofit capability, software APIs, and spare-parts logistics to reduce TCO over a 7–10 year horizon.
- Explore targeted partnerships or tuck-ins: use M&A heuristics in the full report to evaluate small-cap acquisitions that accelerate advanced-packaging handler capabilities or regional service footprints.
Conclusion — the strategic value of this intelligence
For executives drawing 2026 capital and sourcing roadmaps, the handler market offers predictable growth with concentrated supplier power and meaningful technological differentiation. The strategic choices made this year—vendor selection, automation pilots, subsidy-aligned expansions, and compliance embedding—will determine whether companies capture yield and throughput gains or suffer extended ramp cycles. PW Consulting’s full Semiconductor Chip Handler Market study transforms the macro narrative above into executable roadmaps, procurement tools, and vendor playbooks designed for immediate use by strategy, operations, and procurement teams.
Access the full report to retrieve the gated segment-level forecasts, vendor scorecards, and the operational playbooks necessary to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Semiconductor Chip Handler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Perfluoroalkoxy (PFA) Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused industry preview designed to orient executive teams for the pivotal decisions of 2026. This briefing synthesizes macro dynamics, competitive moves, regulatory noise and cost pressures shaping the Perfluoroalkoxy (PFA) market — while preserving the proprietary segmentation and granular datasets that our full report delivers. Use this as a strategic compass: it signals where value and risk concentrate, how leading suppliers are positioning, and which playbooks will matter as companies allocate capital and commercial effort over the next planning cycle.
Perfluoroalkoxy (PFA) Market
Market Trajectory: The Macro Baseline
PFA has demonstrated steady expansion through the 2020–2025 historical window, growing from USD 368.44 Million in 2020 to USD 427.83 Million in the base year 2025. Our forecast horizon (2026–2032) models a mid-single-digit expansion, anchored by a compound annual growth rate (CAGR) of approximately 4.5%. Under our central scenario the market climbs to roughly USD 580.81 Million by 2032, with intermittent volatility driven by raw-material pricing and regulatory tightening. This pace reflects continued demand from high-purity industrial applications — notably semiconductor processing, chemical handling, and specialty tubing — even as incremental end-market adoption unfolds more gradually than in narrative-led projections.
Perfluoroalkoxy (PFA) Market
Why this matters for 2026 decisions
-
Portfolio prioritization: With moderate aggregate growth, 2026 is a year to refine product portfolios — doubling down on high-margin, high-purity grades while pruning lower-return commodity exposures.
Perfluoroalkoxy (PFA) Market -
Supply-chain strategy: The interplay of feedstock volatility and regulatory-driven process upgrades elevates supply-risk as a strategic variable; procurement and supply security will determine margin preservation.
-
CapEx and M&A timing: Investors should treat 2026 as a tactical inflection point to deploy capital into surfactant-free production, traceability systems and targeted bolt-on assets that accelerate access to regulated customers.
Key Market Dynamics and Structural Drivers
Several structural forces converge to define opportunity and exposure in 2026:
-
Regulatory acceleration: The U.S. EPA’s May 2026 proposed rules on PFAS in drinking water — including compliance timelines that in one option extend to 2031 — create a layered compliance landscape. Even where transitional provisions exist, lead customers and large OEMs are shortening their internal timelines, effectively accelerating demand for PFAS-compliant process technologies and documentation.
-
Manufacturing evolution toward surfactant-free processes: Suppliers such as Syensqo and AGC have publicly committed to or demonstrated surfactant-free manufacturing approaches. For buyers, supplier roadmaps on fluorosurfactant elimination are fast becoming a procurement gate.
-
Raw-material and cost pressure: TFE feedstock experienced meaningful price volatility in early 2026 and PFA production saw an 8% cost step-up in 2023 tied to compliance and material price shifts. These inputs magnify the importance of dynamic pricing clauses and hedging strategies in supply contracts.
-
Demand concentration: The market exhibits high supplier concentration at the top end; our concentration analysis signals that the top-tier players control a dominant share of supply, which reinforces the strategic importance of supplier relationships and long-term agreements for downstream integrators.
Competitive Landscape: What leading suppliers are doing
The competitive set is active on product innovation, capacity reconfiguration and application-specific high-purity positioning. Highlights of strategic relevance:
-
The Chemours Company (Wilmington, Delaware). Chemours has expanded and refined its high-purity PFA portfolio — including launches tailored to semiconductor requirements — signaling a supplier intent on defending premium niches where certification, traceability and contaminant control are decisive.
-
Daikin Industries, Ltd. (Osaka). With its NEOFLON series tailored for melt-molding and high-purity tubing, Daikin emphasizes technology transfer to electronics and semiconductor supply chains that prioritize consistent melt flow and minimal extractables.
-
AGC Inc. (Tokyo). AGC’s surfactant-free manufacturing process, announced in recent years, positions it as an operator-focused option for customers seeking PFAS exposure mitigation across their supplier base.
-
Syensqo (Brussels). Syensqo’s disclosure of PFA-free FFKM options and commitments to fluorosurfactant elimination reflect a differentiated sustainability message that resonates with battery and semiconductor OEMs.
-
Regional and niche specialists (e.g., Hubei Everflon, Zeus, RTP). These players are concentrated on dispersions, high‑purity tubing and compound formulations respectively; they compete on flexibility, localized supply and tailored product platforms for medical and semiconductor end-uses. Recent product introductions — including Zeus’s 2026 PFX platform for medical catheters — demonstrate where tactical innovation sits relative to broader capacity investments.
Recent Developments to Watch
-
Product launches and platform innovations (2025–2026) show incumbents defending technical moats around high-purity and extrusion capabilities.
-
Public commitments to eliminate fluorosurfactants (Syensqo, AGC) accelerate non-product regulatory mitigation strategies across the value chain.
-
Raw-material volatility and the 2023 cost step-up underscore the need for active pricing governance and supply‑chain resilience planning in supplier negotiations for 2026 contracts.
What our full report delivers (practical outputs)
PW Consulting’s full PFA Market study contains the operational and decision-grade tools you need for 2026 planning. Key deliverables include:
-
Market sizing and validated historical series (2020–2025) and forward projection models (2026–2032) with scenario toggles for regulatory stringency and feedstock shocks.
-
Supplier scorecards and capacity maps that integrate technology readiness, surfactant elimination timelines and contractual flexibility metrics.
-
Segment-level playbooks (product, application and route-to-market) that translate demand forecasts into prioritized commercial actions and SKU rationalization recommendations. Note: granular segment-level outputs are available in the full report; this preview intentionally omits those line-by-line splits to protect the analytical IP and to guide you to the source for detailed positioning work.
-
Raw-material sensitivity models and pricing pass‑through frameworks enabling rapid stress testing of margin outcomes under alternative TFE pricing scenarios.
-
Regulatory impact matrices with mitigation pathways — from process redesign and certification to customer communication templates and remediation CapEx estimates.
-
Targeted M&A and partnership scouting lists, including integration risk scoring and time-to-benefit estimates for bolt-on capacity or technology acquisitions focused on high‑purity and regulatory-compliant offerings.
-
Commercial negotiation playbook and model supply agreements for 2026 contracting cycles — incorporating indexation, force majeure considerations for regulatory changes, and sustainability commitments.
Strategic Imperatives for Executives in 2026
-
Pursue supplier risk diversification and lock key volumes with conditionality for regulatory-driven process changes. Where possible, insist on supplier roadmaps for surfactant elimination as a contracting KPI.
-
Prioritize high-purity product investments and certification pathways that align with semiconductor and battery customer specifications; these segments are the most durable under regulatory pressure.
-
Deploy dynamic pricing and hedging instruments to manage TFE exposure — establish internal triggers for price renegotiation and pass‑through clauses tied to validated cost indices.
-
Accelerate regulatory scenario planning: integrate the EPA proposed rule options into capital expenditure timing, and stage compliance investments to preserve optionality if timelines extend to 2031 under certain regulatory options.
-
Use targeted M&A to fill capability gaps (e.g., dispersion chemistry, surfactant-free processes, high‑purity extrusion) rather than generic scale buys; integration speed matters more than scale in a concentrated market.
Final note: why this preview — and why now
This briefing signals the contours of strategic choice in a market that is structurally concentrated and increasingly shaped by regulatory and feedstock volatility. The aggregate trajectory is constructive — modest, steady expansion at a roughly 4.5% CAGR through the 2026–2032 forecast window — but the distribution of value and risk within the market is shifting fast. That is why 2026 is a decisive planning year: contractual decisions, CapEx commitments and supplier selections made now will disproportionately determine competitive positions throughout the forecast period.
PW Consulting’s full PFA Market report packages the precise segmentation tables, supplier-level metrics and executable playbooks required to convert this strategic preview into operational plans. For decision-makers preparing budgets, negotiating supply contracts or evaluating M&A opportunities in 2026, the detailed datasets and scenario tools in the full study are essential to move from insight to action.
For detailed analysis of this topic, please visit the official page: Perfluoroalkoxy (PFA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


