



Category: market research
PW Consulting: Fiber-Coupled SLED Market to Reach USD 265M by 2032 (7.45% CAGR)
By PW Consulting, 2026-07-12
Fiber-Coupled SLED Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
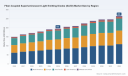
As PW Consulting’s lead industry analyst, I present an evidence-backed overview of the fiber-coupled superluminescent diode (SLED) market tailored to executives and product strategists preparing for 2026. The market has demonstrated steady expansion, growing from approximately USD 150.0 Million in 2020 to USD 195.0 Million in the 2025 base year. Our forecast horizon (2026–2032) models a continuation of this trend, with the market projected to expand at a compound annual growth rate (CAGR) of 7.45%, reaching roughly USD 265.0 Million by 2032. These headline figures quantify a clear commercial runway for suppliers, integrators, and downstream system OEMs—but they only tell part of the story. The purpose of this briefing is to translate that macro trajectory into the discrete strategic choices that will matter in 2026, while preserving the proprietary granularity that lies within our full report.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Why 2026 is a pivotal planning year
-
Technology inflection: Optical coherence tomography (OCT), advanced fiber sensing and certain metrology applications are maturing in parallel with multi-SLED and tunable broadband innovations. Companies that lock in technology leadership or differentiated supply now can capture outsized share as system integration accelerates over the next two to three years.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Supply-chain tightening and regulatory shifts: New export control regimes and critical-mineral licensing introduced by key suppliers are already changing sourcing economics and valid routes to market. Procurement strategies established in 2026 will materially affect lead times and margin profiles through 2027–2029.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Consolidation window: Market concentration metrics indicate a moderate incumbent advantage—top-three vendors control a meaningful but non-dominant portion of revenue, and top-five concentration increases that share materially. This creates both acquisition targets for scale players and white-space opportunities for innovative niche entrants.
Market trajectory and what the top-line numbers conceal
The market’s steady growth—evidenced by a rise from USD 150.0 Million in 2020 to USD 195.0 Million in 2025 and a forecast path to roughly USD 265.0 Million by 2032 at a 7.45% CAGR for 2026–2032—masks divergent microtrends that will decide winners and losers. Pricing ranges for single SLED diodes vary by wavelength, fiber type and customization, and we observe transaction price bands from approximately USD 673 to USD 2,624 per diode in typical industry datasets. Standard lead times clustered around five weeks create a planning cadence for OEMs building to production ramps.
But unit economics, integration complexity, and service-level expectations differ sharply by end-market. Organizations that interpret the headline market growth without overlaying technology roadmaps, regulatory risk matrices, and supplier resilience scenarios will misallocate capital. Our work stresses that the aggregate expansion is necessary but not sufficient to inform product investment, M&A, or channel strategy.
Supply chain and regulatory dynamics — actionable implications
-
Material dependencies: Fiber-coupled SLED devices remain dependent on compound semiconductor materials—InGaAs, InP and GaAs—and their associated supply chains. This creates vectors of risk (single-source substrates, specialty wafer processing) that translate to lead-time and cost volatility for system integrators.
-
Export controls and licensing: Recent policy changes instituted by major material-exporting jurisdictions have introduced licensing requirements for components that use certain Chinese-sourced materials or production technologies. These regulatory shifts are not binary; they create a sliding scale of compliance cost and approval delay that should be stress-tested across procurement scenarios.
-
Price and procurement strategy: Given the observed price dispersion, buyers can improve margin capture by redesigning product specifications to accept alternate fiber terminations, modular SLED assemblies, or multi-sourcing strategies. Conversely, suppliers can protect ASPs by bundling optical engines with calibration and software, reducing direct comparability.
Competition and consolidation — interpreting recent moves
The competitive topology is a mix of diversified photonics suppliers, specialist SLED vendors, and agile start-ups focused on spectral engines. Notable players include established component houses and innovators offering both stock and custom fiber-coupled SLED sources. Recent corporate activity underscores two simultaneous dynamics: strategic consolidation among scale players, and capability-driven partnerships targeting high-value applications such as OCT.
-
Portfolio expansion: Strategic acquisitions and partnerships—highlighted by moves to broaden photonics portfolios and co-develop OCT-focused SLED sources—signal that access to combined optical subsystems and integration capabilities is a priority for market leaders.
-
Innovation-driven entrants: A cohort of specialist firms is commercializing ultrawide-spectrum optical engines, multi-SLED modules and tunable broadband sources. Their ability to deliver differentiated spectral characteristics and tighter system integration can outcompete commodity diode suppliers on total system value.
-
Concentration insight: Market concentration measurements show the top three vendors controlling a meaningful slice of the market while the top five raise that share noticeably—evidence of moderate concentration and an active M&A runway. For buyers and investors, that means predictable supplier selection environments but also opportunities to consolidate value through targeted acquisitions.
What PW Consulting’s full report delivers (practical, executable content)
-
Granular market model: A reproducible forecasting model (2026–2032) with sensitivity scenarios for policy disruption, raw-material shocks and accelerated adoption cases. The public summary here shares top-line CAGR and market endpoints; the full model contains the build-up by product architecture, channel and end-use.
-
Competitive playbooks: Vendor capability maps, product-differentiation matrices, and go-to-market playbooks that prioritize high-margin applications and define switching barriers for system OEMs.
-
Supply-chain stress tests: Scenario analyses that quantify the operational and P&L impact of export controls, semiconductor substrate shortages, and single-source suppliers—plus mitigation roadmaps (dual-sourcing, strategic inventories, licensing strategies).
-
M&A and partnership targets: A curated shortlist of acquisition and alliance candidates by capability cluster (broadband engines, tunable sources, integrated spectral modules), with valuations and synergy estimates modeled under three commercial cases.
-
Procurement and engineering playbooks: Tactical recommendations to trim lead time, reduce cost per system, and accelerate time-to-market—covering spec harmonization, design-for-sourcing, and post-quantum compliance checklists.
Strategic recommendations for 2026
-
Invest in spectral differentiation, not commoditization: Focus R&D and product-management resources on ultra-broadband and tunable SLED engines where integration complexity and IP can sustain premium pricing and create switching costs.
-
Operationalize supply-chain resilience: Implement multi-tier sourcing, qualify alternative wafer suppliers, and establish legally vetted sourcing protocols to navigate new licensing requirements. Build a six- to nine-month buffer for critical components during transitional regulatory periods.
-
Pursue bolt-on M&A or technology partnerships: For incumbents seeking scale, target companies with complementary optical engine technologies or software-enabled calibration services that raise total system value and lower buyer commoditization risk.
-
Adopt a value-based commercial approach: Shift from per-diode pricing to outcome-based offers (e.g., calibrated spectral engines, service-level guarantees for OCT systems) to capture more of the system integration value.
-
Embed regulatory scenario planning into capital allocation: Incorporate licensing timelines and potential export restrictions into investment approvals and supply contracts; stress-test business cases with conservative procurement lead times.
Conclusion and next steps
The fiber-coupled SLED market presents a compelling growth trajectory from a compositional and financial perspective, but success in 2026 will be decided by actions taken now on supply chain resilience, product differentiation, and strategic partnerships. Our full PW Consulting study decodes the microstructure beneath the macro figures—providing the granular segmentation, vendor scorecards, and scenario models necessary to make confident capital, product and M&A decisions.
For executives preparing 2026 budgets and commercial roadmaps, the core takeaways are straightforward: treat the headline CAGR and market expansion as directional impetus, but allocate resources to mitigate supply-side risk, lock in spectral differentiation, and pursue targeted consolidation where it accelerates access to high-value applications. Accessing the complete report provides the operational playbooks and data-driven build-ups that translate those strategic priorities into executable programs.
How to obtain the full analysis
PW Consulting’s comprehensive fiber-coupled SLED market study contains the detailed segmentation, vendor-level profiles, and executable recommendations necessary for board-level decisions in 2026. Contact our team to request the full report, which includes the models and supporting annexes excluded from this preview to preserve comparative advantage for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial RTU Market: 4.2% CAGR to USD 1,060.39M by 2032; Asia Pacific $326.77M
By PW Consulting, 2026-07-12
Industrial Remote Terminal Unit (RTU) Market — Strategic Outlook for 2026 Enterprise Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, strategy-first briefing that frames our full Industrial Remote Terminal Unit (RTU) Market study for executives planning decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the research while deliberately withholding granular segment datapoints and proprietary tables to guide readers to the full report for detailed validation.
Industrial Remote Terminal Unit (RTU) Market
Market trajectory at a glance — what the numbers imply
The RTU market has shown steady expansion through the early 2020s and continues on a modest growth trajectory. Our base-year assessment for 2025 places the global market near USD 801 million, rising at a compound annual growth rate (CAGR) of approximately 4.2% over the 2026–2032 forecast window, reaching just over USD 1.06 billion by 2032. Historical trend analysis shows sustained recovery and investment cycles since 2020, reflecting a combination of legacy-system refreshes, targeted digitalization in industrial verticals, and increasing portfolio mixes that include edge-enabled and wireless-capable RTUs.
Industrial Remote Terminal Unit (RTU) Market
Why this matters for 2026: the market size and mid-single-digit CAGR indicate an environment where disciplined prioritization of capex and differentiated product/service strategies win. Large incumbents and focused specialists alike will chase incremental growth—creating selective opportunity windows for strategic buyers, system integrators, and technology partners.
Industrial Remote Terminal Unit (RTU) Market
Market structure and competitive dynamics — fragmentation with platform concentration
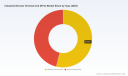
The market is structurally fragmented: the share held by the largest three and five firms is modest, signaling ample room for regional specialists, system integrators, and component vendors to compete. This fragmentation creates strategic consequences:
- Price and specification competition remain intense at the low end, favoring scale players and contract manufacturers.
- At the high end, platform interoperability, cybersecurity, and lifecycle services are primary differentiators.
- M&A and partnership playbooks are the likely medium-term levers for top-tier players to accelerate access to niche capabilities and regional footprints.
Key market participants we track include global automation and control leaders, telecom and communications specialists, industrial computing vendors, and regional RTU manufacturers and integrators. The following qualitative profiles summarize the strategic postures we see in the market (this is an analytical snapshot, not an exhaustive vendor scorecard).
- ABB (Zurich): Leverages broad grid and automation franchises to position RTUs within larger distribution and substations solutions; focus on system-level integration and lifecycle services.
- General Electric (Schenectady): Integrates RTUs into broader asset management and industrial digitalization offers, emphasizing analytics and legacy modernization pathways.
- Schneider Electric (Rueil‑Malmaison): Uses EcoStruxure and system-level offerings to bind RTUs into energy management and process-automation value propositions.
- Honeywell (Charlotte): Positions RTUs as part of its process automation and remote monitoring suites, strong in regulated industries requiring proven safety and compliance traces.
- Siemens (Munich): Offers RTUs within grid automation and industrial digitalization stacks, with emphasis on interoperability and engineering tools.
- Emerson (St. Louis): Focuses on process industries and integration with DCS platforms; competitive where lifecycle services and vendor-managed solutions are required.
- Rockwell Automation (Milwaukee): Competes via control-system integration and scalable automation architectures suited to North American process and discrete markets.
- Motorola Solutions (Chicago): Brings communications and ruggedized networking strengths—relevant where mission-critical remote communications are a core requirement.
- Advantech & Moxa (Taipei): Position as industrial-computing and IIoT gateway specialists that translate RTU data into edge compute and connectivity solutions.
- Yokogawa (Tokyo): Integrates RTUs with DCS and process-control expertise, strong in long-cycle capital projects.
- Red Lion (York) & Fanox (Barcelona): Niche specialists in protocol conversion, remote monitoring, and protection components—important partners for retrofit programs.
- Arteche, Iskra Sistemi, SEL, Dongfang Electronics: Regional and technical specialists providing measurement, protection, and rugged RTU solutions tailored to local grid and industrial standards.
- INTECH Process Automation, Kalki Communication Technologies: Systems integrators and communications specialists that convert vendor stacks into working field deployments at scale.
Strategically, incumbents lean on platform integration and services to expand TAM per customer, while smaller vendors compete on price, agility, and regional compliance expertise. Expect an uptick in alliances pairing global platforms with regional integrators over the next 18–24 months.
Demand drivers and headwinds — shaping priorities in 2026
- Digitalization & IIoT adoption: Edge analytics, remote asset management, and data-driven O&M are primary demand drivers. RTUs that natively support secure edge processing and common industrial protocols gain procurement preference.
- Asset modernization: Utilities and industrial operators with long tail of legacy RTUs will pursue staged refreshes to balance reliability and ROI.
- Cybersecurity mandates: Regulatory and insurer expectations force RTU purchases to include hardened communication stacks and patch-management guarantees.
- Wireless uptake vs. wired reliability: Wireless RTUs unlock lower-install-cost remote monitoring, but mission-critical applications still demand deterministic wired options; product roadmaps must accommodate both.
- Supply chain & materials volatility: Semiconductor supply-chain constraints, and the rising compliance and cost pressures around sustainable packaging and materials, affect lead times and TCO modeling.
Note on regulatory context: broader environmental and packaging regulations in major markets are increasingly relevant to hardware vendors’ supply chains. For example, recent EU and UK directives and taxes on packaging and recycled-content requirements have raised supplier compliance burdens and, in some cases, near-term cost exposure for plastic enclosures and packaging. In Europe, recycled-PET pricing has been higher than virgin PET through 2020–2025 in certain categories—an issue that hardware procurement teams should model into total lifecycle costs and supplier audits.
Strategic playbook for 2026 — recommended actions
- Adopt a two-speed procurement model: fast pilots for wireless/edge RTU use cases and long-lead tender tracks for mission-critical wired deployments.
- Prioritize interoperability and lifecycle services in vendor selection to reduce obsolescence risk and lower long-term TCO.
- Embed cybersecurity and patch-management SLAs into procurement contracts; require supplier transparency on supply-chain resilience.
- Design retrofit-first architectures where practical—use vendor-agnostic protocol gateways and edge compute nodes to extend legacy asset life while enabling phased data enrichment.
- Maintain an M&A/partnership watchlist: regional integrators and niche technology providers offer rapid capability fills for cloud/edge analytics and communications.
- Model regulatory cost exposure linked to packaging and materials compliance as part of capex justification for new hardware rollouts.
What the PW Consulting RTU report delivers (practical content)
Our full study is built for immediate operational use by procurement, OT/IT architects, and corporate strategy teams. Highlights include:
- Market sizing and 2020–2032 forecast with scenario variants and sensitivity to key drivers (base-year 2025 anchoring).
- Segmentation frameworks (by product type, application, and region), plus addressable-market maps for prioritizing growth plays — note: granular segment tables are available in the full report.
- Vendor benchmarking across technical, commercial, and delivery dimensions (capability heatmaps and RFP-ready supplier shortlists).
- Go-to-market playbooks: retrofit vs greenfield decision trees, pilot designs, and integration checklists.
- Financial tools: TCO and ROI templates for procurement justification, and capital planning scenarios under different obsolescence/maintenance assumptions.
- Risk matrix and mitigation playbook covering supply chain, regulatory, and cybersecurity exposures.
- Primary research annex: interview summaries with buyers, integrators, and vendor product leads, plus methodology notes and data sources.
Closing — why use this insight in 2026
By 2026, typical enterprise agendas will combine tighter capital discipline with an increased need to extract operational value from existing assets. The RTU market’s modest growth yet fragmented supplier landscape means that a targeted strategy—combining selective capex, supplier rationalization, and partnerships for analytics and cybersecurity—will generate outsized returns versus blanket replacement programs.
This briefing provides the strategic spine; the full PW Consulting RTU Market report supplies the granular segmentation, interactive models, and vendor-level benchmarking necessary to operationalize these recommendations. We intentionally withheld detailed subsegment tables and proprietary mappings here to ensure readers consult the full dataset for procurement and investment-grade decisions.
To access the comprehensive dataset, vendor scorecards, and downloadable decision tools, please consult the full PW Consulting report and supporting digital workbook.
For detailed analysis of this topic, please visit the official page: Industrial Remote Terminal Unit (RTU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Impact Crusher Market 2026: Strategic Preview for Decision‑Makers
Introduction — Why this preview matters for 2026 planning
As organizations reset capital allocation, supply‑chain priorities, and product‑mix strategies for 2026, an accurate read on the impact crusher market is no longer optional. PW Consulting’s latest market study (base year 2025, forecast 2026–2032) synthesizes demand trajectories, regulatory headwinds, input‑cost volatility, and vendor positioning to convert noise into actionable choices. This preview highlights the study’s strategic takeaways while preserving the granular sub‑segment intelligence that we reserve for the full report—intentionally positioning this piece as a high‑trust trailer that equips executives to prioritize next steps, not to replace the full dataset and scenario models.
Impact Crusher Market
Market trajectory and macro context
The impact crusher market has moved from a niche replacement cycle into a phase of steady, investment‑grade growth. After recovering through the early 2020s, the market reached an estimated USD 86.2 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast window. By 2026 the market is expected to exceed USD 90 Million, with continued expansion through the late 2020s driven by infrastructure activity, recycling mandates, and equipment fleet renewals in mining and aggregates operations.
Impact Crusher Market
For corporate leadership, two far‑reaching implications follow: first, predictable top‑line growth validates multi‑year product development and aftermarket investments; second, the rate of growth is modest enough that competitive advantage will accrue to firms who combine operational excellence, aftermarket capture, and regulatory compliance—rather than to those relying solely on rapid top‑line expansion.
Impact Crusher Market
What is changing beneath the headline numbers
- Shift from pure throughput to lifecycle economics: Buyers increasingly evaluate crushers on total cost of ownership (TCO), factoring energy consumption, wear‑part longevity, uptime, and modularity for multi‑site redeployment.
- Mobility and configurability premium: Mobile and semi‑mobile platforms with faster set‑up, simplified transportability, and modular screening/secondary crushing options are commanding procurement attention in contract tendering and rental markets.
- Sustainability and emissions compliance: Equipment that enables recycling and reduces fleet emissions is being prioritized in public projects and large private contractors’ procurement frameworks.
Regulatory, material‑cost and safety dynamics that will shape 2026 decisions
Procurement, product engineering, and aftermarket strategies must be stress‑tested against a trio of external dynamics that are material to margins and project timelines.
- Standards and compliance: Mobile crushers are increasingly governed by ISO 21873‑1 terminology and commercial requirements; design, testing, and labeling processes must reflect these standards to secure bids and pass regulatory audits.
- Wear‑part specifications: ASTM A128 specifications for austenitic manganese steel affect materials sourcing and supplier qualification. Companies that lock in compliant alloy supply lines and offer validated wear‑part warranties will secure a pricing and availability advantage.
- Input‑cost volatility: Manganese ore prices are linked to broader steel and infrastructure cycles; recently prices moved lower month‑over‑month (to roughly CNY 32.25/mtu in June 2026), but longer‑term demand drivers—urbanization and energy technologies—support price upside risk. Sourcing strategies and hedging policies should be revisited now, not later.
- Workplace and emissions safety: MSHA and regional mobile equipment emission rules are tightening in key markets. Compliance capability (documentation, testing, retrofit paths) is a differentiator in public tenders and long‑term supply contracts.
Competitive landscape — who matters and why
The impact crusher market sits in a moderately concentrated competitive structure. The top three players collectively command a meaningful share of the market, and the top five extend that footprint further—creating both consolidation opportunities and niche openings for specialist players. For decision‑makers, the dynamic is clear: incumbents with broad portfolios are focusing on uptime, modularity, and lifecycle services, while niche and regional manufacturers are leveraging agility and local service networks.
Key vendor behaviors we observed in 2026 that will inform procurement and partnership strategies:
- Product line refreshes with transportability and configurability improvements — exemplified by a major OEM’s launch of a new horizontal impact series designed for easier road transport and site configuration, showcased at a major UK trade show in mid‑2026.
- Rotor and materials engineering advances — a leading Austrian manufacturer introduced next‑generation mobile impact units with rotors engineered for 17–25% higher inertia, paired with automated control systems to increase uptime for aggregate producers.
- Scale and capacity pushes — another OEM debuted a high‑capacity mobile impact crusher capable of headline feed sizes and throughput that target large quarry operations and aggressive recycling programs; these launches signal that vendors are pushing both ends of the market: high throughput and high mobility.
Representative companies demonstrating these strategic postures include global OEMs and specialist mobile‑plant vendors. Their recent product moves and regional positioning illustrate three distinct competitive playbooks: full‑spectrum OEMs pushing integrated systems and services; European mobile specialists emphasizing rotor and control innovation; and North American track‑specialists focusing on on‑site crushing and rental market needs. Each playbook has implications for procurement (e.g., bundling vs. best‑of‑breed), service partnerships, and aftermarket capture.
Report contents — what the full study delivers (practical, operational, and tactical layers)
PW Consulting’s full Impact Crusher Market report provides layered intelligence designed for commercial, product, and strategic planning teams. Highlights include:
- Market sizing and validated time series (2020–2025) and deterministic scenarios for 2026–2032 with sensitivity to commodity cycles and infrastructure spend.
- Scenario modeling (base, upside, downside) that quantifies impacts of regulatory changes, manganese price shocks, and accelerated recycling mandates on market demand and margin pools.
- Competitive diagnostic including vendor profiles, recent product introductions, technology scorecards (mobility, energy efficiency, modularity), and go‑to‑market vectors for each vendor archetype.
- Procurement playbook: decision matrices to evaluate buy vs. rent vs. lease, total cost of ownership calculators, and a supplier‑selection checklist that aligns with ISO and ASTM compliance requirements.
- Aftermarket and services roadmap: prioritized opportunities for spare‑parts margins, predictive maintenance programs, retrofit offerings, and digital‑services monetization pathways.
- Commercial annex: tender language templates, sample specification bundles, and a pricing framework to benchmark capital and spare‑parts offers against market medians.
Note: The report contains detailed regional, type, and application-level splits and unit economics that we do not publish in this preview. Those granular tables and interactive dashboards are available exclusively in the full report to preserve the competitive value of the segment-level intelligence.
Strategic recommendations for 2026 — five high‑impact moves
- Prioritize lifecycle economics in RFPs. Move procurement evaluation away from headline throughput metrics and toward validated uptime, wear‑part life, and energy usage under customer‑relevant duty cycles.
- Lock in compliant materials suppliers. Given ASTM and ISO alignment and the sensitivity to manganese pricing, create multi‑year agreements or option‑based contracts with qualified alloy suppliers to stabilize aftermarket margins.
- Modularization and retrofit pathways. Invest in modular secondary crushing and screening options, and design retrofit kits that enable existing fleets to meet evolving emissions and safety regulations without full replacement.
- Aftermarket service packages as a revenue lever. Build or partner for predictive maintenance, fleet telematics, and guaranteed‑uptime contracts—these convert installed base into repeatable revenue and higher margin streams.
- Scenario‑based capex timing. Use the report’s scenario outputs to time significant capital deployments: accelerate in upside infrastructure scenarios, but stage purchases through rental partnerships when downside commodity risk is elevated.
Closing — how to use this preview
This preview is intended to orient executive priorities and identify the critical questions to ask in 2026 planning cycles: where to invest in R&D, how to structure supply agreements, which supplier archetypes to partner with, and how to monetize installed fleets. If your organization is evaluating procurement strategies, product roadmaps, or aftermarket growth targets, PW Consulting’s full report provides the model outputs, segment‑level splits, and supplier scorecards needed to translate these strategic recommendations into executable plans.
For access to the complete dataset, downloadable dashboards, and the supplier benchmarking annex (including the regional, application, and type‑level breakdowns that underpin our recommendations), please consult the full Impact Crusher Market report on our website.
For detailed analysis of this topic, please visit the official page: Impact Crusher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silage Corn Seed Market to Reach USD 344.8 Million by 2032 at 7.21% CAGR
By PW Consulting, 2026-07-12
Silage Corn Seed Market — Strategic Preview for 2026 Decision-Makers
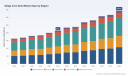
As global dairy and livestock systems face mounting pressure to improve feed efficiency, lower production costs, and mitigate climate risk, the silage corn seed market stands at a strategic inflection point. Our latest PW Consulting study — built on a 2020–2025 historical base and forward-looking to 2032 — shows the market expanding at a compound annual growth rate of 7.21%. The research synthesizes macro sizing, scenario-driven forecasts, supplier positioning, cost and regulatory shocks, and practical playbooks that companies must adopt to convert growth into profitable share gains in 2026 and beyond.
Silage Corn Seed Market
Why this report matters for 2026
-
Timing: 2026 is the first full planning year after multiple 2025 product launches and regulatory updates that materially affect seed development, risk management, and field economics. Boards and commercial leaders must translate these near-term changes into 3–5 year plans now.
Silage Corn Seed Market -
Market trajectory: The market’s steady historical growth combined with an above-average forecast trajectory implies both continued demand and heightened competitive intensity. Strategic moves in R&D, channel coverage, and pricing executed in 2026 will disproportionately shape outcomes for the remainder of the decade.
Silage Corn Seed Market -
Concentration dynamics: Market concentration at the top tier remains high, creating asymmetric opportunities. Established leaders can leverage scale and trait portfolios, while challengers can win by narrowing focus and exploiting gaps in innovation or service.
What the PW Consulting report delivers (practical, executable content)
-
Robust market architecture: a clear articulation of demand drivers, cost pressures, and adoption levers across the value chain, with modeled scenarios that stress-test pricing, yield, and trait-penetration assumptions.
-
Actionable commercial playbooks: segmented go-to-market options for seed houses and distributors, including prioritized channel investments, differentiated product messaging for dairy vs. beef systems, and farm-level ROI calculators to increase adoption.
-
R&D and product strategy guidance: a diagnosis of trait gaps and breeding priorities (e.g., digestibility, drought tolerance, BMR variants, and gene-edited traits), recommended investment pacing, and partnership archetypes for co-development or licensing.
-
M&A and partnership scorecards: framework for evaluating targets by asset type (germplasm, trait stack, distribution footprint), with sensitivity analyses showing how different deal structures affect short- and long-term return profiles.
-
Commercial risk matrix: regulatory and insurance shifts, supply-chain fragilities, and farm economics translated into contingency playbooks for price shocks, seed shortages, or rapid trait adoption.
Competitive landscape — what to watch in 2026
The market is dominated by a small number of global R&D leaders with deep hybrid pipelines, broad distribution networks, and the capital to commercialize advanced trait packages. That said, a vibrant mid-market and regional specialist cohort remain strategically important — both as customers (through licensing or distribution partnerships) and as acquisition targets.
-
Bayer CropScience: Continues to push breeding advances and has moved into gene editing for drought resilience. Expect Bayer to lean into trait differentiation and stewardship programs that help translate genetic advances into demonstrable on-farm value.
-
Corteva Agriscience: With a broad hybrid portfolio and strong channel relationships, Corteva’s pathway to growth emphasizes integrated trait stacks and farm-centric data services that increase stickiness across the growing season.
-
Syngenta: Focused on digestibility-optimized lines and energy-efficient hybrids; Syngenta’s near-term bets will be on partnerships and co-branded products that accelerate adoption in dairy-intensive geographies.
-
KWS, Limagrain, Brevant, Maizex, Hybrid85 and other regional players: These firms compete on niche specialization — forage-centric breeding, non-GMO portfolios, or value pricing and direct shipping. Their agility and local knowledge make them credible challengers in defined segments.
Recent 2025–early-2026 developments reflect this dynamic: new hybrid launches across multiple firms, drought-tolerant gene-edited lines coming to market, and distribution partnerships that increase route-to-farm reach. Taken together, these signals point to faster product turnover and a higher premium on commercialization excellence.
Cost, regulation and operational dynamics shaping 2026 choices
-
Input cost pressure: Field-level economics are shifting. For 2026, industry averages show a step-up in per-acre planting costs compared with 2025. Management teams must account for this when designing price-pack structures and farmer financing offers.
-
Insurance and regulatory flux: The USDA Risk Management Agency’s updated standards and new pilot insurance programs approved in late 2025 change the risk calculus for both farmers and seed firms. Companies should model the impact of these programs on adoption risk and stocking strategies.
-
Seed unit economics: Kernel-level breeding and scaling efficiencies, including cost per 1,000-kernel metrics in major production geographies, are now core inputs to pricing models and inventory decisions.
Strategic implications and recommended 2026 priorities
Companies that treat 2026 as a pivot year — aligning portfolio, go-to-market, and capital allocation decisions to a mid-term (2028–2030) value capture view — will outperform. Below are prioritized actions for executive teams.
-
Prioritize product-to-market velocity. Compress the commercialization funnel for proven trait packages by reallocating marketing and trial resources toward the highest-response geographies and channels. Fast-follower models that shorten shelf-to-farm time will capture disproportionate share.
-
Rebalance pricing and packaging. With farm-level planting costs elevated, experiment in 2026 with conditional pricing (e.g., performance rebates, split-payment structures, bundled agronomic services) to reduce perceived adoption risk while protecting margins.
-
Make targeted R&D bets plus external leverage. Divide R&D spend between core long-lead breeding and near-term gene-editing or trait-acceleration investments. Complement internal work with structured licensing and co-development to derisk time-to-market.
-
Strengthen distribution economics. Reassess distributor incentives and direct-to-farm capabilities; investments in digital ordering, logistic optimization, and seed-finance products can materially increase farmer loyalty and margin capture.
-
Use M&A strategically. Pursue tuck-ins that enhance trait breadth or regional coverage, and consider bolt-on acquisitions that instantly upgrade commercial capacity rather than purely germplasm consolidation.
-
Plan for regulatory and insurance permutations. Build scenario models that incorporate the updated crop-insurance standards and pilot programs, and design commercial offers that align with farmer risk-management choices.
How this preview is designed to spark action — and what is reserved for the full study
This article is intentionally structured as a strategic “trailer”: it surfaces the key directional forces, competitive moves, and executive-level recommendations that should shape 2026 planning. The full PW Consulting Silage Corn Seed Market report contains the granular inputs and proprietary models that drive these conclusions — including regional demand curves, type- and application-level adoption scenarios, company benchmarking scorecards, investor-ready financials, and downloadable ROI tools for field trials.
Concretely, the full study provides:
-
Model spreadsheets that allow users to run their own sensitivity tests against price, yield, and trait-penetration assumptions.
-
Detailed competitor dossiers and GTM mapping that uncover white-space opportunities within and between geographic clusters.
-
Step-by-step commercialization templates for launching new hybrid lines, including trial design, farmer engagement, and distributor incentive mechanics.
Final note to executives
As the silage corn seed market scales, the window to secure advantaged positions narrows. 2026 will reward companies that combine disciplined capital allocation, sharper commercialization, and flexible risk-management solutions for farmers. Our research quantifies the market’s trajectory, unpacks the near-term shocks, and prescribes the operational moves that convert macro growth into durable competitive advantage. For teams preparing budgets, M&A pipelines, or product roadmaps for 2026, this study is the strategic backbone that turns insight into implementation.
PW Consulting remains available to walk leadership teams through a tailored briefing of our findings, run custom scenarios on your portfolio, and co-develop a 90–180 day execution plan aligned to your ambition in this evolving market.
For detailed analysis of this topic, please visit the official page: Silage Corn Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coffee Concentrates Market to Hit USD 315.7M by 2032 at 5.71% CAGR
By PW Consulting, 2026-07-12
Coffee Concentrates Market — Strategic Outlook for 2026 Decision-Making
As organizations enter 2026, the coffee concentrates market sits at an inflection point defined by steady demand growth, shifting channel economics, and growing regulatory and raw‑material complexity. PW Consulting’s latest Coffee Concentrates Market study synthesizes seven years of market dynamics (2020–2025) and a forward-looking forecast (2026–2032) into an operational playbook for commercial leaders. This introduction outlines the report’s strategic value for 2026 decision cycles, highlights the levers that will determine competitive advantage, and previews the types of analysis and tools included — while preserving the granular segmentation that makes this study proprietary and available through the full report.
Coffee Concentrates Market
Macro snapshot: a resilient growth trajectory that rewards timely positioning
The market demonstrated steady expansion through the historical period, growing from a modest base in 2020 to a market size of approximately 215.0 Million USD in the 2025 base year. Under PW Consulting’s baseline forecast, the market continues to expand at a compound annual growth rate of 5.71% across the 2026–2032 horizon, reaching an expected market size north of 315 Million USD by 2032. The growth profile is neither explosive nor stagnant — it is the kind of predictable expansion that invites structured investment, product-line optimization, and targeted M&A rather than speculative scale‑outs.
Coffee Concentrates Market
Why this matters for 2026 corporate decisions
-
Capital allocation: With mid-single-digit CAGR and steady year‑over‑year expansion, executives can model multi-year returns on product development, automation in liquid-fill/packaging, and channel expansion with a meaningful probability of payback. The market favors selective investment into higher-margin formats and go‑to‑market models that reduce working capital intensity.
Coffee Concentrates Market -
Portfolio prioritization: Incremental demand is visible across multiple end uses (retail, foodservice, RTD/ingredient). However, competitive advantage will accrue to players who optimize SKU portfolios and trade up product narratives (e.g., premiumization, organic, low‑sugar) that align with consumer willingness-to-pay rather than expanding breadth indiscriminately.
-
M&A and JV timing: Market concentration metrics show a moderate-to-high incumbent presence at the top end of the industry. Strategic bolt-ons that fill capability gaps — such as cold‑chain expertise, contract-manufacturing scale, or branded DTC infrastructure — are likely to yield higher value than broad horizontal consolidation in 2026.
Competitive landscape — what incumbents and challengers are doing
The competitive field blends global CPG powerhouses, specialty roasters, ingredient suppliers, and regional co‑packers. Global manufacturers bring distribution scale and ingredient‑level R&D; specialty players supply brand equity, premiumization, and close consumer relationships; contract manufacturers and ingredient houses offer industrial formats and bespoke extract capabilities.
-
Large CPGs and global brands — exemplified by multinational beverage players — are leveraging brand licensing and global channels to accelerate retail and foodservice penetration. Their playbooks prioritize scaling shelf-stable formats, co‑branded product launches, and ingredient solutions sold into RTD manufacturing.
-
Specialty and direct‑to‑consumer players focus on experience, provenance, and premium cold‑brew concentrates. These firms tend to command higher ASPs (average selling prices) per SKU and use DTC subscriptions to secure lifetime value and margin density.
-
Industrial producers and co‑packers compete on cost, format range (e.g., bag‑in‑box, bulk syrup), and food‑service relationships. Their strategic advantage lies in scale manufacturing, formula customization, and logistics for large clients such as quick‑service restaurants and beverage manufacturers.
PW Consulting’s report profiles the core market participants in detail, covering their commercial models, product pipelines, manufacturing footprints, and channel strategies. Recent notable market moves — including a global cold brew concentrate launch by a major multinational partner in 2026 and technology investment in low‑sugar concentrate processing announced in late 2025 — are reshaping competitive dynamics and accelerating premium and health‑oriented product introductions.
Supply and cost dynamics: raw material and regulatory noise you must model
Two supply‑side drivers are particularly salient for 2026 planning.
-
Raw material volatility: Weather and crop cycles continue to inject asymmetry into cost forecasts. While global production forecasts show a net increase year‑over‑year driven by gains in certain producing regions, localized declines — including a notable contraction in Brazil’s production for 2025/26 — raise the probability of short‑term price spikes and margin pressure for ingredient‑intensive formats. Commercial teams must be competent in hedging strategies, blended sourcing, and contract terms that insulate margin during transient shocks.
-
Regulatory and taxation variability: Jurisdictional excise and VAT treatments create pockets of elevated cost and complexity for exporters and ingredient sellers. Multiple markets apply specific excise rules to extracts and concentrates, and these can materially affect product economics for export‑oriented manufacturers and formulators. A proactive regulatory mitigation plan — tariff engineering, reformulating for tax classifications, and selective market entry — can be a differentiator.
Format and channel considerations — where to compete
The market’s economics differ by format and channel. Liquid concentrates and frozen extracts offer operational synergies with centralized manufacturing and foodservice distribution, while powdered forms can reduce logistics costs but require formulation capabilities to match sensory performance. On channels, RTD and foodservice maintain steady institutional demand; retail and DTC channels remain the primary arenas for premiumization and brand-led margin expansion.
PW Consulting’s full study includes a non‑linear decision framework that helps leaders map format choices to channel strategies, capital investments, and SKU rationalization. The framework is designed to be operational — providing scenario templates for supply contracts, shelf program economics, and pilot launch P&Ls — not merely descriptive.
Strategic implications and recommended moves for 2026
-
Adopt a three‑lane portfolio strategy: (1) defend core industrial channels with cost and supply integration, (2) selectively scale premium consumer formats through brand partnerships or DTC pilots, and (3) incubate high‑value innovations (e.g., low‑sugar processing, functional additions) through small‑batch launches to validate willingness‑to‑pay.
-
De‑risk supply through blended sourcing and flexible contracts: Build tolerance for short‑term commodity shocks by expanding origin portfolios and negotiating indexed pricing or floor‑price clauses. For manufacturers, invest in formula flexibility that allows rapid substitution between bean grades without sensory compromise.
-
Lock in regulatory pathways early: Where excise or VAT regimes create adverse economics, evaluate reformulation, reclassification, or targeted market exits/entries. Regulatory tax arbitrage can materially improve net revenues at the country level.
-
Pivot commercialization tactics based on channel economics: For retail, focus on premiumization and on-shelf storytelling; for foodservice and ingredient sales prioritize consistency, cost-per-use, and logistics reliability.
-
Use M&A as capability fills, not scale chases: Prioritize acquisitions that close capability gaps (cold‑chain, co‑packing, specialty cold‑brew expertise, or proprietary extraction tech) rather than simply adding incremental volume to existing manufacturing capacity.
What’s inside PW Consulting’s full study (practical, transaction‑ready contents)
The full report is built for implementation. Key deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario variants and sensitivity models suitable for board‑level capital allocation.
-
Commercial playbooks for each format and channel, including unit economics, go‑to‑market canvases, and 18‑month pilot blueprints.
-
Supply‑chain heatmaps and procurement playbooks addressing origins, hedging, and manufacturing footprint optimization.
-
Regulatory matrix across priority markets with mitigation options and tax‑sensitivity analyses.
-
Competitive benchmarking and strategic profiles of core vendors, including capability matrices and suggested partnership archetypes.
-
Transaction support materials: valuation comparables, synergy levers for targets, and integration checklists focused on concentrate businesses.
Why PW Consulting’s view is unique
Our approach blends bottom‑up manufacturing economics with top‑down channel and consumer modeling. We calibrate forecasts with primary interviews across retail, foodservice, and co‑manufacturing stakeholders and validate pricing and volume assumptions against real operational metrics. The result is a forecast and set of playbooks designed to be directly executable by commercial, procurement, and M&A teams in 2026.
Next steps for commercial leaders
-
For C‑suite teams: Use the study to stress‑test capital allocation plans and identify one short‑term (12–18 month) and one medium‑term (24–36 month) strategic initiative to capture share or margin.
-
For procurement and operations: Run a sourcing‑scenario workshop using our supply‑chain models to quantify the P&L impact of origin shifts and hedging strategies under the 2026 price regime.
-
For business development: Map potential bolt‑on targets using our capability‑gap filters and use the included transaction playbooks to accelerate diligence and integration planning.
PW Consulting’s Coffee Concentrates Market report provides the granular segmentation, proprietary forecasts, and playbooks that decision‑makers need to convert the market’s steady growth into durable advantage. For access to the full dataset, segment and regional detail, and the tactical templates referenced above, consult the primary report page and our advisory team to schedule a walk‑through tailored to your firm’s agenda.
For detailed analysis of this topic, please visit the official page: Coffee Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
SMS Firewall Market 2026: Strategic Preview for Executive Decision-Making
As organizations plan technology and security investments for 2026, understanding the trajectory of the SMS Firewall market has never been more strategic. PW Consulting’s latest SMS Firewall Market study synthesizes market sizing, vendor dynamics, regulatory pressure, and deployment economics into a practical decision framework for operators, cloud providers, enterprises, and security buyers. This article serves as a focused preview — demonstrating the analytical depth of the study while withholding detailed tables and granular segment splits to guide readers to the full report for implementation-ready intelligence.
SMS Firewall Market
Market snapshot: momentum, scale and runway
SMS Firewall is a specialist but rapidly maturing segment of messaging security. After steady growth through the early 2020s, the total market expanded from roughly USD 163 million in 2020 to about USD 215 million in 2025. Our forecast shows continued acceleration across the 2026–2032 window: we estimate a compound annual growth rate of approximately 8.5%, taking the market toward an expected USD 345 million by 2032. That trajectory reflects a convergence of three forces: rising A2P messaging volumes, proliferating smishing and grey-route fraud, and the regulatory emphasis on data sovereignty and trusted sender frameworks.
SMS Firewall Market
Why the 2026 decision cycle matters
- Shift from experimentation to industrialization: Early deployments focused on proof-of-concept filtering; in 2026, Tier-1 operators and large enterprises will move to full-scale, sustainable architectures integrating AI-driven filtering, verified-sender protocols, and on-prem-/edge-based policy enforcement.
- Regulatory inflection points: Data sovereignty clauses and national directives (notably in parts of Europe, India and Brazil) are accelerating requirements for on-shore filtering and tight controls on cross-border message routing. These rules convert a security purchase into an operational mandate for many carriers.
- Revenue protection as a board-level issue: SMS revenue leakage from grey-route bypass and SIM-farm abuse is now a measurable line-item threat to commercial messaging revenue streams; decisions in 2026 must balance fraud mitigation with preserving A2P monetization.
Core strategic questions the study answers
- What is the expected addressable market and growth cadence through 2032, and which demand drivers are durable versus transient?
- How do deployment options (cloud, on-premise, managed service) map to regulatory constraints and operating models for Tier-1 carriers versus MVNOs and enterprise SPs?
- What vendor capabilities materially differentiate outcomes—e.g., effectiveness of AI models, URL scanning, verified-sender integration, and threat-intel sharing—and how should procurement score them?
- What are practical migration pathways for operators seeking to upgrade legacy SMS routing without disrupting A2P revenue?
What’s inside the PW Consulting report (practical, implementation-focused)
- Proprietary market-sizing model with historical calibrations (2020–2025) and scenario-driven forecasts (2026–2032), including sensitivity testing for macro messaging trends.
- Technology landscape maps and a decision matrix aligning deployment archetypes (on-prem, cloud, hybrid, managed) with compliance and cost profiles.
- Vendor scorecards and a neutral go-to-market playbook addressing partnerships, routing control, and API integration patterns for operators and enterprises.
- Operational playbooks — runbooks for incident response, false-positive management, customer experience preservation, and revenue-reconciliation processes.
- Commercial frameworks — TCO templates, ROI calculators, and negotiation levers for licensing, managed services, and support SLAs.
- Regulatory impact assessment and a country-level risk index identifying where on-shore filtering or localization will materially change procurement timelines.
- Case studies and technical appendices demonstrating deployment patterns, performance benchmarks, and machine-learning validation approaches.
Note: this preview intentionally omits granular regional and application splits and detailed vendor financials. Those tables, model inputs, and downloadable tools are available exclusively in the full report on our site.
SMS Firewall Market
Competitive landscape — positioning and tactical implications
The SMS Firewall vendor ecosystem blends network-focused specialists, messaging platform incumbents, and emerging security players. Market concentration is notable: the top three vendors account for nearly half of the market’s revenue, and the top five approach roughly two-thirds — a structure that favors scale and integrated network relationships. Below are strategic profiles and implications for buyers.
- BICS (Brussels): Strengths in operator-grade filtering and global SS7/SMPP reach. Ideal for operators seeking deep integration with interconnect routing controls. Recent product expansions emphasize local firewall capabilities to reduce unbillable A2P/P2P traffic.
- Cellusys (Ireland): Differentiates on AI-powered analytics and full-visibility platforms for operators. Attractive to carriers that prioritize real-time anomaly detection and forensic trail capabilities.
- Comviva (India): Positions strongly in APAC and emerging markets with machine-learning driven messaging firewalls; its offerings appeal to operators seeking regional deployments with local support and pricing flexibility.
- Infobip (Croatia): Combines firewall capability with a broad messaging platform—advantages include bundled messaging and threat-intelligence services. Recent large deployments demonstrate scale and spam-blocking effectiveness.
- Mobileum (USA): Known for intelligence-led network protection and URL scanning. Attractive for operators that want to integrate firewall outcomes into broader revenue assurance programs.
- Proofpoint (USA): Brings enterprise-grade security and consolidated threat intelligence; a logical choice for large enterprises with cross-channel fraud concerns.
- Sinch (Sweden): Integrates AI spam filters within a messaging platform — favors customers that want automated A2P fraud protection tied to engagement tools.
- Tata Communications (India): Strong managed-service capability for global operator defenses with an emphasis on anti-spam managed services and global routing governance.
- Twilio (USA): Offers programmable firewall controls appealing to developers and high-volume A2P senders seeking fine-grain programmatic control.
- GMS (Vietnam), Enabld (Ireland), AcePeak (USA): Emerging specialists with focused propositions — 24/7 monitoring, HLR-based controls, and low-capex carrier-grade options respectively. These vendors increasingly participate in operator ecosystems through partnerships and targeted sponsorships at industry events.
Recent vendor activity underscores two themes: (1) rapid productization of AI-driven filtering and verified-sender integrations, exemplified by Sinch and Comviva product enhancements; and (2) strategic commercial partnerships and deployments — Infobip’s large-scale Anam Protect deployment and collaborative managed-service offerings with Tata Communications are instructive examples. Sponsorships and presence at major industry events in 2026 also signal vendor appetite to capture operator mindshare.
Regulatory and operational dynamics shaping procurement
- Data sovereignty: National data-sovereignty clauses across several jurisdictions are tipping procurement toward on-shore or hybrid edge deployments. For many Tier-1 carriers, this shifts the calculus away from fully centralized cloud-only models.
- Carrier responsibility and mandates: European and large regional carriers have moved from advisory to protective postures — Deutsche Telekom’s 2025 initiative to protect its mobile customers from malicious SMS is an example of carrier-led defensive action becoming standard practice.
- Verified-sender ecosystems: The integration of verified-sender protocols with AI firewalls is actively replacing legacy unverified routes. This creates a positive feedback loop where policy enforcement and sender verification together reduce false positives and protect monetization.
Practical guidance for 2026 procurement and architecture
- Adopt a phased deployment with governance gates: Start with a hybrid architecture that enables on-prem filtering for regulated traffic and cloud-native analytics for aggregated threat intelligence.
- Score vendors on three pillars: detection efficacy (precision/recall of AI), operational integrability (SMPP/SMS hub APIs, orchestration), and regulatory proof (compliance, localization capabilities).
- Negotiate outcome-based SLAs: Tie part of licensing or managed-service fees to measurable reductions in grey-route leakage and time-to-block for identified threat classes.
- Invest in telemetry and reconciliation: Implement reconciliation processes to quantify blocked versus legitimate A2P traffic to minimize customer impact and preserve revenue.
- Plan for continuous model validation: Machine-learning models drift; include provisions for periodic model audits, labeled-sample refresh, and collaborative threat-sharing with peers.
How PW Consulting’s report accelerates your 2026 program
Our full SMS Firewall Market report provides the practitioner-level artifacts teams need to move from strategy to execution: downloadable TCO/RoI spreadsheets, vendor RFP templates, deployment runbooks, a vendor positioning map, and scenario-modeled forecasts that can be reparameterized by your traffic profiles. For boards and C-suite stakeholders, the report distills the commercial impact horizon you need to budget and schedule program milestones through 2032.
This preview demonstrates the study’s analytical depth and market perspective while preserving the granular segmentation and proprietary tables that are the report’s practical core. For the full set of models, vendor scorecards, country-level regulatory matrices, and downloadable procurement tools, access the complete SMS Firewall Market report on our website.
Executive next steps
- Commission a 90-day readiness assessment to map existing messaging controls to the architectures described in the report.
- Use our vendor scorecard to shortlist three suppliers for pilot trials that validate detection efficacy against your traffic baseline.
- Schedule a regulatory gap workshop focusing on data-sovereignty and verified-sender obligations in your primary markets.
PW Consulting’s SMS Firewall study is designed to be not just informative but prescriptive: a decision-ready resource to prioritize investments, secure messaging revenue, and meet emerging regulatory obligations through 2026 and beyond. For full access to all datasets and tactical tools referenced here, please visit the report page.
For detailed analysis of this topic, please visit the official page: SMS Firewall Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Radiation Detector Market to Reach USD 3,219.94M by 2032 at 8.2% CAGR | PW Consulting
By PW Consulting, 2026-07-12
Radiation Detector Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking executive preview of our comprehensive Radiation Detector Market study. Grounded in historical analysis (2020–2025) and a seven-year forecast horizon (2026–2032), this briefing articulates the strategic value the full report delivers to corporate leaders making high-stakes decisions in 2026. We demonstrate where meaningful growth and risk converge — while intentionally reserving granular subsegment tables and proprietary scenario outputs for the full report to preserve its commercial value.
Radiation Detector Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a pivot year for procurement cycles in utilities, healthcare capital budgets and national security programs. Our report synthesizes the latest baseline (base year 2025) with near-term regulatory inflection points to advise practical action windows.
Radiation Detector Market -
Scale: The Radiation Detector market has moved from a consolidated but specialized niche to a multi‑billion‑dollar growth market. In our baseline, the global market reached approximately USD 1,845 Million in 2025 and, under central-case assumptions, is projected to expand to roughly USD 3,220 Million by 2032 — a compound annual growth rate of about 8.2% across the forecast period.
Radiation Detector Market -
Concentration: The industry exhibits high supplier concentration at the top — the three largest vendors command a substantial majority of market share, and the top five consolidate over four‑fifths of the market — implications that affect pricing power, standards setting, and channel dynamics.
High‑level market trajectory and implications
From 2020 through 2025 the market exhibited steady expansion driven by healthcare modernization, legacy nuclear facility upgrades, and rising civil security investment. The projected CAGR of 8.2% is not evenly distributed across product types or geographies; rather, it reflects regime shifts in technology adoption (semiconductor detectors, advanced scintillators), regulatory tightening, and growing demand for distributed monitoring solutions. For executives, the headline numbers tell a clear story: the addressable opportunity is expanding rapidly enough to justify accelerated R&D, targeted M&A, or capacity investments — but the optimal path depends on a firm’s risk appetite and strategic objectives.
Key demand drivers and timing considerations
-
Regulatory tightening and standards updates — including new calibration procedures and national compliance mandates — are increasing baseline replacement cycles and creating procurement lift for compliant systems and services. These cycles typically create concentrated tender waves that procurement teams should anticipate in 2026–2028.
-
Healthcare modernization and radiation safety programs are sustaining steady replacement and service demand, while high-resolution imaging and dosimetry innovations open adjacent premium product segments.
-
National security and first‑responder modernization — amplified by geopolitically driven budget shifts — are accelerating demand for portable, isotope‑identifying, and networked detectors.
-
Supply constraints in specific semiconductor inputs and metals continue to shape delivery lead times and component costs. These supply constraints can materially affect time-to-market for advanced solid‑state and CZT‑based detectors.
Supply chain and geopolitical risk — practical red flags for 2026
Strategic sourcing must factor in material and technology concentration risks. Export controls and raw material restrictions have been recent and ongoing considerations: export-control regimes affecting critical materials and certain detector technologies remain active, and at least one major supplier market has maintained export curbs that influence semiconductor and high-density metal availability. For procurement and operations teams, this translates to longer qualification cycles for alternate suppliers, potential premium pricing for forward‑covered components, and the need for playbooks to sustain production continuity under export licensing regimes.
Recommended near-term actions:
-
Conduct a component‑level risk assessment tied to production schedules and key accounts.
-
Pursue dual‑sourcing strategies for semiconductors and shielding materials where feasible.
-
Advance export compliance capability and scenario planning for licensing delays impacting cross‑border contracts.
Regulatory and standards landscape — catalysts and compliance windows
Recent and emerging regulatory inputs carry direct procurement and product‑development implications. New calibration procedures and national monitoring mandates create compliance-driven demand for recertification, replacement detectors, and associated calibration services. Separately, stricter export licensing rules for sensitive technologies are raising the transactional complexity of cross-border deals, particularly for products with advanced isotope identification functionality.
Corporate actions to consider:
-
Accelerate compliance roadmaps to ensure product portfolios meet updated calibration and monitoring standards.
-
Embed regulatory intelligence into product roadmaps to preclude late-stage redesign associated with compliance updates.
-
Integrate export-control expertise into commercial due diligence, especially for international growth strategies and M&A targets.
Competitive landscape — what the top players signal
The market is characterized by a mix of legacy instrumentation firms, specialist dosimetry providers, and fast‑moving niche players in semiconductor and imaging detectors. The top vendors combine broad portfolios (survey meters, dosimeters, high‑resolution spectrometers) with established service and accreditation capabilities — an interplay that raises switching costs for large institutional buyers.
-
Mirion Technologies — established leader offering dedicated products for first responders and comprehensive nuclear measurement systems. Their product breadth positions them well for large institutional contracts and integrated services deals.
-
Thermo Fisher Scientific — leverages scale and portfolio depth across dosimetry and monitoring instruments; attractive to healthcare and large laboratory buyers seeking end‑to‑end vendor relationships.
-
LANDAUER — specialized in occupational dosimetry and badge‑based monitoring; built‑in service and accreditation capabilities provide stickiness among medical and occupational customers.
-
Polimaster — focused on portable and deployable detection systems, including personal and backpack detectors; innovation in field instruments makes them a competitive choice for civil security and mobile response units.
-
Kromek Group — competitive in CZT-based detectors and isotope identification; recent product releases position them for growth in high‑resolution and intelligence-driven applications.
-
AMETEK ORTEC — strengths in high‑resolution semiconductor instruments and spectroscopy solutions; favored where analytical performance commands a premium.
-
Ludlum Measurements — broad portfolio of practical survey and personal meters; well entrenched in industrial and utility maintenance markets.
-
Radiation Detection Company — service‑oriented dosimetry and accredited testing offerings that appeal to regulated occupational markets.
Recent product and demonstration events — including in‑orbit detector tests and new RIID launches — illustrate two market dynamics: first, suppliers are racing at both ends of the spectrum (field‑portable, rugged instruments and high‑resolution laboratory systems); second, demonstrations and standards compliance are increasingly central to commercial differentiation.
Report scope and operational deliverables
Our full report provides practical, actionable intelligence for executives and functional leaders. Highlights include:
-
Market sizing and growth scenarios (historical 2020–2025 and forecasts to 2032) with sensitivity testing under alternate regulatory and supply‑chain shock assumptions.
-
Financial and commercial benchmarks to support pricing, margin improvement, and investment prioritization.
-
Vendor scorecards, capability matrices, and go‑to‑market maps to inform partner, distributor, and acquisition targeting.
-
Procurement playbooks aligned to typical buyer archetypes (utilities, healthcare systems, defense and security agencies, industrial operators), including contract structuring clauses for warranty, calibration, and export compliance.
-
Scenario‑based roadmaps for product development that align R&D spend with near‑term regulatory windows and medium‑term market growth pockets.
-
Service and aftermarket models that quantify lifetime revenue opportunities across calibration, accreditation, and data‑monitoring subscriptions.
How to use this intelligence in 2026 planning
For C‑suite leaders and strategy teams, the value of the report is pragmatic: translate growth forecasts and concentration metrics into decisive actions for portfolios, M&A pipelines, and operational investments. Recommended workflows for calendar‑year 2026:
-
Prioritize targets for capability augmentation where product gaps align with rising regulatory requirements and field performance expectations.
-
Rebalance R&D roadmaps to accelerate features that reduce total cost of ownership for institutional customers (e.g., simplified calibration, remote diagnostics, serviceable modular designs).
-
Define a two‑track supply strategy: near‑term tactical buys to secure components and a medium‑term localization plan to reduce exposure to export‑control volatility.
-
Prepare commercial templates that reflect longer lead times, higher compliance requirements, and potential licensing hurdles for cross‑border sales.
Final observation and call to action
The Radiation Detector market presents an attractive growth trajectory with clear pockets of premiumization tied to performance, compliance, and connected services. Yet, supply‑chain rigidity and evolving export and calibration regimes mean that execution risks are non‑trivial. The macro path to roughly USD 3.22 billion by 2032 (central case) and an 8.2% CAGR masks important heterogeneity that materially affects investment returns.
PW Consulting’s full report delivers the missing granularity — segmented demand profiles, procurement‑ready vendor shortlists, financial models, and scenario maps that translate market projections into investment‑grade decisions. For teams planning capital allocation, product launches, M&A screening, or strategic sourcing in 2026, this intelligence converts uncertainty into competitive advantage.
Contact PW Consulting to access the complete dataset, proprietary subsegment analysis, and bespoke advisory packages tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Radiation Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Spherical Activated Carbon Market to Hit USD 201.5M by 2032 at 6.2% CAGR
By PW Consulting, 2026-07-12
Spherical Activated Carbon Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on our new Spherical Activated Carbon (SAC) market study — a focused, action-oriented body of work designed to inform high-stakes commercial and investment decisions in 2026. The sector is at a structural inflection: demand across environmental remediation, ultrapure processes and advanced materials is rising, input-cost volatility is creating margin pressure, and a concentrated supplier base is shaping competitive dynamics. This article summarizes the strategic takeaways and explains why our study should be on the desk of every CEO, Chief Procurement Officer, and M&A lead weighing SAC exposure this year.
Spherical Activated Carbon Market
Market trajectory and what it means for 2026 planning
Our market model — built on a validated historical series and forward-looking scenario analysis — shows steady expansion through the coming decade. After recovering from early-decade variability, the SAC market reached a solid position in our base year (2025) and is forecast to continue growing at a mid-single-digit compound annual growth rate (CAGR) through the 2026–2032 horizon. By 2032 the market is meaningfully larger than in 2025 under our central case, driven by persistent demand in industrial adsorption, advanced water and gas purification, and specialty electronic and biomedical uses.
Spherical Activated Carbon Market
For 2026 strategic planning, the implication is clear: companies must balance near-term operational resilience with medium-term capacity and product strategy. Cost shocks and regulatory tightening in certain applications will compress margins for commodity-oriented products, while high-value niches — particularly those requiring ultra-low dust, controlled particle distribution, and certified purity — will offer asymmetric return profiles for firms that can execute technically and commercially.
Spherical Activated Carbon Market
How this study helps you act — a practical content map
- Robust market sizing & scenario modeling: A base-year calibration and multiple demand scenarios through 2032 that permit sensitivity testing against input-cost swings and adoption curves.
- Segment-level analysis (by type, application, and region): Deep diagnostic of end-market drivers and adoption dynamics. Note: while this primer highlights directional trends, detailed segment tables and model outputs are available in the full report.
- Supply chain and raw material risk assessment: Granular coverage of feedstock sources (coal, petroleum pitch, resin, bio-precursors), pricing volatility, and alternative sourcing strategies.
- Competitive landscaping: Comparative profiles, capability mapping, and a commercial scorecard of leading producers — focusing on product tech, scale, end-market focus, and strategic moves.
- Commercial playbooks and investment thesis: Actionable guidance for procurement, product roadmap prioritization, strategic partnerships, and M&A scenarios with illustrative valuation sensitivities.
- Regulatory & standards matrix: Practical implications of evolving environmental and purity regulations for product design, certification, and capital planning.
Competitive landscape: who matters and why
The SAC market is neither a fragmented cottage industry nor a closed oligopoly — it sits in the middle. Our concentration metrics show that the top three players capture a material share of supply, and the top five increase that concentration further. That structure creates both opportunity and risk: scale advantages in cost and distribution exist, yet niche technical differentiation remains achievable for agile specialists.
- Kureha Corporation (Tokyo, Japan) — A technology-focused supplier whose petroleum pitch–based spherical grades emphasize high purity, low dust and flowability. Kureha’s strengths are in process control and end-market credibility for environmental applications; it is well-positioned where regulatory requirements penalize dust-prone or variable-grade products.
- Osaka Gas Chemical Group (Tokyo, Japan) — Known for coal-based spherical carbons tailored for gas and liquid phase adsorption. The company’s product engineering and longstanding relationships in gas-treatment make it a pivotal player in industrial gas recovery and emission-control segments.
- Kuraray Co., Ltd. (Osaka, Japan) — Offers low-pulverization spherical products and is part of a broader family with historical ties to larger activated carbon players. Kuraray’s differentiation is technical consistency and access to cross-sector distribution channels via its corporate group.
- Shanxi Xinhua Chemical (Taiyuan, China) & Jining Carbon Group (Jining, China) — Representative of China-based suppliers scaling pitch- and coal-derived spherical grades for air purification and industrial recovery. Their cost-competitive production and proximity to regional demand centers give them logistical advantages, though customers increasingly require third-party certifications for export-grade applications.
- Acro Chemical Corporation (United States) — A niche pitch-based supplier serving specialty chemical and material applications where bespoke particle characteristics matter.
- Xiamen All Carbon Corporation (ACC) (Xiamen, China) — A notable growth story: ACC has broadened commercial availability of next-generation resin-based spherical products targeting semiconductor, ultrapure water, supercapacitors and hemoperfusion. This product expansion is illustrative of the premium opportunities available to companies that can deliver tight specs at scale.
Taken together, the competitive map suggests two viable strategic postures for companies in 2026: (1) invest behind premium, specification-driven offerings that command higher margins and resilient demand, or (2) compete on cost and supply assurance for larger, more price-sensitive industrial uses. Many firms will combine both via product-tier segmentation and selective partnerships.
Raw material and regulatory dynamics shaping 2026 decisions
Three interlocking external dynamics should be at the top of every boardroom agenda:
- Feedstock volatility: Prices and availability for key raw materials — Australian coking coal for certain coal-based grades, coconut shell for bio-based activated carbons, and petroleum pitch for pitch-based SAC — have shown episodic volatility. Recent commodity movements and weather-related supply disruptions highlight the need for multi-sourcing strategies, hedging where feasible, and contract clauses that balance risk across the value chain.
- Product specification trends driven by regulation: Environmental and public-health regulations increasingly favor spherical grades with low pulverization and predictable flow properties. Gas-phase and wastewater treatment standards are trending toward performance requirements that effectively penalize low-quality or high-dust carbons.
- Technology-led demand pockets: Semiconductor fabs, ultrapure water systems, supercapacitors and medical devices (e.g., hemoperfusion) are growing end-markets for specialized spherical carbons. These applications reward suppliers that can demonstrate consistent particle size distributions, low ionic contamination and validated production control systems.
For procurement and product teams, the strategic implications are immediate: prioritize qualified supplier portfolios for critical feedstocks; invest in process controls and certification capabilities; and design commercial contracts that reflect asymmetric risks in feedstock and logistics.
Strategic actions for 2026 — a pragmatic checklist
- Run a rapid stress-test of your SAC-exposed P&L versus commodity and regulatory scenarios using the study’s model framework.
- Assess whether your product portfolio is aligned to high-margin niches (ultrapure, medical, electronic) and what incremental CAPEX or R&D would be required to up-spec existing lines.
- Build redundancy into feedstock sourcing; evaluate nearshoring or strategic backward-integration where long-term supply tightness is probable.
- Prioritize certification and quality documentation for export markets and regulated end-uses — compliance can be a commercially differentiating asset.
- Consider M&A and JV plays to secure technology, distribution or regional manufacturing footholds; concentration metrics indicate that well-targeted consolidation can accelerate scale benefits.
Why PW Consulting’s study is different
Our study is tailored for decision-makers who need to act in 2026. It combines a transparent, auditable market model with qualitative diagnostics and executable playbooks. Beyond high-level forecasts, the report includes supplier scorecards, regulatory heatmaps, contract-risk templates, and scenario-driven valuation workups — the tactical materials that procurement, corporate development and product leadership can use immediately.
We intentionally maintain a “trailer” approach in this primer to preserve the strategic utility of the complete analysis: detailed segment tables, company-level revenues, split-by-application forecasts, and the full sensitivity matrix are available in the main report and interactive model. These deliverables are essential for market-entry sizing, target prioritization in M&A, and contractual negotiation simulations.
Call to action
If your 2026 plan touches activated carbon — as a producer, buyer, investor or technology partner — this is a moment to upgrade insight to action. Use the study to stress-test your assumptions, prioritize investments, and design resilient supply chains and premium product strategies. Contact our research desk to access the full report and the underlying model so your team can run customized scenarios and extract the precise segment-level intelligence needed to seize value in the evolving SAC market.
For detailed analysis of this topic, please visit the official page: Spherical Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motorcycle Audio Systems Market to grow at 6.85% CAGR, reaching USD 184.55M by 2032
By PW Consulting, 2026-07-12
Motorcycle Audio Systems Market — Strategic Outlook for 2026 Decision‑Makers
As motorcycle OEMs, tier suppliers and aftermarket players set budgets and roadmaps for 2026, PW Consulting’s latest Motorcycle Audio Systems Market briefing provides the connective tissue between macro growth trajectories and the tactical moves that will determine competitive advantage. Built on a 2025 base and a detailed 2026–2032 forecast horizon, the study combines numerical forecasting with scenario planning, supply‑chain stress tests and practical go‑to‑market playbooks — all calibrated to a market that is expanding at a compound annual growth rate (CAGR) of 6.85% and is projected to grow substantially through 2032.
Motorcycle Audio Systems Market
Why this research matters for 2026 planning
-
Investment prioritization: With constrained R&D and aftermarket marketing budgets, boards need clear signals where incremental spend will unlock the greatest ROI over the 2026–2032 window. Our briefing ties market growth rates to product lifecycles and buyer willingness to pay.
Motorcycle Audio Systems Market -
Supply chain resilience: Recent tariff policy shifts have changed cost pass‑through dynamics. The report translates regulatory changes into tangible supplier risk scores and cost scenarios for 2026 sourcing decisions.
Motorcycle Audio Systems Market -
Channel strategy: Whether to double down on deep OEM partnerships, accelerate direct‑to‑consumer aftermarket initiatives, or pursue hybrid channel plays depends on near‑term demand trends and concentration dynamics described in the study.
-
M&A and partnership prioritization: We identify where consolidation can rapidly improve gross margins and speed time‑to‑market — a critical consideration given the market’s moderate concentration (CR3 ~45.6%; CR5 ~65.4%).
Market snapshot and trajectory
From 2020 through the 2025 base year, the market demonstrated steady expansion as audio systems evolved from accessory add‑ons into integrated rider‑experience platforms. Our topline modelling — grounded in historical data and product adoption curves — shows that the overall market value climbed materially in the base period and is set to continue growing through 2032. This provides a supportive backdrop for capital allocation but also raises the bar for differentiation: volume growth alone will not guarantee outperformance without strategic moves on product, channel and supply chain fronts.
Key themes shaping the market in 2026
-
Experience integration over component sales — Riders increasingly evaluate audio as part of a broader connectivity and infotainment stack. Successful vendors will transition from selling individual components to offering integrated experience packages that include over‑the‑air updates, app ecosystems and voice interfaces.
-
Modular hardware and software split — Modular designs that decouple premium audio DSP and amplification from the physical speaker architecture reduce SKU proliferation and shorten upgrade cycles, creating recurring revenue potential through software services and paid upgrades.
-
Channel bifurcation: OEM vs. aftermarket — While OEM partnerships remain a high‑margin, volume pathway, the aftermarket is an innovation and margin incubator. The report helps teams decide how much R&D and sales effort to allocate to each channel depending on product positioning and dealer networks.
-
Regulatory and trade disruption — Expanded tariff scopes announced recently have increased landed costs for steel, aluminum and certain components. We translate those public policy moves into actionable procurement stress tests and mitigation options for 2026 sourcing plans.
-
Premiumization and niche targeting — A subset of riders are willing to pay a premium for optimized sound staging, waterproofing and vibration‑tolerant designs. Identifying and commercializing for these segments is a high‑leverage route to margin expansion.
Regulatory and supply‑chain dynamics — what changed and what to do now
Two developments deserve immediate attention. First, the effective expansion of certain tariffs in 2025 has altered the cost calculus for steel and aluminum‑intensive components and imported assemblies. Second, official updates to tariff schedules earlier in 2025 created uncertainty around classification and duties for motorcycle parts. Our report converts these regulatory facts into three tactical tools for procurement and strategy teams: a duty exposure matrix by bill‑of‑materials; alternative sourcing routes with lead‑time and cost trade‑offs; and hedging scenarios showing profit‑impact at different pass‑through levels. For companies planning production runs or negotiating supplier contracts in 2026, these instruments are essential input into pricing, contract duration and inventory policy decisions.
Competitive landscape — what the incumbents are doing
The market combines a mix of established audio specialists and nimble aftermarket innovators. Several players set the pace in recent quarters:
-
Rockford Fosgate: Continues to leverage deep Harley‑Davidson integration knowledge, shipping next‑generation aftermarket kits and extending its brand presence through sponsorships that reinforce affinity with core riders. Their approach underscores a playbook of product depth plus brand activation.
-
BOSS Audio: Focuses on accessible, connectivity‑oriented solutions designed for broad model compatibility — a volume‑oriented strategy that emphasizes distribution breadth across mass‑market and all‑terrain segments.
-
KICKER Audio: Plays to a hybrid approach with plug‑and‑play integration for OEMs and strong aftermarket channel penetration, demonstrating the commercial benefits of offering both retrofit and factory‑fit options.
-
Aquatic AV: Targets direct‑fit, high‑quality premium solutions for touring platforms, highlighting the importance of vehicle‑specific engineering as a differentiator in aftermarket value capture.
-
Wet Sounds: Recent product introductions and expo demonstrations signal a pivot toward experiential, premium kits that prioritize demo capability and dealer enablement.
Across these profiles, three strategic moves recur: deeper vehicle integration (both physical and digital), brand activation in enthusiast channels, and modularization to address both OEM and retrofit use cases. We analyze each company’s strengths, weaknesses and likely next moves without disclosing the granular competitive metrics that reside in the full dataset.
What the full PW Consulting report delivers — practical outputs for 2026
-
Demand forecasts through 2032 with scenario bands tied to macroeconomic and regulatory assumptions, enabling stress tests for capital allocation decisions.
-
Segmented adoption curves by technology and channel, translated into revenue sensitivity models for product roadmap prioritization (note: detailed segment share tables are available in the full report).
-
Supply‑chain exposure maps and mitigation playbooks that include alternate sourcing, duty optimization, and inventory strategies tailored for Q1–Q4 2026 operational planning.
-
Competitive benchmarking and capability scorecards for the leading vendors, including go‑to‑market heat maps and partnership fit assessments.
-
M&A and partnership Maturity Matrix that identifies target archetypes and the expected synergy profiles — revenue, cost and capability — across short and medium horizons.
-
Actionable product launch and dealer enablement templates that translate consumer insights into design requirements, pricing tiers and channel incentive structures.
Strategic imperatives for 2026 — recommended actions
-
Diversify component sourcing now: Lock in secondary suppliers and negotiate flexible terms to mitigate near‑term tariff volatility.
-
Modularize hardware and monetize software: Separate DSP and connectivity layers from physical speaker assemblies to enable upgrades, subscriptions and faster innovation cycles.
-
Pursue OEM co‑development selectively: Secure exclusives for vehicle platforms where integration yields defensible performance advantages and higher ASPs.
-
Invest in demo‑capable channels: For premium kits, in‑person demos at dealerships and expos materially accelerate adoption; allocate marketing dollars accordingly.
-
Use CR‑based M&A filters: Given the market’s mid‑level concentration, focus acquisitions on capability gaps that shift your CR position sensibly without overpaying for scale alone.
-
Prepare pricing playbooks tied to duty scenarios: Map gross margin sensitivity to duty changes and set dynamic dealer pricing thresholds that preserve channel health.
Closing — how to use this briefing
This executive briefing is a strategic primer — designed to translate market motion into a prioritized list of actions for 2026. For teams that need the underlying models, detailed segmentation tables, company scorecards and the tariff‑impact simulations referenced here, the full PW Consulting Motorcycle Audio Systems Market report contains the granular datasets and slide‑ready appendices required to execute. Contact PW Consulting or visit the report page to access the complete intelligence package and the interactive forecast models that will make your 2026 decisions defensible, measurable and actionable.
For detailed analysis of this topic, please visit the official page: Motorcycle Audio Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dashboard Camera Market Poised for 8.67% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Dashboard Camera Market 2026: Strategic Preview for Enterprise Decision-Makers
As PW Consulting’s lead industry analyst, I present a forward-looking synthesis of the dashboard camera (dash cam) market designed to inform boardroom decisions throughout 2026. This is a strategic “trailer” — it surfaces the critical commercial, technological, and regulatory inflection points that will shape supplier economics, product roadmaps, and go-to-market plays across the 2026–2032 forecast horizon, while reserving the granular segmented tables and proprietary model outputs for the full report.
Dashboard Camera Market
Executive snapshot
The dashboard camera market has moved from niche accessory to core vehicle safety and telematics component. Our base-year analysis (2025) and historical window (2020–2025) show consistent expansion: the market grew steadily from its 2020 base and reached a sizable industry scale by 2025. Under current assumptions, the market is projected to expand through 2032 at a compound annual growth rate of 8.67%, reflecting accelerating adoption across consumer, commercial fleet, and OEM channels. Despite growth, the market remains relatively unconcentrated — a structural feature with important strategic consequences for entrants and incumbents.
Dashboard Camera Market
Why 2026 is a strategic inflection
- Regulatory momentum: New mandates and updated mounting/visibility rules are translating safety policy into procurement requirements for commercial operators and OEM platforms alike.
- OEM integration: Vehicle manufacturers are shifting from accessory partnerships toward built-in drive recorders as standard equipment on mainstream models, influencing the balance between aftermarket and factory-fit opportunities.
- Platformization and AI: Dash cams are no longer standalone recording devices; they are becoming sensors feeding AI-enabled risk detection, telematics platforms, and cloud services — changing the value capture model for vendors.
- Cost and supply pressure: Component and storage price inflation in early 2026 is forcing OEMs and aftermarket manufacturers to rethink sourcing, value engineering, and bundled service economics.
Market dynamics and core drivers
Our analysis segments demand drivers into four interacting vectors: regulation and compliance, fleet safety economics, consumer safety and convenience, and technology enablement.
Dashboard Camera Market
- Regulation: Legislative action requiring dash cams in commercial fleets has moved from discussion to statute in select jurisdictions — a pattern that tends to propagate across neighboring regions and industry associations. At the same time, vehicle-code updates on windshield-mounted devices continue to influence product form-factors and mounting solutions.
- Fleet economics: Total cost of ownership (TCO) improvements from incident reduction and faster claims resolution are motivating fleet operators to adopt multi-channel, cloud-connected solutions. Insurers and fleet managers increasingly view dash cams as risk-control investments rather than discretionary spend.
- Consumer adoption: Mainstreaming of driver-assistance features and demand for occupant protection have expanded the addressable market beyond enthusiasts to mass-market buyers — especially as OEMs offer integrated recorders in model lines.
- Technology and services: Advances in low-light sensors, edge AI for real-time event detection, and cloud workflow integration enable new monetizable features (driver coaching, automatic upload, telematics fusion), but they also raise privacy, cybersecurity, and data-governance requirements.
Competitive landscape: who matters and why
The competitive map is diverse: consumer-electronics brands, telematics/IoT platform players, specialist optics and sensor firms, and industrial-system integrators all compete for slices of hardware, software, and recurring-service revenues. Key strategic vectors we observe across core players include platform integration, AI-enabled analytics, and channel specialization.
- Garmin Ltd. (Olathe, KS): Leverages consumer brand recognition and an expanding portfolio of connected LTE models. Strengths include continuity of product experience, GPS expertise, and aftermarket distribution scale. Garmin’s connected offerings illustrate a hybrid hardware-plus-service approach that competes strongly in both consumer and small-fleet segments.
- Thinkware (Coquitlam, BC): Positions itself at the premium end with 4K recording, advanced optics, and AI-enabled parking modes. Thinkware’s product focus supports higher-margin propositions and appeals to safety-conscious consumers and light commercial buyers seeking superior image fidelity.
- Nextbase (Waterloo, UK): Demonstrates how a market leader in a major national market can combine award-winning product design with strong retail and online channels. Nextbase’s approach is instructive for brands targeting rapid consumer adoption while defending against commoditized low-cost imports.
- Samsara (San Francisco, CA): Exemplifies platform-first competition: dual-facing, AI-powered cameras integrated into a broader fleet management suite. Samsara’s model emphasizes subscription revenue, telematics integration, and real-time risk detection — a playbook for firms aiming to capture recurring service economics.
- VIOFO (Taiwan): Focuses on high-performance sensor packages (e.g., STARVIS 2) and multi-channel systems, targeting users demanding professional-grade capture. VIOFO illustrates how component excellence and price-performance balance can win enthusiast and specialist segments.
- IMAGO Technologies GmbH (Friedberg, Germany): Specializes in industrial-grade, trigger-based cameras for event capture and machine monitoring, bypassing continuous-recording paradigms. IMAGO’s product differentiation highlights opportunities where constrained recording modes reduce data overhead and regulatory exposure.
- FUHO Technology (Changhua, Taiwan): Builds on mobile DVR experience to deliver multi-channel fleet systems with IoT connectivity. FUHO’s strengths align with large fleet telematics and logistics operators that require integrated tracking and recording across multiple vehicle zones.
Collectively, these profiles show a market where hardware differentiation, service integration, and channel specialization are all viable pathways. Market concentration remains low, meaning nimble entrants can scale regionally or by vertical specialization — but they must select clear monetization strategies (one-time hardware, bundled service, or platform subscription) early.
Regulatory and cost risk vectors to monitor in 2026
- New mandates for dash cams in commercial vehicles in certain jurisdictions create immediate procurement demand, but also require suppliers to support compliance reporting and evidence retention workflows.
- Federal and state rules on windshield mounting and sightlines continue to alter preferred form-factors and installation kits.
- Material and component inflation — especially flash storage and certain optical components — pressures margins. Pricing strategies and supplier contracts must be revisited to protect gross margins while maintaining competitive price points.
- Data privacy and cybersecurity regulations are converging with vehicle safety laws, increasing the bar for secure cloud ingestion, retention policies, and lawful disclosure processes.
Strategic implications for enterprise leaders in 2026
For executives responsible for product, sales, procurement, or M&A, 2026 is the year to translate macro tailwinds into defensible positions. Below are high-leverage actions we recommend based on scenario analyses in the full study.
- Define your monetization thesis: Decide whether to compete on hardware margins, recurring platform subscriptions, or a hybrid bundling model. Players that delay this choice risk margin erosion from competing incentives across channels.
- Invest in regulated-compliant solutions: Rapidly deploy modular firmware and cloud workflows that support jurisdictional evidence retention and reporting requirements. Compliance is becoming a product feature that unlocks procurement in regulated fleets.
- Prioritize interface standards and partnerships: API-first integrations with major telematics and insurance platforms accelerate adoption. Strategic alliances (or white-label partnerships) with OEMs or fleet management providers can provide scale and lock-in.
- Hedge supply-chain exposure: Lock in storage and optical component capacity through multi-year contracts or alternative sourcing to mitigate short-term pricing shocks. Consider software-defined differentiation to reduce reliance on the most inflationary components.
- Differentiate by data services: Move beyond recording to deliver actionable insights (driver coaching, event triage, automated claims packages). The biggest recurring-revenue pools will belong to firms that own the analytics and workflow automation layer.
- Reassess channel economics: OEM-fit strategies change distribution math; aftermarket brands must compete on convenience, feature-upgradability, and post-sale services to keep lifetime value attractive.
- Prepare for regulatory-first competitive openings: Where local mandates appear, rapid response capability — compliant SKUs, installer networks, and proof-of-compliance feature sets — will determine who wins initial procurement rounds.
What the full PW Consulting Dashboard Camera Market report delivers
To support execution, our comprehensive study (base year 2025; historical 2020–2025; forecast 2026–2032) includes practical, operator-ready deliverables:
- Market-size modeling with scenario runs (conservative, base, accelerated) and sensitivity to regulatory adoption rates and component-price trajectories.
- Go-to-market playbooks for OEM partnerships, fleet procurement programs, and consumer retail strategies.
- Technology roadmaps mapping sensor evolution, edge AI maturity, and cloud-telemetry integration timelines.
- Competitive profiling and a prioritized matrix of potential acquisition targets and alliance partners.
- Supply-chain risk maps and procurement levers to manage storage and component cost volatility.
- Commercial negotiation templates for licensing, data rights, and recurring-revenue arrangements.
We intentionally omit granular regional and application share tables from this preview. Those detailed segmentations, priced models, and downloadable data sets are included exclusively in the full report and interactive dashboard — because the highest-value decisions depend on precise, proprietary splits and scenario-calibrated unit economics.
Immediate next steps for leaders
- Use the next 60–90 days to finalize your monetization position and prioritize product compliance features aligned to your target markets.
- Audit supplier contracts for storage and optical components; implement hedges where exposure is highest.
- Identify at least one strategic partnership or OEM engagement to pilot built-in solutions or managed-service bundles in 2026.
- Request the full PW Consulting Dashboard Camera Market report for executable playbooks, vendor scorecards, and the granular forecasts needed to build FY-2027 budgets and capex plans.
PW Consulting’s 2026 market intelligence is designed to move you from insight to action. The macro trajectory — sustained mid-single-digit-to-high single-digit CAGR through 2032 — creates meaningful upside, but translating that growth into sustainable profits will require explicit choices around product architecture, channel economics, and data ownership. Our full report supplies the segmented data and operational tools your team needs to make and implement those choices with confidence.
For detailed analysis of this topic, please visit the official page: Dashboard Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


