



Category: market research
PW Consulting: Structural Steel Pipe Market to Reach USD 489.1M by 2032 at 3.45% CAGR
By PW Consulting, 2026-07-12
Structural Steel Pipe Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a focused, decision-oriented introduction to our Structural Steel Pipe Market study. This briefing translates the study’s macro findings into actionable strategy for executives who must make procurement, capital allocation, product, and M&A decisions in 2026. The full study contains granular datasets, company scorecards, and downloadable models — this article intentionally emphasizes strategic implications while withholding certain sub‑segment disclosures to encourage direct access to the complete intelligence package.
Structural Steel Pipe Market
Market at a Glance: What the Numbers Mean for 2026
The structural steel pipe market has demonstrated steady recovery and moderate growth through the post‑pandemic period, expanding from approximately USD 298.5 Million in 2020 to USD 386.5 Million in 2025. Our baseline forecast (2026–2032) models a compound annual growth rate (CAGR) of 3.45%, with the market expected to continue an upward trajectory through 2032 under the base scenario.
Structural Steel Pipe Market
Two immediate takeaways for 2026 planning:
Structural Steel Pipe Market
- Volume growth is material but not explosive — organizations must optimize margin and supply resilience rather than assume demand will absorb inefficiencies.
- Price and policy risk will drive margin volatility; procurement strategies and product mix decisions should prioritize flexibility and hedges.
Dynamics Shaping the Market This Year
Five interlocking dynamics define the operating environment in 2026:
- Policy and trade barriers: Elevated tariff regimes and enforcement actions have materially raised import risk and landed costs for finished pipe and key inputs. These policy settings are persistent enough that they need to be assumed in planning scenarios for 2026.
- Input-cost pressure: Scrap commodity prices remained firm into Q1 2026 (e.g., reported scrap at roughly USD 347/MT in China and USD 397/MT in India), raising upstream cost floors for domestic mills and import parity prices.
- Producer pricing behavior: Leading tubular producers have announced sequential price increases and extended lead times; market participants should plan for pass‑through cycles and shorter purchasing windows.
- Demand composition shift: End‑market demand is being influenced by infrastructure programs, energy‑sector capital intensity, and municipal waterworks, which favors certain product specifications and traceability requirements.
- Consolidation and concentration: Market concentration is moderate; the three‑player concentration band is below half the market, signaling room for regional leaders and niche specialists to protect margins through technical differentiation.
What This Means for 2026 Corporate Strategy
Executives should treat 2026 as a year to convert market stability into durable advantage. The modest CAGR masks pockets of higher growth and higher risk — and those pockets are where strategy should be focused. Below, we translate the market facts into five priority actions.
- Lock in critical feedstock and production capacity. With scrap prices elevated and domestic lead times extended, secure multi‑tier supply contracts and maintain buffer inventories for key grades. Negotiate indexed contracts with clear escalation mechanics tied to scrap and freight indices.
- Revise pricing architecture to reflect policy tailwinds. Tariff and import cost volatility requires dynamic pricing clauses and periodic reviews. Protect margins through value‑based pricing for certified, low‑embodied‑carbon products.
- Prioritize product and grade differentiation. High‑strength grades and certified low‑carbon offerings are emergent margin drivers; invest selectively in qualification and small‑batch production before scaling.
- Shift channel and logistic strategies. Shorter lead times and regional protectionism favor localized inventory hubs and near‑term supplier partnerships over long tail, global sourcing.
- Prepare for selective consolidation. Given market concentration dynamics and regional capacity imbalances, 2026 is a window for tuck‑in acquisitions to fill distribution gaps or to acquire specialty capacity with immediate commercial synergies.
Competitive Landscape — Players to Watch
The industry remains a mix of vertically integrated domestic mills, global tubular divisions, and regional ERW/ERW‑focused producers. Our report profiles leading firms and recent corporate actions that will influence competitive moves in 2026.
- Nucor (Charlotte, NC): As a vertically integrated EAF producer and a significant domestic supplier of hollow structural sections and tested pipe, Nucor’s dual advantage lies in feedstock integration and low‑embodied‑carbon certification. Recent pricing actions underscore its ability to influence domestic price benchmarks and set the commercial cadence for structural tubing.
- ArcelorMittal (Luxembourg City): A global tubular player with breadth across high‑strength and welded products. Strategic product launches — including newly commercialized high‑strength grades — can reshape specification choices for high‑value construction and infrastructure projects.
- United States Steel Corporation (Pittsburgh, PA): A major U.S. steelmaker supplying welded and structural pipe for construction and infrastructure; capacity and contract choices by such integrators will determine domestic availability and delivery reliability.
- California Steel Industries (Fontana, CA): A regional ERW producer focused on load‑bearing and low‑pressure applications — an example of how regional specialists can retain margin through service, lead time, and application expertise.
Recent corporate moves matter. Fast‑moving pricing adjustments by leading mills and extended lead times have already altered commercial relationships in early 2026. New product commercialization of higher‑strength welded grades is a technology axis that will reward early adopters in structural design and modular construction niches.
Report Deliverables: What PW Consulting Provides
The full PW Consulting Structural Steel Pipe Market report is designed as an operational tool, not an academic exercise. Key deliverables include:
- An integrated market model (2020–2032) with adjustable assumptions for tariff regimes, scrap prices, and infrastructure spend scenarios.
- Supplier heatmaps and a competitive scorecard evaluating capacity, carbon credentials, product breadth, and logistics performance.
- Price‑to‑cost waterfall templates and a plant‑level unit‑cost benchmarking suite suitable for diligence and procurement negotiations.
- Regulatory scenario playbooks that model the P&L and supply‑chain impact of tariff changes and permit timelines.
- A procurement playbook and a near‑term (90‑day) action checklist to stabilize supply and pricing exposure.
- Deal screens and an M&A target shortlist based on strategic fit and integration economics (note: detailed segment financials and target valuations are available in the premium dataset).
These outputs are accompanied by primary interviews, mill‑level capacity verification, and proprietary price tracking to ensure commercial relevance in 2026 negotiations.
Three Practical 90‑/180‑/360‑Day Moves for Leadership Teams
- 90 days — Defensive and Tactical: Execute indexed supply agreements for critical grades; implement rolling 8–12 week inventory buffers; activate commodity hedges where available; and review contractual pass‑through clauses.
- 180 days — Operational and Product Strategy: Qualify at least one high‑strength or low‑carbon supplier; pilot alternative material specifications that reduce mass without sacrificing code compliance; begin small‑scale retooling if market tests succeed.
- 360 days — Strategic and Portfolio Moves: Pursue M&A or JV options for regional footprint expansion; implement a cost‑to‑serve optimization across channels; and complete a long‑range capital plan that prioritizes flexibility and decarbonization.
Risk Matrix — What Could Upset the Base Case
Key downside shocks include sharp policy escalation, disruptive rises in freight or scrap that exceed our stress scenarios, or a demand slump in the oil & gas sector beyond current assumptions. Upside acceleration would be driven by accelerated infrastructure spending or broad adoption of higher‑specification, high‑strength grades that expand average selling prices.
Why PW Consulting’s Study Is Timely
2026 is a transitional year: protective trade policy, tighter scrap markets, and product‑grade innovations are converging to reshape where value is captured in the structural steel pipe value chain. Our study synthesizes these forces into a single planning toolkit that supports procurement tightening, product strategy, and corporate development decisions — delivering both the evidence base and the playbooks for execution.
Next Steps
If your team is preparing 2026 budgets, negotiating multi‑year supply contracts, or evaluating acquisition targets, the full PW Consulting report will provide the data, templates, and deal screens needed to move from deliberation to execution. The public briefing above outlines the strategic contours; the full subscription includes the proprietary datasets and executable templates referenced throughout.
Contact PW Consulting to arrange a briefing and gain access to the complete report, scenario models, and company scorecards that are essential for making high‑confidence decisions in 2026.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Loyalty Management Market to Reach USD 23.21B by 2032, 12.4% CAGR (PW Consulting)
By PW Consulting, 2026-07-12
Loyalty Management Market — Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high‑level orientation to our Loyalty Management Market research designed specifically to inform enterprise decisions in 2026. This market is no longer a peripheral CRM feature — it is a strategic revenue engine and a regulatory flashpoint. Our study uses a 2025 base year and delivers an actionable forecast across 2026–2032. At a glance, the market grew from USD 5.4 billion in 2020 to USD 10.25 billion in 2025 and is projected to reach USD 23.21 billion by 2032, reflecting a compound annual growth rate of 12.4% in the forecast window. The remainder of this briefing explains why those headline numbers matter, what practical choices they imply for leaders this year, and how our full report converts insight into execution without giving away the specific segment tables that will be available in the complete study.
Loyalty Management Market
Why the 2026 Inflection Matters
-
Market momentum meets regulatory pressure. Rapid adoption and enterprise spend are colliding with tightening privacy frameworks — notably new California requirements effective January 1, 2026, that force explicit Notices of Financial Incentive where loyalty programs exchange material terms and personal data, and ongoing GDPR obligations for transparency and Data Protection Impact Assessments. These rules change program design, consent flows, and vendor contracts in one discontinuous step.
Loyalty Management Market -
Value-centric consumer behaviour has hardened. Inflationary pressures and changing household budgets mean loyalty is increasingly about immediate, demonstrable value. Independent industry research in early 2026 shows a large majority of quick‑service diners prioritize cost savings when choosing brands — a structural shift that influences incentive design across industries.
Loyalty Management Market -
Technology and business model evolution accelerate ROI. API‑first, headless architectures, AI‑driven personalization, and tighter integration with CRM/ERP stacks are turning loyalty programs into measurable profit centers rather than just marketing line items. The forecast trajectory implies significant investment opportunities for both vendors and enterprise adopters over the next six years.
Key Market Dynamics — What Leaders Must Reconcile
-
Scale and concentration: the market demonstrates a moderate concentration profile; leading vendors command a meaningful share while a robust long tail of specialists and vertical players continues to innovate. For procurement teams, this means sourcing choices range from integrated enterprise suites to niche, sector‑specific engines — each with different TCO and governance implications.
-
Platform vs. composable models: buyers must choose between end‑to‑end platforms and modular, API‑based toolchains. The former reduces integration lift; the latter accelerates experimentation and supports faster time‑to‑value when combined with modern data stacks. Our research outlines the tradeoffs in implementation complexity, vendor lock‑in risk, and long‑term extensibility.
-
On‑premise, cloud, and hybrid deployment calculus: cloud adoption is increasing, but many large enterprises retain on‑premise or hybrid deployment requirements for control, compliance, or latency reasons. Architecture decisions now have direct commercial consequences for program agility and cost structure.
-
Data stewardship is table stakes: with new financial‑incentive notice requirements and GDPR DPIA expectations, loyalty program design must embed privacy and purpose limitation from day one. That affects data capture, segmentation logic, retention policies, and the way value is communicated to consumers.
What the PW Consulting Report Delivers — Practical, Actionable Assets
-
Market sizing and growth pathways: macro trajectories and scenario modelling that translate the 12.4% CAGR into investment buckets and expected payback periods across common program archetypes.
-
Decision frameworks: vendor selection scorecards, an RFP template tailored to 2026 compliance needs, and a TCO model that maps integration and operational costs across deployment patterns.
-
Implementation playbooks: step‑by‑step pilots for rapid validation (30–90 day pilots), playbooks for migrating legacy award systems, and a scaling blueprint that connects program KPIs to P&L levers.
-
Compliance and risk toolkit: a regulation checklist reflecting recent California consumer privacy updates and GDPR implications, consent and notice language examples, and a DPIA starter template for loyalty use cases.
-
Data & analytics recipes: customer lifecycle models, real‑time segmentation patterns, and practical guidance on using AI for propensity scoring without violating privacy constraints.
-
Vendor and competitive intelligence: assessed vendor profiles, comparative capabilities matrices, and case studies documenting recent platform partnerships and product updates. (Note: full vendor ratings and regional/vertical splits are reserved for the complete report to preserve the report’s proprietary value.)
Competitive Landscape — Players to Watch and Where They Fit
The loyalty technology ecosystem in 2026 combines global enterprise suites, specialized e‑commerce platforms, and vertical solutions. Leading enterprise vendors offer deep integration with CRM/ERP and broad features for large, data‑intensive programs. At the same time, specialist vendors excel in rapid deployment, lower TCO for SMBs, and vertical tailoring (e‑commerce, retail, QSR, agriculture, etc.).
-
Enterprise suites (examples): Companies that bundle loyalty with marketing clouds and CRM offer the fastest path to enterprise integration and centralized identity. They are best for organizations prioritizing unified customer record‑keeping and cross‑functional orchestration.
-
Omnichannel and retail specialists (examples): Vendors focused on retail and travel bring omnichannel program design, store integration, and workforce enablement — useful where in‑store redemption and POS integration are major requirements.
-
E‑commerce and D2C specialists (examples): Platforms optimized for online merchants emphasize plug‑and‑play setups, conversion optimization, and native integration with reviews, referrals, and UGC — valuable for rapid growth merchants.
-
Vertical innovators (examples): Sector‑specific players (including recent entrants with AI enhancements for agriculture retail and QSR) drive differentiated program mechanics and predictive insights tuned to unique buying patterns.
Notable recent developments in the ecosystem underscore these dynamics: platform partnerships that bring enterprise analytics into play, AI enhancements targeted at predictive loyalty outcomes, and vendor communications emphasizing privacy‑first design. These moves reflect vendor strategies to capture growth while responding to regulatory and consumer shifts.
Our report’s competitive analysis synthesizes these tactics into vendor fit maps and procurement checklists. We also quantify market concentration to help buyers understand negotiating leverage: the top tier of vendors captures a substantial share of commercial activity, while the mid‑market is fragmented and active — creating opportunity for both consolidation and specialist differentiation.
A 2026 Decision Roadmap — Five Immediate Actions
-
Rapid diagnostic (0–30 days): benchmark current loyalty economics, identify immediate regulatory gaps, and map technical debt that would slow migration or expose data risk.
-
Pilot design (30–90 days): structure a hypothesis‑driven pilot that tests value propositions aligned with current consumer motivators (e.g., immediate savings, experiential rewards), includes a privacy‑by‑design consent path, and uses measurable uplift metrics.
-
Vendor shortlisting (60–120 days): apply our RFP template and scorecard to reduce vendor risk — prioritize clarity on data ownership, portability, integration cost, and compliance support.
-
Scale and governance (3–12 months): define a governance model that assigns data stewardship, ROI accountability, and compliance ownership; deploy a phased rollout plan that allows rapid iteration.
-
Measure and iterate (ongoing): use tight KPIs (acquisition cost, redemption velocity, incremental margin, churn delta) and link them back to program levers identified in the report’s ROI models.
Final Word — Why Read the Full Report?
The Loyalty Management Market is simultaneously an opportunity and a compliance challenge. Our research converts the headline growth — from USD 10.25 billion in 2025 to a projected USD 23.21 billion by 2032 at a 12.4% CAGR — into concrete decisions: which architectures to prefer, how to price and design incentives under new privacy regimes, and how to select vendors that balance scale with specialization. The executive summary available here outlines the strategic playbook; the full report contains the actionable work products, vendor scorecards, detailed regional and vertical breakdowns, and downloadable templates that procurement, legal, and product teams will use to implement change in 2026.
To move from insight to execution, organizations should focus on defensible data governance, incentive economics aligned with consumer value expectations, and an implementation approach that reduces time‑to‑value while maintaining regulatory compliance. PW Consulting’s full Loyalty Management Market report equips you to do precisely that — and to justify investments with scenarios, ROI models, and a vendor roadmap tailored to your organization’s risk profile and growth ambitions.
For detailed analysis of this topic, please visit the official page: Loyalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nitrocellulose Market — Strategic Brief for 2026 Decision‑Makers
Executive snapshot
By the end of the 2025 base year, the global nitrocellulose market had recovered from pandemic-era disruption and structural raw‑material shocks, reaching an estimated USD 1,030 Million in annual revenue. Our model projects a steady acceleration through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of approximately 5.0%, taking the market toward the USD 1.45 Billion range by 2032. This trajectory captures the interplay of steady end‑use demand in coatings, inks and speciality finishes, episodic defence procurement, and increasingly volatile upstream feedstock dynamics.
Nitrocellulose Market
Why 2026 is a pivotal year
-
Price and input shock normalization vs. structural reset: 2024–2025 saw sharp input cost movements (notably cotton linter shortages) that materially raised production costs and forced a series of price pass‑through actions among major converters. While some price pressure is cyclical, our scenarios show a new baseline cost structure that buyers and producers must adopt in 2026 planning cycles.
Nitrocellulose Market -
Geopolitics and defence demand are reshaping supply priorities: Reallocation of capacity toward defence and energetic applications — along with strategic acquisitions to secure feedstock — has created localized shortfalls for industrial grades in several jurisdictions. Procurement teams should expect intermittent tightness in at‑risk supply corridors.
Nitrocellulose Market -
Regulatory and safety testing expectations have hardened: Stability and classification testing (including established methods accepted by global authorities) now factor into sourcing and certification timelines. Compliance lead times must be built into supplier qualification programs.
-
Market concentration with room for disruption: The market remains moderately concentrated (CR3 ≈ 40%, CR5 ≈ 55%), which creates both risk—through supplier bottlenecks—and opportunity, as well‑capitalized players execute capacity expansions and M&A to capture premium segments.
Key market dynamics you must plan for in 2026
-
Raw material sensitivity: Even single‑digit percentage swings in cotton linter availability translate into outsized margin impacts across the value chain. Our sensitivity matrices in the full report quantify break‑points where suppliers will either absorb costs, pass them to customers, or curtail volumes.
-
Pricing volatility: Across 2025, we observed double‑digit month‑over‑month spikes in some regional price benchmarks and very large year‑over‑year increases in other markets. That volatility is likely to persist into 2026 in the absence of coordinated inventory and sourcing strategies.
-
Segmentation nuance matters: Demand drivers and margin structures differ sharply between industrial lacquers, printing inks, nail and cosmetic finishes, and energetic grades. Tactical choices—e.g., prioritizing industrial customers versus defense contracts—will materially affect supply risk exposure and working capital requirements.
-
Sustainability and certification as commercial differentiators: Buyers increasingly require suppliers to demonstrate lifecycle credentials. Recent certifications by leading producers are already being used as commercial leverage in contract negotiations.
What PW Consulting’s Nitrocellulose Market Report delivers (practical, actionable modules)
-
Integrated market model: a calibrated, year‑by‑year demand and supply model spanning 2020–2032, with scenario toggles for raw‑material shocks, defence procurement surges, and regulatory constraints. (Note: granular region/application line items are included in the report; this brief intentionally omits those splits.)
-
Price sensitivity toolkit: breakpoint analyses and pass‑through thresholds tailored for procurement and commercial teams; ready‑to‑use negotiation playbooks indexed to supplier archetypes.
-
Supplier risk matrix: quantified exposure scores for capacity, geographic concentration, raw‑material sourcing and compliance lead times, enabling rapid short‑listing of alternative suppliers.
-
M&A and capex playbook: prioritized target profiles, valuation multiples observed in recent transactions, and a risk‑adjusted return model for greenfield vs. bolt‑on expansion — built for C‑suite decision scenarios in 2026.
-
Regulatory and safety roadmap: implications of current classification and testing standards for lead times, on‑boarding and cost of goods, with recommended compliance checkpoints for procurement and quality departments.
-
Sustainability monetization guide: how to translate certifications and lifecycle claims into commercial premiums and preferred supplier status with large customers.
Competitive landscape — who matters and why
The supply map is global and heterogeneous, mixing specialist producers with converters and diversified chemical houses. The following firms are strategically important either because of capacity, vertical integration, geographic reach, or recent strategic moves:
-
Nitrocellulose Group (Thailand) — A large regional producer with industrial product forms serving inks and coatings; notable for manufacturing scale in Asia and for being a reliable regional supplier for converters seeking stable granular and fibrous grades.
-
GRN Cellulose Pvt. Ltd. (India) — A vertically capable producer with both powder and solution forms, active across paints, lacquers, inks and specialty applications. Their diversification across form‑factors makes them an attractive partner for formulators.
-
Companhia Nitro Quimica Brasileira (Brazil) — A global producer with modern facilities and a footprint that matters for Latin American supply resilience, particularly when northern hemisphere supply tightness emerges.
-
Rheinmetall NC GmbH (Germany) — Following the 2025 acquisition of a European incumbent, Rheinmetall’s NC operations are strategically positioned to service energetic and defence markets, and their move underscores defence‑led vertical consolidation.
-
Synthesia Nitrocellulose (Czech Republic) — A European energetic and industrial supplier that has expanded capacity after strategic restructuring; crucial where European buyers need proximate supply for propellants and industrial uses.
-
Major Chinese suppliers (multiple companies) — A cluster of manufacturers supplying film‑forming resins and industrial NC across coatings, inks and adhesives. These players drive cost competition at the global level and are key levers for buyers pursuing low‑cost sourcing.
-
Specialist converters and chemical partners (Europe, North America) — Firms that blend, formulate and add value (including sustainability credentials) to nitrocellulose products; they are often the price setters for finished goods and therefore focal points for downstream risk management.
Recent industry moves you cannot ignore (selected, directional)
-
Strategic acquisitions to secure supply: a notable defence‑oriented acquisition completed in 2025 underscores how state and defence procurement priorities can reallocate capacity away from industrial markets.
-
Input cost pass‑throughs: major global converters have applied price increases on nitrocellulose‑containing products in 2025/26 cycles, reflecting persistent upstream cost inflation and forcing commercial teams to reassess pricing governance.
-
Supply additions tied to defence: announcements of production commencements in Europe to solve artillery and propellant demand point to segmented capacity that may not be fungible for industrial buyers.
-
Sustainability certifications as a competitive lever: recent certifications obtained by select producers are already being used to win preferred supplier status with formulators and brands prioritizing lifecycle footprints.
Strategic implications and recommended 90‑ to 180‑day moves for 2026
-
Update procurement playbook: embed our price‑sensitivity thresholds into contract templates, set indexed pricing clauses tied to agreed raw‑material baskets, and create rolling 90‑day supplier reviews for at‑risk categories.
-
Shortlist dual‑sourcing candidates: target a mix of regional and low‑cost suppliers to balance security and margin pressure; prioritize suppliers with validated certifications and acceptable compliance lead times.
-
Inventory and working‑capital triage: apply our scenario outputs to determine tactical safety stock levels for critical SKUs and build conditional release rules linked to price windows and supply signals.
-
Commercial renegotiation and cost‑to‑serve reviews: use the report’s cost breakdowns to reframe commercial conversations with converters, seeking longer notice periods for price moves and partial cost absorption mechanisms where strategic.
-
Capex and M&A screening for 2026: if your strategy involves vertical integration or securing feedstock, use our M&A playbook to prioritize assets with the best risk‑adjusted returns and the lowest regulatory friction.
How to use this brief and where to get the full intelligence
This brief synthesizes the strategic signals that should inform boardroom and procurement decisions in 2026. PW Consulting’s full Nitrocellulose Market Report contains the granular, transaction‑grade datasets, regional and application splits, supplier scorecards, and downloadable models you need to operationalize these recommendations. To preserve competitive value for clients, the complete section‑level figures and scenario model outputs are available only in the full report.
If your 2026 planning cycle requires hedged sourcing strategies, supplier reclassification, or M&A due diligence, the full report supplies ready‑to‑deploy templates and a calibrated market model. PW Consulting can also deliver executive workshops and bespoke scenario runs tailored to your exposure profile.
For detailed analysis of this topic, please visit the official page: Nitrocellulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Fused Alumina — 2025 market USD 200M; CAGR 4.01% (2026–32)
By PW Consulting, 2026-07-12
White Fused Alumina Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive teaser
As manufacturers and downstream users reposition for a manufacturing rebound and an inflection in raw materials dynamics, white fused alumina (WFA) is re-emerging as a strategic commodity. PW Consulting’s White Fused Alumina Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies this re-emergence and translates it into actionable decision frameworks for 2026. The global WFA market, measured in USD Million, expanded from approximately USD 150.0 Million in 2020 to USD 200.0 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of about 4.01% across our 2026–2032 forecast window, reaching roughly USD 263.3 Million by 2032.
White Fused Alumina Market
Why this matters in 2026
-
Annualized momentum: After multi-year recovery dynamics, 2026 represents a decision point — companies must translate medium-term demand certainty into supply-side commitments (contracts, capacity adjustments, and inventory strategies) that will lock in margins across a modest but steady growth trajectory.
White Fused Alumina Market -
Margin polarization across product grades: Purity-driven, specialty WFA (e.g., ultra-high Al2O3 for precision ceramics and technical polishing) differs materially in value proposition from cost-optimized grades targeted at mass abrasives and refractory linings. Strategic portfolio choices made in 2026 will determine whether firms capture premium segments or defend lower-margin volume.
White Fused Alumina Market -
Concentration & competitive dynamics: The market shows moderate concentration — the top three suppliers account for the low-to-mid thirty percent range, and the top five approach roughly half of global supply. This mix creates opportunities for both scale-driven competitors and niche specialists to shape regional and application-specific pricing and supply strategies.
What PW Consulting’s study delivers — practical, board-ready outputs
Our report is designed as an operational playbook for executives, procurement leaders, and corporate development teams. Highlights include:
-
Market sizing and validated forecasts: Annual market values from 2020 through 2032, with scenario-based outlooks that stress-test demand shocks and feedstock volatility. (Base year: 2025)
-
Supply-side architecture: Detailed mapping of production routes (electric-arc fusion of Bayer alumina, feedstock sensitivity, and furnacing profiles), plant-level capabilities, and capacity utilization frameworks to assess incremental expansion needs and timing.
-
Demand driver intelligence: A granular synthesis of end-market trends — refractories, abrasives, and ceramics — translated into purchase-behavior signals and procurement lead-time expectations.
-
Commercial frameworks: Go-to-market playbooks, price-elasticity models, contract templates (indexation recommendations, minimum take or pay guardrails), and negotiation levers to protect margin while securing volume through 2028.
-
Risk and resilience tools: Supply disruption matrices, geopolitical and trade-scenario stress tests, and hedging options for raw-material inputs and energy — with bespoke mitigation plans for critical nodes in the WFA value chain.
-
Transaction intelligence: A curated short-list of acquisition and partnership targets, valuation benchmarks, and synergy estimates to support inorganic growth or vertical integration plays.
-
Executive dashboards and KPIs: A ready-to-deploy set of metrics (e.g., realized ASP by grade band, purity-adjusted margins, furnace utilization, and time-to-fill) for weekly and monthly monitoring.
Competitive landscape — who matters and why
The WFA market features a mix of global branded manufacturers, national champions, and high-volume, cost-focused producers. Our analysis synthesizes capabilities across quality, scale, geographic reach, and customer intimacy.
-
Washington Mills (North Grafton, Massachusetts): A technology- and quality-led player noted for producing very high-purity WFA (>99% Al2O3). Their focus on engineered grains, powders, and bubbles via electric-arc fusion positions them to capture premium applications in advanced refractories and precision abrasives. For firms targeting performance differentiation, Washington Mills represents both a benchmark and a potential partner for co-development.
-
Imerys (Paris, France): Operating multiple production sites and offering branded fused alumina products under established portfolios, Imerys combines scale with global distribution. Their multi-site footprint supports customer continuity and shorter lead times in key industrial regions; they are a go-to supplier for customers seeking a balance of quality and geographic risk mitigation.
-
Rusal (Moscow, Russia): Vertical integration through alumina production and electric-arc fusion gives Rusal strategic control over feedstock and cost base. However, geopolitical and trade considerations create both risk and opportunity: buyers must weigh short‑term supply economics against long-term diversification and compliance strategies.
-
U.S. Electrofused Minerals (USEM) (Aliquippa, Pennsylvania): As a supplier in fused oxides, USEM competes on industrial-grade offerings and dependable supply to North American markets. Their value is strongest where localized, reliable logistics and technical support matter.
-
MOTIM Electrocorundum (Hungary): A specialist focused on high-quality corundum for refractories and abrasives. European and regional manufacturers targeting higher-purity product mixes will find MOTIM a credible technical partner.
-
Zhengzhou Yufa Group and Henan Ruishi Renewable Resources Group (China): Large-scale Chinese producers emphasize cost-efficient supply and high throughput. Their strategic advantage is price competitiveness and volume flexibility — a decisive factor for commoditized abrasive and refractory applications. Western buyers should consider a two-track sourcing approach that balances cost capture with supplier diversification and quality assurance.
Strategic implications and recommended 2026 actions
Based on the market trajectory and supplier dynamics documented in our study, PW Consulting recommends a set of prioritized actions for corporations planning for 2026 execution:
-
Segmentation-driven portfolio rationalization: Conduct a rapid review of product margins by grade and end-use. If your portfolio mixes across purity and volume-driven products, create clear routing rules for customers (premium SKUs via premium suppliers; commoditized volumes via cost-efficient partners).
-
Contract design & procurement cadence: Move from annual spot buying to hybrid contracts that combine a baseline of fixed-volume agreements with a smaller variable tranche indexed to observable raw-material or energy indices. This reduces exposure to furnace outages and energy-cost spikes while preserving upside participation.
-
Supply-risk hedging: Establish secondary-supplier relationships in at least two geographies to mitigate local disruption. Where possible, secure capacity commitments with manufacturers that have vertically integrated feedstock or a multi-site production model to reduce single-point-of-failure risk.
-
Premiumization & co-development: For firms targeting growth in technical ceramics and precision abrasives, prioritize co-development agreements with high-purity producers to secure early access to new grades and qualification pipelines.
-
M&A and JV scouting: With moderate market concentration and regional pockets of scale, 2026 remains an advantageous window to pursue bolt-on acquisitions or joint ventures that deliver immediate capacity, access to certified grades, or route-to-market expansion.
-
Sustainability roadmap: Energy intensity and raw-material traceability are emerging procurement requirements for many downstream customers. Begin supplier audits focused on energy sources, emissions per ton of WFA produced, and traceability of alumina feedstock to strengthen ESG credentials and defend price premia.
Data confidence and signal prioritization
Our base-year calibration uses 2025 as the reference point, with a five-year historical window (2020–2025) and scenario-driven forecasts through 2032. We apply triangulation across plant-level capacity, national trade flows, and downstream consumption models to arrive at our market totals and the 4.01% CAGR for 2026–2032. The report includes sensitivity ranges that capture feedstock shocks, energy-price volatility, and demand-side acceleration or deceleration.
What we are intentionally holding back — and why
In this preview we purposely omit drill‑down tables and exact split figures across regions, types, and applications. Those core segmentation datasets and customer-level consumption profiles are included in the full PW Consulting report and are essential for transaction diligence, competitive tendering, and procurement tender design. This teaser is intended to demonstrate analytical depth while encouraging stakeholders to access the full intelligence pack for operational implementation.
Next steps — how to use this intelligence in Q1–Q2 2026
-
Procurement leaders: Request the full dataset to run supplier-optimization models and to reprice contracts using our recommended indexation clauses.
-
Corporate development: Use our target shortlist and valuation benchmarks to prioritize M&A conversations and to run rapid synergy screens.
-
Operations and R&D: Engage with identified premium suppliers to scope co-development trials for specialty grades and to secure qualification timelines aligned with product roadmaps.
Final thought
The White Fused Alumina market is neither hyper-booming nor stagnant; it is maturing into a market where quality differentiation, supply resilience, and commercial sophistication will decide winners and losers. Companies that act in 2026 — by aligning procurement structures, securing multi-geography supply, and selectively investing in premium-grade capabilities — will lock in advantaged positions through the remainder of this decade.
For the full report, including regional and application splits, supplier scorecards, and downloadable dashboards, visit the PW Consulting White Fused Alumina Market page to obtain the complete intelligence kit and operational annexes.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Petroleum Needle Coke Market Poised for 6.7% CAGR Through 2032
By PW Consulting, 2026-07-12
Petroleum Needle Coke Market — Strategic Outlook for 2026 Decision-Making
Executive trailer
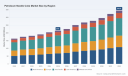
Petroleum needle coke (PNC) sits at the intersection of traditional refining economics and the fast-evolving carbon-materials chains that underpin modern electrification and steelmaking. Our newly completed PW Consulting study, using 2025 as the base year, tracks the market’s journey from historical dynamics (2020–2025) into a rigorous forecast window (2026–2032). The headline: the global market expanded from roughly USD 163.2 million in 2020 to USD 215.0 million in 2025, and is projected to grow at a 6.7% CAGR across 2026–2032, reaching an estimated USD 344.8 million by 2032. For corporate leaders planning investments, offtakes, or restructuring in 2026, this trajectory is both an opportunity and a call for disciplined strategy.
Petroleum Needle Coke Market
Why this study matters in 2026
-
Timing of demand inflection — The convergence of graphite-electrode replacement cycles and accelerating battery-anode capacity expansions creates a near-term window where securing high-quality PNC supply materially affects project economics for both incumbents and new entrants.
Petroleum Needle Coke Market -
Supply-side consolidation and concentration — The market shows meaningful concentration among a small number of integrated producers, shaping pricing power, contract structures, and capacity availability. Our work quantifies concentration and models realistic sourcing scenarios for 2026 procurement.
Petroleum Needle Coke Market -
Regulatory and feedstock uncertainty — Volatile crude and coal-tar derivative markets, combined with tightening environmental rules in several jurisdictions, add execution risk that must be stress-tested in every capital decision made in 2026.
Market trajectory — evidence you can act on
PW Consulting’s base-year analysis documents a steady post-pandemic recovery through 2025, with market value rising from USD 163.15 million in 2020 to USD 215.0 million in 2025. Our scenario-driven forecast then projects the market to continue expanding to USD 225.48 million in 2026, with intermediate milestones at approximately USD 296.4 million by 2030 and USD 344.8 million by 2032 under the central-case assumptions. A 6.7% compound annual growth rate across the forecast period encapsulates technical substitution, capacity additions, and policy-driven share shifts between feedstock routes.
Demand drivers and application dynamics
-
Graphite electrodes remain the backbone of near-term demand, driven by steel industry cycles and capacity rationalization in certain regions. The timing of restocking and electrode replacement schedules creates demand spikes that are highly lumpy and geographically concentrated.
-
Battery anode markets represent the structural growth vector. While battery-grade demand is still a smaller share today, its growth rate outpaces traditional applications and requires higher specification feedstocks and consistent quality over long horizons.
Supply fundamentals and feedstock volatility
PNC supply is fundamentally linked to aromatic-rich refinery residues, predominantly FCC decant oil and other heavy aromatic streams. Price swings in crude, coal tar, and slurry oils propagate quickly into producers’ cost bases; our sensitivity modules quantify how a 10–20% shift in feedstock cost affects cash margins across different plant configurations. Additionally, capacity additions tend to follow investment cycles in delayed-coking and calcination assets — capital-intensive projects that carry long lead times and operating complexity.
Regulation, sustainability, and the low-carbon premium
-
Regulatory tightening in major producing regions has already manifested in material capacity attrition. Notably, environmental enforcement in China led to substantive closures and output restrictions across graphite electrode facilities, creating short-term supply tightness and regional price divergence.
-
At the same time, evolving carbon accounting frameworks in the EU and customer procurement policies in downstream battery and specialty carbon markets are beginning to favor lower life-cycle-emission PNC routes (e.g., petroleum-based vs. coal-based). This creates a bifurcation: product quality remains important, but carbon-intensity profiles are rapidly becoming a second-order commercial requirement.
-
Our report includes an LCA-comparison framework and an EU-alignment heatmap to help buyers and producers quantify the commercial value of low-carbon certification in 2026 contracting rounds.
Competitive landscape — who matters and why
The market is dominated by a handful of integrated and regionally-specialized players whose strategic moves materially shift supply balances. PW Consulting’s competitive chapter profiles leading producers and assesses their strategic postures, investment trajectories, and downstream relationships.
-
Phillips 66 Company (Houston, TX) — An integrated refiner with delayed-coking operations and electrode-grade supply capability. Recent strategic moves include a substantial capacity expansion investment in Louisiana announced in February 2025, aimed at capturing growth from battery-anode demand. They have also concluded long-term supply agreements with anode manufacturers, indicating a vertical-supply strategy that secures demand for expanded output.
-
GrafTech International Ltd. (Brooklyn Heights, OH) — A vertically integrated electrode and specialty-carbon supplier operating petroleum needle coke capacity. GrafTech’s 2025 launch of a lower-carbon “Eco Graphite” product signals the industry’s pivot toward differentiated, sustainability-linked offerings and reflects an R&D and feedstock-diversification approach that de-risks regulatory exposure.
-
ENEOS Corporation (Tokyo) , Seadrift Coke L.P. (Seadrift, TX) , Petrocokes Japan Ltd. (Tokyo) , C-Chem Co., Ltd. (Japan) , and Chinese Petroleum & Chemical Development Company (Taiwan) — These producers combine regional refinery integration with calcination capability or specialized pitch-processing. Their strategic relevance varies by product grade focus (electrode vs. battery) and regional access to feedstocks.
Recent strategic moves—what they reveal
-
Feb 2025: Phillips 66 announced a multi-hundred-million-dollar expansion to increase PNC capacity in Louisiana by approximately 40% — a move explicitly tied to EV battery supply chains.
-
Apr 2025: GrafTech introduced a product produced from a significant recycled-feedstock component, pre-positioning itself for low-CO2 steelmaking contracts and demonstrating how product differentiation can create pricing and offtake advantages.
-
Sep 2025: Phillips 66 signed a long-term supply agreement to support a 30,000 tpa graphite-anode plant in the U.S. — an example of buyers and suppliers seeking to lock-in bilateral arrangements to de-risk critical upstream supply for battery projects.
Strategic implications for 2026 — prioritized actions
-
Secure supply through diversified contracting: For battery-anode projects planned or under construction in 2026, obtain multi-year offtake arrangements with staggered volume and quality clauses. Use price collars and pass-through mechanisms tied to transparent feedstock indices to protect margins.
-
De-risk feedstock exposure: Buyers and producers should model blended-feed scenarios (FCC decant oil, heavy cycle oils, and recycled aromatics) to quantify quality tradeoffs and margin impacts under commodity stress.
-
Invest in qualification pathways: Battery-grade PNC requires rigorous qualification. Allocate resources in 2026 to accelerate lab-to-pilot qualification programs and secure early supply slots with suppliers that have calcination and carbonization capabilities.
-
Pursue low-carbon differentiation: Producers should evaluate retrofits or feedstock blends that reduce cradle-to-gate emissions and develop verifiable LCA dossiers — these can command a commercial premium in tenders and reduce regulatory friction.
-
Prepare scenario-based capital plans: Given the market’s 6.7% CAGR central case and the lumpy nature of demand spikes, treat new greenfield capacity as contingent on confirmed offtake and include modular/capex-light designs where possible.
-
Consider strategic M&A and partnerships: With market concentration favoring a small number of players, targeted acquisitions of feedstock-processing assets or joint ventures with electrode and anode makers can secure margins and reduce exposure to spot volatility.
What PW Consulting’s full report delivers (practical, executable content)
-
Detailed historical and forecast market-sizing (2020–2032) with scenario runs (base, downside, upside) and sensitivity to feedstock and regulatory shocks.
-
Proprietary supply-demand balance models with plant-level capacity, lead times, and utilization assumptions mapped to likely contractual outcomes.
-
Price and margin stress tests linking crude/coal tar/slurry oil dynamics to producer cashflows under different contractual structures.
-
Operator scorecards and supplier capability matrices to support procurement shortlists, including qualification timelines for battery-grade supply.
-
Regulatory risk matrices (China, EU, North America) and a carbon-footprint playbook to help buyers and sellers align capex and procurement strategy with emerging standards.
-
Commercial templates: term-sheet clauses, sample offtake agreements, and negotiation playbooks tailored for 2026 contracting.
How decision-makers should use this study in 2026
Executives should treat the report as both an intelligence brief and a transactional tool. Use the market-sizing and scenario modules to validate internal assumptions; use supplier scorecards to compress qualification timelines; and use the commercial templates to move from intent to executed contracts before mid-2026 when capacity commitments and supply reallocations will crystallize. For investors and M&A teams, our valuation appendices and comparable-transactions analysis provide the levers to translate operational risk into purchase-price adjustments.
Final note — the trailer promise
This article has outlined the strategic contours and actionable directions embedded in PW Consulting’s Petroleum Needle Coke Market study. We have demonstrated the macro trajectory, the major strategic levers, and the competitive moves shaping supply and demand. To preserve the value of our proprietary segment-level models, regional splits, and granular supplier data — the precise inputs that drive deal-level outcomes — those detailed tables, interactive dashboards, and model instances are available exclusively in the full report and via our client portal. For procurement teams, investors, and corporate strategists preparing decisions in 2026, accessing the full dataset and scenario workbooks is the critical next step.
Contact PW Consulting to request the full Petroleum Needle Coke Market report, access the interactive forecast model, or commission a tailored deep-dive aligned to your project timelines and risk appetite.
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Captioning & Subtitling Market to Hit USD 6,150M in 2025
By PW Consulting, 2026-07-12
Captioning and Subtitling Solutions Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
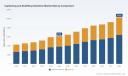
As organizations embed video into every customer, employee and compliance touchpoint, captioning and subtitling moved beyond an accessibility checkbox to become a mission-critical layer of content infrastructure. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps how this transformation is translating into measurable market growth and new buying imperatives. The global market expands from a multi-billion USD base in 2020 to an estimated USD 6,150 Million in 2025, and is forecast to continue on a steady compound annual growth trajectory (CAGR 7.84%) through 2032, when our model projects a market above USD 10 billion (Million USD units throughout).
Captioning and Subtitling Solutions Market
Why this research matters for 2026 strategic planning
- Timing of investment decisions: 2026 is the first full planning cycle after recent regulatory shifts and a visible acceleration of AI-driven live-capabilities. Boards and CIOs who commit to a clear captioning and subtitling strategy this year capture outsized operational and compliance value over the next six years.
- Vendor selection risk-reward: The market shows healthy growth but also distinct specialization: pure-play captioning services, AI-first platforms, and enterprise software suites are coexisting and competing. Choosing the wrong partner risks integration drag, audit exposure, or overspend on bespoke services.
- Operational leverage: Organizations that standardize on cloud-first, auditable captioning pipelines and embed human-in-the-loop QA where it matters will reduce long-run costs while improving accessibility and searchability of video assets.
Macro dynamics shaping the market
Three structural forces are driving the market dynamics that buyers must incorporate into 2026 budgets and vendor roadmaps:
Captioning and Subtitling Solutions Market
- Regulation and standards: Recent regulatory activity—most notably new closed-captioning accessibility rules affecting hardware manufacturers and multichannel programmers—has raised the compliance bar. The regulatory environment now emphasizes developer-accessible display settings and broader obligations for IP-delivered programming. Simultaneously, security and quality certifications (e.g., ISO frameworks) are being positioned as de facto prerequisites for enterprise procurement, particularly for sensitive education, government, and corporate content.
- Real-time AI + human hybrid models: Advances in speech recognition and neural machine translation have made real‑time captioning commercially viable at scale. However, accuracy expectations in broadcast, legal, and academic settings still demand human post-editing or supervised workflows. The winners will be those who operationalize hybrid models that balance latency, accuracy and cost.
- Platformization and verticalization: Buyers are asking for captioning to be embedded within broader media workflows—encoding, OTT publishing, LMS integration, and archival search—rather than treated as a bolt-on. At the same time, vertical-specific feature sets (e.g., verbatim legal transcription, curriculum-aligned subtitle mapping for education, or multi-language dubbing for entertainment) are differentiators in procurement decisions.
Competitive landscape — who matters and why
The competitive field combines specialized captioning houses, AI-driven transcription platforms, and major software/technology vendors. The market’s structure rewards both deep domain expertise and scale of platform reach. Key strategic observations from our vendor analysis:
Captioning and Subtitling Solutions Market
- Specialist live-caption providers (e.g., VITAC, Verbit, Ai‑Media): These firms lead on live and broadcast workflows, low-latency streaming integrations, and service models that mix AI with professional editing. Their strength lies in operational maturity for large-scale events and regulatory compliance for broadcasters.
- AI-native platforms (e.g., Otter.ai, Trint, Amberscript): These vendors excel at developer-friendly APIs, rapid transcription for enterprise use-cases, and scalable cloud deployments. Some emphasize data governance and certification as a procurement differentiator; others trade higher automation for lower per-minute costs.
- Broad media and tech incumbents (e.g., Adobe, Microsoft, IBM): Their advantage is ecosystem integration—captioning as a feature inside creative suites, communication platforms, or cloud AI services. They appeal to customers seeking single-vendor simplicity and deep analytics integration across content pipelines.
- Localization and post-production specialists (e.g., TransPerfect, ZOO Digital, 3Play Media): These players target subtitling, translation and international distribution workflows where linguistic accuracy and quality control are paramount.
- Niche innovators (e.g., SyncWords, AppTek): Focused on specific technical gaps—real-time multi-language live subtitles, voice dubbing, or advanced speech models—these vendors often become tactical partners for broadcasters or event platforms.
Our competitive chapter evaluates each vendor against operational criteria (real-time latency, accuracy/QA model, platform integrations, compliance posture, data governance, pricing transparency, and go-to-market motion). It also maps partnership opportunities—where incumbent broadcasters and OTT platforms can thin-slice vendor capabilities through alliances rather than acquisitions.
Regulatory and standards implications
Regulation is no longer a background risk; it is a leading driver of procurement. Recent rules requiring accessible caption display settings and the expansion of closed-captioning obligations to IP-delivered programming are changing technical spec sheets and RFP checklists. For government and education buyers, the demand for auditable workflows, retention policies and certification-compliant vendors is already influencing vendor shortlists. PW Consulting’s report includes a compliance impact matrix that translates regulatory requirements into technical acceptance criteria and procurement clauses.
Practically useful deliverables inside the full report
This market brief is a trailer. The full PW Consulting study is designed as a hands-on playbook for practitioners and includes:
- Market sizing and a seven-year forecast model (2026–2032) with scenario analyses to stress-test demand drivers under alternative regulatory and technology adoption curves.
- Vendor benchmark framework with scored profiles across technical capabilities, vertical strengths, security posture and commercial terms.
- Procurement toolkit: RFP templates, proof-of-concept (PoC) scripts for live and post workflows, SOW language to protect data privacy and SLAs, and comparative TCO models.
- Implementation blueprints: Integration patterns for common stacks (media asset management, LMS, OTT/CDN), latency optimization playbooks for live events, and QA workflows for hybrid AI/human models.
- M&A and partnership playbook: Valuation multipliers we observe in recent transactions, integration risk checklists, and recommended carve-outs for IP and model licensing.
- Case studies and vendor negotiation guidance that distill lessons from broadcast, education, enterprise and government deployments.
Actionable recommendations for 2026
- Adopt a modular architecture: Treat captioning/subtitling as a callable service (API-first) rather than a standalone vendor tie. This reduces lock-in and makes it easier to apply specialized services where necessary.
- Build hybrid workflows: Standardize on AI-driven first-pass captions, augment with human review only for high-risk content, and instrument quality gates to optimize cost vs. accuracy.
- Prioritize certified providers: For enterprise, education and government use-cases, procurement should require auditable security certifications and contractual commitments on data residency and retention.
- Negotiate outcome-based SLAs: Move beyond uptime clauses to include accuracy bands, latency maximums for live events, and remediation processes to reduce operational disputes.
- Plan for consolidation: Expect an active M&A environment as platform players seek to bolt on live captioning capabilities or as specialists seek scale; prepare data/integration due diligence templates now.
What we intentionally withhold in this preview
Consistent with PW Consulting’s “trailer” approach, this article shares directional insights and the strategic implications of the market’s growth trajectory. We have intentionally not published detailed segment-level tables, regional/application percentage splits, contract-level pricing benchmarks or vendor scorecards here. These proprietary datasets and granular segmentation outputs are available in the full report and underlying models—designed to support procurement negotiations, CapEx approval decks and M&A diligence.
Final note — how to use this intelligence
For senior executives and functional leaders preparing 2026 budgets, the core conclusion is straightforward: captioning and subtitling are transitioning from a compliance/afterthought cost center into a platform-level capability that can unlock reach, discoverability and legal risk mitigation. The market’s projected expansion through 2032 creates both urgency and opportunity—buyers who act with a clear architecture, risk-managed vendor mix and outcome-oriented contracts will realize measurable ROI. PW Consulting’s full study provides the models, vendor intelligence and playbooks to execute that agenda with confidence.
To access the complete segmentation tables, vendor benchmarking, scenario models and procurement toolkits, consult the full PW Consulting report and dataset on the Captioning and Subtitling Solutions Market page.
For detailed analysis of this topic, please visit the official page: Captioning and Subtitling Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diethanol Isopropanolamine (DEIPA) Market Set to Expand at 6.98% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Diethanol Isopropanolamine (DEIPA) Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing is designed to equip senior executives, corporate strategists, and investment committees with the high‑level, decision‑focused intelligence they need entering 2026. Drawing on our 2025 base‑year analysis and our proprietary forecast through 2032, this preview highlights the structural forces, competitive dynamics, and tactical implications that will determine who captures value in the DEIPA market over the next investment cycle. The full study contains the granular segmentation, regional allocations, and vendor scorecards that underpin the conclusions offered here; those detailed datasets are intentionally gated to preserve commercial sensitivity and to direct stakeholders to the full report for transaction‑grade inputs.
Diethanol Isopropanolamine (DEIPA) Market
Snapshot: Market Trajectory and Structural Signal
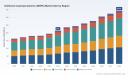
Our consolidated market sizing shows steady expansion over the 2020–2032 horizon. The DEIPA market grew from USD 163.15 Million (USD, Million unit) in 2020 to USD 215.0 Million in the 2025 base year, and our scenario‑validated forecast projects growth to approximately USD 344.8 Million by 2032. The compound annual growth rate (CAGR) implied across the forecast window is 6.98% — a pace that makes DEIPA a mid‑growth specialty chemical segment, attractive to both incumbent producers and adjacent chemical players seeking exposure to construction and performance‑chemicals demand chains.
Diethanol Isopropanolamine (DEIPA) Market
Why This Research Matters for 2026 Decisions
- Capital allocation and capacity planning: The mid‑single‑digit CAGR and predictable end‑market end‑use patterns warrant staged capacity investments and optioning rather than large upfront greenfield builds. Our analysis identifies where flexible, modular expansion will outperform single‑stage scale.
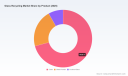
- M&A and partnership screening: A relatively low market concentration (CR3 ≈ 24.6, CR5 ≈ 26.2) signals a fragmented supply base — fertile ground for bolt‑on consolidation and route‑to‑market acquisitions, particularly for firms seeking to pair product portfolios with regional logistics footprints.
- Procurement and price risk management: Raw material volatility and tightening compliance costs mean purchasing strategies (fixed vs floating contracts, indexation, strategic stockpiles) materially affect margin. The report lays out hedging thresholds tied to feedstock price bands and utilization levels.
- Regulatory and sustainability roadmaps: Environmental compliance is a top‑line risk for manufacturers. Operators that invest early in emissions control and VOC mitigation technologies reduce both regulatory risk and future capex dislocation.
Key Market Dynamics Shaping 2026 Strategy
- Demand composition and end‑use resilience: DEIPA remains anchored in construction‑adjacent applications (cement grinding aids, concrete admixtures) while an increasing share of demand is linked to high‑value specialty applications. This demand mix produces a resilient base with episodic acceleration tied to infrastructure cycles and select industrial manufacturing ramps.
- Input cost volatility: The prices of core feedstocks for DEIPA — including isopropanolamine and diethanolamine — have shown periodic volatility linked to upstream energy markets and regional supply disruptions. Firms without disciplined input cost strategies experienced margin compression in 2024–2025; those with active procurement programs maintained spread.
- Regulatory tightening and compliance burden: Our industry outreach indicates increasing pressure in mature markets: over half of manufacturers report environmental compliance issues, with significant shares citing VOC restrictions and difficulty meeting emissions standards. These factors raise the effective cost of production, extend permitting cycles, and in some cases create practical barriers to new capacity.
- Fragmented supply base and specialization: The market structure favors small‑to‑mid sized regional producers and specialist formulators. Low concentration ratios mean national/regional champions can command premium routing advantages in logistics and customer service but lack the scale pricing power of large commodity players.
Competitive Landscape — Strategic Positions and Implications
Our competitive review concentrates on producers and distributors that shape customer choice, technology diffusion, and channel control. Below are strategic syntheses of the core players we evaluated (profiles in the full report include product grades, asset footprints, certifications, and supply‑agreement history):
Diethanol Isopropanolamine (DEIPA) Market
- Nanjing Hongbaoli Group Co., Ltd. (Nanjing, China): A vertically integrated manufacturer with a focused isopropanolamines series. Strengths include localized supply continuity for Chinese construction markets and integration into regional cement additive value chains. Strategic implication: attractive partner for off‑take agreements in Greater China but vulnerable to environmental capex requirements.
- Viswaat Chemicals Limited (India): Positioned as a cost‑competitive producer serving domestic and export construction chemical demand. Strengths include nimble production and existing trade relationships in South Asia; opportunity exists to move up the value chain through performance‑grade product development.
- Amines & Plasticizers Limited (Mumbai, India): One of the larger DEIPA producers in India with established supply to cement grinding aid markets. Strategic implication: potential consolidation target or strategic partner for players seeking scale in South and Southeast Asian markets.
- Bisley International LLC (Houston, USA): A prominent distributor with channel reach into North American industrial and construction segments. Value proposition centers on inventory service, technical support, and regulatory advisement — critical assets where upstream producers lack direct sales presence.
- Hebei InnoNew Material Technology Co., Ltd. and Shandong Inniolamine New Material (China): Both firms emphasize high‑purity DEIPA grades for performance‑critical applications. Their capabilities are strategically important for OEM customers and formulators requiring consistency and traceability.
Collectively, these participants demonstrate a market comprised of national champions, specialty producers, and channel specialists. The balance of bargaining power is situational — procurement teams with diversified supplier lists can command service and price concessions, whereas specialty end‑users depend on a small set of qualified suppliers for consistent quality.
Report Contents — Practical Deliverables
The full PW Consulting DEIPA study includes operationally actionable modules designed for 2026 decision cycles. Key deliverables include:
- Top‑down and bottom‑up market sizing (2020–2032) with scenario overlays and sensitivity bands tied to macroeconomic and construction indices.
- Demand drivers and elasticities by end‑use class, with prioritized use‑case maps for go‑to‑market planning (note: segment‑level tables and regional allocations are proprietary and available in the full report).
- Supply‑side cost models, including feedstock pass‑through mechanics, plant economics at different utilization levels, and margin levers by product grade.
- Regulatory risk matrix with jurisdictional hot spots, compliance capex estimates, and recommended mitigation levers for producers and downstream buyers.
- Vendor benchmarking and procurement due‑diligence checklists — tradeoffs between price, quality, lead time, and compliance.
- Playbooks for M&A screening, JV structuring, and off‑take negotiation templates calibrated to the market’s fragmentation profile.
How to Use This Intelligence in 2026
- For CEOs and corporate development: Use the market concentration and growth assumptions to prioritize inorganic growth in targeted regions or product grades. Pursue smaller, complementary assets that add technical capability and customer access rather than costly multinational platforms.
- For COO and supply chain leads: Implement dynamic purchasing frameworks tied to feedstock indices. Prioritize supplier redundancy in jurisdictions subject to regulatory tightening and build contingency warehousing for critical customers during permit or logistics disruptions.
- For R&D and product management: Invest in formulations and low‑VOC production methods that preempt likely regulation shifts in mature markets and that create differentiation for high‑value end uses.
- For investors and PE teams: Target bolt‑on acquisitions where operational improvement (procurement, quality systems, emissions control) can quickly unlock multiple expansion levers across a fragmented supplier base.
Risk and Scenario Considerations
- Upside scenario: Faster infrastructure spending and nearshoring of construction materials accelerate demand; producers with flexible capacity capture incremental margins.
- Downside scenario: Persistent feedstock price volatility and regulatory closures in mature markets depress capacity utilization and push marginal players to exit, creating short‑term supply squeezes.
- Mitigation levers: Contractual hedging, regulatory certification roadmaps, and strategic inventory layering are pragmatic defenses we recommend for 2026 operational planning.
Conclusion — The Strategic Imperative for 2026
DEIPA is a mid‑growth, structurally important specialty chemical with a clear nexus to construction and select industrial applications. The modestly aggressive CAGR and the fragmented competitive landscape create an environment where disciplined operators can outpace peers through focused product development, regulatory foresight, and targeted consolidation. In 2026, companies that align capital allocation to modular capacity, strengthen procurement governance, and proactively address environmental compliance will capture the outsized margins created by supply disruptions and premiumized product demand.
For transaction‑grade details — full segment breakdowns, regional tables, vendor scorecards, and the proprietary supply‑chain maps that support the recommendations above — please consult the full PW Consulting DEIPA Market report. The report contains the underlying datasets and executable tools necessary to convert these strategic insights into concrete 2026 actions.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Recycling Market to hit USD 5.88B by 2032 at 5.66% CAGR
By PW Consulting, 2026-07-12
Glass Recycling Market — Strategic Briefing for 2026: Why PW Consulting’s Analysis Matters
Executive snapshot
Between 2020 and 2025 the global glass recycling market more than doubled in headline valuation, expanding from approximately USD 2.05 Billion to USD 4.01 Billion (base year 2025). Our forecast through 2032 points to continued, steady expansion — reaching roughly USD 5.88 Billion by 2032 — representing a compound annual growth rate of 5.66% across the 2026–2032 forecast window. These topline dynamics reflect an ecosystem responding simultaneously to policy pressure, energy-and-cost imperatives, and fast-evolving industrial use-cases for recycled glass feedstock.
Glass Recycling Market
As PW Consulting’s lead industry analyst, I prepared this briefing to explain the practical decision-making value of our full Glass Recycling Market study for corporate leadership and investors making choices in 2026. Consider this a high-fidelity preview: we will show the analytical thinking and the risk/return frameworks you need to trust our work, while preserving the tactical segment-level data behind our paywall so that you are incentivized to access the full study for execution.
Glass Recycling Market
Why this report turns 2026 decisions from reactive to strategic
- Investment timing and sizing: The market’s transition from USD ~4.0B in 2025 toward an anticipated ~USD 5.9B in 2032 creates windows for entry, scale-up, and tuck-in acquisitions. Our modelling identifies where near-term capacity constraints and demand pulls create premium spreads for high-quality cullet — critical for capex prioritisation.
- Cost-to-carbon optimization: Each incremental increase in cullet content meaningfully lowers furnace energy consumption (industry evidence shows a near 3% furnace energy drop for every 10% increase in cullet in the batch). The report translates those process efficiencies into EBITDA and capital-return implications for glassmakers and recyclers.
- Regulatory compliance planning: New legislation and target-setting — for example, the Packaging and Packaging Waste Regulation that sets aggressive glass packaging recycling targets — materially alter demand for certified recycled feedstock and create compliance-driven procurement markets. Our scenario maps show timing, likely compliance costs, and procurement options.
- Supply chain and feedstock security: Infrastructure realities, such as the fact that a meaningful share of collected glass is not accepted at material recovery facilities when commingled in single-stream systems, drive a two-track strategy: invest in separations & logistics vs. vertical integration into collection and processing. We quantify trade-offs for both approaches.
- M&A and competitive positioning: The market is consolidating (our concentration metrics place the top three and five players as material influencers on pricing and standards). The full report includes acquisition scorecards and integration playbooks to turn M&A into value creation rather than replacement spending.
What the full report contains — pragmatic, transaction-ready tools
PW Consulting’s Glass Recycling Market study is deliberately practical. It is designed to be used by corporate strategy teams, investors conducting due diligence, operations leaders sizing facilities, and procurement teams negotiating long-term offtake. Below are the core deliverables included in the full study:
Glass Recycling Market
- Bottom-up market sizing and forecast models (2020–2032) that link collection, processing throughput, and end-market demand. The model is provided in an editable workbook so clients can test bespoke scenarios.
- Unit economics and plant-level benchmarks — energy, yields, capex/opex ranges, and payback profiles for common processing routes (municipal MRFs, dedicated glass sorting facilities, cullet beneficiation plants).
- Regulatory impact scenarios that overlay near-term (2026) to medium-term (2032) policy changes on demand and pricing. This includes stress-tests for rising recycled-content mandates and extended producer responsibility (EPR) frameworks.
- Supply-chain playbooks — design options for collection, inbound logistics, and quality control to raise acceptable cullet yields from mixed-stream systems.
- Commercial and go-to-market templates — offtake contracting strategies, indexation recommendations, and quality specifications to reduce basis risk between recyclers and glassmakers.
- Competitive database and M&A playbook — high-level dossiers on strategic participants, capability maps, and an acquisition screening tool calibrated to valuation multiples observed in the sector.
- Risk heatmaps and mitigation plans — covering feedstock availability, contamination, energy price shocks, and litigation/regulatory shifts.
Competitive landscape — who matters and why
The market is shaped by a mix of global miners/processors, glassmakers with closed-loop ambitions, and regional specialist processors. Strategic moves over 2024–2025 illustrate industry intent: capacity investments by independent recyclers, partnerships between glassmakers and recyclers to secure high-quality cullet, and consolidation among larger material suppliers seeking scale and geographic reach.
- Sibelco — a global materials supplier with an established recycling network and many facilities across North America. Their strategic posture is scale plus vertical integration; in late 2025 they completed an acquisition that expands their North American glass recycling footprint and strengthens procurement links into container and fiberglass supply chains.
- Owens-Illinois (O-I) — the container glass giant has operational programmes to increase recycled feedstock utilization and runs corporate recycling initiatives that both reduce scope and create PR/ESG value. Such programmes illustrate how manufacturers can combine procurement discipline with consumer-facing collection efforts.
- Vetropack and Ardagh Group — regional container manufacturers that are leaning into partnerships and localised cullet supply models to insure feedstock quality and reduce transportation intensity.
- Specialist processors (Momentum Recycling, Strategic Materials, and equivalents) — these players supply high-quality cullet and often operate closer to municipal collection systems. Their agility makes them attractive partners or targets for larger manufacturers seeking feedstock security.
- Notable greenfield and expansion signals: recent facility openings and partnerships demonstrate that growth capital is available for projects that meaningfully improve yield and quality — a key signal for investors and corporates assessing timing for brownfield upgrades vs. new builds.
Policy and infrastructure: near-term constraints and long-term tailwinds
Regulation is the accelerant. The recent Packaging and Packaging Waste Regulation sets demanding recycling targets, and several subnational jurisdictions (notably some U.S. states) are already legislating higher recycled content or incentives for recycled-material use. At the same time, structural infrastructure challenges — such as the limited acceptance of glass at many material recovery facilities when commingled — create near-term bottlenecks. These two forces together mean the market’s growth is both policy-driven and engineering-limited: solving the operational constraints unlocks a rapid value uplift.
In practical terms, this creates three actionable priorities for 2026:
- Accelerate pilots that address contamination and separation losses at the collection stage; the delta between collected glass and processed cullet is where immediate margin is created.
- Invest in higher-quality downstream processing where furnace-ready cullet commands premium pricing and reduces energy costs in smelting operations.
- Engage proactively with policymakers and industry coalitions to influence standards for recycled-content verification and logistics incentives — shaping regulation is as valuable as adapting to it.
How to use our study in 2026 planning cycles
Leaders who will make consequential choices in 2026 should view our report as an implementation toolkit rather than a passive desk reference. Use the study to:
- Run multi-scenario investment appraisals that combine plant-level unit economics with policy-triggered demand scenarios.
- Screen acquisition targets using our valuation framework and integration checklist, prioritising targets that close collection-to-process gaps and add furnace-ready cullet capacity.
- Design procurement contracts with built-in quality indices and pass-through mechanisms that align recycler and glassmaker incentives.
- Benchmark operations against a global dataset to identify 6–18 month improvements that materially lower processing costs and raise saleable yield.
- Build stakeholder narratives for investors and regulators that quantify carbon, cost, and circularity benefits from recycled glass adoption.
Final note: what you’ll find behind the paywall
This briefing demonstrates the depth and practical orientation of PW Consulting’s Glass Recycling Market study while adhering to our “trailer” principle: we intentionally withhold the report’s detailed regional, product and application-level splits and the granular financial tables. Those segmented datasets, the editable forecasting workbook, deal comparables, and the facility-level benchmarking dataset are available in the full report and are the elements that deliver execution-ready value to strategy, operations, and M&A teams in 2026.
If your organisation is contemplating capital allocation, partnership selection, or procurement strategies in glass recycling this year, the full study will convert high-level signals into executable roadmaps. Contact PW Consulting to obtain the complete dataset, scenario workbooks, and bespoke advisory support to accelerate your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Convenience Store Software to hit USD 251.2M by 2032 at 4.19% CAGR
By PW Consulting, 2026-07-12
Convenience Store Software Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As convenience retail operators confront accelerating margin pressure, evolving consumer expectations, and heavier regulatory burden, software decisions are moving from tactical IT projects to central commercial strategy. PW Consulting’s latest market study — anchored to a 2025 base year and a 2026–2032 forecast window — quantifies that shift and translates it into executable choices for 2026. The global Convenience Store Software market grew from USD 150 million in 2020 to USD 190 million in 2025 and, under current trajectories, is projected to approach roughly USD 251 million by 2032, representing a compound annual growth path consistent with a mid-single-digit expansion (4.19% CAGR for the forecast interval).
Convenience Store Software Market
Why this research matters to executive decision-makers in 2026
-
Timing maturation vs. disruption: The market is no longer nascent. A steady multi-year climb confirms the technology stack for convenience stores is transitioning from pilot-stage capabilities to enterprise-grade platforms. Strategic buyers must decide in 2026 whether to adopt now to capture operational leverage or to defer and risk integration penalties later.
Convenience Store Software Market -
Investment calibration: With a predictable market growth path through 2032, capital planning can shift from ad-hoc modernization budgets to phased digital roadmaps aligned with revenue uplift, cost-to-serve reductions, and compliance risk mitigation.
Convenience Store Software Market -
Vendor differentiation is sharpening: Our analysis shows a field of specialized suppliers and platform-scale incumbents competing on cloud enablement, AI-driven automation, and verticalized workflows (fuel, tobacco, foodservice). Procurement strategies must therefore weigh feature fit, integration cost, and operational change management rather than price alone.
Key market dynamics shaping 2026 choices
-
Cloud adoption and composable architectures: Cloud-first deployments are accelerating replacement cycles for legacy on-premises systems. For most operators, the cloud promises faster feature delivery, lower upfront capital, and simpler compliance updates — especially pertinent where fiscal/tax complexities are endemic.
-
AI and automation moving beyond experimentation: Labor shortages and high turnover in the c-store workforce are pushing operators to adopt AI for scheduling, demand forecasting, and frontline decision support. Expect 2026 to be the year where pilots scale into working controls that materially reduce shrink and labor cost volatility.
-
Regulatory and data-privacy friction: Rising regulatory complexity — from health-safety mandates to regional privacy regimes — is creating product and process requirements that bind vendor choices. Software that embeds compliance-by-design will save operators substantial remediation costs.
-
Integration with fuel, loyalty, and foodservice ecosystems: Convenience stores are multi-proposition environments. Successful platforms are those that unify point-of-sale, inventory, loyalty, and fuel operations into coherent workflows, reducing reconciliation effort and improving basket-level analytics.
-
Moderate market concentration, active innovation: The landscape features both niche specialists and large retail-software providers. Competitive intensity is focused on ease of deployment, vertical feature sets, and partnership networks rather than pure price wars.
What the PW Consulting report delivers (practical, operational content)
-
Executive playbooks: Decision frameworks for selecting between cloud-first, hybrid, and legacy renewals mapped to operator size, site complexity, and risk appetite.
-
Vendor diagnostic and scorecards: Comparative assessments across product maturity, roadmap alignment, total cost of ownership (TCO) modeling, and integration readiness — with guided weighting templates you can reuse in vendor selection.
-
Implementation roadmaps: Phased migration timelines (pilot → regional rollout → enterprise) including realistic cutover windows, staging configurations for multi-site operators, and a catalog of common pitfalls and mitigations.
-
Operational KPIs and ROI levers: A focused set of metrics and short-run experiments that drive measurable improvements in shrink, labor productivity, and incremental sales from loyalty/foodservice upsell.
-
Compliance and data governance guide: Practical templates for privacy-impact assessments, vendor contract clauses for data residency, and employee training checklists tied to regulatory hot spots.
-
Scenario-based financial models: TCO and payback calculators that quantify choices across deployment types and integration complexity — designed for direct insertion into 2026 capex and operating budgets.
Note: In this preview we outline directions and strategic themes. The full report contains granular regional and application splits, vendor scorecards, and downloadable dashboards. We intentionally withhold those tables here to preserve the actionable exclusivity of the full dataset.
Competitive landscape — who to watch in 2026
The competitive field is defined by a mix of focused convenience retail specialists and broader retail-software incumbents. A short guided tour of representative players highlights how different strategies create differentiated value.
-
AccuPOS (US) — positions itself with c-store-tailored POS and inventory modules that appeal to smaller chains and franchise operators seeking rapid deployment and ease of use.
-
SSCS (US) — specialized in inventory accuracy and back-office controls; attractive to operators prioritizing shrink reduction and reconciliation automation.
-
PDI Technologies (US) — leverages deep fuel and back-office domain expertise to serve integrated fuel-and-convenience operations; differentiation stems from fuel-tax logic and retail accounting workflows.
-
POS Nation (US) — brings bundled POS-hardware solutions designed for rapid rollouts at scale where standardization and predictable support models matter.
-
ADD Systems (South Korea) — focused on wholesale inventory and logistics for fuel-centric convenience models, often chosen in regions where vertical integration matters.
-
DataMax (US) & CStorePro Inc. (US) — emphasize reporting, cloud POS, and operational analytics for chains that want quick insights without building internal BI teams.
-
SHENZHEN KEMAI (China) — competes on cost-effective POS hardware and integrated management suites in markets sensitive to price and speed of deployment.
-
Petrosoft (US), Paytronix (US), and GK Software (US) — represent adjacent value propositions: fuel/c-store operations, loyalty/customer engagement, and omnichannel retail systems respectively; each is extending into convenience retail via verticalized modules.
-
NCR Voyix (US), Oracle (US), and Toshiba Global Commerce Solutions (Japan) — global incumbents with enterprise-grade POS and ERP capabilities, attractive to the largest multi-national operators that require scale, SLAs, and global support networks.
-
Tote.ai (US) — notable for rapid innovation in AI-driven POS and kiosk solutions; recent strategic partnerships (announced in early 2026) highlight how AI-enabled front-end automation is moving into mainstream deployments.
Recent market activity underscores two dynamics in particular: (1) partnerships and pilots around AI POS and kiosks are graduating to commercial rollouts, and (2) trade-show demonstrations and provider roadmaps announced throughout 2025 are translating into 2026 procurement decisions. Operators should expect a wave of platform upgrades driven by both competitive necessity and regulatory demand.
Practical recommendations for 2026 strategy and execution
-
Prioritize compliance-first selections: Choose platforms that can demonstrably implement regional privacy and fiscal rules quickly. The cost of retrofitting compliance after deployment is typically higher than incremental premium paid at selection.
-
Adopt a phased modernization path: Start with pilot clusters that capture typical site complexity (fuel, foodservice, loyalty) to validate integration templates before broader rollouts.
-
Design integration around customer journeys: Ensure POS, loyalty, and inventory share a common data model; investments that improve “basket intelligence” yield disproportionately high ROI on marketing and assortment.
-
Factor in total cost and hidden switching costs: Evaluate vendors on migration tools, data migration support, and third-party ecosystem integrations rather than headline licensing fees alone.
-
Treat AI as operational augmentation: Automate routine tasks (scheduling, reorder triggers) first, and phase predictive models (demand forecasting, dynamic pricing) once data hygiene is proven.
-
Use procurement as a lever for partnerships: Negotiate pilot-to-rollout clauses, SLA-based payments, and performance incentives tied to measured shrink/lift impacts.
Methodology and confidence
PW Consulting’s study synthesizes historical market activity (2020–2025), primary interviews with operators, vendors, and systems integrators, quantitative vendor intelligence, and scenario-based forecasting across the 2026–2032 horizon. Our forecast incorporates rate-of-adoption assumptions validated against transaction-level metrics collected from operators across major markets. The resulting view balances near-term disruption risk with medium-term stabilization, reflecting a market that is large enough to matter to executive agendas but still fragmented enough to reward strategic clarity.
To preserve the commercial utility of the full dataset, this preview omits granular regional, type, and application splits — these are provided in interactive form in the full report along with downloadable vendor scorecards, implementation timelines, and TCO models.
Conclusion — the choice for 2026
For 2026, convenience store operators face a clear strategic fork: accelerate modernization now to capture operational uplift and competitive differentiation, or delay and accept higher future switching costs and regulatory exposure. PW Consulting’s research shows that, given a predictable growth trajectory and an increasingly capable vendor ecosystem, early movers who pair cloud-enabled platforms with disciplined integration and change management will realize the greatest economic upside through 2032.
For operators, investors, and solution providers preparing 2026 strategies, the full PW Consulting Convenience Store Software Market report provides the operational tools, vendor diagnostics, and scenario models needed to convert insight into measurable outcomes. Access the full findings and interactive datasets through PW Consulting’s report page to move from strategic intent to executable plans.
For detailed analysis of this topic, please visit the official page: Convenience Store Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Autoclaved Aerated Concrete (AAC) Market: Strategic Imperatives for 2026 — A Preview
Executive snapshot
Autoclaved Aerated Concrete (AAC) sits at an inflection point. Between 2020 and 2025 the global AAC market expanded steadily, rising from roughly USD 178.5 Million to USD 227.8 Million (base year 2025). Our forecast model projects continued momentum through the 2026–2032 horizon, with a compound annual growth rate of approximately 6.98%, driving the market to roughly USD 359.4 Million by 2032 under the base case. These macro dynamics — steady demand growth, evolving regulation, and supply-side stress — create a landscape where near-term choices (capex, supply agreements, product mixes) will materially affect total returns over the next five years.
Autoclaved Aerated Concrete (AAC) Market
Why this preview matters to executives in 2026
- Validate or challenge current investment plans: The market’s mid-single-digit CAGR supports growth-oriented capital allocation, but timing and geography of capacity additions will determine IRR.
- Price and margin protection: Input volatility — notably cement and lime — has already pressured margins episodically; procurement and hedging strategies are now strategic priorities.
- Regulatory-driven demand swings: Energy codes and low-carbon policies are materially shifting specification choices in construction procurement, accelerating adoption in some markets and creating adoption barriers in others.
- M&A and partnership decisions: Moderate-to-high concentration at the top tiers of the industry points to attractive consolidation opportunities — but value capture requires disciplined target screening.
What the full PW Consulting AAC Market Study delivers (practical, transaction-ready outputs)
The full report is designed for commercial leaders, corporate strategy teams, and private equity investors who need executable intelligence, not just descriptive statistics. Key deliverables include:
Autoclaved Aerated Concrete (AAC) Market
- Top-down and bottom-up market sizing with transparent assumptions (historical 2020–2025 calibration and 2026–2032 scenario funnels).
- Demand-driver heatmaps by policy, construction segment, and technology adoption curves to prioritize markets and product formats.
- Supply-side cost models that isolate the impact of cement, lime and supplementary inputs on manufacturing economics, with sensitivity testing for commodity shocks and carbon-pricing scenarios.
- Regulatory impact analysis (building codes, green certification requirements, waste and fly ash policies) translating compliance into unit demand and specification shifts.
- Competitor landscape and capability matrices to support buy/sell-side diligence, including plant-level capacity, licensing models, and route-to-market footprints.
- Deal origination playbook: acquisition screens, valuation multiples observed in comparable transactions, integration risk checklists and quick-win synergies.
- Commercial growth playbook: product bundling, channel partnerships, specification roadmaps for architects and developers, and pilot frameworks for modular construction strategies.
- Risk & resilience framework: supplier concentration analysis, procurement hedges, inventory strategies, and contingency playbooks for seasonal cement price spikes.
Competitive landscape — positioning and strategic takeaways
The market features an assortment of legacy manufacturers, regional champions, licensed-technology providers, and new entrants. A handful of established players account for a majority share at the top end of the market, creating a competitive environment where scale, technology access, and distribution reach matter.
Autoclaved Aerated Concrete (AAC) Market
- Legacy North American producers: Long-tenured manufacturers with deep project references and established distribution channels retain pricing power in their home markets. Their strengths are brand recognition, developer relationships, and operational know-how for blocks and panels.
- Technology licensors: Firms that offer production technology and licensing know-how enable rapid market entry for new plants while monetizing intellectual property. Licensing models reduce upfront capex for entrants but create a dependency on technology partners for process improvements.
- Regional scale players and recent capacity expansions: Recent capacity expansions and new product launches by regional producers have materially changed competitive dynamics in several markets. These moves create near-term pressure on utilization rates but also accelerate market education and specification adoption.
- Distributors and project-focused specialists: A cohort focused on distribution, system integration, and end-user support is expanding the product footprint into retrofit and modular construction segments — areas where specification and logistics add value beyond commodity pricing.
For dealmakers, the implication is clear: targets should be evaluated not only on current volumes, but on their channel access, specification credentials with architects/developers, and the flexibility of their manufacturing footprint to switch between blocks, panels and engineered elements.
Notable recent moves and what they signal
- Capacity expansion by a regional manufacturer completed in late 2024 doubled production capability at a strategic factory, demonstrating operators’ willingness to back demand growth with tangible asset investments.
- New product introductions from a cement producer in 2025 underline the convergence between raw-material suppliers and finished-product manufacturers — signaling vertical integration and product diversification as active strategic paths.
- New green-building regulations and building-code enforcement in several advanced markets are already influencing procurement committees to favor AAC for thermal performance and embodied-carbon considerations.
Material and regulatory dynamics that will shape 2026 decisions
Cement and lime remain the dominant input cost drivers for AAC production. Recent seasonal cement price surges and ongoing volatility have resulted in compressed margins for many producers, particularly where pass-through is delayed by procurement contracts. At the same time, policy levers — from fly ash substitution strategies in some jurisdictions to stricter energy codes in others — are reshaping the inputs mix and the lifecycle emissions profile of AAC.
- In markets where fly ash substitution is enabled, embodied-carbon reductions and raw-material cost relief can materially improve the business case for AAC adoption.
- Green building certification requirements and energy-code compliance (e.g., country-level thermal performance mandates) are increasing AAC specification wins in new construction and certain retrofits.
- Conversely, regions exposed to cement-supply shocks or logistical bottlenecks will see slower margin recovery unless producers adopt hedging, vertical integration, or alternative binders.
Strategic playbook for 2026 — recommended moves for executives
Based on our modelled scenarios and competitive analysis, PW Consulting recommends a tiered action plan for companies and investors entering or scaling in the AAC market in 2026:
- Immediate (0–12 months): Secure long-term raw-material contracts with indexed pricing clauses; prioritize small, high-impact pilots with developers to convert specification inertia into demonstrable performance cases; and run stress tests on working capital under commodity price swings.
- Near-term (12–36 months): Evaluate selective capacity additions aligned with regional demand signals; pursue licensing or JV arrangements to accelerate market entry where green codes are tightening; implement product modularization pilots that reduce onsite labor and logistics costs.
- Mid-term (36+ months): Consider M&A focused on acquiring channel access, specification leadership, or complementary product lines (e.g., engineered panels, lintels, floor/roof elements) to capture higher-margin system sales rather than only commodity blocks.
Decision-support tools included in the complete study
The full PW Consulting report equips decision-makers with practical tools: scenario-based valuation models, plant-level break-even calculators, a supplier-risk heatmap, and a prioritized list of intervention levers (procurement, product, policy engagement) with quantified impact on EBITDA under multiple commodity and policy scenarios.
Closing: what to expect if you act (and what you miss if you don’t)
For market participants who align strategy with the structural drivers highlighted in this preview — regulation, raw-material dynamics, and modular construction trends — the projected growth offers a clear runway for profitable expansion. Those who delay or treat AAC as a purely tactical product risk being outpaced by better-capitalized and more integrated competitors as specifications and supply chains tighten.
This preview is a strategic teaser: it demonstrates the depth of analysis and the practical tools PW Consulting provides, while reserving detailed segmentation, plant-level economics, and the full competitor scorecards for the comprehensive report. For executives preparing 2026 budgets, M&A pipelines, or procurement strategies, the full study will convert the high-level signals above into concrete, executable decisions.
Next steps
- Request the full report to access the granular segmentation models, regional demand curves, and downloadable valuation and scenario tools.
- Set up a 60–90 minute strategic briefing with our industry team to map these insights onto your specific portfolio or investment thesis.
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


