



Category: market research
PW Consulting: Modular Data Centers to Hit USD 109.88B by 2032 at 17.11% CAGR
By PW Consulting, 2026-07-12
Modular Data Centers Market: Strategic Imperatives for Enterprise Decisions in 2026
Executive snapshot
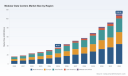
The modular data center market is entering a phase of accelerated maturation and strategic importance for enterprise IT and infrastructure planners. From a historical footprint that expanded from 16.51 Billion USD in 2020 to 36.37 Billion USD in the base year of 2025, our forecast shows continued rapid expansion through the 2026–2032 horizon—reaching 109.88 Billion USD by 2032 at a compound annual growth rate of 17.11% (revenue unit: Billion USD, currency: USD). For C-suite leaders and infrastructure decision-makers preparing 2026 budgets and roadmaps, this trajectory creates a set of discrete opportunities and measurable risks: speed-to-service, modular scalability for AI/HPC, supply-chain resilience, and regulatory and standards-driven compliance requirements.
Modular Data Centers Market
Why 2026 is an inflection point
- AI-driven demand intensity: The performance and density requirements of modern AI and HPC workloads are reshaping what “modular” must deliver—higher power density per rack, integrated liquid-cooling options, and factory-integrated IT stacks ready for rapid turn-up.
- Edge and distributed deployments: Enterprises and service providers are shifting from purely centralized builds to distributed modular footprints that reduce latency and expand availability while lowering time-to-market.
- Standards and safety converge: Recent updates to safety and performance frameworks (notably the revised UL 2755 outline for prefabricated modular systems) and community-driven standardization efforts such as Open Compute Project’s modular sub-project are creating clearer technical baselines—reducing vendor lock-in risk but increasing the compliance bar for providers.
- Commercial consolidation with room for niche leaders: Market concentration metrics show that the top three firms hold a meaningful share (~42.5% CR3) and the top five ~55.2% (CR5), signifying a landscape where scale matters but specialized capabilities and speed-to-market still create advantage for agile suppliers and system integrators.
- Supply-chain and construction economics: Prefabrication and factory-controlled fabrication reduce onsite labor and schedule risk in regions with constrained labor supply and logistics challenges—making modular deployments a preferred risk-managed route for many projects.
What PW Consulting’s Modular Data Centers Market study delivers
- Precision market sizing and a transparent forecast model (base year 2025; historical coverage 2020–2025; forecast 2026–2032) that incorporates demand drivers across cloud, colocation, edge, and enterprise segments.
- Practical decision frameworks for procurement, site selection, and vendor qualification that tie technical choices (cooling architecture, prefabrication level, power distribution topology) to financial KPIs.
- Vendor capability mapping and competitive scenario analysis—covering product roadmaps, integration risk, deployment velocity, and after-sales support models—structured to support RFP and pilot-selection processes.
- Regulatory and standards impact assessment (UL 2755:2025, OCP modular efforts) and a compliance checklist to accelerate approvals and insurance underwriting.
- TCO and ROI templates that model capex/opex trade-offs under different density, utilization, and energy-price scenarios—delivering an enterprise-grade view of breakeven horizons for modular versus traditional builds.
- A risk-adjusted route-to-deployment playbook that addresses supply-chain volatility, factory acceptance testing (FAT) best practices, and commissioning timelines for AI/HPC and edge workloads.
Note: The report contains granular segment-level data and proprietary split analyses that are not published in this prospectus. Access to the full dataset and interactive models is available via our research portal.
Modular Data Centers Market
Competitive landscape — strategic signals to watch
The modular market is being shaped by a mix of global infrastructure incumbents, systems integrators, and specialized modular fabricators. Strategic buyers should watch three broad vendor archetypes: scale integrators with end-to-end lifecycle services, engineering-centric suppliers with deep factory-prefab capabilities, and high-velocity providers focused on AI/edge time-to-service.
Modular Data Centers Market
- Vertiv (Lewisville, Texas) — Vertiv’s prefabricated modular solutions emphasize integrated power, cooling, and IT modules targeted at AI/HPC and high-density applications. Their modular megawatt-scale approach is designed for rapid scaling; enterprises targeting high-density clusters should evaluate Vertiv for turnkey performance and global service footprints.
- Schneider Electric (Boulogne-Billancourt, France) — Schneider’s EcoStruxure modular offerings prioritize adaptable designs for heterogeneous environments. Their strength lies in management integration and broad systems compatibility—an advantage for enterprises seeking a standardized control plane across multiple sites.
- ABB (Zurich, Switzerland) — ABB positions itself around modular, scalable solutions that accelerate colocation deployment and ROI. Their industrial automation expertise can be decisive where flexible power and distribution schemes are key to phased growth.
- Eaton (Dublin, Ireland) — Eaton’s SmartRack modular solutions marry rack-level integration with power and cooling enclosures. A recent product expansion (Jan 2026) in collaboration with Flexnode targeted rapid AI factory deployments, claiming significant compressions in deployment schedules—a strategic signal for buyers needing fast, validated rollouts.
- Flex (Sunnyvale, California) — Flex’s pre-engineered AI infrastructure platforms emphasize accelerated deployment timelines (vendor claims of up to ~30% faster delivery). Their strength is in manufacturing scale and integration velocity for compute, power, and cooling.
- Dell Technologies (Round Rock, Texas) — Dell’s modular approaches focus on modularized racks and integrated compute stacks for edge and high-density contexts, useful where vendor-managed compute and infrastructure lifecycle services are required.
- M.C. Dean (Alexandria, Virginia) — M.C. Dean brings specialized rack and overhead electrical configuration expertise and has strengthened its IP portfolio (patent issuance for a modular support rack system in mid-2026), making them an attractive partner for large campus or distributed installations with complex cabling and electrical requirements.
- Haskell Modular Solutions (Greenville, South Carolina) — Haskell’s factory-controlled fabrication model supports highly customized modular builds with predictable quality and shortened onsite schedules—an option for enterprises with bespoke site constraints.
Recent product and standards developments to factor into vendor selection
- Eaton’s January 2026 expansion (product collaboration with Flexnode) signals continued vendor focus on rapid AI deployment stacks and compressed schedule guarantees; buyers should insist on validated FAT outcomes and SLA-backed delivery timelines.
- Vertiv’s 2025 OneCore announcement highlights an industry trend toward modular architectures that scale from megawatt to hyperscale blocks optimized for AI/HPC; technical interoperability and cooling choices will define performance differentials.
- Siemens’ mid-2025 turnkey edge announcement underscores the growing marketplace for fully integrated, rapid-deployment edge modules suited to both permanent and interim operations.
- Regulatory and standards shifts (UL 2755:2025; OCP modular sub-project) are tightening the compliance envelope—enterprises should require vendor certification and third-party verification as part of procurement criteria.
Operational playbook for procurement and deployment in 2026
- Define workload-first requirements: quantify power-per-rack, expected scaling cadence, and service-level needs tied to application classes (AI training, inference, latency-sensitive edge services).
- Prioritize factory acceptance and modular integration testing: require FAT reports, documented thermal and acoustic performance, and validated interconnect tests for multi-module clusters.
- Embed standards and compliance clauses: ensure vendor commitments to current safety outlines and to any relevant OCP or interoperability frameworks.
- Contract for schedule and risk: include milestone-based payments, liquidated damages for deployment slippage, and options for phased scalability tied to business KPIs.
- Mitigate supply-chain volatility: diversify module suppliers for critical components, secure long-lead items under separate contracts, and evaluate local assembly hubs where lead times or logistics are constraining.
Financial considerations and TCO framing
With the market expanding at a high-teens CAGR and total addressable demand moving toward triple-digit billions by 2032, enterprises must reframe capital planning around modularity as a financial lever: faster time-to-service converts to earlier revenue capture or operational savings; factory-quality controls reduce rework and change-order risk; and standardized modules simplify long-term maintenance and part-procurement. Our report provides scenario-based TCO models that translate density, utilization, and energy-efficiency choices into payback timelines and NPV sensitivities—valuable inputs for 2026 capital allocation and site-portfolio strategies.
Key strategic questions for the C-suite in 2026
- Are we optimizing for speed-to-market (prefabricated/all-in-one modules) or for highest possible customization and futureproofing?
- How will our AI/HPC roadmap change rack-level power, cooling, and footprint requirements over the next 24–48 months?
- Do our procurement and contracting templates require updates to capture factory acceptance, interoperability certification, and regulatory compliance for modular systems?
- Which vendors align to our geographic, lifecycle, and service objectives—do we need vendor diversity to manage concentration risk?
- Have we stress-tested capital plans against the high-growth scenario reflected in market forecasts to 2032, and what is our phased investment trigger?
Conclusion: 2026 will be a year of decisive builds and strategic pilots. The modular data center market’s strong growth profile (17.11% CAGR across 2026–2032) and accelerating product innovation create an environment where early, well-structured decisions can materially alter an enterprise’s infrastructure cost curve and service agility. PW Consulting’s full Modular Data Centers Market report contains the segment-level insights, vendor scorecards, financial models, and procurement templates needed to convert the macro opportunity into executable 2026 programs. For access to the complete dataset, interactive models, and procurement playbooks, please refer to our research portal.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bike Racks Market — Strategic Outlook for 2026: A PW Consulting Brief
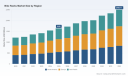
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a concise strategic introduction to our full Bike Racks Market research suite. The market has demonstrated steady, resilient growth through the first half of the decade — expanding from roughly USD 1.2 billion in 2020 to about USD 1.64 billion by the 2025 base year — and is forecast to continue this trajectory into the next planning horizon, reaching close to USD 2.5 billion by the end of the 2026–2032 forecast window at a compound annual growth rate of 6.2%. For corporate leaders preparing capital allocation, product roadmaps, or M&A strategies in 2026, this report crystallizes where value will appear and which operational and regulatory levers must be managed to capture it.
Bike Racks Market
Why this research is a must-read for 2026 strategic decisions
-
Market momentum is measurable and multifaceted. Growth is being driven by urban cycling infrastructure investments, accelerating adoption of e-bikes, shifting consumer preferences for active leisure, and continuing demand from vehicle-mounted transport solutions for both recreational and utility use.
Bike Racks Market -
Timing matters. 2026 is the inflection point for firms that must convert steady market growth into durable share gains. The next 18–24 months are the window for refining product portfolios, securing strategic partnerships, and locking in public procurement and OEM relationships to benefit from the mid-cycle upswing.
Bike Racks Market -
Risk and regulatory hygiene are non-negotiable. Recent safety campaigns and recall events have raised the bar for compliance and aftermarket support. Companies that anticipate these pressures and translate them into product design, quality assurance, and communication strategies will preserve brand equity and protect margins.
What the PW Consulting report delivers — practical, decision-ready content
-
Robust market sizing and demand models calibrated to 2020–2025 historical data and disaggregated forecasts for 2026–2032 — enabling financial planning and TAM/SAM/SOM exercises for new product launches and geographic expansion.
-
Go‑to‑market playbooks tailored to commercial (public/institutional), consumer aftermarket, and OEM channels — including pricing archetypes, margin ladders, and distribution economics.
-
Competitive benchmarking and capability maps that assess product portfolios, manufacturing footprint, distribution reach, and channel strategies for the leading suppliers in the space.
-
Supply chain and cost‑to‑serve analysis that identifies commodity exposure, single‑source vulnerabilities, nearshoring opportunities, and inventory strategies to preserve service levels during demand spikes.
-
Regulatory and standards navigator — practical checklists and testing roadmaps for compliance with dynamic safety and certification regimes (including authoritative vertical fatigue and dynamic testing standards), plus a mitigation playbook for recall scenarios.
-
Scenario-based strategic options and M&A target screens — from tuck‑ins that fill technical gaps (e.g., lightweight materials, e‑bike load systems) to roll‑up strategies in fragmented subsegments.
-
Actionable implementation roadmaps covering product R&D priorities, service & warranty frameworks, and five prioritized strategic initiatives for 12‑ and 36‑month horizons.
Competitive landscape — profile and strategic implications
The competitive set spans specialist commercial suppliers, consumer-oriented equipment brands, and vehicle-transport specialists. Key players include Madrax, RockyMounts, Dero, Thule, Kuat, Yakima, Saris, Hollywood Racks, North Shore Racks, Wagner Companies, Huntco, and SteadyRack. Each brings differentiated strengths:
-
Commercial parking and municipal-focused providers (examples: Madrax, Wagner Companies, Huntco) dominate infrastructure engagements with product lines engineered for durability, anti-theft features, and ease of installation across public works projects.
-
Aftermarket vehicle-mounted specialists (examples: Thule, Yakima, Kuat, RockyMounts, Saris, Hollywood Racks, North Shore Racks) compete on fit-for-vehicle integration, installation speed, and accessory ecosystems. Premium engineering and integrated locking/security features are primary purchase drivers for higher-margin segments.
-
Innovative niche suppliers (examples: Dero, SteadyRack) are expanding into adjacent installation and storage solutions, offering two-tier and space-saving systems targeted at multifamily, workplace, and institutional buyers.
Strategically, the market remains sufficiently fragmented that targeted product differentiation, channel prioritization, and service commitments can convert modest share gains into meaningful revenue growth. Firms with scale in manufacturing and distribution can still amplify returns by reducing lead times and increasing aftermarket revenue through accessories, spare parts, and maintenance contracts.
Regulation, safety and standards — risk and opportunity
-
Recall and safety events have been salient industry signals. Recent national safety campaigns and product recalls tied to latch mechanisms and pivot hardware have imposed direct costs on manufacturers and eroded consumer confidence for some brands. These events make robust validation programs and traceable supply chains essential corporate priorities.
-
Compliance with validated test standards — particularly vertical dynamic fatigue and related mechanical performance tests — is increasingly referenced in procurement specs and commercial tenders. Proactive certification is now a procurement prerequisite in many institutional contracts.
-
Regulatory scrutiny creates a competitive advantage for companies that can demonstrate superior test credentials, rigorous supplier audits, and rapid-response aftermarket service operations. Conversely, firms that deprioritize quality assurance risk product withdrawals, warranty liabilities, and reputational damage.
Market dynamics and product trends shaping 2026 decisions
-
E‑bike proliferation: Higher average bike mass and new battery‑carry requirements are reshaping product design criteria. Buyers increasingly demand racks and carriers explicitly rated for e‑bike loads as a baseline feature.
-
Vehicle electrification and range sensitivity: Lightweight materials and aerodynamic packaging for roof-mounted systems are more valued as EV adoption increases, influencing material and product engineering priorities.
-
Urban infrastructure funding: Local and regional grant programs (a recent example being school-route and community-safe-routes grants awarded in 2025–2026) are accelerating public procurement cycles for commercial bike parking — a predictable source of near-term volume for compliant suppliers.
-
Product innovation cadence: Leading consumer brands continue to iterate quickly (notably product launches and previews from major platform players), increasing emphasis on modularity, tool-free installation, and integrated security features.
Priority strategic moves for 2026
-
Certify for tomorrow, not yesterday: Prioritize conformance to recognized dynamic and fatigue standards across new product introductions and retrofit kits. This lowers bid rejection in institutional procurement and shortens sales cycles.
-
Design for e‑bike realities: Re-engineer hitch and roof platforms for higher static and dynamic loads, and offer clearly documented user instructions and compatibility guides to reduce misuse and liability.
-
Lock in public-sector flows: Build a targeted procurement funnel for grant-funded programs and municipal tenders. Establish pre-qualified vendor status and templated compliance packages to accelerate contract awards.
-
Service as a differentiator: Create bundled service agreements, spare-part programs, and rapid-response recalls remediation capabilities. These lift lifetime value and become a defensible moat against low-cost competitors.
-
M&A and partnerships: Pursue bolt-on acquisitions that bring complementary material technologies, testing capabilities, or commercial sales footprints. Consider strategic partnerships with vehicle OEMs and large rental fleets to secure recurring volumes.
-
Channel rebalancing: Accelerate direct-to-consumer channels for premium products while strengthening retail and installer networks to preserve reach for volume SKUs. Use data from DTC channels to inform product development and warranty provisioning.
How PW Consulting can accelerate your 2026 plan
Our full report contains the granular segmentation, competitive scorecards, price ladders, and regional go-to-market models that operational teams need to translate insights into execution. It also includes scenario-based cash-flow impact modeling for price and volume shocks, detailed supplier risk matrices, and M&A target prioritization lists aligned with five distinct corporate archetypes (market consolidator, technology consolidator, premium niche player, channel integrator, and full-spectrum incumbent).
If your 2026 planning cycle requires a data-driven roadmap — from product engineering and certification sequencing to channel economics and M&A due diligence — our full Bike Racks Market study provides the playbook and the primary-source verification to act with confidence. The executive summary above outlines the landscape and the levers; the full intelligence package contains the segmented market figures, competitive scorecards, and financial models you will need to finalize budgets and board-level recommendations.
Next steps
-
Download the full report to access the detailed segmentation, regional and application breakdowns, and executable 12–36 month implementation plans.
-
Engage PW Consulting for a tailored workshop: in 2–4 weeks we can map your product roadmap to the highest-probability growth corridors and deliver a prioritized action list for 2026 investment.
PW Consulting delivers research that informs decisive action. In a market growing predictably yet punctuated by regulatory and technological inflections, the difference between participation and leadership will be determined by who moves first to operationalize certification, e‑bike readiness, and service-based differentiation. Our full analysis equips leaders to do exactly that.
For detailed analysis of this topic, please visit the official page: Bike Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Leather Market to Reach USD 1,138 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
Leather Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive preview
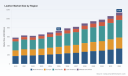
As companies set strategy for 2026, the leather sector sits at an inflection point. Our Leather Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies both the resilience and the disruption potential of the industry. The global market expanded from a mid‑single‑hundred million base in 2020 to roughly USD 732 million by 2025, and our model projects a compounded growth trajectory (CAGR) of approximately 6.5% through 2032—reaching just over USD 1.13 billion by the end of the forecast horizon. These headline dynamics underline a market that is neither static nor hyper‑consolidated: our concentration metrics show modest top‑player share (CR3 ≈ 24%, CR5 ≈ 28%), indicating ample room for scale plays, vertical integration, and niche premiumization.
Leather Market
Why this matters for 2026 corporate choices
- Regulatory timing is forcing capital choices: With major regulatory changes phasing in during 2026–2027, procurement, compliance and product development budgets will need reallocation now to avoid disruptive retrofits later.
- Growth is material but selective: A steady mid‑single‑digit CAGR creates attractive returns for firms that combine cost control with differentiated product and traceability propositions; undifferentiated commodity players will face margin pressure.
- Fragmentation creates opportunity: The relatively low concentration enables M&A roll‑ups and bolt‑on strategies for manufacturers and distributors seeking scale or route‑to‑market acceleration.
Market trajectory and structural drivers
Our bottom‑up forecast layers demand drivers—luxury and premium footwear/fashion resilience, automotive and furniture cyclical rebounds, and expanding specialty applications—against supply‑side constraints including raw hide availability, energy and chemical cost volatility, and tightening environmental compliance. The net is a steady market expansion path that rewards operational excellence and compliance readiness. Crucially, the growth is not uniform: premium, traceable, and compliance‑certified leather grows faster than blended or low‑trace commodity offerings. For this reason, strategic positioning—premium vs. scale commodity—will determine share and margin trajectories through 2026 and beyond.
Leather Market
Regulatory and trade dynamics altering the playing field
- EU Deforestation Regulation (EUDR): The inclusion of cattle hides and prepared leather within EUDR scope (effective December 2026) fundamentally raises the bar for origin proof and due‑diligence across EU supply chains. Companies selling into or sourcing through Europe must operationalize traceability now.
- OEKO‑TEX and voluntary standards: Industry standards are pre‑empting regulation by demanding delivery‑level provenance documentation from slaughterhouses and tanneries—compliance can become a market access enabler, not merely a cost.
- Chemical restrictions: Recent revisions to REACH‑style restrictions in major markets (effective June 1, 2026 in the U.S. federal notices) require immediate reassessment of finishing chemistries and supplier declarations.
- Standards and national policy moves: Draft standards consultations (e.g., India's BIS) and promotional programs are reshaping how sourcing and export promotion are managed in key producing countries.
- Trade volatility: Short‑term export slippage (e.g., a modest decline in U.S. leather exports in FY26) demonstrates how geopolitics and tariffs can affect near‑term revenue and channel strategies.
Competitive landscape — strategic implications from leading players
The sector features a diverse set of competitors ranging from artisanal tanneries to global brand manufacturers. Key archetypes and strategic takeaways:
Leather Market
- Artisanal premium tanneries (e.g., Horween Leather Company): These firms command premium pricing through provenance, craftsmanship and consistent product performance. Strategy implication: invest in brand partnerships and small‑batch traceable supply chains to capture high margin pockets.
- Brand‑led footwear and apparel manufacturers (e.g., Wolverine Worldwide): Brand owners control downstream margins and have the leverage to demand supplier compliance and innovation. Strategy implication: focus on supplier scorecards, long‑term contracts, and collaborative R&D to secure preferred supply.
- Traditional finished‑leather manufacturers (e.g., Weinheimer Leder): Technical tanning expertise and process control are their competitive moats. Strategy implication: upgrade process automation, chemical use optimization and energy efficiency to defend margins under regulatory pressure.
- D2C premium goods (e.g., Saddleback Leather Co.): Direct channels and lifetime warranty models illustrate premium durability plays. Strategy implication: brands can monetize storytelling about provenance, and after‑sales services can extend customer lifetime value.
- Contract furniture and upholstery specialists (e.g., American Leather Holdings): Custom, high‑value segments remain attractive for specialised suppliers with fast customization capabilities.
- Large emerging‑market manufacturers and exporters (e.g., A.V. Thomas, Bhartiya International): Scale, labor efficiency and export focus drive growth. Strategy implication: these players are positioned to capture volume growth but must compress compliance and traceability costs to maintain competitiveness.
Recent industry signals to watch in 2026
- Design and export fairs (e.g., major international leather fairs and talent showcases) are accelerating innovation diffusion and buyer‑seller matchmaking—use these as a live market‑testing channel for product pilots.
- Regulatory submissions and consultations indicate near‑term tightening; treat policy news as leading indicators rather than background noise.
- Industry promotional funding moves—public agencies reallocating budgets to market development—create windows for co‑funded expansion into select markets.
What the full PW Consulting Leather Market report delivers (practical, executive‑ready content)
We designed the report to be actionable for boardrooms and operating teams. Highlights include:
- Revenue and demand models (2020–2032) with scenario sensitivities and a 6.5% central CAGR;
- Segment and channel analyses with decision trees for premium vs. commodity strategies (note: detailed segment line items and regional/application splits are intentionally withheld here to preserve the report’s strategic value);
- Proprietary supplier risk matrix and a traceability checklist you can apply to Tier‑1 and Tier‑2 suppliers;
- Regulatory compliance playbook (EUDR, chemical restrictions, voluntary standards), including a one‑page executive checklist for procurement and legal teams;
- Commercial playbooks—pricing levers, SKU rationalization templates, and retail vs. D2C margin simulations;
- M&A and partnership framework—target screens and integration checklists tailored to acquire scale or capability (e.g., tanning tech, finishing chemistries, traceability platforms);
- Ten actionable near‑term moves and a 24‑month roadmap to operationalize traceability, reduce chemical risk, and capture premium price realization.
Immediate actions for 2026 planning cycles
To convert the market view into decisions this year, companies should prioritize the following:
- Compliance audit within 90 days: Map supplier documentation against EUDR and OEKO‑TEX requirements; implement corrective action plans for any documentation gaps.
- Traceability pilot: Deploy a focused chain‑of‑custody pilot with a core SKU or product family to test data capture, verification and cost impact.
- Re‑price for compliance: Run margin sensitivity analyses that incorporate incremental compliance and testing costs and reprice contracts where indexation is feasible.
- Supplier diversification and contracting: Secure multi‑source arrangements for critical hides and negotiate clauses for shared compliance investments.
- Capex prioritization: Delay non‑strategic brownfield expansion; prioritize investments in finishing processes that reduce chemical exposure and energy consumption.
Monitoring dashboard for leadership
Track these KPIs monthly to maintain strategic control:
- Raw material availability and unit cost variance;
- Traceability compliance rate across active SKUs;
- Regulatory exposure index (jurisdictions + product lines affected);
- EBITDA margin by product family (pre‑ and post‑compliance cost);
- Order book conversion from premium categories vs. commodity categories.
Closing perspective and next steps
The leather market in 2026 is a study in managed transition: stable headline growth and fragmented supply create both runway and pressure. Companies that treat compliance, traceability and product differentiation as strategic levers—not just cost centers—will capture disproportionate share as buyers and regulators raise the bar. The full PW Consulting Leather Market report contains the segmented intelligence, supplier lists, procurement templates and valuation playbooks you need to operationalize these insights; this introduction purposefully omits detailed sub‑segment tables to preserve the report’s utility for subscribers and clients.
To convert insight into action, senior teams should prioritize a rapid compliance audit, a traceability pilot, and a supplier contracting review in Q1–Q2 2026. PW Consulting stands ready to accelerate any of these workstreams with bespoke modeling, vendor due diligence, and M&A advisory support.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hemodialysis Concentrates Market to Reach USD 3,560M by 2032 — PW Consulting
By PW Consulting, 2026-07-12
Hemodialysis Concentrates Market — Strategic Outlook for 2026 Decision-Makers
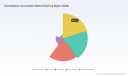
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our Hemodialysis Concentrates Market study designed to inform executive choices in 2026. The market reached an estimated USD 2,350 Million in our base year (2025) after steady expansion from 2020, and our scenario modelling projects it to reach roughly USD 3,560 Million by 2032, reflecting a compounded annual growth rate of 6.2% across the 2026–2032 forecast window. These headline figures frame the commercial context; the full study supplies the granular segmentation, scenario tables and playbooks necessary for executable strategies. This article highlights why that intelligence matters and how senior teams should use it without disclosing the detailed segment-level figures reserved for the full report.
Hemodialysis Concentrates Market
Why this research matters for 2026 strategies
- Triage capital allocation: The market’s mid-single-digit CAGR signals durable demand — yet pockets of higher growth and margin exist. The report helps prioritize R&D and manufacturing capex toward those pockets so investment returns exceed the market average.
- Mitigate regulatory and quality risk: Recent Class 2 recalls and amplified quality scrutiny have made regulatory readiness a competitive differentiator; the report includes a regulatory-risk heatmap and remediation playbook.
- Decompress supply-chain vulnerability: Material-cost volatility and single-sourcing risk for medical-grade inputs require structured hedging and supplier strategies; our procurement models quantify trade-offs between cost, resilience and lead-time.
- Inform M&A and partnership decisions: An industry structure with concentrated market shares among leading players creates specific opportunities for bolt-on acquisitions, capacity deals and strategic alliances — the study ranks targets and synergies by ROI horizon.
- Commercial strategy optimization: Pricing, reimbursement and channel mix differ materially by setting (clinic vs home dialysis). The report combines reimbursement mapping with price-elasticity scenarios to guide contract negotiations and tender strategies.
What the full report contains — operational modules for immediate use
- Transparent market architecture: Historical sizing (2020–2025), forecast scenarios (2026–2032), and sensitivity analyses built on demand drivers and supply constraints. High-level market numbers are presented here; granular regional, type and application splits are available in the full dataset to support market-entry and valuation work.
- Segment playbooks: Actionable strategies for acid vs bicarbonate concentrates, premixed vs dry formats and clinic vs home care deployment — each with product, pricing and channel recommendations tailored to execution in 12–36 month horizons.
- Competitive benchmarking: Detailed company profiles, capability matrices, and a 360° view of R&D, manufacturing footprint, regulatory posture and commercial reach for primary market participants.
- Manufacturing and cost modeling: A factory-level cost model calibrated to medical-grade materials, water purification costs, labour and compliance overheads — enabling build vs buy decisions.
- Regulatory & quality playbook: Practical steps to meet evolving device and chemical quality expectations, FDA engagement templates, and corrective action frameworks influenced by recent recall case studies.
- Supply-chain resilience matrix: Supplier concentration scoring, inventory policy optimisation and contingency sourcing pathways for critical inputs.
- Commercial and reimbursement templates: Tender response playbooks, hospital and homecare contracting guides, and KPI dashboards for post-deal integration.
- M&A and partnership screening: A prioritized list of inorganic targets and partnership archetypes aligned to strategic growth paths — from bolt-ons for manufacturing scale to technology tie-ups for digital/IoT-enabled concentrates.
Market dynamics shaping 2026 decisions
- End-user demand drivers: Demographic trends, CKD prevalence and expanded home-dialysis programs underpin structural demand. The net effect is steady volume growth coupled with rising interest in solution formats that simplify administration and reduce clinic burdens.
- Format innovation and product differentiation: Single-use bicarbonate cartridges and other pre-measured delivery systems are reducing point-of-care complexity and contamination risk. These innovations change buying criteria, switching costs and lifecycle economics for providers.
- Quality and regulatory pressure: Multiple FDA Class 2 device recalls in recent periods illustrate that quality lapses are financially and reputationally costly. Organizations with robust quality systems and rapid corrective-action capabilities gain negotiating leverage and lower recall exposure.
- Cost and input volatility: Medical-grade water systems, electrolytes and acid components remain exposed to supply-chain bottlenecks and regional infrastructure constraints. The report quantifies how these input cost swings translate into gross-margin sensitivity by production model.
- Consolidation and concentration: The market exhibits a high level of concentration among leading players, reinforcing scale advantages in manufacturing, distribution and regulatory compliance. Our competitive index shows the top-three players command a substantial share of the market, with the top five controlling an even larger portion — an important consideration for new entrants and suppliers.
- Reimbursement and procurement complexity: Payer policies and procurement practices vary by jurisdiction, affecting the total addressable revenues realized by manufacturers. The study’s reimbursement appendix decodes major markets and identifies pragmatic pathways to favorable contracting.
Competitive landscape — strategic positioning of core players
- Fresenius Medical Care (Bad Homburg, Germany): A mature global manufacturer with integrated product-and-service offerings, recently advancing digital integration through a unified platform that facilitates concentrate-device interoperability. Their scale supports robust regulatory and distribution capabilities, making them a benchmark for competitors and potential partner or acquirer targeting clinical channels.
- B. Braun Melsungen (Melsungen, Germany): Positions concentrates within broader dialysis systems, leveraging system-level bundling to protect margins and retention. Their integrated approach raises entry barriers for standalone concentrate vendors seeking to displace incumbent suppliers in integrated clinics.
- Nipro Corporation (Osaka, Japan): Focused on machine-compatible concentrates and a strong presence in APAC markets. Their technical compatibility with regional device standards and emphasis on manufacturing quality make them a resilient competitor in price-sensitive markets.
- Rockwell Medical (Wixom, Michigan, USA): Innovator in single-use cartridges and dry/sterile formats, actively commercializing new product types and maintaining visibility through prominent conferences. Recent product introductions and trade-show activity demonstrate a playbook centered on technical differentiation and specialty channel penetration.
- Renacon Pharma (Karachi, Pakistan), Farmasol (Kayseri, Turkey) and Pollet Medical Group (Belgium): These players illustrate regional and vertical-integration strategies: local production scale, niche formulations and acquisition-driven expansion. The 2025 acquisition of Farmasol by Pollet Medical Group exemplifies consolidation aimed at securing supply and manufacturing capacity.
What this means for corporate strategy in 2026 — recommended actions
- Prioritize quality systems now: Invest in pre-emptive validation and traceability protocols. The cost of doing so is significantly lower than the combined financial and commercial impact of a recall.
- Diversify supplier and manufacturing footprints: Reconfigure sourcing to reduce single-point risks for medical-grade water treatment and key electrolytes; consider small-scale localized production to service home-care growth corridors.
- Accelerate format-led R&D: Allocate R&D spend to formats that reduce clinic time and contamination risk (e.g., single-use bicarbonate cartridges), as these command premium pricing in tender processes focused on total cost of care.
- Negotiate integrated value propositions: Bundle concentrates with ancillary services or device connectivity to capture higher-margin, longer-duration contracts with dialysis providers.
- Use M&A strategically: Target acquisition candidates that provide manufacturing scale, regulatory dossiers or geographic access rather than solely top-line accretion; the market’s concentration amplifies the benefit of scale-aligned deals.
- Embed scenario planning in procurement and pricing: Deploy the report’s sensitivity matrices to stress-test commercial plans against recalls, raw-material shocks and reimbursement shifts.
How PW Consulting’s study supports boardroom decisions
- We convert market dynamics into actionable options: where to invest, where to partner, and what to divest — each tied to quantified revenue and margin outcomes under multiple regulatory and supply scenarios.
- Our deliverables include ready-to-use slides and financial models for investment committees and M&A teams, plus operational checklists for manufacturing and quality leaders.
- We provide a tailored decision map for three archetypal players — global OEMs, regional manufacturers and pure-play concentrate specialists — so you can adopt the competitive moves most relevant to your role in the value chain.
This briefing is a strategic extract designed to demonstrate the depth and applicability of the full Hemodialysis Concentrates Market study. The dataset behind our headline market sizing, the segmentation by region, type and application, the company-level revenue and performance matrices, and the scenario-specific models are intentionally retained in the complete report to preserve their proprietary value and to enable secure client-level licensing. For executives preparing investment decks, procurement negotiations, product roadmaps or M&A diligences in 2026, the full report supplies the granular evidence and executable templates to move from strategy to measurable outcomes.
Hemodialysis Concentrates Market
Contact PW Consulting through our research portal to access the full report, licensing options and tailored advisory packages that translate these insights into a 12–36 month execution plan aligned to your risk tolerance and strategic objectives.
Hemodialysis Concentrates Market
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automated Fingerprint Identification Systems (AFIS): Strategic Imperatives for 2026 — A PW Consulting Preview
As governments, border agencies, financial institutions and large enterprises reassess identity infrastructure in the wake of rising security needs and renewed investment cycles, AFIS remains central to identity assurance strategies. This preview distills the strategic value of PW Consulting’s forthcoming AFIS Market report — framed for C-suite and procurement leaders making decisions in 2026 — and highlights actionable themes while deliberately omitting the granular segment-level figures that sit behind our full analysis.
Automated Fingerprint Identification Systems (AFIS) Market
Why this analysis matters for 2026 decision-makers
-
Timing: 2026 is a pivot year. With the base year of our study set at 2025 and a forecast horizon to 2032, organizations launching procurements or platform migrations in 2026 must balance near-term operational needs with a multi‑year technology roadmap.
Automated Fingerprint Identification Systems (AFIS) Market -
Investment discipline: The AFIS market is growing at a steady compound annual growth rate (CAGR) of 7.5% in our forecast window. That growth rate implies meaningful technology refresh cycles and recurring procurement opportunities for both vendors and system integrators. Buyers who lock into immutable architectures risk higher switching costs mid‑cycle.
Automated Fingerprint Identification Systems (AFIS) Market -
Strategic trade-offs: Leaders must make three critical choices in 2026 — prioritize cloud-native scalability vs. on-premise control, invest in multimodal expansion (e.g., palmprint/latent support) vs. deepening fingerprint accuracy, and select vendors with demonstrated integration or certification pathways relevant to their use case.
Market trajectory — headline figures and interpretation
Our market sizing, presented in USD (Million), shows a consistent upward trajectory from the historical period through the forecast horizon. The market grew from a mid‑two‑hundreds base in 2020 to USD 348.0 Million in 2025 (base year). Projections extend to 2032, where AFIS revenues reach a substantially larger footprint under the modeled scenario. This expansion is underpinned by the 7.5% CAGR noted above and reflects both organic replacement cycles and new deployments across public and private sectors.
For executives, the implication is clear: procurement windows in 2026 will intersect with a market that is expanding but also consolidating around differentiated technology stacks and partnerships. Recognizing where the market is on this growth curve is essential to negotiation strategy, total cost of ownership (TCO) modeling, and risk assessment for multi‑year programs.
Drivers, inhibitors and near-term inflection points
-
Drivers: Rising cross‑border mobility and an emphasis on secure digital identities push demand for AFIS capabilities at borders and in law enforcement; financial and commercial adoption of strong biometric authentication adds incremental volumes; and a pivot to cloud and hybrid architectures elevates software and services revenue.
-
Technology accelerants: Advances in algorithmic matching, AI-enhanced latent print identification, and multi‑biometric fusion are improving match rates and operational throughput. These advances change the calculus for legacy vendors and create upgrade pathways for existing deployments.
-
Inhibitors: Data privacy regimes, procurement cycles, interoperability challenges with legacy enrollment databases, and capital constraints in certain public budgets can slow implementation. Cybersecurity and data sovereignty considerations will also shape whether agencies choose cloud, edge, or on-premise models.
-
Inflection points to watch in 2026: certifications and compliance milestones (e.g., national or international acceptance of new algorithmic standards), major national ID or border programs moving into procurement, and the emergence of cloud‑native ABIS/AFIS offerings reaching enterprise readiness.
Technology and product trends shaping supplier selection
-
Cloud-native vs. legacy: Cloud ABIS/AFIS options reduce time-to-deploy and improve horizontal scaling, but they introduce choices around data residency and latency. We advise a staged migration approach for centralized databases and a hybrid model for mission‑critical border operations.
-
Algorithm differentiation: Vendors now market algorithmic boosts (e.g., AI-enhanced matching and latent print capabilities) as a central differentiator. Procurement teams should request matched performance metrics on representative datasets rather than vendor-supplied claim sheets.
-
Hardware-software co‑development: FBI/National standards certified scanners and integrated livescan devices continue to matter. For high-volume sites, throughput and certification compatibility are as important as algorithmic quality.
-
Multimodal extension: Fingerprint systems that are architected to ingest palmprints, facial templates or latent traces offer better long‑term value. Vendors promoting modularity and API-first architectures reduce lock‑in risk.
Competitive landscape — what to look for among leading providers
The AFIS vendor ecosystem is a mix of long-standing incumbents and agile regional specialists. Market concentration metrics indicate that the top three vendors account for a substantial portion of global revenues, with the top five increasing that footprint further — a structure that favors established players but leaves room for niche and regional challengers. Key archetypes we focus on in our analysis include:
-
Global system integrators with deep law‑enforcement pedigree: Companies known for mature AFIS/ABIS platforms, strong algorithm portfolios, and long track records with national programs. These providers are often selected where certification and field-proven scalability are paramount.
-
Cloud and AI-first vendors: Providers emphasizing cloud-native ABIS platforms, elastic matching farms, and AI-enhanced latent identification. They appeal to financial institutions, large-scale civil registries, and agencies prioritizing rapid scaling.
-
Hardware-centric firms: Manufacturers that bundle certified livescan scanners, turnkey appliances and scanner‑software stacks. Their value lies in delivering end‑to‑end, certified solutions with predictable operational profiles.
-
Regional specialists: Local vendors that excel at meeting country‑specific compliance, language and operational needs. For many governments, these suppliers provide a pragmatic balance between capability and on‑the‑ground support.
Our competitive profiles examine, among others, the technical strengths and strategic positioning of major vendors active in AFIS: suppliers offering integrated AFIS/ABIS platforms with advanced matching engines; companies delivering cloud and AI-enhanced services for both public and private customers; firms focusing on certified scanner hardware and livescan management; and regional players advancing multimodal and forensic offerings. Each profile assesses product maturity, certification posture, go‑to‑market focus, partnership ecosystems and probable competitive moves through 2026.
What our full report delivers — operationally actionable intelligence
PW Consulting’s full AFIS Market report is built for practitioners and strategists. It combines quantitative market models, scenario-based forecasts and vendor due diligence into a toolkit you can use within procurement, product planning or corporate development. Highlights include:
-
A validated market model (base year 2025; forecast 2026–2032) that explains which demand pools and purchasing behaviors drive the topline and where growth premium is most likely to accrue.
-
Use-case driven buyer personas and decision frameworks to align requirements across security, privacy and IT stakeholders — helping to write informed RFPs and evaluation criteria.
-
A vendor assessment toolkit that synthesizes capability matrices, certification checklists and third-party validation steps — enabling faster, lower‑risk procurement cycles.
-
Migration playbooks for hybrid, cloud and on‑premise strategies — with phased TCO and integration risk considerations tailored for 2026 program timelines.
-
Scenario stress-tests covering regulatory shocks, major national ID projects and rapid adoption of AI latent‑matching to show upside and downside paths for market participants.
Note: In order to preserve the integrity of competitive positioning and to encourage dialogue with decision-makers, the full report retains detailed segment break‑outs by region, type and application — those granular datasets and strategic recommendations are available exclusively with the complete publication.
Actionable recommendations for executive teams in 2026
-
For buyers: Treat AFIS purchases as platform decisions, not product buys. Require API openness, roadmap guarantees for algorithm upgrades and clearly defined data residency commitments. Negotiate performance-based SLAs tied to matching accuracy and throughput.
-
For vendors: Differentiate on integration velocity and certification pathways. Cloud‑native offerings should emphasize secure hybrid deployment patterns and a clear migration route for legacy customers.
-
For investors and M&A teams: Look for targets with strong algorithm IP, proven government references and modular product architecture. Regional specialists with sticky public sector contracts can be consolidation candidates.
-
For systems integrators and consultancies: Build cross-domain competencies (biometrics, cybersecurity, data governance) and position as orchestration partners for multi-vendor deployments.
How to use this preview
Consider this article a strategic orientation guide ahead of procurement and planning sessions in 2026. Use the high‑level market trajectory, growth assumptions and strategic themes here to: align stakeholder priorities, benchmark RFP timing against market cycles, and identify which vendor archetypes to prioritize for deeper diligence.
For readers ready to move beyond the preview: PW Consulting’s full AFIS Market report provides the necessary datasets, supplier evaluations and implementation playbooks to operationalize a 2026‑era AFIS strategy. It is designed to be directly usable in vendor selection, negotiation and roadmap planning — while containing the granular segmentation and financial models that underpin the strategic recommendations presented above.
Contact PW Consulting to access the full report and a tailored briefing session to translate these insights into an executable 2026 plan for your organization.
For detailed analysis of this topic, please visit the official page: Automated Fingerprint Identification Systems (AFIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold Mix Asphalt Additives Market to Grow at 4.92% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Cold Mix Asphalt Additives Market — Strategic Preview for 2026 Decision-Makers
PW Consulting's new market study on Cold Mix Asphalt Additives positions this segment as a quietly strategic inflection point for materials suppliers, pavement contractors, public works agencies, and investors in 2026. This preview outlines the study’s practical value for near-term corporate decisions, highlights the structural forces reshaping the competitive landscape, and signals where executive teams should concentrate scarce attention and capital. To preserve the report’s commercial integrity this article demonstrates analytical depth while intentionally omitting the granular segment-level tables and region-by-application splits contained in the full report—visit PW Consulting’s Cold Mix Asphalt Additives research page for the complete dataset and vendor scorecards.
Cold Mix Asphalt Additives Market
Why this market matters in 2026
-
Performance meets policy: Cold mix solutions lower the technical and environmental barriers to asphalt rehabilitation, enabling pavement work outside narrow hot‑mix windows and in remote or low-infrastructure settings.
Cold Mix Asphalt Additives Market -
Macro growth with tactical implications: The market has grown steadily from the 2020 base through the 2025 reference year and is forecast to expand across the 2026–2032 horizon at a compound annual growth rate of 4.92% (forecast period). In absolute terms the sector’s scale moves from mid‑hundreds (USD Million, base year 2025) toward a materially larger market by 2032—enough to justify dedicated product lines, supply‑chain investments, and targeted M&A for companies with regional reach or specialty chemistries.
Cold Mix Asphalt Additives Market -
Fragmentation and the premium opportunity: Concentration metrics show a market that is neither a monopoly nor fully commoditized (CR3 ≈ 37.5%, CR5 ≈ 45.2%). This structure creates a two‑track playbook: incumbent suppliers must defend formulation IP and logistics while emerging players can capture premium bio-based or performance-differentiated niches.
What the PW Consulting study delivers (practical contents)
-
Actionable market sizing and near-term forecasts calibrated to a 2025 base year and the 2026–2032 projection window, with scenario sensitivity around raw‑material volatility and regulation-driven adoption curves.
-
Supply‑chain maps and cost‑to-serve models that quantify margin sensitivity to petrochemical feedstock swings, emulsifier availability, and packaging/logistics tradeoffs—tools that allow procurement and finance teams to stress‑test contracts under realistic commodity scenarios.
-
Go‑to‑market playbooks tailored to three corporate archetypes (global chemical majors, regional formulators, and specialized bio‑additive challengers). Each playbook includes channel strategies, sample pricing ladders, and proof‑of‑value messaging for municipal and contractor buyers.
-
Regulatory compliance and risk playbook aligned to multi‑jurisdictional standards (EU REACH, California Proposition 65 analogs, and core Commonwealth frameworks), including a stepwise testing roadmap and estimated time/cost to registration by market.
-
Technology scouting and product roadmaps that evaluate polymer‑modification, bio‑based chemistries, and carbon‑sequestering innovations against durability, workability, and lifecycle‑cost metrics used by municipalities and national agencies.
-
Vendor benchmarking and an M&A target shortlist based on technology fit, geographic coverage, and scalability. The report includes a confidential scoring matrix used by corporate development teams to prioritize diligence targets.
Market dynamics you must factor into 2026 planning
-
Energy and emissions calculus: Cold mix approaches deliver substantial operational benefits versus conventional hot‑mix processes—independent studies show ambient‑temperature application can reduce energy consumption by roughly 35–50% and lower emissions by approximately 40–60%. For organizations evaluating total cost of ownership and sustainability commitments, those reductions materially affect procurement decisions, grant eligibility, and eligibility for green infrastructure funds.
-
Raw‑material volatility: Petrochemical feedstock and crude price swings directly influence the cost base for emulsifiers, amine anti‑stripping agents, and petroleum‑derived adhesion promoters. The net effect is asymmetric risk for formulators with high oil‑based input intensity and limited hedging capability; companies with diversified feedstocks or bio‑based options face less margin stress.
-
Regulatory lift and friction: Green procurement mandates in Europe, North America, and Oceania create demand pull for low‑emission cold mixes—but statutory regimes like REACH and California Proposition 65 also raise non‑trivial compliance costs. Cross‑border product launches must now budget for toxicology dossiers and extended testing timelines, which can extend commercial rollouts by quarters and increase go‑to‑market costs for smaller innovators.
-
Price vs. preference premium for sustainability: Bio‑based alternatives command a market premium—roughly on the order of mid‑teens to low‑twenties percent—reflecting both higher input costs and willingness‑to‑pay by public project owners that prioritize lifecycle emissions. Capturing that premium requires validated EPDs, field performance data, and third‑party certification in many jurisdictions.
Technology and innovation themes
-
Polymer modification is mainstreaming: Polymer‑modified cold additives are improving viscosity control and moisture resistance, enabling higher reclaimed asphalt pavement (RAP) incorporation without sacrificing early strength.
-
Bio‑based formulations are moving from demo to deployment: Recent product launches demonstrate commercialized polymer‑modified, bio‑derived additive systems capable of high RAP content and reduced VOCs—an important proof point for procurement teams that must reconcile sustainability targets with durability requirements.
-
Carbon‑sequestration adjuncts: Novel additions such as biochar show potential to sequester CO₂ within pavements while maintaining traffic durability—opening an adjacent value stream for suppliers able to validate long‑term carbon permanence.
Competitive snapshot — what leading vendors are doing
-
Arkema SA (Courbevoie, France) — Arkema’s ColdGrip® portfolio targets adhesion and moisture resistance by displacing water and promoting bond strength in cold patch applications. Their approach combines applied polymer chemistry with adhesion promoters to extend field service life, which is persuasive for municipal maintenance crews focused on patch longevity. Arkema’s global footprint and application engineering capability make them a credible incumbent for large contracts that demand technical support and supply continuity. (See company resources: https://www.arkema.com)
-
Cargill (Minneapolis, MN, USA) — Cargill’s Anova cold mix additives emphasize polymer‑modified, bio‑based formulations enabling high RAP incorporation, low VOC profiles, and year‑round application flexibility. Their emphasis on bio‑sourcing and supply reliability aligns with government buyers seeking lower‑emission solutions without sacrificing constructability. Cargill’s move into polymer-modified bio‑additives reflects commodity players capturing more value by layering formulation expertise on raw material supply. (See company resources: https://www.cargill.com)
Recent market signals and what they imply
-
Product innovation is accelerating: In mid‑2025 multiple vendors announced new formulations—ranging from polymer‑enhanced bio‑based additives to biochar‑infused mixes that claim CO₂ sequestration. These launches indicate an emergent bifurcation: performance‑first solutions that prioritize durability and logistics, and sustainability‑first solutions that leverage higher‑value procurement channels.
-
Procurement is becoming prescriptive: Public agencies increasingly require documented lifecycle emissions and validated product performance data, which raises the bar for entrants. The combination of green procurement preferences and regulatory compliance obligations amplifies the advantage of vendors who can invest in testing and certification up front.
Strategic implications and recommended next steps for 2026
-
Secure formulation IP or partnerships now. With mid‑single digit market CAGR and growing public procurement incentives, owning a differentiated chemistry—or a reliable licensing channel—will separate margin makers from volume players.
-
Invest in regulatory readiness. Budget for REACH/Proposition‑65 style dossiers and accelerated field trials where you want to compete; the time to first contract is increasingly gated by third‑party validation, not just price.
-
Hedge feedstock risk and de‑commoditize inputs. Consider dual‑sourcing strategies and incremental adoption of bio‑derived intermediates to reduce exposure to crude oil volatility while preserving cost competitiveness.
-
Pursue a two‑track product portfolio: one line optimized for low cost and rapid availability for contractor networks; a parallel premium line with certified sustainability claims aimed at municipal and green‑infrastructure budgets.
-
Use the PW Consulting vendor scorecard and M&A shortlist to prioritize inorganic deals that either fill regional distribution gaps or bring complementary chemistries into the fold.
How to use the full PW Consulting study
Executives preparing 2026 budgets should use the report to stress‑test scenarios across three vectors: cost volatility, regulatory timelines, and procurement demand elasticity for sustainability attributes. The study’s practical tools—cost‑to‑serve models, regulatory checklists, product roadmaps, and a confidential vendor scoring matrix—are designed to convert market intelligence into investment decisions within 60–120 days.
This article provides a high‑resolution view of the forces and decisions that will shape the cold mix additives landscape in 2026. For the complete dataset, segmented forecasts, confidential vendor scorecards, and downloadable decision tools, consult the full PW Consulting Cold Mix Asphalt Additives Market report. PW Consulting’s proprietary appendices contain the granular regional and application splits and the underlying assumptions that corporate strategy, procurement, and M&A teams will require to finalize action plans.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Drug Market to Reach USD 6,831.9M by 2032 with 6.2% CAGR
By PW Consulting, 2026-07-12
Dental Drug Market 2026 — Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a succinct, actionable preview of our new Dental Drug Market study — a practitioner's guide for boards, corporate strategy teams, and private capital preparing decisions in 2026. Anchored on a 2025 base year and a robust 6.2% compound annual growth rate (CAGR) through the near-term forecast, this research translates macro momentum into decision levers you can operationalize today. The purpose of this preview is to outline the strategic value of the full report: we will demonstrate analytical depth and signal the most consequential implications for 2026 moves while intentionally withholding the granular segment tables and proprietary data sets to direct you to the full study for transaction-level intelligence.
Dental Drug Market
Why this study matters in 2026
-
Market scale and trajectory: The dental drug market reached a substantial scale in 2025 (base year) and is poised to expand at a mid-single-digit CAGR. That combination of size and steady growth makes the sector a target for both incremental product strategies and transformative M&A plays.
Dental Drug Market -
Strategic inflection points: Shifts in payer dynamics, regulatory cost structures, and concentrated supplier footprints are creating differentiated winners and losers. Timing and sequencing of investment — not just capability — will determine whether incumbents defend margins or new entrants capture share.
Dental Drug Market -
Decision urgency: For commercial leaders planning product launches, for supply-chain leaders sizing capacity, and for investors underwriting private deals, 2026 is a preparatory year: structural changes in pricing and regulation will begin to materialize in ways that affect IRR and time-to-market.
Core dynamics shaping 2026 strategy
-
Regulatory and payer pressure: The implementation of negotiated prices under new drug-pricing programs has begun to change the pricing baseline for outpatient pharmaceuticals. While these initial negotiations target select drugs, the precedent shifts negotiation leverage among payers and manufacturers. Separately, higher regulatory filing costs and agency fee schedules have raised the fixed-cost threshold for bringing novel dental therapeutics through a formal drug-approval route. Together, these forces raise breakeven timelines for innovation and prioritize product platforms with clear reimbursement pathways.
-
Supply chain and raw-material sensitivity: The dental drug value chain depends on specialized APIs and contract-manufacturing know-how for tasks such as cartridge filling and sterility assurance. Sourcing pressure for key anesthetic APIs and concentrated filling capacity create single-point risks that can quickly affect availability and price. Manufacturers who invest in redundant sourcing, local/nearshore capacity, or backward integration will gain negotiating leverage and stability.
-
Labor and operational specialization: Beyond chemical inputs, this segment relies on trained labor for high-precision manufacturing and clinic-level administration (e.g., cartridge handling, injectable protocols). Wage inflation and skills shortages in production and QC can materially alter unit economics and time-to-scale in emerging geographies.
-
Clinical and product mix evolution: Therapeutic demand centers on pain management, infection control, and procedural adjuncts. Local anesthetics continue to be the single-largest therapeutic category by usage; however, clinical demand for non-opioid analgesics and minimally invasive local-delivery modalities is accelerating. Product innovation is therefore a mix of formulation refinement, delivery convenience, and procedural integration.
Competitive landscape — who to watch and why
The market displays moderate concentration: the top-three companies account for a meaningful share of industry revenues, and the top-five increase that concentration modestly. This structure creates a mix of scale advantages and white-space opportunities for specialists.
-
Septodont Holding (Saint-Maur-des-Fossés, France) — a long-established leader in local and topical anesthetics with global distribution; their recent strategic investment and board participation in a development-stage analgesic specialist signals an explicit move to broaden their pipeline and accelerate injectable innovation.
-
Dentsply Sirona (Charlotte, NC, USA) — integrates pharmacologic adjuncts into broader dental workflows, creating cross-selling opportunities between devices and drug consumables; their product strategy emphasizes clinical interoperability.
-
Henry Schein (Melville, NY, USA) — a distribution powerhouse whose catalog breadth and channel reach make it a vital partner for commercial rollouts; the 2025/2026 catalog refresh expanded anesthetic assortments and demonstrates ongoing channel-led product shaping.
-
Ultradent Products, 3M, Centrix, Pierrel, Huons, Normon, and several agile specialists — each occupies distinct strategic positions: innovation-oriented formulation houses, large industrial players with adjacent oral-care portfolios, regional manufacturers with cost-advantaged production, and niche developers focused on opioid-sparing analgesics. These firms are the primary targets for bolt-on acquisitions, supply agreements, and co-development partnerships.
-
Balanced Pharma Inc. (North Carolina, USA) — a small but strategically important innovator focused on novel dental injectables and opioid-alternative analgesics; strategic backing from larger incumbents has amplified their visibility as an M&A and licensing candidate.
Recent developments with immediate strategic impact
-
Strategic investments and board realignments among incumbents and innovators are accelerating access to differentiated injectable therapies. These moves reduce technical execution risk for novel formulations and signal a near-term uptick in licensing activity.
-
Major distributors are refreshing assortments to capture higher-margin product families and to support bundled procedural offerings — a trend that increases the premium on streamlined SKUs and clinician-friendly packaging.
-
Payer and regulatory changes are shifting pricing benchmarks and increasing the importance of early health-economics evidence generation to secure formulary positioning.
What PW Consulting’s full report delivers — practical, transaction-ready content
Our objective was to produce work that is not merely descriptive but operational. The study contains granular tools you can adopt immediately to inform 2026 decisions. Highlights of deliverables include:
-
Executive dashboards with scenario-based revenue trajectories (base, upside, downside) driven by our 6.2% CAGR assumption and stress-tested for regulatory, reimbursement, and supply shocks.
-
Actionable market-entry playbooks for biologics/formulations vs. generics, including go-to-market sequencing, recommended channel partners, and targeted pricing strategies.
-
Commercial diligence templates: customer segmentation logic, salesforce sizing, list-versus-net pricing sensitivity analyses, and a retailer/distributor negotiation scorecard.
-
Regulatory-impact mapping: timeline implications of current fee and filing environments, recommended evidence packages for expedited payer conversations, and cost models for clinical programs under current agency fee structures.
-
Supply-chain risk matrix and sourcing playbook, including supplier concentration indices, contract-manufacturing scorecards, and recommended nearshoring thresholds to secure continuity for high-priority SKUs.
-
Competitive benchmarking and M&A playbook: capability heatmaps for the leading firms, valuation multiples observed in recent transactions, and a prioritized list of acquisition and partnership targets by strategic objective.
-
Customizable financial model (editable) that integrates unit economics, channel mix, and price erosion curves — built for scenario runs around payer-negotiation outcomes and manufacturing-cost shocks.
How to use this research in 2026 planning
-
Corporate strategy: Use the study’s scenario framework to test inorganic vs. organic growth at multiple price-pressure thresholds. Prioritize investments into product platforms that either protect gross margin through differentiation or materially reduce cost-per-dose via manufacturing scale.
-
Commercial teams: Leverage the go-to-market playbooks to rationalize SKUs, develop distributor partnerships, and design clinician adoption incentives tied to measurable procedural outcomes.
-
R&D and portfolio leaders: Reallocate resources to formulation advances and delivery systems that reduce clinic time, improve safety, and facilitate payer coding — all of which accelerate reimbursement and adoption.
-
Private equity and corporate development: Apply PW’s M&A playbooks and valuation sensitivities to accelerate deal sourcing and to structure earn-outs and milestone payments tied to regulatory and commercial inflection points.
What we intentionally withhold in this preview — and why
To preserve the commercial value of the study for decision-makers, we are not disclosing the full segmentation tables, region-by-region allocations, or product-level revenue splits in this preview. The full report contains proprietary market-calibration data, segment-by-segment forecasting models, and detailed price and volume assumptions that are indispensable for transaction diligence and will be made available through our report portal or consulting engagements.
Final recommendations for 2026 executives
-
Prioritize supply security and alternative sourcing for anesthetic APIs and cartridge-filling capacity; these areas represent the quickest route to stabilizing margin volatility.
-
Accelerate partnerships or minority investments in development-stage innovators that offer opioid-sparing analgesics or clinician-friendly delivery systems; these assets will be highly sought after as payers focus on outcome-based arrangements.
-
Recalibrate launch and pricing playbooks to reflect higher regulatory overhead and payer negotiation risk; embed real-world evidence generation into early commercialization plans.
-
For investors, focus on targets with defensible manufacturing footprints, strong distributor relationships, and modular product platforms that can be rapidly scaled across multiple geographies.
PW Consulting’s full Dental Drug Market report provides the data, models, and playbooks that turn these recommendations into executable programs. For access to the detailed tables, segment models, and a guided briefing with our strategy team, please visit the full report page or contact our client services desk to schedule a 2026 planning workshop.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Epoxidized Soybean Oil (ESBO) Market: Strategic Primer for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a concentrated strategic primer to frame your 2026 planning for the Epoxidized Soybean Oil (ESBO) value chain. This briefing synthesizes our independent market sizing, competitive landscaping, and risk matrix to show where commercial advantage will be won — while reserving the granular segment-level forecasts and model outputs for the full study.
Epoxidized Soybean Oil Market
Why ESBO deserves executive attention in 2026
- ESBO is at the intersection of commodity agriculture and specialty chemicals: it is a bio-based additive with direct sensitivity to soybean oil availability, commodity price cycles, and shifting regulatory regimes tied to plastics and fuels.
- Our base-year market sizing (2025) anchors strategy decisions: the global ESBO market sits just below a half‑billion USD in revenue (2025 base), and our forecast path — underpinned by a 7.58% compound annual growth rate — points to a material scaling opportunity through the 2026–2032 horizon.
- Structural change is underway. Demand dynamics are being reshaped by PVC formulation shifts, sustainability-driven procurement, biofuel policy impacts on feedstock flows, and targeted trade remedies. These forces create both margin pressure and differentiation opportunities for producers, distributors and downstream formulators.
What the 2026 strategic landscape looks like (high level)
- Growth momentum: After steady expansion over 2020–2025, the ESBO market accelerates into the forecast period supported by stronger demand in traditional plasticizer and stabilizer applications plus broadened uptake in specialty uses. Our scenario models show the market roughly doubling in scale from the early 2020s over the medium term under the baseline case.
- Supply-side concentration: The sector exhibits moderate concentration among leading producers and integrated agribusinesses, creating oligopolistic dynamics for sourcing and premium product positioning. Competitive advantage will accrue to firms that combine feedstock control, technical grade differentiation, and route-to-market strength.
- Volatility vectors: Raw material availability (soybean oil), regulatory shifts (trade probes and food-contact rules), and renewable diesel policy are primary sources of near-term upside/downside risk. Commercial teams should assume episodic price swings and intermittent trade restrictions when stress-testing 2026 plans.
How PW Consulting’s ESBO research supports board-level decisions
Our full study is built for executives who must convert market intelligence into defensible action. We structure the work around four decision-use modules:
Epoxidized Soybean Oil Market
- Market Sizing & Scenario Forecasting — transparent methodology, baseline and alternate-path scenarios, and sensitivity to feedstock price and regulatory shocks.
- Commercial Due Diligence — supplier and buyer scorecards, channel economics, margin waterfall analysis, and a pricing playbook designed to navigate volatility while protecting market share.
- Portfolio & Product Strategy — product differentiation levers (e.g., food-contact certification, Kosher status, high-IV/heat-stable grades), licensing and co-development frameworks for formulators, and premiumization pathways for specialty ESO variants.
- M&A and Capex Roadmap — target screens for strategic acquisitions (vertical integration, regional converters, niche specialty players), greenfield vs brownfield build templates, and payback scenarios under multiple commodity-price regimes.
Each module contains executable outputs: decision matrices, model kits, playbooks, and a prioritized action list to be operationalized in 90-, 180- and 360-day horizons.
Epoxidized Soybean Oil Market
Competitive dynamics — what leading firms are doing
The competitive landscape is shaped by a mix of global specialty chemical suppliers, agrichemical/agribusiness integrators, regional manufacturers, and distributors. Across this set, three strategic postures prevail:
- Scale + feedstock control (vertical integration): Large agribusinesses that integrate soybean crushing into their operations can shield margins when crude oil or biodiesel policy diverts feedstock. These firms often have the flexibility to prioritize internal offtake or participate in spot markets selectively.
- Specialty differentiation: Chemical suppliers that combine certification credentials (food-contact, Kosher), tailored formulations, and heat-stable/high-performance grades aim to capture value above commodity ESBO levels. Recent product promotions and launches underscore the importance of technical depth to win formulation share in PVC and niche end-uses.
- Channel & services play: Distributors and toll manufacturers emphasize logistics, packaging flexibility (drums/totes/bulk), and rapid technical support. For many end users, sourcing stability and timely product qualification are as critical as unit price.
Notable recent moves reinforce these themes: capacity upgrades and modernization projects have expanded output capability; new ESBO variants focused on improved compatibility or thermal stability have been launched; and product promotions highlight food-safe and renewable credentials as a commercial differentiator. These developments indicate the market is maturing from a commodity-buyer environment toward one where technical and certifiable product attributes command premium access to certain channels.
Key commercial implications for 2026 planners
- Hedge feedstock risk strategically: Given the tight linkage to soybean oil supply, procurement teams should layer contracts (long-term offtake, index-linked clauses, and option-based hedges) and explore direct sourcing partnerships to manage price exposure and availability.
- Invest in product credentials: Certification (food-contact, Kosher) and demonstrable performance (heat stability, compatibility) accelerate adoption in regulated end markets. R&D and regulatory investment are high-leverage moves that improve price realization and reduce churn.
- Prepare for regulatory theater: Ongoing trade investigations and local content scrutiny require an agile compliance function and contingency sourcing plans. Rapid re-routing capability and tariff mitigation strategies can be decisive during episodic market shocks.
- Deploy selective downstream integration: CPF (capacity, flexibility, footprint) analysis suggests selective M&A or JV activity — particularly in regions with demand growth or where logistics create a competitive moat — can be accretive to margin and resilience.
- Differentiate through service: For converters and formulators, reliable supply, technical service, and packaging flexibility often trump the lowest-cost offer. Sales models should align around value selling rather than strict commodity procurement pitches.
Risk map: what to watch through 2026
- Raw-material pressure: Changes in soybean oil allocation (e.g., diversion to biofuel mandates) can tighten availability and lift prices; procurement teams must stress-test models for multiple feedstock-disruption scenarios.
- Trade and anti-dumping actions: Recent investigations in certain jurisdictions have already impacted flows; expect episodic protectionist measures that re-route trade lanes and alter landed cost math.
- Regulatory & sustainability standards: Evolving plastics regulation and increasing demand for renewable/traceable feedstocks create both barriers and premium opportunities; firms that fail to document chain-of-custody will see limited access to higher-value contracts.
- Technology and substitution risk: New plasticizer chemistries or formulations that reduce reliance on ESBO could emerge; continual product innovation is therefore essential to maintaining relevance.
What the full PW Consulting report contains (practical deliverables)
- Comprehensive market model with transparent assumptions, scenario toggles, and downloadable model artifacts for board use.
- Supply-chain heat maps and supplier scorecards highlighting capacity, technical capability, and strategic fit for potential partners or acquisition targets.
- Regulatory tracker and tariff scenarios tailored to priority markets, plus playbooks for rapid response to trade remedies or import restrictions.
- Commercial levers playbook: pricing frameworks, contract templates, logistics optimization, and SKU rationalization guidance.
- M&A screening dossier with high-probability targets, valuation benchmarks, and integration risk checklists.
Note: The full report contains granular regional and application-level forecasts, detailed split analytics, and company-level volume/price matrices. In keeping with this primer’s “trailer” design, those detailed segment outputs are intentionally withheld here to channel readers to the source study for the complete intelligence package.
Next steps for executives
- Use the headline market sizing and CAGR outlook in this primer to calibrate top-line targets and stress scenarios for 2026 budgeting cycles.
- Commission a rapid commercial due diligence (4–6 week sprint) if you are considering capacity investment, a JV, or an acquisition in the ESBO chain — the timing is right to capture first-mover advantages before premium segments harden.
- Initiate cross-functional workshops (procurement, R&D, regulatory, sales) to define a 180-day plan focused on feedstock resilience, product-certification upgrades, and targeted customer pilots.
For teams ready to translate these insights into actionable plans, PW Consulting offers the full ESBO market study along with bespoke advisory engagements to operationalize the recommendations. Our models and playbooks are built to be immediately integrated into 2026 capital allocation and commercial strategies.
Closing
ESBO is no longer merely a commodity intermediate — it is a strategic lever for formulators, a hedged commodity for agribusinesses, and a focal point for sustainability claims across plastics and packaging. With a clearly defined market trajectory and identifiable risk corridors, 2026 is the year to move from reactive sourcing to strategic positioning. PW Consulting’s full report gives you the maps and decision toolkits to do precisely that.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patrol Boats Market to Grow to USD 63.8 Million by 2032 at 6.7% CAGR
By PW Consulting, 2026-07-12
Patrol Boats Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision‑grade preview of our Patrol Boats Market research — a practical briefing intended to align executive choices with the market dynamics that will matter most through 2026 and beyond. This note signals the strategic value and immediate applicability of the full report while preserving the detailed segment intelligence that we reserve for licensed access.
Patrol Boats Market
Executive snapshot
The global patrol‑boats market has experienced a structural softening across the early 2020s, followed by a clear inflection beginning in 2026. After peaking in the prior decade, total industry revenue contracted between 2020 and 2025 before stabilizing at a base‑year value in 2025. From that base, our forecast anticipates a sustained recovery through 2032, with the market expanding at a compound annual growth rate (CAGR) of 6.7% during the 2026–2032 forecast window and reaching materially higher absolute levels by 2032.
Patrol Boats Market
For procurement leaders, investors and OEM executives, this pattern matters: budget cycles that were deferred or compressed during the downturn are re‑entering the planning horizon, while new mission sets and modular technologies are reshaping procurement criteria. Understanding the timing and shape of that recovery is the primary strategic dividend of this research.
Patrol Boats Market
Why this research matters for 2026 decisions
- Procurement timing and scale: The 2026 inflection creates narrow windows for order placement if organizations want to lock earlier production slots and favorable pricing before a deeper recovery lifts demand and input costs.
- Capability redefinition: Patrol craft are no longer one‑dimensional platforms. Law enforcement, coast guard and expeditionary forces now demand boats configured for hybrid missions — from high‑end interdiction to humanitarian SAR — pushing OEMs to offer configurable modularity rather than single‑purpose models.
- Supply‑chain and localization risks: Recent deliveries and international partnerships underscore a trend toward regional manufacturing footprints that shorten lead times and mitigate trade barriers. These decisions affect total cost of ownership and long‑term sustainment obligations.
- Competitive positioning and consolidation levers: The market’s competitive structure favors scale in engineering, repeatable production and aftermarket services. Buyers and investors must assess vendor roadmaps for product‑platform continuity and integration of mission systems.
Market trajectory — what the numbers tell us (high‑level)
Historical performance (2020–2025) shows a contraction in absolute market revenue driven by fiscal retrenchment, delayed programs, and a temporary softening of non‑defense demand. The 2025 base year reflects that trough. Importantly, the forecast horizon (2026–2032) models a multi‑year rebound underpinned by renewed defense modernisation, coast guard recapitalisation programs, and rising civil search‑and‑rescue and law‑enforcement needs. The projected CAGR of 6.7% is not uniform — the recovery features episodic procurement spikes tied to sovereign programs and offshore security initiatives — but it is sufficiently robust to alter strategic choices on capacity investments, alliance formation and product development roadmaps.
Structural dynamics and demand drivers
- Mission diversification: Patrol craft must now balance speed, endurance and mission modularity. Vessels optimized for interdiction operate against different requirements than those tasked with extended offshore presence or special‑forces insertion. Buyers increasingly specify modular payload interfaces, rapid reconfiguration, and integrated C4ISR packages.
- Technological inflection points: Advances in materials, propulsion and small‑boat launch systems are lowering life‑cycle costs and improving survivability. Examples in the market include rapid‑deploying masts for sensor packages and stabilized collars for RIB platforms that extend sea‑state operability. Diesel‑waterjet combinations and catamaran hull forms are delivering demonstrable increases in top‑end speed and offshore stability.
- Regulatory and operational context: Coast guard and maritime police force profiles are shifting toward multi‑day coastal patrols, stern‑launch RHIB capability, and interoperability with unmanned surface vehicles. These operational requirements are influencing vendor designs and insistence on modularity and sustainment‑friendly architecture.
- Sustainment and total cost of ownership (TCO): Buyers now evaluate TCO across an extended lifecycle horizon that includes crew training, depot repair infrastructures and interoperability of mission systems. The cost calculus is moving decisions away from lowest‑price toward best‑value suppliers who can guarantee availability and rapid parts provisioning.
Competitive landscape — what to watch
The market is shaped by a mix of specialized builders and regional champions that emphasize speed, customization and mission fit. Several leading suppliers exemplify the capabilities suppliers must bring to win in 2026‑era procurements:
- Metal Shark Boats (Jeanerette, LA): A custom aluminum vessel builder emphasizing high‑speed, seaworthy platforms for military and law‑enforcement missions. Recent activity demonstrates strong program execution — including multiple deliveries to national and state government units and completion of a multi‑vessel programme for the U.S. Navy — and the strategic use of international manufacturing partnerships to localize supply and accelerate delivery.
- MetalCraft Marine (Watertown, NY): Known for high‑speed interceptor designs and patented rapid‑hinging mast systems that materially reduce mast‑deployment time for sensor payloads. Their product focus suits agencies needing rapid reaction capability with reduced crew overhead.
- Moose Boats (Vallejo, CA): Specializes in aluminum catamaran and monohull platforms that combine high top‑end speeds with government contracting credentials, making them competitive for domestic law‑enforcement programmes and harbour security assignments.
- Swiftships (Morgan City, LA): Offers a range of steel, aluminum and composite craft scaled for both commercial and military roles — an advantage for countries seeking interoperable fleets and localized sustainment options.
- Zodiac Milpro (Paris): A market leader in RIB and inflatable response craft, delivering modular responder platforms with design features that improve operation in heavy seas and rapid intervention contexts.
- Aresa Shipyard (Arenys de Mar): Provides armored and special‑forces craft tailored to high‑threat littoral operations — a niche that has seen renewed interest as asymmetric threats and coastal incursions rise.
Recent vendor developments — including cross‑border deliveries, government program completions, and partner appointments for regional manufacturing — illustrate a market where execution speed and geopolitical agility matter as much as product capability. These developments should inform bids, partnership decisions and M&A diligence.
Operational implications for buyers and suppliers
- For procuring agencies: Early engagement with OEMs to lock configuration baselines and support packages will preserve program flexibility and reduce schedule risk. Consider contracting for platform commonality across mission sets to reduce training and spare parts inventories.
- For OEMs: Invest in modular open‑architecture interfaces and aftermarket capabilities (training, spare parts, mission‑package swaps). Regional manufacturing partners can shorten lead times and increase program wins in jurisdictions with localization requirements.
- For investors and private equity: The recovery window makes capabilities in rapid production scaling, systems integration, and sustainment particularly attractive. Target acquisitions should be evaluated not only on current backlog but on repeatability of delivery and the ability to convert small‑lot military programs into higher‑volume civilian sales.
Strategic playbook — three immediate moves for 2026
- Map mission‑to‑platform economics: Build decision matrices that compare platform types across lifecycle costs for specific mission profiles (interdiction, SAR, special operations). The best near‑term bets will be those that minimize conversion friction between roles.
- Localize selectively: Use strategic partnerships in priority regions to mitigate tariff and procurement preferences. Partnerships that include licensed production, skills transfer and local content commitments materially increase win rates for government tenders.
- Prioritize aftermarket differentiation: Move from one‑time sales to subscription‑style service contracts for spare parts, training and mission‑package swaps. This shifts buyer calculus from acquisition price to predictable lifecycle spend — and creates defensible recurring revenue for suppliers.
Report contents — practical tools included
The full PW Consulting patrol‑boats report is built as an operational toolkit for executives who must act in 2026. Highlights include:
- Market sizing and validated forecast models (2020–2032) with sensitivity scenarios tied to defence budgets and civil procurement cycles.
- Program‑level vendor scorecards and capability matrices that capture production capacity, modularity, sustainment footprint and export credentials.
- Procurement playbooks for end users: RFP templates, evaluation weightings, and risk allocation language optimized for modular patrol craft.
- TCO calculators and sustainment modelling templates that quantify trade‑offs between hull materials, propulsion choices and depot infrastructures.
- Deal screening tools for investors: integration risk checklists, commercial‑to‑military conversion frameworks, and a shortlist of strategic targets ranked by synergy and defensibility.
- Actionable annexes covering regulatory considerations, interoperability checklists, and recommended contract clauses for transfer of technology and localization.
Note: The full report contains detailed regional, type and application splits and vendor market‑share matrices that are intentionally omitted here to preserve the value of the licensed analysis.
How to use this preview
Treat this briefing as the strategic layer that should sit above program‑level decision‑making. Use our high‑level findings to:
- Accelerate alignment between procurement, legal and operational stakeholders before RFP release.
- Identify candidates for strategic partnerships or bolt‑on acquisitions that improve delivery predictability and aftersales revenue.
- Calibrate negotiation strategies with suppliers around lead times, localization commitments and aftermarket guarantees.
Next steps
If your organization is preparing procurement cycles, investor diligence, or product investments in 2026, the full PW Consulting Patrol Boats Market report delivers the granular intelligence and executable templates you need. Our licensed package includes proprietary splits, vendor rankings, and scenario tables that convert the macro trajectory outlined here into specific procurement and investment actions.
For access to the complete dataset, vendor scorecards and the operational toolset, contact PW Consulting to arrange a briefing and secure your copy of the full study.
For detailed analysis of this topic, please visit the official page: Patrol Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Combine Harvesters Market Poised for 4.5% CAGR, Reaching USD 180M by 2032
By PW Consulting, 2026-07-12
Combine Harvesters Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Combine Harvesters Market study is designed as a strategic compass for executives, investors, and policy teams making critical decisions in 2026. Built on a transparent base year of 2025, a historical window from 2020–2025, and a forward-looking forecast through 2032, the research synthesizes primary-market interviews, manufacturer intelligence, and an econometric forecasting engine. At the macro level, the market expanded from USD 120.0 Million in 2020 to USD 145.0 Million in 2025 and is modelled to reach USD 180.0 Million by 2032, reflecting a compound annual growth rate of 4.5% across the forecast horizon. That steady, mid-single-digit growth masks critical inflection points—technology adoption, policy incentives, and shifting farm economics—that will determine winners and losers over the coming investment cycles.
Combine Harvesters Market
Why this study matters for 2026
-
Timing capital allocation. In an environment where OEMs and distributors are prioritizing digital and autonomy investments, precise, defensible market sizing and forward scenarios allow CFOs and corporate development teams to time CAPEX and M&A more effectively.
Combine Harvesters Market -
Designing profitable product roadmaps. Product leaders will find our mapped buyer journeys, feature willingness-to-pay curves, and operational cost profiles invaluable when balancing hardware complexity, software services, and aftermarket revenue strategies.
Combine Harvesters Market -
Mitigating supply and service risk. Dealers and tier-one suppliers can use our supplier risk matrix and field-service clustering to protect uptime and optimize parts inventory across diverse geographies and crop cycles.
-
Translating policy into market opportunity. With public programs and subsidy schemes influencing upgrade cycles, strategy teams can quantify which incentive structures accelerate replacement and which only reallocate demand.
What the report delivers — practical, transaction-ready outputs
-
Robust market model: Annual historicals (2020–2025) and dynamic scenario forecasts (2026–2032) that support sensitivity testing across price, adoption, and macroeconomic inputs.
-
Commercial segmentation framework: A replicable taxonomy that separates platform type, power class, and application use cases—built to be fed into go-to-market and product planning tools. (Core split datapoints are summarized in the full report to preserve segmentation granularity.)
-
Competitive heat maps: Comparative analysis across product capability (autonomy, throughput, fuel efficiency), brand positioning, distribution reach, and service economics—enabling M&A screening and partnership targeting.
-
Buyer economics and TCO models: Operator-level total cost of ownership scenarios under different utilization and labor-cost assumptions, plus cross-validated field survey inputs for maintenance and lifecycle cost drivers.
-
Scenario playbooks: Four executable market scenarios—Baseline, Technology Acceleration, Policy-Driven Uptake, and Downturn Resilience—each with tactical checklists for OEMs, lessors, and dealers.
-
Deal toolkit: Valuation multiples by capability cluster, integration risk checklists, and three near-term acquisition targets selected based on capability gaps, distribution fit, and aftermarket synergies.
Competitive landscape — reading the footprints of incumbents
The combine harvester market remains led by a mix of global OEMs that combine deep manufacturing scale with growing software and services businesses. Our competitive analysis focuses on strategic positioning rather than raw unit counts, allowing clients to assess where value creation will come from in the next five years.
-
John Deere (Moline, Illinois, United States) — Known for its high-integrated S-Series and X9 machines, Deere’s recent product highlights emphasize automation and operator-assist systems. The company is actively commercializing machine-sync and autopilot features, which create pathways to recurring software revenue and differentiated field productivity metrics.
-
CLAAS KGaA mbH (Harsewinkel, Germany) — CLAAS continues to leverage heritage models while scaling production and brand momentum. Milestones in production demonstrate manufacturing depth, and design continuity positions CLAAS to capitalize on premium segments and special edition releases that reinforce dealer relationships.
-
CNH Industrial N.V. (Amsterdam, Netherlands) — CNH’s high-power CR-series machines target large-scale operations and contractors. Their strategy emphasizes throughput and operating efficiency, which serves well in markets where consolidation of farm acreage and contractorization are accelerating.
-
AGCO Corporation (Duluth, Georgia, United States) — With brands such as Massey Ferguson and Gleaner, AGCO pursues a multi-brand approach to cover distinct channel segments, pairing global OEM capability with regional distribution expertise.
-
Kubota Corporation (Osaka, Japan) — Kubota’s strength in crop-specific solutions (notably in rice- and wheat-dominant regions) and investments in unmanned/autonomous prototypes position the company well in markets where labor constraints drive a premium for automation.
These OEMs are not just competing on metallurgy and horsepower. The strategic battlegrounds are increasingly software-integrated services, dealer experience, financing solutions, and parts availability. Our provider profiles include links to primary product pages and offer a concise view of each company’s strategic intent, R&D focus, and go-to-market mechanics.
Market dynamics shaping strategic choices in 2026
-
Technology and autonomy: Ongoing advances in sensor fusion, machine control, and AI-based harvesting support are altering the economics of labor and throughput. OEMs that move from one-off autonomy features to subscription-grade operational services position themselves to capture higher lifetime value per machine.
-
Labor pressures and service models: Persistent labor gaps in harvesting operations are driving demand for higher automation and new service models—custom-harvesting contractors, equipment-as-a-service, and pay-per-hour harvesting all look more viable under current farm labor dynamics.
-
Policy and subsidy levers: Public programs that incentivize eco-friendlier equipment upgrades are active levers in many markets. Strategic planning must therefore incorporate policy timing and eligibility rules to predict replacement cycles accurately.
-
Aftermarket economics: With field uptime critical to operator economics, dealers who optimize parts logistics and predictive maintenance programs can materially improve fleet utilization—and create differentiated, recurring margin streams.
-
Capital intensity and financing: High-capex assets require flexible ownership models. OEMs and captive finance arms that develop compelling lease and insurance offerings win share by reducing the adoption barrier for smaller operators.
Recent signals and what they imply
-
Market demand volatility: Industry sales reporting has recently signaled a sharp year-on-year sales contraction in certain retail channels. This underscores two realities: (1) inventory and dealer network management must be dynamic; and (2) short-term unit demand swings can mask structural growth in services and retrofit markets.
-
OEM product movements: High-profile product showcases emphasize small-property and rugged-terrain capabilities with integrated autopilot—indicating a deliberate push by tier-one players into smaller-acreage segments and more complex operating environments.
-
Manufacturing milestones: Production volume milestones reaffirm scale advantages but also highlight the importance of capacity planning and supplier diversification as manufacturers pursue both legacy and next-gen platforms.
How to use the report for immediate 2026 plays
-
For strategic planning: Use the scenario models to stress-test five-year product roadmaps against combinations of technology adoption rates and policy shifts. Identify the "minimum viable feature set" that secures aftermarket revenue without overloading initial hardware cost.
-
For commercial teams: Leverage our buyer segmentation and regional dealer mapping to rebalance inventory and prioritize field trials where adoption barriers are lowest and subsidy capture is highest.
-
For M&A and partnerships: Apply the deal toolkit and valuation ranges to rapidly screen targets that fill capability gaps in autonomy, precision agronomy, or distribution reach.
-
For operations and supply chain: Implement the supplier risk matrix and parts-availability scenarios to reduce downtime exposure and optimize spare-parts stocking across critical nodes.
Closing perspective
The combine harvester market in 2026 is at a crossroads: the headline growth is stable, but structural change is accelerating underneath. Executives who combine disciplined market models with targeted investments in software, service, and distribution will be best-placed to convert mid-single-digit market growth into outsized returns. PW Consulting’s Combine Harvesters Market study provides the layered, actionable insight you need to make those choices with confidence—while preserving the granular, proprietary segmentation and financial models that drive high-quality dealmaking and product planning.
To access the complete dataset, subsegment unpacking, and our customizable forecasting model, please visit the PW Consulting report page. Our team is available to translate the findings into a tailored strategic workshop or actionable M&A shortlist specific to your portfolio.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


