



Category: market research
PW Consulting: PSPI Market to Surge to USD 590.2M by 2032 at 21.8% CAGR
By PW Consulting, 2026-07-09
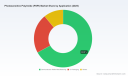
Photosensitive Polyimide (PSPI) Market — Strategic Briefing for 2026 Decisions
PW Consulting presents a targeted industry briefing designed to equip corporate leadership and strategy teams with the high-level intelligence required to make decisive moves in 2026. This note synthesizes our latest market sizing, structural dynamics, competitor posture, and regulatory risk map for Photosensitive Polyimide (PSPI) — while intentionally reserving the detailed segmentation tables, pricing curves, and supplier scorecards for the full report.
Photosensitive Polyimide (PSPI) Market
Market at a glance — the big-picture metrics that matter
- Historical momentum: PSPI moved from approximately USD 55.2 Million (2020) to USD 150.0 Million (2025), reflecting rapid adoption across advanced packaging and display processes.
- Near-term trajectory: our base year is 2025; the market is projected to continue strong expansion into the forecast window. The first full forecast year (2026) is projected at roughly USD 179.0 Million.
- Longer-term scale: by the end of the forecast period, the PSPI market is projected to reach approximately USD 590.2 Million (2032).
- Growth intensity: the compound annual growth rate (CAGR) for the forecast window (2026–2032) is 21.8%, signaling an industry moving from niche specialty-chemical status to strategically significant materials for semiconductor and display ecosystems.
- Market concentration: the industry exhibits a relatively consolidated supplier base (top-3 firms control a dominant share, and the top-5 further consolidate scale), underscoring the strategic impact of capacity moves and customer qualification timelines.
Why 2026 is a strategic inflection point
Several concurrent vectors make 2026 an actionable year for executives: capacity additions announced in 2024–2025 begin commissioning, regulatory transition timelines around certain solvent systems accelerate, and end-market demand (driven by advanced packaging, wafer-level processes, and flexible display lamination) enters a steeper adoption curve. These forces compress decision windows: ordering and qualification lead times for new PSPI grades, long-cycle capital investments by suppliers, and multi-year supply agreements all require clarity from buyers and strategic planners now.
Photosensitive Polyimide (PSPI) Market
From a capital-allocation perspective, the combination of high CAGR and concentrated supply means that first-mover advantage in securing qualified supply or owning differentiated chemistries can materially affect cost-of-goods and time-to-market for advanced packaging and display OEMs.
Photosensitive Polyimide (PSPI) Market
Competitive landscape — who to watch (and why)
The PSPI supplier layer is populated by long-established polymer houses and specialty-chemical players that combine deep formulation know-how with semiconductor qualification capabilities. Our qualitative assessment of the competitive set highlights three tiers:
- Global leaders with scale and integration advantages: companies that have invested in purpose-built PSPI capacity and maintain close relationships with semiconductor foundries and OSATs. Recent capacity programs and customer awards validate their strategic alignment with advanced packaging roadmaps.
- Regional specialists with targeted propositions: players focusing on particular end-markets (e.g., DRAM/logic packaging clusters or OLED panel supply chains) who leverage proximity and co-development to win design-ins.
- Technology differentiators and niche formulators: smaller firms focused on specialized chemistries (e.g., radiation-hardened PSPI, solvent-free formulations, or sub-5 nm optimized materials) that address specific technical windows of opportunity.
Representative firms that appear across our competitive matrix include manufacturers that have publicly announced capacity or product initiatives in 2024–2025 and early 2026. Examples of recent strategic moves that shaped vendor dynamics:
- A major Japanese supplier announced a multi-year capacity expansion program at a flagship facility and received customer recognition for its PSPI grades in late 2025 — a move that materially improves its ability to serve advanced packaging demand.
- A specialist materials vendor launched enhanced PSPI formulations optimized for sub-5 nanometer packaging in 2025, signaling a race to align chemistries with shrinking design rules.
- Regional producers in South Korea and Taiwan expanded electronic-materials production footprints in 2025 to capture demand from leading memory and OSAT clusters.
These public actions underscore an important strategic reality: capacity and qualification cycles now overlap with product-cycle windows in semiconductor roadmaps. Market share gains will therefore accrue to suppliers that align production ramp timing with customer qualification schedules and regulatory-compliant formulations.
Dynamics and risk matrix — the practical headwinds
- Raw material pressure: precursors for PSPI (for example, polyamic acid and certain diamines/dianhydrides) experienced material cost increases in recent years. These input cost shifts have compressed supplier margins and are being managed through a mix of price pass-throughs, formulary reformulation, and efficiency programs.
- Regulatory transition: solvent systems used in some PSPI processes face increasing regulatory scrutiny. The European REACH designation of certain solvents as high-concern substances, coupled with evolving EPA guidance, is accelerating reformulation programs and increasing product development costs for compliant aqueous or alternative-developer chemistries.
- Supply-chain fragility: geopolitical friction and logistics constraints have extended lead times in some geographies by multiple weeks. For buyers with just-in-time inventory models, this creates operational vulnerability during ramp periods.
- Qualification latency: semiconductor-grade PSPI qualification cycles are lengthy and multi-staged. Customers contemplating supplier changes must factor in several quarters (or more) of co-development, reliability testing, and process integration.
In short: margin, compliance, and lead-time pressure converge. Firms that proactively hedge input exposure, accelerate REACH/EPA-compliant reformulations, and secure multi-sourcing or strategic supply partnerships will materially reduce execution risk.
What our full report delivers — practical assets for 2026 execution
The full PW Consulting PSPI Market Report combines rigorous market sizing with operational playbooks. Key deliverables that strategy and procurement teams will find immediately actionable include:
- Validated market-sizing model (historical 2020–2025 and forecast 2026–2032) with sensitivity scenarios tied to packaging nodes and display adoption curves.
- Demand-driver decomposition and event calendar that maps customer qualification windows, key foundry/OSAT milestones, and anticipated ordering cliffs.
- Supplier capacity-mapping and utilization model that highlights near-term bottlenecks and probabilistic timing for incremental tonnage availability.
- Cost-of-supply and input-cost passthrough analysis with scenario-level margin impact for manufacturers and buyers.
- Regulatory-compliance matrix: solvent-phase-out timelines, reformulation cost estimates, and recommended control points for internal product teams.
- Competitive benchmarking: product-positioning scorecards, innovation vectors (e.g., solvent-free PSPI, radiation-hardened variants), and supplier readiness assessments.
- Commercial playbooks: supplier selection criteria, negotiation levers (e.g., co-investment, exclusive supply windows, dual-sourcing triggers), and RFP templates aligned to semiconductor qualification cadence.
- M&A and partnership targets: a prioritised list of tuck-in candidates and joint-development partners, with rationale and three execution pathways (minority investment, JV, full acquisition).
Note: the report intentionally excludes publicly reproducing granular regional and application split percentages in this briefing. Those discrete segmentation layers — central to procurement and investment decisions — are accessible in the full intelligence package.
A prioritized 6–12 month action agenda for 2026
- Immediate (0–3 months): Run a rapid supplier health check — validate lead times, confirm reformulation roadmaps for regulatory compliance, and map qualification timelines for critical PSPI grades.
- Short term (3–6 months): Secure conditional capacity through supply agreements or co-investment structures tied to milestone-based take-or-pay terms; accelerate internal material-substitution pilots where solvent exposure is a compliance risk.
- Medium term (6–12 months): Align product roadmaps with qualified PSPI suppliers and lock integrated process windows (Cpk, thermal budgets) into development milestones; build scenario models for inventory and hedging that reflect lead-time variability.
- Strategic: Evaluate M&A or JV opportunities to internalize critical chemistry capabilities if your roadmap requires differentiated PSPI formulations that are unlikely to be served by commodity suppliers.
Concluding perspective — why our intelligence matters for your 2026 choice
PSPI is transitioning from a specialty niche to a strategic materials category for a wide set of semiconductor and display applications. The combination of rapid demand growth (projected CAGR of 21.8% in the forecast window), concentrated supply, and regulatory shift creates both asymmetric upside for first movers and downside for firms that delay qualification or securement actions.
PW Consulting’s report is designed to be directly operational: not a descriptive industry primer but a decision support toolkit for procurement chiefs, product leaders, and M&A teams. Our objective is to shorten your risk-adjusted time-to-decision by providing validated market math, supplier-readiness diagnostics, and executable commercial templates.
To access the full dataset, the supplier-by-supplier scorecards, the detailed regional and application splits, and the workbook models that underpin the scenarios summarized here, please visit the PW Consulting report page. The full intelligence contains the granular inputs you will need to finalize 2026 capital allocations, supplier agreements, and product qualification plans.
For detailed analysis of this topic, please visit the official page: Photosensitive Polyimide (PSPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oxycodone Hydrochloride Market to Hit USD 595.6M by 2032 (4.65% CAGR)
By PW Consulting, 2026-07-09
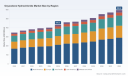
Oxycodone Hydrochloride Market — Strategic Outlook for 2026
Executive preview
PW Consulting’s latest Oxycodone Hydrochloride Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) provides a decision-grade synthesis for executives planning resource allocation, manufacturing posture, and regulatory engagement in 2026. The global market reached USD 434.3 Million in 2025, up from USD 346.8 Million in 2020, and the study models a compound annual growth rate (CAGR) of 4.65% across the 2026–2032 forecast window, culminating in an overall market projection approaching USD 595.6 Million by 2032. These headline dynamics capture both underlying demand resilience in core therapeutic settings and structural supply-side friction that will shape strategic choices this year.
Oxycodone Hydrochloride Market
Why this study matters for 2026 decision-making
-
Timeliness: 2026 is a pivotal year — production quotas, regulatory actions and an uneven supply landscape are converging to create asymmetric risks and opportunities.
Oxycodone Hydrochloride Market -
Actionability: the report distills market evolution into operational workstreams (sourcing, manufacturing, contracting, regulatory strategy) so leaders can convert insight into execution within 90–180 day timeframes.
Oxycodone Hydrochloride Market -
Competitive posture: with a concentrated supplier base and high vulnerability for certain dosage forms, competitive moves (capacity expansions, targeted M&A, specialty partnerships) will materially affect access and margin profiles.
-
Scenario readiness: our scenario models quantify the impact of supply shocks, regulatory delistings and quota shifts on revenue, inventory days, and service levels — enabling stress-tested planning rather than intuition-driven responses.
Market dynamics: drivers, constraints and inflection points
Two themes dominate the near-term narrative. First, demand remains stable across core clinical applications, underpinned by a baseline of legitimate medical need and an aging patient demographic in developed markets. Second, supply-side complexity is intensifying: API quotas, regulatory withdrawals, and episodic product discontinuations are compressing available inventory and raising execution risk for manufacturers and distributors alike.
-
Regulatory/Quota environment: the DEA’s 2026 aggregate production quota for oxycodone establishes the production envelope for the calendar year and has immediate operational implications for API procurement and contract manufacturing scheduling.
-
Regulatory delistings and approvals: recent administrative actions — including withdrawals of specific approvals for certain oral solutions — demonstrate that approval status can change rapidly and should be continuously monitored as an operational risk.
-
Structural shortages: independent vulnerability listings and shortage databases continue to flag oxycodone tablets as structurally at risk. That status increases the premium on redundancy and validated second-source suppliers for customers and payors.
Collectively, these forces mean that 2026 planning must prioritize supply assurance and regulatory agility as much as market-share plays.
Competitive landscape — what leaders should know
The market remains moderately concentrated: the top three players account for a significant portion of market supply, and the top five increase that concentration further. This concentration creates both bargaining power for incumbent suppliers and systemic vulnerability when one or more large manufacturers change capacity or product availability.
-
Endo USA, Inc. (Malvern, PA) — A primary manufacturer and marketer of branded oxycodone/acetaminophen formulations; maintains production capabilities for immediate‑release forms. Recent discontinuations underscore how portfolio decisions by a single incumbent can affect market availability for specific dosage strengths.
-
Par Health (Malvern, PA) — An active generics and API-capable supplier evolving through portfolio restructuring; retains manufacturing operations previously associated with legacy companies. The rebranding and consolidation activities indicate a strategic focus on integrated supply solutions.
-
KVK‑Tech, Inc. (Somerset, NJ) — A supplier noted in shortage monitors for immediate‑release oral tablets; represents a valuable short‑term capacity node but also exemplifies the fragile nature of distributed generic production.
-
Rhodes Pharmaceuticals L.P. (Columbia, MO) — A generics manufacturer supplying standard oral tablet strengths; its role illustrates the importance of commercial distribution networks in maintaining on‑market availability.
-
Amneal Pharmaceuticals (Bridgewater, NJ) — Active in immediate‑release generics and listed as an available supplier in shortage tracking; its continued participation is a stabilizing factor for purchasers.
-
Elite Pharmaceuticals, Inc. (Fort Lauderdale, FL) — Recently launched generic oxycodone/acetaminophen products and represents new entrant competition that can reshuffle short‑term supply dynamics and pricing.
These firm-level vignettes in the report are paired with a proprietary competitive map and supplier-risk scoring. The full analysis draws on manufacturing footprints, regulatory event histories, and shortage-data correlations to indicate which supplier disruptions would have system‑wide consequences versus localized impacts.
What the full report contains (operational, not just descriptive)
-
Top-line market sizing and growth trajectories (2020–2025 history; 2026–2032 forecast). Our models show the market scaling from recent base to projected mid‑cycle levels under multiple scenarios.
-
Demand segmentation and end‑use dynamics with granular scenarios for chronic vs. acute care demand shifts (note: granular segment tables are intentionally withheld from this preview to preserve proprietary modeling value).
-
Supply‑chain topology and single‑point‑of‑failure mapping across API, formulation, and distribution layers.
-
Regulatory event tracker and timeline: continuous monitoring templates for quota announcements, ANDA outcomes, and shortage-list movements.
-
Financial impact matrices: EBITDA sensitivity to price moves, capacity outages, and payer contracting changes.
-
Scenario suite (mild disruption, moderate shortage, severe supply shock) with tactical playbooks for procurement, inventory, and commercial response.
-
M&A and partnership shortlists: prioritized targets and value levers for firms seeking to secure capacity or accelerate market entry.
-
Executive decision dashboards and 90/180/360‑day action roadmaps tailored for manufacturers, wholesalers, and payer procurement teams.
Strategic imperatives for 2026 (prioritized)
-
Lock in supply via diversified API contracts: Given the fixed annual production envelope established by quota authorities, buyers should secure multi‑tier API contracts with clear ramp provisions and fallback sourcing to mitigate allocation risk.
-
Build validated secondary manufacturing paths: Manufacturers and large wholesalers must prioritize validation of secondary CMOs for core strengths to reduce patient impact in case of primary plant downtime or product discontinuation.
-
Embed regulatory monitoring into operations: Maintain a real‑time regulatory feed (approvals/withdrawals, quota notices, shortage lists) integrated into supply‑planning systems so capacity plans can be reweighted within days rather than weeks.
-
Adopt scenario-based contracting: Use contingent contracts and staggered purchasing mechanisms that account for shortage states while preserving price discipline in normal markets.
-
Prioritize portfolio resilience over marginal share gains: Tactical launches or incremental contract wins that rely on fragile single-source supply are high risk; prioritize sustainable, contractible volumes backed by validated capacity.
-
Evaluate M&A and partnership options selectively: Target assets that provide API vertical integration, niche dosage form capabilities, or flexible manufacturing lines that can be retooled quickly.
-
Engage payers and health systems proactively: Work with purchasers to design substitution protocols and shortage contingencies that protect therapeutic continuity without eroding margins unnecessarily.
Implications and next steps
2026 will reward organizations that translate market visibility into operational resilience. The convergence of a fixed production envelope, active shortage listings, and discrete regulatory actions means that the marginal value of reliable supply and regulatory intelligence is higher than in prior cycles. Tactical measures taken in the first half of 2026 — securing diversified API supply, validating secondary manufacturing partners, and embedding real‑time regulatory feeds into operations — will materially reduce downside revenue volatility and reputational risk.
PW Consulting’s full study provides the granular, downloadable models, supplier scoring, and contract templates necessary to operationalize these recommendations. The report is expressly structured to help C‑suite leaders and operational heads create a 90–180 day mitigation plan and a 3‑year strategic playbook for sustained performance.
How to use this preview
Consider this piece a curated executive trailer: it outlines the market architecture, the levers that matter in 2026, and the prioritized actions to reduce exposure. If your team must decide on capital allocation, contract negotiations, or M&A moves before Q3 2026, the full study contains the proprietary segmentation, supplier-level exposures, and financial sensitivity tables you will need to convert strategy into implemented outcomes.
For detailed analysis of this topic, please visit the official page: Oxycodone Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Ear Tags Market to Hit USD 344.8M by 2032 (6.98% CAGR)
By PW Consulting, 2026-07-09
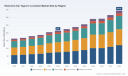
Electronic Ear Tags for Livestock: Strategic Imperative for 2026 — A PW Consulting Preview
Introduction — why this market matters now
The electronic ear tag market for livestock has graduated from niche precision-agriculture tool to core infrastructure for animal health, biosecurity and supply-chain transparency. Our analysis, based on a 2025 base year and a seven-year forecast through 2032, shows a clear and sustained growth trajectory — the global market size expands meaningfully from the 2020–2025 historical window into the forecast period, tracking at a compound annual growth rate (CAGR) of approximately 6.98%. By 2032 the market is projected to be materially larger than it was in 2025, reflecting the combined effects of regulation, procurement programs, technological maturation and commercialization of services layered on physical devices.
Electronic Ear Tags for Livestock Market
For corporate leaders evaluating product roadmaps, channel investments, M&A targets or go-to-market pivots in 2026, this is the inflection year: regulatory mandates and public programs are reshaping demand, new software integrations are compressing implementation friction, and supplier ecosystems remain sufficiently fragmented to reward disciplined consolidation or partnership strategies.
Electronic Ear Tags for Livestock Market
Why 2026 is a strategic decision point
-
Regulatory inflection: The post-2024 regulatory environment—most notably the rulemaking that requires ear tags applied after late-2024 for interstate cattle movement to be both visually and electronically readable—has accelerated procurement cycles among livestock producers and widened the definition of “compliant” device functionality. Parallel actions, including program-level distribution of no-cost RFID tags to eligible producers and region-specific traceability mandates, are creating pockets of immediate demand and new compliance requirements that manufacturers and integrators must internalize when sizing channels and forecasting revenue.
Electronic Ear Tags for Livestock Market -
Legal and policy uncertainty: Litigation challenging mandatory EID requirements is active and may alter adoption timing or cost responsibilities for producers. Executives must therefore build strategies that are robust across contestable regulatory outcomes—balancing near-term execution with contingency plans for shifts in cost pass-through and adoption subsidies.
-
Technology convergence: Bluetooth-enabled readers, improved EID reader integration, and barcode/RFID matching capabilities are reducing labor costs and read-failure rates. Software updates and platform integrations are converting tags from single-purpose identifiers into gateways for digital herd management, enabling monetizable analytics and services.
What the PW Consulting report delivers (practical, actionable content)
Our full market study is designed for decision-makers who need executable guidance rather than academic description. The report combines quantitative forecasting, qualitative competitive analysis and operational playbooks structured to support procurement, product and corporate strategy teams. Highlights include:
- Top-line market forecasts (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario-modeled demand curves tied to specific regulatory and subsidy outcomes.
- Modular go-to-market playbooks: channel segmentation, distributor economics, and pricing levers for hardware, consumables and recurring services.
- Total cost of ownership (TCO) and unit-economics templates to evaluate capex vs. service models (hardware sales, tag-as-a-service, subscription analytics).
- Regulatory and compliance matrix aligned to major jurisdictions and program rules, plus a litigation-risk dashboard to stress-test adoption scenarios.
- Supplier due-diligence pack and M&A screening criteria tailored to the market’s observed concentration and technology clusters.
- Field-proven implementation checklists covering reader infrastructure, integration with herd-management software, and traceability assurance testing.
Note: detailed segmentation tables (by region, species, and tag type), raw model files and vendor scorecards are intentionally reserved for the full report to preserve the competitive value of the underlying data and modeling assumptions.
Market dynamics and investment implications
The forces shaping the market are familiar — regulation, animal-health economics, and digitalization — but their interplay is producing new strategic vectors:
- Demand acceleration from compliance and subsidy programs: Regulatory rules and government-supported tag distribution have created an immediate procurement window for suppliers and integrators. Companies that can demonstrate verified compliance and streamlined distribution will disproportionately capture 2026 demand.
- Fragmented supplier landscape: The industry remains moderately fragmented, with the largest competitors accounting for a relatively modest share of total market value. That fragmentation creates opportunities for roll-up strategies, exclusive distribution partnerships, and platform plays that stitch device-level data into enterprise farm-management systems.
- Services as differentiation: Device specification is becoming table-stakes; differentiation will increasingly come from software integration, analytics, financing and after-sales service. Firms that move up the value chain can turn one-time device sales into annuity revenue and deeper customer relationships.
- Cost pressure and adoption economics: Per-head cost remains a concern for many producers. Successful commercial strategies will either reduce total installed cost through integrated solutions or create compelling ROI narratives (disease risk reduction, market access, logistics efficiencies).
Competitive landscape — who matters and why
The current supplier set includes established device specialists and regional players that have secured program approvals and distribution channels. A concise assessment of key participants reveals where competitive advantage lies:
- Datamars SA (Switzerland) — Strength: broad FDX/HDX product family with USDA 840 AIN and ICAR certifications, and clear product-line extensions (e.g., weighing tags). Strategic posture: premium product quality and certification leadership position Datamars well for program-driven procurement and export markets.
- Allflex USA, Inc. (United States) — Strength: expansive product portfolio and recognized brand across multiple species; compatibility with visual tag systems. Strategic posture: scale player with deep channel relationships and the ability to bundle solutions into enterprise offerings.
- Caisley International GmbH (Germany) — Strength: niche innovations such as tissue-collection integrated tags. Strategic posture: product differentiation through integrated sampling capabilities attractive to vertically integrated operations and genetics-focused buyers.
- Shearwell Data Limited (UK) — Strength: metal tag manufacturing and certified 840-series offerings. Strategic posture: focused on durability and regional compliance—appeals to producers prioritizing longevity and strict regulatory alignment.
- Y-Tex Corporation (United States) — Strength: established tagger systems and USDA-approved 840 series tags. Strategic posture: strong North American channel capabilities and field-support infrastructure.
- All Data Tags LLC, Leader Products, AniTrace, Inc. — Strengths: targeted product designs (button, panel, UHF/HDX/FDX variants) and program approvals. Strategic posture: nimble innovators who can win on specialized specs, speed-to-market and price.
Recent industry developments underscore these competitive themes: software vendors are accelerating reader integration (example: Bluetooth-enabled reader updates roll out in late 2025), device manufacturers continue to publish enriched product catalogs emphasizing compliance and integrated features, and litigation over mandatory tag requirements introduces timing risk for adoption-driven players.
Actionable strategic recommendations for 2026
Based on our scenario work and supplier due-diligence, we recommend executives prioritize the following actions this calendar year:
- Run three adoption scenarios in Q1–Q2: base, accelerated (policy-driven), and delayed (legal challenge) — stress-test supply, working capital and channel incentives under each.
- Secure compliance endorsements early: ensure products are validated against official device lists and maintain documentation for program eligibility; this reduces procurement friction in government-supported deployments.
- Pilot integrated service bundles: pair tags with data ingestion, analytics and financing to demonstrate clear ROI to producers; focus pilots on high-value disease-control or market-access use cases.
- Prioritize interoperability: support standard protocols and reader compatibility to minimize customer switching costs and enable partnerships with farm-management platforms.
- Evaluate M&A and partnership targets: look for targets that fill capability gaps (software telemetry, distribution reach, tissue-sampling tech) and can accelerate entry into prioritized geographies.
- Design contingency procurement: diversify suppliers and build inventory buffers to protect against sudden demand spikes tied to regulatory deadlines.
- Engage with policymakers and producer groups: shape implementation guidance, secure funding programs, and mitigate litigation-driven uncertainty through proactive stakeholder engagement.
Conclusion — how this research informs your 2026 playbook
For leaders deciding where to allocate capital and attention in 2026, electronic ear tags are a strategic lever that combines regulatory compliance, animal-health economics and digital transformation. The market’s steady CAGR and growing addressable use cases make it attractive, but success requires operational rigor: validated compliance, interoperable technology, service-enabled commercial models and contingency planning for regulatory shifts.
PW Consulting’s full report provides the granular segmentation, vendor scorecards, Excel-modelled forecasts and implementation playbooks required to translate the high-level moves above into executable 90–180 day plans. For commercial teams and boards preparing strategic decisions this year, the full dataset and supplier assessments are essential reading.
Next step
Access the full Electronic Ear Tags for Livestock Market report on the PW Consulting portal to obtain the detailed segmentation tables, downloadable financial models and vendor dossiers that underpin the recommendations summarized here. If you would like a tailored briefing or a workshop to translate this analysis into a bespoke action plan for your organization, contact PW Consulting’s Agriculture & Animal Health practice team to schedule a session.
For detailed analysis of this topic, please visit the official page: Electronic Ear Tags for Livestock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
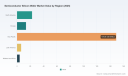
Semiconductor Silicon Wafer Market — Strategic Briefing for 2026 Decision‑Makers
Executive trailer
This introduction outlines the strategic value of PW Consulting’s full Semiconductor Silicon Wafer Market study for companies making capital, sourcing, and product‑roadmap decisions in 2026. The briefing demonstrates our analytical depth—macro demand trajectories, concentration dynamics, supplier actions, and geopolitical headwinds—while reserving the granular segment and regional tables for the full report available on our site. Think of this as the trailer: rigorous, directional, and designed to catalyze executive decisions today while motivating stakeholders to access the complete intelligence set for implementation details.
Semiconductor Silicon Wafer Market
Market snapshot: the headline numbers that matter
At the market level, the silicon wafer industry is on a multi‑year recovery and expansion path. Our model (base year 2025) projects the market to grow from roughly USD 195.6 million in 2025 to approximately USD 312.2 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. Historical trend analysis for 2020–2025 shows durable growth punctuated by cyclical stresses—useful when calibrating timing for capex or inventory moves in 2026.
Semiconductor Silicon Wafer Market
Operational metrics from industry bodies corroborate rising area shipments and revenue recovery: industry shipment volumes expanded into 2025 and accelerated further in early 2026, driven predominantly by AI and high‑bandwidth memory (HBM) demand for advanced epitaxial wafer types. These dynamics are creating both near‑term tightness in selected wafer formats and a longer runway of investment-led capacity additions.
Semiconductor Silicon Wafer Market
Why 2026 is an inflection year for strategic decisions
- AI and advanced packaging are accelerating demand patterns. Customer roadmaps for logic accelerators and HBM stacks are increasing demand for epitaxial and large‑diameter wafers—changing buying rules for OEMs and fabs.
- Supply‑side rebalancing is underway. Leading suppliers are shifting investments from brownfield expansion to targeted equipment upgrades and large‑diameter capacity buildouts—decisions that materially impact lead times and pricing through 2027–2029.
- Policy and financing are reshaping location decisions. Public funding mechanisms (e.g., CHIPS‑style programs) and evolving tariff/export controls are altering where new capacity is financially viable and politically tenable.
- Concentration compresses strategic choice. The wafer supply chain is highly concentrated (top‑3 suppliers account for a large majority of supply, top‑5 even more), which raises first‑mover value for buyers who secure preferred allocations or co‑investment terms.
Immediate strategic implications — what leadership teams must decide in 2026
- Capex timing and scale: Use scenario models that link wafer format demand curves to weighted lead‑time assumptions. Delaying or accelerating greenfield versus brownfield investments will change your cost of supply and market access over a multi‑year horizon.
- Supplier segmentation and contracting: Redefine tiering criteria beyond price—include technology roadmap alignment, allocation governance, and upgrade path commitments. Negotiate volume‑flex contracts with escape clauses tied to wafer format lifecycles.
- Risk mitigation and inventory strategy: Short pockets of format‑specific tightness suggest a hybrid approach: strategic buffer inventories for mission‑critical nodes combined with dynamic hedging for price volatility.
- M&A, JVs, and co‑investment: With high market concentration, selective equity stakes or long‑term supply agreements with leading wafer producers can secure privileged capacity. Evaluate opportunities to vertically integrate selectively where margins and strategic control justify capital deployment.
- Technology and product roadmap alignment: Accelerate co‑development with suppliers for epitaxial, SOI or advanced power substrates as required by your IC roadmaps—timing matters because supplier process windows are finite.
- Regulatory and trade playbook: Integrate tariff scenarios and export‑control contingencies into procurement decisions. Regulatory moves can re‑price geographic sourcing options rapidly; include them in supplier scorecards.
Competitive landscape — who matters and why
The wafer sector is dominated by a small number of high‑capacity, high‑technology suppliers. Market concentration amplifies the strategic value of supplier relationships and the consequences of supplier moves. Key industry players we profile in the full study include:
- Shin‑Etsu Chemical Co., Ltd. — globally leading producer across polished, epitaxial and SOI wafers; deep process expertise and scale (Tokyo‑headquartered).
- SUMCO Corporation — focused supplier across multiple diameters; recent strategic pivot toward equipment upgrades and consolidation of older assets underscores a shift to higher diameters.
- GlobalWafers Co., Ltd. — broad portfolio with accelerating US investment tied to public funding incentives; notable for power device and epitaxial capabilities.
- Siltronic AG — specialist in high‑purity wafers with strong presence in power and advanced logic segments; integration dynamics are noteworthy for European supply strategies.
- SK Siltron Co., Ltd. — supplier with polished and epitaxial strengths; relevant for East Asian and global sourcing decisions.
Recent corporate actions—facility closures, equipment upgrade prioritization, and multi‑billion dollar greenfield expansions—are reshaping allocation risk and the forward cost curve. The full report provides a supplier scorecard, investment maps and scenario‑specific allocation forecasts to help procurement and corporate development teams act with precision.
What the PW Consulting report delivers (practical, executable content)
Our market study is built for execution. Highlights include:
- Proprietary demand model (2020–2032) with scenario toggles for AI uptake rates, memory cycle timing, and advanced packaging adoption—convertible into stratified procurement forecasts for 12–36 month horizons.
- Capex and IRR playbook for wafer producers you may partner with or evaluate for M&A—sensitivity tests on time‑to‑market, yield ramps, and incremental margin curves.
- Supplier scorecards that synthesize technology fit, allocation risk, geopolitical exposure, and financial health into actionable procurement tiers.
- Tariff and export‑control matrix that quantifies downside exposure under plausible policy pathways and recommended mitigations.
- Operational tools: cost‑to‑serve maps, lead‑time heatmaps, and a negotiation checklist to convert strategic intent into binding supplier commitments.
- Playbooks for co‑investment structures and JV term sheets tailored to mitigate dilution and align long‑term capacity commitments with customer demand profiles.
Case‑level guidance (how to use the report in the next 90–180 days)
- Procurement directors: run the supplier scorecard and invite top‑tier suppliers to an allocation RFP tied to staged investment commitments.
- Corporate development: prioritize targets where valuation misalignment exists between local incentives and global demand forecasts; use our capex model to stress test synergies.
- Product & fab planners: re‑baseline BOMs and wafer mix assumptions in your 2027 roadmaps; plan qualification windows that align with supplier upgrade timelines.
- Risk & compliance teams: adopt the tariff sensitivity scenarios and policy triggers in our matrix as part of your quarterly risk register updates.
Why PW Consulting — an outcome focus
Our research combines macro demand forecasting, granular supplier analysis, and executable commercial playbooks. The market’s concentrated supplier base and the overlay of AI‑driven product demand mean that timing, supplier choice, and contractual structure will determine competitiveness for years. The study is designed not merely to inform but to enable buy‑side and strategic decisions in 2026 that lock in lower total cost of ownership, secured allocation, and better strategic optionality.
Next step — access to full intelligence
This briefing intentionally omits the detailed regional and application splits and the proprietary sensitivity tables that underpin our recommendations—the core data that execution teams need. Accessing the full report provides those granular breakdowns, interactive models, and supplier dashboards required to operationalize the strategies summarized here. To obtain the complete dataset, forecasts by wafer type and application, supplier scorecards, and the negotiation playbook, please visit the PW Consulting report page or contact our analyst team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Semiconductor Silicon Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
OPGW Market Strategic Briefing: Why 2026 Decisions Depend on Precision Intelligence
Executive snapshot
Optical Fiber Composite Overhead Ground Wire (OPGW) is no longer a niche component of transmission infrastructure — it is a strategic enabler of grid observability, telecommunications resilience, and renewable corridor integration. Our PW Consulting market study, anchored to a 2025 base year and projecting through 2032, models the OPGW market expanding at a 4.22% CAGR. The market value rises from a mid‑hundreds million USD baseline in 2025 to an anticipated near‑billion USD opportunity by 2032. For capital planners, utilities, EPC contractors, and strategic suppliers, the question for 2026 is not whether to engage with OPGW, but how to allocate limited capex and supplier relationships to capture the most durable value.
Optical Fiber Composite Overhead Ground Wire (OPGW) Market
Why this study matters for 2026 decisions
-
Timing of retrofits vs. new builds: Our scenario models show that near‑term replacement cycles and new high‑voltage projects create discrete decision windows in 2026 where procurement timing materially affects lifecycle cost and service levels.
Optical Fiber Composite Overhead Ground Wire (OPGW) Market -
Standards and acceptance criteria are shifting: A 2025 corrigendum to the IEEE OPGW standard recalibrates environmental and mechanical acceptance testing — these changes directly alter contract specifications, testing regimes, and supplier qualification hurdles that buyers must incorporate into 2026 tenders.
Optical Fiber Composite Overhead Ground Wire (OPGW) Market -
Supply‑chain arbitrage is now a strategic lever: Geopolitical export controls and tariffs on components from certain origins introduce procurement risk premiums for projects in North America and Europe; our stress tests identify which sourcing strategies minimize schedule and cost disruption.
-
Operational value beyond conductors: Smart‑grid enablement is responsible for a material share of recent OPGW deployments. Integrating fiber for telemetry, real‑time monitoring and predictive protection can shift projects from CAPEX‑only to CAPEX+OPEX value streams, changing project appraisal in 2026.
Market trajectory — headline figures (what we disclose here)
Measured against a 2025 base year, our forecast indicates steady growth through the 2026–2032 horizon at a 4.22% CAGR. The model anticipates a meaningful uplift in 2026 as utilities accelerate replacement of aging low‑fiber installations and incorporate higher fiber‑count solutions into new HV corridors. By 2032 the opportunity approaches the upper hundreds of millions of USD annually, reflecting both unit price inflation and expanded fiber adoption on transmission projects.
Cost, installation and regulatory dynamics that will shape 2026 tenders
-
Installation and labour: Specialized splicing and grounding procedures for hybrid fiber‑metal cables impose a premium on labour. Field evidence indicates splicing and protective handling can add a mid‑teens percentage increase in specialized labour time and cost versus standard shield‑wire installs; this has immediate implications for unit labour allowances in 2026 budgets.
-
Material pricing: Recent procurement records show representative per‑meter pricing bands for certain aluminum‑tube OPGW designs; procurement teams must normalize these bands to project‑specific specifications and logistics when assembling 2026 cost baselines.
-
Standards & acceptance testing: The 2025 corrigendum to IEEE’s OPGW guidance tightens environmental and mechanical acceptance criteria. Buyers who do not update their contract test clauses risk delayed acceptance and warranty disputes; conversely, suppliers who pre‑qualify to the revised clauses can speed approval cycles.
-
Smart‑grid integration: Utilities are increasingly attaching non‑power value to OPGW deployments — in several markets roughly a third of new HV projects favour OPGW to enable telemetry and predictive maintenance. This trend alters the ROI calculus for 2026 projects by adding avoided‑downtime and grid‑management benefits to the business case.
-
Geopolitical supply risk: Export restrictions and tariffs on components of certain origins are already influencing bid evaluation and total landed cost in critical markets — a material procurement risk to account for in 2026 supplier scorecards.
Competitive landscape — positioning and strategic implications
The OPGW vendor field sits in a moderate concentration band — our market concentration metrics show leaders capturing a meaningful but not dominant share of the market. This structure creates scope for both established multinational suppliers and regional champions to win strategic programs if they align technology, testing credentials, and local market access.
-
AFL (US): AlumaCore family targets line replacement opportunities with hermetically‑sealed aluminum pipe constructions and high fiber counts. Their design and standards compliance make them an attractive partner where legacy shield wires are being retired and direct replacements are sought.
-
Tratos Group (Italy): Their hybrid OPGW with carbon composite strength members and jelly‑filled sheaths is positioned for projects demanding high mechanical performance with tailored fiber selections — a fit for bespoke corridor upgrades and high‑voltage retrofits.
-
ZTT Group (China): High‑capacity production capabilities and active participation in standards evolution are ZTT’s strengths. Their scale suits ultra‑high voltage projects where volume and project timelines dominate procurement choices.
-
Fujikura (Japan): Emphasizes low‑loss fiber systems optimized for signal stability — relevant where long transmission runs or long‑haul telecom overlay are mission‑critical.
-
NKT Cables (Denmark): Corrosion‑resistant variants target coastal and offshore installations — a niche but growing requirement as transmission projects traverse harsher environments.
-
LS Cable & System, Taihan (South Korea): These players bundle smart‑grid compatibility and monitoring interfaces into their offerings — useful for utilities prioritizing digital grid capabilities.
-
Elsewedy, Sterlite (STL), Hengtong, Jiangsu Hongtu, Sichuan Huiyuan and others: Regional leaders with tailored offerings for emerging markets, high‑density fiber lines, and integrated transmission projects. Their value propositions often hinge on local project support and competitive pricing.
Recent project and standards signals
-
Project planning examples from 2026 highlight the practical migration challenge utilities face: multi‑mile replacements of low‑fiber OPGW with higher fiber counts to restore degraded fiber plant while maintaining shielding responsibilities. Such programs expose vendors and constructors to splice volume, jointing shelter logistics, and schedule risk that must be priced into 2026 bids.
-
Standards updates through late 2025 require procurement and quality teams to recalibrate acceptance testing. Vendors with demonstrable compliance and independent test records will command shorter acceptance cycles and reduced warranty friction.
What our full report delivers (operational content you can act on)
The PW Consulting offering is designed as an operational playbook for 2026 decision‑makers. The full study combines quantitative market modelling with executable workstreams and includes:
-
Scenario‑based demand modelling and procurement timing matrices to prioritize retrofit windows and new corridor capitalization.
-
Unit cost benchmarking (materials, splicing and testing), installation labour allowances, and logistics sensitivity analyses for multiple route archetypes.
-
Supplier scorecards mapped to the revised IEEE acceptance framework, including historic pass/fail profiles and proposed contract language to reduce dispute risk.
-
Supply‑chain risk heatmaps accounting for tariff exposure, single‑source components, and recommended mitigation (dual‑sourcing, component stockpiles, qualifying regional production).
-
Deal playbooks for utilities and EPCs: contracting templates, performance bonds, and testing schedules geared to shorten commissioning cycles.
-
Investment cases and NPV sensitivity tables that incorporate smart‑grid benefit streams and outage‑avoidance value, enabling finance teams to justify 2026 capex.
Practical recommendations for 2026 procurement and strategy
-
Update technical specifications now to reflect the IEEE corrigendum. Incorporate explicit environmental and mechanical acceptance tests to avoid rework at commissioning.
-
Bid for supplier pre‑qualification that includes evidence of field splice throughput and third‑party test results — this reduces schedule and quality risk on complex replacement jobs.
-
Factor specialized labour premiums into unit rates and explore bundled O&M contracts that transfer splice warranty risk to experienced suppliers.
-
Quantify smart‑grid incremental benefits and include them in the business case for OPGW where telemetry and predictive protection reduce outage costs.
-
Mitigate geopolitically driven component risks with a mix of regional sourcing and contingency inventory for critical long‑lead items.
Closing — the value of full intelligence in 2026
The OPGW market presents a window of strategic opportunity as transmission networks modernize and standards evolve. Our study codifies the pathways by which utilities, EPCs and suppliers can translate grid modernization objectives into executable projects with predictable outcomes. This article provides the directional intelligence needed to shape immediate strategy; the full PW Consulting report delivers the granular segmentation, supplier revenue shares, regional assessment and contract‑level models you will need to execute with confidence in 2026. For access to the complete dataset, segmentation tables and actionable templates, please consult the full report.
For detailed analysis of this topic, please visit the official page: Optical Fiber Composite Overhead Ground Wire (OPGW) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Crypto Hardware Wallet Market to Reach USD 344.8M by 2032 at 19.87% CAGR
By PW Consulting, 2026-07-09
Cryptocurrency Hardware Wallet Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest industry briefing on the Cryptocurrency Hardware Wallet Market frames a decisive moment for enterprise strategy in 2026. After a steady recovery through 2020–2025, the market has entered a high-growth phase driven by regulatory mandates, insurance dynamics, and rapid product innovation. Our analysis projects that the market, which exceeded USD 200 million in 2025, will expand at a compound annual growth rate of roughly 19.9% through the 2026–2032 forecast window, creating new value pools and strategic inflection points for manufacturers, custody providers, retailers and enterprise security teams.
Cryptocurrency Hardware Wallet Market
Why this research matters for 2026 planning
-
Actionable foresight in a compliance-first era — Since late 2024, binding custody rules in major jurisdictions have redefined how client assets must be isolated and protected. This shifts demand from point solutions to certified, auditable hardware and changes procurement criteria for regulated entities.
Cryptocurrency Hardware Wallet Market -
Insurance and risk transfer dynamics — Insurers are increasingly linking coverage terms to specific device certifications and operational patterns. Access to underwritten custody solutions now requires visibility into device assurance levels and integration with institutional workflows.
Cryptocurrency Hardware Wallet Market -
Product and distribution bifurcation — Consumer convenience (mobile, NFC and retail availability) and institutional-grade assurances (secure elements, EAL certification, air-gapped workflows) are driving parallel product roadmaps and go-to-market plays. Understanding how these vectors evolve is critical to segment-level pricing, partnerships, and channel strategies.
-
Strategic timing — With the market poised to more than double over the decade at near-20% CAGR, 2026 is not a runway year but an execution year. Decisions made now on R&D allocation, certification roadmaps, and channel expansion will materially affect competitive positioning through 2032.
Market trajectory and macro numbers (what we disclose)
Our base-year reference is 2025. The market has grown from a low-mid-hundreds million-dollar base in 2020 to surpassing USD 200 million by 2025. From 2026 onward, PW Consulting models a robust expansion driven by enterprise adoption, regulatory compliance buys, and retail mainstreaming. Over the forecast period to 2032 the market is modeled to grow at a compound annual growth rate of approximately 19.87%, reflecting accelerating adoption curves as hardware wallets become integral to custody frameworks and personal custody solutions reach retail maturity.
We also assess market structure: concentration metrics indicate a moderately fragmented field with the top three and top five vendors controlling under one-third of market revenue — a dynamic that sustains opportunities for new entrants and niche innovators while allowing leading brands to leverage scale in certification and channel development.
Regulatory and institutional dynamics shaping demand
-
MiCA and custody segregation — The EU’s Markets in Crypto-Assets (MiCA) regime, and its Article 76 custody requirements that became fully binding in late 2024, have institutionalized the use of dedicated offline hardware wallets for client segregation. This regulatory baseline has served as a forcing function for European custodians and influenced global best-practice benchmarks.
-
US supervisory guidance and equivalence — Parallel guidance from US banking authorities and interpretations from the OCC have increased demand for hardware security modules or equivalent secure elements for qualified custody. Interpretation convergence between jurisdictions reduces cross-border uncertainty for global custody providers.
-
Certification, insurability and capital efficiency — Post-2024 changes have linked insurance terms to device-level certifications (e.g., EAL levels) and operational patterns such as multi-party control and air-gapped signing. This has both elevated engineering barriers to entry and created differentiation opportunities for certified vendors.
Competitive landscape — who’s moving the market
Our competitive mapping focuses on vendors that have combined product depth, certification progress and channel momentum to influence enterprise and retail roadmaps. The report provides deep vendor profiles, product positioning analyses and go-to-market intelligence for leading players including:
-
Ledger (Paris, France) — Known for the Nano series signers (now reframed with the “signer” nomenclature) and Flex/Stax lines, Ledger’s portfolio emphasizes broad cryptocurrency coverage and consumer-facing integration. Recent launches include a redesigned Nano Gen5 with Bluetooth Low Energy and customizable design features that increase retail appeal.
-
Trezor (Prague, Czech Republic) — A long-standing open-source player with the Trezor Safe 7 pushing into auditable secure element architectures and quantum-ready claims. Trezor’s positioning balances transparency and institutional-grade control tools.
-
Coinkite (Toronto, Canada) — A niche specialist with the Coldcard lineage focused on Bitcoin-only air-gapped signing devices. Recent product refreshes have reinforced UX and form-factor features favored by advanced users and certain institutional workflows.
-
Blockstream (San Francisco, USA) — Offers open-source, air-gapped devices geared to Bitcoin and Liquid asset workflows, emphasizing verifiable hardware provenance and developer transparency.
-
Tangem (Zurich, Switzerland) — Innovator in card-form, seedless NFC wallets targeting mass retail distribution; recent retail expansion has placed offline crypto wallets into major consumer outlets.
-
Keystone and Ellipal (Hong Kong) — Two players pursuing large touchscreen, fully air-gapped and multi-crypto approaches that speak to both retail and advanced custody use cases.
Recent product and channel moves to watch
-
Product cadence — October 2025 saw simultaneous flagship introductions from Ledger and Trezor, signaling that leading brands are racing on both hardware innovation and messaging (e.g., “signers” vs “quantum-ready”).
-
UX and form-factor differentiation — 2026 product updates show UX is increasingly a competitive frontier: larger screens, redesigned input methods, and NFC/air-gap hybrids are being prioritized to lower operational friction for both retail and enterprise operators.
-
Retail distribution and mainstreaming — Tangem’s expansion into major US retail channels highlights a pathway to consumer scale absent a pure-online model; expect more partnerships that blur retail and digital distribution.
What this report contains (practical utility)
The full PW Consulting market study is designed for executives who must transform market intelligence into strategy. It contains:
-
Quantitative market model — historic (2020–2025) and forecast (2026–2032) revenue scenarios, sensitivities and scenario-based outcomes tied to regulatory and adoption inflection points.
-
Segmentation intelligence — by region, connectivity (USB, Bluetooth, NFC and air-gapped variants) and application (retail/individual vs institutional custody). Note: core segmentation tables and granular splits are reserved for the full report to preserve competitive advantage and to enable detailed licensing.
-
Vendor dossiers — comparative product feature matrices, certification status, go-to-market channels and near-term roadmap signals for the major suppliers in the market.
-
Commercial playbooks — partner selection frameworks, certification prioritization roadmaps, pricing and margin benchmarks, and pocket-sized acquisition checklists for procurement teams.
-
Implementation guides — operational controls for custodians, integration checklists for security architects, and testing protocols aligned with EAL and secure element requirements.
-
Investment and M&A perspective — identification of value-accretive adjacencies, buy-build considerations, and an assessment of consolidation triggers given current concentration dynamics.
How enterprise leaders should use this briefing
-
CISOs and security architects — Use the report to define procurement specs that align device selection with insurer and regulator expectations. Prioritize devices with audited secure elements and documented EAL certifications where insurability is a factor.
-
Product and R&D heads — Map feature investments (e.g., air-gap UX, secure element provenance, operator tooling) to indicated demand pockets and certification pathways that unlock institutional contracts.
-
Channel and distribution teams — Determine whether to pursue mass retail playbooks, white-label OEM partnerships, or institutional partnerships with custody providers based on forecasted revenue profiles and channel economics.
-
Investors and corporate development — Leverage our scenario analysis to appraise target valuations and identify tranche-based investment strategies tied to certification milestones and go-to-market execution.
Trailer principle and next step
This preview surfaces the market drivers, regulatory inflection points, vendor dynamics and the high-level numbers that matter for 2026 planning — including a near-20% CAGR projection and a clear path toward several hundred million dollars of market opportunity by the end of the decade. To preserve the competitive value of the deep, modelled segmentation and the full set of tactical recommendations, the granular regional and application splits, price curves, and device-level revenue shares are provided exclusively in the full PW Consulting report.
Conclusion
For 2026, the Cryptocurrency Hardware Wallet Market is no longer an early-adopter niche but an operational imperative in regulated custody and a consumer product category moving toward mainstream retail presence. The convergence of regulatory requirements, insurer conditions, and product innovation creates a compressed window where decisive moves — certification investments, channel partnerships, or targeted M&A — can secure long-term positioning. PW Consulting’s full study translates the market’s macro momentum into executable steps for leaders who need to act now. Access the complete research to see the segment-level analytics, device-level comparisons and the tactical playbooks that will guide profitable decisions through 2032.
Contact PW Consulting to obtain the full report, request a tailored briefing, or license our vendor and device model for internal use.
For detailed analysis of this topic, please visit the official page: Cryptocurrency Hardware Wallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bancassurance Market at USD 1.27T in 2025, 5.17% CAGR (2026–2032)
By PW Consulting, 2026-07-09
Bancassurance Market 2026: Strategic Imperatives and What Leaders Must Act On
Executive snapshot
From a $950 billion industry at the start of the last decade to an estimated $1.27 trillion in our base year (2025), the bancassurance market is on a steady trajectory that demands boardroom attention. PW Consulting’s proprietary forecast (2026–2032) projects the market to grow at a 5.17% CAGR over the forecast period, resulting in a materially larger and structurally different market by 2032. For executives preparing budgets, partnership roadmaps, and M&A playbooks in 2026, this growth profile compresses the timeline for capability build and makes timing a strategic variable—not just an operational one.
Bancassurance Market
Why 2026 is a strategic inflection point
The coming year is not merely another data point on a growth curve. It is a confluence of regulatory change, digital resilience mandates, and shifting commercial economics for banks and insurers. Recent regulatory moves—ranging from national-level bancassurance directives to supranational digital and data laws—are recalibrating how bancassurance products can be marketed, sold, and technologically supported. Concurrently, capital treatment relaxations in certain jurisdictions and new digital operational resilience obligations increase both the opportunity set and the compliance bar for integrated models.
Bancassurance Market
- Regulatory momentum: New directives and amendments are formalizing bancassurance product definitions, licensing expectations, and marketing protocols in several jurisdictions, changing the threshold for market entry and partnership design.
- Digital resilience and data access: Cross-border regulatory frameworks now require banks and their insurance partners to harden operational resilience and to rethink customer data access models—creating both friction and fertile ground for differentiated product innovation.
- Capital and business-model incentives: Targeted easing of capital requirements in key markets is encouraging banks to consider deeper strategic investments with insurance partners, accelerating the move from distribution-only arrangements to hybrid ownership and captive-insurer structures.
Market dynamics: how growth is getting reshaped
Growth in bancassurance is less about raw demand than about distribution efficiency and the ability to convert banking customer relationships into insurance lifetime value. The market’s historical expansion reflects both product breadth and the widening remit of banks as embedded financial-services platforms. But the next phase of growth will be characterized by:
Bancassurance Market
- Platformization of distribution: Banks are investing to make insurance offerings part of everyday banking journeys via APIs, white-label products, and embedded-insurance models—shifting the economics from transactional commissions to lifetime revenue sharing.
- Data-driven product tailoring: With new data access rules, advanced insurers and progressive banks can design hyper-personalized protection and savings solutions—but only if they resolve consent, portability, and governance issues at scale.
- Operational resilience as a competitive moat: Compliance with digital operational resilience frameworks is becoming a market differentiator: firms that can demonstrate high uptime, secure integrations, and fast recovery will win distribution exclusivity and partner trust.
- Strategic capital allocation: As capital-treatment changes reduce barriers to deeper integration, expect a bifurcation between banks that remain pure-distributors and those that move to partial ownership or captive models to capture higher long-term margins.
Competitive landscape: who matters and why
The bancassurance field is populated by global banking groups that vary in strategy, scale, and market focus. Our analysis profiles leading institutions—ranging from full-service global banks to regionally dominant retail banks—and highlights the strategic approaches that differentiate winners from the rest:
- BNP Paribas (Paris): Uses its global banking network to position bancassurance as a core distribution channel for both life and non-life solutions. Strategic implication: BNP’s integrated approach favors insurers seeking broad, multi-jurisdictional reach.
- Crédit Agricole (Paris): Leverages a retail banking footprint and captive insurance capabilities, underlining a vertically integrated model. Strategic implication: Attractive for insurers seeking predictable scale and deep local distribution partnerships.
- Société Générale (Paris): Focuses on protection, investment, and savings via banking channels—emphasizing packaged customer journeys. Strategic implication: Its model favors product bundling and cross-sell optimization.
- Intesa Sanpaolo (Turin): Prioritizes an extensive domestic network with targeted international reach—ideal for insurers pursuing high-density market penetration.
- HSBC (London): Operates globally with capabilities across life, non-life, and wealth insurance—well-suited for insurers and reinsurers aiming for premium, cross-border products.
- Wells Fargo (San Francisco): Maintains a U.S.-focused distribution approach; useful partner for insurers seeking deep engagement in North American retail banking channels.
- Barclays, ING, ABN AMRO, Lloyds Banking Group: These institutions exhibit a mix of retail & corporate channel strategies, with strengths in regional execution and digital banking integrations.
Across the competitive set, market concentration remains modest—the top three and top five banking groups together capture under one-third of the market—indicating substantial opportunity for mid-sized banks, fintechs, and specialized insurers to carve differentiated niches through technology, product design, and local regulatory agility.
What this means for 2026 corporate decisions
Leaders should treat 2026 as a make-or-accelerate year. Decisions that can no longer wait include:
- Partnership architecture: Decide whether to pursue distribution-only agreements, bancassurance joint ventures, or partial ownership of insurance entities. Each route carries different capital, control, and compliance implications.
- Technology road map: Invest in modular, API-first platforms that allow rapid product rollouts, experiment with embedded insurance offers, and ensure compliance with digital resilience standards.
- Data governance: Implement consented data-sharing frameworks to monetize customer insights while remaining compliant with emerging data access laws; this is both a legal necessity and a commercial enabler.
- Operational risk posture: Align IT and third-party risk management to meet digital resilience mandates and to secure partner approvals—failure here will limit distribution options.
- M&A and inorganic options: Evaluate targeted acquisitions or minority stakes in specialty insurers to accelerate product capabilities or access proprietary underwriting data.
What PW Consulting’s full report delivers (practical, action-oriented)
Our full Bancassurance Market research goes beyond high-level forecasts to provide a practical toolkit senior leaders can deploy in 2026. Highlights include:
- Scenario-based financial models calibrated to different partnership archetypes (distribution-only, JV, partial ownership), enabling rapid valuation and ROI sensitivity analysis.
- Vendor and partner scorecards—standardized criteria for selecting insurance partners, tech vendors, and distribution integrators.
- Go-to-market playbooks for embedded insurance, cross-sell campaigns, and branch-digital integration, complete with KPI templates and pilot design checklists.
- Technology and security due-diligence checklists mapped to digital operational resilience requirements and third-party risk expectations.
- Regulatory tracker and compliance playbook—interpreting recent directives and major laws so you can fast-follow reforms across critical jurisdictions.
- Executive dashboards and interactive tables that break down historical performance (2020–2025), the 2026 inflection scenarios, and detailed forecasts through 2032—ready for board presentations.
To respect competitive sensitivity and our “trailer” principle, the full report reserves granular regional and product-level split tables, detailed competitor market shares, and downloadable modeling templates for report subscribers and clients. These elements are the difference between a well-informed strategic discussion and a fully executable plan.
How to use the report to accelerate value capture in 2026
We advise clients to adopt a three-track approach this year:
- Protect: Shore up compliance and operational resilience to maintain current distribution agreements and avoid regulatory friction.
- Pilot: Launch 6–12 month embedded insurance pilots tied to discrete banking journeys (for example, lending or savings) to test pricing, underwriting, and consent mechanics.
- Scale or partner: Based on pilot outcomes and capital allocation choices, scale winners or fast-track M&A/partnerships to secure shelf space and exclusive distribution terms.
Each of these tracks requires different resource mixes and governance levels; our report provides templates to map those resource implications to expected revenue uplifts and capital needs under multiple scenarios.
Methodology and transparency
The analysis uses a base year of 2025 with historical context from 2020–2025 and a forecast horizon of 2026–2032. All values are presented in USD (Billion) and the market-level CAGR for the forecast window is 5.17%. Our methodology triangulates revenue reporting from banks and insurers, public filings, partner-disclosure data, and a bottoms-up model that accounts for distribution economics, retention rates, and pricing trends.
Next steps and how to access the full intelligence
For executives who must translate vision into validated action plans this year, the full PW Consulting Bancassurance Market report is built as your go-to strategic and operational manual. It contains the detailed regional and product splits, competitor market-share analytics, and downloadable playbooks that we have deliberately excluded from this primer to encourage direct engagement with the full intelligence package.
Visit our report page to access the comprehensive dataset, interactive forecasts, and client-only workshops that will help you convert 2026’s regulatory and digital disruption into durable market advantage.
For detailed analysis of this topic, please visit the official page: Bancassurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: QKD Market Set for Breakout Growth at 31.6% CAGR (2026–2032)
By PW Consulting, 2026-07-09
Strategic Preview: Quantum Key Distribution (QKD) Market — Why PW Consulting’s 2026 Study Is Essential for Executive Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-value orientation to our latest Quantum Key Distribution (QKD) market study. This preview is designed to help C-suite leaders, chief information security officers, investment committees, and infrastructure planners understand why QKD matters in 2026 — and how our research will change the shape of near-term strategic choices. We demonstrate the technical and commercial contours of the market while intentionally withholding granular segment-level figures; the full report contains the detailed splits and operational templates that successful adopters will need.
Quantum Key Distribution (QKD) Market
Macro Market Context: Growth, Scale, and Momentum
QKD has moved beyond academic proof-of-concept to commercial deployments across metropolitan, national, and nascent satellite-enabled networks. In our base year (2025) the market reached a meaningful commercial scale, and our forecast points to continued rapid expansion through the end of the forecast horizon. The report quantifies this trajectory with a multi-year forecast and a compounded annual growth rate (CAGR) that underscores both urgency and opportunity for decision-makers.
Quantum Key Distribution (QKD) Market
- Historical acceleration in the early 2020s has given way to broad commercial interest and larger infrastructure projects by governments and industry incumbents.
- Our modeling captures technology maturation, supply-chain dynamics, and policy-driven demand drivers which together explain a high-growth market profile over the next decade.
Why This Report Matters for 2026 Decisions
- Procurement and network design. QKD requires specialized hardware and dedicated optical channels; the wrong architecture creates stranded assets. Our research includes decision frameworks that align security requirements to deployment architectures and procurement timelines.
- Risk management and cryptographic strategy. For organizations balancing near-term protection against future quantum threats, we provide comparative scenarios that integrate QKD with post-quantum cryptography (PQC), helping you avoid single-track commitments.
- Supplier selection and contractual playbooks. With a concentrated vendor landscape, selection criteria must move beyond feature checklists to include supply-chain resilience, interoperability roadmaps, and validation capabilities; our vendor frameworks and contract templates make that practical.
- Investment and M&A perspective. For investors and corporate development teams, our report highlights where to expect margin expansion, consolidation risk, and platform bets (chip-scale QKD, satellite links, photonic integration).
- Operational readiness and pilots. We give step-by-step pilot designs and KPIs so that a pilot in 2026 can quickly evolve into production in 12–24 months, minimizing integration surprises.
What’s Inside the Full Report (Practical, Actionable Content)
- Market sizing and forecast with scenario analysis (base year and a multi-year outlook).
- Deployment playbooks — from short-range metropolitan links to hybrid terrestrial-satellite architectures.
- Vendor profiles and capability maps, including strengths, risk factors, and suggested procurement questions.
- Technical validation and test plans for integration, including typical failure modes and acceptance criteria.
- Commercial models and total cost of ownership templates that factor capital, operations, and specialized labor.
- Regulatory and standards tracker covering certification risks and likely harmonization pathways.
- Strategic roadmaps for CTOs and CISOs showing recommended timelines for pilots, phased rollouts, and contracts.
Market Dynamics Every Executive Must Understand
- Physical-layer constraints. Photon absorption and signal attenuation in optical fiber impose a practical distance ceiling on unassisted terrestrial QKD links; beyond that, architectures rely on trusted nodes, repeaters (still experimental), or satellite relays. This reality shapes network topology, vendor choice, and unit economics.
- Hardware-first implementation model. QKD cannot be delivered as a pure software or cloud service: it requires specialized endpoint hardware and low-noise optical channels. That means capital investments in fiber and photonics, and vendor lock-in risks if interoperability is not contractually enforced.
- Validation and assurance complexity. Security guarantees depend as much on engineering and hardware integrity as on quantum physics; testing regimes must therefore include hardware-forensics, side-channel assessments, and manufacturing quality controls.
- Standards and certification fragmentation. The absence of an agreed adjudication framework between QKD and PQC has produced a fragmented certification environment — creating compliance risk and procurement ambiguity for large buyers.
- Infrastructure integration friction. Many deployments require dedicated fiber or significant retrofits of existing networks. Integration costs and lead times are non-trivial and are often the hidden drivers of total project cost.
Competitive Landscape — Strategic Profiles and Implications
The vendor landscape is characterized by established photonics incumbents, specialist QKD system integrators, and a new wave of chip-scale entrants. Top-tier vendors dominate commercial deployments today, while recent entrants focus on cost reduction and integration density.
Quantum Key Distribution (QKD) Market
- ID Quantique (Geneva) — Strong in long-distance, multi-site systems and field-proven platforms for financial and government networks. Suitable for buyers prioritizing established operational track records and comprehensive service offerings.
- Toshiba Digital Solutions (Tokyo) — Demonstrated metro-scale deployments and fiber multiplexing innovations. A viable choice where metro-scale integration into commercial fiber is a priority.
- QuantumCTek (Suzhou) — Large-scale infrastructure experience in governmental and financial networks; important partner or competitor in markets with state-sponsored quantum programs.
- KETS Quantum Security (Stratford-on-Avon) — Focuses on chip-scale systems: read for buyers prioritizing size, cost, and potential for endpoint integration at scale.
- QuintessenceLabs (Melbourne) — Offers integrated QKD and secure communications for public sector and finance; competes where compliance and bespoke security services matter.
- MagiQ Technologies (New York) — Component- and system-level capability for network security integrations.
- QNu Labs (Bangalore) — Tailored deployments for government and financial institutions with long link deployments; relevant in markets seeking localized supply chains.
- LuxQuanta Technologies (Barcelona) — Focused on CV-QKD systems with multi-receiver support, pushing performance at metro ranges; relevant for telco and multi-tenant deployments.
- HEQA Security (Tel Aviv), KEEQuant (Munich), SpeQtral (Singapore), Qubitekk (Carlsbad) — Each brings differentiated strengths from enterprise-grade systems to photonic integration and component innovation.
- Thales Alenia Space (Paris) — Active in GEO QKD prototypes and satellite QKD; watch for space-enabled architectures that reframe national and cross-border key distribution.
Recent Developments Shaping 2026 Strategy
- Major terrestrial network deployments and national infrastructure programs signal governments’ commitment to quantum-resilient communications.
- Chip-scale commercial launches and photonic integration breakthroughs aim to shift cost curves and broaden addressable markets.
- Satellite QKD prototypes and space network announcements are elevating strategic options for long-distance, trust-minimized links, but they come with programmatic risk and high lead times.
Actionable Strategic Recommendations for 2026
- Run phased pilots this year. Short metro pilots that validate operational integration and acceptance criteria are the highest-return first step. Use the pilot to stress-test vendor support, QA processes, and operational playbooks.
- Design hybrid cryptographic architectures. Combine QKD where it provides clear physical-layer advantages with PQC for broad-scope protection; avoid binary “QKD-only” or “PQC-only” strategies.
- Insist on interoperability clauses. Given current fragmentation, contractual commitments to APIs, optical interoperability tests, and third-party validation are essential to avoid locked-in upgrade costs.
- Assess supply-chain and manufacturing risk. Photonic components and specialized detectors have constrained sources; build multi-sourcing plans or partner with vendors that disclose manufacturing roadmaps.
- Monitor standards and certification trajectories. Adopt conservative timelines for compliance, and allocate budget to cover evolving certification requirements.
- Align procurement with network topology. The choice between short-range, chip-scale, and satellite-assisted systems should be driven by network topology, regulatory constraints, and total ownership economics — not by vendor pitch decks alone.
Closing: How to Use the Full PW Consulting Study
This preview outlines the strategic levers and operational realities that will determine winners and losers as QKD moves into mainstream procurement cycles. The full PW Consulting study provides the granular inputs executives need: deployable playbooks, validation checklists, vendor scorecards, and the detailed market splits that inform budgeting, procurement, and M&A. We intentionally reserve those granular subsegment figures for the complete report — they are the tactical intelligence that turns strategic intent into executable programs.
If your organization is planning security architecture reviews, strategic investments, or national-scale infrastructure projects in 2026, our report is designed to be the operational blueprint you will use to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Quantum Key Distribution (QKD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Evaporative Cooler Market to Expand at 5.3% CAGR through 2032
By PW Consulting, 2026-07-09
Evaporative Cooler Market: Strategic Outlook for 2026 Decision-Makers (PW Consulting)
Executive snapshot
The global evaporative cooler market is at an inflection point. PW Consulting’s base-year assessment places the market at approximately USD 4,645 Million in 2025, having expanded materially since 2020, and our forecast model shows continued momentum through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.3%, lifting the market toward an estimated USD 6.6+ Billion by 2032. This briefing summarizes the strategic implications that should inform boardroom decisions, capital allocation and go-to-market plans in 2026 while withholding granular segment-level tables and proprietary split data — available in the full report.
Evaporative Cooler Market
Why this research matters in 2026
-
Decisive capital allocation: The market’s steady growth combined with pockets of technology-driven efficiency gains creates differentiated return profiles for product innovators, aftermarket service players and channel investors.
Evaporative Cooler Market -
Regulatory and ESG alignment: Water and energy use are near-term reputational and compliance vectors; companies that can demonstrate materially lower lifecycle water consumption and higher energy efficiency will capture premium access to public-sector tenders and sustainability-minded corporates.
Evaporative Cooler Market -
Channel reconfiguration: Distribution footprints, dealer economics and service networks are reshaping margins. 2026 is a pivotal year to test expanded distributor partnerships, particularly in fast-ramping subregions and verticals.
-
M&A and partnership timing: The market structure—characterized by regional leaders, specialist OEMs and a long tail of local players—creates windows for consolidation and bolt-on acquisitions to secure aftermarket services and proprietary media/adiabatic technologies.
Market dynamics shaping 2026 strategy
Three structural dynamics are driving the market’s trajectory and should be core to any strategic plan:
-
Energy efficiency as a commercial lever. Indirect evaporative solutions are delivering step-change energy savings versus conventional rooftop units in dry climates; published comparisons report energy advantages large enough to reframe lifecycle cost analyses for commercial and data-center buyers. Expect procurement specifications to increasingly favor systems that demonstrate high performance on standardized efficiency metrics.
-
Water and resource scrutiny. In water-constrained regions, residential units can represent a meaningful household-level water draw—public guidance and customer sentiment are pushing adoption of efficient media and smart controls that curtail annual usage. Efficient models now consume a fraction of average residential water use, a fact that will influence rebate programs and municipal adoption incentives.
-
Regulation and guidance are evolving. Recent guidance from the U.S. EPA elevated evaporative coolers’ role in ventilation strategies and conditioned the industry to integrate higher-efficiency filtration when outdoor air quality is a concern. Equally important are procurement and health-safety requirements for indoor deployment — a competitive advantage for vendors providing integrated IAQ solutions.
Technology and product shifts to watch
-
Pumpless and adiabatic advances. Product launches in 2026 introduced pumpless recirculation adiabatic technologies that materially simplify operation and reduce maintenance. Early adopters that integrate these systems into retrofit pathways can shorten payback timelines and lower total cost of ownership for end users.
-
Modularization and service monetization. Modular media packs, sensor-driven controls and subscription-based maintenance are emerging as margin-enhancing strategies—manufacturers that standardize modular service components will be able to scale aftermarket revenues faster than those relying purely on unit sales.
-
Pricing and input-cost pass-through. Several large vendors adjusted pricing in early 2026; manufacturers must balance short-term margin preservation against channel elasticity and tender competitiveness. Pricing strategy must be scenario-tested against supply-chain disruptions and raw-material volatility.
Competitive landscape — where value is created
The industry contains a mix of broad-line manufacturers, specialist industrial suppliers and regionally dominant portable-unit brands. Market concentration remains moderate: the combined share of the top three players is meaningful but far from monopolistic, and the top five account for only a modest uptick above that — a structure that favors strategic consolidation, niche differentiation and channel partnerships.
-
Phoenix Manufacturing Inc. (Phoenix, AZ) — Strengths: broad portfolio spanning residential to agricultural applications; active channel expansion and new mid-tier and specialty product introductions in 2026. Strategic implication: Phoenix’s dual focus on distribution growth and model refresh positions it to capture near-term residential and agricultural demand, but it must continue to invest in service infrastructure to convert market access into recurring revenue.
-
EVAPCO Inc. (Rockville, MD) — Strengths: recognized leader in indirect and large-scale industrial systems and a recent innovator with pumpless recirculation (PuRe-JET™). Strategic implication: EVAPCO’s technology orientation and industrial footprint make it a preferred partner for large commercial and data center projects; competitors should monitor cost-to-install and maintenance differentials when competing for institutional contracts.
-
Portacool (Ankeny, IA) — Strengths: market leader in portable coolers with strong brand recognition across residential and light-commercial segments. Strategic implication: Portacool’s brand equity and channel relationships create defensive moats in portable and seasonal deployments, but it faces pressure to add IoT-enabled controls and service offerings to maintain ASPs.
-
Champion Cooler Corporation (Denison, IA) — Strengths: product breadth in residential and portable categories with recognized series offerings. Strategic implication: Champion can scale by pursuing aftermarket service bundles and strategic distribution partnerships to increase lifetime customer value.
-
Hessaire Products Inc. (Fontana, CA) — Strengths: focused on home and light-commercial portable units with cost-sensitive positioning. Strategic implication: Hessaire is well-placed for price-driven market segments but will need to adopt higher-efficiency media and connectivity options to participate in rebate-driven and specification-heavy commercial tenders.
Recent market signals and competitive moves (implications)
-
Product innovation is accelerating: a major supplier announced pumpless adiabatic technology in mid-2026, simplifying operation and reducing maintenance. Early commercial deployments will serve as proof points for broader adoption in institutional tenders.
-
Distribution expansion continues: a leading manufacturer expanded its Western U.S. distributor footprint in 2026, signaling intensified competition for retrofit projects and localized seasonal demand. Market entrants should assess distributor economics aggressively before scaling.
-
Regulatory guidance is creating tender requirements: the EPA’s indoor air quality guidance in 2026 elevated filtration and ventilation roles for evaporative systems, which will change specification requirements for many public and private sector projects.
-
Price adjustments: headline price increases earlier in 2026 show vendors are testing cost pass-through; procurement teams should re-evaluate lifecycle cost models and contractors should reprice multi-year service agreements accordingly.
What the full PW Consulting report delivers (practical, action-oriented)
The full market study is built for executable decisions. Key deliverables include:
-
A validated market-sizing model with historical calibration and scenario-based forecasts through 2032, enabling sensitivity testing by macroeconomic and climate scenarios.
-
Demand-driver dashboards covering climate, construction activity and retrofit propensity by vertical — presented as decision matrices to prioritize go-to-market resource allocation.
-
Technology and product roadmaps that map performance attributes (energy, water, IAQ) to buyer value propositions and rebate eligibility criteria.
-
Channel and margin playbooks: distributor scorecards, dealer profitability models and three strategic channel expansion templates tailored for OEMs, private label players and aftermarket service providers.
-
Regulatory and compliance toolkit: a practical checklist for procurement clauses, filtration requirements and municipal rebate capture.
-
M&A screening matrix and 12–18 month integration plan for tuck-ins that accelerate service revenue or add proprietary media/adiabatic intellectual property.
-
Implementation checklists and pilot templates to validate new technologies (e.g., pumpless adiabatic systems) in controlled deployments before wide-scale roll-out.
How executives should use these insights in 2026
-
Prioritize pilots that prove operational savings. Short pilots for novel adiabatic/pumpless systems with clear measurement of energy, water and maintenance hours will accelerate specification wins.
-
Lock in distribution selectively. Target distributor partnerships that provide service capability and spare-parts logistics rather than only incremental SKU reach.
-
Design bundled service offers. Convert unit sales into longer-lived revenue by packaging media replacement, filtration upgrades and remote monitoring with multi-year contracts.
-
Embed regulatory readiness into RFP responses. Proactively address IAQ guidance and water-conservation criteria to shorten procurement cycles for public and institutional buyers.
-
Use the M&A playbook to identify regional service platforms or media/IP targets that accelerate access to aftercare revenues and proprietary efficiency tech.
Closing guidance and next steps
For companies deciding where to place bets in 2026, the evaporative cooler market presents a balanced set of opportunities: predictable mid-single-digit growth at the market level, rapid technology-driven differentiation in select verticals, and fragmented competitive dynamics that reward focused consolidation and service innovation. PW Consulting’s full report contains the proprietary segmentation, regional and application-level detail, supplier scorecards and financial models that will enable execution teams to convert strategy into measurable outcomes. Accessing the full dataset and appendices is the recommended next step for any executive preparing 2026 budgets, R&D roadmaps or M&A pipelines.
To obtain the complete study, including the full set of segment tables, scenario models and operational playbooks, please refer to the PW Consulting Evaporative Cooler Market page for purchasing and licensing options.
For detailed analysis of this topic, please visit the official page: Evaporative Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lightning Arrester Market to Reach USD 1,782.6M by 2032 at 5.96% CAGR
By PW Consulting, 2026-07-09
Lightning Arrester Market 2026 — Strategic Preview for Decision Makers
As utilities, EPC contractors, equipment OEMs and investors plan capital allocation for 2026, the Lightning Arrester Market is transitioning from steady replacement spend into a phase where standards, materials and grid modernization collectively reshape competitive advantage. Our PW Consulting Lightning Arrester Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro trajectory, supplier economics and regulatory inflection points so executives can convert complexity into defensible choices. Below is a crafted preview that demonstrates the study’s practical value while preserving the under-the-hood segmentation and case-level intelligence that compel direct access to the full report.
Lightning Arrester Market
Why this market matters in 2026
-
Stable growth with strategic inflection. The global market has expanded consistently since 2020 and, based on our modeling, continues to grow at a mid-single-digit compound annual growth rate (CAGR) over the 2026–2032 forecast horizon. That stability conceals important pockets of accelerating demand linked to high-voltage grid reinforcements, renewables integration and distribution automation.
Lightning Arrester Market -
Standards and harmonization are strategic drivers. Ongoing revisions to critical standards and the timing of their publication will directly affect product certification cycles, aftermarket liability and capital procurement specifications.
Lightning Arrester Market -
Supply-side shocks from raw materials. Volatility in metal-oxide inputs and polymer feedstocks has compressed lead-times and raised cost unpredictability — making supplier selection and contractual protections priorities for buyers and manufacturers alike.
Market trajectory — what the headline numbers tell you
Between 2020 and 2025 the market scaled markedly from its early-decade base, reflecting both replacement cycles and incremental demand from grid projects. By the base year (2025) the global market reached a significant milestone, and our forecast anticipates continued expansion through 2032. This trajectory — grounded in historical monthly and annual shipment data, project pipelines and procurement tender analysis — confirms that the market is large enough to support differentiated value propositions (premium engineering, integrated services, aftermarket analytics) while remaining sufficiently fragmented to reward consolidation and strategic partnerships.
For corporate planners, the implication is clear: size and steady CAGR provide a low-to-moderate growth backdrop, but the real value accrues to firms that align product roadmaps, certification timelines and supply chain resilience with the market’s evolving technical and regulatory demands.
Regulatory and standards inflection points
-
Standards revision timeline — watch for publication impacts. The international work to revise metal-oxide line arrester standards (the IEC/IEEE effort) is progressing, with draft circulation and an expected publication in the medium term. When the new standard is finalized, product certification roadmaps will require updates; lead-time alignment with these deadlines is a critical procurement risk for utilities and OEMs.
-
Standards consolidation — product definition changes. Anticipated harmonization work will lead to the withdrawal or consolidation of older external gap device standards and revisions that reclassify certain non-gapped arresters. This will change testing regimes and, over time, influence the share of certain technologies in tenders — a structural factor to be modeled in CAPEX scenarios.
Supply-side pressures and raw materials
Material inputs that underpin metal-oxide arresters and polymer housings have shown price and availability sensitivity. Tightening supply in key feedstocks has bid up costs and lengthened procurement cycles in early 2026. Strategic responses that featured in our vendor interviews include hedging programs, vertical integration discussions and a renewed focus on design choices that reduce material intensity without sacrificing performance. For buyers, contract design and inventory strategy will be a decisive differentiator between predictable project execution and costly last-minute substitutions.
Competitive landscape — positioning and implications
The market shows a measured degree of concentration: the top three vendors account for a meaningful share of global revenues, and the top five capture nearly half of the market. This structure creates an environment where leading suppliers can set technical norms and where nimble challengers can prosper through specialization, price competitiveness or geographic focus.
-
Siemens Energy (Munich) — Leveraging a century-scale legacy in surge protection, Siemens Energy is extending its polymeric portfolio while preserving IEC/IEEE-certified metal-oxide offerings. Their strength: integrated grid-scale solutions that bundle arresters with monitoring and substation automation — a defensible premium play for utilities prioritizing lifecycle OPEX reduction.
-
ABB (Zurich) — ABB’s positioning centers on high- and medium-voltage arresters for transmission and distribution alike. Expect ABB to compete on system compatibility and global installation footprint; procurement teams should evaluate bundled engineering services and aftermarket commitments as part of total cost of ownership assessments.
-
Schneider Electric (Rueil-Malmaison) — With offerings focused on industrial and utility surge protective devices, Schneider is leveraging its systems-integration capabilities to sell protection as part of plant and substation digitalization projects.
-
Eaton (Dublin) — Eaton’s product breadth across polymeric and porcelain arresters positions the company to serve both legacy networks and modernized grids; their channel strategy favors regional partnerships and localized manufacturing to shorten delivery cycles.
-
Hitachi Energy (Västerås) — Notable for high-voltage AC and DC arresters up to ultra-high voltages, Hitachi addresses large transmission projects and cross-border interconnects. For system planners, Hitachi’s portfolio often aligns with strategic interconnection projects demanding bespoke engineering.
-
Toshiba, Mitsubishi Electric, Sankosha, Otowa, Tridelta, Jera Line, GOTO, MacLean — These players provide a mix of specialization: compact designs, long heritage in MOV technology, IEC/IEEE/ANSI-certified alternatives and regional manufacturing advantages. Together they form a competitive long tail that drives price pressure in commoditized segments while fostering innovation in niche applications (railways, cable protection, residential secondary arresters).
Recent activity — exhibitions, product portfolio anniversaries and trade-show visibility — points to continued marketing emphasis and incremental product launches rather than dramatic disruptive entries. Notable touchpoints in early 2026 include regional exhibitions where incumbents showcased enhanced arrester arrays and polymeric innovations, signaling sustained investments in product evolution rather than wholesale business model change.
What PW Consulting’s full report delivers (practical contents)
-
Granular historical shipment and revenue analysis (2020–2025) and scenario-based forecasting through 2032, built from tender pipelines, supplier shipment logs and project schedules.
-
Risk-mapped supplier profiles that integrate financial strength, production footprint, certification timelines and supplier concentration — actionable for procurement and M&A teams.
-
Procurement playbooks and contract templates that protect buyers against raw-material spikes, lead-time slippage and certification delays.
-
Scenario models that quantify the P&L and balance-sheet impact of standard-migration outcomes, raw-material stress tests and accelerated grid-conversion pathways.
-
Go-to-market strategies for manufacturers: white-space analyses, premium-service bundles, aftermarket analytics and geographic roll-out sequencing that prioritize return on invested capital.
-
Decision matrices for utilities and EPCs to evaluate suppliers on total cost of ownership, regulatory compliance readiness and long-term serviceability.
Strategic takeaways for 2026 decision cycles
-
Align procurement windows with standards publication schedules. Tactical delays or accelerations in buying can materially affect certification risk and retrofit cost.
-
Lock in supply or hedge strategically. Where projects are time-sensitive, early material commitments or validated multi-source strategies reduce execution risk.
-
Differentiate between commoditized and premium opportunities. For new greenfield high-voltage projects, prioritize suppliers with demonstrated HV and DC capabilities; for distribution upgrades, evaluate lifecycle servicing and digital monitoring as value drivers.
-
Use market concentration to your advantage. The presence of a few large suppliers means measured negotiation leverage for buyers, while smaller specialists may be targeted partners for pilot projects and geographic expansion.
Risks and what to monitor
-
Standards delay or unexpected harmonization choices that increase retrofit costs.
-
Raw-material price spikes and supply constraints that erode margin or lead to substitution of proven designs.
-
Regional policy changes that reallocate grid investment or change allowable protection architectures.
-
Competitive shifts driven by consolidation or by new entrants exploiting low-cost manufacturing and certification flexibility.
Next steps — how to use the full PW Consulting study
For 2026 strategic planning, the full Lightning Arrester Market study supplies the operational detail and confidential vendor matrices executives need to make firm procurement, product development and M&A decisions. The report’s scenario models and contract playbooks allow CFOs and CPOs to stress-test budgets, while engineering leaders can map certification roadmaps against project timelines. Finally, the study’s supplier risk framework supports board-level discussions on insourcing, partnership and targeted acquisitions.
To access the complete dataset, including the full segmentation by region, type and application, granular vendor scorecards and the interactive forecast model, please visit our publication page or engage PW Consulting for a tailored briefing. The preview above is intended to orient executive teams to the strategic levers at play in 2026; the detailed intelligence in the full report provides the actionable specificity to convert insight into advantage.
For detailed analysis of this topic, please visit the official page: Lightning Arrester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


