



Category: market research
Virtual Power Plants 2026: Strategic Imperatives from PW Consulting’s Market Brief
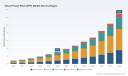
As governments, utilities, and corporate energy buyers confront an accelerating transition to distributed energy resources (DERs), Virtual Power Plants (VPPs) have moved from niche pilots to boardroom-level strategic assets. PW Consulting’s latest market research — based on a 2025 base year and a 2026–2032 forecast window — frames the VPP opportunity as one of the fastest-growing pathways to system flexibility and new revenue streams. The market expands from a multi-billion dollar base in 2025 and, at a compound annual growth rate (CAGR) of 22.61% through the forecast horizon, reaches an order of magnitude larger by 2032. For decision-makers planning 2026 allocations, this research translates macro growth into concrete choices on partnerships, technology stacks, and portfolio priorities.
Virtual Power Plant (VPP) Market
Why 2026 is a Strategic Inflection Point
Three converging forces make 2026 uniquely consequential for corporate strategy in the VPP ecosystem:
Virtual Power Plant (VPP) Market
- Scale-up of DER deployments (residential storage, behind-the-meter solar, EV charging, flexible C&I loads) is maturing from pilots to commercial-scale fleets.
- Utility and market reforms are expanding monetization pathways for aggregated flexibility (capacity, ancillary services, and energy market participation), increasing the addressable value pool available to VPP operators.
- Supply-chain and regulatory shocks—most notably export controls and critical-minerals scrutiny—are reshaping procurement risk and localization needs for batteries, power electronics, and control hardware.
These forces make 2026 more than a planning year: it is the window to decide whether to lead, partner, or play catch-up. With total market revenue rising rapidly (our model shows a jump from around the 2025 base to a substantially larger market by 2032 at the noted CAGR), companies that clarify strategy this year will capture outsized share of the early value pools and shape standards and commercial terms.
Virtual Power Plant (VPP) Market
What the PW Consulting Brief Contains (Practical, Actionable, Non-Technical Summary)
The report is structured as an executive-to-implementation guide designed for corporate strategists, utility planners, investors, and product teams. Key deliverables include:
- Market sizing and trajectory: a transparent model anchored to 2025 base-year data and a multi-scenario forecast through 2032 that quantifies upside under differentiated regulatory and technology adoption cases.
- Commercial use-case mapping: prioritized revenue streams (e.g., capacity, frequency response, energy arbitrage, retail productization) with clear assumptions for value capture and commercialization timelines.
- Technology and operational playbook: comparative evaluation of DERMS/edge orchestration platforms, hardware integration patterns, cybersecurity and data architectures, and operational KPIs for fleet performance.
- Supply-chain risk and procurement checklist: scenario analysis of rare-earth and battery-material constraints, supplier resilience scoring, and sourcing options (vertical integration vs. multi-sourcing).
- Competitive landscape and vendor scorecards: strengths, go-to-market models, and partnership fit for incumbent and emerging players (company profiles and linked public resources are included for quick diligence).
- M&A and partnership frameworks: decision trees and valuation heuristics for acquiring aggregation platforms, battery portfolios, or software capabilities.
- Implementation toolkits: RFP templates, commercial terms to push or defend in supplier contracts, pilot-to-scale transition checklists, and a sample TCO model for 5- to 10-year deployments.
Note: the report deliberately omits public disclosure of granular sub-segment numerical breakouts in summary communications. If you are evaluating market entry, procurement, or M&A, the full dataset and segmented tables provide the necessary resolution for transaction-level decision-making.
Competitive Landscape: Who’s Setting the Pace
VPP competition sits at the intersection of software orchestration, hardware integration, and market access. Key firms we profile include established energy-platform players, grid technology incumbents, and vertically integrated residential aggregators. Representative profiles included in the brief (with direct links for primary research) are:
- Uplight ( https://uplight.com/) — North American leader with large dispatchable capacity under management across residential, C&I, and utility-scale assets; strong utility go-to-market relationships and retail customer programs.
- Next Kraftwerke ( https://www.next-kraftwerke.com/) — European originator of large-scale aggregation, focused on software-driven orchestration of heterogeneous DER fleets.
- Enel X ( https://www.enelx.com/) — Platform and execution capability for utilities and commercial customers with notable DER aggregation scale across multiple continents.
- Siemens ( https://www.siemens.com/) — Full-stack provider linking hardware, grid automation and optimization platforms; attractive for utilities seeking integrated solutions.
- Schneider Electric ( https://www.se.com/) — Broad energy management and automation capabilities, positioned for enterprise and distribution-grid integrations.
- Tesla ( https://www.tesla.com/) — Residential and distributed storage aggregator leveraging Powerwall deployments and retail-to-grid programs.
- AutoGrid Systems ( https://www.auto-grid.com/) — Early and sophisticated DERMS/VPP platform vendor with AI-driven optimization for large fleets.
- Flexitricity ( https://www.flexitricity.com/) and similar specialized aggregators — Agile operators focused on flexible assets and market arbitrage.
- Sunrun ( https://www.sunrun.com/) and EnergyHub ( https://www.energyhub.com/) — Residential aggregators scaling VPPs through customer-facing products and utility partnerships.
These players illustrate three viable strategic archetypes: platform-first software aggregators, utility-centric integrated solution providers, and asset-owning residential aggregators. The market is neither winner-take-all nor deeply concentrated; our concentration metrics show a distributed competitive set where regional champions and specialist operators retain opportunity to scale.
Recent Market Moves: Signals You Can Act On in 2026
Several notable developments in 2025–2026 provide immediate strategic implications:
- Large-scale asset acquisitions and platform consolidation: Major transactions indicate appetite for scale and bundled market access—if you’re an investor or a strategic buyer, prioritize targets that close the gap on market access or control high-value revenue streams.
- Product launches targeting niche monetization: Battery-only and charging-station-based VPPs have emerged, demonstrating new pathways for monetizing EV charging infrastructure and residential storage—pilots now can be designed with clearer commercialization roadmaps.
- Platform expansions by incumbents: Major platform providers have launched capacity expansions aimed at utility-scale aggregation. Partnerships or white-label arrangements can accelerate market entry without the need for heavy capex.
Regulatory and Supply-Chain Dynamics: Risk That Shapes Strategy
Supply-chain and regulatory developments in 2025–2026 materially affect procurement and delivery timelines for VPP projects. Key dynamics we analyze in the brief include:
- Export controls and critical-mineral restrictions implemented by major suppliers, which increase lead times and price volatility for key components.
- Government trade investigations and proposals around processed critical-mineral products that introduce potential tariffs or import conditions affecting VPP hardware economics.
- Policy reforms expanding or standardizing market mechanisms for distributed flexibility, changing the revenue stack and compliance requirements for aggregators.
Strategic takeaway: procurement hedges, dual-sourcing, and selective vertical integration are no longer optional for large-scale VPP programs. The full report provides scenario-based sourcing pathways and supplier resilience scores to operationalize these choices.
Actionable Strategic Playbook for 2026
For executives preparing capital allocation, product roadmap, or partnership decisions in 2026, PW Consulting recommends a focused three-tier agenda:
- Decide your role in the value chain. Choose between asset ownership (which favors unit economics but requires capital), platform orchestration (software-first, lower capex, higher data/IP value), or hybrid models. Use our vendor scorecards and TCO templates to stress-test each option against your balance-sheet and regulatory constraints.
- Lock in market access and regulatory pathways. Prioritize market entry where capacity products and ancillary services provide clear near-term cashflows. Use pilot designs from the report to validate revenue streams within 12–18 months before scaling.
- Hedge the supply chain. Implement multi-sourcing strategies, identify regional manufacturing partners, and evaluate strategic inventory positions for critical components. The report’s supplier resilience framework converts high-level risk into procurement KPIs for 2026 contracts.
What We Don’t Reveal Here — And Why You Need the Full Brief
This preview demonstrates the strategic depth and practical tools contained in PW Consulting’s market brief, but intentionally omits granular sub-segment tables and region-by-application numerical splits that are essential for transaction-level decisions. If you are preparing an RFP, M&A offer, or capital reallocation, you will need the segmented revenue models, region and use-case breakouts, and sensitivity runs that underpin our headline growth figures. Those datasets are included in the full deliverable and are designed to be plugged into internal financial models.
Next Steps
If your 2026 mandate includes one or more of the following — market entry, platform partnership, procurement contracting, or M&A in the VPP space — PW Consulting’s full report will equip your team with the data, frameworks, and playbooks to act confidently. The executive summary here highlights the urgency and the strategic choices; the full report supplies the granular evidence and transaction-ready templates.
Contact PW Consulting to access the complete research, proprietary datasets, and an implementation workshop tailored to your objectives for 2026. The VPP market is moving quickly; firms that convert insight into structured action this year will capture the lion’s share of the early scale-up opportunity.
For detailed analysis of this topic, please visit the official page: Virtual Power Plant (VPP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Powder AM Market to Reach USD 1,055M by 2032 (15.4% CAGR)
By PW Consulting, 2026-07-09
Additive Manufacturing with Metal Powders: 2026 Strategic Briefing
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-focused briefing to orient corporate leaders on where the Additive Manufacturing (AM) with metal powders market stands at the start of 2026 — and what that means for near‑term strategy. This briefing synthesizes the full market study (base year 2025) to expose the structural shifts, competitive battlefield, and the practical levers executives must pull this year. It intentionally surfaces analytical depth while preserving the granular segment tables in the full report — consider this a strategic trailer designed to prompt action.
Additive Manufacturing with Metal Powders Market
Where the market stands: macro trajectory and what it signals
The market for additive manufacturing using metal powders has moved from a specialized, capitalization‑led niche into a predictable growth corridor. By the base year 2025, the market reached roughly USD 390 million (USD Million, base year 2025). Our forecast models project sustained, high‑teens growth through the coming decade, with a compound annual growth rate of 15.4% and a market approaching the USD 1.06 billion mark by 2032. That trajectory reflects a shift from early adopter projects toward production‑scale deployment across targeted verticals and materials systems.
Additive Manufacturing with Metal Powders Market
For executives, three macro takeaways matter: (1) the scale is now large enough to justify dedicated supply‑chain investments and industrialization roadmaps; (2) growth is not uniform — winning positions will be created at the intersection of material innovation, qualification of production processes, and localized supply resilience; and (3) timing matters: capability investments made in 2026–2028 will determine leadership in the 2028–2032 commercial wave.
Additive Manufacturing with Metal Powders Market
Immediate strategic imperatives for 2026
- Secure diversified powder supply and materials roadmaps. Rising tariffs and supply‑chain pressure have made localized production and multi‑sourcing more than risk management — they are value drivers. Firms should map critical metal exposure, qualify at least two powder providers for each strategic alloy, and budget for buffer inventories while conversion and qualification cycles are underway.
- Prioritize qualification and certification as strategic moat builders. The path to volume production is governed less by machine throughput and more by material/process qualification, standards compliance, and validated supply chains. Allocate cross‑functional capital to accelerate qualification campaigns that shorten time‑to‑revenue.
- Embed materials strategy into product design early. Material decisions now dictate manufacturability, cost, and long‑term serviceability. Create a materials decision framework that balances performance, cost, recyclability, and geopolitical supply risk.
- Consider targeted vertical plays rather than broad coverage. The economics and qualification timelines vary sharply by application (e.g., aerospace vs. high‑volume auto components). A focused vertical approach — pairing materials, machine architecture, and aftermarket ecosystems — increases win rates.
- Build partnerships across the value chain. Successful market entrants in 2026 will be those who co‑invest with powder producers, machine vendors, and end customers to de‑risk qualification and scale trials.
Competitive landscape: who matters and why
The market exhibits meaningful concentration among established machine suppliers and leading powder producers. The top domestic and international incumbents control a sizable share of installed capacity and maintain deep integration into qualification and certification pipelines. This concentrated structure creates both barriers and partnership opportunities.
- EOS GmbH (Krailling, Germany) — known for DMLS® laser powder bed fusion systems and an extensive alloy and certified powder portfolio. EOS remains a reference supplier for high‑end production parts where material traceability and system certification are critical.
- Nikon SLM Solutions AG (Lübeck, Germany) — offers large‑format selective laser melting systems and emphasizes integrated materials/process support. Nikon’s play is to enable scale by combining machine capability with system‑level process control.
- GE Additive / Colibrium Additive (Cincinnati, USA) — integrates both laser and electron beam powder bed fusion technologies with in‑house metal powder production. Their vertical approach is designed to shorten qualification cycles for OEMs shifting to AM production.
- 3D Systems Corporation (Rock Hill, USA) — delivers metal powder bed fusion and direct metal printing platforms plus a materials portfolio. 3D Systems positions itself around end‑to‑end solutions tied to application engineering services.
- Xi’an Bright Laser Technologies (Xi’an, China) — focuses on high‑performance laser powder bed fusion systems and end‑to‑end powder solutions, increasingly relevant in cost‑sensitive and large‑format deployments.
- Höganäs AB (Höganäs, Sweden) — longstanding powder producer with a broad portfolio of spherical metal powders optimized for AM. Their strength is in material consistency and global distribution capability.
- Equispheres (Boston, USA) — specializes in engineered aluminum and copper alloy powders crafted for high‑speed, cost‑competitive production. Notably, in April 2026 they showcased new aluminum and copper solutions aimed at thermal and electrical performance in production contexts.
- 6K Additive (Lancaster, USA) — a differentiated entrant producing metal powders from recycled feedstock. 6K announced a marked capacity expansion (a fivefold increase targeting ~1,000 metric tons per year, with the majority brought online by end‑2026), shifting competitive dynamics around sustainable sourcing and cost profiles.
Strategically, incumbents are converging on two plays: (a) verticalization — pooling machines, powders, and qualification to sell validated system outcomes rather than components; and (b) materials differentiation — offering purpose‑built powders (e.g., copper and specialized aluminum alloys) that unlock new applications. New entrants that can demonstrably reduce cost, improve throughput, or shorten qualification time will attract premium partner interest or M&A attention.
Regulatory, supply and materials dynamics shaping strategy
Three structural dynamics deserve explicit attention in 2026 planning:
- Tariffs and localization pressures. Rising global tariffs and logistics friction are accelerating proposals to localize powder production and AM cell deployment. This strengthens business cases for regional powder plants and intra‑company material programs.
- Critical metals concentration remains a vulnerability. Nickel, cobalt and several specialty alloys are geographically concentrated; this risk influences sourcing strategies, contract length, and stockpiling decisions.
- Material innovation is unlocking new economics. Recent introductions — such as copper and specialized aluminum powders engineered for high‑speed production — are removing prior constraints around thermal management, conductivity, and cycle time. These powders change unit economics and open new application windows.
What the PW Consulting report delivers — operational, actionable content
Our full study translates the above dynamics into pragmatic tools executives can use immediately:
- Forward‑looking demand curves to 2032 (by technology class and material family) with scenario sensitivity to tariffs, raw‑material shocks, and adoption rates.
- Supplier and capability maps that identify manufacturing clusters, qualification centers, and critical single‑source exposures.
- Cost models and unit economics templates that quantify break‑even thresholds for part substitution versus conventional manufacturing.
- Risk heatmaps and mitigation playbooks for critical metals, logistics, and regulatory risk.
- Commercial due‑diligence scorecards and an M&A screening list that ranks targets by strategic fit, IP strength, and margin accretion potential.
- Go‑to‑market playbooks and sample qualification roadmaps tailored to aerospace, medical, and high‑throughput industrial applications.
- Templates for in‑house pilot programs and supplier co‑development agreements to accelerate material and process validation.
Each deliverable is accompanied by Excel models and decision matrices so your team can run “what‑if” scenarios in hours rather than weeks. The full report contains the granular segmentation tables and regional/application splits that are essential for execution — these are intentionally withheld from this briefing to centralize access on our platform.
How to use this analysis in your 2026 planning cycle
- Procurement leaders: initiate multi‑year supply contracts with tier‑1 powder producers, and secure options with second‑source suppliers for critical alloys.
- R&D and product teams: prioritize two‑material qualification tracks for strategic product lines and budget for accelerated process validation.
- Operations and plant planning: evaluate localized AM cell pilots in tariff‑sensitive markets and run cost‑sensitivity analyses on onshore vs. offshore powder sourcing.
- Corporate development: use our M&A screening to identify tuck‑ins that deliver near‑term margin improvement or vertical integration benefits (e.g., powder capability, post‑processing, or digital quality platforms).
- Sales and commercial: align go‑to‑market propositions around validated materials and demonstrate total cost of ownership improvements to target OEM buyers.
Final word — timing and next steps
2026 is a pivot year. The industry is transitioning from learning and prototyping to scaled, qualified production—and that transition rewards firms that act now to secure materials, streamline qualification paths, and partner with specialized powder and machine suppliers. PW Consulting’s full Additive Manufacturing with Metal Powders study provides the layered, executable intelligence required to convert strategic intent into measurable commercial outcomes. For teams planning investments, partnerships, or M&A in 2026, this research is the playbook to shorten time‑to‑value.
Access to the detailed segment tables, supplier rankings, and downloadable financial models is available through our report portal — our team stands ready to run a tailored briefing that maps these insights directly to your product lines and markets.
For detailed analysis of this topic, please visit the official page: Additive Manufacturing with Metal Powders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Styrene Butadiene Styrene (SBS) Market — Strategic Outlook for 2026 Decision Makers
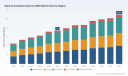
As companies prepare strategy for 2026, understanding the mid-cycle dynamics of the Styrene Butadiene Styrene (SBS) market is no longer optional. PW Consulting’s latest market brief — grounded on a 2025 base year and a seven-year forecast horizon — frames the SBS market as a resilient, growth-oriented industry. Our topline market model projects a recovery and sustained expansion from a 2025 market size of USD 7.4 Billion to a projected market above USD 10.9 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.8% during the forecast window. This trajectory underscores both the structural demand for SBS-based solutions and the strategic inflection points that buyers, producers and investors must navigate in 2026.
Styrene Butadiene Styrene (SBS) Market
Why this research matters for 2026 strategic choices
-
Timing investment and capacity: With the industry moving from post-pandemic volatility toward normalized demand growth, 2026 will be a pivotal year for capacity optimization — determining whether to expand, retrofit, or pursue offtake agreements. Our report quantifies the macro growth runway and models near-term supply-demand balances under multiple scenarios.
Styrene Butadiene Styrene (SBS) Market -
Pricing and margin resilience: Feedstock and logistics cost swings have introduced fresh pressure on margins. Our analysis provides a shortlist of actionable levers — from raw material pass‑through strategies to contract design and hedging practices — that materially affect EBITDA sensitivity in the coming 12–18 months.
Styrene Butadiene Styrene (SBS) Market -
M&A and vertical integration playbook: The market’s competitive topology and pockets of concentration create windows for bolt-on and vertical integration deals. The report maps buyer archetypes, valuation drivers, and integration pitfalls calibrated to 2026 market multiples.
-
Regulatory and trade risk management: Recent trade actions and evolving sustainability expectations mean commercial teams must embed regulatory scenarios into pricing and sourcing decisions. We translate these dynamics into probability-adjusted P&L impacts for 2026 strategy sessions.
Current dynamics shaping the SBS market
-
Feedstock volatility and cost pass-through: Styrene and butadiene feedstocks have shown elevated price volatility. Producers who secure backward integration, stable long-term sourcing, or flexible pass-through clauses will preserve margin flexibility. The report includes sensitivity analysis showing how raw material swings flow through to producer margins under alternative contractual frameworks.
-
Upstream capacity shifts: The industry has seen sizeable new entrants and expansions in recent periods, altering regional flows of material and competitive intensity. For procurement and commercial teams this necessitates revisiting sourcing zones and lead-time assumptions; our supply-mapping tool highlights likely bottlenecks and surplus corridors.
-
Logistics and energy-driven surcharges: Rising energy and freight cost profiles are increasing landed cost variability, particularly for long-haul shipments. The research models realistic landed-cost bands for different commercial strategies (e.g., spot purchases vs. long-term contracts with freight clauses).
-
Trade measures and compliance risk: Anti-dumping rulings and import duties in key markets have re-routed trade flows and raised transaction costs. Our regulatory risk module provides scenario-driven outcomes and mitigation playbooks for sellers and buyers exposed to international sourcing.
-
Sustainability credentials as a commercial differentiator: Certification achievements and low-carbon feedstock programs are moving from “nice-to-have” to table stakes for large buyers. Producers who can credibly demonstrate sustainable sourcing and certified supply chains command a pricing premium in strategic segments; our benchmarking shows which certifications meaningfully move commercial conversations.
Competitive landscape — what leading players are doing
The market’s top-tier manufacturers combine legacy assets, product breadth and technical service capabilities. While competition is material, the landscape remains open to strategic repositioning by ambitious mid-sized players and new integrated entrants.
-
Kraton Corporation (The Woodlands, Texas): A global leader in specialty polymers, Kraton’s portfolio spans SBS block copolymers tailored for thermoplastic elastomers, adhesives, sealants and modified bitumen. In late‑stage cycles Kraton has demonstrated commercial agility — from pricing actions to sustainability certification progress — which has direct implications for competitors’ pricing strategies and contract terms.
-
LCY Chemical Corp. (Taipei): LCY competes with a focus on styrenic block copolymers and engineered TPEs. Its portfolio orientation towards adhesives and performance materials positions it as a nimble supplier for regional formulators prioritizing product performance and technical support.
-
Kumho Petrochemical (Seoul): Known for its linear and radial SBS grades designed for high tensile performance, Kumho’s strengths lie in differentiated product quality for demanding applications such as modified bitumen and specialty adhesives.
-
LG Chem (Seoul): As an integrated chemical and materials firm, LG Chem leverages scale and downstream applications (e.g., waterproofing membranes and thermoplastic elastomers) to pursue strategic partnerships with OEMs and construction-materials groups.
-
TSRC Corporation (Kaohsiung): A longstanding SBS and SIS supplier, TSRC’s technical depth in block copolymers supports its position among formulators seeking product consistency and localized supply in Asia.
-
Asahi Kasei (Tokyo): With a broad performance-materials portfolio, Asahi Kasei competes on innovation and service-led engagements for elastomers and modified bitumen markets.
-
Dynasol Group (Madrid): Dynasol’s solution copolymers and SBS offerings aim at adhesives, sealants and TPE markets, and its strategic playbook centers on niche application engineering and flexible supply arrangements.
Together, established players control a meaningful share of global volumes — roughly two-fifths for the top three and approaching half when the top five are combined — which shapes pricing dynamics, contract structures and the pace of capacity additions. For challenger firms, the path to scale rests on specialization, partnership-driven downstream integration, or geographic arbitrage.
Recent commercial signals
-
Producers have announced industry-wide price adjustments reflecting raw material cost pressures — a signal that cost pass-through remains an active negotiation point between suppliers and buyers.
-
Large-scale capacity projects have come online in multiple regions, intensifying supply-side competition in targeted product grades and exerting short‑term pressure on margins in commoditized segments.
-
Sustainability certifications are becoming operational realities at major manufacturing sites, shifting the supplier selection criteria for downstream customers with decarbonization targets.
What the PW Consulting report contains — practical deliverables
PW Consulting’s SBS Market report is designed as a working toolkit for executive teams, commercial leaders and investors. Key deliverables include:
-
Topline market sizing and CAGR modeling (base year 2025; historical 2020–2025 and forecasts 2026–2032) with scenario variants for slower and faster demand recovery.
-
Supply-side atlas mapping current and announced capacity by technology and vintage, with implications for regional trade flows and logistics chokepoints.
-
Pricing sensitivity models linking styrene/butadiene feedstock scenarios, freight energy profiles and contractual pass-through terms to producer margins.
-
Competitive scorecards for the leading manufacturers, assessing asset quality, product breadth, technical service capability and strategic intent.
-
Regulatory and trade risk matrix — including anti‑dumping exposure, duty scenarios and compliance checklists — with mitigation pathways for buyers and sellers.
-
Commercial playbooks for buyers (sourcing strategies, hedging frameworks, supplier segmentation) and producers (go‑to‑market, product differentiation, sustainable premium capture).
-
Deal flow and M&A playbook: valuation heuristics, integration roadmaps and prioritized targets for bolt-on expansion.
Importantly, while this introduction outlines the report’s strategic architecture and high-level conclusions, it deliberately omits granular subsegment tables and region/application splits. Those detailed datasets and the underlying model are available exclusively in the full report and interactive dashboards.
How to apply the intelligence in 2026
-
For producers: prioritize feedstock risk reduction and accelerate certifications that unlock high-value contracts. Consider selective capacity adjustments where modeling shows short-term oversupply risk versus long-term demand positions.
-
For buyers and formulators: renegotiate contract terms to include dynamic cost pass‑through mechanisms and diversify sourcing to reduce landed-cost volatility. Use the supplier scorecards in the report to re-weight preferred-supplier lists ahead of 2026 procurement cycles.
-
For investors and strategic buyers: target assets that provide either product differentiation (technical grades) or logistical arbitrage (regional hubs). The report’s M&A playbook identifies the most accretive target archetypes under current market conditions.
Next steps
PW Consulting’s SBS Market report is built to inform the crucial strategic decisions companies will make in 2026 — from contract strategy and capacity investment to M&A and sustainability positioning. The topline forecasting shows clear growth potential through 2032, but the operational and regulatory variables outlined above will determine who captures value along the chain.
To access the full dataset, detailed segmentation, and the interactive scenario model, visit our report page. The complete package includes downloadable spreadsheets, supplier scorecards, and a customizable dashboard that translates the research into board-ready decision materials.
For detailed analysis of this topic, please visit the official page: Styrene Butadiene Styrene (SBS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Outlook: Hexafluoropropylene Oxide (HFPO) Market to 2032 — What 2026 Decision‑Makers Need to Know
Executive preview
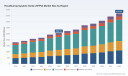
As PW Consulting’s lead industry analyst, I present a concise, decision‑centric view of the Hexafluoropropylene Oxide (HFPO) market intended to inform strategic planning for 2026. HFPO remains a linchpin intermediate for high‑value fluoropolymers, specialty coatings, and selected pharmaceutical and agrochemical syntheses. After a measured recovery and re‑rating between 2020 and 2025, the global HFPO market enters a multi‑year growth phase: our base‑year modeling (2025) finds the market at roughly USD 2.56 billion, and under our central case the market expands at a compound annual growth rate of 7.3% through 2032, reaching just over USD 4.19 billion by the end of the forecast horizon.
Hexafluoropropylene Oxide (HFPO) Market
Why this analysis matters for 2026
Two planning cycles intersect in 2026: near‑term operational choices (sourcing contracts, contamination controls, price hedges) and medium‑term strategic moves (capacity investments, product diversification, M&A). Action taken in 2026 will lock organizations into pathways that either capture the upside of the forecasted expansion or leave them exposed to regulatory and input‑price shocks. This briefing synthesizes the signals that should drive boardroom deliberations in 2026 while deliberately reserving the granular segmentation outputs for the full report.
Hexafluoropropylene Oxide (HFPO) Market
Market dynamics shaping 2026 choices
-
Demand composition and growth vector — HFPO demand is anchored to fluoropolymers (durable, high‑performance resins), with secondary but fast‑growing demand from specialty pharmaceutical and agrochemical intermediates. These end‑markets are sensitive to downstream capital cycles (semiconductor and electronics capex) and regulatory speed on PFAS‑related compounds. The combined effect supports sustained double‑digit pockets of growth even as the broader HFPO market grows at a mid‑single‑digit to high‑single‑digit rate overall (7.3% CAGR in our central scenario).
Hexafluoropropylene Oxide (HFPO) Market -
Upstream cost pressure — Fluorspar and hydrofluoric acid remain critical feedstocks. Industry price monitoring recorded material upward pressure in late 2025 amid constrained Chinese export volumes and firm HF acid demand. Procurement teams must treat feedstock volatility as a first‑order risk when modeling unit economics and negotiating multi‑year contracts.
-
Regulatory and reputational risk — Regulatory frameworks on PFAS derivatives have crystallized in some jurisdictions and remain fluid in others. Notably, U.S. federal drinking‑water rules have established enforceable maximum contaminant levels for HFPO‑derived species, while subsequent administrative actions indicate potential re‑evaluation of enforcement pathways. At the corporate level, operators have already invested in emissions and process‑control technology (for example, demonstrated high‑efficiency thermal oxidation installations at leading facilities). Expect incremental compliance costs and capital projects to increase operating breakevens across the supply chain.
-
Supply structure and concentration — The HFPO market is oligopolistic by design: the top suppliers capture a substantial share of global capacity. This concentration creates signaling power on pricing and technology adoption, while also creating opportunities for new entrants that can differentiate on regulatory compliance, specialty grades, or proximity to growing demand clusters.
Competitive landscape — positioning and strategic implications
Our corporate review highlights several archetypes among active HFPO producers:
-
Scale and integrated producer (e.g., Chemours) — Large, vertically integrated producers retain the advantage of feedstock integration, scale economics, and established global offtake relationships across fluoropolymers and specialty chemicals. These players also lead on environmental controls and transparency, having invested in demonstrated emissions abatement at major facilities. For customers and investors, tier‑one producers offer supply security but will likely price in the cost of compliance and decarbonization.
-
Regional specialists (European and Japanese incumbents) — Firms with deep technical expertise and proximity to high‑value industrial end‑markets emphasize product quality, specialty grades, and technical service. Their strategic playbook is to capture premium margins through tailored offerings for electronics and pharmaceutical customers.
-
Chinese producers and capacity scalers — A cluster of active Chinese manufacturers are expanding capacity and pursuing export channels. These producers compete on cost and increasingly on product purity and environmental performance. Their growth compresses regional margins and accelerates supply‑chain shifts for price‑sensitive buyers.
-
Technology‑differentiated players — A minority of suppliers focus on differentiated HFPO derivatives, higher‑purity streams, or greener process variants. These players are attractive partners for specialty formulators and advanced materials OEMs that value technical collaboration and supply security over lowest cost.
For 2026, buyers and sellers should evaluate counterparties not only on price and capacity, but on documented emissions abatement performance, feedstock security, and the ability to comply with evolving PFAS and drinking‑water standards. The presence of capacity leaders capable of producing tens of thousands of metric tons annually creates both stability and systemic risk, depending on operational reliability and regulatory exposure.
What the full report delivers (practical contents)
PW Consulting’s HFPO market study is structured to support actionable decisions. Key deliverables include:
- Proprietary demand model (2020–2032) with scenarios that isolate semiconductor/electronics capex cycles, pharmaceutical volume ramp, and alternative formulation uptake.
- Supply‑side capacity map and near‑term operational risk register identifying where disruption or compliance investments could re‑allocate volumes.
- Cost and price modeling including feedstock pass‑through sensitivity, delivered price ladders by trade lane, and margin break‑even tables for common contract tenors.
- Regulatory impact matrix that quantifies likely compliance capex, litigation exposure bands, and reputational risk multipliers under alternative policy outcomes.
- Supplier benchmarking with capability heatmaps (purity grades, scale, environmental controls, geographic reach) and a tactical procurement playbook for 12–36 month sourcing negotiations.
- Strategic M&A & JV heatmap identifying the most accretive combinations, and a valuation primer under conservative and aggressive growth cases.
- Operational checklists for site emissions control, stakeholder engagement guidance, and a phased implementation roadmap to align capital projects with regulatory timelines.
Note: to preserve the integrity of our commercial research model and to follow the “trailer” principle of this preview, granular regional and application‑level splits, as well as our downloadable Excel forecast by grade and region, are accessible in the full report and the interactive dashboards on our platform.
Actionable recommendations for 2026 planning
-
Procurement & contracting: Secure blended contracts that include indexation to feedstock and step‑in rights for alternate supply. Prioritize counterparty audits on emissions control and monitoring; insist on contractual covenants around disclosure and remediation funding in case of regulatory escalation.
-
Capex timing and volume commitments: Defer irreversible greenfield investments until clear regulatory pathways stabilize, unless your project includes demonstrable best‑in‑class emissions controls. Consider modular or brownfield expansions with lower capital intensity and faster payback as transitional plays.
-
Portfolio & product strategy: Accelerate development of higher‑purity and specialty HFPO derivatives where margin expansion is justified and compliance risks are lower. For commodity HFPO, prioritize scale and secure feedstock supply.
-
M&A and partnerships: Target bolt‑on assets that enhance technical capability (purity grades, derivative chemistry), environmental compliance credentials, or proximity to critical end markets. Use earn‑outs to mitigate regulatory tail‑risk.
-
Regulatory preparedness: Invest in monitoring, community engagement, and third‑party verification programs now. Demonstrable performance will materially affect permitting timelines, offtake negotiations, and insurance pricing.
-
Scenario planning: Run downside stress tests that combine a supply‑side shock (e.g., a major plant offline) with a regulatory tightening scenario. Determine liquidity buffers and contingency sourcing strategies for each stress level.
Data points you should anchor to (high‑level)
Anchoring the planning process to robust macro numbers removes speculation. Use the 2025 market base and the 7.3% CAGR in your investment hurdle analyses and scenario models. These anchors illustrate the difference between operational decisions that target market share (volume) versus those that optimize margin (specialty or regulated‑compliant offerings).
Closing: the strategic choice for 2026
2026 is less about predicting a single outcome and more about choosing a resilient pathway. Firms that align procurement, compliance, and innovation investments to the structural growth implied by the market trajectory — while preserving optionality against regulatory uncertainty — will convert the HFPO expansion into durable competitive advantage. PW Consulting’s full HFPO research package provides the detailed segmentation, supplier scorecards, and downloadable models necessary to operationalize these recommendations; the preview above is intended to clarify the strategic questions you must answer in 2026 and to demonstrate the practical, data‑driven tools we provide to answer them.
For the full segmentation, interactive dashboards, and the practitioner‑grade Excel forecast, please consult our complete report and data portal (access details available through PW Consulting’s market research page).
For detailed analysis of this topic, please visit the official page: Hexafluoropropylene Oxide (HFPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Directional Drilling Market Poised for 6.65% CAGR Through 2032 — PW Consulting
By PW Consulting, 2026-07-09
Directional Drilling Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analysts, we present a focused, decision-grade introduction to our Directional Drilling Market study — timed to inform capital allocation, procurement, and M&A choices in 2026. This preview is designed as a “trailer”: it demonstrates the analytical depth and practical frameworks that underpin our full report while intentionally withholding granular subsegment tables and proprietary scoring so senior teams are compelled to consult the full deliverable for transaction- or budget-level actions.
Directional Drilling Market
Market Trajectory: What the headline numbers mean for strategy
The directional drilling market has moved from post‑pandemic recovery into a sustained growth phase. Using 2025 as our base year, the global market is estimated at approximately USD 13.9 billion and is forecast to expand to roughly USD 21.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.65% over the forecast horizon (2026–2032). The historical window (2020–2025) captures early volatility and an inflection toward higher-tech drilling solutions; the forecast reflects both continued demand for conventional HDD capacity and accelerated adoption of premium directional and rotary steerable systems.
Directional Drilling Market
For corporate decision-makers in 2026 this trajectory implies three immediate imperatives: preserve optionality in capital plans to capture upside demand, lock in supply‑chain resilience for critical drill‑bit materials, and prioritize technology investments that shorten time‑to‑production and reduce per‑meter costs.
Directional Drilling Market
Why this study is strategically valuable in 2026
- Actionable capital allocation guidance: We translate market growth and technology adoption curves into recommended capex phasing, ROI thresholds and unit economics for utility, pipeline and energy-sector projects.
- Procurement risk-to-opportunity mapping: The study identifies where raw‑material volatility and supplier concentration translate into real price and lead‑time risk for drill bits, reamers and HDD rigs — and prescribes hedging, dual‑sourcing and design‑substitution tactics.
- M&A and partnership signal framework: We convert competitive concentration and capability gaps into a prioritized list of acquisition targets, JV structures and technology partnerships for both incumbents and private equity entrants.
- Regulatory stress-testing: The report models regional regulatory and labor cost shocks against project economics to identify tipping points where previously viable projects become marginal.
What the full report contains (practical modules)
- Executive summary with board‑level recommendations, investment heat maps and three forward scenarios (base, upside and downside) tailored to 2026 planning cycles.
- Market sizing and growth model (2020–2032) with downloadable assumptions, sensitivity tables and a unit economics calculator for client projects.
- Detailed competitive benchmarking: product portfolios, automation stacks, service models and aftermarket economics for leading vendors.
- Supplier risk dashboard: raw material exposures, lead‑time analytics and a recommended supplier diversification playbook.
- Regulatory and labor impact analysis with playbooks for compliance, labor cost mitigation and community‑engagement strategies.
- M&A playbook and valuation multipliers based on segment positioning, marginal cost improvement potential and cross‑sell synergies.
- Contracting and tender strategy templates for contractors and owners to optimize price, schedule and warranty terms.
Competitive landscape — reading the core vendor moves
The directional drilling market shows elevated concentration. The top three firms capture the majority share of revenue, and the top five broaden that dominance further. For executives evaluating competitors, partners or targets, our full study dissects where each firm generates its strategic margin — equipment design, systems automation, aftermarket consumables, or integrated services — and how that maps to future value creation.
Key players examined in the study include:
- Vermeer Corporation (Pella, Iowa) — A market leader in utility and pipeline horizontal directional drills. Vermeer’s strength is its breadth of platform offerings from compact to heavy‑duty rigs and a clear push into machine automation and integrated fluid management. For customers, Vermeer’s installed base offers predictable lifecycle economics and strong dealer networks, but the company faces pressure to continue delivering software‑enabled uptime and remote diagnostics.
- Charles Machine Works / Ditch Witch (Perry, Oklahoma) — Ditch Witch’s product lineup targets both compact urban utility work and heavier pipeline deployments. Its competitive edge lies in robust field support and tailored machine configurations. Strategic choices for Ditch Witch include accelerating digital services and expanding aftermarket parts availability to defend margins under pricing pressure.
- Ulterra Drilling Technologies — A premium supplier of PDC drill bits and downhole tools for oil and gas directional drilling. Ulterra’s R&D focus on bit life and rate‑of‑penetration is critical as operators push to extend laterals and reduce trip time. However, rising PDC production costs and supply constraints (noted below) force product and sourcing adjustments.
- Melfred Borzall, Inc. — A specialist in HDD tooling and reamers, Melfred is an OEM‑preferred supplier whose niche expertise makes it an attractive acquisition target for firms seeking to fill tooling gaps or integrate reamer technologies into a broader service offering.
Materials, manufacturing and the new cost structure
Raw‑material dynamics are reshaping product economics across the value chain. A steep surge in tungsten carbide pricing and tighter export controls has pushed many drill‑bit makers to re‑evaluate material mixes and production geographies. Concurrently, delays and cost increases in synthetic diamond supply have added margin pressure to PDC tool producers. Some U.S. manufacturers are already shifting toward steel‑based designs to maintain price competitiveness; others are investing in alternative cutter geometries and coatings to preserve performance while reducing dependence on volatile commodities.
For procurement and engineering teams, the implication is clear: assume higher base costs for premium cutting elements and embed material‑price escalation clauses, secondary sourcing, and design‑to‑cost initiatives into all three‑year procurement plans. The full report includes a supplier cost‑curve model and recommended bill‑of‑materials sensitivities for common HDD and directional tool sets.
Regulatory and labor dynamics — immediate considerations
Two regulatory developments deserve operational attention. First, regional prevailing‑wage determinations — exemplified by a recent ruling setting elevated wage rates for HDD labor groups in a U.S. state through mid‑2026 — materially affect labor budgets on urban and state‑funded infrastructure projects. Second, industry bodies continue to refine safety standards; active advocacy from trade associations means compliance requirements are likely to become more prescriptive in the near term.
Project sponsors and contractors must re‑price labor contingencies, accelerate productivity programs that lower per‑meter labor exposure, and engage proactively with regulators and associations to shape practical standards. Our modeling shows that in higher‑cost labor jurisdictions, technology that reduces crew size or shortens project duration produces outsized economic benefits.
Scenario planning: triggers and strategic responses
- Base case (our central forecast): Growth continues in line with a 6.65% CAGR as oil & gas lateral extension, utilities modernization and pipeline replacement demand reinforce equipment replacement cycles and premium tool uptake.
- Upside case: Accelerated infrastructure spending and faster fleet electrification/digital upgrades push adoption of higher‑margin rotary steerable systems and automation features, increasing total addressable service revenue beyond base estimates.
- Downside case: Prolonged raw‑material supply constraints and adverse regional regulatory shocks lead to project deferrals and compression of aftermarket margins; smaller contractors bear disproportionate impacts.
How executives should use this preview today
- Use the market trajectory and concentration metrics in corporate planning to set realistic growth targets and to stress‑test current market share assumptions for 2026 board plans.
- Prioritize supply‑chain actions: immediate steps include opening secondary sourcing lanes, negotiating longer lead‑time contracts for high‑risk consumables, and initiating design‑for‑cost projects where tungsten or synthetic diamond exposures are material.
- Review contractual templates to introduce escalation mechanisms and performance‑based warranty language that protect margins when material costs or labor rates spike.
- For M&A teams, apply the competitive profiling here to refine target screening — look for tooling specialists or digital service providers that either complement fleet capabilities or unlock aftermarket revenue streams.
Next step — access the full intelligence
This preview surfaces the analytical frameworks, headline market trajectory and the primary strategic implications you need for 2026 planning. To execute on procurement actions, sanction targeted capex, or begin disciplinary M&A activity you will need the full subsegment tables, regional and application breakouts, supplier scorecards and downloadable model files that are intentionally excluded from this trailer. Access to that granular intelligence and our proprietary scoring methodology is available through the PW Consulting Directional Drilling Market full report package.
Contact PW Consulting to obtain the complete dataset, scenario models and a bespoke briefing that maps these findings to your portfolio and 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Directional Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PBI Market to Hit USD 77.78 Million by 2032 (13.67% CAGR)
By PW Consulting, 2026-07-09
Polybenzimidazoles (PBI) Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
Polybenzimidazoles (PBI) occupy a niche at the intersection of extreme-environment materials, membrane science, and safety-critical textiles. Between 2020 and 2025 the industry recorded modest but resilient demand, with the market moving from the high‑20s (USD Million) range into the low‑30s (USD Million) by the report base year of 2025. From 2026 onward our forecast shows a pronounced acceleration, driven by hydrogen and carbon‑handling membrane opportunities, next‑generation protective apparel, and select industrial high‑temperature applications — the global market is projected to expand at a compounded annual growth rate (CAGR) of 13.67%, reaching roughly USD 77.8 Million by 2032.
Polybenzimidazoles (PBI) Market
This briefing distils the strategic value of our full Polybenzimidazoles Market research for corporate decision‑makers planning 2026 priorities. It demonstrates actionable lines of enquiry and decision frameworks while intentionally withholding granular segment breakdowns to invite access to the full report for transaction‑grade intelligence.
Polybenzimidazoles (PBI) Market
Why this matters for 2026 strategy
-
Timing: 2026 is the inflection point. The modeled expansion from the 2025 base accelerates materially thereafter — presenting a narrow window to secure feedstock, capacity, and strategic partnerships before competition compresses margins.
Polybenzimidazoles (PBI) Market -
Value migration: PBI is transitioning from specialty textiles into membrane and electrochemical applications (e.g., H2/CO2 separation, proton exchange). This moves value upstream toward polymer producers and vertically integrated membrane suppliers.
-
Capital intensity and scarcity: Production requires complex synthesis and high‑temperature spinning, resulting in high capital and operating costs. Early investments in scalable production or licensing can create durable cost advantages.
Market trajectory & implications (data‑driven view)
Observed market behavior from 2020–2025 shows resilience through cyclical pressures; the 2025 market sits at approximately USD 31.7 Million. Under conservative to disruptive policy and technology scenarios we project a multi‑year expansion at a 13.67% CAGR across 2026–2032, with nominal market size approaching USD 77.8 Million by 2032. This trajectory implies:
-
Rapid capacity scaling needs for membrane manufacturing and specialty fiber production — OEMs and converters face a classic "build vs. buy" choice.
-
Commercialization windows that reward first movers in targeted sub‑applications (e.g., industrial H2 separation, advanced firefighter shells, aerospace thermal protection).
-
Margin pressure for undifferentiated commodity resin; premium extraction possible through integrated membrane systems, branded protective fabrics, and service‑embedded offerings.
Competitive landscape — what the leading players signal
The PBI landscape is shaped by a small set of technology‑intensive suppliers, with differentiated positions along the value chain rather than broad horizontal competition. Key incumbents include a sole specialty fiber/polymer producer with established proprietary brands and deeply integrated fabric partnerships, large chemical groups offering engineering PBI grades for high‑temperature components, and regional specialists focused on niche engineering applications.
-
PBI Performance Products, Inc. — A vertically integrated nameplate in PBI polymer and fiber, positioned around its Celazole® brand and long‑standing relationships in protective apparel and high‑temperature specialty markets. Their product family and ongoing marketing initiatives make them the logical anchor partner for apparel OEMs and safety fabric innovators.
-
Mitsubishi Chemical Advanced Materials — A global chemical heavyweight offering high‑performance PBI resin grades engineered for mechanical stability at elevated temperatures. Their strengths are material science depth, scale, and distribution to engineering OEMs requiring predictable thermo‑mechanical performance.
-
Polymics Ltd. — Smaller, agile supplier focused on Celazole® portfolio distribution and engineered thermoplastic applications. Their niche focus enables faster application trials and customized grade development for wear‑resistant, high‑heat components.
Recent industry moves are illustrative rather than exhaustive: strategic product launches for ultra‑lightweight PBI outer shells in protective gear, continued marketing and product support by incumbent polymer houses, and trade show visibility for advanced flame‑resistant fabrics. Collectively these activities indicate a market moving from product proof to commercialization scale‑up.
Technology & application dynamics
Two technical themes dominate the near‑term value creation:
-
Membranes for gas separation and electrochemical devices: PBI membranes have demonstrated commercially attractive H2/CO2 selectivity and operational tolerance to contaminants (H2S, CO, steam) in extended high‑temperature testing. That opens commercial routes into pre‑combustion decarbonization, hydrogen purification, and certain fuel cell PEM applications — creating large addressable markets where polymer performance can substitute or complement inorganic alternatives.
-
Protective textiles and high‑temperature components: PBI fiber and fabric continue to command premium positions in firefighter turnout gear, aerospace thermal protection, and niche industrial safety applications. The emergence of ultra‑lightweight outer shells suggests product innovation can materially expand use cases (improved firefighter ergonomics, reduced heat stress).
These technology pathways imply distinct commercial plays: membrane value accrues with integrated system providers and licensers, while textile value accrues with fabric integrators and branded PPE companies. Strategy must therefore align to the target capture point along the value chain.
Operational and regulatory considerations
-
Production economics: High‑temperature synthesis and spinning processes require specialized equipment and skilled operators. For new entrants, build‑out timelines and capex recovery must be stress‑tested across multiple price and adoption scenarios.
-
Raw material & supplier risk: Feedstock complexity and constrained supplier pools can create single‑point vulnerabilities. Procurement strategies should combine long‑lead supplier contracts, dual sourcing, and inventory buffers.
-
Regulatory posture: Reputation and regulatory compliance matter: notable supplier declarations indicate no use of PFOA in fiber manufacture, and membrane test results support high‑temperature performance claims. Still, environmental and end‑of‑life considerations for specialty polymers are evolving; proactive engagement with regulators and standards bodies is advised.
Practical uses of the full report for 2026 decisions
Executives and investment teams will find the report directly applicable to these priority actions in 2026:
-
Capex & capacity planning: Use scenario forecasts to size greenfield or retrofit investments, evaluate utilization break‑even, and set staged commissioning triggers.
-
Supply chain resilience programs: Identify critical suppliers, quantify inventory needs under stress scenarios, and prioritize contracting or backward integration options.
-
Product & market prioritization: Allocate R&D and commercialization budgets across membranes, textiles, and engineering resins using demand elasticity and margin maps provided in the report.
-
M&A and partnering screen: Shortlists and valuation sensitives for tuck‑ins, licensing, and joint ventures enable target prioritization without overpaying for near‑term optionality.
-
Commercial strategy: Channel segmentation, customer willingness‑to‑pay matrices, and distributor economics inform pricing and promotional tactics for a 2026 go‑to‑market push.
Risks, mitigations and decision checkpoints
Key risks include technological substitution, feedstock scarcity, and slower than expected membrane adoption. The full analysis layers quantitative sensitivity testing (price, adoption, regulation) against a set of mitigation actions:
-
Hedging and supplier contracting to blunt feedstock shocks;
-
Staged capital deployment tied to adoption milestones for membrane pilots;
-
Partnerships with established fabric OEMs to accelerate certification and procurement cycles for protective apparel;
-
Active participation in standards working groups to shape membrane testing protocols and fuel‑cell acceptance criteria.
What the full report contains (practical deliverables)
-
Transparent market sizing methodology and historical audit trail (2020–2025) plus granular forecasting (2026–2032) with scenario overlays.
-
Segmented demand models by application and product form (fiber, film, resin), with sensitivity tables you can adapt to your internal assumptions.
-
Supply chain maps, cost stacks, and unit economics for greenfield vs. contract manufacturing approaches.
-
Competitive benchmarking, capability matrices, and go‑to‑market playbooks tailored for upstream producers, converters, and OEMs.
-
M&A shortlists, due‑diligence templates, and valuation levers specific to PBI technologies and adjacent membrane platforms.
-
Regulatory and standards tracker, including verified supplier declarations and material test outcomes relevant to fuel‑cell and gas‑separation applications.
Closing — strategic posture for 2026
For leaders preparing 2026 roadmaps, PBI represents a high‑value, capital‑intensive segment with asymmetric upside for correctly timed moves. The market’s projected compounded growth from the 2025 base through 2032 creates windows to capture premium margins via vertical integration, performance branding, or targeted licensing. The right playbook blends defensive supply‑chain actions with offensive commercialization and technology partnerships.
Our full market study translates these insights into executable workstreams — from capex decision trees and supplier scorecards to M&A target dossiers. The briefing here highlights the strategic contours; the full report supplies the guarded segmentation and model outputs required to operationalize 2026 decisions. Access to the complete dataset and scenario models will materially reduce execution risk and accelerate value capture.
For detailed analysis of this topic, please visit the official page: Polybenzimidazoles (PBI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ASA Resin Market 2026: Strategic Intelligence Brief — Why This Report Matters for Executive Decision-Making
Executive snapshot
As PW Consulting’s Senior Strategy Advisor, I present a concise yet strategically rich overview of our ASA Resin Market study — designed to inform executive decisions through 2026 and beyond. The ASA resin market, evaluated on a 2025 base year and modeled across a 2026–2032 forecast window, exhibits steady expansion with a mid-single-digit compound annual growth rate (CAGR) of 5.12%. Our modeling shows the market crossing key inflection points in the late 2020s driven by structural demand in mobility, electronics manufacturing, and industrial applications. The three-firm and five-firm concentration metrics (CR3 ≈ 75%, CR5 ≈ 80%) signal an oligopolistic structure where a handful of suppliers exercise meaningful pricing and innovation influence — a critical context for sourcing, M&A, and partnership strategies.
ASA Resin Market
Why this study is a 2026 decision enabler
CEOs, heads of product, supply chain directors, and corporate strategists face a condensed decision horizon in 2026: securing resilient feedstock access, selecting grade portfolios aligned to tightening regulatory regimes, and positioning product roadmaps for electrified and lighter-weight platforms. Our ASA report is purpose-built to translate market momentum — informed by five years of historical observation (2020–2025) and scenario-driven forecasts (2026–2032) — into actionable options. It does this without overwhelming readers with raw tables: we synthesize trends, quantify macro trajectories, and show directional impacts so that leadership teams can prioritize capital allocation, supplier contracts, and go-to-market pivots for the next budgeting cycle.
ASA Resin Market
Market trajectory and what the headline numbers mean
From a macro perspective, the ASA resin market recorded consistent growth through 2025 and our forecast anticipates continued expansion through 2032. The reported CAGR of 5.12% reflects a balanced combination of volume adoption and value-add premiumization (high-performance grades, weather-stable formulations, and specialty compounds). For practitioners, the implication is threefold: first, stable topline growth supports multi-year supplier engagements and capacity investments; second, premiumization enables margin improvement for producers who can differentiate on formulation or downstream compatibility; third, the steady growth underscores a commercial environment where timing — not only capability — determines competitive advantage.
ASA Resin Market
Key dynamics shaping the next investment cycle
-
Raw material volatility and supply-side sensitivity: Acrylonitrile and styrene feedstock availability remains the principal operational risk. Market observations indicate price upticks in mid-2025 (notably a quarter-over-quarter rise in Q2 2025 consistent with roughly a 3.0% move for ASA resin input costs). Buyers must expect periodic volatility and build hedging, dual-sourcing, or inventory strategies into 2026 procurement planning.
-
Regulatory pressure as a demand accelerator: Emerging and evolving regulatory frameworks — REACH-driven material compliance in Europe, tightened fuel economy and CO2 standards in the U.S. (CAFE and comparable targets), and national fuel-consumption benchmarks in large auto markets — increase the attractiveness of ASA for lightweight, weather-resistant exterior components. These regulatory vectors will be a material driver of adoption decisions for OEMs and tier suppliers in 2026.
-
Concentration and supplier power: With the market’s top three and five firms controlling a dominant share, strategic sourcing teams should weigh the trade-offs between supply security and price leverage. The oligopolistic structure favors early partnerships with leading producers for co-development of grades or long-term off-take agreements.
Sector-specific strategic implications
-
Automotive: Light-weighting mandates and electrified vehicle architectures create a differentiated opportunity set for ASA formulations. Priority actions for OEMs and Tier 1s in 2026 include validating ASA grades for structural exterior panels, sequencing qualification plans aligned to vehicle program timelines, and negotiating design-for-cost levers with resin suppliers. The regulatory tailwinds shorten qualification lead times but raise the bar for proof-of-performance under accelerated weathering protocols.
-
Electronics & semiconductor supply chain: As wafer fabrication and IC packaging seek thermoplastics with dimensional stability and contamination control, specialized ASA grades play a targeted role. Procurement and design teams should run concurrent validation streams: one for immediate-build components and another for next-gen packaging where thermal and surface properties will be mission-critical.
-
Additive manufacturing and specialty tooling: The emergence of ASA filament variants for large-format and weather-resistant 3D printing opens new aftermarket and prototyping economies for industrial OEMs and service bureaus. Priorities here include licensing/partnerships with filament manufacturers and evaluating in-house FDM capacity to accelerate product development cycles.
-
Construction & outdoor applications: The combination of weatherability and color stability sustains ASA demand in exterior systems. The strategic focus should be on modular productization and the ability to offer certified longevity claims that meet regional regulatory expectations.
Supply chain and procurement playbook for 2026
Given raw material fluctuations and concentrated supplier power, we recommend a four-track procurement playbook:
-
Diversify feedstock exposure via contractual instruments (index collars, capped cost agreements) and alternative monomer sourcing where feasible.
-
Pursue strategic partnerships with top-tier ASA suppliers for co-development and prioritized capacity access, leveraging modest volume commitments for preferential service levels.
-
Embed qualification acceleration strategies: parallel testing tracks, shared test assets with suppliers, and acceptance of intermediate field trials to shorten product launch timelines.
-
Operationalize a continuous monitoring system for raw-material pricing and regulatory shifts to permit rapid contract renegotiation and inventory adjustments.
Competitive landscape — who to watch and why
The ASA market’s competitive topology is shaped by established petrochemical and specialty polymer players that combine formulation expertise with global manufacturing footprints. Leading names include major European and Asian chemicals groups, integrated petrochemical producers, and regional specialty compounders. Each presents a different strategic proposition: some prioritize performance-grade portfolios for automotive exteriors and high-gloss applications; others pursue breadth through extrusion-optimized and injection-molding grades; a few specialize in filament and additive manufacturing feedstock.
Examples of market-active players and their strategic emphasis (profiles summarized):
-
BASF SE (Germany) — known for specialty filament and performance ASA offerings tailored to additive manufacturing and weather-resistant applications.
-
SABIC (Saudi Arabia) — markets GELOY™-type resins optimized for automotive exteriors and construction profiles, positioning around weatherability and scale.
-
LG Chem Ltd. (South Korea) — focuses on high-performance, high-gloss ASA grades for exterior applications with a strong OEM relationships base in mobility markets.
-
INEOS Styrolution Group (Germany) — offers Luran® S grades aimed at thermal stability and broad processing compatibility for injection molding and extrusion.
-
Kumho Petrochemical, Techno-UMG, and Chi Mei — regional and specialty players that supply targeted ASA grades for consumer and industrial applications, often enabling localized service advantages.
Additionally, cross-industry moves — such as the November 2025 launch of a new ASA filament variant for industrial 3D-printing machines — highlight adjacent innovation trajectories that incumbents and challengers will need to either replicate or counter through partnerships and IP plays.
What the full PW Consulting ASA report delivers (practical utility)
Our market study is structured to be operationally useful. It contains:
-
Scenario-driven demand models covering 2026–2032, stress-tested across raw-material volatility and regulatory adoption curves.
-
Supplier scorecards focused on capability, capacity, geographic exposure, and commercial flexibility — enabling rapid shortlist creation for procurement pilots.
-
Go-to-market frameworks for OEMs and compounders, including qualification timelines, margin levers, and bundling strategies for premium grades.
-
Operational playbooks for R&D and materials teams to accelerate grade qualification in automotive and electronic applications without compromising long-term testing rigor.
-
Risk matrices that marry raw-material price sensitivity with supply concentration to recommend optimal inventory and contractual hedges.
How to use this intelligence in 2026 planning cycles
-
Board-level scenario reviews: Use our forecast scenarios to stress-test product portfolios against regulatory pathways and fuel-efficiency mandates.
-
Procurement negotiations: Present modeled demand curves and supplier scorecards to justify strategic partnership terms and capacity reservations.
-
R&D prioritization: Align compound development roadmaps to the market segments showing the fastest value realization potential, while keeping contingency plans for raw-material dislocations.
-
M&A and alliance screening: Target bolt-on acquisitions or JV partners that close capability gaps (e.g., weatherable high-gloss grades or filament production) — our report provides granular criteria and candidate profiles.
A closing note on scope and next steps
This strategic brief is intentionally selective: it conveys the macro momentum, competitive contours, regulatory drivers, and practical playbooks you need to make informed moves in 2026. For detailed segmentation, granular regional and application-level statistics, price curves, and our proprietary demand model outputs, access to the full ASA Resin Market report is required. Those datasets include the exact split dynamics and modeled sensitivities that underpin the playbooks summarized here — information we reserve for subscribers and clients to preserve analytic value.
Contact PW Consulting to schedule a briefing where we will walk your leadership through the full financial model, scenario options, and a tailored action plan aligned to your 2026 strategic priorities.
For detailed analysis of this topic, please visit the official page: ASA Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Silicate Market from USD 8,080M (2025) to USD 10,323M by 2032 at 3.7% CAGR
By PW Consulting, 2026-07-09
Sodium Silicate Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive teaser
As companies rewire portfolios for resilience and margin recovery, sodium silicate is re-emerging as a quietly strategic commodity. Our PW Consulting market study, anchored on a 2025 base year, shows the global sodium silicate market at approximately USD 8,080 Million in 2025 and projecting forward at a steady compound annual growth rate (CAGR) of 3.7% through the 2026–2032 forecast window. By 2026 the market is modeled to expand to roughly USD 8,466 Million, progressing toward just over USD 10,300 Million by 2032. For executives making capital, sourcing or M&A decisions in 2026, that trajectory—modest but consistent—creates a set of practical choices about where to deploy resources and where to preserve optionality.
Sodium Silicate Market
Why this report matters for 2026 strategy
- Translate mid-single-digit CAGR into actionable capacity and pricing decisions—knowing not only the headline growth but the sensitivity to feedstock and logistics will change investment timing.
- Prioritize product segments and geographies: the right mix of liquid vs. solid grades, and targeted specialty chemistries, materially affects margin and risk exposure.
- Calibrate M&A appetites: consolidation metrics in this market create both platform targets and bolt-on opportunities for specialty or regional market entry.
- Align sustainability roadmaps with regulatory exposure: compliance costs and decarbonization pathways will drive operating cost differentials across producers, especially in high‑regulation regions.
Signals and near‑term dynamics that will shape 2026 outcomes
Three interlinked dynamics will determine near‑term winners and losers:
Sodium Silicate Market
- Feedstock and input volatility. Sodium silicate production depends on silica sand and soda ash; volatility in these inputs flows directly to cash costs and pricing power. Market monitoring shows regional price moves that are already compressing or expanding margins. For example, observed price points in Northeast Asia rose from about USD 0.53/kg in January 2025 to USD 0.55/kg in January 2026, while North American benchmark pricing moved from roughly USD 0.43/kg to USD 0.48/kg over the same interval—an early indicator of regional margin pressure tied to shipping, operating expenses and sector demand composition.
- Regulatory and compliance pressure. Tighter environmental regulations and emissions standards in Europe are raising operational expense baselines for producers. Companies unable to translate compliance into price or efficiency advantages will face margin erosion.
- Demand mix and end‑market health. Water treatment, detergents, construction, and pulp & paper remain core demand drivers, but growth differs by end‑use and region. Shifts in detergent formulation trends, municipal water capex cycles, and construction activity are the proximate demand levers to watch in 2026.
Market structure and competitive context
The sodium silicate market combines global integrators and strong regional specialists. Market concentration is material but not dominating—the top three players account for a majority share, and the top five widen that majority further. This structure produces predictable strategic behaviors: global producers compete on scale and feedstock integration; specialty chemical players compete on product differentiation and technical service; regional manufacturers compete on cost, logistics and tailored service models.
Sodium Silicate Market
Profiling the competitive set: strategic takeaways
- PQ Corporation (Malvern, Pennsylvania). A leading global producer with active capacity expansions in the US, Indonesia and Europe. PQ’s footprint and scale give it the flexibility to optimize feedstock sourcing and to pursue export or localized service strategies depending on regional margin profiles. For PQ, the strategic imperative in 2026 is to convert capacity additions into higher‑value specialty grades while locking in feedstock and logistics agreements to defend margins.
- Nippon Chemical Industrial Co., Ltd. (Japan). A strong manufacturer and exporter with deep channels into detergents and construction. The company’s export orientation and solution selling into detergents position it to capitalize on Asia‑Pacific demand resilience, but exposure to raw material swings will necessitate more aggressive hedging or supplier partnerships.
- Tokuyama Corporation (Japan). Focused on high‑purity and specialty silicates, Tokuyama’s value proposition is technical differentiation. In 2026 the premium plays—specialty grades, controlled particle distributions, and tailored chemistries—will see better margin expansion than commodity blends.
- Ankit Silicate (Morbi, Gujarat, India). An ISO‑certified regional manufacturer of liquid, powder and metasilicates for detergents, ceramics and construction. Local cost advantages and certification credentials make Ankit well positioned to serve domestic and neighboring markets; its strategic moves should prioritize capacity flexibility and product customization.
- Evonik Industries AG (Essen, Germany). Evonik’s integration of sodium silicate offerings with specialty silica and broader chemical portfolios creates cross‑sell and margin‑capture opportunities. For Evonik, the key strategic choices in 2026 are around bundling specialty chemistries, advancing sustainability claims and capturing value higher up the application ladder.
- Qemetica (CIECH Group subsidiary, Poland). As one of Europe’s largest silicate suppliers, Qemetica must manage regulatory cost pressure while exploiting scale into continental supply chains. Strategic options include differentiated technical service, localized decarbonization investments and selective export strategies.
Strategic playbook: what to do in 2026
For corporate leaders, the playbook centers on three parallel tracks: protect margin, grow selectively, and derisk the supply base.
- Protect margin: renegotiate long‑term feedstock contracts with escalation clauses tied to transparent indices; increase efficiency in energy use and emissions control to blunt regulatory cost increases; selectively shift product mix toward higher‑margin specialty grades.
- Grow selectively: prioritize investments where forecasted end‑market growth outpaces the headline CAGR—these are often specialty or application niches rather than broad commodity capacity. Use flexible capacity and tolling agreements to capture upside without committing to large fixed costs.
- Diversify risks: pursue multi‑sourcing for silica sand and soda ash, build inventory and logistics hedges for cost spikes, and consider JVs for market entry where localized service confers advantages.
What the PW Consulting report delivers (practical contents)
Designed as a pragmatic decision toolkit for 2026, the full study includes:
- Comprehensive market sizing and demand models: historical 2020–2025 and probabilistic forecasts for 2026–2032, with scenario variants tied to feedstock and macro assumptions.
- Price and cost sensitivity models: forward price scenarios for sodium silicate and the primary feedstocks, plus margin simulations under different pass‑through and regulatory regimes.
- Competitive dashboards: capability maps, capacity expansion trackers, and strategic positioning for global and regional producers.
- End‑use and application intelligence: qualitative and quantitative demand drivers for detergents, water treatment, pulp & paper, construction and other segments—presented in an actionable format that supports product and go‑to‑market prioritization.
- Supply chain and operational playbooks: sourcing strategies, logistics optimization, and operating models to lower cost and improve resilience in the face of input volatility.
- Regulatory impact and decarbonization pathways: region‑specific compliance cost estimates and practical investment options to reduce emissions intensity.
- M&A and partnership screening: target scouting criteria, valuation ranges, and integration playbooks for buyers and sellers.
- Risk heatmaps and mitigation templates: tailored to executive decision timelines (0–12 months, 12–36 months, 36+ months).
How to use this intelligence in 2026—practical decision triggers
- If your top‑line exposure to detergents or water treatment exceeds internal thresholds, accelerate product development and technical service investments now—these segments reward differentiation.
- If feedstock cost escalation reaches regional breakpoints (as already observed in North America and Northeast Asia), implement contractual pass‑through mechanisms and explore vertical integrations or tolling arrangements.
- For companies with limited sustainability credentials entering Europe, treat emissions compliance as a near‑term capital expense and model worst‑case regulatory scenarios in investment approvals.
- Use M&A as a scale/portfolio play: acquire complementary specialty capabilities or regional platform positions rather than chasing raw capacity alone.
Final provocation—why this is a “must‑have” for 2026 decisions
Sodium silicate will not be a headline growth miracle over the next seven years, but it will be a quietly consequential chemical: small percentage shifts in price, regulation or application mix translate into meaningful P&L swings for producers and users alike. The 3.7% CAGR through 2032 frames a market that is predictable at an aggregate level but richly variegated at the segment level—exactly the type of environment where superior intelligence and execution deliver outsized returns.
The full PW Consulting study contains the granular maps, sensitivity models and regional/application splits that corporate development, procurement and plant operations teams need to convert strategic intent into fiscal outcomes. This article is a trailer: it shows the contours and the strategic implications, while the downloadable report supplies the numbers, dashboards and scenario tools that power boardroom decisions in 2026.
Contact PW Consulting to access the full market model, supplier scorecards and investment playbooks that enable confident action in the sodium silicate value chain.
For detailed analysis of this topic, please visit the official page: Sodium Silicate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mineral Insulated Cables Market to Reach USD 2,351.8M by 2032
By PW Consulting, 2026-07-09
Mineral Insulated Cables Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The mineral insulated (MI) cables market has transitioned from a niche safety- and performance-driven technology to a strategic component in critical infrastructure, industrial process control, and hazardous-area electrification. Using 2025 as the base year and a forecast window that extends through 2032, PW Consulting’s proprietary model shows steady, above-market expansion driven by regulatory tightening, material innovation, and selective demand pockets across energy and built-environment applications. The global market expanded from approximately USD 1,314.15 Million in 2020 to USD 1,654.0 Million in 2025, and — under our central scenario — reaches roughly USD 2,351.8 Million by 2032, reflecting a 2026–2032 compounded annual growth rate of about 5.1%.
Mineral Insulated Cables Market
Why our 2026 intelligence changes decisions
- Time-to-certification and supplier qualification are the new strategic gates. With regulatory updates and more demanding project specifications, procurement timelines now extend by quarters unless suppliers and manufacturers pre-emptively align to new standards.
- Material upgrades are creating product differentiation. High-temperature, corrosion-resistant alloy tubing and new sheath/cladding options are changing both longevity and qualification cost curves for MI cable assemblies.
- Supply-chain resilience is a commercial lever. Manufacturers that control upstream metallurgy and tube production can de-risk lead times and command margin premiums; conversely, buyers that lock strategic supply agreements can protect project schedules and total cost of ownership.
What the full report delivers (practical highlights)
PW Consulting’s Mineral Insulated Cables Market study is intentionally action-oriented. Clients can expect deliverables that translate immediately into procurement, product, and investment choices:
Mineral Insulated Cables Market
- Market sizing and forecasting framework (base year 2025; historical analysis 2020–2025; forward view 2026–2032) with scenario-based sensitivities for commodity shocks and regulatory adoption rates.
- Segment-level demand drivers and margin dynamics across type, application, and region — with quantification of installed-base replacement cycles and new-build demand triggers. Note: this preview omits core segment splits to protect analytical IP; the full dataset includes the granular breakout.
- Supply-chain mapping and raw-material risk assessment, including alloy tubing supply, copper and stainless-steel feedstocks, and the manufacturers that internalize these capabilities.
- Regulatory and standards compass — implications of recent and emerging standards for product testing, certification timelines, and aftermarket liabilities.
- Competitive benchmark and playbook — deep profiles on leading suppliers, capability matrices, and vendor scorecards to guide sourcing and JV/M&A diligence.
- Go-to-market and product strategy recommendations tailored for OEMs, EPCs, and distributors, together with prioritized near-term tactical moves for 2026.
- Excel deliverables and model access for client-specific scenario runs (price escalators, order-book phasing, volume thresholds for vertical integration).
Market dynamics: what’s moving the needle
Several concurrent dynamics are shaping near-term choices:
Mineral Insulated Cables Market
- Regulatory acceleration. New standards and certification expectations are tightening the barrier-to-entry for unqualified suppliers. Case in point: recent standardization activity published in 2025 has redefined material and testing criteria for a range of MI constructions, affecting qualification scopes and lab testing programs.
- Material innovation. The introduction and commercial ramp of high-temperature, corrosion-resistant alloy tubing fundamentally shift performance benchmarks for MI cables, enabling higher operating temperatures and longer service life in aggressive environments.
- Supplier integration and capacity. The economics of MI cable production favor suppliers that internalize upstream processes — from tube forming to cladding — because they can shorten lead times, reduce quality variance, and protect margins.
- End-market concentration of demand. Demand is increasingly project-driven (e.g., energy projects, safety-critical circuits in the built environment, and process industries) which leads to pronounced peaks and troughs in order books that manufacturers must plan for.
Competitive landscape — capability and strategic posture
The market displays a mix of specialized manufacturers, material suppliers, and assembly-focused players. Rather than enumerate share by segment in this preview, we highlight strategic positioning and what it means for purchasers and investors.
- MI Cable Co. (United States) — Operates with a strong assembly and customer-specific orientation, offering precision cut-to-length assemblies and accessory engineering (e.g., braised pigtails, threaded compression glands) tailored for industrial applications. Strategic implication: attractive as a responsive manufacturing partner for project-centric buyers who prioritize configurability and short lead times.
- MICC Corporation (United States) — Known for breadth of MI cable variety and fire-survival wiring offerings. Strategic implication: strong candidate for buyers seeking a single-source multi-technology supplier, particularly for cross-application projects requiring consistent performance standards.
- M.I. Cable Technologies Inc. (Canada) — Focused on bulk supply to OEM thermocouple manufacturers and backed by ISO17025-certified quality systems. Strategic implication: a go-to partner when calibration, traceability, and lab-backed quality assurance are procurement requirements.
- Wrexham Mineral Cables (UK) — Emphasizes MICC products engineered for safety-critical circuits with long service-life claims. Strategic implication: preferred for lifecycle-sensitive projects where replacement windows are multi-decade and end-of-life costs dominate selection criteria.
- KME Italy S.p.A. (Italy) — Combines mineral-insulated cable production with recognized EU certifications for ATEX/CPR, supporting deployment in regulated European markets. Strategic implication: certification-ready supplier for projects where European regulatory acceptance and conformity documentation accelerate approvals.
- Alleima (Sweden) — Supplies high-temperature, corrosion-resistant alloy tubing used in MI cable applications. Recent product and commercial milestones indicate accelerating adoption of advanced alloys in MI constructions, enabling new operating envelopes. Strategic implication: buyers should consider qualifying advanced tubing suppliers early to capture performance advantages and secure long-term pricing.
- Okazaki Manufacturing Company (Japan) — Differentiates through in-house raw material processing and unique manufacturing techniques, enabling scale and consistency. Strategic implication: a resilient source in procurement strategies that prioritize vertical integration and long-run capacity.
Recent developments that matter for 2026 planning
- Alleima launched a high-temperature alloy tubing product engineered to extend MI cable performance at extreme temperatures and secured initial European orders and North American deliveries in early 2025. Shortly thereafter, Alleima was awarded a North American tubing supply contract to a Canadian MI cable supplier following successful trials.
- Regulatory updates in 2025 have clarified material and testing requirements for MI cable constructions, raising the practical cost of entry for non-certified suppliers and tightening buyer specifications.
- Several manufacturers are publicly emphasizing in-house raw-material processing and certification credentials as a means to shorten qualification cycles and to provide traceability across safety-critical projects.
Strategic playbook for 2026 (recommended actions)
For leadership teams—procurement, product, and corporate development—PW Consulting recommends an evidence-based sequence of actions to capture upside and mitigate risk in 2026:
- Prioritize supplier qualification now, not later. Start cross-qualification programs that align with updated standards and include material suppliers as part of the scope (tube suppliers, alloy houses).
- Negotiate conditional long-term supply contracts with tier-1 tubing suppliers to stabilize input pricing and delivery windows; include performance-based clauses tied to qualification outcomes.
- Segment your sourcing strategy: treat high-criticality circuits and long-life installations differently from commoditized assemblies. Use multi-sourcing where failure carries asymmetric cost implications.
- Invest in certification and traceability. Certifications (ISO, ATEX/IMQ/CPR, and equivalent national standards) materially shorten approval cycles for critical projects.
- Evaluate vertical integration selectively—particularly for OEMs that can justify the capital expenditure through recurring, high-margin demand streams or integration synergies.
- Use scenario modeling to stress-test procurement under commodity shock, regional regulation adoption, and accelerated electrification in adjacent industries.
- Build a vendor-sourced innovation pipeline. Engage suppliers on co-development for advanced alloys and sheath/cladding combinations to de-risk first-of-kind projects.
What’s behind the paywall — and why it matters
This preview intentionally demonstrates the analytical depth PW Consulting deploys while withholding core subsegment matrices, granular regional/application splits, company-level revenue breakdowns, and the Excel model that links demand drivers to supplier capacity constraints. Those elements are included in the full report and are essential for transaction due diligence, supplier RFPs, and product roadmapping. In practice, clients who obtain the full dataset are able to:
- Quantify break-even volumes for vertical integration decisions;
- Prioritize candidate suppliers for qualification based on lead-time risk and technology fit;
- Calibrate procurement hedges against material price stress scenarios; and
- Identify near-term M&A targets whose capability sets unlock new applications or geographies.
Closing — how PW Consulting can help
As organizations set budgets and make sourcing commitments in 2026, the MI cables market presents both incremental opportunity and structural risk. Whether you are an OEM designing next-generation thermocouples, an EPC specifying fire-survival power, a distributor optimizing inventory, or a private-equity sponsor assessing consolidation plays, the choices you make now about supplier qualification, material commitments, and technology roadmaps will determine cost and delivery outcomes for years.
PW Consulting’s full Mineral Insulated Cables Market study provides the datasets, vendor scorecards, and scenario models necessary to convert market insight into executable strategy. Contact our team for a briefing or to license the complete report and Excel model.
For detailed analysis of this topic, please visit the official page: Mineral Insulated Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
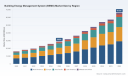
Building Energy Management Systems (BEMS): Strategic Imperatives for 2026 — A Preview from PW Consulting
As organizations accelerate decarbonization, optimize operational cost structures, and pursue smarter facilities, Building Energy Management Systems (BEMS) have shifted from a niche operational tool to a core element of corporate strategy. PW Consulting’s latest market study — anchored on a 2025 base year and covering historical trends through 2020–2025 with forecasts to 2032 — synthesizes the economic, technological, and regulatory inflections that will shape procurement, deployment, and competitive positioning in calendar year 2026 and beyond.
Building Energy Management System (BEMS) Market
Market Trajectory at a Glance
Our analysis estimates the global BEMS market at roughly USD 29 billion in 2025 (base year), having expanded markedly from the 2020 baseline. The market is projected to register a compound annual growth rate (CAGR) of approximately 12.6% through the forecast horizon, culminating in an estimated market size north of USD 66 billion by 2032. This momentum is driven by the convergence of smarter controls, pervasive IoT telemetry, increasingly sophisticated software analytics, and the monetization opportunities from energy flexibility and demand response.
Building Energy Management System (BEMS) Market
Why This Report Matters to Decision-Makers in 2026
- Timing for Investment Decisions: 2026 will be a fulcrum year when pilot investments must transition into scalable rollouts. The report maps revenue trajectories and deployment windows to help CFOs and facility heads prioritize capital allocation across hardware refresh, software subscriptions, and managed services.
- Vendor Selection Under Uncertainty: With a moderate degree of market concentration among incumbent industrial and automation leaders, our vendor intelligence helps procure teams evaluate trade-offs between integrated legacy providers and emerging SaaS-first entrants.
- Operationalization of Net-Zero Targets: The study connects technical BEMS capabilities to measurable emissions and energy-cost KPIs, enabling corporate sustainability teams to translate high-level commitments into procurement and implementation roadmaps.
- Risk-Adjusted Scenarios: Investors and strategists receive scenario-based forecasts reflecting regulatory tightening, energy price shocks, and faster-than-expected tech adoption—critical inputs for stress-testing business cases.
What the Report Contains — Actionable, Tactical, and Strategic
- Market Sizing & Methodology: Transparent modeling that reconciles historical vendor revenues, technology adoption curves, and macro energy trends. The base year (2025) is reconciled with time-series market data to produce deterministic and probabilistic forecasts to 2032.
- Demand Drivers & Adoption Barriers: Deep-dive assessments of regulatory incentives, corporate decarbonization targets, commercial real-estate cycles, and technical friction points such as legacy building systems, integration costs, and cybersecurity exposure.
- Technology Taxonomy & Roadmap: A decomposition of the BEMS stack—control hardware, edge gateways, communications protocols, cloud platforms, analytics layers, and managed services—paired with a three‑year technology adoption timeline and maturity curves.
- Vendor Benchmarking & Strategic Profiles: Multi-dimensional scorecards evaluating product breadth, digital capabilities, go-to-market models, partner ecosystems, and financial resilience. This enables procurement teams to create a shortlist aligned to strategic priorities (e.g., fastest ROI, lowest integration risk, platform extensibility).
- Commercial Models & TCO Tools: Practical templates and sensitivity calculators that compare CapEx vs. OpEx approaches, subscription licensing, and outcomes-based contracts (e.g., shared-savings and performance guarantees).
- Implementation Playbooks: End-to-end guidance for proof-of-concept design, phased rollouts, data governance, stakeholder alignment, and change management to accelerate time-to-value.
- M&A & Partnership Intelligence: Analysis of strategic moves and inorganic consolidation dynamics to inform corporate development and VC/PE deal teams.
Competitive Landscape — Who’s Leading and How They Are Positioning
The competitive field spans large industrial automation vendors, HVAC and controls specialists, and software-first entrants focused on analytics and demand-response services. Leading global players continue to refine integrated platforms, bolstering digital services and cloud-delivered capabilities to capture recurring revenue and deepen customer lock-in.
Building Energy Management System (BEMS) Market
- ABB Ltd.: Building on an expanded digital portfolio after a recent acquisition, ABB is positioning modular digital energy infrastructure and SaaS capabilities as a pathway to scale across fleets. Their strategy underscores integration of portable analytics into traditional electrical and controls offerings.
- Schneider Electric SE: Schneider continues to push integrated building automation with AI-driven energy management, recently introducing enhanced room-level control solutions that reflect a focus on user experience and granular load control as optimization levers.
- Siemens AG: Through evolving building management software, Siemens is emphasizing analytics-driven energy optimization and cross-domain integration—linking BEMS with district energy systems and industrial controls.
- Johnson Controls: Leveraging preconfigured energy dashboards and its analytics platform, Johnson Controls is pursuing outcomes-based service models designed to simplify procurement for large, dispersed real-estate portfolios.
- Honeywell, Trane, Eaton, Emerson, Rockwell, Mitsubishi Electric: These incumbents continue to defend installed bases by coupling controls, electrical distribution, HVAC expertise, and process automation with incremental software and services capabilities.
- EnerNOC: As a demand-response and energy management specialist, EnerNOC and similar service-centric firms are growing in relevance as buildings participate in wholesale flexibility markets and corporate energy programs.
Recent strategic moves—such as ABB’s addition of scalable SaaS capabilities and Schneider’s product launches in 2025—illustrate two convergent trends: hardware incumbents are accelerating software monetization, while software specialists pursue deeper physical-layer integration.
Key Strategic Implications for 2026
- Prioritize Platform Modularity: Select platforms that support phased upgrades—allowing owners to pilot analytics and demand-response features before committing to full hardware refreshes. This reduces sunk cost risk and shortens payback windows.
- Negotiate Outcome-Linked Commercials: Structure vendor agreements that share savings or link payments to verified energy reductions. Our report provides contract templates and measurement, verification (M&V) protocols that legal and procurement teams can adapt.
- Emphasize Data and Cyber Resilience: Treat telemetry as a strategic asset. Institute data governance, role-based access, and vendor SLAs for security patching—areas where many early deployments under-invest.
- Design for Interoperability: Favor solutions that support open standards and third-party integrations to avoid vendor lock-in and to enable composite value chains (e.g., integrating DERs, EV charging, and grid services).
- Build Cross-Functional Capability: Deploy center-of-excellence teams that combine facilities, IT, procurement, and sustainability leads to centralize vendor selection, performance tracking, and continuous improvement.
- Leverage Financial Innovations: Explore ESCO-like arrangements, green bonds, and utility incentives to accelerate deployment without unduly stressing balance-sheet capital.
How to Use This Preview — Next Steps
Consider this article a strategic primer: it highlights macro momentum, vendor positioning, and the practical levers available to executives entering 2026 procurement cycles. For project teams preparing RFPs or investors evaluating platform plays, the full PW Consulting study provides the necessary granularity: scenario-validated market sizing, vendor scoring matrices, detailed go-to-market playbooks, and downloadable TCO models.
If your organization is defining a 2026 BEMS roadmap, treat the next 9–12 months as decisive. Decisions made now on architecture, vendor partnerships, and contracting models will determine whether your buildings realize rapid ROI and meaningful emissions reductions—or whether they become another generation of stranded controls investments.
Closing Advisory
BEMS is no longer a utility line-item; it is an operational backbone for cost control, risk management, and sustainability delivery. In a market expanding at a healthy double-digit CAGR, incumbency advantages matter—but so do speed, software-first propositions, and flexible commercial frameworks. PW Consulting’s full report equips leaders with the data, frameworks, and vendor insights necessary to convert market momentum into measurable business outcomes in 2026. For teams that need to move from intent to implementation, our research offers the roadmaps and tools to get there.
For detailed analysis of this topic, please visit the official page: Building Energy Management System (BEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


