



Category: market research
PW Consulting: Embroidery Machine Market to Reach USD 7,327.75M by 2032 at 3.25% CAGR
By PW Consulting, 2026-07-08
Embroidery Machine Market — Strategic Preview for 2026 Decision‑Makers
As organizations plan capital allocation, product roadmaps, and M&A activity for 2026, the embroidery machine market is entering a phase where incremental growth and structural change intersect. This preview synthesizes the high‑level findings from PW Consulting’s full market research on the Embroidery Machine Market (base year 2025), highlights the strategic choices firms will face in 2026, and describes the practical, decision‑grade assets included in the full report. We deliberately present rigorous, evidence‑based insight here while reserving the full segment‑level matrices and proprietary models for the full release — think of this as a data‑rich trailer that clarifies the stakes and next steps.
Embroidery Machine Market
Macro snapshot (what you need to know now)
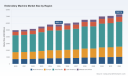
By our accounting, the global embroidery machine market reached approximately USD 5.82 billion in 2025 and is modeled to grow steadily through the 2026–2032 forecast horizon. The medium‑term trajectory reflects a compound annual growth rate of roughly 3.25% across the forecast period, producing a market approaching the mid‑seven billion dollar range by the end of the window. This is a market characterized by steady demand from apparel, home textiles and industrial textile segments, coupled with pockets of higher‑velocity adoption where automation and customization demand converge.
Embroidery Machine Market
For 2026 planning, the implication is clear: growth is consistent but not explosive. That reality favors strategies focused on margin expansion, aftermarket revenue, productivity gains and selective consolidation rather than broad, volume‑driven expansion alone.
Embroidery Machine Market
Core industry dynamics shaping 2026 decisions
- Automation meets customization: Buyers increasingly expect machines that can transition rapidly between small customized runs and higher‑volume production. Vendors supplying modular, multi‑head configurations with intuitive software are winning specification battles.
- Service and aftermarket as profit engines: With unit growth modest, recurring revenue from servicing, spare parts, retrofits and software subscriptions becomes a priority lever for suppliers to lift margins and deepen customer relationships.
- Operational efficiency and sustainability pressures: Regulators and brand owners are pushing reductions in material waste and energy consumption. Compliance and ESG readiness are becoming procurement criteria as important as price and lead time.
- Supply chain and input cost volatility: Critical components and consumables (needles, heads, control electronics) can create cost and availability shocks. Firms with diversified sourcing, standardized modules and robust inventory strategies reduce production risk.
- Labor dynamics: Demand for precision embroidery and on‑demand customization raises the value of skilled operators and technicians while creating incentives for automation where labor is scarce or costly.
- Moderate market concentration: The market is not dominated by a single incumbent; top providers collectively hold a meaningful but not overwhelming share of value, leaving room for regional specialists and new entrants with differentiated technology or service models.
Competitive landscape — who to monitor in 2026
Strategic choices in 2026 should be informed by the capabilities and moves of established players and rapidly scaling manufacturers. Key vendors tracked in our coverage include:
- Brother Industries, Ltd. (Nagoya, Japan) — Known for computerised domestic and prosumer lines such as the Innov‑is series; continuing to bridge consumer and light commercial use with strong brand recognition and service networks. ( https://global.brother/en/gateway)
- Barudan Co., Ltd. (Ichinomiya City, Japan) — Longstanding industrial specialist with a reputation for stitch quality across single‑ and multi‑head platforms. Recent 2026 product introductions signal continued investment in precision and throughput. ( https://barudan.co.jp/en/)
- Tajima Group (Japan) — Broad commercial and industrial portfolio with automatic features and global exhibition activity; remains influential in defining industry performance and interoperability standards. ( https://www.tajima.com/)
- ZSK STICKMASCHINEN GmbH (Germany) — German engineering specialization in flexible single‑ and multi‑head systems; strong in markets prioritizing customization and engineering robustness. ( https://www.zsk.de/en/)
- Ricoma Embroidery Machines (Miami, USA) — Focus on high‑speed, commercial machines aimed at faster throughput and North American production models; recent launches emphasise throughput gains. ( https://ricoma.com/)
- Shenzhen Yunfu Equipment Co., Ltd. (Shenzhen, China) — Rapidly expanding manufacturer focused on computerized single‑head to multi‑head systems with scalable manufacturing and customization services; active international expansion in 2026. ( https://www.yunfuemb.com/)
- HappyJapan Inc. (Japan) — Industrial‑grade machines with a presence at key trade shows targeted at North American buyers and Atlantic market channels. ( https://www.happyjpn.com/en/product/embroidery/)
Notable recent developments we track: new product series launches and high‑speed models from established names, regionally focused expansion by Chinese manufacturers, and intensified trade show activity throughout 2026 — each a sign that vendors are competing on technology, speed to market and service ecosystems.
What the full PW Consulting report delivers (practical, executable content)
The full report is designed for executives and functional leaders who must make or justify investments in 2026. Deliverables include:
- Validated market sizing and scenario forecasts (historical 2020–2025; base year 2025; detailed 2026–2032 scenarios).
- Demand model templates (downloadable Excel) that allow you to test assumptions and customize forecasts for your product portfolio and geographies.
- Go‑to‑market playbooks by channel, including distributor mapping, pricing ladders, and pilot designs for service‑led offerings.
- Aftermarket and spare‑parts monetization frameworks with TCO and lifetime value calculators for OEMs and installers.
- Supplier and procurement playbooks — supplier scorecards, critical‑parts risk matrices, and negotiation checklists to stabilize supply and reduce cost volatility.
- M&A and partnership heatmaps showing strategic targets by capability, geography and integration fit; due diligence checklists tuned to embroidery equipment specifics.
- Technology adoption roadmaps and an innovation radar highlighting areas such as IoT connectivity, predictive maintenance, multi‑needle control systems, and software ecosystems.
- Operational KPIs, implementation roadmaps and pilot templates to accelerate automation projects while protecting near‑term throughput.
These deliverables are purposely operational — they are not high‑level theory. Subscribers receive editable models, slide decks for internal alignment, and vendor scorecards that can be deployed directly in sourcing and product planning workflows.
Actionable recommendations for leaders planning 2026 moves
- Shift investment emphasis from pure unit growth to margin expansion: prioritize aftermarket, software subscriptions, and service contracts that monetize installed base over the long term.
- Modularize product platforms to serve both customization and throughput needs: platform commonality reduces inventory and accelerates new variant introductions.
- Invest in digital and connectivity capabilities that enable predictive maintenance and remote diagnostics — quick wins for service economics and customer retention.
- Harden procurement strategies against component and consumable volatility: dual sourcing, strategic safety stock for critical parts, and longer supplier agreements where necessary.
- Build ESG and efficiency capabilities into new product specs to preempt tightening regulation and satisfy brand‑level sustainability procurement demands.
- Consider targeted M&A in 2026 to acquire niche automation, software or aftermarket capabilities rather than pursuing broad geographic rollouts.
- Design pricing that captures value from speed and precision: differentiated pricing for validated throughput and guaranteed uptime can lift realized ASPs.
How to use this preview as a decision tool
This preview is intended to align executive focus and identify the highest‑impact choices for 2026. If your organization is preparing a capital budget, evaluating acquisition targets, or redesigning service operations, use the insights here to set evaluation criteria and to prioritize pilot investments. For teams executing procurement or product development, the full PW Consulting report contains the models, supplier assessments and implementation templates that translate strategy into deliverables.
PW Consulting’s full research package contains the underlying segmentation matrices, granular regional and application forecasts, and the proprietary financial model that underpins the scenarios summarized above. We intentionally withhold those segment‑level datasets from this preview to protect proprietary inputs and to ensure readers engage the full analytical package when making binding strategic commitments.
Closing — the strategic inflection for 2026
In 2026 the embroidery machine market presents a pragmatic strategic choice: pursue market share in a steady‑growth environment, or shift the playbook toward higher‑margin, service‑led business models and targeted capability consolidation. Suppliers and buyers who align product architecture, aftermarket offerings and sourcing resilience will convert modest top‑line growth into outsized profitability. The full PW Consulting market study provides the decision‑grade tools and granular evidence required to execute that transition — from financial models and supplier scorecards to M&A checklists and go‑to‑market playbooks.
To access the full dataset, customizable models and implementation templates that underpin this preview, consult the PW Consulting Embroidery Machine Market report page or reach out to our industry team for a briefing and demo of the deliverables.
For detailed analysis of this topic, please visit the official page: Embroidery Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nail Polish Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking, decision-focused primer on our newest Nail Polish Market research. This introduction distills the high-impact signals executives will need in 2026 to set product roadmaps, channel strategies, regulatory compliance programs, and M&A priorities. It demonstrates the analytical depth of the full study while intentionally withholding granular segment tables—your next move is best informed by the complete dataset and playbooks hosted on our report portal.
Nail Polish Market
Why this study matters for 2026 decisions
-
Convergence of rapid consumer shifts, tighter product safety regulation, and channel disruption is compressing the window for strategic action. Companies that translate those signals into concrete product, supply-chain, and channel choices now will capture outsized share through the late 2020s.
Nail Polish Market -
The market’s macro trajectory provides a foundation for scenario planning: after steady expansion in the early 2020s, the global nail polish market—measured on a USD Billion basis—is positioned to accelerate through the forecast horizon. Our analysis uses 2025 as the base year and models the 2026–2032 period under multiple risk/stress permutations.
Nail Polish Market -
Regulatory shocks and acute product safety incidents are elevating the value of rapid reformulation capabilities and supplier transparency. Firms with established agile development pipelines and supplier oversight will convert compliance into competitive advantage.
Market trajectory at a glance (what the numbers mean)
Our headline macro findings are purposefully succinct to guide strategic choices: the global nail polish market grew from roughly USD 11 Billion in 2020 to about USD 13.25 Billion in 2025. From the 2026 base, the market projects to expand at a compound annual growth rate (CAGR) of approximately 9.5% through 2032, reaching nearly USD 25 Billion by the end of the period. These figures capture a mix of premiumization, expanding at-home nail care, and resilient salon demand where regulatory clearance permits.
Interpreted strategically, a 9.5% CAGR in a mid-sized consumer beauty segment implies significant opportunity to reallocate investment from declining mass categories into three high-return vectors: product innovation (clean/functional formulations), channel experience (omnichannel and subscription models), and operational resilience (supply chain re-shoring and ingredient diversification).
Key dynamics shaping 2026 and beyond
-
Regulatory acceleration: Since late 2025 regulators in major markets have tightened constraints on specific photoinitiators used in gel systems. The European Union instituted a ban on a widely-used photoinitiator in September 2025, with additional jurisdictions sequencing similar measures thereafter. That regulatory pivot is forcing rapid reformulation and creates a first-mover advantage for brands that can certify salon-safe, compliant alternatives at scale.
-
Product safety incidents: Recent recalls of consumer removers by a key safety regulator in 2026—driven by unacceptable solvent residues—have amplified retailer and consumer scrutiny. This environment rewards transparent ingredient sourcing, third-party certification, and robust recall/traceability infrastructure.
-
Channel evolution and experience economics: E-commerce continues to expand as a demand driver, but experiential retail (salons, specialty beauty stores) remains strategically important for premium lines and professional conversions. Brands that align DTC storytelling with salon endorsement and retail placement will outperform pure-play competitors.
-
Product innovation bifurcation: We observe two parallel innovation paths: (1) performance-led chemistry (longer wear, faster cure, lower hazard profiles) aimed at professional users and discerning consumers; (2) values-led formulations (clean, vegan, toxin-free) targeting health-conscious consumers. Winners will be those who combine performance with credible sustainability claims.
-
Market structure: Concentration is moderate: the top three and top five firms occupy a meaningful share but leave ample room for specialist challengers and private-label players to scale. That structure creates both partnership opportunities for large distributors and acquisition targets for consolidation-minded incumbents.
Competitive landscape — what to watch
The competitive map combines global legacy brands, clean-beauty specialists, and digitally native entrants. Key players have distinct propositions that inform partner selection and M&A prioritization:
-
Legacy salon-to-retail innovators: Established manufacturers with deep professional ties continue to leverage shade breadth and salon credibility. Their strengths are formulation R&D, salon education networks, and long-standing retailer relationships. Product line refreshes in 2026 show incumbents investing selectively in heritage shade libraries reinterpreted for current aesthetics.
-
Clean and niche specialists: Independent brands positioned on vegan and toxin-free platforms are increasingly strategic assets. These firms command strong social followings and premium ASPs (average selling prices), and they are often acquisition targets for larger players seeking instant credibility in clean beauty.
-
Digital-first challengers: Social-native microbrands and indie creators continue to influence color trends and limited-edition dynamics. Their agility in launching collections and building buzz is reshaping promotional calendars across the industry.
Recent product-line activities in 2026—notably multiple spring collection launches by prominent brands—underscore the importance of seasonal cadence and limited editions to drive basket frequency. Those tactical plays also point to a broader strategic shift: incremental innovation plus storytelling yields measurable uplift in customer lifetime value when supported by loyalty mechanics.
Strategic implications: a practical playbook for 2026
-
Prioritize regulatory-first reformulation: For companies selling gel systems or products with photoinitiators, immediate product-mapping against newly restricted chemistries is non-negotiable. Establish a 12–18 month formulation roadmap, with prioritized SKUs, supplier dual-sourcing clauses, and lab validation budgets tied to launch windows aligned with salon buying cycles.
-
Segment investment by return horizon: Reallocate a portion of classic marketing spend into three buckets: channel experience (salon and retail training), direct-to-consumer analytics (to lift repeat purchase rates), and rapid R&D for compliant alternatives. The market’s 9.5% CAGR supports reinvestment that compounds through 2032.
-
Supply-chain resilience: Onboarding TCO (total cost of ownership) evaluations for alternative photoinitiators and key solvents is essential. Contracts should include clear change-management processes that allow reformulation without retail disruption. Build a stock strategy for legacy components during the transition window but avoid overexposure if regulatory sunset dates are clear.
-
Channel orchestration: Align new product launches with omnichannel promotional plans that combine in-salon demos, retailer exclusives, and e-commerce drops. For premium and clean segments, consider subscription and refill programs to increase predictability and lifetime value.
-
M&A and partnerships: Use competitive concentration as a guide: acquisitive buyers should prioritize clean-beauty specialists and digitally native brands that add incremental margin and audience reach. Strategic partnerships with salon education platforms can accelerate professional adoption of compliant formulations.
-
Data and analytics: Invest in a product-to-market analytics engine that links SKU-level performance with channel economics, promotional ROI, and regulatory status—this enables real-time prioritization and reduces the risk of costly full-line recalls or delistings.
What the full PW Consulting report contains (practical, actionable content)
Our comprehensive market study is designed for commercial, R&D, and corporate development teams. It contains:
-
A detailed historical time-series and modeled forecast (2026–2032) with scenario runs calibrated for regulatory shocks and supply constraints.
-
An operational playbook for formulation transitions, including supplier checklists, lab validation timelines, and cost-impact estimators that translate regulatory bans into practical action plans.
-
Channel profitability matrices and promotional lift models to inform retail, salon, and e-commerce investment prioritization.
-
Competitive profiles and a validated watchlist of strategic targets tailored by capability gaps and cultural fit for acquirers.
-
Risk-management frameworks covering recalls, ingredient substitution, and cross-border compliance with recommended governance checkpoints.
Final strategic counsel
2026 is a year for decisive execution. The macro runway—backed by a roughly 9.5% CAGR and a near-doubling of market scale from early-2020s levels through 2032—creates structural upside for firms that can move quickly on reformulation, channel orchestration, and experiential differentiation. Conversely, firms that treat regulatory change as a compliance checkbox risk margin erosion and lost shelf presence.
PW Consulting’s full report supplies the segmented insights, SKU-level economics, and tactical templates firms need to convert the opportunities described here into measurable outcomes. For boards and executive teams preparing 2026 budgets and strategic priorities, this study is a practical strategic asset: deep enough to guide resource allocation, yet structured to be operationalized within quarterly planning cycles.
Next steps
To access the full dataset, scenario models, and the tactical playbooks referenced in this preview, visit our report page. PW Consulting offers tailored briefings and implementation workshops for leadership teams ready to convert insight into action within the next quarter.
For detailed analysis of this topic, please visit the official page: Nail Polish Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Vehicle Axles Market to reach USD 14,449.2M by 2032 at 5.0% CAGR
By PW Consulting, 2026-07-08
Commercial Vehicle Axles Market: Strategic Preview for 2026 Decision-Making
As fleets, OEMs and suppliers confront simultaneous waves of electrification, regulatory tightening and payload-efficiency demands, axle systems have moved from a commoditized component to a strategic lever for commercial-vehicle performance and total-cost-of-ownership (TCO). This preview synthesizes the key market signals from PW Consulting’s latest Commercial Vehicle Axles Market study (base year 2025), highlighting the high-level market trajectory, competitive dynamics, regulatory catalysts and the pragmatic implications that should shape boardroom debate and capex planning in 2026.
Commercial Vehicle Axles Market
Market snapshot: scale, momentum and what it means
PW Consulting’s market model shows the global commercial-vehicle axles market expanding under a mid-single-digit growth path through the coming decade. From an estimated market value of USD 10,259.6 Million in the base year (2025), the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.0% through the forecast horizon (2026–2032), reaching an estimated USD 14,449.2 Million by 2032. This trajectory reflects a steady recovery and structural uplift from the 2020–2025 period, during which the market evolved amid supply-chain shocks, component rationalization and the early waves of drivetrain electrification.
Commercial Vehicle Axles Market
Two implications are immediate for 2026 planning: first, scale alone does not guarantee margin expansion—value capture will increasingly favor players that align axle design with electrified drivetrains, weight-optimization strategies and system-level warranties. Second, growth is uneven by technology and application; achieving above-market returns will require targeted bets rather than broad, undifferentiated production increases.
Commercial Vehicle Axles Market
Dynamics reshaping demand and design
- Electrification and the rise of e-axles: The transition to battery-electric and hybrid commercial vehicles is re-casting axles as active powertrain components rather than passive load-bearing parts. New integrated e-drive axles and electric beam axle concepts are in pilot and near-commercial production, changing requirements for thermal management, NVH, and serviceability. Recent product launches and partnerships (noted below) underscore how quickly this segment is maturing.
- Regulatory pressure and dimensional rules: Tightening CO2 and NOx standards in major markets are influencing vehicle architectures and freight operators’ renewal cycles. Concurrently, proposals to revise axle weight and dimension rules — including allowances for zero-emission vehicles — are altering the economics of lightweighting versus increased payload. These regulatory vectors mean that axle suppliers must be part of system-level compliance strategies for fleets and OEMs.
- Performance differentiation via modularity and integration: Demand is rising for axles that simplify vehicle assembly, offer plug-and-play electrification, or reduce vehicle mass. Suppliers that can offer modular platforms spanning steer, drive and trailer use-cases — with predictable integration paths to braking and telematics systems — will gain specification advantages.
- Aftermarket and uptime economics: As fleets prioritize reliability and duty-cycle uptime, service models (remote health monitoring, swappable e-axle modules, and long-tail parts availability) will materialize as new revenue streams beyond hardware sales.
Competitive landscape — who to watch and why
The axle market remains fragmented by design specialization and regional scale. Market concentration metrics from our study indicate a moderately consolidated supplier base (CR3 ~29.5%, CR5 ~35.2%), leaving meaningful share for nimble challengers and new entrants focused on electrification and system integration.
- Dana Incorporated (Maumee, Ohio) — https://www.dana.com
Dana’s Spicer® and AdvanTEK™ portfolios remain central to traditional drive-axle demand, and the company’s scale in driveline components positions it to capture systems-level opportunities as OEMs seek integrated solutions for medium-duty and heavy-haul segments. Expect Dana to push deeper into electrified tandem architectures and to leverage existing OEM relationships to accelerate adoption. - Cummins Inc. (Indianapolis, Indiana) — https://www.cummins.com
Cummins has extended beyond power units into axle and driveline technology through its Cummins-Meritor initiatives. Recent work on brake integration and driveline uptime features indicates a strategy that bundles reliability and safety advancements with powertrain offerings — a compelling value proposition for emergency-service and heavy-duty operators where uptime is paramount. - Hendrickson International (Woodridge, Illinois) — https://www.hendrickson-intl.com
Hendrickson is notable for pushing early-integrated e-drive axle concepts and lightweight steer solutions. Product introductions that reduce mass while enabling electrified platforms show the company is positioning for the medium-duty electrification inflection. Their moves will pressure rivals to match integrated e-axle performance and serviceability. - Dexko Global / Dexter Group (Elkhart, Indiana) — https://www.dexko.com
With a strong heritage in suspension and steer-axle systems, Dexko’s focus on vocational and heavy-duty specifications makes it a critical supplier to bodybuilders and OEMs that prioritize durability. Watch for aftermarket service offers aimed at preserving fleet uptime. - Shaanxi Hande Axle Co., Ltd. (Xi’an, Shaanxi, China) — https://www.handeaxle.com
A leading producer of axle systems in Asia, Shaanxi Hande is advancing electric beam axle concepts and leveraging partnerships to accelerate technology transfer into heavy- and medium-duty segments. Collaboration with Western technology firms is enabling faster route-to-market for e-axles across regions.
Recent public developments highlight market direction: Hendrickson’s launch of an integrated ELECTRAAX e-drive axle for Class 6–7 vehicles (May 2026) and its STEERTEK NXT weight-reduction updates for bus applications; Cummins’ QuikDisc™ air disc brake integration and driveline uptime innovations (May 2026); and strategic partnerships to co-develop electric beam axles (e.g., Garrett Motion and Shaanxi Hande). These moves signal that product innovation and cross-border alliances are the near-term battlegrounds for share gain.
What the report delivers: practical outputs for 2026 action
PW Consulting’s full report is structured to support decision-making at the executive and product-planning levels. Key deliverables include:
- An up-to-date market model (historical 2020–2025; forecast 2026–2032) with scenario variants that isolate the impact of electrification pace, regulatory tightening and weight/dimension policy shifts on market sizing and revenue growth.
- Competitive benchmarking and capability maps that rank suppliers by systems integration, electrification readiness, aftermarket reach and regional manufacturing footprint.
- Actionable go-to-market frameworks for OEM suppliers and tier-1s that specify product roadmaps, margin levers and partnership archetypes aligned to fleet procurement cycles.
- Service, warranty and aftermarket models that quantify upside from remote monitoring, module swapping and extended warranties under different utilization scenarios.
- A risk register focused on supply-chain bottlenecks (rare-earths, precision gearing), regulatory shock scenarios and technology adoption inflection points, each with mitigation playbooks.
Note: this preview intentionally omits granular segmentation tables and region-by-application numeric splits. The full dataset, included in the report, provides the detailed tables and downloadable models required for precise budget planning and contract negotiations.
Strategic imperatives for 2026
For C-suite teams, product heads and corporate development teams, PW Consulting recommends five prioritized actions for 2026:
- Lock in e-axle partnerships now: OEMs and suppliers should accelerate pilot programs with e-axle specialists and electronics integrators. Winning integration-first slots with targeted OEM platforms will be harder and more expensive after 2027 as demand ramps.
- Design for modularity and serviceability: Product roadmaps must prioritize modular subassemblies, fast-replacement modules, and standardized electronic interfaces to reduce time-to-service and lower lifecycle costs for operators.
- Reassess footprint against regulatory shifts: Use scenario planning to evaluate manufacturing footprint, local content strategies and tariff exposures in light of CO2/NOx rules and proposed axle-weight allowances for ZEVs.
- Monetize aftermarket intelligence: Develop telematics-linked service agreements and parts-sourcing commitments that convert uptime performance into annuity-like revenue streams.
- Consider bolt-on consolidation where it accelerates capability: Given the moderate concentration of the sector, targeted M&A that secures electrification IP, control-software expertise or regional production capacity can create disproportionate strategic advantage.
How PW Consulting can support 2026 planning
Our full Commercial Vehicle Axles Market study provides the complete numerical backbone and executable playbooks that boards and product teams need to convert the high-level signals above into specific investment, sourcing and commercial decisions. If your 2026 planning horizon includes product launches, OEM negotiations or M&A, the report’s downloadable models, supplier scorecards and scenario toolkits will materially shorten time-to-decision and increase the probability of value capture.
For access to the full dataset, granular regional and application splits, and the scenario modeling pack, please consult the PW Consulting report page or reach out to our industry advisory team to arrange a walk-through of the findings and a tailored workshop for your 2026 strategy session.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Axles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roots Blower Market to Hit USD 2,285 Million by 2032, Growing at 4.6% CAGR — PW Consulting
By PW Consulting, 2026-07-08
Roots Blower Market — Strategic Outlook for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a strategic primer on our full Roots Blower Market study — designed specifically to inform capital allocation, product strategy, procurement, and M&A decisions in 2026. The global market is recovering and structurally expanding: on a USD Million basis, our model places the market at approximately 1,680 in the base year (2025), with a near-term lift to roughly 1,813 in 2026 and a projected trajectory to about 2,285 by 2032, reflecting a compound annual growth rate of 4.6% across the forecast horizon (2026–2032).
Roots Blower Market
This article demonstrates the analytic depth and actionable framing embedded in the full report while intentionally withholding detailed subsegment shares and granular regional/application splits — those deliverables are reserved for the comprehensive study and supporting data annexes.
Roots Blower Market
Why this study matters for 2026 decisions
-
Budgeting and capex prioritization: With steady market expansion and clear efficiency-driven dynamics, procurement planners must choose between replacing legacy fleets or retrofitting with energy-optimizing systems (notably VFD-enabled solutions).
Roots Blower Market -
Product & R&D roadmaps: Designers must reconcile legacy robust cast-iron, gear-driven architectures with rising demand for oil-free, low-vibration platforms tailored to semiconductor, biotech, and clean-process users.
-
M&A and partnerships: Moderate incumbent strength and pockets of specialization make the space ripe for bolt-on acquisitions that unlock aftermarket revenues and digital service offerings.
-
Regulatory and compliance planning: Energy-efficiency and industrial emissions targets are rapidly reshaping specification requirements for wastewater and process customers — sourcing and compliance strategies must reflect these constraints.
Macro dynamics shaping the market in 2026
Three converging forces define the market environment:
-
Energy-efficiency pressure: Integration of Variable Frequency Drives (VFDs) with Roots blowers is now a mainstream energy strategy. Field trials and vendor guidance suggest on-demand aeration driven by VFDs can reduce operational energy use by material margins (published engineering guidance cites contagious efficiency improvements in the 20–40% range in wastewater applications). Buyers and OEMs who prioritize VFD integration will materially differentiate on total cost of ownership.
-
Materials and manufacturing constraints: Traditional Roots designs employ cast-iron casings and alloy-steel timing gears with strict metallurgical specifications (e.g., minimum hardness standards for impellers and casings). These specifications drive vendor selection, supply-chain complexity, and lifecycle replacement planning; procurement teams must monitor raw-material lead times and quality controls as part of sourcing risk assessments.
-
Product differentiation through oil-free and low-vibration solutions: For adjacent high-purity industries (semiconductor, biotech), oil-free Roots blowers that meet low-vibration industrial standards are not just desirable — they are a procurement prerequisite. This bifurcation of product requirements creates parallel value pools for industrial-grade versus high-purity applications.
Competitive landscape — positioning and implications
The market is characterized by several established technology leaders and a healthy set of regional specialists. Success in 2026 will hinge on a mix of product breadth, application-focused engineering, aftermarket capabilities, and proven efficiency credentials.
-
Roots Blowers, LLC (Connersville, Indiana) — The historical inventor of the rotary lobe blower retains strong brand recognition and a product portfolio rooted in traditional cast-iron, heavy-duty designs (RAI, RAM, RCS series). Strategic takeaways: its legacy strength in wastewater and industrial process spaces makes it an important bellwether for pricing and spec standards in heavy-duty segments.
-
AERZEN (Emmerthal, Germany) — Offers a spectrum of positive-displacement blowers alongside screw and turbo technologies with a clear emphasis on efficiency and sustainability. Its visible presence at global exhibitions (e.g., IFAT 2026) signals an aggressive go-to-market posture on high-efficiency solutions — a cue for competitors to accelerate demonstrable operating-cost claims.
-
EBARA Precision Machinery Europe — Focused on oil-free, low-noise, and low-vibration designs tailored to semiconductor, biotech, and fine-chem production. For OEMs and systems integrators pursuing high-purity customers, EBARA’s technology and certification positioning defines the bar for allowable noise and particulate performance.
-
Atlas Copco (Nacka, Sweden) — A systems-level player that integrates Roots-type displacement equipment into broader compressed-air and process packages. Atlas Copco’s strength is in system efficiency and aftermarket services — an example of the platform strategy that captures recurring service revenues.
-
Ingersoll Rand (Lexington, Kentucky) — Offers a breadth of positive-displacement blowers and mobile truck blowers for demanding environments. Their diversified channel and product range make them a strategic partner for turnkey contractors and municipal fleets.
Recent vendor activity underscores several tactical themes: AERZEN’s IFAT 2026 showcase reinforced efficiency positioning; smaller OEMs and regional manufacturers introduced new lobe configurations and product series throughout 2025–2026. These moves point to continued innovation at the component level and an accelerating pace of product introductions aimed at segment-specific pain points.
Strategic implications and recommended decision levers for 2026
Below are high-return levers for corporate and operational leaders:
-
Prioritize energy-first retrofits: For municipal and industrial operators, retrofitting legacy units with VFD-capable drives and modern control logic should be evaluated as the default upgrade path in 2026. Our scenario models show that modest capital outlays can materially compress payback horizons when energy price volatility is considered.
-
Segment product portfolios along purity and ruggedness: Build differentiated platforms — one suite that emphasizes oil-free, low-vibration performance for high-purity processes; another focused on cast-iron robustness and simplicity for heavy-duty water and waste applications. This reduces cross-market cannibalization and enables premium pricing where justified.
-
Lock supply of critical metallurgical inputs: Secure long-term contracts or dual-source strategies for cast iron and alloy timing gears. Small manufacturing variances materially impact lifecycle and warranty exposures.
-
Monetize aftermarket and services: Convert installed base into recurring revenue through call-down maintenance contracts, remote monitoring with efficiency guarantees, and retrofit kits. Vendors that demonstrate validated energy savings will command a higher share of lifecycle spend.
-
Use targeted M&A to close capability gaps: Look for tuck-ins that add digital diagnostics, high-purity certifications, or regional manufacturing footprints to accelerate market entry in priority geographies without large greenfield investments.
What the PW Consulting report delivers — practical, decision-ready content
The full Roots Blower Market report is structured to convert insight into immediate action. Highlights include:
-
Robust market sizing (historical 2020–2025 and forecast 2026–2032) with scenario sensitivities tied to energy price and regulation pathways.
-
Segmentation by region, type, and application accompanied by qualitative demand-driver maps (note: granular subsegment shares and exact regional/application figures are available exclusively in the paid dataset).
-
Competitive profiles and benchmarking for leading vendors, including product portfolios, strategic moves, and go-to-market strengths.
-
Technology and regulation matrix: VFD adoption impact assessments, oil-free certification requirements, and materials specification implications for design and sourcing.
-
CapEx/OpEx models and a downloadable financial template for total-cost-of-ownership comparisons across retrofit, replacement, and new-install scenarios.
-
Procurement playbooks and supplier evaluation checklists tuned for metallurgy, lead times, and aftermarket commitments.
-
90–180 day execution roadmaps for operators, OEMs, and investors that translate market signals into prioritized actions.
How to use this intelligence in the next 90 days
-
Month 0–1: Run an internal portfolio review against our energy-efficiency checklist and identify top 10 candidate assets for VFD retrofits or replacements.
-
Month 1–2: Engage two shortlisted vendors (one global systems player, one regional specialist) using our procurement RFP template and comparative TCO model.
-
Month 2–3: Initiate a pilot retrofit or specification change with measurable KPIs (energy, vibration, uptime) and a defined performance guarantee clause.
Closing — why access the full study
The excerpt above synthesizes the market’s direction and the operational levers that matter to executives in 2026. However, strategic execution requires the detailed subsegment breakouts, regional demand curves, and vendor-level benchmarking only available in the full Roots Blower Market study. Those datasets unlock precise addressable-market sizing, competitive share analysis, and the numerical inputs required to populate CapEx, pricing, and M&A models with confidence.
Access the complete report to obtain the withheld subsegment analytics, downloadable financial models, and executable playbooks that will convert the 4.6% CAGR trajectory and the projected USD Million market growth into measurable corporate outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Roots Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Inspection Equipment Market to Reach USD 8,400M by 2032 (7.5% CAGR)
By PW Consulting, 2026-07-08
Semiconductor Inspection Equipment Market: A Strategic Primer for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this concise strategic primer to orient executives, investors, and technical leaders preparing near‑term decisions in 2026. The inspection equipment market sits at the intersection of process control, yield optimization, and risk management for advanced semiconductor manufacturing. Our full market research provides the deep data and models you will need; this introduction frames the core strategic takeaways while deliberately preserving the report’s detailed segment tables and vendor scorecards to encourage direct access to the source intelligence.
Semiconductor Inspection Equipment Market
Market snapshot: macro trajectory and what it signals
Using 2025 as the report base year, the Semiconductor Inspection Equipment market shows a clear mid‑single‑digit expansion profile that accelerates through the balance of the decade. Historically tracked across 2020–2025, the market moved from an early‑cycle trough to renewed investment momentum: in broad terms, revenue expanded from roughly USD 4.5 billion in 2020 to approximately USD 5.6 billion by 2025. Our base‑case forecast for 2026–2032 assumes a compound annual growth rate (CAGR) of 7.5%, taking the market toward an approximate USD 8.4 billion outcome by 2032.
Semiconductor Inspection Equipment Market
These headline numbers matter because inspection equipment is both a leading indicator and an enabler of capital‑intensive node transitions. When fabs commit incremental capacity for advanced logic, memory, or heterogeneous packaging, inspection spend typically precedes or accompanies these investments. The steady CAGR embedded in our forecast reflects a combination of enduring secular drivers (node shrink, packaging complexity, higher testability requirements) and cyclical forces (foundry/operator demand swings, equipment lead times, and regulatory shifts).
Semiconductor Inspection Equipment Market
Why 2026 is a pivotal year for strategic choices
-
Policy and market structure are changing. Recent policy actions—most notably a Department of Commerce rule published in January 2026 adjusting imports of semiconductors and manufacturing equipment—introduce new layers of compliance and supply‑chain planning for buyers and vendors alike. Simultaneously, public programs (for example, CHIPS Act related initiatives) continue to channel capital into advanced prototyping, packaging, and metrology—our research highlights a roughly USD 50 billion public investment envelope across relevant programs that will influence demand flows and partnership dynamics.
-
Technology inflection points are compressing inspection requirements. New imaging and analysis capabilities (including launches in early 2026 that push sensitivity below the 10 nm defect threshold) are shifting buyer evaluation criteria from pure throughput to detection fidelity, data integration, and closed‑loop process control.
-
Supply‑side concentration and capability matter. The market exhibits moderate concentration, with the top three firms representing a majority share and the top five firms accounting for a clear super‑majority. That structure means procurement outcomes hinge on a small set of vendors’ roadmaps and production capacities—an important factor when planning multi‑year tool acquisition or co‑development agreements.
What our report gives you: practical, action‑oriented content
PW Consulting’s full study is built for decision makers. Key deliverables include:
-
A transparent market model (base year 2025) with historical validation (2020–2025) and scenario‑based forecasts (2026–2032) that let you stress‑test CAPEX timing under alternative demand and policy scenarios.
-
Methodology appendix describing data sources, primary interview protocols, and model assumptions—so you can trace each projection back to evidence and judgment inputs.
-
Technology and product roadmaps mapping inspection modalities to process node and advanced packaging use cases, with implementation guides for integrating inspection data into factory automation stacks.
-
Vendor assessment modules—qualitative profiles, market positioning, and go‑to‑market strategies—covering the industry’s core suppliers and challengers, plus supplier risk heatmaps tailored by buyer archetype.
-
Commercial playbooks for procurement, including negotiation checklists, total cost of ownership templates, and recommended test orders to validate vendor claims in production environments.
-
Regulatory and supply‑chain impact analysis that operationalizes recent policy changes and raw‑material dependencies into procurement decisions and contingency plans.
-
Investment and M&A screening tools: valuation sensitivities tied to inspection market share shifts, and recommended due‑diligence questions for targets across the inspection‑metrology value chain.
Competitive landscape — who matters and why
The inspection ecosystem is populated by a mix of specialized metrology firms and diversified equipment OEMs. Our analysis focuses on a core set of firms that shape product innovation and procurement dynamics. In brief:
-
KLA Corporation: A market leader in optical and electron‑beam defect inspection and review systems. KLA’s depth in defect review and inline analytics makes it a near‑default partner for advanced logic and memory fabs seeking tight yield control.
-
Applied Materials, Inc.: A strategic competitor that embeds inspection tools across FEOL/MOL/BEOL process flows. Its strength lies in delivering inspection aligned to deposition, etch, and patterning process control—an important consideration for process node integration.
-
Hitachi High‑Tech Corporation: Strong in CD‑SEM and high‑sensitivity surface inspection; recent product work announced in early 2026 pushes detection thresholds into new sub‑10 nm territory, with implications for early‑defect discovery and analytics accuracy.
-
Nikon Corporation / Nikon Precision: Known for macro and post‑process inspection systems, these teams remain relevant to mask and reticle qualification, especially where optical throughput and automation tie into legacy flows.
-
Camtek Ltd.: A vendor to advanced packaging lines and OSATs, with systems optimized for full‑wafer and panel inspection in high‑volume packaging production.
-
Onto Innovation: Focused on integrated 2D/3D inspection and metrology solutions; recent enhancements (e.g., integrated infrared capabilities) expand utility into sub‑surface defect detection for advanced nodes.
-
Nova Ltd. and other specialized metrology players: These firms provide complementary dimensional and materials metrology that is increasingly embedded into inspection platforms, enabling richer process diagnostics.
Notable near‑term developments that informed our analysis include a January 2026 Department of Commerce import rule, technology launches in early 2026 that improve micro‑defect sensitivity, major system orders and contract awards through 2025, and incremental product enhancements across inspection lines. Each event has a quantifiable effect on vendor delivery risk, customer negotiation leverage, and short‑term booking visibility—factors that are explicitly modeled in our scenario suite.
Strategic actions we recommend for 2026
-
Reframe inspection spend as risk‑mitigation plus value capture. Move beyond CAPEX justification by yield impact alone—link inspection investments to reduced cycle time, faster learning loops, and monetizable quality premiums for differentiated products (e.g., automotive, defense, AI accelerators).
-
Build multi‑vendor roadmaps. Given the market’s moderate concentration and recent policy headwinds, buyers should qualify more than one supplier per critical inspection function and negotiate modular service agreements to hedge against delivery constraints and regulatory exposure.
-
Prioritize software and data integration. Inspection hardware is necessary but not sufficient; the most durable competitive advantage today comes from analytics, anomaly classification, and automated corrective actions that reduce scrap and expedite ramp.
-
Stress‑test procurement under policy constraints. Incorporate regulatory scenarios (e.g., tightened import controls or export licensing timelines) into lead‑time and inventory planning—our models quantify delivery risk impacts across likely timelines.
-
Target partnerships in advanced packaging. As heterogeneous integration accelerates, OSATs and packaging‑focused fabs will increasingly displace volume demand; early collaborations with packaging inspection specialists can secure priority access to capacity and co‑development paths.
How to use the full PW Consulting report
Consider this primer the strategic map; the full report contains the coordinates. If you are preparing a CAPEX cycle, negotiating multi‑year service agreements, evaluating acquisition targets, or designing a metrology roadmap, use our report to:
-
Extract the specific regional, application, and product‑type breakouts that align to your procurement portfolio (these segmented tables are deliberately excluded here to protect the report’s proprietary value).
-
Access vendor scorecards with assessments of technological readiness, manufacturing risk, and partnership appetite.
-
Download the forecast model and run custom scenarios using your own demand assumptions and budget horizons.
Closing — positioning your organization for 2026
The Semiconductor Inspection Equipment market in 2026 is both larger and more strategically complex than many buyers and investors assume. Public policy, material supply constraints, and incremental technological leaps are reshaping procurement priorities. Our base‑case headline—anchored on a 7.5% CAGR for 2026–2032 and a market that expands materially from its 2025 base—signals both opportunity and risk. The right moves this year are those that combine technical validation with contractual flexibility and regulatory foresight.
PW Consulting’s full market study equips leaders with data, tools, and recommended playbooks to make those moves confidently. For detailed segmentation, vendor profiles, and the interactive forecast model (including the granular splits and financial tables reserved exclusively for report subscribers), please consult the full report on our website or contact our advisory desk to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Semiconductor Inspection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bearing Ball Market 2026: Strategic Imperatives for Decision‑Makers — A PW Consulting Preview
As companies prepare budgets, product roadmaps, and M&A pipelines for 2026, the bearing ball market presents a mixture of enduring industrial steady‑state and accelerating pockets of technical disruption. Our latest market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, shows a market that expanded from roughly USD 12,000 Million in 2020 to an estimated USD 14,800 Million in 2025 and is projected to reach approximately USD 20,860 Million by 2032, driven by a steady compound annual growth rate of 5.1% across the forecast period. This briefing pulls forward the strategic implications senior executives and investors must factor into 2026 planning — illustrating the depth of analysis in the full report while intentionally withholding detailed segmentation to direct practitioners to the underlying data models and dashboards.
Bearing Ball Market
Macro takeaways that should guide 2026 decisions
-
Growth is predictable but uneven: The market’s mid‑single‑digit CAGR masks substantial variation by technology, application and end‑market. For corporate planning, this means treating the bearing ball market as a stable backbone for industrial revenue while selectively prioritizing high‑momentum subsegments for capital and R&D allocation.
Bearing Ball Market -
Technology premiumization continues: Miniaturization for medical and semiconductors, high‑speed precision bearings for servo motors, and hybrid material solutions are recurring themes. These are the vectors where margin expansion and differentiation are most attainable.
Bearing Ball Market -
Supply chain and input risk are strategic constraints: Volatility in chrome steel and alloying metals directly affects cost structures and delivery reliability. Recent standards updates for bearing steels have tightened material specifications, creating both compliance obligations and opportunities for suppliers that move early to qualify advanced grades.
-
Consolidation pressure with room for nimble competitors: Market concentration metrics indicate a meaningful presence of large incumbents alongside numerous specialty players. The sector rewards scale in global OEM channels, but focused technology plays can win niche verticals with premium pricing.
What this means for specific strategic functions in 2026
-
Board & Portfolio Strategy — Prioritize a two‑track approach: protect core industrial and automotive franchises while allocating targeted capital to high‑growth technical subsegments (miniature, hybrid ceramics, ultra‑precision). Use the market’s predictable mid‑term revenue growth to underwrite selective risk.
-
Supply Chain & Procurement — Reassess material sourcing protocols: dual‑sourcing, longer hedging horizons, and strategic alliances with steelmakers will reduce margin volatility. Require material provenance and advanced steel grades validation in supplier contracts to meet evolving ISO requirements.
-
R&D & Product Strategy — Fast‑track miniaturization, noise reduction, and corrosion‑resistant solutions for medical and robotics. Invest in design for manufacturability to lower total cost and shorten time‑to‑market for next‑generation precision bearings.
-
Commercial & Go‑to‑Market — Differentiate through systems expertise (bearing + actuator, bearing + lubrication system, lifecycle services). OEM partnerships and co‑engineering arrangements are increasingly decisive for securing design wins.
-
Corporate Development — M&A should target either capability gaps (e.g., ceramic/hybrid materials, mobile robotics bearings) or geographic manufacturing scale. Financial underwriting must embed raw‑material scenario stress tests and integration plans that accelerate product cross‑sell.
Competitive landscape — strategic signals from leading players
The competitive set is a mix of global incumbents and specialized innovators. Incumbents leverage scale, distribution reach, and deep application engineering; smaller players concentrate on material innovation and niche applications. The full report profiles leading suppliers across capability matrices — from high‑volume deep‑groove products to ultra‑precision and hybrid solutions — and provides an actionable assessment of channel strength, technology roadmaps, and likely future moves.
-
Global leaders remain focused on platform plays and system integration. Several have announced partnerships and product launches that signal a shift from component selling toward co‑engineered solutions for surgical robotics, servo motors and high‑precision tools.
-
Specialists are exploiting material and manufacturing advantages. Recent launches of ultra‑low‑noise miniature bearings, high‑speed servo bearings, and corrosion‑resistant miniaturized solutions show that differentiated IP and manufacturing know‑how can command premium placement in targeted verticals.
-
Recent market moves to monitor: precision product introductions at major industry shows, strategic partnerships with robotics developers, and product lines emphasizing sterilization durability and ultra‑low noise. These reveal where R&D focus is translating into near‑term commercial opportunities.
Regulatory and raw material dynamics — operational playbook
Two technical dynamics require immediate board‑level attention. First, raw‑material volatility — particularly in chrome steel and minority alloy elements — is now a persistent margin risk. Companies should embed commodity sensitivity into pricing and procurement models and pre‑qualify alternative steel grades where feasible.
Second, tightening technical delivery requirements (notably the latest editions of bearing steel standards) raise qualification overheads for any product updates. Early compliance programs and collaboration with steel suppliers on new grades (for example, improved through‑hardening and oxygen control) will reduce time‑to‑market for higher‑value bearings.
What’s in the full PW Consulting report (practical, usable content)
-
Proprietary market model: an interactive forecast model covering 2020–2032 with scenario toggles for commodity shocks, electric/automation adoption curves, and medical device penetration.
-
Supplier intelligence: detailed profiles and capability maps for major manufacturers and fast‑growing specialists, including technology roadmaps, manufacturing footprints, and partnership playbooks.
-
Commercial playbooks: channel strategies for OEM penetration, pricing mechanisms to protect margins under commodity stress, and service models to extend lifecycle revenue.
-
Procurement playbook: material risk matrices, dual‑sourcing templates, and qualification checklists aligned with recent bearing steel standards.
-
Deal pipeline & valuation analytics: a short list of acquisition targets by capability, with valuation guidance and integration risk assessments keyed to 2026 synergies and 3–5 year payback horizons.
-
Technology deep dives: comparative analysis of ceramic/hybrid solutions, miniaturized bearings for medical wearables, and high‑speed designs for servo applications — including manufacturability and cost curves.
90/180/360‑day action roadmap for executives
-
0–90 days: Commission a material risk audit; enforce revised supplier qualification clauses for advanced bearing steels; begin prioritized product performance testing for high‑growth subsegments.
-
90–180 days: Launch at least one co‑engineering pilot with an OEM in either medical robotics or servo motors; finalize procurement hedging strategy and secure strategic supply agreements for critical alloys.
-
180–360 days: Execute targeted M&A or joint‑venture plays to acquire missing capabilities (e.g., hybrid ceramic expertise, ultra‑precision miniaturization) and roll out commercial pilots that translate new products into multi‑year contracts.
Final note — why this preview and why now
This preview demonstrates the pragmatic intelligence and scenario planning embedded in PW Consulting’s full Bearing Ball Market study: robust top‑line growth, clear technical vectors for differentiation, and pressing supply‑side governance requirements. We intentionally omit detailed regional, type, and application split figures here to preserve the value of our proprietary segmentation and to invite decision‑makers to review the full models and data tables, which are the basis for executable 2026 strategies.
For executives planning capital allocation, procurement policy, or M&A activity in 2026, the full report provides the empirical foundation and tactical templates to convert market trends into defensible actions. Contact PW Consulting to obtain the full dataset, interactive forecast model, and a tailored briefing that maps these insights directly to your portfolio.
For detailed analysis of this topic, please visit the official page: Bearing Ball Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Greaseproof Paper Market Set for 5.25% CAGR Through 2032
By PW Consulting, 2026-07-08
Greaseproof Paper Market 2026: Strategic Preview for Decision Makers
As global packaging value chains confront tighter food-contact regulations, rising sustainability expectations and fluctuating raw-material costs, greaseproof paper is rapidly moving from a commodity niche to a strategic substrate. This preview synthesizes the macro trends, competitive dynamics and operational levers that PW Consulting’s full Greaseproof Paper Market report (base year 2025) uses to equip executives for high-stakes decisions in 2026. We highlight the headline market trajectory and the strategic questions every C-suite and corporate development team should be tackling—while reserving the segment-level numbers for the full report to protect the actionable intelligence that drives commercial advantage.
Greaseproof Paper Market
Headline Market Trajectory: A Market on a Purposeful Growth Path
The greaseproof paper market has shown resilient expansion through the 2020–2025 historical window and is forecast across 2026–2032 to continue growing at a compound annual growth rate (CAGR) of roughly 5.25%. Measured in USD (Revenue Unit: Million), the market size in the base year (2025) provides a pragmatic anchor for scenario planning, and the 2032 projection frames medium-term capacity, investment and M&A decisions. For procurement, manufacturing and strategic planning teams, the combination of steady CAGR and upward nominal market scale implies predictable baseline demand but increasing differentiation driven by regulation and product innovation.
Greaseproof Paper Market
Why 2026 Is a Strategic Inflection Point
- RegulatoryTurning Point: The EU PFAS ban and similar regulatory pressure in other jurisdictions are shifting the value equation away from fluorochemistries and toward alternative barrier technologies. This alters technology roadmaps, supplier qualification, and labelling claims required for food-contact materials.
- Sustainability Demands: Certifications and ecolabelling schemes (notably Nordic criteria) increasingly mandate energy-efficiency and limits on fossil-oil dependence—making production footprint and supply-chain transparency decision factors for commercial win-rate and pricing power.
- Cost Environment: Coated and processed paper prices show volatility—industry indices such as the pulp and paper producer price index rose to levels that buyers and sellers must factor into contract terms and hedging approaches.
- Consolidation Levers: Market concentration metrics indicate meaningful scale benefits for top suppliers, shaping potential M&A strategies that can be realized in 2026 as buyers seek integrated capabilities (e.g., coating, barrier application, and logistics).
Market Structure and Segmentation (What We Cover, What We Withhold)
Our full report maps the market by region, by product type (e.g., kraft, sulfite, other specialty grades) and by application (food packaging, industrial wrapping, other uses). We model historical uptake and applied forward-looking scenarios to 2032. In this preview we avoid releasing the granular segment-level shares and precise regional figures; these are retained in the full analysis because they represent the primary commercial intelligence our clients use to prioritise channels, geographies and product investments.
Greaseproof Paper Market
At a conceptual level, segmentation drivers are clear: food-contact grades dominate where regulatory conformity and barrier performance are mandatory; industrial wrapping is more tolerant of recycled-content trade-offs; specialty grades compete on functional coatings and release properties. Raw-material pathways—virgin pulp versus recycled fibre combined with silicone or aqueous polymer coatings—remain the technical spine that determines cost, recyclability and regulatory compliance.
Key Dynamics Shaping Supply and Demand
- Regulation and Compliance: The EU PFAS ban is accelerating reformulation away from per- and polyfluoroalkyl substances in greaseproof applications. Manufacturers and converters investing in PFAS-free barrier systems or alternative release technologies will reduce regulatory risk and gain early-adopter advantages in major markets.
- Ecolabelling and Production Footprint: Nordic Ecolabelling criteria require energy-efficient production and restrict fossil-oil dependence—driving investment in process electrification, renewable energy sourcing and close-loop fibre solutions to maintain market access in northern European and premium segments.
- Raw-Material Price Pressure: The indexed price environment for coated and processed papers is elevated, affecting contract pricing and margins. Buyers should evaluate longer-term supply agreements with indexation mechanics, whereas producers must optimize furnish mixes and coating formulations to preserve margins.
- Recycling Quality Constraints: Standards such as the EN 643 limits for undesirable components in post-consumer fibre impose practical limits on recycled-content use for food-contact greaseproof grades, reinforcing the need for certified supply chains and secondary-fibre innovation.
Competitive Landscape: Who Matters—and Why
The market displays a concentrated upper tier where three to five players capture the majority of value and capabilities. That concentration translates into differentiated access to technology, scale manufacturing and certification credentials. Below we synthesize strategic positions of prominent suppliers, focusing on their capability sets rather than market shares (detailed competitor benchmarking is in the full report).
- Nordic Paper (Sweden) — Nordic Paper has positioned itself around natural, fluorochemical-free greaseproof grades and compost-certified ranges from virgin pulp. Their strategy signals a clear alignment with sustainability-driven procurement and ecolabelling requirements. For buyers targeting premium food-contact applications, Nordic’s portfolio reduces regulatory exposure and supports premium pricing.
- Metsä Tissue (Finland) — As a supplier with significant fresh-fibre capacity and an explicit focus on biodegradable, recyclable baking and cooking papers, Metsä’s integrated supply base supports both scale and traceability claims. Their sizable production footprint in Europe makes them a logical partner for customers needing consistent high-fibre quality and certification compliance.
- delfort group (Austria) — delfort’s specialty-paper capabilities—where greaseproof grades sit within a broader high-performance functional-paper portfolio—provide customization advantages. Their emphasis is on functional differentiation (e.g., release, wet-strength, printability) attractive to converters and branded-packaging customers.
- Mondi Group (Austria) — Mondi’s offering focuses on re/cycle functional barrier papers with tailor-made grease and mineral oil barrier technologies, extending into ultra-high barrier solutions. This technical scope positions Mondi as a partner for complex barrier applications where performance (e.g., OTR/WVTR metrics) matters as much as environmental credentials.
- Ahlstrom (Finland) — Ahlstrom’s FluoroFree® technologies and high-performance release-coated papers deliver a differentiated, low-regulatory-risk alternative to legacy fluorinated chemistries. This technology leadership is a strategic asset for converters and food manufacturers migrating to PFAS-free portfolios.
- KRPA PAPER (Czech Republic) — With a long heritage and export reach, KRPA’s catalogue addresses traditional greaseproof demand and niche markets requiring tailored grammages and functional treatments. Their regional manufacturing footprint supports agile supply to central and eastern European customers.
- Pudumjee Paper Products (India) — Pudumjee combines local scale with a focus on sustainable and FDA-compliant greaseproof grades. For multinational buyers regionalising supply chains in South Asia, Pudumjee offers a pragmatic mix of compliance and cost advantages.
Recent product introductions from companies such as Nordic Paper, Wipak and Lecta underscore the rapid pace of formulation and coating innovation. These launches are not isolated marketing activities; they reflect supplier responses to regulatory timelines and converter demand for recyclable, high-performance wraps.
Market Concentration and Strategic Consequences
Concentration ratios indicate that leading suppliers capture a substantial share of value—underscoring the importance of strategic supplier relationships and, for some players, the logic for horizontal consolidation or vertical integration. In practice, this means that:
- Large converters and retailers can expect fewer but more capable suppliers for high-performance, certified grades.
- Smaller producers must focus on niche differentiation—specialty coatings, regional service, or ultra-low-carbon footprints—to defend margins.
- Private equity and corporate strategists will find synergies in bolt-on acquisitions that add coating capability, barrier chemistries or certification credentials.
Strategic Playbook for 2026 Decision Makers
- Procurement: Re-negotiate contracts to include compliance warranties and indexation clauses tied to pulp & paper indices; qualify multiple PFAS-free suppliers to reduce single-source risk.
- R&D and Product: Prioritize investments in fluorine-free barrier technologies and scalable aqueous coating processes that meet recyclability and EN/food-contact limits.
- Operations: Map capital plans against forecast demand to avoid under- or over-capacity; target energy-efficiency upgrades to pre-empt ecolabelling barriers to market access.
- M&A: Evaluate bolt-on acquisitions that add coating technology, regional logistics or certified pulp feedstock to accelerate time-to-market for compliant grades.
- Commercial: Align go-to-market with sustainability claims backed by third-party certification and transparent supply-chain traceability to capture premium placements with food brands and retailers.
What the Full PW Consulting Report Provides
The complete study (base year 2025, historical 2020–2025, forecast 2026–2032) delivers:
- Granular segment models by region, type and application with scenario sensitivity and demand drivers.
- Supplier scorecards, capability maps and a detailed M&A-ready list of targets.
- Cost-curve analysis incorporating pulp indices, coating chemistry cost profiles and energy assumptions.
- Practical checklists for PFAS-transition implementation, ecolabelling compliance pathways and converter qualification templates.
We intentionally withhold the full segment-level tables and specific regional allocations in this preview to preserve the primary commercial intelligence that informs sourcing, pricing and strategic investment decisions. Access to the complete dataset, including downloadable models and supplier dossiers, is available through the PW Consulting portal and is the recommended next step for executives planning actions in 2026.
Closing: Positioning for 2026 and Beyond
The greaseproof paper market is maturing into a strategically important category at the nexus of regulation, sustainability and functional performance. While headline CAGR and market-size trajectory provide a growth baseline, the real value rests in navigating regulatory transitions, securing certified supply and selectively investing in technologies that enable PFAS-free, recyclable solutions. PW Consulting’s full report equips teams with the quantitative models and practical playbooks needed to move from reactive compliance to proactive market leadership—an imperative for any organization looking to make decisive moves in 2026.
For detailed analysis of this topic, please visit the official page: Greaseproof Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microfocus X-ray Sources Market to Hit USD 658.96M by 2032 at 5.56% CAGR
By PW Consulting, 2026-07-08
Microfocus X‑ray Sources Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on Microfocus X‑ray Sources equips senior executives, product leaders and procurement teams with a decision-ready synthesis for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report traces a steady expansion of the market—from roughly USD 337 million in 2020 to USD 450 million in the 2025 base year—and a projected climb to approximately USD 659 million by 2032 at a compounded annual growth rate near 5.6%. These topline dynamics mask important inflection points in technology, regulation and commercial models; our research translates those signals into concrete options for value creation, risk mitigation and competitive positioning.
Microfocus X-ray Sources Market
Why this study matters for enterprise decision-makers in 2026
-
Transition from components to systems: Buyers increasingly evaluate microfocus sources not as stand‑alone tubes but as embedded elements of turnkey inspection, imaging and analysis solutions. Decisions now require integrated product, service and compliance roadmaps.
Microfocus X-ray Sources Market -
Regulatory and safety overlay: Recent standards and clearances—such as ISO guidance on effective focal spot measurement, FDA emphasis on safety for portable systems, and CE/FDA documentation requirements—raise the bar on traceability, test protocols and clinical risk management. Procurement criteria and product development timelines must reflect these constraints.
Microfocus X-ray Sources Market -
Cost and lifecycle pressure: High initial CapEx and ongoing maintenance for tube assemblies are persistent barriers to adoption in capital-constrained buyers (notably in clinical procurement and some industrial segments). Pricing, financing and service models are becoming as strategic as technical differentiation.
-
Technological differentiation: Advances in focal-spot control, nano/microfocus engineering and tube geometries (rod-anode, MesoFocus approaches) are enabling new inspection resolutions and lower-dose workflows, creating product tiering and new use cases that will define leaderboards in the coming three to five years.
What PW Consulting’s report delivers — operational, not theoretical
-
Robust market sizing and forecast model: A transparent, scenario-ready model covering 2020–2032 with sensitivity levers for price, replacement cycles and adoption curves—ready for integration into internal planning tools.
-
Demand-driver decomposition: Actionable analyses linking OEM pipelines, NDT adoption, clinical imaging trends and research lab procurement to near‑term revenue opportunities and downside scenarios.
-
Vendor benchmarking and concentration analysis: Comparative profiles, capability matrices and a market-concentration snapshot that reveals competitive dynamics and partnership opportunities for 2026 planning.
-
Product & technology roadmaps: Gap‑analysis templates for R&D prioritization—focal spot, power-efficiency tradeoffs, cooling and miniaturization—aligned to market willingness to pay and regulatory trajectories.
-
Procurement and commercial playbooks: RFP templates, evaluation scorecards, TCO calculators and service-level contract models that procurement and commercial teams can deploy immediately.
-
Regulatory readiness checklist: Mapped requirements for ISO, FDA and CE pathways, plus documentation templates to accelerate clearances and reduce time to revenue.
-
M&A and partnership origination: Opportunity heatmaps identifying target archetypes (technology tuck-ins, aftermarket services, regional distribution) and valuation sensitivities under alternative growth assumptions.
Competitive landscape — core vendors and what they signal
-
Hamamatsu Photonics (Japan): Established manufacturer focused on sealed microfocus sources for 2D/3D NDT and medical imaging—strong OEM relationships and a reputation for product reliability.
-
Micro X‑Ray (USA): Integrated designer/producer of micro- and mini‑focus tubes across broad voltage/power ranges—notable for configurable solutions that appeal to OEMs requiring modularity.
-
X‑RAY WorX GmbH (Germany): Specialist in high‑resolution open microfocus and rod-anode tubes for CT and DR—recent product updates indicate moves toward submicron resolution capabilities.
-
Comet Group (Switzerland): Offers MesoFocus and sealed microfocus technologies tailored to industrial inspection—strength lies in industrial-grade system integration and reliability.
-
MOXTEK (USA): Producer of microfocus sources and nano‑optic components, with strengths in niche imaging stacks and analytical instrument integrations.
-
Spellman High Voltage Electronics (USA): Supplier of microfocus generators and full-source assemblies for OEMs across medical and industrial domains—notable for high-voltage expertise and customization.
-
Anton Paar (Austria): Provider of high‑brilliance, low‑power microfocus sources for precision applications—targets scientific and laboratory customers demanding stability and compact footprints.
-
Sigray (USA): Developer of nano‑ and microfocus sources with an emphasis on advanced imaging and materials‑science use cases—driving innovation in source miniaturization and analytical performance.
Market concentration is meaningful but not monopolistic: the top tier of vendors collectively control a substantial share of industry revenue, creating attractive windows for targeted carve‑outs, strategic alliances and channel plays for well-capitalized entrants.
Recent developments shaping 2026 tactics
-
X‑RAY WorX announced a catalog update in March 2026 introducing a higher-voltage microfocus tube with submicron capabilities slated for later delivery—an indicator of demand for ultra‑high resolution in advanced NDT and research applications.
-
Industry engagement at shows through 2025 demonstrated continued interest in rod‑anode and specialized tube geometries, signaling that buyers are looking for both resolution and fractional improvements in throughput.
-
Standards and clearances—ISO focal‑spot measurement norms and tightened FDA expectations for portable systems—are pressuring vendors and buyers to validate performance claims with standardized evidence packages and stronger traceability.
-
Procurement friction due to material and maintenance costs persists, reinforcing the need for creative pricing, leasing and shared-service models to unlock stalled purchase cycles.
Strategic implications and recommended moves for 2026
-
For product leaders: Prioritize development that demonstrably reduces lifecycle cost and simplifies compliance evidence (instrument‑embedded QA tools, automated test logs) to accelerate hospital and regulated‑industry adoption.
-
For commercial teams: Offer bundled service contracts and flexible financing (pay‑per‑scan, leasing) to convert CapEx‑averse prospects and to capture aftermarket revenue.
-
For corporate development: Seek tuck‑ins focused on service networks, spare‑parts logistics or niche focal‑spot technologies rather than large horizontal acquisitions—these yield faster integration and clear ROI.
-
For procurement and operations: Implement the report’s vendor evaluation scorecards and TCO models to reduce acquisition complexity and to benchmark service SLAs against industry norms.
-
For regulatory and quality teams: Bake the ISO and FDA expectations into product release gates; invest in documentation automation to shorten clearance cycles and reduce rework.
-
For R&D and engineering: Balance pursuit of ultimate resolution with manufacturability and cost; incremental improvements in focal‑spot reproducibility and tube lifetime often deliver more commercial value than pursuing absolute technical extremes.
How PW Consulting supports execution
-
Custom due diligence and target screening for M&A, including technical diligence, regulatory gap analysis and commercial synergies.
-
Commercialization playbooks: product pricing, service design and channel strategies adapted to microfocus X‑ray business models.
-
Regulatory pathway mentoring: alignment to ISO focal‑spot measurement guidance, FDA 510(k) expectations for portable systems and CE/21‑CFR compliance mapping.
-
Procurement and vendor‑selection support: deployment of scorecards, RFP templates and negotiation frameworks tailored to capital equipment and recurring service portfolios.
In 2026, the microfocus X‑ray market is large enough to reward focused investments and disciplined commercial models, yet dynamic enough that timing and execution will determine winners. PW Consulting’s study condenses the complex technical, regulatory and commercial variables into decision-ready templates, scenario models and negotiation tools that accelerate time to value. For teams preparing budgets, product roadmaps or M&A pipelines this year, the full report contains the granular segment analyses, regional depth and vendor scorecards that support board‑level commitments and operational rollouts—contact PW Consulting or visit our report portal to access the complete dataset and practical attachments.
For detailed analysis of this topic, please visit the official page: Microfocus X-ray Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Sunroof Market Poised for 11.57% CAGR Through 2032
By PW Consulting, 2026-07-08
Automotive Sunroof Market — Strategic Primer for 2026 Decision-Makers
Executive snapshot
The Automotive Sunroof market is entering a decisive phase of scale and sophistication. After an acceleration through the early 2020s, total industry revenues climbed from USD 8.48 Billion in 2020 to USD 15.68 Billion in 2025. Our base-year analysis establishes 2025 as the inflection point: with continuing premiumization, electrification-driven vehicle architectures, and new glass and smart-material innovations, PW Consulting projects the market to expand at a compound annual growth rate (CAGR) of 11.57% through the 2026–2032 forecast window — reaching an anticipated market size north of USD 33 Billion by 2032. Equally important, market concentration is relatively high (CR3 ~68%, CR5 ~81%), which has profound implications for supplier strategy, OEM sourcing, and M&A activity in 2026.
Automotive Sunroof Market
Why this matters for 2026 corporate strategy
-
Timing: 2026 is a window in which investments in roof architecture and related value capture will either lock in product differentiation or leave players exposed to consolidation. Decisions on supplier selection, localized production, and platform integration made this year will determine cost curves and content share for the next vehicle generation cycle.
Automotive Sunroof Market -
Technology convergence: Sunroofs are no longer a single commodity option. They are becoming integrated modules — combining panoramic glass, smart electrochromic surfaces, solar collection, actuation electronics, and acoustic sealing — which requires systems-level sourcing and more advanced supplier qualifications.
Automotive Sunroof Market -
Supplier leverage: A concentrated supplier base means OEM procurement can extract scale benefits but also faces higher switching costs and capacity constraints. For component suppliers and Tier‑1s, 2026 is a make-or-break year to demonstrate modularity, cost-competitiveness, and IP depth.
Market dynamics shaping strategy
-
Premiumization & feature migration: Increasing consumer preference for larger glazing areas and panoramic designs is driving content per vehicle higher. This trend amplifies the importance of NVH performance, thermal comfort, and integrated solar options — features that command material and engineering investment but also support margin recovery through premium OEM pricing.
-
Electrification and weight sensitivity: Lightweighting imperatives in BEV and PHEV platforms are shifting material choices (thermoplastics, high-strength composites, lightweight actuators). Roof systems are now evaluated as part of the vehicle’s energy and range equation, not just as comfort options.
-
Localization and capacity plays: Rapid growth in Asian OEM demand — and related policy incentives — is driving capacity extensions and joint ventures in-region. Localization improves cost competitiveness and BOM stability but requires careful tech-transfer governance to protect IP and quality standards.
-
Regulation & quality risk: Recalls tied to assembly and material defects (for example, instances of sunroof glass detachment reported in 2026) underscore the reputational and warranty risk OEMs and suppliers face. Tighter regulatory scrutiny around occupant safety and glazing standards will increase qualification hurdles and total cost of supplier onboarding.
-
Input-cost volatility: Glass, specialized polymers, and actuator electronics remain exposed to commodity cycles and supply chain bottlenecks. Strategic buyers must model raw-material stress-tests and embed pass-through or hedging clauses into multi-year contracts.
Competitive landscape — capabilities you need on the radar
The market is led by established global players with deep OEM relationships and modular systems capabilities. Key incumbents include:
-
Webasto Group (Stockdorf, Germany) — a global leader in openable and fixed panoramic systems, motorized tilt & slide units, and solar-integrated modules supplying premium and volume OEMs. Recent strategic moves include capacity expansion in Europe and partnership activity in China to accelerate fixed transparent module production.
-
Inalfa Roof Systems Group B.V. (Venray, Netherlands) — known for low-noise modular panoramic systems with integrated glass and sensor platforms, supplying a broad roster of vehicle brands globally.
-
CIE Automotive (Bilbao, Spain) — offers modular roof platforms, electric actuation, and solar-control glass integration across passenger and light commercial segments.
-
Aisin Seiki Co., Ltd. (Nagoya, Japan) — provides advanced multi-panel panoramas, smart-glass options, and robust acoustic sealing tailored to OEM platform requirements.
-
Yachiyo Industry Co., Ltd. (Sayama, Japan) — supplies a mix of tilt & slide, panoramic, and pop‑up systems with motorized and premium material options.
-
Magna International Inc. (Aurora, Canada) — a longtime developer of thermoplastic modular roof panels; as of 2026, its rooftop systems business has been placed into a divestiture process, signaling consolidation and reshuffling among Tier‑1s.
-
Inteva Products LLC (Troy, USA) and Johnan Manufacturing Inc. (USA) — provide critical actuation, electronic controls, and region-focused manufacturing capability critical to North American OEMs.
Collectively, the incumbent cohort controls a large share of global content (CR3 ~68%; CR5 ~81%). This structure favors technology-rich suppliers but also creates openings for nimble innovators offering differentiated materials, integrated solar functionality, or disruptive assembly approaches.
Recent developments that change the playbook
-
Strategic partnerships and local capacity: In 2026, Webasto advanced its China strategy through an equity agreement with a regional glass manufacturer focused on fixed transparent modules — an arrangement that accelerates access to OEM programs in the fastest-growing market. This kind of JV model is becoming a dominant route for foreign suppliers seeking share without compromising localization speed.
-
Portfolio optimization and consolidation: Moves by major systems suppliers to divest or rationalize rooftop businesses indicate potential reconfiguration of supplier capabilities and pricing dynamics. Buyers and investors should expect both bolt-on M&A and targeted carve-outs to reshape supply options through 2027.
-
Capacity expansions in Europe and North America: Select suppliers have already increased panoramic glass production to meet OEM pull-through — signaling near-term capacity tightness and an opportunity for OEMs to lock supply or for Tier‑2s to ramp complementary capabilities.
-
Quality incidents and regulatory scrutiny: High-visibility recalls in 2026 tied to sunroof assembly defects have sharpened OEM attention on supplier process controls, incoming inspection regimes, and contractual liability — increasing the non-recurring engineering (NRE) commitments required to qualify new vendors.
Strategic recommendations for 2026 (prioritized)
-
Define future-content bets at platform-level: Treat roof systems as a cross-functional decision (body, thermal, NVH, electrical architecture). Build scenario-based BOMs for base, premium, and solar-integrated variants across vehicle programs to capture upside and quantify margin sensitivities.
-
Supplier segmentation and dual-sourcing: Given concentration and capacity dynamics, establish primary and secondary sourcing lanes with clear KPIs for quality, lead times, and tech migration. Negotiate holdback provisions and ramp clauses to mitigate supply shocks.
-
Invest in localized partnerships where market growth is fastest: JVs or minority investments with local glass or module manufacturers can accelerate program wins while preserving IP via staged transfers and guarded tooling contracts.
-
Embed rigorous quality governance: Strengthen supplier audit playbooks, adopt integrated testing regimes for glazing adhesion and dynamic loading, and require advanced process FMEAs and digital traceability to reduce recall exposure.
-
Evaluate M&A and divestiture opportunities: For suppliers, selectively pursue bolt-on capabilities (actuation electronics, smart glass) to create bundled offerings. For OEMs and investors, watch carved-out rooftop assets as acquisition targets that can be reshaped to meet platform demands.
What this PW Consulting report delivers — practical, execution-focused content
Our Automotive Sunroof Market research is structured to be a decision-ready toolkit for 2026. Highlights include:
-
Top-down market model with historical (2020–2025) validation and a 2026–2032 forecast, stress-tested under multiple demand, material-cost, and electrification scenarios.
-
Supplier capability maps, technology scorecards, and a competitive playbook that profiles leading vendors across quality, program wins, modularity, and regional capacity.
-
Commercial templates: sourcing/contract clauses, ramp schedules, and supplier KPIs tailored for sunroof systems and integrated glass modules.
-
Risk register and mitigation matrix covering regulatory, material, and assembly risks — including recall case studies and audit checklists for accelerated supplier qualification.
-
M&A and partnership decision frameworks that help buyers prioritize targets, assess valuation multiples for rooftop assets, and design earn-out and integration approaches.
-
Implementation-ready roadmaps for product teams: module architecture options, lightweighting levers, thermal/solar integration trade-offs, and estimated development timelines.
How to use this insight in 90, 180, and 365 days
-
90 days: Complete a supplier stress-test and dual-sourcing plan for priority platforms; defend warranty exposure through targeted quality audits.
-
180 days: Finalize JV/partnership terms or execute rapid capability acquisitions where localization unlocks program share; implement updated contract clauses for cost pass-through and capacity guarantees.
-
365 days: Launch integrated roof variants in next-generation platforms with validated supplier ecosystems and embedded life‑cycle cost modeling to capture higher content margins.
Closing — why consult this report before final 2026 decisions
The Automotive Sunroof market combines strong headline growth with concentrated supplier power and rising technical demands. Our analysis translates the macro growth trajectory into operational priorities: who to partner with, what capabilities to build or buy, and how to protect programs from quality and material shocks. The research surfaces the practical contractual, engineering, and commercial levers that executives must act on in 2026 to convert industry growth into durable competitive advantage.
For proprietary segment-level allocations, OEM-by-OEM content forecasts, and the full set of decision tools referenced above, PW Consulting’s full Automotive Sunroof Market report provides the complete intelligence and executable templates to guide your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Automotive Sunroof Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Metal-Clad Switchgear Market to Reach $296.8M by 2032 at 6.5% CAGR | PW Consulting
By PW Consulting, 2026-07-08
Metal‑Clad Switchgear Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a high‑level strategic preview of our forthcoming Metal‑Clad Switchgear Market study. This briefing is written for executives, portfolio managers, procurement heads and strategy teams who must make decisive investments in 2026. It highlights the report’s practical value, the market’s macro evolution, competitive dynamics and the tactical levers that will determine winners and laggards across the medium‑voltage switchgear value chain. The full study contains the granular segmentation, supplier scorecards and transaction‑level intelligence needed to operationalize these insights — intentionally withheld here to direct readers to the source for full access.
Metal-Clad Switchgear Market
Market Trajectory: A Consolidating but Growing Market
The metal‑clad switchgear market has demonstrated steady expansion through the recent five‑year window. Measured from the historical baseline, the market expanded from approximately USD 145.3 Million in 2020 to USD 192.5 Million in 2025 (base year). Under our central forecast, the market continues to grow across 2026–2032, reaching roughly USD 296.8 Million by 2032. This path represents an underlying compound annual growth rate (CAGR) of approximately 6.5% during the forecast interval.
Metal-Clad Switchgear Market
Put simply, the sector is not a rapid boom market but rather one of durable growth driven by utility grid upgrades, industrial electrification, renewables integration and replacement/retrofit cycles. The steady CAGR and the absolute scale signal a market with room for sustained investment — especially for firms that can lower total cost of ownership, shorten lead times and offer compliance‑ready, prefabricated solutions.
Metal-Clad Switchgear Market
Why this Research Matters for 2026 Decisions
- Investment timing: With growth locked into a predictable trajectory, marginal CAPEX decisions in 2026 should prioritize modularity and recurring revenue (service, spare parts, retrofits) over speculative capacity expansion.
- Procurement strategy: Commodity input volatility and supply‑chain bottlenecks materially affect landed cost and delivery cadence. Tactical procurement (longer index‑linked contracts, vendor development, dual‑sourcing) will preserve margins.
- Regulatory compliance: Standards and procurement specifications updated in late 2025 and early 2026 materially alter approval pathways and qualification timelines for new products — requiring firms to embed compliance early in product roadmaps.
- M&A and partnership timing: A moderately concentrated supplier base creates windows for bolt‑on acquisitions and capacity deals that are likely to yield near‑term margin uplift and enhance aftermarket reach.
Core Demand Drivers and Near‑Term Risks
- Drivers: Grid modernization, distributed energy resources, prefabrication for faster deployment, and industrial capacity restarts underpin baseline demand.
- Cost risk: Raw material pressure — notably copper and steel — has driven production costs higher in 2025 and remains a key input risk in 2026 unless pass‑through mechanisms are adopted.
- Standards & certification: The revision and approval of key standards and national specifications in late 2025 and early 2026 require suppliers to demonstrate compliance and are influencing purchase lead times and acceptance criteria.
- Supply chain resilience: Buyers are increasingly valuing factory‑assembled, fully wired solutions to cut site installation time; suppliers that can guarantee shorter lead times will capture premium pricing.
Report Contents — Practical, Actionable Deliverables
The PW Consulting report is designed as a decision support toolkit, not an academic exercise. Core deliverables include:
- Validated market sizing and demand models (historical 2020–2025; forecast 2026–2032), including sensitivity scenarios for commodity shocks and policy shifts.
- Segmented demand analysis by market axes (regional, product‑type, end‑use) with scenario waterfalls and addressable market estimates suitable for go/no‑go investment decisions.
- Competitor benchmarking and supplier scorecards — technical capability, certification posture, manufacturing footprint, lead time performance, and aftermarket coverage.
- Procurement playbooks and contract templates that embed commodity indexation, delivery SLAs and acceptance testing protocols aligned to the latest standards.
- Product roadmaps and engineering checklists to accelerate certification across IEEE/UL/national specs with estimated timeline and cost buckets.
- Go‑to‑market and channel strategies for OEMs, fabricators and system integrators including partnership match recommendations and target account maps.
- M&A screen and valuation templates tailored to serial bolt‑on or platform consolidation plays in the medium‑voltage equipment space.
- Operational readiness audits and digitalization templates (remote diagnostics, condition monitoring) to monetize aftermarket services.
For confidentiality and to preserve commercial value, detailed split tables and company‑level market shares are retained in the full report and the data appendices accessible via PW Consulting’s distribution channel.
Competitive Landscape — Who Matters and Why
The supplier field blends global system houses with specialized fabricators. Key players covered in our competitive analysis include global platform providers and regional specialists. Highlights:
- Schneider Electric (Rueil‑Malmaison, France) : Offers a broad medium‑voltage metal‑clad portfolio tailored to grid and industrial segments. Strong global service footprint and established brand trust are core assets.
- ABB (Zurich, Switzerland) : Supplies standard metal‑clad lines optimized for substation and industrial deployments; engineering depth and existing utility relationships underpin commercial traction.
- Eaton Corporation (Dublin, Ireland) : Recent design guide updates reflect a strategy to shorten spec‑to‑delivery cycles and simplify engineering approvals for customers.
- Powell Industries (Houston, Texas, USA) : Focuses on ANSI metal‑clad solutions and maintains a strong presence in North American industrial and utility projects; earnings commentary through 2025–2026 provides insight into order flow.
- US specialist fabricators (IEM, Spike Electric, Powercon, IE Corp, Myers Power, S&C, Southwest Electric, Switchgear Power Systems, RESA Power, among others) : These firms compete on custom engineering, short lead times and niche certifications (e.g., stainless steel enclosures, high ampacity offerings, up to 38 kV units).
Two strategic observations emerge from our analysis. First, the market shows moderate concentration — the top three firms account for a meaningful majority of supply, and the top five further consolidate that position. That structure confers pricing discipline and creates acquisition targets among mid‑tier players. Second, differentiation is increasingly non‑product: certification speed, project management competence, prefabrication capability, and aftermarket service networks are decisive in procurement evaluations.
Recent Industry Signals — Late 2025 to Early 2026
- Design guidance and product documentation updates from major OEMs have become effective in late 2025, compressing qualification timelines for new builds.
- Public filings and earnings commentary from leading vendors in early 2026 signal stable order intake with pockets of margin pressure tied to commodity costs.
- Notable contract awards for prefabricated metal‑clad units underline continued demand from municipal utilities and precinct‑scale projects.
- Standards activity — including renewed IEEE editions and updated US federal/building specifications — are reshaping technical acceptance criteria and test requirements.
Strategic Recommendations for 2026
- Prioritize total cost of ownership (TCO) in selection criteria: Move beyond headline capex to quantify lifecycle service, spare parts, downtime risk and warranty obligations in procurement scorecards.
- Hedge material exposure: Introduce commodity indexation clauses or multi‑year purchasing agreements to stabilize margins and avoid reactive price increases.
- Accelerate prefabrication capabilities: Develop factory‑assembled, tested, and instrumented units that reduce on‑site integration time and capture premium margins.
- Embed compliance early: Map product development timelines against the updated standards and spec windows to avoid re‑engineering late in the sales cycle.
- Target aftermarket monetization: Invest in remote monitoring, predictive maintenance services and parts logistics as higher‑margin revenue streams with recurring cash flows.
- Consider acquisitive growth for capability gaps: Identify bolt‑on targets that enhance lead‑time, niche certifications or regional service footprints rather than volume alone.
- Stress‑test scenarios: Run three waterfall scenarios (base, slow‑growth commodity shock, accelerated electrification) to inform CAPEX phasing and working capital plans.
How PW Consulting Can Support Your 2026 Playbook
PW Consulting offers tailored engagements that convert the report’s insights into executable plans: transaction advisory, procurement redesign, engineering‑to‑production acceleration, and aftermarket commercialization. We bring proprietary demand models, supplier diligence frameworks and templates that reduce decision time and implementation risk.
This preview demonstrates the strategic contours you need to consider in 2026. For the full dataset, granular segment splits, detailed competitor scorecards and the downloadable procurement and M&A toolkits, consult the full Metal‑Clad Switchgear Market report available through PW Consulting’s research distribution. The detailed appendices contain the segment‑level numbers and source references that underpin the recommendations above.
For detailed analysis of this topic, please visit the official page: Metal-Clad Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


