



Category: market research
PW Consulting: Collagen Casings Market to reach USD 278.5M by 2032 at 6.05% CAGR
By PW Consulting, 2026-07-08
Collagen Casings Market — Strategic Preview for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our full Collagen Casings Market research. This briefing synthesizes the macro trajectory, competitive posture, regulatory inflection points, and actionable operating levers that matter to executives making capital, procurement, and M&A choices in 2026. It intentionally highlights the strategic conclusions while withholding the granular segmentation tables and unit-level metrics you’ll find in the full report—our “deep cut” that informs boardroom-level decisions.
Collagen Casings Market
Market Snapshot: A resilient growth story
Using 2025 as the base year, the collagen casings market has demonstrated steady expansion through a combination of steady demand for processed meat products, automation in meat processing, and a push for higher food-safety standards. Our modeled baseline shows the market rising from a 2020 footprint to roughly USD 186.0 Million in 2025, and a projected trajectory that reaches the high hundreds of millions of dollars by the end of the 2026–2032 forecast window. The underlying compound annual growth rate (CAGR) for the forecast period is 6.05%—a pace that is meaningful for capacity planning, supplier contracting horizons, and innovation roadmaps.
Collagen Casings Market
Why this matters to executives in 2026
- Capital allocation and capacity timing: A mid-single-digit CAGR implies that incremental capacity additions must be carefully phased to avoid oversupply and margin compression—especially where raw-material volatility exists.
- Procurement and cost management: Given the outsized influence of animal hide input costs on manufacturing economics, procurement strategy and hedging become primary value drivers.
- Regulatory compliance as a competitive moat: Tightening traceability and food-safety rules increase entry costs and create advantages for vertically integrated and certified suppliers.
- M&A and partnership playbook: Moderate market consolidation signals opportunities for bolt-on acquisitions, geographic expansion, or capacity buys that improve utilization.
Market dynamics: demand, supply, and regulatory pressure
Demand-side fundamentals remain anchored in global protein consumption trends and continued growth of convenience and processed meat formats. Premiumization—driven by product aesthetics, texture, and cleaner-label formulations—creates pockets where higher-margin collagen products can outcompete alternative casings.
Collagen Casings Market
On the supply side, two structural factors merit attention. First, raw-material cost volatility: industry analysis shows fluctuations in animal hide prices can represent an outsized portion of total production cost—often approaching half of manufacturing expense in stressed periods. Second, capacity distribution and regional production footprints are shifting as manufacturers pursue regional supply security and faster lead times.
The regulatory and trade environment is in active evolution. Key regulatory drivers include the EU Novel Food Regulation and U.S. food-safety frameworks such as FSMA, which raise traceability and HACCP expectations for collagen casing producers. In 2025 the USDA issued a revised inspection and export certification directive for livestock casings, further tightening requirements for exporters. Trade-policy noise—such as submissions by industry organizations regarding excess capacity in some producing countries—also increases the risk profile for cross-border expansion and provides a backdrop for potential trade dispute actions in 2026.
Segmentation: what to watch (and what we deliberately withhold here)
The market is commonly segmented by geography, casing caliper, and application (e.g., fresh, cooked, dry-cured, smoked, snacks). Our full study models these axes in detail and quantifies size, growth rates, and unit economics across each segment. In this preview we will not publish the granular percentage splits or unit price curves; however, strategically relevant directional insights are:
- Small-caliber casings account for the bulk of total volume by use-case and remain the backbone of the industrial sausage supply chain.
- Medium and large calibers support specialty and value-added applications where processors demand tailored sizing and finishing.
- Application mixes are evolving: while classic formats remain stable, snacking and convenience formats are accelerating innovation requirements for casing performance and appearance.
If you require the regional, caliber, or application-level breakdowns, the full report provides those tables plus downloadable scenario models for stress-testing strategic options.
Competitive landscape: who occupies the value chain and how concentrated is the market
The collagen casings market displays moderate concentration: our market concentration analysis shows the top three players control over half of the market by revenue, and the top five account for a clear majority. This structure yields a mix of scale advantages and niche opportunities:
- Established European incumbents (e.g., manufacturers known for high-quality and customizable large-caliber solutions) compete on technical performance, food-safety credentials, and integrations with automated lines.
- Specialist Japanese and North American firms bring product differentiation—high transparency casings, medical-grade purity, and tailored formulations—targeting premium and regulated segments.
- Chinese producers and regional players pursue volume, cost-competitiveness, and rapid capacity expansion in Asia and export markets; however, trade scrutiny and regulatory traceability requirements alter the risk-reward calculus for buyers sourcing from low-cost suppliers.
Key company profiles covered in the report include players with strengths such as edible and non-edible offerings, large-caliber capabilities, automation integration, medical-grade innovations, and regional scale. The strategic implications are clear: size and certification create barriers in certain channels, while nimble specialists can win in premium, niche, or technically demanding applications.
Operational levers & margin preservation
For executives managing manufacturing and procurement functions, the highest-leverage tactics we recommend are:
- Supplier diversification and backward integration: Reduce exposure to hide-price shocks through multi-sourcing or investments into raw-material processing.
- Value-based pricing and product tiering: Capture premium for higher-spec casings (e.g., improved handling, appearance, or certification) and protect commodity margins through operational efficiency.
- Traceability and certification investments: Prioritize HACCP, ISO, and export-compliant controls to avoid lost access to regulated markets and to make price-premium claims credible.
- Energy and waste optimization: Process optimization materially improves per-unit costs in energy-intensive production steps; sustainability claims also unlock buyer preference.
M&A, capex, and go-to-market moves for 2026
Given the market’s moderate consolidation and the 6.05% projected CAGR, M&A and targeted capex can be value-accretive if executed with attention to timing and integration risk. Practical opportunities include:
- Bolt-on acquisitions to increase regional fill rates and access regulated markets where certification is a barrier to entry.
- Capacity investments focused on higher-margin calibers and niche formats rather than wholesale volume expansion into mature commodity segments.
- Strategic alliances with meat processors to co-develop casing formats that reduce downstream processing costs and improve final-product yields.
- Investments in digital traceability and blockchain-enabled provenance solutions to meet buyer and regulator expectations ahead of peers.
However, investors should model for trade-policy volatility and potential anti-dumping scrutiny in some corridors. Our full report includes scenario valuations and integration playbooks for several deal archetypes.
What PW Consulting’s full report delivers (practical, executable content)
- Verified market sizing and a 2026–2032 forecast model with downloadable scenarios (base, downside, upside).
- Decision-grade competitor dossiers (capabilities, certifications, regional footprints, strategic priorities).
- Supplier risk matrix and procurement playbook that ties raw-material exposure to contract structures and hedging approaches.
- Regulatory impact assessment with a compliance checklist designed for exporters and multinational processors (including FSIS changes and EU traceability requirements).
- Investment and M&A toolkit: valuation sensitivity tables, synergy templates, and integration risk mitigants.
- Operational improvement guide: unit-cost drivers, CAPEX phasing, and a sustainability roadmap with potential ROI scenarios.
Note: this preview intentionally omits the granular regional, caliper, and application-level tables and unit-price series that underpin our models. Those detailed datasets and interactive models are available exclusively with the full report and are designed to plug directly into CFO and procurement workflows.
Final strategic takeaways for 2026
- The market is expanding at a rate that rewards selective capacity and capability investments, not indiscriminate scale plays.
- Raw-material exposure and regulatory compliance are the two dominant risk buckets—mitigating these is a prerequisite for sustainable margin expansion.
- There is tactical runway for consolidation and bolt-on deals, particularly in regional markets where certification and reliable supply create pricing power.
- Technology and product differentiation (e.g., formulations for automated lines, transparency, and specialty collagen variants) are pathways to premiumization.
For procurement teams, strategy leads, and corporate development officers preparing 2026 budgets, the full PW Consulting Collagen Casings Market report is the operational tool to translate these insights into executable plans. Contact our research desk or visit the report landing page to access the full datasets, interactive models, and the vendor due-diligence annex that drive winning decisions.
For detailed analysis of this topic, please visit the official page: Collagen Casings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Tools Market to Hit USD 61.75B by 2032 at 5.5% CAGR
By PW Consulting, 2026-07-08
Power Tools Market 2026: Strategic Preview and Decision Framework
As PW Consulting’s lead industry analyst, I present a strategic preview designed to equip executives, product leaders, and investors with the contextual intelligence they need to make high‑confidence choices in 2026. The global power tools market has moved from recovery into sustained expansion; our base-year analysis (2025) places total industry revenues in the low‑forties (USD Billion), with a compound annual growth rate of roughly 5.5% driving the market through the 2026–2032 forecast horizon. This trajectory creates both structural opportunities and tactical urgency: winners will be those who convert technology shifts, distribution evolution, and regulatory change into repeatable commercial advantage.
Power Tools Market
Why this research matters for 2026 decision cycles
-
Timing: 2026 is a hinge year. Many incumbents are rolling out next‑generation battery systems, modular solutions, and professional channel strategies while the regulatory environment around safety and labeling tightens. Decisions taken now — on R&D prioritization, supply‑chain architecture, and route‑to‑market — will determine whose platforms scale and whose cost bases erode under tariff and raw‑material volatility.
Power Tools Market -
Signal vs. noise: Macro growth is clear: the market has expanded meaningfully from the early 2020s and our model projects continued expansion to the end of the decade. But within that growth is considerable heterogeneity across product types, channels, and use cases. Our report provides the structured decomposition you need to separate structural trends (battery electrification, digital tools, pro-channel consolidation) from transient cyclical effects.
Power Tools Market -
Actionability: Executives tell us they want fewer slides and more executable playbooks. This study blends a rigorous market model with commercial templates — pricing tests, SKU rationalization matrices, and partnership screening tools — so you can move from insight to pilot within 90 days.
Key market dynamics shaping strategy in 2026
-
Electrification and platform consolidation: Lithium‑ion battery innovation remains the single largest structural driver. Leading OEMs are transitioning from tool‑level battery packs to platform strategies that embed batteries, chargers, and software into an ecosystem. Recent product introductions from major players underscore this, and our analysis shows platform winners capture outsized aftermarket and accessory revenue over time.
-
Professionalization of the mid‑market: Professional end‑users demand durability, system compatibility, and serviceability. Firms that pair ruggedized hardware with service contracts, diagnostics, and training are shifting margin pools away from commoditized retail channels into higher‑value professional offerings.
-
Supply chain and price pressures: Tariffs and raw material dynamics continue to influence commercial strategy. Several large vendors have publicly signaled price adjustments and supply re‑engineering in response to tariff and commodity shifts; such moves propagate through dealer margins and rental markets, altering demand elasticities.
-
Safety and compliance as competitive differentiators: Regulatory updates in 2026 — including enhanced electrical labeling requirements and renewed emphasis on site safety — increase the cost of non‑compliance and create openings for vendors that integrate compliance features, clear labeling, and training into their propositions.
-
Channel bifurcation: Consumer retail, professional dealers, rental houses, and direct digital channels are diverging in service levels and economics. Successful go‑to‑market strategies will be channel specific, leveraging SKU segmentation, financing, and localized service footprints.
Competitive landscape — what the leaders are doing
-
Platform plays and new launches: Europe‑based leaders have accelerated integrated solution launches, emphasizing next‑generation battery platforms and expanded outdoor equipment portfolios. These moves are not merely product introductions; they are network plays intended to lock in users to multi‑tool systems and modular storage ecosystems.
-
Scale through brands and channel reach: US and Asia‑based conglomerates combine broad distribution networks with strong professional brands. Several firms are augmenting organic growth with channel partnerships and selective pricing moves to defend share where margin pressure is highest.
-
Industrial and specialist focus: Companies with strong industrial tool portfolios continue to invest in fastening systems, pneumatic integration, and specialized tools for construction and manufacturing — categories where differentiation and customer stickiness remain highest.
-
Notable recent moves: A leading global OEM publicly launched an integrated concrete portfolio and a next‑generation 18V battery platform at a major trade event in early 2026, signaling their intent to widen professional adoption. Another major group reported strong growth in its power equipment segment in 2025, reflecting solid demand and the premiumization of professional products.
Market structure and concentration
-
The market shows moderate concentration: the top three firms account for a material portion of revenue, and the top five capture a clear majority of organized market value. This structure rewards scale in R&D, battery procurement, and channel management but still leaves room for specialist players to thrive in high‑value niches.
Strategic implications and recommended actions for 2026
-
Reprioritize portfolio investment toward platform economics. Allocate R&D to battery chemistry, fast‑charging and thermal management, and modular systems that enable cross‑tool compatibility. Evaluate the marginal ROI of developing proprietary battery tech versus strategic licensing or joint ventures.
-
Design supply resilience into cost models. Conduct a two‑by‑two analysis of suppliers (strategic vs. transactional; high vs. low risk) and create dual sourcing or nearshoring plans for critical components. Hedge for tariff exposure in commercial terms with flexible pricing clauses and inventory buffers aligned to working‑capital tolerance.
-
Monetize aftermarket and services. Build serviceable product road maps — extended warranties, diagnostics-as-a-service, and modular repairs — that increase lifetime value and create recurring revenue streams less susceptible to cycle swings.
-
Channel‑specific go‑to‑market. Develop differentiated propositions for professional versus consumer channels: volume, price tiers, and service levels. Partner with rental and distributor networks to reach episodic demand while preserving premium positioning in professional segments.
-
Embed compliance and safety in product design. Anticipate label and safety standard changes; integrate clear, actionable labeling and onboard digital traceability to reduce end‑user risk and capture procurement preferences from larger contractors.
-
Run scenario‑based M&A and partnership screens. Create three scenarios (base growth at ~5.5% CAGR, accelerated electrification, and adverse supply‑shock) and map targets that shore up capabilities under each. Prioritize targets that accelerate battery competency, software integration, or dealer consolidation.
What PW Consulting’s full report contains (practical, executable content)
-
Proprietary market model: A bottom‑up revenue model covering historical performance and a 2026–2032 forecast, stress‑tested across macro scenarios. This model is delivered as a configurable workbook so you can swap assumptions and test sensitivity in your planning cycle.
-
Technology readiness index: Comparative scoring of battery technologies, power electronics, and integration readiness to help prioritize R&D and acquisition targets.
-
Channel mapping and go‑to‑market playbooks: Tactical templates for OEMs and distributors, including pricing levers, dealer margin tables, rental economics, and a step‑by‑step pilot plan for direct professional e‑commerce.
-
Supplier and input risk dashboard: A ranked map of critical suppliers, tariff exposure analysis, and mitigation strategies to protect margins during commodity cycles.
-
Competitive diagnostic and M&A screen: Qualitative and quantitative benchmarking of leading firms, a candidate shortlist for capability or market consolidation, and integration playbooks that preserve talent and channel relationships.
-
Regulatory impact matrix: Practical guidance on meeting emerging safety and labeling requirements, and a compliance roadmap that reduces deployment friction for large contractors and institutional buyers.
How to use this preview
-
Short‑term (next 90 days): Run an immediate battery/platform gap assessment; prioritize low‑cost pilots that validate retrofit and service propositions with top dealer partners.
-
Medium‑term (6–18 months): Reconfigure road maps and sourcing contracts to secure battery supply and product lifecycle economics; negotiate channel pilots with rental partners to capture episodic, high‑margin demand.
-
Long‑term (18–36 months): Execute on platform consolidation, M&A or capacity investments that lock in system economics and dealer exclusivity where appropriate.
We have intentionally kept this preview high‑level to demonstrate the analytic depth and the practical value of the full study while preserving the proprietary datasets and granular segmentation that power board‑level decisions. The PW Consulting full report includes the detailed segment matrices, channel‑by‑channel forecasts, and the downloadable models you’ll need to operationalize the recommendations above.
To access the complete market dataset, interactive models, and bespoke advisory options, visit our report page or contact our power tools practice for a tailored briefing and scenario workshop. In an industry undergoing rapid platform shifts and regulatory tightening, acting on high‑quality, executable insight will determine who captures the next wave of value.
For detailed analysis of this topic, please visit the official page: Power Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Artificial Tears Market to Reach USD 3,310.2M by 2032 at 9.05% CAGR
By PW Consulting, 2026-07-08
Artificial Tears Market 2026: Strategic Imperatives and Forecast — PW Consulting Insights
As the Artificial Tears market moves from recovery into an era of accelerated reformulation, channel evolution, and heightened regulatory scrutiny, 2026 will be a decisive year for market leaders and challengers alike. PW Consulting’s market model (base year 2025) shows the global artificial tears market expanding from approximately USD 1.82 billion in 2025 to an anticipated USD 3.31 billion by 2032, reflecting a compound annual growth rate (CAGR) of roughly 9.05% over the forecast window. The historical trajectory (2020–2025) underscores steady volumetric and value growth driven by demographic pressure, diagnostic momentum, and product innovation — trends that will inform strategy and capital allocation decisions in 2026.
Artificial Tears Market
Why this research matters for 2026 decision-makers
-
Timing. 2026 is the inflection point between legacy OTC channels and the next wave of preservative-free, value-added formulations. Decisions taken this year on manufacturing, registration, and channel investments will lock in share trajectories for the rest of the decade.
Artificial Tears Market -
Risk management. Recent regulatory events have elevated the cost of quality lapses and misclassification; the commercial impact of a recall or warning letter now runs much deeper than lost sales alone.
Artificial Tears Market -
Capital allocation. With mid-term market value set to nearly double from its 2025 base under our baseline scenario, firms need a prioritized playbook—what to build, buy, or partner—and a clear ROI timeline.
What PW Consulting’s Artificial Tears report delivers (practical scope)
-
Robust market model: five-year historical base (2020–2025) and a seven-year forecast (2026–2032) with scenario outputs (baseline, upside, downside) and sensitivity analyses keyed to regulatory shocks, reimbursement shifts, and raw-material supply disruptions.
-
Commercial playbooks: go-to-market templates for OTC-to-Rx transitions, clinic channel commercialization, e‑commerce rollouts, and private-label partnerships.
-
Regulatory and quality roadmaps: sterility compliance checklists, label strategy matrices, and a recall-readiness playbook tailored for ophthalmic products.
-
Competitive intelligence: strategic profiles, capability maps, pipeline tracking, and M&A target screening across incumbent and emerging players.
-
Reimbursement & evidence toolkit: mapping of reimbursement levers, payer engagement playbooks, and clinical evidence templates tied to diagnostic criteria (e.g., Schirmer testing pathways).
-
Operational diagnostics: manufacturing gap analyses, contract-manufacturing options, and logistics resilience recommendations to mitigate supply-chain and sterility risks.
Market dynamics and growth vectors
-
Demographics and epidemiology. Aging populations and rising prevalence of dry eye disease, combined with chronic screen exposure and contact lens usage, sustain long-term demand for lubricants and therapeutic tear substitutes.
-
Product innovation. Demand is shifting toward preservative-free formulations, longer-retention agents, and vehicle technologies that support dosing frequency reduction—trends that favor firms with formulation R&D and sterile-fill capabilities.
-
Channel evolution. Traditional retail remains important, but prescription-mediated reimbursement and clinic dispensing are growing in influence, altering pricing dynamics and product bundling strategies.
-
Regulatory uplift. Sterility is non-negotiable: ophthalmic products are treated as sterile drug products under FDA standards. OTC pathways that rely on sterility assurance face higher barriers and intensified post-market surveillance.
-
Payer behavior. Medicare and commercial insurers will reimburse artificial tears under defined coding and clinical criteria when prescribed, which elevates the value of physician-directed product adoption supported by diagnostic evidence.
Regulatory shocks and recent industry signals
-
Recall and sterility enforcement. A large-scale recall initiated in March 2026 involving over 3.1 million bottles highlighted the operational and reputational cost of lapses in sterility testing (FDA Official Recall Notice, March 2026). This event has already prompted buyers and distributors to demand higher transparency in supplier QC systems.
-
Misbranding risk. A July 2025 FDA warning letter to a manufacturer for misbranding a sterile lubricant as OTC underscores the regulatory sensitivity around product status and claims in this category (FDA Warning Letter, July 2025).
-
Implication. Companies must re-evaluate label strategies, invest in validated sterilization and cleanroom capacity, and prepare accelerated corrective-action plans to contain downside scenarios.
Competitive landscape — leaders, challengers, and implications
-
Alcon (Fort Worth, Texas) — A portfolio leader with established brands in the artificial tears space. Strengths lie in distribution scale, clinician relationships, and brand equity. Strategic focus for incumbents: defend clinician preference channels and accelerate preservative‑free innovations.
-
AbbVie (North Chicago, Illinois) — Leverages differentiated HydroCell® technology and preservative-free positioning. AbbVie’s advantage is technology-led differentiation that supports justification for clinic adoption and reimbursement conversations.
-
Bausch + Lomb (Bridgewater, New Jersey) — Broad lubricant portfolio and deep channel penetration. Competitive play: bundle therapeutics and diagnostics to create clinic-centric value propositions.
-
Thea Pharma (Jackson, Mississippi) — Niche play with sterile formulations for severe disease and night-time use but faces regulatory exposure from prior warning letters. Strategic emphasis: resolve standing regulatory issues, fortify labeling strategy, and convert specialty use into durable clinic prescriptions.
-
Akorn Consumer Health (Ann Arbor, Michigan) — Known for carboxymethylcellulose-based offerings. Cost and formulary placement are the levers to expand penetration in price-sensitive segments.
-
K.C. Pharmaceuticals (California) — Recent recall events have materially elevated counterparty risk. Near-term strategic priorities should include third‑party QC validation, customer remediation, and transparent communications to restore trust with distributors and clinicians.
-
Market concentration: Our CR3/CR5 analysis shows a moderate concentration profile (top 3 ≈ 37.8%; top 5 ≈ 52.4%), creating room for targeted M&A and niche strategies while limiting the ability of a single incumbent to unilaterally shape price points.
Strategic imperatives for 2026 (what to do, in order)
-
1) Invest in sterility and QA as a competitive moat. Capital allocation to validated sterile filling, environmental monitoring, and third-party audits should be a top 2026 priority. KPI: audit pass rate and time-to-corrective-action.
-
2) Create clinic-aligned value propositions. Build evidence packages (Schirmer-driven endpoints and real-world adherence data) to enable reimbursement conversations and clinic formularies.
-
3) Prioritize preservative-free formulations and dosing convenience. Differentiate on retention time and dosing frequency to win share in premium segments.
-
4) Strengthen supply chain transparency. Adopt serialized lot-tracking and proactive recall simulations to reduce time-to-notice and reputation impact.
-
5) Execute selective M&A and partnerships. Use the moderate concentration landscape to acquire niche technology, expand sterile fill capacity, or secure regional distribution where incumbents are light.
-
6) Embed recall-readiness into commercial contracts. Insist on supplier indemnities, quality SLAs, and joint remediation plans as standard terms.
-
7) Digital patient support. Deploy adherence apps and clinic-to-patient engagement platforms to increase persistence and elevate reimbursement justification.
Scenario planning and trigger-based decision rules
-
Base case. Our baseline models the market growing at roughly 9.05% CAGR from 2026 onward under stable regulatory and supply conditions.
-
Upside. Faster diagnosis adoption, expanded payer coverage for clinic-dispensed products, or a breakthrough vehicle technology can accelerate growth materially—favoring companies that scale manufacturing quickly.
-
Downside. Additional high-profile sterility events or tightened OTC controls could depress demand and compress margins; firms should prepare conservative inventory and recall-cost buffers.
-
Decision rule example. If a supplier audit reveals persistent environmental monitoring failures, trigger immediate dual-sourcing and escalate to a fourth-quarter capital plan to bring sterile-fill in-house.
Why PW Consulting’s report is essential for your 2026 playbook
-
Actionability: the report translates market forecasts into executable roadmaps—contract clauses, CAPEX prioritization, go-to-market timelines, and payer engagement scripts.
-
Proprietary modeling: our baseline and alternative scenarios are built from granular inputs and validated against recent industry shocks, providing stress-tested revenue and margin impacts.
-
Competitive edge: detailed company diagnostics and M&A target screens help buyers and sellers size synergies quickly without committing costly due diligence upfront.
PW Consulting’s Artificial Tears Market study is designed to support board-level strategy sessions, corporate development workstreams, and operational leaders planning 12–36 month initiatives. For access to the full dataset, regional and channel-level segmentation, pricing matrices, and the proprietary company market-share model that underpin our recommendations, visit PW Consulting’s research portal to request the complete report and supporting appendices. The macro trajectory is clear—2026 will separate organizations that treat sterility and clinical evidence as strategic assets from those that view them as compliance costs. Which side will you be on?
For detailed analysis of this topic, please visit the official page: Artificial Tears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum casting market to reach USD 166.7B by 2032 (4.98% CAGR)
By PW Consulting, 2026-07-08
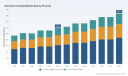
PW Consulting Perspective: Aluminum Casting Market — Strategic Imperatives for 2026
Between 2020 and 2025 the global aluminum casting market demonstrated resilient expansion, rising from approximately USD 94.3 billion to USD 119.4 billion. Our base-year assessment (2025) and forward view to 2032 project continued growth to roughly USD 166.7 billion, representing a compound annual growth rate of about 4.98% over the forecast window. For corporate leaders preparing capital allocation, sourcing, and M&A decisions in 2026, these topline dynamics matter — but only as a starting point. The critical decisions will be shaped by where value migrates across processes, end markets, geographies and technology choices — subjects we analyze with operational depth in our full study.
Aluminum Casting Market
Why 2026 Is a Strategic Inflection Point
2026 is not merely the next year on the calendar; it is the point at which multiple structural drivers converge to reshape competitive advantage in aluminum casting. The sector is being re‑priced by three simultaneous forces:
Aluminum Casting Market
- Regulatory re‑calibration: Carbon border mechanisms and new trade remedies are recasting the cost profile for traded aluminum and downstream cast goods.
- Raw material and input volatility: Alumina and bauxite cost cycles and shifting global supply patterns are compressing margins for unconsolidated producers and advantaging vertically integrated players and recyclers.
- Technology and product evolution: Lightweighting demand from transportation and structural electrification create differentiated value for castings that combine design complexity with high repeatability.
These shifts mean that companies that treat 2026 as “more of the same” risk being outcompeted by firms that accelerate process innovation, circularity initiatives, and defensive commercial strategies.
Aluminum Casting Market
Market Trajectory — Interpreting the Numbers
The macro trajectory we model is unambiguous: a clear recovery through 2025, modest acceleration in 2026‑2029, and compounding improvement into the early 2030s driven by structural end‑market demand and higher recycled-content utilization. Growth is meaningful but not hyperbolic — implying that scale, efficiency and value‑chain integration will dictate winners. The market concentration metrics reinforce this point: the top three players control a material but limited share of demand, and the top five capture roughly half the market, indicating room for consolidation and targeted scale plays.
Value‑Chain Dynamics and Cost Exposure
Value creation and margin resilience in 2026 will depend on three linked competencies:
- Input management and feedstock strategy: With alumina and bauxite supply patterns shifting and price volatility elevated, procurement strategies that combine long‑term offtake, diversified sourcing and integrated recycling deliver superior predictability.
- Process selection and optimization: Casting processes (including high‑pressure die casting, sand casting and permanent mold techniques) differ in capital intensity, cycle time, scrap rates and engineering flexibility. The optimal mix is application‑specific and must be evaluated against total cost of ownership rather than unit price alone.
- Carbon and regulatory pass‑through capability: Carbon border measures and duties on upstream materials require transparent carbon accounting, product traceability, and commercial frameworks to preserve margins when costs are externalized into supply chains.
Our full report maps these exposures to plant archetypes and provides a prioritized remediation matrix for procurement, operations and commercial teams.
Technology, Decarbonization and Circularity — Where to Invest
Technology and sustainability are no longer “nice to have.” They are primary economic levers. In 2026, executives should treat three investment categories as first‑order priorities:
- Recycling and secondary metallurgy: Increasing recycled aluminum content reduces exposure to upstream price cycles and to certain trade measures. Investments in scrap sorting, remelting and alloy control yield rapid payback in volatile markets.
- Low‑carbon process deployment: Demonstrated low‑carbon casting footprints create differentiated access to customers subject to carbon compliance and help avoid margin erosion from border adjustments.
- Advanced casting automation and simulation: Digital process controls, die life optimization, and integrated simulation reduce scrap and speed new product introduction — critical where design complexity meets high volume.
Major industry participants are already advancing these levers. Examples include large integrated producers that emphasize alloy innovation and zero‑carbon casting programs, and precision die casting specialists that invest in process repeatability and tight tolerances for electrified powertrain components.
Competitive Landscape — Strategic Postures and Implications
The competitive field is heterogeneous: vertically integrated primary producers, precision die casters, and component specialists coexist with regional foundries and engineering‑led suppliers. Understanding where each player derives advantage is essential for partnership, supplier selection, and M&A strategy.
- Integrated primary producers: Players with smelting and casting operations command advantages in feedstock control, alloy development and the ability to offer value‑added cast products. These firms are natural partners for OEMs seeking supply security and carbon transparency.
- Global precision die casters: Specialist die casters win on tolerances, automation and fast production ramp. Their investments in tooling and process controls make them critical suppliers for high‑value, high‑volume applications in transportation and industrial markets.
- Automotive‑oriented lightweight specialists: Suppliers focused on high‑pressure die casting and multimaterial assemblies are positioning for a wave of demand around electric vehicles and lightweight structural components.
- Regional foundries and diversified metal groups: These players often compete on cost flexibility and local proximity to customers, but face pressure from scaling and decarbonization investments required to stay competitive in regulated markets.
Our report examines the strategic moves and capability footprints of the sector’s leading firms, highlighting where capacity expansions, innovation awards, and sustainability programs are likely to alter competitive dynamics in 2026 and beyond. We also flag where recent capacity additions and awards signal an acceleration in recycling and alloy innovation trends.
What the PW Consulting Report Contains — Operationally Focused
This study is designed as a decision‑maker’s toolkit. Highlights include:
- Transparent market sizing and a 2026‑2032 forecast model with scenario toggles (baseline, policy shock, and demand‑acceleration scenarios).
- Plant archetype cost curves and a levelized cost sensitivity model for key casting processes to support capex prioritization.
- Supplier due‑diligence templates, alloy traceability checklists, and a procurement hedging playbook tailored to aluminum feedstocks.
- A carbon footprint mapping methodology and regulatory impact model (including sensitivity to cross‑border carbon pricing and trade remedies) to stress‑test contracts and pricing.
- M&A playbooks differentiating scale acquisitions, capability buys (e.g., recycling or precision tooling), and regional consolidation strategies — with actionable valuation drivers rather than generic multiples.
- Commercial strategies for OEM engagement, including tiering criteria, joint development structures, and offtake contracting templates.
To preserve the full strategic value for clients and subscribers, detailed regional, process and application splits, proprietary price and cost matrices, and company‑level financial overlays are included exclusively in the complete report.
Concrete Actions for 2026 Decision‑Makers
Translate insight into execution with a prioritized 90‑day plan:
- Immediate (0–90 days): Run feedstock exposure mapping across all plants; institute carbon tracking for major SKUs; initiate supplier dialogues about recycled content commitments.
- Near term (3–9 months): Reprioritize capex to favor recycling, low‑carbon pilot projects and automation; launch commercially binding pilot contracts with strategic OEM customers.
- Medium term (9–18 months): Execute targeted scale or capability acquisitions where due diligence validates payback under downside scenarios; deploy plant retrofits that unlock unit‑cost savings and compliance advantages.
Each action aligns with the tools and templates in our report to shorten execution timelines and reduce implementation risk.
Conclusion — Use Data to Shape Strategy, Not Just Forecasts
For executives making 2026 choices, the aluminum casting market presents predictable growth tempered by distributed risk. The right response is not to chase volume alone but to optimize for margin resiliency and regulatory alignment: secure feedstock, improve process economics, and accelerate circularity. The PW Consulting aluminum casting study is structured to move teams from insight to action — supplying the scenario models, operational templates and competitive diagnostics executives need to allocate capital and win in the coming cycle.
For access to the full dataset, granular segment and regional breakdowns, company‑level profiles and the interactive forecast model, please consult the complete PW Consulting Aluminum Casting Market report and datasets on our website. The rest of the story — including the exact process, application and regional splits that drive tactical decisions — is contained there.
For detailed analysis of this topic, please visit the official page: Aluminum Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GPR Market to Reach USD 400M in 2025, Poised for 7.5% CAGR (2026–2032) — PW Consulting Insight
By PW Consulting, 2026-07-08
Ground Penetrating Radar (GPR) Market — 2026 Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Ground Penetrating Radar (GPR) Market study — a practical intelligence product designed to inform capital allocation, product strategy, and commercial execution in 2026. Grounded in a clear base year (2025) and a forward-looking forecast window (2026–2032), this preview synthesizes the top-line growth trajectory, competitive dynamics, technology inflection points, and the decision-ready frameworks executives will need this year.
Ground Penetrating Radar (GPR) Market
Top-line framing: growth trajectory and market structure
The GPR market reached an estimated USD 400 million in 2025 and is projected to expand through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of approximately 7.5%, reaching a materially larger industry size by 2032. This pace reflects a steady commercialisation of advanced hardware, broader adoption of high-resolution survey workflows across infrastructure and utilities, and accelerating uptake of software and AI-enabled processing layers that increase field productivity and drive recurring revenue opportunities.
Ground Penetrating Radar (GPR) Market
Market concentration is meaningful: the top three suppliers control a clear majority of industry revenue, and the top five firms together command an even larger share. For strategy teams, that structure implies both visible acquisition targets and the need for focused differentiation in product, software, and service offerings.
Ground Penetrating Radar (GPR) Market
Why this study matters for 2026 decision cycles
- Timing: 2026 is a pivotal year for procurement and product roadmaps — budgets for multi-year infrastructure programmes and asset-replacement cycles are being committed now. Our study aligns with these decision gates, translating industry momentum into executable options.
- Risk mitigation: the market’s steady growth masks pockets of supply-side volatility (components, testing capacity, certification timelines). We provide scenario-based impact runs that let procurement and finance teams stress-test outcomes under different supply and regulatory paths.
- Revenue capture: higher-margin revenue pools are shifting from one-off hardware sales to bundled software, cloud processing, and data-as-a-service. The report quantifies commercial levers and go-to-market plays to accelerate this mix shift without exposing confidential segment granularity in this preview.
Key growth drivers and demand signals
- Infrastructure renewal and urban utility programmes: governments and agencies prioritising asset mapping and subsurface risk reduction are creating recurring demand for reliable, high-throughput GPR solutions.
- Technology convergence: integrations with positioning (GNSS), LiDAR, and high-resolution imaging workflows increase the value of GPR outputs in BIM and digital-twin initiatives — a structural change that supports premium pricing for integrated solutions.
- Software and AI: advances in automated target recognition, signal denoising, and 3D reconstruction are reducing operator skill barriers and accelerating adoption among construction, transport, and remediation users.
- Specialised security and defence applications: vehicle-mounted and ruggedised systems are finding steady demand where rapid standoff detection and cleared-area verification are mission critical.
Technology and product evolution
Operators face a technology choice matrix that balances depth of penetration, resolution, survey speed, and operational ergonomics. Our full study maps the trade-offs across product families and identifies where incremental R&D investment produces disproportionate commercial outcomes (for example, software-driven enhancements that improve effective survey throughput by 20–40%). We also profile pathways for hybrid solutions that combine cart-based, handheld, and vehicle-mounted modalities into single contract offerings — an increasingly common seller strategy to win multi-site deals.
Competitive landscape — what market leaders are doing
The competitive picture is both consolidating and innovating. A handful of established suppliers maintain leadership through broad product portfolios and strong channel networks; several others compete on specialised capabilities or software differentiation. Notable recent moves worth tracking for 2026 strategies include:
- GSSI (Geophysical Survey Systems, Inc.) — strategic integration initiatives: GSSI has formalised collaboration with a GNSS and mass-data workflow partner to embed GPR into geolocated, large-scale construction workflows. This type of partnership accelerates adoption in infrastructure segments where positional certainty and seamless data pipelines are procurement prerequisites.
- IDS GeoRadar — software and platform intensification: IDS has released successive software and monitoring solutions that emphasise AI-enhanced processing and ongoing site monitoring, signalling a push toward subscription-style revenue and higher lifetime customer value.
- Guideline Geo (MALÅ) — scientific and community engagement: continued participation at major technical conferences reinforces their leadership in 3D mapping and research-oriented applications, sustaining product credibility among institutional buyers.
- Sensors & Software, US Radar, Geometrics, and Chemring — targeted specialization: these firms occupy differentiated niches including archaeology, ruggedised/triple-frequency imaging, integrated geophysical platforms, and explosive hazard detection respectively. Their strategies stress depth over breadth, which can complicate incumbent competition for narrowly defined procurement scopes.
For commercial leaders, the implication is clear: defensible positions will require a mix of product breadth, software-enabled value, and targeted partnerships to win complex, multi-stakeholder procurements.
Regulatory, standards, and operational constraints
- Certification and standards bodies are maturing: leading manufacturers are updating quality and environmental certifications and participating in sector associations that set interoperability and training standards. This trend raises the bar for new entrants and can speed adoption among risk-averse institutional buyers.
- Operator competence and licensing: as automated processing reduces skill barriers, regulators in some jurisdictions are tightening training and operational licensing requirements to ensure quality and public safety.
- Supply-chain and component risk: miniaturised electronics and specialised antenna components remain supply-chain pinch points. Our scenarios model the financial and timeline impacts of component scarcity on both OEMs and systems integrators.
What the full PW Consulting GPR report delivers (practical content)
Our full report is constructed as a decision toolkit for executives, investment committees, and product teams. Highlights include:
- Market model (2020–2032): a transparent, auditable revenue model with top-line forecasts, scenario toggles, and sensitivity analysis calibrated to the 2025 base year.
- Strategic segmentation framework: a commercial taxonomy mapping buyer groups, procurement behaviours, and willingness-to-pay matrices — presented as actionable buyer personas rather than raw numerical splits in this preview.
- Competitive scorecards and playbooks: vendor benchmarking that scores capabilities across hardware, software, service, channel reach, and M&A posture — used to prioritise partnership or acquisition targets.
- Use-case ROI calculators: templates that translate product choice into operating-cost reductions, safety benefits, or project-duration savings for major verticals.
- Go-to-market and pricing playbooks: playbooks for channel partners, government tenders, and enterprise direct sales, including contract structuring to capture software/consumable revenue.
- Regulatory and procurement checklist: an executable list to accelerate approvals and specification alignment for infrastructure projects.
Note: this preview purposefully omits granular segmentation tables and exact numeric splits across regions, product types, and applications; these datasets and the underlying assumptions are available in full on the report page for subscribers and corporate clients.
Strategic recommendations for 2026
- Prioritise software-first product roadmaps: differentiate on processing, AI, and workflow integration rather than hardware-only specifications. Small software investments can unlock recurring revenue and improved customer retention.
- Accelerate partnerships with positioning and BIM platform providers: integrations with GNSS and digital-twin platforms materially increase procurement preference in infrastructure projects.
- Adopt a layered distribution strategy: mix direct enterprise sales for high-value accounts with certified channel programs for routine utility and construction buyers to optimise cost-to-serve.
- Pursue tuck-in acquisitions to close capability gaps: given measurable market concentration among leading vendors, acquisitive moves focused on software, monitoring, or niche sensor capabilities can be fast routes to scaled capability.
- Hedge supply-chain exposure: build dual-source strategies for key components, and model procurement contracts that protect margins under short-term component price volatility.
Methodology and data integrity
Our projections are anchored to a 2025 base year and rely on a mix of primary interviews with industry buyers and OEMs, proprietary shipment and pricing surveys, and public disclosures from leading vendors. The forecast period (2026–2032) uses a mix of bottom-up and top-down techniques, cross-validated by PW Consulting’s industry-validated scenarios. The headline CAGR and market size trajectories quoted here are rounded to reflect modelling consensus; the full dataset and scenario toggles are included in the report’s model workbook.
Next steps and how to access the full intelligence
This preview is intended to orient executive teams to the strategic stakes of 2026 and to showcase the practical value of the full PW Consulting GPR Market study. If you are preparing capital plans, R&D roadmaps, partnership evaluations, or M&A screenings this year, the full report provides the necessary quantitative granularity, supplier scorecards, and executable playbooks. Detailed segmentation, vendor-specific market shares, and the complete financial model are available on our report page and via direct inquiry for corporate subscriptions.
Contact our team to request an executive briefing, access the dataset, or commission custom scenario modelling tailored to your organisation’s portfolio.
— PW Consulting, Advanced Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Ground Penetrating Radar (GPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nicotine Pouches Market Hits USD 215M in 2025, Eyes 28.8% CAGR
By PW Consulting, 2026-07-08
Nicot ine Pouches Market — Strategic Preview for 2026 Decision-Making
As of our 2025 base-year assessment, the global nicotine pouches market has moved from an early-adopter phase into a structured commercial category that now requires rigorous strategic positioning. PW Consulting’s latest market study frames the category with a clear macro trajectory: the market expanded from approximately USD 163.2 million in 2020 to about USD 215.0 million in 2025, and under our central case it is projected to continue growing at a compound annual growth rate (CAGR) of 28.8% through the 2026–2032 forecast window, reaching roughly USD 345 million by 2032. That rate of expansion makes 2026 not merely the next fiscal year, but a pivot point for corporate strategy — for incumbents, new entrants and supporters across the tobacco-alternatives ecosystem.
Nicotine Pouches Market
Why 2026 Is a Strategic Inflection
-
Regulatory milestones have created both runway and rulebooks. The U.S. Food and Drug Administration’s authorization of multiple nicotine pouch products in 2025 validated pathway mechanics and timelines, while parallel regulatory guidance on safety-packaging is elevating operational minimums. Together these create a new baseline for market entry costs and time-to-shelf that must be baked into 2026 budgeting and portfolio planning.
Nicotine Pouches Market -
Retail availability and distribution expansion are accelerating. Brands that rapidly convert regulatory wins into national retail footprints in 2026 will capture the highest-velocity demand segments; those that delay will see sales roll to better-prepared competitors.
Nicotine Pouches Market -
Consumer risk and safety narratives are now inseparable from commercial strategy. Rising accidental-exposure reports have triggered calls for child-resistant packaging and other mitigations — these are not optional compliance items but customer- and regulator-facing brand differentiators.
What the Macro Numbers Mean for Executives
-
Scale opportunity: The reported growth from mid-three-figure millions in 2020 to the 2025 base validates market-product fit. The near-30% CAGR through 2032 captures both rapid category adoption and deepening purchase frequency among existing users. This implies that early investments in manufacturing scale, distribution partnerships and brand-building can pay back over a comparatively short payback horizon.
-
Capital allocation: Given the projected expansion trajectory, capital deployed in 2026 toward capacity, regulatory filings and commercial launch readiness is likely to amplify returns versus longer-term, catch-up investments. This re-prioritizes 3–5 year capex plans: allocate for regulatory dossiers, supply-chain redundancy and packaging retooling now.
-
Risk calibration: Fast growth does not eliminate operational and regulatory risk. Executives must model downside scenarios driven by adverse regulatory outcomes, safety incidents, or abrupt flavor restrictions, and pair growth investments with insurance-like mitigations (e.g., dual-sourcing, child-resistant designs, conservative flavor portfolios).
Competitive Landscape — Who Moves the Market
The category is shaped by a small set of multinational tobacco and consumer-nicotine players that bring strong capabilities in regulatory navigation, branded distribution and scale manufacturing. Swedish Match, Altria Group, British American Tobacco (BAT) and Japan Tobacco International (JTI) are central actors whose strategic moves set benchmarks for market access and product design. Recent developments illustrate how regulation and commercial execution interplay:
-
Swedish Match secured U.S. marketing authorization through the PMTA pathway for multiple ZYN variants in early 2025 and followed with filings aiming at modified-risk claims. That sequence demonstrates a two-track strategy: establish market authorization to unlock distribution, then pursue risk communication permissions to expand consumer propositions.
-
Altria leveraged the nicotine pouch pilot program to secure FDA authorization for a set of on! PLUS products in late 2025 and quickly scaled to nationwide retail availability in early 2026 — an exemplar of compressed regulatory-to-retail timelines for well-resourced incumbents.
-
BAT and JTI continue to deploy portfolio breadth—combining tobacco-derived and synthetic nicotine formats and multiple format strengths—to defend distribution channels and meet retailer segmentation demands.
These players bring three relevant capabilities that matter for any challenger or partner: mastery of submission science and regulatory timelines; deep retail and wholesale relationships; and supply-chain control for nicotine inputs and pouch substrates. Successful 2026 strategies will emulate one or more of these capabilities rather than attempt all at once.
Category Dynamics You Must Model
-
Product differentiation: The market is bifurcating between formulations (tobacco-derived vs. synthetic), sensory positioning (flavored vs. unflavored/original), and nicotine strength tiers. Each axis has distinct implications for regulatory review, consumer appeal and manufacturing tolerance. For 2026 strategy, prioritize experiments that reveal margin-robust preferences within your core consumer cohorts rather than broad-spectrum product launches.
-
Distribution vectors: Brick-and-mortar convenience channels, specialty retail, and e-commerce each exhibit different purchase behaviors and compliance obligations. The capacity to convert regulatory clearance into shelf presence — and to manage channel-specific messaging constrained by local rules — will be a primary determinant of first-mover advantage in 2026.
-
Safety and packaging policy: A recent upward trend in accidental-exposure reports (with a significant share involving very young children) has prompted regulators to call for child-resistant packaging and enhanced stewardship. Firms that make safety-by-design a visible element of their market rollout will reduce regulatory friction and gain retailer trust.
What Our Report Delivers — Practical Tools for 2026
PW Consulting’s full report is designed as an operational playbook for 2026 strategy execution. Highlights include:
-
Market-sizing model built from 2020–2025 historicals and bottom-up forecasts across the 2026–2032 horizon — delivered as an editable financial model so teams can re-run scenarios under alternative assumptions.
-
Regulatory roadmap and filing playbook that decodes PMTA/MRTP and equivalent pathways in priority markets, including a timeline template, resource expectations and success-rate benchmarks.
-
Channel-entry decision matrices and go-to-market templates that map product profiles to the retailer types most likely to convert initial demand into repeat purchase.
-
Risk register and mitigation lexicon covering safety, packaging, litigation exposure and flavor policy shifts, with action-level checklists for 90/180/360‑day plans.
-
M&A and partnership screening framework that operationalizes strategic fit criteria, integration signals, and valuation-adjustment levers for targets ranging from ingredient suppliers to regional roll-up candidates.
-
Commercial playbooks: SKU rationalization guidance, pricing elasticity experiments, promotional lift benchmarks and trade-promotion optimization techniques tailored to the nicotine pouch category.
Strategic Imperatives for 2026
-
Secure regulatory runway before scaling: Initiate or complete prioritized filings early in 2026; build parallel tracks for core markets to avoid bottlenecks.
-
Design for safety as brand currency: Implement child-resistant packaging and high-visibility stewardship messaging; this reduces friction with both regulators and retail partners.
-
Adopt a phased SKU rollout: Test a narrow, margin-accretive portfolio in high-conversion channels and expand incrementally based on empirical purchase data.
-
Prioritize channel partnerships with conversion economics: In 2026, winning national distribution or a major e-commerce partner will materially accelerate market share capture.
-
Prepare for consolidation: Given the profile of incumbent capability and the efficiency of scale in regulatory and distribution functions, M&A and strategic alliances should be considered active playbooks rather than contingency options.
Executive Checklist — Questions to Resolve in Q1–Q3 2026
-
Do you have a prioritized list of markets and a clear path to regulatory submission for each?
-
Is your manufacturing supply chain specified and dual-sourced for all nicotine inputs and pouch substrates?
-
What is your channel-entry sequence and the minimum investment required to secure national retail listings within 12 months?
-
Are your packaging designs compliant with emerging child-safety guidance and defensible in product liability scenarios?
-
Have you stress-tested pricing and promotion strategies against scenarios that include flavor constraints or partial market restrictions?
Conclusion — The Strategic Value of Timing and Preparedness
The nicotine pouches category is among the fastest-growing pockets of alternative nicotine products. The scale and pace reflected in our forecast creates asymmetric value for firms that combine regulatory mastery, disciplined product testing and channel-focused commercialization in 2026. The difference between capturing a primary growth wave and being relegated to a follower role will come down to decisions made in the next 6–12 months — choices about filings, packaging, channel partners and targeted product offerings.
PW Consulting’s comprehensive market study packages the necessary analytic rigor and actionable templates to convert the growth opportunity into repeatable, profitable market share. For teams preparing budgets and go-to-market plans for 2026, the study serves as both a strategic compass and a practical playbook. The public preview you are reading deliberately outlines the strategic contours; the full report contains the granular segmentation, channel-by-channel models and financial schedules that operational leaders require to execute with confidence.
Next Step
Access the full study to obtain the complete, downloadable financial model, the regulatory dossier templates and the channel implementation playbooks that will enable you to make evidence-based, high-speed decisions in 2026. PW Consulting’s analysts are available to brief executive teams and to run bespoke scenario workshops that map your specific resources to the market paths that will most likely deliver sustainable advantage.
For detailed analysis of this topic, please visit the official page: Nicotine Pouches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Grippers Market Poised for 5.2% CAGR Through 2032
By PW Consulting, 2026-07-08
Modular Grippers Market — Strategic Preview for 2026 Decision-Makers
As lead industry analyst at PW Consulting, I present a focused intelligence brief that positions our full Modular Grippers Market study as an operative planning tool for executives preparing 2026 capital, product and M&A decisions. This piece is a “trailer” — it summarizes the market trajectory, strategic inflection points and actionable lines of inquiry that must shape boardroom choices this year, while reserving the granular segment-level schedules and proprietary vendor scoring for the full report.
Modular Grippers Market
Market trajectory: what the numbers tell us
The modular grippers market has moved from early industrial uptake to a phase of steady commercialization. Using 2025 as the base year, the market expanded from approximately USD 45.3 Million in 2020 to USD 55.8 Million in 2025. Our modelling projects a continuation of that growth through the forecast horizon, reaching roughly USD 79.8 Million by 2032. That progression implies a compound annual growth rate in the mid-single digits (around 5.2%) — a profile consistent with a technology-infused component market that is maturing but still responsive to automation cycles, materials innovation and open-architecture system adoption.
Modular Grippers Market
Two complementary market structure signals are worth flagging for strategic clarity. First, concentration metrics show that the market is neither a tight oligopoly nor wholly fragmented — top-three firms do not control the majority of value, and the top-five together still leave substantial share to mid-tier specialists and regional players. Second, recent product and system introductions indicate that vendors are competing as much on software-enabled services, energy efficiency and configurability as on traditional mechanical specifications.
Modular Grippers Market
Why this matters for 2026 decisions
- CapEx and automation roadmaps: With steady growth but meaningful variation across applications, procurement teams must balance selectivity and flexibility. Investing in modular grippers today is not a one-off — it should be part of a platform strategy that prioritizes quick-change tooling, standardized interfaces (mechanical and electrical) and scalable control logic to protect future upgrades.
- Product and R&D prioritization: Innovations that reduce operating power, improve sensor integration and support soft-touch handling are the high-probability winners. Energy-optimized electric and hybrid grippers that operate in the low‑watt range are lowering TCO, making electrification a defensible R&D bet.
- M&A and partnerships: The mid-tier presence in the landscape creates opportunities to bolt on niche capabilities — soft-material fingertips, container-unloading modules, or cloud-based predictive maintenance suites — rather than pursuing broad horizontal consolidation alone.
- Supply chain and compliance: Sourcing strategies must incorporate evolving hygiene and food-grade standards as well as standardization requirements (ISO 9001/14001/45001); compliance failures now create integration frictions for global OEMs.
Report highlights: what the full study delivers
The full PW Consulting Modular Grippers Market report is structured to move quickly from insight to implementation. Key practical assets included are:
- Market sizing and trend maps (historical 2020–2025 and forward projections 2026–2032) with scenario variants tied to raw material volatility and adoption curves.
- Segmentation frameworks (by technology family, by functional configuration, and by application cluster) that identify where premium pricing and margin expansion are achievable. Note: selective segment metrics are illustrative in this preview; detailed split tables and elasticities are available in the complete report.
- Supply chain and procurement playbooks — bill-of-material risk matrices, recommended dual-sourcing approaches, and negotiation levers that reflect certification and compliance constraints.
- Vendor scorecards and decision matrices — an evidence-based framework for OEMs and system integrators to qualify suppliers on interface standards, software APIs, energy performance and aftermarket support.
- Case studies and ROI calculators — validated field deployments showing payback pathways under differing labor and throughput scenarios, enabling site-level capex prioritization.
- Regulatory and materials appendix — practical checklists for food, pharma and cleanroom environments, and guidance on selecting elastomers, silicones and hybrid materials for durability and hygiene.
- Technology roadmaps and scenario planning — mapping likely technology inflection points through 2032 and their consequences for prices, margins and lifecycle support.
Competitive landscape: positioning the key players
The market is populated by specialist OEMs, robotics-focused entrants and automation conglomerates. Our competitive analysis synthesizes public product developments, strategic moves and capability adjacencies to show where each player is investing and how they are likely to compete over the next 18–36 months:
- GIMATIC (Italy) — Strong in electric and pneumatic grippers and end-of-arm tooling (EOAT). Recent product evolution emphasizes higher force density in compact packages, targeting spaces where footprint and force matter.
- Zimmer Group (Germany) — A diversified portfolio across pneumatic, intelligent and electric modules. Their strategic push into cloud analytics and remote monitoring points to an attempt to move up the value chain from components to operational services and predictive maintenance.
- OnRobot (Denmark) — A leader in collaborative robot (cobot) grippers and quick-change integration. Their focus remains on easy-to-deploy, modular solutions that minimize integration time for system integrators.
- DESTACO (United States) — Platform capabilities in teachable electric grippers and sensors show intent to win applications where adaptive force and speed control translate into lower error rates and higher throughput.
- SCHUNK and Festo (Germany) — Both bring broad mechatronics portfolios and strong channel coverage. Festo’s bionic systems and SCHUNK’s sealed and collaborative grippers indicate parallel strategies: industrial-grade performance plus function-rich automation modules.
- Parker Hannifin and WEISS ROBOTICS (United States/Germany) — Positioning is complementary: Parker’s traditional strength in pneumatics and machine tools versus WEISS’s servo-electric and smart pneumatic offerings for precision assembly and life sciences.
- Copal Handling Systems and SoftGripping (Netherlands/Germany) — Niche innovators focusing on modular system integrations (palletizing, container unloading) and soft-material handling respectively. These players are attractive targets for OEMs seeking differentiated end-of-line capabilities or gentleness in handling fragile goods.
Recent product and partnership moves underscore the market’s thrust: compact high-force pneumatic evolutions, modular palletizers that integrate grippers into end-of-line automation, teachable electric grippers, and cloud partnerships enabling predictive maintenance. These developments are symptomatic of a market shifting from component sales to solution-led commercial models.
Market dynamics and risk map
- Materials and sourcing: Elastomers and silicone variants remain central to soft-gripper performance. Manufacturers weighing material choices must balance deformation resilience with hygiene certification timelines.
- Regulation and standards: Updated hygiene standards in Europe and cross-industry certification expectations are increasing time-to-deploy unless certification is pre-baked into product design.
- Energy and efficiency: The push toward electric and hybrid solutions is materially lowering operating power per unit — a competitive differentiator for high-duty cycle lines.
- Labor arbitrage and automation economics: Modular grippers are a high-leverage solution for labor-constrained environments; reconfiguration speed can materially reduce manual handling downtime and accelerate line changeovers.
- Concentration and competition risk: With moderate market concentration, pricing pressure from regional specialists and commoditization risk for basic modules are persistent threats to pure-play suppliers.
Practical next steps for executives in 2026
- Run site-level pilots that prioritize tooling interfaces and control-layer standardization — demand vendors demonstrate plug-and-play changeover in live settings.
- Include energy-performance and software support clauses in procurement contracts to capture TCO benefits over hardware-only bids.
- Target bolt-on acquisitions for fast access to soft-grip technologies or end-of-line integration competencies rather than broad horizontal consolidation.
- Require supplier roadmaps and certification evidence up front; make compliance and lifecycle support material to commercial scoring.
- Adopt the report’s ROI models to stress-test capex plans under conservative and accelerated adoption scenarios.
Methodology and credibility
The full PW Consulting study combines primary interviews with OEMs and system integrators, a verified historical datapool (2020–2025), and scenario-based forecasting to 2032. We triangulate public product disclosures, regulatory updates and verified supplier announcements to construct vendor profiles and scorecards. Our base-year is 2025, and our central forecast assumes current regulatory trends and incremental materials innovation continue without major supply shocks.
How to get the full intelligence
This preview outlines the strategic contours you must factor into 2026 planning. If your objectives include procurement scorecards, fixed-site ROI calculators, detailed segment splits and vendor-ranking spreadsheets, the full report and supporting datasets provide those deliverables — plus a proprietary vendor short-listing tool that links technical KPIs to commercial outcomes. Contact PW Consulting to license the complete Modular Grippers Market report and receive a tailored executive briefing that maps our findings directly to your plant footprints, automation timelines and 3-year investment plans.
For detailed analysis of this topic, please visit the official page: Modular Grippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart TV Market to Reach USD 542.6B by 2032 at 11.9% CAGR
By PW Consulting, 2026-07-08
Smart TVs Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As corporate leaders map their 2026 playbooks, few markets present as many converging opportunities and risks as Smart TVs. Our latest PW Consulting market research — anchored on a 2025 base year and projecting through 2032 — synthesizes five years of historical momentum (2020–2025) with forward-looking scenario analysis to deliver decision-ready insight. The headline: the global Smart TVs market has moved from a sizeable consumer electronics category into a strategic technology frontier, expanding at a compound annual growth rate (CAGR) of 11.9% and more than doubling in scale across our forecast horizon.
Smart TVs Market
Why this research matters for 2026 decision-making
2026 will be a pivot year. Companies face simultaneous pressure from component cost inflation, regulatory change, and intensifying competition at both premium and value tiers. Our brief translates those pressures into three actionable decision levers for 2026 leaders:
Smart TVs Market
- Portfolio prioritization: where to increase R&D and capex to defend margin while capturing growth.
- Supply-chain resilience: tactical levers to mitigate semiconductor and memory price shocks that are already feeding through retail prices.
- Monetization and compliance: how to balance platform-level monetization (ads, subscriptions, services) with new data-rights requirements and cross-border trade frictions.
These levers are grounded in the market’s scale and trajectory. In absolute terms, the Smart TVs market expanded markedly during 2020–2025 and enters 2026 with a materially larger base than a half-decade ago; under our central forecast the sector continues to scale rapidly through 2032. For commercial leaders, that trajectory means the next two years are essential for securing platform positions and establishing upstream supplier relationships that will determine total share and margin performance through the decade.
Smart TVs Market
What the market dynamics tell us
Several macro and micro dynamics are reshaping competition and economics in Smart TVs today:
- Component-cost inflation: TV-specific DRAM surged and flash memory costs doubled in the past year due to demand from AI infrastructure; semiconductor cost escalation is a cross-cutting input pressure. Manufacturers and OEMs must prepare for continued input-price volatility and potential retail-level price adjustments in 2026.
- Regulatory shifts: The EU Data Act (effective 12 September 2025) redefines user control over connected-device data — a direct influence on how Smart TV platforms collect, process, and monetize viewing and usage data. Compliance is both a cost and an opportunity; companies that embed privacy-by-design can differentiate and unlock new B2B services to content partners.
- Trade and tariff noise: Reinstated trade measures on select AV imports in 2025 introduce renewed cross-border cost asymmetries. Firms with globally diversified manufacturing footprints or flexible sourcing will be better positioned to manage margin compression.
- Product innovation cycle: 2026 product announcements from major suppliers underline a bifurcation: premium image- and AI-centric platforms vs. aggressive value plays emphasizing scale and OS partnerships. The pace of portfolio refresh has accelerated, making timing and channel execution more critical.
Competition — what to watch
The Smart TVs market remains concentrated among a small set of global incumbents. Our concentration analysis shows the top three firms control a meaningful majority of the market, with the top five commanding an even larger share. That structure creates a dual reality: incumbents can shape standards and platform economics, while mid-tier challengers can exploit narrow gaps through price-technology arbitrage, channel innovation, and service differentiation.
Key players and strategic pointers (executive snapshot):
- Samsung Electronics (HQ: Seoul, South Korea – https://www.samsung.com/us/): Continues to push premium features and AI integration. Recent 2026 moves include refreshed Neo QLED 4K models, a Mini LED lineup, and the introduction of a platform-level AI companion — signaling a combined hardware-plus-software monetization strategy.
- LG Electronics (HQ: Seoul, South Korea – https://www.lg.com/us/): Sustains leadership in panel innovation and form factor. 2026 announcements highlight RGB Mini LED and OLED variants, which maintain LG’s emphasis on premium display performance and differentiated content experiences.
- Sony Group Corporation (HQ: Tokyo, Japan – https://sony.com/en/): Leverages brand strength and imaging IP to command the premium cinematic segment. Sony’s strategic assets are its content relationships and image-processing prowess — critical as consumers pay a premium for superior visual and audio experiences.
- TCL Electronics (HQ: Huizhou, China – https://us.tcl.com/): Operates as a scale challenger that blends aggressive price positioning with strategic OS partnerships and localized channel playbooks. Ideal for organizations focused on share growth through cost and distribution efficiencies.
- Hisense Group (HQ: Qingdao, China – https://www.hisense.com/): A fast-follower on Mini LED and aggressive US-market product launches (notably the 2026 CES lineup), targeting value-conscious segments while expanding premium variants.
- VIZIO (HQ: Irvine, California, USA – https://www.vizio.com/en/home): Plays a distinctly U.S.-centric role with emphasis on platform-level monetization and an established path-to-market in big-box retail channels.
Recent corporate moves in early 2026 underline these dynamics: Samsung’s 2026 OLED and Mini LED upgrades and platform AI positioning; LG’s RGB Mini LED and OLED pushes; and Hisense’s 2026 U.S. introductions that reinforce the intensifying battle along quality and price vectors. These initiatives will shape channel negotiation, R&D allocation, and co-marketing strategies for the year.
What’s inside the PW Consulting brief (practical deliverables)
Our research is designed as a practical toolkit for executives, with granular modelling and scenario outputs you can deploy directly in your 2026 planning cycle. Highlights include:
- Market sizing and forecasting (2020–2032) with base-year validation and sensitivity bands under alternative macro scenarios.
- Segment-level narratives and growth vectors (by panel technology, application, and region) with downloadable templates to re-run the model under custom assumptions.
- Supplier and input-cost stress test: component-price modelling (DRAM, flash, semiconductors, backlights) and the estimated passthrough to retail pricing under multiple elasticity assumptions.
- Competitive benchmarking and M&A heatmaps: capability overlays that identify likely acquisition targets and partnership fits for incumbents and challengers.
- Commercial playbooks: recommended go-to-market approaches for premium vs. value segments, including channel mixes, subscription strategies, and ad-platform monetization roadmaps.
- Regulatory and data governance checklists aligned to recent rules (e.g., EU Data Act) and practical compliance architectures that minimize user-friction while preserving monetization potential.
- Scenario planning frameworks covering tariff shocks, component scarcity, and rapid platform adoption — each with contingency playbooks and P&L sensitivity impacts.
Note: In keeping with our “trailer” approach, we demonstrate methodological transparency and provide high-level outputs here, while detailed tabular segment data and company-level scorecards are accessible in the full report.
Strategic implications and recommended 90–180 day actions for 2026
Based on the research, PW Consulting recommends an immediate set of prioritized actions to convert market growth into durable advantage within 90–180 days:
- Lock in upstream supply: Negotiate multi-year component agreements with price collars or indexation clauses to manage DRAM/flash volatility; explore strategic inventory buffering for critical SKUs.
- Rebalance portfolios toward value-accretive SKUs: Prioritize product variants that combine differentiated UX (AI-enhanced content discovery), durable hardware features (Mini LED/OLED where appropriate), and service attach points (subscriptions and warranty upsells).
- Operationalize data governance: Implement EU Data Act–aligned consent frameworks and a privacy-first telemetry layer to preserve platform analytics capabilities while minimizing regulatory exposure.
- Price and channel optimization: Run rapid elasticity tests in targeted channels; calibrate promotional intensity against forecasted input-cost passthrough and competitor moves.
- Pursue selective partnerships: Identify content and OS partners that can accelerate user engagement and reduce CAC — focus on integrations that improve retention and ARPU, not only one-off sales.
- Evaluate consolidation opportunities: Given market concentration among the top players, mid-tier firms should prioritize bolt-on targets that fill capability gaps (e.g., AI software, content licensing) and create defensible niches.
Final perspective
The Smart TVs market in 2026 is no longer only about pixels; it is a crossroads of hardware economics, software platforms, regulatory frameworks, and content monetization. For leaders, the central question is how to convert the sector’s robust growth trajectory into a durable, differentiated business model before competitors lock in platform advantages. Our new research provides the data, scenarios, and executable playbooks to inform those choices — from boardroom strategy down to SKU-level margin decisions.
To access the full set of tables, the detailed segmentation matrix, company scorecards, and downloadable modelling templates that underpin the conclusions above, please consult the complete PW Consulting Smart TVs Market report.
For detailed analysis of this topic, please visit the official page: Smart TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prepared Flour Mixes Market to Hit USD 410.3M by 2032, 5.1% CAGR
By PW Consulting, 2026-07-08
Prepared Flour Mixes Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst and senior strategy advisor, I present a concise, actionable introduction to our Prepared Flour Mixes Market study — designed to equip executive teams with the context, strategic levers, and risk signals required to make high-conviction decisions in 2026. This briefing synthesizes the study’s headline macro trajectory, competitive dynamics, regulatory and input-risk environment, and the practical use cases embedded in the full deliverable. It also follows a “preview” principle: we demonstrate analytical depth and proprietary framing while intentionally withholding granular segment tables to invite executive teams to the full report and interactive model for transaction‑grade detail.
Prepared Flour Mixes Market
Why this market matters in 2026
- Resilient growth profile: The prepared flour mixes market has expanded steadily from the start of our historical window (2020) and reached an estimated USD 290 million in our base year (2025). Our forecast model projects continued expansion through 2032, reaching roughly USD 410 million under the central scenario. The implied compound annual growth rate for the forecast window (2026–2032) is 5.1% — a rate that supports both incremental investment and strategic repositioning.
- Moderate consolidation: Market concentration is material. The top three firms account for approximately 55% of market value and the top five about 65%. This level of concentration creates asymmetric advantages for scale players (procurement, distribution, co-manufacturing capacity) while leaving attractive niches for focused innovators and regional specialists.
- Strategic timing: 2026 sits at an inflection where consumer demand dynamics (clean label, convenience, protein fortification) intersect with industrial innovation (enzyme systems, premix technology) and regulatory scrutiny — creating windows for product premiumization, manufacturing partnerships, and selective M&A.
What the full study delivers — practical, transaction-ready assets
The report is built for operators and corporate strategists. It moves beyond descriptive industry coverage into executable outputs you can use in boardrooms and deal rooms:
Prepared Flour Mixes Market
- Market sizing and scenario forecasts: Top‑down and bottom‑up constructs covering 2020–2025 historicals, with detailed, model‑driven projections for 2026–2032. The interactive model allows you to stress test demand under differing macro and input‑price scenarios.
- Segment playbooks: Tactical recommendations for product types, channel priorities, and innovation roadmaps (from formulations to packaging). The report explains commercial approaches tailored to household retail, artisan/commercial bakery customers, and food‑service or industrial accounts.
- Supply‑chain and input risk matrices: Wheat and commodity sensitivity analyses, supplier concentration maps, and recommended hedging or vertical integration strategies to mitigate margin compression during commodity shocks.
- Regulatory and safety risk register: Actionable compliance checklists and recall-incident playbooks aligned to current regulatory frameworks and enforcement trends.
- Competitive and M&A playbook: Valuation benchmarks, capability maps, and a prioritized target-screening methodology calibrated to the market’s concentration dynamics.
Dynamics shaping strategic choices in 2026
- Input volatility and margin pressure: After a notable spike in wheat‑flour prices in 2022, the market saw some price normalization into 2023–2024. That historical volatility underscores the need for dynamic procurement strategies — from indexed purchasing and supplier diversification to selective backward integration in milling and premix manufacturing.
- Product safety & traceability are no longer peripheral: The sector’s exposure was reasserted in early 2026 when a quality incident involving glass fragments was notified through the EU rapid alert system. Such events immediately elevate recall risk, insurance costs, and regulatory scrutiny. Leaders should prioritize upstream quality controls, batch‑level traceability, and crisis communications protocols.
- Regulatory and trade nuances matter for cost-to-serve: Tariff classifications and packaging taxes can materially affect landed costs and private‑label economics. Also, jurisdictional nutritional labeling requirements (notably enforced by the U.S. FDA) influence formulation and marketing claims. Companies that proactively optimize product taxonomy, packaging specifications, and label claims extract measurable margin and go‑to‑market advantages.
- Ingredient and formulation innovation accelerate premiumization: Demand for clean-label, protein‑fortified, and alternative‑flour formulations is driving product launches and supplier R&D. Recent new product introductions leverage pulse-based flours and non‑GMO leavening systems, while industrial players are commercializing enzyme‑enhanced premixes that extend shelf life and improve artisan texture — creating differentiated propositions for both retail and commercial buyers.
Competitive landscape — how to read the players and their moves
The competitive universe spans global ingredient conglomerates, specialty bakers, co‑packers, and regional premix houses. Key strategic archetypes emerge:
Prepared Flour Mixes Market
- Scale incumbents (e.g., global CPG and ingredient majors): These players leverage scale in procurement and distribution, enabling broad national and cross-border reach. Their strategic focus is on portfolio breadth, private‑label manufacturing, and platform upgrades (e.g., clean‑label or high‑protein lines).
- Ingredient and technology specialists: Firms investing in formulation science (enzyme systems, premix consistency) are commercializing capabilities that convert into superior dough performance, longer shelf life, and improved cost-in-use for B2B customers.
- Specialty and heritage brands: These players win on brand authenticity, clean‑label credentials, and consumer trust — particularly in at‑home baking segments and premium artisan categories.
Recent corporate moves crystallize these archetypes into near‑term priorities: packaging refreshes for brand reinvigoration; launches of pulse‑based high‑protein mixes targeting health‑oriented consumers; and rollout of enzyme‑enhanced premix systems that promise operational benefits for artisan bakeries. These are not isolated initiatives — they are tactical responses to the same structural demand signals and margin pressures described above.
Strategic implications and recommended actions for 2026
To translate market opportunity into 2026 results, management teams should prioritize a small set of high‑impact initiatives:
- Portfolio rationalization with dual tracks: accelerate investment in clean‑label and functional mixes (protein, fiber), while streamlining low‑margin SKUs. Use the report’s product‑level price elasticity and cannibalization matrices to rank SKU rationalization candidates.
- Supply‑chain resilience and input management: implement multi‑tier supplier mapping and hedging strategies for key inputs. Consider strategic JV or capacity acquisitions in milling or premix co‑manufacturing to secure margins and reduce lead times under stress scenarios.
- Operationalize safety and recall readiness: upgrade traceability to batch-level visibility, standardize QA across co‑packers, and pre‑approve crisis communications scripts and logistics providers. This is a revenue-protection play as much as a compliance one.
- Commercial segmentation and route‑to‑market optimization: align sales motions to three buyer archetypes — retail private label, artisan/commercial bakeries, and food‑service processors — with differentiated value propositions and pricing strategies for each.
- M&A and partnership playbook: target capabilities that accelerate time‑to‑market for premium formulations, extend distribution access, or consolidate regional manufacturing. The market’s concentration profile indicates attractive scale synergies for well‑timed bolt‑ons.
How executives should use the full report
The full PW Consulting Prepared Flour Mixes Market study is designed as an operational toolkit for the initiatives above. Clients will find:
- An interactive financial model to test demand, price, and input shocks against portfolio scenarios;
- Go‑to‑market playbooks with channel KPIs and salesforce incentives tailored to retail, food‑service, and industrial customers;
- M&A screening criteria and a short‑list of capabilities that materially change unit economics (formulation IP, co‑pack capacity, distribution reach);
- Regulatory checklists and a recall playbook aligned to recent enforcement patterns and product safety incidents.
Closing: Where PW Consulting adds immediate value
In 2026, decisions in the prepared flour mixes sector must balance growth ambitions against elevated operational and regulatory risk. PW Consulting’s study synthesizes robust historical performance (2020–2025), an explicit forecast pathway (2026–2032) with a central 5.1% CAGR in the projection window, and an evidence‑based set of strategic moves that map to deal execution, product development, and supply‑chain resilience.
Our work is intentionally structured to support fast, high‑confidence decisions: a board‑ready strategic memo, scenario templates for CFOs, an M&A playbook for corporate development, and a short operational checklist for manufacturing and QA leaders. For executives seeking the full data tables, segment breakouts, interactive model, and recommended target lists, the complete report and client portal provide the layer of granularity required for transaction execution and operational planning.
Contact PW Consulting to review the interactive model and receive a tailored briefing linking these insights to your 2026 P&L and capital plan.
For detailed analysis of this topic, please visit the official page: Prepared Flour Mixes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
E-cigarette Market to Hit USD 37.84B by 2032 at 5.44% CAGR — PW Consulting
By PW Consulting, 2026-07-08
E‑Cigarette Market 2026: Strategic Imperatives for Leadership — PW Consulting Industry Preview
Between 2020 and 2025 the global e‑cigarette market expanded rapidly, moving from an early adolescent category of roughly USD 18.0 Billion to an established, regulation‑intensive market of approximately USD 26.0 Billion in our 2025 base year. Our forward view through 2032 anticipates continued expansion — the modelling embedded in this study projects a compound annual growth rate (CAGR) of 5.44% across the 2026–2032 forecast window, with total market value approaching the high‑30s (USD Billion) by 2032. For executives making capital, portfolio and go‑to‑market choices in 2026, those headline figures frame two simple truths: the market remains commercially meaningful, and the competitive/regulatory landscape will determine which players capture disproportionate upside.
E-cigarette Market
Why this PW Consulting study is mission‑critical in 2026
- Decisions now determine structural positioning: 2026 is a crossroads year — companies will either deep‑freeze into the incumbent regulatory paradigm or invest to lead product, channel and regulatory outcomes across the next strategic cycle.
- Regulation is the market multiplier: authorization and tax policy shifts are translating into selective market access and variable economics across states and channels. Our report isolates these effects so leaders can move from intuition to quantifiable risk/reward.
- Consolidation is selective: market concentration metrics show meaningful share accumulation among a small set of suppliers, but the category remains open to product and distribution innovation. Understanding where scale matters — and where agility wins — is essential for 2026 resource allocation.
- Operational levers matter more than ever: unit economics, channel mix and tax incidence are now the primary determinants of margin sustainability. The report turns these levers into decision‑grade models for pricing, supply and product choices.
Report contents — practical tools and outputs
Our study is explicitly operational. It does not stop at descriptive analysis; it equips commercial, strategy and regulatory teams with templates, models and playbooks that can be executed in 90–180 day sprints. Highlights include:
E-cigarette Market
- Market sizing and demand model (2020–2032): a transparent, auditable Excel model with scenario toggles (policy, pricing, illicit penetration, adoption curves).
- Regulatory tracker and impact matrix: a state‑by‑state and national map of policy levers (tax, authorized product lists, sales restrictions) with quantified implications for volume, margin and compliance cost.
- Go‑to‑market playbooks by channel: differentiated approaches for national retail, regional chains, specialty vape shops and direct‑to‑consumer, including retailer economics and cooperative promotion models.
- Product portfolio prioritization tool: a scoring framework that layers demand elasticity, regulatory risk, unit cost and commercialization lead time to rank SKUs and R&D investments.
- Commercial scenarios and sensitivity analyses: stress‑test outcomes under tax shocks, accelerated regulation, and fast/slow authorization throughput.
- M&A and inorganic growth screeners: proprietary valuation ranges and integration checklists for bolt‑on plays and platform deals.
- Operational playbook: manufacturing scale options, supplier dual‑sourcing templates and inventory policies tailored to regulatory volatility.
- Stakeholder and lobbying playbook: prioritized engagement plans for regulators, trade groups and retail coalitions to preserve market access.
Market dynamics and strategic implications
Several forces are reshaping the category in 2026 — they are interdependent and require coordinated responses.
E-cigarette Market
- Authorization as market access: As of May 2026, the U.S. Food and Drug Administration has authorized a limited set of e‑cigarette products under the Premarket Tobacco Product Application (PMTA) pathway. These authorized products represent the only lawful retail options in specific markets, creating a two‑tier environment where authorization status directly dictates shelf presence and scale economics. For manufacturers and distributors, the implication is clear: getting to — and staying on — the authorized list is a commercial prerequisite, not a regulatory nicety.
- Taxation and price pressure: Several sub‑national jurisdictions implemented or raised tobacco/nicotine taxes in the 2024–2026 window. These moves compress retail margins, accelerate down‑trading behaviors, and in some cases increase the attractiveness of illicit or noncompliant channels. Pricing strategies, tax pass‑through models and SKU rationalization are now core strategy levers.
- Concentration and contestability: The market shows early signs of consolidation, with a small cohort of large firms controlling a meaningful share of retail‑authorized product supply. However, the category remains contestable by virtue of product innovation (hardware form factors, nicotine formulations), channel disruption and regulatory approvals of new entrants. Companies that combine authorization progress with rapid commercialization capability can outpace incumbents.
- Channel bifurcation: Traditional retail and specialized channels are evolving differently. Chain retailers are prioritizing authorized, compliant product assortments; specialty channels remain a locus for experimentation but face mounting compliance costs. Digital direct channels present opportunity but higher regulatory and enforcement scrutiny.
- Illicit market risk: Tax and access shocks create conditions for illicit supply growth. Firms should model not only lost sales but reputational and compliance spillovers; mitigation requires coordinated industry, retail and enforcement engagement.
Competitive landscape — what leading players teach us
The competitive field includes legacy tobacco incumbents, specialized ENDS manufacturers and emerging independents. Our analysis of key players highlights strategic patterns and risk vectors that are instructive for any market participant planning 2026 moves.
- Glas Inc. — Glas’s recent FDA authorization milestone (May 2026) for multiple ENDS products — including the first authorized fruit‑flavored variants — demonstrates the upside from timely regulatory positioning. Commercial execution following authorization will determine whether the company converts regulatory wins into durable retail and consumer momentum.
- JUUL Labs — As a pioneer with an established device ecosystem, JUUL’s path forward rests on re‑establishing trust with regulators and retailers while aligning offerings to authorized nicotine profiles and adult‑use communication strategies. Brand rehabilitation and compliance-first commercialization are central to its playbook.
- Logic Technology Development LLC — Logic’s modular cartridge and power unit approach underscores the product innovation pathway: flexibility in form factor can accelerate retail adoption, but only if paired with a clear regulatory filing strategy and supply chain resilience.
- NJOY LLC — NJOY’s emphasis on authorized pod systems and adult‑oriented messaging illustrates a defensive play focused on retention of compliant distribution and partnerships with channel gatekeepers.
- R.J. Reynolds Vapor Company (Vuse) — As a legacy tobacco player with scale distribution, Vuse leverages channel muscle and manufacturing depth; its competitive advantage is operational — rapid fulfillment, national retail relationships and portfolio breadth — but it must continue to manage political and regulatory scrutiny.
Across these leaders the pattern is consistent: regulatory approvals are a necessary condition for scale, but market leadership depends on the integration of authorization, commercial speed, channel strategy and cost control.
A pragmatic 2026 strategic playbook
For boards and executive teams, the most valuable actions are those that convert insight into near‑term options. Below is a prioritized set of recommendations derived from our modelling and client engagements.
- Make authorization progress non‑negotiable. Invest in PMTA readiness, post‑authorization surveillance capability and legal/regulatory staffing to reduce time‑to‑shelf and protect continuity of supply.
- Adopt dynamic price management. Build price pass‑through testing into commercial pilots and use localized tax scenarios to optimize SKU assortment by channel and state.
- Prioritize channel concentration where you have margin leverage. Focus resource allocation on channels that reward compliance and scale while maintaining a disciplined experiment budget for specialty and DTC channels.
- Stress‑test the balance sheet for tax and enforcement shocks. Ensure working capital and inventory strategies are aligned to rapid regulatory changes and potential retail delistings.
- Use M&A strategically. Target deals that expand authorized product catalogs, accelerate route‑to‑market in critical states, or provide proprietary manufacturing capacity to control unit cost.
- Operationalize compliance and reputation management. Build real‑time regulatory monitoring, retailer education programs and consumer transparency initiatives into the core operating model.
How PW Consulting’s deliverables unlock 2026 decisions
Clients tell us they value two things above all: clarity and executability. This report delivers both. Our proprietary market model converts macro trajectories (the CAGR and the aggregate market path to 2032) into decision‑grade outputs such as break‑even tax levels by SKU, profit sensitivity to authorization delays, and acquisition valuation bands under multiple regulatory scenarios. The report’s interactive tools let strategy teams run “what‑if” permutations in minutes rather than weeks.
Importantly — and deliberately — this preview is a trailer. We have demonstrated the analytic depth and the strategic framing that matter to 2026 choices without disclosing the granular segment tables, regional share charts, SKU‑level volume forecasts or unit price matrices that operational teams need to implement changes. Those datasets, the full scenario cube and the downloadable model are available in the full PW Consulting E‑Cigarette Market report.
Next steps
For executive teams preparing budgets, capital allocation, M&A screens or regulatory strategies for 2026, the essential step is to convert this directional insight into executable plans. Accessing the full report will provide:
- Granular regional and product‑level forecasts and sensitivities
- Downloadable Excel models and scenario toggles
- Regulatory heatmaps and state‑level tax impact tables
- Commercial playbooks and M&A screening templates
PW Consulting stands ready to help translate these outputs into a three‑to‑six‑month implementation roadmap tailored to your company’s ambition and risk tolerance. In a market where authorization and commercial velocity govern outcomes, the difference between a missed opportunity and market leadership is the speed at which insight becomes action.
For detailed analysis of this topic, please visit the official page: E-cigarette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


