



Category: market research
PW Consulting Predicts Material Handling Robotics Market to Soar at 15.01% CAGR, Driving Next‑Gen Warehouse Automation
By PW Consulting, 2026-07-07
Material Handling Robotics Market 2026: A Strategic Preview for Executive Decision‑Making
PW Consulting’s latest Material Handling Robotics Market Research provides senior executives, operations leaders, and investment committees with the strategic intelligence required to make high‑stakes automation decisions in 2026. This release is a curated preview designed to convey the report’s analytical depth, practical utility, and near‑term implications — while preserving the detailed segment intelligence that makes the full report a must‑read for teams preparing capital allocation, pilot programs, or M&A activity this year.
Material Handling Robotics Market Research
Big Picture: Why 2026 Is a Pivotal Year
The robotics-driven automation market for material handling has moved from episodic investment into sustained adoption. PW Consulting’s base‑year assessment (2025) places total market size well into the multi‑billion USD range, and our seven‑year forecast shows persistent expansion through 2032 at a compounded annual growth rate of 15.01%. In practical terms, organizations that align strategy and budget cycles to this growth trajectory can capture outsized productivity gains, reduce exposure to labor volatility, and secure long‑term cost efficiencies.
Material Handling Robotics Market Research
- Growth trajectory: Substantial year‑on‑year expansion through the 2026–2032 forecast window underscores both the scale and urgency of decisions facing manufacturers, logistics providers, and 3PLs.
- Market structure: The market exhibits a moderate level of concentration (CR3 ≈ 38.5%, CR5 ≈ 52.1%), meaning leading global suppliers remain highly influential, but room exists for specialized and regional challengers — particularly in software, system integration, and AMR niches.
- Decision cadence: 2026 is the inflection point for organizations moving from demonstrator pilots to multi‑site rollouts; this report is built to inform both tactical deployments and portfolio strategies.
Core Dynamics Shaping 2026 Decisions
- Labor and productivity pressures: Persistent skilled labor shortages and wage inflation are accelerating ROI timelines for automation investments. The immediate consequence is shorter payback expectations and higher tolerance for upfront capital when paired with measurable throughput gains.
- E‑commerce and fulfillment complexity: Continued e‑commerce expansion raises demand for flexible, goods‑to‑person and goods‑to‑robot flows, favoring modular AMR and integrated robotic solutions that can adapt to SKU proliferation.
- Regulatory and interoperability expectations: Industry 4.0 policies and safety standards are crystallizing interoperability requirements, pushing suppliers to offer modular, standards‑based solutions and certified safety toolchains.
- Input cost sensitivity: High‑grade steel and advanced polymers remain meaningful contributors to production cost—our supply‑side sensitivity analysis shows these inputs account for roughly a quarter to a third of manufacturing cost in automated handling equipment, making procurement strategy and supplier diversification important risk levers.
What the Report Contains — Practical Tools for 2026 Execution
This report is intentionally operational. Beyond headline forecasts, PW Consulting delivers tools and playbooks designed to be used in boardrooms and on factory floors:
Material Handling Robotics Market Research
- Proprietary market forecasting model with scenario ranges to stress‑test capital plans under differing macro and demand assumptions for 2026 decision cycles.
- Vendor benchmarking framework and procurement scorecards that evaluate technology fit, total cost of ownership, service economics, and software openness.
- Deployment playbooks: phased pilot templates, KPI definitions, and scale‑up roadmaps that translate proof‑of‑concept outcomes into enterprise rollouts.
- TCO and ROI calculators tailored to AMRs, articulated robots, cobots, and integrated systems — enabling side‑by‑side comparisons under realistic labor and throughput assumptions.
- Risk and resilience matrices addressing supply‑chain disruption, raw material inflation, and component lead times — with mitigation guidance for procurement and inventory strategy.
- Regulatory compliance checklists and safety integration guidelines that align with cross‑jurisdictional standards and industry best practices.
- Case studies and vendor negotiation playbooks that capture lessons from large scale implementations across manufacturing and logistics.
Competitive Landscape: Strategic Profiles and Market Moves
The Material Handling Robotics ecosystem blends established industrial OEMs with software‑centric AMR pioneers and systems integrators. Executives must evaluate partners across three dimensions: product breadth, solutionization capability (hardware + software + service), and go‑to‑market agility. Below are distilled strategic notes on core players covered in the report.
- FANUC Corporation (Japan) — A stalwart in articulated robotics and palletizing systems. FANUC’s strengths remain mechanical reliability and global service footprint; strategic differentiation will come from expanding digital services and lifecycle monetization.
- ABB Robotics (Switzerland) — Focused on flexible automation and integrated intralogistics. ABB’s advantage is system integration capability across warehousing and production; look for increased emphasis on software platforms to bind solutions.
- KUKA AG (Germany) — Provider of robotic arms and AMR lines. KUKA’s competitive posture centers on integrated internal transport and production automation, with product roadmap moves aimed at tighter fleet orchestration.
- Yaskawa Electric (Motoman, Japan) — Optimized industrial robots for high‑speed material handling. Expect continued focus on throughput performance and specialized end‑effectors for complex picking tasks.
- Kawasaki Heavy Industries (Japan) — Heavy payload robotic systems and automated loading solutions. Kawasaki’s position is strong in high payload applications and heavy industry transitions to automation.
- Daifuku Co., Ltd. (Japan) — Integrated intralogistics systems combining conveyors, AGVs/AMRs, and robotics. Daifuku’s systems strength makes them a preferred partner for turnkey warehouse modernization.
- SSI SCHAEFER (Germany) — Known for highly integrated picking, sorting, and storage automation; excels in large‑scale fulfillment systems backed by strong project execution capabilities.
- Dematic (KION Group, Germany/USA) — Offers AS/RS, AGV/AMR fleets and robotic sortation; strategic moves include closer software integration and service-led offerings for long‑tail customers.
- Stäubli International (Switzerland) — High‑precision robots for cleanroom and industrial contexts; positioned strongly in pharmaceutical and electronics handling where precision and certification matter.
- Jungheinrich AG (Germany) — Combines traditional material handling equipment with automated guided vehicles; diversified channel and aftermarket presence are competitive strengths.
- Honeywell Intelligrated (USA) — Integrated solutions for distribution centers combining conveyors, sortation, and robotics; emphasizes software orchestration and lifecycle services.
- Toyota Material Handling (Japan) — AGVs and integrated robotic solutions paired with strong logistics vehicle platforms; supply chain trust and service networks remain compelling.
- Geek+ (China) — AMR and goods‑to‑person systems with rapid ROI propositions; competitive in high‑velocity e‑commerce deployments and markets prioritizing speed to scale.
- OTTO Motors / Clearpath (Canada) — Focused on industrial AMRs for production logistics; strength lies in vehicle autonomy, safety stacks, and fleet orchestration.
- Seegrid Corporation (USA) — Vision‑guided AMRs that reduce infrastructure burden; attractive to manufacturers seeking flexible, non‑fixed transport automation.
Recent industry activity underscores these trends. MODEX 2026 showcased new AMR and robotic innovations from major OEMs and challengers alike, while product updates from AMR specialists highlighted smarter autonomy and safety improvements — signals that 2026 will emphasize software‑driven differentiation and rapid field upgrades.
Strategic Playbook: Five Priority Actions for 2026
- Prioritize modularity: Opt for architectures that allow incremental expansion of robotic fleets and integration points — this reduces obsolescence risk and supports future interoperability.
- Design pilots with scale in mind: Embed quantifiable KPIs and success thresholds into pilots so that positive outcomes can translate rapidly into enterprise rollouts.
- Assess suppliers on software and service economics: Beyond unit cost, evaluate vendor roadmaps for fleet orchestration software, OTA updates, and lifecycle service economics.
- Mitigate input‑cost risk: Build procurement hedges and multi‑sourcing strategies for critical components and raw materials that influence equipment cost and lead times.
- Invest in change management: Pair technology deployments with workforce reskilling and safety training; this protects productivity during transition and accelerates adoption.
Why PW Consulting’s Report Is Tactical for 2026
Executives need more than high‑level forecasts; they need implementable decisions that reduce execution risk. PW Consulting’s Material Handling Robotics report combines rigorous macro forecasting (with a clear base year and multi‑scenario outlook) and hands‑on playbooks designed for 2026 procurement cycles, CAPEX requests, and operational transformation programs.
This preview outlines the report’s strategic value without disclosing the granular segmentation data that drives vendor selection and site‑level decisions. The full report contains the detailed regional and application splits, supplier share dynamics, and downloadable financial models that organizations use to finalize 2026 budgets and supplier contracts.
Next Steps
For boards, COOs, and supply chain leaders preparing for 2026, the recommended next step is a focused read‑out session of the full PW Consulting report. That session will translate the report’s near‑term forecasts, vendor benchmarks, and deployment templates into a prioritized action plan tailored to your asset base, revenue model, and risk appetite.
PW Consulting stands ready to lead tailored workshops, provide vendor selection support, and run live ROI modeling for pilot and multi‑site rollout programs. The strategic window for action is now — informed choices in 2026 will define operational cost structures and service capabilities for the decade ahead.
For detailed analysis of this topic, please visit the official page: Material Handling Robotics Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antirusting (Anti‑Rust) Agents Market Poised for 5.28% CAGR, New Insights Reveal
By PW Consulting, 2026-07-07
Antirusting Anti Rust Agents Market — 2026 Strategic Outlook from PW Consulting
PW Consulting’s latest market research brief on Antirusting Anti Rust Agents provides a focused, decision-grade vantage point for corporate leaders planning for 2026. The global market reached an estimated USD 5,460 million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 5.28% over the 2026–2032 forecast window, approaching roughly USD 7,827 million by 2032. This release articulates the implications of that trajectory for procurement, product strategy, regulatory compliance and M&A, while preserving the detailed segment-level revenue matrices for subscribers and clients who require full, auditable datasets.
Antirusting Anti Rust Agents Market
Why this report matters for 2026 decision-makers
2026 will be a pivotal year for companies operating in corrosion protection and related chemistries. Macro growth is steady but nuanced: durable industrial demand continues to underpin the market while regulatory and raw-material pressures reshape cost, composition and go-to-market calculus. Executives need a roadmap that translates top-line growth into product roadmaps, supply-chain hedges and disciplined inorganic-growth screening. PW Consulting’s report converts raw market sizing into operational playbooks — enabling procurement teams to stress-test supplier contracts, enabling R&D leaders to prioritize low-risk formulations, and enabling strategy teams to pinpoint consolidation targets that improve scale in critical subsegments.
Antirusting Anti Rust Agents Market
Key takeaways (select highlights)
-
Measured, resilient growth: The market’s projected mid-single-digit CAGR reflects a blend of replacement and new-build demand across heavy industry, transportation and infrastructure. Growth is broad-based rather than concentrated in a single cyclical segment.
Antirusting Anti Rust Agents Market -
Moderate concentration, active opportunity set: The market exhibits modest concentration at the top — a meaningful number of specialist players coexist with large chemical multinationals. That structure creates attractive opportunities for targeted consolidation and technology partnerships to capture scale benefits.
-
Formulation shift and sustainability premium: Demand is migrating toward lower-VOC and water-compatible chemistries, accelerated by customer sustainability mandates and region-specific regulations. Vapor phase inhibitors and silane-based pretreatments are gaining traction as complementary approaches, particularly where hazardous-substance restrictions apply.
-
Regulatory and disclosure headwinds: Evolving EU and U.S. rules on certain phosphate uses and PFAS disclosure are already shaping product roadmaps and supplier qualification processes. Proactive compliance and substitution strategies are therefore essential to avoid business disruption.
-
Input-cost sensitivity is real: Oil-linked feedstocks and key amines have shown price volatility; firms without robust raw-material hedging or formulation flexibility risk margin erosion in short cycles.
Competitive landscape: how the leaders are positioning
The Antirusting Anti Rust Agents market blends global chemical majors with specialty-house innovators. Our report profiles the strategic posture of the principal players and synthesizes capability gaps that are meaningful to acquirers, joint-venture partners and procurement teams.
-
BASF SE (Ludwigshafen, Germany) — Leveraging broad industrial coatings and additive expertise, BASF’s inhibitor platforms are integrated into larger process-chemicals portfolios. Their scale allows cross-selling into adjacent feedstocks and pretreatment chemistries.
-
Henkel AG & Co. KGaA (Düsseldorf, Germany) — Henkel is actively expanding low-VOC rust preventive offerings and demonstrated this at industry shows with an emphasis on manufacturing line compatibility and environmental compliance.
-
Akzo Nobel N.V. (Amsterdam, Netherlands) — Akzo’s strength is in surface coatings and primers; anti-corrosive agents are folded into comprehensive protective systems for marine and heavy-industry customers.
-
The Lubrizol Corporation (Wickliffe, Ohio, USA) — A key developer of additives and industrial lubricant inhibitors, Lubrizol focuses on performance chemistries tailored to metalworking fluids and high-temperature applications.
-
Clariant AG (Muttenz, Switzerland) — Clariant’s synthetic and oil-based rust-preventive lines target machining and storage markets where long-term film properties matter.
-
Cortec Corporation (St. Paul, Minnesota, USA) — A specialty house for VpCI (Vapor phase Corrosion Inhibitor) technologies, Cortec is notable for packaging and storage protection innovations and recent water-based product introductions.
-
Quaker Houghton (Conshohocken, Pennsylvania, USA) — Integrating rust preventives into process fluids is a differentiator for Quaker Houghton; recent certification updates bolster their environmental and operational credentials.
-
Other specialist players — Regional and niche-focused companies (e.g., McGean, Daubert Chemical, Petrofer, Evonik, Lanxess) offer differentiated chemistries and channel relationships that are attractive targets for buyers seeking product-line extension or regional scale.
Our competitive analysis synthesizes R&D pipelines, manufacturing footprint risk, patent positions, and commercial go-to-market models. We score each firm on technical depth, regulatory readiness and M&A fit — an approach that speeds target shortlisting in active processes.
Market dynamics and downside scenarios
-
Raw-material pressure: Brent crude movements and feedstock pricing materially influence margins for oil-soluble inhibitors; key intermediates such as amines have shown volatile spot-price behavior.
-
Regulatory tightening: Restrictions under regional chemical regulations and new disclosure rules for fluorinated substances create reformulation risk and potential phase-outs for legacy products.
-
Trade policy and tariffs: Trade actions that impose duties on specific organic chemicals can increase landed costs for formulators who depend on cross-border raw-material sourcing.
-
Substitution and digitalization: Advances in coating technologies, combined with more stringent asset-maintenance analytics, are changing where and how rust protection is applied — shifting some value from consumables to system-level solutions.
To help clients stress-test exposure, our report includes scenario models that combine input-cost shocks, regulatory timelines and end-market demand cycles. These allow CFOs and strategy teams to quantify margin and cash-flow impacts under plausible 12–36 month disruptions.
What the report delivers: practical, operational tools
Beyond narrative insight, PW Consulting’s deliverables are explicitly built for action. The package includes:
-
Transparent market-sizing methodology and growth drivers, with audited historicals and three forecast scenarios (conservative, base, upside).
-
Supplier and technology heat maps highlighting manufacturing location risk, formulation exclusivities and patent cliffs.
-
Regulatory-compliance matrix tying regional rules to formulation implications and time-to-substitute estimates.
-
Raw-material sensitivity analysis and hedging playbooks that translate commodity moves into unit-margin impacts.
-
Go-to-market frameworks for product segmentation, pricing archetypes and channel optimization for B2B buyers.
-
M&A target-scoring templates and integration risk checklists designed for private-equity sponsors and corporate development teams.
-
Commercial diligence appendices: customer interview summaries, procurement scorecards and sample RFP language for supply contracts.
How executives should use this intelligence in 2026
-
Procurement leaders — Use the raw-material sensitivity and supplier heat maps to renegotiate contracts, diversify feedstock sources, and implement tiered pricing triggers tied to commodity indices.
-
Product and R&D heads — Prioritize low-VOC and water-compatible formulations where market pull and regulatory timelines overlap; accelerate bench-to-commercial timelines for silane- and VpCI-based options in priority verticals.
-
Strategy and corporate development — Apply our M&A scoring to shortlist targets that add complementary chemistries or regional footprint; use the integration checklists to quantify synergy capture prospects.
-
Compliance and sustainability teams — Align reformulation roadmaps with anticipated REACH and U.S. reporting requirements; proactively engage customers with transition guidance to protect long-term revenues.
About the withheld detail — why a deeper download is essential
In keeping with a “trailer” approach, this release surfaces the analytic architecture and executive implications but intentionally omits the granular segment-by-region revenue tables and the detailed application-level breakdowns that many commercial decisions require. The report contains those datasets, including downloadable spreadsheets, audited supplier lists, and deal-ready valuation comparables. For teams evaluating procurement contracts, bidding on supply agreements, or pursuing M&A, access to the full annexes is a practical necessity — the high-level insights here indicate where to look; the subscriber materials show precisely how much.
Next steps and how to access full intelligence
PW Consulting is making a limited number of executive briefings available in Q1–Q2 2026 to discuss bespoke scenarios, supplier risk workshops and M&A target screening based on the full dataset. For access to the complete report, supporting spreadsheets and an invitation to a private briefing, please consult the PW Consulting markets portal. We recommend early engagement: with evolving regulatory timelines and raw-material volatility, the decisions made in the next six to twelve months will materially affect competitive positioning through the end of the decade.
PW Consulting’s Antirusting Anti Rust Agents Market study bridges market-scale forecasting with execution-level tools — enabling leaders to convert market growth into defensible margin and sustainable product portfolios while navigating the increasingly complex regulatory and commodity landscape.
For detailed analysis of this topic, please visit the official page: Antirusting Anti Rust Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bypass Filter Market to Rise from USD 485.6 Million in 2025 to USD 688.78 Million by 2032 at a 5.12% CAGR, Led by Asia-Pacific (USD 172.66M)
By PW Consulting, 2026-07-07
PW Consulting Releases Strategic Brief: Bypass Filter Market Outlook to 2032 — What Executives Must Know for 2026
PW Consulting today publishes a forward-looking strategic brief accompanying our full Bypass Filter Market research report (base year 2025, forecast 2026–2032). The brief synthesizes near-term inflection points, competitive positioning, and pragmatic decision frameworks that corporate leaders, procurement chiefs, and product strategists must apply in 2026 to capture value in a market that is expanding steadily yet varies dramatically by technology, channel and regulation.
Bypass Filter Market
Market snapshot — disciplined growth, concentrated opportunity
The bypass filter market has demonstrated resilient expansion across the 2020–2025 historical window and enters the forecast period with healthy momentum. In nominal USD terms the market increased materially from the early 2020s through 2025, and our modelling projects continued growth across 2026–2032 at a compound annual growth rate (CAGR) of 5.12%. By 2032 PW Consulting forecasts the market to be meaningfully larger than its 2025 baseline, reflecting steady replacement demand, aftermarket upgrades, and selective OEM adoption.
Bypass Filter Market
Concentration metrics indicate a market that is neither a pure commodity nor tightly monopolised — the top three firms control a significant share, and the top five consolidate more than half of industry revenue. That structure creates both competitive pressure and white-space opportunities: scale matters for distribution and OEM programs, while specialised engineering and aftermarket service models create defensible niche positions.
Bypass Filter Market
Why this matters for 2026 decision cycles
- Procurement and total cost of ownership (TCO): Buyers evaluating maintenance strategies in 2026 must recalibrate TCO models to include extended oil drain intervals, particulate capture performance to sub‑micron levels, and the indirect benefits of reduced unscheduled downtime. Our report shows evidence of oil-drain-extension benefits reaching multiple times current intervals in specific marine and industrial applications — a datapoint that should materially affect lifecycle costing and spare‑parts strategies.
- Channel strategy for manufacturers: OEMs and filter manufacturers must decide where to invest between integrated original-equipment contracts, aftermarket dealer networks, and digital-enabled service offerings. The mid‑market and specialist OEMs remain particularly receptive to packaged service agreements that combine physical filters with monitoring and replacement programs.
- Regulatory and compliance risk: Recent rules targeting diesel emissions systems have direct implications for product development and go‑to‑market. A regulatory action of note finalized CARB requirements that disallow bypass devices in verified diesel particulate filter (DPF) emission control systems — a specificity that requires companies to refine product claims, compliance pathways, and customer education so they can avoid being withdrawn or restricted in key segments.
- R&D prioritisation: Advances in media science (microfiberglass and engineered polymer matrices), and the growing availability of centrifugal and remote-monitored bypass technologies, mean R&D budgets should be split between filtration efficiency gains, modularity, and systems integration rather than one-off efficiency claims.
What’s inside the full PW Consulting report (practical, executable content)
We designed the report as an operator’s playbook. It is not a mere collection of historic sales tables; instead, it delivers a linked set of decision tools and evidence-based recommendations executives can action in 2026:
- Scenario-based revenue models (base, upside, downside) calibrated to a 2026 decision horizon, showing where investment returns compress or expand under different adoption and regulatory outcomes.
- Supplier due‑diligence templates that map technical claims (micron ratings, removal efficiency at specific particle classes) to warranty exposure, spare-part logistics, and service-level agreements.
- Procurement negotiation playbook for aftermarket and OEM contracts, including standard KPIs to write into multi‑year supply agreements (e.g., validated cleanliness targets, service response times, and performance warranties tied to lubricant life extension).
- Technology adoption roadmaps with estimated payback windows for centrifugal, depth-media, and spin-on bypass approaches — including a checklist for integrating remote monitoring and condition-based maintenance systems.
- Regulatory impact matrix that converts regional regulatory trends into actionable product and sales decisions — designed to be used by legal, compliance, and product teams working together.
- Investment and M&A screening tool keyed to market concentration dynamics and financial return thresholds that PW Consulting uses internally when advising strategic buyers.
Because this brief follows the “trailer” principle, the full report preserves granular segmentation and financial models behind a subscriber access wall. Executives who need the detailed segmentation and the datasets underpinning the scenarios will find them on the PW Consulting report page.
Competitive landscape — who shapes the agenda
Our analysis highlights a diverse competitive set spanning global filtration conglomerates, specialist bypass system manufacturers, and newer entrants combining filtration hardware with electronics and services. Key firms profiled in the report include:
- Donaldson Company, Inc. — A long-established filtration leader offering bypass cartridges and systems across industrial and lubrication use cases, with deep channel reach and aftermarket capabilities. ( https://www.donaldson.com)
- Parker Hannifin Corporation — Offers hydraulic and industrial bypass solutions including return-line and partial-flow architectures, well positioned in mobile and industrial equipment markets. ( https://www.parker.com)
- HYDAC International GmbH — Known for hydraulic and lubricating oil bypass systems designed to meet high cleanliness targets; a useful benchmark for compliance-driven product design. ( https://www.hydac.com)
- Filtration Solutions Worldwide (FS-2500) — Specialist bypass oil filter systems with claims of high micron efficiency, often targeting marine and heavy industrial applications. ( https://fs2500.com)
- IOW Group — An example of a technology-focused player moving into remote monitoring and centrifuge innovations; recent case trials and trade show activity demonstrate market appetite for higher‑value solutions. ( https://www.iowgroup.com)
- Other notable players: Collins Product Company, Gulf Coast Filters, Kleenoil USA, puraDYN, STAUFF, C.C. Jensen, Mann+Hummel, Frantz Filters/Hot Shot’s Secret — each occupies differentiated niches from centrifugal bowls to spin-on retrofit kits and industrial offline systems.
PW Consulting’s competitive teardown assesses each supplier across engineering differentiation, service model maturity, channel breadth, and regulatory exposure. The report’s companion vendor scorecard can be used in RFP shortlists and vendor consolidation programs.
Regulatory, standards and materials — dynamics that alter product strategy
- Regulation: The CARB clarification prohibiting bypass devices within verified DPF systems is a precise but potent reminder that device-level claims and system-level compliance are not interchangeable. Manufacturers must avoid overbroad claims and design product families that can be certified separately from emission control devices.
- Standards and cleanliness targets: HYDAC and other suppliers cite the practical application of ISO 4406 cleanliness classes as a deployment objective for hydraulic and lubricating oil systems. Achieving these targets often requires bypass solutions that operate independently from main flow, avoiding pulsation and preserving system stability.
- Materials: Filter media selection — polyester, polypropylene, and microfiberglass among them — directly affects both performance at fine micron ratings and lifecycle cost. Sourcing strategies for media and adhesive chemistries should therefore be integrated into supplier negotiations.
- Operational impact: Field evidence highlights that bypass filtration can extend oil drain intervals significantly in marine and industrial diesel applications by removing particles down to 1 micron — a factor that drives the strongest near-term ROI cases for retrofits.
Actionable recommendations for 2026
- Re‑baseline maintenance economics now: Update maintenance and lubrication strategies to incorporate extended oil‑life scenarios. Run pilot programs on at least two platforms (one mobile, one stationary) to validate vendor claims before scaling.
- Segment your go‑to‑market: Pursue a two-track approach: (1) high-value OEM partnerships with integrated services for fleets and large industrial accounts; (2) a retrofit/aftermarket play leveraging dealer networks and digital monitoring to capture replacement and service revenues.
- Mitigate regulatory exposure: Conduct a rapid legal-product review to ensure product claims and installation recommendations do not contravene localized emission control verifications (e.g., CARB). Adjust marketing and certification strategies accordingly.
- Invest selectively in data and monitoring: Remote condition monitoring accelerates aftermarket service revenue and reduces warranty risk. Prioritise sensor-enabled pilot deployments where uptime value is highest and logistics complexity justifies higher service pricing.
- Use M&A and strategic alliances thoughtfully: Given the moderate concentration, bolt-on acquisitions of specialized suppliers or exclusive distribution agreements can quickly change competitive dynamics — but ensure integration plans protect technical know‑how and channel relationships.
How PW Consulting can help
Our full Bypass Filter Market report contains the granular segmentation, vendor scorecards, priced scenarios, and data tables that corporate teams need to translate the high-level insights above into procurement decisions, P&L forecasts, and R&D roadmaps. The brief you are reading is an executive preview designed to clarify the strategic value of the dataset while preserving the detailed models behind a consultative engagement or purchased report.
For licensing the dataset, bespoke scenario modelling, or to receive the full report and vendor scorecard, please visit the PW Consulting research portal where you will find ordering and contact instructions. Our analysts remain available for rapid advisory sessions to support 2026 planning cycles.
PW Consulting’s Bypass Filter Market brief equips decision-makers with an evidence-backed framework for action: identify high-payback pilots, align product messaging with evolving compliance regimes, and structure supplier relationships to capture aftermarket value as this market steadily expands through the early 2030s.
For detailed analysis of this topic, please visit the official page: Bypass Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts DC Motor Governor Market to Grow at a 5.92% CAGR Through 2032
By PW Consulting, 2026-07-07
Dc Motor Governor Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
PW Consulting’s latest Dc Motor Governor Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—translates rigorous market modeling into decision-ready guidance for executives planning product, channel, M&A, and regulatory strategies in 2026. Our analysis traces the market’s evolution across six historical years, quantifies a steady growth trajectory, and translates that trajectory into pragmatic actions firms can use to prioritize investment, optimize portfolios, and preempt supply‑chain and regulatory shocks.
Dc Motor Governor Market
Why this study matters for 2026 decision cycles
The market for dc motor governors has demonstrated resilient expansion over the last half‑decade, rising from approximately USD 512 million in 2020 to about USD 682 million by 2025. Our bottom‑up forecast indicates continued expansion through 2032—approaching the USD 1.02 billion mark—supported by a modeled compound annual growth rate of roughly 5.9% for the forecast window. For executives, that trajectory matters because it reframes resource allocation: growth is meaningful but not hyper‑exponential, favoring strategic investments that improve margin capture, lifecycle services, and embedded controls rather than pure volume plays alone.
Dc Motor Governor Market
- Time horizon alignment: 2026 is a pivotal planning year for capital projects and new product launches informed by multi‑year returns.
- Margin focus: Moderate CAGR implies winners will be those who differentiate on performance, integration, and total cost of ownership (TCO) rather than competing solely on price.
- Risk management: Supply‑chain and regulatory dynamics will shape supplier selection, design choices, and aftermarket strategies.
What the report delivers: practical, executable outputs
PW Consulting intentionally designed this study as an operator’s playbook rather than an academic overview. Key deliverables include:
Dc Motor Governor Market
- Validated market sizing and trend curves (2020–2025 historical; 2026–2032 forecast) with sensitivity bands and scenario variants tied to macroeconomic and regulatory permutations.
- A strategic segmentation framework that maps product architectures (legacy power‑electronics governors, advanced PWM controllers, and emerging digital/intelligent governors) to application archetypes, buyer priorities, and margin pools—presented as decision matrices for product, channel, and service strategies.
- Competitive benchmarking tools: feature‑function comparative matrices, go‑to‑market archetypes, and vendor capability heatmaps that support supplier selection and partnership decisions.
- Investment decision heuristics: prioritized project scorecards and 3‑year roll‑rate models to evaluate R&D, manufacturing scale, and aftermarket service expansion.
- Supply‑chain and materials playbooks: risk ladders for semiconductor and passive component exposure, plus conditional mitigation options (dual‑sourcing, design modularity, inventory hedging triggers).
- Regulatory impact templates that translate energy‑efficiency rules and testing protocols into product spec adjustments and compliance timelines.
Market dynamics shaping tactical moves in 2026
Three high‑level forces will disproportionately influence results in 2026 and beyond:
- Industrial automation and energy‑efficiency imperatives. Continued investment in machine digitization and mandates to improve motor efficiency are expanding demand for precision speed governors that reduce energy consumption and enable predictive maintenance.
- Regulatory tightening. Recent updates to small motor energy conservation standards—particularly actions originating from major energy jurisdictions—are accelerating design cycles and creating compliance as a market entry requirement rather than a differentiator.
- Component supply dynamics. Power electronics and semiconductor supply conditions—and their price volatility—remain a significant determinant of cost structure and time to market. Design strategies that reduce semiconductor depth or enable alternate sourcing improve resilience.
Competitive landscape: what incumbent and niche players need to know
The Dc Motor Governor space remains fragmented, with a mix of global industrial incumbents, specialist drive manufacturers, and regional OEMs. Our competitive analysis focuses on strategic positioning—product depth, channel reach, and innovation orientation—rather than attempting to compress market share tables into a single metric. Highlights of representative players covered in the report include:
- ABB (Zurich, Switzerland) — Known for its DCS800 industrial DC drive family, ABB’s offering emphasizes heavy‑duty capabilities and high field‑current options for demanding industrial applications. ABB’s global service footprint and systems integration expertise make it a primary partner for large end‑users seeking turnkey modernization.
- Sprint Electric (Arundel, United Kingdom) — Specializes in compact digital and analogue DC drives (e.g., PL/X series), prized for straightforward installation and dependable performance in hoists, cranes, and mid‑tier process equipment. Sprint’s approach caters to customers prioritizing simplicity and rapid deployment.
- American Control Electronics / Minarik Drives (South Beloit, IL, USA) — A U.S. specialist focused on industrial and automation markets with a breadth of electronic speed controllers and application‑specific solutions, particularly in retrofit and service‑oriented opportunities.
- Parker Hannifin (USA) — Building on the SSD Drives and Eurotherm legacy, Parker’s DC drive offerings target variable speed needs in OEM and process contexts where integration with motion control systems is critical.
- China‑based OEMs (e.g., DZ Gear Motors; C‑lin) — Regional manufacturers that provide cost‑competitive DC governor solutions across a range of power ratings and are often selected for price‑sensitive or localized supply strategies.
Recent market moves underline different strategic postures. Sprint Electric has actively highlighted its PL/X series and is showcasing these drives in industry exhibitions in 2026—signals that emphasize field sales and channel engagement for incremental share gains. ABB’s product updates continue to broaden high‑current options, reinforcing its platform strategy for heavy industrial modernization.
Strategic playbook for executive teams (prioritized actions for 2026)
Translating market signals into a set of prioritized, executable steps is the core utility of our study. For 2026 planning, companies should consider the following tactical agenda:
- Refocus R&D on TCO and systems integration: Prioritize features that drive measurable energy savings, reduce installation complexity, and smooth integration with PLC/SCADA stacks.
- Embed services early: Develop retrofit and aftermarket bundles—installation, calibration, predictive maintenance—that expand lifetime value and defend against commoditization.
- Re‑examine sourcing strategies: Validate dual‑sourcing for critical semiconductors, adopt modular power‑electronics architectures, and identify qualified regional suppliers to shorten lead times.
- Pursue targeted partnerships: For companies lacking systems integration scale, partner with drives incumbents or system integrators rather than attempting full stack development internally.
- Use regulatory timelines as margin opportunities: Turn compliance investments into commercial arguments—sell lower lifecycle costs and compliance assurance as premium features.
Risk watchlist: early warning indicators
The report provides a concise risk dashboard that executives can monitor with monthly or quarterly cadence:
- Sudden semiconductor allocation changes from major foundries.
- Shifts in energy policy or test‑method updates that change compliance thresholds.
- Rapid adoption of permanent‑magnet motor systems or alternative control architectures that reduce the addressable base for traditional dc governors.
- Price erosion in specific channels due to aggressive regional OEM campaigns.
How to use this research in boardroom and operating plans
Our study is structured to inform both strategic board discussions and operational planning cycles. Use the report to:
- Build three‑year roadmaps with quantified revenue and margin scenarios under conservative, base, and optimistic paths.
- Prioritize capex and R&D by ranking projects via the report’s impact vs. effort matrices.
- Inform M&A screening by applying the competitive heatmaps to target the most accretive capabilities—digital governors, retrofit services, or regional channel control.
- Structure supply‑chain contracts and inventory policies around the mitigation playbook to reduce the probability of disruption.
Next steps and obtaining the full intelligence
This article provides a strategic preview—designed to equip executive teams with the framing and urgency to act in 2026. The full PW Consulting Dc Motor Governor Market report contains the granular analytics, proprietary scenario models, competitive scorecards, and implementation templates required to operationalize these insights. To preserve competitive benefit for subscribing clients, the report omits no operational detail in the full version, including downloadable financial models and supplier assessment templates.
For teams preparing budgets, R&D roadmaps, channel strategies, or M&A screens in 2026, the full report delivers the tools you will use in your planning sessions. Visit our report landing page to review the table of contents, sample exhibits, and subscription options; our analysts are available for briefings and custom deep dives aligned to your internal calendars.
Closing perspective
The dc motor governor market presents a pragmatic growth opportunity—anchored by industrial modernization, regulatory momentum, and serviceable technological evolution. Growth is steady, predictable, and actionable if approached with disciplined prioritization: invest where product differentiation yields TCO advantages, shore up supply resilience, and monetize services to capture long‑tail value. PW Consulting’s report equips leaders to make those choices with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Dc Motor Governor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Pressure Regulators Market to Rise from USD 3,755.2 Million in 2025 to USD 5,326.37 Million by 2032 at a 5.12% CAGR
By PW Consulting, 2026-07-07
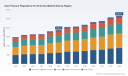
Gas Pressure Regulators for Oil & Gas Market — Strategic Briefing from PW Consulting
PW Consulting’s new market research brief on Gas Pressure Regulators for the Oil & Gas sector is released to inform and equip executive teams making critical 2026 strategic decisions. The study synthesizes historical performance (2020–2025), near-term sizing, and an actionable forecast (2026–2032) to translate technical product dynamics into clear commercial choices. Readers will find a concise, commercially focused roadmap: where to invest, who to partner with, and which regulatory and supply risks to hedge — while the granular segmentation matrices and downloadable decision tools are reserved for the full report.
Gas Pressure Regulators For Oil Gas Market
Executive snapshot: growth, scale and competitive shape
Our baseline analysis shows the market for gas pressure regulators serving oil and gas applications expanded from USD 2,967.07 Million in 2020 to USD 3,755.2 Million in 2025. We forecast the market to reach USD 4,092.34 Million in 2026, and project a compound annual growth rate (CAGR) of 5.12% across the 2026–2032 forecast window. These topline trends underscore a steady, technology-driven demand profile that rewards supplier reliability, product differentiation for harsh-service environments, and integrated digital capabilities.
Gas Pressure Regulators For Oil Gas Market
Market concentration is moderate. The top three suppliers account for roughly 28% of revenue, and the top five for approximately 42%. That structure creates meaningful opportunity for focused consolidation, targeted partnerships, and regional specialization strategies — especially for mid-sized suppliers and new entrants with niche technical strengths.
Gas Pressure Regulators For Oil Gas Market
Why this report matters for 2026 decision cycles
- Capital allocation and portfolio prioritization: Operators and OEMs can quantify where to direct CapEx for pipeline upgrades, distribution modernization, and substitution toward hydrogen/blend‑capable designs.
- Procurement and supplier strategy: The research converts product-level risk (material, testing and certification lead times) into contracting levers managers can use to reduce total cost of ownership.
- R&D and product roadmaps: Insights on performance drivers — noise reduction, no-bleed designs, pilot vs. self-operated trade-offs, and digital monitoring — help product teams prioritize features that unlock premium pricing.
- M&A and partnership screening: Buyers and corporate development teams get a short list of high-leverage niches (e.g., high‑pressure subsea, hydrogen‑compatible valves) where bolt-on deals or JV models accelerate entry.
Key trends shaping demand and supplier economics
- Energy transition and fuel mix evolution: Near-term demand remains anchored to natural gas transmission and distribution, but design requirements are shifting. Regulators must increasingly demonstrate compatibility with hydrogen blends, biogas, and tight emission targets — a technical premium that separates commodity from strategic suppliers.
- Material and supply chain pressure: Stainless steel (notably 316-grade) remains the dominant material choice for corrosion and sour-service resistance. Volatility in metal supply and regional price divergence are persistent margin levers; procurement teams must model multi‑sourcing and inventory buffers.
- Regulatory and standards landscape: Compliance regimes such as IOGP guidance for pressure regulators, NACE MR0175/ISO 15156 for sour-service alloys, and ISO 23555-2 for transmission/distribution regulators are now integral to product certification. Manufacturers without aligned conformity assessment processes face longer qualification cycles and restricted market access.
- Digitalization and aftermarket services: Remote-monitoring features, predictive maintenance algorithms, and integrated safety controls are becoming differentiators. Suppliers that bundle hardware with analytics-enabled service contracts capture aftermarket revenue and reduce customer switching.
- Harsh-environment and subsea demand: Exhibitions in 2025–2026 confirmed rising interest in high-pressure and subsea-capable regulators. Recent industry showcases (ADIPEC 2025 and OTC 2026) highlighted advances in materials, control architectures, and testing methods tailored to these use cases.
What the PW Consulting report delivers (practical, deployable content)
- Independent market sizing and a transparent forecast model (2026–2032) expressed in USD Million, with scenario toggles for slower/faster energy transition pathways.
- Segmentation by type, application and region with anonymized demand profiles to avoid disclosure of customer‑level sensitivities while preserving directionally accurate decision inputs.
- Supplier benchmarking and product feature matrices that map technical capabilities (e.g., pilot vs self‑operated trade-offs, noise-reduction technologies, no-bleed designs) to commercial outcomes.
- Supply chain and raw material risk maps plus recommended procurement mitigations and inventory strategies tailored to 2026 lead times.
- Regulatory compliance checklist and implementation roadmaps for IOGP, NACE/ISO sour-service requirements and ISO pressure regulator standards.
- Practical tools: TCO templates, RFP question banks for technical procurement, and a M&A screening scorecard focusing on technology fit, certification status, and aftermarket potential.
- Use-case playbooks for operators, OEMs and EPC contractors covering distribution upgrades, city-gate modernization, subsea transmission and hydrogen pilot projects.
Competitive landscape — who matters and why
The sector is populated by global incumbents, specialist engineering houses, and regional manufacturers. A concise read on core players covered in the study:
- Emerson (Fisher/TESCOM/Tartarini) — Strengths: broad product portfolio including noise reduction and no-bleed designs, deep service networks and strong safety credentials. Best positioned where regulatory compliance and reliability are non-negotiable.
- Swagelok Company — Strengths: precision control across diverse flow rates, rigorous testing and corrosion-resistant materials. Competitive where high-purity, instrumentation-grade control is required.
- Honeywell — Strengths: systems integration and smart monitoring capabilities; offers pressure regulators coupled with electronic control and safety accessories. Attractive to customers moving toward integrated automation stacks.
- BelGAS (Marsh Bellofram) — Strengths: long-standing product lines for natural gas and propane regulators; strong in legacy distribution applications and farm tap solutions.
- Pietro Fiorentini / FIORENTINI USA — Strengths: focused expertise in metering and pressure regulation across transmission and distribution; differentiated by localized service and system-level solutions.
- Pressure Tech Ltd — Strengths: specialized high-pressure and subsea models; competitive in hydrogen, diving and niche industrial applications where bespoke design is required.
- Cavagna Group, RegO, Maxitrol — Strengths: breadth in LPG, natural gas and industrial applications; often compete on cost, logistics and aftermarket distribution strength.
Our benchmarking section ranks these suppliers not only by product features and global reach but also by certification readiness, lead-time resilience and aftermarket service depth — criteria that matter most in procurement decisions for 2026 deployments.
Strategic implications and recommended actions for 2026
- Prioritize certification and sour-service readiness: Ensure design and procurement teams require conformity evidence to IOGP, NACE/ISO, and relevant ISO regulator standards as pre-qualification. This avoids costly re-tests and market entry delays.
- De-risk material and supplier exposure: Build dual-sourcing strategies for critical stainless-steel components and qualify alternate alloys or coatings for sour-service where appropriate.
- Invest in digital enablement: Pilot smart monitoring retrofits on critical regulator fleets to reduce unplanned outages and capture aftermarket service revenues through subscription models.
- Run hydrogen readiness pilots: Begin targeted pilots for hydrogen-blend compatibility in controlled distribution corridors; capture learnings to inform product roadmap and customer propositions.
- Use M&A selectively: Pursue bolt-ons that add hydrogen-compatible design IP, subsea experience, or established service networks rather than broad horizontal consolidation.
- Short-cycle procurement playbook: Implement staged contracting — award parts supply to multiple qualified vendors, then consolidate to a primary supplier as performance and certification are proven in 12–18 months.
How to act and where to get the full dataset
This briefing is a strategic trailer: it lays out the evidence-based actions procurement, product and strategy teams should take in 2026. The full PW Consulting report contains the granular segmentation, downloadable forecasting models, supplier scorecards with anonymized financials, and the tactical procurement templates referenced above. Access to those deliverables will materially shorten your decision cycle and reduce execution risk.
For a tailored executive briefing, scenario walk-throughs using your fleet data, or a confidential vendor pre-qualification workshop, PW Consulting’s energy practice is available to advise and to operationalize the report’s tools into procurement tenders, R&D prioritization and M&A diligence.
PW Consulting — converting technical complexity in gas pressure regulation into executable commercial advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Gas Pressure Regulators For Oil Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Ablation Systems Market Set to Grow at a 9.25% CAGR Through 2032
By PW Consulting, 2026-07-07
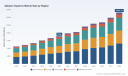
Ablation Systems Market Outlook 2026: Strategic Imperatives for Decision‑Makers
Executive Snapshot
PW Consulting’s Ablation Systems Market Research (base year 2025; historical 2020–2025; forecast 2026–2032) positions the global ablation market as a high‑growth, innovation‑led opportunity for device manufacturers, hospital systems, private equity investors, and reimbursement stakeholders. Our proprietary model estimates the market at USD 7,150 Million in 2025, rising to a projected USD 7,901 Million in 2026 and reaching more than USD 13,280 Million by 2032 — a compound annual growth rate (CAGR) of 9.25% across the forecast window. Market concentration is meaningful but far from monopolistic: the top three vendors account for roughly 42% of market value while the top five control approximately 58% — an environment that rewards both scale and focused differentiation.
Ablation Systems Market Research
Key Takeaways for 2026 Strategy
- Scale and specialization are simultaneous advantages: incumbents with broad electrophysiology and surgical portfolios retain negotiating power, but nimble entrants that own a clinical niche can secure premium reimbursement and access pathways.
- Regulatory progress in 2024–2026 has accelerated adoption of next‑generation energy modalities (including pulsed field and cryo innovations), compressing time‑to‑value for first movers and raising the bar for clinical evidence.
- Reimbursement and inpatient payment rule changes are already reshaping hospital economic calculus for combined procedures; commercial and public payers will be decisive gatekeepers in 2026 procurement cycles.
- Clinical workflow integration — mapping systems, robotics, and ablation platforms — is emerging as a decisive procurement criterion beyond unit price.
Market Trajectory: What the Numbers Imply (without the spoilers)
PW Consulting’s granular forecasting demonstrates a clear, sustained expansion of total addressable spend through 2032 driven by: rising incidence and diagnosis of arrhythmia and tumor indications; broader clinical acceptance of novel energy sources; and the diffusion of minimally invasive approaches into older, higher‑risk patient cohorts. The aggregate figures above encapsulate both volume growth and ASP (average selling price) dynamics. While we do not disclose segment‑level dollar breakdowns in this release, our modeling explicitly reconciles historical sales patterns (2020–2025) with clinical adoption curves to produce the 9.25% CAGR. This is not a steady single‑line expansion — the forecast embeds discrete inflection points tied to regulatory clears, reimbursement updates, and landmark clinical readouts that will materially affect adoption timing in 2026–2028.
Ablation Systems Market Research
Strategic Implications for Corporate and Investor Decision‑Making in 2026
- R&D Prioritization: Align near‑term investment toward technologies that facilitate systems integration (mapping + ablation + imaging) and reduce procedure time and complications. Our scenario modelling shows these attributes disproportionately improve hospital uptake and payer acceptance.
- M&A and Partnership Playbook: With CR5 at ~58%, acquisitive expansion remains a fast track to scale. However, targeted tuck‑ins that add differentiated technology (e.g., PFA, focal cryo, robotics) or access to specific clinical channels (oncology, urology, women’s health) can deliver multiple‑year revenue acceleration without competing head‑on with incumbents.
- Commercial Strategy: Prioritize evidence generation that maps directly to reimbursement levers. Value dossiers that quantify reduced length of stay, adjunct procedure consolidation, and downstream cost avoidance are the strongest determinants of hospital purchasing decisions under recent MS‑DRG updates.
- Market Access: Anticipate and influence payer policy. Providers and device developers that proactively sponsor health‑economics analyses and early‑stage registry data will face fewer access barriers when national or local coverage determinations are revisited.
Competitive Landscape — Who Matters and Why
The ablation space is occupied by a mix of diversified medtech leaders and focused specialists. Each cohort plays a distinct role in shaping 2026 dynamics:
Ablation Systems Market Research
- Large integrated players (examples include Medtronic, Boston Scientific, Abbott, Johnson & Johnson MedTech/Biosense Webster): leverage cross‑portfolio capabilities — mapping systems, catheters, and energy platforms — to offer bundled value propositions. Their competitive edge lies in installed base, capital equipment channels, and ability to fund large randomized or registry studies that de‑risk payer adoption.
- Surgical and niche specialists (examples include AtriCure, AngioDynamics, IceCure): retain leadership where procedural workflow and clinical specialty focus (e.g., surgical AF ablation, IRE for oncology, cryo for localized breast lesions) matter most. These companies can command premium pricing for clearly differentiated clinical outcomes and less crowded reimbursement pathways.
- Technology innovators and robotics (examples include Stereotaxis, Kardium, EDAP TMS): drive new procedural models — robotics, magnetic navigation, HIFU — that target subsegments where conventional approaches are limited or risky. Regulatory milestones for these technologies are high impact catalysts for adoption.
- Adjacents and procedural consumable suppliers (examples include Olympus, CONMED, Merit, Terumo): benefit from distribution breadth and procedure cross‑sell across GI, urology and surgical suites; their role is often to enable adoption of ablation through existing clinician relationships.
Recent corporate events underscore competitive momentum. Notable regulatory wins in late 2024–2026 — including approvals and clearances for dual‑energy systems, pulsed field platforms, cryo devices, robotic ablation catheters, and transurethral thermal systems — have already shifted competitive advantages. PW Consulting’s profiles assess each company across clinical pipeline strength, commercial footprint, manufacturing scale, and evidence strategy; the full report quantifies these dimensions into investment‑grade vendor scorecards that purchasers and investors use to prioritize targets.
Regulatory and Reimbursement Dynamics: The Practical Impact
Regulatory clearances in 2024–2026 have been pivotal. Examples include approvals for dual‑energy and pulsed field platforms and FDA marketing authorization for targeted cryoablation in defined oncology populations. On the reimbursement front, CMS and IPPS updates (including a new concomitant MS‑DRG for left atrial appendage closure and ablation procedures, and FY2026 inpatient payment adjustments) materially alter hospital budgeting and procedure mix decisions.
- What this means for manufacturers: regulatory wins now require parallel payer strategies. A cleared device without a mapped economic case may remain underutilized.
- What this means for hospitals: when inpatient payment policy favors combined procedures, systems capable of delivering consolidated, single‑session care gain operational priority.
- Clinical adoption inflection points: Our sequencing analysis links specific regulatory events to adoption milestones; device developers should plan evidence generation and supply chain scale‑up to coincide with these windows.
What the PW Consulting Report Delivers (Practical, Actionable Content)
- Proprietary market model (USD Million) covering 2020–2032 with scenario toggles for adoption speed, ASP sensitivity, and technology substitution — delivered in Excel for direct integration into corporate planning.
- Vendor competitive scorecards combining clinical pipeline, commercial reach, manufacturing capacity, and M&A appetite — with acquisition probability bands for 2026–2028.
- Go‑to‑market playbooks tailored to four buyer archetypes (large academic centers, regional hospitals, ambulatory surgical sites, and oncology networks) including pricing strategies and clinical champion engagement templates.
- Regulatory and reimbursement tracker with recommended payer engagement timelines keyed to product launch milestones.
- Clinical evidence compendium and recommended study designs (real‑world registries, pragmatic randomized trials, health‑economic models) that align with the thresholds payers currently require.
- M&A heat maps and due diligence checklists that integrate clinical, regulatory, manufacturing, and commercial risk signals.
To preserve the utility of the research for commercial partners and licensees, this release intentionally omits granular segment dollar tables and regional/application percentage splits — those critical inputs are included in the licensed report and the downloadable dataset.
How Strategic Buyers and Hospital Systems Should Use the Report in 2026
- Capital Planning: Use our forecast scenarios to time capital investments in mapping and ablation suites so that procurement coincides with payer coverage windows.
- Vendor Negotiations: Leverage our vendor scorecards to structure multi‑year contracts with performance and access guarantees tied to clinical outcomes.
- Clinical Pathway Design: Adopt the report’s evidence templates to close gaps between regulatory clearance and reimbursement acceptance, reducing lag time to routine use.
- Investor Due Diligence: Use the M&A heat maps and sensitivity analyses to calibrate valuations and integration risk for targets in PFA, cryo, HIFU, and robotics.
Conclusion — Why 2026 Is a Pivotal Year
2026 represents an inflection point where regulatory approvals, payer policy updates, and accumulated clinical evidence converge to accelerate market growth. With a forecast that more than doubles market value from 2025 levels by 2032 under our central scenario, the commercial and clinical stakes are high. PW Consulting’s Ablation Systems Market Research provides the practical analytics, scenario tools, and go‑to‑market playbooks that senior executives and investors need to convert regulatory wins into durable market share and superior returns — while avoiding the common pitfalls of timing, reimbursement misalignment, and under‑capitalized scaleups.
Next Steps
For decision‑grade access to the full dataset (including the detailed segmentation tables, regional and application breakdowns, vendor scorecards, and the downloadable financial model), consult the PW Consulting report page. The full deliverable is calibrated for use in 2026 budgeting cycles and strategic reviews.
For detailed analysis of this topic, please visit the official page: Ablation Systems Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Retail Omni‑Channel Commerce Platform Market Set to Grow at a Robust 18.5% CAGR During 2026–2032
By PW Consulting, 2026-07-07
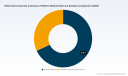
Retail Omni‑Channel Commerce Platform Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As retailers move from tactical channel experiments to programmatic omni‑channel transformation, boardrooms and IT leadership confront a complex decision set in 2026: which platform architecture, deployment model, and partner ecosystem will deliver profitable growth while remaining resilient to rising infrastructure costs and tightening privacy regimes? PW Consulting’s latest Retail Omni‑Channel Commerce Platform Market report (base year 2025) answers that question with an operationally focused roadmap grounded in robust market sizing and scenario analysis. The headline: the market is expanding rapidly — growing at a compound annual growth rate (CAGR) of 18.5% and moving from a mid‑double‑digit billion USD scale in 2025 into the mid‑tens of billions by the end of the forecast horizon — underscoring the urgency for strategic platform decisions this year.
Retail Omni Channel Commerce Platform Market
Why this report matters for 2026 decision‑making
-
Acceleration, not disruption: Investments in unified commerce are maturing from pilot initiatives into enterprise programs. With strong market momentum projected through the forecast period, retailers and brands must shift from vendor evaluation to program governance, vendor orchestration, and measurable operational KPIs.
Retail Omni Channel Commerce Platform Market -
Infrastructure and cost pressure: Cloud adoption and higher performance expectations are driving significant demand in adjacent infrastructure markets. Global data center dynamics and rising construction and colocation costs are increasing the operating baseline for cloud‑native omni‑channel deployments — a factor that materially affects TCO and sourcing choices.
Retail Omni Channel Commerce Platform Market -
Regulatory and data sovereignty friction: A widening patchwork of privacy laws and cross‑border controls (including new U.S. state statutes and heightened international scrutiny) is constraining unified customer data architectures. These constraints turn what was once a technical integration problem into a strategic architecture tradeoff with commercialization consequences.
What the report contains — practical, executable content
-
Concise market sizing and forward scenarios: a defensible macro baseline for 2025 and modeled pathways through the forecast period, enabling spend planning and addressable‑market calculations for platform investments.
-
Vendor evaluation framework: a weighted, procurement‑ready scorecard that balances functional fit (order management, POS, inventory synchronization, composability), non‑functional requirements (scalability, uptime SLAs, data residency), and commercial levers (license models, professional services, ecosystem support).
-
Architecture playbooks: practical blueprints for monolith‑to‑composable migration, headless storefront implementations, hybrid cloud/on‑prem orchestration, and secure customer data fabrics that respect emerging privacy constraints.
-
TCO and runbook models: configurable templates to estimate total cost across CapEx and OpEx, including sensitivity to data center pricing, cloud egress, and managed service premiums.
-
RFP and vendor negotiation playbooks: ready‑to‑use questions, red flags, and pricing negotiation levers tailored for enterprise omnichannel procurements.
-
Operational metrics and adoption roadmaps: recommended KPI ladders (conversion, fulfillment cost per order, inventory days of supply, associate productivity), phased rollouts, and pilot success criteria to de‑risk large‑scale deployments.
-
Compliance checklists: mapped requirements against recent privacy laws and cross‑border restrictions, with prescriptive mitigations for data minimization, consent orchestration, and recordkeeping.
Competitive landscape: who matters and why
The vendor landscape is populated by cloud‑native newcomers and incumbent enterprise suites. Our analysis highlights strategic differentiation factors that matter most to enterprise buyers in 2026.
-
Shopify Inc. — strong momentum for rapid DTC and headless scenarios via its enterprise Shopify Plus and Hydrogen/Oxygen offerings. Ideal for brands seeking a fast, developer-friendly path to unified online‑to‑offline experiences, particularly where speed to market and ecosystem integrations are prioritized.
-
Salesforce, Inc. — Commerce Cloud’s strength is its deep CRM and marketing ecosystem, with AI personalization capabilities that appeal to retailers prioritizing customer lifecycle orchestration and cross‑cloud data unification.
-
Adobe Inc. — positions itself as the Experience‑first commerce provider, combining flexible commerce engines with content and personalization tooling for experience‑driven retailers focusing on conversion uplift through content.
-
Oracle & SAP — both remain the pragmatic choice for very large retailers seeking proven scale in inventory optimization, POS, and backend process unification; selection typically follows enterprise ERP and supply chain considerations.
-
BigCommerce, VTEX, Lightspeed, NCR — offer differentiated strengths across DTC, marketplace, mid‑market to specialty retail, and POS integration. These vendors often appeal to retailers seeking specific channel or regional focus with faster implementations.
-
Composable and MACH specialists (commercetools, Elastic Path, Hygraph) — provide the modularity and API‑first design buyers need for complex, multi‑market architectures; they are increasingly the tactical choice for retailers prioritizing future agility over out‑of‑the‑box functionality.
-
Supply chain and order management players (Manhattan Associates, Infor) — differentiate on fulfillment, OMS, and store‑level execution — critical when cost‑to‑serve and fulfillment SLAs determine profitability of omnichannel channels.
-
Enterprise integrators (IBM, Microsoft Dynamics) — offer platform breadth and enterprise support, particularly attractive to organizations where commerce is embedded into broader ERP, CRM, and data estates.
Recent industry moves illustrate accelerating ecosystem consolidation and interoperability: native integrations for multi‑region commerce platforms, expanded channel feed partnerships, and headless integration tool updates have all appeared in the opening months of 2026. These developments reduce point‑integration friction but also increase the number of viable pairing permutations buyers must evaluate.
Strategic recommendations for 2026 programs
-
Make data architecture a board‑level decision: Privacy laws and data sovereignty rules mean you cannot treat customer data as a fungible IT artifact. Define permitted flows, residency constraints, and a minimal data model before vendor selection.
-
Adopt a ‘composable first’ procurement stance if you face multi‑market or rapid SKU growth: Composability increases option value for future channels and marketplaces, even if the first‑wave implementation appears more costly on day one.
-
Model TCO against infrastructure scenarios: Incorporate rising data center and colocation costs into multi‑year TCO sensitivity; validate cloud pricing assumptions against realistic throughput and storage growth trajectories.
-
Operationalize AI with guardrails: Automation for picks, price optimization, and associate assist can deliver step changes in efficiency, but must be integrated with privacy and consent policies to avoid regulatory friction.
-
Design for phased modernization: Use pilot stores or geographies to validate OMS, inventory orchestration, and returns handling before full‑scale cutovers. Preserve rollback paths and vendor escape clauses to limit vendor lock‑in.
-
Prioritize partner ecosystems and managed services: In higher‑cost cloud and regulated environments, managed services and local delivery partners can control run costs and accelerate compliance implementation.
How to use the report
Consider this market brief your strategic trailer: it outlines the stakes, shows the playbook, and presents the practical tools procurement, IT, and commercial teams need to make defensible choices in 2026. The full report contains the segment‑level analysis, vendor scoring matrices, downloadable templates, and a decision support workbook that operationalizes the recommendations above. We intentionally withheld detailed segment allocations and granular vendor rankings from this public brief to preserve the integrity of our proprietary benchmarking and to provide a single destination for complete, download‑ready insights.
If your organization is planning a commerce platform procurement, migration, or a governance overhaul this year, the report will compress months of work into a structured program with measurable milestones and financial guardrails — enabling you to move from vendor‑centric conversations to outcome‑driven decisions.
Closing
The omni‑channel commerce market in 2026 presents both an opportunity and an execution challenge: rapid market expansion and platform innovation create a favorable investment backdrop, while infrastructure costs and evolving regulation raise the bar for disciplined architecture and governance. PW Consulting’s Retail Omni‑Channel Commerce Platform Market report equips leaders with the market perspective, vendor intelligence, and practical playbooks needed to turn platform investments into sustainable commercial advantage. For access to the complete analysis, segment detail, and execution templates, please visit PW Consulting’s research portal to download the full report and supporting assets.
For detailed analysis of this topic, please visit the official page: Retail Omni Channel Commerce Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Antistatic Coating Market to Grow at a 6.32% CAGR Through 2032
By PW Consulting, 2026-07-07
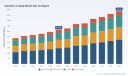
Antistatic Coating Market: Strategic Imperatives for 2026
As companies prepare strategic plans for 2026, the antistatic coating sector is emerging as a critical battleground for sustainability-driven product innovation, supply‑chain resilience, and selective consolidation. PW Consulting’s latest market research — anchored on historical performance (2020–2025) and a forward-looking 2026–2032 forecast — synthesizes market trajectory, regulatory inflection points, raw‑material risk, and competitor behavior into a pragmatic playbook for decision-makers. This executive briefing highlights the report’s strategic value while preserving the high‑granularity segment datapoints that are exclusive to the full report.
Antistatic Coating Market
Market Trajectory: a clear, investible growth path
The antistatic coating market has demonstrated steady expansion, rising from USD 475.2 Million in 2020 to USD 633.48 Million in the base year 2025. Our proprietary forecasting model projects continued growth through 2032, with the market approaching roughly USD 973 Million by the end of the forecast window, driven by a compound annual growth rate (CAGR) of 6.32% (2026–2032). That combination of scale and mid‑single‑digit CAGR makes the sector attractive for both innovation-driven incumbents and strategically minded entrants.
Antistatic Coating Market
Why this report matters for 2026 decision cycles
- Resource allocation: Quantitative trajectories and scenario stress‑tests enable capex prioritization between R&D for sustainable chemistries, manufacturing capacity expansions, and targeted commercial investments.
- Portfolio strategy: A disciplined view on end‑use demand elasticity helps determine whether to pursue deepening participation in electronics and semiconductors versus adjacent industrial and surface‑protection applications.
- M&A and partnerships: Market concentration metrics (moderate top‑player share) identify ripe zones for bolt‑on acquisitions and capacity alliances that deliver immediate share and technological synergies without requiring transformational capital.
- Risk management: Integrated raw‑material sensitivity analyses equip procurement and treasury functions to hedge or diversify exposure to petrochemical feedstock volatility.
Core market dynamics and structural drivers
- Demand composition: Growth is underpinned by a blend of steady industrial demand and episodic uplift from electronics, automotive electrification, and renewable energy asset maintenance. Buyers are demanding functionality (ESD protection, dust repellence) combined with life‑cycle sustainability.
- Regulation and green chemistry: Recent regulatory approvals for low‑VOC liquid antistatic technologies in major jurisdictions and an uptick in green‑certified additive adoption are reshaping formulators’ roadmaps. Manufacturers that can marry performance with compliance will capture preferred supplier status in regulated OEM supply chains.
- Raw‑material pressure: Price volatility in petrochemical‑derived inputs remains a constant strategic stressor. Concurrently, bio‑based antistatic additives are gaining traction as formulators and end‑users prioritize sustainable substitution; this bifurcation forces dual tracks in procurement and R&D portfolios.
- Application innovation: Coatings that combine electrostatic dissipation with anti‑soiling/anti‑adhesive properties (e.g., for solar PV) are moving beyond niche to mainstream, driven by demonstrable efficiency gains in installed assets.
Competition: differentiated plays among incumbent and specialist firms
The market remains moderately fragmented: leading groups capture meaningful share but there is room for consolidation and specialization. Our competitive review focuses on how firms are positioning across the technology stack and go‑to‑market channels.
Antistatic Coating Market
- ACL Staticide, Inc. — With a strong heritage in static control chemistries and a product suite aimed at electronics manufacturing and plastics processors, ACL leverages application expertise and channel relationships in ESD‑sensitive industries. Their strength is product depth and certification alignment for cleanrooms and assembly lines.
- Antistatic Industries — Focused on industrial coatings such as Static Paint and water‑based anti‑dust systems, this player competes on engineered formulations that create safe, static‑controlled environments. Their construct is volume‑oriented industrial adoption and global service support.
- GMM Pfaudler — Differentiated by specialty coatings for glass‑lined equipment, including anti‑static glass treatments using conductive nanoparticles, GMM Pfaudler operates at the intersection of corrosion resistance and antistatic function — important in pharma and fine chemicals where purity constraints are nonnegotiable.
- Chemitek — Innovation on coatings for solar modules that reduce dust adhesion and deliver performance uplifts demonstrates the commercial potential of application‑specific antistatic systems. Their water‑based, PV‑certified offering exemplifies the productization of sustainability claims.
- PPG Industries and Kansai Paint — Large coating houses play a hybrid role: they supply industrial ESD coatings, powder systems, and flooring solutions while leveraging scale to commercialize electrostatic application technologies and broaden distribution across sectors like aerospace and marine.
- 3M Company — As a materials and solutions innovator, 3M’s portfolio of tapes, mats, and static control accessories complements coating solutions and emphasizes systems thinking — often used to bundle service offerings for electronics OEMs and ESD‑sensitive facilities.
Recent corporate moves underscore strategic themes: PPG’s milestone electrostatic application orders indicate commercial acceptance of sustainability‑oriented spraying technologies, while product expansions from regional players highlight a shift toward water‑based and low‑VOC systems. These developments create both competitive threats and partnership opportunities for firms that can scale validated formulations.
What PW Consulting’s report contains — the practical tools for 2026 execution
- Market sizing and high‑resolution forecasting framework (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario variants that stress regulatory tightening, commodity price shocks, and accelerated green adoption.
- Supply‑chain heat maps and supplier‑risk matrices that quantify exposure to petrochemical inputs and propose tactical diversification strategies (sourcing, forward contracting, and vertical integration).
- Technology adoption timelines and product maturation curves for conductive polymers, metal‑ and carbon‑based systems, plus emerging bio‑based additives — enabling R&D prioritization and IP investment decisions.
- Commercial playbooks: go‑to‑market segmentation, route‑to‑market selection, and tender/contracting templates for OEM sourcing teams and coatings manufacturers.
- Competitive benchmarking and M&A opportunity models driven by our market concentration analysis — highlighting acquisition targets that would create immediate scale or fill capability gaps.
- Regulatory compliance compendium: a practical set of checklists for low‑VOC and green chemistry validation to accelerate time‑to‑market in regulated jurisdictions.
Strategic recommendations for 2026 planning
- Prioritize dual‑track formulation roadmaps: maintain high‑performance petrochemical‑based lines while accelerating at least one commercial green formulation (water‑based or bio‑additive) to meet OEM sustainability mandates.
- Hedge raw‑material risk by diversifying supplier sets and pursuing long‑term agreements for key inputs; where possible, localize critical feedstock sourcing to reduce exposure to freight and geopolitical volatility.
- Consider targeted acquisitions or joint ventures to acquire application expertise (e.g., PV, aerospace) rather than generalized capacity; bolt‑ons that deliver certification and channel access accelerate commercial traction.
- Invest in application services and performance guarantees (e.g., dust‑reduction efficacy or ESD lifetime) to transform coatings from a commoditized product into a value‑added service with higher margin capture.
- Monitor and influence regulatory developments: engage in industry consortia to shape green chemistry standards and to secure early acceptance for new technologies in major procurement specs.
About market concentration and competitive moves
Our concentration analysis indicates a market where top three players hold meaningful but not dominant share, and the top five approach half the market — a structure that supports both competitive differentiation and strategic consolidation for firms seeking scale. For 2026, this configuration favors disciplined M&A for mid‑sized players and targeted innovation plays for specialists.
Limitations and how to obtain the full dataset
In keeping with our “trailer” approach, this briefing presents the strategic narrative and the macro parameters you need to inform high‑level decisions. The full PW Consulting Antistatic Coating Market report provides the complete segmentation detail, year‑by‑year breakdowns, unit‑level price curves, and the granular regional and end‑use split tables that procurement, corporate development, and R&D teams will require to execute tactical initiatives. Access to the full dataset unlocks model inputs, downloadable templates, and vendor scorecards.
Call to action
For executive teams preparing 2026 budgets, the timing to act is now: incorporate the outlined dual‑track formulation strategy, secure supply‑chain options, and evaluate selective inorganic moves informed by our concentration and scenario analysis. To receive the full report, the forecast models, and a tailored briefing with our industry strategy leads, please contact PW Consulting’s Antistatic Coating Market practice — our team will provide the deep segment data and implementation playbooks that have been withheld from this public summary.
For detailed analysis of this topic, please visit the official page: Antistatic Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digestive Enzyme Complex Market Poised for Robust Expansion with a 7.21% CAGR, New Insights Reveal
By PW Consulting, 2026-07-07
Digestive Enzyme Complex Market: Strategic Imperatives for 2026 — Pw Consulting Digest Release
Executive snapshot
As the global digestive enzyme complex market transitions from niche clinical applications into more diversified consumer- and practitioner-oriented channels, executives must calibrate strategy to a market that is growing steadily yet remains fragmented. Our new Pw Consulting Digest synthesizes a comprehensive model — built on a 2025 base year — that shows the market reached approximately USD 1.10 billion in 2025 and is expected to expand into the mid‑teens of percentage points annually over the next decade, with a compound annual growth rate of 7.21% across the 2026–2032 forecast window. By 2032 the market is projected to approach USD 1.8 billion, driven by converging forces in healthcare access, consumer wellness trends, and supply‑side adjustments in enzyme sourcing and manufacturing.
Digestive Enzyme Complex Market
Why 2026 is a decision inflection point
-
Post‑pandemic demand normalization and a maturing supplement landscape are creating pressure to differentiate. Pure price competition is no longer a durable route to growth; scientific provenance, supply chain transparency, and channel partnerships will decide winners.
Digestive Enzyme Complex Market -
Regulatory clarity around enzyme sources and manufacturing controls — particularly for pancreatic enzyme replacement therapies (PERT) and porcine‑derived inputs — is tightening in key markets. Firms that embed regulatory design into product development will avoid late‑stage compliance costs and launch delays.
Digestive Enzyme Complex Market -
Supply dynamics remain a strategic risk and an opportunity. A combination of government procurement actions and API capacity investments announced in 2025–2026 signal that security of raw material and API throughput will be a competitive lever for prescription and high‑touch practitioner channels.
What Pw Consulting’s Digest delivers to senior leaders
This release is not a high‑level overview. It is a practitioner’s playbook designed to be actionable in the boardroom and during investor due diligence. Highlights include:
-
A vetted market model calibrated to historical performance (2020–2025) and a detailed 2026–2032 forecast scenario set. The model is built to be scenario‑sensitive so you can stress‑test decisions under alternative demand, price and supply assumptions.
-
Commercial scorecards for suppliers, CMO partners and finished goods competitors that synthesize quality certifications, GMP footprint, clinical validation, and go‑to‑market reach.
-
A regulatory tracker with practical compliance milestones — including characterization and safety requirements — mapped to product classes (prescription PERT, over‑the‑counter digestive complexes, enzyme‑augmented probiotic formats) so teams can time development and filings.
-
Supply‑chain heat maps and mitigation playbooks addressing porcine sourcing, microbial production scale‑up, and plant‑based enzyme procurement strategies.
-
Go‑to‑market playbooks for three strategic archetypes: clinical/prescription leadership, practitioner‑channel specialists, and mass retail/online value brands — each with recommended R&D, manufacturing and commercial investment timing.
-
Deal flow and inorganic growth frameworks that prioritize targets by strategic fit (technology, capacity, channel) and illustrate likely valuation differentials driven by validated clinical data or secured API supply.
Competitive landscape — who matters and why
The sector remains moderately concentrated: a group of established pharmaceutical and ingredient specialists coexists alongside nimble supplements brands and purpose‑built enzyme manufacturers. Market leadership is not monopolized; the top players collectively capture less than half of the market, leaving ample room for mid‑market consolidation and niche innovation.
Key corporate archetypes and the strategic implications we draw in the report:
-
Large pharmaceutical incumbents (e.g., AbbVie/Creon franchise) — Command trust in prescription PERT and enjoy deep regulatory experience and channel access into gastroenterology practices. Their decisions on API capacity and contract manufacturing reverberate across the PERT supply chain. For non‑prescription entrants, competing on clinical parity demands significant investment or strategic partnerships.
-
Ingredient specialists and enzyme manufacturers (Amano, Bioseutica, National Enzyme/ADM/Deerland, Advanced Enzyme Technologies, DSM‑Firmenich) — These firms are gatekeepers for enzyme sourcing, technical know‑how, and scale. Their proprietary extraction or microbial fermentation platforms determine cost curves and product differentiation opportunities (e.g., lactose‑ or gluten‑targeted enzyme specialties).
-
Dedicated supplement brands and contract manufacturers (Enzymedica, Specialty Enzymes & Probiotics, Garden of Life, NOW Foods, Integrative Therapeutics, Metagenics, Pure Encapsulations) — These actors translate enzyme science into consumer propositions. Their strengths vary — some compete on clinical testing and practitioner trust, others on clean‑label and price accessibility. The most attractive partners for rapid market entry are those that combine formulation expertise with e‑commerce and practitioner network access.
-
Hybrid entrants and innovators — New product categories that combine enzymes with probiotics, targeted substrates, or personalized dosing are emerging. Recent launches and product expansions demonstrate demand for combined digestive‑microbiome propositions targeted at practitioners and premium e‑commerce channels.
Recent developments that reshape 2026 strategies
-
New product launches that pair enzymes with probiotics or targeted microbiome‑support ingredients are accelerating category overlap and widening adoption among clinical practitioners and online consumers.
-
Supply announcements and API capacity investments by major players are reducing single‑point failure risk in the medium term but may compress margins for manufacturers who cannot secure forward contracts or backward integration.
-
Regulatory guidance continues to emphasize source characterization and contaminant controls. For companies pursuing animal‑derived enzymes, documented traceability and third‑party certification are non‑negotiable for market access in developed markets.
Strategic recommendations for 2026 corporate planning
-
Secure supply now, optimize later: Evaluate multi‑sourcing and long‑term offtake agreements for API or enzyme concentrates. Consider tolling arrangements or minority stakes in critical suppliers to maintain optionality without full vertical integration.
-
Differentiate on provenance and evidence: Invest selectively in clinical or mechanism‑of‑action studies that match your go‑to‑market channel. Provider channels value clinical validation; retail consumers value clean‑label certification and sustainability claims backed by traceability.
-
Segment commercialization by channel archetype: For prescription/PERT, prioritize regulatory and supply investments. For practitioner channels, invest in medical education and distribution partnerships. For mass retail and e‑commerce, optimize cost of goods, packaging, and digital conversion funnels.
-
Pursue bolt‑on M&A with capability gaps in mind: Target small manufacturers with GMP credentials or ingredient innovators with proven cost advantages or novel microbial fermentation platforms to accelerate time‑to‑market.
-
Design for regulatory resilience: Implement source‑characterization workflows and third‑party testing regimes that reduce launch risk across jurisdictions; embed regulatory KPIs in R&D gates.
-
Monitor adjacent innovation: Enzyme‑microbiome combinations and enzyme delivery formats that improve stability or targeted release are potential disruptors. Keep an option value budget for licensing early‑stage innovations.
How the full Pw Consulting report supports execution
The Digest is a condensed, actionable briefing. The full Pw Consulting Digestive Enzyme Complex Market report provides the unlocks needed for execution: a downloadable financial model that allows management to run custom scenarios; supplier due‑diligence templates; a prioritized M&A target list with commercial and technical valuation drivers; and a regulatory playbook with jurisdictional checklists. We balance transparency with commercial discretion — the full segmentation tables, regional breakdowns, and proprietary company scoring are reserved for the complete report to maintain data integrity and client value.
Next steps for leaders
-
Schedule a single‑day strategy workshop with Pw Consulting to translate the forecast scenarios into a 12–24 month roadmap tailored to your business archetype.
-
Request the full report to obtain the model, supplier scorecards and our prioritized M&A shortlist. The report will enable your team to quantify tradeoffs between CAPEX for manufacturing capacity versus contractual resilience with third‑party suppliers.
-
Engage our regulatory team for a targeted gap assessment if you rely on animal‑derived enzymes or plan to enter markets with stringent characterization requirements.
Closing perspective
The digestive enzyme complex market presents a classic strategic paradox — clear growth but dispersed value. Success in 2026 will not be won by scale alone; it will be won by firms that marry technical supply assurance, regulatory foresight, and channel‑specific commercialization. Our Pw Consulting Digest equips executives to make those choices with confidence, offering the strategic frameworks and operational tools needed to convert market growth into sustainable advantage.
For detailed analysis of this topic, please visit the official page: Digestive Enzyme Complex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Satellite Manufacturing and Launch Systems Market to Expand at an 8.26% CAGR, Accelerating Growth Through 2032
By PW Consulting, 2026-07-07
Satellite Manufacturing and Launch System Market: Strategic Imperatives for 2026
As governments and commercial actors accelerate space deployment, executives face a narrowing window to translate strategic intent into durable advantage. PW Consulting’s new Satellite Manufacturing And Launch System Market report — built on a comprehensive 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes market dynamics, competitive vectors, regulatory headwinds, and operational playbooks that will determine winner and follower outcomes in 2026. The market we model stands at USD 35,450 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 8.26% through 2032, reaching a materially larger opportunity by the end of the forecast period. This briefing summarizes the report’s strategic value for 2026 decision-making while preserving the deeper segmentation intelligence available in the full study.
Satellite Manufacturing And Launch System Market
Market Snapshot: Why 2026 Is a Pivotal Inflection Year
-
Momentum and scale: After a sustained expansion through 2020–2025, the satellite manufacturing and launch ecosystem is entering a phase where scale economics intersect with operational cadence. The base-year market size (2025) and the 8.26% CAGR underpin scenarios where mid-decision horizons (2026–2028) determine capacity utilization and competitive positioning through 2032.
Satellite Manufacturing And Launch System Market -
Concentration and competitive tensions: The market exhibits a moderate concentration profile; the top three and top five players account for a meaningful share of industry revenue, creating a landscape where incumbent advantages in manufacturing scale and launch manifest but do not preclude disruptive entrants.
Satellite Manufacturing And Launch System Market -
Capex rhythm vs. demand cadence: Capital-intensive launch programs are reaching a synchronization point with satellite constellation rollouts. Organizations that resolve the timing mismatch between factory throughput, launch manifest, and regulatory approvals in 2026 will capture asymmetric returns later in the cycle.
Five Strategic Themes Shaping 2026 Decisions
-
1) Vertical integration vs. modular specialization: The industry is polarizing between actors who pursue end-to-end control (manufacture + launch integration) and those who optimize specialized stacks (smallsat buses, payloads, or launch services). Each choice carries trade-offs in margin, capital needs, and export/regulatory exposure. Our report provides decision heuristics to evaluate capex allocation against time-to-market and risk appetite.
-
2) Supply chain resilience and critical materials: Shortages and export controls affecting high-purity gallium and germanium, together with concentrated sources for advanced detectors and solar cells, create strategic supply-risk corridors. In 2026, firms must choose between near-term component hedging, verticalizing key suppliers, or redesigning architectures to reduce dependency on constrained inputs.
-
3) Regulatory and orbital governance as a commercial factor: Recent spectrum rule updates and strengthened debris mitigation requirements mean compliance is now a design constraint, not an afterthought. Teams should embed regulatory gating in product roadmaps and partner diligence to avoid launch delays and market access friction.
-
4) Manufacturing scale and facilities: Cleanroom capacity and specialized assembly infrastructure remain limited globally. Investing in scalable iso-grade cleanrooms or securing long-term capacity slots creates a competitive moat for producers targeting high-frequency constellation deployments.
-
5) Launch cadence and insurance dynamics: A clarified launch manifest and reliable frequent-launch providers reduce program risk and insurance premiums. Strategic contracting for launch capacity — including mixed portfolios of rideshares and dedicated heavy-lift services — will be a differentiator in 2026.
What the Report Delivers to Executives
-
Rigorous market sizing and scenario models calibrated to 2025 base-year performance and stress-tested across demand, regulatory, and materials scenarios for 2026–2032.
-
Competitive intelligence and vendor scorecards that benchmark technology readiness, manufacturing throughput, launch reliability, and export-control exposure — presented as decision-ready matrices rather than raw vendor rankings.
-
Supply chain risk maps that identify single-source dependencies, substitution pathways, and regional chokepoints for critical components and cleanroom capacity.
-
Go-to-market playbooks for constellation operators, government contractors, and emerging national players — including contracting templates for launch slots, tech-transfer checklists, and partner selection criteria.
-
M&A and partnership screens that identify tactical targets (manufacturing IP, niche payload specialists, launch-integration service providers) and financial models for integration planning.
-
Operational dashboards and KPIs for 2026 execution: throughput per cleanroom, launch manifest hit rate, supplier lead-time variance, and regulatory compliance milestones.
Competitive Landscape: Positioning and Strategic Moves
The competitive map combines legacy aerospace primes, launch specialists, and vertically integrated newcomers. Key archetypes and implications:
-
High-volume integrators (example archetype: SpaceX): Achieve accelerated learning curves through repeated production and launch cycles. Their playbook focuses on reducing per-satellite costs, internalizing launch risk, and controlling fleet economics. For established competitors, the defensive options include targeting differentiated payload offerings, securing exclusive launch windows, or pursuing partnership models.
-
Legacy primes (example archetypes: Boeing, Lockheed Martin, Northrop Grumman): Leverage deep relationships in government and defense, proven system integration capabilities, and GEO/MEO heritage. Their near-term challenge is adapting production organizational models to the cadence and cost expectations of commercial constellations without eroding margins.
-
European system houses (example archetypes: Airbus Defence and Space, Thales Alenia Space): Compete on engineered, high-reliability products and institutional customers. They can win by coupling platform advances with assured access to launch frameworks and by capturing a share of government modernization budgets.
-
Small-sat and launch specialists (example archetypes: Rocket Lab, Blue Origin, Rocket Lab’s Photon offerings): Target rapid, lower-cost deployment niches and in-orbit manufacturing/servicing experiments. Their strategic advantage is agility; partnerships with OEMs for standardized bus designs expand their TAM.
-
National and sovereign players (example archetypes: ISRO, CASC): Provide alternative access to launch and manufacturing capacity, often with different commercial constraints and price points. For multinational suppliers, understanding export-control and local content implications is critical.
Recent operational and corporate developments underscore these dynamics — from high-frequency launches of new-generation constellation satellites to funding injections accelerating heavy-lift readiness. These events recalibrate launch supply assumptions and partnership opportunities entering 2026.
Actionable Roadmap for 2026 (Prioritized Moves)
-
1) Run three 18-month scenarios (base, optimistic, stress) that explicitly model launch cadence slippage, key material embargoes, and spectrum/regulatory delays. Convert scenarios into capital-allocation triggers.
-
2) Secure conditional capacity: Execute option agreements for cleanroom time and launch slots to protect go-to-market timelines while avoiding full upfront capex where possible.
-
3) Deploy supply-chain playbooks: Initiate dual-sourcing or design-for-substitution projects targeting components at material risk. Where substitution is infeasible, explore strategic inventory or JV manufacturing to lock supply.
-
4) Integrate regulatory and orbital-sustainability disciplines into product development: mandate passivation and deorbiting designs, embed spectrum mitigation planning, and map export-license timelines into delivery milestones.
-
5) Pursue targeted partnerships and bolt-on M&A that accelerate capability rather than diversify away from core advantages — for example, payload specialists, in-orbit-servicing technology, or launch-integration firms.
How PW Consulting’s Report Enables Execution in 2026
The study is engineered to be operational: each strategic insight is paired with a toolkit — templates, KPIs, supplier due-diligence checklists, and financial models — that can be adopted by product, supply-chain, and corporate-development teams. For executives preparing 2026 budgets and board-level strategy reviews, the report converts ambiguous space-industry dynamics into prioritized initiatives, measurable milestones, and acceptable-risk levers.
PW Consulting’s approach blends quantitative modeling with qualitative expert interviews and proprietary scenario stress-testing. We protect value by presenting high-confidence topline sizing (2025 base and 2026–2032 growth trajectory) while reserving granular subsegment breakouts and supplier-level intelligence for the full report — a deliberate design to ensure readers contact the source for transaction-grade insights.
Next Steps
Leaders who want to translate these strategic themes into action plans for 2026 should engage with our report to obtain the executable modules: the launch-capacity contracting playbook, supply-chain mitigation templates, and a prioritized M&A shortlist calibrated to your risk profile. Visit PW Consulting’s Satellite Manufacturing And Launch System Market page to download the executive summary and arrange a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Satellite Manufacturing And Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


