



Category: market research
PW Consulting Market Insight: Casting & Splinting Sector to Hit USD 4,580.0 Million by 2032, Growing at a 6.18% CAGR (USD 3,010.0 Million in 2025; Top‑5 Firms Hold 56.8%)
By PW Consulting, 2026-07-02
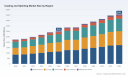
PW Consulting Releases Strategic Preview: Casting and Splinting Market Outlook to 2032 — A Tactical Guide for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Casting and Splinting Market report, designed to inform executive decision-making in 2026. Anchored on a 2025 base year and a five‑year historical window (2020–2025), the research models the market through 2032 under a 6.18% compound annual growth rate (CAGR). The preview highlights macro drivers, competitive movement, regulatory and reimbursement headwinds, and the practical tools in the full report that procurement leaders, product teams, and investors will rely on to set strategy in the year ahead.
Casting And Splinting Market
Why this preview matters for 2026 planning
-
Timing: With procurement cycles, capital planning and product roadmaps set in 2026, understanding where value pools expand and where margin pressure intensifies is essential for prioritizing investments.
Casting And Splinting Market -
Clarity: The market is transitioning from commodity immobilization products toward performance-differentiated solutions (lightweight materials, breathable systems, and customized devices). Executives need a concise translation of these trends into actionable choices.
Casting And Splinting Market -
Risk mitigation: Supply‑chain and raw‑material concentration, evolving reimbursement rules, and regulatory review pathways create decision points that can materially affect go‑to‑market timing. This preview flags those inflection points.
Macro picture — growth, concentration and the strategic implications
The casting and splinting sector is on a sustained growth path from the 2025 baseline, driven by demographic pressure, increasing elective orthopedic procedures, sports-medicine demand, and faster adoption of advanced materials and personalized devices. Our model projects robust expansion to 2032 on a mid-single‑digit CAGR (6.18%), reflecting both underlying clinical demand and product substitution dynamics.
Market concentration metrics point to a moderately consolidated landscape: the top three players account for a meaningful share of industry revenues, and the top five approach parity with other medical consumables segments. This structure favors scale players with broad distribution and R&D resources, while leaving strategic space for agile specialists to capture premium niches through innovation or service differentiation.
Regulatory, reimbursement and procurement dynamics you cannot ignore
-
Reimbursement complexity: Casting and splinting supplies continue to be governed by HCPCS codes (e.g., Q4001–Q4051), which differentiate by material type, patient age bands and anatomic site. Accurate coding and documentation (neurovascular assessments, wound status) remain essential to secure appropriate reimbursement.
-
Regulatory pathways: New materials and device designs typically follow FDA 510(k) pathways. Manufacturers planning material substitutions, bio‑based resins, or integrated electronics should allocate time and budget for regulatory validation early in product development.
These two levers—reimbursement and regulatory—are primary gating factors for commercial adoption and can materially alter ROI timelines for new product initiatives.
Material and technology shifts: where innovation is concentrating
Material substitution is a dominant theme. Fiberglass and other synthetic composites continue to edge out traditional plaster in many clinical settings due to superior strength‑to‑weight ratios and faster setting times. At the same time, thermoplastics and 3D‑printed custom splints are emerging as high‑value options where comfort, fit and reduced patient follow‑up matter. Expect innovation to cluster around three areas:
-
Performance materials — lighter, breathable, faster-curing formulations that enhance patient comfort and throughput in emergency and outpatient settings.
-
Customization — 3D printing and thermoformable systems that enable better fit and potentially shorter immobilization windows for select indications.
-
Service augmentation — modular systems and disposables that reduce clinician application time and improve infection control protocols.
Competitive landscape — patterns from recent activity
Our competitive review examines legacy incumbents, specialist innovators, and global distributors. Key movements observed through late‑stage 2025 and early 2026 include product launches featuring bio‑based resins and thermo‑responsive technology, modular high‑ventilation systems aimed at sports and emergency use, and the introduction of 3D‑printed custom splints for personalized care.
Selected strategic behaviors and implications:
-
Product innovation by incumbents: Established manufacturers are refreshing portfolios with semi‑rigid, breathable tapes and modular splinting systems that directly target clinician workflow and patient comfort. These moves are defensive (protecting share) but also open premium price points.
-
Channel partnerships and distribution scale: Recent strategic partnerships to expand hospital and clinic coverage underline the importance of commercial reach and value-added service levels in procurement negotiations.
-
Specialist play for customization: Additive manufacturing entrants and thermoplastic specialists are carving out use cases where bespoke fit and comfort translate into measurable clinical benefits — a potential pathway to adjacent service revenues.
Our full competitive mapping profiles major players and their strategic postures, enabling clients to benchmark product pipelines, distribution strengths, and M&A appetites.
What the full report contains — practical tools for strategy teams
The full PW Consulting report goes beyond narrative and delivers operational tools that executives can deploy immediately. Highlights include:
-
Market sizing and multi‑scenario forecasts through 2032 (base year 2025), with sensitivity testing for adoption curves and price migration.
-
A validated segmentation framework (by product family, material class and channel) and growth drivers for each segment. Note: detailed segment tables and regional splits are available in the full report.
-
Competitive intelligence dossiers on incumbent manufacturers, distributors and specialist entrants — including recent product launches, partnership activity and strategic roadmaps.
-
Reimbursement mapping aligned to HCPCS codes and practical documentation checklists to maximize reimbursement capture.
-
Regulatory playbook outlining common 510(k) pitfalls and timelines for material and design changes.
-
Supplier and raw‑material risk matrix and mitigation playbook for procurement teams.
-
M&A and partnership screening criteria and a short‑list of mid‑market targets matched to acquirers by strategic fit.
How to apply these findings in 2026 — tactical recommendations
-
For manufacturers: Prioritize portfolio upgrades that reduce clinician time and improve patient experience (breathability, weight, cure time). Allocate regulatory budget early when integrating new resins or 3D processes.
-
For distributors: Invest in value‑added services (training, application support, digital ordering) to defend margins as product commoditization continues in mainstream lines.
-
For hospitals and health systems: Reassess procurement specifications to balance unit cost against clinician time and downstream outcomes; leverage reimbursement mapping to avoid under‑coding.
-
For investors and PE: Identify targets with differentiated IP in materials or scalable customization workflows; prioritize targets with clear reimbursement and regulatory pathways.
Methodology and data integrity
PW Consulting’s forecast combines historical market data (2020–2025), primary interviews with clinicians, procurement leaders and manufacturers, and a proprietary demand model that projects out to 2032. Financials are expressed in USD (Millions) with 2025 used as the base year for forward valuation. Competitive concentration metrics and scenario variance are calculated using audited company disclosures and verified secondary sources. Where applicable, sensitivity runs illustrate upside adoption of advanced materials and downside scenarios driven by reimbursement pressure.
Next steps — secure the full intelligence
This preview is intended to orient 2026 strategy planning and to highlight where granular intelligence is most valuable. The full report contains the segment tables, regional breakdowns, unit pricing benchmarks, and downloadable templates that enable immediate operational action. PW Consulting invites commercial leaders, product heads, and investors to access the complete dataset and bespoke advisory services to translate these insights into a 90‑day action plan.
To obtain the full Casting and Splinting Market report and discuss tailored strategic engagements, please visit the PW Consulting research center or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Casting And Splinting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Bone Graft Market to Hit USD 2,147.56 Million by 2032, Growing at a 6.72% CAGR
By PW Consulting, 2026-07-02
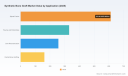
Synthetic Bone Graft Market — 2026 Strategic Brief: PW Consulting Executive Insights
As healthcare providers, device manufacturers, and investors plan their 2026 agendas, the synthetic bone graft market presents a mix of steady growth, technology-driven disruption, and regulatory inflection points that will separate winners from laggards. PW Consulting’s new market study (base year 2025; forecast 2026–2032) shows the industry advancing from approximately USD 988.45 million in 2020 to USD 1,362.16 million in 2025, with our base-case projection growth to roughly USD 2,147.56 million by 2032 — an implied compound annual growth rate (CAGR) of 6.72% across the 2026–2032 forecast window. This brief highlights the strategic implications of those dynamics for corporate decision‑makers in 2026 and explains what practical intelligence our full report delivers (note: fine-grained regional and subsegment tables are reserved for the full report to preserve the report’s role as the primary source of granular market detail).
Synthetic Bone Graft Market
Why 2026 Is a Pivotal Year for Strategic Positioning
-
Regulatory momentum is reshaping product trajectories. The device class and clearance pathway (most synthetic bone grafts reach market via FDA 510(k) as Class II devices) remains familiar, but recent expanded clearances and novel material approvals are creating new commercial use-cases and competitive pressure.
Synthetic Bone Graft Market -
Clinical evidence and reimbursement signals are converging. While many bone substitutes are currently treated as inherent to the primary surgical procedure, a small but growing set of regulatory and coding developments are enabling distinct pathways to recognition — and, therefore, value capture — for differentiated products.
Synthetic Bone Graft Market -
Material innovation is accelerating adoption vectors. Advances in hydroxycarbonapatite (HCA) chemistries, bioactive glass formulations, magnesium-based void fillers and flowable, stand-alone graft technologies are forcing incumbents and challengers to re-evaluate R&D, manufacturing and market-entry strategies.
Core Macro Findings (Executive Summary)
-
Market size and trajectory: The market has demonstrated consistent expansion through 2020–2025 and, under our base-case assumptions, is expected to grow at ~6.72% CAGR during 2026–2032, doubling market value in roughly a decade. This trajectory supports both organic growth strategies and continued M&A activity.
-
Moderate market concentration: Top-three vendors account for just under half of market revenue (CR3 ≈ 48.6%), and the top-five control approximately 62.4% — a structure that favors scale but leaves meaningful room for specialist players with differentiated technology or clinical positioning.
-
Technology and clinical differentiation matter most: Manufacturers that can combine meaningful clinical evidence, clear regulatory positioning, and defensible manufacturing scale will be able to extract premium pricing or secure preferred placement in hospital formularies.
Competitive Dynamics: What the Leading Players Are Doing
-
Incumbent orthopedics majors (e.g., market leaders with integrated orthopedics portfolios) continue to leverage broad commercial channels and bundling strategies. Their scale allows heavy investment in surgeon education, logistics and clinical studies.
-
Specialist companies are accelerating clinical differentiation. Recent examples include next‑generation HCA-based launches, expanded device clearances that broaden indications beyond spine into tumor/trauma/osteomyelitis use-cases, and novel material approvals (notable launches and clearances in 2025 and 2026). These moves indicate a two‑track market: standardized commodity substitutes versus premium, evidence-backed differentiated products.
-
M&A and partnership flows will intensify. Given the moderate concentration and fragmented mid-market, strategic acquirers will target bolt-on technologies (e.g., bioactive glass, magnesium-based fillers, flowable / stand-alone grafts) to broaden clinical portfolios quickly.
Selected Vendor Posture and Implications
-
Large, diversified orthopedics firms: Continue to compete on reach and integrated solutions; their play is to defend surgical channels and embed substitutes into broader biologics portfolios.
-
Focused innovators: Recent regulatory and commercial wins from novel-material specialists demonstrate the commercial viability of seeing differentiated biology and delivery as a scalable route-to-market.
-
Smaller technology developers: Regulatory clearances for new chemistries and delivery formats create acquisition interest, but successful scaling requires early commitments to manufacturing quality, health economic evidence and surgeon adoption programs.
Practical, Actionable Content in the Full Report
PW Consulting’s full market study is built for decision-makers and is intentionally operational. The report includes:
-
A fully transparent market model (historical 2020–2025 + detailed forecast 2026–2032) with scenario toggles to test adoption rates, pricing sensitivity, reimbursement shifts and regulatory outcomes.
-
Commercial playbooks for new product launches, including sample surgeon engagement frameworks, hospital procurement approaches, and distributor/channel strategies by product archetype.
-
Regulatory and reimbursement trackers that map likely 510(k) comparators, evidence thresholds for expanded indications, and pathways to improved coding or coverage visibility.
-
Competitor profiles and benchmarking (product portfolios, go-to-market footprint, pipeline assets and recent corporate events), together with a M&A target shortlist and valuation range methodologies.
-
Clinical evidence roadmaps and RWE study templates to support HTA, payer conversations and hospital adoption cases.
Strategic Playbook for 2026 — Recommended Actions
-
Prioritize differentiated materials: Allocate R&D resources to chemistries with meaningful clinical differentiation (e.g., bioactive glass, magnesium formulations, engineered HCA) or to delivery formats that expand indications (flowable, injectables, stand-alone grafts). Differentiation reduces direct price competition with commoditized ceramics.
-
Build regulatory roadmaps early: For new materials and expanded indications, engage regulators early to clarify substantial equivalence strategies, pre‑submission feedback and potential data requirements. Recent 510(k) precedents suggest that expanded claims can materially widen addressable markets when supported by targeted clinical evidence.
-
Design reimbursement and value dossiers in parallel with trials: Because many suppliers still face “inherent-to-procedure” reimbursement norms, sponsors should invest in health economic models and real-world evidence demonstrating incremental value (reduced reoperation, faster fusion, lower complication rates) that can underpin contracting conversations.
-
Refine commercial segmentation: Focus sales resources on high-opportunity surgical specialties and centers of excellence where product differentiation translates to formulary preference. Pursue strategic OEM/distributor partnerships where internal reach is limited.
-
Prepare for M&A play: Companies with unique materials or evidence packages should prepare sell-side materials now; acquirers should actively screen mid-market innovators addressing spine and complex void-filling indications.
-
Invest in manufacturing resilience: New material classes often require different production and quality infrastructure. Early capex planning reduces time-to-market risk and protects gross margins as adoption rises.
Signals to Monitor — 12 to 24 Month Watchlist
-
Regulatory clearances that broaden labeled indications from spine-only to tumor/trauma/osteomyelitis applications.
-
New CPT or reimbursement guidance that shifts payment from “inherent” to reportable, or the assignment of RVUs to category III codes.
-
Large-scale RWE or randomized studies showing durable clinical benefits (fusion rates, reoperation avoidance) that justify differential pricing.
-
Material supply chain pressure or production innovations that change cost curves for ceramics, polymers or metallic fillers.
-
M&A activity clustering around differentiated chemistries or flowable/stand‑alone graft technologies.
Concluding Perspective and Call to Action
For executives mapping 2026 priorities, the message is clear: the synthetic bone graft market is large, growing and selectively open to premiumization through material and clinical differentiation. The measured CAGR and the market’s concentration profile indicate that both scale and specialty plays can be profitable — but each requires a distinct set of commitments in evidence generation, regulatory strategy and channel execution.
PW Consulting’s full Synthetic Bone Graft Market report contains the granular segmentations, regional splits, price decks and downloadable financial model you need to translate these insights into executable plans. To access the detailed tables and the operational toolkits referenced here — including the forecast model and competitor scorecards — please visit our report landing page or contact your PW Consulting account executive.
For detailed analysis of this topic, please visit the official page: Synthetic Bone Graft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cost Estimating Software Market Poised to Reach USD 3,328.8 Million by 2032, Driven by an 8.5% CAGR
By PW Consulting, 2026-07-02
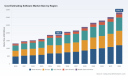
Cost Estimating Software Market 2026: Strategic Imperatives from PW Consulting’s Market Brief
Executive summary
As enterprises prepare budgets and strategic roadmaps for 2026, the Cost Estimating Software market is transitioning from a productivity play into a decisioning backbone for capital-intensive sectors. PW Consulting’s latest market brief — built on a 2020–2025 historical database and a 2026–2032 forecast — finds that the market expands at a steady compound annual growth rate of 8.5%. Our modelling shows total market value rising from a mid-single billion USD base in 2025 to a materially larger market by the end of the 2032 forecast horizon, reflecting sustained adoption of cloud delivery, AI-assisted takeoff, and integrated BIM/5D workflows.
Cost Estimating Software Market
Why this report matters to 2026 corporate decision-makers
-
Timing capital investment: Capital owners and contractors face competing demands for digital transformation spend. This brief quantifies where cost-estimating solutions create immediate ROI through error reduction, faster bid cycles, and enhanced risk signalling — enabling CFOs and procurement to prioritize investments that pay back within planning cycles.
Cost Estimating Software Market -
Vendor selection and negotiation: With a moderately concentrated vendor landscape (CR3 ~38.5%; CR5 ~52.1%), procurement teams can use our competitive scorecards and TCO modelling to structure contracts that balance functionality, data portability, and long-term support.
Cost Estimating Software Market -
Technology roadmap alignment: Product and IT leaders will find guidance on sequencing AI, cloud, and BIM integrations so that incremental upgrades compound in value rather than create costly point-solutions.
-
M&A and partnership signals: For corporate strategy teams, the brief highlights subsegments and capability gaps that create attractive bolt-on acquisition targets or partnership opportunities without disclosing the detailed segment-level financials from our premium dataset.
Market trajectory and what the headline numbers reveal
PW Consulting’s base-year calibration (2025) and trend analysis indicate a market that has accelerated beyond the post-pandemic recovery into a structural growth phase driven by SaaS adoption and AI-enabled workflows. Our forecast to 2032 incorporates four scenario layers — conservative, baseline, accelerated adoption, and market shock — with the baseline reflecting the 8.5% CAGR over the forecast period. The implication: organizations that delay a measured transition to cloud and AI-assisted estimating risk being outpaced on bid accuracy and cycle time improvements by peers who standardize on modern platforms.
Key dynamics shaping vendor and buyer strategies
-
Cloud economics and subscription alignment: Shifts toward subscription models have converted large, upfront license expenses into recurring operational costs. For vendors, cloud hosting is now a dominant line-item; for buyers, it enables predictable OPEX but demands rigorous cost-of-service evaluation and data governance clauses.
-
Labor and skills scarcity: The industry continues to rely on specialized estimator talent for validation and rule-set maintenance. Our interviews and scenario analysis show that AI-assisted quantity takeoffs and predictive analytics materially reduce estimator workload for repeatable tasks but increase demand for higher-value review capabilities and database stewardship.
-
Regulatory and security posture: Increasingly stringent privacy laws and state-level regulations in the U.S., alongside GDPR and cross-border data controls, force both vendors and enterprise clients to bake compliance and encryption into procurement requirements — not as checkbox items, but as central to bid confidentiality and IP protection.
-
Integration with digital delivery stacks: The greatest productivity gains come when estimating tools are embedded into BIM/5D and project execution platforms. Vendors that offer tight integrations — or open APIs that enable supplier ecosystems — capture outsized wallet share from large general contractors and owners.
Competitive landscape — strategic profiles and implications
The market shows a mix of large, integrated platform providers, specialist preconstruction tools, and regional players targeting vertical niches. Below we synthesize strategic positioning for select vendors to inform vendor shortlists, alliance planning, and threat assessment.
-
Procore Technologies (United States) — A cloud-first construction management platform with embedded estimating, takeoff, and budget capabilities. Procore’s strength is its project lifecycle anchor; organizations seeking a single-platform approach should evaluate the trade-offs between breadth and depth of estimating functionality.
-
Autodesk, Inc. (United States) — With ProEst integrated into Autodesk Construction Cloud, Autodesk leverages BIM linkage and design-to-estimate workflows. Strategic buyers with heavy BIM dependence will find Autodesk attractive for its end-to-end design-construction continuity.
-
Trimble Inc. (United States) — Trimble’s play emphasizes integration across construction technology stacks, pairing estimating with field data capture and surveying. Trimble targets customers seeking cross-domain operational consistency.
-
STACK Construction Technologies (United States) — A specialist in cloud-based takeoff and preconstruction. Recent AI enhancements for symbol recognition and rapid counting accelerate modelled benefits for high-volume contractors focused on speed-to-bid.
-
Sage Group plc (United Kingdom) — Sage Estimating’s move to cloud with AI-enabled takeoffs and native PDF handling (announced Feb 2026) marks a strategic shift toward modern deployment models while retaining strength in database-driven, templated estimating for established construction accounting environments.
-
HCSS, Buildertrend, Bluebeam, PlanSwift — These firms excel in specialized workflows: heavy civil bidding, residential contractor management, PDF takeoffs, and rapid quantity calculations. Buyers should map these strengths to procurement categories where specialized capability yields measurable margin improvement.
-
Enterprise and process-industry platforms (Cleopatra Enterprise, Nomitech/CostOS, RIB, Oracle, Bentley, Glodon) — These vendors address large, complex projects — turnarounds, infrastructure, and industrial capital programs — with parametric and BIM-capable estimating plus lifecycle cost management. Their products are often selected where integration with engineering and asset information is a procurement prerequisite.
Recent market moves and tactical takeaways
-
Product roadmaps: Stack and Sage’s recent AI and cloud feature pushes demonstrate a clear migration path: vendors are investing to automate repetitive estimating tasks while preserving human-in-the-loop governance. For buyers, pilot projects that focus on high-volume, repeatable scopes will show the fastest ROI.
-
M&A signal scanning: The concentration metrics and visible product gaps suggest continued strategic acquisitions — particularly by platform players seeking to bolt-on superior takeoff or parametric capabilities. Corporate development teams should monitor tuck-in targets that ease integration with BIM or expand regional coverage.
-
Procurement negotiation: Given recurring cloud costs are now material, negotiation should center on data egress, model ownership, SLAs for indexing and database updates, and uplift clauses for AI features — not only sticker price.
What PW Consulting’s full report delivers (practical contents)
-
Comprehensive market sizing and baseline forecasts (base year 2025; historical 2020–2025; forecast 2026–2032), with scenario modelling that isolates adoption, pricing, and macro impact paths.
-
Vendor scorecards assessing functionality, integration depth, cloud architecture, security posture, support models, and pricing structure — mapped to buyer archetypes (owner, GC, subcontractor, EPC, industrial).
-
A practical 90-day implementation playbook for pilots that aligns success metrics, data migration checklists, estimator enablement plans, and change-management tactics.
-
M&A and investment watchlist that identifies capability gaps across AI takeoff, 5D BIM, and parametric estimating — with suggested valuation levers based on recurring revenue multiples and integration risk.
-
Case studies illustrating realized savings and bid-win improvements from implementations in construction, manufacturing, and energy sectors (anonymized to protect client confidentiality).
-
Interactive tools and worksheets (ROI calculator, TCO comparator, vendor shortlisting matrix) to accelerate board-level decision-making.
Risks, headwinds, and triggers to watch in 2026
-
Regulatory tightening and cross-border data controls may elevate compliance costs for cloud-hosted platforms; buyers should require proof points for regional data residency and third-party audits.
-
Estimator skill scarcity is unlikely to abate in the short term; investments in internal upskilling and change management are required to realize AI benefits without introducing new operational risks.
-
Macro volatility in material and labor markets can expose weakness in static cost databases; organizations should prioritize vendors with dynamic pricing feeds and predictive analytics to preserve estimate accuracy under stress.
Call to action
For executives planning 2026 capital allocation, procurement, or M&A moves, PW Consulting’s market brief provides both the macro lens and the operational playbook to act with conviction. We intentionally omit detailed segment-level financials from this summary to preserve the investigative value of the full report: our premium dataset contains granular regional, application, and deployment splits, vendor-by-vendor market shares, and drill-down profitability matrices. If your 2026 decisions require executable guidance — from a pilot scope to acquisition targets — access the full report and accompanying toolset for end-to-end decision support.
Contact PW Consulting to schedule a briefing and receive the full market dataset, vendor scorecards, and the 90-day implementation playbook tailored to your organization’s operating model.
For detailed analysis of this topic, please visit the official page: Cost Estimating Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: M‑Cresol Market Set to Grow at 3.9% CAGR, Hitting USD 707.23 Million by 2032
By PW Consulting, 2026-07-02
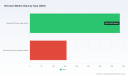
PW Consulting: Strategic Brief — Global M‑Cresol Market Outlook (2026–2032)
PW Consulting today releases an executive briefing that encapsulates the strategic value of our forthcoming M‑Cresol Market report for corporate decision‑making in 2026. The global M‑cresol market reached roughly USD 541.1 Million in our 2025 base year and, under the scenarios modelled in this study, is projected to grow at a compound annual growth rate (CAGR) of approximately 3.9% across the 2026–2032 forecast window, approaching the low‑to‑mid USD 700 Millions range by the end of the period. This briefing outlines the actionable intelligence and risk frameworks built into the full report — intentionally high‑level here, with granular tables and firm‑level metrics reserved for the complete publication.
M Cresol Market
Why this report matters for 2026 decision cycles
-
Procurement precision: Our price‑and‑cost models translate feedstock volatility into contract negotiation levers and inventory strategy recommendations, enabling procurement teams to lock in margins with index‑linked and outcome‑based clauses.
M Cresol Market -
Operational resilience: Producers can prioritise capex to address regulatory compliance and feedstock substitution, supported by plant‑level cost curve diagnostics that identify the assets most at risk from margin compression.
M Cresol Market -
M&A and portfolio allocation: Investors receive a decision framework that flags consolidation opportunities and stress points in the value chain based on concentration metrics, margin pools and geography‑driven tariff exposure.
-
Policy and sustainability planning: The report maps environmental and safety regulation implications across operating models, providing a timeline for necessary investments in pollution control and waste management to avoid regulatory shock in 2026 and beyond.
What is included in the PW Consulting M‑Cresol Market report
-
Market sizing and forecast (2020–2032) with top‑line scenarios and sensitivity analyses that isolate the impacts of feedstock prices, energy inflation and trade policy shifts.
-
Price formation and production cost modelling: dynamic models that tie toluene/benzene/naphtha indices to per‑tonne production economics and downstream price pass‑through.
-
Proprietary competitive benchmarking: ranked scorecards across capacity, product quality (including high‑purity synthetic grades), technology stack, asset age and disclosed commercial strategies.
-
Supply‑chain stress tests and trade‑flow simulations that quantify the commercial consequences of tariff changes, feedstock shortages, and regional energy price divergence.
-
Commercial playbooks for buyers and sellers, including sample contract language, hedging strategies, inventory optimisation algorithms and go‑to‑market templates for specialty grades.
-
M&A, greenfield and brownfield investment decision matrices: NPV and IRR outputs under multiple policy and price scenarios, and an acquisition screening model that flags attractive targets by margin profile and geographic arbitrage potential.
-
Regulatory and ESG readiness checklists, including estimated capital requirements to meet evolving phenolic compound controls and worker safety expectations.
Market dynamics shaping 2026 strategy
Two structural forces dominate the current landscape: feedstock dependency and regulatory pressure. M‑Cresol production is intrinsically linked to petroleum‑derived feedstocks (notably toluene and benzene), and movements in these raw material markets materially shift production economics. The latter half of 2025 showed divergent signals — a moderation in feedstock‑driven costs in some regions attributable to naphtha declines, while toluene prices ticked up in others, tightening margins for producers exposed to that index. Our models convert these movements into clear profitability thresholds for different production routes.
Trade policy is an equally consequential variable. Phenolic compounds under HTS code 3814 have been exposed to trade measures that add a material tariff burden on certain imports; this, combined with region‑specific levies introduced in early 2025, reshapes competitive dynamics by increasing landed costs for affected supply. The net effect is a re‑rating of regional arbitrage: some local assets gain competitiveness, while cost‑sensitive import routes become less viable without structural price concessions.
Regulatory trends on environmental controls and worker safety are converging across major markets. Phenolic compounds are receiving increased regulatory scrutiny, raising the bar for compliance spend. Our scenario work identifies the production footprints most sensitive to these regulatory shifts, and estimates the capital intensity of remediation investments required to preserve operations under tightening rules.
Competitive landscape — concentrated but segmented
The M‑Cresol supply base is materially concentrated, with the largest three suppliers controlling a majority share and the top five nearing solid concentration. This structure produces two commercial realities: first, meaningful pricing power exists at the top end for premium, high‑purity synthetic grades; second, supply risks can be acute for specialised downstream consumers reliant on a narrow set of suppliers.
Key industry participants analysed in the report include LANXESS AG (Cologne), Sasol Limited (Johannesburg), Mitsui Chemicals (Tokyo), Atul Ltd (Valsad), a number of Chinese producers with substantial regional capacity, and dedicated specialty players in Japan and India. Each exhibits different strategic postures: some prioritise high‑purity synthetic routes suited to pharmaceutical and electronics applications; others leverage byproduct or coal‑tar streams to serve industrial grade markets. Coal‑gasification byproducts, for example, create a distinctive cost profile and route to market that incumbent commodity players can exploit.
We include an appraisal of recent industry developments — such as the December 2025 decline in production costs in some regions tied to feedstock softening — and assess how these episodic events alter competitive positioning over a 12–18 month horizon. The report’s firm‑level profiles synthesize disclosed strategy with inferred positioning from observed trade flows and capacity trends.
Strategic imperatives and recommended actions for 2026
-
For producers: prioritise product differentiation through investment in purification and control technologies to capture margins in high‑purity segments; adopt flexible feedstock pathways and hedge strategies to blunt short‑term index volatility.
-
For buyers (agrochemical, pharmaceutical, resin manufacturers): diversify supplier portfolios across production routes and geographies; negotiate volume‑weighted price collars and conditional supply commitments linked to feedstock indices to share risk with suppliers.
-
For investors and M&A teams: screen assets using the report’s concentration and margin maps — target bolt‑on plays that add purity capability or geographic access to markets shielded from high tariff exposure.
-
For policymakers and corporate sustainability leaders: phase‑in compliance expenditures and pilot waste‑minimisation technologies now to avoid operational interruptions, and consider incentives that lower the upfront cost of environmental upgrades.
What we do not disclose here (and why you need the full report)
This briefing intentionally omits the granular segmentation tables, regional allocations by application, company volume shares and plant‑level cost tables that drive transaction‑grade decisions. Those datasets underpin the pricing and M&A models and are included exclusively in the full PW Consulting report and accompanying data workbook. If you are evaluating a sourcing strategy, capex decision, or acquisition in 2026, relying on headline growth rates without access to the underlying segmentation and trade‑flow matrices will materially understate execution risk.
How PW Consulting supports executive teams
Our advisory work pairs the quantitative outputs from this market study with hands‑on implementation support: bespoke procurement playbooks, due‑diligence templates for asset purchase, negotiation warrooms for contract renewals, and regulatory compliance roadmaps. Engagements typically begin with a 2–4 week diagnostic that calibrates the syndicated models to your firm’s procurement mix, asset locations and risk appetite.
Next steps
For access to the full M‑Cresol Market report, plant‑level datasets, executable commercial playbooks and a private briefing with the PW Consulting chemicals team, visit the PW Consulting website or contact our research desk. The full report contains the proprietary scenarios, firm benchmarking and transaction models essential for shaping defensible strategies in 2026 and beyond.
PW Consulting — converting market complexity into strategic advantage.
For detailed analysis of this topic, please visit the official page: M Cresol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Tool Change Spindle Market to Grow at 5.31% CAGR — Hits $787.8M in 2025 and Eyes $1.13B by 2032 as Asia‑Pacific Leads with $362.1M
By PW Consulting, 2026-07-02
Automatic Tool Change Spindle Market 2026: A Strategic Preview for Executive Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Automatic Tool Change Spindle Market
Executive summary
The automatic tool change (ATC) spindle market is moving from niche precision applications toward broad adoption across CNC-based manufacturing. Our latest market model—anchored on a 2025 base year—projects the market expanding from an estimated USD 787.77 Million in 2025 to roughly USD 1,130.82 Million by 2032, representing a compound annual growth rate (CAGR) of 5.31% over the 2026–2032 forecast period. For 2026 planning cycles, this trajectory signals steady, investable growth rather than a short-term bubble; it rewards strategic, capability-focused investments that reduce cycle time, enable lights-out operations, and insulate OEMs and shops from labor volatility.
Automatic Tool Change Spindle Market
Why this matters in 2026
-
Capital allocation: Organizations must prioritize investments that yield near-term efficiency (reduced downtime, fewer manual interventions) and mid-term resilience (supply-chain flexibility, modular upgrades).
Automatic Tool Change Spindle Market -
Technology selection: Differentiation is shifting from raw spindle speed to system-level integration—how spindles, ATC mechanisms, tool management software, and machine controls operate as a cohesive cell.
-
M&A and partnership timing: The market’s steady CAGR creates selective opportunities to acquire strategic suppliers or to form alliances that accelerate time-to-market for modular electrospindles, retrofit ATC systems, and software-enabled tool-life optimization.
Market trajectory and what the numbers reveal
The market path captured by our model shows a clear and continuous recovery and scaling pattern from the early-2020s baseline through the 2026 planning horizon and beyond. Management teams should interpret the mid-single-digit CAGR not as lackluster but as an indicator of disciplined adoption: ATC spindles are being embedded where they deliver quantifiable operational ROI—high-mix, high-speed milling, and lights-out cell deployments—rather than being spec’d indiscriminately.
For decision-makers, the takeaway is practical: prioritize categories and configurations that deliver measurable reductions in unit cost and setup time over a 12–36 month horizon, and treat higher-speed or specialty-bearing solutions as targeted plays for verticals with strong margin support (advanced composites, high-precision aerospace components, and micro-machining for electronics).
Key market dynamics shaping 2026 decisions
-
Labor scarcity and automation acceleration — Skilled CNC labor shortages continue to push shops toward automation. ATC adoption is a pragmatic response to retain throughput and improve scheduling flexibility; expect procurement teams to demand integration packages (spindle + ATC + tool management) rather than point-product buys.
-
Raw material pressure and margin compression — Rising input costs for critical components (notably precision bearings) have translated into meaningful production-cost increases for small and mid-tier manufacturers. Pricing discipline and design-for-cost (DfC) initiatives—standardized modular spindle platforms, alternative bearing suppliers, and service-friendly lubrication systems—will be central to protecting margins.
-
Retrofit and aftermarket growth — As OEMs target installed base monetization, retrofit ATC kits and retrofit-friendly spindle designs are creating a second wave of demand. Service models and upgrade paths will be a competitive differentiator.
-
Regulatory and trade considerations — Import/export dynamics and regional supply concentrations for high-precision components require procurement teams to build multi-sourced strategies and to validate alternate suppliers for critical lead-time risk mitigation.
Competitive landscape: who matters and why
The market is characterized by a mix of specialized spindle manufacturers, regional system integrators, and emerging U.S.-based producers targeting localized demand. Market concentration is moderate—enough to reward scale but still allowing nimble players to capture niche value.
-
GMN USA (USA; subsidiary of GMN Germany) — A technology leader in high-speed CNC spindles with ATC integration. Their product guidance updates underscore the importance of serviceability and selection criteria for high-speed applications. For 2026, GMN’s emphasis on maintenance regimes and high-RPM offerings positions them as a partner for high-throughput, high-precision lines.
-
Celera Motion (Novanta) (USA) — Known for precision air-bearing spindles capable of extreme speeds. Their strengths are in ultra-precision and lightweight-material machining; companies targeting composites and non-ferrous micro-machining will likely continue to evaluate these solutions for select toolpaths where surface finish and thermal stability are mission-critical.
-
Teknomotor (Italy) — A key European provider of electrospindles for wood and aluminum processing. Their rapid tool-change electrospindles are attractive to manufacturers seeking fast changeovers in high-mix lines.
-
Jingjiangcity Jianken (China) — A sizable player in pneumatic ATC spindle motors and air-cooled high-speed models. Their cost-positioning and established product lines make them a natural choice for volume-oriented processing where CAPEX sensitivity is high.
-
CNC Depot (USA) — U.S.-based ATC spindle manufacturer emphasizing routing and milling power levels suitable for light industrial to mid-size production, an appealing option for regional shops prioritizing local support.
-
SPINOGY (Germany) — Modular high-frequency motor spindles designed for full automation. Their modularity is well-aligned with trends toward quick-change tooling ecosystems and robotic integration in milling cells.
-
Air Turbine Tools (USA) — Offers retrofit-minded high-speed spindles with ATC compatibility; their patented mounting approaches are relevant for shops seeking finishing and detail-first upgrades without full machine replacement.
-
PwnCNC (USA) and RapidChange ATC (USA) — Both address a broad range from hobbyist to light industrial segments with modular and affordable ATC solutions; they exemplify the market’s lower-cost innovation tier that widens addressable adoption.
Notable recent developments
-
January 2026 — GMN USA published updated product guidance focused on selection and maintenance of ATC spindles, emphasizing lifecycle planning for high-speed models. This marks a broader industry focus on after-sales support and prescriptive maintenance packages.
-
December 2025 — Sienci Labs released detailed material on integrating automatic tool changers with spindles on CNC routers, reflecting growing ecosystem education and the proliferation of retrofit pathways.
Strategic playbook for 2026
Executives evaluating moves in 2026 should prioritize three strategic vectors: integration, modularity, and risk-managed scale.
-
Integration-first procurement: Buy for cell-level performance, not part-level specs. Procurement should require bidders to demonstrate full-path metrics—cycle-time reduction, mean-time-between-failure (MTBF) under targeted loads, and tool-change time under representative tool libraries.
-
Modular product architectures: Invest in spindles and ATC systems with common mechanical interfaces and standardized communication protocols (e.g., for tool-ID and life-cycle telemetry) to enable faster upgrades and lower total cost of ownership.
-
Service and aftermarket monetization: Build service contracts that include predictive maintenance, spare-parts kits, and retrofit upgrade paths. Service revenue will increasingly offset margin pressure from higher input costs.
-
Retrofit-first growth for OEMs: OEMs should develop validated retrofit kits and channel programs to monetize the installed base; this often has faster payback than new-machine sales in constrained capex environments.
-
Risk-balanced sourcing: Map critical components (especially bearings and high-frequency motor modules), and qualify at least two alternate suppliers to reduce single-point supply risk.
-
Targeted M&A and partnerships: Focus acquisitions on complementary capabilities—sensorized tool interfaces, robotics-ready spindle couplers, and software tool-management platforms—rather than broad, horizontal consolidation.
What’s inside the full PW Consulting report (practical, operational deliverables)
Our report is designed as an operational toolkit for 2026 planning cycles. Highlights include:
-
Market model with annualized forecasting through 2032, scenario sensitivity analyses, and a downloadable dataset for internal financial modeling.
-
Supplier scorecards covering technology maturity, support footprint, retrofit compatibility, warranty terms, and service economics.
-
Tool-change and spindle TCO calculators to model CAPEX/OPEX trade-offs for new machines vs retrofit, including service-plan scenarios and spare-parts stocking strategies.
-
Supply-chain risk maps and mitigation playbooks focused on critical bearing suppliers and motor-component concentration risks.
-
Case studies across representative verticals illustrating practical adoption pathways, measured ROI, and lessons learned in production ramp-up.
-
Technology maturity and IP landscape assessments that identify near-term disruptors (modular electrospindles, air-bearing high-speed units) and where to position R&D bets.
-
Actionable go-to-market and after-market service strategies for OEMs and independent retrofitters—complete with channel-development checklists and a prioritized list of capability gaps to close in 12–24 months.
Call to action
The Automatic Tool Change Spindle Market is no longer a narrow engineering curiosity—it's an operational lever for resilience, productivity, and near-term margin protection. For 2026 capital plans, the question is not whether to engage with ATC technology, but how to engage: which vendors to partner with, which retrofit pathways to enable, and how to structure service economics to preserve margins in a tightening input-cost environment.
PW Consulting’s full report provides the granular vendor intelligence, scenario models, and executable playbooks your leadership team needs to move from aspiration to measurable outcomes. To access the complete dataset, supplier appendices, and executable templates referenced in this briefing, visit our report page and download the full study.
For detailed analysis of this topic, please visit the official page: Automatic Tool Change Spindle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Laser Line Dielectric Mirror Market Poised to Reach USD 675.05 Million by 2032
By PW Consulting, 2026-07-02
Laser Line Dielectric Mirror Market 2026: Strategic Implications from PW Consulting’s Forward-Looking Analysis
PW Consulting’s latest market study on Laser Line Dielectric Mirrors offers a practical, decision-focused roadmap for executives, product leaders, and supply-chain managers planning moves in 2026 and beyond. Combining a structured forecasting framework with vendor benchmarking, technology readiness assessments, and supply-chain stress-testing, the report translates market momentum into actionable options—without sacrificing the rigor required for capital allocation, sourcing strategy, and product roadmap prioritization.
Laser Line Dielectric Mirror Market
Macro snapshot: steady growth, concentrated supply, rising strategic risk
Our analysis shows that the global laser line dielectric mirror market reached USD 441.6 Million in 2025 and is expected to expand at a compound annual growth rate (CAGR) of approximately 6.25% through our forecast window. Under PW Consulting’s base-case projection, this trajectory takes the market toward roughly USD 675 Million by the end of the planning horizon. Growth is driven by sustained demand in industrial laser processing, medical instrumentation, scientific research, and defense applications—each governed by distinct performance and procurement imperatives.
Laser Line Dielectric Mirror Market
Market structure matters. Measured concentration metrics indicate a mid-level consolidation: the three largest players account for just over 32% of market value while the five largest capture roughly 48%. That profile creates a market where specialized high-performance vendors coexist with agile regional suppliers—an environment that rewards technical differentiation, supply-chain robustness, and downstream partnerships.
Laser Line Dielectric Mirror Market
Why this matters for 2026 decision cycles
- Capital allocation: A multi-year growth path with a mid-single-digit CAGR validates incremental capacity investments for specialist coatings (e.g., ion-beam sputtering, IBS) and for high-LIDT product lines, but argues against broad-based greenfield capacity unless tied to a clear OEM commitment.
- Product strategy: Demand is bifurcating—commodity mirrors optimized for price and lead-time coexist with premium, application-specific mirrors (ultrafast, high-LIDT, multi-wavelength stacks). R&D and product roadmaps should prioritize either scale or technologic differentiation, not both, unless supported by strategic partnerships.
- Sourcing & procurement: Recent export controls and raw-material constraints increase the cost of downtime. Procurement teams should adopt dual-sourcing, strategic inventory, and supplier qualification playbooks to reduce single-point-of-failure exposures.
Supply-chain headwinds and material realities
Two structural factors are reshaping supplier economics and procurement risk. First, regulatory measures and export controls imposed by major producing countries have tightened access to certain coating materials and specialty substrates, extending lead times and introducing price volatility. Second, core substrates and coating architectures—ranging from fused silica and Zerodur to multi-micron dielectric stacks—remain the technical backbone of performance claims, with standard high-reflectance coatings commonly requiring several microns of deposition for peak performance at common laser lines.
For procurement and operations leaders, this means three pragmatic responses in 2026: (1) execute supplier redundancy and near‑shoring where feasible; (2) qualify alternative materials and process routes preemptively; and (3) incorporate scenario-based buffer stock policies that balance working capital with revenue-at-risk from production interruptions.
Competitive landscape: differentiated capabilities, clear stratification
The competitive set spans long-established opto-mechanics houses, specialist thin-film coaters, and vertically integrated OEMs. Across the vendor universe, capability patterns are clear: a subset of suppliers focus on ultra-high-reflectivity and high laser-induced damage threshold (LIDT) mirrors for high-energy and ultrafast lasers; others emphasize catalog breadth, modularity, or cost-competitive volume offerings.
- Specialist high-performance vendors: Companies that promote ultra-high reflectivity (>99.9% in some cases) and elevated LIDT dominate premium niche segments. These companies are attractive partners for OEMs and for defense and scientific users whose procurement decisions prioritize lifetime and performance over unit price.
- Catalog and systems suppliers: Larger optics firms maintain broad catalogs and tight integration with system-level customers. Their strengths include supply continuity, global service networks, and established qualification processes for OEM acceptance.
- Regional and fast-follow manufacturers: Agile manufacturers, particularly those focused on UV and narrowband variants, are competing on lead time and customization. They can capture aftermarket and mid-tier OEM work, especially where price sensitivity is higher.
Representative market participants include legacy optics houses and specialist coating firms—in each case, success derives from specific technical propositions: high-damage-threshold coatings, IBS and e‑beam deposition expertise, large-area mirror assemblies, and multiwavelength/broadband designs. Recent vendor developments illustrate how players are pressing both product and go-to-market advantages through catalog refreshes, new thin-film series, trade-show product validation, and supplier excellence recognition.
What PW Consulting’s report delivers to practitioners
PW Consulting’s Laser Line Dielectric Mirror report is intentionally operational. Key deliverables include:
- Demand-side segmentation and scenario models that translate application trends into volumetric and revenue risk profiles under multiple demand-shock scenarios;
- Vendor scorecards built from capability, capacity, quality (including LIDT performance) and lead-time metrics—designed for procurement RFIs and strategic sourcing;
- Technology readiness assessments covering coating processes (IBS, ion-assisted deposition, e-beam), substrate choices, and emerging material substitutes with cost-performance trade-offs;
- Supply-chain resilience playbooks—dual-sourcing matrices, buffer-stock algorithms, and localization decision frameworks calibrated to 2026 procurement constraints;
- Commercial playbooks for OEMs and system integrators outlining bundling strategies, warranty & test-spec alignment, and aftermarket monetization opportunities;
- Financial and M&A frameworks for buyers evaluating tuck-ins, capability buys, or capacity-driven acquisitions—complete with sensitivity sweeps tied to material price and lead-time risk.
Each deliverable is accompanied by reproducible templates, step-by-step supplier evaluation checklists, and a library of vendor profiles that allow teams to move from insight to execution quickly.
Strategic recommendations for 2026
- Prioritize modular investments: For manufacturing players, invest selectively in modular coating and metrology upgrades that shorten qualification cycles for new coatings. This reduces time-to-market for high-margin specialty mirrors.
- Lock in strategic supply: Negotiate multi-year offtake or volume agreements with high-quality substrate suppliers and leading coaters; structure contracts with material-indexed pricing and lead-time SLAs to hedge against export-control volatility.
- Segment go-to-market: Define separate product streams for premium, specification-driven customers and for catalog/volume segments. Align sales incentives and R&D roadmaps accordingly.
- Build resilience into procurement: Implement a phased dual-source plan for critical coating materials and consider localized inventory hubs in target end-markets to shorten response times for OEM customers.
- Explore targeted M&A: Buyers seeking technical depth should prioritize bolt-on acquisitions that add IBS capabilities, high-LIDT test labs, or domain expertise in ultrafast optics rather than broad capacity plays.
Regulatory watch and material innovation
Regulatory developments affecting exports of certain materials and production equipment are a live issue. Firms should adopt an early-warning approach to policy changes and embed regulatory scenario analysis into procurement cadence. In parallel, material substitution and process innovation (e.g., lower-dependence coating stacks or alternative rare-earth-free architectures) represent a medium-term de‑risking pathway that should be part of R&D roadmaps for 2026–2028.
Call to action: what to ask next
For executives shaping 2026 plans, the immediate questions are operational rather than theoretical: Which suppliers will you qualify this year? How much strategic inventory is defensible? Where will you place next incremental investment—capability, geography, or partner alliance?
PW Consulting’s report equips leaders to answer these questions with concrete numbers, vendor evaluations, and scenario-tested sourcing playbooks. To preserve the competitive value of granular segment-level forecasts and the vendor scorecards that power procurement decisions, PW Consulting provides full datasets, customized sourcing simulations, and client-side workshops through the complete report package.
Closing perspective
The laser line dielectric mirror market is mature in its core physics but dynamic in its commercial and supply-chain dimensions. 2026 will be a year where winners are defined less by basic optics know-how and more by agility—how fast they can qualify alternative materials, contract for critical supplies, and align product portfolios to differentiated end-user needs. PW Consulting’s analysis is designed to move teams from strategic intent to executable programs within months, not quarters.
For access to the full report, including segment-level forecasts, vendor scorecards, and the reproducible templates mentioned above, request the PW Consulting Laser Line Dielectric Mirror 2026 report and schedule a briefing with our senior analysts. The detailed datasets and supplier benchmarking are intentionally gated to ensure competitive confidentiality and to provide clients with tailored decision-support for their 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Laser Line Dielectric Mirror Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Servo Electric Press Brake Market Poised to Rise from USD 810.5 Million in 2025 to USD 1,436.54 Million by 2032 on 8.52% CAGR
By PW Consulting, 2026-07-02
Servo Electric Press Brake Market — Strategic Briefing for 2026 Decision-Makers
Executive Summary
PW Consulting’s latest market study on the Servo Electric Press Brake market (base year 2025, forecast 2026–2032) distils the competitive, operational, and regulatory dynamics that will determine winners and losers as manufacturers accelerate Industry 4.0 transitions. The global market has expanded materially over the past half-decade and, with a compound annual growth rate of 8.52% in our base-to-forecast window, is positioned to nearly double in value by the end of the forecast period. For executives planning capital allocation, supplier strategy, and automation roadmaps in 2026, the report translates these macro trends into concrete playbooks, risk templates, and implementation milestones — all designed to reduce execution risk and shorten time-to-value.
Servo Electric Press Brake Market
Why This Report Matters for 2026 Strategy
-
Timing capital deployment: With a market that has grown markedly from the early-2020s through 2025 and is projected to continue at an ~8.5% CAGR, procurement windows and release cycles for new servo-electric models will influence price, lead times, and upgrade options available to buyers in 2026.
Servo Electric Press Brake Market -
Balancing CapEx and OpEx: The shift from hydraulic to servo-electric architectures alters lifetime cost profiles — lower energy consumption, reduced maintenance related to hydraulic fluids, and potential shifts in labor requirements. Our financial models quantify payback ranges across typical shop-floor scenarios to guide investment approval.
Servo Electric Press Brake Market -
Competitive differentiation: Vendors are building value through automation, connectivity, and advanced measurement systems. Understanding vendor roadmaps and capabilities is essential for selecting partners who can support both immediate productivity gains and longer-term smart factory initiatives.
Market Trajectory — Macro View (what we disclose)
Our topline analysis shows the global Servo Electric Press Brake market achieved significant scale by 2025, with the market value crossing the high hundreds of millions of USD mark in the base year. Forecasting to 2032, the market is expected to approach mid-to-high billion-dollar territory under our central scenario given the prevailing growth drivers and adoption curves. These topline metrics are accompanied in the full report by sensitivity scenarios that stress-test outcomes under slower/wider macro cycles, supply-chain disruption, and faster-than-expected regulatory shifts.
Key Market Dynamics
-
Energy efficiency as a purchase trigger — Servo-electric architectures consume power only during actuation, yielding up to half the energy draw versus hydraulic systems in many operating patterns. This characteristic is rapidly shifting procurement criteria from feature lists to lifecycle energy and sustainability metrics.
-
Regulatory and sustainability pressure — Strengthening emissions and hazardous-waste directives in major markets (notably regulatory regimes that discourage hydraulic fluid use) are accelerating replacements and new purchases of electric systems, especially in regulated manufacturing clusters.
-
Industry 4.0 connectivity — Open standards (e.g., OPC-UA) and advanced CNC integration are moving from ‘nice-to-have’ to ‘must-have’ for OEMs aiming for deterministic production lines. Buyers are increasingly demanding units that integrate seamlessly with MES/ERP, vision systems, and robotic endpoints.
-
Automation and labour dynamics — Labour shortages and the push for higher throughput are driving adoption of bending cells and collaborative robotic integrations. Servo-electric platforms enable tighter process control and reduced operator intervention, supporting mixed-production and quick-changeover environments.
What the Report Contains — Practical, Actionable Assets
This is not a theoretical market narrative. PW Consulting delivers a set of tools intended for immediate use by procurement leads, plant managers, and corporate strategy teams:
-
Executive decision matrix — a one-page scoring model that ranks suppliers across technical, commercial, and risk dimensions tailored to common buyer archetypes (high-throughput OEM, job-shop, regulated environment, low-TCO seeker).
-
CapEx/OpEx pro formas — configurable models that calculate payback, NPV, and TCO under different duty-cycle assumptions and electricity price sensitivities.
-
Procurement playbooks — negotiation scripts, clause libraries for service-level agreements (SLAs), and spare-parts stocking recommendations tied to vendor reliability profiles.
-
Implementation checklists — step-by-step guides for retrofits, integration with robotic cells, and commissioning protocols that reduce downtime risk during deployment.
Competitive Landscape — What Buyers Need to Know
Market concentration is moderate: the top three players account for a significant but non-dominant share of market revenue, and the top five collectively command slightly more than half of the market. This structure creates a competitive supplier field where incumbents compete on performance and new/regionally focused suppliers compete on price and responsiveness.
-
Amada (Isehara, Japan) — Strong in precision and full-automation integration, Amada’s EGB and HG series appeal to buyers seeking established control ecosystems and deep application engineering support. Amada remains a go-to for high-reliability, high-precision deployments where engineering services and local support networks are decisive.
-
TRUMPF (Ditzingen, Germany) — TRUMPF emphasizes energy efficiency and smart-factory connectivity. Their TruBend line is often selected by buyers prioritising measurement systems and long-term digitalization strategies. Expect premium pricing balanced by lower integration friction in mature Industry 4.0 environments.
-
Bystronic (Niederönz, Switzerland) — Bystronic is positioned on speed and combined-cut/bend productivity, attractive for high-mix environments that pair laser cutting and bending in automated lines.
-
SafanDarley (Lochem, Netherlands) — With a very broad tonnage range and a clear emphasis on energy-efficient operation, SafanDarley appeals to organisations seeking a single-vendor strategy across multiple capacity classes.
-
LVD (Gullegem, Belgium) — LVD’s adaptive laser-bending technology and wide product range make it a candidate for precision-focused shops and those standardising across product families.
-
Salvagnini & Prima Power (Sarego & Collegno, Italy) — Both firms are strong in flexible automation for mixed or high-volume production and showcase integrated bending cells that reduce touch points and increase throughput.
-
Accurpress (USA), Durma (Turkey), JialiPress (China) — These suppliers offer differentiated value propositions from heavy-duty reliability in North American environments to cost-competitive, compact systems for SMEs and fast-scaling intelligent fabrication platforms.
Recent vendor activity underscores the continued emphasis on automation and range extension: Prima Power’s robotic-bending showcases, SafanDarley’s catalog expansion of its E-Brake family, and product showcases from regional players highlighting energy-efficient, clean-operation units. PW Consulting’s vendor heatmaps and product-feature matrices in the full report synthesize these moves and identify which firms are likely to be partnerable for OEM programs, which will remain suppliers-of-choice for retrofit projects, and which are most exposed to margin pressure.
Segmentation and the Data You Won’t Find Here
The report includes a granular segmentation by geography, tonnage class, and end-application with scenario-based forecasts and install-base evolution through 2032. In this briefing we deliberately omit the disaggregated figures and percentage shares to preserve the investigatory value of the full dataset and to encourage direct engagement for buyer-specific benchmarking. If your team requires the regional, tonnage, or application splits for supplier shortlisting or to build order-quantity models, the full report provides validated tables and downloadable datasets.
Recommendations for 2026 Tactical Plans
-
Run a two-track procurement approach: pilot robotic-bending cells on select lines while negotiating long-lead strategic units with preferred vendors to lock lead times and price protections.
-
Prioritise suppliers that demonstrate open-protocol connectivity and modular automation ecosystems to avoid early obsolescence as control standards converge.
-
Embed energy and sustainability KPIs into supplier scorecards — the energy delta between electric and hydraulic architectures is a predictable lever to improve factory-level carbon intensity.
-
Hedge supply risk with mixed-sourcing: combine a global incumbent for critical lines with regional OEMs for lower-tier, fast-replacement cells to optimise total cost and responsiveness.
-
Use our CapEx/OpEx templates to evaluate retrofit vs greenfield decisions — in many cases modest upfront premium for servo-electric units yields improved throughput and lower operating costs in under three years.
Final Word — How to Use This Report
For leaders preparing 2026 budgets and 3–5 year automation strategies, this PW Consulting study acts as both a strategic compass and a practical toolbox. It combines market-scale forecasting, vendor benchmarking, risk assessment, and executable procurement/implementation materials to accelerate decisions and reduce costly rework. The topline growth trajectory and mid-market concentration trends are clear: the window to re-architect bending operations for energy, labour, and connectivity gains is now. For full segmentation tables, scenario datasets, vendor scorecards, and the downloadable implementation templates referenced above, access the complete report via our publication page.
For detailed analysis of this topic, please visit the official page: Servo Electric Press Brake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cross Laser Light Market Poised for 6.0% CAGR — From USD 515.49M in 2025 to USD 775.11M by 2032
By PW Consulting, 2026-07-02
Cross Laser Light Market: Strategic Briefing for 2026 — PW Consulting
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a tactical preview of our Cross Laser Light Market study (base year 2025, forecast 2026–2032). This briefing highlights the report’s strategic value for executive decision-making in 2026 — showing the kind of insight and recommendations the full analysis delivers while intentionally reserving detailed segment-level tables and proprietary forecasts for the full report.
Cross Laser Light Market
Market snapshot: what matters to C-suite and product leaders
The cross laser light market reached USD 515.49 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.0% over the 2026–2032 forecast window, reaching an estimated USD 775.11 Million by 2032. These headline numbers reflect healthy, steady demand driven by continued investment in construction layout tools, industrial alignment solutions, and growing use in specialized laboratory and medical positioning contexts. For 2026 planning, the takeaway is clear: the market presents incremental growth opportunities that reward targeted product differentiation, supply-chain resilience, and regulatory-compliant design.
Cross Laser Light Market
Why 2026 is a strategic inflection point
-
Technology consolidation. Manufacturers are converging around higher-visibility green-beam systems, integrated drivers for diode modules, and combination units that blend point, line, and cross projections. Product launches in late 2025 and early 2026 signal a move toward higher-brightness modules and 360° coverage for professional use-cases.
Cross Laser Light Market -
Regulatory clarity is tightening. Global safety frameworks such as IEC 60825-1 and updated FDA guidance relevant to surveying, leveling and alignment lasers are raising the bar for compliance. Companies that invest early in certification and documentation avoid costly rework while accelerating channel acceptance.
-
Sector-specific adoption. Construction, interior fit-out, and industrial automation remain the primary end-markets. However, precision positioning in medical and laboratory environments is a growing high-margin niche that rewards higher-spec, certified devices and close OEM partnerships.
Key market dynamics executives must internalize
-
Regulation and standards shape product roadmaps. IEC 60825-1 conformity, CE/TUV safety approvals, and U.S. FDA considerations should be embedded into product development timelines. For hazardous-environment applications, approvals such as MSHA are core to market access in mining and select industrial segments.
-
Product differentiation is increasingly technical. Buyers value high-visibility green beams, robust self-leveling mechanisms, waterproof/shock-resistant housings, integrated electronics for lifetime monitoring, and modular optics that support both cross-lines and point projections.
-
Supply-chain concentration risk. Laser diode availability and the quality of driver electronics are critical bottlenecks. Procurement strategies must consider multi-sourcing, safety stock for key modules, and partnerships with component specialists to avoid production and delivery disruption.
-
Channel economics matter. Traditional professional tool channels remain dominant for jobsite-grade units, while OEM and B2B procurement channels drive volume for industrial and mining modules. Service contracts and aftermarket consumables (batteries, mounts, calibration) are meaningful margin levers.
-
Competitive investments are accelerating. Recent product releases — including high-brightness industrial modules and new 360° electronic self-leveling green cross-line units — indicate incumbents are prioritizing high-visibility, higher-spec models to capture professional users willing to pay a premium.
Competitive landscape: structure, capability clusters, and implications
The market is populated by legacy power tools brands, specialized laser module manufacturers, and vertically integrated industrial suppliers. Each cluster brings different strengths for a 2026 strategy:
-
LAP GmbH Laser Applikationen (Lüneburg, Germany — https://www.lap-laser.com): Known for industrial crosshair lasers (XtrAlign series) with durable designs and long-life modules, LAP is a reference for precision alignment in automotive and wood-processing lines. Their focus on ruggedized, long-lifetime products makes them a natural partner for industrial integrators.
-
Laser Tools Co., Inc. (USA — https://lasertoolsco.com): A leader in intrinsically safe alignment lasers, including MSHA-certified models for hazardous environments. Recent product introductions through late 2025 and early 2026 signal strengthening capabilities in high-brightness, combination systems designed to reduce downtime in heavy industries.
-
World Star Tech Inc. (Markham, Canada — https://worldstartech.com): A module-level specialist that designs diode modules with integrated drivers and optical generators. Their ISO 9001 certification and custom solutions model position them as a preferred supplier for OEMs seeking tailored laser modules for machine vision and instrumentation.
-
Major tool brands — Bosch, DeWalt (Stanley Black & Decker), Hilti, Leica Geosystems, Klein Tools: These firms leverage wide professional distribution, brand trust, and field-oriented features (self-leveling, rugged housings). They compete primarily on visibility, durability, and service networks.
-
Value and scale players — Huepar, Kapro: These manufacturers offer high-feature sets such as 360° green-beam models and competitive pricing, creating pressure in the mid-market but also driving adoption of advanced form factors.
Strategic implication: 2026 is an acquisition- and partnership-friendly environment. Companies seeking rapid capability access (e.g., intrinsic safety, high-brightness modules, custom drivers) should evaluate bolt-on acquisitions, OEM supply agreements, or co-development arrangements rather than attempting multi-year internal builds.
What the full PW Consulting report delivers (practical, operational outputs)
-
Market sizing and validated growth trajectories (top-line and by major application group), with transparent methodology and scenario modelling to stress-test 2026 budgets.
-
Product and technology landscaping: comparative feature matrices, component sourcing maps, and a technology readiness timeline to guide R&D prioritization.
-
Regulatory and compliance playbook: practical checklists for IEC 60825-1, FDA-relevant considerations for SLA devices, CE/TUV pathways, and MSHA approvals where applicable.
-
Competitive diagnostics: concise vendor profiles, recent product-intro tracking, go-to-market maps, and an M&A heatmap identifying likely targets for capability or channel acquisition.
-
Commercial playbook: pricing benchmarks, channel margin models, and a 12-month go-to-market sprint plan (product launches, trade shows, dealer training, and aftermarket subscription pilots).
-
Scenario planning and sensitivity analysis: demand shock, supply constraints, and regulatory tightening scenarios with recommended mitigation actions and trigger points.
Actionable recommendations for 2026 decision cycles
-
Prioritize compliance-first product adjustments. Incorporate IEC 60825-1 alignment at prototype stages and ready FDA-facing documentation for any devices servicing laboratory or medical users — reduce time-to-market friction.
-
Target differentiated optics and driver electronics. Invest in green-beam visibility and integrated driver modules to win professional users who value brightness and stability; consider co-development with module specialists to shorten delivery cycles.
-
Hedge supply risk. Lock multi-year component contracts for key diode suppliers, and include dual-sourcing clauses in vendor agreements. Maintain strategic buffer inventory for critical subassemblies through at least H1–2026.
-
Rebalance channel strategies. For premium professional units, leverage branded tools channels and service contracts; for industrial volume modules, prioritize OEM partnerships and direct B2B procurement channels.
-
Explore targeted M&A and partnerships. Evaluate small, highly specialized module makers and intrinsic-safety-certified suppliers as acquisition candidates to accelerate capability without heavy CAPEX.
-
Monetize aftermarket services. Develop calibration-as-a-service, extended warranty packages, and consumable bundles to improve lifetime value and stabilize revenues against cyclical equipment purchases.
Using this preview in your 2026 planning
This briefing is a strategic overview intended to catalyze executive alignment. For product planning, prioritize safety certifications and optics upgrades in Q1–Q2 2026. For procurement and supply-chain directors, begin contract talks and alternative sourcing pilots now. For corporate development teams, request our M&A heatmap and target shortlist to accelerate diligence.
Next steps and where to get the full intelligence
The full PW Consulting Cross Laser Light Market report contains the detailed segment-by-segment models, pricing matrices, regional demand curves, and vendor scorecards that support the strategic recommendations above. This release intentionally omits the granular segmentation tables and proprietary metrics so that decision-makers who require actionable numbers and executable roadmaps will access the full dossier and bespoke briefings.
Contact PW Consulting to request the full report, receive the vendor scorecard, or schedule a custom briefing to translate these insights into a 90‑day action plan for your business.
— PW Consulting, Strategy & Industry Research
For detailed analysis of this topic, please visit the official page: Cross Laser Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inertia Base Market Reaches USD 364.5 Million in 2025; Forecast to Top USD 530.2 Million by 2032 at 5.5% CAGR
By PW Consulting, 2026-07-02
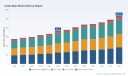
Inertia Base Market Research — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s Inertia Base Market Research (base year 2025) synthesizes five years of historical performance (2020–2025) and delivers a seven‑year forecast (2026–2032) to inform capital, procurement and product strategy for organizations that design, specify, procure or manufacture inertia bases and related vibration‑control systems. The global market reached USD 364.5 Million in 2025 and is projected to expand at a steady 5.5% CAGR through the 2026–2032 forecast window, reflecting a combination of steady HVAC and industrial investment, rising compliance requirements, and renewed focus on lifecycle cost and reliability in mission‑critical facilities.
Inertia Base Market Research
Why this matters for 2026 strategic decisions
-
Timing and investment: With the market entering a period of steady expansion, 2026 is a pivotal year to convert strategic intent into tangible initiatives — whether that means capacity investment, channel consolidation, or product differentiation focused on high‑value applications.
Inertia Base Market Research -
Risk mitigation: Heightened seismic and vibration standards mean specification teams will need validated solutions that meet IBC/ASHRAE requirements while minimizing lifecycle disruption and warranty exposure for equipment OEMs and end users.
Inertia Base Market Research -
Cost and labor pressures: Pre‑fabricated, labor‑saving designs and integrated isolator interfaces are increasingly important as on‑site labor cost and schedule risk rise, particularly in retrofit and urban construction projects.
Market trajectory — the big picture
The inertia base market is maturing. After steady growth through 2020–2025, the sector is forecast to grow at roughly a mid‑single digit CAGR (5.5%) to 2032. This trajectory reflects continued demand from HVAC, industrial pumping and mission‑critical infrastructure, tempered by substitution pressures from alternative isolation strategies and localized supply dynamics. The market’s concentration metrics (CR3 ~32.5%, CR5 ~48.2%) indicate a landscape where a handful of established players capture meaningful share, but there remains sufficient fragmentation and opportunity for differentiated entrants.
What the report delivers — practical, transaction‑grade analysis
Inertia Base Market Research is built to be operationally useful for executives, engineers, and procurement teams. The full report includes:
-
Granular market sizing and top‑down/bottom‑up forecasts across the 2026–2032 horizon, with sensitivity scenarios that stress test demand under alternative construction and retrofit cycles.
-
Buyer personas and procurement playbooks: specification checklists, total cost of ownership models, and lead‑time strategies to reduce install risk and protect equipment warranties.
-
Vendor benchmarking and RFP templates designed to accelerate shortlisting and to surface performance and compliance differentials during supplier selection.
-
Installation and engineering guidance, including recommended concrete‑pour practices, isolator pairing strategies and interface details that preserve start‑up torque and vibration attenuation objectives.
-
Deal support materials — market entry roadmaps, M&A screening criteria, and commercial due diligence modules that quantify addressable opportunity and integration complexity.
Note: this briefing intentionally omits the report’s proprietary segment tables and region/application breakdowns. Access to the full dataset and the interactive model is available through the Inertia Base Market Research portal.
Competitive landscape — who matters and why
The sector is characterized by a mix of specialists and systems suppliers. Established manufacturers combine steel frame expertise with concrete‑fill design, integrated isolator brackets and compliance know‑how. Key players profiled in the report include U.S.‑based specialists that offer concrete‑filled frames and modular pour forms, European engineering firms providing rigid platforms for impact machinery, and regional suppliers that optimize labor‑saving prefabrication.
-
Kinetics Noise Control (USA): Known for concrete‑filled KINETICS® CIB frames in multiple configurations, with emphasis on integrated perimeter channels and isolator brackets. Their product design reflects a focus on lowering center of gravity and controllable amplitude for chillers and large pumps.
-
VMC Group (USA): Offers both seismic and non‑seismic concrete pouring forms and stock inertia bases engineered for HVAC pumps and fans, often coupled with spring isolators for specified deflections; positions itself on compliance and standardized availability.
-
Novia Corporation (USA): Emphasizes manufacturer‑warranty compliance via standard and custom bases that pair with isolation mounts to control start‑up torque and protect rotating equipment.
-
Acrefine (USA): Competes on labor savings through pre‑welded welded steel frames ready for concrete fill, targeting contractors and EPCs seeking reduced site labor.
-
Isotech, ISAT, Vibro‑Acoustics, Farrat, Vibrasystems and Diamond Walraven: Each brings regional strengths — from seismic‑rated systems to rigid platforms for impact machinery — enabling buyers to match technical needs to supply footprint and service expectations.
The competitive dynamic favors suppliers that combine product engineering (frame geometry, isolator interface, pour depth optimization) with regulatory competence and rapid delivery. Market share concentration data underscores opportunity for focused M&A to build full‑suite capabilities or expand channel reach.
Supply chain, materials and installation dynamics
-
Primary inputs: Structural steel channels/I‑beams, rebar and concrete pours remain the dominant bill of materials. Typical concrete fill depths (commonly in the 6–12 inch range) materially influence mass and vibration damping characteristics and are a recurring engineering decision in the specification process.
-
Prefabrication vs. field fabrication: Pre‑welded frames and stock inertia bases materially reduce on‑site labor, shorten schedules and limit variability in final inertial properties — a key differentiator in urban retrofit projects with constrained installation windows.
-
Logistics and lead times: Heavy, bulky frames and site pour coordination create friction. Suppliers that streamline on‑site coordination (pre‑cut rebar cages, integrated isolator brackets, engineered pour sequencing) win on total installed cost.
Regulatory and standards landscape
Compliance with building and vibration control standards is an active demand driver. ASHRAE guidance and IBC seismic requirements are elevating technical thresholds for inertia base design, particularly where seismically rated isolators are specified. The practical effect: procurement teams increasingly require documented compliance and testing evidence — a factor that can lengthen evaluation cycles but raises barriers to low‑cost, non‑compliant suppliers.
Strategic implications & recommendations for 2026
For executive teams preparing 2026 budgets and roadmaps, the report crystallizes several pragmatic courses of action. Below are prioritized recommendations drawn from scenario analysis and buyer economics.
-
Prioritize specification‑led differentiation: OEMs and suppliers should embed isolator interface standards and compliance documentation into product offerings to capture higher‑margin, specification‑driven demand.
-
Invest in prefabrication and modularity: Allocate capex to modular frame production and pre‑welded inventories to reduce lead times and site labor exposure — especially valuable in retrofit and time‑sensitive projects.
-
Enhance channel and service footprint: Expand local service presence or partner with regional installers to overcome logistics constraints and to shorten sales cycles that are lengthened by seismic and warranty reviews.
-
Pursue targeted M&A or JV plays: The market concentration profile suggests attractive roll‑up economics for mid‑market players that can acquire complementary engineering capability or broaden geographic scope without eroding margins.
-
Embed compliance into go‑to‑market: Make IBC and ASHRAE compliance a visible part of product messaging; provide pre‑validated documentation packages to specifiers to accelerate approvals.
Use cases where the report adds immediate ROI
-
Large facilities and data centers planning multi‑year chiller or pump refresh cycles can use the report’s TCO models to compare install and lifecycle costs across base types and isolator pairings.
-
Contractors and EPCs evaluating pre‑fabricated vs. field‑fabricated strategies can quantify labor savings and schedule risk reduction to support bid decisions.
-
Private equity and corporate development teams can accelerate commercial diligence with vendor scorecards and scenario valuation models tailored to inertia base product lines.
How to act on these insights
PW Consulting recommends three near‑term steps for 2026 planning cycles:
-
Run a three‑month vendor audit focused on compliance documentation and delivery performance to reprioritize preferred suppliers before bid season.
-
Pilot prefabricated frame adoption on one major retrofit project to validate labor and schedule benefits, then scale on subsequent programs.
-
Engage PW Consulting’s market modeling module to overlay your portfolio and supplier roster against regional demand scenarios and the report’s forecast to quantify upside and downside by quarter.
Next steps and how to get the full intelligence
This briefing demonstrates the report’s practical value while intentionally withholding the proprietary regional and application split tables to preserve the tactical advantage for subscribers. The full Inertia Base Market Research package includes the complete segmentation datasets, interactive forecast model (USD Million, historical 2020–2025, forecast 2026–2032), supplier scorecards and downloadable RFP templates. For procurement teams, engineering leads, and strategic investors planning actions in 2026, accessing the full report will enable execution with confidence and measurable ROI.
Contact PW Consulting to request the executive briefing deck, schedule a custom workshop, or license the interactive forecast model for your internal planning and procurement systems.
For detailed analysis of this topic, please visit the official page: Inertia Base Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Accuracy Polarimeters Market to Climb from USD 285.5 Million in 2025 to USD 425.05 Million by 2032 at a 5.85% CAGR
By PW Consulting, 2026-07-02
High Accuracy Polarimeters Market: Strategic Imperatives for 2026 — PW Consulting Insights
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to present a strategic preview of our latest market research: High Accuracy Polarimeters Market — Base Year 2025, Forecast 2026–2032. This briefing synthesizes the report’s core strategic implications for corporate decision-makers who must act in 2026 to secure competitive advantage in laboratory instrumentation, quality control, and life‑sciences manufacturing.
High Accuracy Polarimeters Market
Why 2026 Is a Pivotal Decision Point
The high‑accuracy polarimeters market has shifted from incremental replacement cycles to technology-driven renewal. Our analysis of historical data (2020–2025) shows a steady expansion from the low‑hundreds of millions USD to a 2025 baseline of USD 285.5 Million, reflecting sustained demand across pharmaceutical quality control, chemical research, and food/beverage QC. Over the forecast window (2026–2032) we expect the market to grow at a compound annual growth rate (CAGR) of 5.85%, reaching approximately USD 425.05 Million by 2032.
High Accuracy Polarimeters Market
That trajectory converts into clear, time‑sensitive imperatives for stakeholders: instrument purchasers must align procurement cycles to capture advances in multi‑wavelength measurement, automated calibration, and compliance functionality; vendors must prioritize software and services that lock in recurring revenue; investors and M&A teams must identify consolidation opportunities while the market remains moderately concentrated yet contestable.
High Accuracy Polarimeters Market
What Our Report Delivers: Actionable, Not Academic
PW Consulting designed this study to be used at the negotiation table, in the lab, and in the boardroom. The report combines quantitative forecasting with pragmatic toolkits that drive 12–24 month decisions. Key operational deliverables include:
- Robust market sizing and a transparent methodology that links historical shipments, installed base replacement patterns, and new‑build laboratory CAPEX to our 2026–2032 projections.
- TCO (Total Cost of Ownership) models calibrated for common procurement scenarios — from single‑site QC labs to global instrument fleets — that incorporate purchase price, downtime risk, calibration cadence, and service contracts.
- Vendor scorecards and decision matrices that evaluate precision claims, compliance features (21 CFR Part 11, GMP Annex 11 readiness), calibration traceability (NIST‑traceable plates and IQ/OQ deliverables), and software interoperability.
- Operational playbooks for installation qualification, performance qualification, and cross‑site harmonization to accelerate validation timelines in regulated environments.
- M&A heatmaps and competitive scenarios that highlight where share shifts are most likely given current R&D investments, aftermarket structures, and strategic partnerships.
- Case studies demonstrating measurable ROI from instrument upgrades — e.g., reductions in sample rework, faster release cycles, and lower regulatory risk exposure.
These deliverables are purposefully pragmatic: we show how to convert market direction into procurement windows, SLA specifications, and product roadmaps — while reserving detailed segment tables and proprietary vendor ratings for subscribers to the full report.
Competitive Landscape: Who Wins and Why
The supplier ecosystem mixes well‑established precision instrument manufacturers with regional value players. The market is moderately concentrated: the top three suppliers collectively account for a significant portion of industry revenue, and the top five amplify that concentration while leaving room for specialized entrants and aftermarket services to capture niche value.
Leading incumbents differentiate along three vectors: measurement precision and multi‑wavelength capability, regulatory and data‑integrity features, and integrated temperature control with plug‑and‑play validation (IQ/OQ). A few illustrative vendor positions we analyze in depth:
- Rudolph Research Analytical (Hackettstown, NJ) — recognized for its AUTOPOL series, with leading edge accuracy and extensive pharma‑oriented compliance features; strong in automated calibration and temperature control suites.
- A. KRÜSS Optronic (Hamburg) — positions its P‑series for high optical density ranges and food/pharma QC workflows; emphasis on ruggedization and measurement range.
- Anton Paar (Graz) — builds on modular MCP platform strategies, stressing low maintenance, regulatory compliance, and integration into QC ecosystems.
- Bellingham + Stanley / Xylem Analytics (UK) — competes on speed and stability with digital systems optimized for production‑line and chemical QC throughput.
- Schmidt + Haensch (Berlin) — focuses on modularity, tablet and software integration, and legacy market replacement in sugar and industrial labs.
- Torontech (Canada) and HINOTEK (China) — offer competitively priced automated polarimeters with growing presence in North American and Asia‑Pacific labs respectively, supported by local service networks.
Recent industry signal events reinforce these competitive themes. Independent product roundups and market recognitions in early 2026 highlighted the performance extremes now available — from ultra‑high precision instruments to value options — which accelerates buyer expectations. Separately, vendor public positioning in 2025 emphasized regulatory readiness (21 CFR Part 11, GMP) and reduced maintenance as major selling points. Our report assesses these claims against third‑party validation criteria and published pharmacopeial standards.
Market Dynamics and Strategic Implications
Several cross‑cutting dynamics will determine winners in 2026:
- Regulatory and data‑integrity requirements are shifting procurement focus from upfront price to validated workflows. Instruments that ship with NIST‑traceable calibration artifacts and comprehensive IQ/OQ documentation reduce time‑to‑operation and regulatory risk.
- Service and calibration ecosystems are increasingly decisive. Vendors with dense service footprints or partner‑enabled calibration networks capture aftermarket revenue and embed customers long‑term.
- Software and data interoperability matter. Compliance features (electronic signatures, audit trails) are table stakes in pharma—buyers now scrutinize APIs, LIMS integration, and secure cloud storage options.
- Technology bifurcation: a premium tier of ultra‑high‑precision, multi‑wavelength polarimeters competes on absolute measurement capability, while a broader market segment values reliability, speed, and cost‑of‑ownership — creating distinct go‑to‑market strategies.
- Supply chain and manufacturing resilience are non‑trivial. Lead times for opto‑mechanical assemblies and temperature control modules can materially affect procurement roadmaps in 2026, especially for multi‑site standardization projects.
Five Strategic Moves for 2026
- Buyers — Shift to validation‑light procurement: Require NIST‑traceable calibration artifacts and vendor‑supplied IQ/OQ packages in RFPs. Use our TCO templates to compare true costs over 5–7 years rather than sticker price.
- Vendors — Productize compliance and services: Embed validation kits and subscription calibration services into base offerings. Differentiate on API‑first data strategies and modular hardware that reduces field service events.
- Investors / M&A teams — Target aftermarket and software stacks: Look beyond instrument sales to recurring calibration, spare parts, and software licensing. Smaller regional service specialists offer attractive roll‑up opportunities to accelerate share gains.
- R&D leaders — Prioritize multi‑wavelength and ultrafast stabilization: Roadmaps should balance incremental accuracy improvements with features that cut sample throughput and validation time; these yield the fastest ROI for production labs.
- Operations — Harden supply chain planning: Build dual‑source contingencies for critical opto‑mechanical components and formalize lead‑time buffers in capital replacement schedules to avoid QC bottlenecks.
How PW Consulting’s Report Translates Into Decisions
For executive teams planning 2026 spend cycles, the report converts market projections and vendor benchmarking into executable plans: prioritized vendor shortlists, validation timelines, procurement contract templates, and a quantified business case for instrument upgrades versus deferred maintenance. For strategy teams, our M&A scenarios identify where consolidation can unlock synergies in service networks and software licensing — valuable context when negotiating acquisition premiums.
Importantly, while this preview outlines the strategic landscape and the practical levers that matter in 2026, it deliberately omits proprietary segmentation tables, detailed regional/application shares, and full vendor scorecards — the granular insights that deliver the competitive advantage are conserved for the full PW Consulting report and subscriber portal.
Next Steps
Executives, procurement leads, and investors should treat 2026 as a window to reset polarimeter strategies for the next technology cycle. To obtain the full dataset, vendor scorecards, and the interactive TCO models needed to operationalize the recommendations above, visit the PW Consulting report page or contact our market research desk for subscription access and tailored briefings.
PW Consulting’s High Accuracy Polarimeters Market study equips you to make confident, compliant, and cost‑effective decisions in 2026 — positioning your organization to capture the value created by precision measurement advances across regulated laboratories and production environments.
For detailed analysis of this topic, please visit the official page: High Accuracy Polarimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


