



Category: market research
PW Consulting Forecasts LCP Antenna Market to Reach USD 2,475.5 Million in 2025, Rising at a 17.98% CAGR to USD 7,876.3 Million by 2032
By PW Consulting, 2026-07-02
LCP Antenna Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive summary
As wireless ecosystems move deeper into mmWave, high‑frequency 5G and emerging satellite and IoT node topologies, Liquid Crystal Polymer (LCP) antennas are transitioning from niche premium components to an essential design lever for performance, miniaturization and thermal stability. PW Consulting’s latest LCP Antenna Market report uses a 2025 base year and an expanded 2026–2032 forecast horizon to deliver an actionable roadmap for C‑suite leaders, procurement heads and product strategists.
Lcp Antenna Market
Key macro takeaways: the global market exceeded the USD 2.4 billion mark in 2025 and is forecast to expand at a near‑18% CAGR through 2032, reaching roughly USD 7.9 billion by the end of the forecast period. Market concentration is meaningful — the top three players account for well over half of supply, and the top five approach near‑total dominant share — conditions that create both barriers and strategic opportunities for new entrants and incumbents alike.
Lcp Antenna Market
Why this matters for 2026 decision cycles
-
Capital allocation: With a sustained high growth rate, investment windows for capacity expansion, test and measurement capability and packaging automation are time‑sensitive. Boards deciding CAPEX vs. M&A must weigh rapid top‑line expansion against supply chain constraints.
Lcp Antenna Market -
Roadmap prioritization: Product teams must choose where to migrate to LCP‑based antennas versus alternative substrates to balance cost, RF performance and form‑factor gains. The technical and commercial inflection is now — delayed decisions risk forfeiting handset or module BOM slots.
-
Sourcing and localization: Geopolitical trade measures and concentrated resin supply create short‑ to medium‑term sourcing risk. Procurement strategies that blend dual‑sourcing, regional inventory buffers and long‑lead supplier agreements will materially reduce project volatility.
Market trajectory — what the numbers conceal and reveal
The headline CAGR (≈17.98%) and the projection to roughly USD 7.9 billion by 2032 signal a market in scale‑up mode rather than steady maturation. That pace is being driven not only by handset adoption but by a widening set of high‑frequency applications — from compact base station components to advanced automotive radar and premium IoT devices — that demand the low dielectric loss, dimensional stability and high‑frequency handling of LCP substrates.
Importantly, growth is not evenly distributed: technology, supply chain placement and OEM ecosystem dynamics create winner‑takes‑much pockets. This is reflected in concentration metrics and the pattern of recent commercial wins and volume ramps documented in our coverage.
Competitive landscape — strategic dynamics to watch
PW Consulting’s competitive analysis synthesizes technical capability, customer alignment and go‑to‑market positioning among the market’s relevant players. A few illustrative dynamics:
-
Large, diversified electronics incumbents have leveraged system‑level relationships to secure early, high‑volume allocations for LCP antenna modules — turning customer intimacy into scale advantages. Recent publicized production ramps demonstrate how design wins convert quickly into manufacturing leverage.
-
Tier‑1 interconnect and component suppliers with strong materials expertise are integrating vertically into LCP antenna subassemblies to capture higher value‑add and protect margin pools against commoditization of raw laminates.
-
Regional specialists and flexible PCB houses are differentiating through cost engineering and proximity to consumer electronics OEMs, supporting rapid qualification cycles for handset launches.
Case signals from the market: one major supplier began mass production of a compact 28 GHz antenna‑in‑package module and reported multi‑million unit monthly shipments into a single handset customer during early 2025 — a concrete example of how technical readiness and a channel relationship can unlock scale. Another leading connectivity supplier launched an LCP module that materially reduced signal loss at mmWave bands — a product performance delta that directly influences OEM material selection debates.
Supply chain, materials and regulatory dynamics — risks that require strategic hedging
-
Raw material concentration: Global LCP resin capacity is notably concentrated in a handful of suppliers, with one producer accounting for a near‑third share of resin capacity following a major asset consolidation. This concentration creates susceptibility to capacity outages, price steps and contractual power shifts.
-
Upstream specialty monomers and film‑grade resin sourcing are patchy. New entrants in China are moving toward pilot and batch supply for film‑grade LCP, but technology qualification and scale timelines introduce medium‑term uncertainty.
-
Trade and regulatory pressure: Cumulative tariff regimes and import measures on polymer‑based electronic components add a non‑trivial layer to landed cost. In parallel, LCP antenna products must navigate certification frameworks (e.g., FCC, CE), which introduce both testing cost and time‑to‑market friction.
-
Price and lead‑time volatility: Specialty polymer supply chains can experience price shocks due to constrained monomer availability, generating project‑level margin variance and inventory policy implications.
What PW Consulting’s report delivers (practical, actionable content)
Our report is intentionally structured to move organizations from uncertainty to execution. Key deliverables include:
-
Decision playbooks: Concrete recommendations for CAPEX timing, supplier qualification milestones and a procurement scorecard that maps supplier capability to risk tolerance.
-
Go‑to‑market tactics: Bundled model options for suppliers (e.g., contract manufacturing partnerships, co‑development agreements, licensing of antenna IP) that accelerate OEM qualification while protecting margin.
-
Scenario‑based financial models: Three strategic scenarios (conservative, base, upside) that translate market growth assumptions into revenue and capacity needs for 2026–2028 planning cycles. Models are provided in editable formats to allow rapid stress‑testing against your internal assumptions.
-
Supply‑chain heatmaps and mitigation templates: Prioritized actions to reduce single‑source exposure, hedge resin cost risk and align inventory policies with launch calendars.
-
Competitive dossier: Profiles and capability matrices for leading players, including production footprints, recent product introductions, and customer alignment — enabling quicker partner selection and acquisition screening.
-
Regulatory & certification checklist: Turnkey test and compliance roadmaps for device OEMs and module houses entering or scaling LCP antenna integration.
How senior leaders should apply these insights in 2026
-
CEOs and Boards — Treat LCP as a strategic domain, not just a procurement line item. Consider targeted M&A or JV moves to secure resin or module capacity where internal scale is insufficient.
-
Heads of Product — Integrate antenna substrate choices into product spend gates earlier. Performance wins at mmWave are frequently decided at prototype and early qualification stages; late substrate swaps carry significant cost and schedule penalties.
-
Procurement & Supply Chain — Move from transactional buying to supplier partnership agreements that include capacity reservations, hedged pricing instruments and joint contingency plans for material dislocations.
-
R&D and Test — Prioritize mmWave testbeds and environmental qualification for LCP assemblies to shorten qualification cycles with OEMs and tier‑one partners.
Competitive moves to expect and prepare for
Given the high growth and concentrated supplier base, expect continued vertical integration by system suppliers, aggressive capacity expansions by key resin producers, and strategic partnerships between flexible PCB houses and materials providers. OEMs under time pressure will increasingly favor suppliers that can demonstrate both technical performance at mmWave bands and resilient, geo‑diverse supply chains.
Why PW Consulting’s intelligence is uniquely actionable
-
We combine granular production‑level intelligence (validated production ramps, product loss‑reduction claims, contract allocations) with macro supply modeling to highlight where near‑term bottlenecks will create pricing or allocation windows.
-
Our playbooks translate market signals into executable steps — from contract templates to sourcing scorecards — that reduce analysis paralysis and accelerate decision velocity.
-
The report intentionally reveals strategic implications while withholding select granular segmentation tables in the public summary, to preserve the competitive value of the full dataset for subscribers and paying clients.
Next steps and call to action
For leaders planning 2026 budgets and product roadmaps, the critical window for decisive action is now. PW Consulting’s LCP Antenna Market report equips teams with the market sizing, concentration analysis and supplier dossiers necessary to move from planning to procurement and production. To access the full datasets, regional and application segmentation, and editable scenario models referenced in this release, consult the full report page and speak with our advisory team for a tailored briefing.
Closing note
LCP antenna technology is at a strategic inflection point. Firms that combine a precise understanding of market scale and concentration with disciplined supply‑chain hedging and early design‑in will capture disproportionate share of the growth opportunity. PW Consulting’s research is designed to be the practical playbook you consult when translating that strategic intent into board‑approved actions in 2026.
For detailed analysis of this topic, please visit the official page: Lcp Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oct-4 Antibody Market Poised for Robust Expansion — 7.19% CAGR Expected Through 2032
By PW Consulting, 2026-07-02
Oct-4 Antibody Market — 2026 Strategic Briefing: Critical Insights for Life-Sciences Decision Makers
PW Consulting’s Oct-4 Antibody Market report (base year 2025; forecast 2026–2032) crystallizes the commercial and scientific dynamics that will determine competitive advantage through 2026 and beyond. The market is anchored by a global research demand ecosystem and, according to our model, was valued in 2025 at approximately USD 88.45 Million and is projected to expand at a compound annual growth rate (CAGR) of 7.19% through 2032, approaching the mid-hundreds of millions by the end of the forecast window. For executive teams preparing budgets, R&D roadmaps, go-to-market plans or M&A pipelines, this report turns high-level growth signals into actionable options and prioritised next steps.
Oct-4 Antibody Market
Why this report matters in 2026
-
Timing: 2026 is the inflection year for buyers and suppliers as reagent quality expectations, single‑cell workflows, and ChIP/epigenetics use-cases converge — straining legacy supply models and rewarding validated, reproducible reagents.
Oct-4 Antibody Market -
Budget allocation: Procurement and R&D leaders must decide where to allocate finite budgets across antibody types (monoclonal, polyclonal, recombinant/conjugated) and application investments (stem cell, oncology, discovery workflows). The report quantifies macro demand and risk scenarios to support those trade-offs.
Oct-4 Antibody Market -
Commercial strategy: Suppliers and investors need clarity on where product differentiation (validation data, conjugates, ChIP/ChIP‑seq grade, lot-to-lot consistency) creates premium pricing power versus where scale and distribution win.
-
Regulatory and reputational risk: All commercial Oct‑4 antibodies remain labeled for Research Use Only (RUO); the report details practical compliance steps and messaging strategies to avoid diagnostic or therapeutic misinterpretation.
What the PW Consulting Oct-4 Antibody report delivers (practical scope)
-
Clear, auditable market-sizing and forecasting methodology grounded in primary interviews, supplier shipment proxies, and demand-driver modelling (2020–2025 historical baseline; 2026–2032 forecast).
-
Driver analysis tying growth to research funding flows, stem-cell and oncology publication trends, and technological adoption curves (single‑cell, flow cytometry, ChIP‑seq, IHC/IF).
-
Competitive benchmarking with vendor scorecards that evaluate catalog breadth, technical validation, channel strength, citation impact and manufacturing resilience.
-
Operational playbooks for procurement and R&D labs — sample validation matrices, lot acceptance testing protocols, and supplier diversification checklists.
-
Commercial go-to-market templates for suppliers: positioning, channel economics, bundling strategies, and targeted account models.
-
Scenario analyses and sensitivity models that stress-test outcomes under different adoption speeds, price erosion, and supply disruption events.
-
An annex of primary interview highlights, supplier calls, and reproducibility case studies — enabling rapid internal alignment and evidence-based decisions.
Data-driven outlook: What the headline numbers mean
The Oct‑4 antibody market is growing steadily, with our forecast indicating a roughly mid-single-digit to high-single-digit CAGR across the 2026–2032 horizon. That growth rate reflects a combination of sustained academic demand (notably in pluripotency and developmental biology), increasing translational oncology work where Oct‑4 is interrogated as a tumor marker, and rising adoption of advanced applications that require higher‑validated reagents (e.g., ChIP‑seq, flow cytometry with conjugates, single‑cell immunophenotyping).
For corporate planners this translates into three practical imperatives: (1) invest selectively in validated, higher-margin products that support complex workflows; (2) protect revenue by ensuring supply‑chain redundancy for high‑use SKUs; and (3) use pricing and access strategies to monetize validation services, training and bundled assay kits alongside primary antibody sales.
Competitive landscape: who wins and why
-
Portfolio breadth vs. validation depth: Large life‑science platforms with global distribution maintain leadership through extensive catalogues and channel access. These vendors win volume-driven accounts and institutional contracts.
-
Validation-centric specialists: High-quality reagent providers that emphasize batch-specific validation, recombinant clones and ChIP‑grade products capture premium workflows where reproducibility is paramount.
-
Flow-optimized suppliers: Vendors that offer conjugated reagents and validated clones for cytometry capitalize on the expanding single-cell and immunophenotyping market.
-
Mid-market and regional players: These firms win on cost, localized service and flexible MOQ; they play a critical role in academic and emerging-market ecosystems.
-
Market concentration: The sector shows a moderate degree of concentration at the top — the three largest suppliers capture a meaningful share of the market while the top five increase the competitive barriers to entry in key segments. This structure rewards scale in distribution and sustained investment in validation data.
PW Consulting’s vendor profiles and scorecards (included in the report) assess each provider across commercialization vectors: catalog diversity (monoclonal, polyclonal, recombinant, conjugates), application validation (WB, IHC, IF, Flow, ChIP), citation and academic footprint, and supply resilience. Recent marketplace moves illustrate these dynamics: several suppliers refreshed Oct‑4 listings with expanded IHC‑P or ChIP‑validated SKUs, and one choir of specialist vendors emphasized batch‑level validation for ChIP‑seq users. These are not cosmetic updates — they signal where suppliers expect margin expansion and which workflows will be prioritized by customers in 2026.
Regulatory and product stewardship considerations
-
RUO labeling: All commercial Oct‑4 antibodies carry explicit Research Use Only disclaimers and are not authorized for diagnostic or therapeutic use. The report provides compliant messaging templates that preserve commercial utility while minimizing regulatory exposure.
-
SKU lifecycle management: The industry has seen replacement of discontinued clones with alternative catalog numbers; procurement teams must track these changes to avoid validation gaps in longitudinal studies.
Actionable strategic recommendations for 2026
-
For suppliers: Prioritize investment in validated recombinant clones and ChIP‑grade reagents — these create defensible product lines. Pair product launches with robust validation datasets and reproducibility evidence; customers will pay for certainty.
-
For procurement leads: Implement a two-tier sourcing model — a validated, premium primary supplier for critical assays, and a cost‑effective secondary supplier for routine work. Adopt lot‑level acceptance testing as a procurement standard.
-
For R&D heads: Treat antibody validation as an operational discipline. Mandate internal verification for any new lot or SKU, and standardize acceptance criteria across labs to protect data integrity and grant competitiveness.
-
For investors/M&A teams: Look for targets that combine strong validation IP, a focused premium product line (e.g., ChIP‑seq grade antibodies), and efficient manufacturing footprints. Moderate market concentration presents opportunities to consolidate specialty providers under platform players.
-
For product and marketing teams: Shift from pure product listings to workflow playbooks — bundle antibodies with protocol tips, lot‑verification data, and technical support to reduce buyer friction and improve retention.
How to use the Oct‑4 report — delivering immediate impact
-
Board & investment committees: Use the scenario models to stress-test revenue assumptions and establish realistic valuation multiples for specialty reagent assets.
-
Commercial teams: Deploy the supplier scorecards to re-price key accounts and prioritize channel investments in markets where the demand-supply balance favors premium offerings.
-
Laboratory leadership: Implement the procurement playbook and acceptance matrix to reduce experimental failures and downstream rework costs.
-
Strategy teams: Align R&D roadmaps with identified high-growth applications and consider partnerships that package antibodies with complementary assays or digital validation services.
PW Consulting’s Oct‑4 Antibody Market report is designed as a pragmatic toolkit: it combines top-line market sizing and a rigorous CAGR forecast with granular, execution-oriented guidance and vendor assessments. The report intentionally preserves certain proprietary segmented datasets and full SKU‑level tables to ensure clients who require transaction-level intelligence obtain the complete, validated download from our source portal.
Next steps
For teams preparing 2026 plans, the immediate priority is to align procurement, R&D and commercial initiatives around validated reagent strategies and supply resilience. PW Consulting’s Oct‑4 Antibody Market report provides the evidence base and playbooks to do just that. Visit our report page to access the full dataset, vendor scorecards, and downloadable tactical templates — the detailed segmentation tables and SKU‑level analyses are available exclusively in the full study for subscribers and single‑report purchasers.
For detailed analysis of this topic, please visit the official page: Oct-4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TDI 80/20 market at USD 2.85B in 2025, set to grow at 3.8% CAGR to ~USD 3.7B by 2031 as Asia‑Pacific claims nearly 48% share
By PW Consulting, 2026-07-02
TDI 80/20 Market: Strategic Imperatives for 2026 — A PW Consulting TDI 80/20 Market Brief
As corporate leaders plan capital allocation, procurement strategy, and product roadmaps for 2026, the TDI 80/20 isomer blend emerges as a quietly pivotal raw material shaping competitive positions across flexible polyurethane foam, CASE (coatings, adhesives, sealants, elastomers), and specialty foam applications. PW Consulting’s TDI 80/20 Market TDI 80/20 Market report synthesizes market-scale dynamics, supply structure, regulatory risk and technology-driven efficiency gains into a decision-ready playbook. This brief highlights the report’s strategic value for 2026 while preserving the proprietary segmentation and scenario outputs that we hold as report gated content.
TDI 80/20 Market
Why TDI 80/20 matters to 2026 corporate strategy
-
Macro stability with selective disruption: Our base-year analysis (2025) positions the global TDI 80/20 market as a multi-billion-dollar market (USD, revenue unit: Million). Under the central forecast, the market grows at a mid-single-digit CAGR through the 2026–2032 horizon (3.8%), reflecting stable underlying demand in flexible foam applications alongside episodic cost and regulatory shocks.
TDI 80/20 Market -
Concentrated supply, concentrated leverage: The market’s supply side is meaningfully concentrated: the top three producers control a clear majority share while the top five capture nearly four-fifths of global production capacity. For buyers, this concentration translates into counterparty risk and price-setting power that must be actively managed. For producers and investors, consolidation dynamics create scalable advantages for those who can optimize feedstock integration and logistics.
TDI 80/20 Market -
Cost structure sensitivity: TDI manufacturing remains tightly coupled to upstream aromatics and energy markets and is exposed to intermittent feedstock price shocks and logistics disruptions. Marginal cost movements reverberate quickly through contract negotiations in foam, CASE and related downstream segments.
What PW Consulting’s report delivers (practical content for 2026 decisions)
-
Actionable market sizing and bottom-up demand forecasts: We present a year-by-year market size model anchored to 2025 with scenario-based trajectories to 2032, isolating the effects of end-use demand, substitution dynamics and regulatory headwinds.
-
Supply-side mapping and scenario playbooks: The report maps incumbent and emergent producers, technology variants (liquid-phase vs gas-phase phosgenation, purity differentials), incremental capacity projects, and plant-level risk assessments — all organized to support negotiations, hedging and sourcing decisions.
-
Cost and margin response toolkit: We provide a workbook logic for building feedstock pass-through clauses, contract indexation templates, and stress-tested margin simulations that finance teams can operationalize in supplier contracts and internal planning cycles.
-
Regulatory and safety compliance playbook: Beyond a summary of current frameworks, the report lays out pragmatic steps to reduce compliance cost, optimize occupational safety investments, and structure insurance and contingency plans under tightening chemical-control regimes.
-
M&A and JV decision framework: For strategic investors, the report contains a checklist and valuation multipliers adjusted for concentration, scale economies, and feedstock integration premium — with sensitivity to policy and trade interventions.
-
Commercial go-to-market blueprints: For foam OEMs and formulators, the report includes SKU-level impact guidance (purity and additive interactions), sourcing scorecards, and supplier selection matrices tailored to regional logistics and product quality tolerances.
Competitive landscape: implications for buyers, sellers and investors
The TDI 80/20 market is dominated by a small set of global and regional champions with distinct strategic postures. Understanding each archetype is critical when shaping procurement strategies, partnership outreach, or acquisition targets.
-
Integrated scale leaders: Established integrated chemical majors retain a strategic edge through feedstock integration, global distribution networks and long-standing consumer relationships. Their investments in energy efficiency and modernization are lowering operating intensity and CO2 footprints — an important competitive lever in procurement dialogs and sustainability positioning.
-
Technology-differentiated players: Producers using advanced process technologies (including modernized gas-phase systems) can supply higher-purity streams and win specifications in premium bedding, automotive seating and specialty CASE applications. These capabilities translate to pricing power in quality-sensitive channels.
-
Regional champions: Local producers in high-demand regions play a volume-and-service game — offering proximity, rapid logistics and customs familiarity. However, these players are exposed to feedstock availability and regulatory shifts that can alter regional cost curves quickly.
-
Recent strategic moves: In the past 18 months, leading firms have prioritized capacity additions and plant modernizations, while some markets have tightened import measures and trade remedies. For corporate strategists, these moves meaningfully reshape sourcing grid options and justify contingency inventory planning or dual-sourcing strategies.
Market dynamics and risk vectors to monitor in 2026
-
Feedstock volatility: Aromatics and energy price moves materially change TDI cost profiles. Procurement teams should bake-in scenario stress tests and consider financial hedging or long-term indexation clauses to protect margins.
-
Regulatory escalation: TDI is controlled under strict worker-safety and chemical management frameworks globally. Expect compliance costs to rise with tighter exposure limits, stricter handling rules and expanded reporting obligations in key consuming regions. These changes have direct implications for plant retrofit CAPEX and operating expense trajectories.
-
Trade and policy interventions: Governments in some demand centers are maintaining or initiating trade remedies and anti-dumping measures that alter import economics; commercial and legal teams should incorporate tariff scenarios into sourcing and price-setting models.
-
Decarbonization and energy efficiency: Plant modernizations that deliver significant energy and emissions reductions are accelerating. Buyers and investors should factor supplier-level emissions intensity into longlists and consider contracting with partners demonstrating measurable improvements.
-
Supply concentration risk: High concentration among a few suppliers means operational disruptions, major project commissioning and strategic alliances can tilt regional availability. Contingency planning — including alternate feedstock pathways or temporary formulation adjustments — should be part of continuous sourcing playbooks.
Strategic recommendations — 6 practical moves for 2026
-
Implement dynamic sourcing scorecards: Upgrade supplier evaluation to include not only price and lead time but also process technology, emissions profile, and regulatory resilience. Treat supplier selection as a portfolio optimization problem rather than a bilateral negotiation.
-
Lock in flexible contract mechanics: Negotiate hybrid contracts that combine fixed volumes with index-linked tranches and force majeure protections calibrated to chemical-specific risks.
-
Prioritize supplier modernization partners: Where product premium permits, prefer suppliers that have demonstrable energy efficiency and emissions reductions — these will face lower compliance costs and less risk of shutdowns under stricter regulations.
-
Stress-test M&A targets against policy scenarios: For acquirers, stress test valuations against trade remedy persistence, feedstock shocks and required safety CAPEX to avoid overpaying for perceived scale alone.
-
Operationalize inventory and logistics buffers: Given regional trade measures and concentration risk, maintain tactical buffer stock policies and diversify logistics nodes to minimize production interruptions.
-
Invest in formulation flexibility: R&D teams should prioritize formulations that can tolerate minor feedstock variability or enable substitution pathways to reduce single-supply dependency.
How PW Consulting’s report supports execution
The full TDI 80/20 Market TDI 80/20 Market report contains the granular models, contract templates, plant-level risk matrices and scenario outputs that corporate teams need to operationalize the strategic recommendations above. It combines quantitative market sizing (anchored to 2025 base-year figures and projection models through 2032 at an aggregate CAGR of 3.8% in the forecast window) with qualitative field intelligence gathered from supply-chain actors, plant visits, and regulatory authorities.
We deliberately structure the report to serve as an execution tool — not just an intelligence brief — with downloadable financial models, procurement playbooks, and an M&A valuation checklist tailored to the TDI 80/20 value chain. To protect competitive sensitivity and support depth of insight, segment-level numbers and plant-capacity matrices are maintained behind our report access portal.
Next steps for decision-makers
-
Procurement leaders should request the supplier risk matrix and the indexation clause templates to begin renegotiations this quarter.
-
Corporate development and private equity teams should leverage our M&A stress-test workbook before entering LOI stages for regional assets.
-
Operations and sustainability teams should review the plant modernization benchmark to prioritize retrofit CAPEX that yields cost and emissions co-benefits.
PW Consulting’s TDI 80/20 Market TDI 80/20 Market report is designed as the practical, decision-grade resource for 2026. For the full dataset, plant-level assessments, and the executable templates described above, please visit the PW Consulting report page or contact our advisory desk to request access. Our analysts stand ready to run custom scenarios tailored to your portfolio, sourcing footprint, and risk tolerance.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Party Costumes Market Set to Reach USD 8.61 Billion by 2032
By PW Consulting, 2026-07-02
Party Costumes Market 2026 Outlook: Strategic Imperatives for Revenue, Resilience, and Retail Relevance
PW Consulting’s latest market research – the Party Costumes Market Report (base year 2025, forecast 2026–2032) – reframes the business questions that costume manufacturers, retailers, licensors and private-equity investors must answer heading into 2026. Our analysis shows that the global market has expanded materially since 2020 and reached an estimated USD 5,650 Million in 2025. Looking forward, the category is projected to grow at a steady 6.2% CAGR through 2032, guided by evolving consumer occasions, shifting channel economics, and supply-chain volatility. This release summarizes the strategic implications without disclosing the granular segmentation data reserved for subscribers and decision-makers seeking to operationalize the findings.
Party Costumes Market
Why this report matters for 2026 planning
-
Actionable forecasting: With the market in growth mode, planning assumptions that blindly extend historic seasonality will under- or over-index inventory in key channels. Our report blends scenario-based demand forecasting with supplier capacity constraints to give CFOs and supply-chain leads a range of plausible revenue and margin outcomes for the 2026 season.
Party Costumes Market -
Tariff- and freight-aware cost modeling: The category’s manufacturing footprint remains Asia-centric, and 2025’s tariff adjustments drove wholesale price pressures and consumer expectations of higher retail prices. Our deliverables include a tariff sensitivity module and freight-cost passthrough playbook that let procurement teams quantify the P&L impact of alternative sourcing strategies.
Party Costumes Market -
Channel-first assortment playbooks: Omnichannel dynamics are now table stakes. The report provides differentiated assortment and pricing frameworks for online-first retailers, seasonal pop-up players, and legacy big-box networks to optimize inventory turns while protecting gross margin in a largely seasonal category.
-
Competitive positioning and licensing ROI: Licensing and IP partnerships continue to drive much of the category’s top-line potential. We evaluate license premium elasticity and provide a negotiation playbook to help merchandise and legal teams evaluate whether a high-cost IP lift justifies the expected uplift in sell-through and average selling price (ASP).
What’s inside the report: Practical tools, not just charts
-
Integrated forecast model: A dynamic Excel-based forecast that includes base, downside and upside scenarios for 2026–2032, incorporating tariff corridors, freight shocks, and consumer-spend elasticity assumptions.
-
SKU rationalization matrix: A prioritization framework for SKU proliferation that balances assortment breadth against working-capital and fulfillment constraints for seasonal peaks.
-
Supplier scorecard & diversification planner: A templated RFP and scorecard for evaluating current suppliers and near-shore or on-shore alternatives—complete with lead-time impact analysis and MOQ trade-offs.
-
Channel profitability playbooks: Margin and inventory-velocity templates for online marketplaces, specialty stores, big-box retail, and seasonal pop-ups—designed to support channel-specific promotional and pricing tactics.
-
Licensing & IP ROI calculator: A tool for legal and commercial teams to model license fees, royalty structures and marketing spend against expected incremental revenue and conversion lift.
-
Sustainability and compliance checklist: Practical steps to mitigate reputational and regulatory risks in high-volume costume production, including supplier audits, traceability requirements, and material substitution levers.
-
Executive playbook: A 90-day action plan for CEOs and heads of merchandising to prepare for the next season—priorities, milestones and KPI triggers tied to the forecast scenarios.
Competitive landscape: strategic takeaways for incumbents and challengers
The party-costumes ecosystem combines global branded incumbents, specialty retailers, large-format party goods chains, nimble Asian manufacturers and a broad wholesale/rental layer. The market’s structure favors three strategic archetypes: IP-driven licensors and branded manufacturers, scale-oriented multi-channel retailers, and low-cost supply specialists. Each archetype faces distinct opportunities and risks in 2026.
-
Rubie’s Costume Company – as a leading global manufacturer and distributor with long-standing licensed relationships and multi-region sourcing, Rubie’s is well-positioned to monetize blockbuster IP and capture scale efficiencies. Its primary strategic advantage is integrated licensing and a mature supply chain; its challenge is balancing license-cost inflation with retail price sensitivity.
-
Disguise Inc. – with deep entertainment partnerships and a strong foothold in children’s character costumes, Disguise benefits from brand affinity and churn-proof demand around hit franchises. The company’s focus should be on margin protection through licensing renegotiation clauses and on diversifying SKUs to capture adjacent adult demand during off-peak periods.
-
Spirit Halloween and Party City – both operate at different ends of the same seasonal spectrum. Spirit’s pop-up model delivers high conversion density in limited windows; Party City’s combined brick-and-mortar and e-commerce footprint gives it year-round reach. For both, inventory agility and dynamic pricing engines that respond to live sell-through data will be primary competitive differentiators in 2026.
-
Specialist suppliers (Smiffys, Leg Avenue, Roma Costume, California Costumes) – niche positions—whether regional strength, fashion-forward design, or adult-focused assortments—remain durable. Their upside lies in premiumization and direct-to-consumer amplification, but they must invest in licensing and digital marketing to scale beyond existing channels.
-
Asian manufacturers and wholesalers (Boloparty, Lucida, Party King, Unique Industries, Forum Novelties) – cost and manufacturing agility remain core strengths. They also present attractive contract-manufacturing and private-label opportunities for retailers aiming to insulate margins. These suppliers are, however, exposed to tariff regimes and freight-rate volatility—risks we quantify in the report’s sourcing scenarios.
-
Peris Costumes Group and rental specialists – as the experiential economy expands, rental and theatrical supply channels are a strategic hedge against seasonality. Rental operators benefit from asset amortization and repeat revenue but must balance inventory capex with utilization rates and maintenance costs.
Industry dynamics shaping 2026 decisions
-
Tariff and cost shocks: Recent tariffs and import-cost movements caused measurable upstream price increases in 2025 and changed shopper expectations. Procurement teams must model 5–19% wholesale cost shifts and create flexible contractual levers to protect retail margins while preserving price competitiveness.
-
Consumer spending patterns: Occasion-led spending remains robust—consumers continue to allocate significant budgets to celebration and costume occasions. That said, spending is increasingly skewed by channel and cohort; our consumer-demand mapping helps clients target high-conversion cohorts without over-indexing inventory.
-
IP-driven demand spikes: Entertainment tie-ins and film releases create concentrated demand windows. Retailers with tight merchandising calendars and fast replenishment can convert these spikes into outsized category margins; those without will face markdown risk.
-
Trade shows and product innovation: The early 2026 trade-show circuit highlighted inflatable costumes and franchise-driven designs. Such innovations are catalysts for category growth but also increase complexity in production lines and fulfillment.
-
Sustainability and circularity: Consumer and regulatory pressure is pushing brands to consider rental models, recyclable materials, and take-back programs—initiatives that affect cost structure and unit economics but can unlock customer loyalty and new revenue streams.
Strategic imperatives for 2026 (what leaders should do now)
-
Operationalize tariff scenarios: Build hedging and dynamic pricing mechanisms into your 2026 retail calendar. Our tariff-impact templates convert customs scenarios into SKU-level margin outcomes so you can prioritize SKUs for margin protection or promotional support.
-
Diversify sourcing and reduce single-origin exposure: Near-shore options and dual-sourcing strategies reduce risk. Use the supplier scorecard from the report to quantify lead-time vs. cost trade-offs and implement a staged qualification program.
-
Adopt channel-specific assortments: Move away from uniform assortment plans. Tailor allocations to the channel economics and customer journeys of online marketplaces, specialty retailers and pop-up environments.
-
Lock in licensing flex: Negotiate performance-linked licensing terms and marketing co-invest commitments to reduce fixed royalty burdens and align IP cost with realized sell-through.
-
Invest in faster demand signals: Retailers should prioritize in-season telemetry—sell-through rates, web conversion lift, and A/B pricing experiments—to reduce markdown risk and improve SKU turn.
How PW Consulting’s report helps convert insight into action
This report is built to be a workhorse for commercial teams. Beyond the public summary, subscribers receive the full dataset, interactive dashboards, the forecast model and the suite of commercial playbooks described above. We intentionally withhold granular regional and application splits in this press release to preserve the tactical value of the underlying segmentation and to ensure proprietary scenario outputs are used by decision-makers in a controlled advisory setting.
If your 2026 strategy depends on reliably managing seasonality, licensing spend, sourcing shocks and channel reinvention, PW Consulting’s Party Costumes Market Report provides the quantitative foundations and practical tools you need to move from hypothesis to executable plan. For access to the full segmentation, downloadable models and a tailored briefing with our lead analysts, please visit the report page or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: Party Costumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 14430 Cylindrical Lithium‑Ion Battery Market Poised to Grow at 5.85% CAGR in 2026–2032 with Asia‑Pacific in the Lead
By PW Consulting, 2026-07-02
14430 Cylindrical Lithium‑Ion Battery Market — Strategic Insights for 2026 Decision‑Making
Executive summary
PW Consulting’s 14430 Cylindrical Lithium‑Ion Battery Market study (base year 2025) delivers a decision‑grade view for executives preparing strategy and capital allocation plans in 2026. The market, which reached roughly USD 115 million in 2025, is forecast to expand through the 2026–2032 horizon at a 5.85% compound annual growth rate to an estimated USD 171 million by 2032. Market concentration metrics indicate a mid‑to‑highly consolidated supply base (CR3 ≈ 48.5%, CR5 ≈ 62.2%), a structure that favors established suppliers but still leaves room for focused challengers and specialized niche plays.
14430 Cylindrical Lithium Ion Battery Market
Why this report matters for 2026
-
Timely alignment: 2026 will be a pivotal year as raw‑material volatility and regulatory shifts reshape sourcing and pricing. Our report translates those macro shifts into supplier‑level risk and cost implications for 14430 cell users.
14430 Cylindrical Lithium Ion Battery Market -
Actionable risk management: We map short‑term disruptions (tariff adjustments, export controls) into mitigations—dual sourcing, inventory strategies, contractual protections—that procurement and supply‑chain teams can implement within quarters, not years.
14430 Cylindrical Lithium Ion Battery Market -
Product positioning and roadmap: For product, engineering and business‑development leaders, we translate chemistry, form factor and certification differentials into go‑to‑market options and win themes for consumer, industrial and regulated device segments.
-
Deal support: For corporate development and private equity, the report is structured to enable fast screening of acquisition targets and JV partners using standardized scorecards and valuation scenarios tied to realistic market trajectories.
What’s inside — practical, execution‑oriented content
-
Market sizing and forward scenarios: A base forecast with upside/downside scenarios reflecting raw‑material shocks, accelerated LFP adoption and demand elasticity for portable‑power devices.
-
Supplier scorecards and differentiation frameworks: Standardized assessments of technical capability, certification and quality systems, manufacturing footprint sensitivity, and supply reliability.
-
Total cost of ownership (TCO) models: Cell cost, pack integration economics, warranty exposure and end‑of‑life recycling credits are modeled across buyer archetypes.
-
Regulatory and trade impact briefings: Practical checklists and contract clause templates to mitigate tariff and export‑control exposure introduced in 2025–2026 regulatory actions.
-
Go‑to‑market playbooks: Product launch and channel strategies by application archetype, including certification roadmaps and test‑validation timelines for medical and regulated devices.
-
M&A and partnership pipeline: A prioritized shortlist of provider archetypes with valuation multipliers and integration risk flags for deal teams to pursue.
Key market dynamics shaping 2026 strategy
Three industry currents dominate the decision calculus for 14430 cells in 2026:
-
Raw‑material volatility and chemistry mix shifts. Despite a broader decline in pack prices in 2025 driven by manufacturing efficiency and greater LFP adoption, upstream commodity price swings—most notably a late‑2025 rebound in lithium carbonate and ongoing cobalt supply tightness following export controls—raise margin risk for chemistries reliant on nickel/cobalt inputs. Buyers must evaluate chemistry exposures across their product portfolio and quantify sensitivity to commodity scenarios.
-
Demand re‑profile and application evolution. Global battery demand surged in 2025, with pronounced growth in LFP and energy storage segments. For the 14430 form factor this means a bifurcation: continued traction in compact, high‑cycle consumer and medical devices, while new use cases (IoT, smart sensors, portable medical units) require tighter safety and cert compliance. Product teams should prioritize cell selection matrices that balance energy density against lifecycle and certification needs.
-
Regulatory and trade headwinds. Recent executive actions adjusting reciprocal tariffs and export quotas introduced late in 2025 materially affect cross‑border sourcing economics and lead times. Buyers need playbooks for tariff pass‑through, origin re‑routing and contingency qualification to avoid single‑sourcing exposure during 2026 procurement cycles.
Competitive landscape — how to read supplier positioning
The 14430 supply base today blends legacy manufacturers and specialized Chinese producers. Instead of naming every product spec, contemplate supplier archetypes and what each brings to a 2026 sourcing strategy:
-
Tier‑A diversified electronics groups: Firms with broad product portfolios and rigorous safety systems tend to command premium pricing and shorter qualification tail risk. Their recent safety documentation updates underscore an emphasis on compliance and differentiated risk management—attributes attractive to medical and other regulated device OEMs.
-
Contract‑manufacturing and pack specialists: Suppliers that focus on custom packs and capacity variants offer agility in tailoring solutions for OEMs that need unique form‑factor or high‑rate variants. For companies aiming to accelerate time‑to‑market, these suppliers reduce integration risk but may require tighter IP and quality governance.
-
Niche commodity players: Producers emphasizing competitive pricing and energy density often target high‑volume consumer and power‑tool segments. Their strengths are cost and scale; their weakness is often slower product certification timelines and greater exposure to commodity swings.
Recent supplier activities are instructive: a handful of firms refreshed product documentation and industry guides in late 2025 and early 2026, signaling a focus on transparency, SDS updates and channel education—an indicator that safety and specification clarity will be competitive levers through 2026.
Strategic recommendations for executives in 2026
-
Quantify chemistry exposure now. Build a short, medium and long‑term P&L sensitivity to lithium carbonate and cobalt price scenarios and stress‑test your product roadmap against LFP migration and density trade‑offs.
-
Dual‑source and localize critical nodes. Where tariffs and export constraints intersect with long lead times, create prioritized dual‑sourcing strategies and assess nearshoring or regional warehousing to blunt transit and customs risk.
-
Prioritize certification and SDS governance for regulated end uses. Medical and other regulated applications increasingly select suppliers with up‑to‑date safety documentation and certification footprints; accelerate vendor audits and naming conventions to compress qualification windows.
-
Use supplier scorecards in procurement negotiations. Shift discussions from price per cell to TCO metrics (cycle life, capacity fade, warranty exposure) to secure contracts that reflect whole‑life economics rather than headline unit price.
-
Monitor consolidation opportunities. The market concentration profile suggests value in targeted M&A for acquiring technical IP or expanding capacity in high‑growth niches; use our valuation templates to rapidly screen targets.
How PW Consulting’s report equips your 2026 roadmap
Our 14430 market study is purpose‑built for executives who require fast, executable intelligence rather than broad generalities. Clients receive:
-
Decision matrices that convert market scenarios into prioritized actions by function (Procurement, R&D, BD, Legal).
-
Supplier scorecards and qualification checklists that compress vendor selection cycles from months to weeks.
-
TCO and NPV tools pre‑loaded with market assumptions and sensitivity levers you can adapt to internal forecasts.
-
A regulatory impact appendix summarizing recent trade and export developments and practical contractual language to mitigate exposure.
Note: the report deliberately keeps certain granular segment tables and supplier price curves gated behind the full report because those are often the most material inputs to commercial negotiation and M&A diligence. Access to the full dataset and downloadable models is available on the report landing page for verified purchasers.
Next steps
For 2026 planning cycles, time and clarity matter. Start with a short engagement: a 2‑week supplier‑risk triage that maps your current buy profile to the market scenarios in this report. For teams preparing larger strategic moves—product launches, capacity investments or deals—we provide deep‑dive workshops that convert our findings into a 12‑month execution plan.
Contact PW Consulting to secure access to the full 14430 report and the accompanying toolset that turns numbers into executable decisions for 2026.
For detailed analysis of this topic, please visit the official page: 14430 Cylindrical Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flat Panel Loudspeaker Market to Expand at a 6.81% CAGR Through 2032
By PW Consulting, 2026-07-02
Flat Panel Loudspeaker Market — Strategic Outlook for 2026: PW Consulting Executive Brief
Executive summary
PW Consulting’s new market study on Flat Panel Loudspeakers delivers a forward-leaning strategic brief designed for decision-makers planning budgets, product roadmaps, and M&A activity in 2026. The category has transitioned from niche audiophile and specialist AV use into a broader set of commercial, automotive and consumer touchpoints. Our base-year sizing and seven-year forecast frame this migration: the market grew materially from the start of the decade and the report’s forecast (2026–2032) is driven by a compounded annual growth rate of 6.81%. These macro dynamics create predictable opportunities—and clear operational pitfalls—for manufacturers, system integrators, chipset suppliers and private investors.
Flat Panel Loudspeaker Market
Why this matters for 2026 decisions
2026 is a pivot year. Companies who finalize strategy now will be executing against 6–18 month product and supply-chain timelines that determine competitive position in the 2027–2029 window. The market’s growth trajectory provides room for sustained investment, but it is uneven: success depends on aligning technology selection, channel model and supply-chain resilience. Our study translates the long-term projection into actionable 12–24 month plays that reduce execution risk while preserving optionality for consolidation or rapid scale.
Flat Panel Loudspeaker Market
What the PW Consulting report delivers (practical outputs)
- Independent market sizing (historical 2020–2025 and forecast 2026–2032) and scenario modelling that convert the headline CAGR into revenue-impact scenarios suitable for board-level planning.
- Competitive scorecards and capability maps for the leading players in bending-wave, DML, planar magnetic and related flat-panel technologies—benchmarking product attributes, channel reach and go-to-market strength.
- Technology risk matrix: DSP and amplifier IC supply sensitivities, component sourcing exposure, and redesign-cost overlays to quantify time-to-market penalties.
- Tariff and regulatory impact analysis that translates trade actions and tariff inversion effects into margin stress tests and sourcing playbooks.
- Commercial playbooks: four GTM archetypes (OEM partnerships, direct-to-project integration, channel-first consumer rollouts, and zone-audio systems) with recommended pricing heuristics, launch sequencing and pilot KPIs.
- M&A and partnership shortlist: due-diligence templates, integration checklists and valuation multipliers calibrated to market concentration and technology defensibility.
- Operational checklists and an executive-ready risk register with trigger-based contingency actions for supply or regulatory shocks.
Market dynamics at a glance
After steady expansion through 2020–2025, the flat panel loudspeaker category enters a phase of structural growth and selective concentration. Our analysis shows the overall market value has grown meaningfully over the historical period and is expected to continue expanding under the report’s baseline scenario through 2032 at a 6.81% CAGR. The near-term environment combines increasing design adoption in new use-cases with persistent operational headwinds—chiefly trade/tariff complexity and semiconductor supply volatility—that materially influence time-to-revenue for new platforms.
Flat Panel Loudspeaker Market
Competitive landscape — who to watch and why
The competitive field contains specialized technology leaders and nimble system vendors. Our qualitative assessment highlights distinct strategic positions that matter when designing partnership or M&A strategies:
- FlatPanel Audio (San Jose, CA) — A DML-focused player positioning itself for professional AV and architectural integration. Its DML500 series and weather-resistant variants target reverberant environments where diffuse radiation reduces the need for extensive acoustic treatments. For buyers and integrators, the value proposition centers on system-level simplicity and predictable room behavior.
- Magnepan (White Bear Lake, MN) — An incumbent in the audiophile planar-magnetic segment, emphasizing handcrafted, high-fidelity solutions for stereo and multi-channel deployments. Their product positioning supports premium margins and brand-led distribution strategies.
- Flatt Speakers (Phoenix, AZ) — Specializes in thin, weather-resistant planar transducers using multi-cell micro-transducer arrays. These products are engineered for intelligibility and durability in installations that prioritize directivity and reduced installation counts versus conventional cone loudspeakers.
- Tectonic Audio Labs / Tectonic Elements (Woodinville, WA) — Advances in bending-wave and Balanced Mode Radiator (BMR) systems place this group at the intersection of professional and automotive applications; recent CES showcases underscore their roadmap toward broader drive-unit adoption.
- Brown Innovations (USA) — Known for directional ceiling-tile form-factors that enable isolated audio zones and accessibility features; attractive to museums, exhibits and commercial spaces requiring targeted sound without intrusive fixtures.
- Wisdom Audio (Reno, NV) — Focused on high-performance planar magnetic and line-source flat-panel designs for premium home-theater installations; their engineering depth supports collaborations in custom install and boutique AV channels.
Collectively, the top-tier participants exhibit a moderate level of market concentration driven by technology-specialist leadership and pockets of regional strength. Our competitive chapter includes vendor scorecards, channel maps and differentiation matrices intended to inform partnership and procurement decisions.
Regulatory and supply-side headwinds
Two external themes reoccur across vendor strategies and customer requirements in 2026 planning:
- Trade and tariff complexity. Recent tariff structures have created asymmetries (“tariff inversion”) where components sourced from certain geographies face higher duties than finished assemblies. For companies with cross-border BOMs, this drives a reassessment of local assembly, inventory strategies and total landed cost models.
- Semiconductor and IC volatility. Lead times for critical DSP and Class‑D amplifier ICs have extended beyond 26 weeks in pockets, producing redesign costs that industry estimates place in the USD 50,000–200,000 range per platform and launch delays that can reach half a year. These constraints directly affect product-shelf schedules and launch sequencing.
Technology and product strategy implications
Design and architecture choices now have cascading commercial consequences. The report synthesizes technology tradeoffs into a practical decision framework:
- Choose directivity and dispersion profiles based on installation economics, not only audiophile metrics—DML and bending-wave approaches reduce room treatment costs, while planar-magnetic excels on fidelity in critical listening rooms.
- Prioritize modular electronics and software-defined audio blocks to reduce redesign exposure when key ICs are constrained.
- Productize installation simplicity: weather-resistant, low-profile and ceiling-tile form-factors will accelerate adoption in commercial retrofits and public spaces.
Recommended 2026 playbook for executives
Based on our cross-functional modelling and scenario analysis, executives should consider the following prioritized actions for 2026:
- Lock in strategic component agreements with dual-sourcing clauses for DSP and amplifier ICs; quantify redesign cost buffers in product budgets now (USD-scale contingencies are prudent).
- Re-evaluate BOM localization for high-tariff exposure items; run quick landed-cost simulations to compare near-term margin recovery via localized assembly versus absorb-and-pass-through pricing.
- Accelerate modular product families that allow channel-specific feature sets without full re-engineering—this reduces SKUs and shortens time-to-market when chips are available.
- Pilot targeted commercial use-cases (museum, retail, corporate) where the value proposition of directed audio and minimal acoustic treatment is easiest to monetize; treat pilots as capability proofs supporting larger systems wins.
- Consider tuck-in acquisitions that add installation engineering, channel access or unique IP—smaller strategic buys can accelerate scale more effectively than greenfield expansion in a moderately concentrated market.
- Embed tariff and regulatory monitoring into procurement cadence; designate trigger levels that automatically shift orders or activate contingency suppliers.
- Invest in software and integration services: controlled sound zones, beam-steering profiles and accessibility features increase product differentiation and recurring-service revenue potential.
- Maintain a staged capital plan that preserves optionality for consolidation if market concentration accelerates; our market concentration chapter provides valuation guardrails and integration risk checklists.
How to use the full report
This executive brief highlights the strategic contours and the immediate actions that leaders need to consider in 2026. The full PW Consulting report contains the detailed segment breakdowns, vendor scorecards, financial models and downloadable scenario workbooks that translate the headline CAGR and market trajectory into board-ready decision packages. In keeping with our “trailer” approach, we have deliberately omitted granular regional and application split figures from this summary—to access the full segmentation matrices, vendor ranking tables and modeled P&L impacts, please consult the complete report on our website.
Final note
Flat panel loudspeakers sit at the intersection of acoustics, materials science and embedded electronics. For companies that align technology roadmaps with pragmatic supply strategies and channel-first commercialization, the category offers durable growth. For those that delay contingency planning, regulatory shifts and semiconductor volatility can rapidly convert opportunity into execution risk. PW Consulting’s market study is structured to convert these macro realities into concrete, time-phased actions for 2026—helping clients lock in advantage while keeping optionality for the consolidation and scale-up phase beyond 2027.
For detailed analysis of this topic, please visit the official page: Flat Panel Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Liposomal Glutathione Market Poised for 8.79% CAGR Through 2032
By PW Consulting, 2026-07-02
Liposomal Glutathione Market — 2026 Strategic Preview for Corporate Decision-Makers
PW Consulting’s latest market study on Liposomal Glutathione delivers a focused, practical intelligence package designed to inform high-stakes decisions in 2026. This briefing distills the report’s strategic utility for corporate leaders — investors, R&D heads, commercial teams and M&A advisors — while preserving the granular datasets and proprietary segment matrices that are available exclusively in the full report.
Liposomal Glutathione Market
Market snapshot: scale, momentum and trajectory
After a measured expansion during 2020–2025, the liposomal glutathione market reached an estimated USD 186.15 million in 2025. Our scenario-driven forecast through 2032 anticipates sustained acceleration under a base case, reaching approximately USD 335.89 million by 2032 — an implied compound annual growth rate (CAGR) of 8.79% for the 2026–2032 forecast window. That growth profile places liposomal glutathione among the faster-growing specialty nutraceutical categories, driven by consumer affinity for antioxidant and cellular-support claims, advances in oral delivery technologies, and premiumization across supplement formats.
Liposomal Glutathione Market
What this report delivers — operational, not ornamental
- Dynamic sizing and forecasting model: interactive scenarios (base, upside, downside) with sensitivity levers for pricing, raw-material cost and channel mix that you can plug into internal financial models.
- Go-to-market playbooks: launch and scaling blueprints for new liposomal SKUs across liquid, capsule and novel hybrid formats — including channel roll-out sequencing and promotional mechanics optimized for 2026 consumer and trade landscapes.
- Commercial diagnostics: pricing ladders, margin waterfall templates, and retailer/distributor negotiation frameworks for direct-to-consumer, specialty retail and practitioner channels.
- Regulatory and claims checklists: a practical compliance matrix aligned to DSHEA, FTC guidance and common international considerations for claims, labeling and substantiation.
- Supply chain and quality assurance protocols: critical control points for reduced L-glutathione sourcing and liposome manufacture, plus supplier qualification templates and traceability KPIs.
- Competitive and M&A playbook: identification criteria for strategic targets, valuation multipliers used in our transaction models, and integration risk profiles.
- Primary intelligence appendices: interview transcripts, supplier scoring, and a proprietary dataset of product SKUs tracked across leading markets (available in full report).
Strategic implications for 2026 decision-making
Leaders must translate growth forecasts into specific bets. The following implications are immediately actionable for 2026 strategic planning:
Liposomal Glutathione Market
- Prioritize product formats that match channel economics: While liposomal delivery is application-agnostic in concept, unit economics differ materially across liquid, softgel/capsule and powdered sachet presentations. The report’s playbooks show when to favor premium liquid formats versus scale-oriented capsule SKUs to maximize short-term margin and long-term brand equity.
- Secure upstream raw-materials now: The core active, reduced L‑glutathione, is commonly produced by yeast fermentation, and liposomes are typically formed from phosphatidylcholine sources. Supplier concentration and lead times create near-term procurement risk. Hedging strategies, multi-sourcing, and strategic toll-manufacturing partnerships mitigate supply shocks and ensure launch timelines.
- Embed clinical and bioavailability evidence into early R&D: Oral bioavailability claims drive premium pricing but also attract regulatory and competitive scrutiny. Investment in comparative bioavailability studies, validated analytic methods for glutathione speciation, and robust batch-level release testing reduces commercial friction and supports higher ASPs.
- Plan routing for compliance and claims: Liposomal glutathione is marketed as a dietary supplement under DSHEA in the U.S., which reduces pre-market regulatory barriers but heightens the need for conservative claims and substantiation. Marketing teams should align copy with FTC and FDA precedent to avoid enforcement risk while maintaining consumer-relevant positioning.
- Allocate channel investment to DTC and practitioner channels: Early-adopter consumers and clinical practitioners continue to drive trial and repeat purchase. Our channel diagnostics identify when to scale DTC acquisition spend versus trading promotional spend to brick-and-mortar partners.
Competitive landscape — what the leaders are doing
The market shows moderate fragmentation with room for both branded leaders and specialized innovators. Our concentration analysis indicates a cluster of established players with a combined market share that leaves meaningful opportunity for consolidation and new entrants pursuing differentiated value propositions.
- Quicksilver Scientific (Louisville, CO, USA) — focuses on highly bioavailable liquid and spray formulations and leverages professional-channel endorsement. Their technical positioning emphasizes enhanced absorption and practitioner education as a core commercial lever.
- LivOn Laboratories (Henderson, NV, USA) — a notable incumbent with proprietary Lypo-Spheric encapsulation technology. Their model demonstrates how platformed encapsulation IP can underpin premium pricing and global licensing opportunities.
- Seeking Health (Santa Paula, CA, USA) — emphasizes ingredient provenance and non-GMO sunflower phospholipids for liposome formation. Their strategy highlights transparency and practitioner-facing education as differentiators in clinical and wellness channels.
- Core Med Science (USA) — brings a mix of capsule and liquid dosage forms with an emphasis on higher-potency reduced L‑glutathione. Their approach underscores the trade-off between potency-led claims and manufacturing complexity.
- Empirical Labs (USA) — supplies liquid liposomal glutathione positioned for detox and antioxidant support. Their product positioning provides a useful case for targeting segmented consumer needs within the antioxidant category.
For 2026, expect incumbent differentiation to revolve around three axes: encapsulation technology (bioavailability credibility), supply-chain assurance (sourced reduced glutathione and phospholipids), and channel specialization (practitioner vs. mass-market). The report’s competitor scorecards and heat maps identify specific capability gaps that are ripe for acquisition or partnership.
Regulatory, claims and labeling — practical guidance
Liposomal glutathione is predominantly marketed as a dietary supplement under DSHEA in the U.S., so products typically do not require FDA pre-market approval. However, absence of pre-approval does not mean absence of regulatory risk. FTC guidance on health claims, FDA expectations for structure/function statements, and local regulatory nuances in export markets require proactive governance.
- Ensure label claims are defensible: maintain documentation linking claims to accepted science and avoid disease claims that trigger elevated regulatory scrutiny.
- Standardize disclaimers and substantiation dossiers: maintain an export-ready dossier for each SKU to accelerate entry into new jurisdictions.
- Invest in quality systems aligned to current good manufacturing practices (cGMP) and to the specific analytical needs of liposomal assays (e.g., particle-size, encapsulation efficiency, glutathione redox state).
M&A and partnership playbook
At the convergence of attractive growth (single-digit-plus CAGR), technical differentiation, and moderate market concentration, the segment attracts both financial and strategic buyers. Our M&A playbook, included in the full report, outlines three optimal target archetypes for 2026 acquirers:
- Technology owners: firms with proprietary encapsulation platforms or bioavailability data that can be cross-applied across nutritional actives.
- Manufacturing scale players: toll manufacturers or vertically integrated producers capable of securing raw-material supply and ensuring consistent GMP throughput.
- Channel specialists: consumer brands with strong practitioner or DTC traction that can be scaled via international distribution or co-branding.
Valuation guidance in the report reflects revenue growth, margin dynamics, and IP defensibility; integration risk matrices help buyers assess post-deal synergies and one-time costs.
Methodology and confidence framework
Our conclusions are built from an integrated methodology combining primary stakeholder interviews, SKU-level retail tracking, supplier and clinical literature reviews, and a bottoms-up demand model. The forecast uses three scenarios and is stress-tested against a range of input assumptions — raw-material pricing swings, differential channel adoption curves, and incremental clinical breakthroughs. We document margins of error and provide a decision-maker’s sensitivity dashboard so corporate teams can translate macro scenarios into actionable capex, inventory and marketing plans.
How to use this intelligence in 2026
- Investment committees: use the report’s scenario outputs to set hurdle rates and to time equity or strategic investments into manufacturing or brand assets.
- Product and R&D teams: leverage the bioavailability and formulation playbooks to prioritize development sprints with clear commercial return criteria.
- Commercial teams: apply the go-to-market templates to optimize launch sequencing and to set CAC/LTV targets by channel.
- Procurement and operations: adopt the supplier qualification frameworks and traceability KPIs to reduce supply-side risk and secure margins.
PW Consulting’s Liposomal Glutathione Market report is structured to be a working tool for 2026 planning cycles — not an academic summary. It equips leaders with the scenario levers, operational templates and competitive intelligence necessary to convert market projections into executional outcomes.
Next steps
For access to the complete datasets, SKU-level tracking, proprietary segmentation tables and the downloadable scenario models that underpin these strategic recommendations, please consult the full report on our site. The full package includes the segmented revenue matrices and supplier scoring that have been intentionally withheld from this preview to protect the integrity of our primary-sourced datasets and to ensure you receive a decision-ready intelligence product.
For detailed analysis of this topic, please visit the official page: Liposomal Glutathione Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low and Medium Capacity Gas Generator Market Valued at USD 3,100 Million in 2025
By PW Consulting, 2026-07-02
Low and Medium Capacity Gas Generator Market: Strategic Imperatives for 2026 — PW Consulting Insight
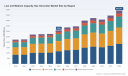
As companies reset capital plans and product roadmaps for 2026, PW Consulting’s new Low and Medium Capacity Gas Generator Market report provides the evidence-based, executable guidance executives need to convert uncertainty into competitive advantage. Anchored on a 2025 base year and a detailed historical review covering 2020–2025, the study delivers an independent view of market scale (reported in USD Million), medium-term growth dynamics and scenario-tested recommendations across OEMs, project developers, asset owners and investors. The headline: after rising from a multi-year base in 2020, the market reached roughly USD 3.10 billion in 2025 and—under our central projection—trends toward a roughly 6.82% compound annual growth rate through the 2026–2032 forecast window.
Low And Medium Capacity Gas Generator Market
Why this report matters for 2026 decision cycles
-
A changing risk calculus: volatility in fuel markets and shifting policy incentives have re-priced the economics of distributed gas generation. The market’s recent trajectory and our forecast envelope provide decision thresholds for capex approvals, product launches, and M&A screening in 2026.
Low And Medium Capacity Gas Generator Market -
From backup to value stack: buyers are increasingly assessing gas gensets not only for reliability but also for integration with hybrid systems, demand response programs and local energy markets. Our analysis surfaces which product attributes capture the highest willingness-to-pay across buyer archetypes.
Low And Medium Capacity Gas Generator Market -
Tightening regulatory backdrop: recent public policy moves and proposed adjustments to greenhouse gas reporting and tax credit regimes materially affect project-level returns. The report translates those policy shifts into quantifiable decision triggers for commercial teams and CFOs.
What’s inside — practical, transaction-ready deliverables
The full report is organized to support immediate action as well as medium-term strategy. Highlights include:
-
Market sizing and forecast methodology — transparent assumptions, sensitivity ranges and scenario runs that let buyers and suppliers stress-test plans against high and low fuel price and policy outcomes.
-
Go-to-market playbooks — segmented routes to market, commercial models, and pricing templates designed for low- and medium-capacity product families (tailored for channel, rental, project and OEM-direct models).
-
Technology & product roadmaps — assessment of engine architectures, bi-fuel and hybrid integration levers, emissions-control options, and near-term R&D priorities that unlock lifecycle cost advantages.
-
Regulatory and incentives matrix — actionable guidance on leveraging federal programs and tax instruments, and on structuring projects to preserve eligibility as reporting rules evolve.
-
Supply chain heatmaps and procurement playbooks — critical-path component risk scoring, on-shore vs off-shore sourcing trade-offs, and inventory strategies to reduce lead-time exposure.
-
Competitive benchmarking and M&A screening — comparative scorecards across manufacturing capability, systems integration, installed base service economics and platform extensibility to identify acquisition targets and partnership fits.
-
Project-level financial templates — CAPEX/OPEX modelling, TCO comparisons against alternatives, and investor-ready sensitivity tables (fuel, carbon price, uptime).
Competitive landscape — who is shaping outcomes
The low- and medium-capacity gas generator market exhibits a moderate level of concentration, with leading suppliers capturing a meaningful share but space remaining for differentiated entrants. Our report benchmarks the incumbent cohort across technical capability, channel strength and aftermarket economics.
-
Caterpillar Inc. — Well-positioned with a broad portfolio spanning continuous and standby applications. Recent product activity (for example, the introduction of the G3512 and expanded G3500-H series) underscores Caterpillar’s dual focus on emissions performance and operational continuity for mission-critical owners.
-
Cummins Inc. — Competes through integrated systems: engines plus controls and power electronics. Its emphasis on natural gas and bi-fuel solutions supports commercial and industrial use cases where fuel flexibility and system optimization matter most.
-
Generac Power Systems — A strong channel play into residential and commercial segments, with scalable approaches that enable stepwise upgrades and rental-market penetration for mid-capacity needs.
-
Kohler Co. (Rehlko) — Focuses on reliability and field-proven designs for commercial standby; innovation in controls and digital diagnostics is a core differentiator for facility managers.
-
MTU Onsite Energy (Rolls‑Royce Power Systems) — Emphasizes higher-end medium-capacity sets with sustainability features and service propositions tailored to mission-critical installations.
-
Atlas Copco AB — Offers portable and stationary equipment with an orientation toward construction and industrial temporary power markets, where mobility and rapid deployment are key.
-
Mitsubishi Heavy Industries Ltd. — Brings depth in turbine-based and medium-capacity platforms, suited for larger commercial deployments and integrated energy projects.
For commercial strategists, the takeaway is clear: incumbents compete on a mix of product breadth, service economics and integration capability. Our benchmarking highlights where premium pricing is defensible and where cost leadership wins share.
Market dynamics to watch in 2026
-
Fuel price volatility: Short-term spikes and month-to-month swings in natural gas prices materially affect dispatch economics. The market saw pronounced intra-year volatility in early 2026; scenario testing against such swings is a must for procurement and asset owners.
-
Policy and incentives: Federal funding for high-efficiency generators and recent tax code developments alter project IRRs. We map which technology options and project structures are most likely to retain eligibility under evolving rules.
-
Regulatory reporting risks: Proposed changes to greenhouse gas reporting will influence the valuation of carbon-related credits and may require changes to compliance strategies for energy projects.
-
Service and digitalization: Aftermarket and remote diagnostics are where margin pools grow. Suppliers that can monetize uptime through subscriptions or performance guarantees will capture disproportionate value.
Concrete recommendations for 2026
-
For OEMs: Prioritize modular product families that enable fast configuration for hybrid and bi-fuel options; accelerate digital telematics rollouts tied to service contracts; use scenario-based cost modelling with fuel-price stress tests to inform capex allocation.
-
For project developers and asset owners: Structure offtake agreements and hedge strategies that account for volatile fuel trajectories; exploit available federal funding windows for high-efficiency systems; design procurement specifications that preserve future conversion pathways (e.g., hydrogen-ready interfaces).
-
For investors and M&A teams: Focus diligence on installed-base service economics and control-platform portability; screen targets for software-enabled revenues and clear paths to margin expansion through aftermarket offerings.
-
For utilities and large consumers: Revisit distributed generation strategies to combine resiliency with market participation; evaluate embedded generation as grid deferral alternative using our TCO templates under multiple fuel price and regulatory scenarios.
How to use this intelligence in 90 days — a pragmatic roadmap
-
0–90 days: Run a rapid portfolio assessment using the report’s stress-testing templates; prioritize retrofit candidates and pilots where federal incentives materially improve returns.
-
90–360 days: Implement product or service pilots that bundle remote diagnostics, uptime guarantees and flexible fuel options; begin supplier rationalization using the supply‑chain heatmaps.
-
12–36 months: Scale modular platforms and roll out integrated commercial models (subscription or availability-based pricing), while preparing for longer-term decarbonization options.
Where this “trailer” leaves you — and what the full report provides
This preview demonstrates the depth of PW Consulting’s proprietary analysis—transparent forecasting, scenario-tested financials and execution-ready playbooks—designed to de-risk 2026 spending decisions. To preserve the commercial integrity of our datasets and the competitive advantage they confer, detailed segment tables, granular regional and application splits, and company-level scorecards are contained in the full report and accompanying dashboards.
Clients and decision-makers preparing budgets, product roadmaps or M&A pipelines for 2026 will find the full report indispensable. It includes downloadable financial models (USD Million), customizable scenario inputs, and a ranked list of strategic moves mapped to ROI timelines. For an executive briefing or to access the dataset and model licenses, contact PW Consulting to arrange a tailored walkthrough.
Final note
The low and medium capacity gas generator market is at an inflection: technology capability, fuel economics and policy incentives are converging to reshape where and how these assets deliver value. PW Consulting’s 2026-focused guidance equips leaders to make timely, defensible choices—balancing short-term volatility with a clear, strategic path to sustainable returns.
For detailed analysis of this topic, please visit the official page: Low And Medium Capacity Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Corrugating Grease Market to Reach USD 295.56 Million by 2032, Growing at a 4.62% CAGR
By PW Consulting, 2026-07-02
Corrugating Grease Market 2026: Strategic Imperatives for Operations, Procurement and Product Development
As corrugated packaging volumes rebound and production intensity rises, lubrication strategies that were once peripheral to plant economics are now central to operational resilience. PW Consulting’s Corrugating Grease Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical data with forward-looking scenario analysis to give executives the actionable intelligence they need for 2026 decision-making. The headline: the global market for corrugating grease—measured in USD millions—continues to expand at a steady mid-single-digit compound annual growth rate (CAGR 4.62%), with modeled revenue trajectories through 2032 that reflect both steady replacement cycles and periodic premiumization tied to high-temperature specialty lubricants.
Corrugating Grease Market
Why 2026 is a Strategic Inflection Point
-
Operational cadence: Many corrugators are executing multi-year maintenance and conversion schedules in 2026, creating a narrow window to lock in lubricant standards, vendor relationships, and roll-conversion timelines that will affect serviceability and TCO for the next 3–7 years.
Corrugating Grease Market -
Raw material transition pressures: Upstream shifts—driven by raw material availability, environmental constraints on extraction, and regulatory scrutiny—are forcing formulators to re-evaluate thickener and base-oil choices. Companies that plan now to validate alternative chemistries will avoid late-cycle supply shocks and reformulation costs.
Corrugating Grease Market -
Certification and food-safety expectations: For corrugators supplying food packaging, NSF H1 registration and demonstrable incidental-contact compliance are non-negotiable. Certification timelines and pilot trials must be integrated into supplier selection for 2026 projects.
What the Report Provides (Practical, Executable Deliverables)
The PW Consulting report is intentionally structured to move a procurement or operations leader from hypothesis to execution. Highlights include:
-
Robust market sizing and validated forecast tables (2020–2032), including alternative scenarios for raw-material shock, accelerated premiumization, and delayed capex cycles—presented both in aggregate and across the standard segmentation axes (type, application, region). Note: the public summary intentionally excludes granular segment disclosures; full datasets and downloadable spreadsheets are available through the report portal.
-
Supplier scorecards and a five-factor sourcing matrix that benchmark technical performance, certification footprint, pricing transparency, conversion support, and regional supply resilience—designed for direct insertion into RFx evaluation templates.
-
Formulation risk map and reformulation playbook: a prioritized list of base oil / thickener substitution pathways, regulatory trigger points (including regional REACH-like scenarios), cost impact ranges, and recommended validation-test protocols to reduce pilot-to-deployment time.
-
Maintenance economics model: a configurable tool that translates lubricant choice, relubrication interval, and bearing failure rates into work-order forecasts and maintenance-staffing needs. The model supports sensitivity analysis for 2026 budget cycles.
-
Go-to-market scenarios for lubricant suppliers and end-users: from conservative continuity plans to aggressive conversion strategies that seek cost-out via extended relubrication intervals and lower life-cycle friction losses.
Market Structure and Competitive Dynamics
The corrugating grease market exhibits a moderate level of concentration: the top three firms account for a meaningful share of industry demand while the top five expand that influence further. This balance has strategic implications for buyers and suppliers alike:
-
For buyers: concentrated R&D and brand trust around established PFPE/PTFE chemistries create switching friction but also opportunities for negotiation on service bundles, plant-conversion support, and long-term pricing frameworks.
-
For entrants and regional players: differentiation via service (e.g., lubrication audits, converted plant case studies), targeted NSF H1 registrations, and localized supply chains can overcome incumbent chemical preferences—particularly where operators prioritize total cost of ownership over raw-material brand equity.
Profiles in Competitive Advantage
Our coverage highlights a small set of firms that shape technical expectations and customer choices in corrugating greases. Readers will find full profiles in the report; below are executive snapshots to frame competitive positioning:
-
Chemours (Krytox): Recognized for PFPE/PTFE-based high-temperature greases that have, over years of application, established a de facto performance benchmark for heated roll bearings in single-facer corrugators. Their product portfolio emphasizes thermal stability, film strength and long relubrication intervals—attributes that command premium pricing but also reduce downtime exposure.
-
FUCHS Lubricants (Nye Lubricants): Brings a combined strength of global lubrication systems expertise and food-grade, PTFE-thickened formulations. Their integrated service model—plant conversions and ongoing lubrication programs—illustrates how lifecycle services can be monetized and how they reduce buyer switching costs.
-
LUBCON: A specialist supplier offering application-specific greases and engineered lubrication solutions. Their focus on high-temperature performance for corrugating machinery illustrates the breadth of niche suppliers that support customized plant needs.
-
IKV Tribologie: Notable for NSF H1 registrations and formulations designed for incidental food contact, serving corrugators with strict food-safety requirements. Their product strategy underscores how compliance can be turned into a differentiator.
Raw Materials, Regulation and the Reformulation Imperative
Two intersecting trends are particularly important for 2026 planning:
-
Upstream material dynamics: Ongoing shifts in thickener preferences and base oil selection—driven by extraction constraints, competing industrial demand, and cost volatility—mean formulators and end-users must quantify reformulation risk. The report models supplier concentration at key raw-material nodes and outlines hedging approaches (long-term offtake, dual-sourcing, and qualifying low-risk substitutes).
-
Regulatory and certification pressures: Regions with heightened environmental scrutiny increase the probability of expedited restrictions on certain extraction or processing pathways. Separately, NSF H1 registration remains a gating factor for suppliers serving corrugators that produce food-contact packaging. Our regulatory scenario work shows how certification lead times should be factored into 2026 procurement calendars to avoid line stoppages.
Operational Playbook: Three Actions for 2026
Based on scenario modeling and primary interviews across manufacturers and greasing specialists, PW Consulting recommends a prioritized three-point playbook for operations and procurement leaders:
-
Run conversion pilots in Q1–Q2 2026: Select one high-utilization corrugator line to trial an alternative grease formulation, instrument bearing temperatures, and measure relubrication interval impacts. Use the results to validate lifecycle savings claims before enterprise-wide rollouts.
-
Lock in certification timelines and supplier service contracts: For lines producing food packaging, require NSF H1 proof points up front and establish service-level agreements that include lubricity testing, inventory buffers, and emergency support windows tied to pricing escalators.
-
Hedge raw-material exposure: Implement a two-track sourcing strategy—long-term agreements with incumbent suppliers for proven chemistries plus development agreements with alternative-formulation suppliers to create optionality should supply stressors or regulatory changes accelerate.
Evidence-Based Forecasting: What the Numbers Tell Us
Our aggregated models show the market continuing to expand from a 2025 baseline into the 2030s under the baseline CAGR of approximately 4.62%. This trajectory assumes an ongoing mix of replacement demand and selective premiumization where high-temperature, long-life greases justify higher unit values. Importantly, the market-level forecast masks heterogeneity across types, applications and regions—an intentional opacity in this release designed to incentivize decision-makers to access the full datasets and the accompanying sensitivity analyses available in the comprehensive report.
How PW Consulting’s Report Helps You Decide
We designed this report to answer the questions executives will face in 2026:
-
Which lubricant chemistries should be prioritized to lower lifecycle costs versus which create unacceptable supply or regulatory risk?
-
How should procurement structure contracts to capture both price advantages and technical-service value?
-
What is the appropriate timeline for certification trials and plant conversions so that 2026 capital and maintenance budgets reflect true deployment windows?
Each of these questions is supported in the report by primary interview evidence, lab-validation frameworks, and a downloadable decision-support toolkit that executives can use to workshop supplier strategies with their leadership teams.
Next Steps
PW Consulting’s Corrugating Grease Market report provides the deep-dive analytics, supplier intelligence and operational playbooks required to govern lubricant strategy through 2026 and beyond. This summary has highlighted the strategic contours and the kinds of executable recommendations contained in the full report while preserving the provenance of our granular segment and supplier datasets. For the complete market tables, supplier scorecards, and the decision-support toolkit, please download the full report from our website or contact a PW Consulting industry specialist to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Corrugating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hirschsprung Disease Drug Market to Reach USD 683.08 Million by 2032 — 2026–2032 Forecast at 5.01% CAGR
By PW Consulting, 2026-07-02
Hirschsprung Disease Drug Market: Strategic Outlook for 2026 — PW Consulting Briefing
As the landscape for Hirschsprung disease therapeutics approaches a pivotal inflection, PW Consulting publishes a focused strategic briefing derived from our full Hirschsprung Disease Drug Market report (base year 2025, forecast 2026–2032). This preview synthesizes the macroeconomic trajectory, competitive inflection points, regulatory dynamics and the commercial imperatives that should shape corporate decisions in 2026. Our purpose here is to establish the analytical frame and the operational questions executives need answered now — while guiding you to the full report for the granular segmentation and modeling that underpins confident action.
Hirschsprung Disease Drug Market
Macro snapshot: a compact market with asymmetric upside
Between 2020 and 2025 the global Hirschsprung disease drug market expanded meaningfully, reflecting an active treatment and post‑surgical management ecosystem. In 2025 PW Consulting’s base valuation places the market at approximately USD 485 million, and our consolidated forecast projects a steady compound annual growth through 2032 (CAGR ~5.01%), reaching roughly USD 683 million by the end of the forecast window. These figures describe a market that is small relative to broad therapeutic areas but large enough to fund specialized R&D and to attract strategic interest from orphan‑disease investors, pediatric specialty biotechs and select large pharma franchises seeking differentiated pediatric assets.
Hirschsprung Disease Drug Market
Two implications flow from the numbers: first, clinical and regulatory milestones — not mass volume alone — will drive valuation and commercial opportunities; second, the market structure supports premium pricing for first‑in‑class disease‑modifying therapies while maintaining ongoing demand for supportive care products. The result is an asymmetric opportunity: modest absolute market size but outsized value creation potential around novel curative or disease‑modifying approaches.
Hirschsprung Disease Drug Market
Why 2026 is a strategic inflection year
2026 represents a calendar in which scientific progress, regulatory momentum and commercial preparations converge. A tangible example: NEU‑001 — a first‑in‑class intrarectal combination therapy in development by Neurenati Therapeutics Inc. — received FDA Orphan Drug and Rare Pediatric Disease designations in March 2025 and EMA Orphan Drug designation in October 2025. NEU‑001’s pathway puts human trials on the horizon in 2026, and a successful entry to clinical development will reframe the competitive narrative.
Importantly, no pharmacologic therapy that modifies the underlying enteric nervous pathology of Hirschsprung disease is currently approved; current drug use remains focused on supportive management of complications such as Hirschsprung‑associated enterocolitis and post‑surgical bowel dysfunction. Standard management protocols continue to reference antibiotics combined with rectal irrigations for HAEC, and laxatives or botulinum toxin injections are routinely used for bowel management. The arrival of a therapy intended to regenerate enteric neurons would therefore shift treatment paradigms — with attendant downstream effects on trial design, payer appraisal and provider adoption.
Report scope — what decision‑makers will find in the full study
- Forward‑looking market sizing and consolidated forecasts (2020–2032) with scenario modeling that isolates base, accelerated and disruption pathways under alternate launch and reimbursement conditions.
- Competitor and pipeline mapping covering clinical stage, mechanism of action, regulatory designations and likely commercial windows — including detailed profiles and strategic options for emerging first movers.
- Regulatory and reimbursement playbooks: analysis of orphan drug incentives, pediatric design considerations, and payer evidence requirements across major jurisdictions.
- Commercial launch readiness tools: segmented go‑to‑market templates, provider engagement roadmaps, hospital procurement dynamics, and channel optimization frameworks.
- Operational checklists for manufacturing scale‑up, pediatric CMC risk mitigation, and clinical supply strategies tailored to small patient populations.
- Transaction and investment diligence modules: valuation sensitivities, M&A comparators, partnership archetypes and a proprietary market concentration assessment.
- Primary research inputs: KOL interviews, hospital pharmacy purchasing patterns, and payer sentiment analysis that anchor quantitative forecasts to on‑the‑ground realities.
To preserve the strategic value of this briefing and to comply with our “trailer” principle, we have intentionally omitted granular regional and product‑class splits here; the full report contains the detailed matrices and downloadable models that enable executable 2026 strategies.
Competitive dynamics and the rise of first‑in‑class entrants
Our concentration analysis reveals a market that is moderately distributed: the top few participants account for a material but not dominant share of the overall market, leaving white space for well‑executed entrants with differentiated clinical profiles. This structure favors innovators that can demonstrate durable clinical benefit and align early with pediatric specialists, surgical centers and payer decision frameworks.
Neurenati Therapeutics Inc., headquartered in Montreal, is illustrative of the new‑era entrant. Their investigational product NEU‑001 is positioned as an intrarectal, neurotrophic growth factor‑based therapy intended to regenerate the enteric nervous system — fundamentally different from current supportive treatments. Regulatory milestones attained in 2025 accelerate the timeline for clinical data generation and create a potential first‑mover advantage if human studies validate safety and efficacy. For incumbent suppliers of antibiotics, laxatives and botulinum toxin therapies, the strategic question becomes one of portfolio diversification: pursue licensing or acquisition of novel assets, partner on evidence generation, or double down on complementary care bundles that will remain necessary during and after any disease‑modifying therapy’s introduction.
Commercial and payer considerations
Orphan and rare pediatric designations reshape commercial dynamics. They typically shorten regulatory timelines, offer market exclusivity advantages and, in some jurisdictions, enable premium pricing environments — but they do not remove payer scrutiny. Payers will demand robust pediatric efficacy data, safety over modest patient cohorts, and health economic models that reconcile upfront therapy costs with avoided long‑term resource utilization (reduced hospitalizations for HAEC, fewer surgical interventions, diminished lifelong bowel management needs).
Channels of care — hospital pharmacies, specialist clinics and evolving online pharmacy models — each present unique contracting, reimbursement and logistics requirements. Manufacturers must prepare differentiated channel strategies that reflect pediatric cold‑chain handling, hospital formulary dynamics, and the need for education and support programs for caregivers. Generating real‑world evidence from registries and payer data will be essential to secure coverage and to manage value‑based contracting conversations.
Priority recommendations for corporate leaders in 2026
- Establish early clinical and regulatory alliances. Engage pediatric surgery and gastroenterology KOLs to co‑design adaptive pediatric protocols that address both efficacy and real‑world applicability.
- Lock in payer evidence plans prior to pivotal trials. Map long‑term cost offsets (hospitalizations, surgical revisions, chronic management) and design HEOR studies that can be delivered alongside clinical development.
- Create an acquisition and partnership shortlist. For incumbents in supportive care, identify 1–3 biotech targets or platform technologies that could accelerate entry into disease‑modifying space.
- Prioritize manufacturing and CMC risk mitigation for pediatric formulations. Early investments in pediatric‑friendly delivery systems and scalable CMC pathways reduce launch friction.
- Design pilot reimbursement constructs. Work with health systems on pilot access programs or outcomes‑based arrangements that de‑risk initial market entry and build utilization evidence.
- Build a cross‑functional launch task force now. Integrate clinical, regulatory, HEOR, commercial and patient advocacy leadership to compress the time from approval to meaningful patient access.
- Allocate capital for post‑launch RWE and registry investments. Lifelong follow‑up data will be decisive in longer‑term payer assessments and guideline updates.
How PW Consulting supports 2026 decision‑making
PW Consulting offers tailored advisory that converts the high‑level insights in this briefing into executable 90‑, 180‑ and 360‑day playbooks. Our services include bespoke market models calibrated to your asset’s profile, due diligence support for licensing and M&A, regulatory strategy workshops focused on pediatric pathways, payer engagement simulations and launch readiness assessments that stress‑test supply, distribution and training plans.
The full Hirschsprung Disease Drug Market report contains the detailed regional and product‑class splits, downloadable financial models in USD (revenue unit: Million), competitive scorecards, and playbooks referenced above. These deliverables are designed to bridge the gap between boardroom strategy and field execution — allowing leaders to act with precision in 2026 while preserving optionality for multiple development and reimbursement scenarios.
Closing: a compact market demanding decisive, evidence‑led moves
The Hirschsprung disease therapeutic arena exemplifies a rare‑disease market where clinical innovation, regulatory incentives and commercial discipline converge. The market’s modest absolute size belies the strategic stakes: a single positive clinical program that demonstrably modifies disease course can reprice the entire landscape. For 2026, the imperative is clear — align clinical design with payer‑oriented evidence generation, prepare operational pathways for pediatric launches, and pursue targeted partnerships that accelerate both science and access.
PW Consulting’s full report delivers the granular segmentation, scenario models and operational playbooks necessary to pursue those paths. Contact our team or visit the report page to access the in‑depth datasets and advisory services that will turn 2026 choices into durable advantage.
For detailed analysis of this topic, please visit the official page: Hirschsprung Disease Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


