



Category: market research
PW Consulting Forecasts 5% CAGR as Lead-Based Rare Earth Alloy Market Expands from USD 306 Million in 2025 to USD 430.6 Million by 2032
By PW Consulting, 2026-07-02
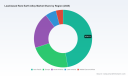
Lead-Based Rare Earth Alloy Market — Strategic Briefing: 2026 Playbook
PW Consulting’s new market study on Lead-Based Rare Earth Alloys (base year 2025; historical coverage 2020–2025; forecast 2026–2032) frames 2026 as an inflection year for corporate strategy. The underlying market has been both resilient and increasingly exposed to upstream rare-earth volatility: after recovering from early-decade fluctuations, global industry revenues reached approximately USD 306.0 Million in 2025 and are projected to grow at a compound annual growth rate (CAGR) of roughly 5.0% through 2032 (our scenario central-case points to an overall market above USD 430 Million by 2032). For executives, investors, and policy teams, the study translates these macro dynamics into near-term decision levers — while reserving granular segment-level figures for subscribers to the full dataset.
Lead Based Rare Earth Alloy Market
Why 2026 matters: a convergence of price, policy and production
-
Upstream price shocks: Q2 2026 saw pronounced upward pressure on rare-earth concentrates used as feedstock for lead-based alloys; reported quarter-over-quarter increases approached mid-double-digits, a change that materially shifts raw-material cost curves for alloy producers and downstream battery manufacturers.
Lead Based Rare Earth Alloy Market -
Policy acceleration: government capital flows and industrial programs in 2025–2026 (notably in North America and other markets) are actively financing metallurgical capacity, separation and metallization projects aimed at reducing concentrated supply-chain risk.
Lead Based Rare Earth Alloy Market -
Regulatory tightening: lead-containing alloys remain subject to robust environmental and occupational health controls. Compliance costs and permitting timelines are now a non-trivial part of capital planning for primary alloy producers and recyclers alike.
Market trajectory and interpretive takeaways
The market’s historical pattern (2020–2025) shows recovery after near-term disruption, followed by steady expansion into our forecast window. That growth is underpinned by persistent demand from legacy applications such as lead-acid battery grids — where rare-earth additions materially improve corrosion resistance and mechanical reliability — and by specialized industrial niches (radiation shielding, corrosion-protective alloys, and various cable and sheathing uses). While the headline CAGR of ~5% signals steady upside, the underlying volatility of rare-earth feedstock prices and the concentrated nature of supply require differentiated strategies rather than uniform capacity expansion.
Key dynamics that should shape 2026 capital and commercial plans
-
Feedstock governance is now strategic: sharp moves in rare-earth concentrate pricing mean procurement teams must move beyond spot buying. Long-term offtakes, index-linked pricing clauses, and equity into upstream raw-material projects are legitimate tools to stabilize margins.
-
Product-form differentiation reduces commoditization: companies that offer alloys in a range of finished forms (wire, foil, strip, custom master alloys) capture premium margins and stickier customer relationships. Investments in finishing lines and quality traceability yield higher returns than undifferentiated melt-and-sell models.
-
Regulatory foresight reduces execution risk: lead-related environmental and workplace regulations materially affect capital allocation and logistics. Early engagement with regulators, and pre-emptive investment in emissions control and worker protection systems, shortens time-to-market for expansions.
-
Supply-chain localization is a hedging strategy: industrial policy incentives in several markets now make local metallurgical investments more attractive to OEMs and system integrators seeking to de-risk battery and shielding supply chains.
Competitive landscape — what the leadership map looks like
The sector shows moderate concentration: our market-concentration indicators place the leading three firms with a material share of the market and the top five commanding a clear majority — a structure that shapes pricing power, access to feedstock, and technology diffusion. A brief, non-exhaustive strategic read on principal players:
-
Integrated metal groups with upstream control (examples among established Chinese producers): these players leverage captive lead and rare-earth inputs to protect margin and manage feedstock availability. Their competitive edge lies in integration economics, scale of operations, and established logistics networks.
-
Non-ferrous diversified companies (manufacturers of zinc, germanium and related metals): companies that combine multiple non-ferrous streams can optimize smelting and refining synergies, offering flexibility in alloy formulations and often holding strong relationships with downstream battery manufacturers.
-
Specialist alloy and processing houses: manufacturers focused on master alloys and value-added forms (wire, foil, capillary, precision strip) compete on product differentiation, quality control, and custom formulations — areas where premium pricing and long-term contracts are common.
-
Mining-linked entrants and miners moving downstream: groups with mining assets in non-ferrous or rare-earth domains have the option to vertically integrate, influencing raw-material allocations and creating potential upstream-downstream arbitrage.
For companies considering partnership or M&A, the priority screen should emphasize: access to secured rare-earth feedstock; finished-form processing capability; regulatory compliance track-record; and customer concentration risks in battery and industrial end-markets.
What PW Consulting’s report delivers (practical, transaction-ready content)
Subscribers will find operationally focused modules designed for decision-makers implementing 2026 strategies:
-
Validated market-size model covering 2020–2025 with a granular, scenario-based forecast through 2032 (central, upside, downside) and sensitivity to rare-earth price trajectories.
-
Supply-chain maps and cost-curve analysis that show where margin pressure originates and how processing steps contribute to final alloy economics.
-
Price-impact scenarios tied to upstream concentrate shocks and regulatory cost migrations, including short- and medium-term cash-flow implications for producers and OEMs.
-
Competitive benchmarking and capability heatmaps for leading and mid-tier firms (production technologies, product forms, geographic reach, feedstock access, and compliance posture).
-
Commercial playbooks for OEMs and alloy suppliers: offtake negotiation templates, hedging instruments, and contract structures that balance security of supply with price flexibility.
-
M&A and partnership screens: target prioritization criteria, valuation overlays, and integration risk checklists tailored to the alloy sector’s unique environmental liabilities and permitting timelines.
Note: the full report contains detailed segment breakdowns, regional splits and application-level tables to inform precise budgeting and target selection; these data are intentionally omitted from this briefing to preserve exclusivity for subscribing clients.
Actionable recommendations for 2026 (prioritized)
-
Lock in feedstock optionality now. Negotiate staggered offtakes and consider minority upstream investments to mute next-cycle price shocks. Use indexed contracts to align supplier economics and avoid outright spot exposure.
-
Invest selectively in downstream finishing. If you are a producer, allocate CAPEX to value-added forms (strip, foil, wire) that are critical to high-margin segments. If you are an OEM, secure preferred-supplier agreements for finished forms to guarantee quality and lead times.
-
Accelerate compliance-driven upgrades. Budget for emissions control and workplace safety enhancements as a near-term cost of entry for new capacity — this reduces regulatory stoppage risk and shortens approval cycles for expansions.
-
Segment customers by exposure and profitability. Prioritize contracts with battery OEMs and industrial customers that internalize alloy performance gains (corrosion resistance, cycle life) and are willing to accept premium pricing for consistency.
-
Pursue strategic alliances rather than broad acquisitions in the near term. Where capital is constrained, joint ventures with feedstock holders or technology partners deliver asymmetric access without full balance-sheet commitments.
-
Integrate scenario planning into quarterly strategy reviews. Given the sector’s linkage to rare-earth price cycles and policy shifts, firms that institutionalize scenario analyses will execute capex and commercial decisions with materially lower downside.
Conclusion — playing for stable growth in an uncertain upstream landscape
The lead-based rare earth alloy market presents a classic strategic trade-off in 2026: steady end-market demand and modest headline growth (CAGR ~5%) sit alongside episodic upstream shocks and regulatory tightening that can rapidly compress margins and reprice projects. For pragmatic corporates, the path forward is not “more of the same” but smarter integration: securing feedstock optionality, increasing product differentiation, and embedding regulatory resilience into project economics. PW Consulting’s full study operationalizes these priorities with models, playbooks and M&A screens calibrated to the realities of 2026. For teams making binding capital commitments this year, the choice is between reactive bargaining on volatile inputs and adopting a structured, layered approach to supply, product and regulatory risk — the latter consistently delivers superior value in our simulations.
To access the full dataset, detailed segment tables, and bespoke scenario outputs that underwrite executable 2026 plans, please consult the report landing page (subscription required) or contact PW Consulting’s industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Camouflage Netting Market to Expand at a 7.25% CAGR Through 2032, Driven by Rising Defense Demand
By PW Consulting, 2026-07-02
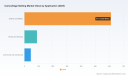
Camouflage Netting Market 2026 Outlook: Strategic Imperatives for Buyers, Suppliers and Investors
PW Consulting’s latest Camouflage Netting Market report—anchored on a 2025 base year with a seven-year forecast horizon (2026–2032)—is designed to be the decision-grade resource that procurement teams, product leaders and investors will rely on as defence and commercial customers reset priorities for the coming procurement cycles. The global market has expanded steadily from the early 2020s and reached USD 745.2 Million in 2025. With an expected compound annual growth rate (CAGR) of 7.25% across the forecast period, PW Consulting projects the market to surpass the USD 1.2 billion threshold by the end of the forecast window, driven by multispectral capability requirements, modularization and new commercial use-cases.
Camouflage Netting Market
Why this report matters for 2026 strategies
-
Timing: 2026 will be the first full fiscal year for multiple defence modernization programmes that reprioritised signature management after 2024–25 sensor capability updates. That makes this report an actionable read-ahead for budget allocation and vendor selection cycles starting now.
Camouflage Netting Market -
Decision relevance: The analysis connects procurement levers (tender behaviour, specification trends, and testing regimes) to supplier economics, enabling teams to translate capability requirements into sourcing and investment decisions.
Camouflage Netting Market -
Risk mapping: We quantify exposure to raw material price shocks and provide hedging and supplier diversification playbooks tailored to camouflage netting manufacturing—essential to protect margins amid volatile polyester resin markets and supply chain reconfiguration.
Key market dynamics shaping 2026 decisions
-
Multispectral signature management is no longer optional. The transition from visual-only concealment to integrated visual/near-IR/thermal and radar signature reduction is accelerating procurement demand for advanced netting systems that combine lightweight form factors with multispectral performance.
-
Operational mobility and modularity are influencing product specs. Forces and commercial users are prioritizing systems that are rapidly deployable, compatible with sensor suites and amenable to field repair—favours that benefit modular, textile-based solutions over heavy rigid structures.
-
Raw material volatility and sustainability are dual forces. Historic polyester resin price swings have demonstrably pressured margins; concurrently, defense and commercial buyers increasingly require sustainability narratives (recycled polyester, plant-based fibres) without compromise to multispectral performance.
-
Consolidation and concentrated competition. The top tier of suppliers captures a meaningful share of the market, creating a competitive environment where innovation, defence contract positioning and service layers (integration, maintenance, testing) determine win rates.
What the report contains: practical, procurement-ready content
-
Market sizing and forecast model (2020–2032): a transparent model that traces historical growth and projects demand drivers and sensitivity across defence, hunting/recreation and commercial/architectural end-users. The model is provided in editable format so buyers and suppliers can run bespoke scenarios.
-
Procurement playbook and tender intelligence: a synthesis of recent tenders, award patterns and specification trends, plus a playbook for structuring RFPs to balance performance, cost and logistical risk. Includes a consolidated tender log for ongoing opportunities.
-
Supplier scorecard framework: a repeatable scoring methodology to evaluate suppliers on multispectral performance, delivery risk, compliance/certification, price transparency and lifecycle support. The scorecard is designed for use in supplier selection panels and pre-qualification phases.
-
Cost-to-serve and TCO models: bottom-up cost frameworks that incorporate raw material swings, labour, testing and certification expenses, and expected lifecycle replacement intervals to produce realistic TCO scenarios for defence and commercial customers.
-
Product and technology benchmarking: comparative analysis of leading systems (lightweight screens, 2D/3D textile constructions, thermal suppression coatings and modular mobile camouflage kits) with clear lines to procurement specifications and test protocols.
-
Risk matrix and mitigation playbook: scenario stress tests (raw material shock, export restrictions, manufacturing disruption), with recommended mitigation levers such as multi-sourcing strategies, regional inventory buffers and strategic partnerships with fibre suppliers.
-
Go-to-market and diversification strategies for suppliers: blueprints for entering adjacent commercial markets (film & entertainment, events, architecture) and for layering services (installation, maintenance, retrofit kits) to uplift margins.
Competitive landscape—what strategists should watch
The market features a mix of established defence-focused technology suppliers and specialist manufacturers addressing commercial niches. The sector’s concentration metrics indicate a moderately consolidated market where the top firms command a disproportionate share of institutional procurement spend. For supply-side strategists, the implications are clear: technological differentiation, contract-level relationships and after-sales capability increasingly determine market share gains.
-
Saab (Barracuda) : A global leader in multispectral systems with product lines that emphasize ultra-lightweight screening and multisensor signature management. Saab’s integrated approach—combining sensor defeat across visual, near-IR, thermal and radar bands—sets a high bar for buyers prioritizing platform-level survivability.
-
Fibrotex / Fibrotex USA : A supplier positioned strongly in defence programmes with modular ULCANS offerings and multiple national contract wins. Recent strategic wins and integration into national procurement programmes demonstrate the commercial payoff of early investment in multispectral R&D and localised production footprints.
-
CamoSystems : Notable for scalable manufacturing and private-label capabilities that serve tactical, hunting and distribution channels globally. Their focus on product breadth is a competitive advantage in commercial channels where price-performance is paramount.
-
Camonets and J & S Franklin : Regional specialists that combine product compliance (fire retardancy, custom sizes) with tailored market offerings for defence support, events and film. Their depth in niche channels illustrates the value of diversified end-use strategies.
-
Seyntex, Nitex, Miranda Military, Sterlite Camotech : Each brings distinct capabilities—high-tech multispectral constructions, regional supply resilience, 3D textile innovations and thermal-protection variants respectively—creating a competitive mosaic where partnerships and specification alignment create access to tier-1 procurement pathways.
Recent deal and product signals — implications for 2026
-
Contract awards and procurement tenders continue to shift demand toward advanced, field-validated systems. Recent high-profile contracts and tenders indicate that major buyers are prioritizing integrated multispectral performance and lifecycle support.
-
Product launches show a parallel commercialisation path: suppliers are introducing coatings and modular kits aimed at IR suppression and multispectral concealment that are rapidly being adopted by both military and civilian customers.
-
Geopolitical and policy levers (national defence budgets and program-level prioritizations) are materially affecting procurement timetables; teams that track these policy cycles will find procurement windows opening in calendar 2026 and beyond.
Actionable recommendations for 2026 planning
-
Buyers: Prioritise multispectral performance requirements and test-based acceptance criteria in RFPs; require lifecycle guarantees and field-repairability clauses to reduce long-term ownership costs.
-
Suppliers: Invest in lightweight multispectral materials and modular architectures. Lock in raw material supply agreements and consider regionalized assembly to meet sovereign sourcing needs.
-
Investors: Look for suppliers that combine IP-rich multispectral capabilities with service-enabled revenue models (installation, retrofit kits, maintenance contracts)—these businesses show better margin defensibility as procurement evolves.
-
Commercial entrants: Consider private-label manufacturing partnerships and carve-out product lines for film, events and architectural use-cases where certification and fire-retardant variants open immediate channels.
How PW Consulting supports implementation
Our advisory offering pairs the market report with hands-on services: bespoke supplier due diligence, tender-response optimisation, contract negotiation support, and TCO implementation workshops. We also provide customised scenario runs of the forecast model to stress-test capital allocation options and supplier strategies under multiple market conditions.
Next steps
This brief highlights the strategic contours that will matter for 2026 decision-making. The full PW Consulting Camouflage Netting Market report delivers the underlying datasets, supplier scorecards, editable forecast model and procurement playbooks that purchasing teams and investors require to convert insight into action. For a demonstration of the model, a tailored briefing or to license the full report and annexes, please visit our website or contact PW Consulting’s defence and industrial textiles practice.
For detailed analysis of this topic, please visit the official page: Camouflage Netting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Light Therapy Devices Market to Grow at a 7.15% CAGR, New Report Forecasts
By PW Consulting, 2026-07-02
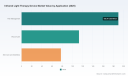
Infrared Light Therapy Device Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Infrared Light Therapy Device Market summarizes the commercial, clinical, and operational intelligence that leaders must act upon in 2026. Built on a 2020–2025 historical base and a detailed 2026–2032 forecast, the report models the market’s trajectory from a 2025 base of USD 380.0 Million to a projected USD 616.32 Million by 2032, representing a compound annual growth rate (CAGR) of 7.15%. This briefing distills the report’s strategic value while intentionally withholding segment-level figures — a preview designed to show analytical depth and operational utility, and to guide you to the full dossier for transaction-grade detail.
Infrared Light Therapy Device Market
Why 2026 Is a Pivotal Year
-
Transition from consumer wellness to clinical adoption: 2026 marks an inflection in buyer sophistication. Devices are moving beyond lifestyle claims toward regulated clinical indications, clinical partnerships, and reimbursement visibility.
Infrared Light Therapy Device Market -
Regulatory clarity and reimbursement mechanics are converging: ongoing Class II device pathways and CPT-level coverage create practical go/no-go tests for new products entering the market.
Infrared Light Therapy Device Market -
Component economics and scale effects will determine margin winners: LED sourcing and BOM structure materially influence unit economics and strategic positioning in the mid-term.
What the Report Contains — Practical, Transaction-Ready Output
-
Comprehensive market sizing and trend model (2020–2032) with scenario variants (base, upside, downside) for planning and valuation.
-
Go-to-market playbooks tailored to product archetypes (portable, wearable, full-body, clinical bed) covering channel selection, pricing frameworks, and service models.
-
Regulatory roadmap templates for 510(k)/Class II clearances and label strategy aligned to claims (pain, wound care, dermatology), including timelines and evidence requirements.
-
Reimbursement impact analysis, mapping CPT codes and payer levers to revenue paths for clinics and outpatient providers.
-
Supplier and cost model with transparency on key BOM drivers (including LED unit costs and their share of manufacturing cost), plus alternative sourcing options and risk mitigants.
-
Competitive benchmarking and company scorecards that synthesize capability in product engineering, regulatory evidence, go-to-market strength, and partnership potential.
-
M&A and partnership scan with prioritized targets and valuation frameworks for roll-up, distribution partnerships, and OEM strategies.
Market Dynamics & Key Drivers
-
Demand drivers: growing clinical evidence for pain management, wound healing and aesthetic indications; consumer wellness adoption; and integration into athletic recovery and rehab programs.
-
Regulatory environment: non-invasive infrared devices are widely treated as Class II in key markets, with 510(k) pathways required for pain relief indications under applicable device codes. Manufacturers must map device claims to FDA guidance and plan for associated premarket submissions.
-
Reimbursement and utilization: physical therapy billing frameworks (including CPT code 97026 for infrared therapy) offer practical reimbursement pathways in certain care settings; however, capture depends on coding discipline and documented clinical workflows.
-
Cost structure pressures: high-power, medical-grade LEDs — particularly at higher near-infrared wavelengths — continue to represent a significant portion of BOM cost. Our analysis shows these components can account for a substantial single-digit to low double-digit percentage of device manufacturing cost and remain a primary lever for margin improvement.
-
Concentration and competitive dynamics: the market remains fragmented with modest top-tier concentration (our market concentration metrics indicate relatively low CR3 and CR5 shares), creating runway for differentiated entrants and consolidation plays.
Competitive Landscape — Strategic Implications
The competitive field blends fast-moving consumer-focused brands, medically oriented device makers, and clinical-system suppliers. Several archetypes stand out:
-
Direct-to-consumer innovators with clinical aspirations — companies offering modular or portable panels and wearables focused on recovery and wellness. These players leverage strong marketing, modular design, and emerging FDA engagement to accelerate adoption in home and semi-clinical settings.
-
Clinically oriented solution providers — manufacturers of whole-body beds and professional devices that partner with hospitals and sports medicine networks, emphasizing certified workflows and institutional procurement processes.
-
Hybrid manufacturers that combine strong engineering (high-power LEDs, optimized wavelengths) with regulatory clearances and clinical studies to target both consumer and clinical channels.
Representative company moves and their strategic signals:
-
Product innovation at higher wavelengths: recent launches increasing near-infrared output indicate a R&D focus on tissue penetration and therapeutic efficacy. Firms amplifying output are effectively targeting clinical endpoints where penetration depth matters.
-
Regulatory momentum: FDA Class II clearances for portable OTC devices highlight a pathway for scaling consumer adoption while maintaining clinical credibility; expect more product clearances to shape channel economics in 2026–2027.
-
Clinical evidence investment: published studies demonstrating significant symptom reduction in targeted populations materially support payor conversations and clinician adoption; companies with defensible study programs gain pricing leverage.
-
Distribution partnerships with hospital systems signal a push into institutional channels and a move to secure recurring consumption and higher ASPs (average selling prices).
Strategic Playbook for 2026 Decision-Makers
-
Prioritize regulatory-first product roadmaps. For any new device launch in 2026, build the 510(k) pathway and associated clinical endpoints into product development timelines from day one; post-market evidence plans should be budgeted as core GTM spend, not optional.
-
Invest selectively in clinical evidence that unlocks reimbursement. Targeted single-indication, well-powered clinical trials (e.g., for arthritis or wound adjunct therapy) deliver the fastest ROI in payer and institutional procurement discussions.
-
Optimize BOM by locking preferred LED suppliers and negotiating volume tiers. Given the outsized role of high-power LEDs in manufacturing cost, secure multi-year agreements or explore vertical integration where economics permit.
-
Adopt hybrid channel strategies. Combine DTC brand momentum with credentialed clinical distribution to capture both consumer wallet-share and institutional reimbursement — structuring offerings by service level (consumer, clinic, hospital).
-
Design service and subscription models. Shift part of the value capture to recurring service (protocol subscriptions, device-as-a-service for clinics) to stabilize revenue and increase LTV.
-
Screen M&A for capability gaps. Acquisitions should be evaluated for regulatory clearance assets, clinical study portfolios, channel reach, or proprietary LED/optical engineering rather than broad market share only.
-
Plan for scenarios: build three-year financial models that stress-test reimbursement rollouts, LED cost inflation, and speed-to-clearance. Use these to set contingency capital buffers and prioritization gates.
Scenario Outlook & Key Sensitivities
Our baseline forecast, reflecting a 7.15% CAGR through 2032, assumes steady clinical adoption, incremental regulatory approvals, and moderated LED cost inflation. Upside scenarios accelerate with faster payer acceptance and wider institutional deployments; downside scenarios arise from restrictive claims enforcement or supply-chain shocks in LED supply.
Key sensitivities to monitor in 2026:
-
Regulatory rulings that tighten or broaden permitted claims.
-
Reimbursement policy shifts, including local payer coverage decisions and utilization limits tied to clinical codes.
-
Raw material pricing volatility for medical-grade LEDs and optics.
-
M&A activity that changes competitive concentration and distribution control.
How Executives Should Use the Full Report
-
Download the full report to access transaction-ready datasets: segment-level forecasts, pricing curves, product archetype P&L, supplier cost breakouts, and company scorecards that underpin the analysis summarized here.
-
Use the included regulatory templates and clinical evidence playbooks to align R&D budgets and commercialization timelines with anticipated 2026 submission windows.
-
Engage PW Consulting for tailored advisory: scenario modeling for specific product proposals, vendor negotiation support for LED procurement, or M&A diligence focused on clinical evidence and regulatory positioning.
Closing thought: the infrared therapy device market is maturing from a fragmented, innovation-led field into a strategically contestable space. Companies that align product design with regulatory pathways, secure cost-advantaged supply, and invest in targeted clinical evidence will capture disproportionate upside as the market scales from 2026 onward.
— PW Consulting, Senior Strategy Consultant & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Education Fuels Flutes Market — Valued at USD 467.18 Million in 2025, Poised to Reach USD 627.72 Million by 2032 at a 4.31% CAGR
By PW Consulting, 2026-07-02
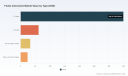
Flutes Instrument Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
PW Consulting’s new Flutes Instrument Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers the market intelligence executives and investors need to make high‑stakes decisions in 2026. The global market has expanded from roughly USD 382 million in 2020 to an estimated USD 467 million in 2025 and is projected to continue growing to approximately USD 628 million by 2032 at a compound annual growth rate (CAGR) of 4.31%. These headline figures frame a market that is mature in developed territories, yet dynamic where education funding, cultural programming, and product innovation intersect.
Flutes Instrument Market
Why this report matters for 2026 decision cycles
-
Timing and horizon alignment: 2026 will be a pivot year for manufacturers and distributors adjusting to trade policy volatility, rising sustainability expectations, and renewed public investments in music education—our forecast horizon (2026–2032) identifies actionable windows for product launches, capacity shifts, and M&A moves.
Flutes Instrument Market -
Macro to micro translation: We translate topline growth into demand scenarios for product tiers (student, intermediate, professional) and channel implications (bricks, e‑commerce, institutional procurement), while preserving the granularity companies need to stress‑test plans.
Flutes Instrument Market -
Risk‑aware strategy: The report embeds regulatory shocks—most notably tariff disruptions—and supply chain fragilities into scenario planning so leadership teams can prioritize hedges and contingency playbooks.
What PW Consulting’s Flutes report includes (practical, operational content)
-
Market sizing and trend decomposition: A reproducible top‑down and bottom‑up methodology, year‑by‑year market values (2020–2025) and a firm forecast (2026–2032) with sensitivity ranges tied to policy and education spending assumptions.
-
Demand drivers and use‑case analysis: Detailed treatment of education programs, performance/professional demand, and hobbyist markets—mapped to lifecycle purchasing behavior and replacement cycles.
-
Competitive benchmarking and vendor scorecards: Standardized assessments of product breadth, manufacturing footprint, brand equity, distribution strength, and innovation capability for leading makers and brands.
-
Supply chain and cost model: Input cost mapping (materials, labor, logistics), tariff exposure analysis, and manufacturing relocation case studies with TCO (total cost of ownership) scenarios.
-
Route‑to‑market playbooks: Channel economics for school procurement, rental and rental‑to‑own models, retail merchandising, and digital direct‑to‑consumer strategies.
-
M&A and partnership pipeline: Target archetypes, valuation heuristics, and integration checklists for bolt‑on acquisitions in accessories, headjoint specialists, and regional distribution platforms.
-
Regulatory and cultural risk register: Up‑to‑date intelligence on tariffs, certification requirements, and cultural programming that affect demand.
-
Decision dashboards: KPI templates and monitoring triggers to convert market intelligence into board‑level actions.
Competitive landscape — positioning and implications
The flutes market features a mix of scale manufacturers with broad wind instrument portfolios and a resilient artisanal tier that commands premium pricing and institutional reputation. Market concentration is moderate: the top three firms capture a meaningful share of global value and the top five amplify that position—this structure causes strategic tension between volume players and niche artisan makers.
-
Scale brand leaders: Companies with diversified wind portfolios and global distribution benefit from scale economics and channel reach. Their strengths are product breadth (student through professional), robust dealer networks, and investments in manufacturing consistency. Sustainability moves—such as redesigned packaging to reduce waste and improve the customer experience—signal brand investments that reduce non‑product frictions and resonate with younger buyers and institutional purchasers.
-
Exclusive and artisanal manufacturers: A cluster of premium, handmade makers—many located in traditional hubs—sustain high margins through craftsmanship, custom work, and orchestral market adoption. These firms leverage reputation, bespoke service, and limited production to defend pricing even as regulatory and shipping costs vary.
-
Mid‑market and educational specialists: Manufacturers that prioritize entry and intermediate instruments—often using offshore production models—compete on value, supply reliability to school programs, and after‑sales service. Their playbook centers on partnerships with education systems and rental programs that lower adoption barriers.
Strategic implications
-
Scale manufacturers must balance cost control with brand elevation to avoid commoditization in the student segment while protecting premium channels.
-
Artisanal makers should systematize knowledge capture (e.g., headjoint craft techniques) and consider selective industrial partnerships to scale without diluting heritage branding.
-
Distributors and retailers will need to redesign inventory and warranty models to manage tariff‑related price volatility and to support institutional procurement cycles.
Recent industry dynamics that will shape 2026
-
Trade and tariff volatility: Recent tariff measures on woodwind instruments have materially increased landed costs for imported instruments and accessories. These measures have already contributed to export downturns in affected markets and should be central to 2026 sourcing strategies and pricing models.
-
Public investment in music education: Government funding and policy initiatives in several emerging economies are driving demand for beginner and student instruments. For firms that can align production and distribution to institutional procurement timelines, this is a tangible growth lever.
-
Cultural programming and visibility: Major museum exhibitions and regional recognition of artisan clusters are expanding consumer awareness beyond core markets, creating marketing and licensing opportunities that savvy brands can monetize.
-
Sustainability and packaging: Small but meaningful packaging redesigns and other sustainability gestures are becoming brand differentiators; they also present cost considerations that must be weighed against customer lifetime value gains.
2026 Strategic playbook — recommendations by stakeholder
-
Manufacturers: Conduct a tariff‑stress TCO analysis for each supply line; prioritize nearshoring of critical components where lead times or tariff exposure is highest; develop modular product platforms to shorten lead times for institutional specs.
-
Retailers and distributors: Build rental and school‑procurement bundles; implement dynamic pricing linked to landed cost indices; co‑invest with manufacturers in local service hubs to extend product life and customer loyalty.
-
Investors and M&A teams: Target platform deals that consolidate regional distribution or strengthen accessory ecosystems (casework, headjoints, cases) and prioritize targets with captive institutional relationships.
-
Education and policy partners: Design procurement frameworks that balance cost with instrument longevity and maintenance; consider bulk‑buy plus local maintenance agreements to secure better long‑term outcomes.
Decision scenarios and monitoring framework
We outline three rapid scenarios—base (moderate growth at consensus), downside (extended tariff and logistic disruption), and upside (accelerated education funding and cultural demand). For each, the report provides specific triggers and a monitoring dashboard: enrollment and procurement notices, landed cost indices, inventory aging across channels, and artisan order lead times. These are the indicators that shift resource allocation between production, marketing, and M&A.
Next steps — how to convert insight into action
For C‑suite leaders preparing 2026 roadmaps, this study translates market growth projections into tactical imperatives: optimize supply chains against tariff regimes; segment product investment between scalable student volumes and high‑margin custom instruments; and commit to measurable sustainability initiatives that lower lifecycle cost and elevate brand preference. Our vendor scorecards and downloadable financial models (available in the full report) enable teams to run bespoke what‑if analysis and prioritize capital deployment with conviction.
PW Consulting’s Flutes Instrument Market report is designed as a decision tool: it gives executives the context, the playbooks, and the triggers to move from insight to confident action in 2026. For complete segment‑level breakdowns, vendor rankings, and the full set of scenarios and financial models, please consult the full report on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Low‑Powered Electric Motorcycle & Scooter Market to Reach USD 60.92 Billion by 2032
By PW Consulting, 2026-07-02
Low Powered Electric Motorcycle and Scooter Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market research on the Low Powered Electric Motorcycle and Scooter market delivers a forward-looking, execution-focused intelligence package designed to inform board-level strategy and near-term operational choices. Our independent market model shows the global market expanding from roughly USD 27.3 billion in 2025 to approximately USD 60.9 billion by 2032, representing a compound annual growth rate (CAGR) of 12.15% across the 2026–2032 forecast window. This press briefing summarizes the strategic implications for corporate leaders while preserving the granular segment-level tables and company scorecards for subscribers who need transaction-grade detail.
Low Powered Electric Motorcycle And Scooter Market
Why this report matters for 2026
-
Timing: 2026 is a hinge year. Cost declines in key battery components, evolving safety regulation, and the transition of urban mobility policies are converging, creating both runway and risk for incumbents and new entrants.
Low Powered Electric Motorcycle And Scooter Market -
Precision: Executives require models that translate headline CAGR into SKU-level demand, channel economics, and margin sensitivities. Our report couples a transparent market-sizing model with scenario stress-tests calibrated to real commodity and regulatory trajectories.
Low Powered Electric Motorcycle And Scooter Market -
Actionability: Beyond market numbers, the report delivers playbooks on manufacturing footprint optimization, battery strategy (buy vs. build vs. swap), and commercialization roadmaps tailored to fleet, last-mile, and personal-commute use cases.
Market trajectory and macro drivers
The mid-2020s market landscape is shaped by three interlocking dynamics. First, adoption momentum remains robust—our model captures a doubling of market value over the forecast horizon driven by increasing urban electrification and substitution of conventional low-powered two-wheelers. Second, input-cost dynamics are materially supportive: lithium-ion battery pack prices fell by an estimated 20% in 2024, and lithium prices similarly eased, improving supplier margins and lowering breakeven points for new models. Third, regulatory tightening on safety and battery handling—in multiple jurisdictions—raises the bar for product certification and after-sales processes in 2026.
These forces create a dual mandate for companies: accelerate Go-to-Market investments to capture expanding demand while hardening compliance, quality control, and warranty provisioning to avoid reputational and regulatory setbacks.
Competitive landscape — concentrated yet contestable
The market remains moderately concentrated at the top: the three largest groups account for a meaningful share of revenue, and the top five expand that footprint further. This structure produces a competitive field where scale advantages coexist with differentiated opportunities for nimble, software-first newcomers and regionally dominant manufacturers.
-
Yadea Group Holdings Ltd. (China) — a high-volume global producer focused on affordable urban two-wheelers and scale manufacturing. Its cost and distribution advantages make it a defensive leader in mass-market segments.
-
NIU Technologies (China) — focused on smart, connected scooters with IoT integration and battery-swapping propositions; a leader in digital services monetization and urban telematics.
-
AIMA Technology Group (China) — strong play in entry-level models with export orientation and manufacturing breadth.
-
Indian OEMs (Hero Electric, Ather Energy, Ola Electric, TVS, Bajaj) — collectively shaping the region’s rapid electrification with distinct strategies: from premium connected models to rapid-volume, low-cost platforms.
-
Gogoro (Taiwan) — notable for its battery-swapping ecosystem, offering an alternative ownership and infrastructure model that remains attractive in dense urban cores.
-
Global OEMs and specialists (Piaggio/Vespa, Honda, Vmoto Soco, Zero Motorcycles, Sunra) — representing a mix of legacy brand electrification and specialist entries into new price-performance bands.
Recent market signals illustrate shifting competitive playbooks. Zero Motorcycles’ November 2025 unveiling of the LS1 scooter at EICMA signals performance-brand moves into more accessible scooter segments. Sunra’s December 2025 strategic summit emphasized flagship models with Bosch drivetrains and removable lithium-ion batteries—underscoring partnerships between OEMs and tier-1 system suppliers.
Segment dynamics and emerging hotspots
We observe durable demand bifurcation along three axes—product form (scooters vs. motorcycles), battery architecture (removable and swappable packs vs. fixed lithium-ion systems), and end-use (personal commuting vs. commercial/last-mile). Each axis creates distinct margin pools and route-to-market requirements. Importantly, falling battery pack costs are compressing crossover points where higher-spec models become viable at mass-market price points.
Strategic hotspots to watch in 2026 include:
-
Battery ecosystems: Swapping infrastructure versus fast-charging and managed BaaS (Battery-as-a-Service) models; commercial operators and urban municipalities are experimenting with hybrid approaches.
-
Software and telematics monetization: IoT features, OTA updates, and subscription services are a differentiator for margin expansion and fleet management contracts.
-
Fleet electrification and last-mile logistics: While personal commuting continues to dominate unit demand, rapid growth in delivery fleets creates concentrated volume contracts—requiring tailored durability and service models.
-
Compliance and safety engineering: Stricter safety rules for batteries and vehicle classification in 2026 make certification pathways and supplier audits a board-level priority.
What the PW Consulting report contains (practical deliverables)
-
Transparent market model with historical series (2020–2025) and base-year calibration (2025), plus scenario-driven forecasts to 2032. The model is provided in Excel with adjustable levers for battery price, urban penetration, and regulatory tightening.
-
Competitive scorecards for >50 OEMs and strategic supplier maps identifying tier‑1 battery and motor partners, including trade-offs for in-house vs. outsourced battery management systems.
-
Go-to-market playbooks for three archetypes—scale-volume OEMs, premium connected brands, and fleet-focused suppliers—covering pricing, distribution, warranty, and service network design.
-
Regulatory and certification matrix mapping key standards (including applicable NHTSA vehicle rules and UL 2850 safety outlines) across primary markets and the likely 2026–2028 compliance timeline.
-
Supply-chain stress-test suite assessing raw material volatility, logistics disruptions, and component lead-time scenarios, with recommended hedging and nearshoring approaches.
-
Merger & acquisition playbook and valuation benchmarks for strategic buyers and private equity, based on EBITDA multiples adjusted for scale, software revenue share, and BaaS exposure.
Strategic recommendations for 2026
For executive teams planning resource allocation this year, our research supports the following prioritized moves:
-
Revisit battery strategy now. With downward pressure on pack costs, firms that secure flexible supply (mixture of spot purchases, long-term offtakes, and strategic swaps) will sustain margin expansion while reducing time-to-market for higher-spec models.
-
Invest in product safety and certification pipelines. Expect regulators to require stricter battery and vehicle testing; allocate engineering bandwidth and third-party certification budget to avoid market-entry delays.
-
Differentiate via software and fleet solutions. Prioritize connected services that lock in recurring revenue—fleet telematics, predictive maintenance contracts, and BaaS subscriptions materially improve unit economics.
-
Optimize manufacturing footprint for modularity. Adopt platform architectures that allow rapid SKU differentiation while controlling fixed costs; consider contract partnerships in regions with favorable input-cost trends.
-
Target selective partnerships and buyouts. Use the next 12–18 months to pursue small tuck-ins for software firms or battery-ecosystem partners rather than large scale M&A, unless clear synergies in distribution or technology exist.
How to use this intelligence
Leaders should treat the core report as both a predictive tool and an operational playbook. Use the model to run “what-if” scenarios against your product plan, feeding bespoke assumptions on pricing, service costs, and battery economics. Leverage the supplier maps to run accelerated due diligence schedules, and adopt the regulatory matrix to construct a certification roadmap aligned with planned launches.
Because this briefing omits the full segment-level tables and confidential company scorecards, we encourage decision-makers to consult the full PW Consulting report for transaction-level inputs—detailed regional demand splits, SKU-specific margins, and the downloadable forecast model that underpins our public numbers.
Closing
PW Consulting’s Low Powered Electric Motorcycle and Scooter market study combines rigorous macro modeling with hands-on operational advice intended to reduce execution risk in 2026. The market’s projected growth—supported by favorable battery-cost trends but complicated by tightening safety regimes—creates a landscape where the right strategic moves this year can determine winners for the next decade.
For enterprise access to the full data model, company scorecards, and bespoke scenario workshops, please visit the PW Consulting report page or contact our strategy team directly to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Spectrum Analyzer Market Poised for 7.42% CAGR, Reaching USD 700.1 Million by 2032
By PW Consulting, 2026-07-02
Laser Spectrum Analyzer Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on Laser Spectrum Analyzers distills actionable intelligence for corporate leaders, product strategists, and procurement teams preparing to make high‑stakes decisions in 2026. Grounded in a detailed historical review (2020–2025) and a robust forecast (2026–2032), the report synthesizes commercial dynamics, supplier positioning, and near‑term risks that will materially affect capital allocation and go‑to‑market choices.
Laser Spectrum Analyzer Market
Executive snapshot
Our analysis finds that the global laser spectrum analyzer market stood at USD 424.2 Million in the base year 2025. Under the central scenario, the market is projected to expand at a compound annual growth rate (CAGR) of 7.42% across the 2026–2032 forecast window, reaching approximately USD 700.1 Million by 2032. Market concentration is meaningful: the leading three suppliers account for a majority share, while the top five firms collectively command close to seven in every ten dollars of market revenue—an important context for competitive strategy.
Laser Spectrum Analyzer Market
Why 2026 is a strategic inflection point
-
Technology convergence is accelerating. Laser spectrum analyzers are migrating from large benchtop research instruments toward integrated, modular test solutions embedded in manufacturing and network‑level diagnostics. This increases demand heterogeneity and creates product development opportunities for vendors that can balance resolution, speed, and form factor.
Laser Spectrum Analyzer Market -
Supply chain and regulatory headwinds are no longer peripheral. Recent changes in export control regimes and semiconductor equipment restrictions that take effect through 2026, combined with materials and helium supply volatility, are already influencing lead times and component budgets for test equipment purchases.
-
Market consolidation and specialization proceed in parallel. While a handful of incumbents preserve strong positions through breadth and global reach, specialist players are winning on niche performance attributes—high resolution, compact PXIe form factors, and integrated light‑source ecosystems—creating differentiated value for end users.
Key demand drivers and use cases to watch
-
Telecommunications and high‑capacity networks: sustained investment in optical networks and advanced fiber architectures keeps laser characterization and channel analysis as major pull factors.
-
Semiconductor photonics and component manufacturing: tighter process controls and wafer‑level photonics testing are accelerating demand for instruments that combine high resolution with throughput‑friendly ergonomics.
-
Research, aerospace, and defense: precision wavelength metrology and linewidth analysis remain indispensable where accuracy, traceability, and environmental robustness matter.
Competitive landscape — who matters and why
The market architecture blends global test & measurement conglomerates with specialized optical instrumentation companies. Each cohort plays a distinct strategic role:
-
Bristol Instruments (Victor, NY) has carved a reputation for combining Michelson interferometer architectures with FFT analysis to deliver hybrid wavelength metering and spectrum analysis. Their emphasis on frequency stabilization and multi‑laser control positions them well in advanced laser labs and precision manufacturing applications.
-
Thorlabs Inc. (Newton, NJ) competes on modularity, price‑performance, and a broad accessory ecosystem. Their OSAs appeal to both research and telecom laboratories that require fiber‑coupled and free‑space flexibility with competitive noise floors and resolution.
-
Yokogawa Test & Measurement Corporation (Tokyo) remains a reference brand for high‑stability optical spectrum analysis across a wide wavelength span. Their multi‑decade product lineage underpins enterprise purchasing decisions where long‑term service and calibration ecosystems matter.
-
Anritsu and EXFO bring telecom‑grade measurement suites with lab‑to‑field workflows—critical for customers balancing R&D validation and network commissioning.
-
Specialized entrants such as Quantifi Photonics , HighFinesse , and APEX Technologies are differentiating via compact form factors, sub‑µm configurations, and high resolving power for VCSEL and component‑level characterization.
-
Regional and vertically oriented suppliers (e.g., Shimadzu , Optoplex , O/E Land , and CNI Laser ) focus on integrated solutions or pricing/availability advantages in specific end markets.
Recent vendor moves and tactical implications
-
Product launches and platform extensions are accelerating. For example, Shimadzu’s announced SPG‑V500 (InGaAs) launch expands wavelength coverage in communications bands and signals renewed vendor competition in high‑speed spectrum measurement for optical comms markets.
-
Bristol Instruments’ recent multi‑laser control and high‑resolution wavelength meter introductions indicate a push toward bundled stabilization and measurement workflows—an attractive proposition for R&D and industrial laser subsystems.
-
Innovative ecosystem showcases (e.g., Quantifi Photonics integrating novel light sources) foreshadow product roadmaps that prioritize cross‑vendor interoperability, which buyers should prioritize in procurement specifications.
Risk map: supply, regulation, and cost pressures
-
Export control regimes: Updated U.S. export controls affecting semiconductor equipment (with 2026 effective elements) introduce compliance complexity for vendors and OEMs. Decision‑makers should embed regulatory scenario planning into supplier selection and contractual commitments.
-
Component and raw materials: Geopolitical strains in semiconductor supply chains are lengthening lead times and amplifying price volatility for critical optical components and specialty gases. Procurement teams must recalibrate inventory policies and dual‑source strategies.
-
Helium and specialty inputs: Regional conflicts and trade restrictions are disrupting helium availability—impacting manufacturing processes that some suppliers rely on. This creates a secondary operational risk that can influence delivery schedules and pricing.
Strategic recommendations for 2026
In light of the above, we recommend pragmatic, prioritized actions for firms making 2026 decisions:
-
Adopt a two‑track sourcing policy. For mission‑critical test equipment, secure capacity with established global vendors while qualifying fast‑to‑deploy specialist suppliers for niche measurement needs. Include export‑control clauses and dual‑sourcing triggers in contracts.
-
Invest in modular product roadmaps. Product leaders should prioritize architectures that allow software upgrades and plug‑in hardware modules to extend lifecycle value and defray capital intensity.
-
Embed regulatory and supply‑chain scenarios in capex planning. Factor in potential lead‑time extensions and compliance costs tied to semiconductor equipment controls; run stress tests on procurement budgets under multiple compliance outcomes.
-
Pursue targeted partnerships and M&A selectively. Acquihires and technology partnerships with compact‑form factor or light‑source specialists can accelerate time‑to‑market for integrated solutions, while distributor alliances can mitigate regional service risk.
-
Standardize measurement interoperability. Buyers should specify open interfaces and calibration traceability in tenders to avoid vendor lock‑in and to future‑proof instrumentation investments.
What the PW Consulting report delivers — practical deliverables
This study is purpose‑built for executive decision cycles in 2026. It includes:
-
A transparent market model with historical reconciliation (2020–2025) and a segmented forecast (2026–2032) that supports scenario analysis and sensitivity testing against price and adoption assumptions.
-
Supplier scorecards and capability maps that evaluate product performance, distribution reach, service networks, and regulatory exposure—designed to underpin RFP shortlists and supplier negotiations.
-
Operational toolkits: procurement checklists, contract language templates for export controls, lead‑time mitigation playbooks, and a calibration & service‑cost calculator to estimate TCO over instrument lifecycles.
-
Commercial strategy templates for vendors and OEMs, covering product positioning, channel strategies, and a prioritized M&A heatmap that highlights adjacencies likely to accelerate growth or consolidate capabilities.
-
Scenario planning modules that model the financial and operational impact of supply disruptions, export control escalations, and accelerated adoption curves across core end‑user segments.
How leaders should use this report in 2026
For corporate strategy teams, the report serves as a decision primer for R&D budgeting, M&A screening, and product roadmaps. For procurement and operations leaders, it provides the frameworks and checklists needed to secure supply continuity and manage compliance risk. For vendors, it offers benchmarking and route‑to‑market prescriptions to protect margin and expand into adjacent use cases.
Access and next steps
PW Consulting’s Laser Spectrum Analyzer Market report is intentionally structured to be both rigorous and actionable. The public summary offered here is designed as a strategic teaser—showcasing our analytic depth while reserving detailed segmentation cells, exact regional and end‑use splits, and model-level assumptions for the full report. Organizations that require the detailed datasets, supplier scorecards, and scenario workbooks should consult the complete study to inform procurement contracts, product investments, and M&A diligence in 2026.
For bespoke briefings, custom scenario runs, or supplier due diligence support tied to this market study, PW Consulting’s industry team is available to provide targeted advisory engagements tailored to your timeline and risk appetite.
For detailed analysis of this topic, please visit the official page: Laser Spectrum Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Fiber Composites Market to Expand at 5.24% CAGR Through 2032, Fueled by Asia-Pacific Demand
By PW Consulting, 2026-07-02
Glass Fiber Composites Market: Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I am pleased to present an executive preview of our Glass Fiber Composites Market report — a practice-oriented intelligence product designed to shape capital allocation, procurement strategy, product roadmaps, and M&A decisions in 2026. The global glass fiber composites market has moved from recovery into a structurally stronger growth phase: our analysis records an increase from a 2020 base through a 2025 market size of USD 66,450 Million (base year 2025) and forecasts expansion to approximately USD 95,008 Million by 2032 at a compounded annual growth rate (CAGR) of 5.24% across the 2026–2032 horizon. This preview highlights why that trajectory matters for corporate leaders next year, what to watch for in supply-side dynamics, and how our report equips practitioners with operational tools — while intentionally withholding core sub‑segment datapoints to encourage direct engagement with the full report for transaction‑grade insights.
Glass Fiber Composites Market
Why 2026 is a Strategic Inflection Point
2026 marks the transition from short‑term patchwork responses to sustained strategic repositioning across the glass fiber value chain. Several converging forces are amplifying the need for deliberate, data‑backed choices:
Glass Fiber Composites Market
- Steady market expansion: The medium‑term CAGR of 5.24% supports disciplined capacity additions and longer payback CAPEX, but timing and location of investments will determine returns.
- Supply‑side realignment: Large incumbent and regional players are executing capacity programs and product upgrades that shift feedstock availability, grade mix and lead times.
- Policy and trade frictions: Tariffs and trade remedies in key markets continue to alter landed costs and sourcing strategies.
- Customer demand evolution: End markets (transportation electrification, wind power, infrastructure modernization, and electronics miniaturization) are changing material specifications and tolerances, favoring specialty grades and integrated supply solutions.
High‑Level Market Trajectory — What the Numbers Imply
The headline growth from USD 66.45 billion in 2025 to roughly USD 95.01 billion by 2032 (CAGR 5.24%) masks important strategic nuances that matter to executives:
Glass Fiber Composites Market
- Growth is broad‑based but not uniform. Some end‑use sectors are maturing faster in demand, while others are reshaping product requirements (for example, thermoplastic versus thermoset formulations and high‑performance specialty fibers).
- Moderate industry concentration (CR3 ~38.5%; CR5 ~45.2%) indicates a market where large players retain meaningful leverage, yet mid‑tier and regional suppliers can still win by specializing, integrating downstream, or pursuing cost leadership in targeted geographies.
- Financial and operating models need to reflect multi‑year timelines: given capital intensity and lead times for new lines, companies that lock favorable feedstock contracts and engineered solutions early will secure competitive advantage.
What Corporate Leaders Must Prioritize in 2026
We translate macro forecasts into a concise set of actionable priorities for CEOs, heads of strategy, procurement, and R&D teams:
- Supply‑chain resilience and hedging: With glass fiber prices showing regionally divergent trajectories (e.g., U.S. prices around 1,458 USD/MT in December 2025 and projected to 1,482 USD/MT in Q1 2026; China prices observed near 1,382 USD/MT in Q4 2025 with a short‑term projection to 1,413 USD/MT), commercial teams must re‑assess indexation clauses, strategic safety stock, and multi‑sourcing to protect margins against price volatility.
- Selective capacity expansion vs asset optimization: Public announcements and brownfield investments (examples highlighted in our data set) indicate that new high‑grade and electronic‑grade capacity is coming online. Corporates should model scenarios comparing incremental ROI from adding capacity versus upgrading yields and throughput at existing plants.
- Portfolio tilt to specialty fibers and value‑added services: Demand for performance grades (semiconductor packaging, aerospace interfaces, high‑strength composites) is rising. Targeted product development and closer customer integration (prepreg, pultruded profiles, hybrid laminates) yield higher margin and lower commoditization risk.
- Regulatory and trade playbooks: Persistent anti‑dumping duties and tariff regimes in key jurisdictions require scenario playbooks that combine local production, bonded warehouses, and tariff engineering to sustain competitiveness.
Competitive Landscape — Who Moves the Needle
The competitive map is a mix of diversified industrial conglomerates, dedicated glass fiber manufacturers, and pultrusion specialists. The companies we profile in the full study include multinational incumbents and regional leaders whose recent moves and strategic postures are consequential for market participants. Representative players include:
- Global reinforcers with integrated manufacturing footprints and broad end‑market exposure — leaders in E‑glass and specialty rovings that can scale to serve construction, wind, and transportation volumes.
- Large Chinese producers executing aggressive capacity rollouts, particularly for electronic‑grade and energy‑grade fibers — a dynamic reshaping regional supply balances.
- Specialty fiber manufacturers and pultruders focused on high‑performance niches — including S‑glass and engineered pultruded systems for infrastructure and advanced composites.
Company profiles in the full report include strategic posture, product portfolios, capex timelines, and scenario impact matrices — enabling buyers, potential JV partners and private equity sponsors to calibrate exposure and identify acquisition targets. For confidentiality and to preserve the “trailer” nature of this preview, we selectively present company characteristics here and reserve granular competitive metrics and valuations for the main report.
Recent Developments That Will Shape 2026 Dynamics
- Capacity and product announcements: Recent investments in specialty capacity — for example, an announced expansion to electronic‑grade glass fiber lines and new microfiberglass production facilities — are indicative of supplier priorities toward higher value applications. Such moves compress lead times for specialty grades while creating new competition in those segments.
- Price signals: Raw material price baselines differ across regions and continue to trend modestly upward into early 2026 — a near‑term input pressure that buyers should bake into contract negotiations and price pass‑through models.
- Policy environment: Trade remedies and duties remain active levers in certain markets, driving regional sourcing adjustments and localized production responses.
What’s Inside the Full Report — Practical, Transaction‑Grade Content
Our full study is built for decision speed and operational relevance. Key deliverables include:
- Market sizing and validated growth curves (historical 2020–2025; detailed forecasting 2026–2032) with sensitivity scenarios under alternate demand and raw‑material price paths.
- Segment playbooks — for resin systems, end markets and geographies — showing where to allocate R&D, where to pursue scale, and where partnerships or buyouts are likely to outperform greenfield investments. (Note: detailed sub‑segment financials and percent splits are intentionally available in the full report only.)
- Supplier maps and capacity overlays at a transactional granularity, including planned expansions and likely impact windows for product availability and pricing.
- Procurement templates: contract clauses, indexation strategies, and stock policies calibrated to short‑term price trajectories and long‑term strategic supply alignment.
- M&A playbook and target screening criteria, with scorecards for strategic fit, synergies, and integration risk.
- Regulatory and trade readiness matrix: tailored responses to common duty regimes and environmental product declarations that affect specification and tender outcomes.
Signals to Monitor in 2026 — Early Warning and Opportunity Triggers
- Feedstock and price momentum: Quarterly moves in regional glass fiber pricing and volatility in freight will be the first lever for margin compression or expansion.
- Commissioning of announced lines: The timing and ramp rates of recently announced capacity projects will affect tightness in specialty grades and opportunity windows for premium pricing.
- Policy shifts: Any changes in anti‑dumping measures or tariff rulings in key markets will materially alter trade flows and should trigger immediate sourcing reassessments.
- Customer specification shifts: Accelerated adoption of thermoplastic composites in specific transportation applications or increased use of higher‑performance glass in wind blades will change mix and profitability for producers and converters.
How PW Consulting’s Report Supports Immediate 2026 Actions
For executive teams pursuing quick wins in 2026, the report functions as an operational toolkit: it enables rapid supplier re‑scoping, short‑list generation for targeted acquisitions, CAPEX prioritization models, and procurement negotiation playbooks. For boards and investors, it supplies stress‑tested scenarios that inform valuation multiples and downside protections in transaction documents.
Next Steps — Accessing the Full Intelligence
This release is intentionally framed as a strategic “trailer:” it demonstrates the depth and applicability of our analysis while withholding detailed sub‑segment tables, regional/application splits, and company‑level financials that are included in the licensed report. To obtain the full dataset, proprietary models, supplier maps and the transaction playbook required for 2026 decision execution, please access the complete Glass Fiber Composites Market report from PW Consulting.
Our team stands ready to run bespoke scenario workshops, tailor the procurement templates to your commercial contracts, or provide due‑diligence briefs for potential M&A targets identified in the report. In a market moving at the pace of regulatory change, trade intervention and targeted capacity expansion, timely, operational intelligence will determine who captures the step‑change in value during 2026–2032.
For detailed analysis of this topic, please visit the official page: Glass Fiber Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Ion Free Photoresist Developer Market Tops USD 1,400.2 Million in 2025
By PW Consulting, 2026-07-02
Metal Ion Free (MIF) Photoresist Developer Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research on Metal Ion Free (MIF) photoresist developers delivers a focused intelligence package tailored for semiconductor executives, procurement leads, process engineers, and corporate strategists preparing plans for 2026 and beyond. Our study shows the MIF developer market reached approximately USD 1.40 billion in 2025 and is on a steady expansion trajectory — the market is forecast to approach roughly USD 2.30 billion by 2032, reflecting a compound annual growth rate (CAGR) of 7.38% over the 2026–2032 forecast horizon. This briefing highlights the strategic implications of those dynamics without revealing the full tranche of segment-level metrics reserved for subscribers.
Metal Ion Free (MIF) Photoresist Developer Market
Why this market matters for 2026 strategy
- Purity as an operational imperative: Metal-ion contamination is a barrier to yield and reliability as nodes push below 0.5 µm. MIF developers remain the de facto standard for chemically amplified and DNQ-based resist processes where ionic control is mission-critical.
- Sustainable competitiveness: OEMs and materials suppliers are accelerating investments in environmentally friendlier chemistries and lower-waste processing; early movers gain procurement leverage and regulatory insurance.
- Mid-cycle inflection for buyers and suppliers: With the MIF market already at scale and growing at a mid-single-digit-plus CAGR, 2026 is a decision year for lock-ins, qualification roadmaps, and capex alignment with lithography and advanced packaging roadmaps.
Core market dynamics — what is changing in 2026
- Upstream feedstock sensitivity: Tetramethylammonium hydroxide (TMAH) is the principal raw material for aqueous MIF developers (commonly formulated at ~2.38 wt% / 0.261N). Pricing and availability swings in TMAH materially affect cost structures across the value chain. Our monitoring showed regional TMAH pricing softness in Q2 2025 driven by demand softness in broader electronics, an input that buyers should include in 2026 procurement scenarios.
- Regulatory and quality drivers: Regulatory preference for metal-ion-free chemistries in high-resolution lithography is translating into longer qualification cycles but steadier long-term demand for MIF formulations. Device makers prioritizing reliability at advanced nodes are unlikely to trade purity for short-term savings.
- Product differentiation beyond concentration: Suppliers are increasingly competing on formulation adjuncts — surfactants for improved wetting and residue removal, compatibility with immersion and in-line track systems, and eco-friendly additive packages. These attributes create switching frictions and can justify premium pricing.
- Consolidation versus niche specialization: While established global suppliers retain scale advantages, smaller formulators and lab-to-production specialists are exploiting rapid qualification windows in regional fabs and R&D environments, creating a mixed competitive landscape.
Competitive landscape — what the leading players are doing
The MIF developer segment is characterized by a mix of global chemical leaders, specialty formulators, and distribution-focused players. Key strategic moves observed through mid‑2025 signal where competitive pressure and partnership opportunities will concentrate in 2026:
Metal Ion Free (MIF) Photoresist Developer Market
- Merck KGaA (AZ Electronic Materials): Continues to set technical benchmarks with its AZ® MIF portfolio, including surfactant-enhanced variants for wetting and residue control. Recent launches emphasize eco-compliance and bespoke partnerships with tier‑one semiconductor manufacturers, underscoring a dual playbook of product innovation and customer intimacy.
- Fujifilm Electronic Materials: Leveraging high-purity process capabilities and a strong track record in photochemicals, Fujifilm has expanded its MIF offerings and complementary stripper chemistries to support integrated process flows and sustainability objectives.
- Tokyo Ohka Kogyo (TOK): Focused on node-optimized MIF formulations, TOK’s product positioning emphasizes lithography compatibility at advanced process nodes — a strategic axis for foundry and logic supply chains that will demand tight process windows in 2026.
- Dow Inc.: With legacy Microposit credentials and widely used 0.26N TMAH products (and surfactant variants), Dow remains a reference supplier for many legacy and high-volume resist systems, offering scale and track compatibility that favors long production runs.
- Specialty and regional players (KemLab, Allresist, MicroChemicals): These firms occupy strategic niches — drop-in replacements, lab-to-production supply, and localized distribution. Their agility, cost positioning, and technical service model make them important alternatives for process qualification teams and small- to mid-scale fabs.
Collectively, the landscape is a blend of scale incumbency and targeted disruption. For buyers in 2026, supplier selection will hinge on a balance of qualification risk, cost-to-qualify, sustainability alignment, and roadmap fit with lithography equipment and resist chemistry choices.
Metal Ion Free (MIF) Photoresist Developer Market
Practical contents of the PW Consulting report (what you will find)
Our full report is engineered for action — it translates market forecasts into decision-ready frameworks and qualification playbooks. Highlights include:
- Executive decision matrices that align supplier selection criteria with five procurement archetypes (high‑volume production, R&D pilot fabs, advanced packaging, foundry qualification, and contingency sourcing).
- Supply‑chain risk scorecards quantifying exposure to TMAH price swings, single‑sourcing risks, and regulatory compliance pathways for environmentally constrained jurisdictions.
- Technology compatibility guides that map MIF chemistries to major resist families and track/immersion process types, including practical checklists for process engineers to accelerate wafer‑level qualification.
- Commercial benchmarking tools: pricing dynamics, margin pressure scenarios, and go‑to‑market plays for suppliers contemplating value‑added services (e.g., on‑site mixing, waste treatment partnerships, and joint development agreements).
- 50+ company profiles and strategic dossiers — from global chemical majors to nimble specialists — each including capability overviews, recent product/partnership developments, and likely strategic moves through 2026.
- Scenario-driven forecasts and investment triggers: clear decision thresholds that tell procurement and corporate development teams when to accelerate long‑lead qualifications, pursue multi‑year contracts, or open alternative sourcing pilots.
Strategic recommendations for 2026
- Lock down reliability — then optimize price: Prioritize supplier validation for device reliability and yield. Once process compatibility is proven, negotiate multi-year pricing that includes clauses for TMAH cost pass-through and sustainability-related improvement milestones.
- Diversify qualification lanes: Maintain at least two qualified MIF suppliers across critical fabs to reduce single-source vulnerability and to retain leverage during feedstock volatility.
- Invest in eco-compliance playbooks: Suppliers launching eco-friendly MIF formulations are reducing downstream permitting and waste‑treatment exposures; device makers should quantify projected OPEX reductions from lower waste handling and use that as part of TCO assessments.
- Exploit surfactant and additive differentiation: Where process windows are tight, the right surfactant-enhanced formulation can lower defectivity and cleaning cycles — consider technical pilot projects with such vendors before committing to scale purchases.
- Make M&A and partnership decisions on capability, not just capacity: For suppliers looking to grow, acquiring or partnering with lab-to-production specialists accelerates customer access with lower qualification friction than greenfield expansions.
Risks to monitor through 2026
- Feedstock price volatility: A rebound in TMAH demand or supply disruptions could materially shift vendor economics and contract terms.
- Regulatory tightening: Accelerated restrictions on hazardous chemistries in key manufacturing hubs could favor vendors with greener portfolios, potentially disadvantaging legacy formulations.
- Qualification lag: Lengthy qualification cycles for advanced nodes can delay supplier switching even when cost or sustainability benefits are compelling.
What we are not disclosing here (and why you should download the full report)
In line with our “trailer” approach, this briefing deliberately omits the granular regional and application split tables, specific vendor share percentages, and detailed price-by-application scenarios that are essential for executing procurement and M&A moves. Those datasets — including full segmentation, supplier share matrices, and downloadable vendor scorecards — are available only in the full PW Consulting MIF Photoresist Developer Market report, which also contains step-by-step qualification checklists and executable contract language templates tailored for 2026 negotiations.
Final note for executives
By 2026, decisions on MIF developer sourcing will not be purely transactional. They will be integrated bets across process reliability, environmental compliance, and cost resilience. PW Consulting’s market forecast (USD ~1.40 billion in 2025 growing to ~USD 2.30 billion by 2032 at a 7.38% CAGR) establishes the commercial backdrop; our operational toolset and supplier playbooks translate that backdrop into executable strategies. For teams preparing budgets, supplier negotiations, or R&D roadmaps in 2026, this report provides a prioritized set of actions and the data foundation to defend them.
Access the full report to retrieve the segmented datasets, vendor scorecards, and tactical checklists needed to implement a 2026-ready MIF strategy.
For detailed analysis of this topic, please visit the official page: Metal Ion Free (MIF) Photoresist Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Polarizer for OLED Market to Expand at a 10.32% CAGR Through 2032
By PW Consulting, 2026-07-02
Polarizer for OLED Market — Strategic Snapshot for 2026 Decision-Making
By PW Consulting — Senior Strategy Advisor & Chief Industry Analyst
Polarizer for OLED Market
Executive preview
The polarizer segment for OLED displays is at an inflection point. Our new Polarizer for OLED Market report, with a 2025 base year and a forecast horizon through 2032, shows the market expanding from roughly USD 2.19 billion in 2025 to an expected USD 4.35 billion by 2032, at a compound annual growth rate (CAGR) of 10.32% over the forecast window. That trajectory reflects sustained demand from mainstream OLED form factors while being tested by accelerating technology shifts that could displace conventional polarizers in targeted applications.
Polarizer for OLED Market
This release is written for executives who must set 2026 budgets, capex plans, supplier strategies, and M&A priorities. Below we outline the strategic implications, competitive dynamics, and playbooks that the report contains in operational form — while intentionally withholding detailed regional and application-level splits to preserve the full report’s commercial value.
Polarizer for OLED Market
Why this matters for 2026 planning
-
Timing matters: 2026 is a pivot year. The market scale and the above-trend CAGR create room for expansion, but concurrently, commercially viable polarizer-free innovations and alternative optical stacks are moving from R&D into productization. Procurement, R&D, and corporate development functions must be aligned now to either capture upside or insulate performance.
-
Concentration amplifies strategy effect: The market is relatively concentrated — the top three suppliers command the majority share, and the top five control an even larger portion — which means strategic moves by market leaders (capacity, pricing, or technology licensing) cascade quickly through the ecosystem and can reshape supplier economics within 12–18 months.
-
Material and policy exposures are asymmetric: Profitability depends not only on product innovation but also on management of PVA/iodine supply chains and geopolitical factors like tariff regimes. Gross margins in the industry have been reported in the mid-teen to low-twenties range; preserving that requires active raw-material and policy risk mitigation.
What the report delivers (practical contents)
-
High-resolution market forecast (2026–2032) with scenario trees reflecting variable adoption curves for polarizer-free solutions and flexible OLEDs.
-
Risk-quantified raw-material model that links iodine and PVA price scenarios to supplier margin sensitivity and suggests hedging and sourcing tactics.
-
Competitive playbooks for incumbents and challengers — covering product differentiation, cost-to-serve optimization, licensing models, and partnership archetypes with panel makers.
-
Decision-ready M&A and JV frameworks (valuation multipliers adjusted for concentration metrics and technology-risk premiums), plus integration checklists focused on optical film manufacturing and downstream coating capabilities.
-
Go-to-market modules for premium vs. volume segments, including price elasticity tests, channel mapping, and a 12–24 month partner engagement cadence tailored to foldable and large-area OLED use cases.
-
KPIs and early-warning indicators to trigger tactical moves — e.g., PVA/iodine price spikes, tariff announcements, display OEM design wins for polarizer-free stacks, or capacity announcements by top suppliers.
Competitive landscape — what to watch
The supplier fabric blends long-established optics specialists with vertically integrated chemical and display groups. Leaders bring distinct advantages:
-
Nitto Denko Corporation (Japan) — recognized for ultra-thin polarizers and high-performance circular polarizers optimized for flexible and high-contrast OLEDs. Nitto’s deep material science and production know-how make it a natural partner for smartphone and high-end panel makers seeking yield stability at scale.
-
Sumitomo Chemical (Japan) — a major PVA-based film producer whose strength lies in optical film chemistry and consistency for premium consumer-electronics panels. Sumitomo’s upstream polymer competencies create defensible margins on premium offerings.
-
LG Chem / Shanjin Optoelectronics (Korea / China) — leveraging retained OLED-specific capabilities and regional manufacturing footprints, they are prominent in supplying circular polarizers for large-size and flexible panels where supply chain proximity matters.
-
Samsung SDI / Ace Digitech (Korea) — notable for tailoring polarizers to foldable and premium handset displays; however, their strategic posture is currently under review as they balance internal display synergies and third-party supply opportunities.
-
BenQ Materials (Taiwan) — a leader in bendable circular polarizers for foldables, with a focused product roadmap aimed at the flexible-device segment and strong OEM relationships in that domain.
-
Other regional producers (Polatechno, Optimax, Sunnypol, CMMT, SAPO Photoelectric, WINDA, Tunghsu) provide capacity diversity and represent local market dynamics that can be leveraged for cost competitiveness or rapid localized scale-up.
Collectively, this mix of specialist optics firms and generalized chemical producers shapes an ecosystem where technological differentiation, supply security, and scale economies determine winners. Our report includes operational profiles, plant-by-plant capabilities assessments, and supplier scorecards to support vendor selection.
Technology and disruption signals
-
Polarizer-free designs are materializing. Independent industry analysis forecasts polarizer-less OLED shipments to reach 244 million units by 2032, driven by innovations like COE and OLED transmittance control films (OTF). These developments can materially reduce unit polarizer demand in selected product classes (notably certain TVs and smartphone subsegments).
-
SAM display wins and awards (e.g., polarizer-free LEAD technologies) are an early indicator of design wins that will propagate through OEM supply chains within 18–36 months; suppliers must watch patent filings and conference demonstrations closely.
-
R&D and material science remain a competitive moat — ultra-thin flexible polarizers and advanced compensation films will retain high value in categories where polarizer-free solutions cannot yet match optical performance or durability (e.g., some AR/VR and automotive safety-critical displays).
Supply chain & policy risk — the near-term playbook
Raw materials anchor the cost base. Polarizer film production is heavily reliant on polyvinyl alcohol (PVA) and iodine; the global iodine market is sizable (projected at approximately USD 3.21 billion in 2026) with Chile supplying a dominant share of output. These inputs are volatile and can compress margins unless actively managed.
Additionally, tariff and trade policy are active levers. Historical tariff concessions in some jurisdictions have supported localization; anticipated policy shifts in 2026 — particularly in major manufacturing nations — could alter landed costs and sourcing logic. US-China tariff dynamics also represent a persistent tail risk for cross-border suppliers.
Practical responses include: multi-sourcing critical inputs, strategic iodine forward purchases or tolling agreements, selective upstream investment (e.g., minority stakes in key chemical suppliers), and contracting clauses that pass through raw-material inflation.
Strategic recommendations for 2026
-
Adopt a dual-track product strategy: continue to invest in ultra-thin and flexible polarizers for near-term high-margin opportunities, while establishing R&D pilots or partnerships to integrate polarizer-free options where they align with OEM roadmaps.
-
Prioritize supplier resilience: lock in multi-year agreements with key PVA and iodine suppliers, and create contingency plans for tariff-driven re-shoring or near-shoring of capacity.
-
Use the year to secure selective vertical integration: small, targeted investments in upstream chemical capability or strategic tolling partnerships can defend margins in commodity-stressed scenarios without the capital intensity of full upstream M&A.
-
Prepare for consolidation: given industry concentration, scale matters. Build an M&A playbook focused on acquiring specialty film capabilities and proprietary coatings rather than broad chemical portfolios — execute deals that deliver immediate route-to-market and customer contracts.
-
Institute a real-time signal dashboard: track PVA/iodine price indices, tariff policy calendars, key OEM design-win disclosures, and patent filings for polarizer-free technologies as triggers for tactical reallocation of resources.
What we intentionally withhold here
To preserve the actionable value of our market intelligence and to comply with our “trailer” approach, this release omits the detailed region-by-region and application-by-application numeric breakdowns, and finer-grained pricing curves that are included in the full report. Those granular segmentation tables and supplier-level shipment forecasts are available in the complete Polarizer for OLED Market report.
Next steps
If your 2026 strategy includes procurement, capacity investment, M&A, or product repositioning in the optical films space, PW Consulting’s full report equips you with the models, supplier scorecards, scenario playbooks, and negotiation templates necessary to act decisively. Contact our team to schedule a briefing and obtain the full dataset and executable annexes.
PW Consulting — bringing market foresight to strategic action.
For detailed analysis of this topic, please visit the official page: Polarizer for OLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Exit Interview Management Software Market Poised to Grow at 11.14% CAGR, Reaching USD 951.12 Million by 2032
By PW Consulting, 2026-07-02
Exit Interview Management Software Market: Strategic Imperatives for 2026 — PW Consulting Preview
As organizations retool people strategies in response to persistent labor market churn, exit interview programs have moved from a compliance checkbox to a strategic data source. PW Consulting’s latest market study — using 2025 as the base year and projecting through 2032 — quantifies that shift. The global market for exit interview management software reached USD 454.1 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 11.14%, approaching USD 951.12 Million by 2032. This preview distills the report’s most consequential takeaways for corporate decision-makers preparing vendor, budgetary, and programmatic choices in 2026, while preserving the detailed segment, vendor-share, and pricing matrices for full-report subscribers.
Exit Interview Management Software Market
Why Exit Interview Software Matters for 2026 Decisions
-
From data capture to retention strategy: Exit interviews are no longer isolated post-mortems. Modern platforms convert qualitative departure feedback into leading indicators that inform hiring, engagement, and retention investments.
Exit Interview Management Software Market -
Acceleration of AI-enabled insight extraction: Vendors are embedding sentiment analysis and predictive turnover modeling into their offerings. These capabilities rapidly shorten the time between signal detection and intervention design.
Exit Interview Management Software Market -
Integration pressure: Organizations increasingly require seamless data flow between exit systems and core HR stacks (HCM, ATS, payroll). The choice of vendor now depends as much on integration patterns as feature lists.
-
Regulatory enforcement and data governance: Evolving privacy regimes demand consent-oriented designs and robust deletion workflows — failure to comply creates material legal and reputational risk.
-
Total cost of ownership (TCO) sensitivity: Labor and cloud-hosting costs are rising inputs to program economics, influencing the balance between off-the-shelf SaaS, extended-platform suites, and bespoke implementations.
What PW Consulting’s Report Delivers (Practical, Actionable Content)
-
Executive decision playbook — a step-by-step guide for procurement committees and HR leaders covering vendor selection criteria, RFP language, pilot design, and 12–24 month rollout milestones.
-
Vendor assessment framework — standardized scoring across integration maturity, analytics depth, data governance, implementation velocity, and commercial flexibility. The report applies this framework to market-leading and emerging vendors (detailed profiles and scorecards available in the full report).
-
TCO and ROI models — configurable templates that let CFOs and HR leads stress-test scenarios against varying employee churn rates, average cost-to-hire assumptions, and cloud-hosting fees.
-
Compliance and privacy checklist — practical controls mapped to GDPR and recent U.S. state-level data protection rules, designed for both legal review and technical implementation teams.
-
Implementation blueprints — reference architectures for common integration patterns (HCM-first, ATS-first, or hybrid), migration risk matrices, and change-management tactics to accelerate user adoption.
-
Sample templates — customizable exit survey instruments, stakeholder communication plans, governance charters for employee feedback data, and KPI dashboards for monthly executive review.
Competitive Dynamics: How to Read the Vendor Map
-
Platform incumbents vs. specialist challengers: The market is populated by employee-experience suites that include exit modules as part of a broader offering, and focused platforms that compete on agility, price, or depth of exit-specific functionality. Buyers should map vendor strengths to their integration and analytics priorities rather than defaulting to brand familiarity alone.
-
Profiles to watch (high-level):
-
Qualtrics — positions its exit capabilities within an enterprise-grade experience management suite; recent product enhancements emphasize AI-driven sentiment detection and predictive turnover modeling, accelerating insight-to-action cycles.
-
Culture Amp — combines exit workflows with a broader employee experience platform; strategic HCM integrations announced recently strengthen its appeal to organizations seeking seamless HR data flows.
-
Glint (Medallia) — leverages real-time listening and action planning to convert exit signals into retention initiatives, attractive to firms focused on employee lifecycle analytics.
-
Peakon (Workday) — bundling within a larger HCM ecosystem increases appeal for customers seeking native integration and predictive analytics around turnover drivers.
-
Officevibe, 15Five, Lattice — these providers emphasize usability, rapid deployment, and configurable workflows; recent updates have expanded automated follow-up capabilities and template libraries.
-
-
Recent vendor moves are shaping selection criteria: Qualtrics’ AI features (late 2025), Culture Amp’s integration tie-ups (mid-2025), and Lattice’s automation enhancements (spring 2025) change the calculus for buyers who place a premium on analytics sophistication and integration depth.
-
Market structure note: competition is meaningful but not monopolistic. Organizations that prioritize differentiators such as AI maturity, integration compatibility, and data governance can create negotiating leverage during procurement.
Regulatory, Labor, and Cloud Cost Factors to Incorporate in 2026 Planning
-
Privacy regimes: GDPR-compliant consent flows, data minimization, and employee rights to erasure are baseline requirements for EU operations; U.S. state-level privacy laws are converging on similar expectations — vendors’ technical controls must be verified during proof-of-concept stages.
-
Operational labor costs: Fully loaded HR specialist compensation levels are a material input to program economics; higher labor costs increase the value of automation that reduces manual outreach and case management.
-
Hosting and compute economics: Cloud storage and compute fees are non-trivial for organizations with high survey volumes and long retention windows. Standard AWS pricing ranges for HR SaaS workloads should be factored into vendor TCO comparisons and monthly licensing negotiations.
Practical 90-Day Strategic Playbook for 2026
-
Day 0–30: Rapid assessment — inventory current exit touchpoints, data flow diagrams, and compliance exposures. Identify quick wins (standardize exit templates; implement consent capture) and candidates for automation.
-
Day 30–60: Vendor shortlisting and PoC — apply PW Consulting’s vendor assessment framework to produce a 3–5 vendor shortlist. Run focused proofs of concept centered on three priorities: integrations, data governance, and analytic output.
-
Day 60–90: Pilot and governance enablement — execute a controlled pilot, define KPIs (time-to-insight, survey response rate, actionable themes identified), and operationalize governance processes for data retention and access.
-
Beyond 90 days: Scale with measurement — move to phased rollout, embed exit-derived KPIs into HR dashboards, and align retention interventions (manager training, stay interviews, role design) to measured turnover drivers.
What This Preview Hides — And Why It Matters
In keeping with a "trailer" approach, this release surfaces the strategic signals and practical frameworks that matter for 2026 decisions, but intentionally preserves the granular tables, regional and application-level splits, vendor market shares, and price-by-feature benchmarks for the full report. Those subsegment data points are central to vendor negotiation, budgeting, and internal approvals — and they are presented in our report as interactive models and downloadable templates so purchasing committees can run organization-specific scenarios.
Next Steps for Executives
-
Download the full PW Consulting Exit Interview Management Software Market report to access the detailed vendor scorecards, segmentation analytics, and model inputs necessary for procurement and budget approvals.
-
Engage PW Consulting for a tailored briefing and hands-on workshop to calibrate the TCO models to your organization’s churn profile, HR cost structure, and technology stack.
-
Use the report’s procurement artifacts to accelerate RFP cycles and secure better commercial terms by benchmarking against the market-growth trajectory and peer procurement behaviors.
PW Consulting’s Exit Interview Management Software Market study is built for leaders who need to turn departing-employee intelligence into measurable retention outcomes. The market is growing, technology capabilities are maturing, and regulatory pressure is increasing — 2026 is the year to move from ad hoc exit practices to a governed, analytics-driven program that measurably reduces turnover cost and improves workforce stability.
For detailed analysis of this topic, please visit the official page: Exit Interview Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


