



Category: market research
PW Consulting Forecast: Compressed Air Leak Detector Market to Reach USD 693.35 Million by 2032, Growing at a 6.8% CAGR
By PW Consulting, 2026-07-01
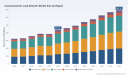
Compressed Air Leak Detector Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As organizations re-anchor industrial efficiency and decarbonization targets for 2026, compressed air leak detection is emerging from a niche maintenance practice into a strategic investment class. PW Consulting’s latest Compressed Air Leak Detector Market report—anchored on a 2025 base year with historical coverage from 2020–2025 and a detailed forecast through 2026–2032—translates market dynamics into executable intelligence for procurement, operations, and corporate development leaders. The brief below outlines why this market matters for 2026 decisions, the levers that will determine winners and losers, and the exact ways our report equips executives to act. For the full segmented datasets and proprietary country/application-level modeling, please consult the complete report page.
Compressed Air Leak Detector Market
Why 2026 Is a Decision Point
The compressed air leak detector market is not marginal: after growing from approximately USD 325 million in 2020 to USD 437 million in 2025, the market is projected to expand to roughly USD 462 million in 2026 and reach nearly USD 693 million by 2032. This trajectory implies a compound annual growth rate of roughly 6.8% across the forecast window. That pace is significant for buyers and investors because it signals a maturing market where product differentiation, service models, and integration with energy-management platforms will be the primary value drivers.
Compressed Air Leak Detector Market
For 2026, the implication is clear: companies that defer investment in leak detection technologies risk losing near-term energy savings and longer-term competitiveness tied to sustainability and regulatory reporting. Conversely, early adopters who pair leak detection with data analytics, maintenance workflows, and ISO-compliant reporting stand to capture disproportionate operational upside.
Compressed Air Leak Detector Market
Key Market Dynamics Shaping 2026 Strategy
-
Energy-efficiency mandates and ISO alignment: Facility managers are increasingly tying compressed-air optimization to ISO 50001 energy management systems and clean-production commitments. Ultrasonic and acoustic imaging tools are now commonly used to document energy efficiency improvements required for ISO-compliant reporting.
-
Operational targets become financial targets: Industrial operators aiming to reduce leak-related flow losses to single-digit percentages of total system throughput (industry practice references 5–10% targets) create a predictable, quantifiable ROI case for leak detection investments—making capex approval cycles shorter when business cases are modeled reliably.
-
Technology convergence: The market is evolving from handheld ultrasonic detectors to system-level solutions incorporating acoustic imaging cameras, sensor networks, and cloud analytics. This expands addressable use-cases from ad hoc surveys to continuous monitoring and digital twin inputs.
-
Supply-chain considerations: Core sensor technologies—particularly MEMS microphones and ultrasonic transducers—are critical inputs. Our sector analysis indicates supply stability across 2025–26, but component concentration remains a monitoring point for procurement risk mitigation.
-
Regulatory and quality drivers: Standards like ISO 8573-1 that define compressed air purity increase the value proposition of routine leak detection in sensitive applications (pharmaceuticals, food & beverage, semiconductors), where contamination and downtime carry high costs.
Technology and Product Trends to Prioritize
-
Acoustic imaging for scale: Acoustic cameras have moved from demonstration tools to high-impact instruments for rapid campus-level surveys. They shorten detection cycles and improve prioritization of corrective actions.
-
Handheld ultrasonic detectors remain tactical essentials: Low-cost, portable units continue to be indispensable for frontline maintenance teams, enabling quick triage and immediate savings on common leak sources.
-
Monitoring and analytics integration: Vendors that expose open APIs or provide pre-integrated analytics for energy management systems create stickier customer relationships and recurring revenue streams.
-
Services and outcomes-based models: Expect a rise in inspection-as-a-service and performance-contracting offerings that package detection, fixes, and guaranteed energy-savings—an attractive option for capital-constrained facilities teams.
Competitive Landscape — Who Matters in 2026
The market shows moderate concentration, with the largest three suppliers commanding a substantial share and the top five firms accounting for a material portion of revenue. This structure favours established players with broad distribution, product breadth, and service ecosystems while leaving room for focused specialists and regional champions.
-
Teledyne FLIR (Wilsonville, OR): A leader in acoustic imaging, FLIR’s camera series extends the range and visualization capabilities of leak detection—allowing operators to locate pressurized air, gas, and vacuum leaks at longer distances and translate ultrasound signals into actionable visual overlays. Their strength lies in integrated optics and robust field software that support large-scale survey workflows.
-
UE Systems (Elmsford, NY): A specialist in ultrasonic detection, UE Systems’ Ultraprobe family and ultrasound cameras are designed for both handheld diagnostics and structured leak-survey campaigns. Their toolset includes leak-rate estimation and energy-savings calculators, which are vital for building executive-level ROI cases.
-
EXAIR Corporation (Cincinnati, OH): Focused on practical, cost-effective handheld devices, EXAIR’s ultrasonic detectors lower the barrier to entry for smaller plants and rapid-response maintenance teams. Their products emphasize ease of use and immediate field-readout features.
-
CS Instruments (Tannheim, Germany): With acoustic cameras and software features tailored for ISO 50001 reporting, CS Instruments connects leak detection to compliance and documented energy saving—appealing to regulated industries and enterprises with formal energy management programs.
-
Specialists and regional innovators: Companies like Superior Signal, SUTO iTEC, LeakMaster, OptiNav, and SDT Ultrasound each bring targeted capabilities—whether it’s lower-cost high-performance handhelds, compact acoustic imagers suited for trade-show launches, automated testing systems, or robust solutions for noisy industrial environments. Their differentiation often lies in price-performance for specific verticals or unique deployment models.
Recent Strategic Moves and What They Signal
-
Acquisition activity — Atlas Copco (February 2026): The acquisition of a US-based vacuum and leak-detection systems provider indicates consolidation interest from large industrial players seeking to augment compressed-air portfolios with advanced detection and vacuum technologies. Expect more bolt-on M&A as industrial OEMs chase integrated solutions.
-
Product refreshes and launches: New product entries and flagship upgrades—illustrated by several vendor launches and tradeshow showcases in 2025–26—signal ongoing product innovation in both masterless air-leak testers and acoustic imaging systems, with vendor roadmaps prioritizing range, user experience, and data outputs for energy reporting.
-
Market communications: Promoted product series and trade-show strategies from well-known test-and-measure vendors underscore a shift from point solutions to consulting-led sales that help customers quantify energy savings and carbon reductions.
Practical Contents of the PW Consulting Report — What You’ll Get
This research pack is designed as a playbook for decision-makers. Among the deliverables are:
-
Comprehensive market sizing (historical 2020–2025 and forecast 2026–2032) with scenario testing and sensitivity around key variables such as energy prices, regulatory tightening, and component supply risks.
-
Technology landscaping that maps the competitive attributes of ultrasonic detectors, acoustic imaging, and sensor-based monitoring—highlighting typical use-cases, deployment timelines, and integration complexity.
-
Vendor profiles with go-to-market strategies, distribution footprints, recent product developments, and SWOT-style assessments—allowing procurement teams to shortlist suppliers against bespoke selection criteria.
-
Commercial models and procurement playbooks, including TCO templates, inspection-as-a-service contract frameworks, and checklist-driven pilot plans to accelerate rollout and capture energy savings within one operating cycle.
-
Regulatory and standards advisory tailored to ISO 50001 and ISO 8573-1 implications—practical guidance on how leak-detection outputs can be used in formal compliance workflows.
-
Forward-looking scenario analysis that quantifies how consolidation, product commoditization, or a rapid shift to monitoring-as-a-service might impact pricing, margins, and supplier selection through 2032.
Actionable Recommendations for 2026
-
Prioritize pilots that connect detection to dollars: Run focused pilots that demonstrate energy- and cost-savings with rapid payback. Use standardized calculators and ISO-aligned reporting to accelerate internal approvals.
-
Evaluate providers by platform openness: Give preference to suppliers that support APIs and easy data export for integration with energy management systems and existing maintenance CMMS workflows.
-
Design procurements for scale and continuity: Favor procurement frameworks that allow conversion from handheld-led surveys to camera-based campaigns and then to continuous monitoring when ROI thresholds are met.
-
Watch M&A and partnership activity closely: Large OEM acquisitions and distribution partnerships will reshape channel economics; clients should anticipate vendor consolidation when negotiating multi-year deals.
Conclusion — The Strategic Upside
Our analysis shows that compressed air leak detection is no longer only an operations improvement activity: it is a measurable lever for energy, compliance, and resilience. With the market expanding at an average annual pace near 6.8% across the forecast horizon, executives who move decisively in 2026 can secure immediate savings, reduce regulatory risk, and build a foundation for longer-term monitoring-led services.
PW Consulting’s full report provides the granular segmentation, country-level forecasts, vendor scorecards, and implementation templates required to convert these insights into a 90–180 day action plan. The summary above is intentionally curated to spotlight strategic implications while preserving the detailed proprietary analytics available in the full study.
Next Steps
To access the complete dataset, vendor benchmarking matrices, and the procurement playbook for pilots and rollouts, please visit the PW Consulting report page. Our team is available to run a tailored briefing for executive committees, procurement teams, or engineering leaders to translate report findings into a bespoke 2026 roadmap.
For detailed analysis of this topic, please visit the official page: Compressed Air Leak Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cotton Moisture Meter Market to Expand at 5.25% CAGR (2026–2032), Reaching USD 208.18 Million by 2032
By PW Consulting, 2026-07-01
PW Consulting Strategic Brief: Cotton Moisture Meter Market — Positioning Your 2026 Decisions
As cotton value chains tighten margins and regulatory and quality demands increase, moisture measurement has moved from an operational convenience to a strategic control point. PW Consulting’s latest Cotton Moisture Meter Market Research (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes commercial, regulatory and technological vectors that will determine winners and laggards through 2026 and beyond. The market’s steady compound annual growth rate (CAGR) of 5.25% and a clear upward trajectory in total market size underlie investment cases across suppliers, ginners, textile processors and instrumentation integrators.
Cotton Moisture Meter Market Research
Why this report matters for 2026 planning
-
Operational economics: Moisture control affects drying energy consumption, throughput and final fiber quality — making meter selection a tangible line-item in cost and margin models.
Cotton Moisture Meter Market Research -
Regulatory compliance and market access: Accreditation, classing rules and export regimes increasingly condition which instruments can be used for official measurement, with downstream consequences for procurement and certification strategies.
Cotton Moisture Meter Market Research -
Technology and integration: The convergence of portable meters, online monitoring systems and lab analyzers creates new choices for automation, traceability and real-time process control.
-
Competitive differentiation: Instrument manufacturers and service providers that translate measurement accuracy into actionable process KPIs will capture higher-value commercial relationships.
Market trajectory: a concise view
Between 2020 and 2025, the cotton moisture meter market recorded consistent expansion, reflective of rising demands for process control and quality assurance across cotton-producing and processing regions. The market base grew from just over USD 110 million in 2020 to a 2025 base exceeding USD 145 million. Our forecast through 2032 models continued expansion to a market exceeding USD 200 million, driven by steady adoption of online monitoring, upgrades in ginning equipment, and stronger quality-control protocols within classing and textile finishing facilities.
This growth is supported by an observed market concentration profile where the top three suppliers account for a material share of the market, while the top five extend that reach modestly further — a structure that supports both competitive innovation and opportunities for niche play and regional champions.
What the full report delivers (practical, actionable content)
-
Market sizing and robust methodology: Transparent, reproducible demand models covering historical shipments and revenue (2020–2025) and scenario-based forecasts (2026–2032), with sensitivity testing for energy price, cotton prices and trade policy shocks.
-
Commercial use cases and ROI models: Payback estimates for meter upgrades in gins and mills, decision trees for handheld vs. online vs. laboratory solutions, and TCO frameworks tailored to smallholder aggregators, industrial gins and textile mill operators.
-
Procurement playbooks: Vendor selection scorecards, specification checklists (accuracy, calibration, maintenance, data output formats), and service-level benchmarking that procurement and operations teams can apply immediately.
-
Integration blueprints: Guidance for embedding moisture meters into PLCs, MES and traceability layers, plus interfacing templates for common data protocols used in modern gin and mill automation.
-
Risk matrices: Impact analyses of regulatory constraints (e.g., classing approvals), export tariff dynamics, and supply-chain disruption scenarios for critical components and calibration standards.
-
Go-to-market and M&A insights: Identification of strategic adjacencies (e.g., dryer manufacturers, HVI labs, IoT service providers) and an M&A watchlist with real-world valuation comparables and integration pitfalls.
-
Field-validated case studies: In-situ performance benchmarking across ginning, textile processing and lab contexts, demonstrating the measurable improvements in yield, quality retention and dryer energy efficiency.
Competitive landscape: what to watch in 2026
The competitive set combines specialist handheld manufacturers, agricultural equipment players and laboratory analyzer vendors. Leading firms balance hardware accuracy, calibration services and integration capabilities. Notable players analyzed in depth include:
-
Agreto (Austria) — Established in the ginning-focused handheld segment, Agrèto’s HFM II device exemplifies products tailored for on-farm and gin process control. Recent certification developments bolster its position where compliance with ginning equipment standards is a procurement discriminator.
-
Chalfront Moisture Meter (Beijing) — A China-based manufacturer focused on digital testers that emphasize accuracy and repeatability in seed cotton and lint contexts. Their product strategy is emblematic of vendors prioritizing cost-performance for high-volume, price-sensitive markets.
-
Farmex (USA) — A portable, non-destructive measurement specialist whose firmware and calibration updates reflect a product development approach centered on field usability and ongoing software-supported improvements.
-
DICKEY-john (USA) — A larger ag-technology firm that adapts grain analyzer platforms for cotton moisture, illustrating a route to market via multi-commodity instrument strategy and trade-show-led product positioning.
-
Foss (Denmark) — Known for laboratory-grade analyzers, Foss demonstrates the premium end of the market where instruments serve HVI and processing-lab needs, and where accreditation and repeatable lab performance are essential.
-
Shanghai Grain Moisture Meter & Zhejiang Top Instrument (China) — Regional manufacturers offering cotton-specific meters for field and gin use, and representing the breadth of domestic offerings in major cotton-producing countries.
Recent company developments reinforce strategic moves across the value chain: a trade-show showcase that moves product narratives into global buyer consciousness; firmware updates that materially alter calibration behavior in high-moisture environments; and certifications that unlock compliance-driven procurement. These are the types of tactical events that can change demand trajectories in the near term.
Regulatory and operational dynamics
-
Classing and accreditation: ISO 17025 accreditation remains a gating factor for labs performing HVI testing and for instruments used in official contexts. Firms aiming at lab sales must address accreditation-compliant workflows and documentation.
-
USDA guidance and limits: The USDA recommends ginning at a specified low-moisture window to protect fiber integrity; this guidance continues to influence dryer setpoints, process-control tolerances and which meters are viable in official vs. process-control roles.
-
Energy implications: Seed cotton moisture above certain thresholds triggers drying that consumes measurable energy; drying at commercial gin scale typically consumes on the order of tenths to single-digit kilowatt-hours per bale. These energy numbers turn moisture measurement into a direct cost driver for gins and cotton processors.
-
Trade policy noise: Export restrictions and tariff regimes alter regional demand patterns for ginning equipment and process control tools. Firms with export-dependent footprints must model policy shock scenarios into 2026 capital planning.
-
Official measurement scope: Portable cotton moisture meters are generally not approved for official USDA classing and are commonly restricted to gin process control. This distinction shapes channel strategies, marketing claims and after-sales service obligations.
Strategic implications for suppliers and buyers
-
For suppliers: Move beyond product accuracy into data services. Vendors that package meters with calibration-as-a-service, analytics for process optimization and integration options for mill digitization will command premium contracts.
-
For ginners and mills: Prioritize TCO and interoperability. Selection criteria should weight calibration cadence, data output formats, and the ability to integrate with dryer controls and MES to capture energy and quality savings.
-
For investors and M&A teams: Look for targets that can cross-sell across handheld, online and lab segments, or that offer compelling software services; certification and channel access (e.g., established dealer networks) are material multipliers.
-
For policy and standards stakeholders: Expect continued pressure to harmonize instrument proficiency testing and accreditation practices to reduce measurement-driven trade disputes and to support automation uptake.
How to use this research in 2026 decision cycles
-
Operational budgeting: Input the report’s ROI models into 2026 capital expenditure cycles to quantify payback for sensor upgrades vs. energy savings and quality premiums.
-
Supplier negotiation: Use vendor scorecards and benchmark pricing proxies to sharpen RFPs and to design performance-based service agreements with penalties/rewards tied to measurement accuracy and uptime.
-
Product roadmap alignment: Instrument manufacturers should align firmware and calibration roadmaps with lab accreditation requirements and industry process tolerances to preserve addressable market access.
-
M&A and partnership screening: Prioritize targets with complementary data capabilities, accreditation-ready lab footprints, or channel relationships in key cotton-producing networks.
Next steps — where to get the full intelligence
This briefing is a strategic preview designed to highlight the levers that will matter in 2026. The full PW Consulting Cotton Moisture Meter Market Research report contains the complete datasets, segmented demand models, regional and application breakdowns, supplier share tables, and the proprietary Excel modelling tool you can apply to site-level CAPEX decisions. We intentionally withhold granular segment tables and specific contractual comparables in this public brief to preserve the investigative value of the paid study.
For procurement teams, product strategists, investors and policy advisors preparing 2026 plans, the report provides the actionable detail needed to convert market insight into measurable outcomes. Contact PW Consulting to access the full report package, model licenses and bespoke advisory engagements that translate these findings into operational initiatives and deal strategies.
For detailed analysis of this topic, please visit the official page: Cotton Moisture Meter Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: DC‑AC Hybrid Solar Pump Market Poised to Expand at 11.28% CAGR Through 2032
By PW Consulting, 2026-07-01
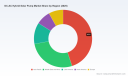
Dc Ac Hybrid Solar Pump Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to introduce our latest market intelligence briefing on the Dc Ac Hybrid Solar Pump market. This release distills the report’s strategic value for corporate decision-makers facing critical investment, product, and go‑to‑market choices in 2026. It is designed as a high‑signal preview: we show the analytical depth that informs confident action while preserving proprietary segment-level detail to encourage direct engagement with the full report.
Dc Ac Hybrid Solar Pump Market
Executive snapshot: where the market stands and where it is headed
Our analysis uses 2025 as the report’s base year, with a historical build from 2020–2025 and a forward-looking forecast window covering 2026–2032. The Dc Ac Hybrid Solar Pump market demonstrates robust expansion dynamics: it stood at approximately USD 970.31 Million in 2025 and is forecast to more than double to roughly USD 2,052.95 Million by 2032. This trajectory reflects a compound annual growth rate (CAGR) of 11.28% over the forecast period (2026–2032), driven by accelerating rural electrification programs, decarbonization of agricultural water use, and increasing hybridization in off-grid and grid‑connected pumping solutions.
Dc Ac Hybrid Solar Pump Market
Why this matters for 2026 decision-makers
- Timing of investments: With the market poised for sustained double-digit growth, 2026 is a pivotal year to convert strategic intent into operational commitments — whether that means scaling production capacity, locking supply agreements, or deploying channel pilots in priority markets.
- Product roadmaps and differentiation: Hybrid architectures (AC/DC flexible inputs, integrated MPPT and VFD control, and BLDC motor efficiencies) are now table stakes for commercial relevance. Firms that sequence technical differentiation ahead of competitors will shorten payback windows for customers and capture premium service revenues.
- Supply chain and margin protection: Raw material inflation — especially in photovoltaic inputs — is altering cost structures for complete hybrid systems. Procurement strategies and design choices that reduce module intensity per unit of delivered water will be decisive in 2026.
What the full report delivers (practical, actionable content)
- Proven forecasting grounded in microscenario modeling: we translate macro drivers (policy, grid access trends, farm economics) into quantified demand scenarios across the 2026–2032 horizon.
- Market architecture and go‑to‑market playbooks: decision matrices that match product archetypes (from low‑power community pumps to high‑output hybrid borehole systems) to channel strategies, financing models, and after‑sales service frameworks.
- Supply chain risk register and mitigation blueprints: stress-tested supplier maps, alternative sourcing options for key PV inputs, and contract structures to hedge raw material volatility.
- Commercial pricing frameworks and TCO templates: customer‑level total cost of ownership models that help commercial teams substantiate value propositions for irrigation, drinking water, and industrial use cases.
- Competitive positioning scorecards and M&A playbook: comparative assessments of leading vendors, capability gaps, and recommended inorganic moves for entrants and incumbents seeking scale.
Competitive landscape — who matters and why
The market exhibits a moderate concentration profile: the top three players collectively command roughly 38.5% of revenue share, while the top five account for about 52.2%. This structure leaves a meaningful role for fast followers, regional specialists, and differentiated technology providers.
Dc Ac Hybrid Solar Pump Market
- Grundfos Holding A/S (Denmark) — Known for SQFlex and similar hybrid solutions, Grundfos combines global brand strength with field‑proven inverter integration. Their product breadth and service network make them a logical anchor for large‑scale off‑grid and grid‑interactive deployments.
- LORENTZ GmbH & Co. KG (Germany) — A specialist with a focused product philosophy around solar and hybrid pumping. Strategic partnerships (e.g., prior collaboration with Xylem) and vertically oriented product engineering give LORENTZ advantages in reliability‑critical and high‑uptime applications.
- Chinese OEMs and innovators — A set of agile manufacturers (exemplified by manufacturers such as DIFFUL, HYBSUN, VEICHI, Deye, EDWIN PUMP, Rafsun, Samking, and Oswal) are driving cost innovation and rapid product iteration. Their portfolios range from compact DC/AC hybrid units to high‑capacity pumps, often backed by competitive warranty and distribution offers.
- Competitive dynamics — Established multinational OEMs leverage brand and after‑sales networks to defend higher price points, while regionally focused OEMs compete fiercely on price, customization, and rapid delivery. Partnerships and channel alliances, rather than pure price competition, are emerging as decisive vectors.
Recent vendor moves and what they signify
- DIFFUL’s 2026 technical updates indicate intensified focus on system matching and MPPT sophistication — a response to customer demand for integrated, low‑complexity hybrid solutions that simplify installation and commissioning.
- LORENTZ’s prior partnership activity highlights a strategic choice observed across the market: technology alliances and distribution partnerships accelerate adoption faster than organic field expansion alone, particularly in emerging regions where financing and after‑sales ecosystems are still maturing.
Market dynamics shaping near‑term opportunity and risk
- Raw material pressure: Early 2026 has seen an uptick in photovoltaic module input costs, with silver and polysilicon volatility increasing system BOM risk. In many manufacturing operations, raw materials constitute the majority of operating costs — making design efficiency and volume purchasing critical for margin preservation.
- Policy and incentive tailwinds: North American and specific national incentives remain an important demand accelerator. Extensions under recent policy frameworks continue to support residential and small‑commercial solar adoption, but local regulatory shifts (for example, changes in property tax treatment for installed systems) can materially alter project economics at the margin.
- Fragmented end‑use economics: Irrigation and community water supply use‑cases continue to dominate unit demand, but industrial and municipal applications are scaling where reliable hybrid operation reduces downtime risk and operating cost for large water users.
Strategic implications and recommended actions for 2026
For executives making near‑term strategic choices, our research suggests five pragmatic priorities:
- Hedge supply‑chain exposure now: Secure medium‑term supply arrangements for photovoltaic components and negotiate indexed contracts or shared‑risk clauses. Consider vertical partnerships with module suppliers to stabilize cost and lead times.
- Prioritize product modularity: Offer modular hybrid kits that simplify field integration (plug‑and‑play MPPT/inverter modules, standardized controllers). Modularity reduces installation time and allows rapid adaptation to regional electrification contexts.
- Refine channel economics: Tailor pricing and financing for agricultural co‑ops, microfinance partners, and government tenders. Bundled service and performance guarantees will unlock premium segments and reduce buyer hesitation.
- Invest in differentiation beyond price: Build value through digital telemetry, predictive maintenance services, and outcome‑based contracts (e.g., uptime SLAs). These features increase switching costs and open recurring revenue streams.
- Targeted M&A and alliances: Evaluate bolt‑on acquisitions in regions where after‑sales is the growth limiter, or secure technology partnerships to close capability gaps (e.g., integrated energy management, hybrid inverter IP).
Decision‑grade deliverables in the full PwC Consulting report
Clients purchasing the full Dc Ac Hybrid Solar Pump market report will receive:
- Detailed scenario outputs and sensitivity analyses that translate macro drivers into expected units and revenue under alternative policy and commodity cost paths.
- Regionally granular go‑to‑market matrices and distributor selection frameworks (note: we deliberately withhold public distribution of detailed regional splits here—these are proprietary to the full report).
- Vendor scorecards with technical, commercial, and after‑sales metrics to support shortlist creation and negotiation strategies.
- Implementation roadmaps and a 12‑month execution checklist for manufacturers and distributors entering or scaling in the hybrid solar pumping segment.
Closing perspective — positioning for 2026 and beyond
The Dc Ac Hybrid Solar Pump market is transitioning from early adoption to mainstream scaling. The combination of policy incentives, declining balance‑of‑system costs (subject to raw material cycles), and growing recognition of hybrid solutions’ value has created a multi‑year runway for growth. For executives, the critical inflection point is immediate: secure supply, sharpen product‑to‑channel fit, and lock in customer‑facing differentiation in 2026 to capture disproportionate share as the market expands toward the USD 2+ billion horizon in 2032.
To access the full dataset, proprietary segmentation tables, and the operational playbooks that will inform 2026 capital and commercial decisions, please visit our report landing page or contact the Pw Consulting research team. The full report contains the revenue split matrices, regional deployment maps, and vendor benchmarking that are essential for executing the strategies summarized in this brief.
For detailed analysis of this topic, please visit the official page: Dc Ac Hybrid Solar Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Primary Cell Culture Market to Climb from USD 6,854.2 Million in 2025 to USD 15,632.35 Million by 2032 at a 12.5% CAGR — North America and Primary Cells Set to Lead
By PW Consulting, 2026-07-01
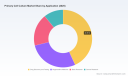
Primary Cell Culture Market — Strategic Insights for 2026 Decision-Makers
PW Consulting announces a tactical market intelligence brief designed to inform investment, commercial and operational decisions across the primary cell value chain
As companies prepare budgets and strategic roadmaps for 2026, PW Consulting’s new Primary Cell Culture Market report delivers a practical, risk-aware playbook rooted in an updated market sizing and a forward-looking scenario set. The market has demonstrated robust expansion over the past half-decade, growing from a multi-billion-dollar base in 2020 to an enlarged footprint by 2025. PW Consulting projects continued acceleration through the 2026–2032 forecast window at a compounded annual growth rate (CAGR) of 12.5%, with demand trajectories pushing the market well into the tens of billions by the end of the period. This release highlights the report’s decision-grade value without revealing the granular segment and regional tables reserved for subscribers.
Primary Cell Culture Market
Why this report matters for 2026
-
Fast-evolving regulatory expectations and R&D funding are reshaping buyer priorities. Recent public guidance and targeted funding have elevated the role of primary cell models in IND-enabling studies and organ-on-chip platforms — dynamics that materially alter product roadmaps and commercial positioning.
Primary Cell Culture Market -
Raw-material and supply-chain stress are now front-and-center in supplier selection and contract negotiation. Price pressure and export controls affecting key inputs have introduced new cost and access risks that alter margin modeling and geographic go-to-market choices.
Primary Cell Culture Market -
Market consolidation and specialization are co-occurring. The market remains concentrated among a handful of established vendors while a healthy tier of specialized challengers is expanding capabilities in areas such as 3D scaffolds and metabolically competent primary hepatocytes. Our concentration metrics — which show top-three and top-five aggregate positions — indicate a landscape in which scale and niche expertise both confer advantages.
Core dynamics shaping strategy in 2026
-
Regulatory acceleration: Regulatory authorities are increasingly recognizing primary-cell–based models as critical components of IND-enabling packages for specific therapeutic areas. This shifts buyer willingness to pay for validated, traceable cellular products and accompanying QC data, raising the bar for supplier certifications and documentation.
-
Research funding and technological substitution: Large-scale public investments in organ-on-chip and complex in vitro models increase the total addressable market for high-fidelity primary cells and specialized culture media — but they also invite competition from emerging integrated systems vendors offering bundled solutions.
-
Input cost volatility and sourcing constraints: Upstream price shocks — notably in serum and other biologics — have squeezed supplier margins and led some customers to pursue serum-free alternatives or multi-supplier sourcing strategies. Export control tightening in certain jurisdictions has created regional access differentials that matter for clinical and commercial supply plans.
-
Commercial sophistication: Buyers demand more than catalog access — they want authenticated provenance, donor metadata, lot-level QC, and co-development capability. Vendors that pair product breadth with services (e.g., assay development, custom donor sourcing) are gaining preferential supplier status among large pharma and CRO customers.
Strategic implications — five priority actions for 2026
-
Rebalance product portfolios toward validated, higher-value offerings. Firms should identify which primary cell formats and complementary media/assay services move from “nice-to-have” to “must-have” under revised regulatory expectations and payer coverage changes. Prioritize investments where scientific validation and data provenance command price premiums.
-
Operationalize supply-chain resilience. Build multi-tier supplier maps, implement stress-test scenarios for critical inputs, and negotiate conditional pricing or capacity commitments. Consider nearshoring or regional stocking strategies where export controls and logistics disruption pose material risks to clinical timelines.
-
Monetize data and quality. Packaging provenance, batch-level analytics, and regulatory-ready documentation as part of a premium offering can unlock new revenue streams and strengthen switching costs. Vendors should develop standardized data deliverables that align with client regulatory dossiers.
-
Adopt a partnership-first commercial model. Biotech and academic customers increasingly prefer co-development arrangements for custom primary-cell solutions. Structured partnership templates and milestone-based pricing reduce time-to-adoption for complex assays and help distribute development risk.
-
Prepare for selective M&A and bolt-on acquisitions. Target acquisitions should be evaluated for immediate revenue synergies, access to specialized cell types or culture platforms, and regulatory-qualified manufacturing capabilities. Due-diligence checklists must include sourcing transparency, IP status, and QC reproducibility benchmarks.
What’s in the PW Consulting report — operational and commercial tools
The report is intentionally tactical. Beyond a validated market-size model and growth scenarios, subscribers receive plug-and-play deliverables designed to accelerate decision-making in 2026:
-
Executive decision matrix mapping investment options to NPV sensitivities under three regulatory and pricing scenarios.
-
Vendor scorecard templates that weigh product breadth, QC rigor, geographic access, and service capability — built for easy integration into procurement RFPs.
-
Supply-chain stress-test models and risk mitigation playbooks, including alternative sourcing ladders for critical biological inputs and contingency warehousing options.
-
Commercial playbooks for segment-specific GTM — from academic accounts to enterprise pharma — with sample contractual clauses and SLAs oriented to cell provenance and traceability.
-
M&A due-diligence checklists focusing on biological validation, regulatory clean-room status, and backward traceability of primary cell lots.
-
Regulatory impact matrix aligning changing agency guidance and reimbursement updates to product development and labeling strategies.
Competitive landscape — positioning and recent moves
The market is anchored by established life-science and specialty suppliers that combine global reach with validated product portfolios, alongside nimble niche players that push technical differentiation. PW Consulting’s competitive analysis evaluates capability stacks across product depth, service overlay, QC standards, and go-to-market execution.
-
Thermo Fisher Scientific — A global platform player with a broad primary-cell brand recognized across drug discovery and toxicology workflows. Recent portfolio expansions into pulmonary cell types underscore a strategy of filling disease-model gaps to serve large pharma customers seeking regulatory-ready inputs.
-
Lonza — A supplier combining cryopreservation expertise with optimized culture media; recent catalog updates emphasize donor-matched offerings that appeal to developers prioritizing reproducibility and lot-to-lot consistency.
-
Merck KGaA (Sigma-Aldrich) — A broad bioscience supplier with an extensive cell catalog; their emphasis remains on providing diverse primary-cell types to research markets backed by distribution scale.
-
ATCC — A quality- and authentication-focused provider whose credentials make it a preferred source when regulatory-grade provenance is required. Recent trade-show activity signaled deeper engagement with immuno-oncology end-users.
-
Sartorius (PromoCell) — Differentiates through specialized cell types and serum-free media kits; recent ISO certification activity strengthens its position for clinical and regulated applications.
-
ScienCell, Celprogen, AcceGen, BioIVT and other specialists — These vendors push technical differentiation (3D scaffolds, large catalogs, metabolically competent hepatocytes, etc.) and often serve as nimble partners for bespoke assay development.
Recent vendor moves—product expansions, catalog updates, certification achievements, and trade-show showcases—signal an industry that is both innovating and professionalizing. PW Consulting’s vendor heat maps and capability matrices help buyers and investors separate transient marketing moves from durable capability shifts.
Risk factors to monitor entering 2026
-
Regulatory unpredictability: Shifts in agency guidance can materially affect product acceptability in regulatory submissions; firms should track guidance cycles and maintain alignment dossiers.
-
Input-cost inflation and sourcing restrictions: Volatility in biological-supply markets can compress margins and delay projects; hedging strategies and alternative-medium investments deserve priority.
-
Technological substitution risk: Integrated organ-on-chip and synthetic biology platforms may absorb growth that otherwise would have accrued to traditional primary cell sales; assess partnership and integration pathways early.
How to use the report in your 2026 planning cycle
Procurement leaders can reuse PW Consulting’s vendor scorecards and supplier negotiation playbooks to reduce sourcing risk and improve TCO. R&D heads should apply the regulatory impact matrix and technology adoption scenarios to reprioritize assay roadmaps and external collaborations. Corporate development teams will find the M&A diligence templates and scenario-based valuation adjustments useful to triage targets and set realistic price corridors. Finally, commercial teams can implement the go-to-market playbooks immediately to refine customer targeting and packaging strategies in light of evolving reimbursement and regulatory signals.
Access and next steps
PW Consulting’s Primary Cell Culture Market report combines a validated market-size model, concentration metrics, scenario-driven forecasts for 2026–2032, and hands-on operational tools to accelerate execution. To preserve the competitive edge for clients, the report intentionally withholds line-item segmentation tables and granular regional splits from public excerpts. For organizations preparing 2026 strategy, the report serves as both a compass and a toolkit — turning macro trend intelligence into actionable plans.
Contact PW Consulting to request the full report, data workbook, and the suite of plug-and-play deliverables that will support your 2026 strategic decisions.
For detailed analysis of this topic, please visit the official page: Primary Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Fungal & Anti-Bacterial Paints Market Poised for 7.45% CAGR as Asia-Pacific and Water-Based Formulations Drive Growth
By PW Consulting, 2026-07-01
Anti Fungal and Anti Bacterial Paints Market — Strategic Imperatives for 2026: A PW Consulting Report Preview
Executive summary
The anti fungal and anti bacterial paints market is entering a decisive phase. Our latest PW Consulting research, using 2025 as the base year and covering historical performance from 2020–2025 with a forward-looking forecast through 2032, shows an industry expanding from a multi‑billion dollar base toward nearly USD 8.0 billion by 2032. The forecast period (2026–2032) is characterised by a steady compound annual growth rate (CAGR) of 7.45%. For executive teams planning for 2026, this trajectory creates a clear set of strategic imperatives across product development, regulatory readiness, supply‑chain resilience, and growth through partnerships—and our full report is designed to turn those imperatives into executable priorities.
Anti Fungal And Anti Bacterial Paints Market
Why 2026 is a pivotal planning year
-
Market momentum: The category recorded consistent expansion across 2020–2025 and moves into a higher growth plateau in the forecast horizon. That creates both a runway for scale and a narrowing window for firms to secure channel and formulation advantages.
Anti Fungal And Anti Bacterial Paints Market -
Regulatory inflection: Policymaking in key jurisdictions is actively reshaping the risk profile for biocidal additives and labelling compliance—changes that will materially affect time‑to‑market and product claims in 2026 and beyond.
Anti Fungal And Anti Bacterial Paints Market -
Consolidation potential: The market concentration profile points to meaningful shares held by leading manufacturers, yet enough fragmentation remains for targeted consolidation and differentiated niche plays.
What the market dynamics mean for corporate decision‑makers
-
R&D prioritisation: With customers demanding longer‑lasting, low‑odour, low‑VOC, and easy‑clean formulations, R&D investment decisions should prioritise durable active systems and compatibilising additives that meet evolving regulatory tests. Companies that move from single‑feature antimicrobial claims to combined performance claims (antibacterial + antifungal + cleanability) will unlock premium positioning.
-
Regulatory and claim strategy: The EU’s moves to streamline biocidal product rules and extend data protection periods, and continued U.S. EPA review cycles for common biocides, require a proactive dossier‑management approach. Firms must allocate budget and capability to global label compliance, accelerated testing, and proactive engagement with regulatory authorities to avoid market disruptions.
-
Supply‑chain and raw‑material risk management: Silver, copper and zinc‑based actives remain central to product portfolios. Price volatility in specialty additives is a margin lever—supply contracts, hedging strategies, and exploration of lower‑cost actives or plant‑based alternatives should be top of procurement agendas for 2026.
-
Go‑to‑market and channel strategy: Demand is driven by healthcare, food & beverage, institutional, and residential refurbishment. Companies need differentiated commercial approaches by end‑user: direct specification for institutional buyers, distributor enablement for contractors, and retail‑focused messaging for homeowner segments.
-
M&A and partnership playbook: The combination of scale economies and technical know‑how makes bolt‑on acquisitions and strategic alliances attractive. The market is ripe for deals that enhance active‑ingredient portfolios, testing capabilities, and premium brand access.
Competitive landscape — capability map and strategic moves
The competitive topology is populated by global paint majors, regional specialists and additive innovators. Market leaders blend large commercial footprints with in‑house antimicrobial technologies; adjacent players focus on formulation chemistry or additive supply. Key archetypes include:
-
Global coatings conglomerates with integrated R&D and distribution (examples include established architectural and industrial coatings firms). Their advantage: scale, regulatory teams, and established relationships with institutional specifiers.
-
Technology‑first additive suppliers and biotech entrants (producers of silver, plant‑based and patented actives). These players can create differentiation via licensing and white‑label partnerships.
-
Regional specialists and eco‑focused brands that capitalise on low‑VOC, odourless formulations and local building code compliance. These firms often win in retrofit and residential segments.
Recent market events underscore these dynamics. Industry players are actively showcasing advanced test methods for antifungal and algae resistance, and strategic combinations among large manufacturers have been announced that will reshape portfolio footprints. For market participants, these developments signal both competitive threats and partnership opportunities.
Regulation and raw‑material volatility — strategic consequences
-
Regulatory timing is a commercial factor: Extended data protection windows and ongoing BPR and EPA reviews reduce uncertainty for approved actives but raise the bar for new entrants. A deliberate regulatory investment—covering safety dossiers, accelerated in‑house testing, and legal review of labelling claims—should be budgeted into 2026 roadmaps.
-
Raw‑material price swings: Silver and specialty additive markets are prone to rapid oscillation. Margin protection requires a mix of supplier diversification, longer‑term purchase agreements, and reformulation roadmaps that reduce dependency on single actives without losing efficacy.
Practical content of the PW Consulting report — what you will get
Our full market study is structured to be directly actionable for commercial, product and corporate development teams. Highlights include:
-
Market sizing and topline forecasts (2020–2032) with scenario modelling to stress‑test pricing, raw‑material shocks and regulatory timelines.
-
Competitive scorecards and capability matrices for leading manufacturers, additive suppliers and niche specialists—covering technology, channel strength, claim verification and geographic reach.
-
Regulatory roadmap and compliance checklist tailored to EU and U.S. frameworks, including a timeline of likely bottlenecks and mitigation strategies.
-
Go‑to‑market playbooks for priority buyer segments (healthcare, food processing, institutional procurement, and residential retrofit), with sample specification language and commercial incentive structures.
-
Procurement levers and a raw‑material risk matrix, including negotiation templates and alternative active pathways to protect gross margins.
-
M&A and partnership playbook with valuation sensitives, integration checklists and post‑deal value capture milestones focused on antimicrobial assets.
-
Data appendices and modelling tools—financial projections, sensitivity analysis, and proprietary test‑to‑claim mapping to support product claims and marketing compliance.
How to use these insights in 2026 tactical planning
-
Short term (next 12 months): Prioritise regulatory dossiers for key actives; implement raw‑material hedges; fast‑track one formulation upgrade that demonstrably improves cleanability and VOC profile to support premium pricing.
-
Medium term (12–36 months): Execute one strategic partnership or bolt‑on acquisition to acquire either testing capability or an additive technology; roll out channel‑specific commercial pilots to de‑risk scale‑up.
-
Long term (36 months+): Build a portfolio that blends core high‑value formulations with licensed additive pathways to maintain flexibility as biocidal policy evolves globally.
Call to action
PW Consulting’s Anti Fungal and Anti Bacterial Paints Market report is built to be prescriptive for 2026 decision cycles—equipping leaders with market modelling, regulatory playbooks and commercial templates. This preview outlines the strategic contours; the full report contains the granular segmentation, regional breakdowns, company scorecards and downloadable financial models that procurement, R&D and corporate development teams will need to operationalise these recommendations. To access the complete dataset, scenario models and bespoke advisory options, please visit the PW Consulting report landing page or contact our industry advisory team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Anti Fungal And Anti Bacterial Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wafer FOUP Market to Reach USD 1,045 Million in 2025; Forecast Points to 8.7% CAGR Through 2032
By PW Consulting, 2026-07-01
Wafer FOUP Market 2026: Strategic Imperatives for Semiconductor Leaders
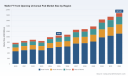
PW Consulting’s latest market study on Wafer Front Opening Universal Pods (FOUPs) positions the segment as a critical, yet often underappreciated, lever in semiconductor supply-chain resilience and process yield optimization for 2026 and beyond. The FOUP market reached approximately USD 1,045 million in 2025 and — driven by capacity expansions, automation upgrades, and contamination-control investments across fabs — is modeled to grow at a compound annual growth rate (CAGR) of 8.7% through our 2026–2032 forecast horizon, reaching roughly USD 1,874 million by 2032. These headline figures understate the tactical and strategic choices that fab operators, equipment suppliers, and materials vendors must make this year.
Wafer Front Opening Universal Pod (FOUP) Market
Why FOUPs Matter Now — Beyond a Container
FOUPs are no longer passive transport vessels. As process nodes shrink, EUV overlay tolerances tighten, and advanced packaging flows increase wafer handling frequency, FOUPs influence contamination budgets, tool uptime, and automation throughput. Two converging forces are elevating their importance:
Wafer Front Opening Universal Pod (FOUP) Market
- Process sensitivity: Particle budgets and microenvironment stability inside carriers increasingly translate into measurable yield impact, especially for EUV-intensive processes and advanced logic nodes.
- Operational scale and automation: New fabs and AMHS deployments raise FOUP throughput expectations while tightening requirements for standardization, materials performance, and integration with factory automation.
Market Trajectory: Interpreting the Macros
PW Consulting’s time-series model, calibrated on historical data from 2020–2025 and validated against supplier shipment signals and fab buildouts, captures both cyclical effects and structural growth. After pandemic-era volatility and mid-cycle corrections, the market regained momentum in 2024–2025 as capex resumed and regional supply diversification projects matured. Our central forecast foresees steady expansion at the 8.7% CAGR cited above, driven by replacement cycles, increased unit counts per fab, and growing adoption of higher-specification carriers (e.g., purge-capable and advanced sealing FOUPs) in process-critical environments.
Wafer Front Opening Universal Pod (FOUP) Market
These aggregate metrics yield practical inference: capital planners should expect non-trivial FOUP demand when sizing AMHS investments and in contract negotiations for wafer handling automation. Procurement and operations teams that treat FOUPs as a line-item expense rather than a systems component risk underestimating their total cost of ownership (TCO) impact over multi-year production ramps.
Industry Structure and Competitive Dynamics
The FOUP market exhibits significant concentration among a small number of global suppliers. Our competitive analysis shows a high market share concentration among leading manufacturers, underscoring both supplier bargaining power and the importance of strategic vendor selection for buyers. Key dynamics shaping competitive behavior include:
- Standards-driven lock-in: SEMI compliance (M31, E1.9, E47.1, E15.1, E57, E62, and related interfaces) remains the baseline for interoperability with AMHS and automated tools; suppliers that accelerate standards alignment enjoy faster qualification cycles.
- Materials differentiation: High-purity, low-outgassing polymers and conductive components (E7–E10 grade materials) are technical differentiators that materially reduce contamination risk and extend FOUP lifecycles.
- Service and aftermarket: Cleaning, recertification, and component repair services are emerging as margin drivers and retention levers for suppliers; buyers benefit from bundled service-level agreements to reduce lifecycle costs.
Representative suppliers we examined — from global incumbents to regional specialists — include Entegris (U.S.), ePAK International (Malaysia/global), Miraial (Japan), Shin-Etsu Polymer (Japan), Gudeng Precision (Taiwan), and multiple other Asia-based and U.S. suppliers. Their product positioning ranges from high-capacity 300mm standard FOUPs to nitrogen-purgeable and diffusion-control variants, and from commodity manufacturing to value-added service models. Recent supplier moves (production expansion in North America, refreshed product catalogs, and targeted supply agreements) signal tactical responses to both demand growth and geopolitical sourcing diversification.
Recent Industry Signals to Monitor
- Supply agreements and service expansion: Notable orders and cleaning-equipment contracts with major memory and logic fabs indicate a tightening market for ancillary services that support FOUP life extension.
- Reshoring and capacity investments: Production facility expansions in North America and incremental localization efforts in Japan reflect supplier strategies to mitigate geopolitical and logistics risks for key customers.
- Product refreshes: Catalog updates and new product introductions highlight continued feature competition around purge options, slot capacity, and automation compatibility.
Regulatory and Materials Constraints
Beyond commercial dynamics, regulatory and technical constraints shape procurement windows and qualification timetables. SEMI standards remain the technical backbone for dimensional tolerances and automation interfaces. Concurrently, a limited set of polymer formulations compatible with low particle generation and long-term dimensional stability constrains supplier flexibility and extension strategies. Buyers must therefore plan qualification cycles that accommodate both standards testing and accelerated aging or outgassing assessments.
Practical, Actionable Content in the Full Report
The PW Consulting FOUP Market report is designed as a decision-ready playbook for 2026. It integrates market modeling with practical tools and intelligence, including (but not limited to):
- A validated market sizing framework and scenario-based forecasts through 2032, including sensitivity analyses tailored to capex timing and yield-improvement programs.
- Supplier dossiers and a vendor-selection matrix that score capabilities across technical fit, geographic footprint, capacity flexibility, service offerings, and risk exposure.
- Procurement playbooks for fab operators that map qualification steps, typical lead times, and cost levers (purchase vs. lease, cleaning contracts, spare pools), with sample timelines calibrated to standard fab ramp plans.
- Contamination-risk quantification templates linking FOUP microenvironment attributes (sealing performance, material outgassing, purge efficacy) to process-level yield impact estimates.
- Supply-chain stress tests and sourcing strategies that model the implications of regional disruptions, lead-time shocks, and rapid capacity shifts.
To preserve competitive value for subscribers and corporate decision-makers, the report intentionally withholds granular regional and application split tables in this public release. Those detailed segmentations, supplier shipment-level estimates, and contract-level benchmarks are available in the full report package on our website.
Strategic Recommendations for 2026 Decision-Makers
- Adopt a systems view: Treat FOUPs as components in yield and automation systems. Incorporate FOUP TCO into tool uptime and yield improvement business cases rather than isolating them as packaging spend.
- Accelerate vendor qualification in 1H–2H 2026: Given forecast demand growth and supplier lead times, start parallel qualification tracks with primary and secondary suppliers now to avoid constraint-driven premium sourcing later in the year.
- Layer inventory and service contracts: Combine strategic buffer inventories for critical fabs with long-term cleaning and recertification contracts to minimize unexpected downtime and reduce life-cycle costs.
- Prioritize materials and purge capabilities for EUV/advanced nodes: For nodes with tight contamination budgets, prioritize carriers with validated purge and sealing performance; invest in lab-level joint testing with suppliers to close uncertainty fast.
- Use regional diversification defensively: Balance cost efficiencies with geopolitical risk. Work with suppliers that offer multi-region manufacturing or contract manufacturing partnerships to mitigate single-source exposure.
- Incentivize modularity and retrofit compatibility: Select FOUP configurations that facilitate interchangeability and retrofit into existing AMHS to future-proof investments against incremental process changes.
For Suppliers: Commercial and Product Playbooks
FOUP manufacturers and tiered suppliers should consider three concurrent strategies to capture the growth opportunity:
- Differentiate on end-to-end value: Expand cleaning, repair, and lifecycle services to lock customers into longer revenue streams and to demonstrate measurable TCO reductions.
- Invest in materials and standards leadership: Accelerate certification to SEMI updates and invest in low-outgassing polymer formulations to be the preferred partner for advanced-node fabs.
- Pursue geographic flexibility: Target targeted capacity investments or partnership models near major fab clusters to shorten lead times and offer localized service contracts.
Closing Perspective
The FOUP market is shifting from a commoditized ancillary market to a strategic focal point that affects yield, uptime, and capital efficiency. With a 2025 market base of roughly USD 1,045 million and a clear growth trajectory through 2032 at an 8.7% CAGR, companies that incorporate FOUP strategy into their 2026 procurement, process, and supply-chain plans will gain incremental yield and resiliency advantages. Our report equips decision-makers with the models, supplier intelligence, and procurement playbooks necessary to act decisively — while the full dataset and granular segmentation remain reserved for report subscribers and corporate clients.
To obtain the comprehensive dataset (including detailed regional and application splits, supplier shipment tables, and downloadable procurement templates), visit the PW Consulting FOUP Market report page and download the full report package. Strategic windows in 2026 are short; leaders should act now to align supply, certification, and lifecycle strategies with the evolving market dynamics.
For detailed analysis of this topic, please visit the official page: Wafer Front Opening Universal Pod (FOUP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Dust Collectors for Mining Market at USD 1,324.31 Million in 2025, Poised to Hit USD 1,907.33 Million by 2032 with a 5.35% CAGR
By PW Consulting, 2026-07-01
PW Consulting Releases Strategic Preview: Dust Collectors For Mining Market — A Decision-Grade Briefing for 2026
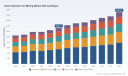
PW Consulting today publishes a strategic preview of its forthcoming market research report, Dust Collectors For Mining Market (base year 2025, forecast 2026–2032). The briefing synthesizes the macro trajectory that will shape procurement, engineering and M&A decisions in 2026: the global market reached approximately USD 1,324.31 Million in 2025 and, under our central forecast, is set to expand at a compound annual growth rate (CAGR) of about 5.35% through the 2026–2032 horizon, reaching approximately USD 1,907.33 Million by 2032. This release is intended as a high-confidence, actionable orientation for senior executives; detailed segment-level figures and vendor shares are reserved for the full report and supporting models.
Dust Collectors For Mining Market
Why this matters for 2026 planning
2026 represents a pivotal year for the mining sector’s dust control capital agenda. Regulatory drivers—which now prioritize engineering controls as primary compliance measures—are compressing timelines for equipment upgrades and retrofits. Engineering-focused compliance requirements, combined with renewed scrutiny on respirable crystalline silica, are converting what were previously multi-year replacement cycles into near-term procurement and deployment programs. At the same time, input-cost volatility (notably in steel and heavy-gauge fabrication costs) is recalibrating vendors’ cost structures and buyers’ TCO calculations. The interplay of regulation, raw-materials economics and tightening timelines means that 2026 purchasing decisions will have outsized impact on asset-level compliance, OPEX, and safety outcomes through the next decade.
Dust Collectors For Mining Market
What the report delivers — practical, operational content
- Rigorous market sizing and transparent methodology: we disclose base-year calculations, growth drivers and sensitivity analyses that inform the headline growth path.
- Regulatory impact playbook: granular scenarios quantifying the compliance-driven demand uplift across retrofit vs. greenfield projects and the corresponding implementation timelines and risk levers.
- Technology assessment and deployment decision frameworks: comparative evaluation of baghouse, cartridge, wet scrubbing, electrostatic and cyclone approaches for key mining use-cases (selection criteria, performance anchors, maintenance burden, and safety considerations).
- Procurement and CAPEX playbooks: RFP templates, sample technical specs, vendor selection matrices, warranty & spare-parts approaches and financing options tailored for 2026 budget cycles.
- Operational models: TCO calculators, life-cycle filter-replacement scheduling, and predictive-maintenance use cases that can be parameterized with a mine’s operational profile.
- Competitive intelligence toolkit: vendor scorecards, capability maps, aftermarket-service positioning and a prioritized list of strategic partnership and M&A candidates for consolidation plays.
- Risk & mitigation matrices: supply-chain stress-testing (steel input risk, lead-time exposure), contingency plans and contractual clauses to lock delivery and performance.
All of the above is delivered with client-ready spreadsheets and configurable decision-support dashboards; the trailer nature of this release highlights scope and utility while preserving the granular tables and regional splits for the paid report.
Dust Collectors For Mining Market
Competitive landscape — where incumbents and challengers are placing their bets
The market exhibits moderate concentration: our analysis shows the combined share of the top three suppliers sits in the low-to-mid 30% range, and the top five account for under half of industry revenues. This structure implies meaningful room for differentiation through service, digitalization and specialized designs. Key vendors we profile in depth include established industrial filtration and systems houses such as Donaldson Company, Inc., Camfil APC, RoboVent, Sly Inc., Imperial Systems, C&W DustTech, Ducon Environmental Systems, Scientific Dust Collectors, AAF International, Camcorp and Baghouse.com. Each brings distinct strengths—ranging from proprietary media and filter-cleaning technologies, to heavy-gauge, explosion-proof housings, to modular, field-deployable collector arrays—making competitive positioning as much about aftermarket service and warranty terms as it is about initial equipment specs.
From a strategic standpoint, three structural trends are visible across vendor strategies: first, a push for modular, quickly deployable systems that reduce downtime risk at transfer points and crushing lines; second, increased emphasis on aftermarket consumables and service contracts for predictable annuity revenue; third, a nascent but accelerating shift to monitoring and predictive maintenance enabled by IIoT sensors and analytics. Vendors that can bundle hardware, consumables and guaranteed-performance SLAs will be best positioned to capture the compliance-driven budgets in 2026.
Regulatory and input-cost dynamics shaping supplier and buyer strategies
Regulation is the single most binding near-term constraint: final rules that establish lower PEL thresholds for respirable crystalline silica require engineering controls as the first line of defence, with compliance milestones that compress capital decision timelines for many MNM operations. This regulatory imperative increases urgency for engineering-grade solutions—especially at high-risk areas such as conveyors, transfer points, crushers and load zones—where retrofits are both technically feasible and immediately impactful.
Simultaneously, fluctuations in steel and heavy-gauge raw-material inputs are influencing equipment pricing and vendor margins. Fabrication-intensive collector solutions are sensitive to changes in metals pricing and logistics costs, which makes early contracting and hedging of long-lead bulk materials an actionable consideration for both buyers and suppliers. The combined regulatory + cost dynamic means procurement teams should prioritize fixed-price commitments, staged deployment windows, and close vendor performance guarantees to insulate project economics.
Actionable recommendations for executive decision-makers in 2026
- Prioritize capital planning for compliance-critical sites: identify first-wave retrofits and ring-fence funding in 2026 budgets to meet regulatory deadlines without creating execution bottlenecks.
- Adopt a TCO-first procurement approach: evaluate vendors on lifecycle expenses (filter change intervals, spare parts availability, energy draw) rather than only upfront CAPEX.
- Negotiate SLAs that include performance verification and enforcement clauses tied to particulate limits and downtime allowances.
- Pilot IIoT-enabled monitoring on high-risk assets to validate predictive-maintenance models before network-wide rollout.
- Hedge against material cost volatility: consider split award strategies or phased procurement to lock critical long-lead items while maintaining price flexibility for standard components.
- For investors and OEMs: explore tuck-in acquisitions focused on aftermarket consumables and local service networks to secure recurring revenue streams and shorten payback cycles.
Competitive plays vendors should consider now
- Productize compliance-as-a-service: bundle equipment, installation, testing and periodic verification to simplify buyer procurement and create annuity income.
- Differentiate on speed and modularity: offer standardized modules that reduce field installation time and permit staged scaling in large operations.
- Invest in filtration media R&D to extend run-times and reduce frequency of interventions—an immediate OPEX lever buyers prize.
- Strengthen presence at decision-oriented venues: recent trade show activities and product promotions demonstrate that on-floor demonstrations and thought leadership will remain high-impact channels in 2026.
How to use this preview — next steps
This document is a strategic preview intended to inform board-level and operational planning for 2026. The full Dust Collectors For Mining Market report contains the complete set of segment breakdowns, regional and application-level demand models, vendor market-share tables, pricing benchmarks, and the downloadable decision-support workbook that enables project-specific scenario runs. For procurement teams, engineering leads and transaction advisors preparing for 2026 execution windows, the full deliverable provides the empirical detail and ready-to-run tools necessary to convert compliance requirements into executable capital programs.
About PW Consulting
PW Consulting is an independent strategy and industry research firm specializing in capital-intensive industrial markets. Our market studies combine primary survey intelligence, granular supplier analysis and scenario-based financial modelling to produce decision-grade guidance for corporate leaders, private equity investors and technology suppliers. This preview reflects our multidisciplinary approach—policy-aware, cost-sensitive and execution-oriented—to the mining dust-collection value chain.
For detailed analysis of this topic, please visit the official page: Dust Collectors For Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Veterinary Examination Light Market Reaches USD 403.0 Million in 2025; LED Segment Leads with USD 319.4 Million
By PW Consulting, 2026-07-01
Veterinary Examination Light Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market research brief on the Veterinary Examination Light market distills actionable intelligence for executives, procurement leads, product teams, and M&A advisors preparing for 2026. Built on a robust historical base (2020–2025) and a detailed forecast (2026–2032), the study quantifies a stable, mid-single-digit growth trajectory (5.28% CAGR across the forecast window) and maps the commercial, regulatory, and technological inflection points that will shape supplier and buyer strategies in the coming 18–36 months.
Veterinary Examination Light Market
Quick strategic takeaways
- Market scale and momentum: The global market expands from a mid-three-hundred million USD base in 2025 to a significantly larger opportunity by 2032 (detailed figures included in the full report), driven by technology refresh cycles, increasing adoption of LED-based platforms, and widening clinical expectations in companion-animal and specialty care.
- Consolidation signal: The top-tier concentration is meaningful but not prohibitive — the three- and five-firm concentration ratios indicate room for both incumbents to extend leadership and for focused challengers to gain share through product differentiation or channel excellence.
- Business priorities for 2026: Resilient sourcing, product modularity, higher CRI and thermal management specifications, camera/video integration for telemedicine/referral workflows, and compliance with medical device standards will be decisive in procurement and specification choices.
Market evolution and what the numbers say
PW Consulting’s topline sizing shows the Veterinary Examination Light market progressing from the early-2020s base through a recovery and growth phase into 2026 and beyond. After a period of modest fluctuation across 2020–2024, the market reached an estimated USD 403.0 Million in our base year (2025). Under our central forecast, the market continues to expand at a compound annual growth rate of roughly 5.28% through 2032, reaching a substantially larger addressable pool by the end of the projection period. This pace reflects a mix of replacement demand, upgrades to LED and integrated systems, and incremental purchases driven by the growth of veterinary outpatient services and specialty referral centers.
Veterinary Examination Light Market
Those preparing strategic plans for 2026 should treat these numbers as directional evidence of a stable, investible sector: not ultra-high growth, but attractive for companies that can execute on product innovation, channel strategies, and supply-chain resilience.
Veterinary Examination Light Market
Key demand and supply drivers
- Technology migration: LED platforms continue to displace legacy halogen designs due to longevity, reduced heat, and energy efficiency. Buyers are demanding higher color rendering indices, better thermal management, and increasingly, camera/video integration for documentation and teleconsultation.
- Clinical expectations: Veterinary clinics and hospitals are upgrading lighting to meet the needs of soft-tissue procedures and expanded outpatient services; this is complemented by adopters in academic and research contexts who require reproducible lighting characteristics for training and study.
- Regulatory and standards pressure: Compliance with medical electrical equipment standards is a differentiator—manufacturers that demonstrate adherence to recognized standards and maintain quality management certifications reduce procurement friction in institutional sales.
- Supply-chain and trade dynamics: Manufacturers with localized production footprints are better positioned to manage tariffs, lead times, and custom integration requests. Recent industry behavior shows a clear bias toward suppliers that can guarantee shorter lead times and predictable warranty support.
What PW Consulting’s report delivers — the operational intelligence
Our report is explicitly designed as a decision-support tool for 2026. It combines market sizing and forecast rigor with practical, executable outputs:
- Buyer decision frameworks: procurement scorecards, total cost of ownership templates, and specification matrices that link clinical requirements to product features and service commitments.
- Supplier benchmarking and scorecards: quality, warranty, production footprint, channel strength, and aftermarket service assessments for the leading global and regional vendors.
- Commercial playbooks: targeted GTM strategies for OEMs, distributors, and private-label manufacturers across clinic, hospital, and academic segments, with go-to-market tactics calibrated by buyer persona.
- Pricing and contract guidance: dynamic pricing models, tender negotiation levers, and sample SLA language for 2026 procurement cycles.
- M&A and partnership lenses: candidate screening criteria for roll-up strategies, bolt-ons to enhance service capabilities, and integration checklists for lighting + camera/video or lighting + IT connectivity bundles.
- Supply-chain risk matrix: supplier redundancy planning, localization trade-offs, and tariff mitigation playbooks to minimize delivery disruption.
- Regulatory and compliance annexes: summary of relevant medical-device standards and certification expectations that buyers and OEMs must factor into purchasing and R&D roadmaps.
Competitive landscape — who matters and why
The competitive set spans specialized lighting houses, diversified medical-device groups, and regional manufacturers. PW Consulting profiles each player not merely by product portfolio but by what truly drives competitive advantage in 2026: manufacturing footprint, service capabilities, product durability, integration readiness, and channel reach.
- Burton Medical LLC (Addison, IL, USA): A long-established U.S. manufacturer with a deliberate domestic production strategy to insulate customers from global supply-chain shocks. Their positioning around reliability and Made-in-USA lead times makes them a default option for procurement organizations prioritizing lead-time certainty and localized support.
- Waldmann Lighting Company (U.S. operations; German HQ): Known for veterinary-focused surgical and exam lights with strong color rendering and heat-management features. Their product ergonomics and clinical design focus appeal to referral centers and clinics performing routine procedures.
- Huot Instruments / StarTrol: Rugged, long-warranty LED platforms with articulated arms and a reputation for longevity—attributes that reduce total cost of ownership for high-use clinic environments.
- ACEM Spa and RIMSA (Italy): European engineering-led players with product families that scale from exam-level to surgical-grade lighting; compliance with recognized safety standards and quality certifications is a core selling point in institutional procurement.
- Brandon Medical (UK): Differentiates with integrated HD video and camera systems—an increasingly important capability for referral hospitals and institutions deploying telemedicine and teaching applications.
- Regional manufacturers (Mindray, GPC Medical, Narang Medical, Medical Illumination, Surgiris and others): Provide competitive pricing and locally adapted configurations, and in some markets they form the backbone of equipment refresh cycles where value and channel proximity dominate.
Across this set, PW Consulting highlights that the market concentration is notable but allows for disruption: the three-firm concentration (CR3) and five-firm concentration (CR5) ratios reflect meaningful share by top players while leaving competitive space for fast-followers and niche specialists to expand through targeted investments.
Recent signals you must factor into 2026 plans
- Product refreshes and catalog updates continue to push higher illuminance and CRI levels while adding focusable optics and dimming features; catalog releases in early 2026 confirm this trend.
- Manufacturers emphasizing domestic production or diversified footprints are reducing lead-time risk and mitigating tariff exposure — a clear procurement preference emerging in 2025–2026.
- Regulatory compliance (medical electrical standards) and quality certifications are becoming table stakes for institutional sales; suppliers lacking certified processes face longer approval cycles and lost tenders.
- Integration of cameras and video systems into exam and surgical lighting is evolving from a niche upgrade to a mainstream requirement for referral centers and teaching hospitals.
Practical implications for corporate decision-making in 2026
- Procurement leaders should adopt a TCO + resiliency framework: quantify not only price but warranty, repairability, spare-parts lead times, and supplier geographic risk.
- Product teams must prioritize modularity and integration: design LED platforms that can accept camera modules, different mounting configurations, and IoT-enabled monitoring to stay relevant across clinic tiers.
- M&A strategists should look for targets that add either high-margin service capabilities (preventive maintenance, calibration) or integration expertise (video/IT), rather than purely volume plays.
- Channel and distribution leaders must invest in training and service networks—post-sale uptime and rapid parts replacement are major competitive differentiators.
- Compliance and regulatory functions should map certification timelines into product-roadmap gating decisions to avoid lost opportunities in institutional tender cycles.
Accessing the full intelligence
This article summarizes the strategic contours of PW Consulting’s Veterinary Examination Light market report and highlights the decision-grade outputs that will matter in 2026. In keeping with our “trailer” principle, we have showcased the analytical depth and decision frameworks while intentionally withholding detailed subsegment tables, region-by-region breakdowns, and proprietary pricing matrices. These core datasets and the full set of annexes are available through PW Consulting’s report access portal and are essential for teams that must build investment cases, procurement RFPs, or M&A screeners.
For executives preparing budgets, sourcing strategies, or product roadmaps for 2026, the full report provides the granular inputs and executable templates needed to act with confidence. PW Consulting remains available for bespoke briefings, scenario modeling, and M&A advisory to translate the market forecast and supplier intelligence into concrete business outcomes.
For detailed analysis of this topic, please visit the official page: Veterinary Examination Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Surface Oil Recovery Machines Market to Grow at a 4.58% CAGR, Reaching USD 732.05 Million by 2032
By PW Consulting, 2026-07-01
Surface Oil Recovery Machines Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As organizations reassess operational resilience and regulatory readiness going into 2026, the Surface Oil Recovery Machines market presents a steady, actionable growth trajectory that demands strategic attention. PW Consulting’s latest market study — built on a 2025 base year and a detailed historical review from 2020–2025 — projects a compound annual growth rate (CAGR) of 4.58% across the 2026–2032 forecast window. The global market, measured in US Dollars (Millions), reached a substantive size in 2025 and is expected to expand meaningfully by the end of the forecast period. For procurement leaders, OEMs, private equity investors and regulators, the report translates this macro momentum into concrete operating levers and decision frameworks essential for 2026 planning cycles.
Surface Oil Recovery Machines Market
Why this market matters in 2026
-
Operational risk and response capability: Surface oil recovery equipment is no longer a niche compliance item — it is a frontline capability for minimizing environmental, financial and reputational exposure. Capital investments and contractor engagements made in 2026 will determine response effectiveness for the next decade.
Surface Oil Recovery Machines Market -
Predictable, investable growth: With a mid-single-digit CAGR through 2032, the market offers predictable demand patterns that support investment in product development, repeatable service models and aftermarket ecosystems.
Surface Oil Recovery Machines Market -
Fragmented supplier landscape: Market concentration remains modest, creating opportunities for smart consolidation, strategic partnerships and differentiated service propositions that can scale quickly if timed with regulatory shifts or major offshore projects.
-
Regulatory inflection points: Recent and pending regulatory activity around response protocols and product approvals will reshape procurement specifications and can create immediate demand spikes for compliant systems.
Market trajectory — what the macro numbers say
PW Consulting’s topline sizing anchors 2025 as the base year and models a steady expansion across 2026–2032. While we intentionally reserve granular segment figures in this preview, the headline dynamics are clear: the sector is growing at a sustainable pace that supports both organic innovation and targeted M&A. For executives building 3–5 year plans, the implications are straightforward — prioritize modular, field-proven technologies and flexible commercial models (rental, outcome-based contracts, and rapid deployment pools) that capture recurring service revenue as the installed base matures.
Competitive landscape — positioning and implications
-
Elastec: Known for high-efficiency skimmers and certified production processes, Elastec’s strength is rapid-response systems that meet standardized testing criteria. Their ASTM/ISO emphasis positions them well where procurement is specification-driven. Strategic implication: partner or compete by matching certification and field validation timelines.
-
DESMI: A global player with strong offshore credentials, DESMI’s footprint and experience in large-scale spill events make it a preferred supplier for complex marine deployments. Strategic implication: leverage DESMI-like service bundles when bidding for long-term response contracts.
-
Vikoma International: Recent product introductions underscore a push toward versatile, quick-deploy solutions suited for a wide range of hydrocarbon types. Their ongoing product cadence signals a play for broader market segments and rapid adoption among responders. Strategic implication: buyers should test multi-oil capability in procurement trials; investors should watch product differentiation as a growth lever.
-
Lamor Corporation: Focused on harsh-environment and Arctic-capable systems, Lamor exemplifies a technology-led niche strategy with premium positioning. Strategic implication: firms operating in extreme conditions should prioritize specialized skimmers and tailored maintenance programs.
-
Industrial-focused specialists (Abanaki, Oil Skimmers, SkimOIL, Zebra Skimmers): These vendors dominate process- and wastewater-oriented applications with compact, cost-effective skimmers. Strategic implication: industrial end-users benefit from lifecycle cost modeling and integration of recovery systems into routine maintenance regimes.
-
Regional and niche players (Aqua-Guard, Markleen, New Naval): Smaller innovators are accelerating with lightweight, high-capacity designs and rapid-deployment models showcased at recent trade events. Strategic implication: prime candidates for pilot programs, OEM partnerships or bolt-on acquisitions.
Recent industry signals to factor into 2026 strategy
-
Product innovation: Notable product launches and trade-show reveals over the past 18–24 months demonstrate accelerated engineering cycles toward versatile, higher-throughput skimmers. Buyers should include hands-on acceptance tests in procurement language to validate claims under representative conditions.
-
Testing and certification: The development of standardized testing protocols by regulatory bodies represents a turning point. Buyers and OEMs that align early with new test regimes will shorten market uptake cycles and reduce rejection risk during emergency activations.
-
Regulatory continuity and evolution: Longstanding frameworks (e.g., federal oil spill statutes and associated MOAs) remain operative while conditional approval timelines for response products have been extended in some jurisdictions, creating both compliance urgency and temporary procurement windows.
-
Supply chain noise: Raw material price fluctuations and localized procurement constraints introduce cost and lead-time volatility. Sensible 2026 strategies will combine buffer inventory, prioritized sourcing and design choices that reduce exposure to commodity swings.
Strategic playbook for 2026
-
Procurement readiness: Build pre-qualified vendor lists with cross-validated field performance and warranty structures. Include clear acceptance tests tied to anticipated oil types and sea states.
-
CapEx allocation: Favor modular systems that can be upgraded without full replacement. Prioritize investments that improve turnaround time and reduce total cost of ownership through service contracts and predictive maintenance.
-
M&A and partnership targets: Focus on bolt-on technologies that fill capability gaps (e.g., Arctic adaptability, ultra-lightweight rapid-deploy units, or integrated pumping systems). Use the market’s modest concentration to acquire scale at attractive multiples.
-
Operational resilience: Integrate recovery assets into broader emergency response plans and conduct multi-stakeholder exercises to validate interoperability with contractors, regulators and ports.
-
Regulatory alignment: Monitor evolving test protocols and certification windows closely; early alignment can yield preferential procurement outcomes in regulated tenders.
What PW Consulting’s report delivers (practical contents)
The full report is engineered as a toolkit for decision-makers, not only as a market narrative. Key deliverables include:
-
Market sizing and seven-year forecasts (2026–2032) with sensitivity scenarios and downside stress cases.
-
Vendor scorecards and comparative capability matrices that translate technical specs into procurement-ready decision criteria.
-
Field validation protocols and sample acceptance tests linked to likely real-world oil types and environments.
-
Regulatory impact assessments and a matrix of near-term compliance triggers that could drive procurement or retrofit programs.
-
Commercial playbooks for OEMs and service providers — go-to-market approaches for rental models, service contracts and outcome-based pricing.
-
M&A heatmaps and integration checklists for investors seeking consolidation targets with realistic synergy pathways.
-
Supply chain resilience templates, including dual-source frameworks and inventory optimization models tailored for recovery equipment categories.
How to use this intelligence in 2026 planning cycles
-
Chief Procurement Officers: incorporate the vendor scorecards and acceptance tests into 2026 RFQs to reduce operational risk and shorten onboarding timelines.
-
Asset Owners and Operators: prioritize investments that enhance deployability and interoperability; schedule exercises with shortlisted suppliers.
-
OEM and Service Providers: use the competitive benchmarking and M&A heatmaps to identify white spaces and scale opportunities.
-
Regulatory and Response Agencies: adopt the testing protocol analyses to harmonize local procurement rules with emerging standards.
Closing perspective
The Surface Oil Recovery Machines market in 2026 sits at the intersection of predictable demand growth, technological differentiation and regulatory tightening. The market’s modest concentration presents strategic opening for both incumbents and new entrants — but the tide favors those who combine certified, field-validated technology with flexible commercial models and robust supply chains. PW Consulting’s forthcoming report equips leaders to convert macro projections and competitive signals into executable plans that reduce response times, control lifecycle costs and capture enduring service revenue. For teams that require the complete dataset, full segmentation, and downloadable annexes, the report’s repository contains the granular intelligence and implementation templates necessary to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Surface Oil Recovery Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Hair Styling Tools Market to Expand at a 5.19% CAGR During 2026–2032
By PW Consulting, 2026-07-01
Hair Styling Tools Market 2026 Strategic Preview — Actionable Intelligence for Executive Decision-Making
PW Consulting’s latest Hair Styling Tools Market study provides a concentrated, decision-ready briefing for C-suite leaders, product strategists, and M&A teams preparing plans for 2026. The global market reached USD 38,461.74 Million in 2025 (base year) and—driven by product innovation, premiumization and an acceleration of at‑home salon technologies—is projected to grow at a 5.19% CAGR across the 2026–2032 forecast window, reaching USD 54,845.25 Million by 2032. This preview distills the strategic implications of those headline dynamics while preserving the granular subsegment intelligence for subscribers of the full report.
Hair Styling Tools Market
Why this report matters for 2026
-
Signal-to-noise: As category innovation proliferates (AI-driven heat control, wet‑to‑dry functionality, nano‑moisture systems and cordless automation), executives need a concise translation of product trends into commercial levers—pricing, channel rollout, and SKUs—rather than a catalog of features.
Hair Styling Tools Market -
Investment lens: With the market exhibiting a mid-single-digit CAGR through 2032, the opportunity favors firms that combine differentiated technology with scalable manufacturing and distribution. Our modeling highlights where returns on incremental R&D and channel investment are densest.
Hair Styling Tools Market -
Risk calibration: New material costs and regulatory updates are compressing margins in specific parts of the value chain; timely mitigation strategies are now a competitive necessity.
Key market dynamics (executive summary)
-
Premiumization and tech-led differentiation continue to elevate average selling prices in developed channels, while mass channels remain volume drivers through frequent replacement cycles and promotional activity.
-
At‑home salon adoption—spurred by post‑pandemic behavioral shifts and the diffusion of multi‑functional devices—remains a structural growth contributor. Industry-level growth in adjacent beauty devices underscores the durability of this trend.
-
Supply‑side pressures are non‑trivial: copper, a critical input for heating elements, rose sharply in late 2025 (approx. a 15% YoY increase to roughly USD 9,500/metric ton in Q4 2025), creating an immediate cost headwind for legacy heating architectures.
-
Regulatory & safety environment is tightening. The EU’s REACH restrictions on certain flame retardants remain binding inputs into product composition decisions, and UL 859’s 2024 update requires enhanced dielectric strength testing for hair dryers—changes that affect time-to-market and compliance spend.
-
Concentration metrics show a moderately consolidated landscape: the top three and top five incumbents capture a material yet not prohibitive share of market value—leaving room for nimble challengers and category winners from adjacent markets.
Competitive landscape—how the leaders are playing
Our intelligence map focuses on capability vectors rather than raw share-by-segment figures (those are contained in the full dataset). Several profiles merit strategic attention:
-
Dyson (HQ: Singapore) — Technology-first premiumization. Continued product cadence around Coanda airflow and plate innovations (wet‑to‑dry Airstrait launched in October 2025) reinforces a strategy of commanding price premiums through perceived hair health benefits.
-
GHD (Huddersfield, UK) — Salon-grade performance scaled to consumer channels. Its 2025 Chronos launch—employing AI-based heat control—signals a push to make professional thermal control accessible in the premium consumer tier.
-
Conair (Stamford, CT, USA) — Portfolio breadth and channel depth. Conair’s expansion into cordless auto‑curlers and strong mass-market distribution keeps it a defensive incumbent across value tiers.
-
Panasonic and Philips — Platform R&D & consumer electronics integration (nanoe and SenseIQ). These players leverage broader CE competencies to add moisture-preserving and sensor-driven features that resonate in health‑conscious segments.
-
T3 Micro, Remington (Spectrum Brands), Revlon/Hot Tools (Helen of Troy), Andis, Valera, Babyliss and Tescom — each occupies distinct niches (premium styling, professional salon tools, value-driven multi-pack consumables, or regionally dominant product lines) that collectively maintain category dynamism.
The competitive implication for 2026: incumbents with strong IP around user outcomes (reduced damage, shorter styling time) can protect margins, while challengers with superior route‑to‑consumer economics (D2C + selective retail) can accelerate share gains without matching R&D spend.
Strategic playbook for 2026
-
Product strategy: Prioritize technologies that demonstrably lower hair damage and reduce styling time. Investments in sensor-enabled control and alternate heating materials yield disproportionate willingness-to-pay in premium cohorts.
-
Supply chain & procurement: Hedge raw material exposure (especially copper) via strategic contracts, alternative alloy research, and modular heating element designs that facilitate sourcing flexibility.
-
Regulatory & compliance: Fast-track design reviews against REACH and UL updates—non-compliance is an order-cycle tax that can negate new-product ROI. Plan for incremental testing timelines and certification costs in 2026 product launch roadmaps.
-
Channel & services: Expand aftercare/consumable ecosystems (brush heads, batteries, protective plates) and subscription models to smooth revenue streams. Use digital diagnostics (app pairing, predictive maintenance) to embed customer lifetime value.
-
M&A & partnerships: Target smaller engineering-rich players (cordless lithium‑ion expertise, AI control algorithms, or patented airflow tech) to close capability gaps quickly. Our screening model flags sub‑threshold targets that would materially accelerate time-to-market for differentiated features.
Risk map and contingency scenarios
-
Regulatory shock: A widened interpretation of chemical restrictions or stricter electrical safety mandates could delay launches; mitigate via pre-competitive testing consortia.
-
Commodity volatility: Continued metal price inflation compresses gross margins on thermal components. Scenario planning in the report quantifies margin erosion and required price or cost countermeasures.
-
Product safety optics: While no major category recalls were reported in 2025 (minor ongoing brush replacements noted), reputational shocks remain high-impact and low-frequency—tighten post-market surveillance and recall playbooks.
What’s in the full report (practical deliverables)
PW Consulting’s full Hair Styling Tools Market report is designed as an operational toolkit for 2026 execution. Subscribers receive:
-
Detailed historical (2020–2025) and forecast (2026–2032) market sizing down to product and application granularity, with alternative scenarios.
-
Channel and route‑to‑market playbooks (retail assortments, D2C launch calendars, salon partnership frameworks) calibrated to ROI thresholds.
-
Competitive deep dives and capability matrices for the leading OEMs and challenger brands, including IP mapping and recent product timelines.
-
Supply chain risk analytics, including commodity sensitivity tables and recommended procurement hedges.
-
Regulatory checklist and implementation roadmap aligned to major markets.
-
Actionable M&A target shortlist and three model transaction structures (bolt-on tech acquisition, JV for geographic scaling, minority growth investment).
How to apply these insights in 90 / 180 / 360 days
-
90 days: Audit your product roadmap against updated safety standards and raw material sensitivities; prioritize two near-term SKUs for cost-in-use optimization.
-
180 days: Launch controlled channel experiments for sensor-enabled premium SKUs and pilot subscription/consumable offerings to validate LTV uplift.
-
360 days: Execute at least one strategic acquisition or partnership to close an identified capability gap, and roll out a compliance‑driven redesign program where necessary.
Final perspective
The hair styling tools category is at a practical inflection point: headline growth is solid (5.19% CAGR to 2032), but the winners in 2026 will be those who convert technological novelty into reproducible consumer outcomes, embedded revenue models, and supply‑chain resilience. PW Consulting’s full report arms leaders with the missing middle between trend headlines and executable corporate plans—detailed, testable, and directly tied to P&L and balance-sheet levers. For firms ready to move decisively in 2026, the next step is a targeted data extraction and workshop we run with executive teams to map the roadmap into capital and commercial milestones.
Access to the complete dataset, segment-level forecasts, and the closed‑door comparator matrices is available through the PW Consulting report portal. Subscribers will receive an executive briefing pack tailored to board-level decision cycles and a granular implementation deck for product, channel, and M&A teams.
For detailed analysis of this topic, please visit the official page: Hair Styling Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


