



Category: market research
PW Consulting Forecasts Solid State Chip Battery Market to Expand at a 19% CAGR, Driving Rapid Growth Through 2032
By PW Consulting, 2026-07-01
PW Consulting: Strategic Brief — Solid State Chip Battery Market Outlook and 2026 Decision Playbook
Executive snapshot — why this matters for 2026
The solid state chip battery market is at a strategic inflection point. Our new market study shows a sustained high-growth trajectory: the market expanded more than twofold between 2020 and 2025 and is projected to continue growing at a multi‑year compound annual growth rate of approximately 19% through 2032. That pace drives very different capital allocation, partner selection, and product road‑maps than incumbent lithium‑ion strategies. For executive teams planning capital deployment, supplier agreements, or new product launches in 2026, this report translates macro momentum into operational choices that materially affect time‑to‑market, margin capture, and regulatory risk exposure.
Solid State Chip Battery Market
What PW Consulting’s report delivers — practical, decision‑ready content
- Proven market sizing and forecasting model: transparent assumptions, scenario outputs (base / upside / downside), and sensitivity levers you can apply to your own portfolio decisions.
- Technology readiness roadmap: maturity assessments for thin‑film, bulk, and quasi‑solid approaches; commercialization pathways and likely calendar windows for pilot → qualification → series production.
- Manufacturing economics and capex playbooks: scalable process architectures, key bottlenecks, and cost curves for solid electrolytes vs conventional chemistries, including break‑even scenarios under different material cost declines.
- Regulatory and standards matrix: mapped timing and impact of imminent rules and standards across Asia, Europe, and North America, with compliance checklists for product, transport, and safety testing.
- Supplier and competitor heatmaps: differentiated supplier profiles, technology differentiators, IP posture indicators, and a pragmatic assessment of qualification timelines—designed for vendor selection and M&A screening.
- Commercial go‑to‑market playbooks: pricing levers, channel strategies for chip‑scale and automotive adjacencies, and customer qualification templates used by Tier‑1 OEMs.
- Actionable risk register: prioritized technical, regulatory, and supply chain risks with mitigation KPIs and trigger points for strategic pivots.
Market dynamics shaping 2026 choices
Several forces converge in 2026 to make the next 12–18 months decisive for both incumbents and challengers. First, the underlying growth profile (strong double‑digit CAGR) is creating a near‑term premium on speed: pilot lines and successful customer qualifications translate directly to share capture. Recent industry moves illustrate this dynamic — sample shipments, prototype deliveries, and the commissioning of pilot assembly lines are no longer symbolic milestones; they are the minimum table stakes for supply discussions with automotive and high‑reliability electronics OEMs.
Solid State Chip Battery Market
Second, material and manufacturing realities constrain upside without targeted innovation. Solid electrolyte raw materials remain several times more expensive than conventional Li‑ion components, while interface stability and moisture‑sensitive processes complicate scale‑up. These technical bottlenecks are the primary determinants of realistic cost decline curves and therefore of the timing when solid state technologies displace incumbent chemistries in higher‑value applications.
Solid State Chip Battery Market
Third, regulatory and standardization activity is accelerating and will materially influence deployment strategies. National technical standards, evolving hazardous‑materials rulemaking, and new safety standards tailored to solid‑state chemistries are converging in 2026–2027. Companies that engage early with standards bodies and align testing and packaging strategies will avoid costly rework and shipping interruptions.
Competitive landscape — pockets of progress, clear leadership signals
The competitive field is a mix of specialist startups, established battery manufacturers, and automotive OEMs that have moved upstream. A few observable patterns matter strategically:
- Partnerships between cell developers and OEMs are the dominant route to automotive qualification. Several companies have public partnerships or customer engagements that demonstrate access to OEM product development cycles; this reduces technology‑to‑vehicle lead time for selected suppliers.
- Pilot production and qualification milestones are the new currency. Firms that can demonstrate sample shipments and formal customer qualification in 2025–2026 materially improve their odds of series contracts in the subsequent 12–36 months.
- IP and materials positioning will drive competitive advantage. Organizations that secure patents on electrolyte formulations and electrode interfaces — while building manufacturing know‑how — will create barriers to entry even if cell architectures are conceptually similar across players.
- Market concentration is meaningful but not prohibitive: a relatively small set of players capture a material share of current market value, yet the market remains contestable given the number of specialized entrants and the diversity of application end‑markets.
For strategic planning, these dynamics imply that decisions on equity stakes, JV structures, and exclusivity terms should be calibrated to the supplier’s demonstrated progression through pilot runs and qualification gates — not simply to press announcements or theoretical energy‑density claims.
Recent signals that matter for 2026 strategy
- Patent activity and near‑term pilot plans from large cell makers indicate push‑button plans to reach higher energy densities and shorten commercialization timelines. Expect IP portfolios to influence licensing and cross‑licensing discussions.
- Qualification and sample‑shipping announcements from several players show that technology risk is beginning to shift from lab to pilot; procurement teams must update vendor evaluation criteria accordingly.
- Regulatory and standardization steps scheduled for 2026 create both compliance obligations and opportunities to shape requirements favourable to particular architectures. Early engagement yields competitive advantage.
How strategy teams should act in 2026 — pragmatic prescriptions
We recommend a prioritized set of actions for executives responsible for product strategy, supply chain, and corporate development:
- Adopt a phased exposure strategy. Allocate pilot‑stage commitments to multiple technological approaches (thin‑film, bulk, hybrid) while reserving larger capital for suppliers that clear qualification milestones tied to your product road‑map.
- Invest in standards and regulatory engagement. Assign resources to influence, track, and operationalize standards workstreams to avoid common rework and transport disruptions.
- Hedge material cost risk with vertical anchors. Secure strategic agreements for critical electrolyte precursors or pursue equity positions in materials startups to protect margin pathways as volumes scale.
- Update logistics and product specifications now. New state‑of‑charge shipping limits and updated hazardous goods rules require immediate changes to procurement and distribution policies for 2026 shipments.
- Prepare for M&A arbitrage. Targets with demonstrated pilot throughput, validated IP on interfaces, or unique manufacturing tooling will be the most accretive acquisitions for market share or margin expansion.
Using the report in practice — what you’ll get when you download
The full PW Consulting report contains the underlying datasets, segmentation tables, supplier scorecards, and executable templates that we reference in this release. Subscribers and purchasers receive:
- Interactive forecast models for bespoke scenario analysis;
- Supplier diligence playbooks with red‑flag indicators and due diligence checklists;
- Regulatory compliance roadmaps matched to product classes and transport vectors;
- Quarterly monitoring dashboards tracking pilot lines, qualification milestones, patent filings, and standards activity.
We intentionally present this executive preview to highlight the strategic levers and decision windows that will define 2026 outcomes—while reserving the detailed segmentation tables and proprietary valuation models for the full report package.
Next steps — how PW Consulting can help
For corporate boards, strategy teams, and investors evaluating exposure to the solid state chip battery ecosystem in 2026, we offer targeted support: bespoke diligence, supply‑chain scenario modeling, pilot partner matchmaking, and regulatory readiness workshops. If you are planning capital deployment, supplier exclusivity negotiations, or M&A activity in the next 12 months, schedule a briefing to review the report’s models against your specific product and market assumptions.
PW Consulting’s Solid State Chip Battery Market report is tailored to convert high‑level growth forecasts into executable strategic moves. The growth opportunity is real, but so are the technical, regulatory, and manufacturing pitfalls. In 2026, the companies that translate pilots and qualifications into repeatable production economics — while managing standards and logistics risk — will define the competitive frontier.
For detailed analysis of this topic, please visit the official page: Solid State Chip Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RTD Module Market Tops USD 751.0 Million in 2025, Set for a 5.18% CAGR Through 2026–2032
By PW Consulting, 2026-07-01
PW Consulting Releases Strategic Brief: Resistance Temperature Detector Module Market — A 2026 Decision-Ready Outlook
Executive summary
As industrial automation, process control, and safety-critical monitoring intensify their reliance on precision temperature sensing, the Resistance Temperature Detector (RTD) module market is entering a phase of steady, investment‑grade expansion. Our new PW Consulting market brief synthesizes five years of historical performance and a seven‑year forecast to 2032, establishing a clear fact base for capital allocation, product road‑mapping, and M&A screening in 2026.
Resistance Temperature Detector Module Market
- Market trajectory: RTD module demand climbed consistently through the first half of the decade and reached a notable base in 2025. Our modeling shows continued expansion through 2032 driven by industrial digitalization and rising standards-driven replacement cycles.
- Growth rate: Across the forecast horizon (2026–2032) the market is expected to grow at a compound annual growth rate (CAGR) of 5.18%, supporting mid-single-digit strategic planning assumptions for suppliers, systems integrators, and large end users.
- Concentration: Competitive intensity sits in a moderate-to-high range, with the top three and top five suppliers capturing a meaningful share of the market — a structure that favors scale, channel reach, and system‑level integration capabilities.
Why this brief matters to 2026 decision makers
Three practical realities make an up‑to‑date RTD module intelligence product essential for 2026 planning:
Resistance Temperature Detector Module Market
- Capital allocation clarity: Whether you are sizing R&D budgets for new signal‑conditioning platforms or evaluating factory automation upgrades, expect consistent demand that supports disciplined investment but rewards targeted differentiation (signal isolation, linearization, and harsh‑environment robustness).
- Portfolio prioritization: With product lifecycles lengthening in mission‑critical applications, deciding which RTD module form factors and feature sets to prioritize is now a function of both technological fit and channel economics. Our brief converts market momentum into prioritization matrices you can act on immediately.
- Competitive playbooks: The market’s moderate concentration means incumbents retain advantages, but focused challengers can win specialty niches. The intelligence in this brief equips commercial and product teams with tactical entry points and defensive counters pertinent to 2026 market moves.
What the report delivers — operationally useful, not academic
PW Consulting designed the report to be transaction‑grade and execution-oriented. Key deliverables include:
Resistance Temperature Detector Module Market
- Validated market sizing and forward scenarios — a base case aligned to macro industrial indicators plus upside/downside sensitivity runs for 2026 board deliberations.
- Decision frameworks for procurement and product development — vendor-selection scorecards, TCO templates for module vs. integrated sensor purchases, and prioritization rubrics for feature investments (e.g., isolation, surge protection, multi‑wire support).
- Channel and route‑to‑market playbook — partner archetypes, distributor economics, and account‑based selling strategies tailored to OEMs, systems integrators, and end‑users in process industries.
- Technology radar and roadmap implications — where RTD module innovation is most likely to add value (precision linearization algorithms, digital telemetry readiness, ruggedization for harsh engine/combustion environments).
- Regulatory and standards compendium — an actionable summary of the IEC/ASTM landscape that affects calibration, interchangeability, and procurement specifications for 2026 tenders.
- Competitive intelligence and M&A heatmap — capability gaps, likely acquisition targets by capability and geography, and earn‑out scenarios calibrated to current market concentration dynamics.
- Risk register and mitigation playbooks — raw material exposure, supply chain stress tests, counterparty scenarios, and rapid response templates for quality‑control incidents.
Market dynamics you must factor into 2026 strategy
Our analysis synthesizes supply‑side constraints, standards evolution, and demand pull from automation programs:
- Raw material and component trends: The ecosystem underpinning RTD elements — particularly thin‑film platinum technologies — has scale and strategic implications. Suppliers of sensor elements and thin‑film platinum substrates are now a strategic input to module OEMs, influencing pricing power, lead times, and qualification cycles.
- Standards and interchangeability: International standards such as IEC 60751 and updated reference methods (frequently aligned with ASTM guidance) remain the backbone of specification language used by procurement teams. Compliance and documented calibration strategies materially affect supplier selection and warranty exposure.
- Industrial automation penetration: Broad adoption of high‑resolution RTD modules is being driven by tighter process control requirements, energy‑efficiency mandates, and predictive maintenance programs — all of which increase the value of signal conditioning, isolation, and digital output capabilities.
- Consolidation pressure and specialization: A market structure where the top suppliers capture a significant portion of value encourages both acquisitive scale plays and focused differentiation. Expect ongoing horizontal and vertical consolidation, and selective carve‑outs of non‑core product lines as companies sharpen portfolios for 2026 competition.
Competitive landscape — how leading suppliers are positioned
We profile the leading RTD module and sensor suppliers to give buyers and corporate strategists a clear orientation of capability sets and strategic intent. Highlights:
- Omega Engineering: Broad product breadth across probes, assemblies, and transmitters. Strength in quick‑to‑market product availability and strong laboratory/commercial channel presence. Strategic advantage: comprehensive product depth that supports rapid deployment; watch for further system‑level bundling.
- TE Connectivity: Deep materials and sensor element expertise, with manufacturing prowess in thin‑film platinum and wire‑wound elements. Strategic advantage: materials control and application in harsh environments — a lever for premium positioning in automotive and industrial segments.
- Minco Products: Niche expertise in custom RTDs for aerospace, defense, and medical use cases. Strategic advantage: high‑reliability, custom engineering offerings that command premium margins and long qualification cycles.
- Honeywell & Watlow: Strong automation and process‑control pedigrees; both integrate RTD offerings into broader control and heating portfolios. Strategic advantage: system integration and channel access into large industrial accounts.
- Dataforth, Opto 22, Rockwell Automation: Signal‑conditioning and PLC/I/O capabilities that blur the line between module supplier and systems provider. Strategic advantage: embedded options for automation platforms, shortening customer procurement cycles.
- Pyromation, JUMO, ABB, Axiomatic: Regional strengths and specialized module offerings for process industries and harsh environments. Strategic advantage: local service networks and certifications that matter for regulated industries.
Our full competitive profiles include capability matrices, partnership maps, and likely 12–24 month strategic moves — material that procurement teams and corporate development groups will find directly actionable.
How to use the brief in practical 2026 scenarios
The report is structured around use cases that executives will confront in 2026. Examples include:
- Product roadmap decisions: Use our feature‑value scoring to decide whether to prioritize isolated signal conditioning vs. higher channel counts vs. integrated diagnostics in your next product cycle.
- Procurement strategy: Employ the vendor scorecards and TCO templates to renegotiate supplier contracts, structure multi‑year supply agreements, or selectively dual‑source critical RTD elements.
- M&A preparation: Apply the M&A heatmap to identify tuck‑ins that fill gaps in ruggedization, digital telemetry, or channel reach; the brief provides initial valuation bands and accretion/dilution sensitivities suitable for 2026 diligence planning.
- Channel expansion: Use our go‑to‑market playbook to evaluate distributor partnerships and systems integrator alliances that accelerate adoption in process industries and building HVAC modernization projects.
Call to action — where to get the full intelligence
This press brief is a controlled disclosure designed to demonstrate the analytical depth of PW Consulting while reserving the granular segment and regional tables, company‑level scorecards, and download‑ready templates for subscribers. The full report includes the granular datasets, interactive scenario spreadsheets, and supplier negotiation scripts that corporate teams will use directly in 2026 planning cycles.
To access the comprehensive dataset, proprietary segmentation, and the practitioner’s toolkit, visit the PW Consulting report landing page. Our team is also available for tailored executive briefings, bespoke modeling, and implementation workshops designed to convert the report’s insights into near‑term actions.
Conclusion
The RTD module market presents a reliable growth runway with clear windows of strategic opportunity for suppliers and buyers alike. With a forecasted mid‑single‑digit CAGR through 2032 and a market structure that rewards both scale and specialization, 2026 is the year to sharpen product portfolios, fortify supply chains, and align commercial models to the rising demand for precision, safety, and integrated automation. PW Consulting’s market brief equips leaders with the fact base and execution playbooks required to make those decisions confidently.
For detailed analysis of this topic, please visit the official page: Resistance Temperature Detector Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Drone System Market to Expand at 26.35% CAGR, Reaching USD 13,775.4 Million by 2032
By PW Consulting, 2026-07-01
PW Consulting Release: Anti-Drone System Market — 2026 Strategic Imperatives for Decision-Makers
PW Consulting today publishes an executive market brief accompanying our full Anti Drone System Market report, designed to arm procurement leaders, defense planners, critical-infrastructure operators, and strategic investors with the evidence-based insights necessary to make high-consequence decisions in 2026. The market for anti-drone systems has evolved from niche airspace-protection products to an integrated platform market: after accelerating from under USD 1 billion in 2020 to USD 2.68 billion in 2025, our model forecasts continued rapid expansion to roughly USD 13.78 billion by 2032 — a compound annual growth rate (CAGR) of 26.35% across the 2026–2032 forecast window. This release explains why 2026 is an inflection year and how the report translates that macro trajectory into practical, action-ready guidance.
Anti Drone System Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory and procurement forces are aligning. Recent policy shifts — from tightened FAA enforcement against dangerous drone operations to expanded counter-UAS authorities in the FY 2026 NDAA — mean organizations can no longer treat counter-UAS as optional. Standardization and testing regimes (including the Pentagon’s and NATO’s recent activity) are creating clearer paths to fielding and certification.
Anti Drone System Market -
Operational demand is maturing into programmatic spending. Governments and large enterprises are moving from one-off buys toward capability programs and recurring service models. The Department of Homeland Security’s new program executive office and associated procurement funding for major-event protection exemplify a broader shift toward organized, accelerated adoption.
Anti Drone System Market -
Technology bifurcation is accelerating. Advances in sensor fusion, AI-driven C2, RF-cyber options, and directed-energy effectors are creating differentiated value propositions. At the same time, increased investment in long-range radar and detection R&D has raised the performance floor for viable solutions.
-
Competitive and capital dynamics are intensifying. Large prime awards and high-profile funding rounds are reshaping supplier economics and partnership opportunities across the value chain.
What Our Report Delivers — Actionable, Operational, and Procurement-Grade
PW Consulting’s Anti Drone System Market report is built for decision-makers who need more than high-level statements. The deliverable translates market dynamics into operational programs and procurement playbooks. Key practical contents include:
-
Proprietary market-sizing and forecasting models (2020–2032) with scenario variants tied to policy, conflict, and technology adoption drivers.
-
A technology taxonomy and performance matrix that maps detection, tracking, classification, and defeat technologies to mission profiles — enabling side-by-side capability comparisons and fit-for-purpose selection frameworks.
-
Vendor profiling and capability scorecards for all material suppliers, including architecture-level interoperability assessments and maturity indicators.
-
Procurement playbooks and RFP templates that embed testing, verification and validation (TV&V) checkpoints, data-rights considerations, and privacy/legal compliance language aligned to current US and allied guidance.
-
Operational deployment roadmaps, including pilot-to-scale decision gates, total-cost-of-ownership (TCO) models, and crew/system training requirements for multi-vendor deployments.
-
Risk and resilience primers covering supply-chain dependencies, obsolescence pathways (hardware and software), sanctions/export controls, and cyber-vector mitigations for counter-UAS platforms.
-
Investment and M&A advisory sections identifying capability adjacencies and white-space entry points for private capital seeking exposure to the sector.
Competitive Landscape — Structure, Leaders, and Strategic Implications
Our competitive analysis finds a market that is neither a pure oligopoly nor completely fragmented. The top three vendors account for roughly one-third of market revenues, and the top five cover just over half — a concentration profile that creates both defensive scale advantages for primes and room for focused specialists to win program-level roles.
-
Prime systems integrators. Large defense primes have leveraged their radar, sensor, and effector portfolios to offer layered counter-UAS architectures. These suppliers emphasize integration with existing air-defense ecosystems, large-system warranties, and programmatic contracting advantages derived from scale and institutional trust.
-
Specialists and software-native vendors. A cohort of smaller firms is competing on innovation velocity — AI-driven C2 platforms, RF detection suites, and non-kinetic mitigation options. These firms often win initial deployments based on speed of implementation and lower per-site acquisition costs, and they frequently serve as technology partners to primes.
-
Emerging disruptors backed by capital. Recent funding rounds and targeted contracts are enabling new entrants to scale sensor development and long-range detection capabilities rapidly. Capital-backed firms are becoming attractive acquirers or JV partners for incumbents seeking to supplement product roadmaps.
Representative examples (non-exhaustive) illustrate market roles and trajectories: established defense integrators delivering layered radar-to-effector solutions; RF- and AI-first companies providing fast-to-deploy detection and classification stacks; and specialist vendors offering innovative mitigation modes, from RF-cyber takeover to autonomous capture. Recent high-profile events — NATO’s counter-drone testing at its new Innovation Range, the DHS program office launch with targeted funding for major-event security, substantial private capital injections into radar startups, and large prime contract awards for integrated radar and effector packages — crystallize these trends and the competition for both capability leadership and programmatic share.
Strategic Recommendations for 2026 Decision-Makers
Drawing on our quantitative models and qualitative vendor assessments, PW Consulting highlights seven priority actions for organizations choosing how and when to invest in counter-UAS capability this year:
-
Design for layers, procure tactically. Adopt a layered architecture (detection, classification, defeat) but procure via pilot programs that validate each layer’s contribution to mission outcomes before enterprise-wide rollouts.
-
Require open integration and modularity. Contracting teams should mandate modular interfaces, defined data models, and an upgrade path for sensor and software modules to reduce lock-in and enable rapid capability refresh.
-
Use standardized V&V gates. Insist on standardized testing and certification as part of procurement (leveraging emerging NATO and DoD guidance), including privacy and communications-interception compliance checkpoints.
-
Prioritize software and AI investments. Software-defined detection and classification deliver outsized improvements over incumbent sensor-only upgrades; budget for lifecycle software support and AI model retraining.
-
Plan supply-chain resilience. Map critical components, assess supplier concentration, and include contingency sourcing in acquisition contracts to mitigate geopolitically driven disruptions and export control impacts.
-
Balance buy-build-partner decisions. For many organizations, a hybrid approach—buy core detection capability, build integration, and partner for specialized defeat modes—offers the fastest path to operational readiness with manageable risk.
-
Align procurement cadence with policy windows. The current regulatory momentum and dedicated program funding present a narrow window to secure favorable contract terms and pilot funding; program leaders should accelerate readiness activities to match procurement timelines.
How This Report Supports Board-Level and Program-Level Decisions
For executive teams and program sponsors, our report converts market trajectory into a decision framework: when to accelerate capital allocation, which capabilities to prioritize for immediate risk reduction, and what shape a multi-year procurement road map should take to balance performance, compliance, and lifecycle costs. For investors, the analysis highlights where returns are most likely to accrue — platforms that combine high-margin software services with recurring operations and maintenance revenue, and specialists that can be scaled or folded into prime ecosystems.
For readers ready to move from strategy to action: the full PW Consulting Anti Drone System Market report contains the detailed segmentation, vendor scorecards, downloadable datasets, and procurement templates necessary to operationalize the guidance summarized here. In keeping with our “trailer” approach, this press brief presents the strategic signals and high-level market contours; the detailed, source-level tables and segment breakdowns are available exclusively in the full report.
Next Steps
-
Download the full report to access market models, supplier scorecards, procurement RFP templates, and TV&V protocols.
-
Contact PW Consulting for a tailored advisory engagement: we support program design, vendor selection, pilot execution, and M&A due diligence aligned to your operational and business goals.
PW Consulting’s Anti Drone System Market report is authored by our defense and airspace-security practice and reflects synthesis of proprietary modeling, primary interviews with procurement officers and technologists, and a continuous monitoring of policy and capital flows. As threats and regulations evolve, so must the procurement playbook — this brief sets the 2026 agenda; the full study provides the tools to execute it.
— PW Consulting, Strategic Advisory and Industry Analysis
For detailed analysis of this topic, please visit the official page: Anti Drone System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Solid-State Battery Market Poised for Breakout Growth — 67.35% CAGR Projected Through 2032
By PW Consulting, 2026-07-01
EV Solid-State Battery Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's new market study on EV solid‑state batteries frames 2026 as a pivotal year for industrial strategy. Our analysis tracks an accelerating curve: the market moved from a modest base in 2020 to just over USD 1,050 million in 2025 (base year), and under our central forecast expands into the tens of billions by the early 2030s — implying an extraordinarily steep compound annual growth rate (CAGR) throughout the forecast window. For executives and investors planning resource allocation, partnerships, manufacturing footprints, or M&A activity next year, the report distills the evidence you need to move from speculative positioning to executable strategy.
Ev Solid State Battery Market
Why 2026 Is an Inflection Point
-
Commercial readiness is converging with regulatory and incentive tailwinds. Multiple OEM and battery developers have announced prototype validations and pilot production milestones through 2024–2025, and several are publicly targeting late‑decade commercialization. Those timelines mean 2026 is the window for committing capital to scale pilots into automotive‑grade production rather than remaining at the demonstration phase.
Ev Solid State Battery Market -
Policy and incentives are reshaping cost equations. North American production credits and European regulatory thresholds tied to energy density and recyclability are already influencing site selection, supplier contracts, and product specifications. These measures materially impact project IRR calculations and time‑to‑market decisions.
Ev Solid State Battery Market -
Supply chain and material dynamics are normalizing but remain a source of competitive differentiation. Key inputs such as lithium metal foil and sulfide electrolytes have real‑world price bands that buyers and procurement teams must incorporate into cost models. Component cost curves and the emergence of domestic production incentives will determine where gigafactories are viable without chronic subsidy dependence.
What Our Report Delivers — Practical, Decision‑Ready Tools
We designed the report for executives who need actionable intelligence, not academic prose. Highlights include:
-
Comprehensive market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario variants to stress‑test upside, baseline and downside commercialization pathways.
-
Technology readiness and commercialization timelines for major solid‑electrolyte chemistries, mapped against manufacturing scale factors and projected cost curves.
-
Unit cost buildups and sensitivity analyses that translate raw material and component price swings into vehicle electrification economics and OEM payback timelines.
-
Supply chain and raw‑material risk matrices covering sourcing alternatives, inventory strategies, and strategic stockpiling options for critical inputs.
-
Regulatory and standards playbook — practical checklists to meet regional compliance milestones (including recyclability and minimum performance standards) and adoption timelines for industry testing norms.
-
Commercial partner and M&A playbooks that outline the expected negotiation levers, valuation approaches for IP‑rich startups versus scale‑focused incumbents, and a staged contracting template for offtake and co‑investment structures.
-
Operational readiness templates for pilot to series production transitions, including CAPEX estimates, staffing profiles, and quality assurance gating criteria tailored to automotive qualification cycles.
Competitive Landscape — Who Matters and Why
The market shows meaningful concentration around a mix of incumbent battery makers, incumbent OEMs, and specialized new entrants. Our report quantifies this concentration and interprets what it means for partnership strategy and competitive response.
-
Toyota Motor Corporation (Japan) — Pursuing multi‑generation solid‑state prototypes with aggressive range and charging targets. Toyota’s vertical integration and automotive systems expertise make it a bellwether for mainstream EV adoption tempos.
-
Samsung SDI (South Korea) — Demonstrating high energy‑density prototype cells and extending collaborations with automakers; a capable partner for scaled EV integration when production ramps are required.
-
LG Energy Solution (South Korea) — Focused on sulfide chemistry and piloting automotive lines; its legacy cell manufacturing capability gives it a time‑to‑scale advantage for automotive qualifications.
-
CATL (China) — Working to condense solid‑state technology towards mass production with a manufacturing footprint designed for rapid volume scaling; a strategic competitor in global supply dynamics.
-
QuantumScape (USA) — Anode‑free lithium‑metal approach and validated prototypes with large OEM partners; its IP posture and partner relationships make it a high‑impact acquisition or strategic alliance target.
-
Solid Power, ProLogium, Blue Solutions, Murata, Toshiba — A cohort of specialized suppliers and innovators offering differentiated approaches (sulfide, ceramic, polymer and miniaturized cells). Each presents either a sourcing opportunity or a potential consolidation target depending on a firm’s vertical strategy.
Our concentration metrics show a market where the top few players hold material influence, but substantial room remains for new entrants and niche specialists — provided they can clear automotive qualification gates and secure supply chain resilience.
Industry Signals and Recent Developments
-
Prototype and pilot progress: Several firms shipped validated samples and ramped EV‑cell production during 2024–2025, moving the industry out of purely lab‑scale claims and into supply‑chain engineering conversations.
-
Raw material and component trends: Lithium metal foil and bulk sulfide electrolyte prices have stabilized into observable ranges, enabling more reliable cost forecasting for 2026 investment cases.
-
Regulatory and standardization dynamics: Regional regulations mandate energy density and recyclability thresholds in the coming years while established testing standards define automotive qualification paths — these are non‑negotiable for market access.
Strategic Recommendations — What to Do in 2026
Our recommendations are calibrated to organizational roles and time horizons. Below are priority actions for the coming 12 months.
-
OEMs: Move from LOI to limited series commitments with technology partners only after completion of vehicle‑level validation tests. Protect optionality by structuring staged offtake contracts with technology milestones rather than single‑stage large take‑or‑pay agreements.
-
Battery manufacturers: Invest in flexible pilot lines that can accommodate more than one solid‑electrolyte chemistry. This hedges technology risk while enabling faster qualification for multiple OEM programs.
-
Suppliers of critical materials: Expand turnkey supply agreements and consider nearshoring options to capture regional incentives. Hedging strategies for lithium metal and specialized electrolytes will be decisive for margin protection.
-
Investors and PE: Prioritize capital for assets that de‑risk scale (equipment suppliers, pilot‑line integrators, IP‑light contract manufacturers). For equity in IP‑rich startups, use milestone‑based tranche structures tied to automotive qualification stages.
-
Policymakers and economic development agencies: Structure incentives to reward not only headline manufacturing but the full value chain — cell assembly, electrode fabrication, and recycling infrastructure — to avoid bottlenecks downstream.
Roadmap — First 90 Days to First Year
-
0–90 days: Conduct a rapid readiness assessment using our operational templates; secure conditional offtake/partnership terms; begin supply‑chain audits for critical inputs.
-
90–270 days: Execute pilot‑line capex decisions, finalize key supplier agreements, and lock in regulatory compliance roadmaps for your target markets.
-
270–365 days: Complete OEM validation loops, finalize series‑production contracts or staged investment agreements, and scale workforce and quality systems for automotive qualification.
Why PW Consulting’s Analysis Matters for 2026
Decision cycles in EV battery supply chains are long and capital‑intensive. Our report converts macro momentum — the rapid market expansion implied by multi‑year growth trajectories — into specific operational choices that preserve optionality while positioning for scale. The difference between signing the right partnership in 2026 and waiting can mean the difference between leading or following during the next wave of electrification.
Next Steps — Accessing the Full Intelligence
This briefing highlights the strategic contours you need now; the full report contains the proprietary models, detailed scenario outputs, supplier scorecards, and executable templates that senior teams will use to finalize 2026 budgets and projects. To obtain the full dataset, interactive models, and practitioner playbooks, please visit PW Consulting’s market portal or contact our client services team for an executive briefing.
PW Consulting — turning accelerating market signals into disciplined industrial strategy for the solid‑state era.
For detailed analysis of this topic, please visit the official page: Ev Solid State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Distilled Gum Turpentine Market Poised for a 4.81% CAGR Through 2032
By PW Consulting, 2026-07-01
Distilled Gum Turpentine Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview
As companies reposition supply chains and product portfolios for a post-pandemic, decarbonizing economy, distilled gum turpentine has re-emerged as a strategically important, bio-based intermediate and solvent. PW Consulting’s new Distilled Gum Turpentine Market report—anchored on a 2025 base year and projecting through 2032—delivers the analytical backbone that procurement, R&D, and corporate development teams need to make high-confidence decisions in 2026.
Distilled Gum Turpentine Market
High-level, market growth is steady: the global distilled gum turpentine market expanded meaningfully through the first half of the decade and is forecast to continue expanding at a compound annual growth rate (CAGR) of 4.81% over the forecast horizon. That trajectory underpins the twin realities facing corporates this year: sustained demand for pine-derived turpentine as a renewable feedstock, and ongoing supply-side tightness that elevates strategic risk if unintended exposures remain unmanaged.
Distilled Gum Turpentine Market
Why 2026 is a strategic inflection point
-
Recovery and composition: Demand recovery across coatings, adhesives, flavors & fragrances, and selected specialty chemical chains has shifted the product mix toward higher-value fractions and rectified grades. This is changing margin dynamics across the value chain and creating differentiated commercial opportunities for producers and buyers.
Distilled Gum Turpentine Market -
Supply consolidation and concentration: The market displays moderate concentration at the top end, with the largest three and five players controlling a material share of global supply. This concentration creates windows for strategic partnerships, offtake agreements, and targeted investments that can move a mid-sized buyer from price-taker to price-anchored counterparty.
-
Regulatory scrutiny and downstream labeling: Regional regulatory regimes continue to evolve—particularly in Europe and North America—affecting product registration, labeling, and permitted uses. These changes are reshaping commercial terms and product specifications for turpentine-containing formulations.
Market snapshot (what the headline numbers mean)
Our market model documents the evolution of total industry revenues from the historical period into the forecast window, showing steady expansion through 2025 and a continued upward path through 2032. The projected CAGR of 4.81% reflects a mix of volume growth and gradual value capture as higher-purity and specialty grades increase their share in applications such as fragrance intermediates, pharmaceutical intermediates, and high-performance solvents.
For decision-makers, the key takeaways are straightforward: the market is large enough to sustain multiple strategic plays (procurement optimization, upstream investment, or downstream product differentiation), yet concentrated enough that supplier selection and contractual design will materially affect cost of goods sold and margin performance in 2026.
Practical, decision-ready content in the report
The report is built to be operationally useful in Q1–Q3 2026. Rather than a high-level narrative, PW Consulting provides an actionable toolkit built around a granular but commercially guarded base of analysis. Highlights include:
-
Proprietary demand model segmented by application cluster and grade tier (alpha-pinene rich, beta-pinene heavy, rectified pharmaceutical grades), with scenario capability to stress-test demand under alternative macro and substitution assumptions.
-
Supplier scorecard and strategic sourcing playbook: capacity maps, reliability indices, ESG and traceability checklists, typical commercial levers, and a templated RFP that buyers can adapt to extract better pricing and security of supply.
-
Pricing and margin sensitivity analysis: drivers include resin/tapping yields, rosin co-product dynamics, freight and logistics volatility, and regulatory cost pass-throughs. The model enables corporate procurement to quantify the P&L impact of feedstock shocks and hedging strategies.
-
Regulatory risk matrix: country- and region-level implications of registration regimes, labeling obligations, and potential restrictions—paired with mitigation pathways for formulators and importers.
-
M&A and partnership playbook: identification of capability gaps (e.g., fractionation, rectification to pharmacopeial standards, domestic supply hubs), likely acquisition targets by capability, and valuation sensitivities under constrained supply scenarios.
-
Go-to-market options for downstream firms: grade-selection decision trees, innovation pathways for bio-based aromatics, and sample commercial structures (tolling, captive supply, joint ventures) to secure feedstock while limiting capital outlay.
Competitive landscape: who matters and why
Our qualitative and proprietary assessments profile leading producers and material regional players—ranging from integrated European terpene specialists to family-run producers in the Americas and Asia. Each player brings different strategic relevance depending on buyer priorities (cost, traceability, grade purity, or geographic proximity).
-
Established terpene integrators remain central: producers with deep fractionation capabilities and downstream chemistry know-how are uniquely positioned to capture margin in higher-value product lines (e.g., terpineol, high-purity alpha-pinene). Recent capacity additions and fractionation investments among leading European players signal continued value migration to ultra-pure derivatives.
-
Regional, forest-based suppliers command resilience on traceability: family-owned and regionally anchored producers that use traditional tapping methods offer differentiated sustainability credentials and supply-chain transparency. For buyers with ESG mandates or pharmaceuticals-grade requirements, these suppliers often become strategic partners.
-
New product introductions are shifting supplier differentiation: product launches of high-purity alpha-pinene lines and other BioRenewables platform offerings demonstrate how incumbents are leveraging turpentine streams to move into higher-margin chemical intermediates—broadening the set of competitive outcomes.
Recent commercial moves to watch (implications for 2026)
-
Capacity upgrades and automation are changing commercial bargaining power. Select suppliers have completed facility modernizations and are commissioning improved distillation and fractionation assets—this increases available high-purity supply but also raises the bar for entrants attempting to undercut on quality.
-
Product launches focused on higher-purity streams broaden substitution options for formulators and intermediates manufacturers. Buyers evaluating reformulations should begin qualification tracks in 2026 to realize cost or performance gains in subsequent product cycles.
-
Price and raw-material tightness persist. Recent market activity has shown that oleoresin and rosin market dynamics—driven by weather, tapping yields, and co-product processing rates—can create periods of acute margin pressure. Procurement teams must embed volatility scenarios into contract structures and inventory strategies.
Risk management and strategic playbook for 2026
We recommend a three-tiered approach for corporate decision-makers planning resource allocation and commercial strategy this year:
-
Near-term (0–12 months): Establish flexible offtake mechanisms combined with strategic safety stock for critical grades; begin supplier audits focused on traceability and REACH/labeling compliance; launch product requalification programs where substitution to higher-purity, bio-based intermediates offers margin or sustainability benefits.
-
Medium-term (12–36 months): Pursue joint-investment options with trusted suppliers to secure access to fractionation or rectification capacity; consider bolt-on M&A in regions where domestic supply reduces logistical and regulatory complexity; integrate price-sensitivity outputs into product pricing and procurement scorecards.
-
Longer-term (3–7 years): Build capabilities in derivative chemistry and circular sourcing to capture more value from terpene streams; where strategic, vertically integrate select upstream tapping or rosin processing assets to reduce exposure to co-product volatility and improve margin resilience.
What this means for specific corporate functions
-
Procurement: Move beyond commodity bids to supplier partnerships that include capacity reservation, quality campaigns, and shared-risk commercial terms.
-
R&D and Product Development: Prioritize early qualification of alternative grades and begin formulation roadmaps that allow switching between turpentine fractions and synthetic substitutes, balancing performance, cost, and regulatory safety.
-
M&A and Corporate Development: Use concentration metrics and supplier capability maps in the report to screen targets that close capability gaps or provide regional supply hubs—especially in markets with evolving regulatory burdens.
-
Risk and Compliance: Operationalize the report’s regulatory matrix to ensure labeling, registration, and workplace hazard communication processes are aligned with the latest standards in major markets.
Why PW Consulting’s report is uniquely actionable
We combine a robust, transparent market model with practitioner-focused deliverables—supplier scorecards, a procurement RFP template, a regulatory mitigation playbook, and M&A screening criteria. The report was designed to be used at the deal table or in cross-functional strategy sessions, not simply to inform executives from a distance.
Importantly, our approach follows the “pre-release” philosophy: we show the analytical scaffolding and strategic implications necessary for 2026 planning, while protecting the detailed, proprietary segment-level tables and valuation outputs that buyers and partners rely on to act decisively. Those granular datasets and interactive models are available with the full report purchase.
Next steps for leaders who need to act in 2026
-
Request the supplier scorecard and scenario model to stress-test your current supply agreements under adverse feedstock and regulatory scenarios.
-
Run a short-form commercial diligence using our templated RFP and qualification checklist to re-baseline supplier risk and renegotiate terms where appropriate.
-
Engage our corporate development team to use the report’s M&A playbook when evaluating acquisition targets or JV partners that close strategic gaps.
Conclusion
Distilled gum turpentine sits at the intersection of renewable chemistry, traditional forestry supply chains, and evolving regulatory expectation. The market’s steady expansion—supported by a multi-year CAGR and an evolving competitive topology—creates opportunities for those who align procurement, R&D, and corporate development around a coordinated strategy in 2026.
For a full set of proprietary tables, interactive scenario models, supplier-level metrics, and the practical templates referenced above, access PW Consulting’s complete Distilled Gum Turpentine Market report and supporting toolset on our website. The granular intelligence contained in the full report is the difference between informed planning and operationally executable strategy in 2026.
For detailed analysis of this topic, please visit the official page: Distilled Gum Turpentine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Linear Sorter Market to Expand from USD 3,240.5 Million in 2025 to USD 5,289.3 Million by 2032 at a 7.25% CAGR
By PW Consulting, 2026-07-01
Linear Sorter Market 2026 Strategic Outlook: Why 2026 Is the Decision Year for Sortation Investment
Executive summary
PW Consulting’s latest Linear Sorter Market report (base year 2025, forecast 2026–2032) synthesizes seven years of market dynamics into a practical roadmap for executives making capital and operational choices in 2026. Our top-line modelling shows the global linear sorter market expanding from roughly USD 3.24 billion in 2025 to an expected USD 5.29 billion by 2032, representing a compound annual growth rate (CAGR) of approximately 7.25% over the forecast period. That trajectory reflects both the maturing adoption of high-throughput sortation and an acceleration driven by shifting fulfillment models, modular system designs, and continued automation investments across logistics-intensive sectors.
Linear Sorter Market
Why 2026 matters to boards and COOs
- Investment windows are compressing. Equipment lead times, integration complexity and supplier roadmaps mean procurement choices made in 2026 will shape throughput capacity and cost profiles for the next decade.
- Modularity is no longer optional. Facilities moving from seasonal spikes to continuous omnichannel fulfillment require sortation solutions that scale in discrete, low-risk increments.
- Macro forces are tightening margins. Labor pressures, rising logistics unit costs and input-price volatility (notably steel and components) make capital efficiency and predictable TCO critical selection criteria.
- Regulatory and labor constructs are shifting operations. Recent craft and workforce determinations in major postal systems are changing how induction and sortation tasks are staffed — an operational risk that must be resolved during solution selection and rollout.
Market trajectory in practical terms
The market’s growth profile — mid-single-digit CAGR with a clear acceleration in the latter half of the decade — signals a broad class of adopters moving from pilot projects to system-wide deployments. For 2026 decision-makers, this implies two immediate priorities: accelerating proof-of-concept cycles where legacy systems constrain throughput, and negotiating procurement terms that lock in performance and price protections against raw-material swings.
Linear Sorter Market
Dynamics that will shape vendor selection and deployment
- Demand-side drivers: Continued e-commerce expansion and parcel density require systems that accommodate heterogeneous parcel mixes and provide deterministic sort accuracy at scale.
- Supply-side constraints: Steel and component supply cycles remain a source of lead-time and price volatility; procurement strategies should embed escalation clauses, staged delivery, and alternative sourcing scenarios.
- Technology evolution: Architectural diversity — from sliding-shoe to cross-belt and narrow-belt solutions — affords choice but raises integration complexity. The right architecture is less about the “latest gadget” and more about throughput profile, footprint, energy use, and maintainability.
- Consolidation and competition: The market exhibits moderate concentration at the top; our concentration metrics indicate that the three largest suppliers capture a meaningful share of the market but that a broader field of regional specialists and OEMs remain influential. This market structure creates opportunity for strategic sourcing (competitive tendering, multi-supplier deployments) and for partnerships that combine global OEM capability with local engineering services.
Competitive landscape — capabilities to watch
Our vendor assessment synthesizes product capability, global delivery footprint, service models and roadmap clarity. Key players in the competitive set demonstrate differentiated strengths:
Linear Sorter Market
- Fives Intralogistics (France) — Notable for high-speed shoe-sorter platforms aimed at parcel operators and for a visible presence at major trade venues, signaling an aggressive new-product cadence and expanded systems integration focus.
- BEUMER Group (Germany) — Integrates linear sortation within broader loop and distribution portfolios; attractive to customers seeking a single-vendor approach for large-scale automated hubs.
- Dematic (KION Group, Germany/USA) — Offers proven high-volume FlexSort solutions and brings deep software and intralogistics integration expertise for complex distribution scenarios.
- Wayzim & ConfirmWare (China) — Regional specialists pushing compact, space-optimized layouts and narrow-belt designs that appeal in dense urban facilities and mixed-load environments.
- Honeywell Intelligrated / Transnorm (USA/Germany) — Known for modular, high-throughput sliding-shoe families and robust aftermarket services, positioning them for customers prioritizing uptime and throughput guarantees.
- Vanderlande, Okura Yusoki, Intralox and Gosunm — Each contributes unique technical differentiators: integration of cross-belt architectures, specialized carton handling, container-directed sorting and solutions for complex package geometries.
Recent vendor activity underscores product and commercial momentum: in late 2025 several vendors exhibited next-generation sortation platforms at regional and global trade events, and major contract awards for specialized sorter modifications highlight ongoing innovation in induction and bundle handling. These near-term moves will influence supplier roadmaps and should be reflected in RFP timelines for 2026 projects.
What the PW Consulting report delivers — practical assets for decision-makers
Our research is structured to support procurement, engineering and corporate strategy teams with executable tools rather than abstract forecasts. Deliverables include:
- Concise executive dashboards that map demand scenarios to required throughput and footprint for 2026–2028 deployment waves.
- Vendor scorecards and a weighted selection matrix covering TCO, integration risk, service SLAs and roadmap alignment.
- CapEx, OpEx and payback models calibrated to real-world throughput ramps and labor-replacement scenarios, with sensitivity to steel and component cost swings.
- Implementation playbooks: phased rollout sequencing, brownfield retrofit guidance, and mechanical/electrical integration checklists for seven common facility archetypes.
- Pilot-to-scale templates: KPI definitions, acceptance criteria, and commissioning checklists that shorten time-to-value and reduce go-live risk.
Importantly, in keeping with our “trailer” approach, this communiqué presents the market arc and strategic implications while preserving detailed, transaction-level tables and proprietary segmentation models for licensed report access. Those datasets include regional and application-level sizing, vendor revenue shares by segment, and granular CAPEX assumptions that materially affect procurement negotiations.
Actionable implications for 2026 planning cycles
- Procurement: Issue staged RFPs that separate core sortation hardware from value-added software/integration to enable multi-sourcing and to reduce vendor lock-in.
- Operations: Prioritize modular installations that can be validated in a single shift window; require vendors to deliver deterministic commissioning timelines and spares strategies.
- Finance: Use scenario-linked TCO models to compare refresh vs. retrofit outcomes under commodity-price stress and seasonal demand variance.
- Risk & Compliance: Account for evolving labor determinations and craft assignments in tender specifications; build labor contingency line items into OPEX models.
- Strategic M&A and Partnerships: Consider bolt-on relationships with regional integrators to combine global OEM technology with local installation and aftermarket capabilities.
How executives should use this report in 2026
Boards and senior operational leaders should treat the PW Consulting Linear Sorter Market report as a decision-enabling dossier: it converts macro trajectory into specific, testable procurement strategies, and supplies the commercial levers necessary to manage price, schedule and risk. The report is designed to inform three front-line actions in 2026 — fast-prototyping of one high-value site, disciplined tendering for a multi-site deployment, and renegotiation of maintenance terms to reflect increased automation utilization.
Next steps & where to get the full intelligence
This press release outlines the strategic contours and practical implications of the linear sorter market through 2032. For teams preparing 2026 capital plans and vendor selections, the full PW Consulting report includes the granular models, regional and application splits, and vendor revenue benchmarking required to finalize procurement strategies. We intentionally reserve those detailed tables and bespoke scenario outputs for report subscribers and corporate clients; visit our report page to download the executive summary, request a vendor briefing, or commission a tailored workshop.
Authored by: Senior Strategic Advisor & Chief Industry Analyst, PW Consulting — delivering market clarity and executable plans for supply-chain and intralogistics leaders preparing for the critical decisions of 2026.
For detailed analysis of this topic, please visit the official page: Linear Sorter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Brake Hoses Market Hits USD 22,030 Million in 2025, Poised for 4.12% CAGR Through 2032
By PW Consulting, 2026-07-01
Brake Hoses Market — 2026 Strategic Preview
Executive summary
As original equipment and aftermarket dynamics converge under intensifying safety standards, the global brake hoses market presents a stable, predictable growth corridor for 2026 decision-making. Our analysis shows the market expanded from approximately USD 17,850 million in 2020 to roughly USD 22,030 million in 2025, and PW Consulting projects a continuation of expansion across the 2026–2032 horizon with an implied compound annual growth rate of 4.12%. By 2032 the market is modeled to approach the upper end of the next decade’s demand band, underpinned by incremental vehicle production, regulatory reinforcement and selective material migration toward higher-performance constructions.
Brake Hoses Market
Why this report matters for 2026 planning
- Actionable foresight: The friction between OEM performance expectations and aftermarket cost pressures makes 2026 a pivotal year for supplier selection, costing models and certification roadmaps. This report translates macro trajectories into operational choices that reduce implementation risk.
- Regulatory timing: With FMVSS 106 and SAE J1401—and their associated certification and DOT registration obligations—remaining non-negotiable, companies must align product design, testing and supplier onboarding timelines to compliance milestones. Our report maps those timelines against procurement and certification lead-times.
- Capital allocation: Whether your organisation is considering capex to localize production, invest in stainless/PTFE manufacturing lines, or pursue M&A, the report offers investment-grade scenario outputs that link market growth, margin pressure and concentration metrics to expected return windows.
Market dynamics shaping 2026
The next 12–18 months will be defined by three convergent forces: regulatory intensification, vehicle fleet transitions (including hybrid and electric architectures), and selective material substitution. Synthetic rubber remains the baseline for cost-sensitive applications; however, stainless steel braid and PTFE solutions are gaining traction where thermal performance and corrosion resistance materially alter total lifecycle cost.
Brake Hoses Market
Regulatory requirements continue to set the floor for product performance. FMVSS 106 prescribes labeling and baseline performance thresholds while SAE J1401 drives test protocols for expansion, burst strength and environmental endurance. In practice, OEMs frequently specify test passports that exceed statutory minima, creating a bifurcated demand profile: large-scale, standardized rubber assemblies for mass-market fitment, and higher-value specialized hoses for premium and commercial segments.
Brake Hoses Market
Supply-chain realities—raw material pricing volatility for synthetic rubber and the logistics footprint for braided assemblies—will pressure lead times and working capital in 2026. The market concentration profile is moderate: the top three players account for roughly one-third of industry revenue, and the top five approach the mid-forties percentage mark, indicating a competitive field where scale helps but niche specialists retain influence.
Competitive landscape — strategic implications
We assessed incumbent and rising players through the lens of capability clusters: scale manufacturers, specialized high-performance suppliers, vertically integrated OEM partners, and regionally dominant independents.
- Scale and breadth — Global industrial players that include brake hoses as part of broader fluid power portfolios provide reliability of supply and global logistics platforms. These firms typically win OEM programs where cost-optimization and multi-region sourcing matter.
- Technology and performance — Suppliers with advanced materials expertise and high-throughput testing regimens command premium positioning for thermal- or chemical-resistant applications. Their value proposition is less about price and more about lifecycle risk mitigation.
- Vertical integration and aftermarket reach — Vertically integrated manufacturers that control assembly, testing and distribution are advantaged in tightly regulated aftermarket channels where DOT registration and traceability are decisive procurement filters.
- Regional champions and specialist OEMs — Companies with near-monopolistic presence in particular national markets or strong OEM relationships can act as defensive partners or attractive acquisition targets, depending on a buyer’s strategic intent.
Representative profiles illustrate these dynamics:
- A Japan-headquartered specialist with dominant domestic share exemplifies how focused incumbency secures margin and program continuity for local OEMs while selectively exporting expertise.
- Global industrial suppliers headquartered in North America and Europe leverage diversified product portfolios to bundle fluid-transfer solutions for customers seeking single-source complexity reduction.
- Highly specialized European and Asian manufacturers maintain differentiation through rigorous testing standards and customer-specific engineering for heavy commercial and high-performance passenger applications.
- Newer vertically integrated producers that secured early DOT approvals have rapidly captured aftermarket share across multiple OEMs by shortening certification cycles and controlling assembly traceability.
Recent signals and what they mean for 2026
- Trade-show participation and technology showcases reflect ongoing product innovation and the continued importance of industry forums for specimen approval and procurement relationships.
- New product launches that emphasize compliance to SAE and FMVSS testing indicate suppliers are balancing cost with incremental performance — a sign that incremental design improvements are a primary battleground.
- Updated certification lists and compliance registries highlight an administrative burden that, if mishandled, introduces market access risk for both aftermarket players and component exporters.
Strategic playbook for 2026 — five practical moves
- Certify early, test often: Accelerate SAE J1401 and FMVSS 106 testing cycles for any new material or end-fitting design. Early certification de-risks ramp and opens aftermarket channels faster.
- Diversify supplier archetypes: Combine scale suppliers for base volumes with niche specialists for premium programs. This hybrid supplier model balances cost, performance and resilience.
- Prioritise traceability: Implement serialized packing and assembly traceability where DOT registration is required; aftermarket and fleet operators are increasingly demanding end-to-end supply chain visibility.
- Material strategy alignment: Define material roadmaps that map rubber for high-volume cost control and stainless/PTFE for performance-critical fitments; allocate R&D and capex accordingly.
- Prepare M&A and partnership playbooks: Look for targets that plug capability gaps (e.g., certification know-how, vertical assembly, geographic distribution), and structure earn-outs tied to certification milestones and OEM approvals.
What PW Consulting’s full report delivers (practical, not platitude)
The published Brake Hoses Market report is designed as an operational toolkit for procurement leaders, product managers and M&A teams. Key deliverables include:
- High-resolution top-down market model (base year 2025; forecast 2026–2032) with scenario sensitivities tied to vehicle production, regulatory tightening and material-cost swings.
- Supplier scorecards that evaluate capability across certification, production footprint, testing regime, vertical integration, and aftermarket reach—scored and ranked for fast shortlist creation.
- Regulatory impact matrix that translates FMVSS 106 and SAE J1401 obligations into program-level action items and project timelines for certification, labeling and DOT registration.
- Commercial playbooks: procurement negotiation levers, volume/price breakpoint models, inventory policy recommendations and penalty-avoidance clauses tailored to brake-hose supply contracts.
- Technology deep dives on material substitution, assembly techniques and end-fitting design trade-offs, including relative lifecycle cost frameworks (CAPEX, OPEX, warranty exposure).
- M&A diagnostics and target-filter templates that prioritize candidates by capability gaps, integration risk and near-term certification hurdles.
- Implementation timelines and a staged roadmap that align R&D, testing, supplier onboarding and go-to-market for a 12–24 month activation horizon.
To respect commercial sensitivities and our “teaser-first” approach, the public summary demonstrates methodology and strategic pathways while withholding the full granular segmentation tables and company-level revenue breakdowns that corporate teams need for contracting and bid preparation. Those are available in the complete report and via tailored consulting engagements.
How to use the insight in 90 days
- Month 0–1: Run supplier diagnostic using our scorecard tool to create a shortlist aligned to certification risk and volume needs.
- Month 2: Initiate concurrent testing cycles for prioritized designs; begin DOT registration where required and lock temporary supply lines for high-volume rubber assemblies.
- Month 3: Finalize supplier commercial terms anchored to our breakpoint models; trigger any strategic M&A or joint-venture diligence for capability gaps that cannot be cost-effectively built in-house.
Final note — where to get the full intelligence
The 2026 planning window rewards organisations that combine regulatory discipline with pragmatic supplier strategies. PW Consulting’s Brake Hoses Market report turns industry dynamics into executable priorities—mapping certification deadlines to procurement actions, and linking material choices to warranty and lifecycle outcomes. For teams ready to convert insight into contract language, capex decisions and M&A moves, the full dataset, supplier-level diagnostics and scenario workbooks are available on PW Consulting’s research portal or through our advisory team.
Contact PW Consulting to schedule a briefing; we will walk your leadership through the supply-side stress tests, certification calendars and a bespoke action plan calibrated for your geographic and product footprint.
For detailed analysis of this topic, please visit the official page: Brake Hoses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2,2‑Dimethylbutyric Acid Market to Reach USD 53.52 Million by 2032 on a 4.82% CAGR; Asia Pacific Leads with USD 15.94M (2025)
By PW Consulting, 2026-07-01
PW Consulting Release: Strategic Insights from the 22 Dimethylbutyric Acid Market Report — What Industry Leaders Must Know for 2026
Executive summary
PW Consulting’s new 22 Dimethylbutyric Acid Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) provides a decision-grade roadmap for corporate strategy, procurement, and R&D through the coming investment cycle. The global market has expanded from approximately USD 30.45 Million in 2020 to USD 38.50 Million in 2025 and is projected to reach roughly USD 53.52 Million by 2032, representing a compound annual growth rate (CAGR) of 4.82% over the forecast period. These headline numbers understate the report’s practical value: beyond topline sizing, PW Consulting delivers scenario-tested strategic options, supplier risk matrices, and actionable go-to-market playbooks tailored for chemical producers, pharma intermediates customers, and specialty distributors targeting 2026 execution.
22 Dimethylbutyric Acid Market
Why this report matters for 2026 decision-making
-
Timely market inflection: With steady mid-single-digit CAGR and a predictable trajectory to 2032, 2026 becomes a pivotal year for stepping up capacity rationalization, locking in feedstock agreements, and initiating differentiated product lines (e.g., higher-purity grades and derivative intermediates).
22 Dimethylbutyric Acid Market -
Operational levers vs. commercial levers: Our analysis separates short-cycle commercial actions (pricing, offtake structures, inventory policy) from long-cycle operational investments (new synthesis routes, green chemistry adaptation, capacity debottlenecking), enabling clearer capex prioritization in 2026 board plans.
22 Dimethylbutyric Acid Market -
Concentration and consolidation signals: The market exhibits measurable concentration among established players (top-three and top-five concentration metrics are explicitly modelled in the report), which informs M&A and partnership strategies for mid-tier producers looking to scale quickly or shore up feedstock security.
Market dynamics and structural drivers
Our qualitative and quantitative synthesis highlights three enduring structural drivers that will shape 2026 outcomes:
-
End-market demand drivers — demand from pharmaceutical intermediates, agrochemical synthesis, and specialty fragrances continues to expand, but at varying intensities and margin profiles. Customers are increasingly demanding higher-assay materials and enhanced traceability, prompting suppliers to refine grade segmentation and certification capabilities.
-
Supply-side technology and process economics — multiple validated synthesis pathways exist and are commercially deployed, ranging from carbonylation processes to Grignard CO2 addition sequences and halide-to-nitrile–hydrolysis routes. These alternatives differ on yield, impurity profiles, capital intensity, and environmental footprint; our report quantifies the competitiveness of each pathway under realistic feedstock price scenarios and regulatory constraints.
-
Trade, tariffs, and inspection regimes — classification under established HS codes and associated tariff regimes materially affects landed cost and sourcing decisions. For example, current customs and supervisory requirements can impose both direct tariff costs and non-tariff friction that change the economics of cross-border supply in key corridors. The report models these effects and shows how they reshape regional sourcing patterns and contract tenors.
Regulation, tariffs, and compliance implications
For commercial and procurement leaders, non-tariff elements are often the decisive cost. The compound’s customs classification and inspection regime requires disciplined import/export documentation management and can introduce delivery uncertainty when suppliers or intermediaries lack certifications. PW Consulting’s compliance module provides a vendor readiness checklist and an auditable supplier scorecard tied to tariff sensitivity and certificate-of-inspection risk — a tool we recommend integrating into 2026 sourcing playbooks.
Competitive landscape — strategic profiles of notable players
The report includes a focused competitive assessment of incumbent producers, active regional suppliers, and laboratory-grade distributors. Key takeaways:
-
TNJ Chemical (China) — a vertically integrated manufacturer supplying high-assay material with multi-pack formats and third-party verification. Strengths include production scale, certification experience, and export capability. Areas to watch: margin pressure from global feedstock swings and potential overexposure to single-channel customers.
-
OTTO KEMI (India) — positions itself as a research-grade and export-oriented supplier with logistical reach. Its competitive edge is agile customer service for small-to-medium orders; its strategic opportunity lies in upgrading downstream processing and expanding into higher-value pharmaceutical intermediates.
-
Central Drug House (CDH) Fine Chemicals (New Delhi) — ISO-certified, focused on analytical-reagent and small-batch packaging. CDH’s strength is compliance and lab-channel trust; for 2026 it could pursue premiumization or licensing to capture higher-margin specialty niches.
-
Tokyo Chemical Industry (TCI, Japan) — an established laboratory-supply player offering detailed specifications and safety documentation. TCI’s brand in regulated lab channels and robust SDS documentation positions it well for partnerships with pharmaceutical R&D arms that demand traceability and specification fidelity.
-
Shijiazhuang Dowell Chemical — a fine chemical manufacturer with reported annual capacity for related dimethylbutyric acids on the order of low-hundred metric tons and regular exports to regulated markets. This supplier’s strength is scale and derivative product capability (e.g., acid chlorides); its strategic implications include potential for downstream integration or targeted JV activity.
Collectively, the competitive map shows a mix of specialty lab suppliers, regional manufacturers, and vertically positioned exporters. Our ranking and SWOT matrices (included in the report) help buyers and investors prioritize counterparties for 2026 contracts or strategic investments.
Supply chain risk and procurement playbook for 2026
Procurement teams face a three-part imperative: secure quality-differentiated supply, reduce landed-cost volatility, and ensure regulatory compliance. Our recommended 2026 playbook includes:
-
Implementing multi-tier sourcing with at least two certified suppliers per major region and a rapid qualification track for niche high-purity lots.
-
Embedding tariff and certificate risk into total-cost-of-ownership models rather than relying on unit price alone — especially important when supervisory inspection regimes or MFN/general tariff differentials exist.
-
Negotiating hybrid commercial terms (fixed-price tranches plus index-linked volumes) to balance supplier margins and buyer predictability during the 2026 budget cycle.
R&D and process improvement priorities
For producers and technology investors, our technical teardown prioritizes three R&D tracks:
-
Yield improvement and impurity control in established carbonylation and Grignard-based routes, using targeted purification and continuous-flow adaptations to reduce solvent consumption and increase throughput.
-
Development of lower-impact syntheses and greener work-ups to reduce EHS costs and prepare for tighter export inspection and environmental scrutiny.
-
Product differentiation around assay tiers, traceable analytics, and derivative chemical capabilities (e.g., acid chlorides) to capture higher-margin downstream demand.
We reference several recent patent families and process disclosures in the report that validate commercial feasibility for these routes and quantify expected capital and opex trade-offs; those process-level models form the foundation of PW Consulting’s capex prioritization tool included with the full deliverable.
Report contents — what you will find inside
The PW Consulting report is intentionally operational. Included modules cover:
-
Market sizing and forecast (2020–2032) with scenario variants tied to feedstock price bands and regulatory shocks.
-
Granular segmentation by geography, product type (assay tiers), and end-use application — each segment is accompanied by demand drivers, margin analysis, and growth corridors. (Note: to preserve the report’s commercial value this press release omits segment share tables; full segment-level data is available in the report package.)
-
Detailed supplier benchmarking, capacity maps, and a buyer-supplier risk matrix that incorporates tariff, certification, and logistics sensitivity.
-
Technical appendices on synthesis routes, yields, impurity profiles, and environmental considerations, with quantitative modeling that compares process economics across patent-proven methods.
-
Strategic recommendations for M&A, JV formation, and pricing strategies tailored to 2026 budget cycles and to multi-year commercial commitments.
How to use this report in your 2026 planning
For CEOs and Board members: the report delivers a prioritized set of capital and commercial decisions with projected payback and downside scenarios. For procurement and operations leaders: it provides vendor selection criteria, contract templates, and an operations-to-procurement checklist to reduce supply interruption risk. For R&D and technical directors: the appended process models and patent reviews identify the highest-return improvements and the likely competitive response over the next 24 months.
Next steps and access
PW Consulting’s 22 Dimethylbutyric Acid Market report is designed as both an intelligence playbook and an execution kit for 2026. This press release intentionally illustrates the depth of our analysis while withholding detailed segment share tables and certain bespoke financial models to preserve the strategic value of the full study. To obtain the complete report, individual modules, or a tailored executive briefing for your team, please contact PW Consulting or visit our report landing page for licensing and advisory options.
Prepared by: PW Consulting — Senior Strategic Advisors and Industry Analysts. Historical base: 2020–2025; base year: 2025; forecast period: 2026–2032; headline CAGR: 4.82% (USD, revenue unit: Million).
For detailed analysis of this topic, please visit the official page: 22 Dimethylbutyric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Preeclampsia Therapeutics Market Set to Rise at a 4.88% CAGR — From USD 1,286.1 Million in 2025 to USD 1,795.15 Million by 2032, Led by North America (USD 510.2M)
By PW Consulting, 2026-07-01
Preeclampsia Therapeutic Market: Strategic Imperatives for 2026 — PW Consulting Release
Executive summary
PW Consulting’s newest market research report on Preeclampsia Therapeutics provides a strategic blueprint for life‑science executives, investors, and policy-makers preparing decisions in 2026. Grounded in a seven‑year historical review (2020–2025) and a forward forecast window (2026–2032), the report translates epidemiology, clinical innovation pipelines, regulatory dynamics, reimbursement realities, and supply‑chain constraints into prescriptive guidance. Our base‑year analysis (2025) shows a global market on the cusp of steady expansion, and our scenario modeling projects a compound annual growth rate (CAGR) of approximately 4.9% across the 2026–2032 forecast period. PW Consulting frames what that growth means for R&D prioritization, commercial strategies, M&A, and country‑level access initiatives.
Preeclampsia Therapeutic Market
Why this market matters in 2026
- Clinical unmet need remains acute: preeclampsia continues to be managed largely with repurposed antihypertensives, magnesium sulfate for seizure prophylaxis, and low‑dose aspirin for prevention in select high‑risk groups; no disease‑modifying therapeutic has FDA approval as of 2026.
- Commercial runway is emerging: our macro model shows the market recovering from pandemic‑era and supply disruptions, with an addressable global revenue base that rose materially between 2020 and 2025 and is forecast to continue expanding through 2032.
- Regulatory inflection points are near‑term: several clinical programs and diagnostics have reached important milestones, creating tangible regulatory and partnership catalysts for 2026 activity.
Market trajectory — a numbers‑informed narrative (high‑level)
PW Consulting’s top‑line modeling reflects a market that expanded significantly from 2020 to 2025, with intermittent volatility driven by diagnostic adoption, supply issues, and trial readouts. Our forecast baseline for 2026 positions global therapeutic revenues above the 2025 base, with progressive expansion to the end of the forecast window. The report quantifies this trajectory in detail and demonstrates a 2026–2032 CAGR of roughly 4.88%, reflecting measured but sustained uptake of advanced therapeutic candidates, incremental adoption of diagnostics that better stratify risk, and gradual improvements in access across several market clusters.
Preeclampsia Therapeutic Market
Key market drivers and headwinds
- Driver — Pipeline innovation: Novel modalities (siRNA, recombinant proteins, targeted apheresis, and small molecules optimized for pregnancy safety) are progressing through early‑ and mid‑stage trials. These programs introduce differentiated mechanisms of action that, if validated, will shift treatment paradigms from purely supportive care to disease modification.
- Driver — Diagnostic enablement: Wider deployment of sFlt‑1/PlGF ratio testing and improved risk stratification enable targeted trial enrollment and may accelerate value demonstration to payers and health systems.
- Headwind — Regulatory and evidentiary bar: Sponsors must demonstrate maternal and fetal safety with robust endpoints and long‑term follow‑up; our regulatory playbook highlights common agency requests and adaptive design options to shorten development timelines without compromising safety.
- Headwind — Supply and access constraints: Persistent supply‑chain weaknesses in low‑ and middle‑income countries continue to produce stock‑outs of cornerstone medicines, complicating consistency of standard care and limiting trial generalizability unless proactively addressed.
Competitive landscape: who to watch (selected profiles)
PW Consulting’s company dossiers synthesize corporate strategy, scientific rationale, clinical status, and partnership traction. Highlights from our competitive analysis:
Preeclampsia Therapeutic Market
- DiaMedica Therapeutics (Minneapolis): Advancing DM199, a recombinant tissue kallikrein‑1 candidate in Phase 2 for early‑onset preeclampsia. Our timeline model incorporates their productive pre‑IND interactions and Health Canada Phase 2 clearance, while accounting for regulator‑requested non‑clinical work expected in mid‑2026. This creates a realistic gating item for 2026–2027 go/no‑go decisions.
- Comanche Biopharma (USA): Developing an siRNA (CBP‑4888) targeting sFLT1 isoforms — an approach with high biological plausibility and regulatory interest, but requiring careful placental safety and delivery‑platform validation.
- Kyowa Kirin (Tokyo): A major biopharma with late‑stage capabilities and global commercial reach exploring candidates in the preeclampsia space; their involvement raises partnering and out‑licensing probabilities for smaller innovators.
- Advanced Prenatal Therapeutics (USA): Pursuing targeted apheresis technologies — a potentially disruptive, non‑pharmacologic intervention that shifts cost‑and‑care pathways for severe presentations.
- Additional emerging entrants include small biotech innovators (AI‑enabled small molecules, recombinant placental growth factor proteins, mitochondrial protectants) revealing a diversified technology set that underpins the multi‑modality forecast.
Recent catalytic events and what they imply for 2026 decision‑makers
- Regulatory progress by DiaMedica (productive FDA pre‑IND discussions and Health Canada Phase 2 clearance) suggests that development timelines will concentrate activity in 2026–2027; sponsors and investors should prepare for accelerated data readouts or strategic partnerships contingent on non‑clinical deliverables.
- Diagnostic approvals (e.g., state‑level rollout of sFlt‑1/PlGF ratio testing) are already improving clinical decisioning and will influence market access conversations by enabling more precise trial designs and payer negotiations.
- Academic initiatives (e.g., a Gates Foundation‑supported mitochondrial trial) indicate that philanthropic and grant funding will remain a meaningful bridge for mechanistic research and early human proof‑of‑concept studies.
Concentration and commercial implications
The global preeclampsia therapeutic market exhibits moderate concentration: our concentration metrics indicate that the top three players account for a meaningful but not overwhelming share of market revenues, and the top five increase that share further. This structure creates both opportunities and threats — incumbent advantages in distribution and scale, but also room for differentiated entrants with strong clinical evidence or novel delivery platforms to secure niche leadership. PW Consulting’s commercial playbooks outline partnership archetypes and licensing structures optimized for these dynamics.
What the PW Consulting report gives you — practical, board‑ready deliverables
Beyond the market narrative, the report contains operational tools designed for immediate use in 2026 planning cycles:
- Scenario‑based financial models with sensitivity analysis on uptake, price, and access across multiple development outcomes (base, conservative, and upside cases for 2026–2032).
- Regulatory roadmaps and exemplar briefing packages tailored to North American, European, and select emerging‑market pathways, including common agency requests observed across recent pre‑IND/IND interactions.
- A clinical landscape tracker that maps active programs, trial designs, comparator strategies, and likely readout windows — updated to incorporate the latest 2025–2026 milestones.
- Payer engagement frameworks and value‑dossier templates that link clinical endpoints to real‑world outcome measures relevant to obstetric and neonatal stakeholders.
- Supply‑chain and manufacturing risk maps, highlighting critical raw‑material vulnerabilities and contingency strategies to safeguard clinical and commercial supply continuity.
- Commercial readiness scorecards and go‑to‑market templates for hospital systems, specialty distribution, and diagnostics complementarity.
Recommended 2026 actions for corporate leaders
- Prioritize translational programs that explicitly address pregnancy safety and placental biology — evidence packages that reduce regulatory friction will materially accelerate time to market.
- Negotiate diagnostics and companion‑test strategies early. Preeclampsia drug value is tightly coupled to the ability to identify appropriate patients and demonstrate improved maternal‑fetal outcomes.
- Stress‑test supply chains against LMIC constraints and consider tiered access models. Donor and philanthropic partnerships remain strategic levers to expand trial representativeness and future adoption.
- Align pipeline financing and partnership timelines to the regulatory gating items identified in the report — practical contingency costings are included to guide budgeting for required non‑clinical studies or additional endpoints.
- Use concentration dynamics to craft targeted M&A or licensing plays: small, differentiated contenders with early clinical validation can deliver outsized strategic value to mid‑ and large‑cap partners.
Why PW Consulting’s report is strategically different
Our analysis combines quantitative forecasting with actionable playbooks. We do not merely report market sizes — we translate those sizes into real options for executives making 2026 decisions. The report’s unique strengths include integrated regulatory choreography, payer‑centric value mapping, and an operational toolkit that spans from IND planning to hospital procurement strategy.
Access to the full intelligence
This press release provides a high‑level orientation and selective highlights from PW Consulting’s Preeclampsia Therapeutic Market report. To preserve competitive value and guide strategic engagement, detailed segment‑level splits, pricing assumptions by channel, and granular regional forecasts are available exclusively in the full report and online data workbook. Executives seeking to convert 2026 market potential into executable programs are encouraged to consult the full deliverable for downloadable models, KOL transcripts, and the proprietary clinical trial tracker.
For board presentations, investor diligence, or operational planning in 2026, PW Consulting’s report is oriented to actionable decision points — not just descriptive metrics. Contact PW Consulting to schedule a briefing and to obtain the full dataset and executive briefing package.
For detailed analysis of this topic, please visit the official page: Preeclampsia Therapeutic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fertility Drugs Market to Rise from USD 5.32B in 2025 to USD 8.05B by 2032 at a 6.1% CAGR — Injectables (USD 4.21B) and Gonadotropins Lead, North America Tops at USD 1.86B
By PW Consulting, 2026-07-01
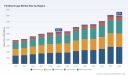
Fertility Drugs Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s latest market study on Fertility Drugs synthesizes five years of historical dynamics and a forward-looking seven-year forecast to give executives, investors, and policy-makers the actionable intelligence they need for 2026 planning. Anchored on a 2025 base year and an independently modeled forecast through 2032, the report combines granular commercial scenarios, supply-chain stress testing, and competitor playbooks to inform high-stakes choices across R&D, manufacturing, and go-to-market strategy.
Fertility Drugs Market
Market at a Glance: Robust Growth, Concentrated Supply
From 2020 through 2025 the global fertility drugs market expanded from roughly USD 3.95 billion to about USD 5.32 billion, reflecting sustained demand for assisted reproductive technologies and wider therapeutic use of fertility agents. PW Consulting’s forecast anticipates continued expansion from 2026, with a compound annual growth rate of approximately 6.1% over the 2026–2032 horizon, arriving at a market size in the vicinity of USD 8.05 billion by 2032.
Fertility Drugs Market
Two structural observations are vital for strategic planners: first, the market is meaningfully concentrated at the top—our concentration metrics show that the three largest players control a commanding share of revenue, with the top five firms representing an even larger portion. Second, revenue remains skewed toward biologics and injectable formats, which drives different commercial, regulatory, and manufacturing considerations than markets dominated by oral generics.
Fertility Drugs Market
Why 2026 Is a Pivotal Year for Corporate Decision-Making
- Policy pressure and pricing reform: Recent policy initiatives, including government-backed programs introduced in late 2025 that target IVF drug pricing, are reshaping payer dynamics and creating new reimbursement risk and opportunity. Companies must present defensible value-for-money propositions and new distribution models that align with emerging public procurement mechanics.
- Supply fragility and raw material risk: Shortage updates for key gonadotropins in 2026 highlight the fragility in biologics supply chains. Organizations that can de-risk active pharmaceutical ingredient access and scale flexible manufacturing will obtain a near-term competitive advantage and preserve clinic relationships.
- Generics and biosimilar momentum: The market is entering a phase in which launches of generics and biosimilars for core fertility agents are accelerating. This will pressure prices in certain segments and open choices for payers and clinics—requiring incumbent innovators to rethink lifecycle and access strategies.
Report Deliverables: Practical Tools for Executives
The PW Consulting report is intentionally operational. Rather than providing static charts, it equips decision makers with models and playbooks they can apply directly to 2026 initiatives. Key deliverables include:
- Revenue and scenario models: A set of deterministic and probabilistic models covering base, accelerated-generic, and disruption scenarios—calibrated to our 2026–2032 forecast. These models support sensitivity tests around price erosion, reimbursement shifts, and clinic utilization changes.
- Launch and access playbooks: Tactical guidance for new compound introductions, biosimilar market entry, and line extensions—covering pricing corridors, formulary submission timing, and clinic partnership frameworks.
- Supply-chain resilience tool kit: A prioritized set of interventions (dual-sourcing strategies, contract manufacturing partnerships, fill/finish optimization, and inventory hedging templates) tailored to biologics-heavy portfolios.
- Payer and procurement impact assessments: Country-level reimbursement scenarios and payer negotiation scripts that reflect evolving public initiatives and private clinic networks.
- Competitive response playbooks: Market-entry, defense, and consolidation tactics specific to the fertility drugs landscape, with actionable M&A scouting lists and partnering archetypes.
Competitive Landscape: Strategic Implications for 2026
The competitive map combines large multinational innovators, specialized reproductive medicine players, and a growing cohort of generics and biosimilar entrants. Our analysis of incumbents and challengers yields the following strategic takeaways:
- Incumbent innovators (e.g., established branded portfolios): Firms with comprehensive fertility portfolios retain scale advantages in clinic relationships, clinical evidence, and integrated service offerings. To defend position in 2026 they should prioritize: (a) value-based contracting pilots with large clinic groups and payers, (b) manufacturing partnerships to shore up supply, and (c) targeted lifecycle investments—such as digital adherence and bundled services—that increase switching costs.
- Specialist reproductive medicine companies: These players can exploit clinical intimacy and product specificity to maintain margin resilience. Strategic options include co-development of biosimilars with regional partners, exclusive clinic agreements, and development of adjacent services (e.g., diagnostics, patient navigation) to deepen revenue per patient.
- Large diversified pharma: Global pharma companies bring scale manufacturing, regulatory muscle, and distribution reach—assets that facilitate rapid response to shortages and large procurement opportunities. However, to compete in price-sensitive segments they will need lean product versions, focused go-to-market models, and often local partnerships.
- Generics and biosimilar entrants: Cost-driven manufacturers in India, China, and established generic players are poised to exploit price arbitrage and address shortages. Their success will hinge on regulatory approvals, supply reliability, and strategic partnerships with clinic networks.
Recent industry developments reinforce these dynamics. The market has seen generic launches of core ovulation-inducing agents and expanded access to generic antagonists, while regulators have issued shortage notices for critical gonadotropins—amplifying opportunity for biosimilars and alternative supply chains.
Key Strategic Moves for 2026
For executive teams planning 2026 priorities, PW Consulting recommends a three-pillar approach:
- Defend revenue through differentiated value: Invest in bundled care offerings, digital adherence tools, and clinic-level service packages that make switching to lower-cost alternatives less attractive for physicians and patients.
- Prepare for biosimilar and generic pressure: Accelerate biosimilar development where scientifically and commercially viable; pursue licensing or co-marketing agreements to capture volume economics; and deploy selective price-led tactics in low-margin segments.
- Harden supply and margin resilience: Map critical raw materials and biologics nodes, qualify alternate suppliers, and negotiate flexible contract-manufacturing arrangements that can be scaled under shortage scenarios.
What Our Competitive Profiles Reveal
Our company-level profiling goes beyond product lists to assess strategic posture—R&D pipelines, manufacturing footprints, commercial reach, and partnership appetites. Examples of insights readers will find in the full report:
- How leaders with established gonadotropin portfolios can leverage clinical evidence and patient-support programs to sustain premium pricing in key markets.
- Where specialist companies should focus clinical and market access investments to convert performance advantages into share gains.
- How large pharmas can deploy global supply chains to arbitrage shortages and rapidly scale generic or biosimilar introductions where regulatory paths are favorable.
- Which generics manufacturers are positioned to capitalize on short-term supply gaps and lower-cost clinic channels—creating near-term volume opportunities.
Regulatory and Reimbursement Watch — Implications for Action
Regulatory shifts and reimbursement reform are accelerating. Recent policy statements targeting IVF drug pricing introduce a new layer of public procurement dynamics, and agency shortage notices have already changed clinic behavior. Our report includes an up-to-the-minute regulatory tracker and practical templates for engaging with payers and regulators—essential for companies that must balance patient access with commercial viability.
Next Steps: How to Use This Intelligence
PW Consulting’s Fertility Drugs Market report is designed as both a strategic compass and a tactical manual for 2026. Companies engaged in any of the following will find immediate value:
- R&D leaders prioritizing biosimilar or reformulation projects;
- Commercial teams planning market access, pricing, and clinic partnerships under new procurement regimes;
- Supply-chain and operations executives building resilience into biologics manufacturing footprints;
- Investors and corporate development teams evaluating M&A targets, partnerships, and licensing opportunities.
To preserve the strategic edge for our clients, PW Consulting has deliberately presented overarching market sizing, concentration metrics, and forward growth rates here while reserving detailed segment-level matrices, country-by-country forecasts, and proprietary price-elasticity models for the full report. Those datasets and our interactive scenario models enable precise quantification of revenue risk and opportunity at the product, regional, and channel level.
Accessing the Full Analysis
For decision teams preparing budgets, partner strategies, or R&D roadmaps for 2026, the full PW Consulting report provides the empirical backbone necessary to commit capital with confidence. The comprehensive package includes downloadable models, competitor scorecards, and bespoke consulting hours for tailored workshops.
Contact PW Consulting to arrange a briefing and to obtain the full dataset and scenario tools that underpin the findings summarized above. Our team stands ready to help translate these market dynamics into defensible, revenue-driving actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fertility Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


