



Category: market research
Fire Pump Market to Hit $665M by 2032: Why 4.96% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
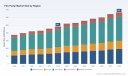
Global Fire Pump Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
The fire pump sector has evolved from a commoditized infrastructure component into a strategically differentiated business segment where reliability, regulatory compliance, and technical integration define market positioning. Over the historical review window from 2020 through 2025, global market revenue expanded from approximately 375 million USD to 482 million USD, reflecting a compound annual growth rate of 4.96 percent. Forward projections through 2032 indicate continued expansion toward roughly 665 million USD, driven by sustained capital formation in commercial real estate, industrial facilities, and offshore energy infrastructure. The trajectory is not uniform. Growth phases are shaped by regulatory cycles, regional construction activity, raw material volatility, and the pace at which manufacturers integrate monitoring capabilities, hydraulic efficiency, and application-specific engineering into product portfolios.
The market structure remains moderately concentrated. Three leading players collectively account for approximately 45 percent of total revenue, while the top five capture around 55 percent. This concentration level indicates a sector where established manufacturers hold meaningful share through product breadth, certification expertise, and long-term service relationships, yet it also leaves meaningful room for regional specialists, project-driven integrators, and technology-enabled entrants to capture niche positions. For executive teams evaluating exposure to fire protection equipment, the landscape presents a blend of stable baseline demand, cyclical project volatility, and clear differentiation opportunities for firms that can align product development with compliance evolution and end-user operational expectations.
Core Macro Dynamics and Structural Shifts
The revenue curve over the 2020 to 2025 period demonstrates steady expansion rather than explosive growth, which is typical of essential safety equipment markets where demand is anchored to building codes, industrial capacity additions, and asset life-cycle replacement programs. The moderation in growth velocity after the early post-2020 recovery reflects a normalization phase in which supply chains adjusted to elevated input costs, lead-time variability, and workforce constraints in fabrication and testing operations. As the market moves through the 2026 to 2032 forecast horizon, growth is expected to be sustained by ongoing urban development, industrial modernization, and energy sector projects that require integrated pump skids and high-pressure fire protection systems.
Three structural challenges define the current inflection point. First, raw material cost variability, particularly in steel-intensive pump housings, casings, and skid assemblies, introduces margin pressure and pricing complexity. Recent market data indicates that US steel prices averaged approximately 1,086 USD per metric ton in May 2026, up 3.5 percent from April, with hot-rolled coil near 1,109 USD per ton in June 2026. For manufacturers, this environment demands disciplined cost management, hedging strategies, and product engineering that reduces material intensity without compromising hydraulic performance or code compliance.
Second, regulatory frameworks continue to shape procurement cycles and product qualification requirements. The NFPA 20 Standard for the Installation of Stationary Pumps for Fire Protection remains the foundational reference for selection and installation as of 2026, while ASSE 15010 water-based fire protection certification qualifications and processes are undergoing changes beginning in early 2025 for inspection and testing of fire pumps. For suppliers and specifiers, evolving certification expectations create both administrative burden and competitive advantage for organizations that can streamline compliance, documentation, and field verification.
Third, the market faces an ongoing tension between standardization and customization. End-users in commercial building sectors increasingly favor packaged pump systems and compact configurations that simplify installation and maintenance, while oil and gas, marine, and large industrial facilities require engineered solutions that address site-specific pressure, flow, and environmental conditions. Balancing these demands requires manufacturing flexibility, modular design philosophies, and service teams capable of supporting both off-the-shelf and project-engineered deployments.
Key Drivers Shaping Market Trajectory
Technology Innovation and Monitoring Integration
A defining trend in the fire pump sector is the transition from purely mechanical reliability to connected, condition-aware systems. Historically, fire pumps were evaluated primarily on flow capability, pressure performance, and durability under intermittent duty cycles. Today, manufacturers are embedding telemetry, remote status monitoring, and diagnostic interfaces that enable facility operators and service contractors to track run-hours, alarm states, and performance deviations without manual inspection alone. This shift aligns with broader operational expectations in commercial real estate and industrial facilities, where uptime assurance, predictive maintenance, and rapid response capability are increasingly tied to asset management strategies.
Product launches in recent months illustrate this direction. In January 2026, Armstrong Fluid Technology introduced a new range of Constant Speed Vertical-In-Line Fire Pumps with high-pressure ratings up to 160 PSI for both 60Hz and 50Hz markets. The expansion into higher-pressure vertical in-line configurations reflects demand for compact, high-performance solutions suitable for taller buildings, space-constrained mechanical rooms, and applications where vertical footprint limitations constrain traditional horizontal installations. Vertical in-line designs also appeal to specifiers seeking reduced installation complexity and simplified alignment, provided the hydraulic and reliability requirements are met for the intended duty point.
Regulatory Environment and Certification Evolution
Regulation is not merely a constraint in this market; it is a design parameter and a commercial gate. NFPA 20 continues to define the baseline expectations for stationary fire pump selection and installation, creating a shared technical language across manufacturers, engineering firms, authorities having jurisdiction, and service providers. At the same time, evolving certification processes such as the ASSE 15010 updates introduce new scrutiny around inspection and testing practices. For manufacturers, the practical implication is that product approval, documentation rigor, and test protocol alignment are becoming differentiators in bidding and specification capture. Firms that invest early in certification readiness and clear compliance narratives tend to reduce deployment friction and improve win rates in regulated markets.
For purchasers and engineering teams, regulatory dynamism creates the need for supplier partners who can interpret standards consistently across regions and project types. In practice, this means that product capability alone is insufficient unless accompanied by repeatable installation guidance, commissioning support, and post-installation testing documentation that satisfies jurisdictional requirements. The regulatory layer therefore reinforces the value of established brands and technically credible service networks, while also opening opportunities for manufacturers that can simplify compliance through integrated documentation packages and standardized test evidence.
Demand-Side Changes in Commercial and Industrial Sectors
Demand patterns are shaped by the interplay of construction pipelines, facility modernization programs, and risk management priorities. Commercial buildings remain a dominant application area, with fire pump demand linked to new development, code-driven renovations, and replacement cycles in aging mechanical systems. Industrial facilities represent the second major demand pillar, where fire protection requirements intersect with process safety, hazardous area considerations, and large-scale infrastructure planning. In both segments, purchasers are increasingly focused on lifecycle economics rather than lowest initial equipment cost, which advantages solutions that combine reliability, serviceability, and remote monitoring capabilities.
Water Pumps Market
In parallel, energy sector activity continues to influence demand for engineered fire pump skids and high-pressure systems. Contract awards such as Sulzer’s November 2025 win for multiple integrated pump skids for Petrobras P-84 and P-85 FPSOs, with delivery in early 2026, underscore how offshore and large industrial projects generate specialized demand for integrated packages rather than standalone pump units. These projects reward suppliers with skid integration expertise, application engineering depth, and the ability to deliver systems that meet both fire protection and broader process interface requirements.
Supply Chain Resilience and Cost Structure Adaptation
The sector’s cost structure is sensitive to steel pricing, casting lead times, machining capacity, and the availability of qualified assembly and test labor. Companies that have strengthened supply chain resilience through multi-sourcing, forward inventory positioning, and modular subassembly strategies are better positioned to maintain delivery reliability during input price spikes. Equally important is product design discipline: pumps and skid systems that optimize material usage, standardize components across product lines, and reduce rework in fabrication can absorb input cost pressure more effectively than less standardized designs.
From a commercial standpoint, this environment favors manufacturers that can offer transparent pricing mechanisms, delivery certainty, and configuration flexibility. Procurement teams are increasingly weighing supplier reliability and compliance readiness against unit price, particularly for projects where delay costs and inspection risks are significant. This dynamic reinforces the strategic value of regional manufacturing footprints, localized service capabilities, and strong relationships with distributors and installation contractors.
Competitive Landscape and Strategic Positioning
Differentiation Vectors Among Leading Players
The market’s leading participants compete across several overlapping dimensions: product range breadth, application-specific engineering, certification depth, service networks, and increasingly, digital monitoring and integration. Pentair manufactures Aurora and Fairbanks Nijhuis fire pumps in horizontal and vertical configurations for global fire protection systems, positioning itself around established brand lines and a broad configuration portfolio. Grundfos produces fire pumps within a wider pump portfolio, leveraging its broader hydraulic competence and distribution relationships. NAFFCO offers fire protection pumps and related equipment for commercial and industrial use, often competing on regional responsiveness and bundled system solutions in Middle East and broader project markets.
Flowserve supplies industrial pumps including fire pump solutions, drawing on its broader engineered pump capabilities and industrial service infrastructure. Sulzer provides integrated fire pump skids and solutions for oil and gas and general fire protection, which aligns well with project-based demand where skid-level integration and application engineering matter. Kirloskar Brothers manufactures fire pumps for municipal and industrial applications, reflecting strength in regional manufacturing and cost-competitive engineering. SPP Pumps produces specialist fire pumps for fixed and portable systems, and Peerless Pump Company designs and manufactures horizontal and vertical fire pumps, including its FireConnect monitoring system, which illustrates how traditional pump manufacturers are extending into connected diagnostics to differentiate their offerings.
Armstrong Fluid Technology offers end-suction, horizontal, vertical in-line, and multi-stage fire pumps, giving it coverage across common commercial and industrial configurations. Rosenbauer produces fire pump systems integrated into fire trucks and apparatus, representing a distinct adjacency where pump capability is embedded into mobile fire suppression platforms. Waterous has manufactured US-made fire pumps, engines, and suppression equipment since 1886, competing on legacy, domestic production, and specialized suppression system integration. CET Fire Pumps MFG Inc. produces portable fire pumps with gas and diesel engines, plus skid units and foam systems, addressing niche mobile and specialized suppression needs. Xylem provides fire pumps under the AC brand for municipal and industrial fire protection, leveraging its broader water technology and infrastructure positioning.
Filter Pump Market
Market Concentration and Evolution Patterns
With a three-firm concentration near 45 percent and a five-firm concentration near 55 percent, the market is consolidated enough that scale, certification portfolios, and global distribution matter, yet fragmented enough that specialized players can win on application fit, regional proximity, and service agility. Over the next several years, two evolutionary patterns are likely to persist. The first is selective consolidation through capability acquisition, particularly where a manufacturer seeks broader product coverage, stronger skid integration capabilities, or access to a specialized monitoring or control technology. The second is continued differentiation among regional and application-focused players who compete on responsiveness, local certification expertise, and integration with local engineering and contractor ecosystems.
New entrants face meaningful barriers in this market, including code familiarity, test and certification requirements, service network expectations, and the need for reliable production quality. However, entry opportunities exist where modular packaged systems, compact vertical configurations, and connected monitoring reduce installation complexity and improve service economics. Companies that can demonstrate consistent compliance documentation, predictable lead times, and strong field support can gain traction even in competitive bidding environments.
Forward-Looking Trends and Commercial Implications
Trend One: Connected Diagnostics as a Standard Expectation
Remote monitoring and condition awareness are likely to move from premium option to expected capability in a growing share of commercial and industrial applications. As facility operators consolidate maintenance workflows and seek earlier warning of mechanical or electrical anomalies, pumps equipped with status telemetry, fault logging, and integration-friendly interfaces will be easier to specify and retain in service. The commercial implication is that manufacturers offering genuine monitoring value—rather than superficial connectivity—will improve after-service revenue potential and strengthen customer retention. A practical risk is that monitoring features must be supported by reliable data infrastructure, cybersecurity considerations, and service processes capable of acting on the information collected.
Trend Two: High-Pressure and Compact Vertical Solutions Gaining Share
The expansion of high-pressure vertical in-line options reflects demand for space-efficient, high-performance configurations suitable for tall buildings, constrained mechanical rooms, and applications where footprint and installation simplicity matter. This trend favors manufacturers that can deliver reliable vertical designs with robust sealing, alignment, and bearing arrangements while meeting code requirements across 50Hz and 60Hz regions. For procurement teams, compact and high-pressure solutions can reduce installation cost and improve building layout flexibility, but they require careful specification to ensure duty-point suitability and long-term serviceability.
Trend Three: Integrated Skid and Application-Engineered Packages in Energy and Industrial Projects
Offshore and large industrial projects continue to create demand for integrated skid systems that combine pumps, drivers, controls, and interface engineering into coordinated packages. Contract awards in FPSO and similar large-scale energy projects demonstrate that suppliers with skid integration capability and application-specific design competence can secure high-value projects even in concentrated markets. The commercial opportunity lies in expanding from component supply to system-level value creation, where integration reduces field engineering burden and improves commissioning reliability. A key uncertainty is project timing and capital expenditure variability in energy markets, which can shift demand from steady pipelines to episodic large contracts.
Strategic Implications for Decision-Makers
For Fire Pump Manufacturers and Integrators
- Align product roadmaps with compliance evolution and monitoring expectations. Invest in certification readiness, documentation clarity, and telemetry features that deliver actionable maintenance insight rather than simple data visibility.
- Strengthen cost and supply chain resilience. Standardize key components, manage steel exposure through procurement discipline and design efficiency, and protect delivery reliability during input price volatility.
- Expand toward system-level value where appropriate. Skid integration, packaged systems, and application-specific engineering can improve project margins and differentiate offerings in industrial, energy, and complex commercial deployments.
- Build service-aligned commercial models. In a market where uptime, installation correctness, and compliance documentation matter, service responsiveness and commissioning support can be as decisive as product specifications.
For Investors and Strategic Acquirers
- Prioritize businesses with durable compliance positioning, recurring service relationships, and credible monitoring or integration capabilities. Brand heritage alone is insufficient without modern product support and service economics.
- Evaluate regional specialists for capability tuck-ins. Strong local certification knowledge, contractor relationships, and application focus can complement broader platforms and accelerate entry into specific geographies or end markets.
- Monitor steel cost exposure and margin discipline as part of due diligence. Companies with standardized designs, flexible sourcing, and transparent cost pass-through mechanisms are better positioned to preserve profitability when input prices fluctuate.
- Watch for consolidation driven by product coverage gaps and digital capability needs. Targets that add vertical configurations, packaged systems, or connected diagnostics may offer strategic leverage beyond revenue scale.
For Procurement, Engineering, and Facility Decision-Makers
- Evaluate total lifecycle value rather than initial price alone. Installation complexity, commissioning support, compliance documentation, and serviceability can materially affect operating risk and long-term cost.
- Specify with monitoring and serviceability in mind. Where uptime assurance is critical, select configurations that enable condition tracking and simpler field support, and ensure that service providers can act on the data provided.
- Confirm compliance readiness early. Verify that proposed pump systems align with NFPA 20 expectations and current inspection and testing practices, including any changes to certification processes, to avoid delays during commissioning and jurisdictional review.
- Plan for supply-side variability. Given steel price movements and project timing risk, include delivery certainty, lead-time transparency, and contingency planning in procurement decisions, especially for time-sensitive commercial and industrial projects.
The fire pump market is entering a phase in which growth is supported by steady demand fundamentals, but competitive outcomes will increasingly depend on compliance mastery, product differentiation, and the ability to deliver reliable installation and service performance. The most compelling commercial opportunities will accrue to manufacturers and integrators that combine technical breadth with execution discipline, and to buyers who specify with lifecycle performance and regulatory alignment in mind. For teams that require detailed segmentation data, regional demand patterns, type-level revenue splits, and company-level competitive profiles to support planning and investment decisions, the full research report provides expanded datasets and tailored scenarios that build on the strategic direction outlined here.
PW Consulting
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
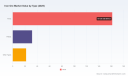
The Iron Ore Market at a Strategic Inflection Point: Navigating Growth, Disruption, and Value Creation
The global iron ore market is entering a phase defined by steady expansion layered with structural volatility. Valued at approximately $215.0 billion in 2025, the market has demonstrated consistent upward momentum since 2020, reflecting a compound annual growth rate of 3.9% through the 2032 forecast horizon. This trajectory projects the sector past the $340 billion threshold by the end of the decade, driven by sustained steel production, evolving metallurgical demands, and shifting trade dynamics. The numbers tell a story of durable demand, but beneath the aggregate figures lies a more complex reality: capacity expansions, regulatory shocks, price normalization, and strategic realignments are reshaping how value is captured across the supply chain. For executives, investors, and procurement leaders, the imperative is no longer simply tracking volume growth. It is understanding where margins will compress, where premium differentiation will emerge, and how supply architecture will reorganize in response to policy and technology shifts.
Market Context and the Core Challenges Defining This Cycle
The iron ore sector’s expansion from roughly $163 billion in 2020 to the $215 billion midpoint in 2025 reflects a market that has absorbed pandemic-era disruptions, supply chain recalibrations, and cyclical price swings while maintaining a clear growth path. Yet the headline trajectory masks three interconnected challenges that will dictate competitive outcomes over the next several years.
First, price normalization is compressing revenue expectations for operators that relied on elevated unit values to justify capital expenditures and margin expansion. After averaging above $112 per ton in the first nine months of 2024, global iron ore unit values declined to approximately $99 per ton in the comparable period of 2025. This pull-back matters because pricing discipline is no longer guaranteed by tight supply alone; buyers are increasingly sophisticated, alternative raw materials are gaining traction in specific metallurgical applications, and freight and logistics costs continue to introduce volatility into realized pricing. Operators and traders must now plan for a regime where volume growth, grade optimization, and cost efficiency matter more than riding a rising price cycle.
Second, regulatory interventions are fragmenting trade flows and forcing regional repositioning. The restoration and escalation of steel tariffs on imports from all countries, raised to a 50% level effective in early 2025, has reshaped the competitive calculus for exporters targeting North American markets. Tariffs of this magnitude do not merely raise costs; they alter sourcing strategies, incentivize domestic production where feasible, and compress the economics of long-distance iron ore shipments into protected markets. This creates a bifurcated landscape: regions with integrated steel ecosystems and policy support can defend share, while export-dependent operators must navigate narrower margins and more complex negotiation dynamics with steelmakers seeking to manage input costs.
Third, the structural transition toward lower-emission steelmaking is introducing both opportunity and friction. Direct reduction pathways and alternative feedstock requirements are growing, but the capital intensity of conversion, the availability of suitable iron ore grades, and the readiness of downstream infrastructure mean that demand shifts will be uneven across regions and customer segments. The market is not moving in a single direction; it is splitting into metallurgical niches where premium fines, specialized pellets, and consistent quality specifications command different pricing logic than commoditized volumes. Companies that treat iron ore as a homogeneous bulk commodity will face increasing difficulty in defending position as customers tailor input strategies to decarbonization targets and operational flexibility.
The Forces Reshaping Supply, Demand, and Competitive Positioning
The iron ore market’s evolution is being driven by a set of interlocking forces that extend beyond cyclical supply and demand. Understanding these drivers is essential for identifying where growth will be durable and where exposure will be most vulnerable.
Technology and metallurgical innovation are redefining what constitutes valuable iron ore. As steelmakers evaluate direct reduction, hydrogen-enabled pathways, and more efficient blast furnace operations, the premium attached to consistent high-grade material, low impurities, and predictable granulometry is increasing. Operations that can deliver concentrate and pellet feed with tight specification control are better positioned to capture margin resilience, particularly in segments where metallurgical performance translates directly into energy savings or emission reductions downstream. Technology-driven differentiation is not limited to the mine site; it extends to beneficiation capabilities, logistics optimization, and the ability to align product specs with customer conversion processes. In this environment, the value of a tonne is increasingly a function of what it enables rather than what it weighs.
Policy and regulatory environments are becoming a decisive competitive variable. Trade policy is no longer a background condition; it is an active determinant of routing, customer mix, and pricing power. The imposition of higher steel import tariffs has intensified the strategic importance of local and regional supply security for steel producers, while simultaneously pressuring exporters to identify alternative demand centers or negotiate terms that account for policy-driven cost structures. Regulatory trajectories around emissions, mining approvals, and indigenous or community agreements also influence the speed and cost of capacity additions. Projects that can align with clear regulatory frameworks and long-term development agreements gain a meaningful advantage in execution certainty, while operators facing shifting approval regimes or policy volatility must price that risk into their expansion plans.
Demand-side behavior is shifting as steel producers balance volume requirements with cost control and decarbonization mandates. The largest application segment for iron ore remains steel production, and that anchor demand provides the market’s underlying stability. However, buyer behavior is becoming more segmented. Large integrated steelmakers are increasingly negotiating around grade consistency, delivery reliability, and total cost of conversion rather than focusing solely on spot price movements. At the same time, direct reduction and other alternative processes are expanding their share of attention, creating incremental demand for materials suited to those pathways. The practical implication is that demand is consolidating around relationships and specifications, not just price. Suppliers that can demonstrate operational consistency and align product attributes with customer process requirements are better positioned to secure longer-term arrangement stability, even in a normalizing price environment.
Supply chain and cost structure dynamics are reshaping where and how iron ore reaches markets. Logistics remains a critical lever in realized economics, particularly for long-haul export routes. Any disruption in port capacity, rail throughput, or maritime freight introduces volatility that can erode the advantage of low-grade-cost production. At the same time, cost structures are being tested by the need to maintain output while managing inflation in energy, labor, and capital equipment. The operators that navigate this phase effectively are those treating the supply chain as an integrated system: mine planning, processing efficiency, stockpile management, and shipping coordination are increasingly evaluated as a single margin equation rather than separate functions. In a market where unit values have moderated, the ability to reduce cost per tonne and protect throughput continuity becomes a primary source of competitive advantage.
Competitive Landscape: Positioning, Differentiation, and the Evolving Structure of the Market
The iron ore market remains concentrative, with a relatively small group of large-scale operators controlling a substantial share of global supply. This concentration creates a landscape where scale, asset quality, and strategic optionality matter enormously. Yet the competitive dynamics are not static. Recent operational milestones, project developments, and regional adjustments illustrate how the leading players are actively reshaping their positions.
The major integrated producers continue to compete on the basis of tonnage reliability, ore quality, and the ability to sustain output through market cycles. Operations anchored in established mining complexes with mature infrastructure benefit from scale economics and logistics familiarity, while also facing the ongoing challenge of maintaining production levels, managing stockpile balances, and responding to cost pressures. In this context, the recent achievement of record Pilbara output by one of the leading Australian producers, alongside the first ore shipment from the Simandou high-grade project in Guinea, highlights two contrasting but complementary strategic thrusts: maximizing the productivity of long-established assets while opening new high-grade supply corridors that can shift grade mix and market access over time. The shipment of a significant cumulative volume milestone from the Pilbara region further underscores how legacy operations remain central to global supply, even as new projects begin to contribute incremental tonnage.
Worldwide Iron Ore Trade Market
In South America, a leading Brazilian producer recently reached a seven-year high in iron ore output, surpassing a key Pilbara-based peer’s volume for the first time since 2018. This reversal is strategically significant because it shows that operational reliability and capacity execution can alter the ranking of major suppliers within a single cycle. For the market, it signals that the balance of supply between established regions is not fixed; it responds to operational performance, infrastructure utilization, and the ability to keep complex mining and logistics systems running at target levels. Premium concentrate, fines, and pellet offerings from major Brazilian and South African operations continue to play a differentiated role, particularly for customers seeking material that supports specific metallurgical outcomes.
The competitive picture also includes producers with more regionally concentrated footprints. In North America, a major domestic steel and mining company’s decision to idle portions of its Minnesota operations as part of a stockpile reduction strategy reflects a more tactical approach to balancing supply, inventory, and market conditions. The resulting decline in U.S. domestic iron ore production illustrates how quickly regional supply can adjust when operators choose inventory discipline or cost management over volume retention. This kind of localized adjustment matters because it interacts directly with policy-driven demand dynamics. When import tariffs raise the cost of foreign material, domestic supply becomes more strategically valuable, but only if it is available at a competitive cost and in sufficient quantity to support steelmaking schedules.
Steelmakers with integrated mining interests add another layer to the competitive landscape. By controlling upstream supply in select assets, these companies can better align raw material availability with steel production planning, reduce exposure to spot market volatility, and support longer-term operational continuity. Recent infrastructure expansion in Liberia, including the completion of a new concentrator facility and the extension of a long-term mineral development agreement, demonstrates how integrated players are building longer-duration supply visibility in emerging regions. This type of move is not merely about adding tonnage; it is about securing a predictable input base that supports downstream strategic planning over decades rather than quarters.
Taken together, the competitive landscape is evolving along several axes. Scale remains essential, but it is no longer sufficient on its own. Differentiation is increasingly tied to grade consistency, logistical reliability, regional access, and the ability to align product specifications with evolving steelmaking requirements. At the same time, the market is not moving toward uniform consolidation. Instead, it is developing pockets of integration around key supply corridors and customer relationships, while leaving room for specialized operators that can serve premium or regionally targeted niches. New entrants and project developers face high barriers in the form of capital intensity, permitting complexity, and the need to establish reliable offtake and logistics arrangements, but targeted projects that can deliver distinctive grade profiles or open new export routes can still alter local competitive dynamics.
What the Next Three to Five Years Will Likely Bring
The iron ore market’s medium-term trajectory will be shaped by the interaction of demand durability, supply execution, policy direction, and metallurgical transition. Several trends are likely to define strategic outcomes over the next three to five years.
Trend one: volume growth will continue, but margin capture will depend on grade and specification management. The market is projected to expand steadily toward the mid-2030s, supported by ongoing steel production and incremental demand from alternative reduction pathways. However, as unit values moderate and buyers become more selective, the ability to command premium realization will increasingly hinge on product consistency, impurity control, and alignment with customer processes. Suppliers that can reliably deliver high-quality fines and pellets with predictable metallurgical behavior will be better positioned to preserve pricing leverage, while those competing primarily on volume may face greater pressure from both substitutes and more demanding procurement standards.
Trend two: trade policy and regional supply security will redraw procurement maps. Tariff structures, domestic production levels, and logistics constraints are likely to keep regional sourcing strategies in sharp focus. In markets where import costs are elevated by policy, steelmakers will continue to weigh the trade-off between domestic supply, established export relationships, and the operational implications of switching sources. This does not mean globalization retreats entirely, but it does mean that supply routing will be more deliberately engineered. Exporters with diversified destination markets, flexible logistics, and credible grade offerings will have more optionality, while those heavily exposed to a single policy-sensitive corridor will need to plan for discontinuity and negotiate accordingly.
Trend three: decarbonization-driven demand segmentation will accelerate, but unevenly. The shift toward lower-emission steelmaking will not unfold at the same pace across every region or producer. Some customers will pursue direct reduction and related pathways more aggressively, increasing interest in materials that support those processes. Others will continue to optimize blast furnace operations and look for iron ore attributes that reduce energy intensity or improve yield. The result will be a more segmented demand environment in which premium product lines, specialized pellets, and consistent concentrate supply gain relative importance. Companies that invest early in understanding customer conversion needs and align product development with those requirements will have an advantage in securing more resilient demand channels.
Carbonate Ore Market
These trends create commercial opportunity, but they also carry risk. Price volatility may persist if macroeconomic conditions, freight markets, or policy adjustments shift quickly. Capital projects can face delays from permitting, community engagement, or cost inflation, altering the timing and composition of new supply. And the pace of metallurgical transition may be slower or faster than anticipated, affecting the trajectory of demand for specific grades and product forms. Strategic planning must therefore account for multiple scenarios rather than a single linear forecast.
Strategic Actions for Decision-Makers
For steel manufacturers and integrated producers, the priority is to treat iron ore procurement as a strategic input system rather than a commodity purchasing function. That means investing in supplier relationships that deliver specification reliability, evaluating total cost of conversion rather than nominal price alone, and building sourcing flexibility that can respond to tariff changes or logistics disruptions. Where feasible, securing longer-term supply visibility through structured agreements or integrated access can reduce exposure to abrupt market shifts, particularly in policy-sensitive regions. At the same time, manufacturers should monitor how customer-facing decarbonization targets affect raw material requirements, and align internal planning with the grade and form factors that support those goals.
For investors and capital allocators, the opportunity lies in distinguishing between operators that are built for volume exposure and those that can capture value through differentiation and execution discipline. Assets with strong logistics integration, consistent high-grade output, and credible cost control are better positioned to perform across a range of price environments. Equally important is the regulatory and project execution profile of new supply. Developments that combine clear alignment with local agreements, defined export routes, and metallurgically valuable product characteristics offer more resilient upside than undifferentiated tonnage additions. Portfolio exposure should also account for regional policy risk, especially where tariff or trade policy changes can rapidly alter the attractiveness of specific supply corridors.
For procurement leaders and supply chain decision-makers, resilience should be designed into sourcing strategies before disruption forces a reaction. That includes maintaining visibility into multiple qualified suppliers, understanding the specification dependencies of internal steelmaking or fabrication processes, and stress-testing the impact of freight fluctuations and policy changes on total landed cost. Stockpile and inventory strategies should be evaluated not only for working capital implications but also for their effect on operational continuity if supply interruptions occur. In an environment where unit values can shift and trade policy can reshape relative costs quickly, the organizations that perform best will be those that combine cost discipline with optionality and deep supplier intelligence.
PW Consulting
The iron ore market is large enough to absorb disruption and flexible enough to reward precision. The winners in the next phase will be those who move beyond aggregate growth assumptions and build decisions around grade strategy, regulatory exposure, logistics resilience, and customer-aligned product value. For organizations that need granular segment data, regional cost structures, and customized scenario planning to support those choices, a full research report with detailed segmentation, competitive benchmarking, and forward-looking market modeling can provide the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Iron Ore Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Irrigation Controllers Market: Why 8.82% CAGR & Sensor Shifts Redefine Growth
By PW Consulting, 2026-09-21
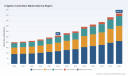
Strategic Outlook: Navigating Growth and Transformation in the Irrigation Controllers Market
Market Trajectory and Core Challenges
The global irrigation controllers market is entering a period of sustained expansion, driven by the intersection of resource scarcity, technological maturity, and regulatory alignment. Measured in USD millions, the market has grown from approximately 200 million in 2020 to 260 million in 2025, reflecting a compound annual growth rate of 8.82 percent across the historical and forecast window extending to 2032. By the end of the outlook period, market revenue is projected to reach 465.56 million, signaling a structural acceleration rather than a cyclical upturn. This trajectory is underpinned by consistent year-over-year gains, with growth steepening notably in the latter half of the forecast as smart controller adoption moves from early-adopter segments into mainstream commercial and agricultural deployments.
Despite the favorable macro outlook, the industry faces several inflection points that will shape competitive outcomes over the next five years. First, regulatory fragmentation is intensifying. Water efficiency mandates, certification requirements, and rebate architectures vary widely across jurisdictions, creating compliance complexity for manufacturers seeking scale. Second, material cost volatility and trade policy shifts are compressing margins in the short term while forcing supply chain reconfiguration. Third, the definition of "connected" is evolving rapidly. Early smart controllers relied on basic scheduling and remote access; the next generation integrates real-time sensor feedback, predictive weather modeling, and interoperability with broader water management ecosystems. Companies that treat connectivity as a feature rather than a platform risk losing relevance as procurement standards rise.
Key Drivers Reshaping the Market
Technology Innovation and the Shift to Adaptive Control
The transition from timer-based and fixed-schedule systems to weather-based and sensor-driven controllers represents the most consequential technical shift in the category. Weather-based controllers currently account for the largest share of product-type revenue, reflecting their broad applicability across residential, commercial, and agricultural settings. Sensor-based systems, however, are gaining traction in applications where precision and automation deliver measurable operational savings. The value proposition has moved beyond water conservation alone. Advanced controllers now enable labor reduction, pressure management, leak detection, and integration with centralized facility or farm management platforms. This evolution is mirrored in recent industry activity: exhibitors at the 2026 Irrigation Show, co-located with Groundwater Week in Las Vegas, showcased a wave of innovations spanning connectivity upgrades, energy-efficient designs, and hybrid control architectures. Startup winners announced at the 2025 show further highlighted emerging product directions, including alkaline battery-powered GSM controllers that extend reliable operation in off-grid or low-infrastructure environments. These developments indicate that the technology frontier is expanding in both connectivity and deployment flexibility, opening new addressable use cases.
Policy and Regulatory Dynamics as a Demand Accelerator
Regulatory frameworks are increasingly acting as both a compliance gate and a demand catalyst. The US EPA's updated WaterSense criteria for irrigation controllers, requiring independent certification for efficiency and performance with new labeled controllers available as of March 2026, establish a clearer benchmark for procurement teams and municipal buyers. Certification is becoming a de facto market access requirement in higher-value segments, particularly where public funding or rebate eligibility is tied to labeled products. At the municipal level, rebate programs are lowering the effective purchase price for end users. Programs such as the 2026 Woodbury, Minnesota initiative and the Hays, USA program offer discounts of up to 100 dollars for WaterSense-labeled smart controllers, directly stimulating adoption among residential and small commercial buyers.
State and local building codes are reinforcing this pull. In Minnesota, for example, WaterSense-certified controllers are required for all new systems installed after 2020, embedding the technology into standard construction and landscaping practice. At the same time, government-sector validation is building confidence in performance claims. The US Department of Energy's Federal Energy Management Program notes that advanced controllers, including both sensor-based and weather-based models, demonstrate water use reductions of 15 to 40 percent in federal applications. This range is significant because it spans diverse climates, system ages, and management practices, suggesting that well-deployed smart controls can deliver consistent savings across varied conditions. For commercial and institutional buyers, these documented outcomes reduce perceived risk and strengthen the business case for upgrade cycles.
Demand-Side Behavior and the Broadening Application Base
Demand is evolving along two reinforcing paths. In agriculture, controllers are increasingly positioned as components of precision farming systems rather than standalone timing devices. The emphasis is on matching irrigation output to crop needs, soil conditions, and evapotranspiration patterns, often in concert with drip and micro-irrigation infrastructure. This application orientation favors controllers that integrate with broader agronomic data flows and can operate reliably in demanding field environments. In non-agricultural settings, demand is driven by a mix of water cost sensitivity, sustainability commitments, and regulatory compliance. Commercial property managers, municipal grounds departments, and landscape contractors are all evaluating controllers through the lens of total cost of ownership, including labor savings from remote management, reduced water billing, and eligibility for incentives. The growing share of non-agricultural applications in market revenue reflects this diversification, as does the continued strength of agricultural demand in regions where irrigation efficiency directly affects yield stability and input costs.
Supply Chain and Cost Structure Pressures
Cost dynamics are introducing both constraints and opportunities. The Irrigation Association reported that a 25 percent tariff on steel and aluminum imports announced in February 2025 will increase costs for irrigation manufacturers and components. For hardware-intensive products, these input cost pressures can affect pricing strategy, margin structure, and the economics of localized production. The impact is not uniform; companies with diversified supplier bases, flexible manufacturing footprints, or higher-value product mixes may absorb or offset cost increases more effectively than those dependent on commodity-driven assemblies. At the same time, the same cost environment is accelerating interest in design efficiencies, component standardization, and software-led value creation that can differentiate offerings without proportionally increasing bill-of-materials expense. Procurement teams are increasingly weighing total cost of ownership against upfront price, which creates room for premium, certified, and integrated solutions when they can demonstrate clear operational returns.
Smart Irrigation Controllers Market
Competitive Landscape and Leading Strategies
Established Players and Divergent Positioning
The competitive set reflects a blend of established irrigation brands, precision agriculture specialists, and software-leaning control innovators. Hunter Industries, headquartered in Tualatin, Oregon, focuses on smart Wi-Fi and internet-connected controllers, including the MCC series and Hydrawise integration. Its positioning emphasizes residential and light commercial usability, remote management, and ecosystem connectivity that lowers the barrier to adoption for contractors and end users. Rain Bird Corporation, based in Glendora, California, offers modular and weather-based smart options through the ESP-ME3, LNK WiFi, and ESP-TM2 series. Its strategy leans on modularity, serviceability, and a broad installed base that supports retrofit and upgrade cycles. The Toro Company, in Bloomington, Minnesota, provides DXi central control and Irritrol Rain Master controllers for commercial and residential applications. Toro's recent catalog release effective January 2026 underscores a focus on clear product segmentation and pricing transparency across central control and distributed controller lines, catering to projects that require scalable management across multiple zones or sites.
Netafim brings a precision agriculture orientation, with digital farming and NMC Junior Pro controllers designed for drip systems and field-level control. Its value proposition is tightly linked to yield optimization, water precision, and integration with broader agricultural management practices. Galcon, operating globally from Israel, specializes in advanced smart controllers for residential, agricultural, and golf applications, emphasizing multi-zone flexibility and application-specific programmability. HydroPoint Data Systems, based in Santa Barbara, California, develops weather-based and sensor-integrated smart controllers for commercial and agricultural use, with a positioning that blends data-driven control logic and connectivity suitable for managed properties and institutional landscapes.
Market Structure and Strategic Implications
Market concentration remains elevated, with the top three companies accounting for approximately 62.5 percent of revenue and the top five representing about 78.2 percent. This concentration indicates that scale, brand recognition, distribution relationships, and installed-base advantages still matter significantly. However, concentration also masks meaningful segmentation in product architecture, application focus, and region-specific demand. The presence of strong regional and application specialists suggests that differentiation is increasingly achieved through fit rather than sheer breadth. Manufacturers that can align certification readiness, connectivity standards, and application-specific features with local rebate and code environments are better positioned to capture share in high-growth pockets. At the same time, the pipeline of startup activity and niche product launches indicates that new entrants can find openings by targeting underserved use cases, such as off-grid power options, simplified installation profiles, or specialized integrations for municipal and institutional procurement.
The competitive trajectory is likely to feature both consolidation and continued specialization. Larger incumbents may pursue tuck-in acquisitions or partnerships to expand software capabilities, sensor integration, or regional service coverage. Specialist players may deepen application expertise and certification compliance to defend and expand niches. The key differentiator over the next several years will be the ability to deliver verified performance, interoperable connectivity, and a clear path to total cost of ownership savings for the buyer, rather than connectivity alone.
Future Trends and Commercial Opportunities
Trend One: Certification-Driven Procurement and Incentive-Linked Adoption
As WaterSense labeling and state or municipal code requirements become more embedded in procurement standards, certified controllers will increasingly function as a baseline expectation in higher-value segments. The commercial opportunity lies in aligning product portfolios, documentation, and channel enablement with certification criteria and incentive architectures. Manufacturers and distributors that can streamline the path to compliant deployment, provide clear performance evidence, and support rebate navigation will gain an advantage in municipal, institutional, and regulated residential channels. For buyers, the practical implication is that selection criteria should incorporate certification status, verified water savings ranges, and compatibility with local incentive programs as standard evaluation factors.
Trend Two: Integrated Control as a Platform for Water Management
Controllers are evolving from isolated scheduling devices into nodes within broader water and site management platforms. The trend toward sensor integration, weather-based adaptation, and centralized control broadens the scope of value that can be delivered, including pressure optimization, leak indication, and multi-site management. This creates opportunities for solutions that emphasize interoperability, data usability, and service-oriented business models. For commercial property portfolios, agricultural operators, and landscape service providers, the upside is in reducing manual oversight, improving consistency across sites, and tying control decisions to operational metrics that matter to finance and sustainability teams. The risk is that fragmented ecosystems or proprietary locks can slow adoption; buyers will increasingly favor solutions that connect to existing infrastructure and reporting workflows without demanding wholesale replacement.
Trend Three: Cost and Supply Chain Realignment shaping Product Architecture
Input cost pressures and trade policy uncertainty are likely to continue influencing product design and sourcing decisions. Over the next three to five years, expect more emphasis on modular architectures, selective localization, and design choices that reduce exposure to volatile commodities while preserving performance. This environment favors companies that can balance cost discipline with differentiation through software, usability, and certified performance. For investors and manufacturers, the strategic question is whether cost pressures will consolidate supply around a smaller set of globally scaled producers or whether regionalized, application-tuned offerings will capture meaningful share by better matching local requirements and incentive environments. The answer will vary by region and application, and both dynamics can coexist.
PW Consulting
Strategic Action Points for Decision Makers
For Manufacturers and Product Leaders
Prioritize certification readiness and total cost of ownership proof. Align product development with the latest WaterSense criteria and other relevant efficiency standards, and prepare clear documentation that supports procurement and rebate eligibility. Invest in connectivity and interoperability that reduce integration friction for contractors and end users, and ensure that field serviceability and supply chain resilience are designed into the product roadmap, not treated as afterthoughts. Where input cost pressure is acute, explore modular design and supplier diversification to protect margins without eroding performance.
For Investors and Strategic Partners
Focus on segments where regulation, incentives, and verified savings converge to create durable demand. The strongest near-term opportunities are likely in certified smart controllers for municipal and institutional procurement, precision agriculture integrations that tie control to yield and input efficiency, and service-oriented models that monetize remote management and analytics. When evaluating targets or partnerships, assess certification posture, channel access, installed-base momentum, and the ability to demonstrate water and labor savings in real-world deployments. Monitor startup activity for novel power, connectivity, and integration approaches that could redefine sub-segments or become acquisition targets.
For Procurement and Operations Leaders
Use efficiency certification and incentive availability as initial screening criteria, then evaluate total cost of ownership across water savings, labor reduction, serviceability, and interoperability. Favor solutions that can integrate with existing management workflows and provide usable data for ongoing optimization. In regions with code mandates or active rebate programs, align replacement and new-install cycles with certified options to secure compliance and financial support. Build internal evaluation standards that reflect documented savings ranges and the operational realities of your sites or portfolios, rather than relying on generic feature checklists.
Worldwide Environment Controllers Market
The irrigation controllers market is moving from a phase of incremental smartification to one where certification, integration, and verified performance determine competitive outcomes. Companies and buyers that treat controllers as part of a broader water management strategy, and that align product and procurement decisions with regulatory and incentive realities, will capture more of the value created by the next wave of adoption. For decision makers seeking deeper segmentation, region-specific dynamics, and customized scenario analysis, the full research report provides detailed breakdowns and extended data to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Labels Market 2026: What 5.37% CAGR Reveals About the $12.5M Shift
By PW Consulting, 2026-09-21
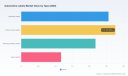
Automotive Labels Market: Strategic Shifts and Commercial Opportunities in a Transforming Landscape
The automotive labels market has evolved from a static compliance function into a dynamic strategic interface. What was once viewed as a low-cost, commoditized component of vehicle manufacturing now sits at the intersection of traceability mandates, material science innovation, and the accelerating complexity of global supply chains. Parking at approximately $8.67 billion in 2025 and projected to reach $12.5 billion by 2032, the sector is expanding at a compound annual growth rate of 5.37 percent. This trajectory is not merely a reflection of unit volume growth; it signals a structural upgrade in how labels are engineered, specified, and integrated into vehicle lifecycles. For executives navigating procurement, product development, or market entry, the label portfolio has become a lever for differentiation, risk mitigation, and regulatory alignment.
Market Landscape and Core Challenges
The market’s growth pattern over the past half-decade reveals a mature yet accelerating ecosystem. Revenue expanded from $6.67 billion in 2020 to $8.67 billion in 2025, with the pace of expansion firming as vehicle platforms grew more complex and compliance requirements tightened. The forward curve suggests continued upward momentum, crossing the $10 billion threshold by 2028 and reaching $11.51 billion by 2030. This is not a market driven by cyclical inventory swings alone; it reflects sustained investment in labeling infrastructure that supports everything from end-of-line identification to warranty tracking and circular material management.
Structural Complexity and Specification Fragmentation
One of the most pressing challenges is the fragmentation of application requirements across interior, exterior, engine bay, and specialty compartments. Each zone imposes distinct thermal, chemical, UV, and abrasion tolerances. A label that performs reliably on a dashboard surface may fail underhood within months, while asset and tracking labels must endure exposure to fuels, coolants, and repeated mechanical contact. Engineers and procurement teams increasingly face a dilemma: standardize labeling specifications to reduce complexity, or maintain zone-specific formulations to guarantee performance. This tension raises validation costs, extends qualification cycles, and complicates supplier negotiations.
Regulatory Tightening and Certification Burden
Labeling has become a compliance checkpoint rather than a purely aesthetic or informational element. Quality management expectations such as IATF 16949 certification now shape supplier evaluation, requiring label providers to demonstrate consistent process control, traceability, and failure-mode rigor. At the same time, environmental and safety directives are layering additional specifications onto label content, placement, and material composition. Heavy-duty engine and vehicle emission labeling, for example, must align with recognized regulatory exemplars, compelling manufacturers to ensure that labels not only survive harsh operating conditions but also carry accurate, auditable information. These requirements are tightening validation windows and elevating the cost of non-compliance, particularly for multi-region platforms.
PW Consulting
Material Science Constraints and Sustainability Pressures
The push toward lighter vehicle architectures and more sustainable material portfolios is reshaping label performance expectations. Traditional label constructions are being re-examined for compatibility with new substrates, adhesives that must release cleanly during recycling, and surface treatments that do not interfere with downstream material recovery. Suppliers that cannot accommodate lightweight material requirements or circular material flows risk exclusion from next-generation programs. At the same time, the cost structure of specialty polymers, adhesives, and coatings remains sensitive to input volatility, pressuring margins even as value-added capabilities expand.
Key Drivers Reshaping the Market
Innovation in Adhesive Chemistry and Label Construction
The most visible driver is the advancement of pressure-sensitive adhesives and engineered facestock designed for demanding automotive environments. Recent product launches have demonstrated constructions tailored to lightweight material applications, unlocking new feasibility for label placement on substrates that previously posed adhesion or surface-energy challenges. Validation work has further reinforced confidence in these solutions, with published test results confirming durability under real road conditions. These developments matter because they shorten the gap between laboratory performance and field reliability, enabling OEMs and tier suppliers to specify labels with greater certainty and reduce rework.
Regulatory Alignment and Traceability Mandates
Policy and regulatory environments continue to push the market toward higher accountability. Labels are increasingly expected to support track-and-trace functions, warranty documentation, and safety communication across vehicle lifecycles. For heavy-duty and emission-sensitive applications, compliance frameworks require label content and durability that withstand inspection scrutiny and operating stress. This regulatory direction is not static; it compounds across regions and vehicle classes, making it essential for suppliers to maintain agile specification management and documentation capabilities. Companies that treat compliance as a design input rather than a post-production check gain speed and reduce launch risk.
Demand-side behavior is also shifting. Consumers and fleet operators are placing greater emphasis on transparency, safety communication, and evidence of responsible material use. Brand labels are no longer limited to logos and model identification; they increasingly carry information that supports resale value, serviceability, and sustainability claims. At the same time, engineering teams are demanding labels that simplify assembly, reduce line disruptions, and survive longer service intervals. These expectations are nudging the market toward solutions that combine aesthetic precision with functional resilience.
Worldwide Label Rolls Market
Supply Chain Reconfiguration and Cost Dynamics
The label supply base is responding to broader manufacturing shifts. Regional sourcing preferences, lead-time sensitivity, and the need for closer technical collaboration are encouraging more localized service models and tighter integration with vehicle programs. At the same time, cost structures are being reassessed as manufacturers balance performance requirements against budget constraints. Suppliers that can offer consistent quality, rapid technical support, and material options aligned with lightweight and circular objectives are better positioned to navigate these dynamics. The result is a market where differentiation is increasingly rooted in technical service, validation support, and portfolio flexibility rather than price alone.
Competitive Landscape and Leader Strategies
The market features a concentrated group of established players alongside specialized providers that compete on certification depth, material innovation, and regional responsiveness. Concentration levels indicate that a relatively small number of firms command a substantial share of revenue, reinforcing the importance of scale, portfolio breadth, and OEM relationships. Yet within this structure, distinct strategic positions are emerging.
Leading Positions and Differentiation Levers
- Firms with broad, durable polyolefin and polyester portfolios are leveraging chemical resistance and OEM compliance as core value propositions, particularly for vehicle parts labeling where longevity and consistency are non-negotiable.
- Players focused on tested automotive solutions are expanding coverage across underhood, interior, and electric vehicle battery contexts, aligning constructions with global OEM specifications and lightweight material requirements. Validation and public testing results are being used to reduce buyer uncertainty and accelerate qualification.
- Industrial and automotive specialists emphasizing durable materials for harsh environments are reinforcing their relevance in asset labeling and safety-critical applications, where failure is not an option.
- Circular-focused suppliers are repositioning portfolios around recyclable label constructions and advanced adhesive technologies, including adhesives that enable cleaner material recovery and circular automotive applications. Rebranding efforts and new portfolio showcases signal a strategic pivot toward sustainability-aligned offerings.
- Custom-engineered and certification-led providers are differentiating through local service, UL-recognized constructions, and quality management alignment, reducing lead-time friction and enhancing trust in program-critical applications.
- Specialty adhesive developers and label material innovators are focusing on pressure-sensitive systems designed for automotive labeling needs, enabling partners to tailor constructions without sacrificing performance.
- Adhesive and label solution suppliers serving safety and branding contexts are broadening their relevance by connecting material capabilities to compliance and brand communication requirements.
Portfolio Evolution and Strategic Repositioning
Recent activity illustrates how incumbents are adapting. One major supplier launched special constructions for automotive labeling solutions, explicitly targeting new possibilities for vehicle applications and lightweight material compatibility. That same supplier published testing results confirming durability under road conditions, reinforcing the credibility of its technical claims. Another prominent player rebranded its automotive label business to sharpen its focus on adhesive materials and circular applications, while showcasing a new plastic label portfolio designed for circular automotive use. These moves are not cosmetic; they reflect a deliberate effort to align portfolios with the performance, compliance, and sustainability expectations now shaping procurement decisions.
Consolidation Dynamics and Entry Pathways
The competitive landscape is likely to evolve along two parallel tracks. Established players will continue to consolidate technical capabilities, expand validation libraries, and deepen OEM relationships to protect share in high-specification segments. At the same time, niche entrants and regional specialists can gain traction by solving specific pain points: faster local service, specialized certification support, tailored adhesive systems, or circular material compatibility. The barrier to entry is not purely capital; it is the ability to demonstrate consistent performance under automotive conditions and to navigate quality management expectations. Companies that can prove reliability quickly and integrate into supplier qualification processes will find pathways even in a concentrated market.
Wire Marking Labels Market
Forward Outlook: Trends and Commercial Implications
Trend 1: From Compliance Label to Lifecycle Data Carrier
Over the next three to five years, labels are expected to function less as static identifiers and more as durable data carriers that support traceability, service, and end-of-life handling. Track-and-trace and asset labeling segments are already gaining prominence as manufacturers seek better visibility across components, warranty workflows, and aftermarket channels. The commercial opportunity lies in integrated label systems that combine durable construction with standardized information architecture, enabling smoother data handoffs between manufacturing, service networks, and recycling streams. The risk is over-engineering: if information requirements keep expanding without alignment across regions or vehicle programs, validation complexity and cost can rise faster than value.
Trend 2: Sustainability-Linked Label Architectures
Circular economy expectations will continue to reshape material choices. Adhesive technologies that support recyclability, label constructions compatible with lightweight substrates, and portfolios explicitly designed for automotive circularity will become more relevant in procurement evaluations. Suppliers that can document material compatibility, adhesive release behavior, and compliance with broader sustainability goals will have an advantage in programs where material recovery and responsible sourcing are prioritized. The uncertainty here stems from the pace of standardization: if circular labeling requirements remain fragmented, suppliers may need to maintain multiple constructions, increasing complexity and limiting scale benefits.
Trend 3: Technical Validation as a Commercial Differentiator
As label performance expectations rise, publicly demonstrated validation and application-specific testing will become stronger purchase criteria. Buyers are increasingly risk-averse about underhood exposure, interior durability, and battery-area conditions, especially where failure could affect safety perception, warranty exposure, or program timing. Companies that publish robust testing outcomes and maintain transparent qualification processes will shorten evaluation cycles and build trust. The downside is that validation is resource-intensive, and smaller players may struggle to keep pace unless they concentrate on a narrow set of high-value applications where deep expertise can offset scale disadvantages.
Actionable Guidance for Decision Makers
For automotive manufacturers and tier suppliers, the priority is to treat labels as a qualified system rather than a commodity line item. Standardize core performance expectations where possible, but preserve application-specific flexibility for underhood, battery, interior, and asset contexts. Invest in early supplier engagement during platform design so that label constructions are validated alongside materials and assembly processes, reducing late-stage rework. Align procurement criteria with both durability and compliance documentation, including quality management expectations and traceability needs, so that launch risk and post-launch exposure are minimized.
For investors and market entrants, focus on the segments where performance validation and sustainability alignment create defensible positioning. Track-and-trace, asset labeling, and circular-compatible constructions offer avenues for growth, but success depends on the ability to demonstrate real-world durability and to navigate certification and documentation requirements. Evaluate potential targets or partners not only on portfolio breadth but also on validation libraries, technical service responsiveness, and the capacity to support lightweight and circular material requirements. Scale alone is insufficient; credibility in demanding applications is the stronger moat.
For procurement and supply chain leaders, build label sourcing strategies that balance consistency with agility. Where multi-region platforms are involved, prioritize suppliers that can manage specification variation without sacrificing lead-time reliability or quality control. Use validation evidence and application-specific test results as inputs to supplier selection, and require clear documentation trails for compliance-critical labels. Maintain optionality in the supply base for specialized constructions, particularly where circular material goals or lightweight substrate needs are evolving faster than internal standards can adapt.
The market’s trajectory suggests that labels will continue to gain strategic relevance as vehicles become more complex, regulations tighten, and sustainability expectations move from aspiration to specification. Decision makers who integrate label strategy into platform design, supplier qualification, and lifecycle planning will be better positioned to manage cost, compliance, and brand integrity over the long term. For those seeking deeper segmentation data, region-specific dynamics, and tailored recommendations aligned to specific business models, the full research report provides a more granular view of the opportunities and trade-offs shaping the automotive labels market.
For detailed analysis of this topic, please visit the official page: Automotive Labels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shock Absorber Market 2026: Why the 5% CAGR Trajectory Redefines Revenue Drivers
By PW Consulting, 2026-09-21
Strategic Shifts in the Global Shock Absorber Market: Navigating Growth, Innovation, and Consolidation
The global shock absorber market is entering a phase of steady expansion, underpinned by consistent demand from automotive production and a gradually modernizing aftermarket. Valued at approximately 21.47 billion USD in 2020, the market has progressed to roughly 27.4 billion USD in 2025, reflecting a compound annual growth rate of about 5.0 percent through the forecast horizon extending to 2032. This trajectory points toward a market size approaching 38.55 billion USD by the end of the forecast period, signaling that suspension damping systems remain a structurally important component category even as vehicle architectures and powertrains evolve.
For executives and investors, the headline growth figure is only the starting point. The more important question is where value is being created, which segments are gaining share, and how manufacturers are responding to cost pressure, regulatory change, and technological differentiation. The market is not simply getting larger; it is becoming more segmented by performance requirements, regional supply dynamics, and the pace of vehicle platform renewal. Companies that treat shock absorbers as commodities risk margin erosion, while those that align product roadmaps with OEM integration needs, aftermarket replacement cycles, and regulatory-driven performance standards are better positioned to capture durable profitability.
The market’s current shape also reflects a moderately concentrated competitive environment. A small group of leading suppliers accounts for a meaningful share of global activity, yet no single player dominates the field outright. That structure matters because it leaves room for differentiated strategies: some firms compete through scale and OEM partnerships, others through specialized high-performance or motorsport-grade products, and still others through regional cost leadership and aftermarket distribution strength. Understanding these strategic choices is essential for anyone evaluating partnership options, acquisition targets, or long-term positioning in the damping systems space.
Core Challenges and Inflection Points
Despite the positive growth outlook, the market is navigating several structural challenges that are reshaping competitive dynamics. The first is the tension between cost control and performance upgrading. Manufacturers face rising input pressure from materials such as steel and hydraulic fluids, and those pressures have been amplified by supply disruptions linked to geopolitical instability. When raw material and fluid costs climb, the margin structure of damping products becomes more sensitive, especially for suppliers serving price-sensitive replacement channels or commercial vehicle segments where total cost of ownership is a major purchase criterion.
A second challenge lies in the regulatory environment. Stricter vehicle safety expectations and emissions-related efficiency targets are changing what automakers require from suspension systems. In the United States, guidelines from the National Highway Traffic Safety Administration influence how shock absorbers are designed and integrated, while new EPA greenhouse gas emissions standards for passenger cars and light trucks through model year 2026 are encouraging efficiency-oriented technologies that can indirectly support advanced damping solutions. At the same time, trade and partnership agreements such as the EU–Japan Economic Partnership are reducing tariffs on automotive components, making it easier for multinational suppliers to coordinate OEM supply across borders but also intensifying competitive exposure.
A third inflection point is the shift in application mix and vehicle architecture. As electric vehicles, heavier passenger vehicles, and more sophisticated commercial platforms gain prominence, damping requirements are changing in ways that affect both product design and replacement behavior. The aftermarket remains a substantial demand base for passenger vehicle components, while commercial vehicles continue to represent a distinct, durability-driven segment. Suppliers must therefore manage two parallel demands: one shaped by OEM specification and platform cadence, the other shaped by replacement cycles, distributor networks, and performance expectations in the service market.
Key Drivers of Market Change
Technology Innovation and Damping Performance
Technological differentiation is becoming one of the clearest ways to defend margins and win OEM programs. Passive dampers still form the backbone of many applications, but the market is increasingly shaped by advances in valve design, adaptive damping, and integrated electronic suspension capabilities. Recent product-level developments illustrate this direction. In early 2026, Monroe Ride Solutions announced a breakthrough in passive damper valve technology intended to improve ride comfort and handling without necessarily requiring more complex electronic architectures. That kind of innovation matters because it can enhance perceived performance while preserving the cost and reliability advantages that make passive systems attractive in high-volume applications.
At the same time, sustainability-oriented engineering is entering the product conversation. In 2025, Showa Corporation announced an eco-friendly hydraulic fluid designed to support carbon neutrality goals. While a single fluid formulation may appear incremental, it reflects a broader shift in which suppliers are expected to address not only ride quality and durability but also environmental footprint and regulatory alignment. As automakers search for efficiency gains and lower-emission components, damping technologies that contribute to vehicle efficiency or reduce the environmental impact of production and servicing can become a meaningful part of the value proposition.
Policy, Safety, and Emissions Pressure
Policy is not only shaping what can be sold; it is influencing how products are engineered and where suppliers choose to locate their partnerships. Regulatory expectations around safety and emissions are encouraging demand for high-performance and adaptive systems that can support better vehicle control, stability, and efficiency. In practical terms, this creates a stronger incentive for OEMs to specify damping solutions that can meet tighter testing and validation requirements, especially in markets where safety standards and emissions rules are advancing rapidly.
Trade policy is adding another layer. By lowering tariff barriers on automotive components, agreements such as the EU–Japan partnership are facilitating cross-border OEM collaboration for suppliers with international manufacturing and engineering footprints. That does not automatically make all suppliers equal; instead, it tends to reward firms that can combine technical capability with a flexible supply footprint, since global programs increasingly require consistent quality, quick responsiveness, and the ability to serve multi-region vehicle programs without excessive cost friction.
Demand-Side Shifts in Passenger and Commercial Vehicles
Consumer and commercial buyer behavior is evolving in ways that affect both product specification and aftermarket demand. Passenger vehicle owners are increasingly aware of ride quality, noise, and handling, and that awareness can translate into stronger demand for replacement components that restore or improve original performance characteristics. At the same time, vehicle parc growth and aging fleets in several regions continue to support a robust replacement market, which gives aftermarket-oriented suppliers a steady source of demand even when new vehicle production cycles fluctuate.
Commercial vehicle demand tells a related but distinct story. Heavy-duty usage patterns, load variability, and total cost of ownership concerns place a premium on durability and consistent damping performance. For operators, the choice of shock absorbers is less about premium perception and more about uptime, service intervals, and protection of other suspension components. That creates a market in which reliability and serviceability can be as important as headline performance metrics, and it rewards suppliers that can demonstrate measurable outcomes in commercial applications.
Supply Chain and Cost Structure Dynamics
Cost structure is reshaping the competitive field. Higher material costs and intermittent supply disruption have pressured producers to improve sourcing resilience, hedge volatility where possible, and focus on design efficiency. In a market where many components are mechanically mature, value creation increasingly comes from manufacturing precision, process control, and the ability to reduce waste or rework without compromising performance. Suppliers that can maintain cost discipline while upgrading product capability typically gain an advantage, especially when they can pass credibility in quality and service life through OEM validation and aftermarket trust.
Regional dynamics also influence cost and availability. Asia Pacific remains a strategically important production and demand base, while North America and Europe continue to represent large, mature demand centers with different channel structures and regulatory expectations. The practical implication is that suppliers often need a multi-regional approach: local or near-local production and distribution can reduce exposure to logistics volatility and improve responsiveness to OEM and service-channel needs, while global scale can support cost efficiency and technology sharing across programs.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is defined by a group of well-established manufacturers with different strategic emphases. KYB Corporation and Showa Corporation bring strong OEM integration capabilities and a deep history in hydraulic damping technology for passenger vehicles, trucks, and commercial applications. ZF Friedrichshafen AG and thyssenkrupp Bilstein GmbH occupy strong positions in high-performance and adaptive suspension solutions, with an emphasis on OEM integration across passenger cars, commercial vehicles, and off-highway use. Tenneco Inc., through its Monroe brand and DRiV ride control products, maintains a notable presence in both replacement and OEM-facing ride control systems for light vehicles and commercial trucks. KONI B.V. is associated with premium damping systems across automotive, motorsport, and commercial applications, while Gabriel and Tokico maintain strong aftermarket and OEM supply traditions in their respective domains.
A second tier of players adds regional specificity and niche capability. Mando Corporation is notable for its focus on AI-enabled and EV-specific adaptive shock absorbers and suspension systems, reflecting a forward-looking angle on electrification and smart suspension. Hitachi Astemo and Mubea contribute high-performance damping and industrial-adjacent quality emphasis, Arnott Inc. extends the field into air suspension and shock absorber products for light and commercial applications, and Loosoo underscores the importance of Asian market supply chains with an OEM and aftermarket focus.
Differentiation Strategies Among Leaders
The leading firms are not all competing for the same prize. Some pursue scale and broad OEM coverage, relying on engineering breadth, global production capacity, and the ability to meet multiple vehicle platforms with consistent quality. Others lean into performance credibility and brand positioning, particularly where motorsport heritage, handling reputation, or premium aftermarket perception can support pricing power. A third group emphasizes application specialization, designing products around commercial durability, off-highway duty cycles, or the particular needs of electrified vehicle platforms.
This divergence creates a market in which “winning” depends heavily on the target segment. In OEM programs, the decisive factors are often validation performance, integration compatibility, delivery reliability, and cost competitiveness across the program lifecycle. In the aftermarket, brand recognition, distribution reach, packaging clarity, and perceived restoration of original ride quality can be equally important. In commercial applications, the emphasis shifts again toward service life, load handling, and fleet economics. Suppliers that understand which game they are playing are more likely to build defensible positions than those that attempt to compete on all fronts simultaneously.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The structure of the market appears likely to continue evolving along several paths. Consolidation may proceed where scale economies, global program coverage, and engineering investment requirements favor larger players, particularly in OEM-facing segments. At the same time, fragmentation can persist in performance aftermarket, regional replacement channels, and specialized applications where local brand strength, service relationships, and product specialization matter more than global scale. New entrants and technology-focused suppliers may find openings in areas such as adaptive damping, electronic suspension integration, and EV-specific component design, where product complexity and software-adjacent capability raise barriers but also create differentiation opportunities.
For decision-makers observing this landscape, the key is to avoid treating the field as either fully consolidated or fully fragmented. It is better understood as layered: concentrated at the top in terms of global reach and program presence, yet still diverse in product types, application focus, and channel strategy. That layered structure means M&A, partnership, and licensing dynamics can be as important as organic product competition, especially when suppliers look to expand into adaptive systems, air suspension, or regional production footprints.
Future Trends and Commercial Opportunities
Toward Smarter and More Efficient Damping Systems
Over the next three to five years, one clear trend is the continued movement toward damping systems that are more responsive, more efficient, and better integrated with vehicle electronics. Even where fully active suspension remains a premium or niche proposition, the broader direction favors components that can support improved ride control, safety-related handling performance, and efficiency goals. Suppliers that can offer valve technology, control compatibility, and packaging flexibility will be well placed to participate in this shift. Commercial opportunity lies not only in high-end applications, but also in making advanced performance accessible in high-volume platforms where cost constraints remain tight.
Electrification and Changing Vehicle Architecture
Electrification is reshaping platform design, vehicle weight distribution, and NVH expectations, all of which influence damping requirements. Electric vehicles can change ride behavior and suspension loading patterns, while the need to manage efficiency and durability remains central. This creates demand for suspension solutions tailored to EV platforms, including adaptive and AI-enabled concepts that can help optimize comfort and control without compromising efficiency targets. For manufacturers, the opportunity is to align product development with the needs of next-generation vehicle architectures before platform decisions become locked in. For investors, the relevant question is which suppliers are building credible EV-related damping capabilities rather than simply extending traditional product lines.
Aftermarket Renewal, Regional Growth, and Supply Resilience
A third trend is the ongoing importance of the replacement market and regional demand diversification. Even as new vehicle production cycles vary, there is a durable base of demand from aging passenger fleets and commercial vehicles in service. Growth in specific regions can create localized opportunities for suppliers that invest in distribution strength, regional manufacturing, or tailored product assortments. At the same time, the market’s exposure to raw material volatility and logistics disruption encourages suppliers to build more resilient sourcing and production arrangements. Companies that can combine regional proximity with consistent quality and competitive cost structures are more likely to protect margins through cycles of input volatility.
These trends do not eliminate uncertainty. Demand can shift with vehicle sales cycles, regulatory timelines can change, and technology roadmaps may be reweighted as automakers balance cost, performance, and electrification priorities. The commercial opportunity is real, but it is not uniformly distributed: it tends to accrue to firms that can move quickly on product adaptation, maintain strong OEM or channel relationships, and manage cost and supply risk without sacrificing performance credibility.
Actionable Implications for Decision-Makers
For manufacturers, the central priority is to match product strategy with the segment economics in which they compete. That may mean investing in valve technology and passive damping refinements for high-volume programs, building adaptive or EV-specific capability where platform trends point that way, or strengthening aftermarket brand and distribution where replacement demand is the main growth engine. It also means treating cost resilience as a strategic capability, not just a procurement task, since material volatility and supply disruption can quickly erode the economics of otherwise strong product lines.
For investors, the useful question is less about whether the market is growing than about which business models are likely to convert growth into margin and share. Attention should be directed toward suppliers with clear differentiation, credible OEM relationships, and evidence of progress in higher-value damping solutions or regional expansion strategies. Equally important is scrutiny of exposure to input cost volatility, regulatory risk, and dependence on specific vehicle production cycles. In a moderately concentrated market, valuation logic should account for both scale advantages and the durability of competitive differentiation.
For procurement and sourcing leaders, the immediate focus should be on balancing performance requirements with supply security and total cost. That includes evaluating suppliers not only on unit price, but also on engineering support, program flexibility, quality consistency, and the ability to accommodate changing regulatory and safety expectations. In environments where tariff reductions and cross-border OEM collaboration are expanding, procurement decisions can also benefit from mapping supplier footprints and partnership options across regions, especially where multi-market vehicle programs are involved.
Industrial Hydraulic Shock Absorber Market
The broader takeaway is that the shock absorber market is large enough to support multiple successful strategies, but selective enough that positioning matters. The firms gaining advantage are those that combine technical relevance with disciplined execution, align product roadmaps with vehicle and regulatory trends, and manage the cost and supply dynamics that increasingly shape outcomes. Detailed segment-level data, company-level benchmarks, and regional scenario analysis can sharpen these decisions further, especially for teams planning investments, procurement strategies, or long-range product development in the damping systems space.
Automotive Stabilizer Bar Market
For detailed analysis of this topic, please visit the official page: Shock Absorber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Full Body Scanner Market 2026: Why 9.8% CAGR Signals a Structural Shift
By PW Consulting, 2026-09-21
The Invisible Shield: Strategic Trends and Commercial Opportunities in the Full Body Scanner Market
Global security screening has entered a phase of accelerated evolution. The full body scanner market, valued at approximately $390 million in 2025, has expanded from a niche security technology into a critical infrastructure component spanning aviation, critical facilities, and institutional protection. With a projected compound annual growth rate of 9.8 percent through 2032, the market is expected to surpass $745 million by the end of the forecast period. This trajectory reflects more than steady demand growth; it signals a structural shift in how governments, transport operators, and facility managers approach threat detection. The sector is moving from reactive, checkpoint-based screening toward continuous, intelligent, and minimally disruptive security architectures. For executives and capital allocators, understanding the forces reshaping this space is no longer optional. It is a prerequisite for positioning assets, product roadmaps, and procurement strategies in a landscape where regulatory expectations, technological maturity, and operational throughput are converging.
Market Landscape and Structural Friction
The size and growth rate of the full body scanner market tell a clear story of expanding adoption, but the underlying dynamics reveal where pressure points are forming. Demand has been historically anchored in transport security, particularly aviation checkpoints, where passenger volumes, regulatory mandates, and threat evolution keep procurement cycles active. At the same time, the market is broadening into critical infrastructure protection and institutional environments, driven by heightened awareness of concealed threats and the need for non-intrusive screening in sensitive zones.
This expansion is not frictionless. Three structural challenges are shaping how the market will mature over the next several years.
Balancing Throughput with Privacy and User Experience
Security technology has long faced the tension between thoroughness and speed. Full body scanners must detect concealed objects without creating bottleneck conditions or eroding public trust. As deployments scale beyond major international hubs into regional airports, mass transit facilities, and correctional or government environments, operators are increasingly sensitive to passenger and visitor experience. Solutions that reduce false alarm rates, shorten inspection cycles, and avoid ionizing radiation are becoming competitive differentiators rather than optional features. Equipment that imposes excessive operational friction risks underutilization, regardless of technical capability.
Certification Complexity and Interoperability
The regulatory environment for people screening continues to tighten, and that reality is reshaping procurement timelines. Advanced imaging systems must meet detection capability standards, operational safety requirements, and increasingly specific deployment guidelines. Recent clarifications in checkpoint planning guidance and the certification of specific millimeter-wave and transmission X-ray platforms illustrate how compliance is becoming more structured and more demanding. The upside is clearer procurement criteria. The downside is longer validation cycles, region-specific certification pathways, and the need for vendors to demonstrate performance under standardized conditions. For buyers, this creates a more predictable but more rigorous evaluation process. For suppliers, it raises the barrier to entry and rewards platforms with proven certification histories.
Market Fragmentation and Contracting Dynamics
Market concentration remains relatively modest, with leading players holding a combined share that leaves substantial room for regional specialization, application-specific deployments, and localized service ecosystems. That structure has benefits: it allows differentiated solutions to gain traction in specific verticals. It also creates complexity for enterprises trying to standardize equipment across multiple sites or geographies. Procurement teams must weigh the advantages of specialized systems against the operational burden of managing multiple platforms, training regimes, and maintenance contracts. As large-scale events and multi-site security programs accelerate, the pressure to harmonize equipment while retaining flexibility will intensify.
Core Drivers Reshaping Demand and Capability
Behind the headline growth numbers, several interconnected drivers are redefining what buyers expect from full body screening technology and how suppliers compete.
PW Consulting
Technology Innovation: From Detection to Intelligent Interpretation
The most consequential shift is the move from raw imaging toward AI-assisted detection and automated threat interpretation. Modern millimeter-wave and transmission X-ray platforms are increasingly designed to reduce operator workload by highlighting anomalies, classifying object types, and lowering false alarm rates. This matters operationally because screening throughput is no longer determined solely by hardware speed. It is increasingly defined by the total inspection workflow, including alarm resolution, repatron screening frequency, and staff training requirements. As systems become more interpretable and adaptive, they enable faster passenger flow, more consistent detection outcomes, and broader deployment in environments where highly specialized operators may not be available.
Policy and Regulatory Momentum
Regulatory activity is acting as both a constraint and a catalyst. Updated checkpoint planning guidance has helped clarify expectations for advanced imaging technology deployments, while certification milestones for specific scanner families have established new reference points for airport and checkpoint use. In parallel, policy discussions are expanding the scope of where body imaging equipment can be deployed, with legislative activity opening doors to screening in correctional and institutional settings. The practical effect is twofold. First, compliance is becoming more standardized, which favors established platforms with documented certification trails. Second, new application areas are being formally recognized, creating incremental demand beyond traditional transport security.
Demand-Side Evolution Across Sectors
Demand is no longer driven by a single sector’s procurement cycle. Aviation remains a central anchor, but the rationale is broadening. High-profile international events, expanding mass transit networks, and increased attention to facility hardening are pushing security planners to evaluate full body scanners as part of layered screening architectures. The growing emphasis on non-ionizing solutions also reflects changing risk calculations. Operators in high-throughput environments want effective detection without introducing additional radiation exposure concerns or complex safety protocols. This is particularly relevant as screening moves into settings where public familiarity with security procedures may be lower and user acceptance becomes a critical success factor.
Cost Structure, Service Models, and Deployment Economics
The commercial character of the market is shifting alongside the technology. Procurement decisions increasingly factor in total cost of ownership rather than upfront hardware price alone. Maintenance agreements, calibration requirements, software updates, and operator training all influence the economic case for a given platform. At the same time, contract activity around large-scale and time-bound deployments demonstrates that buyers value vendors who can deliver not only equipment but also integration support, site readiness, and rapid scale-up. Contracting patterns suggest that suppliers with end-to-end deployment capability and strong regional service networks are gaining an advantage, especially when security programs must be stood up quickly for events, new terminals, or expanded checkpoint areas.
Competitive Positioning and the Evolving Playing Field
The competitive landscape is defined less by a single dominant platform than by a combination of technological pedigree, certification status, and vertical specialization. Several established players illustrate the different ways companies are positioning themselves.
X-Ray Security Scanner Market
Differentiation Through Detection Architecture
Some suppliers compete primarily on non-invasive transmission X-ray technology designed to identify concealed objects within the body. Their value proposition centers on a specific detection approach that addresses threat concealment in a way that complements or differs from millimeter-wave imaging. In a market where operational requirements vary by site and threat profile, this kind of specialization can be strategically valuable for buyers seeking a particular screening modality or a layered security design.
Security Screening Market
Millimeter-Wave Leadership and Certification as a Moat
Other providers have built their positioning around millimeter-wave microwave imaging, emphasizing full body coverage, AI-assisted detection of metallic and non-metallic objects, and certification pathways aligned with aviation passenger screening. Recent certification achievements and major contract awards underscore how regulatory validation and large-scale deployment readiness can become competitive moats. When a platform is certified for airport use and subsequently selected for high-visibility deployments at host-city airports or national checkpoint networks, it signals not just technical capability but also operational reliability and compliance maturity. For competitors, that raises the stakes. For buyers, it reduces procurement uncertainty.
Throughput, Integration, and Checkpoint Design
A third dimension of competition is the ability to deliver high-throughput screening that integrates smoothly into checkpoint architecture. Systems marketed around accurate, non-ionizing detection and operational efficiency appeal to operators managing heavy passenger flow. In this context, differentiation often comes from ergonomics, footprint, throughput consistency, and the ability to minimize secondary screening disruptions. As checkpoints evolve into more modular and scalable environments, suppliers that can adapt equipment to varied spatial constraints and passenger volumes are better positioned to win multi-site contracts.
Market Evolution: Consolidation Pressure and Vertical Expansion
The market is not yet dominated by a small set of incumbents, but consolidation pressures are emerging. Larger security and technology groups with broad portfolios can cross-sell screening equipment alongside broader detection, integration, and services offerings. At the same time, niche specialists can thrive by dominating specific applications, regions, or regulatory environments. New entrants are likely to face a steep climb unless they bring a clear advantage in detection performance, certification readiness, cost structure, or deployment speed. The more probable trajectory is a hybrid landscape: a handful of scaled platforms with broad certification and service coverage, supplemented by specialized solutions for targeted use cases. Buyers will increasingly compare vendors not just on hardware specs but on the completeness of their deployment, training, and lifecycle support model.
Forward Trends: Where the Market Is Heading
Looking ahead over the next three to five years, several trends are likely to shape both demand patterns and commercial strategy.
Trend One: AI-Assisted Screening Becomes the Baseline Expectation
Intelligent interpretation will move from premium feature to expected capability. As operators face pressure to maintain throughput while improving detection consistency, systems that reduce reliance on subjective image interpretation will gain preference. This trend opens commercial opportunities for vendors that can demonstrate measurable improvements in alarm resolution, staff efficiency, and repeat screening rates. It also raises the importance of software lifecycle management, because AI-driven functionality depends on continuous updates, performance monitoring, and operational calibration. Buyers should anticipate that screening technology will increasingly be evaluated as a software-dependent service as much as a hardware purchase.
Trend Two: Application Expansion Beyond Traditional Transport Hubs
Full body scanners will continue to penetrate institutional, critical infrastructure, and event-driven settings. Legislative and regulatory movements that authorize body imaging equipment in correctional and similar environments point to a wider acceptance of these systems where access control and concealed threat detection are priorities. Large-scale international events and expanded transport networks will further encourage temporary and permanent deployments. The opportunity here is not simply more units, but new procurement models: short-term rental or rapid-deployment contracts, multi-site standardization programs, and modular checkpoint designs that can be scaled up or down depending on traffic and threat conditions.
Trend Three: Compliance and Certification as Strategic Procurement Filters
As detection standards become more explicit and certification pathways more established, compliance status will increasingly act as a gatekeeper in procurement decisions. Platforms with documented approvals and alignment to updated checkpoint requirements will enjoy shorter evaluation cycles and stronger positioning in regulated environments. The flip side is that buyers will need to plan for longer lead times when introducing new systems, especially if site-specific validation or regional certification is required. Suppliers that invest early in certification and documentation will be better equipped to capture demand when security programs are refreshed or expanded.
These trends carry risk as well. Rapid technological evolution can shorten product lifecycles and pressure margins. Regulatory shifts can alter deployment opportunities in unexpected ways. Public acceptance and privacy considerations can influence where and how screening is deployed, particularly in non-aviation environments. And for buyers, overcommitting to a single platform too early can create lock-in if operational needs or certification requirements change.
Strategic Actions for Decision Makers
The market’s direction suggests different priorities depending on the reader’s role, but several actions are broadly relevant.
For Manufacturers and Technology Providers
- Double down on certification readiness and documentation. In a market where compliance increasingly shapes procurement, a clearly validated detection capability and a traceable certification record can shorten sales cycles and improve win rates.
- Treat software and AI-assisted functionality as core products, not add-ons. Differentiation will depend on false alarm reduction, throughput consistency, and updateability. Plan for lifecycle support, including calibration, performance monitoring, and operator-facing software improvements.
- Build deployment and service capacity for scale-up events. Multi-site and event-driven contracts reward vendors that can deliver equipment, integration, training, and support quickly and reliably.
For Investors
- Evaluate companies on total deployment capability, not just hardware specs. Certification momentum, service networks, and contract execution history are indicators of commercial durability.
- Look for exposure to application expansion. Transport remains essential, but growth in critical infrastructure and institutional settings can diversify revenue streams and reduce dependence on any single procurement cycle.
- Monitor regulatory catalysts. Certification approvals, updated checkpoint guidance, and new authorization frameworks can shift demand faster than macroeconomic indicators, creating asymmetric opportunities for well-positioned vendors.
For Procurement and Security Program Leaders
- Prioritize total operational impact over sticker price. False alarm rates, throughput, training burden, and maintenance requirements often determine whether a system performs well in live conditions.
- Align equipment choices with layered security architecture. Full body scanners should complement existing screening methods and fit the operational profile of the site, whether that is high-throughput aviation or controlled-access institutional environments.
- Plan for certification and integration timelines early. New deployments may require validation, site preparation, and staff training that extend beyond hardware delivery. Building that into the program schedule reduces disruption and improves adoption.
The full body scanner market is transitioning from a security niche into a broader screening infrastructure category, shaped by intelligent detection, evolving compliance expectations, and expanding application scope. For organizations operating in this space, the value of precise segmentation data, company-level benchmarking, and scenario-based forecasting is rising quickly. A detailed research report can help translate these macro trends into actionable planning inputs, including market size breakdowns by region and type, application-level demand patterns, competitive positioning across key vendors, and procurement-relevant developments that may affect deployment timing and vendor selection. For decision makers weighing product strategy, capital allocation, or multi-site security programs, that level of detail can shorten evaluation cycles and reduce uncertainty when it matters most.
For detailed analysis of this topic, please visit the official page: Full Body Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Paracetamol Market: Why the 4.5% CAGR Trajectory Changes Everything by 2032
By PW Consulting, 2026-09-21
Paracetamol Market: Strategic Trends and Commercial Opportunities Through 2032
The global paracetamol market has reached a significant inflection point, with total revenues climbing to approximately USD 11,500 million in 2025 and a projected trajectory toward USD 15,300 million by 2032. This expansion reflects a compound annual growth rate of 4.5 percent across the 2026 to 2032 forecast window, building on a period of steady recovery and structural reshaping from 2020 through 2025. The market's resilience stems from paracetamol's entrenched position as a first-line analgesic and antipyretic, yet the operating environment is no longer defined by stable demand and predictable margins. Instead, manufacturers, distributors, and investors are navigating a landscape shaped by raw material volatility, evolving regulatory expectations, and shifting consumer preferences that favor differentiated delivery formats. Understanding where value is being created—and where it is being eroded—requires looking beyond headline figures to the underlying dynamics that will dictate competitive outcomes over the next several years.
Market Snapshot and Emerging Challenges
The paracetamol sector has grown from a baseline of roughly USD 9,000 million in 2020 to its current scale, with the pace of expansion accelerating modestly as healthcare systems stabilized and over-the-counter self-medication regained momentum following pandemic-era disruptions. Growth has been broad-based, but regional performance tells a more nuanced story. Asia Pacific and North America together account for the largest revenue shares, reflecting both high population density in the former and strong branded distribution networks in the latter. Europe remains a mature but stable contributor, while Latin America and the Middle East and Africa represent smaller but strategically important markets where access-to-medicine initiatives and pricing reforms continue to shape volume trajectories.
Industry concentration offers another lens on market structure. The top three players command roughly 35 percent of global revenue, while the top five extend that share to approximately 45 percent. Such concentration indicates that scale, supply chain leverage, and regulatory expertise remain meaningful barriers to entry, yet it also signals room for specialization. Smaller and mid-tier manufacturers can compete effectively by focusing on niche formulations, regional regulatory approvals, or value-added delivery systems rather than attempting to match incumbents across every segment.
Several challenges are reshaping how companies approach the market. First, the supply chain for para-aminophenol, the primary precursor for paracetamol synthesis, experienced notable disruption in 2025 when export controls imposed by China constrained global availability. This episode exposed the sector's reliance on a concentrated precursor base and highlighted the vulnerability of cost structures that lack diversification or contractual flexibility. Second, pricing pressures intensified in key markets. In India, the National Pharmaceutical Pricing Authority documented sharp increases in paracetamol prices during 2025, driven by raw material cost escalation and the complex interplay of government production-linked incentive schemes that altered competitive dynamics among domestic manufacturers. Third, the regulatory environment is becoming more demanding. Amendments to US FDA monographs expected in 2026 are projected to raise labeling compliance costs, adding a new layer of expense for both branded and generic producers operating in or exporting to the United States.
For executives, these challenges translate into three immediate priorities: securing more resilient raw material sourcing, preparing for incremental compliance costs that may compress margins on low-differentiation products, and evaluating whether existing portfolio mixes align with markets where pricing power can be defended.
Key Drivers Shaping Market Trajectory
Technological and Formulation Innovation
Innovation in paracetamol has shifted from the molecule itself to the way it is delivered, absorbed, and experienced by patients. Recent developments underscore this focus. In early 2025, Haleon completed a bioequivalence study of an orodispersible paracetamol tablet at a 500 mg dose in healthy adults under fasting conditions. By mid-2025, ClinicalTrials.gov recorded the completion of a Phase 1 bioequivalence study for similar orodispersible tablets. These activities point to a broader industry effort to improve convenience, adherence, and perceived efficacy, particularly in segments where swallowing conventional tablets is a barrier for certain patient populations.
Orodispersible formats are not merely a technical exercise; they represent a pathway to premium positioning in over-the-counter channels where consumer perception and ease of use influence purchase decisions. Companies that can demonstrate consistent bioavailability, stable manufacturing processes, and acceptable taste profiles are better placed to capture share in categories where differentiation has historically been thin. The commercial implication is clear: formulation capability is becoming a competitive lever, and manufacturers that invest in delivery-system expertise can reduce reliance on commodity pricing dynamics.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and cost structures. In India, the National Pharmaceutical Pricing Authority's 2025 findings on paracetamol price increases illustrate how domestic policy can amplify or mitigate the effects of raw material inflation. Production-linked incentive schemes, while intended to strengthen domestic manufacturing capacity, have interacted with cost escalation in ways that produced noticeable price movements and altered competitive positioning among local suppliers.
In the United States, anticipated FDA monograph amendments for 2026 are expected to increase labeling costs for paracetamol products. While these changes do not alter the drug's clinical role, they do affect the economics of product line management. Companies with complex SKU portfolios, multiple packaging configurations, or extensive distribution footprints will need to model the cumulative impact of compliance costs and decide where simplification or consolidation can preserve profitability. Parallel attention to pharmacovigilance expectations remains relevant, as regulatory bodies continue to evaluate the broader safety narrative around widely used analgesics, even when clinical evidence remains reassuring.
Demand-Side Shifts and Consumer Behavior
Consumer behavior continues to evolve in ways that influence both volume and product mix. A growing preference for self-care and accessible over-the-counter options has reinforced demand for paracetamol across multiple indications, including headache, fever, cold and cough, and muscle cramps. The application landscape is broad, and the relative weight of each use case varies by region and demographic profile. What matters strategically is that demand is not monolithic; it is segmented by age, presentation, and purchase context, which creates opportunities for targeted product design and channel strategy.
Recent safety research has also contributed to a more stable demand environment by addressing long-standing public questions. A February 2026 meta-analysis published by UpToDate found no association between prenatal paracetamol use and autism or ADHD risk in low-bias studies with long follow-up. In January 2026, MedicalXpress released findings supporting the safety of paracetamol and ibuprofen in infants under one year of age, with no link to eczema or other measured risks. In April 2026, JAMA Network published a trial comparing acetaminophen versus opioid addition to ibuprofen for pediatric pain relief, contributing to ongoing discussions about optimal analgesia strategies. Collectively, these developments help sustain confidence in paracetamol's role in both adult and pediatric settings, reducing the likelihood that safety concerns will materially disrupt demand in mainstream markets.
Supply Chain and Cost Structure Dynamics
The cost side of the equation has become a strategic focal point. China's dominant position in paracetamol precursor supply has been a defining feature of the market. A May 2026 US State Department report highlighted China's roughly 70 percent share of para-aminophenol supply, with direct US imports at only 17 percent. That concentration became more consequential in 2026, when an Iran-related conflict triggered vessel shortages that restricted API movement from China and drove paracetamol raw material prices up by more than 26 percent in India.
These events are not isolated; they reveal structural dependencies that companies must manage proactively. Firms that depend on single-source precursor procurement or that lack visibility into tiered supplier networks are exposed to both price shocks and availability risk. Conversely, organizations that have built multi-source strategies, maintained strategic inventory buffers for critical inputs, or invested in forward contracting are better positioned to stabilize costs and protect supply continuity. The broader lesson is that supply chain design is now a competitive differentiator in a market where margins on undifferentiated products are already under pressure.
Competitive Landscape and Leading Strategies
The paracetamol market features a mix of large multinationals, established Indian API and formulation producers, and regional specialists. This blend creates a competitive environment in which scale, geographic reach, and formulation capability interact in different ways across segments.
Among the companies shaping the market, several Indian manufacturers stand out for their high-volume production of paracetamol API and finished dosage forms. Granules India Limited, based in Hyderabad, is a major producer of paracetamol API and tablets with extensive global supply relationships. IOL Chemicals and Pharmaceuticals Limited, headquartered in Ludhiana, is an active manufacturer and exporter of paracetamol API and formulations. Farmson Pharmaceutical Gujarat Private Limited, operating from Gujarat, produces paracetamol API and tablets under WHO-GMP and other recognized standards. These firms illustrate the strategic importance of cost-efficient, compliant manufacturing in a market where precursor dynamics and pricing regulation can move quickly.
Larger integrated players bring a different set of advantages. Sun Pharmaceutical Industries Ltd, based in Mumbai, operates as a global pharmaceutical company with paracetamol tablet and API production capabilities. Cipla Ltd, also headquartered in Mumbai, manufactures paracetamol tablets and formulations across multiple markets. Their scale, regulatory infrastructure, and distribution reach allow them to compete across both generic and branded contexts, though they must still navigate the same raw material and compliance pressures affecting the broader industry.
On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. These organizations typically compete on brand equity, patient-facing positioning, and broader portfolio integration rather than price alone.
Acetaminophen Market
The strategic positioning of these players diverges in ways that matter for competitive planning. Indian API and formulation manufacturers often emphasize volume, cost discipline, and export capacity, leveraging regulatory certifications and production efficiency to serve both domestic and international markets. Multinationals and branded players more frequently invest in patient convenience, formulation variety, and trust-based consumer relationships, which can support pricing resilience in categories where differentiation is credible. Companies that combine strong manufacturing fundamentals with formulation-driven differentiation are increasingly well placed to navigate both commodity pressure and premium opportunity.
PW Consulting
Market structure is evolving through selective consolidation and parallel fragmentation. On one hand, larger players continue to seek efficiencies in supply, regulatory management, and distribution, which can lead to tighter integration across API, formulation, and packaging. On the other hand, specialized niche participants are carving out positions around delivery formats, regional approvals, and patient-centric packaging that do not require matching the full scale of the largest competitors. New entrants face meaningful hurdles given existing concentration and regulatory complexity, but targeted entry remains possible where formulation novelty, local market knowledge, or channel access provides a defensible starting point.
Recent industry events reinforce the strategic significance of these divergent paths. Safety and clinical developments have reinforced demand confidence in established use cases, while formulation work on orodispersible tablets indicates where incremental differentiation is being pursued. At the same time, raw material disruptions and pricing actions in key markets show that even well-positioned companies must manage upstream dependencies and regulatory cost exposure with discipline.
Antipyretic and Analgesic Market
Forward Outlook: Trends and Commercial Implications
Trend One: Greater Emphasis on Delivery Format Differentiation
Over the next three to five years, formulation differentiation is likely to become a more visible feature of competition, especially in over-the-counter channels where consumer choice is shaped by convenience, taste, and perceived ease of use. Orodispersible and other patient-friendly formats are attracting clinical and commercial attention, and companies that can bring these formats to market with consistent quality and credible bioequivalence data may gain incremental pricing latitude. The commercial opportunity lies in aligning format innovation with target populations and channel strategies, rather than treating new delivery systems as a generic upgrade. A related risk is that differentiation only pays off when it is supported by manufacturing reliability, taste acceptability, and clear consumer communication; otherwise, premium positioning is difficult to sustain.
Trend Two: Supply Chain Reconfiguration and Sourcing Diversification
The concentration of para-aminophenol supply and the price shocks associated with geopolitical and logistical disruptions point toward a longer-term shift in sourcing strategies. Companies are likely to pursue a combination of multi-source procurement, closer supplier relationships, and regional capacity planning to reduce exposure to single-point failures. For manufacturers with significant exposure to precursor imports, this may mean renegotiating supply terms, qualifying alternative sources, or adjusting production planning to absorb short-term volatility more efficiently. The opportunity here is to convert supply chain resilience into a more stable cost base and more dependable fulfillment, both of which support customer trust and margin protection. The risk is that diversification takes time and capital, and that transitional periods can create their own inefficiencies if supplier qualification and quality assurance are not managed carefully.
Trend Three: Regulatory Cost Management as a Core Competency
As labeling and monograph requirements evolve, particularly in major markets such as the United States, regulatory cost management will become a more central element of portfolio strategy. Companies that proactively rationalize SKU complexity, streamline packaging variations, and align compliance processes with manufacturing workflows are more likely to preserve margins than those that treat regulatory changes as an external cost to be absorbed passively. This trend also intersects with market access and pricing policy in regions such as India, where domestic regulation can interact with raw material economics in ways that drive price outcomes. Businesses that monitor these dynamics closely and incorporate them into planning will be better positioned to anticipate margin shifts and adjust product strategies before pressure becomes acute.
Implications for Decision Makers
For manufacturers, the immediate priority is to strengthen upstream resilience while identifying where formulation or delivery improvements can support differentiation. This means reviewing precursor sourcing strategies, testing alternative supply paths, and assessing whether current portfolio complexity is justified by the margin it generates. Where product lines are commoditized, simplification can reduce compliance burden and improve operating efficiency. Where there is credible potential for a differentiated format, targeted development and evidence generation can create a more defensible position in specific consumer segments.
For investors, the market rewards companies that combine cost discipline with credible differentiation and that demonstrate visibility into supply risk. The most attractive profiles are likely those with diversified sourcing, manageable regulatory exposure, and a clear strategy for where premium positioning is possible. It is equally important to distinguish between growth that comes from volume recovery and growth that is supported by product or process advantages, because the durability of each differs. Raw material volatility and regulatory cost changes should be treated as structural considerations rather than temporary noise, and valuation assumptions should reflect the sensitivity of margins to those factors.
For procurement and supply chain leaders, the priority is to reduce single-point dependencies and increase transparency across tiered suppliers. This includes mapping exposure to precursor concentration, evaluating contractual protections, and planning for periods of elevated cost or constrained availability. Building scenarios that account for geopolitical disruption, vessel availability, and regional pricing actions can improve responsiveness and reduce the likelihood of reactive purchasing at unfavorable terms. Procurement strategy in this market is not only about price; it is about continuity, quality assurance, and the ability to support manufacturing stability when upstream conditions shift.
Bringing the Analysis Together
The paracetamol market is moving through a phase in which growth is real but not uniform, and where competitive advantage will increasingly depend on how well companies manage supply exposure, regulatory cost pressure, and the opportunity to differentiate through formulation and patient-facing value. Demand fundamentals remain strong across core indications, and recent clinical and safety developments have helped sustain confidence in the molecule's role. At the same time, precursor concentration, pricing dynamics in key markets, and evolving compliance expectations mean that the path to profitable growth is narrower than it may appear from headline size alone.
Companies and investors that gain the deepest visibility into these interacting forces will be best positioned to act early—whether that means restructuring sourcing, refining portfolio complexity, investing in format differentiation, or reassessing where pricing power can be defended. The strategic window is open now, before further regulatory changes, supply disruptions, or competitive moves reshape the terms of participation.
For decision makers seeking detailed segmentation data, company-level benchmarks, and scenario-based guidance tailored to specific geographies and product lines, the full PW Consulting research report provides a more granular view of the market and its strategic levers. The broader analysis presented here is intended to frame the most important choices; the complete study is designed to support the next step in planning with deeper segmentation, competitive mapping, and forward-looking scenarios.
For detailed analysis of this topic, please visit the official page: Paracetamol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solar Encapsulation Materials Market: Why 7.83% CAGR and EVA's Lead Change Strategy
By PW Consulting, 2026-09-21
Global Solar Encapsulation Materials Market: Strategic Trends & Commercial Opportunities
The solar encapsulation materials marketplace has matured from a commodity-driven segment into a strategically critical layer of photovoltaic module performance and longevity. During the 2020-2025 historical period, the sector demonstrated steady expansion, driven by accelerating photovoltaic deployment, material innovation, and shifting module architectures. Current valuations place the overall market at approximately 5.87 billion USD for 2025, with a projected trajectory toward 9.95 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.83 percent across the 2026-2032 forecast window, signaling sustained structural demand rather than cyclical fluctuations.
Behind these headline figures lies a more nuanced transformation. Encapsulation has evolved from a passive protective function to an active enabler of module efficiency, reliability, and warranty economics. This shift is reshaping competitive dynamics, supply network configurations, and investment priorities. Decision-makers evaluating exposure to solar value chains must look beyond volume growth and understand the material, technological, and geographic realignments that are redefining commercial viability in this segment.
Market Snapshot and Structural Realities
The encapsulation sector operates at the intersection of polymer engineering, module architecture, and long-term performance guarantees. Crystalline silicon photovoltaic systems continue to anchor the majority of demand, reflecting their dominant position across utility-scale, commercial, and residential installations. Within the material mix, ethylene vinyl acetate (EVA) retains a leading position, accounting for roughly 55 percent of the market in 2025, while polyolefin elastomer (POE) represents the fastest-growing category, driven by compatibility with advanced cell architectures and improved moisture and potential-induced degradation resistance.
Regional demand is distributed across major solar manufacturing and deployment hubs, with North America holding a notable share, Asia Pacific maintaining strong volume leadership, and Europe sustaining steady consumption supported by local manufacturing incentives and project pipeline development. The market remains moderately concentrated, with the top three suppliers capturing approximately 62.5 percent of revenue and the top five reaching around 75.0 percent. This structure indicates that scale, formulation expertise, and module-maker relationships confer meaningful advantages, even as demand fragmentation across geographies and module types creates room for specialized entrants.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market faces structural frictions that will determine which participants capture value in the next cycle. Three challenges stand out as particularly decisive.
LED Encapsulation Market
Material specification pressure and warranty economics. Twenty-five-year module warranties have become standard expectations rather than premium differentiators. Encapsulants must now demonstrate high gel content, robust moisture barriers, and sustained potential-induced degradation resistance under diverse operating conditions. Failure to meet formulation thresholds increases financial exposure for module makers and complicates downstream bankability. The requirement for gel content above 50-70 percent for POE and EPE formulations, and above 75-80 percent for EVA, illustrates how material performance has become a gatekeeper for commercial acceptance.
Architecture transitions reshaping demand composition. The rise of TOPCon, heterojunction, bifacial, and tandem-oriented concepts is changing encapsulant requirements. Traditional EVA formulations optimized for earlier-generation cell designs require reformulation or replacement when paired with high-efficiency back-contact structures, bifacial light management, or emerging perovskite combinations. Suppliers that can deliver co-extruded solutions tailored to these architectures are gaining strategic relevance, while general-purpose material providers face margin and volume pressure.
Supply network localization and geopolitical realignment. End-users and manufacturers increasingly prioritize supply resilience over lowest-cost sourcing. The expansion of U.S. production capacity for high-performance encapsulants reflects a broader effort to reduce import dependencies and align material availability with domestic module assembly and deployment timelines. At the same time, emerging manufacturing centers in South and Southeast Asia are driving regional demand for cost-competitive yet specification-grade encapsulants. These parallel forces are bifurcating procurement strategies between premium localized supply and volume-driven regional sourcing.
Strategic Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
Encapsulation technology is moving rapidly from commodity film production to engineered material systems that support incremental module efficiency gains and durability requirements. Co-extruded structures are gaining prominence because they enable layered functionality, such as improved UV stabilization, enhanced moisture resistance, or tailored optical properties, without requiring separate processing steps. For bifacial modules, premium anti-reflective and optimized encapsulant films can deliver absolute efficiency improvements in the range of 0.5-1.0 percent, which translates into meaningful energy yield differences over a project lifecycle. This performance link justifies price premiums in the order of 15-25 percent for specification-grade films and reinforces the commercial logic of advanced material investment.
Recent product activity confirms the pace of innovation. Next-generation co-extruded POE and EPE formulations optimized for TOPCon and bifacial modules have advanced toward commercialization, with some offerings demonstrating enhanced potential-induced degradation resistance beyond 300 hours. In parallel, new encapsulant film generations incorporating UV down-conversion technology and ultrafast-cure EVA variants have entered the market alongside capacity expansions designed to support higher-volume deployment. These developments indicate that material innovation is no longer confined to laboratory feasibility; it is being scaled into commercial supply pipelines linked to module-maker qualification cycles.
Policy, Regulation, and Warranty-Driven Standards
Regulatory and financing environments are tightening the performance bar for encapsulants indirectly but powerfully. Long-duration warranties, bankability requirements, and durability expectations are translating into practical formulation thresholds. Advanced encapsulants for bifacial and next-generation modules must meet stringent moisture barrier and potential-induced degradation resistance requirements to support extended warranty commitments. This has elevated the importance of certificate-backed validation, standardized testing, and consistent batch quality.
At the same time, industrial policy and trade dynamics are reshaping where production is located and how supply chains are structured. Domestic capacity expansion in the United States is reducing exposure to cross-border disruptions for high-performance encapsulants used in advanced module types. This localization trend is not merely about cost; it is about securing predictable supply for products where qualification cycles are long and switching costs are high. In parallel, export-oriented manufacturers in Asia are aligning production with regional demand centers and international qualification requirements, creating a more geographically diversified but increasingly specification-sensitive competitive landscape.
Demand-Side Evolution and Module Architecture Shift
Demand growth is being shaped by both volume and value. Solar installation continues to expand across utility, distributed, and commercial segments, but the more strategically important shift is the changing composition of module technology adoption. Crystalline silicon remains the backbone of the market, yet the rising share of high-efficiency variants is altering encapsulant selection criteria. Bifacial modules, TOPCon cells, and back-contact configurations increasingly require materials that preserve optical performance while protecting cell interfaces over decades of operation.
For module manufacturers, this means encapsulant choice is becoming a design decision with direct implications for energy yield, degradation profile, and total cost of ownership. For buyers of finished modules, encapsulant quality is increasingly visible through warranty terms, degradation guarantees, and long-term performance expectations. As a result, encapsulant material is transitioning from a hidden component to a value-differentiating element in product positioning, especially in competitive segments where efficiency and reliability claims are scrutinized during procurement and financing.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being driven by raw material economics, processing complexity, and the premium attached to specification-grade products. Polyolefin-based materials are growing faster than established EVA streams, supported by their compatibility with advanced module designs and improved durability profiles. However, higher-performance films often involve more complex extrusion and formulation requirements, which affect conversion economics and supplier capability thresholds.
The cost dynamic is not simply about raw material price movement; it is about the widening spread between standard and premium encapsulants. Suppliers capable of delivering consistent high gel content, UV stabilization, and co-extrusion performance can capture meaningful margins through specification differentiation, while undifferentiated commodity production faces intensifying competition and pressure from regional capacity additions. This bifurcation is encouraging strategic positioning around either volume reliability or advanced material differentiation, with limited middle ground for players unable to meet either cost or specification targets consistently.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines large multinational polymer and materials companies with specialized regional manufacturers that have built strong relationships with module makers and emerging production hubs. Several patterns define current strategic positioning.
Hangzhou First PV Material Co., Ltd. has established a strong position as a large-scale producer of EVA and POE encapsulation films for crystalline silicon modules, with a product focus that extends to TOPCon, heterojunction, bifacial, and high-efficiency applications. Its scale and breadth allow it to address mainstream and advanced architectures simultaneously, making it a relevant reference point for suppliers seeking to balance volume and specification growth.
Jiangsu Sveck New Material Co., Ltd. has built a profile around EVA, POE, and high-performance co-extruded encapsulant films, with particular emphasis on serving module manufacturers in emerging markets such as Vietnam and India. This geographic orientation reflects an understanding that demand growth is not limited to established hubs and that regional supply proximity can reduce logistics risk and improve responsiveness.
Shanghai HIUV New Materials Co., Ltd. has focused on high-performance polymer materials and UV-resistant encapsulation technologies, emphasizing long-term stabilization and durability. This durability-centered positioning aligns with warranty-driven procurement and suggests a strategy oriented toward performance assurance rather than lowest-cost volume.
Changzhou Betterial Film Technologies Co., Ltd. has moved toward advanced polymer film solutions for photovoltaic encapsulation, including tandem perovskite and back-contact module technologies. This forward-looking product direction illustrates how some suppliers are positioning for next-generation cell concepts before they reach mass deployment, aiming to secure early qualification advantages.
Zhejiang Sinopont Technology Co., Ltd. is expanding its development of high-barrier co-extruded encapsulation films and TOPCon-compatible POE materials, reinforcing the broader industry emphasis on formulation precision for advanced cell architectures. Similarly, Hanwha Solutions, Mitsui Chemicals, Kuraray, SKC, Bridgestone, and Coveme represent established material capabilities and regional strengths, while U.S. and European names such as 3M, STR Holdings, Dow, DuPont, and Eastman contribute advanced polymer chemistry and specialty encapsulant expertise.
RenewSys India and Alishan Green Energy illustrate the growing role of Indian manufacturers in EVA, POE, EPE, and TPO supply. Alishan's recent moves are particularly notable: the company launched a new generation of encapsulant films including low-acid EVA, EPE-NT, and EPE-DC with UV down-conversion technology, expanded capacity to approximately 6.6 GW, and continued toward a 10 GW target by the end of 2026. This scale-up, combined with product differentiation, signals that emerging-market suppliers are not only competing on cost but are also building specification-grade portfolios for advanced applications.
Evolution of Market Structure
The market is simultaneously consolidating at the top and fragmenting in the middle. Concentration among leading suppliers reflects the advantages of scale, formulation depth, qualification track records, and long-standing relationships with module manufacturers. At the same time, technological differentiation is creating niches for specialized players focusing on co-extrusion, UV management, ultrafast curing, or next-generation cell compatibility.
Chip Encapsulation Resin Market
This dual dynamic suggests that the competitive frontier will not be defined purely by price. Instead, it will be shaped by the ability to meet specific module requirements, support qualification timelines, maintain batch consistency, and provide supply continuity in a geopolitically sensitive environment. New entrants with differentiated technology can gain traction in targeted segments, but broad-based competition is intensifying where specifications are relatively standardized and regional capacity is expanding. As manufacturing footprints shift and advanced module adoption accelerates, the landscape is likely to reward suppliers that can combine technical precision with dependable commercial execution.
Forward Outlook: Trends for the Next 3-5 Years
Trend 1: Advanced, Co-Extruded, and Architecture-Specific Encapsulants Will Become the New Baseline for Premium Modules
Over the next several years, co-extruded and architecture-tailored encapsulants will move from differentiated offerings to expected components in high-efficiency and bifacial modules. TOPCon and bifacial adoption will continue to expand, and suppliers that can deliver formulations optimized for moisture resistance, UV behavior, and potential-induced degradation control will be better positioned to secure qualification and repeat procurement. The commercial implication is clear: module manufacturers will increasingly weigh encapsulant performance as part of product design rather than treating it as a generic input.
For suppliers, this trend favors investment in formulation engineering, testing infrastructure, and application-specific product lines. For buyers, it means selection criteria will shift toward proven compatibility with target cell architectures and verifiable long-term stability. The opportunity lies in aligning encapsulant development with module roadmaps early, reducing rework and qualification delays.
Trend 2: Regional Supply Localization Will Deepen Where Premium Modules Are Made and Deployed
Localization of high-performance encapsulant production will continue in regions where advanced module manufacturing and project deployment are concentrated. In the United States, facility expansions for advanced encapsulants are strengthening domestic supply for bifacial, TOPCon, and next-generation high-efficiency modules, mitigating import dependencies from Asia. This pattern is likely to encourage parallel investments in other regions seeking to secure material availability for domestic manufacturing and export-quality production.
PW Consulting
The strategic implication is that supply chain design will become more regionalized and more sensitive to qualification continuity. Suppliers that can build localized capacity or reliable regional partnerships will increase their relevance to customers who prioritize resilience and predictable delivery. At the same time, cost-competitive regional producers in Asia will continue to serve volume demand, creating a market structure where premium localization and efficient regional supply coexist.
Trend 3: Durability-Weighted Procurement Will Redefine Value Comparison Across Materials
Procurement decisions will increasingly incorporate lifetime performance considerations rather than initial material cost alone. Warranty expectations, degradation profiles, and bankability requirements are pushing buyers to evaluate encapsulants through the lens of long-term reliability. Gel content thresholds, moisture barrier performance, and potential-induced degradation resistance are becoming practical decision metrics because they directly affect warranty exposure and asset longevity.
This shift creates opportunity for suppliers that can document durability with consistent quality and credible validation. It also introduces risk for manufacturers that compete primarily on price without robust formulation control. Over time, the market will likely see more explicit differentiation between standard and premium encapsulant tiers, with premiums justified by efficiency, durability, and qualification readiness rather than brand alone.
Risks and Uncertainties
While the outlook is favorable, several uncertainties could alter the pace or direction of value capture. Raw material cost volatility and polymer feedstock dynamics can affect margins, especially for suppliers with limited pricing power. Overcapacity in commodity-grade production could compress returns if demand growth does not absorb new capacity in certain regions. Qualification cycles are lengthy and can delay the commercial payoff of advanced formulations, creating execution risk for companies investing ahead of module adoption curves. Finally, technology transitions in next-generation cells, including tandem and back-contact concepts, remain uneven in timing and scale, which could shift encapsulant demand patterns faster than suppliers anticipate.
Actionable Guidance for Decision-Makers
For Module Manufacturers
Treat encapsulant selection as a product architecture decision rather than a procurement commodity exercise. Align material qualification with your cell technology roadmap, prioritizing suppliers that can demonstrate compatibility with bifacial, TOPCon, and other advanced designs while maintaining batch consistency. Build early-stage testing and qualification into development plans to reduce launch risk and avoid late-stage redesigns. Where warranty and bankability requirements are stringent, prioritize documented durability metrics such as gel content, moisture barrier performance, and potential-induced degradation resistance alongside cost.
For Investors and Strategic Buyers
Evaluate exposure to encapsulant suppliers based on technology differentiation, regional supply positioning, and qualification relationships rather than volume alone. Companies with credible co-extrusion capabilities, UV and durability-focused formulations, and the ability to scale advanced materials for high-efficiency modules are better positioned to capture premium segment growth. At the same time, assess whether capacity expansions are aligned with actual regional demand and whether pricing power is sustainable given regional supply additions. Portfolio value will increasingly depend on a supplier's ability to serve specification-grade demand without being dragged into undifferentiated commodity competition.
For Procurement and Supply Chain Leaders
Diversify sourcing strategies to balance premium localized supply with regional volume options, especially where module assembly, deployment, and warranty exposure create supply continuity requirements. Use qualification lead times to build relationships with suppliers that can support long-term consistency rather than short-term spot pricing. Incorporate performance-based criteria into purchasing decisions, including durability validation and compatibility with target module architectures. This approach reduces switching risk and strengthens resilience against supply disruptions, qualification delays, and regional production shifts.
The strategic significance of encapsulation materials will continue to rise as module architectures become more advanced and warranty expectations more demanding. Market participants that understand the interplay between formulation innovation, regional supply strategy, and procurement-driven durability requirements will be best positioned to manage risk and capture value. For professionals seeking deeper segmentation detail, competitive benchmarking, and tailored scenario analysis across regions and applications, the full PW Consulting research report provides expanded data sets and customized strategic guidance to support immediate planning decisions.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Quality Sensor Market Insights: How a 7.9% CAGR Reshapes Competition Through 2032
By PW Consulting, 2026-09-21
Navigating the Air Quality Sensor Market: Strategic Trends and Commercial Opportunities
Market Evolution and Structural Challenges
The air quality sensor market has transitioned from a niche environmental monitoring segment to a foundational infrastructure component across industrial, commercial, and consumer domains. By 2025, global market revenue reached approximately USD 5.95 billion, reflecting a steady expansion trajectory from the USD 3.85 billion recorded in 2020. The forward-looking horizon paints a clear growth arc: the market is projected to expand to USD 6.56 billion in 2026, USD 7.53 billion in 2028, and cross the USD 10 billion threshold by 2032. This progression translates to a compound annual growth rate of 7.9 percent across the 2026 to 2032 period, indicating that demand momentum is not cyclical but structurally embedded in how buildings, cities, and industrial facilities are managed.
Beneath the headline figures, the industry operates in a moderately concentrated environment. The top three players capture roughly 25.5 percent of total revenue, while the top five account for 31.2 percent. This concentration level suggests that while established sensor manufacturers hold meaningful scale advantages in calibration, supply chain resilience, and regulatory certification, the market remains accessible enough for specialized innovators and regional integrators to compete on application-specific performance, integration simplicity, or cost efficiency.
The industry currently sits at a structural inflection point, shaped by two persistent challenges. The first is the durability and lifecycle economics of low-cost sensing platforms. Short operating lifespans, often ranging from two months to two years for entry-tier devices, create recurring replacement cycles, calibration overhead, and total cost of ownership variability that complicate long-term deployment models. For commercial building operators and municipal monitoring networks, this introduces maintenance uncertainty and data continuity risks that traditional procurement models were not designed to absorb.
The second challenge is the tightening of regulatory and trade conditions around critical hardware inputs. Export controls on rare earth materials and permanent magnets, such as those introduced under China’s Ministry of Commerce Announcement No. 61 of 2025, have added new layers of supply chain compliance and foreign approval requirements starting in late 2025. For sensor manufacturers and system integrators, this translates into sourcing uncertainty, potential lead-time volatility, and the need to re-evaluate supplier diversification strategies before procurement bottlenecks affect production schedules.
A third pressure point lies in the widening gap between laboratory-grade accuracy and field-deployed real-world performance. Independent evaluation programs such as AQ-SPEC have continued to release field evaluation reports covering particulate and gas monitoring devices, underscoring the market’s growing expectation that sensor performance claims must be validated under operational conditions rather than controlled environments alone. As monitoring networks scale and data feeds increasingly inform compliance decisions, facility management, and public information systems, the tolerance for unexplained drift, cross-sensitivity, or inconsistent environmental compensation is shrinking.
Core Drivers Shaping Market Trajectory
Technology innovation remains the most direct growth catalyst, but the center of competitive advantage has shifted. Rather than isolated sensor components, the value is increasingly created through integrated environmental modules that combine particulate, gas, and contextual readings in a single form factor. Recent product activity illustrates this direction: Sensirion’s environmental sensor modules have been incorporated into indoor air quality monitors designed to deliver simultaneous PM, gas, and environmental measurements, reinforcing the industry’s movement toward multi-parameter visibility rather than single-pollutant point sensing. Similar integration logic is visible across building-grade platforms, where sensor capability is being packaged together with interfaces and software connectivity that reduce deployment friction.
A parallel innovation thread is the push toward safer and more sustainable sensor chemistry. The introduction of the first galvanic lead-free oxygen sensor reflects a broader industry re-evaluation of consumable sensor materials, particularly where maintenance frequency, environmental handling, and long-term deployment safety intersect. In industrial and environmental monitoring contexts, such developments matter because they influence not only device performance but also operational procedures, spare-part logistics, and regulatory acceptability over the equipment lifecycle.
PW Consulting
Policy and regulatory evolution is compounding these technical shifts. Building performance standards, occupational health expectations, and municipal air quality transparency initiatives are expanding the footprint of monitoring requirements. In parallel, independent evaluation frameworks are becoming more influential in procurement decisions, pushing manufacturers and system integrators to treat validated field performance as a commercial prerequisite rather than a technical footnote. The market is therefore moving toward an environment where accuracy claims, calibration support, and documented real-world behavior directly affect vendor credibility and purchasing decisions.
Demand-side behavior is also changing the shape of the market. Facility operators are increasingly treating air quality data as an operational input rather than a compliance checkbox. In commercial buildings, data centers, and managed indoor environments, air quality visibility is being linked to equipment protection, comfort management, and operational efficiency. In outdoor contexts, measurement networks are gaining relevance for urban planning, environmental monitoring programs, and situational awareness applications. The effect is a broader application base in which sensors are selected not only for detection capability but also for ease of integration, maintenance burden, and compatibility with existing building or asset management ecosystems.
Supply chain and cost structure dynamics complete the picture. Sensor producers and integrators are having to balance miniaturization, material availability, and manufacturing scale against the expectation of competitive pricing. Where low-cost sensors expand accessibility, they also intensify lifecycle management concerns and can shift the real economic question from unit price to total cost over deployment. This is especially relevant for organizations planning network-scale rollouts, where replacement frequency, calibration support, and field service requirements can outweigh initial hardware economics.
Competitive Positioning and Market Structure
The competitive landscape is defined by a mix of diversified industrial suppliers, specialized sensing experts, and platform-oriented manufacturers. Each group is pursuing a distinct route to value, and the differences in their product emphasis reveal how the market is segmenting.
Automotive Cabin Air Quality Sensor Market
Honeywell International Inc. anchors its position in industrial-grade air quality sensing, with offerings such as MIDAS and Sensepoint aimed at gas and particulate monitoring in commercial and industrial settings. This focus gives the company a strong fit with environments where robustness, process integration, and compliance-oriented performance are primary concerns. The strategic advantage here is not just detection capability but the ability to serve demanding installation contexts where downtime, environmental stress, and integration complexity raise the bar for sensor reliability.
Sensirion AG has built visibility around compact environmental sensor modules that combine multiple measurement functions in a single package. The uptake of these modules in indoor air quality monitoring devices reflects a strategy centered on enabling downstream manufacturers and system builders with ready-to-integrate sensing building blocks. In this model, value is created by reducing integration effort, broadening measurement coverage, and supporting a wide range of device form factors rather than competing primarily as a finished monitoring equipment brand.
Bosch Sensortec GmbH emphasizes MEMS-based multi-sensor solutions and compact particulate sensing for indoor air quality measurement. The strategic logic is similar in part to Sensirion’s, but with a distinct emphasis on highly miniaturized, embedded sensing suitable for products that must balance performance with size, power, and cost constraints. This positions the company well in consumer-adjacent and commercial building applications where space and integration simplicity matter.
Alphasense Ltd and Figaro Engineering Inc. represent the more specialized sensor chemistry and detection side of the market. Alphasense’s focus on electrochemical and optical gas sensors for industrial and environmental monitoring, including recent developments in lead-free oxygen sensing, points to a strategy built on measurement specificity and application reliability. Figaro’s TGS series electrochemical gas sensors reinforce a similar niche, where toxic gas and air quality monitoring demand stable, recognizable detection characteristics and predictable maintenance behavior. These players compete on measurement trust and application fit, often in settings where misinterpretation of sensor output carries operational or safety consequences.
Platform and systems-oriented players such as Siemens AG, Teledyne Technologies, TSI Incorporated, 3M Company, Aeroqual Ltd, and AKCP illustrate the market’s diversification across building management, environmental monitoring, aerosol and particle measurement, and specialized deployment scenarios. Siemens’ recent redesign of air quality sensors with touch interfaces and mobile app integration signals a move toward more operator-friendly building and facility monitoring experiences, where usability and connectivity are part of the commercial proposition. Teledyne’s gas and particulate sensor solutions and TSI’s aerosol and particle counter expertise reflect long-standing strengths in measurement integrity for environmental and industrial assessment workflows. 3M’s integration of particulate and gas detection into monitoring systems and Aeroqual’s portable and fixed sensor network offerings show how sensing capability is increasingly being sold as part of broader monitoring architectures. AKCP’s all-in-one sensor for data center dust and gas monitoring highlights a growing application-specific demand: protecting sensitive equipment environments through targeted air quality visibility.
The market structure appears to be evolving along two tracks at once. On one side, consolidation pressure exists among players that can combine sensor performance, calibration support, certification, and integration ecosystems at scale. On the other, differentiation is intensifying around application-specific needs, form-factor constraints, connectivity expectations, and lifecycle economics. New entrants and specialist suppliers are not necessarily trying to outperform incumbents across the board; many are competing by solving a particular deployment pain point more cleanly, whether that is miniaturization, multi-parameter integration, field validation, or maintenance-friendly consumable design.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, one of the clearest trends is the normalization of integrated multi-parameter sensing as a baseline expectation rather than a premium option. As indoor and outdoor monitoring deployments mature, buyers will increasingly compare solutions based on how well they combine particulate, gas, and environmental readings in a maintainable package, and how easily those outputs feed into building, facility, or municipal data workflows. The commercial opportunity here sits not only in sensor hardware but in the surrounding integration logic: calibration support, data compatibility, and ease of operational adoption.
Worldwide Air Quality Sensor ICs Market
A second trend is the growing operational importance of validated field performance. Independent field evaluation activity is reinforcing a market expectation that measurement claims must hold up in deployed conditions. For suppliers, this opens a differentiation path centered on transparent performance documentation, robust environmental compensation, and sustained calibration reliability. For buyers, it increases the value of evidence-based selection and post-deployment performance monitoring. Organizations that treat validation as part of the procurement process are likely to reduce downstream data quality risk and maintenance surprises.
A third trend is the continued specialization of monitoring solutions by environment and use case. Data centers, commercial buildings, industrial sites, and outdoor networks each place different demands on accuracy, response time, maintenance cadence, and integration style. As a result, market growth will not be evenly distributed across generic sensor categories. Instead, it will concentrate where sensor packaging, software experience, and service models align closely with the operating realities of a specific environment. The commercial opportunity for manufacturers and integrators is to move from broadly advertised detection capability to clearly articulated deployment value in a defined setting.
These trends carry associated risks. Supply chain constraints around critical materials and magnets could affect cost predictability and product availability if not managed through sourcing diversification and design flexibility. Low-cost sensor durability remains a structural limitation in some segments, meaning that scaling deployment without accounting for replacement and maintenance cycles can undermine long-term economics. In addition, the widening use of sensor data in operational and public-facing contexts raises the stakes for data quality, making performance inconsistency more costly than in earlier phases of market development.
Strategic Actions for Decision-Makers
For sensor manufacturers and device builders, the priority is to align product roadmaps with the market’s shift toward integration, validation, and lifecycle manageability. This means treating multi-parameter capability, field reliability, and usability not as separate features but as interconnected commercial requirements. Differentiation is increasingly likely to come from how well a solution reduces deployment friction, supports sustained accuracy, and fits into the operational environment where it will be maintained, not just installed. Supply chain resilience should also be designed into product strategy early, particularly where material constraints or export-related approvals may influence availability and lead times.
For investors, the opportunity is less about broad market growth alone and more about identifying which business models are best positioned to capture value in a maturing landscape. Companies that can combine credible field performance, application-specific fit, and scalable integration support are better placed to defend margins than those competing primarily on unit price in commoditizing segments. The lifecycle economics of low-cost sensors, the influence of independent evaluation programs, and the impact of material trade controls all point to a market where durability, documentation, and supply chain planning can be as important as sensing performance itself.
For procurement teams and end-user organizations, the strategic task is to move beyond surface-level specification comparisons and evaluate total deployment risk. This includes weighing calibration support, replacement intervals, integration complexity, and the availability of independent field evidence alongside initial hardware cost. In network-scale or mission-critical deployments, the most cost-effective solution on paper may not be the most economical over time if it introduces higher maintenance burden or data reliability risk. Procurement criteria that account for field performance history and long-term serviceability are more likely to produce stable operational outcomes.
For organizations seeking to shape strategy with greater precision, detailed segmentation data, application-level demand patterns, regional deployment dynamics, and company-specific positioning can materially improve planning quality. A deeper research perspective can help translate these market-level trends into segment-specific priorities, whether the focus is on indoor versus outdoor monitoring, industrial-grade versus compact sensing, or the integration requirements of a particular deployment environment. The commercial decisions that matter most are often the ones that require finer granularity than headline market size and growth rate can provide.
For detailed analysis of this topic, please visit the official page: Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thioctic Acid (ALA) Market at $985M: 5.92% CAGR Trajectory & 3 Strategic Shifts Reshaping the Industry
By PW Consulting, 2026-09-21
Navigating the Thioctic Acid (Alpha Lipoic Acid) Market: Strategic Trends and Commercial Opportunities
The Thioctic Acid (Alpha Lipoic Acid) market has matured beyond its origins as a niche chemical intermediate into a strategic ingredient spanning pharmaceuticals, nutraceuticals, and personal care. Global revenue climbed from $650.0 million in 2020 to an estimated $985.0 million in 2025, with a projected compound annual growth rate of 5.92 percent through 2032. This trajectory reflects broader shifts in preventive health, oxidative-stress management, and the convergence of clinical-grade efficacy with consumer-facing formulations. Yet the expansion path is uneven. Structural cost pressures, regulatory scrutiny, and geographic supply concentration are reshaping how manufacturers, investors, and procurement teams approach the category. Understanding where value accrues—and where it erodes—requires a clear read on technological differentiation, policy signals, and the evolving purchasing behavior of end markets.
Market Landscape and Structural Challenges
The baseline trajectory of the ALA market is anchored by steady volume growth and expanding application breadth. Revenue expanded consistently from 2020 through 2025, with the most pronounced inflection occurring between 2023 and 2024 as formulation adoption accelerated across multiple end-use channels. Forward projections indicate sustained growth through the early 2030s, positioning the category as a durable component of the broader bioactives ecosystem. This expansion is not uniform across applications or regions. Dietary supplements and cosmetics together represent the dominant commercial weight, while pharmaceutical-grade formulations maintain a meaningful but slower-moving share tied to clinical validation cycles and reimbursement pathways. Asia Pacific and North America anchor demand volume, with Europe contributing steady consumption supported by established supplement infrastructure. By molecular form, the market is increasingly bifurcated between racemic blends and enantiomer-pure variants, a distinction that increasingly influences pricing, formulation flexibility, and downstream marketing claims.
Concentration and Fragmentation Dynamics
Market structure remains moderately consolidated, with the largest players commanding a combined share in the mid-thirties and the top five entities approaching nearly half of total commercial activity. This concentration coexists with a long tail of regional suppliers, contract formulators, and research-grade distributors. The resulting landscape presents both stability and vulnerability. Consolidation has improved quality consistency and supply visibility for large-scale buyers, yet it also concentrates execution risk around a limited number of manufacturing nodes. Meanwhile, smaller regional players compete on agility, local regulatory navigation, and specialized enantiomer or derivative offerings, creating a segmented environment where competitive advantage depends on more than scale alone.
PW Consulting
Key Challenges at the Current Inflection Point
Several structural frictions are redefining how stakeholders position themselves in the ALA market. First, raw material volatility has become a persistent margin test. Octanoic acid prices swung between 15 and 25 percent during 2024 and 2025 as El Niño-related disruptions affected palm kernel and coconut oil availability. Because octanoic acid is integral to ALA conversion pathways, this input movement directly inflated production costs and compressed the economics of supplement formulators and private-label buyers who operate on thin spreads. Second, regulatory uncertainty is reshaping demand visibility, particularly in Europe, where ongoing scrutiny under Article 8 proceedings may reduce the addressable supplement market meaningfully. The prospect of tighter claim structures or usage limitations has prompted formulation teams to reevaluate ingredient positioning, shelf-life planning, and geographic allocation of inventory. Third, geographic concentration in sourcing remains a latent operational risk. With a concentrated share of global capacity centered in China, supply chain shocks such as shipping route disruptions highlighted the fragility of relying on a narrow set of origin points. Buyers with lean inventories and just-in-time procurement models faced disproportionate exposure, reinforcing the need for diversified origin strategies and buffer planning.
Core Demand Drivers Shaping the Category
The growth of ALA is not driven by a single tailwind but by intersecting forces across technology, regulation, consumer behavior, and cost architecture. Each driver alters where investment should flow and how product portfolios should be constructed.
Technological Differentiation and Form Advances
Innovation in molecular form and stabilization has emerged as a decisive commercial lever. The shift from racemic blends toward stabilized enantiomer forms reflects a broader consumer and formulation preference for bioavailability and consistent performance. Suppliers offering stabilized R-lipoic acid or solvent-free grades have carved defensible positions by aligning molecular purity with formulation stability, lower excipient load, and clearer claim narratives. These advances do not merely improve technical specs; they influence downstream pricing power and the ability to serve premium supplement and cosmeceutical applications where performance consistency is a purchase driver. In practical terms, form innovation has become a gatekeeper to higher-margin segments and a differentiator against commoditized bulk supply.
Worldwide Thiochemicals Market
Policy, Regulatory, and Reimbursement Signals
Regulatory dynamics are acting as both a filter and a directional signal. In the United States, compounded ALA remains accessible for patient use through established bulk drug substance pathways, preserving a channel for clinical and customized applications. In parallel, marketing environments for combination products face tighter constraint. Recent restrictions on DHA/EPA nutrient claims have limited how omega-3-enriched ALA supplements can be promoted, compelling brands to reposition messaging around antioxidant support, nerve health, and metabolic wellness rather than synergistic fatty-acid narratives. European scrutiny adds an additional layer of uncertainty. Potential adjustments to supplement usage could reshape regional demand, pushing manufacturers to diversify geographic exposure and to validate formulations against evolving compliance expectations before committing to large-scale inventory. These policy developments reward companies that invest early in compliance readiness, claim substantiation, and flexible formulation architectures.
Consumer Behavior and Application Expansion
Demand-side behavior continues to tilt toward preventive wellness and multi-benefit formulations. ALA benefits from its dual visibility as an antioxidant agent and a metabolic support ingredient, allowing it to enter product architectures spanning nerve comfort, energy metabolism, and skin-care antioxidant coverage. In supplements, the ingredient is increasingly paired with complementary actives in comprehensive wellness regimens. In cosmetics, the emphasis on oxidative stress mitigation and skin resilience has opened room for ALA in premium topical formats. Importantly, consumer purchasing is increasingly influenced by transparency around origin, purity, and molecular form. Buyers are less responsive to generic ingredient listings and more attentive to differentiators such as stabilized enantiomers, solvent-free processing, and documented quality systems. This behavioral shift raises the bar for supplier positioning and rewards brands that can translate technical superiority into clear consumer and practitioner messaging.
Supply Chain Architecture and Cost Structure Evolution
Cost structure evolution is reshaping sourcing strategies. The octanoic acid price volatility of 2024-2025 underscored how input concentration can cascade into margin pressure across conversion and formulation. Beyond raw material swings, logistics risk has become a strategic consideration. The Red Sea shipping disruptions demonstrated how quickly geographic concentration in manufacturing capacity can translate into delivery uncertainty, particularly for buyers dependent on a limited set of origin countries. In response, supply chain design is moving toward multi-origin sourcing, regional safety stock, and longer-term supplier agreements that stabilize pricing while preserving flexibility. For manufacturers, this means that cost leadership is no longer purely a function of scale; it increasingly depends on input hedging, logistics redundancy, and the ability to maintain consistent quality across multiple production sites.
Competitive Positioning and Strategic Moves
The competitive field is defined by companies that have chosen distinct lanes of differentiation: enantiomer purity, solvent-free processing, medical-grade quality systems, and application-specific formulation expertise. These choices shape pricing, customer segments, and resilience to regulatory and cost shocks.
Differentiated Leaders and Value Propositions
Several established players illustrate how strategic focus translates into market positioning. One group of suppliers emphasizes high-purity ALA for cosmeceutical and nutraceutical applications, building brand trust around consistent assay and documented quality for formulators who require reliable input characteristics. Another tier focuses on solvent-free grades for dietary supplements and pharmaceutical use, positioning around cleaner processing profiles and suitability for sensitive formulations. A third orientation centers on bio-enhanced stabilized enantiomer forms, targeting applications where bioavailability and stability are central to the value narrative. Alongside ingredient suppliers, branded supplement manufacturers and formulators convert these inputs into finished products with specific nerve-support and antioxidant messaging. Across these categories, the common thread is that technology and quality claims are no longer optional enhancements; they are the primary mechanisms for distancing from bulk commodity pricing.
Competitive Evolution: Integration, Specialization, and New Entrants
The market is evolving along multiple axes simultaneously. Larger, integrated suppliers are expanding application coverage, attempting to serve pharmaceutical, supplement, and cosmetic channels with consistent quality systems and broader grade portfolios. This integration can strengthen negotiation leverage with downstream buyers and reduce dependency on any single channel. At the same time, specialization continues to thrive. Niche players that concentrate on stabilized enantiomers, research-grade material, or region-specific GMP supply maintain relevance by serving customers who value technical specificity and local compliance familiarity. New entrants typically emerge by targeting underserved formulation needs or by offering differentiated processing attributes that incumbent bulk suppliers do not prioritize. The resulting landscape is neither purely consolidated nor fully fragmented. It is a layered market in which scale, technical specificity, and compliance readiness each create distinct lanes of advantage.
Competitive Implications for Commercial Strategy
For buyers and investors, the practical implication is that supplier selection must account for more than unit cost. Evaluation criteria increasingly include molecular form availability, processing attributes, country-of-origin exposure, and the supplier’s ability to navigate evolving regulatory expectations. For manufacturers, competitive positioning depends on whether they can convert technical differentiation into formulation performance, claim support, and supply reliability. Companies that treat ALA as a commodity input risk margin erosion and exposure to volatility; those that integrate quality narratives, form differentiation, and diversified sourcing into their planning are better positioned to protect pricing and expand premium product lines.
Forward Outlook: Trends Defining the Next Three to Five Years
Looking toward the late 2020s and early 2030s, three trends are likely to shape where value is created and where risk concentrates.
Stabilization and Enantiomer Premiumization
The market is likely to continue shifting toward stabilized and enantiomer-pure forms in higher-value applications. As formulators and brands seek consistent bioavailability and stronger claim narratives, demand for premium grades should outpace growth in bulk racemic supply. The commercial opportunity lies in building product architectures that make molecular differentiation visible to practitioners and consumers, while ensuring that stability claims are substantiated through robust quality documentation. The uncertainty here is regulatory interpretation: if claim environments tighten, the premiumization path depends on the ability to justify performance benefits without overextending marketing language.
L-Alanine Market
Geographic Rebalancing and Supply Resilience
Supply concentration risk will continue to drive rebalancing. Buyers and manufacturers will likely diversify origin points, increase regional inventory buffers, and strengthen contractual safeguards against logistics shocks. This creates opportunities for suppliers in alternative regions to capture share by offering reliable quality, transparent documentation, and flexible commercial terms. The risk is that diversification introduces complexity in quality harmonization and cost management, requiring disciplined vendor qualification and ongoing audit processes. Companies that treat resilience as an investment rather than a reactive measure will be better placed to maintain continuity when disruption recurs.
Regulatory Navigation as a Competitive Advantage
Regulatory developments in key regions will function as both constraint and selection mechanism. In Europe, potential adjustments to supplement usage could compress demand in the near term while rewarding manufacturers with prepared compliance strategies and reformulated product options. In the United States, continued access for compounded use preserves clinical and customized pathways, but marketing constraints on combination products will require sharper positioning. The companies most likely to capture opportunity are those that build regulatory intelligence into product planning, maintain claim substantiation readiness, and keep formulation portfolios flexible enough to adapt to shifting compliance boundaries without sacrificing core consumer benefits.
Strategic Actions for Decision Makers
Different roles within the market face distinct priorities, but a few strategic moves apply broadly and can improve positioning regardless of whether the focus is manufacturing, investment, or procurement.
For Manufacturers and Formulators
- Prioritize form and processing differentiation that translates into measurable formulation advantages, such as stability, lower excipient burden, and cleaner processing profiles, rather than competing primarily on bulk pricing.
- Build multi-origin sourcing and agreed buffer inventory to reduce exposure to raw material swings and logistics disruptions, and structure supplier relationships to provide pricing visibility over longer horizons.
- Align product claims and documentation with evolving regulatory expectations early, especially in regions where scrutiny may reshape addressable demand, so reformulation and repositioning can be managed proactively.
For Investors and Capital Allocators
- Assess exposure to enantiomer purity, solvent-free processing, and application diversification when evaluating companies, because these attributes increasingly determine margin resilience and pricing power.
- Monitor regulatory trajectories in Europe and the United States as signals that can alter demand visibility, and weigh portfolio exposure against potential claim constraints or usage adjustments.
- Seek suppliers and brands with demonstrated quality systems and supply resilience, since geographic concentration and input volatility remain structural risks that can affect continuity and profitability.
For Procurement and Supply Chain Leaders
- Diversify source geography and establish qualification protocols that account for both quality consistency and continuity risk, rather than optimizing solely on spot pricing.
- Negotiate commercial terms that provide clarity on input cost linkage, especially for conversion-dependent materials, to reduce surprise margin compression when commodity prices move.
- Treat ALA sourcing as a multi-dimensional decision that includes molecular form availability, processing attributes, and documentation readiness, so downstream product performance and compliance posture are protected.
The Thioctic Acid (Alpha Lipoic Acid) market is moving from broad expansion toward a more differentiated and compliance-sensitive phase. Growth remains attractive, but the reward is increasingly concentrated in players who can combine technological specificity, supply resilience, and regulatory readiness. A deeper look at segment-level demand shifts, regional dynamics, grade-level pricing behavior, and competitive benchmarking can sharpen planning and reduce exposure to volatility. For stakeholders seeking a more granular view with tailored scenario analysis and actionable recommendations, the complete PW Consulting research report provides the detailed breakdowns and customized guidance needed to convert market intelligence into execution.
For detailed analysis of this topic, please visit the official page: Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


