



Category: market research
PW Consulting: Micro Gas Generator Market Hits $176.58M in 2025, Projected 6.98% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Micro Gas Generator Market: Strategic Intelligence for 2026 and Beyond
The global energy landscape is undergoing a profound transformation, driven by the urgent need for distributed power solutions, heightened efficiency standards, and an accelerating shift toward low-emission technologies. For enterprises operating in or adjacent to the energy sector, understanding the trajectory of micro gas generators is no longer optional—it is a strategic imperative. As we release our latest comprehensive market research on the Micro Gas Generator Market, this article serves as a foundational overview, highlighting the macro-level trends and competitive dynamics that define the opportunity space through 2032 while compelling a deeper dive into the full intelligence package available for executive decision-makers.
A Market in Structural Growth Mode
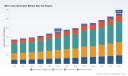
The Micro Gas Generator Market has demonstrated consistent expansion over the past half-decade, evolving from a niche distributed energy solution into a critical component of modern power infrastructure. Historical data from 2020 through 2025 reveals a market that has steadily climbed in revenue terms, reflecting sustained demand across multiple verticals. This upward trajectory is not merely cyclical; it is structural, underpinned by technological maturation, regulatory tailwinds, and an increasingly volatile macroeconomic environment that favors on-site generation.
Looking ahead, our forecast model projects continued robust growth across the 2026 to 2032 horizon. The compound annual growth rate anticipated over this forecast period underscores the market's resilience and its capacity to absorb new capacity additions. Revenue projections escalate meaningfully year over year, suggesting that scale effects, cost reductions in core technologies, and expanding application breadth will compound over time. For corporate strategists, these top-line indicators signal a market that is both expanding and maturing—conditions that reward early movers with clear positioning strategies.
Drivers Shaping the Market Trajectory
Several interlocking forces are accelerating adoption of micro gas generator technologies. Understanding these dynamics is essential for any organization evaluating product roadmaps, partnership strategies, or market entry considerations.
- Distribution of power generation assets is becoming a priority for industries seeking to reduce reliance on centralized grids. Micro gas generators offer modular, scalable solutions that can be deployed close to load centers, minimizing transmission losses and enhancing energy security.
- Efficiency mandates and emissions regulations are compelling end-users to evaluate combined heat and power configurations. Technologies capable of running on natural gas, biogas, and renewable natural gas align directly with decarbonization roadmaps and qualify for incentive programs designed to reward high-efficiency, low-emission systems.
- Input cost volatility in industrial energy markets is reshaping total cost of ownership calculations. As natural gas prices fluctuate and procurement strategies adapt, organizations are weighing the economic merits of on-site generation versus grid procurement, with micro gas turbines presenting a compelling hedge against supply disruption and price spikes.
- Technological convergence—particularly in microturbine design, air-bearing systems, and hybrid configurations—is broadening the addressable use cases. From industrial facilities to commercial buildings and specialized mobile power applications, the versatility of these systems is expanding the customer base.
The Competitive Arena: Who Is Setting the Pace
The competitive landscape of the Micro Gas Generator Market is characterized by a mix of established manufacturers, specialized technology providers, and emerging players vying to capture share in a growing field. Our research profiles the key companies that are defining product standards, securing high-profile deployments, and shaping industry expectations around performance and sustainability.
At the forefront stands Capstone Green Energy Corporation, a leading manufacturer of microturbine systems that form the technological core of many micro gas generator offerings. Headquartered in Van Nuys, California, Capstone provides a broad range of combined heat and power units spanning 30 to 1000 kW, catering to distributed power generation needs across industrial and commercial applications. The company's recent strategic moves illustrate the kind of corporate agility that matters in this market. In May 2026, Capstone Energy+—formerly operating under the Capstone Green Energy brand—completed a rebranding exercise to emphasize its focus on circular, scalable, and clean energy solutions, simultaneously closing a $112.5 million strategic investment. This capital infusion reinforces the company's ability to scale operations and invest in product development.
Worldwide Wood Gas Generator Market
Operational momentum has accompanied this financial and strategic repositioning. In April 2026, Capstone powered a premier Utah hospitality destination with its microturbine energy solution for efficient on-site power generation, demonstrating the technology's appeal in high-visibility commercial settings. Toward the end of 2025, the company secured repeat orders from a leading Mexican food manufacturer for its C1000S Microturbine CHP System and was selected by a major frozen Mexican food producer for the C800S Microturbine Energy Solution. Additionally, in October 2025, Capstone was awarded a contract by Valparaiso Community Schools for high-efficiency CHP systems, highlighting the technology's relevance in institutional and public-sector applications.
Beyond the North American leader, the competitive field includes a diverse set of players with distinct technological focuses and geographic footprints. Bladon Micro Turbine, based in the United Kingdom, produces Micro Turbine Gensets featuring high-speed microturbines and air-bearing technology tailored for distributed power generation. In the Netherlands, MTT Microturbine specializes in low-cost micro gas turbine systems aimed at domestic, small, and medium-sized enterprise power generation—addressing price-sensitive segments that remain underserved in many regions. FlexEnergy Solutions, also headquartered in the United States, manufactures microturbine-based systems for both power-only and CHP applications, emphasizing high-efficiency designs that meet distributed energy requirements.
European and global coverage widens further with Ansaldo Energia SpA in Italy, which offers microturbine solutions for combined heat and power and industrial distributed generation, and Aurelia Turbine in Finland, focused on efficient power generation applications. ICR Turbine Engine Corporation, another U.S.-based developer and producer, targets distributed energy and CHP uses, while UAV Turbine supplies microturbine systems encompassing both portable and industrial power generation options. Rounding out the competitive mosaic, Brayton Energy in the United States manufactures hybrid microturbine systems designed for versatile power generation scenarios.
Micro Gas Generator Market
This array of companies illustrates a market where differentiation hinges on technology specificity, application fit, and the ability to navigate regional regulatory and economic conditions. Concentration metrics indicate that while no single entity dominates the market outright, a cluster of leading firms commands a meaningful share of revenue, creating both competitive pressure and collaboration opportunities.
What the Full Report Delivers
While this overview establishes the macro context and competitive contours, the complete Micro Gas Generator Market research study goes substantially deeper, providing the granular intelligence that strategy teams require to make actionable decisions. The report is structured to support multiple use cases, from market entry assessments and competitive benchmarking to investment prioritization and risk evaluation.
- Detailed segmentation analysis that breaks down the market by type, application, and region, offering clarity on which sub-segments are driving growth and where saturation or disruption risks may emerge.
- Company profiles and competitive positioning assessments that evaluate the strategic posture, product portfolios, and recent moves of key market participants, enabling apples-to-apples comparison across technology approaches and business models.
- Market dynamics analysis that synthesizes regulatory developments, raw material cost trends, incentive structures, and macro energy price movements into a coherent picture of the forces shaping demand and supply.
- Forecast data spanning the 2026 to 2032 period, with revenue projections and growth rate estimates that allow scenario planning under varying conditions.
- Technology and application deep dives that correlate product characteristics with end-user requirements, helping buyers and sellers align specifications with real-world performance expectations.
The report avoids superficial aggregation. Instead, it isolates the variables that matter most for decision-making—capacity deployment trends, regional demand differentials, application-specific adoption curves, and the interplay between fuel costs and system economics—presenting them in a format designed for executive consumption and strategic planning.
Market Dynamics and External Influences
No market analysis is complete without situating the industry within its broader environment. The Micro Gas Generator Market does not operate in a vacuum; it is shaped by energy prices, environmental regulations, and procurement incentive frameworks that vary by jurisdiction and evolve over time. For instance, U.S. industrial natural gas prices averaged 6.03 USD per thousand cubic feet in 2025, establishing a baseline against which on-site generation economics are measured. Yet price volatility remains a reality, as evidenced by natural gas prices falling to 3.22 USD per MMBtu in June 2026, reflecting ongoing fluctuations in industrial energy markets that complicate long-term cost forecasts and reward flexible procurement strategies.
Regulatory and incentive landscapes further influence adoption patterns. Microturbine-based CHP systems can qualify for U.S. Environmental Protection Agency Combined Heat and Power incentives due to their high efficiency and low emissions profile, improving the financial case for deployment in eligible settings. Additionally, manufacturers such as Capstone have emphasized that their microturbines operate on natural gas, biogas, and renewable natural gas, positioning their products to support low-emission distributed power applications in alignment with sustainability targets. These capabilities are particularly relevant as organizations seek to demonstrate progress on decarbonization while maintaining operational reliability. With over 9,000 global installations attributed to leading clean technology manufacturers in this space, the installed base provides both a proof point for technology maturity and a foundation for service, support, and incremental innovation.
Strategic Implications for 2026 Decision-Makers
The confluence of market growth, technological diversification, and external volatility creates a decision environment that rewards rigorous analysis. For organizations evaluating participation in or exposure to the Micro Gas Generator Market, the strategic questions are clear: Which sub-segments offer the best balance of growth and competitive defensibility? How should product portfolios be positioned to capture demand from both established industrial users and emerging application areas? What partnerships, acquisitions, or R&D investments will strengthen a firm's ability to compete as the market scales and differentiates?
Our research is designed to equip leadership teams with the answers. By combining historical context, forward-looking forecasts, and detailed competitive and dynamic analysis, the study reduces uncertainty and sharpens strategic focus. It provides the evidentiary basis for capital allocation decisions, market entry evaluations, and product strategy refinements, ensuring that executives are not operating on assumptions but on validated market intelligence.
Access the Full Strategic Intelligence
This article has illuminated the broad contours of the Micro Gas Generator Market—its growth trajectory, its key players, and the forces shaping its evolution. Yet the depth required for high-stakes strategic decisions lies within the full report. Detailed segmentation data, company-by-company competitive assessments, regional demand patterns, application-specific revenue breakdowns, and forward-looking scenario analyses are all essential components that cannot be fully captured in a summary format.
For decision-makers who need to move beyond surface-level trends and into the specifics that drive resource allocation, partnership selection, and competitive positioning, we invite you to access the complete Micro Gas Generator Market research. The full study delivers the comprehensive, data-rich intelligence necessary to navigate this dynamic market with confidence in 2026 and through the forecast horizon to 2032.
For detailed analysis of this topic, please visit the official page: Micro Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hazardous Location Lighting Market Hits $531.56M in 2025, Booms 4.88% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Lighting in Hostile Environments: A 2026 Decision-Making Framework
The global infrastructure landscape is undergoing a period of intense recalibration. As industries expand into more remote and hazardous operational theaters, the demand for reliable, compliant, and energy-efficient illumination has become a critical boardroom priority. Our latest research release, the Hazardous Location Lighting Market report, provides a comprehensive roadmap for navigating this complex sector between 2026 and 2032. This analysis is not merely a collection of statistics; it is a strategic instrument designed to help stakeholders align capital allocation with safety mandates and technological shifts.
Hazardous Location Lighting Market
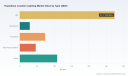
For decision-makers operating in heavy industry, energy, or infrastructure development, understanding the trajectory of hazardous location lighting is essential. The market has demonstrated resilience and steady growth over the past five years, recovering from global supply chain disruptions to establish a robust upward trend. In 2020, the market valuation stood at approximately $418.88 million, growing to $531.56 million by 2025. This historical performance underscores the inelastic demand for specialized lighting solutions that ensure operational continuity in high-risk zones. The forecast period projects this momentum to continue, with revenue expected to reach $558.27 million in 2026 and climb toward $741.3 million by 2032. This growth trajectory, reflecting a compound annual growth rate of 4.88 percent, signals a mature yet expanding market where strategic positioning can yield significant long-term returns. However, these aggregate figures only tell part of the story. The real value lies in understanding the drivers behind these numbers and how they intersect with regulatory changes and technological advancements.
Market Dynamics and Regulatory Pressures
The hazardous location lighting sector is defined by its stringent compliance requirements. Unlike general industrial lighting, products designed for explosive atmospheres must meet rigorous safety standards to prevent ignition sources. The regulatory environment is tightening, creating both barriers to entry and opportunities for compliant innovators. A significant development shaping the 2026 landscape is the introduction of new product model certification requirements under NEC 2026. This update mandates specific model-level IIC gas group approvals for explosion-proof LED lights, moving beyond broader family ratings. For procurement managers and engineering teams, this means that legacy approvals may no longer suffice, necessitating a review of current inventory and future procurement strategies to ensure full compliance.
Furthermore, the technical benchmarks for safety and efficiency are being raised. The DesignLights Consortium finalized SSL V6.0 technical requirements for hazardous location lighting in November 2025, mandating safety testing by OSHA NRTL or equivalent bodies. This standard emphasizes the importance of verified safety testing alongside performance metrics. Companies that have already aligned their product lines with these emerging standards are better positioned to capture market share, while those lagging risk exclusion from major supply contracts. These regulatory shifts are not just compliance hurdles; they are market segmentation tools that favor established players with robust certification portfolios. Our report dives deep into how these regulations impact different regions and product categories, helping you anticipate compliance costs and timelines.
On the material side, the construction of explosion-proof lighting fixtures relies on heavy-duty materials such as stainless steel, aluminum, or glass-reinforced polyester for enclosures and components. The availability and pricing of these raw materials can influence manufacturing costs and final product pricing. As supply chains stabilize, manufacturers are optimizing material usage to balance durability with cost efficiency. Understanding the interplay between material costs and regulatory requirements is crucial for forecasting margin pressures and pricing strategies in the coming years.
Technological Shifts and Application Diversity
The transition from traditional lighting technologies to advanced LED solutions is a dominant theme in this market. While legacy technologies such as incandescent, fluorescent, and high pressure sodium fixtures still hold presence in specific niches, LED has become the primary driver of growth and innovation. LED luminaires offer superior energy efficiency, reduced maintenance requirements, and longer lifespans, which are critical advantages in hazardous environments where access for maintenance can be dangerous and costly. The shift is evident across various applications, including oil and gas, mining and steel, railway, power and energy, and military and public safety sectors.
Each application segment presents unique challenges and lighting requirements. For instance, the oil and gas sector demands robust solutions capable of withstanding explosive gases and harsh environmental conditions, often requiring Zone 1/2 or Division 1/2 certifications. Mining and steel industries require lighting that can endure dust, heat, and physical impact. Railway and power sectors have specific visibility and reliability standards. Military and public safety applications often require portability and extreme durability. Our analysis explores how different lighting types are suiting these diverse needs, highlighting where LED adoption is accelerating and where traditional technologies remain relevant due to specific operational constraints. We examine the nuances of these applications without oversimplifying, providing a clear view of where demand is concentrated and how it is evolving.
Recent industry exhibitions highlight the pace of innovation. For example, Dialight Corporation exhibited ATEX and IECEx-certified LED lighting solutions, including ProSite LED Floodlights and SafeSite high bay luminaires, at Hazardex Live 2026 in February. Such events demonstrate the industry's focus on showcasing certified, high-performance products that meet the latest safety standards. The presence of major manufacturers at these venues underscores the competitiveness of the market and the importance of continuous product development to maintain technological leadership. By analyzing these trends, our report helps you identify which technologies are gaining traction and which vendors are leading the innovation curve.
Competitive Landscape and Key Players
The market is characterized by a competitive landscape where consolidation and specialization are key strategies. The top three companies hold a combined market concentration of 45.0 percent, while the top five control 55.0 percent. This indicates a moderately concentrated market with room for niche players but dominated by large conglomerates with extensive resources and global reach. Several key companies define the current competitive dynamics, each bringing distinct strengths to the hazardous location lighting sector.
- Eaton Corporation plc , headquartered in Dublin, Ireland, is recognized as a leader in the Crouse-Hinds series LED luminaires. Their HPL and HPLN series are specifically engineered for Zone 1/2 and Zone 21/22 hazardous environments, featuring global certifications and energy-efficient designs. Eaton's strength lies in its comprehensive portfolio and global distribution network, making it a go-to partner for multinational projects requiring standardized compliance.
- Hubbell Incorporated , based in Stamford, Connecticut, USA, produces the Killark VML-X series of high and low bay LED fixtures. These products are certified for Class 1 Div 2 and Zone 2 hazardous locations, catering to industrial settings where safety and performance are paramount. Hubbell's focus on durable, high-bay solutions makes it a strong contender in heavy industrial applications.
- Dialight Corporation , located in New Jersey, USA, provides ProSite LED floodlights and SafeSite high bay luminaires with ATEX and IECEx certifications. Their recent participation in Hazardex Live 2026 highlights their commitment to showcasing advanced solutions for industrial hazardous areas. Dialight's specialization in LED technology for harsh environments positions them as an innovator in the space.
- Emerson Electric Co. , through its Appleton Group in St. Louis, Missouri, offers Areamaster Connect LED luminaires and Linmaster series for Class I Division 2 hazardous locations. Emerson emphasizes energy savings of up to 80 percent with their solutions, appealing to operators focused on reducing total cost of ownership while maintaining safety standards. Their connected lighting options also align with Industry 4.0 trends.
- Signify Holding N.V. , headquartered in Eindhoven, Netherlands, manufactures industrial and hazardous area LED lighting solutions, including long-life fixtures designed for harsh environments. Signify's strong brand presence in lighting and focus on sustainability and longevity make it a significant player, particularly in regions with strict energy efficiency mandates.
These players are not just competing on product features; they are competing on certification breadth, global service support, and technological integration. Recent developments, such as Dialight's exhibition of certified solutions, reflect the ongoing race to meet evolving standards and customer expectations. Our report provides a detailed competitive analysis, examining market share dynamics, product strategies, and the strategic moves these companies are making to solidify their positions. We analyze how their offerings map to different regulatory zones and application needs, giving you a clear picture of the competitive field.
Worldwide Helideck Explosion Proof Light Market
Strategic Implications for 2026 and Beyond
For stakeholders planning their 2026 strategies, the hazardous location lighting market presents several actionable insights. First, the tightening regulatory environment means that compliance is no longer optional; it is a competitive differentiator. Procurement teams must verify that suppliers meet the latest NEC 2026 and DesignLights Consortium requirements to avoid project delays or safety liabilities. Second, the shift toward LED technology is accelerating, driven by energy savings and operational reliability. Investment in LED infrastructure in hazardous zones can yield significant long-term savings and reduce maintenance risks. Third, the competitive landscape favors vendors with global certifications and robust service networks. Partnerships with established players like Eaton, Hubbell, Dialight, Emerson, or Signify can provide access to proven technologies and localized support.
Our full report goes beyond these high-level observations to provide granular data on regional demand patterns, type-specific growth rates, and application-level analysis. We break down the market forces driving growth in different areas and identify which segments are poised for expansion. The detailed segmentation analysis allows you to pinpoint opportunities aligned with your specific business interests, whether you are looking at regional markets, product types, or end-use applications. You will gain insights into pricing trends, technology adoption curves, and the impact of raw material costs on the supply chain. We also explore the implications of market concentration, helping you understand the balance of power among key suppliers and the potential for new entrants.
The data spans the historical period from 2020 to 2025 and provides a detailed forecast through 2032. This longitudinal view enables trend analysis and scenario planning. You can see how the market evolved from the pandemic era through recovery and into the current growth phase, and how it is projected to mature. Such context is invaluable for long-term capital planning and risk assessment. By accessing the complete intelligence, you can move from reactive compliance to proactive strategic positioning.
In conclusion, the Hazardous Location Lighting Market research report serves as an essential resource for navigating the complexities of this vital industry. With rigorous data, expert analysis, and a focus on strategic decision-making, it empowers you to make informed choices that drive safety, efficiency, and growth. To access the full depth of our analysis and secure the intelligence needed for your 2026 planning, we invite you to explore the complete report. The details that will shape your strategy are waiting to be uncovered.
For detailed analysis of this topic, please visit the official page: Hazardous Location Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LNG Liquefaction Market Hits $215M in 2025, Projected 8.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the LNG Liquefaction Equipment Market 2026: A PW Consulting Strategic Brief
As global energy trade realigns around natural gas security, flexible supply chains, and decarbonization pathways, the LNG liquefaction equipment sector has transitioned from a cyclical capital goods segment to a structural enabler of export diversification and buyer-side procurement resilience. PW Consulting’s latest market research release examines the full architecture of this market, providing executives, investors, and procurement strategists with a decision-grade intelligence framework calibrated for 2026 and the forecast horizon through 2032.
LNG Liquefaction Equipment Market
This article serves as a strategic preview of the complete report. It synthesizes the observable macro trajectory, the structural segmentation patterns, the competitive theater now being redefined by recent contract executions, and the operational dynamics that are reshaping cost, schedule, and technology selection in liquefaction programs. It is designed to demonstrate the analytical depth of the full dataset while preserving the exact segmentation figures, regional share distributions, and granular revenue breakdowns that our clients rely on for capital allocation, competitive benchmarking, and commercial positioning.
The 2026 Growth Trajectory: From Post-Pandemic Recovery to Structural Expansion
The market for LNG liquefaction equipment has moved decisively beyond the volatility of the early 2020s. The historical record shows a measured recovery across the 2020 to 2025 period, followed by an acceleration that establishes a robust baseline heading into the forecast window. According to the full research dataset, total market revenue has expanded from 163.15 million USD in 2020, through 177.66 million USD in 2021 and 180.05 million USD in 2022, to 183.07 million USD in 2023, climbing further to 201.3 million USD in 2024 and reaching 215.0 million USD in 2025. This progression reflects not only the restoration of project delays and supply chain normalization, but the emergence of sustained demand for liquefaction systems across both greenfield export capacity and mid-tier modular deployments.
Looking forward, the forecast period from 2026 to 2032 charts a clear path of compounding growth. The model projects revenue advancing to 236.46 million USD in 2026, 251.25 million USD in 2027, and 263.25 million USD in 2028, before an inflection step-up to 300.93 million USD in 2029, 322.5 million USD in 2030, 349.2 million USD in 2031, and 373.44 million USD in 2032. This trajectory is underpinned by a forecast CAGR of 8.2%, a rate that positions the liquefaction equipment segment as a disciplined growth market rather than an episodic boom cycle. For strategic planners, the significance of this 8.2% CAGR lies in what it implies about capital intensity, technology refresh cycles, and the competitive urgency of securing preferred equipment slots in late-2020s train expansions.
The full report contextualizes these headline numbers within a broader analytical architecture that explains the timing, magnitude, and structural logic of the 2029 step-change. Rather than presenting raw figures in isolation, the study maps them against contracting pipelines, modularization economics, train-scale dynamics, and vendor capacity constraints, transforming the top-line numbers into a decision-support system for capacity planning, partnership strategy, and risk-weighted procurement horizons.
Inside the Research: What Decision-Makers Will Find in the Full Report
A market research deliverable earns its strategic value only when it translates macro trends into actionable intelligence. The full PW Consulting study is structured to support that translation. It moves beyond a single aggregate view and decomposes the market into the operational, manufacturing, and infrastructure dimensions that determine real-world competitive outcomes.
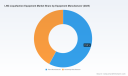
The report provides a multi-dimensional segmentation framework that covers system-level equipment architectures, equipment manufacturing pathways, plant size classifications, and regional deployment patterns. This structure allows readers to isolate demand drivers across refrigerant compression, pumping and storage, power systems, and auxiliary categories, and to understand how plant configuration choices, modular versus stick-built construction philosophies, and plant sizing strategies influence both equipment mix and commercial positioning.
Within the plant-size lens, the dataset examines distinct deployment profiles, including small-scale LNG facilities, mid-scale plants, large export-oriented complexes, and floating LNG platforms. Each category carries different procurement patterns, technology preferences, cadence of equipment orders, and competitive access barriers. The research evaluates how these profiles interact with project financing structures, liquefaction cycle selection, and the increasing role of scalable modular solutions in compressing delivery timelines.
At the equipment manufacturing level, the analysis distinguishes between plant manufacturers and assembly manufacturers, clarifying the division of responsibility, integration risk, and commercial leverage that defines the current supply chain. This distinction is essential for procurement teams seeking to balance technology ownership against fabrication capability, for investors assessing vertical integration strategies, and for operators evaluating EPC partnerships with embedded equipment supply relationships.
The regional architecture of the market is equally critical. The full report covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, mapping where demand is concentrated, where equipment supply is scaling, and where project execution dynamics are most likely to generate near-term procurement pressure. The research avoids superficial regional rankings and instead examines the structural conditions that differentiate market access, lead-time expectations, and competitive intensity across geographies.
Beyond segmentation, the study integrates competitive profiling, recent contract executions, technology adoption patterns, modularization trends, labor and fabrication dynamics, and infrastructure developments that shape the competitive playing field. It is designed to be read alongside internal capital models, procurement planning cycles, and technology roadmaps, giving executives a common reference point for comparing vendor propositions, negotiating equipment package scopes, and anticipating bottlenecks.
Competitive Theater: Who Shapes the Liquefaction Equipment Landscape in 2026
The competitive environment in LNG liquefaction equipment is defined by a blend of proprietary process technology providers, primary equipment suppliers, modular solution developers, and large engineering-procurement-construction integrators. Market concentration, as captured in the full dataset, reflects a landscape where the top players collectively command a significant but not dominant share of revenue, leaving substantial space for differentiated capability, niche technology positioning, and regional execution strength. The CR3 and CR5 concentration metrics in the report provide an evidence-based starting point for understanding how competition is structured and where entry, partnership, or displacement opportunities may emerge.
Honeywell remains a central force in liquefaction process technology. Its equipment portfolio and cycle solutions are widely deployed across major export projects, anchoring its role in the refrigerant compression and heat exchange architecture that underpins liquefaction trains. The company’s technology footprint is reinforced by recurring selection in new train awards and its established presence in global LNG production workflows.
Baker Hughes operates as a core primary equipment supplier, with a focused position in refrigerant turbo compressors and gas turbine power systems that supply the mechanical and energetic core of liquefaction facilities. Its product relevance extends across export-oriented plants where reliability, efficiency, and long-term service integration are critical to project economics.
Technip Energies brings a distinct angle through modular liquefaction engineering and standardized SnapLNG concepts, alongside full engineering support for export terminals and liquefaction plants. Its approach reflects the broader industry shift toward scalable, repeatable, and faster-to-deploy plant configurations, making it a relevant benchmark for operators evaluating modular versus conventional delivery modes.
Kiewit and Bechtel anchor the large-scale execution side of the market. Both firms lead EPC programs for major LNG liquefaction and export projects, with responsibilities spanning module integration, pretreatment, pipe racks, process technology integration, and full facility construction. Their roles matter because the boundary between equipment supply and EPC execution increasingly shapes commercial risk, schedule certainty, and the strategic value of early equipment-selection decisions.
What gives this competitive set strategic importance in 2026 is not static market share, but the way recent contracts are revealing shifting alliances, modular technology adoption, and equipment-package contracting. These patterns are not decorative details; they inform pricing power, slot availability, technology preference, and the likelihood of localized fabrication versus global supply. The full report unpacks these competitive signals in depth, using recent project activity as a lens on where capabilities are being monetized and where competitive gaps may open.
2026 Activity Snapshot: What Recent Contracts Reveal About Market Direction
Recent developments in liquefaction projects are already reshaping how equipment suppliers, EPC firms, and operators interact across the value chain. The activity observed in early 2026 provides a forward-looking signal of execution priorities, technology choices, and fabrication strategies that directly affect equipment demand.
Technip Energies’ recent EPC contract execution for a 9.5 MTPA export facility reflects the continued scaling of modular-capable engineering solutions in large export infrastructure. The award underscores how modular liquefaction concepts are being embedded into substantial projects, influencing scope boundaries, equipment package structures, and delivery sequencing.
Honeywell’s technology supply agreement for Rio Grande LNG Train 4 and Train 5 demonstrates the continued relevance of established coil-wound heat exchanger equipment and C3MR process technology in high-profile export expansions. Selection of this type reinforces the importance of proven liquefaction cycle architecture in securing long-cycle export train awards, and it signals sustained demand for high-efficiency heat exchange and associated equipment packages.
Kiewit’s lump-sum turnkey EPC execution for a Texas LNG facility, including module fabrication for liquefaction, pretreatment, and pipe rack systems, highlights the intensifying role of self-performed work and integrated module fabrication in controlling schedule and cost outcomes. When a single EPC entity manages both on-site execution and off-site module fabrication, equipment procurement timing, coordination risk, and fabrication capacity become strategic variables rather than background logistics.
Baker Hughes’ additional order for primary liquefaction equipment on Rio Grande LNG Train 5, including gas turbines and centrifugal compressors, further illustrates how core rotating and compression equipment continues to anchor project schedules and equipment package value. These orders reveal the layering of equipment commitments within multi-train programs and the importance of aligning equipment delivery with modular construction milestones.
Beyond contract awards, the surrounding operational context matters. Module fabrication for liquefaction, pretreatment, and pipe rack systems is proceeding in Texas, reflecting localized fabrication strategies that can reshape lead times and labor deployment. The Rio Grande LNG project’s phased construction across multiple trains demonstrates the modular EPC approach in practice, with successive train progression creating a cadence of recurring equipment and integration demands. Technology adoption is another structural signal: one major equipment provider’s liquefaction technology is reported to be used in nearly two-thirds of global LNG fuel production, reinforcing the gravitational pull of established cycles in new selection decisions. Meanwhile, modular scalable solutions are increasingly delivering large tonnages of LNG modules as part of standardized liquefaction train offerings, tightening the link between modularization capability and competitive differentiation.
Taken together, these developments indicate that 2026 is a year when execution logic is shaping equipment market outcomes as much as project announcements are. The full report builds this context into a structured competitive reading that helps clients anticipate where bottlenecks, leverage points, and partnership opportunities will arise.
Strategic Implications for 2026 Decision-Making
For executives navigating LNG liquefaction equipment markets, 2026 is not simply a forecast year; it is a planning inflection point. The combination of an 8.2% CAGR, a stepped revenue path into the late 2020s, and an increasingly modularized, contract-dense competitive environment means that strategic decisions made now will influence equipment access, technology positioning, and cost outcomes across the 2026 to 2032 horizon.
Procurement teams need to understand where equipment demand is being concentrated by train configuration, plant size strategy, and modularization choice, and how those choices alter vendor leverage. Investors require segmentation visibility not merely to assess size, but to judge which system categories, manufacturer types, and plant-size segments are likely to see the strongest compounding demand and the most intense competitive contestation. Competing firms need competitive intelligence that goes deeper than headline company profiles to reveal how recent contracts, fabrication strategies, and technology selection patterns are redrawing the practical boundaries of market access.
The full PW Consulting report is designed to support all of these decisions. It gives readers the structure, evidence, and analytical language needed to evaluate equipment package scopes, prioritize manufacturing and partnership relationships, and align capital and procurement strategies with the underlying shape of the market.
Helium Liquefier Market
Why the Full Report Matters
This article provides the strategic frame and the visible portion of the analysis. The complete research report goes further. It delivers the segmentation breakdowns that reveal how system types, equipment manufacturer categories, plant size profiles, and regional markets interact to shape total demand; it presents the exact market size progression and concentration metrics that anchor scenario planning; it profiles the core companies with competitive context and recent activity integration; and it translates project-level developments into procurement, technology, and execution implications that can be applied across internal decision processes.
Most importantly, the full report preserves the precision that strategic planning requires without diluting it into oversimplified rankings. It is built for teams that need to compare vendor propositions, assess scope boundaries, forecast equipment ordering windows, and understand how competing modular and EPC strategies are reshaping the commercial landscape.
For executives, investors, procurement leaders, and competitive strategists preparing for 2026 and beyond, the complete PW Consulting LNG Liquefaction Equipment Market research is the next step in converting market intelligence into commitment-ready strategy. Explore the full dataset and segmentation detail to gain the complete view needed for capital, contract, and competitive decisions.
For detailed analysis of this topic, please visit the official page: LNG Liquefaction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dispensing Systems Market Hits $57.99B in 2025, Projects 6.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Precision: Navigating the Dispensing Systems Market Trajectory Through 2032
The global dispensing systems market is entering a decisive growth cycle, driven by tightening quality standards, the rise of automated production, and accelerating demand across high-tech manufacturing verticals. As organizations plan capital allocation and technology roadmaps for 2026 and beyond, understanding where the market is heading—and which capabilities will separate leaders from laggards—has become a critical competitive advantage. Our latest Dispensing Systems Market research study provides a structured, forward-looking intelligence framework designed to support executive decision-making through the 2026–2032 forecast horizon.
Why 2026 Marks a Strategic Inflection Point
The market has moved steadily from 41.9 billion USD in 2020 to approximately 58.0 billion USD in 2025, reflecting sustained expansion across multiple industrial and life sciences applications. The projected trajectory continues with a forecast valuation near 59.8 billion USD in 2026, progressing toward roughly 89.1 billion USD by 2032. With a compound annual growth rate of 6.7 percent, this is not a market defined by sudden volatility but by compounding structural demand. For strategic planners, that consistency is both an opportunity and a warning: steady growth rewards early positioning, but it also intensifies competition for market share as incumbents scale and new entrants refine niche technologies.
Dispensing Systems Market
Several cross-currents are reshaping how companies think about dispensing investments this year. Precision fluid control is no longer a back-office manufacturing concern. It is increasingly tied to product reliability, regulatory compliance, yield improvement, and ultimately brand credibility. In medical device assembly, electronics encapsulation, and pharmaceutical filling, consistency is not optional. Stringent quality and product consistency requirements enforced by FDA and ISO standards are pushing manufacturers toward dispensing solutions that can deliver repeatable performance under stringent inspection regimes. At the same time, advancements in robotics, closed-loop control, and integrated work cells are expanding what automated dispensing can achieve on high-mix production lines.
This is exactly why a 2026-focused intelligence view matters. Executive teams need more than a headline growth figure. They need context on how demand is shifting across system types, where adoption is accelerating, and which operational pressures are turning dispensing from a component purchase into a strategic capability.
What This Research Delivers: An Executive-Level Roadmap
Our Dispensing Systems Market study is built as a decision-support platform rather than a static data sheet. It translates macro growth signals into actionable insight across technology, application, and competitive dimensions, giving leaders a clearer line of sight into where to invest, consolidate, or differentiate.
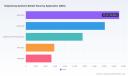
The report examines the evolving architecture of dispensing solutions, including manual, automated, and robotic system categories. Rather than treating these as isolated product groups, the analysis maps how each category fits into different manufacturing environments, volume profiles, and precision requirements. That distinction is essential because the value proposition of a dispensing system changes depending on whether the priority is flexibility, throughput, repeatability, or contamination control.
The research also explores demand patterns across major end-use environments, including electronics, automotive, healthcare and pharmaceutical, aerospace, and packaging applications. These sectors are not moving in lockstep. Some are being pulled forward by miniaturization, sensor proliferation, and advanced assembly requirements. Others are being reshaped by traceability mandates, sterile processing expectations, or the need to handle higher-viscosity materials with greater control. The study breaks down those dynamics so strategy teams can identify which application pockets offer the strongest alignment with their own capabilities and which carry higher barriers to entry.
Beyond segmentation, the report evaluates the operational and regulatory forces that are quietly redefining competitive requirements. In life sciences and pharmaceutical production, dispensing equipment increasingly must support aseptic processing, containment discipline, and sterile drug production workflows. In medical device manufacturing, quality consistency and documentation rigor have become embedded in procurement criteria. In electronics and related high-precision sectors, the push for finer deposits, lower waste, and tighter process control is accelerating adoption of more sophisticated dispensing equipment. These trends are not abstract compliance issues; they directly influence purchasing criteria, vendor selection, and long-term service expectations.
Competitive Landscape: Where Consolidation and Differentiation Converge
The market remains concentrated, with a small group of established players commanding a significant share of revenue. That concentration matters because it shapes pricing power, technology diffusion, and partnership dynamics. Companies that can combine precision engineering, application-specific know-how, and strong service networks are well positioned, while those relying on commoditized hardware face increasing pressure.
Several firms stand out for their focus on differentiated dispensing technologies and target vertical expertise. Nordson EFD continues to emphasize precision fluid dispensing systems, automated robotic dispensers, and single-use packaging for manufacturing applications. Its recent activity underscores the importance of live demonstration and application-specific positioning, including automated fluid dispensing systems presented for medical device assembly and encapsulation, as well as demonstrations focused on wearable medical technology sensor encapsulation. That pattern illustrates a broader industry shift: competitive advantage is increasingly earned through application proof points, not specification sheets alone.
Fisnar remains focused on fluid dispensing equipment, valves, and integrated robot work cells for adhesives, resins, and industrial liquids, reflecting the continuing importance of modular, integration-ready architectures. Musashi Engineering contributes a strong precision orientation, with emphasis on liquid dispensing systems and ultra-micro control equipment for industrial manufacturing environments where minute fluid handling matters. Fluid Metering, Inc. differentiates around valveless ceramic metering pumps and dispensers designed for precise fluid control in lab, chemical, and industrial applications—an approach that highlights the role of pump and metering technology in achieving consistent output.
GPD Global targets high-performance fluid dispensing systems for electronics, PCB, semiconductor, and solar manufacturing, sectors where process discipline and contamination sensitivity reward specialized solutions. In the pharmaceutical and sterile production space, Comecer concentrates on aseptic dispensing and filling systems for pharmaceutical, radiopharmaceutical, and sterile drug production. Its recent tabletop dispensing system announcement for standalone filling and closing of injectable and non-injectable vials points to the growing demand for compact, flexible solutions that still meet stringent sterile processing requirements.
The competitive field also includes firms with strong customization and application-engineering capabilities. Hernon Manufacturing focuses on custom adhesive dispensing systems, valves, and integrated solutions for high-viscosity manufacturing, while GP Reeves builds around customized automated fluid dispensing systems for production and assembly lines. SPEC, Inc. brings a specialized emphasis on ink dispensing systems and integrated mixing equipment for coatings and industrial applications, and JagCo contributes automated adhesive, fluid, and robotic dispensing systems for manufacturing precision. Together, these players illustrate a market where broad capability and vertical specialization are both viable paths—but only when paired with convincing integration, service, and process validation support.
Recent activity across these companies reinforces a clear theme. Trade show demonstrations, product announcements, and application-focused showcases are increasingly oriented toward real-world performance in regulated or high-precision environments. That suggests the market is maturing from hardware comparison toward solution validation. Buyers are less interested in whether a system can dispense, and more interested in whether it can do so consistently within their specific process constraints.
Market Dynamics Shaping 2026 Decisions
A few strategic dynamics will influence how companies prioritize dispensing investments over the next several years.
Dispensing Robot Market
- Regulatory and quality pressure is becoming a demand catalyst. In medical device manufacturing and electronics production, expectations for quality, traceability, and product consistency are tightening. That environment favors dispensing systems with stronger process control, repeatability, and validation support.
- Automation is moving from efficiency tool to precision enabler. As labor constraints, variability, and throughput demands intensify, automated and robotic dispensing solutions are increasingly evaluated for their ability to reduce variability and support complex assembly or encapsulation tasks.
- Application specialization is reshaping purchasing criteria. Different verticals impose different constraints on viscosity handling, contamination control, deposit size, speed, and documentation. Companies that can align system design with those constraints gain an advantage in qualified supplier lists and repeat sourcing.
- Sterile and aseptic processing requirements are elevating the importance of integrated system design. In pharmaceutical and life sciences environments, dispensing equipment is being assessed not only on dispensing accuracy but also on cleanliness, containment, and compatibility with sterile workflows.
- Demonstration-led commercialization is gaining importance. Recent product showcases and live demonstrations suggest that the market values tangible proof of performance in target use cases, especially where failure is costly or compliance exposure is high.
For strategy teams, the implication is straightforward. Dispensing investment decisions should be evaluated not just against unit cost, but against compliance readiness, integration complexity, application fit, and long-term serviceability. In many cases, the most cost-effective system on paper is not the most strategically sound choice once total operating risk is considered.
How to Use This Intelligence for 2026 Planning
This Dispensing Systems Market research study is designed to support multiple planning functions. For portfolio and product teams, it provides a structured view of where demand is expanding and where application requirements are becoming more demanding. For operations leaders, it helps frame the trade-offs between manual, automated, and robotic approaches in different production contexts. For commercial and business development teams, it offers a way to benchmark competitive positioning, identify emerging solution expectations, and prioritize the verticals most aligned with organizational strengths.
The report also supports scenario thinking. Because growth is projected to persist through 2032, companies can use the analysis to test whether their current capabilities will be sufficient as requirements tighten, or whether they need to invest earlier in precision control, automation integration, or regulatory-aligned system design. The goal is not simply to forecast size, but to improve decision quality under uncertainty.
Why the Full Study Matters
Macro figures tell part of the story, but they do not reveal which segments are driving momentum, how technology preferences are shifting, or where competitive intensity is most likely to compress margins. They do not show which application requirements are becoming disqualifying factors, or how leading companies are translating regulatory and precision demands into differentiated offerings. Those insights require a deeper, more structured examination.
The complete report goes further by mapping market structure, competitive positioning, application-specific demand signals, and the operational forces that will shape purchasing behavior through the end of the decade. For teams preparing 2026 investment decisions, supplier strategies, or technology roadmaps, that level of detail is essential.
If your objective is to move beyond surface-level market sizing and understand where precision dispensing is heading, the full study offers the analytical depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Dispensing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Bio Methanol Market to Reach $215M in 2025, Growing at 8.1% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-16
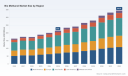
Strategic Intelligence for the Bio Methanol Transition: Why the 2026 Market Landscape Demands Precision
The global energy and chemical transition is entering a decisive phase. As regulatory frameworks tighten and capital allocation shifts toward low-carbon alternatives, bio methanol has emerged as a critical bridge fuel and chemical building block. For executives navigating supply chain restructuring, fleet decarbonization mandates, and feedstock security, understanding the trajectory of this market is no longer optional. The latest research from PW Consulting provides a comprehensive, data-driven blueprint of the bio methanol sector, calibrated specifically to inform enterprise strategy across the 2026 to 2032 forecast horizon.
Drawing on rigorous primary analysis and validated market modeling, this study maps revenue trajectories, competitive positioning, feedstock economics, and application-level demand signals. The market size stood at approximately USD 215.0 million in 2025 and is projected to reach USD 233.57 million in 2026, expanding to USD 344.8 million by 2032. This progression reflects a compound annual growth rate of 8.1 percent, signaling sustained structural demand rather than short-term volatility. The report is designed for strategic decision-makers who require actionable intelligence on where capital, partnerships, and operational capacity should be deployed to capture value in an increasingly regulated and competitive environment.
Market Trajectory and Revenue Architecture
The historical baseline from 2020 through 2025 reveals a market that has absorbed supply chain disruptions, feedstock price variability, and early-stage regulatory uncertainty while maintaining a clear upward trajectory. Revenue expanded from USD 163.15 million in 2020 to USD 200.52 million in 2024, before stepping to the 2025 baseline of USD 215.0 million. The forecast period begins with a measured acceleration in 2026 and compounds steadily through the end of the decade, reaching USD 311.71 million in 2030 and USD 344.8 million in 2032.
This growth profile underscores a transition from pilot-scale experimentation to commercial deployment. The 8.1 percent CAGR reflects the compounding effect of regulatory tailwinds, expanding vessel and transportation decarbonization requirements, and the maturation of renewable hydrogen and biomass integration pathways. Decision-makers evaluating market entry, capacity expansion, or offtake agreements will find the forecast architecture particularly useful for stress-testing investment cases across multiple demand and cost scenarios. The study deliberately avoids superficial headline numbers, instead providing the structural logic behind each forecast milestone so that strategy teams can align their models with realistic adoption curves and feedstock availability constraints.
Report Scope and Actionable Intelligence
The research is structured to serve operational, commercial, and corporate development functions simultaneously. Rather than offering isolated statistics, the report integrates macro-level sizing with granular segmentation logic, regulatory mapping, and competitive benchmarking. The scope encompasses the full value chain from feedstock sourcing through production economics, distribution considerations, and end-use demand dynamics. Key sections include demand drivers by application category, feedstock availability and cost structures, regional market maturation patterns, and a detailed competitive landscape that maps company strategies against market share concentration and expansion roadmaps.
Each analytical module is designed to support specific business decisions. Supply chain and procurement teams can evaluate feedstock security and cost variability, while commercial leaders can assess demand intensity across marine, transport, and chemical feedstock channels. Corporate development and M&A professionals will find the competitive mapping and recent transaction activity particularly relevant for identifying partnership opportunities, capacity constraints, and consolidation trends. The report also includes forward-looking signals on pricing mechanisms, certification frameworks, and regulatory milestones that directly affect project economics and offtake structuring.
Competitive Landscape and Strategic Positioning
The bio methanol market is characterized by a moderately fragmented structure with meaningful concentration among established producers and an expanding cohort of specialized renewable fuel developers. The study highlights several core companies that are shaping commercial-scale production, technology adoption, and geographic expansion. Södra has pioneered commercial-scale production of bio-methanol from forest biomass at the Mönsterås pulp mill facility, demonstrating the viability of integrated forestry-to-fuel pathways. Enerkem operates commercial-scale waste-to-bio-methanol facilities, including the first commercial Edmonton plant and expansions such as Ecoplanta in Spain producing hundreds of thousands of tonnes annually, positioning it at the center of municipal and industrial waste conversion strategies.
Biodiesel Market
Methanex Corporation has moved aggressively into low-carbon production by acquiring OCI's methanol business and progressing renewable methanol capacity, including 40,000 to 60,000 tonnes annually from renewable natural gas at Geismar starting between 2025 and 2028. Proman continues to develop renewable methanol production sites globally with a focus on bio- and low-carbon methanol alongside broader methanol and energy operations. BASF SE is producing bio-methanol utilizing sustainable feedstocks as part of its portfolio of low-carbon chemical solutions, aligning chemical feedstock demand with decarbonization targets. Carbon Recycling International Inc. converts CO2 into sustainable methanol with production capacity exceeding 200,000 tonnes per year, representing a leading pathway in carbon capture utilization. OCI N.V. operates bio-methanol production facilities, including the BioMCN site, with a clear focus on low-carbon methanol expansion.
Market concentration metrics place the top three players at 28.4 percent and the top five at 35.2 percent, indicating room for new entrants while rewarding scale, feedstock access, and certification capability. Recent corporate activity reinforces this pattern. In October 2025, Methanex Corporation completed the acquisition of OCI Global's international methanol business, including facilities positioned for low-carbon and renewable methanol expansion. In May 2025, European Energy began commercial production of e-methanol at the Kassø facility, the world's first large-scale commercial e-methanol plant with 42,000 tonnes annual capacity. In July 2025, Platts launched daily price assessments for certified UK waste biomethane Guarantees of Origin starting 1 September 2025, creating a more transparent feedstock pricing reference point. These developments illustrate how consolidation, technology diversification, and pricing infrastructure are converging to reshape competitive dynamics.
Regulatory Drivers and Demand Catalysts
Regulatory momentum is a defining feature of the current market cycle. The FuelEU Maritime Regulation entered into force in 2025 with phased GHG intensity targets for ships, with full inclusion effective in 2026, directly strengthening the case for renewable marine fuels. Alongside this, the EU ETS phases in 40 percent in 2024, 70 percent in 2025, and 100 percent in 2026 for shipping emissions, increasing the economic cost of fossil-based operations and improving the relative attractiveness of low-carbon alternatives. These frameworks are not abstract policy signals; they translate into fleet planning decisions, fuel procurement strategies, and long-term charter economics.
Feedstock economics also shape market outcomes. Biomethane production costs exhibit a wide range, with 90 percent of potential between USD 10 per GJ and USD 30 per GJ, making feedstock selection, sourcing geography, and certification quality central to project viability. The launch of UK waste biomethane price assessments for RGGOs, with daily pricing starting 1 September 2025 and covering carbon intensity from 0 to 25 g CO2e/MJ, adds a critical layer of transparency for producers and buyers negotiating renewable feedstock contracts. For chemical and transportation end-users, these developments create both compliance obligations and commercial opportunities, particularly for organizations that can secure certified supply early and integrate lifecycle carbon accounting into procurement decisions.
Segmentation Logic and Strategic Implications
The report's segmentation framework is built to help executives identify where demand intensity, feedstock suitability, and regional readiness intersect. The analysis separates market dynamics by geographic maturity, feedstock pathways, and application channels, allowing strategy teams to evaluate which segments offer the most favorable risk-adjusted returns under current regulatory and cost conditions. Rather than presenting static percentage splits, the study explains the underlying logic of segment performance, including the influence of waste availability, biomass logistics, renewable natural gas access, and certification requirements on commercial viability.
This approach is especially valuable for companies deciding where to allocate development capital or negotiate offtake agreements. Marine fuel demand is shaped by maritime decarbonization mandates and vessel retrofit cycles. Transportation applications depend on fuel infrastructure readiness and regional incentive structures. Chemical feedstock demand reflects the broader shift toward sustainable inputs in industrial supply chains. By connecting segment behavior to regulatory timelines, feedstock economics, and producer capacity pipelines, the report enables more precise scenario planning and portfolio prioritization.
Bio Methanol Market
Why This Study Matters for 2026 Decision-Making
2026 represents a pivotal year for strategic positioning in the bio methanol market. Regulatory mandates become fully operational, pricing references mature, and commercial-scale projects move from construction to ramp-up. Organizations that wait for perfect clarity risk entering the market at higher cost or without secured feedstock and offtake alignment. The PW Consulting study is designed to reduce that uncertainty by providing a structured, evidence-based view of market size, growth drivers, competitive moves, and segment-level demand logic.
The report equips leadership teams with the context needed to evaluate investment timing, partner selection, and capacity strategy. It also serves as a reference point for aligning internal assumptions with external market realities, particularly around carbon intensity requirements, feedstock cost variability, and consolidation activity. Because the study emphasizes decision-useful structure over raw data dumps, readers can translate findings directly into operational roadmaps, procurement strategies, and commercial positioning.
For organizations seeking a complete view of the forecast tables, regional and feedstock-level segmentation detail, application demand breakdowns, and full company profiles with expansion roadmaps, the full report is available through the PW Consulting research portal. The complete dataset and accompanying analytical modules are intended to support precise modeling, strategic planning, and confident execution throughout the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Bio Methanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pharmaceutical Autoclaves Market to Hit $448M by 2032, 4.68% CAGR
By PW Consulting, 2026-09-16
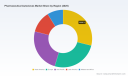
The Imperative for Sterility: Strategic Outlook for the Pharmaceutical Autoclaves Market 2026-2032
Executive Overview
In the landscape of pharmaceutical manufacturing, the autoclave is not merely a piece of equipment; it is the guardian of product integrity. As the industry navigates a period of heightened regulatory scrutiny, complex production pipelines, and geopolitical supply chain realignments, the demand for reliable steam sterilization has never been more critical. Our newly released comprehensive study on the Pharmaceutical Autoclaves Market provides the intelligence required to maneuver this essential segment. With a projected market valuation reaching significant milestones by the end of the decade, understanding the trajectory of this sector is paramount for capital allocation, capacity planning, and competitive positioning.
The historical trajectory from 2020 through 2025 demonstrates a resilient growth pattern, establishing a robust baseline for the forecast period extending to 2032. This market research is designed not just to report figures, but to translate them into actionable strategic directives. For stakeholders facing procurement decisions in 2026, the difference between cost-effective efficiency and operational compromise often lies in the nuanced understanding of market dynamics, technological advancements, and regulatory pressures detailed within this report.
Market Trajectory and Structural Insights
The growth narrative for pharmaceutical autoclaves is defined by steady expansion driven by the foundational need for sterile processing. Following a historical phase where the market solidified its value well above the $250 million mark, the forecast period indicates a sustained Compound Annual Growth Rate of 4.68%. This consistent progression suggests that despite macroeconomic fluctuations, the core requirement for validated sterilization in pharma manufacturing remains inelastic. By 2032, the market value is expected to reflect the cumulative impact of infrastructure upgrades and capacity expansions initiated in the mid-2020s.
Analysis of capacity segmentation reveals critical operational insights for manufacturers. While smaller unit capacities under 200 liters maintain a presence suitable for specific laboratory applications, the segment spanning 200 to 1000 liters represents a substantial portion of revenue generation. Furthermore, high-capacity units exceeding 1000 liters command a significant share, reflecting the industry-wide trend toward large-scale biopharmaceutical production and fill-finish operations. This bifurcation suggests a market that serves both specialized research needs and massive commercial manufacturing scales, requiring distinct procurement strategies for different organizational tiers.
Revenue distribution across applications further underscores the breadth of opportunity. Pharmaceutical companies constitute the dominant application segment, leveraging sterilization for terminal sterilization processes and aseptic filtration support. Pharmaceutical laboratories form the secondary but vital pillar, utilizing these systems for R&D validation and small-batch production. The interplay between these two segments indicates that demand is not solely dependent on commercial drug launch volumes but is also buoyed by sustained investment in early-stage drug discovery and process development.
Regulatory Pressures and Operational Dynamics
The regulatory environment is a primary catalyst reshaping procurement cycles and equipment specifications. A pivotal development occurred in 2024 when ISO 17665:2024 regarding moist heat sterilization validation gained FDA recognition. This standard mandates full compliance for pharmaceutical equipment by 2027. This timeline creates an immediate urgency for manufacturers to audit existing sterilization capabilities. Those relying on legacy equipment or non-compliant validation protocols face a compressed window to upgrade, driving demand through the forecast period.
Beyond specific standards, the broader push for digital compliance is altering equipment preferences. Industry market data suggests that over 67% of hospitals prioritize automated steam sterilizers with digital compliance tracking to meet reimbursement standards for infection control. While this statistic originates from the hospital sector, it creates a spillover effect in pharmaceutical manufacturing where data integrity and traceability are increasingly scrutinized by regulatory bodies. Consequently, integration of automated data traceability features is becoming a differentiator rather than a luxury.
Biopharmaceutical Biopharma Autoclaves Market
Infrastructure modernization is another key dynamic. More than 10,000 pharmaceutical sites upgraded sterilization units between 2023 and 2025 to align with new GMP and FDA standards. This wave of upgrades suggests a market moving from a replacement cycle to a modernization cycle, where efficiency, energy consumption, and footprint are evaluated alongside basic sterilization efficacy. However, modernization comes with cost implications. The reliance on stainless steel and advanced alloys for chambers and components contributes to higher material costs, pressuring margins and influencing total cost of ownership calculations for buyers.
Competitive Dynamics and Key Player Strategies
The market concentration indicates a moderately consolidated landscape. The top three entities hold a combined share of 48%, while the top five control 64%. This structure suggests room for niche players to thrive through specialization while allowing larger incumbents to leverage scale for service networks and R&D investment.
Strategic Profiles of Market Leaders
STERIS Corporation (Mentor, Ohio, United States) continues to anchor its position through comprehensive steam sterilizers and integrated sterilization equipment. Their focus on digital validation for pharmaceutical terminal sterilization ensures alignment with GMP compliance, making them a preferred partner for large-scale regulated facilities. In mid-2024, the company expanded its pharmaceutical sterilization support services across North America and Europe, deepening client stickiness through after-sales engagement rather than just hardware sales.
Getinge AB (Gothenburg, Sweden) emphasizes scalability and energy efficiency with its GMP-compliant terminal sterilizers, specifically the G-Series and GSS configurations. A notable product launch in early 2024 introduced upgraded GSS steam sterilizer configurations featuring automated data traceability. This move directly addresses the regulatory shift toward digital compliance, positioning Getinge as a forward-thinking solution provider for clients preparing for the 2027 FDA deadlines.
Belimed AG (Sulgen, Switzerland) has aggressively pursued international growth. In 2025, the company partnered with multiple Asian pharmaceutical firms, supplying a significant volume of large-capacity autoclaves tailored for vaccine manufacturing. This strategy highlights the geographic shift in manufacturing capacity and the critical role of sterilization in pandemic preparedness and vaccine supply chains. Their MST-V and PST.2 series continue to be benchmarks for energy-efficient designs.
Fedegari Autoclavi S.p.A. (Albuzzano, Italy) specializes in high-performance GMP washer-sterilizers and custom autoclaves for biopharmaceutical and sterile drug production. In 2025, the group completed construction of a new Biotech Plant in Ireland, supplied with high-performance GMP washers and autoclaves. This facility became the largest plant outside China, signaling a strategic expansion beyond Asian markets and reinforcing their capability to support large-scale global operations.
Shinva Medical Instrument Co., Ltd. (Jining, China) represents the growing influence of Asian manufacturers. In 2025, ChinDevelop independently developed and introduced the new LAS-M Series Vertical Autoclave. These high-output systems are designed for both domestic and export pharma applications, indicating a move from generic equipment to specialized, proprietary solutions that compete on both price and feature parity.
Sakura Seiki Co., Ltd. (Tokyo, Japan) and Yamato Scientific Co., Ltd. (Tokyo, Japan) focus on high-pressure steam sterilizers and washer-sterilizers engineered for validation in the pharmaceutical and food industries. Their reputation for precision engineering appeals to manufacturers where validation protocols are particularly rigorous.
Tuttnauer Ltd. (Netherlands) offers pharmaceutical line autoclaves with automatic sliding doors, featuring chamber volumes ranging from 250L to 2000L. This capacity range bridges the gap between laboratory scale and production scale, serving regulated biopharma operations that require flexibility without sacrificing regulatory adherence.
Yamato Scientific Co., Ltd. (Tokyo, Japan) provides laboratory and industrial steam sterilizers with high-performance features for aseptic processing and pharma applications, complementing the broader ecosystem of Japanese precision engineering.
Astell Scientific Ltd. (Powys, UK) is noted for square-chamber steam sterilizers ranging from 33 to 2000 liters, integrated with wastewater and effluent decontamination systems. This holistic approach addresses the full lifecycle of sterilization waste, a growing concern in environmental compliance.
DE LAMA S.p.A. (San Martino Siccomario, Italy) offers saturated steam, air-steam mixture, and HyPerPure H2O2 sterilizers with validation services for pharmaceutical and medical device manufacturing, showcasing the diversification of sterilization technologies beyond standard steam.
LTE Scientific Ltd. (Oldham, UK) and Rodwell Autoclave Company (Basildon, UK) provide multi-purpose lab and large-capacity steam sterilizers and precision laboratory and production autoclaves respectively. These players often cater to specific regional needs or specialized production requirements where customization is valued over mass production.
Strategic Implications for 2026 Decision-Making
As we move into 2026, the intersection of regulatory deadlines and capacity constraints will define the negotiation landscape for procurement leaders. Pharmaceutical manufacturing accounts for nearly 38% of total steam sterilization equipment demand. This dominance means that capital expenditure trends in the pharma sector directly dictate the market's health. With accelerated adoption of high-capacity pre-vacuum models, manufacturers must evaluate whether their current infrastructure can support the throughput requirements of next-generation biologics and sterile injectables.
The data on market concentration reveals that while the top players hold significant sway, the fragmented nature of the lower tier allows for competitive bidding opportunities. However, focusing solely on price can be hazardous given the regulatory landscape. The cost of non-compliance or validation failure far outweighs minor savings on equipment acquisition. Therefore, the strategic value of this market research lies in its ability to quantify the risk-adjusted cost of ownership.
Moreover, the geographic distribution of demand implies that supply chain resilience is a priority. With significant revenue generated across North America and Europe, alongside growing contributions from the Asia Pacific region, global sourcing strategies must account for local regulatory nuances and logistical reliability. The recent expansions by key players into Ireland and Asia indicate where the manufacturing hubs are shifting, offering clues on where to establish strategic partnerships or sourcing relationships for long-term stability.
The raw material dynamics also warrant attention. The reliance on advanced alloys for chambers and components suggests that lead times and pricing volatility may persist. Procurement teams should factor in material cost fluctuations when budgeting for capital projects in 2026 and beyond. Integrating these macroeconomic variables into the equipment selection process is essential for protecting project margins.
Pharmaceutical Autoclaves Market
Why Access the Full Intelligence
While the overview above outlines the structural currents of the market, the granular details necessary for precise execution are contained within the full report. The surface-level trajectory confirms growth, but the specific segmentation data, regional revenue splits, and detailed competitive benchmarking are essential for refining investment thesis statements. For instance, knowing the exact split of revenue by capacity tier allows for targeted R&D planning, while regional breakdowns help identify emerging markets with favorable regulatory environments.
The report also provides a deep dive into recent developments that serve as proxies for future behavior. Events such as facility expansions, specific product launches, and strategic partnerships analyzed in detail reveal the long-term strategic intents of competitors. Understanding that a key competitor has just opened a massive plant in Ireland or launched a new vertical autoclave series provides the context needed to anticipate market supply shifts and competitive responses.
Ultimately, this study serves as a bridge between high-level strategy and operational reality. It equips stakeholders with the knowledge to navigate the ISO 17665:2024 compliance timeline, the capex trends driving demand, and the competitive moves defining the industry. For executives, plant managers, and investors looking to secure a position in the Pharmaceutical Autoclaves Market through 2032, the comprehensive analysis provided in our full research offering is an indispensable tool. It transforms raw data into a roadmap for sustainable growth and risk mitigation in a sector where sterility is synonymous with success.
To access the complete segmentation analysis, detailed company profiles, and the full five-year forecast model, we invite you to review the complete market research document. This intelligence is curated to support high-stakes decision-making in the coming years.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Autoclaves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart City ICT Market Hits $215B in 2025, Forecasted to Surge to $344.8B by 2032
By PW Consulting, 2026-09-16
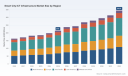
Navigating the Urban Intelligence Ecosystem: Strategic Imperatives for the Smart City ICT Infrastructure Market
The global urban landscape is undergoing a structural transformation driven by the convergence of digital connectivity, data analytics, and intelligent automation. As municipalities and private developers race to deploy integrated technology ecosystems, the demand for robust Information and Communications Technology infrastructure has become the cornerstone of modern urban planning. PW Consulting's latest comprehensive study on the Smart City ICT Infrastructure Market offers a critical lens through which stakeholders can interpret this accelerating evolution. This report is not merely a collection of statistics; it is a strategic compass designed to guide investment decisions, technology roadmap planning, and competitive positioning through the remainder of the decade.
Understanding the trajectory of this sector requires more than surface-level observation. It demands a rigorous examination of historical performance, forward-looking projections, and the underlying forces reshaping how cities function. The following analysis previews the depth of our findings, highlighting the market's growth narrative, the technological pillars driving adoption, the intensifying competitive arena, and the regulatory frameworks that will dictate deployment standards. For executives, investors, and policy architects, the insights contained within this research serve as an essential foundation for capitalizing on the opportunities inherent in the urbanization of intelligence.
Market Trajectory and Growth Dynamics
The economic scale of the Smart City ICT Infrastructure Market underscores its transition from a niche innovation sector to a fundamental component of global infrastructure spending. Based on a comprehensive historical analysis spanning from 2020 to 2025, the market has demonstrated consistent expansion, reflecting the increasing prioritization of digital urban solutions worldwide. In the base year of 2025, the total market revenue reached approximately 215.0 billion USD. This figure represents a significant accumulation of value over the past five years, driven by accelerated digitization initiatives and the post-pandemic emphasis on resilient urban systems.
Looking toward the forecast period from 2026 through 2032, the growth momentum is projected to sustain a robust pace. Our analysis indicates a compound annual growth rate (CAGR) of 10.39 percent over this horizon. Such a rate signals not only continued adoption but also the deepening integration of ICT layers into legacy urban systems. By 2032, the market is anticipated to expand substantially, crossing the threshold of 344.8 billion USD. This trajectory suggests that smart infrastructure will move beyond pilot phases and isolated implementations, becoming embedded in the standard operational fabric of cities across varying levels of economic development.
However, raw revenue figures only tell part of the story. The market's expansion is fueled by distinct technological and application drivers, each carrying its own risk-return profile and implementation complexity. Understanding which segments will catalyze the next wave of value creation requires a nuanced breakdown of the market architecture, which our full report delineates with granular precision. Stakeholders seeking to allocate capital or forge partnerships must look beyond the aggregate numbers to identify where the Margin of impact is highest.
Technological Pillars and Application Verticals
The Smart City ICT Infrastructure Market is characterized by a multi-layered technology stack that enables the collection, transmission, processing, and actuation of urban data. Our research dissects these layers to reveal which technologies are commanding the largest share of investment and which are poised for rapid scaling. The IoT ecosystem remains a dominant force, serving as the sensory nervous system of the smart city by connecting physical assets to digital management platforms. Complementing this connectivity layer, advancements in artificial intelligence and machine learning are transforming raw data streams into actionable insights, enabling predictive maintenance, traffic optimization, and energy efficiency.
On the application front, the deployment of ICT infrastructure is heavily concentrated in sectors that directly impact citizen quality of life and municipal operational efficiency. Smart Transportation and Mobility represents a critical vector of investment, as cities seek to alleviate congestion, reduce emissions, and enhance public transit reliability through real-time data integration. Beyond mobility, Smart Governance and Administration is emerging as a key area where ICT infrastructure supports transparent, data-driven decision-making and streamlined public service delivery. Additional applications span environmental monitoring, public safety, and utility management, each requiring specialized infrastructure configurations.
For technology providers and solution integrators, the interplay between type and application is where competitive differentiation is forged. Our report provides a detailed mapping of how specific ICT components align with high-growth application verticals, highlighting the synergies and bottlenecks that define deployment success. This level of detail is crucial for organizations aiming to tailor their offerings to the most receptive market segments and avoid the pitfalls of fragmented, non-interoperable solutions.
Competitive Landscape and Strategic Positioning
The arena for smart city infrastructure is populated by a diverse cohort of global technology leaders, each leveraging distinct heritage strengths to capture market share. Cisco, headquartered in San Jose, California, continues to anchor its strategy on robust networking capabilities, 5G platforms, and IoT connectivity solutions that form the backbone of city-wide communication grids. Their focus on data platforms for governance and service efficiency positions them as a foundational player in the infrastructure layer.
IBM brings a complementary strength in data analytics, AI, and IoT platforms tailored for infrastructure management, utilities, and transportation. Their emphasis on real-time operational insights appeals to municipal operators seeking to derive value from complex data environments. Meanwhile, Huawei delivers a comprehensive suite of ICT infrastructure, including 5G networks, cloud computing, and AI capabilities, often integrated with intelligent operation centers that support planning, security, and service optimization. Their end-to-end approach allows for tight integration across multiple urban domains.
Worldwide Modern AI Infrastructure Market
European industrial giants also play pivotal roles. Siemens offers IoT, edge computing, and digital twin solutions that integrate deeply with physical smart infrastructure, targeting urban mobility, energy, and sustainability applications. ABB focuses on power automation and smart grid technologies, providing IoT-enabled infrastructure solutions essential for efficient urban energy distribution. Honeywell rounds out this competitive set with smart sensors, analytics, and infrastructure solutions dedicated to energy management, transportation, and environmental monitoring.
Market concentration metrics indicate a competitive environment that is broad rather than monopolistic. The CR3 stands at 24.6 percent, and the CR5 at 26.2 percent, suggesting that while tier-one players hold significant influence, ample space remains for specialized vendors, regional specialists, and innovative disruptors. This fragmentation creates opportunities for strategic partnerships, M&A activity, and niche technology insertion. Our report analyzes the battleground positioning of these key enterprises, examining recent developments and strategic moves that signal where the market is heading.
Smart City ICT Infrastructure Market
Industry Dynamics: Regulation, Funding, and Standardization
The deployment of smart city ICT infrastructure does not occur in a vacuum; it is shaped by an evolving ecosystem of regulatory frameworks, public funding mechanisms, and standardization efforts. Recent legislative and institutional actions highlight the growing commitment of governments to accelerate digital urban transformation. In the United States, legislative measures such as H.R.4649 have authorized significant appropriations to support smart city and community technology developments, including broadband infrastructure, signaling a long-term fiscal commitment to closing the digital divide and enabling advanced urban services.
In Europe, the European Commission has bolstered support through pilot project funding, allocating additional resources for digital infrastructure deployment and AI-enabled services across energy and mobility sectors in smart cities and rural communities. These initiatives are complemented by broader programs like the Digital Europe Programme, which fosters large-scale pilots aimed at strengthening data infrastructure and intelligent services. Furthermore, cross-border recognition of successful implementations is evident in award programs that highlight operational projects delivering measurable impact, reinforcing best practices and driving replication.
Standardization bodies are also actively working to bring coherence to the fragmented landscape of smart city technologies. Initiatives such as ISO/IEC AWI 21252 and ISO/IEC PWI 5217 are under development to provide guidance on ICT infrastructure planning and digital infrastructure design, respectively. Additionally, ETSI TC ATTM is advancing standards for sustainable digital multi-service cities. These standardization efforts are critical for ensuring interoperability, security, and sustainability, and they will increasingly influence procurement criteria and vendor selection. Organizations that align their strategies with emerging standards will gain a distinct advantage in compliance-driven markets.
Strategic Value for 2026 Decision-Making
For enterprise leaders and investors, the 2026 horizon represents a inflection point where early experimentation gives way to scaled deployment and commercial maturity. The strategic value of this research report lies in its ability to translate market intelligence into actionable decision frameworks. By synthesizing historical data, forward-looking forecasts, segmentation analysis, and competitive intelligence, the report enables stakeholders to:
- Identify high-growth segments and prioritize investment based on verified market sizing and growth rates.
- Anticipate competitive shifts and evaluate partnership or acquisition opportunities among key players.
- Navigate regulatory and standardization developments to mitigate compliance risks and align product roadmaps.
- Understand the macroeconomic and regional drivers that will shape demand across different geographies.
- Leverage funding trends and public-sector initiatives to inform go-to-market strategies and business development.
The full report goes beyond the executive overview to deliver the granular data, detailed company profiles, and scenario-based analysis required for robust strategic planning. It provides the comprehensive intelligence necessary to make informed choices in a market defined by rapid technological change and complex stakeholder dynamics. Readers are encouraged to access the complete repository of insights to secure a decisive edge in navigating the smart city ICT infrastructure landscape.
For detailed analysis of this topic, please visit the official page: Smart City ICT Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Truck Loader Cranes Market to Hit $344.8M by 2032 at 5.56% CAGR
By PW Consulting, 2026-09-16
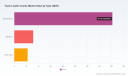
Navigating the Future of Heavy Lifting: Strategic Insights into the Global Truck Loader Cranes Market
The global logistics and construction sectors are currently navigating a period of significant transformation. At the heart of this evolution lies the Truck Loader Cranes Market, a critical component of material handling infrastructure that bridges the gap between transport and operational efficiency. As enterprises prepare for the fiscal and operational realities of 2026 and beyond, understanding the trajectory of this market is not merely an option but a strategic imperative. Our latest comprehensive market research provides a granular look into the forces shaping this industry, offering the intelligence needed to make informed investment and procurement decisions.
This report is designed to serve as a definitive guide for stakeholders ranging from OEM strategists to fleet managers. By analyzing historical performance from 2020 through 2025 and projecting trends through 2032, we uncover the underlying mechanics of growth, consolidation, and technological adoption. The following insights preview the depth of analysis available in the full study, highlighting why this intelligence is vital for securing a competitive edge in the upcoming business cycle.
Market Trajectory and Growth Dynamics
The economic backbone of the truck loader crane industry is defined by resilient demand and steady expansion. Our analysis indicates that the global market has demonstrated consistent upward momentum over the past half-decade. In 2020, the market valuation stood at approximately 163.15 million USD. Driven by recovery patterns in construction and logistics, this figure climbed to 181.92 million USD by 2022 and continued its ascent to reach 205.87 million USD in 2024.
Looking toward the immediate future, the base year of 2025 is estimated at 215.0 million USD. The forecast period projects sustained growth, with the market expected to reach 230.72 million USD in 2026. This trajectory suggests a Compound Annual Growth Rate (CAGR) of 5.56 percent throughout the forecast period ending in 2032. By the end of this cycle, the market is poised to approach 344.8 million USD. These figures underscore a narrative of stability amidst volatility, driven by infrastructure investments and the ongoing need for efficient material handling solutions in both developed and emerging economies.
Truck Loader Cranes Market
Key Drivers Influencing Market Expansion
Several macroeconomic and industrial factors are converging to support this growth curve. Infrastructure development remains a primary catalyst, particularly in regions experiencing rapid urbanization. As construction projects scale in complexity, the demand for versatile lifting equipment that can be deployed quickly and operated safely on truck beds increases. Furthermore, the logistics sector continues to optimize last-mile delivery and warehouse operations, relying heavily on truck-mounted solutions to reduce manual handling and improve throughput.
However, growth is not without headwinds. The industry is currently sensitive to fluctuations in raw material costs, specifically regarding steel, aluminum, and specialty alloys. These inputs directly influence production costs and pricing timelines for critical components. Additionally, global supply chain constraints have intermittently impacted the manufacturing of electronic and hydraulic control systems. Semiconductor availability remains a critical variable, occasionally leading to extended lead times for advanced crane models equipped with telematics and sophisticated control interfaces.
Technological Evolution and Product Segmentation
The market is broadly categorized by crane type and application, each segment presenting unique opportunities and challenges. In terms of technology, articulating boom cranes currently dominate the landscape, reflecting their versatility in tight operating environments. Stiff boom cranes maintain a significant presence where reach and lift capacity are the primary requirements. The continued innovation in these categories is evident in recent product launches across the industry.
Innovation in Control Systems and Efficiency
Modern truck loader cranes are increasingly defined by their electronic integration rather than just mechanical capacity. The shift toward smarter control systems is a central theme in our research. For instance, the adoption of advanced hydraulic control systems and user interfaces is enhancing operational precision and safety. Manufacturers are focusing on modular designs that allow for easier maintenance and upgrades, aligning with the industry's push toward sustainability and regulatory compliance.
Recent developments highlight this shift. In early 2025, major players showcased new models at industry trade shows such as bauma in Munich. These unveilings included next-generation articulating cranes and specialized truck-mounted models designed for specific regional needs. By early 2026, the focus had shifted toward the widespread deployment of advanced control systems across existing product ranges, updating hydraulics and valves to improve efficiency and integrate with broader fleet management systems.
Tower Crane Market
Application-Specific Demands
The usage landscape is diverse, with construction representing a substantial portion of demand. This sector requires equipment that can withstand harsh conditions while offering high productivity. Mining and oil and gas operations also contribute significantly, demanding rugged machinery capable of handling heavy loads in remote locations. The interplay between application needs and equipment specifications is a key area of analysis in our report, helping buyers match capabilities to operational requirements without overcapitalizing on unnecessary features.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global giants and specialized regional manufacturers. Our analysis of market concentration reveals a moderately fragmented environment. The top three competitors hold a combined share of approximately 24.6 percent, while the top five control around 26.2 percent. This fragmentation suggests that while brand recognition is important, there is ample room for niche players and specialized solutions to capture value.
Several key companies define the current competitive boundaries. PALFINGER AG, headquartered in Austria, continues to lead in articulating and telescopic loader cranes. Their recent world premiere of the PK 880 TEC model underscores their commitment to innovation in truck-mounted applications. Similarly, Hiab Group from Finland remains a pivotal player, particularly known for their knuckle boom solutions and the SPACEevo control system. Their recent updates to hydraulics and valves across the EFFER loader crane range highlight a strategic focus on software and control integration.
HMF Cranes, based in Denmark, marks a significant milestone with their 80th anniversary, reinforcing their legacy as truck crane specialists. Their new 6120K model emphasizes strength and durability, catering to users who prioritize longevity. In the Americas, Manitex International in the United States leverages strong domestic recognition through brands like National Crane, focusing on hybrid and telematics solutions to meet modern efficiency standards.
Asian manufacturers are also making notable inroads. UNIC Crane Corporation in Japan emphasizes quality and performance in global markets with their distinctive red truck-mounted cranes. Tadano Cranes and KATO WORKS CO., LTD. continue to leverage Japanese precision engineering, offering specific series tailored for construction and material handling. The presence of these diverse players creates a dynamic environment where innovation is driven by competition across multiple fronts, from material strength to digital integration.
Regulatory Environment and Operational Compliance
Navigating the regulatory landscape is as crucial as selecting the right hardware. Safety standards and emissions regulations are increasingly dictating design choices and operational protocols. Compliance with standards such as EN 12999 is essential when mounting loader cranes on trucks to ensure safety and legal operation. These regulations apply strict criteria to the structural integrity and stability of the equipment.
Beyond safety, environmental considerations are reshaping the market. Stringent emissions norms are pushing OEMs toward lighter, fuel-efficient, and modular systems. The industry is seeing a gradual shift where electric power take-off (ePTO) options and hybrid solutions are becoming more relevant, particularly in urban environments where noise and exhaust emissions are closely monitored. Our report details how these regulatory pressures are influencing purchase cycles and encouraging the adoption of newer, compliant technologies over legacy equipment.
Strategic Implications for 2026 Decision Makers
For executives and strategists planning for 2026, the data points to several actionable insights. First, the steady growth rate suggests that demand will remain robust, but supply chain resilience must be a priority. Procurement strategies should account for potential lead times influenced by electronic component availability and raw material pricing. Second, the shift toward integrated control systems implies that future-proofing fleets requires an eye on software compatibility and telematics capabilities, not just mechanical load ratings.
Third, the competitive landscape offers opportunities for partnership and diversification. With a CR3 of 24.6 percent, no single entity dominates the market completely. This allows buyers to negotiate effectively and explore varying value propositions from different manufacturers. Understanding the specific strengths of competitors—whether it is PALFINGER's range of TEC models or HMF's focus on durability—enables more targeted procurement aligned with specific operational profiles.
Why This Research Matters
Access to precise, validated data is the foundation of sound strategy. While macroeconomic trends provide a broad view, the specific nuances of segmentation, regional performance, and company profiling are where true competitive advantages are found. Our full report goes beyond the summary figures to provide a deep dive into the segments driving this growth. We analyze the split between different regions to identify where the highest velocity of adoption is occurring. We break down the application sectors to reveal which industries are driving the most revenue. And we profile the key companies to help you benchmark competitors and potential partners.
The raw market size over time tells a story of resilience, but the underlying splits reveal the opportunities. For example, knowing which region commands the largest share versus which region is growing fastest can dictate expansion strategies. Understanding the dominance of specific crane types helps in forecasting replacement cycles and technology upgrades. These details are critical for avoiding strategic blind spots.
This executive summary serves as a preview of the comprehensive intelligence available in our full Truck Loader Cranes Market Research report. To access the detailed segmentation breakdowns, regional revenue analysis, and in-depth competitive profiling required to formulate your 2026 strategy, we invite you to explore the complete study. The full document provides the specific data points necessary to validate assumptions and secure your position in this evolving market.
For detailed analysis of this topic, please visit the official page: Truck Loader Cranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Geothermal Heat Pump Market to Hit $228M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Geothermal Heat Pump Market 2026–2032: Strategic Intelligence for the Energy Transition
The global transition toward decarbonized building infrastructure has placed geothermal heat pumps at the center of HVAC innovation and investment strategy. After five years of consistent expansion, the industry now stands at a critical inflection point. Over the historical period from 2020 to 2025, total market revenue climbed steadily from approximately 112.34 million USD to 148.0 million USD, reflecting sustained demand across residential, commercial, and industrial sectors. Our latest comprehensive market study projects this momentum to continue through the forecast window of 2026 to 2032, with a compound annual growth rate of 6.5 percent and a projected market valuation exceeding 228.0 million USD by the terminal year. These figures represent more than incremental growth; they signal a structural realignment of heating and cooling procurement driven by regulatory mandates, incentive architectures, and technological maturation.
For executive teams, capital allocators, and operational leaders navigating the 2026 landscape, this research report serves as a decision-grade intelligence asset. The following overview outlines the strategic scope, analytical architecture, and competitive context embedded within the study, demonstrating how the findings can be operationalized for product roadmapping, market entry planning, supply chain optimization, and competitive positioning.
Geothermal Heat Pump Market
Macro Trajectory and Forward-Looking Market Signals
Market expansion in the geothermal heat pump sector is no longer a linear extension of past performance. It is increasingly shaped by intersecting forces: tightening refrigerant compliance timelines, evolving federal and state-level tax credit frameworks, and rising capital sensitivity around imported HVAC components. The baseline trajectory from 2025 through 2032 indicates consistent year-over-year revenue progression, with notable acceleration anticipated as commercial retrofitting programs scale and residential deployments benefit from expanded incentive eligibility windows that extend through 2032.
The competitive landscape remains moderately concentrated, with the top three firms collectively commanding a significant share of total industry revenue and the top five firms extending that footprint further. This concentration underscores the importance of understanding not only market sizing but also the strategic maneuvers that allow emerging players and regional specialists to capture differentiated value pools. The report dissects these structural dynamics with granular attention to pricing behavior, channel strategies, and regional deployment pacing, enabling stakeholders to anticipate where market share will migrate over the next several years.
Report Architecture and Actionable Content Framework
This study is designed as an execution-oriented reference rather than a static sizing exercise. The analytical framework is organized around three core pillars, each structured to translate high-level industry trends into tangible corporate strategies:
- Segmentation and Demand Mapping: The report categorizes the market across technology configurations, application verticals, and geographic demand centers. Rather than presenting isolated percentage breakdowns, the analysis connects each segment to underlying adoption drivers, including building stock characteristics, drilling and installation economics, refrigerant transition readiness, and regional policy environments. This approach enables readers to identify which end-use environments are experiencing the fastest adoption inflection and which are facing friction points that require strategic mitigation.
- Competitive Positioning and Corporate Strategy Evaluation: Profiles of leading manufacturers and specialized operators are synthesized with recent product launches, partnership announcements, and standardization milestones. The analysis moves beyond corporate descriptors to examine strategic intent: where companies are reallocating R&D resources, how they are adapting product architectures to meet low-GWP refrigerant requirements, and which commercial models are proving most effective in scaling residential and commercial deployments.
- Regulatory, Incentive, and Cost-Driver Analysis: Policy and reimbursement frameworks are evaluated as strategic variables rather than background conditions. The study traces how tax credit structures, efficiency certification pathways, and refrigerant phase-out schedules are reshaping project economics. Attention is also given to upstream cost pressures stemming from tariffs on critical HVAC components, including compressors, heat exchangers, and refrigerants, which are influencing margin structures and sourcing strategies across North America and Europe.
Each section is cross-referenced to provide a unified view of how market sizing, competitive behavior, and external policy signals interact. Executives can use this integrated lens to stress-test product portfolios against upcoming compliance deadlines, evaluate partnership opportunities in high-growth deployment corridors, and model margin scenarios under varying component cost and incentive realization assumptions.
Competitive Landscape and Strategic Maneuvers
The geothermal heat pump industry features a blend of global HVAC incumbents, regional specialists, and emerging residential-focused innovators. Our analysis tracks how these companies are differentiating through technology adaptation, channel expansion, and strategic collaborations.
Among established manufacturers, several firms have actively recalibrated their product lines to align with evolving refrigerant standards and serviceability expectations. Recent product relaunches and model updates emphasize low-GWP refrigerant integration and improved field-service design, reflecting a broader industry shift away from legacy refrigerants that are being phased out in major markets. These transitions are not purely technical exercises; they carry implications for inventory planning, training pipelines, and installer partnership models. Companies that have moved early to align with next-generation refrigerant architectures are positioning themselves to reduce compliance risk while capturing demand from specifiers seeking future-proof installations.
Parallel to product-level innovation, the competitive landscape is being reshaped by collaboration-driven scaling strategies. Strategic partnerships have emerged as a critical mechanism for accelerating residential deployment, particularly in markets where installation capacity, permitting complexity, and customer acquisition costs have historically constrained growth. By aligning with broader HVAC distribution networks and deployment specialists, select market participants are constructing pathways to higher-volume residential rollouts that would be difficult to achieve through standalone operations.
The report provides detailed competitive intelligence on leading players, including Carrier Corporation, Bosch Thermotechnology, NIBE Energy Systems, Trane Technologies plc, ClimateMaster Inc., WaterFurnace International, BDR Thermea, Stiebel Eltron, Viessmann Group, and Dandelion Energy. Each profile is contextualized within broader strategic themes: how multinational firms leverage scale and integrated HVAC portfolios, how European manufacturers differentiate through energy-efficient ground-source system design, and how U.S.-based specialists are building niche leadership in residential and commercial ground-source applications. The study also examines recent standardization activity, including updated design and installation guidelines from industry bodies, which are influencing engineering practices and creating new compatibility expectations across product ecosystems.
A concrete illustration of the commercial and public-sector value proposition is visible in recent institutional deployments. Notably, a large school district completed geothermal heat pump upgrades across ten facilities, achieving substantial annual energy savings and outlining expansion plans to additional campuses. Projects of this nature reinforce the financial and operational case for geothermal adoption in public infrastructure and provide a reference architecture for commercial entities evaluating similar retrofitting pathways.
Regulatory, Reimbursement, and Cost Dynamics Shaping 2026 Decisions
The operating environment for geothermal heat pump stakeholders in 2026 is defined by a combination of compliance acceleration, incentive accessibility, and cost volatility. Understanding how these forces interact is essential for accurate forecasting and risk-adjusted planning.
On the regulatory front, the phase-down of legacy refrigerants has moved from anticipated policy to implemented reality. Major markets have moved to restrict the production and use of higher-GWP refrigerants, with manufacturers shifting engineering and sourcing toward compliant alternatives. This transition affects product design, supply chain logistics, and service infrastructure, creating both challenges and differentiation opportunities. Companies that have already aligned their portfolios with low-GWP refrigerant pathways are better positioned to navigate procurement constraints and installer readiness requirements.
Incentive architecture remains a powerful demand catalyst. Residential and commercial adopters continue to benefit from federal tax credit provisions that support qualifying installations through the early 2030s. Residential programs offer meaningful credit coverage through established energy efficiency pathways, while commercial frameworks provide base investment tax credit rates that can be expanded significantly when projects meet prevailing wage, domestic content, or energy community criteria. The strategic implication is twofold: early engagement with incentive compliance can materially improve project economics, and incentive optimization is increasingly becoming a competitive differentiator in commercial proposals and utility-coordinated programs.
Geothermal Power Market
At the same time, cost pressures are intensifying on the input side. Tariffs on imported HVAC components are elevating upfront installation costs and prompting supply chain reevaluation. Compressors, heat exchangers, and refrigerant sourcing are among the components drawing heightened cost attention, particularly for projects in North America and Europe. The report analyzes how these cost dynamics are influencing pricing strategies, manufacturing localization discussions, and procurement timing, helping stakeholders model realistic cost trajectories rather than relying on static assumptions.
Strategic Implications for Corporate Decision-Makers in 2026
The data and analysis presented in this study converge on a set of strategic imperatives for organizations operating in or entering the geothermal heat pump market. First, portfolio alignment with next-generation refrigerant standards should be treated as a near-term execution priority, not a long-range planning item. Second, incentive optimization and compliance readiness must be embedded into commercial proposal development, particularly for commercial and institutional projects where bonus credit pathways can meaningfully shift ROI profiles. Third, supply chain exposure to component tariffs requires proactive sourcing strategies, inventory planning, and scenario modeling to protect margin integrity in a volatile input-cost environment.
For companies evaluating market entry or expansion, the segmentation analysis in the report highlights where adoption momentum is strongest and where structural friction remains highest. For incumbents, the competitive profiles and recent development timeline illuminate where rivals are concentrating investment, which product features are becoming table stakes, and where partnership-based scaling is outpacing standalone deployment models. For investors and strategic planners, the market trajectory and concentration metrics provide a foundation for sizing opportunity pools while the detailed segment and dynamic layers enable more precise allocation decisions.
Closing Perspective
The geothermal heat pump market is evolving from a specialized efficiency solution into a strategically significant component of broader building decarbonization efforts. The convergence of regulatory momentum, incentive availability, product maturation, and cost-structure realignment creates a complex but navigable environment for organizations that can integrate market intelligence into execution planning. This research report is intended to provide that integration: a rigorous, forward-looking framework that converts macro trajectory and competitive behavior into actionable corporate strategy. The full dataset, segmented modeling, and detailed competitive evaluation are available through the complete study, enabling decision-makers to move beyond general market directionality and into the precise intelligence required for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Geothermal Heat Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hospitality Property Management Software Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Insights into the Hospitality Property Management Software Market 2026–2032
The hospitality industry stands at a critical inflection point. As operational complexities multiply and traveler expectations evolve, the technology stack underpinning property management has shifted from a back-office utility to a central driver of revenue, guest experience, and competitive differentiation. Our latest market research on the Hospitality Property Management Software Market delivers a comprehensive, forward-looking intelligence framework designed specifically for executives navigating 2026 strategic planning cycles. This report does not merely catalog historical performance; it decodes the structural shifts, adoption vectors, and competitive realignments that will determine market positioning over the next seven years.
For hotel operators, software vendors, investors, and technology integrators, the difference between reactive adaptation and proactive strategy lies in precise, validated intelligence. The following analysis previews the strategic architecture of our study, demonstrates why granular market mapping matters for 2026 decision-making, and outlines how the full report transforms raw data into actionable growth pathways.
Market Trajectory and the 2026 Strategic Imperative
The Hospitality Property Management Software Market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD by 2025. This trajectory reflects more than organic growth; it signals a fundamental recalibration of how properties manage reservations, front-desk operations, channel distribution, and guest engagement. Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 6.98 percent, with market valuation expected to reach 228.59 million USD in 2026, 247.44 million USD in 2027, and 268.04 million USD in 2028 before continuing toward 344.8 million USD by 2032.
Hospitality Property Management Software Market
These figures establish a clear directional signal, but macro aggregates alone cannot guide allocation decisions. The strategic value for 2026 executives lies in understanding where growth concentrates, which deployment models are capturing premium value, which functional modules are driving procurement cycles, and how regional maturity curves intersect with regulatory and labor-cost pressures. Our report dissects these layers without exposing segment-level percentages in public summaries, ensuring that only stakeholders who access the complete dataset can benchmark their positioning against precise market shares, adoption rates, and regional revenue breakdowns.
Property Management Software Market
For 2026 planning, this translates into three immediate imperatives: first, aligning technology roadmaps with the accelerating preference for connected, API-driven environments; second, stress-testing operational workflows against labor-market constraints that are reshaping staffing models; and third, evaluating compliance readiness as data-security mandates continue to influence vendor selection and implementation timelines.
Report Architecture: Actionable Intelligence for Enterprise Decision-Making
The full study is structured around operational utility rather than academic observation. Each chapter maps directly to procurement, product, or M&A decision points that hospitality executives face in 2026 and beyond.
Core analytical components include:
- Historical performance reconstruction spanning 2020 through 2025, establishing baseline adoption cycles, pricing normalization, and regional expansion patterns that inform 2026 forecasting accuracy.
- Forward-looking valuation modeling for 2026–2032, built on scenario-adjusted demand drivers, deployment-model transitions, and functional-module purchasing rhythms.
- Segmentation mapping across geographic markets, technology architectures, and application verticals, designed to reveal where procurement budgets are reallocating and which property profiles are leading early adoption.
- Competitive positioning frameworks that evaluate vendor portfolios, partnership strategies, product-release cadence, and ecosystem reach, enabling benchmarking against incumbents and challengers.
- Regulatory and operational dynamics analysis, including compliance-cost trajectories, data-privacy enforcement patterns, and labor-market adaptations that are reshaping software requirements.
- Technology integration and automation touchpoints, with emphasis on revenue-management add-ons, guest-facing mobility tools, and back-office analytics that influence total cost of ownership and ROI timelines.
The report deliberately maintains a tiered disclosure model. High-level trajectory and structural insights are presented here to establish analytical credibility; the precise regional revenue splits, application-module valuations, and deployment-model breakdowns are reserved for the complete dataset. This approach ensures that enterprise readers who request the full intelligence package receive decision-grade granularity rather than diluted aggregates.
Competitive Realignment and Strategic Positioning
The vendor landscape reflects a clear bifurcation between cloud-native, integration-heavy platforms and legacy-adjacent enterprise systems that are modernizing through analytics and ERP linkage. Our analysis tracks how these players are competing on ecosystem breadth, guest-experience orchestration, and revenue-optimization capabilities rather than standalone property-management functionality alone.
Key competitive profiles under examination:
- Cloudbeds continues to expand its unified cloud-based hotel management platform, bundling PMS, distribution, guest experience, and revenue marketing integrations targeted at independent and mid-market properties. Its recent launch of a Preferred Partner Program demonstrates a deliberate push toward ecosystem orchestration, connecting hoteliers with adjacent technology solutions rather than competing solely on core PMS features.
- Mews has scaled a cloud-based hospitality platform centered on modern hotelier workflows, with adoption spanning more than 15,000 properties across 85-plus countries. Its partnership trajectory, including integrations with major franchise networks, reflects a strategy of embedding PMS capabilities within broader international distribution and operational frameworks.
- Hotelogix positions its cloud PMS around AI-driven revenue management and automation, targeting independent hotels and resorts that require lightweight but intelligent operational tooling.
- Agilysys offers a full-featured PMS that integrates POS, CRS, channel managers, and guest engagement tools, making it relevant for hotels, resorts, and multi-property portfolios seeking consolidated operational control.
- StayNTouch emphasizes mobile guest-centric capabilities, kiosk check-ins, and a broad integration library, recently advancing its product roadmap with operational enhancements in its 5.90 release cycle.
- RMS Cloud delivers a cloud-native PMS tailored to hotels, motels, holiday parks, and serviced apartments across more than 70 countries, underscoring the importance of property-type specialization in competitive positioning.
- Oracle Hospitality pursues enterprise-grade PMS capabilities with AI-driven analytics, ERP integration, and sustainability features, appealing to large portfolios that require scalable infrastructure and cross-functional data connectivity.
- SAP embeds PMS functionality within broader ERP architectures, targeting large portfolios where back-office accounting, analytics, and financial consolidation are inseparable from front-office management.
- Infor leverages hospitality-specific PMS design with deep ERP roots and analytics, positioning itself for hotels that demand operational granularity alongside enterprise financial and supply-chain linkage.
Recent market movements reinforce how quickly partnership and product strategies are reshaping procurement considerations. In April 2025, Choice Hotels International introduced Mews cloud PMS as a new option for international franchisees, signaling how franchise networks are diversifying technology stacks across geographies. In August 2025, StayNTouch released its PMS version 5.90 with operational enhancements, illustrating the continuous improvement cadence that buyers now expect as a baseline rather than a differentiator. In March 2026, Cloudbeds announced a new Preferred Partner Program to connect hoteliers with technology solutions, further evidencing the industry's shift toward ecosystem-driven value creation.
The full report evaluates these moves within a structured competitive framework, analyzing how vendor concentration, integration depth, and regional availability influence deal velocity and customer retention. Market concentration metrics indicate that the top three players account for approximately 24.6 percent of revenue, while the top five represent roughly 26.2 percent, suggesting a landscape that remains fragmented enough for targeted entrants yet consolidated enough for incumbents to defend through ecosystem lock-in and service quality.
Regulatory Pressure, Labor Constraints, and the Compliance-Roi Equation
Market dynamics in 2026 are being shaped as much by external constraints as by technological ambition. Compliance requirements for GDPR, PCI-DSS, and local privacy regulations now apply to more than 95 percent of large deployments, and over 95 percent of enterprise PMS platforms meet these standards. While this high baseline demonstrates industry maturity, it also introduces a nuanced cost structure: heightened data-security and privacy compliance expenses are exerting negative pressure on overall market economics, particularly for operators managing multi-property portfolios or expanding into jurisdictions with stringent enforcement regimes.
Simultaneously, labor-market realities are accelerating the commercial appeal of automation. AI-driven revenue-management add-ons within PMS platforms are improving ROI by automating forecasting, optimizing pricing decisions, and freeing staff in labor-shortage regions. This convergence—rising compliance overhead alongside labor-cost compression—is altering procurement criteria. Buyers increasingly evaluate platforms not only on front-desk efficiency or booking throughput, but also on how effectively software reduces manual intervention, supports audit readiness, and scales without proportional headcount growth.
These dynamics inform three strategic questions that our report addresses in depth: which compliance architectures minimize implementation friction while preserving data sovereignty; how automation modules are being priced and packaged relative to core PMS functionality; and which property profiles are most exposed to labor-driven operational risk, making automation adoption a defensive as well as offensive investment.
Why Full Intelligence Access Matters for 2026 Decisions
The hospitality technology market rewards precision. A directional growth rate or a general observation about cloud adoption can inform conversation, but it cannot support budget allocation, vendor shortlisting, partnership evaluation, or market-entry timing. Decision-makers require segment-level visibility to answer questions such as which regions are absorbing incremental investment fastest, how cloud-based, on-premise, and hybrid architectures are redistributing revenue shares, and which application modules are anchoring procurement cycles versus serving as supplementary add-ons.
Our research is designed to close that gap. The complete report delivers precise regional revenue mappings, deployment-model valuations, application-level breakdowns, vendor benchmarking matrices, and scenario-adjusted forecasts that tie market behavior to operational realities. By reserving these specifics for the full intelligence package, we ensure that the analysis retains its decision-grade integrity and that stakeholders who invest in the complete dataset gain a measurable advantage in planning, negotiation, and strategic positioning.
For executives preparing 2026 roadmaps, the immediate next step is to align internal assumptions with validated market structure. Whether the objective is to evaluate a software procurement cycle, assess a technology partnership, benchmark against competitors, or identify growth vectors in underpenetrated segments, the full report provides the granular references needed to move from observation to execution.
From Observation to Execution: Accessing the Complete Dataset
Strategic advantage in the Hospitality Property Management Software Market will belong to organizations that combine forward-looking vision with precise, current intelligence. The trajectory through 2032 points to continued expansion, but the distribution of that growth—by region, by deployment model, by application module, and by vendor ecosystem—will determine which players capture disproportionate value and which operate from behind.
The complete report translates high-level market signals into a structured decision framework, enabling executives to test assumptions, prioritize investments, and anticipate competitive responses with confidence. To access the full regional breakdowns, deployment-architecture valuations, application-level revenue splits, competitive benchmarking, and scenario-based forecasts, request the complete market research dataset. The intelligence contained within is built for 2026 planning cycles and designed to support the operational, financial, and strategic choices that will shape hospitality technology portfolios through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Hospitality Property Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


