



Category: market research
Strategic Intelligence for the Concrete Mixer Market: Why Our 2026 Industry Report Matters
In an era where industrial equipment markets are shaped by rapid technological adoption, shifting regulatory landscapes, and volatile supply chain dynamics, capital allocation and product roadmap decisions require more than surface-level market sizing. The global concrete mixer market stands at a critical inflection point. Infrastructure stimulus programs, residential and commercial construction rebounds, and the gradual electrification of heavy-duty mobile equipment are converging to reshape competitive positioning and demand patterns across every major geography. Our newly released Concrete Mixers Market research was designed specifically for executives, investors, and procurement leaders who need actionable clarity rather than retrospective summaries. This overview outlines the strategic value embedded in the full study and explains how decision-makers can leverage its findings to navigate the 2026 operating environment with confidence.
A Market in Transition: Trajectory, Scale, and the Decision-Maker’s Lens
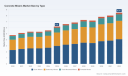
Over the past five years, the concrete mixer sector has demonstrated steady expansion against a backdrop of cyclical construction demand and component cost pressures. Historical data from 2020 through 2025 reflects a market that grew from approximately 4.78 billion USD to 6.2 billion USD, navigating brief contractions while maintaining long-term momentum. Looking ahead, the forecast period from 2026 through 2032 projects continued growth at a compound annual growth rate of 4.5 percent, with projected revenue scaling toward 8.51 billion USD by the end of the forecast window. These figures establish a clear baseline: demand is not merely rebounding, it is structurally evolving.
For strategy teams, the value of these numbers lies not in the headline but in the underlying drivers. The transition from legacy mechanical systems to smarter, lighter, and more efficient mixing platforms is reshaping unit economics. Simultaneously, the competitive intensity of the sector is evident in market concentration metrics, where the top three players account for roughly 45 percent of revenue and the top five capture approximately 60 percent. Such concentration suggests both the presence of established incumbents with scale advantages and meaningful room for disruptors targeting niche applications, regional gaps, or specific operational pain points such as licensing constraints, emissions compliance, and on-site precision.
Raw material volatility, particularly in steel pricing, has introduced meaningful variability in production costs for critical components including drums and chassis. At the same time, procurement validation processes from state departments of transportation continue to standardize approved admixtures and accessories, reinforcing the importance of compliance-ready equipment specifications. Regulatory signals also warrant close attention. In key jurisdictions, energy policy assessments have highlighted that commercially viable zero-emission concrete mixer trucks remain unavailable as of 2026, underscoring the strategic horizon for electrification and alternative powertrain investments. These dynamics do not merely influence costs; they redefine which product architectures will win procurement approvals, fleet adoption, and long-term service contracts.
Inside the Research: Operational Content Built for Execution
This study was structured to support concrete decision-making rather than abstract observation. Readers will find a comprehensive mapping of the market across the primary axes that matter to product planning, channel strategy, and competitive positioning. The report examines segment-level demand characteristics across mixer architectures, application environments, and regional operating conditions, providing a structured lens through which to evaluate where growth is most durable and where margin pressure is most likely to emerge.
Concrete Mixers Market
Beyond segmentation, the analysis delivers an actionable view of the competitive landscape. Profiles of leading manufacturers and emerging specialists are synthesized to highlight differentiators in product design, service ecosystems, and market focus. Rather than treating competition as a static roster, the research connects company positioning to real-world developments that shape buyer preferences. This includes attention to product launches, technology integrations, and event-driven showcases that signal where incumbents are doubling down and where new entrants are carving out defensible positions.
The report also integrates market dynamics that frequently fall outside conventional sizing exercises but carry direct implications for commercial strategy. Material cost behavior, regulatory developments, procurement validation practices, and reimbursement frameworks are examined for their influence on demand elasticity, total cost of ownership, and equipment selection criteria. By linking these forces to segment and regional behavior, the study equips readers to anticipate where pricing power may shift, where specification requirements may tighten, and where operational efficiency will become a decisive competitive advantage.
Worldwide Self Loading Concrete Mixers Market
Competitive Landscape: Leaders, Specialists, and the Shape of Differentiation
The competitive field in concrete mixing equipment is defined by a mix of global heavy-equipment brands, regional specialists, and technology-focused innovators. Large-scale manufacturers continue to anchor the market with broad product portfolios spanning mixer trucks, batching systems, and heavy-duty mobile equipment. Their strength lies in distribution reach, fleet-scale support, and the ability to align mixing solutions with broader construction and infrastructure workflows. For buyers managing large pours, long haul distances, and stringent uptime requirements, these players often serve as default procurement options.
At the same time, a distinct layer of specialists is reshaping expectations around on-site precision, operational flexibility, and regulatory convenience. Volumetric mixing approaches, portable continuous systems, and lightweight configurations are gaining relevance among residential, utility, and mid-sized commercial producers who prioritize exact dosage control, reduced mobilization constraints, or simplified licensing requirements. In this context, product innovation is not only about durability or capacity; it is increasingly about reducing friction in the customer’s operating model. Innovations that improve visibility during transport, enable smaller crews, or reduce licensing burden are becoming meaningful differentiators in competitive bids and repeat purchase decisions.
Recent developments reinforce this direction. Attention to electrification and hybrid platforms reflects a growing demand for efficiency and emissions reduction, even in the absence of fully commercialized zero-emission mixer trucks in some major markets. Parallel innovation in real-time monitoring and drum-level intelligence points to a broader shift toward connected equipment, where transport visibility and quality control are integrated into the hardware itself. Showcase activity at major industry events has also highlighted refreshed model lines with advanced drivetrain and chassis characteristics, signaling that conventional heavy-duty platforms are being refined rather than abandoned. Collectively, these moves illustrate a market where incumbents and challengers are competing on multiple fronts: scale, specialization, technology, and total cost of ownership.
2026 Decision Framework: Turning Macro Visibility into Strategic Action
For executives evaluating market participation, capacity expansion, product development, or procurement strategy, the immediate question is not whether the concrete mixer market is growing, but where the most defensible opportunities reside in 2026 and beyond. The research is built to answer that question through disciplined analysis rather than generalized optimism. Several strategic themes emerge consistently across the data and qualitative context.
- Segment selection matters more than aggregate growth. Demand patterns differ substantially across mixer types and application environments. Organizations that align product portfolios with the most stable and highest-value use cases can better withstand component cost fluctuations and cyclical construction variance.
- Total cost of ownership is becoming a decisive differentiator. With steel price volatility affecting component costs and regulatory signals pointing toward future emissions constraints, buyers are increasingly weighing operating efficiency, maintenance burden, and compliance readiness alongside upfront price.
- Technology adoption is moving from optional to expected. Real-time monitoring, hybrid or electrified platform exploration, and lightweight designs that simplify deployment are beginning to influence purchasing criteria, particularly among producers seeking leaner operations and reduced licensing friction.
- Regional strategy requires localized insight. Demand concentration, infrastructure priorities, and procurement standards vary widely by geography. A successful market approach depends on understanding which regions offer the most reliable demand pull and which segments are most sensitive to local specification and validation requirements.
The full study expands each of these themes into operational guidance. It connects market size and growth expectations to segment-level behaviors, maps the strategic implications of recent product and policy developments, and highlights where competitive pressure is likely to intensify. For investors, the analysis supports more precise evaluation of market entry timing, end-market exposure, and technology risk. For manufacturers and distributors, it informs product planning, regional prioritization, and the design of service offerings that align with evolving buyer expectations. For procurement and fleet leaders, it sharpens the criteria for specification, supplier selection, and lifecycle cost modeling.
Why the Full Report Is the Strategic Next Step
A market overview can signal direction, but it cannot replace the granularity required to act. The complete Concrete Mixers Market research translates macro trajectory into decision-grade intelligence by combining validated sizing and forecast data with segment behavior, competitive profiling, and dynamic market forces. It is designed to reduce uncertainty around which product strategies, geographic priorities, and customer segments deserve disproportionate attention in the 2026 planning cycle.
Readers who require only high-level context may find this summary useful as a directional reference. Leaders responsible for capital deployment, product roadmaps, bidding strategy, or portfolio optimization will benefit from the deeper segmentation, competitive intelligence, and operational context available in the full publication. The report also provides a structured basis for scenario planning, helping teams prepare for multiple futures rather than betting on a single narrative.
To access the complete analysis, including detailed market sizing, forecast pathways, segment assessments, and the full competitive and dynamic landscape, visit the source page for the Concrete Mixers Market research. The complete report equips decision-makers with the depth required to convert market signals into strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Concrete Mixers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air & Water Pollution Control Market Hits $143.5M in 2025, Projected 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
The Air & Water Pollution Control Equipment Market: Navigating Growth, Regulation, and Consolidation in 2026
The global Air & Water Pollution Control Equipment Market stands at a critical inflection point as we move deeper into 2026. For industrial leaders, environmental executives, and capital allocators, the sector is no longer defined solely by compliance checklists or reactive remediation. It has evolved into a strategic imperative where operational resilience, regulatory anticipation, and technological differentiation converge. Our latest comprehensive research publication examines this shifting landscape, offering a structured, forward-looking intelligence framework designed specifically to inform capital planning, competitive positioning, and long-cycle investment decisions throughout 2026 and beyond.
Pre-Inflection Trajectory and Base Performance
The market has already transitioned from a phase of post-pandemic recovery into a sustained, structurally supported growth corridor. Spanning a meticulous historical review from 2020 through 2025, the analysis establishes a clear baseline of consistent expansion. Revenue progression across this period demonstrates steady compounding, anchored by tightening environmental mandates, industrial modernization cycles, and the steady replacement of legacy control systems. Against this backdrop, the forecast horizon extending to 2032 paints a trajectory of durable acceleration. The projected five-year compound annual growth rate of 5.5 percent signals a market that is broadening rather than merely inflating, driven by cross-sector demand and the gradual but irreversible shift toward higher-efficiency abatement technologies.
This sustained climb is not a transient reaction to isolated policy shocks or temporary capital reallocations. Instead, it reflects the maturation of a sector where pollution control has become deeply embedded in core engineering specifications, environmental health and safety governance, and plant-level lifecycle economics. The sheer scale of the projected expansion, measured in hundreds of millions of USD, underscores how both air and water control infrastructure have graduated from discretionary retrofit expenditures to baseline operational necessities across heavy industry.
A Study Built for Executive Decision-Making
The market study was engineered to function as an operational compass rather than a static data repository. At its core, the report delivers granular segmentation that isolates the structural drivers of demand across both air and water control disciplines. By examining equipment typologies, industrial applications, and regional deployment patterns, the analysis reveals where growth is organically emerging and where saturation or pricing pressure is beginning to reshape procurement strategies. Importantly, the segmentation insights expose the shifting balance between mature end-markets and high-velocity industrial verticals, providing context on how capital flows are redistributing across competing applications.
Beyond pure segmentation, the publication maps the competitive architecture that defines today’s marketplace. The industry operates with a deliberately distributed player base, where collective top-tier coverage accounts for less than one-third of aggregate market share. This moderate concentration level indicates room for specialized innovators, regional specialists, and technology-led entrants to capture meaningful share without navigating an impenetrable oligopoly. The research dissects this competitive topology by evaluating how incumbent firms are recalibrating their portfolios, where adjacent technology plays are creating cross-market opportunities, and which operational models are proving most resilient as procurement cycles lengthen and engineering customization demands increase.
For procurement directors and engineering managers, the report provides actionable intelligence on specification migration trends, retrofit economics, and lifecycle cost dynamics. For investors and corporate strategy teams, it maps consolidation pathways, partnership vectors, and geographic diversification considerations that are actively reshaping deal flow and M&A rationale across the environmental equipment ecosystem.
Market Dynamics and the Regulatory-Industrial Feedback Loop
The contemporary demand environment is being propelled by a reinforcing cycle of regulatory progress and industrial modernization. On the compliance axis, sustained reductions in criteria air pollutants and precursor emissions over the past decades have not eliminated the need for advanced control systems; rather, they have shifted the technical benchmark upward. Smaller particulate fractions, complex volatile organic compound streams, and stricter water effluent parameters now require higher-precision filtration, more selective adsorption, and tightly integrated monitoring architecture. The consequence is a market where incremental upgrades and full-system replacements coexist, creating a steady baseline of demand even in mature stationary-source environments.
Simultaneously, macroeconomic and supply-side variables are injecting a fresh layer of complexity into procurement timelines and engineering economics. Recent sharp upward movements in key polymer and resin input costs, driven by shipping disruptions that have perturbed global trade flows, are directly affecting the manufacturing economics of polymer-based components used across pollution control assemblies. For OEMs and system integrators, this translates into nuanced margin management, strategic inventory buffering, and accelerated evaluation of alternative material streams. The research captures how these raw material dynamics are filtering through to final equipment pricing, lead-time expectations, and vendor negotiation leverage during 2026 procurement cycles.
These operational pressures are unfolding alongside continued consolidation and strategic realignment at the corporate level. Industry participants are actively rewiring their business portfolios to concentrate resources on high-margin control technologies and high-growth geographic clusters. The resulting realignment is creating a more differentiated competitive field, where firms that can combine application-specific engineering depth with robust service and monitoring capabilities are pulling ahead in bid evaluations and long-term service contracts.
Air & Water Pollution Control Equipment Market
Competitive Architecture and Strategic Positioning
The competitive landscape of the air and water pollution control sector is characterized by a blend of established process-engineering houses, regional specialists, and technology-focused innovators. Each major participant brings a distinct operational footprint and a targeted capability set that aligns with specific industrial emissions profiles and water treatment requirements.
CECO Environmental, headquartered in Addison, Texas, continues to anchor its offering in advanced filtration and emissions control systems spanning scrubbers, cyclones, biofiltration, and thermal oxidizers. Its portfolio is particularly oriented toward power, refinery, and broader industrial air pollution control deployments, where integrated system design and emissions reduction reliability drive end-user selection. Ducon Environmental Systems, based in Farmingdale, New York, complements this landscape with a focused toolkit of advanced air pollution control systems including wet electrostatic precipitators, baghouses, cyclones, wet scrubbers, and activated carbon platforms, all engineered for demanding industrial emissions control scenarios.
Across the Atlantic, Airnord in Copenhagen has positioned itself in the high-tech segment of air pollution control, emphasizing electrostatic precipitators and comprehensive emissions management systems that cater to facilities requiring precision particulate and aerosol capture. In India, Thermax from Pune delivers industrial air pollution control systems designed for both particulate and gaseous pollutant abatement, reflecting the intense demand dynamics of rapidly industrializing environments where cost-performance optimization remains paramount.
KC Cottrell, operating from Seoul, South Korea, rounds out a significant Asia-Pacific engineering presence with air quality control systems that include electrostatic precipitators, fabric filters, flue gas desulfurization, and denox solutions tailored for power generation and industrial applications. Its technology breadth underscores the growing integration of multi-pollutant control strategies within single plant environments.
Water-side capability is equally critical to the broader market narrative. Pentair, headquartered in London, contributes advanced water and wastewater treatment solutions that encompass sophisticated filtration and pollution control equipment, addressing both municipal-grade treatment expectations and industrial discharge compliance. HUBER Group, based in Berching, Germany, reinforces this spectrum with high-quality machines, plants, and equipment designed for municipal and industrial water, wastewater, and sludge treatment, offering a portfolio that bridges mechanical separation, biological processing, and sludge handling.
Recent corporate movements illustrate how quickly the competitive map is being redrawn. In June 2025, FLSmidth announced an agreement to divest its Air Pollution Control business to Rubicon Partners, with the business continuing as Airnord while retaining its existing technology base and customer relationships. That transition highlights how asset-level portfolio pruning can sharpen a company’s strategic focus without disrupting installed-base continuity. More recently, in mid-2026, CADAIR Environmental Technology showcased advanced industrial air pollution control solutions for volatile organic compounds and emission reduction at IE Expo China, signaling continued product-level innovation and regional engagement. Similarly, Anguil’s return to the 48th annual SESHA Symposium in Tempe, Arizona, in April 2026 for air pollution control discussions reflects ongoing emphasis on specialty industrial safety, emissions management, and direct operator-facing technology engagement.
Together, these profiles and developments illustrate an ecosystem where specialization, geographic reach, and post-acquisition brand continuity are becoming decisive factors in competitive positioning. Rather than competing purely on equipment commoditization, leading players are differentiating through application-specific engineering, lifecycle service models, and the ability to navigate complex multi-stack, multi-stream control challenges.
How to Use This Research in 2026 Strategy Planning
The market study is structured to support three distinct decision-making layers. First, for corporate strategy and corporate development teams, it provides a framework to evaluate where inorganic growth, partnership, or geographic expansion carries the highest probability of sustainable returns. The analysis clarifies the segments where demand is expanding fastest and where competitive intensity may compress future profitability, helping leadership avoid overinvestment in already crowded applications while identifying overlooked value pools.
Second, for engineering, procurement, and operations leaders, the research offers a structured view of technology migration patterns, retrofit versus greenfield decision drivers, and material cost sensitivities that influence total cost of ownership. By understanding where specification requirements are shifting and how supply-side cost pressures are propagating through equipment classes, teams can better sequence capital expenditures, negotiate supplier agreements, and de-risk long-lead procurement decisions.
Third, for investors and market entrants, the report maps the competitive fragmentation, concentration dynamics, and recent realignment events that shape entry feasibility and partnership opportunities. The moderate market concentration observed in the sector suggests that scale alone is not the sole gatekeeper to market success; differentiated technology, service integration, and regional execution capability remain highly valuable. This creates a landscape where disciplined niche strategies and targeted technology plays can achieve meaningful market penetration without requiring broad-spectrum scale from day one.
The research also incorporates operational real-world variables, including recent raw material cost shifts affecting polymer-based component sourcing and the continuing regulatory momentum that sustains demand across stationary sources. By integrating these external pressures directly into segment-level analysis, the report enables decision-makers to stress-test strategies against both regulatory continuity and supply-chain volatility rather than relying on idealized planning scenarios.
Water Treatment Equipment Market
Accessing the Full Intelligence Package
This article has provided a strategic overview of the forces shaping the Air & Water Pollution Control Equipment Market as organizations navigate 2026 planning cycles. Yet the full value of the research lies in its detailed segmentation architecture, end-market deployment logic, competitive profiling, and forward forecasts that move well beyond high-level narrative. To capture the complete analytical depth required for precise capital allocation, product portfolio decisions, and competitive benchmarking, we invite you to explore the full report at its source webpage. There, the complete data sets, segmentation breakdowns, and company-level profiles are available to support the more granular work of strategy formulation, procurement sequencing, and investment prioritization.
In a market where regulatory momentum, material cost dynamics, and corporate realignment are simultaneously reshaping competitive advantage, timely and structured intelligence is not simply useful; it is foundational to making resilient decisions. We look forward to supporting your strategic work with the full depth of this analysis.
For detailed analysis of this topic, please visit the official page: Air & Water Pollution Control Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Fan Market Hits $14.35B in 2025, Projected 4.8% CAGR to $19.97B by 2032
By PW Consulting, 2026-09-16
Navigating the Next Era: Strategic Intelligence for the Electric Fan Market (2026–2032)
The electric fan industry stands at a critical inflection point. Driven by tightening global energy regulations, accelerating electrification in adjacent sectors, and sustained demand across residential, commercial, and industrial applications, the market is undergoing a structural transformation that rewards strategic foresight over reactive positioning. As organizations plan capital allocation, product roadmaps, and supply chain resilience for the coming half-decade, access to rigorously validated, forward-looking intelligence is no longer optional—it is a competitive necessity.
Our latest Electric Fan Market Research Report has been engineered specifically to bridge the gap between macroeconomic trajectory and ground-level execution. Covering the historical baseline from 2020 through 2025 and projecting forward across the 2026–2032 forecast horizon, the study translates complex market dynamics into actionable decision frameworks. Below, we outline the analytical architecture of the report and demonstrate how it equips leadership teams to navigate uncertainty, capitalize on regulatory shifts, and align product portfolios with the trajectories that will define the next growth cycle.
The Macro Trajectory: Reading the Growth Curve Without Losing Sight of Execution
The market’s headline trajectory reflects a steady, compounding expansion. Total industry revenue reached approximately 14.35 billion USD in 2025, building on a consistent upward cadence from the 11.5 billion USD baseline recorded in 2020. The forecast period projects measured but sustained momentum, with the market advancing toward nearly 20 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 4.8 percent, a figure that masks considerable variation across product architectures, end-use environments, and regional demand cycles.
Why Aggregate Figures Alone Mislead Strategic Planning
Leadership teams that anchor decisions exclusively on top-line projections risk misallocating resources. The same 4.8 percent CAGR that describes the aggregate market fractures meaningfully when viewed through the lens of application intensity, motor technology transitions, and regional regulatory calendars. Residential replacement cycles, commercial retrofit mandates, and industrial airflow optimization projects each follow distinct procurement rhythms and compliance timelines. Likewise, ceiling, table, pedestal, wall, and exhaust fan architectures occupy different price tiers, distribution channels, and performance expectations. The report deconstructs these layers systematically, enabling readers to identify which segments will absorb incremental demand, which will face margin compression from efficiency mandates, and where supplier concentration creates both partnership opportunities and vulnerability.
Rather than presenting static share tables, the analysis maps demand elasticity against policy triggers, raw material cost volatility, and manufacturing capacity shifts. This approach allows strategy teams to model scenario outcomes—whether evaluating entry into higher-efficiency motor categories, assessing geographic expansion priorities, or stress-testing supply agreements against regulatory phase-ins.
Regulatory Acceleration as a Strategic Filter
Policy is no longer a peripheral compliance issue; it is a market-shaping force that redraws competitive boundaries. Two landmark regulatory updates from the European Commission are already redefining the operational baseline for manufacturers, distributors, and specifiers. The Ecodesign Regulation 2024/1834, effective as of July 2026, imposes stricter energy performance standards, explicit repairability requirements, and rigorous load/speed testing protocols for electric fans equipped with motors rated between 125 W and 500 kW, superseding the prior Regulation (EU) 327/2011. In parallel, Commission Regulation (EU) 2025/2481 refines the Ecodesign framework for industrial fans by clarifying definitions, transitional provisions, verification tolerances, and speed-test corrections.
Operational Implications for Product Development and Compliance Teams
These frameworks create a dual imperative. First, they raise the performance floor for continued market access in Europe, which rewards manufacturers with robust testing infrastructure and penalizes those relying on legacy motor designs. Second, they shift the commercial conversation from pure upfront cost toward total cost of ownership, serviceability, and verified efficiency claims. The report integrates these regulatory milestones into a forward compliance calendar, mapping how certification pathways, documentation requirements, and testing protocols will evolve through the forecast period. Readers gain a structured view of where compliance investment yields market access, where design iteration can unlock premium positioning, and where regulatory lag in other regions may create temporary arbitrage opportunities.
Standards Modernization Beyond Europe
On the certification front, UL Solutions initiated a phased transition away from holographic labels for electric fan products, moving instead to non-holographic labels featuring the Enhanced UL Certification Mark. This shift streamlines verification logistics while reinforcing brand-level traceability expectations. Subsequent milestones, including the opening of a new electric motor energy efficiency laboratory in Japan, signal a broader global emphasis on motor-grade verification for fan systems. By embedding these standards developments into the market narrative, the report helps organizations forecast certification lead times, anticipate labeling and packaging adjustments, and align engineering schedules with laboratory capacity constraints.
Competitive Architecture: Who Is Positioning Where, and Why It Matters
The electric fan market is characterized by a moderately concentrated competitive landscape, with the top three players collectively commanding roughly 35 percent of revenue and the top five approaching just over half of total market share. This concentration level creates a dynamic environment: incumbents retain meaningful scale advantages in distribution and brand recognition, while specialized manufacturers exploit technology differentiation, vertical integration, and regional compliance readiness to capture high-value niches.
Profile of Strategic Players and Their Market Moves
BorgWarner has been advancing its eFan R10 high-voltage electric fan system, a tightly integrated package combining an e-motor and inverter engineered specifically for battery-electric vehicle applications. The company’s production supply commitments for North American and European OEMs, alongside a confirmed supply agreement with a production ramp scheduled for the fourth quarter of 2027, illustrate how traditional automotive and power electronics players are embedding fan systems directly into electrified vehicle architectures. This move signals a broader convergence between thermal management, motor control, and fan technology that traditional household fan manufacturers must monitor closely.
AMETEK’s Airtechnology division has been deepening its focus on high-performance electric fans, including a recent development presentation of its most advanced and largest electric fan to date, measuring 496 mm in diameter and designed for hydrogen-powered aircraft auxiliary power unit applications. This expansion into extreme-duty, high-reliability environments highlights a profitable trajectory for manufacturers capable of meeting stringent aerospace and hydrogen propulsion requirements, where performance and certification rigor command premium economics.
Ceiling Fans Market
Mechatronics Fan Group continues to provide a broad portfolio of electric fans and related components, positioning itself as a flexible supplier across multiple performance tiers and application contexts. Sunon Fans has maintained a strong focus on DC electric fans and blower motors, aligning product development with the wider industry migration toward higher-efficiency, lower-energy-consumption motor architectures. Orion Fans offers axial and centrifugal electric fans, while PUI Audio, Inc. and Centurion Electric contribute additional DC electric fan capabilities and component-level offerings. Collectively, these players demonstrate that competitive advantage is increasingly determined by motor technology, application-specific engineering, and the ability to satisfy evolving certification requirements rather than by volume alone.
Demand Architecture: Where Growth Concentrates and Why
The market’s end-use structure reveals clear concentration patterns. Residential applications form the largest revenue pool, reflecting continuous replacement demand, housing stock dynamics, and consumer sensitivity to energy costs. Commercial applications represent a substantial secondary tier, driven by building code expectations, retrofit programs, and the operational economics of continuous airflow management. Industrial applications, while smaller in aggregate revenue, exhibit distinct procurement characteristics: higher specification thresholds, longer replacement cycles, and stronger responsiveness to regulatory updates and energy performance mandates.
The report does not stop at share allocation. It examines the purchasing behavior, specification criteria, and compliance triggers that differentiate these segments, enabling strategy teams to calibrate product roadmaps and channel strategies accordingly. For example, residential demand often responds to seasonal promotion cycles and retail distribution readiness, while industrial demand is more tightly coupled to capital expenditure planning, maintenance scheduling, and verification standards. Recognizing these behavioral differences is essential for accurate forecasting and resource allocation.
Supply-Side Realities: Cost Structures, Materials, and Replacement Economics
Strategic planning in this market must account for the economics of maintenance and replacement as much as new product sales. Industry market data indicates that replacement of AC fan motors for electric fans ranges broadly, with total installed costs—including parts and labor—averaging around 500 USD and spanning a range from 60 USD to 1,200 USD depending on motor size, accessibility, and system complexity. This cost dispersion matters because it shapes end-user decisions between repair and replacement, influences after-market service revenue, and affects the attractiveness of modular or service-friendly designs.
The analysis incorporates these cost dynamics to help readers assess where design-for-serviceability can create value, where supply chain bottlenecks could inflate replacement costs, and how motor efficiency mandates may shift the replacement calculus over time. By connecting raw material considerations, labor intensity, and certification requirements, the report provides a more complete picture of profitability levers than unit volume alone would reveal.
Inside the Report: Operational Tools for Decision-Makers
The study is designed to function as a working strategic resource, not a static reference document. It integrates qualitative industry assessment with structured quantitative modeling to support a range of executive decisions, from capacity planning and geographic prioritization to product portfolio optimization and partnership evaluation.
Electric Fan Market
Analytical Scope and Practical Output
- Historical baseline and forward projection: A time-series view from 2020 to 2032 that connects recent market performance with forecast trajectories, allowing readers to test assumptions against documented historical progression and forward estimates.
- Segment-level decision frameworks: Structured analysis of product architectures and application environments to help teams identify where demand intensity, pricing power, and regulatory exposure differ most significantly.
- Competitive and supply-side intelligence: Company-level assessments of core players, including their product focus areas and recent commercial or technical developments, contextualised within broader market concentration dynamics.
- Regulatory and certification mapping: A forward-looking integration of Ecodesign updates, UL certification mark transitions, and laboratory capacity developments to support compliance planning and time-to-market projections.
- Scenario-ready structure: Analytical scaffolding designed to support internal modeling, whether teams are evaluating market entry, portfolio repositioning, supplier negotiations, or regional expansion timing.
Throughout the report, the emphasis is on interpretability and application. Findings are presented with enough granularity to inform specific decisions while preserving the strategic context needed to avoid over-indexing on short-term fluctuations. The goal is to give leadership teams a defensible foundation for prioritizing investments, sequencing product launches, and aligning commercial execution with the forces that will most heavily influence market outcomes through 2032.
How to Use This Intelligence in 2026 Planning Cycles
Companies entering 2026 planning cycles face a set of converging questions: How should motor technology roadmaps adapt to tighter efficiency and repairability requirements? Which regional markets will reward early compliance investment? Where can differentiated fan architectures command sustainable premiums? How should organizations interpret recent OEM supply agreements and aerospace-adjacent developments as indicators of broader technology spillover? The report is built to support structured answers to each of these questions without prescribing one-size-fits-all prescriptions.
For product and engineering leaders, the analysis highlights where efficiency upgrades, modular service design, and certification readiness can create durable differentiation. For commercial and channel teams, it clarifies where demand behavior diverges by application and region, enabling more precise go-to-market sequencing. For supply chain and procurement teams, it situates recent certification, standards, and material cost developments within an operational framework that supports negotiation strategy and inventory planning.
Conclusion: Turning Trajectory Into Advantage
The electric fan market is expanding along a clearly defined growth curve, but growth alone does not guarantee advantage. The organizations that will capture disproportionate value in the 2026–2032 period are those that align product strategy with regulatory direction, match portfolio emphasis to segment-specific demand behavior, and interpret competitor moves as signals of technological convergence rather than isolated product launches. This report provides the structured intelligence required to make those alignments deliberate rather than incidental.
Detailed segment breakdowns, forward forecasts, competitive profiles, and regulatory timelines are developed comprehensively within the full study. To access the complete market model, scenario-ready data sets, and the deeper competitive analysis that supports executive decision-making, visit the source page for the full Electric Fan Market Research Report and explore the intelligence built for the 2026 planning horizon and beyond.
For detailed analysis of this topic, please visit the official page: Electric Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Gene Therapy Market Forecast: $12B in 2025, 19.25% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Gene Therapy Revolution: Strategic Intelligence for 2026 Corporate Decision-Making
The global gene therapy landscape has entered a definitive phase of commercial acceleration. After years of clinical promise and regulatory caution, the sector is now characterized by tangible revenue generation, expanding indication profiles, and a regulatory environment that is actively streamlining development pathways. For executive teams, board members, and investment strategists, the challenge has shifted from assessing feasibility to orchestrating scalable commercialization, supply chain resilience, and market access frameworks. Our latest comprehensive study on the Gene Therapy Market delivers the operational intelligence required to navigate this inflection point with precision.
Between 2020 and 2025, the industry demonstrated a consistent upward trajectory, with revenue climbing from approximately 4.89 billion USD to 12.0 billion USD. This foundational growth establishes a robust baseline as we enter the 2026 to 2032 forecast period. Current projections indicate that the market will surpass 14.5 billion USD in 2026 and continue its aggressive expansion, reaching roughly 40.82 billion USD by the close of the forecast window. This progression reflects a compound annual growth rate of 19.25 percent, a pace that places gene therapy among the most dynamic segments in modern biopharma. Understanding the structural drivers behind this momentum, the competitive architectures shaping it, and the operational complexities that will determine execution success is no longer optional. It is a strategic imperative.
The 2026 Decision-Making Imperative
Gene therapy commercialization in 2026 operates within a fundamentally altered ecosystem. Regulatory agencies have recognized that traditional development frameworks often misalign with the unique biology and manufacturing realities of advanced therapy medicinal products. In response, policymakers are recalibrating approval pathways, reimbursement mechanisms, and manufacturing oversight to accelerate patient access while preserving safety standards. Simultaneously, payers and health technology assessment bodies are grappling with the economic implications of one-time, high-upfront interventions. These converging forces create both unprecedented opportunity and substantial execution risk.
Corporate leaders must now address questions that extend far beyond clinical efficacy. How should organizations structure manufacturing partnerships to mitigate supply chain volatility? Which geographic markets will offer the most favorable regulatory and reimbursement environments for specific therapeutic modalities? How can commercial teams design pricing and access strategies that align with evolving payer expectations without compromising long-term franchise value? The answers require granular, scenario-tested intelligence that generic market summaries cannot provide. Our research is engineered to fill that gap, transforming macroeconomic trends into actionable strategic roadmaps.
Understanding the Market Architecture
The revenue trajectory observed over the past half-decade reflects more than incremental adoption. It signals the maturation of delivery technologies, the successful navigation of pivotal clinical trials, and the emergence of standardized manufacturing protocols that reduce historical bottlenecks. The forecast period through 2032 suggests that these gains will compound rather than plateau. Several structural factors underpin this outlook.
- Therapeutic pipelines are diversifying across hematologic, neurologic, oncologic, and ophthalmic indications, reducing historical concentration risk and expanding the addressable patient population.
- Delivery vector innovation continues to improve transduction efficiency and tissue specificity, enabling developers to target diseases that were previously considered pharmacologically inaccessible.
- Manufacturing and supply chain infrastructure is undergoing targeted investment, though organizations must still navigate significant cost pressures related to ultra-cold logistics and specialized biological raw materials.
- Regulatory flexibility is increasing, with oversight bodies implementing more adaptive chemistry, manufacturing, and controls frameworks to reduce development friction and accelerate submission timelines.
Our analysis dissects how these forces interact across technology platforms, therapeutic categories, and regional commercial environments. Rather than presenting static snapshots, the report maps the causal relationships that will determine which programs achieve sustainable commercial traction and which encounter structural headwinds.
Competitive Landscape and Strategic Positioning
The gene therapy market is defined by a relatively concentrated leadership tier, with a small group of multinational organizations commanding a substantial share of commercial revenue and pipeline value. This concentration reflects the capital intensity of development, the technical complexity of manufacturing, and the strategic advantage of established regulatory and commercialization infrastructure. Yet the competitive dynamics extend well beyond market share arithmetic.
Leading organizations are executing differentiated strategies that align with their therapeutic focus, manufacturing capabilities, and partnership ecosystems. Novartis continues to leverage its pioneering position in neuromuscular gene therapy, building commercial infrastructure around transformative treatments for spinal muscular atrophy. Bristol-Myers Squibb has integrated cell and gene therapy assets into a broader oncology portfolio, using CAR T and related modalities to strengthen its hematologic malignancy franchise. Janssen Biotech, operating within Johnson & Johnson, has advanced CAR T platforms that target multiple myeloma, emphasizing the convergence of cellular engineering and commercial scale.
Vertex Pharmaceuticals has positioned itself at the intersection of gene editing and hemoglobinopathies, bringing forward therapies for sickle cell disease and beta-thalassemia that represent a paradigm shift in chronic disease management. bluebird bio maintains a multi-product portfolio spanning hematologic and cerebral adrenoleukodystrophy indications, reflecting a strategy built on durable patient relationships and specialized delivery networks. Sarepta Therapeutics has expanded the frontier of neuromuscular intervention with gene therapy programs for Duchenne muscular dystrophy, while BioMarin Pharmaceutical and CSL Behring have targeted hemophilia with single-dose approaches that promise to redefine standard-of-care economics. Smaller but highly specialized players such as Krystal Biotech and PTC Therapeutics are capturing niche indications with breakthrough potential, demonstrating that focused platforms can still achieve meaningful commercial differentiation.
The research provides detailed competitive profiling that goes beyond corporate descriptions. It evaluates pipeline adjacency, manufacturing scalability, regulatory posture, and commercial execution risk, enabling decision-makers to benchmark their positioning against the strategies of peers and potential partners.
Stem Cell Therapy Market
Dynamics Shaping Commercial Execution
Market growth alone does not guarantee commercial success. The operational realities of gene therapy commercialization introduce complexities that require deliberate strategic design. Several dynamics are particularly consequential in 2026.
Reimbursement frameworks are evolving rapidly to accommodate the economic profile of one-time interventions. High upfront costs have prompted payers to explore outcome-based agreements that tie compensation to durable clinical benefit, shifting financial risk and aligning incentives across manufacturers, providers, and insurers. In parallel, public payer programs have introduced mechanisms such as expanded New Technology Add-on Payment frameworks to offset a substantial portion of qualifying therapy costs during the early adoption phase. European markets have moved further toward mandating outcomes-based managed entry agreements for single-dose gene therapies, creating a harmonized expectation that commercial strategies must incorporate real-world evidence generation and long-term follow-up infrastructure.
Manufacturing and supply chain management remain among the most capital-intensive and operationally sensitive components of gene therapy programs. Biological raw materials and cold-chain logistics can represent a significant share of total supply chain expenditure due to the requirements for ultra-cold shipping and specialized handling. Organizations that fail to secure resilient sourcing, validated distribution networks, and contingency capacity risk delays that can erode clinical momentum and commercial launch windows.
Regulatory developments continue to reshape development velocity. Recent flexibilities in chemistry, manufacturing, and controls requirements reflect a broader willingness to adapt oversight frameworks to the unique characteristics of cell and gene therapies. Updated approvals and expanded product lists demonstrate that regulatory pathways are becoming more navigable, but they also raise the stakes for organizations that must maintain compliance while accelerating timelines.
Our report integrates these dynamics into a cohesive operational framework. It identifies where cost structures are most sensitive, which regulatory adaptations offer the greatest timeline advantages, and how market access strategies can be structured to satisfy payer requirements without constraining long-term pricing flexibility.
What the Report Delivers
This study is designed for strategy, business development, commercial operations, and investment teams that require more than high-level market narratives. It delivers an integrated analytical architecture that connects macroeconomic growth indicators with the operational, competitive, and regulatory factors that determine execution outcomes. The report includes the following core components.
- A comprehensive market sizing and forecast model that traces revenue evolution from historical baselines through the 2026 to 2032 projection period, with scenario analysis that accounts for regulatory, clinical, and commercial variables.
- A structured segmentation analysis that examines technology platforms, therapeutic applications, and regional commercial environments, emphasizing the interplay between modality characteristics and market access conditions.
- Detailed competitive profiling of leading manufacturers and specialized developers, including pipeline positioning, product portfolio strategy, manufacturing considerations, and commercial execution risk factors.
- An operational dynamics assessment covering reimbursement architecture, regulatory developments, supply chain cost structures, and the practical implications of outcomes-based agreements for pricing and launch planning.
- Strategic recommendations that translate analytical findings into actionable guidance for market entry, partnership evaluation, capacity planning, and portfolio prioritization.
Throughout the analysis, we maintain a focus on decision utility. Every dataset, framework, and competitive observation is oriented toward helping organizations answer concrete questions: where to allocate resources, which partnerships offer the strongest strategic fit, how to anticipate payer and regulator behavior, and what operational capabilities must be built or secured before launch.
Why This Research Matters Now
The gene therapy market is transitioning from a phase of technological validation to one of commercial scaling and strategic differentiation. In this environment, organizations that rely on fragmented data sources or outdated assumptions risk misjudging both opportunity and exposure. The convergence of regulatory flexibility, reimbursement innovation, and expanding clinical evidence creates a narrow window in which strategic decisions will have disproportionate long-term impact.
Access to the complete research enables teams to move beyond directional awareness and into precise planning. It provides the depth required to evaluate pipeline adjacency, assess manufacturing and supply chain exposure, model reimbursement scenarios, and benchmark competitive positioning with confidence. Most importantly, it reveals the market-specific data and scenario analyses that allow leaders to stress-test their strategies against realistic contingencies rather than optimistic projections.
The full study includes the granular segmentation values, regional commercial breakdowns, modality-level growth trajectories, and competitive intelligence that organizations need to construct informed, defensible strategies for the 2026 to 2032 period. To access the complete dataset, detailed segmentation analysis, and executive recommendations, visit the PW Consulting research portal and obtain the full Gene Therapy Market report. Equip your team with the intelligence required to convert market momentum into sustainable strategic advantage.
Gene Therapy Market
For detailed analysis of this topic, please visit the official page: Gene Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Captioning & Subtitling Solutions Market to Hit $10.31B by 2032 at 7.84% CAGR
By PW Consulting, 2026-09-16
Unlock Strategic Advantage in the Captioning and Subtitling Solutions Market: A 2026 Outlook
In an era where digital content consumption is exploding across borders and platforms, accessibility and localization have moved from compliance checkboxes to strategic imperatives. The Captioning and Subtitling Solutions Market is at the forefront of this transformation, driven by stringent regulatory frameworks, the rise of AI-powered transcription, and an insatiable demand for multilingual content. As enterprise leaders navigate the complexities of 2026, understanding the nuanced dynamics of this sector is critical for making informed investment and operational decisions.
This article serves as a strategic primer based on our latest comprehensive market research. It provides a high-level overview of the market trajectory, competitive forces, and regulatory pressures shaping the landscape. However, to truly equip your organization with the granular intelligence needed to outperform competitors, we invite you to delve into the full report. Below, we outline the macro-environment and the strategic value hidden within our detailed analysis.
Closed Caption Services Market
Market Trajectory and Growth Catalysts
The market has demonstrated resilience and robust expansion over the past half-decade. From a base of approximately 4,270 million USD in 2020, the industry has climbed steadily, reaching an estimated 6,150 million USD in 2025. This growth reflects more than just inflation; it represents a structural shift in how media is produced, distributed, and consumed. With a projected Compound Annual Growth Rate (CAGR) of 7.84 percent during the forecast period through 2032, the market is on track to surpass 10,000 million USD by the end of the decade.
Several key drivers are fueling this expansion. Regulatory bodies globally are tightening accessibility mandates, compelling broadcasters, streaming services, and corporate entities to adopt compliant captioning solutions. Simultaneously, the proliferation of Over-The-Top (OTT) platforms and the globalization of content libraries require scalable subtitling and dubbing workflows that traditional manual methods cannot support. The integration of artificial intelligence and machine learning into transcription workflows is reducing turnaround times and costs, making high-quality accessibility viable for smaller content producers and large enterprises alike.
However, growth is not uniform. The interplay between software solutions and professional services, the shift between cloud-based and on-premises deployment, and the varying demands across end-users such as SMEs versus large enterprises create a complex web of opportunities. Our research dissects these vectors to reveal where value is being created and where risks lie.
Exploring the Report Scope: Depth Where It Matters
To support strategic planning, our latest study offers a multi-dimensional view of the market. We move beyond simple top-line numbers to examine the structural components that define competitive advantage. The report covers the period from 2020 through 2032, providing both historical context and forward-looking forecasts.
Key areas of investigation include:
- Component Analysis: Evaluating the balance between standalone software solutions and managed services. As organizations seek to integrate captioning directly into their content management systems, the demand for API-driven software is evolving. Conversely, high-stakes environments still rely heavily on human-in-the-loop services for accuracy.
- Deployment Models: The shift toward cloud-based infrastructure is reshaping cost structures and scalability. We analyze the penetration rates of cloud versus on-premises deployments to help IT leaders decide on infrastructure strategies that align with security requirements and operational flexibility.
- End-User Segmentation: Different sectors have distinct needs. Educational institutions require specific compliance features for online learning, while broadcasters focus on real-time latency and integration with playout systems. Corporate entities are increasingly using captioning for internal communications and training. Understanding the revenue contribution and growth potential of each segment is vital for targeted go-to-market strategies.
- Application Verticals: From broadcast and corporate communications to content production, education, and government, each application area faces unique regulatory and technical challenges. The report details how solution providers are tailoring their offerings to meet these specific demands.
Importantly, this summary does not disclose the specific revenue splits or percentage shares within these segments. Those granular insights are reserved for clients who need to benchmark their performance against precise market shares and identify underserved niches. Accessing the full report reveals the exact valuation of each sub-segment, allowing for precise market sizing and opportunity assessment.
Competitive Landscape: Navigating a Crowded Field
The market is characterized by a mix of specialized accessibility providers, large technology corporations, and localization service giants. Our analysis identifies key players who are defining the standard for quality, speed, and integration. Understanding their strategic positioning is essential for assessing partnership opportunities, acquisition targets, or competitive threats.
Specialized firms are leading the charge in AI-driven live captioning and real-time transcription. Companies like VITAC and Verbit are expanding their capabilities across multiple languages, offering solutions that integrate seamlessly with platforms like Zoom, YouTube, and various streaming environments. Ai-Media focuses heavily on broadcast captioning and cloud networks for live events, while Amberscript emphasizes security certifications and multilingual support for transcription and subtitling. Rev and 3Play Media continue to serve media and enterprise sectors with strong compliance credentials, and SyncWords is pushing the boundaries of real-time AI captions for live streams with voice dubbing.
On the technology side, giants such as Adobe, IBM, and Microsoft are embedding captioning capabilities into their broader ecosystems. Adobe integrates subtitle generation into video creation tools, while Microsoft leverages Azure and AI tools for communication platforms. IBM offers Watson-based solutions for accessibility. These integrations lower the barrier to entry for basic captioning but may lack the specialized workflow features required for professional broadcast or high-volume localization. Meanwhile, companies like TransPerfect and ZOO Digital Group bring deep expertise in translation and localization, bridging the gap between captioning and global content distribution.
Other notable participants include Telestream for media workflow encoding, CaptioningStar and The Captioning Studio for post-production services, and platforms like Amara and Dotsub that facilitate community or platform-based subtitling. AppTek, Otter.ai, and Trint contribute advanced speech technology and transcription capabilities that feed into the broader captioning value chain.
Market concentration data suggests a moderately fragmented landscape, where the top players hold significant share but leave room for innovation and niche specialization. Our report provides detailed profiles, including headquarters, recent developments, and specific offering summaries for each key company. We analyze how these players are adapting to regulatory changes and technological shifts. For instance, the Federal Communications Commission (FCC) has recently adopted final rules requiring manufacturers and distributors to make closed captioning display settings readily accessible. Such regulations directly impact how providers design their user interfaces and compliance features.
To understand the full competitive matrix, including direct and indirect competitors, pricing strategies, and partnership ecosystems, the complete report is indispensable. We reserve the specific market share percentages and detailed competitive benchmarking for our subscribers, ensuring they have an edge in strategic planning.
Regulatory Dynamics and Industry Shifts
Regulation remains a primary catalyst for market demand. In 2025, the FCC adopted rules mandating that closed captioning display settings be readily accessible to individuals who are deaf or hard of hearing. This applies to covered apparatus and multichannel video programming distributors. Furthermore, proposals to modify Telecommunications Relay Service (TRS) rules indicate an ongoing evolution in accessibility standards.
Captioning and Subtitling Solutions Market
These regulatory developments create compliance urgency for broadcasters, streaming services, and hardware manufacturers. Failure to comply can result in significant penalties and reputational damage. Consequently, organizations are seeking solutions that not only meet current standards but are adaptable to future changes. Standards such as ISO 27001 and 9001 are increasingly becoming prerequisites for secure transcription platforms, ensuring data privacy and quality assurance.
Beyond regulation, technological innovation is accelerating. Real-time captioning for live events, automated translation for global audiences, and integration with virtual meeting platforms are becoming standard expectations. The launch of new applications, such as those offering FCC-certified real-time captions for video calls, demonstrates the market's responsiveness to user needs. Our research tracks these developments to help enterprises anticipate technological inflection points.
Strategic Imperatives for 2026 Decision Makers
As you plan for 2026 and beyond, several strategic questions arise. How should you balance investment in proprietary software versus outsourcing to service providers? Which deployment model minimizes risk while maximizing scalability? How do you stay ahead of regulatory changes without over-investing in premature technologies?
Our report provides the framework to answer these questions. By analyzing historical data from 2020 to 2025 alongside forecasts through 2032, we offer a longitudinal perspective that highlights trends and anomalies. The distinction between software and services revenue, for example, can inform whether you should build internal capabilities or partner with external providers. Similarly, understanding the adoption curves of cloud-based solutions helps in IT budget planning.
We also examine the role of AI in reducing costs and improving accuracy. While machine-generated captions have improved, the need for human review in critical contexts remains. The hybrid model is evolving, and our analysis identifies which sectors are leading this transition.
For investors, the market offers attractive growth potential with a clear path to double-digit valuation by 2032. For operational leaders, the focus is on efficiency, compliance, and user experience. Our research provides the data foundation to support both perspectives.
Accessing the Full Intelligence
This overview scratches the surface of a complex and rapidly evolving market. The true value of our research lies in the detailed segmentation data, competitive profiles, and scenario analyses that are not publicly available. We have deliberately omitted specific revenue figures for sub-segments, regional breakdowns, and precise market share allocations to maintain the integrity and exclusivity of the full report.
To gain access to the complete dataset, including exact valuations for every component, deployment type, end-user, and application segment, as well as deep-dive profiles of all key companies and regulatory impact analyses, please visit our source page. There, you will find the full Captioning and Subtitling Solutions Market research, designed to empower your strategic decisions with precision and confidence.
Don't rely on generic market summaries. Equip your team with the specific intelligence needed to navigate the opportunities and challenges of 2026. Click through to access the full report and secure your competitive edge.
For detailed analysis of this topic, please visit the official page: Captioning and Subtitling Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Heating Furnace Market Hits USD 12.4 Billion in 2025, Projects 5.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Outlooks Redefining the Global Heating Furnace Market: Insights for 2026 Decision-Makers
Navigating the Circ Plastic Surge and the Shifting Energy Landscape
The global heating furnace industry stands at a critical inflection point as we move into 2026. Shaped by tightening energy efficiency regulations, evolving utility economics, and sustained demand for high-performance climate control and thermal processing solutions, the sector is poised for measured but meaningful expansion over the coming years. For executives across manufacturing, distribution, building services, and industrial engineering, one question dominates the current planning cycle: how should organizations allocate capital and refine product strategy when the rules of the market are being rewritten in real time. Our Heating Furnace Market research report delivers the analytical depth required to answer that question with confidence. Rather than offering another retrospective on past volumes, this study translates confirmed market trajectories into a forward-looking decision framework designed specifically for 2026 strategy sessions, capacity planning, and competitive positioning.
The industry has already demonstrated considerable momentum over the past five years. Between 2020 and 2025, total market revenue advanced from approximately 8.4 billion USD to 12.4 billion USD, reflecting steady adoption of modern furnace architectures, broader electrification initiatives, and sustained investment across both residential comfort systems and industrial thermal applications. The forward trajectory suggests continued gains, with the market expected to reach roughly 13.2 billion USD in 2026 and expand toward 17.9 billion USD by 2032. A compounded annual growth rate of 5.5 percent frames this projection, offering a disciplined baseline for scenario modeling, pipeline forecasting, and go-to-market planning. These figures represent far more than aggregate sizing; they point to an ecosystem in which product differentiation, regulatory alignment, regional targeting, and supply chain resilience increasingly determine long-term market share. For leaders operating in the heating furnace space, the strategic challenge is no longer whether the market will grow, but how to capture the most profitable segments within that growth while anticipating shifts in technology preference, energy pricing, and compliance requirements.
Why This Report Is Engineered for 2026 Executive Decision-Making
Market intelligence is only as valuable as its relevance to immediate operational and strategic choices. The Heating Furnace Market study has been structured to function as a working strategic asset rather than a static reference document. From the opening chapters, the report anchors the prevailing growth narrative within a detailed competitive and structural analysis, linking macro expansion to the underlying forces that will shape purchasing behavior, product mix, and pricing dynamics through 2032. The intent is to provide leadership teams with a clear line of sight from broad market direction to the specific implications that matter in 2026: how to prioritize R&D investments, where to concentrate geographic or channel resources, how to interpret competitor movements, and which external pressures warrant immediate mitigation planning.
One of the report’s central objectives is to separate durable structural growth from short-term volatility. Total market expansion can mask significant variation in segment attractiveness, channel economics, and regional demand drivers. By mapping those distinctions without oversimplifying them, the research gives executives a richer foundation for budgeting, inventory planning, and product portfolio design. The forecast period captures both the immediate operational horizon of 2026 and the longer planning window through 2032, allowing decision-makers to test short-term initiatives against multi-year market behavior. This dual horizon approach is particularly useful in a sector where regulatory timelines, utility cost projections, and manufacturing lead times all operate on different cycles. For strategy, finance, and operations leaders, that alignment is essential.
Inside the Study: Operational Content Built for Execution
A market study earns trust when it converts high-level trends into actionable detail. This report is built around the operational questions that typically arise in cross-functional planning meetings. It begins with a comprehensive overview of market size, growth trajectory, and the principal variables influencing demand, then moves into the structural features that define the competitive environment. The analytical scope includes the type-based architecture of the furnace market, the application segments that shape purchasing behavior, and the regional distribution of demand. Each dimension is examined in terms of strategic importance rather than raw enumeration, enabling leaders to understand where concentration, opportunity, and risk are most likely to emerge.
- Market sizing and growth analysis across the full historical-to-forecast window, with emphasis on trend continuity and inflection points.
- Structural breakdown by furnace type, including the strategic positioning of gas, electric, and induction-based solutions within modern heating and thermal processing requirements.
- Application-level analysis covering residential, commercial, and industrial demand patterns, focusing on the drivers that differentiate purchasing cycles, specification requirements, and service expectations.
- Regional evaluation of market dynamics, highlighting the areas where growth velocity, infrastructure development, and regulatory context create distinct strategic implications.
- Assessment of competitive structure, including concentration patterns and the strategic posture of leading participants.
Beyond segmentation, the report integrates an examination of the forces shaping market behavior. Regulatory developments, energy pricing expectations, commodity cost movements, and technology standardization efforts all influence the operating environment. By incorporating these elements directly into the analysis, the study avoids the common limitation of preserving market data in isolation. Instead, it demonstrates how external conditions interact with product design choices, channel strategy, and customer value propositions. The result is a research framework that can be applied to pricing strategies, product roadmaps, capacity planning, and market entry evaluations with greater confidence than generic industry summaries typically allow.
Where Competition Is Moving: Strategic Signals from Leading Players
Competitive intensity remains a defining feature of the heating furnace market. The report profiles a set of established participants whose product portfolios, technology emphasis, and regional footprints illustrate the broader strategic directions shaping the sector. These companies offer useful reference points for understanding where value is being created, which performance attributes are becoming table stakes, and how differentiation is evolving in a market that increasingly rewards efficiency, controllability, and total cost of ownership.
Among the firms examined, Carrier stands out for its emphasis on high-efficiency gas and electric furnace platforms incorporating advanced variable-speed technology and ENERGY STAR certification. This positioning reflects a broader industry shift toward precision airflow management, comfort consistency, and lower operating cost over the equipment lifecycle. Trane Technologies, through its Trane and American Standard lines, similarly underscores reliability and high AFUE performance while integrating smart control functionality into the user experience. In practice, this indicates a competitive environment in which furnace selection is increasingly tied not only to heating output, but also to intelligent system integration and diagnostic accessibility. Lennox International reinforces the premium end of the residential and light commercial spectrum by focusing on quiet operation, high-efficiency configurations, and advanced modulating technology. Such offerings suggest that acoustic performance, staged heating precision, and refined installation experience are becoming meaningful differentiators where product maturity and installer reputation intersect.
The value-oriented portion of the market is represented by companies such as Rheem Manufacturing Company and Goodman Manufacturing Company. Rheem and Ruud systems emphasize a balance of efficiency, durable construction, and accessible pricing, supporting a strategy that targets broad installer acceptance and repeat service reliability. Goodman and Amana platforms pursue a similar objective through energy-efficient designs and dependable performance at an accessible price point. Taken together, these profiles illustrate the strategic fork that many manufacturers continue to navigate: compete on premium performance and technology integration, or compete on value, durability, and scale efficiency without sacrificing compliance and core performance standards.
Heating Furnace Market
The competitive landscape also includes specialized suppliers that serve distinct industrial and commercial thermal requirements. Inductotherm Group, for example, provides induction heating furnaces tailored for metal processing applications, reflecting the continued relevance of purpose-built thermal equipment alongside broader HVAC-oriented furnace markets. This segmentation matters because industrial heating demand does not move in lockstep with residential replacement cycles or commercial retrofit programs. Understanding where industrial, commercial, and residential markets diverge in specification, procurement, and service expectations is essential for companies that operate across multiple customer categories or are evaluating adjacency opportunities.
Electric Furnace Transformer Market
Regulatory Pressure, Energy Economics, and the 2026 Compliance Horizon
No strategic assessment of the heating furnace market is complete without a clear-eyed view of the external forces reshaping demand and product requirements. Several regulatory and economic developments are particularly relevant for 2026 planning. The U.S. Department of Energy finalized an energy efficiency standard for gas furnaces requiring 95 percent AFUE for non-weatherized and mobile home models, with publication in the Federal Register and an implementation timeline targeting late 2028. For manufacturers and distributors, this is not merely a compliance milestone; it is a design horizon that affects product development cycles, inventory transitions, and competitive positioning well before the rule takes effect. Companies that anticipate the standard early can align engineering priorities, documentation, and channel education in advance, while late movers risk abrupt product rationalization or margin compression during transition.
On the economic side, the U.S. Energy Information Administration projected residential natural gas pricing near 14.00 USD per MMBtu in 2024, with the electricity-to-gas price ratio expected to approach 4.0x by 2027. Fuel price relationships strongly influence customer preferences, installer recommendations, and the relative attractiveness of electric versus gas furnace solutions in different regions. When electricity costs rise faster than natural gas, the value equation for electric heating systems can shift in complex ways, especially when efficiency ratings, climate conditions, and building insulation profiles vary. These dynamics reinforce the need for a segmented go-to-market strategy rather than a uniform product message. The report incorporates this energy pricing context so decision-makers can evaluate demand sensitivity across fuel types and regions with a more realistic operating assumption set.
In parallel, ASHRAE continues to shape the performance environment through standardization and operational guidelines. ASHRAE Guideline 36-2024 establishes uniform sequences of operation for HVAC systems designed to maximize energy efficiency and performance. More recently, ASHRAE 15-2025 standards regulate refrigerant use in air conditioning and heating systems for commercial equipment. While refrigerants are often discussed in connection with cooling equipment, these standards have broader implications for integrated heating and cooling systems, installer training, and equipment selection in commercial applications. Together, these developments point to an industry in which compliance is becoming more intertwined with performance claims, system design, and commissioning practices.
Commodity cost pressure adds another layer of planning complexity. In 2025, input costs including steel used in furnace construction experienced increases tied to global supply chain conditions. Even when demand remains steady, rising material costs can pressure margins, alter pricing strategies, and force trade-offs between build specifications and competitive positioning. Firms with diversified sourcing strategies, disciplined bill-of-materials management, and clear visibility into cost pass-through dynamics are better positioned to sustain profitability through such cycles. The report addresses these pressures as part of the overall market environment so leadership teams can incorporate realistic cost assumptions into their financial models and strategic scenarios.
Recent Product and Technology Activity as a Strategic Barometer
Short-term product announcements can reveal much about where companies believe the market is heading. Recent activity at major industry events provides useful signals. In March 2025, Beckett Thermal Solutions introduced THE BOLTRA next-generation power burner for combustion and thermal technologies at the AHR Expo, highlighting continued innovation in combustion system performance and thermal efficiency. Also at the AHR Expo in March 2025, Navien showcased new system furnace and air conditioner models aimed at residential applications, indicating sustained emphasis on integrated comfort solutions and product refresh cycles. Earlier in the year, Fieldpiece previewed new HVAC test and measurement tools for installation and diagnostics, reinforcing the growing importance of service-side precision, commissioning accuracy, and technician enablement.
These developments matter because they illustrate three concurrent themes: the push for higher efficiency and better combustion or electrical performance, the integration of heating equipment into broader system architectures, and the increasing dependence on diagnostics and installer capability as part of the value proposition. For manufacturers and distributors, the implication is that competitive advantage is no longer confined to the hardware itself. It also includes how well equipment can be installed, validated, serviced, and optimized in the field. Reports that only track incremental product launches risk missing this shift; this study treats such activity as evidence of strategic direction and operational priority rather than isolated news items.
What Is Contained in the Full Study and What Demand It Serves
The complete Heating Furnace Market report extends well beyond the strategic overview presented here. It provides a structured, evidence-based analysis designed for teams that need to move from broad market awareness to specific commitments. The report’s depth is intended to support multiple uses: strategic planning, market entry evaluation, competitive benchmarking, channel strategy refinement, and investment prioritization. By keeping the emphasis on usable intelligence rather than exhaustive enumeration, the study enables leaders to ask sharper questions and make more defensible decisions.
- Detailed market sizing and forecast analysis covering historical evolution and the projection period through 2032.
- Segment-level insight across furnace types and application categories, with strategic interpretation of where demand is strongest and why.
- Regional market context that distinguishes leading demand centers from slower or transitional markets without reducing complexity to simplistic rankings.
- Competitive landscape analysis covering major players, product positioning, and market structure indicators such as concentration trends.
- Integration of regulatory, energy pricing, and input cost developments to translate external conditions into business impact.
- Recent industry activity and product-focused developments that highlight technology direction and market signaling.
In practice, this means the report can help a manufacturing executive assess which product technologies warrant continued investment, support a distributor in determining where regional demand is strongest and most resilient, guide a service organization in anticipating compliance-driven product transitions, or inform an investor and strategy team evaluating the balance of growth opportunity against competitive intensity. The objective is to equip each audience with analysis that is specific enough to inform action but broad enough to remain relevant across multiple planning scenarios.
A Decision Framework for the Next Planning Cycle
As 2026 approaches, the heating furnace market is best understood as a sector defined by disciplined growth, rising performance expectations, and an increasingly complicated compliance and cost environment. The trajectory from 12.4 billion USD in 2025 toward nearly 17.9 billion USD by 2032 suggests sustained opportunity, but opportunity of this kind rewards preparation more than opportunism. Companies that align product strategy with regulatory timelines, account for shifting fuel economics, understand competitive differentiation beyond basic specifications, and anticipate the operational demands placed on installers and service teams will be better positioned to capture value.
This report has been created to serve as that strategic preparation tool. It brings together market scale, growth expectations, segmentation context, competitive dynamics, and external pressures into a single analytical framework tailored for executive decision-making. To explore the full findings, detailed segmentation interpretation, competitive profiles, and forward-looking scenario analysis, readers are encouraged to access the complete Heating Furnace Market research report for the comprehensive intelligence needed to support confident 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Heating Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Oil & Gas Flexible Pipes Market to Hit $2.29B by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
Flexible Pipes for Oil and Gas Market: Strategic Intelligence for 2026 and Beyond
The global energy infrastructure landscape is undergoing a structural shift, driven by the relentless expansion of deepwater offshore operations and the accelerating substitution of traditional steel components with advanced flexible piping systems. As operators navigate increasingly complex geological challenges and stringent operational standards, the demand for reliable, high-performance flexible pipes has transitioned from a niche requirement to a core strategic imperative. PW Consulting’s latest market study, Flexible Pipes for Oil and Gas Market, provides a comprehensive, data-driven blueprint designed to equip executives, procurement leaders, and strategic planners with the actionable intelligence needed to navigate the 2026–2032 forecast period.
Built on a rigorous analytical framework spanning historical performance from 2020 through 2025 and a forward-looking projection window extending to 2032, this report does not merely catalog market movements. It decodes the underlying mechanics of supply chain resilience, material innovation, regulatory alignment, and competitive positioning. The following overview outlines the strategic architecture of the study, highlights the operational dimensions covered, and demonstrates why this intelligence is essential for capital allocation, risk mitigation, and long-term portfolio planning in the current market cycle.
Macro Trajectory and the 2026 Decision Horizon
The market has demonstrated consistent expansion over the past half-decade, with revenue scaling from 850.0 million USD in 2020 to an estimated 1,480.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.5 percent, a pace that underscores the sector’s resilience amid volatile commodity cycles and shifting drilling economics. As the market enters 2026, baseline projections indicate continued momentum, with revenue expected to reach 1,527.5 million USD before accelerating toward a projected 2,292.0 million USD by 2032.
For strategic planners, these figures are more than historical markers; they represent a validated demand curve that must be factored into capacity planning, supplier negotiations, and technology investment roadmaps. The 2026 inflection point is particularly critical. Operators are balancing immediate production targets with long-term decarbonization and efficiency mandates, creating a procurement environment where material selection, system durability, and compliance readiness directly influence total cost of ownership. This report isolates the macroeconomic and sector-specific drivers shaping this transition, enabling decision-makers to align their sourcing strategies with verified growth pathways rather than speculative trends.
Structural Breakdown: Material, Application, and Regional Architecture
Flexible pipe ecosystems are fundamentally defined by their material composition, deployment environment, and geographic distribution. The study maps these structural layers with precision, examining how polymer-based and composite formulations compete across different operational profiles. High-density polyethylene continues to anchor a substantial portion of the market, valued for its corrosion resistance, manufacturability, and cost efficiency in standard pressure regimes. Parallel to this, polyamides and polyvinylidene fluoride occupy specialized niches where chemical compatibility, temperature tolerance, and mechanical fatigue resistance dictate performance outcomes. Composite and hybrid formulations are also gaining traction as operators seek weight reduction and extended service life in extreme subsea conditions.
Application segmentation reveals a clear operational divide. Offshore deployments dominate the revenue landscape, reflecting the industry’s strategic pivot toward deepwater and ultra-deepwater reserves where rigid piping systems face logistical, installation, and maintenance constraints. Onshore applications, while comparatively smaller in scale, remain vital for midstream transfer, water management, and brownfield retrofits where flexibility reduces civil engineering overhead and accelerates commissioning timelines.
Geographically, the market exhibits a pronounced concentration in established energy corridors, with North America commanding the largest revenue share, followed by the Asia Pacific region and Europe. Latin America and the Middle East and Africa represent emerging growth vectors, shaped by basin development cycles, regulatory modernization, and increasing foreign direct investment in upstream infrastructure. The report’s regional analysis moves beyond headline figures to examine supply chain localization trends, logistics constraints, and country-specific certification requirements that influence market entry timing and partnership structuring.
Oil and Gas Hoses Market
Competitive Landscape and Strategic Positioning
The flexible pipe sector is characterized by a moderately concentrated competitive field, with the top three players collectively commanding 45.2 percent of market revenue and the top five firms capturing 55.8 percent. This structure reflects a market where scale, certified engineering capability, and long-term operator relationships serve as formidable barriers to entry. Yet, the landscape is far from static. Technological differentiation, material innovation, and targeted contract wins are continuously reshaping competitive hierarchy.
Flexible Pipes for Oil and Gas Market
TechnipFMC maintains its position as a global leader in the design, manufacture, and supply of flexible pipes for subsea oil and gas applications, including risers and flowlines. Its operational footprint and engineering depth have been reinforced by recent contract awards, including two substantial engagements by Petrobras to design, engineer, and manufacture flexible gas injection risers and risers/flowlines for the Campos Basin. National Oilwell Varco continues to expand its portfolio of flexible pipe systems for offshore oil and gas, spanning shallow and deepwater applications. The company’s strategic focus on high-pressure performance was underscored by a new product line launch in mid-2025, followed by a pre-commercial agreement with Petrobras to develop CO2-resistant flexible pipes tailored for deepwater high-CO2 environments.
Baker Hughes supplies flexible pipe systems for subsea and onshore oil and gas, covering risers, flowlines, and jumpers, and has actively showcased its latest system architectures at major industry forums such as the Offshore Technology Conference in 2026. Strohm, formerly known as Airborne Oil & Gas, has carved a specialized position through the manufacture of bonded thermoplastic composite pipes engineered for high-performance subsea applications. SoluForce, operating under Pipelife Nederland B.V., focuses on high-pressure flexible composite pipes for oil, gas, and water transport, leveraging reinforced thermoplastic technology to address pressure cycling and fatigue challenges.
Magma Global produces m-pipe® carbon fibre composite pipes specifically developed for subsea oil and gas risers and flowlines, offering weight and corrosion advantages in demanding environments. ContiTech extends its industrial hose and flexible pipe expertise into oil and gas applications, while Shawcor’s Flexpipe Systems division develops and manufactures flexible pipe systems designed for oil and gas pipeline integration. Prysmian Group rounds out the competitive field by supplying cables and flexible pipes for subsea and onshore production systems, emphasizing integrated infrastructure solutions.
The report’s competitive benchmarking module examines pricing architectures, technological roadmaps, contract win patterns, and regional manufacturing footprints. It identifies where incumbents hold structural advantages and where emerging players are creating disruption through material substitution, modular design, or targeted service delivery models. For executives evaluating vendor consolidation, partnership opportunities, or in-house capability development, this analysis provides a clear map of competitive vulnerabilities and strategic white space.
Operational Intelligence: Dynamics, Compliance, and Cost Architecture
Market performance in the flexible pipe sector is tightly coupled to a matrix of regulatory, material, and operational variables. The study dissects these dynamics to reveal how they influence margin structures, project timelines, and procurement risk. ISO 13628 series standards govern the design and operation of unbonded flexible pipe systems for subsea production, establishing baseline requirements for structural integrity, fatigue resistance, and environmental compatibility. Complementing this, API 17J certification is required for unbonded flexible pipe systems in oil and gas operations, making compliance readiness a non-negotiable prerequisite for market access and operator approval.
On the cost side, polymer material prices remain subject to fluctuation driven by petroleum derivative markets, directly impacting production costs and margin sustainability. The report quantifies these sensitivities and maps them against contract structures, inventory strategies, and supplier diversification models. It also evaluates how raw material availability, manufacturing lead times, and transportation constraints interact to shape total project economics. Understanding these cost architecture layers is essential for organizations seeking to stabilize procurement spending, negotiate favorable terms, or justify vertical integration initiatives.
Beyond compliance and cost, the study examines the broader industry context that continues to propel demand. Deepwater offshore expansion remains a primary catalyst, as operators pursue reserves in progressively challenging environments where flexible piping offers installation agility, reduced weight, and lower lifecycle maintenance burdens. The ongoing substitution of steel components further accelerates adoption, particularly in riser systems, flowlines, and dynamic applications where mechanical fatigue and corrosion management are critical. These macro trends are layered with project-specific considerations, including water depth, pressure profiles, chemical exposure, and installation methodology, all of which are addressed in the report’s application-focused analysis.
Inside the Report: Methodology, Tools, and Decision-Ready Outputs
PW Consulting’s Flexible Pipes for Oil and Gas Market study is structured to deliver immediate operational value alongside long-range strategic perspective. The report integrates historical revenue tracking, demand forecasting, material and application segmentation, regional mapping, and competitive profiling into a single, coherent intelligence framework. Each section is designed to support a specific decision function, from capital expenditure planning and supplier evaluation to risk assessment and technology investment prioritization.
Key deliverables include a detailed market size and forecast model spanning the 2020–2032 horizon, with clear delineation of base-year baselines and forward projections. Segmentation analysis breaks down revenue distribution by material type, application environment, and geographic region, enabling readers to isolate the segments most relevant to their operational footprint. Competitive profiling maps the strategic positioning of leading manufacturers, highlighting recent contract awards, product launches, pre-commercial agreements, and trade show activations that signal shifting priorities and capability expansions.
The study also incorporates a dynamics module that examines regulatory frameworks, cost drivers, macro trends, and raw material sensitivities, providing context for pricing strategy, compliance planning, and supply chain design. Methodological transparency is maintained throughout, with clear assumptions, data sourcing protocols, and scenario boundaries that allow readers to stress-test projections against their own operational parameters. Supplementary tools, including segmentation cross-references and competitive tracking tables, are integrated to support rapid benchmarking and internal dissemination.
Throughout the report, analysis is anchored in verifiable market mechanics rather than superficial trend statements. The objective is to equip readers with a defensible basis for procurement decisions, partnership evaluations, capacity planning, and technology roadmap alignment. By connecting macro growth signals to granular operational variables, the study enables organizations to move from reactive monitoring to proactive strategy execution.
Strategic Imperatives for 2026 and the Forecast Horizon
As the market advances through the 2026–2032 period, three strategic imperatives will define competitive outcomes. First, procurement organizations must align sourcing strategies with verified demand trajectories and material cost sensitivities, ensuring that contract structures and supplier portfolios can absorb commodity volatility without compromising project economics. Second, engineering and operations teams must prioritize compliance readiness and performance certification, recognizing that regulatory alignment is not merely a technical checkbox but a market access requirement that influences bidding eligibility and operator trust. Third, competitive positioning will increasingly hinge on technological differentiation, whether through composite material adoption, high-pressure system design, CO2-resistant formulations, or integrated infrastructure offerings that reduce installation complexity and lifecycle cost.
PW Consulting’s Flexible Pipes for Oil and Gas Market study provides the foundational intelligence required to navigate these imperatives with confidence. The full report contains the complete dataset, segmentation breakdowns, competitive tracking detail, regional supply chain analysis, and forecasting models that underpin the strategic narrative presented here. Organizations that secure this intelligence will be better positioned to calibrate investment timing, negotiate from a position of informed leverage, and align their flexible pipe procurement and engineering strategies with the realities of a growing, evolving, and increasingly demanding market.
For executives, analysts, and project leaders seeking to convert market complexity into structured decision advantage, the complete study offers the depth, precision, and operational relevance required to act decisively in 2026 and throughout the forecast window.
For detailed analysis of this topic, please visit the official page: Flexible Pipes for Oil and Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cleanroom Air Filters Market to Reach $1.2B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Cleanroom Air Filters Market: Strategic Imperatives for 2026 and Beyond
Executive Overview
The global cleanroom air filters market stands at a pivotal inflection point. From a baseline of approximately 652.0 million USD in 2025, the sector is projected to expand to roughly 890.1 million USD by 2026, continuing a steady trajectory toward nearly 1.2 billion USD by 2032. This growth, underpinned by a compound annual growth rate of 5.2 percent across the 2026 to 2032 forecast window, reflects more than incremental demand. It signals a structural recalibration of how critical industries approach contamination control, regulatory compliance, and operational resilience. For executives, procurement leaders, and capital allocators, the coming cycle demands a nuanced understanding of technological differentiation, supply chain reconfiguration, and shifting compliance architectures.
This analysis introduces our latest comprehensive Cleanroom Air Filters Market research, designed specifically to equip decision-makers with actionable intelligence ahead of the 2026 planning cycle. Rather than presenting a static snapshot, the report functions as a strategic operating manual. It dissects historical performance, maps forward-looking demand vectors, and evaluates competitive positioning with surgical precision. The following sections outline the core analytical pillars, competitive dynamics, and forward-looking scenarios that will shape capital deployment, vendor selection, and market entry strategies over the next several years.
Market Architecture and Forward Trajectory
Historical Performance and Growth Inflection
The past five years have demonstrated consistent expansion for cleanroom filtration systems, with revenue climbing from 506.02 million USD in 2020 to a validated baseline of 652.0 million USD in 2025. This trajectory reflects sustained capital expenditure in high-purity manufacturing environments, accelerated facility standardization, and an uncompromising stance on airborne particle control. The 2026 projection of 890.1 million USD indicates a pronounced year-over-year acceleration, suggesting that multiple demand drivers are converging simultaneously rather than operating in isolation.
Looking ahead, the forecast period extends through 2032, with revenue milestones scaling progressively to 952.23 million USD in 2027, 987.3 million USD in 2028, 1.024 billion USD in 2029, 1.088 billion USD in 2030, 1.168 billion USD in 2031, and a terminal estimate of 1.197 billion USD in 2032. This steady compounding pattern is not merely a statistical artifact. It reflects durable structural demand, incremental technology adoption cycles, and a global manufacturing footprint that increasingly treats cleanroom integrity as a non-negotiable operational requirement.
Key Demand Vectors Shaping the Forecast
The market is shaped by several overlapping forces that will dictate growth velocity and regional prioritization. Semiconductor fabrication continues to demand tighter particle control as feature sizes shrink and yield sensitivity intensifies. Pharmaceutical and biologics production has tightened environmental validation protocols, particularly as contract development and manufacturing organizations scale sterile fill-finish operations. Concurrently, the rise of lithium-ion battery production, advanced medical device assembly, and controlled hospital environments has broadened the application spectrum beyond traditional high-volume cleanroom deployments. These vectors are not uniform in their pacing. Some accelerate rapidly in response to technology roadmaps, while others evolve more gradually as regulatory frameworks mature and capital cycles align.
Material science evolution also plays a central role. HEPA and ULPA filter media increasingly incorporate high-grade microglass fibers and advanced polymers, with production costs influenced by shifts toward sustainable material sourcing in medical-grade cleanroom applications. This dynamic creates both margin pressure and differentiation opportunities for manufacturers that can optimize pleatability, reduce pressure drop, and maintain compliance without compromising throughput.
Competitive Landscape and Strategic Positioning
Profiling the Core Players
The competitive field is anchored by a cohort of established filtration specialists and diversified industrial manufacturers, many of whom maintain concentrated positions in high-efficiency cleanroom solutions. Camfil, headquartered in Stockholm, Sweden, specializes in HEPA and ULPA cleanroom panels, ceiling modules, and Pharmaseal ducted filter systems tailored for ISO 5 to 8 environments and pharmaceutical or biotechnology facilities. Parker Hannifin, based in Cleveland, Ohio, offers complete lines of cleanroom HEPA and ULPA standalone and pre-filters with efficiencies reaching up to 99.9995 percent for critical manufacturing applications. 3M, from St. Paul, Minnesota, manufactures Filtrete HEPA air purifier filters and industrial filtration cartridges deployed in cleanroom environments for particle removal.
Cleanroom Air Filters Market
Donaldson Company, headquartered in Bloomington, Minnesota, provides panel collector filters and industrial air filtration systems, including cleanroom solutions for pharmaceutical and semiconductor applications. Freudenberg Filtration Technologies, operating from Weinheim, Germany, supplies HEPA and ULPA filters, Fan Filter Units, and BIBO containment systems for cleanroom and battery manufacturing environments. MANN+HUMMEL, based in Linden, Germany, develops HEPA and ULPA filters and ceiling systems specifically for cleanroom applications in operating theaters, pharmaceuticals, and microelectronics. AAF International, from Louisville, Kentucky, offers HEPA and ULPA filters, containment systems, and full-line air filtration for cleanroom, semiconductor, and pharmaceutical use. Dafco Filtration Group, based in Canada, produces high-efficiency cleanroom filters and specialized filtration solutions for controlled environments. Nippon Muki, headquartered in Tokyo, manufactures ULPA to pre-filter systems and cleanroom equipment for semiconductor, LCD, and high-purity applications. Hollingsworth and Vose, from East Walpole, Massachusetts, stands as a global leader in HEPA and ULPA filter media engineered for cleanroom performance with low pressure drop and superior pleatability. CleanAir Solutions, Inc., located in Fairfield, California, specializes in HEPA filters and Fan Filter Units for modular hardwall and softwall cleanrooms and contamination control.
Market Concentration and Competitive Differentiation
The industry exhibits notable concentration, with the top three firms capturing approximately 55 percent of market revenue and the top five firms extending that share to roughly 65 percent. This concentration suggests that scale, technical certification capabilities, and compliance infrastructure remain powerful moats. At the same time, it creates opportunities for mid-tier specialists to compete on application-specific engineering, regional service coverage, and customized containment architectures. Differentiation is increasingly driven by validation readiness, installation efficiency, filter lifecycle economics, and the ability to integrate containment systems with broader facility airflow strategies.
Recent Corporate Developments Reshaping the Field
The competitive landscape is actively evolving through capacity expansion, portfolio enhancements, and strategic consolidation. In September 2025, Camfil expanded HEPA and ULPA filter production at its Manesar plant, increasing supply capacity for hospitals, pharmaceutical cleanrooms, and biotechnology laboratories while aligning output with EN 1822 and ISO 29463 standards. In November 2025, Freudenberg Filtration Technologies launched next-generation Fan Filter Units, upgraded BIBO containment systems, and NMP-resistant filters designed for semiconductor, pharmaceutical, and lithium-ion battery cleanrooms, emphasizing improved energy efficiency. Also in November 2025, AAF International introduced the AstroScan M system for in-situ validation and leak testing of bag-in and bag-out HEPA containment systems in cleanroom applications. More recently, in January 2026, Cleanova acquired U.S.-based Airflotek and TES-Clean Air Systems to expand capabilities in advanced cleanroom and high-efficiency air filtration solutions for controlled environments.
Air Filters Market
These developments illustrate a broader pattern: manufacturers are investing not only in incremental capacity but also in validation technologies, containment integration, and application-specific material resistance. The result is a market where product performance and compliance documentation are becoming inseparable from commercial competitiveness.
Regulatory and Technical Dynamics Defining Market Behavior
Cleanroom filtration performance is governed by a dense framework of standards that shape procurement criteria, vendor qualification, and lifecycle planning. HEPA and ULPA filters are required to meet EN 1822 and ISO 29463 standards for particle removal and integrity testing in pharmaceutical and semiconductor applications. Filter performance for cleanroom applications is further governed by IEST CC RP-CC001 protocols for DOP and PAO leak testing, alongside MPPS efficiency verification at the 0.12 to 0.3 micron range. For hospitals and biopharma facilities, cleanroom installations must comply with ISO 14644-1 classifications for air cleanliness levels, particularly across Class 5 to 8 sterile environments.
On the commercial side, pharmaceutical and medical device cleanroom filtration solutions can be eligible for capital equipment reimbursement under relevant DRG and CPT codes for hospital containment systems supporting sterile production. This reimbursement pathway can influence procurement timing, facility budgeting, and vendor selection in healthcare-adjacent deployments. Together, these regulatory and reimbursement dynamics create a compliance-first purchasing environment where documentation, testing transparency, and lifecycle validation often outweigh price alone.
What the Full Report Delivers for 2026 Decision-Making
Our Cleanroom Air Filters Market research translates these macro trends into a structured, decision-ready framework. The report provides a complete market sizing and forecast architecture built on historical performance from 2020 through 2025 and a forward projection spanning 2026 to 2032. It examines segmentation across type, application, and regional demand structure, while preserving strategic confidentiality around granular splits that are most valuable when accessed in full. The analysis includes competitive profiling, market concentration assessment, and scenario-based interpretation of how supply-side actions and demand-side adoption cycles may interact over the forecast horizon.
Operationally, the report is designed to support multiple use cases. Strategic planners can use it to calibrate capacity investments and assess demand durability across application categories. Procurement teams can use it to contextualize vendor offerings against compliance requirements and performance benchmarks. Investors and corporate development groups can use the competitive and concentration analysis to evaluate consolidation risks, partnership opportunities, and market entry barriers. Throughout, the report emphasizes practical interpretation over raw data presentation, ensuring that figures are linked to decision logic rather than isolated as abstract statistics.
Strategic Takeaways for Executive Teams
The cleanroom air filtration market in 2026 will reward organizations that treat contamination control as a strategic capability rather than a commoditized procurement line. Several themes stand out for leadership teams preparing their next planning cycle.
- The forecast trajectory indicates that demand expansion is broad-based, but growth will not be uniform across applications, regions, or filter categories. Prioritization should follow application criticality and compliance intensity rather than headline market size alone.
- Regulatory validation and standards alignment have become core commercial differentiators. EN 1822, ISO 29463, IEST testing protocols, and ISO 14644-1 classification requirements are entering purchasing decisions as gating criteria, not afterthoughts.
- Market concentration suggests that scale players hold structural advantages in certification infrastructure and global supply consistency, but targeted specialists can compete effectively through application-specific engineering, containment integration, and localized service models.
- Recent capacity expansions, product launches, and acquisitions point to an industry actively tightening its offerings around energy efficiency, containment validation, and material resistance for advanced manufacturing. Vendors that can demonstrate measurable operational benefits beyond particle capture will gain a stronger position in qualified buyer evaluations.
- Material cost dynamics and sustainable sourcing shifts are beginning to influence production economics, especially in medical-grade cleanroom applications. Lifecycle cost modeling and filter change-out strategy will become increasingly important in total cost of ownership assessments.
For executives, the central question is no longer whether cleanroom air filtration demand will grow, but where value will concentrate as the market matures. The companies and institutions that succeed in 2026 will be those that align procurement, compliance, and capacity planning with a clear view of application-specific demand, technical differentiation, and competitive momentum.
Closing Perspective
The cleanroom air filters market is moving from steady expansion into a phase defined by standards intensification, application diversification, and selective consolidation. The 2026 to 2032 forecast window offers a multi-year lens through which to evaluate capital allocation, vendor partnerships, and market positioning. This report is built to provide that perspective with analytical rigor and practical relevance. For teams that need a complete view of segmentation structure, regional demand architecture, company-by-company positioning, and forward scenarios, the full research delivers the depth required to convert market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Cleanroom Air Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Facility Management Market to Hit $3.38T by 2032, Driven by 6.8% CAGR
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Facility Management Services Market: A 2026 Outlook
The Facility Management (FM) Services Market is undergoing a structural shift that extends far beyond routine maintenance. What was once viewed as a back-office support function has evolved into a strategic lever for operational efficiency, sustainability compliance, and workplace experience. As organizations enter 2026, the ability to navigate this evolving landscape is no longer optional—it is a core competitiveness. Our latest market research provides a comprehensive, decision-ready blueprint for executives who need to anticipate demand shifts, optimize procurement strategies, and align facility portfolios with broader corporate objectives.
This report is not a static snapshot. It is a forward-looking analytical framework designed to translate market complexity into actionable intelligence. Whether you are a real estate operator, a corporate facilities leader, a public institution planner, or an investor evaluating service-provider exposure, the insights herein are calibrated to support 2026 strategic planning cycles.
Macro Trajectory: What the Numbers Reveal for 2026 Planning
The market has demonstrated consistent expansion over the past half-decade, and the momentum is projected to intensify through the end of the decade. Drawing on a historical baseline spanning 2020 to 2025 and a forecast horizon extending through 2032, our analysis places the overall market valuation at approximately 2.15 billion USD in 2025, with a projected climb to exceed 2.28 billion USD in 2026. The trajectory continues upward, reaching nearly 3.4 billion USD by 2032, supported by a compound annual growth rate of 6.8 percent.
These figures are not merely historical artifacts; they are signals. The sustained expansion reflects a confluence of operational digitization, regulatory tightening, and the reorganization of how organizations consume space. For strategic planners, the implication is clear: FM is no longer a discretionary cost line but a mission-critical service category with measurable impact on asset performance, tenant retention, and compliance readiness. The 6.8 percent CAGR underscores a market that is expanding faster than many traditional service segments, creating both opportunity and fragmentation risk for organizations that lack a disciplined sourcing or partnership strategy.
Structural Dimensions: How the Market Is Organized
Understanding where growth is concentrated requires a clear view of how the market is segmented. Our research disaggregates the landscape across multiple operational dimensions, enabling leaders to identify which service categories, user segments, and geographies align with their organizational footprint and risk tolerance.
The service architecture divides into core operational categories, each with distinct demand drivers. Hard services—encompassing physical infrastructure maintenance, HVAC, electrical, plumbing, and structural upkeep—represent the backbone of facility operations. Soft services, including cleaning, security, concierge, workplace experience, and administrative support, increasingly intersect with employee retention and brand perception. A third tier captures specialized and emerging service lines that are growing in relevance as organizations pursue integrated solutions rather than siloed contracts. Each category carries different margin profiles, labor intensity, and technology adoption curves, making the segmentation essential for contract structuring and vendor evaluation.
End-user demand is similarly diversified. Commercial portfolios drive consistent volume, but industrial facilities, institutional campuses, residential complexes, and government infrastructure each present unique compliance requirements, service-level expectations, and procurement cycles. This diversification means that a one-size-fits-all FM strategy is increasingly inadequate. Organizations must map their asset mix to the appropriate service tier, anticipate sector-specific regulatory pressures, and calibrate outsourcing versus in-house decisions accordingly.
On a regional level, the market exhibits pronounced geographic variation in maturity, demand density, and service complexity. Some regions reflect established, service-intensive environments where competition is fierce and differentiation hinges on technology and sustainability credentials. Others are experiencing faster relative growth as urbanization, infrastructure modernization, and regulatory adoption accelerate FM penetration. For multinational operators and regional portfolios alike, geographic context shapes everything from pricing dynamics to talent availability and delivery models.
Market Dynamics: The Forces Reshaping FM Execution in 2026
Behind the headline growth lies a set of operational pressures that are redefining how FM services are delivered, priced, and governed. These dynamics are not peripheral; they are central to contract viability, service quality, and long-term portfolio performance.
-
Labor scarcity and cost escalation. Workforce participation trends are projected to decline, tightening the availability of skilled HVAC, electrical, and plumbing technicians who are essential to facility operations. The resulting scarcity inflates wage expectations and, in some cases, delays maintenance projects by up to a quarter. For operators, this translates into tighter scheduling windows, higher service costs, and greater exposure to downtime if contingency planning is insufficient.
-
Regulatory and sustainability mandates. Government building maintenance regulations and corporate sustainability goals are accelerating demand for specialized decarbonization services and comprehensive energy management solutions. Organizations are no longer treating environmental compliance as a separate initiative; it is becoming embedded in facility operations, influencing equipment upgrades, monitoring practices, and vendor selection criteria.
-
Standards and certification as trust signals. Frameworks such as ISO 41001 are increasingly referenced as providers seek to demonstrate compliance with requirements for effective and efficient facility management delivery. Certification and documented operational discipline are becoming differentiators in competitive bids, particularly for institutional and government contracts where accountability and auditability carry heightened weight.
-
Digital integration and data-enabled operations. The market is steadily shifting toward technology-enabled service models. Spatial data, digital twins, connected building platforms, and integrated software tools are moving from pilots to production deployments. This transition is reshaping how providers forecast maintenance needs, optimize labor deployment, and report on energy and performance metrics.
These dynamics create a dual challenge for decision-makers. On one side, they raise the bar for service quality and compliance. On the other, they open pathways for providers and clients who can operationalize technology, standardize processes, and demonstrate measurable outcomes. The organizations that thrive in 2026 will be those that treat FM as an integrated system rather than a collection of discrete tasks.
Facility Management (FM) Services Market
Competitive Landscape: Who Is Shaping the Market and How
The FM services market features a broad mix of established facility operators, integrated service providers, and technology platforms that increasingly blur the line between software and services. Our research profiles the core companies that are defining competitive benchmarks, expanding service portfolios, and repositioning themselves around workplace experience, sustainability, and operational integration.
Among the most prominent global players, several themes emerge. Large U.S.-based commercial real estate and facilities firms are expanding beyond traditional management into integrated workplace and building operations models. European and international service groups are emphasizing workplace experience, sustainability, and cross-regional delivery capabilities. Specialized contractors continue to anchor hard services and property support in commercial, industrial, and public-sector environments. At the same time, technology-oriented companies are embedding software, platforms, and analytics into FM delivery, enabling more predictive maintenance, energy oversight, and operational transparency.
The competitive field is not static. Recent activity shows a clear pattern of consolidation, capability expansion, and targeted partnerships designed to capture demand in high-growth verticals and regions.
-
In early 2025, one major global services provider secured multiple outsourcing contracts for integrated workplace and maintenance services, reinforcing its footprint in combined service delivery.
-
Also in early 2025, a leading U.S.-based commercial services firm completed an acquisition to establish a new building operations and experience segment, signaling a strategic pivot toward more holistic portfolio management.
-
A global services group expanded its U.S. presence through an acquisition designed to strengthen cross-selling opportunities in integrated facility management.
-
A partnership formed in mid-2025 brought spatial data capabilities into digital twin modeling for North American industrial portfolios, highlighting the growing role of data-driven building representation in operations and planning.
-
Later in the year, a new decarbonization and energy management service launch targeted North American logistics and warehousing, illustrating how FM providers are tailoring offerings to sector-specific sustainability and operational demands.
Worldwide HVAC Cleaning Services Market
These developments matter for 2026 strategy because they show where incumbents are placing bets. Acquisitions and partnerships are not only reshaping provider capabilities; they are also redefining the value propositions available to clients. Organizations evaluating FM partners should look beyond contract pricing and assess whether providers have the integrated capabilities, technology fluency, and sector-specific experience to support long-term operational goals.
What Our Research Delivers: A Practical Decision Toolkit
This report is built to support execution, not just awareness. It translates market structure, growth trajectory, and competitive activity into tools that procurement, operations, real estate, and executive teams can use immediately.
Within the full study, readers will find detailed coverage of service category dynamics, end-user demand patterns, and regional variation, structured to help leaders map their portfolios against market realities. The analysis examines how hard services, soft services, and emerging service tiers interact with labor constraints, regulatory pressure, and technology adoption. It also evaluates the strategic implications of recent provider moves, including consolidation, capability expansion, and digital partnerships, so that organizations can anticipate shifts in vendor behavior and service availability.
Beyond descriptive analysis, the report provides an operational lens on market concentration and competitive positioning. By examining how demand is distributed and how leading providers differentiate, the research helps clients assess sourcing risk, evaluate partnership fit, and identify where specialized capabilities may create advantage. The goal is to equip decision-makers with a clear framework for contract strategy, vendor selection, service integration, and portfolio-level planning.
Why This Research Matters for 2026 Decisions
The Facility Management Services Market is entering a phase where strategic foresight yields measurable operational advantage. Growth is steady, but the underlying forces—labor constraints, sustainability mandates, digital transformation, and provider consolidation—are changing the terms of engagement. Organizations that wait for issues to surface in the form of delays, cost overruns, or compliance gaps will find themselves reacting rather than shaping outcomes.
Our research is designed to convert market complexity into clarity. It helps leaders answer the questions that matter in 2026: how to align FM strategy with asset portfolios, which service dimensions deserve priority investment, how to evaluate providers in a consolidating and technology-intensive market, and where regional and sector-specific dynamics are likely to influence cost and delivery. The full report expands on these themes with the depth and structure required for formal planning, procurement reviews, and executive decision-making.
Next Steps for Strategic Leaders
For executives and operational leaders preparing for the 2026 planning cycle, the opportunity lies in moving from general awareness to precise, evidence-based action. The market trajectory, segmentation structure, competitive activity, and operational dynamics outlined here are intended as a foundation—not the final word. The complete study provides the granular analysis, provider profiles, and decision frameworks needed to translate insight into execution.
We invite you to explore the full Facility Management Services Market research to access the detailed intelligence that supports confident, forward-looking decisions. In a market expanding toward sustained multi-billion-dollar scale, the organizations that act with structured insight will be best positioned to manage cost, compliance, and performance in the years ahead.
For detailed analysis of this topic, please visit the official page: Facility Management (FM) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hearables Market Hits $215M in 2025, Poised for 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
Hearables Market Strategic Outlook 2026: Navigating the Next Wave of Audio Intelligence
The global hearables market has entered a decisive inflection point. Where early adoption revolved around convenience and basic wireless connectivity, the category now sits at the intersection of consumer electronics, health technology, spatial computing, and artificial intelligence. Market valuation reached approximately 215.0 million USD in 2025, extending a consistent upward trajectory from 163.15 million USD in 2020. Forward projections indicate sustained momentum, with the market advancing toward 234.68 million USD in 2026 and continuing to expand through the end of the forecast period in 2032. This compression of growth timelines, paired with an estimated compound annual growth rate of 6.98 percent across the 2026 to 2032 horizon, signals more than incremental consumer demand. It reflects structural shifts in how audio devices are positioned, manufactured, and integrated into daily workflows, fitness routines, and wellness ecosystems.
For executive teams, product leaders, and investment strategists, this environment demands more than headline figures. The real strategic challenge lies in interpreting what is driving the expansion, where competitive intensity is concentrating, how supply-side disruptions and regulatory shifts are reshaping cost structures, and which product architectures are likely to command premium positioning in the years ahead. The hearables category has matured into a landscape where regional execution, form-factor differentiation, application-specific use cases, and component-level supply chain design all influence margin profiles and market share outcomes. Understanding these layers is no longer optional for organizations seeking to anticipate demand rather than react to it.
Worldwide Consumer and Enterprise Hearables Market
Why a 2026 Decision Framework Requires Granular Intelligence
The period from 2026 onward will be defined by convergence. Manufacturers are no longer competing solely on sound quality or battery endurance; they are competing on integrated sensing, adaptive noise management, hearing health functionality, and seamless ecosystem compatibility. At the same time, cost pressures from tariffs, raw material constraints, and semiconductor sourcing volatility are forcing more deliberate portfolio planning. In this context, strategic decision-making depends on knowing not just that the market is expanding, but where value is accumulating and which structural headwinds require preemptive mitigation.
Hearables Market
Several forces make this the right moment for a detailed market assessment. First, consumer expectations are shifting toward devices that function as always-on companions for music, communication, fitness tracking, and environmental awareness. Second, enterprise and professional users are driving demand for hearables that support hybrid collaboration, call clarity, and platform integration. Third, the hearing health overlap is creating new product pathways and regulatory considerations that blur the line between consumer audio and assistive technology. Each of these vectors alters the competitive equation, and each requires a precise reading of market architecture rather than broad directional assumptions.
Evidence of the market's accelerating complexity can already be seen in recent product introductions. At CES 2026, for example, multiple launches emphasized open-ear designs and certified noise reduction as practical solutions for daily use and athletic applications. These releases reflect a broader industry movement toward comfort-centric ergonomics, situational awareness, and hybrid use cases that span commuting, outdoor activity, and workplace environments. The strategic implication is clear: successful product roadmaps will need to account for lifestyle integration, environmental robustness, and user-specific acoustic preferences, rather than treating audio performance as a standalone specification.
What the Research Delivers: Analytical Depth Designed for Executive Action
Our latest Hearables Market study is built to translate category momentum into decision-grade intelligence. The analysis moves beyond high-level demand signals to examine the structural mechanisms shaping growth, including segmentation patterns, regional execution dynamics, and the competitive behaviors that determine which players secure durable advantage. The report is designed to support three core planning functions: market entry and expansion evaluation, product portfolio strategy, and supply chain risk positioning.
To accomplish this, the study provides a detailed breakdown of market structure across multiple analytical dimensions. It maps how distinct device categories are contributing to overall revenue evolution, allowing stakeholders to understand where volume concentration and differentiation opportunities intersect. It also examines application-driven demand patterns, clarifying how usage contexts such as music and entertainment, fitness-oriented listening, and gaming-related audio consumption influence product requirements, pricing tolerance, and lifecycle expectations. Regional demand is similarly assessed to identify where consumption is scaling most rapidly and where market maturity, channel dynamics, and competitive saturation require different strategic approaches.
Equally important, the report analyzes market concentration to reveal how revenue is distributed among leading participants. This concentration analysis provides a practical lens for evaluating competitive vulnerability, partnership opportunities, and the extent to which the market remains open to new entrants or specialized niche players. In a category where scale advantages, brand equity, and technology integration all matter, understanding concentration patterns helps decision-makers gauge the realism of aggressive growth targets and the likelihood of consolidation pressure.
Beyond segmentation and concentration, the research connects product-level developments with broader industry dynamics. It examines how active noise management, open-ear and bone-conduction form factors, AI-enabled acoustic optimization, and premium sound reproduction are reshaping consumer value propositions. It also assesses how professional-grade communication features, hearing-health integration, and ecosystem alignment influence enterprise and hybrid-use demand. These product trends are evaluated not as isolated innovations, but as strategic signals that indicate where future revenue streams are likely to be anchored.
Competitive Landscape: Strategic Positioning Among the Leaders
The competitive environment is defined by a mix of ecosystem-driven incumbents, audio specialists, and component-level technology providers whose designs influence downstream product capabilities. Apple continues to reinforce its position through the AirPods lineup, including the AirPods 4 and AirPods Pro models built around the H2 chip. Its strategy emphasizes integrated hardware-software performance, open-ear ANC design exploration, and the expansion of hearing health features that extend the device's role beyond entertainment. By linking acoustic performance with platform ecosystem benefits, Apple maintains a strong reference point for premium consumer expectations.
Bose remains focused on immersive listening experiences through offerings such as the QuietComfort Ultra Earbuds and Ultra Open Earbuds. Its approach highlights ActiveSense AI ANC and OpenAudio technology, targeting users who value environmental adaptability and high-quality sound in both enclosed and open-ear configurations. Bose's continued investment in noise management and comfort-oriented design reinforces its relevance in premium segments where acoustic refinement and wearability are central purchase drivers.
Samsung has pushed its Galaxy Buds series toward AI-optimized performance, high-resolution audio, and ANC 2.0 capabilities, with the Galaxy Buds 4 Pro representing the company's current emphasis on connected device intelligence and refined sound reproduction. Its strength lies in aligning hearables with a broader mobile ecosystem and in delivering feature-rich products that serve both consumer and lifestyle use cases. Samsung's positioning illustrates how hardware differentiation and ecosystem integration can reinforce one another in a crowded market.
Sony continues to compete through the WF-1000XM series, where advanced noise cancellation and high-fidelity sound reproduction remain central to the brand's value proposition. Sony's strategy underscores the enduring importance of acoustic excellence and feature credibility, particularly among users who treat earbuds and headphones as serious audio equipment rather than accessories alone. In a market increasingly shaped by hybrid usage, Sony's emphasis on sound quality helps maintain a distinct premium lane.
Across the broader competitive field, a range of specialized players is expanding the boundaries of what hearables can deliver. Anker Innovations has advanced open-ear designs such as the Soundcore AeroFit 2, emphasizing custom-molded fit, long battery life, and AI compute-in-memory chip architecture. Shokz has focused on open-ear and bone-conduction categories, including the OpenRun Pro 2 with an IP55 rating, the OpenFit Pro with TÜV-certified noise reduction, and the OpenDots clip-on earbuds. These products illustrate how ergonomic innovation and environmental durability can open new usage scenarios, particularly for active and outdoor consumers.
Professional and enterprise-oriented brands are also shaping the market's direction. Jabra's Evolve2 and Elite series are positioned around professional-grade earbuds with ANC and seamless Microsoft Teams integration, highlighting the growing importance of collaboration-ready audio in hybrid work settings. Sennheiser continues to emphasize premium sound quality and noise cancellation through the Momentum True Wireless series, reinforcing a reputation for audio fidelity. Philips is extending the hearables frontier into hearing health with Lifeline and BT series hearing aids integrated with hearables technology, an approach that blurs consumer and medical-adjacent categories and introduces new design, compliance, and market-access considerations.
Underpinning many of these product strategies is the role of component and reference-design suppliers. Airoha Technology, as a MediaTek subsidiary, supplies Bluetooth audio SoCs and reference designs used in TWS earbuds and headphones, influencing how quickly manufacturers can bring power-efficient, feature-rich products to market. This supplier dimension matters because competitive timing, feature adoption, and cost efficiency are often determined long before the consumer sees the final product. In practical terms, the hearables market is not only a contest of brand and design; it is also a contest of component architecture and development velocity.
Market Dynamics: Supply Constraints, Tariffs, and Strategic Realignment
The growth outlook cannot be separated from the operational pressures currently affecting the industry. Raw material disruptions have emerged as a meaningful constraint, particularly where silicon supply shortages linked to the Russia-Ukraine conflict have affected MEMS microphone production. These disruptions have delayed deliveries and increased component prices, creating cost volatility for manufacturers that depend on precision acoustic components. Compounding this issue, tariff actions have added further complexity to sourcing and pricing strategies. In the U.S. market, substantial tariffs on Chinese products have disproportionately affected wireless headphones and smart home devices, with manufacturers paying significant tariff costs in 2025. Additional tariff exposure on Chinese MEMS and PCB suppliers has intensified the push toward regional diversification and raised costs for microphone manufacturers.
At the same time, regulatory adjustments are reshaping sourcing assumptions. Executive actions affecting certain tariff measures on integrated circuits have altered the cost and availability landscape for audio component sourcing, creating a moving target for procurement teams and product planners. The cumulative effect is a market environment in which pricing, margin planning, and supply continuity must be modeled with greater flexibility. For companies operating at scale, this means diversification of supplier bases, reassessment of bill-of-materials exposure, and closer coordination between design engineering and procurement. For newer or smaller entrants, it means that barriers to cost-efficient scaling may be higher than headline demand trends suggest.
These dynamics also have strategic implications for product architecture. When component availability and tariff exposure influence cost structures, design teams often need to evaluate alternative acoustic configurations, material selections, and manufacturing footprints. The result is a market in which operational resilience is becoming part of competitive strategy. Companies that treat supply chain design as a secondary concern risk losing margin control; companies that integrate sourcing risk into product planning can protect price positioning and improve launch reliability. In an environment where revenue is expanding but input costs are volatile, the ability to manage upstream exposure is increasingly a differentiator.
What 2026 Decision-Makers Should Look For Next
The hearables market is not simply growing; it is being reshaped by overlapping technology trends, changing consumer expectations, and a more demanding operating environment. That combination creates opportunity, but only for organizations that can distinguish between temporary headwinds and structural shifts. The most effective decisions in 2026 will come from understanding where demand is most durable, which product categories are gaining strategic relevance, how competitive concentration affects market access, and where supply-side pressures are likely to influence pricing and margin outcomes.
This report is designed to provide that clarity. It offers a detailed mapping of market size evolution, segmentation behavior, concentration patterns, competitive positioning, and industry dynamics that affect execution risk. By integrating product-level developments with macroeconomic and regulatory context, it gives stakeholders a practical foundation for planning product roadmaps, evaluating expansion scenarios, and anticipating the forces that will shape the next phase of category growth.
For organizations that need to move from market awareness to market advantage, the full study provides the underlying detail necessary to support informed investment, portfolio design, and competitive positioning. The complete analysis, including deeper segmentation assessments and regional demand patterns, is available through the full report.
For detailed analysis of this topic, please visit the official page: Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


