



Category: market research
PW Consulting: Convenience Store Software Market Hits $190M in 2025, Projected 4.19% CAGR Through 2032
By PW Consulting, 2026-09-16
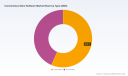
Navigating the Next Wave: Strategic Intelligence for the Convenience Store Software Market Through 2032
The convenience store sector stands at a critical inflection point. As operators balance thin margins, labor volatility, and accelerating consumer expectations, software is no longer a back-office utility but a core competitive lever. Our latest research release, the Convenience Store Software Market study, provides a structured, forward-looking intelligence framework designed specifically for executive decision-making in 2026 and beyond. This briefing outlines how the report translates macro trends, competitive movements, and operational pressures into actionable strategy.
Why 2026 Demands a Clearer Market Lens
The global convenience store software market has demonstrated steady expansion through the 2020–2025 historical window, moving from an estimated USD 150.0 million in 2020 to approximately USD 190.0 million by 2025. That trajectory reflects more than nominal growth; it signals a structural shift in how retailers procure, integrate, and scale technology. Looking ahead through the 2026–2032 forecast period, the study maps a compounded annual growth rate (CAGR) of roughly 4.19 percent, positioning the market to reach just over USD 251.2 million by 2032.
These figures are not abstract benchmarks. For multi-site retailers, franchise networks, and independent operators, they represent the size of the addressable technology ecosystem in which procurement choices will be made, vendor contracts negotiated, and operational roadmaps built. Our analysis distills what those numbers imply for capital allocation, platform standardization, and digital transformation sequencing—without overstating certainty or masking the assumptions behind the projections.
Worldwide Retail Billing Software Market
Forecast Architecture: What the Numbers Mean for Executive Planning
The forecast is constructed across a disciplined time horizon, anchoring executive planning in 2026 while extending visibility through 2032. The 2026 baseline sits at approximately USD 196.73 million, with the model projecting progressive movement through 2027–2029 before reaching the terminal 2032 estimate. Rather than presenting a single line of growth, the report contextualizes how expansion is distributed across deployment models, application categories, and geography.
The research intentionally avoids reducing the market to isolated percentage splits, because real purchasing behavior is rarely segment-pure. Instead, the study examines how cloud-based and on-premises solutions interact within the same operator footprint, how application priorities shift from transaction processing to inventory intelligence and customer engagement, and how regional maturity levels influence adoption timing. This integrated view gives leadership teams a more realistic basis for evaluating vendor roadmaps, integration costs, and rollout sequencing.
Operational Drivers Reshaping the Market
Several contemporaneous forces are compressing timelines and raising the stakes for software investment. Labor constraints remain one of the most persistent operational challenges. Shortages and high turnover are accelerating demand for AI-enabled tools that automate scheduling, inventory tracking, and day-to-day workflows, reducing dependence on manual processes. In parallel, regulatory complexity is intensifying around data privacy, health safety, and sector-specific compliance, including regional frameworks such as GDPR. These requirements are not peripheral; they are becoming procurement criteria.
Infrastructure dynamics are also influencing platform preferences. Cloud-based systems are increasingly viewed as a way to simplify compliance with complex fuel and tobacco tax obligations, an operational burden that can strain smaller teams and fragmented back offices. The result is a market in which software selection has become a compliance, efficiency, and risk-management decision at the same time. Our report maps these drivers against adoption patterns so that leadership can anticipate where pressure will translate into spend and where it will create implementation friction.
Competitive Landscape: Capability Differentiation Over Brand Scale
The market is populated by a diverse mix of specialists and broader retail technology providers. Understanding their positioning matters because competitive advantage in this sector is increasingly defined by the depth of domain fit rather than the breadth of a general platform. The study profiles the companies shaping the ecosystem, including AccuPOS, SSCS, PDI Technologies, POS Nation, ADD Systems, DataMax, SHENZHEN KEMAI, CStorePro Inc., Petrosoft, Paytronix, GK Software, NCR Voyix, Oracle Corporation, Toshiba Global Commerce Solutions, and Tote.ai.
Each player brings a distinct orientation. Some emphasize POS and inventory management tailored specifically to convenience stores. Others concentrate on inventory accuracy, data management, or back-office precision for fuel and c-store operations. A subset focuses on wholesale inventory and fuel logistics, while others lean into loyalty, customer engagement, omnichannel retail management, or enterprise-grade POS and ERP solutions for large operators. Emerging entrants are also pushing AI-powered POS and kiosk-based foodservice technology into fuel and convenience environments.
Recent activity reinforces how rapidly this field is evolving. In February 2026, Tote.ai was selected by Spinx to deploy an AI POS system with self-service kiosks and foodservice capabilities across all locations, with go-live planned for the second half of 2026. Earlier in the cycle, GK Software demonstrated omnichannel POS and retail solutions at the NACS Show 2025, highlighting adoption among seven of the top 20 convenience store companies. Toshiba Global Commerce Solutions also showcased future-oriented convenience retail technology, including POS and AI solutions, at the same event. These developments point to a market where integration, automation, and customer-facing experience are converging, and where vendor selection increasingly determines operational agility.
Concentration Dynamics and Procurement Implications
Market structure matters as much as market size. The report includes concentration metrics that frame how competitive the landscape is from a buyer's perspective. With a CR3 near 28.5 percent and a CR5 around 35.0 percent, the sector is moderately fragmented, but not shallow. This has direct implications for negotiation strategy, vendor diversification, and switching costs. For operators evaluating platform consolidation, the concentration picture helps clarify where leverage exists, where dependency risk may accumulate, and where specialized providers can outperform broader suites on domain-specific functionality.
Rather than leaving procurement teams to infer these dynamics from product brochures, the study places concentration in the context of deployment choices and application priorities. This enables a more grounded assessment of how much room there is for differentiation, where standards are beginning to form, and which capabilities are becoming table stakes rather than optional upgrades.
What the Study Delivers Beyond High-Level Estimates
The report is designed as an operational reference, not a static snapshot. It combines market sizing with qualitative and structural analysis intended to support real decisions in budgeting, vendor evaluation, and rollout planning. Key elements include:
- A historical and forecast baseline that situates current demand within a longer adoption curve, helping leaders distinguish cyclical noise from durable growth signals.
- A multi-dimensional segmentation view that connects deployment models, application categories, and regional maturity without reducing the market to disconnected data points.
- A structured competitive profiling section that maps offering focus, geographic roots, and capability emphasis across the companies actively shaping the market.
- An integrated dynamics section that ties regulatory complexity, compliance burdens, labor constraints, and cloud-based operational advantages to purchasing behavior and implementation risk.
- Up-to-date momentum indicators drawn from recent partnerships, trade show activity, and product direction, giving decision-makers a current read on where innovation is being commercialized.
Taken together, these components create a shared language for strategy, operations, and procurement teams. The objective is to enable more disciplined questions: Which capabilities should be standardized and which should remain flexible? Where does compliance pressure justify earlier investment? How should deployment models be chosen across sites with different operating realities? The report provides the analytical scaffolding to answer those questions with greater confidence.
How Leadership Teams Can Use This Intelligence in 2026
For executives planning the next investment cycle, the study serves as a decision filter. It helps clarify whether a near-term purchase is primarily an efficiency play, a compliance play, or a customer-experience play, and it connects each objective to the broader market trajectory. The forecast and competitive mapping also support scenario thinking: what changes if cloud adoption accelerates faster than expected, if AI-enabled automation becomes a stronger hiring and training mitigant, or if regulatory requirements tighten further across key regions.
Equally important, the research is built to support vendor conversations with more precision. By understanding where specialized providers concentrate their value and where larger platforms extend their reach, operators can evaluate proposals against a clearer benchmark. That reduces the risk of buying into generic capability claims and increases the likelihood of selecting solutions that fit the operational cadence of convenience retail.
Accessing the Full Strategic Picture
This briefing is intended as a directional preview. The complete report extends well beyond the summary signals presented here, offering a fuller mapping of market structure, competitive positioning, and the operational forces shaping adoption through 2032. For teams that need to move from high-level awareness to procurement-ready insight, the full study provides the depth required to align technology strategy with business strategy.
The convenience store software market is expanding within a defined but dynamic corridor, and the operators who navigate it most effectively will be those who treat software selection as a strategic process rather than a tactical purchase. Our research is designed to make that process more transparent, more evidence-based, and more actionable for 2026 decision-making and the years that follow.
Convenience Store Software Market
For detailed analysis of this topic, please visit the official page: Convenience Store Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
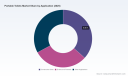
Navigating the Portable Toilets Market: Strategic Insights for 2026 Decision-Making
The portable toilets industry stands at a pivotal juncture as we move through 2026. What was once considered a purely utilitarian sector has evolved into a complex market driven by stringent hygiene standards, event normalization, infrastructure expansion, and technological innovation. For executives, investors, and operational leaders, understanding the underlying currents of this market is no longer optional—it is a prerequisite for capital allocation, supply chain optimization, and competitive positioning.
Our latest comprehensive market research delivers a granular, data-backed exploration of the portable toilets landscape, calibrated to support high-stakes decisions throughout the 2026-2032 forecast window. This overview outlines the strategic architecture of the study, the competitive forces reshaping the sector, and the operational imperatives that forward-looking organizations must address now.
The Macro Trajectory: Growth Patterns and Structural Inflection Points
The global portable toilets market has demonstrated consistent expansion over the past half-decade, with historical valuations climbing steadily from 146.0 million USD in 2020 to 192.0 million USD in 2025. This trajectory reflects more than cyclical demand; it signals a structural recalibration of how temporary sanitation is provisioned across construction, hospitality, municipal operations, and large-scale entertainment.
Looking ahead, the forecast period from 2026 through 2032 projects continued momentum, with the market expected to reach 203.25 million USD in 2026 and scale toward 327.72 million USD by 2032. The compound annual growth rate of 7.94 percent underscores a sector that is absorbing broader economic recovery, infrastructure investment cycles, and evolving consumer expectations around cleanliness and accessibility. For strategists, this growth curve is not merely a top-line projection—it is a signal that procurement models, fleet management strategies, and technological adoption timelines must be recalibrated to avoid displacement by more agile competitors.
The research framework maps these macro movements against underlying demand generators, allowing decision-makers to isolate which growth vectors are structural versus transient. By aligning operational planning with verified expansion pathways, organizations can allocate fleet capacity, service territories, and capital expenditure with greater precision.
Competitive Architecture and Strategic Positioning
The portable toilets landscape is characterized by a moderately fragmented but increasingly consolidated competitive environment. The top three players collectively account for 24.8 percent of market revenue, while the top five capture 31.5 percent. This concentration profile suggests that scale advantages in logistics, servicing networks, and procurement are becoming decisive, yet sufficient white space remains for specialized operators and regional leaders to compete on service quality, compliance adherence, and technological differentiation.
Several established enterprises define the current competitive baseline. PolyJohn, headquartered in Whiting, Indiana, has long served as a leading manufacturer of portable toilets, sinks, and ancillary accessories. In February 2026, the company acquired EcoFab to accelerate the global deployment of advanced vacuum toilet systems, a move that signals a clear strategic pivot toward premium, technology-enabled sanitation solutions. Satellite Industries, based in the United States, operates as the largest manufacturer across a broad portfolio encompassing portable restrooms, restroom trailers, restroom trucks, septic trucks, slide-ins, unit haulers, vacuum technology, modular solutions, consumables, and deodorizers. Its vertical breadth positions it as a one-stop infrastructure partner for large-scale deployments.
United Site Services (USS) stands as the nation's leading provider of portable restroom rentals, offering standard, deluxe, flushing, and ADA-compliant portable toilets. Its rental-centric model emphasizes compliance, fleet availability, and customer-facing service reliability. Rumpke, headquartered in Cincinnati, Ohio, differentiates through sustainability-minded manufacturing, offering portable toilets, VIP restroom trailers, and ADA-compliant units constructed using recycled plastic. WM provides portable toilet rentals and sanitation solutions tailored to construction, events, and festivals, leveraging its broader waste and environmental services ecosystem to deliver integrated site management. Stallion Infrastructure Services rounds out the competitive field as a manufacturer and provider of premium portable toilets, ADA-accessible units, high-rise models, and luxury restroom trailers, targeting high-visibility and high-comfort deployment scenarios.
The strategic implications of this competitive map are clear. Organizations that rely solely on commodity rental models face margin compression as larger players leverage consolidated logistics and manufacturing scale. Conversely, firms that invest in differentiated unit types, compliance-ready ADA configurations, and vacuum or modular technologies can command premium positioning. The research deconstructs these competitive dynamics into actionable matrices, enabling leaders to benchmark their capabilities against peer trajectories and identify whitespace for acquisition, partnership, or product-line expansion.
Technology, Sustainability, and Material Innovation as Differentiators
Technological and material innovation is no longer peripheral to the portable toilets sector; it is a core driver of competitive advantage and operational efficiency. The adoption of blow-molded construction with recycled plastic in portable toilet units illustrates how sustainability mandates and cost considerations are converging. Manufacturers that integrate recycled feedstocks without compromising structural integrity or hygiene standards are positioning themselves favorably with municipal buyers, environmentally conscious event organizers, and regulatory bodies.
Vacuum toilet systems represent another critical frontier. By reducing water consumption and improving waste containment, vacuum-enabled units address both operational cost pressures and environmental compliance requirements. PolyJohn's acquisition of EcoFab in early 2026 explicitly targets the acceleration of advanced vacuum toilet systems for global deployment, signaling that incumbent players view this technology as a strategic growth lever rather than a niche experiment. For operators and procurement teams, the emergence of vacuum and modular solutions introduces new considerations around servicing frequency, infrastructure compatibility, and total cost of ownership.
The research evaluates these technological shifts through a practical lens. Rather than treating innovation as an abstract trend, the study maps technology adoption curves against application requirements, regional procurement preferences, and servicing economics. This allows decision-makers to determine where early adoption yields competitive advantage and where incremental upgrades suffice.
Regulatory Dynamics and Procurement Realities
Regulatory and procurement environments exert significant influence on market behavior, particularly in municipal and public-sector channels. Recent bid activity illustrates the steady cadence of public procurement for portable toilet rental and servicing, including cycles issued by US cities and counties for 2026 periods. Documents from jurisdictions such as Union County, New Jersey, and Wisconsin demonstrate how local governments structure competitive bidding for sanitation services, often emphasizing compliance, availability guarantees, and cost transparency.
Tax and fiscal policies further shape procurement behavior. In Washington state, portable toilet rentals are exempt from retail sales tax, a policy arrangement that directly influences net deployment costs for contractors, event producers, and municipal operators. Such regulatory nuances may appear granular, but they materially affect pricing strategy, margin planning, and regional market entry decisions.
The study incorporates these regulatory and procurement realities into a broader dynamics framework. It examines how bid structures, compliance requirements, tax treatments, and municipal planning cycles interact with private-sector demand, creating a multi-layered demand environment that rewards operators with robust compliance infrastructure and flexible service models.
Worldwide Portable Shelter Market
Within the broader application landscape, construction sites, events and festivals, and other deployment contexts each impose distinct operational requirements. Construction environments prioritize durability, frequent servicing, and mobility across evolving job-site layouts. Events and festivals demand rapid deployment, aesthetic considerations, ADA compliance, and high-capacity throughput during concentrated usage windows. Other applications span municipal programs, emergency response, agricultural operations, and industrial facilities, each with specialized sanitation and accessibility needs. The research dissects these application profiles to help organizations align fleet composition, servicing schedules, and unit specifications with the most profitable demand segments.
Fleet Strategy, Service Economics, and Total Cost of Ownership
Portable toilets businesses operate at the intersection of manufacturing, logistics, and recurrent service. Unit pricing is only one component of competitiveness; servicing frequency, route optimization, water and chemical consumption, maintenance intervals, and disposal logistics collectively determine profitability. As fleet sizes expand and deployment territories broaden, organizations that fail to optimize service economics risk margin erosion even in a growing market.
Portable Toilets Market
The research provides a structured evaluation of the operational levers that drive total cost of ownership. It examines how unit design influences servicing intervals, how geographic dispersion affects route density and labor efficiency, and how consumables management—deodorants, chemicals, and replacement components—impacts recurring costs. By connecting these operational variables to demand patterns and competitive benchmarks, the study equips leaders with a practical framework for fleet planning and service-model design.
For organizations considering expansion, the analysis highlights where scale delivers cost advantages and where localized service quality can justify premium pricing. For existing operators, it identifies efficiency gaps that can be closed through route redesign, unit-type standardization, or targeted technology adoption.
What the Research Delivers: Actionable Intelligence for 2026 and Beyond
This market study is designed as a decision-support instrument rather than a static overview. It combines historical validation, forward-looking projections, competitive profiling, and operational context into a unified analytical architecture. The following elements form the core of the research deliverable:
- Comprehensive market sizing and growth trajectory mapping across the forecast horizon, enabling scenario planning for capacity, investment, and territory strategy.
- Competitive profiling of leading manufacturers and service providers, with attention to product portfolios, recent strategic moves, and positioning across standard, premium, and technology-enabled segments.
- Segment-level analysis that clarifies how unit types and application environments shape demand intensity, pricing dynamics, and service requirements.
- Regulatory and procurement context that connects municipal bidding behavior, tax treatments, and compliance expectations to practical market-entry and pricing considerations.
- Technology and material innovation assessment, including vacuum systems, recycled plastic construction, and modular configurations, with implications for servicing economics and competitive differentiation.
- Market concentration and competitive structure analysis that helps organizations gauge the balance between scale-driven consolidation and niche specialization.
Each section is structured to support concrete decisions: whether to expand fleet capacity, enter a new region, invest in premium or ADA-compliant unit lines, pursue partnerships or acquisitions, or redesign servicing operations for improved margin performance. The research avoids generic commentary in favor of structured, decision-oriented analysis that can be directly integrated into strategic planning processes.
Strategic Implications for Leadership Teams
The portable toilets market in 2026 rewards organizations that combine operational discipline with strategic foresight. Growth is real, but it is not uniformly accessible. Companies that treat the sector as a low-complexity rental business will find themselves outpaced by competitors who leverage technology, compliance expertise, and service-model innovation to capture higher-value deployments.
Leadership teams should consider several strategic priorities. First, align fleet composition and unit specifications with the application profiles that offer the strongest returns, rather than pursuing undifferentiated volume. Second, evaluate technology adoption—particularly vacuum systems and recycled-material construction—not as optional enhancements but as potential levers for cost control, compliance readiness, and premium positioning. Third, strengthen procurement and bidding capabilities for municipal and public-sector opportunities, where structured procurement cycles can provide recurring revenue streams for operators with the right compliance and service infrastructure. Fourth, assess the competitive field with an eye toward consolidation, acquisition, or partnership opportunities, especially as larger players expand through capability-enhancing moves.
The research provides the evidentiary foundation for these decisions. By translating macro growth patterns, competitive movements, regulatory context, and operational economics into a coherent decision framework, it enables leaders to move beyond intuition and act on verified market intelligence.
Accessing the Full Intelligence Package
The portable toilets market is evolving quickly, and the window for proactive strategic positioning is open now. Organizations that delay comprehensive analysis risk ceding territory, margin, and capability advantages to more informed competitors. This study is built to shorten the distance between market complexity and executive decision-making.
For a complete view of market sizing, segmentation dynamics, competitive profiles, regulatory context, and forward-looking projections, we invite you to access the full research report. The detailed intelligence package provides the depth required to calibrate investment plans, refine operational strategy, and anticipate the competitive shifts that will define the 2026-2032 period.
For detailed analysis of this topic, please visit the official page: Portable Toilets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Nitrocellulose Market at $1,030M in 2025 and $1,452M by 2032 for a 5% CAGR
By PW Consulting, 2026-09-16
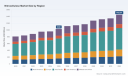
The Strategic Imperative: Navigating the Nitrocellulose Market Beyond 2026
The global nitrocellulose sector stands at a critical inflection point. Driven by shifting defence procurement priorities, volatile raw material economics, and intensifying sustainability mandates, industry leaders can no longer rely on legacy planning frameworks. PW Consulting’s newly released Nitrocellulose Market Research study provides a forward-looking intelligence architecture designed specifically for executive decision-makers operating through 2026 and beyond. This study translates multi-year market trajectories into actionable strategic playbooks, enabling organizations to optimize procurement, reshape competitive positioning, and de-risk capital allocation in an increasingly fragmented landscape.
At its core, the global market valuation reflects a steady but accelerating expansion pattern. From a base of 810.0 million USD in 2020, the sector climbed to 1,030.0 million USD by 2025, and forward projections extending through 2032 outline a decisive upward trajectory, with the market positioned to surpass 1,452.0 million USD by the close of the forecast horizon. This growth narrative is underpinned by a compound annual growth rate of 5.0 percent across the 2026 to 2032 projection window. These macro figures are not merely statistical markers; they represent structural demand shifts, capacity reallocation decisions, and pricing power dynamics that will directly influence margin profiles, supplier negotiations, and regional manufacturing footprints. The study contextualizes this trajectory by mapping growth acceleration against real-world supply-side constraints, downstream application evolution, and macroeconomic pressure points that will define operational realities for the next seven years.
Decoding the Market Architecture
This research report is engineered for practical deployment. Rather than presenting isolated data points, the study constructs a multi-dimensional analytical framework that equips leadership teams with the tools to stress-test assumptions and model scenario outcomes. The report examines historical performance across 2020 to 2025, establishing a rigorous baseline that isolates cyclical fluctuations from secular trends. From this foundation, the 2026 to 2032 forecast phase integrates bottom-up demand modeling with top-down economic indicators to produce granular growth pathways.
Readers will encounter detailed segmentation analyses that dissect market structures across product classifications, application verticals, and geographic corridors. Each segmentation layer is evaluated for growth elasticity, pricing sensitivity, and substitution risk, allowing executives to identify high-yield expansion pockets without exposing themselves to oversaturated channels. The study also quantifies supply-side bottlenecks, mapping feedstock availability thresholds, production load factors, and logistical friction points that historically distort supply-demand equilibrium. By linking these physical market constraints to financial impact models, the report enables procurement directors and strategy leads to anticipate price volatility windows and structure hedging strategies accordingly.
Beyond quantitative modeling, the study embeds qualitative intelligence that rarely surfaces in conventional market summaries. Synthesized findings cover regulatory compliance evolution, transport and storage mandates, and testing protocol revisions that directly affect product grading, export eligibility, and end-user adoption. These operational parameters are cross-referenced with regional manufacturing capacities to highlight where compliance readiness translates into competitive moats, and where regulatory lag creates market entry barriers for new or expanding players.
Competitive Landscape and Strategic Positioning
The current competitive ecosystem reflects a deliberate shift toward capacity consolidation, supply chain resilience, and differentiated specialty positioning. Historically fragmented production has gradually concentrated among operators that control integrated conversion capabilities, maintain rigorous quality controls, and manage dual-use feedstock portfolios. High market concentration metrics indicate that top-tier manufacturers command substantial pricing influence, yet localized demand pockets, application-specific grading requirements, and regional logistics still create viable niches for agile mid-tier suppliers.
Leading manufacturers profiled in the study span multiple continents, illustrating how divergent strategic priorities shape regional competitiveness. Operators in Southeast Asia and South Asia have invested heavily in manufacturing scale for industrial-grade variants, targeting high-volume downstream channels such as printing inks, wood coatings, automotive paints, and leather finishing. These producers emphasize throughput efficiency, cost-optimized formulation routes, and export logistics tailored to fast-moving consumer and industrial supply chains. In parallel, European and North American incumbents have increasingly prioritized dual-use production architectures, aligning industrial-grade manufacturing with defence and energetic applications that command premium pricing and longer contract horizons. The study maps these strategic divergences and evaluates how each player’s capacity footprint, certification portfolio, and customer concentration influence market share stability and margin resilience.
Recent corporate activity underscores how quickly the competitive balance can shift. A notable European industrial and defence group completed the acquisition of a legacy nitrocellulose subsidiary in 2025, explicitly citing supply chain security for propellant and industrial applications as a primary motivation. This transaction signals a broader industry pattern: vertical integration and strategic M&A are being deployed not solely for growth, but for risk mitigation in environments where feedstock reliability, manufacturing continuity, and export control compliance are increasingly interlinked. The study dissects these moves to reveal which consolidation paths create genuine structural advantages, and which risks creating overcapacity misalignment.
At the same time, price actions across major downstream distributors in 2025 illustrate the acute pressure cascading through the value chain. Multiple global and regional players implemented pricing increases on nitrocellulose-containing products, citing sustained raw material cost escalations, logistics friction, and geopolitical supply disruptions. These price adjustments are not isolated events; they are market signals that the study tracks and contextualizes within broader cost-pass-through dynamics, contract duration trends, and substitution sensitivity thresholds. By synthesizing these developments, the report equips readers with an early-warning framework to anticipate when price momentum will stabilize, when downstream markets will push back, and which suppliers will retain negotiating leverage.
Forces Reshaping Market Trajectory
Multiple concurrent forces are compressing decision cycles and elevating the cost of strategic inertia. Feedstock economics remain the most immediate pressure point. Cotton linter supply constraints triggered significant cost increases in recent years, directly impacting nitrocellulose input economics. Since feedstock availability is tightly coupled to agricultural cycles, processing capacity allocation, and regional export flows, suppliers and buyers alike must navigate a cost environment where short-term spikes can quickly translate into long-term contract restructuring. The study models how these input dynamics propagate through manufacturing cost curves, influencing producer pricing behavior and downstream formulation strategies.
Nitrocellulose Market
Geopolitical realignment and defence investment reallocation have introduced an additional layer of demand volatility. As governments and defence contractors adjust procurement plans, certain nitrocellulose grades face intensified demand from energetic and propellant channels, sometimes drawing material away from traditional industrial applications. This cross-segment competition amplifies price dispersion and complicates forecast accuracy. The report quantifies these spill-over effects and identifies which downstream verticals face the highest exposure to defence-driven supply diversion, enabling procurement teams to secure alternative sourcing corridors before bottlenecks tighten.
Regulatory and compliance frameworks are also evolving at a pace that demands proactive adaptation. Classification standards, stability testing protocols, and transport safety requirements continue to be refined, with recognized testing criteria serving as gatekeepers for market access and international trade eligibility. Suppliers that maintain rigorous testing compliance and transparent documentation gain preferential positioning with multinational buyers and regulated end markets. The study evaluates how compliance maturity correlates with commercial access, contract velocity, and risk exposure, providing a practical benchmark for manufacturers and distributors seeking to strengthen their regulatory posture.
Nitrocellulose Membranes Market
Sustainability certification has emerged as a parallel competitive axis. Environmental management standards, carbon accounting frameworks, and chain-of-custody certifications are increasingly weighted in supplier selection processes, particularly among European and North American buyers with strict procurement mandates. Recent certification achievements by select manufacturers reflect a strategic recognition that sustainability credentials are no longer optional add-ons, but commercial differentiators that influence contract awards and long-term partnership formation.
Why the 2026 Decision Window Demands This Intelligence
The 2026 planning horizon presents a compounding set of strategic challenges. Supply chains are still recalibrating after recent disruption cycles. Pricing architectures remain sensitive to input volatility and procurement concentration. Capacity expansions and acquisitions are reshaping the competitive field faster than many organizations can update internal scenario models. In this environment, decisions made on incomplete or lagging market intelligence expose portfolios to margin erosion, supply shortfalls, and misaligned capital deployment.
This study is structured to eliminate that blind-spot risk. It combines verified historical baselines with forward-looking modeling to help executives answer three foundational questions: where will structural growth concentrate, which supply and pricing pressures will persist, and how should sourcing and manufacturing strategies be adjusted to protect margins while capturing share. By integrating segmentation dynamics, competitive moves, regulatory shifts, and cost-structure analysis into a single intelligence framework, the report enables leadership teams to move from reactive crisis management to proactive portfolio design.
What the Full Study Delivers
The complete research package extends well beyond macro indicators. It provides detailed segmentation breakdowns, regional capacity assessments, product-grade performance comparisons, and application-level demand drivers. It maps competitive positioning through operational benchmarks, recent corporate developments, and supply chain integration patterns. It also delivers scenario-based pricing outlooks, regulatory compliance roadmaps, and sourcing risk matrices tailored for procurement, strategy, and executive planning functions.
Because the nitrocellulose market rewards foresight and penalizes delay, the study is designed for immediate operational integration. Whether your mandate involves renegotiating supply contracts, evaluating regional manufacturing entry, optimizing product-grade mix, or stress-testing exposure to raw material volatility, the report provides the structured intelligence required to act decisively.
Executive teams that secure access to the full dataset will be positioned to model outcomes with higher precision, anticipate inflection points earlier, and align commercial strategy with the realities shaping the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Nitrocellulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Cocoa Market Hits $620M in 2025, Projected $984M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
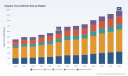
Strategic Intelligence for the Organic Cocoa Market: Navigating Growth, Compliance, and Competitive Dynamics in 2026
Executive Overview: Why This Study Matters for 2026 Decision-Makers
The global organic cocoa sector is entering a decisive inflection point. Over the past five years, the market has transitioned from a niche, ethically driven segment into a core component of mainstream food and beverage supply chains. Our latest market research synthesizes five years of historical performance with a seven-year forward outlook, delivering a structured intelligence framework designed specifically for executives, procurement leaders, and strategy teams operating in 2026 and beyond. This study is not a static snapshot. It is a decision-support architecture that connects macroeconomic momentum, regulatory realignments, supply chain restructuring, and competitive positioning into a single actionable narrative.
For organizations evaluating capital allocation, product portfolio expansion, sourcing partnerships, or regional market entry, the actionable insight lies in understanding how structural demand shifts intersect with compliance timelines and concentration patterns. The research abstracts raw figures into strategic signals, enabling leadership teams to model scenarios, stress-test assumptions, and prioritize initiatives that align with the trajectory of the organic cocoa ecosystem.
Macro Trajectory: Translating Five-Year Evolution into Forward Momentum
Historical performance from 2020 through 2025 reveals a market that has consistently expanded despite macroeconomic volatility, input cost fluctuations, and periodic supply disruptions. The trajectory demonstrates resilient demand absorption across multiple downstream channels, supported by consumer preference shifts toward clean-label, sustainably sourced, and certified ingredients. By the close of the base year, the market had reached a scale that firmly embeds organic cocoa within mainstream procurement strategies rather than treating it as a peripheral premium offering.
The forward projection window spanning 2026 through 2032 outlines a sustained growth path anchored by a compound annual growth rate of 6.98 percent. This rate is not merely a statistical output; it reflects the combined effect of expanding certified cultivation footprints, rising institutional procurement standards, and the gradual integration of organic derivatives into mass-market formulations. The growth curve implies that companies positioning themselves now will capture compounding advantages in supplier relationships, processing capacity alignment, and brand differentiation. Conversely, organizations that delay strategic adaptation risk encountering tighter certified supply availability, elevated compliance friction, and intensifying competition for premium-origin material.
Revenue scaling over the forecast horizon underscores the importance of capacity planning and derivative mix optimization. As total market value advances toward the high nine-hundred-million range by the end of the projection period, the relative contribution of intermediate cocoa derivatives versus finished applications will shape sourcing strategies, pricing architectures, and margin structures. Decision-makers require a clear understanding of how volume growth translates into derivative demand, processing bottlenecks, and downstream formulation opportunities. This research provides that translation layer, enabling teams to align procurement forecasts with production capabilities and commercial roadmaps.
Structural Dynamics: Regulation, Value Creation, and Supply Chain Realignment
The operating environment for organic cocoa is being reshaped by regulatory tightening, certification architecture upgrades, and producer-side operational adjustments. Beginning in early 2025, the European Union Organic Regulation framework introduced enhanced compliance expectations for imported organic cocoa, including strengthened audit requirements and Group of Operators controls. The transition phase concluded at the end of 2024, and full compliance obligations intensified throughout 2025 for suppliers targeting European markets. These measures elevate traceability standards, increase documentation rigor, and place renewed pressure on cooperative structures and segregation practices.
A critical strategic consideration is the compliance readiness gap across smaller producer organizations. Industry observations indicate that a significant share of small-scale Fairtrade organic cocoa producer organizations do not yet fully meet the new EU requirements related to membership structure and operational segregation. At the same time, regulatory adjustments have extended certain compliance deadlines for smaller enterprises, creating a temporary window for adaptation but also introducing uncertainty around supply continuity and certification status during 2026. For buyers and processors, this environment demands more rigorous supplier due diligence, clearer certification pathway mapping, and contingency planning for origin-dependent sourcing portfolios.
On the producer side, organic cocoa cultivation continues to present a structurally distinct cost and value proposition. By avoiding synthetic fertilizers and associated input dependencies, organic systems reduce certain recurring production costs while enabling price premiums that can improve farmer-level economics when market conditions support them. This dynamic reinforces the strategic relevance of long-term cooperative relationships, capacity-building programs, and certification support initiatives. Recent institutional engagement in origin markets, including partnerships focused on uniting producer groups and expanding organic and fair-trade certification coverage, illustrates how development-oriented support can accelerate supply base maturation. These interventions matter because they influence both the quantity and the reliability of certified supply flowing into international markets.
Together, these dynamics create a market environment where compliance capability, traceability infrastructure, and cooperative readiness function as strategic differentiators rather than administrative obligations. Organizations that treat these factors as core elements of their sourcing strategy will secure more resilient supply access and stronger positioning in premium procurement channels.
Strategic Segmentation Insights Without the Noise
Effective market strategy requires an understanding of how value is distributed across product forms and end-use channels, without becoming lost in fragmented data points. The research framework emphasizes three structural lenses that matter most for 2026 planning:
-
Derivative mix relevance: Organic cocoa is not a monolithic commodity. The relative scale and growth behavior of cocoa butter, cocoa liquor, and cocoa powder directly influence formulation strategies, pricing sensitivity, and processing requirements. Procurement teams must evaluate which derivative pathways align with their product architecture, margin targets, and processing capabilities. Understanding where the largest revenue concentration sits within the derivative spectrum helps organizations prioritize supplier discussions, capacity commitments, and inventory strategies.
-
Application-driven demand behavior: Demand is heavily shaped by how organic cocoa is incorporated into end products. Confectionery remains the dominant application environment, reflecting the central role of organic cocoa in chocolate and snack formulations. At the same time, bakery products and beverages represent meaningful demand channels with distinct sourcing attributes, quality specifications, and procurement cycles. Companies need to understand how application mix influences volume stability, specification requirements, and pricing dynamics rather than relying on generic market aggregates.
-
Regional demand architecture: Demand is distributed across multiple geographic markets, each with different regulatory exposure, consumer preference intensity, and import dependency patterns. Europe represents a major demand center with stringent certification expectations. North America reflects strong premium and clean-label consumption trends. Asia Pacific, Latin America, and the Middle East and Africa collectively contribute diverse demand profiles shaped by local processing capacity, export orientation, and emerging consumer segments. Regional nuance matters because sourcing accessibility, logistics complexity, and compliance pathways differ materially by market.
By abstracting segmentation into strategic implications rather than isolated statistics, the study equips decision-makers to evaluate where to concentrate commercial effort, which derivative and application combinations offer the most resilient growth paths, and how regional demand patterns should influence sourcing geography and risk allocation.
Competitive Landscape: Concentration, Capability, and Positioning
The organic cocoa market is characterized by a moderately concentrated competitive structure, with a meaningful share of market value held by a limited number of established processors, integrated traders, and specialist suppliers. Concentration patterns indicate that scale, certified supply chain control, and processing capability remain important competitive levers. At the same time, the presence of specialized organic processors, cooperative-linked exporters, and premium brand manufacturers demonstrates that differentiation through traceability, origin identity, and certification integrity continues to create viable market niches.
Several types of players define the competitive field:
-
Integrated global suppliers and processors: Large international companies with broad ingredient portfolios and established sustainable sourcing programs maintain strong positions by combining scale, multi-origin access, and traceable supply architectures. Their relevance lies in the ability to serve bulk and premium demand simultaneously while investing in certification, segregation, and supply chain transparency.
-
Specialist organic processors: Focused operators with dedicated organic processing capacity play a critical role in converting certified beans into liquor, butter, and powder for distinct application segments. Their competitive advantage often rests on controlled processing environments, origin-specific sourcing relationships, and the ability to maintain organic integrity through the production chain.
-
Origin-based cooperatives and exporters: Producer-linked organizations with multiple organic certifications contribute directly to supply resilience and traceability narratives. Their strategic importance extends beyond volume; they enable provenance storytelling, support compliance readiness at the farm level, and provide buyers with structured relationships that can reduce supplychain friction.
-
Premium chocolate and ingredient brands: Brands that combine manufacturing with direct sourcing or proprietary processing create differentiated offerings based on flavor profile, ethical sourcing claims, and application-specific ingredient quality. Their presence reinforces the premiumization trend and demonstrates how organic cocoa can support brand-level differentiation in consumer-facing markets.
-
Specialized ingredient and bakery-focused suppliers: Companies oriented toward chocolate, bakery, and foodservice applications provide organic cocoa ingredients tailored to formulation needs. Their role highlights the importance of application-specific quality parameters and supply consistency for downstream manufacturing customers.
Recent institutional developments reinforce the importance of certification support and cooperative strengthening in origin markets. Partnerships aimed at uniting producer groups, expanding organic and fair-trade certification coverage, and introducing improved agroforestry practices illustrate how supply-side capacity building can influence long-term availability and quality consistency. For commercial stakeholders, these developments are strategically relevant because they affect the reliability of certified supply, the pace at which new producer organizations reach export readiness, and the overall robustness of traceable organic chains.
In this environment, competitive advantage is increasingly determined by the ability to secure dependable certified supply, maintain processing integrity, and demonstrate verifiable traceability. Organizations that combine procurement foresight with supplier development partnerships and compliance readiness will be better positioned to navigate both demand growth and regulatory complexity.
What the Report Delivers: Operational Intelligence for Planning and Execution
This market research is structured to move beyond descriptive overviews and provide practical intelligence that can be embedded into planning processes. The report is designed for cross-functional use, supporting strategy, procurement, commercial development, and risk management teams with a shared evidence base.
Key components include:
-
Market sizing and forward trajectory analysis: A consolidated view of historical performance and forecast progression, organized to help leadership teams understand the pace of expansion, the shape of the growth curve, and the implications for capacity planning and investment timing.
-
Strategic segmentation interpretation: Analysis of how value is distributed across cocoa derivatives and end-use applications, translated into procurement, formulation, and portfolio implications rather than isolated percentage breakdowns.
-
Competitive positioning and supplier mapping: A structured overview of the principal companies shaping the market, their operational models, and the strategic roles they play across processing, trading, branding, and origin-based supply. This enables stakeholders to identify partnership candidates, benchmark capabilities, and understand where consolidation or specialization is most likely to influence pricing and availability.
Organic Cocoa Market -
Regulatory and compliance pathway context: Practical framing of the EU organic compliance environment, transition timelines, and the implications of certification architecture changes for sourcing strategies, supplier qualification, and risk mitigation.
-
Supply chain and origin dynamics: Evaluation of how cooperative readiness, certification support, and producer-side practices influence the reliability and quality of certified organic cocoa entering international markets.
-
Actionable planning frameworks: Structured guidance for translating market intelligence into sourcing decisions, product development priorities, regional engagement strategies, and scenario-based contingency planning.
Cocoa Market
The study is built to support decision-making under uncertainty. Rather than presenting market data as a static backdrop, it connects size, growth, concentration, segmentation behavior, and regulatory dynamics into a coherent operational narrative. This allows executives to answer practical questions about where demand is heading, which supply relationships deserve reinforcement, how compliance readiness should influence supplier selection, and which market segments offer the most favorable combination of growth potential and strategic control.
How to Use This Intelligence in 2026
For organizations operating in or entering the organic cocoa market, the strategic imperative is to align commercial ambition with supply realism. Growth potential is meaningful, but it is mediated by certification readiness, processing capacity, regulatory compliance, and the behavior of concentrated incumbents. The most effective 2026 strategies will be those that combine demand-side opportunity assessment with supply-side due diligence and compliance-aware procurement design.
Leadership teams can use this research to prioritize actions such as:
-
Validating whether current sourcing portfolios are resilient to evolving organic compliance expectations and origin-side certification gaps.
-
Assessing whether derivative and application focus areas match the strongest demand and margin opportunities across the forecast horizon.
-
Identifying supplier and processor partners whose operational models, traceability systems, and certification capabilities align with long-term procurement requirements.
-
Evaluating regional demand patterns and supply access considerations when planning market entry, expansion, or reformulation initiatives.
-
Integrating concentration dynamics into pricing, negotiation, and risk-management assumptions, especially where a limited number of suppliers shape availability in key segments.
The study is intended to serve as a working intelligence asset rather than a one-time read. By linking macro trajectory, segmentation logic, competitive structure, and regulatory context into a single framework, it helps organizations convert market complexity into executable strategic choices.
Conclusion: Positioning for Durable Advantage in a Maturing Organic Cocoa Market
The organic cocoa market is no longer defined solely by ethical consumption trends or premium niche positioning. It is becoming a structurally important ingredient category shaped by regulatory evolution, supply base maturation, derivative demand behavior, and competitive concentration. The growth path projected through 2032 indicates that organizations which invest now in sourcing integrity, compliance readiness, and differentiated supply relationships will be better equipped to capture value as the market scales.
This research provides the strategic context needed to make those investment decisions with greater confidence. It translates market size and growth momentum into operational relevance, frames segmentation in terms of procurement and formulation implications, and maps the competitive field in a way that supports partnership selection, risk planning, and commercial prioritization. The full report builds on this foundation with detailed analysis designed to support execution-level decision-making across the 2026 to 2032 horizon.
For executives seeking a complete view of market sizing, segmentation logic, competitive positioning, regulatory dynamics, and actionable planning frameworks, the full study offers the comprehensive intelligence required to move from directional awareness to precise strategic execution.
For detailed analysis of this topic, please visit the official page: Organic Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eyeglass Edging Machines Market Hits $1,056 Million in 2025, Projected 5.8% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global Eyeglass Edging Machines Market
The global ophthalmic equipment landscape is undergoing a period of deliberate, technology-driven expansion. As optical retailers, manufacturing labs, and healthcare procurement teams plan capital expenditures through 2032, the Eyeglass Edging Machines Market stands at a structural inflection point. Drawing on our latest Eyeglass Edging Machines Market research, this analysis outlines how industry participants can translate macro trajectories, competitive dynamics, and regulatory shifts into executable 2026 strategies. The report is built to move beyond headline growth figures and deliver the granular, decision-grade intelligence that operations leaders, product managers, and M&A strategists require.
Market Trajectory and the Strategic Case for 2026 Investment
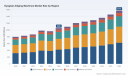
Historical performance through 2025 demonstrates a market that has matured past early-cycle volatility and is now anchored by sustained demand for precision finishing systems. From a base of 800 million USD in 2020, the market advanced through middle-single-digit year-over-year gains, crossing the 1 billion USD threshold in 2025 at a valuation of 1,056.0 million USD. Looking forward, the forecast period from 2026 to 2032 maps a clear acceleration path, beginning at 1,097.54 million USD in 2026 and advancing steadily toward 1,570.0 million USD by 2032. This trajectory reflects a compound annual growth rate of 5.8 percent, a figure that looks modest in isolation but hides meaningful operational implications: product cycle timing, regional capacity reallocation, and the marginal economics of automation adoption will increasingly separate performance leaders from the pack.
For 2026 decision-makers, the immediate takeaway is that growth is no longer a uniform tide. The market is bifurcating between high-throughput, fully integrated finishing lines and specialized systems tailored to in-office, boutique, or specialty-lens workflows. Companies that treat this as a monolithic opportunity risk over-indexing on the wrong system class, overpaying for capacity that does not match their patient or retail volumes, or underestimating the consumable economics that define total cost of ownership. Our research frames the market around this operational reality, so that investment decisions are calibrated to deployment context rather than headline valuation alone.
Operational Landscape: What the Report Delivers
The Eyeglass Edging Machines Market research is structured to support parallel workstreams, from product roadmap planning to supplier evaluation and channel strategy. Rather than presenting static market sizing, the report delivers an operational playbook built around the following components, each designed to feed directly into 2026 planning cycles:
- Deployment and investment mapping by machine architecture. The study evaluates how automatic, semi-automatic, and manual edging platforms are allocated across installation environments. This breakdown helps buyers and manufacturers gauge where throughput, labor substitution, and consistency advantages concentrate, and where flexibility, footprint, or capital constraints still justify lower-automation configurations.
- Application-driven demand analysis. Revenue concentration in optical retail labs, optical manufacturing, and other end-use channels is examined in the context of workflow differences, turnaround expectations, and service models. The goal is to clarify which customer segments are expanding fastest in volume, which are demanding higher precision or faster changeover, and how machine specifications should align with those expectations.
- Regional deployment intelligence. The report assesses how installed base, procurement patterns, and service infrastructure vary across major geographic markets. This regional framing supports localization choices for distributors, service partnerships for OEMs, and pricing strategy for new product introductions.
- Consumable and lifecycle economics. A recurring theme throughout the analysis is that edging machine economics are inseparable from the consumables that sustain them. Grinding wheel performance, block compatibility, and abrasive replacement cycles shape not only operating cost but also service attachment rates. The report connects machine selection to recurring consumable demand so that buyers can model total cost over a realistic service life.
- Competitive benchmarking and positioning. The study maps how leading manufacturers differentiate on throughput, lens compatibility, integration with in-office workflows, and service support. Rather than treating competition as a brand list, the report frames it as a set of design choices and go-to-market models that influence purchasing decisions in different channels.
Each section is built to reduce ambiguity at the point of decision. Procurement teams can use the comparison frameworks to narrow equipment shortlists. Product leaders can use the deployment dynamics to identify where feature investment will generate the strongest differentiation. Executive teams can use the consolidated market view to align capacity expansion, channel investment, and M&A focus with where structural demand is strongest.
Competitive Dynamics: Differentiation, Timing, and Regional Footprints
The competitive set in this market is global, but competitive advantage is increasingly local and application-specific. A diversified group of established optics and ophthalmic equipment manufacturers is competing on machine reliability, lens compatibility, throughput, and integration with surrounding lab or in-office workflows. The companies profiled in the study illustrate how this battlefield is being shaped: Coburn Technologies, headquartered in California, offers in-office optical lens edgers such as the HPE-990 and HPE-910 for precision finishing of standard and specialty lenses, including hydrophobic and high-curve varieties, positioning its equipment around clinical finishing quality and office-friendly deployment. Huvitz Corporation, based in South Korea, manufactures lens edging systems including the HPE-990 lens-over-frame sunglass edging system and related models for optical labs and in-office use, linking product design to both lab productivity and specialized frame-over-lens applications.
In higher-volume finishing environments, Nidek Co., Ltd., headquartered in Japan, produces ophthalmic lens edgers such as the LE-9000SX and ME-1200 for high-volume optical finishing, including models compatible with industrial applications, emphasizing throughput and consistency. Essilor International, from France, provides lens edging systems under the Essilor Instruments brand, including the ES 800 and ES 700 series edgers and Mr. Blue models for ophthalmic lens processing, reflecting a broad-based integration strategy across optical finishing ecosystems. Visionix, operating through its Briot heritage in France, manufactures comprehensive lens finishing systems including the Briot Couture and Emotion series for high-volume and lab optical edging, reinforcing the importance of finishing-line integration and repeatability. MEI Srl, based in Italy, offers compact automatic lens edgers such as the EasyFit Trend and Trend series designed for small optical labs and block-less processing, addressing space-constrained or lower-volume settings where versatility matters. Topcon Corporation, also from Japan, supplies optical lens edgers and related finishing equipment for ophthalmic and lab applications, contributing deeper lab-side equipment depth to the competitive field. Innava Medical Ophthalmics, Inc., in the United States, provides ophthalmic equipment including lens edgers for clinical and lab use, broadening the clinical-to-lab bridge in North American procurement. In Asia, Shanghai Supore Instruments Co., Ltd. manufactures lens edgers and optical lab machinery including automatic models for precision edging, while Ningbo FLO Optical Co., Ltd. produces automatic lens edging machines for optical manufacturing and repair applications, both reflecting expanding domestic manufacturing capabilities and export-oriented capacity.
Recent product activity underscores how quickly competitive positioning can shift around a single platform. In August 2025, Coburn Technologies introduced the HPE-990 Lens Edger, a premium in-office finishing system with enhanced capabilities for standard and specialty lenses including high-curve and hydrophobic types. In May 2025, Huvitz launched the HPE-990 lens-over-frame sunglass edging system, unveiled at MIDO 2025 and planned for expansion in North America. These moves matter because they illustrate a recurring strategic pattern: manufacturers are sharpening differentiation by lens type, workflow setting, and regional rollout timing rather than by competing on broad, undifferentiated hardware specifications alone. The report uses these developments to show where competition is tightening, where regional roll-out windows create first-mover advantages, and where consumables or service attach may become the real margin battleground.
Eyeglass Edging Machines Market
Market Dynamics and the 2026 Operating Environment
Equipment purchases do not happen in isolation; they are shaped by supply-chain behavior, regulatory pressure, and labor economics. Three dynamics in particular are shaping the 2026 decision environment.
First, consumable supply chains are becoming a strategic variable rather than a background cost item. Premium diamond-abrasive wheels used in lens edgers face tight global supply chains, which disproportionately affects precision segments of the market where edge quality, surface integrity, and repeatability are non-negotiable. For buyers, this means machine selection increasingly needs to account for abrasive compatibility and supplier continuity, not only for capital cost. For manufacturers, it means the durability and flexibility of grinding solutions can become a purchase driver in their own right.
Second, regulatory expectations are shifting the specification baseline upward. Stricter dust-emission norms for optical workshops in the EU and North America require modern enclosed systems in lens edger operations, pushing buyers toward equipment that meets tighter environmental and occupational health standards without sacrificing throughput. At the same time, the new EN IEC 60601-2-57:2026 standard sets safety and performance requirements for non-laser light source equipment, with enforcement beginning in 2026. Compliance is not a static checkbox; it can influence design features, service obligations, and buyer risk tolerance, especially for organizations operating across multiple jurisdictions. These requirements increase the value of verified compliance documentation and validated installation support.
Third, labor economics are reshaping the value proposition of automation. Advanced grinding wheel technology and ergonomic improvements in lens edgers reduce reliance on skilled manual operators while improving finish quality on materials such as polycarbonate and Trivex. This does not eliminate the need for skilled oversight, but it changes where that skill is applied. Operations can shift from repetitive finishing labor toward setup optimization, quality control, and machine uptime management. For 2026 planning, that means the business case for automation is increasingly tied to consistency, throughput stability, and training burden, not just labor cost reduction.
Optical Lens Edger Market
Together, these dynamics create a market environment in which the most valuable intelligence is not simply how large the market is, but how it behaves under real operating constraints. The report connects these forces to equipment decisions so that buyers and manufacturers can anticipate where specifications, service coverage, and consumable strategy will matter most.
Why This Research Supports Better 2026 Decisions
In a market growing at a 5.8 percent CAGR over a seven-year forecast horizon, the competitive advantage lies in timing, targeting, and specification discipline. The difference between generic market awareness and decision-ready intelligence is the ability to answer practical questions: Which machine class fits a given deployment profile? Where are regional procurement and service dynamics likely to support or constrain a rollout? How should product roadmaps respond to regulatory and consumable supply pressures? Where are the competitive white spaces that a new launch or channel investment can exploit?
The Eyeglass Edging Machines Market research is built to answer those questions without forcing every buyer into the same conclusion. It preserves enough segmentation depth for operational use while keeping the analysis focused on strategic implications. The report is intended for executives, category managers, product planners, and investors who need to convert a multi-year growth narrative into a coherent 2026 action plan.
The full study contains the detailed market sizing, segmentation breakdowns, regional deployment context, competitive profiles, and forward-looking scenario framing needed to support investment, procurement, and product strategy decisions. Readers seeking complete data tables, segment comparisons, and the full set of company and regulatory analyses are encouraged to explore the full report on the source page for comprehensive intelligence tailored to 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Eyeglass Edging Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrafast Lasers Market Hits $2.34B in 2025, Forecast 16.62% CAGR to $6.89B by 2032
By PW Consulting, 2026-09-16
Ultrafast Lasers Market 2026: Strategic Intelligence for Enterprise Decision-Making
The Pulse of Modern Precision
Ultrafast lasers have evolved from specialized laboratory instruments into foundational technologies that enable precision manufacturing, advanced healthcare, and next-generation scientific discovery. These systems, characterized by extremely short pulse durations on the femtosecond and picosecond scales, deliver unparalleled control over material interaction without generating excessive thermal damage. As industrial processes demand finer tolerances and new applications emerge across quantum technologies and medical devices, the ultrafast laser sector is undergoing a structural transformation that requires careful strategic navigation.
For enterprise leaders, investors, and technology strategists, understanding the trajectory of this market is no longer optional. The convergence of industrial automation, semiconductor miniaturization, and emerging healthcare applications creates a complex landscape where timely intelligence determines competitive positioning. This report provides the analytical framework necessary to interpret market signals, evaluate competitive dynamics, and identify high-value opportunities across the ultrafast laser ecosystem.
Macro Trajectory: A Market in Acceleration
The ultrafast lasers market has demonstrated consistent expansion over the past half-decade, building momentum that extends well into the forecast horizon. Historical valuation patterns from 2020 through 2025 reveal a sector that has repeatedly exceeded baseline growth expectations, driven by broadening application adoption and sustained capital investment in precision technologies. This upward trajectory establishes a robust baseline for forward-looking analysis and signals that demand drivers are structural rather than cyclical.
Looking ahead to the 2026 through 2032 forecast period, the market is positioned for continued expansion at a compound annual growth rate of 16.62 percent. This growth rate reflects accelerating integration of ultrafast laser systems into production environments, alongside expanding deployment in research and medical contexts. The revenue trajectory projects a market valuation that underscores the strategic importance of this technology category for organizations operating across multiple industrial and scientific verticals. Revenue projections are measured in USD millions, providing a standardized framework for comparative financial planning and investment prioritization.
For decision-makers, this macroeconomic profile carries several implications. The sustained growth rate indicates that ultrafast lasers are transitioning from emerging technology status to mainstream industrial utility. Organizations that delay engagement risk ceding positioning to competitors who are already embedding these systems into their operational toolkits. Conversely, early movers who align their technology roadmaps with verified market data can secure advantages in vendor relationships, application development, and market segment prioritization.
The forecast horizon further reveals inflection points that warrant strategic attention. As the market scales, shifts in supply chain capacity, competitive intensity, and application-specific demand patterns will reshape the landscape in ways that historical data alone cannot predict. Comprehensive analysis is required to distinguish between temporary fluctuations and durable structural changes, ensuring that strategic decisions rest on verified intelligence rather than extrapolation.
Segment Architecture and Application Versatility
The ultrafast laser market spans multiple technology typologies, each serving distinct operational requirements and end-use contexts. Fiber-based laser architectures continue to command significant attention due to their compactness and cost-effectiveness, particularly for microprocessing and industrial material modification. Titanium-sapphire systems remain critical for advanced research and specialized scientific applications where tunability and pulse characteristics are paramount. Diode-pumped configurations offer specific advantages in certain manufacturing and imaging scenarios, while mode-locked variants serve niche but high-value applications requiring precise temporal control.
This technological diversity creates a segmented market where competitive positioning varies significantly by product category. Organizations evaluating ultrafast laser procurement or investment must understand how these technology segments map to their specific operational needs. A manufacturing environment focused on high-throughput material processing may prioritize different capabilities than a research institution requiring tunable wavelengths for experimental protocols. The report provides detailed segmentation analysis that maps technology characteristics to application requirements, enabling stakeholders to align procurement strategies with verified performance benchmarks.
Application domains further diversify the market landscape. Material processing represents a substantial demand driver, encompassing industrial manufacturing, semiconductor precision work, and advanced micromachining applications. Medical and healthcare deployments leverage ultrafast laser capabilities for surgical procedures, diagnostic imaging, and therapeutic device development. Consumer electronics applications increasingly incorporate these technologies for precision component fabrication. Scientific research continues to serve as both a demand source and an innovation incubator, with discoveries in laboratory settings frequently translating into commercial production techniques. Additional application categories contribute to the broader ecosystem, reflecting the technology's versatility across multiple sectors.
The interplay between technology types and application domains creates a multi-dimensional market structure where winners are not uniformly distributed. A company that excels in fiber laser manufacturing may face different competitive pressures than one focused on titanium-sapphire systems for research instrumentation. Understanding these segment-specific dynamics is essential for accurate competitive assessment and strategic planning.
Competitive Arena: Players Shaping the Landscape
The ultrafast laser market features a diverse array of established corporations and specialized innovators, each pursuing distinct strategic positions. Coherent Corp, headquartered in the United States, offers a comprehensive range of ultrafast scientific laser oscillators and amplifiers serving research, OEM instrumentation, and industrial applications. TRUMPF, based in Germany, provides ultrafast lasers tailored for industrial materials processing, semiconductor applications, and precision manufacturing environments. IPG Photonics, also United States-based, manufactures compact and cost-effective ultrafast fiber lasers with pulse durations spanning from 250 femtoseconds to 5 picoseconds for microprocessing and industrial deployment.
Amplitude Systèmes, operating from France, holds a recognized position as a world leader in femtosecond lasers for industry, science, and medical applications, delivering systems for micromachining and medical device production. Ekspla, based in Lithuania, supplies industrial femtosecond laser systems for advanced imaging, ultrafast material processing, and micromachining tasks. NKT Photonics, from Denmark, delivers next-generation ultrafast lasers targeting quantum computing, aerospace, and industrial manufacturing applications. Light Conversion, also headquartered in Lithuania, provides high-performance femtosecond laser systems for industrial and scientific applications with emphasis on reliability. Menlo Systems, based in Germany, manufactures femtosecond fiber lasers and amplifiers for high-output power applications across research and industrial contexts. IMRA America, operating from the United States, specializes in femtosecond fiber lasers for material processing, biomedical, and imaging applications. Clark-MXR, United States-based, produces femtosecond lasers and micromachining systems alongside contract manufacturing services. Thorlabs, also from the United States, offers photonics solutions including ultrafast laser components and systems for both research and industrial use.
This competitive field reflects a market characterized by both specialized expertise and broad technological ambition. Recent corporate activities illustrate the dynamic nature of this landscape. In January 2026, IMRA America notified the Foreign-Trade Zone Board of proposed production activity for femtosecond fiber laser systems in Ann Arbor, Michigan, within FTZ 70, encompassing optical components and materials. This development signals continued investment in domestic manufacturing capacity for advanced laser technologies. Earlier in June 2025, IPG Photonics showcased innovative fiber laser technologies and new product launches at Laser World of Photonics in Munich, demonstrating ongoing product development and market engagement. In August 2024, NKT Photonics announced delivery of three next-generation laser subsystems to IonQ for trapped-ion quantum computing and networking equipment, highlighting the technology's expanding role in quantum infrastructure. By May 2026, IPG Photonics earned the 2026 SPIE Prism Award in the Lasers category for its novel 8-kilowatt compact single-mode laser source with high beam quality, validating continued innovation in high-power ultrafast systems.
Structural Dynamics and Operational Realities
Beyond technology and competition, the ultrafast laser market operates within a complex environment of regulatory, labor, and supply chain factors that influence production timelines, cost structures, and deployment feasibility. These structural dynamics require careful consideration in strategic planning and investment evaluation.
Regulatory frameworks introduce compliance considerations that affect market participants differently depending on their operational scope and geographic footprint. Certain optical sources and sub-components fall under export control classifications, creating compliance requirements and potential limitations for advanced optical materials used in ultrafast laser systems. Organizations operating across international markets must navigate these requirements carefully, as regulatory exposure can influence sourcing strategies, partnership structures, and market access.
Workforce dynamics present another critical consideration. The production of advanced laser systems, including ultrafast lasers, faces challenges related to skilled labor availability. Technical manufacturing and engineering roles require specialized expertise that remains in limited supply, creating potential bottlenecks for production scaling and innovation deployment. Organizations that invest in workforce development, training partnerships, and talent retention strategies position themselves to mitigate these constraints while competitors struggle with staffing gaps.
Supply chain fragility introduces additional operational complexity. Specialty components and advanced materials required for ultrafast laser manufacturing face availability constraints and performance variability, resulting in extended lead times, production delays, and quality control challenges. The ecosystem for low-volume, high-risk commodities is particularly constrained, requiring deliberate supplier relationships and collaborative supply chain management to maintain production continuity. These dynamics affect not only manufacturers but also downstream customers who depend on reliable access to production-grade laser systems.
Ultrafast Lasers Market
Material considerations further compound supply chain challenges. Limited availability and performance issues of advanced laser system components directly impact manufacturing timelines and product quality. Organizations operating in this space must develop contingency strategies, maintain buffer inventories where feasible, and establish diversified supplier networks to reduce vulnerability to single-source disruptions.
Strategic Imperatives for 2026 and Beyond
The ultrafast lasers market presents a landscape rich with opportunity but demanding rigorous analysis to navigate successfully. For enterprises evaluating technology adoption, investment allocation, or competitive positioning, the strategic questions are multifaceted. Which technology segments align with specific operational requirements? How do competitive dynamics vary across applications and geographies? What supply chain and regulatory factors should influence procurement timing and vendor selection? How should organizations balance near-term production needs against long-term innovation trajectories?
Answering these questions requires access to granular analysis that goes beyond aggregate market figures. Segment-level growth patterns, regional demand variations, application-specific adoption curves, and competitive benchmarking all contribute to a complete strategic picture. Organizations that rely on high-level summaries risk missing the nuanced signals that determine successful market engagement. The difference between a well-timed investment and a misaligned procurement decision often rests on details that only comprehensive analysis can reveal.
This report, the Ultrafast Lasers Market study from PW Consulting, is designed to provide that depth. It delivers detailed segmentation breakdowns, competitive profiling, regional demand analysis, and operational context that enables decision-makers to move from general awareness to actionable insight. The analysis covers the full 2020 through 2032 timeline, connecting historical performance with forward-looking projections to identify durable trends and potential inflection points.
For organizations seeking to understand where ultrafast laser technologies fit within their strategic roadmap, this research offers the evidence base necessary for confident decision-making. The market's growth trajectory, technological diversity, and competitive intensity all demand analysis that is sufficiently detailed to support precise planning while remaining accessible enough to inform executive-level strategy.
Accessing Complete Market Intelligence
The insights summarized here represent an entry point into a comprehensive analytical resource. Full segmentation data, complete competitive profiles, regional demand breakdowns, and detailed scenario analysis are available in the complete report. Enterprise leaders, technology strategists, and investment professionals who require verified market intelligence for critical decisions will find the full study provides the depth and specificity necessary to translate market awareness into operational advantage.
Worldwide Ultrafast Lasers for Micromachining Market
To access the complete Ultrafast Lasers Market report and obtain the detailed intelligence required for strategic planning in 2026 and beyond, please visit the PW Consulting research portal for full report access and acquisition options.
For detailed analysis of this topic, please visit the official page: Ultrafast Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Deburring Machine Market Hits $534M in 2025, Poised to Reach $691M by 2032
By PW Consulting, 2026-09-16
The Automatic Deburring Machine Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation, driven by relentless demands for precision, efficiency, and sustainability. Within this shifting terrain, the automatic deburring machine market stands out as a critical enabler of modern production workflows. As industries grapple with tightening tolerances, escalating labor costs, and increasingly stringent environmental regulations, the role of automated surface finishing solutions has evolved from a discretionary upgrade to an operational imperative. Our latest comprehensive market research report on the Automatic Deburring Machine Market offers a meticulously curated intelligence package designed to equip executives, product planners, and investors with the structural insights needed to navigate the 2026–2032 horizon with confidence.
This analysis transcends superficial market sizing. It maps the interplay of technological maturation, regional industrial realignments, and competitive pressures that will define procurement strategies, capacity investments, and partnership frameworks in the years ahead. For decision-makers operating in metal fabrication, automotive, aerospace, or precision electronics, the report serves as a strategic compass, translating macro-level trajectories into actionable commercial intelligence. The following overview outlines the report's core architecture, highlights the operational drivers reshaping the sector, and demonstrates how the full study can be leveraged to de-risk strategic planning for the remainder of the decade.
Market Trajectory: A Structural View of Growth and Resilience
Over the past half-decade, the automatic deburring machine sector has demonstrated remarkable resilience, navigating supply chain volatility, fluctuating raw material costs, and shifting capital expenditure cycles. Historical tracking from 2020 through 2025 reveals a market that has steadily consolidated its footing, with revenue climbing toward the 534 million USD mark in the base year. This upward momentum is not merely cyclical; it reflects a structural recalibration of manufacturing priorities, where consistent edge quality, reduced scrap rates, and repeatable throughput have become non-negotiable benchmarks for competitive operations.
Worldwide Single Axis Automatic Tapping Machine Market
Looking forward, the forecast period extending through 2032 projects a measured yet steady expansion, anchored by a compound annual growth rate of approximately 3.85 percent. While this growth rate may appear moderate at first glance, it belies the nuanced dynamics beneath the surface. The trajectory is being shaped by divergent regional industrial policies, accelerating automation adoption in high-mix production environments, and the gradual replacement of legacy manual finishing workflows. By 2032, the market is positioned to approach the 690 million USD threshold, a milestone that underscores both the maturity of established applications and the emergence of new use cases in advanced manufacturing. Importantly, this growth will not be evenly distributed across customer segments, geographies, or technology platforms. The strategic value of our report lies in its ability to isolate where value is actually concentrating, which sub-segments are experiencing structural shifts, and which regional ecosystems are poised for accelerated capital deployment.
Core Report Architecture: From Macro Trends to Operational Playbooks
Our research is structured to serve multiple internal functions simultaneously. Rather than presenting a monolithic narrative, the report is organized into modular, decision-ready sections that allow strategy, procurement, R&D, and competitive intelligence teams to extract precisely what they need without wading through irrelevant data. The study begins with a comprehensive market overview that establishes baseline sizing, growth vectors, and the macroeconomic forces currently influencing capital equipment spending. From there, the analysis drills into the structural components that drive purchasing behavior and technology adoption patterns.
The segmentation framework examines the market across multiple axes, including machine typology, end-use application domains, and geographic distribution. Each dimension is evaluated not merely in terms of revenue allocation but through the lens of operational drivers: how different machine architectures align with specific part geometries, production volumes, and surface finish requirements; how application segments are evolving from traditional high-volume stamping and casting environments toward more complex, high-precision components; and how regional industrial policies, labor market conditions, and supply chain localization efforts are reshaping procurement preferences. The report deliberately avoids static snapshots, instead emphasizing the directional momentum of each segment and flagging inflection points where investment timing or technology selection could materially impact competitive positioning.
Complementing the structural analysis is a detailed examination of market dynamics. This section dissects the forces currently accelerating or constraining adoption, including the persistent shortage of skilled finishing labor, the rising cost of manual quality assurance, and the growing influence of environmental compliance mandates that are pushing manufacturers toward energy-efficient, lower-waste automated systems. The study also tracks the upstream supply ecosystem, analyzing how the availability and pricing of specialized abrasives, high-precision polymers, and integrated material handling components are influencing total cost of ownership calculations. By connecting these dynamic variables to real-world procurement thresholds, the report enables managers to anticipate cost pressures, evaluate alternative technology pathways, and structure supplier negotiations with a clearer understanding of underlying market mechanics.
Competitive Landscape: Navigating a Fragmented but Consolidating Field
The automatic deburring machine ecosystem is characterized by a diverse array of participants, ranging from established European engineering firms with decades of heritage in metal finishing to agile Asian manufacturers leveraging integrated automation expertise and emerging regional players targeting cost-sensitive, high-growth industrial clusters. Our competitive analysis maps this landscape with granularity, profiling the core capabilities, technological differentiators, and strategic positioning of key market participants.
Automatic Deburring Machine Market
In the Americas and Asia, companies such as Timesavers LLC have built their reputation on comprehensive automated deburring and metal finishing lines that leverage advanced abrasive technologies tailored for high-throughput metal part processing. Their operational model emphasizes integrated material flow and consistent surface outcomes across varied part configurations. Meanwhile, ARKU GmbH in Germany continues to strengthen its position with the EdgeBreaker series, which is specifically engineered for stamped, laser-cut, and plasma-cut components, combining automated handling with precise edge treatment in a single workflow. This focus on seamless integration between cutting and finishing processes has made the platform particularly attractive to manufacturers seeking to reduce intermediate handling steps and minimize secondary operations.
In East Asia, Sugino Corp. has carved a distinct niche with high-pressure water jet CNC deburring and parts washing systems, including the JCC series designed to address complex geometries that traditional mechanical methods struggle to finish uniformly. Their approach highlights the growing convergence between deburring and integrated cleaning, reflecting broader industry trends toward multi-function workstations that compress cycle times. United Surface Solutions LLC contributes a complementary perspective with centrifugal deburring equipment and water recycling systems, exemplified by the CPC250 upright barrel machine, which appeals to operations prioritizing media efficiency and environmental compliance.
The competitive field also includes regional specialists with strong positioning in sheet metal and precision fabrication. Valgro India Limited offers automatic deburring and edge rounding machines that rely on brush or belt grinding methodologies, targeting manufacturers seeking flexible, cost-effective solutions for panel and enclosure processing. Autopulit S.A. in Spain has built a reputation around CNC and robotized deburring platforms designed for sheet metal and precision component workflows, emphasizing programmable control architectures that adapt to high-mix production schedules. Fladder Danmark A/S complements this landscape with automatic deburring, sanding, and surface grinding machines featuring programmable controls that span metal, wood, and plastic applications, illustrating the cross-material versatility that some end-users increasingly demand.
Japan's Murata Machinery, Ltd. represents another strategic archetype, offering deburring machines seamlessly integrated with broader automated production systems, supporting both high-volume and low-volume manufacturing scenarios. This systems-level approach resonates with facilities pursuing vertical integration and reduced changeover times. Rounding out the core competitive set, Kramer Industries Inc. provides deburring and finishing equipment tailored to metal fabrication, automotive, and aerospace applications, reinforcing the importance of domain-specific engineering in high-stakes sectors where surface integrity directly impacts downstream performance.
Recent trade show activity and product announcements further illustrate the pace of innovation and the strategic signaling occurring across the competitive field. Throughout late 2025, multiple manufacturers showcased next-generation platforms at major industrial exhibitions. Valgro India Limited presented advanced deburring and finishing solutions, including automatic deburring machines, at FABTECH 2025 in Chicago. ARKU GmbH exhibited its EdgeBreaker 6000 universal deburring machine at Blechexpo 2025, emphasizing leveling and deburring capabilities for coil lines. Lissmac highlighted a compact SBM-XS automatic deburring machine at the same event, focusing on automation concepts for edge processing. Timesavers LLC also demonstrated its automated deburring portfolio at FABTECH Chicago. These exhibited developments are not isolated product launches; they signal broader strategic priorities around automation density, footprint optimization, and workflow integration, all of which carry direct implications for procurement strategy and vendor evaluation.
The competitive structure itself warrants close attention. Market concentration metrics indicate a moderately fragmented environment, with the top three players collectively holding a meaningful but not dominant share, and the top five approaching a slightly higher threshold of combined presence. This fragmentation suggests that regional specialists, application-focused vendors, and emerging technology providers retain substantial room to differentiate through niche engineering, localized service networks, or integration partnerships. For buyers and investors, this dynamic creates both opportunity and complexity: the diversity of offerings expands choice, but it also demands rigorous capability mapping to avoid overpaying for features that do not align with specific production requirements.
Structural Drivers Shaping 2026 Decision-Making
Several interlocking forces are redefining how manufacturers evaluate automatic deburring investments in 2026 and beyond. The most persistent is the ongoing pressure on skilled labor availability. Across metal fabrication, automotive component production, and precision machining, facilities continue to encounter difficulties in recruiting and retaining operators capable of delivering consistent manual deburring quality at scale. This labor constraint is not a temporary anomaly; it reflects deeper demographic and training pipeline challenges that are accelerating the business case for automation. By deploying automatic deburring machines, manufacturers can standardise edge quality, reduce dependence on highly variable manual processes, and redirect skilled personnel toward higher-value supervisory, programming, and quality engineering roles.
A second, closely related driver is the economic calculus around labor cost escalation. As remuneration expectations in sheet metal processing, precision component fabrication, and related sectors continue to rise, the total cost differential between manual finishing and automated solutions is narrowing in favor of the latter. Beyond direct wage inflation, manufacturers are accounting for the hidden costs of human error, inconsistent repeatability, and rework cycles that erode throughput. Automatic deburring systems address these pain points by delivering predictable output quality across shifts and production runs, which in turn supports tighter process control and more reliable downstream assembly or coating operations.
Environmental and regulatory pressures are simultaneously reshaping the technology benchmark. Manufacturers are increasingly required to demonstrate energy efficiency, reduced waste generation, and optimised consumable usage across their surface finishing workflows. This regulatory push is prompting equipment developers to redesign machine architectures for lower power draw, improved media recovery, and integrated water or abrasive recycling loops. For procurement teams, the implication is clear: energy consumption profiles, consumable lifecycle costs, and compliance documentation are becoming as important as initial capital outlay and throughput specifications. Our report integrates these considerations into the evaluation framework, helping decision-makers weigh total cost of ownership against evolving compliance expectations.
Upstream material dynamics also play a critical role. The performance and longevity of automatic deburring systems depend heavily on the availability and quality of specialized abrasives, high-precision polymers, and engineered media formulations. Supply trends in these component categories are increasingly aligned with sustained adoption in high-volume metal finishing, but pricing volatility, lead time variability, and regional sourcing constraints can affect operational continuity. The report maps these supply-side variables to provide a clearer picture of which technology pathways are most resilient under current material conditions and which may expose facilities to greater procurement risk.
How the Full Study Translates Intelligence into Advantage
While the macro trajectory and competitive themes outlined here provide a valuable orientation, the full research study delivers the depth required for concrete strategic action. The complete report supplies the granular segmentation data, regional growth differentials, application-specific adoption curves, and technology preference shifts that executives need to calibrate manufacturing investments, evaluate vendor shortlists, and identify high-probability opportunities for process optimisation. It also includes scenario-based projections that account for alternative macroeconomic conditions, raw material price trajectories, and regulatory pacing, enabling planners to test the robustness of their assumptions against multiple futures.
For competitive strategists, the study offers a structured framework for mapping rival capabilities, predicting likely product roadmap moves, and identifying whitespace where differentiated offerings can capture margin. For procurement and operations leaders, it provides the comparative benchmarks necessary to align machine selection with part complexity, volume profiles, and quality requirements, reducing the risk of over-specification or under-investment. For investors and corporate development teams, the analysis highlights consolidation pressure points, regional growth hotspots, and technology adjacencies that may influence valuation logic or partnership strategy.
The value of this intelligence is maximised when it is integrated into a structured decision process rather than treated as a static reference document. Our research is designed to feed directly into capacity planning workshops, vendor evaluation scorecards, capital allocation reviews, and regional expansion assessments. By grounding those conversations in a rigorously sourced, forward-looking analysis, organisations can move from reactive equipment purchasing to proactive capability building, aligning their deburring workflows with the broader strategic imperatives of precision, efficiency, and sustainability that will define competitive manufacturing through 2032.
To access the complete segmentation breakdowns, regional growth differentials, competitive capability matrices, dynamic scenario models, and the full vendor profiling framework, we invite you to consult the complete Automatic Deburring Machine Market research publication. The full study delivers the unredacted intelligence required to transform high-level market awareness into precise, executable strategy for 2026 and the decade ahead.
For detailed analysis of this topic, please visit the official page: Automatic Deburring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tire Protection Chains Market to Reach $157M by 2032, 5.3% CAGR (2026-2032)
By PW Consulting, 2026-09-16
Navigating the 2026 Landscape: Strategic Intelligence for the Tire Protection Chains Market
The industrial machinery sector is currently undergoing a phase of recalibration, where the balance between operational durability and cost efficiency dictates procurement strategies. Within this complex ecosystem, the Tire Protection Chains Market stands out as a critical component for heavy-duty vehicle maintenance and operational safety. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a fundamental requirement for stakeholders aiming to optimize asset longevity and manage risk in mining, forestry, and transport sectors. This insight draws from our latest comprehensive study, designed to equip decision-makers with the foresight needed to navigate the coming years.
The period from 2020 to 2025 established a solid foundation for this sector, recovering from early pandemic-era disruptions and stabilizing around steady growth trajectories. Looking forward, the forecast period spanning 2026 to 2032 suggests a continued industrial reliance on robust tire protection solutions. Specifically, our analysis projects the global market size to reach 157.0 million USD by 2032, up from an estimated 117.06 million USD in 2026. This represents a Compound Annual Growth Rate (CAGR) of 5.3 percent. These figures underscore a market that is expanding at a measured but consistent pace, driven by the fundamental need to protect high-value equipment from abrasive surfaces and harsh environmental conditions.
Market Drivers and Operational Dynamics
Several key forces are propelling this growth. Primary among them is the sustained activity in heavy industries such as mining and tunneling, where ground conditions demand enhanced tire protection. The durability of heavy-duty equipment is paramount, and tire protection chains serve as a critical defensive layer against premature wear and failure. Furthermore, regulatory frameworks continue to shape market behavior. For instance, specific EU transport policies mandate the carriage of suitable snow chains for goods vehicles over 3.5 tonnes during winter months, ensuring a baseline demand in regions with seasonal weather challenges. Beyond compliance, the operational imperative to reduce downtime in open-pit mining and quarrying drives the adoption of advanced chain systems.
Material science also plays a pivotal role in defining current market dynamics. Steel dominates the material composition within this sector, accounting for a significant portion of segment share due to its balance of strength and flexibility. High-alloy steel drop-forged links remain the standard raw material feedstock for tire protection chains, ensuring that manufacturers can meet rigorous performance standards. Concurrently, quality certification standards such as EN-TSE 663 and ISO 9001 remain mandatory for quality certification of tire protection chains produced by active manufacturers. Compliance with these standards is not optional; it is a barrier to entry that separates credible suppliers from the rest of the field.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration, where a handful of key players command significant share. Our analysis indicates that the top three competitors hold approximately 50 percent of the market, while the top five command around 60 percent. This concentration suggests that while there is room for niche players, scale and established reputation remain critical advantages.
Among the prominent entities, pewag International GmbH continues to reinforce its position as a manufacturer of heavy-duty tire protection chains for open-pit mining, quarrying, and earth-moving vehicles. With production facilities in Austria and the USA, pewag emphasizes durability and innovation, notably introducing a new nano-alloy chain series in early 2024. This series, tested across nine countries, reported significantly higher wear resistance in slag transport applications, highlighting the trend toward material innovation. Later in 2026, promotional content released by the company further emphasized built-to-last chains for mining and steel works, signaling a sustained focus on high-demand industrial sectors.
Tire Protection Chains Market
Las Zirh ŞDL, based in Istanbul, Turkey, has emerged as a leading manufacturer with own-brand forging and heat treatment capabilities. Exporting to over 70 countries under EN-TSE 663 and ISO 9001 standards, Las Zirh has actively engaged at major industry forums, such as the Global OTR Conference in Antwerp. Their presence there highlighted expansion and production capacity evolution, positioning them among the top three manufacturers globally. This geographic expansion underscores the growing importance of Central Asian and European manufacturing hubs in serving global demand.
RUD Ketten Rieger & Dietz GmbH u. Co. KG remains a global leader supplying Erlau brand tire protection chains, emphasizing innovation in high-alloy round-link design. Their historical dominance in global supply demonstrates the value of brand heritage combined with technical specialization. Meanwhile, companies like Omega Chains in South Africa and Quality Chain Manufacturing Company in the United States serve specific regional and industrial needs, often providing authorised options for major equipment manufacturers like Sandvik. These regional players often highlight cost savings and specific compatibility advantages that appeal to localized procurement teams.
Other notable participants include Laclede Chain Company in the United States, an established manufacturer since 1854, and Schneeketten AG in Austria, which extends high-quality snow and tire protection offerings to heavy-duty industrial uses. European suppliers such as Veriga Lesce d.o.o. in Slovenia and Nordic Traction Group in Finland contribute specialized traction and protection solutions for heavy vehicles. In Asia, Tianjin Shanxing Metal Products and Tianjin Tongwei Metal Products Co., Ltd. are active in global supply chains for mining equipment, with Tianjin Tongwei holding ISO 9001:2015 certification for forged tire protection chains. Dedicated producers like TPC Tyre Protection Chains focus on compatibility and durability for loaders and earth-movers, rounding out a diverse ecosystem of providers.
Segmentation and Application Insights
Understanding where demand originates is crucial for strategic planning. The market is divided across several structural dimensions that define customer needs. By type, the market features distinct system configurations, including Link-Ring, Ring-Ring, and Ring-Locking systems. Each system offers varying degrees of flexibility, tensioning capability, and protection coverage, influencing their adoption in different operational contexts. By application, demand is spread across segments such as slag and scrap handling, mining and tunneling, forestry and agriculture, and transporting or traction needs. The diversity in applications suggests that a one-size-fits-all approach is insufficient; suppliers must tailor their value propositions to specific industry verticals.
Worldwide Automotive Tire Socks Market
Regional distribution also plays a significant role in shaping market strategies. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique infrastructure challenges, regulatory environments, and economic drivers that influence procurement cycles. For multinational corporations, understanding these regional nuances is essential for supply chain optimization and market entry strategies. The interplay between regional industrial activity and the availability of protection solutions creates distinct opportunities for growth in emerging markets versus sustaining innovation in mature economies.
Strategic Implications for 2026 and Beyond
For enterprise decision-makers, the 2026 outlook offers several actionable takeaways. First, the projected growth rate indicates stable demand, but competition for market share will intensify among the consolidated top players. Companies should evaluate their supply chains for resilience, ensuring that material sourcing, particularly for high-alloy steel, remains secure amidst global fluctuations. Second, the emphasis on certification and compliance cannot be overstated. With standards like EN-TSE 663 and ISO 9001 remaining mandatory, procurement teams must verify that vendors meet these rigorous criteria to avoid operational risks and liability issues.
Third, innovation in material technology, as seen with recent nano-alloy introductions, presents an opportunity for differentiation. Organizations that adopt advanced chain systems may realize long-term cost savings through extended service life and reduced downtime, even if initial procurement costs are higher. Finally, the geographic spread of both manufacturers and demand suggests that localized service and support capabilities are becoming a key competitive differentiator. Being able to provide rapid deployment and maintenance support in key operational hubs can strengthen customer loyalty and contract retention.
Our detailed market study provides the granular data and qualitative analysis necessary to act on these insights. It delves into specific segmentation splits, historical performance metrics, and comprehensive company profiles that are essential for building robust business cases. The full report offers a complete view of the competitive dynamics, including detailed profiles of the key companies driving the market, recent developments, and a deep dive into the regulatory and raw material factors influencing supply chains.
To access the complete intelligence required to finalize your 2026 strategy, we invite you to visit our source webpage. There, you will find the full dataset, including specific regional revenue contributions, detailed application segment breakdowns, and precise competitive positioning analysis. Empowering your organization with this level of detail ensures that your decisions are grounded in verified data rather than assumptions. Navigate the future of the Tire Protection Chains Market with confidence by exploring the full scope of our research today.
For detailed analysis of this topic, please visit the official page: Tire Protection Chains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Marijuana Market to Hit $84.79B by 2032 with 20.3% CAGR
By PW Consulting, 2026-09-16
Navigating the Green Horizon: Strategic Intelligence for the Legal Marijuana Market (2026-2032)
The global legal marijuana industry has transitioned from a speculative frontier to a mature, capital-intensive sector defined by rapid expansion and complex regulatory frameworks. As we move through 2026, the strategic imperative for stakeholders has shifted from simple market entry to sophisticated positioning within a highly fragmented yet consolidating landscape. PW Consulting's latest comprehensive study on the Legal Marijuana Market offers a critical roadmap for navigating this evolution, providing the granular intelligence necessary to capitalize on projected growth trajectories while mitigating regulatory and operational risks.
This industry is no longer defined solely by aspirational forecasts. The historical momentum is undeniable. Between 2020 and 2025, the global revenue landscape expanded from approximately 5.02 billion USD to 23.38 billion USD, reflecting a compound annual growth rate that has consistently outpaced broader consumer goods sectors. Looking forward, our forecast period spans from 2026 through 2032, projecting a continuation of this aggressive upward trend. The market is anticipated to reach substantial milestones over this horizon, driven by deepening legalization pipelines, evolving consumer preferences, and increasing integration into mainstream healthcare and wellness ecosystems. Understanding the velocity of this growth is not merely an academic exercise; it is a foundational requirement for capital allocation, supply chain planning, and long-term portfolio strategy.
The 2026 Strategic Inflection Point
2026 represents a pivotal year for the industry, characterized by significant regulatory recalibrations that will reshape competitive dynamics for the remainder of the decade. The most notable development involves recent actions by the US Department of Justice, where FDA-approved marijuana products and state-licensed medical marijuana have been placed in Schedule III. This administrative shift, initiated with a new hearing process for broader rescheduling from Schedule I to III, signals a fundamental change in how federal authorities view cannabis-derived products. For market participants, this transition implies a potential reduction in regulatory friction, altered tax structures, and expanded opportunities for institutional investment that were previously constrained by stricter classifications.
Alongside rescheduling developments, operational costs and compliance requirements continue to evolve. Industry participants must now account for specific administrative fee structures, such as the 2026 calendar year fee of 113 USD per kg mandated by the DEA. While these figures may appear incremental on a per-unit basis, they accumulate significantly across large-scale manufacturing and distribution networks. Our report dissects how these regulatory costs interact with pricing strategies, margin preservation, and market accessibility, ensuring that executives can model their operational expenses with precision rather than relying on outdated assumptions.
The convergence of rescheduling initiatives and updated compliance frameworks creates a strategic inflection point. Companies that proactively align their research and development, manufacturing capabilities, and market outreach with these evolving standards will secure a distinct advantage. Those that treat regulatory shifts as peripheral concerns risk facing structural disadvantages in procurement, distribution, and brand legitimacy. Our analysis provides a detailed examination of these dynamics, mapping out the operational implications of federal policy adjustments across different business models.
Decoding a Fragmented Competitive Landscape
The competitive architecture of the legal marijuana market is characterized by a unique blend of specialized research manufacturers, emerging commercial brands, and regional incumbents. Despite the market's rapid revenue expansion, concentration remains comparatively modest. Our data indicates a CR3 of 15.0 percent and a CR5 of 21.0 percent, underscoring an environment where no single entity dominates the broader landscape. This fragmented structure presents both opportunities and challenges: it allows new entrants and mid-tier players to carve out sustainable niches, yet it also demands astute differentiation strategies to avoid commoditization in an increasingly crowded field.
A distinct segment of the market is anchored by DEA-registered bulk manufacturers whose operations are tightly coupled with research and regulatory compliance. Companies such as Biopharmaceutical Research Company LLC, Groff NA Hemplex LLC, Irvine Labs Inc., Maridose LLC, National Center for Development of Natural Products, Royal Emerald Pharmaceuticals Research and Development, and Scottsdale Research Institute represent the institutional backbone of the research-grade supply chain. These organizations operate under stringent federal registration and are integral to the development, standardization, and scientific validation of cannabis-based materials. Their presence highlights a critical dimension of the market that often goes underappreciated in consumer-facing analyses: the foundational role of regulated research manufacturing in enabling product innovation, quality assurance, and clinical exploration.
Understanding the strategic positioning of these key players is essential for deciphering supply chain bottlenecks, partnership opportunities, and future consolidation patterns. Our report provides in-depth corporate profiles, operational footprints, and strategic assessments of these entities, alongside a broader competitive mapping that extends across commercial manufacturers, formulators, and distribution networks. By examining how research-focused manufacturers intersect with commercial scalability, readers gain a holistic view of the value chain and the leverage points available for strategic collaboration or competitive displacement.
Structural Dimensions of Growth
The expansion of the legal marijuana market is not uniform across all product categories or utilization channels. Instead, growth manifests through distinct structural segments, each with its own demand drivers, manufacturing requirements, and consumer adoption curves. Our analysis segments the market to reveal where value creation is most concentrated and where future share shifts are likely to occur.
Product format dynamics continue to evolve as consumers and medical practitioners seek varied delivery methods that balance potency, convenience, and dosage precision. The market encompasses traditional flower products, which maintain a foundational role in both medical and adult-use channels, alongside concentrates that cater to extraction-heavy manufacturing and specialized formulations. Edibles represent another critical vertical, reflecting broader consumer trends toward discreet, measured, and integrated consumption experiences. Additional product categories further diversify the offer, creating a multi-layered ecosystem where manufacturers must navigate distinct regulatory thresholds, shelf-life considerations, and formulation complexities.
On the application side, the market bifurcates into medical use and recreational use, each governed by different demand stimuli, clinical validation requirements, and purchasing behaviors. Medical applications continue to drive rigorous demand for standardized products, clinical documentation, and practitioner engagement, while recreational channels are shaped by brand differentiation, consumer experience, and retail accessibility. The interplay between these two streams influences everything from pricing architecture to marketing compliance, and our report dissects the strategic nuances inherent to serving each segment without conflating their distinct operational requirements.
Geographic expansion patterns further complicate the strategic picture. Regional markets exhibit varying levels of maturity, regulatory openness, and cultural acceptance, which in turn shape supply chain logistics, partnership structures, and growth pacing. Our report maps these regional variations to highlight where early-mover advantages are crystallizing, where regulatory gateways are predicted to open, and how cross-border dynamics may influence future competitive intensity. The analysis is designed to help executives prioritize geographic initiatives based on realistic risk-reward profiles rather than generalized growth narratives.
Why This Research Matters for 2026 Decision-Making
As the industry accelerates toward the latter half of the decade, decision-makers require more than high-level market summaries. They need actionable intelligence that connects macroeconomic trends to operational realities. This report is engineered to serve as a strategic companion for executive teams, investment committees, and operational leaders who must make time-sensitive decisions under conditions of regulatory uncertainty and competitive fluidity.
The study integrates a multi-year historical baseline with a forward-looking forecast window, allowing readers to benchmark current performance against both retrospective trends and projected trajectories. By anchoring analysis in concrete historical figures and extending through 2032, the report enables scenario planning that accounts for varying growth velocities, regulatory adoption curves, and competitive responses. This temporal depth is critical for capital planning, capacity expansion, and product pipeline development, ensuring that strategic initiatives are aligned with realistic market evolution rather than short-term hype cycles.
In addition to quantitative forecasting, the report delivers qualitative depth through competitive profiling, regulatory impact assessments, and segment-level strategic implications. Readers will find structured analyses of how key industry players are positioned, how recent policy changes alter the cost and compliance landscape, and where structural opportunities exist for differentiation. The content is designed to be directly applicable to strategic planning documents, investment memos, and operational roadmaps, bridging the gap between market data and executable business strategy.
Legal Marijuana Market
Hemp Market
Furthermore, the report addresses the operational realities that often determine success or failure in this sector. From manufacturing scale-up considerations to distribution compliance and brand positioning within a fragmented field, the analysis highlights the practical levers that executives can pull to strengthen market posture. By synthesizing market sizing, competitive intelligence, and regulatory context into a unified framework, the study provides a decision-ready resource that reduces ambiguity and supports evidence-based planning.
Accessing the Full Strategic Blueprint
The legal marijuana market in 2026 and beyond will reward organizations that combine agility with analytical rigor. As regulatory frameworks continue to evolve and competitive intensity rises, the ability to access precise, forward-looking intelligence will separate resilient market participants from those that are forced into reactive positioning. This report is built to serve as that intelligence foundation, offering the depth, structure, and strategic relevance required for high-stakes decision-making.
While this overview highlights the macro trajectory, the regulatory inflection points, and the competitive architecture shaping the industry, the complete study contains detailed segmentations, granular market sizing across product types and applications, regional breakdowns, and extended competitive assessments that are essential for precise strategic execution. To access the full dataset, comprehensive company profiles, and the complete forecast model, we invite you to visit the source page and request the complete PW Consulting Legal Marijuana Market research. Equip your organization with the intelligence needed to navigate the next phase of industry expansion with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Legal Marijuana Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoke Evacuation System Market Hits $185M in 2025, Forecasted to Reach $318M by 2032 at 8.1% CAGR
By PW Consulting, 2026-09-16
Strategic Foresight in the Smoke Evacuation System Market: Navigating the 2026 Decision Landscape
The operating room has evolved from a purely clinical environment into a regulated, safety-centric ecosystem where invisible hazards demand visible solutions. Surgical smoke, once dismissed as an unavoidable byproduct of modern electrosurgery and minimally invasive techniques, is now recognized as a credible occupational health risk carrying particulate matter, volatile organic compounds, and potential pathogens. For healthcare executives, procurement leaders, and medical device strategists, this shift represents more than a compliance checkbox. It signals a structural realignment in capital allocation, vendor partnerships, and perioperative workflows. PW Consulting's latest Smoke Evacuation System Market research is designed specifically for decision-makers operating in this new reality. By projecting market trajectories from a 2025 base year through 2032, the report translates historical momentum into actionable intelligence, framing 2026 not as a continuation of past patterns, but as a pivotal inflection point for strategic intervention.
Smoke Evacuation Tubing Market
Market Trajectory and the Architecture of Growth
The historical record tells a clear story of accelerated adoption. Between 2020 and 2025, the global smoke evacuation system market expanded from a modest baseline to $185.0 million, reflecting a compound trajectory that outpaces many traditional surgical accessory categories. This growth is not accidental. It is the cumulative result of clinical awareness, regulatory pressure, and the physical expansion of minimally invasive procedural volume. Looking ahead, the forecast period through 2032 projects a sustained expansion pathway, anchored by an 8.1% CAGR that carries the market toward the $318.0 million threshold. These figures do more than chart revenue. They expose the timing of capital windows, the spacing of procurement cycles, and the maturation curve of hospital formulary adoption.
For executives mapping 2026 budgets, this trajectory carries immediate operational weight. The transition from $175.75 million in 2024 to $185.0 million in 2025, and onward to $205.54 million in 2026, signals that institutional demand is moving past early-adopter phases into broader standardization. Facilities that delay equipment evaluation or vendor negotiation risk entering a more crowded, price-sensitive procurement environment. Conversely, organizations that align capital planning with this growth curve can secure favorable terms, lock in service contracts, and position themselves ahead of reimbursement cycles. The report unpacks these timing dynamics without reducing them to static snapshots, instead mapping the cadence at which procurement teams should evaluate total cost of ownership, workflow integration, and sustainability of disposable supply chains.
Regulatory and Reimbursement Currents Reshaping Purchase Logic
The financial calculus for smoke evacuation equipment can no longer be isolated from policy momentum. Across multiple jurisdictions, legislative and administrative actions are converting occupational safety recommendations into reimbursable or mandated expenditures. Washington State, for example, has opened pathways for hospitals to secure reimbursement of up to $1,000 per operating room for qualifying surgical smoke equipment purchases, with registration through a vendor payee number required to capture the funds. Florida's legislative analysis underscores the counterweight of cost exposure, with initial per-room investments reaching up to $2,000 and recurring disposable costs approximating $19 per procedure. At the national level, eighteen U.S. states have enacted legislation requiring hospitals to provide surgical smoke management equipment, and additional states continue to move through legislative pipelines.
These dynamics reshape purchasing behavior in three measurable ways. First, they compress decision timelines, pushing facilities to evaluate equipment before mandates or reimbursement windows close. Second, they elevate the importance of per-procedure economics over upfront sticker price, making disposable efficiency, filter longevity, and tubing replacement cycles central to vendor selection. Third, they increase the strategic value of documentation and compliance readiness, since reimbursement and regulatory adherence frequently depend on verifiable equipment deployment and usage records. Our analysis integrates these policy vectors directly into the procurement narrative, showing how capital planning must now account for legislative timing, reimbursement eligibility, and state-specific cost thresholds. The report details how these pressures alter vendor negotiations, service-level expectations, and the financial modeling that hospital administrators use to justify perioperative upgrades.
Competitive Architecture and the New Differentiation Frontier
The market's competitive structure reflects both consolidation and targeted specialization. Concentration metrics indicate that the top three players command approximately 45.8% of revenue, while the top five extend their reach to roughly 67.2%. This hierarchy matters because it defines the negotiation bandwidth available to procurement teams, the service coverage models likely to be offered, and the pace at which new features migrate from innovation to standard specification. Yet within this consolidated frame, competitive advantage is increasingly determined by integration depth, clearance velocity, and workflow alignment rather than by brand legacy alone.
Smoke Evacuation System Market
Several organizations illustrate how product strategy is evolving under these conditions. I.C. Medical, Inc., based in Phoenix, Arizona, has positioned itself around specialized smoke evacuation instrumentation, including the Crystal Vision surgical smoke evacuator, the PenEvac electrocautery pencil, and filtration accessories engineered for operating room smoke plume management. ConMed Corporation, headquartered in Utica, New York, advances a different integration model with the PlumeSafe X5 Smoke Management System and the VisiClear surgical smoke evacuator, targeting streamlined OR plume control. KARL STORZ SE & Co. KG, from Tuttlingen, Germany, emphasizes compatibility within minimally invasive laparoscopic workflows by developing integrated smoke evacuation systems paired with ENDOFLATOR insufflators. Olympus Corporation, based in Tokyo, contributes a complementary approach through the OR-VAC surgical smoke evacuator, telescopic smoke evacuation pencils, and related operating room accessories.
The competitive field extends further across both established device manufacturers and workflow-focused innovators. Stryker Corporation, located in Kalamazoo, Michigan, embeds smoke evacuation capabilities within broader electrosurgical and operating room equipment platforms. Erbe Elektromedizin GmbH, from Tübingen, Germany, integrates smoke evacuation functionality directly into electrosurgical generators, aligning plume management with energy device control. Alesi Surgical, operating from the United Kingdom, pursues an alternative technical pathway with its Ultravision electrostatic smoke management system. Aspen Surgical Products, Inc., based in Davisburg, Michigan, supplies smoke evacuation systems and accessories tailored for surgical use, while Medimaxtech, Inc., distributes systems through hospital contracts designed for operating room deployment.
Recent regulatory milestones reveal how quickly product positioning can shift. In August 2024, ConMed Corporation secured FDA 510(k) clearance for the PlumeSafe X5 Smoke Management System, reinforcing its presence in the surgical smoke evacuation segment. In October 2025, KARL STORZ received FDA clearance for the ENDOFLATOR plus insufflator with an integrated surgical smoke evacuation system for laparoscopic procedures, a move that ties plume management directly to insufflation workflow. These clearances do more than validate engineering claims. They alter the comparison criteria that procurement committees use, introducing questions about compatibility with existing laparoscopic towers, service response times, consumable standardization, and the cost impact of adding evacuation functions to instruments already in the procedural pathway. The report examines these competitive moves within a structured vendor evaluation framework, helping readers understand which attributes translate into purchasing leverage and which represent product differentiation that may or may not justify premium positioning.
Report Architecture: From Macro Signals to Procurement-Grade Intelligence
This research is constructed to support execution, not merely observation. While high-level market size and growth trajectories provide the strategic frame, the majority of the analysis is devoted to decision-grade detail. The report maps product categories, application environments, and regional demand patterns in a way that allows procurement, clinical engineering, and commercial strategy teams to align their internal models with external market behavior. Instead of presenting isolated percentages or fragmented figures, the analysis connects product segmentation to workflow realities, links application environments to procedure volume dynamics, and ties regional variation to procurement cadence, regulatory exposure, and reimbursement readiness.
Readers will find practical structures designed for immediate use. The segmentation discussion clarifies how smoke evacuating systems, evacuation pencils and wands, filters, tubings, and fusion products and accessories relate to one another in real operating room settings, enabling more accurate forecasting of consumable burn rates, service intervals, and replacement cycles. The application analysis situates smoke evacuation demand within the procedural contexts that generate the highest plume exposure, including laparoscopic, orthopedic, and medical aesthetic surgeries, alongside other clinical environments, supporting volume-based purchasing logic and case-mix planning. The regional dimension is evaluated through the lens of adoption maturity, policy intensity, and capital deployment patterns, helping organizations gauge where demand is consolidating, where it is expanding, and where competitive pressure is most likely to intensify.
Beyond segmentation, the report integrates regulatory tracking, reimbursement pathway analysis, and cost-structure evaluation into a unified decision framework. Hospital administrators and ambulatory surgery center operators can use these sections to model per-room investment thresholds, compare recurring disposable economics, and identify the documentation requirements that determine whether reimbursement or compliance objectives are achievable. Commercial teams can use the same material to anticipate purchasing committee priorities, align product positioning with integration expectations, and time launches or contract renewals to match procurement cycles. The analysis is deliberately built to bridge clinical safety objectives and financial discipline, ensuring that recommendations can be defended in both operational and budget-review settings.
Translating 2026 Intelligence into Operational Advantage
The value of this research lies in its ability to convert market motion into decision timing. For hospital and surgery center leaders, the 2026 planning window is not simply a budget cycle. It is the moment when regulatory momentum, reimbursement pathways, and product clearance activity converge to reshape equipment standardization. Facilities that treat smoke evacuation as a discrete accessory purchase risk underpricing the total lifecycle impact and overestimating the flexibility of future procurement. Organizations that instead evaluate evacuation performance alongside workflow compatibility, consumable economics, and state-level reimbursement exposure are better positioned to negotiate service terms, consolidate vendor relationships, and protect perioperative throughput.
For medical device and equipment strategists, the same intelligence clarifies where competitive pressure is likely to concentrate. The combination of elevated market concentration, recurring regulatory clearances, and reimbursement-driven purchasing creates a landscape in which feature parity alone is insufficient. Differentiation increasingly depends on demonstrable integration with existing electrosurgical or laparoscopic platforms, predictable disposable cost structures, and compliance support that reduces administrative friction for hospital buyers. The report provides the context needed to test product positioning against these expectations, anticipate procurement committee objections, and calibrate go-to-market timing against the rhythm of hospital capital planning.
The dataset and analytical structure behind this overview extend far beyond the summary framing. Detailed segmentation logic, competitive benchmarking, procurement sensitivity considerations, and policy-linked demand drivers are developed in full within the complete study. Readers seeking the operational figures, scenario models, and vendor evaluation detail required to finalize 2026 capital plans, contract strategies, or commercial positioning will find the complete intelligence package structured for that purpose. The macro trajectory outlined here is intended as a strategic preview: enough depth to validate the analytical rigor, while preserving the precise segmentation and scenario detail that decision-makers need before committing budget or negotiating terms.
Conclusion: Positioning for a Compliance-Driven Growth Cycle
The smoke evacuation system market is moving from niche consideration to structured procurement priority. Historical expansion, regulatory mandates, reimbursement mechanisms, and concentrated competitive activity are combining to create a purchasing environment where timing, integration, and total cost discipline determine outcomes. PW Consulting's research translates these forces into a single decision framework, linking market growth signals to the practical requirements of hospital procurement, clinical engineering, and device strategy. For executives entering 2026, the objective is no longer to determine whether smoke evacuation matters. The objective is to decide how to buy, when to standardize, and which vendor attributes will deliver measurable value under the next cycle of regulatory and reimbursement pressure. The full report is structured to support those decisions with the depth, clarity, and procurement-grade detail required for confident action.
For detailed analysis of this topic, please visit the official page: Smoke Evacuation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


