



Category: market research
Wireless Router Market 2026-2032: 8.9% CAGR vs. 74% Dual-Band Dominance
By PW Consulting, 2026-09-21
Strategic Shifts in the Wireless Router Market: Navigating Growth, Competition, and Emerging Opportunities (2025–2032)
The global wireless router market has entered a new phase of expansion, characterized by steady revenue growth, accelerating technological transitions, and shifting regulatory frameworks. From 2020 through 2025, industry revenue climbed from approximately USD 108 million to USD 150 million, reflecting sustained demand for reliable, high-performance connectivity. Looking ahead to 2032, the market is projected to reach USD 271.95 million, supported by a compound annual growth rate of 8.9 percent. This trajectory signals more than incremental expansion; it points to a structural realignment in how networks are designed, deployed, and monetized. For executives and investors, the question is no longer whether the market will grow, but which segments, capabilities, and strategic positions will capture disproportionate value as the landscape matures.
Routers Market
1. Market Landscape and Core Challenges
The revenue curve from 2020 to 2025 shows a market recovering from supply-constrained years and then moving into a demand-led growth phase. Growth in 2021 and 2022 was followed by continued expansion through 2023 and 2024, with 2025 closing at USD 150 million. The forecast period from 2026 to 2032 indicates accelerating annual increments, with revenue expected to cross USD 163 million in 2026 and approach USD 228 million by 2030 before reaching the 2032 target. This pattern reflects a market that is transitioning from hardware replacement cycles toward higher-value networking solutions that support denser device ecosystems, cloud-managed deployments, and increasingly distributed enterprise environments.
Market concentration remains moderate. The top three players account for roughly 25.5 percent of revenue, while the top five reach approximately 35.2 percent. This level of concentration suggests a competitive field where scale matters but does not dictate outcomes. Regional dynamics are uneven, with some geographies showing stronger residential adoption and others leaning toward enterprise and service-provider deployments. Across application segments, residential use continues to anchor total demand, while enterprise and other specialized deployments contribute meaningful incremental revenue as organizations upgrade legacy connectivity infrastructure. By product type, the market is moving away from basic single-band offerings toward dual-band architectures as the volume baseline, with tri-band solutions gaining traction in performance-sensitive environments.
Key Challenges and Inflection Points
- Spectrum and regulatory fragmentation : Wireless routers operate within an evolving spectrum management environment. Recent regulatory actions point toward more flexible sharing models, but uneven coordination across jurisdictions can create deployment complexity, compliance overhead, and product adaptation costs.
- Performance expectations outpacing baseline hardware : Consumer and enterprise users increasingly expect consistent throughput, low latency, and seamless device handling. As device density rises, routers that cannot manage interference, prioritize traffic, or maintain stability under load face rapid obsolescence.
- Margin pressure from commoditization at the entry level : Basic router segments remain vulnerable to price competition, while value creation shifts toward differentiated features, service attach, and software-driven management. Companies relying on volume without clear performance or ecosystem advantages risk seeing gross margins erode.
2. Key Drivers of Market Change
Technology Innovation and Breakthroughs
The most visible driver is the steady progression of Wi-Fi standards and the associated hardware capabilities required to exploit them. The introduction of Wi-Fi 7–class routers, such as TP-Link’s ARCHER BE9700 launched in November 2025 with enhanced 6 GHz band support, illustrates how product roadmaps are shifting toward higher throughput and improved performance in congested environments. The practical impact is not merely faster theoretical speeds; it is better handling of simultaneous workloads, more reliable connectivity for dense device households and offices, and stronger positioning for applications that demand predictable performance. As these capabilities filter from flagship models into broader portfolios, they raise the baseline for competitive products and push the market toward higher ARPU through feature-rich devices.
Equally important is the growing role of intelligent network management. Regulatory attention to artificial intelligence and machine learning for spectrum sharing, including the FCC’s August 2025 report recommending an internal working group to improve spectrum utilization efficiency, signals a longer-term expectation that network equipment will need to operate more adaptively. For wireless routers, this trend supports features such as dynamic channel selection, traffic prioritization, interference mitigation, and remote diagnostics. Hardware is increasingly only one part of the value proposition; the ability to manage the radio environment intelligently is becoming a differentiator.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and product strategy. The FCC’s January 2026 order modernizing spectrum sharing for satellite broadband reflects a broader push to expand wireless connectivity through less restrictive rules, which can stimulate demand for complementary ground-side equipment and improve overall connectivity ecosystems. At the same time, the European Commission’s proposed Digital Networks Act, published in January 2026, strengthens coordination of radio spectrum management and promotes spectrum sharing as a default under a “use it or share it” principle. This addresses fragmentation across Member States but also introduces a compliance environment where spectrum efficiency and interoperability become strategic priorities rather than optional enhancements.
Another regulatory dimension is the FCC’s 2025 reclassification of broadband internet access service as an information service, which limits regulatory authority over net neutrality rules for wireless router and ISP deployments. While this does not directly dictate router design, it influences the commercial environment in which ISPs, OEMs, and channel partners operate. Reduced regulatory constraints on certain service practices can alter bundling strategies, managed-service models, and the balance of features prioritized by service providers versus retail customers.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being shaped by two parallel forces: higher connectivity expectations at home and more distributed, performance-sensitive enterprise environments. Residential users increasingly treat Wi-Fi as essential infrastructure supporting working from home, gaming, streaming, smart home devices, and multi-device households. This elevates the importance of reliability, coverage, and ease of management. In enterprise settings, organizations are expanding hybrid work, branch connectivity, and IoT-enabled operations, which increases demand for routers and gateways that can support secure, stable, and manageable networks without requiring excessive on-site IT intervention.
A related demand-side shift is the growing preference for solutions that reduce total cost of ownership through remote management, automated troubleshooting, and firmware agility. Buyers are more willing to pay for operational simplicity and predictable performance than for raw specifications alone. This shifts competitive advantage toward vendors that can combine hardware quality with software experience and serviceable support models.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures in the wireless router market are influenced by component availability, manufacturing scale, and the balance between retail and channel-led distribution. As product complexity increases with newer Wi-Fi generations and additional radio bands, bill-of-materials pressure can rise. At the same time, mature manufacturing ecosystems and competitive sourcing can help offset some of that pressure, particularly for high-volume segments. Companies that can manage component planning, align product cycles with demand, and avoid excess inventory exposure are better positioned to protect margins during transitional periods.
There is also a structural shift in how value is captured across the supply chain. Where legacy router markets often competed on unit price, current dynamics reward vendors that can integrate performance, manageability, and ecosystem compatibility. This favors players that can coordinate silicon selection, antenna design, firmware development, and user experience into a coherent offering rather than treating the router as a standalone commodity device.
3. Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The competitive field includes established consumer-focused players, enterprise and service-provider specialists, and emerging niche brands. NETGEAR, based in San Jose, California, continues to compete on a broad consumer and prosumer portfolio, with an emphasis on performance-oriented home networking and connected device management. ASUS, headquartered in Taipei, has built a strong reputation around feature-rich router platforms that blend performance with software differentiation, appealing to users who prioritize customization, gaming, and advanced networking controls. TP-Link, based in Shenzhen, competes at scale with a wide range of price-performance options and has expanded its presence in higher-end categories, including Wi-Fi 7–enabled devices, aiming to cover both volume and premium demand. ASUSTeK, also in Taipei, contributes enterprise and broader hardware capabilities that can intersect with networking infrastructure needs beyond consumer routers.
On the service-provider and enterprise side, Calix and Arris bring a different strategic focus. Calix, also based in San Jose, emphasizes platforms and services that support broadband service operators, aligning router and gateway offerings with managed service requirements. Arris, headquartered in Suwanee, Georgia, has historically participated in broadband access and connectivity ecosystems where router and network equipment intersect with carrier deployment models. These players differentiate less on retail branding and more on integration, deployment support, and compatibility with operator infrastructures. Other participants such as Arcadyan Technology, Sagemcom, Inseego, and GL.iNet occupy distinct positions, ranging from telecom-oriented manufacturing to specialized secure or travel-friendly router solutions, each targeting narrower customer needs that larger broadline vendors may not fully address.
Differentiation in this market increasingly depends on three elements: radio and throughput performance, software and management experience, and channel or ecosystem alignment. Vendors that combine strong hardware execution with intuitive setup, remote management, security posture, and reliable firmware support tend to earn higher retention and stronger word-of-mouth in residential markets. In enterprise and carrier-adjacent segments, differentiation shifts toward interoperability, serviceability, and scalability.
Evolution of the Market Structure
The market is moving along two concurrent paths: gradual consolidation at the top and continued differentiation at the edges. Moderate concentration indicates that scale leaders exist, but there is still room for specialized players to compete by focusing on specific customer segments, use cases, or feature priorities. Over the next several years, the structure is likely to remain pluralistic rather than becoming dominated by a small number of winners, because demand is diversified across retail, enterprise, and service-provider channels.
At the same time, pressure is building for portfolio rationalization. As higher-performance standards become mainstream, vendors that cannot move up the value curve may find themselves confined to low-margin segments. New entrants and niche brands can still succeed by addressing underserved needs, such as secure travel routers, privacy-oriented configurations, or connectivity solutions tailored to specific professional environments. The broader trend is therefore not pure consolidation but a layered market in which broadline vendors compete on reach and portfolio breadth, while specialized players compete on precision and differentiation.
WiFi Home Router Market
4. Future Trends and Commercial Opportunities
Trend 1: Wi-Fi 7 Adoption as a Growth Catalyst, Not a Niche Upgrade
Wi-Fi 7–class features, including enhanced use of the 6 GHz band and improved handling of high-throughput workloads, are likely to move from flagship introductions into broader commercial relevance over the next few years. This matters because adoption is not simply about marketing a new standard; it reshapes purchasing criteria across residential upgrades and performance-sensitive enterprise deployments. As more environments deploy dense device sets and demanding applications, routers that can manage congestion and deliver consistent performance will gain share. The commercial opportunity lies in tiered portfolios that allow customers to migrate at different pace and price points, while preserving upgrade paths that protect longer-term relevance.
Trend 2: Spectrum Efficiency and Smarter Network Management as Competitive Requirements
The regulatory direction toward spectrum sharing and improved utilization, supported by initiatives such as the FCC’s AI and machine learning recommendations and the European Digital Networks Act, suggests that routers will increasingly be evaluated on how well they operate within shared and dynamic spectrum environments. Devices that can adapt to interference, optimize channel use, and support remote management will be better positioned in both retail and service-provider channels. The opportunity here extends beyond hardware sales to managed services, software subscriptions, and support models that monetize ongoing network performance rather than one-time device purchases.
Trend 3: Hybrid Demand Between Retail, Enterprise, and Service Provider Channels
The market is likely to see continued overlap between consumer-style retail routers, enterprise-grade managed gateways, and carrier-provisioned equipment. This hybrid demand creates opportunities for vendors that can serve multiple channels with shared platforms but distinct configurations, branding, and support models. Companies that design for flexibility can capture value across segments without fully duplicating development effort. However, channel conflict, certification requirements, and differing customer expectations create execution risk, especially for organizations that attempt to serve all segments without clear positioning.
Risks and Uncertainties
- Regulatory divergence : Spectrum rules, device certification, and service regulations may evolve at different speeds across regions, raising product adaptation costs and slowing launch timing.
- Adoption asymmetry : Premium features may penetrate certain markets faster than others, creating uneven product cycles and inventory risk if demand forecasts misread regional maturity.
- Competitive escalation in performance claims : As higher standards become common, differentiation may narrow at the hardware level, pushing competition toward software, brand trust, and service quality, where execution barriers can be high.
5. Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Prioritize performance and manageability over specification stacking : Buyers increasingly value stable throughput, practical coverage, and easy administration. Roadmaps should balance radio upgrades with firmware, diagnostics, and user experience improvements that deliver perceived reliability.
- Build tiered portfolios with clear upgrade paths : Instead of treating new standards as a single premium product moment, create migration ladders that allow customers to enter at different price points while preserving future relevance.
- Prepare for spectrum efficiency as a design requirement : Product teams should anticipate regulatory pressure for better spectrum utilization and incorporate adaptive management capabilities that reduce interference and improve operational efficiency.
For Investors and Corporate Strategists
- Focus on value capture beyond unit sales : Companies that can attach managed services, software features, or support relationships are better positioned to defend margins than those competing primarily on hardware volume.
- Assess channel alignment carefully : Retail, enterprise, and service-provider paths reward different capabilities. Investment theses should consider whether a company’s distribution, certification footprint, and support model match its target segment.
- Monitor regulatory catalysts : Spectrum sharing reforms and broadband policy shifts can influence demand speed, product requirements, and competitive dynamics. These are not background issues; they can change the pace and shape of adoption.
For Procurement and Enterprise Buyers
- Evaluate total cost of ownership rather than sticker price : In denser environments, the cost of poor performance, manual troubleshooting, and premature replacement can exceed the savings from lower upfront pricing.
- Require evidence of real-world stability and manageability : Benchmarking should include device density, reload and recovery behavior, firmware update processes, and remote management capabilities, not only peak throughput claims.
- Plan for upgrade cycles aligned to usage growth : As device counts and application demands increase, procurement strategies should anticipate transition points rather than reacting after performance bottlenecks appear.
The wireless router market is entering a period in which growth is supported by clear demand tailwinds, but competitive advantage will depend on execution quality across hardware, software, and channel strategy. The most successful players will be those that treat performance, spectrum efficiency, and manageability as interconnected requirements rather than isolated product features. For organizations seeking a deeper view of segment-level sizing, regional dynamics, company positioning, and scenario-based forecasts, the full PW Consulting market research report offers more granular data and customized strategic recommendations to support planning across manufacturing, investment, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Wireless Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bacterial Vaginosis Drug Market: Why 8.92% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Strategic Horizons in the Bacterial Vaginosis Drug Market: Trends and Commercial Opportunities
Bacterial vaginosis represents one of the most prevalent vaginal conditions globally, creating a persistent demand for effective therapeutic solutions. The drug market serving this indication has evolved from a landscape dominated by generic antimicrobials to one increasingly shaped by differentiated formulations, extended intellectual property strategies, and geographic expansion. Understanding the strategic undercurrents in this space requires looking beyond headline revenue figures to examine the interplay of clinical innovation, regulatory pathways, reimbursement dynamics, and competitive positioning.
Worldwide Vaginal Antifungal Market
Market valuations over the historical window from 2020 through 2025 reflect steady expansion, with the sector reaching a baseline size in 2025 that sets the stage for continued growth through the forecast horizon ending in 2032. The trajectory implies a compound annual growth rate of approximately 8.92 percent across the projection period, signaling durable demand rather than a temporary surge. This growth is not uniformly distributed across therapeutic categories or indications; instead, it reflects concentrated activity around specific treatment modalities, prioritized patient populations, and regions with evolving healthcare access frameworks. The market remains moderately concentrated, with the top three participants accounting for more than half of total revenue and the top five approaching seventy percent, indicating that scale, brand recognition, and regulatory moats continue to confer meaningful advantages.
1. Market Status and Core Challenges
The current market environment is defined by a tension between established therapeutic standards and the push for more convenient, better-tolerated options. Metronidazole and clindamycin formulations have long served as the backbone of bacterial vaginosis treatment, supported by extensive clinical experience and broad availability. Yet their dominance coexists with persistent challenges around recurrence rates, patient adherence to multi-day regimens, and the need for alternatives that reduce systemic exposure or improve convenience. These clinical friction points create openings for single-dose or simplified delivery approaches, but they also raise the bar for demonstrating differentiated value in a crowded field.
A second pivotal challenge lies in the balance between innovation and generic competition. Branded products with extended exclusivity windows can capture premium positioning and drive short-term revenue momentum, but the underlying therapeutic classes remain susceptible to cost pressure once patent protections recede or when generic equivalents gain regulatory clearance. This dynamic forces companies to weigh the timing of lifecycle investments, the scope of patent coverage, and the durability of their commercial infrastructure against the risk of rapid price erosion.
A third inflection point involves the fragmentation of care pathways and payer expectations. Treatment decisions are influenced not only by clinical efficacy but also by ease of administration, tolerability profiles, and how consistently therapies are covered under pharmacy benefit designs. Manufacturers seeking to expand adoption must navigate varying reimbursement landscapes, provider education gaps, and patient awareness levels that differ substantially across care settings. The result is a market where commercial success depends as much on ecosystem engagement as on the intrinsic merits of a molecule or formulation.
2. Key Drivers of Market Change
Several interlocking forces are reshaping the competitive and commercial landscape. Understanding these drivers provides a clearer view of where investment and strategic focus are likely to generate the strongest returns.
Technological Innovation and Formulation Breakthroughs
Innovation in this market is increasingly centered on delivery optimization and regimen simplification rather than entirely new molecular entities. Single-dose oral and vaginal options address a core patient need: reducing the burden of multi-day treatment while maintaining efficacy. These approaches can improve adherence, lower the risk of incomplete therapy, and potentially reduce recurrence driven by suboptimal compliance. At the same time, formulation science is advancing around tolerability and local versus systemic exposure, enabling products to differentiate on convenience and side-effect profiles even within established drug classes.
The strategic significance of these innovations is amplified when they are paired with robust intellectual property positioning. Extended exclusivity through method-of-use, composition, and formulation patents can create a multi-year window during which a product can establish prescribing habits, secure payer coverage, and build brand loyalty before broader competition emerges. This combination of clinical differentiation and legal protection has become a defining feature of value creation in the segment.
Policy and Regulatory Environment
Regulatory dynamics play a central role in shaping both the pace of innovation and the defensibility of commercial positions. Approvals that recognize specific patient populations, age thresholds, or indication expansions can open new addressable groups and extend the commercial life of a therapy. The regulatory process also functions as a gatekeeper for generic entry and therapeutic equivalence determinations, meaning that timing differences in filings, labeling, and bioequivalence data can materially affect market share trajectories.
In parallel, the regulatory framework influences how long a company can sustain premium pricing and brand preference. Patent listings that cover core formulations and labeled indications contribute to barriers against rapid substitution, particularly when combined with limited numbers of directly equivalent alternatives in the near term. These protections do not eliminate competition, but they alter the timeline and intensity of competitive entry, giving innovators room to invest in commercialization and real-world evidence generation.
Demand-Side Shifts in Patient and Provider Behavior
On the demand side, there is growing emphasis on treatments that reduce recurrence risk and improve the patient experience. Clinicians and patients alike are increasingly attuned to the limitations of regimens that are difficult to complete or that produce nuisance side effects, and this awareness is shifting preference toward options that are simpler to administer and easier to tolerate. This is especially relevant in populations where adherence barriers are pronounced or where repeated episodes create cumulative burden.
Provider adoption is also being shaped by the availability of clear differentiation. When multiple products exist within the same class, clinicians look for tangible distinctions in dosing frequency, application method, or safety profile to guide prescribing. Educational outreach, guideline inclusion, and real-world performance data therefore become critical complements to regulatory approval, influencing how quickly a new or repositioned product can gain traction in routine practice.
Supply Chain and Cost Structure Considerations
Cost structures across this market are influenced by the interplay of branded exclusivity, generic manufacturing scale, and distribution complexity. Generic producers benefit from established manufacturing pathways and broad distribution networks, enabling competitive pricing and wide geographic reach. Branded players, by contrast, must justify premium positioning through differentiated attributes, patient support programs, or specialized distribution arrangements that add value beyond the molecule itself.
Geographic expansion adds another layer of complexity. Entering regions with varied regulatory requirements, procurement models, and healthcare infrastructure demands flexible commercial strategies. Partnerships that combine local market knowledge with product supply can accelerate adoption, but they also require careful coordination around pricing, access, and quality assurance. As companies pursue growth beyond mature markets, the ability to tailor supply and commercialization models to local conditions becomes a decisive factor in realizing opportunity.
3. Competitive Landscape and Leading Strategies
The competitive field blends large multinational manufacturers with targeted innovators and established generic suppliers. Each group brings a distinct strategic posture, and the interactions among them define the market's evolution.
Strategic Positioning of Leading Participants
Specialized innovators have focused on building defensible niches through single-dose offerings and long-duration exclusivity. One company has leveraged a single-dose oral granule product as the only oral treatment of its kind approved for bacterial vaginosis in patients twelve years and older, supported by multiple Orange Book patent listings that extend protection into the 2040s. This approach combines clinical differentiation with a durable intellectual property foundation, allowing the company to position the product as a streamlined alternative within a market otherwise dominated by multi-day regimens.
Worldwide Postmenopausal Vaginal Atrophy Drugs Market
Another innovator has pursued a parallel path with a single-dose vaginal gel, differentiating on delivery method and convenience while securing global rights through licensing arrangements. By aligning product development with distribution partnerships, this strategy seeks to extend geographic reach and commercial scale without bearing the full burden of in-region infrastructure. Such licensing models can accelerate penetration in new markets while preserving capital for further development and lifecycle management.
Larger diversified manufacturers maintain presence through branded and generic versions of established therapies, using scale, multi-Region supply, and broad formulary relationships to sustain share. These players often compete on availability, cost, and integration with existing procurement channels, while also exploring lifecycle extensions where feasible. Generic specialists contribute additional price competition and regional breadth, reinforcing the market's baseline accessibility and placing pressure on premium-priced alternatives to demonstrate clear differentiation.
Differentiation and Moat-Building Strategies
Across these participants, several strategic themes recur. First, regimen simplification is used not only as a clinical advantage but also as a commercial anchor, helping products stand out in prescribing decisions and patient conversations. Second, patent strategy is deployed to protect not just the molecule but also the method, composition, and specific labeled uses, extending the effective commercial horizon beyond the core compound patent. Third, partnership structures are increasingly important for scaling internationally, with licensing and exclusive distribution agreements enabling faster market entry and shared execution risk.
These strategies are not mutually exclusive. A company can combine a differentiated formulation with robust IP, then extend reach through regional collaborations, creating layers of defensibility that are more durable than any single element alone. The most resilient positions tend to integrate clinical convenience, legal protection, and commercial access in a way that makes substitution less attractive to prescribers and payers alike.
Evolution of the Competitive Structure
The market is moving along a path that blends concentration at the top with ongoing segmentation below. The leading branded innovators capture disproportionate attention and revenue in the near term, especially when exclusivity and differentiation align. At the same time, the broader field remains active with generic alternatives and regional manufacturers that sustain access and price competition. This structure suggests continued differentiation rather than rapid consolidation, with companies competing on convenience, tolerability, coverage, and distribution depth rather than price alone.
New entrants and license-driven expansions are likely to keep pressure on the boundaries of existing franchises. Opportunities will arise for players that can bring credible single-dose or improved-tolerance options into underserved regions, or that can create value through partnership models that combine product assets with local commercialization capability. The market's evolution will therefore be shaped by a mix of lifecycle extension by incumbents and targeted entry by specialists, each leveraging distinct assets and go-to-market strengths.
4. Future Trends and Commercial Opportunities
Projecting the next three to five years requires connecting clinical, regulatory, and commercial signals into coherent trajectories. Several trends are likely to define where value is created and where risk accumulates.
-
Continued emphasis on regimen simplification and adherence-friendly designs. Therapies that reduce dosing frequency or streamline administration are expected to gain further attention as prescribers and patients prioritize convenience and completion. Products that can demonstrate reliable efficacy alongside a simpler regimen will be well positioned to capture share, particularly if supported by favorable tolerability and clear clinical guidance. The commercial opportunity lies in pairing regulatory approval with provider education and patient support to convert structural advantage into habitual use.
-
Geographic expansion into underpenetrated regions. Growth in the forecast period is likely to be supported by increasing access in regions where awareness, diagnostic capacity, and treatment infrastructure are improving. Companies that establish localized distribution, appropriate pricing tiers, and partner ecosystems can convert demographic and epidemiological demand into sustainable revenue. The key risk is execution complexity: varying regulatory requirements, procurement practices, and reimbursement models can slow adoption if not addressed early and with local insight.
-
Lifecycle management through intellectual property and indication breadth. As some products benefit from extended exclusivity, the market will see sustained periods where branded differentiation holds premium positioning. This creates opportunities for companies to invest in real-world evidence, expand labeled uses where scientifically justified, and reinforce prescriber familiarity. The countervailing risk is that overreliance on exclusivity without clinical or commercial differentiation can leave a product vulnerable when competition eventually arrives, especially if generic or alternative branded options gain traction on price or convenience.
These trends point to a market where advantage is constructed rather than simply inherited. The most attractive commercial opportunities will sit at the intersection of clinical convenience, durable protection, and capable execution in target geographies. Conversely, players that depend on a single attribute without supporting evidence, coverage, or distribution may find their position eroded more quickly than anticipated.
5. Actionable Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the board. Clear positioning, disciplined execution, and timely intelligence will separate opportunities that scale from those that stall.
PW Consulting
For Manufacturers and Product Owners
Prioritize differentiation that is clinically meaningful and commercially tangible. A simpler regimen, improved tolerability, or a clearly defined patient population can provide a persuasive basis for preference, but only if it is reinforced through provider education, patient support, and payer engagement. Simultaneously, protect the commercial horizon with a deliberate IP strategy that covers formulation, method, and use where feasible, and evaluate partnership structures that can extend reach without overextending internal resources. Build supply and access models that are adaptable to regional conditions, especially when pursuing growth in markets with distinct procurement and reimbursement dynamics.
For Investors and Capital Allocators
Assess durability of advantage, not just near-term revenue momentum. Exclusivity timelines, the breadth of patent coverage, and the presence of credible alternatives all influence how long a product can sustain premium positioning. Favor opportunities where clinical convenience is paired with execution capability in target regions, and where licensing or distribution agreements create scalable pathways without disproportionate capital risk. Be attentive to the timing of generic entry and to the extent to which a product's differentiation is likely to withstand substitution pressure once protections recede or competing options mature.
For Procurement and Access Stakeholders
Balance cost considerations against total value, including adherence, recurrence risk, and ease of administration. Where multiple options exist within the same class, evaluate not only unit price but also the practical impact of regimen complexity and tolerability on completion and outcomes. Engage early with suppliers on supply reliability, market-specific access terms, and evidence packages that support formulary decisions. A disciplined evaluation framework that incorporates clinical usability and patient experience can improve both cost efficiency and treatment success over time.
The bacterial vaginosis drug market is entering a phase where differentiation, protection, and execution intersect more tightly than in the past. Companies and investors that understand these dynamics in detail, and that align strategy with the realities of prescribing behavior, payer expectations, and regional access, will be better positioned to capture sustainable value. For decision-makers seeking deeper segmentation, region-specific demand patterns, and tailored scenario analysis, a comprehensive research report can provide the granularity needed to translate these strategic insights into concrete planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Bacterial Vaginosis Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Daylight Fluorescent Pigments Market: Why 8.2% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Daylight Fluorescent Pigments Market: Strategic Trends and Commercial Opportunities (2026–2032)
The daylight fluorescent pigments sector has evolved from a specialized color additive into a strategic material class influencing product visibility, brand differentiation, and functional performance across multiple end-use industries. With the total market revenue projected to expand from approximately $465.4 million in 2025 toward $787.5 million by 2032, the segment is on track for a compound annual growth rate of 8.2% over the forecast window. This trajectory reflects more than a simple recovery from prior volatility. It signals a structural shift in how manufacturers, formulators, and product designers approach color engineering, safety signaling, and sustainable material selection.
The market’s recent expansion has been robust but uneven. Revenue moved from $356.11 million in 2020 to $388.01 million in 2022, then accelerated to $422.73 million in 2023 and $429.05 million in 2024. The step-up to $465.4 million in 2025 marks a continued inflection rather than a one-time rebound, with forward estimates reaching $515.12 million in 2026 and $580.19 million in 2028. By 2030, the market is expected to cross the $679.74 million threshold, and the pace of growth suggests sustained upward momentum through 2032. This pattern underlines a market that is gaining commercial relevance in parallel with tighter regulatory expectations and rising performance demands from end customers.
A defining feature of the current landscape is the balance between established scale and technical specialization. Market concentration metrics show that the top three participants command roughly 52% of revenue, while the top five account for about 58%. This indicates a moderately consolidated structure with meaningful room for differentiated mid-tier players, regional specialists, and application-focused innovators. The segment is not yet dominated by a single technology pathway or formulation philosophy. Instead, it is being shaped by competing priorities: color intensity, durability, regulatory compliance, carrier chemistry, and total cost of ownership.
Understanding this market now requires more than tracking shipment volumes or color trends. It requires reading the intersection of chemistry, regulation, application engineering, and procurement behavior. The companies that succeed in the next cycle will be those that can convert performance requirements and compliance pressures into defensible product platforms, not just incremental color variations.
Market Status and Core Challenges
The daylight fluorescent pigments market is moving through a period in which growth is increasingly tied to formulation quality and regulatory readiness rather than raw capacity expansion. Historically, many buyers treated fluorescent pigments as a relatively interchangeable aesthetic input. That assumption is eroding. Buyers in coatings, plastics, inks, and specialty applications are asking for stronger colorfastness, better dispersion behavior, improved stability under heat and light exposure, and formulation compatibility with waterborne or low-emission systems. These expectations are changing the commercial value proposition across the supply chain.
One core challenge is the pressure to reformulate legacy chemistries. Regulatory scrutiny around certain azo-based structures and volatile organic compound profiles is narrowing the acceptable formulation space, particularly in European and North American markets. The result is not simply a compliance exercise. It is a broader redesign effort that touches raw material selection, resin carriers, pigment surface treatment, and downstream application performance. Suppliers that depend heavily on older chemistry pathways face the dual burden of technical redevelopment and customer qualification cycles.
A second challenge is cost volatility embedded in petrochemical-linked inputs. Rising prices for key precursors such as melamine and toluene have increased production costs and squeezed margin flexibility for manufacturers that cannot pass through price adjustments quickly. In a market where performance differentiation is becoming more important, cost pressure is especially disruptive for producers competing primarily on price. It also raises the strategic importance of input hedging, process efficiency, and formulation optimization.
A third challenge is the shifting trade and classification environment. Recent tariff classification rulings for fluorescent pigments from China, effective in mid-2025, add a new layer of complexity to sourcing and pricing strategies. For global formulators and end-product manufacturers, this means that supply continuity, landed cost, and regulatory classification must be evaluated together rather than as separate procurement decisions. The practical consequence is a market in which regional sourcing flexibility and multi-supplier qualification are becoming more valuable than in the past.
These challenges do not suggest stagnation. They point to a market that is being reshaped by technical standards, compliance thresholds, and cost discipline. That reshaping creates winners among companies that treat performance, sustainability, and supply resilience as integrated design goals.
Key Drivers Analysis
Several forces are converging to drive the market’s expansion and change its competitive logic. The most important are technological reformulation, regulatory acceleration, demand-side performance expectations, and supply chain cost dynamics. Each one interacts with the others, so their combined effect is greater than the sum of individual trends.
Technological innovation is moving the market beyond bright color alone. Recent product activity illustrates how formulation science is becoming a strategic differentiator. In March 2025, DayGlo Color Corp introduced an eco-friendly daylight fluorescent pigment series using bio-based raw materials for sustainable applications in packaging and textiles. That launch is significant because it connects sustainability claims with a traditionally performance-driven category. In April 2025, Wanlong Chemical Co., Ltd. showcased its AX Series at a major plastics trade event, emphasizing brilliance and performance for plastics and rubber applications. This points to continued demand for high-impact color in durable and processed substrates. Separately, in September 2025, SINLOIHI launched new pigment formulations for LED-based decorative paints with enhanced colorfastness, addressing a fast-emerging use case where color stability under specialized lighting conditions matters. Radiant Color N.V. also expanded its Resin Centre of Excellence in Belgium in 2025 to increase specialized resin production and R&D for sustainable fluorescent pigments. Taken together, these developments show that innovation is spreading across sustainability, durability, resin technology, and application-specific performance rather than concentrating in a single area.
Fluorescent Lighting Market
Policy and regulatory dynamics are acting as both a constraint and an acceleration mechanism. The European Union’s REACH framework and related environmental regulations are systematically restricting legacy azo-based chemistries and increasingly shaping allowable VOC and resin carrier profiles in synthetic fluorescent pigments. These requirements are not confined to Europe. Regulatory pressure across North America and parts of Asia is also tightening around chemical composition, emissions, and end-use safety. The commercial impact is twofold. First, reformulation cycles are becoming a normal cost of doing business in advanced markets. Second, compliance- ready products are gaining preferential access in applications where customer specifications, brand standards, and export requirements demand lower-risk material profiles. As a result, regulatory readiness is becoming a market-access advantage rather than a purely defensive investment.
Demand-side behavior is changing because end markets are asking for more from color. Fluorescent pigments are increasingly used not only for visual impact but also for safety signaling, brand visibility, product authentication cues, and functional differentiation. In plastics and coatings, there is rising interest in pigments that can survive processing conditions, maintain appearance over time, and remain compatible with more environmentally oriented carrier systems. In inks and decorative applications, performance requirements are tightening around brightness retention and resistance to fading under varied exposure conditions. Even in textiles and sportswear, buyers are looking for brighter, longer-lasting color options that can support both aesthetics and durability. This shift means that value is increasingly determined by how well the pigment functions within the final system, not simply how it looks in isolation.
Supply chain and cost structure changes are reinforcing the need for strategic sourcing. The combination of rising petrochemical-based input costs, evolving trade classifications, and more demanding qualification processes is making supply reliability and formulation consistency more valuable. Manufacturers that can stabilize input risk, improve process efficiency, and offer predictable performance across applications are gaining leverage. At the same time, customers are increasingly willing to pay for outcomes such as reduced rework, better dispersion, lower emissions, and stronger compliance documentation. In this environment, the cost conversation is shifting from unit price alone to total cost across the application lifecycle.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established global specialists and application-oriented regional manufacturers. DayGlo Color Corp, headquartered in Cleveland, Ohio, remains the original and largest manufacturer of daylight fluorescent pigments, serving plastics, coatings, automotive, safety equipment, and consumer products with high-performance pigments, dispersions, inks, toners, and dyes. Its scale and application breadth give it a strong platform for cross-industry reach, and its recent eco-friendly product launch indicates a push toward more sustainable raw material foundations.
Radiant Color N.V., based in Houthalen, Belgium, specializes in high-performance and special-effect fluorescent pigments, dispersions, dyes, and resin technology for industrial, cosmetic, and food-contact applications. Its Belgium resin center expansion reflects a strategy centered on specialized resin development and sustainable pigment engineering, which positions the company as a formulation-focused player rather than a purely volume-driven supplier.
Wanlong Chemical Co., Ltd., located in Ruian, Zhejiang, China, manufactures daylight fluorescent pigments for plastics, rubber, coatings, inks, and textiles, with AX Series and eco-friendly formulations. Its trade presence and product emphasis show a strong commitment to performance-led positioning in plastics and rubber applications, aligning with demand in durable goods and processed materials.
Sinloihi Co., Ltd. in Japan produces ultra-bright durable fluorescent pigments for coatings, inks, and textiles, and has recently moved into LED-based decorative paint formulations with enhanced colorfastness. Its direction suggests an increasing focus on lighting-conditioned decorative applications and long-term appearance retention. Other players such as Aron Universal Ltd. in India and LuminoChem Ltd. illustrate the growing importance of specialized roles, including sportswear and fashion applications, aqueous system compatibility, and high-temperature industrial use. Huangshan Jiajia Fluorescent Material Co., Ltd. further reflects ongoing capacity expansion for packaging and textile colorants in China. These companies do not all compete on the same axis. Some differentiate through application depth, some through resin and carrier technology, and others through regional manufacturing agility.
PW Consulting
The market structure is evolving in ways that favor both consolidation and targeted differentiation. Concentration at the top suggests that scale, brand recognition, and application breadth remain important, but the moderate level of concentration also leaves space for specialists that can deliver unique performance profiles or sustainable formulations. The more probable trajectory is not a simple shakeout but a layered market in which global leaders occupy broad application space while regional and specialty players capture niche demand through technology, compliance readiness, or local manufacturing advantage.
A key strategic question for leading firms is how to balance scale, innovation, and regional exposure. The most effective positioning appears to combine three elements: durable performance claims that survive real application conditions; compliance-forward formulations that reduce customer friction in regulated markets; and supply flexibility that helps customers manage cost and classification risk. Companies that rely on a single strength, such as brightness alone or low price alone, face greater exposure as purchase criteria widen. Companies that can offer integrated value across chemistry, performance, and sustainability are better placed to influence specification decisions.
Future Trends Forecast
Looking across the 2026 to 2032 window, three trends are likely to shape the market’s next phase.
The first trend is the mainstreaming of sustainable reformulation. As regulatory expectations continue to tighten and customer sustainability programs become more operational, bio-based inputs, lower-impact carriers, and reformulated pigment systems will move from early-adopter status toward broader commercial expectations. This does not mean every application will switch at the same pace. It does mean that sustainability will increasingly function as a qualification criterion in coatings, packaging, textiles, and industrial applications. Suppliers that build credible sustainable platforms early will have an easier path into specification lists, particularly in brands and industries with public material goals.
The second trend is performance-led specialization by application. Demand will continue to fragment by use case requirements: color stability in LED environments, heat resistance in processing-intensive plastics, dispersion quality in coatings, and durability in textiles and safety gear. This favors companies that can tailor pigment systems to specific processing and exposure conditions rather than sell a generic color additive. Over time, application-specific performance will become a more efficient way to compete than broad claims of brightness alone.
The third trend is supply chain reconfiguration. Trade classifications, input cost variability, and regulatory divergence across regions will push buyers toward more diversified sourcing strategies, stronger supplier qualification, and greater attention to landed cost and compliance documentation. For manufacturers, this means regional capability, responsive technical support, and predictable batch consistency will matter more than before. For buyers, it means that dual sourcing and prequalified alternative formulations will become standard risk management tools.
These trends create commercial opportunities, but they are not risk-free. One uncertainty is the speed and uniformity of regulatory adoption across regions. If compliance expectations diverge sharply, suppliers may need to maintain multiple formulation pathways, increasing complexity and cost. Another risk is raw material cost volatility, which can compress margins if pricing power is limited. A third risk is the possibility that sustainability claims outpace verifiable technical performance, creating credibility gaps with demanding end users. The market will reward companies that can align sustainability, performance, and cost discipline rather than treat them as separate priorities.
Actionable Recommendations for Decision-Makers
For manufacturers and formulators, the most valuable move is to treat reformulation and performance optimization as market-access investments rather than cost centers. Building compliance-ready and application-validated pigment platforms now can shorten customer qualification cycles later. It is also prudent to strengthen technical service capability around dispersion, processing stability, and LED or lighting-specific performance, since these are increasingly part of the purchasing conversation. Where possible, manufacturers should diversify input sourcing and evaluate carrier alternatives that reduce exposure to petrochemical-linked cost volatility while maintaining performance consistency.
Phosphorescent Pigments Market
For investors and corporate development teams, the strategic signal is that value creation is shifting toward companies with defensible formulation assets, strong application reach, and credible sustainability narratives. Scale still matters, but it is no longer sufficient by itself. Due diligence should focus on whether a company’s technology pipeline can support next-generation regulatory expectations, whether its product portfolio aligns with high-growth application segments, and whether its cost structure can withstand input price fluctuations. Capacity expansion alone is a weaker signal than the ability to bring differentiated, compliant, and stable products to market repeatedly.
For procurement and sourcing leaders, the priority is to move beyond unit price comparisons and evaluate total application risk. That includes assessing formulation compatibility, regulatory status in target markets, colorfastness and durability performance, and supplier resilience under changing trade classifications. Pre-qualifying alternative suppliers and maintaining a short list of compliant formulations can reduce exposure to tariff, cost, and supply disruption risks. Buyers should also consider how pigment performance affects downstream outcomes such as rework, appearance retention, and compliance documentation, since these can materially change total cost over the product lifecycle.
In a market expanding at a steady pace toward 2032, the most important differentiator will be how well companies convert technical, regulatory, and cost pressures into practical advantage.
Download the Full Strategic Report
For a deeper view of market sizing, segmentation breakdowns, regional context, and company-level dynamics, the complete PW Consulting report provides additional detail and customized analysis for specific strategic decisions. The full study can be used to support specification planning, sourcing strategy, investment evaluation, and competitive positioning with more granular data than the overview above.
For detailed analysis of this topic, please visit the official page: Daylight Fluorescent Pigments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Underfill Market to Hit $945M by 2032: 5 Shifts Reshaping the $517M Base
By PW Consulting, 2026-09-21
The Underfill Market: Strategic Trends and Commercial Opportunities Beyond the Numbers
The underfill market has evolved from a niche materials segment into a critical enabler of advanced semiconductor packaging, driven by the relentless scaling of computing performance and the structural vulnerabilities of miniaturized interconnects. As of the base year 2025, the total addressable market for underfill solutions stands at approximately 516.72 million USD, building on a compound annual growth trajectory that has propelled revenue from 335.83 million USD in 2020 to a projected 944.58 million USD by 2032. This expansion reflects a 9.0 percent CAGR across the forecast window, a pace that outstrips broader electronic materials growth and signals a structural shift rather than a cyclical upturn. The market’s maturation is tempered by a moderate concentration profile, with the top three players commanding roughly 45 percent of revenue and the top five reaching about 55 percent, leaving meaningful whitespace for differentiated formulators and regional specialists.
Across the forecast horizon extending through 2032, the revenue curve steepens as advanced packaging adoption accelerates and form factor constraints force more aggressive underfill integration. The growth is not uniformly distributed; it is concentrated where thermal stress, mechanical reliability, and miniaturization intersect—environments that increasingly demand faster flow profiles, rework-compatible chemistries, and selective thermal or optical properties. For executives and capital allocators, the underfill market now operates as a strategic input layer where material choices directly influence yield, board-level reliability, and total cost of ownership in high-value assemblies.
Tube Filler Market
Key Challenges and Inflection Points Shaping the Market
Despite robust demand tailwinds, the underfill sector faces a set of interconnected challenges that will separate resilient players from those caught in margin compression. First, feedstock volatility has moved from an intermittent nuisance to a structural cost pressure. Epichlorohydrin supply disruptions, combined with freight surcharges, have pushed spot epoxy prices to multi-year highs, crimping gross margins for smaller formulators and forcing tougher sourcing and pricing decisions across the value chain. This pressure is especially acute for producers who lack backward integration or long-term offtake agreements, as raw material swings can quickly erase the pricing power that technical differentiation normally provides.
Second, regulatory scrutiny is reshaping formulation roadmaps and trade flows simultaneously. Environmental mandates in key markets are accelerating the phase-down of hazardous constituents in electronic materials, pushing developers toward compliant chemistries that must still meet stringent mechanical and thermal targets. At the same time, trade actions—including anti-dumping investigations and duties on epoxy resins in several jurisdictions—have recalibrated regional supply dynamics, with knock-on effects on availability and pricing for downstream underfill producers. The net effect is a market where compliance and sourcing resilience are now procurement criteria, not afterthoughts.
Third, application requirements are fragmenting faster than traditional product lines can accommodate. The underfill universe spans capillary, no-flow, molded, and specialty variants, each with distinct process windows and property demands. High-performance computing, silicon photonics, and sensor-dense modules increasingly require materials that balance mechanical protection with thermal management or optical clarity, often within tighter tolerances and higher throughput expectations. Suppliers that treat these as variations of a single offering risk falling behind formulators who design for specific application envelopes and reliability profiles.
Core Drivers Reshaping Demand and Competitive Dynamics
Technological innovation continues to be the most visible driver. Advances in advanced packaging architectures have expanded the envelope of where underfills are deployed, from conventional flip-chip assemblies to ball grid array configurations and chip scale packaging approaches that push device density and thermal flux. In parallel, formulation science has progressed toward faster flow characteristics, lower stress profiles, and targeted enhancements such as thermal conductivity or optical transparency. These are not incremental tweaks; they are responses to reliability requirements at the edge of thermal-mechanical limits, where underfill performance directly affects lifecycle durability and rework economics. Recent product introductions illustrate this trajectory: capillary-grade epoxy systems optimized for complex AI and high-performance computing large-body packages, no-flow and molded variants tuned to reduce voids and residual stress, and specialized underfills engineered for silicon photonics, image sensors, and AR/VR modules where optical clarity and low stress are non-negotiable.
Policy and regulatory developments are accelerating formulation shifts even as they introduce trade uncertainty. Environmental directives targeting hazardous substances in electronic components are compelling formulators to develop compliant chemistries without sacrificing flow, adhesion, or thermal performance. Concurrently, trade measures on epoxy resins—investigations, duty impositions, and sharp declines in certain import flows—have reshaped regional availability and pricing. These forces create a bifurcated environment: manufacturers in regions with stable feedstock access and aligned regulatory timelines gain a cost and continuity advantage, while others must invest in supply diversification, alternative chemistries, or localized production footprints to protect delivery and margin.
Demand-side behavior is also changing the growth equation. End-equipment manufacturers are increasingly connecting underfill selection to system-level reliability, rework flexibility, and lifecycle cost rather than treating it as a commodity input. As devices become denser and environments harsher—think edge AI hardware, automotive-grade electronics, and sensor-laden modules—procurement and engineering teams evaluate underfill options through the lens of risk reduction and assembly efficiency. This is evident in the growing emphasis on materials that support faster processing, lower void rates, improved vibration resistance, and thermal-shock endurance, especially in aerospace-grade and MEMS-adjacent applications where failure modes are costly.
Supply chain and cost structure dynamics further amplify these trends. With certain epoxy feedstocks experiencing multi-year price highs and regional trade flows constrained, the cost of underfill is less a function of volume alone and more a function of feedstock strategy, formulation efficiency, and process compatibility. Formulators that can balance performance with throughput, enable rework where needed, and reduce downstream defects gain levers to protect margins even in a higher input-cost environment. Meanwhile, demand for specialty grades—such as thermally conductive, nano-filled, or optically clear formulations—creates pockets of pricing resilience that are less exposed to commodity epoxy swings.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The market’s competitive architecture reflects a blend of established global formulators and specialized specialists, each pursuing distinct routes to defensibility. Henkel has leaned into performance leadership for advanced packaging, offering epoxy underfill systems designed for capillary flow and complex AI/HPC package geometries, with an emphasis on flow behavior and reliability under demanding conditions. NAMICS focuses on flip-chip and capillary underfills with stress-optimized formulations, targeting applications where mechanical robustness and thermal cycling performance are central to field reliability.
In the high-reliability assembly segment, H.B. Fuller positions around epoxy underfills for PCB assembly and flip-chip/BGA/WLCSP applications, emphasizing fast flow, reworkability, and structural reinforcement—an approach that aligns with manufacturers seeking to balance throughput with repair economics. Parker LORD contributes thermoset epoxy options for densely populated flip-chip and advanced encapsulation, with formulations aimed at compatibility and process reliability. Epoxy Technology has carved a niche with optically clear, low-stress underfill formulations suitable for flip-chip, potting, and encapsulation, addressing applications where transparency and stress control are critical. Master Bond extends into thermally conductive and nano-filled epoxy underfills, emphasizing vibration and thermal-shock resilience for electronics and MEMS devices, an angle that maps well to ruggedized assemblies. YINCAE has expanded a product family spanning optical-clear and high-conductivity underfills, including releases targeting large chips, silicon photonics, and advanced packaging with improved thermal dissipation.
The strategic differentiation across these players clusters around three axes: application-centric formulation, processing economics, and reliability tailoring. Application-centric players design chemistries for specific package types and use cases, such as optical modules or heat-dense advanced packages. Process-oriented players optimize for flow speed, void reduction, and rework compatibility to reduce total assembly cost. Reliability-oriented players engineer for stress, thermal-shock, and vibration performance in environments where failure is expensive. The strongest portfolios combine two or more of these axes, but few compete equally across all of them, leaving room for focused specialists to capture value in high-demand niches.
Market structure is evolving along two parallel paths. Consolidation pressure is rising where scale in formulation, sourcing, and global distribution confers cost and continuity advantages, especially in a high-feedstock-cost environment. At the same time, differentiation is intensifying as application requirements bifurcate—advanced packaging, silicon photonics, sensors, and ruggedized electronics each pull material development in different directions. This creates an opening for new entrants and regional specialists who can move quickly on targeted form factors, localized supply relationships, or compliance-forward chemistries, even as larger incumbents defend share through breadth and process integration. Recent product launches—capillary systems for large-body AI packages, optical-clear underfills for photonics and imaging modules, and thermally conductive variants for heat management—underscore how fast the competitive frontier is moving and how product timing increasingly matters as much as technical merit.
Forward Outlook: Three Trends That Will Define the Next 3 to 5 Years
The first trend is the deepening integration of underfill selection into advanced packaging roadmaps. As package architectures become more heterogeneous and thermal-mechanical loads increase, underfill will be specified earlier in design cycles, with property targets tied to specific board-level and system-level reliability goals. This will favor suppliers that can translate application requirements into formulation choices rapidly and can support validation with consistent process performance. Commercial opportunity lies in co-development models, application-specific grades, and technical support that reduces qualification time for OEMs and contract assemblers.
The second trend is the widening value gap between commodity and specialty underfills. Commodity-grade capillary and no-flow products will remain volume drivers, but the fastest margin recovery and stickier customer relationships will accrue to formulations with targeted thermal, optical, or mechanical properties—particularly where reworkability, low void content, and vibration or thermal-shock resilience directly reduce downstream cost. Companies that can protect feedstock costs while delivering these attributes will command pricing resilience even as spot epoxy prices fluctuate. Opportunity resides in building lines that balance throughput with differentiation, and in aligning product portfolios with high-growth applications such as AI/HPC packaging and photonics-enabled modules.
The third trend is the recalibration of regional supply and regulatory alignment. With trade measures and environmental mandates shaping availability and formulation priorities, regional continuity and compliance readiness will become competitive differentiators. Manufacturers that secure feedstock diversity, anticipate regulatory shifts, and localize where trade dynamics warrant will reduce delivery risk and margin volatility. The opportunity is to structure supply and product strategy around regional demand profiles and compliance timelines, while avoiding over-reliance on single-source inputs that are exposed to trade or logistics shocks. The principal risk here is timing: if trade enforcement or feedstock constraints tighten faster than regional alternatives scale, short-term availability and cost pressure could disrupt qualifying processes and delay program ramps.
Strategic Implications by Stakeholder
For packaging manufacturers and device assemblers, the priority is to treat underfill selection as a reliability and cost lever rather than a commodity line item. That means mapping application envelopes—thermal flux, mechanical stress, optical requirements, rework needs—to formulation properties, and qualifying materials that reduce voids, accelerate process flow, and improve field durability. It also means stress-testing feedstock continuity and trade exposure in the supply base, since margin protection increasingly depends on sourcing strategy as much as on volume discounts.
PW Consulting
For investors, the opportunity is concentrated in differentiated formulators and application-focused specialists that can capture margin resilience in specialty grades while managing feedstock and trade risk. Favor companies with clear application alignment, process-efficient chemistries, and the ability to support validation quickly. Caution is warranted where portfolios are overly exposed to commodity epoxy swings without offsetting differentiation, or where regional supply is tightly coupled to trade-sensitive feedstocks. The market’s growth profile supports participation, but returns will accrue to those who combine technical focus with supply resilience.
For procurement and supply chain leaders, the mandate is to expand qualification beyond price-per-kilogram and ensure continuity under shifting trade and regulatory conditions. Diversify qualified sources, build scenario plans for feedstock volatility, and include compliance readiness in sourcing criteria. Where possible, align with suppliers who can provide application-specific support, consistent quality, and transparent feedstock strategies, reducing the chance that a single disruption cascades into qualification delays or cost overruns.
Worldwide Underfill Dispenser Market
The underfill market is entering a phase where technical fit, supply resilience, and application timing determine competitive advantage more than volume alone. For decision-makers seeking deeper segmentation, company-specific benchmarks, and tailored sourcing or investment scenarios, a comprehensive research study can translate these trends into actionable plans for specific product lines, regions, and customer segments.
For detailed analysis of this topic, please visit the official page: Underfill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dairy Packaging Market 2026: Why 4.89% CAGR and Plastic Dominance Reshape the Industry
By PW Consulting, 2026-09-21
Dairy Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global dairy packaging market has demonstrated steady expansion over the past half-decade, moving from approximately USD 18.48 billion in 2020 to an estimated USD 23.68 billion in 2025. This growth trajectory reflects a compound annual growth rate of 4.89 percent across the historical period, with the market projected to reach USD 33.17 billion by 2032. The expansion is not uniform across geographies or material categories, but rather reflects a complex interplay of regional demand patterns, material preferences, and packaging format adoption. North America and Europe continue to represent the largest revenue pools, while Asia Pacific has emerged as a highly dynamic growth region, driven by rising dairy consumption, developing cold-chain infrastructure, and shifting retail formats.
Despite the positive top-line momentum, the sector is confronting several structural challenges that are reshaping competitive dynamics. First, regulatory pressure around recycled content and packaging waste is accelerating across multiple jurisdictions, forcing manufacturers to redesign portfolios ahead of compliance deadlines. Second, input cost volatility and raw material availability are compressing margins, particularly for plastic-based solutions where resin pricing and circular feedstock access remain uneven. Third, the market is experiencing a functional divergence between traditional aseptic and ambient-stable formats versus fresh and chilled dairy packaging, each requiring distinct material performance, barrier properties, and supply chain capabilities. These overlapping pressures mean that scale alone is no longer a sufficient competitive moat; packaging suppliers must simultaneously manage sustainability compliance, line-speed compatibility, and regional demand nuances.
A further complication lies in market concentration. The top three participants account for roughly 28.5 percent of total market value, while the top five hold approximately 35.2 percent. This fragmentation suggests that while leading suppliers command meaningful share, a substantial portion of revenue is distributed across regional specialists, material providers, and niche format manufacturers. For procurement leaders and investors, this concentration profile signals both competitive optionality and the need for careful supplier evaluation, as performance differences in barrier technology, recyclability, and regional compliance readiness can materially affect total cost of ownership.
Key Demand Drivers
Technology Innovation and Barrier Performance
Material and format innovation remains one of the most consequential drivers of market evolution. Suppliers are increasingly engineering cartons, films, and rigid containers that reduce or eliminate aluminum barriers, integrate higher recycled content, and maintain aseptic or high-barrier performance for sensitive dairy products. Recent commercial deployments illustrate this direction: SIG Combibloc introduced an alu-free aseptic carton system for milk in Slovenia, combining a full-barrier design with reduced material complexity. In parallel, paper-based barrier cartons have been extended to high-speed production lines, with early deployment in Asia for soy milk applications. These developments reflect a broader industry shift toward formats that balance shelf-life requirements with recyclability and material simplification. For dairy processors, the practical implication is a widening set of packaging options that can align with sustainability targets without sacrificing operational efficiency, provided that line compatibility and sealing performance are validated early in the qualification process.
Innovation is also visible in flexible and rigid plastic solutions. High-performance butter wraps and specialized film structures have expanded the functional envelope for dairy subsegments that require moisture, oxygen, and aroma barriers under chilled or ambient conditions. At the resin level, polymer suppliers are increasingly emphasizing recycled and bio-attributed grades for dairy cups, trays, and films, responding to both regulatory mandates and brand-owner commitments. The strategic takeaway is that packaging performance is no longer defined solely by barrier integrity or fill-speed compatibility; it now encompasses material provenance, end-of-life pathways, and compliance with emerging recycled-content thresholds.
Policy and Regulatory Environment
Regulatory momentum is a defining driver of packaging decisions in the dairy sector. In the United States, Washington State has established a stepped recycled-content requirement for plastic dairy milk containers, beginning at 15 percent post-consumer recycled content in 2028, rising to 25 percent by 2031, and reaching 50 percent by 2036. California's SB 54, which entered into force in May 2026, imposes minimum recycled content requirements on single-use dairy packaging and reinforces producer responsibility obligations. At the same time, seven U.S. states have implemented Extended Producer Responsibility programs that include specific mandates tied to dairy containers, adding operational complexity for multi-state processors and packagers.
In Europe, the Packaging and Packaging Waste Regulation entered into force in February 2025, with general application beginning in August 2026, and sets minimum recycled content targets for plastic packaging from 2030 onward. These regulatory layers are not isolated administrative requirements; they are reshaping sourcing strategies, material selection, and supplier qualification criteria. Dairy brands operating across regions must now navigate a patchwork of deadlines, recycled-content thresholds, and reporting obligations. For packaging suppliers, the opportunity lies in offering materials and formats that are pre-aligned with these requirements, reducing the compliance burden for dairy customers while creating defensible differentiation in regulated markets.
Consumer and Buyer Behavior
Demand-side changes are reinforcing the sustainability and functionality agenda. Retailers and foodservice operators are increasingly specifying packaging that supports recycled-content claims, reduces material complexity, and aligns with broader corporate sustainability commitments. Consumers, in turn, are responding favorably to packaging that communicates responsible sourcing and recyclability, particularly in categories such as fluid milk, yogurt, and plant-based dairy alternatives where brand positioning often hinges on health and environmental attributes. This behavior does not automatically translate into premium pricing, but it does influence shelf allocation, private-label specifications, and tender criteria, especially among large retail chains and regional distributors.
Worldwide Dairy Logistics Market
At the same time, dairy consumption patterns are diversifying. Fresh and chilled categories continue to grow in many markets, while ambient and shelf-stable formats remain important for distribution efficiency and export reach. Plant-based dairy alternatives are also expanding the addressable market for cartons, pouches, and bottles designed for liquid foods with varying viscosity and acidity profiles. The combined effect is a more segmented demand environment in which packaging suppliers must demonstrate flexibility across formats, line speeds, and application requirements rather than relying on a single standardized solution.
Supply Chain and Cost Structure
Cost structure and supply chain resilience are increasingly central to packaging strategy. Resin availability, recycled feedstock supply, and energy inputs all influence the economics of dairy packaging, and regional disparities in circular infrastructure can create uneven access to compliant materials. Suppliers with integrated film extrusion, resin production, or regional conversion capacity are better positioned to manage these variables, but even they must contend with line-speed requirements, changeover efficiency, and qualification timelines when introducing new materials or barrier designs. For dairy processors, the cost conversation is shifting from unit price toward total cost of ownership, including compliance risk, line performance, spoilage reduction, and downstream recyclability. This reframing favors suppliers that can provide documented material provenance, consistent quality across batches, and clear roadmaps for meeting future recycled-content thresholds.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global packaging systems providers, flexible and rigid material specialists, and resin suppliers that enable downstream packaging performance. Tetra Pak and SIG Combibloc remain prominent in aseptic carton and pouch systems for liquid dairy, with positioning that emphasizes barrier performance, line compatibility, and increasingly, material reduction and recycled-content roadmaps. Elopak focuses on gable-top cartons for dairy, juice, and plant-based beverages, with recent expansion into U.S. production capacity for sustainable carton formats. Amcor and Berry Global bring broad flexible-film and rigid-plastic capabilities, respectively, with product portfolios that span dairy films, bottles, tubs, and closures. Huhtamaki contributes paperboard cartons and plastic trays for dairy applications, while Winpak and ProAmpac emphasize flexible pouches, films, and high-performance wraps for fluid dairy and cheese products. Alfipa specializes in PET bottles and closures for dairy and yogurt, and INEOS Styrolution supplies recycled and bio-attributed polystyrene for dairy cups and trays, including recent sour cream cup launches with recycled content for German retail.
The strategic differentiation among these players is less about presence in every category and more about depth in specific performance niches. Leading carton and aseptic system providers are investing in aluminum-free and paper-based barrier options that can be deployed on high-speed lines, reducing material complexity while preserving shelf-life performance. Flexible packaging specialists are expanding high-barrier film structures and butter wraps that address moisture, oxygen, and aroma challenges with narrower material footprints. Resin suppliers are positioning recycled and bio-attributed grades as enablers for compliance and brand claims, effectively embedding themselves earlier in the value chain. This pattern suggests a market in which value is increasingly captured by suppliers that can combine technical reliability, documented sustainability attributes, and regional compliance readiness.
Luxury Packaging Market
Market evolution is likely to feature both consolidation and differentiation. Larger multi-material suppliers may pursue bolt-on capabilities that broaden their format coverage or strengthen regional production footprints, while regional specialists can thrive by serving localized compliance requirements, specific dairy subsegments, or niche format needs. New entrants and niche players may find opportunity in recycled-content resins, mono-material designs, and format simplification, particularly where regulatory deadlines create near-term demand for compliant alternatives. For procurement teams, the practical implication is to evaluate suppliers not only on current pricing and capacity, but also on their ability to meet upcoming recycled-content mandates, support line-speed requirements, and provide transparent material documentation across regions.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the mainstreaming of reduced-material and aluminum-free barrier formats for dairy packaging. As high-speed line compatibility improves and commercial deployments expand beyond early adopters, these formats can become viable options for a broader set of fluid milk and liquid dairy applications. The commercial opportunity lies in offering processors a path to simplify material streams, improve recyclability perception, and align with retailer and regulatory expectations without sacrificing operational performance. Suppliers that can demonstrate reliable sealing, barrier durability, and compatibility with existing or upgraded filling lines will be well positioned to capture demand during this transition.
A second trend is the accelerating alignment of packaging portfolios with recycled-content mandates and Extended Producer Responsibility obligations. As deadlines approach in the United States and Europe, dairy brands and packagers will increasingly prioritize materials with documented recycled content, traceable sourcing, and clear compliance roadmaps. This creates opportunities for resin producers, film extruders, and converters that can supply consistent recycled or bio-attributed grades at scale, as well as for packaging systems providers that can integrate these materials into certified formats. The related risk is supply concentration: recycled feedstocks and compliant resins may remain constrained in certain regions, leading to price volatility or qualification bottlenecks if demand surges ahead of infrastructure build-out.
A third trend is the continued segmentation of dairy packaging by consumption channel and product type. Fresh and chilled categories will place greater emphasis on cold-chain compatibility, moisture resistance, and convenience features, while ambient and export-oriented products will continue to value aseptic stability, light protection, and extended shelf life. Plant-based dairy and hybrid beverages will further expand demand for cartons, pouches, and bottles designed for varied rheology and acidity. The commercial opportunity here is format specialization: suppliers that can tailor barrier properties, opening systems, and fill-speed performance to specific subcategories can command stronger positioning than those offering generic solutions. The uncertainty is that channel growth may diverge by region, and regulatory or retail specifications may shift faster than packaging qualification cycles, requiring suppliers and processors to maintain agile development pipelines.
Underlying these trends is the persistent challenge of balancing performance, cost, and compliance. Innovations that reduce material complexity or increase recycled content must still meet barrier, hygiene, and line-speed requirements. Regulatory progress may accelerate demand for compliant materials, but uneven regional infrastructure can create short-term constraints. Consumer and retailer preferences may favor sustainability claims, yet price sensitivity in private-label and commodity dairy segments can limit willingness to pay. Navigating this environment will require disciplined portfolio planning, early supplier engagement, and a clear understanding of which packaging attributes truly influence commercial outcomes in each market.
Strategic Recommendations for Decision Makers
For dairy manufacturers and brand owners, the priority is to align packaging strategy with near-term regulatory deadlines and long-term material goals without disrupting line performance. This means qualifying reduced-barrier, aluminum-free, and higher-recycled-content options early, validating compatibility with existing filling lines, and mapping compliance requirements across the regions where products are sold. Procurement teams should request documented material provenance, recycled-content consistency, and clear roadmaps for meeting future thresholds, treating these attributes as part of total cost of ownership rather than optional enhancements. Where possible, companies should prioritize suppliers that can support multiple formats or provide transitional solutions that bridge current performance needs and future compliance targets.
For packaging manufacturers and material suppliers, the strategic opportunity lies in building defensible differentiation through technical reliability and compliance readiness. Investing in high-speed line compatibility for sustainable formats, expanding recycled and bio-attributed material options, and strengthening regional production or qualification capabilities can create meaningful advantage in a fragmented market. Suppliers should also consider how to communicate performance and compliance clearly to dairy customers, since documentation, repeatability, and transition support are increasingly decisive in tender evaluations. In a market where the top five participants account for just over a third of total value, focused strength in a specific format, material, or region can be a durable positioning strategy.
For investors and strategic planners, the market presents a profile of steady growth with selective pockets of faster value creation. Revenue is expanding at a mid-single-digit pace, but the most attractive opportunities are concentrated in sustainable barrier innovation, recycled-content supply chains, and format specialization aligned with regulatory and retail demand. Due diligence should therefore focus on a supplier's ability to meet upcoming mandates, its exposure to regional compliance risk, its line-speed and barrier performance track record, and its access to compliant feedstocks. Portfolio exposure should be evaluated not only by current revenue share, but by the company's positioning relative to the regulatory and technology shifts that will shape purchase decisions through 2032. For decision makers seeking deeper segmentation data, regional breakdowns, and tailored scenario planning, the full PW Consulting dairy packaging research report provides the detailed granularity needed to translate these trends into precise commercial actions.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nanodiamond Powder Market CAGR 7.62%: Beyond Growth to Strategic Shifts
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Detonation Synthesis Nanodiamond Powder Market
Market Current State and Core Challenges
The detonation synthesis nanodiamond powder market has transitioned from a niche advanced materials segment into a commercially significant industry, underpinned by a consistent revenue trajectory across the historical period through 2025 and a projected expansion phase extending to 2032. The market has demonstrated compound annual growth that reflects steady industrial adoption, with valuation milestones crossing into higher hundred-million-dollar territory in recent years and maintaining momentum across the forecast window. This trajectory signals maturation rather than speculative hype, anchored by recurring demand from precision manufacturing, surface engineering, and industrial lubricant applications.
Commercial scaling, however, encounters structural friction. First, production consistency at the nanoscale remains a persistent bottleneck. Detonation synthesis inherently yields particles with variable size distributions, surface functionalization profiles, and residual impurity levels. Batch-to-batch reproducibility directly influences downstream performance in high-tolerance applications, forcing manufacturers to invest heavily in post-synthesis classification, purification, and surface engineering. Second, regulatory and compliance frameworks are tightening across key end markets. Evolving safety, environmental, and quality standards for nanomaterials are reshaping procurement requirements and documentation expectations. In parallel, stricter characterization mandates in European markets have raised operational complexity for suppliers seeking to maintain access to regulated sectors. Third, geopolitical and security dynamics are constraining the transnational movement of explosive-related materials essential to detonation-based synthesis. This supply-side friction forces regionalization of certain production steps, increases logistics overhead, and compels manufacturers to redesign sourcing and inventory strategies around fragmented regulatory boundaries.
PW Consulting
Together, these forces define the market's current inflection point: demand is broadening, but the path to reliable, compliant, and cost-efficient scaling is narrowing into a more disciplined operating environment where technical quality, documentation rigor, and supply resilience carry as much commercial weight as base material pricing.
CVD Diamond Market
Key Drivers of Market Change
Technological Innovation and Material Engineering
Advancements in surface functionalization, particle classification, and dispersion stabilization are reshaping the commercial value of detonation synthesis nanodiamond powder. As end users demand repeatable performance in polishing slurries, lubricant formulations, and composite matrices, suppliers are moving beyond commodity-grade powders toward engineered variants with tailored surface chemistry and controlled agglomeration behavior. This shift increases the technical barriers to entry but also expands margin potential for producers capable of delivering application-specific material profiles. The emphasis on functional consistency is particularly relevant where nanodiamonds interact with sensitive substrates, advanced coatings, or high-performance mechanical interfaces, making precision and reproducibility key commercial differentiators rather than optional enhancements.
Policy and Regulatory Environment
Regulatory consolidation is simultaneously creating trust and adding operational cost. The establishment of clearer safety, environmental, and quality expectations for nanodiamond materials is fostering broader industrial integration, especially in biomedical and aerospace-adjacent applications where material integrity and traceability are non-negotiable. At the same time, the cost of compliance is rising in certain jurisdictions, particularly where nanomaterial characterization and safety documentation requirements have become more demanding. Manufacturers that proactively align production, testing, and documentation practices with emerging expectations are better positioned to secure long-term supply agreements, while those lagging behind face growing friction in regulated procurement cycles. Potential future restrictions on production processes or workplace exposure limits could further reshape operating economics, making early regulatory readiness a strategic asset rather than a reactive expense.
Alongside domestic regulatory shifts, transnational trade constraints are altering sourcing logic. Security-related controls on explosive-related materials used in detonation synthesis increasingly complicate cross-border movement, forcing companies to evaluate regional production footprints, inventory buffering, and localized processing options. This dynamic favors organizations with flexible supply architectures and discourages over-reliance on single-geography synthesis routes.
Demand-Side Shifts in Industrial and High-Performance Applications
Demand is increasingly driven by performance optimization rather than cost substitution alone. In precision polishing compositions, the push for finer surface finishes, reduced tool wear, and consistent removal rates is reinforcing interest in nanoscale diamond additives that deliver predictable cutting and abrasion behavior. In lubricant and tribological applications, buyers are evaluating nanodiamond additives for potential improvements in friction management, wear reduction, and thermal stability under demanding operating conditions. Composite material developers are also exploring nanodiamond incorporation as a route to enhance mechanical, thermal, or functional properties, though adoption often depends on dispersion quality and compatibility with matrix systems. Across these demand segments, the purchasing criterion is shifting from bulk availability toward verified performance, lot consistency, and technical support capability.
Supply Chain and Cost Structure Evolution
The cost structure of detonation synthesis nanodiamond powder is increasingly shaped by energy intensity, purification requirements, and compliance overhead rather than raw input pricing alone. Energy consumption during synthesis and downstream processing, combined with the need for classification and surface treatment, positions manufacturing as a process-heavy activity where margin protection depends on throughput efficiency and yield control. Supply chain resilience has also become a cost and continuity factor. With certain inputs and intermediate materials subject to trade and security constraints, companies are investing in buffer inventories, multi-source procurement, and regional processing networks to reduce disruption risk. This transition favors suppliers that can demonstrate stable lead times, controlled quality, and transparent documentation, especially for customers operating under strict procurement or qualification timelines.
Competitive Landscape and Leading Strategies
The market remains relatively fragmented at the top, with a limited group of established players holding meaningful but not dominant share. This structure creates room for differentiation through product quality, application engineering, regulatory readiness, and customer intimacy rather than scale alone. Companies that treat nanodiamond powder as an engineered material solution, rather than a standardized commodity, tend to build more durable commercial relationships and defend pricing more effectively in mature application categories.
Adámas Nanotechnologies, based in Virginia, USA, has positioned itself around application-tailored offerings that emphasize controlled particle characteristics and customer-specific material support. Its commercial relevance rests on the ability to translate synthesis output into reproducible material formats suited to precision use cases, where buyers value technical consistency and collaborative problem-solving. Carbodeon Ltd. Oy, operating from Finland, has built recognition around specialized functional materials and surface-engineered nanodiamond products, with a strong orientation toward high-performance industrial and technology-facing applications. Its differentiation often centers on material functionality, purity control, and the ability to meet demanding specification thresholds.
Synthetic Diamond Grit Market
Ray Techniques Ltd., based in Israel, has pursued a focused approach tied to advanced nanodiamond solutions and specialized production know-how. In a market where end-user qualification cycles can be lengthy, companies with clear process expertise and the ability to document material behavior gain an advantage in sectors where performance proof carries substantial weight. PlasmaChem GmbH, from Germany, contributes to the competitive field through a materials science orientation that appeals to buyers seeking reliable functional powders and well-defined product attributes. Its positioning reflects a broader European emphasis on documentation, specification discipline, and application readiness. Advanced Abrasives Corporation, in the USA, represents the industrial-grade side of the landscape, where commercial strength is linked to integration with abrasive and surface-treatment applications, supply reliability, and knowledge of downstream processing requirements.
Strategically, leading players generally differentiate along three axes: material consistency and specification control, application-specific engineering and technical support, and compliance or documentation readiness for regulated customers. The most resilient firms combine these elements rather than relying on a single advantage. As a result, competition is less about absolute price leadership and more about total value delivery across quality, availability, and qualification support.
The market structure is likely to evolve through selective consolidation and functional specialization rather than rapid concentration. Larger industrial material suppliers may pursue acquisitions or partnerships to secure nanodiamond capabilities, while smaller producers may compete by focusing on niche grades, proprietary surface treatments, or regional supply advantages. New entrants face meaningful hurdles in reproducibility, scale-up, and qualification, but can still succeed by targeting underserved application needs or offering distinct material formats. For incumbents, the strategic imperative is to protect reputation for consistency while expanding into higher-value application configurations that reduce exposure to commodity-style price competition.
Future Outlook: Trends and Commercial Implications
From Generic Powders to Application-Engineered Grades
Over the next three to five years, the market is likely to move further toward differentiated product architectures. Purchasers in polishing, lubrication, and composite applications are expected to demand more clearly defined particle characteristics, surface states, and dispersion behavior. Suppliers that standardize quality while offering configurable grades will be better positioned to capture premium demand. The commercial opportunity lies in building modular product platforms that can address multiple end-use requirements without sacrificing reproducibility, enabling customers to standardize on a smaller set of trusted materials while still meeting application-specific targets.
Regulatory Readiness as a Competitive Moat
Compliance and documentation capabilities will increasingly separate suppliers that win regulated procurement cycles from those that face repeated qualification friction. As expectations around safety, characterization, and traceability become more entrenched, manufacturers that invest early in standardized testing, record-keeping, and customer-facing technical documentation will reduce time-to-qualification and lower the risk of procurement disruption. This trend favors organized, process-disciplined producers and creates an opening for buyers to consolidate sourcing around suppliers with demonstrated regulatory maturity. The principal risk is that compliance requirements may continue to escalate unevenly across regions, forcing companies to maintain parallel documentation or operational practices to preserve market access.
Regionalization and Supply-Architecture Adaptation
Trade and security constraints surrounding explosive-related inputs are likely to reinforce regionalization of certain synthesis and processing activities. Over the forecast period, companies may increasingly design supply networks that reduce dependence on cross-border movement of sensitive materials, while still preserving cost efficiency and quality control. This shift creates opportunities for localized processing, regional inventory hubs, and partnerships that distribute risk across jurisdictions. It also introduces uncertainty: companies that fail to adapt sourcing models may face longer lead times, higher logistics costs, or intermittent access constraints. Buyers, in turn, may place greater weight on supply continuity assurances when evaluating vendors, especially for mission-critical or hard-to-qualify applications.
Strategic Recommendations for Decision-Makers
For Manufacturers and Material Suppliers
Prioritize reproducible product quality and surface engineering capability as core commercial assets. Invest in classification, purification, and functionalization processes that allow a single platform to serve multiple application segments without compromising consistency. Align internal documentation, characterization, and safety practices with emerging regulatory expectations before they become binding procurement requirements, since early readiness shortens qualification cycles and reduces market-access risk. Where possible, build supply flexibility around sensitive inputs and intermediate materials to mitigate trade-related disruption and protect continuity for high-value customers.
For Investors and Corporate Development Teams
Evaluate opportunities based on technical differentiation and application attachment rather than volume assumptions alone. Companies with defensible surface-engineering know-how, clear quality control systems, and active engagement in regulated or performance-critical end markets are more likely to sustain pricing power and durable customer relationships. Pay close attention to supply-chain exposure, regional production assumptions, and compliance readiness, as these factors increasingly influence margin stability and scalability. In consolidation scenarios, the most attractive targets are typically those that combine material expertise with operational discipline and the ability to support demanding qualification processes.
For Procurement and Sourcing Leaders
Shift sourcing criteria toward verified lot consistency, technical support capacity, and qualification readiness, especially when nanodiamond powders are used in precision polishing, lubricant enhancement, or composite development. Favoring suppliers with transparent characterization practices and documented quality systems can reduce downstream variability and shorten internal approval timelines. Where supply continuity is critical, diversify across vendors with different production footprints or regional setups, and confirm that documentation and compliance practices align with procurement and regulatory requirements. Treat material specification discussions as strategic conversations rather than transactional price negotiations, since long-term performance reliability often determines total cost more than unit price alone.
As the market continues to mature, the commercial winners will be those that convert technical consistency, regulatory readiness, and supply resilience into dependable customer value. For decision-makers seeking deeper segment-level insight, demand scenarios, competitive benchmarks, and tailored sourcing or investment implications, an expanded analysis is available through the full PW Consulting research report, where detailed data and customized guidance can support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Detonation Synthesis Nanodiamond Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oligosaccharide Market 2026: 6.5% CAGR Trajectory and Strategic Shifts Across Key Segments
By PW Consulting, 2026-09-21
Oligosaccharide Market: Strategic Trends and Commercial Opportunities Through 2032
The global oligosaccharide market has entered a phase of structural expansion, transforming from a niche ingredient category into a mainstream strategic asset for food, nutrition, and pharmaceutical innovators. Valued at approximately USD 170.0 million in 2025, the market is projected to reach USD 261.0 million by 2032, advancing at a compound annual growth rate of 6.5 percent across the forecast horizon. This trajectory reflects more than incremental demand; it signals a fundamental recalibration of how manufacturers, regulators, and end consumers view complex carbohydrates as functional, health-modulating ingredients. For executives navigating long-cycle product portfolios, the window to shape positioning, secure supply resilience, and align with regulatory momentum is narrowing. Understanding where the market is headed, and why, separates reactive pricing plays from durable competitive advantage.
Market Snapshot and Structural Realities
The data points to a market that has consistently added value over the past five years, with revenue climbing from USD 122.0 million in 2020 to the current baseline of USD 170.0 million. Growth is not accelerating chaotically; it is compounding steadily, which suggests that buyer preferences, formulation science, and production economics are converging rather than shifting unpredictably. The market remains moderately fragmented in terms of concentration, with the top three players accounting for roughly 34.2 percent of revenue and the top five reaching 45.8 percent. This distribution matters because it indicates room for specialized entrants and regional champions to compete on formulation expertise, proprietary processing, or localized regulatory navigation, while the largest players leverage scale, integrated supply chains, and broad application portfolios.
The current environment is not characterized by unconstrained expansion. Instead, it is defined by several inflection points that will determine which organizations capture disproportionate value over the next three to five years. First, osmotic tolerance between health claims, formulation functionality, and cost efficiency remains a persistent tension for product developers. Oligosaccharides are no longer evaluated solely on prebiotic efficacy; they must also deliver taste, texture, stability, and dose usability across diverse matrices. Second, regulatory alignment is accelerating in key infant nutrition and functional food categories, effectively converting compliance requirements into competitive moats. Companies that anticipate claim substantiation and ingredient approval timelines will gain shelf and contract advantages, while laggards risk reformulation delays and market entry gaps. Third, feedstock and processing economics are becoming more sensitive to macro variables, making cost-to-serve and process flexibility strategic differentiators rather than back-office concerns. These dynamics do not weaken the market outlook; they clarify where value will be created and defended.
Core Drivers Reshaping the Competitive Equation
Market movement over the forecast period is being pulled by a small number of structural forces that interact across technology, regulation, demand behavior, and supply chain economics. Recognizing how these forces compound is essential for portfolio planning and investment coordination.
Technological innovation and process maturity are reshaping what is commercially viable. Advanced enzymatic synthesis, precision fermentation, and more selective purification methods are reducing the complexity gap between bulk carbohydrate production and high-purity functional ingredients. The practical effect is broader applicability across infant formula, dietary supplements, and pharmaceutical-adjacent formulations, where consistency, purity, and repeatability are non-negotiable. Public disclosures from late 2025 and early 2026 reinforce this direction: a major 2'-fucosyllactose supply initiative is moving into global distribution following collaboration between leading ingredient and chemical companies, while a dedicated short-chain fructo-oligosaccharide producer simultaneously expanded from three to four production lines and completed the full operation of a fourth facility equipped with automated quality control and advanced enzymatic synthesis. These moves indicate that leaders are not simply adding capacity; they are upgrading process capability to meet stricter specification requirements and higher batch-to-batch reliability expectations.
Xylooligosaccharides (XOS) Market
Regulatory and policy dynamics are converting scientific consensus into commercial clarity. In infant nutrition, regulatory frameworks are increasingly permitting oligosaccharide blends that better approximate the functional profile of human milk, creating formulation pathways that were more restrictive in prior cycles. European food safety authorities continue to maintain verification and health claim processes for key oligosaccharide categories in infant nutrition and functional foods, which raises the bar for documentation but also stabilizes demand for ingredients with established dossiers. Meanwhile, major Asian markets have updated infant-formula standards to align with international reference frameworks, coinciding with persistently large birth cohorts that sustain baseline demand for nutritionally complete early-life products. The strategic implication is that regulatory harmonization, when paired with clear claim routes, lowers perceived risk for manufacturers and accelerates adoption in categories that previously required lengthy internal validation.
Demand-side evolution is expanding the addressable use cases beyond traditional gut health narratives. Consumers and institutional buyers are increasingly treating oligosaccharides as multifunctional ingredients that support formulation goals across digestion, metabolic comfort, and product differentiation. This broadening mindset is especially visible in dietary supplements and food and beverage applications, where brands seek ingredients that can carry both functional positioning and label clarity. At the same time, procurement teams are placing greater weight on ingredient provenance, processing transparency, and supply consistency. The result is a buyer environment that rewards credible science, reproducible specification performance, and the ability to integrate into diverse production lines without compromising product stability.
Supply chain and cost structure shifts are introducing both pressure and opportunity. Feedstock pricing remains tied to broader commodity markets, with sucrose-linked inputs affecting enzymatic synthesis economics in regions where industrial energy costs are structurally elevated. This does not make cost management impossible, but it does make it a strategic variable. Organizations that design for feedstock flexibility, regional sourcing redundancy, and energy-efficient processing are better positioned to protect margins when input volatility spikes. Conversely, manufacturers that depend on narrow input channels or inflexible process designs face greater exposure to cost transmission that cannot be fully absorbed by downstream pricing.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of global scale players, specialized ingredient manufacturers, and regional producers with distinct processing strengths. No single archetype dominates every application, and the market’s moderate concentration allows multiple winning strategies to coexist.
Fructooligosaccharide (FOS) Market
Large integrated companies are leveraged around application breadth, process know-how, and global distribution. In infant nutrition and specialized formulations, firms with fermentation and enzymatic capabilities are competing on purity, consistency, and the ability to supply human milk oligosaccharide-related ingredients such as 2'-fucosyllactose at commercial scale. Their advantage lies in the combination of scientific credibility, production repeatability, and the operational capacity to support stringent customer requirements across multiple geographies. These players also benefit from the ability to cross-link ingredient development with broader nutrition portfolios, which can shorten time-to-market for blended or multi-functional offerings.
Specialized manufacturers are competing on product range, application specificity, and responsiveness. Several firms focus on fructo-oligosaccharides, galacto-oligosaccharides, isomalto-oligosaccharides, and xylo-oligosaccharides for food, infant formula, and prebiotic uses, with differentiation rooted in chain-length control, format flexibility, and the ability to supply both powder and syrup forms. This group often wins by aligning closely with formulators’ practical needs, including solubility profiles, sweetness impact, stability under processing conditions, and dosage convenience. Regional players with strong local regulatory familiarity and efficient production layouts can also outperform on total delivered cost, particularly where logistics and import friction would otherwise erode competitiveness.
PW Consulting
Recent operational developments point to a landscape that is expanding in capability while tightening in quality expectations. Capacity additions are being paired with process modernization rather than treated as simple volume plays. The completion of dedicated production lines, implementation of automated quality control, and investment in enzymatic synthesis infrastructure suggest that the next phase of competition will center on reliability, specification control, and the ability to fulfill increasingly specific formulation briefs. At the same time, large dairy-linked and nutrition-oriented operators are expanding adjacent capacities that support broader functional ingredient portfolios. This signals an industry trend toward more integrated ingredient ecosystems, where oligosaccharides are not isolated commodities but components of broader formulation strategies spanning protein, lipid, and carbohydrate functionalities.
The market structure is likely to evolve through selective consolidation and continued differentiation rather than uniform concentration. Larger players may pursue strategic combinations that strengthen geographic coverage, application portfolios, or process technology. Smaller and mid-sized firms will likely continue to defend niches through formulation expertise, specialized molecule profiles, and fast response to customer formulation changes. New entrants will find opportunity primarily where they bring a distinct technical angle, such as novel purification routes, alternative feedstock pathways, or targeted health-claim positioning supported by robust documentation. The enduring competitive advantage will belong to organizations that can combine credible science, scalable and controllable production, and the commercial agility to serve multiple application categories without diluting quality.
Forward Outlook: Trends and Commercial Implications
The next three to five years will likely be shaped by three interlocking trends that translate directly into commercial opportunities and execution risks.
Precision and specification escalation will become the norm rather than the exception. As regulatory frameworks mature and application requirements become more demanding, buyers will increasingly differentiate between generic functional carbohydrate supply and ingredients that meet tightly controlled purity, chain-length, and batch-consistency parameters. The commercial opportunity here is clear: suppliers that can deliver repeatable specifications, transparent documentation, and application-specific formats will be able to command stronger commercial terms and longer-term supply relationships. The risk is equally clear. Organizations that compete primarily on price without corresponding quality and reliability infrastructure will face margin compression and reduced negotiating leverage as customers rationalize supplier bases.
Category convergence will expand the value pool across food, supplements, and infant nutrition. Regulatory alignment and formulation science are making it easier to position oligosaccharides across adjacent use cases without treating each category as entirely separate. This convergence creates opportunities for integrated product strategies, co-development with downstream brands, and portfolio architectures that capture demand across multiple consumption occasions. For manufacturers, the strategic task is to design ingredient platforms that can flex across applications while maintaining the documentation and consistency credentials required in higher-scrutiny categories. For investors, the opportunity lies in identifying operators whose process technology and application roadmap can serve more than one demand channel without sacrificing regulatory credibility.
Supply resilience and input-cost agility will move from operational concerns to strategic differentiators. As feedstock and energy cost sensitivity persists, the ability to source flexibly, manage regional cost structures, and engineer processing efficiency will shape both competitiveness and customer confidence. Companies that can demonstrate supply redundancy, predictable quality under variable input conditions, and transparent cost governance will be better positioned to secure long-term agreements. The uncertainty to monitor includes potential volatility in raw material markets, energy cost fluctuations in key production regions, and changes in trade or import dynamics that can alter delivered economics. Planning that assumes a single stable cost trajectory is likely to underprepare organizations for the range of plausible scenarios.
Actionable Priorities for Decision Makers
The commercial path forward depends on the role an organization plays in the value chain, but several priorities apply broadly.
- For ingredient and product manufacturers: invest in specification control and process modernization before expanding volume alone. The most durable position will come from repeatable purity, format flexibility, and documentation readiness that supports both food and supplement use cases. Align product development with regulatory and claim trajectories in target geographies rather than treating compliance as a late-stage checkpoint. Build feedstock and energy flexibility into sourcing strategies so that cost pressures do not force reactive discounting or inconsistent supply.
- For investors and corporate development teams: evaluate opportunities based on technological defensibility, application breadth, and the ability to meet rising quality expectations. Volume growth is attractive, but the more valuable question is whether a platform can sustain premium positioning as specifications tighten and buyer consolidation accelerates. Pay attention to companies that are upgrading enzymatic synthesis, automated quality control, and multi-format capability, because these capabilities tend to translate into longer-term commercial resilience rather than temporary capacity advantages.
- For procurement and R&D leaders: treat oligosaccharide sourcing as a multi-factor decision involving functionality, stability, documentation, and supply reliability, not just price per unit. Prioritize suppliers that can support application-specific requirements and provide clear evidence trails for regulatory and claim contexts. Diversify where feasible to reduce exposure to single-source risk, especially for formulations that depend on consistent performance across geographies or production lines.
The strategic stakes in this market are rising because the ingredient is becoming more central to product differentiation, regulatory positioning, and consumer-facing health narratives. That makes timely, granular intelligence valuable for anyone deciding where to allocate capital, how to structure supply relationships, or which formulation roadmaps to prioritize. Detailed segment-level demand splits, regional absorption patterns, company-specific capability mapping, and scenario-based volume and pricing assumptions can materially improve the quality of those decisions. For teams that need a sharper operational lens, the full PW Consulting research report provides the deeper segmentation, competitive benchmarking, and forward modeling required to convert these strategic signals into concrete plans.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
WiFi Thermostats Market: Decoding the 21.07% CAGR and $17.35M Growth Roadmap
By PW Consulting, 2026-09-21
The WiFi Thermostats Market: Strategic Trends and Commercial Opportunities Through 2032
The global WiFi thermostats market has entered a phase of accelerated expansion, transforming from a niche smart home accessory into a core component of energy management infrastructure. Driven by escalating energy costs, expanded utility rebate programs, and rapid advances in sensor and connectivity technologies, the sector is reshaping how residential, commercial, and industrial facilities approach heating and cooling control. Understanding the underlying dynamics of this market requires moving beyond headline figures to examine the structural shifts that will define competitive positioning, product roadmaps, and investment allocation over the next several years.
Thermostats Market
Market Landscape and Core Challenges
Scale, Trajectory, and Concentration Dynamics
From a valuation of approximately $1.75 million in 2020, the WiFi thermostats market has climbed steadily to reach $4.55 million in 2025, with forward projections indicating sustained momentum through the end of the decade. The forecast period spanning 2026 to 2032 anticipates a compound annual growth rate of 21.07 percent, reflecting robust adoption curves across multiple end-use segments and geographic regions. Revenue is expected to reach $5.6 million in 2026, escalate to $8.12 million by 2028, and surpass $12 million by 2030, ultimately reaching $17.35 million by 2032. This trajectory underscores the market's transition from incremental consumer adoption to broader infrastructure integration, where smart climate control becomes a baseline expectation rather than a premium differentiator.
Market concentration tells a nuanced story. The top three players collectively account for roughly 45 percent of total revenue, while the top five expand that share to approximately 52 percent. This moderate concentration suggests a landscape that remains accessible to well-positioned challengers, yet increasingly rewards scale advantages in distribution, brand recognition, and platform ecosystem integration. Companies that can harmonize hardware performance, software interoperability, and retail or channel partnerships are capturing disproportionate share, while smaller players face mounting pressure to justify differentiation in a category where core functionality is becoming commoditized.
Key Challenges and Inflection Points
Three structural challenges define the current market environment and will determine which participants thrive over the forecast horizon.
Interoperability and protocol fragmentation remain persistent friction points. Although industry alliances have made meaningful progress toward unified standards, the reality on the ground is a patchwork of proprietary ecosystems, varying degrees of open API support, and inconsistent implementations across HVAC manufacturers. For end users, this creates purchase hesitation and post-installation regret when devices fail to communicate seamlessly with existing smart home or building management platforms. For manufacturers, it necessitates continuous engineering investment to maintain compatibility across an expanding field of third-party integrations, raising development costs and slowing time-to-market for feature upgrades.
Regulatory compliance is reshaping product design and market access. Jurisdictions with aggressive energy efficiency mandates are introducing certification requirements that directly affect which models can be sold, installed, and incentivized. In certain regions, occupant-controlled smart thermostats must meet specific energy savings performance thresholds to qualify for rebate eligibility or even market entry. These requirements compress the margin for low-cost, minimally featured products and push manufacturers toward designs that embed advanced scheduling algorithms, occupancy detection, and usage analytics. Companies that treat compliance as a checkbox exercise risk losing eligibility for utility programs that serve as critical demand catalysts.
Margin compression and supply chain complexity create a third pressure point. The segment below the $150 price threshold remains highly competitive, with retailers and online marketplaces driving down average selling prices through bundling, promotional cycles, and private-label alternatives. Meanwhile, the tier above $150 commands a larger revenue share but demands higher engineering investment, more sophisticated sensor arrays, and stronger software support. Manufacturers must navigate the tension between volume-driven growth and value-driven profitability, all while managing component availability, firmware update lifecycles, and the increasing expectation for continuous post-sale software improvements.
Key Drivers of Market Evolution
Technological Innovation and Sensor Integration
The pace of hardware and software innovation is a primary catalyst for market expansion. Modern WiFi thermostats increasingly incorporate radar-based occupancy detection, advanced air quality monitoring, and onboard diagnostics that provide real-time feedback on HVAC system health. These capabilities transform the device from a simple temperature regulator into an energy intelligence hub, enabling more granular scheduling, proactive maintenance alerts, and adaptive comfort profiles. The integration of widely adopted interoperability frameworks has further reduced barriers to cross-platform compatibility, allowing thermostats to function as coordinated nodes within broader home or building automation networks rather than isolated appliances.
Smart Thermostats Market
Recent product introductions illustrate how manufacturers are translating these technical capabilities into market-facing differentiation. In early 2025, a major incumbent unveiled a new smart thermostat model at a leading consumer technology exhibition, emphasizing interoperability certification and energy efficiency validation, with retail availability scheduled for the spring season. Later in the year, the same company expanded its premium lineup with a high-resolution touchscreen model that introduced live doorbell video streaming, indoor air quality monitoring, and integrated HVAC diagnostics, positioning the device at the upper end of the price spectrum. By early 2026, that premium model had received recognition as the leading smart heating and cooling product in its category, signaling strong market receptivity to feature-rich, multi-function devices. These moves reflect a broader industry pattern: manufacturers are using innovation cycles not merely to update form factors, but to deepen the value proposition around energy management, system health, and ecosystem integration.
Policy and Regulatory Environment
Government efficiency mandates and utility incentive programs are reshaping demand patterns with remarkable speed. In California, occupant-controlled smart thermostats are required to meet specific certification standards tied to energy savings compliance, creating a clear regulatory baseline that filters out non-compliant products and channels demand toward models that demonstrably reduce heating and cooling waste. Beyond this jurisdiction-specific mandate, a broader network of utility and state-level programs has emerged, offering financial incentives that directly lower the effective purchase price for qualified devices.
Multiple programs now provide rebates or cash-back incentives of up to $100 for ENERGY STAR-certified smart thermostats, with eligibility tied to certification status, installation timing, and sometimes mandatory WiFi registration after deployment. Some programs target self-installed units purchased within a defined calendar window, while others pair incentives with specific installation requirements or participation in broader demand-response initiatives. These incentives serve as powerful demand accelerators, particularly in price-sensitive segments where the upfront cost of a smart device has historically been a barrier. For manufacturers and retailers, aligning product portfolios with rebate eligibility criteria is no longer optional; it is a core commercial strategy that directly influences conversion rates and average selling prices in participating markets.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are evolving rapidly on both the residential and commercial fronts. In residential settings, consumers increasingly view smart thermostats as part of a broader home efficiency and comfort strategy rather than standalone gadgets. Rising utility costs, heightened awareness of carbon footprints, and the normalization of app-based home management have made programmable, learning, and remotely accessible thermostats a practical purchase rather than a speculative luxury. The growing preference for devices that can integrate with voice assistants, geofencing routines, and multi-room comfort schedules reflects a desire for seamless, low-friction energy management that operates in the background without requiring constant manual intervention.
Commercial operators face a different but complementary set of drivers. Facility managers and building owners are under increasing pressure to reduce operational energy expenditures while maintaining occupant comfort and meeting sustainability reporting requirements. Smart thermostats in commercial contexts are valued for their ability to centralize scheduling, respond to occupancy patterns, and integrate with broader Building Management Systems that aggregate data across lighting, HVAC, and security functions. The shift toward hybrid work schedules and variable occupancy patterns has further amplified the need for adaptive climate control that can optimize energy use without sacrificing comfort during peak usage periods.
Supply Chain and Cost Structure Dynamics
The cost structure of WiFi thermostats is being reshaped by both component-level advancements and shifting manufacturing footprints. Improvements in low-power wireless modules, embedded processors, and sensor integration have gradually reduced the bill of materials for core functionality, enabling manufacturers to add features without proportionate cost increases. At the same time, the expectation for continuous firmware updates, cloud connectivity, and long-term software support introduces ongoing operational costs that must be factored into product pricing and lifecycle planning. Companies that can balance hardware economies with sustainable software support models are better positioned to maintain margins as the market matures and competition intensifies.
Distribution channel dynamics also play a role in cost and margin outcomes. Retail partnerships, online marketplaces, and direct-to-consumer channels each carry distinct customer acquisition costs, return profiles, and brand exposure benefits. The availability of utility rebates and energy certification programs further influences channel strategy, as products that are explicitly listed for incentive eligibility tend to perform more predictably in markets where consumers are aware of and actively seeking those savings. Aligning supply chain agility with channel-specific demand patterns is becoming a critical capability, particularly as regional incentive programs adjust eligibility windows and certification requirements.
Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The market's leading participants have carved out distinct strategic identities that reflect their heritage, ecosystem leverage, and target customer segments. Resideo Technologies, operating from its Scottsdale headquarters, serves as the primary provider of Honeywell Home WiFi smart thermostats, with a portfolio spanning multiple series models that incorporate interoperability certification, energy monitoring, and HVAC integration. The company's recent product cadence demonstrates a dual-track strategy: expanding accessibility through mainstream models with efficiency certification while simultaneously pushing into the premium tier with high-resolution displays, air quality sensing, and diagnostic capabilities. Recognition from industry award programs in early 2026 underscores how this approach has resonated with evaluators and early adopters who value both energy performance and feature depth.
ecobee, based in Toronto, has built its identity around advanced sensing and environmental awareness. Its thermostat lineup emphasizes radar-based occupancy detection, air quality monitoring, and comprehensive WiFi connectivity, targeting customers who prioritize comfort precision and indoor environmental quality alongside energy savings. By differentiating on sensor sophistication and whole-home awareness, ecobee positions its devices as integrated components of a healthier, more responsive living environment rather than simple temperature controllers.
PW Consulting
Google, through its Alphabet Inc. umbrella, brings a platform-centric approach to the category. Its thermostat offerings are built around AI-driven learning, geofencing capabilities, and interoperability support, leveraging the company's broader ecosystem to deliver seamless integration with mobile devices, voice assistants, and automated routines. The strategic advantage here lies in user familiarity, software continuity, and the ability to bundle climate control into a wider smart home experience that reduces setup complexity and encourages long-term engagement.
Emerson Electric Co., headquartered in St. Louis, has focused on optimized smart home integration, voice control compatibility, and energy-efficient HVAC performance. Its thermostat designs emphasize reliability, straightforward installation, and smooth interoperability with existing home automation setups, appealing to customers and installers who value stability and ease of use alongside measurable energy improvements.
Evolution of the Market Structure
The competitive field is evolving along multiple axes simultaneously. Consolidation pressure exists, particularly as larger platform owners and diversified home technology companies seek to bundle climate control into broader offerings. At the same time, market fragmentation persists in the value-oriented segment, where regional brands, private-label offerings, and online-first competitors compete aggressively on price and feature lists. The result is a market that rewards clear strategic positioning rather than uniform feature escalation.
One emerging trend is the bifurcation between utility-aligned, compliance-focused devices and premium, experience-driven models. The former category benefits directly from incentive programs and regulatory mandates, making certification and rebate eligibility central to go-to-market strategy. The latter category competes on design, sensor capabilities, software experience, and ecosystem integration, appealing to customers willing to pay a premium for advanced functionality and aesthetic integration. Companies that attempt to straddle both segments without clear differentiation risk diluting their brand message and stretching engineering resources across incompatible priorities.
New entrants and ecosystem incumbents are also reshaping competitive dynamics. Platform companies with existing user bases, cloud infrastructure, and software development capabilities can leverage thermostat rollouts as extensions of broader smart home or building management strategies, using hardware as an engagement touchpoint rather than a standalone profit center. Traditional hardware manufacturers, meanwhile, are investing in software maturity, interoperability certifications, and service ecosystems to defend against platform-driven competition and to increase switching costs for end users who value long-term reliability and continuous feature updates.
Future Trends and Commercial Opportunities
Trend One: Energy Intelligence as a Standard Expectation
Over the next three to five years, the defining shift in the WiFi thermostats market will be the transition from basic remote control to proactive energy intelligence. Devices will increasingly be expected to learn occupancy patterns, adjust to utility rate structures, participate in demand-response events, and surface actionable insights about HVAC performance and energy waste. This trend opens commercial opportunities for manufacturers that can package analytics, scheduling optimization, and utility program participation as clear, user-facing value propositions rather than buried technical features. For commercial and industrial buyers, the opportunity lies in integrating thermostat data into broader facility energy management dashboards, turning climate control devices into sources of operational intelligence that support sustainability reporting and cost reduction initiatives.
The risk side of this trend centers on data privacy expectations and software sustainability. As devices collect more usage patterns and environmental data, end users and enterprise purchasers will scrutinize data handling practices, cloud dependency, and long-term update commitments. Manufacturers that fail to communicate transparent data policies or that underinvest in post-sale software support risk losing trust and facing attrition as competitors offer clearer privacy assurances and more predictable update roadmaps.
Trend Two: Incentive-Driven Demand and Compliance as Market Gateways
Regulatory mandates and utility incentives will continue to function as powerful demand gateways, particularly in regions where energy costs are high and efficiency goals are aggressive. The pattern of rebates and certification requirements is likely to expand rather than contract, with more jurisdictions aligning smart thermostat eligibility with broader decarbonization and grid flexibility objectives. Commercial opportunities here include designing product lines that are explicitly optimized for rebate qualification, ensuring that marketing and retail execution clearly communicate incentive availability, and building installer and consumer education programs that reduce friction in the rebate redemption process.
The uncertainty lies in the variability and timing of program availability. Incentives can be capped, paused, or reconfigured based on funding cycles and policy priorities, creating demand volatility if product planning assumes perpetual rebate availability. Companies that treat incentives as accelerators rather than structural revenue foundations, and that maintain product relevance even in the absence of active rebate windows, will be more resilient to program fluctuations.
Trend Three: Ecosystem Integration and Platform Competition
The market's future will increasingly be shaped by how well thermostats integrate into broader smart home and building management ecosystems. Consumers and facility operators alike prefer cohesive experiences where climate control, lighting, security, and air quality operate as coordinated systems rather than disconnected devices. This trend favors participants that can demonstrate reliable cross-platform compatibility, straightforward setup processes, and ongoing software compatibility as third-party ecosystems evolve.
Commercial opportunities include partnerships with platform providers, open API strategies that encourage third-party integrations, and product designs that make the thermostat a visible, intuitive node within a larger automation environment. The associated risk is over-reliance on any single ecosystem partner, which can create vulnerability if platform priorities shift, compatibility standards change, or competitive dynamics alter the value of integration. A balanced approach that maintains multi-platform support while delivering a distinct, reliable user experience offers the most sustainable path.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize certification alignment and interoperability as foundational product requirements rather than optional add-ons. Devices that meet prevailing energy efficiency standards and support widely recognized connectivity frameworks are better positioned to qualify for incentive programs, integrate with third-party ecosystems, and withstand regulatory shifts across multiple jurisdictions. Simultaneously, invest in software maturity and post-sale support as a differentiator. As hardware features become more comparable across competitors, the quality of scheduling algorithms, update reliability, and user-facing energy insights will increasingly determine long-term satisfaction and repeat engagement.
Consider a segmented product strategy that clearly separates compliance-aligned, incentive-friendly models from premium, experience-driven devices. Each segment requires distinct engineering priorities, channel execution, and messaging. Blurring the lines between them can lead to confused positioning, margin erosion, and missed opportunities in both the incentive-sensitive and premium experience markets.
For Investors and Strategic Allocators
Evaluate participants based on their ability to sustain software value and navigate regulatory complexity, not solely on hardware shipment growth. The market's rapid expansion masks divergent underlying quality among competitors, particularly in how well companies manage certification requirements, ecosystem integration, and long-term firmware support. Companies that treat these dimensions as core competencies are better positioned to defend margins and capture share as the market matures and early-adopter enthusiasm gives way to more discerning, value-focused purchasing.
Monitor the trajectory of utility and state-level incentive programs as a leading indicator of regional demand intensity. Shifts in rebate availability, certification thresholds, and installation requirements can rapidly alter which product tiers and features are commercially attractive in specific markets. Portfolio exposure that accounts for geographic and program-level variability is more resilient than strategies that assume uniform, uninterrupted incentive support.
For Procurement and End-User Decision Makers
When evaluating WiFi thermostats, prioritize compatibility with existing HVAC equipment, support for relevant efficiency certifications, and clarity around post-installation software support. The most attractive device on a feature list may not be the best fit if it lacks certification eligibility for local incentive programs or if its software update commitments are unclear. In commercial and industrial settings, assess integration pathways with existing building management systems and verify that data access, scheduling controls, and demand-response participation capabilities align with operational requirements.
Treat the purchase decision as an entry point into an ongoing energy management relationship rather than a one-time hardware transaction. Devices that offer transparent energy insights, reliable scheduling, and sustained software support deliver greater long-term value than those that emphasize a narrow set of launch-time features without a clear roadmap for continued improvement.
Conclusion
The WiFi thermostats market is advancing rapidly, propelled by technology maturation, regulatory pressure, utility incentives, and shifting consumer and enterprise expectations. The growth trajectory through the end of the decade reflects a category that is transitioning from discretionary smart home upgrades to integral components of energy management strategy. Success in this environment will belong to participants that combine clear product segmentation, robust certification and interoperability alignment, and sustained software investment with a disciplined approach to regional incentive dynamics and ecosystem integration.
For leaders who need to move beyond high-level market narratives and into actionable, segment-specific planning, a comprehensive research report is available that provides deeper breakdowns of regional and price-tier dynamics, end-use performance patterns, detailed competitive benchmarking, and customized strategic recommendations aligned with specific business objectives. Accessing that level of detail can shorten decision cycles, sharpen product and investment prioritization, and ensure that market entry or expansion strategies are built on a precise understanding of where demand is forming, which compliance and incentive structures matter most, and how competitive positioning is likely to evolve as the market scales toward its next growth phase.
For detailed analysis of this topic, please visit the official page: WiFi Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Capecitabine Market Value Hits $494M in 2025: Decoding the 6.01% CAGR Growth Path to 2032
By PW Consulting, 2026-09-21
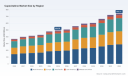
The Capecitabine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The capecitabine market has matured from a niche oncology therapy into a widely deployed oral chemotherapy option with established clinical pathways, global distribution footprints, and a pricing landscape shaped by generics competition and brand stewardship. Recent market data underscore a steady, compounding growth trajectory: global revenue climbed from roughly 369 million in 2020 to 494 million in 2025, with the market projected to expand from about 508 million in 2026 to more than 743 million by 2032, reflecting a compound annual growth rate near 6.0 percent. This pace signals durable demand, but it also masks structural shifts underway across regulatory requirements, product innovation, supply chain resilience, and competitive positioning. For executives and investors, the challenge is no longer whether capecitabine will grow—it is how each stakeholder can navigate a landscape where volume expansion, risk management, and differentiation increasingly determine commercial outcomes.
Understanding the market today requires looking beyond top-line growth to the forces reshaping how capecitabine is prescribed, manufactured, distributed, and reimbursed. The category sits at the intersection of oncology care delivery, regulatory modernization, and generic supply dynamics. That combination creates both opportunity and fragility. Growth is being driven by broad utilization across multiple tumor types and care settings, yet the same breadth makes the market sensitive to therapy substitutions, formulary decisions, and manufacturing disruptions. In the sections that follow, the focus is on what matters most for strategic planning: the core challenges framing the market, the drivers altering pace and margin, the competitive profiles shaping access, the trends likely to unfold over the next three to five years, and the actions different stakeholders can take now.
Market Context and Core Challenges
The capecitabine market has demonstrated consistent expansion, with annual revenues moving from the high 360-million range in 2020 to just under 500 million by 2025 and continuing upward through the forecast horizon. Growth is broad-based, with significant shares concentrated across major oncology indications and distributed through both hospital and retail/online pharmacy channels. Regionally, North America and Asia Pacific represent substantial portions of total value, alongside meaningful European demand and smaller but notable contributions from Latin America and the Middle East and Africa. The competitive structure remains relatively fragmented, with top three players holding roughly 26 percent of market value and the top five near 29 percent, indicating that no single manufacturer dominates the category outright. This environment supports multiple commercial models—branded stewardship, generic scale, and specialty distribution—but also raises questions about pricing discipline, supply reliability, and how brand differentiation will compete as more players enter the space.
Several challenges define the current inflection point. First, the regulatory baseline is tightening around patient safety and treatment personalization. Updated prescribing information and safety labeling have begun to reshape treatment protocols, placing greater emphasis on pre-treatment screening for enzyme deficiencies that affect drug metabolism. These requirements are clinically rational, but they introduce operational complexity for providers, pharmacy networks, and manufacturers who must ensure adherence across varied care settings. Second, supply chain reliability has emerged as a recurring risk. Even for a well-established oral oncology product, demand spikes and manufacturing or logistics disruptions can lead to shortages, as seen in recent episodes affecting specific branded and generic presentations. In a market where continuity of care is paramount, shortages not only create clinical inconvenience but can also shift purchasing behavior and erode trust in supply commitments. Third, the competitive landscape is evolving through both consolidation and fragmentation. Brand rights and distribution agreements have changed hands, while multiple generic manufacturers continue to build volume across regions. The result is a market where access, pricing, and channel relationships matter as much as product formulation.
Key Drivers Shaping the Capecitabine Market
Innovation and Next-Generation Formulations
Product innovation is one of the more consequential drivers in the mid-term outlook. While capecitabine is a long-established agent, a next-generation formulation has entered clinical evaluation with the aim of improving exposure to the active metabolite and refining the safety profile relative to standard monotherapy. Early-phase data have drawn attention because they suggest the possibility of enhanced efficacy or tolerability without abandoning the core therapy paradigm. If later-stage trials confirm these signals, the impact could extend beyond a single product: improved formulations may influence prescribing preferences in oncology settings, support combination strategies, and create a basis for differentiation that is not solely dependent on price. Even where new formulations do not replace existing options, the clinical conversation around optimization can shift expectations and encourage manufacturers to invest in value-added positioning.
Regulatory Modernization and Testing Requirements
Regulation is increasingly a structuring force rather than a compliance afterthought. Recent regulatory actions have included label updates that revise indications, dosage regimens, and safety information, including considerations around dihydropyrimidine dehydrogenase deficiency. In parallel, guidance has moved toward making genetic testing a prerequisite before treatment initiation in relevant contexts. This shift aligns with broader oncology trends emphasizing precision prescribing and risk mitigation, but it also affects workflows and procurement. Providers must integrate testing into care pathways, pharmacies must manage counseling and documentation, and manufacturers need to ensure that product information and support materials reflect new expectations. Where regulatory updates are clear and consistent, they can reduce uncertainty and support adoption; where they vary by region, they create fragmentation that complicates global planning.
PW Consulting
Demand-Side Shifts in Oncology Care Delivery
Demand is being shaped by how cancer care is delivered and accessed. Capecitabine remains attractive in part because of its oral administration, which supports flexible treatment models and can reduce the burden of frequent clinic visits for eligible patients. As oncology services expand in outpatient and community-based settings, oral therapies with established efficacy profiles continue to find use across colorectal, breast, gastric, pancreatic, and other indications. At the same time, payer and formulary dynamics influence which versions are accessed and at what price. Hospitals and retail/online pharmacies both play substantial roles in distribution, meaning that channel strategy and contracting are as important as clinical fit. The net effect is a demand environment that is resilient but sensitive to reimbursement policy, site-of-care preferences, and the availability of reliable supply at the point of care.
Supply Chain, Cost Structure, and Access Reliability
Cost structure and supply reliability are recurring drivers of commercial performance in generic-heavy oncology categories. Manufacturing scale, quality control, logistics, and regional sourcing decisions all influence margin and availability. Episodes of unexpected demand and interruption have demonstrated that even mature products can face shortage risk when supply planning does not keep pace with utilization or when distribution channels encounter disruption. For buyers, this creates a need to diversify sources, monitor inventory buffers, and assess supplier robustness beyond price alone. For manufacturers, it underscores the value of predictable production, responsive distribution, and clear communication during constraints. In market segments where multiple suppliers compete, the ability to maintain continuity can be a more durable advantage than temporary price positioning.
Competitive Landscape and Leading Strategies
Branded Stewardship and Rights Transitions
A defining feature of the competitive landscape is the interaction between branded product stewardship and the broader generic ecosystem. One originator and marketer continues to anchor the branded position for capecitabine tablets in colorectal and breast cancer treatment, maintaining clinical familiarity and long-standing provider relationships. At the same time, another major pharmaceutical company acquired worldwide rights to the branded product in 2023 and now markets it across key regions, including China and Japan. This transition illustrates how brand ownership can shift while still preserving access to a recognized product identity in important markets. For incumbents and new rights holders alike, the strategic priority is to manage formulation consistency, provider education, and region-specific compliance while defending the clinical value proposition against generic substitution where appropriate.
Generic Scale, Distribution Partnerships, and Regional Reach
On the generic side, several manufacturers have built profiles based on tablet production and channel partnerships. Indian-based producers supply U.S. and international markets through arrangements with distributors and pharmaceutical services companies, extending reach across retail and hospital channels. Another group of manufacturers markets generic tablets through established U.S. pharmaceutical partners, while additional producers distribute through other major service networks. Outside the United States, branded and generic positions coexist, with manufacturers in Australia and other regions producing and marketing their own presentations. The pattern suggests that competitive advantage in generic segments depends on three things: reliable manufacturing capacity, efficient distribution agreements, and the ability to meet regional requirements without sacrificing consistency. Companies that can align supply with channel needs and regulatory expectations are better positioned to capture volume when shortages or demand shifts occur.
Competitive Evolution: Consolidation, Differentiation, and Entry Dynamics
The market structure is not static. The concentration metrics indicate a moderately fragmented landscape, leaving room for both consolidation and new entry. Rights acquisitions have already altered the branded side, and similar moves could continue as companies seek to strengthen oncology franchises or acquire established product identities. On the generic side, entry is facilitated by manufacturing capability and distribution relationships, but sustainable positioning increasingly depends on more than low price. Differentiation can come from continuity of supply, consistent quality, responsive customer support, and alignment with testing and safety requirements. Over time, the competitive field is likely to separate into tiers: players with strong regional relationships and dependable supply, and those that remain more vulnerable to channel and regulatory shocks. For decision-makers, the implication is to look beyond brand names and short-term pricing to assess whether a supplier can be relied upon across cycles of demand and disruption.
Forward Outlook: Three to Five-Year Trends
Tighter Integration of Safety, Testing, and Prescribing Workflows
As regulatory expectations around genetic screening and safety information become more embedded, the market is likely to move toward greater integration of testing and prescribing workflows. This trend will affect hospitals, pharmacies, and manufacturers in different ways. Providers will need streamlined processes to confirm eligibility and manage exceptions. Manufacturers and service partners may invest in educational materials, decision support, and communication that reduce friction in implementation. For commercial strategies, the opportunity is not simply compliance; it is the chance to position products and services as easier to use safely and consistently. Suppliers that help institutions manage the operational burden of testing and counseling can strengthen relationships and reduce the likelihood of adoption barriers. The risk is that uneven implementation across regions or institutions creates confusion or slows utilization, particularly where guidance is not fully harmonized.
Formulation and Clinical Optimization as a Differentiator
Clinical optimization is set to become a more visible battleground. If next-generation formulations continue to demonstrate improved exposure and safety signals in later trials, they could influence prescribing in gastrointestinal and other advanced cancers, especially where clinicians are balancing efficacy with tolerability. Even before any new formulation achieves broad adoption, the direction of travel matters: the category is increasingly framed by the question of how to deliver the therapeutic benefit of capecitabine with a better patient experience or a more favorable risk profile. For manufacturers, this opens a pathway to differentiation based on clinical value rather than price alone. For investors, it suggests that early-stage programs with clear mechanistic rationale and well-designed trials may carry strategic optionality, though development risk remains substantial and outcomes are uncertain until pivotal data are available.
Oxaliplatin Market
Supply Resilience as a Commercial Moat
Supply resilience is expected to play a larger role in competitive advantage. Repeated interruptions in specific branded and generic presentations have highlighted that availability can be as decisive as price in oncology procurement. The practical consequence is that procurement teams and hospital networks will increasingly evaluate suppliers on continuity, lead-time reliability, and the ability to manage regional demand fluctuations. For manufacturers, this means that robust production planning, quality systems, and logistics responsiveness will be central to commercial performance. Markets in which demand grows steadily but supply remains vulnerable will reward suppliers that can demonstrate dependable access. The downside risk is that shortage events or quality concerns in specific lots or regions can quickly shift purchasing and reputation, making resilience a strategic necessity rather than an operational detail.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Holders
Manufacturers should treat supply continuity and regulatory readiness as core commercial assets, not back-office functions. That means investing in production reliability, clear lot traceability, and proactive communication during constraints, as well as ensuring that labeling, safety information, and support materials reflect current guidance. Where branded products are involved, stewardship should emphasize clinical consistency, provider education, and region-specific compliance, especially in markets where rights have changed hands. Where generic positions are the focus, competitive advantage will likely come from dependable access, efficient distribution partnerships, and the ability to meet local requirements without sacrificing quality. Companies should also monitor formulation innovation closely, since even partial clinical gains can reshape expectations in the category and create new positioning opportunities.
For Investors and Strategic Planners
Investors should evaluate capecitabine exposure with an emphasis on resilience, channel strength, and regulatory alignment rather than volume growth alone. Growth is likely to continue at a steady pace, but the composition of value will increasingly favor participants that can manage safety requirements, maintain availability, and navigate regional differences. In due diligence, it is worth examining supplier robustness, distribution relationships, and exposure to shortage or quality risk, as well as any pipeline programs that could affect long-term positioning. Close attention to label updates, testing requirements, and regional regulatory variation will help anticipate shifts in demand patterns and procurement behavior. The commercial upside is real, but it is best captured by those who can distinguish durable structural advantages from short-term pricing dynamics.
Worldwide Azacitidine Market
For Procurement, Hospitals, and Pharmacy Networks
Procurement and clinical operations teams should prioritize diversified sourcing and contingency planning for oral oncology products, even where the category is mature. This includes maintaining visibility into multiple suppliers, understanding buffer strategies, and ensuring that testing and safety workflows are aligned with current prescribing expectations. Contracts and service-level expectations should reflect the importance of continuity, with attention to lead times, substitution rules, and communication protocols in the event of disruption. Where possible, institutions can benefit from working with partners that offer clear quality systems, responsive support, and consistent availability. As regulatory and clinical expectations evolve, procurement strategies that incorporate both clinical reliability and supply resilience will be better positioned to sustain patient access without unnecessary cost or interruption.
The capecitabine market is moving through a phase where growth and complexity are advancing together. Demand remains broad, the category spans multiple care settings and indications, and the competitive field includes both established branded stewardship and a vigorous generic ecosystem. At the same time, regulatory modernization, supply fragility, and clinical innovation are reshaping how value is created and captured. For executives, investors, and procurement leaders, the most useful question is not whether the market will expand, but which capabilities will determine who gains share, who protects margins, and who maintains uninterrupted access. Detailed segmentation, regional patterns, supplier profiles, and scenario analysis are available in the full PW Consulting research report, which provides the deeper data and customized guidance needed to translate these trends into specific commercial decisions.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cochlear Implants Market: Why 7.5% CAGR Growth and $3B Valuation Reshape 2032 Strategy
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Cochlear Implants Market
Market Overview: Scale, Growth, and the Emerging Equilibrium
The global cochlear implants market has entered a phase of steady expansion, underpinned by advancements in implant technology, broader clinical indications, and sustained reimbursement support across major healthcare systems. Valued at approximately 1,280.0 million USD in 2020, the market has progressed through consistent year-over-year gains to reach an estimated 1,850.0 million USD in 2025. Over the 2020-2025 historical period, growth reflects both volume expansion and incremental pricing power tied to product innovation. Looking ahead, the trajectory is expected to accelerate modestly, with the market projected to reach 3,064.02 million USD by 2032, translating to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window.
PW Consulting
This growth path is not uniform. The pace of adoption is increasingly shaped by the interaction of clinical evidence, device capabilities, and reimbursement stability rather than raw demographic demand alone. Market concentration remains pronounced, with the top three players accounting for 62.0 percent of total revenue and the top five representing 85.0 percent. Such concentration signals a mature competitive order, yet the underlying dynamics are shifting as technology differentiation, geographic expansion, and regulatory flexibility create space for strategic repositioning.
For executives and investors, the central implication is that growth in this space will be earned through differentiation and access, not simply through volume. The companies and capital that navigate the technical and commercial inflection points effectively will capture disproportionate value as the market expands toward the 3 billion USD threshold.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the market is confronting a set of structural challenges that will define competitive outcomes over the next several years. Three stand out as particularly consequential.
1. The Technology-Reimbursement Tension
Device capabilities are advancing rapidly, with smart implant platforms, firmware-upgradeable architectures, and expanded pediatric candidacy reshaping clinical value propositions. At the same time, reimbursement frameworks remain stable but not infinitely elastic. The persistence of established coding and coverage structures provides predictability for providers and patients, but it also places a ceiling on how quickly premium pricing can be transferred through the system. Manufacturers that introduce higher-cost, feature-rich platforms must demonstrate differentiated outcomes and total-cost-of-care advantages to secure broad adoption without triggering payer resistance.
2. Geographic Adoption Asymmetry
Demand is not materializing at the same pace across regions. Mature markets benefit from established clinical pathways, higher awareness, and favorable reimbursement, while emerging regions face a combination of access barriers, cost sensitivity, and unevenly distributed surgical capacity. This asymmetry creates both a growth opportunity and a commercial risk: companies that can adapt product portfolios, service models, and pricing to lower-threshold markets can unlock volume, but generic expansion without local clinical and reimbursement strategy often underperforms.
3. Competitive Moats Under Pressure from Programmatic Procurement
The participation of major implant systems in government volume-based procurement programs introduces a new dimension of price competition in large addressable markets. While such programs can expand access and stabilize volume, they also compress margins and reward scale, supply-chain efficiency, and local partnerships. Incumbents with strong clinical heritage must now balance their differentiation narrative against the reality of organized price discovery in key public procurement environments.
Core Growth Drivers
Technology Innovation and the Shift Toward Upgradable Platforms
One of the most significant drivers of commercial momentum is the transition from static implant systems to architectures that support post-implant enhancement. The approval of the Nucleus Nexa System as the world's first smart cochlear implant with firmware upgrade capability marks a notable change in how value can be delivered over the device lifecycle. Rather than relying solely on surgical revision to access newer capabilities, this model opens the door to ongoing performance improvements, feature additions, and potentially longer effective device longevity. For clinicians and patients, the appeal lies in future-proofing the implant; for manufacturers, it creates a platform narrative that can support both initial adoption and long-term engagement.
At the same time, expansion of pediatric candidacy is broadening the addressable population. Recent regulatory progress allowing implantation for children from 7 months of age onward with bilateral sensorineural hearing loss extends the intervention window earlier in development, which can strengthen the clinical case for timely cochlear implantation. Earlier intervention aligns with longstanding optimization arguments in pediatric hearing care, and it gives manufacturers a stronger foundation to engage pediatric centers and referral networks.
Stable Policy and Reimbursement Foundations
A second driver is the durability of the reimbursement and coding environment in key markets. The continued effect of the relevant cochlear device implantation code without revision supports billing predictability for providers, while sustained coverage under national framework decisions maintains a stable pathway for patient access. This stability does not eliminate pricing pressure, but it reduces one category of uncertainty that often slows adoption in medical device markets. In practical terms, it allows manufacturers and healthcare providers to invest in program development, surgeon training, and patient identification with greater confidence that the procedural and coverage basis will remain in place.
Demand-Side Evolution: Earlier Intervention and Broader Candidacy
Demand is being reshaped not only by technology but by clinical behavior. The combination of smarter implant platforms and wider pediatric indications encourages earlier referrals and more aggressive candidacy assessment. As clinical confidence grows around earlier intervention and long-term outcomes, the pool of eligible patients expands beyond the traditional severe-to-profound loss segment. This shift is especially relevant in pediatric care, where timing can influence language development and educational trajectories, and in adult populations, where evolving expectations around auditory performance and connectivity are raising the bar for what patients consider an acceptable outcome.
Supply Chain, Cost Structures, and Programmatic Access
A third driver is the reorientation of cost structures around scale and public procurement. Participation in volume-based procurement programs can lower per-unit pricing but also secures volume commitments and broadens access in large markets. For manufacturers, this dynamic rewards operational efficiency, disciplined cost management, and the ability to sustain quality while competing on program terms. It also encourages strategic positioning around local service, training, and aftercare, since procurement wins often depend on more than the implant itself. In this environment, cost structure is not merely an internal efficiency issue; it is a market-access strategy.
Competitive Landscape and Leading Strategies
The market's concentration profile reflects the strength of established incumbents, but the strategic playbooks differ in ways that matter for future positioning.
Cochlear Limited: Platform Leadership and Smart Implant Differentiation
Cochlear has built its position on a broad implant and bone conduction portfolio, and its recent smart implant milestone reinforces a platform-oriented strategy. By delivering an FDA-approved system with firmware upgrade capability, Cochlear is emphasizing lifecycle value rather than a one-time device transaction. This approach supports clinicians who want to offer patients a more future-ready solution and gives the company a narrative that ties innovation to long-term patient engagement. The strategic advantage here is differentiation through architecture: if upgradability becomes a standard expectation, early leaders in this category can shape procurement criteria and clinical preference.
MED-EL: Pediatric Expansion and Indication Breadth
MED-EL's recent FDA approval expanding pediatric candidacy for children 7 months and older illustrates a strategy centered on indication breadth and early-life intervention. By extending the addressable pediatric population, MED-EL strengthens its relevance in one of the most clinically important and referral-sensitive segments. The broader implication is competitive: as more companies secure expanded pediatric indications, the market may see intensified activity around early identification programs, family engagement, and center-level partnerships. MED-EL's positioning suggests that indication expansion can be as commercially meaningful as hardware features when it opens a clearer path to earlier adoption.
Advanced Bionics: Scale, Procurement Alignment, and Portfolio Breadth
Advanced Bionics, supported by Sonova's broader hearing care ecosystem, demonstrates a different form of strength: alignment with large-scale public procurement and a diversified processor portfolio. Selection for China's volume-based procurement program highlights the importance of being competitive in organized purchasing environments while maintaining a credible clinical and product narrative. In practical terms, this positions the company to capture volume in markets where programmatic access is a decisive factor. The strategic lesson is that scale and procurement readiness can be just as important as feature leadership in certain geographies, especially where public spending shapes adoption.
How the Landscape Is Evolving
The competitive order is not static. Several trends are shaping its evolution:
- Differentiation is moving from device-only features to lifecycle and service value, including firmware upgradability, patient engagement, and clinical support.
- Pediatric and early-intervention indications are becoming a contested ground, with regulatory wins translating into center-level influence and referral momentum.
- Programmatic procurement is introducing structured price competition in major markets, rewarding scale, cost discipline, and local ecosystem partnerships.
- Geographic expansion remains a source of growth, but success increasingly depends on adapting to local reimbursement, surgical capacity, and pricing expectations rather than relying on global product uniformity.
For new entrants, the bar is high givenconcentration, but niches exist around specialized candidacy segments, regionally tailored access models, and complementary technologies that enhance outcomes or lower total cost of care. Consolidation is possible where scale and procurement readiness matter most, while fragmentation may persist in segments where clinical specialization and local relationships drive decisions.
Future Trends and Commercial Implications
Trend 1: Lifecycle Value Becomes a Purchase Criterion
As upgradable and smart implant platforms gain regulatory acknowledgment and clinical traction, procurement and clinical decisions may increasingly weigh post-implant enhancement potential. This shift creates opportunities for manufacturers that can credibly support firmware-based improvement, remote management compatibility, and long-term performance assurances. It also raises the stakes for companies whose portfolios remain oriented around static device value, since the comparison set may gradually move toward total lifecycle benefit rather than initial specification alone.
Dental Implants Market
The associated risk is that lifecycle claims must be substantiated with evidence and supported by manageable cost models. If payers or providers perceive upgradability as a source of added cost without clear outcome advantages, the premium may be difficult to sustain.
Trend 2: Earlier Pediatric Intervention Drives Referral and Program Competition
Expanded pediatric candidacy is likely to intensify competition for early identification pathways, family counseling, and center-level adoption. The commercial opportunity lies in building robust referral networks, supporting screening and diagnostic workflows, and demonstrating that earlier implantation can deliver meaningful developmental and educational value. Over the next three to five years, companies that invest in pediatric program enablement may see stronger repeat engagement and more resilient center relationships.
The uncertainty here is clinical and operational: earlier candidacy must be matched by appropriate patient selection, surgical capacity, and follow-up infrastructure. If capacity lags behind indicated demand, adoption may be uneven and program performance could vary by region.
Trend 3: Programmatic Procurement Reshapes Pricing and Access in Large Markets
Volume-based procurement and similar mechanisms are likely to remain influential where governments seek to broaden access while managing expenditure. This trend favors organizations that can combine competitive unit economics with reliable service, training, and supply assurance. It also encourages portfolio strategies that can perform on both clinical differentiation and program economics. For investors and executives, the implication is that revenue growth in these markets may come with margin discipline, making operational execution a strategic differentiator.
The downside risk is that procurement-driven pricing can pressure returns if not offset by volume scale, cost efficiencies, or value-added services. Companies that cannot adapt their cost structures or local operating models may find their market share vulnerable even when their clinical reputation remains strong.
Strategic Recommendations for Decision Makers
For Manufacturers and Commercial Leaders
Prioritize lifecycle differentiation and indication expansion as parallel growth levers. Firmware-upgradable platforms, stronger pediatric candidacy, and robust center support can reinforce both initial adoption and long-term value. At the same time, prepare for programmatic procurement by strengthening cost structure, supply reliability, and local partnership capabilities. In practical terms, product strategy and market-access strategy should be developed together rather than sequentially.
For Investors and Capital Allocators
Look beyond top-line growth and assess how companies are positioned for the three forces shaping the market: lifecycle value, pediatric indication breadth, and procurement-driven pricing. The most resilient business models will likely combine credible differentiation with operational discipline and the ability to win in organized purchasing environments. Evaluate exposure to regions where adoption asymmetry can be addressed through tailored access strategies, and consider whether a company's roadmap aligns with the direction of clinical and regulatory change.
For Providers, Procurement Teams, and Health System Leaders
Evaluate implant choices with a longer time horizon, weighing not only immediate performance but also upgrade potential, support infrastructure, and total cost of care. As candidacy expands and device architectures evolve, procurement decisions should account for clinical program needs, follow-up capacity, and the ability to serve broader patient populations. In procurement-intensive settings, prioritize partners that can demonstrate reliable delivery, training, and service alongside competitive pricing.
Breast Implants Market
Closing Perspective
The cochlear implants market is moving from a period of broad-based growth to a more nuanced environment where technology architecture, indication strategy, reimbursement stability, and procurement dynamics jointly determine commercial outcomes. The market's expansion toward the 3 billion USD range by 2032 is supported by a credible 7.5 percent CAGR, but the distribution of value will depend on how effectively companies convert innovation into access, evidence, and operational readiness. For executives, investors, and procurement leaders, the most valuable next step is to ground strategic choices in detailed segment, regional, and product-level intelligence that connects these macro trends to specific portfolio and market decisions.
For detailed analysis of this topic, please visit the official page: Cochlear Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


