



Category: market research
PW Consulting: Thermoplastic Edgeband Market Set to Grow at 7.2% CAGR Through 2032
By PW Consulting, 2026-07-12
Thermoplastic Edgeband Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused strategic primer on the Thermoplastic Edgeband market designed to inform executive decisions in 2026. This introduction synthesizes macro trajectories, competitive moves, supply-side shocks and regulatory currents to highlight where value will be created — and where risk will accumulate — over the 2026–2032 forecast horizon. To preserve the tactical edge of our subscribers, detailed segment breakdowns and raw tables are intentionally withheld from this preview; the full report contains the granular datasets, regional and application splits, and company scorecards that operational teams require.
Thermoplastic Edgeband Market
Market snapshot: scale and growth trajectory
The market for thermoplastic edgebanding has demonstrated resilient expansion through the early 2020s, growing from approximately USD 2,100 Million in 2020 to about USD 2,955 Million in 2025 (base year). Our forecast projects continued expansion at a compound annual growth rate (CAGR) of 7.2% across 2026–2032, lifting total market value to roughly USD 4,817 Million by 2032. Early forecast years reflect steady demand continuity (2026 estimated at ~USD 3,104 Million), with acceleration in the latter half of the decade driven by material substitution, premiumization and digital decor adoption.
Thermoplastic Edgeband Market
Why this report matters for 2026 decisions
- Allocation of CAPEX and capacity timing: With visible capacity additions and plant investments announced across regions, the report helps manufacturing leaders decide where and when to expand, retrofit or idle extrusion lines to avoid overcapacity or missed demand windows.
- Product portfolio prioritization: As finishing technologies (laser edges, zero-joint systems, 3D haptics) move from niche to mainstream, providers must decide which product families (PVC, ABS, PP, PMMA, specialty) to scale or sunset. Our scenario models quantify the ROI of switching production trains under varying raw-material price and regulation cases.
- Sourcing and procurement hedging: Raw-material volatility is a primary margin lever. The report includes stress-tested cost scenarios and supplier concentration maps to guide forward contracts, local sourcing, and vertical integration decisions.
- M&A and partnership targets: With the industry exhibiting moderate consolidation (CR3 ~58%, CR5 ~68%), the study identifies the strategic rationales and valuation brackets for bolt-on acquisitions versus greenfield expansions.
- Compliance and sustainability planning: Anticipated regulatory shifts on PVC usage and end-of-life handling necessitate pre-emptive product and material strategies. We provide a regulatory-readiness checklist and certification roadmaps.
What’s in the full report (practical, actionable modules)
- Executive dashboard: one-page view of market size, growth drivers and downside scenarios calibrated to 2026 planning cycles.
- Demand model: bottom-up demand drivers by end-use and application with sensitivity to housing, furniture cycles and commercial fit-outs.
- Cost and margin simulator: raw-material (PVC, ABS, PP, PMMA) cost curves, freight and tariff overlays enabling margin forecasting at SKU-level.
- Competitive heatmaps and supplier scorecards: manufacturing footprint, product capabilities, channel strength and strategic intents (R&D, capacity moves).
- Go-to-market playbooks: channel strategies for OEM, distributor and direct-sell models, including price-pack architecture for premium vs. commodity tiers.
- Scenario planning compendium: three multi-factor scenarios (Base, Raw-Material Shock, Rapid-Substitution) with recommended tactical playbooks for each.
- Implementation toolkit: procurement clause templates, sample contract hedges, and an eight-week sprint plan for pilot launches of new edgeband SKUs.
Competitive landscape — who to watch and why
The market combines established global extrusion leaders with agile regional players. Key incumbents continue to invest selectively in capacity, digitization and premium finishes, while mid-sized manufacturers pursue volume growth via logistics and localized supply chains.
Thermoplastic Edgeband Market
- SURTECO (Buttenwiesen, Germany): A long-standing leader with deep extrusion experience and a broad portfolio spanning PVC and ABS, SURTECO’s international distribution reach and emphasis on circular/sustainable designs make it a go-to partner for multinational furniture manufacturers seeking consistent multi-region supply and décor matching.
- REHAU (Reinbek, Germany): REHAU’s strengths lie in advanced color-matching and laser-edge technologies. Recent investments expanding high-resolution inkjet printing for 3D-texture haptic edge bands indicate a push to capture higher-margin, design-driven segments where differentiation and shorter lead times matter.
- MKT (Germany): Specialist positioning in premium ABS and PP lines, along with finishes such as mirror gloss and anti-fingerprint, places MKT at the premium end of the market where design fidelity and processing compatibility enable price premiums.
- ROMA PLASTIK (Gebze, Turkey): A significant exporter with large decor catalogs, Roma Plastik’s continued investment in logistics and distribution is geared toward fast delivery to neighboring markets and cost-competitive supply to EU and MENA buyers.
- Döllken-Kunststoffverarbeitung (Gladbeck, Germany): Known for processing suitability and certifications (including Greenguard), Döllken’s product positioning addresses customers prioritizing low emissions and high process yields.
Recent corporate moves reinforce two near-term themes: capacity rebalancing and capability upgrading. For example, Wilsonart’s 2026 expansion in Texas targets ABS supply for healthcare furniture, signaling demand pockets where compliance and sterilization requirements favor specific polymers. REHAU’s additional inkjet lines underscore the commercial viability of high-resolution, tactile edge bands. Regional expansions from Asian and Turkish producers, plus logistics investments, point to intensifying competition on lead times and total delivered cost.
Market dynamics, headwinds and regulatory inflection points
- Raw-material volatility: Polypropylene, a core feedstock, rose ~19.2% between 2021–2023. Such swings materially affect production economics for PP-based edgebands and magnify the value of procurement hedges and flexible compounding capabilities.
- Regulatory pressure and material substitution: Environmental regulations and end-of-life concerns have elevated interest in non-chlorinated alternatives. ABS, being chlorine-free and incinerable under authorized conditions, is increasingly positioned as a strategic alternative to PVC in regulated markets.
- Trade and tariff friction: New tariff measures (including recent duties on certain imports) increase landed costs for cross-border suppliers and enhance the strategic case for nearshoring or local inventory hubs to serve sensitive verticals.
- Geopolitical supply disruptions: Sanctions and energy-market shocks stemming from the Russia–Ukraine conflict have amplified feedstock (ethylene/ethylene-derived PVC) cost volatility, necessitating contingency planning for polymer supply chains.
- Industry sentiment: Our sector canvass finds that roughly 42% of manufacturers cite raw-material price volatility and environmental regulation as top operational challenges — a material share that should shape both short-term procurement and longer-term product strategy.
Strategic imperatives for 2026
- Re-assess product mix through a regulatory lens: Accelerate ABS and specialty polymer capabilities where market access risks for PVC are rising, and evaluate recycling-ready formulations where certification yields commercial advantage.
- Invest selectively in digital decor and haptic finishes: Moves by market leaders to boost inkjet and texture capacity demonstrate clear margin upside in design-led segments — prioritize pilot projects tied to blue-chip furniture accounts.
- De-risk supply via regional sourcing hubs: Given tariff shifts and freight volatility, nearshoring and multi-sourcing lower the chance of production stoppages and protect gross margins.
- Embed cost-curve scenarios into pricing: Adopt dynamic pricing linked to polymer indices and freight to preserve margins while maintaining competitiveness in distributed markets.
- Scan M&A for capability and channel gaps: With medium concentration at the top, bolt-ons that add high-resolution decor, zero-joint tech or logistics networks deliver faster scale than organic builds in many cases.
Methodology and report credibility
The underlying study uses a 2025 base year, a historical window from 2020–2025 and a forecast period of 2026–2032. Estimates are derived from bottom-up market modeling calibrated against primary interviews with producers, distributors and end-users, and cross-checked against trade, customs and macroeconomic indicators. Market concentration is moderate at the top: CR3 approximates 58% and CR5 about 68%, reinforcing a market structure where leading players can shape technical standards and channel economics.
Next steps — how to use this intelligence
If you are preparing 2026 budgets, sizing capital projects, negotiating long-term polymer supply contracts, or evaluating M&A prospects in surface finishes and furniture supply chains, this study provides the decision-grade analytics and executable tools you need. The full report contains the complete segment tables, regional and application splits, SKU-level margin simulations and vendor scorecards that operational teams must access to execute confidently.
To request the full dataset, tailored scenario briefings or a 60-minute strategic workshop with our lead analyst team, please visit the PW Consulting research portal. This preview highlights the strategic imperatives and directional signal; the full intelligence unlocks the tactical playbooks your teams need to win in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Thermoplastic Edgeband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SST Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Strategic Preview: Solid State Transformers (SST) Market — Why PW Consulting’s 2026 Research Is a Boardroom Imperative
As organizations accelerate electrification, digital infrastructure expansion, and decarbonization initiatives, Solid State Transformers (SSTs) have moved from laboratory curiosity to near-term commercial reality. PW Consulting’s 2026 SST Market study — grounded on a 2025 base year and projecting through 2032 — synthesizes macro forecasts, technology economics, regulatory inflection points, and competitive positioning into an actionable playbook for executive teams, corporate strategy units, and infrastructure investors. The global SST market, measured in USD million, shows a clear upward trajectory: after crossing a notable milestone in our 2025 base year, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 horizon, reaching materially higher levels by 2032. This report is purpose-built to support high-stakes 2026 decision cycles — procurement, partnerships, factory investments, and regulatory engagement.
Solid State Transformers (SST) Market
What makes this research strategically valuable for 2026 decisions?
- Timely commercialization inflection: Multiple vendors have signaled product-readiness and early deployments for 2026, shifting SSTs from experimental to investable. That changes the profile of risk for supply chain investments, pilot capital, and utility integration pilots.
- Policy-driven demand windows: Large public programs and changing electrical equipment regulations are creating procurement windows and rate-case rationales that favor early movers. Our research maps these policy timelines to commercial opportunity, enabling advocacy and bid-timing precision.
- Capital allocation clarity: With quantified market growth and scenario-based TAM/SAM analyses, the study helps CFOs and corporate development teams size near-term investment needs and evaluate M&A targets with informed upside assumptions.
- Deployment playbooks: The report does more than forecast; it prescribes vendor selection criteria, validation protocols, and operational integration steps to de-risk first-of-a-kind commercial rollouts.
Market trajectory — headline numbers you can act on
PW Consulting’s base-year snapshot (2025) establishes the commercial market for SSTs and provides a reference for capital planning. From that base, our forecast models project consistent expansion driven by multi-sector demand and regulatory tailwinds. The market is projected to grow at a 6.98% CAGR through 2032, reflecting steady adoption across renewables, EV fast-charging, data center electrification, and advanced distribution applications. Near-term growth (2026–2028) is shaped by first-wave commercial deployments and policy-funded grid modernization programs; medium-term expansion (2029–2032) reflects scaling manufacturing, falling component costs, and integration into mainstream utility planning.
Solid State Transformers (SST) Market
Drivers, constraints, and the economics that matter
- Regulatory accelerants: Material public programs and regulatory decisions are actively reducing adoption barriers. Significant federal funding for grid resilience initiatives is creating grant- and incentive-funded pathways for SST pilots and distribution modernization. Likewise, equipment regulations that phase out legacy insulating gases are catalyzing demand for digital, gas-free alternatives.
- System-level value: SSTs offer capabilities beyond voltage conversion — dynamic power flow control, multi-port dispatching, and embedded power electronics that can materially improve asset utilization in microgrids, data centers, and charging hubs. Our valuation frameworks quantify incremental system benefits (capacity deferral, energy optimization, ramping services) and translate them into payback scenarios for utilities and large C&I customers.
- Cost structure friction: Wide-bandgap semiconductors (e.g., silicon carbide) are a double-edged sword — they enable compact, high-performance SST designs but currently account for a substantial share of BOM cost and remain several times more expensive than silicon alternatives. As a result, SST manufacturing costs today are multiple times higher on a per-kVA basis compared with conventional transformers; the report models cost-reduction trajectories based on anticipated SiC adoption curves, volume ramp assumptions, and supply concentration risks.
- Integration and standards gaps: Realizing full system value requires updates to protection schemes, distribution operations, and interconnection standards. We highlight the minimum set of interoperability, telemetry, and protection requirements to include in procurement RFPs to avoid costly retrofits.
Technology and supply chain implications
Transitioning from prototypes to volume SST production has cascading implications across the supply chain. Our report dissects a practical technology roadmap that buyers and manufacturers can use to align product roadmaps with the expected cost curve. Key areas covered include:
Solid State Transformers (SST) Market
- Component concentration risk for wide-bandgap semiconductors and the impact of long lead-times on factory scheduling.
- Design choices that materially affect serviceability and total lifecycle cost — modular power stages, thermal management approaches, and serviceability-by-design options for utility crews.
- Sourcing strategies for critical passive components, packaging, and thermal systems to avoid single-sourcing pitfalls.
- Quality and test regimes necessary for reliability targets in utility and data center environments, plus recommended acceptance testing templates.
Competitive landscape — who to watch (and why)
The SST supplier ecosystem is emerging with a mix of deep incumbents and specialized startups. PW Consulting’s vendor analysis combines product roadmaps, go-to-market strategies, and recent strategic moves to give corporate buyers and investors a concise competitive map.
- DG Matrix (Raleigh, NC) — A provider of multi-port SST platforms designed for AI data centers, microgrids, and electrification use cases. Recent strategic partnerships and Series A funding have accelerated commercialization pathways and validate customer interest in multi-port dispatchable solutions.
- Amperesand (Singapore) — Focused on medium-voltage platforms for critical infrastructure and industrial electrification, with manufacturing capability in the U.S. and targeted commercial deliveries in 2026 to hyperscalers and Fortune-scale customers.
- Eaton Corporation (Dublin, Ireland) — Leveraging acquisitions to internalize medium-voltage SST technology for data centers, energy storage, and EV charging ecosystems; their scale positions them as a mainstream integrator able to combine legacy switchgear and SST capabilities.
- WattEV (Long Beach, CA) — Building modular SSTs aimed at megawatt-class heavy-duty vehicle charging, with production-ready units targeted for imminent deployment and clear targeting of the heavy transport charging market.
Each of these players demonstrates a different go-to-market vector — from specialist platforms for AI/data center clients to incumbents leveraging established distribution channels. Our competitive profiles include vendor scorecards that assess manufacturability, integration readiness, service model, and commercial traction.
What the report contains — practical, operational deliverables
PW Consulting’s SST Market report is intentionally structured to be a working tool for teams contemplating near-term commitments. Highlights include:
- Market sizing and scenario forecasts (2026–2032) with sensitivity cases and unit-volume assumptions tied to policy and technology milestones.
- Segmented demand narratives by application—renewables integration, EV fast-charging, data center electrification, distribution modernization—and a methodology for translating system-level value into procurement criteria (note: detailed segment tables and granular percentages are reserved for the full report to preserve commercial sensitivity).
- Vendor due diligence templates and an RFP checklist that include recommended test specifications, warranty constructs, and service-level expectations.
- CapEx/Opex modeling templates, including multi-year TCO comparisons that explicitly model SiC price trajectories, manufacturing yield assumptions, and secondary benefits like capacity deferral.
- Regulatory and incentive playbook that maps major federal and regional funding programs, standards timelines, and rate-case levers for utility deployment economics.
- Deployment playbooks for pilots and scale rollouts — procurement sequencing, interconnection coordination, and stakeholder engagement scripts for utilities, regulators, and large C&I customers.
How executives should use this intelligence in 2026
- Procurement timing: Use the report’s policy and vendor-readiness timelines to align RFPs with supplier capacity and incentive windows, minimizing carry costs and securing favorable terms.
- M&A and partnerships: Identify strategic acquisition targets or JV partners that fill capability gaps (power electronics, system integration, service ops) and use our valuation framework to size accretive deals.
- Factory and CAPEX planning: Apply the cost-crossover scenarios to decide whether to co-locate assembly near semiconductor suppliers, enter licensing agreements, or adopt a fabless model.
- Regulatory engagement: Target state and federal regulatory processes identified in the report to secure rate-basing approval, grid-interconnection waivers, or incentive qualification for early deployments.
Why this is a “trailer” and how to get the full picture
This article is a strategic preview: it demonstrates the depth of our analysis and highlights near-term decision levers while deliberately withholding granular segment-level tables and the full vendor-scorecard detail that materially inform procurement and investment selection. For teams preparing RFPs, CAPEX proposals, or M&A diligence in 2026, the complete report includes the detailed segmentation, down-to-kVA modeling, supplier cost curves, and downloadable templates necessary to execute with confidence.
Next steps
- For procurement and strategy leads: request the full report to obtain the RFP checklist, TCO model, and vendor scorecards tailored to your application mix.
- For investors and corporate development teams: engage PW Consulting for a targeted diligence package that overlays our forecast on your asset base and risk appetite.
- For utilities and regulators: leverage our policy playbook to craft rate-case narratives and pilot evaluation criteria that capture SST-specific system benefits.
PW Consulting’s 2026 SST Market study translates a nascent technology wave into executable strategy. If your 2026 capital and operational plans touch distribution modernization, fleet electrification, data center resilience, or grid-edge services, this research gives you the language, the scenarios, and the tactical tools to act — precisely when timing and positioning matter most.
For detailed analysis of this topic, please visit the official page: Solid State Transformers (SST) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Billet Casters Market: Strategic Outlook for 2026 — A PW Consulting Executive Brief
As industrial supply chains and heavy-metal metallurgy enter a new phase of modernization, the billet casters market presents a blend of enduring capital intensity and differentiated technological trajectories. This PW Consulting industry brief previews our comprehensive Billet Casters Market report (base year 2025, historical 2020–2025, forecast 2026–2032). Below we synthesize the high-level market trajectory, the decision-relevant findings our full study provides, and the strategic questions every procurement, engineering, and M&A team should be asking in 2026. This is an executive “trailer”: we demonstrate analytical depth and the report’s practical value while reserving detailed segment tables and project-level models for the full publication.
Billet Casters Market
Why this market matters for 2026 decision-making
Billet casters sit at the intersection of metallurgy, process automation, and heavy equipment investment. Our top-line sizing shows the market expanding materially through the 2020s — growing from around USD 200 Million in 2020 to approximately USD 260 Million by 2025 and projected to approach USD 376 Million by 2032. The forecast period (2026–2032) reflects a compound annual growth rate of 5.5%, driven by replacement cycles, upgrades for higher-alloy and larger-section capabilities, and continued mini-mill expansions that favor modular, compact caster platforms.
Billet Casters Market
For executives making capex, sourcing, or product roadmap choices in 2026, that trajectory has three practical implications: (1) timing matters — early investment in modernization yields a differentiated yield on product quality and throughput; (2) supplier selection is strategic — a relatively concentrated supplier base means technological and after-sales capabilities are decisive; and (3) total project economics go well beyond the machine price — civil works, integration, and operating performance shape lifecycle returns.
Billet Casters Market
What our full report delivers (practical, operational content)
- Actionable market sizing and forecast model at the industry level (base year 2025; historical series 2020–2025; forecast 2026–2032), including sensitivity scenarios for alloy demand, energy cost shocks, and mini-mill adoption curves.
- Capital and lifecycle cost frameworks: comprehensive capex/opex templates that map machine category (modular vs. high-end multi-strand) to expected total project outlays, commissioning timelines, and NPV breakeven under several throughput profiles.
- Technology dossiers that compare vertical, horizontal and curved caster architectures across quality outcomes (inclusion control, internal soundness), casting speed envelopes, and retrofit friendliness.
- Supplier benchmarking: capability matrices that evaluate engineering depth, global service footprint, spare-parts lead times, and digitalization maturity — essential for risk-weighted procurement.
- Regulatory and compliance playbook: certification requirements for ultra-large sections and high-alloy grades, and a checklist for contracting competitive warranty and performance guarantees.
- Practical procurement tools: RFQ templates, scoring rubrics, and a phased acceptance test plan tailored for multi-strand high-end machines.
Market structure and concentration — what to infer
The market exhibits moderate-to-high concentration: the top three suppliers account for a majority share of installed high-end capacity, and the top five extend that dominance further. For buyers this creates both risk and opportunity. On one hand, incumbent vendors with decades of metallurgical know-how and global spares networks command pricing power for premium configurations. On the other, their dominance means differentiated niche vendors can win by focusing on modularity, short lead-times, or highly localized service models.
Competitive landscape — core players and recent strategic moves
Our competitive analysis focuses on suppliers that shape technology trajectories and service expectations. Below are high-level profiles and notable developments that underscore strategic positioning in 2025–early 2026:
- SMS group GmbH (Düsseldorf, Germany) — A legacy engineering house with deep capabilities in complex billet caster designs (multi-strand, vertical and curved). SMS has been active on modernization projects, delivering advanced mechanical soft-reduction and quality-focused retrofits that target internal billet soundness.
- Danieli & C. Officine Meccaniche S.p.A. (Buttrio, Italy) — Known for integrated plant solutions and oscillation technologies that prioritize surface and internal quality for demanding grades. Danieli continues to secure orders for ultra-large, high-alloy billet lines and runs a service organization focused on upgrades and lifecycle support.
- Primetals Technologies (London / global) — With modular offerings aimed at mini-mill and rebar-integrated operations, Primetals builds systems optimized for square/rectangular sections and high-speed downline integration. Its ownership structure and Indian manufacturing footprint reinforce competitiveness in price-sensitive retrofit segments.
- Electrotherm E&T Ltd. (Ahmedabad, India) — A specialist in compact, modular casters suitable for induction-melt shops and ingot-to-billet conversions; attractive where footprint and small heat sizes are constraints.
- Concast India Private Ltd. (Primetals subsidiary) — Focused on delivering modular 5–7 strand solutions to domestic mini-mills, emphasizing quick delivery and integration with existing rolling lines.
Notable recent developments (indicative, non-exhaustive) illustrate how competition is unfolding: large orders for ultra-large section lines and modernization contracts for multi-strand casters signal sustained demand at the high end, while modular suppliers continue to capture mini-mill retrofit opportunities. These contrasting deal types — high-capex flagship projects versus compact, rapid-delivery modular machines — define two parallel competitive plays in 2026.
Cost, input risks, and project economics
Project procurement teams should treat machine price as the start, not the finish, of evaluation. Our analysis synthesizes industry cost composition and identifies the cost buckets that matter most in negotiation and lifecycle assessment:
- Raw material content (high-grade alloy steels, refractory parts, copper mold components) typically comprises a material portion of the machine bill of materials; supply-chain volatility in these inputs directly transmits into lead-time and price risk.
- Precision fabrication, welding and hydraulic/electromechanical integration are significant labor-intensive cost drivers; these activities also determine field reliability and commissioning duration.
- R&D, certification, and metallurgical process validation—especially for high-alloy grades and ultra-large sections—add a non-negligible premium and can extend project timelines if not planned early.
- Advanced multi-strand machines with electromagnetic stirring and dynamic cooling command premium pricing and deliver superior rolling yields; lifecycle returns depend on alloy mix, scrap reduction and downstream rolling yield improvement.
- Typical total greenfield project costs for high-end caster installations can cross substantial capital thresholds once civil works and ancillary equipment are included; even modular projects have non-trivial integration costs.
Opportunities, risks and strategic moves for 2026
We identify three near-term strategic plays where companies can extract disproportionate value:
- Quality-led differentiation — For producers targeting premium alloy markets, investing in advanced caster features (soft reduction, electromagnetic stirring, dynamic cooling) converts directly into downstream premium pricing by reducing internal defects and improving tensile/creep performance for critical grades.
- Modularity and speed-to-market — Mini-mill operators and retrofit projects prioritize compact, modular casters with short lead times; OEMs that standardize modular platforms and spare-parts kits will win these high-velocity deals.
- Service and lifecycle contracting — Given the concentration of supplier capability, extended service contracts, predictive maintenance packages, and performance guarantees are becoming negotiation levers; buyers should quantify the present value of uptime and quality improvements when choosing suppliers.
Key risks that could materially alter the 2026–2032 outlook include sustained spikes in energy prices, an unexpected slowdown in construction of long steel plants, or trade-policy changes that disrupt raw-material flows. Conversely, rising demand for high-alloy sections in power-generation and petrochemical applications could accelerate high-end machine orders beyond our base-case forecast.
How to use the full PW Consulting report
Our full Billet Casters Market study is designed as a working tool for procurement teams, plant engineers, strategy groups, and investors. It includes downloadable models, an RFQ checklist, supplier scorecards, and scenario-capable financial models that allow you to stress-test purchase decisions under alternative alloy-mix and throughput assumptions. The report also contains detailed segmentation tables and granular regional/application breakdowns that are intentionally withheld in this preview — these are essential inputs for deal-level decisions and are available via the report portal.
Methodology note
The study uses a 2025 base year with historical tracking from 2020–2025 and a forecast horizon of 2026–2032. Market sizing blends bottom-up equipment shipments, validated order-intake data, and capital expenditure signals from steel producers; sensitivity scenarios model alloy-demand elasticity, project-level capex variation, and vendor-market-share displacement. Concentration metrics reported in the study reflect installed base and recent order flows and are summarized at the top-line level in this brief.
Next steps for readers
- If you are evaluating a caster purchase or upgrade in 2026, map your decision against the report’s capex/opex templates and request the supplier scorecards to build a risk-weighted shortlist.
- For M&A or investor diligence, use the scenario models in the full report to simulate demand shocks and to quantify integration value from spare parts and service-platform consolidation.
- To operationalize improvements in yield and quality, deploy the report’s technology dossiers and commissioning checklists during vendor selection and FAT/SAT negotiations.
PW Consulting’s Billet Casters Market study provides the actionable intelligence that industrial leaders need to make defensible, value-accretive decisions in 2026. For access to the full data tables, supplier scorecards, and downloadable financial models, please consult the report portal where the complete analysis is published.
For detailed analysis of this topic, please visit the official page: Billet Casters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoked Salmon Market to Reach USD 788 Million by 2032 at 5.6% CAGR
By PW Consulting, 2026-07-12
Smoked Salmon Market — Strategic Outlook for 2026: Navigating Growth, Risk and Differentiation
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet forward-looking briefing designed to inform executive decisions in 2026. This preview synthesizes the full Smoked Salmon Market study — a practical roadmap for commercial leaders, investors, and category managers — highlighting why the market warrants renewed attention, where near-term risks concentrate, and which strategic moves are most likely to generate durable competitive advantage.
Smoked Salmon Market
Market snapshot: resilient category, clear growth trajectory
The global smoked salmon category has demonstrated resilience through recent volatility. After recovering from pandemic-era disruption, the market recorded steady growth from 2020 through 2025, reaching a total market size of approximately USD 541 million in our 2025 base year. Our forecast models — calibrated to supply-chain realities, consumer demand signals, and recent commercial activity — indicate a compound annual growth rate of 5.6% over the coming forecast horizon, carrying the market toward roughly USD 788 million by 2032.
Smoked Salmon Market
Two observations are central for 2026 planning. First, the underlying demand remains intact: consumers continue to pay premiums for provenance, texture and convenience formats. Second, the category exhibits episodic supply-side sensitivity — regulatory actions, recalls and export restrictions have in recent periods produced localized disruptions that temporarily compress supply and create windows for margin recovery or competitor repositioning.
Smoked Salmon Market
Why this report matters to 2026 decision-makers
- Investment priming: Provides decision-quality demand and supply scenarios and break-even horizons for incremental factory, cold-chain or smokehouse investments.
- Risk mitigation: Converts regulatory and recall risks into operational playbooks — including monitoring thresholds, audit sequencing, and supplier remediation steps — to avoid value-destroying interruptions.
- Commercial optimization: Prioritizes trade and private-label strategies using retailer negotiation levers, assortment recommendations, and price-pack architecture for premium and convenience segments.
- M&A and partnership signal map: Identifies subscale producers and capability adjacencies that are attractive consolidation targets or sourcing partners under different market scenarios.
What’s in the full study (practical deliverables)
- Market sizing and probabilistic forecasts (2026–2032) with scenario-specific revenue paths and sensitivity to price, input cost and trade barrier shocks.
- Demand-driver diagnostics: consumer preference matrices (premiumization, sustainability, convenience), seasonality patterns, and channel elasticity for retail vs. foodservice.
- Supply-chain heat map: risk-ranked suppliers, single-source vulnerabilities, logistics pinch points, cold-chain cost benchmarks and a contingency sourcing ladder.
- Regulatory and compliance playbook: step-by-step Listeria control measures aligned to FDA guidance, import-permit checklists, and cross-border certification workflows.
- Commercial playbooks: private-label vs. branded margin models, pack-sizing experiments, and retailer segmentation strategies to maximize shelf velocity.
- Operational checklists: site-level CAPEX prioritization for smokehouses, quality-assurance protocols, and recall-response templates mapped to legal and communications timelines.
- M&A and partnership due-diligence templates: value-creation levers, integration milestones and realistic synergy capture timelines for consolidation scenarios.
The study is written for operators who need executable plans, not abstract forecasts. It pairs quantitative scenario outputs with stepwise implementation guides so executives can move from insight to action within quarters, not years.
Competitive landscape — what the market structure means for strategy
The smoked salmon category is characterized by moderate concentration: leading groups hold meaningful share but substantial regional and format-level diversity persists. That structure creates three strategic playbooks that work in parallel: scale-driven cost leadership, niche premiumization (artisan/small-batch provenance), and channel-tailored private-label partnerships. Each named participant fits into this spectrum differently.
- Acme Smoked Fish Corporation (Brooklyn) — A high-volume cold-smoked specialist with significant private-label capabilities. Strength: deep retailer relationships and large-scale production. Strategic implication: capable of rapid shelf-coverage but sensitive to brand-agnostic price competition and food-safety scrutiny.
- Ocean Beauty Seafoods / Echo Falls (Seattle) — Diversified across hot and cold formats with established branded SKUs. Strength: product breadth and route-to-market. Strategic implication: innovation and packaging initiatives can expand addressable occasions; watch for margin dilution if scaled primarily through promotions.
- Haifa Smoked Fish (Jamaica, NY) — Retail and foodservice distributor focusing on cold-smoked products. Strength: distribution reach. Strategic implication: recall events highlight the need for upgraded environmental monitoring despite distribution advantages.
- Honey Smoked Fish Co. (Alaska) — Artisan hand-trimmed hot-smoked fillets; clear premium positioning. Strategic implication: premium margins and strong provenance stories but limited scale unless paired with partners for wider distribution.
- Boston Smoked Fish Co. — Broad retail and foodservice family packs; local sourcing story. Strategic implication: good fit for regional expansion and co-packing partnerships.
- Forman & Field (East London) and Bakkafrost Scotland — Heritage and origin-focused players; supply high-value formats to European and export markets. Strategic implication: superior positioning on provenance and tradition; potential upside from premium European demand.
- Trident Seafoods — Recent line expansion underscores capacity to invest behind new premium SKUs and to scale quickly. Strategic implication: competitive pressure on premium price points; watch for distribution expansion that accelerates retailer listings.
- Natural Grocers — Recent private-label launch (May 2026) in MSC-certified wild smoked salmon underscores retailer willingness to vertically integrate premium, sustainability-labeled SKUs.
- Suempol (Poland) — European producer offering hot-smoked and organic variants; strategically positioned to supply European mainland demand and private-label customers.
Recent dynamics that should influence 2026 strategy
- Product recalls in 2025 among established suppliers exposed Listeria-control as a lasting operational risk. These events have real cost implications: lost shelf trust, increased audit frequency, and accelerated retailer compliance demands.
- Retailers are accelerating private-label introductions that combine sustainability credentials with value — a structural pressure on mid-tier branded SKUs, and an opportunity for cost-efficient co-manufacturers.
- Regulatory noise is material: U.S. import restrictions and permit regimes, plus evolving FDA Listeria guidance, are increasing friction and compliance cost for cross-border suppliers. Companies that build robust import and traceability processes will win preferential access.
- Supply-side expansion by vertically integrated seafood processors is increasing competitive pressure at the high end; incumbents with heritage brands must translate story to repeatable retail economics.
Practical 2026 recommendations — prioritized and actionable
- Short-term (next 12 months): institute mandatory environmental Listeria monitoring across facilities, agree dual-sourcing for critical SKUs, and deploy a recall-response kit (communications, logistics, legal templates) to cut time-to-remediation.
- Medium-term (12–36 months): invest selectively in value-accretive capacity (small-batch cold-smoke lines, MAP packaging) that enables premiumization and longer shelf-life; pursue private-label agreements that deliver guaranteed volumes while protecting branded SKUs through premium lines and provenance storytelling.
- M&A and partnerships: prioritize bolt-on acquisitions that close capability gaps (cold-chain logistics, certified smokehouses, MSC-certified supply) rather than trophy deals; focus on integration pathways that secure retail listings and immediate margin uplift.
- Commercially: reprice trade allowances to reflect higher sanitation and compliance costs; pilot smaller pack formats and convenience-ready SKUs to capture growing consumption occasions outside traditional meal times.
Closing — how to use the full PW Consulting study
This preview outlines the strategic contours executives must consider in 2026. The full PW Consulting Smoked Salmon Market study provides the underlying models, granular scenario outputs and implementation-level templates that enable rapid execution. Critical items withheld here (detailed regional splits, format-level unit economics, and downloadable model files) are available in the full report on our site for teams that need transaction-ready intelligence or board-level decision packs.
For teams preparing budgets, supplier contracts, or M&A pipelines: treat 2026 as a year to harden operations against compliance shocks while investing judiciously in formats and channels that compound returns as demand grows at an anticipated 5.6% CAGR. In a moderately concentrated market where both scale and provenance matter, the right blend of operational rigor and differentiated product strategy will determine who captures the next wave of category value.
For detailed analysis of this topic, please visit the official page: Smoked Salmon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
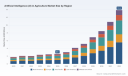
Artificial Intelligence in Agriculture Market: Strategic Imperatives for 2026 Decision‑Makers
As agribusinesses, equipment OEMs, technology vendors and public-sector leaders enter 2026, the AI in agriculture market is shifting from experimental pilots to enterprise-scale deployments. Our PW Consulting baseline finds the market valued at USD 2.6 Billion in 2025 and accelerating rapidly: modeled growth to USD 13.9 Billion by 2032 at a compound annual growth rate of 22.85% underscores both the scale of the opportunity and the urgency of strategic action in the next 12–18 months. This executive introduction summarizes the report’s practical value for corporate strategy, investment prioritization, and implementation roadmaps — while preserving the report’s proprietary segment-level detail to guide readers to the full study for transaction‑grade intelligence.
Artificial Intelligence (AI) in Agriculture Market
Why this report matters for 2026 strategic decisions
-
Timing decisions: 2026 is a hinge year. Technology maturity, regulatory guidance and capital availability are converging — creating windows for first‑mover advantage in core farm-management and automation services.
Artificial Intelligence (AI) in Agriculture Market -
Resource allocation: The report translates broad market momentum into actionable capital deployment plans — clarifying where to allocate R&D, M&A, and go‑to‑market spend to accelerate ROI.
Artificial Intelligence (AI) in Agriculture Market -
Partnership and ecosystem strategy: The landscape is multi‑layered — OEMs, cloud platforms, crop‑science firms and niche AI specialists are all competing and co‑creating. Our analysis helps firms choose when to partner, when to buy and when to build.
-
Regulatory and data governance readiness: With evolving frameworks from regional authorities and federal initiatives for agricultural AI, the ability to demonstrate accountable, explainable AI will be a contract and compliance differentiator.
What the report delivers — practical, operational intelligence
-
Market sizing and scenario planning: A rigorous bottom‑up market model (historical 2020–2025 base, forward forecasts 2026–2032), with alternative adoption scenarios tied to key technology, regulatory and commodity price inflection points.
-
Use‑case ROI playbooks: Field‑tested templates for precision farming, crop health monitoring, autonomous equipment, irrigation optimization and livestock monitoring — each with unit economics, payback sensitivities and scaling checklists.
-
Vendor evaluation framework: A decision matrix that scores vendors on technical fit, data interoperability, deployment risk, and commercial terms — designed for procurement and piloting teams.
-
Deployment blueprints: Integration architectures for cloud‑edge‑sensor stacks, reference implementation for data pipelines, and an operations guide for moving from pilot to fleet‑level orchestration.
-
Regulatory & risk playbook: Practical templates to operationalize compliance with regional AI guidance, agricultural safety rules and data‑sharing agreements, including clauses for model transparency and ethical use.
-
Case studies and supplier diligence: Real-world deployments across farm sizes and crop systems, plus a diligence checklist for investment teams evaluating target companies or technologies.
Market dynamics shaping strategic choices
-
Macro demand drivers: Food security pressures, sustainability targets, and persistent labor shortages are pushing farm operators to deploy AI solutions that reduce input waste, close labor gaps, and lift yield per hectare.
-
Infrastructure and cost realities: Field‑level data collection requires capex — IoT sensors, solar‑powered connectivity and edge compute introduce meaningful upfront cost. Our report models these infrastructure vectors and their impact on TCO across farm archetypes.
-
Regulatory momentum: Policy frameworks in major markets are maturing — coordinated AI plans and federal strategies are introducing standards for transparency, accountability and dataset benchmarking. Organizations must design AI governance into product roadmaps to avoid deployment delays and procurement exclusions.
-
Standards and dataset benchmarking: New initiatives to standardize agricultural machine learning datasets and evaluation benchmarks are reducing model development risk but will favor players who contribute to and adopt common data formats and APIs.
-
Technology stack evolution: Advances in computer vision, machine learning, multispectral/hyperspectral sensing, and autonomous robotics are deepening value capture but shifting the economics from one‑off hardware sales to recurring data and analytics subscriptions.
Competitive landscape — strategic positioning of key players
The competitive environment is differentiated by capability clusters rather than single‑player dominance. Four archetypes emerge, each with distinct implications for partnerships and market entry.
-
Integrated equipment OEMs: Established agricultural machinery manufacturers are embedding AI into autonomous guidance, precision application and fleet telematics. Their strength lies in hardware integration and dealer networks; their challenge is transitioning to service and software economics. Strategic action: pursue OEM partnerships for field trials, insist on open data access and anticipate bundled commercial models.
-
Cloud and enterprise platform providers: Large cloud vendors are packaging IoT, satellite, and analytics capabilities into farm‑grade platforms that support rapid scaling. These platforms lower the barrier to data aggregation and model training but create vendor lock‑in risks. Strategic action: evaluate hybrid cloud strategies and negotiate interoperability clauses.
-
Ag‑science and input firms: Crop‑science companies are embedding digital agronomy and AI advisory into their product suites to drive yield and input optimization. Their advantage is agronomic data and advisory networks; the tradeoff is impartiality when recommending inputs. Strategic action: structure transparency provisions and independent validation for advisory outputs.
-
Specialist AI and sensing startups: Niche vendors focus on hyperspectral imaging, leaf‑level analytics, and machine‑vision driven disease detection. These innovators accelerate feature development and often become M&A targets or strategic partners for scale. Strategic action: use targeted investments or partnership pilots to capture innovation while protecting IP and data rights.
Recent market activity validates these archetypes. Notable developments in the last 18 months include strategic startup collaboration programs from major OEMs, cross‑sector partnerships combining generative and agronomic intelligence, consolidation moves among hyperspectral analytics firms, and product launches that expand precision spraying and robotics capabilities. Collectively these events signal accelerated commercialization and increased capital deployment into operational AI systems.
Actionable framework for 2026 decisions
-
Define prioritized business outcomes: Translate broad ambitions (e.g., sustainability credentials, labor reduction, yield uplift) into quantifiable KPIs that will drive vendor selection and pilot metrics.
-
Structure defensible pilots: Design pilots to validate economics at scale — include data maturity assessments, sensor placement plans, and success criteria tied to financial outcomes rather than purely technical benchmarks.
-
Build a data & governance baseline: Adopt standardized schemas and compliance checklists; require vendor commitments for data portability and model explainability as part of contracting.
-
Choose partnering and procurement models: Evaluate tradeoffs between platform adoption, bolt‑on specialist tools, and co‑development. Negotiate commercial terms that align incentives for long‑term data sharing and model improvement.
-
Plan for scale: Use our scaling checklist to budget for sensor refresh cycles, connectivity upgrades and workforce reskilling — and to model the transition from capital expenditures to subscription revenue models.
How to use the full PW Consulting study
The full Artificial Intelligence in Agriculture Market report is designed as a plug‑and‑play strategic toolkit for 2026. It contains the detailed segmentations, regional and application-level analyses, vendor scorecards, transaction compendia, and downloadable financial models needed for board‑level investment decisions, M&A diligence, and product roadmaps. If your team is preparing capex plans, negotiating strategic partnerships, or designing a pilot‑to‑scale program, the full study provides the raw tables, sensitivity analyses and vendor comparisons necessary to execute with confidence.
Final perspective — prioritize speed with discipline
The numbers tell a clear story: rapid market expansion creates both upside for incumbents with scale and acute risk for organizations that delay foundational choices. In 2026, winning requires moving faster than a multi‑year adoption timeline while embedding governance, interoperability and measurable economics into every deployment. PW Consulting’s study equips leaders with the analytical depth to justify investment and the practical templates to operationalize AI across farm systems — while reserving the full, transaction‑grade segmentation and vendor benchmarking for the complete report.
For a hands‑on briefing and access to the core data tables, vendor scorecards and ROI models that underpin these conclusions, please consult the full PW Consulting Artificial Intelligence in Agriculture Market study.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence (AI) in Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Hand Dryers Market to Reach USD 372.52 Million by 2032 (CAGR 8.2%)
By PW Consulting, 2026-07-12
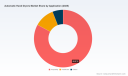
Automatic Hand Dryers Market — Strategic Outlook for 2026 Decision-Makers
As organizations reconfigure facilities and procurement strategies for a post-pandemic, sustainability-focused built environment, automatic hand dryers have moved from a cost line-item to a strategic asset. PW Consulting’s new market study frames that transition with a clear numerical backbone: the global automatic hand dryers market expanded from USD 163.15 Million in 2020 to USD 215.0 Million in the base year 2025, and we project a continued compound annual growth rate (CAGR) of 8.2% through our forecast window (2026–2032), reaching an estimated USD 372.52 Million by 2032. For 2026 corporate planning cycles this report is designed as a decision-ready briefing that ties demand dynamics to near-term operational choices.
Automatic Hand Dryers Market
Why this market matters to 2026 corporate strategy
-
Procurement and total cost of ownership are being repriced. Buyers now expect energy metrics, hygiene certifications, and life-cycle costs to be bundled into purchasing decisions. The growth trajectory through 2032 amplifies the importance of selecting supplier partners who can deliver verifiable energy and hygiene credentials while scaling with demand.
Automatic Hand Dryers Market -
Regulatory and standards compliance is no longer peripheral risk. ADA accessibility rules, UL 499 safety standards, NSF Protocol P335 hygienic criteria, and RoHS restrictions are actively shaping product specifications and acceptance in major buyer segments. Non-compliance can blunt adoption and expose owners to retrofit costs.
Automatic Hand Dryers Market -
Sustainability and brand risk are tightly coupled. Building owners and hospitality operators are prioritizing low-energy, HEPA-filtered, and touchless solutions as part of guest experience and sustainability reporting. The market’s growth rate signals expanding buyer willingness to pay for such differentiated attributes.
-
Supply-side scale matters. Recent capacity moves and product launches indicate manufacturers are positioning for higher throughput and product differentiation — decisions that will affect lead times and competitive pricing throughout 2026.
How the PW Consulting study supports 2026 decisions
We built the report to be operationally useful for three types of corporate stakeholders: strategic buyers (corporate procurement, facility management), product leaders (R&D, product marketing), and corporate development professionals (M&A, partnerships). Key deliverables include:
-
Verified market sizing and a 2026-2032 forecasting model calibrated to usage and replacement cycles — presented in USD Million with the base year 2025 anchored at USD 215.0 Million and an 8.2% CAGR to 2032.
-
Decision frameworks for procurement that translate energy, HEPA filtration, and accessibility certifications into total cost of ownership and payback analyses.
-
A regulatory matrix mapping UL, ADA, NSF P335, and RoHS implications to product design, testing, and market entry timelines.
-
Commercial playbooks for channel strategies, aftersales service, and warranty programs that preserve margin while accelerating adoption in high-value end customers.
-
Scenario-based supply-chain stress tests calibrated for 2026 planning: capacity disruptions, raw-material price shifts, and accelerated retrofit programs in institutional portfolios.
-
Competitive intelligence dossiers and supplier scorecards that assess capabilities, capacity, and innovation focus without disclosing confidential market shares in this preview.
Macro market character — what the numbers tell us
The headline growth path reflects a convergence of factors: heightened demand for touchless, hygienic drying options; building retrofits in hospitality and institutional sectors; and a steady replacement cycle in commercial properties. Importantly, the market remains moderately fragmented: the combined market share of the three largest suppliers sits in the mid-20s percentile band, and the five-firm concentration is only marginally higher. That structure creates both opportunity — for scale players to consolidate via differentiated offerings and services — and risk — for smaller suppliers who may struggle to meet increasingly stringent certification and volume requirements.
Technology and product dynamics to prioritize in 2026
-
High-speed jet and low-energy designs continue to dominate product conversation. Buyers seek units that balance rapid drying times with lower electricity draw, and that narrative will influence procurement specifications throughout 2026.
-
HEPA and hygienic design are table stakes in many buyer segments. Industry advocacy groups and awareness programmes have accelerated interest in filtered solutions, and several vendors have launched or announced HEPA-equipped models in the past 18 months.
-
Certification-led purchasing. Demonstrable compliance with UL 499 and NSF P335, plus ADA accessibility confirmation, shortens sales cycles and reduces procurement friction for institutional buyers.
-
Smart features and connectivity are an emerging value lever. Sensor diagnostics, usage analytics, and predictive maintenance unlock service revenue and reduce downtime — areas where product leaders can capture incremental margin in 2026.
Competitive landscape — core players and recent moves
Our competitive overview focuses on established manufacturers and their differentiated propositions. For 2026 strategy, several firm-level profiles are especially instructive:
-
Excel Dryer Inc. (East Longmeadow, MA) — known for the XLERATOR family of high-speed sensor-activated jet hand dryers, with HEPA filtration options and ADA-compliant models. The company has recently expanded its U.S. manufacturing footprint to increase capacity, a signal of confidence in rising institutional and commercial demand.
-
World Dryer Corporation (West Bend, WI) — positions itself on energy efficiency with the SMARTdri Plus series and modular HEPA options. Their emphasis on low operational consumption aligns them with sustainability procurement mandates.
-
American Dryer, Inc. (Bensenville, IL) — offers touchless high-speed ranges designed for commercial/institutional users, including value- and premium-tier lines that address diverse buyer budgets and spec requirements.
-
Danish Design A/S (Denmark) — emphasizes hygienic Scandinavian design with models such as LOKI and BJØRK; product aesthetics and perceived hygiene performance make them relevant in higher-end hospitality applications.
-
American Specialties, Inc. (U.S.) — brings robust stainless-steel and matte-finish models like TURBO ADA and Roval series to the market, with attention to durability and ADA compliance.
Market activity through 2025–2026 reinforces two practical lessons for buyers and investors: manufacturing capacity and product compliance matter materially, and advocacy/industry association efforts are shaping buyer expectations. InterClean 2026 and World Hand Hygiene Day 2026 events highlighted persistent demand for touchless, HEPA-filtered dryers — a trend reflected in supplier roadmaps and recent product launches.
Recent developments that will influence 2026 procurement cycles
-
Product launches: Major vendors continued to refine HEPA-equipped and more efficient models through 2025, signaling that product obsolescence windows are shrinking for non-filtered or higher-energy units.
-
Capacity moves: Select manufacturers have expanded production capabilities to relieve anticipated bottlenecks — a critical consideration for procurement teams planning multi-site rollouts in 2026.
-
Industry advocacy: Association-led promotions and hygiene campaigns in 2026 have elevated buyer awareness and are shortening procurement timelines for HEPA-compliant, touchless solutions.
Practical recommendations for 2026
-
Prioritize certified HEPA-filtered, low-energy models for new installations and retrofits in environments where hygiene is mission-critical. The market premium for certified hygienic performance is widening.
-
Factor accessibility and safety standards (ADA, UL 499, NSF P335) into RFPs from the start to avoid spec churn and retrofit costs.
-
Assess supplier scale and service capabilities. Given moderate market concentration and rising demand, supplier continuity and spare-part availability will influence lifecycle costs.
-
Include smart monitoring and service contracts in procurement conversations to unlock uptime and extended warranty benefits while smoothing CapEx profiles.
-
Use scenario-based budgeting: model for a faster adoption case that aligns with the market’s 8.2% CAGR — this guards against supply chain constraints and inflationary price pressure.
What you will find in the full PW Consulting report
The comprehensive deliverable includes detailed sub-segment analysis, buyer use-cases, supplier scorecards, an investment matrix for M&A and capacity expansion, and downloadable financial models. In this introduction we present market scale and pace — but we intentionally reserve granular regional, type, and application split tables and value-by-segment forecasts for the paid report to preserve competitive integrity and to ensure readers access the full methodology and data appendices.
Closing — making the 2026 window decisive
For executives and procurement leaders planning capital and supply decisions in 2026, the automatic hand dryers market presents both immediate operational priorities and longer-term strategic choices. The market’s growth path — from USD 215.0 Million in 2025 to an estimated USD 372.52 Million by 2032 at an 8.2% CAGR — underscores that investments made this year in compliant, energy-efficient, and serviceable products will compound in value. PW Consulting’s full study equips you to convert that macro trajectory into executable 12–36 month programs in procurement, product development, and corporate development.
To access the full dataset, supplier scorecards, and the scenario modelling workbook referenced here, please consult the PW Consulting Automatic Hand Dryers Market report online.
For detailed analysis of this topic, please visit the official page: Automatic Hand Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Structural Steel Pipe Market to Reach USD 489.1M by 2032 at 3.45% CAGR
By PW Consulting, 2026-07-12
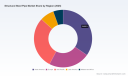
Structural Steel Pipe Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a focused, decision-oriented introduction to our Structural Steel Pipe Market study. This briefing translates the study’s macro findings into actionable strategy for executives who must make procurement, capital allocation, product, and M&A decisions in 2026. The full study contains granular datasets, company scorecards, and downloadable models — this article intentionally emphasizes strategic implications while withholding certain sub‑segment disclosures to encourage direct access to the complete intelligence package.
Structural Steel Pipe Market
Market at a Glance: What the Numbers Mean for 2026
The structural steel pipe market has demonstrated steady recovery and moderate growth through the post‑pandemic period, expanding from approximately USD 298.5 Million in 2020 to USD 386.5 Million in 2025. Our baseline forecast (2026–2032) models a compound annual growth rate (CAGR) of 3.45%, with the market expected to continue an upward trajectory through 2032 under the base scenario.
Structural Steel Pipe Market
Two immediate takeaways for 2026 planning:
Structural Steel Pipe Market
- Volume growth is material but not explosive — organizations must optimize margin and supply resilience rather than assume demand will absorb inefficiencies.
- Price and policy risk will drive margin volatility; procurement strategies and product mix decisions should prioritize flexibility and hedges.
Dynamics Shaping the Market This Year
Five interlocking dynamics define the operating environment in 2026:
- Policy and trade barriers: Elevated tariff regimes and enforcement actions have materially raised import risk and landed costs for finished pipe and key inputs. These policy settings are persistent enough that they need to be assumed in planning scenarios for 2026.
- Input-cost pressure: Scrap commodity prices remained firm into Q1 2026 (e.g., reported scrap at roughly USD 347/MT in China and USD 397/MT in India), raising upstream cost floors for domestic mills and import parity prices.
- Producer pricing behavior: Leading tubular producers have announced sequential price increases and extended lead times; market participants should plan for pass‑through cycles and shorter purchasing windows.
- Demand composition shift: End‑market demand is being influenced by infrastructure programs, energy‑sector capital intensity, and municipal waterworks, which favors certain product specifications and traceability requirements.
- Consolidation and concentration: Market concentration is moderate; the three‑player concentration band is below half the market, signaling room for regional leaders and niche specialists to protect margins through technical differentiation.
What This Means for 2026 Corporate Strategy
Executives should treat 2026 as a year to convert market stability into durable advantage. The modest CAGR masks pockets of higher growth and higher risk — and those pockets are where strategy should be focused. Below, we translate the market facts into five priority actions.
- Lock in critical feedstock and production capacity. With scrap prices elevated and domestic lead times extended, secure multi‑tier supply contracts and maintain buffer inventories for key grades. Negotiate indexed contracts with clear escalation mechanics tied to scrap and freight indices.
- Revise pricing architecture to reflect policy tailwinds. Tariff and import cost volatility requires dynamic pricing clauses and periodic reviews. Protect margins through value‑based pricing for certified, low‑embodied‑carbon products.
- Prioritize product and grade differentiation. High‑strength grades and certified low‑carbon offerings are emergent margin drivers; invest selectively in qualification and small‑batch production before scaling.
- Shift channel and logistic strategies. Shorter lead times and regional protectionism favor localized inventory hubs and near‑term supplier partnerships over long tail, global sourcing.
- Prepare for selective consolidation. Given market concentration dynamics and regional capacity imbalances, 2026 is a window for tuck‑in acquisitions to fill distribution gaps or to acquire specialty capacity with immediate commercial synergies.
Competitive Landscape — Players to Watch
The industry remains a mix of vertically integrated domestic mills, global tubular divisions, and regional ERW/ERW‑focused producers. Our report profiles leading firms and recent corporate actions that will influence competitive moves in 2026.
- Nucor (Charlotte, NC): As a vertically integrated EAF producer and a significant domestic supplier of hollow structural sections and tested pipe, Nucor’s dual advantage lies in feedstock integration and low‑embodied‑carbon certification. Recent pricing actions underscore its ability to influence domestic price benchmarks and set the commercial cadence for structural tubing.
- ArcelorMittal (Luxembourg City): A global tubular player with breadth across high‑strength and welded products. Strategic product launches — including newly commercialized high‑strength grades — can reshape specification choices for high‑value construction and infrastructure projects.
- United States Steel Corporation (Pittsburgh, PA): A major U.S. steelmaker supplying welded and structural pipe for construction and infrastructure; capacity and contract choices by such integrators will determine domestic availability and delivery reliability.
- California Steel Industries (Fontana, CA): A regional ERW producer focused on load‑bearing and low‑pressure applications — an example of how regional specialists can retain margin through service, lead time, and application expertise.
Recent corporate moves matter. Fast‑moving pricing adjustments by leading mills and extended lead times have already altered commercial relationships in early 2026. New product commercialization of higher‑strength welded grades is a technology axis that will reward early adopters in structural design and modular construction niches.
Report Deliverables: What PW Consulting Provides
The full PW Consulting Structural Steel Pipe Market report is designed as an operational tool, not an academic exercise. Key deliverables include:
- An integrated market model (2020–2032) with adjustable assumptions for tariff regimes, scrap prices, and infrastructure spend scenarios.
- Supplier heatmaps and a competitive scorecard evaluating capacity, carbon credentials, product breadth, and logistics performance.
- Price‑to‑cost waterfall templates and a plant‑level unit‑cost benchmarking suite suitable for diligence and procurement negotiations.
- Regulatory scenario playbooks that model the P&L and supply‑chain impact of tariff changes and permit timelines.
- A procurement playbook and a near‑term (90‑day) action checklist to stabilize supply and pricing exposure.
- Deal screens and an M&A target shortlist based on strategic fit and integration economics (note: detailed segment financials and target valuations are available in the premium dataset).
These outputs are accompanied by primary interviews, mill‑level capacity verification, and proprietary price tracking to ensure commercial relevance in 2026 negotiations.
Three Practical 90‑/180‑/360‑Day Moves for Leadership Teams
- 90 days — Defensive and Tactical: Execute indexed supply agreements for critical grades; implement rolling 8–12 week inventory buffers; activate commodity hedges where available; and review contractual pass‑through clauses.
- 180 days — Operational and Product Strategy: Qualify at least one high‑strength or low‑carbon supplier; pilot alternative material specifications that reduce mass without sacrificing code compliance; begin small‑scale retooling if market tests succeed.
- 360 days — Strategic and Portfolio Moves: Pursue M&A or JV options for regional footprint expansion; implement a cost‑to‑serve optimization across channels; and complete a long‑range capital plan that prioritizes flexibility and decarbonization.
Risk Matrix — What Could Upset the Base Case
Key downside shocks include sharp policy escalation, disruptive rises in freight or scrap that exceed our stress scenarios, or a demand slump in the oil & gas sector beyond current assumptions. Upside acceleration would be driven by accelerated infrastructure spending or broad adoption of higher‑specification, high‑strength grades that expand average selling prices.
Why PW Consulting’s Study Is Timely
2026 is a transitional year: protective trade policy, tighter scrap markets, and product‑grade innovations are converging to reshape where value is captured in the structural steel pipe value chain. Our study synthesizes these forces into a single planning toolkit that supports procurement tightening, product strategy, and corporate development decisions — delivering both the evidence base and the playbooks for execution.
Next Steps
If your team is preparing 2026 budgets, negotiating multi‑year supply contracts, or evaluating acquisition targets, the full PW Consulting report will provide the data, templates, and deal screens needed to move from deliberation to execution. The public briefing above outlines the strategic contours; the full subscription includes the proprietary datasets and executable templates referenced throughout.
Contact PW Consulting to arrange a briefing and gain access to the complete report, scenario models, and company scorecards that are essential for making high‑confidence decisions in 2026.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Loyalty Management Market to Reach USD 23.21B by 2032, 12.4% CAGR (PW Consulting)
By PW Consulting, 2026-07-12
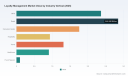
Loyalty Management Market — Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high‑level orientation to our Loyalty Management Market research designed specifically to inform enterprise decisions in 2026. This market is no longer a peripheral CRM feature — it is a strategic revenue engine and a regulatory flashpoint. Our study uses a 2025 base year and delivers an actionable forecast across 2026–2032. At a glance, the market grew from USD 5.4 billion in 2020 to USD 10.25 billion in 2025 and is projected to reach USD 23.21 billion by 2032, reflecting a compound annual growth rate of 12.4% in the forecast window. The remainder of this briefing explains why those headline numbers matter, what practical choices they imply for leaders this year, and how our full report converts insight into execution without giving away the specific segment tables that will be available in the complete study.
Loyalty Management Market
Why the 2026 Inflection Matters
-
Market momentum meets regulatory pressure. Rapid adoption and enterprise spend are colliding with tightening privacy frameworks — notably new California requirements effective January 1, 2026, that force explicit Notices of Financial Incentive where loyalty programs exchange material terms and personal data, and ongoing GDPR obligations for transparency and Data Protection Impact Assessments. These rules change program design, consent flows, and vendor contracts in one discontinuous step.
Loyalty Management Market -
Value-centric consumer behaviour has hardened. Inflationary pressures and changing household budgets mean loyalty is increasingly about immediate, demonstrable value. Independent industry research in early 2026 shows a large majority of quick‑service diners prioritize cost savings when choosing brands — a structural shift that influences incentive design across industries.
Loyalty Management Market -
Technology and business model evolution accelerate ROI. API‑first, headless architectures, AI‑driven personalization, and tighter integration with CRM/ERP stacks are turning loyalty programs into measurable profit centers rather than just marketing line items. The forecast trajectory implies significant investment opportunities for both vendors and enterprise adopters over the next six years.
Key Market Dynamics — What Leaders Must Reconcile
-
Scale and concentration: the market demonstrates a moderate concentration profile; leading vendors command a meaningful share while a robust long tail of specialists and vertical players continues to innovate. For procurement teams, this means sourcing choices range from integrated enterprise suites to niche, sector‑specific engines — each with different TCO and governance implications.
-
Platform vs. composable models: buyers must choose between end‑to‑end platforms and modular, API‑based toolchains. The former reduces integration lift; the latter accelerates experimentation and supports faster time‑to‑value when combined with modern data stacks. Our research outlines the tradeoffs in implementation complexity, vendor lock‑in risk, and long‑term extensibility.
-
On‑premise, cloud, and hybrid deployment calculus: cloud adoption is increasing, but many large enterprises retain on‑premise or hybrid deployment requirements for control, compliance, or latency reasons. Architecture decisions now have direct commercial consequences for program agility and cost structure.
-
Data stewardship is table stakes: with new financial‑incentive notice requirements and GDPR DPIA expectations, loyalty program design must embed privacy and purpose limitation from day one. That affects data capture, segmentation logic, retention policies, and the way value is communicated to consumers.
What the PW Consulting Report Delivers — Practical, Actionable Assets
-
Market sizing and growth pathways: macro trajectories and scenario modelling that translate the 12.4% CAGR into investment buckets and expected payback periods across common program archetypes.
-
Decision frameworks: vendor selection scorecards, an RFP template tailored to 2026 compliance needs, and a TCO model that maps integration and operational costs across deployment patterns.
-
Implementation playbooks: step‑by‑step pilots for rapid validation (30–90 day pilots), playbooks for migrating legacy award systems, and a scaling blueprint that connects program KPIs to P&L levers.
-
Compliance and risk toolkit: a regulation checklist reflecting recent California consumer privacy updates and GDPR implications, consent and notice language examples, and a DPIA starter template for loyalty use cases.
-
Data & analytics recipes: customer lifecycle models, real‑time segmentation patterns, and practical guidance on using AI for propensity scoring without violating privacy constraints.
-
Vendor and competitive intelligence: assessed vendor profiles, comparative capabilities matrices, and case studies documenting recent platform partnerships and product updates. (Note: full vendor ratings and regional/vertical splits are reserved for the complete report to preserve the report’s proprietary value.)
Competitive Landscape — Players to Watch and Where They Fit
The loyalty technology ecosystem in 2026 combines global enterprise suites, specialized e‑commerce platforms, and vertical solutions. Leading enterprise vendors offer deep integration with CRM/ERP and broad features for large, data‑intensive programs. At the same time, specialist vendors excel in rapid deployment, lower TCO for SMBs, and vertical tailoring (e‑commerce, retail, QSR, agriculture, etc.).
-
Enterprise suites (examples): Companies that bundle loyalty with marketing clouds and CRM offer the fastest path to enterprise integration and centralized identity. They are best for organizations prioritizing unified customer record‑keeping and cross‑functional orchestration.
-
Omnichannel and retail specialists (examples): Vendors focused on retail and travel bring omnichannel program design, store integration, and workforce enablement — useful where in‑store redemption and POS integration are major requirements.
-
E‑commerce and D2C specialists (examples): Platforms optimized for online merchants emphasize plug‑and‑play setups, conversion optimization, and native integration with reviews, referrals, and UGC — valuable for rapid growth merchants.
-
Vertical innovators (examples): Sector‑specific players (including recent entrants with AI enhancements for agriculture retail and QSR) drive differentiated program mechanics and predictive insights tuned to unique buying patterns.
Notable recent developments in the ecosystem underscore these dynamics: platform partnerships that bring enterprise analytics into play, AI enhancements targeted at predictive loyalty outcomes, and vendor communications emphasizing privacy‑first design. These moves reflect vendor strategies to capture growth while responding to regulatory and consumer shifts.
Our report’s competitive analysis synthesizes these tactics into vendor fit maps and procurement checklists. We also quantify market concentration to help buyers understand negotiating leverage: the top tier of vendors captures a substantial share of commercial activity, while the mid‑market is fragmented and active — creating opportunity for both consolidation and specialist differentiation.
A 2026 Decision Roadmap — Five Immediate Actions
-
Rapid diagnostic (0–30 days): benchmark current loyalty economics, identify immediate regulatory gaps, and map technical debt that would slow migration or expose data risk.
-
Pilot design (30–90 days): structure a hypothesis‑driven pilot that tests value propositions aligned with current consumer motivators (e.g., immediate savings, experiential rewards), includes a privacy‑by‑design consent path, and uses measurable uplift metrics.
-
Vendor shortlisting (60–120 days): apply our RFP template and scorecard to reduce vendor risk — prioritize clarity on data ownership, portability, integration cost, and compliance support.
-
Scale and governance (3–12 months): define a governance model that assigns data stewardship, ROI accountability, and compliance ownership; deploy a phased rollout plan that allows rapid iteration.
-
Measure and iterate (ongoing): use tight KPIs (acquisition cost, redemption velocity, incremental margin, churn delta) and link them back to program levers identified in the report’s ROI models.
Final Word — Why Read the Full Report?
The Loyalty Management Market is simultaneously an opportunity and a compliance challenge. Our research converts the headline growth — from USD 10.25 billion in 2025 to a projected USD 23.21 billion by 2032 at a 12.4% CAGR — into concrete decisions: which architectures to prefer, how to price and design incentives under new privacy regimes, and how to select vendors that balance scale with specialization. The executive summary available here outlines the strategic playbook; the full report contains the actionable work products, vendor scorecards, detailed regional and vertical breakdowns, and downloadable templates that procurement, legal, and product teams will use to implement change in 2026.
To move from insight to execution, organizations should focus on defensible data governance, incentive economics aligned with consumer value expectations, and an implementation approach that reduces time‑to‑value while maintaining regulatory compliance. PW Consulting’s full Loyalty Management Market report equips you to do precisely that — and to justify investments with scenarios, ROI models, and a vendor roadmap tailored to your organization’s risk profile and growth ambitions.
For detailed analysis of this topic, please visit the official page: Loyalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nitrocellulose Market — Strategic Brief for 2026 Decision‑Makers
Executive snapshot
By the end of the 2025 base year, the global nitrocellulose market had recovered from pandemic-era disruption and structural raw‑material shocks, reaching an estimated USD 1,030 Million in annual revenue. Our model projects a steady acceleration through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of approximately 5.0%, taking the market toward the USD 1.45 Billion range by 2032. This trajectory captures the interplay of steady end‑use demand in coatings, inks and speciality finishes, episodic defence procurement, and increasingly volatile upstream feedstock dynamics.
Nitrocellulose Market
Why 2026 is a pivotal year
-
Price and input shock normalization vs. structural reset: 2024–2025 saw sharp input cost movements (notably cotton linter shortages) that materially raised production costs and forced a series of price pass‑through actions among major converters. While some price pressure is cyclical, our scenarios show a new baseline cost structure that buyers and producers must adopt in 2026 planning cycles.
Nitrocellulose Market -
Geopolitics and defence demand are reshaping supply priorities: Reallocation of capacity toward defence and energetic applications — along with strategic acquisitions to secure feedstock — has created localized shortfalls for industrial grades in several jurisdictions. Procurement teams should expect intermittent tightness in at‑risk supply corridors.
Nitrocellulose Market -
Regulatory and safety testing expectations have hardened: Stability and classification testing (including established methods accepted by global authorities) now factor into sourcing and certification timelines. Compliance lead times must be built into supplier qualification programs.
-
Market concentration with room for disruption: The market remains moderately concentrated (CR3 ≈ 40%, CR5 ≈ 55%), which creates both risk—through supplier bottlenecks—and opportunity, as well‑capitalized players execute capacity expansions and M&A to capture premium segments.
Key market dynamics you must plan for in 2026
-
Raw material sensitivity: Even single‑digit percentage swings in cotton linter availability translate into outsized margin impacts across the value chain. Our sensitivity matrices in the full report quantify break‑points where suppliers will either absorb costs, pass them to customers, or curtail volumes.
-
Pricing volatility: Across 2025, we observed double‑digit month‑over‑month spikes in some regional price benchmarks and very large year‑over‑year increases in other markets. That volatility is likely to persist into 2026 in the absence of coordinated inventory and sourcing strategies.
-
Segmentation nuance matters: Demand drivers and margin structures differ sharply between industrial lacquers, printing inks, nail and cosmetic finishes, and energetic grades. Tactical choices—e.g., prioritizing industrial customers versus defense contracts—will materially affect supply risk exposure and working capital requirements.
-
Sustainability and certification as commercial differentiators: Buyers increasingly require suppliers to demonstrate lifecycle credentials. Recent certifications by leading producers are already being used as commercial leverage in contract negotiations.
What PW Consulting’s Nitrocellulose Market Report delivers (practical, actionable modules)
-
Integrated market model: a calibrated, year‑by‑year demand and supply model spanning 2020–2032, with scenario toggles for raw‑material shocks, defence procurement surges, and regulatory constraints. (Note: granular region/application line items are included in the report; this brief intentionally omits those splits.)
-
Price sensitivity toolkit: breakpoint analyses and pass‑through thresholds tailored for procurement and commercial teams; ready‑to‑use negotiation playbooks indexed to supplier archetypes.
-
Supplier risk matrix: quantified exposure scores for capacity, geographic concentration, raw‑material sourcing and compliance lead times, enabling rapid short‑listing of alternative suppliers.
-
M&A and capex playbook: prioritized target profiles, valuation multiples observed in recent transactions, and a risk‑adjusted return model for greenfield vs. bolt‑on expansion — built for C‑suite decision scenarios in 2026.
-
Regulatory and safety roadmap: implications of current classification and testing standards for lead times, on‑boarding and cost of goods, with recommended compliance checkpoints for procurement and quality departments.
-
Sustainability monetization guide: how to translate certifications and lifecycle claims into commercial premiums and preferred supplier status with large customers.
Competitive landscape — who matters and why
The supply map is global and heterogeneous, mixing specialist producers with converters and diversified chemical houses. The following firms are strategically important either because of capacity, vertical integration, geographic reach, or recent strategic moves:
-
Nitrocellulose Group (Thailand) — A large regional producer with industrial product forms serving inks and coatings; notable for manufacturing scale in Asia and for being a reliable regional supplier for converters seeking stable granular and fibrous grades.
-
GRN Cellulose Pvt. Ltd. (India) — A vertically capable producer with both powder and solution forms, active across paints, lacquers, inks and specialty applications. Their diversification across form‑factors makes them an attractive partner for formulators.
-
Companhia Nitro Quimica Brasileira (Brazil) — A global producer with modern facilities and a footprint that matters for Latin American supply resilience, particularly when northern hemisphere supply tightness emerges.
-
Rheinmetall NC GmbH (Germany) — Following the 2025 acquisition of a European incumbent, Rheinmetall’s NC operations are strategically positioned to service energetic and defence markets, and their move underscores defence‑led vertical consolidation.
-
Synthesia Nitrocellulose (Czech Republic) — A European energetic and industrial supplier that has expanded capacity after strategic restructuring; crucial where European buyers need proximate supply for propellants and industrial uses.
-
Major Chinese suppliers (multiple companies) — A cluster of manufacturers supplying film‑forming resins and industrial NC across coatings, inks and adhesives. These players drive cost competition at the global level and are key levers for buyers pursuing low‑cost sourcing.
-
Specialist converters and chemical partners (Europe, North America) — Firms that blend, formulate and add value (including sustainability credentials) to nitrocellulose products; they are often the price setters for finished goods and therefore focal points for downstream risk management.
Recent industry moves you cannot ignore (selected, directional)
-
Strategic acquisitions to secure supply: a notable defence‑oriented acquisition completed in 2025 underscores how state and defence procurement priorities can reallocate capacity away from industrial markets.
-
Input cost pass‑throughs: major global converters have applied price increases on nitrocellulose‑containing products in 2025/26 cycles, reflecting persistent upstream cost inflation and forcing commercial teams to reassess pricing governance.
-
Supply additions tied to defence: announcements of production commencements in Europe to solve artillery and propellant demand point to segmented capacity that may not be fungible for industrial buyers.
-
Sustainability certifications as a competitive lever: recent certifications obtained by select producers are already being used to win preferred supplier status with formulators and brands prioritizing lifecycle footprints.
Strategic implications and recommended 90‑ to 180‑day moves for 2026
-
Update procurement playbook: embed our price‑sensitivity thresholds into contract templates, set indexed pricing clauses tied to agreed raw‑material baskets, and create rolling 90‑day supplier reviews for at‑risk categories.
-
Shortlist dual‑sourcing candidates: target a mix of regional and low‑cost suppliers to balance security and margin pressure; prioritize suppliers with validated certifications and acceptable compliance lead times.
-
Inventory and working‑capital triage: apply our scenario outputs to determine tactical safety stock levels for critical SKUs and build conditional release rules linked to price windows and supply signals.
-
Commercial renegotiation and cost‑to‑serve reviews: use the report’s cost breakdowns to reframe commercial conversations with converters, seeking longer notice periods for price moves and partial cost absorption mechanisms where strategic.
-
Capex and M&A screening for 2026: if your strategy involves vertical integration or securing feedstock, use our M&A playbook to prioritize assets with the best risk‑adjusted returns and the lowest regulatory friction.
How to use this brief and where to get the full intelligence
This brief synthesizes the strategic signals that should inform boardroom and procurement decisions in 2026. PW Consulting’s full Nitrocellulose Market Report contains the granular, transaction‑grade datasets, regional and application splits, supplier scorecards, and downloadable models you need to operationalize these recommendations. To preserve competitive value for clients, the complete section‑level figures and scenario model outputs are available only in the full report.
If your 2026 planning cycle requires hedged sourcing strategies, supplier reclassification, or M&A due diligence, the full report supplies ready‑to‑deploy templates and a calibrated market model. PW Consulting can also deliver executive workshops and bespoke scenario runs tailored to your exposure profile.
For detailed analysis of this topic, please visit the official page: Nitrocellulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Fused Alumina — 2025 market USD 200M; CAGR 4.01% (2026–32)
By PW Consulting, 2026-07-12
White Fused Alumina Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive teaser
As manufacturers and downstream users reposition for a manufacturing rebound and an inflection in raw materials dynamics, white fused alumina (WFA) is re-emerging as a strategic commodity. PW Consulting’s White Fused Alumina Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies this re-emergence and translates it into actionable decision frameworks for 2026. The global WFA market, measured in USD Million, expanded from approximately USD 150.0 Million in 2020 to USD 200.0 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of about 4.01% across our 2026–2032 forecast window, reaching roughly USD 263.3 Million by 2032.
White Fused Alumina Market
Why this matters in 2026
-
Annualized momentum: After multi-year recovery dynamics, 2026 represents a decision point — companies must translate medium-term demand certainty into supply-side commitments (contracts, capacity adjustments, and inventory strategies) that will lock in margins across a modest but steady growth trajectory.
White Fused Alumina Market -
Margin polarization across product grades: Purity-driven, specialty WFA (e.g., ultra-high Al2O3 for precision ceramics and technical polishing) differs materially in value proposition from cost-optimized grades targeted at mass abrasives and refractory linings. Strategic portfolio choices made in 2026 will determine whether firms capture premium segments or defend lower-margin volume.
White Fused Alumina Market -
Concentration & competitive dynamics: The market shows moderate concentration — the top three suppliers account for the low-to-mid thirty percent range, and the top five approach roughly half of global supply. This mix creates opportunities for both scale-driven competitors and niche specialists to shape regional and application-specific pricing and supply strategies.
What PW Consulting’s study delivers — practical, board-ready outputs
Our report is designed as an operational playbook for executives, procurement leaders, and corporate development teams. Highlights include:
-
Market sizing and validated forecasts: Annual market values from 2020 through 2032, with scenario-based outlooks that stress-test demand shocks and feedstock volatility. (Base year: 2025)
-
Supply-side architecture: Detailed mapping of production routes (electric-arc fusion of Bayer alumina, feedstock sensitivity, and furnacing profiles), plant-level capabilities, and capacity utilization frameworks to assess incremental expansion needs and timing.
-
Demand driver intelligence: A granular synthesis of end-market trends — refractories, abrasives, and ceramics — translated into purchase-behavior signals and procurement lead-time expectations.
-
Commercial frameworks: Go-to-market playbooks, price-elasticity models, contract templates (indexation recommendations, minimum take or pay guardrails), and negotiation levers to protect margin while securing volume through 2028.
-
Risk and resilience tools: Supply disruption matrices, geopolitical and trade-scenario stress tests, and hedging options for raw-material inputs and energy — with bespoke mitigation plans for critical nodes in the WFA value chain.
-
Transaction intelligence: A curated short-list of acquisition and partnership targets, valuation benchmarks, and synergy estimates to support inorganic growth or vertical integration plays.
-
Executive dashboards and KPIs: A ready-to-deploy set of metrics (e.g., realized ASP by grade band, purity-adjusted margins, furnace utilization, and time-to-fill) for weekly and monthly monitoring.
Competitive landscape — who matters and why
The WFA market features a mix of global branded manufacturers, national champions, and high-volume, cost-focused producers. Our analysis synthesizes capabilities across quality, scale, geographic reach, and customer intimacy.
-
Washington Mills (North Grafton, Massachusetts): A technology- and quality-led player noted for producing very high-purity WFA (>99% Al2O3). Their focus on engineered grains, powders, and bubbles via electric-arc fusion positions them to capture premium applications in advanced refractories and precision abrasives. For firms targeting performance differentiation, Washington Mills represents both a benchmark and a potential partner for co-development.
-
Imerys (Paris, France): Operating multiple production sites and offering branded fused alumina products under established portfolios, Imerys combines scale with global distribution. Their multi-site footprint supports customer continuity and shorter lead times in key industrial regions; they are a go-to supplier for customers seeking a balance of quality and geographic risk mitigation.
-
Rusal (Moscow, Russia): Vertical integration through alumina production and electric-arc fusion gives Rusal strategic control over feedstock and cost base. However, geopolitical and trade considerations create both risk and opportunity: buyers must weigh short‑term supply economics against long-term diversification and compliance strategies.
-
U.S. Electrofused Minerals (USEM) (Aliquippa, Pennsylvania): As a supplier in fused oxides, USEM competes on industrial-grade offerings and dependable supply to North American markets. Their value is strongest where localized, reliable logistics and technical support matter.
-
MOTIM Electrocorundum (Hungary): A specialist focused on high-quality corundum for refractories and abrasives. European and regional manufacturers targeting higher-purity product mixes will find MOTIM a credible technical partner.
-
Zhengzhou Yufa Group and Henan Ruishi Renewable Resources Group (China): Large-scale Chinese producers emphasize cost-efficient supply and high throughput. Their strategic advantage is price competitiveness and volume flexibility — a decisive factor for commoditized abrasive and refractory applications. Western buyers should consider a two-track sourcing approach that balances cost capture with supplier diversification and quality assurance.
Strategic implications and recommended 2026 actions
Based on the market trajectory and supplier dynamics documented in our study, PW Consulting recommends a set of prioritized actions for corporations planning for 2026 execution:
-
Segmentation-driven portfolio rationalization: Conduct a rapid review of product margins by grade and end-use. If your portfolio mixes across purity and volume-driven products, create clear routing rules for customers (premium SKUs via premium suppliers; commoditized volumes via cost-efficient partners).
-
Contract design & procurement cadence: Move from annual spot buying to hybrid contracts that combine a baseline of fixed-volume agreements with a smaller variable tranche indexed to observable raw-material or energy indices. This reduces exposure to furnace outages and energy-cost spikes while preserving upside participation.
-
Supply-risk hedging: Establish secondary-supplier relationships in at least two geographies to mitigate local disruption. Where possible, secure capacity commitments with manufacturers that have vertically integrated feedstock or a multi-site production model to reduce single-point-of-failure risk.
-
Premiumization & co-development: For firms targeting growth in technical ceramics and precision abrasives, prioritize co-development agreements with high-purity producers to secure early access to new grades and qualification pipelines.
-
M&A and JV scouting: With moderate market concentration and regional pockets of scale, 2026 remains an advantageous window to pursue bolt-on acquisitions or joint ventures that deliver immediate capacity, access to certified grades, or route-to-market expansion.
-
Sustainability roadmap: Energy intensity and raw-material traceability are emerging procurement requirements for many downstream customers. Begin supplier audits focused on energy sources, emissions per ton of WFA produced, and traceability of alumina feedstock to strengthen ESG credentials and defend price premia.
Data confidence and signal prioritization
Our base-year calibration uses 2025 as the reference point, with a five-year historical window (2020–2025) and scenario-driven forecasts through 2032. We apply triangulation across plant-level capacity, national trade flows, and downstream consumption models to arrive at our market totals and the 4.01% CAGR for 2026–2032. The report includes sensitivity ranges that capture feedstock shocks, energy-price volatility, and demand-side acceleration or deceleration.
What we are intentionally holding back — and why
In this preview we purposely omit drill‑down tables and exact split figures across regions, types, and applications. Those core segmentation datasets and customer-level consumption profiles are included in the full PW Consulting report and are essential for transaction diligence, competitive tendering, and procurement tender design. This teaser is intended to demonstrate analytical depth while encouraging stakeholders to access the full intelligence pack for operational implementation.
Next steps — how to use this intelligence in Q1–Q2 2026
-
Procurement leaders: Request the full dataset to run supplier-optimization models and to reprice contracts using our recommended indexation clauses.
-
Corporate development: Use our target shortlist and valuation benchmarks to prioritize M&A conversations and to run rapid synergy screens.
-
Operations and R&D: Engage with identified premium suppliers to scope co-development trials for specialty grades and to secure qualification timelines aligned with product roadmaps.
Final thought
The White Fused Alumina market is neither hyper-booming nor stagnant; it is maturing into a market where quality differentiation, supply resilience, and commercial sophistication will decide winners and losers. Companies that act in 2026 — by aligning procurement structures, securing multi-geography supply, and selectively investing in premium-grade capabilities — will lock in advantaged positions through the remainder of this decade.
For the full report, including regional and application splits, supplier scorecards, and downloadable dashboards, visit the PW Consulting White Fused Alumina Market page to obtain the complete intelligence kit and operational annexes.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


