



Category: market research
PW Consulting: Hydrogenated DLC Market to Hit USD 217.9M by 2032 at 5.85% CAGR
By PW Consulting, 2026-07-12
Hydrogenated Diamond-Like Carbon (DLC) Coatings: Strategic Imperatives for 2026
As a strategic advisor at PW Consulting, I present an executive primer that frames our full Hydrogenated Diamond-Like Carbon (DLC) Coating Market study—designed to inform high-stakes decisions in 2026. This piece highlights the report’s analytical depth, synthesizes the market’s macro trajectory, and outlines the pragmatic use-cases that should drive board-level conversations. Per our “trailer” approach, we demonstrate methodological rigor and actionable perspective while intentionally reserving detailed subsegment figures for the full report.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Macro snapshot and trajectory (why numbers matter)
Our analysis uses 2025 as the base year and covers historical performance from 2020–2025 with forward-looking forecasts through 2032. The hydrogenated DLC market shows a resilient growth profile with an underlying compound annual growth rate (CAGR) of 5.85% across the forecast horizon. After a period of volatility in the early 2020s, the market recovered and entered a structural expansion phase driven by multiple secular forces—lightweighting and efficiency demands in mobility, tougher wear performance requirements in industrial tooling, and rising clinical and precision-device applications.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
From a planning perspective for 2026, the headline figures matter because they translate strategic choices into tangible outcomes: a market base in 2025 that supports immediate investment decisions; a mid-single-digit CAGR that justifies staged capacity expansion rather than aggressive overbuild; and a 2032 market endpoint that signals significant, but not explosive, upside—requiring focused, differentiated plays rather than broad market bets.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
What this report delivers — operational and strategic content
- Transparent market sizing and dynamic scenario modelling: calibrated bottom‑up and top‑down approaches with sensitivity analysis for raw-material shocks, production scale, and demand elasticity.
- Actionable segmentation logic: commercial, industrial, and medical use-cases mapped to purchase drivers and adoption hurdles—presented with decision-ready filters (note: detailed subsegment figures are included in the full study).
- Technology and performance roadmap: process comparison (PACVD vs. PVD variants), coating chemistries, deposition economics, and real-world lifecycle testing outcomes that affect TCO and Total Cost of Ownership calculations.
- Supply-chain and manufacturing playbook: vendor evaluation frameworks, capital- and asset-light manufacturing models, and sourcing strategies under different demand scenarios.
- Competitive benchmarking and M&A playbook: scorecards, transaction comparators, and due-diligence templates to accelerate target screening or divestiture planning.
- Regulatory and standards landscape: compliance pathways, testing protocols, and certification timelines relevant to automotive, defense, and medical device buyers.
- Practical tools: downloadable financial model in USD Million, NPV templates, supplier scorecards, and risk matrices ready for board review.
Competitive landscape: positioning the key players
The industry exhibits a balance between global coating specialists and regional applied-surface players. Market concentration is moderate: the three largest players account for roughly 28.5% of market capacity, while the top five represent about 42.1%, signaling a competitive field where technical differentiation and customer relationships are decisive.
- Oerlikon Balzers (Liechtenstein): A leading PACVD player with deep OEM relationships in automotive and aerospace. Their strength lies in scale, robust process control, and a broad global service footprint.
- IHI Group / Ionbond (Switzerland / Japan): Combines coating technology breadth with a strong presence in tooling and precision components. Their portfolio spans both hydrogenated and non-hydrogenated solutions—useful for clients seeking multi-process suppliers.
- Calico Coatings (United States): A specialist focused on hydrogenated a-C:H lines for industrial applications, known for agile customer support and application engineering for mid-market manufacturers.
- IBC Coatings Technologies (United States): Differentiates through testing rigor and military-grade qualifications—an attractive partner for defense and high-reliability industrial segments.
- Acree Technologies (United States): Targets automotive, industrial, and medical niches with applied surface treatments—an option for co-development and localized service models.
- Miba Group / Teer Coatings (Austria): Strong in powertrain and engine component coatings, combining material science with deep OEM integration in mobility powertrain systems.
- CemeCon (Germany): Known for high-performance coatings for toolmaking and wear-critical applications, with a focus on advanced DLC variants and hybrid solutions.
For 2026 execution plans, the critical takeaway is that supplier selection must be made against a matrix of technical fit, capacity responsiveness, geographic service capability, and co-development willingness—rather than purely on headline brand presence.
Strategic recommendations for 2026 decision-makers
Executives evaluating exposure to the hydrogenated DLC opportunity should prioritize the following actions over a 6–36 month horizon.
- Near-term (0–12 months): Run targeted pilot programs with two contrasting supplier archetypes (a global integrator and a nimble specialist) to validate performance claims and quantify unit economics under real operating conditions. Use the report’s pilot checklist and test-protocol templates to accelerate execution.
- Medium-term (12–24 months): Commit to selective capacity or supply agreements only after validated pilots. Structure contracts with performance milestones and shared IP clauses to de-risk capex while preserving upside.
- Mid-to-long-term (24–36 months): Build strategic partnerships for joint development in adjacent coatings (hybrid DLC solutions, multilayer stacks) that target differentiated price-performance for EV powertrains and high-speed tooling segments.
- Cross-cutting actions: integrate the report’s scenario outputs into capex planning, update supplier scorecards quarterly, and institute an IP watch and standards-compliance calendar to anticipate regulatory drift.
Risk matrix and decision levers
Key risks that should influence 2026 decisions are concentration of critical equipment suppliers, potential shifts in raw-material prices, standardization of testing protocols across regions, and the pace of adoption in core end markets (notably automotive powertrain and precision medical devices). The full report provides quantified downside scenarios and mitigation levers—ranging from dual-sourcing strategies to licensing arrangements and flexible manufacturing partnerships.
How to use this report to accelerate value capture
PW Consulting’s Hydrogenated DLC study is built to be operational: boards and strategy teams can use the included financial model to translate adoption scenarios into P&L and cash-flow impacts, use vendor scorecards to accelerate procurement cycles, and apply our M&A playbook to screen targets within days rather than months. The report is particularly useful for executives who must reconcile incremental performance benefits of DLC coatings with capital allocation, supplier risk, and time-to-market constraints.
We designed the public primer to show the analytical frame and strategic implications while preserving the detailed subsegment economics and supplier-level metrics for report subscribers. That deeper intelligence is necessary when you are sizing pilots, negotiating supply agreements, or preparing investment memoranda.
Next steps
- Download the full market model and vendor benchmarks to run custom scenarios for your product lines.
- Request a tailored briefing with our industry analysts to map opportunities specific to your supply chain, product portfolio, and risk profile.
- Use the included pilot checklist and test protocols immediately to de-risk first deployments and capture early learning.
For 2026, the strategic imperative is clear: treat hydrogenated DLC coatings as a performance enabler that requires careful, evidence-based scaling. The PW Consulting study equips decision-makers with the frameworks, data, and tactical tools needed to convert technical advantage into commercial value—while the detailed segment-level intelligence available in the full report supports transactional and operational execution.
For detailed analysis of this topic, please visit the official page: Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Pipes for Oil & Gas Market Set to Reach USD 2,292M by 2032; 6.5% CAGR
By PW Consulting, 2026-07-12
Flexible Pipes for Oil & Gas: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
As the global energy industry transitions into a more complex mix of conventional and low‑carbon strategies, flexible pipes retain an outsized strategic role. PW Consulting’s latest market study — anchored on a 2025 base year and validated across a 2020–2025 historical window — shows the industry growing at a compound annual growth rate (CAGR) of 6.5% through our 2026–2032 forecast. The total addressable market expanded materially in the first half of the decade and is projected to reach approximately USD 2.3 billion (Million-USD unit) by 2032. This brief distils the study’s executive takeaways and explains how the full analysis should inform capital allocations, supplier strategies, and technology bets in 2026.
Flexible Pipes for Oil and Gas Market
Why this study matters for 2026 decisions
- Timing of investment: The market’s steady mid‑single-digit CAGR and the uneven distribution of project awards mean that 2026 will be a decisive year for de‑risking supply and capacity commitments. Early movers who align procurement with validated demand scenarios will capture outsized share while preserving margin.
- Supplier selection & resilience: Consolidation dynamics and capacity constraints have concentrated market power among a few global vendors (our analysis shows the top three players capture a substantive share of market revenue, with the five largest firms controlling a clear majority). Procurement teams must balance performance, certification pedigree, and strategic optionality when selecting partners.
- Material & cost exposure: Polymer feedstock pricing — driven by petroleum derivatives — is a primary margin lever. Firms that adopt active raw‑material hedging, multi‑material qualification, and localized sourcing will protect margins through 2026’s procurement cycles.
- Regulatory and technical gating factors: Compliance with ISO 13628 series and API 17J remains non‑negotiable for unbonded flexible systems. Buyers and technology developers should prioritise certification roadmaps as milestones in R&D and delivery schedules.
What PW Consulting’s full study delivers (practical, actionable)
- Proprietary market sizing and validated historical series (2020–2025) plus scenario‑based forecasts to 2032, with transparent methodology and sensitivity parameters for price, CapEx cycles, and offshore activity.
- Supply‑chain and capacity maps highlighting manufacturing bottlenecks, lead‑time drivers, and logistics choke points for subsea and onshore deployments.
- Cost models down to raw‑material exposure (polymer cost curves), manufacturing overheads, and freight/installation imprints — delivered as downloadable Excel workbooks for quick internal modelling.
- Regulatory matrix and certification playbook outlining timelines and resource implications for ISO 13628 and API 17J compliance, including test‑matrix prioritisation for new materials.
- Vendor benchmarking and capability heatmaps covering technology stack, manufacturing footprint, project track record, and commercial playbooks (bid tactics, warranty structures, and liability exposure).
- M&A and partnership intelligence: target screens, valuation perimeter templates, and integration checklists tuned to flexible‑pipe technologies and composite alternatives.
- Commercial templates and negotiation levers for long‑lead equipment, including recommended contract clauses that protect buyers against polymer price and supply volatility.
- Scenario playbooks: stress‑tested plans for accelerated deepwater build‑out, CO2‑rich field development, and a slower demand path tied to energy transition outcomes.
Competitive landscape — who matters and why
The market is anchored by a set of global system integrators and specialised composite suppliers. Our competitive assessment combines technical capability, commercial footprint, and recent go‑to‑market moves to create an actionable picture for 2026 planning.
Flexible Pipes for Oil and Gas Market
- TechnipFMC (UK): A world leader in flexible-pipe design and supply for subsea risers and flowlines. Recent large contract awards for gas injection risers and combined riser/flowline packages underscore its continued strength on large, integrated offshore projects. For buyers, TechnipFMC represents a low‑execution‑risk partner for complex, deepwater scopes.
- National Oilwell Varco (NOV, USA): NOV has been aggressive on product development, launching high‑pressure flexible pipe lines and entering pre‑commercial agreements for CO2‑resistant solutions with major operators. NOV’s moves make it a technology‑centric option for fields with elevated CO2 or high‑pressure service requirements.
- Baker Hughes (USA): As an established supplier of risers, flowlines, and jumpers, Baker Hughes remains visible in trade shows and industry fora, signalling continued emphasis on system completeness and aftermarket services — a key differentiator for operators seeking single‑vendor accountability.
- Specialist composite players (Strohm, SoluForce, Magma): These firms are advancing bonded thermoplastic and carbon‑fibre composite alternatives. Their offerings are increasingly relevant for projects that prioritise weight reduction, fatigue performance, or aggressive chemical environments. Expect selective partnerships with majors on early‑adopter field trials.
- Established diversified suppliers (ContiTech, Shawcor, Prysmian): These vendors provide industrial‑scale manufacturing and broad product portfolios. They are often competitive on price and logistics for high‑volume onshore and nearshore applications.
Collectively, the top three players capture a significant slice of the market, while the top five widen that concentration further — a structure that shapes competitive dynamics, pricing, and procurement leverage.
Flexible Pipes for Oil and Gas Market
Key market dynamics and risks to monitor in 2026
- Material volatility: High‑density polyethylene remains the dominant raw material platform for flexible systems; material price swings directly alter production economics. Companies should model polymer price scenarios as a first‑order sensitivity in capex and pricing strategies.
- Deepwater acceleration and steel substitution: Continued deepwater developments and a preference for polymer/composite replacements for certain steel components are meaningful demand drivers, but they require demonstrable life‑cycle performance and qualification evidence.
- Standards and certification: ISO and API standards are gating factors for acceptance on many projects. Late or under‑resourced certification programs are a common cause of project slippage and cost overruns.
- CO2 and aggressive chemistries: Fields with high CO2 concentrations are catalysing innovation in CO2‑resistant flexible solutions. Early movers in material qualification will secure first‑mover advantage on niche but high‑value projects.
- Supply and capacity risks: Lead times for specialised manufacturing, coupled with concentrated fabrication capacity, create upside risk in a rapid demand cycle; conversely, a demand pause exposes high‑fixed‑cost producers to margin compression.
How executive teams should use the report in 2026
- Investment prioritisation: Use our scenario outputs to identify which project portfolios warrant bespoke flexible‑pipe investment, and which are better served by contracted supply or composite trials.
- Sourcing & contracting: Adopt our contract templates and supplier scorecards to lock down multi‑year supply with price‑adjustment mechanisms tied to polymer indices and milestone‑based acceptance tests.
- Technology strategy: Prioritise R&D spend on qualification areas with fastest path to commercial acceptance (CO2 resistance, fatigue life, and third‑party certification).
- M&A and partnerships: Leverage our target screens and integration playbooks to identify bolt‑on acquisitions that fill capability gaps (e.g., composite fabrication, testing labs, or regional spool capacity).
- Risk management: Integrate the report’s stress cases into CapEx approval processes and board reporting to ensure that downside scenarios are modeled in funding and contract structures.
What we intentionally withhold here — and why
To preserve actionable value for decision makers, this executive brief demonstrates the study’s methodological rigor and strategic implications while intentionally refraining from publishing granular regional and application‑level splits or core segment dollar amounts. Those detailed breakdowns — including regional market allocations, type/application perfor‑mance, vendor scorecards with quantitative rankings, and the downloadable modelling workbooks — are contained in the full PW Consulting report and interactive dashboard. This “teaser” approach is designed to give you clear insight into the study’s conclusions and to protect the ready‑to‑use intelligence that will inform bidding, sourcing, and M&A activity.
Next steps — making the study work for your 2026 plan
- Request the full report and the accompanying Excel models to run company‑level scenario tests against our base, upside, and downside forecasts.
- Schedule a tailored workshop with our market and technical teams to align vendor strategies, certification roadmaps, and procurement timelines to your project milestones.
- Use our vendor benchmarking to short‑list partners for pilot programmes on CO2‑exposed or deepwater fields where material and fatigue performance are critical.
PW Consulting’s Flexible Pipes for Oil & Gas Market study is structured to be immediately operational for 2026 decision cycles — translating market forecasts, standards compliance, vendor positioning, and material economics into executable procurement, investment, and R&D choices. To access the full datasets, vendor scorecards, and downloadable modelling tools, please visit the PW Consulting report portal or contact our industry team to arrange a private briefing.
For detailed analysis of this topic, please visit the official page: Flexible Pipes for Oil and Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Electronic Power Steering Market — Strategic Primer for 2026 Decision-Makers
By PW Consulting — Senior Strategy & Industry Analysis
Automotive Electronic Power Steering Market
Executive preview
The transition to electric, software-defined, and safety-integrated steering architectures is no longer a distant industry storyline — it is the operating context for 2026 planning cycles. Our Automotive Electronic Power Steering (EPS) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, supplier strategy, regulatory dynamics, technology inflection points and procurement playbooks into an actionable roadmap for OEMs, Tier‑1 suppliers, investors and policy teams. The market grew from approximately USD 198.0 Million in 2020 to USD 273.7 Million in 2025 and is forecast to expand to USD 286.6 Million in 2026 and reach roughly USD 397.0 Million by 2032, implying a compound annual growth rate (CAGR) of about 5.57% over the forecast horizon. Market concentration remains high: the top three firms control an estimated 78% of reported revenues, while the leading five account for around 90% — a structural characteristic that shapes negotiating power, innovation diffusion, and M&A dynamics.
Automotive Electronic Power Steering Market
Why this study matters for 2026 strategy
Two planning realities define urgency in 2026. First, regulatory and safety mandates are accelerating EPS adoption and functional complexity, converting what was a mechanical cost‑center into a strategic chassis and software development area. Second, architectural convergence (EPS + ADAS + steer‑by‑wire readiness) is creating winner-take-disproportionate returns for suppliers who can deliver integrated, validated systems at scale. Our research translates those realities into three pragmatic decision levers for 2026:
Automotive Electronic Power Steering Market
- Resource allocation: whether to build, buy, or partner for steer‑by‑wire and torque‑overlay capabilities;
- Supplier strategy: how to structure long‑term contracts, local footprint and co‑development terms to secure supply and update cycles; and
- Product and IP planning: where to invest in sensor fusion, solid‑state sensing, and software safety stacks to protect up‑front engineering spend and post‑launch margins.
Market trajectory and implications
The EPS market has demonstrated resilient expansion through 2020–2025, accelerated by electrification and CO2 compliance drivers. The modest but steady CAGR of 5.57% forecast for 2026–2032 masks important structural shifts: unit growth is being compounded by rising electronic content per vehicle, higher validation costs for safety-rated torque overlay, and the premium commanded by steer‑by‑wire subsystems. For 2026 boardrooms, the implication is clear — growth is not simply about volume; it is about value capture within the system stack (mechanical, electromechanical, power electronics, and software).
Regulatory and standards tailwinds
Recent regulatory moves materially reshape product roadmaps and procurement criteria. Notable policy inflection points include tightened CO2/efficiency regimes and new safety assessment protocols that implicitly favor electronic steering solutions over hydraulic systems. Additionally, vehicle safety rating bodies now treat lane‑keeping assistance functionality as a rated feature, which creates technical prerequisites (such as EPS torque overlay and redundancy) for OEMs seeking premium safety scores. These regulatory constraints convert product reliability and software determinism into commercial differentiators.
Technology convergence and supply‑chain effects
Material advances (higher‑strength gear materials, precision manufacturing) and sensor evolution (solid‑state and sensor‑fusion approaches) are simplifying architectures while improving NVH and durability. At the same time, steer‑by‑wire development is transitioning from lab demonstrations to series production — an inflection that carries new supplier roles (actuator integrators, backup power architects, safety‑certified software houses). This convergence amplifies two operational realities for 2026:
- Up‑front validation budgets and functional safety certification timelines will constitute a larger share of program CAPEX, necessitating earlier alignment between OEM system architects and chosen Tier‑1 partners;
- Sourcing strategies must incorporate software SLAs, cybersecurity roadmaps, and hardware redundancy plans in addition to traditional mechanical supply metrics.
Competitive landscape — what the leading players signal
The EPS supplier base shows a dual structure: a small group of global incumbents with system breadth and validation depth, and a broader tier of regional specialists focusing on cost and volume. Key global players include established system integrators and component specialists that are actively competing on system performance, ADAS integration and steer‑by‑wire readiness. Recent industry movements underline who is closest to commercialization and how competition is evolving:
- Nexteer Automotive: expanding its product suite for heavier vehicles and moving to series production for steer‑by‑wire programs — an indicator that full drive‑by‑wire is pushing into mainstream OEM platforms.
- Robert Bosch GmbH and ZF Friedrichshafen AG: continuing to iterate on integrated EPS+ADAS solutions and leveraging their systems know‑how to anchor OEM relationships across vehicle segments.
- Japanese incumbents (NSK, JTEKT, Denso): emphasise precision, force‑feedback and backup power solutions, with validated subsystems already embedded in premium BEV and PHEV programs.
- Asia‑Pacific suppliers (Mando, Hyundai Mobis, China Automotive Systems): pursuing aggressive volume and localization plays, evidenced by recent volume shipments and regional contract awards.
These dynamics produce a two‑track competitive field. Track one: system integrators that compete on validated steer‑by‑wire platforms and safety‑certified software ecosystems. Track two: high‑volume suppliers that deliver cost‑optimized EPS iterations for mainstream platforms but must now invest to remain relevant as content per vehicle rises.
Recent developments — what they reveal about timing and risk
Concrete examples from 2025–2026 reveal the timing of commercialization and the nature of contract opportunity windows:
- A leading supplier’s series production launch of a steer‑by‑wire system in 2026 signals that certification and OEM validation cycles are moving from multi‑year pilot phases into production ramps; procurement teams should expect new qualification gates on supply contracts.
- Product portfolio expansions and OEM validations in 2025–2026 show that suppliers are layering high‑output and backup solutions into existing product families, compressing the time between prototype and production readiness.
- Volume shipment contracts between regional suppliers and global OEMs demonstrate that localization and scale are win conditions in certain geographies — and that cost pressures remain front and center despite added electronic content.
Taken together, these moves indicate that 2026 is an inflection year where early movers will capture platform positions and late movers face elongated, more expensive catch‑up investments.
Actionable intelligence contained in the full study
The report provides operational tools designed to shorten decision cycles and de‑risk investments:
- Proprietary market sizing and scenario model (USD, revenue unit: Million) that allows users to run sensitivity analyses across regulatory, material cost, and pace‑of‑adoption assumptions for 2026–2032;
- Supplier scorecards and supplier SWOTs focused on systems delivery, functional safety track record, software capability and global footprint;
- Program playbooks covering build vs. buy thresholds, qualification milestones, and sample contract terms for tiering and co‑development;
- Risk heatmaps and mitigation blueprints for supply chain, IP, and regulatory compliance; and
- Financial impact snapshots for OEMs and suppliers showing margin implications of increased ESW (electronic steering weight) and validation overhead.
The full deliverables include an interactive Excel model, a procurement checklist for 2026 programs, and a buyer’s guide to structuring partnerships around steer‑by‑wire and torque‑overlay requirements.
Strategic recommendations for 2026 planning
Based on the synthesis of market growth, competitive positioning and regulatory pressures, PW Consulting advises stakeholders to prioritize the following actions this year:
- Establish a clear systems roadmap that aligns EPS hardware and software milestones with ADAS development timelines — treating steering as a joint mechanical‑software program rather than a discrete hardware procurement.
- Secure at least two qualified suppliers for critical EPS subsystems to mitigate single‑point risks, and negotiate staged IP/royalty sharing to balance upfront engineering costs with long‑term licensing exposure.
- Invest selectively in solid‑state sensing and actuator reliability testing facilities or partner with test houses to shorten validation cycles and improve time‑to‑market.
- For investors and M&A teams: prioritize targets that combine software safety stacks with scalable actuator manufacturing; for OEMs: favor suppliers with demonstrated series production capability for steer‑by‑wire if premium safety and autonomy packages are strategic priorities.
- Embed regulatory monitoring into project gating. With emission and safety protocols now directly influencing steering architecture decisions, early regulatory alignment avoids late redesigns and resale impact.
Closing — the strategic value of this research
The EPS ecosystem is evolving from a component market to a systems battleground. For 2026, decisions about engineering investment, supplier structure and platform differentiation will determine whether organizations capture the increased electronic content value, or become price takers in a concentrated supplier market. Our study offers a pragmatic, scenario‑based foundation for those decisions: robust market sizing (USD, revenue unit: Million), competitor diagnostics, regulatory impact mapping, and a practical set of procurement and engineering playbooks. This briefing demonstrates the depth of analysis you can expect; the full report contains the confidential, segment‑level data and interactive models necessary to operationalize strategy. Visit our source page to access the complete study and the supporting analytical toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Portable Toilets Market to Hit USD 327.72M by 2032 at 7.94% CAGR
By PW Consulting, 2026-07-12
Portable Toilets Market 2026: Strategic Insights for Action — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our full Portable Toilets Market study — an evidence‑based roadmap intended to shape high‑confidence commercial decisions in 2026. This preview conveys the report’s core takeaways, the decision levers executives must prioritize, and why immediate action will materially affect revenue, cost and risk profiles over the next planning cycle. To preserve the tactical advantage embedded in our proprietary segmentation and scenario models, the granular sub‑segment matrices and vendor scorecards are reserved for the full report.
Portable Toilets Market
Why this market matters in 2026
The portable toilets market is transitioning from a largely transactional rental industry to a technology‑enabled, sustainability‑driven ecosystem. After a steady recovery period in the early 2020s, the market reached a meaningful scale in our base year (2025) and is now on a structurally higher growth trajectory. Our topline model shows the global market moving from the 2025 base through the forecast period (2026–2032) at a compound annual growth rate (CAGR) of 7.94%. Under our central forecast, that trajectory drives the market toward roughly USD 327.7 million by 2032.
Portable Toilets Market
Two structural shifts underpin this growth: first, the professionalization and consolidation of rental and servicing models; second, accelerated product innovation around vacuum systems, luxury sanitation, ADA compliance, and circular manufacturing. Together these forces increase average revenue per unit, create higher aftermarket revenue streams (consumables, deodorants, servicing subscriptions), and raise barriers to entry for low‑cost incumbents.
Portable Toilets Market
What the full study delivers: pragmatic, transaction‑ready intelligence
PW Consulting designed this study to be directly actionable for C‑suite, corporate development, procurement, and field operations teams. The full report contains:
- Topline market sizing and a seven‑year forecast with scenario sensitivity (base, upside, downside) and clear assumptions tied to construction activity, live events recovery, and regulatory pacing.
- Unit economics models for rental fleets (capex, opex, utilization) and ROI breakeven timelines by equipment class.
- Segmentation matrices across product type, application, and region — with elasticities on price, service frequency, and maintenance intensity. (Note: detailed segment share tables are available in the full report.)
- Competitive landscaping and a ranked M&A target list with valuation heuristics, integration risks, and synergies (cost, route density, cross‑sell potential).
- Procurement playbooks — supplier scorecards, sourcing strategies for recycled polymer inputs, and mitigation steps for raw‑material volatility.
- Regulatory and tender tracker covering municipal bid behavior, tax treatments, ADA compliance trends, and environmental permitting that materially affect service obligations.
- Operational blueprints for digitalization: telematics, fill‑level sensing, predictive routing and staffing models that reduce empty miles and service costs.
- Risk matrices covering supply chain, labor, environmental fines, and reputational risk — with mitigation playbooks tailored to rental operators, manufacturers, and event planners.
Competitive landscape: consolidation runway and capability gaps
The market remains moderately fragmented: concentration metrics show that the top three firms account for under one‑quarter of global share, with the top five still well below one‑third of the market. This dispersion creates both acquisition runway for scale‑seeking players and white‑space for differentiated product and service plays.
- PolyJohn (Whiting, Indiana) — A manufacturing stalwart known for portable toilets, sinks, and accessories. Its February 2026 acquisition of EcoFab signals a deliberate expansion into advanced vacuum toilet systems, accelerating its product roadmap and creating a technology arbitrage opportunity for customers seeking lower water usage and improved odor control.
- Satellite Industries (United States) — The largest manufacturer with a broad portfolio spanning restroom trailers, septic trucks, modular solutions and consumables. Satellite’s scale in both hardware and aftermarket supplies positions it as a one‑stop provider for large event and municipal contracts.
- United Site Services (USS) (United States) — The nation’s leading rental provider; strong in standard and ADA‑compliant offerings. USS’s route density and national footprint deliver operational advantages for time‑sensitive tenders but leave opportunity to increase per‑unit profitability through tech‑enabled services.
- Rumpke (Cincinnati, Ohio) — A provider leveraging recycled plastic in unit manufacture and offering VIP trailers and ADA units. Rumpke’s focus on circular inputs aligns with corporate sustainability mandates and creates differentiation where green procurement criteria influence public and private tenders.
- WM (United States) — The broader environmental services firm provides portable sanitation as part of an integrated waste services portfolio. WM’s bundled selling approach is especially effective in construction and long‑duration municipal engagements.
- Stallion Infrastructure Services (United States) — A niche provider of premium and high‑rise solutions and luxury trailers. Stallion illustrates a viable premiumization path that captures higher margins in event and hospitality verticals.
Together, these players illustrate three playbooks that will shape M&A and competitive strategy in 2026: scale consolidation (roll‑ups to capture route density), technology plays (vacuum systems and telematics), and premium/sustainability verticalization (luxury units, recycled materials, and compliance solutions).
Market dynamics that will dictate near‑term strategic moves
- Sustainability and circular manufacturing: Manufacturers increasingly use blow‑molding with recycled plastics for unit bodies. This is not only a marketing differentiator but a procurement lever — clients with ESG targets will prefer vendors with demonstrable recycled content and end‑of‑life recovery programs.
- Regulatory and municipal procurement: Several US municipalities issued tenders for portable toilet rental and servicing for 2026 (including county and municipal bids). In some jurisdictions, rental services receive tax treatment that materially affects contract economics. Firms should map local tax and tender cycles into their go‑to‑market calendars.
- Product innovation and performance: Vacuum toilet systems and luxury flushing units are moving from pilot projects to commercial deployments. These technologies change utilization patterns (longer productive life, different cleaning cadence) and create aftermarket service opportunities.
- Digital operations: Telematics (fill‑level sensors, route optimization) are proven ROI drivers. Early adopters cut empty‑mile costs substantially and improve responsiveness in event deployments.
Strategic implications and recommended 2026 priorities
For executive teams planning 2026 initiatives, our study prioritizes the following actions — each paired with practical KPIs that appear in the full report:
- Adopt a differentiated fleet strategy: Segregate assets into cost‑efficient standard units and higher‑margin premium or vacuum units. Track utilization, maintenance cost per service, and PPE & consumable attachment rates. Run pilots to quantify margin differentials before large‑scale fleet transitions.
- Make targeted technology investments: Invest in telematics across a representative fleet cohort to validate savings in routing and servicing. Shortlist vacuum and advanced flushing systems for high‑value contracts where water scarcity or hygiene standards are non‑negotiable.
- Pursue consolidation where route density creates synergy: Use the full report’s M&A heatmap to identify targets with complementary geographies, under‑utilized fleets, or strong public tender pipelines. Expected outcomes include faster route density improvements and cross‑sell into events and construction segments.
- Embed circular procurement and recycling economics: Negotiate recycled polymer supply contracts and secure takeback agreements. Incorporate lifecycle emission metrics into bids to win ESG‑weighted tenders.
- Revise commercial models for municipal and large event contracts: Account explicitly for local tax treatments, compliance obligations, and service frequency requirements. Structure multi‑year pricing with CPI or input‑price collars.
- Develop aftermarket and consumables revenue streams: Bundled servicing, deodorant subscriptions, and preventive maintenance plans increase ARPU and create more predictable revenue.
How to use this preview — and the next step
This preview is intended to align leadership around the strategic tradeoffs and near‑term priorities we see as essential in 2026. The full PW Consulting Portable Toilets Market report provides the playbooks, models, and deal scoring required to execute these moves with confidence — including:
- Detailed segment economics and pricing sensitivity tables;
- Vendor scorecards and M&A target dossiers with integration checklists;
- Operational templates for telematics deployment and route optimization pilots;
- Regulatory tender calendars and a matrix showing tax and compliance impacts by jurisdiction.
Leaders preparing budgets or pursuing M&A in 2026 should treat this study as prescriptive: the difference between incremental improvement and meaningful market capture will come from combining fleet modernization, targeted acquisitions, and service innovation — executed with a clear, data‑driven plan. For organizations that want to convert these insights into a 100‑day plan, PW Consulting offers tailored workshops and scenario modeling to operationalize the findings.
Closing perspective
The portable toilets sector is no longer a low‑margin, commoditized corner of services. It is evolving into a modular, capital‑efficient market where technology, sustainability and tender‑savvy operators will earn a disproportionate share of growth. With the market growing at an expected 7.94% CAGR through 2032 and compelling opportunities for differentiation across product, service and geographic plays, 2026 represents a critical inflection year. PW Consulting’s full report equips decision‑makers with the actionable intelligence required to convert that inflection into durable competitive advantage.
For access to the full dataset, proprietary segment breakdowns, and the operational playbooks referenced here, please contact PW Consulting. The detailed annexes and vendor scorecards are provided exclusively with the full research package.
For detailed analysis of this topic, please visit the official page: Portable Toilets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrafast Lasers Market to hit USD 6,887 Million by 2032 (16.62% CAGR)
By PW Consulting, 2026-07-12
Ultrafast Lasers Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this strategic preview of our Ultrafast Lasers Market study to help executive teams, corporate development units, and R&D leaders prioritize decisions in 2026. The objective here is to surface the high-fidelity signals that matter—market trajectory, competitive positioning, structural risks, and where actionable value can be captured—while reserving the full segmented detail for the primary report. Think of this as a briefing trailer: rigorous, directional, and designed to accelerate a decision to obtain the full playbook.
Ultrafast Lasers Market
Market trajectory and what it means for 2026
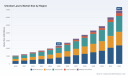
Ultrafast lasers are in a clear growth phase. Using 2025 as the study base year, the global market expanded materially through the first half of this decade, and the outlook from 2026–2032 is robust. Our model (USD, revenue unit: Million) shows the market crossing the multi-billion-dollar threshold in the late 2020s and accelerating toward several billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate of approximately 16.6%, reflecting sustained demand across materials processing, medical & healthcare, scientific research, and advanced electronics.
Ultrafast Lasers Market
Why this matters for 2026 decisions:
Ultrafast Lasers Market
- Capital allocation windows are open now. A double-digit CAGR means earlier movers can secure development, capacity, and contracts at terms that will be harder to obtain later as demand concentrates.
- Product roadmaps that hit market readiness in the 2026–2028 window are positioned to capture disproportionate share as adoption curves steepen.
- Supply chain and regulatory constraints (detailed below) create optionality value for firms that can build resilient sourcing and compliance capabilities in 2026.
Competitive landscape — who matters and why
The ultrafast lasers market exhibits moderate concentration: the top three firms account for a majority share of industrial revenue, and the top five together hold an even larger portion. This concentration creates two strategic realities—market leaders can shape price, standards, and channel structures, while mid-tier and niche players can capture value by specializing in adjacent segments or by offering integrated solutions that reduce customer switching costs.
Principal companies we track (representative profiles):
- Coherent Corp (United States) — Offers a complete range of ultrafast scientific oscillators and amplifiers across research, OEM, and industrial channels ( https://www.coherent.com).
- TRUMPF (Germany) — Strong in industrial materials processing and precision manufacturing solutions, with deep machine-integration expertise ( https://www.trumpf.com).
- IPG Photonics (United States) — Known for compact, cost-effective ultrafast fiber lasers optimized for microprocessing and industrial usage ( https://www.ipgphotonics.com).
- Amplitude Systèmes (France) — Femtosecond systems leader focused on micromachining and medical device applications ( https://amplitude-laser.com).
- Ekspla (Lithuania), NKT Photonics (Denmark), Light Conversion (Lithuania), Menlo Systems (Germany), IMRA America (United States), Clark-MXR (United States), Thorlabs (United States) — each brings specialized product, systems, or OEM engineering capabilities relevant to targeted use cases (see full profiles in the report).
Recent competitive moves highlight evolving battlegrounds:
- IPG Photonics showcased ultrafast innovations at Laser World of Photonics in mid-2025 and won a major SPIE award in May 2026 for a high-power compact source—signaling continued R&D and branding momentum in high-power fiber solutions.
- NKT Photonics has moved from product delivery into strategic partnerships, notably delivering subsystems to a quantum computing supplier—an example of lasers enabling adjacent high-value ecosystems.
- IMRA America’s 2026 Foreign-Trade Zone production notification in Michigan signals onshoring of femtosecond fiber manufacturing capacity within the U.S., with implications for lead times, compliance, and U.S. supply resilience.
Structural headwinds and operational risks (and practical mitigations)
Several non-market forces will shape winners and losers in 2026. Our study integrates these "industry context" factors and provides playbooks to mitigate them.
- Regulatory constraints: Certain optical sources and components fall under defense-related export controls (e.g., items identified on the U.S. Munitions List), raising ITAR/ export compliance costs and limiting go-to-market pathways for some advanced products. Strategic recommendation: establish a compliance-first product taxonomy and segregate export-controlled product lines from those that can scale globally without restrictions. The report includes a compliance checklist and decision tree for product development and partnership selection.
- Labor and skills gap: Skilled labor shortages for precision assembly and optical engineering constrain scaling. Tactical moves: partner with regional universities for apprenticeship programs, invest in automation of repeatable assembly stages, and design modular subsystems that reduce manual integration time. We quantify the trade-off between automation CAPEX and shortened time-to-revenue in our financial models.
- Raw material and supplier constraints: Lead times for specialty components (nonlinear crystals, gain media, precision optics) remain extended. Mitigations include strategic inventory hedging, dual-sourcing programs, and selective vertical integration for “bottle-neck” components. The report maps supplier concentration and recommends which components are priority candidates for in-house production versus long-term contracts.
- Supply chain fragility: Low-volume, high-risk commodity supply chains require collaborative risk sharing. Recommended approaches: develop supplier scorecards tied to performance SLAs, invest in supplier development, and use geographically diversified sourcing to minimize single-point failures.
Commercial and product strategy recommendations for 2026
Based on scenario modelling, customer interviews, and technology assessments, firms should prioritize the following:
- Define a two-track product strategy: (1) defend and extend core modules for established industrial customers (service contracts, integrated laser-heads, system-level guarantees), and (2) accelerate a “disruptor” line aimed at high-growth pockets (consumer electronics microprocessing, advanced medical device manufacturing, and quantum subsystem suppliers). The full report provides a timeline-driven roadmap and R&D milestones for each track.
- Negotiate supplier financing and forward-purchase contracts in 2026 to lock down critical optics and pump diodes; include clauses for demand-growth scalability. Our procurement playbook includes model contracts and sensitivity analyses for price and lead-time volatility.
- Leverage partnerships with OEM integrators and system houses to provide bundled solutions that reduce customer integration risk; value-capture models in the report quantify margin uplift from systems sales versus component sales.
- Pursue targeted M&A or strategic JV plays focused on thin but critical capabilities—nonlinear crystals, compact amplifier modules, or real-time beam-monitoring electronics—rather than broad, horizontal consolidation. The report ranks acquisition targets by strategic fit and integration complexity.
What PW Consulting’s full study delivers (practical, executable content)
This preview highlights themes; the full Ultrafast Lasers Market report contains the operational tools that senior teams will use to act in 2026:
- Detailed market-sizing and validated demand scenarios (historical 2020–2025 base, forecast 2026–2032, revenue unit: USD Million) and sensitivity runs tied to adoption curves.
- Go-to-market playbooks for product, pricing, and channel strategies across industrial, medical, scientific, and electronics end-markets.
- Supplier and component maps with recommended sourcing strategies, dual-sourcing candidates, and suggested inventory policies to manage lead-time risk.
- Regulatory and compliance roadmaps (including ITAR/export-control decision trees) and an implementation checklist for product development and international sales.
- Commercial models—TCO, pricing elasticity, and ROI calculators—designed to evaluate leasing vs. outright sale, service tiering, and spare-parts strategies.
- Competitor dossiers with capability matrices, recent strategic moves, and M&A targets, plus stakeholder matrices to support diligence and negotiations.
- Operational playbooks for workforce upskilling, automation deployment, and quality-management practices specific to ultrafast laser assembly and testing.
How to use this preview in your 2026 planning cycle
If you are budgeting, negotiating supplier contracts, or refining your product roadmap for 2026, use this preview to:
- Accelerate capital allocation decisions for R&D and capacity by referencing the market’s growth trajectory and the timing of opportunity windows in the next 24 months.
- Prioritize compliance and supply-chain programs now; regulatory and sourcing lead times will materially affect your time-to-market.
- Prepare tactical M&A playbooks focused on capability fills rather than market share grabs—our scenarios show higher near-term ROI from bolt-on capabilities that shorten customer integration cycles.
Next steps — how PW Consulting can help
For teams ready to act in 2026, PW Consulting offers tailored briefings, acquisition diligence support, supplier negotiation workshops, and integration planning built from the full study. The complete report contains the granular segmented data, exact regional and application breakdowns, and financial schedules you’ll need to finalize investments and contracts. Use this preview to align executive priorities—then commission a customized deep-dive to convert strategy into executable programs.
In short: the ultrafast lasers sector is entering a phase where technological leadership, supply-chain resilience, and regulatory-savvy commercialization will define value creation. The market’s growth dynamics make early 2026 the decisive moment to set the terms of competition for the latter half of this decade.
For detailed analysis of this topic, please visit the official page: Ultrafast Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zener Diodes Market to Reach USD 1,063.11 Million by 2032 at 4.2% CAGR
By PW Consulting, 2026-07-12
Zener Diodes Market 2026: Strategic Imperatives for Decision Makers
Market snapshot
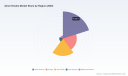
The Zener diodes market has moved from a compact specialty segment into a core building block of modern power-management and protection architectures. Our baseline analysis (base year 2025) shows the market expanding from roughly USD 654 million in 2020 to USD 797 million in 2025, and, under our central forecast, progressing to approximately USD 1,063 million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 4.2% across the 2026–2032 projection window. That steady, mid-single-digit expansion masks important inflection points—miniaturization, automotive qualification, and transient-protection demand driven by large-scale compute and communications deployments—that will define competitive advantage in 2026 and beyond.
Zener Diodes Market
Why this research matters for 2026 decisions
- Strategic clarity in a fragmented market: With the market exhibiting modest overall growth and a relatively low top-player concentration (CR3 ~25.4%, CR5 ~33.0%), there is room for both incumbents and focused challengers to expand share. However, scale alone is insufficient; product differentiation and go-to-market agility matter more than ever.
- Design-to-supply alignment: 2026 will be the year many OEMs consolidate system-level design choices (power islands, transient suppression strategies, and packaging standards). Choosing a Zener strategy now determines qualification timelines, inventory commitments, and total cost of ownership through 2028.
- Risk calibration against structural shocks: Supply-chain disruptions and demand spikes (notably from AI server motherboard procurement cycles) have and will continue to create asymmetric lead-time and pricing pressures. Buyers who align sourcing and design-in strategies with resilient suppliers will sustain lower product-development friction.
Macro dynamics shaping vendor and buyer strategies
- Miniaturization and packaging technology: Leadless and sidewall-plated packages such as DFN variants are becoming standard in designs where board real estate is constrained. Suppliers introducing robust, miniaturized packages gain preferential design-ins for portable and space-constrained applications.
- Automotive and reliability qualification: AEC-Q101 and PPAP capability are now de facto requirements for suppliers targeting automotive and certain industrial segments. Products with explicit automotive qualification reduce customer lead time to production and unlock higher-margin segments.
- Precision and low-noise variants: Tight-tolerance devices (±1%–±2%) and low-bias-current series are moving from niche to mainstream as sensor interfaces and high-speed digital front ends demand cleaner, more predictable clamping and regulation behavior.
- Supply chain pressure points: Recent industry data indicate dramatic lead-time inflation for certain suppliers—where single-digit-week leads stretched into the 48–52+ week band—while pricing rose materially (noted increases around 20% in affected lines). This dynamic is concentrated in components servicing AI compute and similar high-velocity markets, but the spillover affects broader supply availability and commercial terms.
- Process control and manufacturability: Suppliers demonstrating high maturity (for example, validated Cpk metrics in qualification runs) materially reduce qualification risk and offer a faster ramp to production. This is a decisive selection criterion for large OEMs.
Competitive landscape — what to watch in 2026
The competitive field mixes global diversified semiconductor houses with focused discrete specialists. Across the leading players we track, several capability tiers and strategic postures have emerged:
Zener Diodes Market
- Broad portfolio and systems play: Companies such as Texas Instruments and Microchip position Zener diodes within a broader protection and power-management portfolio. Their recent product introductions and data-sheet promotions in early 2026 underscore an integrated protection strategy that speaks to system architects seeking single-vendor simplicity.
- Form-factor and precision differentiation: Vishay and Diodes Incorporated are leveraging packaging and process improvements—leadless DFN packages, sidewall plating, and ion-implanted epitaxial processes—to offer smaller, tighter-tolerance devices. These moves address miniaturization and precision demands in consumer, industrial, and automotive segments.
- Automotive and reliability-focused specialists: Toshiba and Nexperia are pushing AEC-Q101-qualified lines, ±1% tolerance families, and low-bias/low-noise variants explicitly aimed at automotive and high-reliability industrial applications. Their product roadmaps shorten qualification cycles for customers that require PPAP-capable supply.
- Discrete and transient protection specialists: onsemi and other discrete-focused vendors continue to compete on transient robustness, multi-device configurations (e.g., dual common-cathode), and portfolio depth for power-management customers.
Recent product and portfolio moves bear attention: Texas Instruments’ 2026 introduction of Zener devices as part of an expanded protection lineup, Toshiba’s November 2025 CMZBxxA series for surge and switching protection, Vishay’s October 2025 DFN1006-2A package expansion, and Diodes Incorporated’s December 2025 tight-tolerance surface-mount updates all signal where customer demand and R&D investment are converging.
Zener Diodes Market
Strategic implications and recommended actions for 2026
- Supplier portfolio optimization: Blend a small set of high-capability, automotive-qualified suppliers with a flexible second-tier network to balance qualification speed and price leverage. Prioritize suppliers demonstrating mature process control metrics and who communicate lead-time transparency.
- Design-for-availability: Standardize on a limited set of package families and tolerance classes across platforms to ease cross-platform inventory pooling and allow rapid substitution if a supplier experiences capacity constraints.
- Qualification acceleration: Invest in concurrent qualification tracks (parallel lab, reliability and in-system testing) to reduce time-to-production. When suppliers offer AEC-Q101 or PPAP-capable parts, fast-track those options for automotive/industrial programs.
- Value-based pricing and cost-to-serve: For manufacturers, capture margin by offering differentiated variants (e.g., ±1% tolerance, low-noise lines, automotive-grade) at premium price points. For OEM buyers, conduct lifecycle TCO assessments—factoring yield improvements and MTBF benefits from higher-grade Zener solutions—rather than accepting unit-price as the sole procurement metric.
- M&A and partnership focus areas: Target capabilities that accelerate miniaturized packaging, advanced process technologies (ion implantation, planar silicon), or capacity for automotive-qualified runs. Strategic partnerships with wafer-foundries or packaging specialists can shorten lead-time volatility exposure.
- Scenario planning for compute-driven demand shocks: Model inventory and contractual terms around plausible AI/data-center procurement spikes. Hedging strategies, capacity pre-booking, and dual-sourcing are practical mitigants against the demonstrated risk of price and lead-time shocks.
What PW Consulting’s Zener Diodes Market report contains (practical, execution-focused)
This study is built for 2026 decision-makers who need both a strategic view and executable detail. The report combines:
- Market sizing and trend analysis across a 2020–2032 horizon with scenario variants calibrated to demand shocks and adoption accelerators.
- Supply-chain risk maps and mitigation playbooks (lead-time stress testing, contractual levers, inventory optimization heuristics).
- Product and technology roadmaps highlighting packaging, process, and tolerance innovations and their likely adoption timelines.
- Vendor benchmarking and heat maps (capability, qualification, vertical focus, and commercial behavior) with raw vendor data and contactable profiles for procurement teams.
- Actionable go-to-market modules: a buyer’s checklist for qualification, a supplier scorecard template, and a sample RFP language set tailored for automotive and high-reliability programs.
- Commercial scenarios and pricing elasticity models to support negotiation and sourcing strategies under volatile demand conditions.
Note: this article intentionally omits the granular regional, type, and application splits and the full numerical segmentation tables that are included in the report. Those detailed breakdowns are critical for SKU-level sourcing and program planning and are available in the full report materials.
How to use these insights in 2026
- CEOs and business-unit leaders: Use the market trajectory and concentration metrics to set portfolio priorities—scale up investment where differentiation yields premium positioning, and de-emphasize commoditized low-margin offerings.
- Procurement and supply-chain leaders: Implement lead-time and price-stress scenarios drawn from the report to define contract terms, safety-stock levels, and dual-sourcing triggers.
- R&D and product teams: Prioritize development on tight-tolerance, low-noise, and automotive-qualified variants and choose packages aligned with customer roadmaps for miniaturization.
- M&A teams: Leverage the report’s gap analysis to identify acquisition targets that fill capability or capacity shortfalls—especially in packaging, process technology, or automotive qualification lanes.
Conclusion — an executive roadmap for 2026
The Zener diodes market in 2026 is characterized by steady growth, pockets of rapid demand-driven stress, and clear technical vectors—miniaturization, automotive qualification, and precision variants—that separate winners from the rest. With a market base approaching USD 800 million in 2025 and an expected climb to about USD 1.06 billion by 2032 at a 4.2% CAGR, companies must choose between chasing scale in a fragmented space or establishing defensible differentiation through qualification, packaging, and process excellence.
PW Consulting’s full Zener Diodes Market report provides the granular segmentation, supplier-level data, and scenario modeling necessary to operationalize these strategic choices. For teams that must convert insight into procurement tactics, product roadmaps, or M&A targets in 2026, the complete dataset and templates in the report are designed to accelerate decision velocity while de-risking execution.
Next step
To access the detailed segmentation tables, supplier scorecards, and executable playbooks referenced here, please consult the full report materials available on our publication page.
For detailed analysis of this topic, please visit the official page: Zener Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Titanium Diboride Market to Expand at 4.5% CAGR Through 2032
By PW Consulting, 2026-07-12
Titanium Diboride Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a concise strategic primer that frames the Titanium Diboride (TiB2) market through the 2026 decision window. This “teaser” synthesizes the report’s most consequential macro findings and strategic implications while intentionally withholding granular segment-level datapoints to steer market participants to the full study. The objective: give C-suite and corporate development teams the contextual clarity needed to prioritize actions in 2026, while reserving the detailed, transaction‑relevant intelligence for the report itself.
Titanium Diboride Market
Macro snapshot you need now
- Base year and scope: The analysis uses 2025 as the base year, traces historical dynamics through 2020–2025, and projects the market across a 2026–2032 forecast horizon.
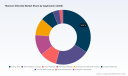
- Market trajectory: The TiB2 market is expanding at a moderate compound annual growth rate (CAGR) of about 4.5% over the forecast period. After a multi‑year recovery, the market value reached the mid‑double digits (Million USD) range by 2025 and is modeled to continue steady expansion into 2032.
- Market structure: Concentration is material—roughly three firms account for a clear majority of supply, and the top five consolidate an even larger share—indicating an industry with meaningful scale advantages, specialized know‑how, and barriers to rapid fragmentation.
These macro datapoints frame the economics for investment, capacity planning, procurement, and M&A through 2026. They also imply that scale and technology leadership will likely determine winners as demand niches mature.
Titanium Diboride Market
Why TiB2 matters to strategic agendas in 2026
- Cross‑sector leverage: TiB2’s unique combination of hardness, electrical conductivity, and thermal stability underpins a widening set of high‑value applications—from defense armor and aerospace ceramics to sputtering targets for semiconductor thin films and additive manufacturing feedstock. For firms active in adjacent material value chains, TiB2 is increasingly a strategic input rather than a niche commodity.
- Technology inflection points: Improvements in powder grades, nano‑structuring, and AM‑compatible formulations are unlocking new design options for lightweight armor, cutting tools, and high‑temperature components. These technology shifts reframe product roadmaps and supplier selection criteria.
- Supply‑side sensitivity: Boron feedstock dynamics, environmental regulation of mining and processing, and freight/logistics volatility directly affect cost curves and available capacity. Notably, global boric acid prices moved modestly downward in early 2026 amid stable supply conditions, but regulatory and logistical factors remain material risk drivers for 2026 procurement strategies.
What PW Consulting’s full report delivers (practical, transaction‑grade content)
The full Titanium Diboride Market report is built for action; it is designed to support investment committees, procurement teams, product leaders, and M&A advisors. Key deliverables include:
Titanium Diboride Market
- Robust market sizing and growth scenarios—base, upside, and downside—driven by demand trajectories across end markets and technology adoption curves.
- Segment and regional intelligence with quantifiable volumes and revenue breakdowns (note: granular splits are omitted from this primer to preserve advisory value in the full report).
- Price and feedstock sensitivity analysis that models boron input cost swings, regulatory cost pressure, and freight variability across short‑ and medium‑term horizons.
- Supplier and capacity map with capability matrices—identifying incumbent producers, niche specialists (e.g., sputtering‑grade suppliers), and low‑cost producers—plus capex commitments and near‑term capacity changes.
- Technology and product roadmaps evaluating nanostructured vs. bulk TiB2 developments, additive manufacturing grade emergence, and implications for product specifications and qualification timelines.
- Commercial playbooks tailored to different buyer profiles: OEMs, defense primes, semiconductor fabs, and specialty chemical companies—covering procurement levers, qualification, and tier‑1 supplier strategies.
- Risk matrix and mitigation playbook—covering regulatory, feedstock, logistical, and geopolitical scenarios with recommended contracting and hedging approaches.
- M&A and partnership playbook—valuation frameworks, target screening criteria (technology, capacity, customer access), and integration pitfalls specific to TiB2 businesses.
Competitive landscape — what we see and why it matters
The TiB2 sector exhibits a mix of legacy specialty producers, diversified materials conglomerates, and regionally important manufacturers. Strategic implications differ by player type:
- Treibacher Industrie AG (Austria) — a European leader in high‑purity TiB2 powders. Its strength lies in quality and relationships with industrial and aerospace end users; competitive strategy should focus on premiumization and long‑cycle supply contracts.
- 3M/Ceradyne (United States) — dominant in defense and armor applications through longstanding government procurement relationships. For military and aerospace suppliers, aligning to defense qualification timelines remains a lucrative but resource‑intensive route.
- Materion Corporation (United States) — a go‑to for sputtering targets and thin‑film materials for semiconductor and electronics markets. Their business highlights the high margins and technical barriers in electronic‑grade TiB2 segments.
- Japan New Metals Co., Ltd. — focused on specialty, precision, and export markets; strategic edge is quality control and niche application development in advanced tooling and electronics.
- H.C. Starck GmbH (Mitsubishi Materials Group) — positioned as a high‑purity producer with recent product introductions aimed at additive manufacturing. Such moves accelerate adoption curves in aerospace and automotive sectors.
- Shandong Pengcheng and Dandong Chemical Engineering Institute (China) — large regional producers supplying ceramics, cathode materials for aluminum smelting, and industrial cutting tool markets; they emphasize scale and cost competitiveness.
Recent industry moves underscore shifting dynamics. In mid‑2025, Kyocera expanded capacity in South Korea to strengthen regional production presence; shortly before that, a major European producer launched a new TiB2 grade optimized for additive manufacturing. These actions point to two near‑term trends: a regional rebalancing of capacity, and product innovation that compresses qualification timelines for AM and aerospace buyers.
Strategic scenarios and decision levers for 2026
Executives can translate market context into specific, prioritized actions for 2026. We outline three pragmatic scenarios and the associated levers:
- Protect and optimize margins (incumbent producers)
- Secure long‑dated boron feedstock contracts with indexed pricing and force majeure protections; establish multi‑sourcing to reduce vulnerability to regulatory or logistic disturbances.
- Invest selectively in higher‑margin product grades (e.g., AM‑ready or sputtering grades) while rationalizing low‑margin, high‑volume SKUs.
- Accelerate market entry or scale (new entrants and investors)
- Target bolt‑on acquisitions to rapidly obtain certification assets and customer access rather than greenfield capacity, given the market’s moderate CAGR and concentration dynamics.
- Pursue tolling and JV models with regional partners to limit capital intensity and shorten commercialization timelines.
- Downstream hedging and integration (OEMs and strategic buyers)
- Consider dual‑sourcing strategies and strategic stockpiles for critical programs (defense, aerospace) and implement qualification roadmaps to reduce single‑supplier dependency.
- Explore co‑development contracts for AM‑tailored grades to accelerate product performance while sharing development costs and lead times.
Risk checklist — what could materially alter 2026 plans
- Feedstock shocks: Even modest shifts in boric acid availability or logistics can cascade into spot price spikes and margin compression. Early 2026 saw a softening in boric acid spot values, but regulatory and freight volatility remain latent threats.
- Qualification lag for AM and aerospace: New TiB2 grades can be technically superior but require long certification cycles; misjudging timelines can lead to overcapacity or missed demand windows.
- Geopolitical/regulatory shifts: Environmental rules affecting boron mining and processing can change cost structures and force regional reshoring of certain value chain elements.
How to use this primer — and where to find the full intelligence
This briefing is designed to orient boardrooms, corporate development teams, and procurement leaders ahead of 2026 planning cycles. It highlights the market’s steady growth profile (CAGR ~4.5%), concentrated supplier base, and technology‑led demand inflection points—elements that should shape capital allocation, sourcing, and product roadmaps for the coming 12–18 months.
For transaction‑grade analysis, detailed regional and application breakdowns, supplier scorecards, calibrated price models, and executable M&A playbooks, please consult the full Titanium Diboride Market report. The complete study contains the granular segmentation and financial models that firms require to underwrite investments, negotiate supply contracts, and build qualification programs with confidence.
PW Consulting stands ready to brief management teams on the full findings and translate the report’s implications into a prioritized 90‑day action plan tailored to your strategy and role in the value chain.
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Marijuana Market at USD 23.38B in 2025, set to grow 20.3% CAGR
By PW Consulting, 2026-07-12
Legal Marijuana Market — 2026 Strategic Preview for Corporate Leaders
Executive snapshot
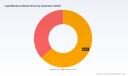
The legal marijuana market is entering a decisive growth chapter. After accelerating rapidly through 2020–2025, the industry’s scale and structural dynamics will drive high-stakes choices for incumbents, new entrants, investors, and policy-makers in 2026. Our PW Consulting market study — built on a 2025 base year with a historical window spanning 2020–2025 and a detailed forecast through 2032 — shows the market continuing to expand at a compound annual growth rate (CAGR) of 20.3% over the forecast window. This trajectory transforms previously niche strategic questions (supply security, regulatory compliance, product mix) into enterprise-level imperatives.
Legal Marijuana Market
The macro picture: growth, inflection and what it means
From an inflection that began in the early 2020s, market scale has moved from a lower-base consumer research phase into a robust commercial market by 2025. The dataset underpinning our study tracks that evolution and projects meaningful scale by 2032. That scale matters because it changes the economics of every activity in the value chain — from upstream cultivation and extraction to downstream branding, distribution and professionalized medical delivery.
Legal Marijuana Market
Three high-level structural forces explain the pace of expansion and its persistence:
Legal Marijuana Market
- Regulatory reclassification and normalization: policy shifts are lowering legal frictions and unlocking institutional channels for investment and distribution.
- Product and channel diversification: the move from a single-category, largely informal market to multi-product portfolios (flower, concentrates, edibles and other formats) is widening addressable demand and enabling premiumization strategies.
- Scale-driven economics and professionalization: as firms invest in standardized cultivation, extraction, and quality-control systems, cost curves improve, and professional supply chains supplant ad hoc sourcing.
Why 2026 decisions are consequential
The combination of rapid market scale-up and regulatory inflection means decisions taken in 2026 will disproportionately determine competitive positioning for the remainder of the decade. Firms face a binary choice: embed capabilities now (regulatory functions, licensed supply, retail channels, compliance-grade manufacturing) or play catch-up later at materially higher cost. Practical strategic priorities for 2026 include capital allocation across capacity and R&D, legal and compliance buildout, channel partnerships, and M&A or JV screening to secure margins and feed growth.
Competitive structure and supplier dynamics
The market remains fragmented by several measures — concentration ratios indicate that the three largest firms control a modest share of value, and the top five likewise leave sizeable mass in the hands of regional and local players. That fragmentation presents two realities for strategists:
- Opportunity for consolidation: low top-line concentration creates runway for roll-up strategies, cross-border partnerships, and national scale plays that can capture economies of scale in distribution, branding and compliance.
- Persistent local complexity: regulatory and licence fragmentation means local incumbents will continue to be critical partners; national players must balance centralized processes with local adaptability.
A specific sub-set of market participants — DEA-registered bulk manufacturers that produce marijuana for research and clinical purposes — play an outsized role in the R&D and regulatory pathway even if they are not consumer-facing brands. These entities provide the raw material and controlled supply necessary for clinical trials, pharmaceutical development and regulatory submissions. Their existence and licensing status create a visible channel for clinical-grade supply that larger commercial players will increasingly interface with as medical and regulatory pathways normalize.
Key examples of such suppliers include established DEA-registered bulk manufacturers that serve the research and clinical ecosystem. Their footprint is strategically non-trivial: they are gatekeepers for clinical R&D and potential partners (or acquisition targets) for firms pursuing medical claims or pharmaceutical pathways.
Regulation as the strategic axis
2026 will be remembered as a regulatory inflection year. In April 2026, a major reclassification decision placed FDA‑approved marijuana products and state‑licensed medical products into a lower federal schedule, and an administrative process was initiated to consider broader rescheduling. This step materially reduces certain federal barriers and creates a staged pathway for broader normalization.
Operationally, the new regulatory posture changes several levers that matter to corporates:
- Compliance and cost dynamics: firms must re-run licensing, manufacturing and transport models under the new regime. For example, administrative fees and compliance charges — a unit-level regulatory cost in 2026 has been published at $113 per kg — become explicit inputs to commercial business cases and contract negotiations.
- Capital and financial access: reduced scheduling risk improves access to institutional capital and banking services, making larger-scale financing feasible for capital-intensive players.
- R&D acceleration: clearer pathways for clinical research lower the friction for clinical trials, pharmacological development and product registration.
What our PW Consulting study delivers — practical, transaction-ready outputs
This report is designed as a decision-support toolkit for C-suite and strategic teams. We intentionally present a “trail” of insights here while preserving segmented datasets and valuation models for readers who access the full study. Highlights of the practical deliverables include:
- Integrated quantitative model — an interactive forecast covering 2026–2032 with scenario toggles (policy, pricing, adoption curves) and sensitivity analysis to test financing and capex assumptions.
- Regulatory playbook — timeline scenarios, compliance checklists, cost modeling templates (including the latest administrative fee schedules), and structured approaches to licensing strategy and government affairs.
- Commercial blueprints — go-to-market templates for national roll-outs, product prioritization frameworks for flower vs. extracts vs. edibles, pricing ladders, and channel mix optimization guides.
- M&A and partnership framework — a screened universe of strategic targets, acquisition valuation templates, integration checklists and a five‑step diligence playbook tailored to market fragmentation dynamics.
- Supply chain and operations diagnostics — maps of upstream sourcing options, contract manufacturing frameworks, quality and traceability KPIs, and contingency plans for regulatory shocks.
- Investor-grade briefing materials — executive summaries, board-ready slides, and a valuation model that converts market scenarios into NAV and IRR outcomes for deal teams.
We deliberately withhold segment-level tables, regional splits and company-level revenue figures in this preview to preserve the integrity of our client-grade deliverables. Those items — including interactive dashboards and downloadable models — are available in the full report package.
Priority actions for executives — a practical 90‑day roadmap
The following steps convert the study’s insights into operational moves that should be actionable within a quarter:
- Immediate scenario modeling: run three scenarios (baseline, accelerated normalization, delayed regulation) against your P&L and balance-sheet to quantify funding needs and breakeven timelines.
- Secure supply continuity: initiate or re-negotiate supply contracts with research-grade producers and licensed cultivators to lock in quality and compliance guarantees.
- Regulatory & finance alignment: update banking and treasury partners on strategic plans and secure conditional financing lines tied to regulatory milestones.
- Product portfolio triage: prioritize SKUs and formats based on profitability per channel and projected acceptance under new regulatory guidance, then accelerate development sprints for top two product families.
- M&A screening: field a short list of targets that offer either geographic scale, manufacturing capability, or regulatory licences; run a light diligence using our template to identify quick wins.
Risks and watch‑points into 2027
Growth and opportunity come with elevated downside scenarios that executives must monitor closely:
- Regulatory reversals or delays in broader rescheduling could reintroduce federal friction and slow institutional adoption.
- Operational compliance lapses become more costly as enforcement becomes normalized — companies need robust quality systems.
- Price compression in commoditized product segments could erode margins if firms race to scale without differentiation.
- Supply-chain bottlenecks in extraction and formulation capacity can create forced mix changes and margin volatility.
Conclusion — strategic posture for 2026
The legal marijuana market is no longer a peripheral growth story; it is a mainstream industry undergoing commercialization at scale. The 2026 inflection amplifies both opportunity and execution risk. Firms that combine disciplined scenario planning, targeted investment in regulated supply and compliance, and nimble commercial execution will capture outsized value as the market professionalizes.
PW Consulting’s comprehensive study translates these macro signals into transaction-ready intelligence, operational playbooks and an interactive forecast calibrated to current regulatory developments. For senior leaders who need the complete segment-level breakdowns, the interactive model, and company-level dossiers that inform M&A and capital decisions, the full report provides the detailed evidence base and templates required to act confidently in 2026.
Requesting the full study will give you access to the granular dashboards, sensitivity templates and diligence tools necessary to convert the 20.3% CAGR trajectory and regulatory shifts into executable strategy. PW Consulting stands ready to support scenario modeling, target screening and rapid implementation planning.
For detailed analysis of this topic, please visit the official page: Legal Marijuana Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gene Therapy Market 2026: Strategic Preview for Corporate Decision-Makers
As gene therapy accelerates from pioneering science to scalable commercial reality, executive teams face a compressed window in 2026 to convert technological promise into durable business advantage. PW Consulting’s Gene Therapy Market study — based on a 2025 base year and projecting through 2032 — synthesizes market trajectories, regulatory inflection points, commercial bottlenecks and competitor strategies into an actionable playbook. This preview highlights the research’s strategic value for 2026 decisions, demonstrates the depth of our analysis, and intentionally refrains from publishing the granular segmentation tables that are included in the full report.
Gene Therapy Market
Market snapshot: growth dynamics and structural context
The gene therapy market has moved from nascent to high-growth in less than a decade. Our historical series shows a clear acceleration through 2020–2025 and, with the report’s forecast period spanning 2026–2032, we estimate continued robust expansion at a compound annual growth rate (CAGR) of approximately 19.25% across the forecast window. In practical terms, the market that stood in the single-digit billions in the early 2020s is projected to scale to multiple tens of billions of USD by the early 2030s.
Gene Therapy Market
Two structural characteristics underpin this expansion and should guide 2026 strategy: first, the market remains moderately concentrated at the top, with leading incumbents controlling a meaningful share of commercialized assets and platform capabilities; second, cost and logistics remain non-trivial — ultra-cold chains and biologics-grade inputs continue to represent a material portion of supply chain cost bases, in some cases accounting for roughly one-fifth to two-fifths of total distribution and production costs.
Gene Therapy Market
Why this report matters for 2026 corporate decisions
- Prioritize portfolio bets with quantified upside and risk: With steep growth projected through 2032, companies must distinguish between platform plays (vector development, manufacturing) and product plays (indication-specific therapies). Our model maps revenue potential against timing and probability-of-success to reveal which bets reach break-even within a typical corporate planning horizon.
- Prepare for regulatory acceleration and conditional approvals: In January 2026 regulators signaled increased flexibility in chemistry, manufacturing and control (CMC) requirements for cell and gene therapies, lowering certain entry barriers. The report models how this regulatory shift shortens expected time-to-market for different development strategies and where increased CMC risk persists.
- Design reimbursement and contracting strategies now: High one-time costs for single-dose therapies necessitate innovative payer approaches. The research evaluates outcome-based agreements, annuity and risk-sharing models, and recent policy movements (including proposed expansions to new-technology reimbursement mechanisms) to map realistic revenue realization scenarios across major payers.
- Mitigate supply-chain exposure: Cold-chain logistics and specialized raw materials are concentration points for cost and disruption. We quantify sensitivity of commercial margins to logistics cost shocks and provide sourcing and vertical-integration scenarios that can materially improve gross-margin profiles.
Core strategic imperatives for 2026
- Lock platform flexibility: Build or acquire modular vector and manufacturing capabilities that can serve multiple clinical programs to reduce COGS volatility.
- Negotiate payer-first evidence generation: Embed real-world evidence (RWE) and outcomes-based endpoints into late-stage trials to streamline managed-entry agreements in major markets.
- Design hybrid commercial models: Combine centralized manufacturing for quality consistency with regional fill-finish capabilities to reduce cold-chain miles and tariff exposure.
- Prioritize differentiated indications: Favor indications where clinical differentiation, durable efficacy and manageable patient populations align to justify premium pricing and payer negotiation.
Competitive landscape: what leading players signal
The commercial field combines large diversified biopharma and specialized gene-therapy pioneers. Our competitive analysis focuses on strategic posture—platform depth, commercial execution, and pipeline breadth—rather than confidential sales figures. Highlights from the ecosystem:
- Novartis (Basel): With marketed assets addressing rare neuromuscular disease, Novartis demonstrates the playbook for converting single-product approvals into integrated patient-access programs and manufacturing scale-up. Their experience underlines the importance of post-launch lifecycle management and global reimbursement engagement.
- Bristol-Myers Squibb (New York): As a major oncology and cell-gene therapy participant, BMS illustrates how CAR-T and related modalities can be integrated into existing oncology franchises, leveraging commercial channel synergies and payer relationships to accelerate adoption.
- Janssen Biotech / J&J (Beerse): The company’s multiple myeloma asset underscores opportunities in complex oncology indications where high per-patient value must be balanced with manufacturing throughput constraints.
- Vertex Pharmaceuticals (Boston): Vertex’s advances in hemoglobinopathies demonstrate the strategic value of deep disease expertise and partnerships that facilitate curative-intent development for genetically-defined populations.
- bluebird bio (Cambridge): A specialist with multiple blood-disorder programs, bluebird’s trajectory highlights both the upside of platform-centric innovation and the operational demands of delivering multiple gene therapies to market.
- Sarepta, BioMarin, CSL Behring, Krystal Biotech, PTC Therapeutics: Each firm represents a different go-to-market approach—niche orphan focus, broad rare-disease portfolios, established biologics manufacturing strength, or cutaneous and CNS specialization. The competitive map in the report translates these profiles into likely partnership, M&A and co-development scenarios.
Collectively, market leaders suggest three likely competitive dynamics through 2028: (1) platform consolidation and strategic partnerships around vector supply and manufacturing, (2) regional specialization where companies leverage existing payer relationships, and (3) differentiated commercialization for high-value, one-time treatments with bespoke access agreements.
Regulatory and reimbursement environment — implications for 2026 strategy
- Regulatory adaptivity reduces certain bottlenecks: The FDA’s January 2026 guidance on more flexible CMC pathways should speed several late-stage programs, but companies must still meet product-specific quality expectations. Tactical implication: accelerate CMC investments in parallel with pivotal trials to be market-ready faster.
- Payer models are shifting: Outcome-based managed-entry agreements and proposed expansions of add-on reimbursement mechanisms change the calculus for pricing and cash-flow modeling. Firms that design evidence-generation and contracting capabilities now will capture premium value later.
- Supply chain as a strategic asset: Given that cold-chain and biological raw materials can account for a substantial share of costs, supply-chain resilience has become a competitive moat—especially for players seeking to scale beyond early adopters.
What the PW Consulting report contains (practical deliverables)
The full Gene Therapy Market report is organized to support strategic decision-making across corporate functions. Key deliverables include:
- Market model with annual revenue forecasts (historical 2020–2025 base series and detailed 2026–2032 projections), sensitivity scenarios and break-even analysis for different commercialization pathways.
- Regulatory and reimbursement playbook, including modeled outcomes for outcome-based contracting, NTAP-like mechanisms, and region-specific managed-entry requirements.
- Supply-chain cost mapping and scenarios that quantify the impact of logistics, raw-material pricing and manufacturing scale on gross margins.
- Competitive profiles and strategic positioning matrices for leading firms, including partnership likelihood scores and suggested M&A targets by strategic intent.
- Go-to-market templates for clinical-stage companies covering launch sequencing, stakeholder engagement timelines, and payer negotiation playbooks.
- Appendices with methodological assumptions, data sources and redacted segmentation matrices; the full, unredacted segment-level tables and granular regional/application splits are available exclusively with the report purchase.
How to use these insights in a 2026 boardroom
- Investment committees: Use our model to test valuation scenarios under different reimbursement and manufacturing cost assumptions. Identify the investment tranche that aligns with acceptable payback periods given the expected market growth trajectory.
- Commercial leaders: Build payer engagement roadmaps now that prioritize outcome evidence generation and contract pilots in markets with supportive policy frameworks.
- R&D/CMC teams: Reallocate near-term budgets to derisk CMC readiness in parallel with late-stage clinical activities—regulatory flexibility shortens windows but requires readiness to meet quality and comparability expectations.
- Supply-chain and procurement: Implement dual-sourcing and regional fill-finish strategies to reduce cold-chain distances and improve margin resilience.
Concluding perspective and next steps
Gene therapy will reshape therapeutic categories and payer economics during the remainder of this decade. The market’s projected high-teens CAGR through 2032 signals opportunity at scale — but seizing that opportunity requires early commitment to manufacturing readiness, payer-focused evidence generation, and pragmatic commercial models. PW Consulting’s report consolidates the quantitative forecasts, regulatory and reimbursement mapping, and competitive playbooks needed to chart a defensible path through 2026 and beyond.
For an executive-ready briefing, access to the complete segmentation tables, and the full suite of actionable tools (financial models, negotiation templates, and partnership prioritization matrices), please consult the full Gene Therapy Market report on our website. The preview above is intentionally selective to protect the granular intelligence that differentiates strategic execution from tactical noise.
For detailed analysis of this topic, please visit the official page: Gene Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Messaging Platform Market to Hit USD 130.99M by 2032 at 5.7% CAGR
By PW Consulting, 2026-07-12
Messaging Platform Market 2026 — Strategic Preview for Business Leaders
As organizations reshape how they communicate with customers, partners and employees, messaging platforms have moved from convenience to strategic backbone. PW Consulting’s latest Messaging Platform Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes five years of observed dynamics with a forward-looking view that is explicitly built for decision-makers planning investments, integrations and M&A in 2026. The market reached USD 89.65 Million in 2025 and, at a compound annual growth rate (CAGR) of 5.7%, is projected to approach roughly USD 131.0 Million by 2032 — a steady expansion that hides a great deal of structural change and opportunity beneath the headline numbers.
Messaging Platform Market
Why this research matters for 2026 planning
-
Timing for architecture and procurement. With steady growth and rising compliance demands, 2026 is a moment to recalibrate platform architecture decisions — differentiate where to buy, build or partner to avoid technical debt while preserving optionality for AI and multi-channel expansion.
Messaging Platform Market -
Risk-adjusted investment. The market shows material concentration among a few leading vendors (top-3 firms account for a substantial portion of market share, and the top-5 an even larger slice), which affects pricing, support models and potential lock‑in. Buyers must factor vendor bargaining power into TCO and exit options.
Messaging Platform Market -
Regulatory binary. New and evolving frameworks (GDPR, DORA, NIS2) and industry-level migrations such as ISO 20022 have immediate implications for message data handling, retention, cross-border routing and auditability. Non-compliance carries operational and reputational risk that will become non-negotiable in procurement and vendor contracts.
-
Product and partner strategy. The pathway to value increasingly runs through integrations — API ecosystems, RCS and rich messaging, payment rails, and identity services. Establishing clear platform interoperability priorities in 2026 will accelerate time-to-value from pilots to scaled use cases.
How to read the headline numbers
The aggregate market trajectory — from roughly USD 63.0 Million in 2020 to USD 89.65 Million in 2025, then onward to nearly USD 131.0 Million by 2032 — reflects more than user growth. It captures platform modernization (cloud migration and API economics), expansion of business-focused messaging services, and a layering of AI-enabled capabilities into routing, content generation and compliance. The CAGR of 5.7% is moderate, but beneath it are pockets of accelerated disruption (enterprise collaboration tooling, RCS business messaging, programmable messaging APIs) and pockets of commoditization (basic SMTP/email services).
Core strategic themes for boardrooms and product teams
-
From channels to conversational platforms. Companies must move from thinking in discrete channels to orchestrating customer journeys across asynchronous messaging, in-app chat, SMS/RCS and collaboration hubs. The winners will provide consistent identity, state and audit trails across touchpoints.
-
AI as augmentation, not buzzword. AI is rapidly migrating from experimental to operational: autonomous routing, intent detection, and summarization are being showcased publicly. The prudent strategy is to prioritize use cases with measurable ROI (reduction in handle time, increased conversion rates, improved compliance automation) and instrument outcomes.
-
Regulatory-first design. Compliance requirements no longer belong exclusively to legal teams. Messaging platforms must bake in data sovereignty, record-keeping and incident response workflows at design time to pass certification and procurement gates in regulated industries.
-
Infrastructure resilience and materials supply. Scalable cloud architecture remains necessary but not sufficient. Physical-layer considerations — specialized polymers and energy-efficiency requirements in networking hardware — are increasingly referenced in vendor SLAs and long-term capacity planning, particularly for service providers and telco-grade deployments.
-
Monetization and partner economics. Programmable messaging APIs and platform-as-a-service models create new revenue levers but require disciplined pricing, developer experience and channel management to avoid margin erosion as usage scales.
Competitive landscape — what to expect from leading vendors
The market is populated by a mix of enterprise incumbents, cloud platform giants, specialized messaging vendors and nimble API-first challengers. Each archetype brings different strengths and trade-offs:
-
Platform giants and enterprise suites: Established technology companies provide deep integration with business applications and large customer bases, making them attractive for organizations prioritizing single-vendor roadmaps and broad application compatibility.
-
API-first and communications platforms: Firms focused on programmable messaging and cloud communications emphasize developer experience, rapid time-to-market and fine-grained pricing models; they are often chosen where rapid experimentation and scale are required.
-
Telco and carrier-focused solutions: Vendors offering white-label or carrier-grade capabilities emphasize resilience, regulatory compliance for communications service providers, and integration with core network elements.
-
Regional specialists and open-source centric players: These vendors compete on price-efficiency, customization and local compliance expertise, and they are frequently preferred for sovereign or regulated deployments.
Representative firms covered in the report include established software giants, API communicators and specialist messaging vendors. Each profile in the study contains an assessment of strategic posture, go-to-market focus, recent product developments and partnership trajectories — enabling buyers to map vendor capabilities to their own strategic requirements without wading through marketing claims.
Recent catalysts shaping 2026 decisions
-
RCS approval and richer mobile messaging: Regulatory and operator approvals for richer messaging formats in major markets have opened new channels for branded, interactive experiences. This shifts ROI calculus for customer engagement programs and requires new integration patterns.
-
AI-enabled product advancements: Several vendors have demonstrated autonomous messaging features and resiliency enhancements in live showcases and product releases, accelerating the timeline for enterprise pilots moving into production.
-
Standards and payments interoperability: The global switch to ISO 20022 across many financial flows unlocks new cross-border use cases for messaging platforms tied to payments and reconciliation, but also imposes interoperability and security constraints.
-
Regulatory consolidation in Europe and beyond: Initiatives to aggregate demand for critical raw materials and the rollout of digital operational resilience rules are altering supplier risk profiles and vendor selection criteria — particularly for hardware-dependent, telco-grade solutions.
What’s inside PW Consulting’s full report (practical deliverables)
-
Executive dashboard and decision matrix: one-page summaries that map strategic goals to recommended platform archetypes and procurement triggers.
-
Vendor scorecards and migration blueprints: comparative assessments across technology, compliance posture, TCO, integration ease and support models, plus step-by-step migration roadmaps.
-
Use-case playbooks and KPI templates: ready-to-run playbooks for high-priority enterprise scenarios (customer care, payments-related messaging, internal collaboration) with measurable KPIs and data-collection templates.
-
TCO and supplier risk models: scenario-based financial models that quantify near-term costs versus long-term vendor lock-in and exit costs.
-
Regulatory compliance checklist and audit templates: practical artifacts to accelerate procurement and certification in regulated industries, addressing GDPR, DORA and NIS2 implications for messaging data.
-
M&A and partnership playbook: framework for target screening, diligence checklists focused on IP, data governance, and customer concentration, and integration roadmaps post-deal.
-
Roadmap for adopting AI and RCS: sequencing guidance that prioritizes low-friction, high-impact pilots and defines escalation criteria for enterprise-wide rollouts.
How executives should act in the next 12 months
-
Align leadership on one prioritized business case for messaging platform modernization (cost reduction, revenue enablement, compliance) and measure it vigorously.
-
Run vendor PoCs against real, production-like data and integrate compliance gates into PoC exit criteria.
-
Require vendor transparency on supply-chain risk and hardware dependencies where telco-grade availability or sovereignty matters.
-
Embed legal and security early in API and partner contract negotiation to standardize data residency, audit rights and breach-response obligations.
-
Design API and product roadmaps to retain portability: insist on standard protocols, documented migration paths and exportable data schemas to preserve strategic flexibility.
Final perspective — where value will accrue
Growth in the messaging platforms market will be less about raw user numbers and more about the platform capabilities that unlock monetizable interactions, guarantee compliance at scale and reduce operational friction. Organizations that treat messaging platforms as strategic infrastructure — governed, measurable and architected for interoperability — will convert a modest market expansion into outsized competitive advantage. Conversely, those that defer decisions risk layered technical debt and missed opportunities to monetize conversational channels as payment rails, identity fabrics and customer-engagement engines converge.
PW Consulting’s full study provides the granular vendor assessments, scenario models and practical artifacts that boards, CTOs and product leaders need to move from intent to action in 2026. For access to the complete findings, vendor scorecards and templates designed to accelerate implementation, please consult the source report page.
For detailed analysis of this topic, please visit the official page: Messaging Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


