



PW Consulting Forecasts Residential Interior Door Market to Hit $20.95 Billion by 2032 at 5.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Residential Interior Door Market: Strategic Intelligence for 2026 Decision-Makers
The residential interior door market is undergoing a quiet but significant transformation. No longer viewed as a commoditized building component, interior doors are increasingly recognized as critical elements of home performance, privacy, acoustics, design identity, and sustainability compliance. As construction cycles recover, renovation activity accelerates, and consumer expectations evolve toward smarter, healthier, and more customized living spaces, manufacturers, distributors, contractors, and private investors face a complex landscape that rewards foresight over guesswork.
Pw Consulting’s latest Residential Interior Door Market study is designed to cut through this complexity. Rather than offering superficial trends, the report delivers a structured, execution-ready intelligence framework that connects macro market trajectories with granular competitive positioning, segment-specific growth vectors, and regulatory-driven shifts in material and manufacturing preferences. For executives formulating 2026 operating plans, capital allocation strategies, and product roadmaps, this research serves as both a diagnostic tool and a forward-looking navigation system.
Market Trajectory: A Decade of Steady Expansion with 2026 as a Strategic Inflection Point
Historical performance and forward-looking projections place the residential interior door category on a consistent growth path. The market has expanded from approximately $9.95 billion in 2020 to an estimated $14.3 billion in 2025, reflecting resilient demand across housing turnover, remodeling cycles, and design-led replacement programs. Looking ahead, the study maps the market toward a projected valuation exceeding $20.9 billion by 2032, anchored by a compound annual growth rate of 5.5 percent throughout the forecast window.
These figures are not merely aggregate indicators; they reflect underlying momentum that varies meaningfully across product architectures, application contexts, geographic demand centers, and buyer segments. For leadership teams, the strategic implication is clear: growth is real, but it is unevenly distributed. Companies that treat the category as a uniform market risk misallocating resources, entering overheated segments, or overlooking high-margin niches. Exact regional shares, application-level breakdowns, and material-specific revenue contributions are addressed in depth within the full report, where they are modeled alongside pricing elasticity, channel dynamics, and competitive intensity to reveal where profitable expansion is most achievable.
2026 Dynamics: What Is Shaping Demand, Pricing, and Go-to-Market Strategy
Several concurrent forces are redefining how residential interior doors are specified, manufactured, and sold. Understanding their interaction is essential for strategic planning.
Sustainability and Material Standards as Demand Drivers
Responsibly sourced wood, low-VOC finishes, and certified manufacturing practices are transitioning from differentiators to baseline expectations. Buyers, retailers, and increasingly regulated building programs are prioritizing products that align with broader environmental and indoor-air-quality goals. At the same time, updated energy-efficiency considerations and evolving material standards are elevating interest in advanced composite formulations and sustainable door cores. The report dissects how these preferences are reshaping sourcing economics, product architecture choices, and brand positioning across competing portfolios.
Renovation Activity and Housing Demand as Volume Anchors
A robust pipeline of home improvement projects and sustained housing activity continues to underpin steady transactional volume for interior door products. While new-build cycles fluctuate, the renovation channel has proven more resilient, often favoring variety, finish customization, and solution-based selling. The study evaluates how renovation-led demand differs from new-construction demand in terms of order characteristics, specification behavior, and competitive vulnerability, enabling readers to calibrate sales and inventory strategies accordingly.
Trade Friction, Sourcing Strategy, and Cost Pressure
Trade restrictions on imported wood and door components remain a persistent variable in pricing and supply planning. For U.S.-based manufacturers, these dynamics influence raw material availability, finished-goods cost structures, and the relative attractiveness of domestic versus imported supply chains. The analysis examines how leading players are adapting their procurement footprints and product mix decisions in response, and where margin protection is becoming a competitive differentiator.
Smart-Home Integration and Evolving Specification Behavior
Consumer expectations are increasingly shaped by the broader smart-home ecosystem and the desire for doors that contribute to acoustic comfort, privacy, and integrated home functionality. This is not always a matter of embedded electronics; it increasingly involves specification alignment, finish coordination, sound-reduction capabilities, and design compatibility with connected-home aesthetics. The report assesses how these expectations are influencing product development priorities and retail specification strategies.
Segmentation Architecture: Where the Growth Dividends Are Concentrated
One of the study’s core analytical strengths is its segmentation framework. The market is evaluated across multiple dimensions that matter operationally: material preferences, application contexts, and regional demand centers. Each axis reveals a distinct competitive logic.
Material strategies continue to define both cost structure and brand identity. Wood remains a foundational reference point for premium positioning and custom specification, while composite alternatives are gaining traction where durability, consistency, and sustainability credentials intersect. Glass, steel, and other specialty materials occupy targeted niches tied to design statements, acoustic requirements, or specific residential applications. Rather than presenting static shares, the report layers these material preferences against pricing behavior, channel fit, and regional demand intensity to expose where category leadership is being contested and where white space remains.
Application-level analysis is equally critical. Interior doors are specified differently depending on whether they serve private sleeping areas, high-use transitional spaces, moisture-adjacent environments, or secondary rooms with distinct functional and aesthetic requirements. Each application carries its own drivers for privacy, acoustics, moisture resistance, style coordination, and replacement frequency. The study maps these nuances to reveal which applications exhibit the strongest renewal cycles, which are most sensitive to design trends, and which offer the most attractive unit economics for manufacturers and distributors.
Regional demand patterns further complicate the picture. Mature markets display different growth mechanics than emerging demand centers, and local building norms, renovation intensity, trade exposure, and channel maturity all shape how products are positioned and sold. The complete report quantifies these regional dynamics with sufficient granularity to support market-entry decisions, distribution planning, and localized product strategy without revealing the precise splits here, preserving the analytical exclusivity that enterprise buyers expect.
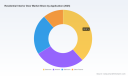
Residential Interior Door Market
Competitive Landscape: Differentiation in a Moderately Concentrated Market
The market structure reflects a moderate level of concentration, with the top three players accounting for approximately 35 percent of revenue and the top five reaching roughly 42 percent. This indicates that while scale players hold meaningful share, a substantial portion of the market remains accessible to specialized manufacturers, regional champions, and design-led brands that compete through customization, craftsmanship, and portfolio breadth.
The competitive set illustrates the diversity of strategic approaches now defining the category. JELD-WEN continues to leverage a broad product architecture spanning wood, composite, and molded interior doors, with solid-core options positioned around sound reduction and consistent specification. Masonite complements this landscape with premium fiberglass and wood offerings, including series designed for elevated aesthetics and residential performance. TruStile Doors differentiates through custom stile-and-rail interiors that span premium MDF, wood, glass, resin, leather, and metal options, appealing to buyers seeking tailored design outcomes. Simpson Door Company draws on a long heritage of handcrafted custom wood doors, reinforcing craftsmanship as a competitive asset. Lynden Door aligns with sustainability-minded procurement through green-certified materials and custom wood offerings, while Rogue Valley Door emphasizes interactive design tools that support specification and customization. Woodgrain competes on breadth of design expression through stile-and-rail and router-carved interiors with extensive design libraries. Andersen Windows and Doors and Pella Corporation integrate interior door offerings within broader residential portfolios, using cross-category relationships as a commercial advantage. ProVia positions professional-class interior doors with customizable cores and overlays, appealing to specification-driven projects.
Recent corporate activity reinforces the strategic tempo of the category. In early 2026, Therma-Tru introduced new ¾-Lite Shaker interior doors and sidelites, signaling continued interest in refined, specification-friendly designs. Later in the year, Masonite showcased its Calden three-panel interior door at a major builders’ event, highlighting the ongoing push toward visually differentiated, multi-panel configurations that resonate with design-led residential projects. These launches are not isolated product updates; they are indicators of where manufacturers are placing bets on aesthetics, functionality, and channel appeal. The full report contextualizes each major competitor’s positioning, product emphasis, and strategic vulnerabilities, enabling readers to benchmark their own portfolios and identify adjacency opportunities without relying on generic competitive summaries.
What the Report Delivers: A Practical Toolkit for 2026 Strategy
This study is built for action. It is structured to help leadership teams answer the questions that matter most when planning product investments, channel expansion, pricing strategy, and competitive response. The report includes:
- A demand-and-supply assessment that connects historical performance to forward projections, with scenario-based views that account for renovation intensity, housing activity, and trade-related cost pressure.
- Multi-dimensional segmentation analysis covering material categories, application contexts, and regional demand patterns, designed to reveal where growth is strongest, where margins are most defensible, and where competitive intensity is rising.
- A competitive profiling section that evaluates leading manufacturers by product emphasis, differentiation logic, and strategic positioning, providing a comparative lens for portfolio planning and market-entry evaluation.
- An examination of market dynamics, including sustainability mandates, certification expectations, material sourcing constraints, and smart-home-aligned specification trends, framed in terms of commercial impact rather than abstract observation.
- Strategic implications for manufacturers, distributors, builders, and investors, with guidance on where to concentrate resources, which customer segments warrant deeper engagement, and how to align product roadmaps with emerging demand signals.
Throughout, the analysis maintains a disciplined focus on decision utility. Figures, shares, and forward estimates are presented with enough context to support judgment, but the most sensitive segmentation data and regional revenue distributions are reserved for the full report. This approach ensures that the complete intelligence product remains a proprietary asset for teams that need to make specific capital, sourcing, and positioning decisions with confidence.
Why This Study Matters for 2026 Planning
The residential interior door market is not defined by a single megatrend. It is shaped by the interplay of renovation economics, material sustainability expectations, trade-driven cost dynamics, design-led specification behavior, and a competitive field that rewards both scale and specialization. In that environment, generalization is a liability. Winning strategies require clarity on which applications are expanding, which materials are gaining pricing power, which regions offer the best risk-adjusted opportunity, and how competitors are translating product innovation into commercial advantage.
Pw Consulting’s Residential Interior Door Market report is intended to provide that clarity. It gives executives a structured, evidence-based foundation for 2026 decision-making, while preserving the deeper segmentation and competitive intelligence needed to convert insight into action. For organizations that need to know not only where the market is heading, but where to place bets now, the full study offers the granularity, benchmarking, and strategic framing necessary to move from awareness to execution.
The market trajectory is visible; the competitive and segmentation details that determine success are not. Accessing the complete analysis is the next step for teams ready to align their 2026 plans with the realities of a maturing, increasingly differentiated residential interior door category.
Wood Interior Doors Market
For detailed analysis of this topic, please visit the official page: Residential Interior Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Vending Machines Market Hits $8.82 Billion in 2025, Projecting 10.6% CAGR to 2032
By PW Consulting, 2026-09-16
The Smart Vending Machines Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The global smart vending machines market is undergoing a structural transformation that goes far beyond the traditional convenience retail model. As automated retail intersects with artificial intelligence, contactless payment infrastructure, and mission-critical dispensing in healthcare and public health settings, organizations face a pivotal moment. This research provides the strategic foundation needed to make informed capital allocation, partnership, and market-entry decisions across the 2026-2032 forecast horizon.
Worldwide Vending Machine Payment System Market
For executives evaluating whether to deploy, invest in, or partner with smart vending infrastructure, the question is no longer whether automation will reshape point-of-sale access. The question is where value will concentrate, which applications will command pricing power, and how regulatory and reimbursement dynamics will shape viable business models. This report has been designed to answer those questions with the granularity and commercial relevance that enterprise strategy teams require.
A Market Built on Accelerated Adoption and Structural Tailwinds
Over the historical review period from 2020 through 2025, the smart vending machines market demonstrated consistent, compounding growth. Total revenue expanded from approximately 5.32 billion USD in 2020 to 8.82 billion USD by 2025, reflecting an industry that has moved beyond early experimentation into mainstream operational integration. The growth trajectory is not merely incremental. It is supported by a convergence of demand-side forces: consumer expectation for 24/7 autonomous access, enterprise demand for inventory visibility, and the emergence of specialized dispensing use cases in medical and public health environments.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a CAGR of 10.6 percent, with market revenue reaching 10.08 billion USD in 2026 and climbing to 18.09 billion USD by 2032. These figures reflect a market that is growing through both organic retail automation and the diversification of vending into strategic, non-traditional endpoints. For decision-makers, the strategic implication is clear: this is a market where timing and positioning matter. The organizations that act with a precise understanding of where growth is accelerating, and why, will be better placed to capture share and avoid misallocated capital.
It is worth emphasizing that the headline figures only tell part of the story. Behind the aggregate numbers lies a multidimensional landscape shaped by product category performance, deployment environments, regional maturity, and the regulatory context in which automated dispensing operates. The full report isolates these dimensions so that strategy teams can move from directional awareness to targeted action.
What the Report Delivers: Operational Intelligence, Not Generic Observation
This market research has been constructed for practitioners who need to make investment, procurement, partnership, and rollout decisions under real commercial constraints. Rather than offering a high-level summary, the study provides a structured analytical framework that connects market sizing to market logic. The following components are central to the analysis:
- Historical revenue performance and forward-looking market sizing across the 2026-2032 forecast window, enabling multi-year planning and scenario-based budgeting
- Segment-level evaluation across product categories and application environments, with attention to how demand patterns differ by context and what that means for deployment strategy
- Regional market structure and maturation pathways, helping organizations understand where adoption is advanced, where growth momentum is strongest, and where infrastructure or regulatory conditions shape opportunity
- Competitive positioning analysis that examines the strategies, capabilities, and recent moves of leading participants across commercial vending, healthcare dispensing, and public health applications
- Market dynamics assessment covering technological enablement, operational requirements, reimbursement behaviors, and regulatory classification considerations that influence market entry and scaling
- Practitioner-oriented synthesis designed to translate analytical findings into strategic options for vendors, investors, facility operators, and public-sector stakeholders
The intent is to provide a usable decision-support tool. Whether your interest lies in evaluating a new product rollout, assessing a potential acquisition target, identifying underserved application areas, or mapping competitive vulnerability, the report is built to connect quantitative structure with qualitative commercial reasoning.
Competitive Landscape: A Market Shaped by Diverse Motivations
One of the most strategically important features of the smart vending machines market is the diversity of participants and motivations shaping its evolution. The competitive space is not dominated by a single business model or end-use logic. Instead, it brings together commercial technology providers, healthcare institutions, academic and public-health operators, and community-facing organizations, each with distinct objectives and deployment strategies.
Recent activity illustrates this divergence clearly. In the commercial technology segment, providers are advancing AI-enabled platforms that emphasize real-time inventory monitoring, contactless payment integration, and flexible placement models for businesses and healthcare facilities. These developments signal a shift toward smarter operational control, lower friction for end users, and more adaptable economics for site partners. At the same time, healthcare and public-health institutions are expanding automated dispensing solutions for time-sensitive, access-critical needs, including overdose prevention supplies and wellness resources.
Several developments from late 2025 through early 2026 highlight this dual trajectory. A commercial provider expanded its AI-powered smart vending platform with enhanced inventory monitoring and contactless payment capabilities, reinforcing the growing importance of software-defined vending operations. In parallel, health systems and public health departments have advanced the deployment of naloxone dispensing machines across hospital campuses and community sites, with early installations reporting substantial utilization within their first months of operation and subsequent expansion to additional locations. These deployments show that automated vending is increasingly embedded in mission-driven contexts where availability, anonymity, and 24/7 access are core to the value proposition.
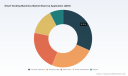
Smart Vending Machines Market
This landscape has meaningful implications for market structure. The level of concentration suggests that while leading players hold significant share, there remains room for specialization, regional deployment advantages, and differentiated application expertise. Enterprise stakeholders therefore need to assess competitors not only by scale, but by application fit, regulatory readiness, partnership model, and operational sophistication. The report examines these competitive dimensions in depth, enabling readers to understand where incumbency advantages exist and where targeted entrants may find viable openings.
Regulatory and Operational Dynamics That Will Shape Strategy
Smart vending strategy cannot be separated from the operational and regulatory environment in which equipment is deployed. In particular, the medical and public-health dimensions of automated dispensing introduce requirements that differ substantially from commercial convenience retail. Automated dispensing units used in medical contexts are classified as Class II medical devices by the U.S. Food and Drug Administration and require 510(k) clearance. This classification is not a minor compliance detail; it affects development timelines, product validation, market access, and the cost structure of healthcare-oriented vending solutions.
At the same time, reimbursement and procurement behaviors are evolving. Hospitals and clinics are increasingly deploying automated dispensing units for over-the-counter medications, personal protective equipment, and wellness products, indicating a broader institutional acceptance of vending as an operational tool rather than a novelty. In the public-health space, harm reduction vending machines for naloxone and related supplies operate under state and county public health guidelines, with basic dispensing arrangements not requiring additional federal reimbursement updates. These dynamics create an environment in which compliance readiness, institutional alignment, and deployment flexibility can be as important as hardware performance.
Infrastructure realities also shape opportunity. Vending placements are not uniform in content or economics. Even within adjacent markets, product mix and site-specific utilization patterns can diverge significantly, influencing revenue potential and machine design. For organizations planning market expansion or portfolio optimization, these factors underscore the need to evaluate each opportunity through the appropriate operational lens. The full report examines these dynamics as part of a broader integrated view, so that strategy teams can incorporate regulatory exposure, procurement behavior, and site-level complexity into their planning assumptions.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment demands more than awareness of top-line growth. Enterprises are being asked to evaluate where to commit capital, which deployment models are defensible, how to interpret competitive moves across both commercial and health-facing segments, and what regulatory pathways will define feasible scale. A market expanding toward the projected 2032 revenue level will not reward undifferentiated participation. It will reward organizations that can align their strategy with the underlying structure of demand, the economics of deployment, and the compliance realities of the application areas they pursue.
This report is designed to support exactly that kind of strategic clarity. It translates market structure into actionable perspective: where growth is concentrated, how applications differ in their value logic, what distinguishes leading operators in their respective domains, and which dynamics are likely to shape the next phase of market evolution. By integrating historical evidence, forward-looking sizing, competitive intelligence, and operational context, the study gives decision-makers a more reliable foundation for planning than headline figures alone can provide.
Access the Full Strategic Assessment
The analysis presented here outlines the strategic importance of the smart vending machines market and the essential questions this research addresses. However, the full report goes further. It provides the segmented evaluation, competitive detail, regional maturation context, and operational dynamic mapping that organizations need before making investment or deployment commitments. For strategy, operations, and commercial leadership teams preparing for 2026 and beyond, the complete market intelligence is essential.
To access the full dataset, segmentation evidence, competitive profiles, and application-specific strategic implications, visit the source page for the complete Smart Vending Machines Market research. The complete report is designed to support concrete decision-making, from market-entry assessment to partnership evaluation and deployment prioritization.
For detailed analysis of this topic, please visit the official page: Smart Vending Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Proline Market Report: $595.9M in 2025, Projected $907.91M by 2032, 6.65% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the L-Proline Market: Navigating Growth and Complexity in 2026 and Beyond
The global amino acid landscape is undergoing a structural transformation, driven by shifting consumer preferences, evolving pharmaceutical demands, and increasingly complex supply chain economics. At the center of this evolution lies L-proline, a non-essential amino acid that has quietly transitioned from a specialized biochemical intermediate to a strategic commodity with broad industrial, nutritional, and therapeutic applications. As enterprises recalibrate their market positioning and supply chain resilience strategies for the coming years, decision-makers require more than surface-level industry commentary. They need granular, forward-looking intelligence grounded in rigorous primary research and validated market modeling.
Our newly released Proline Market report delivers precisely that. Designed for executives, strategy planners, procurement leaders, and investment analysts, this study maps the trajectory of the global L-proline sector across a comprehensive historical and forecast horizon. The findings illuminate not only where the market has been, but where it is structurally headed, providing a decision-ready framework for navigating volatility, capturing emerging demand, and executing competitive positioning with precision.
The 2026 Decision Imperative: Why Timing and Context Matter
Market entry, capacity expansion, partnership formation, and procurement strategy all depend on accurate contextual awareness of macroeconomic and sector-specific dynamics. For L-proline, the convergence of several forces creates a uniquely critical planning window for 2026. Post-pandemic supply chain recalibration has forced manufacturers to reevaluate sourcing dependencies, while rising demand for non-animal-derived ingredients, sports nutrition formulations, and pharmaceutical intermediates has accelerated product development cycles across multiple downstream industries.
The structural shift toward plant-based and fermentation-derived amino acid production continues to reshape cost architectures and competitive moats. Simultaneously, regulatory scrutiny around raw material sourcing, manufacturing transparency, and quality standardization is elevating compliance from a back-office function to a boardroom priority. In this environment, strategic decisions made without a clear view of market velocity, concentration patterns, and application-level demand trajectories carry heightened risk.
Our analysis is calibrated to this reality. By anchoring projections in a multi-year historical baseline and extending the forecast through 2032, the report provides a disciplined, evidence-based pathway for leaders who must act decisively rather than speculate.
Proline Market
Market Trajectory and Structural Signals
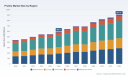
The global L-proline market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $441 million in 2020 to an estimated $596 million in 2025. This growth reflects sustained demand across health and dietary supplement formulations, animal feed nutrition, and pharmaceutical synthesis pathways. Looking ahead, the market is projected to advance at a compound annual growth rate of 6.65 percent, reaching a valuation of roughly $643 million in 2026 and continuing its upward trajectory toward approximately $908 million by 2032.
Several structural signals underpin this momentum. First, downstream demand for amino acid-enabled formulations has broadened beyond traditional food and beverage applications. Nutritional science advancements, clinical research into amino acid metabolism, and consumer wellness trends have collectively expanded the addressable market for proline-based compounds. Second, manufacturing innovation—particularly in fermentation efficiency, strain optimization, and downstream purification—has improved yield economics and expanded grade flexibility for industrial buyers. Third, manufacturing geography continues to evolve, with production capacity increasingly distributed across major industrial corridors to mitigate single-region risk exposure.
For strategic planners, these trends carry actionable implications. Procurement teams must assess whether incumbent suppliers can sustain cost competitiveness as fermentation technology scales. Product developers need visibility into grade availability, purity specifications, and regulatory status across target applications. Investors and corporate development teams require clarity on concentration dynamics, capacity expansion signals, and the pace at which emerging players can scale. Our report addresses each of these dimensions with targeted analysis designed for execution.
Worldwide Prolactin Market
What the Proline Market Report Delivers
This study is engineered for practical use, not academic abstraction. It provides a complete analytical architecture that organizations can integrate directly into forecasting models, market entry evaluations, competitive benchmarking, and supply chain planning workflows. The report covers:
- Historical performance tracking (2020–2025): Year-over-year revenue progression, volume and value trends, and macroeconomic demand drivers that shaped the baseline period.
- Forward-looking forecast (2026–2032): Market size projections, growth rate trajectories, and structural inflection points that decision-makers should monitor as planning horizons extend.
- Type segmentation analysis: A detailed comparison of plant-based and animal-based proline supply streams, including production methodology distinctions, grade suitability, cost structures, and demand migration patterns across end-use sectors.
- Application-level demand mapping: Cross-sector evaluation of how proline is deployed in health and dietary supplements, animal feed, and pharmaceutical formulations, with emphasis on consumption drivers, formulation trends, and regional purchasing behavior.
- Regional market intelligence: Assessment of demand concentration, supply chain geography, trade dynamics, and localization trends across key industrial markets, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape profiling: Detailed company profiles, operational focus areas, production capabilities, and strategic positioning of leading manufacturers and emerging participants.
- Concentration and competitive intensity metrics: Structured analysis of market share distribution among top-tier players, indicating where consolidation pressure exists and where fragmentation creates entry or disruption opportunities.
Each section is designed to enable direct integration with internal strategy processes. Whether your team is evaluating supplier diversification, assessing a potential M&A target, modeling product launch scenarios, or stress-testing cost assumptions against raw material volatility, the report provides a defensible foundation for those decisions.
Competitive Dynamics and the Manufacturing Frontier
The L-proline competitive landscape reflects a blend of established multinational amino acid producers, specialized fermentation manufacturers, and regional players with strong downstream integration. The market’s top three participants collectively account for approximately 48.5 percent of revenue, while the top five extend their combined share to roughly 62.3 percent. This concentration profile indicates a market with clear incumbency advantages in scale, process know-how, and downstream customer relationships, but also suggests room for competitive repositioning as regional capacity expands and application-specific demand fragments.
Leading manufacturers demonstrate distinct strategic orientations. Ajinomoto Co., Inc., headquartered in Tokyo, Japan, has built its proline capability around industrial-scale fermentation processes designed for bulk amino acid supply across food, pharmaceutical, and nutrition channels. Evonik Industries AG, based in Essen, Germany, positions L-proline as a non-animal-derived, non-essential amino acid available in multiple industrial grades, serving feed, pharmaceutical, and specialty applications. Meihua Holdings Group Co., Ltd., operating from China, leverages corn fermentation routes to supply proline as an upstream raw material for human medical purposes, sports nutrition food, and special medical applications. KYOWA HAKKO BIO CO., LTD., also based in Tokyo, focuses on amino acid manufacturing including related proline compounds through innovative industrial fermentation methods.
Regional production capability continues to deepen. Sichuan Tongsheng Amino Acid Co., Ltd. manufactures L-proline as part of a broader amino acid portfolio targeting food, pharmaceutical, and animal nutrition markets. Zhejiang NHU Co., Ltd. produces L-proline through fermentation for use in the food industry, human medical purposes, and pharmaceutical intermediates. Shijiazhuang Jirong Pharmaceutical Co., Ltd. supplies L-proline as upstream raw material for drugs treating chronic diseases and related pharmaceutical applications. Together, these participants illustrate how proline manufacturing is not only a commodity play but also a capability-dependent business where fermentation efficiency, grade versatility, and downstream integration shape competitive durability.
Strategic buyers and competitors should pay close attention to how these manufacturers differentiate on grade availability, scale economics, supply reliability, and regulatory alignment. In a market where certain amino acids have become increasingly problematic due to high inclusion rates, elevated pricing, limited global production volumes, or manufacturing complexity, proline’s relative positioning depends on continued process optimization and supply chain transparency. The report provides structured evaluations that help organizations determine which suppliers can support long-term contractual commitments and which represent tactical sourcing options under specific demand scenarios.
Raw Material Pressures and the Cost Architecture Reality
No analysis of the L-proline market is complete without addressing input-side economics. Amino acid manufacturing remains highly sensitive to feedstock pricing, fermentation yield variability, downstream purification costs, and logistics exposure. Industry assessments have highlighted that six amino acids—serine, glutamine, asparagine, histidine, proline, and arginine—have emerged as particularly challenging due to a combination of high inclusion rates, elevated prices, low global production volumes, and manufacturing complexity.
This context matters because cost pressure is rarely uniform across the amino acid portfolio. For proline specifically, competitive advantage increasingly hinges on production efficiency, feedstock flexibility, and the ability to deliver consistent grade quality at scale. Organizations that rely on proline as an upstream input for pharmaceutical synthesis or nutrition formulations must understand how cost volatility transmits through their supply chain and where strategic buffers, alternative sourcing arrangements, or specification adjustments can preserve margin integrity.
Our report integrates these dynamics into the broader market framework, examining how raw material exposure, production complexity, and regional capacity trends interact with pricing behavior and buyer negotiation leverage. Rather than offering static cost snapshots, the analysis maps the structural variables that will shape procurement economics and manufacturing competitiveness over the forecast period.
Why This Report Is Built for 2026 Strategy Execution
Decision-making in 2026 will be shaped by the intersection of demand expansion, supply chain recalibration, technological advancement in fermentation, and increasing transparency requirements across food, nutrition, and pharmaceutical value chains. In that environment, organizations need intelligence that is simultaneously broad enough to capture macro momentum and precise enough to guide category-level actions.
The Proline Market report is structured to meet that standard. It combines historical validation with forward-looking forecasting, maps competitive and application-level dynamics, and provides the analytical scaffolding necessary to translate trend observation into strategic action. More importantly, it preserves strategic discretion: by identifying where the largest decision-relevant opportunities and risks reside, it helps leaders prioritize the questions that matter most before committing capital, capacity, or commercial resources.
Access the Full Intelligence Architecture
The complete Proline Market report extends well beyond the strategic overview presented here. It contains detailed segmentation breakdowns, regional demand and supply mappings, company-level capability assessments, and forecast scenarios designed for internal planning, investment evaluation, and procurement strategy. For teams that require defensible numbers, structured competitive context, and actionable market direction, the full study is the necessary reference point.
To access the complete dataset, segmentation detail, and full competitive profiles, visit the Proline Market research page on the PW Consulting platform. There, you can review the full scope of the analysis, evaluate the report against your internal planning requirements, and secure the intelligence needed to make 2026 and beyond decisions with confidence.
For detailed analysis of this topic, please visit the official page: Proline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electroporator Market Poised to Hit $344.8M by 2032 on 5.67% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Evolving Electroporator Market: A 2026 Outlook
The global electroporator market stands at a critical inflection point as we navigate through 2026. For executive leaders, investment committees, and strategic planners, understanding the trajectory of this sector is no longer optional—it is a prerequisite for capitalizing on emerging opportunities in cell therapy, gene editing, and precision medical devices. PW Consulting is pleased to present our comprehensive Electroporator Market research, designed to equip decision-makers with the intelligence necessary to navigate the complexities of the forecast period spanning 2026 to 2032.
As we analyze the historical data from 2020 to 2025, a clear trend of consistent growth emerges. The market revenue has demonstrated resilience and expansion, reflecting the increasing adoption of electroporation technologies across both research and clinical applications. This upward trajectory is projected to continue, driven by technological advancements, regulatory shifts, and the expanding footprint of biotechnology manufacturing. Our latest report delves into these dynamics, offering a granular view of the forces shaping the market landscape.
This article serves as a strategic preview, highlighting the core themes and analytical depth contained within our full market study. While we share high-level insights to establish the context, the specific quantitative breakdowns, regional nuances, and detailed company profiling are reserved for our comprehensive report. For stakeholders seeking actionable intelligence to inform capital allocation, product development, and market entry strategies, the full document provides the granular data required for confident decision-making.
Market Trajectory and Growth Dynamics
The electroporator market has transitioned from a niche laboratory tool to a cornerstone technology enabling breakthrough therapies. Historical performance over the last five years indicates a steady acceleration in revenue generation. Building on this foundation, our forecasts indicate sustained growth through the end of the decade. The projected Compound Annual Growth Rate (CAGR) underscores the market's robust expansion potential, signaling that demand is not merely cyclical but rooted in fundamental shifts within the biotechnology and medical device sectors.
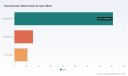
Electroporator Market
This growth is fueled by several converging factors. The rise of cell and gene therapies has amplified the need for reliable, scalable transfection methods. Electroporation has emerged as a preferred technique for delivering genetic material into cells, offering advantages in efficiency and versatility compared to alternative methods. Furthermore, the clinical application of irreversible electroporation (IRE) for tissue ablation represents a significant value driver, expanding the addressable market beyond research laboratories into hospital settings.
Our analysis covers the forecast horizon from 2026 to 2032, a period in which we anticipate increased commercialization of advanced electroporation platforms. Stakeholders must understand the magnitude of this growth to position their portfolios effectively. The revenue projections suggest a market that will more than double its current size by the end of the forecast period, creating substantial opportunities for vendors who can align their offerings with the evolving needs of end-users. However, realizing this value requires a nuanced understanding of market segments, competitive pressures, and regulatory environments, which our full report details extensively.
Technology and Application Landscapes
The electroporator market is characterized by diverse technology types and a wide array of applications. Our research examines the prevailing categories that define the competitive landscape. In terms of product types, the market includes various film-based and specialized electroporation solutions catering to different throughput and efficiency requirements. These include established technologies that dominate volume usage as well as emerging variants designed for specialized workflows. The interplay between these types influences pricing, performance expectations, and adoption rates across different user segments.
Application diversity is another critical dimension. The market serves multiple end-use sectors, ranging from semiconductor manufacturing processes to biopharmaceutical production and clinical interventions. High-volume applications drive significant revenue, while niche uses often command higher margins and foster innovation. Our segmentation analysis explores how demand varies across these applications, identifying which areas are experiencing the fastest adoption and where growth bottlenecks may exist. Understanding these application-specific dynamics is essential for companies looking to target their marketing efforts or develop new product lines that address unmet needs.
It is important to note that while we discuss the structure of the market, the detailed regional and application-level revenue figures, as well as specific market share percentages by type, are disclosed in our full report. These data points are vital for granular strategic planning, allowing clients to benchmark their position against the broader market and identify high-potential regions or segments for expansion. The report provides a complete breakdown of these splits, enabling a precise assessment of where value is being generated.
Regulatory Framework and Industry Compliance
The regulatory environment plays a pivotal role in shaping the electroporator market, influencing product development cycles, market access, and reimbursement prospects. Recent years have seen increased regulatory activity, particularly concerning medical device clearances and compliance standards. Our report integrates the latest regulatory intelligence to help clients anticipate changes and ensure their strategies remain compliant.
A key development in this space involves the clearance of electroporation systems for specific clinical indications. For instance, recent FDA actions have expanded the use of irreversible electroporation devices for tissue ablation, including applications in prostate tissue. Such clearances validate the clinical utility of the technology and open new revenue streams for device manufacturers. Additionally, other electroporation systems have received clearance as substantially equivalent to predicate devices, streamlining the path to market for compatible technologies.
Beyond device-specific approvals, broader regulatory standards impact product design and validation. Standards related to sterilization validation, such as ISO 11135 for ethylene oxide and ISO 11607 for primary packaging, are critical for ensuring the safety and sterility of medical devices. Similarly, biocompatibility testing in accordance with ISO 10993-1 and FDA guidance remains a cornerstone of regulatory submissions. Our report highlights how adherence to these standards affects time-to-market and competitive positioning.
In the context of reimbursement and coding, specific procedural codes are increasingly relevant for the adoption of irreversible electroporation procedures. For example, CPT codes designated for percutaneous and open irreversible electroporation ablation with imaging guidance are used for billing purposes. Awareness of these coding structures is essential for companies marketing to healthcare providers, as it influences the economic viability of procedures for hospitals and clinics. Our full analysis discusses the implications of these regulatory and reimbursement factors on market demand.
Electroporation Buffer Market
Competitive Landscape and Strategic Positioning
The electroporator market features a mix of established life science corporations, specialized technology providers, and innovative medical device companies. Competitive intensity is shaped by the diverse capabilities of these players, ranging from broad-spectrum research instruments to highly specialized clinical systems. Our report provides an in-depth profile of the key companies driving the market, analyzing their strategic moves, product portfolios, and growth trajectories.
Among the notable players, Thermo Fisher Scientific stands out for its comprehensive offering of electroporation instruments, including systems designed for high-efficiency transfection in research, bioprocessing, and cell therapy workflows. These solutions are integral to many laboratory and manufacturing environments, reflecting the company's strength in supporting a wide range of applications. Similarly, Bio-Rad Laboratories maintains a strong presence with electroporation systems that facilitate cell transfection, nucleic acid delivery, and gene editing across various cell types, solidifying its reputation for reliability and performance.
Lonza Group contributes to the competitive landscape through platforms that support gene editing, cell engineering, and therapeutic development. Its solutions are particularly relevant in the context of advanced therapy medicinal products, where efficient and reproducible cell modification is critical. Eppendorf AG offers compact systems tailored for the transformation of microorganisms, addressing the needs of academic and industrial research labs focused on microbial genetics and bioprocessing.
Specialized companies also play a vital role. AngioDynamics designs and manufactures the sole FDA-cleared irreversible electroporation device for tissue ablation, with recent expansions covering prostate tissue use. This focused approach highlights the clinical potential and regulatory pathway specific to IRE applications. MaxCyte develops scalable electroporation platforms for cell therapy, gene editing, and large-scale manufacturing, addressing the growing demand for scalable solutions in the biopharmaceutical sector. Other players like Mirus Bio and BTX provide distinct solutions for transfection of challenging cell types and delivery of genes, drugs, and proteins, respectively. Harvard Bioscience supplies systems and accessories for cell transfection and gene delivery, catering to research applications.
Recent market activities underscore the dynamism of this landscape. For example, the FDA clearance expansion for the NanoKnife System in late 2024 marked a significant milestone for clinical electroporation. Similarly, other companies have achieved regulatory milestones that enhance their market access. Our full report analyzes these developments in the context of competitive strategy, assessing how such events shift market share dynamics, influence partnerships, and create new standards for technology adoption. We also examine the market concentration metrics to provide insights into the level of competition and the dominance of major players.
Strategic Insights for 2026 and Beyond
As we look toward the remainder of 2026 and the forecast period extending to 2032, several strategic implications emerge for market participants. The growth trajectory suggests that demand will continue to outpace supply in certain high-value segments, creating opportunities for companies that can innovate effectively and scale their operations. However, success will depend on more than just product quality; it will require a deep understanding of the end-user ecosystem, including regulatory hurdles, reimbursement realities, and integration with existing workflows.
For researchers and bioprocessing companies, the availability of scalable and efficient electroporation platforms will be a key differentiator. As cell therapies move from clinical trials to commercial manufacturing, the ability to perform transfection at scale with consistent results becomes paramount. Vendors who can demonstrate robust performance, reproducibility, and regulatory compliance will be well-positioned to capture this growing need.
In the medical device sector, the expansion of clinical indications for irreversible electroporation offers a pathway to new revenue streams. Companies that can navigate the regulatory landscape, secure necessary clearances, and educate healthcare providers on the benefits of these procedures will drive adoption. The interplay between device performance, clinical outcomes, and reimbursement codes will shape the pace of uptake in hospital settings.
Our report also explores regional variations in market development. While global growth is robust, certain areas exhibit higher maturity and adoption rates, while others are emerging as potential growth engines. Understanding these regional nuances allows companies to tailor their market entry strategies, prioritize distribution partnerships, and allocate resources where they can achieve the highest return on investment. The detailed regional data provided in our full study enables a precise mapping of these opportunities.
Furthermore, the competitive dynamics will likely evolve as larger conglomerates leverage their broad portfolios and as specialized firms carve out niches with innovative technologies. Mergers, acquisitions, and strategic partnerships may reshape the industry structure. Our analysis tracks these potential shifts and provides a framework for assessing the impact of competitive actions on market positioning.
Navigating the Market with Precision Intelligence
The electroporator market represents a convergence of scientific innovation, clinical need, and commercial opportunity. For organizations operating in or investing in this space, the ability to anticipate trends, understand competitive pressures, and align strategies with market realities is essential. PW Consulting's Electroporator Market report is designed to be the definitive resource for achieving this alignment.
This article has provided a high-level overview of the market forces, growth drivers, regulatory context, and competitive landscape. However, to fully capitalize on the insights presented, stakeholders require the detailed quantitative data and granular analysis that form the core of our research. The complete report includes exhaustive segmentation breakdowns, precise revenue forecasts by segment, comprehensive company profiles with strategic assessments, and in-depth analysis of regional markets. These elements are critical for developing specific, actionable strategies.
We invite executives, analysts, and investors to access the full market research for a complete understanding of the electroporator market's potential. Our team is available to discuss how the findings can be tailored to your specific strategic needs, whether you are evaluating market entry, assessing competitive threats, or planning product development roadmaps. In a rapidly evolving market, having access to precise, up-to-date intelligence is the key to unlocking value and achieving sustainable growth.
For detailed analysis of this topic, please visit the official page: Electroporator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engineered Stone Market Hits $26.5B in 2025, 7.1% CAGR to $42.8B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: Navigating the Engineered Stone Market Expansion Through 2032
Executive Overview
The engineered stone sector stands at a pivotal juncture as we move through 2026. Marked by sustained revenue growth, evolving regulatory frameworks, and intensifying competitive dynamics, the market demands a nuanced strategic lens. Our latest Engineered Stone Market research report provides decision-makers with a comprehensive, data-grounded view of where the industry has been, where it is heading, and how leading enterprises are positioning themselves to capture durable competitive advantage.
Drawing on historical performance data from 2020 through 2025 and a forward-looking forecast window extending to 2032, this study translates macroeconomic momentum into actionable intelligence. The global engineered stone revenue trajectory has demonstrated consistent expansion, advancing from approximately 18.81 billion USD in 2020 to an estimated 26.5 billion USD in 2025. Looking ahead, the market is projected to reach roughly 29.28 billion USD in 2026 and continue its upward climb toward 42.83 billion USD by 2032, supported by a compound annual growth rate of 7.1 percent. These figures represent more than sequential growth; they reflect structural shifts in consumer preferences, building material innovation, and manufacturing localization strategies that will define market leadership over the next decade.
Why This Report Matters for 2026 Decision-Making
Enterprise strategy in engineered stone cannot rely on static assumptions. Regulatory mandates are reshaping production standards. Trade policy interventions are altering supply chain architectures. Competitors are investing heavily in next-generation surface technologies and sustainable material formulations. In this environment, a forward-looking, multi-dimensional analysis is not optional; it is foundational to capital allocation, market entry planning, product portfolio optimization, and risk mitigation.
Our report is designed to serve as a strategic compass for executives navigating this complexity. Rather than offering a static snapshot, the analysis integrates historical performance patterns, forward-looking demand signals, competitive positioning assessments, and regulatory trajectory mapping into a single, cohesive intelligence framework. The goal is to equip leaders with the clarity required to make informed decisions in 2026 and beyond, while recognizing that the market's evolution will reward those who anticipate change rather than react to it.
Importantly, this preview offers a strategic orientation and methodological outline. The full report contains the granular segmentation breakdowns, precise regional revenue distributions, type-level and application-level market shares, and detailed forecasting models that enable precise scenario planning. Those deeper data layers are essential for operationalizing the trends described here and are available through the complete research release.
Macro Trajectory and Growth Architecture
The engineered stone market's expansion over the past half-decade has been characterized by steady, compounding growth rather than episodic spikes. Revenue progressed from 19.77 billion USD in 2021, to 20.99 billion USD in 2022, and 22.6 billion USD in 2023, before accelerating to 24.83 billion USD in 2024. This progression reflects underlying demand resilience across residential and commercial end-use sectors, alongside manufacturing scale-up and product innovation cycles that have broadened the material's application footprint.
Engineered Stone Market
The forecast horizon suggests that momentum will be maintained, though not uniformly. Growth is expected to advance through 2027 with revenue approaching 30.34 billion USD, then continue toward 31.78 billion USD in 2028 and 34.69 billion USD in 2029. By 2030, the market is projected to reach 36.1 billion USD, with a notable acceleration phase anticipated through 2031 and 2032, culminating in an estimated 41.11 billion USD and 42.83 billion USD respectively. The 7.1 percent compound annual growth rate across the forecast period signals a market that is scaling on the back of both volume expansion and value enhancement, as premium surface solutions and technologically advanced material formulations gain stronger market penetration.
For strategic planners, the implication is clear. Growth will not be evenly distributed across product types, end-use applications, or geographies. The full research delves into how these growth vectors differ by segment, revealing where demand is maturing, where it is accelerating, and where competitive intensity is likely to reshape share dynamics. That segmentation intelligence is critical for companies evaluating capacity investments, distribution expansion, and product-mix adjustments.
Market Concentration and Competitive Architecture
The engineered stone landscape is marked by meaningful concentration, with a small group of established players commanding a substantial share of industry revenue. The market's top three competitors collectively represent approximately 62.5 percent of total market value, while the top five extend that footprint to roughly 67.2 percent. This concentration reflects the strategic advantages of scaled manufacturing, brand recognition, proprietary surface technologies, and established channel relationships.
Several core enterprises define the competitive frontier. Caesarstone, headquartered in Israel, has built its reputation on premium engineered quartz surfaces with an emphasis on health-compliant formulations and global distribution reach. Its recent operational moves underscore a dual focus on regulatory readiness and commercial expansion. In early 2026, the company launched a full collection of zero crystalline silica quartz surfaces in Australia to align with evolving regulatory standards for worker safety, and later in the year announced first-quarter earnings that highlighted digital platform development and production expansion. The company also introduced an eco-friendly quartz surface line incorporating recycled glass and bio-resins, signaling a broader strategic orientation toward sustainability-led product differentiation.
Cambria, based in the United States, competes with an emphasis on American-made engineered quartz surfaces, innovative design portfolios, lifetime residential warranties, and a strong positioning around natural aesthetics. At a major industry showcase in 2026, Cambria unveiled what it described as the leading edge of quartz innovation, including new designs and application concepts that point toward broader usage scenarios and premiumization within the quartz category.
Cosentino, operating from Spain, stands as a global leader in engineered stone surfaces, with its Silestone quartz and Dekton ultracompact stone offerings anchored by sustainable HybriQ technology. The company demonstrated its innovation cadence by debuting the first collection of its Éclos surface brand alongside new Dekton collections at a prominent 2026 industry event. Its investment posture also reflects long-term capacity planning; in 2025, Cosentino committed 120 million euros to expand Dekton ultracompact stone production capacity through new production lines, an indication of confidence in sustained demand for high-performance surface materials.
LG Hausys, headquartered in South Korea, manufactures Viatera quartz engineered stone surfaces with domestic United States production capabilities and premium collections, reinforcing the strategic importance of localized manufacturing in serving key demand markets. MSI Surfaces, also United States-based, offers Q Premium Natural Quartz engineered stone countertops with domestic manufacturing in South Carolina and a broad color portfolio, underscoring the continued relevance of manufacturing proximity, product variety, and countertop-centered demand in the broader engineered stone ecosystem.
These competitive dynamics illustrate a market where brand equity, technology differentiation, compliance readiness, and production footprint are increasingly intertwined. The full report provides detailed company profiling, strategic positioning analysis, and competitive interaction mapping that help executives benchmark their own capabilities and identify whitespace opportunities.
Regulatory Tailwinds and Constraints
Regulation is now a first-order strategic variable in engineered stone, influencing product design, manufacturing processes, distribution strategies, and market access. The regulatory environment in 2026 reflects heightened attention to worker safety, material composition, and import-related industry impacts, creating both compliance obligations and competitive differentiators for firms that adapt early.
One notable development involves health and safety standards tied to crystalline silica content. Caesarstone's 2026 launch of a zero crystalline silica quartz surface collection in Australia was explicitly oriented toward regulatory compliance, illustrating how product formulation strategies are being reshaped by jurisdictional safety requirements. In parallel, California's occupational safety framework advanced toward a more restrictive posture, with a state board voting to adopt a petition banning the fabrication of engineered stone containing more than 1 percent crystalline silica. These actions point to a broader trajectory in which material composition, fabrication practices, and downstream worker protection are becoming central to product viability in certain markets.
Trade and import dynamics are also exerting strategic pressure. A United States trade commission determination in April 2026 concluded that increased quartz surface imports were causing serious injury to the domestic industry. This finding introduces potential trade remedy implications that could affect import volumes, pricing structures, and competitive positioning between domestically manufactured and imported surfaces. For market participants, the implications extend beyond immediate tariff or duty considerations to longer-term questions about supply chain localization, production capacity planning, and competitive exposure in the US market.
These regulatory vectors do not affect all regions, product types, or applications equally. Their strategic impact depends on manufacturing origin, product formulation, end-market exposure, and the pace at which compliance requirements are adopted and enforced. The report's regulatory analysis section maps these developments against market segments and company profiles, enabling leaders to assess exposure, anticipate compliance costs, and identify potential competitive advantages for firms that proactively align product and process strategies with emerging standards.
Engineered Quartz Stone (EQS) Market
Product Innovation, Sustainability, and Application Evolution
Innovation in engineered stone is increasingly multidimensional. It spans formulation science, aesthetic design, durability performance, sustainability credentials, and application breadth. The companies profiled in this research are investing across these dimensions, and the resulting product landscape is becoming more differentiated.
Zero crystalline silica formulations represent one clear innovation pathway, particularly for markets where worker safety regulation is tightening. Eco-friendly surface lines that integrate recycled glass and bio-resins reflect another axis of differentiation, aligning material innovation with broader sustainability expectations from specifiers, builders, and end consumers. Ultracompact stone technologies and new surface brands introduced at major industry events indicate that manufacturers are also expanding the performance envelope of engineered surfaces, targeting applications that demand higher mechanical resilience, weather resistance, or design flexibility.
Application-wise, countertops remain a central demand anchor within the engineered stone ecosystem, supported by residential renovation activity, new housing construction, and commercial fit-out requirements. Flooring and other application categories contribute additional growth channels, though their relative weighting and growth trajectories vary by region and by product type. The full report examines how these application categories interact with product types and regional demand profiles, providing the kind of segmented insight needed to prioritize go-to-market focus and product development resources.
Strategic leaders should note that innovation Leadership is not solely about launching new collections. It is about aligning product roadmaps with regulatory trajectories, sustainability expectations, distribution channel capabilities, and the aesthetic and performance requirements of construction and design professionals. The report's innovation analysis section evaluates these alignments across the competitive set, helping executives anticipate where product differentiation will translate into share gains versus where it may simply raise the baseline for market entry.
What the Full Study Delivers
This report is structured to support complex strategic decisions with layered, practical intelligence. Beyond the macro growth narrative and competitive context outlined here, the complete study provides:
- Detailed historical and forecast revenue analysis across the full 2020 to 2032 window, including year-by-year projections that support budgeting, capacity planning, and investment timing.
- Segment-level market size and growth assessment by product type, application, and region, enabling targeted market entry, expansion, and portfolio prioritization decisions.
- Competitive profiling of core market participants, including strategic positioning, product and technology emphasis, production footprint considerations, and recent commercial developments.
- Regulatory and trade policy mapping that connects compliance developments to market access, formulation strategy, and competitive exposure across key jurisdictions.
- Industry dynamics analysis that integrates demand drivers, supply-side constraints, innovation trends, and sustainability shifts into a cohesive strategic framework.
- Scenario-ready insights that help leadership teams evaluate alternative growth paths, assess risk concentration, and align operational plans with market reality.
The objective is not simply to describe the market, but to make it legible as a strategic arena. For CEOs, business unit leaders, investors, and strategy professionals, the report is designed to reduce ambiguity around where growth is coming from, which competitors are best positioned to capture it, and what structural factors will shape profitability and market access over the forecast period.
Closing Perspective
The engineered stone market in 2026 is defined by a combination of durable demand growth, accelerating regulatory specificity, and competitive intensification among scaled, innovation-focused players. Revenue expansion from recent historical levels toward a projected 42.83 billion USD by 2032 reflects a sector that is evolving in both substance and strategy. Success in this environment will depend on the ability to interpret market signals early, align product and production strategies with regulatory and sustainability expectations, and deploy capital with precision into the segments and geographies where competitive advantage can be sustained.
This report provides the intelligence architecture required to make those decisions with confidence. To access the full segmentation data, detailed company profiles, regional and type-level breakdowns, and the complete forecast models that underpin the analysis, please refer to the complete Engineered Stone Market research release.
For detailed analysis of this topic, please visit the official page: Engineered Stone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SST Market to Hit $344.8M by 2032, 6.98% CAGR in Solid State Transformers
By PW Consulting, 2026-09-16
Unlocking the Next Grid Revolution: Why the Solid State Transformer Market Demands Strategic Attention in 2026
The global electrification landscape is undergoing a structural transformation that many industry observers have long anticipated but few have quantified with precision. As distributed energy resources, high-density AI data centers, and heavy-duty electric mobility converge, the conventional transformer paradigm is reaching its operational and economic limits. Our latest market research on Solid State Transformers (SST) provides decision-makers with a rigorous, data-grounded view of this inflection point, framed explicitly for strategic planning across the 2026–2032 horizon.
The core value of this analysis lies in its direct alignment with enterprise decision cycles. Organizations evaluating grid-edge infrastructure, energy storage integration, or next-generation charging networks cannot rely on legacy power electronics benchmarks. SST architectures deliver voltage conversion, power factor correction, fault isolation, and bidirectional energy flow within a single compact platform. Yet the commercial trajectory of these systems depends on a complex interplay of manufacturing scale, wide-bandgap semiconductor pricing, regulatory incentives, and application-specific validation. Our research strips away speculative commentary and replaces it with a structured view of where capital, engineering effort, and partnership strategies should be directed in the near term.
Market Trajectory and the Strategic Imperative for 2026 Planning
The SST market has moved beyond early proof-of-concept phases into a period of measurable commercialization momentum. Our historical review from 2020 through 2025 captures a sustained expansion curve, driven by pilot deployments, utility interest, and accelerating demand from power-intensive digital infrastructure. Looking forward, the forecast window through 2032 outlines a market path that compounds at a CAGR of 6.98 percent in USD Million terms. This growth rate is meaningful not because it is explosive, but because it reflects a deliberate industrial scaling process rather than a transient technology fad.
For executives building investment committees or technology roadmaps, the strategic implication is clear. The market is large enough to warrant dedicated resource allocation, yet still fragmented enough that early positioning can shape vendor relationships, standard influence, and deployment backlogs. The revenue progression across the forecast period indicates that SST adoption will not occur as a single step-change event. Instead, it will unfold through sequential waves tied to data center expansion, renewable integration mandates, and commercial heavy-duty charging rollout. Understanding the sequencing of these waves is essential for timing procurement commitments, manufacturing capacity decisions, and partnership negotiations.
It is equally important to recognize that macroeconomic tailwinds alone do not guarantee successful commercialization. The research deliberately avoids presenting oversimplified adoption timelines. Instead, it maps the operational and financial friction points that determine which players convert pilot activity into repeatable revenue. That perspective is what makes the report actionable for 2026 planning: it shows where growth is structurally supported and where it is contingent on cost reduction, supply chain maturity, or regulatory follow-through.
Regulatory Catalysts and Manufacturing Realities Shaping Commercial Viability
Policy frameworks and material economics are exerting simultaneous pressure on the SST value chain. In the United States, the Department of Energy Grid Resilience and Innovation Partnerships program has allocated over USD 10.5 billion toward next-generation distribution infrastructure, creating a public funding layer that can de-risk early deployment and stimulate utility and industrial adoption. At the regional level, state public utility commissions in California, New York, and Texas have moved toward rate-based treatment for solid-state transformer deployments, which directly affects project economics for end users and system integrators.
In Europe, the revised F-gas regulation mandating SF6 phase-out in new medium-voltage switchgear by 2030 has sharpened the search for alternative distribution architectures. This regulatory shift does not automatically translate into SST demand, but it does open a policy-aligned pathway for technologies that can deliver precise voltage control and compact substation footprints without reliance on incumbent insulating gases. The strategic insight for market participants is that regulatory momentum often precedes commercial scale; organizations that anticipate the compliance calendar can align product development and pilot programs ahead of peak procurement windows.
On the supply side, cost dynamics remain a defining constraint. Silicon carbide power devices typically account for 30 to 40 percent of total SST system cost and can cost three to five times more than equivalent silicon counterparts. This material cost structure, combined with the broader reality that SST manufacturing expenses remain two to three times higher than conventional transformers on a per-kVA basis, means that competitiveness will hinge on design optimization, volume production, and application selection. The report examines how different players are navigating this cost equation, not as a generic challenge, but as a differentiated strategic variable across distribution-oriented, power-oriented, and traction-oriented implementations.
Segment Architecture: Where Value Is Concentrated and Where It Is Emerging
A core strength of the research is its structured segmentation framework, which helps organizations translate market size into operational priorities. Rather than presenting isolated share figures, the analysis explains how the market breaks down across type, application, and regional demand patterns, and why those distinctions matter for product strategy and go-to-market design.
By type, the research distinguishes among distribution, power, and traction solid-state transformer pathways. Distribution-focused SST units address localized grid-edge conversion and utility-scale feeder modernization, while power-oriented platforms are increasingly aligned with high-load digital infrastructure and energy storage interfaces. Traction applications, though smaller in current scope, represent a specialist segment tied to rail and heavy-mobility electrification. Each category carries its own qualification requirements, cost curves, and customer procurement cycles, which is why aggregate market forecasts must be interpreted through the lens of segment-specific economics.
By application, the study evaluates how SST technology maps onto renewable energy integration, electric vehicle charging infrastructure, power distribution, and traction use cases. These application segments are not interchangeable. Some demand high reliability and grid-forming capability; others prioritize modular scaling and fast response under intermittent generation. The research highlights how the same underlying SST architecture can be positioned differently depending on the customer’s operational constraints and service-level expectations.
Regionally, the analysis explores how demand intensity varies across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. These geographic patterns reflect differences in grid modernization pace, electrification priorities, and industrial policy. The report does not reduce regional opportunity to a single headline number; instead, it contextualizes each territory’s likelihood of near-term SST integration based on infrastructure urgency, utility business models, and manufacturing or deployment ecosystems. For companies planning export strategy, pilot siting, or local partnerships, that regional nuance is often the difference between a credible market entry and an inflated projection.
Competitive Landscape: Who Is Moving Now and How the Field Is Shaping Up
The SST market remains comparatively concentrated at the top tier, with the top three players accounting for roughly 24.6 percent and the top five for about 26.2 percent of market share. This structure indicates that while the field is open enough for specialist entrants, scale advantages in supply chain, qualification, and customer access are already beginning to matter. The report profiles the companies that are most actively translating technology readiness into commercial positioning, with emphasis on their strategic moves rather than simple corporate descriptions.
DG Matrix, headquartered in Raleigh, North Carolina, has focused its Interport multi-port solid-state transformer platform on AI data centers, electrification, and microgrid applications. Its recent moves suggest a deliberate push to align SST hardware with the power density and flexibility requirements of next-generation digital infrastructure. In February 2026, the company announced a strategic partnership with Exowatt to integrate Interport SST technology into dispatchable renewable systems for gigawatt-scale AI-era infrastructure. That same month, DG Matrix closed a Series A funding round led by Engine Ventures to support commercialization of its multi-port platform. Together, these actions signal a strategy centered on pairing SST capability with renewable dispatchability and data-center demand clusters.
Amperesand, based in Singapore, is developing medium-voltage solid-state transformer platforms for critical infrastructure, AI factories, and grid electrification, with U.S. manufacturing and 2026 commercial deployments in view. In February 2026, the company targeted its first commercial medium-voltage SST deliveries to Fortune 100 customers and hyperscalers. For organizations evaluating supplier options, the notable point is not merely product specification but the combination of regional manufacturing footprint, medium-voltage focus, and direct engagement with large enterprise buyers.
Solid State Transformers (SST) Market
Worldwide Phase-Shifting Transformers Market
Eaton Corporation, headquartered in Dublin, Ireland, has strengthened its position through acquisition, completing the purchase of Resilient Power Systems Inc. in August 2025 to accelerate commercialization of medium-voltage solid-state transformer technology for data centers, energy storage, and EV charging infrastructure. This move illustrates how established power management players are using targeted technology acquisitions to close capability gaps and shorten the path from prototype to deployable product. The strategic lesson is that capability consolidation is already underway, and procurement teams should evaluate not only standalone innovators but also how larger platforms may bundle SST capabilities into broader energy and power services.
WattEV, located in Long Beach, California, is developing modular solid-state transformer solutions for megawatt heavy-duty electric truck charging stations, with production-ready units targeted for 2026. In January 2026, the company unveiled its modular SST technology and confirmed its production-ready deployment timeline. This positioning matters because heavy-duty charging represents one of the most demanding application environments for voltage control, thermal management, and modularity. Companies tracking SST adoption should therefore view WattEV’s trajectory as an indicator of how quickly high-power mobility charging can move from demonstration to operational scale.
Taken together, these developments show a competitive field that is simultaneously specialized and consolidating. Specialist firms are pushing application-specific SST platforms, while larger players are acquiring or integrating medium-voltage capability to serve multi-market demand. The report assesses these patterns not as a static vendor list, but as a moving landscape where partnerships, funding, and customer commitments are becoming as important as product specifications.
What the Report Delivers: Operational Scrutiny for Investment and Deployment Decisions
This market research is designed to support concrete decisions rather than high-level awareness. It synthesizes market sizing, segmentation logic, competitive activity, and regulatory context into a format that can be used by strategy, engineering, procurement, and investment teams. The emphasis is on what organizations can act on in 2026 and beyond.
Key analytical deliverables include:
- A structured view of market evolution across the 2026–2032 forecast period, with historical context from 2020–2025 to ground near-term expectations.
- Segment-level analysis across type and application, showing how demand drivers differ and why the cost and qualification profile of each segment affects adoption timing.
- Regional demand context that helps identify where pilot programs, partnerships, or export strategies are most likely to generate traction.
- A competitive scan of core SST players and recent corporate developments, including acquisitions, partnerships, funding, and product announcements.
- An assessment of regulatory and material-cost factors that shape commercialization risk, including utility rate treatment, gas phase-out mandates, and wide-bandgap semiconductor economics.
- Practical guidance on where SST value is most defensible today and where it remains contingent on manufacturing scale and system-level integration.
Importantly, the report is built to support scenario planning. Because SST adoption is not uniform, organizations benefit from understanding which segments are closest to commercial repeatability and which still require further cost compression or utility acceptance. That distinction helps avoid over-indexing on headline market potential while missing the operational constraints that determine actual revenue conversion.
Strategic Recommendations for Executive Decision-Making
For enterprises evaluating the SST opportunity in 2026, the research suggests a disciplined approach that balances technology optimism with commercialization realism. The market is expanding, but expansion does not automatically translate into profitable participation. The following priorities emerge from the analysis.
- Align SST evaluation with application-specific value creation. The strongest early-case economics are likely where SST delivers multiple functions simultaneously, such as voltage conversion, isolation, and bidirectional control within a compact footprint.
- Track material cost and manufacturing scale as first-order variables. Wide-bandgap semiconductor pricing and per-kVA manufacturing premiums will influence competitiveness until volume production and design standardization reduce premium levels.
- Use regulatory signals as timing indicators rather than guaranteed demand triggers. Public funding programs and SF6 phase-out mandates shape the environment, but actual procurement still depends on utility business models, customer qualification processes, and total cost of ownership.
- Plan for a concentrated but active supplier landscape. Early market leaders are building momentum through partnerships, acquisitions, and targeted funding, so organizations should evaluate both specialist innovators and integrated platform players for fit with their deployment roadmap.
- Focus pilot selection on provable operational outcomes. In a market where premium costs remain significant, pilots that demonstrate reliability, serviceability, and integration value will have stronger positioning than those based solely on technology novelty.
The SST market is entering a phase where strategic clarity matters more than generalized enthusiasm. Companies that understand segment economics, competitive momentum, and regulatory pathways will be better positioned to select deployment opportunities, negotiate supplier relationships, and organize internal investment around realistic commercialization timelines.
Conclusion: From Market Signal to Actionable Intelligence
Solid-state transformers are no longer an abstract power-electronics concept. They are becoming a deliberate option for organizations seeking more controllable, more compact, and more flexible energy conversion at the grid edge and within high-load infrastructure. The question for 2026 is not whether the technology matters, but where it matters first, how quickly cost and scale will improve, and which companies are converting technical capability into commercial execution.
This report provides the structured intelligence required to answer those questions with discipline. It combines market sizing, segment logic, competitive developments, and regulatory context into a decision-oriented framework that can inform capital allocation, product strategy, and partnership planning. For leaders who need to move beyond broad estimates and toward a usable deployment and investment thesis, the full analysis offers the depth, segmentation, and competitive detail that an executive briefing alone cannot provide.
To turn this overview into a workable strategy, we recommend accessing the complete SST market research, where the full segmentation detail, company profiles, regulatory map, and forecast structure are available in their entirety. That is where market potential becomes operational instruction, and where strategic intent can be matched to the commercial realities of building, buying, or partnering around solid-state transformer technology in the years ahead.
For detailed analysis of this topic, please visit the official page: Solid State Transformers (SST) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Cladding Market Hits $565.45M in 2025, Poised for 9.46% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
Strategic Horizons in the Laser Cladding Material Market: A 2026 Executive Briefing
Setting the Stage for Industrial Transformation
The landscape of industrial manufacturing is undergoing a quiet but profound shift. As asset lifecycles extend and operational efficiency becomes non-negotiable, surface engineering technologies have moved from peripheral maintenance tools to core strategic enablers. Among these, laser cladding stands out for its precision, minimal thermal distortion, and ability to deposit high-performance materials exactly where they are needed. Our latest market research examines the commercial trajectory of laser cladding materials, offering a structured view of how supply, demand, and competitive forces are converging as we enter 2026.
Historical momentum tells a clear story. Between 2020 and 2025, the global market for these specialized materials expanded from approximately 359.71 million USD to 565.45 million USD, reflecting sustained adoption across sectors that prioritize component longevity, performance restoration, and weight-sensitive design. This trajectory is not merely a reflection of cyclical demand; it is anchored in a structural transition toward additive and near-net-shape repair methodologies that reduce downtime and conserve high-value substrates. As organizations map their capital allocation for the coming years, understanding the cadence of this expansion becomes essential.
Looking ahead, the forecast period from 2026 through 2032 projects continued growth, with the market expected to reach an estimated 1,053.0 million USD by the end of the horizon. This expansion is underpinned by a compound annual growth rate of 9.46 percent, signaling a robust and sustained uptake rather than a short-term surge. For decision-makers, such a rate suggests that laser cladding materials will increasingly move from niche applications into broader industrial workflows, reshaping procurement strategies, supplier relationships, and capacity planning across multiple verticals.
The strategic relevance of this research lies in its ability to translate macro momentum into actionable intelligence. By mapping the interplay between material chemistry, deposition performance, regional demand centers, and application-specific requirements, we provide a framework that helps executives anticipate supply constraints, evaluate partnership opportunities, and align R&D investments with emerging use cases. This is not a static snapshot; it is a forward-looking lens designed to support resilient planning in a market defined by continuous technical refinement.
Macro Dynamics and the 2026 Decision Anchor
Entering 2026, enterprises face a dual imperative: capture the upside of accelerating demand while mitigating the risks of an increasingly concentrated supplier landscape. Market concentration data indicates that the top three players account for roughly 49.0 percent of total revenue, while the top five collectively represent 52.0 percent. Such concentration implies that pricing dynamics, technical support capabilities, and supply chain reliability are increasingly shaped by a handful of globally positioned organizations. For procurement leaders and strategy teams, this environment demands a deliberate approach to supplier diversification, qualification pipelines, and long-term offtake agreements.
The material ecosystem itself is evolving in response to performance expectations. Engineers are selecting consumables based on a matrix of deposition efficiency, bond strength, corrosion and wear resistance, and compatibility with specific laser parameters. Nickel-based, cobalt-based, and iron-based alloy families, alongside carbide blends and specialized formulations, each occupy distinct performance niches. The optimum choice depends less on a single metric and more on the intersection of operating environment, component geometry, and post-clad heat treatment requirements. Our research dissects these trade-offs without reducing them to oversimplified rankings, ensuring that decision-makers can match material families to real-world operational constraints.
Regional demand patterns further complicate the planning picture. Industrial activity, regulatory environments, and local manufacturing footprints create uneven adoption curves across geographies. Some markets are driven by heavy industrial repair cycles and energy infrastructure maintenance, while others reflect advanced manufacturing ecosystems with high throughput requirements and stringent quality documentation. Rather than presenting static regional shares, our analysis maps demand intensity against local industrial capabilities, logistics considerations, and technical service availability. This approach helps organizations identify where partnerships, distribution channels, or localized qualification efforts will yield the highest returns.
Application-side demand is equally multifaceted. Aviation, automotive, power generation, oil and gas, mining, and construction each impose distinct performance criteria and lifecycle expectations on clad surfaces. Components in flight-critical environments demand materials that balance strength retention with fatigue resistance. Power generation assets require coatings that withstand thermal cycling and corrosive media. Mining and construction equipment prioritize wear resistance under abrasive conditions. Our report examines how these application profiles shape volume expectations, specification sensitivity, and the pace at which new material grades gain acceptance in qualified workflows.
What the Research Delivers: A Practical Toolkit for Strategy Teams
Comprehensive market intelligence must be usable, not merely descriptive. This report is structured to serve as a working reference for product managers, procurement strategists, R&D leads, and investment analysts. It combines quantitative trajectory analysis with qualitative assessment of technology readiness, qualification barriers, and commercial positioning. The objective is to equip teams with a clear sense of where value is being created, where bottlenecks are likely to emerge, and how to sequence decisions over the 2026 to 2032 window.
Laser Cladding Material Market
The research framework covers the following core dimensions:
- Market Sizing and Trajectory: A year-by-year view of market scale from historical baselines into the forecast horizon, enabling scenario planning around volume growth, pricing environments, and capacity investments.
- Material Family Assessment: An evaluation of alloy and composite categories based on deposition behavior, mechanical performance, and compatibility with common laser cladding systems, helping teams align specification choices with application requirements.
- Application Landscape: A breakdown of demand drivers across major end-use segments, highlighting where performance thresholds, regulatory qualifications, and procurement cycles influence adoption speed.
- Regional Demand Context: A qualitative mapping of geographic demand intensity relative to industrial structure, service infrastructure, and supply chain accessibility, supporting decisions on market entry, distribution, and technical support localization.
- Competitive Positioning: A structured review of key participants, their product architectures, and areas of focus, providing context for partnership evaluation, procurement risk assessment, and benchmarking.
Beyond these structural elements, the report integrates practical aids designed for immediate application. These include supplier evaluation criteria aligned with deposition consistency and particle size control, guidance on qualifying new material grades for recurring repair or production workflows, and a decision lens for balancing standard offerings against custom formulations. For organizations exploring expansion into higher-value component refurbishment or performance-critical coatings, the analysis clarifies where technical barriers are declining and where specialized know-how still commands a premium.
The emphasis throughout is on clarity of implication. Rather than leaving readers with isolated figures, the report connects market movement to operational consequences: how demand intensity affects lead times, how material selection influences process repeatability, and how competitive concentration shapes negotiation leverage. This makes the research suitable for both strategic planning sessions and operational readiness reviews.
Worldwide Wall Cladding Market
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The supplier base in this market reflects a blend of broad-scale material producers and focused specialists. Several organizations have built their positioning around deposition-optimized powders, engineered particle size distributions, and application-specific alloy formulations. Their commercial strategies differ in subtle but important ways, and understanding these differences is critical for procurement planning and technology partnership selection.
Höganäs AB, headquartered in Höganäs, Sweden, has established a recognized presence through its Surfit® family of cobalt-, nickel-, and iron-based overlay welding powders. These materials are designed for high-speed laser cladding deposition, making them particularly relevant for operations where throughput and consistency are prioritized alongside performance. The company's emphasis on deposition efficiency aligns with industrial users seeking to reduce processing time while maintaining coating integrity.
OC Oerlikon Management AG, through its Oerlikon Metco business in Wohlen, Switzerland, supplies MetcoClad™ and MetcoMed™ alloy powders and wires for laser cladding and plasma transferred arc applications. Its portfolio spans multiple alloy families and delivery formats, supporting both industrial repair and specialized coating requirements. The breadth of its offering positions it as a resource for organizations that require a range of material options within a single procurement relationship.
Welding Alloys, based in Redditch, United Kingdom, focuses on laser-cladding-specific cored wires and consumables intended for hardfacing and wear-resistant coatings. Its product design reflects a strong orientation toward durabilty in demanding service conditions, appealing to users in sectors where abrasive wear and surface degradation are primary failure modes.
Wall Colmonoy Corporation, located in Madison Heights, Michigan, USA, produces Colmonoy® nickel-based, Wallex® cobalt-based, and Colferoloy™ iron-based laser cladding powders with tailored particle size distributions. The attention to particle size engineering supports process control and deposition consistency, factors that matter greatly in qualified production environments and precision repair workflows.
American Cladding Technologies, operating in the United States, provides laser cladding materials and systems centered on industrial repair and coating applications. Its more integrated approach to materials and application support can be attractive to organizations seeking to streamline qualification and deployment across recurring maintenance programs.
Alabama Specialty Products, also based in the United States, supplies custom laser cladding powders and materials with a particular focus on aerospace and energy sector component refurbishment. Its specialization underscores the premium that high-compliance sectors place on tailored formulations, documentation, and application alignment.
Together, these participants illustrate the spectrum of commercial approaches in the market: from broad alloy portfolios and deposition-focused product design to custom-formulation expertise and application-integrated support. The presence of meaningful concentration among leading suppliers reinforces the importance of evaluating not only material performance but also technical service, qualification assistance, and supply continuity. Our report examines these competitive dynamics in greater depth, helping teams understand where differentiation is material to outcomes and where standardization may reduce complexity.
Strategic Implications for 2026 and Beyond
For executives planning across 2026 and the subsequent forecast period, several strategic themes emerge. First, the pace of adoption suggests that laser cladding materials will increasingly intersect with broader asset management and predictive maintenance agendas. Components that once moved directly to replacement may now be economically restored, altering the economics of spare parts, inventory, and downtime planning. Organizations that integrate material selection into their reliability strategies can capture cost and performance advantages that are difficult to retrofit later.
Second, the demand for consistent deposition quality is elevating the importance of particle size control, alloy homogeneity, and compatibility with specific laser parameters. As qualification standards tighten and production environments become more automated, the margin for variability narrows. Procurement teams should therefore treat supplier technical capability and process documentation as core evaluation criteria, not secondary considerations.
Third, regional and application-specific demand will continue to diverge. Some markets will expand through heavy industrial repair cycles and energy infrastructure maintenance, while others will grow through advanced manufacturing and performance-driven coating programs. A disciplined approach to market prioritization, supported by clear qualification pathways and service readiness, will separate organizations that capture demand from those that merely monitor it.
Fourth, the concentrated supplier environment calls for deliberate relationship strategies. Long-term collaboration with suppliers that offer reliable quality, responsive technical support, and transparent supply planning can reduce operational risk. At the same time, maintaining qualification flexibility across multiple material families and vendors can protect against disruptions and preserve negotiating balance.
Our full market research translates these themes into detailed projections, segment-level context, and a structured competitive assessment designed to support concrete decisions. The complete dataset, scenario frameworks, and supplier evaluation tools are available in the full report, where we expand on the intersections of material performance, application requirements, and regional demand intensity that shape the 2026 to 2032 outlook.
Obtaining the Full Intelligence Package
The laser cladding material market is entering a phase in which technical precision and commercial strategy are increasingly inseparable. Organizations that approach this landscape with a clear understanding of growth trajectories, material trade-offs, and competitive dynamics will be better positioned to optimize procurement, accelerate qualification cycles, and align R&D with high-value applications. This briefing provides the strategic outline; the complete research delivers the granular intelligence required to act with confidence. We invite strategy, procurement, and engineering leaders to explore the full report for the detailed analysis, extended forecasts, and practical evaluation tools that support informed decision-making throughout the forecast horizon.
For detailed analysis of this topic, please visit the official page: Laser Cladding Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mine Ventilation Market Hits $155M in 2025, 5.9% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperative: Navigating the Mine Ventilation Equipment Market Through 2032
The underground mining sector stands at a critical operational inflection point. As global demand for critical minerals accelerates and legacy infrastructure faces increasing regulatory scrutiny, the machinery that sustains underground airflow has evolved from a basic utility into a strategic asset class. PW Consulting’s latest Mine Ventilation Equipment Market research provides a comprehensive, data-driven blueprint for executives, operations directors, and capital allocation teams who must make high-stakes decisions in 2026 and beyond.
This insight brief outlines the macro trajectory, competitive architecture, and regulatory-economic currents shaping the sector. It is designed to demonstrate the analytical depth of our full study while highlighting exactly where targeted intelligence will separate proactive operators from reactive followers.
A Market Defined by Resilient Growth and Structural Complexity
Drawing on historical performance from 2020 through 2025 and extending a forward-looking trajectory through 2032, the market demonstrates a consistent upward arc. The sector moved from a base valuation in the early 2020s to an estimated 155.0 Million USD by 2025. Our baseline projection places the market at approximately 165.46 Million USD in 2026, with sustained expansion carrying it toward roughly 230.98 Million USD by the close of the forecast window. This trajectory reflects a compound annual growth rate of 5.9 percent, a figure that underscores the sector’s resilience against broader commodity cycles.
What makes this growth particularly noteworthy is not the headline number alone, but the underlying composition. The equipment base is heavily weighted toward core airflow generation technologies, while thermal management and auxiliary climate control solutions represent a meaningful secondary pillar. Demand distribution across mineral extraction domains reveals a pronounced reliance on coal mining operations, yet metal mining continues to contribute substantial volume as underground metallurgical projects scale. Regionally, the landscape is distinctly multi-polar, with no single geography holding outright dominance, which creates both sourcing flexibility and fragmented go-to-market challenges for global manufacturers.
For decision-makers, these structural patterns carry immediate implications. Capital planning cannot treat ventilation as a uniform procurement line item. Instead, it requires a segmented view that aligns equipment lifecycles with mine-specific operational horizons, regional supply chain realities, and the evolving cost of compliance. Our full report dissects these layers without exposing the granular breakdowns, preserving the analytical edge required to act decisively before competitors recalibrate.
Operational Content Designed for Execution, Not Just Observation
PW Consulting’s research methodology is built around actionable intelligence. Rather than stopping at macro forecasting, the study maps the operational terrain that procurement, engineering, and corporate strategy teams navigate daily. The report delivers a structured, multi-dimensional examination of the market, organized to support parallel workstreams.
- Technology and Product Architecture: A detailed evaluation of the equipment categories that constitute the market, including the performance trade-offs, installation constraints, and maintenance profiles that differentiate core airflow systems from climate regulation solutions.
- Application-Specific Demand Mapping: An exploration of how ventilation requirements diverge across extraction methodologies, with emphasis on the operational intensity, airflow volume targets, and safety specifications that drive procurement cycles in different mining environments.
- Regional Procurement and Deployment Patterns: A geographic assessment that examines supply chain maturity, local content expectations, logistical hurdles, and the varying pace of capital project execution across major mining corridors.
- Pricing, Input Costs, and Margin Architecture: Analysis of how raw material inputs—particularly steel and specialized polymers—interact with manufacturing complexity and after-sales service expectations to shape supplier pricing strategies and buyer negotiation leverage.
- Lifecycle and Total Cost of Ownership Modeling: Frameworks for comparing upfront equipment cost against long-term energy consumption, downtime risk, and retrofit requirements, enabling more accurate capital budgeting and lease-versus-buy evaluations.
Each section integrates primary market logic with observable industry behavior, allowing readers to benchmark internal assumptions against external realities. The report is structured to be referenced during budgeting cycles, vendor evaluations, and risk assessments, rather than read once and filed.
Competitive Architecture and Strategic Positioning
The vendor landscape reflects a blend of entrenched industrial manufacturers, specialized engineering firms, and regionally anchored innovators. Market concentration data indicates a moderately consolidated environment, with the leading trio of players accounting for a substantial share of revenue and the top five collectively representing a majority of market activity. This concentration does not imply static dominance; rather, it highlights the competitive intensity surrounding technology integration, service network coverage, and application-specific customization.
Mining Equipment Market
Several internationally recognized firms anchor the upper tier of the market. Howden, operating from the United Kingdom, continues to leverage deep industrial airflow heritage, with recent field deployments underscore its focus on optimization and site-specific engineering integration. Epiroc and Sandvik, both headquartered in Sweden, bring complementary underground equipment ecosystems that increasingly incorporate ventilation as part of broader mine productivity and safety agendas. TLT-Turbo, based in Germany, has reinforced its technical positioning through smart-controlled fan platforms designed for underground environments, aligning with broader industry moves toward connected equipment. Minetek, with its Australian operational base, has strengthened its product pipeline through the introduction of higher-efficiency fan series, reflecting a clear emphasis on performance gains and energy-conscious design.
Across the Americas, firms such as Twin City Fan & Blower, New York Blower Company, ABC Industries, Chicago Blower, and Hurley Ventilation maintain active roles in addressing regional demand, often competing on engineering responsiveness, component availability, and localized service capacity. In parallel, Australia-based specialists including Zitron and Clemcorp Australia contribute to the market through focused product development and regional project execution. Sibenergomash-BKZ extends the competitive field from Russia, adding geographic and supply chain complexity for operators managing cross-border procurement or evaluating alternative sourcing routes. Parag Fans & Cooling Systems, based in India, reflects the growing relevance of cost-competitive manufacturing and export-oriented capacity within the broader vendor ecosystem.
The recent timeline of product activity reinforces how competition is shifting from pure equipment supply toward performance optimization and digital integration. Howden’s May 2026 ventilation optimization installation for a major gold mining operation illustrates the growing premium on site-tuned airflow management. Minetek’s January 2025 launch of its high-efficiency Raptor Series—along with the simultaneous announcement of efficiency gains—demonstrates how manufacturers are competing on energy performance as a direct value proposition. TLT-Turbo’s January 2025 introduction of a smart fan concept for underground mining further signals that intelligent control, monitoring, and adaptive operation are becoming central differentiators.
For corporate strategy teams, this competitive map raises critical questions. Which vendors can reliably support multi-site deployments? Where do service networks and spare parts availability create long-term risk? Which technology roadmaps align with a mine’s automation trajectory and regulatory exposure? The full report evaluates these dynamics in greater depth, providing comparative context that helps buyers and investors avoid over-reliance on surface-level brand recognition.
Regulatory, Economic, and Operational Currents Reshaping Demand
Market growth does not occur in a vacuum. Several intersecting forces are redefining how ventilation equipment is specified, purchased, and maintained.
Safety Regulation as a Continuous Upgrade Driver
Regulatory frameworks are increasingly prescriptive about underground airflow, methane management, and system reliability. In the United States, MSHA 30 CFR Part 75 Subpart D establishes specific requirements for underground coal mine ventilation to ensure adequate airflow and safety, creating a compliance baseline that directly influences equipment selection and retrofit timing. Beyond individual jurisdictions, broader guidance such as the UNECE’s February 2025 direction on tackling methane emissions from coal mine ventilation systems highlights a global shift toward emissions-conscious ventilation design. These regulatory currents are not limited to compliance checklists; they actively push operators toward system upgrades that can satisfy both safety mandates and efficiency expectations.
Mine Ventilation Equipment Market
Energy Efficiency Mandates and Operational Cost Pressure
Stricter safety standards and energy efficiency mandates require upgrades to ventilation systems in underground mines, a reality that interacts directly with operating cost structures. Ventilation represents a significant share of underground energy consumption, and operators are increasingly scrutinizing fan performance, duct losses, and control logic as part of broader cost-reduction programs. As a result, procurement decisions are moving beyond initial capital cost toward lifecycle energy impact, maintenance intervals, and adaptability to changing mine geometries.
Automation, Labor Dynamics, and Digital Control Demand
Automation and labor shortages drive demand for advanced mine ventilation equipment with digital controls. As mining organizations confront skilled labor constraints and seek to reduce dependence on manual intervention, equipment that supports remote monitoring, automated airflow adjustment, and integrated diagnostics becomes operationally attractive. This trend reinforces the strategic relevance of intelligent fan systems, sensor-driven control architectures, and service models that can sustain performance without expanding onsite labor requirements.
Material Supply and Construction Realities
The physical basis of ventilation equipment remains rooted in durable construction materials. Steel and specialized polymers are primary raw materials for constructing durable mine ventilation fans and ducts, meaning that procurement planning must account for input availability, cost volatility, and lead-time variability. Equipment choices that appear favorable on performance grounds can be challenged by material sourcing constraints, especially when projects span multiple regions or require rapid deployment schedules.
Strategic Decisions That Define 2026 and the Forecast Horizon
The intersection of steady market expansion, concentrated vendor competition, and intensifying regulatory and operational pressures creates a clear strategic mandate: mining organizations must treat ventilation equipment planning as a forward-looking competency rather than a reactive procurement function. The years ahead will reward operators who can align technology selections with compliance trajectories, energy objectives, labor strategies, and project timelines.
Several decision points will be especially consequential:
- When to retrofit versus when to standardize: Operators must evaluate whether existing installations can be optimized through controls and component upgrades, or whether full system replacement offers better long-term alignment with safety and efficiency requirements.
- How to evaluate vendor roadmaps: Selection criteria increasingly include digital readiness, service coverage, parts availability, and the ability to support multi-site standardization without sacrificing site-specific performance.
- Where regional dynamics alter sourcing logic: Differences in supply chain maturity, local content expectations, and deployment pace mean that the optimal vendor or equipment configuration in one corridor may be suboptimal in another.
- How to quantify total cost of ownership under shifting input costs: Energy performance, maintenance burden, and material-driven pricing changes must be modeled together to avoid decisions that optimize only the purchase price.
These are not abstract considerations. They directly affect capital efficiency, operational continuity, and risk exposure across the forecast period. The challenge is that the necessary judgment depends on access to structured, current, and comparison-ready intelligence rather than fragmented market noise.
Access the Full Intelligence Framework
PW Consulting’s complete Mine Ventilation Equipment Market study provides the analytical foundation required to navigate these choices with confidence. The full report extends beyond the macro trajectory and competitive overview presented here, delivering the detailed segmentation logic, regional deployment context, vendor evaluation structure, and forward scenarios that executives need for 2026 planning and multi-year capital strategy.
The market’s direction is clear enough to warrant action, but the precise allocation of resources—by equipment category, application environment, regional pathway, and vendor relationship—requires the deeper breakdown contained in the complete study. For teams evaluating procurement strategy, vendor partnerships, expansion timing, or investment exposure, the full research package offers the level of specificity needed to convert market awareness into executable advantage.
Those seeking the complete dataset, comparative vendor context, and forward-looking scenario detail are encouraged to access the full report through the official PW Consulting market research portal. In a sector where compliance, energy, and operational continuity converge, timely access to structured intelligence is not simply an advantage—it is a prerequisite for sound strategic decisions.
For detailed analysis of this topic, please visit the official page: Mine Ventilation Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


