



PW Consulting: Hardness Testing Machine Market Hits $359.47 Million in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Precision: The 2026 Hardness Testing Machine Market Outlook
In the high-stakes environment of global manufacturing, material integrity is not merely a technical specification; it is the foundation of safety, reliability, and brand reputation. As we navigate through 2026, the Hardness Testing Machine Market stands at a critical inflection point. The transition from traditional manual methods to automated, AI-integrated systems is reshaping how industries validate material properties. For stakeholders, investors, and operational leaders, understanding the trajectory of this market is essential for capitalizing on emerging opportunities and mitigating supply chain risks.
This insight serves as a strategic overview of our comprehensive market research report, designed to equip decision-makers with the intelligence needed to navigate the forecast period of 2026-2032. By analyzing historical trends and projecting future growth, we uncover the underlying forces driving demand and the competitive maneuvers defining the landscape.
Market Trajectory and Growth Dynamics
The global demand for precision testing equipment has demonstrated remarkable resilience and expansion over the past half-decade. Reflecting on the historical performance from 2020 to 2025, the market has evolved from a base of approximately 302.17 million USD to a projected 359.47 million USD in 2025. This steady accumulation of value underscores the indispensability of hardness testing across critical sectors.
Looking ahead, the growth trajectory accelerates. The market is poised to reach 390.32 million USD in 2026, marking a significant step up in valuation. Our forecasts indicate that this momentum will sustain, with the market size expected to surpass the 500 million USD threshold by 2030, eventually reaching 554.71 million USD by 2032. This expansion is driven by an estimated Compound Annual Growth Rate (CAGR) of 6.5 percent throughout the forecast period.
Such growth is not uniform; it is concentrated in specific technological advancements and regional industrial hubs. However, the overarching narrative is one of consistent upscale movement. Companies that align their product development and supply chain strategies with this 6.5 percent growth curve will find themselves better positioned to capture market share as the total addressable market expands.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global giants and specialized regional players. Analysis of the concentration ratios reveals a fragmented yet competitive environment. The top three players hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This indicates that no single entity dominates the entire ecosystem, leaving ample room for strategic differentiation and niche targeting.
Key industry leaders are leveraging distinct technological advantages to secure their positions. Buehler, based in Illinois, continues to push the boundaries with Wilson Vickers, Knoop, and Rockwell hardness testers equipped with advanced optical systems and DiaMet software. Their focus on optical precision highlights a trend towards digitizing measurement outcomes. Similarly, ZwickRoell from Germany offers a comprehensive portfolio covering metals, ceramics, plastics, and rubber, emphasizing versatility across material types.
In the North American sector, LECO Corporation and Mitutoyo maintain strong footholds with specialized Rockwell hardness testers, catering to high-volume industrial requirements. Innovation is also evident among European and Asian manufacturers. INNOVATEST in the Netherlands and Struers in the UK provide broad hardness testing solutions, while Chinese manufacturers like Laizhou Huayin Testing Instrument and Beijing Time High Technology focus on Brinell testers and related equipment, often targeting cost-sensitive segments.
Further diversifying the landscape, EMCO-TEST from Austria and Tinius Olsen from the USA contribute with general hardness testers and indentation hardness systems respectively. AFFRI Inc in Italy distinguishes itself with automatic hardness testing machines supporting multiple scales, addressing the need for throughput efficiency. Qualitest, operating out of the United Arab Emirates, offers a vast range of over 100 models spanning Rockwell to Vickers and portable units, highlighting the demand for variety. Foundrax in the UK rounds out the key players with a focus on Brinell hardness testing equipment.
Technological Advancements and Industry Dynamics
The momentum in this sector is heavily influenced by technological integration and regulatory compliance. The industry is witnessing a shift where artificial intelligence begins to revolutionize hardness testing. Recent updates from ZwickRoell in August 2025 highlighted advancements in AI for precision, signaling a move towards smarter, self-calibrating systems that reduce human error.
Portability and on-site capability remain critical drivers. In April 2025, Cisam-Ernst showcased portable hardness testers, including the Computest Lite compact wireless Rockwell hardness tester, emphasizing the need for quick on-site measurements in field conditions. Furthermore, exhibitions such as SAMPE China in June 2026 saw Tinius Olsen showcasing indentation hardness systems and automation solutions, reinforcing the link between testing equipment and broader manufacturing automation trends.
Compliance with international standards acts as both a barrier to entry and a trust signal. ISO standards such as ISO 6506-2:2017 and ISO 6508 specify requirements for both fixed location and portable hardness testing machines. Additionally, ASTM E18-24 Standard Test Methods for Rockwell Hardness of Metallic Materials, published in October 2025, keeps the regulatory framework current. ISO/TC 164/SC 3 continues to standardize indentation testing methods including Brinell, Knoop, Leeb, Rockwell, and Vickers hardness. Adherence to ISO 6508-2:2017 for verification and calibration procedures on various scales ensures that equipment meets rigorous force repeatability and hysteresis requirements. Manufacturers who integrate these standards directly into their product design gain a competitive advantage in regulated industries like aerospace and automotive.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data points to several actionable insights. First, the growth rate suggests that investment in capacity expansion or R&D for automated testing solutions is timely. Second, the fragmented market concentration implies that partnership or acquisition strategies could yield significant consolidation benefits. Third, the emphasis on standards suggests that compliance certification should be viewed as a marketing asset rather than a mere regulatory hurdle.
However, navigating this landscape requires granular data that goes beyond top-line figures. Understanding the specific revenue contributions of different testing types, the nuanced demand patterns across applications, and the regional intensity of consumption is vital for precise strategic planning. Our full report delves into these specifics, providing a detailed segmentation analysis that breaks down the market by type, application, and region without revealing the sensitive data here.
Hardness Testing Machine Market
Hardness Testing Device Market
Conclusion and Call to Action
The Hardness Testing Machine Market is on a clear upward path, fueled by industrial automation, stricter quality standards, and technological innovation. The window to optimize supply chains and product portfolios according to these trends is open now. To fully leverage the 6.5 percent CAGR and the projected 554.71 million USD market size by 2032, stakeholders need access to the complete intelligence package.
We invite you to explore the full depth of our research. The complete report provides the missing pieces of the puzzle, including detailed segmentation splits by region, type, and application, along with comprehensive company profiles and risk analyses. Equip your organization with the precise data needed to make informed decisions in 2026 and beyond. Access the full market intelligence today to secure your strategic advantage.
For detailed analysis of this topic, please visit the official page: Hardness Testing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Traditional Whiteboard Market to Reach USD 284 Million by 2032 Amid 3% CAGR
By PW Consulting, 2026-09-16
Traditional Whiteboard Market 2026: Strategic Intelligence for the Modern Enterprise
In an era dominated by digital collaboration tools and cloud-based workflows, the physical act of writing, erasing, and visualizing ideas on a traditional whiteboard remains a cornerstone of organizational communication. The Traditional Whiteboard Market has demonstrated remarkable resilience, evolving through material innovations and shifting workplace dynamics while maintaining its foundational role in education, commercial offices, and healthcare environments. As we enter 2026, decision-makers across sectors face a critical need to understand how this legacy market is positioned for sustained growth, competitive pressures, and strategic procurement. This newly released market research provides a comprehensive, data-driven roadmap designed specifically to inform enterprise strategy, supply chain planning, and facility investment decisions for the 2026–2032 horizon.
Why 2026 Demands a Reassessment of Traditional Whiteboard Strategy
The market has navigated a period of consolidation and moderate expansion. Following a compound annual growth rate of approximately 3.0% through the forecast period, revenue trajectories reflect a market that is neither stagnant nor explosively disruptive, but rather steadily maturing with predictable demand cycles. Base-year valuations anchored in 2025 establish a clear benchmark, while historical performance from 2020 through 2025 reveals how supply chain adaptations, educational infrastructure investments, and corporate workspace reconfigurations have collectively shaped consumption patterns. Entering 2026, procurement leaders and strategic planners must look beyond unit-cost considerations and evaluate how material durability, installation flexibility, and end-user workflow integration will dictate long-term value.
Our research deliberately avoids superficial market summaries. Instead, it delivers a structured analytical framework that maps revenue evolution, identifies structural demand drivers, and highlights the operational realities that influence purchasing decisions. By focusing on the interplay between product longevity, environmental conditions, and user behavior, the study equips executives with the context needed to align capital allocation with actual utilization patterns rather than speculative trends.
Navigating a Contained but Competitive Landscape
One of the most defining characteristics of the Traditional Whiteboard Market is its relatively fragmented yet concentrated competitive structure. The top three players collectively command a modest share of total industry revenue, while the top five extend their influence only slightly further. This concentration profile signals a market where regional specialization, product differentiation, and service-level commitments often outweigh pure scale advantages. For enterprises evaluating supplier partnerships or assessing market entry risks, understanding this distribution is essential to constructing resilient sourcing strategies and avoiding overreliance on a narrow supplier base.
Our analysis examines how established manufacturers leverage geographic manufacturing footprints, warranty structures, and application-specific engineering to maintain market positioning. We explore how companies operating across multiple verticals balance standardized production with customized configurations, and how warranty commitments and material certifications influence procurement confidence in institutional settings. The research also maps how competitive intensity varies across product categories, revealing where pricing pressure is most acute and where value-based differentiation remains viable.
Product and Application Realities Shaping Procurement Decisions
Material Choices and End-User Expectations
The market continues to be defined by distinct material categories, each with clear performance trade-offs that directly influence adoption in specific environments. Glass-based surfaces have gained traction in settings where aesthetic finish and long-term write clarity are prioritized. Melamine-based boards remain widely deployed due to their cost efficiency and broad compatibility with standard mounting systems. Porcelain steel surfaces appeal to high-traffic institutional and healthcare environments where surface integrity, chemical resistance, and frequent cleaning cycles are operational necessities. Rather than treating these categories as interchangeable, our research evaluates how each aligns with real-world usage intensity, maintenance expectations, and total cost of ownership considerations.
White Board Market
Where Demand Actually Materializes
Demand is not uniformly distributed across end-use environments. Educational institutions continue to represent the largest consumption base, driven by classroom configuration cycles, replacement schedules, and the pedagogical value of spontaneous visual collaboration. Commercial office environments follow as a substantial secondary demand center, where meeting-room renewal programs, hybrid workspace designs, and collaborative zone planning sustain steady procurement activity. Healthcare settings, while smaller in absolute volume, present specialized requirements around surface hygiene, compliance with cleaning protocols, and durability under rigorous maintenance routines. Our report dissects how these application segments differ in purchasing cadence, specification criteria, and vendor evaluation processes, enabling planners to tailor sourcing approaches rather than applying one-size-fits-all procurement models.
Regional Dynamics and Supply Chain Considerations
Geographic demand patterns reflect broader economic activity, institutional investment cycles, and local manufacturing capabilities. North American markets exhibit strong institutional procurement stability and a mature commercial office refresh environment. European demand is shaped by educational budget frameworks, workplace regulation trends, and a growing emphasis on sustainable product specifications. Asia Pacific presents a distinct profile influenced by rapid educational infrastructure development, expanding corporate real estate portfolios, and localized manufacturing ecosystems. Latin American and Middle East/Africa markets, while smaller in aggregate scale, offer targeted opportunities tied to specific institutional modernization initiatives and regional distribution partnerships.
Our research integrates these regional realities into a cohesive operational view. We examine how supply routes, import dependencies, domestic manufacturing capacity, and local service networks influence delivery reliability and post-installation support. For enterprises managing multi-site deployments or evaluating cross-border procurement, these insights help reduce friction in forecasting, inventory planning, and vendor selection.
Competitive Profiles That Matter for Strategic Sourcing
The competitive field includes manufacturers with distinct positioning strategies, ranging from education-focused product lines to broad commercial and healthcare portfolios. Several players have built recognition around specialized surface treatments, magnetic functionality, frameless designs, and freestanding configurations tailored to specific user environments. Others emphasize custom fabrication, long-duration warranties, or region-specific distribution models that strengthen their relevance in institutional procurement cycles.
Our report profiles leading participants and examines how their product architectures, branding approaches, and manufacturing commitments translate into market relevance. We assess how companies differentiate through write performance, surface durability, mobility options, and presentation integration features, and how these attributes resonate with education administrators, office facility managers, and healthcare procurement teams. The analysis also considers how warranty structures and domestic production claims influence buyer confidence, particularly in environments where long service life and low maintenance burden are prioritized over initial acquisition cost.
Traditional Whiteboard Market
What the Report Delivers: Operational Intelligence, Not Just Market Sizing
This research is designed to support concrete decision-making across multiple organizational functions. It goes beyond headline figures to provide an actionable structure that procurement teams, strategy planners, and facility leaders can apply directly to planning processes.
- Historical performance context from 2020 through 2025, establishing a clear baseline for interpreting near-term revenue movement and demand stability
- Forward-looking projections through 2032 that map expected market progression under baseline conditions, helping organizations align capital planning with realistic growth expectations
- Material and application segmentation analysis that clarifies where specification differences matter most and how end-use environments drive purchasing behavior
- Competitive landscape mapping that identifies concentration patterns, differentiation pathways, and supplier evaluation criteria relevant to enterprise procurement
- Regional demand framing that supports multi-market planning without reducing complex local dynamics to oversimplified rankings
- Operational context drawn from manufacturing activity, supply responses, and end-user behavior trends that illuminate how the market functions in practice
The study is structured to help readers answer practical questions: Which product attributes justify premium specification in high-use environments? How do replacement cycles differ across education, office, and healthcare settings? What supplier characteristics should be weighted most heavily in multi-site procurement programs? By addressing these questions within a consistent analytical framework, the report enables more disciplined planning and reduces reliance on anecdotal procurement assumptions.
Using This Intelligence to Strengthen 2026 Decision-Making
Strategic value emerges when market data is connected to operational realities. In the Traditional Whiteboard Market, that connection is especially important because purchases are often distributed across departments, budget cycles, and facility teams. A classroom replacement program, a corporate office refresh initiative, or a healthcare wing renovation may all involve whiteboard procurement, but each operates under different specification priorities, approval pathways, and usage expectations.
Our research helps unify these perspectives by showing how demand patterns, product characteristics, and competitive dynamics intersect in practice. Procurement leaders can use the findings to benchmark sourcing criteria, evaluate supplier proposals against market-consistent specifications, and anticipate how replacement and expansion needs may evolve over the forecast period. Strategy and operations teams can incorporate the market trajectory into broader workplace planning, ensuring that physical collaboration infrastructure is treated as a deliberate component of organizational design rather than an incidental facility expense.
For organizations considering supplier diversification, regional sourcing adjustments, or specification standardization across sites, the report provides the context needed to weigh trade-offs with greater confidence. It also supports scenario thinking by clarifying which market segments are structurally larger, which material categories align with particular operating conditions, and how competitive concentration shapes negotiation leverage and supply continuity considerations.
Access the Full Market Intelligence
This overview is intended to demonstrate the scope, rigor, and strategic relevance of the full study. The complete Traditional Whiteboard Market research contains the detailed segmentation analysis, competitive profiling, regional demand mapping, and forecast structures that enterprise decision-makers require for 2026 planning and beyond. Core data tables, segment-level breakdowns, company-specific strategic assessments, and operational context are developed in full within the report to support procurement modeling, facility planning, and market positioning exercises.
To access the complete dataset and apply these insights directly to your organization's planning processes, visit the source page for the full report. The detailed intelligence inside is structured to be immediately useful for strategy reviews, budget forecasting, supplier evaluations, and multi-site operational planning throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Traditional Whiteboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CRO Market Projected to Reach USD 152.6 Billion by 2032, Growing at 8.85% CAGR
By PW Consulting, 2026-09-16
Navigating the CRO Landscape: Strategic Intelligence for 2026 Decision-Makers
The global pharmaceutical and biotechnology sectors are entering a period of profound transformation. As research and development pipelines grow more complex, biopharma sponsors are increasingly relying on Contract Research Organizations to manage clinical execution, regulatory navigation, and data-driven trial optimization. PW Consulting's latest CRO Market study delivers a comprehensive, forward-looking assessment of this ecosystem, providing executives with the analytical rigor required to make informed capital allocation, partnership, and operational decisions in 2026 and beyond.
This report is designed not as a static snapshot, but as a strategic navigation tool. It synthesizes historical performance across 2020 through 2025 with a detailed forecast horizon extending to 2032. By mapping growth trajectories, competitive pressures, and structural shifts in service delivery, the study equips leadership teams with the contextual intelligence needed to anticipate market movements rather than simply react to them.
Macro Market Trajectory: Growth Foundations and Forward Outlook
The CRO sector has demonstrated consistent expansion over the past half-decade, evolving from a supportive outsourcing function into a core strategic infrastructure for drug development. Historical data reveals a sector that has repeatedly absorbed volume increases, therapeutic complexity, and regulatory evolution while maintaining secular growth. From a baseline perspective anchored in 2025, the market has already crossed significant valuation thresholds, reflecting sustained sponsor demand for integrated development capabilities, specialized laboratory services, and accelerated trial delivery models.
Contract Research Organization (CRO) Market
Looking toward the forecast window of 2026 through 2032, the market is projected to continue its upward trajectory at a compound annual growth rate of 8.85 percent. This expansion is not uniform across all phases or segments; rather, it reflects selective acceleration in high-complexity areas, sustained demand for late-stage execution, and growing reliance on analytical and data-management services that reduce development risk. The forecast period captures a critical inflection point where operational efficiency, digital trial capabilities, and regulatory alignment become decisive competitive differentiators.
Revenue projections through 2032 illustrate a market that scales materially beyond current levels, reinforcing the strategic importance of early positioning. Organizations that understand where growth concentrates, which service lines command premium value, and how competitive dynamics shift over the forecast horizon will be better positioned to negotiate partnerships, structure internal capabilities, and capture margin resilience in an increasingly contested environment.
Core Dimensions of Market Composition
A clear understanding of how the CRO market is structured is essential for strategic planning. The study examines the industry through multiple analytical lenses, each illuminating a different facet of demand, competition, and value creation.
- By service model, the landscape spans clinical research execution, early phase development, laboratory and diagnostic support, and consulting-oriented engagement. Each category carries distinct operating economics, client retention dynamics, and scalability profiles that influence how sponsors select partners and how providers differentiate their offerings.
- By therapeutic focus, demand patterns reflect the scientific and regulatory demands of specific disease areas. Oncology, infectious disease programs, cardiovascular studies, and neurology and related indications each present unique trial design requirements, patient recruitment challenges, and data-generation expectations that shape service utilization and pricing dynamics.
- By geography, regional demand reflects variations in sponsor density, regulatory maturity, trial infrastructure, and cost structures. The study maps where development activity is concentrated, how execution capabilities are distributed, and what this implies for near-term capacity constraints and long-term market entry strategies.
These structural dimensions are examined not in isolation but in combination, allowing decision-makers to see how service demand, therapeutic complexity, and regional dynamics interact to create pockets of opportunity and pressure. Rather than presenting fragmented percentages in isolation, the report integrates these elements into a coherent view of where value is created and where competitive intensity is most acute.
Competitive Landscape: Concentration, Capabilities, and Strategic Positioning
The CRO market is characterized by a meaningful degree of concentration among established full-service and integrated providers, while simultaneously accommodating a diverse set of specialized and regionally focused operators. The study's competitive analysis evaluates how scale, scientific depth, data infrastructure, and therapeutic expertise influence market share, client relationships, and expansion pathways.
Market Concentration and Structural Implications
Concentration metrics indicate that a relatively small group of large providers commands a substantial share of aggregated industry revenue, reflecting the advantages of integrated service portfolios, global trial networks, and established sponsor relationships. At the same time, the remaining market is distributed across mid-tier and specialized firms that compete on speed, therapeutic specialization, regional access, or differentiated scientific capabilities. This dual structure matters for strategy: large providers often compete on breadth and risk-sharing, while smaller and mid-sized firms frequently win on agility, niche scientific expertise, and targeted regional execution.
Key Players and Strategic Profiles
The report profiles a broad set of organizations whose strategies define the current competitive environment. These include full-service clinical development organizations, integrated laboratory and imaging-enabled providers, firms combining trial execution with commercial launch support, and players with strong discovery-to-development or manufacturing-linked capabilities. The profiles assess operating models, service breadth, geographic reach, and the strategic logic behind recent moves in partnerships, acquisitions, and technology integration.
Among the firms analyzed are organizations headquartered across North America, Europe, and Asia-Pacific, reflecting the globalized nature of modern drug development. Their differing emphases illustrate the range of competitive approaches in the market: some prioritize end-to-end clinical delivery and analytics-driven trial management, others emphasize late-stage and government-sponsored research, while still others build value around integrated laboratory services, safety assessment, regulatory solutions, or combined development and manufacturing capabilities. Understanding these strategic orientations helps sponsors and investors evaluate fit, risk, and long-term positioning.
Recent Strategic Moves Shaping the Field
Competitive dynamics are also being reshaped by a series of notable developments that signal where the industry is placing its bets. In late 2025, one major full-service provider was recognized for excellence in clinical development, underscoring the continued premium on execution quality and sponsor trust. Around the same period, a leading laboratory and clinical services organization acquired a digital trial data and management platform for a substantial enterprise value, signaling the strategic importance of data infrastructure, decentralized trial capabilities, and technology-enabled operations.
In parallel, long-term clinical and commercial partnerships between major research organizations and platform technology providers have reinforced the trend toward deeper integration between trial execution and digital ecosystems. Collaborative initiatives involving artificial intelligence have also emerged, aimed at accelerating clinical development workflows, improving data quality, and reducing cycle times. Collectively, these moves highlight an industry in which technology, data, and partnership architecture are becoming as strategically important as traditional scientific and operational capabilities.
Market Dynamics: Technology, Regulation, and Operational Evolution
The CRO sector does not expand in a vacuum. Its trajectory is shaped by intersecting forces that influence how trials are designed, executed, and evaluated. Three dynamics are especially salient for 2026 planning.
Rare Disease CRO Service Market
Technology-Enabled Trial Execution
Digital tools, advanced data management, and AI-assisted workflows are increasingly central to clinical development. Sponsors are seeking partners that can integrate real-world evidence, analytics-driven trial management, and streamlined data capture into the development process. This shift is changing evaluation criteria for service providers, with capability in data integration, operational visibility, and adaptive trial support becoming key differentiators. The market study examines how these technology-oriented demands are influencing service mix, investment priorities, and competitive advantage.
Regulatory Standards and Evaluation Frameworks
Regulatory expectations and consensus standards continue to shape development strategies, particularly for organizations navigating early feasibility, device-related evaluations, and complex clinical assessments. Standards-developing bodies and consensus-standards adoption processes play a pivotal role in defining the quality, risk management, preclinical, and clinical evaluation expectations that sponsors and service providers must meet. Familiarity with these frameworks significantly influences regulatory strategy, especially in early-stage programs where alignment with recognized standards can reduce uncertainty and accelerate progression.
The report contextualizes these regulatory dynamics without treating them as isolated compliance issues. Instead, it frames them as structural drivers of demand for specialized expertise, quality systems, and regulatory-aware trial design. For CROs and sponsors alike, the ability to operate confidently within evolving standards environments is becoming a core strategic capability rather than a back-office function.
Service Integration and Value-Chain Positioning
A broader trend toward integration is evident across the market. Sponsors increasingly prefer partners that can connect clinical execution, laboratory support, imaging, data management, and regulatory consulting within a coherent delivery model. This preference is pushing providers to expand their value-chain footprint, whether through organic build-out, targeted acquisitions, or strategic alliances. The study analyzes how integration affects pricing power, client retention, operational risk, and the ability to support complex programs from early development through later-stage execution.
What the Study Delivers: Operational Content for Decision-Makers
This CRO Market study is built for practical use. Beyond high-level market sizing and growth trajectories, it provides decision-makers with structured analysis that can be applied directly to strategy, sourcing, investment, and competitive planning.
- A forecast-backed view of market evolution from 2026 through 2032, anchored in historical performance from 2020 to 2025, enabling scenario-aware planning rather than single-point estimates.
- Segment-level analysis across service categories, therapeutic areas, and geographic demand patterns, integrated to reveal where growth is most durable and where competitive intensity is rising.
- Detailed competitive profiling of leading and emerging providers, with attention to operating models, capabilities, and the strategic rationale behind recent partnerships, acquisitions, and technology initiatives.
- Assessment of the structural forces shaping the market, including digital trial infrastructure, regulatory-standard alignment, and value-chain integration, framed in terms of their implications for sourcing strategy and long-term positioning.
- Contextual intelligence on the operating environment, including the role of consensus standards and regulatory-review practices in influencing clinical evaluation pathways and early feasibility strategies.
Each section is designed to support concrete decisions: which partners align with a given development strategy, where capacity and expertise are likely to tighten, how service mix may shift as programs become more complex, and which competitive moves are likely to reshape sourcing options over the forecast period.
Strategic Implications for 2026 and Beyond
For executives planning in 2026, the central takeaway is that the CRO market is growing, but growth alone does not guarantee advantage. The real strategic question is how to align internal development ambitions with an external service environment that is becoming more concentrated at the top, more differentiated in the middle, and more technology-dependent across the board.
Organizations that approach CRO engagement strategically, rather than transactionally, will be best placed to manage risk and accelerate delivery. That means evaluating partners not only on cost and timeline, but also on data infrastructure, regulatory fluency, therapeutic depth, and the ability to support integrated development pathways. It also means recognizing that recent industry moves around digital trial capabilities, AI-enabled workflows, and major platform acquisitions are not isolated headlines; they are indicators of where competitive advantage is being built.
Likewise, sponsors and investors should pay close attention to concentration trends and the strategic behavior of leading providers. A market in which a limited number of large firms command a substantial share of revenue will reward early relationship-building, clear capability requirements, and disciplined evaluation of long-term partnership options. At the same time, specialized and regionally oriented providers will continue to offer important alternatives for programs that demand focused expertise or specific geographic access.
Conclusion: From Market Intelligence to Actionable Strategy
The CRO sector is entering a phase in which scale, scientific capability, technological integration, and regulatory alignment converge to define competitive success. PW Consulting's CRO Market study provides the analytical foundation needed to navigate that convergence with confidence. By combining historical context, forecast-driven perspective, and competitive intelligence into a single strategic framework, the report helps executives move from awareness to action.
The full study contains the detailed segmentation analysis, company-specific evaluation, and forward-looking market logic required to translate these insights into concrete decisions for 2026 planning and beyond. For teams seeking a deeper, data-rich view of where the market is headed and how to position accordingly, the complete report offers the comprehensive intelligence necessary to support informed, strategically aligned action.
For detailed analysis of this topic, please visit the official page: Contract Research Organization (CRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Next Wave: Strategic Intelligence for the Billet Casters Market Through 2032
The global billet casters market is entering a decisive phase of evolution. As steelmakers and aluminum producers balance capacity expansion with the imperative for higher metallurgical quality, the equipment that transforms molten metal into usable billets has become a critical leverage point in the value chain. PW Consulting's latest in-depth market research on the Billet Casters Market is designed to give executives, investors, and technology strategists the clarity required to navigate this landscape through 2032. This article previews the strategic architecture of the study, outlining how its data-driven framework, competitive mapping, and operational cost intelligence can be translated into actionable decisions in 2026 and beyond.
Why 2026 Demands a Reset in Equipment Strategy
Over the past half-decade, the market has transitioned from a post-pandemic recovery posture to a structurally recalibrated growth trajectory. Historical performance from 2020 through 2025 reveals a market that weathered supply chain disruptions, shifting demand cycles, and capital expenditure hesitancy, yet sustained a clear upward path. Building on that foundation, the forecast window extending to 2032 projects a compound annual growth rate of 5.5 percent, measured in USD millions. This trajectory is not merely a top-line exercise; it reflects the cumulative effect of modernizing legacy casting lines, integrating high-speed continuous casting machines, and addressing the rising demand for precision-defined billets in advanced steel grades and non-ferrous applications.
For decision-makers evaluating capital allocation in 2026, the strategic question is no longer whether the market is expanding, but where the margin for competitive advantage lies. Upgrading a single casting strand, selecting between vertical and horizontal configurations, or incorporating electromagnetic stirring and dynamic secondary cooling can reshape throughput, energy consumption, and scrap rates over the life of a plant. The research underlines that these are not isolated equipment purchases; they are strategic bets on future metallurgical performance, operational resilience, and total cost of ownership. A nuanced reading of market momentum, paired with granular technology and cost benchmarks, helps executives prioritize investments that compound value rather than simply adding capacity.
What the Research Delivers: Content Built for Execution
This study is structured to move beyond descriptive market size and into the operational and commercial territory that influences real budgets and timelines. It opens with a rigorous reconstruction of historical demand through 2025, establishing a defensible baseline against which the 2032 outlook can be stress-tested. From there, the analysis extends into forward-looking scenarios that account for plant modernization cycles, regional capacity additions, and the interplay between product type adoption and end-use requirements.
The report also dissects the economics that shape purchasing decisions. Equipment valuation is influenced not only by the caster itself but by the surrounding ecosystem of design, fabrication, integration, and commissioning. Precision machining, welding, and hydraulic system integration represent a significant share of project value, while research and development together with certification activities add further layers of cost and risk. High-grade alloy steels, refractory materials, and copper for mold tubes and specialized components account for a substantial portion of the total caster cost. On the infrastructure side, greenfield installations encompassing civil engineering and ancillary equipment can reach or exceed fifty million dollars. These cost structures matter because they determine the financial logic behind renovation versus replacement, and because they vary meaningfully across segments, geographies, and machine specifications.
Beyond costs, the study connects technical choices to regulatory and standards-driven realities. Billet casters operating in today's environment must satisfy metallurgical industry standards and safety certifications, particularly when processing high-alloy grades and ultra-large sections approaching diameters of 1000 mm. The research translates these compliance requirements into procurement implications, illustrating how specification rigor, testing protocols, and documentation expectations influence vendor selection, project timelines, and long-term service obligations.
Casters Market
Competitive Landscape and Recent Moves That Matter
The market exhibits a consolidated structure, with the top three participants collectively holding a substantial share and the top five extending that footprint further. This concentration creates a landscape where technology leadership, service networks, and localized execution capabilities are often as important as headline pricing. The research profiles the core companies shaping this environment, examining their engineering philosophies, product families, and go-to-market positioning.
Among the leaders, SMS group GmbH continues to advance its Concast division's custom billet caster offerings, spanning vertical and curved designs with strand configurations from one to ten and casting speeds up to seven meters per minute. Danieli & C. Officine Meccaniche S.p.A. positions its Q-CAST billet casters with POWER MOULD and HY-POWER oscillation systems as a route to higher productivity and billet and bloom quality across varied steel market requirements. Primetals Technologies Limited, through its wholly owned subsidiary Concast India Private Ltd., emphasizes modular casters for mini-mills with a focus on square and rectangular sections and high-speed rebar integration, while Electrotherm E&T Ltd. addresses smaller heat sizes down to five tons with compact, modular designs suited to existing ingot-to-billet conversion scenarios. Concast India Private Ltd. extends this modular logic with five- to seven-strand configurations tailored for steel billet production in mini-mill environments.
What distinguishes the current period is the cadence of live project activity. In October 2025, Danieli & C. Officine Meccaniche S.p.A. secured a contract for a new three-strand continuous casting machine designed to produce ultra-large high-alloy round billets up to 1000 mm in diameter, including specialized grades such as P91 and P92. In January 2026, SMS group GmbH was awarded a modernization contract for an eight-strand continuous caster at a second plant location, with Dynamic Mechanical Soft Reduction intended to improve billet inner quality. Earlier in July 2025, Concast India Private Ltd. received an order for a new billet caster handling 100- to 200-mm square sections, integrated with a high-speed rebar outlet. In April 2025, Danieli's service team completed an upgrade of a six-strand billet caster in Italy, reinforcing the recurring value of modernization alongside new capacity.
These developments are not isolated headlines; they are signals. They reveal where premium specifications are being demanded, how service-led upgrade cycles are being monetized, and why integration with downstream outlet configurations is increasingly part of the value proposition. The study maps these patterns to competitive behavior, highlighting where incumbents defend share through advanced casting technologies and where challengers compete on modularity, footprint, and integration with smaller melt shops.
Dynamics Shaping Investment Logic in 2026
Several intersecting dynamics will determine how aggressively capital is deployed and how equipment specifications are negotiated. Energy efficiency has emerged as a decisive differentiator for high-end multi-strand machines. Advanced casters equipped with electromagnetic stirring, dynamic secondary cooling, and heightened automation command a premium price range between 15 million and 45 million dollars per machine. The business case for such specifications depends on the balance between throughput gains, metallurgical consistency, and operating cost reduction over the machine's service life.
At the same time, total project economics must account for more than the equipment invoice. Greenfield installations require civil engineering, utilities interfaces, and ancillary equipment, pushing aggregate spend to fifty million dollars or more in certain configurations. For organizations operating in brownfield contexts, the calculus shifts toward footprint compatibility, retrofit complexity, and the ability to sustain production continuity during installation and commissioning. The research helps decision-makers compare these pathways using consistent cost and capability benchmarks rather than ad hoc quotations.
Billet Casters Market
Another important dynamic is the tightening relationship between product specifications and downstream performance. As producers target higher-alloy steels and increasingly demanding non-ferrous billets, the tolerance for internal defects, centerline segregation, and surface quality issues narrows. This raises the strategic importance of casting speed control, mold design, oscillation systems, and cooling precision. The report connects these technical levers to segment-level demand signals and to the competitive responses of equipment suppliers, enabling procurement teams to evaluate proposals against a clearer standard of operational readiness.
Strategic Applications for 2026 Decision-Making
This research is intended to be used, not merely read. For capital planning teams, it provides a structured basis to align budget cycles with realistic equipment lead times, installation complexity, and the cost architecture of competing solutions. For technology and procurement leaders, it offers a way to benchmark vendor claims on oscillation systems, mold technology, strand configuration, and downstream integration against the broader market's observed direction. For strategy and corporate development functions, the study clarifies where concentration creates bargaining power and where niche configurations can serve as differentiators in specialized applications.
- Prioritize investment pathways that balance immediate capacity needs with long-term quality and energy performance, using the forecast period to test multiple upgrade and expansion scenarios.
- Evaluate proposals against consistent cost and specification baselines that include machining, welding, hydraulic integration, R&D, certification, and ancillary infrastructure rather than comparing machine prices in isolation.
- Align procurement with regulatory and standards expectations for high-alloy grades and ultra-large sections, ensuring that compliance requirements are factored into vendor selection and project scheduling.
- Use competitive intelligence to anticipate where incumbents will defend share through advanced casting technologies and where modular, smaller-footprint solutions can open opportunities in mini-mills and conversion projects.
- Incorporate recent project activity into scenario planning, recognizing that large-diameter high-alloy billets and dynamic soft reduction upgrades reflect shifting performance priorities that may influence future specification trends.
Where to Focus Next
The full scope of this research extends into more detailed comparative frameworks, scenario analyses, and operational benchmarks that are essential for precise budgeting and vendor evaluation. Because competitive dynamics, cost structures, and specification trends vary meaningfully across segments and project types, the most valuable intelligence resides in the granular layers of the study rather than in the headline totals alone. Readers seeking to translate market momentum into concrete capital decisions will find the complete report most useful when paired with internal plant data, project timelines, and specification roadmaps.
The market for billet casters is no longer defined by volume growth alone. It is being reshaped by quality demands, energy economics, compliance rigor, and the pace of technological differentiation among leading suppliers. PW Consulting's Billet Casters Market research is built to help organizations read these signals correctly and act on them with confidence. For executives preparing 2026 decisions and beyond, the study offers a disciplined way to connect market direction to equipment strategy, cost logic, and competitive positioning. The next step is to examine the detailed intelligence that underpins this outlook and to apply it within the specific constraints and ambitions of each organization's operating environment.
For detailed analysis of this topic, please visit the official page: Billet Casters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Server Cabinet Market Hits $330M in 2025, Projected 9.1% CAGR to 2032
By PW Consulting, 2026-09-16
The Strategic Imperative of Server Cabinet Infrastructure in the Age of AI
The modern data center is no longer merely a repository for digital information; it is the physical substrate of artificial intelligence. As computational workloads shift from general-purpose processing to high-density GPU clusters and AI training environments, the foundational infrastructure that houses these assets—the server cabinet—has emerged as a critical strategic component. For enterprise decision-makers, IT architects, and supply chain leaders, understanding the nuanced dynamics of the server cabinet market is no longer optional. It is a prerequisite for operational resilience, cost efficiency, and technological competitiveness.
PW Consulting's latest in-depth research on the Server Cabinet Market offers a comprehensive lens into this evolving landscape. This article serves as a strategic overview of the market's trajectory, highlighting the macroeconomic forces, competitive pressures, and technological shifts that define the sector. It is designed to contextualize the findings of our full report, providing executives with the necessary framework to appreciate the depth of intelligence available in the complete study.
The transition from traditional enterprise computing to AI-driven hyperscale environments has fundamentally altered the requirements for rack and cabinet systems. Power density, thermal management, and modularity are no longer secondary considerations; they are primary drivers of procurement strategy. As organizations plan their infrastructure roadmaps through 2032, the ability to anticipate market shifts, understand competitor moves, and evaluate regional supply dynamics will separate industry leaders from followers.
This analysis draws upon extensive historical data and forward-looking projections to map the growth trajectory of the sector. By examining the interplay between semiconductor value chains, raw material volatility, and the escalating demands of high-performance computing, we uncover the underlying currents shaping the market. The following sections detail the market size evolution, the competitive architecture among key players, and the dynamic forces driving demand.
Market Size and Growth Trajectory: A Decade of Expansion
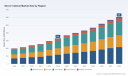
The server cabinet market has demonstrated consistent and robust growth over the past five years, reflecting the broader expansion of global data center capacity. Historical data from 2020 through 2025 reveals a steady upward trend, with the market expanding from approximately 200.0 million USD in 2020 to 330.0 million USD in 2025. This growth underscores the increasing reliance on structured physical infrastructure to support digital transformation initiatives across industries.
Looking ahead, the forecast period from 2026 to 2032 indicates continued acceleration. The market is projected to reach 368.91 million USD in 2026, with growth compounding annually at a CAGR of 9.1 percent. By the end of the forecast horizon in 2032, the market is expected to attain a revenue scale of 606.0 million USD. This trajectory suggests that demand for server cabinet solutions will remain resilient, driven by the proliferation of data-intensive applications and the ongoing construction of new data center facilities.
It is important to note that while the server cabinet market is a distinct segment, it operates within a broader enclosures ecosystem that has also shown significant expansion. Independent industry data points to the wider server rack cabinet enclosures market growing from 3.07 billion USD in 2025 to 3.37 billion USD in 2026, reflecting a CAGR of 9.93 percent. This broader context reinforces the notion that physical infrastructure investment is scaling in tandem with computational demands, validating the strategic importance of focused market intelligence.
For stakeholders, these figures are not merely statistics; they represent planning parameters. Capital expenditure budgets, procurement cycles, and capacity planning must all align with this growth rhythm. The consistency of the CAGR suggests that the market is maturing but still possesses ample room for expansion, particularly as new technological paradigms emerge.
Competitive Landscape: Dominance and Differentiation
The server cabinet market is characterized by a concentrated competitive structure, with a small group of established players commanding a significant share of the revenue pool. Market concentration data indicates that the top three companies account for 70.0 percent of the market, while the top five firms collectively hold 85.0 percent. This level of consolidation implies that incumbents possess substantial resources, established distribution networks, and deep technical expertise, creating high barriers to entry for new competitors.
Among the leading entities, several companies have distinguished themselves through specialized offerings tailored to the evolving needs of modern data centers. Vertiv Group Corp., headquartered in Ohio, USA, has positioned itself at the forefront of the AI infrastructure wave. The company focuses on integrated power and cooling solutions paired with modular high-density rack enclosures specifically engineered for AI and GPU workloads. Their recent product launches highlight a commitment to supporting power densities exceeding 50kW per rack, incorporating advanced thermal management and liquid cooling compatibility.
Eaton Corporation plc, based in Ireland, brings a different strength to the market. Their offering emphasizes advanced power management and reliability-focused server rack and cabinet systems. In an environment where uptime and energy efficiency are paramount, Eaton's approach appeals to enterprises seeking robust, mission-critical infrastructure. Meanwhile, Rittal GmbH & Co. KG, a German manufacturer, provides flexible modular racks and enclosures tailored to diverse deployment needs, offering adaptability for organizations with varied spatial and operational constraints.
Schneider Electric SE, headquartered in France, continues to be a major force with its NetShelter rack solutions, which integrate power, cooling, and monitoring capabilities into unified systems. This holistic approach simplifies management and reduces integration friction for large-scale deployments. On the North American front, L-com, based in Massachusetts, has focused on high-density networking equipment with 42U server rack cabinets available in multiple depth options. Their recent launch of new black and white variants with three depth configurations demonstrates responsiveness to specific networking density requirements.
Other notable players contribute specialized expertise to the ecosystem. Chatsworth Products, Inc., located in California, offers the ZetaFrame Cabinet System designed for high-density deployments and AI/HPC environments. AMCO Enclosures, in Illinois, provides custom electronic racks, cabinets, and shielded enclosures, catering to niche requirements that standard products may not address. Longhorn Reels, based in Texas, has gained attention for precision-engineered custom server rack systems for AI data centers, and recently expanded its manufacturing capabilities in early 2026 to meet the surging demands of AI data centers and chip manufacturing facilities. Martin Enclosures, in New Hampshire, emphasizes high-performance server racks and cabinets built in the USA, while RackSolutions offers high-quality racks and cabinets for data center and enterprise use across the country.
These companies are not merely competing on price; they are competing on technological capability, supply chain reliability, and alignment with the specific demands of next-generation computing. Recent developments illustrate this dynamic. Vertiv's October 2025 product launch addressed the need for high-density enclosures supporting over 50kW per rack with liquid cooling compatibility. L-com's January 2025 launch focused on depth options for high-density networking. Longhorn Reels' February 2026 expansion signaled the industry's response to the growing needs of AI and chip manufacturing.
Market Dynamics and Structural Shifts
The server cabinet market is being reshaped by a confluence of macro trends, regulatory influences, and material realities. Understanding these dynamics is essential for anticipating future demand patterns and supply chain risks.
Server Chassis Market
A primary driver is the rise of AI and high-density GPU deployments. Traditional server cabinets were designed for relatively modest power densities, but modern AI workloads require systems capable of handling extreme thermal loads and power delivery. The industry is increasingly demanding modular, high-power server cabinet systems exceeding 50kW per rack. This shift is not incremental; it represents a fundamental redesign of physical infrastructure. Cabinets must now accommodate advanced cooling solutions, including liquid cooling compatibility, and support the structural and electrical requirements of GPU-accelerated servers.
The semiconductor industry's role in this ecosystem cannot be overstated. According to a recent report from the Semiconductor Industry Association, semiconductors account for 95 percent of an AI Data Server Rack's value. This statistic highlights the deep interdependence between cabinet infrastructure and the broader semiconductor supply chain. As semiconductor availability, pricing, and technological advancements fluctuate, they directly influence the value proposition and design priorities of server cabinets. Procurement strategies must account for this linkage, as disruptions in chip manufacturing or supply can cascade into delays and cost pressures for cabinet deployments.
Raw material costs also play a critical role in shaping market dynamics. Server cabinet manufacturing relies on steel, aluminum, and advanced components, all of which are subject to price volatility. Company filings and sector analysis from 2025 indicate that rising material costs are tied to semiconductor supply chain volatility and broader macroeconomic factors. For manufacturers, managing input costs while maintaining competitive pricing requires sophisticated supply chain management and potentially hedging strategies. For buyers, understanding these cost drivers can inform negotiation tactics and long-term contracting decisions.
Regulatory and vertical-specific demands are adding another layer of complexity. Government and defense verticals are driving requirements for modular, scalable rack solutions that support secure, high-density computing environments. These sectors often impose stringent security, durability, and compliance standards, creating specialized demand pockets that reward manufacturers with the capability to deliver customized, certified solutions. As public sector investments in secure computing infrastructure grow, these requirements will increasingly influence overall market composition.
Segmentation Insights and Strategic Considerations
While the full report provides an exhaustive breakdown of market segmentation, certain high-level structures warrant attention for strategic planning. The market is analyzed across multiple dimensions, including regional distribution, product type, and application vertical. Each of these axes reveals important patterns regarding demand concentration, growth potential, and competitive positioning.
Geographically, the market exhibits distinct regional characteristics. Historical and projected data suggest that North America, Europe, and Asia Pacific represent significant revenue pools, with Latin America and the Middle East and Africa contributing additional, albeit smaller, shares. Regional dynamics are influenced by the location of hyperscale data center campuses, enterprise IT spending patterns, and local manufacturing or supply chain capabilities. Decision-makers operating across multiple regions must navigate differences in regulatory environments, logistics infrastructure, and competitive intensity. The complete report offers detailed regional analysis to support localization strategies and market entry evaluations.
In terms of product type, the market is segmented between open frame racks and enclosed cabinets. Enclosed cabinets typically command a larger share of the revenue, reflecting the growing need for security, thermal control, and organized cable management in modern facilities. Open frame racks remain relevant for specific use cases where airflow and accessibility are prioritized over enclosure. The balance between these types is shifting as deployment environments become more complex and space-constrained. Understanding the relative demand for each type helps inform product portfolio decisions and procurement specifications.
Server Cabinet Market
Application segmentation further illuminates where demand is originating. Hyperscale data centers, enterprise data centers, and colocation facilities each present unique requirements. Hyperscale operators prioritize scale, efficiency, and integration with advanced cooling and power systems. Enterprise data centers often balance performance with flexibility and existing infrastructure compatibility. Colocation providers must meet the diverse needs of multiple tenants while maintaining operational efficiency. The interplay among these application segments influences product design, service offerings, and pricing models. The full study delves into these application-level nuances, providing actionable guidance for targeting specific customer profiles.
Value of the Full Research for 2026 Decision-Making
As enterprises finalize their 2026 strategies and look toward the remainder of the decade, the Server Cabinet Market research from PW Consulting provides a critical decision-support tool. The insights contained in the full report go beyond high-level market sizing to offer granular, actionable intelligence that can inform procurement, product development, investment, and competitive positioning.
For procurement and operations leaders, the report delivers detailed segmentation data, including regional revenue splits, type-based market shares, and application-specific demand patterns. These figures enable precise demand forecasting, inventory planning, and supplier evaluation. By understanding which regions and applications are expanding most rapidly, organizations can align their sourcing strategies and prioritize high-growth opportunities.
For product managers and engineering teams, the competitive profiles and recent development tracking offer a window into the innovation landscape. Understanding the specific capabilities that competitors are bringing to market—such as high-density enclosures, liquid cooling compatibility, modular flexibility, and custom engineering—helps identify gaps and differentiation opportunities. The report's analysis of product launches, expansions, and strategic moves allows teams to benchmark their own roadmaps against industry trends.
For executives and investors, the market concentration data and macro dynamics provide context for assessing industry structure and risk. The high concentration among top players suggests that scale, brand, and technological leadership are valuable assets. At the same time, the presence of specialized manufacturers serving niche requirements indicates that targeted innovation can carve out sustainable positions. The integration of raw material cost dynamics, semiconductor value chain linkages, and regulatory drivers equips decision-makers with a holistic view of the forces that will shape profitability and growth.
The complete report also addresses the practical aspects of data interpretation, offering frameworks for translating market intelligence into strategy. Whether the goal is to evaluate market entry, assess competitor threats, optimize supply chain resilience, or align capital allocation with demand forecasts, the research provides the foundational data and analysis needed to act with confidence.
Conclusion: Navigating Infrastructure Transformation
The server cabinet market stands at the intersection of physical infrastructure and digital ambition. As AI workloads intensify, data centers expand, and computational demands push the boundaries of power and thermal management, the cabinet that houses the equipment is no longer a passive enclosure. It is an active enabler of performance, efficiency, and reliability.
The growth trajectory projected through 2032 reflects the sustained importance of this infrastructure layer. With a CAGR of 9.1 percent and a market scale extending beyond 600 million USD by the end of the forecast period, the sector offers both opportunity and complexity. Navigating this environment requires more than intuition; it demands rigorous, up-to-date market intelligence.
PW Consulting's comprehensive Server Cabinet Market research is designed to meet that need. By combining historical analysis, forward-looking projections, competitive profiling, and dynamic context, the report equips stakeholders with the insights required to make informed, strategic decisions. The full study reveals the detailed segmentation, regional breakdowns, and application-specific data that underpin the market's evolution, providing the depth necessary for precise planning.
For leaders who recognize that the future of computing is inseparable from the quality of its physical foundation, this research offers a clear path forward. Access the complete report to unlock the full spectrum of data, analysis, and strategic recommendations that will drive your organization's success in the years ahead.
For detailed analysis of this topic, please visit the official page: Server Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MOSFET & IGBT Gate Drivers Market Hits $174M in 2025, Expected 6% CAGR by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: MOSFET & IGBT Gate Drivers Market 2026-2032
In the rapidly evolving landscape of power electronics, the gate driver acts as the critical intermediary between control logic and high-power switching components. As industries pivot toward electrification, automation, and renewable energy integration, the demand for robust, efficient, and isolated gate driver solutions has become a cornerstone of systemic reliability. PW Consulting presents its latest comprehensive analysis: the MOSFET & IGBT Gate Drivers Market report. This document serves as a strategic compass for stakeholders navigating the complex dynamics of the 2026 landscape and beyond. By leveraging extensive primary and secondary research, this study provides a granular understanding of market trajectories, competitive maneuvers, and technological shifts that will define the next half-decade.
Market Trajectory and Growth Dynamics
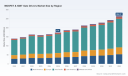
The global market for MOSFET and IGBT gate drivers has demonstrated resilience and steady expansion over the past five years. Historical data from 2020 to 2025 reveals a market that has successfully navigated supply chain volatility and shifting demand patterns. Starting from a revenue base of approximately 140.0 million USD in 2020, the sector climbed to 174.0 million USD by 2025. This trajectory underscores the increasing reliance on power semiconductor interfaces in modern infrastructure. Looking forward, the forecast period from 2026 to 2032 projects a continued upward trend. The market is expected to reach 186.56 million USD in 2026 and accelerate toward 264.27 million USD by 2032.
Compound Annual Growth Rate
The report identifies a steady Compound Annual Growth Rate (CAGR) of approximately 6.0 percent throughout the forecast period. This growth is not merely a function of volume but is driven by value addition through advanced features such as integrated protection, higher output currents, and compatibility with wide-bandgap semiconductors. For enterprise strategists, this CAGR signifies a maturing market where differentiation is key. The incremental growth suggests that while the core industrial base remains stable, new applications in electric vehicles and renewable energy are providing the necessary uplift to sustain momentum. Understanding the velocity of this growth is essential for capacity planning and R&D investment decisions.
Technological Segmentation and Critical Insights
The market is structurally divided into distinct categories based on isolation technology, device type, and application verticals. Our analysis delves deep into how these segments interact with current technological trends. Isolated gate drivers continue to hold a significant portion of the market share, driven by safety requirements in high-voltage environments. However, non-isolated drivers remain vital for cost-sensitive and low-voltage applications. The report explores the trade-offs between capacitive coupling isolation and traditional photocoupler methods, highlighting how recent product launches are reshaping performance benchmarks.
Application Drivers
End-use applications are the primary engines of demand. Industrial automation and motor drives represent a substantial pillar of consumption, where precise control and reliability are non-negotiable. Simultaneously, the renewable energy sector and electric vehicle powertrains are exerting increasing pressure on the supply chain for high-performance driver ICs. The interplay between these sectors creates a complex web of demand signals. For instance, the push for silicon carbide (SiC) and gallium nitride (GaN) devices requires gate drivers capable of handling higher switching frequencies and voltages. Our report dissects these requirements to help clients identify which application verticals offer the highest return on investment for specific product portfolios.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration level, with the top three players accounting for roughly 24.6 percent of the market and the top five holding approximately 31.2 percent. This fragmentation indicates ample opportunity for both incumbent giants and specialized niche players to capture value. The competitive environment is intense, with major semiconductor firms constantly launching new families of drivers to address evolving standards.
Key Industry Players
Our report provides detailed profiles of leading companies that are defining the standards of the industry. Infineon Technologies AG continues to leverage its EiceDRIVER portfolio, offering output currents up to 18 A with integrated protections for MOSFETs, IGBTs, and SiC devices. Texas Instruments Incorporated remains a dominant force with its isolated gate driver ICs utilizing capacitive coupling isolation, known for high shipment volumes. STMicroelectronics N.V. is actively promoting its STDRIVE and STGAP families, targeting industrial and automotive segments with robust isolated solutions.
Gate Drivers Market
ROHM Semiconductor and ON Semiconductor Corporation are focusing on integration strategies, with ROHM supporting industrial and consumer systems, while ON Semiconductor integrates gate drivers with power semiconductors specifically for EV and industrial use cases. NXP Semiconductors N.V. contributes high-performance control solutions for automotive and industrial segments, ensuring compatibility with advanced microcontroller ecosystems.
Analog Devices, Inc. brings legacy Maxim technologies into the fold, offering a mix of isolated and non-isolated drivers for power conversion. Microchip Technology Inc. has recently strengthened its position with a new family of 600V gate drivers supporting half-bridge and three-phase configurations, announced in early 2026. Littelfuse, Inc. has made strides in the automotive sector with automotive-qualified low-side drivers featuring adjustable negative bias for safer SiC operation, a product launched in late 2025. Toshiba Electronic Devices & Storage Corporation has enhanced safety functions in industrial equipment through its SiC MOSFET gate driver photocouplers. Additionally, Power Integrations, Inc. and Semtech Corporation continue to supply specialized solutions for power conversion and high-power switching respectively.
Supply Chain and Operational Dynamics
Navigating the supply chain remains a critical challenge for manufacturers. Industry analysis indicates that lead time fluctuations and raw material availability issues continue to affect gate driver production. The reliance on advanced materials, particularly silicon carbide, introduces constraints due to high initial costs and supply chain limitations. These factors can limit expansion in certain applications where cost sensitivity is high. Furthermore, geopolitical tensions and potential export controls on critical semiconductors create risks for global supply chains. Enterprises must develop resilient sourcing strategies to mitigate these disruptions.
Regulatory and Safety Standards
Strict quality and safety standards in automotive and industrial applications are driving the need for enhanced protection features within gate driver ICs. Regulatory compliance is no longer just a checklist; it is a competitive differentiator. Products that incorporate integrated safety mechanisms, fault detection, and robust isolation ratings are gaining preference in tenders and design-in opportunities. The report details how regulatory frameworks are influencing design cycles and time-to-market.
Recent Strategic Developments
Recent product launches highlight the pace of innovation. In January 2026, Microchip Technology Inc. announced a new family of 600V gate drivers capable of supporting half-bridge, high-side/low-side, and three-phase configurations for industrial and consumer motor control. This move targets the growing demand for versatile motor control solutions. In October 2025, Littelfuse, Inc. unveiled the IX4352NEAU, an automotive-qualified low-side gate driver with integrated adjustable negative gate drive bias, designed for safer SiC MOSFET and IGBT operation in EV powertrains. Earlier, in March 2025, Toshiba launched the TLP5814H SiC MOSFET gate driver photocoupler with enhanced safety functions and specific output current ratings, catering to industrial equipment needs. These developments signify a trend toward higher voltage tolerance, improved safety, and specialized automotive qualifications.
Strategic Value for 2026 Decision Making
This report is designed to empower decision-makers with actionable intelligence. In an environment where technology cycles are shortening and competitive pressure is mounting, access to precise market data is invaluable. The analysis provided herein goes beyond superficial trends to offer a deep dive into revenue projections, segmentation nuances, and competitive strategies. Whether you are planning a product launch, evaluating supply chain risks, or assessing potential acquisition targets, this study provides the foundational data required to build robust strategies.
Why This Report Matters
Investing in this research means investing in clarity. The MOSFET & IGBT Gate Drivers Market is at a pivotal point where energy efficiency and electrification trends converge. By understanding the specific growth drivers and the strategic moves of key competitors like Infineon, Texas Instruments, and STMicroelectronics, your organization can position itself advantageously. The report avoids generic assertions, focusing instead on data-backed forecasts and real-world product developments that signal future market directions. For stakeholders aiming to maximize market share and optimize operational efficiency in 2026 and beyond, this intelligence is indispensable.
MOSFET & IGBT Gate Drivers Market
Conclusion
The MOSFET & IGBT Gate Drivers Market represents a critical nexus in the power electronics value chain. With a projected growth path leading to 264.27 million USD by 2032 and a steady CAGR of 6.0 percent, the sector offers significant opportunities for those equipped with the right insights. PW Consulting's latest report delivers a comprehensive view of the landscape, from supply chain vulnerabilities to competitive product launches. We invite you to access the full detailed intelligence to ensure your strategic decisions are grounded in the most accurate and up-to-date market data available.
For detailed analysis of this topic, please visit the official page: MOSFET & IGBT Gate Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bike Lock Market Hits $1.69B in 2025, Projected 5.5% CAGR to Reach $2.46B by 2032
By PW Consulting, 2026-09-16
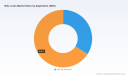
Strategic Intelligence for the Cycling Security Sector: Navigating the Bike Locks Market 2026-2032
The bicycle lock market stands at a critical inflection point. As urban mobility shifts toward sustainable transport and cycling infrastructure expands globally, the demand for dependable security solutions has evolved from a basic accessory requirement into a complex commercial ecosystem. Our newly released Bike Locks Market research report maps this transformation across a seven-year forecast horizon, offering enterprise decision-makers a structured view of revenue trajectories, competitive positioning, and the regulatory forces reshaping product development cycles.
For executives evaluating growth strategies, supply chain investments, or product portfolio adjustments, this study functions as a decision architecture rather than a static data snapshot. The following overview outlines the strategic framework embedded in our analysis and explains why the findings carry immediate operational relevance for 2026 planning.
Bike Locks Market
Market Trajectory and Structural Shifts
The commercial footprint of the bike locks sector has demonstrated consistent expansion over the past half-decade. Historical revenue data from 2020 through 2025 reflects steady accumulation, moving from approximately 1,300 million USD at the start of the evaluation window to nearly 1,700 million USD by the most recent base year. This progression is not merely the result of population growth or casual cycling adoption; it signals a maturing security consciousness among consumers, fleet operators, and municipal buyers who now treat locking hardware as a non-negotiable component of urban mobility.
Looking forward, the forecast window spanning 2026 through 2032 projects continued expansion at a compound annual growth rate of 5.5 percent. By the close of the prediction period, total market revenue is positioned to surpass the 2.4 billion USD threshold. This trajectory carries meaningful implications for capital allocation. Companies that treat the market as a low-differentiation commodity space will encounter margin compression, while organizations that align product roadmaps with authentication technology, material durability, and certification compliance will capture disproportionate share in both the OEM and aftermarket channels.
The structural composition of demand reveals two distinct commercial engines. Original equipment manufacturer integrations continue to represent a substantial baseline, particularly as bicycle assemblers embed locking mechanisms directly into frame designs or bundle security hardware into premium tier offerings. Simultaneously, the aftermarket segment dominates overall consumption, reflecting a consumer willingness to upgrade, replace, or layer additional protection around existing cycles. Understanding how these channels intersect with regional purchasing behaviors and type-specific preferences is essential for any firm planning go-to-market execution in the coming years.
Competitive Architecture and Strategic Positioning
The bike lock landscape remains moderately concentrated, with the top three participants controlling a little over half of total industry revenue and the five largest firms collectively accounting for roughly seven-tenths of the market. This concentration does not imply stagnation; rather, it signals an environment where established players compete on engineering pedigree and certification credibility while smaller innovators pursue specialized vulnerabilities such as angle-grinder resistance, connected access, or flexible textile construction.
Several organizations define the competitive boundaries of this sector. Kryptonite, headquartered in Canton, Massachusetts, maintains a formidable presence through its portfolio of U-locks, chain offerings, and integrated anti-theft protection systems supported by registered coverage programs. Their approach illustrates how service-layered security can complement hardware sales, creating recurring engagement with end users. ABUS, based in Wetter, Germany, operates with a distinct certification-focused strategy, emphasizing Sold Secure ratings across its folding, chain, and U-lock lines while continually refining security hardware engineering. Their emphasis on standardized security validation positions them as a reference point for buyers navigating compliance-heavy procurement environments.
Litelok, operating from Swansea in the United Kingdom, has built a reputation around high-security U-locks produced in a solar-powered domestic facility, an attribute that resonates with sustainability-conscious procurement teams and brand-conscious retailers. Hiplok, also UK-based, addresses an adjacent use case through wearable, chain, and anti-angle-grinder designs that prioritize portability without sacrificing resistance profiles. Black X, located in Sharon, Massachusetts, represents the smart-lock vanguard with its Titan Smart Bike Lock lineup, which combines angle-grinder-resistant U-lock architecture with app-based access control. Altor Locks, from Virginia, pursues a hand-assembled philosophy for folding and APEX lock series, targeting buyers who value artisanal production alongside cut resistance.
International innovation continues to appear across different technical vectors. ULAC, based in Taiwan, integrates fingerprint recognition, alarm functionality, and RFID protocols into bicycle lock designs, demonstrating how electronic authentication is moving from concept to commercial availability. texlock, from Leipzig, Germany, differentiates through textile-based flexible and U-lock constructions manufactured in-house, appealing to segments that prioritize lightweight portability and non-conventional material engineering.
Recent Product Launches and the Innovation Tempo
The pace of product evolution accelerated noticeably in early 2026. Black X announced the release of its Titan Smart Bike Lock lineup, featuring a U-lock engineered to resist angle-grinder attacks while pairing physical security with connected app-based access. This release underscores a broader industry movement toward hybrid protection models, where mechanical resistance meets digital authentication and user convenience. ABUS responded with a 2026 season catalog refresh that introduced new frame locks, improved-handling folding locks, and enhanced security designs. The simultaneous renewal of catalog depth by both a smart-lock specialist and a traditional engineering leader illustrates how quickly the competitive agenda is shifting.
These developments matter beyond product shelves. They influence procurement specifications, retail assortment strategies, and the expectations of cycling fleets that now evaluate locking hardware as part of a broader asset-protection stack. Companies that monitor the cadence of innovation and align internal development cycles accordingly will be better positioned to capture early adoption demand and avoid being outpaced by feature-rich entrants.
Regulatory and Certification Forces Reshaping Demand
Market growth does not occur in a regulatory vacuum. In the United Kingdom, Sold Secure ratings ranging from Bronze to Diamond have become the standard certification benchmark for many bicycle locks, with the Master Locksmiths Association owning the testing house that administers this certification framework. For manufacturers and distributors targeting UK procurement channels, certification compliance is not optional; it is a commercial gate. Product designs that fail to align with recognized rating tiers face structural barriers to retail placement and fleet contracts.
Quality and design integrity have also entered sharper focus. ABUS addressed manufacturing defects identified in the 2025 Granit Super Extreme 2500 folding lock base of shackle through design corrections incorporated into the 2026 version. Similarly, Kryptonite’s earlier production issues involving the anti-grinder covering on the shackle of its New York Diamond locks were resolved in subsequent manufacturing runs. These events highlight a broader operational reality: security hardware requires rigorous post-launch monitoring, rapid engineering remediation, and transparent communication with downstream partners. Firms that institutionalize these practices protect brand credibility, while those that treat defect resolution as an afterthought risk erosion in both retail trust and fleet procurement confidence.
Where the Market Heads: Strategic Implications for 2026
The convergence of steady revenue expansion, moderate but meaningful concentration, and accelerating innovation creates a market environment in which strategic clarity determines competitive outcomes. Several implications stand out for enterprise stakeholders.
- Revenue planning should account for sustained but not explosive growth, using the 5.5 percent CAGR as a baseline for scenario modeling rather than a ceiling.
- Product strategy must balance mechanical resistance engineering with authentication and connectivity features, since buyer expectations increasingly span both physical protection and digital convenience.
- Certification alignment, especially around recognized rating frameworks, should be treated as a market-access requirement rather than a decorative claim, particularly in regions where procurement standards are tightening.
- Supply chain resilience and post-launch quality remediation deserve executive attention, given the reputational sensitivity of security hardware and the rapid product refresh cycles now visible across major players.
- Channel strategy should reflect the fact that aftermarket demand remains substantial while OEM integration continues to embed locking hardware deeper into bicycle design, creating opportunities for bundled value propositions and co-development arrangements.
Inside the Study: What Decision-Makers Will Find
Our full Bike Locks Market research report extends well beyond headline figures. It provides a structured operational toolkit for teams responsible for strategy, product management, sales planning, and competitive intelligence. The study is built to support concrete decisions rather than abstract market awareness.
Locker Locks Market
At the core of the report is a detailed segmentation analysis that disentangles how demand distributes across lock types, application channels, and geographic regions. This breakdown allows readers to identify where growth is concentrated, which formats face substitution pressure, and how regional purchasing patterns influence product mix decisions. Rather than presenting fragmented percentages in isolation, the analysis connects segmentation behavior to commercial logic, helping teams understand not only where value sits but why it accumulates there.
The competitive profiling section delivers granular company-level intelligence on the major participants and innovative challengers shaping the landscape. Each firm profile examines product focus, geographic base, differentiation strategy, and recent commercial moves, giving readers a comparative lens for assessing partnership opportunities, competitive threats, and whitespace positioning. Recent development tracking further enriches this view by documenting product releases, catalog updates, and certification-related events that signal near-term market direction.
Market dynamics are treated as an integrated system rather than a list of isolated factors. The study examines how regulatory certification standards, manufacturing quality events, and evolving buyer expectations interact to shape demand volatility and product acceptance. This framing helps organizations anticipate disruption points, particularly where compliance requirements or quality perceptions can alter procurement outcomes quickly.
Forecast models are constructed to support scenario planning across the 2026 to 2032 horizon. Revenue projections, growth drivers, and structural assumptions are documented in a way that allows strategy teams to test internal plans against external trajectories. The report also includes analytical frameworks for evaluating market concentration, channel interplay, and the strategic implications of smart-lock adoption, material innovation, and security certification trends.
How to Use This Intelligence
This research is designed for immediate operational use. Product leaders can align roadmaps with the formats and features gaining traction. Sales and distribution teams can calibrate regional and channel priorities based on demand concentration patterns. Corporate development and competitive intelligence groups can track the trajectory of major players and emerging entrants, especially where connected security and material engineering are creating new differentiation angles. Procurement and risk functions can use the certification and quality discussion to strengthen vendor evaluation criteria.
Most importantly, the report gives leadership a coherent narrative for 2026 decision-making: a market expanding at a steady pace, shaped by recognizable competitive forces, influenced by certification gatekeeping and quality signals, and increasingly responsive to hybrid protection concepts that merge physical resistance with convenience-enhancing technology.
Access the Complete Market Intelligence
The overview above captures the strategic structure of our analysis, but the full commercial value lies in the underlying detail. The complete Bike Locks Market report provides the segmentation depth, company profiles, certification context, and forecast logic needed to translate market awareness into executable plans. For teams preparing investment decisions, product launches, or market-entry evaluations, the complete dataset and analytical commentary offer the precision required to act with confidence. Explore the full study to access the comprehensive intelligence behind these strategic conclusions.
For detailed analysis of this topic, please visit the official page: Bike Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Blue Light Glasses Market to Hit $3.77B by 2032 with 8% CAGR
By PW Consulting, 2026-09-16
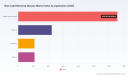
Strategic Vision 2026: Navigating the Blue Light Blocking Glasses Market Amidst Regulatory Shifts and Digital Wellness Trends
The global landscape for eyewear is undergoing a significant transformation, driven by the ubiquity of digital screens and a heightened consumer awareness of eye health. As we move into 2026, the Blue Light Blocking Glasses Market stands at a critical juncture where technological innovation intersects with complex trade dynamics. This article serves as an introduction to PW Consulting's comprehensive market research report, designed to equip industry stakeholders with the actionable intelligence needed to navigate this evolving terrain. The following analysis outlines the macroeconomic trajectory, competitive intensity, and regulatory headwinds that will define strategic decision-making in the coming year and beyond.
Market Trajectory and Growth Dynamics
Our latest analysis indicates a robust expansion phase for the blue light blocking eyewear sector. Based on a historical review spanning from 2020 to 2025 and projections extending through 2032, the market demonstrates a consistent upward trend. The revenue trajectory shows a growth from approximately 1,500 million USD in 2020 to an estimated 2,200 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, with market valuation expected to reach nearly 3,770 million USD by the end of the forecast window.
The Compound Annual Growth Rate (CAGR) during the forecast period is projected at 8.0 percent. This rate signals a healthy expansion that outpaces many traditional optical segments, underpinned by the permanent shift toward remote work, increased screen time among various demographics, and the mainstreaming of preventive health measures. For business leaders, this growth rate is not merely a statistic; it represents the speed at which market share opportunities are evolving and the urgency required to adapt product lines and distribution channels.
Strategic Implications of Market Size
The scale of this market offers ample room for diversification. However, growth is not uniform across all vectors. The increasing penetration of digital devices across all age groups suggests that demand will remain resilient, yet price sensitivity and brand differentiation will become more pronounced as the market matures. Companies that rely solely on volume without addressing specific consumer pain points regarding sleep quality, eye strain, or aesthetic appeal may find themselves squeezed by more specialized competitors.
Competitive Landscape and Key Players
The market structure is characterized by a mix of premium niche players and broader eyewear retailers integrating blue light filtering as a standard feature. Our report provides detailed profiles of the principal entities shaping this landscape. Understanding the positioning of these key companies is vital for any strategic assessment.
Corporate Profiles and Technological Differentiation
Several core companies define the current competitive boundaries. Felix Gray, headquartered in New York, positions itself in the premium segment with proprietary lens technology that claims to filter significantly more harmful blue light while maintaining lens clarity. Their strategy targets screen users focused on both eye strain reduction and sleep improvement. Similarly, Swanwick Sleep manufactures Swannies, utilizing science-backed lenses designed to block a high percentage of blue-weighted light, with a specific focus on circadian rhythm support and sleep quality.
On the technology-intensive end, GUNNAR Optiks, based in Carlsbad, specializes heavily in the gaming and computer usage niche. Their patented lens technology is designed to block a substantial portion of blue light, catering specifically to users with prolonged screen exposure. In contrast, JINS, based in Tokyo, offers a more integrated approach with JINS SCREEN lenses available on both prescription and non-prescription frames, emphasizing everyday eye strain reduction in both digital and artificial lighting environments.
The market also sees significant volume driven by affordable online retailers and optical chains. Zenni Optical, based in New Jersey, provides accessible options through their Blokz brand, incorporating polymer-based HEV filtering into standard lenses. EyeBuyDirect and GlassesUSA follow a similar direct-to-consumer or online retail model, offering customizable styles and price tiers that democratize access to blue light protection. Pixel Eyewear rounds out the competitive set with a focus on productivity, designing frames for professionals who prioritize reduced eye fatigue during work hours.
Concentration and Market Power
Our analysis highlights a moderate level of market concentration. The top three companies are estimated to hold a significant portion of the market share, while the top five expand that dominance further. This concentration suggests that while barriers to entry exist, there is still space for agile players who can identify underserved niches or offer superior value propositions. However, for larger incumbents, maintaining this share will require continuous investment in lens technology and brand loyalty programs.
UV and Blue Light Blocking Material Market
Regulatory Environment and Cost Pressures
No strategic plan for 2026 is complete without addressing the regulatory and tariff landscape. The economics of importing optical products have shifted notably recently, impacting margin structures across the supply chain. Industry sources indicate that Section 301 tariffs on Chinese imports for optical products, including blue light blocking glasses, have increased total duties on Chinese-origin frames and lenses to ranges between 27.5 percent and 33.5 percent as of March 2025.
Furthermore, additional government measures imposed in February 2025 introduced a 10 percent tariff on eyewear imports. These compounded duties directly affect the cost basis for imported goods, forcing companies to make difficult decisions regarding pricing strategies, inventory stocking, and supply chain diversification. Manufacturers relying heavily on Asian supply chains must evaluate the risk exposure of their cost structures. Successful navigation of this environment may require shifting sourcing locations, absorbing costs to maintain market share, or leveraging domestic manufacturing capabilities where feasible.
Blue Light Blocking Glasses Market
Segmentation and Demand Drivers
Understanding where demand originates is crucial for targeted marketing and product development. The market is segmented across regions, types, and applications, each with distinct growth drivers. While global expansion is evident, mature markets in North America and Europe continue to show strong demand driven by high digital penetration and disposable income. Meanwhile, the Asia Pacific region presents a high-growth opportunity fueled by increasing smartphone and computer usage rates alongside rising health consciousness.
In terms of product type, the split between non-prescription and prescription glasses reflects the dual nature of consumer demand. Non-prescription options cater to the general wellness audience seeking protection without vision correction, while prescription segments integrate blue light filtering into standard vision care, offering convenience and comprehensive eye health solutions. The application side reveals diverse use cases. Digital device users represent the largest cohort, driven by everyday screen exposure. Gamers constitute a significant specialized segment requiring high-performance lenses for prolonged sessions. Students and other categories also contribute to the demand pool, each requiring tailored messaging and product features.
Our full report delves deeper into the specific volume contributions and revenue splits of these segments without exposing the granular data here. However, it is clear that a one-size-fits-all approach is insufficient. Brands must align their inventory and marketing narratives with the specific needs of gamers, professionals, students, or general wellness consumers to maximize conversion and retention.
Operational Insight and Strategic Utility
This market research report is designed to be more than a collection of statistics. It serves as a strategic toolkit for executives, product managers, and investors. The document includes a thorough examination of supply chain dynamics, consumption patterns, and the technological benchmarks set by leading lens manufacturers. By analyzing the interplay between consumer behavior and regulatory constraints, the report offers a roadmap for risk mitigation and opportunity capture.
Key operational insights include an assessment of how tariff fluctuations impact landed costs and the subsequent pricing power of various brands. We also analyze the effectiveness of different marketing channels in reaching the core demographics, from digital-native advertising for gamers to clinical partnerships for prescription segments. The report evaluates the sustainability of current growth rates against potential market saturation points in mature regions.
Conclusion: Preparing for 2026 and Beyond
The Blue Light Blocking Glasses Market is poised for substantial growth, but the path forward is fraught with complexities. The combination of an 8.0 percent CAGR, evolving consumer expectations around health and aesthetics, and the pressure of increasing import duties creates a challenging environment for unprepared players. Strategic agility is paramount. Companies must balance the drive for volume with the necessity of margin protection in the face of tariff hikes.
Success in 2026 will belong to organizations that can accurately forecast demand shifts, optimize their supply chains against regulatory volatility, and differentiate their offerings in a crowded marketplace. Whether leveraging premium technology claims like those of Felix Gray and GUNNAR, or driving accessibility through models like Zenni and EyeBuyDirect, the strategic imperative is clarity of purpose and depth of market understanding.
This overview provides a snapshot of the market dynamics at play. To access the full depth of data, including precise segmentation revenue figures, detailed company benchmarking, and region-specific forecasts, we invite you to explore the complete PW Consulting market research report. This intelligence is essential for crafting a resilient strategy that capitalizes on the opportunities of the next forecast period while safeguarding against emerging risks.
For detailed analysis of this topic, please visit the official page: Blue Light Blocking Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


