



PW Consulting: Biobanking Market Hits $73.5B in 2025, Projected to Reach $114.22B by 2032 at 6.6% CAGR
By PW Consulting, 2026-09-16
The Biobanking Market at an Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global biobanking ecosystem is no longer a peripheral support function for life sciences. It has become a central infrastructure layer that determines the pace of translational research, the credibility of clinical trials, and the operational viability of precision medicine programs. As regulatory expectations rise, automation matures, and cross-institutional data sharing becomes both a mandate and a competitive advantage, executives in pharma, biotech, diagnostics, and healthcare delivery are facing a shared question: how should capital, partnerships, and operational roadmaps be aligned for the years ahead?
This article introduces PW Consulting's latest Biobanking Market research, a study designed specifically to support enterprise decision-making in 2026 and beyond. Rather than offering surface-level market commentary, the report translates macro momentum into actionable strategy by examining growth trajectories, segmentation logic, competitive positioning, regulatory pressure points, and the practical realities of scaling biobanking operations. The goal is to give leaders a defensible foundation for investment decisions, vendor selection, market entry planning, and long-term capacity strategy.
Why 2026 Is a Defining Year for Biobanking Strategy
Biobanking has entered a phase in which historical growth patterns and forward-looking operational choices increasingly diverge. Over the 2020-2025 period, the market expanded from approximately 55.3 billion USD to 73.5 billion USD, reflecting the compound effect of rising sample demand, better sample management practices, and expanding research pipelines. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, with the market projected to reach roughly 75.97 billion USD in 2026 and advance toward 114.22 billion USD by 2032. The implied compound annual growth rate of 6.6 percent is not merely a top-line statistic. It is a signal that biobanking is moving from fragmented, project-dependent scaling to more systematic, protocol-driven growth.
For executives, that signal matters because growth at this pace reshapes more than revenue forecasts. It influences how organizations think about capacity planning, regional footprint, technology adoption, and partnership models. A market growing at this level will not be won by incremental improvement alone. Firms need to determine where to build, where to buy, where to integrate, and where to standardize. They also need to understand which demand drivers are durable, which segments are consolidating, and how competitive intensity is likely to change as larger ecosystems invest in automated storage, sample logistics, and interoperable data frameworks.
The strategic challenge is compounded by the fact that biobanking now sits at the intersection of science, compliance, and infrastructure economics. High-quality sample preservation, traceability, and access are no longer optional capabilities; they are prerequisites for credible collaboration across research networks, contract organizations, and clinical programs. At the same time, capital intensity, energy requirements, and regulatory complexity create uneven adoption curves across facility types and geographies. The 2026 landscape therefore rewards firms that can separate short-term noise from structural opportunity and translate that distinction into operational choices.
What the Report Delivers: A Practical Blueprint, Not Just a Market Snapshot
This study is built to support decisions, not just descriptions. It combines historical context, forward-looking forecasts, and operational analysis into a single framework that business leaders can use to pressure-test assumptions. The report is organized to answer the questions that typically determine whether a market opportunity is commercially actionable:
- How the overall market has evolved and what the next several years are likely to look like under baseline and scenario conditions
- Which structural segments are shaping demand, and how value is distributed across different biobanking types and end-use applications
- Where regional dynamics are creating concentration, divergence, or growth opportunities
- How leading suppliers are positioned, what capabilities matter most, and how the competitive field is being reshaped by automation, service models, and infrastructure investment
- Which regulatory and operational forces are changing the cost of participation, especially for smaller repositories and cross-border initiatives
- What practical implementation considerations should inform procurement, partnership, and capacity decisions in 2026
A central feature of the report is its emphasis on real-world applicability. Rather than leaving the reader with abstract market sizing, it connects growth indicators to operational realities such as automation requirements, sample handling workflows, quality and accreditation expectations, and the financial burden of ultra-low temperature preservation. The study also examines the changing role of standards and accreditation frameworks that are increasingly defining what "competent" biobanking looks like in practice. In an environment where consistency, sample integrity, and data governance are closely scrutinized, these factors directly affect which organizations can participate in high-value collaborations and which must adapt before they can scale.
Equally important, the report investigates the market's concentration profile and what it reveals about competitive dynamics. With a meaningful share of activity held by a relatively small group of established players, the landscape is neither fully fragmented nor fully consolidated. That mixed structure creates both partnership opportunities and entry barriers. For incumbents, it raises the question of how to defend core positions while expanding into adjacent services and automation-enabled workflows. For newer entrants and private capital-backed organizations, it raises the question of which niches are accessible, which require substantial infrastructure commitments, and which can be won through specialization rather than scale alone.
Competitive Landscape: Who Is Shaping the Next Phase
The competitive field in biobanking reflects a blend of industrial suppliers, automation specialists, logistics providers, and service-oriented organizations. Several companies stand out because their portfolios touch the core infrastructure of sample storage, retrieval, processing, and biobank management. Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, remains closely associated with automated storage systems, temperature-controlled equipment, and laboratory information management solutions designed for sample management. Becton, Dickinson and Company, headquartered in Franklin Lakes, New Jersey, continues to provide cryogenic systems and broader sample collection and storage solutions. PHC Holdings Corporation, headquartered in Tokyo, contributes automated cryopreservation and storage systems, while Hamilton Company, based in Reno, Nevada, focuses on robotic automation and liquid handling for biobanking workflows.
The landscape also includes organizations that approach biobanking from different operational angles. Azenta Life Sciences, based in Chelmsford, Massachusetts, develops automated storage and retrieval systems relevant to cryogenic sample management. Cryoport, Inc., headquartered in Santa Ana, California, specializes in cryogenic logistics and storage solutions. Tecan Trading AG, in Switzerland, provides laboratory automation and robotics for sample processing. Lonza Group Ltd., also based in Basel, offers services and equipment associated with cell and tissue storage. Taylor-Wharton, headquartered in Asheville, North Carolina, manufactures cryogenic freezers and storage systems. Charles River Laboratories, in Wilmington, Massachusetts, supplies equipment and services for research sample management. Stemcell Technologies Inc., in Vancouver, Canada, addresses specialized equipment and consumables for stem cell biobanking. Promocell GmbH, in Heidelberg, Germany, provides storage and processing solutions for cellular samples. Brooks Life Sciences, based in Chelmsford, Massachusetts, delivers automated sample management and storage systems.
Strategic implications of the competitive mix
This breadth of players matters because biobanking is increasingly solved as a system rather than a single product purchase. Organizations must evaluate not only the quality of a freezer or automation module, but also how well equipment, software, logistics, and service support integrate into a coherent workflow. That reality favors suppliers that can reduce operational friction and improve traceability across the full sample lifecycle. It also creates room for specialization. Some firms compete on high-throughput automation, others on cryogenic logistics, and others on consumables, cell-specific workflows, or research-grade services.
A useful way to read the competitive environment is through the lens of value migration. As sample volumes rise and collaboration networks expand, value is shifting toward capabilities that support repeatability, auditability, and interoperability. That shift is pushing established hardware and service providers to strengthen digital sample management, workflow integration, and remote monitoring features. At the same time, it is raising the importance of partnerships between equipment vendors, contract research organizations, and biobank networks that need to align on standards and exchange samples or data across institutional boundaries.
Stem Cell Banking Market
The report examines these competitive dynamics in greater depth than a simple company list can convey. It maps where scale advantages exist, where differentiation is becoming decisive, and where the demand for integrated solutions may create consolidation pressure or partnership-led growth. Because the market remains concentrated enough to reward established infrastructure players yet diverse enough to sustain specialist innovators, the strategic question is rarely whether competition exists. It is which competencies will command premium positioning as procurement teams evaluate total cost, reliability, and compliance readiness.
Regulatory, Operational, and Infrastructure Dynamics
Market growth in biobanking cannot be interpreted without acknowledging the operational constraints that shape adoption. One significant factor is capital and energy intensity. Automated storage systems and robotic repositories require substantial investment and ongoing energy consumption for ultra-low temperature preservation. These requirements limit adoption among smaller facilities, creating an uneven landscape where larger organizations and well-funded networks can move faster on automation while smaller repositories must weigh the cost of participation against their own operational scale.
Regulatory complexity adds a second layer of pressure. Biobanking operates within a range of international requirements, including GDPR, HIPAA, and 21 CFR Part 11. These frameworks create operational complexity and financial burden, particularly for smaller repositories that may lack the administrative and technical capacity to manage compliance at scale. In practice, this means that regulatory readiness is becoming a strategic differentiator. Organizations that can demonstrate consistent data governance, sample traceability, and quality control are better positioned to participate in cross-border studies, multi-site research, and high-value partnerships.
At the same time, standardization efforts are maturing. The ISO 20387:2018 standard specifies general requirements for the competence, impartiality, and consistent operation of biobanks, including quality control for biological material and data collections. European Accreditation launched a Multilateral Agreement for biobanking in 2025, with further extensions planned for 2026. These developments are not abstract. They are becoming practical criteria by which biobanks are evaluated by partners and funders, and they increasingly influence which facilities can credibly join federated platforms or cross-institutional programs.
Recent industry developments that reframe the road ahead
Recent signals from Europe illustrate how biobanking strategy is being reframed at the infrastructure level. In April 2026, BBMRI-ERIC published a 10-Year Roadmap for biobanking development through 2035, emphasizing One Health integration and infrastructure alignment across Europe. The same month, BBMRI-ERIC announced the selection of eight biobanks for dedicated funding under the EvolveBBMRI project to integrate into the BBMRI-ERIC Federated Platform. These moves matter because they show that biobanking is being treated not only as a scientific resource but also as coordinated infrastructure with alignment, interoperability, and long-term sustainability as explicit goals.
For organizations operating in or adjacent to this space, the implications are practical. Federated platforms, shared standards, and roadmap-driven investment can create new demand for compatible systems, quality processes, and service models. They also raise the bar for organizations that intend to participate in broader research ecosystems. Strategic planning in 2026 must therefore account for the fact that infrastructure alignment is becoming part of the market's growth logic, not just a compliance exercise.
How to Use This Research for 2026 Enterprise Decisions
The value of this study lies in its ability to connect market direction with decision quality. Executives can use it to evaluate whether current biobanking investments are aligned with likely demand, whether partnership strategies should prioritize automation compatibility, quality accreditation, and data interoperability, and whether regional or application-specific opportunities warrant dedicated capacity. The report is also designed to support vendor and technology evaluations by clarifying which capabilities matter most in a market where sample integrity, traceability, and operational consistency increasingly determine commercial relevance.
Because the report is structured around both macro trends and operational detail, it can support a range of decisions:
- Capacity and investment planning, including whether to expand in-house biobanking capability or rely on external service providers
- Procurement prioritization, especially when balancing automation, storage, logistics, and software integration
- Partnership and collaboration strategy, including how to position within federated networks or multi-site research programs
- Risk assessment around regulatory complexity, accreditation readiness, and the operational burden of compliance in different settings
- Market entry and expansion decisions, informed by segmentation structure and concentration patterns
The emphasis throughout is on actionable clarity. Leaders do not need another high-level overview. They need evidence that helps them determine where the market is durable, where it is fragile, and where their organization can most effectively allocate resources in the coming years.
Biobanking Market
Closing Perspective
The biobanking market in 2026 is best understood as an infrastructure market entering a more disciplined growth phase. Demand is expanding, automation is becoming a competitive necessity for many players, and regulatory and standards frameworks are increasingly shaping who can participate in high-value collaborations. At the same time, capital intensity, energy requirements, and fragmented compliance obligations continue to differentiate large and small operators. In that environment, strategic advantage comes from understanding not just that the market is growing, but how growth is being distributed, what operational capabilities it rewards, and which competitive positions are likely to strengthen over time.
PW Consulting's Biobanking Market research is designed to provide that understanding at the level of detail required for serious planning. It offers the market context, competitive analysis, segmentation logic, and operational considerations needed to support decisive action in 2026 and the forecast years that follow. For organizations that need the full segmentation view, competitive mapping, and implementation insight to move from hypothesis to execution, the complete report is available through our research portal.
For detailed analysis of this topic, please visit the official page: Biobanking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ribbon Fiber Cable Market Hits $2.58B in 2025, Growing at 8.9% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Pulses Beneath the Surface: Why the Ribbon Fiber Optic Cable Market Demands Executive Attention in 2026
Capital allocation in fiber infrastructure has reached a decisive inflection point. For network operators, hyperscale tenants, and optical equipment leaders, the ribbon fiber optic cable category is no longer a niche alternative. It has become a foundational enabler of bandwidth density, deployment speed, and total cost efficiency across everything from fiber-to-the-x builds to intercontinental data center interconnects. Our newly released Ribbon Fiber Optic Cable Market study was designed to transform that strategic reality into a decision-ready intelligence framework. This article previews the analytical architecture of the report, highlights the structural forces reshaping the competitive field, and explains why the full dataset is essential for boards and strategy teams navigating the 2026 to 2032 investment horizon.
The Strategic Imperative of Density, Speed, and Cost Discipline
The ribbon fiber category has earned its place in forward-looking infrastructure roadmaps by solving three persistent bottlenecks simultaneously: duct and rack space constraints, fiber count ceilings, and installation labor intensity. As bandwidth demand compounds across enterprise campuses, wholesale metro networks, and hyperscale campuses, the industry is shifting away from incremental single-fiber scaling toward high-density ribbon architectures that compress physical footprint while accelerating splicing, handling, and deployment timelines. That transition is not cosmetic. It recomputes the economics of civil works, reduces exposure to skilled labor scarcity, and changes the relative attractiveness of different cable formats under constrained right-of-way conditions. The strategic question for 2026 is no longer whether ribbon fiber has a role, but which designs, counts, and supplier ecosystems will outperform under specific deployment conditions, procurement regimes, and margin pressures.
Blueprint of the Market Study: A 2026-Ready Intelligence Architecture
This study is built for operators and investors who need more than a top-line growth estimate. It places the ribbon fiber optic cable market inside a rigorous, forward-looking analytical structure that connects historical performance to the 2026 to 2032 forecast window. The report definition base year is 2025, with historical analysis spanning 2020 through 2025 and a forecast horizon extending to 2032, all valued in USD billions. The study integrates that trajectory with segmentation logic that lets decision-makers evaluate where value is accumulating, which applications are scaling fastest, and how regional deployment cycles influence supplier demand. Rather than presenting the market as a single growth line, the analysis separates type dynamics, application-driven pull, and regional demand patterns so that procurement, capacity planning, and supplier negotiations can be calibrated to actual operating conditions.
Practically, the report is structured to support concrete decisions. It maps the market by cable configuration, application pull, and regional deployment intensity, giving leadership the context needed to prioritize fiber count strategies, hedging approaches, and sourcing footprints. It also evaluates competitive positioning through concentration metrics and company-level profiles, which allows teams to assess market vulnerability, partnership opportunities, and the strategic importance of supplier differentiation beyond fiber count alone. The segmentation architecture is deliberately comprehensive because ribbon fiber economics vary sharply across environments: a hyperscale data center interconnect, a metro duct build, and a rural fiber-to-the-x program face different density requirements, regulatory constraints, and labor profiles. The study treats those differences as decision inputs, not background noise.
Analytical Pillars Built for Execution
- Type evaluation that contrasts multi-mode and single-mode ribbon offerings across fiber count flexibility, density advantages, and deployment suitability
- Application analysis covering fiber-to-the-x, data center interconnects, and other network uses, with attention to how each environment shapes cable specification needs
- Regional demand mapping that reflects where infrastructure investment cycles are concentrated and how procurement environments differ by geography
- Competitive concentration analysis, including CR3 and CR5 readings, to frame supplier power, diversification risk, and negotiation leverage
- Company and product intelligence that compares leading cable and connectivity players on architecture, handling characteristics, density gains, and application fit
- Emerging industry developments such as product compatibility programs and awards that signal architectural validation and cross-vendor integration momentum
Market Trajectory: What the Growth Arc Signals for Strategy Teams
The headline trajectory is powerful, but the real strategic value lies in what that trajectory implies for capacity timing, supplier selection, and deployment sequencing. Over the 2020 to 2025 review period, the market moved from below one billion USD to a materially higher base, and the forecast suggests continued expansion through the end of the decade and into the early 2030s. That sustained upward path reflects more than cyclical demand. It reflects a structural re-rating of fiber density as a first-order requirement in an environment where bandwidth growth, space constraints, and deployment economics are increasingly inseparable. The forecast CAGR of 8.9 percent over the 2026 to 2032 window underscores that this is not a short-lived surge; it is a multi-year shift in how high-capacity optical connectivity is planned, specified, and deployed.
For strategy teams, the implication is that ribbon fiber is becoming a core part of long-cycle infrastructure planning rather than a tactical substitute. That matters because long-cycle planning changes the calculus for supplier relationships, technology roadmaps, and capital exposure. A market expanding on this schedule rewards organizations that can align product specification, installation process, and sourcing strategy with where capacity will be needed, when it will be needed, and under which regulatory and cost conditions. The report provides the structured context to make those choices deliberately rather than reactively.
Growth Pattern and Decision Implications
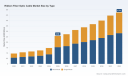
The overall market size progression used in the study reflects that forward momentum. From 2020 through 2025, the base evolution spans from approximately 0.96 billion USD to 2.58 billion USD, with the forecast band advancing through the forecast window and reaching 4.74 billion USD by 2032. Those figures are presented in the report as part of a broader analytical narrative, not as isolated endpoints, because the real challenge for leadership is to interpret growth in relation to segmentation, concentration, and application-specific pull. The report keeps the emphasis on relative positioning and strategic sequencing so that executives can see how the market is evolving, where the share shifts are likely to concentrate, and which decisions are most sensitive to timing.
Segmentation and Application Signals Without Losing the Strategic Thread
One of the study’s most valuable contributions is its treatment of demand by type and by application, which helps executives understand why different deployments favor different ribbon approaches. The type split in the reporting framework distinguishes multi-mode and single-mode ribbon products, each with different strengths in reach, density, and network architecture fit. The application breakdown makes clear that ribbon fiber is being pulled by a range of use cases, with fiber-to-the-x representing the largest share of application-driven demand, data center interconnects holding a significant and strategically important position, and other applications contributing additional demand layers. That mix matters because application economics differ sharply in terms of fiber handling, splicing complexity, installation environment, and long-term scalability.
Regional context is just as important. The study distributes demand across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, reflecting the geographic unevenness of infrastructure investment, policy support, and deployment velocity. The report avoids flattening those regions into a single narrative, because regional procurement behavior, manufacturing footprints, and fiber deployment cycles directly influence which suppliers win, which specifications scale, and which contracts become strategically critical. By preserving that regional specificity within the analysis, the study gives leaders a more usable view of where demand is forming and how supplier competition is being shaped on the ground.
Competitive Landscape: Concentration, Differentiation, and the New Battleground for Density
The ribbon fiber market is not a commodity game. The study’s competitive concentration metrics show that the top three suppliers account for roughly 30 percent of market share, while the top five collectively command approximately 45 percent. That concentration structure has strategic consequences. It suggests that a meaningful share of scaling demand is being captured by established players with differentiated product architectures, strong manufacturing footprints, and broad application coverage. At the same time, it also indicates room for specialized challengers, regional winners, and cross-ecosystem partnerships to influence customer choice through technical differentiation, installation efficiency, and deployment flexibility.
The competitive profiles compiled in the report demonstrate that differentiation is increasingly being won on more than raw fiber count. The leading companies are shaping buyer preference through cable architectures that reduce physical size, shorten installation time, improve handling, and increase usable density in constrained pathways. For example, the study examines suppliers whose ribbon designs are engineered to compress cable outer diameter, eliminate gel-dependent construction where high-density indoor or outside-plant performance is required, and accelerate deployment in data center and OSP settings. Other profiles focus on intermittently bonded ribbon approaches that make high-density cables easier to handle, fold, or roll, which changes the practical experience of installation teams and can materially affect total deployment time. The report also maps offerings that push fiber counts into the thousands with reduced diameter profiles for underground and high-capacity applications, as well as designs built for hyperscale data centers with non-metallic construction and extremely high fiber counts.
Equally important, the study highlights companies whose ribbon products are being positioned for practical density gains in fiber-to-the-x and enterprise environments, where installation time savings and duct efficiency can change program economics. It also covers players focused on high-density ribbon patch cords and compact cable formats for data-center applications, alongside companies serving enterprise, tactical, and industrial requirements with ribbon configurations designed for durability and handling resilience. The competitive analysis therefore reflects a market in which technical claims must be matched with operational reality: density, bend performance, installability, compatibility with downstream components, and fit with regional procurement expectations.
Strategic Reading of Leading Profiles
The report treats competition as a multi-dimensional problem rather than a simple vendor list. Some suppliers compete on extreme fiber count and compact geometry aimed at hyperscale and high-capacity environments. Others compete through handling innovations that make ribbon easier to deploy in field conditions. Others build strength around application-specific variants for metro, FTTH, and enterprise networks, or around compatibility with domestic procurement mandates and regional supply expectations. The study’s company profiles are structured to help strategy teams compare these positions directly, understand where each supplier creates value, and anticipate where procurement negotiations are likely to center on specifications, lead times, and installation efficiency rather than price alone.
Ribbon Fiber Optic Cable Market
Momentum Points: Compatibility, Recognition, and Supply-Side Pressure
Recent industry developments reinforce the direction of the market and the importance of tracking how ribbon fiber is being validated and adopted in live deployment ecosystems. One notable signal is the product compatibility program pairing drop closures with rollable ribbon fiber optic cable, which showcases how integration between closure hardware and high-density cable design can streamline FTTx network design and deployment. That kind of interoperability focus matters because ribbon adoption does not depend on cable performance alone; it depends on whether the broader outside-plant and termination ecosystem can absorb high-density architectures efficiently. A second signal is the recognition of a 13824-fiber ribbon and wrapping tube cable design with a major product award for hyperscale data center applications, which reflects the industry’s increasing emphasis on extreme-density, non-metallic, high-capacity cable formats for campus-scale data infrastructure.
Just as important, the study incorporates supply-side dynamics that can alter both cost assumptions and sourcing strategies. Input cost pressure is visible in recent pricing trends for bend-insensitive fiber, where per-kilometer costs rose sharply between mid-2025 and early 2026 amid sustained demand and supplier caution about further increases. That kind of movement affects margin planning, product pricing, and the timing of large specification commitments. At the same time, the report addresses how domestic content and procurement policy environments are shaping purchase behavior, with some major providers adjusting assembly and manufacturing footprints to align with local sourcing expectations. Policy support for digital inclusion and data-sovereignty requirements is increasingly converging across regions in ways that favor domestic fiber optic cable production and procurement. These dynamics are not peripheral; they influence where capacity should be sourced, how flexible the supply chain needs to be, and which suppliers can offer adaptable local or compliant manufacturing pathways.
Why the 2026 Decision Window Requires the Full Study
Executives evaluating ribbon fiber strategies in 2026 need more than a directional market narrative. They need to understand which cable types are gaining share in which applications, how regional demand patterns translate into supplier exposure, where competitive concentration is rising, and how cost and policy pressures might reshape total deployment economics. The public-facing growth figures and competitive structure outlined here confirm that ribbon fiber is a strategically significant category with a durable multi-year trajectory. Yet the operational decisions that separate winners from followers depend on the deeper segmentation data, concentration detail, application nuance, and supplier positioning contained in the full report.
The complete study gives strategy teams the ability to connect market size to deployment reality. It helps procurement teams assess supplier risk and negotiation leverage. It helps network planners align ribbon specifications with application requirements and regional conditions. It helps investors and corporate development teams understand where density innovation, compatibility programs, and manufacturing adaptation are creating defensible advantage. Most importantly, it creates a shared analytical frame for decisions that will shape infrastructure economics for the rest of the decade.
Next Steps: Turn Directional Confidence into Decisive Intelligence
This preview is intended to establish the strategic relevance and analytical rigor of the Ribbon Fiber Optic Cable Market study, while preserving the segment-level detail that makes the report a decision tool rather than a summary. The directional growth path, competitive structure, application momentum, and supply-side pressures described here justify immediate strategic attention. The full report is where that attention becomes actionable: it delivers the specific segmentation values, regional demand patterns, supplier comparisons, and deployment context that allow leadership teams to convert market growth into a disciplined 2026 strategy. For organizations planning capacity, negotiating supply, or evaluating where ribbon fiber fits into their infrastructure roadmap, the complete study offers the granularity required to move from informed anticipation to confident execution.
Fiber Optic Cable Assembly Market
For detailed analysis of this topic, please visit the official page: Ribbon Fiber Optic Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: School Furniture Market Hits $4.8B in 2025, Projects 7.2% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Global School Furniture Market Through 2032
Introduction to the 2026 Market Intelligence Brief
As educational paradigms shift rapidly toward flexible learning environments and increasing emphasis on health-centric infrastructure, the global school furniture market stands at a pivotal juncture. Our latest market research delves into the complex interplay of demand drivers, regulatory shifts, and competitive positioning that will define the industry over the next decade. This article serves as a strategic preview of the full study, highlighting the macroeconomic trajectories and structural dynamics that corporate leaders must parse to secure growth in 2026 and beyond.
Trajectory and Scale: A Decade of Sustained Expansion
The market has demonstrated remarkable resilience and consistent expansion over the past half-decade. Historical data from 2020 through 2025 reveals a clear upward trajectory, with total industry revenue climbing from a baseline of USD 3,300 million to an estimated USD 4,800 million in 2025. This growth reflects sustained capital allocation toward educational infrastructure and a structural pivot toward higher-quality, ergonomically optimized classroom equipment.
Looking forward, the revenue forecast extends through 2032, projecting a compound annual growth rate of 7.2 percent. By the close of the forecast horizon, total market revenue is anticipated to reach approximately USD 7,780 million. Such figures underscore a sector that is not merely expanding in nominal terms but is also maturing in terms of product sophistication and compliance requirements. For corporate planners, these numbers signal sustained demand velocity rather than a transient post-pandemic rebound, making long-term capacity planning and portfolio optimization imperative.
Core Drivers: Policy, Pedagogy, and Compliance Standards
Several converging forces are propelling this expansion. First, global education spending remains a strategic priority for governments and private institutions alike. Upgrades to aging classroom infrastructure, combined with the integration of modern pedagogical approaches, are accelerating replacement cycles and driving demand for furniture that supports collaborative, movable, and technology-integrated learning setups.
Second, regulatory and standards-based compliance has become a defining feature of procurement decision-making. The industry is witnessing heightened attention to durability, safety, and environmental accountability. The widely referenced BIFMA X6.1 standard for educational seating continues to shape product specifications across pre-school through adult education environments, ensuring that seating solutions meet rigorous performance criteria. Concurrently, the updated BIFMA Furniture Surfaces Guideline (BIFMA G8.1-2026) provides detailed protocols for surface performance against cleaning, sanitizing, and disinfecting products. These guidelines directly influence material selection, coating technologies, and lifecycle durability, especially in high-traffic institutional settings.
Additionally, the BIFMA LEVEL certification program has gained traction among institutions seeking to align purchasing decisions with environmentally and socially responsible criteria. Together with the general-purpose and educational seating standards codified in ANSI/BIFMA X5.1 and X6.1, these frameworks create a compliance layer that rewards manufacturers and suppliers who invest early in certified, specification-ready product lines.
Educational Furniture Market
A recent industry development highlights the active role of standards bodies in this ecosystem. In February 2026, BIFMA published the updated Furniture Surfaces Guideline, hosted sessions on industry leadership and standards development during its 360 Conference, and released the Outdoor Furniture Whitepaper covering performance and sustainability criteria relevant to educational outdoor spaces. These deliverables reflect a broader push toward holistic environmental and hygiene considerations that extend beyond the traditional indoor classroom.
Product Archetypes: Seating, Storage, and Specialized Lab Solutions
The market is structured around distinct product families that serve different functional needs within educational environments. Seating remains the dominant category, reflecting the centrality of ergonomic and durable seating to daily student comfort and institutional compliance. Storage solutions constitute a substantial complementary segment, supporting organizational demands across classrooms, libraries, and administrative areas. Specialized laboratory furniture represents a focused but high-value category, where durability, chemical resistance, and modularity demand differentiated engineering and specification processes.
Beyond product type, application context shapes purchasing behavior. Classroom environments form the core application base, driven by large-volume procurement and frequent replacement schedules. Library and laboratory settings contribute additional demand, often characterized by higher specification thresholds and longer asset lifecycles. A residual application stream encompasses administrative, multipurpose, and specialty environments, ensuring diversified revenue channels across the sector. These structural distinctions matter for market entrants and incumbents alike because they influence SKU complexity, lead times, and the nature of specifier relationships with school districts and institutional buyers.
Competitive Landscape: Incumbency, Specialization, and Geographic Footprints
The competitive arena is characterized by a mix of established regional manufacturers and globally oriented suppliers, with a moderate degree of concentration among leading players. The top three participants collectively account for approximately 52.3 percent of industry revenue, while the top five extend their combined share to roughly 68.4 percent. Such concentration indicates the presence of scaled incumbents with established supply chains, specifier relationships, and compliance portfolios, but it also leaves meaningful space for differentiated players in niche categories, specialized applications, and regional procurement ecosystems.
School Furniture Market
Several companies illustrate the breadth of strategic positioning in the market. Smith System, headquartered in Grand Haven, Michigan, specializes in wholesale ergonomic and flexible school furniture designed for K-12 classrooms, including desks, chairs, and collaborative systems that span elementary through high school levels. Haworth, based in Holland, Michigan, provides institutional and educational furniture solutions encompassing tables, seating, and modular systems tailored to both higher education and K-12 learning environments. VS Furniture, operating from Germany, offers school and office furniture with a strong emphasis on ergonomic systems and modular solutions for education facilities. Krueger International, located in Green Bay, Wisconsin, manufactures institutional furniture including school and educational seating and tables under BIFMA standards, underscoring a compliance-oriented product philosophy.
Virco, based in Placentia, California, focuses on durable school desks, chairs, and modular seating solutions for educational institutions, highlighting an emphasis on longevity and cost-effective lifecycle performance. Insalco provides contract furniture that includes school and library seating and storage systems for educational use, bridging institutional procurement requirements with functional versatility. Robert H. Lord offers school furniture developed under BIFMA X6.1 educational seating standards, reflecting alignment with sector-specific seating criteria. PSI-New England Storage Products supplies storage and seating solutions for school environments as part of institutional furniture contracts, illustrating the role of specialized storage and ancillary seating providers in holistic facility planning.
Strategically, the market rewards firms that can combine compliance readiness, ergonomic credibility, and flexible system design. In practice, winning suppliers often differentiate through durable material platforms, service-oriented specification support, and regionally attuned distribution models that reduce procurement friction for school districts and facility managers.
Strategic Imperatives for 2026 Decision-Makers
Corporate leaders evaluating this market should focus on several actionable priorities. First, compliance integration must move from reactive to proactive. As cleaning, sanitizing, and disinfecting protocols become embedded in procurement specifications, product surfaces, edges, and materials need documented performance evidence. Firms that pre-position their portfolios against evolving surface-performance guidelines and educational seating standards will shorten specification cycles and reduce qualification risk.
Second, portfolio architecture should balance volume stability with premium differentiation. While seating remains the volume backbone of the market, storage and specialized lab furniture offer higher margin potential and longer replacement intervals. Companies that can bridge both mass-market reliability and specification-grade engineering are better positioned to capture institutional budget allocations across multiple procurement categories.
Third, geographic strategy should reflect regional procurement rhythms and funding patterns. Some regions exhibit stronger institutional investment profiles and mature specifier networks, while others present growth headroom tied to infrastructure modernization and expanding enrollment. The distribution of revenue across major regions underscores that a one-size approach is insufficient; instead, localized service coverage, specification support, and compliance documentation are essential to capturing share in each territory.
Fourth, sustainability credentials are transitioning from optional differentiators to procurement expectations. Certification frameworks that evaluate environmental and social responsibility resonate with institutional buyers and can influence vendor shortlists. Manufacturers and suppliers that embed sustainability into material sourcing, production practices, and product end-of-life considerations can strengthen competitive positioning in specification-driven bids.
Fifth, modular and flexible system design should be treated as a strategic asset. As learning spaces adapt to varied pedagogical modes, furniture that supports reconfiguration, durable mobility, and collaborative use cases aligns with buyer demand for multi-functional, future-ready environments. Suppliers capable of offering integrated seating, storage, and collaborative modules can differentiate not just on product but on total-space value.
What the Full Study Delivers: Applied Intelligence for Execution
This market research goes beyond high-level sizing to provide operational granularity that supports planning, forecasting, and competitive benchmarking. The study maps revenue distribution across region, product type, and application, enabling leaders to identify the most attractive sub-segments for investment, capacity allocation, and go-to-market tailoring. It also examines the competitive architecture in greater depth, profiling leading players and their positioning along dimensions such as compliance readiness, product specialization, geographic reach, and service models.
In addition, the report analyzes regulatory and standards developments with an eye toward commercial impact, translating technical guideline updates into implications for material selection, surface engineering, certification strategy, and procurement dialogue. Procurement dynamics, specifier behavior, lead-time expectations, and lifecycle cost considerations are assessed to help firms optimize pricing architecture and channel strategy. The study also incorporates scenario sensitivity around growth pacing, allowing decision-makers to test assumptions against alternative demand paths and adjust portfolio commitments accordingly.
For organizations engaged in manufacturing, distribution, specification, or institutional procurement, the full report provides the structured intelligence needed to prioritize SKUs, allocate sales resources, refine compliance documentation, and time market entry or expansion moves with greater confidence.
Conclusion: Positioning for Informed Growth
The school furniture market is entering a period of steady, standards-shaped expansion. With a projected compound annual growth rate of 7.2 percent and revenue expected to approach USD 7,780 million by 2032, the sector offers durable opportunity for firms that can align product quality, compliance readiness, and regional execution. The convergence of ergonomic expectations, hygiene-conscious surface performance, sustainability certification, and modular flexibility is reshaping what buyers value and how competition unfolds. Leaders who act on these signals now will be better positioned to secure share, reduce specification friction, and build resilient revenue channels across the forecast horizon. This research is designed to convert those signals into actionable strategy, and we invite stakeholders to explore the complete findings for the full intelligence set needed to guide 2026 decisions.
For detailed analysis of this topic, please visit the official page: School Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long-Term Care Software Market Set to Hit $642.7M by 2032, Growing at 8% CAGR
By PW Consulting, 2026-09-16
Navigating the Long-Term Care Software Market: Strategic Intelligence for 2026 and Beyond
The long-term care ecosystem is undergoing a structural transformation driven by aging demographics, evolving reimbursement models, and the rapid infusion of artificial intelligence into clinical workflows. For executives, investors, and technology leaders operating in this space, 2026 represents a critical inflection point. The convergence of regulatory complexity, operational pressure, and digital maturity demands more than off-the-shelf software; it requires a rigorous, forward-looking understanding of where the market is headed and how competitive dynamics will reshape value capture over the next several years.
Our newly released Long-term Care Software Market research study is designed to meet that exact need. Spanning a historical retrospective from 2020 through 2025 and a detailed forecast horizon extending to 2032, this report maps the trajectory of a sector that has already demonstrated remarkable resilience and growth. The total market revenue, measured in USD millions, climbed steadily from 281.2 in 2020 to 376.8 in 2025, and we project it will reach 406.78 in 2026 before continuing its upward arc toward 642.7 by 2032. This sustained expansion is underpinned by a compound annual growth rate of 8.0 percent across the forecast period. These figures are more than historical markers; they form the baseline for capacity planning, investment allocation, partnership strategy, and product roadmap decisions that will define organizational performance throughout the decade.
Yet size and speed alone do not tell the full story. The strategic value of this research lies in its ability to translate macro-level momentum into actionable intelligence for enterprise decision-making in 2026 and beyond. By examining the structural forces shaping demand, the competitive architectures defining supply, and the regulatory currents altering compliance and revenue cycles, this report equips leaders with the contextual clarity required to move from reactive adaptation to proactive positioning.
Decoding the Growth Trajectory: What the Numbers Mean for Enterprise Strategy
The long-term care software market has evolved from a fragmented collection of niche record-keeping tools into a strategically vital technology category. The steady revenue progression from 2020 through 2025 reflects not only increased adoption but also deepening penetration across care settings, expanding feature sets, and growing recognition of software as an operational backbone rather than a compliance accessory. The forecast to 2032 suggests that this momentum will intensify rather than plateau, fueled by ongoing digitization of care delivery, interoperability mandates, and the increasing complexity of reimbursement frameworks.
For enterprise strategists, the 8.0 percent CAGR is best interpreted not as a static growth indicator but as a signal of converging demand drivers. Facilities and agencies are under simultaneous pressure to improve clinical outcomes, optimize staffing, streamline documentation, and maintain financial viability amid shifting case-mix methodologies. Software that addresses these intersections—rather than isolated pain points—will command premium positioning and stronger retention. The research unpacks these demand-layer dynamics in detail, allowing leaders to distinguish between transient adoption trends and durable structural shifts.
Behavioral Health Software Market
Equally important is the forecast’s emphasis on market concentration. With the top three firms accounting for 37.5 percent of revenue and the top five capturing 45.8 percent, the competitive landscape exhibits moderate consolidation while still leaving meaningful room for specialized players, regional champions, and emerging entrants. This concentration structure matters because it shapes pricing power, integration partnerships, channel access, and the pace at which innovation diffuses across the market. Understanding where consolidation pressure is likely to intensify—and where fragmentation will persist—is essential for go-to-market planning, M&A evaluation, and capability investment.
Inside the Report: The Analytical Framework You Need for Decision-Making
This study is built around a structured, operator-centric analytical framework designed to surface not just what is happening, but why it matters and what to do about it. The report moves beyond surface-level charting to deliver a multi-dimensional assessment of market mechanics, competitive behavior, and implementation realities.
Market Sizing, Forecasting Methodology, and Scenario Thinking
The revenue trajectory from 2020 through 2032 is anchored in a transparent methodology that integrates historical demand patterns, deployment velocity, and forward-looking adoption indicators. Rather than presenting a single deterministic path, the analysis includes scenario considerations that help leaders stress-test assumptions around regulatory timing, reimbursement changes, and technology adoption cycles. This approach supports more resilient planning for product investments, sales capacity, and partnership commitments.
Application Contexts and Deployment Realities
Long-term care software is not a monolithic category. It is deployed across a diverse set of care environments, each with distinct workflow demands, staffing models, and compliance obligations. The report examines how software value propositions differ across nursing facilities, assisted living settings, and home-based care agencies, highlighting where operational efficiency, documentation burden reduction, and reimbursement alignment converge. By mapping these application dynamics, the study enables organizations to tailor messaging, packaging, and integration strategies to the realities of each care setting.
Long-term Care Software Market
Type-Level Evaluation and Functional Priorities
The report also disentangles the functional architecture of the market, examining how core record-keeping platforms, revenue cycle enablement tools, and complementary operational modules compete and coexist. Rather than treating these categories as isolated silos, the analysis explores how integration depth, interoperability, and workflow orchestration increasingly determine buyer preference. Leaders evaluating build-versus-buy decisions, platform expansion, or partnership strategies will find detailed guidance on where functional differentiation is still achievable and where commoditization pressure is rising.
Competitive Profiling and Strategic Posture Assessment
Competitive analysis in this study goes beyond company descriptions. Each profiled organization is assessed through the lens of market positioning, technological differentiation, go-to-market orientation, and recent strategic moves. This enables readers to identify which players are pursuing platform breadth, which are deepening vertical specialization, and which are leveraging AI or automation to reshape service delivery economics. The profiles are structured to support benchmarking, partnership evaluation, and competitive response planning.
Competitive Architecture: How Leading Players Are Shaping the Market
The competitive landscape of the long-term care software market is defined by a blend of established multi-product platforms, vertically focused EHR providers, and companies accelerating AI-enabled capability development. The following organizations represent core forces shaping market direction, buyer expectations, and the pace of innovation.
PointClickCare
Headquartered in Chicago, Illinois, PointClickCare has built a strong reputation around AI-powered EHR platforms designed for skilled nursing, senior living, and post-acute care. Its offering emphasizes real-time data access, transitions of care coordination, and reimbursement optimization. Recent strategic momentum underscores this direction: in March 2026, the company launched a next-generation EHR for practice groups, integrating AI-driven workflows such as ambient scribing to streamline senior care documentation and reduce administrative burden. This move highlights a broader industry push toward minimizing clinician friction while preserving documentation integrity and revenue accuracy.
MatrixCare
Based in Bloomington, Minnesota, MatrixCare provides EHR and home health solutions tailored to both facility-based and home-based care organizations. Its platform supports MDS/RAI processes, billing operations, and quality reporting, positioning it as a comprehensive compliance-and-operations partner for organizations managing complex regulatory and reimbursement requirements. In an environment where case-mix accuracy and reporting reliability directly affect financial performance, MatrixCare’s alignment with these workflows gives it a distinct relevance in the market.
WellSky
WellSky, headquartered in Overland Park, Kansas, offers a long-term care EHR together with its SkySense AI solution, targeting operational efficiency, documentation quality, and clinician productivity in skilled nursing and post-acute settings. In February 2026, WellSky expanded SkySense AI into long-term care and skilled nursing facilities, embedding AI capabilities directly within the long-term care EHR to strengthen operational workflows and documentation outcomes. This expansion illustrates how AI is moving from pilot initiatives into production-grade deployments that aim to measurably improve day-to-day care operations.
Netsmart Technologies
Operating from Cleveland, Ohio, Netsmart Technologies provides the myUnity and GEHRIMED EHR platforms for post-acute and long-term care providers, spanning senior living, home health, and value-based care coordination. Its emphasis on care coordination and cross-setting continuity reflects a growing market expectation that long-term care software must support not only facility-level documentation but also broader care pathways and reimbursement models tied to outcomes and transitions.
American HealthTech
American HealthTech, based in Ridgeland, Mississippi, delivers EHR solutions for long-term care facilities with a focus on MDS/RAI automation, case-mix optimization, and reimbursement tools. Its capabilities in reimbursement-linked workflows have made it a notable presence in the market, and its acquisition by PointClickCare signals the ongoing consolidation and platform-integration dynamics shaping the sector. This type of strategic combination often accelerates feature convergence, broadens deployment scale, and reshapes competitive boundaries.
Optimus EMR and HealthMEDX
Optimus EMR contributes a cloud-based EHR system designed for skilled nursing and long-term care facilities, aligning with the broader market shift toward cloud deployment models and simplified IT operations. HealthMEDX rounds out the competitive field with EHR solutions oriented specifically toward skilled nursing and long-term care providers, reinforcing the continued relevance of purpose-built clinical and operational functionality in this segment. Together, these players demonstrate that while platform scale matters, specialized focus and deployment flexibility remain important considerations for buyers evaluating long-term fit.
Market Dynamics: Regulation, Reimbursement, and the Pressure to Adapt
No long-term care software strategy can be built in isolation from the regulatory and reimbursement environment. In 2025 and 2026, a series of policy and compliance developments have materially altered the operational requirements placed on technology platforms. These changes are not peripheral; they directly influence feature priorities, implementation timelines, risk exposure, and the value proposition of different software architectures.
One significant development is the FY 2026 PDPM ICD-10 Mapping tool released by CMS, which introduced 34 changes effective October 1, 2025. These updates affect MDS/RAI coding and reimbursement calculations in long-term care facilities, placing renewed importance on software that can accurately support coding workflows, maintain alignment with mapping changes, and reduce the risk of reimbursement disruption. For technology leaders, this kind of regulatory cadence means that update agility and coding integrity are no longer optional enhancements; they are core expectations.
At the same time, the HIPAA Security Rule has seen new amendments effective in 2026, requiring 72-hour breach reporting and biannual vulnerability scanning for in-scope systems used in long-term care EHR platforms. These requirements heighten the compliance burden for vendors and provider organizations alike, increasing the strategic importance of security architecture, audit readiness, and operational resilience. Software decisions now must account not only for clinical and financial functionality but also for the capacity to meet more demanding security and reporting obligations without introducing administrative overload.
The FY 2026 Skilled Nursing Facility PPS Final Rule further reinforces this dynamic by updating quality reporting and case-mix requirements that long-term care software must support for compliance. As reimbursement frameworks become more complex and more closely tied to quality and documentation accuracy, platforms that can streamline compliance workflows while preserving clinical usability gain a meaningful competitive advantage. The market is increasingly rewarding solutions that treat regulatory alignment as an integrated operational capability rather than a bolt-on feature.
Why This Research Matters for 2026 Decision-Making
The strategic value of this report lies in its ability to connect market structure to decision quality. For executives assessing product investment, the research provides a clear view of where growth is most durable and where feature differentiation is becoming harder to sustain. For commercial leaders, it offers context on how competitive positioning, concentration patterns, and recent AI-driven product launches are reshaping buyer expectations. For risk and compliance teams, it frames the regulatory environment as a strategic variable rather than a static constraint, helping organizations anticipate the operational implications of reimbursement mapping changes, security rule amendments, and quality reporting updates.
Most importantly, the study is designed to support integrated decision-making. Market growth, competitive behavior, and regulatory change do not occur in separate lanes; they interact continuously. A platform’s ability to support MDS/RAI accuracy, for example, affects reimbursement performance, which in turn influences buyer demand, vendor positioning, and consolidation incentives. By examining these interconnections explicitly, the report helps leaders avoid siloed planning and make choices that hold up under real-world complexity.
What Is Next: Moving from Market Awareness to Strategic Action
The long-term care software market is expanding at a pace that rewards preparation and penalizes delay. With revenue projected to move from 406.78 in 2026 toward 642.7 by 2032, organizations that invest early in the right technology partnerships, capability-building, and competitive intelligence will be better positioned to capture value as the market matures. Those that rely on fragmented insights or outdated assumptions risk reacting to changes after they have already reshaped the competitive landscape.
To access the full analytical depth behind these findings—including detailed segmentation context, competitive benchmarks, scenario considerations, and deployment-level implications—we invite you to explore the complete report on our website. The full study provides the comprehensive intelligence needed to translate market momentum into concrete strategic choices, whether your focus is product strategy, commercial planning, partnership development, or organizational readiness for the next phase of long-term care digital transformation.
In a market defined by regulatory change, AI acceleration, and sustained demand growth, clarity is a competitive advantage. This research is built to deliver that clarity—so your 2026 decisions are informed not only by where the market has been, but by where it is going.
For detailed analysis of this topic, please visit the official page: Long-term Care Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Voltage DC-DC LED Drivers Market to Reach $458.6M by 2032, Growing at 6.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Low Voltage DC-DC LED Drivers Market: Strategic Foresight for 2026 and Beyond
Executive Summary
The global landscape for low voltage DC-DC LED drivers is undergoing a structural transformation. As lighting systems migrate toward higher efficiency, smarter controls, and lower power architectures, the demand for precision power conversion has intensified across residential, commercial, industrial, and mobility sectors. Our latest market intelligence report maps this evolution with granular rigor, offering enterprise decision-makers a clear vantage point to align product roadmaps, supply chain strategies, and capital allocation with the trajectory set for 2026 and the following years.
This study is not a static snapshot of historical sales figures. It is a forward-looking strategic compass designed for executives who must navigate component shortages, regional regulatory shifts, and intensifying competition among semiconductor and module manufacturers. By weaving together historical performance, medium-term forecasting, and competitive positioning, the report equips stakeholders with the analytical foundation required to make confident, time-sensitive decisions in an increasingly fragmented ecosystem.
Market Trajectory and Macro Dynamics
Between 2020 and 2025, the low voltage DC-DC LED driver market demonstrated a steady expansion profile, recovering from a temporary contraction in 2024 before resuming upward momentum. The baseline data confirms that revenue reached approximately 245.8 million USD in 2020, climbed through successive years, and crossed the 309.5 million USD threshold by 2025. Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.2 percent, with estimated revenue scaling from 337.58 million USD in 2026 toward 458.6 million USD by the end of the forecast window.
This growth trajectory is underpinned by several interlocking forces. First, the ongoing replacement of legacy lighting infrastructure with energy-efficient LED solutions continues to drive baseline demand, particularly in retrofit and new-build scenarios where low-voltage topologies offer advantages in thermal management and system integration. Second, the proliferation of intelligent lighting ecosystems—requiring precise current regulation, dimming compatibility, and compatibility with microcontroller-driven control planes—has elevated the functional bar for DC-DC driver components. Third, supply chain normalization and localized sourcing initiatives are gradually reshaping procurement patterns, influencing both cost structures and time-to-market expectations.
Low Voltage DC-DC LED Drivers Market
Crucially, the 6.2 percent CAGR is not a uniform assumption across all sub-segments. The report dissects where growth concentrates, which drivers face margin compression, and how end-use adopters recalibrate their purchasing cycles in response to component availability and total cost of ownership calculations. Enterprise readers will find particular value in the way these macro trends are mapped to actionable procurement and engineering strategies rather than treated as abstract numerical outputs.
Segmentation Architecture and Demand Drivers
The study segments the market along three primary dimensions—geography, converter topology, and end-use application—providing a layered view of where volume flows and where differentiation becomes decisive. Rather than presenting isolated percentage breakdowns, the analysis emphasizes the relative weight, growth rhythm, and strategic implications of each segment.
From a regional perspective, the Americas, Europe, and Asia Pacific collectively anchor the bulk of global demand, each shaped by distinct regulatory frameworks, construction cycles, and manufacturing footprints. Latin America and the Middle East and Africa represent smaller but structurally evolving bases, where infrastructure modernization programs and import substitution efforts are beginning to alter demand patterns. The report explores how supply logistics, certification requirements, and local partnership ecosystems influence competitive positioning across these regions without reducing the narrative to static share figures.
On the technology side, the market divides between isolated and non-isolated DC-DC converter architectures. Isolated solutions remain critical in applications demanding galvanic separation for safety, noise immunity, or system-level grounding strategies, while non-isolated topologies continue to gain traction in cost-sensitive, space-constrained, and efficiency-optimized designs. The analysis evaluates how design-in preferences shift as engineers balance bill-of-materials constraints against reliability and compliance mandates, and how component suppliers tailor reference designs, evaluation boards, and support materials to capture design wins early in the development cycle.
Application-side segmentation reveals equally nuanced dynamics. Architectural and decorative lighting continues to serve as a substantial volume center, driven by interior retrofit programs, hospitality upgrades, and retail refresh cycles. Commercial and industrial lighting contributes a significant share, with growth fueled by warehouse modernization, smart-building integrations, and energy-code compliance initiatives. Automotive and transportation lighting represents a specialized but expanding frontier, where low-voltage DC-DC drivers must meet stringent thermal, vibration, and electromagnetic compatibility expectations. Medical and healthcare devices form a smaller yet high-spec segment, emphasizing reliability, noise performance, and long lifecycle support, while miscellaneous applications round out the demand base with niche but strategically relevant use cases.
For decision-makers, the strategic takeaway lies in recognizing that no single segment behaves uniformly. Growth pockets emerge where application requirements, regulatory tailwinds, and component readiness intersect, and the report provides the contextual scaffolding needed to prioritize those intersections.
Competitive Landscape: Strategies, Positioning, and Design-Win Dynamics
The market features a concentrated set of influential participants, with the top three firms collectively accounting for roughly 37.2 percent of total revenue and the top five reaching approximately 47.8 percent. This level of concentration signals a landscape where scale, portfolio depth, and ecosystem support materially influence competitive outcomes, even as specialized players carve out defensible niches through application-specific engineering and agile customization.
Texas Instruments maintains a prominent position through its DC-DC LED driver controllers and reference designs aimed at flicker-free low-voltage LED lighting in both portable and fixed installations. Its strategy emphasizes design-in enablement, offering evaluation platforms and application notes that accelerate integration for engineering teams seeking predictable performance. Analog Devices competes with a strong analog IC heritage, co-developing next-generation low-voltage DC-DC LED driver ICs tailored for automotive and consumer lighting applications. Its approach underscores the importance of co-engineering relationships and application-specific optimization in high-performance segments.
STMicroelectronics contributes PWM-dimmable LED driver ICs and complementary power management solutions, supporting DC-DC LED lighting systems where signal integrity and dimming compatibility are paramount. Infineon Technologies focuses on the ILD family of hysteretic buck DC-DC LED driver ICs, which support high currents up to 1.5 A and efficiencies up to 98 percent for general lighting applications—a profile that appeals to efficiency-driven designs and thermally constrained layouts. Diodes Incorporated provides medium- and low-voltage DC-DC LED driver ICs, including the AL8871Q and AL8862QEV2 for driving high-current LEDs, reinforcing its role in cost-conscious yet performance-aware designs.
Molex differentiates through CoreSync and Transcend Smart low-voltage DC/DC LED drivers built for constant current LED engines in lighting fixtures, positioning itself at the intersection of driver electronics and fixture-level integration. LEDdynamics offers the BuckToot low-voltage DC/DC LED driver for constant-current LED applications in fixtures, emphasizing simplicity and reliability for targeted use cases. ON Semiconductor supplies both discrete and IC solutions supporting DC-DC LED driver applications in lighting power management, broadening its addressable design scenarios across multiple system architectures. Monolithic Power Systems rounds out the competitive set with MP2489 and similar hysteretic control buck LED drivers featuring DC and PWM dimming for low-voltage LED systems, highlighting efficiency and control flexibility as recurring themes in this segment.
The strategic implication for market participants is clear. Differentiation increasingly depends on more than raw component specifications. Reference quality, application support, compliance documentation, lead-time reliability, and collaboration with fixture or system designers all affect win rates. The report examines how these players position themselves across the design-in funnel, where they face margin pressure, and how they navigate the tension between standardized product lines and customized engineering engagements.
Report Scope: What Decision-Makers Will Find Inside
This study is structured to translate market intelligence into operational guidance. It combines a rigorous quantitative backbone with qualitative analysis that speaks directly to product planning, sourcing, and competitive strategy. The scope includes:
LED Drivers Market
- A detailed historical reconstruction and forward forecast that contextualizes revenue patterns across the 2020–2032 horizon, with particular emphasis on inflection points and recovery dynamics.
- A segmentation analysis that isolates the relative significance of regions, converter topologies, and end-use applications, highlighting how growth concentrates and where competitive intensity varies.
- A comprehensive competitive assessment of key manufacturers, covering product families, positioning, and strategic implications for design-win capture and portfolio development.
- An examination of demand-side drivers, including efficiency mandates, smart-lighting adoption, retrofit cycles, and application-specific performance requirements that shape purchasing behavior.
- Supply-side considerations such as component availability, design-in support ecosystems, compliance and certification pressures, and the impact of regional sourcing shifts on cost and timeline planning.
- Strategic recommendations tailored to different stakeholder roles, from product management and engineering to procurement and market-entry planning.
The report is designed to be referenced, not merely read. Tables, comparative profiles, and scenario-aware commentary enable teams to filter insights according to their specific priorities, whether they are evaluating supplier alternatives, assessing market-entry timing, or calibrating investment against likely demand growth in targeted segments.
Strategic Implications for 2026 Decision-Making
For organizations planning initiatives around 2026, the most valuable insight is not simply that the market is expanding, but how that expansion is structured. The 6.2 percent CAGR provides a useful baseline, yet its real meaning lies in the uneven distribution of opportunity across applications, topologies, and geographies. Companies that treat the market as a monolith risk misallocating engineering resources, over-indexing on slow-moving segments, or underestimating the competitive pressure in high-growth pockets.
Procurement and supply chain teams should pay close attention to the interplay between converter architecture preferences and component availability. Isolated and non-isolated designs appeal to different system constraints, and the relative attractiveness of each depends on safety requirements, thermal budgets, bill-of-materials sensitivity, and the availability of qualified alternates. Understanding where design wins are most likely to occur—and what design-in support is needed to secure them—can materially improve forecast accuracy and reduce downstream sourcing risk.
Product and engineering leaders will find value in the way the report connects application requirements with component capabilities. Whether a team is developing architectural fixtures, commercial lighting platforms, automotive illumination subsystems, or healthcare-grade devices, the expectations for efficiency, dimming behavior, reliability, and compliance differ substantially. The study maps those differences into a structured framework that helps teams set specification priorities, evaluate reference designs, and anticipate the trade-offs that will shape commercial viability.
Commercial strategy teams should also consider the concentration dynamics of the competitive field. With the top firms holding a meaningful share, scale advantages in portfolio breadth and ecosystem support matter, but specialized players continue to succeed by aligning closely with niche requirements and delivering focused engineering value. The report examines where broad portfolios create leverage and where specialized offerings command premium positioning or stronger loyalty in targeted application sets.
Conclusion: Turning Market Intelligence into Time-Sensitive Advantage
The low voltage DC-DC LED drivers market is advancing along a path defined by efficiency imperatives, application diversification, and increasingly sophisticated design-in competition. The 2026–2032 outlook presents a credible growth arc, but realizing the value of that arc requires more than awareness of headline numbers. It requires a clear understanding of where demand concentrates, which technical and commercial levers matter most, and how leading participants compete for design influence across multiple application domains.
This report is built to provide exactly that understanding. It synthesizes historical context, forecast discipline, competitive analysis, and application-level demand dynamics into a single integrated view, enabling stakeholders to move from observation to action. For executives, engineers, and commercial leaders preparing for 2026, the difference between reactive planning and proactive strategy lies in the quality of the intelligence behind the decision.
To explore the full segmentation detail, competitive profiles, regional demand context, and forecast scenarios, access the complete study through our official market research portal. The complete dataset and extended commentary are available there for teams that require the depth needed to shape product plans, sourcing strategies, and market-entry decisions with precision.
For detailed analysis of this topic, please visit the official page: Low Voltage DC-DC LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Dental Intraoral X-ray Sensor Market to Grow at 8.59% CAGR Reaching $473M by 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Dental Intraoral X-ray Sensors Market in 2026 and Beyond
The global dental imaging landscape is undergoing a profound transformation, driven by the accelerating adoption of digital diagnostics and the relentless pursuit of clinical precision. As stakeholders prepare for the strategic initiatives of 2026, understanding the trajectory of the Dental Intraoral X-ray Sensors Market becomes not just an option but a necessity for informed decision-making. Our latest comprehensive research study offers a definitive guide through this evolving ecosystem, providing the granular intelligence required to position organizations at the forefront of innovation and growth.
The market has demonstrated robust momentum over the past half-decade, establishing a strong foundation for sustained expansion. Historical analysis from 2020 through 2025 reveals a consistent upward trajectory, with the global valuation climbing from 142.0 million USD to a substantial 265.0 million USD in 2025. This progression underscores the industry's resilience and the growing integration of digital sensors into standard dental practices. Looking ahead, the forecast period spanning 2026 to 2032 projects a compelling compound annual growth rate of 8.59 percent. By 2032, the market is anticipated to reach 473.0 million USD, signaling a future where digital imaging becomes ubiquitous across diverse clinical settings. This macroeconomic outlook forms the backbone of our analysis, offering a reliable framework for long-term capacity planning and investment strategies.
Such growth is not merely a function of volume but is deeply rooted in technological evolution and shifting clinical priorities. The transition from traditional film-based methods to digital intraoral sensors represents a paradigm shift in diagnostic efficiency and patient safety. Evidence suggests that optimized digital environments can reduce average X-ray exposure significantly compared to legacy methods, aligning with broader healthcare trends toward minimizing radiation doses while enhancing image fidelity. This technological advantage, coupled with favorable reimbursement structures under codes such as CPT 70350 for radiographic services, creates a supportive economic environment for adoption. However, navigating this landscape requires more than a high-level view; it demands a nuanced understanding of the specific drivers, restraints, and opportunities that define each segment of the value chain.
Unpacking the Competitive Arena
The competitive dynamics within the dental intraoral sensor sector are characterized by a mix of established giants and innovative challengers, each vying for differentiation through product performance and ecosystem integration. Market concentration analysis indicates that the top three players hold a combined share of approximately 40.0 percent, while the top five account for 55.0 percent. This structure suggests a market where scale and brand recognition matter, yet ample room remains for specialized players to capture value through technological distinctions or regional expertise.
Leading the charge is Dentsply Sirona, headquartered in Charlotte, North Carolina. As a manufacturer of Schick intraoral sensors, including the Schick 33 with 33 lp/mm resolution and the AE series, the company continues to set benchmarks for high-quality digital X-ray imaging in dental practices. Their portfolio reflects a deep commitment to reliability and image clarity, crucial factors for practitioners seeking consistent diagnostic outcomes. Similarly, DEXIS, based in Quakertown, Pennsylvania, has carved a significant niche with its DEXIS Ti2 and IXS intraoral sensors, known for high-clarity images and durable hardware. Beyond hardware, DEXIS emphasizes integrated workflows through its DTX Studio software, a strategy that was reinforced by a significant product launch in February 2026. This update introduced expanded AI capabilities for pathological findings on 2D intraoral X-ray images, marking a pivotal step in bridging hardware performance with intelligent diagnostic support. Furthermore, in September 2025, DEXIS released the Imprevo intraoral scanner powered by IS ScanFlow 2.0 innovation, enhancing wireless freedom and precision for digital dentistry workflows, thereby broadening their appeal to practices seeking comprehensive digital solutions.
Planmeca Oy, originating from Helsinki, Finland, brings a distinct focus on user experience and patient-centered design with its Prosensor HD intraoral sensors. The emphasis on exceptional image quality and usability resonates with clinicians prioritizing ergonomics and workflow efficiency. In the Asia Pacific region, Vatech, based in Hwaseong, South Korea, continues to expand its footprint with EzSensor HD and EzSensor UHD intraoral sensors, supporting high-resolution digital X-ray applications. Their growth trajectory reflects the broader dynamism of the Asian market, where digital adoption rates are rising rapidly. Carestream Dental LLC, located in Atlanta, Georgia, maintains a strong presence through its RVG 5200 and other RVG intraoral sensors, integrated within broader digital imaging solutions that leverage the company's extensive distribution network.
The competitive field also includes specialized innovators and emerging players. Owandy Radiology, from Croissy-Beaubourg, France, recently marked a milestone with the launch of its third-generation Opteo intraoral sensor in May 2025. This product is designed for enhanced image clarity, speed, and reliability, showcasing the continuous iteration of sensor technology to meet clinical demands. Freedom Technologies Group, LLC, based in Carmel, Indiana, differentiates itself as a distributor and provider of DC-Air wireless direct-conversion intraoral X-ray sensors. Their offering features Bluetooth connectivity and a zero-profile design, addressing the growing demand for wireless convenience and reduced patient discomfort. Acteon Group, headquartered in Mérignac, France, supplies SOPIX and SOPIX 2 digital X-ray sensors, emphasizing reliable clinical diagnosis and precise tissue differentiation, which are critical for complex restorative and endodontic procedures.
Regulatory milestones and emerging market entrants further shape the landscape. Qpix Solutions Inc, based in Morrisville, North Carolina, achieved a significant regulatory feat in November 2025 by receiving FDA 510(k) clearance for its EzSensor HD and EzSensor UHD digital intraoral sensors. This clearance validates the device's safety and efficacy, opening doors for broader commercial deployment in the United States. Meanwhile, XpectVision Technology Co., Ltd, from China, continues to produce the ZXSZ series intraoral X-ray sensors, focusing on global distribution and technology integration. These developments highlight the global nature of innovation and the increasing importance of regulatory compliance in accessing key markets.
Regulatory Imperatives and Technological Standards
Strategic planning in this sector must account for a rigorous regulatory environment. All dental intraoral X-ray sensors must comply with FDA 510(k) clearance requirements as Class II medical devices under 21 CFR 872.1800. This regulatory framework ensures that devices meet essential performance and safety standards before reaching the market, influencing product development timelines and market entry strategies. Additionally, ISO 10993-1 biocompatibility standards apply to sensor housings and cables for medical-grade materials in direct oral contact. Compliance with these standards is non-negotiable for manufacturers aiming to assure clinicians and patients of the safety and quality of their products. These regulatory layers add complexity but also serve as barriers to entry that can protect established players with robust quality management systems.
Segmentation Dynamics and Market Drivers
The market's growth is fueled by distinct segmentation drivers that our report analyzes in depth. The type segment reveals a prevailing preference for wired sensors, which continue to dominate in terms of revenue contribution, reflecting their established reliability and cost-effectiveness in many practices. However, the wireless segment is gaining traction, driven by the demand for improved ergonomics and flexibility in clinical workflows. This shift is exemplified by products like the DC-Air wireless sensors and the integration of wireless capabilities in broader imaging ecosystems. The balance between wired and wireless adoption varies by region and practice type, and understanding these nuances is critical for product positioning and marketing strategies.
In terms of application, diagnostic use cases account for the lion's share of market activity. Clinicians rely on intraoral sensors for precise caries detection, periodontal assessment, and endodontic diagnosis, making diagnostic functionality the primary value proposition. Therapeutic and cosmetic applications, while smaller in volume, represent specialized niches where imaging supports treatment planning and aesthetic outcomes. The end-user landscape is similarly stratified, with dental clinics representing the largest segment due to their sheer number and high frequency of imaging procedures. Dental hospitals, while fewer in count, contribute significantly through higher-volume usage and the complexity of cases handled. These structural insights inform channel strategies, pricing models, and service support requirements tailored to each customer type.
Regional Perspectives and Global Opportunities
Geographically, the market exhibits diverse growth patterns shaped by healthcare infrastructure, economic development, and regulatory environments. North America remains a dominant force, supported by advanced dental infrastructure and high adoption rates of digital technologies. Europe follows as a significant market, characterized by strong regulatory standards and a mature dental sector. The Asia Pacific region, while currently smaller in absolute terms compared to North America and Europe, is poised for rapid expansion driven by increasing healthcare expenditure, growing awareness of oral health, and the expanding presence of key manufacturers. Latin America and the Mideast and Africa present emerging opportunities, where infrastructure development and trade dynamics influence market penetration. Our analysis avoids simplistic generalizations, instead providing context-aware insights that help stakeholders identify the most promising corridors for expansion or partnership.
What This Research Delivers
This market research report is designed as a strategic tool for executives, product managers, investors, and policymakers. It moves beyond aggregate numbers to provide actionable intelligence across multiple dimensions. Readers will find a detailed examination of market size and forecasts, contextualized within historical trends and future projections. The report dissects the competitive landscape, offering profiles of key companies, their product portfolios, and recent strategic moves such as product launches and regulatory clearances. This competitive intelligence enables benchmarking and helps identify gaps in the market that may represent opportunities for innovation or acquisition.
Furthermore, the study explores market dynamics comprehensively, analyzing drivers, restraints, opportunities, and challenges. It delves into the impact of reimbursement policies, regulatory requirements, and technological advancements on market growth. The segmentation analysis provides a granular view of how different product types, applications, and end-users contribute to the overall market, allowing for targeted strategy development. The regional analysis offers a nuanced understanding of geographic variations, supporting decisions related to market entry, localization, and resource allocation. Additionally, the report includes a value chain analysis, examining the roles of raw material suppliers, manufacturers, distributors, and end-users, which is essential for optimizing supply chain efficiency and identifying leverage points.
Strategic Outlook for 2026
As organizations formulate their strategies for 2026, the dental intraoral X-ray sensors market presents a landscape rich with potential but also complex with challenges. The integration of AI capabilities, as demonstrated by recent updates to imaging platforms, points toward a future where diagnostic support becomes more intelligent and integrated. Wireless technology continues to evolve, addressing usability concerns and expanding the flexibility of clinical setups. Regulatory compliance remains a critical success factor, with firms needing to stay abreast of evolving standards and clearance processes. Reimbursement landscapes and healthcare policies will continue to influence adoption rates, requiring stakeholders to monitor policy developments closely.
Dental Intraoral X-ray Sensors Market
Success in this environment depends on the ability to synthesize market data with strategic foresight. Companies must balance the pursuit of technological leadership with the pragmatic needs of their customers, whether they are individual clinics seeking reliable, cost-effective tools or large hospital networks demanding seamless integration and high throughput. Understanding the competitive positioning of peers, the nuances of regional markets, and the specific requirements of different application segments is paramount. This report serves as a compass in that endeavor, providing the depth and breadth of analysis necessary to navigate the market with confidence. The insights contained within are structured to support a wide range of strategic decisions, from product development and portfolio optimization to market expansion and partnership formation.
For those seeking to capitalize on the growth trajectory of this sector, the time to act is now. The convergence of favorable market fundamentals, technological innovation, and evolving clinical needs creates a window of opportunity for organizations ready to invest in a deeper understanding of the landscape. We invite stakeholders to access the full scope of our research to unlock the detailed data, forecasts, and strategic recommendations that will empower their decision-making in 2026 and beyond. The complete analysis offers the granularity required to turn market intelligence into competitive advantage, ensuring that your organization is well-positioned to thrive in the evolving world of dental digital imaging.
Intraoral Optical Scanner Market
For detailed analysis of this topic, please visit the official page: Dental Intraoral X-ray Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Expansion Joint Market Hits $596.4M in 2025, On Track for $880.73M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Horizon: Strategic Intelligence for the Concrete Expansion Joint Market (2026-2032)
The global construction landscape is undergoing a structural recalibration. As infrastructure ages, urbanization accelerates, and climate resilience becomes a non-negotiable engineering standard, the systems that accommodate movement, stress, and thermal expansion in concrete structures are moving from the background to the center of strategic procurement discussions. The concrete expansion joint market, long viewed as a commodity-adjacent segment, is now a critical nexus where materials science, regulatory compliance, and lifecycle asset management intersect. For executives navigating procurement, engineering, or market entry decisions in 2026 and beyond, generic industry narratives no longer suffice. Precision, traceability, and forward-looking scenario modeling have become table stakes.
This report has been engineered to serve as a decision-grade intelligence framework. Rather than offering retrospective summaries, it maps the operational, financial, and competitive contours that will define market behavior across the forecast horizon. What follows is a structural preview of the analytical architecture, the macro trajectory, and the competitive undercurrents that procurement leaders, product strategists, and infrastructure investors will need to internalize before committing capital or renegotiating supply contracts.
Worldwide Railway Expansion Joints Market
The Macroarc: Growth, Momentum, and the 2032 Trajectory
Understanding where the market is headed requires first grounding the conversation in a verified historical baseline. Drawing on an eight-year observational window from 2020 through 2025, the market has demonstrated consistent expansion, evolving from a 478.4 million USD revenue base in 2020 to 596.4 million USD by 2025. That progression reflects more than incremental volume growth; it signals a maturation in specification practices, a broadening of application mandates, and a gradual shift from reactive repair cycles toward proactive joint system integration during initial construction phases.
Projecting this momentum forward, the trajectory through 2032 maps a disciplined but robust expansion curve. Starting from an estimated 623.0 million USD in 2026, the market is positioned to reach approximately 880.73 million USD by the close of the forecast period. This pathway is underpinned by a compound annual growth rate of 5.8 percent, a figure that encapsulates the compounding effect of infrastructure renewal programs, material upgrades, and sustained demand across multiple end-use environments. For decision-makers, this growth rate is not merely a headline statistic; it is a planning parameter that informs capacity allocation, supplier diversification, and long-term contract structuring. The forward curve suggests a market that is expanding without overheating, creating room for differentiated value plays while maintaining enough competitive intensity to reward operational efficiency and technical differentiation.
The critical takeaway for 2026 strategy teams is that the next seven years will not be defined by sudden volatility, but by the compounding impact of specification trends, regional project pipelines, and material cost pass-through dynamics. Organizations that anchor their planning to this sustained growth trajectory, rather than to short-term contractual fluctuations, will be better positioned to navigate procurement cycles with strategic foresight.
What the Report Delivers: From Framework to Actionable Intelligence
A market research document only earns its place on a strategy desk when it translates into actionable levers. This study has been structured to bridge that gap. Rather than stopping at top-line sizing, the analysis dives into the operational layers that determine how growth is distributed, captured, and defended. The report is organized to serve multiple internal stakeholders simultaneously, from procurement and supply chain leads to product development, regional business development, and competitive intelligence teams.
Concrete Expansion Joint Market
Scope and Analytical Architecture
The research framework is built around three interlocking lenses that together provide a complete view of market mechanics. Each lens is designed to answer a distinct set of strategic questions while remaining fully integrated with the broader market narrative.
- Regional Market Architecture. The analysis maps how demand, project pipelines, and procurement preferences distribute across major geographic zones. Rather than treating regions as uniform blocks, the report examines the underlying drivers shaping consumption patterns, including infrastructure renewal velocity, specification standards, and local material availability. This geographic lens is essential for organizations evaluating market entry, export expansion, or regional supplier rationalization.
- Product-Type Competitive Positioning. Expansion joint solutions are not interchangeable. The report dissects the market by type, analyzing how engineered rubber and elastomeric systems, foam-based solutions, asphalt configurations, and cork alternatives compete across performance requirements, installation contexts, and lifecycle cost profiles. This segmentation is particularly actionable for manufacturers refining product portfolios, sales teams tailoring value propositions, and procurement groups evaluating total cost of ownership rather than unit price alone.
- Application-End-Use Mapping. Demand does not emerge uniformly across use cases. The study tracks how expansion joint requirements flow from buildings, roads, bridges, and ancillary applications, revealing where specification intensity is highest, where tolerance thresholds drive material selection, and where maintenance cycles reshape replacement demand. This application lens helps stakeholders align product roadmaps, service offerings, and regional targeting with the most responsive demand pools.
Beyond segmentation, the report integrates competitive benchmarking, supply chain exposure, and procurement behavior analysis. It traces how concentration patterns shape pricing power, how specification influence is distributed among key players, and how end-users are recalibrating their evaluation criteria in response to performance reliability and compliance requirements. The intent is to provide a reference architecture that can be directly overlaid onto internal planning models.
Competitive Landscape: Positioning, Differentiation, and Market Concentration
No market strategy is complete without a clear view of the players shaping supply, specification, and customer expectations. The concrete expansion joint segment exhibits a moderately fragmented competitive structure, with market concentration metrics indicating that the top three firms account for approximately 18.5 percent of aggregate revenue, while the top five extend to roughly 22.3 percent. This concentration profile suggests a landscape where scale confers advantages in specification access and supply chain leverage, but where differentiated engineering, regional presence, and application specialization still create meaningful pockets of competitive insulation.
Two organizations exemplify the strategic poles that define current competition. D.S. Brown Company, headquartered in North Baltimore, Ohio, has built its positioning around engineered rubber and elastomeric expansion joint systems tailored for bridges and pavements. Its product philosophy emphasizes movement accommodation, durability, and engineered performance under structural stress. In May 2025, the company reinforced this positioning through updated technical communications highlighting strip seals as a long-lasting sealed expansion joint system capable of handling movement exceeding four inches. This kind of specification-level communication demonstrates how leading participants are competing not merely on product availability, but on performance narratives that align with engineering priorities and lifecycle expectations.
Sika Emseal, operating from the United States, represents a complementary but distinct competitive profile. Its focus spans elastomeric concrete expansion joint systems, covers, and sealants designed for buildings and broader infrastructure applications. The emphasis here extends beyond movement accommodation to integrated sealing performance, coverage systems, and compatibility with building and civil specifications. Together, these participants illustrate how the market is being shaped by firms that translate materials capability into specification relevance, whether through structural joint engineering or integrated sealing and coverage solutions.
For strategists, the competitive takeaway is straightforward: growth in this market will not be captured by undifferentiated capacity alone. It will be earned by organizations that can align product architecture with application-specific performance demands, articulate reliable lifecycle value, and navigate the specification pathways that govern procurement decisions. The report dissects these dynamics in greater detail, mapping how competitive positioning interacts with regional demand, application mix, and pricing behavior.
Market Dynamics and Operating Conditions: What Is Shaping Margins and Execution
Growth trajectories do not unfold in a vacuum. The profitability, execution risk, and supply planning assumptions that underpin 2026 decision-making are being reshaped by a set of operating conditions that demand active management rather than passive monitoring. Raw material exposure, regulatory formulation constraints, and price transmission dynamics are now central variables in joint system procurement and production planning.
Raw Material Exposure and Formulation Complexity
The economics of expansion joint and sealant production are tightly coupled to feedstock markets. Polyurethane sealant formulation, for example, depends on isocyanate and polyol inputs, with pricing closely linked to toluene di-isocyanate and MDI production economics as well as petroleum-derived raw material costs. This linkage means that margin structures are increasingly sensitive to petrochemical price movements, not as an occasional shock, but as a continuous planning variable.
The pressure intensified in early 2026. In the first quarter, prices for Dimethyldichlorosilane rose by 28 percent year-on-year, driven by operational outages at Chinese chlor-alkali units and higher tariffs on silicon metal. Simultaneously, Wacker announced a mid-single-digit price increase in April 2026 in response to supply disruptions in the Middle East and elevated energy tariffs in Europe. These movements are not isolated events; they signal a broader environment in which input cost volatility is becoming a recurring feature of the supply landscape, especially for performance sealants and engineered elastomeric systems.
Regulatory Pressure and Compliance-Driven Cost Dynamics
Beyond raw materials, regulatory frameworks are reshaping formulation strategies and production economics. Stringent VOC emission limits imposed by regulatory bodies have increased formulation complexity and elevated production costs for construction sealants, including those used in concrete joint systems. For suppliers, this means that compliance is no longer a checkbox exercise; it is a product architecture consideration that affects raw material selection, processing requirements, and ultimately cost structures. For buyers, it introduces a new dimension to specification evaluation, where emissions performance, regulatory conformity, and long-term durability must be weighed alongside upfront pricing.
These dynamics create a dual effect on the market. On one side, cost pressure is real and increasingly visible in supplier pricing behavior and contract negotiations. On the other, regulatory and performance expectations are raising the barrier to entry for undifferentiated products, reinforcing the value of engineered solutions that can meet both compliance thresholds and structural performance requirements. Organizations that treat these forces as separate issues, rather than as interconnected drivers of specification and cost, risk misjudging both margin exposure and competitive positioning.
Why This Report Matters for 2026 Decision-Making
The concrete expansion joint market is entering a phase where strategic clarity outperforms tactical reactivity. Growth is steady, competition is intensifying in specific application and product niches, and the cost and compliance environment is demanding more sophisticated procurement and product planning than in prior cycles. For executives, the central challenge is no longer whether the market is expanding, but how to allocate resources, structure supplier relationships, and align product or service strategies with the segments and regions where value is being created most reliably.
This research is designed to address that challenge directly. It provides the structural context needed to evaluate where demand is concentrated, how competitive advantage is being built, and which operating conditions will most affect margins and execution over the forecast period. It is intended for teams that need to move beyond aggregate market narratives and into the segmentation logic, competitive behavior patterns, and supply-side dynamics that actually shape procurement and investment outcomes.
The full study contains the detailed segmentation breakdowns, competitive profiles, regional demand architecture, and forward scenario analysis required to translate this landscape into concrete planning assumptions. The complete intelligence framework, including product-type splits, application-end-use distribution, regional demand architecture, and extended competitive profiling, is available through the full report. For strategy, procurement, and business development teams preparing for 2026 and the years that follow, the depth of that analysis is where directional insight becomes executable strategy.
For detailed analysis of this topic, please visit the official page: Concrete Expansion Joint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Stainless Steel Floor Drains Market to Hit $2.13B by 2032 at 3.6% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Stainless Steel Floor Drain Market: Navigating Growth and Compliance in 2026
The global landscape for industrial and commercial drainage infrastructure is undergoing a subtle but significant transformation. As hygiene standards tighten and infrastructure spending accelerates, the stainless steel floor drain market stands at a critical juncture. For executives, investors, and strategic planners, understanding the trajectory of this sector is no longer optional—it is a prerequisite for risk mitigation and opportunity capture. PW Consulting is pleased to introduce our latest comprehensive market research study, designed to equip stakeholders with the actionable intelligence needed to navigate the complexities of the 2026 fiscal year and beyond.
This report serves as a definitive guide to the revenue streams, competitive forces, and regulatory drivers shaping the industry. By analyzing historical performance from 2020 through 2025 and projecting trends through 2032, we provide a robust framework for decision-making. The following analysis outlines the strategic value embedded within this research, highlighting why deep-dive intelligence is essential for maintaining competitiveness in a market characterized by moderate growth and high compliance barriers.
Market Trajectory and Historical Context
Understanding where the market has been is essential to forecasting where it is going. Our analysis covers a detailed historical period from 2020 to 2025, establishing a baseline of revenue performance against which future growth can be measured. The data indicates a resilient market structure that has weathered raw material fluctuations and shifting construction priorities. Looking ahead, the forecast period spans from 2026 to 2032, offering a long-term view for capital allocation and capacity planning.
The overall market size has demonstrated a steady upward trajectory. In 2025, the market commanded a revenue position of approximately 1656.0 Million USD. This figure reflects the cumulative demand across various sectors, driven by both replacement cycles in existing infrastructure and new installation requirements in burgeoning commercial zones. To quantify the expected pace of this expansion, the compound annual growth rate (CAGR) is projected at 3.6 percent throughout the forecast period. While this growth rate suggests maturity rather than explosive volatility, it underscores a stable demand environment where market share gains are often won through operational efficiency and compliance adherence rather than sheer market expansion alone.
By 2032, the revenue landscape is expected to evolve significantly. Strategic planning requires acknowledging that this growth is not linear. Intermediate years may present variations based on macroeconomic factors, yet the long-term consensus points toward a robust 2133.1 Million USD valuation by the end of the forecast window. For stakeholders, this implies that while the market is not doubling in size overnight, the absolute value accumulation offers substantial opportunities for players who can optimize their supply chains and product portfolios to capture steady recurring revenue.
Competitive Landscape and Key Players
The market is fragmented yet defined by a core group of established manufacturers who set the standards for quality and innovation. Our report provides an exhaustive profiling of key companies that dominate the supply chain. Understanding the positioning of these entities is critical for benchmarking and partnership strategies. The research delves into the operational footprints, product specialties, and strategic moves of industry leaders such as Josam Company, AWI Manufacturing, Jay R. Smith Mfg. Co., Zurn Industries, Blucher (Watts Water Technologies), CustomDrains, and Sioux Chief Manufacturing Company.
Josam Company, based in Elkhart, Indiana, remains a pivotal player, offering a wide array of 304/304L and 316L stainless steel solutions including trench drains and retrofit liners. Their recent activity highlights a focus on specialized project references, such as installations featured in Royal Winery and Venn Brewing projects in early 2025. These moves signal a strategy of deepening penetration in niche commercial sectors where hygiene and aesthetics converge. Similarly, AWI Manufacturing and Jay R. Smith Mfg. Co., both headquartered in Montgomery, Alabama, continue to leverage decades of manufacturing experience to serve food, dairy, and commercial settings. Their longevity suggests a strong grip on traditional distribution channels and established contractor relationships.
Stainless Steel Floor Drains Market
On the global front, Blucher, operating under Watts Water Technologies, extends the reach of stainless steel drainage systems internationally, while Zurn Industries focuses on high-grade solutions for industrial and high-traffic environments. Notably, Zurn expanded its hygienic drainage product line in 2025 specifically targeting pharmaceutical and food processing applications. This strategic pivot indicates a broader industry trend where manufacturers are aligning their R&D efforts with stringent regulatory requirements in high-value sectors. CustomDrains and Sioux Chief Manufacturing Company round out the competitive field, with the former specializing in custom systems for pharmaceutical and food processing facilities, and the latter maintaining a strong presence in residential and commercial segments.
Market concentration remains relatively moderate, with a CR3 of 24.6 percent and a CR5 of 26.2 percent. This structure suggests that while leading firms hold significant influence, there is ample room for specialized players to thrive through customization and regional expertise. The report analyzes how these concentration levels impact pricing power and supply chain resilience, providing context for procurement strategies.
Linear Shower Drains Market
Regulatory Dynamics and Compliance Drivers
One of the most critical value propositions of this research is its detailed examination of the regulatory environment. In the stainless steel floor drain sector, compliance is not merely a legal hurdle; it is a market driver that dictates product design and market access. Our analysis integrates the latest regulatory updates to help clients anticipate compliance costs and certification timelines.
Commercial kitchen drains, for instance, must meet rigorous standards including NSF/ANSI 14 and NSF/ANSI 51, in addition to ASME A112.6.3 for performance. Failure to comply can result in exclusion from major commercial projects. Furthermore, foodservice and commercial applications are increasingly subject to HACCP hygienic design principles and EHEDG guidelines. These standards necessitate specific design features that prevent bacterial growth and facilitate easy cleaning, directly influencing manufacturing specifications and material choices.
Beyond product-specific standards, macroeconomic legislation plays a substantial role. In 2025, the Infrastructure Investment and Jobs Act continued to channel billions into wastewater management and public facility refurbishment. This influx of capital creates a favorable tailwind for municipal and commercial drainage projects. However, capturing this value requires navigating the complexities of government contracting and ensuring that product specifications align with public infrastructure mandates. The report dissects how these legislative frameworks translate into tangible demand drivers across different project types.
Supply Chain and Material Cost Considerations
Strategic planning in 2026 must account for the volatility of raw material costs. Stainless steel pricing is inherently linked to nickel costs and broader market trends. As of late 2025, the price per pound for 304 grade stainless steel ranged from 1.45 USD to 2.06 USD. This fluctuation directly impacts margins for manufacturers and procurement budgets for large-scale installers. Our research does not just report these figures; it contextualizes them within hedging strategies and supplier negotiation tactics.
Understanding the cost structure is vital for pricing strategy. Companies that can secure stable supplies of 304 and 316L grades while maintaining flexible manufacturing processes will hold a competitive advantage. The report examines how key players are managing these input costs and whether shifts in material preference are occurring in response to price volatility. For buyers, this intelligence informs contract negotiations and inventory management decisions.
Product Segmentation and Application Insights
The market is diversified across several product types and application verticals, each with distinct growth characteristics. Our segmentation analysis covers traditional water seal floor drains, spring-type drains, suction stone drains, gravity drains, and other specialized types. Traditional water seal solutions continue to hold a significant share of the market, reflecting their established reliability and code compliance in many jurisdictions. However, innovation in spring-type and suction stone technologies is gaining traction in specific high-performance environments.
Application-wise, the demand is spread across household, commercial, municipal, industrial, and marine uses. Commercial applications represent a substantial portion of revenue, driven by the ongoing development of hospitality, food service, and healthcare facilities where hygiene is paramount. Municipal usage is supported by the aforementioned infrastructure spending, focusing on public buildings and wastewater systems. Industrial and marine sectors, while smaller in relative volume, often command higher specifications and margins due to the corrosive and high-load environments they must withstand.
The report provides a granular look at how these segments interact. For example, the overlap between commercial food processing and industrial hygienic applications creates a specialized niche where manufacturers like CustomDrains and Zurn are focusing their efforts. By understanding the specific requirements of each application, businesses can tailor their go-to-market strategies more effectively.
Strategic Value for 2026 Decision-Making
Why does this research matter for your 2026 strategy? The answer lies in the convergence of steady market growth, regulatory tightening, and competitive differentiation. A 3.6 percent CAGR suggests a stable market, but in such an environment, market share is often a zero-sum game. Gaining share requires superior execution in compliance, cost management, and customer service.
For manufacturers, the report offers insights into product development pipelines that align with regulatory trends, such as the increased focus on hygienic design in pharmaceutical applications. For distributors and contractors, it provides a roadmap of regional demand and key supplier capabilities. For investors, the analysis of market concentration and revenue projections helps assess the viability and risk profile of potential targets or holdings.
Access to complete intelligence is the differentiator. While macroeconomic trends provide context, the specific interplay of regional dynamics, detailed product performance, and competitor roadmaps determines success. Our full study unlocks these layers, providing the data necessary to move from reactive planning to proactive strategy.
Conclusion and Next Steps
The Stainless Steel Floor Drain Market is poised for sustained, moderate growth backed by essential infrastructure needs and hygiene regulations. However, navigating this landscape requires more than general knowledge; it demands precise, data-driven insights. PW Consulting's latest market research is designed to fill that gap, offering a comprehensive view of the revenue landscape, competitive dynamics, and regulatory frameworks defining the industry through 2032.
To access the full suite of data, including detailed regional breakdowns, specific segment valuations, and deep-dive competitor profiles, we invite you to explore the complete report. Equip your organization with the intelligence needed to make informed decisions in 2026 and secure a competitive advantage in this evolving market.
For detailed analysis of this topic, please visit the official page: Stainless Steel Floor Drains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


