



PW Consulting Forecast: Refined Wood Vinegar Market Poised for 6.02% CAGR, Reaching USD 11.35 Million by 2032
By PW Consulting, 2026-07-13
Refined Wood Vinegar: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive preview for executives, investors and product strategists
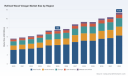
Refined wood vinegar sits at an inflection point. PW Consulting’s latest Refined Wood Vinegar Market report (base year 2025) synthesizes seven years of historical performance and a seven‑year forecast horizon to show a predictable, investment‑grade growth path: the global market expanded from roughly USD 5.6 million in 2020 to USD 7.54 million in 2025 and is projected to reach approximately USD 11.35 million by 2032 at a compound annual growth rate (CAGR) of 6.02% (2026–2032). This trajectory reflects steady commercialisation across agriculture, feed, and selected industrial niches where quality‑differentiated, purified pyroligneous acid is gaining traction.
Refined Wood Vinegar Market
Why this market matters to 2026 decisions
For strategic leaders making resource allocation, sourcing, or M&A decisions in 2026, the refined wood vinegar market offers a classic “adjacent growth” opportunity: predictable topline expansion combined with meaningful margin dispersion driven by product grade, process technology and route‑to‑market. The market is neither a red‑hot consumer bubble nor a stagnant commodity — it is consolidating around quality and traceability. Our concentration analysis indicates a moderate level of supplier consolidation (CR3 ~42.2%; CR5 ~58.4%), which signals both opportunity for scale players to strengthen pricing power and room for specialised entrants to capture premium niches.
Refined Wood Vinegar Market
Key macro and structural drivers
-
Quality and refinement premiums. Refined products command higher pricing than crude by‑products because of additional purification (tar removal, controlled acetic acid content and stabilization), certification potential and lower levels of undesirable compounds. Buyers increasingly pay for validated purity and consistent batch performance.
Refined Wood Vinegar Market -
Circular agricultural value chains. Pyrolysis and biochar projects are turning biomass waste into long‑life carbon assets and simultaneously producing wood vinegar as a commercially valuable co‑product. High‑integrity carbon removal projects that follow robust MRV standards make dual‑output economics attractive to project developers and agricultural off‑takers.
-
Regulatory and organic market access. When processed to meet organic product standards, refined wood vinegar can secure listings (e.g., OMRI), unlocking certified organic channels that prefer traceable, low‑contaminant inputs for soil health and biostimulant applications.
-
Segmentation-led demand. Demand is spreading across plant growth regulation, animal feed adjuncts, smoked/food‑flavor applications and select personal care/medical formulations — but the value capture varies sharply by grade and by the degree of refinement and certification.
What the report provides (practical, transaction‑ready content)
PW Consulting’s report is built for decision makers who need actionable intelligence in 90 days or less. It includes:
-
A validated market model (2020–2032) with scenario and sensitivity analyses that let procurement and strategy teams stress‑test price, volume and adoption assumptions.
-
A supplier scorecard and capability map covering process technologies, quality controls, certification track record and commercial footprint—used to prioritize partners or acquisition targets.
-
Go‑to‑market and channel playbooks for entering or expanding in organic agriculture, animal nutrition and specialty industrial segments.
-
A regulatory and standards compendium focused on thresholds relevant to organic certification and MRV alignment for carbon projects (practical checklists for COA, SGS/ISO evidence and OMRI pathways).
-
Price and margin benchmarks across grades and packaging formats, plus a risk register and mitigation roadmap tailored to supply volatility and raw material changes.
Strategic implications for 2026 — recommended actions
The market requires discipline in three areas: upstream feedstock and process control, product quality and certification, and commercial channel specialization. Our top recommendations for 2026 decision cycles:
-
Lock downstream value via grade and certification segmentation. Prioritise product lines that can be certified for organic use and that provide clean COAs; these win premium shelf space and longer contracts with agritech integrators.
-
Integrate or secure feedstock through partnerships with biochar and waste‑to‑energy projects. Projects that produce biochar and wood vinegar together offer favorable economics and stronger sustainability narratives — a particular advantage where carbon removal MRV standards are part of the buyer’s buying criteria.
-
Invest in purification capability or contract with refined‑grade specialists. The market is bifurcating between commodity, industrial pyroligneous acid and refined, stabilized formulations tailored for biological applications — margins follow technical differentiation.
-
Set a regional go‑to‑market prioritisation driven by channel access and regulatory ease rather than broad geographic volume pursuit. Targeting high‑value distribution channels (organic input resellers, premium feed formulators and niche food processors) delivers faster ROI than unfocused volume plays.
-
Embed traceability and MRV readiness into commercial agreements. For sellers aiming at premium sustainability demand, the ability to demonstrate co‑benefits for carbon projects and validated MRV adherence is now a negotiation advantage.
Competitive landscape — what to watch
The supplier base includes vertically integrated biochar operations, technology‑led pyrolysis producers and specialist refiners. Notable players we profile and benchmark in the report include VerdiLife, Nara Tanka Industries, Hongsen Carbon, Nettenergy B.V., ACE (Singapore), TAGROW, Canada Renewable Bioenergy Corp., Byron Biochar, Seneca Farms Biochar and PyroAg. Each represents a different positioning:
-
Technology and refinement leaders: Companies with advanced distillation/refinement processes (e.g., those removing tar and controlling acetic acid) position themselves for high‑margin, application‑specific contracts.
-
Volume and industrial suppliers: Factory‑scale operators that supply drums/IBC and ISO‑certified bulk grades remain important sources for composting, odor control and industrial uses where price and availability dominate.
-
Integrated biochar value chains: Producers who co‑produce biochar and wood vinegar can offer lower delivered cost and complementary sustainability claims attractive to institutional buyers and carbon project developers.
Recent moves underscore these dynamics: a February 2026 industrial partnership to deploy biochar carbon removal projects that generate wood vinegar as a co‑product highlights the sector’s integration into carbon value chains; and earlier product rebranding by a US biochar producer emphasizing the absence of methanol and tar illustrates the importance of perceived product safety for agricultural customers.
Risk matrix and watchlist for 2026
-
Quality non‑conformance: Mixed or poorly purified batches can erode trust quickly in specialty channels; robust COA processes are non‑negotiable.
-
Feedstock volatility: Dependence on specific biomass streams can create operational risk; multi‑feedstock flexibility is a resilience measure.
-
Regulatory and certification shifts: Evolving organic or environmental standards could change eligibility for premium channels; be proactive with compliance investment.
-
Market consolidation pressure: Given moderate concentration metrics, consolidation or exclusive offtake deals by larger players can re‑shape local supplier economics — be prepared with partnership or exit strategies.
How clients are using this intelligence
Across our client base, the report is being used in three ways in 2026 planning cycles:
-
Due diligence for acquisitions and joint ventures — using supplier scorecards and scenario models to set bid ranges and integration synergies.
-
Commercial strategy development — to design premium product SKUs, packaging and channel incentives that reflect certification and traceability value.
-
Project economics for biochar‑plus models — evaluating co‑product revenue attribution and MRV alignment to justify capex and offtake structures.
Closing — the strategic moment
Refined wood vinegar’s growth is steady and structurally supported by sustainability trends, process innovation and emergent circular business models. For 2026, the decisive moves are not merely volume plays but capability and credibility plays: refine, certify, and partner. Organisations that secure feedstock certainty, demonstrate validated purity, and align with high‑integrity carbon and organic standards will capture disproportionate value as the market evolves.
Next steps
PW Consulting’s full report contains the proprietary models, granular segmentations, supplier scorecards and a tactical 90‑day implementation plan that we deliberately omit here to preserve the value of the source intelligence. To access the complete dataset and tailor the findings to your situation, visit the PW Consulting Refined Wood Vinegar report page or contact our industry team for a briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Refined Wood Vinegar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report forecasts 6.85% CAGR for the High-Speed Packaging Machine market through 2032
By PW Consulting, 2026-07-13
High‑Speed Packaging Machine Market — 2026 Strategic Preview from PW Consulting
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high‑altitude, decision‑grade preview of the High‑Speed Packaging Machine market built to inform boardroom conversations and capital allocation choices in 2026. Our new market model uses 2025 as the base year and traces actuals across 2020–2025 before projecting demand through 2032. At the top line, the global installed and order pipeline expanded from approximately USD 13.3 billion in 2020 to about USD 18.5 billion in 2025. Our forecast anticipates continued expansion through 2032, reaching roughly USD 29.4 billion, driven by a compound annual growth rate of 6.85% across the 2026–2032 horizon.
High Speed Packaging Machine Market
Why this preview matters for 2026 decisions
2026 will feel like a pivot year for strategic buyers, OEMs, and investors in the packaging‑equipment ecosystem. Several simultaneous dynamics—supply‑chain normalization, sharper regulatory pressure on recyclability, renewed capital spending in food & beverage and pharmaceuticals, and accelerating e‑commerce throughput needs—combine to change the value equation for high‑speed machinery:
High Speed Packaging Machine Market
- Capital intensity versus agility: Buyers are balancing the unit economics of ultra‑high throughput lines with the operational flexibility of modular, reconfigurable platforms.
- Sustainability as a design constraint: Regulatory regimes and producer responsibility fees are increasingly shaping machine specifications and aftermarket services.
- Service and data monetization: As machines get faster, the aftermarket (predictive maintenance, upgrades, retrofits) becomes a critical lever for lifetime ROI.
What PW Consulting’s report delivers (practical, execution‑oriented)
We designed the full report to be more than a market map; it is a playbook for 2026 decisions. Key deliverables include:
High Speed Packaging Machine Market
- Proprietary market sizing and demand model (2020–2032) with scenario toggles for price shocks, regulatory tightening, and adoption curves for recyclability‑friendly technologies.
- Capital planning templates: TCO calculators, payback sensitivity matrices, and OEE uplift models tailored to high‑speed formats.
- Vendor evaluation and sourcing toolkit: decision matrices that weigh throughput, service coverage, retrofitability, energy profile, and compliance readiness.
- M&A and partnership scorecards: screening criteria for strategic buys, joint ventures, and minority investments focused on technology gaps and aftermarket potential.
- Supply‑chain risk map and mitigation playbook covering raw material volatility, single‑source components, and regional manufacturing dependencies.
- Technology adoption roadmap: modularization, servo and motion control evolution, in‑line quality inspection integration, and digital twin deployment timelines.
- Regulatory compliance checklist and design inputs for recyclable and recycled‑content packaging lines aligned to evolving EU/US/UK policies.
Interpreting the macro numbers without giving everything away
The headline growth trajectory — rising from USD ~18.5 billion in 2025 to nearly USD 29.4 billion by 2032 at a mid‑single‑digit CAGR — signals an industry large enough to reward scale, but also open enough to allow focused innovators to capture outsized pockets of value. Market concentration remains moderate: the top three global players account for roughly a third of market revenue, and the top five under half. That structure supports both continued organic competition and opportunistic consolidation, particularly in services, software layers, and platform modularity.
Competitive dynamics — what leading suppliers are doing now
Across the OEM landscape, winners are pursuing three mutually reinforcing plays: throughput leadership, platform modularity, and services/data monetization. Highlights from our competitive analysis and recent corporate developments:
- Syntegon (Bosch Packaging Technology) — Continues to lead on blister and precision pharma lines, investing in servo‑driven architectures for maximum speed and repeatability. Their 2025 Cyclone launch underscores how performance milestones can re‑price entire subsegments.
- IMA Group & Marchesini Group — Italian players remain strong in cartoning and monobloc integration, focusing on high throughput tailored to beverage, dairy, cosmetics, and pharmaceutical bottling and secondary packaging.
- Krones, Sidel, and Tetra Pak — Beverage and liquid packaging leaders continue to push filler and forming speeds while pairing hardware with line control software, sustainability certifications, and customer financing offers to reduce buyer friction.
- GEA, Multivac, Coesia, Ishida, Heat & Control, NJM (Romaco) — These suppliers have differentiated via niche capabilities (aseptic filling, thermoforming, high‑speed weighing, snack and case packing), and by deep aftersales networks that convert installation projects into recurring revenue.
- Recent corporate activity — new high‑speed launches, trade‑show demonstrations of 80k–120k bph fillers, updated sustainability certifications, and marquee installations in Asia‑Pacific — collectively illustrate that product and sustainability innovation remain the principal ways suppliers compete for tier‑one accounts.
Regulatory and input‑cost realities shaping machine design and procurement
Three non‑market forces stand out as determinative for 2026 planning:
- Regulation: Tighter rules on recycled content and extended producer responsibility in multiple jurisdictions are forcing OEMs and brand owners to re‑engineer both packaging formats and machine changeover sequences to support recyclable or recycled packaging streams.
- Raw‑material price volatility: Stabilization in plastics pricing after 2024 disruptions has reduced immediate cost shock risk, but energy and metal costs (notably aluminum) remain a vector of input volatility that impacts canning and metal‑forming equipment economics.
- Compliance costs: New producer fees and plastic taxes — already in effect in some markets — introduce variable per‑unit costs that change the ROI calculus for high‑speed mono‑format lines versus flexible, multi‑format lines.
Five strategic actions for 2026 (prioritized)
- Adopt modular platforms: Specify machines that can be reconfigured economically to protect against format obsolescence and to capture e‑commerce and premiumization opportunities.
- Embed sustainability as a performance metric: Require audited recyclability performance and retrofit pathways in RFQs; factor producer responsibility liabilities into TCO models.
- Lock in aftermarket economics: Negotiate multi‑year service contracts, digital‑data agreements, and upgrade paths that de‑risk uptime for ultra‑high throughput lines.
- Scenario plan CapEx: Use tiered IRR thresholds tied to regulatory scenarios and raw‑material shocks; prioritize projects with shorter payback or strategic optionality.
- Leverage partnerships: Where internal development is slow, use M&A, JV, or strategic partnerships to acquire software stacks, niche throughput technologies, or regional service footprints.
How to use this preview and where the full value lies
This article is intentionally a “trailer” — designed to demonstrate the depth of analysis and to surface strategic implications without publishing the granular regional, type, or application split tables that are essential for transaction work, procurement negotiation, and plant‑level investment. The full PW Consulting report includes interactive dashboards, downloadable CapEx models, supplier scorecards, and the granular segmentation data that operations, procurement, and M&A teams will require to finalize 2026 budgets and tactics.
If you are making capital commitments, drafting procurement specifications, or executing M&A in 2026, frame decisions around flexibility, sustainability readiness, and service economics rather than purely headline throughput. For many organizations, incremental investment in modular, connected equipment and aftermarket capabilities will deliver a superior risk‑adjusted return compared with single‑format, maximum‑speed installs.
Next steps
- For a detailed briefing, request PW Consulting’s full High‑Speed Packaging Machine Market report and the companion scenario models. The full package contains the regional and application detail that underpins the strategic recommendations above.
- For customized support — from CapEx modelling to vendor selection and transaction due diligence — contact our Strategy & Transactions team to schedule a tailored workshop and receive a bespoke excerpt of the dataset.
PW Consulting’s 2026 market intelligence is built to move from insight to action. Use it to test assumptions, stress‑test plans, and prioritize investments that create durability in throughput, compliance, and aftermarket value.
For detailed analysis of this topic, please visit the official page: High Speed Packaging Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Real-Time Shelf Monitoring Market Poised for Rapid Expansion — 13.52% CAGR Expected
By PW Consulting, 2026-07-13
Real Time Shelf Monitoring Systems: Strategic Imperatives for 2026 — PW Consulting Market Preview
As retailers and consumer-packaged-goods (CPG) companies accelerate their shift to data-driven store operations, real time shelf monitoring (RTSM) has moved from a pilot-stage curiosity to a mission-critical capability. PW Consulting’s latest market study — based on a 2020–2025 historical analysis and a 2026–2032 forecast horizon — synthesizes commercial realities, vendor capabilities, and practical decision frameworks that enterprise leaders will need to act on in 2026. This preview highlights the strategic value contained in the full report while preserving the granular segmentation and vendor scoring that subscribers will find in the source document.
Real Time Shelf Monitoring System Market
Market Trajectory and What It Means for Strategic Planning
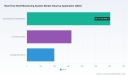
The RTSM market has shown sustained, above-market growth: our topline analysis places the market at approximately USD 550 million in 2020, expanding to USD 1,125 million by the 2025 base year. Looking forward under current adoption and technology trends, we forecast continued rapid expansion — the market is projected to exceed USD 1.2 billion in 2026 and reach roughly USD 2.73 billion by 2032, representing a compound annual growth rate (CAGR) of 13.52% across the forecast period.
Real Time Shelf Monitoring System Market
Implication for 2026 planning: this rate of growth implies a maturing market where winners will be those who move beyond point solutions to platform plays, deliver measurable in-store ROI, and build integration pathways into retailers’ core systems (POS, WMS, ESL, analytics). Enterprises should treat RTSM as a multi-year program — not a one-off project — and allocate capital accordingly in 2026 planning cycles.
Real Time Shelf Monitoring System Market
What PW Consulting’s Report Contains (Practical, Actionable Items)
- Market sizing and forward-looking scenario analysis that supports budgetary planning and capital allocation for 2026–2028 initiatives.
- Vendor evaluation framework and comparative scorecards (technology capability, deployment model, data governance, integration depth, and commercial terms) to streamline RFP and shortlisting processes.
- Implementation playbooks and PoC templates — camera placement guidelines, sampling protocols, data labeling expectations, and KPI definitions (shelf compliance, out-of-stock reduction, replenishment lead times, sales uplift models).
- Technology decision matrices that help buyers evaluate trade-offs between computer vision, robotics, RFID/ESL-integrated solutions, and sensor-based approaches, including recommended architectures for edge versus cloud processing.
- Commercial tools: subscription vs. CapEx TCO models, SLA and outcome-based contracting templates, and a procurement checklist focused on interoperability and vendor lock-in mitigation.
- Privacy & compliance toolkit addressing GDPR and regionally evolving privacy regimes, plus a vendor-agnostic matrix for assessing privacy-by-design claims.
- Use-case ROI calculators and industry-specific adoption roadmaps for grocery, convenience, and specialty retail formats—presented as configurable templates for enterprise teams.
These deliverables are designed to move a retailer or CPG from strategy to pilot to scaled rollout within 12–24 months, with measurable governance and KPIs to track progress.
Competitive Landscape — How Leading Vendors Are Positioning
The market shows a balanced mix of specialized vision-first vendors, robotics innovators, and traditional retail-technology players extending into shelf monitoring. Current market concentration metrics (CR3 approx. 32.5%; CR5 approx. 44.8%) indicate a market that is neither a pure oligopoly nor highly fragmented — incumbents have meaningful share, but there is ample room for focused entrants and regional champions.
- Trax Retail (Singapore / Boston) — Trax’s strength is mature, AI-driven image recognition and deep experience in planogram compliance and execution analytics. Their platform orientation and large-scale deployments make them a default consideration for global retailers seeking a proven enterprise-grade partner.
- Focal Systems (USA) — Known for shelf-facing cameras and a Shelf AI platform, Focal targets operational automation and automated replenishment use cases. Their integrated hardware-software approach shortens time-to-value for replenishment-focused pilots.
- Pensa Systems (Austin, Texas) — Pensa has accelerated platform expansion into full retail formats and upstream supply-chain contexts. Their recent platform broadening (April 2026) makes them an interesting contender for retailers seeking a single partner for shelf and back-room visibility.
- Vispera (Istanbul) — With an image-recognition product (Shelfsight) tailored to shelf-facing camera deployments, Vispera combines lightweight deployment models with analytics oriented to out-of-stock detection and planogram compliance.
- VusionGroup (SES-imagotag) (France) — Vusion’s Captana solution is notable for integration with electronic shelf labels (ESL) and the use of mini-cameras designed to avoid monitoring individuals — an important privacy-forward engineering choice aligned with GDPR constraints.
- Simbe Robotics (San Francisco) — Simbe’s Tally autonomous robots and Store Intelligence platform deliver a robotics-driven data capture model. Recent product updates (Tally 4.0 in January 2026) extend runtime and edge AI capabilities, enabling more frequent and higher-fidelity shelf scans across large store fleets.
- ParallelDots (India/global) — ParallelDots offers the ShelfWatch image recognition platform, bringing a cost-competitive option that resonates with price-sensitive markets and regional rollouts.
Strategically, we observe three vendor moves worth watching in 2026: platform consolidation (bundling shelf intelligence into broader store operations suites), horizontal expansion into supply-chain/back-room operations, and deeper ESL/IoT integrations that convert shelf-state signals into automated pricing and replenishment actions.
Regulation, Standards, and Technology Convergence
Two industry dynamics are reshaping buyer requirements:
- Privacy compliance: GDPR and similar regional privacy regimes have pushed vendors toward camera designs and data-processing models that minimize person-identifiable data. Deployments that advertise “no-person capture” or on-device anonymization are becoming procurement table stakes.
- Standards-driven integration: The convergence between RTSM systems and electronic shelf labels (ESL) is accelerating. Live linkages between shelf imagery, product metadata, and price/label infrastructure enable new closed-loop automation opportunities but also raise integration complexity.
Practical Guidance for Enterprise Decision-Makers in 2026
For retailers and CPGs planning RTSM investments in 2026, PW Consulting recommends a three-track approach:
- Fast-Start Pilots (0–6 months) : Run constrained PoCs that target a single high-value aisle or store cluster to validate detection accuracy, operational integration, and uplift assumptions. Use our PoC templates to set realistic success criteria.
- Platform & Integration Planning (6–18 months) : Specify required integrations (POS, ESL, WMS, replenishment engines) and demand APIs/data contracts during procurement. Prioritize vendors with flexible integration modes (edge-first, hybrid cloud) to future-proof deployments.
- Scale & Governance (18–36 months) : Prepare to move from pilots to fleet rollouts with clear SLAs, data governance rules, and an outcomes-based commercial model. Build a cross-functional center of excellence (store ops, IT, merchandising, legal) to manage change and measure sustained ROI.
Risks and Mitigations
- Data quality risk — mitigate with strict ground-truthing, controlled lighting and camera mounting standards, and periodic model revalidation.
- Vendor lock-in risk — mitigate with API-first contracts, modular procurement, and rights to labeled datasets for model portability.
- Operational adoption risk — mitigate via change management programs that align store teams on replenishment workflows and exception handling processes.
- Privacy/regulatory risk — adopt privacy-by-design benchmarks from our compliance toolkit and require vendors to demonstrate anonymization and data minimization practices.
Why PW Consulting’s Report Matters for 2026 Budgets
Decision-makers often ask: should RTSM be treated as a technology investment, a store operations program, or a merchandising capability? Our analysis shows it is all three — and financial planning should reflect this hybrid nature. The market’s growth profile and vendor evolution make 2026 a pivotal year for establishing scalable, vendor-agnostic architectures and contracting models that convert shelf visibility into sustained margin improvement.
The full PW Consulting report provides the granular segmentation, vendor scoring, regional adoption patterns, and scenario-based financial models that operational and procurement teams need to finalize 2026 budgets and rollout schedules. This preview outlines the strategic contours; the complete intelligence — including vendor scorecards, detailed segmentation tables, and downloadable PoC artifacts — is available on our report page.
Next Steps
- Download the full PW Consulting Real Time Shelf Monitoring System Market report to access the complete dataset, vendor rankings, and downloadable implementation tools.
- Contact our advisory team for a tailored briefing or to commission a workshop that maps the report’s findings to your organizational priorities and 2026 operating plan.
PW Consulting is committed to helping retailers and CPGs translate shelf-level data into reliable, repeatable, and auditable operational outcomes. In a market expanding at a projected 13.52% CAGR, 2026 is the year to move from experimentation to enterprise deployment — with governance, measurement, and vendor strategy front and center.
For detailed analysis of this topic, please visit the official page: Real Time Shelf Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Wireless POS Terminal Market Poised for Robust 9.25% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
PW Consulting Strategic Brief: Smart Wireless POS Terminal Device Market — 2026 Decision Playbook (Report Preview)
Executive snapshot
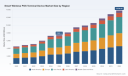
As enterprises plan hardware refreshes, channel expansions and service innovations for 2026, PW Consulting’s new market study on Smart Wireless POS Terminal Devices provides an evidence-based, execution-oriented foundation for strategic choices. Built on a comprehensive base year of 2025 and a 2026–2032 forecast horizon, the study synthesizes historical performance (2020–2025), a 9.25% compound annual growth rate view and forward-looking scenario analysis to help commercial, product and corporate development teams prioritize investments while managing regulatory and operational risk.
Smart Wireless Pos Terminal Device Market
Why this research matters to 2026 decision-makers
-
Market momentum: The smart wireless POS market has shown robust growth from its 2020 baseline through 2025 and is forecast to continue expanding at a mid-to-high single-digit CAGR. The 2025 whole-market benchmark and the 2032 projection included in our study illustrate a clear runway for vendors, integrators and enterprise buyers to rationalize multi-year hardware and services commitments.
Smart Wireless Pos Terminal Device Market -
Timing and window of opportunity: With product lifecycles, certification lead times and channel build-out measured in quarters, early 2026 is the practical decision point for vendors and large merchants who need to align procurement, certification and pilot programs to benefit from the next three product cycles.
Smart Wireless Pos Terminal Device Market -
Regulatory and security convergence: New security baselines such as PCI PTS 7.x and the ubiquity of EMV/NFC on Android SmartPOS are reshaping both product roadmaps and procurement checklists — making certification readiness a gating factor for market access in many geographies.
What the report delivers (practical, actionable modules)
PW Consulting’s report is designed as a practitioner’s toolkit rather than an academic compendium. At a glance, the deliverables include:
-
Market sizing & forecast model (2020–2032) with scenario toggles you can run in your own financial model.
-
Regulatory and certification roadmap (PCI PTS 7.x, EMV/NFC compliance, regional certification sequences) with task-level timing for product teams.
-
Vendor scorecards and a transparent benchmarking framework covering hardware, OS/platform, connectivity, lifecycle management and ecosystem partnerships.
-
Go-to-market playbooks for OEMs, ISVs, acquirers and value-added resellers — including channel economics, leasing models, and managed services packaging.
-
Technology prioritization matrix: tradeoffs between Android-based SmartPOS, mPOS integrations and ruggedized mini POS devices for mobile and fixed scenarios.
-
Supply-chain and component risk map — silicon, radios, and certification bottlenecks — with mitigation options (dual-sourcing, extended lifecycles, modular designs).
-
Deal and M&A screeners highlighting logical consolidation targets and partnership archetypes based on capability gaps and concentration dynamics.
-
Ready-to-use templates: PoC specification, RFP checklists, TCO calculators and procurement scorecards tailored for enterprise buyers and channel partners.
Competitive landscape — who matters and why
The market is characterized by a mix of global OEMs, platform-native entrants and specialized vertical players. The top-tier competitive picture shows moderate concentration: a multi-player leadership cluster controls a meaningful but not dominant share of the market, leaving room for challengers that combine software, services and differentiated hardware to scale quickly.
-
Ingenico (Paris) — Strengths in portable wireless hardware with proven security stacks and broad merchant acceptance; well-positioned where field services and retail mobility intersect.
-
Verifone (San Jose) — Deep global acquirer relationships and a wide product portfolio across mPOS and countertop segments; favorable for partners seeking integrated payments and enterprise-grade deployments.
-
PAX Technology (Shenzhen / North America HQ) — Rapid innovation on Android-based SmartPOS lineups, emphasizing hospitality and restaurant solutions; aggressive product cadence and competitive commercial programs make PAX a go-to for price/performance-driven rollouts.
-
Newland Payment Technology (Fuzhou) — Focus on globally certified Android devices and emerging market scale; a pragmatic option for international deployments requiring certification breadth.
-
Castles Technology (Taipei) — Compact wireless form factors and solid EMV/NFC implementations; appeals to channel partners focused on small footprint and low-cost installations.
-
NEXGO (Shenzhen) — Specialized in durable mini wireless POS with IP ratings for mobile environments; attractive for transportation and outdoor use cases.
-
Worldline (Bezons) — Recent launches of Android SmartPOS platforms for SMEs in Europe show a strategic pivot toward integrated payments + apps; its European distribution and bundled services create stickiness for small-to-medium businesses.
-
Square (Block) — Platform-first approach that transforms mobile devices into full POS systems; particularly disruptive in very small merchant segments and new commerce models.
-
Toast — Restaurant-first hardware and integrated management tools; a strong vertical playbook for F&B operators seeking close coupling of POS and operations software.
-
NCR Voyix — Provider of integrated wireless POS systems with a focus on large retail and hospitality chains; combines hardware, software and services for enterprise deployments.
Recent vendor moves illustrate the market’s tactical dynamics: major launches of Android SmartPOS builds in Europe, refreshed mini POS devices with rugged certifications, and trade-show demonstrations of next‑generation self-service integrations. These actions emphasize product differentiation around security, app ecosystems and vertical-fit solutions.
Regulatory, platform and security dynamics shaping vendor and buyer choices
-
Certification as a competitive gate: PCI PTS 7.x is increasingly a non-negotiable requirement for new wireless POS devices. Procurement timelines must accommodate certification lead times and post-certification lifecycle support for cryptographic modules.
-
Android SmartPOS adoption: With Android-based devices representing a substantial portion of devices sold globally as of 2023, vendors that can manage OS update cadence, app lifecycle and secure boot/attestation will outcompete hardware-only suppliers.
-
Contactless and EMV/NFC: Compliance with EMV and NFC standards is table stakes in major markets; the differentiator becomes how payment devices integrate customer-engagement apps, loyalty services and value-added business apps.
-
Connectivity stack: Multi-radio support (cellular, Wi‑Fi, Bluetooth) and offline‑first transaction continuity are critical for distributed, mobile and transport deployments.
Practical go-to-market plays for 2026
-
Vendors: Prioritize certification roadmaps, modular designs to shorten variant time-to-market, and bundled SaaS offerings to increase lifetime value. Use channel pilots to validate leasing and managed services economics before large-scale rollouts.
-
Acquirers & ISVs: Move from device-agnostic procurement to capability-driven sourcing: require proof of secure update paths, app sandboxing and local support footprints in RFPs.
-
Enterprises (merchants & operators): Use the report’s TCO templates to align procurement with real operational KPIs (transaction success rate, field-repair MTTR, firmware update OPEX) rather than focusing on headline device price.
How to use this report in your 2026 planning cycle
-
Quarter 1 — Strategy Alignment: Use the market sizing and scenario modules to set revenue and coverage targets; prioritize regions and verticals where certification and channel economics align.
-
Quarter 2 — Product & Supply Readiness: Run the certification and component-risk playbook; lock in suppliers for radios and secure elements; finalize ruggedization and OS update policies.
-
Quarter 3 — Pilots & Channel Activation: Deploy the PoC templates and RFP scorecards to pilot devices in representative merchant segments; iterate commercial terms with channel partners.
-
Quarter 4 — Scale or Exit Decisions: Leverage the M&A screens and vendor scorecards to decide on rollouts, strategic partnerships or divestitures ahead of the 2027 product cycle.
Final note — what you will find in the full report
This preview outlines the strategic frames and core issues executives must address in 2026. The full PW Consulting Smart Wireless POS Terminal Device Market report contains detailed, downloadable financial models, region- and application-level forecasts, vendor scorecards and executable playbooks (including ready-made RFPs and PoC templates) that are essential for transactional and strategic decision-making. For procurement teams, product leaders and M&A strategists who require the underlying datasets and segment-level intelligence, the report provides the granular inputs and scenario variants needed to convert insight into action.
Call to action
To obtain the complete report, interactive models and consulting engagement options, visit PW Consulting’s publications page or contact our industry practice. PW Consulting stands ready to support tailored workshops that convert these insights into a prioritized 12–36 month action plan aligned to your organizational objectives.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Smart Wireless Pos Terminal Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wireless WAN Solutions Market to Rise from USD 7,650 Million in 2025 to USD 19,713.74 Million by 2032 at a 14.48% CAGR — 5G and Hardware Lead Growth as Top 5 Hold 62.3%
By PW Consulting, 2026-07-13
Wireless WAN Solutions Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
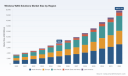
As organizations accelerate distributed digital transformation, wireless wide area network (Wireless WAN) solutions have moved from tactical redundancy to strategic infrastructure. PW Consulting’s latest Wireless WAN Solutions Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative market sizing—anchored by a 2025 market of USD 7,650 million and a 2026 projected step to roughly USD 8,727 million—with qualitative frameworks that directly inform enterprise decisions in 2026. The market exhibits a robust compound annual growth rate (CAGR) of 14.48% across the forecast window, signaling continued vendor investment, rising service adoption, and expanding solution breadth.
Wireless Wan Solutions Market
This briefing article is intentionally a “trailer”: it reveals the analytic logic, strategic insights, and practical levers that will shape procurement, architecture and M&A choices in 2026, while preserving the report’s proprietary segment-level detail to motivate access to the full deliverable.
Wireless Wan Solutions Market
What the full report delivers (practical, actionable contents)
- Market sizing and growth scenarios — deterministic and three-statement scenario analyses that reconcile historical uptake with technology inflection points and macro drivers.
- Demand archetypes and buyer personas — enterprise decision pathways for retail edge, industrial OT, multi-site healthcare, and mobile-first field services, mapped to procurement triggers and SLAs.
- Technology and architecture playbooks — decision matrices for selecting between hybrid SD‑WAN + cellular uplinks, private 5G, and managed cellular access, including TCO modeling templates and deployment phasing guides.
- Regulatory and spectrum impact maps — concise summaries of jurisdictional constraints, spectrum availability, and export-control exposures that materially affect vendor selection and supply chain design.
- Vendor benchmarking and competitive scorecards — qualitative and quantitative assessment across commercial, technical, and operational dimensions, paired with a vendor risk heatmap.
- M&A and partnership screening tools — bespoke scoring models for inorganic growth targets and alliance prioritization, aligned to integration complexity and revenue synergy timelines.
- Operational checklists and KPIs — pilot acceptance criteria, measurable service-level definitions (latency, throughput, resiliency), and an operations playbook for multi-vendor orchestration.
- Customizable financial models and dashboards — downloadable spreadsheets to stress-test procurement scenarios under variance in spectrum cost, small-cell deployment CAPEX, and vendor pricing.
Market trajectory and strategic implications
The Wireless WAN market’s trajectory from the early 2020s into 2026 reflects two reinforcing dynamics: first, a secular shift to edge-first applications that demand ubiquitous, low-latency connectivity; second, vendor commercialization of 5G and advanced SD‑WAN integration. PW Consulting’s baseline projection shows meaningful expansion from the mid‑2020s into the early 2030s, culminating in an expected market size of approximately USD 19.7 billion by 2032 under the primary scenario.
Wireless Wan Solutions Market
For enterprise strategists planning 2026 budgets, three implications flow directly from the CAGR and trajectory:
- Strategic window for capability capture: with ~14.5% CAGR, 2026 is an inflection year where early adopters of combined private 5G and resilient SD‑WAN architectures can secure differentiated performance before broad market commoditization.
- Unit costs will change shape: economies emerge in software and service layers faster than hardware, shifting procurement from CAPEX-heavy rollouts to hybrid CAPEX/OPEX models and managed service consumption.
- Vendor selection matters more than price alone: the speed of vendor evolution—driven by network integrations, protocol support, and ecosystem partnerships—creates asymmetric switching costs that favor forward-compatible platforms.
Competitive landscape — structure, players and recent moves
The market demonstrates moderate concentration: the top three vendors account for nearly half of industry revenue, and the top five capture over 60%—a posture that mixes established systems integrators and network operators with niche specialist vendors. That structure produces both stability and opportunity: enterprises can source from proven incumbents for scale projects, while specialist providers accelerate vertical-specific innovation.
Key vendor dynamics to watch in 2026:
- Cisco Systems (San Jose, CA) — leverages integrated routing and SD‑WAN stacks with increasingly ruggedized hardware for industrial deployments. Recent product updates reinforce cellular uplink and orchestration capabilities for hybrid WANs.
- Ericsson (Stockholm) — continues to push 5G RAN and core advancements that lower barriers for private and shared wireless WAN deployments, including low‑power and reduced‑capability device profiles that expand IoT coverage.
- Nokia (Espoo) — its investments in standalone 5G core and edge routing strengthen its role for carriers and large enterprises requiring high throughput backhaul and service chaining.
- Huawei Technologies (Shenzhen) — remains a major supplier of integrated RAN and edge networking equipment, with deep cost and integration offers in markets where regulatory constraints permit widespread adoption.
- Major US carriers (Verizon, T‑Mobile and the incumbent Sprint legacy) — provide differentiated managed services, private 5G options, and urban mmWave capacity; their nationwide rollouts and protocol activations materially expand enterprise choice sets.
- Specialists (Pepwave, VMware/Broadcom) — multi‑WAN bonding, sophisticated cellular failover, and cloud‑native SD‑WAN orchestration remain critical for multi-site resiliency and rapid deployment scenarios.
- Consumer/mobile-focused operators (Cricket Wireless et al.) — increasingly participate in enterprise segments via wholesale and MVNO models to serve mobile broadband needs.
Recent vendor developments through 2024–2025 underscore these trends: product launches that support reduced-capability IoT devices, expanded 5G standalone deployments, ruggedized industrial routers with sub‑6GHz 5G support, and broadened mmWave urban coverage. These moves tighten the roadmap for enterprises evaluating pilot-to-production timelines in 2026.
Regulatory, spectrum and infrastructure context (what keeps CFOs and CTOs awake)
Regulatory and infrastructure factors will materially influence 2026 decisions. Recent and relevant items include mid-band spectrum allocations that underpin densification strategies, network‑neutrality regimes that affect traffic management and SLAs in certain jurisdictions, export controls that constrain supplier choice for cryptography‑enabled equipment, and evolving 3GPP releases that introduce public safety and ultra‑reliable low‑latency communications (URLLC) features.
On the cost side, small-cell deployment remains a non‑trivial component for densified urban backhaul—enterprise planners must account for multi‑site site lease, power, and backhaul integration expenses when modeling rollout economics. PW Consulting’s models stress‑test these variables to expose breakeven points for private 5G versus managed cellular and hybrid SD‑WAN options.
Actionable strategic recommendations for 2026
- Prioritize hybrid architectures: adopt an SD‑WAN-first approach that can natively integrate cellular uplinks and private 5G. This minimizes rip-and-replace risk and preserves workload portability across cloud and edge.
- Run a two‑track procurement process: simultaneously engage incumbent-scale vendors for core orchestration and niche suppliers for edge resilience to reduce single‑vendor dependence while maintaining integration discipline.
- Embed regulatory and spectrum contingencies into RFPs: require vendor responses to include alternative supplier paths and cryptography compliance statements to mitigate export-control and spectrum-access risks.
- Structure pilots for measurable learning: define acceptance criteria tied to latency, failover recovery, and operational overhead. Use short, multi‑site pilots to validate orchestration and monitoring before capex commitments.
- Optimize finance models: favor vendor contracts with flexible consumption tiers and network-as-a-service options to convert upfront CAPEX into manageable OPEX during the growth phase.
- Invest in operational readiness: build cross-functional runbooks covering multi‑SIM management, edge security, and life‑cycle firmware control to reduce mean time to repair and compliance exposure.
- Monitor consolidation and partner moves: given the market concentration dynamics, expect continued M&A and alliances; keep vendor‑management options open to leverage bargaining power during contract renewals.
How PW Consulting’s report supports 2026 decision-making
The report is designed to be directly operational for 2026 procurement cycles: it provides vendor scorecards that map to procurement clauses, downloadable TCO and ROI models tuned to current small‑cell cost ranges and spectrum availability assumptions, and a regulatory appendix that clarifies country‑level constraints. For executive teams, the report distills strategic choices into a one‑page roadmap that aligns architecture, sourcing, and investment timing with risk appetite.
For security and compliance leads, the vendor risk heatmap and export-control matrix offer immediate filters to accelerate shortlists. For network and operations teams, the deployment blueprints and pilot acceptance checklists shorten time to production while preserving observability and resilience targets.
Next steps and access
PW Consulting’s Wireless WAN Solutions Market report is the prescriptive intelligence package for enterprises finalizing 2026 network strategy. This article outlines the report’s analytical foundations and strategic value; the full publication contains the fine-grained segment insights, downloadable models, and vendor scorecards withheld here to preserve proprietary value.
Visit the PW Consulting market portal to access the full report, scenario spreadsheets, and a companion executive workshop package that helps translate findings into a 90‑day implementation plan. For tailored briefings, PW Consulting offers strategy sessions that apply the report’s models to your topology, regulatory footprint, and financial constraints.
For detailed analysis of this topic, please visit the official page: Wireless Wan Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Refrigeration Packaging Market Poised for Robust 8.42% CAGR in 2026–2032 Forecast
By PW Consulting, 2026-07-13
Refrigeration Packaging Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As global supply chains enter a phase of consolidation and technology-led differentiation, refrigeration packaging has moved from a commoditized inputs category to a strategic lever for resilience, sustainability, and margin protection. PW Consulting’s new Refrigeration Packaging Market study (base year: 2025; forecast period: 2026–2032) provides the market intelligence that senior executives, procurement leaders, and product strategists will need to convert uncertainty into competitive advantage in 2026.
Refrigeration Packaging Market
Why this study matters for 2026 decision-making
-
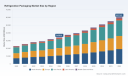
Clear forward-looking sizing: The report presents a validated market model that traces the refrigeration packaging market from 2020 through 2025 and projects to 2032. The total market grows from historical scale in 2020 through an estimated 34,250.6 USD Million in 2025 to a projected 60,316.2 USD Million by 2032, driven by sustained demand across cold chain logistics, pharmaceuticals, and food supply. Management teams can use these topline projections to stress-test capacity plans, M&A targets, and procurement frameworks.
Refrigeration Packaging Market -
Trusted growth trajectory: Our base forecast uses an industry-calibrated compound annual growth rate of 8.42% across the 2026–2032 window — a useful planning anchor for capital allocation, product roadmaps, and channel investments that must span multiple budget cycles.
Refrigeration Packaging Market -
Fragmented competitive dynamics: Market concentration metrics indicate substantial room for consolidation and differentiation: leading-trio and leading-five concentration levels reflect a market where nimble innovators and scale players coexist. The resulting landscape produces recurring opportunities for regional roll-ups, capability-driven partnerships, and platform plays for circular packaging services.
What the report contains — operationally focused, decision-ready content
-
Actionable market model: Granular topline history and forecasts (2020–2032) with scenario variants (base, downside, and technology-accelerated) so finance and strategy teams can quantify revenue and EBITDA outcomes under alternative assumptions.
-
Commercial playbooks: Go-to-market strategies for incumbent manufacturers and new entrants, including channel segmentation, price-to-serve archetypes, and seller enablement for parcel, pallet, and pharmaceutical customers.
-
Supplier and cost sensitivity tools: A customizable cost-model that maps raw material price volatility (foam products, polyurethane, EPS, phase-change materials) into landed packaging cost per shipper, enabling procurement to size hedging and strategic inventory policies.
-
Innovation radar and technology adoption timelines: Evaluation of reusable systems, advanced insulation panels, phase-change material innovations, and integrated monitoring — with recommended pilot-size, success metrics, and scaling triggers.
-
Sustainability & regulatory roadmap: Practical guidance to align product design and take-back strategies with emerging producer responsibility regimes, including compliance timelines and fee-exposure estimates that feed directly into product P&L models.
-
M&A playbook and integration checklist: Screening criteria, valuation multipliers typical for different sub-segments, and a post-merger integration blueprint focused on manufacturing footprint rationalization and product portfolio consolidation.
Market dynamics that will shape 2026 choices
-
Raw material volatility and margin pressure — but with clarity: Industry inputs continue to matter. Industry indicators show elevated producer prices in polystyrene foam manufacturing and observable pricing signals for polyurethane and expandable polystyrene (EPS). Our report quantifies the pass-through sensitivity and identifies high-leverage procurement levers — from long-term supplier agreements to design-for-material-efficiency — that procurement and R&D teams should implement now.
-
Regulatory acceleration on end-of-life responsibility: Multiple U.S. states have advanced EPR (extended producer responsibility) frameworks that reassign end-of-life costs for packaging to producers. For refrigeration packaging, this signals near-term increases in total cost of ownership for disposable formats and incentives for reusable or recyclable designs. Companies must incorporate EPR fee exposure into 2026 pricing and product development decisions.
-
Technology and business-model bifurcation: The market is splitting between capital-intensive reusable solutions (service-led models, depot networks) and optimized single-use or curbside-recyclable products (cost-focused, scale manufacturing). Each path has different margin mechanics, working capital needs, and customer acceptance curves — the report provides playbooks for both.
Competitive landscape — how to read the field in 2026
The refrigeration packaging market is populated by global specialists, large packaging platforms, and focused innovators. PW Consulting’s competitive analysis synthesizes capability maps, commercial positioning, and strategic intent for leading firms to help clients identify partners, targets, or threats.
-
Sonoco ThermoSafe — a global reference in temperature-controlled solutions. Their broad engineering services, consulting capabilities, and large suite of insulated shippers make them a go-to partner for pharma manufacturers seeking turnkey cold chain assurance. Expect continued investment in biologics-focused engineering and service expansion.
-
Insulated Products Corporation (IPC) — volume-driven innovation in recyclable and curbside-friendly solutions. IPC’s focus on paper-based liners and simple, scalable products positions it well for e-commerce and parcel-focused cold chains where return logistics are challenging.
-
Cryopak — engineering depth and material versatility. Their emphasis on testing, phase change materials, and thermal engineering appeals to customers requiring validated, regulated shipments — particularly life sciences and food safety applications.
-
Pelton Shepherd Industries — specialist in gel/ice packs with sustainable options. Their product-engineering focus reduces thermal risk for elastic use cases (secondary packaging, last-mile), and sustainability variants respond to procurement policies emphasizing recyclability.
-
Peli BioThermal — reusable systems and global service network. With investments in service centers and an installed base of reusable shippers, Peli is a natural partner for pharma companies shifting to circular models where lifecycle cost and regulatory compliance matter more than unit price.
-
Cold Chain Technologies (CCT) — hybrid focus on curbside recyclability and reusable pallet shippers. Their product portfolio is tuned to life sciences customers who balance regulatory rigor against sustainability KPIs.
-
Nordic Cold Chain Solutions — agile innovator. Recent launches (notably a GLP‑1 & Small‑Format Packaging Innovation Lab) signal strategic focus on parcel and small-format pharmaceutical distribution — a growth corridor as personalized medicines and DTC healthcare expand.
-
Sealed Air & Amcor — packaging platform players. While broader in scope, both leverage scale in materials science and sustainability programs to enter temperature-controlled packaging categories, often through partnerships or targeted product lines.
Recent strategic moves worth noting
-
Nordic Cold Chain Solutions launched a GLP‑1 & Small‑Format Packaging Innovation Lab (March 2026) to accelerate solutions for small-format, high-value pharmaceutical shipments. This move underscores the commercial importance of parcel-scale biologics distribution and the need for rapid prototyping capability.
-
Peli BioThermal expanded its Allentown, Pennsylvania service center (November 2025), increasing throughput for reusable shippers and reinforcing the economics of depot-based circular models. This highlights how service infrastructure investments materially change unit economics for pharmaceutical customers.
How executives should act in 2026 — six strategic recommendations
-
Re-run the cost model now: Update procurement scenarios to include current raw material trends and EPR exposure. Apply sensitivity testing to understand when design changes or supplier diversification become urgent.
-
Prioritize pilots by P&L impact: Use the report’s pilot-readiness matrix to sequence investments — start with small-format, high-value pharmaceutical pilots and sustainable parcel solutions that deliver measurable TCO reductions within 12 months.
-
Decide on service economics for reuse: Quantify depot density required to make reusable shippers accretive in your routes-to-market; partner with service providers where scale is insufficient to justify standalone investments.
-
Design for compliance and circularity: Embed EPR cost forecasts into product pricing and select materials that align with likely fee structures and customer procurement requirements.
-
Monitor entrant and platform activity: Watch innovations from both niche specialists and global packaging incumbents for capability gaps that can be exploited via partnerships or bolt-on acquisitions.
-
Use data as a competitive moat: Deploy integrated monitoring and thermal validation across high-value flows to enable price differentiation and reduce claims / spoilage costs.
About the report and next steps
PW Consulting’s Refrigeration Packaging Market report is engineered for executives who need immediate, implementable insight. It combines a transparent market model (2020–2032), scenario-based forecasts using an 8.42% modeled CAGR for 2026–2032, supplier and product scorecards, procurement tools, and regulatory compliance frameworks. The work is deliberately practical — focused on the decisions that procurement, product, and commercial leaders must make in 2026.
To preserve the strategic value of the proprietary segmentation and to enable confidential client workshops, detailed sub-segment tables, regional breakdowns, and the downloadable cost-sensitivity model are available only through our report portal. Access the full dataset and tailored advisory options via the PW Consulting report landing page.
For detailed analysis of this topic, please visit the official page: Refrigeration Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Target Drones Market Set to Expand at an 8.12% CAGR During 2026–2032, New Insight Reveals
By PW Consulting, 2026-07-13
Aerial Target Drones Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new Aerial Target Drones Market report delivers an evidence-based playbook designed to sharpen executive decision-making as defence programs and commercial counter-UAS use cases accelerate in 2026. The market has moved from an early, program-driven niche into a structurally expanding defense ecosystem: total industry revenue grew from roughly USD 4.13 billion in 2020 to USD 6.25 billion in 2025, and PW Consulting’s projection shows continued expansion into the forecast window (with the market poised to exceed USD 10.7 billion by 2032 at a compound annual growth rate of about 8.12%). For defense primes, system integrators, component suppliers and private-equity investors, that trajectory requires immediate reassessment of supply chains, product roadmaps, and go-to-market plays.
Aerial Target Drones Market
Why this report matters in 2026
-
Timing: 2026 is the inflection point for procurement and indigenization policies (notably in the U.S. and allied states). Programs that can demonstrate domestic sourcing, resilience to component choke points, and rapid integration into live-fire training cycles will capture outsized budget allocations.
Aerial Target Drones Market -
Scale: The business case is moving from bespoke platform sales to recurring production, sustainment, and services revenue. Buyers are shifting procurement criteria to total lifecycle cost and rapid replenishment capability, not just unit performance.
Aerial Target Drones Market -
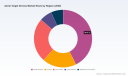
Competitive consolidation: Market concentration metrics indicate a moderately concentrated market (CR3 ~48.5%, CR5 ~62.8%), meaning the leading suppliers already control a meaningful share of volume and platform-standardization opportunities. Late entrants must either underwrite rapid scale or secure unique mission capabilities to compete.
Key market dynamics and strategic implications
-
Regulatory reshaping: Recent policy actions—such as U.S. export-control clarifications in early 2026 and tightening domestic-content requirements embedded in defense budgetary guidance—will accelerate allied procurements while increasing compliance overhead for multinational suppliers. Companies should treat export and domestic-sourcing policies as program risks and competitive levers simultaneously.
-
Supply-chain fragility: System-level production is constrained by chokepoints in magnets, battery cells, and semiconductor supply. Vendors that secure alternative sources, long-lead contracts, or component stockpiles will gain near-term pricing and delivery advantage. For OEMs and tier-one suppliers, vertical integration of key subassemblies or strategic partnerships with component specialists will be a defensible response.
-
Shift to services and simulation: As live-fire training demand rises, there is higher willingness to procure bundled services (target launch, telemetry, data analytics, and post-exercise maintenance). Service-first pricing models lower barriers to adoption and create recurring revenue streams that materially change lifetime cash flow profiles versus pure platform sales.
-
Technology convergence: Advances in propulsion mixes (fixed, rotary, hybrid), signature management, and autonomous behaviors are enabling more realistic threat representation. Programs that combine high-fidelity threat emulation with repeatable logistics will be prioritized by training commands and test ranges.
Competitive landscape — what to watch
Our analysis profiles incumbent leaders and emerging challengers across system types and mission sets. Key players include established defense primes and specialist UAV manufacturers that together form the backbone of current procurements and technology development.
-
Kratos Defense & Security Solutions (San Diego, CA) — A high-volume supplier of subscale aerial target systems. Recent contract activity includes multiple U.S. Navy awards through early 2026, reinforcing Kratos’s production momentum and program delivery profile. Kratos’s product family and manufacturing footprint position it to serve both repeat-training cycles and larger Navy acquisition plans.
-
QinetiQ (Farnborough, UK) — Known for the Banshee range and support services, QinetiQ continues to secure follow-on sole-source support awards. Their global service model and live-fire range integration capability make them a go-to for customers seeking turnkey training solutions.
-
Griffon Aerospace (Madison, AL) — A supplier of widely used subscale platforms for air defense training and testing. Griffon’s depth in logistics and fleet sustainment supports customers requiring high sortie rates and quick turnaround.
-
Boeing (Arlington, VA) — Operating at the full-scale end of the spectrum, Boeing’s conversion programs for retired fighter assets remain a strategic option for certain weapon-testing and end-to-end lethality validation programs. Recent DoD awards to convert legacy fighters into aerial targets demonstrate the continuing role of full-scale target solutions.
-
AeroTargets International (USA) and Air Affairs Australia (part of QinetiQ) — Specialists with focused product lines for range-operator and counter-UAS missions. Their portfolios are attractive to buyers favoring modularity and rapid fielding.
-
Northrop Grumman, Lockheed Martin — Large primes maintain program-level relationships and systems-integration capabilities that can bundle target services into broader training and test-range modernization efforts.
Recent program milestones and contract awards further validate the market’s momentum: notable 2025–2026 actions show sustained procurement funding and collaborative development activity between OEMs and national suppliers. These actions are proxies for growing training demand and an emphasis on sovereign capability.
What the report contains — practical deliverables for executives
PW Consulting’s report is structured to be directly actionable for strategic planning, capture strategies, and investment diligence. Key contents include:
-
Modelled market-size and revenue-growth forecasts through 2032 with scenario sensitivity to policy, supply-chain, and procurement ramp assumptions.
-
Commercial and program-level buyer profiles, procurement timelines, and decision criteria for government and commercial range operators.
-
Competitive heat maps, capability matrices, and supplier benchmarking that reveal where incumbents hold defensible advantage and where gaps invite disruption.
-
Technology and R&D roadmaps assessing propulsion mixes, autonomy, and signature technologies—aligned with cost-to-performance breakpoints for customer segments.
-
Supply-chain risk assessment detailing critical component exposures and mitigation levers, including recommended supplier diversification and vertical-integration paths.
-
Go-to-market playbooks covering pricing, contracting strategies, sustainment-commercialization options, and partnership models designed to accelerate capture in 2026 program windows.
-
Deal flow and M&A checklists identifying targets by capability, production scale, and aftermarket footprint—prioritized for strategic or financial buyers.
To preserve competitive confidentiality and to comply with the “trailer” briefing approach, the report highlights sector-level segmentation and full modeling outputs but intentionally withholds raw subsegment tables and certain bidder-level pricing curves in this public release. Subscribers receive the complete, auditable datasets and build-your-own scenario workbooks.
How to use this intelligence in 2026
-
Procurement and Program Planning: Align near-term capacity expansions with the program ramps and compliance timelines embedded in your procurement forecasts. Prioritize suppliers that can demonstrate non-exposed component sources and validated production rates.
-
Partnerships and JVs: For companies lacking indigenous supply of key subsystems, pursue fast-track partnerships or equity stakes in Tier‑2 suppliers that solve magnet, battery or RF/avionics constraints.
-
Service-led commercialization: Convert platform relationships into services contracts (target-as-a-service, sortie-lifecycle support) to secure recurring revenue and higher lifetime margins.
-
M&A and divestment: Use the report’s valuation comparators and capability maps to identify high-leverage acquisition targets—particularly firms with sustainment footprints or unique signature-emulation technologies.
-
Regulatory and compliance readiness: Embed export-control and domestic-content audit trails into proposal responses. Compliance is increasingly a competitive differentiator in allied procurements.
Executive takeaway
In an industry moving from program-driven orders to program-of-record scale, strategic clarity will determine winners. The Aerial Target Drones market is expanding at an industry-level CAGR of just over 8% across the 2026–2032 forecast window, underpinned by predictable training demand, renewed investments in lethality testing, and policy-driven indigenization. Companies that act now—securing supply chains, shifting business models toward services, and locking early partnerships—can transform near-term growth into durable market leadership.
PW Consulting’s full report provides the detailed segment modeling, contract-level case studies, and scenario workbooks required to operationalize these recommendations. For decision-makers preparing budgets, capture plans or investment theses for 2026, the report is designed as an immediately deployable toolkit.
Next steps
-
Request the full dataset and scenario workbook to stress-test your 2026 roadmap against policy and supply-chain shocks.
-
Schedule a brief with PW Consulting’s lead analyst team to map a customized playbook for production scale, GTM execution, or M&A prioritization.
For detailed analysis of this topic, please visit the official page: Aerial Target Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aldosteronism Treatments Market Poised to Grow at a 5.5% CAGR Through 2032, Says New Report
By PW Consulting, 2026-07-13
Aldosteronism Treatments Market 2026: Strategic Intelligence for Execution — PW Consulting Insight
Executive snapshot
As health systems recalibrate care pathways and pharmaceutical portfolios in response to shifting clinical guidelines and breakthrough approvals, our new Aldosteronism Treatments Market report delivers the kind of actionable intelligence executives need to make high-confidence decisions in 2026. Anchored on a 2025 base year, our macro forecast shows the global market growing at a steady compound annual growth rate (CAGR) of 5.5% through 2032, expanding from roughly USD 2.15 billion in 2025 to just over USD 3.12 billion by 2032. That trajectory reflects not only secular demand for proven mineralocorticoid receptor antagonists (MRAs) and potassium-sparing diuretics, but also the emergence of novel mechanism entrants that will reshape therapeutic choice and payer dynamics.
Aldosteronism Treatments Market
Why 2026 is a pivotal inflection point
Three intertwined developments make 2026 a strategic watershed for companies operating in aldosteronism and related hypertensive indications:
Aldosteronism Treatments Market
- Clinical-guideline momentum: The Endocrine Society’s 2025 guideline update elevated the clinical profile of primary aldosteronism screening and reaffirmed MRAs (particularly spironolactone) as a foundational medical therapy. This has accelerated demand signals from specialty care and primary care alike — but also sharpened price and access scrutiny across payers.
- Regulatory innovation: The May 2026 FDA approval of baxdrostat (Baxfendy), the first-in-class aldosterone synthase inhibitor for add-on uncontrolled hypertension, broadens clinical choices and creates immediate commercial questions about positioning in primary aldosteronism management, where trials are ongoing.
- Generic backbone and supply stability: Established generic suppliers continue to anchor treatment affordability and reimbursement pathways, preserving broad access while exerting margin pressure on originator brands.
What the report delivers — practical, transaction-oriented outputs
PW Consulting’s report is designed not as academic narrative but as an operations playbook for 2026 decision-makers. Key components include:
Aldosteronism Treatments Market
- Proprietary market sizing and an auditable forecast model (2026–2032) that integrates incidence/prevalence trends, screening uptake projections and therapy-mix scenarios to quantify upside and downside cases.
- Scenario-based commercial models for novel entrants versus generic incumbents, enabling CFOs and commercial leads to stress-test price erosion, formulary acceptance and net revenue outcomes under alternative access environments.
- A validated competitive map with tactical dossiers for the principal market participants — including originator and generic players — assessing pipeline positioning, lifecycle levers and likely go-to-market strategies.
- Regulatory and reimbursement playbooks tailored to major payer archetypes, with step-by-step recommendations for reimbursement dossiers, evidence generation sequencing and contracting approaches.
- Launch and HCP engagement checklists that convert trial readouts and guideline changes into measurable demand-creation and adoption milestones.
- Risk matrices addressing manufacturing and API continuity, pricing pressures, and real-world safety surveillance commitments that affect commercialization timelines and valuation.
Competitive landscape — who matters (and why)
The competitive environment combines established branded players, high-profile novel entrants and a deep pool of generics manufacturers. Understanding each archetype’s strategic objectives is essential to designing effective commercial and partnering decisions in 2026:
- Major branded incumbents: Companies with marketed MRAs (including long-standing drugs) retain durable clinical credibility and established formulary channels. Their priorities in 2026 will be defending share through evidence generation, indication expansion where permissible, and selective lifecycle pricing.
- Innovator entrants: The approval of baxdrostat is the clearest example of how a novel mechanism can alter clinical algorithms. Innovators with pipeline molecules will need differentiated positioning (e.g., patient subpopulations, biomarker-driven use) and a compelling health-economic narrative to displace entrenched generics.
- Generics and contract manufacturers: A robust generic supply base underpins competitive pricing and payer willingness to reimburse. Generics providers will compete on cost, supply reliability and tender responsiveness — making them essential partners or adversaries depending on corporate strategy.
For executives evaluating alliances, licensing or M&A, the report’s company dossiers synthesize product portfolios, regulatory status, and near-term launch catalysts across the competitive set.
Market dynamics and drivers to watch in 2026
Several interdependent dynamics will determine commercial outcomes over the next 12–36 months:
- Screening and diagnosis rates: Uptake of systematic screening pathways materially expands addressable patient populations. Segments tied to improved detection will see disproportionate revenue impact versus those reliant on routine hypertension care.
- Guideline-driven prescribing: With guideline updates favoring particular MRAs for primary aldosteronism, real-world utilization patterns may shift without immediate price changes — but cumulative impact on volume is significant.
- Payer negotiation environment: Generic availability moderates list prices and accelerates formulary placement; novel entrants must therefore build robust value dossiers and prepare for outcomes-based contracting or restricted access in early years.
- Clinical evidence flow: Near-term readouts from trials of aldosterone synthase inhibitors in primary aldosteronism will be determinative for label expansion and commercial adoption; our timeline models show staggered inflection points tied to these data releases.
- Supply-chain resilience: The generic API market is mature but requires active mitigation of single-supplier risk for certain intermediates; contract manufacturing contingency planning remains a hands-on priority.
Strategic imperatives for 2026 — recommended actions
Executives can translate market insights into immediate actions. The following are priority plays we recommend for different corporate archetypes:
- Innovator pharma with late‑stage assets — Accelerate targeted evidence generation. Prioritize head-to-head or add-on studies in well-phenotyped primary aldosteronism cohorts to demonstrate incremental benefit versus MRAs. Build a payer-value dossier that quantifies hospitalization avoidance, diagnostic-driven cost offsets, and patient-centric outcomes.
- Branded market defenders — Deploy lifecycle management that combines real-world evidence (RWE) programs, line-extension strategies and selective value-based agreements. Emphasize safety and long-term outcomes where generics cannot match trial-backed claims.
- Generic manufacturers — Strengthen tender-response capabilities and secure multi-supplier API contracts. Differentiate on supply reliability and bundle services (e.g., adherence programs) that raise switching costs for institutional buyers.
- Private equity and corporate development teams — Use the report’s scenario models to stress-test acquisition targets: evaluate not only current market share but also the target’s evidentiary assets, payer relationships and manufacturing footprints that protect cash flows under margin compression.
- Market-access and commercial teams — Prepare tiered launch plans that define payer-subpopulation segmentation, milestone-based contracting frameworks and HCP education campaigns timed to guideline and trial catalysts.
Actionable timing: a 12–24 month calendar
Timing matters. Our report maps a pragmatic calendar for 2026 commercial moves tied to regulatory, guideline and trial-event milestones. Highlights include:
- Immediate (0–6 months): finalize reimbursement strategy templates, secure API supply agreements, and initiate RWE protocols keyed to guideline recommendation changes.
- Medium term (6–18 months): deploy selective payer pilots and outcomes-based contracts for novel entrants; prepare segmented marketing campaigns for high-yield specialist channels.
- Longer term (18–36 months): scale manufacturing post-launch, extend indications supported by pivotal readouts, and consider consolidation opportunities if consolidation economics are favorable.
Why this report is strategically valuable for 2026 decisions
Senior leaders told us they need four things from market intelligence in 2026: speed, practicability, strategic clarity and defensibility. This report delivers all four. Our blend of auditable market sizing (with transparent assumptions), scenario-based commercial economics, competitor dossiers, and a prioritized action plan turns broad market trends into executable initiatives — while preserving the commercial confidentiality required for high-stakes negotiations.
What we deliberately withhold — and why
In line with our “trailer” approach, this public briefing signals the lines of opportunity and risk without reproducing the granular, proprietary segmentation tables and payer-specific price models that underpin transaction-level decisions. Buyers of the full report receive the detailed regional and product-split matrices, downloadable model workbooks, and supplier-level supply-chain maps necessary to operationalize the recommendations. This preserves the competitive value of the dataset and enables customized consulting engagements where required.
Next steps — how to use our work
For teams preparing budgets, launches, or M&A due diligence in 2026, we recommend three immediate steps:
- Obtain the full report and model workbook to run company-specific scenarios against our baseline and stress cases.
- Set up a PW Consulting strategy workshop to convert report recommendations into an internal 90‑day execution plan aligned to your commercial, regulatory and manufacturing calendars.
- Engage our market-access specialists to draft payer- and HTA-tailored evidence packages in parallel with ongoing clinical programs.
Closing
The Aldosteronism Treatments Market in 2026 presents a rare combination of steady baseline growth and disruptive opportunity. Between durable generics, a changing guideline landscape, and the arrival of novel mechanisms, the choices companies make this year will determine competitive positioning for the next decade. PW Consulting’s report brings the evidence, scenarios, and pragmatic playbooks executives need to act — while protecting the proprietary detail that turns insight into commercial advantage. Contact our research team to license the full report and model, and schedule a tailored strategy session to align these insights to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Aldosteronism Treatments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


