



PW Consulting: One-Box Electro-Hydraulic Braking Systems Poised to Expand at a Robust 12.0% CAGR Through 2032, New Market Insight Reveals
By PW Consulting, 2026-07-13
One Box Electro-Hydraulic Braking Systems: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s latest One Box Electro Hydraulic Braking System Market report (base year 2025, forecast period 2026–2032) synthesizes proprietary modeling, supplier diligence, and scenario-driven strategy work to equip executive teams for decisive action in 2026. The market has moved from a nascent systems integration challenge into a clear commercial inflection. Our modeling shows the global market expanding from roughly USD 1.7 billion in 2020 to USD 2.5 billion in 2025, and — at a compound annual growth rate of 12.0% — tracking toward just over USD 5.5 billion by 2032. For automotive suppliers, OEMs and private equity investors, that trajectory reframes product roadmaps, M&A appetite, and go-to-market priorities for the next 18–36 months.
One Box Electro Hydraulic Braking System Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 will be the year when integration economics and regulatory push converge. Manufacturers who align product architectures, software stacks, and manufacturing footprints now will secure preferred OEM programs and margin recovery in the medium term.
One Box Electro Hydraulic Braking System Market -
Technology leverage: One-box architectures reduce system cost and packaging complexity but raise requirements for controls software, functional safety validation, and supplier cross-domain coordination. Our report identifies the most material technical and commercial levers — and the typical pitfalls firms encounter when scaling from lab to production.
One Box Electro Hydraulic Braking System Market -
Consolidation dynamics: The market exhibits meaningful concentration. The top three suppliers account for the majority share of the market and the top five for an even larger proportion, underscoring that scale, integration capability and global OEM relationships remain decisive competitive advantages.
What PW Consulting delivers — practical, action-oriented content
-
Rigorous market sizing and scenario framework: We provide a transparent methodology linking vehicle parc and platform forecasts to ASP and penetration curves. The report includes base, conservative and accelerated scenarios (sensitivity to EV uptake, regulatory timing, and supply constraints) to stress-test investment cases.
-
Decision-grade playbooks: For suppliers and OEM suppliers we deliver go-to-market templates tailored to four strategic archetypes — scale integrators, niche specialists, software-first players, and contract manufacturers — outlining near-term KPIs, investment sequencing, and partner ecosystems necessary to win.
-
Commercial and procurement tools: A supplier selection matrix, cost-down levers by Bill-of-Materials category, and a negotiation checklist for volume contracts designed to be used in 2026 sourcing rounds.
-
Technology & product roadmap analysis: Comparative assessment of one-box topologies, software partitioning strategies, and validation requirements for ASIL levels. We map recommended R&D focus areas by risk/impact for the next 24 months.
-
Supply chain and manufacturing guidance: Site selection criteria, modular assembly approaches, and a resilience playbook addressing critical component constraints (including electronic control modules and pressure actuation subsystems).
-
Regulatory and safety intelligence: Practical guidance to align product certification pathways with forthcoming regulatory milestones and to anticipate the most likely areas of increased compliance scrutiny.
-
M&A and partnership screening: A shortlist methodology to identify tuck-in targets or strategic partners, plus valuation sensitivities and integration checklists focused on capture of cross-sell and engineering synergies.
-
Executive dashboards and investor briefing packs: Condensed slide sets and talking points specifically prepared for 2026 board-level funding decisions or investor diligence.
Competitive landscape — strategic implications
The market is led by established tier-one systems integrators with global OEM relationships and deep cross-domain engineering capability. Key players include Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG and Hyundai Mobis. Each brings differentiated strengths that shape competitive dynamics and define the choice sets for OEMs and fleets:
-
Robert Bosch GmbH — strategic edge: deep systems integration expertise and proven actuation suites (including booster and control integration) position Bosch to capture programs that prioritize rapid validation cycles and global production scale. Their strengths make them a default partner for OEMs seeking lowest technical risk.
-
Continental AG — strategic edge: a strong portfolio of combined actuation and control modules and program execution experience enables Continental to compete on both cost and integration speed, particularly where packaging constraints are critical.
-
ZF Friedrichshafen AG — strategic edge: strong vehicle-dynamics integration and experience with electro-hydraulic subsystems enable ZF to pursue differentiated propositions where braking is coupled tightly with advanced stability and ADAS features.
-
Hyundai Mobis — strategic edge: focused product lines for electrified powertrains and close OEM alignment give Mobis rapid route-to-production advantages on certain EV platforms.
Strategic takeaway: incumbent strength is not immutable. Scale, software competence, rapid validation capability and manufacturing agility define the barriers to entry. Mid-tier suppliers who can demonstrate secure software stacks, validated functional-safety pathways, and stable sourcing for critical components can still win niche or platform-specific programs — but they must move decisively in 2026.
Key market dynamics shaping 2026 choices
-
Electrification and packaging pressure: As EVs and hybrids proliferate, packaging and energy recovery imperatives make one-box systems attractive. OEMs will increasingly request integrated modules that streamline assembly line processes and weight targets.
-
Software and system reliability: The marginal value in one-box systems is driven by embedded controls and software feature sets. Investment in modular, updatable software architectures will unlock aftermarket revenue and OTA (over-the-air) improvement cycles.
-
Regulatory trajectories: Safety and emissions-adjacent regulations are accelerating testing and certification demands. Manufacturers must align product release schedules with evolving test protocols to avoid costly program delays.
-
Supplier consolidation: Procurement teams will favor fewer, deeply integrated suppliers to reduce program management overhead — a structural tailwind for larger players and a headwind for fragmented suppliers.
-
Cost and localization pressures: Macro-cost inflation and OEM localization preferences will push suppliers to optimize regional manufacturing footprints and supply base strategies in 2026 planning cycles.
Concrete recommendations for 2026 — a practical checklist
-
For Tier-1 integrators: accelerate software modularization and invest in scalable validation rigs. Prioritize multi-OEM program wins where you can amortize validation and tooling costs.
-
For mid-tier suppliers: identify one OEM platform to win in 2026 as a beachhead. Use that program to validate your control stack and secure a reference case demonstrating manufacturability and functional safety.
-
For OEMs: consolidate supplier lists to 2–3 strategic partners per platform, but retain a nimble secondary suppliers pipeline for risk mitigation. Bake in phased qualification milestones to de-risk 2027–2028 production ramps.
-
For investors: prioritize targets with proven software IP, defensible margins via integrated BOM positions, and established validation processes. Avoid assets with unproven high-volume manufacturability unless acquisition includes experienced operational leadership.
-
Operationally: start 2026 with a six-quarter plan that sequences engineering validation, tooling investment, and supplier qualification. Add contingency runway for semiconductor lead times and test-lab bottlenecks.
What we deliberately withhold — and why
To preserve the commercial utility of this brief while respecting the “trailer” intent of our release, PW Consulting is intentionally omitting the granular regional, type and application split tables from this executive summary. The full report contains detailed, auditable segment tables, per-region and per-application penetration curves, supplier-level share models, and downloadable Excel workbooks used in our scenario simulations. These datasets are essential if you require line-item projections or intend to embed our models into your internal financial planning.
How to use the full report in your 2026 planning
-
Integrate our scenario outputs into CapEx prioritization to stress-test manufacturing investments under different EV adoption paths.
-
Use the supplier selection matrix during Q2–Q3 sourcing windows to shape long-lead component contracts and lock in price/downside protections.
-
Leverage the M&A screening tools to build a short-list of targets that accelerate your software or production footprint ambitions without requiring greenfield development.
Next steps — PW Consulting support
For leadership teams making budget and program choices in 2026, this report is structured to be an immediate operational asset: a strategy playbook and a modeling toolbox in one. PW Consulting can provide rapid-deployment advisory services to apply the report directly to your organizational context, including tailored scenario re-runs, supplier diligence support, and M&A target vetting.
To access the full dataset, detailed segment tables, and the Excel models referenced in this brief, please visit the PW Consulting report page. Our team will arrange a briefing and model handover so your 2026 planning process is informed by validated intelligence and executable recommendations.
For detailed analysis of this topic, please visit the official page: One Box Electro Hydraulic Braking System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Electric Motor Market to More Than Double to USD 16.42 Billion by 2032 on a 12.25% CAGR
By PW Consulting, 2026-07-13
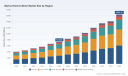
Marine Electric Motor Market — 2026 Strategic Brief: Why this report will shape your electrification decisions
PW Consulting’s latest Marine Electric Motor Market report (base year 2025) synthesizes quantitative projection models, supplier intelligence, technology roadmaps and procurement-grade decision tools to guide boardroom and commercial teams through the critical 2026 planning window. The market is transitioning from niche retrofit projects to mainstream vessel architectures: global demand has more than doubled since 2020 and is projected to expand at a compound annual growth rate of approximately 12.25% into the forecast horizon. On a headline basis, the market grew from around USD 4.1 billion in 2020 to roughly USD 7.3 billion in 2025 and is forecast to exceed USD 8.3 billion in 2026, accelerating toward an estimated USD 16.4 billion by 2032. These dynamics create discrete tactical and strategic inflection points for shipowners, OEMs, suppliers and investors in 2026.
Marine Electric Motor Market
Why this matters to executives in 2026
- Investment timing: With robust near-term growth, capital allocation decisions made in 2026 will determine access to constrained production capacity and the ability to secure preferential OEM engagement.
- Procurement strategy: Rapid product evolution and supply-side concentration on critical raw materials mean single-source procurement or late contracting can significantly raise TCO and delivery risk.
- Product roadmap alignment: From small recreational outboards to high-power inboard systems, technology choices made now (type of motor, magnet technology, integration strategy) will lock in lifecycle efficiency and retrofit flexibility for a decade.
- Regulatory compliance and commercial opportunity: New IMO measures and tightened energy-efficiency planning raise both compliance risk and market demand; early movers capture first-mover commercial advantages in retrofit and newbuild segments.
What the PW Consulting report delivers — practical, decision-ready content
- Proprietary demand model with scenario variants (base, accelerated decarbonization, supply-constrained) and downloadable forecast datasets calibrated to 2020–2025 historicals and extended to 2032.
- Fully auditable financial templates: capex/opex lines, TCO calculators, and payback analyses tailored to propulsion and auxiliary installations across vessel archetypes.
- Supplier scorecards and negotiation playbooks: capability matrices, technology readiness, warranty and service footprints, and recommended commercial terms segmented by buyer profile.
- Supply-chain heatmaps and risk registers: material exposure (magnets, copper), manufacturing bottlenecks, and logistics vectors—plus mitigation options such as strategic inventory, long-term offtake, and co-investment models.
- Technology deep dives: permanent-magnet architectures, synchronous/asynchronous options, novel topologies (including recent trapezoidal stator radial-flux designs), and integration pathways for hybrid-electric systems.
- Case studies and implementation roadmaps: sample retrofit and newbuild programs with stepwise milestones, certification checklists, and expected operational outcomes.
- M&A and partnership screening tools: valuation heuristics for target assessment, strategic fit matrices and playbooks for technology licensing or joint development agreements.
Market dynamics shaping 2026 opportunity
- Regulatory push: The IMO’s 2025–2027 policy package — including a global fuel standard and strengthened SEEMP requirements — creates a deterministic demand tailwind for low- and zero-emission propulsion. These rules enter force in 2027 and are already prompting fleets to accelerate electrification pilots and design-for-electrification in newbuild contracts.
- Raw material and energy supply constraints: The industry faces concentration risk for rare earth elements used in high-power permanent-magnet motors, with primary production concentrated in a small number of jurisdictions. Parallel pressure on copper supply driven by broader electrification increases material cost volatility and project scheduling risk in 2026.
- Technology maturation and product proliferation: Smaller, higher-power-density motor topologies and integrated pod and inboard systems are moving from prototype demonstrations to catalog entries, shortening the commercialisation curve for advanced propulsion units.
- Capital markets and financing: Growing availability of green financing and incentive structures for decarbonization makes financed electrification projects more accessible — but lenders increasingly require robust lifecycle models and demonstrated supplier security before funding.
Competitive landscape — who matters and what to watch
The market is characterized by a mix of large industrial incumbents and agile specialist challengers. Leading global suppliers and a cohort of fast-moving innovators are each carving distinct strategic plays; together they shape OEM sourcing, pricing dynamics and integration choices.
Marine Electric Motor Market
- ABB (Zurich, Switzerland) — Strengths: integrated electric propulsion systems and strong installed base in commercial and specialized vessels. Strategic implication: ABB is a default partner for operators seeking turnkey electrification in larger vessel segments; competitors should anticipate bundled solutions and lifecycle service contracts.
- Siemens (Munich, Germany) — Strengths: high-efficiency motors and integrated drives for heavy maritime and offshore applications. Strategic implication: Siemens will continue to anchor large-scale projects where electrification is paired with complex power management and automation.
- Ingeteam / Indar (Zamudio, Spain) — Strengths: broad power range and proven reliability on merchant and specialized ships. Strategic implication: strong contender for retrofits and mid-to-high power newbuilds where established marine credibility is required.
- TECO-Westinghouse (Round Rock, USA) — Strengths: rugged marine-grade motors and long heritage in shipboard systems. Strategic implication: appeals to fleets prioritizing durability and long service lifecycles, particularly in demanding operating profiles.
- Torqeedo, ePropulsion, Evoy, Elco Motor Yachts — Strengths: nimble innovation in outboards, pod drives and leisure/commercial segments with high-efficiency small- to medium-power units. Strategic implication: these firms are accelerating product cycles for small craft and will influence standards, charging/installation norms and aftersales partnerships.
- WEG, Nidec — Strengths: scale manufacturing capability and adaptable motor platforms. Strategic implication: positioned to provide cost-competitive alternatives and to support OEMs requiring volume production and global service footprints.
Recent product and trade-show activity through 2025–2026 demonstrates two parallel flows: incumbents scaling proven architectures for large vessels, and smaller players accelerating power-density improvements and integration for leisure and short-haul commercial craft. Expect continued alliance activity between system integrators and magnet or inverter specialists as manufacturers seek performance-density gains while managing supply-chain exposure.
Marine Electric Motor Market
Supply-chain and technology risk mitigation
- Diversify magnet sourcing and consider magnetless architectures where lifecycle economics and reliability support substitution. Contractual hedges, consortia purchasing, and strategic equity stakes in upstream suppliers are viable options for materially exposed buyers.
- Lock early delivery slots with high-quality manufacturers for 2026–2027 production windows; consider staggered procurement to manage cashflow and avoid single-point delivery risk.
- Invest in holistic TCO models that incorporate commodity volatility, maintenance intervals and potential regulatory penalties to ensure procurement decisions are resilient across scenarios.
Six strategic recommendations for 2026 decision-makers
- Run fast pilots with clear metrics: short-run retrofit pilots (6–18 months) with pre-agreed data sharing enable suppliers and shipowners to derisk full-scale rollouts.
- Adopt a layered supplier strategy: combine a primary systems partner for integration with two qualified secondary suppliers for critical components and aftersales to manage continuity risk.
- Embed material-hedging clauses into supplier contracts: indexed pricing bands, capped pass-throughs and minimum acceptance quantities reduce exposure to rare earth and copper swings.
- Use PW Consulting’s scenario tools to stress-test fleet electrification pathways against regulatory timelines and fuel-cost scenarios before committing to fleet-wide conversion plans.
- Pursue strategic partnerships with inverter and battery suppliers early to capture integration benefits and improve certification timelines.
- Prioritise modularity in design specifications to enable technology refreshes without full-system replacement, protecting investments against rapid product evolution.
How PW Consulting supports execution
Our Marine Electric Motor Market report bundles the quantitative forecast workbook with actionable deliverables — vendor scorecards, procurement RFx templates, capex/opex calculators and a step-by-step implementation playbook. The deliverables are designed for rapid hand-off to procurement, technical and finance teams so that 2026 programs move from approval to contract award with control over timing, cost and compliance exposure.
For decision-makers planning capital allocation, supplier negotiations or M&A activity this year, the report provides the calibrated market view and negotiation playbooks required to convert the current growth trajectory into durable competitive advantage. To access the full dataset, segmented intelligence and the downloadable toolset, please visit PW Consulting’s Marine Electrification insights page to obtain the complete report and advisory options.
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flutes Instrument Market Poised for Steady Expansion at a 4.31% CAGR in 2026–2032 Forecast
By PW Consulting, 2026-07-13
Flutes Instrument Market — Strategic Preview for 2026: Actionable Intelligence from PW Consulting
Executive summary
PW Consulting’s new Flutes Instrument Market report delivers a focused, decision-ready briefing for executives planning resource allocation, product strategy, and channel investments in 2026 and beyond. The global market for flutes stood at USD 467.18 Million in 2025 and has demonstrated steady recovery from the pandemic era, rising from USD 382.15 Million in 2020. Our 2026–2032 forecast projects the market to grow at a compound annual growth rate (CAGR) of 4.31%, reaching approximately USD 627.72 Million by 2032. These headline metrics underline a market large enough to justify targeted strategic plays, yet sufficiently specialized to reward companies that execute differentiated value propositions.
Flutes Instrument Market
Why this report matters for 2026 corporate planning
- Timing for resource reallocation: With a mid-single-digit CAGR and evident post-2020 momentum, 2026 is a pivotal year for shifting investment from broad-based volume plays to targeted innovation (e.g., premiumization, sustainable packaging, and new educational channels).
- Risk-calibrated market entry: Trade friction and tariff volatility introduce execution risk for import-dependent models; our intelligence identifies where to localize manufacturing, adjust pricing frameworks, and design compliant supply chains.
- Channel and product prioritization: The market structure favors firms that align product tiers (student, intermediate, professional) with the right distribution and service models—school programs, institutional contracting, and premium direct-to-consumer experiences.
- M&A and partnership signals: Moderate market concentration (top-3 vendors account for ~43% and top-5 for ~56% of market sales) means consolidation and strategic alliances can quickly shift competitive dynamics—use our report to evaluate targets and partnership rationales.
Data-driven positioning without the spoilers
To preserve the strategic value of this preview, we present high-level, verifiable metrics (overall market size, growth rate, concentration) while deliberately reserving granular regional, application and type splits for the full report. Clients will find rich tables, dynamic dashboards, and downloadable models that unpack those segment-level figures, enabling revenue-scenario modeling and price-volume forecasting tailored to your business. This “trailer” approach demonstrates our method and findings while inviting teams to access the full dataset for executable plans.
Flutes Instrument Market
What’s inside the full PW Consulting report (practical deliverables)
- Market sizing and baseline time series (2020–2025) with scenario-based forecasts (2026–2032) that support budgeting and three-tier planning (conservative, base, aggressive).
- Segmentation frameworks (by geographic market, instrument type, and end-use) with interactive sensitivity analysis and break-even maps for manufacturing, import, and distribution choices.
- Channel and go-to-market playbooks: recommended direct-to-consumer, distributor, and institutional strategies for each product tier, including margin calculators and lead-time impact models.
- Supply-chain and cost-pressure analysis: import tariff scenarios, sourcing alternatives, manufacturing footprint optimization, and inventory buffers tuned to instrument lead times.
- Competitive benchmarking: detailed company profiles, product positioning matrices, go-to-market strengths, IP and craftsmanship differentiation, and acquisition targets with quantified fit scores.
- Risk register and mitigation plans covering regulation, trade policy, currency exposure, and demand shocks from education budgets.
- Practical implementation templates: product roadmap prioritization, trade-show and institutional sales calendars, and a 12–24 month M&A diligence checklist.
Competitive landscape — who matters and why
The flute market blends global brands, regional volume players, and a cluster of highly specialised artisanal makers. Strategic implications differ by competitor archetype:
Flutes Instrument Market
- Global integrated manufacturers (e.g., Yamaha Corporation): Scale across student through professional tiers, global distribution reach, and brand trust make them natural partners for institutional programs. Recent moves toward sustainable packaging reinforce a combined product-and-brand experience play that competitors should monitor and, where relevant, emulate.
- Volume/education specialists (e.g., Trevor James, Jupiter, Conn-Selmer/Armstrong): These makers dominate accessibility and price-sensitive channels. They are positioned to capture demand from school programs and beginner segments; incumbents should consider product-adjacent services (rental, maintenance) to protect margin.
- Premium Japanese makers (e.g., Muramatsu, Miyazawa, Altus, Sankyo): Their Japan-based craftsmanship and R&D focus attract professional and advancing players. They set quality benchmarks that define high-price tiers and act as natural partners for artist endorsements and orchestral supply contracts.
- US artisan cluster (Powell, Wm. S. Haynes, Brannen Brothers, Burkart, Di Zhao, and peers): The Boston and broader New England ecosystem delivers ultra-premium, custom instruments prized by orchestras and soloists. Recognition of Greater Boston as a global premium hub in 2025 amplifies brand value for these makers—opportunities exist to scale bespoke services via limited editions, artist collaborations, and experiential marketing.
- Hybrid strategies (Gemeinhardt, Pearl): Firms blending local manufacturing for specific components with offshore assembly achieve favorable cost-quality balance for mid-tier and professional instruments. These models are resilient in tariff environments if component localization is strategically deployed.
Recent developments that should inform 2026 strategy
- Yamaha’s 2025 sustainable packaging redesign demonstrates how product presentation and ESG credentials can be a low-friction lever to improve perceived value at entry price points.
- Regional recognition: the 2025 spotlight on Boston’s artisanal cluster elevates premium makers’ bargaining power with orchestras and collectors, creating aftermarket and service opportunities beyond primary instrument sales.
- The Musical Instrument Museum’s “Magical Flute” exhibition (launched December 2025) is enlarging public interest and can be leveraged by brands for co-marketing, provenance storytelling, and cross-channel promotions.
- Policy and trade noise: 2025 U.S. tariffs on woodwind instruments have reached effective levels up to 27.4% in some cases; export figures showed an 8.4% decline in U.S. musical instrument exports in early–mid 2025 versus prior averages. These disturbances matter for pricing strategy and sourcing decisions in 2026.
- Demand drivers: continued government investments in music education across emerging Asian markets present structural expansion opportunities for student-focused manufacturers and for companies willing to build institutional relationships.
Strategic plays for 2026 — prioritized and actionable
- Localize selectively: Protect margin and access by localizing critical components or assembly in tariff-sensitive markets. Use our cost-benefit templates to identify the break-even point for localization vs. import.
- Product tier segmentation: Differentiate offers by lifecycle stage—promote rental and service bundles in educational markets, emphasize customization and limited editions for premium buyers, and support mid-tier with upgrade paths and trade-in programs.
- Capitalize on sustainability and experience: Align packaging, materials sourcing and repair services with ESG narratives; invest in premium unboxing and post-sale service for higher lifetime value.
- Partnerships with public institutions: Establish curricula and rental agreements with schools and conservatories in growth markets, leveraging government music-education initiatives to secure volume and visibility.
- Digital and direct engagement: Build D2C channels focused on configurators, virtual try-before-you-buy tools, and artist-led content to shorten the consideration cycle for intermediate and professional buyers.
- M&A and alliance playbook: Target bolt-on artisanal brands to capture premium margins, or consolidate distribution in strategic territories to mute tariff impact.
How PW Consulting’s report translates into a 2026 action plan
Executives will find an immediately usable 90–day activation plan inside the full report: prioritized initiatives by expected return and implementation complexity, vendor and partner shortlists, and a set of KPIs for quarterly tracking. The report’s downloadable financial model lets teams stress-test scenarios—tariff shocks, demand surges from education programs, and premiumization rate changes—so CFOs can model cash flow and capital allocation implications quickly.
Closing — next steps
For decision-makers preparing budgets and strategic roadmaps in 2026, PW Consulting’s Flutes Instrument Market report provides the empirical foundation and tactical tools necessary to convert market signals into competitive advantage. This brief exposes the market shape, concentration dynamics, and near-term risks; the full report contains the granular segment data, model access, and company-level detail required to operationalize those insights.
Access the full report and the interactive dataset on PW Consulting’s website to download the executive toolkit, request a bespoke briefing, or arrange a scenario workshop tailored to your organization’s product and distribution footprint.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive eMMC & UFS Embedded Storage Market to Expand from USD 4,100 Million in 2025 to USD 10,906.09 Million by 2032 at a 15.02% CAGR
By PW Consulting, 2026-07-13

Automotive Embedded Storage (eMMC & UFS): Strategic Imperatives for 2026 — PW Consulting Market Outlook
PW Consulting’s latest Automotive Embedded Storage (eMMC and UFS) Market report delivers an evidence-based roadmap for OEMs, Tier‑1 suppliers, semiconductor manufacturers, and procurement teams that must make binding product, sourcing and qualification decisions in 2026. Our model shows the addressable automotive embedded storage market expanding from approximately USD 4.1 billion in 2025 to roughly USD 10.9 billion by 2032 — a compound annual growth rate (CAGR) of 15.02% over the forecast horizon. These headline metrics set the strategic frame: the next 18–36 months will determine which players capture the high-value trajectories in infotainment, ADAS, and telematics systems.
Automotive Embedded Storage (eMMC and UFS) Market
Why this matters now: timing, qualification cycles and value capture
-
Qualification Lead Times: Automotive qualification cycles for eMMC and UFS typically span 18–24 months. Decisions taken in 2026 therefore materially shape 2028–2029 vehicle programs and unit economics. Late entrants face locked-out design slots and extended time-to-revenue.
Automotive Embedded Storage (eMMC and UFS) Market -
Technology Transition: The market is undergoing a structural shift toward higher-performance UFS families for cockpit and ADAS storage while eMMC remains relevant for cost-sensitive modules. Managing the mix of legacy and next‑gen architectures is a core strategic trade-off.
Automotive Embedded Storage (eMMC and UFS) Market -
Supply and Pricing Pressure: NAND supply tightness and rising contract/spot prices through early 2026 are creating allocation constraints that directly affect automotive builds. Customers must treat storage as a constrained commodity in sourcing strategy and inventory planning.
Key market dynamics that will dictate competitive outcomes
-
Demand Drivers — In‑vehicle compute growth: Higher-resolution maps, sensor fusion, AI inferencing at the edge, and richer infotainment experiences are increasing per-vehicle storage requirements. Our bottom-up use-case modeling shows per-platform storage density growth outpacing unit production, driving revenue expansion even under conservative car production scenarios.
-
Technology Mix — UFS acceleration: UFS is rapidly gaining share in high-performance applications (cockpit, domain controllers, ADAS logging) due to throughput, power, and software ecosystem advantages. eMMC remains competitive where cost and proven qualification are priority.
-
Supply Side — Concentration and constraints: NAND production remains concentrated geographically, exposing supply chains to geopolitical, export-control and logistics shocks. Major supplier capacity optimization has compressed available MLC/QLC volumes for automotive programs and is contributing to elevated pricing.
-
Regulatory & Safety Requirements: Automotive storage must meet AEC‑Q100 and often ISO 26262/ASIL requirements for systems that affect functional safety. Suppliers that integrate safety features, traceable manufacturing and deterministic failure modes command a premium in qualification assessments.
-
Market Structure — High concentration: The competitive landscape is relatively consolidated; the top three suppliers control the majority share and the top five capture near-total market volume, creating structural entry barriers for smaller vendors but also predictable partnering opportunities for OEMs and Tier‑1s looking to diversify risk.
What’s in the PW Consulting report — actionable content for 2026 decisions
-
Proprietary market sizing and scenario models: Detailed base‑year calibration (2020–2025) and forward forecasts (2026–2032) across device types, application buckets and supplier tiers, with sensitivity analysis for NAND price and allocation shocks.
-
Supplier scorecards and qualification playbooks: Comparative assessments of technical roadmaps, automotive-grade portfolios, production footprints, and expected capacity curves — designed to inform sourcing shortlists and dual‑sourcing plans without requiring OEMs to run independent, time‑consuming benchmarking tests.
-
Time‑to‑market & qualification timelines: Actionable Gantt-style templates that map design, validation, AEC‑Q100 qualification and production ramp activities. These show critical decision gates where procurement contracts, design freezes and test plans must be aligned.
-
Supply‑risk heatmaps & mitigation levers: Geographic concentration, supplier concentration, and BOM exposure are combined into decision matrices with suggested contractual, inventory and forecasting policies tailored to different OEM risk appetites.
-
Commercial playbook: Pricing negotiation playbooks, memory buy strategies (consignment, take‑or‑pay, hedged forward buys), and recommended clauses to secure allocations during NAND tightness episodes.
-
M&A and partnership intelligence: Identification of value-accretive vertical and horizontal moves — for semiconductors, controller IP providers and flash integrators — and suggested diligence checklists for acquiring or partnering with niche automotive storage specialists.
Competitive landscape — what to watch in supplier strategies
-
Samsung Electronics — Leveraging early mass production of automotive-grade UFS and a broad portfolio, Samsung is strongest on integration, power-performance optimization for IVI systems, and scale. For OEMs, Samsung represents a low‑execution‑risk anchor for high-volume cockpit programs.
-
Micron Technology — Micron’s push into automotive UFS 4.1 with G9 NAND and ASIL‑B compliant solutions signals a focus on high‑reliability and safety‑critical applications. Their roadmap and recent qualification shipments position them as a go‑to for ADAS/logging applications requiring stringent functional safety attributes.
-
KIOXIA — A strong contender on automotive UFS innovation and sampling cadence; KIOXIA’s historical first‑to‑sample posture in UFS technologies makes them attractive for customers prioritizing performance headroom and roadmap alignment.
-
SK hynix — Focused on high performance and system‑level optimization, SK hynix’s strength lies in NAND architecture evolution that supports next‑gen in‑vehicle compute nodes.
-
Western Digital (SanDisk) — Offers a mature iNAND portfolio with wide capacity support and automotive qualifications; compelling where long-term reliability and existing design heritage are prioritized.
-
Controller and integration specialists (e.g., Silicon Motion) — Controller IP and validated reference designs materially lower OEM integration risk. Recent platform validations (e.g., Snapdragon Cockpit compatibility) de‑risk adoption of Ferri‑UFS/eMMC solutions in cockpit stacks.
-
Regional and niche suppliers (Longsys, Flexxon, Kingston, ATP) — These players compete on tailored automotive-grade eMMC/UFS offerings, temperature and endurance specs, and localized support. They are often pivotal for programs seeking diversification from the hyperscalers.
Recent supplier moves and strategic implications
-
Micron’s late‑2025 shipment of UFS 4.1 qualification samples (G9 NAND, ASIL‑B) tightens the race for safety‑oriented storage and suggests an acceleration of safety‑grade offerings into production programs starting late 2026–2027.
-
KIOXIA’s sampling of advanced UFS devices indicates that suppliers are preparing for a swift transition in infotainment and high‑bandwidth ADAS storage needs; OEMs should map these sampling timelines to internal calibration/testing windows.
-
Controller validations (e.g., Silicon Motion on Snapdragon Cockpit) reduce integration risk and shorten OEM validation cycles. Design teams should prioritize validated stacks where possible to compress time‑to‑production.
Risk management and 2026 playbook — recommended actions
-
Lock in dual‑source strategies for critical platforms: Combine a large incumbent supplier for volume stability with a qualified secondary supplier to reduce allocation risk.
-
Negotiate allocation‑sensitive contracts: Include allocation guarantees, volume‑flex levers and price‑pass mechanisms tied to NAND indices where possible.
-
Accelerate qualification of UFS lines for high‑value compute domains: Given qualification lead times, prioritize early validation of UFS options for next‑generation cockpit/ADAS stacks.
-
Adopt staged architecture strategies: Design modular storage interfaces to allow field upgrades or supplier swaps with minimal ECU redesign cost.
-
Build inventory buffers prudently: Where critical, and cashflow allows, targeted strategic buys can smooth supply shocks; align with finance on depreciation and obsolescence mitigation plans.
Conclusion — the strategic value of the PW Consulting report for 2026
Decisions made in 2026 about storage architecture choices, supplier shortlists, and contractual commitments will disproportionately determine who captures the fastest‑growing pockets of the market as it expands from roughly USD 4.1 billion in 2025 to about USD 10.9 billion by 2032 at a 15.02% CAGR. Our report synthesizes macro forecasts, supplier benchmarking, qualification playbooks and supply‑risk matrices into an actionable guide designed for teams that cannot afford trial‑and‑error in a constrained supply environment.
To preserve the competitive value of our proprietary splits, detailed regional and application‑level tables and full supplier scorecards are available in the paid report and on our portal. Clients who engage with PW Consulting receive tailored briefings and scenario workshops to convert the report’s insights into executable procurement and product roadmaps.
For access to the full dataset, segmentation tables, and to schedule a strategy workshop, please visit PW Consulting’s report page or contact our Automotive Practice team.
For detailed analysis of this topic, please visit the official page: Automotive Embedded Storage (eMMC and UFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Fiber Laser Market to Expand at 11.24% CAGR (2026–2032), Driving Rapid Clinical Adoption
By PW Consulting, 2026-07-13
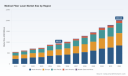
Medical Fiber Laser Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
PW Consulting’s latest industry brief on the Medical Fiber Laser Market synthesizes five years of historical performance (2020–2025) and delivers a forward-looking, decision-grade view across the 2026–2032 forecast horizon. This report is written for CEOs, corporate development teams, product leaders, and private equity investors preparing high-conviction strategies for 2026. It combines rigorous market-sizing, competitive mapping, regulatory and reimbursement intelligence, and executable commercial playbooks — while deliberately reserving the granular segment-level tables for the full report to preserve client value.
Medical Fiber Laser Market
Market snapshot: trajectory and scale
At a macro level the market demonstrates robust, sustained expansion. PW Consulting’s topline sizing shows the global medical fiber laser market growing from USD 554.4 Million in 2020 to USD 950.29 Million in the base year 2025, and accelerating through the forecast to reach USD 2,023.26 Million by 2032 — a compound annual growth rate (CAGR) of 11.24% over the 2026–2032 period. This growth reflects broad-based adoption across urology, dermatology, dentistry and soft-tissue surgical specialties, increased availability of compact thulium and erbium fiber platforms, and dynamic commercial models (capital sale, subscription, and single-use consumables).
Medical Fiber Laser Market
Why this matters for 2026 enterprise decision-making
- Timing of investment: The market’s double-digit CAGR means that choices made in 2026 (R&D allocation, manufacturing scale-up, or distribution partnerships) will have outsized impact on revenue capture across the forecast window.
- Commercial model selection: As platforms migrate from capital equipment only to hybrid capital + recurring consumables models, companies must validate unit economics and lifecycle margin curves before committing to wide rollout.
- Regulatory rhythm: The device class and 510(k)-centric regulatory environment favors fast followers and modular claims strategies; readiness in regulatory dossiers will materially accelerate access to high-value clinical channels.
- M&A and partnership windows: With market concentration moderate at scale (CR3 ~42.5%, CR5 ~61.8%), there is clear room for consolidation and strategic partnerships that can shift share rapidly in targeted subsegments.
Five strategic imperatives for 2026
- Prioritize platform/consumable economics: Map lifecycle margins across device and fiber consumables; use PW Consulting’s pricing-sensitivity model to simulate adoption under varied reimbursement scenarios.
- Build clinical adoption playbooks: Translate improved procedural outcomes (e.g., reduced retropulsion in stone surgery with thulium designs) into reproducible hospital procurement wins via KOL-driven protocols and bundled training.
- Regulatory-first product development: Design product roadmaps with modular 510(k) strategies to minimize iterative regulatory cycles and accelerate geographic launches where pathways are established.
- Flexible go-to-market: Test hybrid commercial routes — direct sales in leading markets, distributor partnerships in selectively strategic markets, and OEM/white-label deals for specialty fibers.
- Targeted M&A and alliances: Acquire or partner for either high-margin consumable streams or niche IP (e.g., specialized laser fiber designs or wavelength-specific systems) that strengthen total addressable market coverage without diluting core competencies.
Competitive landscape — what the market signals
PWC’s competitive scan identifies established laser OEMs, surgical-device companies with distribution muscle, and specialist fiber producers as distinct but overlapping competitor archetypes. Leading names in the space include IPG Photonics (IPG Medical), Coherent, Quanta System, Acclaro Medical, Boston Scientific, Cook Medical, Light Guide Optics, and Olympus — each bringing differentiated advantages in wavelength expertise, fiber design, channel access or regulatory scale.
Medical Fiber Laser Market
- IPG Photonics (IPG Medical): Known for thulium fiber platforms and surgical fiber delivery serving urology applications; distribution relationships amplify reach into high-volume procedural channels.
- Coherent: Recently launched purpose-designed thulium platforms for urology, reflecting incumbent OEM strategies to target therapeutic use-cases with tailored support assemblies.
- Quanta System: European-origin TFL systems focused on urology and delicate soft-tissue procedures; distribution partnerships strengthen cross-border access.
- Acclaro Medical: Focused on a differentiated erbium-doped fluoride fiber platform for dermatology, supported by clinical evidence generation to expand indications.
- Boston Scientific & Cook Medical: Strategic distributors and channel anchors that can accelerate adoption by pairing fiber systems with established clinical offerings and salesforces.
- Light Guide Optics & Olympus: Specialized in fibers and integrated systems respectively, these players highlight the importance of delivery-device compatibility and regulatory clearances for market acceptance.
Recent milestones shaping 2026 strategy
- Acclaro Medical’s clinical presentations in March 2026 expanded dermatology evidence for a 2910 nm erbium-based fiber platform, a signal that clinical data continues to be the decisive barrier to mainstream uptake.
- Light Guide Optics’ FDA 510(k) clearance (late 2024/announced in formal 2025 filings) for surgical laser fibers underscores the priority of regulatory-cleared delivery devices in commercial contracts.
- Boston Scientific’s late-2025 regulatory update for holmium fiber consumables evidences ongoing lifecycle management by incumbents to maintain share through packaging, shelf-life and compatibility enhancements.
- New market entrants and Chinese-origin OEMs securing 510(k) clearances in 2025 signal intensifying competitive supply and downward pressure on specific component pricing — a commercial risk and an opportunity for higher-volume players.
Regulatory and reimbursement dynamics
Medical fiber laser systems and surgical fibers are regulated predominantly under established Class II pathways in major markets. Devices typically pursue 510(k) clearances demonstrating substantial equivalence for indications such as soft tissue ablation, coagulation and lithotripsy. Compliance with GMP, labeling, and post-market surveillance remain non-negotiable operational requirements. On reimbursement, procedures using fiber lasers generally map to existing CPT/DRG codes for laser surgery; there were no fiber-laser-specific procedure codes as of 2025 — meaning reimbursement upside will be earned through demonstrated value rather than new coding lanes.
What the PW Consulting report delivers (practical contents)
The full PW Consulting report is designed as a playbook not a textbook. Highlights include:
- Proprietary market-sizing and scenario models (2020–2032) with sensitivity to pricing, adoption latency, and reimbursement shocks.
- Go-to-market decision matrices that prioritize markets, channels and customer segments by expected ROI and time-to-contribution.
- Regulatory pathway maps for the U.S., EU and selected APAC markets, including checklist-level guidance for 510(k) strategies and labeling claims shaping clinical trials.
- Commercialization templates: sample contracting terms, consumable margin waterfall models, and distributor scorecards proven in laser device rollouts.
- Competitive benchmarking (profiles, product roadmaps, recent filings) and a short-list of pragmatic M&A targets with rationale and valuation comparables.
- Clinical adoption playbooks and KOL engagement frameworks that translate technical advantages (e.g., reduced retropulsion, high-frequency dusting capability) into purchasing decisions.
Risk scenarios and mitigation
PW Consulting models three practical risk scenarios — baseline, aggressive-competition, and reimbursement-adverse — each with explicit triggers and mitigation actions. Key risks include faster-than-expected entrant pricing pressure, regulatory delays for claim expansion, and slower hospital adoption cycles. Mitigations emphasized in the report include staged capacity investments, dual-sourcing for critical fiber components, and prioritized evidence-generation partnerships to secure early adopters.
How to use these insights in 90/180/360 day plans
- 90 days: Validate product-market fit with a compact pilot using the report’s clinical and purchasing playbooks; secure regulatory pre-submission meetings where appropriate.
- 180 days: Execute channel tests (direct vs. distributor), lock initial consumable pricing bands, and begin targeted clinical studies designed with our KOL templates.
- 360 days: Ramp manufacturing commitments aligned to scenario-based demand forecasts and evaluate M&A targets prioritized by the report’s strategic filters.
Conclusion — why this brief matters to C-suite teams
Medical fiber lasers occupy a high-leverage corner of the medtech landscape: accelerating technological innovation, shifting commercial economics, and a regulatory environment that rewards disciplined execution. PW Consulting’s report turns market complexity into an actionable strategic path: quantify opportunity, prioritize investments, hedge against regulatory and competitive shifts, and design commercial models to capture recurring revenue. For executives planning resource allocation in 2026, the insights in this brief are decision-enabling — and the full report contains the confidential segment-level analytics, modeled scenarios, and tactical playbooks required to operationalize these insights.
To access the complete report, which includes full segment tables, vendor scorecards, and downloadable financial models, please visit our report landing page or contact PW Consulting’s Sales & Insights team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Medical Fiber Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Manga & Anime Licensing Market to Expand at 11.5% CAGR, Reaching USD 37,388 Million by 2032
By PW Consulting, 2026-07-13
PW Consulting: Strategic Preview — Manga & Anime Licensing Market Outlook (2026–2032)
Executive summary
The global manga and anime licensing market is entering a strategic inflection point. After accelerating through the early 2020s, the market expanded from roughly USD 10 billion in 2020 to an estimated USD 17.5 billion by 2025. Our analysis projects continued robust growth through the 2026–2032 forecast window at a compound annual growth rate of approximately 11.5%, with the total addressable licensing market approaching the mid‑tens of billions by the early 2030s. For executives planning 2026 budget cycles, content slate decisions, or distribution alliances, this report provides the evidence base and applied frameworks necessary to convert market momentum into durable revenue and IP ownership advantages.
Manga And Anime Licensing Market
Why this matters for 2026 decision-making
-
Market scale and velocity: Sustained double‑digit CAGR through the forecast period shifts licensing from a niche income stream into a core strategic revenue pillar for media conglomerates, publishers, game companies, and consumer brands. Capital allocation, talent pipelines, and M&A theses must reflect that reality by 2026.
Manga And Anime Licensing Market -
Vertical integration premium: Companies that control creation, distribution, and merchandise channels are better positioned to capture downstream licensing economics. Recent transactions and JV activity highlight a premium being placed on integrated IP pipelines.
Manga And Anime Licensing Market -
Platform and regional dynamics: Streaming platforms, D2C merchandising, and gaming tie‑ins are redefining monetization windows. Meanwhile, regulatory, local market, and anti‑piracy actions are reshaping risk-adjusted returns across territories—making market entry and licensing term design more complex and consequential.
What PW Consulting’s report delivers — practical, executable content
We designed this study as a decision tool for C‑suite and licensing teams. The report combines market sizing and forecasting with practitioner‑grade playbooks and contractual tools, including:
-
Proprietary total market and trend models that reconcile historical performance (2020–2025) with scenario‑based forecasts for 2026–2032, enabling sensitivity analysis for macro and micro drivers.
-
Go‑to‑market blueprints for licensors and licensees — covering streaming exclusives, timed theatrical windows, merchandising roadmaps, and app/game integration strategies.
-
IP valuation and royalty benchmarking methodology, including step‑by‑step templates for structuring advance/royalty blends, minimum guarantees, and territory carve‑outs that balance upside capture with distribution partner incentives.
-
Localization and distribution playbooks that prioritize translation, cultural adaptation, and regulatory compliance to maximize per‑market yield while managing cost and speed to market.
-
Risk frameworks addressing copyright enforcement, anti‑piracy enforcement levers, AI ingestion and content‑use exposure, and regulatory shifts—each with operational controls and contract clauses you can implement immediately.
-
M&A and JV decision matrices for acquiring IP owners, stakes in studios, or distribution platforms — complete with target prioritization criteria and integration checklists.
-
Executive dashboards and investor‑grade slide packs summarizing KPIs such as revenue per title, lifetime merchandising yield, and channel mix scenarios (digital, physical, theatrical, experiential).
Competitive landscape — who matters and why
The market’s competitive architecture blends traditional IP holders, platform aggregators, and media conglomerates. The report maps strategic positioning for each major actor and highlights near‑term moves that will affect licensing bargaining power.
-
Crunchyroll (Sony Pictures Entertainment): Continues to expand both streaming reach and direct‑to‑consumer merchandising capabilities, recently launching branded online stores across Southeast Asia. This intensifies platform leverage for exclusive windows and merchandise co‑development.
-
Toei Animation: As a steward of several high‑value legacy franchises, Toei’s licensing approach remains a bellwether for how classic IP will be stewarded across emerging platforms and experiential channels.
-
Aniplex (Sony Music Entertainment Japan): Deepening production capacity through recent studio acquisitions, Aniplex is converting production control into scalable licensing pipelines that increase capture of downstream revenues.
-
Shueisha / VIZ / Shogakukan / Kodansha: These publishers continue to dominate manga IP origination. Their partnership and distribution arrangements in North America and beyond will be determinative for print‑digital balance and English‑language adaptations.
-
Bandai Namco: An example of a commercial model that monetizes IP across games, toys, and merchandise at scale—reported licensing‑related revenues demonstrate the revenue ceiling for well‑executed franchise commercialization.
-
Netflix and other global streamers: Aggressive commissioning of originals and co‑productions is altering licensing windows and creating alternative revenue pools for studios willing to prioritize global exclusivity over territory‑by‑territory licensing.
-
Specialist licensors and distributors (Sentai, GKIDS, Square Enix): Niche players retain strategic value through theatrical distribution expertise, collector‑market credibility, and rights management for titles that are cultural or fiscally specialized.
Recent industry developments with strategic implications
-
Consolidation and production scaling: Studio acquisitions and JV launches (including notable 2025–2026 moves) are shortening the path from IP creation to worldwide licensing — favoring organizations that can operationalize cross‑border production pipelines quickly.
-
Retail & D2C acceleration: Platform operators are increasingly controlling merchandising channels, which changes margin pools and bargaining dynamics for licensees and retail partners.
-
Regulatory and rights landscape: Government policy signals (domestic support principles for creative industry growth and clarified guidance on AI/copyright use) are reducing legal ambiguity but raising compliance requirements that must be embedded in licensing agreements.
-
Piracy enforcement pressure: Recent legal actions against piracy platforms are creating enforcement precedents that licensors can leverage in contract negotiations and anti‑counterfeiting strategies.
Strategic actions for 2026 planning
Based on our scenario work and company‑level analysis, we recommend that leaders prioritize the following actions in their 2026 plans:
-
Shift from channel‑first to IP‑first capital allocation: Prioritize investments that grow and protect original IP portfolios (sequels, cross‑media adaptation rights, merchandising exclusives) rather than short‑term distribution deals.
-
Design flexible licensing terms: Embed performance collars, renegotiation triggers tied to streaming metrics, and downstream revenue‑share mechanisms to capture value as titles scale globally.
-
Operationalize anti‑piracy and AI governance: Adopt contractual clauses and technical controls that reflect recent national guidelines on AI use and international enforcement trends to limit rights leakage.
-
Invest in D2C and experiential channels: Accelerate direct merchandising platforms and event strategies to capture higher lifetime per‑fan revenue, while using platform partnerships to extend reach selectively.
-
Prioritize market access strategies for high‑growth geographies: Use hybrid partnerships (local distributors + global platforms) to mitigate regulatory complexity while preserving monetization upside.
-
Use M&A as capability playbooks: Acquire studios or minority stakes where production control will materially shorten time to monetization and boost negotiated licensing economics.
Why PW Consulting’s intelligence is unique
We combine granular, reproducible market models with implementable legal and commercial templates. The report is built around the executive workflows of licensing teams — from VP licensing to CFO — and includes scenario stress tests, integration checklists, and reproducible financial models validated against public filings and market behaviors.
Next steps — how to access the full intelligence
This release is a strategic preview designed to establish the decision context for 2026. To protect client value and commercial confidentiality we have intentionally withheld detailed regional and application splits, as well as title‑level revenue tables. Subscribers to the full PW Consulting Manga & Anime Licensing Market report receive:
-
Complete model files with downloadable forecasts and sensitivity toggles.
-
Full segmentation by region, type, and application (broken down to actionable units for commercial negotiation).
-
Contract templates, sample term sheets, and royalty benchmarking tables keyed to revenue and channel scenarios.
-
Customized advisory sessions to apply the models to your 2026 planning and go‑to‑market execution.
Contact PW Consulting to request a briefing or to license the full report and datasets. Our team of industry experts will walk you through the models and translate findings into a prioritized action plan tailored to your commercial objectives.
For detailed analysis of this topic, please visit the official page: Manga And Anime Licensing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Low‑Powered Electric Motorcycle & Scooter Market to Expand at a 12.15% CAGR
By PW Consulting, 2026-07-13
Low Powered Electric Motorcycle And Scooter Market: Strategic Imperatives for 2026
PW Consulting today publishes a forward-looking industry brief accompanying our full Low Powered Electric Motorcycle And Scooter Market report (base year 2025). The market reached a definitive scale in 2025 — and, under our base forecast, is expected to expand at a compound annual growth rate of approximately 12.15% through 2032. This trajectory reshapes competitive dynamics, supplier economics and regulatory risk profiles. The analysis that follows is curated to help boards, corporate strategy teams, private equity investors and mobility operators make informed, immediate decisions in 2026. For full segmented datasets, interactive models and annexes, please refer to the complete report on the PW Consulting site.
Low Powered Electric Motorcycle And Scooter Market
Why 2026 is a Pivotal Inflection Point
-
Cost and component dynamics are shifting the unit economics. A material reduction in battery-pack and critical mineral prices over 2024–2025 has improved margin potential for manufacturers and opened space for new business models (battery ownership, swapping and subscription-based services).
Low Powered Electric Motorcycle And Scooter Market -
Regulatory attention is intensifying. Governments and standards bodies have tightened safety and classification rules for electric two‑wheelers, while internationally recognised frameworks (including vehicle safety regulations and UL safety outlines for vehicle systems) are influencing product design and time-to‑market requirements.
Low Powered Electric Motorcycle And Scooter Market -
Market structure remains neither hyper‑consolidated nor atomistic: a small set of large producers coexists with many regional and specialist players, creating both pressure for scale and opportunities for targeted acquisitions or rapid market entry via partnerships.
-
Urban mobility and logistics economics continue to evolve. The segment that serves personal commuting is still a primary volume driver, but commercial last‑mile use cases are changing product specifications and aftersales needs.
What PW Consulting’s Report Delivers — Practical, Decision‑Ready Tools
-
Forecast Model: A company-calibrated market model (2026–2032) with scenario capabilities (base, upside and downside) that allow executives to stress-test capital allocation and pricing strategies.
-
Cost & Supply Chain Toolkit: Bottom-up supply‑chain cost models for battery pack composition, motor and power electronics that quantify sensitivity to commodity swings and supplier concentration.
-
Competitive Benchmarking: Strategic profiles and capability matrices for the leading OEMs and new entrants, focused on product architecture, go‑to‑market muscle, software/IP and manufacturing flex.
-
Regulatory & Safety Matrix: A consolidated compliance checklist mapped to key markets and product classes, including recommended testing sequence and timeline to certification.
-
Go‑to‑Market Playbooks: Channel, fleet and subscription playbooks with KPIs for deployment pilots, dealer enablement and urban operator partnerships.
-
M&A & Partnership Framework: Rapid screening criteria, valuation levers and integration blueprints for targets that deliver scale, technology or distribution advantages.
-
Operational Templates: Pilot scorecards, warranty economics calculators, battery lifecycle management procedures and a risk heatmap for supply and regulatory shocks.
Key Strategic Implications for Executives in 2026
-
Re‑think battery strategy: With continued downward pressure on pack prices and raw lithium cost volatility, firms must decide between owning battery assets, enabling swap ecosystems, or outsourcing to capture margin without capital strain.
-
Prioritise software and services as a differentiation axis: Connectivity, fleet management and subscription features are shifting value from pure hardware to bundled recurring revenue — a critical factor in valuation and margin expansion.
-
Design for compliance and resilience: Incorporate safety certification pathways and thermal management standards into early stage product development to avoid costly rework and market delays.
-
Localise manufacturing selectively: Prioritise localized assembly or cell sourcing in markets where regulation, import duty structures and logistics materially affect price competitiveness.
-
Tailor product roadmaps to dual demand streams: Maintain a clear product split between high‑volume personal commuting designs and more robust platforms for commercial last‑mile use, with differentiated service propositions.
-
Prepare for consolidation opportunities: Given the market’s mid‑level concentration, strategic M&A and alliances can rapidly improve scale and provide access to distribution or technology that would be expensive to build organically.
Competitive Landscape — How Incumbents and Challengers are Positioning
The competitive map is being redrawn along three axes: scale/cost, software-enabled differentiation and ecosystem plays (battery swapping, aftersales and fleet management). Leading manufacturers and new entrants exemplify these vectors.
-
Large-scale incumbents focus on cost and distribution: Several established OEMs leverage manufacturing scale to defend volume-oriented segments and export markets.
-
Smart, connected challengers push software and services: Vendors with integrated IoT, telematics and battery-swapping approaches are transforming retention economics and recurring revenue potential.
-
Regional specialists and legacy brands pursue premium or heritage positioning: Iconic marques and premium innovators are converting brand equity into electrified portfolios targeted at urban buyers willing to pay for design and performance.
Notable corporate positions reviewed in the report include high-volume manufacturers, IoT‑centric platform players, battery‑swap ecosystem builders, India’s high-growth producers and traditional motorcycle OEMs moving into electric segments. Recent market signals that we have analysed include a mainstream manufacturer’s launch of a new scooter platform in late 2025, and a strategic summit by a notable producer showcasing a full‑size model with a third‑party motor and removable lithium-ion battery. These moves demonstrate both product diversification and continued investment in battery systems and modular platforms.
Operational Playbook — Tactical Actions for 2026
-
Supply chain triage: Run a 60‑day battery and motor supplier stress test, mapping alternate sources and qualification lead times.
-
Rapid pilots: Deploy 3–5 pilot vehicles with integrated telematics and warranty telemetry to generate real-world reliability datasets and unit economics before scaling.
-
Regulatory fast‑lane: Engage early with certification bodies and adopt the UL and national vehicle safety frameworks as project milestones to avoid launch pauses.
-
Dealer & fleet alignment: Reconfigure channel incentives to prioritise battery health, service subscriptions and residual value guarantees that reduce consumer total cost of ownership.
Investor & M&A Lens — What Buyers Should Prioritise
-
Value drivers are shifting: IP in software/telemetry and recurring revenue models command premium multiples relative to pure hardware; battery-ownership and swap revenues are key differentiators.
-
Due diligence focus: Assess supply‑contract resiliency, product certification status, and aftersales economics (warranty claims, battery health metrics) — these factors materially affect post‑deal integration risk.
-
Integration roadmap: Successful consolidation requires rapid harmonisation of SKUs, cross‑platform telematics and unified warranty policies to unlock cost synergies.
How to Use This Report Over 90 Days
-
Day 0–30: Strategic reset — senior leadership review, scenario stress‑tests of forecast model, and supplier concentration mapping.
-
Day 30–60: Tactical execution — launch pilot programmes, commence regulatory certification paths, and begin partner negotiations for battery and software partnerships.
-
Day 60–90: Decision cadence — finalise capex allocations, commit to manufacturing footprints or partnership structures, and shortlist M&A targets if inorganic growth is required.
Concluding Recommendation
For companies operating in, or entering, the low-powered electric motorcycle and scooter market, 2026 is the year to convert optionality into repeatable advantage. The combination of improving battery economics, evolving regulatory expectations and the growing importance of software and service revenues creates a clear playbook: secure resilient supply chains, architect products for certifiability, and build recurring‑revenue service layers that protect margin and increase customer lifetime value.
This briefing is a strategic preview intended to demonstrate our analytical depth and practical orientation. The full PW Consulting report contains the complete market model, segmented demand analyses, company share tables and downloadable templates that underpin the recommendations above. Access the full intelligence pack and the interactive scenario model on PW Consulting’s report page to translate these insights into your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 14430 Cylindrical Lithium‑Ion Battery Market Poised to Expand at a 5.85% CAGR Through 2032
By PW Consulting, 2026-07-13
14430 Cylindrical Lithium‑Ion Battery Market — Strategic Preview for 2026 Decision Makers
Executive summary
PW Consulting’s market brief on the 14430 cylindrical lithium‑ion battery segment synthesizes seven years of historical performance and a detailed 2026–2032 outlook to support near‑term corporate strategy. The market recorded steady expansion through 2020–2025, reaching an estimated USD 115.0 million in 2025, and is projected to grow at a 5.85% compound annual growth rate (CAGR) across the 2026–2032 forecast window, arriving at roughly USD 171.2 million by 2032 under our base scenario. Market concentration is meaningful but not prohibitive: the top three players account for nearly half of industry revenue, while the top five approach two‑thirds—conditions that favor both focused partnerships and tactical new entrants.
14430 Cylindrical Lithium Ion Battery Market
Why this briefing matters for 2026 planning
- Time‑sensitive decisions: 2026 is a hinge year where raw‑material volatility, regulatory shifts and chemistry adoption patterns converge; procurement, product roadmaps and M&A plans set in 2026 will determine cost and supply resilience for the next product cycle.
- Opportunity to re‑architect risk: modest but persistent market growth and moderate concentration create windows for vertical integration, contract consolidation, or selective outsourcing depending on corporate appetite for control vs. cost efficiency.
- Strategy calibration: product development, certification timelines and channel strategies need alignment with both tightening safety expectations and shifting chemistry preferences among battery pack OEMs.
Market dynamics — what we measured and why it matters
Our analysis combines historical shipments and revenue patterns (2020–2025) with primary interviews, supplier intelligence and materials cost modeling to produce a probabilistic forecast through 2032. Key dynamics shaping the 14430 market in 2026 are:
14430 Cylindrical Lithium Ion Battery Market
- Raw‑material and pack price swings: battery pack prices dropped to a record low in 2025 driven by manufacturing efficiency and wider LFP adoption, even as commodity prices (notably lithium carbonate and certain cobalt supply disruptions) experienced volatile rebounds late in 2025. The composite effect compresses margins for some suppliers while advantaging chemistries and producers with integrated sourcing or LFP expertise.
- Chemistry reallocation: the market is seeing accelerated share gains for lower‑cost chemistries in applications where form factor and energy density tradeoffs are acceptable. This chemistry mix shift alters supplier selection, certification needs, and lifecycle cost calculations for OEMs and pack integrators.
- Regulatory and trade pressure: new reciprocal tariff adjustments and export controls introduced in 2025–2026 are rerouting sourcing strategies and prompting regional contingency planning for imports, certifications and after‑sales liabilities.
- End‑market demand heterogeneity: demand drivers differ by use case—portable consumer devices, medical instruments, and specialized industrial tools each impose distinct performance and safety thresholds, which create differentiated procurement pathways and product specifications for the 14430 form factor.
Strategic implications for corporate stakeholders
- Procurement and supply chain leaders: prioritize layered supplier strategies that combine a primary relationship with one of the established tier‑one manufacturers and vetted secondary suppliers capable of rapid scale or customization. Locking in safety‑certified inventories and multi‑year pricing collars for critical chemistries will reduce exposure to short‑term commodity spikes.
- Product and R&D leaders: accelerate validation programs for alternative chemistries and safety systems. For devices where size and peak power requirements permit, LFP variants can materially lower system cost and improve thermal stability; where energy density is non‑negotiable, invest in advanced BMS and abuse‑tolerance features.
- Commercial and go‑to‑market teams: adjust channel and pricing models to reflect tightening expectations around certifications and after‑sales liability. OEMs should demand traceability and SDS compliance from suppliers as a commercial prerequisite.
- Corporate development and investors: pursue bolt‑on acquisitions that add chemistry depth (e.g., LFP know‑how), testing/certification capabilities, or regional production footprints to mitigate tariff and logistics risk. The moderate concentration metrics indicate room to consolidate value through targeted deals.
Competitive landscape — who matters and how to engage
Our competitive review emphasizes supplier positioning, product strengths and recent moves. The 14430 ecosystem mixes established electronic component leaders, specialized cylindrical cell makers, and regional manufacturers serving niche applications.
14430 Cylindrical Lithium Ion Battery Market
- Murata Manufacturing Co., Ltd. (Kyoto, Japan) — a recognized electronics component leader that offers 14430 series cells engineered for high‑rate and higher‑reliability applications. Recent SDS updates underline Murata’s emphasis on safety documentation and regulatory alignment, making them a natural partner for customers prioritizing compliance and global distribution.
- DNK Power (China) — positioned as a flexible manufacturer focusing on custom battery packs and a range of cell capacities. Their commercial model is attractive to OEMs needing bespoke pack integration and accelerated sampling, but buyers should validate long‑term quality consistency via factory audits and batch testing.
- Topwell Power (China) — a supplier oriented toward consumer electronics applications with integrated protection circuit module options. Their value proposition centers on cost‑competitive modules for volume consumer applications; consider them for scale programs where certifications and performance envelopes align with product needs.
- BZ Battery / Benzo Energy (Guangdong, China) — specializes in tailored cells for portable consumer devices, particularly lifestyle and vaping categories. Their strength is speed of customization; for regulated markets evaluate product qualification lead times and documentation completeness.
- PKCELL (Shenzhen, China) — emphasizes energy density and reliability with ISO/CE/RoHS credentials and application notes for outdoor/portable electronics. Recent product information pushes show an intent to capture outdoor and ruggedized device segments.
- ELB Energy Group (China) — brings NCM variants into the cylindrical portfolio, useful where higher energy density drives product differentiation. Evaluate for performance‑driven applications but validate supply continuity against raw‑material price sensitivity.
- Mottcell (China) — offers 3.2V LiFePO4 and emphasizes wholesale supply and quality credentials. Their recent industry guide release demonstrates a focus on positioning and transparency for energy storage applications, which can be helpful for buyers seeking LFP alternatives.
Recent company developments (SDS updates, product promotions and industry guides) illustrate the market’s twin focus on safety compliance and targeted commercial positioning. These signals affect supplier selection and speed to market: prefer suppliers with up‑to‑date safety documentation and published application notes to shorten qualification cycles.
What the PW Consulting report includes — practical deliverables
This report is built as an operational playbook for executives and functional leaders. Key deliverables include:
- Validated market sizing and a scenario‑based forecast (2026–2032) with sensitivity analysis tied to commodity shocks and regulatory shifts.
- Supplier maps with capability matrices, certification checklists and recommended audit scripts to accelerate vendor due diligence.
- Application‑level buyer guides (safety, BMS integration, lifecycle cost modeling) that translate cell‑level decisions into system‑level outcomes.
- Commercial playbooks for procurement (negotiation levers, contract structures, hedging approaches) and go‑to‑market playbooks for cell suppliers entering new verticals.
- Regulatory tracker and risk matrix highlighting tariff impacts, export controls and documentation timelines that materially affect cross‑border sourcing.
- Raw‑material exposure dashboard and recommended mitigation tactics for chemical price volatility and supply disruptions.
How to use this intelligence in 2026 — recommended actions
- Within 30–60 days: run a supplier risk diagnostic using our audit script; secure conditional capacity commitments with at least one certified vendor.
- Within 90–180 days: complete chemistry validation trials (including LFP) and update BOM decisions to reflect total cost of ownership, not unit cell price alone.
- By end of 2026: finalize regional sourcing plans to mitigate tariff exposure; decide on targeted M&A or strategic JV options informed by our concentration and capability matrices.
Conclusion — the strategic value for 2026
The 14430 cylindrical battery segment presents a pragmatic growth story: measured expansion coupled with shifting chemistry preferences and regulatory headwinds create a landscape where clear, data‑backed decisions will materially affect competitive position. PW Consulting’s report distills this complexity into actionable interventions for procurement, product, commercial and corporate development teams. We intentionally provide a high‑level strategic preview here to guide immediate 2026 priorities; the full report contains the underlying segmentation tables, regional and application breakdowns, model‑level data, and downloadable scenario workbooks that CFOs and SBU leaders will need to finalize budgets and vendor commitments.
Next step
Access the full market intelligence package to obtain the detailed segmentation, company scorecards, and downloadable datasets required to operationalize the recommendations above. Our clients use these deliverables to compress qualification timelines, hedge commodity exposure, and align product roadmaps with near‑term regulatory realities.
For detailed analysis of this topic, please visit the official page: 14430 Cylindrical Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


