



PW Consulting: Microtubule Inhibitor Drugs Market Poised to Expand at a 5.5% CAGR Through 2032
By PW Consulting, 2026-07-13
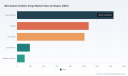
Microtubule Inhibitor Drugs Market: Strategic Bearings for 2026 — A PW Consulting Brief
As oncology portfolios and translational pipelines shift toward precision payloads and antibody–drug conjugates (ADCs), microtubule inhibitor drugs remain a cornerstone of cytotoxic and targeted combination strategies. PW Consulting’s latest market research — with a 2025 base year and a forecast horizon covering 2026–2032 — quantifies a steady expansion of the microtubule inhibitor market and distills practical imperatives for enterprise decision-makers entering 2026. This briefing highlights the report’s strategic value without disclosing the proprietary segmentation details reserved for subscribers.
Microtubule Inhibitor Drugs Market
Executive snapshot
Our analysis shows the global microtubule inhibitor market has demonstrated resilient growth through the early 2020s and is projected to continue expanding over the coming decade. After recovering and expanding in the 2020–2025 historical window, the market enters the 2026–2032 forecast period with a compound annual growth rate (CAGR) of approximately 5.5%. By the end of the forecast horizon, PW Consulting anticipates clear upside driven by novel ADC approvals, ongoing lifecycle management of legacy agents, and geographic and indication-level expansion.
Microtubule Inhibitor Drugs Market
Why this report matters for 2026 planning
- Investment prioritization: The market’s mid-single-digit CAGR combined with concentrated competitive dynamics requires disciplined capital allocation. Our report translates macro momentum into actionable thresholds for go/no-go decisions across discovery, clinical development, and commercialization.
- Portfolio optimization: Organizations can use the report’s scenario modelling to test combinations (e.g., microtubule inhibitors plus targeted therapies or immuno-oncology agents) and to rank indications and assets by commercial potential and de-risked development timelines.
- Commercial strategy: The evolution of ADCs and ADC-adjacent reimbursement frameworks is reshaping payer negotiations. The report provides a pragmatic playbook for launch sequencing, list-price architecture, and contracting strategies tailored to the oncology value chain in 2026.
- M&A and alliance targeting: With a market that remains meaningfully concentrated among leading manufacturers, the intelligence in this study supports targeted bolt-on acquisition screening and strategic partnerships to access payload technologies, linker chemistry, or regional commercialization capabilities.
Market trajectory — context, not numbers
Across the historical period we studied, established microtubule agents retained meaningful commercial value as both stand-alone therapies and payloads for ADC constructs. Looking forward, PW Consulting projects steady growth driven by four structural forces: (1) continued use of established microtubule-stabilizing and -destabilizing agents in core oncology indications; (2) the rapid maturation of ADCs that employ microtubule-inhibiting payloads, unlocking new indications and combination regimens; (3) geography-specific access expansion tied to regulatory and reimbursement evolution; and (4) life-cycle strategies by originators and generics that influence pricing and volume dynamics.
Microtubule Inhibitor Drugs Market
For executives, the headline numeric drivers are unambiguous: the sector’s baseline market size at the 2025 base year provides a robust foundation, and, under conservative assumptions, the market grows at roughly a mid-single-digit CAGR through 2032. This steady compounding underscores the need for multi-year strategic plays rather than near-term tactical wins alone.
Competitive landscape — who matters and why
The microtubule inhibitor ecosystem blends large integrated pharmaceutical players with specialist oncology developers. The report profiles leading firms whose portfolios and strategic moves will materially shape market structure and access in 2026:
- Pfizer Inc. — A long-standing marketer of paclitaxel formulations, Pfizer’s scale in manufacturing and global commercialization continues to anchor the market for taxane-class therapies. Their strategic options include differentiated formulations, sterile manufacturing scale-up, and potential ADC collaborations.
- Sanofi S.A. — With cabazitaxel in its oncology portfolio, Sanofi’s focus on post-docetaxel prostate cancer care and lifecycle management projects maintains a foothold in specialist indications. Sanofi’s development and label strategies will influence competitive positioning in second- and third-line settings.
- Bristol-Myers Squibb — Beyond stabilizers marketed for breast cancer, BMS’s investment in ADC payload strategies and combination programs makes it a notable competitor for clinical-stage partnerships and for securing therapeutic niches created by biomarker-led patient subsets.
- Eisai Co., Ltd. — As the marketer of non-taxane microtubule agents, Eisai demonstrates how differentiated mechanism-of-action within the class can sustain commercial relevance, particularly in indications needing novel cytotoxic modalities.
- Eli Lilly and Company — Lilly’s oncology capabilities and R&D investments provide optionality: either developing in-house microtubule-related innovations or acquiring payload/linker technologies to support ADC strategies against high-unmet-need tumor types.
- AbbVie Inc. — AbbVie’s recent regulatory milestone with a c‑Met-directed ADC bearing a microtubule inhibitor payload (accelerated approval in mid-2025) validates the commercial pathway for such constructs and signals how payer and regulatory bodies are evaluating these therapies.
Market concentration remains meaningful: top incumbents capture a material share of revenue, but pockets of white space remain for specialized payload providers, ADC innovators, and companies that can out-execute commercialization in selected oncology niches.
Regulatory and reimbursement dynamics shaping 2026 decisions
Two regulatory developments in our review underscore structural implications for 2026:
- Regulators have shown a willingness to grant accelerated approvals for ADCs that demonstrate strong early activity in biomarker-defined populations — a dynamic validated by recent approvals of c‑Met-directed and BCMA-directed ADCs in 2025. For strategy teams, this increases the value of biomarker-led early-phase trials and compels rapid evidence-generation plans to convert accelerated approvals to full approvals.
- Payer positioning around ADCs — particularly those with microtubule-inhibitor payloads — is evolving. In several markets, payers continue to view microtubule payload ADCs as high-value oncology options across multiple indications; this creates both pricing support and an imperative for robust real-world evidence (RWE) generation and outcomes-based contracting capabilities.
What the PW Consulting report delivers — practical, transaction-ready intelligence
We structure the report to be directly usable by C-suite leaders, business development teams, and commercial planners. Key operational deliverables include:
- Top-line market model (historical and forecast through 2032) with scenario toggles to test price, uptake, and approval timing assumptions.
- Segment-level playbooks (by molecule class and clinical indication) that translate clinical trial outcomes into commercial forecasts and margin sensitivities.
- A regulatory timeline and approval-risk heat map to prioritize indications and de-risk development portfolios in 2026 planning cycles.
- Payer engagement guides and reimbursement scenario matrices suitable for early HTA discussions and contracting pilots.
- An M&A and partnering screening toolkit highlighting capability gaps versus market opportunities and recommended deal structures for payload acquisition or commercialization partnerships.
- Commercial launch sequencing templates and Go-to-Market (GTM) templates designed to accelerate market entry while protecting price and access.
Strategic recommendations for executives planning in 2026
- Prioritize biomarker strategies: Accelerated regulatory pathways favor agents with clear companion diagnostic strategies. Invest in diagnostic partnerships early to shorten approval timelines and strengthen label claims.
- Treat ADC payloads as platform bets: For companies without established payload technologies, consider asset-light access via licensing or co-development rather than costly in-house builds unless a differentiated scientific rationale exists.
- Build payer evidence programs now: With payers increasingly receptive to ADCs but demanding robust comparative and RWE, allocate budget for post-approval registries and outcomes programs as part of launch preparations.
- Design portfolio de-risking playbooks: Use the report’s scenario models to map sensitivity to price erosion, generics entry, and combination-therapy cannibalization — then sequence clinical investments to maximize optionality.
- Monitor competitive concentration: Dominant players will continue to influence access and pricing dynamics. Look for niche indications or underserved geographies where mid-sized or specialized players can win despite concentration at the top.
Closing — the strategic value proposition
PW Consulting’s Microtubule Inhibitor Drugs Market report is built for decision-makers who need both a clear quantitative baseline and immediately actionable strategic guidance. It combines rigorous market-sizing (anchored on a 2025 base year and a transparent 2026–2032 forecast), competitive intelligence on incumbent and emergent players, and operational toolkits intended to shorten the time from insight to execution.
We deliberately present this briefing as a high-fidelity preview. The full analysis contains the granular segmentation, interactive financial models, and proprietary scenario outputs that are essential for deal teams, R&D strategy groups, and commercial leaders preparing for 2026. PW Consulting clients and subscribers can access the full dataset and modeling workbench to run bespoke scenarios aligned to their risk tolerance and strategic objectives.
For executive access to the full report and the accompanying analytical tools, please visit our report portal or contact your PW Consulting account lead for an enterprise briefing and secure model walkthrough.
For detailed analysis of this topic, please visit the official page: Microtubule Inhibitor Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Transfer Vinyl Market Poised for a 6.45% CAGR Through 2032
By PW Consulting, 2026-07-13
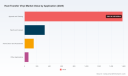
Heat Transfer Vinyl Market 2026: A Strategic Preview for Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise yet strategically rich preview of our forthcoming Heat Transfer Vinyl (HTV) Market report — a resource designed to shape high-confidence decisions for 2026. This briefing synthesizes the report’s macro view, near-term risk vectors, and the practical playbook we provide to commercial, product and corporate development teams. We deliberately surface the intelligence you need to test hypotheses and prioritize action while reserving granular segment-level metrics for the full report.
Heat Transfer Vinyl Market
Market snapshot: scale, trajectory, and competitive posture
The HTV market is well into a steady expansion phase. From a 2025 baseline of roughly USD 2.12 billion, our model anticipates continued growth through the forecast window, underpinned by an expected compound annual growth rate (CAGR) of 6.45% (2026–2032). By the end of the forecast horizon, the market is projected to climb materially versus 2025 levels, a trajectory driven by rising demand for customized apparel, sportswear innovations, new printing/transfer technologies, and sustainability-driven reformulation.
Heat Transfer Vinyl Market
Market structure remains moderately fragmented: the combined share of the three largest players sits in the low-to-mid 30% range, and the top five firms control just over two-fifths of the market. That concentration profile creates dual opportunities — scale benefits for established manufacturers and attractive niches for agile challengers able to combine technical differentiation with localized service models.
Heat Transfer Vinyl Market
Why this matters for 2026 decision-making
- Allocate capital to high-conviction innovations: The market’s growth rate supports investment in next-generation PU formulations, printable HTV systems, and sustainable chemistries that meet tightening regulatory requirements in key markets.
- Prioritize supply-chain resilience: Volatility in vinyl and resin supply, recent plant turnarounds and commodity swings have shown how margin exposure can materialize quickly. Procurement strategies and dual-sourcing plans should be stress-tested now.
- Use channel leverage to win share: Distribution partnerships and ecosystem plays (hardware + consumable bundles) are accelerating reach into SMEs and professional decorators. Strategic alliances can be a faster route to scale than greenfield expansion.
- Refine M&A thesis: Fragmentation means attractive tuck-in targets exist that offer technology upgrades, regional distribution, or adjacent product lines (e.g., printable films, heat presses).
Report deliverables — what you will get (practical, executable)
Our full report is organized to move teams from insight to implementation. Key deliverables include:
- Actionable market sizing and forward scenarios calibrated for 2026 planning cycles. We provide a base case, downside stress test, and upside adoption scenario to guide CAPEX and inventory decisions.
- Supply-chain risk heatmaps highlighting raw-material dependencies, single-source exposures, and critical lead-time sensitivities by production step.
- Regulatory and sustainability roadmap with thresholds and triggers that matter to product teams (e.g., chemical-restriction timelines, recyclability milestones, low-VOC targets) and a checklist for reformulation prioritization.
- Commercial playbooks for three archetypal companies — a global incumbent, a regional challenger, and a pure-play innovator — including go-to-market KPIs, pricing tolerance ranges, and channel incentive designs.
- An M&A decision framework with valuation drivers, integration risk scorecards, and a list of acquisition criteria mapped to likely targets (technology, distribution, geographic footprint).
- Competitive threat dossiers synthesizing public and proprietary signals for 12+ key vendors, including product roadmaps, patent, and partnership landscapes.
Competitive landscape — who’s shaping the market and how
The HTV ecosystem blends global materials specialists, equipment vendors, and consumer/SMB platform players. Several dynamics stand out:
- Technology and brand leadership: Long-standing HTV specialists continue to assert leadership through breadth of product range and specialty lines (glitter, stretch, printable, metallic). Their scale supports R&D and global branding that matters to large apparel decorators and licensing partners.
- Channel consolidation: Recent distribution arrangements and reseller expansions are accelerating. Notable partnerships that expanded access in North America and consolidated supply to key decorator channels have implications for regional incumbency and pricing power.
- Hardware + consumable convergence: The consumer/SMB ecosystem led by integrated cutter and heat-press makers is broadening product bundles to lock users into consumable cycles. This vertical integration increases lifetime value per customer and raises barriers for standalone film suppliers unless they integrate with platform players.
Strategic implications by player type
- Global material leaders retain advantage through product breadth and specialty formulations. Their near-term priority should be accelerating eco-friendly reformulations and expanding printable HTV lines for industrial digital workflows.
- Regional specialists and Asian manufacturers can compete on price and speed-to-market, and will gain if they invest in qualified quality systems and certifications required by Western OEMs and retailers.
- Platform and equipment vendors represent both distribution partners and competitors — partnering with them can fast-track SMB penetration, but it requires careful commercial terms to avoid margin erosion.
Industry dynamics: raw materials, regulation and product evolution
Three structural shifts should be on every executive’s radar for 2026:
- Raw-material pressure and margin squeeze: PVC resin markets showed renewed upward pressure in early 2026 amid plant maintenance cycles and recovering downstream demand. Producers exposed to PVC volatility must model margin scenarios and use hedging, alternative formulations, or strategic inventory as buffers.
- Regulatory-driven material transitions: Across major markets, policy and retailer chemical standards are accelerating substitution away from legacy PVC formulations toward polyurethane (PU) and polyester-based films that offer lower emissions and better end-of-life profiles. This is not a binary move; it creates transitional product windows and opportunities for value-added differentiated chemistries.
- Demand-side product sophistication: Performance requirements for sportswear (stretch, wash durability, hand feel) and printability for digital textile workflows are raising the technical bar. Firms that control both formulation and application guidance will capture premium pricing.
Recent market moves that foreshadow 2026 winners
- Distribution alliances that broaden market access and shorten customer adoption cycles are becoming decisive enablers for share gains.
- Product launches that integrate consumables with improved end-user hardware — including faster, lower-temperature presses compatible with multi-technology transfers — are expanding addressable use cases among prosumers and micro-businesses.
- Corporate investments in traceability and RFID-enabled film solutions signal the beginning of a secondary product tier focused on supply-chain authentication and value-add in packaging and premium apparel.
Strategic recommendations — prioritized actions for 2026
We recommend a three-track program for companies aiming to strengthen commercial returns in 2026:
- Short-term (0–6 months): Execute a supply-chain stabilization plan (dual-source critical resins, increase safety stock for high-use SKUs, and renegotiate lead times). Launch a targeted promo with channel partners to convert SMB users to higher-margin specialty films.
- Medium-term (6–18 months): Accelerate reformulation programs to meet imminent chemical and recyclability standards. Pilot bundled hardware-consumable offerings with select platform partners to prove unit economics before scale-up.
- Long-term (18+ months): Build or acquire digital-printable HTV capabilities and invest in traceability-enabled film products to capture premium segments in performance and branded apparel markets. Use M&A to fill gaps in distribution or to acquire environmentally preferred chemistries.
How PW Consulting’s report supports execution
The full report includes the verification datasets, supplier scorecards, and an executable playbook we describe above. It is intentionally structured to support cross-functional planning: procurement teams receive supplier heatmaps and contingency templates; R&D gets reformulation milestones aligned to regulatory timelines; commercial teams receive channel partnership frameworks and a prioritized list of SKU rationalizations designed to protect margin while supporting growth.
We adhere to a “preview” philosophy in this brief — we have shown the macro outlook, the competitive dynamics, and the specific strategic levers that matter in 2026 while withholding granular split-level KPIs and region-by-application tables to preserve the report’s full operational value. Those detailed segment and pricing matrices are included in the full deliverable and are essential for models, valuations, and negotiation strategies.
Next steps
- If you are leading procurement, request the supplier risk appendix to stress-test your resin exposure.
- If you run product or R&D, secure the reformulation roadmap and the prioritized test matrix for switching to low-VOC PU and polyester-based films.
- If you are in corporate development, receive the M&A target shortlist and the integration scorecards that align with 2026 value-creation milestones.
For commercial teams planning their 2026 go-to-market, this report is designed to be the action manual — enabling you to recalibrate pricing, prioritize SKU investments, and structure channel incentives that capture share without sacrificing margin. To access the full datasets, scenario models, and competitor dossiers referenced here, please visit the PW Consulting report page for the Heat Transfer Vinyl Market study.
PW Consulting remains available for bespoke briefings and rapid workshops to convert the report’s insights into an executable 90-day plan tailored to your company’s appetite for investment, risk tolerance, and strategic objectives.
For detailed analysis of this topic, please visit the official page: Heat Transfer Vinyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Missile Decoy Launcher System Market Poised for 5.51% CAGR Through 2032
By PW Consulting, 2026-07-13
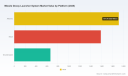
Missile Decoy Launcher Systems Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As geopolitical friction, naval modernization programs and evolving missile threats reshape defence procurement priorities, the missile decoy launcher systems market has become a strategic battleground. PW Consulting’s forthcoming Missile Decoy Launcher System Market report (base year 2025, forecast 2026–2032) shows an industry returning to robust, predictable growth — an addressable market of approximately USD 4,163.0 Million in 2025, forecast to grow to roughly USD 6,060.0 Million by 2032 at a compound annual growth rate (CAGR) of 5.51% during the 2026–2032 period. For defense program managers, systems integrators, OEMs and investors planning decisions in 2026, the implications are concrete: time-to-market, modularity, supply-chain security and interoperability will determine winners.
Missile Decoy Launcher System Market
Executive summary — why this market matters in 2026
-
Demand drivers are anchored in naval modernization and allied procurement programs, with soft‑kill countermeasures rising in priority as part of layered ship self‑defence architectures.
Missile Decoy Launcher System Market -
Technology is shifting from legacy expendable dispensers toward trainable, modular launchers and active expendable decoys capable of adaptive responses against coordinated and advanced seekers.
Missile Decoy Launcher System Market -
Market structure shows moderate concentration — the top three suppliers control nearly half the market while the top five approach two‑thirds — creating a competitive environment in which niche technology specialists can capture disproportionate value through integration and services.
Market trajectory and strategic implications
Historical momentum between 2020 and 2025 demonstrates steady expansion driven by fleet upgrade cycles and renewed procurement budgets across NATO and allied navies. The projected rise to roughly USD 6,060.0 Million by 2032 reflects a multi-year replacement and capability enhancement cycle rather than a short-lived spike. For corporate strategists and procurement authorities, this forecastable growth window (CAGR ~5.5%) enables planned investments in capability development, industrial base expansion, and long‑lead material sourcing — provided those investments are calibrated to program timelines and export/regulatory constraints.
Crucially, this is not a volume-only market. Value migration is occurring toward systems that offer trainability, multi-spectral payload compatibility, integration with ship combat systems and through-life support. Companies that can offer demonstrable system-of-systems interoperability, reduced integration risk, and predictable logistics will capture premium share of contracting activity.
Technology and procurement dynamics to watch
-
Trainable, modular launchers: Procurement specifications increasingly favor trainable bases and multi‑payload architecture to counter diverse RF, IR and multi-modal seekers. Systems that can be reprogrammed and reconfigured in the field reduce obsolescence risk and shorten upgrade cycles.
-
Active expendables and offboard decoys: Active decoys that can mimic signatures and manoeuvre to attract advanced seekers are moving from niche to mainstream in high-threat environments. Integration with launcher and shipboard fire-control networks is a critical differentiator.
-
Supply‑chain and materials: High-strength alloys, precision electronics and specialty propellants underpin reliability and performance. Sourcing strategies and supplier diversification are emerging as non‑negotiable risk mitigators.
-
Regulatory and interoperability frameworks: Export controls, bilateral agreements and interoperability standards will shape market access; contractors who can pre-certify solutions for major alliance standards will enjoy competitive advantage.
Competitive landscape — who’s shaping the market and how
The market features established prime contractors and specialized niche suppliers. Several competitive archetypes are apparent:
-
Integrated primes with platform-level influence: Companies such as BAE Systems, Lockheed Martin and L3Harris remain pivotal due to their roles in platform programs and integration responsibilities. Their involvement in established active decoy programmes (e.g., Nulka) provides both technological depth and program leverage.
-
System specialists with naval focus: Firms like Terma, Safran Electronics & Defense, Rheinmetall and Elbit Systems bring purpose-built decoy launcher solutions (trainable launchers, multi-axis systems and multi-ammunition softkill systems). Their products are often chosen for specific vessel classes and modernization blocks.
-
Payload and expendable specialists: Chemring, IrvinGQ and Rafael concentrate on decoy payloads (corner reflectors, chaff/flare, active expendables) and have strong IP in signature management and spectral tradecraft.
-
National/regional providers and integrators: Entities such as Emgepron and emergent entrants (e.g., TEKOM’s new trainable launcher) underline the rising importance of sovereign supply chains and localized industrial participation clauses in procurement.
Recent contract awards and product announcements illustrate these patterns. Collaborative wins for naval decoy control and launching systems reflect consolidation of integration roles across technology partners. Similarly, selection of trainable bases for major ship classes points to a procurement preference for adaptable launchers that can be upgraded over platform life cycles. These transactions and unveilings reinforce the market’s trajectory toward modular, interoperable, and exportable solutions.
Market structure and competitive strategy
With the top three companies accounting for almost half the market and the top five comprising over 60%, the environment is moderately consolidated. That structure creates strategic openings: large primes can consolidate through platform integration and long-term contracts, while mid‑sized specialists can win by owning critical IP (e.g., trainable bases, active decoy electronics) and by becoming indispensable subsystem suppliers to primes. New entrants should evaluate partnerships, certified supplier pathways, or targeted M&A to bypass long lead times to qualification.
Actionable recommendations for 2026 decision‑makers
-
Prioritize modularity and interoperability: When defining RFPs or product roadmaps, require modular interfaces and open architecture to future-proof investments and simplify mid-life upgrades.
-
Invest in integration competence: Winning full-line contracts increasingly depends on demonstrating low-integration-risk solutions. Build or partner for integration proof points with common combat management systems.
-
Secure critical supply chains: Identify long‑lead components (precision electronics, specialty alloys, rocket motors) and create dual-source strategies or local production where regulatory or political risk is material.
-
Design for through‑life value: Offer bundled sustainment, obsolescence management and upgrade packages — customers are willing to pay for reduced total ownership risk.
-
Pursue alliance-aligned certifications: Prioritize interoperability testing against alliance standards and arrange pre‑certification pathing to accelerate procurement approvals in key buyer markets.
-
Scan for high-value niches: Assess opportunities in active expendable development, signature management algorithms and trainable launcher avionics as potential M&A or JV targets.
What PW Consulting’s full report delivers (practical, actionable content)
Our full Missile Decoy Launcher System Market report translates the strategic context above into operational tools for 2026 decision-making. It includes:
-
A validated market model with historic and forecasted demand (2020–2032), sensitivities and scenario analyses that inform procurement timing and investment sizing.
-
Vendor/technology profiles and a supplier capability matrix assessing production capacity, certification readiness, exportability and integration risk.
-
Procurement playbooks and commercial models for prime contractors and subsystem suppliers, including bid/no‑bid frameworks and pricing levers for through-life support offers.
-
Risk matrices for supply chains, regulatory exposures and technology obsolescence, with mitigation checklists tailored to the decoy launcher ecosystem.
-
Go‑to‑market strategies for new entrants and growth plans for incumbents, covering partnership roadmaps, IP strategies and M&A screening criteria.
-
A bank of primary-interview insights and program-level trackers for major naval modernisation programs and competitive contract awards to inform near-term capture plans.
Using the intelligence in 90 days
For senior leaders aiming to convert insight into action within the next quarter, we recommend a three-step plan: (1) run a rapid capability gap assessment against the modularity and integration criteria laid out in our report; (2) validate your supply‑chain exposure against the report’s risk matrices and prioritize mitigations for high‑impact components; (3) initiate targeted partnership discussions (technology or manufacturing) with suppliers identified as strategic matches in the supplier capability matrix. These steps reduce go-to-market risk and position organisations to capture award timelines that will crystallize through 2026.
Conclusion — positioning for durable advantage
The missile decoy launcher systems market presents steady growth and shifting value pools that favor systems-level integrators and specialized technology owners. The near-term imperative for 2026 is clear: move beyond product-centric selling to deliver integrated, upgradeable solutions with resilient supply chains and proven interoperability. PW Consulting’s full report provides the modelling, supplier intelligence and execution playbooks required to turn these imperatives into contracts, partnerships and program wins.
For procurement officers, program directors and corporate strategists seeking a deeper view — including vendor scorecards, procurement trackers and scenario-driven forecasts — PW Consulting’s full report offers the proprietary analysis and operational templates you will need to make calibrated decisions in 2026. Access details are available on PW Consulting’s publications page.
For detailed analysis of this topic, please visit the official page: Missile Decoy Launcher System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Oct-4 Insight: Global Antibody Market to Rise from USD 88.45 Million in 2025 to USD 143.85 Million by 2032 at a 7.19% CAGR
By PW Consulting, 2026-07-13
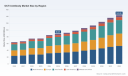
Oct-4 Antibody Market 2026 Strategic Brief: How PW Consulting’s Oct-4 Antibody Market Report Translates Data into Decisions
PW Consulting today releases the Oct-4 Antibody Market — Oct-4 Antibody Market Research Report (base year 2025). Our analysis synthesizes longitudinal sales data (2020–2025), forward-looking forecasts through 2032, and primary-level competitive intelligence to deliver an actionable strategic playbook for life-science suppliers, institutional purchasers, and investors making critical decisions in 2026. This executive brief highlights the report’s strategic value while preserving the proprietary, segment-level data that we reserve for readers of the full report.
Oct-4 Antibody Market
Market snapshot: scale, trajectory, and concentration (what every board should know)
The Oct-4 antibody market reached approximately USD 88.45 Million in 2025 and exhibits sustained momentum driven by demand in stem cell research, oncology translational studies, and reagent-led discovery workflows. Our forecast projects a compound annual growth rate (CAGR) of 7.19% across the 2026–2032 period, with the market approaching the mid-to-high hundreds of millions of USD by 2032 under the base-case scenario. Concentration metrics indicate a market where leading firms exercise meaningful share — our CR3 and CR5 assessments (48.5% and 62.15%, respectively) point to a moderately consolidated competitive structure that still leaves room for specialized entrants and differentiated product plays.
Oct-4 Antibody Market
Why the 2026 decision window matters
-
Timing of platform investments: With steady growth expected, 2026 is a pivotal year for capital allocation decisions — whether to expand antibody R&D, accelerate recombinant antibody programs, or invest in conjugation and validation services that raise average selling prices and margins.
Oct-4 Antibody Market -
Customer procurement cycles: Academic and translational labs are replacing legacy reagents and accelerating adoption of validated recombinant antibodies. Suppliers who can demonstrate reproducible performance and batch-level data will disproportionately win 2026 purchasing cycles.
-
M&A and partnership windows: Moderate concentration implies acquisition opportunities to consolidate validation capabilities, geographic reach, or portfolio breadth. Strategic acquirers should prioritize targets with defensible validation data, niche application depth (e.g., ChIP-seq grade reagents), or strong channel relationships.
What the report delivers — practical, transaction-ready intelligence
PW Consulting assembled a practitioner-focused toolkit inside this report so that senior management teams can convert market insight into executable plans. Key inclusions:
-
High-resolution revenue model (historical and forecast through 2032) with sensitivity scenarios for adoption, pricing, and raw-material cost volatility.
-
Actionable go-to-market playbooks for monoclonal vs. polyclonal strategy, recombinant engineering, and conjugation services (PE/fluorophore, HRP, biotin) that map to buyer evaluation criteria.
-
Validation and regulatory checklist that operationalizes RUO labeling constraints and outlines how to design claim language and supporting data packages for research users while avoiding diagnostic/clinical use implications.
-
Supply-chain and manufacturing risk matrix that prioritizes contingency options for critical raw materials, host systems, and contract manufacturing relationships.
-
Procurement playbook for large institutional buyers to optimize total cost of ownership via vendor segmentation, qualification workflows, and batch acceptance criteria.
-
Company scorecards and competitive positioning maps, combining capability assessment (e.g., recombinant platforms, ChIP-grade validation) with commercial reach.
Competitive landscape — how incumbent capabilities map to buyer needs
The Oct-4 antibody ecosystem includes global life-science platforms, specialized reagent houses, and emerging regional players. Our qualitative and quantitative assessments emphasize technological differentiation (e.g., recombinant monoclonals, ChIP-seq grade polyclonals), validation depth, citation footprint, and channel strength. Below is a high-level synthesis of competitive positioning for the core players covered in our study.
-
Bio‑Techne / Novus Biologicals (Minneapolis, MN, USA) — Strength: extensive catalog breadth and deep citation presence in stem cell literature. Strategic advantage comes from portfolio depth across formats (monoclonal, polyclonal, conjugated) and strong academic channel relationships. Commercial moves to watch: continued emphasis on reproducibility data and bundle offerings with complementary stem cell reagents.
-
Thermo Fisher Scientific / Invitrogen (Waltham, MA, USA) — Strength: scale, global distribution, and multiple product formats including recombinant clones. Thermo Fisher’s go-to-market benefits suppliers with demanding global procurement standards. Risk/Opportunity: incumbency provides pricing power but invites challengers to exploit niche validation gaps.
-
Cell Signaling Technology (Danvers, MA, USA) — Strength: reputation for high-quality validation and focus on embryonic stem cell and pluripotency markers. Their validation-first positioning allows premium pricing; challenge is scaling breadth without diluting perceived quality.
-
Abcam (Cambridge, UK) — Strength: recombinant monoclonal clones and strong translational research uptake. Abcam’s platform supports rapid clone replacement and catalog rationalization—key in an environment where discontinued SKUs are frequently replaced with alternatives.
-
Proteintech, GeneTex, BioLegend, R&D Systems, Santa Cruz, STEMCELL Technologies, Diagenode, Enzo Life Sciences, Sigma‑Aldrich (Merck), CUSABIO — These firms form a competitive middle where differentiation is delivered through select strengths: validated species cross-reactivity, ChIP/ChIP‑seq grade antibodies, flow cytometry-conjugated reagents, or cost competitive catalog SKUs. Tactical playbooks for these players focus on deepening application-specific claims, publishing targeted validation studies, and strengthening reseller/channel ties.
Recent product and catalog developments — signals for 2026 tactical moves
-
Several vendors updated Oct‑4 listings and validation materials in 2025–2026, including ChIP‑grade annotations and IHC-P validations, which signal an industry shift toward application-specific assurance. Suppliers that publish batch- or lot‑specific validation data gain credibility with translational customers.
-
Product rationalizations and SKU replacements remain common; teams must actively manage catalog migrations to prevent revenue erosion when popular clones are discontinued or reissued under new catalog numbers.
-
All commercial Oct‑4 antibodies are marketed as Research Use Only (RUO) and carry explicit disclaimers; vendors and buyers must align on compliant labeling and messaging to avoid inadvertent clinical claims.
Strategic imperatives for 2026
Based on our forecast and competitive review, PW Consulting recommends five immediate priorities for stakeholders:
-
Prioritize validation transparency: Invest in batch-level validation datasets (WB, ICC/IF, IHC, ChIP where relevant) and publish reproducibility studies to win translational labs and CROs.
-
Differentiate by application depth rather than catalog breadth alone: ChIP‑seq grade or flow-conjugated Oct‑4 reagents command premium positioning and reduce direct price competition.
-
Defend and extend channel partnerships: Institutional contracts and distributor networks remain decisive — secure preferred‑supplier status through performance guarantees and streamlined procurement processes.
-
Design acquisition screens around validation assets and data: Targets with defensible, reproducible data packages and specialized application focus are higher-value and integrate more cleanly into larger platform portfolios.
-
Build SKU‑migration playbooks: Anticipate regulatory-driven or supply-driven SKU changes and proactively communicate replacements with customers to preserve loyalty and minimize revenue loss.
What the full report unlocks (and why you’ll want it)
The public brief above highlights our core findings and recommended actions. The full Oct‑4 Antibody Market report contains the underlying datasets, segment-level forecasts, and company-level scorecards necessary to operationalize the recommendations — including:
-
Granular revenue waterfalls and scenario models by antibody format and application (available only in the full report).
-
Validation matrices mapping antibody clones to peer‑reviewed citations and application performance metrics.
-
Vendor playbooks and negotiation templates for institutional buyers and suppliers preparing 2026 contracts.
-
Detailed M&A screening criteria and integration checklists for potential acquirers.
Closing — pragmatic foresight for a competitive 2026
For leadership teams evaluating allocation of R&D capital, commercial expansion, or M&A activity in 2026, the Oct‑4 antibody market presents both predictable growth and asymmetric opportunity. Steady CAGR and a moderately concentrated supplier base favor disciplined investments in validation, application specialization, and channel strengthening. PW Consulting’s Oct‑4 Antibody Market report converts these market dynamics into transaction-ready guidance and proprietary data—precisely the intelligence leaders need to make defensible decisions in 2026. For access to the full datasets, segmentation breakdowns, and company scorecards, consult the complete report.
For detailed analysis of this topic, please visit the official page: Oct-4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrocarbon & PTFE High-Speed Digital CCL Market Hits USD 485.5 Million in 2025, Poised for Further UpswingPW Consulting Forecast: Front-Loaded Industrial Parts Washer Market to Expand at a 3.85% CAGR Through 2032
By PW Consulting, 2026-07-13

Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study (base year 2025) shows the high-speed digital and high-frequency CCL market continuing on a strong multiyear growth trajectory. The market expanded from roughly USD 315 million in 2020 to about USD 486 million in 2025 and, under our base-case modeling, is projected to approach USD 899 million by 2032 at a compound annual growth rate (CAGR) of ~9.2% (2026–2032 forecast period). For corporate leaders preparing budgets, capex plans, product roadmaps and M&A strategies in 2026, this report is designed to translate those headline dynamics into operational choices that materially affect competitive position.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market
Why this matters for 2026 corporate strategy
-
Demand mix is shifting: accelerated uptake of hyperscale data center interconnects, continued 5G rollouts and a rising ADAS/automotive radar content per vehicle are changing product priorities from generic laminates toward ultra-low-loss PTFE systems and engineered hydrocarbon-ceramic hybrids.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market -
Input-cost and regulatory volatility are elevating supply-chain and product-risk considerations. Material price swings and proposed regulatory constraints on PFAS-class chemistries mean that procurement, compliance and product-design teams must be tightly integrated with commercial planning.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market -
Market concentration is meaningful: the top three suppliers account for a majority of supply (CR3 ~55.4%) and the top five control well over two-thirds of the market (CR5 ~68.2%). This concentration impacts pricing power, technology access and M&A bargaining positions going into 2026.
Market trajectory and macro drivers (what we rigorously modeled)
Our model synthesizes historical performance (2020–2025) with bottom-up demand drivers across networking, cloud, telecom infrastructure and automotive electronics to produce scenario-based forecasts for 2026–2032. Key modeled levers include: server and switch port density growth, 5G infra capex cadence, automotive electronics content per vehicle, and defense/aerospace qualification cycles. Those levers explain both the steady baseline CAGR we report and the asymmetric upside in our accelerated-adoption scenarios.
Raw material and regulatory headwinds you must price into 2026 plans
-
PTFE resin market dynamics: PTFE prices exhibited material dispersion by geography in late 2025 (for example, US market benchmark levels were reported near USD 12,500/MT while China benchmarks tracked materially lower). High-purity PTFE supply is concentrated among a small set of chemical producers, creating potential price volatility in the 15–25% range under stress scenarios. Procurement strategies that ignore this concentrated supplier base will overexpose production schedules.
-
Hydrocarbon resin inflation: a notable price increase (reported up to ~11% effective March 23, 2026) illustrates how feedstock and operating-cost pressures can rapidly change margins for hydrocarbon-based CCLs. Cost-to-serve and product-level margin models must be updated continuously.
-
Regulatory risk: proposed EU REACH restrictions targeting certain PFAS chemistries could, if enacted, increase compliance costs and speed the need for reformulations or non-PFAS alternatives. Companies with early investment in PFAS alternatives or robust regulatory-engineering capability will preserve time-to-market advantage.
Competitive landscape — who matters and why
The market combines global majors with regional specialists; each has differentiated strengths that buyers and investors must map against their strategic objectives. Our report provides in-depth profiles, but key strategic observations include:
-
Rogers Corporation (Chandler, AZ) — strong technology breadth across hydrocarbon ceramic laminates and PTFE-based solutions. Recent capacity additions in Europe underline a dual focus on defense/automotive and global supply resilience.
-
AGC Inc. and its Taconic business — global reach with vertically integrated PTFE and hydrocarbon offerings. Taconic’s PTFE-focused portfolio gives AGC a competitive edge where ultra-low loss is non-negotiable.
-
Isola Group, TUC and ITEQ — market players with strong position in high-speed digital and cloud-server applications, emphasizing manufacturability and surface-finish ecosystems for multi-layer PCB supply chains.
-
Shengyi Technology — aggressive capacity expansion to capture 5G and data-center demand signals growth from local manufacturing scale and cost competitiveness.
-
Panasonic — technology-driven differentiation; recent product launches target ultra-high bitrate network equipment where signal integrity requirements are most acute.
For 2026, supplier selection should be driven less by single-factor pricing and more by multi-criteria assessment: technical performance (loss tangent, lamination yield), supply security, regulatory resilience and collaboration capability for system-level qualification.
What’s inside the PW Consulting report (practical, action-oriented deliverables)
-
Full-market model (2020–2032) in downloadable format with scenario toggles and sensitivity to raw-material price and technology-adoption curves.
-
Segment-level demand drivers and supplier scorecards (technology, capacity, geographic footprint, commercialization roadmap). Note: detailed segment numbers are included in the full report and data pack — this preview omits those tables to preserve subscriber value.
-
Margin and cost-to-serve benchmarking by product family, with “pressure-point” analysis under the PTFE and hydrocarbon price shocks we observed in 2025–2026.
-
Regulatory-impact scenarios and a compliance playbook addressing potential PFAS restrictions, including reformulation timelines, qualification protocols and cost-estimation templates.
-
M&A and partnership playbook: target profiles, valuation heuristics, and integration risk checklists tailored for CCL assets and adjacent resin/chemical suppliers.
-
90/180/360-day operational and commercial checklists for procurement, R&D and sales leaders to convert macro forecasts into executable 2026 plans.
Concrete recommendations for 2026 (prioritized)
-
Establish dual-sourcing for high-purity PTFE and negotiate volume-flex contracts with price collars. Given the supplier concentration and documented price dispersion, long-term spot exposure is unacceptably risky for volume-sensitive manufacturers.
-
Accelerate hybrid-material development (e.g., hydrocarbon-ceramic or ceramic-filled systems) as an alternate route to achieve low-loss without exclusive dependency on PTFE. This reduces formulation/regulatory risk and can optimize cost/performance trade-offs for server and telecom segments.
-
Design for regulatory optionality: prioritize materials and processes that can be qualified under multiple chemistries so that an adverse REACH outcome does not force requalification across the entire customer base.
-
Revisit pricing architecture to incorporate material-linked pass-through clauses and scenario-based margin floors. Ensure commercial agreements with hyperscalers and OEMs include mechanisms for material-cost adjustment tied to published indices.
-
Capex discipline: unless your strategy is to capture share through scale, prefer modular capacity expansion and tolling partnerships over high-fixed-cost greenfield projects. Our case work shows this reduces downside under slower adoption scenarios while preserving upside optionality.
-
M&A focus: prioritize targets that fill capability gaps (e.g., vertical resin supply, advanced surface treatments, or localized high-frequency laminate production) and limit integration risk via staged earn-outs tied to qualification milestones.
90/180/360-day tactical roadmap for boards and executive teams
-
90 days: complete supplier risk audit; secure conditional offtake/price collars with key resin suppliers; start cross-functional regulatory gap assessment.
-
180 days: execute at least one pilot with an alternative hybrid laminate for a major customer segment; finalize capex option analysis (brownfield vs. partnership vs. tolling); update product roadmap to include regulatory contingency versions.
-
360 days: complete qualification of at least one non-PFAS-compliant material in a strategic OEM account; close at least one strategic partnership or targeted acquisition that increases resilient access to critical feedstock or opens a high-growth regional market.
How PW Consulting’s report will change your 2026 decisions
Leaders who use the full PW Consulting study will benefit from data-driven scenario planning tied to executable playbooks: from renegotiating supplier contracts and staging capacity to prioritizing R&D investment and structuring M&A. The report converts macro growth (a near-term market approaching half a billion USD in 2025 and significant upside by 2032) into defensible, time-phased actions that reduce downside and capture the market’s asymmetric upside.
Closing — where to get the full intelligence
This preview highlights the strategic contours you must factor into 2026. The full PW Consulting market report and data pack include the segmented demand tables, supplier-level revenue estimates, downloadable financial models and detailed scenario outputs that informed the recommendations above. To access the complete analysis, proprietary models, and supplier scorecards (including segment-level numbers and downloadable spreadsheets), visit our report page or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roadmarking Paints Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
The global roadmarking paints market is at a crossroads. After steady growth through the early 2020s, our analysis shows the total market reached an estimated USD 7.18 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.8% through the 2026–2032 forecast horizon. This trajectory reflects a mix of continued infrastructure spending, evolving environmental rules, and technology shifts in formulation and application. For executives making capital-allocation, procurement and product strategy decisions in 2026, the choices made now will materially affect competitive position and margin resilience over the next strategic cycle.
Roadmarking Paints Market
Why this brief matters to 2026 decision-makers
- It translates macro momentum into executable options. We move beyond headline growth to show how regulatory shifts, raw-material volatility and product substitution dynamics will affect pricing, tender outcomes and specification compliance.
- It frames risk vs. reward for investment in formulation R&D, application equipment and supply-chain diversification—areas where one-time decisions drive multi-year returns.
- It highlights where scale creates advantage and where nimbleness wins: helping boards decide whether to invest organically, form strategic partnerships, or pursue tuck-in M&A to acquire capabilities fast.
Core market dynamics shaping 2026 strategy
- Regulatory tightening on emissions and specifications. New and updated standards (including recent updates to road-paint specifications) are increasing compliance costs for manufacturers and public purchasers. Environmental limits on VOCs are pushing accelerated adoption of waterborne and low-VOC chemistries, while specification revisions create local approval hurdles that can delay procurement cycles (Sector Analysis, 2026).
- Raw-material price volatility. The cost and availability of key inputs—resins, thermoplastic compounds and specialty glass beads—remain uneven across supplier networks. This volatility compresses margins and raises project-cost uncertainty, especially for budget-constrained infrastructure programs (Analysts Insights, April 2026).
- Technology and application shifts. Demand is diversifying across waterborne systems, thermoplastic products and cold-plastic solutions. Application equipment, curing time and lifecycle performance are becoming competitive differentiators, not just product features.
- Moderate market concentration. The industry exhibits a moderate level of consolidation: scale offers procurement and approval advantages while specialized regional and niche players retain pockets of strength. This creates differentiated strategic options for incumbents and challengers alike.
- Procurement and total-cost-of-ownership scrutiny. Local authorities and contractors are moving beyond unit price toward lifecycle and performance metrics, including retroreflectivity longevity and maintenance intervals. That rebalances tender evaluation criteria and opportunity for value-selling approaches.
Competitive landscape — what leading players are doing
- PPG Industries (ENNIS-FLINT family). The company leverages large-scale formulation capability across waterborne and solvent-based traffic paints and brings global distribution and specification experience. Its strength is in scale-driven procurement, broad specification approvals and integrated product portfolios that simplify tender responses.
- Swarco. Offers a broad set of systems, including solvent-based, waterborne and two-component solutions, with strong project-service integration. Swarco’s competitive edge is systems thinking—combining materials with application and maintenance services for municipalities and highways.
- Meon Ltd. As a focused specialist, Meon emphasizes line-marking paints and cold-plastic systems for roads, parking and airports. Its agility and product specialization make it an attractive partner or acquisition target for companies seeking immediate capability in cold-plastic application and smaller-scale municipal contracts.
- Axalta Coating Systems. Axalta brings industrial coatings expertise to roadmarking formulations, including spirit-soluble and modified alkyd chemistries. Their strengths include industrializing formulation scale and working with large infrastructure contractors on specification alignment.
- Cloverdale Paint Inc. A regionally trusted supplier with formulations approved for Canadian infrastructure specifications, Cloverdale demonstrates the importance of local approvals and regulatory alignment as competitive moats in specific markets.
Collectively, leading suppliers balance formulation R&D, approvals management and route-to-market scale. But our analysis also shows openings for focused players that can deliver demonstrably superior lifecycle performance, faster application times or regulatory-compliant solutions at competitive cost.
Roadmarking Paints Market
What the PW Consulting report delivers — practical, transaction-ready content
- Proprietary market-sizing model (base year 2025, forecast 2026–2032) with scenario-driven outputs and sensitivity levers for raw-material price, regulatory tightening, and infrastructure spend cadence.
- Regulatory-impact playbook: step-by-step mitigation strategies for VOC and specification changes, including product reformulation pathways, testing protocols and certification timelines.
- Procurement and sourcing playbook: dual-sourcing templates, hedging clauses for volatile inputs, supplier scorecards and a risk matrix for resin and bead suppliers.
- Competitive scorecards: qualitative and quantitative benchmarking (formulation breadth, regulatory approvals, application service capability, geographic reach) for market-leading and emerging suppliers.
- M&A and partnership roadmaps: prioritized targets by capability gap, integration checklists and projected synergies for business development teams pursuing inorganic growth.
- Investment cases for application equipment and maintenance services: ROI calculators accounting for lifecycle durability, rework frequency and labor/equipment costs.
- Executive dashboards and datasets: interactive outputs for board-level scenario sessions and procurement negotiation support (note: detailed segment figures and raw datasets are available in the full report).
Actionable recommendations for 2026
- Prioritize compliance-led product roadmaps. Accelerate low-VOC and waterborne portfolios where regulatory risk is highest and where procurement is moving toward low-emission specifications.
- Hedge raw-material exposure. Implement dual-sourcing and indexed-supply contracts for glass beads and thermoplastic resins; examine financial hedges or long-term framework agreements tied to input indices.
- Segment go-to-market by value proposition, not solely by channel. Use performance guarantees and lifecycle-based bids to win tenders where total cost of ownership matters most.
- Invest selectively in application capability. For players targeting highways and airports, evaluate equipment investments that reduce curing time and rework. For contractors, service bundles tied to durability metrics can create recurring revenue and margin protection.
- Pursue tuck-in M&A to close capability gaps. Cold-plastic application expertise, testing laboratories and regional approvals are high-impact capabilities to acquire rapidly.
- Embed sustainability and circularity into procurement specs. Pilot recycled-glass bead programs and document environmental benefits to support bids and public-sector sustainability targets.
- Revise pricing models to reflect input volatility. Build indexed clauses and short-term adjustment mechanisms into long-term contracts to protect margins while remaining competitive.
Scenario planning — three lenses to use in 2026
- Baseline (policy-normal): Market expands in line with the central projection (5.8% CAGR). Under this scenario, firms that combine moderate R&D investment with selective supply-chain hedging capture steady share and margin recovery.
- Upside (accelerated infrastructure): Faster public spending and specification harmonization lead to demand pull for long-life, higher-spec products—benefiting incumbents with national-scale approvals and suppliers that can scale formulation production quickly.
- Downside (regulatory shock + raw-material squeeze): Sudden tightening of VOC rules or steep bead/resin price spikes compress margins and force rapid reformulation. In this scenario, nimble specialists that can reformulate quickly and offer lifecycle savings for procurers will outperform.
Each scenario in our full model is accompanied by decision trees and tactical response playbooks—enabling procurement, product and corporate development leaders to translate uncertainty into prioritized actions.
Roadmarking Paints Market
How PW Consulting supports clients through 2026
- Bespoke due diligence and target-screening for M&A and partnerships in roadmarking technologies and application services.
- Supplier risk diagnostics and contracting playbooks to lock in competitive input costs while preserving flexibility.
- Specification harmonization programs that shorten approval timelines and reduce product line complexity.
- Pilot design and field-testing oversight for new formulations to accelerate public-spec approvals and performance claims.
- Commercial model redesign to capture lifecycle value in tenders and service contracts.
Conclusion: the roadmarking paints market offers predictable growth but rising complexity. With a USD 7.18 billion base in 2025 and a structural CAGR of 5.8% across our forecast period, the market will reward organizations that proactively manage regulatory risk, secure raw-material continuity and align product portfolios to lifecycle-driven procurement. PW Consulting’s report synthesizes those implications into transaction-ready guidance and operational playbooks—enabling leaders to convert 2026 disruptions into durable advantage.
For access to the full forecast models, vendor scorecards, regulatory timelines and the interactive dashboards that underpin these recommendations, visit the PW Consulting report portal and download the Roadmarking Paints Market full report.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Primary Zinc‑Carbon Battery Market at USD 2,121.6 Million in 2025, Set to Expand at 1.8% CAGR Through 2032
By PW Consulting, 2026-07-13
Primary Zinc-Carbon Battery Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As PW Consulting’s lead industry analyst, I present a concise strategic briefing derived from our newly released Primary Zinc-Carbon Battery Market study (base year: 2025). The research synthesizes historical performance (2020–2025), near-term outlook and a 2026–2032 forecast. At a headline level, the global primary zinc-carbon battery market stood at approximately USD 2.12 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 1.8% through the 2026–2032 forecast window, reaching roughly USD 2.40 billion by 2032. These aggregate dynamics, coupled with middling market concentration (CR3 ≈ 42.5%, CR5 ≈ 58.8%), frame the practical choices executives must make in 2026.
Primary Zinc Carbon Battery Market
Why this report matters for 2026 decision-makers
-
It converts headline stability into tactical actions. A modest CAGR masks divergent pockets of risk and opportunity — from price-sensitive consumer channels to industrial low-drain segments — and our study shows how to prioritize investments accordingly.
Primary Zinc Carbon Battery Market -
It links near-term operational levers (procurement, SKU rationalization, private-label sourcing) to medium-term capital choices (manufacturing footprint, automation, product differentiation) using scenario-driven financials tailored for 2026 decisions.
Primary Zinc Carbon Battery Market -
It decodes regulatory and raw-material trajectories (sustainability standards, manganese and zinc supply trends, and evolving trade measures) so procurement and commercial teams can convert compliance into competitive advantage rather than cost pass-through.
What the market picture really says (not the press release)
Between 2020 and 2025 the market exhibited resilience punctuated by episodic volatility — a pattern that continued into our 2026 starting point before a gradual recovery through the forecast horizon. The headline CAGR of 1.8% reflects a mature, slow-growth industry where margin expansion and share gains are achieved through operational excellence, channel optimization and selective product innovation rather than large demand shocks.
Market concentration metrics indicate a landscape where global incumbents maintain scale advantages but local and OEM specialists continue to secure meaningful share. That configuration favors targeted partnerships, nimble regional strategies, and disciplined cost management for new entrants and incumbents alike.
Competitive landscape — how the major players are positioning
-
Panasonic Energy Co., Ltd. (Japan) — Leveraging global brand equity and a diversified consumer portfolio, Panasonic prioritizes quality and channel coverage in developed markets while selectively managing cost across low-drain SKUs.
-
Energizer Holdings, Inc. (United States) — Sustains a dual approach of branded premium and broad-distribution super heavy duty lines that address both retail and industrial buyers; focus is on margin preservation and portfolio clarity.
-
GP Batteries (Hong Kong) — Positions itself around reliable mid-market propositions and eco-branded product lines; strength lies in regional distribution relationships across Asia and emerging markets.
-
Large Chinese OEMs and exporters (e.g., Linyi Huatai, Shandong Huatai, PKcell, Johnson New Eletek) — Aggressively scale through cost leadership and private-label partnerships, emphasizing export channels and trade-show driven commercial outreach.
-
Eveready Industries India — Targets price-sensitive domestic and regional segments with economy-focused SKUs and strong local brand recognition.
-
FDK, Toshiba — Maintain stable, heritage positions focused on reliability and OEM relationships in both consumer and selective industrial uses.
Collectively, these players create a competitive topology where brand-driven premium plays coexist with high-volume private-label supply chains. Our study profiles each firm's go-to-market, manufacturing posture, and likely 2026 playbook — but deliberately withholds granular SKU share tables to protect clients’ proprietary strategies (see full report for those data).
Raw materials, regulation and geopolitics — the operational wind tunnel
-
Electrolytic manganese dioxide (EMD) remains central to cathode sourcing. Our analysis notes that zinc-based battery demand accounts for a meaningful share of EMD’s end-use markets, which underpins pricing resilience and supplier negotiation dynamics.
-
Manganese demand for battery and broader industrial applications is forecast to grow at a higher rate than the primary zinc-carbon category, creating potential cross-market competition for high-grade materials and suggesting procurement hedging as a 2026 priority.
-
Zinc supply trends are stable, with moderate mining growth projected in baseline scenarios. This dampens the likelihood of sharp input-cost shocks but increases the strategic value of long-term off-take and index-linked supply agreements for large-volume buyers.
-
Regulatory pressure — notably the EU’s Batteries Regulation — raises the bar for traceability, recycled content and responsible sourcing. For 2026, compliance is not just legal overhead: it is a conduit for market access and buyer preference in developed channels.
-
Geopolitical trade dynamics (including recent tariff adjustments) are already reshaping procurement footprints. Firms that have proactively diversified suppliers and secured tariff-mitigating structures in 2025–2026 will enjoy structural cost and delivery advantages.
Practical contents of the PW Consulting report — what you get
-
Demand and price-sensitivity models with scenario toggles (base, downside, green-transition accelerated) calibrated to 2026 procurement and sales targets.
-
Supply-chain heatmaps that identify lowest-risk sourcing corridors and near-shore options, paired with a supplier scoring workbook you can apply to prioritize RFPs.
-
Competitive playbooks summarizing strategic postures of major global and regional manufacturers, plus a risk matrix linking supplier concentration to logistics and regulatory exposure.
-
SKU rationalization frameworks and gross-margin impact calculators for private-label versus branded strategies — practical tools to run trade-offs in a boardroom-friendly format.
-
M&A and partnership screening templates that rank targets against scale, cost base, channel access and compliance readiness.
-
Executive dashboards and slide-ready summaries for immediate use in strategy sessions and investor briefings.
Operational playbook for 2026 (what to act on, and in what order)
-
Quarter 1 (Immediate) — Lock in supply: convert flexible purchase orders to medium-term off-takes with key EMD and zinc suppliers; implement indexation clauses and minimum-volume guarantees where advantageous.
-
Quarter 2 (Organize) — SKU streamlining: use our margin-impact model to retire low-turn, low-margin SKUs and reallocate manufacturing capacity to higher-yield sizes and private-label runs.
-
Quarter 3 (Differentiate) — Invest in compliance and traceability: audit key suppliers against EU Battery Regulation requirements and build a compliant narrative for developed-market retailers.
-
Quarter 4 (Scale) — Pursue targeted partnerships or bolt-ons: prioritize targets that add route-to-market, near-shore capacity or proprietary process advantages rather than scale-for-scale M&A.
What this briefing purposely omits — and why
In keeping with a “trailer” approach, this article demonstrates the rigor and practical value of our analysis while intentionally withholding proprietary segment-level allocations and granular region-by-application tables. These datasets underpin the precise commercial levers that can materially change 12–24 month P&L outcomes; they are available exclusively in the full PW Consulting report and associated client deliverables. If your team needs the full dataset, segmented forecasts, and Excel tools to run custom scenarios, the complete report provides that operational depth.
Bottom line for 2026
The primary zinc-carbon battery market is a mature, low-growth sector at the aggregate level. That reality shifts the locus of value creation to the operational and strategic details: procurement sophistication, channel and SKU optimization, compliance-enabled market access, and selective partnerships. Firms that treat 2026 as the year to convert headline stability into structural advantage — by locking in supply terms, rationalizing portfolios, and positioning for regulatory-driven preference — will outperform peers operating on price alone.
PW Consulting’s Primary Zinc-Carbon Battery Market report is designed as an actionable toolkit for precisely those decisions. The executive dashboards, supplier-scoring tools, and scenario models are built to be integrated directly into 2026 planning cycles. For companies where battery components are a material input or product line, this report should be considered a strategic planning imperative rather than optional reading.
Next steps
-
Schedule a briefing with our consulting team to walk through the tailored scenario outputs for your footprint and P&L.
-
Request the full report and vendor-risk workbook to unlock the segment-level intelligence that informs procurement, commercial and M&A decisions in 2026.
PW Consulting — transforming market clarity into operational advantage. Contact our industry practice to access the full Primary Zinc-Carbon Battery Market study and the supporting analytics your 2026 strategy requires.
For detailed analysis of this topic, please visit the official page: Primary Zinc Carbon Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Etifoxine Hydrochloride Market Poised to Expand at 5.2% CAGR Through 2032
By PW Consulting, 2026-07-13
Etifoxine Hydrochloride Market — Strategic Preview: PW Consulting Releases Actionable Intelligence for 2026 Decision-Makers
PW Consulting today publishes an executive preview of our forthcoming Etifoxine Hydrochloride Market report — a practice-focused intelligence package designed to inform board-level and commercial strategy through 2026 and beyond. Grounded in a rigorous historical analysis (2020–2025) and forward-looking forecasts for 2026–2032, this study synthesizes market sizing, regulatory context, clinical developments, supplier dynamics, and competitive positioning to help pharmaceutical, biotech, and investor clients convert uncertainty into prioritized action.
Etifoxine Hydrochloride Market
Headline macro takeaways
-
Base year and horizon: the report uses 2025 as its base year and models trends across a 2026–2032 forecast window, building on a historical series from 2020–2025.
Etifoxine Hydrochloride Market -
Market growth trajectory: the global Etifoxine Hydrochloride market is projected to continue a steady expansion, with a compound annual growth rate (CAGR) of approximately 5.2% over the forecast period. Our model shows identifiable inflection points tied to regulatory events and product launches that materially affect near-term uptake.
Etifoxine Hydrochloride Market -
Market scale context: PW Consulting’s topline model estimates the market in 2025 at USD 85.0 Million (revenue unit: Million USD) with a projected rise into the late‑cycle forecast, providing a quantifiable runway for commercial programs and portfolio prioritization.
-
Concentration and competitive structure: market concentration metrics indicate a moderately concentrated landscape (CR3 ≈ 45.5%; CR5 ≈ 58.2%), implying meaningful influence by several incumbents while leaving space for targeted entrants and niche players.
Why this report matters for 2026 strategic planning
-
Regulatory shifts are disrupting established assumptions. Recent regulatory outcomes and safety reviews have restricted usage in specific patient subgroups, while approvals and post-marketing commitments in key jurisdictions are changing how products are positioned commercially. Executives need granular regulatory scenario planning to avoid downstream reimbursement and liability risk.
-
Competitive moves are accelerating. Brand owners, generics manufacturers, and API suppliers are executing strategic launches and supply agreements that will re-draw commercial boundaries in several national markets. These moves affect access, price erosion timelines, and channel strategies.
-
Clinical re‑purposing and new indications could reshape demand. Ongoing and planned clinical trials exploring new therapeutic applications create upside optionality for companies that can align development and commercialization efforts early.
-
Supply‑chain resilience matters. API sourcing and manufacturing capabilities — including secondary sourcing and regulatory compliance of suppliers — are critical levers that influence time‑to‑market and margin performance.
What the report delivers — operational, decision‑grade content
-
Proprietary market model: transparent topline and scenario-based forecasts (2026–2032) with sensitivity testing for pricing, uptake curves, and regulatory outcomes. Note: detailed segment-level tables and region/application breakdowns are available in the full report (preview intentionally omits subsegment datapoints to preserve premium insights).
-
Go‑to‑market playbooks: tailored strategies for originators, first-to-file generics, and API suppliers covering launch sequencing, pricing frameworks, tender vs. retail channels, and payer engagement.
-
Regulatory & safety matrix: jurisdiction-by-jurisdiction summary of approvals, constraints, pharmacovigilance obligations and label risks, including scenario pathways for potential label revisions or additional contraindications.
-
Clinical pipeline tracker: live registry of ongoing and planned trials, prioritized by commercial impact and likelihood of success; includes trial design, enrollment assumptions, and expected data readouts.
-
Supply‑chain and manufacturing map: supplier profiles, capacity assessments, quality/regulatory compliance checks, and contingency pathways to mitigate single‑source exposure.
-
Competitive landscape & M&A readiness: profiles of incumbent players, disruptive entrants, ROIC-focused valuation frameworks, and a short‑list of high‑conviction partnership/acquisition targets.
-
Risk register and mitigation playbook: cross-functional risk assessments (regulatory, clinical, commercial, reputational) with prioritized mitigation tactics and KPIs for 12–36 month timeframes.
Competitive landscape — distilled insights
-
Biocodex (France) — legacy brand stewardship: Biocodex remains the steward of the established brand franchise in markets where Etifoxine has historical uptake. Their entrenched brand recognition and clinician familiarity confer a durable advantage on brand loyalty and formulary positioning in certain markets.
-
Sun Pharmaceutical Industries (India) — scale and regulatory momentum: Sun Pharma’s recent regulatory approvals and active post‑marketing surveillance commitments indicate a deliberate strategy to commercialize at scale where regulatory pathways permit. Their established commercial footprint and cost base enable competitive pricing strategies and rapid national rollouts.
-
API manufacturers (Metrochem API, Global Calcium, others) — strategic suppliers: multiple specialized API manufacturers have articulated Etifoxine in their portfolios, creating an increasingly diversified upstream supply environment. For companies considering entry or expansion, securing long‑lead API contracts and auditing supplier compliance will be decisive.
-
Regional generics entrants (e.g., Nizhpharm) — tactical launches: localized generic launches demonstrate how regional players can capture share quickly by leveraging approvals and country-specific supply chains. These entrants often drive rapid price compression in localized markets and can be attractive partners for licensing or distribution agreements.
Regulatory and clinical dynamics to watch in 2026
-
Safety‑driven label evolution: prior regulatory reviews have confirmed continued use in many patients but introduced clear contraindications tied to severe cutaneous and hepatic reactions. Companies must incorporate these constraints into promotion, labeling, and risk‑management strategies.
-
US absence and global opportunity mapping: Etifoxine is not approved in the United States; this absence creates a defined geographic boundary and opportunity set for companies focusing on Europe, Asia, and other markets where regulatory pathways are accessible.
-
Clinical re‑purposing signals: new trials, including studies assessing prevention of chemotherapy‑induced peripheral neuropathy (trial start dates aligned with 2026), could materially expand the clinical use case. Early engagement with principal investigators and payers will be critical if positive signals emerge.
-
Pharmacovigilance and post‑marketing commitments: regulators in several jurisdictions are expecting active PMS programs tied to newly approved products; these obligations influence launch timing and cost assumptions for market entrants.
Practical implications and recommended actions for 2026
-
For originators: protect brand equity through targeted education and safety communications, accelerate lifecycle programs for differentiated formulations or delivery, and evaluate selective licensing in markets where commercial reach is limited.
-
For generics and contract manufacturers: prioritize regulatory-ready dossiers and secure multi‑tier API supply; consider value-add services (e.g., bundled pharmacovigilance) to raise tender competitiveness beyond price alone.
-
For investors and M&A teams: use our scenario-driven valuation overlays to separate durable cashflow targets from opportunistic, timing‑sensitive plays — the market’s CR3/CR5 dynamics favor focused roll-ups in select regions.
-
For clinical developers: prioritize adaptive trial designs and engage payers early on novel indications to shorten the commercialization path if efficacy signals arise.
How to use PW Consulting’s report in boardroom planning
-
Integrate our forecast and scenario outputs into 2026 budgeting cycles to stress‑test revenue projections under divergent regulatory and competitive outcomes.
-
Adopt the supplied go‑to‑market playbooks as templates for country rollouts and tender strategies; customize based on internal capabilities and partnership options.
-
Leverage the supplier mapping and due‑diligence checklists to accelerate supplier qualification and reduce time‑to‑market risk.
-
Commission a tailored deep‑dive (PW Consulting engagement) to convert our high‑confidence recommendations into executable project plans with defined milestones and KPIs.
Access and next steps
This preview highlights the strategic value of the PW Consulting Etifoxine Hydrochloride Market report for 2026 decision-making. The full report contains the detailed segment tables, country-level opportunity matrices, pricing curves, and our proprietary scenario model that underpin the strategic recommendations above. To obtain the comprehensive dataset, modeling files, and bespoke advisory support, please contact PW Consulting’s market analytics team or visit our report landing page.
PW Consulting’s analysts stand ready to brief executive teams and investment committees on demand, and to tailor our findings into transaction‑ready diligence packages or operational playbooks that accelerate time to value in the Etifoxine Hydrochloride opportunity set.
For detailed analysis of this topic, please visit the official page: Etifoxine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


