



PW Consulting: Kynam Agarwood Market Poised to Reach USD 1.63 Billion by 2032, Growing at a 8.65% CAGR
By PW Consulting, 2026-07-13
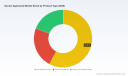
Kynam Agarwood Market 2026: Strategic Briefing — PW Consulting
Executive teaser
The PW Consulting Kynam Agarwood Market report is a practice-oriented strategic tool for corporations, investors, and supply-chain managers preparing decisions in 2026. Our analysis traces the market from a documented historical base (2020–2025) through a robust forecast window (2026–2032), quantifying the sector’s growth trajectory while preserving commercial confidentiality on granular segment shares. In summary: the global Kynam agarwood market expanded materially during 2020–2025, reached an estimated market value of USD 912.5 Million in the report base year (2025), and is projected to continue expanding to roughly USD 1,630.9 Million by 2032 — a compound annual growth rate of 8.65% across the 2026–2032 forecast period.
Kynam Agarwood Market
Why this matters for 2026 decision-makers
- Volume and value dynamics: The market’s mid-to-high single-digit CAGR through 2032 indicates sustained buyer appetite and rising commercialisation of premium-grade agarwood products. That trajectory supports medium-term investment in capacity, traceability, and branded product development.
- Structural change: Cultivation scale-up and scientific grafting processes are reshaping supply economics and quality standardization, compressing some traditional margins while creating opportunities for differentiated, certified supply chains.
- Regulatory and reputational risk: Kynam-related species are covered under international trade controls that require documented compliance; failure to embed provenance and permitting into sourcing strategies will materially increase business risk in cross-border trade.
Market trajectory: what the headline numbers tell us
From a historical series covering 2020–2025 and a forecast through 2032, the report isolates three investment-relevant signals. First, the market has demonstrated consistent expansion during the historical period, culminating in a base-year valuation of USD 912.5 Million. Second, the projected path to 2032 nearly doubles the market size in value terms, reflecting a combination of premiumisation, expanding downstream demand (perfumery, high-end incense, and wellness), and increasing industrialization of cultivation. Third, the 8.65% CAGR projected for 2026–2032 highlights that companies entering or scaling within this window will likely operate in an environment where both price and quality differentiation matter.
Kynam Agarwood Market
Core dynamics shaping 2026 strategies
- Supply modernization: Advances in grafting and seedling programs have moved from artisanal craft to reproducible agronomy. Public-private initiatives in production hubs are accelerating adoption of higher-survival grafting techniques and distributing large numbers of certified seedlings to farmers—shifting supply toward cultivated sources with traceable provenance.
- Compliance overlay: With relevant Aquilaria species listed under international trade controls, export-import processes require stringent documentation. Buyers and brand owners must adopt traceability protocols and align procurement to CITES-compliant channels to avoid shipment delays and reputational damage.
- Quality and premiumisation: Demand for certified, high-grade resin continues in perfumery and targeted wellness applications. Whereas commoditised raw chips remain a market pillar, premium Kynam derivatives are opening pathways for value capture through branded oils, curated musk blends, and authenticated finished goods.
- Consolidation pressure vs fragmentation: The Kynam arena remains relatively fragmented; a limited number of vertically integrated players have begun to scale, but market share concentration remains modest. This fragmentation creates options for M&A, selective partnerships, and contract cultivation schemes to secure supply.
Competitive landscape — strategic profiles and implications
Our competitive review identifies a set of players whose capabilities matter to 2026 plans. Below we summarize their strategic positions and the implications for buyers, investors, and partners.
Kynam Agarwood Market
- SILVANSON (Ruipearl / Oudchips.com) — Based in Maoming, Guangdong, SILVANSON operates patented grafting programs and manages large-scale plantations with vertically integrated processing and international warehousing. Their strengths: traceability systems aligned with export compliance and direct logistics presence in Gulf Cooperation Council markets. Strategic implication: multinational buyers seeking CITES-compliant, traceable supply can shorten lead times by partnering with such fully integrated exporters — but should price-in a premium for certified, traceable product.
- Hoang Giang Agarwood Ltd. (HAGA Oud) — A Vietnam-headquartered manufacturer focused on 100% natural Oud from plantation-grown Aquilaria. Their model emphasizes scale manufacturing and strong export ties into GCC markets. Strategic implication: contract manufacturing relationships and private-labeling arrangements are credible options for brands targeting Middle Eastern luxury segments.
- Binh Nghia Agarwood Co., Ltd — A prominent Vietnamese multi-factory producer with a leadership role in local industry associations. Their position offers buyers a gateway to diversified product forms (chips, oil, incense, powder). Strategic implication: engagement with association-led suppliers can provide market intelligence advantages and smoother access to pooled services such as certification, quality testing, and trade facilitation.
- Huidong Green Kynam Agarwood Seedling Development Co — Specialist in seedling and grafting propagation in Guangdong, supporting county-level expansion programs and high-volume seedling distribution. Strategic implication: sourcing upstream genetic material and participating in public-private cultivation programs can secure long-term supply and reduce exposure to raw-material price volatility.
- Senhai Essence (Agarwood.ai) — Focused on grafting, cultivation, and processing, with an emphasis on integrating digital traceability and product innovation. Strategic implication: technology-enabled suppliers can accelerate compliance and offer data-enabled provenance claims that enhance brand positioning.
Recent developments to watch entering 2026
Notable operational shifts in production geographies signal the sector’s direction. Government-supported cultivation expansion programs and county-level conversion initiatives have scaled seedling distribution and promoted grafting adoption. These interventions materially change the supply outlook by increasing cultivated output, improving survival rates, and integrating local financing mechanisms for growers. Companies that align early with these programs—through offtake agreements, financing, or extension services—will gain preferential access to next-wave supply.
Actionable recommendations for 2026 planning
- Embed traceability as a procurement requirement: mandate CITES-compliant documentation, batch-level provenance, and independent testing for all suppliers before scaling purchases.
- Pursue blended sourcing strategies: combine partnerships with certified large-scale growers for core supply and specialist artisanal suppliers for differentiated, limited-edition products.
- Invest in upstream partnerships: consider minority equity or revenue-share models with seedling producers and plantation projects to secure staged supply and influence cultivation practices.
- Differentiate through productization: develop premium offerings anchored on authenticated origin narratives, laboratory-verified quality metrics, and value-added processing (micro-distilled oils, curated incense collections).
- Allocate due diligence budget to regulatory and reputational risk mitigation: legal review of cross-border permits, ESG screening, and supply-chain audits should be incorporated into procurement cycles.
- Monitor consolidation signals: be prepared to move quickly on strategic M&A or exclusive distribution pacts as market consolidation accelerates and the share of vertically integrated players grows.
What the PW Consulting report delivers (practical modules)
This report is designed as a transaction-and-execution tool rather than a purely academic study. Its contents include:
- Executive dashboards with headline market metrics and scenario-based forecasts to support budgeting and investment committees.
- A purchaser’s playbook for supplier selection, contract design, compliance checklists, and sample contractual clauses for offtake and quality warranties.
- Due-diligence templates for plantation and processing audits, including traceability verification steps and laboratory test panels.
- Commercial modelling templates that allow users to test sourcing mixes, margin impacts, and payback periods for upstream investments.
- Competitive company dossiers with strategic posture analyses (R&D, vertical integration, export footprint) and tactical recommendations for partnership or acquisition approaches.
- Regulatory and trade annexes summarizing relevant controls and documentation requirements and best-practice flows for cross-border trade.
Next step — where to get the full intelligence
This briefing highlights the strategic value of the PW Consulting Kynam Agarwood Market report for decisions to be made in 2026. For access to the full dataset, granular segment modelling, company-level scorecards, and downloadable commercial templates, please consult the report landing page. The full deliverable contains the detailed breakdowns and proprietary appendices that underpin the recommendations above — intentionally withheld here to preserve actionable value for report subscribers.
PW Consulting stands ready to support bespoke advisory work: supplier diligence, strategic sourcing programs, or transaction advisory related to Kynam supply chain projects. Contact our Market Strategy team to schedule a briefing and see the underlying datasets that support the forecasts and tools summarized in this release.
For detailed analysis of this topic, please visit the official page: Kynam Agarwood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Food-Grade Urolithin A Market Poised to Surpass USD 759.12 Million by 2032, Backed by a 17.5% CAGR
By PW Consulting, 2026-07-13
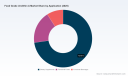
Food-Grade Urolithin A Market — 2026 Strategic Outlook (PW Consulting Preview)
PW Consulting’s latest market research brief on the Food-Grade Urolithin A market offers a focused, decision-ready view for executives planning resource allocation, product roadmaps, and M&A activity in 2026. Built on a base year of 2025 and a detailed forecast horizon of 2026–2032, the report models an industry accelerating from an estimated USD 245.5 Million in 2025 to roughly USD 759.1 Million by 2032, representing a compounded annual growth rate (CAGR) of 17.5% over the forecast period. This preview highlights the report’s strategic value to commercial leaders while preserving granular sub-segment intelligence for subscribers and clients.
Food Grade Urolithin A Market
Why this report matters for 2026 corporate decisions
-
Timing and scale: Rapid projected growth and a multi-year expansion window mean near-term choices on capacity, contracts, and claims will disproportionately influence 2026–2028 market share trajectories. Our modeling shows the market moving from a niche, clinically anchored ingredient to broader commercial adoption across supplements and functional food & beverage formulations.
Food Grade Urolithin A Market -
Commercial risk-return calibration: With an observed market concentration driven by leaders that have clinical depth and regulatory recognition, the most defensible strategies for new entrants are either differentiated science-backed positioning or cost/scale leadership in upstream supply. The report quantifies trade-offs between premium positioning and margin compression in mass-market pathways (detailed scenario matrices are available in the full release).
Food Grade Urolithin A Market -
Regulatory and claims playbook: Urolithin A’s GRAS recognition (GRN 791) and growing human clinical evidence create a unique opportunity to translate clinical endpoints into consumer-facing positioning — but only if substantiation, labeling, and use-case-specific dosing are addressed. The report provides pragmatic regulatory pathways, claim architecture options, and a timeline for claim defensibility across major markets.
-
Supply chain and procurement strategy: Given the mix of proprietary-supply and broadly available food-grade manufacturers, procurement teams need a differentiated sourcing matrix that reconciles price, purity, supply assurance, and quality certifications. Our supplier risk heatmaps and contract design templates enable procurement leaders to fast-track vendor selection without sacrificing compliance.
-
R&D and formulation implications: Formulators face constraints around stability, dose delivery, and compatibility with typical matrices (powders, RTD beverages, bars, yogurts). The full report’s formulation compendium outlines best-practice excipients, microencapsulation options, and pilot test protocols that reduce time-to-market for prototypes in 2026.
What the PW Consulting report contains — practical deliverables
-
Market sizing and forecast model (2020–2032): transparent assumptions and a downloadable financial model for sensitivity testing of price, penetration, and volume scenarios.
-
Five strategic scenarios for 2026–2028: pathways ranging from premium clinical-led rollouts to scaled commodity supply plays, each with revenue, margin, and break-even analyses.
-
Regulatory & claims matrix: jurisdiction-by-jurisdiction guidance for compliant positioning, dossier requirements, and likely enforcement focus areas.
-
Supplier landscape and sourcing toolkit: a vetted supplier directory, conformity and certification checklists, quality audit templates, and contract negotiation playbooks (note: the directory includes both proprietary and open-market producers; detailed scoring is available to subscribers).
-
Clinical evidence mapping: synthesis of human and preclinical studies mapped to potential consumer benefits (muscle function, mitochondrial health, immune support, cognitive endpoints), with recommended claim language tiers and substantiation thresholds.
-
Commercial go-to-market playbooks: retail and direct-to-consumer approaches, co-packing and private-label considerations, pricing frameworks, and channel-specific merchandising recommendations.
-
Risk register and mitigation blueprints: supply disruption scenarios, regulatory adverse events, and reputational risks — each with prioritized mitigation actions and contingency cost estimates.
Competitive landscape — what we found
The Food-Grade Urolithin A market combines a small set of well-capitalized, clinically oriented licensors and product owners with a broader base of manufacturers and bulk suppliers. Market concentration metrics indicate that the top three players control the majority of the market and the top five command an even larger share (CR3 ~68.5%; CR5 ~82.3%), underscoring a marketplace where scale, regulatory positioning, and clinical evidence meaningfully differentiate competitive advantage.
-
Amazentis SA (Timeline Nutrition / Mitopure) — Headquarters: Lausanne, Switzerland. Profile: The company that commercialized Mitopure and secured GRAS recognition remains the most clinically advanced participant. Recent milestones — including multiple human trials and the company’s announcement of its 25th human clinical trial milestone in late 2025 — reinforce its leadership in longevity- and mitochondrial-health–oriented positioning. For strategic partners, Amazentis represents a premium, science-first supply path with licensing and co-branding implications.
-
Daicel Corporation — Profile: A regional, diversified chemical/ingredients supplier with capabilities to produce food-grade Urolithin A suitable for nutraceutical and functional food use. Daicel and similar established suppliers can offer stability and scale for brands seeking regulatory-compliant supply without exclusive licensing terms.
-
Bulk and contract manufacturers (China-based and others) — Profile: A broad cohort of manufacturers provide high-purity Urolithin A powders and food-grade compliant intermediates. These players support cost-competitive supply and rapid order fulfillment, but buyers must manage quality variability, certification evidence, and logistics. The report’s supplier due-diligence templates are tailored to mitigate these specific risks.
Strategic takeaway: the market structure creates clear entry buckets for different corporate profiles. Companies with clinical assets and brand strength can pursue premium licensing and co-development. Ingredient distributors and contract manufacturers can capture volume growth but must demonstrate GMP, traceability, and consistent purity to compete with premium licensers.
Regulatory and scientific drivers
-
GRAS status as a commercial lever: The U.S. GRAS designation for Mitopure enables certain food applications at defined serving sizes and has been an inflection point for formulations in protein shakes, bars, RTD beverages, and yogurts. That regulatory anchoring materially reduces time-to-market risk for formulations that adhere to labeled use-cases.
-
Clinical evidence is a defendable moat: Multiple human studies focused on mitochondrial endpoints, muscle and immune function, and cognitive markers provide a credible pathway for differentiated health claims if companies invest in rigorous, indication-specific trials. The report’s clinical-to-claim roadmap helps prioritize sponsors’ investments to maximize commercial ROI.
-
Raw material sourcing and route-to-supply matter: Urolithin A is a gut-microbiota metabolite derived from ellagitannins. Commercial production uses synthetic chemistry or microbial fermentation from natural precursors; each route has different cost structures, impurity profiles, and certification challenges. Our supply-path decision framework quantifies these trade-offs for procurement and R&D teams.
How companies should use this preview to act in 2026
-
For brands and CPG marketers: prioritize SKU pilots that align with substantiated endpoints, secure supply agreements that include quality SLAs, and plan phased rollouts that combine premium SKUs with broader mainstream options.
-
For ingredient suppliers: accelerate capacity investments where margin visibility exists, lock multi-year contracts with high-quality off-takers, and invest in certifications and clinical partnership opportunities to climb the value chain.
-
For investors and M&A strategists: prioritize targets that combine clinical ownership, regulatory positioning, and predictable manufacturing footprints. The market’s high concentration suggests acquisitive consolidation opportunities for players seeking scale and proprietary claims.
-
For regulators and quality assurance teams: expect increased scrutiny around labeling, claim substantiation, and upstream traceability as market adoption grows; proactive transparency programs will reduce enforcement risk and speed approvals for cross-border distribution.
Next steps — where to get the full intelligence
This preview demonstrates the strategic importance of Urolithin A for 2026 planning — from supply decisions to clinical investment prioritization. PW Consulting’s full Food-Grade Urolithin A Market report contains the proprietary segmentation, supplier scoring, and scenario-level financials required to operationalize the insights summarized here. To access the complete dataset, supplier directory, and customizable financial model (including downloadable case templates and go-to-market playbooks), visit PW Consulting’s report page or contact our industry advisory team for a tailored briefing.
For clients planning immediate action in 2026, PW Consulting offers a limited series of deep-dive workshops that map the report’s scenarios to your organization’s balance sheet, supply commitments, and product pipeline. These workshops are structured to produce an actionable 90-day implementation plan aligned to your preferred strategic pathway.
PW Consulting — translating fast-moving nutraceutical science into pragmatic commercial advantage.
For detailed analysis of this topic, please visit the official page: Food Grade Urolithin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E‑Beam Accelerators Market Poised for Steady 4.15% CAGR Through 2026–2032, New Insight Report Reveals
By PW Consulting, 2026-07-13
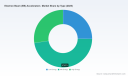
E Beam Accelerators Market — Strategic Preview for 2026 Corporate Decision-Making
Executive snapshot
PW Consulting’s new industry briefing on the E Beam Accelerators market draws a clear line from historical performance (2020–2025) into a forward-looking forecast spanning 2026–2032. The market has expanded from an estimated USD 120.0 Million in 2020 to roughly USD 180.0 Million in 2025, reflecting steady uptake across industrial, medical and packaging end‑uses. Under our base-case assumptions, total industry revenues are projected to grow at a compound annual growth rate (CAGR) of approximately 4.15% through the 2026–2032 forecast window, reaching a market size in the order of USD 270.0 Million by 2032.
E Beam Accelerators Market
Why this preview matters for 2026 decisions
-
Timing capital allocation: 2026 is a transitional year for many adopters — systems ordered now will reflect a new wave of integrated service models (monitoring, performance guarantees) and modular hardware designs. Our analysis identifies the breakpoints where earlier deployments become operationally or financially suboptimal compared with next‑generation accelerators.
E Beam Accelerators Market -
Supplier selection and risk management: the market exhibits moderate concentration (CR3 ~45%; CR5 ~65%), indicating a small group of influential incumbents alongside a competitive tail of specialist integrators. This structure carries implications for lead times, aftermarket support and price negotiation power when committing to multi‑year service contracts.
E Beam Accelerators Market -
Regulatory and demonstration effects: recent contract wins and cross‑border deliveries are accelerating acceptance in new jurisdictions, changing the calculus for market entry and capacity expansion. Purchasers and investors need to factor in regulatory staging and certification timelines into 2026 procurement roadmaps.
What the report delivers — practical, decision‑grade content
This report was built for executives and investment teams who must translate technology trends into immediate actions. Highlights of the deliverables include:
-
Actionable market sizing and scenario modelling: an audited historical series (2020–2025), a base forecast (2026–2032) and upside/downside scenarios linked to key variables such as service‑contract penetration, capital equipment lifecycles and macroeconomic sensitivity.
-
Investment-ready financial tools: capex/opex templates calibrated to typical installation profiles, payback and IRR calculators for greenfield vs upgrade pathways, and sensitivity tables that stress-test ROI under energy price and throughput volatility.
-
Procurement and supplier evaluation frameworks: vendor shortlisting matrices, total cost of ownership (TCO) comparators that incorporate maintenance and yield impacts, and contract clauses to mitigate delivery and performance risk.
-
Technology and product roadmaps: comparative analysis of low-, mid- and high-energy architectures, modularity trade-offs, and likely near-term innovations (digital monitoring, remote diagnostics, hybrid EB/X-ray solutions) that buyers should require in RFPs.
-
Regulatory & compliance playbook: mapping of certification steps, typical timelines and mitigation strategies for jurisdictions that are opening to electron beam technologies.
-
M&A and partnership scouting: prioritized lists of target archetypes, diligence checklists, and estimated valuation multipliers consistent with the current market concentration and growth trajectory.
Competitive landscape — who to watch and why
The sector combines incumbent system manufacturers, regional integrators and specialized engineering houses. The following profiles summarize the strategic positioning and recent moves of core players, informing vendor negotiation and partnership strategies without disclosing proprietary market shares:
-
NHV Corporation (Japan) — A full‑spectrum manufacturer covering the entire energy range with integrated services. NHV’s recent commercial focus on production‑line monitoring reflects a broader industry shift: buyers increasingly demand operational continuity and process assurance. The company’s first‑use contract for an EPS monitoring system with a tire OEM (March 2026) and its visible presence at sector trade shows (wire 2026) signal an aggressive push to embed recurring service revenue alongside hardware sales.
-
CGN Dasheng Electron Accelerator Technology Co., Ltd. (China) — A vertically integrated designer and installer with experience in irradiation centers and high‑throughput applications. CGN Dasheng’s delivery of a system into the European market (October 2025) exemplifies cross‑regional expansion and the growing competitiveness of non‑Western suppliers on price, scale and delivery. Procurement teams should expect increasing competition on lead times and turnkey scope.
-
Vivarad S.A. (France) — Known for broad energy-range offerings and a global installed base. Vivarad’s strength lies in standardized platforms that reduce integration risk for industrial users. Their footprint is a reminder that robustness and field service networks remain decisive selection criteria for high‑uptime operations.
-
Wasik Associates (United States) — A specialist in custom, turn‑key systems geared toward niche industrial and medical applications. Wasik’s engineering‑led model is appealing for customers with non‑standard web speeds, product geometries or regulatory requirements; expect them to be a preferred partner for bespoke integrations.
-
Mevex Corporation (Canada) — Focused on linear accelerators for sterilization and materials modification. Mevex is a benchmark for performance and regulatory experience in high‑power applications; their technology roadmap is relevant for buyers prioritizing high throughput and validated sterilization processes.
-
IBA Industrial (Belgium) — Supplier of Rhodotron® accelerators and large industrial irradiation projects. IBA’s contract activity (e.g., multi‑accelerator installations) highlights the scale opportunity for OEMs that can deliver multi‑unit, high‑availability solutions.
-
Energy Sciences Inc. (United States) — A leader in low‑voltage EB systems for packaging and coatings. Energy Sciences’s product specialization underlines how targeted technology plays can command premium margins and rapid adoption in specific value chains.
Recent industry dynamics that will shape 2026
-
Service integration: the NHV EPS monitoring contract shows vendors moving beyond hardware to offer line‑level assurance services, changing how buyers assess lifecycle costs.
-
Cross-border technology flows: CGN Dasheng’s European delivery demonstrates a maturing export profile for Asian suppliers — a dynamic that is compressing price differentials and forcing incumbents to compete on service and lead time.
-
Large-scale installations: multi‑accelerator projects continue to be focal points for industrial consolidation and for players capable of end‑to‑end project execution.
Strategic implications and recommended 2026 actions
For corporates, investors and technology buyers, the report translates market trends into a concrete set of actions to prioritize in 2026:
-
Define investment triggers: use our ROI templates to identify whether to retrofit, upgrade, or greenfield — and at what throughput thresholds each option becomes preferable.
-
Negotiate for service outcomes: include performance SLAs and monitoring integration in procurement contracts to capture the value of uptime and yield improvements demonstrated by recent vendor offerings.
-
Prioritize supplier risk mapping: given moderate market concentration, create a ranked supplier map that incorporates delivery lead times, aftermarket footprint and regulatory track record to avoid single‑source exposures.
-
Adopt a staged deployment approach: pilot systems equipped with modular controls and standardized interfaces reduce upgrade cost and shorten validation cycles.
-
Explore strategic partnerships: consider co‑development or service partnerships with vendors that bring complementary strengths (e.g., an equipment supplier plus a digital monitoring specialist) to capture recurring revenue streams.
-
Use M&A pragmatically: the market structure and growth profile create opportunities to buy capability (service networks, regional approvals) rather than only capacity; our report highlights target archetypes and valuation considerations.
How to use the full report
This release is a strategic preview designed to orient 2026 planning. The full PW Consulting E Beam Accelerators Market report contains the proprietary detail needed to operationalise the recommendations above: granular scenario tables, supplier TCO models, stepwise procurement checklists, and an appendix of validated contacts for vendor due diligence.
Final note — what this preview does and does not disclose
We have provided verified macro metrics and a strategic reading of market direction to support executive planning. To preserve the investigatory value of our research and to protect client confidentiality, the report intentionally withholds specific sub‑segment revenue breakdowns and detailed region/application percentages from this public summary. For practitioners who require the full fidelity—down to segment forecasts, country‑level demand curves and vendor scorecards—the full dataset and interactive models are available through PW Consulting’s online report portal.
Next steps
-
Download the full report to access the interactive models and supplier scorecards.
-
Book a briefing with our industry team to walk through scenario outputs tailored to your use case (capex planning, supplier RFPs, M&A diligence).
-
Request a customized supplier shortlisting workshop that uses our validated frameworks and market contacts to produce an executable procurement plan within 6–8 weeks.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicone Vasculature Models Market to Reach USD 490.24M by 2032 at 7.51% CAGR
By PW Consulting, 2026-07-13
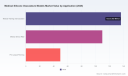
Medical Silicone Vasculature Models Market — Strategic Briefing for 2026 Decision Makers
As healthcare systems, device developers, and academic centres accelerate investments in realistic simulation, the market for medical silicone vasculature models is moving from niche laboratory tools to strategic platform assets. PW Consulting’s newly released market study (base year 2025; forecast 2026–2032) synthesizes market sizing, competitive dynamics, regulatory drivers, and go-to-market playbooks to support high-stakes 2026 decisions. This briefing highlights the study’s strategic value, the levers that will determine winners and laggards, and the practical next steps executives should adopt — while deliberately keeping detailed segment-level tables and model-by-model pricing behind our report paywall to preserve exclusive value for subscribers.
Medical Silicone Vasculature Models Market
Market at a Glance — Growth Trajectory and What It Means
The market for silicone vascular phantoms has expanded consistently over the last half-decade, reflecting growing demand from medical training, device development, and pre-surgical planning. Our sizing (USD, Million) shows a clear multi-year growth path from the low hundreds in 2020 to nearly USD 296 million in 2025, continuing to an estimated USD 490 million by 2032. This projects to a compound annual growth rate (CAGR) of approximately 7.51% across the forecast horizon.
Medical Silicone Vasculature Models Market
Why this matters for 2026 strategy:
Medical Silicone Vasculature Models Market
- Scale economics are emerging. The market is large enough that investments in manufacturing automation, in-house materials expertise, or contract manufacturing can materially improve gross margins.
- Predictable growth supports multi-year R&D roadmaps for advanced simulation products (e.g., multimaterial hybrids, patient-specific anatomies) and justifies capital allocation into equipment and clinical partnerships.
- Stable CAGR reduces the risk of speculative product bets; decisions can be staged across 18–36 month milestones informed by demand signals captured in this study.
Who Moves the Market: Competitive Structure and Strategic Implications
The competitive landscape is characterized by a mix of specialized fabricators, simulation-focused medtech firms, and academically-rooted spin-offs. Market concentration is modest: the top three players account for a meaningful share but not a dominant stranglehold, while the top five approaches half the market — a structure that enables both scale-focused consolidation plays and differentiated niche strategies.
- United Biologics (Irvine, CA) — known for anatomically representative models and a proprietary silicone formulation oriented to endovascular training and device demonstration.
- BDC Laboratories (Wheat Ridge, CO) — positions itself on engineering compliant mock vessels for cardiovascular device testing and simulation, with active trade-show engagement to drive OEM relationships.
- TrandoMed (Ningbo, China) — leverages 3D-print-driven manufacturing for neuro, coronary, and peripheral simulators at scale.
- Elastrat (Geneva), Mentice (Gothenburg), Preclinic Medtech (Shanghai), MedScan3D (Galway), and Swiss Vascular (Zurich/ETH spin-off) — collectively represent a set of providers that combine regional specialization, patient-specific capabilities, and academic linkage for R&D programs.
Recent signals you should factor into 2026 planning: ETH Zurich’s spin-off (Swiss Vascular) officially launched anatomically exact cerebral silicone models in mid-2025, a move that validated university-to-market pathways for high-fidelity phantoms. Meanwhile, established suppliers continue to engage target customers at industry venues (e.g., BDC’s presence at MD&M West in early 2026), underscoring the importance of direct clinical engagement for pipeline conversion.
Market Dynamics — Materials, Standards, and Supply-Chain Fragilities
From a sourcing and regulatory standpoint, three dynamics will determine near-term supplier viability and product acceptance:
- Raw material cost and specification. Medical-grade liquid silicone rubber (LSR) remains the input that sets floor economics for model pricing. Recent European LSR spot pricing clustered in a narrow band (roughly USD 7.20–7.77 per kg as of mid-2025), but manufacturers report variability driven by batch quality, additive packages, and supply-chain tightness — all of which materially affect unit cost on thin-margin, small-batch runs.
- Standards-led adoption. Compliance testing for cardiovascular devices increasingly references standardized silicone mock vessels (ISO 7198, ASTM F2477) and regulators encourage anatomically tortuous 3D models for simulated use testing — the FDA’s guidance on guidewire testing explicitly points to the utility of patient-like silicone anatomies. Firms that can certify models for standardized testing and provide traceable documentation will reduce friction in device validation cycles and command premium positioning.
- Manufacturing technology convergence. The intersection of high-resolution 3D printing, novel casting techniques, and hybrid composite approaches is redefining what “simulation fidelity” means. Buyers are demanding not just geometry but mechanical match (compliance, friction, and response to devices), which raises the bar for process control, quality systems, and data to demonstrate equivalence to biological tissue.
Strategic Playbook for 2026 — Where to Compete and How
Based on our multi-dimensional analysis, we recommend executives calibrate their 2026 actions across five strategic vectors:
- Segment focus: Prioritise use-cases with recurring demand and high willingness to pay — device R&D customers and simulation training programs with institutional purchasing cycles. Pre-surgical planning remains high-value but lower-volume; serve it with premium, patient-specific offerings partnered with clinical innovators.
- Product architecture: Adopt a tiered portfolio — commodity, configurable, and bespoke. Commodity lines can be automated; configurable offerings should be supported by an online configurator and SLA-backed delivery; bespoke patient-specific models require clinical integrations and higher margin expectations.
- Go-to-market: Build direct clinical champions and OEM co-development partnerships. Presence at clinical conferences and hands-on workshops is essential to shorten the sales cycle and create reference cases for device testing programs.
- Supply resilience: Lock in medical-grade LSR contracts and qualify redundant suppliers. Consider backward integration into critical elastomer compounding for firms with volume scale, or contract-manufacturer partnerships to shield capital outlay while ensuring traceability for regulated testing.
- Regulatory and quality systems: Invest in documentation and test-bench evidence that mirrors ISO/ASTM protocols and FDA simulated-use expectations. Certifications and validated test data will be differentiators for device OEM procurement.
Investment and M&A Considerations
With mid-single-digit market concentration and accelerating growth, the market is ripe for both horizontal consolidation and vertical capture. Private equity and strategic acquirers should evaluate targets against three criteria:
- Technical differentiation — proprietary materials, validated mechanical matching methods, or process patents.
- Customer access — entrenched relationships with device OEMs, hospitals, and training networks that create recurring revenue streams.
- Operational scalability — ability to convert bespoke workflows into semi-configurable, repeatable manufacturing processes.
Smaller players with strong clinical footprints are attractive tuck-ins for platform companies seeking to broaden their product suites with patient-specific capabilities. Conversely, large medtech OEMs could capture margin by internalizing model production for device testing and regulatory submissions.
What PW Consulting’s Full Report Delivers (Practical Content)
The study is engineered for executives who must act in 2026. It blends strategic narrative with operational toolkits, including:
- Verified market sizing and a 2026–2032 forecast model (USD, Million) with scenario toggles for adoption rates and pricing trajectories.
- A commercialization playbook detailing pricing architecture, channel economics, and a 12–24 month go-to-market sprint roadmap.
- Regulatory alignment matrices mapping product features to ISO/ASTM testing and FDA guidance to shorten device validation cycles.
- Supplier and raw-material procurement intelligence, including LSR market behaviour, risk-mitigation actions, and supplier qualification checklists.
- Competitive profiles and practical due-diligence templates for M&A or supplier selection — including capability heatmaps and integration risk scoring.
- Customer use-case playbooks for device OEMs, academic simulation centres, and hospital purchasing teams, with turnaround time and cost-to-serve benchmarks.
Note: To preserve strategic exclusivity, detailed subsegment allocations, individual company revenue lines, and model-level price lists are omitted from this public briefing and are available inside the full report.
Actionable Next Steps for 2026
- Run a 90-day supplier resilience assessment focused on LSR sourcing and qualifying a backup compounder.
- Pilot a configurable product line with one device OEM partner to validate margin uplift and shorten clinical adoption cycles.
- Allocate a small dedicated budget to regulatory evidence generation (bench tests aligned to ISO/ASTM and FDA scenarios) to unlock higher-margin device-testing contracts.
- Commission a valuation review if pursuing M&A — target assets that combine clinical relationships with technical IP.
Concluding Assessment
The medical silicone vasculature models market is at an inflection point: steady, predictable growth combined with rising technical and regulatory complexity creates a competitive landscape that rewards operational excellence, clinical intimacy, and materials mastery. For 2026, the smartest bets are not speculative new product lines but disciplined moves that translate product fidelity into repeatable business models: supplier contracts that control cost, regulatory evidence that shortens procurement cycles, and sales motions that convert clinical champions into long-term customers.
PW Consulting’s full market study provides the granular intelligence, financial models, and execution templates needed to turn these strategic imperatives into delivered value. For teams ready to convert market momentum into market leadership, the report is designed as a practical playbook — the next-step roadmap to decisive action.
For detailed analysis of this topic, please visit the official page: Medical Silicone Vasculature Models Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CPVC Power Pipe Market to Reach USD 2,590.72M by 2032 at 6.67% CAGR
By PW Consulting, 2026-07-13
Cpvc Power Pipe Market — Strategic Outlook for 2026: Executive Preview from PW Consulting
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused executive preview of our new Cpvc Power Pipe Market study. This briefing is designed to demonstrate the report’s strategic value for corporate decision-making in 2026: where to allocate capital, how to structure supply chains, which competitive moves to prioritize, and what regulatory or commodity risks require active mitigation. The content below highlights the macro drivers, tactical implications, and competitive contours uncovered in our analysis — while intentionally withholding granular segment allocations to guide readers to the full report for transaction-grade intelligence.
Cpvc Power Pipe Market
Why this research matters for 2026 decisions
-
Market trajectory: The global Cpvc power pipe market has expanded steadily during 2020–2025 and, at the 2025 base year, reached a material market size (measured in USD Million). PW Consulting forecasts continued compound growth through our 2026–2032 horizon at a CAGR of 6.67%, with the market scaling meaningfully by 2032. This mid-single-digit growth profile creates a predictable backdrop for investment, capacity planning, and M&A activity in the near term.
Cpvc Power Pipe Market -
Actionability: The study translates growth projections into actionable planning tools — supply-side scenarios, procurement playbooks, unit-cost sensitivity models, and go-to-market playbooks — enabling commercial and operational leaders to convert a favorable macro outlook into defensible business cases in 2026.
Cpvc Power Pipe Market -
Timing: 2026 is a pivot year. Firms that lock in resilient raw material contracts, shore up alternative supply routes, and crystallize regulatory compliance strategies will capture the most attractive margins as demand continues to grow and supply-side frictions persist.
High-level market snapshot (what we modeled)
-
Historical base and trajectory: PW Consulting’s model covers 2020–2025 as its historical base and projects a detailed forecast from 2026–2032. Readers will find year-by-year modeling that ties demand drivers to end-market dynamics and capex cycles, providing a transparent bridge from observed historical growth into our forward-looking scenarios.
-
Forecast envelope: At the headline level, the market’s steady growth and the elasticity of demand to power grid investments, telecommunications expansion, and industrial modernization underpin our 6.67% CAGR forecast through the period. We overlay three scenario paths to capture demand shocks, supply disruptions, and faster-than-expected infrastructure stimulus.
-
Concentration: The market remains relatively fragmented from a supplier share perspective, with a modest top-tier concentration. That positioning creates space for regional leaders and specialty players to consolidate through distribution partnerships, product differentiation, or selective M&A.
Key dynamics shaping strategy in 2026
-
Raw material and input-price volatility: Our segmentation and cost models incorporate observed feedstock behavior. Notably, CPVC production remains sensitive to PVC resin and chlorine feedstock dynamics — US CPVC pricing reached notable levels mid‑2025, and prior quarters showed material spot-price movement (including a c.6% quarter-over-quarter decline in certain PVC spot markets in Q2 2025). These swings materially affect unit economics for producers and distributors; prudent firms will operationalize hedging and indexed supply contracts.
-
Regulatory and trade friction: Environmental audits and tightened emissions or production constraints in parts of Europe and China reduced available CPVC output in 2025, while tariff actions raised premiums in import-dependent markets. The combination raises the value of localized manufacturing and vertically integrated resin-to-pipe strategies.
-
Demand composition: Continued investment in urban power grid upgrades, fiber-to-the-home/telecom protective conduits, and industrial power installations drives steady demand. However, the mix across these application categories influences product specifications (e.g., high voltage vs. common-grade CPVC) and commercial approaches.
-
Technology and standards: Certification and material performance (temperature rating, chemical resistance, flame-retardant properties) remain decisive buying criteria for large institutional purchasers and utilities. Access to leading CPVC compounds and trusted certification partners is therefore a strategic advantage.
Competitive landscape — strategic positioning of core players
Our competitor analysis focuses on established resin suppliers, global manufacturers, and regional champions. The report contains deeper profiling, benchmarking, and suggested counter-strategies for each competitor highlighted below.
-
Lubrizol Corporation (Corzan Industrial Systems / FlowGuard) — As a leading CPVC resin and compound provider, Lubrizol is the upstream anchor for many downstream players. Its control over compound technology and licensing relationships creates margin and specification advantages. Strategic implication: resin access and licensing partnerships are critical levers for suppliers seeking premium product positioning.
-
Charlotte Pipe and Foundry Company — A U.S.-based manufacturer known for industrial-grade Corzan CPVC products and strong compliance credentials (NSF, ANSI). Its “made in USA” positioning supports government and large-commercial procurement preferences. Strategic implication: competitors should assess hybrid manufacturing plus local finishing to compete on lead times and certification.
-
IPEX Inc. — North American operator offering end-to-end CPVC systems; strong distribution networks and catalog breadth are differentiators. Strategic implication: distributors with deep channel access can convert product breadth into share gains when paired with technical service capabilities.
-
Georg Fischer Piping Systems (GF Harvel) — Provides full thermoplastic solutions, appealing to industrial and power customers seeking integrated valve and fittings ecosystems. Strategic implication: product-system bundling (pipe + fittings + valves + aftermarket service) raises customer switching costs.
-
NIBCO Inc. — Known for industrial fittings and valves; complements producers who lack full accessory lines. Strategic implication: partnership or distribution deals for fittings can broaden addressable market without high-capex expansion.
-
Major Indian players (Astral, Supreme, Finolex, Prince, Ashirvad) — These firms combine large domestic manufacturing footprints, cost-competitive production, and growing export orientation. They are well-positioned to serve regional infrastructure programs and capture shifting trade flows. Strategic implication: Western buyers should pursue joint ventures or supplier diversification to leverage cost advantages while mitigating regulatory risk.
-
China Lesso Group & specialized manufacturers (e.g., Hebei Shentong) — Integrated producers with scale in construction-grade CPVC and electrical conduit solutions. Their manufacturing depth supports aggressive pricing in export markets, but regulatory scrutiny and tariffs can complicate market access. Strategic implication: local assembly or tariff-compliant routing can neutralize headwinds for importers.
What the PW Consulting report contains (practical components)
-
Comprehensive market sizing and forecast model (2020–2032) with scenario sensitivity to raw material prices, tariff regimes, and infrastructure stimulus packages.
-
Supply-chain heatmap that identifies single points of failure, critical feedstock dependencies, and alternative sourcing routes by region and product class.
-
Unit-cost and margin models for common vs. high‑voltage CPVC constructions, including a customizable template executives can use for tender evaluation and pricing decisions.
-
Regulatory risk matrix and compliance playbook focused on emissions, product certification, and import/export controls — built to support procurement and legal teams preparing bids in 2026.
-
Competitive benchmark pack: capability maps of the leading suppliers, distribution networks, IP/licensing relationships (notably Corzan licensing footprints), and supplier scorecards for joint-venture screening.
-
Commercial go-to-market strategies for incumbents and new entrants — channel design, value-added services, and bundling approaches that increase win rates for utility and industrial tenders.
-
Transaction support appendices including an M&A target shortlist, integration risk checklist, and due-diligence templates keyed to CPVC-capable assets.
How to use this research in 2026 — recommended moves by function
-
Procurement: Shift from spot-only sourcing to hybrid contracts that combine indexed pricing, volume commitments, and contingency clauses for force majeure linked to regulatory shutdowns. Begin negotiations now to lock favorable terms before anticipated demand uptick later in the year.
-
Operations & Capex: Prioritize flexible production lines or partner with toll manufacturers to scale capacity without full greenfield exposure. Target short-lead-time investments that improve local content and reduce tariff risk.
-
Commercial: Segment bids by application rigor (e.g., grid, telecom, industrial) and emphasize certifiable performance outcomes. Use value-add services (installation training, extended warranties, onsite testing) to differentiate in utility procurements.
-
Strategy & M&A: Assess bolt-on deals that close distribution gaps or secure resin access. Prioritize targets offering certification, regional permitting advantages, or proprietary compound formulations.
-
Risk & Compliance: Build a regulatory watchlist focused on environmental inspections and potential export controls. Pre-validate alternative logistics routes and bonded inventory plans for regions with tariff vulnerability.
-
Finance: Use the report’s sensitivity models to stress-test underwriting assumptions for new projects and to set dynamic pricing floors tied to feedstock indices.
Concluding perspective and next step
For 2026, the Cpvc power pipe market presents a blend of reliable demand growth and tangible supply-side complexity. The headline growth trajectory creates room for commercial expansion and disciplined capital deployment. Yet raw material volatility, regulatory intervention, and tariff-driven supply re-shoring elevate the value of informed, proactive strategy. PW Consulting’s full Cpvc Power Pipe Market report equips decision-makers with the models, playbooks, and competitive benchmarks required to convert market opportunity into durable advantage.
Note: this executive preview intentionally omits detailed regional and application-level splits to preserve the tactical intelligence contained in the full study. To access the full dataset, scenario tables, supplier scorecards, and transaction support appendices, visit our report page or contact PW Consulting’s research desk for licensing and enterprise access.
For detailed analysis of this topic, please visit the official page: Cpvc Power Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicone Resin Market — USD 5.52B in 2025 to USD 8.42B by 2032 at 6.22% CAGR
By PW Consulting, 2026-07-13
Silicone Resin Market 2026: Strategic Preview for Corporate Decision-Makers
Introduction — Why 2026 is a Strategic Inflection Point
The global silicone resin market is transitioning from recovery to strategic expansion. After a steady rise from approximately USD 4.09 billion in 2020 to USD 5.52 billion in 2025, the sector is projected to continue its growth arc through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of 6.22%, reaching roughly USD 8.42 billion by 2032. For executives planning capital allocation, product roadmaps, or M&A strategies in 2026, this report delivers the kind of forward-looking, operationally oriented intelligence that converts market visibility into actionable choices.
Silicone Resin Market
Market Snapshot: Performance and Structure
-
Historic momentum (2020–2025): Demand recovered across coatings, electronics, and specialty industrial applications, lifting global revenue by more than 35% over five years.
Silicone Resin Market -
Near-term trajectory (2026–2032): At a 6.22% CAGR, the market profile favors premiumization—higher-margin, technically differentiated resin grades—and selective geographic expansion tied to electronics and clean‑energy value chains.
Silicone Resin Market -
Competitive concentration: The market exhibits moderate concentration, with the top three firms accounting for a meaningful share of revenue and the top five representing a clear leadership tier. This dynamic creates differentiated pathways for scale players and niche specialists alike.
Drivers and Dynamics Shaping 2026 Decisions
Several structural forces will dominate corporate strategy in 2026. Understanding their interplay is essential for risk-managed growth.
-
End-market pull for performance: Demand for heat-stable, weather-resistant, and electronic-grade silicone resins continues to expand, driven by higher operating temperatures in electrified powertrains, miniaturized consumer electronics, and more stringent exterior durability expectations in coatings.
-
Raw-material and input-cost volatility: Metallic silicon price volatility has meaningfully impacted cost-of-goods-sold dynamics. Recent upward movement in feedstock pricing underscores the need for procurement hedging, differentiated supplier terms, and margin-protection strategies.
-
Regulatory and compliance overlays: Regional chemical regulations have already altered formulation choices and supply chains. Compliance-driven reformulation and certification are now part of routine product development budgets.
-
Logistics, classification and trade barriers: Shipping code amendments and tariff regimes are materially affecting landed costs and lead times. Companies must embed regulatory monitoring into commercial planning to avoid margin erosion and service disruptions.
-
Sustainability and certification filters: Sustainability screening—whether linked to green building standards or procurement ESG policies—is reshaping buyer preferences. Scrutiny on fluorinated chemistries and persistent substances is creating both product-level risks and market opportunities for compliant alternatives.
Regulatory & Operational Noise to Watch
-
Regulatory restrictions on specific cyclic siloxanes are already influencing formulations in regulated markets, prompting reformulation and new product launches designed to meet tightened thresholds.
-
Transport classification updates and enhanced labeling requirements are increasing downstream compliance costs and shaping route-to-market decisions for suppliers and consumers alike.
-
Trade measures, including tariff regimes, continue to incentivize regional sourcing and local footprint strategies for players targeting growth in tariff-impacted markets.
Segmentation Lens — Where the Value Is (and What We Withhold)
The report organizes demand by region, resin chemistry, and end-application to expose where margin pools and structural growth pockets exist. We deliberately avoid listing granular share or dollar splits in this preview; instead, the full analysis provides a downloadable model with line-item breakdowns by geography, type, and application. For executives, the critical takeaway is this: commercial and R&D priorities should be informed by both aggregate market growth and micro-segmentation dynamics that affect price realization and technical differentiation.
Supply-Side Landscape and Strategic Implications
Market leadership is held by a mix of global chemical majors and specialized silicone producers. The sector’s structure presents distinct strategic playbooks:
-
Scale leaders leverage integrated value chains and regulatory compliance capabilities to offer broad portfolios and secure large-volume contracts.
-
Specialists and regional players compete on application engineering, custom-formulation services, and speed-to-spec.
Notable corporate maneuvers over the last 18 months illustrate divergent yet complementary strategies: selective capacity expansion to serve coatings demand, targeted product launches for high-heat electronics segments, and certification updates to unlock regulated markets. These moves signal where incumbents expect the highest returns and where new entrants may face the toughest competition.
Competitive Mapping — Core Players and Strategic Postures
-
Dow (Midland, Michigan) — A global industrial champion with a SILRES portfolio oriented to protective coatings, electrical insulation, and molded parts. Recent certification work enhances access to regulated markets.
-
Wacker Chemie AG (Munich) — A technology-driven supplier focusing on high-temperature coatings, release agents, and electronics encapsulation; capacity expansions underscore confidence in coatings demand.
-
Shin-Etsu Chemical (Tokyo) — The world’s largest silicone producer; product breadth includes toner and paint resins and recently launched heat-resistant grades for automotive electronics.
-
Momentive Performance Materials (Waterford, New York) — Specialist in high-performance resins for industrial and automotive applications, emphasizing technical services and tailored solutions.
-
Elkem ASA (Oslo) — Offers resins used in electrical varnishes and high-performance coatings; represents a balanced play between industrial chemistry and application know-how.
-
KCC Corporation (Siheung, South Korea) — Regional champion with strong position in coatings, inks, and electronics protection; competes on application engineering and regional service.
Market concentration metrics indicate a meaningful advantage for the upper tier, but also leave room for agile specialists and regional champions to capture niche premium segments.
What This Means for 2026 Strategy — Actionable Recommendations
Companies facing 2026 choices should orient plans across five practical dimensions:
-
Portfolio & R&D: Prioritize heat-resistant and electronics-grade formulations that align with electrification and miniaturization trends. Invest in low‑risk reformulations to pre-empt regulatory headwinds.
-
Supply chain & procurement: Implement multi-source strategies for key feedstocks, negotiate performance-linked contracts, and explore regional production or tolling options to mitigate tariff and transport risk.
-
Commercial & pricing: Differentiate on total cost of ownership—service levels, regulatory support, and certification—rather than on price alone. Use modular pricing tied to specification tiers for premium grades.
-
CapEx & footprint decisions: Align capacity investments with validated long-cycle contracts and customer commitments; where demand uncertainty persists, consider flexible capacity options such as co‑manufacturing or asset-light partnerships.
-
M&A & partnerships: Target bolt-on acquisitions that add formulation capabilities, regional market share, or certification assets. Joint development agreements with OEMs can accelerate adoption in regulated end-markets.
Risk Matrix and Scenario Planning
Executives should prepare for three actionable scenarios:
-
Base case: Gradual premiumization and steady demand growth (reflective of the central 6.22% CAGR) with manageable cost headwinds.
-
Upside: Rapid adoption of high-margin specialty resins in electronics and industrial coatings, driven by accelerated electrification and stricter durability specs.
-
Downside: Supply-chain shocks or tighter chemical restrictions that force unplanned reformulation and elevate compliance costs—requiring contingency sourcing and faster regulatory engagement.
What PW Consulting’s Full Report Delivers
This market brief is a strategic teaser. The full PW Consulting Silicone Resin Market study contains the operational detail that decision-makers need to convert insight into execution, including:
-
Granular, downloadable market models (region-by-region, chemistry-by-chemistry, application-by-application) and scenario variants.
-
Supplier scorecards with capability assessments, capacity maps, and strategic posture analysis for the leading firms and emerging challengers.
-
Cost and margin sensitivity tools tied to feedstock pricing and transport amendments, enabling margin-preservation simulations.
-
Regulatory compliance playbooks addressing region-specific restrictions and certification pathways.
-
Commercial playbooks for pricing, co-development, and channel strategy tailored to resin grade and end-market dynamics.
-
M&A and partnership screening frameworks to identify high-value targets and integration pathways.
How to Use This Intelligence in 90 Days
-
Week 1–4: Validate procurement exposures and run feedstock sensitivity scenarios using the model provided in the report.
-
Week 5–8: Align R&D and commercial teams on prioritized product tiers and initiate fast-track reformulation where regulatory risk is high.
-
Week 9–12: Engage potential manufacturing partners for tolling or regional supply, and scope targeted M&A or JV opportunities informed by our supplier scorecards.
Closing — Why PW Consulting’s Analysis Matters
Decisions made in 2026 will determine who captures the premium growth in silicone resins through the next decade. This preview highlights the structural growth, regulatory complexity, and competitive dynamics that executives must factor into capital, product, and commercial plans. PW Consulting’s full study couples these strategic insights with transaction-ready models and operational playbooks—tools designed to move leadership from intent to impact without losing optionality in a market defined by both technical nuance and regulatory change.
For the complete dataset, segmented forecasts, and executable recommendations, access the full report and interactive models on our publication page.
For detailed analysis of this topic, please visit the official page: Silicone Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solid Fuel Testing Market at USD 482.5M in 2025, 4.59% CAGR
By PW Consulting, 2026-07-13
Solid Fuel Testing Market: Strategic Preview for 2026 Decision-Makers
Executive summary
The solid fuel testing market is maturing into a critical diagnostic layer for energy, waste-management and bioenergy value chains. Our PW Consulting study—anchored on 2025 as the base year and projecting through 2032—shows a steady expansion driven by stricter environmental regimes, fuel diversification, and an accelerating need for verified quality in traded and industrial fuels. Between 2020 and 2025 the market expanded consistently; our forecast through 2032 implies a mid-single-digit compound annual growth rate (CAGR) of 4.59% across the 2026–2032 period, and an expected market scale increase from the 2025 baseline into the later forecast years. For executives planning budgets, capex, or M&A in 2026, these dynamics translate into both opportunity and risk: demand for testing services will widen, but value will increasingly concentrate around providers that offer integrated laboratory capability, sampling reliability, and regulatory assurance.
Solid Fuel Testing Market
Why this study matters for 2026 strategy
- Investment prioritization: Project pipelines for lab upgrades, mobile-sampling fleets, and digital QA/QC platforms must be evaluated against an industry that is growing predictably but becoming more competitive. A measured, phased investment approach is recommended to avoid over-capitalization in narrow service lines.
- Procurement and contracting: Buyers of testing services should renegotiate contracts to include outcome-based KPIs (e.g., sampling representativeness, turnaround SLAs, chain-of-custody transparency) rather than purely price-driven scopes.
- Regulatory readiness: Regulatory revisions—particularly in emissions and renewable fuel mandates—create both compliance obligations and testing revenue streams. Firms that build regulatory-forward testing capabilities will capture disproportionate share of new mandates.
- M&A and partnership lenses: Given the market’s moderate concentration (the top three players account for a material share, and the top five approach half of the market), targeted acquisitions of regional niche labs or technology-enabled sampling specialists remain high-impact plays.
Market trajectory: a data-informed view
Our synthesis of historical performance and forward-looking scenarios shows a resilient market that benefits from structural drivers—fuel portfolio diversification, circular-economy feedstock conversion, and tighter emissions regimes. The market base year (2025) provides the operational starting point for 2026 planning: the sector is no longer nascent, but neither is it fully consolidated. Growth is steady and quantifiable; the 4.59% CAGR across the forecast window signals that compounding demand will create meaningful cumulative volume by the late 2020s. For corporate planning, this means predictable topline expansion for those who secure long-term service contracts and invest in accreditation and turnaround efficiency.
Solid Fuel Testing Market
Regulatory and policy dynamics shaping 2026 decisions
- Renewable fuels mandates: U.S. Renewable Fuel Standard updates (applicable volumes and percentage standards established for 2026–2027) are reshaping feedstock economics and increasing demand for certified testing of cellulosic, biomass-based and advanced biofuels.
- Emissions rule adjustments: Recent U.S. EPA actions affecting mercury emission standards and implementation timelines for certain coal units create near-term uncertainty for some coal-fired operators while creating demand for confirmatory and compliance testing.
- Standards and accreditation: ISO/ASTM alignment and the proliferation of ISO 17025-accredited facilities remain decisive competitive differentiators. Clients will increasingly select partners that can meet cross-border export and compliance requirements.
Competitive landscape: who matters and why
The competitive field mixes global testing giants, regional specialists, and independent technical labs. Market concentration is meaningful: the combined share of the top three and top five providers signals a marketplace where scale and accreditation matter, but where niche capability can still command premium positioning.
Solid Fuel Testing Market
- Intertek Group plc (London): A full-suite testing and inspection provider with strength in international standards compliance for coal, coke and biomass. Intertek’s integrated commercial-quality and regulatory testing model positions it well to serve multinational traders and utilities needing single-source assurance.
- SGS S.A. (Geneva): Global reach and laboratory depth—recent expansions into solid-waste fuel testing and broader lab footprints—give SGS advantages in cross-commodity workflows and in projects converting waste feedstocks into compliant fuels.
- Bureau Veritas (Paris): Offers specialist testing including petrography and coke-reactivity analyses. Recent capability development in key European laboratories underscores a focus on sustainable fuel analysis and advanced test methods.
- ALS Limited (Brisbane): Regional strength in sampling and analysis makes ALS a preferred partner for operators in Australasia with exposure to coal logistics and port-based quality control.
- AmSpec (U.S.), Control Union (Netherlands), McCreath Laboratories (U.S.), Standard Laboratories (U.S.): These players reflect the market’s heterogeneous demand: biomass-focused certification, accredited biomass labs in export corridors, port-focused onsite services, and dedicated biomass testing specialists. Their value lies in technical specialization, lab accreditations, and fast turnaround in target corridors.
Recent company developments reveal strategic moves worth noting: Bureau Veritas’ laboratory capability advances (late 2025) and Control Union’s ISO 17025-accredited biomass laboratory in Vietnam signal supply-side investments aimed at export-oriented biomass flows. SGS’s earlier expansion into solid-waste fuel testing underscores a pivot to circular-economy feedstocks. For 2026 planning, competitors’ lab-capability expansion and geographic coverage should be mapped against your customer contracts and trade exposures.
Operational and commercial implications for buyers and providers
- For buyers: Institutionalize a multi-factor testing procurement scorecard that weights accreditation, sampling systems, digital reporting, and dispute-resolution mechanisms. Prepare for spot-volume volatility by incorporating scalable lab-sourcing clauses and partnering with providers that offer mobile or near-port capabilities.
- For providers: Differentiate through accreditation bundling (e.g., ISO 17025 + industry-specific endorsements), investment in rapid analytical techniques, and digital client portals that reduce reporting friction and enable subscription-style revenue.
- For investors and M&A teams: Prioritize targets that bring either accreditations in jurisdictions tied to export corridors, proprietary sampling technology, or specialized testing methods (e.g., trace element profiling, petrography) that raise client switching costs.
What PW Consulting’s report delivers to operational teams
Our full study is intentionally practical. It contains:
- Clear methodological notes on sample representativeness, chain-of-custody, and standardized test selection.
- Operational playbooks for laboratory investment, including capex benchmarking, ROI timelines, and staffing models tailored to different throughput scenarios.
- Procurement templates and SLA language for long-term testing contracts, with penalties and escalation processes mapped to typical dispute triggers.
- Regulatory-impact matrices that translate policy scenarios (e.g., renewable fuel volume changes, emissions rule shifts) into testing demand curves and required capabilities.
- Competitive intelligence dossiers on leading providers, capability-gap analyses, and suggested partnership or acquisition targets by strategic objective.
- Risk registers and mitigation approaches for sampling fraud, non-compliance, and supply-chain contamination events.
Strategic actions to prioritize in 2026
- Lock in accreditation and cross-border acceptability for laboratories that handle export volumes—this reduces friction as renewable fuel mandates evolve.
- Invest selectively in rapid, trace-element and calorific measurement technologies that reduce turnaround and increase commercial value to customers.
- Negotiate flexible, outcome-focused contracts with testing providers to manage price and capacity exposure without sacrificing quality.
- Monitor regulatory developments closely; create internal triggers that shift procurement, CapEx, or M&A posture as policy makes demand structural rather than temporary.
Conclusion — the strategic payoff
For leaders making decisions in 2026, the solid fuel testing market represents a low-volatility, mid-growth opportunity where technical credibility and custody integrity are the core currencies. PW Consulting’s analysis provides the operational toolset—financial scenarios, procurement playbooks, and capability roadmaps—needed to convert macro trends into defensible commercial outcomes. We intentionally preserve detailed segment-level allocations in the preview: the full, proprietary segmentation, regional demand profiles and the granular revenue sheets are available in the complete report and are essential for transaction-level or procurement-level execution.
Accessing the full PW Consulting Solid Fuel Testing Market report will equip your team with the numbers, models, and templates required to execute confidently in 2026—whether your focus is service procurement, laboratory investment, or strategic M&A.
For detailed analysis of this topic, please visit the official page: Solid Fuel Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrolyzed Formula Market to Hit USD 6,980M in 2025 with 8.8% CAGR
By PW Consulting, 2026-07-13
Hydrolyzed Formula Milk Powder Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted, action-oriented briefing on the hydrolyzed formula milk powder market that frames the commercial and regulatory landscape executives must navigate in 2026. This piece is a “trailer” — designed to demonstrate the methodological depth and strategic line-of-sight our full market study provides, while intentionally withholding the granular segment tables and proprietary model outputs that are included only in the full report.
Hydrolyzed Formula Milk Powder Market
Market snapshot: growth trajectory and structural context
The hydrolyzed formula market has moved from a sizable niche to a mainstream, strategically important segment within early-life nutrition. Our base-year analysis shows the market expanding from approximately USD 4.75 billion in 2020 to about USD 6.98 billion in 2025. Under our central forecast, the market is expected to grow at a robust compound annual growth rate (CAGR) of 8.8% through the forecast window, reaching an estimated USD 12.6 billion by 2032. This trajectory underscores two simultaneous forces: a persistent clinical and consumer demand for hypoallergenic and tolerance-improving formulas, and continued commercialization and geographic expansion by major CPG and ingredient players.
Hydrolyzed Formula Milk Powder Market
The market is structurally concentrated: the top three manufacturers account for the majority share, and the top five capture an even larger proportion — creating a high-barrier environment for standalone entrants but a favorable one for suppliers, private-label manufacturers, and value-accretive consolidation playbooks.
Hydrolyzed Formula Milk Powder Market
Why the 2026 decision calendar is pivotal
- Regulatory inflection points demand strategic re-alignment. Changes in regulatory classification, nutrient requirements, and permitted ingredient lists alter R&D priorities, label claims, and timelines to market. 2026 is the first full year in which several critical regulatory updates take effect, making immediate compliance planning essential.
- Ingredient sourcing and cost volatility are now core strategy levers. Established dairy-derived hydrolysates continue to dominate ingredient supply chains; securing long-term access to high-quality whey and milk hydrolysates is a competitive advantage and a risk mitigation necessity.
- Channel and premiumization strategies diverge. Growth is being captured simultaneously in clinical-use products and in premium/organic positioning; players must decide whether to chase clinical differentiation, premium consumer segments, or a dual-track approach supported by channel segmentation.
- Consolidation and private label create margin compression pressures. Retailers and contract manufacturers are leveraging cost leadership and store-brand strategies in multiple markets — prompting incumbents to sharpen portfolio economics and clinical evidence strategies to protect ASPs.
Regulatory and ingredient dynamics to factor into 2026 plans
- Regulatory updates. The European Commission’s late-2025 amendment to protein requirements for formulas based on hydrolysates redefines composition categories and permitted protein sources effective January 2026. Concurrently, U.S. regulatory practice continues to constrain permissible labeling and product claims (including controlled descriptions related to atopic dermatitis and hypoallergenicity) and enforces comprehensive nutrient and safety requirements for any formula sold domestically. These shifts increase the value of a living regulatory compliance map tied to product roadmaps.
- Ingredient concentration. Milk-based hydrolysates — particularly whey protein hydrolysates — maintain dominant share in ingredient consumption due to established dairy supply chains and their suitability for infant nutrition formulations. For 2026 planning, this means procurement strategy (long-term contracts, dual-sourcing, and supplier partnerships) and ingredient-traceability investments should be prioritized.
- Clinical evidence and label permissions. The regulatory environment rewards robust clinical evidence linked to specific formulations. Companies that can combine credible clinical research with permissible, nuanced label claims will enjoy sustained commercialization advantages.
Competitive landscape: what the leaders are doing (and what that implies)
The competitive field is composed of diversified nutrition majors, regional specialists, ingredient suppliers, and private-label manufacturers. The market’s concentration around a small set of global leaders creates distinct strategic dynamics: scale benefits for clinical R&D and manufacturing, and specialization opportunities for ingredient and regional players.
- Nestlé (Vevey, Switzerland). Nestlé’s extensively hydrolyzed offerings combine deep clinical positioning with global distribution muscle. Their strategy emphasizes proven hypoallergenic formulations and broad market availability. For challengers, this raises the bar on evidence generation and on claims discipline; for suppliers, Nestlé represents a high-volume, quality-focused customer.
- Danone / Nutricia (Paris, France). With extensive hydrolyzed brands and an expanding U.S. footprint, Danone focuses on clinical differentiation and global rollouts supported by channel muscle in both pharmacy and hospital segments. Competitors should expect aggressive geographic expansion from Danone in clinical channels.
- Mead Johnson / Reckitt (Evansville, USA). Their Nutramigen line underscores an emphasis on clinically oriented positioning and tailored formulas for complex indications. Reckitt’s route-to-market strength in HCP channels and training programs is an execution model to watch.
- Abbott Nutrition (Abbott Park, USA). Abbott capitalizes on strong brand recognition and a balanced portfolio that spans mainstream hypoallergenic products to specialized clinical powders. Their U.S. market presence and regulatory familiarity create high entry costs for new entrants seeking hospital or HCP endorsements.
- Perrigo (Dublin, Ireland). As a leading manufacturer of private-label and store-brand hydrolyzed formulas, Perrigo represents the principal margin-compression threat. Retailers and contract manufacturers leveraging scale will continue to pressure branded players’ value propositions.
- Meiji Group (Tokyo, Japan). Meiji’s regional focus and deep insights into Asian infant nutrition preferences translate into product variants optimized for local tolerance and flavor expectations — an important playbook for regional champions.
- HiPP (Germany), Arla Foods Ingredients (Denmark), FrieslandCampina (Netherlands). HiPP leads with organic and hypoallergenic positioning; Arla and FrieslandCampina are critical upstream partners supplying specialized hydrolysates. Ingredient suppliers wield outsized influence over formulation innovation, margin models, and supply continuity.
Collectively, these firms demonstrate three competing strategic archetypes: (1) clinical and evidence-led global incumbents, (2) regional/resolution players optimizing local taste and regulatory fit, and (3) cost/scale private-label operators compressing price-sensitive segments. Your 2026 roadmap should explicitly choose which archetype — or combination — you will align with.
What PW Consulting’s full report delivers (practical components)
Our comprehensive study is structured to convert insight into action. Highlights include:
- Granular market sizing and forecast models (2020–2032) with scenario sensitivity for regulatory and raw-material shocks.
- Competitive intelligence dossiers for each major player, including product portfolios, channel strategies, manufacturing footprints, and recent go-to-market moves.
- A regulatory compliance matrix mapping jurisdictional differences, claim-permissibility, and transitional timelines through 2026–2028.
- Ingredient supply-chain maps and risk scores, including supplier concentration, traceability, and cost pass-through modeling.
- Commercial playbooks: SKU rationalization templates, price-elasticity testing procedures, private-label defense strategies, and e-commerce acceleration plans.
- M&A and partnership screening tools that identify bolt-on capabilities (ingredient tech, clinical assets, regional manufacturing) and provide high-level valuation gates.
- Operational roadmaps for scaling production safely and compliantly, including recommended quality-management KPIs and traceability investments.
Note: While this preview outlines the study’s analytical architecture, the proprietary segment-level tables, region-by-channel revenue matrices, and downloadable financial models are withheld here to preserve actionable exclusivity available in the complete deliverable.
Prioritized actions for executives in 2026 (90–180 day plan)
- Regulatory readiness sprint. Establish a cross-functional regulatory task force to map new EU protein-category rules and U.S. label constraints against your product portfolio. Fast-track reformulations where necessary to avoid distribution interruptions.
- Secure ingredient continuity. Negotiate multi-year supply agreements with tier-1 hydrolysate suppliers and identify qualified secondary sources. Build ingredient buffers and ingredient-substitution decision rules into your ERP.
- Rationalize SKUs by channel. Rapidly assess SKU economics across hospitals/HCP, pharmacy, e-commerce, and retail to eliminate low-margin variants and redeploy CAPEX to high-return SKUs.
- Invest selectively in clinical evidence. Prioritize clinical studies that unlock permissible claims or HCP endorsements in target geographies — a relatively modest investment that can materially defend price realization.
- Prepare for private-label pressure. Develop a differentiation playbook (e.g., traceability storytelling, ingredient provenance, clinical endorsements) and consider strategic OEM partnerships to capture private-label volumes without brand dilution.
- Audit manufacturing compliance and scale capacity. Ensure all facilities meet the tightened documentation and nutrient-specification regimes and model incremental capacity needs through 2027.
Final perspective
The hydrolyzed formula milk powder market presents an attractive growth runway driven by medical demand, formulation innovation, and geographic expansion — but it is being re-shaped by regulatory updates and supply-chain dynamics that will determine winners and laggards in 2026 and beyond. The combination of high concentration among incumbents and the growing importance of upstream ingredient control means that strategic moves today (regulatory-planning, ingredient contracting, SKU and channel choices, and focused clinical investment) will disproportionately determine commercial outcomes over the next three to five years.
PW Consulting’s full report delivers the granular segment analytics, scenario models, and execution templates you need to convert this outlook into a defensible 2026 strategy. To access the complete dataset, models, and tailored strategic recommendations, please visit our report page or contact your PW Consulting representative for the full deliverable and a confidential walk-through of the findings.
For detailed analysis of this topic, please visit the official page: Hydrolyzed Formula Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


