



PW Consulting: Fungal Infection Diagnosis Market to hit USD 6.07 Million by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-12
Fungal Infection Diagnosis Market — Strategic Outlook for 2026 Decisions
The landscape for fungal infection diagnostics is entering a phase of deliberate commercialization and clinical consolidation. Our PW Consulting Fungal Infection Diagnosis Market study (base year 2025) shows a market that has expanded steadily from the 2020 base period, reaching an estimated USD 3.65 Million in 2025 and forecast to grow at a compound annual growth rate (CAGR) of 7.5% through 2032 — when the model projects a market size north of USD 6 Million. For executive teams planning investments or repositioning portfolios in 2026, this research provides the actionable intelligence needed to translate regulatory shifts, reimbursement dynamics, and platform innovation into measurable commercial outcomes.
Fungal Infection Diagnosis Market
Why 2026 Is a Pivotal Inflection Point
-
Regulatory momentum. Recent clearances and authorizations have reshaped the go-to-market calculus for fungal diagnostics: a De Novo authorization for a PCR assay addressing Candida auris and label expansions for direct-from-blood molecular panels meaningfully broaden clinical use cases and infection‑control workflows.
Fungal Infection Diagnosis Market -
Clinical demand is maturing. Rising numbers of immunocompromised patients, expanded invasive-procedure volumes in tertiary centers, and heightened hospital infection‑prevention focus are increasing demand for rapid, reliable fungal testing across acute-care and laboratory settings.
Fungal Infection Diagnosis Market -
Platform convergence and stewardship. Molecular panels, antigen assays, and rapid β‑D‑glucan screening are converging in clinical pathways. Hospitals are increasingly demanding rapid diagnostic results that integrate with antimicrobial stewardship programs to reduce empiric antifungal use and length of stay.
-
Commercial opportunity windows. With a projected 7.5% CAGR across 2026–2032, the market is neither nascent nor saturated — it rewards targeted clinical evidence generation, regulatory strategy, and nimble commercialization.
What the PW Consulting Report Delivers
This study is built to support operational decision-making in 2026. Key deliverables include:
-
Market model (USD Million): historical series (2020–2025), a 2025 base, and scenario-based forecasts for 2026–2032 with sensitivity to adoption, pricing, and regulatory outcomes.
-
Market dynamics and demand drivers: clinical adoption curves, hospital procurement behaviors, and integration into stewardship and infection-control pathways.
-
Regulatory & reimbursement tracker: timelines for recent clearances and practical guidance for navigating De Novo/510(k) strategies and CPT coding impacts.
-
Competitive intelligence and supplier matrix: profiles of incumbent and emerging providers, product positioning, strengths/weaknesses, and likely strategic moves.
-
Commercial playbooks: launch sequencing, pricing strategy, clinical evidence roadmaps (including pediatric considerations), and channel tactics for hospitals, reference labs, and point‑of‑care settings.
-
M&A and partnership screen: prioritized targets and fit criteria for inorganic growth, licensing, and co-development to accelerate time-to-market.
-
Primary-source annexes and editable data tables: underlying assumptions, unit economics, and addressable‑market spreadsheets to feed internal financial models.
Note: this introductory brief intentionally omits granular region, type, and application split figures; full segmentation tables and downloadable datasets are included exclusively in the complete report.
Competitive Landscape — Who Matters and Why
The fungal diagnostics market shows a concentrated competitive structure (top-three firms control a majority share; top-five approach three-quarters of market value), which creates both barriers and corridors of opportunity. Incumbent companies have entrenched positions via cleared assays, platform footprints in hospital labs, or strong partnerships with reference labs. Key strategic profiles include:
-
Associates of Cape Cod, Inc. — Known for the Fungitell® family (including a STAT single-sample format), the company offers a rapid screening assay for (1→3)-β-D‑glucan that remains the clinical standard for many invasive fungal infection workups. Their single-sample, rapid formats create clear use cases for emergency and inpatient triage workflows.
-
T2 Biosystems, Inc. — The T2Candida Panel is distinct as a direct‑from‑blood molecular diagnostic with demonstrated clinical impact on time‑to‑result and antifungal stewardship. Its pediatric label expansion in 2024 materially increases addressable hospital networks and demonstrates the strategic value of pursuing pediatric indication pathways.
-
DiaSorin Molecular LLC — The De Novo authorization for a direct PCR test targeting Candida auris underscores the regulatory pathway advantage of early, novel assay submissions addressing urgent infection‑control needs. Their product is strategically positioned for hospital surveillance and colonization-control programs.
-
Bio‑Rad Laboratories — With an FDA‑cleared antigen assay for Aspergillus galactomannan, Bio‑Rad represents incumbent strength in antigen-based diagnostics for invasive aspergillosis — a product class that complements molecular panels in comprehensive diagnostic pathways.
-
Bruker Daltonik GmbH — The MALDI Biotyper CA System and its clinically validated libraries enable rapid species identification from cultured isolates and provide interoperability with clinical microbiology workflows. Their platform’s role in species ID is a defensive asset against rapid molecular assays seeking to displace culture-dependent steps.
-
GenMark Diagnostics, Inc. and BD — Both provide multiplex PCR panels and integrated platforms used in blood-culture identification, which drives adoption through workflow efficiency and established lab footprints.
Recent regulatory and product events — De Novo authorization for a C. auris PCR (July 2024), pediatric clearance for a direct-from-blood molecular panel (September 2024), and single‑sample β‑D‑glucan test authorization (July 2024) — materially affect go-to-market tactics and competitive defenses. These moves expand clinical addressable markets and reduce friction for infection-control adoption in hospitals and children’s facilities alike.
Strategic Implications for 2026 Decision‑Makers
-
Prioritize label-expansion and pediatric strategies. The market reward for pediatric clearances is immediate access to large hospital networks and can speed payor acceptance in pediatric-centric institutions.
-
Invest in evidence for stewardship outcomes. Payers and hospitals increasingly require demonstration of downstream value (reduced antifungal days, shorter LOS). Comparative-effectiveness data — not only analytical performance — drives procurement decisions.
-
Design modular commercial models. Given the mix of hospital laboratories, reference labs, and infection-control programs, flexible pricing (subscription, reagent‑only, and instrument lease) increases uptake among differing buyer personas.
-
Leverage regulatory pathway knowledge as market access advantage. De Novo and pediatric clearances achieved by peers create playbooks that new entrants can emulate to accelerate adoption, but they also raise the bar for clinical validation.
-
Plan for platform interoperability. Labs prefer assays that integrate with LIMS and stewardship dashboards. Investments in connectivity and interpretive reporting improve product stickiness.
-
Use competitive concentration to inform M&A: with a concentrated top end of market, well‑targeted M&A or licensing deals can be the fastest route to meaningful scale — but price discipline is essential given incumbent valuation premiums.
Risk Matrix & Scenario Planning
-
Regulatory risk: stricter post-market requirements or novel CLSI standards could extend timelines for new assays. Mitigation: staged clinical studies and early regulatory consultations.
-
Reimbursement uncertainty: coding and reimbursement policy shifts can impact unit economics. Mitigation: proactive engagement with payors, capture of real-world outcomes that demonstrate cost offsets.
-
Competitive displacement: platform players with broader panels may commoditize single-analyte tests. Mitigation: focus on unique clinical value (speed, sensitivity, infection-control utility).
-
Epidemiologic volatility: pathogen prevalence shifts (e.g., local C. auris outbreaks) influence short-term demand. Mitigation: maintain flexible manufacturing and regional surveillance intelligence.
Immediate Next Steps for 2026
-
Run a rapid gap analysis against the report’s playbooks: identify which clinical claims and evidence packages are required to unlock the largest near-term hospital contracts.
-
Define a prioritized regulatory roadmap: choose between De Novo, 510(k) with predicate strategies, or expanded labeling for pediatric use based on product maturity and clinical data availability.
-
Establish partnerships with reference labs and infection-control networks to pilot deployment and capture real-world outcomes quickly.
-
Evaluate M&A targets using the report’s fit criteria to accelerate scale in underserved clinical settings or to acquire complementary platform capabilities.
For executives preparing budgets and product plans in 2026, the PW Consulting study transforms market projections into an executable plan — from clinical evidence investments to commercialization tactics and M&A priorities. To preserve competitive advantage and foster confident investment decisions, the full report includes the complete regional and application split tables, granular segment modeling, and the underlying financial workbooks required to run bespoke scenario analyses. Access the complete dataset and company dossiers through the PW Consulting report portal to obtain the detailed segmentation and downloadable models that are intentionally omitted from this public summary.
For detailed analysis of this topic, please visit the official page: Fungal Infection Diagnosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Aluminium Extrusions Market to Reach USD 368.3M by 2032 at 8% CAGR
By PW Consulting, 2026-07-12
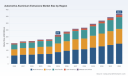
Automotive Aluminium Extrusions Market — Strategic Preview for 2026 Decision-Making
As automotive manufacturers and suppliers reset product roadmaps and capital plans for a post‑pandemic, electrified future, aluminium extrusions occupy a decisive position in the race to deliver lighter, safer and more energy‑efficient vehicles. PW Consulting’s forthcoming Automotive Aluminium Extrusions Market research — base year 2025, forecasting through 2032 — synthesizes the macro trajectory and the competitive dynamics firms must internalize to make confident 2026 investments.
Automotive Aluminium Extrusions Market
Why this research matters for 2026
-
Timing: With the study’s base year anchored in 2025 and a forecast window beginning in 2026, the analysis maps directly onto the investment horizon of many OEM and Tier‑1 capital projects, procurement contracts, and localization initiatives.
Automotive Aluminium Extrusions Market -
Market momentum: The global market shows a clear recovery and structural expansion — growing from approximately USD 153 million in 2020 to USD 215 million in 2025, and forecast to reach about USD 368 million by 2032 at a compound annual growth rate of 8.0%. This growth profile creates a runway for capacity investments, alloy development, and downstream integration.
Automotive Aluminium Extrusions Market -
Decision relevance: The report translates market growth into actionable choices — where to site capacity, which alloy platforms to prioritize, how to balance recycled content with mechanical performance, and how to reshape sourcing strategies in the face of supply concentration.
What’s changing in the market — dynamics that will shape 2026 plans
-
Electrification is accelerating aluminium demand: OEMs increasingly specify aluminium extrusions for EV structural frames and battery enclosures to achieve the twin goals of lightweighting and crash performance. This is not a marginal trend — industry research indicates aluminium content per vehicle is accelerating and will materially exceed early‑2020 levels as automakers reengineer platforms around battery packs.
-
Higher extrusion content per vehicle: Engineering trends and supplier designs have pushed extrusion content upward — historical estimates show a rise from roughly 35 pounds per vehicle in 2020 toward nearly 45 pounds by 2025, with modern vehicle architectures often containing around 50 pounds of extrusions in front‑end and roof structures. These per‑vehicle gains multiply quickly across global vehicle build plans.
-
Supply‑side consolidation and concentration: The market exhibits notable concentration at the top. The three largest suppliers control a substantial share of the market, and the top five command an even higher cumulative share. For procurement and risk managers, that concentration translates into both negotiating leverage and potential single‑point vulnerabilities.
-
Decarbonization and circularity: Low‑carbon and recycled aluminium is a competitive imperative. Leading suppliers are investing in closed‑loop recycling, low‑emission smelting, and alloy development targeted at retaining mechanical performance while lowering embodied carbon per kilogram.
-
Design complexity and integration: As multi‑material vehicles proliferate, extrusions are no longer standalone parts; they are engineered into hybrid assemblies, cast‑to‑extrusion joins, and adhesive‑integrated structural modules. Suppliers that can offer engineering services and validated assembly solutions win share more rapidly.
What the report contains — practical, transaction‑ready intelligence
-
Market sizing and scenario forecasts (2026–2032): Base‑year grounding plus three demand scenarios calibrated to EV penetration, aluminium price pathways, and vehicle production forecasts.
-
Value‑chain mapping and cost stacks: From billet sourcing to extrusion, heat treatment, finishing and machining — with pragmatic levers to reduce unit costs and carbon intensity.
-
Technology and alloy roadmaps: Comparative analysis of the 6xxx and 7xxx alloy families, high‑strength tempering routes, and secondary operations that affect part performance in crash and fatigue.
-
Buyer playbooks: Procurement frameworks, hedging approaches for aluminium feedstock, and supplier scorecards tailored for OEMs and Tier‑1s.
-
Operational diagnostics: Plant capacity planning templates, OEE benchmarks, and recommendations for ramp sequencing when converting legacy lines to higher‑precision extrusion workflows.
-
Risk registers: Supply concentration assessment, geopolitical scenarios, and near‑term raw material disruption matrices with mitigation options.
-
Deal and partnership playbooks: M&A valuation heuristics, JV structuring principles for local content programs, and cross‑border supply‑chain strategies.
Competitive landscape — strategic profiles and implications
The market features a mix of integrated upstream producers, specialist extruders, and regional champions. PW Consulting’s competitive analysis highlights strategic posture, capability gaps, and partnership vectors for the players that matter to OEMs and Tier‑1s.
-
Constellium SE (France) — Advanced extrusion systems and tailored structural components. Strength: engineering depth and program integration for structural integrity and sustainable mobility. Strategic implication: Constellium is a go‑to for OEMs seeking co‑development of crash‑relevant profiles and aluminium‑heavy architectures.
-
Novelis Inc. (United States) — Focus on high‑strength recycled alloys. Strength: closed‑loop recycling and rolled products that complement extrusion ecosystems. Strategic implication: Novelis’s emphasis on recycled content increasingly aligns with OEM ESG mandates, making it an attractive upstream partner for low‑carbon supply chains.
-
Norsk Hydro ASA (Norway) — Low‑carbon and recycled extrusion platforms. Strength: green aluminium credentials and supply integration. Strategic implication: Buyers with strict Scope 3 targets should prioritize contracts offering low‑emission aluminium claims validated by lifecycle analysis.
-
Kaiser Aluminum Corporation (United States) — High‑strength extrusion capabilities for EV battery frames and crash‑absorbing components. Strength: niche technical capability in high‑performance alloy systems. Strategic implication: Kaiser is well positioned to serve segments where mechanical performance and dimensional precision cannot be compromised.
-
UACJ Corporation (Japan) — Precision fabrication and tightly controlled process engineering. Strength: high‑volume, high‑precision production for body structures. Strategic implication: Asian OEMs and global platforms requiring tight dimensional and surface standards will favor UACJ’s offerings.
-
Arconic Corporation (United States) — Lightweight and corrosion‑resistant extrusion solutions. Strength: broad systems integration and multi‑material design support. Strategic implication: Arconic’s service breadth makes it a strong Tier‑1 candidate for global programs requiring coordinated materials engineering.
-
Bonnell Aluminum (United States) — IATF‑16949 certified supplier with OEM presence. Strength: certification pedigree and supplier reliability for mainstream automotive production. Strategic implication: Procurement teams will consider Bonnell for high‑volume closures and body‑in‑white integration where quality systems are non‑negotiable.
-
ETEM Gestamp Aluminium Extrusions (Bulgaria) — Crash‑relevant profiles and machined parts for OEMs and Tier‑1s. Strength: European footprint and tailored crash‑management designs. Strategic implication: Localized supplies for European programs and short lead‑time needs favor ETEM’s model.
-
Press‑Metal Aluminium Holdings Berhad (Malaysia) — Regional supplier for body‑in‑white components. Strength: competitive cost base and regional integration. Strategic implication: Cost‑sensitive programs and regional content policies make Press‑Metal a logical partner in Asia and adjacent markets.
-
Gränges AB (Sweden) — Extruded profiles for transportation applications. Strength: niche expertise in transport and finishing services. Strategic implication: Gränges is attractive for customers prioritizing surface engineering and downstream finishing standards.
Strategic takeaways for executives planning in 2026
-
Prioritize alloy and process flexibility: Given the pace of EV adoption and regulatory pressure on embodied carbon, firms must be capable of switching alloy mixes and heat‑treatment routes without costly line changeovers.
-
Embed carbon transparency into sourcing: Contracts with traceable recycled content and verified emissions data will increasingly be a procurement differentiator, not just a marketing advantage.
-
De‑risk supply concentration: With the top suppliers controlling a significant share of capacity, parallel sourcing, strategic stockpiles, and regional qualification pipelines are prudent tactics.
-
Make engineering services a commercial lever: Suppliers that offer co‑design, crash simulation, and assembly validation can capture part value and accelerate OEM time‑to‑market.
-
Plan capacity with scenario discipline: Use the report’s scenario forecasts to stress‑test capex decisions against EV adoption curves, aluminium price volatility, and geopolitical supply shifts.
How this preview intentionally withholds core segmentation
This article is designed as a strategic trailer: it highlights the market’s scale, growth trajectory and the practical levers that leaders must evaluate in 2026. To preserve the commercial utility of the full analysis, we have intentionally omitted the detailed segmentation matrices and the granular regional and application‑level splits that underpin supplier targeting, plant siting, and M&A valuation models. Those detailed matrices — including regional demand distribution, application mixes, and alloy‑level revenue breakdowns — are included in the full PW Consulting report and are essential for transaction execution and program qualification.
Next steps — how executives should use this intelligence
-
Procurement chiefs: Use the market concentration signals and supplier profiles to redesign sourcing strategies and hedge feedstock exposure.
-
Product and engineering leads: Validate alloy choices and extrusion content against the report’s scenario outputs before finalizing platform redesigns.
-
Strategy and corporate development teams: Leverage the report’s M&A playbook and valuation heuristics when screening acquisition targets or forming JVs to secure local content.
-
Operations and plant managers: Apply the operational diagnostics and ramp sequencing templates to reduce time‑to‑qualified production and mitigate rework rates.
For procurement contracts, capex decisions, and platform engineering that will be locked in during 2026, decision quality demands both a clear view of the macro growth curve and access to the granular segmentation that determines unit economics. PW Consulting’s full Automotive Aluminium Extrusions Market report provides that end‑to‑end intelligence — including the regional, application and alloy‑level breakdowns required to finalize supplier selections, capacity allocations and acquisition targets. Contact PW Consulting to access the complete dataset, detailed scenario models, and the supplier due‑diligence annex that underpins our recommendations.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Extrusions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Footwear Market to Reach USD 455.8 Million by 2032 at 6.4% CAGR
By PW Consulting, 2026-07-12
Military Footwear Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As defense planners recalibrate sourcing policies and OEMs reposition manufacturing footprints, the global military footwear market is entering a phase of steady, policy-driven growth. Our PW Consulting baseline places 2025 as the report's base year (historical window 2020–2025) and models the market through 2032. The market is expected to expand at a compound annual growth rate (CAGR) of 6.4% across the 2026–2032 forecast period, rising from roughly USD 296 million in 2025 to a forecast in the mid‑400s (USD million) by 2032. Market concentration remains low-to-moderate (CR3 ≈ 24.6%, CR5 ≈ 36.5%), underlining a fragmented supplier landscape with meaningful opportunities for scale-driven consolidation and niche specialization.
Military Footwear Market
Why this study matters for 2026 corporate strategy
Two forces converged in late 2024–2026 to reshape the operating logic of military footwear suppliers: regulation-driven reshoring and an intensifying procurement discipline from defense logistics authorities. The inclusion of the BOOTS Act as an amendment in the FY2026 National Defense Authorization Act, the U.S. Army Footwear Certification Program’s stricter certification and inspection cadence, and active Defense Logistics Agency (DLA) engagement (industry webinars and committee meetings in 2025 and a presolicitation for recruit athletic footwear in early 2026) create a new baseline of compliance, traceability, and domestic-content expectations. For strategy teams, these are not academic changes — they directly affect unit economics, capital planning, and go-to-market choices for 2026 and beyond.
Military Footwear Market
What the macro numbers tell you — and what they don’t
-
Growth trajectory: A 6.4% CAGR through 2032 signals reliable demand growth driven by modernization programs, training throughput, and expanding non-traditional procurements (e.g., specialized athletic footwear for recruit and resilience programs).
Military Footwear Market -
Scale and headroom: With 2025 market size near USD 296 million and a projected rise into the mid‑400s by 2032, the market is large enough to absorb strategic investment but small enough that focused investments in domestic capacity or differentiation can materially alter competitive position.
-
Fragmentation: CR3 and CR5 metrics highlight a market where top suppliers are important but not dominant; opportunities exist both for consolidation and for agile challengers to capture contract-led share.
Regulatory and procurement dynamics that will shape 2026 decisions
-
Mandatory domestic content: Implementation of the BOOTS Act and sustained enforcement of the Berry Amendment mean procurement favors 100% U.S.-manufactured footwear with domestic materials for many categories. Expect higher landed costs for compliant suppliers but better protection from foreign competition in DoD channels.
-
Certification and inspection: The U.S. Army Footwear Certification Program imposes prescriptive quality and inspection regimes with two‑year certification cycles and mid‑cycle reviews. Suppliers must invest in process controls, test laboratories, and traceable Bill-of-Material systems to avoid disqualification.
-
DLA engagement and pipelines: The Defense Logistics Agency’s 2025 industry webinars and October committee meeting, plus the February 2026 presolicitation for recruit athletic footwear, signal ongoing alignment between procurement planners and manufacturers — a practical avenue for suppliers to shape requirements but also a reminder that procurement calendars will increasingly drive production planning.
-
Labor and cost pressure: Berry-compliance elevates labor and material costs relative to offshore alternatives. Competitive strategies must therefore shift from low-cost sourcing to productivity, automation, and total-cost-of-ownership value propositions.
Supply chain and manufacturing imperatives
For 2026 operational plans, five manufacturing and supply-chain priorities rise to the top:
-
Certify early, inspect often — make compliance a design constraint. Investments in quality management systems and audit readiness will shorten lead times during procurement cycles and reduce contract risk.
-
De-risk through capacity partnerships — contract manufacturing in the U.S., modular lines, and shared-capacity arrangements can provide the domestic sourcing ribbon without full greenfield capex. Recent facility expansions by domestic OEMs illustrate the capital intensity and timeline of scaling made-in‑America capacity.
-
Automate selectively — automation and advanced assembly reduce the labor delta to offshore options; targeted automation for sole assembly, cutting, and finishing generates outsized productivity benefits.
-
Material strategy and supplier integration — securing U.S.-sourced leather, textiles, and polymer compounds requires multi-year supplier agreements and near-shore backup suppliers to satisfy certification traceability.
-
Service and lifecycle economics — offering rebuilds, sole replacement, and condition-based maintenance programs turns footwear into a lifecycle service, which can align with procurement budgets focused on total cost of ownership.
Product and commercial strategy — beyond the boot
Winning in 2026 will be less about single-product pricing and more about portfolio logic and program alignment:
-
Modularity: Platforms that share last patterns, midsoles, and upper modules reduce SKUs while enabling role-specific variants for training, operational use, or parade applications.
-
Data-enabled value propositions: Embed sensor-ready components or lifecycle tracking to support condition-based replacement programs favored by logistics managers.
-
Performance and sustainability: Lightweight, durable materials and demonstrable lifecycle environmental improvements will influence both civilian resale channels and non-combat procurement lines.
-
Commercial channels and dual-use strategies: Maintain civilian product lines to smooth demand cyclicality and capture economies of scale, while aligning select SKUs to defense certification standards to shorten conversion times when contracts arise.
Competitive landscape: capabilities to watch
The market is populated by established domestic manufacturers with deep relationships to DoD procurement and newer global brands that increasingly adapt lines for Berry compliance. Key company archetypes to watch include:
-
Legacy domestic suppliers with government legacy contracts and institutional knowledge — companies with long histories of supplying U.S. services typically excel at compliance, traceability, and program continuity.
-
Regional specialty brands that combine European technical footwear expertise with U.S. supply arrangements — these players often lead on product innovation and tactical performance metrics.
-
Mid-market manufacturers scaling domestic capacity — recent capacity investments by several U.S.-headquartered manufacturers illustrate a strategic bet on long-term procurement certainty under Berry and legislative preferences.
While we profile representative suppliers in the full report, the salient competitive insight for 2026 is this: incumbency and compliance matter as much as product performance. With CR3 and CR5 indicating fragmentation, there is room for both consolidation and focused challengers that pair domestic production with operational agility.
Scenario triggers and short-term decision checkpoints for 2026
-
Regulatory enforcement schedule: Track BOOTS Act implementing guidance and any amendments to Berry interpretive guidance; supplier qualification timelines must align with those rulings.
-
Procurement pipelines and solicitations: Monitor DLA and service branch RFP calendars; the presolicitation for recruit athletic footwear is a template for recurring program opportunities.
-
Certification cadence: Prepare for mid-cycle inspections under the Army Footwear Certification Program; failing an inspection can remove a supplier from pools for months.
-
Capital availability and M&A windows: Given market fragmentation, watch for strategically timed acquisitions of manufacturing platforms or raw-material suppliers to purchase near-term scale and compliance credentials.
Recommended 90–180 day action plan for executives
-
Compliance sprint: Complete a gap analysis against the Army Footwear Certification Program and initiate corrective action for traceability and BOM controls.
-
Capacity hedging: Negotiate short-term shared-capacity agreements with U.S. partners to secure domestic production slots while evaluating any greenfield investments.
-
Commercial alignment: Map current product lines to likely procurement categories (including recruit and athletic lines) and designate a fast-track SKU list for certification.
-
M&A screen: Run a rapid screen for target acquisitions that add certified capacity, U.S.-sourced materials, or logistics capability with minimal integration risk.
-
Bid readiness: Align costing models to reflect Berry-driven labor and materials premiums and develop lifecycle-based commercial offers that highlight TCO advantages.
What’s in the full PW Consulting report (practical modules)
-
Market sizing and validated forecast models (2020–2032) with downloadable time-series data and scenario toggles.
-
Regulatory and procurement landscape matrix with implementation timelines and audit checklists.
-
Detailed company profiles and capability maps including production footprints, compliance credentials, and strategic moves.
-
Supply-chain risk model and cost-to-compliance simulation to quantify domestic production impacts on margin and cash flow.
-
Go-to-market playbook for prime contractors and subcontractors, including bid‑build templates, value-based pricing models, and lifecycle service propositions.
-
M&A and partnership playbook with a prioritized target list and integration KPIs for acquiring capacity or materials security.
The report intentionally refrains from publishing detailed segmented shares and contract-level datapoints in this preview. Those granular datasets, procurement timelines, and interactive models are available in the full research package and are designed to be used directly in board-level decision frameworks and bid preparation.
Conclusion — the strategic horizon for 2026
For executives and procurement leaders, 2026 is a year to convert regulatory certainty into strategic advantage. The market’s steady growth and procurement policy tilt toward domestic content create a window where the right investments in compliance, capacity, and lifecycle offerings can yield outsized returns. Given the market’s fragmentation, disciplined M&A and capability-led partnerships can accelerate scale and compliance credentials faster than organic build alone. Use the next six months to lock compliance, secure capacity, and validate product portfolios against certification requirements — the full PW Consulting report provides the data, scenarios, and operational templates to make those decisions with precision.
For detailed analysis of this topic, please visit the official page: Military Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrasonic Flaw Detector Market Set to Expand at 7.8% CAGR Through 2032
By PW Consulting, 2026-07-12
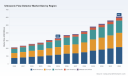
Ultrasonic Flaw Detector Market: Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
Between 2020 and 2025 the global market for ultrasonic flaw detectors moved from an early‑maturing niche toward a predictable growth phase, driven by stronger demand for non‑destructive testing across heavy industry, transport and energy sectors. Using 2025 as the base year, our research places the market at roughly USD 333 million and models a clear upward trajectory through the 2026–2032 forecast window, with a compound annual growth rate (CAGR) of 7.8% that sees the market roughly double in scale by the end of the period. This combination of steady organic demand and pockets of rapid adoption (phased‑array, digital workflows, service models) creates a set of high‑leverage strategic choices for suppliers, integrators and investors in 2026.
Ultrasonic Flaw Detector Market
Why this matters for 2026 decision cycles
- Investment timing: The projected mid‑to‑late decade acceleration means product roadmaps and capital allocation plans begun in 2026 will capture the most commercially attractive portion of the cycle.
- Go‑to‑market focus: Buyers increasingly prefer integrated hardware + software inspection solutions and service contracts; vendors who can bundle calibration, training and digital reporting will win share and margin.
- Regulatory and procurement risk: Heightened standardization around calibration and phased‑array verification is changing procurement checklists — compliance will be table stakes for enterprise contracts.
Forces shaping supply, demand and returns
Our analysis groups the dynamics into four influencing layers:
Ultrasonic Flaw Detector Market
- Technology: Phased‑array ultrasonic testing and interpretive software continue to migrate from specialized labs into routine field inspection. Portable devices are evolving into software‑centric instruments with cloud‑enabled data management and automated analysis pipelines.
- Standards and regulation: Recent updates to calibration and verification standards — including new emphasis on equipment traceability and reference block accuracy — change buyer evaluation criteria and extend sales cycles for non‑compliant offerings. UNE‑EN ISO 22232‑1 and related ISO updates are shaping RFP language and acceptance testing practices.
- Supply chain and components: Piezoelectric transducer technology remains the dominant sensor architecture; our sector analysis shows bulk piezoelectric segments capturing the lion’s share of related sensor demand by 2026, a structural factor that keeps unit costs down but concentrates raw‑material exposure in a few supplier lines.
- Operational economics: Adoption of automated inspection workflows reduces technician dependency, shortens on‑site time and lowers training burden. That same automation shifts value from hardware unit sales to software licenses, data services and recurring calibration/maintenance revenues.
Competitive landscape — who matters and why
The market is neither a monopoly nor highly fragmented: the leading vendors command meaningful share, but mid‑tier and regional suppliers remain important partners for field service and low‑cost segments. Top incumbent brands combine global channel reach with recognized hardware platforms; smaller vendors compete on price, service agility and local relationships.
Ultrasonic Flaw Detector Market
- Waygate Technologies (Houston, USA) — A platform leader with broad portable and phased‑array portfolios (Mentor UT family, Krautkramer models). Strengths: deep enterprise relationships in energy and heavy industry, advanced phased‑array capabilities and validated calibration workflows. Strategic implication: incumbency advantage in large industrial tenders but exposure to price competition at the base of the market.
- Evident Scientific / Olympus IMS (Waltham, USA) — Offers conventional and phased‑array systems (EPOCH, OmniScan series) with strong software ecosystems for data capture and analysis. Strengths: integration of hardware and analytics; preferred by service providers focused on complex inspections. Strategic implication: prime target for partnerships where software differentiation is the sales hinge.
- Sonatest (Pune, India) — Competes on portable and phased‑array products designed for field use (WAVE, Veo3, Sitescan lines). Recent product documentation updates in 2025 sharpen its product claims and channel collateral. Strengths: agile product refresh cycles and competitive pricing. Strategic implication: an effective challenger for growth in emerging markets and service fleets.
- Danatronics (USA) — Specialist in compact portable detectors (ECHO FD, Echo Pro), with a 2025 product launch emphasizing simplified user workflows. Strengths: focused product set with rapid time‑to‑market. Strategic implication: attractive acquisition target for larger firms wanting entry into specific portable segments.
- SIUI (Shantou, China) — Offers compact, cost‑effective portable detectors tailored for general industry. Strengths: low‑cost manufacturing and wide distribution in price‑sensitive markets. Strategic implication: continuing price pressure at the low end; necessity for western OEMs to upgrade service and compliance offerings to defend margins.
- NDT Systems Inc., Zetec Inc., Elcometer — These vendors add depth across legacy digital systems, high‑performance UT equipment and ergonomically designed handhelds. Strengths: niche specialization and strong aftermarket/service presence. Strategic implication: consolidation candidates or strategic partners for service expansion.
Market concentration is moderate: the top three vendors capture less than half of total revenue, and the top five capture just over half. That structure leaves room for targeted M&A and regional plays while preserving substantial opportunity for differentiated product and service strategies.
Strategic playbook for 2026
For executives preparing 2026 plans, the following moves translate the market outlook into action:
- Prioritize software and data services: Reallocate R&D budgets from incremental hardware refinements into analytics, cloud reporting and AI‑assisted defect calling. Even modest subscription revenue can materially improve long‑term value capture.
- Invest in compliance and verification: Ensure product roadmaps and factory calibration workflows comply with evolving standards. Winning enterprise deals increasingly hinges on transparent calibration traceability.
- Secure piezoelectric supply lines: Evaluate multi‑sourcing, long‑term purchase agreements or vertical partnerships for transducer supply to dampen component volatility and avoid single‑source risk.
- Design a hybrid go‑to‑market: Combine global OEM branding with local service partners to reach price‑sensitive segments without eroding margin in premium accounts. Use training and certification programs as lock‑in mechanisms.
- Hunt for tuck‑ins that add service revenue: Identify mid‑tier vendors with strong field service footprints or complementary software capabilities — these are the most accretive M&A targets for revenue growth and faster ARR conversion.
- Repackage offerings for OPEX buyers: Create inspection‑as‑a‑service and managed‑inspection programs tailored to oil & gas, aerospace and manufacturing customers that prefer predictable operating expenditures.
What PW Consulting’s full study delivers — operational and executable
This research is designed to be a practical toolkit for 2026 decision‑makers rather than a high‑level narrative. Deliverables include:
- Comprehensive market sizing and trajectory model (2020–2032) with scenario toggles — base, upside, downside — accessible as an interactive spreadsheet so finance teams can re‑run forecasts under alternative assumptions.
- Go‑to‑market playbooks for three archetypes (OEMs, service integrators, financial sponsors) including customer segmentation frameworks, price/value matrices and channel economics.
- Competitive benchmarking dashboard mapping product feature sets (portable vs stationary, phased‑array capability, software integrations), route‑to‑market strengths and aftermarket footprints for the eight core vendors profiled.
- Regulatory and compliance matrix that translates standards (calibration, verification, traceability) into product and process requirements, acceptance checklists and suggested certification timelines.
- Supply‑chain heat map and cost‑sensitivity analysis focused on transducer inputs and electronics — with practical mitigation options (buffer inventory, dual‑sourcing, supplier partnerships).
- M&A shortlist and valuation frameworks for acquisitive players — including suggested integration playbooks to convert hardware sales into recurring service revenue.
- 90/180/365‑day tactical action plan designed to accelerate wins in core accounts, deploy pilots of automated inspection workflows, and prioritize certification investments required by large buyers.
Practical first steps for executives in 2026
Short list of immediate actions to translate insight into results:
- Run a gap analysis between your product calibration processes and the latest standards; select a short list of corrective investments with clear ROI timelines.
- Launch a pilot that bundles inspection hardware with standardized cloud reporting and a subscription analytics tier; measure uplift in customer retention and bid conversion rates.
- Negotiate transducer supply options with at least two suppliers and model the P&L impact of tiered pricing scenarios across expected unit volumes.
- Identify one mid‑tier service firm with strong regional presence and evaluate a partnership or bolt‑on acquisition to accelerate service revenue and field coverage.
Conclusion — what this intelligence enables
For boards and executive teams planning allocations and strategic moves in 2026, the ultrasonic flaw detector sector presents a rare combination: steady, predictable growth at the market level combined with tactical inflection points at the product, service and regulatory layers. The winners will be those who convert hardware credibility into recurring data and service revenue, align product roadmaps to tightened calibration standards, and secure resilient component supply while defending premium accounts against low‑cost entrants.
Next step
PW Consulting’s full Ultrasonic Flaw Detector Market report includes the detailed tables, interactive models and segment‑level intelligence required to underwrite 2026 investments and M&A decisions. For access to the complete dataset, scenario models and proprietary company profiles, please visit our report page and request the executive briefing package.
For detailed analysis of this topic, please visit the official page: Ultrasonic Flaw Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
EMP Filters Market to Hit USD 196.2M by 2032 at 9.5% CAGR - PW Consulting
By PW Consulting, 2026-07-12
Electromagnetic Pulse (EMP) Filters Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As governments and critical-infrastructure operators move from awareness to deployment, the market for Electromagnetic Pulse (EMP) and High-altitude Electromagnetic Pulse (HEMP) filters has entered a sustained growth phase. Our analysis shows the global market expanding from roughly USD 65 million in 2020 to about USD 104 million in 2025, with a compound annual growth rate of 9.5% projected through the 2026–2032 forecast horizon. By 2032 the market is expected to approach the USD 200 million range. For executives planning 2026 capital allocations, procurement strategies, and technology partnerships, this trajectory signals an inflection: EMP protection is no longer a niche defence line-item but an operationally material element of resilience planning.
Electromagnetic Pulse (EMP) Filters Market
Why this matters for decisions in 2026
-
Threat environment is changing. Intentional electromagnetic interference (IEMI), non‑nuclear EMP events and targeted transient attacks are now recognized vectors against networked systems. Organizations that treat EMP protection as a point-in-time compliance exercise risk costly rework or service interruptions.
Electromagnetic Pulse (EMP) Filters Market -
Standards and testing are differentiating factors. Military-grade specifications such as MIL-STD-188-125-1A remain the benchmark for point-of-entry protection in high-risk assets; meanwhile, civilian attenuation requirements differ materially. Procurement teams must match attenuation profiles and independent acceptance testing to the actual threat model rather than default to “military-grade” premiums.
Electromagnetic Pulse (EMP) Filters Market -
Market economics favour quick movers. The submarket is growing at a near‑double‑digit CAGR, which translates into expanding supplier activity, product launches, and distributor partnerships. Firms that establish credible supplier relationships, validation processes and deployment pilots in 2026 will secure preferred access to constrained capacity and specialized engineering services.
Market dynamics and demand drivers
Three structural forces are driving the EMP filters market:
-
Critical‑infrastructure hardening: Power utilities, telecom operators and defense agencies are budgeting for layered protection as part of resilience programs. The shift to decentralized energy, electrified transport, and dense telecommunications nodes increases both exposure and the number of points requiring protection.
-
Technology and product evolution: Suppliers are delivering broader portfolios—ranging from low-voltage point-of-use filters and filtered connectors to now-commercial medium‑voltage HEMP filters designed for substation and distribution-level protection. This extends the applicability of EMP protection beyond tactical platforms into utility-scale assets.
-
Certification and trust: Independent acceptance testing by accredited labs and adherence to recognized standards are table-stakes. Buyers are increasingly demanding documented performance (insertion loss, pulse handling, and acceptance testing) and traceable certification to de‑risk procurement and lifecycle support.
Competitive landscape — what to watch
The supplier base exhibits meaningful specialization: dedicated EMP/HEMP filter manufacturers, connector and interconnect specialists, and systems integrators that pair filters with shielding and transits. Market concentration is moderate: the three largest suppliers account for a material share of revenue and the top five firms consolidate a clear majority of market value, which creates both competitive pressure and partnership opportunities.
Strategic implications by supplier archetype:
-
Specialist filter manufacturers (example capabilities): These vendors focus on high‑insertion‑loss, military‑grade filters and transportable solutions. Their strengths include in-depth testing, legacy defense procurement relationships, and rapid response engineering for bespoke configurations—critical when attenuation requirements or transient profiles fall outside commodity specifications.
-
Connector and interconnect manufacturers: Firms that integrate filter elements into connectors and planar arrays bring advantages where space, weight and MIL‑DTL form‑factors matter. For airborne and ruggedized applications, these suppliers reduce system-level integration risk.
-
System integrators and shielding specialists: Vendors that combine filters with shielded racks, cable transits and enclosure systems are winning large, turnkey procurements for hospitals, data centres and SCIF-grade installations. Their value proposition is integration and lifecycle assurance rather than component-level price.
Recent vendor activity underscores the market’s momentum: some suppliers introduced medium-voltage HEMP filters for utility applications, others launched integrated EMP protection suites for critical operations, and certain niche manufacturers expanded channel coverage through distribution agreements in new geographies. For buyers, these developments mean an expanding vendor set but also the need to validate new product claims against independent test reports and field acceptance data.
Regulation, standards and technical realities
-
Standards set performance expectations but do not eliminate buyer due diligence. MIL‑STD‑188‑125‑1A remains a reference for point-of-entry protection in high-threat environments, including requirements for high insertion loss across wide frequency bands. Civilian HEMP use-cases, however, often require different attenuation profiles; matching requirement to asset criticality reduces over‑engineering and unnecessary CAPEX.
-
Certification pathways matter. Practitioners should require independent acceptance testing and chain‑of‑custody documentation. Vendors that can demonstrate verified performance through accredited third-party labs earn a procurement premium and reduce program risk.
What the PW Consulting report contains (practical value for 2026)
The full PW Consulting market study is organized to convert insight into actionable steps. Highlights include:
-
Validated market sizing and growth forecasts (2020–2032) with scenario analyses that stress-test demand under alternative threat, regulatory and technology adoption paths.
-
Vendor profiles and capability matrices that evaluate certification status, testing capacity, product breadth, and aftermarket service—presented as a buyer’s decision framework for shortlisting suppliers.
-
Procurement playbooks: specification checklists, acceptance-testing requirements, suggested contractual guardrails (including repair/replace SLAs, spare parts provisioning and obsolescence management).
-
Technology assessment: attenuation performance trade-offs, connectorized versus point‑of‑entry solutions, and system-level integration considerations for grid, communications and secure facilities.
-
Supply‑chain map and risk register: lead‑time sensitivity, single-source exposures, and mitigation strategies for constrained components and test-lab throughput.
-
Investment and M&A compass: screening criteria for acquiring niche manufacturers, partnering with integrators, or establishing distribution partnerships in growth geographies.
Actionable recommendations for 2026 planning
-
Align threat model to attenuation specification. Rather than defaulting to the highest attenuation spec, define asset criticality and disturbance scenarios to determine whether military‑grade attenuation or civilian HEMP performance is appropriate.
-
Run pilot deployments on medium-voltage feeders and high-risk points of entry. Recent commercial availability of medium‑voltage HEMP filters enables pilots at substations; a 2026 pilot program positions utilities to validate performance and develop installation standards before broader rollouts.
-
Standardize acceptance testing in procurement contracts. Require documented third‑party tests and field acceptance signatures; include clause for periodic re‑testing after major firmware/hardware changes in the protected systems.
-
Design for layered protection and lifecycle support. Combine filter technology with physical shielding, sealing solutions for cable transits and connectorized filtering where space‑constrained integration matters.
-
Adopt supplier diversification plus strategic partnerships. The market’s concentration suggests a limited set of proven suppliers for certain performance levels; use dual‑sourcing and distribution partnerships to secure capacity while negotiating technical transfer and local support arrangements.
-
Embed EMP considerations into capex planning. Treat EMP protection as a resilience investment tied to asset availability targets; use the market’s growth profile to negotiate multi‑year pricing and service agreements.
How PW Consulting can accelerate your 2026 program
This preview highlights the strategic choices decision-makers face next year—selection of technical profiles, supplier risk management, pilot planning, and budget prioritization. The full PW Consulting study contains the granular segmentation, regional and application-level modelling, vendor scorecards and price curves needed to translate these recommendations into procurement schedules and investment cases. To access the detailed breakdowns, scenario outputs and supplier dossiers that inform an actionable 2026 roadmap, please consult the complete report and supporting annexes.
Decision-makers who treat EMP protection as a strategic resilience discipline in 2026—not an afterthought—will convert rising market momentum into durable operational advantage.
For detailed analysis of this topic, please visit the official page: Electromagnetic Pulse (EMP) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roll Bond Evaporator Market to Hit USD 2,887M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-12
Roll Bond Evaporator Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies plan capital allocation, product roadmaps and supply-chain hedges for 2026, the roll bond evaporator market presents a mix of steady expansion and structural pressure points. Our analysis at PW Consulting places the global market at approximately USD 1,988 Million in the base year 2025, growing at a compound annual growth rate (CAGR) of 5.8% through the forecast window to reach roughly USD 2,887 Million by 2032. This trajectory reflects steady end-market demand across refrigeration and HVAC sectors, coupled with accelerating regulatory and refrigerant-transition drivers that will re-shape technical specifications, supplier economics and buyer expectations.
Roll Bond Evaporator Market
Why this research matters for 2026 strategy
- Timing of regulatory tightening: Energy-efficiency and refrigerant-phase down mandates that took effect or were strengthened in 2024–2025 create immediate retrofit and new-design demand profiles for 2026 product lines.
- Margin pressure from materials and process requirements: Aluminum material specs and brazing/welding process control are converging into higher-cost, higher-value production envelopes that reward process discipline and scale.
- Competitive consolidation dynamics: A moderately concentrated supplier landscape means strategic moves (partnerships, targeted M&A, capacity expansions) in 2026 can materially alter access to key OEM channels.
Market dynamics shaping 2026 choices
Three categories of dynamics will disproportionately influence corporate outcomes next year:
Roll Bond Evaporator Market
- Regulatory and standards acceleration — Recent policy shifts have raised the bar for evaporator thermal performance and refrigerant compatibility. Notable examples include incremental efficiency requirements from the US Department of Energy (tightened annually since 2019 and further clarified in late‑2025) and stricter Ecodesign performance expectations in the EU. The Kigali Amendment’s accelerated HFC phase‑down has also raised the technical bar for maintaining cooling capacity while migrating to lower‑GWP refrigerants (source references included in the full study).
- Technology and materials convergence — Industry practice is migrating toward optimized aluminum roll bond architectures, where sheet thickness, brazing quality and internal channel density directly affect energy performance and manufacturability. Product-level choices made in 2026 — from fin density to brazing method investments — will determine compliance costs and lifetime energy savings for end customers.
- Supply‑chain and scale economics — The need for higher-precision manufacturing (tight tolerances, consistent weld integrity) favors suppliers with established process controls and scale. Procurement teams should be prepared for tiered pricing structures linked to thermal performance bands rather than simple per-unit cost comparisons.
Regulatory and raw-material implications
Regulatory imperatives are not abstract long‑term threats: they create near-term technical specifications that directly feed into product design choices for 2026 production runs. Key implications we highlight:
Roll Bond Evaporator Market
- Adoption of lower‑GWP refrigerants requires re‑validation of evaporator geometries and brazing processes to preserve capacity under different thermodynamic conditions; manufacturers must build testing and qualification cycles into 2026 development timelines.
- Energy-efficiency standards demand measurable performance improvements. Companies must evaluate retrofit-compatible designs and next‑generation evaporator options that deliver higher seasonal efficiencies with predictable manufacturing yields.
- On materials, common manufacturing practice uses aluminum sheet in specific thickness ranges to balance manufacturability and capacity. Sourcing strategies should therefore consider material-grade availability, pricing volatility and supplier qualification lead times.
Competitive landscape — practical takeaways
The roll bond evaporator supplier base blends global diversified OEMs with specialized regional manufacturers. Market concentration metrics indicate a moderately consolidated field, with the top three players accounting for a significant portion of market throughput and the top five representing a broader dominant cohort. This concentration creates both risk and opportunity for buyers and investors.
- Global diversified players — Large incumbents with integrated thermal management portfolios (examples include multinational HVAC and refrigeration groups) combine scale manufacturing, cross-product integration and strong OEM channel relationships. Their strengths are predictable supply, R&D budgets and system-level integration capabilities — important for OEM partners seeking single‑source validated assemblies.
- Specialist manufacturers — Niche and regional specialists offer flexibility in custom geometries, faster iteration cycles and competitive pricing for non‑system applications. They are attractive targets for OEMs seeking design differentiation or for buyers wanting rapid pilots ahead of broader rollouts.
- Implication for 2026 sourcing — Procurement teams should design segmented sourcing strategies: secure primary capacity with scale players for baseline needs and use specialists for differentiated SKUs and rapid prototyping. The right balance reduces disruption risk while enabling product innovation.
Representative company profiles in our benchmarking (detailed scorecards are part of the full report) include diversified system integrators and specialized evaporator manufacturers. Each has distinct strengths: system integration and broad channel access, advanced brazing and manufacturing capabilities, or design flexibility for compact and display‑grade refrigeration. Our competitive matrix evaluates firms across manufacturing footprint, thermal R&D capabilities, refrigerant‑compatibility testing, service network and price/quality positioning.
What the report delivers (practical, executable content)
PW Consulting’s full study is designed as an actionable toolkit for commercial, R&D and procurement leaders preparing 2026 plans. Key deliverables include:
- Curated executive dashboards with historical performance (2020–2025) and scenario‑based forecasts (2026–2032) that map demand sensitivity to regulatory and refrigerant-transition scenarios.
- Vendor scorecards and a supplier selection framework that quantifies manufacturing quality, thermal performance validation, lead‑time reliability and partnership fit — intended to shorten due diligence cycles.
- Technology‑roadmap guidance highlighting high‑impact design levers (e.g., channel geometry, brazing process investments, materials selection) and suggested R&D test plans to de‑risk compliance with emerging standards.
- Commercial playbook for pricing, channel strategy and retrofit market entry, including value-based pricing models that align supplier compensation with delivered energy savings and compliance outcomes.
- Scenario planning templates and sensitivity analyses that allow teams to stress-test capital and sourcing plans against abrupt refrigerant supply shocks, aluminum price swings and tighter efficiency mandates.
- Regulatory compendium summarizing recent policy actions and compliance timelines across major jurisdictions, with recommended product adaptation milestones for 2026 and beyond.
Actionable recommendations for 2026 (prioritized)
- Lock down compliant capacity — Prioritize qualification agreements with at least two suppliers: one scale partner for volume and one specialist for design innovation. Include contractual clauses that accelerate capacity expansion or technology transfer if regulatory thresholds change.
- Invest in thermal validation — Allocate development budget for bench and field testing under low‑GWP refrigerants now; delayed qualification will push product launches and increase redesign cost in 2026.
- Reconfigure procurement metrics — Move from unit‑cost procurement toward performance‑based procurement that rewards suppliers for achieving defined seasonal energy performance and refrigerant compatibility targets.
- Explore targeted M&A or JV moves — Given moderate market concentration, acquiring or partnering with specialists can rapidly expand product breadth and shorten time‑to‑market for compliant solutions.
- Monitor raw‑material pathways — Integrate aluminum sourcing into scenario models; small changes in sheet specification or availability can impact yield and energy performance.
Research integrity and the “trailer” approach
In this preview we present high‑confidence, macro-level insights and strategic implications to support 2026 decision-making. The full PW Consulting report contains granular regional and application splits, supplier-level quantitative benchmarks, and proprietary demand-model outputs that underpin the forecasts shown here. To preserve the strategic value of those granular datasets — and in line with our “trailer” principle — detailed segmentation figures and supplier scorecards are provided in the complete report package and on the report web page.
Next steps for executives
Executives preparing 2026 budgets should use this preview to validate three immediate actions: (1) finalize supplier qualification priorities, (2) reallocate R&D and testing budget to refrigerant‑transition validation, and (3) update procurement KPIs to include performance and regulatory compliance metrics. Teams that act this year will turn regulatory and material disruption into competitive differentiation in the 2026 product cycle.
To access the full dataset, regional and application breakdowns, supplier scorecards and executable templates referenced in this preview, please consult the PW Consulting report page. The full study contains the complete quantitative underpinnings and tactical playbooks necessary to operationalize 2026 strategies.
For detailed analysis of this topic, please visit the official page: Roll Bond Evaporator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electron Beam Resists Market Poised for 6.5% CAGR Through 2032
By PW Consulting, 2026-07-12
Electron Beam Resists Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new Electron Beam Resists Market study delivers a market-centric, execution-ready intelligence package calibrated to the calendar year 2026. At the macro level, the market has expanded from roughly USD 280 million in 2020 to about USD 355 million in 2025 and is projected to continue its upward trajectory, reaching an estimated USD 544 million by 2032. This trajectory implies mid-single-digit compound annual growth across the forecast horizon (the model uses a 6.5% CAGR for 2026–2032), driven by continued investment in high-resolution patterning for semiconductors, advanced storage media, and emerging nanofabrication processes.
Electron Beam Resists Market
Why this report matters for decisions in 2026
- Make capital-allocation choices with confidence: the report translates forecast ranges into capital- and capacity-planning thresholds for R&D, production scale-up, and contract manufacturing.
- Prioritise product and developer chemistry investments: we show where HSQ-like chemistries and PMMA derivatives are likely to capture incremental value, and where formulation breakthroughs will re-shape adoption curves.
- De-risk supply and procurement: the research quantifies exposure to raw-material cost swings and minimum-order constraints and provides mitigation playbooks for 12–36 month procurement cycles.
- Inform M&A and partner screening: the competitive analysis and vendor scorecards isolate acquisition targets and strategic partnerships most likely to accelerate entry into advanced lithography segments.
What the research delivers — operational, decision-grade content
- Validated historical market sizing (2020–2025) and high‑granularity forecasting (2026–2032) with upside/downside scenarios tied to device demand, research funding, and regulatory shifts.
- Commercial segmentation by technology class, application family, and go-to-market channel (including channel economics and buyer behavior matrices).
- Supply‑chain stress-testing: vendor concentration maps, raw-material sourcing risk scores, lead-time elasticities, and minimum-order sensitivity models.
- Technology deep dives: performance envelopes for HSQ-based, PMMA, and hybrid resist chemistries, including process compatibility and resolution metrics.
- Competitive playbooks: vendor scorecards, pricing matrices, and capability gaps for incumbents and scale-up challengers.
- Regulatory and environmental impact assessment: developer chemistry pathways, waste management constraints, and compliance timing for major jurisdictions.
- Commercial due diligence toolkits: integration checklists, synergy calculators, and two-way earn-out model templates for potential acquisitions.
Market dynamics shaping the 2026 strategic agenda
Several structural and tactical forces will determine winners and losers over the next 24–36 months. First, demand remains anchored in semiconductor patterning and next‑generation data storage — both of which require sustained improvements in resolution, line edge roughness, and process latitude. Parallel growth pockets are emerging in nanoimprint lithography and specialized research markets, creating opportunities for premium pricing on high‑performance formulations.
Electron Beam Resists Market
Second, formulation innovation is accelerating. Recent product introductions demonstrate that commercially viable HSQ alternatives and optimized PMMA derivatives are reaching reproducible sub‑5 nm performance in production‑oriented workflows. These advances compress the timeline for adoption by foundries and advanced research fabs, increasing the premium for resist vendors that can demonstrate process robustness across temperature and storage conditions.
Electron Beam Resists Market
Third, regulatory and sustainability pressures are re-shaping process chemistry choices. A notable example is the industry move toward safer developer chemistries: choline‑based developers, presented publicly in 2025, are positioned as less hazardous and more biodegradable alternatives to traditional alkaline developers. For manufacturers and OEMs, this trend will influence procurement specifications, customer acceptance criteria, and potentially production footprint decisions in jurisdictions with tightening chemical controls.
Finally, raw-material economics matter more than ever. For certain HSQ-style formulations recently commercialized, raw‑material production costs were reported in the upper four‑digit dollar range per liter with minimum order quantities that effectively set a one‑liter commercial unit and limited shelf life to about six months. That profile creates working‑capital and inventory risks for smaller buyers while motivating larger-scale purchasers to pursue volume contracts or backward integration.
Competition and technology briefs — who to watch
- Allresist GmbH (Germany) : A focused developer and manufacturer of multiple e‑beam resist chemistries. Recent milestones include the commercial launch of a new HSQ‑category product in late 2025 that demonstrated repeatable sub‑5 nm line widths across extended sample storage conditions, and public presentation of a choline‑based developer as a safer alternative to legacy alkaline developers. Allresist’s incremental innovations — including compatibility adjustments for conductive resists used on insulating substrates — make it a technology leader in application‑specific formulations.
- EM Resist Ltd (United Kingdom) : Specialist supplier of high‑resolution HSQ negative-tone resists and positive‑tone PMMA variants. The company introduced a higher concentration HSQ formulation in early 2025 and is active in niche nanofabrication research channels, a profile that makes it both a partner for early adopters and a potential acquisition target for larger chemical houses seeking high‑resolution capabilities.
- Kayaku Advanced Materials (United States) : A broad supplier with established PMMA and mr‑EBL series resist lines targeting microelectronics and research markets. Kayaku’s scale and distribution footprint position it well for customers seeking supply security and global logistics, especially as minimum order quantities and shelf life considerations increasingly differentiate suppliers.
Market structure and consolidation outlook
The sector exhibits moderate concentration: the largest three firms account for a meaningful share of market revenue, and the top five increase that concentration materially. That structure creates a dual dynamic. On the one hand, incumbent vendors can leverage scale to absorb raw-material input volatility and to underwrite product development. On the other hand, mid‑tier and specialist suppliers exploit niche process advantages and faster innovation cycles to capture value in high‑margin applications. The competitive landscape therefore supports both bolt‑on M&A for established chemical groups and organic growth plays for agile formulators partnering with foundries and research labs.
Strategic plays for companies making 2026 decisions
- Procurement and supply: lock in multi‑year agreements for critical precursors, evaluate contract manufacturing partnerships to reduce MOQ exposure, and model inventory buffers that reflect six‑month shelf‑life constraints on some HSQ precursors.
- R&D and product positioning: prioritize formulations that balance resolution with process latitude and environmental compliance; accelerate validation trials with a small set of strategic fabs to shorten qualification cycles.
- Go‑to‑market and commercial partnerships: co‑develop application notes and process recipes with leading academic and industrial users to reduce adoption friction and create visible performance references.
- M&A and alliances: target specialist HSQ and developer chemistry teams for bolt‑on acquisitions where IP and process know‑how are the primary assets; for larger players, invest in vertical integration of high‑cost precursors that present supply risk.
- Regulatory and ESG risk mitigation: proactively transition to developer chemistries with lower occupational and environmental hazards, anticipate customer specification shifts, and incorporate compliance timelines into product launch calendars.
How PW Consulting’s deliverables translate into boardroom actions
Our report is structured to transform market insight into executable decisions. Each chapter ties forecast outputs to a specific governance action: capital-expenditure thresholds for manufacturing expansion, vendor selection rules for procurement, deal‑structuring templates for M&A, and a regulatory roadmap that links product design to compliance milestones. The suite includes downloadable financial models (sensitivity-tested), supplier heatmaps, vendor scorecards, and scenario playbooks that allow commercial teams to quantify trade-offs in minutes rather than weeks.
Next steps — where to find the depth
This article highlights the strategic contours and decision levers that matter for 2026. For operational leaders needing the underlying datasets — including regional and application splits, vendor-level revenue and pricing assumptions, technology performance matrices, and full scenario model workbooks — the complete PW Consulting report provides the granular tables, charts, and model files required to translate strategy into execution. Access to the full dataset includes custom briefing sessions and a one‑day workshop option to calibrate the findings to your portfolio or transaction thesis.
In an environment where chemistry choices, raw‑material economics, and regulatory shifts are converging to re‑price differentiation, the right intelligence — timely, specific, and operational — becomes a competitive weapon. PW Consulting’s Electron Beam Resists Market study is designed to be that weapon for 2026 decision-makers.
For detailed analysis of this topic, please visit the official page: Electron Beam Resists Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mid-Infrared Lasers Market to Reach USD 2,052.71M by 2032 at 9.5% CAGR - PW Consulting
By PW Consulting, 2026-07-12
Mid‑Infrared Lasers Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this executive preview to orient senior executives, investors, and R&D leaders on the near‑term choices that will define competitive advantage in the mid‑infrared (mid‑IR) lasers space in 2026. Our full market study (base year 2025) combines a detailed, audited market model with forward‑looking scenario analysis across 2026–2032. In short: the mid‑IR lasers market has moved from an early growth niche into a broadly commercial technology platform, and PW’s analysis quantifies why a strategic response this year cannot be deferred.
Mid-infrared Lasers Market
High‑level market trajectory (what you need to know now)
- Market momentum: The mid‑IR lasers market has demonstrated sustained growth through the 2020–2025 historical period and, on the basis of our validated demand and supply assumptions, we forecast continued expansion across 2026–2032 at a compound annual growth rate of 9.5% (USD, revenue unit: Million, base year 2025).
- Scale and inflection: The market has reached a scale at which purchasing decisions by industrial OEMs, defense integrators, and medical platform vendors shift supplier economics and accelerate consolidation — creating windows for both incumbent expansion and agile new entrants.
- Concentration signal: Market share concentration among the largest suppliers indicates a moderate-to-high barrier for commoditized offerings, while niche, high‑margin specialties remain accessible to focused innovators.
Why this report matters for 2026 decision‑makers
- Actionable investment prioritization: We translate growth vectors into prioritized R&D and capex roadmaps so boards can allocate 2026 budgets to product lines with defensible margins and clear go‑to‑market routes.
- Commercial and procurement playbooks: Sourcing strategies and contractual designs to mitigate component tariff exposure and geopolitical sourcing risk are laid out in executable form.
- M&A and partnership scouting: Target profiles, valuation heuristics, and integration risks for bolt‑on acquisitions and strategic alliances are provided to accelerate deal cycles.
- Regulatory & compliance triggers: The study maps emerging standards and government engagements that create market access thresholds and competitive chokepoints for mid‑IR sensing systems.
What the full report contains — practical, decision‑grade modules
- Market sizing & forecast: A reconciled USD Million model covering 2020–2025 (historical) and granular scenario forecasts through 2032, with transparent assumptions and sensitivity levers.
- Technology & product taxonomy: Comparative roadmaps for semiconductor lasers, fiber and fiber‑pumped systems, quantum cascade devices, supercontinuum sources and ultrafast mid‑IR platforms — including maturity maps and manufacturing constraints.
- Demand segmentation & buyer economics: Use‑case driven adoption curves (industrial processing, spectroscopy, remote sensing, medical diagnostics, defense) with buyer willingness‑to‑pay frameworks and lifecycle cost analysis.
- Competitive benchmarking: Strategic profiles for incumbent and emerging suppliers, product differentiation matrices, and capability heatmaps to support sourcing and partner selection.
- Supply chain and manufacturing assessment: Component criticality ranking, single‑point vulnerabilities, supplier concentration indices and actionable recommendations for dual‑sourcing and inventory strategies.
- Regulatory & geopolitical scenario planning: Scenario playbooks that quantify the P&L impact of tariff regimes, standards adoption, export controls and cross‑border R&D collaboration constraints.
- Commercial models & go‑to‑market templates: Price elasticity models, channel economics, pilot program contract templates, and launch checklists for commercialization in regulated markets.
- M&A playbook: Valuation models, integration risk checklists, and five prioritized archetypes of acquisition targets tailored to different strategic intents (tech‑acquisition, capacity, channel access, or vertical integration).
Current market dynamics and directional insights
Several structural shifts are simultaneously shaping demand and supply:
Mid-infrared Lasers Market
- Technology convergence is broadening addressable applications — tunable semiconductor devices, QCLs and interband cascade lasers are improving spectral reach and wall‑plug efficiency, while fiber‑delivered and supercontinuum sources are simplifying system integration for spectroscopy and imaging use cases.
- Defense and security procurement continues to underwrite innovation in high‑power, ruggedized systems, creating spillover opportunities for commercial sensing and process control OEMs.
- Regulatory activity and standards work are maturing: collaborative efforts between government agencies and standards bodies have begun to formalize guidance for mid‑IR sensors linked to tunable lasers, raising compliance thresholds and opening opportunities for certified platforms.
- Geopolitical and trade policy developments — including tariff adjustments introduced in early 2025 — are driving reconfiguration of sourcing strategies for both components and finished systems.
Competitive landscape — who matters and why
The competitive field features a mix of industrial incumbents, specialized laser houses, and emerging system integrators. A few illustrative strategic profiles from our analysis:
Mid-infrared Lasers Market
- IPG Photonics — leveraging fiber‑pumped hybrid architectures and advanced mid‑IR femtosecond combs to bridge metrology and industrial processing markets. Their technology push raises the bar on performance while opening new premium use cases.
- DRS Daylight Solutions (Leonardo DRS) — a leader in tunable external‑cavity quantum cascade lasers and modular systems for defense and advanced sensing. Recent recognition for semiconductor laser innovation highlights their R&D intensity and defense market access.
- Thorlabs and NKT Photonics — bring strong platform and distribution capabilities for research and industrial spectroscopy, with supercontinuum and high‑performance fiber lasers that simplify application integration.
- Specialists (LumIR, Sacher, Nanoplus, mirSense, Quantune, LEUKOS, Light Conversion, Hamamatsu) — occupy differentiated niches across wavelengths, power, packaging, and application–specific instrumentation. These firms are often targets for strategic partnerships or bolt‑on acquisitions by larger laser OEMs or systems integrators.
From a strategic perspective, incumbents are increasingly pursuing one of three paths: (1) deepening vertical integration to control supply chains and margins; (2) platformizing through modular instrument ecosystems; or (3) focusing on high‑value niche applications where differentiation and IP can sustain premium pricing. Each path has distinct investment and execution implications for 2026.
Immediate 2026 playbook — recommended moves by time horizon
- Next 6 months: Run a vulnerability scan of your supply chain exposure to tariffed components and identify two alternate suppliers for each single‑source item; initiate compliance gap review for emerging mid‑IR standards affecting your systems.
- 6–18 months: Pilot a productized mid‑IR sensing bundle with a strategic vertical partner (e.g., process OEM or defense integrator) to validate price points and operational integration; negotiate long‑lead component contracts with tier‑one suppliers.
- 18–36 months: Execute targeted M&A or joint development agreements focused on either spectral source IP or system integration capabilities, depending on your strategic archetype; commit to manufacturing scale‑up if demand signals meet internal ROI thresholds.
Risk scenarios and triggers — what keeps management awake
- Tariff shock scenario: Rapid increases in component tariffs create immediate margin erosion for vertically thin suppliers; trigger actions include renegotiation of supply contracts and price‑indexation clauses.
- Standards and certification tightening: If standards bodies accelerate certification timelines, late movers face costly redesigns — recommended mitigation is early engagement with standards committees and pre‑compliance testing investments.
- Technology substitution: Breakthroughs in alternative sensing technologies could compress pricing — maintain a watchlist of adjacent technologies and protect optionality through licensing or cross‑sector partnerships.
How PW Consulting’s study turns insight into executable outcomes
The full report is built as a decision support system rather than a descriptive white paper: it includes a downloadable financial model in USD Million, a prioritized action matrix for leadership, procurement playbooks, and a short‑list of M&A targets and partnership candidates vetted against our strategic criteria. We show not just where growth is likely to occur, but how to capture it with measurable milestones and KPIs.
Closing — the “trailer” invitation
This preview demonstrates the depth and immediacy of the opportunities — and the risks — that will shape mid‑IR laser strategies in 2026. To preserve our clients’ competitive advantage we have intentionally reserved core sub‑segment tables, granular regional and application splits, and detailed company financials for the full report. Access to those data tables, the interactive forecast model, and the supplier due diligence pack is available on our report landing page or by contacting PW Consulting directly for a briefing.
For executives preparing capital allocation, M&A scouting, or product roadmaps this year, acting with informed urgency will be decisive. PW Consulting’s Mid‑Infrared Lasers Market study provides the playbook — if you want the full set of maps, metrics and models, let’s set a briefing.
For detailed analysis of this topic, please visit the official page: Mid-infrared Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


