



PW Consulting: Rice Cracker Market to reach USD 26.92B by 2032 at 3.1% CAGR
By PW Consulting, 2026-07-12
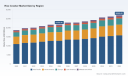
Rice Cracker Market — 2026 Strategic Preview for Decision-Makers
As global snacking continues its steady evolution, rice crackers have moved from regional specialty to a mainstream, multi-modal category with clear strategic implications for 2026 planning cycles. PW Consulting’s latest study (base year 2025) synthesizes five years of historical dynamics and projects the market forward across 2026–2032. In aggregate terms the market stood at approximately USD 21,784 million in 2025 and is forecast to grow to roughly USD 26,920 million by 2032, reflecting a compound annual growth rate of 3.1% over the forecast window. This preview highlights the study’s enterprise-level value: what to act on now, which signals to monitor, and where to drill into proprietary datasets to build 2026 budgets, product roadmaps, and M&A plans.
Rice Cracker Market
Why this matters for 2026 corporate decisions
- Stable, predictable expansion with selective disruption: The category’s mid-single-digit trajectory masks important pockets of acceleration — premium hand-crafted variants, vacuum-fried innovations, and convenience-led formats — as well as structural headwinds such as raw-material volatility. Leaders who treat the market as a portfolio of micro-opportunities will outpace those managing to a headline CAGR alone.
- Supply chain and raw-material risk are material: USDA and FAO indicators point to year-on-year fluctuations in rice availability and pricing that will influence input cost and sourcing strategies through 2026. Companies must translate macro crop forecasts into procurement and hedging actions today.
- Regulatory and labeling shifts are non-negotiable: Updated definitions of “healthy” in major markets place constraints and opportunities on formulation, front-of-pack claims, and marketing. Early compliance-first product launches will capture shelf space and distributor preference.
- Consolidation window is opening: The category exhibits moderate concentration — scale matters for distribution, private label partnerships and cost-to-serve economics, but regional champions and specialized manufacturers still command advantage in innovation and speed-to-market.
What the full PW Consulting report delivers (practical takeaways)
- Transparent market-sizing methodology and scenario-based forecasts (base year 2025; 2026–2032 outlook) with downloadable models for sensitivity testing.
- Actionable segmentation maps across geography, product type and channels — labeled for commercial prioritization and investment-readiness. (Note: high-level segmentation exists in the full dataset; this preview intentionally withholds line-item splits.)
- Channel playbooks for retail, modern trade and foodservice including SKU assortment strategies, private-label economics, and promotional elasticity assumptions.
- Product innovation scanner: sensory and process taxonomies (e.g., frying vs. vacuum-frying, glutinous/non-glutinous formulations), margin implications, and suggested pilot recipes for health-forward and premium lines.
- Competitor benchmarking templates and vendor heatmaps that link capability gaps to potential partners and acquisition targets.
- Supply-chain stress tests incorporating USDA and FAO crop scenarios, rice-price shocks, and cost passthrough mechanics to help finance teams stress test P&Ls.
- Regulatory impact matrix covering labeling changes and country-specific claim pathways (with recommended wording and pack-design mitigations).
- M&A and investment playbooks with prioritized targets and integration checklists to accelerate due diligence.
Competitive landscape — what to watch
The rice cracker competitive map is a mix of entrenched local champions and export-oriented specialists. Key players we profile in depth include Kameda Seika Co., Ltd., Fujian Hanwei Foods Co., Ltd., Thai-Nichi Industries Co., Ltd., Namchow (Thailand) Ltd., and Want Want Holdings Limited. Each offers a distinct strategic lesson:
Rice Cracker Market
- Kameda Seika Co., Ltd. (Tokyo) — A dominant domestic player with a broad portfolio and strong brand equity; scale advantage in Japan underpins R&D investment and distribution depth. Its experience highlights how broad assortments and strong domestic channels can insulate margin pressure.
- Fujian Hanwei Foods Co., Ltd. (Fujian) — Specializes in vacuum-fried variants and export-led snack lines; recent product introductions show how processing innovation can create premium price points while addressing texture and health perceptions.
- Thai-Nichi Industries Co., Ltd. (Thailand) — Longstanding exporter of Japanese-style rice crackers; their playbook is instructive for positioning heritage product formats in new retail channels and for leveraging B2B export partnerships.
- Namchow (Thailand) Ltd. — Active in global trade shows and promotional channels; recent exhibition activity underlines the importance of experiential marketing in generating distributor interest for thin-format novelties.
- Want Want Holdings Limited (Taiwan) — A major regional manufacturer and exporter with established production capacity in Vietnam; their footprint offers a model for lower-cost regional manufacturing coupled with multi-market brand strategies.
Recent corporate moves — trade-show participations and new product launches across 2025–2026 — spotlight two themes: (1) suppliers are investing in premium and plant-based innovations to capture higher-margin segments; and (2) export-oriented players are doubling down on trade promotion to secure distribution in fast-growing overseas channels. PW Consulting’s profiles include capability matrices, recent M&A noise, and go-to-market readiness scores for each company.
Rice Cracker Market
Market dynamics and risk signals
- Raw material volatility: Public-source forecasts indicate a material decline in certain crops in 2026/27 and broadly weaker global milled rice output year-on-year. Those shifts translate to input cost pressure and sourcing risk that directly affect gross margins for commodity-based SKUs.
- Price momentum: FAO rice price indices in early 2026 showed short-term upticks versus the prior month, even as year-on-year pressures moderated. Expect episodic input-driven price moves rather than a steady trend.
- Regulatory change: Evolving definitions of “healthy” and tightened front-of-pack requirements mean some existing formulations will need relabeling or reformulation to retain shelf claims in major export markets.
- Consumer preference shifts: Demand is bifurcating between value-driven, high-velocity snack formats and premium, craft-oriented variants that command better margins. Health-forward positioning — lower oil, whole-grain or alternative flours, and clean labels — continues to gain.
- Channel evolution: E-commerce and convenience channels are accelerating adoption of impulse snacks and bundle-based offers; foodservice demand is recovering post-pandemic but expects different pack sizes and shelf-life requirements.
Priority recommendations for 2026 (what good looks like)
- Immediate (0–12 months): Lock in multi-supplier rice contracts with price collars or indexation clauses; prioritize SKU rationalization to protect margin on high-cost inputs; initiate regulatory gap audits for labeling and health-claim compliance.
- Near-term product moves (6–18 months): Pilot 2–3 premium SKUs (e.g., vacuum-fried or artisanal hand-grilled variants) targeted at wholesale channels and high-margin e-commerce. Use limited-time flavors to test repeat-purchase mechanics before full roll-out.
- Operations & cost-to-serve (12–24 months): Invest selectively in automation and yield improvements in frying/drying steps; evaluate co-manufacturing or leased capacity in lower-cost jurisdictions to diversify production risk.
- Commercial & channel (12–36 months): Reconfigure assortment by channel: emphasize larger multipacks and private-label value SKUs in modern trade, and premium single-serve formats for travel retail and convenience. Negotiate trade-fund trade-offs tied to joint marketing investment.
- M&A & partnerships (18–36 months): Prioritize targets that add either unique processing capability (e.g., vacuum-frying), regional distribution control, or proprietary flavor intellectual property. Integration playbooks should focus on SKU delisting and shared procurement synergies.
- Long-term resilience: Build traceability programs upstream to control rice sourcing volatility; consider strategic equity stakes in upstream milling or co-op sourcing arrangements.
How PW Consulting’s report accelerates execution
This study combines a rigorous, auditable forecast model with playbooks, financial templates and competitor intelligence designed to accelerate decision-making. For executives allocating 2026 CapEx, planning launches, or sizing M&A transactions, the report translates macro scenarios into P&L outcomes and a prioritized action matrix. Importantly, while this preview highlights the study’s strategic frames and select company-level analysis, the full research contains granular segmentation, regional and application splits, price and margin matrices, and downloadable spreadsheets that operational teams can apply directly to 2026 budgets.
Next steps — where to dig deeper
If your organization is evaluating expansion, product innovation, sourcing changes, or M&A in rice-based snacks for 2026, PW Consulting’s full report provides the calibrated datasets, competitor scorecards and executable playbooks needed to move from strategy to execution. For procurement leads, R&D heads and corporate development teams, the most valuable next step is access to the underlying segment tables and scenario models — these are intentionally omitted from this preview to protect analytical value. Visit the source webpage to access the full dataset, interactive models, and a confidential briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Rice Cracker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Nutrition market to grow at 6.98% CAGR, reaching USD 39,890M by 2032
By PW Consulting, 2026-07-12
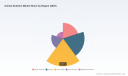
Animal Nutrition Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As global food systems accelerate toward higher productivity, sustainability and regulatory scrutiny, the animal nutrition market is entering a phase of sustained expansion and strategic realignment. Our PW Consulting Animal Nutrition Market study (base year 2025) captures this inflection: the global market has grown from roughly USD 20 billion in 2020 to USD 25 billion in 2025 and is set to grow at a compound annual growth rate of 6.98% into the next planning horizon, reaching nearly USD 40 billion by the end of the 2032 forecast period. For leaders making go/no‑go investment, M&A, and commercial decisions in 2026, this report converts macro momentum into operational imperatives.
Animal Nutrition Market
Why this research matters for 2026 decision-making
-
Timing for scale and specialization: Steady market growth combined with a fragmented supplier base creates a narrow window in which scale-driven investments and selective acquisitions can materially shift competitive position.
Animal Nutrition Market -
Regulatory velocity: New pathways and digital tools for ingredient review are compressing time to market for novel additives and formulations — firms that embed regulatory intelligence into product development will unlock first‑mover advantages.
Animal Nutrition Market -
Input-cost exposure: While feed raw material availability has shown signs of stability in recent seasons, volatility remains a strategic risk; procurement and formulation agility will determine margin resilience.
-
Commercial differentiation: Buyers increasingly demand integrated solutions (nutrition + health + traceability). Vendors who can translate efficacy data into repeatable, scaled services will capture premium share.
What the PW Consulting report delivers — practical, transaction‑ready content
-
Transparent market sizing and forecasts built on a reproducible methodology — we provide both top‑down and bottom‑up views, scenario overlays and sensitivity testing keyed to commodity and demand drivers.
-
Segment and species demand models (for protein supply chains, feed types and additive categories) that translate shifts in animal production and consumer preferences into SKU‑level revenue implications — presented in an executive format for boardrooms and an operational format for commercial teams.
-
Supply‑side intelligence including supplier maps, capacity baselines, logistics chokepoint analysis and raw material exposure matrices with hedging and contingency playbooks.
-
Regulatory tracker and compliance playbook — step‑by‑step for global markets, with a focus on the new tools and pathways accelerating ingredient review cycles.
-
Competitive benchmarking suite featuring strategic profiles, capability heatmaps and business model diagnostics that isolate sources of margin and defendable differentiation.
-
M&A readiness materials: target screening filters, valuation sensitivities for technology vs. scale plays, 100‑day integration templates and synergy capture checklists.
-
Commercial growth playbooks: pricing frameworks, account segmentation, product bundling strategies and pilot templates for rapid field validation of new formulations.
-
Financial toolkit and dashboards — standardized templates to stress-test investment cases against multiple commodity and regulatory scenarios.
Competitive landscape — reading the leaders' playbooks
The animal nutrition sector shows a low to moderate level of concentration. This structural reality favors both incumbent scale players and nimble specialists with strong technical advantage or channel partnerships. Our report examines the strategic positioning of the sector’s most consequential firms and what their moves imply for the market structure in 2026:
-
Cargill — an integrated solutions provider with capabilities across ingredients, premixes and feed formulation. Their play is to leverage scale, integrated sourcing and customer relationships to defend margins while selectively investing in higher‑value additives and services.
-
ADM Animal Nutrition — focuses on customized ingredient solutions and formulations, increasingly positioning itself as a technology‑enabled ingredient partner for large integrators and feed manufacturers.
-
Alltech — retains a research and innovation led posture, emphasizing biologicals, probiotics and health‑oriented additives designed to reduce antibiotic reliance and improve on‑farm performance.
-
Nutreco — pursues sustainability and feed‑to‑food traceability as differentiators, integrating nutrition science with transparent supply chains to address end‑market sustainability requirements.
-
Land O’Lakes — a cooperative model that leverages local market intimacy, channel ownership and integrated services for dairy and livestock customers, creating durable customer retention despite competitive pressure.
-
Phibro, Kemin, Purina and other specialists — focus on niche science, functional additives and customer‑centric product portfolios. These players present attractive targets for acquirers seeking technical capability or margin improvement through premium product lines.
Regulatory and raw material dynamics to monitor in 2026
-
Regulatory acceleration: The introduction of digital and AI‑assisted tools for ingredient review — and industry training programs focused on submission readiness — is materially shortening approval cycles. Firms without a regulatory intelligence function will face slower commercialization and higher compliance costs.
-
Guidance and policy alignment: Recent formalization of consultation pathways by major regulators (including finalized guidance frameworks) requires companies to systematize regulatory dossiers and invest in compliant data generation early in product development.
-
Raw material outlook: Recent season projections indicate robust production volumes for key feed staples, which supports price stability assumptions in our base forecast. That said, regional supply chain disruptions and weather risk remain plausible downside scenarios; procurement strategies should include multi‑sourcing, forward contracting and formula volatility clauses.
-
Market engagement forums: Major trade events continue to scale — they remain important places to validate product claims, secure pilot partnerships and read competitor roadmaps. IPPE (2026) and VICTAM (2025 Latin America) are cited examples where new product launches and commercial deals are frequently catalyzed.
-
Innovation pipeline: New product launches combining vitamins and precision nutrients signal an industry shift toward consolidated, performance‑oriented formulations that simplify farm‑level dosing and reduce logistic complexity.
Strategic moves we recommend for 2026
-
Rebalance the portfolio: Prioritize investment in high‑margin additives and bundled solution offerings while paring low‑margin commodity exposure where scale does not deliver a sustainable cost advantage.
-
Build regulatory capability: Create an embedded regulatory function that partners directly with R&D and commercial teams to accelerate submission readiness and capture first‑mover access to new ingredient approvals.
-
Pursue targeted M&A: Seek bolt‑on acquisitions that add technical differentiation (e.g., biologicals, mycotoxin mitigation, targeted vitamins) rather than undifferentiated capacity, unless scale is the explicit strategic objective.
-
Operationalize procurement resilience: Adopt commodity stress tests, hedging playbooks and regional sourcing networks to reduce margin exposure to short‑term price spikes.
-
Commercialize data: Use field trial platforms and performance analytics to create pay‑for‑performance or outcome‑linked contracts with large producers and integrators.
-
Invest in sustainability and traceability: Respond to buyer and regulator demand with certified sourcing, lifecycle impact metrics and transparent reporting — these investments are increasingly table stakes for premium buyers.
How to use the full PW Consulting report
The full report transforms the strategic themes above into executable programs: it contains the granular regional and application splits, product‑level demand curves, supplier scorecards, company benchmarking dashboards and downloadable financial models needed to build 2026 operating plans and investment memoranda. If your team needs an immediate playbook, our report also includes ready‑to‑deploy templates for commercial pilots, regulatory submissions and M&A diligence.
PW Consulting’s Animal Nutrition Market study is designed as both a strategic compass and a practical toolkit. The next 12–18 months will separate firms that adapt their business models to tighter regulatory timelines, greater demand for measurable outcomes, and continued feed input uncertainties from those that lag. For leaders deciding where to allocate capital, talent and product development effort in 2026, the study provides the market context, risk scenarios and transaction‑grade intelligence to act with conviction.
To access the full dataset, segmented forecasts, and proprietary company dashboards referenced throughout this brief, visit the PW Consulting research page and request the complete Animal Nutrition Market report — the granular insights you need to convert market growth into sustainable competitive advantage are included in the full release.
For detailed analysis of this topic, please visit the official page: Animal Nutrition Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Anchors Market to Reach USD 4.64B by 2032 at 3.42% CAGR
By PW Consulting, 2026-07-12
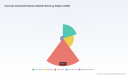
Concrete Anchors & Fasteners Market — Strategic Briefing for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, actionable introduction to our full Concrete Anchors & Fasteners Market study. This briefing distills the structural forces, competitive dynamics, and decision levers that will matter most for capital allocation, sourcing, product strategy, and M&A through 2026 — while preserving the detailed, proprietary segmentation and scenario outputs for subscribers of the full report.
Concrete Anchors/Fasteners Market
Why this market matters in 2026
Concrete anchors and fasteners sit at the intersection of construction activity, infrastructure renewal, industrial installation, and building-code evolution. After a steady recovery in the early 2020s, the global market achieved an estimated size of USD 3.65 Billion in the base year 2025 and is forecast to grow to approximately USD 4.64 Billion by 2032 — a compound annual growth rate of about 3.42% across the 2026–2032 forecast horizon. That trajectory reflects structural demand from commercial and industrial capex, selective residential resilience, and public-sector infrastructure programs.
Concrete Anchors/Fasteners Market
For corporate leadership, 2026 is a year for translating macro certainty into tactical advantage: locking supply chains against raw-material volatility, optimizing channel footprints as installer buying patterns shift, and positioning product portfolios for tightening regulatory acceptance criteria in post-installed anchors.
Concrete Anchors/Fasteners Market
High-level market dynamics you must plan for
- Demand continuity with pockets of premiumization. Market growth is moderate and uneven: routine repair, refurbishment, and retrofit work underpin baseline demand while specific segments demonstrate willingness to pay for certified, higher-value solutions (e.g., systems with extended performance warranties or specialty chemical anchors).
- Raw-material pressure and cost management. Carbon steel remains the primary raw material used across the category. Price volatility in carbon steel is a persistent input risk that flows through supplier margins and buyer procurement decisions — making hedging, supplier diversification, and design-for-material-efficiency core 2026 priorities.
- Regulatory and code-driven gatekeeping. Post-installed anchors increasingly must meet qualification standards (notably ACI 355.2 for mechanical anchors and ACI 355.4 for adhesive anchors, as referenced by the 2024 International Building Code). Companies that can articulate certified test protocols, provide supporting documentation, and internalize compliance costs will win a disproportionate share of specification-driven tenders.
- Commercial dynamics: distribution/installer influence. The buyer base remains fragmented at the installer level but consolidated upstream among OEMs and large distributors. Go-to-market sophistication — from technical sales to installer training and on-site specification support — is now a differentiator, not just a cost center.
- Product innovation is manufacturing + install efficiency. Recent launches emphasize speed, repeatability, and lowered rework risk. A March 2026 product introduction — a reusable template system for rapid anchor-bolt placement — exemplifies the category’s move toward time-saving installation aids that reduce labor variability and schedule risk on foundation and slab works.
What the full report provides (practical, execution-focused)
PW Consulting’s comprehensive study was designed for executives who need more than market numbers — they need executable playbooks. Key deliverables include:
- Executive summary with investment and go/no-go thresholds tied to growth scenarios for 2026–2032.
- Market-sizing and historical trend analysis validating the USD 3.65 Billion base and the 3.42% CAGR through 2032, with sensitivity to macro construction cycles.
- Regulatory impact matrix mapping ACI/IBC acceptance pathways by anchor type, including an actionable compliance checklist for product teams and certifying laboratories.
- Raw-material risk models and procurement response playbooks that quantify the P&L impact of carbon-steel price swings and present hedging and contract structures.
- Channel and route-to-market playbooks for distributor partnerships, national account engagement, and installer ecosystem development — including margin and service-level benchmarks.
- Commercial pricing and value-capture frameworks that reconcile installer willingness-to-pay with differentiated product features (mechanical vs. adhesive systems, installation aids, and testing services).
- Competitive landscaping with strategic profiles of the leading global OEMs and regional challengers, plus an M&A screening tool calibrated to market concentration and synergies.
- Case studies and three-year implementation roadmaps for capex deployment, manufacturing footprint optimization, and product-line rationalization.
Competitive landscape — who matters and why
The market combines global OEMs, specialist manufacturers, and regional brands that leverage local manufacturing and distribution. The competitive set includes longstanding engineering-led players focused on system performance and certification, global distributors offering breadth, and nimble regional manufacturers that compete on lead times and “made-in” credentials.
- Hilti Corporation — engineering-centric, premium positioning, strong in system warranties and installer training programs.
- Simpson Strong-Tie — deep anchoring systems expertise, broad product mix across mechanical and adhesive arenas, strong U.S. specification relationships.
- ITW Construction Products (Red Head) — historical strength in adhesive anchors and chemical systems; integrated distribution partnerships.
- MKT Fastening LLC — U.S.-manufactured focus, attractive for buyers prioritizing local supply and rapid delivery.
- fischer fixings & Würth Group — European engineering and distribution scale, with emphasis on steel fixings and heavy-duty anchors.
- Powers Fasteners — recognized for wedge anchors and contractor-oriented solutions; close ties to professional installer channels.
- Rawlplug — growth through product breadth across screw, mechanical, and chemical anchors; gains where modular performance matters.
- Concrete Fastening Systems & Cobra Anchors — regional specialists that compete on product availability, U.S. sourcing credentials, and price-performance.
Collectively, leading OEMs command material share at the global level, but the market still rewards regional agility, certification accessibility, and channel intimacy. Recent product introductions that reduce on-site labor or rework demonstrate how innovation can shift specification preferences faster than raw capacity investments.
Strategic implications and recommended 2026 actions
- Procurement & Supply Chain: Establish multi-tier contracts with steel suppliers, include indexation clauses linked to industrial steel benchmarks, and pilot inventory pooling with key distributors to reduce lead-time spikes.
- Product & R&D: Prioritize product variants that simplify installation and reduce inspection risk. Invest in certification kits and field demonstration resources to accelerate spec acceptance under ACI/IBC pathways.
- Go-to-market: Rebalance sales compensation to reward specification wins and training programs. Create installer accreditation programs to lock in repeat usage for higher-margin systems.
- M&A & Portfolio Moves: Target regional manufacturers with complementary footprint or proprietary installation aids rather than purely volume plays. Use our M&A screening tool to size accretion potential under three putative integration scenarios.
- Risk Management: Integrate raw-material price scenarios into product pricing models and tender bids. Maintain a dedicated compliance resource to track ACI updates and provide rapid route-to-compliance for new products.
How this brief should be used in boardroom decisions
Use this briefing as the strategic framing for three board-level decisions in 2026:
- Approval of a 12–24 month capex plan to expand capacity for higher-margin, certified anchor systems.
- Mandate to procurement to execute layered supply agreements and pilot distributor consignment models in two strategic regions.
- Greenlight for a bolt-on acquisition or partnership that accelerates installation-aid capabilities or broadens certified product portfolios.
Next steps — where to find the detailed evidence
This article purposefully highlights the strategic themes and operational implications while withholding the granular segmentation and regional/application breakdowns that underpin model-driven recommendations. The full PW Consulting report contains those detailed charts, quantitative segmentation, sensitivity tables, and the proprietary M&A screening dataset you’ll need to translate strategy into action.
For access to the complete dataset, scenario outputs, and a tailored briefing for your executive team, please consult the PW Consulting market page or contact your account director. Subscribers will receive the full dossier including appendices on methodology, primary interviews, and the regulatory compliance checklist that maps directly to ACI 355 series requirements.
PW Consulting remains available to facilitate a 90-minute executive workshop where we can: validate assumption sets against your operations, prioritize immediate tactical moves for 2026, and map a 36-month transformation program for product, channels, and supply chain resilience.
For detailed analysis of this topic, please visit the official page: Concrete Anchors/Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Asia‑Pacific Holds 52.8% of the Urea Market — Outlook to 2032
By PW Consulting, 2026-07-12
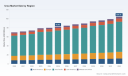
Urea Market 2026: Navigating a Low-Growth, High-Volatility Landscape — Strategic Insights from PW Consulting
As companies set strategy for 2026, choices made this year will determine competitive positioning across the urea value chain for the rest of the decade. Our new market study — anchored on a 2025 base year and projecting through 2032 — shows a mature global market expanding at a modest compound annual growth rate (CAGR) of 3.1% from 2026 to 2032. The market size recorded in 2025 stands at USD 82.62 Million (revenue unit: Million). Under our base forecast, the market rises to USD 104.41 Million by 2032. These headline metrics frame a story of steady demand underpinned by core agricultural consumption, but punctuated by intermittent supply shocks, input-cost volatility and a fast-accelerating sustainability agenda.
Urea Market
Why this study matters for 2026 decision-makers
-
Timing: 2026 is a pivot year. Feedstock markets that eased in 2025 have shown renewed volatility, regulatory pressure on fertilizers is intensifying, and technology pathways for low-emissions urea are entering early commercialization. Strategic moves made now — investments, sourcing shifts, product repositioning — will capture value or lock in rising cost exposure.
Urea Market -
Precision: The study translates headline growth into actionable scenarios for capex prioritization, product-mix optimization, and commercial hedging. We map the implications of a 3.1% CAGR onto unit economics and cash flow sensitivities across six operational archetypes (co-located ammonia-urea complexes, seafreight exporters, mid-scale inland producers, toll processors, specialty formulators, and controlled-release innovators).
Urea Market -
Risk-to-reward clarity: The report integrates near-term disruptions and medium-term structural shifts to create decision-ready matrices — helping executives balance short-term profitability with long-term strategic resilience.
Market dynamics shaping strategy in 2026
-
Feedstock and cost volatility: Ammonia remains the dominant input and a primary driver of urea cost curves. Recent months have delivered mixed signals — production costs fell meaningfully in some markets late in 2025, yet ammonia prices rebounded into late-2025. At the same time, liquid sulfur moved sharply higher within a year, exerting upward pressure on production costs where sulfur feed is integral to routes or logistics. These movements increase the importance of flexible sourcing, long-term offtakes and hedging frameworks for producers and large buyers.
-
Supply shocks and trade flow sensitivity: The industry continues to exhibit sensitivity to localized energy and infrastructure disruptions. A major exporter experienced a temporary halt to operations in early 2026, underlining the risk of concentrated production footprints. Our modelling shows short interruptions have outsized effects on regional freight and spot pricing — a reminder that geographic and logistical diversification matter even in a modest-growth market.
-
Regulatory and trade headwinds: Trade policy moves in key markets are already reshaping commercial flows. Import barriers and targeted tariffs introduce margin risk for seaborne suppliers and elevate the value of regionalized supply. Simultaneously, regulatory scrutiny around emissions and nutrient runoff is fueling demand for premium and stabilized products, which command a price differential and require different go-to-market capabilities.
-
Product and technology inflection: 2025–2026 saw credible progress on product-level emissions claims and new application formats. Manufacturers and technology suppliers verified emissions reductions from stabilized urea formulations, and several markets scaled nano-urea production for concentrated application formats. Separately, green ammonia-to-urea routes are moving from pilot to early commercial stages with selective off-takers already contracting low-carbon volumes. These trends create a bifurcated market: commodity urea with tight margin management, and premium segments driven by sustainability and agronomic performance.
Competitive landscape — direction without the proprietary detail
The industry is neither atomized nor monopolized. Market concentration is moderate: the largest global players collectively hold a substantial share of seaborne flows and capacity, but national champions and regional producers maintain significant local dominance. This creates room for both scale-driven exporters and agile regional specialists.
-
Large integrated fertilizers and ammonia majors are leveraging scale and feedstock integration to defend margins. Their strategies emphasize reliability of supply, incremental low-carbon product offerings and control over seaborne logistics.
-
Regionally focused companies and traders compete on customer intimacy, service models and tailored product mixes (e.g., enhanced-efficiency fertilizers for specialty cropping systems).
-
Newer entrants and portfolio players are targeting premium niches — controlled-release, stabilized products, nano-formulations — where technical differentiation can translate to higher margins and customer stickiness.
Our full company profiles include detailed financial and operational benchmarking across the peer set, including plant footprints, product portfolios, recent capital projects and strategic priorities. For example, leaders in Europe and North America are advancing low-carbon urea routes and enhanced-efficiency formulations, while Gulf-region producers continue to dominate seaborne export capabilities. Major publicly listed players and state-backed groups all feature in the competitive map, and our scorecards evaluate them on scale, feedstock security, decarbonization readiness, and commercial agility.
What’s included in the PW Consulting urea study (practical toolkit)
-
Integrated forecast model (2026–2032) — top-line market trajectories and scenario variants that stress-test demand and supply under different oil, ammonia and trade assumptions.
-
Cost and margin curve analyses — plant-level cost buckets, feedstock sensitivities, and break-even maps for different operational archetypes.
-
Supply-side inventory — a validated register of major production assets (operational status, technology route, ownership structure), plus a pipeline tracker for announced projects and commissioning windows.
-
Policy & regulatory scenarios — trade-policy shocks, emissions pricing, and nutrient management regimes modelled for commercial impact through 2032.
-
Product segmentation playbooks — go-to-market guidance for commodity, stabilized and specialty urea products, including pricing strategy, channel design, and agronomic validation requirements.
-
Company scorecards and M&A decision framework — tailored diligence checklists, valuation sensitivities and integration blueprints for both bolt-on and transformational deals.
-
Operational resilience & procurement protocols — actionable measures to reduce exposure to feedstock swings and logistical disruptions, including contract templates and shortlists of risk-mitigation partners.
Strategic actions for corporate leaders in 2026
-
Stress-test your portfolio against at least three cost scenarios: commodity-soft, feedstock-shock, and premium-adoption. Use the study’s scenario engine to quantify bottom-line sensitivity and inform capex gating decisions.
-
Prioritize feedstock security: lock in long-term ammonia supply or consider co-investment in upstream capacity where scale economics justify. For trading and merchant businesses, diversify shipping and storage footprints to mitigate short interruptions that can cascade into spot price spikes.
-
Define a clear product stratification strategy. Maintain competitive pricing in the commodity core, while selectively expanding stabilized and enhanced-efficiency offerings where agronomic data and local regulation support a premium.
-
Make decarbonization decisions commercial. Select pilot customers and long-term offtakers for low-carbon urea volumes; structure offtake agreements and price premia based on verified emissions reduction claims.
-
Use M&A selectively. Small, targeted acquisitions can accelerate entry into specialty segments or improve route-to-market in high-value regions. Larger transactions should be justified by feedstock synergies or the ability to capture seaborne supply economics.
-
Embed geopolitics into procurement. Tariff and trade barriers are no longer rare events; model tariff scenarios and quantify the elasticity of your trading routes to rapid policy shifts.
Signal events and near-term monitors
-
Operational continuity at large export hubs — any extended outage can reshape spot spreads and create short-term arbitrage opportunities.
-
Ammonia cost trajectory and sulfur market behavior — these are the principal levers on the cost curve; procurement teams must have live-tracking and hedging playbooks.
-
Regulatory approvals for stabilized and nano-formulations — verification of emissions or agronomic claims materially affects premium potential and market acceptance.
-
New commissioning waves in target markets — domestic production expansion can compress imports and change regional pricing dynamics.
Closing — the value proposition of the full report
Our 2026 urea market study is designed as a decision accelerator. It combines rigorous forecasting with hands-on tools — models, scorecards, procurement playbooks and scenario generators — so executives can move from insight to action within weeks, not months. This article outlines the strategic contours and immediate implications; the full report contains the granular datasets, segmented forecasts, and company-level metrics required for transaction-level or operational planning.
For teams preparing budgets, negotiating offtake agreements, evaluating decarbonization investments, or sizing M&A targets, the difference between a prudent and a transformative decision in 2026 will be the quality of the market intelligence behind it. PW Consulting’s full study gives you that edge.
Access to the full dataset, regional and application splits, plant-level profiles and the interactive forecast model is available on our report landing page — where the detailed numbers and tools required to execute on the strategies above are provided to subscribers and clients.
For detailed analysis of this topic, please visit the official page: Urea Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra-Pure Sulfuric Acid Market Outlook — 3.2% CAGR to 2032
By PW Consulting, 2026-07-12
Ultra-Pure Sulfuric Acid Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a forward-looking briefing designed to equip C-suite and strategy teams with the context they need as 2026 unfolds. Our Ultra-Pure Sulfuric Acid (UPSA) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) shows a compact, technically intensive market that has demonstrated steady, measured expansion—rising from roughly USD 0.5 Million in 2020 to about USD 0.6 Million in 2025. We expect continued, low-single-digit compound annual growth through the forecast window, with a 3.2% CAGR and a projected market size approaching USD 0.74 Million by 2032 (values in USD Million).
Ultra-Pure Sulfuric Acid Market
This briefing is a “trailer”: it communicates the report’s strategic value, highlights key dynamics and competitive moves, and outlines the kinds of actionable insights the full study delivers—while intentionally withholding granular segment-level figures and confidential modelling outputs to preserve the motivation for accessing the full report.
Ultra-Pure Sulfuric Acid Market
Why this market matters to 2026 strategic agendas
- Enabler of high-value ecosystems: Ultra-pure sulfuric acid is a critical consumable in semiconductor wafer processing, select pharmaceutical synthesis routes, and advanced chemical manufacturing. Its purity and supply reliability directly influence yield, throughput and contamination risk across wafer fabs and other precision plants.
- High technical and regulatory barrier to entry: Producing UPSA at semiconductor-grade purity requires specialized technology, rigorous quality systems, and regulatory compliance frameworks, creating defensible positions for incumbent manufacturers.
- Supply chain sensitivity: Feedstock volatility (notably elemental sulfur pricing and supply dynamics) and evolving environmental standards make procurement strategy and feedstock risk management top priorities for both suppliers and large end-users.
- Market structure concentrates influence: The market is relatively consolidated—top-tier suppliers command a majority share—so actions by a few players (capacity expansions, product qualification programs, strategic supply agreements) can materially affect availability and commercial terms.
What the full report delivers (practical scope)
- Validated historical market sizing (2020–2025) and a transparent forecasting model (2026–2032) with scenario analysis that isolates demand drivers tied to semiconductor capex, regional fab builds, and selected specialty chemical flows.
- Commercial playbooks for buyers and suppliers: qualification timelines, contamination mitigation protocols, specification harmonization checklists, and contracting templates aligned to semiconductor vendor practices.
- Supplier scorecards and a competitive benchmarking matrix evaluating production footprint, purity capability, on-spec yield, cost-of-quality, and go-to-market models—designed to inform sourcing and M&A diligence.
- Regulatory risk maps and compliance checklists (US, EU, and key APAC jurisdictions), plus stress-tested operational scenarios for emissions and reporting obligations under recent regulatory updates.
- Operational mitigation strategies: feedstock hedging options, co-product valorization, and recommendations for near-source buffer inventory and micro-logistics to minimize downtime risk for fabs and critical synthesis lines.
Market dynamics you must track in 2026
- Feedstock and input-cost volatility: Elemental sulfur supply tightness and price movements have reappeared as a material input risk. Supply constraints driven by fertilizer and metals-processing demand—together with recovery rates at refineries—are driving procurement teams to revisit supplier diversification and forward purchase programs.
- Regulatory tightening and reporting: Recent enforcement and reporting regimes (for example, US EPA New Source Performance Standards for sulfuric acid plants and chemical reporting mandates) increase compliance costs and lengthen qualification lead times for new production assets. These dynamics raise the bar for greenfield entrants and elevate the value of trusted, audited suppliers.
- Fab and regional capex alignment: New semiconductor capacity investments—particularly in regions with coordinated incentives—are stimulating localized demand spikes for ultra-pure chemicals. Strategic suppliers are responding with targeted capacity projects and qualification partnerships; buyers must map supplier roadmaps to their fab ramp schedules to avoid bottlenecks.
- Concentration and bargaining dynamics: With the top suppliers collectively commanding a significant share of market supply, commercial negotiations are asymmetric. Buyers with predictable multi-year volumes can secure favorable terms; smaller consumers face higher exposure to spot-price swings and lead-time risk.
Competitive landscape — what incumbents are doing
The industry is anchored by global chemical groups and specialty electronic-chemicals firms that combine legacy process knowledge with electronic-grade quality systems. Key market participants include established multinational producers and niche specialists known for semiconductor qualification programs and stringent materials management.
Ultra-Pure Sulfuric Acid Market
- Strategic capacity shifts: Leading producers have recently signaled capacity investments targeted at semiconductor-grade capability. Announcements include European capacity expansions expected to come online in the mid-decade window—moves that are explicitly intended to serve wafer-cleaning and fabs backed by public incentives.
- Vertical positioning: Some players are integrating quality and logistics services—offering on-site blending, dedicated-purity packaging, and qualification support—to shorten time-to-qualification for wafer fabs and to capture higher-margin service revenue.
- Selective regionalization: Suppliers are calibrating footprint strategies to align with the nearshoring of semiconductor fabs; where demand volumes justify investment, providers are accelerating local capacity and qualification roadmaps to de-risk customer supply chains.
Our report’s company-level assessments profile leadership, technical differentiators and commercial strategies for principal suppliers—providing procurement and corporate strategy teams with the intelligence needed to prioritize supplier engagement and M&A screening.
Regulatory and ESG considerations that change deals
- Emission and reporting regimes: New source performance and chemical reporting standards require firms to quantify and manage emissions and to report production/use data—factors that can increase time and cost to scale new capacity and that also affect the diligence profile for potential targets.
- Environmental performance as commercial leverage: Fabricators increasingly require suppliers to demonstrate low environmental impact and traceable audits. Suppliers that can prove lower emissions intensity, circular feedstock usage or best-in-class waste management will gain commercial preference.
- Permitting and community risk: Local permitting complexity can extend project timelines; the full study includes a permitting risk heatmap and mitigation playbook for planned capacity expansions.
Actionable recommendations for 2026 corporate agendas
- Buy-side: Secure qualification paths now. If your operations depend on ultra-pure sulfuric acid, initiate multi-party qualification programs tied to fab ramp schedules. Consider staged supply agreements that combine committed volumes with capped spot exposure to balance cost and security.
- Supply-side: Turn purity expertise into service revenue. Beyond commodity supply, package qualification support, contamination-control advisory services, and tailored logistics into higher-margin offerings—particularly for semiconductor customers that value fast time-to-production.
- Investors and M&A teams: Screen for strategic assets. With market concentration favoring a few high-capability suppliers, mid-sized assets that shorten qualification timelines or expand regional presence can be accretive. Prioritize targets with audited quality systems, low time-to-qualify, and manageable environmental footprints.
- Risk management: Hedge feedstock exposure and plan buffers. Given feedstock price movement and periodic shortages, design procurement strategies combining forward contracts, strategic inventory, and alternate sourcing lanes to preserve uptime for critical processes.
- Regulatory readiness: Build compliance into commercial proposals. Factor emissions and reporting obligations into pricing and project timelines. Early engagement with local regulators and transparent reporting roadmaps can materially shorten approval cycles.
What you will not find here (and why it matters)
To preserve the report’s utility as an operational decisioning tool, this preview omits granular segment-level allocations, region-by-region revenue breakdowns, and precise application share figures. Those outputs—alongside supplier scorecards, pricing curves, and bespoke scenario models—are included in the full PW Consulting report and are essential for contract negotiation, capex scheduling, and M&A valuation work.
Next steps — how to use our work in 2026 planning
- Commission the full report for procurement and technical teams to obtain the segment-level forecasts, supplier benchmarking and qualification timelines necessary for contracts and capex alignment.
- Use the included scenario models to stress-test your supply plans against feedstock-constraint and regulatory-change scenarios for robust contingency planning.
- Engage PW Consulting for a tailored supplier diligence or target-screening engagement if you are evaluating capacity build, JV or acquisition opportunities.
In markets where purity, reliability and regulatory certainty drive commercial outcomes, having the right intelligence is not optional—it’s a competitive differentiator. PW Consulting’s Ultra-Pure Sulfuric Acid Market study is designed to convert industry complexity into clear actions for 2026. For the detailed segmentation, vendor profiles, and financial models that corporate and procurement teams require to execute with confidence, consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Ultra-Pure Sulfuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Continuous Emission Monitoring Systems (CEMS) Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
As regulatory scrutiny and corporate net-zero commitments intensify, the global Continuous Emission Monitoring Systems (CEMS) market has entered a multi-year growth phase. Our analysis, anchored on a 2025 base year and a comprehensive historical window (2020–2025), shows the market expanding at a compound annual growth rate (CAGR) of 9.4% through the 2026–2032 forecast horizon. From a market size of roughly USD 2.25 Billion in 2025, projected trajectories point to a materially larger installed base and service economy by 2032, driven by regulatory upgrades, technology substitution, and increasing demand for multi-pollutant, data-integrated solutions.
Continuous Emission Monitoring Systems (CEMS) Market
Why this research matters in 2026
- Regulatory inflection points: 2026 is not business as usual. Major compliance frameworks are being modernized—most notably the US EPA's ECMPS 2.0 rollout and revisions to European industrial emissions guidance—that will materially affect reporting, data format requirements, and the permissible measurement ranges for CEMS. These changes create both compliance risk and procurement opportunity windows.
- Technology parity and differentiation: Laser-based techniques, FTIR, hybrid analyzers, and improved particulate sensing are converging toward higher fidelity, lower maintenance, and expanded multi-species capability. Vendors that translate these technical advances into lower total cost of ownership (TCO) and simpler regulatory acceptance will capture share.
- Services and data monetization: As installations proliferate, the aftermarket—calibration, remote diagnostics, software updates, and data assurance—will represent an increasingly valuable margin pool. Buyers must evaluate OPEX impacts alongside capital costs.
- Supply chain and integration risk: CEMS is no longer plug-and-play; it sits at the intersection of field instrumentation, local control systems, and enterprise data platforms. Procurement decisions in 2026 must incorporate integration roadmaps and cyber-physical risk assessments.
What the PW Consulting CEMS study delivers
This report is designed for executives who must convert regulatory change and technology trends into investment-grade decisions during 2026. It provides actionable, operational intelligence across the entire investment timeline—from initial vendor shortlisting to multi-site rollout and aftermarket optimization.
Continuous Emission Monitoring Systems (CEMS) Market
- Proven market-sizing and forecast methodology with sensitivity scenarios reflecting regulatory acceleration and slower adoption paths.
- Clear articulation of near-term demand drivers and inhibitors, including an up-to-date regulatory matrix and compliance timelines affecting procurement cycles.
- Technology decision frameworks that translate instrument-level performance into plant-level KPIs: measurement accuracy, drift, calibration cadence, spare-parts footprint, and integration effort.
- Practical TCO models and deployment cost envelopes that allow finance teams to compare models across procurement, leasing, and service-centric contracting strategies.
- Vendor evaluation scorecards and RFP templates tailored for different buyer archetypes (large utility, mid-sized industrial, engineering service provider).
- Implementation playbooks and failure-mode checklists drawn from field deployments and supplier audits to minimize first-year performance risk.
Industry dynamics shaping 2026 decisions
- Policy and standard updates: The upcoming ECMPS 2.0 release (scheduled for Q1 2026) and tightened European compliance thresholds are accelerating replacement cycles for legacy systems and expanding the addressable market for high-fidelity, multi-gas analyzers.
- New product momentum: Recent product introductions—such as a hybrid laser-paramagnetic analyzer released in early 2026—indicate a vendor shift toward hybrid platforms that balance sensitivity with operational robustness. These launches are meaningful because they shorten the technology adoption lag for end-users who prioritize regulatory defensibility.
- Consolidation and concentration: Market concentration metrics show a moderate consolidation: the leading three vendors account for nearly half of industry revenues, and the top five approach roughly two-thirds. This structure informs competitive dynamics—scale matters for service coverage and software ecosystems, but niche specialists remain strategically important for bespoke or hard-to-measure pollutants.
- Cross-industry demand: Beyond the obvious utility and heavy-industrial buyers, demand pockets are emerging where multi-component, low-drift measurement capability matters—these include process industries, waste-to-energy, and large industrial complexes pursuing integrated emissions and energy optimization programs.
Competitive landscape: strategic takeaways for buyers and investors
We profile established global leaders, specialist instrument builders, and emerging systems integrators. The vendor universe shows differentiated positions along product breadth, regulatory pedigree, and aftermarket/service capability.
Continuous Emission Monitoring Systems (CEMS) Market
- ABB Ltd. (Zurich, Switzerland) — Recognized for its hardware breadth and compliance-focused offerings, ABB’s multi-component platforms deliver certified low-range measurement capability. Strategic buyers should engage ABB when project requirements prioritize regulatory defensibility and broad multi-gas coverage.
- Siemens AG (Munich, Germany) — With a process-analytics orientation, Siemens competes on systems integration and alignment with industrial control architectures. Their strength lies in marrying analytics to plant automation for operations-led emissions management.
- Emerson Electric Co. (St. Louis, USA) — Emerson’s recent introduction of a hybrid laser-paramagnetic analyzer underscores a push toward hybrid architectures that increase measurement scope while reducing maintenance. Emerson is a strong candidate where hybrid performance and supplier lifecycle support are decision criteria.
- Teledyne Technologies Inc. (Los Angeles, USA) — Teledyne’s component-level expertise—particularly in particulate monitors and high-performance gas modules—makes it a vital partner for OEMs and EPCs designing bespoke systems or upgrades.
- HORIBA, Ltd. (Kyoto, Japan) — Focused on integrated CEMS with robust software stacks, HORIBA is frequently selected by buyers seeking turnkey stack-gas monitoring with strong data processing capabilities.
- Thermo Fisher Scientific Inc. (Waltham, USA) — A go-to for compliance-critical analyzers in jurisdictions with strict EPA-aligned requirements, Thermo Fisher combines regulatory legacy with broad field acceptance.
- SICK AG (Waldkirch, Germany) — SICK’s particulate monitoring pedigree and integrated system offerings suit projects where dust measurement and continuity of reporting are central.
- DURAG GROUP (Hamburg, Germany) — Known for advanced dust and gas analyzers and industry-focused systems, DURAG is a fit for complex installations requiring specialized measurement chains.
- ENVEA Group (Paris, France) — ENVEA’s multi-pollutant stacks, including dioxins and mercury capability, position the company in niches with elevated regulatory complexity.
- Fuji Electric Co., Ltd. (Tokyo, Japan) — Fuji’s multi-component, real-time CEMS offerings are attractive for process industries seeking broad flue-gas visibility.
- Gasmet Technologies Oy (Helsinki, Finland) — FTIR specialists like Gasmet provide simultaneous multi-gas and VOC analysis that is particularly useful in complex-species monitoring and fugitive emissions screening.
- AMETEK, Inc.; IMR Environmental; M&C TechGroup; California Analytical Instruments — These firms occupy important niches: compliance analyzers, environmental monitoring, continuous process monitoring, and regionally focused gas analyzer expertise. They are commonly used in hybrid procurement strategies where OEM-supply is combined with specialist integration.
Strategic implications for 2026 execution
- Align procurement with regulatory timelines: Given the timing of ECMPS 2.0 and similar updates, staged procurement that prioritizes high-risk sites and regulatory hot spots will protect compliance while smoothing capex profiles.
- Prioritize TCO and service networks: The choice between a lower-capex instrument and a service-rich supplier will often be decided by the site’s ability to perform on-site calibration and the criticality of uninterrupted data streams. Factor lifecycle service availability into vendor scoring.
- Design for data integration: Contracts should include data-format and API requirements, cyber-security provisions, and provisions for third-party validation to reduce lock-in risk and ensure auditability.
- Use pilots to de-risk technology adoption: Pilot deployments of hybrid or FTIR systems on representative stacks reduce uncertainty and reveal operational integration costs not obvious in vendor literature.
- Consider M&A and partnership screening: For investors, the moderate concentration in the market suggests opportunities to consolidate regional specialists or to back service platform plays that aggregate data across portfolios.
How to convert this intelligence into 90-day actions
- Run a rapid compliance gap assessment across your asset base, prioritizing sites with imminent reporting changes or known measurement blind spots.
- Initiate vendor shortlists using the scorecards in this report, conducting RFIs that request lifecycle cost models and integration case studies rather than list prices.
- Launch 3–6 month pilots for at least two different technology approaches (e.g., hybrid vs. FTIR) to validate TCO assumptions under operational conditions.
- Negotiate service-level agreements that include data integrity clauses, spare parts turnaround times, and remote diagnostics—then incorporate them into your capital planning.
Closing – a pragmatic invitation
For executives who must build defensible 2026 budgets, select the right CEMS partners, or evaluate acquisition targets, this PW Consulting study provides the analytical scaffolding and operational tools to turn regulatory and technology change into competitive advantage. The analysis above intentionally highlights strategic signals and supplier positioning while withholding the granular segment-level tables and proprietary vendor scoring that are central to competitive procurement. To access the full segmentation, supplier scorecards, methodology, and downloadable RFP templates, please visit our report page for the complete dataset and tailored briefings.
For detailed analysis of this topic, please visit the official page: Continuous Emission Monitoring Systems (CEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cigarette Market at USD 808.49M in 2025, 2.45% CAGR to 2032
By PW Consulting, 2026-07-12
Cigarette Market 2026: Strategic Preview for Decision Makers
As PW Consulting’s Lead Industry Analyst, I offer a concise but strategically rich preview of our full Cigarette Market study — a report designed to equip senior executives with the situational awareness and decision-ready frameworks needed for 2026. Below I surface the macro signals, competitive implications, and high‑impact decision levers that every C‑suite, investor, and policymaker should factor into near‑term plans. This piece intentionally demonstrates our analytical depth while reserving the granular segment tables and company‑level data sets for the full report available via our platform.
Cigarette Market
Market snapshot: what the headline numbers reveal
Using 2025 as the base year, our market architecture shows a mature global market that is neither collapsing nor booming — but evolving. The market size in 2025 reached approximately USD 808.5 Million (base year 2025, historical series 2020–2025). Our forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 2.45%, with the market continuing to expand modestly through 2032 under a set of industry‑specific structural drivers and regulatory pressures.
Cigarette Market
- Stability with pockets of volatility: the aggregate trajectory to 2032 implies steady growth punctuated by discrete year‑to‑year variations driven by policy, pricing actions, and supply shocks.
- Concentrated competitive structure: the market exhibits a high degree of concentration among a few global incumbent groups, a dynamic that intensifies the strategic importance of scale, distribution reach, and regulatory influence.
Why these macro facts matter for 2026 decisions
- Capital allocation under constrained growth: a contained CAGR around 2.45% means that incremental revenue from organic volume expansion will be modest industry‑wide. Management teams must therefore prioritize margin expansion (pricing, cost control, product mix) and selective inorganic moves that increase strategic control of growth levers.
- Regulatory sensitivity: with multiple regulatory inflection points expected to take effect or evolve in the 2026–2028 window, firms face asymmetric execution risk. Proactive regulatory scenario planning — rather than reactive cost‑cutting — is the superior value protection strategy in 2026.
- Supply chain resilience as competitive moat: volatility in tobacco leaf and clove markets and periodic natural‑resource shocks can compress margins suddenly. Firms that invest in diversified sourcing, direct farming partnerships, and financial hedges will preserve competitive profitability.
Report practicalities — what the full study gives you
The PW Consulting Cigarette Market report is intentionally operational. It is structured for executives who need to act now, not just theorize. Key deliverables include:
Cigarette Market
- Granular market sizing and validated forecasts (2026–2032) with sensitivity scenarios reflecting regulatory, taxation, and consumer preference shocks.
- Decision-ready playbooks: pricing and promotion playbooks for taxed markets, go‑to‑market templates for accelerated online penetration, and SKU rationalization frameworks aimed at preserving margins.
- Competitive benchmarking and capability maps: relative position analyses across manufacturing scale, distribution reach, alternative product portfolios, and regulatory affairs capability.
- M&A and partnership heatmaps: prioritized targets and partnership modes aligned to complementary gaps (e.g., next‑gen heated systems, reduced‑risk products, direct retail presence).
- Country and regulatory dashboards: curated regulatory timelines, excise tax scenarios, and enforcement risk indicators tailored to executives and public affairs leads.
- Supply chain and sourcing risk matrix: supplier concentration, critical raw material exposures, and recommended mitigation levers, including farming partnerships and inventory strategies.
These assets are supported by primary interviews, proprietary shipment intelligence, and cross‑validated public disclosures. The full report contains downloadable data tables and dashboards not reproduced here — designed to be used directly in board decks and investor diligence.
Competitive landscape — how the incumbents are shaping market structure
The market remains oligopolistic. A small number of global players control the lion’s share of manufacturing, brand equity, and distribution muscle. This concentration underpins strategic behaviors we expect to influence 2026 outcomes:
- Scale and brand stewardship. Global leaders leverage scale for cost advantages and deploy flagship brands to defend premium margins. Expect continued focus on sustaining leadership brands while selectively incubating alternate product formats.
- Portfolio diversification toward reduced‑risk products. Incumbents are increasingly balancing combustible portfolios with heated‑tobacco and nicotine alternatives as hedges against regulatory and demand shifts.
- Geographic and channel optimization. Firms are reconfiguring exposure across markets and accelerating channel investments (including e‑commerce and direct‑to‑consumer pilots) where regulatory frameworks permit.
Key players covered in the report include global groups with varied strategic postures: established multinational manufacturers based in Europe, North America, and Asia, each combining legacy combustible portfolios with differing commitments to next‑generation formats. Our company profiles synthesize public disclosures, shipment intelligence, and recent strategic moves to create actionable competitor playbooks you can use in boardroom debates.
Recent events and regulation shaping 2026 strategy
Several concrete developments provide a near‑term roadmap of risk and opportunity:
- Product innovation is accelerating: recent launches of advanced heated tobacco systems and compact reduced‑risk devices underscore intensifying competition in non‑combustible formats. These product introductions are not mere extensions; they are strategic hedges that alter channel, marketing and regulatory engagement needs.
- Tax and enforcement updates are reshaping economic returns: changes in taxation across major jurisdictions and emergent enforcement priorities for novel products elevate the cost of market entry and intensify compliance demands for 2026.
- Price adjustments in response to fiscal changes: manufacturers in several markets have adjusted pricing to absorb excise and structural tax changes while protecting margins — a tactical play that has implications for illicit trade dynamics and volume elasticity assumptions.
- Raw material and agronomic exposures: direct sourcing strategies and leaf price fluctuations materially affected last‑year profitability for major manufacturers; firms with greater vertical integration or long‑term contracts fared better.
Strategic recommendations for 2026
The path to preserving and growing value in 2026 is multidimensional. Based on our scenario analysis and stress tests, we recommend executives prioritize these actions:
- Rebalance the portfolio toward margin resilience. Optimize SKU breadth and pricing architecture to prioritize margin contribution per point of distribution.
- Accelerate investment in next‑gen products selectively. Prioritize segments where regulatory clarity is emerging and consumer acceptance is evident; treat others as opportunistic pilots until policy risk subsides.
- Fortify supply chains and farmer partnerships. Expand direct sourcing where feasible, and put in place commodity price hedges and buffer inventories for critical leaf inputs.
- Deploy scenario‑based regulatory playbooks. Build a small, empowered team to run rapid regulatory impact analyses and prepare communications and lobbying strategies tied to discrete policy milestones through 2028.
- Use M&A and partnerships defensively and offensively. Consider acquisitions that close capability gaps (e.g., heating technology, digital loyalty platforms), and use JV structures in high‑risk jurisdictions to share execution risk.
- Digitize distribution thoughtfully. Expand online channels where legally permissible and integrate them with loyalty and harm‑minimization communication strategies to capture customer lifetime value.
How PW Consulting can support execution
Our full Cigarette Market package equips clients with a playbook for immediate execution and a living data set for ongoing monitoring. Specific services include market entry due diligence, merger integration roadmaps, pricing optimization models, regulatory intelligence subscriptions, and custom scenario workshops for executive teams.
Importantly, this preview omits the granular segment and regional tables that matter when you move from strategy to execution. The full report contains those datasets, including downloadable tables, slice‑and‑dice dashboards, and company‑level market share matrices that enable transactional decisions and board reporting.
Next step — access the intelligence you need
For 2026, the difference between tactical survival and strategic progress will be how quickly organizations convert high‑level signals into prioritized actions. Our comprehensive report provides the data, scenarios, and operating playbooks to do exactly that. Visit our report landing page to access the complete dataset, segmented analysis, and client‑only tools that translate these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Cigarette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SBC Market at USD 2,900M in 2025, poised for 5.5% CAGR (2026-2032)
By PW Consulting, 2026-07-12
Single Board Computer (SBC) Market — 2026 Strategic Primer
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused executive primer on our Single Board Computer (SBC) market study — a practitioner’s intelligence product designed to inform high-stakes corporate decisions in 2026. This overview distills the report’s strategic value, highlights the competitive fault lines reshaping supplier choice, and outlines the operational playbooks that matter for procurement, product architecture and M&A evaluation. It deliberately previews our analytical approach and headline market dynamics while reserving the granular segment and share data for the full report — the actionable intelligence that enables confident decisions.
Single Board Computer (SBC) Market
Market at a Glance: headline sizing and trajectory
By our base year (2025) accounting, the global SBC market reached roughly USD 2.9 billion. Looking forward, the market is expected to expand at a compound annual growth rate (CAGR) of approximately 5.5% across the 2026–2032 forecast horizon, taking the market into the low‑to‑mid USD 4‑billion range by 2032. That steady growth masks meaningful structural change: the market is shifting from hobbyist and education-first use cases to commercially driven deployments in edge AI, industrial automation and embedded IoT. For any organization evaluating platform choices or supplier strategies in 2026, the question is no longer whether SBCs fit your architecture — it is which SBC ecosystem, BOM structure and partner model will minimize technical debt and maximize time-to-market over the next five to seven years.
Single Board Computer (SBC) Market
Why this study matters for 2026 decision cycles
-
Portfolio prioritization under uncertainty — SBCs are now strategic components in product roadmaps for gateways, vision systems, and compact AI inferencing nodes. Our study translates macro growth into actionable decision triggers: when to standardize on ARM-based reference platforms, when to preserve x86 or RISC‑V options for legacy or specialized workloads, and when to hedge across multiple architectures to protect roadmap optionality.
Single Board Computer (SBC) Market -
Supply-chain realism — component concentration and SoC pricing dynamics materially affect unit economics. For higher‑spec boards, ARM-based SoCs represent the dominant cost position in the bill‑of‑materials, a factor you must quantify when negotiating supplier contracts or planning BOM substitutions. The report includes a procurement sensitivity model that shows how supplier pricing and SoC availability scenarios impact product gross margins.
-
Regulatory & export-policy risk — export controls on advanced semiconductors create asymmetric availability across regions and can upend supplier selection for multinational deployments. Our legal and trade annex translates current control regimes into practical sourcing constraints and contingency checklists suitable for product and legal teams.
-
Technology inflection points — the rapid introduction of AI‑capable boards and compute modules is changing system partitioning. Our technology roadmap maps the timing and practical thresholds (performance-per-watt, NPU availability, thermal envelopes) that tip a design from “software-only” to “hardware-accelerated” edge AI.
What the full report delivers (practical, hands‑on content)
-
Market-sizing methodology and validated historical series (2020–2025) plus scenario-driven forecasts (2026–2032) — with sensitivity bands reflecting supply shocks and accelerated AI adoption.
-
BOM and cost engineering playbooks that quantify the cost impact of alternate SoCs, memory tiers and connectivity options; includes vendor negotiation levers and SKU rationalization frameworks.
-
Go‑to‑market and channel strategies for enterprises and OEMs: design partnership models, volume discount strategies, and fulfilment architectures for global rollouts.
-
Competitive mapping and positioning matrices that analyze product, pricing, and downstream ecosystem strengths — essential for supplier selection and M&A screening.
-
Risk and compliance annexes: export control implications, quality management standards relevance (e.g., ISO 9001 in manufacturing chains), and an IP/supply compliance checklist for accelerated prototyping.
-
Decision tools — downloadable templates and dashboards: supplier scorecards, TCO calculators, migration roadmaps and an edge‑AI readiness index to benchmark candidate SBCs against project requirements.
Competitive landscape — who matters and why
The SBC ecosystem combines legacy community-driven players, nimble Chinese OEMs, and industrial suppliers focused on ruggedized, certified modules. Understanding each cohort’s strengths is essential to match a supplier to your program risk profile.
-
Raspberry Pi Foundation (Cambridge, UK): the de facto standard-bearer in community and education markets, and increasingly present in commercial prototyping thanks to strong software ecosystem and brand recognition. Recent product moves extend their keyboard-form and module offerings, reinforcing their role as a baseline reference platform for developers.
-
BeagleBoard.org Foundation (Oakland Twp, MI): maintains a strong open‑source interoperability and standards posture. For organizations prioritizing open hardware/software stacks and long‑term maintainability, BeagleBoard’s community-driven models reduce integration friction.
-
Chinese OEMs (Orange Pi, Radxa, Banana Pi, Khadas, FriendlyElec): these manufacturers are accelerating technical feature parity and price performance. Recent launches demonstrate broader support for high‑performance compute and alternative ISAs (including RISC‑V experiments), creating competitive pressure on traditional suppliers.
-
Industrial suppliers (Avalue Technology, Axiomtek, Kontron): focus on ruggedization, certification, and enterprise lifecycle support. Their Pico‑ITX and industrial SBCs are designed for longer product lifecycles and deterministic supply — crucial for automation and mission‑critical deployments.
New entrants and module vendors such as LattePanda and Quectel are also relevant for niche x86 use cases and integrated IoT prototyping respectively. Across the board, product launches from late 2025 through early 2026 underscore two dynamics: (1) feature convergence between hobbyist and industrial boards (performance, memory, onboard NPUs), and (2) faster cadence of new SKUs, which increases obsolescence risk for long‑lifecycle systems.
Recent product and market signals (selection)
-
Multiple vendors accelerated high‑performance and AI‑capable board releases in late 2025 and early 2026 — an indicator that vendors are racing to capture developer mindshare and early enterprise adopters.
-
Industrial suppliers introduced ultra‑compact Pico‑ITX solutions targeting AI-native portable systems — a clear signal that edge AI is pushing form‑factor innovation into certified industrial footprints.
-
Open‑source and community foundations continue to invest in interoperability standards — a structural advantage for enterprises seeking predictable software stacks and long-term maintainability.
Strategic implications and recommended actions for 2026
-
Define a platform taxonomy aligned to business objectives: “innovation,” “volume product,” and “mission‑critical” should map to distinct procurement rules (community boards for R&D, vetted OEMs for scaled products, industrial suppliers for critical systems).
-
Embed BOM scenario planning in product development: require suppliers to provide alternate SoC and memory pathways; run our sensitivity model to quantify margin and lead‑time risk for each design choice.
-
Prioritize supplier audit and compliance timelines: export controls and quality certifications materially affect cross‑border rollouts — integrate legal and T3 supplier audits before committing to long‑lead contracts.
-
Adopt a staged validation program for AI-capable boards: bench and field tests should validate performance, thermal behaviour, and software stack compatibility under representative loads — reduce surprise later in production.
-
Consider strategic partnerships and minority investments: selective engagement with innovative OEMs can secure supply and early access to roadmap features—particularly where RISC‑V or alternative architecture support is a strategic hedge.
How to use the full PW Consulting SBC study
The report is built for execution teams: product managers, procurement, and corporate development. Use it to (a) accelerate supplier shortlists with our scorecards, (b) quantify cost and time-to-market trade-offs with the included TCO and BOM models, and (c) identify M&A and partnership targets via our competitive matrices and recent developments tracker. Importantly, the granular segment intelligence (regional splits, application shares, vendor revenue shares and CR metrics) is intentionally held in the substantive report package to preserve its value as decision-grade intelligence.
Conclusion — a pragmatic next step
For 2026, SBC strategy is less about whether to adopt and more about how to adopt resiliently. The market’s steady growth trajectory and rapid technical iteration require disciplined platform governance, supply‑chain contingency planning, and deliberate investment in software portability. Our study supplies the models, supplier intelligence, playbooks and compliance tools required to make those calls. For the detailed segment allocations, competitive shares and downloadable decision tools that execute the strategies summarized here, access the full PW Consulting SBC Market report and the accompanying Excel workbooks.
Contact PW Consulting for an executive briefing, tailored supplier scorecard, or deployment readiness assessment to translate these insights into an executable 2026 SBC strategy.
For detailed analysis of this topic, please visit the official page: Single Board Computer (SBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


