



PW Consulting: Marker Pens Market to Hit USD 443.2M by 2032 at 5.78% CAGR
By PW Consulting, 2026-07-12
Marker Pens Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our Marker Pens Market study — a pragmatic intelligence package designed to support boardroom decisions in 2026. This overview demonstrates the analytical depth of our work while intentionally withholding granular segment tables and regional breakdowns to encourage direct access to the full report. What follows is an executive trailer: the context, the high‑level market geometry, the competitor dynamics that matter, and the practical playbook for near‑term strategic moves.
Marker Pens Market
Why this 2026 preview matters
Marker pens are a deceptively resilient product category. Over the period we reviewed (2020–2025), the global market expanded steadily, driven by persistent demand across education, corporate, creative and industrial end‑uses. Using 2025 as our base year, the market reached USD 300.0 Million (USD Million basis), and our model projects continued expansion through 2032 — reaching the high hundreds by the end of the forecast period at a compound annual growth rate (CAGR) of 5.78% for 2026–2032. This translates into multi‑year, predictable demand that supports a variety of strategic moves: capacity investments, portfolio premiumization, sustainability retrofits, and channel restructuring.
Marker Pens Market
How PW Consulting’s research supports 2026 decisions
-
Actionable market sizing and demand scenarios — We provide defensible topline forecasts and three stress‑tested scenarios (base, upside, downside) calibrated to supply shocks, regulatory tightening, and alternate consumer sentiment paths. That means you can stress test capex and working capital plans under realistic conditions rather than optimistic extrapolation.
Marker Pens Market -
Go‑to‑market and channel playbooks — Detailed guidance on optimizing retail, institutional procurement and D2C/e‑commerce mix, with margin simulations that show where re‑pricing or packaging innovation unlocks incremental EBIT. We map buyer economics so commercial teams can run value‑based negotiations with distributors and large institutional accounts.
-
Product and innovation roadmap — Prioritized use cases for premium inks, low‑VOC formulations, washable variants and specialty tips. Our R&D decision matrices link development cost, time‑to‑market and marginal value so R&D budgets are allocated to the highest ROI product features for 2026–2028.
-
Supply chain and sourcing diagnostics — A supplier risk heat map, alternative raw material pathways and a practical checklist for onshoring vs. offshore tradeoffs, informed by recent large‑scale investments and realignment across the industry.
-
Regulatory and sustainability playbook — Compliance checklists that convert complex rules into operational tasks: labeling requirements, low‑VOC production pathways, packaging and country‑of‑origin marking obligations, and costed mitigation options for solvent reductions.
-
M&A and competitive response templates — A short list of strategic targets by capability and consolidation rationale, plus playbooks for integration that preserve innovation pipelines and customer relationships.
Market dynamics that should shape 2026 capital allocation
Three themes dominate the market landscape and should inform capital allocation decisions this year:
-
Sustainability and regulatory tightening. Safety labeling for art materials and stricter environmental requirements across major developed markets are raising compliance and formulation costs. Manufacturers that proactively reformulate toward low‑emission and non‑toxic inks gain both license to operate and commercial differentiation with sensitive buyer cohorts (parents, schools, healthcare, and corporate buyers).
-
Operational realignment & onshoring. Several major players have moved to reconfigure production footprints to shorten lead times and reduce supply chain fragility. Onshoring choices can increase fixed costs but yield faster replenishment, lower inventory buffers and stronger control over quality for premium lines.
-
Premiumization and experiential packaging. The category’s growth is increasingly shaped by product experiences — collector sets, themed and artist collaborations, and refillable or reusable packaging. Packaging is shifting from a simple container to an engagement tool that supports brand loyalty and higher price points.
Competitive landscape: who shapes the game
The Marker Pens market remains moderately concentrated. The top three firms account for a significant share of the market, and the top five increase that concentration further — a dynamic that creates both predictable benchmarks and defensive pressures for smaller innovators. Our competitor intelligence focuses on strategic moves, capacity choices, product innovation and brand plays rather than simple headline market shares.
-
Newell Brands — A dominant consumer brand steward, Newell continues to leverage iconic labels. Recent strategic moves include a material onshoring effort and refreshed product innovations and packaging designed to support premium multipacks and enhanced in‑store visibility.
-
BIC Group — A mass‑market operator that plays aggressively on design collaborations and broad distribution. Their consumer‑facing campaigns are tailored to trend cycles, increasing relevance in youthful and fandom audiences.
-
Faber‑Castell AG — A premium art market incumbent with consistent investment in artist‑grade formulations and curated product lines that support higher ASPs and professional channels.
-
Other notable players — Established manufacturers from Japan, Germany, India and the US that balance professional, creative and institutional offerings. Each company differentiates on ink chemistry, tip technology, brand heritage and channel reach.
Recent industry moves that matter in 2026
-
Major brand onshoring and capacity investments: significant capital redeployments to shorten supply chains and improve responsiveness have already altered supplier bargaining dynamics and serve as a blueprint for companies considering similar investments.
-
Product extensions and premium packaging: market leaders continue to invest in themed collections, dual‑tip lines, and reusable packaging as ways to raise wallet share without broadening distribution footprints.
-
Marketing through cultural partnerships: targeted collaborations (e.g., with artists and influencers) have proven effective to accelerate premiumization and to convert occasional buyers into repeat purchasers.
-
Regulatory signals: incremental changes in labeling and packaging rules have elevated operational compliance from a back‑office cost center to a strategic constraint requiring early design consideration.
Implications for strategic choices in 2026
For executives making capital and commercial decisions in 2026, three high‑impact decisions should be prioritized:
-
Decide the role of manufacturing footprint: If your strategy leans to premium, responsiveness and reduced lead times, plan onshore capacity investments and shorter supply chains with a corresponding review of labor and automation models. If the priority is cost leadership, secure low‑cost raw material contracts and deepen relationships with validated offshore partners.
-
Invest in reformulation and certification: Prioritize low‑VOC and non‑toxic ink programs that align with international safety labeling standards. Certification and labeling are not just compliance costs — they are demand signals for large institutional buyers.
-
Monetize brand experiences: Reallocate a portion of commercial budgets from traditional promotions to co‑created product lines and reusable packaging that deliver higher lifetime value per customer.
What this preview intentionally omits (and why)
To preserve the strategic value of the full PW Consulting Marker Pens Market report, this preview intentionally omits the detailed regional and application splits, specific segment revenue tables and pricing matrices. Those granular datasets underpin viable buy/sell valuations, buyer negotiation strategies and precise SKU rationalization — and are included in the full report along with downloadable models. The purpose of this trailer is to present the high‑value conclusions and the operational levers executives need now, while directing decision makers to the report for the raw inputs and proprietary tables required for transaction planning and board approvals.
Next steps for executives
-
Commission a 90‑day rapid audit: Use our template to validate your top three product lines on the dimensions of margin, regulatory risk and channel velocity.
-
Run a scenario workshop: Use the three PW Consulting demand scenarios to stress test 2026 capex and supply chain choices with finance and operations teams.
-
Engage with our M&A play desk: If consolidation is a strategic priority, request our shortlist of targets categorized by capability and integration risk.
Concluding note
The marker pens category is far from commoditized; it is a mature market with clear levers for value creation in 2026. Whether you are a C‑suite executive planning capacity investments, a commercial leader resetting channel strategy, or a product head prioritizing the next R&D quarter, the intelligence in our full Marker Pens Market study converts general industry awareness into executable choices. If your mandate for 2026 includes improving margins, mitigating regulatory exposure, or accelerating premium growth, the material we assembled will materially shorten your decision cycle.
To access the full dataset, detailed segmentation, competitor scorecards, and the downloadable financial models referenced in this preview, please visit the PW Consulting Marker Pens Market report landing page.
For detailed analysis of this topic, please visit the official page: Marker Pens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fishing Nets Market to reach USD 331.04M by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
Fishing Nets Market — 2026 Strategic Outlook (PW Consulting)
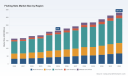
The global fishing nets market is at a tactical inflection point. After steady expansion through the early 2020s, the sector’s total recorded market value reached an estimated USD 215.0 Million in our base year (2025). PW Consulting’s forecast shows the market reaccelerating across 2026–2032 at a compound annual growth rate (CAGR) of 6.5%, moving toward an expected market size north of USD 330 Million by the end of the forecast horizon. For executives sizing production investments, negotiating supplier contracts, or evaluating M&A and product-innovation plays, those topline dynamics are the starting point — not the full story. This preview explains why our Fishing Nets Market study is a decision-useful asset for 2026 planning while intentionally preserving the granular segment tables and regional splits found only in the full report.
Fishing Nets Market
Why this study matters for 2026 decisions
- Capital allocation that matches market tempo. The macro growth rate and trajectory clarify the window for scale investments in automated manufacturing, high-value material integration, and recycling capacity. Knowing the likely market envelope reduces the risk of overbuilding fixed assets or missing first-mover advantage.
- Supplier and raw-material strategy. Raw-material choices (from conventional polyamides to high-performance fibers and emerging biodegradable polymers) are driving lifecycle economics. The study quantifies how material selection alters total cost of ownership, replacement cadence, and end-of-life liabilities — insights essential to multi-year procurement contracts.
- Regulatory and circular-economy de-risking. Rapid regulatory shifts in key jurisdictions are transforming end-of-life handling and creating recovery opportunities. Our analysis shows which compliance-driven investments will become table stakes versus which can be monetized through secondary markets.
- Competitive playbook for consolidation or niche defense. With market concentration remaining modest, targeted roll-ups or capability-focused partnerships can materially change competitive position. We provide the market maps and valuation sensitivities required to execute informed M&A screening.
- Product and go-to-market prioritization. The report translates growth dynamics into prioritized product roadmaps and channel strategies for commercial, aquaculture and recreational segments, enabling faster time-to-value for R&D and pilot programs.
What the full report delivers (operationally focused)
- Executive summary and investment thesis tailored for C-suite decision points in 2026.
- Market-sizing methodology and reconciled historical series (2020–2025) with a transparent forecast model for 2026–2032, including sensitivity scenarios around fuel, polymer pricing, and accelerated regulation.
- Segment and subsegment analyses with modular dashboards (region, material, application) — note: the preview omits the detailed split tables to preserve strategic confidentiality.
- Material-cost and lifecycle cost models comparing conventional polymers, high-performance fibers, and biodegradable alternatives.
- End-of-life pathways and circular-economy playbooks — technical feasibility, capital requirements, and revenue recovery curves for recycling/upcycling options.
- Technology and manufacturing benchmarking: manual, semi-automated and fully automated lines, labor productivity, and capex-per-tonne comparisons.
- Competitive landscape and supplier shortlists with capability matrices, commercial terms benchmarking, and partnership targets.
- Regulatory tracker and scenario planning for major jurisdictions affecting fisheries and marine waste.
- Actionable 90-day and 12-month playbooks for procurement, product development and M&A teams.
Competitive landscape: strategic implications from leading players
The sector combines legacy craft specialists, regionally concentrated manufacturers, and a growing set of technology-led suppliers. Market concentration metrics indicate a fragmented global footprint (with the top three and top five shares at modest single-digit to low-double-digit levels), which creates opportunity for scale-driven consolidation or capability-driven differentiation.
Fishing Nets Market
- Garware Technical Fibres Ltd. (Mumbai, India) — A vertically integrated specialist with in‑house fiber-to-finished-product capability and proprietary low-drag formulations. Garware’s advantage is control over the value chain, enabling rapid iterations on material science and premium positioning for high-tenacity requirements. Strategic question for competitors: can you match material IP or win on service and lifecycle economics?
- Duluth Fish Nets (Duluth, Minnesota, USA) — A heritage handcrafted specialist serving domestic fleets and recreational users. Duluth’s moat is brand trust and bespoke capability. For buyers prioritizing customization or nearshore supply, artisanal operators remain defensible despite automation trends.
- Altela (France) — A transformer and supplier to netmakers offering competitive cost and lead-time optimization. Companies like Altela are critical to the low-cost tier of the value chain and can become acquisition targets for producers seeking to vertically integrate sourcing efficiency.
- King Chou Marine Technology Co., Ltd. (Taiwan) — Focused on polyethylene and nylon nets plus aquaculture cage systems for offshore operations. Its strength lies in high-performance offshore solutions — an attractive capability given the growing offshore aquaculture investments.
- Euronete (Portugal) — Automated manufacturing and close OEM integrations make Euronete a go-to supplier for fleet-scale contracts. OEM ties can produce long-term, high-volume contracts that act as a barrier to smaller players.
- Bridon International Ltd. (UK) — A ropes-and-twine specialist supporting demanding North Sea and North Atlantic operations. Bridon demonstrates how complementary product lines (ropes, twines) add stickiness to commercial relationships.
- Van Beelen Industry & Trade (Netherlands) — Dyneema®-based solutions extend service life and lower replacement cost of ownership for deep‑sea fleets. This material-led value proposition is central to discussions on premiumization and TCO-driven procurement.
- Khon Kaen Fishing Net Factory (Thailand), Shyh Yung Fa Fishery Equipment (Taiwan), Memphis Net & Twine (USA) — These regional manufacturers provide scale, processing competence, and near-market responsiveness. They exemplify the varied routes to competitiveness: low-cost scale, processing technology, and domestic proximity.
Market dynamics, recent developments and tactical risks
Several contemporaneous signals are reshaping strategic priorities for 2026:
Fishing Nets Market
- Sustainability and circularity are moving from compliance to commercial opportunity. Initiatives to collect and upcycle end-of-life nets (including a recent national startup program and institutional cleanup projects in Europe) indicate both reputational and feedstock value. Regulatory shifts in key markets are reclassifying recovered nets in ways that enable recovery and recycling economics to be captured by the private sector.
- Material innovation is bifurcating the market. Trials of biodegradable polymers and adoption of high-performance fibers like Dyneema® change replacement cycles and lifetime costs. Early pilots show biomass and operational performance benefits in aquaculture trials — a clear signal for operators to pilot and measure, not merely to speculate.
- Trade and tariff levers are influencing component costs. Targeted tariff relief in certain markets for floats and buoys reduces input cost volatility for net assemblers and creates localized opportunities for cost arbitrage.
- Ghost-net remediation is a reputational and regulatory flashpoint. High-visibility collection ops increase pressure on producers and fleets to demonstrate end-of-life pathways, with implications for product warranties and service offerings.
Practical 90‑day plan for management teams
- Run an internal TCO exercise for current net suites vs. Dyneema and biodegradable pilots; define three fleet/test sites and KPIs (durability, catch-efficiency, replacement cadence).
- Initiate supplier bilateral audits focused on circularity and traceability; shortlist 2–3 strategic partners for supply agreements and recycling commitments.
- Map regulatory exposure across your operating jurisdictions and create compliance-triggered investment thresholds (e.g., when recovery obligations create a payback case for in-house recycling).
- Finance: model consolidation scenarios using our valuation sensitivities to prioritize bolt-on acquisitions or JV structures that accelerate entry to recycling and automation capabilities.
- R&D/Marketing: design a pilot launch for eco-labelled nets targeting fleets and aquaculture customers willing to pay for verified lifecycle impact reductions.
PW Consulting’s full Fishing Nets Market report provides the quantified inputs, supplier scorecards and the scenario models required to execute the 90‑day plan above. This preview outlines the strategic levers — the full intelligence package contains the granular matrices and proprietary data necessary to operationalize them.
Next steps
For executives preparing 2026 budgets or seeking M&A and procurement advantage, the full report is the working tool: it includes the segment-level tables, regional dashboards and supplier scorecards referenced but intentionally withheld in this overview. Contact PW Consulting to obtain the full study, request a bespoke briefing, or commission a tailored workshop that translates these strategic directions into board-ready action plans.
For detailed analysis of this topic, please visit the official page: Fishing Nets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Night Light Market — Strategic Outlook for 2026: Executive Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our forthcoming Night Light Market study. This executive preview is designed to orient corporate leaders, product strategists, and investment committees preparing for decisions in 2026. It highlights the strategic value of the full report, summarizes the macro dynamics that will shape vendor and investor outcomes, and outlines the actionable, decision-grade deliverables contained in the full study — while intentionally withholding core segment-level datapoints to preserve the report’s commercial value.
Night Light Market
Why this study matters for 2026 decisions
The night light category has evolved from a commoditized accessory into a diversified node at the intersection of lighting, IoT, safety regulation, and consumer gifting. Our market model — calibrated to a 2025 base year and a forecast horizon through 2032 — shows steady expansion driven by product innovation, channel shifts, and energy-transition dynamics. The global market expanded from the mid-hundreds of millions of USD in 2020 to an estimated total market size of USD 295 Million in 2025, and our modelling projects growth to roughly USD 400 Million by 2032 at a compound annual growth rate (CAGR) of 4.5% over the forecast period.
Night Light Market
That steady CAGR masks important inflection points relevant to 2026 planning: rising adoption of integrated commercial fixtures, the mainstreaming of rechargeable and motion-activated devices, and regulatory scrutiny that elevates product safety as a competitive moat. For firms contemplating product roadmaps, pricing shifts, or cross-border manufacturing decisions in 2026, the implications are clear — incremental revenue gains will accrue to players that pair design for compliance with channel-specific propositions (retail gift, e‑commerce, commercial lighting) and lower total cost of ownership for end customers.
Night Light Market
Core strategic themes you need to watch
-
Product-to-channel alignment: Night lights now span purpose-built commercial fixtures and impulse-purchase consumer goods. Commercial product innovations — exemplified by integrated flush-mount downlights with built-in night functionality — represent a materially different buyer, sales process, and lifetime-value profile than gift-oriented novelty night lights. 2026 strategies must separate channel economics and tailor SKUs accordingly.
-
Energy transition as a demand signal: Nighttime luminosity data and urban energy transition metrics are emerging as leading indicators for demand shifts. Recent high-resolution visualizations of nighttime light changes underscore geographic shifts in energy consumption and industrial activity — signals that buyers and planners can use to anticipate growth pockets and distribution priorities.
-
Compliance and product safety: Historical regulatory actions continue to inform design requirements. Robust design-for-compliance is non-negotiable in 2026; firms that proactively engineer to avoid recalls and fines will gain time-to-market advantages and channel trust.
-
Supply chain and tariff sensitivity: Material composition (plastics, glass, connectors) and tariff classification are routine but consequential drivers of landed cost. Procurement and IP-aware sourcing strategies can preserve margin even in modestly inflationary environments.
-
Low-power and off-grid innovation: Motion-activated and solar-powered variants change total cost-of-ownership dynamics. With active-mode consumption often measured in fractions of a single digit of watts, energy-efficient designs reduce buyer sensitivity to operational cost and open opportunities in sustainability-focused specifications.
What the full report delivers (practical, operational assets)
-
Transparent market sizing and forecast model: An auditable Excel model covering 2020–2025 historicals and 2026–2032 forecasts. The model includes alternate scenarios, sensitivity levers for raw material cost, and a reconciled demand-driver approach (end-use adoption, per-household penetration, and channel conversion rates).
-
Go-to-market playbooks by channel: Tactical revenue plans for retail, e‑commerce, and commercial channels — including SKU rationalization, margin ladders, promotional cadence, and suggested partner profiles for 2026 launches.
-
Supply chain and cost-mitigation toolkit: Component bill-of-material comparisons, tariff exposure mapping, and a supplier-risk dashboard that identifies single‑source dependencies and levers for onshore/nearshore resilience.
-
Regulatory & product safety checklist: Design-for-compliance templates, a prioritized remediation roadmap for common failure modes, and a compliance budget benchmark for 2026 product programs.
-
Technology and sustainability assessment: Competitive benchmarking across LED, motion-activation, rechargeable battery systems, and solar-integrated options, plus a practical rubric for quantifying lifecycle and energy-savings claims in B2B tenders.
-
50+ company profiles and M&A scorecard: Profiles of established suppliers and emergent challengers, including financial proxies, strategic fit matrices, and acquisition valuation bands targeted at strategic and financial buyers.
-
Commercial scenarios and playbooks for 2026: Tailored recommendations for market entry, SKU simplification, bundling, private-label strategies, and co‑development partnerships with commercial lighting integrators.
Competitive landscape — focused takeaways
Our competitive mapping identifies a mix of specialized manufacturers, gift/novelty suppliers, and incumbent commercial lighting brands. Market concentration is moderate: the top three firms account for roughly 40% of market share, and the top five account for about 55%. This structure leaves room for regional champions and differentiated product plays, but also rewards scale in distribution and compliance capabilities.
-
Fuzhou Maz-Tek Electronic Co., Ltd.: A China-based manufacturer with breadth in LED night lights and motion-activated toilet/night solutions. Their strength lies in turnkey manufacturing and gift-market packaging — an efficient partner for retailers seeking fast SKU churn. Strategic consideration: pursue co-development agreements that lock in volume while migrating higher-margin custom designs to controlled IP clauses.
-
Onefire: Focused on portable, rechargeable LED night lights for home and travel. Onefire exemplifies how rechargeable form factors capture higher ASPs and better repeat purchase economics through accessory and battery programs. Strategic consideration: portable/rechargeable leaders are natural acquirers for accessory ecosystems and consumer-facing subscription services.
-
Ankeral: Supplier of custom cartoon night lights positioned for gift and impulse retail. Their value is in licensing and co-branding — an effective short path to retail shelf presence. Strategic consideration: licensing partnerships can be leveraged to enter high-margin gifting segments but require robust IP and quality controls to mitigate recall risk.
-
Cooper Lighting Solutions: A U.S.-based incumbent in commercial lighting whose product strategy increasingly blurs the line between ambient fixtures and night-light functionality. Their January 2026 launch of flush-mount LED downlights with integrated night light functionality exemplifies the premiumization of night-time illumination in commercial spaces. Strategic consideration: lighting incumbents can bundle specification-led night-light features into larger projects, raising switching costs for specifiers and installers.
Recent developments that alter the playbook for 2026
-
Nighttime luminosity research: A high-resolution visualization released in April 2026 highlights shifting urban brightness patterns tied to energy transition and industrial relocation. For market planners, these datasets act as early indicators for geographic demand reallocation and will be embedded in our predictive geospatial module.
-
New product introductions: The move by commercial lighting incumbents toward integrated night-light fixtures underscores an urgent need for consumer-market players to defend premium spaces via differentiated features or channel specialization.
-
Regulatory and raw-material realities: Legacy product-safety precedents — including historic recalls — remain a design constraint. Tariff classifications and raw material sourcing (plastic and glass components) directly affect landed costs and product returns; our report includes an actionable tariff-impact model and supplier diversification pathways.
-
Energy-efficiency and off-grid adoption: Motion-activated devices typically consume under a few watts when active, and solar-powered variants have demonstrable household-level savings in early adopter geographies. These technical differentials materially change purchase rationales for both residential buyers and specification-driven commercial buyers.
Recommended 2026 actions — prioritized
-
Embed compliance into product development: Make design-for-compliance a gating criterion for all 2026 launches; the cost of retrofits after a recall far exceeds pre-launch assurance spending.
-
Segment your portfolio by channel economics: Separate commercial-spec, retail-impulse, and gifting SKUs; assign distinct margin and inventory policies to each.
-
Pursue selective nearshoring or dual-sourcing: Use tariff-exposure mapping to prioritize nearshore capacity for higher-margin SKUs while maintaining offshore cost leadership for commoditized lines.
-
Invest in low-power differentiation: Prioritize motion-activated, rechargeable, and solar-integrated SKUs where lifecycle benefits can be quantified and sold to B2B buyers.
-
Target bolt-on M&A for channel access: Identify targets with established retail relationships or IP in aesthetic design to accelerate shelf presence without the 12–18 month organic build cycle.
Next steps — how to use the full report
This preview is a strategic orientation. The full Night Light Market report from PW Consulting provides the granular, auditable data and executable templates required to operationalize the recommendations above — including the complete segmentation tables, regional and application splits, SKU-level pricing, and vendor scorecards that are intentionally omitted here to preserve the report’s commercial utility.
For strategy teams preparing 2026 budgets, product leaders sizing SKUs, and corporate development teams screening targets, the full study delivers the evidence base and playbooks needed to move from hypothesis to execution. Access to the complete dataset and proprietary models will enable you to run scenario simulations using your own cost and channel assumptions.
To request the full report and the accompanying modelling files, or to commission a tailored strategic workshop that applies the study’s insights directly to your 2026 planning cycle, please contact PW Consulting via our report webpage.
For detailed analysis of this topic, please visit the official page: Night Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PhotoMos Relays Market to Grow at 4.82% CAGR Through 2032
By PW Consulting, 2026-07-12
PhotoMos Relays Market — Strategic Briefing for 2026 Decision-Makers
As organizations reconfigure product roadmaps and supply chains for the post-pandemic semiconductor era, PhotoMos relays occupy an outsized strategic position across measurement, test, industrial, medical, automotive, and telecommunication systems. PW Consulting’s latest market study—based on a 2025 base year, a 2020–2025 historical series and a 2026–2032 forecast window—translates discrete technical trends and competitive moves into high-consequence choices for 2026 executives. Our headline findings: the PhotoMos relays market trajectory is steady and durable, with a compound annual growth rate (CAGR) of 4.82% and a market value rising from approximately USD 439.7 Million in 2025 to an anticipated USD 609.99 Million by 2032. This briefing explains the strategic value of that research while preserving the granularity that directs serious buyers to the full report.
PhotoMos Relays Market
Why this research matters for 2026 strategy
-
Investment prioritization: The market’s mid-single-digit CAGR signals continued commercial viability without runaway commoditization. For product leaders and BD teams, the question is not whether to play, but how to differentiate (software-enabled value, packaging, thermal performance, and reliability guarantees) within a concentrated supplier market.
PhotoMos Relays Market -
Supply-chain choreography: Our modelling shows inventory and lead-time dynamics that materially affect time-to-market for systems integrating PhotoMos relays. Procurement strategies built on year-to-year spot sourcing will face higher execution risk than those built on dual-sourcing, qualified second sources, and early-life qualification partnerships.
PhotoMos Relays Market -
Regulatory and geopolitical exposure: Semiconductor controls and export regulation have already begun to shift sourcing geographies for critical components. Firms that treat PhotoMos relay procurement as a tactical commodity purchase, rather than as part of a regulated semiconductor sourcing strategy, will expose product roadmaps to avoidable delays in 2026.
Market snapshot — a disciplined, data-driven foundation
PW Consulting’s topline series shows the PhotoMos relays market growing from roughly USD 349.6 Million in 2020 to USD 439.7 Million in 2025, then continuing on to a projected USD 609.99 Million by 2032. These figures are presented in USD and modelled at the Million revenue unit level. The growth pattern reflects compounding secular demand from electrification (notably power storage and EV-adjacent applications), incremental adoption in test and measurement instruments, and ongoing replacement demand in industrial and medical equipment.
Two structural attributes are especially relevant for 2026 planning. First, market concentration is meaningful: the top three firms account for a majority share (CR3 approximately 55%), and the top five approach two thirds of the market (CR5 ~65%). Second, product development is active—manufacturers continue to push miniaturization, higher voltage handling, and reduced parasitic characteristics—so technical differentiation is both feasible and rewarded in targeted end-markets.
Drivers, friction points and strategic implications
-
Technical evolution: Ongoing improvements in MOSFET output photo-relay architectures are delivering lower on-resistance, higher voltage capability, and smaller footprints. For platform owners, this enables tighter integration and potential BOM cost reductions, but it also raises the bar for qualification testing and lifecycle support.
-
End-market pull: Test & measurement and telecommunication equipment continue to demand low-leakage, fast switching relays. Simultaneously, battery management and EV-adjacent systems are creating demand for higher-voltage PhotoMos variants. Product strategists should map roadmap timelines to these demand pockets and evaluate whether in-house qualification can be accelerated without compromising reliability.
-
Supply-side friction: Our sector intelligence recorded semiconductor lead times for PhotoMos-class components at 40 weeks in March 2026—an increase of 67% versus the prior month—driven by upstream wafer capacity and packaging congestion. The practical impact in 2026 is longer NPI cycles, deferred revenue recognition, and the need for more conservative safety stock policies.
-
Regulatory overlay: Since December 2024, export restrictions and rule expansions from major jurisdictions affect access to certain raw materials and process equipment. These regulatory dynamics create a persistent risk of supply re-routing and price volatility for certain inputs critical to PhotoMos manufacturing.
Competitive landscape — what matters at the supplier level
The PhotoMos supplier universe combines long-established industrial electronics players with focused optoelectronics specialists. Several incumbent firms dominate on scale, distribution reach, and product families; smaller players compete on custom packaging, rapid lead times, and niche qualification tracks.
-
Panasonic Corporation (Kadoma, Osaka, Japan) remains a reference brand, leveraging its PhotoMOS® family for broad applications from measurement to automotive. Recent initiatives—consistent dimensional unification notices and new high-voltage and low-footprint product launches announced across late 2025 and early 2026—signal a dual strategy of platform consolidation and technical platform extension aimed at industrial BMS and compact test equipment segments.
-
OMRON Corporation (Kyoto, Japan) continues to sell MOSFET relay equivalents for industrial switching, with a focus on reliability and marketplace recognition in factory automation and measurement equipment. Their offering is positioned for general-purpose switching where proven field reliability matters.
-
Toshiba Electronic Devices & Storage Corporation (Tokyo, Japan) and NEC Corporation (Minato, Tokyo, Japan) both play on breadth—serving factory automation, industrial equipment, and measurement domains with photorelay portfolios that emphasize higher-current and high-reliability specifications.
-
IXYS Integrated Circuits Division (Littelfuse, Beverly, MA, USA) presents an optimised OptoMOS® line for power and high-reliability applications, targeting system integrators who require validated components for harsh environments.
-
Regional and niche specialists, such as Cosmo Electronics and Okita Works, supply focused parts for control circuits and specialized form factors. These vendors remain important as secondary sources or for highly-customised programs.
For 2026 decision-makers, supplier selection should be treated as a weighted optimisation problem: balance technical fit, qualification timelines, contractual protections (lead-time and price), and geopolitical exposure. The market’s moderate concentration means that primary suppliers can exert leverage during constrained cycles, so qualified secondary sources and long-lead purchase agreements are practical mitigants.
What the full PW Consulting report delivers (operational content)
Our full report transforms the high-level market arc into executable guidance. Key deliverables include:
-
A transparent forecasting model with scenario variants (base, constrained-supply, and accelerated-adoption) that executives can adapt to internal volume assumptions.
-
Supplier profiles with product architecture comparisons, historical product roadmaps, and an assessment of each supplier’s vulnerability to material and regulatory constraints.
-
Qualification and procurement playbooks, including recommended test matrices, accelerated reliability sampling approaches, and sample contract language for lead-time guarantees.
-
Practical NPI timelines that align relay qualification gates with system-level milestones, reducing the risk of late-stage substitution.
-
Executive decision frameworks—scorecards and go/no-go checklists—that translate technical trade-offs into commercial outcomes (time-to-market, BOM cost, warranty exposure).
Importantly, the report intentionally withholds detailed numerical splits by region, type, and application in this public briefing. That segmentation granularity—central to channel strategy and regional procurement decisions—is available exclusively in the full report and associated data workbook.
Strategic recommendations for 2026
-
Lock in dual-qualified suppliers for all critical relay families and structure contracts to cover extended lead-time scenarios. Prioritise suppliers that can demonstrate alternative upstream sources or captive packaging capacity.
-
Accelerate component-level qualification for higher-voltage and low-footprint PhotoMos variants if your roadmap targets BMS, EV-adjacent, or compact medical equipment segments—these are the fastest-growing pockets in our base forecast.
-
Build a regulatory watch into procurement and supplier management. Given recent export control changes, treat materials and component sourcing as part of your regulatory compliance function rather than a pure commodity activity.
-
Invest in supplier engineering partnerships rather than transactional sourcing. Co-development reduces qualification time and creates switching costs that can be commercially advantageous when supply tightness returns.
Concluding perspective — how to use this briefing
This briefing outlines why PhotoMos relays are strategically relevant in 2026 and the practical levers companies should consider when making procurement, product, and partnership decisions. PW Consulting’s full market study supplies the operational data and segment-level analytics that convert this high-level guidance into specific project plans—without exposing competitive segmentation data in public channels. For teams building roadmaps or negotiating supplier agreements this year, the report is a compact toolkit: a quantitative forecast, supplier-risk diagnostics, and tactical playbooks calibrated for the current supply-regulation environment.
To access the full dataset, supplier matrices, and the downloadable forecasting workbook, please consult the PW Consulting market page associated with this PhotoMos relays study. The full report includes the detailed, segment-level intelligence that procurement leads and product strategists need to convert the 4.82% CAGR and the USD 439.67 Million (2025) market baseline into confident, executable 2026 plans.
For detailed analysis of this topic, please visit the official page: PhotoMos Relays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Market to Hit USD 228.06B by 2032 — 7.52% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Hydrogen Generation Market — Strategic Outlook for 2026 Decision-Makers
As energy transition agendas accelerate and industrial decarbonization moves from ambition to execution, hydrogen generation has emerged as a strategic battleground for investment, technology selection and policy engagement. PW Consulting’s latest market study (base year 2025) synthesizes historical performance (2020–2025), near-term signals and a seven-year forecast (2026–2032) to equip executives with the decision-grade intelligence needed in 2026. The global hydrogen generation market expands from roughly USD 89 billion in 2020 to USD 137.8 billion in 2025, with our forecast pathway reaching about USD 228.1 billion by 2032 at a compound annual growth rate of 7.52% (2026–2032). This analysis explains why those headline numbers matter for capital allocation, technology sourcing, and policy-driven project economics — while preserving the detailed segmentation and project-level data in the full report to protect client value and encourage direct engagement.
Hydrogen Generation Market
Why 2026 Decisions Will Define Competitive Positioning
Three dynamics converge in 2026 to create a narrow window for decisive action. First, policy clarity in critical markets has materially shortened the timeline for projects to qualify for incentives and tax credits — a condition that alters returns on investment and the attractiveness of different production routes. Second, cost declines in electrolyzer equipment and modular manufacturing are beginning to translate into real options for end-users and utilities choosing between on-site versus merchant supply models. Third, incumbent industrial players and specialized electrolyzer manufacturers are simultaneously scaling, creating both partnership opportunities and competitive threats.
Hydrogen Generation Market
- Policy timing: Recent rulemaking and legislative timelines (notably U.S. 45V Clean Hydrogen Production Tax Credit clarifications and accelerated eligibility milestones) make project start dates and construction milestones strategic variables for 2026 planners.
- Technology economics: Public domain estimates and industry scenarios point to converging cost trajectories for electrolyzer capital expenditure and operating assumptions; these inform breakeven analyses against legacy steam-methane pathways.
- Market structure: Market concentration is moderate: the top three suppliers account for a meaningful but non-dominant share of the market, while the top five widen competitive leverage — an environment suitable for both scale plays and niche specialization.
Market Trajectory at a Glance
Understanding the total market evolution is the starting point for strategy. The hydrogen generation market demonstrated steady growth through 2020–2025 and enters a phase of accelerated investment in the late 2020s. Our forecast shows the market expanding from USD 137.8 billion in 2025 to approximately USD 228.1 billion by 2032, reflecting a 7.52% CAGR over the 2026–2032 forecast window. These aggregate figures capture simultaneous expansion of traditional production routes, merchant supply infrastructure, and a fast-growing pipeline of electrolysis-based projects — driven by industrial demand for low-carbon feedstock, emerging mobility use cases, and power/energy storage experiments.
Hydrogen Generation Market
For corporate strategists, the macro numbers imply two practical conclusions: capital deployment should be phased to capture technology cost declines while preserving optionality for off-ramps enabled by merchant market development; and commercial teams must prioritize offtake and storage strategies that convert capacity into contracted revenue streams during early-market uncertainty.
Key Value Drivers and Material Risks
- Policy and incentives: Tax credits that tier by lifecycle emissions and deadlines for commencement of construction materially influence project IRR and choice of carbon mitigation pathways. Executives should explicitly model incentive sensitivity in 2026 to determine project timing.
- Electrolyzer capital cost trajectory: Independent forecasts project a wide span of electrolyzer capex under high-deployment scenarios. This range is a primary determinant of green-hydrogen competitiveness by the end of this decade; strategic procurement and supplier partnerships can capture manufacturer learning curves.
- Operating costs and LCOH drivers: Recent public estimates for fixed operating costs (for example, PEM electrolyzer operating assumptions) provide a defensible starting point for operational budgeting. Electricity sourcing and utilization profiles remain the single largest determinant of delivered cost for electrolytic hydrogen.
- Feedstock and integration risk: For fossil-based routes, natural gas feedstock price variability and decarbonization commitments require parallel capex for CCS/backstop technologies, altering long-term economics versus electrolytic pathways.
- Infrastructure and storage: Emerging projects (including large-scale electrolysis installations and salt-cavern storage pilots) underscore the need for integrated supply-chain planning across production, liquefaction, storage and transportation.
Competitive Landscape — Who Matters and Why
Our assessment reviews technology vendors, industrial gas majors, and integrated systems providers. The market is populated by specialty electrolyzer manufacturers, legacy industrial-gas companies, and diversified equipment suppliers — each with distinct strategic advantages and limitations.
- Electrolyzer specialists: Companies focused on PEM, alkaline and novel AEM stacks have moved from demonstration to commercial scale. These firms are competing on stack performance, modularity, and manufacturing scale. Strategic partnerships and long-term procurement agreements will be decisive for project developers seeking deployment certainty.
- Integrated suppliers: Industrial gas majors and diversified energy companies bring breadth across production, distribution and merchant markets. Their competitive edge is an integrated value chain and established customer base in industrial offtake sectors.
- Project developers & system integrators: A third cohort combines electrolysis supply with project development capabilities, enabling turnkey solutions and accelerating time-to-market for corporate offtakers and utilities.
Notable market movements through 2024–2025 illustrate these dynamics: commissioning of utility-scale electrolysis capacity in China and demonstration green-ammonia facilities in Europe signal a maturing project pipeline; salt-cavern and liquefaction pilots in North America showcase storage and distribution innovation. For 2026 strategy, watch three company archetypes — pure-play electrolyzer firms scaling manufacturing, industrial gas incumbents extending into green-product markets, and integrators bundling offtake, storage and logistics into turnkey offers.
Recent Industry Signals That Matter in 2026
- Large-scale electrolysis projects and green-ammonia demonstrations indicate the practical operability of high-capacity renewable-electrolysis supply chains.
- Commercial-scale storage and liquefaction pilots validate merchant and long-haul distribution options that can unlock new regional arbitrage opportunities.
- Regulatory clarifications and tax-credit timelines have compressed the calendar for projects seeking incentives, requiring earlier commitment to construction starts for qualification.
What the PW Consulting Study Delivers — Practical Tools, Not Just Charts
Beyond market totals and high-level narratives, the report is designed as a playbook for corporate action. Core deliverables include:
- Scenario-based financial models that project levelized cost of hydrogen under multiple electricity, capex and incentive pathways — model templates are provided so teams can plug in corporate assumptions.
- Technology roadmap with TRL-adjusted timelines and procurement guidance for PEM, alkaline, AEM and legacy reforming routes — focused on commercial readiness and supply-chain risk mitigation.
- Competitive supplier profiles and an actionable short-listing methodology to assess partner fit by scale, geography and delivery capability.
- Policy impact matrix that quantifies the sensitivity of project IRR to prevailing incentive structures, permitting timelines and emissions thresholds — including step-change scenarios driven by tax-credit tiering.
- Go-to-market playbooks for offtake models (merchant, captive, and hybrid), with sample term-sheet language and contractual levers to allocate long-term price and volume risk between producers and buyers.
- Implementation roadmap and checklists for site selection, grid connection, permitting, and community/stakeholder engagement to accelerate “shovel-ready” conversion.
To preserve the strategic value of the report, granular dataset exports and element-level segmentation (by region, technology, application and hydrogen color classifications) are retained exclusively in the full publication and data pack. Those datasets power detailed project-level assessments, procurement auctions and regulatory-compliance scenarios — and are intentionally not reproduced in public summaries.
How Executives Should Use this Intelligence in 2026 — Five Practical Moves
- Lock in optionality: Use staged contracts and conditional EPC milestones that preserve access to tax credits and incentive windows while limiting stranded-capacity risk.
- Secure offtake alignment: Prioritize offtake agreements with flexible volumes and indexing that reflect evolving electrolyzer utilization and merchant market development.
- Negotiate supplier roadmaps: Embed manufacturer performance milestones and price-collar provisions into long-lead equipment contracts to capture technology learning curves.
- Stress-test scenarios: Run downside cases that combine slower-than-expected electrolyzer cost declines with delayed permitting and tighter incentive eligibility to calibrate capital buffers.
- Engage policy levers: Proactively align project timelines and GHG-lifecycle reporting to maximize eligibility for tiered incentives and to shape local permitting outcomes.
Conclusion — Where This Study Adds Value in 2026
PW Consulting’s Hydrogen Generation Market study translates a complex confluence of policy, technology and market dynamics into operational guidance for decision-makers. By combining a transparent market forecast (2020–2025 history, 2026–2032 forward view with a 7.52% CAGR) with scenario-ready financial models, supplier analysis, and policy-impact tools, the study equips C-suite and investment teams to make evidence-based commitment decisions in 2026. The report purposely reserves detailed segmentation and project-level datasets for the full publication — because those are the inputs that convert strategic intent into executable programs.
For access to the complete dataset, interactive models and the supplier short lists referenced here, please consult the PW Consulting publication page and data portal — where the full intelligence package, including exportable spreadsheets and playbooks, is available for corporate subscribers and project partners.
For detailed analysis of this topic, please visit the official page: Hydrogen Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Extended Warranty Market to Reach USD 295M by 2032 at 9.0% CAGR
By PW Consulting, 2026-07-12
Extended Warranty Service Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking, decision-focused preview of our Extended Warranty Service Market study. Between 2020 and 2025 the market expanded from USD 100 Million to USD 150 Million (base year 2025), driven by rising product complexity, digital distribution, and evolving consumer expectations. Our forecast (2026–2032) projects a continued compound annual growth of 9.0%, taking the market toward roughly USD 295 Million by 2032. This briefing explains why those macro dynamics matter for corporate strategy in 2026 while deliberately withholding granular subsegment tables and exact regional or application shares — a curated invitation to the full report for tactical execution details.
Extended Warranty Service Market
Why the Extended Warranty Market Demands Executive Attention in 2026
-
Structural revenue resilience: Extended warranty services are shifting from a seasonal upsell to a predictable, recurring-revenue line for manufacturers, retailers, and specialist providers. The market’s steady climb from 2020 through 2025 and the forecasted double‑digit tailwinds in several quarters signal a durable monetization path for product lifecycles that were previously revenue-neutral after sale.
Extended Warranty Service Market -
Technology-driven differentiation: Advanced vehicle electronics, connected appliances, and smart devices have increased both failure modes and service complexity. This is attracting insurers and fintech players who can underwrite, price, and manage claims using telematics, diagnostics, and predictive analytics — converting service liability into a managed profit center.
Extended Warranty Service Market -
Distribution evolution: Digital marketplaces, retailer-integrated protection plans, and OEM-embedded offerings are redistributing margin and control across the value chain. Companies that understand channel economics in 2026 will extract higher lifetime value from customers and avoid margin erosion from commoditized third-party resellers.
-
Regulatory and reimbursement pressure: Recent state-level statutes and evolving agency guidance create compliance obligations that affect product design, disclosure, and reimbursement mechanics. Prepared organizations can turn compliance into competitive advantage; unprepared ones face distribution bottlenecks and elevated dispute rates.
Market Dynamics: Drivers, Headwinds, and Strategic Implications
-
Key growth drivers: Increasing product complexity, proliferation of subscription-style ownership, extension of protection to new product categories, and consumer acceptance of paid protection are driving the market’s expansion. Our historical-to-projection trajectory highlights how these drivers compound over time.
-
Operational headwinds: Claims inflation, parts scarcity, and repair labor shortages add pressure to margins. Additionally, reimbursement frameworks and consumer protection rules are introducing greater transparency and potential cost pass-throughs for servicers.
-
Channel and product innovation: The most effective players in 2026 will combine modular coverage design, dynamic pricing linked to telematics or usage, and frictionless claims via digital-first repair ecosystems. This is not hypothetical — product roadmaps and recent launches show incumbents shifting in this direction.
-
Regulatory watchlist: New statutory requirements around plan forms and insurer involvement, coupled with federal guidance on reimbursement limits, mean companies must revalidate contractual terms and claims processes. Regulatory readiness should be a board-level priority for firms with cross-jurisdictional operations.
Competitive Landscape — Positioning and Strategic Moves
The competitive field comprises global insurers, specialist vehicle providers, retailer-aligned digital protectors, and marketplace platforms. The market remains relatively fragmented; leading firms have meaningful scale but do not dominate the market entirely, leaving room for targeted consolidation and new entrants with differentiated capabilities.
-
Assurant, Inc.: A specialist in protection services that is doubling down on integrated product bundles. Recent product launches combining vehicle protection with device repair illustrate how Assurant is packaging vertical expertise with cross-category benefits — a model that raises switching costs and improves retention.
-
Asurion: Strong in retail and carrier channels with deep repair-network capabilities. Asurion’s playbook focuses on rapid claims fulfillment and B2C distribution scale, which is essential for high-volume, low-ticket warranties.
-
Vehicle specialists (Endurance Warranty Services, CarShield, CARCHEX): These providers compete on tailored mechanical coverage, flexible underwriting, and customer financing. Their strength is brand affinity in the automotive aftercare segment and agility in pricing niche risks.
-
Global insurers (AIG, AXA, Allianz Partners, AmTrust): These incumbents leverage balance sheet scale, reinsurance access, and broad distribution to offer white-label programs to OEMs and retailers. Their advantage is capital efficiency for large warranty portfolios and regulatory know‑how for cross-border programs.
-
Digital-first players (SquareTrade under Allstate): They exemplify integration of ecommerce, streamlined claims, and retailer partnerships. Their model highlights the economics of embedding warranty at point-of-sale and servicing via standardized repair channels.
Recent developments underscore these strategic shifts. In 2025, a major consumer electronics OEM expanded its in-country protection program to include broader home appliance coverage — a move that signals OEMs are integrating extended protection into core customer propositions. Also in 2025, a leading protection specialist launched a bundled vehicle and device protection product for advanced vehicle technologies; this hybrid approach is emblematic of product convergence across categories.
What Our Full Report Delivers (Operational Value You Can Act On)
The complete PW Consulting Extended Warranty Service Market report is built for teams that need to move from insight to implementation. Highlights include:
-
Validated market sizing and scenario forecasts (base year 2025; historical window 2020–2025; forecast 2026–2032) with sensitivity tables that let you stress-test pricing, claims inflation, and channel mix assumptions.
-
Actionable go-to-market frameworks for OEMs, insurers, and retailer partners — including distribution economics, partner revenue shares, and GTM playbooks tailored to different ownership and channel models.
-
A competitive playbook covering product design, digital claims orchestration, vendor selection criteria for repair networks, and technology architecture required to scale usage-based and connected warranties.
-
M&A and partnership screeners: a prioritized list of capability adjacencies, criteria for tuck-in versus transformational deals, and financial models that quantify synergies for sample transactions.
-
Regulatory and compliance matrix: jurisdictional obligations, required contract disclosures, and practical remediation steps to align sales, legal, and claims operations with emerging standards.
-
Implementation roadmap with 90/180/360-day milestones, capability sprints (data, underwriting, claims automation), and KPI dashboards to monitor revenue per contract, retention, and claims loss ratio.
Strategic Recommendations: Priorities for 2026
-
Embed product differentiation at the point of sale. Use modular coverage constructs and optionality (e.g., higher-tier tech support, remote diagnosis) to reduce price-driven churn and raise average revenue per user.
-
Invest in claims automation and predictive maintenance. Shortened cycle times and lower service costs materially affect loss ratios; invest now to capture the compounding returns over the forecast horizon.
-
Mobilize regulatory readiness. Conduct a rapid compliance audit focused on contract forms, disclosure requirements, and reimbursement policies. Align legal, underwriting, and product teams on remediations ahead of new enforcement timelines.
-
Diversify distribution and consider white-label offerings. Retailer and OEM partnerships accelerate scale and capture customer lifecycle economics — but require tight SLAs and integrated data flows.
-
Explore targeted M&A to secure repair networks, telematics capabilities, or digital claims platforms. The market’s fragmentation creates attractive tuck-in opportunities to buy capabilities instead of building them.
Conclusion — How to Use This Preview
The Extended Warranty Service Market is moving from an accessory line item to a strategic revenue engine. By 2026, executives must decide whether to lead (invest in product, data, and distribution), follow (partner with best-in-class providers), or exit (de-risk by divesting warranty portfolios). Our research shows that early investments in digital claims, regulatory preparedness, and channel integration pay back across retention and margin metrics as the market grows at a mid‑high single-digit CAGR through 2032.
This preview intentionally omits detailed regional and application splits and other granular tables to preserve the strategic integrity of the research. For the full dataset, detailed segmentation analysis, vendor scorecards, and implementation templates — which translate these strategic implications into executable 90–360 day plans — please consult the complete PW Consulting Extended Warranty Service Market report on our website.
For detailed analysis of this topic, please visit the official page: Extended Warranty Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pool Water Treatment Market to Reach USD 5.83B by 2032 at 6.3% CAGR
By PW Consulting, 2026-07-12
Swimming Pool Water Treatment Equipment Market 2026: A Strategic Preview for Decision‑Makers
As senior industry advisors at PW Consulting, we present a focused, decision‑centric preview of our latest market research on the Swimming Pool Water Treatment Equipment market. This briefing distills the strategic implications you must act on in 2026 — from product and channel choices to compliance, M&A and service economics — while intentionally reserving granular subsegment figures for the full report.
Swimming Pool Water Treatment Equipment Market
Market snapshot — Where we stand and where we’re heading
The global market for swimming pool water treatment equipment has demonstrated steady expansion over the past half‑decade, growing from an estimated USD 2.5 Billion in 2020 to approximately USD 3.8 Billion in 2025. Our baseline forecast projects continued momentum into the next planning horizon: a compound annual growth rate (CAGR) of roughly 6.3% through 2032, with the market approaching the high‑single‑digit‑billion USD range by the end of the forecast period. These topline dynamics reflect a combination of residential pool proliferation, rising commercial and public aquatic investments, and accelerated adoption of energy‑efficient, automated water treatment systems.
Swimming Pool Water Treatment Equipment Market
Why this report matters to 2026 strategic planning
- Timing and resource allocation. The market’s mid‑single‑digit CAGR signals a stable growth runway, but not an open field. Firms must allocate R&D and capex selectively — prioritizing product features that translate to measurable lifecycle cost advantages (energy, chemical use, and maintenance) to capture premium positions.
- Certification and regulatory gating. Recent standards updates and certification requirements are creating immediate go/no‑go barriers to market access in several jurisdictions. Compliance portfolios (third‑party certifications and documented test protocols) are increasingly decisive in tender and channel selection processes.
- Services and aftermarket economics. With installed‑base growth, service and consumables emerge as durable revenue streams. Companies that bundle monitoring, predictive maintenance and replenishment models capture disproportionately higher lifetime value.
- Channel and go‑to‑market resilience. Distribution ecosystems are fragmenting between traditional pool specialists and large, digitally enabled retailers. Winning in 2026 requires fine‑grain channel segmentation and differentiated partner incentives.
What the full report delivers (practical, actionable contents)
Our full market study is built to be used, not shelved. It contains:
Swimming Pool Water Treatment Equipment Market
- Topline market sizing and a seven‑year forecast (2026–2032) with scenario modeling that isolates demand drivers and sensitivity to regulatory shifts.
- Go‑to‑market playbooks for manufacturers and distributors: product positioning, pricing bands, channel economics, and promotional models tuned for residential, commercial and public pool segments.
- Operational guidance on cost‑to‑serve optimization, supply chain resilience measures, and localization strategies for manufacturing and spare parts logistics.
- Service‑led growth templates: aftermarket monetization frameworks, subscription options, and KPIs for retention and installed‑base monetization.
- Regulatory and certification roadmaps explaining the implications of new standards, required test matrices, and timeframes for compliance.
- Detailed competitive benchmarking and strategic profiles of leading vendors, including capability maps, innovation thrusts, and M&A playbooks for both acquirers and targets.
- Primary research insights — interviews with channel partners, facility operators and procurement officers — and supplier scorecards that identify operational strengths and risk exposures.
- Practical M&A diligence checklists and valuation sensitivities tailored to the sector’s unique mix of hardware, consumables and recurring services.
Competitive landscape — positioning and tactical implications
The market exhibits moderate concentration at the top: the top three global players account for roughly the mid‑40% range of total industry revenue, while the five largest firms approach the mid‑50% range. That structure supports both scale advantages and pockets of opportunity for differentiated challengers.
- Pentair plc (Twickenham, UK). A broad product portfolio and frequent SKU refreshes underpin its ability to serve diversified channels. Recent catalog rollouts and SKU expansions underscore a platform strategy — invest in product family depth to maintain distribution shelf share and OEM relationships.
- Hayward Industries (Charlotte, NC, USA). Known for engineered solutions and channel reach in North America, Hayward’s positioning favors integrated systems and trade‑professional relationships; a continued focus on installation simplification and diagnostics will defend share.
- Fluidra S.A. (Sant Cugat, Spain). European engineering and global distribution give Fluidra a strong play in premium residential and leisure portfolios. Its strategic path combines organic innovation with selective partnerships.
- Waterco Limited (Sydney, Australia). An active consolidator: recent acquisition activity and geographic expansion (including a new MENA base) signal an ambition to convert regional presence into global scale in filtration and sanitisation equipment.
- Emaux, LASWIM and other Asia‑Pacific manufacturers. These firms are closing quality and compliance gaps rapidly; expect continued pressure on mid‑tier price segments as suppliers combine competitive manufacturing cost bases with international certification portfolios.
- Specialists and consumer brands (Culligan, Maytronics, Zodiac, and others). These players capitalize on service models, robotic automation, and retail channel strengths. They are particularly well‑positioned to take aftermarket and bundled service revenue.
Strategic takeaway: incumbents must defend scale benefits while pursuing modular, certified products that allow premium service attachment. Challenger manufacturers should invest in compliance and distribution playbooks rather than competing on components alone.
Regulatory and certification imperatives shaping 2026 procurement
- New industry standards have raised technical thresholds for acceptance in many procurement processes. For example, revised national standards set clear performance metrics that equipment must meet — creating a de‑facto minimum spec for suppliers bidding into major projects.
- Model code and public‑health frameworks increasingly reference specific product certifications as preconditions for onsite use. Certifications for pool chemicals and treatment systems now determine eligibility for many municipal and institutional tenders.
- Environmental rules and energy performance expectations are accelerating the shift toward low‑energy filtration and automated chemical dosing systems. Providers without documented energy or lifecycle benefits will face margin compression.
- Manufacturers from China and other APAC markets are rapidly adopting international quality standards (ISO 9001, CE, ETL, RoHS and similar marks), which changes the calculus for price‑sensitive buyers who previously prioritized local suppliers.
Decision scenarios for 2026 — recommended strategic moves
- Conservative growth with margin protection: Prioritize retrofit kits and service contracts for existing installed bases. Invest in authorized‑service networks and consumable subscriptions to boost recurring revenue without heavy capex.
- Aggressive expansion: Target MENA and APAC growth corridors via acquisitions or JV partnerships that combine distribution access with certified manufacturing capabilities. Ensure acquisition targets have documented quality systems and certification stacks to avoid costly rework.
- Product innovation focus: Fast‑track energy and automation features that demonstrably reduce chemical and electricity consumption — use field pilots with tier‑one operators to build ROI case studies for scaled rollouts.
- Regulatory first mover: Secure necessary certifications ahead of competitors to become the supplier of choice for institutional tenders and large commercial projects where compliance is a procurement gate.
How to use this preview — immediate next steps
- Executive teams: set a 90‑day plan to validate compliance gaps across your product portfolio and define a certification roadmap.
- Product leaders: prioritize two feature bets for 2027 releases — one focused on energy savings, one on ease of service/install.
- M&A teams: short‑list targets that improve either distribution reach or add a certified manufacturing base; use our M&A checklist to accelerate diligence.
- Sales and channel heads: reweight channel incentives to favor bundled service sales and subscription agreements.
About this PW Consulting study
The research uses 2025 as a base year, with historical analysis from 2020–2025 and forward projections across 2026–2032. Our methodology combines primary interviews, supplier and channel surveys, trade data, and documented certification registries. The full report provides the detailed, segment‑level numbers, supplier scorecards, and executable templates that boards and commercial leaders need to convert insight into action.
If you are aligning strategy, capital allocation, or product roadmaps for 2026, the full PW Consulting report contains the granular market breakdowns, segment forecasts and competitive diagnostics you will need to operationalize these recommendations. Contact our research desk or visit the report page to access the complete intelligence package, including downloadable models and a suite of decision‑support tools.
For detailed analysis of this topic, please visit the official page: Swimming Pool Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Elastomeric Infusion Pumps to hit USD 1.38B by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Elastomeric Infusion Pumps Market — Strategic Outlook for 2026 Decision‑Makers
As health systems, payers, and device manufacturers prepare budgets and strategic roadmaps for 2026, the Elastomeric Infusion Pumps Market presents a clear, actionable growth story — but one that requires nuanced interpretation. PW Consulting’s latest industry study (base year 2025; historical series 2020–2025; forecast 2026–2032) quantifies and contextualizes that story: the market reached approximately USD 885.0 Million in 2025 and is projected to expand to roughly USD 975.8 Million in 2026, continuing on a compound annual growth path of 6.98% through the 2026–2032 forecast window, culminating in a market environment materially larger by 2032.
Elastomeric Infusion Pumps Market
Why this study matters for 2026 decisions
-
It converts headline growth into operational choices. The mid-single-digit-plus CAGR translates into concrete implications for manufacturing scale, inventory strategies, and reimbursement negotiations — particularly for players deciding whether to prioritize ambulatory/home infusion versus inpatient channels.
Elastomeric Infusion Pumps Market -
It exposes strategic inflection points. Recent regulatory shifts, reimbursement clarifications, and raw‑material dynamics mean that a “business-as-usual” playbook will underperform. Companies that align product development, quality assurance, and go‑to‑market tactics with these inflection points will capture outsized value.
Elastomeric Infusion Pumps Market -
It equips investors and M&A teams. The market’s structure and growth trajectory are sufficient to support bolt-on acquisitions, contract manufacturing expansions, and niche product entries — but target selection must be informed by clinical use cases, regulatory readiness, and durable reimbursement coding.
Market trajectory — what the numbers imply (not just enumerate)
Across 2020–2025 the market showed resilience through pandemic disruption and shifting care pathways. The 2025 market size (USD 885.0 Million) reflects recovery and adoption of ambulatory infusion paradigms. The forecast baseline (2026) and the 6.98% CAGR through 2032 reflect accelerating demand driven by outpatient surgery, home-administered antibiotic and chemotherapy regimens, and escalating interest in simplified infusion modalities that reduce hospital bed days.
For operators, the implication is straightforward: modest but sustained growth enlarges the economic runway for incremental product investments, while also increasing competitive pressure on manufacturing capacity and component sourcing.
Key dynamics shaping the market
-
Regulatory tightening and device assurance: The FDA’s Infusion Pump Improvement Initiative has raised the bar for documentation, safety assurance cases, and real‑world testing. Manufacturers must now build defensible, traceable risk mitigation dossiers — a nontrivial investment that favors companies with established engineering and quality systems.
-
Reimbursement stability matters more than headline rates: Recent policy actions have reaffirmed separate payment pathways for specific infusion therapies in outpatient settings, preserving access economics for ambulatory devices. The practical effect for manufacturers and hospital purchasing groups is that sustained payer recognition reduces commercialization risk, but success still depends on local coding strategies and contracting execution.
-
Raw‑material and formulation innovation: Advances in medical‑grade elastomers — silicone blends with polyurethane and polyisoprene variants — are materially altering flow stability characteristics and shelf behaviour. These materials choices influence device performance (flow precision, relaxation time), sterilization workflows, and supply‑chain complexity.
-
Cost and capital patterns: Elastomeric devices retain an up‑front cost advantage relative to reusable electronic pumps, particularly for single‑use clinical pathways in ambulatory care. That cost profile makes them attractive in low‑resource and home care settings, but also compresses margins for commodity suppliers.
-
Safety signals and market trust: Isolated malfunction reports and MAUDE entries underscore the reputational sensitivity of infusion devices. Transparent post‑market surveillance and rapid corrective‑action capacity are now a commercial necessity as much as a regulatory one.
Segmentation and what we deliberately withhold here
The full report contains granular segmentation by region, device type (continuous vs. variable vs. patient‑controlled), and clinical application (e.g., pain management, antibiotic therapy, chemotherapy), together with multi‑scenario forecasts. In keeping with the “trailer” principle of this executive summary, we demonstrate analytical depth while intentionally withholding the fine‑grained split figures and regional/application-level revenue tables. This is to ensure clients rely on the complete dataset and methodology inside the paid report before making high‑stakes capital or M&A decisions.
Competitive landscape — profiles and strategic implications
-
Baxter International Inc. — Offers SimplFusor ambulatory systems that emphasize mobility and reduced device weight versus electronic alternatives. Strategic view: Baxter’s strength in hospital procurement and established home infusion channels makes it a natural partner for integrated therapy bundles; its risk is slower iteration on next‑gen elastomer materials versus agile niche players.
-
Avanos Medical, Inc. — Producer of the ON‑Q system focused on post‑surgical pain management and disposable components. Strategic view: Avanos’ continued reimbursement recognition for ON‑Q improves its commercial defensibility; competitors should monitor payer coding stability and consider complementary products that broaden procedural applicability.
-
B. Braun Melsungen AG — Offers continuous and variable‑rate systems; recently an EasyPump device had a reported over‑infusion event in early 2026. Strategic view: Quality governance and transparent post‑market response will determine whether the incident becomes a transient reputational issue or a lasting competitive liability.
-
Fresenius Kabi AG — Supplies integrated home infusion solutions; strategic position strengthened by global home care penetration and product breadth. Strategic view: Large OEMs can leverage scale to absorb regulatory and testing costs, but must avoid commoditization of core disposable components.
-
Nipro Corporation & Terumo Corporation — Japanese OEMs with strong ambulatory and hospital ties. Strategic view: Regional manufacturing agility and supply‑chain integration make these players attractive partners for localized rollouts and regulatory filings.
-
ICU Medical, Smiths Medical, Leventon, First Medical Source (InfuLife) — A mix of component specialists, AI‑enabled product developers, and cost‑focused suppliers. Strategic view: The market’s middle tiers are where consolidation and vertical integration will accelerate; companies with differentiated clinical evidence or lower total cost of ownership will be acquisition targets.
Recent developments — catalytic events to watch
-
Early 2026: A reported over‑infusion event associated with a major OEM’s elastomeric device highlighted the need for robust post‑market surveillance and faster communication channels between manufacturers and clinicians.
-
Early 2026: Reimbursement policy updates reaffirmed separate outpatient payment pathways for certain ambulatory pumps, reducing short‑term commercial uncertainty for established products.
-
March 2026: New product introductions (e.g., disposable smart elastomeric pumps) signal a move toward multifunctional devices that address intermittent and continuous therapy needs — a potential vector for differentiation if paired with clinical evidence and payer engagement.
What’s inside the full PW Consulting study (practical contents)
-
Market sizing and forecasting models (2020–2032) with downloadable datasets and sensitivity scenarios.
-
Segment deep dives: methodology, assumptions, and market drivers for device type, clinical application, and region (granular tables and heat maps available in the report).
-
Supply‑chain analysis: raw material sources, test protocols for elastomer blends, supplier concentration risks, and cost pass‑through sensitivities.
-
Regulatory and reimbursement playbook: mapping of FDA expectations, coding pathways, and payer engagement strategies tailored to outpatient and home infusion rollouts.
-
Competitor benchmarking: strategic profiles, capability matrices, recent M&A and product moves, and a strategic 2x2 for go‑to‑market positioning.
-
Commercialization checklists: clinical evidence requirements, field training templates, and pricing scenarios tied to payer negotiations.
-
M&A and partnership playbook: valuation heuristics, integration risks, and three investment cases (bolt‑on, platform expansion, disruptive entry).
Actionable recommendations for 2026
-
Prioritize regulatory readiness now. Prepare robust safety assurance dossiers aligned to the FDA’s guidance — this reduces time‑to‑market risk and enhances buyer confidence.
-
Lock in supply of medical‑grade elastomer formulations and qualify secondary sources. Material performance now differentiates flow stability and shelf life.
-
Design payer engagement around outpatient coding stability. Preserve economic access by documenting total cost of care benefits (reduced inpatient days, readmission avoidance) rather than only device price.
-
Invest selectively in product features that translate to clinical adoption: simple dosing verification, ease of use for home caregivers, and integration with telehealth follow‑up tools.
-
For investors: target mid‑tier suppliers and specialty technology companies with validated clinical use cases — these are the most likely consolidation candidates.
How to use this research
Use the full PW Consulting report to convert macro growth (USD 885.0 Million in 2025, USD 975.8 Million in 2026, 6.98% CAGR through 2032) into tactical plans: determine manufacturing scale‑up timelines, prioritize R&D investments, and shape payer conversations. The executive summary you are reading is a strategic preview; the full dataset, scenario models, and competitor dossiers are required to execute with confidence.
For procurement teams, product leaders, M&A groups, and private equity investors preparing 2026 plans, this study offers a rigorous, executable roadmap — demonstrated methodology, complete transparency on assumptions, and the specific operational checklists you need to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Elastomeric Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


