



PW Consulting: E-Cigarette Atomizers to Reach USD 6.69B by 2032 at 9.1% CAGR
By PW Consulting, 2026-07-12
Electronic Cigarette Atomizer Market — Strategic Outlook for 2026 Decision‑Makers
Executive teaser: why this research matters for 2026
As companies prepare 2026 budgets and strategic plans, the Electronic Cigarette Atomizer market presents both accelerated growth and amplified complexity. Our PW Consulting market study crystallizes a clear growth trajectory—anchored in rigorous historical analysis and scenario‑based forecasting—while also exposing the operational, regulatory, and competitive frictions that will determine who captures value. This article previews the strategic takeaways senior executives and investors need to consider before committing capital in 2026, while intentionally withholding granular segment breakdowns to preserve the commercial value of the full report.
Electronic Cigarette Atomizer Market
Market trajectory at a glance
The atomizer market has moved from mid‑single‑digit levels earlier in the decade into a higher‑growth phase. Measured in USD Million, the total market increased steadily across the 2020–2025 historical window and our base‑year estimate for 2025 stands as a robust platform for expansion. We forecast continued acceleration across the 2026–2032 period, with a compound annual growth rate (CAGR) of 9.1% through 2032. By modeling multiple demand, pricing, and regulatory scenarios, the study quantifies upside and downside paths for enterprise planning—helping firms set realistic production, R&D, and go‑to‑market timing in 2026.
Electronic Cigarette Atomizer Market
What this growth really means for corporate strategy
-
Demand scaling: Growth at a ~9% CAGR requires companies to rethink capacity and supplier relationships. Firms that locked fixed costs around pre‑2024 volumes risk margin compression unless they implement flexible manufacturing or contract hedging.
Electronic Cigarette Atomizer Market -
Product and platform choices: The market is shifting toward differentiated atomizer technologies and integrated systems. Firms that can pair hardware thermals, coil chemistry, and firmware to a clear value proposition will command premium margins.
-
Timing bets: 2026 is a tactical year for launch sequencing. Rapid product rollouts without regulatory clearance or supply certainty invite costly recalls or stockouts; conversely, waiting too long forfeits share in adjacent segments.
Competitive landscape — concentrated but open to disruption
The atomizer market shows moderate concentration at the top. Market concentration metrics indicate that the three largest firms collectively account for a meaningful, but not dominant, share—leaving room for nimble challengers and component specialists to climb. Competitive dynamics are shaped by hardware innovation cycles, channel control, and manufacturing scale.
-
Innokin (Shenzhen) — recognized for advanced pod systems and smart‑chip integration; recent launches emphasize firing speed and battery efficiency, illustrating the product innovation premium available to incumbents.
-
VOOPOO (Shenzhen) — leverages proprietary chipset technology to differentiate on user experience and performance; platform lock‑in creates defendable niches for firmware‑enabled features.
-
Geekvape (Shenzhen) — positions around ruggedized form factors and modular systems; durability claims and reliability testing are central to its commercial appeals, especially to distribution partners seeking lower return rates.
-
Yocan (Shenzhen) — focuses on ceramic atomizers and concentrate devices; recent product introductions broaden addressable applications and underscore the growth potential in adjacent inhalation categories.
-
Selected Shenzhen OEMs — several specialty manufacturers continue to supply rebuildable and mechanical components; their agility in small‑batch innovations is an acquisition target for larger platforms seeking new form factors.
Recent corporate developments—product launches with ultra‑fast firing chips, capacity expansions, and new ceramic‑based product lines—illustrate that innovation and scale remain the two levers to watch in 2026. Our full report includes a mapped competitive matrix and capability heatmap that ties each supplier to specific technical and commercial strengths.
Regulatory, trade and supply‑chain dynamics that will drive 2026 outcomes
-
Regulatory timing and cost: New and tightening rules in key markets impose both time‑to‑market constraints and cost overlays (e.g., excise or duty mechanics being introduced in several jurisdictions). Compliance calendars should now be front‑ended in new product project plans to avoid missed selling windows.
-
Market‑access requirements: Ingredients and product‑listing mandates in major regulatory regimes require pre‑market submissions and documentation—impacting launch lead times and SKU rationalization decisions.
-
Tariffs and trade policy: Recent tariff adjustments on components from major manufacturing hubs mean landed costs can swing materially between sourcing options. Scenario modeling in the report quantifies cost sensitivity to tariff and freight shocks.
-
Raw material volatility: In 2025 some upstream materials experienced extended lead times. Companies that implement multi‑sourcing, strategic inventory buffers, or long‑lead contracting will be better positioned to meet 2026 demand shocks.
Supply chain playbook for 2026
Our analysis prescribes four practical moves for operations leaders:
-
Implement dynamic procurement contracts that balance price floors with volume flex points to manage PP and VG lead‑time volatility.
-
Adopt modular assembly cells to shift capacity across atomizer types without large capex, enabling fast response to shifting product mixes.
-
Build regulatory readiness into supplier selection—favor vendors with documented compliance processes to shorten CE, FDA or region‑specific submissions.
-
Stress test distribution agreements against tariff scenarios and rework channel economics in your 2026 P&L if land‑border costs rise.
Commercial go‑to‑market and product positioning insights
Our segmentation analysis (detailed in the full report) shows distinct buyer cohorts with divergent priorities—performance, convenience, and cost. Strategic choices in 2026 should be guided by three imperatives:
-
Precision segmentation: Avoid broad‑brush portfolios. Focused SKUs with clear technical differentiation outperform in both retail and specialty channels.
-
Channel economics: Payment terms, returns, and co‑op marketing materially affect margin—especially as retail partners demand more promotional support amid competition.
-
Adjacency and bundling: Cross‑selling atomizers with device firmware, consumables, or subscription services can lift lifetime value and offset unit price pressure.
What the PW Consulting report contains — practical, executable modules
The full market study is structured to support immediate 2026 decision cycles. Key modules include:
-
Validated historical market sizing and a transparent forecasting model with scenario toggles for demand, tariff, and regulatory paths;
-
Segment and sub‑segment analysis with buyer archetypes and price‑sensitivity elasticities (note: granular segment tables are reserved for subscribers);
-
Comprehensive competitive landscape with capability mapping, recent strategic moves, and M&A/partnership readiness;
-
Supply‑chain risk matrix highlighting single‑source exposures, lead‑time profiles, and mitigation playbooks;
-
Regulatory impact assessments and launch‑timing calendars keyed to major markets; and
-
Actionable 100‑day and 12‑month roadmaps for product, operations and channel teams, including cost‑to‑implement estimates and KPI templates.
How to use this research in 2026 planning
-
Board and investor briefings: Use the macro projections and scenario outputs to stress test investment cases and capital allocation between R&D, manufacturing and M&A.
-
Product portfolio prioritization: Reconcile SKU profitability against forecasted demand mix and regulatory timelines—retire or delay low‑value releases.
-
Procurement and ops planning: Reconfigure contracts and safety stocks informed by modeled supply‑chain lead times and tariff sensitivity.
-
M&A and partnership scouting: Target acquisitions that close capability gaps identified in our capability heatmap, or lock supply through strategic JV structures.
Final strategic imperatives
Entering 2026, firms in the Electronic Cigarette Atomizer market face a classic strategic triad: accelerate innovation, harden supply chains, and navigate an evolving regulatory terrain. The market growth path is attractive, but value capture will accrue to organizations that translate forecasting rigor into operational discipline and regulatory foresight. Our study equips leaders with the quantitative baseline and pragmatic playbooks needed to convert market growth into durable competitive advantage.
Next steps — where to get the detailed intelligence
This article highlights the strategic contours and operational levers that will matter in 2026. For the full data tables, segmented forecasts, company scorecards, and downloadable modeling tools that underpin these conclusions, please refer to the PW Consulting Electronic Cigarette Atomizer Market report. The full study includes the specific segment breakdowns, regional allocations, and detailed financials that decision‑makers require to finalize budgets and go‑to‑market plans.
For detailed analysis of this topic, please visit the official page: Electronic Cigarette Atomizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rocket Engine Market 2026: Strategic Imperatives from PW Consulting’s Market Preview
Executive snapshot
By the end of PW Consulting’s base year (2025) the global rocket engine market had scaled to approximately USD 11,700 Million (revenue, Million USD), up materially from roughly USD 8,682 Million in 2020. Our analysis projects a steady recovery-and-investment phase through the late 2020s, with the market growing at a compound annual growth rate (CAGR) of 5.52% during the 2026–2032 forecast period and approaching roughly USD 17,070 Million by 2032. For executives planning capital allocation, partnership strategies or capability roadmaps in 2026, this macro trajectory implies selective expansion rather than indiscriminate capacity build-out: growth is meaningful, but it rewards targeted capability, supply-chain resilience and regulatory agility.
Rocket Engine Market
Why 2026 is a strategic inflection
2026 is shaping up as a year when programmatic maturation, regulatory updates and material-supply constraints converge to re-shape procurement and investment decisions. Public and private programmes are moving from prototype demonstrations into scaled deployments; at the same time, export-control adjustments and government-directed funding are reframing where and how manufacturers choose to localize capability. Market participants who recognize these structural shifts early can trade lower-risk, near-term contract capture for differentiated long-term positioning.
Rocket Engine Market
Key dynamics shaping decisions this year
- Demand normalization with differentiated pockets of acceleration: The market’s medium-term growth profile reflects normalization after a period of intense investment in new launch architectures. However, pockets of accelerated demand—driven by new medium- and heavy-lift programs, hypersonics, and national defense modernisation—will create asymmetrical opportunities for suppliers with the right technology and certification footholds.
- Regulatory and export-control tightening: Changes to space-related export controls and broader propulsion-related standards are increasing the salience of compliance as a competitive barrier. Licensing timelines, technical data distribution and foreign-participation constraints will materially influence program timelines in 2026.
- Supply-chain and raw-material volatility: Recent shortages of critical raw materials have produced substantial input-cost swings in rocket motor production. This volatility elevates the value of supply-chain engineering—materials substitution, dual-sourcing and inventory hedging become strategic capabilities rather than line-item risks.
- Government-directed industrial policy: Targeted public funding and procurement (including modernisation investments and domestic production incentives) are reshaping the competitive footprint. Strategic grants and procurement can accelerate incumbents or catalyze new entrants depending on execution speed.
Competitive landscape — an overlay, not a deep-dive
The market remains a mix of scale-focused incumbents and aggressively engineered challengers. Leading firms continue to vertically integrate engine manufacture with launch and vehicle systems to capture more value across the stack, while specialist propulsion houses concentrate on high-performance subsystems and components. Recent corporate and operational moves clarify four strategic archetypes in play: vertically integrated launch primes, independent engine specialists, additively enabled disruptors, and defense-focused solid-propulsion houses.
Rocket Engine Market
- Vertically integrated launch primes: Companies that design, manufacture and operate complete launch systems continue to capture outsized strategic advantages through systems integration and iterative flight cadence. Their investments in reusable architectures and high-thrust liquid engines are reshaping cost curves and launch-service contracting assumptions.
- Independent propulsion specialists: Long-established propulsion firms retain core roles across upper stages, in-space propulsion and defense programs. Corporate restructurings and private-equity transactions have accelerated repositioning in this group, presenting both consolidation opportunities and specialization pathways for buyers and partners.
- Additive-manufacturing challengers: A cohort of younger firms is scaling production using additive manufacturing and compact turbomachinery, offering flexibility and speed-to-market on small- and medium-class engines. Their competitive edge lies in shorter iteration cycles and lower unit tooling costs.
- Defense and solid-propulsion players: Solid rocket motor capacity remains strategically important for national security and tactical programs. Investments in domestic-scale manufacturing—supported by government grants and facility expansions—are altering where solid-propulsion manufacturing will be concentrated over the next decade.
Notable public developments through early 2026 illustrate these dynamics: manufacturing expansions by firms scaling both liquid and solid production capacity, production milestones for additively produced engines, major facility investments in North America, and strategic transactions reshaping ownership of legacy propulsion assets. These moves collectively accelerate capability rebalancing across the supply base and will influence award-weighting in RFPs and IRAD (internal research and development) priorities in 2026.
Operational risks and regulatory headwinds
- Export-control and data governance: Recent updates to exporter guidance mean that cross-border collaboration and customer-engagement models must be restructured to avoid compliance risk. Firms will need export-control-by-design in engineering data flows and partner selection.
- Material-cost and sourcing shocks: Surging prices for strategic inputs have compressed margins and created program-level cost uncertainty; procurement teams must accelerate dual-sourcing, near-shoring and strategic inventory strategies.
- Ceremony-to-certification timelines: Performance standards and test methodologies—across manned/unmanned and novel propulsion categories—are extending qualification cycles. This increases time-to-revenue for new engine types without parallel increases in early-stage funding.
- Consolidation and M&A timing: Corporate restructuring and private-equity transactions in the propulsion space create windows both for strategic acquisitions and for divestiture-induced capability vacuums. Buyers should calibrate transaction timelines against procurement cycles to avoid integration-induced program slippage.
What the PW Consulting report delivers — practical, actionable content
Our full market study goes well beyond headline forecasts. It equips decision-makers with the tactical inputs needed to shape 2026 strategies while protecting our proprietary segmentation data to encourage direct report access. Highlights include:
- Scenario-based demand models aligned to program timelines and policy levers, enabling planners to stress-test CAPEX and hiring plans against alternative market paths.
- Supply-chain playbooks that quantify supplier concentration risks, recommend dual-sourcing priorities and outline material substitution pathways that preserve performance.
- Partnering and M&A decision frameworks—diagnostic tools that align technology roadmaps with corporate development objectives and help prioritize targets by capability, certification progress and contract backlog.
- Regulatory compliance checklists and a practical roadmap to operationalize export-control requirements and emerging testing standards across product lifecycles.
- Operational benchmarks for manufacturing scale-up, including additive-manufacturing throughput metrics, test-facility capacity planning and workforce-skill requirements tied to realistic ramp profiles.
Recommended 90-day actions for 2026 planning
- Prioritize resiliency over maximality: Do not assume demand will automatically absorb large greenfield capacity. Instead, align capacity increases with secured contract milestones and staged investment triggers.
- Recalibrate supplier contracts: Lock in tiered procurement agreements with indexed pricing and contingencies for critical raw materials to moderate margin volatility.
- Adjust go-to-market for export controls: Build a compliance-first engagement model for international partnerships and integrate licensing timelines into commercial bids.
- Pursue targeted partnerships: For firms lacking full-stack capability, prioritize equity-light partnerships that secure flight-proven engines or manufacturing slots rather than long-term capital investments.
- Invest in test and qualification throughput: Engineering teams must accelerate component-level testing and certifications to compress the path from prototype to flight.
Where judgment will matter most
Three judgment calls will determine winners in 2026:
- Speed vs. scale: Whether to scale capacity rapidly to capture projected demand or to move incrementally while securing program wins.
- Vertical integration vs. specialization: Choosing to internalize propulsion capabilities can protect margins but raises capital intensity; specialization allows faster innovation but can limit contract eligibility.
- Public-partner engagement: Deciding how aggressively to pursue government-funded domestic supply programs and how to align bids with national-security priorities.
Conclusion — the strategic payoff
In aggregate, the 2026 operating environment rewards disciplined, insight-driven decision-making. The market’s mid-single-digit CAGR through 2032 implies room for growth, but that growth is uneven and policy-dependent. Executives who combine supply-chain engineering, regulatory foresight and selective partnerships will both capture near-term revenue and establish durable competitive moats.
Next steps
PW Consulting’s full report contains the granular segmentation, competitive matrices and program-level forecasts that inform executable plans. The material in this preview outlines the strategic posture you need in 2026; the full dataset and playbooks provide the implementation details. Contact our research desk or visit our report page to access the complete study and the proprietary segmentation that underpins contract- and site-level investment decisions.
For detailed analysis of this topic, please visit the official page: Rocket Engine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Chip Handler Market — USD 680M in 2025, 4.7% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Semiconductor Chip Handler Market — Strategic Briefing for 2026 Decisions
Executive snapshot
The semiconductor chip handler market is maturing into a mission-critical enabler of advanced packaging and high-throughput test flows. From a base of USD 550 Million in 2020 the market expanded to USD 680 Million by the 2025 base year and is forecast to reach approximately USD 928 Million by 2032. The medium-term trajectory implies a compound annual growth rate of 4.7% across the 2026–2032 forecast window. Market concentration is material: the top three firms capture roughly two-thirds of revenue (CR3 ≈ 65%), while the five largest firms approach three quarters (CR5 ≈ 75%).
Semiconductor Chip Handler Market
Why this matters for 2026 corporate decision-making
- Capital planning: a modest, steady expansion at ~4.7% CAGR signals predictable capacity needs rather than explosive replacement cycles—useful for capex phasing and leasing strategies.
- Supplier strategy: high concentration creates both dependency risks and supplier-bargaining asymmetries; buyers should prioritize supplier resilience and flexible contracts.
- Technology roadmap alignment: handler innovation (automation, thermal control, vision systems, AI-driven maintenance) is tightly coupled with packaging trends and test flow automation—decisions on internal development vs. third-party integration will materially affect time-to-volume for new products.
- Regulatory & geopolitical risk: export controls and incentive programs change the calculus for regional sourcing and capacity expansion—2026 is a pivot year for aligning commercial plans with policy constraints and funding opportunities.
What PW Consulting’s Semiconductor Chip Handler Study delivers (practical, decision-ready content)
This research is structured as a working toolkit for 2026 strategy execution rather than a purely descriptive market paper. Core deliverables include:
Semiconductor Chip Handler Market
- Robust market-sizing and trend narrative from 2020–2025 (historical) and a seven-year forecast (2026–2032) with scenario analysis (base, upside, downside) to stress-test capex plans.
- Buy-side decision frameworks: a supplier selection scorecard, total cost of ownership (TCO) template, and retrofit vs. greenfield decision trees for handler investments.
- Vendor diagnostics and competitive playbooks: strategic profiles, capability maps, and partner-fit matrices that translate vendor capabilities into procurement requirements by test-type and packaging architecture.
- Supply-chain mapping: critical upstream inputs, single-point-of-failure analysis, and mitigations for raw-material and labor constraints relevant to handler OEMs and subsystem suppliers.
- Operational KPIs and deployment playbooks: throughput modeling, thermal-management validation steps, and an AI-enabled predictive-maintenance pilot plan that can be executed in 90–180 days.
- M&A and partnership roadmaps: valuation heuristics, capability-acquisition checkpoints, and integration milestones for buyers seeking rapid access to advanced handler technologies or regional service networks.
- Primary intelligence: interviews with OEMs, OSATs, IDMs, and service providers; field-validated case studies showing real-world TCO outcomes and yield impacts post-handler upgrades.
Note: the full report contains gated, granular segmentation tables (by handler type, function, application, and region) and proprietary quantitative splits—these are intentionally withheld here to direct readers to the full dataset and vendor scorecards.
Semiconductor Chip Handler Market
Competitive landscape — how to read vendor behavior in 2026
The handler market is dominated by a small set of specialists and systems integrators. Understanding each player’s strategic vectors is essential when shaping supplier portfolios or evaluating partner investments.
- Advantest Corporation (Tokyo) — Strengths: high-throughput platforms and a clear focus on AI/HPC test stacks. Strategic implications: best partner for buyers prioritizing scale and front-line test automation for logic and memory at advanced nodes. Recent visibility at SEMICON events underscores continued product and ecosystem investments.
- Cohu, Inc. (San Diego) — Strengths: modular handler architectures and thermal-control subsystems. Strategic implications: candidates for integration when thermal management and flexible reconfiguration across device families are priority objectives.
- ASMPT (Singapore) — Strengths: breadth across assembly and test automation; tight fit to advanced packaging flows. Strategic implications: attractive for OSATs and IDMs seeking turnkey assembly-to-test solutions and tighter interface engineering across process stages.
- TESEC Corporation (Tokyo) — Strengths: niche capabilities in discrete, MEMS, and power IC handlers. Strategic implications: strong fit for specialized high-reliability device lines where test mechanics differ from commodity ICs.
- Boston Semi Equipment (USA) — Strengths: agile product development in pick-and-place and SLT lines; recent product-line expansions broaden the addressable final-test portfolio. Strategic implications: potential supplier for mid-volume lines and custom automation projects.
- SRM Integration (Penang) — Strengths: high-speed IC handlers and custom automation for final test. Strategic implications: regional advantage in Southeast Asia for buyers co-locating with back-end assembly clusters.
- HON. PRECISION (Taichung) — Strengths: Taiwan-based engineering depth for flash/memory and MEMS test handlers. Strategic implications: logical partner for memory-oriented test lines and nearshore support to Taiwanese fabs and OSATs.
- Pentamaster (Penang) — Strengths: integration of vision systems and pick-and-place automation for final test and power modules. Strategic implications: good fit where vision-enabled inspection and automation yield are prioritized.
- NS Technologies (Kanematsu Group, Japan) — Strengths: throughput-oriented handlers supporting logic, memory, and automotive chips. Strategic implications: a viable partner for scale-out initiatives where global service and high throughput are required.
Recent vendor moves—exhibitions, product launches, and demo roadmaps—confirm the market’s focus on AI-enabled optimization, thermal precision, and modular architectures suitable for mixed-technology lines. These tactical shifts are summarized in the full report alongside vendor scorecards and risk matrices.
Industry dynamics and risk factors shaping 2026 outcomes
- Regulatory overlays: U.S. export controls on advanced compute chips and related equipment introduce conditionality for some sales channels and OEMs. Buyers and suppliers must embed compliance checkpoints into procurement and partnership agreements.
- Policy tailwinds: CHIPS Act funding and allied programs materially influence capital availability for domestic expansion in the U.S.—this creates windows for co-investment and subsidy-aligned capacity planning in 2026.
- Raw-material dependencies: substrates and mechanical components rely on epoxy resins, metal alloys, and ceramics; volatility or quality constraints in these inputs directly affect handler lead times and retrofit feasibility.
- Labor and automation: handler adoption continues to accelerate as firms mitigate labor scarcity and raise throughput. Investments in semi- and fully-automatic handlers should be benchmarked against labor cost curves and expected yield improvements.
- Energy and operational efficiency: leading handlers are embedding AI-driven predictive maintenance and software-defined optimization to reduce energy consumption and operating expense—key for sustainability targets and OPEX reduction in 2026.
Recommended 90–180 day actions for decision-makers
- Execute a supplier resilience stress test: map single-source dependencies, validate alternate vendors, and negotiate short-term capacity options tied to clear service-level metrics.
- Initiate a pilot for AI-enabled predictive maintenance: select one high-volume line, instrument key handler assets, and run a 90–day trial to quantify downtime reduction and energy savings.
- Align CAPEX with scenario outputs: reserve growth-capex tranches tied to the forecast scenarios in this report so that expansion is triggered by measurable demand or incentive milestones.
- Embed export-control and subsidy compliance into contracts: add clauses that account for licensing regimes and CHIPS program commitments to de-risk cross-border procurement and co-investments.
- Prioritize retrofitability in specs: when issuing RFPs, score vendors not only on throughput but on modular retrofit capability, software APIs, and spare-parts logistics to reduce TCO over a 7–10 year horizon.
- Explore targeted partnerships or tuck-ins: use M&A heuristics in the full report to evaluate small-cap acquisitions that accelerate advanced-packaging handler capabilities or regional service footprints.
Conclusion — the strategic value of this intelligence
For executives drawing 2026 capital and sourcing roadmaps, the handler market offers predictable growth with concentrated supplier power and meaningful technological differentiation. The strategic choices made this year—vendor selection, automation pilots, subsidy-aligned expansions, and compliance embedding—will determine whether companies capture yield and throughput gains or suffer extended ramp cycles. PW Consulting’s full Semiconductor Chip Handler Market study transforms the macro narrative above into executable roadmaps, procurement tools, and vendor playbooks designed for immediate use by strategy, operations, and procurement teams.
Access the full report to retrieve the gated segment-level forecasts, vendor scorecards, and the operational playbooks necessary to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Semiconductor Chip Handler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Depaneling Machine Market to Hit USD 344.8M by 2032 at 6.98% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Depaneling Machine Market — Strategic Outlook for 2026 Decision-Makers
Executive trailer
As PW Consulting’s lead industry analyst, I present a distilled, decision-oriented preview of our full Depaneling Machine Market research. Between 2020 and 2025 the global depaneling market demonstrated resilient growth and recovery dynamics; our baseline year is 2025 and the market is projected forward through 2032 at a compound annual growth rate (CAGR) of approximately 6.98%. This trajectory implies meaningful expansion opportunities for OEMs, EMS providers, and capital planners in 2026—provided they align technology choices, production footprints, and compliance programs with accelerating requirements in electronics miniaturization, automotive electrification, and medical device traceability.
Depaneling Machine Market
Why this matters for 2026 strategic decisions
-
Capital allocation sizing: With a clear CAGR and an established historical baseline, investment cycles for depaneling equipment move from discretionary to programmatic. Companies planning capacity upgrades in 2026 must reconcile CAPEX timing with expected production mixes and product life-cycle peaks.
Depaneling Machine Market -
Technology selection is consequential: Laser, router, and blade/router hybrids each deliver different trade-offs across throughput, edge quality, particulate generation, and substrate compatibility. Decisions made in 2026 will lock manufacturing capabilities for multiple product generations.
Depaneling Machine Market -
Regulatory and customer-driven requirements are non-negotiable: Standards such as IPC acceptability criteria, ISO/TS and IATF frameworks for automotive, and ISO 13485 for medical electronics demand validated, burr-free, particle-controlled singulation processes. Vendors and buyers must plan validation pathways and supplier quality agreements early in procurement cycles.
Market snapshot (strategic view)
Our analysis captures the market progression from 2020 through a 2025 baseline and projects through 2032. After a period of fluctuation and recovery in the early 2020s, the market reached a stable base in 2025 and is forecast to grow steadily thereafter under a near-7% CAGR. This growth is driven by several structural forces—higher PCB complexity, increasing use of flexible and rigid-flex substrates, demand for low-defect singulation in safety-critical applications, and the ongoing adoption of automation across SMT lines. Importantly, the market concentration remains relatively low: the top three players collectively control roughly one-quarter of market share, and the top five only marginally more—indicative of a fragmented landscape with significant regional and application-specific niches.
Forces shaping the market in 2026
-
Technological evolution: Laser depaneling has matured as a stress-free, dust-minimizing process that supports thin, densely populated boards and flexible substrates. Milling and routing still provide advantages in certain material stacks and cost-sensitive applications. The strategic choice is often hybrid: deploy laser where cleanliness and precision matter, and routing where material removal and cycle time dominate.
-
Regulatory and quality constraints: Automotive (IATF, AEC-Q), medical (ISO 13485), and IPC standards impose post-depaneling verifications and particulate/burr control that translate into process controls, inline inspection, and traceability investments. Compliance requirements are increasingly a differentiator in supplier selection rather than a basic hygiene factor.
-
Supply chain and localization: OEMs weighing reshoring or nearshoring must factor in local availability of depaneling expertise, service networks, and the ability to validate processes to specific industry norms. The fragmented vendor base can be both a benefit—choice and specialization—and a challenge—service variability.
-
Product complexity and throughput demands: As PCBs trend toward higher layer counts, tighter tolerances, and mixed rigid-flex assemblies, line planners must balance takt time with singulation quality. Inline depaneling systems integrated with AOI and handling reduce manual touchpoints but require higher upfront systems integration competence.
Competitive landscape — what to watch
The vendor ecosystem includes established European automation specialists, Asian laser system manufacturers, and a mix of regional equipment providers focusing on tailored solutions. The market’s fragmented structure favors specialized suppliers that can pair hardware with application know-how and validation services.
-
European automation and optics players continue to innovate on precision and modularity; notable product introductions in 2026 emphasize flexibility for mixed-volume production runs and inline integration.
-
Laser system vendors from Asia and Europe are competing on proprietary optics and process recipes that reduce particulate generation and minimize thermal stress—features that accelerate acceptance in medically regulated and automotive contexts.
-
Regional Taiwanese and Chinese manufacturers reinforce competitiveness through cost-optimized mechanical systems and rapid aftermarket support in APAC manufacturing hubs.
Recent industry developments highlight these dynamics: several vendors launched or demonstrated new models and inline systems in early 2026, while partnership activity with automotive and electronics OEMs points toward faster adoption of validated inline depaneling solutions. These moves validate two strategic trends—(1) demand for modular systems that scale across prototype to high-volume lines, and (2) stronger integration between depaneling and upstream/downstream SMT automation.
Strategic playbook for 2026
-
Adopt a capability-first procurement approach: Specify required edge quality, particulate thresholds, process validation steps, and inline integration capabilities—then evaluate vendors against these capability buckets rather than price alone. This reduces rework costs and supplier replacement risk.
-
Plan for mixed-technology fleets: Expect to operate multiple depaneling technologies concurrently. Use decision matrices that weigh lifecycle cost, material compatibility, mean time between failures, and service footprint to determine deployment mixes by product family.
-
Embed regulatory validation into project timelines: For automotive and medical programs, allocate time and budget for process validation, both internal and customer-specific. Early supplier engagement on validation protocols saves months during product ramp.
-
Commit to data-driven quality: Integrate in-line inspection, particle monitoring, and edge-quality analytics. Instrumentation that provides closed-loop feedback will be a source of cost-savings and a commercial differentiator for suppliers offering it.
-
Negotiate after-sales as a strategic asset: Service contracts, spare parts locality, and remote diagnostics materially affect uptime. For multi-site manufacturers, harmonize equipment models to simplify spares and training unless specific production requirements dictate otherwise.
What the PW Consulting Depaneling Machine Market report delivers
Our full study is structured to support executable decisions in 2026. The report includes:
-
Market sizing and validated forecast model from 2020—2032 with scenario analyses that stress-test demand assumptions against technology adoption curves.
-
Vendor benchmarking and capability maps that score suppliers on precision, throughput, service network, and regulatory experience—presented to inform RFP shortlists and supplier development plans.
-
Operational playbooks: process selection checklists, integration templates for inline deployment, and validation protocols tailored for automotive and medical compliance regimes.
-
Commercial tools: multi-year TCO calculators, depreciation and payback models, and sensitivity analyses that link equipment choices to unit economics and SKU-level production volumes.
-
Risk heatmaps and mitigation frameworks for supply, regulatory, and technology obsolescence risks—aligned to procurement cadence and product roadmaps.
To preserve the strategic edge for our subscribers, detailed segment-level splits and proprietary vendor scoring matrices are intentionally excluded from this preview. Those granular inputs—critical when sizing purchase lots, negotiating service contracts, and mapping validation timelines—are available through the complete research package.
Actionable next steps for executive teams
-
Portfolio owners: Map product families to depaneling capability buckets now; initiate supplier qualification where compliance-critical products are scheduled to ramp in 2026–2027.
-
Operations and automation leads: Prioritize pilots that integrate depaneling with inline AOI and handling for representative SKUs. Use pilot data to refine cycle time and yield assumptions in CAPEX models.
-
Procurement: Use our vendor capability framework to create a balanced RFP short-list combining global players with regional specialists, and tender on performance outcomes rather than just equipment specs.
-
R&D and quality: Bake depaneling validation into product development timelines—particularly for flexible, rigid-flex, and high-density boards destined for regulated markets.
Closing — the strategic value of attending to depaneling decisions in 2026
Depaneling is no longer a peripheral equipment choice; it is a determinative part of manufacturing capability that impacts yield, product reliability, and regulatory compliance. With a near-7% projected CAGR and a fragmented supplier landscape, 2026 is a pivotal year for firms to translate growth forecasts into concrete investments and supplier strategies. PW Consulting’s full report provides the granular segmentation, vendor scores, and operational templates necessary to convert strategic intention into operational reality. For the detailed segment-level data, vendor scorecards, and TCO models that underpin production and procurement decisions, access our comprehensive study through the official PW Consulting distribution channels.
For detailed analysis of this topic, please visit the official page: Depaneling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Online Exam Proctoring Market to Hit USD 2.75B by 2032, 15.5% CAGR
By PW Consulting, 2026-07-12
Online Exam Proctoring Market 2026: Strategic Preview for Corporate Decision-Makers
As organizations accelerate the digitization of assessment and certification, online exam proctoring has transitioned from a niche convenience to a core component of credentialing, compliance testing, and high-stakes assessment strategies. This preview synthesizes the essential strategic implications of PW Consulting’s new Online Exam Proctoring Market study (base year 2025, forecast 2026–2032) and explains why C‑suite and procurement leaders must treat proctoring capability as a 2026 strategic priority.
Online Exam Proctoring Market
Executive snapshot
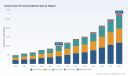
The proctoring market has entered a rapid growth phase. Our macro model shows market value rising from under USD 500 Million in 2020 to approximately USD 1.0 Billion in 2025, with a compounded annual growth rate of 15.5% through the forecast window. By 2032 the sector is projected to exceed USD 2.7 Billion—an expansion driven by rising remote certification volumes, regulatory acceptance of remote testing, and continuous improvements in AI‑enabled monitoring and secure delivery infrastructure.
Online Exam Proctoring Market
Why this matters for 2026 decision cycles
- Strategic risk management: Organizations that postpone a clear proctoring strategy face escalating compliance and reputational risks. Remote assessment is no longer experimental; it is embedded in core business processes for hiring, licensing, and internal compliance testing.
- Vendor selection impacts total cost of ownership and downstream agility. Proctoring tools touch identity verification, data protection, LMS integration, and candidate experience; vendor choices made in 2026 will shape operational costs and legal exposure for years.
- Competitive differentiation. Employers and credentialing bodies that optimize remote assessment processes reduce time‑to‑credential and improve candidate throughput—advantages that compound across talent pipelines and commercial certification programs.
Market dynamics shaping 2026 plays
Four dynamics are decisive for vendors and buyers:
Online Exam Proctoring Market
- Regulatory & privacy headwinds
Data protection regimes—most notably GDPR and a growing number of biometric privacy statutes—are enforcing stricter controls over video, facial recognition, and voice data. These frameworks require demonstrable data minimization, purpose limitation, and, increasingly, explicit consent flows. Organizations must evaluate vendors against privacy‑by‑design criteria and prepare for jurisdictional constraints on certain biometric modalities.
- Security and public‑sector assurance
Public‑sector procurement is moving toward cloud assurance frameworks. Recent vendor certifications and readiness designations are signaling a bifurcation: suppliers that can demonstrate formal cloud security posture and government‑grade accreditation will dominate public tenders and large enterprise deals.
- Infrastructure realities
Reliable proctoring depends on consistent upstream and downstream bandwidth and resilient streaming technologies. Minimum bandwidth expectations and proctor‑side capacity planning are operational constraints—especially for large, synchronous exams. Adaptive low‑bandwidth streaming and smart session management will be key differentiators for deploying at scale in variable connectivity environments.
- AI and trust trade‑offs
Automated proctoring and advanced analytics reduce human review costs but raise explainability, bias, and appealability concerns. Buyers must balance automation benefits with transparent human‑in‑the‑loop processes, vendor explainability commitments, and defensible incident review workflows.
Competitive landscape — what to watch
The vendor field combines legacy test‑delivery specialists, AI‑first entrants, and assessment platform integrators. Our qualitative analysis of leading players yields five tactical points for 2026 procurement and strategy teams:
- PSI — A contender with strong assessment heritage that is accelerating into secure cloud proctoring. Recent enterprise and public‑sector certifications and partnership renewals underscore a positioning toward regulated, high‑assurance customers. For buyers targeting government or large credentialing programs, certification posture and auditability are decisive.
- Honorlock & Proctorio — Firms emphasizing AI detection and device‑level analytics. These solutions appeal where scale and low marginal cost per session matter most, but buyers must validate detection accuracy, false positive handling, and privacy safeguards, especially where biometric processing is contested.
- ProctorU & Examity — Firms with established live‑monitoring and hybrid offerings; attractive to organizations prioritizing candidate experience and a human‑verified audit trail. They remain relevant where due‑process and candidate appeal channels are important.
- Respondus & LockDown approaches — Browser‑level control remains a staple for reducing surface‑area risk in LMS ecosystems. These technologies are complementary to AI monitoring—particularly in high‑volume academic deployments—and procurement should plan for browser‑lock strategies as part of multi‑layered defense.
- Specialists & integrators (Inspera, OctoProctor, ProctorTrack, Constructor, Examus, Meazure Learning) — These vendors differentiate through LMS/assessment platform integrations, biometric identity verification, or flexible deployment models (including bring‑your‑own‑proctor). Decision frameworks in our report help buyers assess fit based on use case: academic testing, professional certification, or corporate compliance exams.
Recent market signals (implications for 2026)
- Certifications and government readiness are accelerating: vendors obtaining cloud security designations demonstrate the premium attached to public‑sector trust. Expect procurement cycles in government and regulated industries to favor certified providers.
- Milestone volumes reported by several providers indicate growing operational scale. Scalability questions now emphasize multi‑proctor concurrency planning and incident resolution SLAs rather than mere feature parity.
- Regulatory incidents and evolving privacy case law will continue to shape permissible technical architectures (for example, approaches that avoid raw biometric retention will gain preference).
What our full study delivers — practical, purchaseable intelligence
PW Consulting’s full report is designed as an executive‑to‑operational playbook. It contains:
- Market sizing and trajectory (2020–2032) with scenario analysis that isolates demand drivers and sensitivity to regulatory shocks.
- Vendor scorecards and quadrant mapping against commercial, security, and privacy dimensions—intended to accelerate RFP short‑listing without re‑inventing evaluation criteria.
- Actionable procurement assets: RFP templates, decision matrices, and contract clauses for data protection and incident management tailored to proctoring engagements.
- Deployment playbooks covering on‑premises vs cloud tradeoffs, hybrid architectures, bandwidth and proctor staffing models, and candidate experience optimization recipes.
- ROI and TCO models calibrated to common use cases (academic testing, certification, corporate compliance), enabling CFOs to model financeable adoption pathways.
- Privacy impact assessment templates and a technical checklist for adaptive streaming, encryption at rest/in transit, and biometric minimization strategies.
Strategic recommendations for 2026
- Treat proctoring as a cross‑functional program: Combine legal, IT, assessment design, and procurement into a single governance forum. This reduces the risk of mismatched requirements (e.g., strong proctoring tech with insufficient privacy controls).
- Prioritize vendor certification and auditability: If you serve regulated populations or bid on public tenders, select vendors with demonstrable security credentials and transparent audit logs.
- Design for contested outcomes: Establish clear appeal workflows, human review thresholds, and explainability SLAs before scaling automated proctoring to high‑stakes assessments.
- Benchmark candidate experience alongside detection metrics: High churn in candidate completion rates often traces back to fragile connectivity assumptions or intrusive UX; invest in pilot cohorts that mirror the lowest‑bandwidth regions you serve.
- Modularize your architecture: Build an assessment stack where browser lockdown, identity verification, and monitoring modules can be swapped without re‑engineering the LMS—this preserves negotiation leverage and enables rapid compliance adjustments.
Final note — this preview versus the deep dive
This article highlights why proctoring decisions in 2026 must be strategic rather than tactical. The full PW Consulting study supplies the granular models, vendor benchmarking, and operational toolkits necessary to convert insight into executable programs—without forcing procurement teams to start from first principles. For teams preparing procurement rounds, migration plans, or compliance roadmaps, our full report provides the segmented intelligence and appendices that operational leaders use to sign contracts and mobilize delivery teams.
To access the complete dataset, vendor assessments, scenario models, and deployment checklists that underpin these conclusions, please refer to the primary report release on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Online Exam Proctoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Perfluoroalkoxy (PFA) Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused industry preview designed to orient executive teams for the pivotal decisions of 2026. This briefing synthesizes macro dynamics, competitive moves, regulatory noise and cost pressures shaping the Perfluoroalkoxy (PFA) market — while preserving the proprietary segmentation and granular datasets that our full report delivers. Use this as a strategic compass: it signals where value and risk concentrate, how leading suppliers are positioning, and which playbooks will matter as companies allocate capital and commercial effort over the next planning cycle.
Perfluoroalkoxy (PFA) Market
Market Trajectory: The Macro Baseline
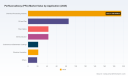
PFA has demonstrated steady expansion through the 2020–2025 historical window, growing from USD 368.44 Million in 2020 to USD 427.83 Million in the base year 2025. Our forecast horizon (2026–2032) models a mid-single-digit expansion, anchored by a compound annual growth rate (CAGR) of approximately 4.5%. Under our central scenario the market climbs to roughly USD 580.81 Million by 2032, with intermittent volatility driven by raw-material pricing and regulatory tightening. This pace reflects continued demand from high-purity industrial applications — notably semiconductor processing, chemical handling, and specialty tubing — even as incremental end-market adoption unfolds more gradually than in narrative-led projections.
Perfluoroalkoxy (PFA) Market
Why this matters for 2026 decisions
-
Portfolio prioritization: With moderate aggregate growth, 2026 is a year to refine product portfolios — doubling down on high-margin, high-purity grades while pruning lower-return commodity exposures.
Perfluoroalkoxy (PFA) Market -
Supply-chain strategy: The interplay of feedstock volatility and regulatory-driven process upgrades elevates supply-risk as a strategic variable; procurement and supply security will determine margin preservation.
-
CapEx and M&A timing: Investors should treat 2026 as a tactical inflection point to deploy capital into surfactant-free production, traceability systems and targeted bolt-on assets that accelerate access to regulated customers.
Key Market Dynamics and Structural Drivers
Several structural forces converge to define opportunity and exposure in 2026:
-
Regulatory acceleration: The U.S. EPA’s May 2026 proposed rules on PFAS in drinking water — including compliance timelines that in one option extend to 2031 — create a layered compliance landscape. Even where transitional provisions exist, lead customers and large OEMs are shortening their internal timelines, effectively accelerating demand for PFAS-compliant process technologies and documentation.
-
Manufacturing evolution toward surfactant-free processes: Suppliers such as Syensqo and AGC have publicly committed to or demonstrated surfactant-free manufacturing approaches. For buyers, supplier roadmaps on fluorosurfactant elimination are fast becoming a procurement gate.
-
Raw-material and cost pressure: TFE feedstock experienced meaningful price volatility in early 2026 and PFA production saw an 8% cost step-up in 2023 tied to compliance and material price shifts. These inputs magnify the importance of dynamic pricing clauses and hedging strategies in supply contracts.
-
Demand concentration: The market exhibits high supplier concentration at the top end; our concentration analysis signals that the top-tier players control a dominant share of supply, which reinforces the strategic importance of supplier relationships and long-term agreements for downstream integrators.
Competitive Landscape: What leading suppliers are doing
The competitive set is active on product innovation, capacity reconfiguration and application-specific high-purity positioning. Highlights of strategic relevance:
-
The Chemours Company (Wilmington, Delaware). Chemours has expanded and refined its high-purity PFA portfolio — including launches tailored to semiconductor requirements — signaling a supplier intent on defending premium niches where certification, traceability and contaminant control are decisive.
-
Daikin Industries, Ltd. (Osaka). With its NEOFLON series tailored for melt-molding and high-purity tubing, Daikin emphasizes technology transfer to electronics and semiconductor supply chains that prioritize consistent melt flow and minimal extractables.
-
AGC Inc. (Tokyo). AGC’s surfactant-free manufacturing process, announced in recent years, positions it as an operator-focused option for customers seeking PFAS exposure mitigation across their supplier base.
-
Syensqo (Brussels). Syensqo’s disclosure of PFA-free FFKM options and commitments to fluorosurfactant elimination reflect a differentiated sustainability message that resonates with battery and semiconductor OEMs.
-
Regional and niche specialists (e.g., Hubei Everflon, Zeus, RTP). These players are concentrated on dispersions, high‑purity tubing and compound formulations respectively; they compete on flexibility, localized supply and tailored product platforms for medical and semiconductor end-uses. Recent product introductions — including Zeus’s 2026 PFX platform for medical catheters — demonstrate where tactical innovation sits relative to broader capacity investments.
Recent Developments to Watch
-
Product launches and platform innovations (2025–2026) show incumbents defending technical moats around high-purity and extrusion capabilities.
-
Public commitments to eliminate fluorosurfactants (Syensqo, AGC) accelerate non-product regulatory mitigation strategies across the value chain.
-
Raw-material volatility and the 2023 cost step-up underscore the need for active pricing governance and supply‑chain resilience planning in supplier negotiations for 2026 contracts.
What our full report delivers (practical outputs)
PW Consulting’s full PFA Market study contains the operational and decision-grade tools you need for 2026 planning. Key deliverables include:
-
Market sizing and validated historical series (2020–2025) and forward projection models (2026–2032) with scenario toggles for regulatory stringency and feedstock shocks.
-
Supplier scorecards and capacity maps that integrate technology readiness, surfactant elimination timelines and contractual flexibility metrics.
-
Segment-level playbooks (product, application and route-to-market) that translate demand forecasts into prioritized commercial actions and SKU rationalization recommendations. Note: granular segment-level outputs are available in the full report; this preview intentionally omits those line-by-line splits to protect the analytical IP and to guide you to the source for detailed positioning work.
-
Raw-material sensitivity models and pricing pass‑through frameworks enabling rapid stress testing of margin outcomes under alternative TFE pricing scenarios.
-
Regulatory impact matrices with mitigation pathways — from process redesign and certification to customer communication templates and remediation CapEx estimates.
-
Targeted M&A and partnership scouting lists, including integration risk scoring and time-to-benefit estimates for bolt-on capacity or technology acquisitions focused on high‑purity and regulatory-compliant offerings.
-
Commercial negotiation playbook and model supply agreements for 2026 contracting cycles — incorporating indexation, force majeure considerations for regulatory changes, and sustainability commitments.
Strategic Imperatives for Executives in 2026
-
Pursue supplier risk diversification and lock key volumes with conditionality for regulatory-driven process changes. Where possible, insist on supplier roadmaps for surfactant elimination as a contracting KPI.
-
Prioritize high-purity product investments and certification pathways that align with semiconductor and battery customer specifications; these segments are the most durable under regulatory pressure.
-
Deploy dynamic pricing and hedging instruments to manage TFE exposure — establish internal triggers for price renegotiation and pass‑through clauses tied to validated cost indices.
-
Accelerate regulatory scenario planning: integrate the EPA proposed rule options into capital expenditure timing, and stage compliance investments to preserve optionality if timelines extend to 2031 under certain regulatory options.
-
Use targeted M&A to fill capability gaps (e.g., dispersion chemistry, surfactant-free processes, high‑purity extrusion) rather than generic scale buys; integration speed matters more than scale in a concentrated market.
Final note: why this preview — and why now
This briefing signals the contours of strategic choice in a market that is structurally concentrated and increasingly shaped by regulatory and feedstock volatility. The aggregate trajectory is constructive — modest, steady expansion at a roughly 4.5% CAGR through the 2026–2032 forecast window — but the distribution of value and risk within the market is shifting fast. That is why 2026 is a decisive planning year: contractual decisions, CapEx commitments and supplier selections made now will disproportionately determine competitive positions throughout the forecast period.
PW Consulting’s full PFA Market report packages the precise segmentation tables, supplier-level metrics and executable playbooks required to convert this strategic preview into operational plans. For decision-makers preparing budgets, negotiating supply contracts or evaluating M&A opportunities in 2026, the detailed datasets and scenario tools in the full study are essential to move from insight to action.
For detailed analysis of this topic, please visit the official page: Perfluoroalkoxy (PFA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Feed Ingredients to hit USD 52.9B by 2032 at a 3.6% CAGR
By PW Consulting, 2026-07-12
Animal Feed Ingredients Market 2026: Strategic Briefing for Executive Decision-Making
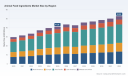
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing designed to equip C-suite and business-unit leaders with the strategic context they need to make high-confidence decisions in 2026. Our full Animal Feed Ingredients Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes hard market sizing, competitive dynamics, regulatory shifts, and raw-material risk to convert market intelligence into executable options. The market we track expanded from roughly USD 29.7 billion in 2020 to about USD 41.3 billion in the 2025 base year, and it is forecast to grow at a compound annual growth rate of 3.6% toward the 2032 horizon (reaching an estimated USD 52.9 billion). This macro trajectory frames the near-term choices executives must confront in 2026.
Animal Feed Ingredients Market
Why this briefing matters for 2026 decisions
-
Timing and resource allocation: With the market in a mid-cycle growth phase, managers face trade-offs between volume-led expansion and margin-protection investments (e.g., precision additives, quality assurance, logistics). Our study clarifies the return profiles of those alternatives under multiple price and regulation scenarios.
Animal Feed Ingredients Market -
Innovation window: Recent regulatory acceleration in several jurisdictions has shortened approval timelines for microbiome- and emissions-related additives, compressing the window for first-mover advantage. Companies that strategically align R&D, regulatory affairs, and commercialization will capture disproportionate value from premium additives and differentiated formulations.
Animal Feed Ingredients Market -
Supply-chain choreography: Volatility in grains and oilseed markets, coupled with evolving trade policy in priority export markets, means procurement strategy is now a competitive lever rather than a back-office function. Executives must decide whether to double down on vertical integration, secure offtakes, or diversify supplier bases in 2026.
Topline market dynamics
The animal feed ingredients market shows resilient, steady growth: from roughly USD 29.7 billion in 2020 to USD 41.3 billion in our 2025 base year and continuing upward to an estimated USD 52.9 billion by 2032 under our central-case projection (CAGR ~3.6%). This is not a hyper-growth theme, but it is large, strategic, and increasingly sophisticated — where incremental improvements in feed conversion, animal health, and regulatory compliance translate directly into meat, dairy, and aquaculture producers’ margins.
Three structural forces shape outcomes in 2026:
-
Cost pass-through pressure and raw-material cycles: Grain and oilseed price dynamics remain the primary determinant of short-run margin swings for conventional ingredient classes. Commodity prices moderated in 2025, and 2026 projections show continued stability in certain grains — an opportunity for processors and integrated suppliers to optimize mix and capture margin.
-
Shift from commodity to specialty: Growth in value-added feed additives, enzymes, amino acids, and targeted premixes is outpacing commodity volumes in many channels as producers seek productivity and sustainability gains. Regulatory facilitation of microbiome-focused solutions further accelerates adoption.
-
Regional policy inflections: Trade and fiscal policy moves in key import and export markets are re-shaping logistics economics — creating new export corridors while compressing margins in previously protected niches.
Regulation and raw-material signals you cannot ignore in 2026
-
Shortened approval timelines for gut- and emissions-focused inputs: A recent regulatory initiative has materially reduced time-to-market for products that meaningfully alter the gut microbiome or reduce enteric emissions. For strategy teams, this changes pipeline prioritization — invest in categories with accelerated approval and first-to-market potential.
-
Grain and oilseed pricing context: Stable-to-moderate grain prices observed in 2025 and similar 2026 projections create a favorable backdrop for demand recovery in sensitive livestock segments. However, soybean meal price volatility remains a persistent input risk; hedging and diversified sourcing should be part of any procurement playbook.
-
Trade policy shifts: Fiscal and tariff policy changes in selective emerging markets are opening up export opportunities and altering landed cost calculations. Firms with nimble commercial teams can exploit these short-term arbitrage windows to secure new customers and long-term contracts.
What the full report delivers (practical, executable content)
PW Consulting’s comprehensive report is designed to be immediately operational for strategy, commercial, and procurement teams. Highlights include:
-
Top-down and bottoms-up market sizing with historical validation and scenario-based forecasts to 2032 — enabling capital planning and revenue targets aligned to market trajectories.
-
Product and channel playbooks that translate technical ingredient trends (from commodity to specialty) into commercial tactics for pricing, bundling, and field support.
-
Regulatory impact matrix and go/no-go decision trees for product registration and market entry, reflecting shortened approval timelines for microbiome and emissions innovations.
-
Raw-material sensitivity models and procurement options analysis (hedging, vertical integration, strategic offtake), calibrated to recent grain and oilseed price paths.
-
Competitive heatmaps, capability benchmarking, and M&A candidate screens to inform inorganic growth strategies and partnership prioritization.
-
Client-ready slide decks and an executive dashboard for ongoing monitoring of price, policy, and demand indicators.
Competitive landscape — what to watch in 2026
The market displays moderate concentration: the top three players account for a little over half of global revenue, while the top five capture roughly two-thirds. This structure creates a balance — large incumbents retain scale economics and distribution reach, while mid-sized and specialty players lead on innovation and niche solutions. For 2026, the following competitive moves merit attention:
-
Scale players (global traders and processors): Firms with upstream origination and processing capabilities continue to leverage logistics and distribution networks to secure volume contracts and stabilize supply. Investments in regional production assets remain a key defensive and offensive lever.
-
Specialty ingredient and additive firms: Companies focused on enzymes, amino acids, probiotics, and mycotoxin solutions are the primary innovation engines. Their agility in registrational pathways and formulation expertise positions them to capture premium value as producers shift toward productivity-enhancing inputs.
-
Integrated animal nutrition divisions: Vertically integrated feed companies and divisions of larger agri-business players are experimenting with bundled offers (ingredients + premixes + advisory services), seeking to lock in lifetime customer value.
Notable corporate developments in the recent 12–18 months illustrate these dynamics. Strategic acquisitions in specialty additives have consolidated capabilities in gut health and mycotoxin mitigation, while partnerships and capital infusions into animal nutrition businesses reinforce the focus on scale plus innovation. Investments in regional manufacturing assets — exemplified by new, high-capacity feed plants — demonstrate that global players continue to optimize local supply footprints to serve fast-growing consumption corridors.
Operational and M&A implications for 2026
-
Prioritize capability fills over broadscale M&A: In a market where regulation accelerates category adoption, acquiring specific formulation, regulatory, or application expertise is often higher-return than chasing topline expansion via commodity bets.
-
Optimize go-to-market by livestock segment: Different livestock classes react to price and productivity levers in distinct ways. Tailored commercial models — from performance-based contracts to bundled advisory services — will prove decisive.
-
Secure supply: Use a mix of long-term contracts, strategic stocks, and selective integration to manage commodity cycles. For 2026, locking favorable offtakes in regions where fiscal changes remove import frictions presents an immediate arbitrage opportunity.
-
Pivot R&D roadmaps: Re-allocate a portion of R&D budgets toward microbiome and emissions-reducing solutions that now face shortened regulatory pathways. Fast-follower strategies can work where first-mover clinical data is scarce but registration is expedited.
Three actionable recommendations for 2026
-
Implement a short-cycle product commercialization track: Create a fast-track path that coordinates regulatory, manufacturing scale-up, and field trial teams to exploit accelerated approval windows for targeted additives.
-
Undertake a targeted supplier diversification program: Identify two to three strategic suppliers per major input category and negotiate mixed hedging/profiled contracts to reduce P&L volatility without sacrificing flexibility.
-
Build partnership and bolt-on acquisition pipelines: Focus on specialty players with differentiated science and registrational momentum; these assets are both defensive (protecting margin) and offensive (driving premium product sales).
Conclusion — how to use this intelligence in 2026
The animal feed ingredients market in 2026 is a large, steady-growth arena where marginal improvements in product performance, regulatory agility, and supply resilience compound into sizable commercial advantage. Executives who combine disciplined procurement, targeted innovation investment, and selective inorganic moves will secure outsized returns. PW Consulting’s full report provides the granular, proprietary segmentation, supplier profiles, and scenario tools necessary to operationalize the strategies summarized here — including the region- and ingredient-level detail and financial models that we intentionally reserve for the full product.
For teams preparing budgets, evaluating acquisition targets, or refreshing product roadmaps this year, the report is designed to be a decision-ready playbook: not just what’s happening, but what to do next. Visit our report page to access the complete dataset, interactive dashboards, and bespoke advisory options that will convert insight into 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Animal Feed Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Native Starches Market Reaches USD 24.71 Billion in 2025
By PW Consulting, 2026-07-12
Native Starches Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare strategy roadmaps for 2026, native starches sit at the intersection of food innovation, industrial reformulation, and sustainability-driven supply chain transformation. PW Consulting’s forthcoming Native Starches Market study (base year 2025; forecast 2026–2032) synthesizes market dynamics, competitor moves, and risk vectors into an actionable framework for C-suite and corporate development teams. This preview outlines the strategic value of the full study, highlights the high-level market trajectory, and summarizes competitive and operational flashpoints that will determine winners in the next planning cycle — while preserving the granular segment intelligence available in the full report.
Native Starches Market
Why this study matters for 2026 decision-making
-
Clear market momentum: Between the historical window and the forecast horizon, the native starches market exhibits steady expansion underpinned by demand in food and adjacent industrial applications. The study’s baseline shows multi-year growth culminating in a robust outlook through 2032, driven by product reformulation, label-friendly ingredient demand, and selective industrial uptake.
Native Starches Market -
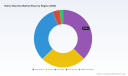
Actionable foresight for capital allocation: With a compounded annual growth rate of approximately 5.05% across the forecast window, the market is neither commodity-tame nor hyper-volatile — a profile that favors disciplined capacity investments, targeted R&D, and partnership-led expansion over indiscriminate greenfield buildouts.
Native Starches Market -
Competitive and regulatory inflection points: Fragmented market structures, certification trends, and raw-material cost variability create pockets of premium opportunity (e.g., label-friendly, non-GMO, sustainably certified starches) and downside risk (emissions, compliance, input-price shocks). The report prioritizes these themes for 2026 planning cycles.
Market trajectory at a glance
PW Consulting’s consolidated market model charts a recovery-and-growth arc. The market expanded through the early 2020s, accelerating toward the 2025 baseline. From that base, our forecast anticipates steady growth through 2032, driven by incremental gains across food, industrial, and specialty use-cases. The model is built from bottom-up demand drivers, price and volume scenarios, and supply-side capacity adjustments — producing a mid-case consistent with the ~5% CAGR noted above. Readers should treat this preview as directional; the full report contains the underlying sensitivity analyses and scenario permutations used to derive the headline projection.
What’s in the full report — practical content for executives
-
Executive dashboard: concise KPIs, market sizing and growth drivers, and three investment-case archetypes for roll-up decisions in 2026 (capacity-led, specialty-led, or channel-led).
-
Methodology and data appendix: transparent sourcing, modeling assumptions, and reconciliation of global trade versus domestic consumption flows for robust valuation work.
-
Segment playbooks: go-to-market playbooks for core product types and end-use clusters, with recommended pricing strategies, technical dossier checklists, and customer segmentation matrices.
-
Supply chain deep dives: supplier maps, procurement levers and hedging templates, cold-chain and processing bottleneck analysis, and a procurement playbook tailored to agricultural-commodity input risk.
-
Regulatory & sustainability toolkit: certification pathways (including renewable-carbon and mass-balance schemes), emissions compliance checklists, and cost-benefit analysis for sustainability investments.
-
Competitive intelligence: company profiles, recent developments, an M&A radar, and a 12–24 month action calendar you can apply directly to business development and investor outreach.
-
Scenario & sensitivity analyses: upside and downside market scenarios tied to raw-material price shocks, substitution trends, and rapid adoption of label-friendly alternatives.
Competitive landscape — what incumbents and challengers are doing
The native starch arena is characterized by a mix of global ingredient houses, regionally strong cooperatives, and specialized processors. Overall market concentration remains modest; leading groups do not fully dominate the space, leaving room for agile competitors and niche specialists to capture premium segments. The CR3 and CR5 metrics we track underscore a marketplace where scale matters for raw-material access and cost-efficiency, but where differentiation and technical capabilities deliver outsized margins.
-
Cargill, Incorporated — A large-scale integrator with broad native-starch capabilities across multiple botanical sources. Cargill’s strength lies in its upstream raw-material footprint and its ability to integrate starch offerings into broader food-ingredient platforms for texturizing and thickening.
-
Roquette Frères — A major product innovator with a wide native starch portfolio and a strategic tilt toward label-friendly and plant-based credentials. Recent product introductions and certification achievements evidence Roquette’s push into differentiated native starch formats tailored to confectionery and coating applications.
-
AGRANA Beteiligungs AG — A producer focused on potato, corn, and wheat pathways, recently active on capacity expansion through partnership models. AGRANA’s joint-venture approach illustrates how mid-sized processors can scale selectively to serve European and export markets.
-
Emsland Group, Royal Avebe, KMC Ingredients, and MGP Ingredients — Collectively, these companies represent the cooperative and specialist cohort, leveraging botanical expertise and regional supply chains to serve both food and industrial needs with focused portfolios.
These profiles demonstrate three broad competitor archetypes: integrated multinationals that prioritize scale and cross-product bundling; specialty processors that win on botanical or process expertise; and cooperative models that secure raw-material reliability. Each archetype implies distinct strategic levers for 2026 — from vertical integration and long-term supply contracts to premium product development and co-investment with growers.
Recent developments that shape 2026 tactics
-
Product innovation is accelerating. A notable example is the launch of thermally soluble, label-friendly starches designed for confectionery and coatings — a category that opens reformulation opportunities for FMCG manufacturers seeking cleaner labels without sacrificing functionality.
-
Certification and sustainability credentials are becoming table stakes. Leading producers are securing renewable-carbon and mass-balance certifications to access sustainability-driven procurement programs and to mitigate buyer-level ESG risk.
-
Capacity expansion via partnerships: joint ventures and capacity-sharing agreements indicate a preference for capital-light scaling when demand is uncertain. Such structures are efficient ways to increase throughput while preserving financial flexibility.
-
Compliance and legacy environmental liabilities remain an operational risk. Historical regulatory actions in related processing segments serve as reminders that emissions and permitting exposures can carry balance-sheet and reputational costs if not proactively managed.
Operational levers for 2026 — what we recommend
-
Prioritize product differentiation over scale-first plays. Invest in label-friendly formulations and specialty botanical formats where margin expansion is demonstrable.
-
Lock in raw-material security with hybrid sourcing: combine long-term contracts, local cooperative partnerships, and strategic inventory buffers to reduce exposure to agricultural volatility.
-
Make certification a commercial enabler. ISCC-style and similar certifications are increasingly embedded in buyer specs; the incremental cost of certification often pays back through access to higher-margin customers.
-
Evaluate partnerships for capacity flexibility. JVs and tolling arrangements offer a lower-risk path to expand capacity into new geographies or product formats.
-
Embed emissions and compliance due diligence into M&A and capex approvals to avoid legacy liabilities that erode ROI.
-
Run a price–volume sensitivity analysis for product portfolios to understand margin resilience under input-price spikes — and design pass-through mechanisms for key customers.
How PW Consulting supports execution
Our full Native Starches Market study is designed as an execution tool, not just an analytical document. Clients receive modular deliverables that can be deployed directly into investment committees, procurement negotiations, or R&D prioritization workshops. Deliverables include a one-page investment memo, a 12-month commercialization sprint plan, supplier scorecards, and a tailored risk-heatmap aligned with corporate risk tolerances.
This preview intentionally omits the granular regional and application-level split tables, price-by-origin matrices, and the full company-level financial comparatives that our subscribers rely on for transaction and operational work. Those elements are available within the full report package to preserve the commercial value of proprietary modeling.
Next steps — using the preview to inform 2026 plans
-
Use the headline CAGR and trajectory to update medium-term demand assumptions in your strategic planning cycle, replacing ad-hoc estimates with a scenario-based approach.
-
Leverage competitor archetypes to stress-test your capability gaps: where do you compete on scale, where do you compete on specialty, and where should you consider partnerships?
-
Institute a short-term tactical plan (90–180 days) to shore up raw-material sourcing and to scope certification projects that can be operational by late 2026.
-
Contact PW Consulting for an executive briefing and a customized extraction of the report’s playbooks — including the confidential segmentation tables and price-sensitivity models that will be decisive for M&A and capex decisions.
In sectors where small formulation benefits compound across thousands of SKUs, having the right market intelligence is the difference between margin recovery and margin erosion. PW Consulting’s Native Starches Market study gives you that intelligence packaged for decision-making in 2026 — rigorous, operational, and calibrated to the realities of agricultural sourcing and ingredient innovation.
For detailed analysis of this topic, please visit the official page: Native Starches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


