



PW Consulting: Pet Water Dispenser Market to reach USD 341.7M by 2032, 7.35% CAGR
By PW Consulting, 2026-07-12
Pet Water Dispenser Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our Pet Water Dispenser Market study designed to inform boardroom decisions in 2026. The product category has moved beyond commodity water bowls into a technology- and regulation-driven market. Our baseline analysis (base year 2025) shows the global market expanded materially over the first half of the decade and is projected to continue robust growth through the forecast period. Specifically, the market grew from a mid‑hundreds million USD base in 2020 to approximately USD 207 Million in 2025, and our scenario models project a continuation to roughly USD 341.7 Million by 2032 — a compound annual growth rate of about 7.35% during the forecast window. This trajectory makes the segment strategically relevant for manufacturers, platform retailers, pet care brands, and investors evaluating near-term product bets and medium-term consolidation plays.
Pet Water Dispenser Market
Why this research matters in 2026
-
Market maturation and premiumization: Buyers are increasingly trading up to automated, hygienic, and connected dispensers — creating higher-margin premium niches.
Pet Water Dispenser Market -
Regulatory and material constraints: New safety and material standards in major jurisdictions are elevating product specification costs and creating barriers for unprepared suppliers.
Pet Water Dispenser Market -
Technology-enabled differentiation: AI telemetry, app connectivity, and integrated pet ecosystems are emerging as defensible product moats for strategic players.
-
Consolidation dynamics: The category already shows meaningful concentration among leading players, inviting targeted M&A and partnership strategies for challengers and incumbents alike.
What the PW Consulting report delivers (practical, operational outputs)
-
Market sizing and forecast methodology: Transparent assumptions, sensitivity tests, and scenario outputs to stress-test investment cases.
-
Competitive intelligence dossiers: Strategy maps, product feature matrices, pricing tiers, and go-to-market footprints for all notable vendors.
-
Regulation & standards tracker: Jurisdictional requirements, compliance roadmaps and implementation cost estimates for EU, North American and APAC markets.
-
Innovation playbook: Prioritized product feature roadmaps (filtration, sensors, connectivity, autonomy), R&D timelines, and supplier selection guidelines.
-
Commercial playbooks: Channel strategies for retailers, marketplace tactics, private‑label considerations, subscription & consumables models (filters/refills).
-
Operational risk matrix: Supply chain scenarios, quality control KPIs, and cost-to-compliance modeling to quantify margin impacts.
-
M&A & partnership targets: Screening criteria and shortlists for bolt-on acquisitions, IP buys and strategic alliances.
Core market dynamics to monitor
-
Regulatory tightening: Policy changes are no longer peripheral. EU directives and North American material standards are pushing buyers toward certified BPA‑free components, antimicrobial surfaces, and improved electrical safety. These shifts increase the technical bar for new entrants and raise cost baselines for product upgrades.
-
Hygiene and user trust: Noise reduction, durable plastics or metal construction, and multi-stage filtration have transitioned from differentiators to purchase triggers for premium buyers; warranty lengths and post-sale support are increasingly part of the value proposition.
-
Connectivity and data: Smart fountains that report sip frequency, water quality, and battery status allow OEMs to move from one‑time sales to recurring revenue (consumables, remote monitoring, subscription analytics) — and to offer differentiated services to veterinary partners and breeders.
-
Power and autonomy mix: Electric, battery-operated and no-power autofill solutions each address distinct use cases. Product roadmaps must be purpose-built: portability and cordless convenience drive certain channels while continuous‑power, high-throughput designs target multi‑pet households or shelters.
-
Channel evolution: Direct-to-consumer digital storefronts, marketplaces with social proof, and traditional pet retail co-exist; institutional channels (veterinary clinics, shelters) favor higher-durability products with service agreements.
Competitive landscape — what leading players reveal about strategy
-
PETKIT (Shanghai) — PETKIT has leaned into smart, connected fountains with advanced motion sensing and AI hydration monitoring. Recent product showcases emphasize ecosystem play (federated devices, integrated feeders). Strategic implication: PETKIT is competing on feature richness and data services; peers should assess platform interop and telemetry monetization.
-
Radio Systems Corporation (Missouri) — With established Drinkwell lines in durable materials, Radio Systems emphasizes reliability and retail breadth. Strategic implication: incumbency in traditional channels gives pricing and distribution leverage, but must be paired with product upgrades to defend against smart entrants.
-
Doskocil Manufacturing (Kansas) — Offers gravity and automatic dispensers with practical filtration options. Strategic implication: strong value-tier positioning and low-complexity manufacturing make Doskocil an attractive consolidator or private-label partner for mass-market channels.
-
Rolf C. Hagen (Ontario) — Cat-oriented offerings under established brands prioritize consumer trust and category recognition. Strategic implication: brand equity enables premium pricing in certain pet verticals; cross-category bundling (e.g., fountains plus litter or grooming) is a route to deepen customer lifetime value.
-
Xiaomi (Beijing) — Leverages IoT ecosystems to deliver integrated pet fountains that tie into broader smart home platforms. Strategic implication: ecosystem players can accelerate adoption via platform subsidies, but may prioritize hardware margin trade-offs for user acquisition.
-
Torus Pet International (Hong Kong) — Focused on filtered portable and gravity dispensers, with no‑power autofill tech. Strategic implication: low‑tech energy‑free innovations address price‑sensitive and off‑grid segments, and are compelling for emerging markets and outdoor use cases.
-
Gex Corporation (Japan) — Emphasizes automation and reliable engineering for the APAC market. Strategic implication: strong regional R&D and distribution relationships make Gex a steady competitor in local channels and an attractive partner for co-development.
Recent product and market signals (directional)
-
Leading innovators are integrating AI-based sip tracking and feeder interoperability into flagship devices — signaling a push for platform control and recurring services.
-
Independent testing and journalistic reviews of cordless, battery-operated models have raised consumer awareness of portable, app-monitored designs — accelerating non‑plug adoption in specific use cases.
-
Product launches over the past 24 months show iterative improvements in filtration, noise reduction and motion detection rather than wholesale form-factor disruption — an important sign for product roadmap prioritization.
Strategic imperatives for executives in 2026
-
Invest in certification and materials engineering: Prioritize FDA/EU-compliant plastics and antimicrobial finishes now to avoid costly retrofits and market access delays later.
-
Build telemetry-first products: Even low-end SKUs should be designed with optional connectivity or straightforward upgrade paths to capture service revenue and user behavior data.
-
Design consumables as margin anchors: Filter replacement and service subscriptions are a defensible recurring revenue stream — design for easy, lock-in consumable fulfillment.
-
Segment product roadmaps by validated use cases: Differentiate between single‑pet households, multi‑pet homes, and institutional buyers; avoid one-size-fits-all designs.
-
Pursue targeted M&A: Look for filtration IP, IoT platform providers, and regional distributors to accelerate market access and consolidate share efficiently.
-
Prepare channel‑specific offers: Create veterinary-grade SKUs with hygiene documentation, retailer-exclusive bundles for brick-and-mortar partners, and D2C bundles emphasizing subscription convenience.
-
Operational resilience: Localize critical components, diversify filtration media suppliers, and build testing capacity to mitigate regulatory-driven recalls.
-
Sustainability strategy: Commit to recyclable or biodegradable materials and clear end-of-life programs; sustainability is increasingly a purchase driver for premium buyers.
What you will find in the full PW Consulting report (and what we’ve intentionally held back here)
-
Complete regional and channel revenue splits, SKU-level benchmarking, price-band elasticities and margin bridges — presented with interactive models that allow custom scenario runs.
-
Actionable M&A target lists with scoring across strategic fit, valuation range, and integration risk.
-
Retail and e-commerce playbooks tailored to North America, Europe and APAC, plus a consumables commercialization roadmap.
-
Confidential supplier scorecards and a prioritized implementation plan for manufacturing upgrades and certification timelines.
We have intentionally withheld core segmented tables and granular regional percentages from this preview to protect analytical value and to drive a direct engagement that will enable access to our dynamic models and proprietary appendices. For 2026 strategic planning, the full report provides the quantitative backbone and the operational playbooks necessary to convert market growth into sustainable share and margin gains.
Conclusion: The Pet Water Dispenser market presents a compelling combination of steady growth, rapid feature-driven premiumization, and regulatory tailwinds that together create near-term upgrade opportunities and longer-term consolidation potential. Executives who align product roadmaps to hygiene and connectivity standards, and who pair that with recurring-revenue consumable strategies, will be best positioned to capture the projected growth through 2032. To access the detailed segmentation, scenario models and executional playbooks, contact PW Consulting for the full market report and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Pet Water Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wave Soldering Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Wave Soldering Machine Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I invite you to a concise, decision-focused preview of our Wave Soldering Machine Market study — the intelligence product designed to shape high-stakes capital allocation, supplier selection, and technology roadmaps in 2026. The market is no longer a slow-moving electromechanical niche: it recorded sustained expansion from the start of the last decade and, with our base year at 2025, the global installed and aftermarket opportunity sits squarely in growth mode. Our model pegs the 2025 market at roughly USD 215 million and forecasts expansion to an estimated USD 345 million by 2032, delivering a compound annual growth rate of 6.98% over the 2026–2032 forecast window. This trajectory is driven by simultaneous forces of regulation, sustainability pressure, automation economics, and component-level material dynamics.
Wave Soldering Machine Market
Why this study is strategically material for 2026
-
Actionable clarity in a shifting regulatory and standards landscape. New traceability and data-integration expectations (notably IPC-CFX adoption and QPL-oriented approaches for FAT/SAT workflows) are changing supplier evaluation criteria and post-installation responsibilities. Purchasing teams must now factor data interoperability and long-term traceability compliance into procurement and acceptance tests.
Wave Soldering Machine Market -
Sustainability is altering total cost of ownership calculus. Recent product innovations focus on dross reduction, nitrogen inerting efficiency, and energy-optimized heating. These technological attributes materially influence operating expenditure lines and downtime frequency — making lifecycle models more sensitive to thermal management and gas-consumption characteristics than they were five years ago.
Wave Soldering Machine Market -
Labor and productivity inflection. Field studies and academic reports demonstrate that modern wave soldering lines, when paired with robust process controls and inline profiling, can reduce the headcount required per shift by a significant margin while cutting defect rates. For manufacturers operating mixed volumes, the decision to retrofit selective wave modules or to invest in fully automated cells has direct and measurable implications on unit costs and throughput variability.
-
Supply-chain and raw-material volatility. Solder material pricing and availability continue to be relevant risk vectors for board-level manufacturing planning. Manufacturers and procurement teams must reconcile short-term price signals with multi-year sourcing strategies to avoid margin erosion during periods of constrained alloy availability.
Key strategic implications for corporate planners
-
CapEx sequencing: Prioritize modularity. Buyers should favor platforms that support incremental upgrades (e.g., nitrogen inertion modules, selective wave cells, inline inspection) to postpone large capital outlays while preserving the option to scale as volumes and regulatory demands grow.
-
Procurement as a systems integration decision: Evaluate vendors not solely on thermal and soldering performance but on data interfaces, traceability support, and service model maturity. FAT/SAT readiness aligned with IPC-CFX reduces deployment risk and accelerates time-to-quality.
-
Operational risk management: Embed dross-management and scrap reduction as selectable KPIs in vendor SLAs. Recent product introductions show measurable reductions in consumable waste and maintenance windows; buyers can translate these into quantifiable OPEX offsets in payback calculations.
-
Workforce strategy: Build cross-functional lines between process engineering and maintenance. As lines become more automated, the value shifts toward expertise in thermal profiling, trace-data analytics, and predictive maintenance.
What PW Consulting’s Wave Soldering Machine Market Study delivers
This study is structured as an executive-to-operational playbook for 2026 decisions. High-level deliverables include:
-
Macro market sizing and forward-looking scenarios: a clear baseline and sensitivity runs that reflect alternative adoption rates for nitrogen inerting, selective wave retrofits, and energy-efficiency upgrades.
-
Technology and product taxonomy: a concise mapping of wave, selective, and hybrid systems, common retrofit paths, and the engineering trade-offs relevant to throughput, first-pass yield and maintainability.
-
Procurement toolset: decision frameworks, FAT/SAT templates compatible with modern traceability standards, buyer checklists, and TCO models with configurable inputs for labor, energy, consumables and service.
-
Vendor benchmarking and commercialization plays: qualitative and quantitative assessments of incumbent suppliers, channel specialists, and systems integrators — including go-to-market strengths, installed-base characteristics, and aftermarket footprint analysis.
-
Operational playbooks: process control checklists, recommended profiling discipline, and guidance on integrating thermal profiling and inline analytics to reduce defects and optimize throughput.
To respect the “trailer” principle of this brief, we highlight the structure and strategic value of these modules while intentionally withholding granular regional and application-level splits and vendor scorecards — those are accessible in the full report and are critical for site-specific investment decisions.
Competitive landscape: who matters and why
The competitive map blends global OEMs, regional specialists, and analytic/optimization companies. Vendors differentiate across a few structural axes: full-tunnel versus selective wave topology, nitrogen-inert capability, inline handling and inspection integration, sustainability and energy-optimization features, and aftermarket analytics.
-
Kurtz Ersa GmbH (Germany) — recognized for full-tunnel nitrogen wave platforms and selective wave lines; recent marketing and training materials emphasize updated POWERFLOW ULTRA systems that target high-reliability electronics markets.
-
SEHO Systems GmbH (Germany) — notable for delivering complete automated soldering lines with deep focus on PCB handling and FlowLine integration for inline inspection and material flow control.
-
Pillarhouse International Ltd. (UK) — long-established selective wave specialist with a large installed base in aerospace, defense and automotive segments; strength is selective soldering for complex assemblies.
-
ITW EAE / Vitronics Soltec (USA) — portfolio includes sustainability-focused options such as the EcoWave family; recent industry recognition highlights dross reduction and reduced maintenance footprints.
-
Solderstar LLC (USA) — profiling and thermal data capture specialists whose shuttle and profiling systems are used to validate process consistency and reduce setup variability across wave platforms.
-
Chuxin SMT / S&M Co. Ltd. (China) — focused on intelligent wave machines with nitrogen options and export-focused integration bundles, reflecting the growing role of regional OEMs in cost-competitive mid-volume deployments.
-
Other notable players — TAMURA, Nordson, SAMSUNG Techwin, JUKI, Cortex Beam — each bring complementary strengths: high-volume equipment design, IoT-enabled process controls, integrated SMT line strategies, and analytics tools for process optimization.
While the market features prominent multinational OEMs, it also supports specialists who command premium positions within vertical niches (military, aerospace, high-reliability automotive). The competitive environment rewards differentiation in process control, service-response capability, and the ability to demonstrate validated lifetime cost improvements.
Recent developments shaping near-term choices
-
Industry recognition for sustainability-oriented features: an EcoWave option garnered a New Product Introduction award in early 2026 for measurable dross reduction and reduced maintenance downtime.
-
Catalog and training refreshes from major OEMs signal an emphasis on operator enablement and standardized qualification materials — a positive for buyers who need to accelerate ramp-up with limited specialist labor.
-
Trade-show and regional market activity continues to drive localized demand signaling: product showcases and regional expositions highlight demand heterogeneity and the need for adaptable commercial models.
-
Standards and traceability mandates — notably the growing emphasis on IPC-CFX-compatible interfaces — are accelerating purchases of equipment that can be integrated into enterprise quality and MES systems without bespoke development.
How to use this intelligence in 2026
For boardrooms and operating committees, the actionable outcomes from this study are straightforward: align procurement with traceability and sustainability standards now, prioritize modular platforms that buy optionality, and require vendors to demonstrate lifecycle OPEX improvements through independent profiling data. For manufacturing leaders, the imperative is to build cross-disciplinary teams that can convert thermal profiling and trace data into continuous improvement loops. For investors and M&A teams, the landscape highlights attractive targets among service-oriented specialists and analytics vendors that amplify OEM product value.
PW Consulting’s full Wave Soldering Machine Market report contains the granular splits, vendor scorecards, downloadable TCO models and operational appendices needed to convert this strategic picture into executable procurement and deployment plans. If your 2026 investments must de-risk deployment, shorten time-to-quality, and optimize lifecycle costs, this study is designed to be the playbook you use before you commit. Contact our research desk or visit our report page to access the complete dataset and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Wave Soldering Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microwave Pyrolysis Market to 2032 — 5.8% CAGR, USD 299.11M
By PW Consulting, 2026-07-12
Microwave Pyrolysis Market — Strategic Preview for 2026 Decision-Makers
As companies, investors, and policy teams set strategic agendas for 2026, microwave pyrolysis is transitioning from laboratory promise to commercial-scale relevance. PW Consulting’s forthcoming Microwave Pyrolysis Market study synthesizes the latest commercial product introductions, regulatory momentum, and feedstock economics into an operational playbook that helps leaders convert technical potential into executable business outcomes. This preview outlines the study’s strategic value, summarizes high-level market dynamics, and highlights the practical tools inside the full report — deliberately withholding granular segment tables so that executives who need the full decision-grade dataset are directed to the source report.
Microwave Pyrolysis Market
Market snapshot: measured growth, practical scale
We forecast the global microwave pyrolysis market to move from an evaluated base of USD 201.69 Million in 2025 into a multi-hundred million-dollar opportunity through the 2026–2032 horizon, tracking a compound annual growth rate (CAGR) of 5.8% over the forecast period. The model integrates historical performance (2020–2025), near-term commercial product rollouts, and sensitivity to feedstock and policy variables. Growth is steady rather than explosive — a profile that rewards disciplined, capital-efficient scaling and early contractual control of feedstock streams.
Microwave Pyrolysis Market
Why this matters for 2026 strategy
- Timing: 2026 will be a pivotal year when a small number of commercially engineered microwave pyrolysis modules become broadly available for deployment. That transition changes the value proposition from “pilot risk” to “deployment planning.”
- Capital allocation: With mid-single-digit CAGR and measured absolute growth, the optimal approach for corporate venturing and infrastructure investment is staged deployment tied to offtake and feedstock agreements rather than large upfront capacity bets.
- Regulatory leverage: Tightening environmental regulations in several advanced markets accelerate commercial adoption — making early regulatory-compliant project scoping a competitive advantage.
- Operational readiness: The technology’s modular nature compresses time-to-operation, shifting emphasis from long-lead construction to faster site selection, permitting, and feedstock logistics.
What the full PW Consulting study delivers (practical, hands-on)
- Robust market sizing and forecast engine — transparent methodology aligning historical data (2020–2025) with forward scenarios (2026–2032), including base, upside, and downside cases.
- Commercialization readiness map — maturity assessment by solution archetype (lab/pilot systems vs. continuous commercial modules), with clear go/no-go criteria for stepping from pilot to commercial operation.
- Feedstock economics and sensitivity modelling — break-even and margin sensitivity to feedstock price movements, with an industry-relevant benchmark: microwave pyrolysis biofuel economics become competitive when feedstock costs remain below approximately USD 80 per metric ton.
- Regulatory and permitting playbook — region-by-region regulatory dynamics framed as decision levers (e.g., permitting timelines, emissions compliance, waste-handling standards) that alter project economics and timeline assumptions.
- Modular deployment and capex/opex templates — real-world timelines and cost buckets for modular installations versus traditional builds, reflecting the ability to deploy units in months rather than years.
- Competitor and partner benchmarking — focused intelligence on leading technology vendors, incumbents, and potential system integrators, paired with transaction-play scenarios (licensing, JV, OEM partnerships).
- Investment and M&A roadmap — criteria-driven approaches for sourcing targets, valuing IP-rich start-ups, and structuring earn-outs tied to throughput or product quality milestones.
- Risk register and mitigation tactics — operational, technical, feedstock, regulatory, and market risks prioritized for practical mitigation and monitoring.
- Decision-support assets — downloadable models, scorecards for vendor selection, an executive briefing slide pack, and a one-page investment memo template for internal approvals.
Competitive landscape: what to watch in 2026
The market structure is concentrated at the top, a dynamic we quantify in the report and that has direct implications for market entry and partnership strategies. Leading technology vendors are already bifurcating the market between research/pilot-focused systems and commercially engineered continuous modules designed for plastic-to-material circularity.
Microwave Pyrolysis Market
- Resynergi — positioned as an early commercial provider with modular Continuous Microwave Assisted Pyrolysis (CMAP) units designed to convert plastic waste into reusable pyrolysis products. The company’s commercial offering is notable for integration with an established fabricator and warranty partner, which materially de-risks procurement and commissioning for industrial buyers. Recent product rollouts in early 2025 moved the firm from demonstration to market-available solutions, changing the operational calculus for plastic-waste processors and municipal partnerships.
- Sairem — a supplier anchored in research and laboratory applications, delivering high-temperature microwave furnaces and plug-and-play reactors tailored for academia, R&D centers, and pilot projects. Sairem’s portfolio is valuable for organizations that need controlled experimental platforms, pilots that feed into technology selection decisions, or institutions focused on feedstock chemistry and product specification optimization.
Strategic implications: the split between research-focused and commercial-system providers creates a natural staging path for adopters: use research-grade platforms to validate feedstock-to-product chemistry, then switch to modular commercial systems for scale. For corporate buyers, partnering with a fabrication/warranty-capable OEM can accelerate time-to-revenue and reduce project execution risk.
Operational and commercial levers — what successful adopters will do
- Secure feedstock via long-term contracts and municipal partnerships. Feedstock price and consistency are primary drivers of unit economics.
- Leverage modular system suppliers to compress implementation timelines. The ability to commission in months — rather than years — converts early mover advantage into tangible revenue sooner.
- Negotiate integrated service and warranty terms with fabricators and system integrators. A commercially produced, warranted module materially reduces commissioning risk compared with bespoke builds.
- Design projects with staged capacity additions tied to validated product yields and offtake agreements. Financial models that assume stepwise ramp-up mitigate the risk of over-capacity and capital inefficiency.
- Build regulatory-first project schedules in jurisdictions with stringent environmental regimes to capitalize on policy-driven demand for compliant waste-management solutions.
Risk considerations — early failure modes and mitigations
- Feedstock variability: Test feedstock blends at scale before committing to full-capacity installations; include flexible preprocessing in the design scope.
- Technology maturity gaps: Insist on factory acceptance tests, performance guarantees, and staged payments tied to throughput and product quality metrics.
- Market concentration effects: Given industry concentration among top vendors, procurement should incorporate supplier risk assessments and fallback plans (service contracts, spare parts stock).
- Policy shifts: Monitor emerging emissions and waste-handling standards; include regulatory trigger points in project decision gates to avoid stranded assets.
How PW Consulting’s study boosts 2026 execution
Our analysis converts public announcements, technical literature, vendor disclosures, and market transactions into a decision-ready framework. Key deliverables tailored to 2026 needs include:
- A ready-to-run financial model calibrated to PW Consulting’s market baseline — enabling rapid scenario analysis for joint ventures, greenfield projects, and retrofits.
- Vendor scorecards and an RFP template aligned to operational KPIs (throughput reliability, energy intensity, product quality, warranty terms).
- Site-selection heuristics that balance feedstock logistics, permitting risk, and access to offtake markets.
- A playbook for structuring offtake agreements (fuel, chemical intermediates, char products) and for prioritizing circular-economy value capture.
Final perspective: action priorities for 2026
For corporate strategy teams, the immediate priorities are straightforward: (1) validate feedstock economics against the USD 80/ton sensitivity threshold embedded in our modeling, (2) engage with modular CMAP suppliers and fabricators to understand lead times and warranty terms, and (3) secure regulatory clarity for target jurisdictions to quantify permitting timelines. For investors, the landscape favors staged capital allocation into technologies that can demonstrate repeatable product specifications and serviceable commercial references. For policy-makers and public-sector partners, modular deployments offer rapid capacity addition to meet circularity targets without long infrastructure lead times.
PW Consulting’s Microwave Pyrolysis Market study provides the detailed datasets, vendor deep dives, and executable templates needed to move from strategic intent to fielded assets in 2026. If your organization is evaluating entry, partnership, or procurement decisions in the coming 12–18 months, this report will materially shorten your path from assessment to execution.
Next steps
Access to the full report is required to view PW Consulting’s proprietary segment-level breakdowns, vendor financials, and downloadable decision models. These core intelligence elements are intentionally reserved for report subscribers to ensure decision integrity and confidentiality. Reach out to PW Consulting to obtain the complete study, request a tailored briefing, or commission a deep-dive workshop that maps the findings to your portfolio.
For detailed analysis of this topic, please visit the official page: Microwave Pyrolysis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cleanroom Consumables to reach USD 7.36B by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
Cleanroom Consumables Market — Strategic Outlook for 2026 Decision-Making
As cleanroom-dependent industries recalibrate for accelerated semiconductor cycles, stricter sterile-manufacturing norms, and heightened sustainability expectations, the market for cleanroom consumables is entering a strategic inflection point. PW Consulting’s latest Cleanroom Consumables Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical performance with scenario-driven forecasting to give procurement, operations, and corporate strategy teams the actionable intelligence they need for high-stakes 2026 decisions.
Cleanroom Consumables Market
Macro snapshot: why this moment matters
By conventional metrics the market is sizable and resilient: our model shows continued compound annual growth through the forecast window, underpinned by rising demand across life sciences, semiconductors, and advanced manufacturing. Specifically, the market reached USD 4,750 Million in 2025 and is projected to grow at a 6.5% CAGR, reaching roughly USD 7,362 Million by 2032. Concentration remains relatively low at scale — the top three and top five players account for only single-digit shares beyond the mid‑teens and low‑twenties respectively — indicating a fragmented vendor landscape that rewards supply differentiation, certification depth, and logistical excellence.
Cleanroom Consumables Market
What the report delivers — practical, transaction-ready insights
- Forward-looking demand models calibrated to end‑market adoption curves and regulatory milestones (2026–2032). These models are built to be integrated into procurement S&OP and capital planning workflows.
- Price and cost‑to-serve analytics that quantify the impact of raw-material volatility and transportation dynamics on consumable spend.
- Supplier benchmarking and playbooks for vendor selection, qualification, and dual-sourcing strategies, including a pragmatic framework for balancing single‑use validation needs with sustainability targets.
- Regulatory impact maps that translate recent policy shifts into operational checklists for sterile manufacturing, glove procurement, and device‑grade consumables.
- Scenario analyses (baseline, supply‑stress, high‑demand) with recommended action triggers — ideal for risk committees, procurement war-rooms, and M&A diligence.
- Strategic initiatives and ROI estimates for adoption of digital monitoring (IoT-enabled consumable tracking), circularity pilots, and automation in cleanroom logistics.
Key dynamics reshaping supply, price and compliance
- Raw-material and cost pressure: Polyester and polymer feedstock volatility are no longer episodic risks. Polyester futures surged in early 2026, lifting upstream input costs and squeezing margins for wiper and garment manufacturers. Our analysis quantifies how a mid‑teens input cost shock propagates through wholesaler pricing and can erode lean inventory advantages if unhedged.
- Regulatory tightening: The revised EU GMP Annex 1 (effective since 2025) and recent FDA device- and glove-related guidance have increased validation overheads and certification requirements for sterile-production consumables. This drives higher total cost of ownership for low‑cost suppliers and elevates the comparative value of certified partners with documented sterile-process controls.
- Supply fragility for single-use categories: Nitrile and other glove supply disruptions persisted into late 2025, forcing procurement waivers and spot buying that materially increased per‑unit costs in crisis windows. Buyers that structured multi-year validated supply agreements or developed in-market buffer strategies demonstrated better continuity and lower effective cost.
- Digital and service differentiation: IoT and analytics for consumable monitoring are moving from pilot to procurement criterion. Platformized solutions that combine inventory telemetry with quality traceability create stickier supplier relationships and measurable reductions in overstock and contamination incidents.
Competitive landscape — what to look for in a vendor
The competitive field mixes global chemical and industrial groups, specialist manufacturers, and regional system integrators. Leaders differentiate across three vectors: validated quality systems, breadth of sterile offerings, and supply-chain resilience.
Cleanroom Consumables Market
- Large diversified suppliers — firms such as DuPont and Kimberly‑Clark bring scale, certification depth, and broad distribution networks. They offer rapid qualification for complex programs but can command pricing premia tied to brand and validated processes.
- Specialist manufacturers — companies like Texwipe, Contec, and Valutek focus on low‑lint materials, high‑precision wipes, and packaging for ISO‑sensitive environments. These players often lead in niche performance innovations (e.g., sub‑micron particle control) and provide flexible OEM arrangements.
- Regional and technical innovators — Micronclean, Berkshire, Nitritex, and Micronova combine local manufacturing with technical garments and ESD capabilities, useful for multi-site rollouts that require fast lead times and regional compliance mastery.
Recent corporate moves underscore strategic themes: Contec’s 2025 EcoShield sustainability program signals product-level decarbonization and recycled-material pathways; ABN’s SmartCleanroom 4.0 platform launch reflects rapid convergence between consumables and operational monitoring; and Berkshire’s 2026 capacity expansion in Texas highlights continued investment to serve semiconductor and life-sciences demand. For buyers, these actions translate into differentiated value propositions — sustainability-labeled SKUs, telemetry-enabled replenishment, and improved local availability — which should factor into 2026 sourcing decisions.
How to convert insights into 2026 actions — a decision checklist
- Stress-test suppliers against three scenarios: normal demand, sudden surge (e.g., fab ramp or vaccine campaign), and prolonged raw-material inflation. Ensure contracts include price-collar and capacity‑reservation clauses that align incentives without disabling flexibility.
- Prioritize validated sterile capability: for critical sterile-drug and device lines, prefer suppliers with documented Annex 1/FDA alignment and end‑to‑end traceability. Validation costs may be higher upfront but reduce lot‑release failures and recall exposure.
- Layer sustainability with risk mitigation: pilots for recycled‑content wipes or washing-and-reuse programs should be evaluated alongside contamination risk — not as a pure cost center but as a phased program with defined quality gates.
- Adopt telemetry in consumable logistics: IoT-enabled replenishment reduces stockouts and ties procurement to usage-based contracting. Embed consumable data into quality‑management systems to accelerate root‑cause analysis in contamination events.
- Hedge raw-material exposure: use a mix of forward contracts, dual-sourcing, and localized inventory buffers calibrated by SKU criticality. Our report provides a practical hedging matrix that maps material exposure to contract levers.
- Use procurement to shape product design: combine early supplier involvement with specification flexibility (e.g., alternative polymer blends or coating choices) to open low-risk substitution paths when supply tightens.
Scenario playbooks and KPIs we recommend
For executive teams, the report includes three playbooks tailored to strategic positioning:
- Continuity-first (risk-averse manufacturers): emphasizes validated multi-sourcing, increased safety stock for key disposable items, and long-term supplier partnerships with contractual service levels.
- Cost-leadership (large high-volume buyers): focuses on volume-based agreements, specification harmonization, and capital investment in in-house sterilization or finishing capabilities where TCO justifies.
- Innovation-driven (OEMs and niche fabs): prioritizes co-development with specialist suppliers, early adoption of smart monitoring, and sustainability pilots that create market differentiation.
Each playbook is accompanied by a small set of KPIs (days of cover for critical SKUs, validated supplier ratio, telemetry-enabled inventory percentage, cost‑per‑lot impact of raw-material inflation) so teams can translate strategy into measurable outcomes rapidly.
Research methodology and validation
Our baseline combines primary interviews with procurement officers, quality leads, and supplier operations managers, triangulated against manufacturer financials and proprietary shipment data. The forecasting approach blends bottom‑up SKU-level demand curves for major end markets with top‑down macro drivers. Importantly, we provide sensitivity bounds rather than single-point estimates — enabling users to re-run assumptions for their specific exposure.
Why PW Consulting’s study should be in your 2026 toolkit
Decision-makers face simultaneous pressures: tighter sterile regulations, episodic raw-material shocks, and a fast-evolving vendor ecosystem that now includes digital and sustainability levers. Our Cleanroom Consumables Market study is designed as a decision accelerator — not a raw-data dump. It packages operational playbooks, vetted supplier assessment criteria, and risk-triggered actions that can be embedded into procurement RFx, quality-validation plans, and capex prioritization discussions.
To preserve the tactical value for users preparing procurement negotiations and competitive responses, this overview intentionally holds back granular segment-level allocations and SKU-by-SKU projections. The full report includes executable annexes — supplier scorecards, SKU criticality matrices, and downloadable models — that will enable teams to operationalize the insights presented here.
Next steps
- Use this overview to align stakeholders on priority risks for 2026 (raw-material exposure, certification needs, and inventory telemetry).
- Request the full report for SKU‑level forecasts, supplier scorecards, and customizable scenario models to support RFPs, validation programs, and capital allocation.
- Engage PW Consulting for a targeted workshop to translate the playbook most applicable to your enterprise (continuity, cost leadership, or innovation) into a 90‑day action plan.
PW Consulting’s Cleanroom Consumables Market study equips leaders with both the strategic lens and the operational toolset necessary to make confident, measurable decisions in 2026. For procurement teams, quality leaders, and corporate strategists, the stakes are immediate: decisions made this year will determine continuity, cost, and compliance outcomes through the next industry cycle.
For detailed analysis of this topic, please visit the official page: Cleanroom Consumables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-Ferrous Scrap Market at USD 663.96B in 2025; 3.6% CAGR to 2032
By PW Consulting, 2026-07-12
Non‑Ferrous Scrap Metal Market — Strategic Preview for 2026 Decision‑Making
Executive snapshot
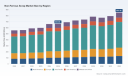
As corporations and investors set strategy for 2026, the non‑ferrous scrap metal market presents a mix of structural growth, regulatory inflection points, and concentrated technological competition. Our latest PW Consulting study (base year 2025) traces the market through a five‑year historical window (2020–2025) and projects behavior across 2026–2032. The market expands from a mid‑hundreds‑billion USD base in 2020 to roughly USD 664 Billion in 2025, with a compound annual growth rate of 3.6% embedded across the forecast window. By 2032 the market is modeled to reach approximately USD 853 Billion, albeit with non‑linear year‑to‑year dynamics that require strategic flexibility rather than static plans.
Non Ferrous Scrap Metal Market
Why this matters for 2026
-
Timing of capital allocation: The trajectory and volatility we model—including short troughs and recoveries during the 2026–2032 forecast—mean that mid‑cycle capital commitments (plant upgrades, sorting automation, logistics hubs) should be phased and optioned rather than fully front‑loaded.
Non Ferrous Scrap Metal Market -
Competitive positioning: The market exhibits moderate consolidation (CR3 ~32.5%, CR5 ~38.0%), indicating national and regional leaders can shape feedstock flows and service standards, but there remains material room for agile regional specialists and technology disruptors to capture share.
Non Ferrous Scrap Metal Market -
Regulatory arbitrage and policy risk: Recent measures and anticipated rules in key jurisdictions will alter cross‑border flows and merchant economics—creating both constraints and protected domestic demand pockets that savvy value‑chain participants can monetize.
Market trajectory and the signal lines to watch in 2026
Beyond headline growth, our model highlights three structural drivers that will govern outcomes for companies and investors next year:
-
Feedstock quality and sorting yields. Improvements in automated sorting and sensor recovery raise the realized yield from mixed non‑ferrous streams, compressing unit processing costs and improving downstream metallurgy outcomes. Strategic buyers must evaluate technology ROI against incremental margin capture—our models quantify break‑even timelines under multiple volatility scenarios.
-
Downstream processing capacity. Capacity additions, retrofits, and localized policies are reshaping where processed scrap is converted back into intermediate and primary‑grade material. The capital cycle that accelerated in 2024–2026 creates pockets of incremental throughput—timing market entry to coincide with these capacity ramps materially affects realized prices and contract leverage.
-
Commodity price cycles and substitution. Macro forecasts from major institutions project upward pressure on aluminum and copper through at least 2027 due to primary supply constraints. Our scenario analyses layer these inputs with demand elasticity estimates to show when recycled feedstock becomes decisively more economical than primary metal for specific downstream uses.
Regulation, capital flows and geopolitical friction — what to expect
Regulatory actions and public financing in late 2025/early 2026 are not peripheral—they alter whole market architectures. Notable moves include tightened export policies in Europe for aluminum scrap beginning in 2026 and new state‑level licensing regimes in markets such as California for copper scrap transactions. Public capital is also mobilizing: a major European financial institution sanctioned multi‑hundred‑million USD support for recycling capacity and process optimization in 2025, signaling that public debt and grant instruments will be available to accelerate decarbonization and local processing agendas.
For 2026 strategy this means:
-
Short‑term logistics and contract design must anticipate shifts in cross‑border flows—sourcing strategies that worked in 2024 may require re‑routing or price adjustment clauses to remain effective.
-
Investment decisions should factor in conditional public financing—projects that align with circular economy objectives have a higher probability of securing concessional funding and permits.
Competitive landscape — who will move the market in 2026
The competitive set is a mix of vertically integrated processors, large commodity recyclers, regional specialists, and national traders. Each archetype pursues different levers—capex intensity, feedstock control, technological differentiation, or network breadth.
-
Sims Metal Management Inc. — A global processor and trader with investments in advanced recovery and AI‑enabled sorting. Sims has publicly announced capacity expansions in the U.S. and U.K. during early 2026, strengthening its ability to process complex streams and e‑waste. For peers, the lesson is clear: analytics‑driven sorting plus scale materially compresses delivered costs and increases high‑purity yield capture.
-
OmniSource Corporation — An integrated North American operator with broad processing capabilities. Its playbook emphasizes regional vertical integration and stable offtake relationships with downstream fabricators and smelters—an attractive strategy where export frictions emerge.
-
European Metal Recycling (EMR) — A U.K.‑headquartered trader/processor leaning into copper and aluminum grades with extensive pan‑European procurement. EMR is an example of the regional champion leveraging logistics scale and supplier contracts to offset rising primary metal costs.
-
Aurubis AG — An integrated non‑ferrous producer that combines recycling with smelting, and recently commissioned a substantial copper recycling facility in North America in 2025. Integration into primary metal production grants Aurubis preferred economics on complex scrap streams and resilience against feedstock volatility.
-
Shapiro Metals , American Iron & Metal , Manaksia Aluminium , and Hayes Metals — Regional leaders and specialists who compete on responsiveness, feedstock relationships, and local market knowledge. Their strengths become especially pronounced where regulatory shifts re‑regionalize supply chains.
Strategic playbook for 2026 — recommended actions
Based on our integrated modeling and company benchmarking, PW Consulting advises firms to pursue a three‑track strategy in 2026:
-
Defensive operational moves: Lock in flexible logistics contracts; accelerate sensor‑based sorting pilots; and implement dynamic pricing clauses in supplier and offtake agreements to handle commodity swings.
-
Selective growth: Prioritize brownfield expansions and retrofit projects supported by public financing or off‑take prepayments. Avoid greenfield projects unless paired with firm feedstock contracts or concessional funding that improve IRR under downside price scenarios.
-
M&A and partnership scouting: Target bolt‑on recyclers with local feedstock control, technology providers for sorting/AI, and smelters seeking to secure high‑quality recycled input. Use staged earn‑outs and performance‑linked consideration to price in near‑term commodity risk.
What the full PW Consulting report delivers
This preview intentionally highlights the strategic contours without revealing the fine‑grained analytics that underpin investment decisions. The full research package (base year 2025; historical 2020–2025; forecast 2026–2032) contains the operational tools and data tables that corporate strategists and deal teams use, including but not limited to:
-
Proprietary demand and supply model with yearly market sizing, price‑sensitivity scenarios, and a probabilistic view of the 2026–2032 trajectory (CAGR 3.6% central case).
-
Granular regional and application split sheets, interactive segment dashboards and elasticity matrices (note: segment‑level figures are excluded from this preview to preserve commercial value).
-
Capex and ROI templates for sorting technologies, shredding and hydrometallurgical upgrades, with payback curves under multiple commodity scenarios.
-
Negotiation playbooks for long‑term supply contracts, sample contract clauses to mitigate policy and price developments, and compliance checklists for emerging licensing regimes.
-
Competitive scorecards evaluating operational footprint, technology adoption, and balance sheet capacity for the core set of global and regional players mentioned above.
How to use these insights in 2026 planning cycles
Senior leaders should integrate the report into three planning activities this year: budget refresh, capital allocation committee reviews, and M&A screening. Use the dataset to stress‑test budgets against a downside price scenario and to identify high‑leverage, low‑cost interventions (process automation, procurement contract redesign, and targeted retrofits) that improve margin without requiring large new greenfield capital.
Closing: the signal for investors and operators
The non‑ferrous scrap market in 2026 is not merely a commodity play; it is the interface where circular economy policy, advanced recovery technology, and capital allocation converge. With a modeled market size rising from the mid‑hundreds of billions in 2020 to the high‑hundreds by 2032 and a steady 3.6% CAGR across our forecast, the arithmetic favors participants who combine operational discipline with strategic optionality. The full PW Consulting report supplies the granular inputs, contract templates, and decision‑ready models that will turn this arithmetic into value. For companies that need to convert scenario outputs into deployment timelines and deal pipelines, this is the toolkit to use.
To access the complete dataset, regional and application splits, and executable playbooks referenced in this preview, please visit the PW Consulting report page for the Non‑Ferrous Scrap Metal Market — the detailed intelligence that powers decisive 2026 strategy.
For detailed analysis of this topic, please visit the official page: Non Ferrous Scrap Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Power System Analysis Software to Hit USD 5,731.3M by 2032 (8.5% CAGR)
By PW Consulting, 2026-07-12
Electric Power System Analysis Software Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategy advisor and head industry analyst, I prepared this executive preview to orient utility executives, investor teams, technology buyers, and M&A sponsors on the strategic stakes of the Electric Power System Analysis Software market as they make resource-allocation decisions in 2026. The full market research package contains granular segment, regional, vendor and scenario detail; this preview surfaces the analytic framework, key structural signals, and practical imperatives — while intentionally withholding the granular splits and proprietary scorecards that you will find in the full study.
Electric Power System Analysis Software Market
Market framing: pace, scale and the shape of growth
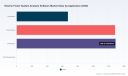
The market for electric power system analysis software has entered a sustained growth phase. Using 2025 as the base year and a historical window from 2020–2025, our topline is straightforward: the market is expanding at an expected compound annual growth rate of 8.5% across our forecast horizon (2026–2032). After steady recovery and reinvestment during the early 2020s, the global market moves from a multi‑billion dollar base in 2025 to materially larger levels through the early 2030s, reflecting a shift from episodic tool purchases to continuous platform investments underpinning grid operations, planning and resilience.
Electric Power System Analysis Software Market
Three quantitative touchpoints anchor the trajectory we model: the 2025 base, the opening forecast year (2026) when many utility programs move from pilots to scale, and the 2032 horizon where the combined effects of electrification, DER integration and advanced analytics reshape fundamentals. These macro markers underscore the difference between tactical software refreshes and strategic digital transformation programs that now dominate vendor roadmaps and buyer considerations.
Electric Power System Analysis Software Market
Structural drivers and nonlinear demand vectors
- Decarbonization + electrification: Accelerating renewable penetration and electrification of transport and industry increase the complexity of steady‑state and transient studies. Planning models must now account for variability, storage and active power electronics at scale.
- DER aggregation and market reforms: Policy actions like DER aggregation mandates and updated reliability standards compel utilities and grid operators to adopt software capable of modeling heterogeneous, highly dynamic asset fleets.
- Large, concentrated loads and interconnection pressure: New scenarios (including updated EPRI projections) show rapid growth in high‑density, energy‑intensive consumers such as data centers, creating interconnection and stability challenges that require higher‑fidelity modeling.
- Operationalization of planning: Buyers increasingly require solutions that bridge planning, operations and market functions — digital twins, real‑time analytics and closed‑loop workflows are now procurement validators, not optional features.
- Cloud, AI and model interoperability: Migration to cloud architectures and the integration of machine learning for anomaly detection and scenario reduction are redefining vendor differentiation and the total cost of ownership calculus.
Market structure and competitive implications
The market exhibits moderate concentration. A handful of vendors hold meaningful scale, but a sizeable portion of value remains distributed among specialized suppliers, regional integrators, and independent research houses. That structure creates three predictable competitor behaviors: horizontal incumbent expansion (platforms bundling simulation with automation or asset management), focused specialist innovation (high‑fidelity solvers, visualization, and digital twins), and services‑led differentiation (integrators converting licenses into long‑term contracts).
For executives, this means supplier selection is as much about architectural fit and ecosystem compatibility as it is about immediate feature parity. Consolidation risk and opportunities for tuck‑ins are real: incumbents are buying capabilities to bridge cloud, analytics and DER orchestration, while specialized vendors remain acquisition targets for larger automation and software houses.
What the full report delivers — practical, transaction‑ready intelligence
PW Consulting’s full Electric Power System Analysis Software report is designed for decision cycles that span procurement, investment, product strategy and M&A. Highlights include:
- Transparent market sizing and scenario methodology: detailed assumptions, sensitivity runs and back‑tested historical fit for 2020–2025 with forecasts through 2032.
- Demand‑side mapping: buyer personas, procurement cadences for utilities, TSO/ISO, IPPs, industrials and large commercial loads, plus budget timing and TCO models.
- Vendor scorecards and capability matrices: feature, deployment model (cloud/SaaS vs on‑prem), integration readiness, support footprint and roadmap alignment (note: proprietary scorecards are not published in this preview).
- Use cases and implementation playbooks: templates for pilots, scale‑up, data ingestion, and organizational change management tested in multiple utility environments.
- Regulatory and standards impact assessment: mapping NERC, FERC and other policy levers to buying triggers and compliance timelines.
- M&A and partnership playbook: valuation multiples observed, consolidation scenarios, and diligence checklists specific to software + services combinations.
- Cyber and resilience lens: scenario planning for extreme weather, cascading failures and targeted cyber incidents, including recovery and verification procedures.
To preserve the teaser nature of this preview, the full regional, type and application split tables and the vendor scorecards are available only in the paid report. That detailed intelligence is the actionable content buyer teams use to prioritize pilots, budget requests, and RFP requirements.
Competitive landscape — how leading vendors position themselves
- PowerWorld Corporation (Champaign, Illinois) — Known for highly visual simulation capabilities and interactive platforms that scale to large transmission models. Their strength lies in operator‑facing visualization and scenario playback that accelerate stakeholder alignment in planning exercises.
- ETAP / Operation Technology Inc. (Irvine, California) — A leader in the digital twin narrative, ETAP emphasizes end-to-end modeling across design, operations and maintenance. Buyers value their integrated stacks for lifecycle management and dynamic/transient capabilities.
- PSI AG (NEPLAN) (Küsnacht, Switzerland) — NEPLAN’s modular architecture targets planners who need flexible, composable toolchains for transmission, distribution and industrial networks, making it attractive for complex, multi‑vector projects.
- OATI / Open Systems International (Bloomington, Minnesota) — Focused on grid modernization, OATI combines energy management with DERMS and market tools that are compelling for utilities seeking operational modernization rather than point‑tool replacement.
- ABB, Siemens, GE — Large automation and systems integrators that embed analysis tools into broader T&D solutions. Their advantage is portfolio breadth and procurement simplicity for large utilities that prefer one‑stop suppliers.
- Eaton, Schneider, DIgSILENT, Bentley — A mix of distribution‑focused modeling vendors and established simulation houses. These firms often win on depth of modeling, regional sales networks and domain‑specific integrations (e.g., distribution automation, industrial microgrids).
Five priority strategic actions for 2026
- Design modular roadmaps, not rip‑and‑replace projects: prioritize modular APIs, data standards and staged migrations from desktop to cloud‑enabled digital twins.
- Align procurement with regulatory timelines: incorporate compliance windows for DER aggregation and interconnection studies into procurement and pilot schedules to avoid implementation lags.
- Run outcome‑focused pilots: evaluate vendors under operational load — interconnection studies, contingency analysis and automated protection coordination workflows — to validate model fidelity, not just feature lists.
- Pursue hybrid vendor strategies: combine scale incumbents for core operational integration with specialist best‑of‑breed tools for advanced simulation and real‑time analytics where needed.
- Embed commercial and technical KPIs into contracts: TCO, model convergence rates, time‑to‑insight, and integration SLA clauses reduce vendor risk and improve delivery predictability.
Using this preview — next steps
This preview is intentionally diagnostic rather than prescriptive. It highlights market direction, vendor postures and the critical questions that procurement, engineering and corporate strategy teams must resolve in 2026. For teams preparing budget submissions, RFPs, or M&A diligence, the full report includes: complete regional/type/application splits, proprietary vendor scorecards, scenario‑weighted demand curves, and detailed case studies with implementation timelines and cost models.
Contact PW Consulting or visit our report page to access the complete dataset and tools that operationalize the analysis in this preview. The granular breakdowns and vendor matrices are the working products that convert this high‑level intelligence into awardable RFPs, board memoranda and investment memoranda.
Conclusion
In 2026 the Electric Power System Analysis Software market is no longer a niche corner of engineering departments: it is a strategic technology stack that underwrites system reliability, market participation, and the integration of renewable and distributed assets. Our research shows consistent growth supported by policy, asset mix change and new load patterns; the key decision for enterprises this year is how to convert market momentum into durable, interoperable capability without locking into brittle point solutions. Use the full PW Consulting study as the operational playbook for that conversion — the preview above provides the strategic orientation, the full report provides the execution map.
For detailed analysis of this topic, please visit the official page: Electric Power System Analysis Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isolator Gloves Market to Reach USD 327M by 2032; 5.25% CAGR (2026–2032) — PW Consulting
By PW Consulting, 2026-07-12
Isolator Gloves Market — Strategic Preview for 2026 Corporate Decision-Making
PW Consulting’s latest Isolator Gloves Market study supplies a focused, decision-ready synthesis for executives planning spend, sourcing, product development, and compliance strategies in 2026. Grounded in a 2020–2025 historical base and a 2026–2032 forecast horizon, the market demonstrates steady expansion — from USD 205.0 Million in 2020 to USD 230.0 Million in the 2025 base year, with a projected trajectory to approximately USD 327.0 Million by 2032 at a compound annual growth rate (CAGR) of 5.25%. This preview highlights the study’s strategic value while intentionally withholding granular segmentation tables to direct stakeholders to the full report for proprietary, transaction-grade detail.
Isolator Gloves Market
Why this study matters in 2026
- Regulatory imperatives are defining procurement and CAPEX — recent and evolving guidance requires documented glove replacement policies and contamination control strategies that materially affect operating procedures and TCO.
- Visibility into validated performance is now a strategic advantage — buyers must weigh not only unit cost but validated sterilization tolerance, life-cycle performance, and demonstrable contamination profiles under typical isolator/RABS regimes.
- Supply resilience and contractual design are urgent — moderate market concentration creates opportunity and risk: strategic sourcing, dual-sourcing and near-shoring are viable levers for manufacturers and pharma end-users.
- Product innovation and service bundling matter more than ever — sterilization compatibility, materials engineering (e.g., advanced elastomers), and provider services (validation, field support) materially shape vendor selection.
Macro picture — what the numbers say (teaser)
Overall market scale and momentum provide the baseline for capital allocation: after recovering from near-term volatility, the isolator gloves market is set on a steady growth path. The study’s base-year accounting and seven-year outlook produce a robust forecast built from longitudinal pricing, consumption drivers in pharmaceutical manufacturing and other sterile environments, and regulatory demand shocks. With a 5.25% CAGR across the forecast period, the sector presents predictable expansion for suppliers while demanding disciplined compliance and operational controls from buyers.
Isolator Gloves Market
Regulatory dynamics that will drive 2026 decisions
- FDA and EMA compliance framing — updated guidance requires written glove replacement frequencies within critical-component procedures and mandates inclusion within contamination control strategies. These requirements increase the visibility of glove performance in audits and supplier selection.
- PDA risk management expectations — contemporary guidance underscores that mitigating glove-related contamination requires combinatory controls (materials, process, environment, and testing), elevating demand for integrated solutions rather than single-component sales.
- ISO sampling thresholds — industry standards now require demonstrable contamination recovery rates at the very low end of the detection spectrum for isolator gloves, changing validation acceptance criteria and raising the bar for supplier qualification.
- Sterilization and installation validation — GMP guidance continues to reinforce that gloves for Grade A environments must be sterile on installation or processed via validated decontamination methods, increasing downstream validation and logistics complexity.
Competitive landscape — how leading suppliers are positioned
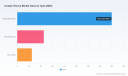
The market structure is moderately concentrated: the three largest suppliers account for a meaningful share of supply, and the top five encompass nearly half the market. This concentration profile creates a contest between established OEMs and specialist providers over specification leadership and value-added services.
Isolator Gloves Market
- Ansell (Richmond, Victoria, Australia) — leverages premium polymer portfolios (e.g., EPDM and nitrile) and validated product lines engineered for repeated autoclave sterilization and EN ISO protection standards. Ansell’s strength is in material science, global distribution, and brand trust in regulated environments.
- Terra Universal — specializes in system-level integration, manufacturing gloves and sleeves engineered for seamless inclusion in contamination-controlled glovebox and RABS systems. Their differentiation lies in end-to-end equipment compatibility and engineering services.
- Germfree (Ormond Beach, Florida, USA) — focuses on sterile nitrile isolator gloves validated for high-stringency ISO Class environments, positioning toward pharmaceutical and aseptic process customers who prioritize sterilization records and environmental compatibility.
- Piercan — supplies one-piece seamless gloves and sleeves for enclosed handling systems with emphasis on fit, tactile performance, and bespoke sizing. Their niche strength is in dexterity-centric applications and custom manufacturing runs.
Collectively, these vendors illustrate two strategic archetypes: material/brand leaders that compete on validated polymer performance and global scale, and system/integration specialists that compete on compatibility, customization, and field services. For buyers and investors, the strategic question is whether to prioritize validated specification conformity or integrated system performance when awarding contracts or pursuing M&A.
What the full report delivers (practical content preview)
PW Consulting’s full study goes beyond high-level forecasts to deliver tools that directly inform 2026 tactical and strategic decisions. The report includes:
- Comprehensive market sizing and a bottom-up forecast model covering 2026–2032 (downloadable Excel model).
- Scenario analyses with sensitivity to regulatory tightening, raw material disruptions, and accelerated automation adoption.
- Supplier scorecards and procurement playbooks (including qualification checklists and recommended SLA/contract clauses).
- Validation and contamination-control templates (SOPs, sampling plans, and change-control prompts tailored for sterile environments).
- TCO and pricing frameworks that embed sterilization, replacement frequency, and lifecycle cost into buyer evaluations.
- M&A and partnership screens highlighting target archetypes and expected synergies.
Strategic playbook — prioritized actions for 2026
- Operationalize regulatory requirements — convert high-level guidance into concrete SOP updates: documented glove replacement criteria, contamination-control strategy inclusion, and validation schedules tied to inspection calendars.
- Reconfigure supplier strategy — segment suppliers by validated performance, integration capability, and service footprint; prioritize dual-sourcing for mission-critical lines and execute short-term spot coverage for supply gaps.
- Invest in validation and QA capacity — expand internal testing capabilities or secure preferred supplier service contracts for contamination recovery verification and autoclave compatibility testing.
- Deploy value-based contracting — shift from unit-price procurement to outcome-based contracts that incorporate validated contamination metrics, replacement frequency, and service response times.
- Pursue selective partnerships and bolt-on acquisitions — favor targets that add sterilization expertise, in-country manufacturing, or service-led differentiation to reduce time-to-compliance and improve margins.
- Monitor material innovation and sustainability — incorporate polymer lifecycle data and end-of-life handling into procurement criteria to reduce regulatory and reputational risk.
Risk scenarios to monitor closely
- Regulatory acceleration — more prescriptive regulation could force rapid capital investment in qualification and create temporary shortages.
- Raw-material supply shock — elastomer shortages or price shocks could compress margins and shift procurement to long-lead contracts.
- Consolidation and vertical integration — could alter bargaining dynamics and raise barriers for specialist providers.
- Validation failures — a single high-profile contamination event tied to glove performance could trigger broad contract re-bids and reputational damage.
How to use this preview to drive 2026 decisions
Executives should treat the preview as a stimulus for three immediate actions: first, commission a short-form audit of glove-related SOPs and supplier validations to identify exposure; second, launch a procurement sprint to re-evaluate top vendors under outcome-based metrics; third, allocate discretionary R&D or M&A scouting resources to suppliers that bring validated sterilization or integration capabilities.
Accessing the full intelligence
This article intentionally presents expert synthesis and strategic guidance while withholding granular regional, application and type-level split data — the core, transaction-ready intelligence that informs procurement bids, valuation models and M&A diligence is available in the full PW Consulting Isolator Gloves Market report and its downloadable models. For clients preparing capital allocation, procurement negotiations, or regulatory remediation plans in 2026, access to that granular dataset and the supplier scorecards will materially shorten decision cycles and reduce execution risk.
Contact PW Consulting through our report portal to obtain the full dataset, interactive forecasting model, supplier scorecards, and validation templates that underpin the recommendations outlined above.
For detailed analysis of this topic, please visit the official page: Isolator Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cement Clinker Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting publishes its comprehensive Cement Clinker Market study (base year 2025; historical window 2020–2025; forecast 2026–2032), corporate decision-makers face a pivotal planning horizon. The industry’s steady structural growth — underpinned by a projected compound annual growth rate (CAGR) of 3.8% over the 2026–2032 forecast period — masks accelerating disruption around decarbonization, capacity footprint optimization, and trade-policy volatility. This preview outlines the strategic value of the full study for 2026 planning cycles, highlights the competitive dynamics shaping near-term risks and opportunities, and summarizes the actionable components executives will find in the report. To preserve the report’s proprietary intelligence this article signals the insights to be gained without reproducing the detailed segment tables that reside behind PW Consulting’s paywall.
Cement Clinker Market
Macro Trajectory: A Stable Market With Strategic Inflection Points
PW Consulting’s market sizing traces a clear recovery and expansion pattern: the global clinker market climbed from a 2020 baseline and reached an estimated USD 357.5 Billion in the report’s base year, 2025. Under the central forecast, the market increases to approximately USD 462.5 Billion by 2032, aligning with the mid-single-digit CAGR of 3.8% over the 2026–2032 window. The headline numbers indicate reliable underlying demand — driven by ongoing infrastructure programs, housing markets in growth economies, and industrial construction — yet the arithmetic belies the strategic complexity operators must manage.
Cement Clinker Market
- Growth is broad-based but uneven: macro demand will be influenced regionally by public infrastructure spend, urbanization rates, and the pace of industrial activity. The full report contains the granular regional and application breakdowns that inform plant-level and route-to-market decisions.
- Volume growth will coexist with cost and regulatory pressure: fuel and raw-material logistics, plus tightening emissions rules, will increasingly shape capacity economics and retrofit investment cases.
Why This Study Matters for 2026 Corporate Planning
For executives preparing 2026 budgets, investment committees, or M&A strategies, this research is designed to convert market-level visibility into boardroom-ready guidance. The strategic value can be summarized in three decision-use cases:
Cement Clinker Market
- Capital-allocation prioritization: identify which clinker assets merit modernization versus debottlenecking or retirement under plausible carbon price and fuel-cost scenarios.
- Supply-chain resilience planning: stress-test procurement strategies for limestone, clay, and gypsum, together with logistics options that mitigate tariff and export-exposure risks.
- Portfolio rationalization and M&A playbooks: benchmark regional asset economics and competitor moves to validate greenfield versus acquisition pathways.
Competitive Landscape: What the Major Players Are Signalling
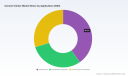
The clinker industry remains concentrated around integrated producers that can optimize upstream raw-material sourcing and downstream cement blending. Leading global and regional players are actively reshaping footprints and technology roadmaps. Our study profiles these companies with a focus on strategic initiatives that bear on clinker supply economics, including recent corporate developments:
- Holcim (Zug, Switzerland) — Demonstrated a high-profile electrification pathway in early 2026 by producing Portland-quality clinker using only electricity in a pilot with SaltX Technologies. This move illustrates the potential for disruptive low-carbon production routes, and it raises questions about scale-up timelines, power price sensitivity, and retrofit capex economics.
- Titan America (Athens, Greece) — Executed a targeted inorganic expansion in January 2026 with an acquisition that strengthens its Mid‑Atlantic footprint. The deal underscores ongoing consolidation in higher-cost markets where scale and integration reduce per-ton clinker cost.
- Heidelberg Materials (Hamburg, Germany) — Announced a redesign of its European clinker network as part of a longer-term strategy, signaling continued emphasis on capacity optimization and cost-to-serve improvements across mature markets.
- GCC (Tampa, United States) — Advanced both debottlenecking and major expansion projects in 2026, pointing to opportunities for volume-led margin gains where local demand growth and logistics advantages align.
- CEMEX and CRH — These integrated players continue to leverage plant networks and blended cement strategies to manage clinker utilization and respond to regional demand shocks.
Collectively, these actions illustrate two concurrent themes: (1) incumbents are actively balancing organic capacity upgrades with selective acquisitions, and (2) technological and operational levers (electrification pilots, debottlenecking, asset redesign) are being prioritized to reduce unit costs and emissions intensity.
Regulatory, Trade and Input Risks — Practical Implications
The 2026 planning horizon must explicitly account for regulatory and trade dynamics that are already reshaping clinker economics. Our study incorporates and interprets the latest signals, including:
- Trade flows and export status: the United States shifted to net exporter status for clinker in 2025, altering regional trade balances and competitive pressure in nearby markets. Key suppliers such as Turkey, Canada, and Vietnam now figure prominently in trade-based supply strategies.
- Tariff and trade-policy effects: 2025 tariff actions have had measurable, if uneven, impacts on cement and clinker markets — affecting both price formation and investment incentives along supply chains.
- Environmental regulation pressure: proposed standards for cement kiln operations and hazardous waste handling add both compliance cost and strategic constraints, potentially curbing greenfield modernization in certain jurisdictions unless exemptions or technology-based solutions are available.
These dynamics increase the value of scenario-based modeling for 2026: capital plans must be stress-tested not just for demand shock but for price, carbon-constraint, and trade-swing sensitivities. The full report offers scenario matrices and break-even tables to support that work.
Technology and Decarbonization Roadmap
Decarbonization is no longer a long-term aspiration; for clinker producers it is now a mid-term business problem with direct CAPEX and OPEX consequences. Our analysis disaggregates the viable technical pathways (fuel-switching, electrification pilots, carbon capture readiness, and efficiency-led debottlenecking) and assesses them against three practical criteria: implementation lead time, capital intensity, and sensitivity to power and carbon prices.
- Electrification pilots (e.g., Holcim’s April 2026 demonstration) show technical feasibility at laboratory and demo scale but leave open questions around grid capacity, electricity sourcing premiums, and plant-level retrofit costs.
- Operational optimization (debottlenecking, kiln efficiency, alternative fuels) remains the highest-confidence route to near-term emissions and cost improvements, and is often the fastest to value-capture.
- CCS and other end-state solutions are included in longer-range scenarios where the report quantifies implied carbon price thresholds for economic viability.
What the Full Report Provides — Practical, Actionable Content
PW Consulting’s full report is purpose-built for executive teams and transaction advisors. Key deliverables include:
- Comprehensive base-year market sizing and historical trend analysis (2020–2025) and a granular forecast (2026–2032) with scenario sensitivity.
- Segment-level demand drivers by region, by application, and by clinker type — presented with actionable unit-economics and transport-cost overlays (note: detailed segment tables are available in the full report).
- Competitive benchmarking and profile dossiers for incumbent and emerging players, including strategic initiatives, capex plans, and M&A pipelines.
- Regulatory impact assessment, trade-flow modeling, and a compliance-cost playbook for jurisdictions with tightening kiln standards.
- Decarbonization technology roadmap with investment case templates, payback matrices, and supplier ecosystem mapping.
- Transaction support tools: valuation comparables, synergies calculator for M&A, and diligence checklists tailored to clinker assets.
Decision Checklist for 2026
As you finalize budgets and strategic priorities for 2026, consider this compact checklist drawn from the report’s recommendations:
- Re-run capital-allocation models incorporating at least two carbon-price scenarios and a power-price sensitivity for electrification projects.
- Identify short-list assets for low-cost debottlenecking or efficiency retrofits that deliver rapid margin uplift before committing to larger-scale modernization.
- Map near-term trade exposure by plant and customer cluster to prepare contingent logistics and pricing strategies against tariff and export shifts.
- Prioritize M&A targets that add scale in strategically important corridors or that accelerate low-carbon capability.
Final Note — Why Access the Full Study
This preview underscores why 2026 is an inflection point for clinker producers, traders, and downstream cement manufacturers. The market’s steady top-line growth (from USD 357.5 Billion in 2025 to an estimated USD 462.5 Billion by 2032 at a 3.8% CAGR) creates room for investment, but the real value will be captured by actors who integrate regulatory foresight, technology transition planning, and disciplined footprint optimization into their strategic planning.
PW Consulting’s full Cement Clinker Market report provides the detailed segmentations, tables, and proprietary models that corporate strategists and investment teams need to act with confidence. For confidential briefings, bespoke scenario runs, or to access the complete dataset and segmentation tables, PW Consulting’s industry team is available to assist with tailored deliverables aligned to your 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Cement Clinker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


