



PW Consulting: Diesel Common Rail Injection Market to Reach USD 324.47 Million by 2032 (CAGR 5.8%)
By PW Consulting, 2026-07-12
Diesel Common Rail Injection Systems: Strategic Implications for 2026 — A PW Consulting Perspective
Executive snapshot
As powertrain strategies bifurcate between electrification and optimized internal combustion, diesel common rail injection systems remain a strategically important technology for many OEMs, suppliers and fleet operators — particularly across commercial and off-highway applications. Our market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, quantifies a steady recovery and structural growth pathway: the market expands at a compound annual growth rate of 5.8% over the forecast period. In practical terms, the industry moves from a mid-hundreds million USD base in 2025 into a low-hundreds million USD market by the end of the outlook, reflecting sustained demand driven by regulatory tightening, fuel-efficiency optimization, and technology migration toward higher-pressure, electronically controlled injection platforms.
Diesel Common Rail Injection System Market
Why this research matters for 2026 decision cycles
-
Strategic resource allocation: Capital and R&D budgets approved in 2026 will determine which platform architectures survive the next product cycle. This study maps where incremental investment yields the highest ROI under realistic regulatory scenarios.
Diesel Common Rail Injection System Market -
Partnership and sourcing decisions: With supplier concentration elevated — the top three players account for a meaningful share of the market and the top five consolidate a majority — decisions on supplier diversification, strategic alliances, and long-term procurement contracts must be informed by competitor capabilities and capacity risk.
Diesel Common Rail Injection System Market -
M&A and portfolio optimization: Our scenario-driven valuation overlays and stress-tests identify subsegments where bolt-on acquisitions or divestitures will meaningfully alter competitive positioning without requiring full vertical integration.
-
Compliance-forward product roadmaps: Evolving emission standards across jurisdictions create differentiated technical requirements. The report converts regulatory signals into engineering and cost-to-compliance milestones to help prioritize development pathways.
Market dynamics that will shape 2026 strategies
-
Regulatory pushpoints: Recent rulemaking — including locomotive emissions standards enacted in China in 2025, the introduction of Euro 7 provisions touching light commercial vehicles, and continuing tightening under BSVI-class regimes in India — is increasing the bar for NOx and particulate control. Our analysis translates these mandates into concrete performance and testing vectors for injection system design.
-
Technology trajectory: The displacement of mechanically governed systems by high-pressure, electronically controlled common rail architectures is now mature. OEMs are prioritizing injectors and control units capable of higher injection pressures and more frequent multiple injection events, while balancing cost and reliability for commercial duty cycles.
-
Cost versus compliance trade-offs: The push for ultra-high-pressure systems and piezoelectric injectors improves emissions and fuel economy but raises system cost and complexity. Our model quantifies break-even horizons for incremental hardware investments against fuel savings and emissions-compliance penalties across realistic duty cycles.
-
Supply chain risk and localization: Geopolitical pressures and vehicle content localization policies are reshaping distribution of module assembly and component sourcing. The study identifies chokepoints — such as precision injector manufacturing capacity and high-pressure pump supply — and offers mitigation pathways.
Competitive landscape — what established suppliers are betting on
The competitive field is concentrated and technology-led. Several global suppliers have clear platform plays and differentiated go-to-market strategies. Our competitive deep-dive examines capabilities, product portfolios, and strategic intent for the leading suppliers:
-
Robert Bosch GmbH (Gerlingen, Germany): Bosch continues to push modularity with high-pressure common-rail platforms that extend to 2,700 bar and incorporate both piezo and solenoid injectors. Its strength is an integrated system approach — pumps, rails, injectors and ECUs — which supports medium-duty and off-highway modularization as a defense against commoditization.
-
Cummins Inc. (Columbus, Indiana, United States): Cummins anchors its position with mid- and heavy-duty XPI common rail solutions rated for high pressures and designed for extreme duty cycles. Their focus on pump lubrication strategies and leakless injectors targets fuel economy and regulatory durability requirements common in heavy transport and industrial markets.
-
Hyundai Kefico Corporation (Gunpo, South Korea): Kefico’s strategy centers on competitively engineered systems up to 2,200 bar, optimized for passenger and commercial vehicle platforms. They play a regional and OEM-focused game, using cost-competitive system integration to win high-volume production contracts.
-
Weifu High-Technology Group (Wuxi, China): Weifu balances compliance with cost by addressing commercial vehicles and engineering machinery for markets where localized standards are rising. Their roadmap emphasizes meeting stringent emissions norms through high-precision modules tailored for regional regulatory regimes.
-
Continental AG (Hanover, Germany): Continental’s product line emphasizes piezo injectors and ECU integration for passenger and light commercial vehicles, positioning itself where integration with vehicle electronics and ADAS architectures can create bundling opportunities.
-
DENSO Corporation (Kariya, Japan): DENSO focuses on compact, high-reliability components — injectors, pumps and suction control valves — aimed at OEMs seeking packaging efficiency and long service intervals.
-
BorgWarner Inc. (Auburn Hills, Michigan, United States): BorgWarner pursues end-to-end injection solutions that fit passenger, light commercial and heavy-duty segments, leveraging system-level design to compete on integration and warranty performance.
Our competitive chapters synthesize public statements, patent flows and technical benchmarks to present supplier scorecards: technology readiness, cost curve positioning, manufacturing footprint, and strategic partnerships. These scorecards are built to inform sourcing strategy and potential JV targets in 2026.
What the PW Consulting report delivers (practical takeaways)
-
Market modelling with transparency: A reproducible demand model reflecting historical 2020–2025 trends and a 2026–2032 baseline forecast. The model isolates drivers such as vehicle parc evolution, fuel price assumptions, and regulatory tightening.
-
Regulatory-to-engineering translation: Actionable matrices that convert emission requirements into injector performance targets and testing protocols, enabling engineering teams to set verifiable development milestones.
-
Supplier due diligence toolkit: A customizable RFI/RFP checklist and supplier health dashboard to evaluate capacity, quality, IP exposure and geopolitical risk.
-
Technology and cost roadmaps: Scenario-based projections that show when investments (e.g., adoption of piezo injectors or ultra-high-pressure pumps) pay back under different fuel and emissions price regimes.
-
M&A and partnership playbooks: Value-creation blueprints for bolt-on acquisitions and technology licensing arrangements, including backward and forward integration cases.
-
Execution-ready slides: A set of executive summaries, board-ready decision memos and one-page investment theses designed to accelerate 2026 approvals.
Strategic recommendations for 2026 planners
-
For OEM product leaders: Prioritize flexible injection system architectures that support scalable pressure and injector variants. This enables platform reuse across multiple vehicle families while meeting tightening emissions requirements without wholesale redesigns.
-
For Tier-1 suppliers: Invest selectively in precision manufacturing capacity and software-enabled calibration capabilities. Control over ECU calibration and injector characterization differentiates total-cost-of-ownership outcomes for fleet customers.
-
For CFOs and corporate development teams: Use the provided scenario valuations to stress-test M&A targets. Focus on targets that close capability gaps (e.g., piezo injector know-how, high-pressure pump machining) rather than purely volume plays.
-
For procurement chiefs: Introduce multi-sourcing strategies for critical components while negotiating capacity reservation clauses. Our supplier health dashboard identifies the minimum redundancy necessary to maintain production resilience.
-
For investors: Look for companies that combine systems integration strength with cost-competitive manufacturing footprints; these will best convert regulatory-driven demand into sustainable margin expansion.
How to use this research in 90 days
-
Month 1 — Alignment: Run the regulatory-to-engineering matrix against your current product roadmap; identify three non-compliant or marginal platforms and agree corrective investment or phase-out decisions.
-
Month 2 — Sourcing and supplier strategy: Deploy the RFI/RFP checklist to your incumbent and two alternative suppliers; perform the supplier health assessment and secure conditional capacity commitments where risk is concentrated.
-
Month 3 — Investment and M&A: Use the report’s valuation scenarios to prioritize one to two strategic investments or partnerships; prepare board materials using the execution-ready slide set for 2026 capital allocation.
Final note — why PW Consulting’s analysis is different
We combine system-level engineering translation with commercial and regulatory scenario analysis, producing decision-ready outputs rather than descriptive market estimates. The market demonstrates durable growth with a clear compliance-led tailwind and concentrated supplier economics — a landscape where the timing of investment, rather than scale alone, will determine winners in 2026. Our report exposes the levers corporate leaders must pull, while reserving the most actionable, segmented figures and supplier scorecards for the full report to support transactional decisions.
Next steps
For executives preparing 2026 budgets and strategic headlines, PW Consulting’s comprehensive study provides the playbook to convert regulatory change and technology evolution into competitive advantage. Access to the complete report includes the full segment-level modelling, supplier scorecards and scenario-specific investment templates that are intentionally excluded from this executive preview.
For detailed analysis of this topic, please visit the official page: Diesel Common Rail Injection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PPD Market to hit USD 737.5M by 2032 at 4.75% CAGR; Asia Pacific $221.19M
By PW Consulting, 2026-07-12
p-Phenylenediamine (PPD) Market Outlook 2026: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise but deep preview of our p-Phenylenediamine (PPD) Market research — a tactical guide for boards, corporate strategy teams, and commercial leaders preparing decisions in 2026. The PPD value chain sits at the intersection of specialty chemicals, consumer personal care, and industrial elastomers. Our 2025 base-year study and forward-looking model to 2032 combine quantitative trend projection with decision-grade, operational diagnostics. Below we summarize the strategic takeaways and the practical modules inside the full report, while intentionally withholding proprietary segment-level tables to invite a closer read of the full intelligence pack.
p-Phenylenediamine (PPD) Market
Why PPD matters for 2026 corporate strategy
PPD is a small-molecule intermediate with outsized commercial sensitivity. Its end-uses — hair dyes, textile dyes, rubber processing, photographic and various industrial intermediates — expose manufacturers and buyers to a mix of consumer-regulatory risk, feedstock cost volatility, and concentrated supply. From a capital allocation and commercial planning perspective, three attributes make PPD a 2026 priority:
p-Phenylenediamine (PPD) Market
- Predictable baseline growth: Our model uses a 2025 base and projects a compound annual growth rate (CAGR) of 4.75% across the forecast horizon, driven by continued demand in hair dye and rubber-processing segments alongside steady industrial applications.
- Feedstock sensitivity: PPD manufacturing is materially exposed to aniline and benzene feedstocks and shows meaningful margin swings tied to short-term raw material dynamics and logistics constraints.
- Regulatory asymmetry: Recent regulatory initiatives and proposals — from tightened chemical handling and emissions oversight to proposed limits on PPD concentration in colorant formulations — create uneven demand impacts across geographies and applications.
Headline market sizing (high level)
Using 2025 as the base year, the total PPD market is quantified in our model and shows expansion over the forecast period. The market trajectory captures post‑pandemic recovery dynamics, the impact of regulatory measures, and structural shifts in end‑use demand. The headline statistics — which we disclose publicly to orient executive planning — show mid‑single-digit CAGR growth and a materially larger market by the end of the forecast window. For the full, interactive model (country-level demand curves, price scenarios, and unit economics), please consult the complete report page.
p-Phenylenediamine (PPD) Market
Competitive landscape and what it means for strategy
The global PPD supply base blends regional champions, specialty players and diversified chemical majors. Market concentration at the top end is moderate: the three-largest producers account for a meaningful share of supply, and the five-largest firms control a clear majority. This structure creates both competitive risk (capacity-driven price cycles) and opportunity (strategic partnerships with leading producers).
- Aarti Industries and select Indian specialty players are executing capacity and quality upgrades with enhanced safety and ESG credentials; these moves strengthen their position in premium and regulated markets.
- Large chemical groups and East Asian volume producers continue to emphasize cost leadership and integrated feedstock sourcing; capacity investments in high‑purity grades support textile and rubber intermediates at scale.
- Recent strategic transactions and targeted facility investments by diversified global players signal consolidation of higher‑margin specialty lines and vertical integration to control feedstock and technical know‑how.
For commercial teams, the implication is straightforward: supplier selection must account for capacity elasticity, regulatory compliance history, and the ability to provide formulation support under tighter chemical limits. For M&A and corporate development, look for bolt-on targets that expand technical grade ranges and regulatory-compliant production footprints.
Regulatory & raw-material dynamics to watch in 2026
- Heightened safety and emissions oversight in major producing countries is raising compliance costs and restricting storage/transport flexibility. Companies with modernized facilities and documented environmental management systems gain a sourcing advantage.
- Feedstock markets are showing renewed firmness, with price spikes and logistics tightness driving cost pass-through challenges. Buyers should expect periodic, multi‑week price dislocations and plan hedging or contracting strategies accordingly.
- Regulatory proposals in consumer markets — including efforts to reduce allowable PPD levels in dye formulations — could compress demand for technical PPD in specific geographies and products. Firms must model both compliance costs and potential product reformulation timelines.
- Sub‑national regulatory attention (e.g., candidate chemicals lists and public comment processes) introduces geographic unpredictability for derivative products; legal and regulatory monitoring should be elevated to board reporting frequency.
What our full report contains — decision‑grade deliverables
The PW Consulting PPD Market report is intentionally practical. We organize findings into modules that feed directly into 90–180 day action plans and three‑to‑five‑year capital allocation decisions. Key deliverables include:
- Interactive market model (2020–2032) with scenario toggles: base, regulatory‑constrained, high‑raw‑material, and accelerated substitution. Users can re-run demand and margin forecasts by changing price, regulation and capacity inputs.
- Supply‑side heatmaps and plant‑level benchmarking showing safety, emissions, and ESG risk scores — enabling rapid supplier triage without disclosing proprietary segment numbers in this preview.
- Raw material sensitivity and pass‑through frameworks: quantitative rules-of-thumb and contractual clauses for price escalators, minimum purchase commitments, and feedstock sharing arrangements.
- Regulatory impact matrices with pathway maps for product reformulation: practical steps and CAPEX estimates required to comply with evolving hair-dye thresholds and chemical handling rules.
- Commercial playbooks for producers and buyers: pricing architecture options (indexation vs fixed), channel segmentation strategies, and technical services that create differentiation in commoditized markets.
- M&A and partnership shortlist: evaluated targets and JV structures prioritized by strategic fit, deliverable synergies, and integration risk (available in full report annexes).
- Stress tests and downside scenarios: tailored guidance for contract portfolios, inventory strategies, and contingency logistics planning under acute supply shocks.
Competitive moves we are monitoring
Several vendor actions over the past two years crystallize likely market outcomes. Capacity upgrades with modern environmental safety systems, strategic acquisitions into specialty intermediates, and facility investments on quality expansion trajectories are all visible. Sustainability credentials — including recognized third‑party supplier ratings — are emerging as differentiators for buyers in regulated consumer markets. These developments reframe procurement from price-only conversations to integrated supplier risk management.
Actionable recommendations for 2026
- Prioritize supply‑security contracts with clauses for regulatory contingency and feedstock pass-through; consider diversified multi‑sourcing to mitigate regional regulatory or logistical shutdowns.
- Accelerate product‑level compliance roadmaps for consumer-facing formulations where regulatory thresholds are under evaluation. Early reformulation pilots reduce risk and create first‑mover marketing advantages.
- Incorporate ESG and safety benchmarking into supplier scorecards; allocate incremental spend to suppliers with verified modernized facilities if regulatory risk is material for your end markets.
- For producers: deploy a dual product strategy — cost-competitive volume grades for industrial channels and premium, high‑purity grades with value‑added technical support for cosmetics and specialty dyes.
- M&A teams: prioritize assets that expand high‑purity capacity, regional compliance footprints, or technical service capabilities rather than simple volume additions.
How executives should use the full PW Consulting report
Executives should treat the full PPD report as a toolkit: a live market model for quarterly planning, a supplier‑risk playbook for procurement, and a strategic dossier for M&A committees. The report enables scenario rehearsals — from short, sharp raw material surges to multi-year regulatory transitions — and translates those scenarios into prioritized actions with estimated timelines and resource implications.
Final note — where this preview intentionally stops
This introduction deliberately demonstrates methodological rigor and strategic focus while withholding granular regional and application-level splits, unit price curves, and facility-level capacities contained in the full intelligence pack. Those detailed tables and the interactive model are core intellectual property: they are the operational inputs you will need to execute with confidence in 2026.
To obtain the complete market model, plant-by-plant benchmarking, prioritized M&A shortlist, and the regulatory compliance playbook, please visit our report page or contact PW Consulting directly. Our team stands ready to run bespoke scenario workshops with your executive and procurement teams to turn these insights into executable plans.
For detailed analysis of this topic, please visit the official page: p-Phenylenediamine (PPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 1-Octene Market Set to Reach USD 297.7M by 2032 at 5.12% CAGR
By PW Consulting, 2026-07-12
1-Octene Market: Strategic Preview for 2026 Decision-Makers
The 1-octene market sits at an important inflection point as we enter 2026. After steady expansion through the early 2020s, the market has demonstrated resilient end‑market demand and improving technology-driven supply economics. PW Consulting’s upcoming 1-Octene Market study synthesizes historical performance and forward-looking scenarios to help corporate strategists, commercial teams, and investors convert macro trends into concrete near‑term choices that will define competitive position across the 2026–2032 planning window.
1-Octene Market
Market snapshot: what the headline numbers tell you
Between 2020 and 2025 the global 1-octene market experienced multi-year growth driven primarily by polyethylene comonomer demand and continued adoption in surfactant and specialty lubricant applications. Our compiled market totals show clear expansion during the base period, and the outlook indicates continued enlargement through the forecast horizon. The market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.12% during the 2026–2032 forecast period, reaching a materially larger scale by 2032.
1-Octene Market
Two strategic takeaways flow directly from these macro dynamics. First, steady volume growth combined with moderate concentration (market-share metrics indicate a fragmented supplier base) creates opportunities for differentiation through technology, cost position and service model rather than purely through scale. Second, the pace of growth supports targeted capacity additions and partnerships—but timing and location will determine whether new entrants capture premium margins or face a commoditizing supply environment.
1-Octene Market
Why this report matters for 2026 corporate decisions
-
Investment prioritization: Our analysis translates market growth trajectories into demand buckets and stress-tested scenarios to evaluate the business case for brownfield expansions, debottlenecking, or greenfield projects within a 36–60 month execution window.
-
Procurement and feedstock strategy: With ethylene remaining the dominant upstream feedstock, the study maps feedstock exposure and shows how contracting structures (long‑term vs. index-linked) alter margin profiles under several oil/ethylene price scenarios.
-
Technology & differentiation: The report benchmarks catalytic and oligomerization technologies—identifying which process innovations deliver step-change cost, yield, or sustainability advantages important for 2026 supplier selection and partnership decisions.
-
Regulatory and operational readiness: Practical guidance on handling and transport, industry regulatory context (including food-contact listings where relevant), and product stewardship obligations that influence logistics design and commercial risk.
What’s inside: actionable modules in the full study
-
Concise market model (historical 2020–2025 and detailed forecast 2026–2032) with scenario toggles for demand shocks, feedstock volatility and new capacity.
-
Commercial playbook: routes to market by customer segment, margin pools across the value chain, and go‑to‑market templates for upstream and merchant producers.
-
Technology deep-dive: technical comparisons of oligomerization platforms, catalyst systems and emerging bio‑derived routes; CAPEX/OPEX benchmarking for greenfield and retrofit options.
-
Regulatory and safety annex: consolidated references to food contact regulation status, transport/handling updates and SDS considerations that affect logistics and insurance.
-
Competitive landscaping and deal flow tracker: profiles of major producers, recent announcements and an assessment grid for M&A or JV targets.
Competitive landscape: who matters and why
The supplier landscape for 1-octene is characterised by a mix of global diversified chemicals majors, specialist olefin producers and regionally focused complexes. Market concentration metrics point to a low-to-moderate degree of dominance by the top suppliers, leaving room for strategic moves that change relative position without necessarily requiring absolute scale.
-
Chevron Phillips Chemical Company LP (Houston): A longstanding supplier with branded offerings for linear alpha olefin comonomer markets. Recent product stewardship updates and transport guidance underscore the importance of operational rigor—an important consideration for buyers seeking predictable logistics and risk management.
-
SABIC (Riyadh): Deploys proprietary low-pressure oligomerization technology with integrated value chain advantages in regions where feedstock integration delivers cost benefits; a natural strategic partner or competitor depending on regional positioning.
-
Shell (The Hague): Combines integrated petrochemical platforms with active catalyst partnerships—an approach that accelerates low‑carbon and bio‑derived pathways and is likely to shape medium-term supply options for sustainability‑minded customers.
-
INEOS (London): Plays across linear alpha olefin portfolios and can leverage flexible commercial structures to serve specialty and polymer markets where technical service differentiates pricing.
-
Sasol (Johannesburg): Maintains unique production routes that can be relevant in specific regional feedstock or energy contexts; companies with non‑standard upstream linkages should study the supply implications closely.
-
ExxonMobil Chemical (Irving): Recent announcements highlight catalytic process innovations that aim at higher yield and lower energy intensity—technology that can alter cost and emissions equations for licensees and integrated producers.
Recent disclosed moves underline two themes: (1) incremental technology and catalyst developments that improve yield, energy use and impurity profiles; and (2) capacity additions in Asia intended to feed regional polyethylene demand. Both dynamics increase the importance of timing—first movers on catalyst partnerships or process upgrades can capture margin uplift, while late movers may face a more price‑competitive environment.
Market dynamics and risk factors to watch in 2026
-
Feedstock volatility and integration risk: Ethylene remains the primary upstream input. Firms with favourable ethylene access or hedging strategies will enjoy structural cost advantage; purchasers without vertical integration should consider hybrid sourcing strategies.
-
Regulatory clarity and product stewardship: 1‑Octene’s status in food contact regulations is established in key jurisdictions; no material reclassifications were recorded in 2024–2025. However, transport and handling guidance continues to be refined by suppliers and will influence logistics costs and incident exposure.
-
Capacity build in Asia and regional imbalances: Announced capacity expansions in major Asian complexes change the forward supply curve—buyers and investors must model regional flow economics rather than relying solely on headline global demand growth.
-
Technology and sustainability transitions: Catalyst partnerships and bio‑sourcing initiatives are moving from pilot to commercial scale. These developments introduce new competitive dimensions—life‑cycle emissions and feedstock origin will increasingly affect offtake terms with large polymer and consumer-facing customers.
Strategic playbook for 2026
-
For producers: Prioritise selective capital allocation—focus on retrofit projects and catalyst licenses that improve yield or lower energy intensity, rather than undifferentiated greenfield capacity. Evaluate tolling and merchant models to fill plant utilisation gaps quickly.
-
For polymer and surfactant manufacturers: Secure flexible offtake contracts with logical indexation and clause structures that share upside and downside with suppliers. Invest in upstream partnerships to access differentiated 1‑octene grades aligned to product performance needs.
-
For investors and PE: Target assets with demonstrable feedstock integration, proprietary technology or service‑differentiated commercial models. Beware of plain-vanilla merchant plants in regions where new capacity is already announced.
-
For procurement and supply chain leaders: Re-examine logistics routes and safety protocols in light of updated SDS and transport guidance. Scenario‑test supply interruptions and incorporate transport liability into supplier scorecards.
How to use the full PW Consulting report
This article is a strategic preview designed to orient your 2026 decisions. The full PW Consulting 1-Octene Market report provides the granular models, supplier scorecards, techno‑economic comparisons and scenario tables you need to execute with confidence. If your 2026 plan includes capacity planning, technology licensing, regional sourcing changes, or M&A, the full study supplies the primary data and decision templates to convert our insights into executable investments.
Conclusion: a pragmatic edge for 2026
In a market characterised by steady growth, technological change and regional capacity shifts, 2026 will reward organisations that pair macro awareness with tactical precision—those who align feedstock strategy, select differentiated technology partners, and hard‑wire logistics resilience into commercial contracts. PW Consulting’s 1-Octene Market study is structured to give you both the high‑level view and the operational detail needed to make those calls while preserving the market granularity and supplier intelligence that can only be accessed in the full report.
To move from strategic intent to execution-ready decisions, access the complete study for scenario models, supplier matrices and the appendices that operationalise the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: 1-Octene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
In-Pipe Inspection Robot Market: Strategic Outlook for 2026 — A PW Consulting Preview
Executive summary
The in-pipe inspection robot market is entering a phase of sustained, technology-driven expansion. Our proprietary topline analysis shows the global market expanding from USD 1,020 Million in 2020 to USD 1,330 Million in the 2025 base year, and we forecast growth to USD 2,185 Million by 2032 — an implied compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window. For companies making 2026 strategic choices — from product roadmaps and channel investments to M&A and procurement strategy — the question is no longer whether to engage with in-pipe robotics, but how to position for differentiated value capture as the market professionalizes.
In-pipe Inspection Robot Market
Why this research matters for 2026 decision-makers
-
Capital allocation with conviction. With mid-single-digit to high-single-digit CAGR dynamics and a market that more than doubles over the coming decade, 2026 is a pivot year for allocating R&D and deployment capital. Buyers must balance the economics of longer-range, higher-cost multi-sensor platforms against the operational benefits of lower-cost, task-specific crawlers. Our analysis frames that trade-off in ROI terms so CFOs can prioritize investments across portfolio cohorts.
In-pipe Inspection Robot Market -
Regulatory-driven demand windows. New and evolving regulations (e.g., ATEX Zone 1 requirements for explosion-proof devices in hazardous sectors and U.S. PHMSA mandates for internal inspections of unpiggable gas mains) are creating defined procurement cycles and accelerated replacement needs in regulated end markets. Companies that align product certification timelines and approval strategies with these regulatory windows will secure advantaged procurement pipelines in 2026–2027.
In-pipe Inspection Robot Market -
Supply chain and unit-economics sensitivity. Advanced in-pipe robots increasingly depend on specialized components — high-performance Li-ion cells, ruggedized imaging arrays, and ATEX/IECEx-rated enclosures. Our field interviews and supplier mapping highlight that lithium-ion component disruptions and battery supply constraints are material near-term risks that inflate per-unit costs and delay deployments; many advanced platforms carry substantial upfront costs, which in turn shapes buyer selection and financing models.
-
Competitive positioning in a consolidating but not concentrated market. The landscape is characterized by a handful of established platform providers and a growing set of specialized entrants. The top three suppliers collectively command a meaningful share of commercial deployments, while the top five approach a near-majority presence — a dynamic that rewards differentiated technology, reseller networks, and strong after-sales service ecosystems.
Report contents — what you will get (practical, decision-ready deliverables)
-
Executive decision framework — a one-page playbook for 2026 capital and procurement choices, mapping use-case severity to platform class and payback windows.
-
Market model and topline forecasts — end-to-end revenue curves and sensitivity scenarios across our 2026–2032 forecast horizon, plus upside/downside stress tests driven by regulatory adoption and component scarcity.
-
Vendor scorecards — standardized evaluation matrices covering technology maturity, certification readiness (ATEX/IECEx/PHSMA alignment), service footprint, and GTM strength for the leading vendors.
-
Go-to-market playbooks — channel strategies (direct, distributor, OEM embed), pricing archetypes (capex sale vs. as-a-service), and recommended field-support models to maximize installed-base lifetime value.
-
Procurement and piloting templates — RFP language, test acceptance criteria, benchmark inspection runs, and KPIs to validate performance claims during vendor pilots.
-
Supply-chain risk matrix and mitigation options — alternative sourcing paths, strategic component bundling, and inventory strategies to reconcile Li-ion shortages and certification lead times.
-
Deployment case studies and ROI calculators — anonymized, real-world deployment economics across municipal, industrial, and hazardous-sector scenarios to support business case sign-off.
-
Regulatory and standards annex — a concise mapping of regional certification regimes, critical compliance milestones, and recommended product-certification roadmaps.
Competitive landscape — who to watch and how they differ
The vendor ecosystem combines established platform vendors, specialty manufacturers, and integrators. Below is a strategic snapshot of the primary companies covered in our study (selected profiles are illustrative of the full vendor analysis contained in the report):
-
Envirosight LLC (United States) — Known for robust wheeled and tracked inspection platforms optimized for municipal sewer and industrial pipeline maintenance; strong emphasis on rugged CCTV and multi-sensor modularity. URL: https://envirosight.com
-
CUES Inc. (United States) — Provider of in-pipe crawlers and rehabilitation equipment with deep relationships in water and sewer utilities; strong aftermarket and operator training capabilities. URL: https://cuesinc.com
-
RedZone Robotics (United States) — Focused on tracked platforms with integrated sensing suites for condition assessment; notable for utility-focused analytics and deployment services. URL: https://redzonerobotics.com
-
Fiberscope (United States) — Brings ATEX-certified, explosion-proof inspection robots to hazardous industries; recent product introductions expand viability in oil, gas, chemical and pharmaceutical pipelines. URL: https://fiberscope.net
-
Nexxis (United States) — Modular crawlers and tractors built for long-range industrial inspection; emphasis on customization and integration with NDT sensors. URL: https://nexxis.com
-
ULC Technologies (Canada) — Specialist in live-gas deployment systems and structural integrity platforms; known for solutions that reduce disruption during gas-main inspection activities. URL: https://ulctechnologies.com
-
Pipe Trekker (United States) — Portable, battery-operated crawlers targeting smaller-diameter municipal and stormwater systems with an emphasis on ease-of-use and low mobilization cost. URL: https://www.pipetrekker.com
-
Deep Trekker (Canada) — Battery-powered crawlers and underwater-capable platforms for small-diameter and partially submerged environments; strong sell-through in inspection-for-hire operators. URL: https://deeptrekker.com
-
Eddyfi Technologies / Inuktun brand (Canada) — Integrates advanced nondestructive testing (NDT) capabilities into in-pipe robotics, enabling higher-fidelity condition assessments for critical infrastructure. URL: https://www.eddyfi.com
Recent industry developments and regulatory dynamics
Key events that are reshaping the competitive and operational environment include:
-
Product certification and launches: The market is seeing focused product introductions for hazardous environments; for example, an ATEX Zone 1 certified inspection robot was announced that materially expands opportunities in oil, gas, and chemical sectors.
-
Public-sector deployments: Multiple municipal and regional authorities have recently piloted or deployed advanced inspection robots — including long-range, high-resolution video inspection projects — which are pushing performance expectations for commercial providers.
-
Regulatory tailwinds: PHMSA and similar regulators globally are formalizing inspection expectations for unpiggable pipelines, creating sustained procurement schedules and certification prerequisites that favor vendors with demonstrated compliance pathways.
-
Supply and cost pressures: Persistent lithium-ion supply-chain disruptions and the higher upfront price points of multi-sensor robots are constraining smaller utilities and accelerating interest in as-a-service and leasing offerings.
-
Standards fragmentation: Divergent regional certification frameworks (e.g., ATEX in Europe vs. North American equivalents) extend approval timelines and introduce interoperability challenges for global suppliers.
High-level strategic actions for 2026
-
Hedge supply chain risk now. Secure key components through multi-sourcing agreements, strategic inventory positions, or contract manufacturing alliances to mitigate Li-ion and imaging supply volatility.
-
Pursue targeted certification investments. For vendors, prioritizing ATEX/IECEx and regionally equivalent certifications will unlock hazardous-sector revenues; for buyers, require vendor roadmaps that include certification milestones in procurement contracts.
-
Deploy pilot-to-scale pathways. Structure tiered pilots with explicit acceptance criteria (imaging quality, autonomy, mean time to repair, data integration) and pre-negotiated purchase or leasing terms to reduce procurement friction.
-
Bundle software and services. Differentiate via analytics, predictive maintenance modules, and field-service SLAs; subscription and managed-service models can lower adoption barriers for smaller utilities.
-
Evaluate M&A selectively. Buyers and platform vendors should consider acquisitions that fill gaps in certification, NDT integration, or service coverage to accelerate market access without diluting core R&D.
What we intentionally withhold in this preview
In keeping with our “trailer” approach, this introduction conveys the market scale, growth trajectory, regulatory vectors, and practical implications for 2026. Detailed segment-level tables, regional and application-specific revenue breakdowns, granular vendor market shares, and underlying primary-research appendices are reserved for the full PW Consulting in-pipe inspection robot market report. Those granular datasets and procurement-ready artifacts are where the real execution value resides.
Next steps — how to use this insight
For executives and procurement leads preparing 2026 budgets: treat this analysis as the strategic framing to inform scenario planning. For product and commercial leaders: use the vendor and certification insights to accelerate product-certification roadmaps and channel alignment. And for investors and M&A teams: the market’s medium-term growth and measured consolidation dynamics indicate windows for targeted acquisitions, particularly where certification or service footprint can be acquired to shorten time-to-revenue.
PW Consulting’s full report contains the actionable models, vendor scorecards, pilot templates, and scenario-sensitive market tables you need to convert strategic intent into executable programs. Contact our research team or visit the full study to access the complete dataset and practitioner toolkits.
For detailed analysis of this topic, please visit the official page: In-pipe Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hand Tools Market to Reach USD 24,031.4M by 2032 at 4.88% CAGR
By PW Consulting, 2026-07-12
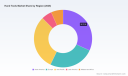
Hand Tools Market 2026 Strategic Outlook — A PW Consulting Industry Brief
As the hand tools industry moves from recovery into a structurally different growth phase, 2026 will be a pivotal year for executives, procurement leaders, product heads and private equity investors. PW Consulting’s latest Hand Tools Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes macro trajectories, near-term shock scenarios and actionable go-to-market playbooks. The global market, measured in USD (Million), expanded materially through the pandemic recovery—rising from the low teens in 2020 to an institutional base in 2025—and our forecast projects steady, mid-single-digit growth through 2032 at a compound annual growth rate of 4.88%. This brief explains why that macro picture matters for 2026 decision-making, what strategic levers will move the needle, and how our full report converts insight into executable workplans.
Hand Tools Market
Why this report matters for 2026 decisions
- Investment framing: With predictable mid-single-digit growth, capital allocation decisions must discriminate between stable cash-generative core product lines and higher-growth, margin-accretive adjacencies (digital services, tool-as-a-service, premium professional ranges).
- Supply chain resilience: Ongoing trade-policy volatility and input-cost fluctuations require near-term procurement hedges and medium-term strategic reshoring or supplier diversification. Our scenarios quantify the P&L impact under alternate tariff and steel-cost paths.
- Portfolio optimization: The industry remains structurally fragmented—market concentration metrics indicate that top players account for a meaningful but far-from-dominant share—creating opportunities for bolt-on M&A, brand consolidation, and regional champions to scale.
- Go-to-market transformation: Channel economics are shifting as professional buyers demand tool ecosystems and subscription services, while DIY channels continue to benefit from e-commerce and big-box assortment strategies. Pricing, assortment and warranty models need rework.
Key market dynamics shaping 2026
- Demand composition. Construction and renovation cycles remain the principal demand engines, complemented by durable aftermarket replacement and an expanding DIY consumer base. These underlying drivers are sensitive to regional capex cycles and housing activity.
- Input & trade policy volatility. Recent tariff and steel-duty actions have altered the cost base for many manufacturers. For 2026 planning, firms must model multi-scenario input-cost paths and maintain a near-term playbook for duty-pass-through, origin optimization and supplier requalification.
- Product innovation & safety. Trade fairs and expos in 2026 showcased a wave of insulated and ergonomically optimized hand tools, reflecting heightened demand among electricians and HVAC professionals for safety-certified toolsets. This shift creates opportunities for premiumization and higher ASPs when paired with professional warranties and certification partnerships.
- Channel evolution. Professional toolmakers are investing in diagnostics, inventory-as-a-service, and mobile commerce for technicians, while traditional retail channels continue to optimize SKU rationalization and private-label offers to compete on price and assortment.
- Regulatory & compliance pressure. Evolving standards around safety and materials are raising product-development costs and time-to-market for new tool lines; proactive regulatory mapping has become core to product roadmaps.
Competitive landscape — what incumbent and challenger strategies look like
The competitive map is diverse, from global conglomerates to specialist family-owned manufacturers. Leading firms play distinct strategic roles:
Hand Tools Market
- Stanley Black & Decker Inc. (New Britain, CT) leverages a portfolio strategy—bridging mass-market and professional segments through brands such as DEWALT and CRAFTSMAN—focusing on system-selling, channel breadth and aftermarket parts availability.
- Snap-on Incorporated (Kenosha, WI) competes on premium, professional-grade tools, diagnostics and integrated solution offerings targeted at service technicians, emphasizing high-margin, recurring revenue elements.
- Klein Tools, Inc. (Lincolnshire, IL) specializes in professional electrical and construction tools, with a focus on technical differentiation, durability claims and legacy trust among trade professionals.
- Milwaukee Tool (Brookfield, WI) is executing an aggressive product-innovation cadence and portfolio expansion across heavy-duty hand tools and complementary power tool ecosystems; recent product catalog and exhibition activity in early 2026 signal continued investment behind professional tooling systems.
- Robert Bosch GmbH (Gerlingen, Germany), Apex Tool Group (Charlotte, NC), Channellock, Inc. (Meadville, PA), KNIPEX (Wuppertal, Germany) and GEDORE (Remscheid, Germany) round out the competitive set with mix-driven strategies: regional strength, premium positioning, or industrial OEM focus.
Notable developments to watch: Milwaukee’s early-2026 catalog and trade-show rollout underline their innovation and channel activation tempo; Apex Tool Group announced a leadership transition with an explicit mandate to sharpen its hand-tools portfolio—changes that will influence competitive M&A and product investment decisions in 2026.
Hand Tools Market
What PW Consulting’s full report delivers (practical, actionable content)
We designed the report as an operator’s toolkit—structured to inform quarterly planning and multi-year strategy alike. Key deliverables include:
- Market sizing and validated demand models (historical 2020–2025; forecast 2026–2032) with scenario toggles for demand shocks and tariff pathways.
- Competitive scorecards and capability heatmaps for leading and regional players, highlighting channel strength, R&D cadence, and manufacturing footprints.
- Supply-chain stress testing and supplier-concentration analytics, with practical mitigation playbooks for sourcing, dual-sourcing thresholds and cost-pass-through strategies.
- Pricing and margin sensitivity matrices by product archetype, enabling rapid SKU rationalization decisions and premiumization pathways for professional ranges.
- Go-to-market playbooks: distributor economics, direct-to-professional models, e-commerce rollouts, and service bundling tailored to corporate and small-business buyers.
- M&A screening templates and integration checklists for bolt-on consolidation in fragmented subsegments—complete with valuation frameworks and synergy capture timetables.
- Product development and compliance roadmaps (including insulation and safety certification moves highlighted in 2026 trade activity), with time-to-revenue estimates for reengineered ranges.
- Executive dashboards and interactive models (access-restricted) so leadership teams can stress-test strategies against user-defined scenarios.
Note: while the full dataset includes regional and application-level splits, this executive brief intentionally omits granular tables and financial allocations to preserve the report’s strategic value and direct readers to the full interactive resource.
How to use these insights for 2026 execution
- Procurement & operations: Implement dual-sourcing for critical inputs, renegotiate index-linked contracts where possible, and model inventory buffers that balance service levels with working capital efficiency.
- Portfolio & pricing: Prioritize investment in high-velocity, high-margin professional ranges and selective premiumization (safety-certified, ergonomics, lifetime warranties). Use the pricing elasticity matrices to inform promotion / discount cadence in retail channels.
- Channel strategy: For professional-focused brands, accelerate fleet and subscription models for trade customers; for mass-market channels, refine private-label strategies and optimized shelf assortments informed by SKU-level profitability analysis.
- M&A & partnerships: Target additive capabilities—diagnostics, inventory-as-a-service, regional distribution hubs—that close capability gaps quickly and generate near-term synergies.
- Product innovation: Invest in safety-certified insulated tools and integrated tool ecosystems; accelerate time-to-market through modular design and platform-based R&D to reduce costs and shorten product cycles.
- Risk & compliance: Build tariff-contingent costing into product P&Ls and maintain a regulatory watchdesk to anticipate changes that can affect certification and market access.
Methodology & confidence
Our conclusions are grounded in a blended methodology: primary interviews with buyers, suppliers and channel partners; detailed company financials and public filings; customs and trade data; product and patent analysis; and on-the-ground validation at trade shows and distributor networks. The report’s scenario-based forecasting and sensitivity analysis ensure decision-makers can move from strategy to operational plans with quantifiable risk buffers.
Market concentration metrics show meaningful space for consolidation and differentiation. For companies evaluating acquisition, divestiture or substantial organic investment in 2026, the report supplies the scoring algorithms and integration playbooks needed to convert analysis into action.
Conclusion — why download the full study
PW Consulting’s Hand Tools Market study is designed to be the single reference for annual planning and multi-year strategic bets in 2026. It converts high-level growth expectations—the market’s mid-single-digit CAGR through 2032 and the trajectory from the 2020 base to the 2025 benchmark—into practical, measurable actions across procurement, product, channels and M&A.
To unlock the granular regional and application splits, manufacturer-level financial breakdowns, and the interactive scenario model that underpins the dashboards summarized here, access the full report and executive toolkit on the PW Consulting website. The full deliverable contains the tables and model access rights you will need to stress-test your 2026 plans and convert insight into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Hand Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic-Grade H2O2 Market Set to Grow at 7.1% CAGR Through 2032
By PW Consulting, 2026-07-12
Electronic‑Grade Hydrogen Peroxide Market — Strategic Outlook for 2026 Decision‑Makers
Executive preview
As semiconductor and advanced electronics manufacturing accelerate into a new cycle of capital investment and node migration, electronic‑grade hydrogen peroxide (EG‑H2O2) has re‑emerged as a strategically critical chemical. Our market model shows a sustained upward trajectory from the prior half‑decade into the next planning horizon, with the global market expanding from roughly USD 304 million in 2020 to about USD 429 million in the 2025 base year, and an anticipated compound annual growth rate of 7.1% through the 2026–2032 forecast window. By 2032 the market is projected to approach the high‑six‑hundreds (USD), reflecting both volume growth and ongoing premiumization driven by tighter purity specifications, localization of supply, and specialty‑grade differentiation.
Electronic Grade Hydrogen Peroxide Market
Why PW Consulting’s study matters for 2026 decisions
- Timing: 2026 is a decisive year for procurement commitments and capex schedules in semiconductor fabs built under recent public and private investment programs. Our research converts projected fab build‑outs and process node timelines into demand signals for EG‑H2O2, enabling procurement teams to time contracts and investments to avoid shortages or oversupply.
- Specification risk: SEMI and industry specifications are converging on ultra‑low metallic impurity ceilings for advanced nodes. This report translates those technical thresholds into supplier qualification checklists, contamination‑control playbooks, and risk maps that buyers and quality engineers can act on immediately.
- Supply chain resilience: With a market that is neither atomized nor monopolistic (our concentration analysis shows the top three suppliers control a material majority of capacity while the top five extend that dominance), the balance of supplier power and the fragility of local supply pockets matter. The study provides scenario modelling that quantifies the pricing and availability impact of single plant outages, raw material volatility and new regional capacity additions.
High‑level market dynamics
Demand drivers are multi‑vector: incremental semiconductor wafer area per fab, higher cleaning frequency accompanying advanced node lithography and etch processes, and differentiated product grades for display and other high‑value electronics segments. On the supply side, producers are investing in dedicated purification trains, ultra‑clean packaging, and regional plant expansions to capture customers who increasingly value nearshore supply and vendor traceability.
Electronic Grade Hydrogen Peroxide Market
Notable market mechanics that 2026 strategists must factor into decisions include: (1) the premium yield associated with certified electronic grade manufacturing—small contamination differences translate into outsized yield and earnings impact for customers; (2) regulatory nudges that favor peroxide as a chlorine‑free oxidant in both wastewater and certain process chemistries; and (3) feedstock price volatility which can compress supplier margins and drive short‑term price moves. Our modelling incorporates these levers to produce demand, price and margin scenarios under alternative regulatory and input‑cost regimes.
Electronic Grade Hydrogen Peroxide Market
Regulation, standards and their strategic implications
- Standards compliance: SEMI’s latest electronic‑grade specifications set metallic impurity limits at the sub‑ppb level for advanced node processes. Suppliers and end‑users must synchronize capability roadmaps and quality assurance protocols to meet these thresholds — non‑compliance is a revenue and reputational risk for both sides.
- Environmental policy: U.S. EPA and EU REACH policy direction increasingly favors chlorine‑free chemistries in select applications, creating structural tailwinds for peroxide adoption in certain segments of the electronics industry.
- Industrial policy: Public investment initiatives that target domestic semiconductor capacity expansion uplift local demand for EG‑H2O2 and increase the strategic value of near‑site supply. For corporate planners, this changes the calculus for greenfield versus contract manufacturing and for on‑site storage and purification assets.
Competitive landscape — what to watch in 2026
The supplier ecosystem blends global chemical majors with specialized purifiers and regional champions. Key strategic themes we identify across the competitive set are: capacity clustering with selective regional localization; technology differentiation based on purification and contamination control; and commercial models that range from long‑term offtake contracts to spot delivery and on‑site service offerings.
- Global majors with dedicated electronic‑grade portfolios have invested in purification platforms and joint ventures to secure proximity to advanced fabs. One notable example is a multinational supplier that has recently doubled nameplate capacity at a China facility and operates a joint venture in a leading semiconductor manufacturing hub — an explicit strategic move to capture regional demand and shorten lead times.
- Specialists and legacy electronic‑grade producers compete on ultra‑low contamination performance, packaging integrity, and qualification track records. Their value proposition is safety of supply for the most demanding nodes where elimination of trace metals and particulates is mission‑critical.
- Regional producers in large electronics manufacturing markets have closed the gap on quality, offering competitive sub‑ppb impurity profiles. For many fabs, qualifying a domestic supplier reduces cross‑border logistics risk and supports domestic content goals, but this requires rigorous audit and long‑term engagement.
Supply shocks, input cost sensitivity and margin pressure
Raw material and logistics costs remain a recurring operational risk. Recent commodity surveillance recorded a notable month‑over‑month rise in hydrogen peroxide pricing, and our sensitivity analysis demonstrates that short pulses in feedstock costs or packaging supply constraints can materially affect small, highly concentrated suppliers. For buyers, the implication is straightforward: contract clauses that share or mitigate input cost shocks, and diversified sourcing, will materially reduce price and operational volatility.
What the PW Consulting report delivers — practical components
Our study is structured to be directly actionable for commercial, procurement, and strategic planning teams. Core deliverables include:
- Forward‑looking demand model that translates fab build schedules, wafer starts, and process node mix into volumetric demand for EG‑H2O2 across the 2026–2032 horizon.
- Price and margin scenarios that integrate feedstock cost pass‑through, capacity utilization, and supplier concentration, with sensitivity tables for rapid executive decisions.
- Supplier scorecards and qualification matrices that combine technical performance (impurity profiles, packaging integrity), commercial robustness (delivery lead times, contract flexibility), and geopolitical exposure.
- Regulatory impact assessment that quantifies likely adoption shifts under alternative policy developments (e.g., accelerated local content rules, stricter waste discharge limits).
- Operational playbooks: procurement clauses, on‑site storage recommendations, emergency response plans for supply interruptions, and a step‑by‑step supplier qualification checklist aligned to SEMI and industry QA expectations.
- M&A and greenfield case frameworks that assess returns on capacity expansions, purification upgrades, and vertical integration into upstream peroxide production or downstream specialty mixing and packaging.
Strategic actions for 2026 — three prioritized moves
- Procurement: Move from ad hoc spot buying to a tiered sourcing strategy that secures long‑term capacity with at least two qualified suppliers per region, combined with a negotiated price escalation mechanism tied to defined feedstock indices.
- Quality & operations: Invest in supplier audits and on‑site qualification wells to shorten the qualification timeline for alternative suppliers. For wafer fabs, even small improvements in contamination control can justify the incremental cost of premium supply.
- Portfolio & corporate development: Evaluate minority equity stakes or offtake agreements with high‑quality regional producers that demonstrate robust purification capabilities. Where strategic, consider co‑funded capacity expansions that lock supply and share capital risk.
Use cases: who benefits from the report
- Chief Procurement Officers — for structuring contracts, hedging strategies, and pool sourcing approaches.
- Head of Manufacturing/Quality — for aligning supplier qualification to process node timelines and contamination budgets.
- Corporate Development and Strategy teams — for identifying M&A targets, JV partners, and capex partnering opportunities.
- Policy and sustainability teams — for assessing regulatory risk and planning transitions to greener chemistries.
What we intentionally withhold here — and why
This preview emphasizes the shape of the opportunity and the high‑level quantitative framework without disclosing the proprietary, granular split data and scenario tables that underpin supplier‑level decisions. The report intentionally reserves detailed regional and application‑level revenues, individual supplier volumes, and the full sensitivity matrices for subscribers, because those granular inputs are the core commercial intelligence companies use to reprice supply and adjust capital plans.
Closing perspective
Electronic‑grade hydrogen peroxide sits at the intersection of chemical purity engineering, regional industrial policy, and semiconductor manufacturing economics. For 2026, decisions around supplier selection, contract tenor, local capacity, and contingency planning will determine whether firms capture steady, low‑volatility supply or are exposed to episodic price and availability shocks. PW Consulting’s study synthesizes technical standards, regulatory momentum, supplier investments, and demand modelling into an operational playbook. The top‑line market growth and concentration metrics point to opportunity — but the decisions that protect yield and margin depend on the granular intelligence contained in our full report.
To convert this strategic preview into executable plans for procurement, quality assurance, and corporate development, the full research package provides the necessary segmental detail, supplier scorecards and scenario modelling that senior teams will use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Electronic Grade Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diffraction Gratings Market to Hit USD 367.1 Million by 2032
By PW Consulting, 2026-07-12
Diffraction Gratings Market 2026: Strategic Imperatives for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the Diffraction Gratings market to inform executive strategies during 2026. This note synthesizes our latest market modeling (base year 2025), competitive landscaping, technological inflection points, and regulatory constraints—framing clear actions for procurement, R&D investment, and M&A prioritization. The analysis that follows signals the strategic value of our full report: deep, executable intelligence designed to reduce risk and accelerate time-to-value. Sensitive segment-level tables and granular regional breakdowns are intentionally withheld in this preview to preserve the actionable premium of the full study.
Diffraction Gratings Market
Macro trajectory and what it means for 2026 decisions
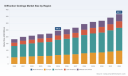
From a macro perspective, the market has expanded steadily from the early 2020s into 2025, and our base-year modeling quantifies that upward trajectory. Between 2020 and 2025 the sector demonstrated resilient growth, and our forecast through 2032 projects continued expansion—underpinned by a compound annual growth rate of 5.98% for the 2026–2032 horizon. By design, our projections integrate supply-side constraints, adoption lags in high-spec space/defense programs, and accelerating demand from quantum sensing, advanced spectroscopy, and high-energy laser systems.
Diffraction Gratings Market
For 2026 planning cycles, the implications are straightforward: demand is growing, but opportunity is concentrated in technically demanding subsegments and mission-critical programs that value performance, qualification pedigree, and supply security over commoditized cost competition. Procurement teams should therefore prioritize supplier qualification and long-lead strategic contracts; R&D and product teams should orient roadmaps to tolerance-driven performance (efficiency, polarization ratio, wavefront error); and business development should align GTM resources to a smaller set of high-value end-markets.
Diffraction Gratings Market
Where the growth is driven (high-level)
- Advanced sensing and instrumentation: continued upgrades of laboratory, aerospace, and defense spectroscopy platforms demand gratings with tighter efficiency and stray-light control.
- Quantum and photonics subsystems: transmission and holographic solutions tailored to wavelength stability and low scatter are emerging as a high-value vertical.
- Space and astronomy programs: mission timelines and payload qualification cycles create premium, low-volume opportunities that reward suppliers with heritage and process documentation.
- Laser and high-energy applications: robustness against high fluence, polarization insensitivity, and thermal stability are differentiators.
Note: detailed application- and region-level forecasts are part of the full report. This preview intentionally omits those granular splits to preserve commercial exclusivity.
Market structure and concentration
The market demonstrates moderate concentration: our concentration metrics indicate that leading suppliers collectively control a meaningful share of revenue and technical supply capacity. This dynamic creates both opportunity and risk. For established vendors, concentration supports pricing discipline and margin stability in specialized segments. For new entrants, barriers include capital-intensive tooling, certified cleanroom capacity, and the ability to demonstrate parentage on high-stakes programs.
In 2026, procurement managers and corporate development teams must read concentration as a lever: strategic partnerships or minority stakes can secure capacity without the multi-year CAPEX cycle required to build world-class facilities in-house.
Competitive landscape: capabilities that matter
Our company-level review in the full study profiles suppliers across manufacturing method (ruled, holographic, ion-etched, replicated), substrate materials (silica, Zerodur, SiC, ULE), and certification posture. Highlights from public and proprietary sources:
- OPCO Laboratory (United States): recognized for precision ruled gratings produced with ruling engines and diamond tooling, serving spectroscopy, defense, aerospace, and semiconductor inspection markets. Their ITAR registration and heritage in reflective-coated substrates make them a common partner on defense contracts.
- Ibsen Photonics (Denmark): a leader in transmission gratings for quantum sensors and pulse compression; ISO 9001/13485 certification supports high-volume, high-qualification medical and quantum sensing programs.
- Thorlabs and Edmund Optics (United States): broad product portfolios covering ruled and holographic gratings across UV–IR bands, with solutions geared to instrumentation and applied research markets where catalog availability and lead time are decisive.
- HORIBA (Japan / France): deep expertise in custom holographic and ion-etched gratings for space and astronomy, with demonstrated production for mission hardware and large-format replicas on ULE/Zerodur substrates.
- RP Photonics (Switzerland): an authoritative resource on grating physics and efficiency optimization—valuable as a technical reference and collaborator on performance modeling.
- Omega Optical, Holographix, LightSmyth Technologies: niche specialists in replication, UV deep-transmission variants, and polarization-insensitive designs respectively—each representing potential partners for scaling production or solving high-energy laser challenges.
Our vendor scorecards evaluate capability along five decision-critical axes: optical performance (efficiency, scatter, polarization), manufacturing scale (substrate sizes, groove density range), program qualification (cleanroom class, documentation, heritage), export/compliance posture (ITAR/Export Control), and commercial flexibility (lead times, MOQ, replication options). These scorecards are included in the full report and are constructed to support RFP and supplier selection workflows.
Technology and production dynamics
Technological progress is not uniform across the market. Key trends we monitor include:
- Manufacturing hybridization: combination of ruling-engine capability and ion-etch or holographic replication to deliver both high performance and scalable volumes.
- Large-format competence: suppliers are expanding capability for gratings approaching meter-scale with ISO 6-class process controls to maintain wavefront error targets—critical for astronomy and Earth-observation instruments.
- Materials engineering: increased use of ULE, Zerodur, and SiC for thermal stability in space optics, and polymer replication for cost-effective VUV–LWIR coverage.
- Specialty coatings and blazed geometries: necessary to meet efficiency and polarization specifications for laser vs. spectroscopy applications.
These capabilities translate directly into procurement and product design decisions. For systems integrators pursuing space or high-energy laser contracts, supplier proof of process control (including cleanroom class, polarization tolerance records, and test data) is as important as quoted price.
Regulatory and compliance guardrails
Regulatory constraints materially affect market access and program execution. Relevant dynamics include:
- Export controls: ITAR and national export screening apply to suppliers and transactions involving defense- or high-energy-laser-related gratings; non-compliance risks program disruptions.
- Quality standards: ISO 9001 and, where medical or quantum sensor production is involved, ISO 13485 certification are often contractual prerequisites.
- Tolerance-driven requirements: space missions and specialized UV devices demand tight polarization and efficiency tolerances; suppliers must demonstrate measurement traceability and process capability.
Companies entering or scaling in this market must build compliant supply chains and documentation processes early to avoid costly rework and procurement disqualifications.
Strategic recommendations for 2026
Based on our modeling and supplier assessments, we advise executives to prioritize the following actions in 2026 planning cycles:
- Secure qualified capacity: enter multi-year purchase agreements with suppliers who demonstrate both technical pedigree and export-compliant processes. For mission-critical programs, prioritize dual-sourcing strategies that combine heritage suppliers and niche specialists.
- Invest selectively in upstream capability: firms with recurring demand profiles should evaluate targeted vertical integration—either through replication capability or strategic minority investments in suppliers—to shorten lead time and protect margins.
- Align product roadmaps to high-value specifications: reprioritize R&D toward polarization-insensitive designs, deep-UV transmission, and large-format grating performance that command premium pricing.
- Operationalize certification early: accelerate ISO/quality and export-control readiness as part of bid qualification, not as a post-award activity.
- Use M&A as a capability accelerator: given moderate market concentration, acquisitions of niche engineering houses or replication capacity can yield rapid capability and customer access—our full study includes an M&A playbook with valuation heuristics and integration risks.
What the full PW Consulting report delivers
The full Diffraction Gratings Market study is structured for practical execution. It contains:
- Demand-side TAM and bottom-up forecasts by type, application and region (historical 2020–2025, forecast 2026–2032), with sensitivity scenarios tied to aerospace mission timelines and quantum adoption curves.
- Supplier scorecards and comparative capability matrices, including lead-time benchmarking and manufacturing footprints.
- Pricing and margin analysis across production methods (ruled, holographic, ion-etched, replicated) and substrate categories.
- Regulatory checklist and compliance playbook for ITAR, ISO pathways, and export controls.
- Go-to-market and procurement playbooks: RFP templates, qualification gates, and contract structures aligned to long-lead, high-spec procurements.
- Case studies: mission support engagements, replication scale-up, and failure-mode remediation examples.
Because segment-level splits and client-ready spreadsheets are material to tactical decision-making, those detailed tables are reserved for the full report and accompanying client deliverables.
Final short-term actions for leadership
- Procurement: begin supplier pre-qualification against the five-axis scorecard and commence export-control diligence on shortlist candidates.
- R&D/Product: prioritize one development sprint to prototype polarization-insensitive or deep-UV grating variants aligned to a prioritized customer use case.
- Corporate Development: identify 2–3 buy/build targets—specialists with either replication scale or unique substrate expertise—to evaluate against the M&A playbook in our report.
- Risk & Compliance: perform an export-control exposure map tied to targeted programs and suppliers to quantify mitigation costs and lead-time impacts.
In an expanding but technically demanding market, competitive advantage accrues to organizations that combine technical rigor, certified manufacturing, and disciplined supply-chain strategy. PW Consulting’s full Diffraction Gratings Market study provides the applied intelligence to convert market growth into defensible, profitable initiatives in 2026 and beyond. For the complete dataset, supplier scorecards, and the full set of tactical playbooks referenced above, access the full report and client portal.
For detailed analysis of this topic, please visit the official page: Diffraction Gratings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive T&I Market to Reach USD 28.16B by 2032 at 4.78% CAGR
By PW Consulting, 2026-07-12
Strategic Preview — Automotive Testing, Inspection & Certification: Navigating 2026 with Precision
Executive snapshot
As OEMs, Tier-1 suppliers and regulators accelerate vehicle electrification, connectivity and autonomous capabilities, the global Automotive Testing, Inspection, and Certification (TIC) market is moving from a cost center to a strategic enabler. Our new PW Consulting market study — base year 2025, forecasting through 2032 — quantifies that transition and converts it into decision-ready guidance for 2026 investments.
Automotive Testing, Inspection, and Certification Market
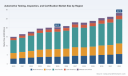
Key macroframe: the market expanded from roughly USD 15 billion in 2020 to about USD 20.3 billion in 2025, and is projected to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 4.78% through the 2026–2032 forecast horizon, reaching an estimated USD 28.2 billion by 2032. These headline numbers capture both the structural demand uplift from EVs/ADAS and the one-off ramp-ups tied to regulatory cycles and large platform launches.
Automotive Testing, Inspection, and Certification Market
Why this report matters for 2026 decisions
- Timing matters: 2026 is the hinge year when pilot programs for next‑gen vehicle platforms convert into scalable production commitments. The allocation of testing budgets, lab capacity and certification pathways in 2026 will determine time-to-market and cost-to-certify over the next three product cycles.
- Regulatory complexity is rising: New type-approval frameworks, cybersecurity standards (ISO/SAE 21434) and battery conformity routes are fragmenting testing needs. The report maps these requirements to operational steps and cost drivers so you can prioritize compliance investments rather than react to audit cycles.
- Service model transformation: The TIC value chain is shifting from episodic testing to continuous assurance (e.g., over-the-air validation, component traceability). Our research shows where to pilot contractual models—test-as-a-service, shared proving grounds, bundled homologation offerings—so you can lock in preferred supplier models before they become scarce.
Market dynamics and structural drivers
The market’s moderate compound growth conceals divergent dynamics underneath. On one axis, electrification and high-voltage battery systems are driving specialized laboratory and field-testing demand — safety, thermal runaway, lifecycle and second-life validation. On another, automated driving and connected features are increasing simulation, scenario-based testing and cybersecurity validation needs. These parallel vectors create cross-cutting opportunities for TIC providers that can combine electrochemical, software and systems-level capabilities.
Automotive Testing, Inspection, and Certification Market
Regulatory momentum amplifies these technical trends. Our study documents recent, material actions by leading firms and their interactions with regulators and OEMs: for example, SGS has expanded ISO/SAE 21434 training and Common Criteria evaluations across multiple jurisdictions, and has received approvals from major OEMs for passenger vehicle testing. Applus+ has published roadmaps for certain conformity assessment routes and strengthened its metrology footprint through acquisitions. These developments underscore two realities: first, certification competency is increasingly discipline‑specific (cybersecurity, battery, ADAS), and second, strategic M&A and capability partnerships are the fastest way to secure market access.
Competition landscape — positioning and strategic implications
The TIC arena remains fragmented: the top three players account for under a quarter of global revenue and the top five only a little more, creating a competitive mosaic of global platform providers, regional specialists and niche laboratories. In practice, this means scale matters for capital‑intensive services (proving grounds, climatic chambers, high-voltage battery labs), while reputation, accreditation and local regulatory relationships drive wins in homologation and connected‑vehicle assurance.
- SGS SA (Geneva) — Strengths: end-to-end compliance across vehicles, components, batteries and electronics; expanding cybersecurity training and Common Criteria services. Strategic view: well-positioned for cross-disciplinary projects where a single trusted auditor is preferred by OEMs.
- Bureau Veritas (Neuilly‑sur‑Seine) — Strengths: full-spectrum testing covering safety, emissions and connected systems. Strategic view: excels in regulatory-heavy engagements and public-private certification programs.
- Intertek (London) — Strengths: validation of components and systems with emphasis on functional and performance testing. Strategic view: competitive where component makers outsource validation to accelerate supplier qualification.
- TÜV SÜD & TÜV Rheinland (Germany) — Strengths: ISO‑accredited laboratories, type approval and battery safety testing. Strategic view: dominant in markets where tight regulatory alignment and accreditation marksmanship are table stakes.
- DEKRA (Stuttgart) — Strengths: proving grounds, automotive labs and ADAS/autonomy validation. Strategic view: a go-to partner for large-scale field validation and end-to-end test programs.
- Applus+ (Madrid) — Strengths: technical testing and metrology; recent acquisition to bolster northern Spain metrology leadership and active CRA conformity roadmaps. Strategic view: aggressive expansion through targeted acquisitions and regulatory engagement.
- Eurofins, UL, Element, Mistras — Strengths: specialized materials, electronics, safety certification and non‑destructive testing. Strategic view: niche leaders that increasingly win bundled contracts when clients demand material‑to‑system traceability.
Recent developments worth watching
- Applus+ completed a strategic acquisition to strengthen metrology in northern Spain and has publicized conformity assessment roadmaps tied to Module H during 2026 — a signal that regional labs are consolidating capability where regulatory pathways are clarifying.
- SGS secured approvals from a major OEM for passenger vehicle testing and expanded its ISO/SAE 21434 training footprint across multiple countries in late 2025–2026 — demonstrating how cybersecurity assurance is becoming a commercial differentiator.
- Market concentration metrics in our study indicate a low-to-moderate consolidation level across global revenue pools, which implies significant runway for both organic growth and bolt-on acquisitions by mid-sized players.
What the PW Consulting report delivers — practical, executable outputs
This study is engineered for strategists, corporate development teams, and lab operations leaders who must make binding choices in 2026. Deliverables include (but are not limited to):
- Proprietary market model with historical series (2020–2025), 2026 base adjustments and scenario-driven forecasts through 2032, enabling sensitivity testing against regulatory timelines and platform launch schedules.
- Regulatory and standards matrix mapping the operational steps required for compliance across major frameworks (cybersecurity, battery safety, type approval), and the expected audit timelines that drive certificate lead times.
- Service-level playbooks for four priority offerings: battery testing & safety, ADAS/ADAS‑to‑autonomy validation, cybersecurity & software assurance, and materials/electronics validation. Each playbook contains staffing plans, typical lab investments, sample commercial models and break-even illustrations for 24–60 month horizons.
- Competitive scorecards and capability heatmaps for the eleven leading providers analyzed — enabling rapid vendor shortlisting based on technical depth, geographical coverage and accreditation fit for specific programs.
- M&A and partnership screening toolkits: target lists by capability cluster, indicative valuation levers for bolt‑on acquisitions, and integration risk checklists that reflect regulatory and accreditation transfer issues.
- Operational readiness checklists for in‑house versus outsourced decisions, including decision trees that quantify the hidden costs of fragmented testing across multiple suppliers.
- Executive-ready dashboards and a downloadable data pack (CSV) containing the study’s models and inputs for client-led scenario analysis. Note: detailed regional/application splits and price decks are available only in the full report package.
Strategic recommendations for 2026
- Legal & regulatory first-mover positioning: Invest in targeted accreditations (e.g., cybersecurity labs, CRA conformity routes) where lead-time to approval is measured in quarters, not years. Early accreditation converts into preferential OEM supplier status.
- Build modular capability stacks: Prioritize interoperable assets (battery cyclers convertible for second‑life testing; simulators usable across ADAS and V2X scenarios) to protect capital while serving diverse demand streams.
- Partner or acquire selectively: Given market fragmentation, mid-size TIC providers can buy capability faster than they can develop it. Use the PW M&A toolkit to prioritize targets that close accreditation gaps rather than simple geographic footprints.
- Commercial innovation: Pilot subscription/test-as-a-service commercial models with strategic OEMs to secure recurring revenue and reduce utilization volatility tied to single platform launches.
- Data & digital trust: Invest in secure test-data platforms and independent attestation capabilities. As over-the-air validation and lifecycle traceability become procurement criteria, the ability to demonstrate data integrity will affect RFP outcomes.
How to use this preview
This article is a strategic teaser: it situates the market, highlights competitive movements and provides actionable direction for 2026 resource allocation. The full PW Consulting report contains the granular regional and application splits, price benchmarking, detailed financial multiples for targets, and the raw model files that clients use to stress-test their 2026 budgets and M&A pipelines. If your 2026 plan depends on time-to-certify, lab capacity or targeted acquisitions, the full data pack is required to operationalize the recommendations summarized here.
PW Consulting’s Automotive TIC study turns market signals into executable moves. For teams gearing up to make binding capital, partnership or outsourcing decisions in 2026, this report is intended to be the difference between tactical response and strategic advantage.
For detailed analysis of this topic, please visit the official page: Automotive Testing, Inspection, and Certification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


